Cambridge IGCSE Accounting 0452 — 2019 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/19 · 6 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme20 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Tebogo is a trader
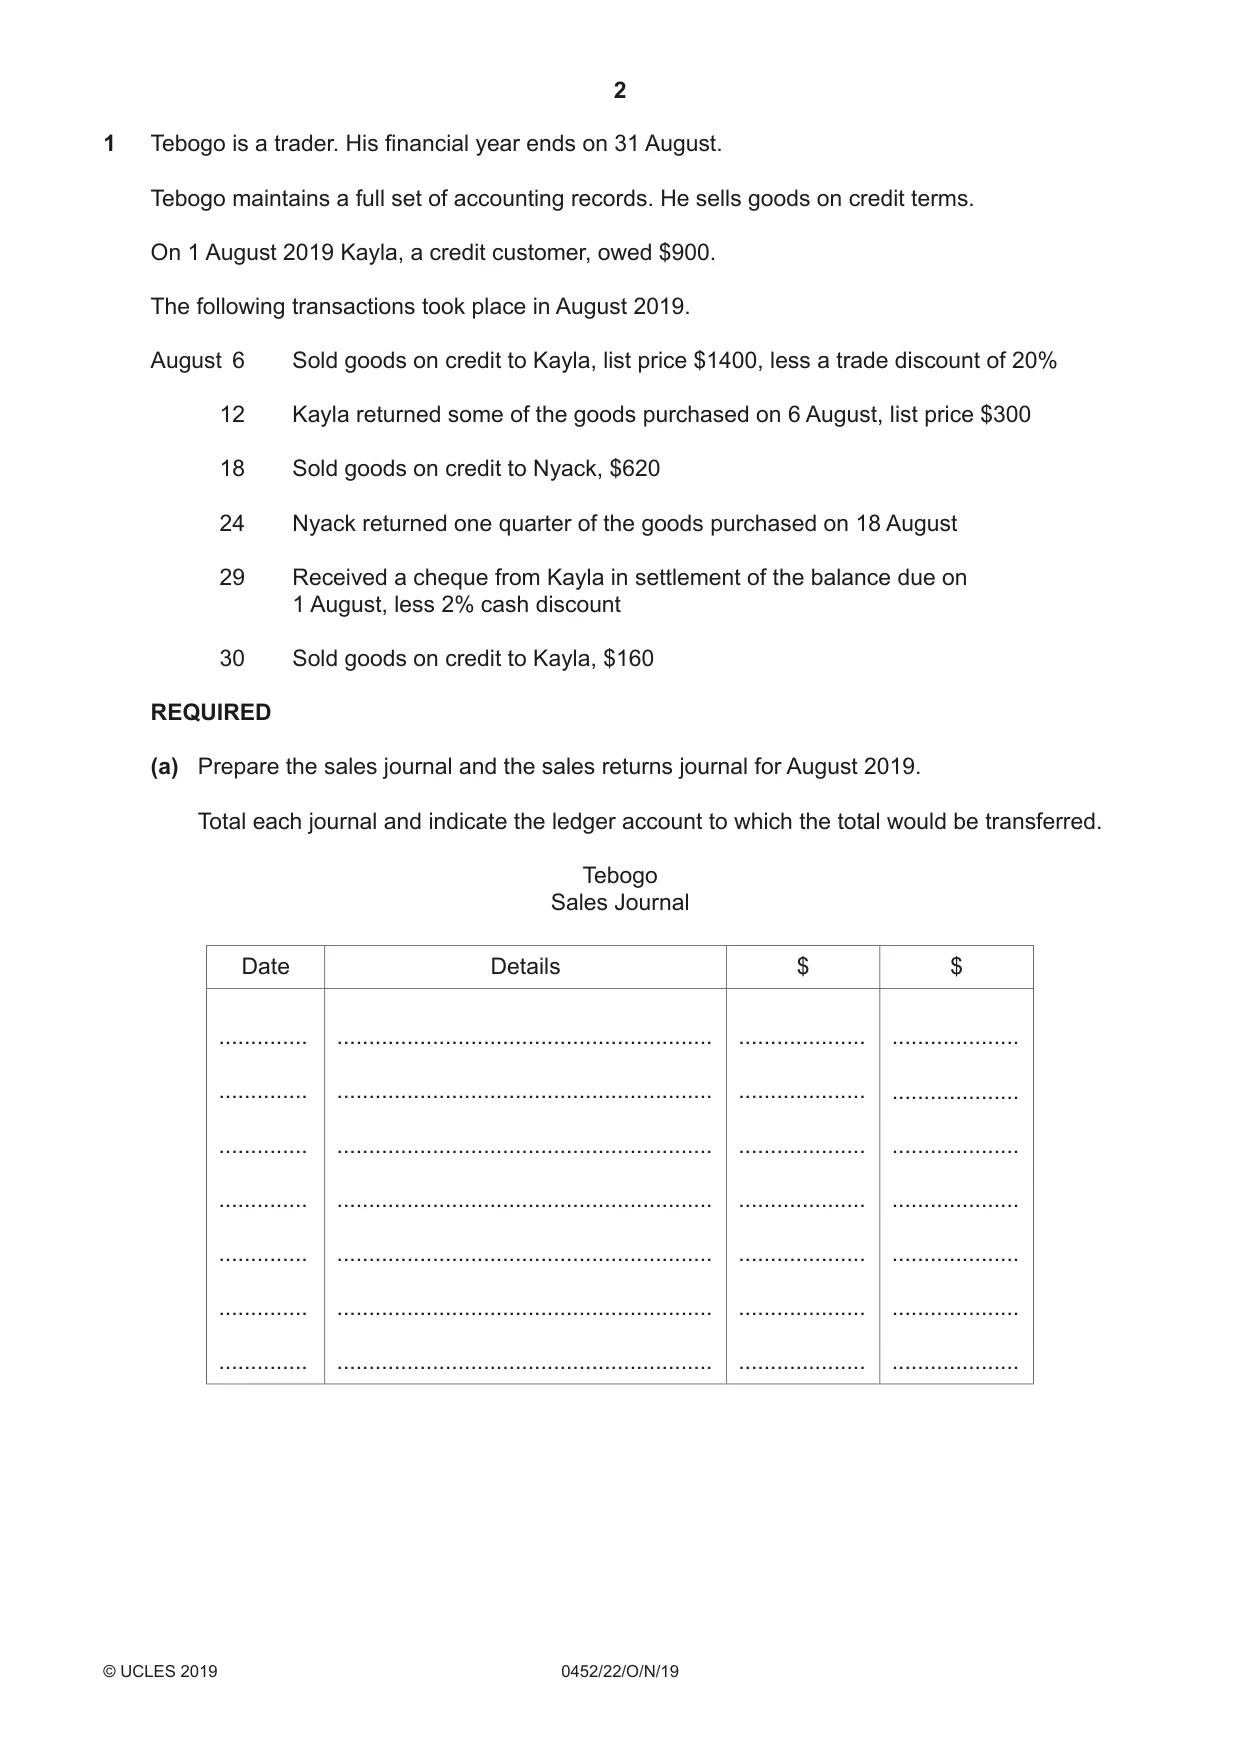
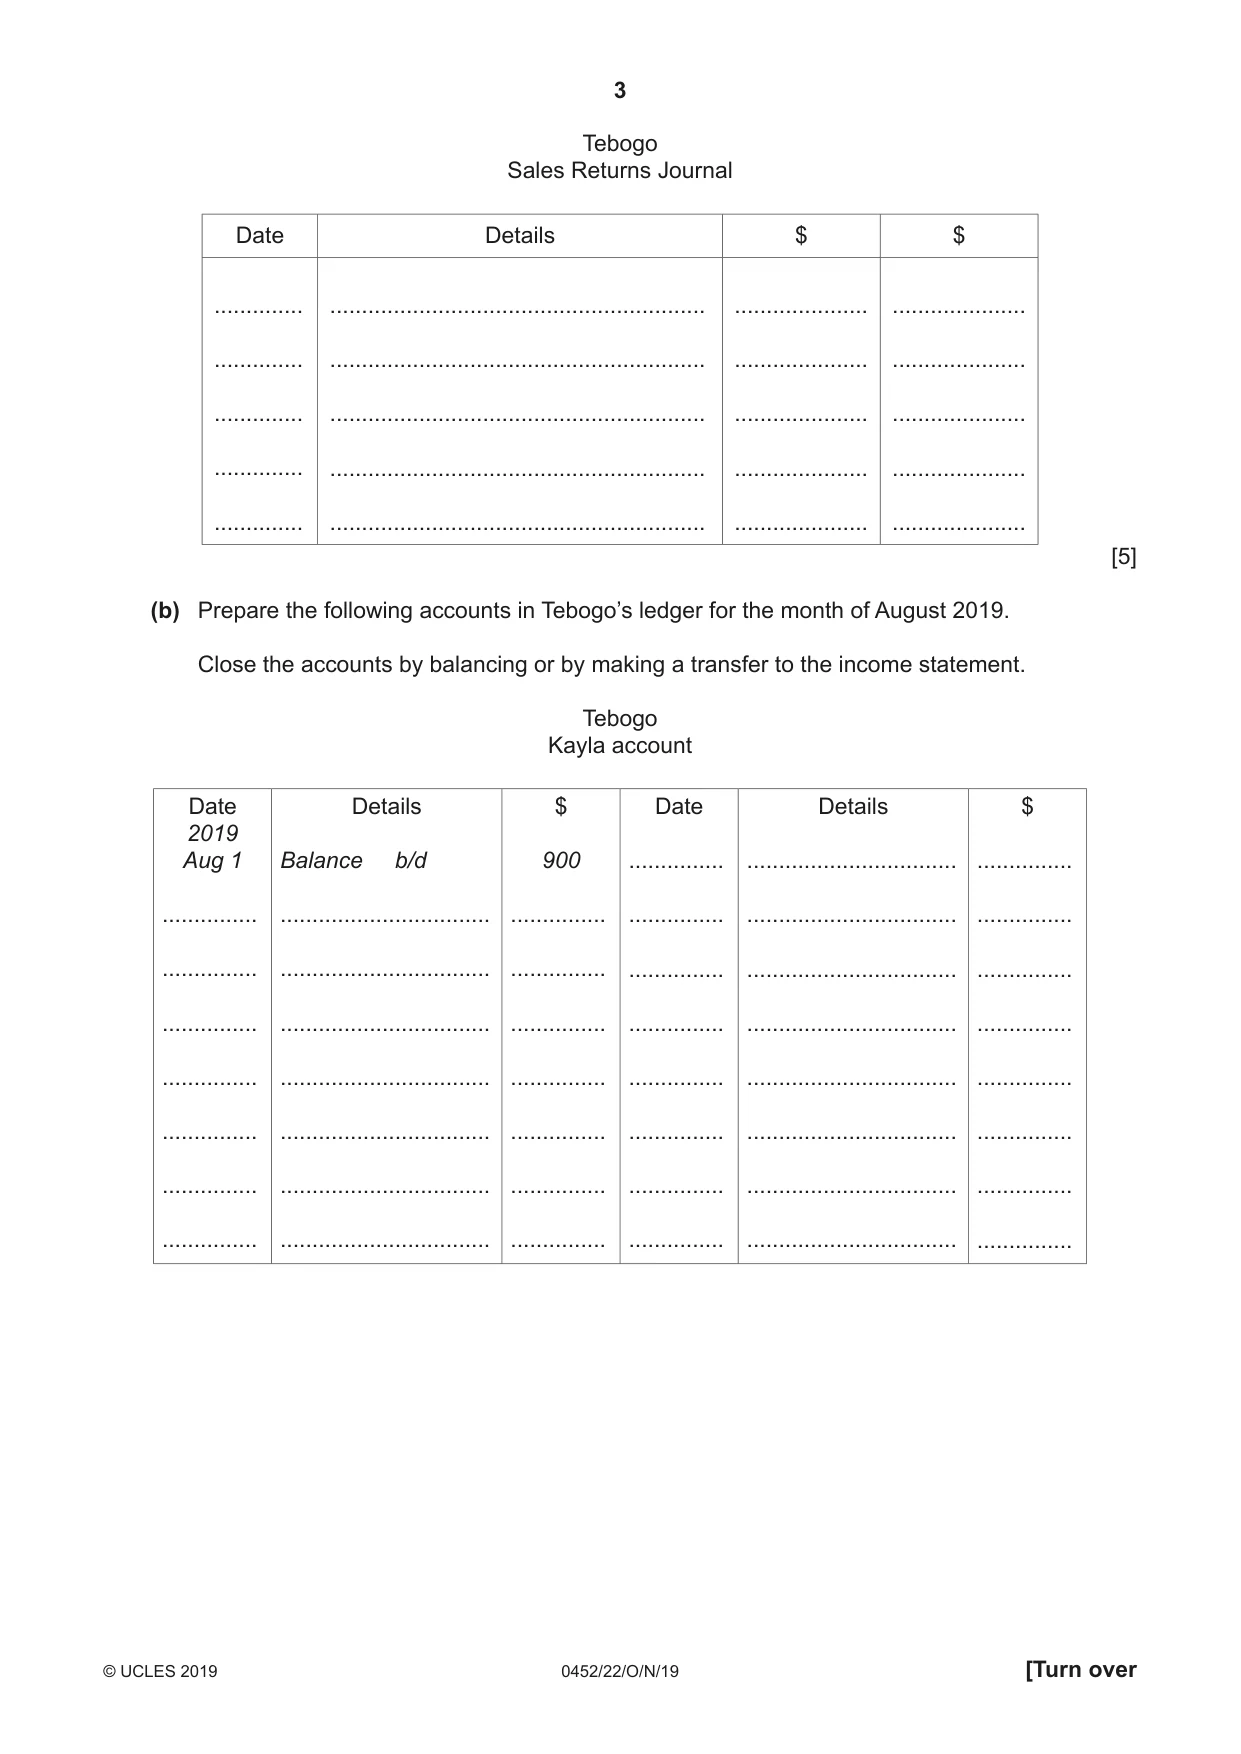
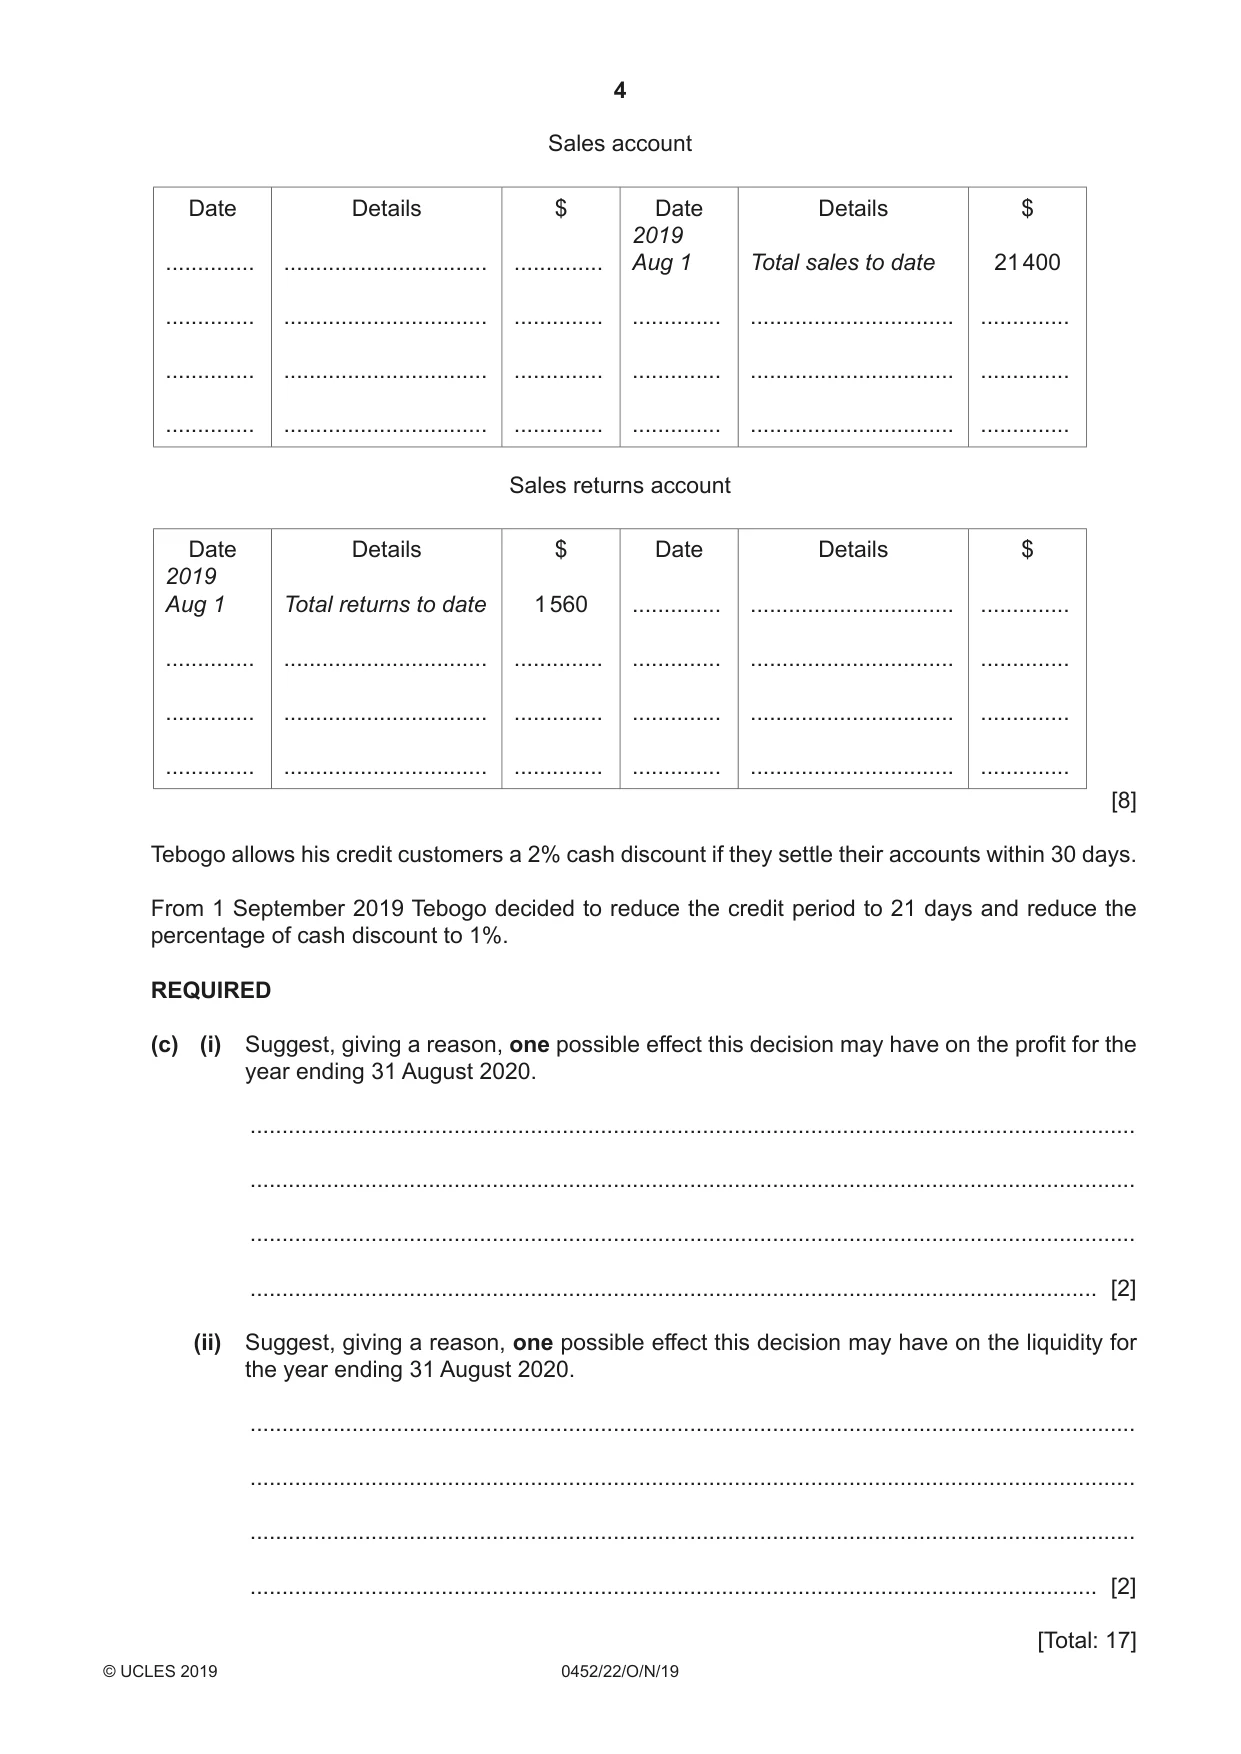
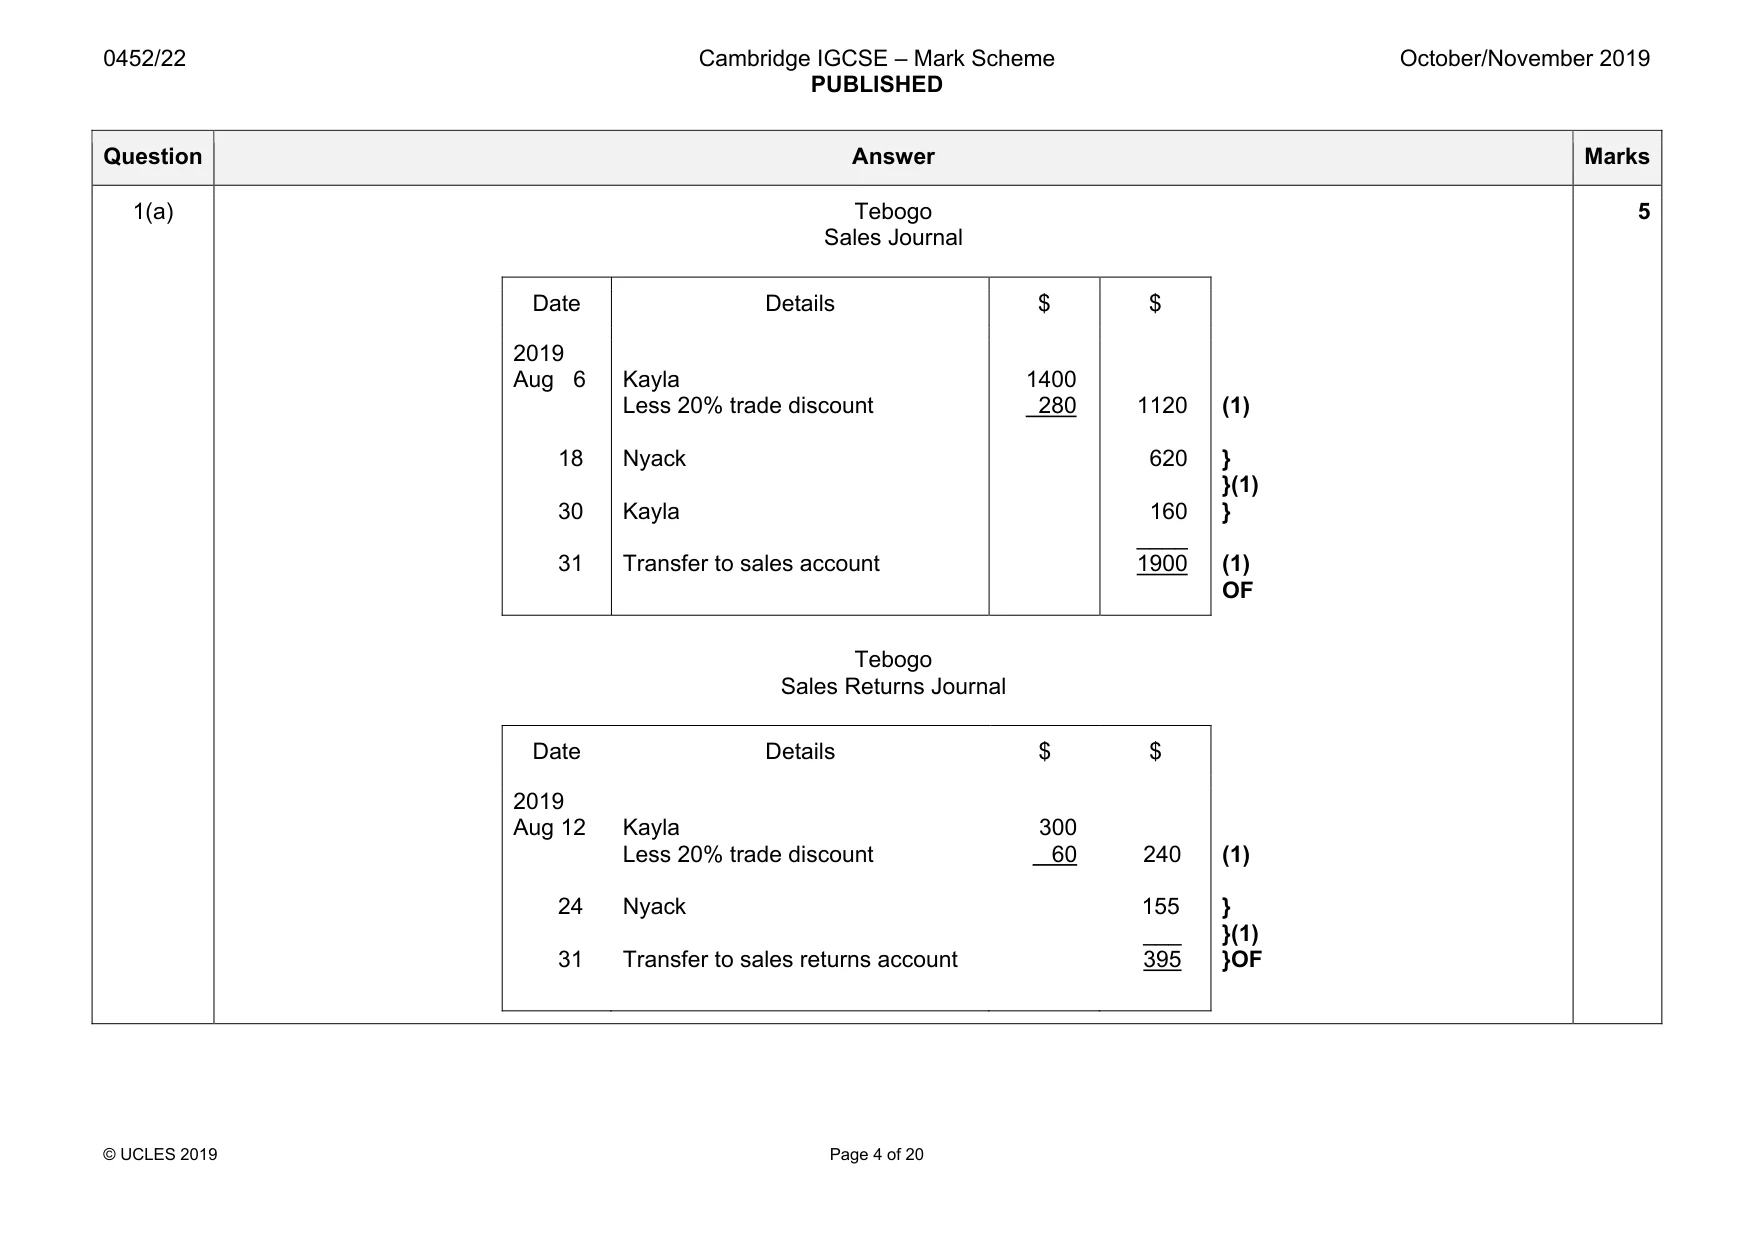
1 Tebogo is a trader. His financial year ends on 31 August. Tebogo maintains a full set of accounting records. He sells goods on credit terms. On 1 August 2019 Kayla, a credit customer, owed $900. The following transactions took place in August 2019. August 6 Sold goods on credit to Kayla, list price $1400, less a trade discount of 20% 12 Kayla returned some of the goods purchased on 6 August, list price $300 18 Sold goods on credit to Nyack, $620 24 Nyack returned one quarter of the goods purchased on 18 August 29 Received a cheque from Kayla in settlement of the balance due on 1 August, less 2% cash discount 30 Sold goods on credit to Kayla, $160 REQUIRED (a) Prepare the sales journal and the sales returns journal for August 2019. Total each journal and indicate the ledger account to which the total would be transferred. Tebogo Sales Journal Date Details $ $ .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... .............. ........................................................... .................... .................... Tebogo Sales Returns Journal Date Details $ $ .............. ........................................................... ..................... ..................... .............. ........................................................... ..................... ..................... .............. ........................................................... ..................... ..................... .............. ........................................................... ..................... ..................... .............. ........................................................... ..................... ..................... [5] (b) Prepare the following accounts in Tebogo’s ledger for the month of August 2019. Close the accounts by balancing or by making a transfer to the income statement. Tebogo Kayla account Date Details $ Date Details $ 2019 Aug 1 Balance b/d 900 ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... ............... ................................. ............... Sales account Date Details $ Date Details $ 2019 .............. ................................ .............. Aug 1 Total sales to date 21 400 .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. Sales returns account Date Details $ Date Details $ 2019 Aug 1 Total returns to date 1 560 .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. .............. ................................ .............. [8] Tebogo allows his credit customers a 2% cash discount if they settle their accounts within 30 days. From 1 September 2019 Tebogo decided to reduce the credit period to 21 days and reduce the percentage of cash discount to 1%. REQUIRED (c) (i) Suggest, giving a reason, one possible effect this decision may have on the profit for the year ending 31 August 2020. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Suggest, giving a reason, one possible effect this decision may have on the liquidity for the year ending 31 August 2020. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] [Total: 17]
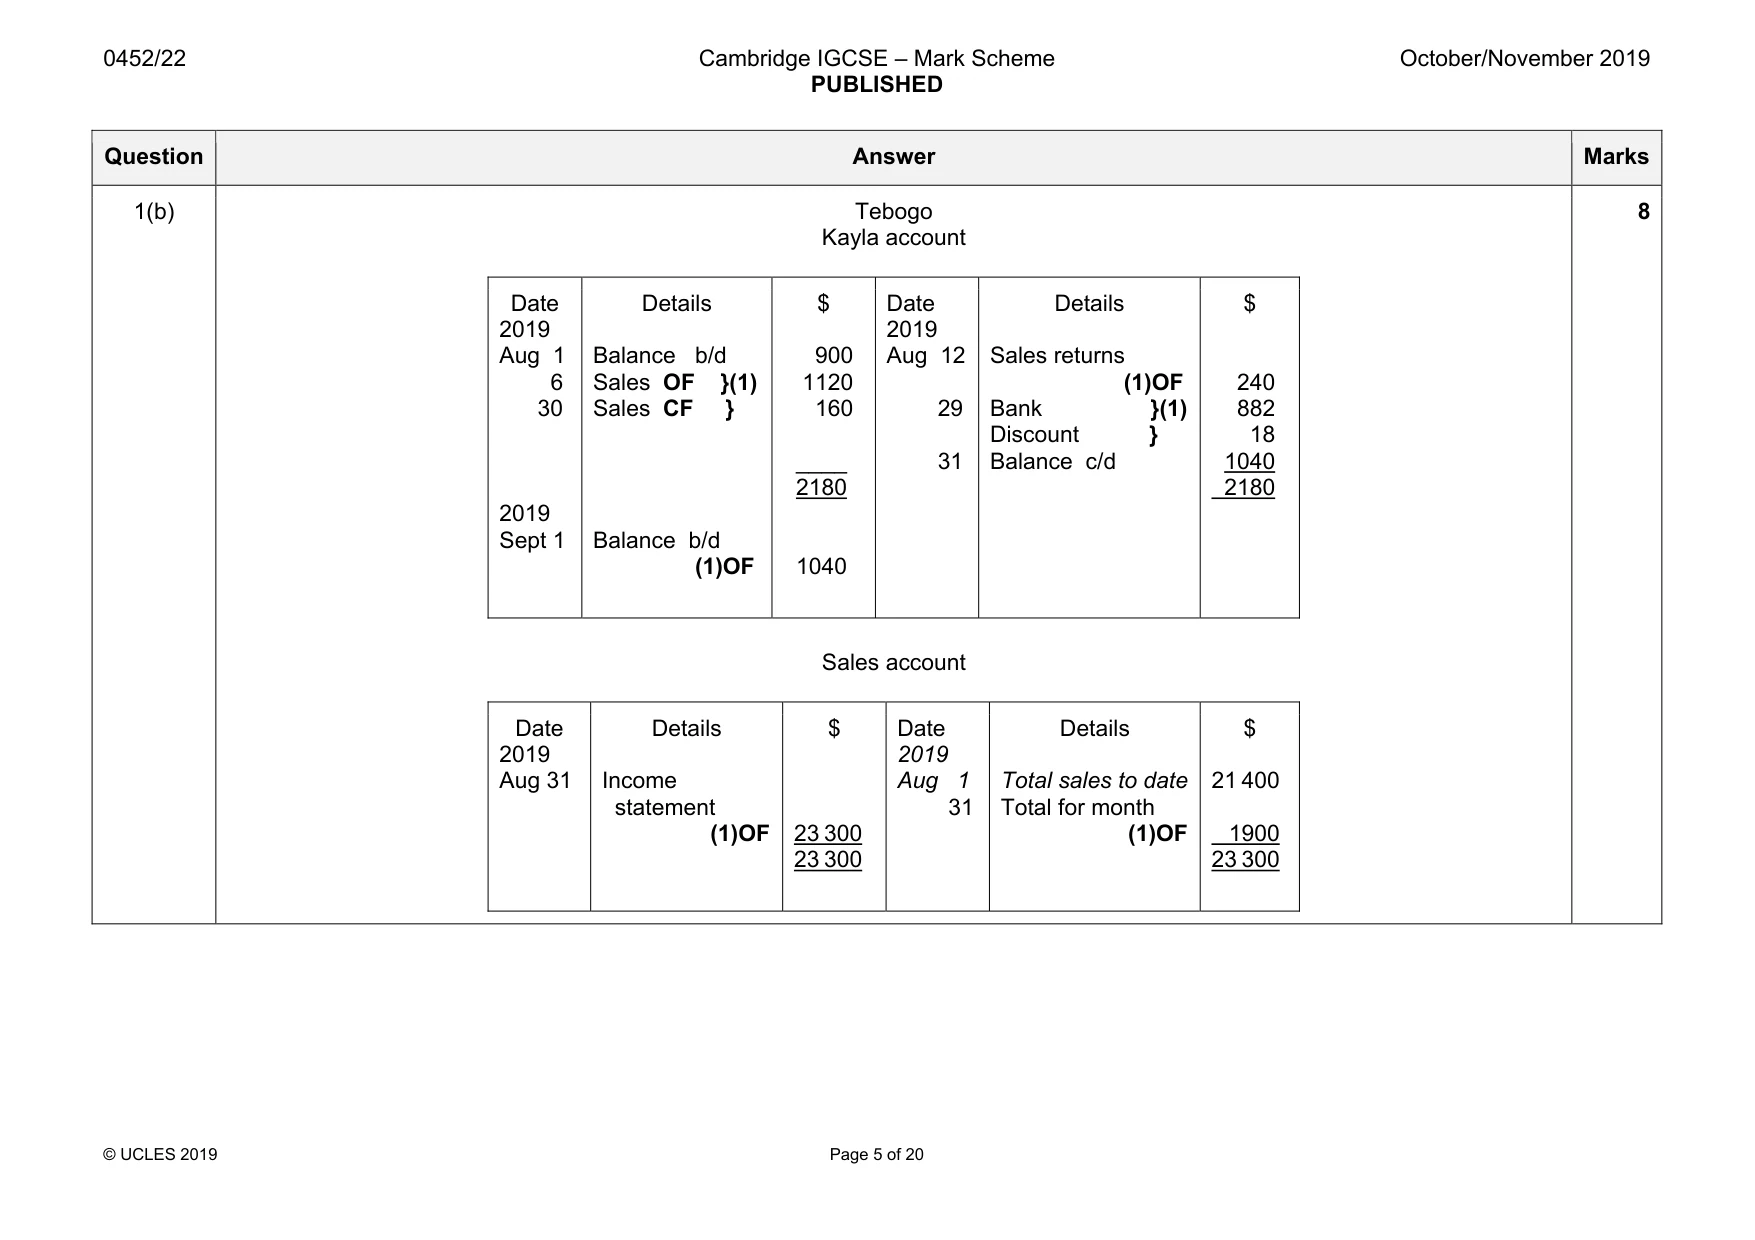
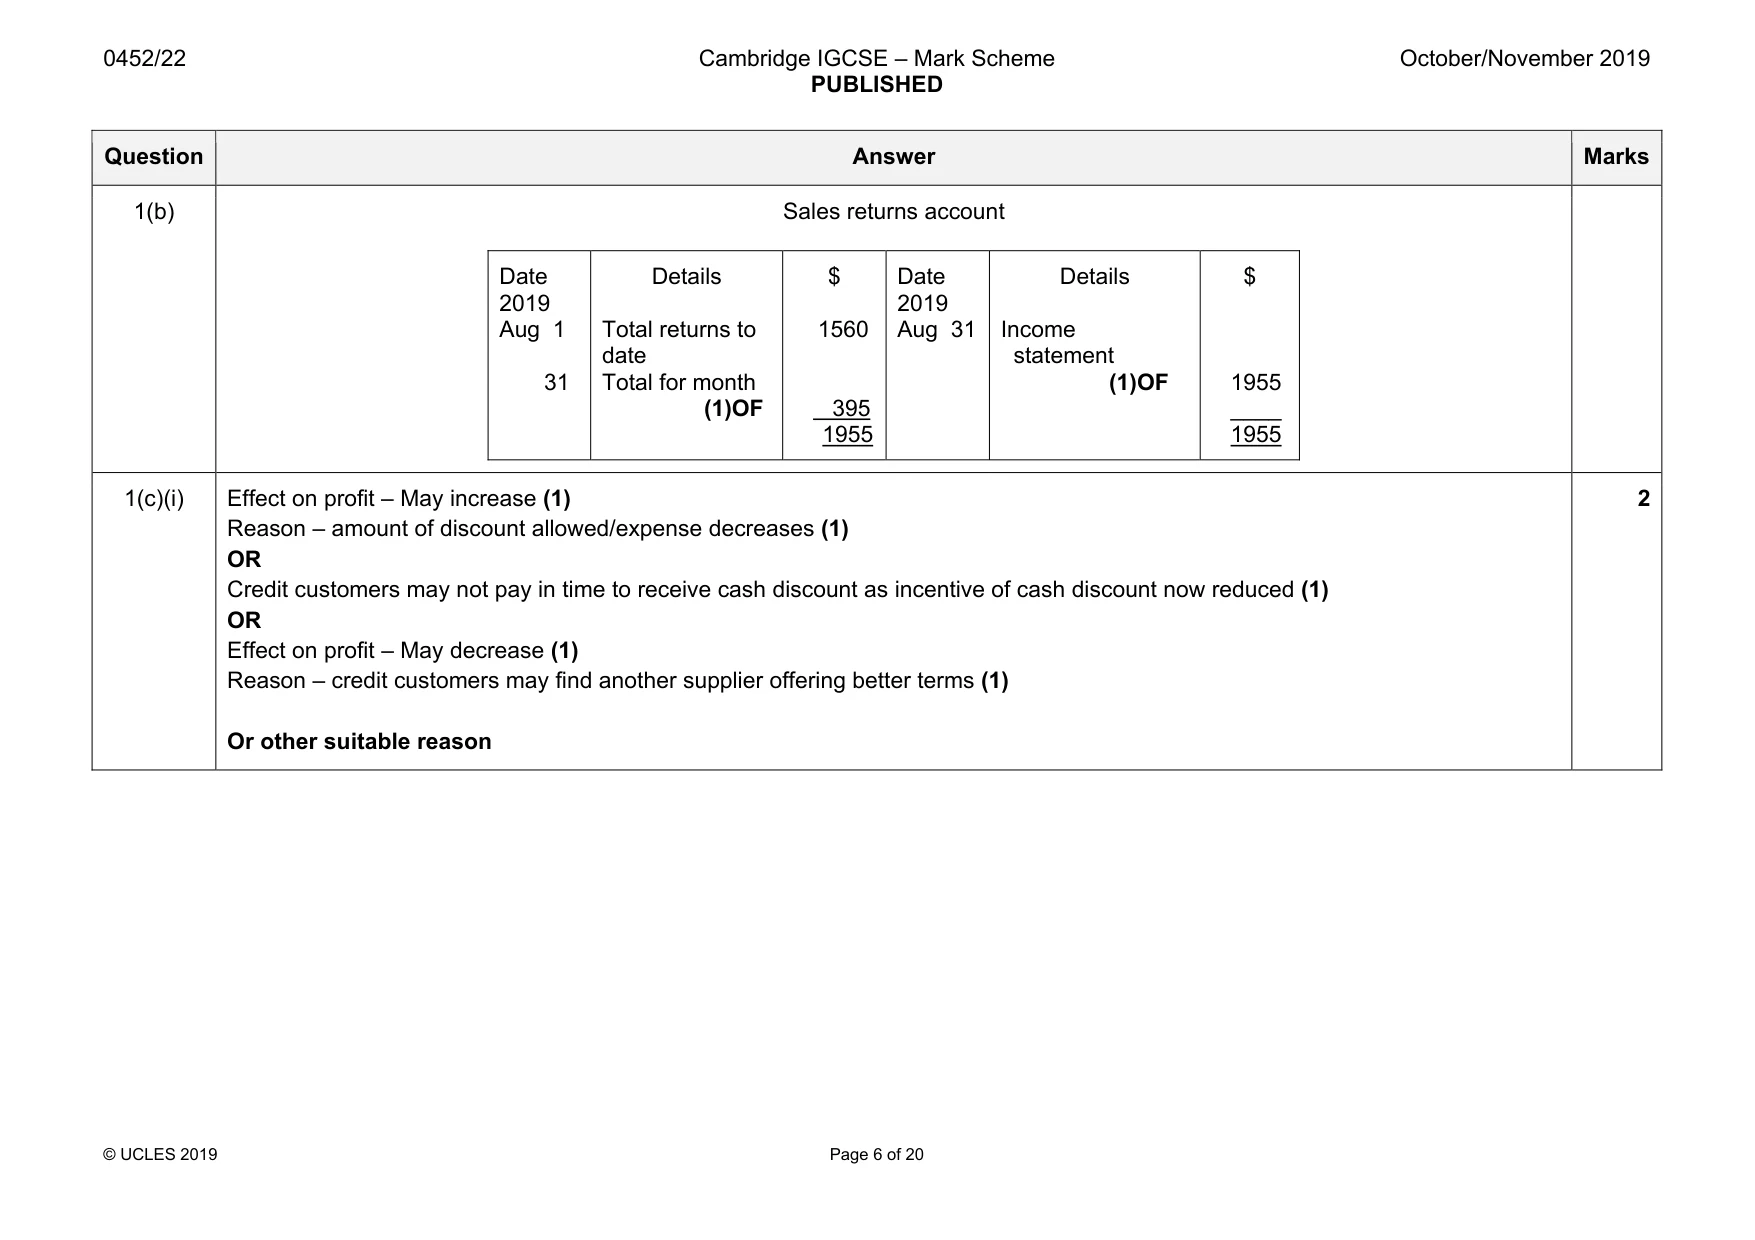
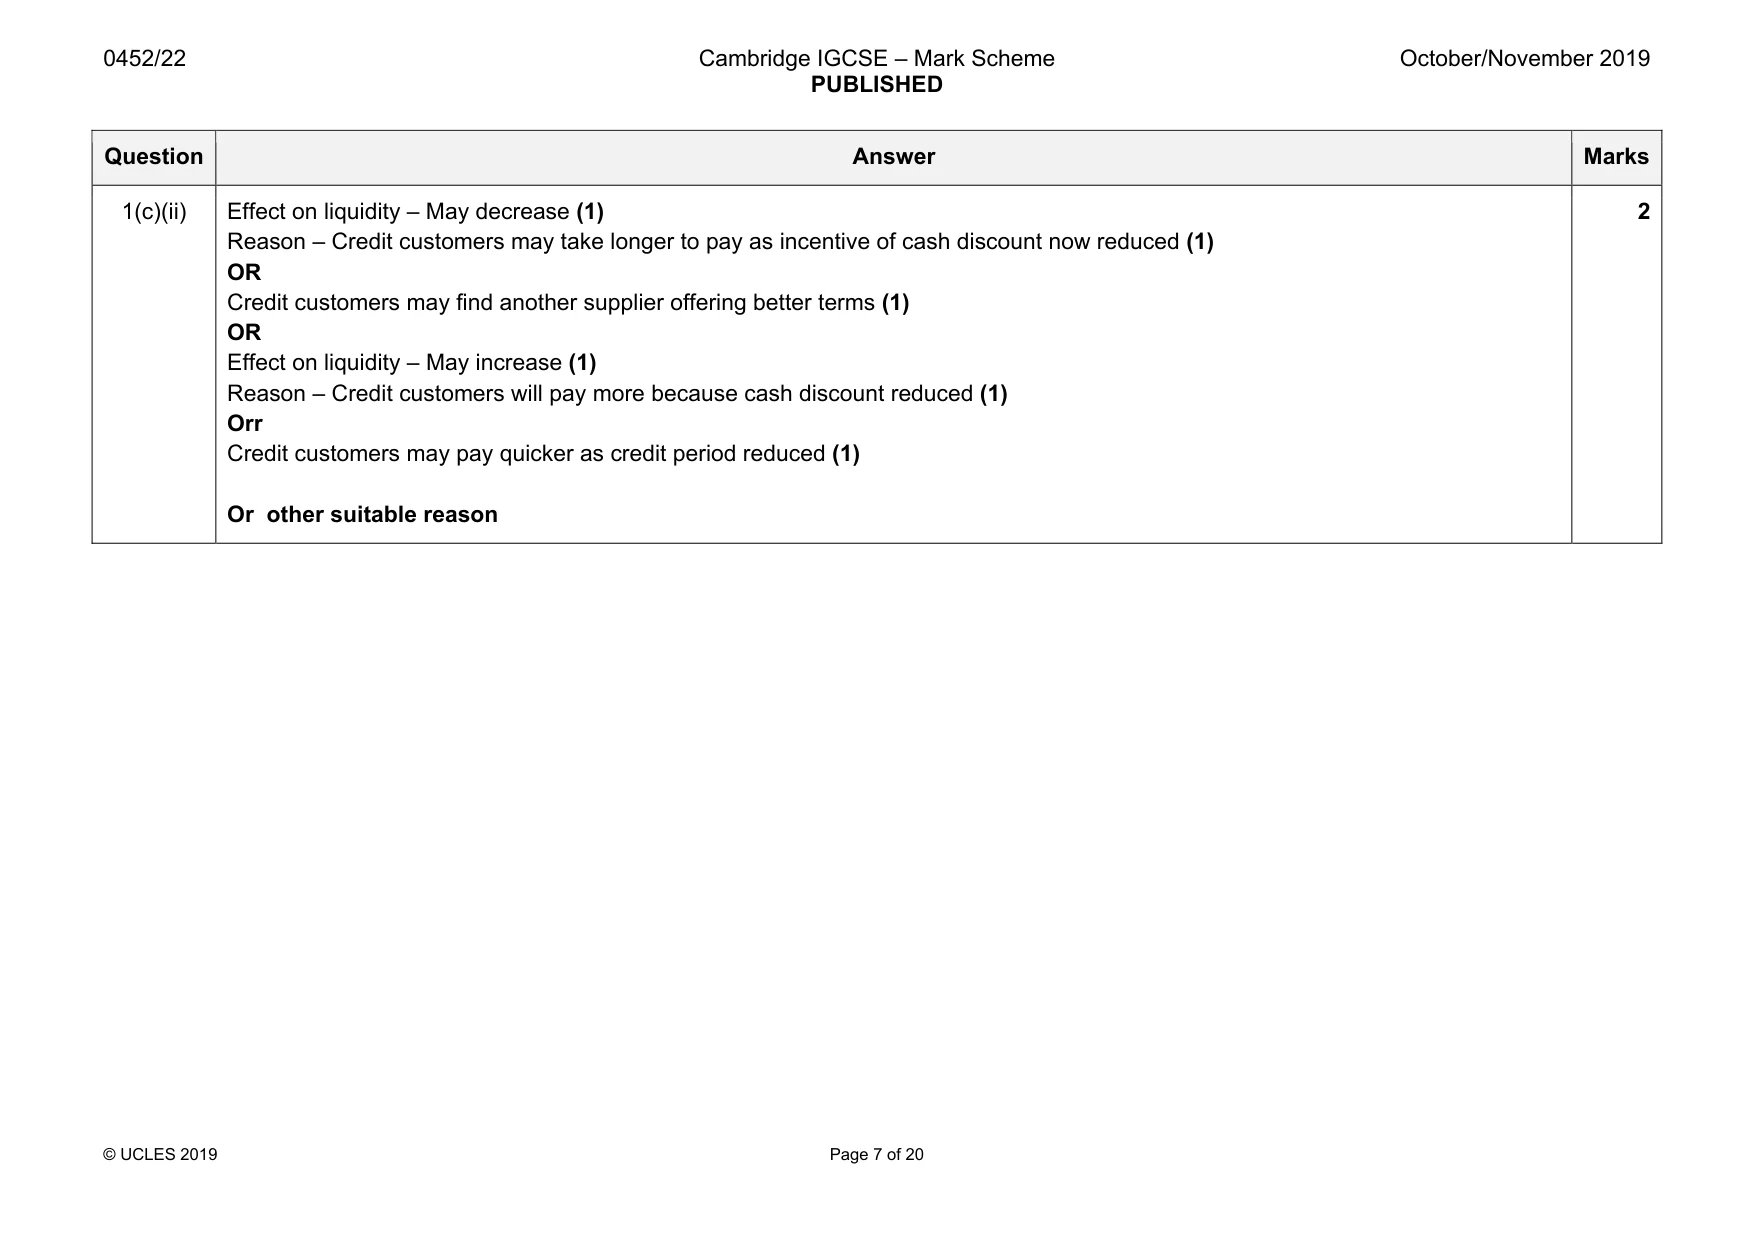
Mark scheme: 1(a) Tebogo Sales Journal Date Details $ $ 2019 Aug 6 18 30 31 Kayla Less 20% trade discount Nyack Kayla Transfer to sales account 1400 280 1120 620 160 ____ 1900 (1) } }(1) } (1) OF Tebogo Sales Returns Journal Date Details $ $ 2019 Aug 12 24 31 Kayla Less 20% trade discount Nyack Transfer to sales returns account 300 60 240 155 ___ 395 (1) } }(1) }OF 5 Question Answer Marks 1(b) Tebogo Kayla account Date 2019 Aug 1 6 30 2019 Sept 1 Details Balance b/d Sales OF }(1) Sales CF } Balance b/d (1)OF $ 900 1120 160 ____ 2180 1040 Date 2019 Aug 12 29 31 Details Sales returns (1)OF Bank }(1) Discount } Balance c/d $ 240 882 18 1040 2180 Sales account Date 2019 Aug 31 Details Income statement (1)OF $ 23 300 23 300 Date 2019 Aug 1 31 Details Total sales to date Total for month (1)OF $ 21 400 1900 23 300 8 Question Answer Marks 1(b) Sales returns account Date 2019 Aug 1 31 Details Total returns to date Total for month (1)OF $ 1560 395 1955 Date 2019 Aug 31 Details Income statement (1)OF $ 1955 ____ 1955 1(c)(i) Effect on profit – May increase (1) Reason – amount of discount allowed/expense decreases (1) OR Credit customers may not pay in time to receive cash discount as incentive of cash discount now reduced (1) OR Effect on profit – May decrease (1) Reason – credit customers may find another supplier offering better terms (1) Or other suitable reason 2 Question Answer Marks 1(c)(ii) Effect on liquidity – May decrease (1) Reason – Credit customers may take longer to pay as incentive of cash discount now reduced (1) OR Credit customers may find another supplier offering better terms (1) OR Effect on liquidity – May increase (1) Reason – Credit customers will pay more because cash discount reduced (1) Orr Credit customers may pay quicker as credit period reduced (1) Or other suitable reason 2
Q2 · Amelia opened a business on 1 April 2017
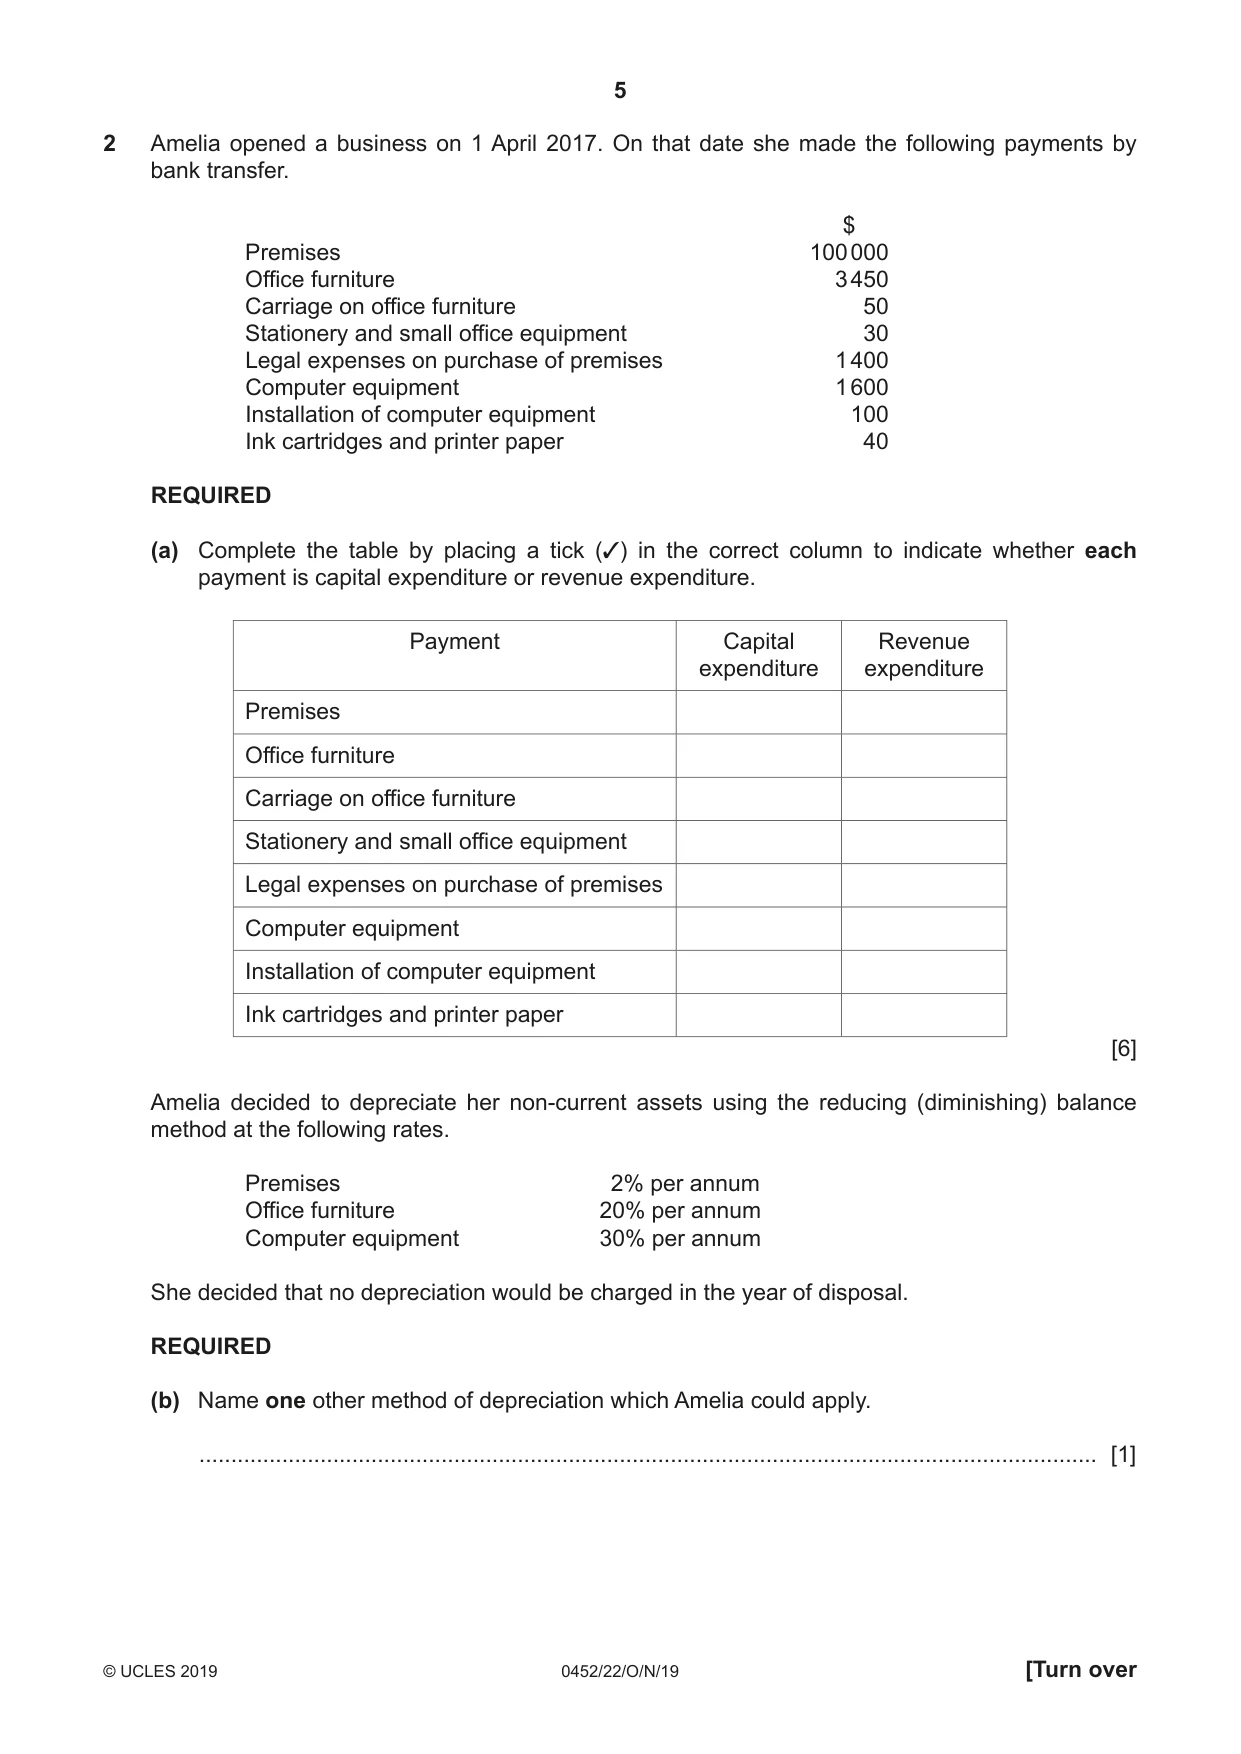
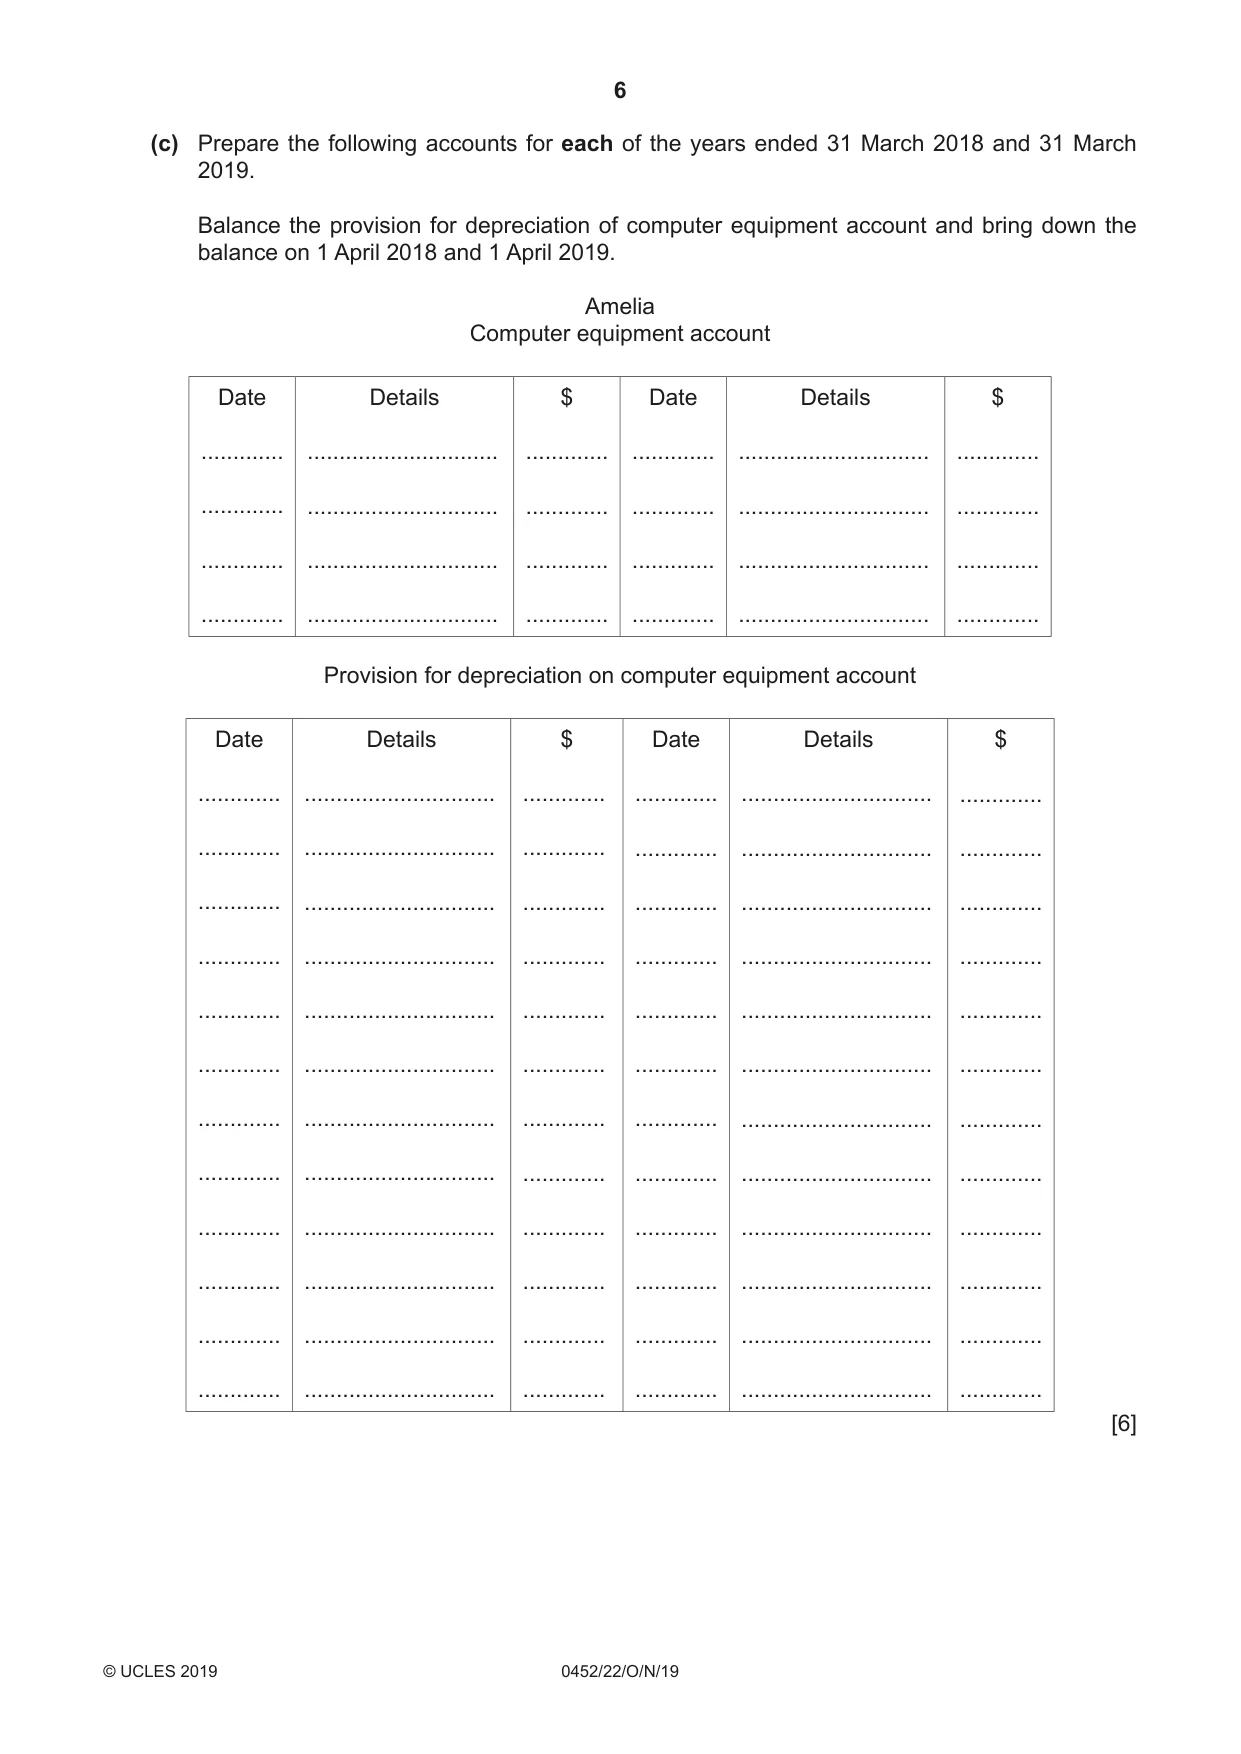
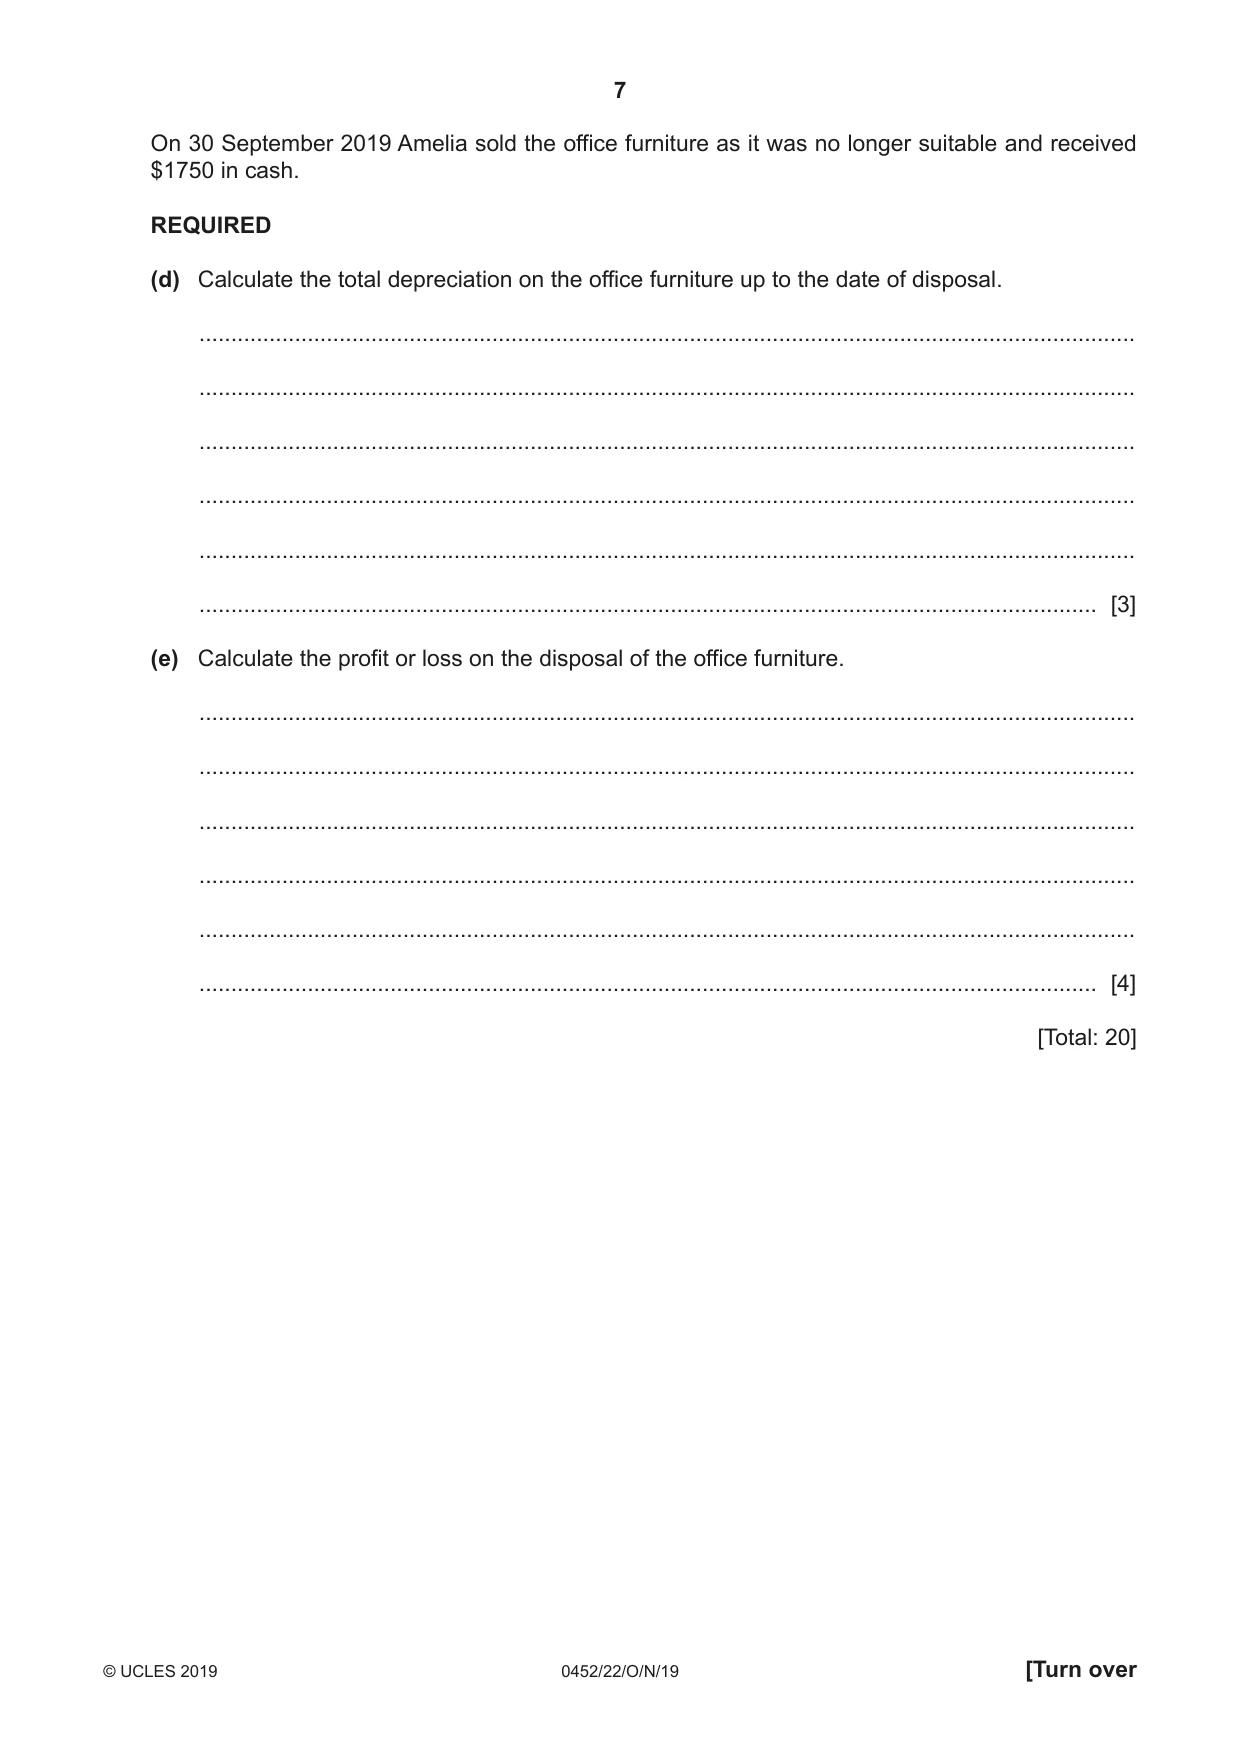
2 Amelia opened a business on 1 April 2017. On that date she made the following payments by bank transfer. $ Premises 100 000 Office furniture 3 450 Carriage on office furniture 50 Stationery and small office equipment 30 Legal expenses on purchase of premises 1 400 Computer equipment 1 600 Installation of computer equipment 100 Ink cartridges and printer paper 40 REQUIRED (a) Complete the table by placing a tick (3) in the correct column to indicate whether each payment is capital expenditure or revenue expenditure. Payment Capital Revenue expenditure expenditure Premises Office furniture Carriage on office furniture Stationery and small office equipment Legal expenses on purchase of premises Computer equipment Installation of computer equipment Ink cartridges and printer paper [6] Amelia decided to depreciate her non-current assets using the reducing (diminishing) balance method at the following rates. Premises 2% per annum Office furniture 20% per annum Computer equipment 30% per annum She decided that no depreciation would be charged in the year of disposal. REQUIRED (b) Name one other method of depreciation which Amelia could apply. ............................................................................................................................................. [1] (c) Prepare the following accounts for each of the years ended 31 March 2018 and 31 March 2019. Balance the provision for depreciation of computer equipment account and bring down the balance on 1 April 2018 and 1 April 2019. Amelia Computer equipment account Date Details $ Date Details $ ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. Provision for depreciation on computer equipment account Date Details $ Date Details $ ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. [6] On 30 September 2019 Amelia sold the office furniture as it was no longer suitable and received $1750 in cash. REQUIRED (d) Calculate the total depreciation on the office furniture up to the date of disposal. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (e) Calculate the profit or loss on the disposal of the office furniture. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] [Total: 20] Question 3 is on the next page.
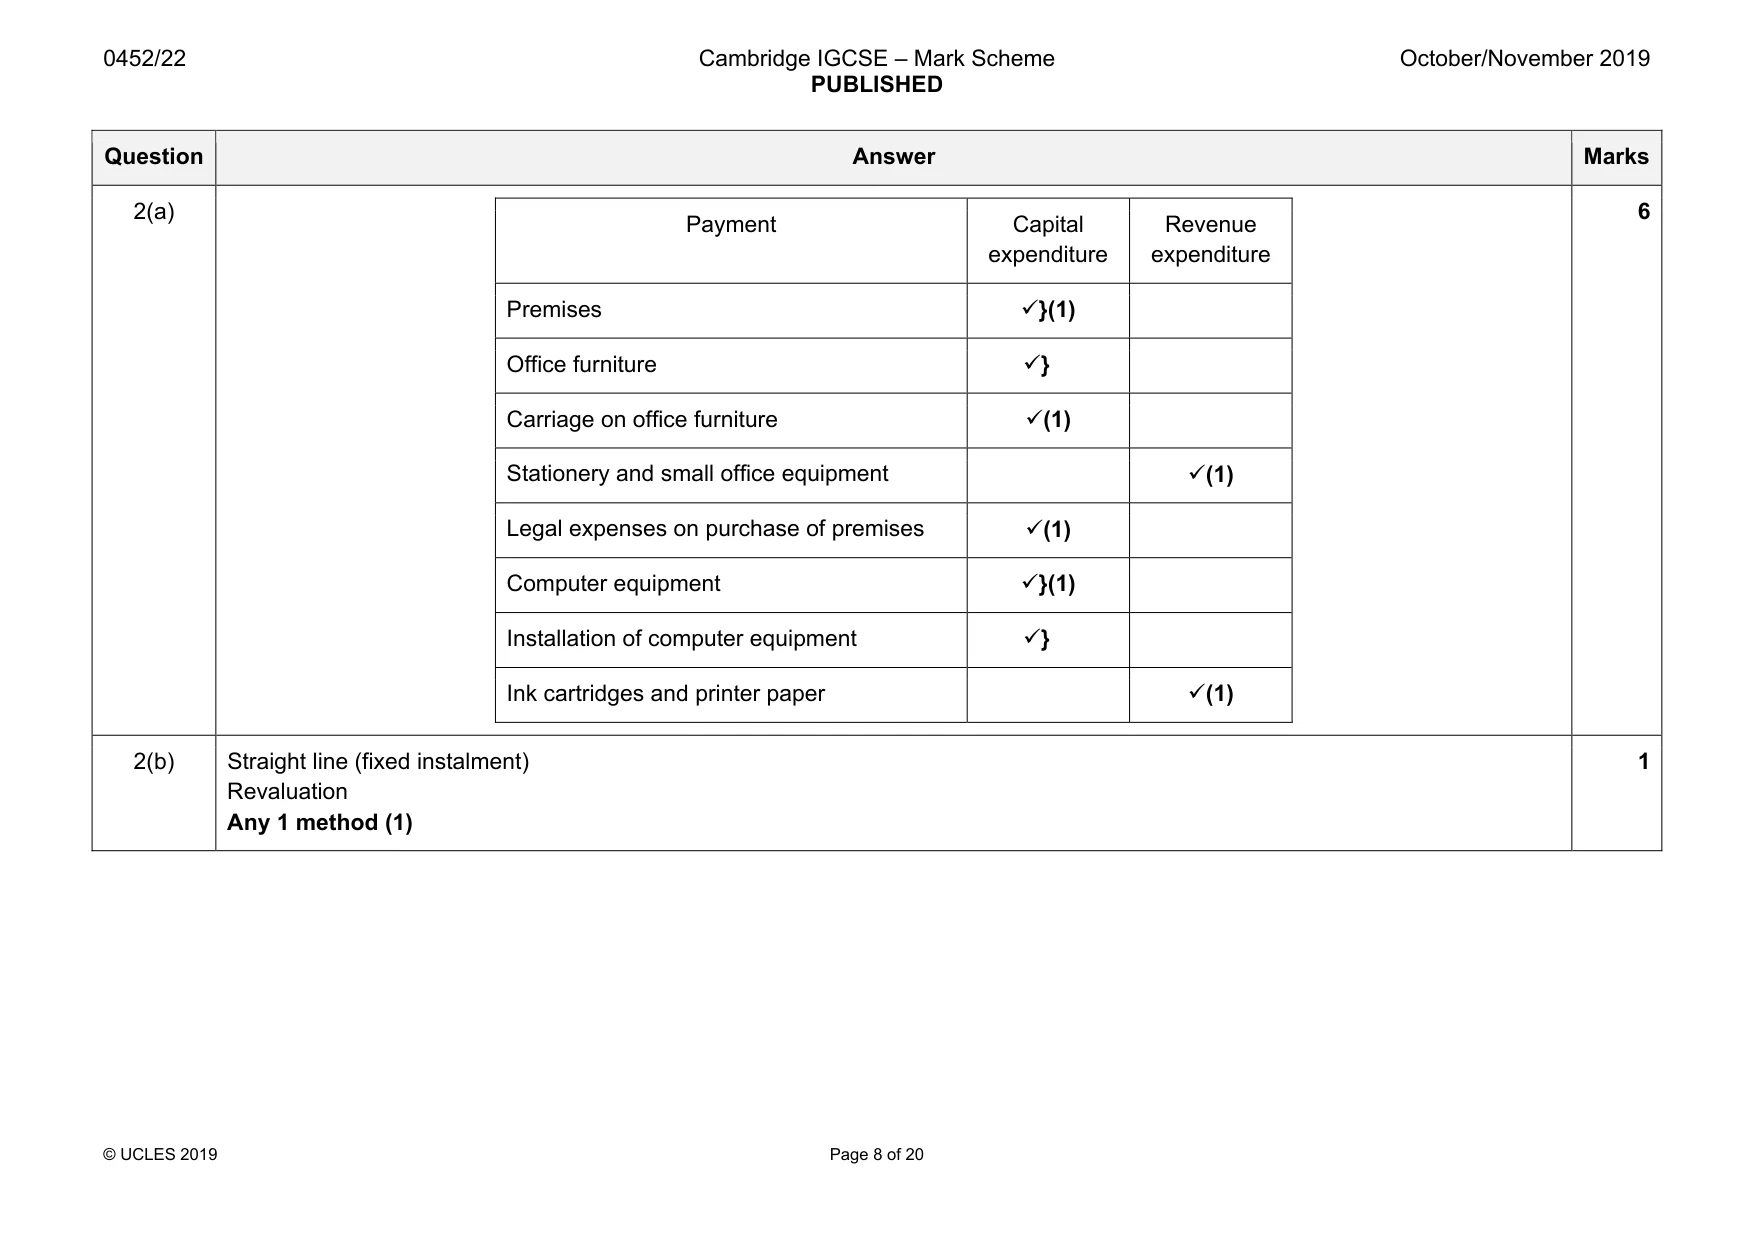
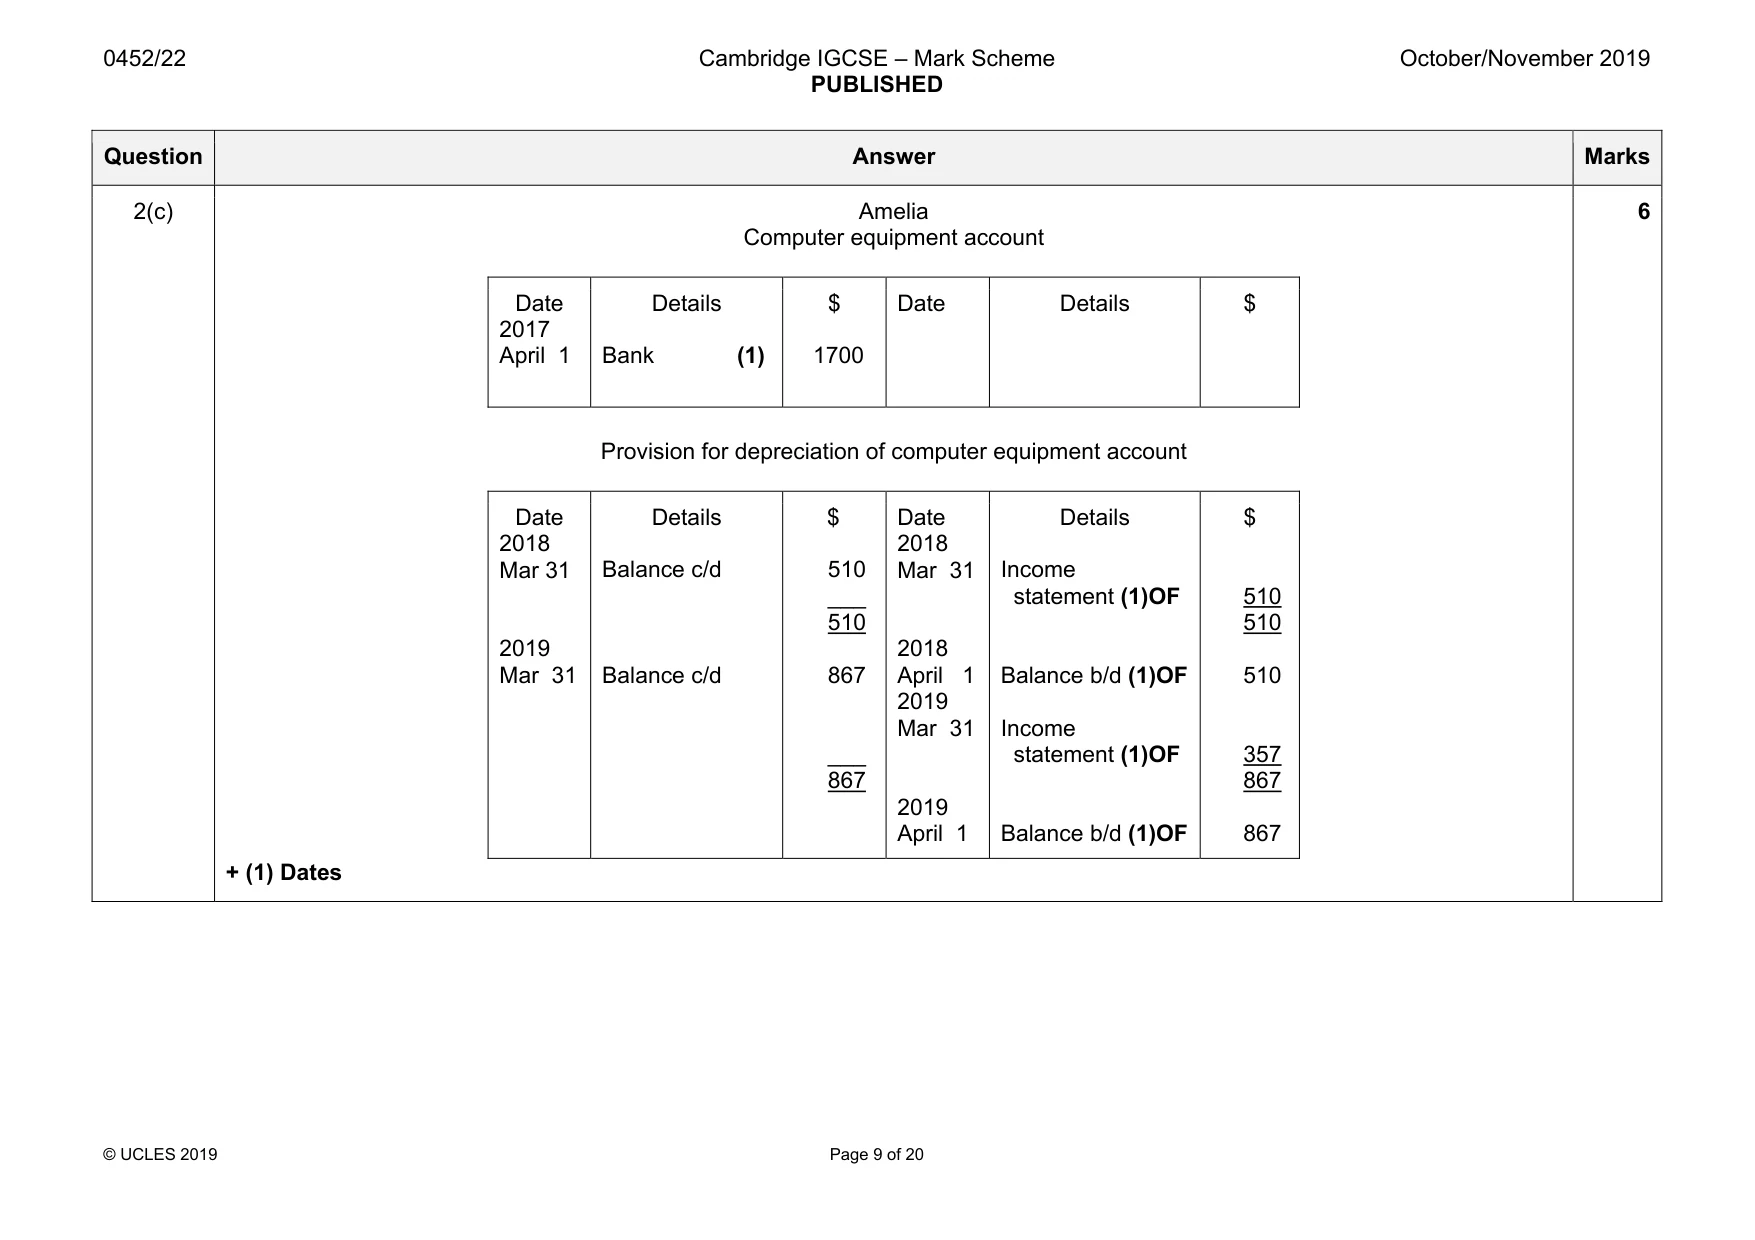
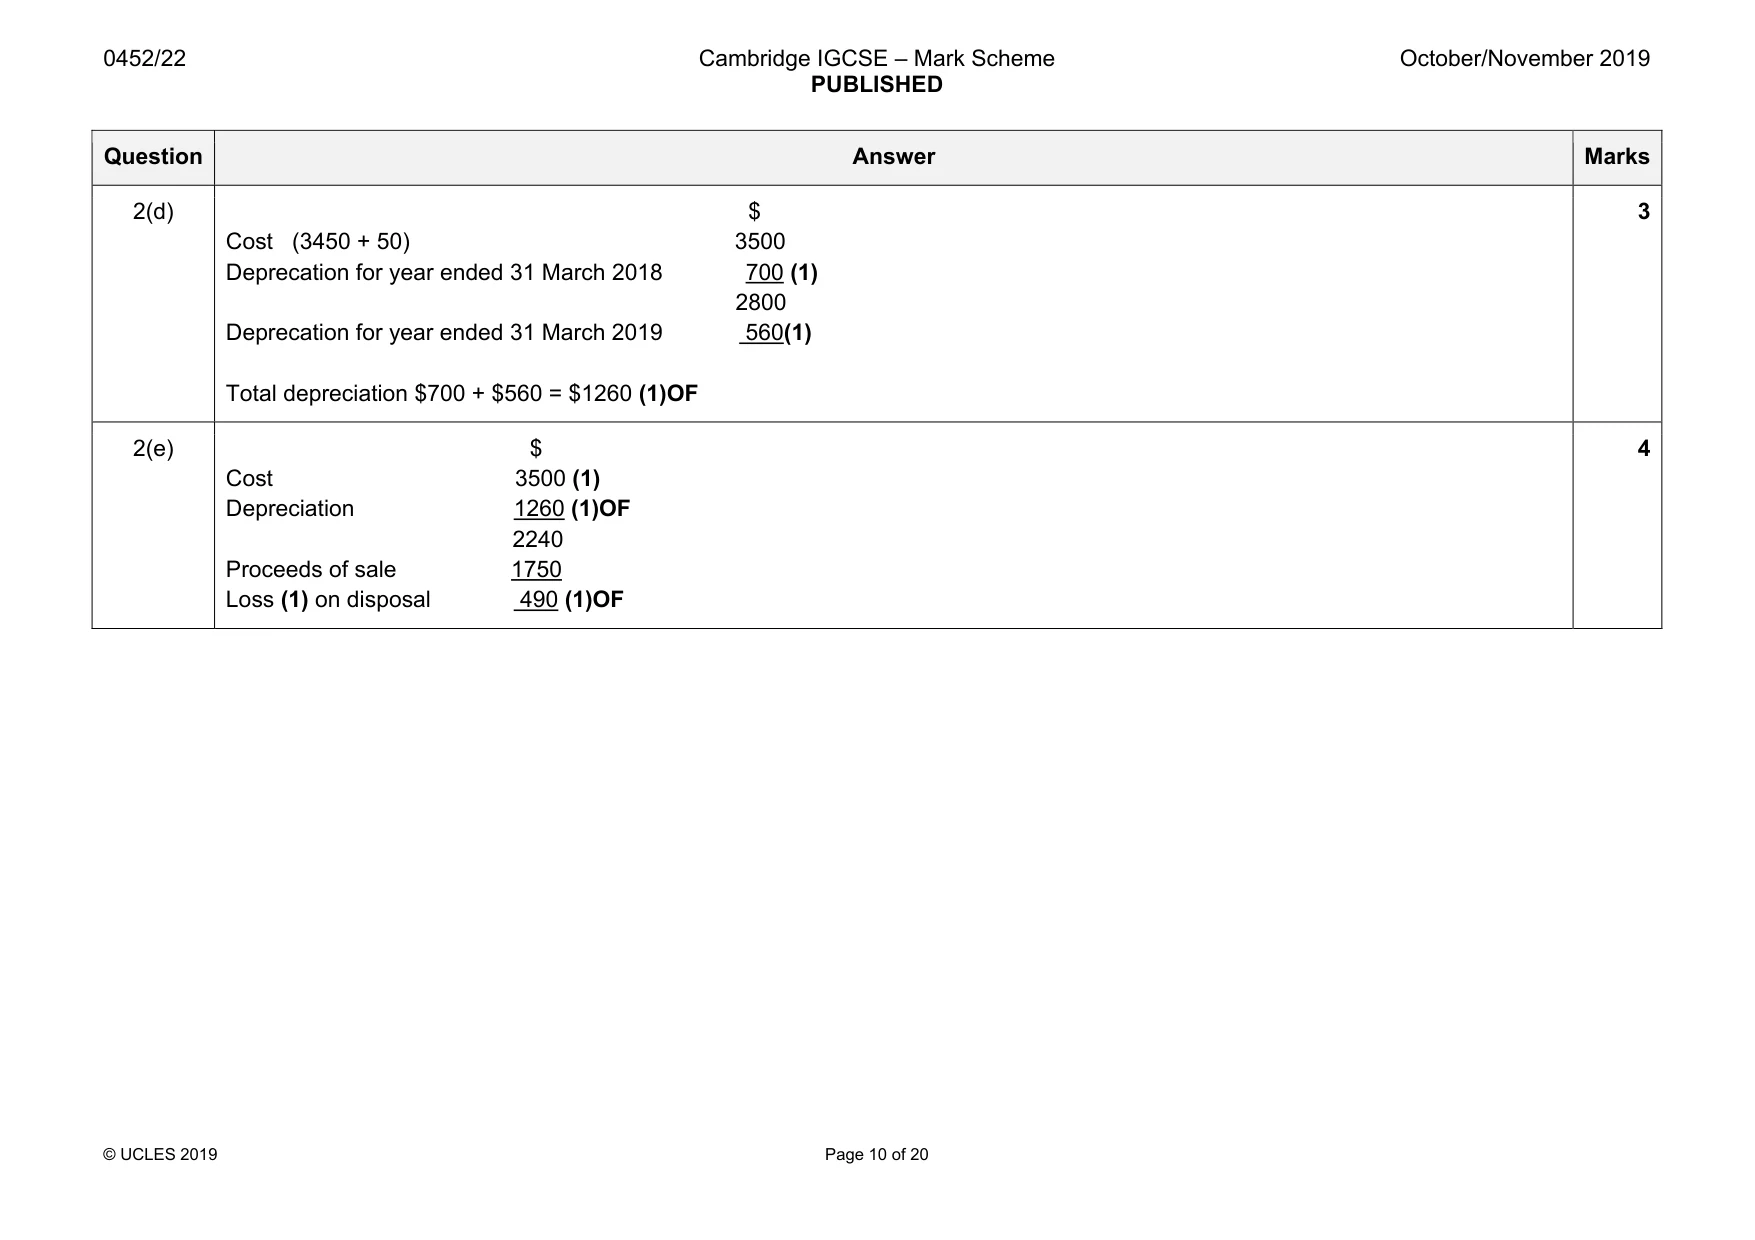
Mark scheme: 2(a) Payment Capital expenditure Revenue expenditure Premises 9}(1) Office furniture 9} Carriage on office furniture 9(1) Stationery and small office equipment 9(1) Legal expenses on purchase of premises 9(1) Computer equipment 9}(1) Installation of computer equipment 9} Ink cartridges and printer paper 9(1) 6 2(b) Straight line (fixed instalment) Revaluation Any 1 method (1) 1 Question Answer Marks 2(c) Amelia Computer equipment account Date 2017 April 1 Details Bank (1) $ 1700 Date Details $ Provision for depreciation of computer equipment account Date 2018 Mar 31 2019 Mar 31 Details Balance c/d Balance c/d $ 510 ___ 510 867 ___ 867 Date 2018 Mar 31 2018 April 1 2019 Mar 31 2019 April 1 Details Income statement (1)OF Balance b/d (1)OF Income statement (1)OF Balance b/d (1)OF $ 510 510 510 357 867 867 + (1) Dates 6 Question Answer Marks 2(d) $ Cost (3450 + 50) 3500 Deprecation for year ended 31 March 2018 700 (1) 2800 Deprecation for year ended 31 March 2019 560(1) Total depreciation $700 + $560 = $1260 (1)OF 3 2(e) $ Cost 3500 (1) Depreciation 1260 (1)OF 2240 Proceeds of sale 1750 Loss (1) on disposal 490 (1)OF 4
More questions on Accounting for depreciation and disposal of non-current assets
Q3 · The financial year of the KS Sports Club ends on 31 July
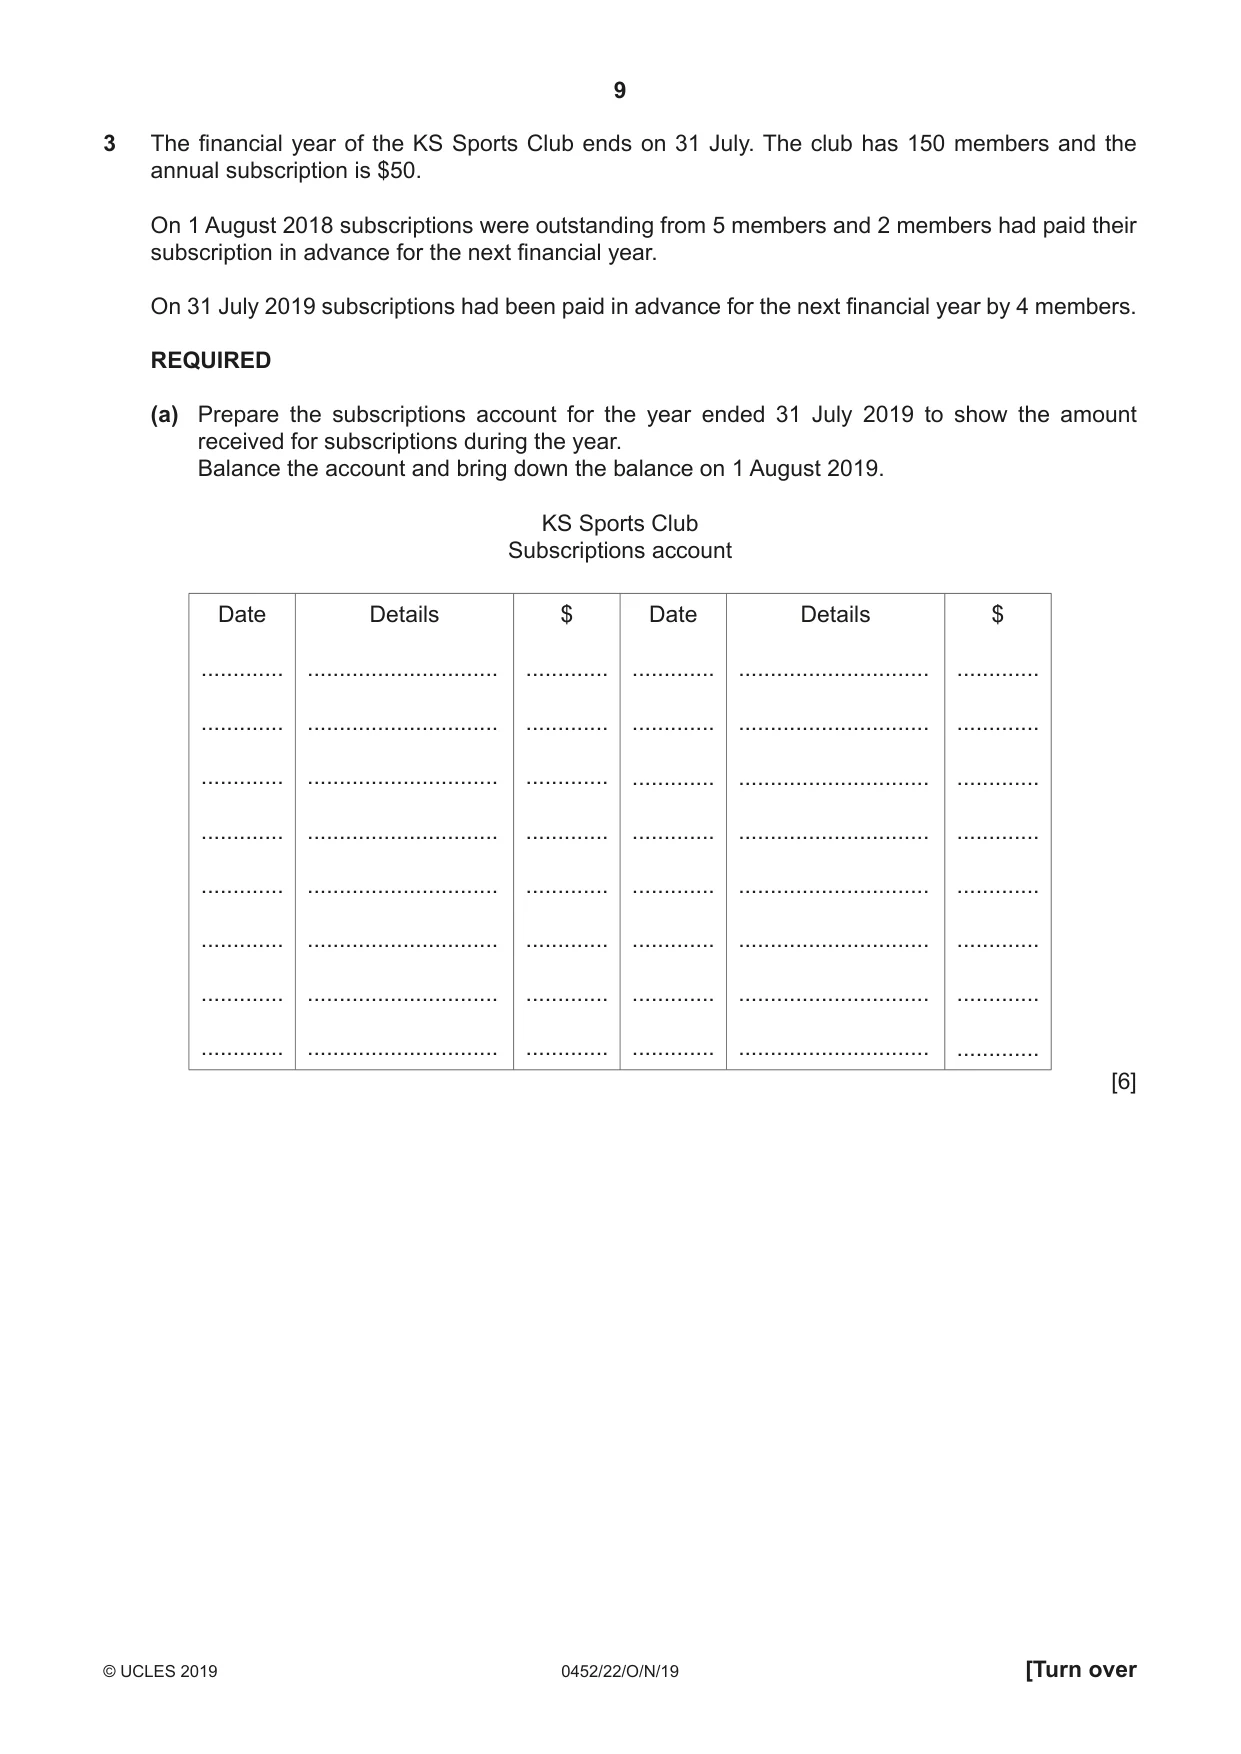
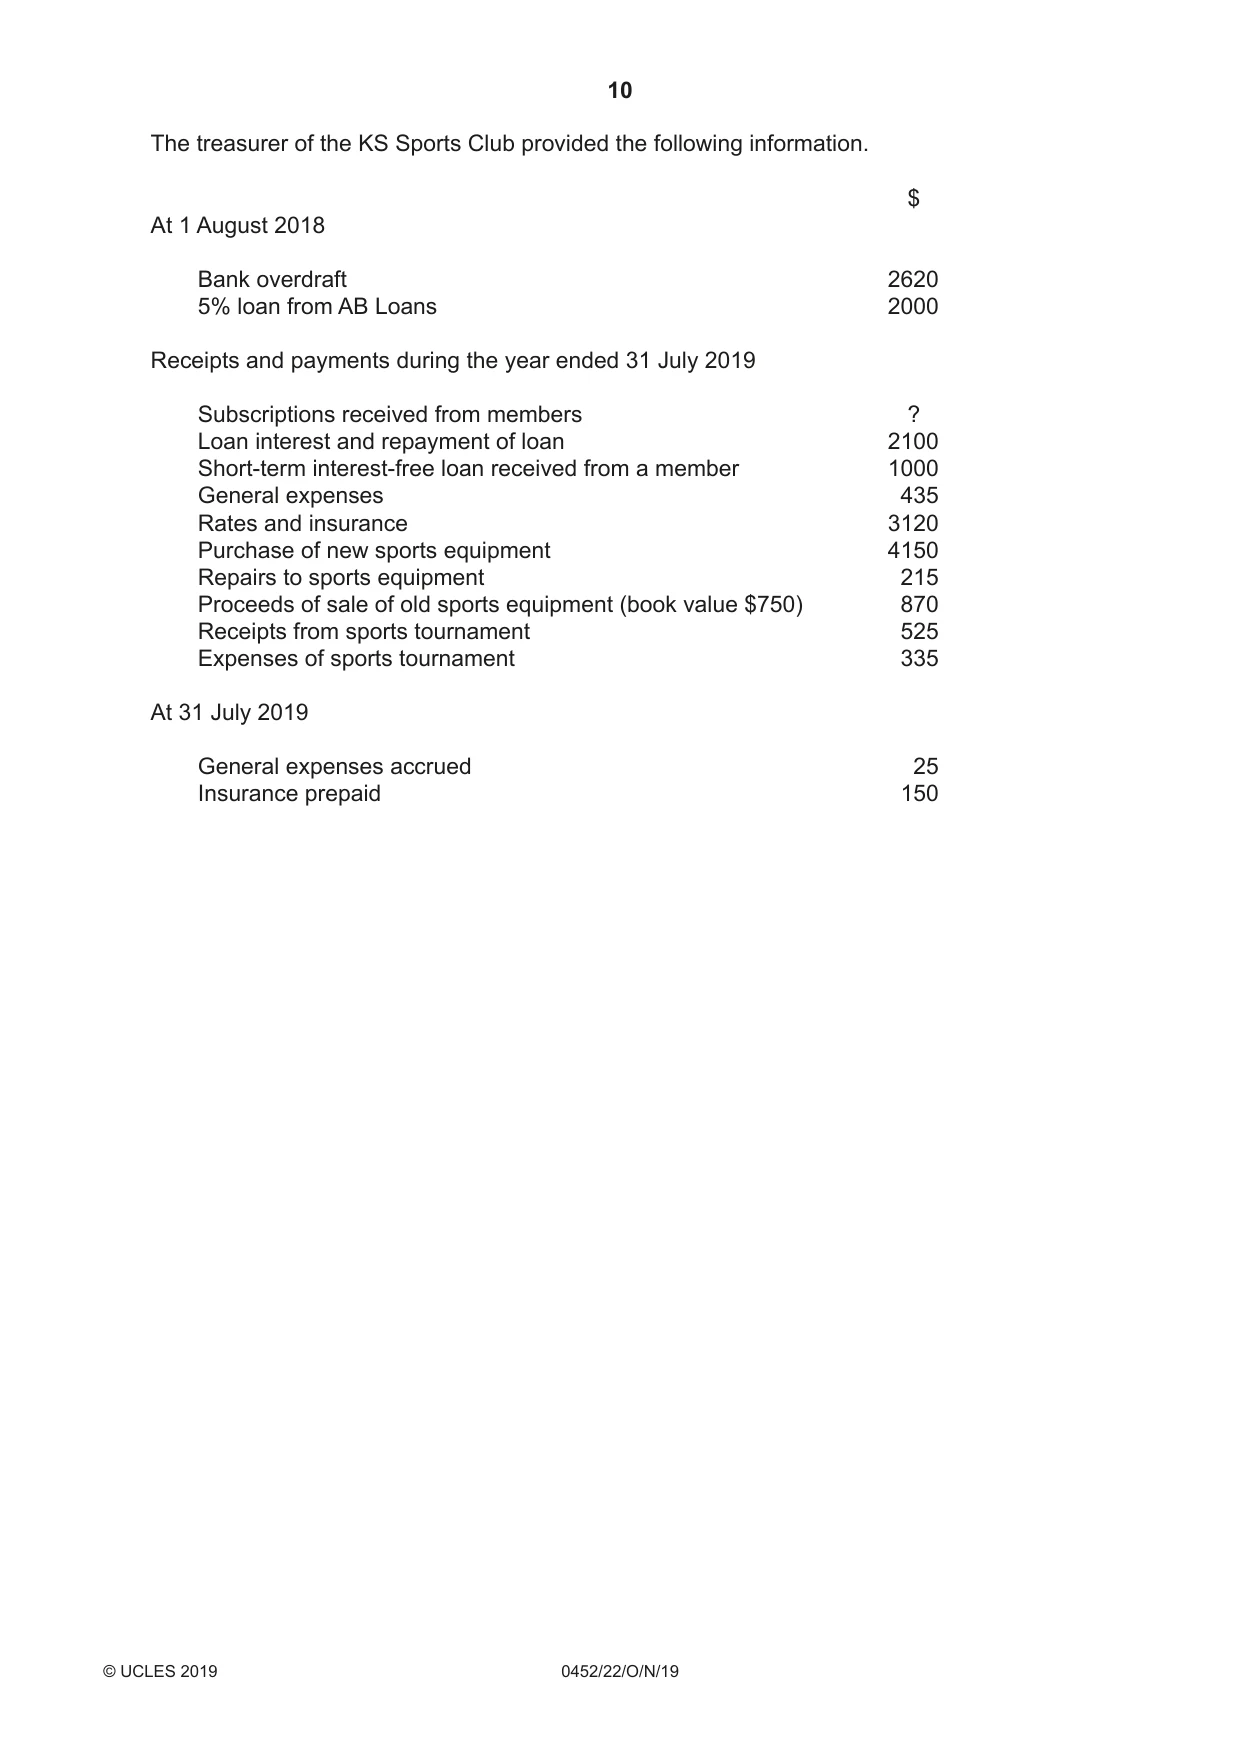
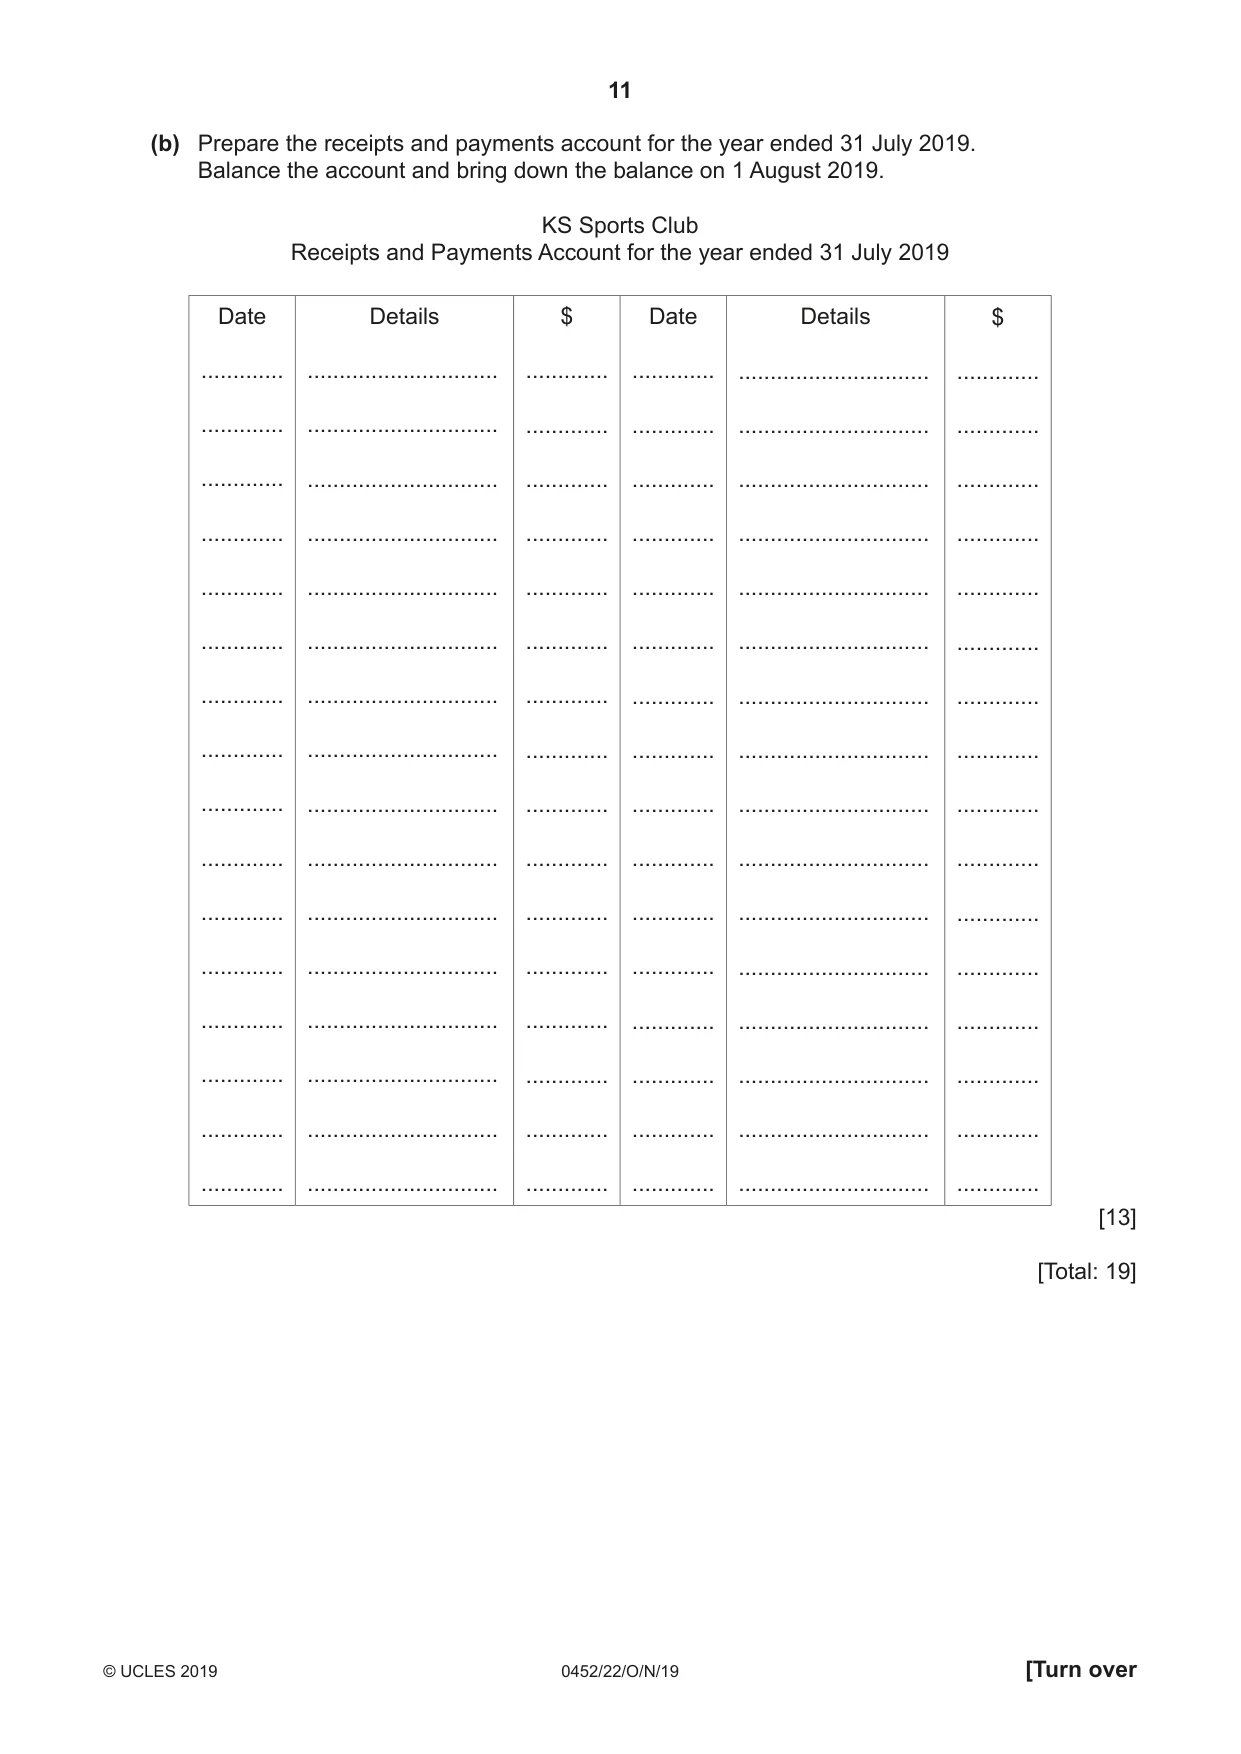
3 The financial year of the KS Sports Club ends on 31 July. The club has 150 members and the annual subscription is $50. On 1 August 2018 subscriptions were outstanding from 5 members and 2 members had paid their subscription in advance for the next financial year. On 31 July 2019 subscriptions had been paid in advance for the next financial year by 4 members. REQUIRED (a) Prepare the subscriptions account for the year ended 31 July 2019 to show the amount received for subscriptions during the year. Balance the account and bring down the balance on 1 August 2019. KS Sports Club Subscriptions account Date Details $ Date Details $ ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. [6] The treasurer of the KS Sports Club provided the following information. $ At 1 August 2018 Bank overdraft 2620 5% loan from AB Loans 2000 Receipts and payments during the year ended 31 July 2019 Subscriptions received from members ? Loan interest and repayment of loan 2100 Short-term interest-free loan received from a member 1000 General expenses 435 Rates and insurance 3120 Purchase of new sports equipment 4150 Repairs to sports equipment 215 Proceeds of sale of old sports equipment (book value $750) 870 Receipts from sports tournament 525 Expenses of sports tournament 335 At 31 July 2019 General expenses accrued 25 Insurance prepaid 150 (b) Prepare the receipts and payments account for the year ended 31 July 2019. Balance the account and bring down the balance on 1 August 2019. KS Sports Club Receipts and Payments Account for the year ended 31 July 2019 Date Details $ Date Details $ ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. [13] [Total: 19]
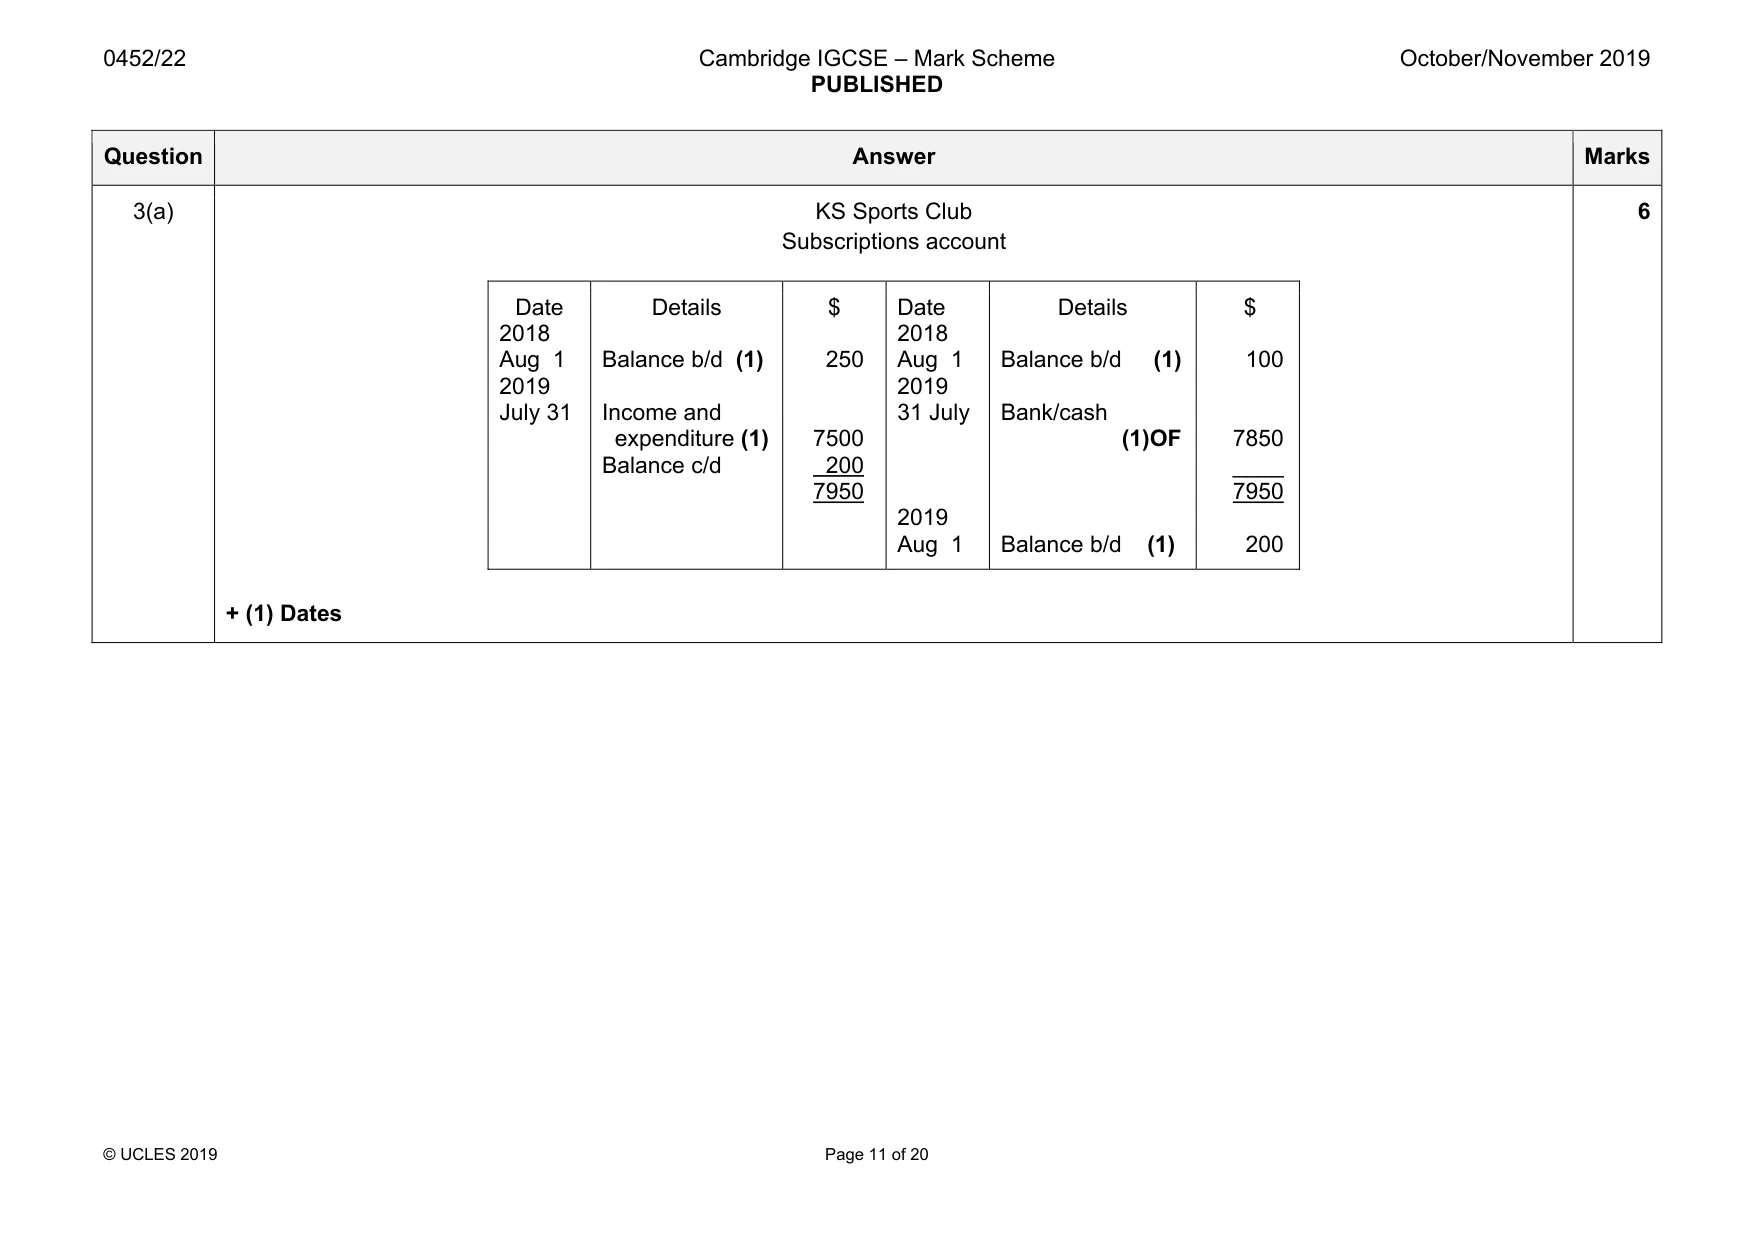
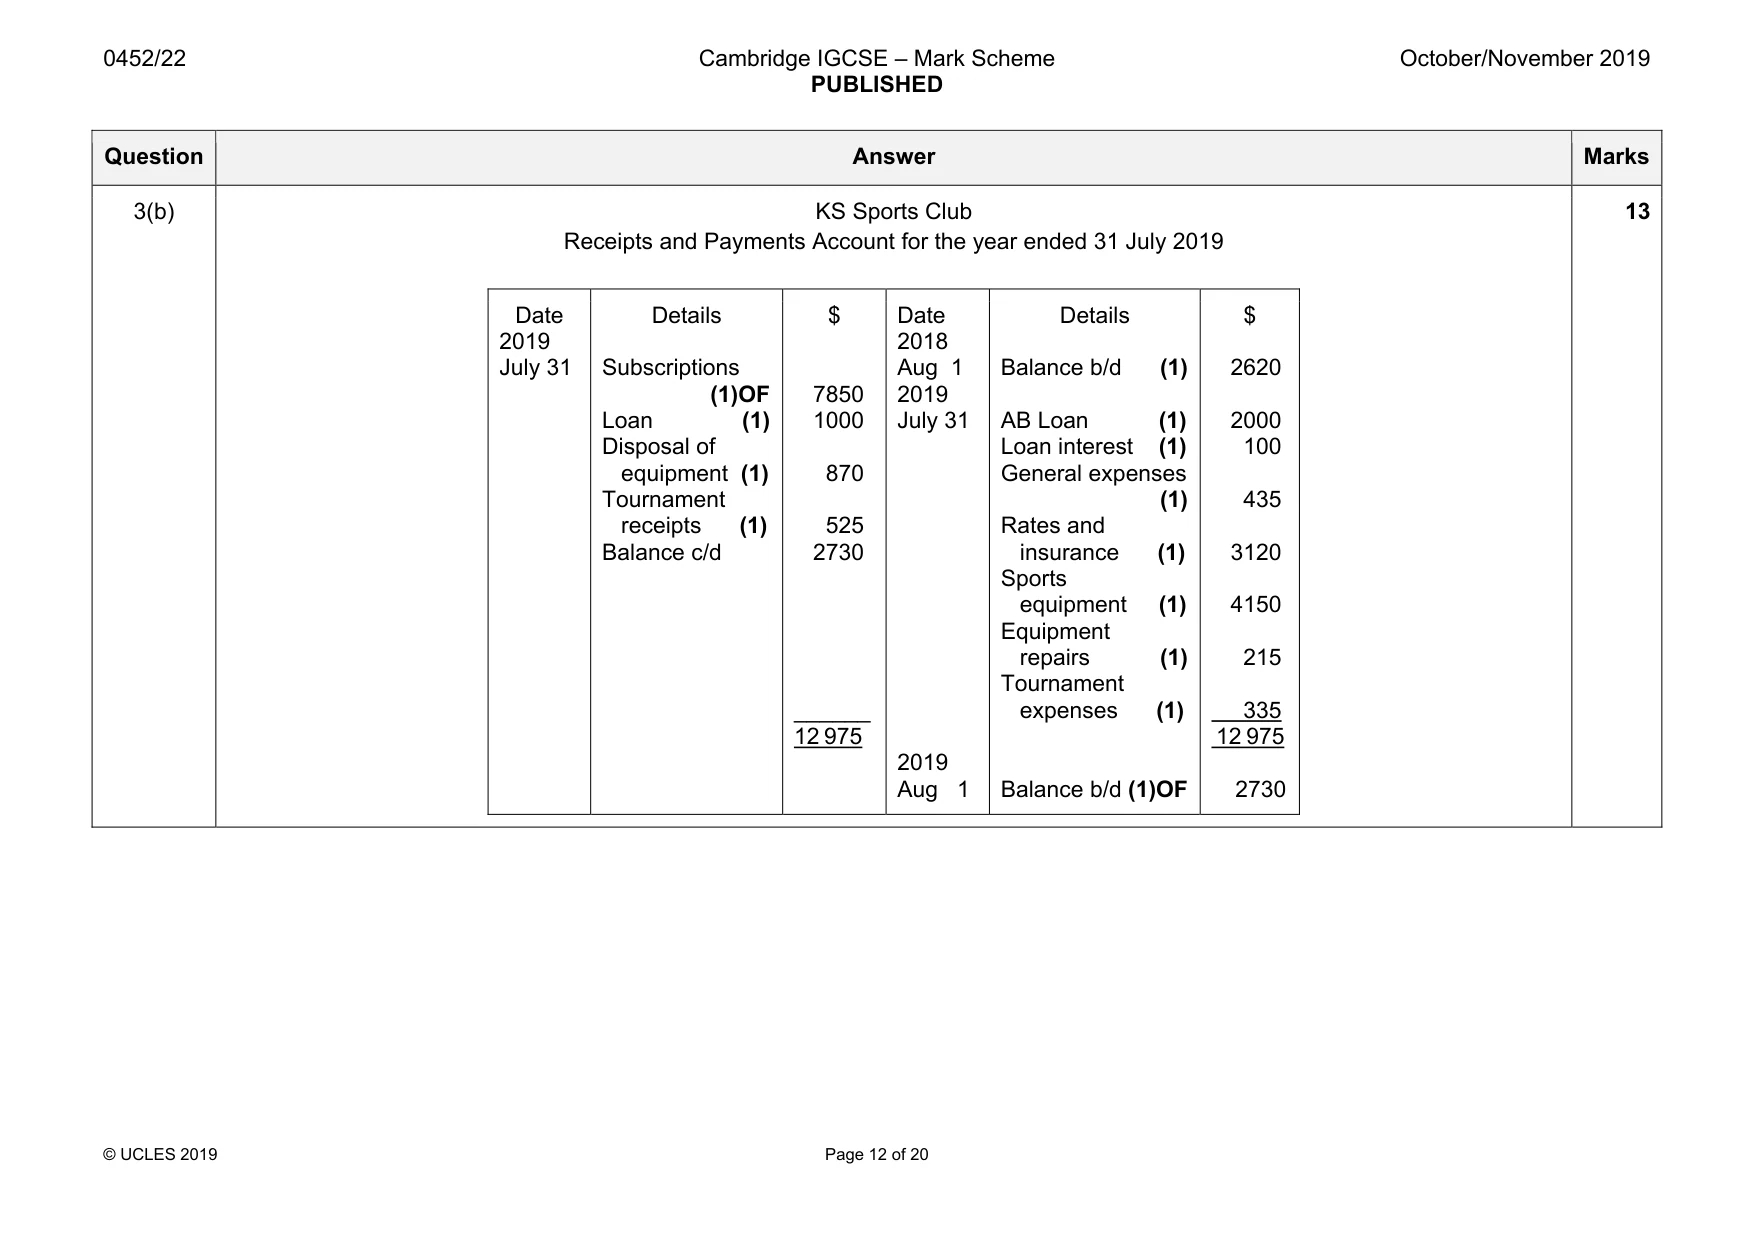
Mark scheme: 3(a) KS Sports Club Subscriptions account Date 2018 Aug 1 2019 July 31 Details Balance b/d (1) Income and expenditure (1) Balance c/d $ 250 7500 200 7950 Date 2018 Aug 1 2019 31 July 2019 Aug 1 Details Balance b/d (1) Bank/cash (1)OF Balance b/d (1) $ 100 7850 ____ 7950 200 + (1) Dates 6 Question Answer Marks 3(b) KS Sports Club Receipts and Payments Account for the year ended 31 July 2019 Date 2019 July 31 Details Subscriptions (1)OF Loan (1) Disposal of equipment (1) Tournament receipts (1) Balance c/d $ 7850 1000 870 525 2730 ______ 12 975 Date 2018 Aug 1 2019 July 31 2019 Aug 1 Details Balance b/d (1) AB Loan (1) Loan interest (1) General expenses (1) Rates and insurance (1) Sports equipment (1) Equipment repairs (1) Tournament expenses (1) Balance b/d (1)OF $ 2620 2000 100 435 3120 4150 215 335 12 975 2730 13
Q4 · Mariam’s financial year ends on 30 September
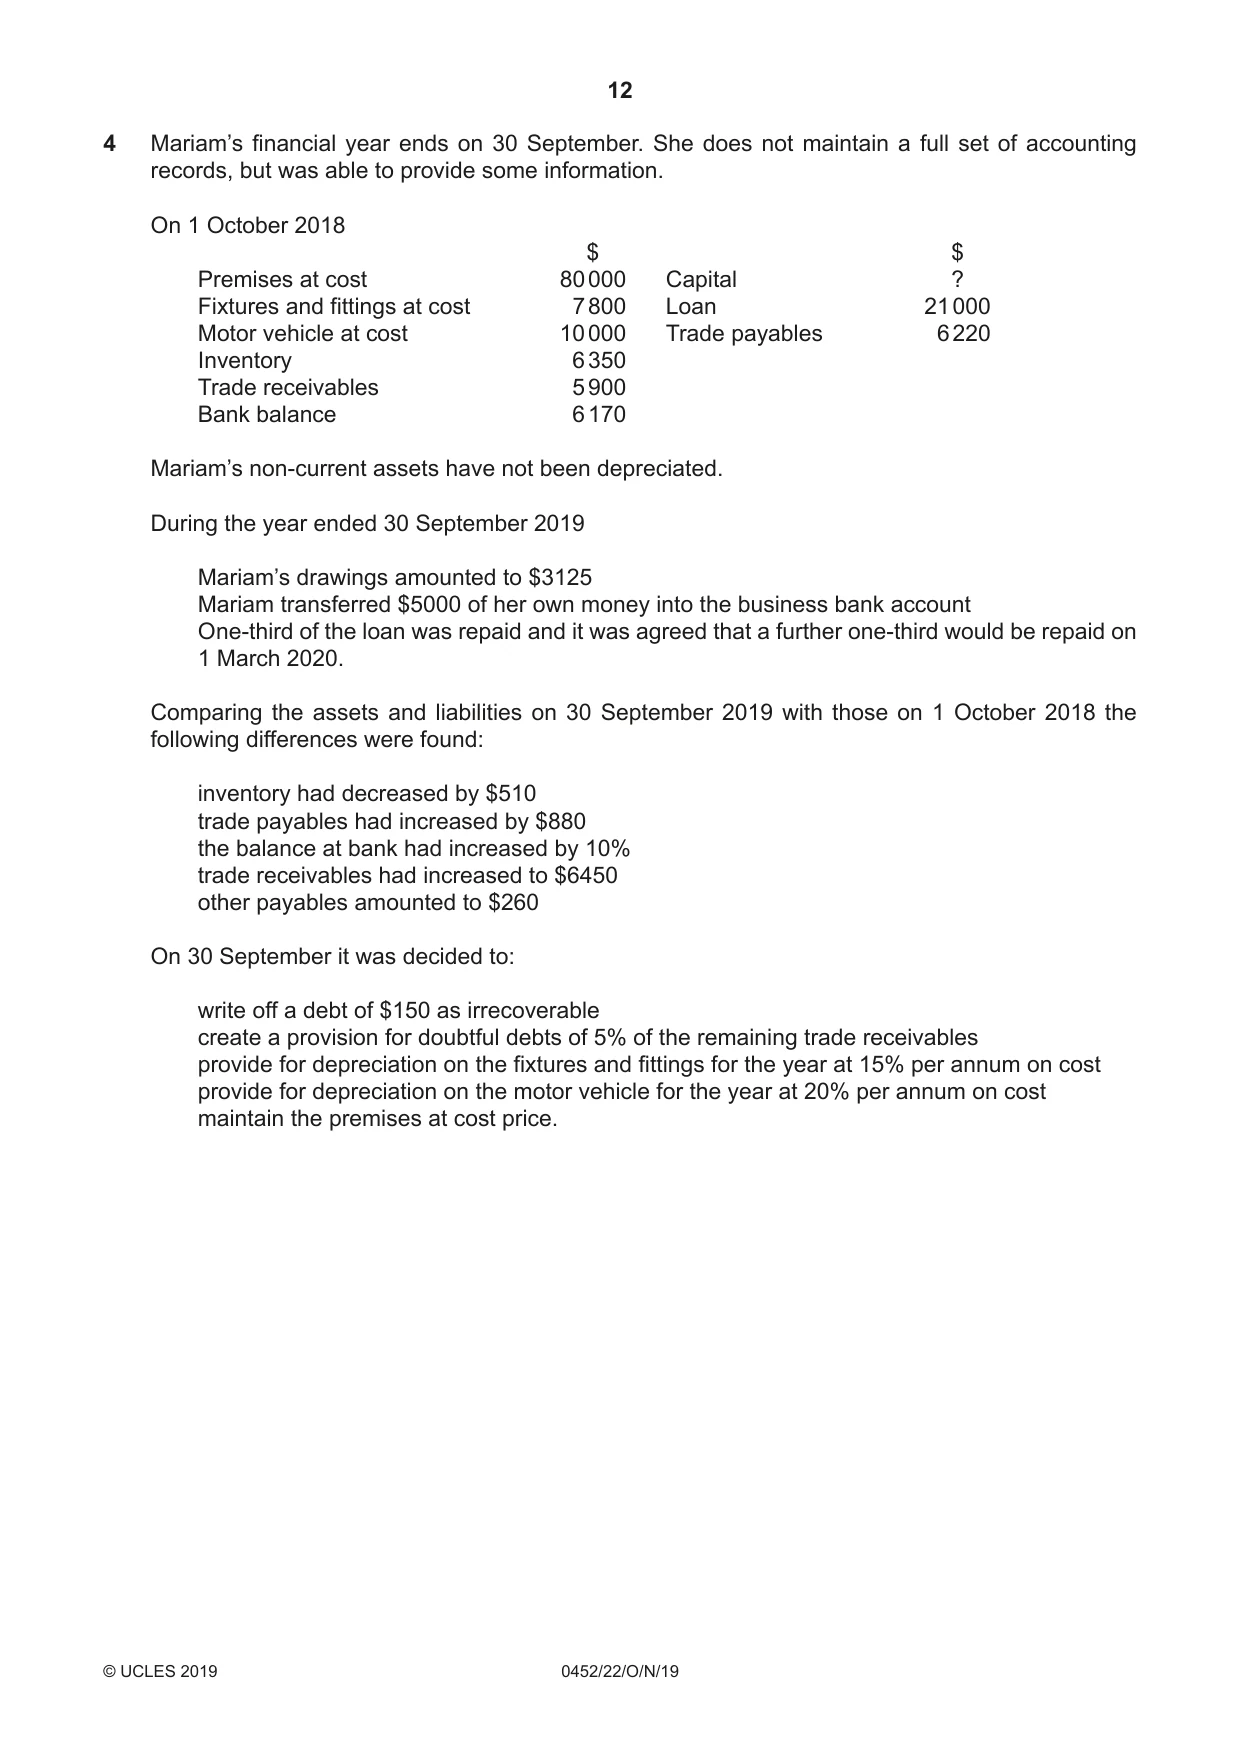
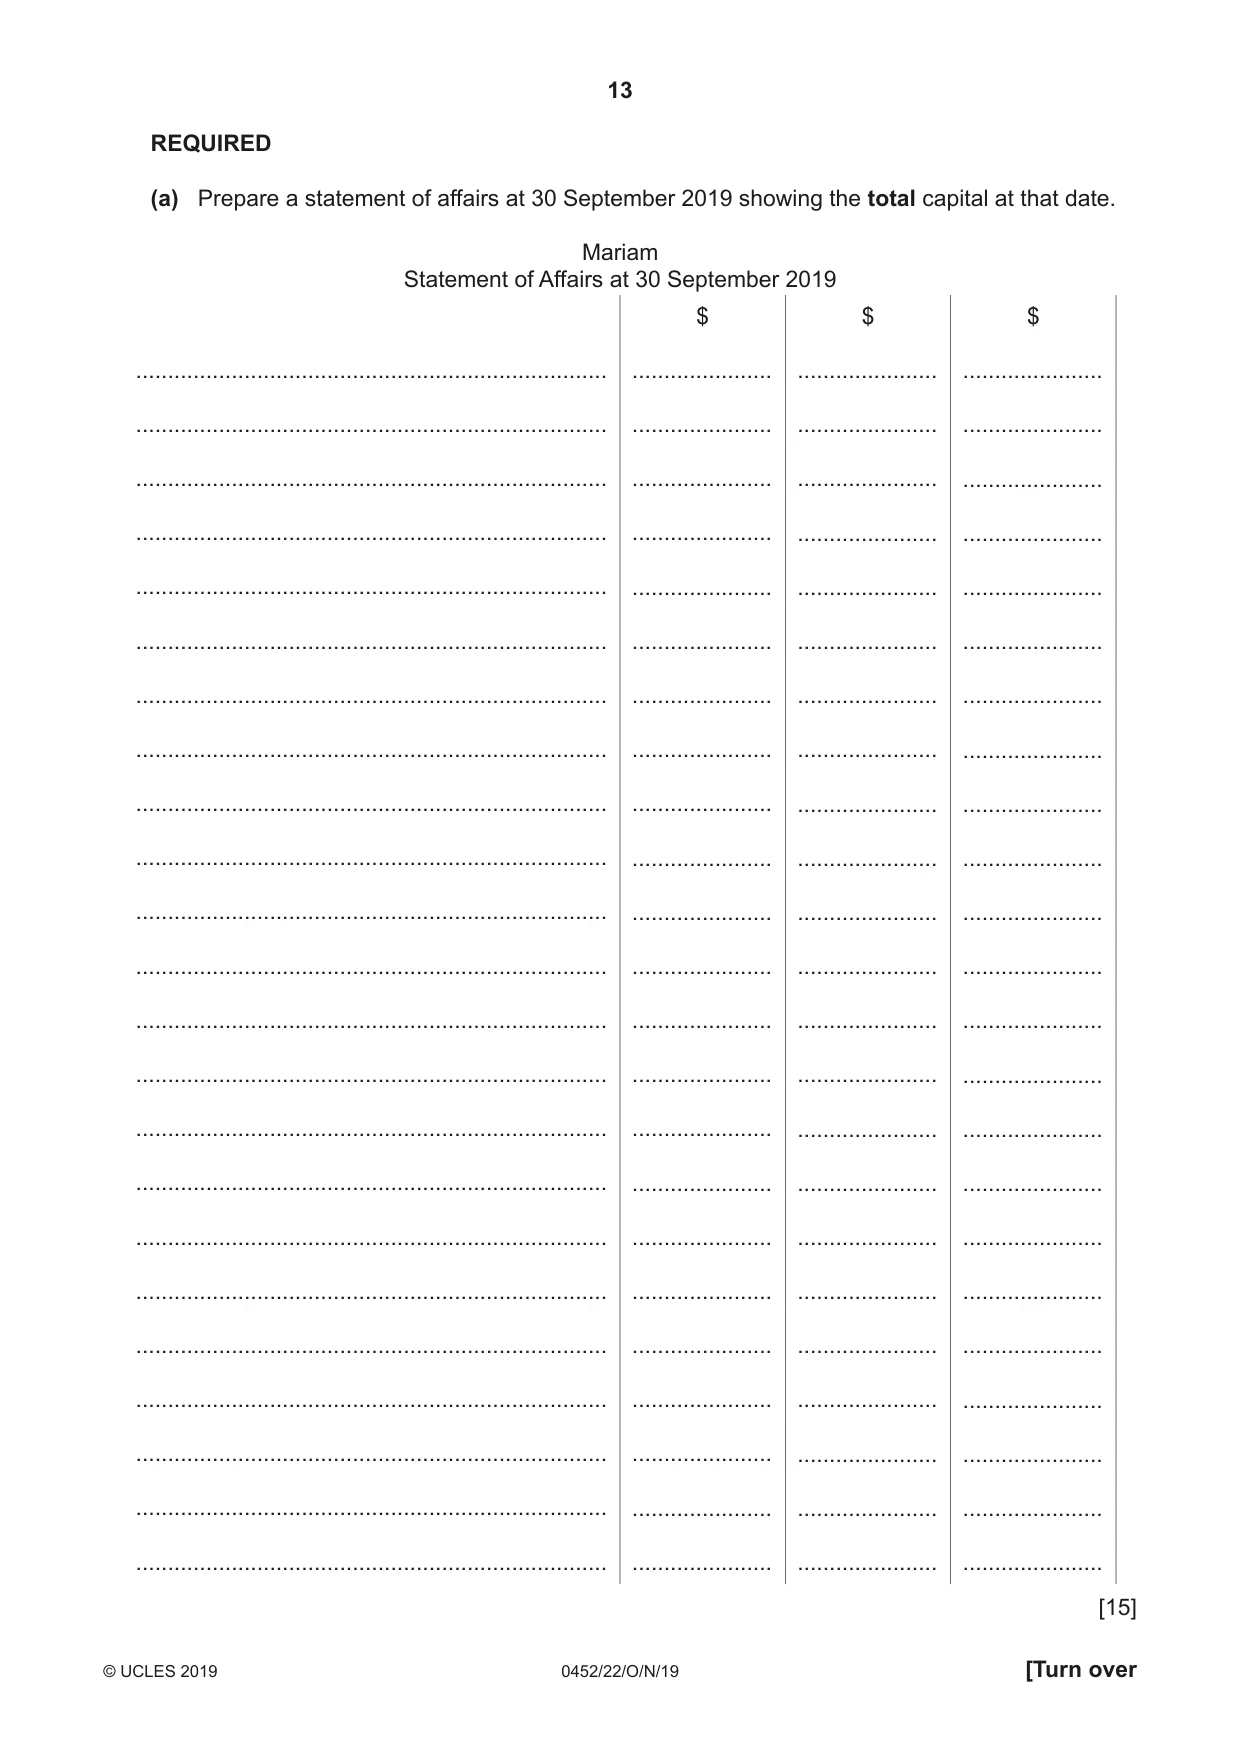
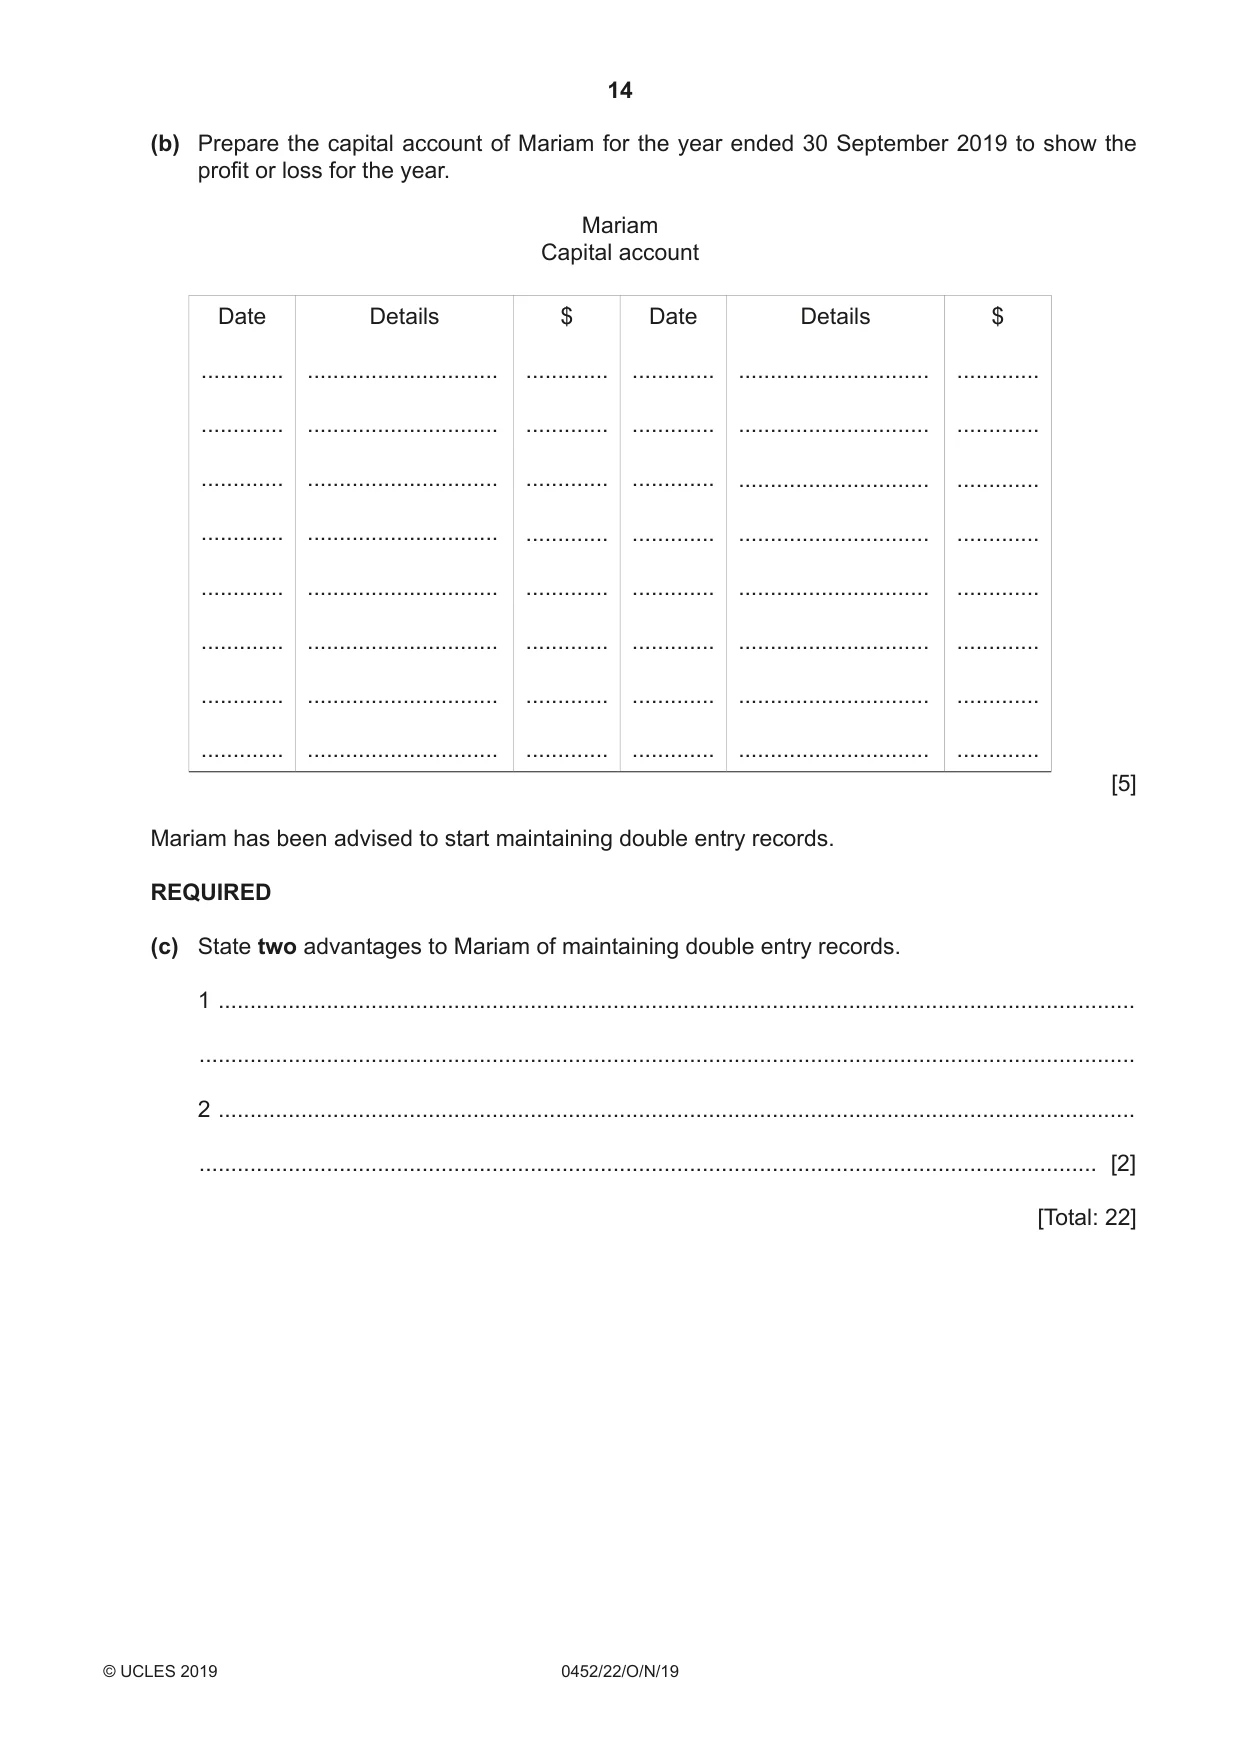
4 Mariam’s financial year ends on 30 September. She does not maintain a full set of accounting records, but was able to provide some information. On 1 October 2018 $ $ Premises at cost 80 000 Capital ? Fixtures and fittings at cost 7 800 Loan 21 000 Motor vehicle at cost 10 000 Trade payables 6 220 Inventory 6 350 Trade receivables 5 900 Bank balance 6 170 Mariam’s non-current assets have not been depreciated. During the year ended 30 September 2019 Mariam’s drawings amounted to $3125 Mariam transferred $5000 of her own money into the business bank account One-third of the loan was repaid and it was agreed that a further one-third would be repaid on 1 March 2020. Comparing the assets and liabilities on 30 September 2019 with those on 1 October 2018 the following differences were found: inventory had decreased by $510 trade payables had increased by $880 the balance at bank had increased by 10% trade receivables had increased to $6450 other payables amounted to $260 On 30 September it was decided to: write off a debt of $150 as irrecoverable create a provision for doubtful debts of 5% of the remaining trade receivables provide for depreciation on the fixtures and fittings for the year at 15% per annum on cost provide for depreciation on the motor vehicle for the year at 20% per annum on cost maintain the premises at cost price. mber 2019 sho am 30 September $ ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... (b) Prepare the capital account of Mariam for the year ended 30 September 2019 to show the profit or loss for the year. Mariam Capital account Date Details $ Date Details $ ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. ............. .............................. ............. [5] Mariam has been advised to start maintaining double entry records. REQUIRED (c) State two advantages to Mariam of maintaining double entry records. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ............................................................................................................................................. [2] [Total: 22] PLEASE TURN OVER
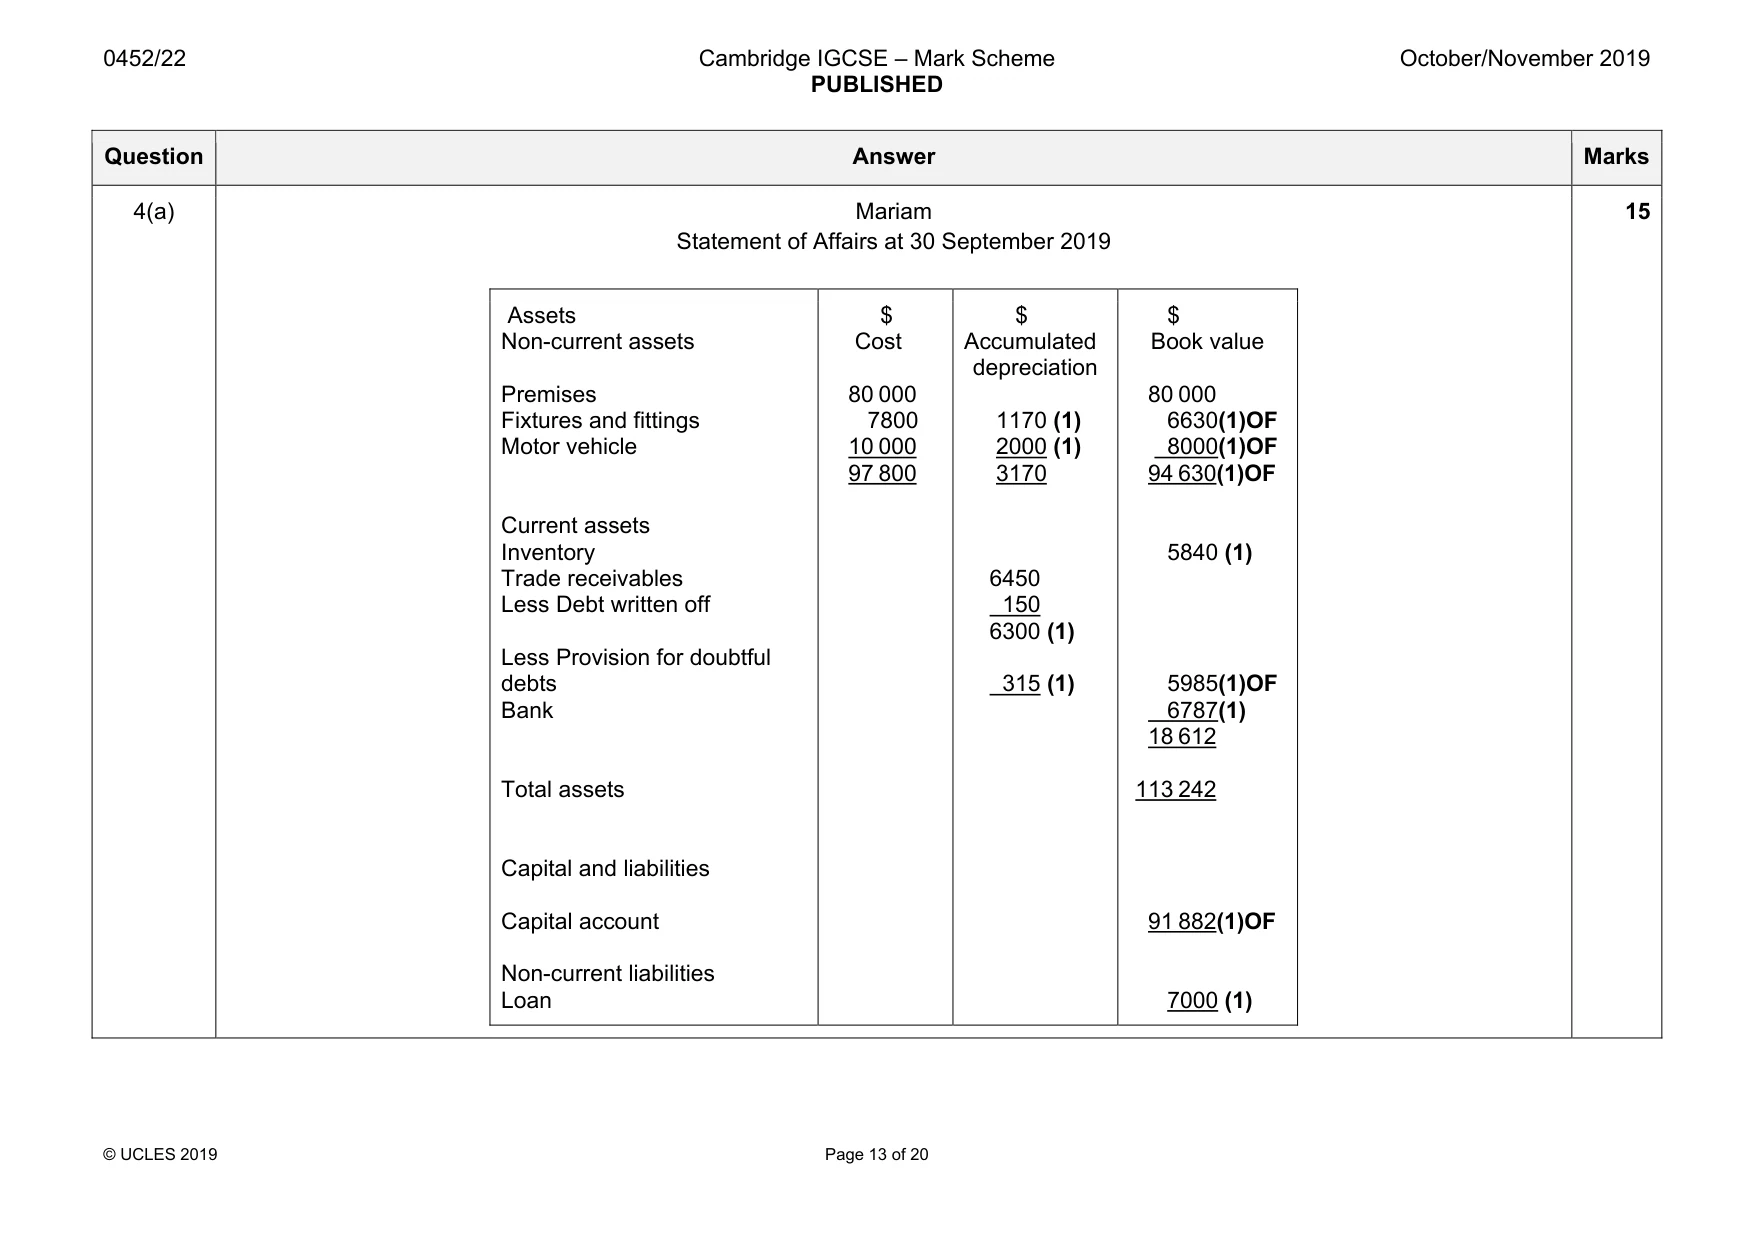
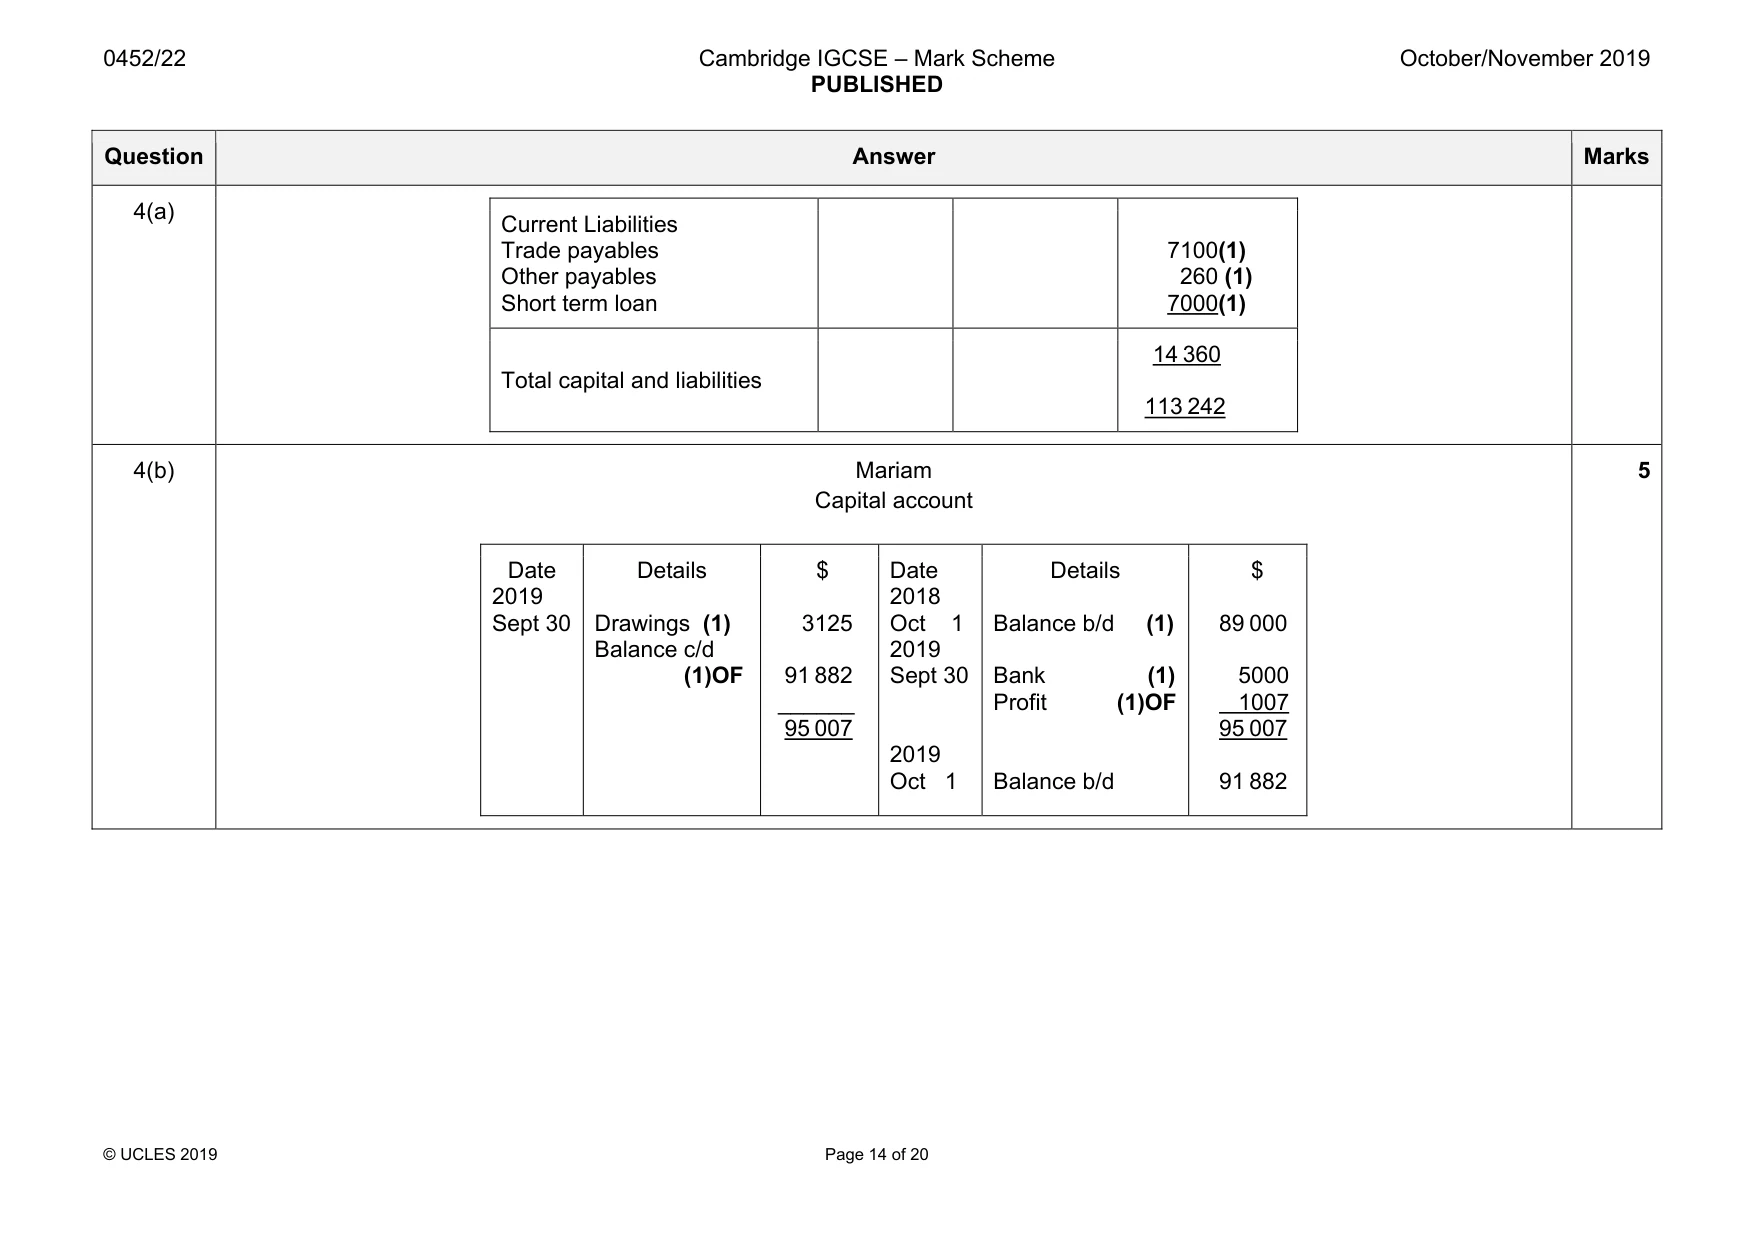
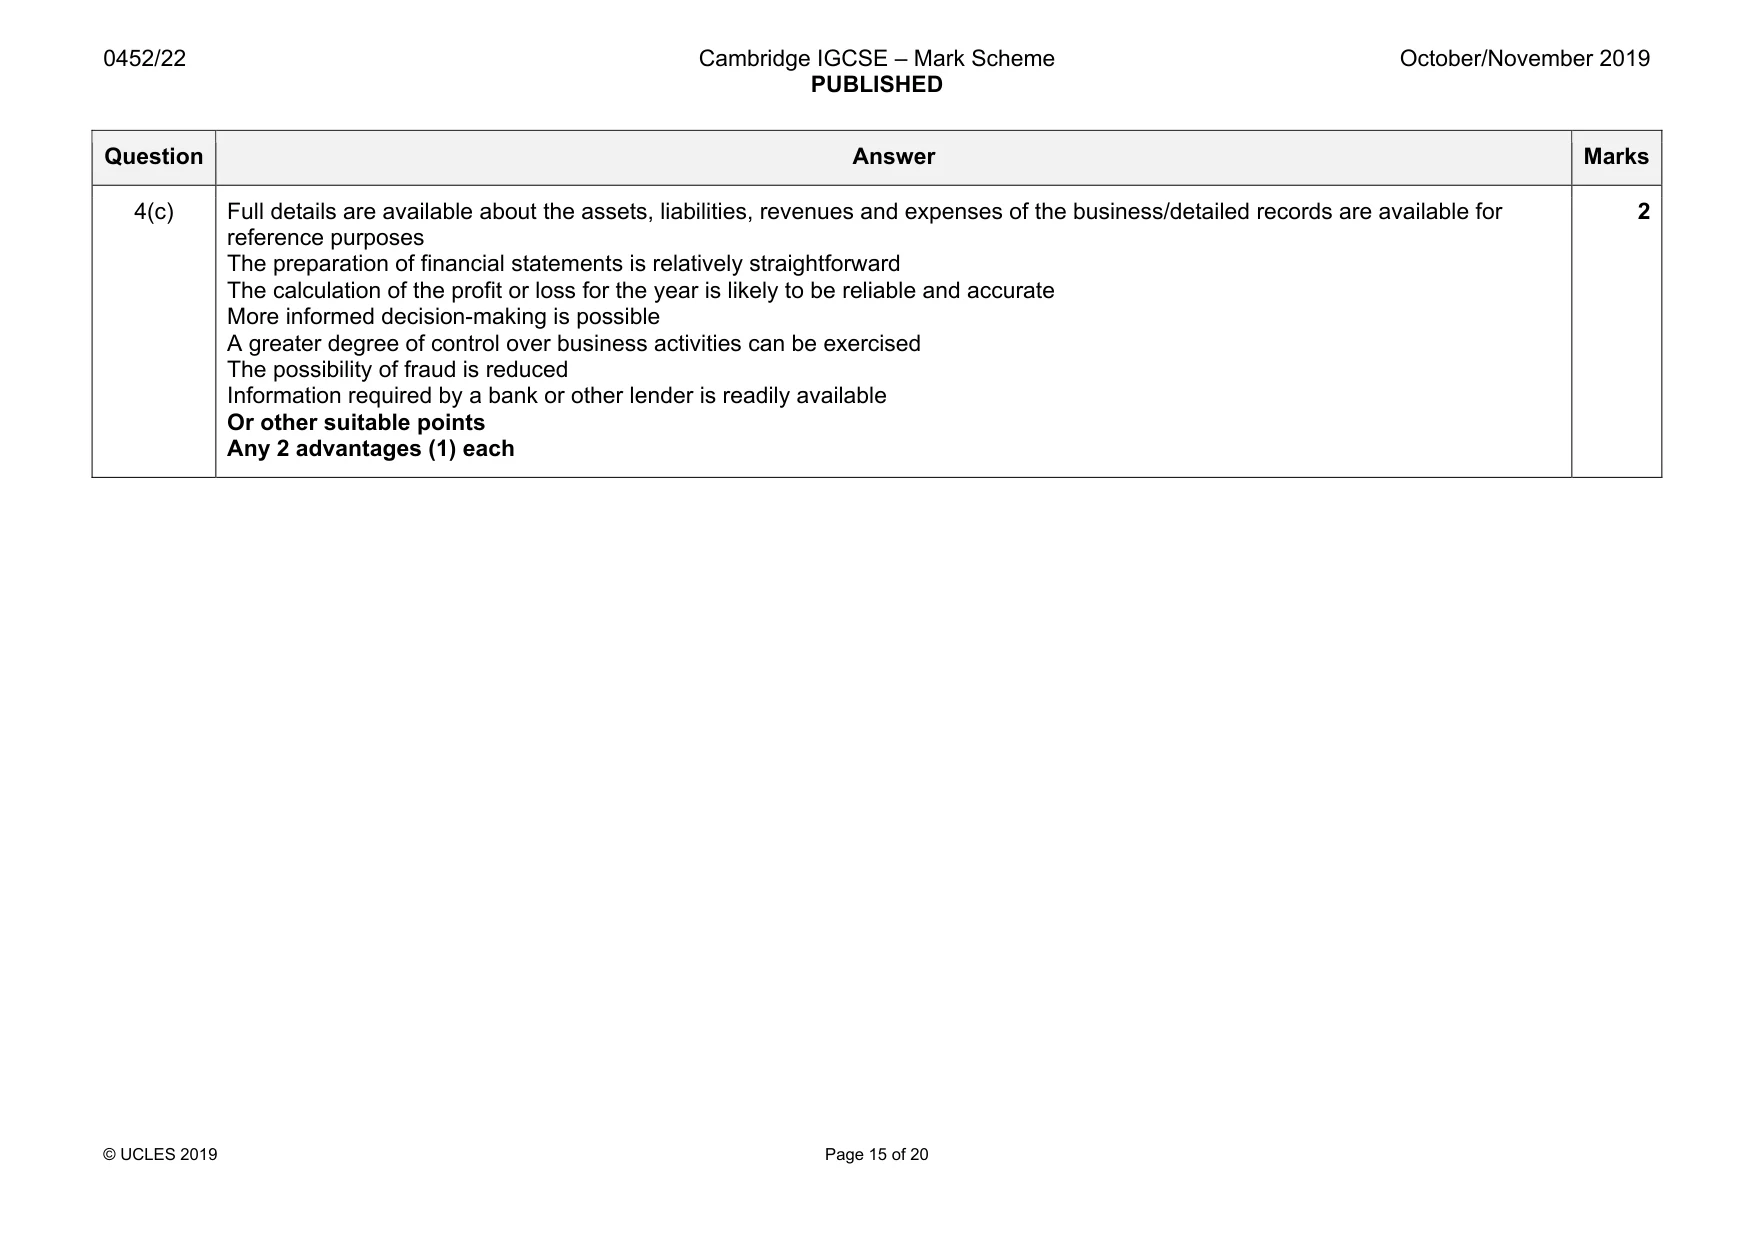
Mark scheme: 4(a) Mariam Statement of Affairs at 30 September 2019 Assets Non-current assets Premises Fixtures and fittings Motor vehicle Current assets Inventory Trade receivables Less Debt written off Less Provision for doubtful debts Bank Total assets Capital and liabilities Capital account Non-current liabilities Loan $ Cost 80 000 7800 10 000 97 800 $ Accumulated depreciation 1170 (1) 2000 (1) 3170 6450 150 6300 (1) 315 (1) $ Book value 80 000 6630(1)OF 8000(1)OF 94 630(1)OF 5840 (1) 5985(1)OF 6787(1) 18 612 113 242 91 882(1)OF 7000 (1) 15 Question Answer Marks 4(a) Current Liabilities Trade payables Other payables Short term loan 7100(1) 260 (1) 7000(1) Total capital and liabilities 14 360 113 242 4(b) Mariam Capital account Date 2019 Sept 30 Details Drawings (1) Balance c/d (1)OF $ 3125 91 882 ______ 95 007 Date 2018 Oct 1 2019 Sept 30 2019 Oct 1 Details Balance b/d (1) Bank (1) Profit (1)OF Balance b/d $ 89 000 5000 1007 95 007 91 882 5 Question Answer Marks 4(c) Full details are available about the assets, liabilities, revenues and expenses of the business/detailed records are available for reference purposes The preparation of financial statements is relatively straightforward The calculation of the profit or loss for the year is likely to be reliable and accurate More informed decision-making is possible A greater degree of control over business activities can be exercised The possibility of fraud is reduced Information required by a bank or other lender is readily available Or other suitable points Any 2 advantages (1) each 2
Q5 · Sabir’s financial year ends on 30 September
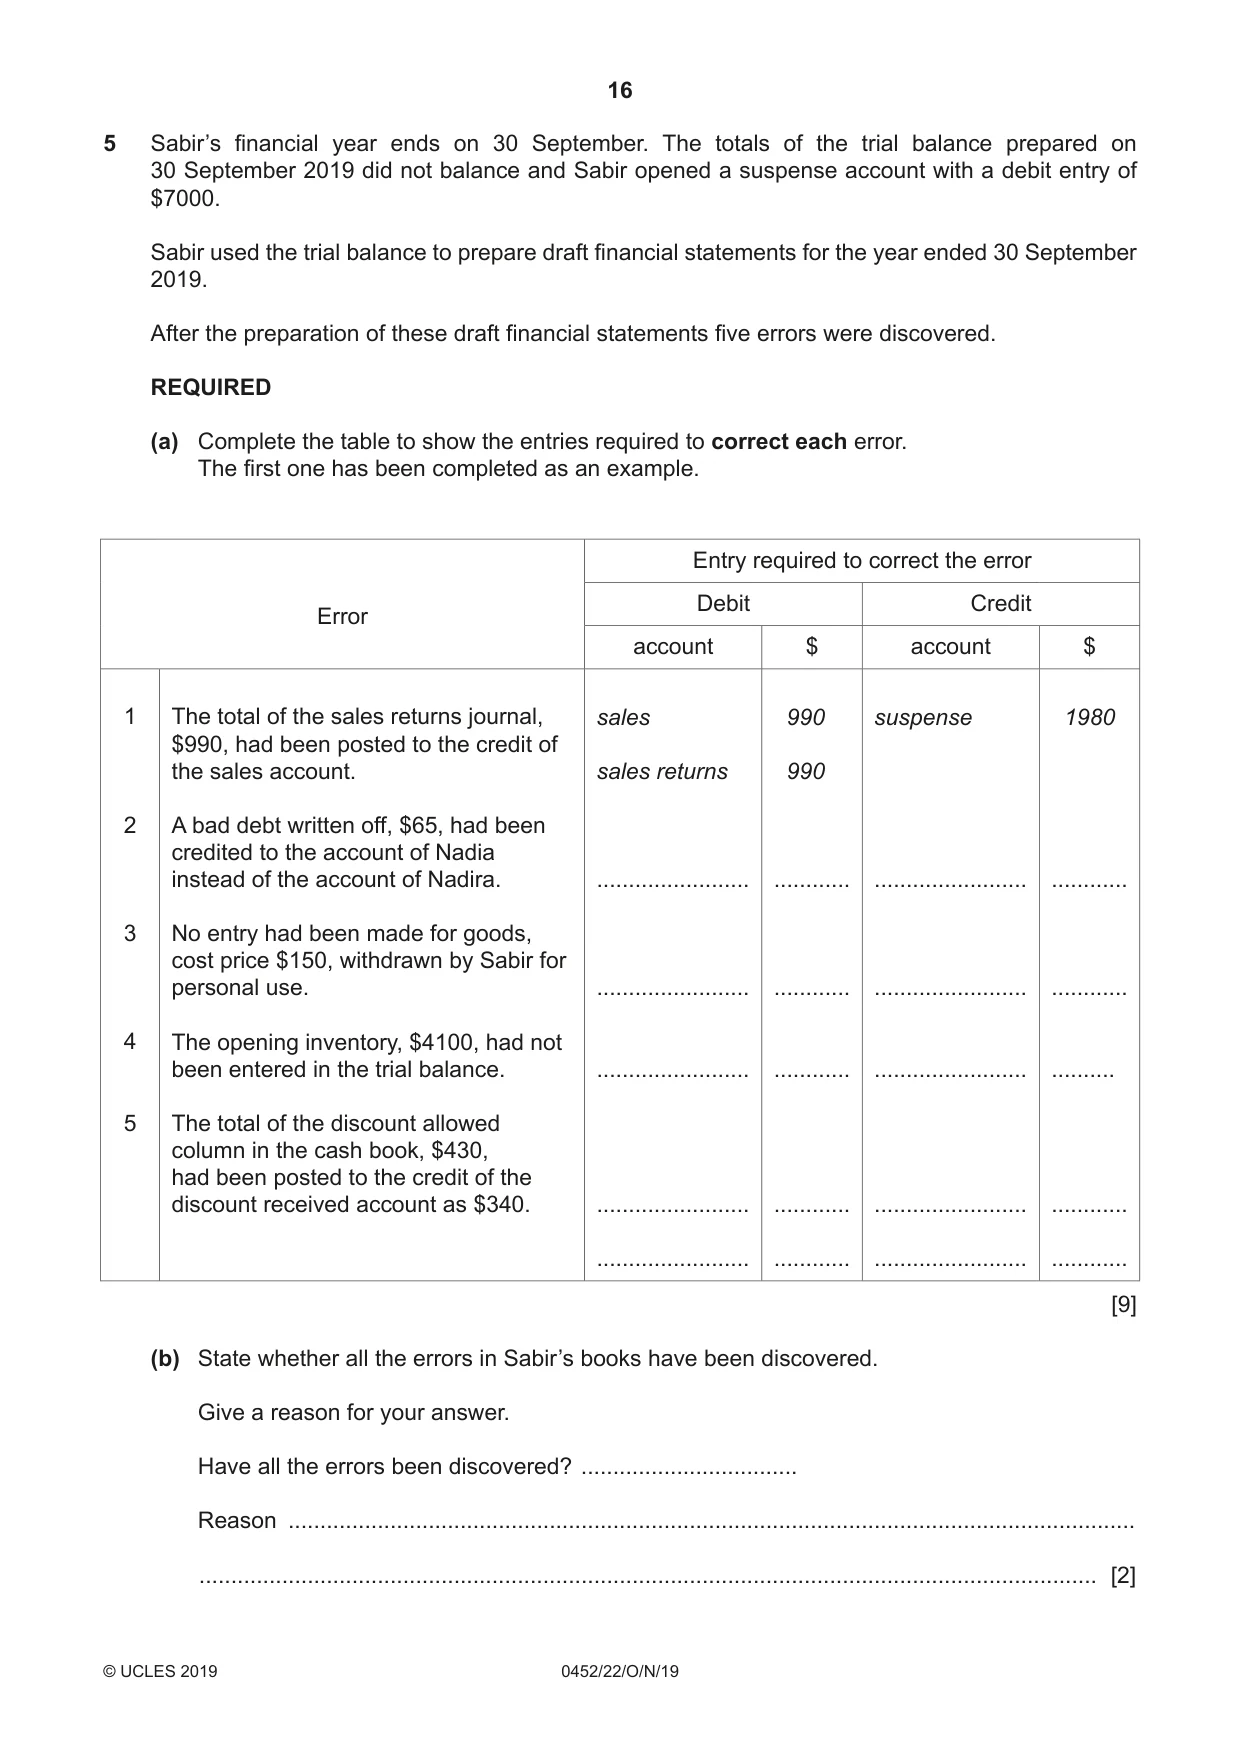
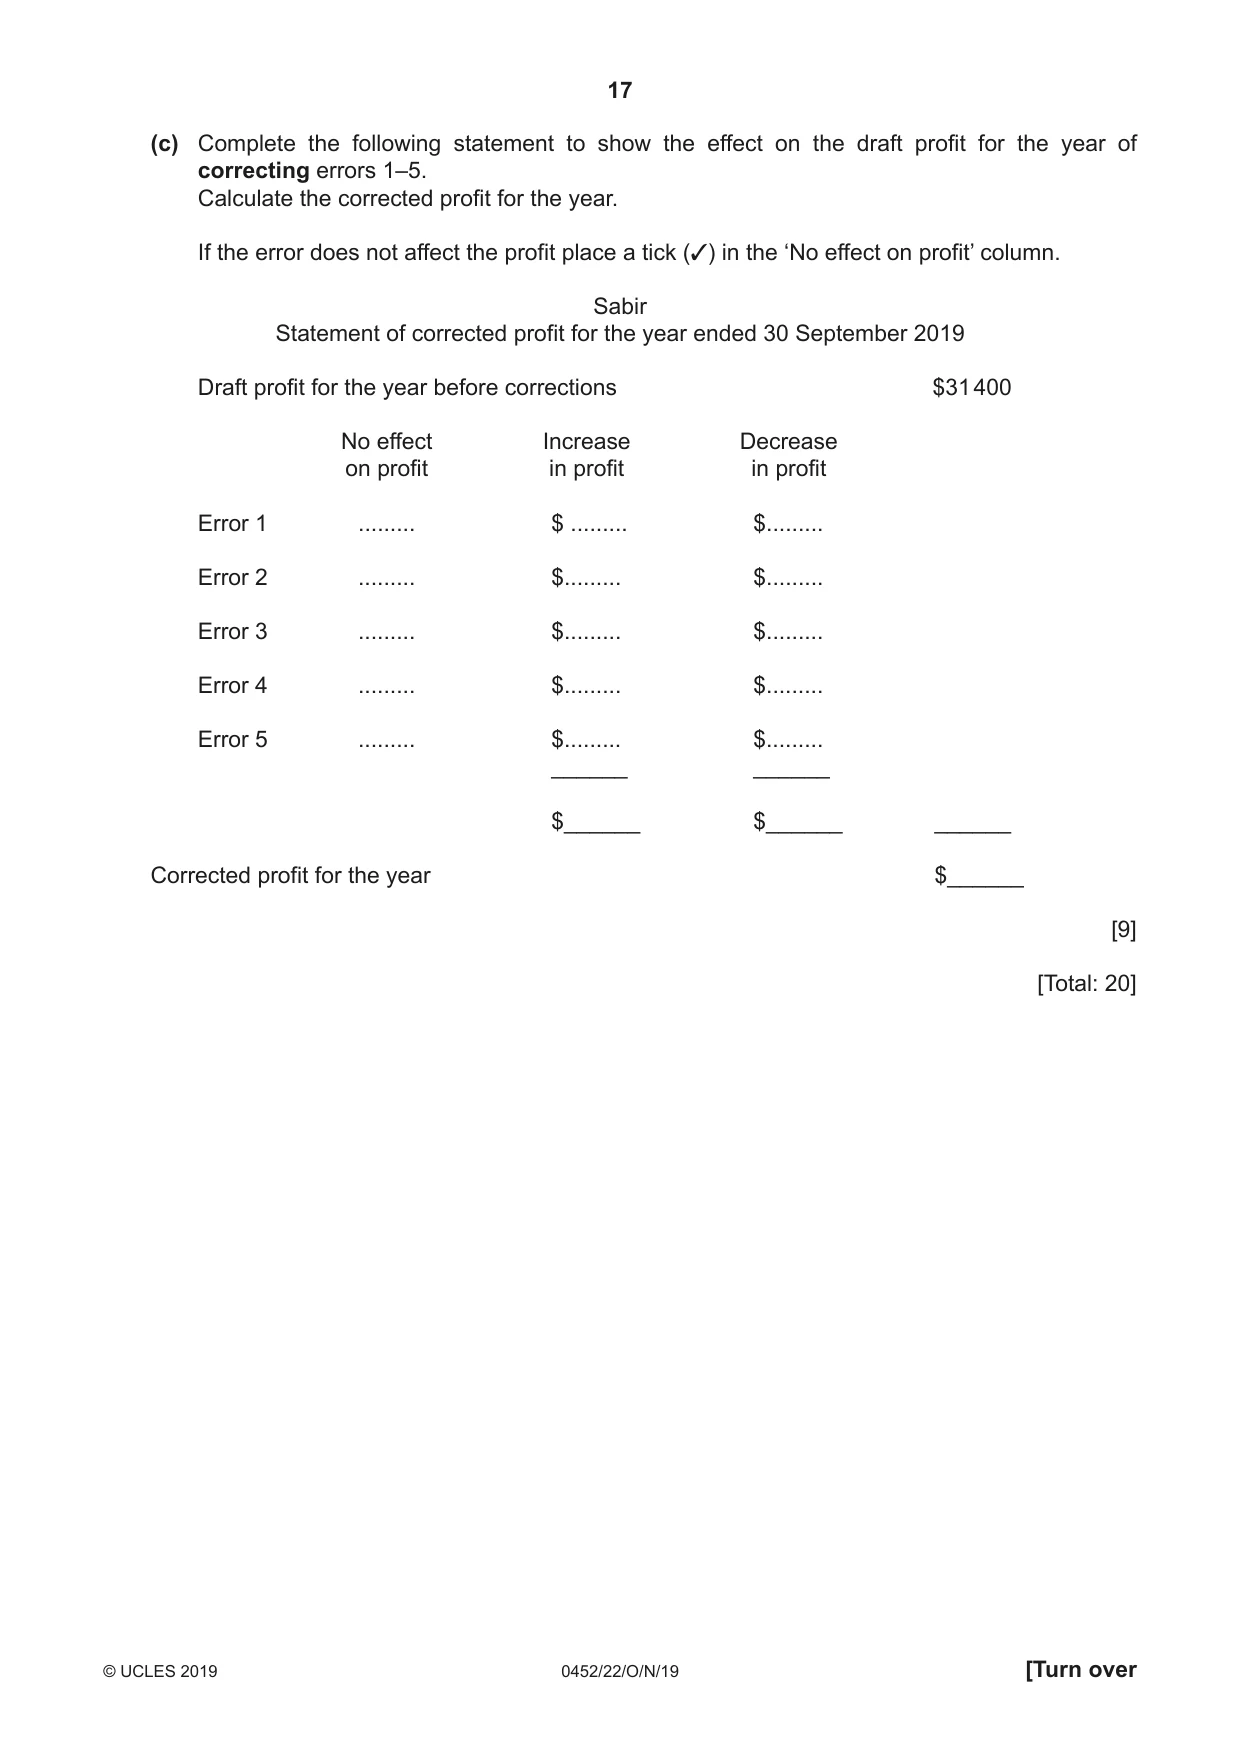
5 Sabir’s financial year ends on 30 September. The totals of the trial balance prepared on 30 September 2019 did not balance and Sabir opened a suspense account with a debit entry of $7000. Sabir used the trial balance to prepare draft financial statements for the year ended 30 September 2019. After the preparation of these draft financial statements five errors were discovered. REQUIRED (a) Complete the table to show the entries required to correct each error. The first one has been completed as an example. Entry required to correct the error Debit Credit Error account $ account $ 1 The total of the sales returns journal, sales 990 suspense 1980 $990, had been posted to the credit of the sales account. sales returns 990 2 A bad debt written off, $65, had been credited to the account of Nadia instead of the account of Nadira. ........................ ............ ........................ ............ 3 No entry had been made for goods, cost price $150, withdrawn by Sabir for personal use. ........................ ............ ........................ ............ 4 The opening inventory, $4100, had not been entered in the trial balance. ........................ ............ ........................ .......... 5 The total of the discount allowed column in the cash book, $430, had been posted to the credit of the discount received account as $340. ........................ ............ ........................ ............ ........................ ............ ........................ ............ [9] (b) State whether all the errors in Sabir’s books have been discovered. Give a reason for your answer. Have all the errors been discovered? .................................. Reason ..................................................................................................................................... ............................................................................................................................................. [2] (c) Complete the following statement to show the effect on the draft profit for the year of correcting errors 1–5. Calculate the corrected profit for the year. If the error does not affect the profit place a tick (3) in the ‘No effect on profit’ column. Sabir Statement of corrected profit for the year ended 30 September 2019 Draft profit for the year before corrections $31 400 No effect Increase Decrease on profit in profit in profit Error 1 ......... $ ......... $......... Error 2 ......... $......... $......... Error 3 ......... $......... $......... Error 4 ......... $......... $......... Error 5 ......... $......... $......... ______ ______ $______ $______ ______ Corrected profit for the year $______ [9] [Total: 20]
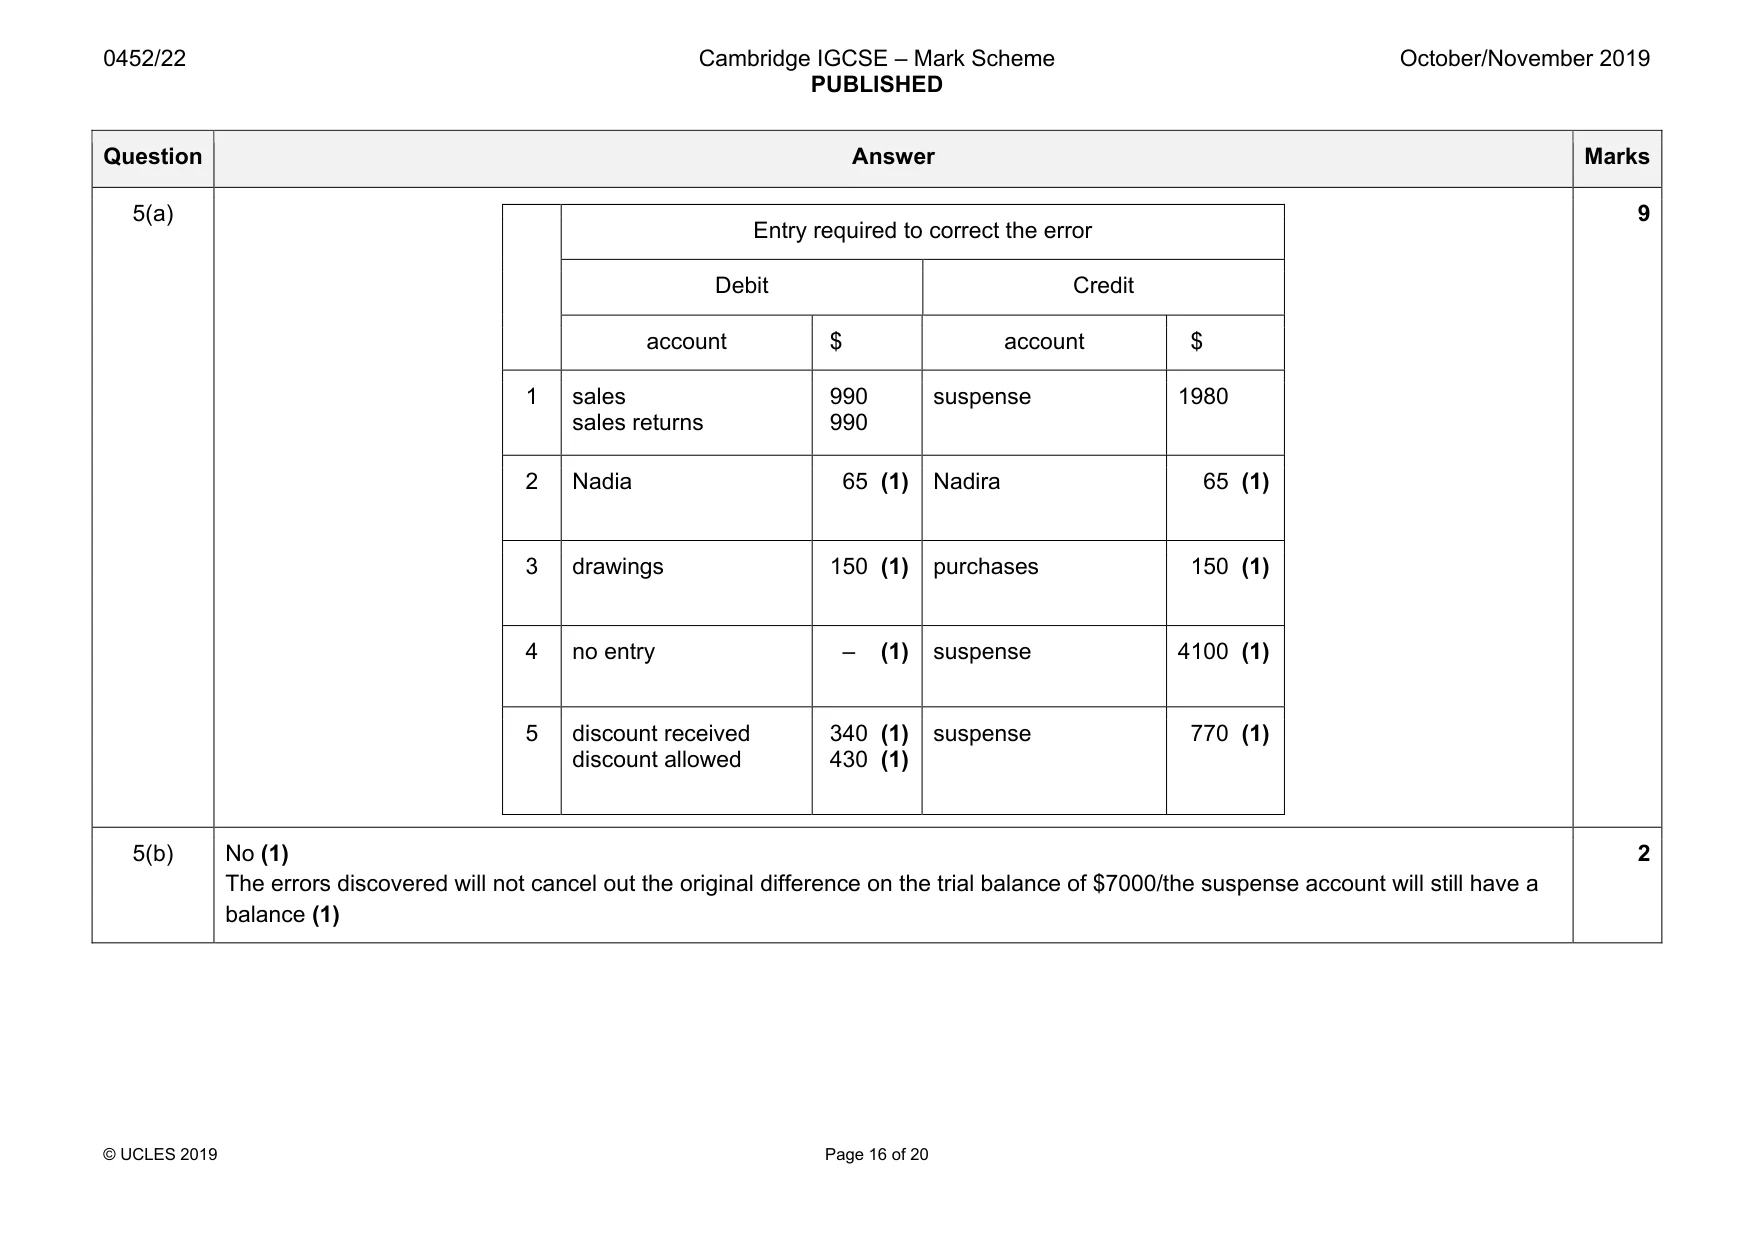
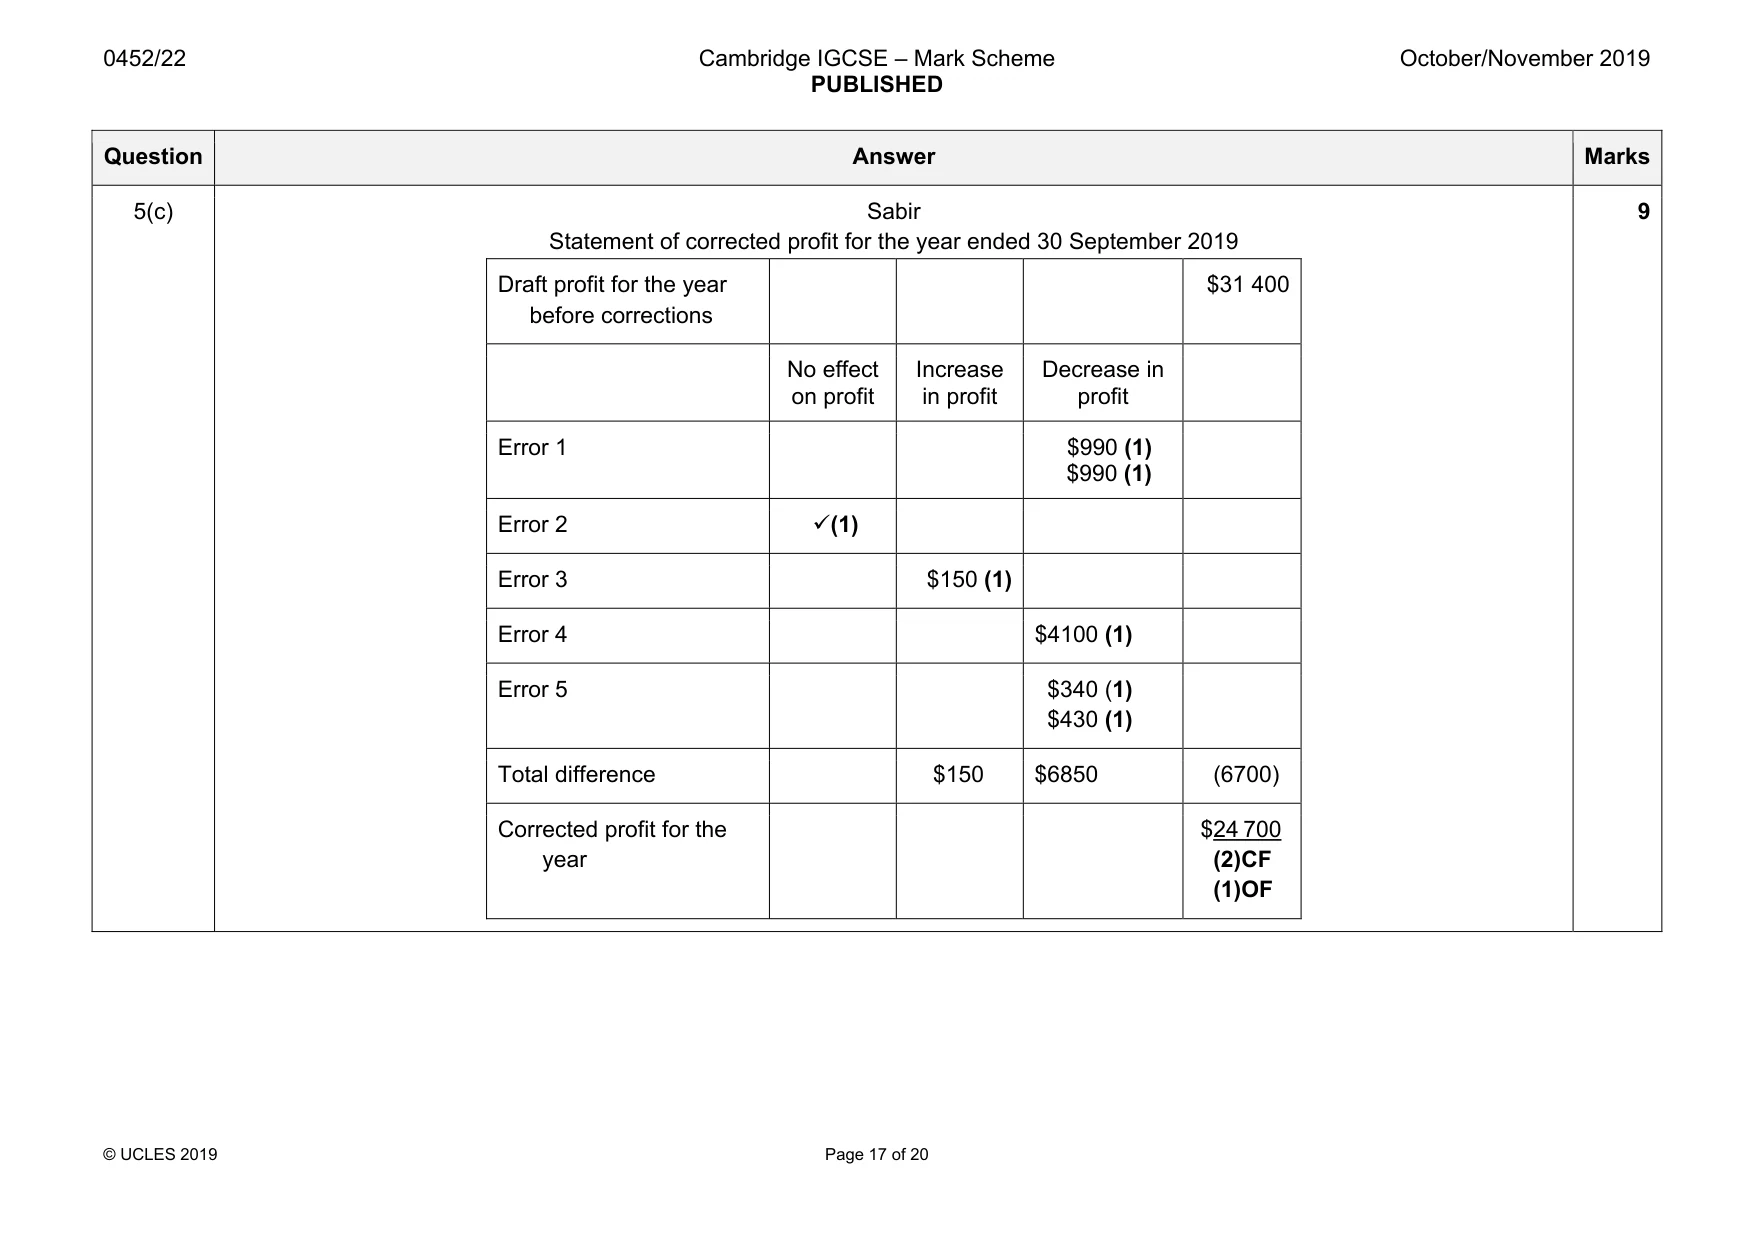
Mark scheme: 5(a) Entry required to correct the error Debit Credit account $ account $ 1 sales sales returns 990 990 suspense 1980 2 Nadia 65 (1) Nadira 65 (1) 3 drawings 150 (1) purchases 150 (1) 4 no entry – (1) suspense 4100 (1) 5 discount received discount allowed 340 (1) 430 (1) suspense 770 (1) 9 5(b) No (1) The errors discovered will not cancel out the original difference on the trial balance of $7000/the suspense account will still have a balance (1) 2 Question Answer Marks 5(c) Sabir Statement of corrected profit for the year ended 30 September 2019 Draft profit for the year before corrections $31 400 No effect on profit Increase in profit Decrease in profit Error 1 $990 (1) $990 (1) Error 2 9(1) Error 3 $150 (1) Error 4 $4100 (1) Error 5 $340 (1) $430 (1) Total difference $150 $6850 (6700) Corrected profit for the year $24 700 (2)CF (1)OF 9
Q6 · Rashida started a business trading in fruit and vegetables on 1 July 2017
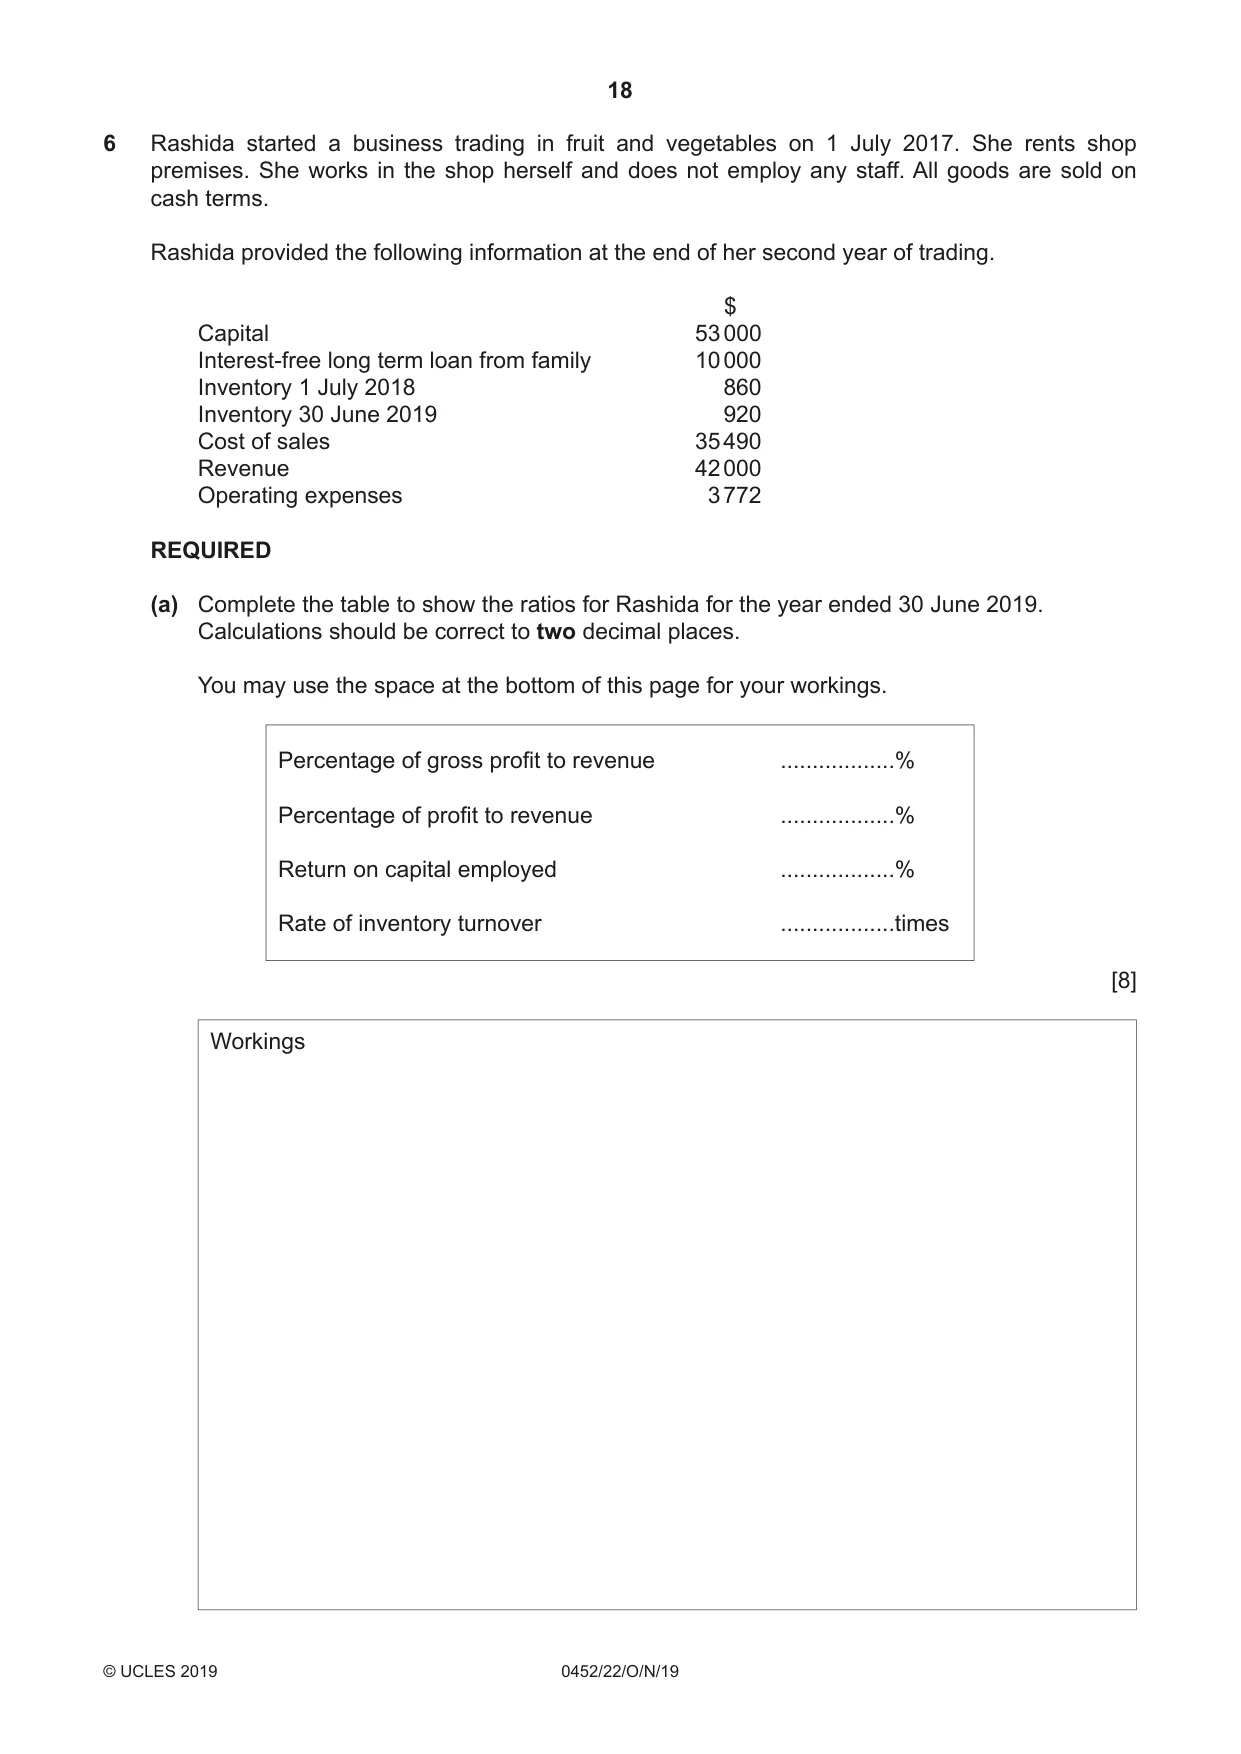
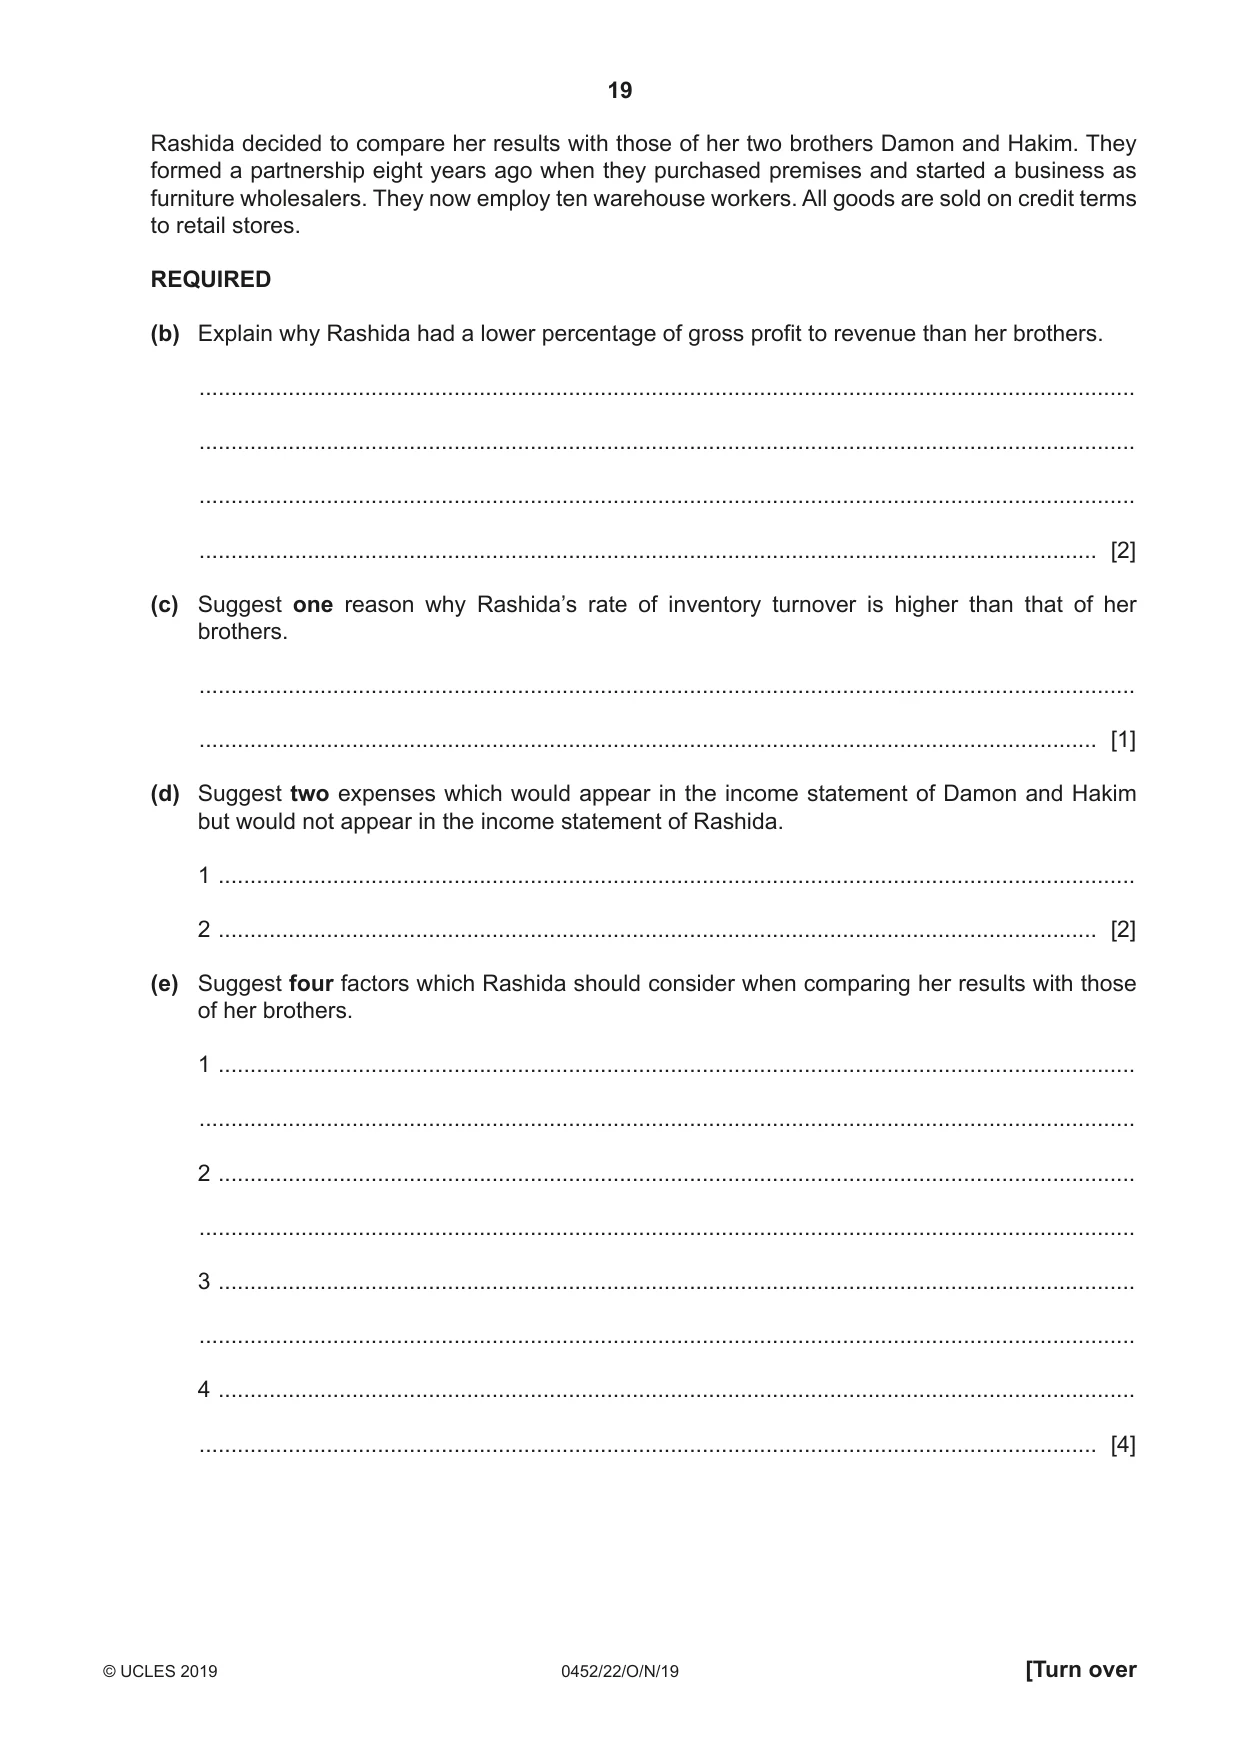
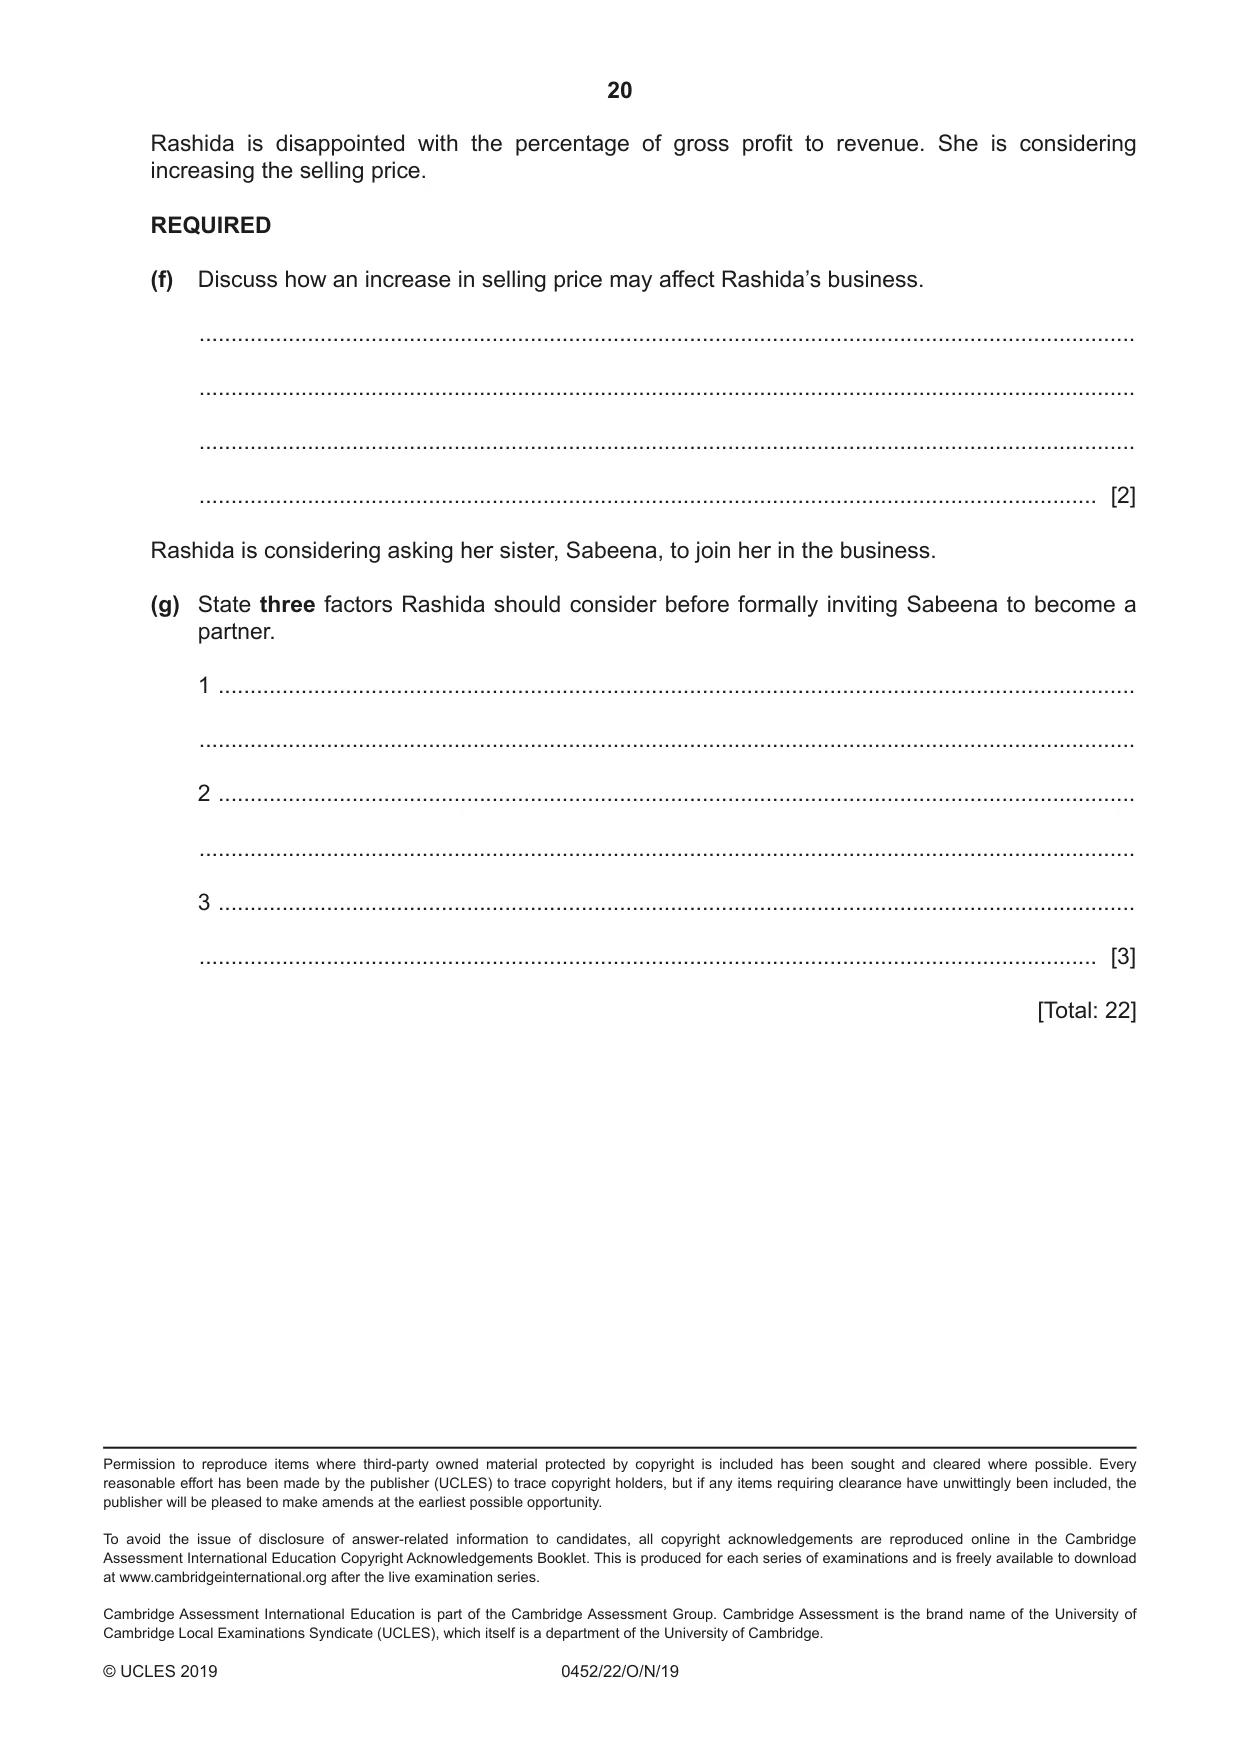
6 Rashida started a business trading in fruit and vegetables on 1 July 2017. She rents shop premises. She works in the shop herself and does not employ any staff. All goods are sold on cash terms. Rashida provided the following information at the end of her second year of trading. $ Capital 53 000 Interest-free long term loan from family 10 000 Inventory 1 July 2018 860 Inventory 30 June 2019 920 Cost of sales 35 490 Revenue 42 000 Operating expenses 3 772 REQUIRED (a) Complete the table to show the ratios for Rashida for the year ended 30 June 2019. Calculations should be correct to two decimal places. You may use the space at the bottom of this page for your workings. Percentage of gross profit to revenue ..................% Percentage of profit to revenue ..................% Return on capital employed ..................% Rate of inventory turnover ..................times [8] Workings Rashida decided to compare her results with those of her two brothers Damon and Hakim. They formed a partnership eight years ago when they purchased premises and started a business as furniture wholesalers. They now employ ten warehouse workers. All goods are sold on credit terms to retail stores. REQUIRED (b) Explain why Rashida had a lower percentage of gross profit to revenue than her brothers. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Suggest one reason why Rashida’s rate of inventory turnover is higher than that of her brothers. ................................................................................................................................................... ............................................................................................................................................. [1] (d) Suggest two expenses which would appear in the income statement of Damon and Hakim but would not appear in the income statement of Rashida. 1 ................................................................................................................................................ 2 .......................................................................................................................................... [2] (e) Suggest four factors which Rashida should consider when comparing her results with those of her brothers. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... 4 ................................................................................................................................................ ............................................................................................................................................. [4] Rashida is disappointed with the percentage of gross profit to revenue. She is considering increasing the selling price. REQUIRED (f) Discuss how an increase in selling price may affect Rashida’s business. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Rashida is considering asking her sister, Sabeena, to join her in the business. (g) State three factors Rashida should consider before formally inviting Sabeena to become a partner. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ............................................................................................................................................. [3] [Total: 22]
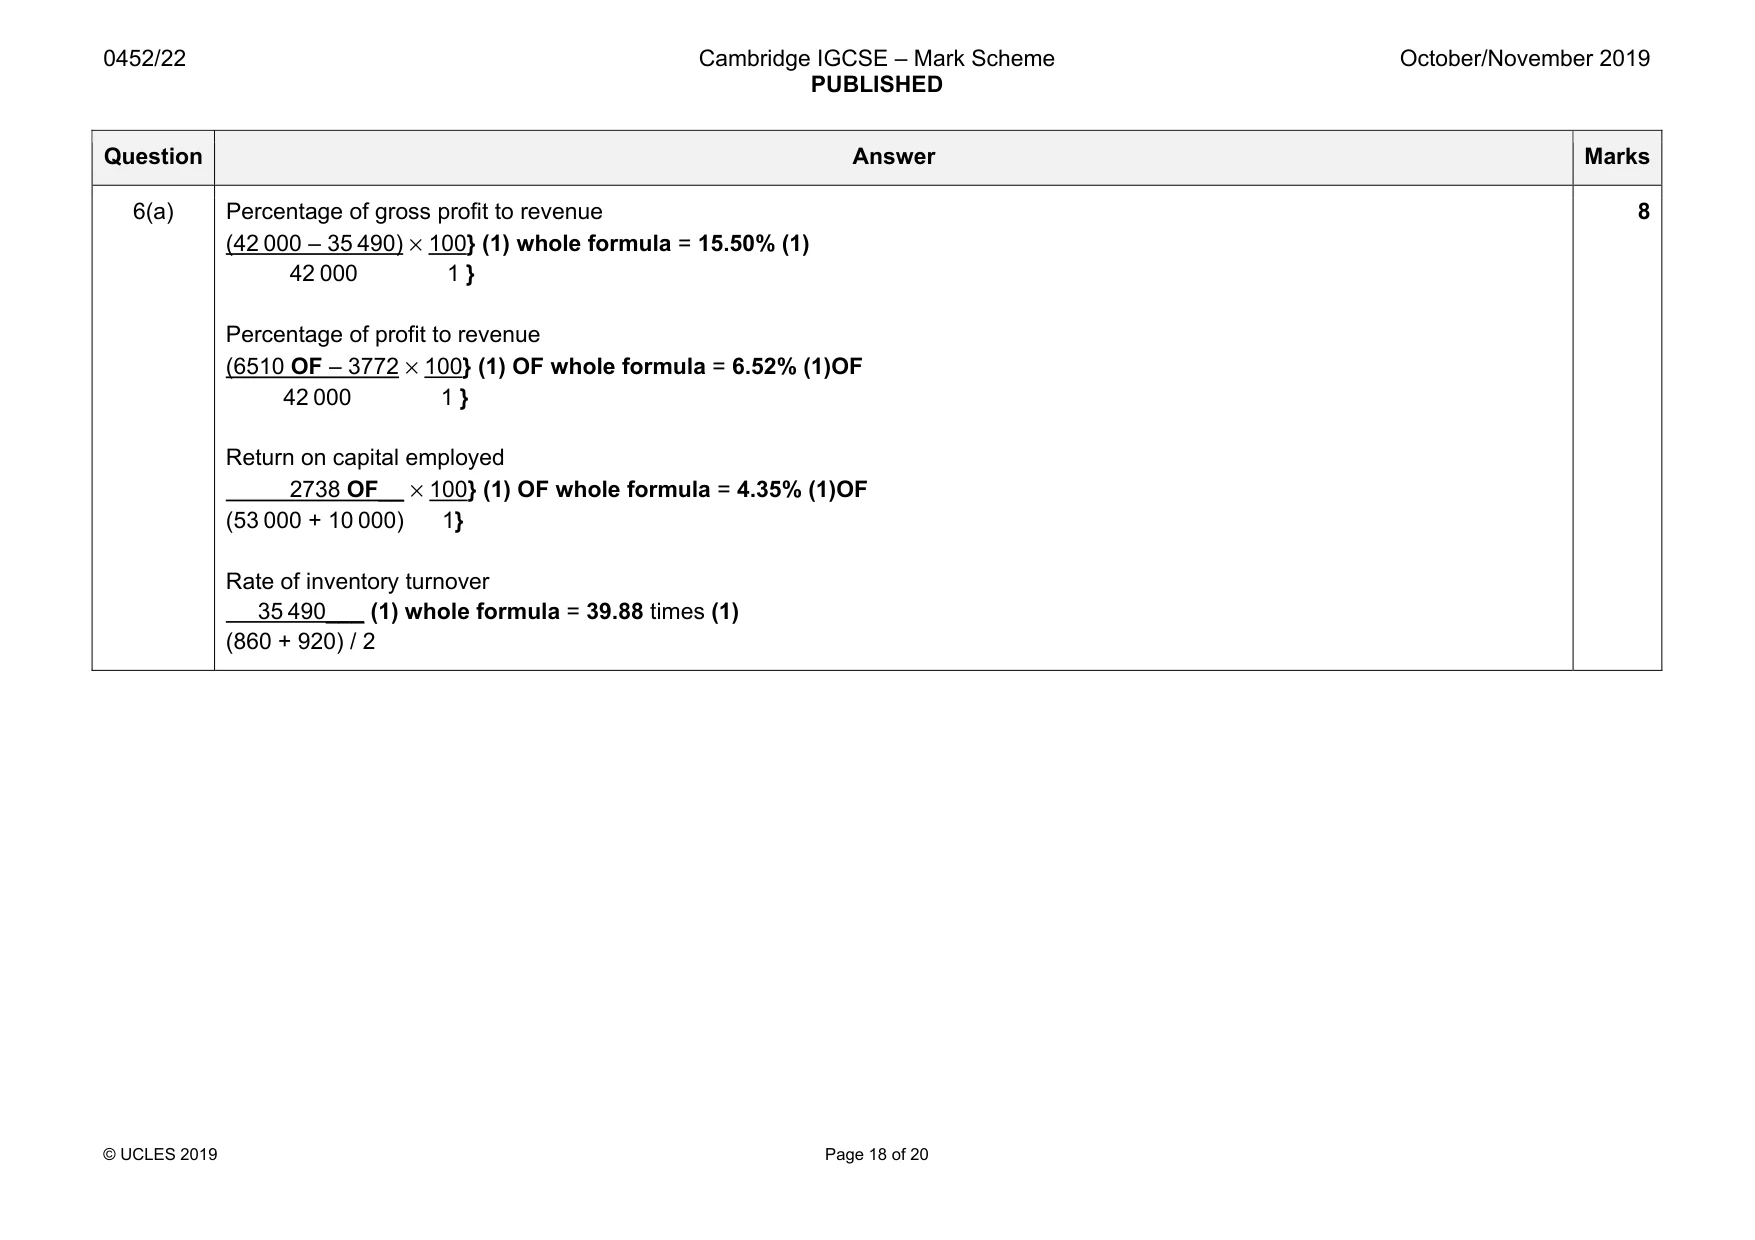
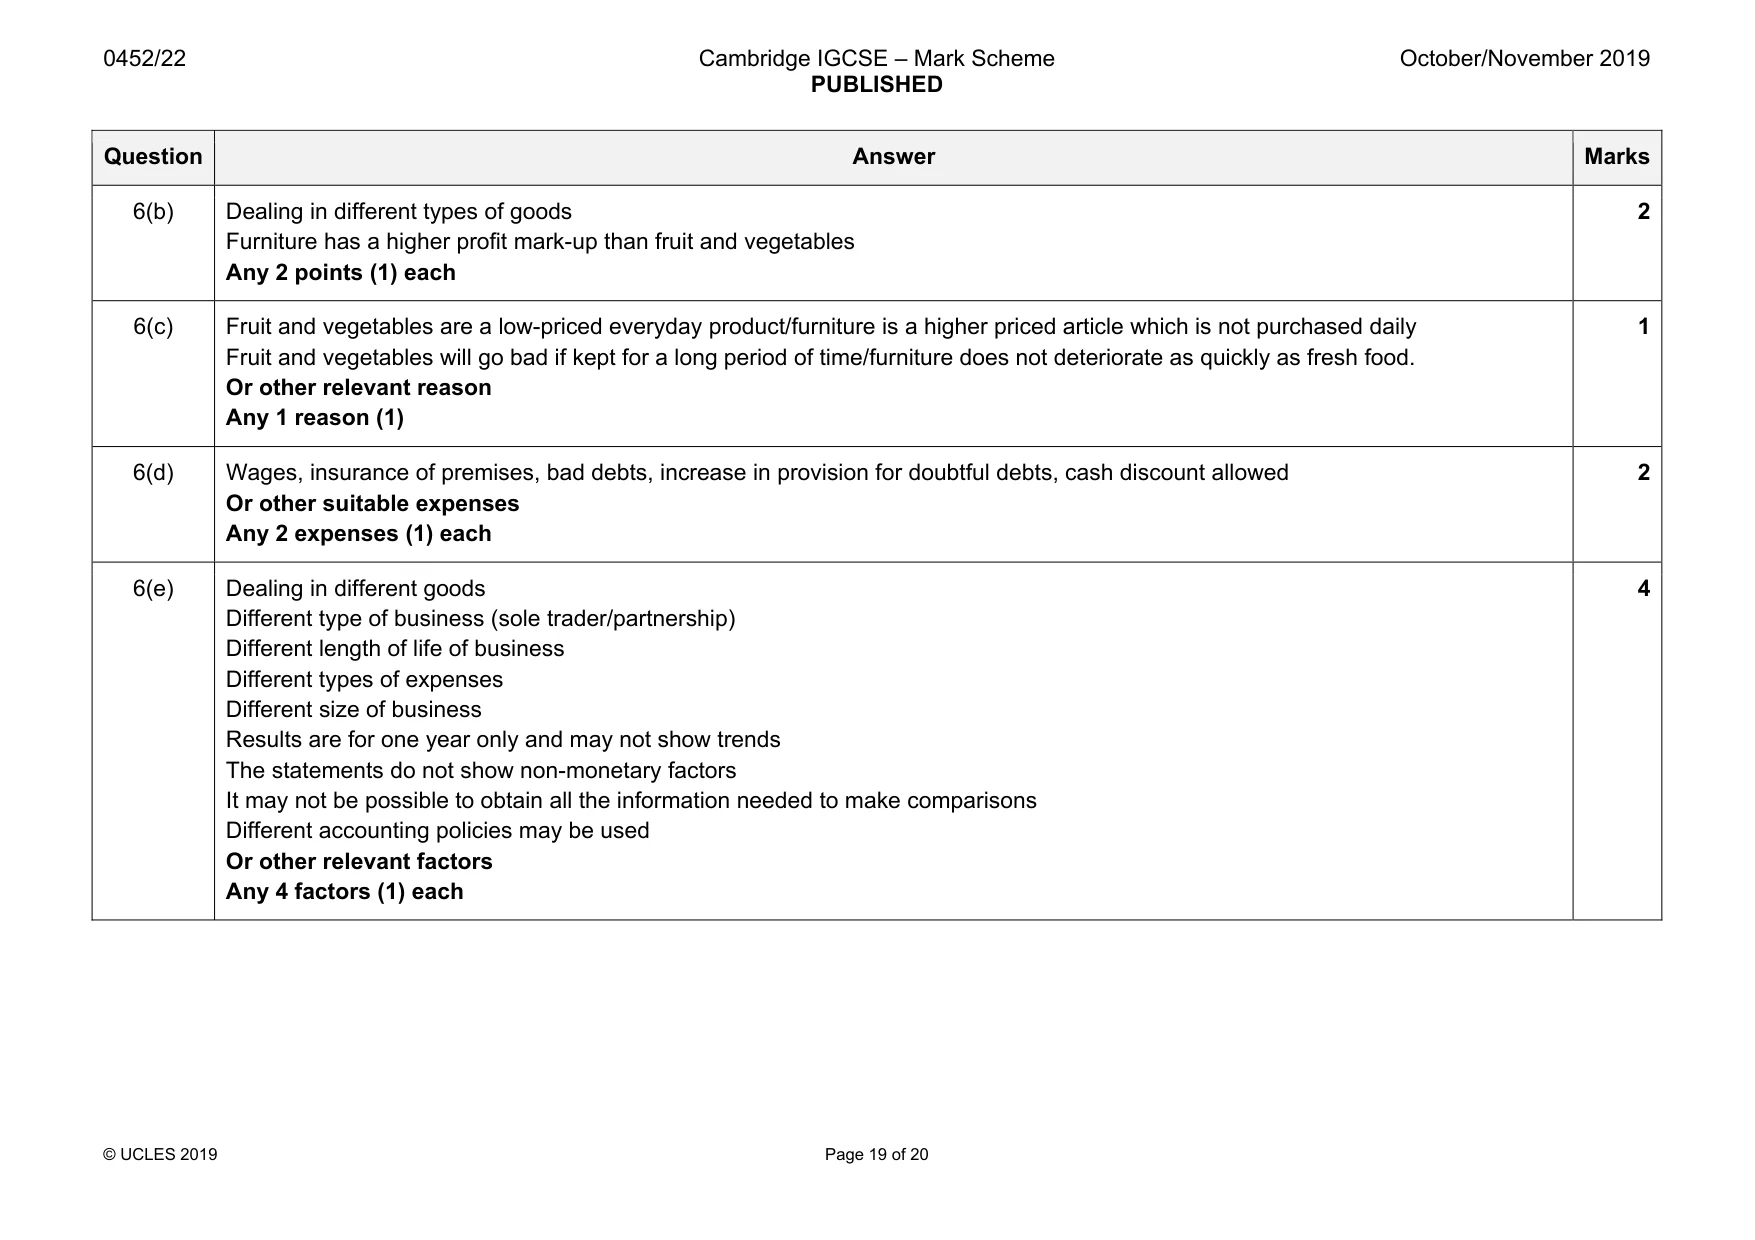
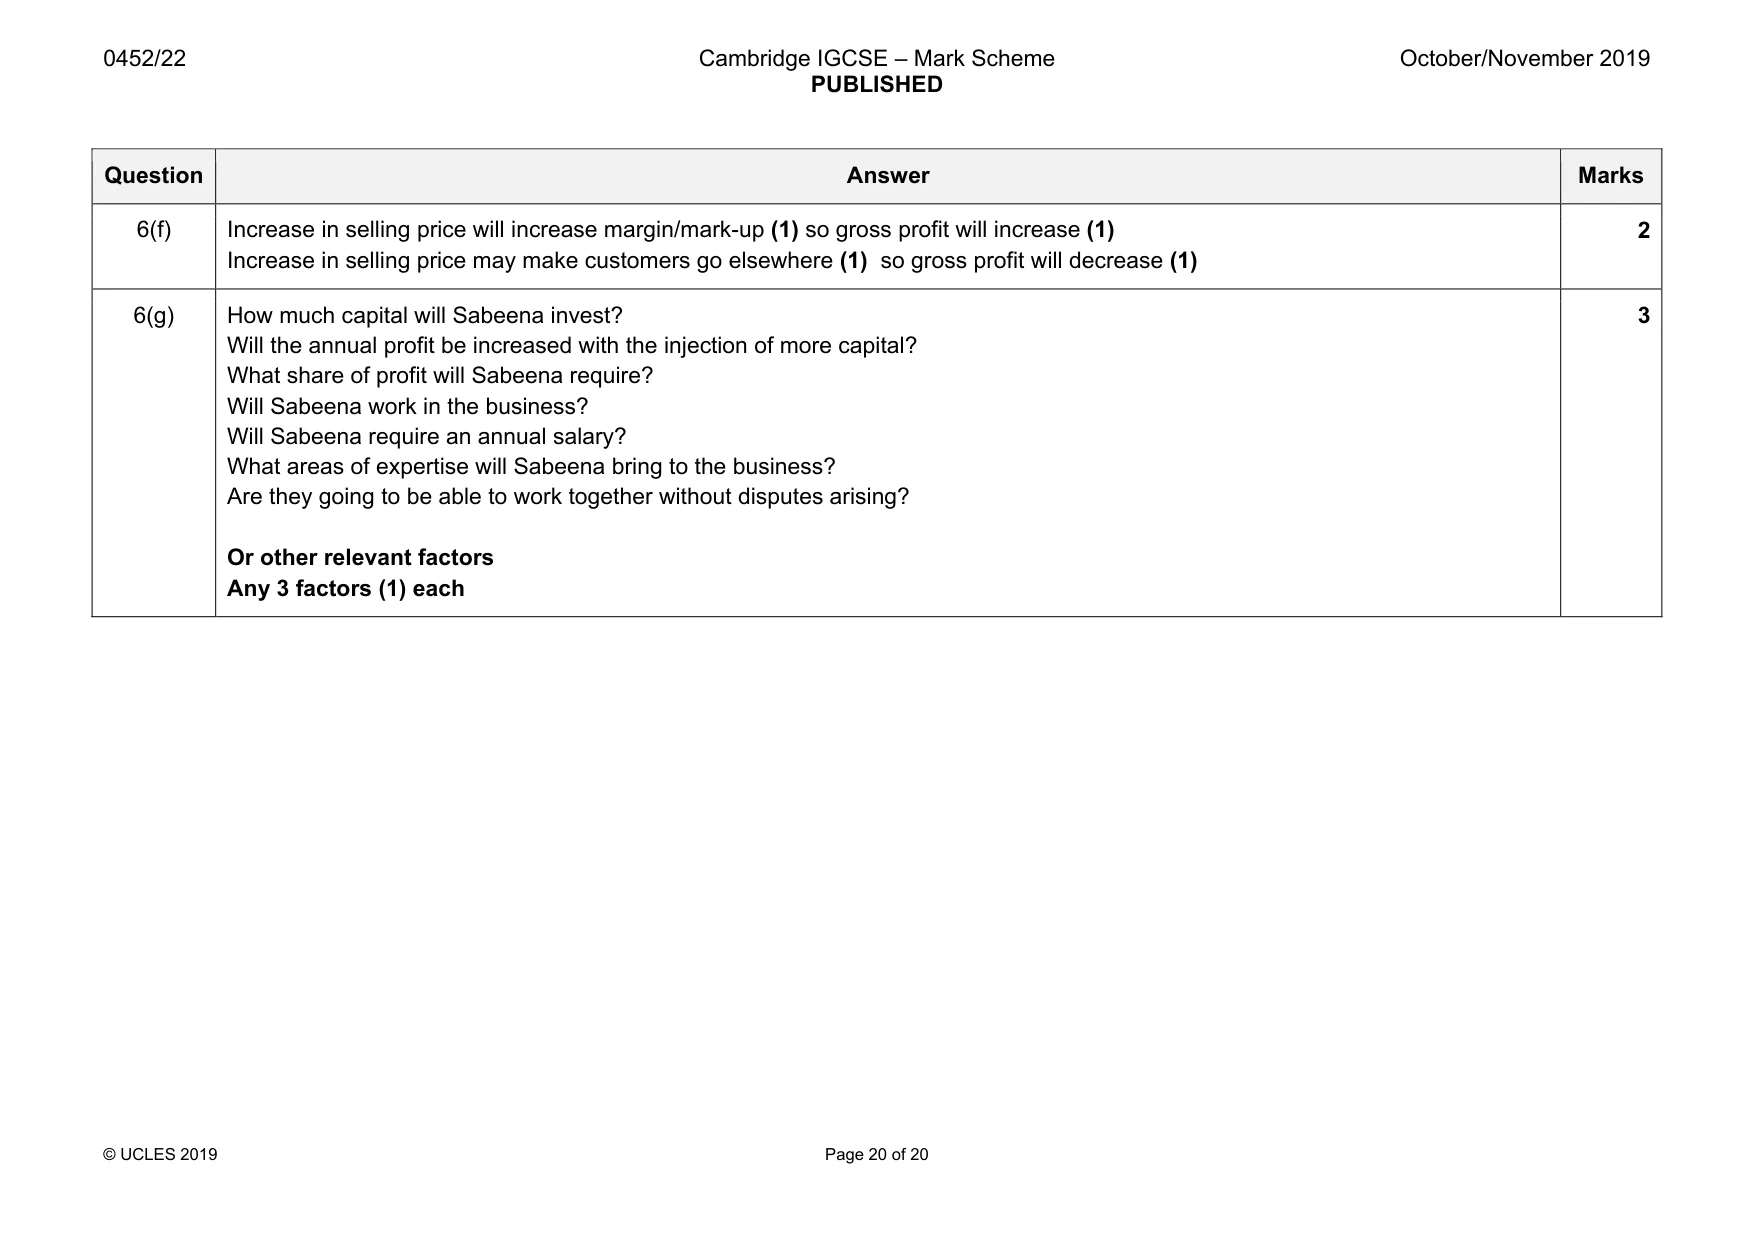
Mark scheme: 6(a) Percentage of gross profit to revenue (42 000 – 35 490) × 100} (1) whole formula = 15.50% (1) 42 000 1 } Percentage of profit to revenue (6510 OF – 3772 × 100} (1) OF whole formula = 6.52% (1)OF 42 000 1 } Return on capital employed 2738 OF__ × 100} (1) OF whole formula = 4.35% (1)OF (53 000 + 10 000) 1} Rate of inventory turnover 35 490___ (1) whole formula = 39.88 times (1) (860 + 920) / 2 8 Question Answer Marks 6(b) Dealing in different types of goods Furniture has a higher profit mark-up than fruit and vegetables Any 2 points (1) each 2 6(c) Fruit and vegetables are a low-priced everyday product/furniture is a higher priced article which is not purchased daily Fruit and vegetables will go bad if kept for a long period of time/furniture does not deteriorate as quickly as fresh food. Or other relevant reason Any 1 reason (1) 1 6(d) Wages, insurance of premises, bad debts, increase in provision for doubtful debts, cash discount allowed Or other suitable expenses Any 2 expenses (1) each 2 6(e) Dealing in different goods Different type of business (sole trader/partnership) Different length of life of business Different types of expenses Different size of business Results are for one year only and may not show trends The statements do not show non-monetary factors It may not be possible to obtain all the information needed to make comparisons Different accounting policies may be used Or other relevant factors Any 4 factors (1) each 4 Question Answer Marks 6(f) Increase in selling price will increase margin/mark-up (1) so gross profit will increase (1) Increase in selling price may make customers go elsewhere (1) so gross profit will decrease (1) 2 6(g) How much capital will Sabeena invest? Will the annual profit be increased with the injection of more capital? What share of profit will Sabeena require? Will Sabeena work in the business? Will Sabeena require an annual salary? What areas of expertise will Sabeena bring to the business? Are they going to be able to work together without disputes arising? Or other relevant factors Any 3 factors (1) each 3
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2019 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.