Cambridge IGCSE Accounting 0452 — 2019 May/June Paper 2 · Variant 3
0452/23/M/J/19 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Annabel is a wholesaler
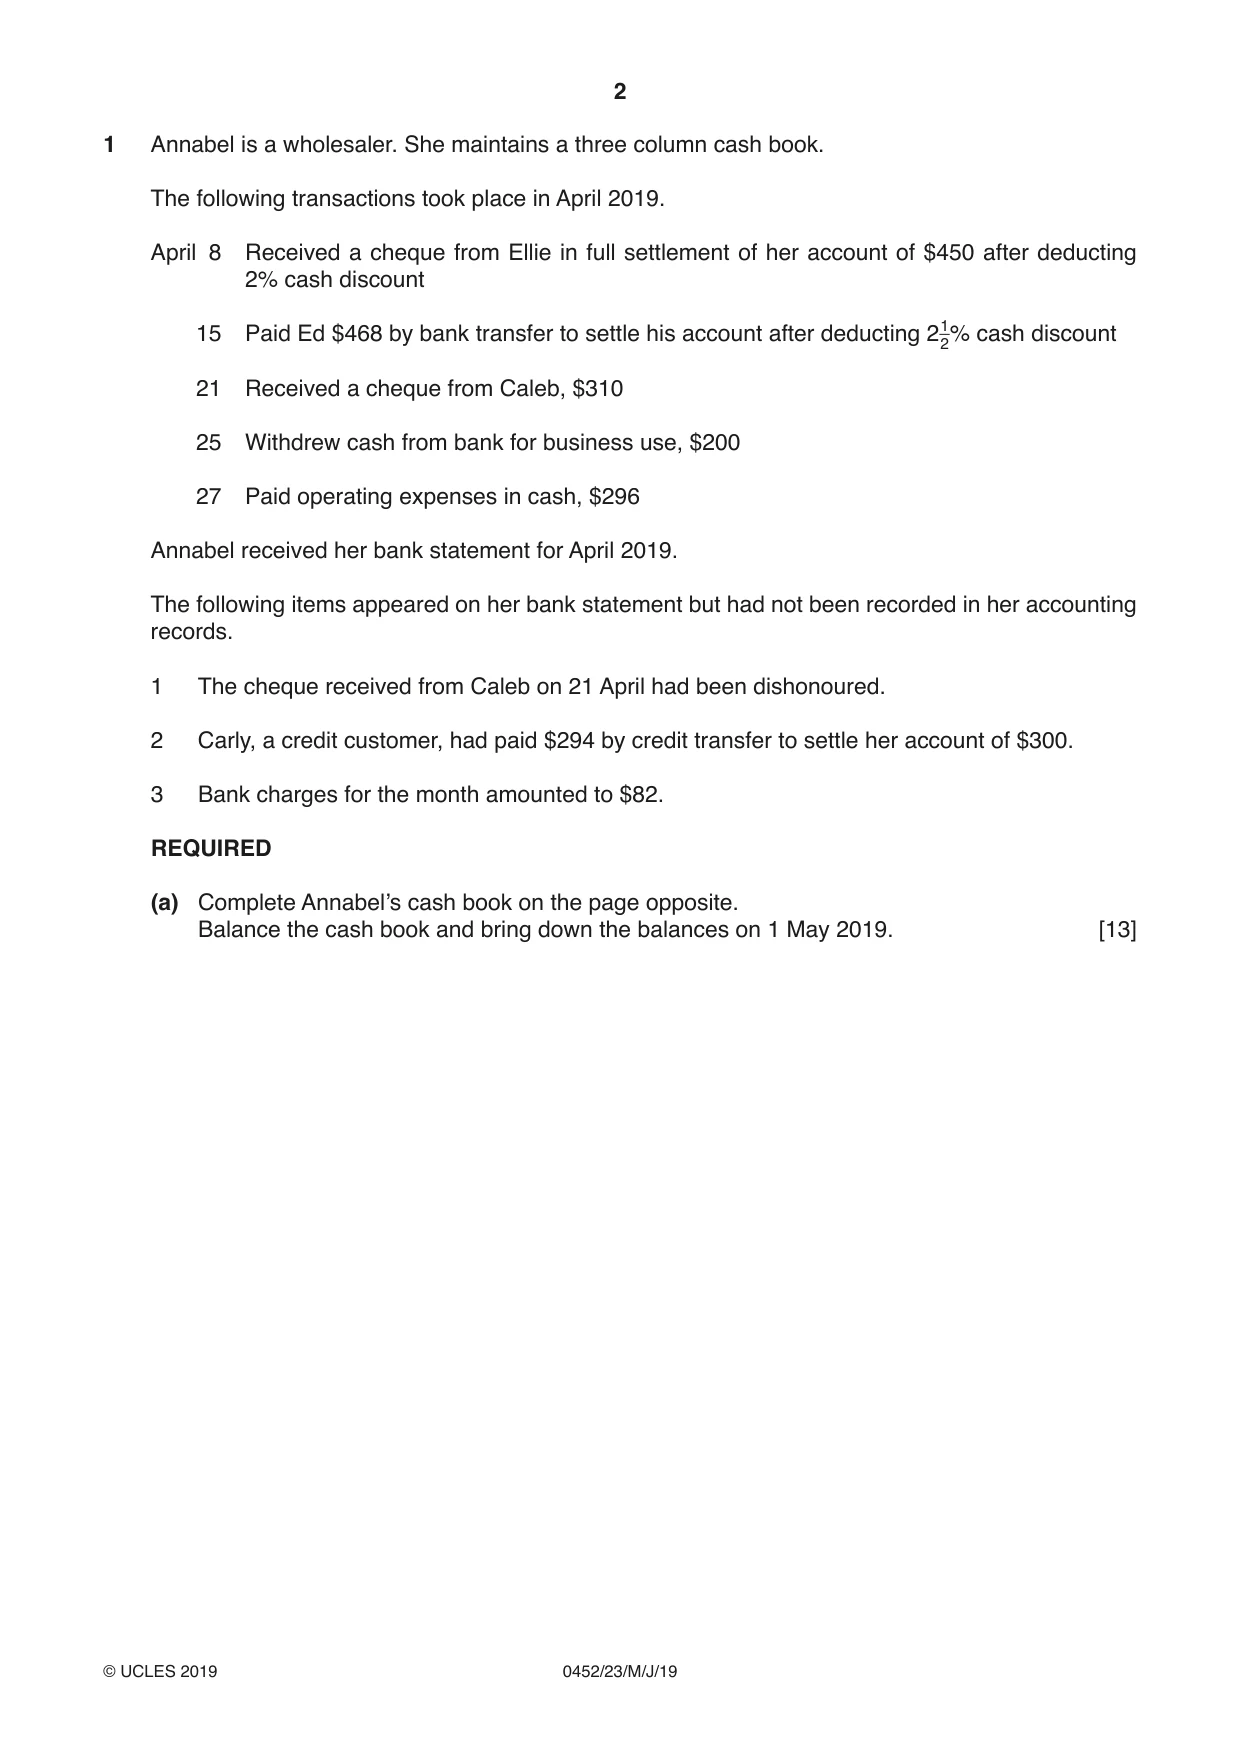
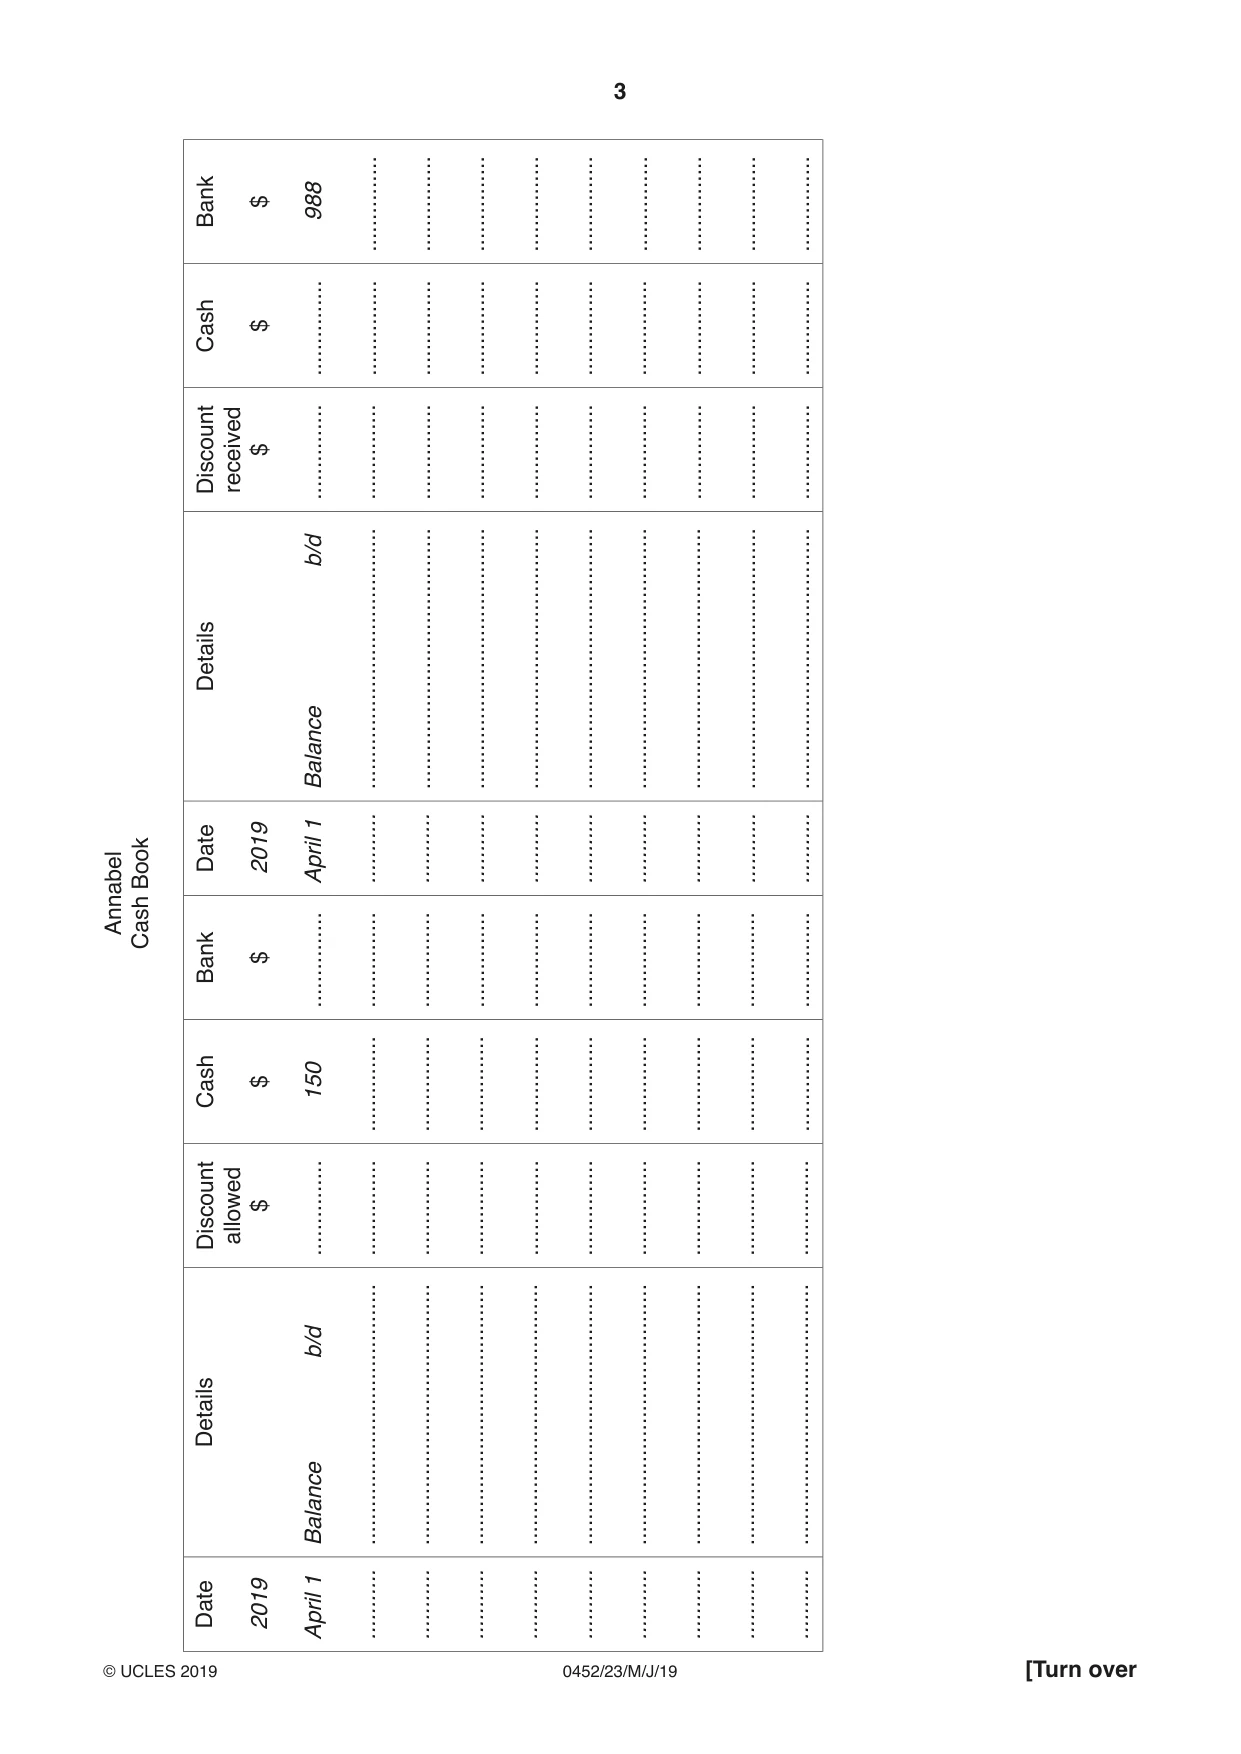
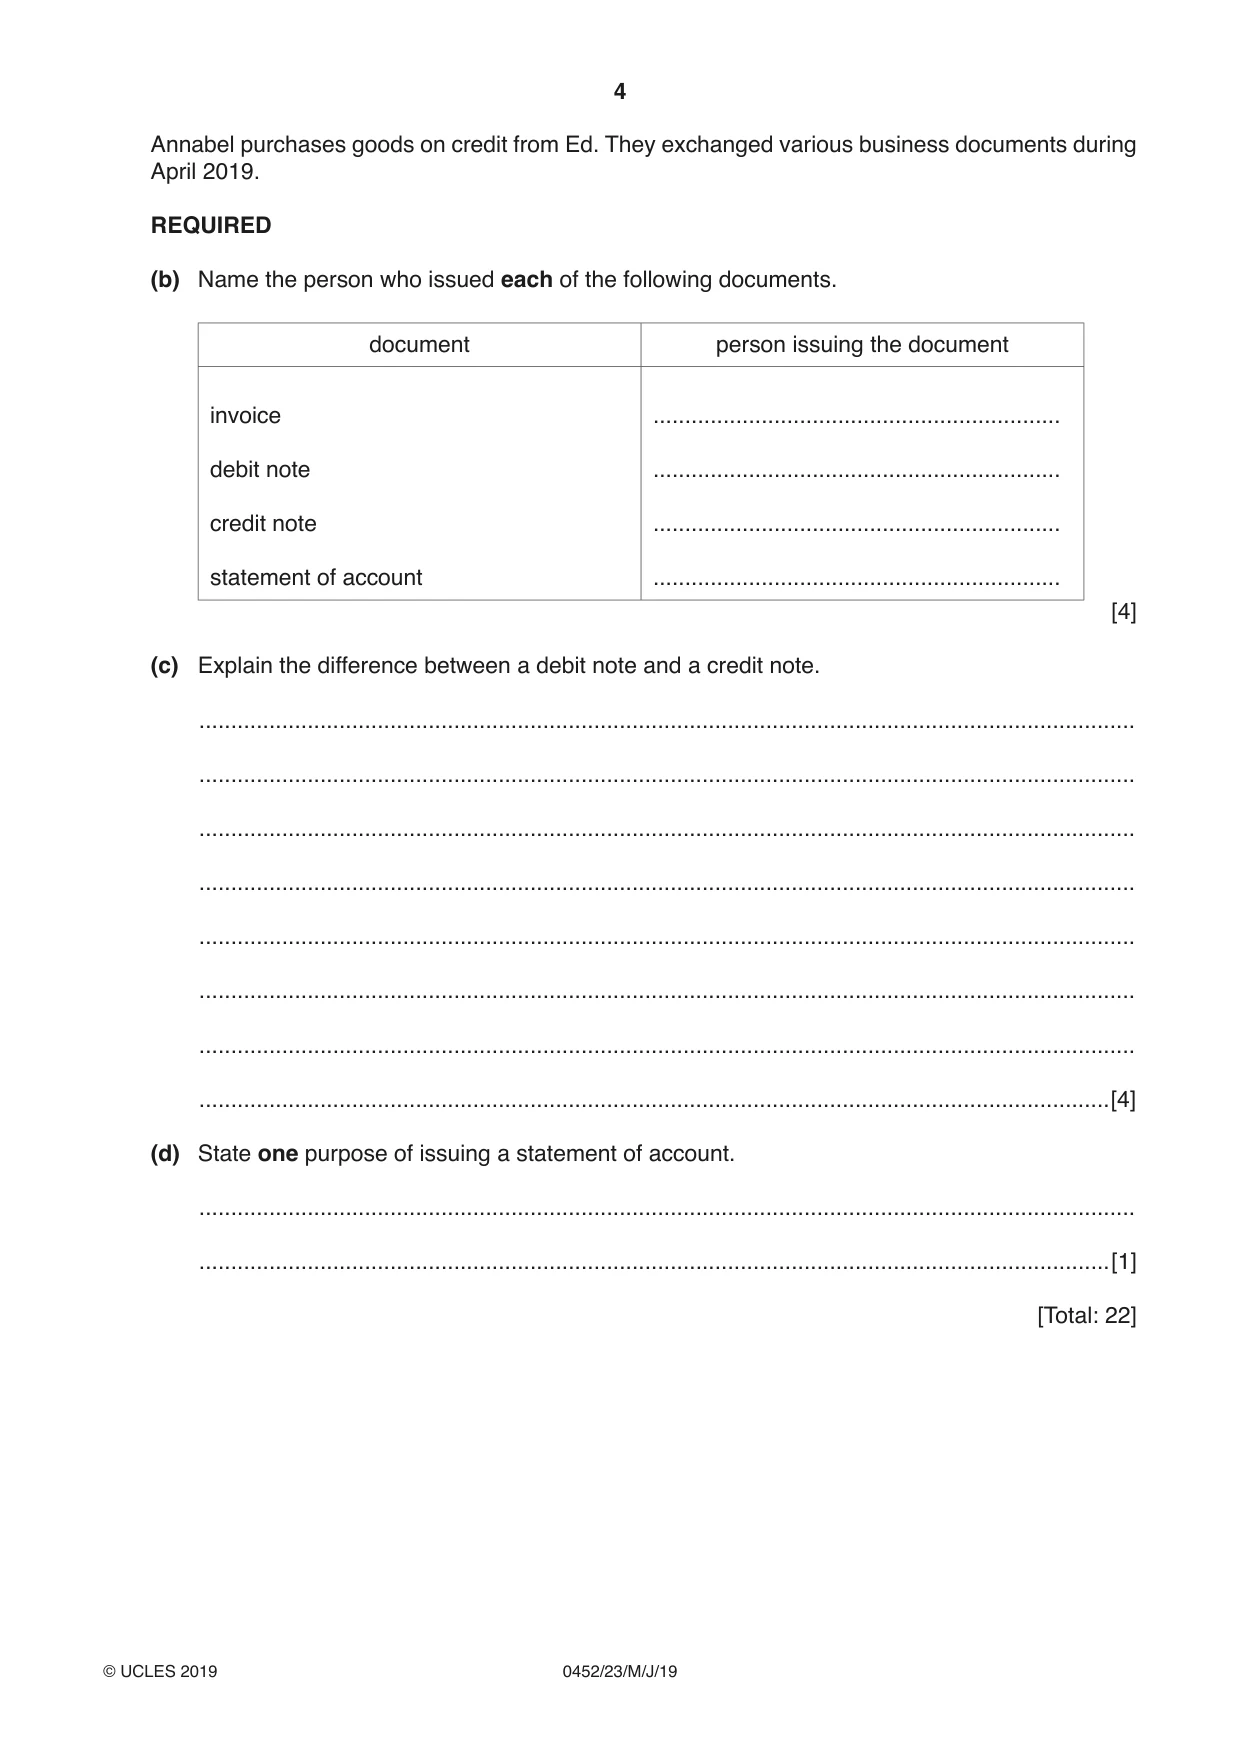
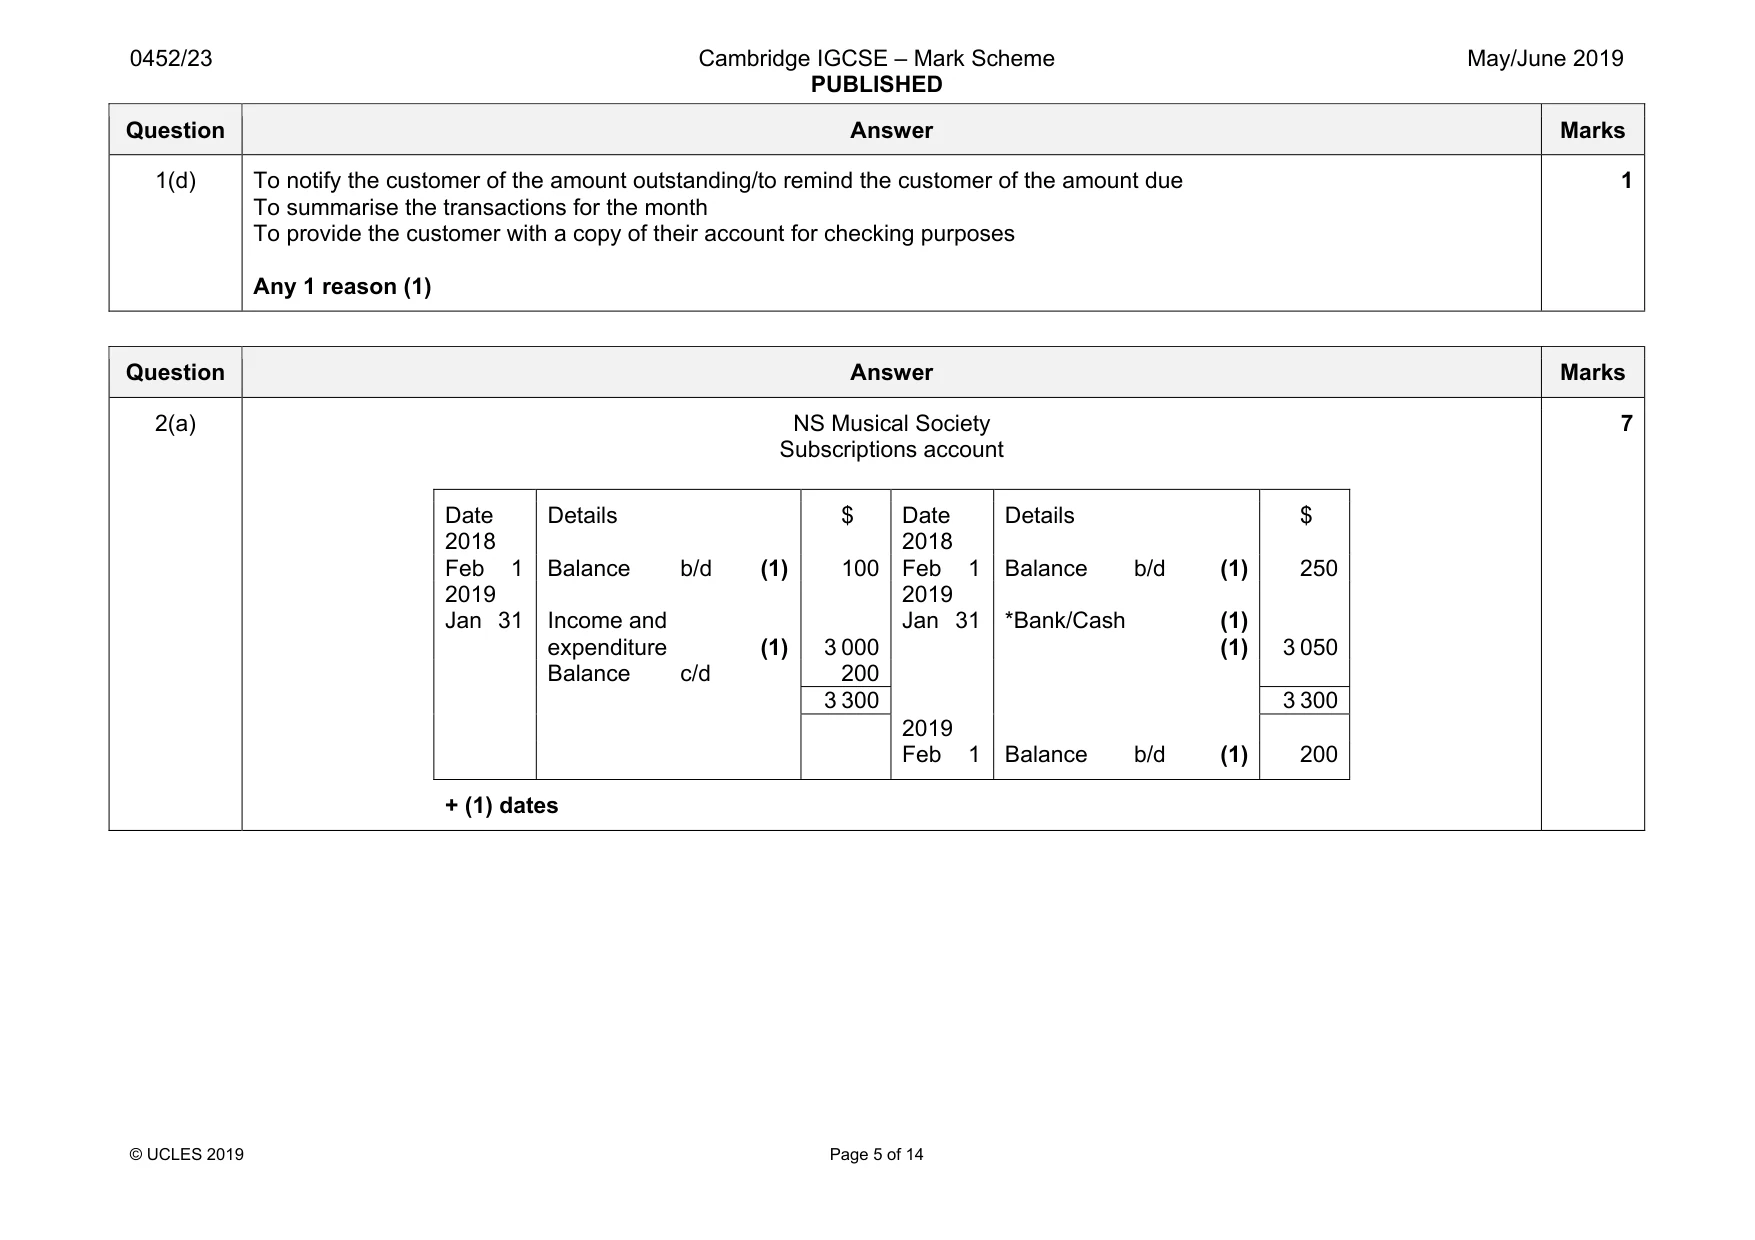
1 Annabel is a wholesaler. She maintains a three column cash book. The following transactions took place in April 2019. April 8 Received a cheque from Ellie in full settlement of her account of $450 after deducting 2% cash discount 15 Paid Ed $468 by bank transfer to settle his account after deducting 212% cash discount 21 Received a cheque from Caleb, $310 25 Withdrew cash from bank for business use, $200 27 Paid operating expenses in cash, $296 Annabel received her bank statement for April 2019. The following items appeared on her bank statement but had not been recorded in her accounting records. 1 The cheque received from Caleb on 21 April had been dishonoured. 2 Carly, a credit customer, had paid $294 by credit transfer to settle her account of $300. 3 Bank charges for the month amounted to $82. REQUIRED (a) Complete Annabel’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 May 2019. [13] $ 988 Bank ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Cash ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountreceived ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... b/d Details Balance ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Date 2019 1 Book April ........... ........... ........... ........... ........... ........... ........... ........... ........... Annabel Cash $ Bank ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ 150 Cash ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountallowed ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... b/d Details Balance ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Annabel purchases goods on credit from Ed. They exchanged various business documents during April 2019. REQUIRED (b) Name the person who issued each of the following documents. document person issuing the document invoice ................................................................ debit note ................................................................ credit note ................................................................ statement of account ................................................................ [4] (c) Explain the difference between a debit note and a credit note. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[4] (d) State one purpose of issuing a statement of account. ................................................................................................................................................... ...............................................................................................................................................[1] [Total: 22] PLEASE TURN OVER
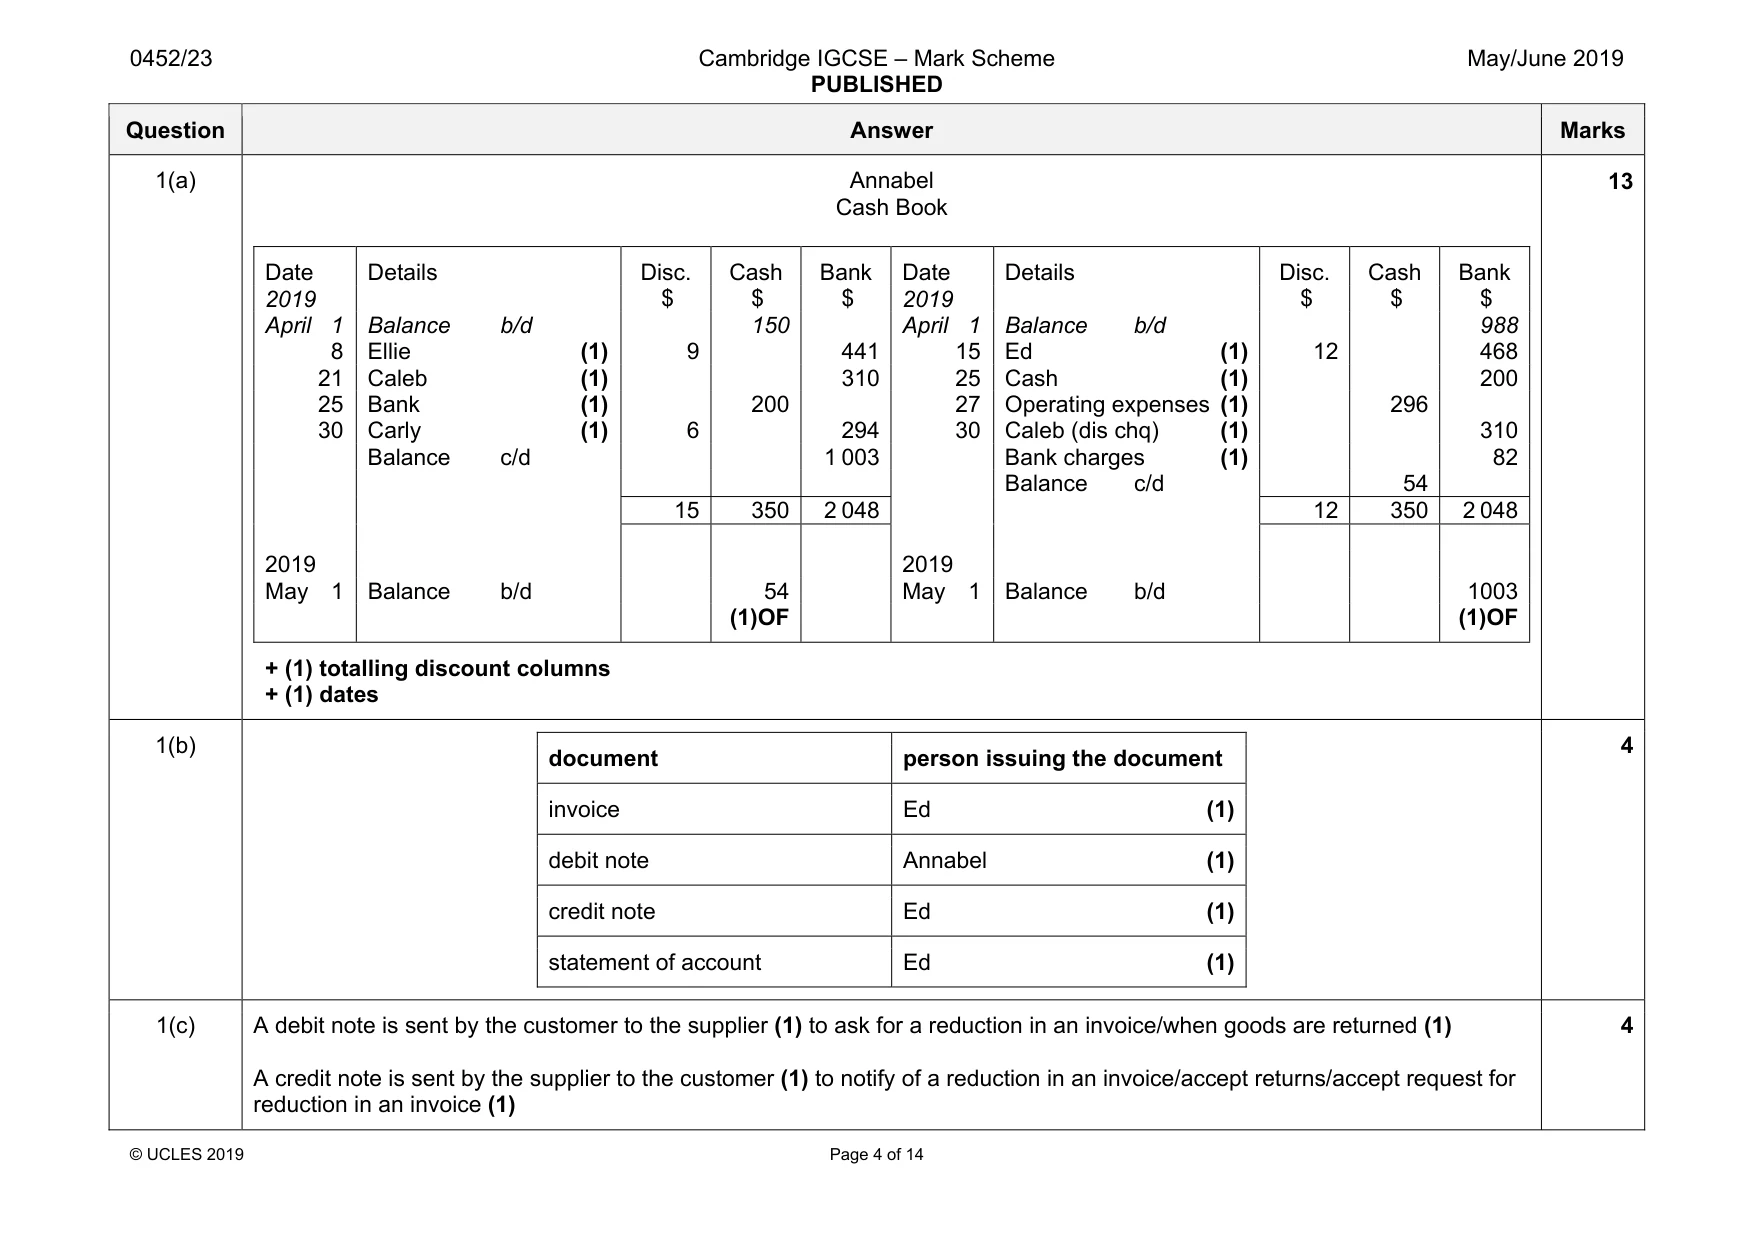
Mark scheme: 1(a) Annabel Cash Book Date Details Disc. Cash Bank Date Details Disc. Cash Bank 2019 $00 $00 $00 2019 $00 $00 $00 April 1 Balance b/d 150 April 1 Balance b/d 988 8 Ellie (1) 9 441 15 Ed (1) 12 468 21 Caleb (1) 310 25 Cash (1) 200 25 Bank (1) 200 27 Operating expenses (1) 296 30 Carly (1) 6 294 30 Caleb (dis chq) (1) 310 Balance c/d 1 003 Bank charges (1) 82 Balance c/d 54 15 350 2 048 12 350 2 048 2019 2019 May 1 Balance b/d 54 May 1 Balance b/d 1003 (1)OF (1)OF + (1) totalling discount columns + (1) dates 13 1(b) document person issuing the document invoice Ed (1) debit note Annabel (1) credit note Ed (1) statement of account Ed (1) 4 1(c) A debit note is sent by the customer to the supplier (1) to ask for a reduction in an invoice/when goods are returned (1) A credit note is sent by the supplier to the customer (1) to notify of a reduction in an invoice/accept returns/accept request for reduction in an invoice (1) 4 Question Answer Marks 1(d) To notify the customer of the amount outstanding/to remind the customer of the amount due To summarise the transactions for the month To provide the customer with a copy of their account for checking purposes Any 1 reason (1) 1
Q2 · The financial year of the NS Musical Society ends on 31 January
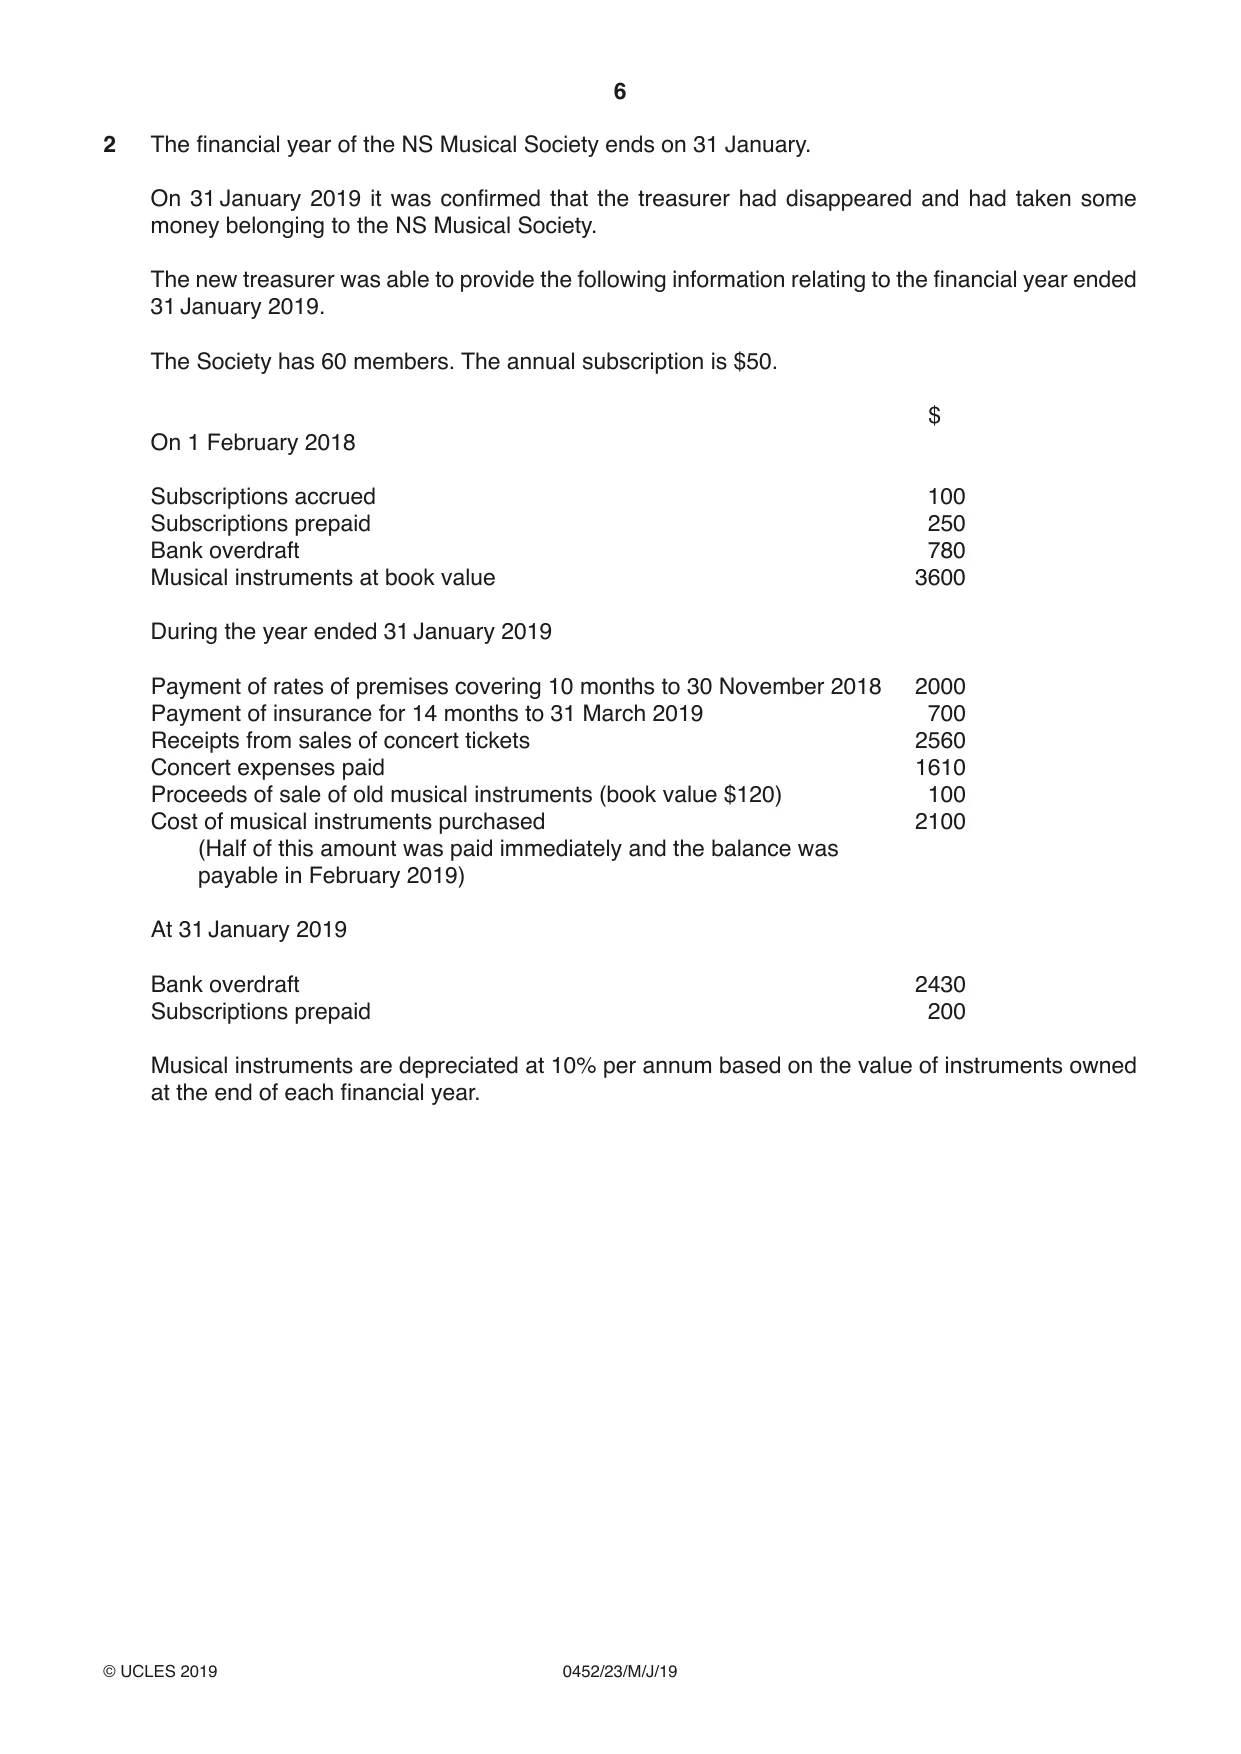
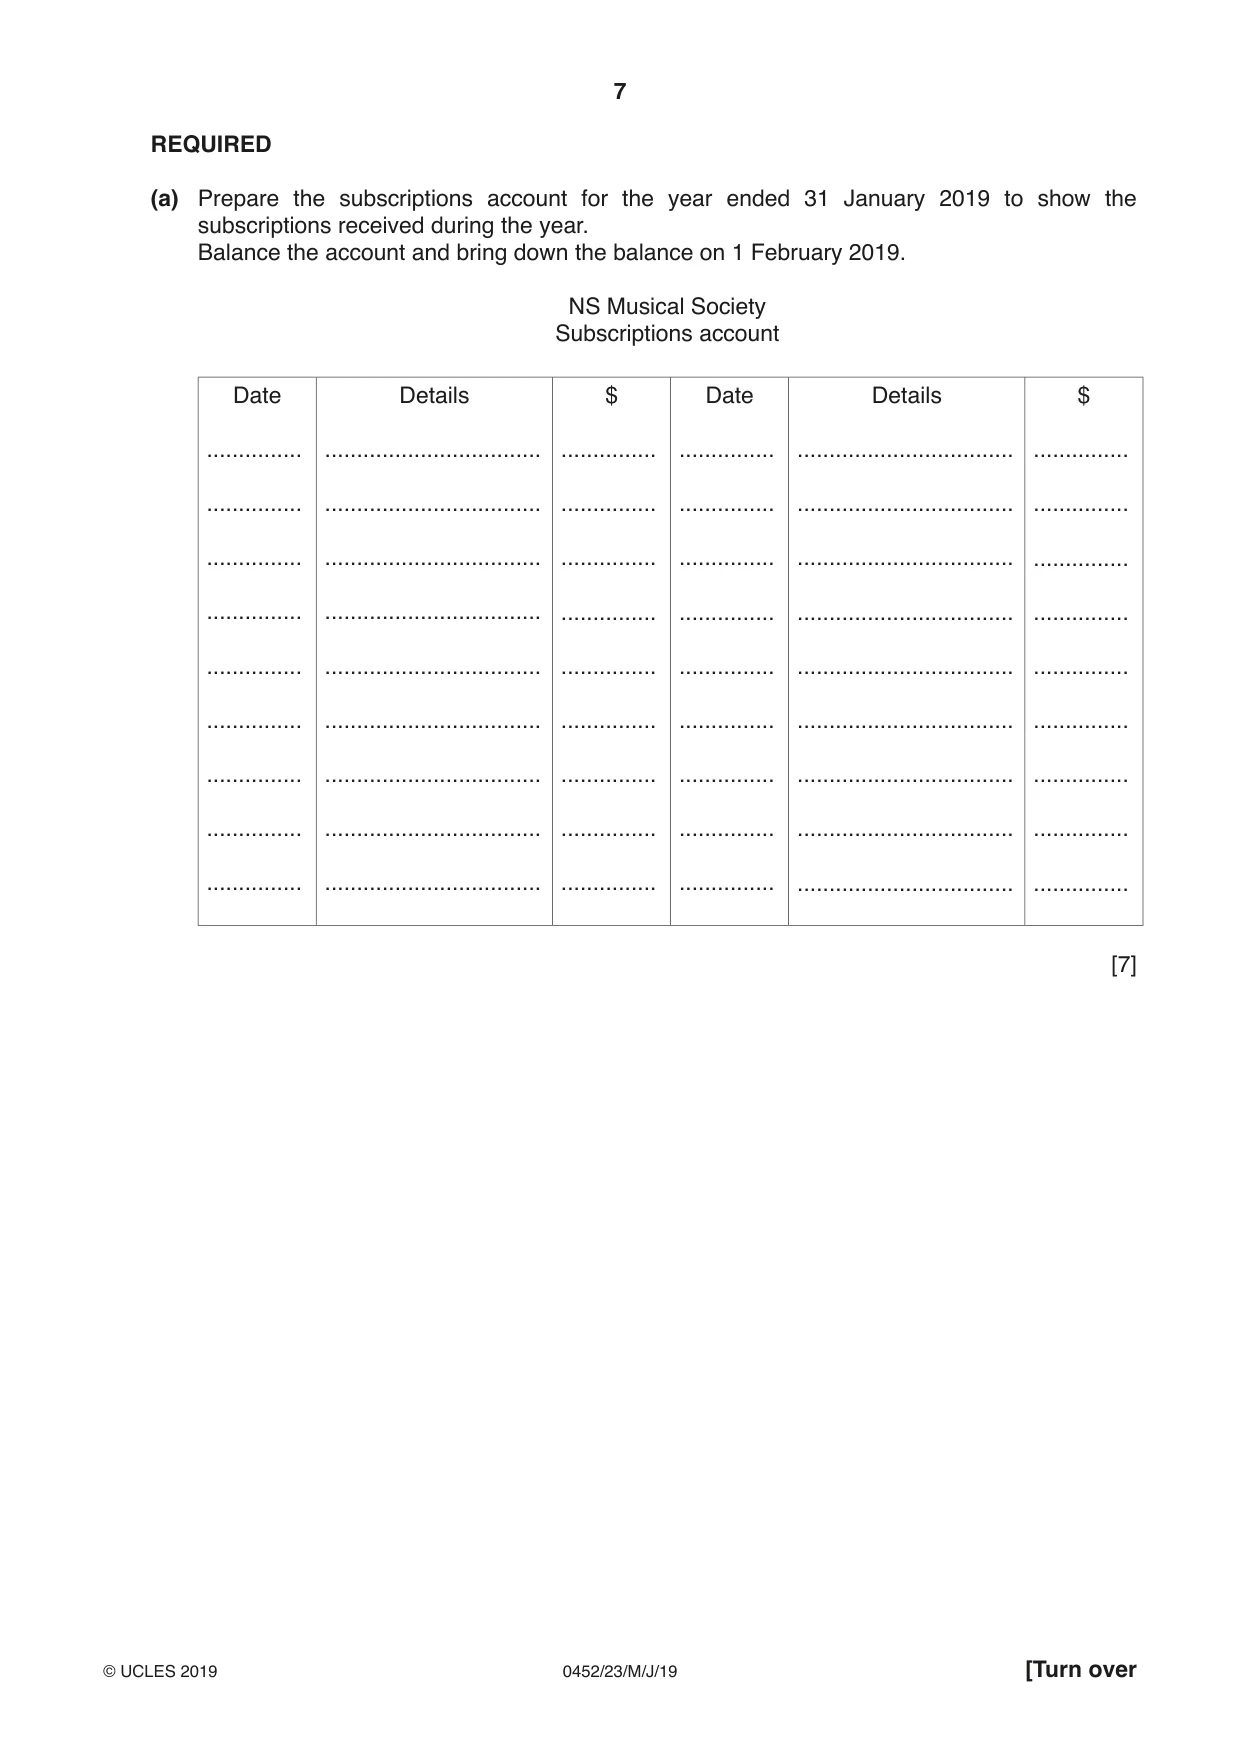
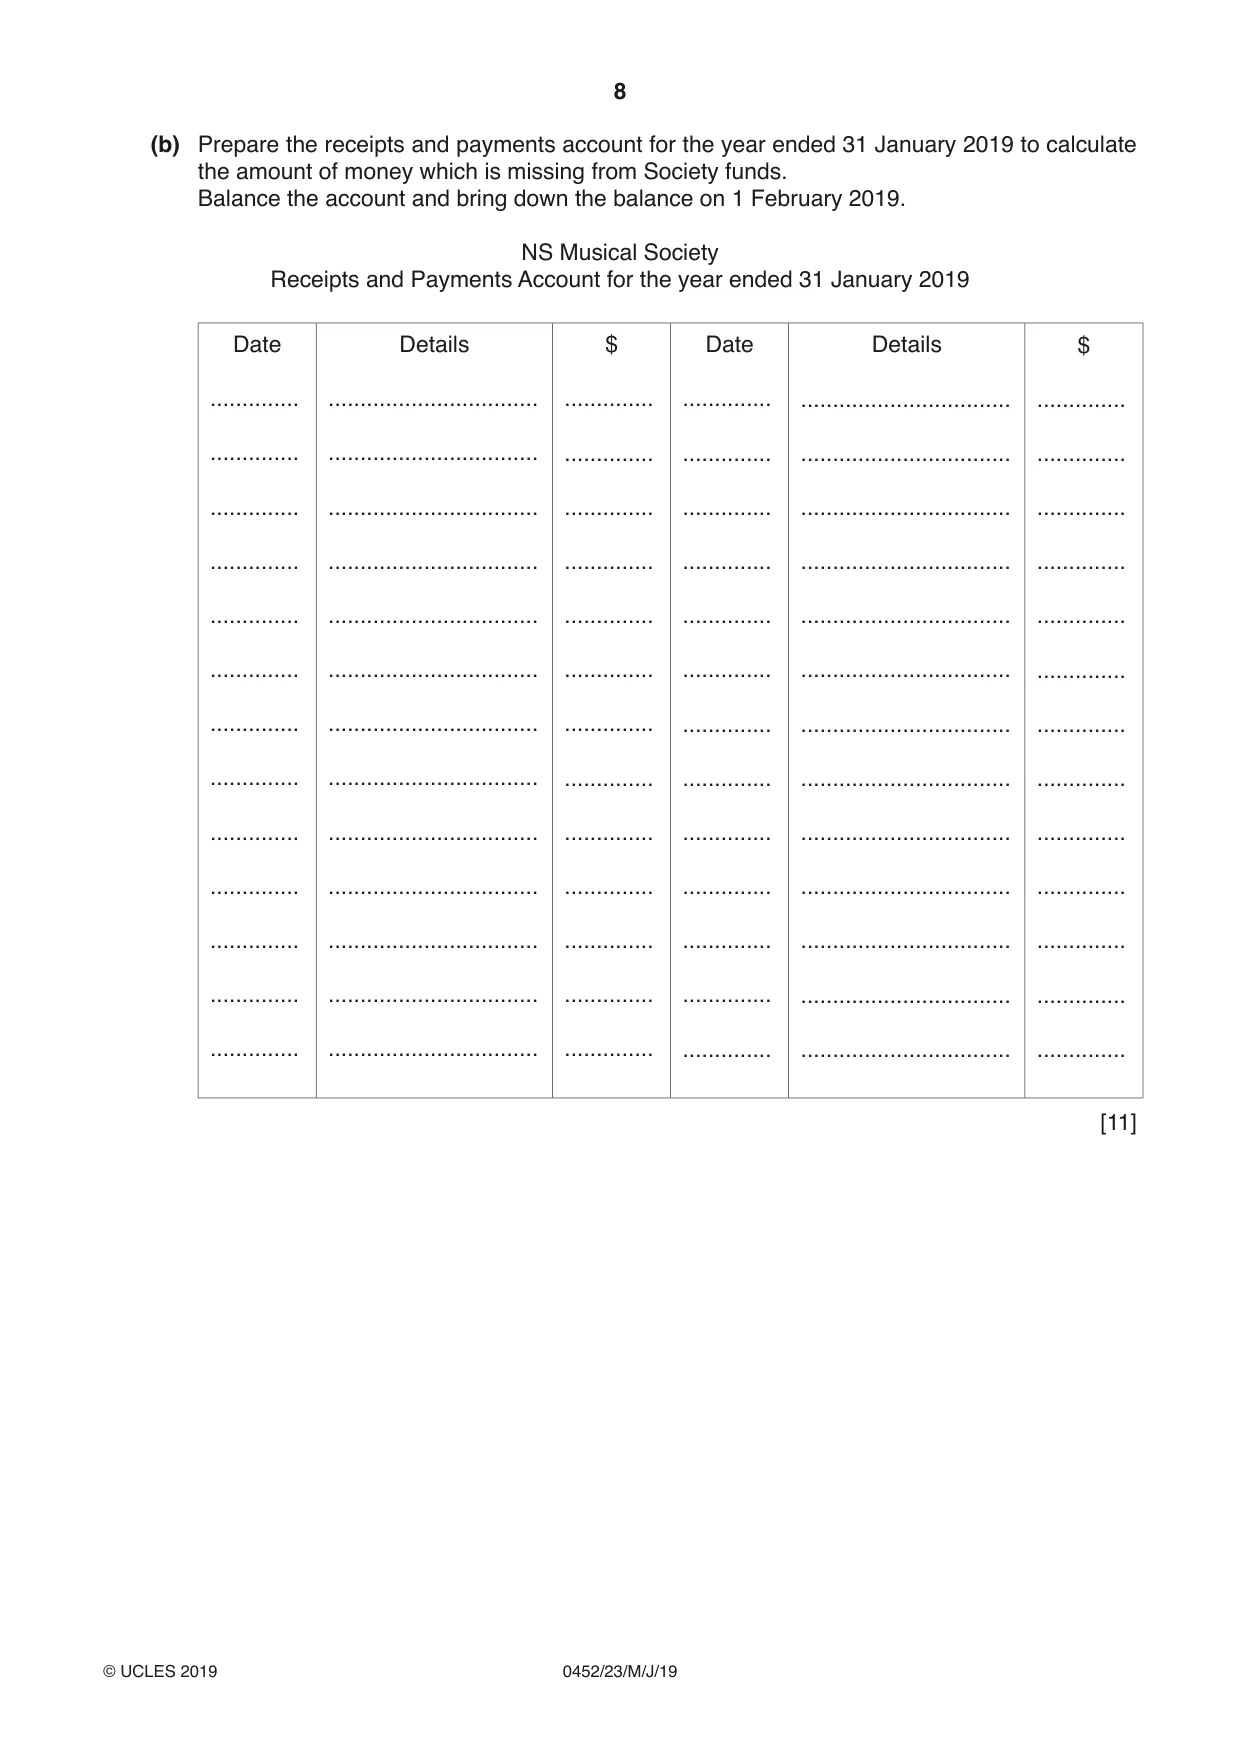
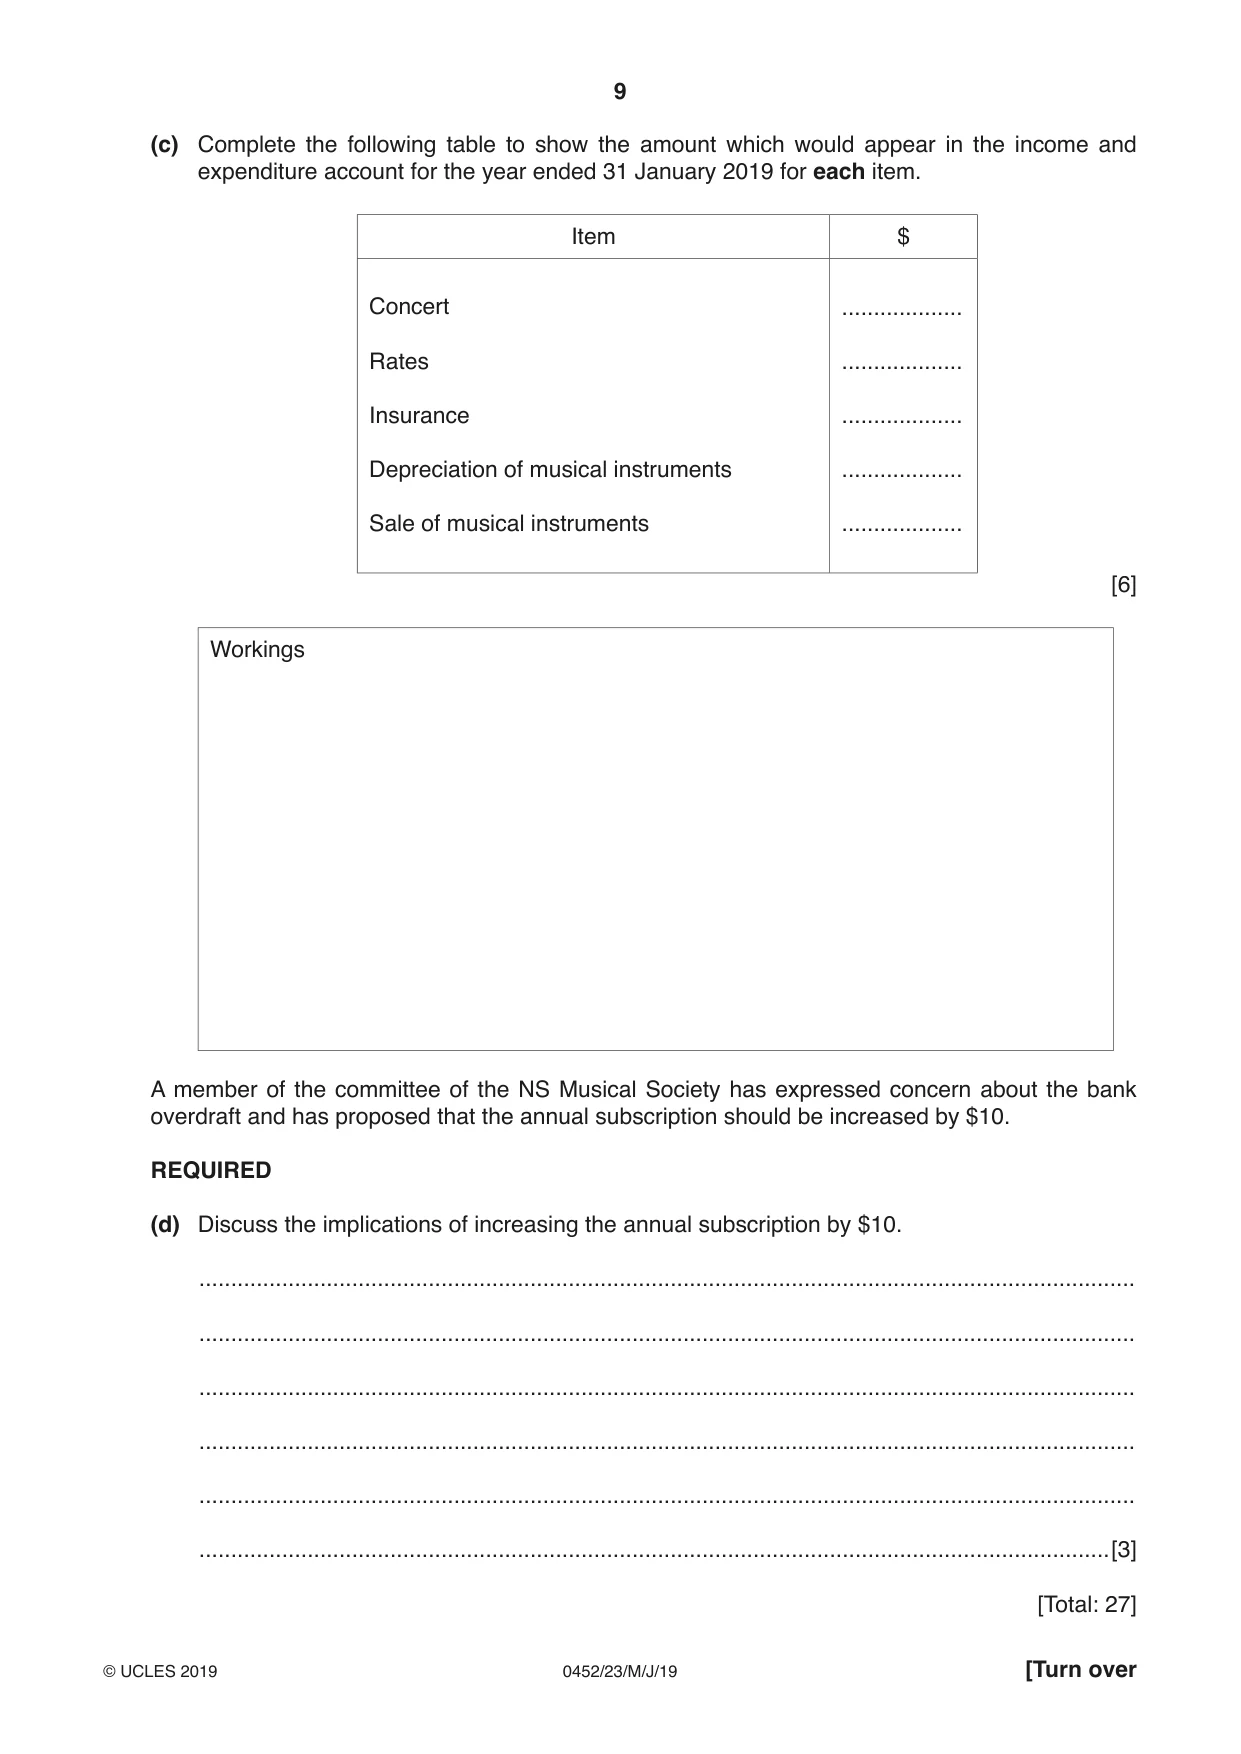
2 The financial year of the NS Musical Society ends on 31 January. On 31 January 2019 it was confirmed that the treasurer had disappeared and had taken some money belonging to the NS Musical Society. The new treasurer was able to provide the following information relating to the financial year ended 31 January 2019. The Society has 60 members. The annual subscription is $50. $ On 1 February 2018 Subscriptions accrued 100 Subscriptions prepaid 250 Bank overdraft 780 Musical instruments at book value 3600 During the year ended 31 January 2019 Payment of rates of premises covering 10 months to 30 November 2018 2000 Payment of insurance for 14 months to 31 March 2019 700 Receipts from sales of concert tickets 2560 Concert expenses paid 1610 Proceeds of sale of old musical instruments (book value $120) 100 Cost of musical instruments purchased 2100 (Half of this amount was paid immediately and the balance was payable in February 2019) At 31 January 2019 Bank overdraft 2430 Subscriptions prepaid 200 Musical instruments are depreciated at 10% per annum based on the value of instruments owned at the end of each financial year. REQUIRED (a) Prepare the subscriptions account for the year ended 31 January 2019 to show the subscriptions received during the year. Balance the account and bring down the balance on 1 February 2019. NS Musical Society Subscriptions account Date Details $ Date Details $ ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... [7] (b) Prepare the receipts and payments account for the year ended 31 January 2019 to calculate the amount of money which is missing from Society funds. Balance the account and bring down the balance on 1 February 2019. NS Musical Society Receipts and Payments Account for the year ended 31 January 2019 Date Details $ Date Details $ .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. [11] (c) Complete the following table to show the amount which would appear in the income and expenditure account for the year ended 31 January 2019 for each item. Item $ Concert ................... Rates ................... Insurance ................... Depreciation of musical instruments ................... Sale of musical instruments ................... [6] Workings A member of the committee of the NS Musical Society has expressed concern about the bank overdraft and has proposed that the annual subscription should be increased by $10. REQUIRED (d) Discuss the implications of increasing the annual subscription by $10. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[3] [Total: 27]
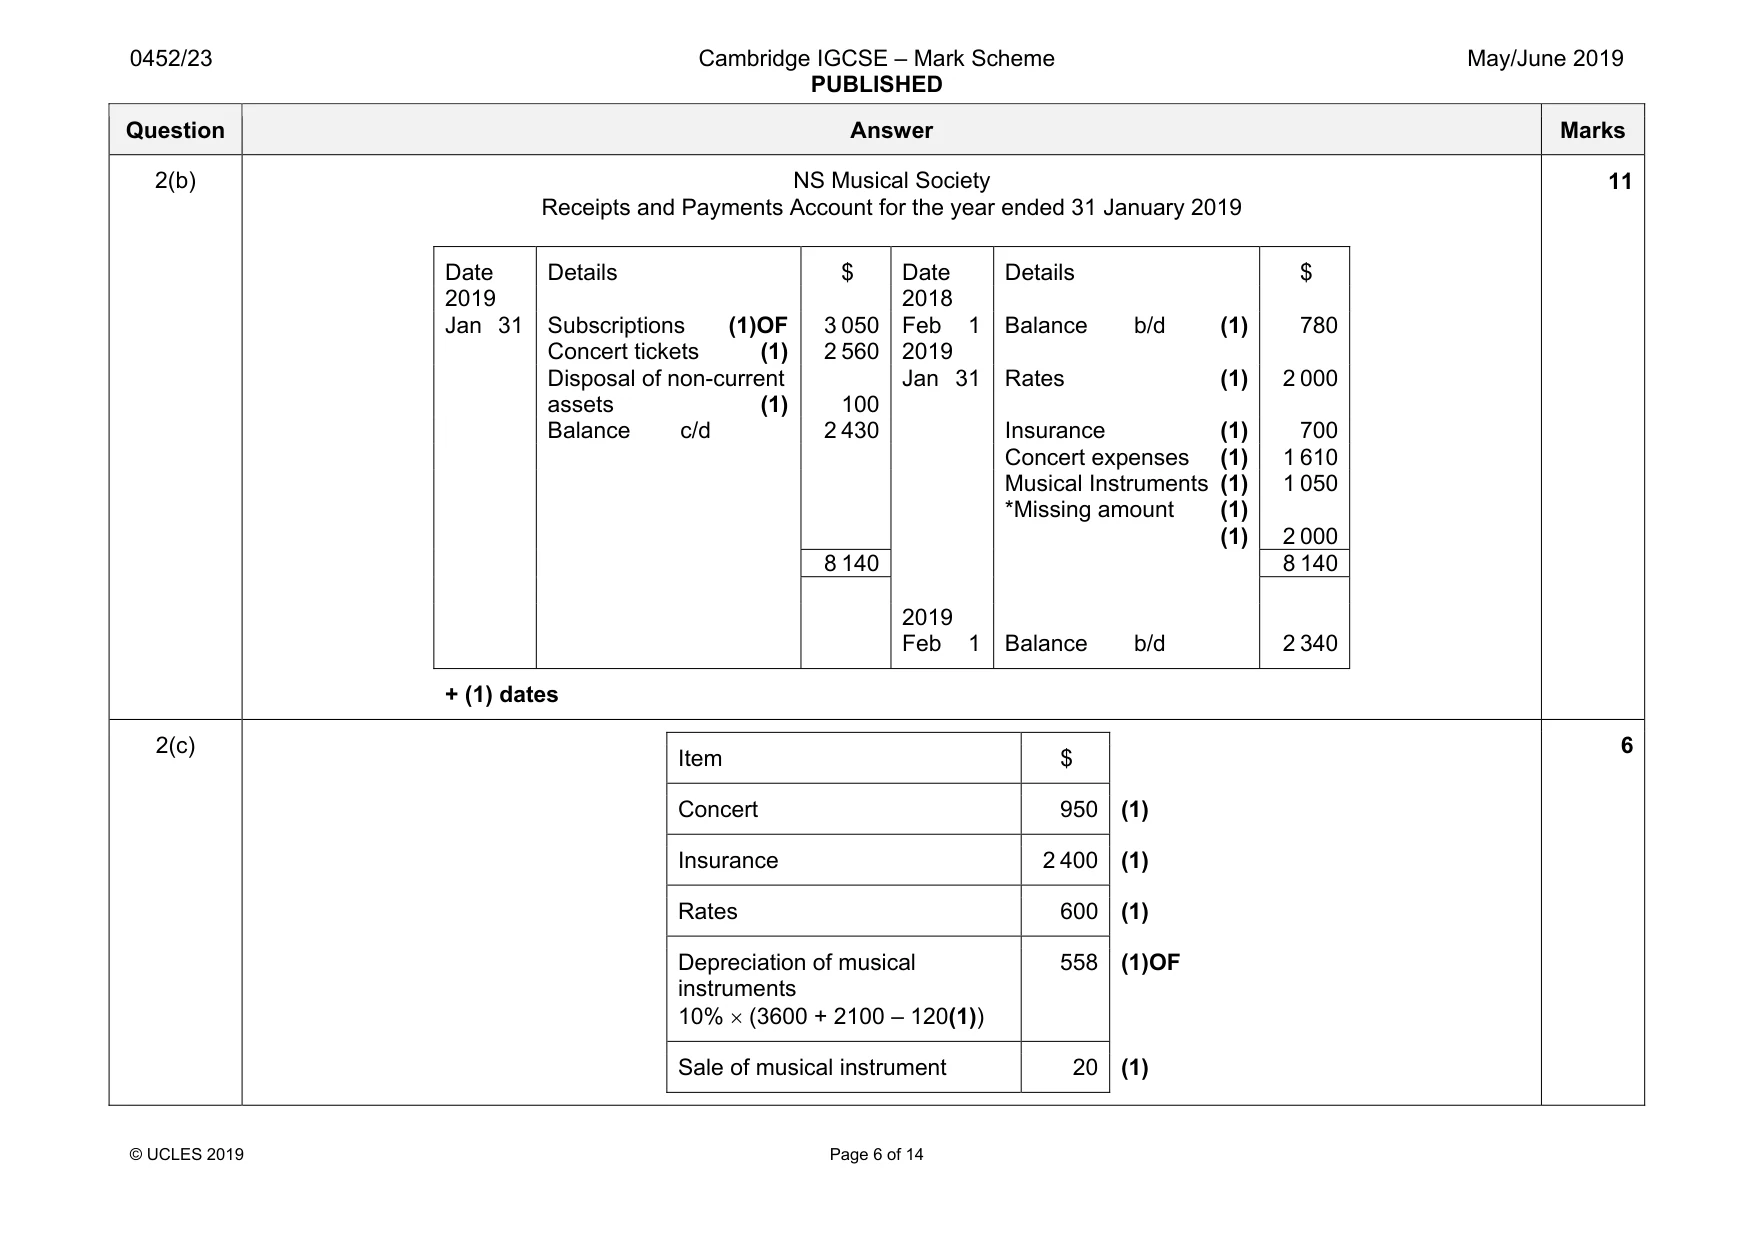
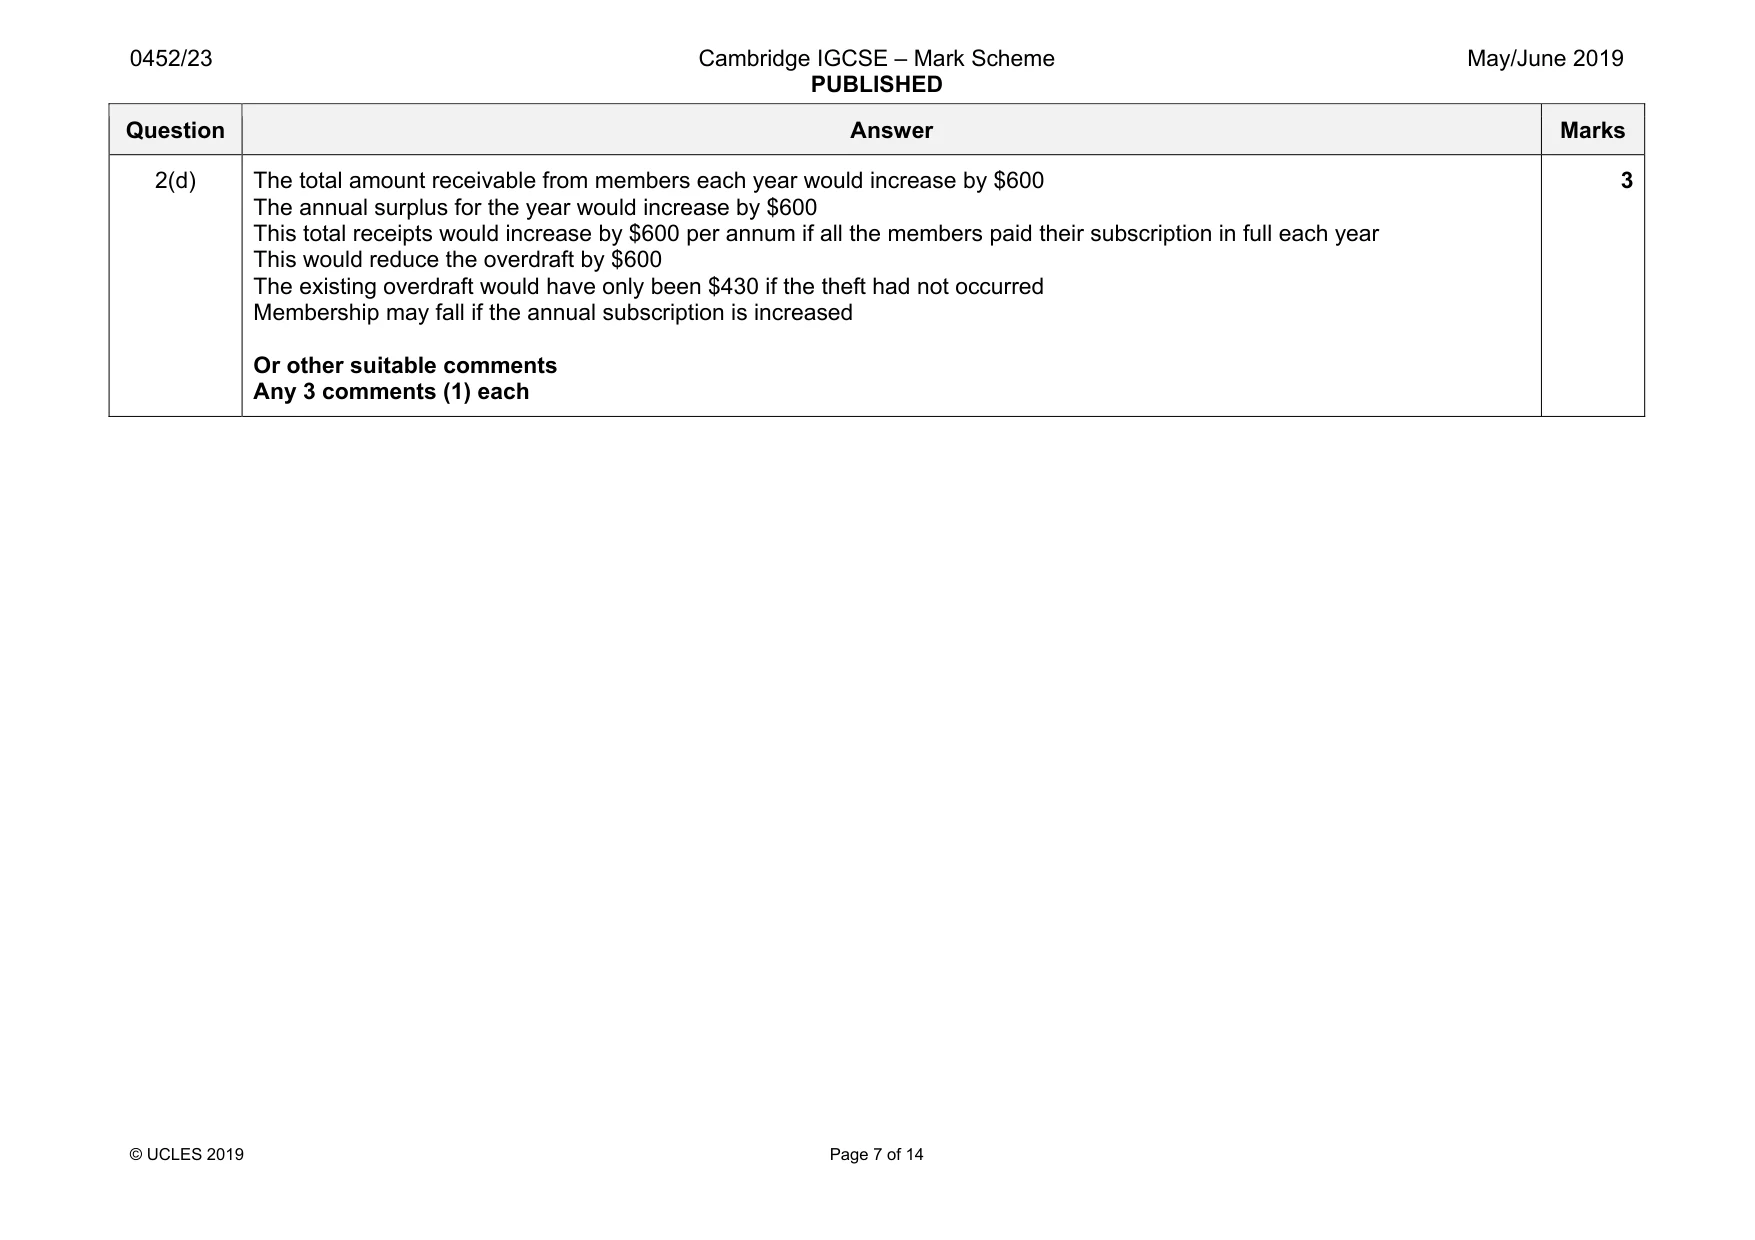
Mark scheme: 2(a) NS Musical Society Subscriptions account Date Details $00 Date Details $00 2018 2018 Feb 1 Balance b/d (1) 100 Feb 1 Balance b/d (1) 250 2019 2019 Jan 31 Income and expenditure (1) 3 000 Jan 31 *Bank/Cash (1) (1) 3 050 Balance c/d 200 3 300 3 300 2019 Feb 1 Balance b/d (1) 200 + (1) dates 7 Question Answer Marks 2(b) NS Musical Society Receipts and Payments Account for the year ended 31 January 2019 Date Details $00 Date Details $00 2019 2018 Jan 31 Subscriptions (1)OF 3 050 Feb 1 Balance b/d (1) 780 Concert tickets (1) 2 560 2019 Disposal of non-current assets (1) 100 Jan 31 Rates (1) 2 000 Balance c/d 2 430 Insurance (1) 700 Concert expenses (1) 1 610 Musical Instruments (1) 1 050 *Missing amount (1) (1) 2 000 8 140 8 140 2019 Feb 1 Balance b/d 2 340 + (1) dates 11 2(c) Item $00 Concert 950 (1) Insurance 2 400 (1) Rates 600 (1) Depreciation of musical instruments 10% × (3600 + 2100 – 120(1)) 558 (1)OF Sale of musical instrument 20 (1) 6 Question Answer Marks 2(d) The total amount receivable from members each year would increase by $600 The annual surplus for the year would increase by $600 This total receipts would increase by $600 per annum if all the members paid their subscription in full each year This would reduce the overdraft by $600 The existing overdraft would have only been $430 if the theft had not occurred Membership may fall if the annual subscription is increased Or other suitable comments Any 3 comments (1) each 3
Q3 · Jamal opened a toy factory on 1 March 2018
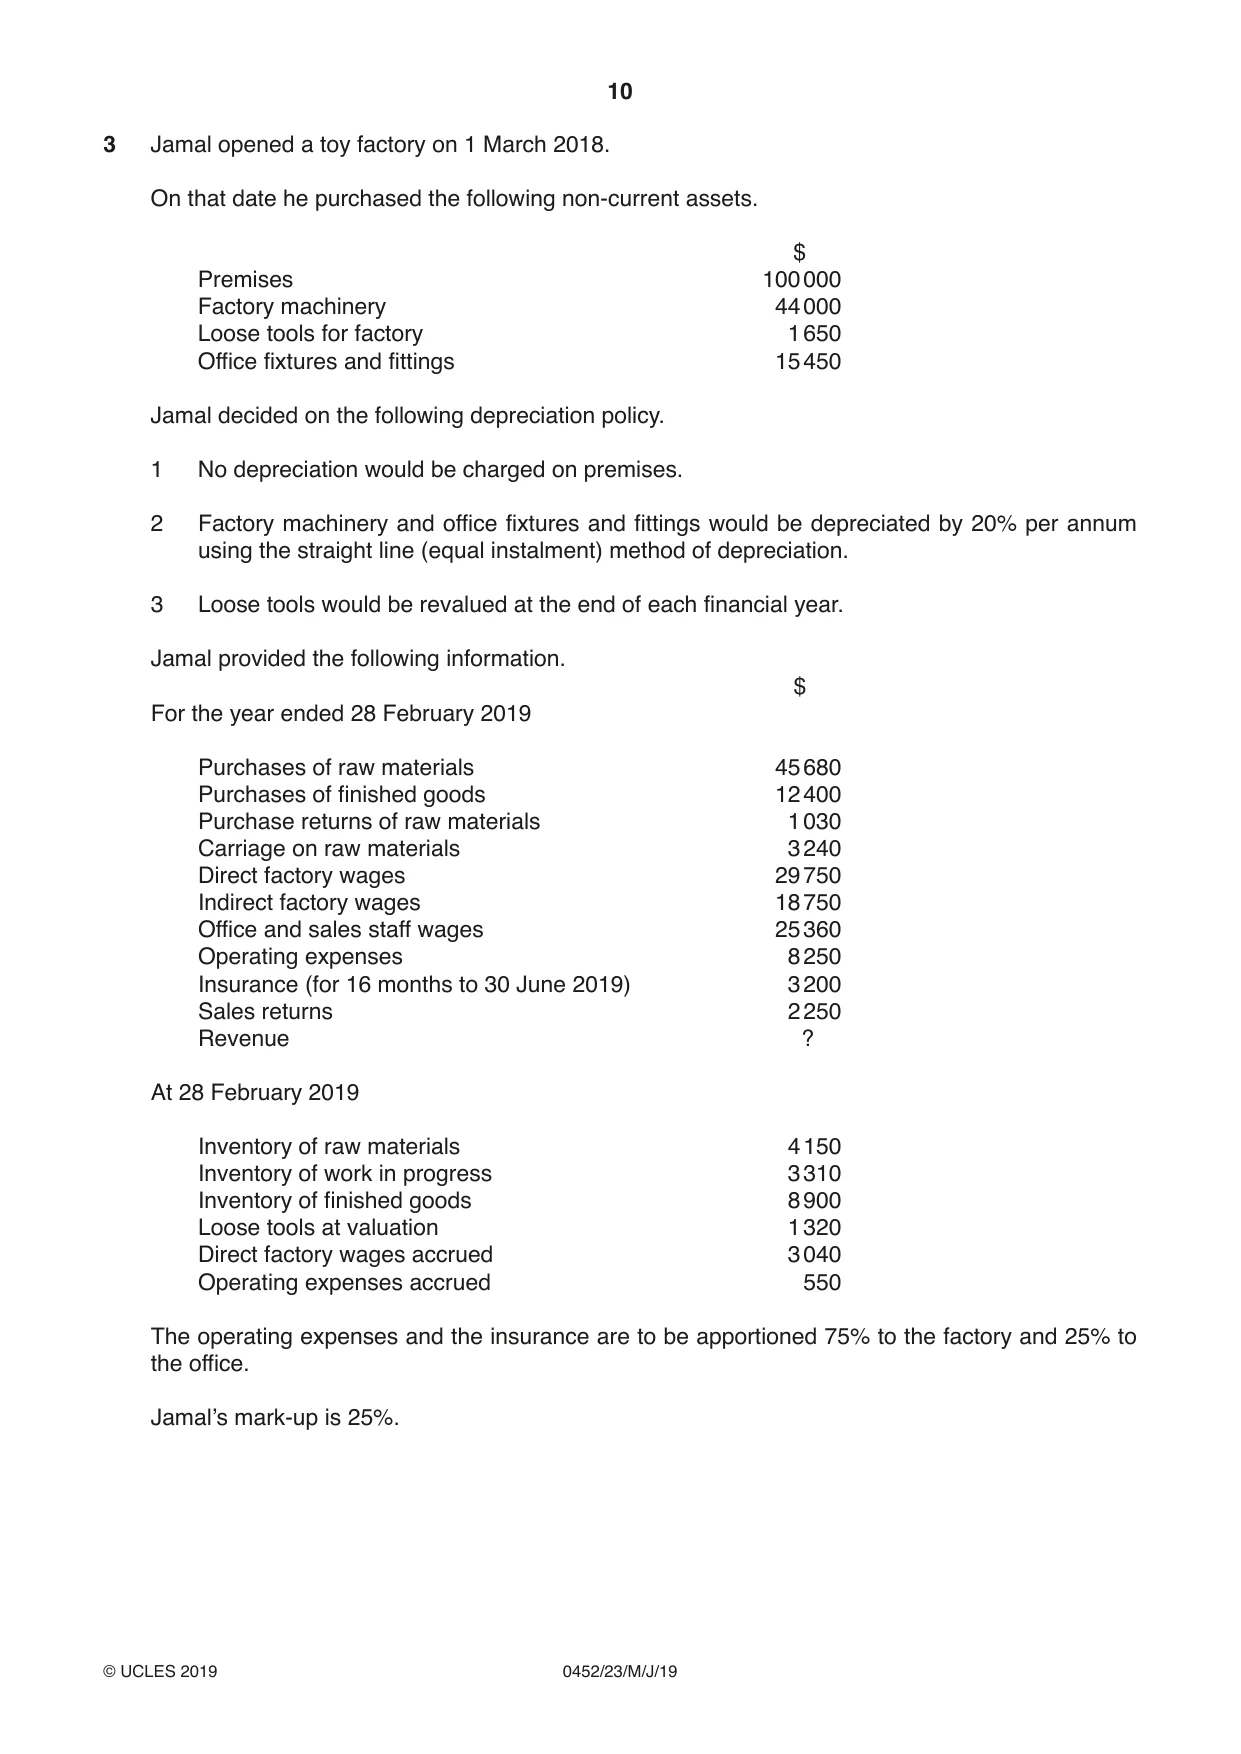
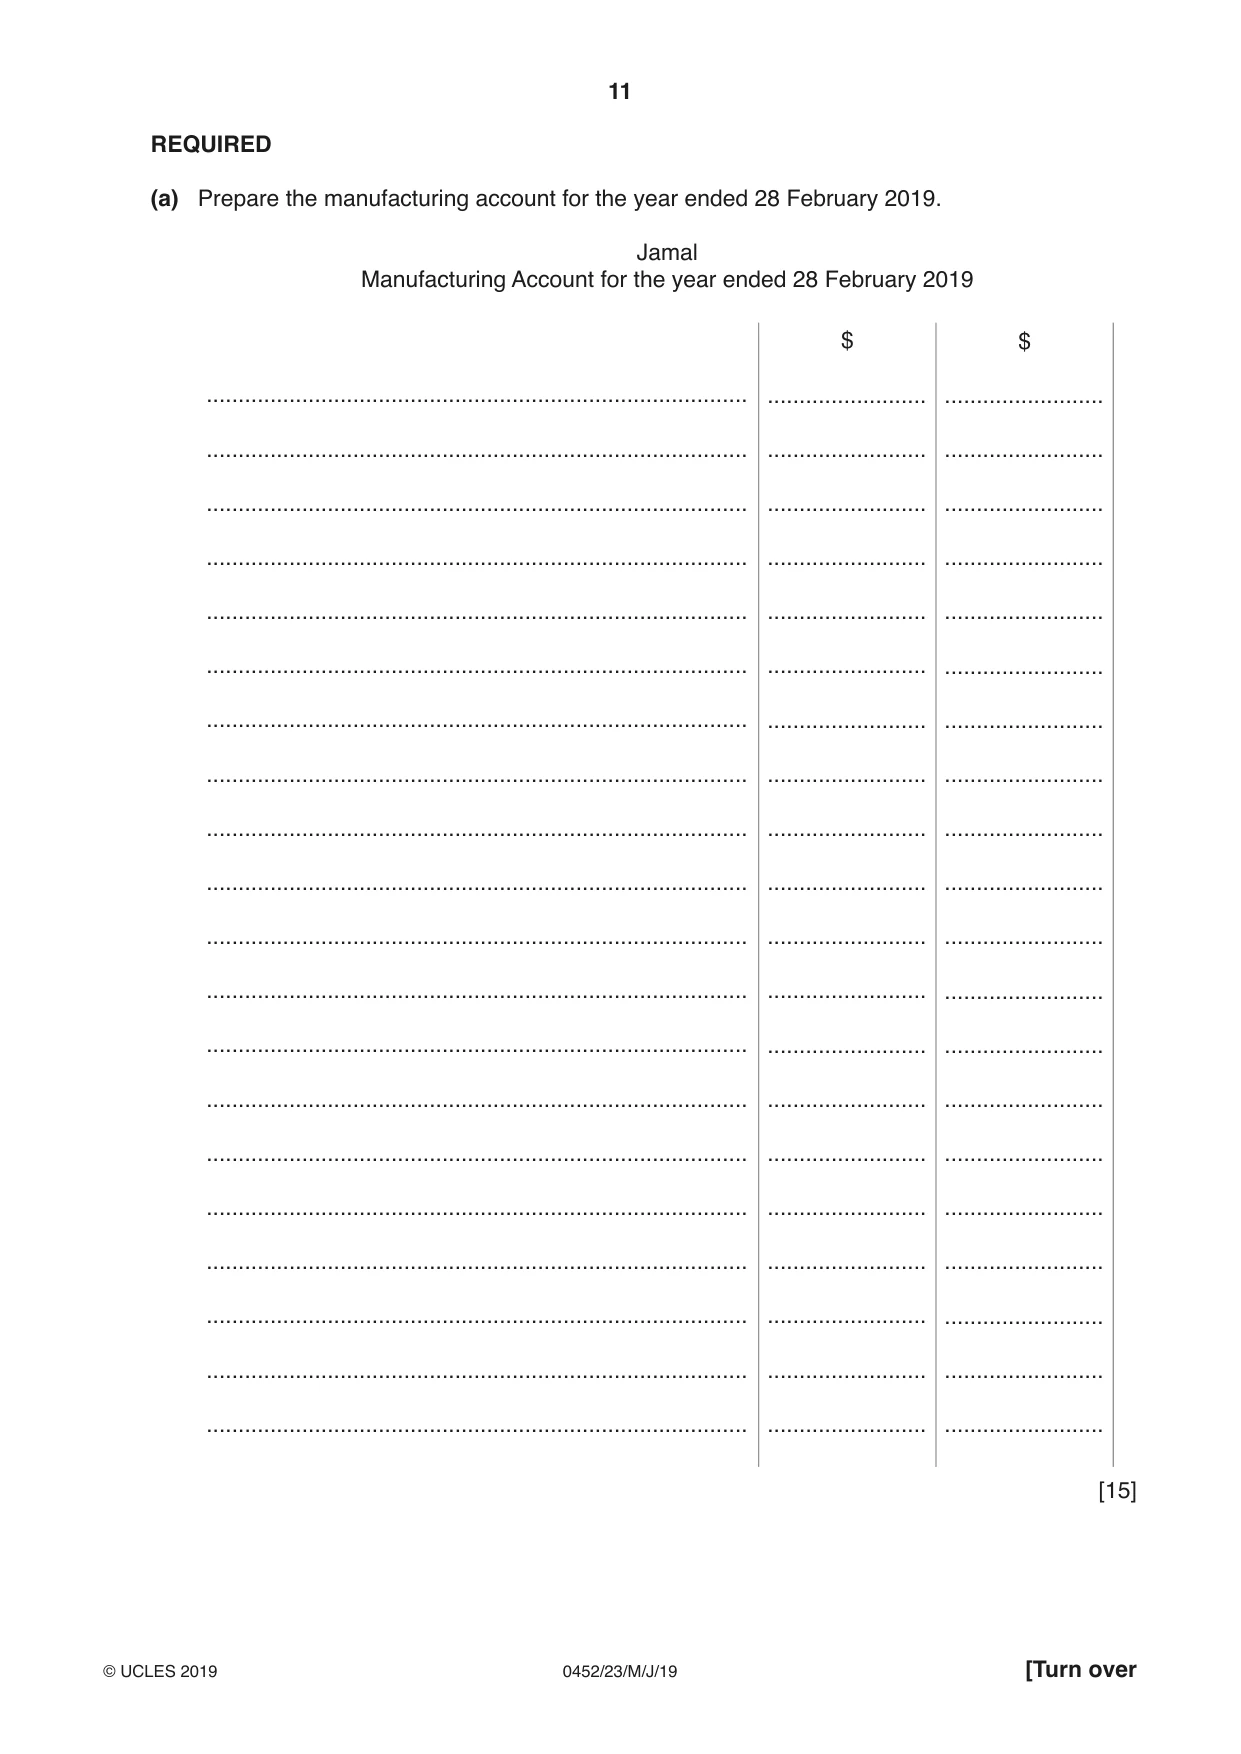
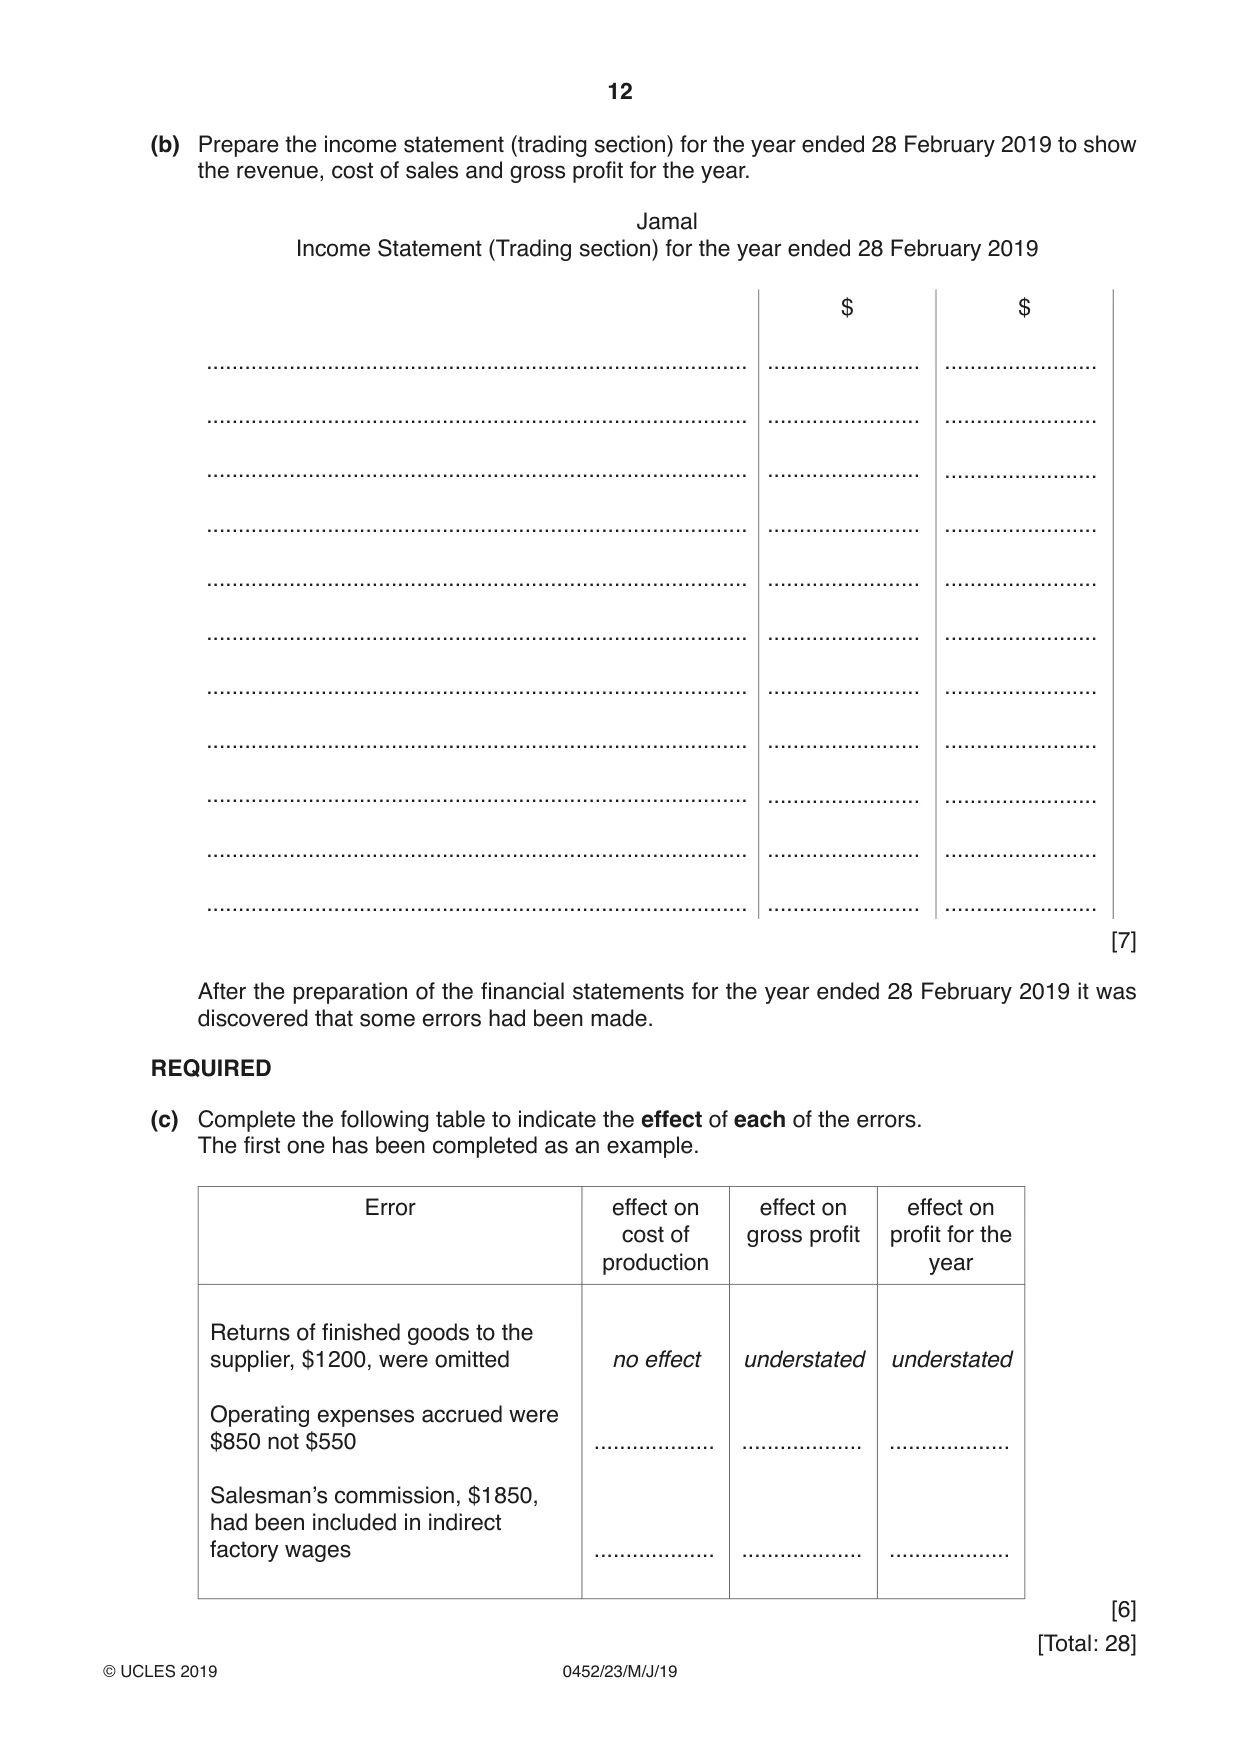
3 Jamal opened a toy factory on 1 March 2018. On that date he purchased the following non-current assets. $ Premises 100 000 Factory machinery 44 000 Loose tools for factory 1 650 Office fixtures and fittings 15 450 Jamal decided on the following depreciation policy. 1 No depreciation would be charged on premises. 2 Factory machinery and office fixtures and fittings would be depreciated by 20% per annum using the straight line (equal instalment) method of depreciation. 3 Loose tools would be revalued at the end of each financial year. Jamal provided the following information. $ For the year ended 28 February 2019 Purchases of raw materials 45 680 Purchases of finished goods 12 400 Purchase returns of raw materials 1 030 Carriage on raw materials 3 240 Direct factory wages 29 750 Indirect factory wages 18 750 Office and sales staff wages 25 360 Operating expenses 8 250 Insurance (for 16 months to 30 June 2019) 3 200 Sales returns 2 250 Revenue ? At 28 February 2019 Inventory of raw materials 4 150 Inventory of work in progress 3 310 Inventory of finished goods 8 900 Loose tools at valuation 1 320 Direct factory wages accrued 3 040 Operating expenses accrued 550 The operating expenses and the insurance are to be apportioned 75% to the factory and 25% to the office. Jamal’s mark-up is 25%. REQUIRED (a) Prepare the manufacturing account for the year ended Jamal Manufacturing Account for the year en ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... ..................................................................................... (b) Prepare the income statement (trading section) for the year ended 28 February 2019 to show the revenue, cost of sales and gross profit for the year. Jamal Income Statement (Trading section) for the year ended 28 February 2019 $ $ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ ..................................................................................... ........................ ........................ [7] After the preparation of the financial statements for the year ended 28 February 2019 it was discovered that some errors had been made. REQUIRED (c) Complete the following table to indicate the effect of each of the errors. The first one has been completed as an example. Error effect on effect on effect on cost of gross profit profit for the production year Returns of finished goods to the supplier, $1 200, were omitted no effect understated understated Operating expenses accrued were $850 not $550 ................... ................... ................... Salesman’s commission, $1 850, had been included in indirect factory wages ................... ................... ................... [6] [Total: 28] PLEASE TURN OVER
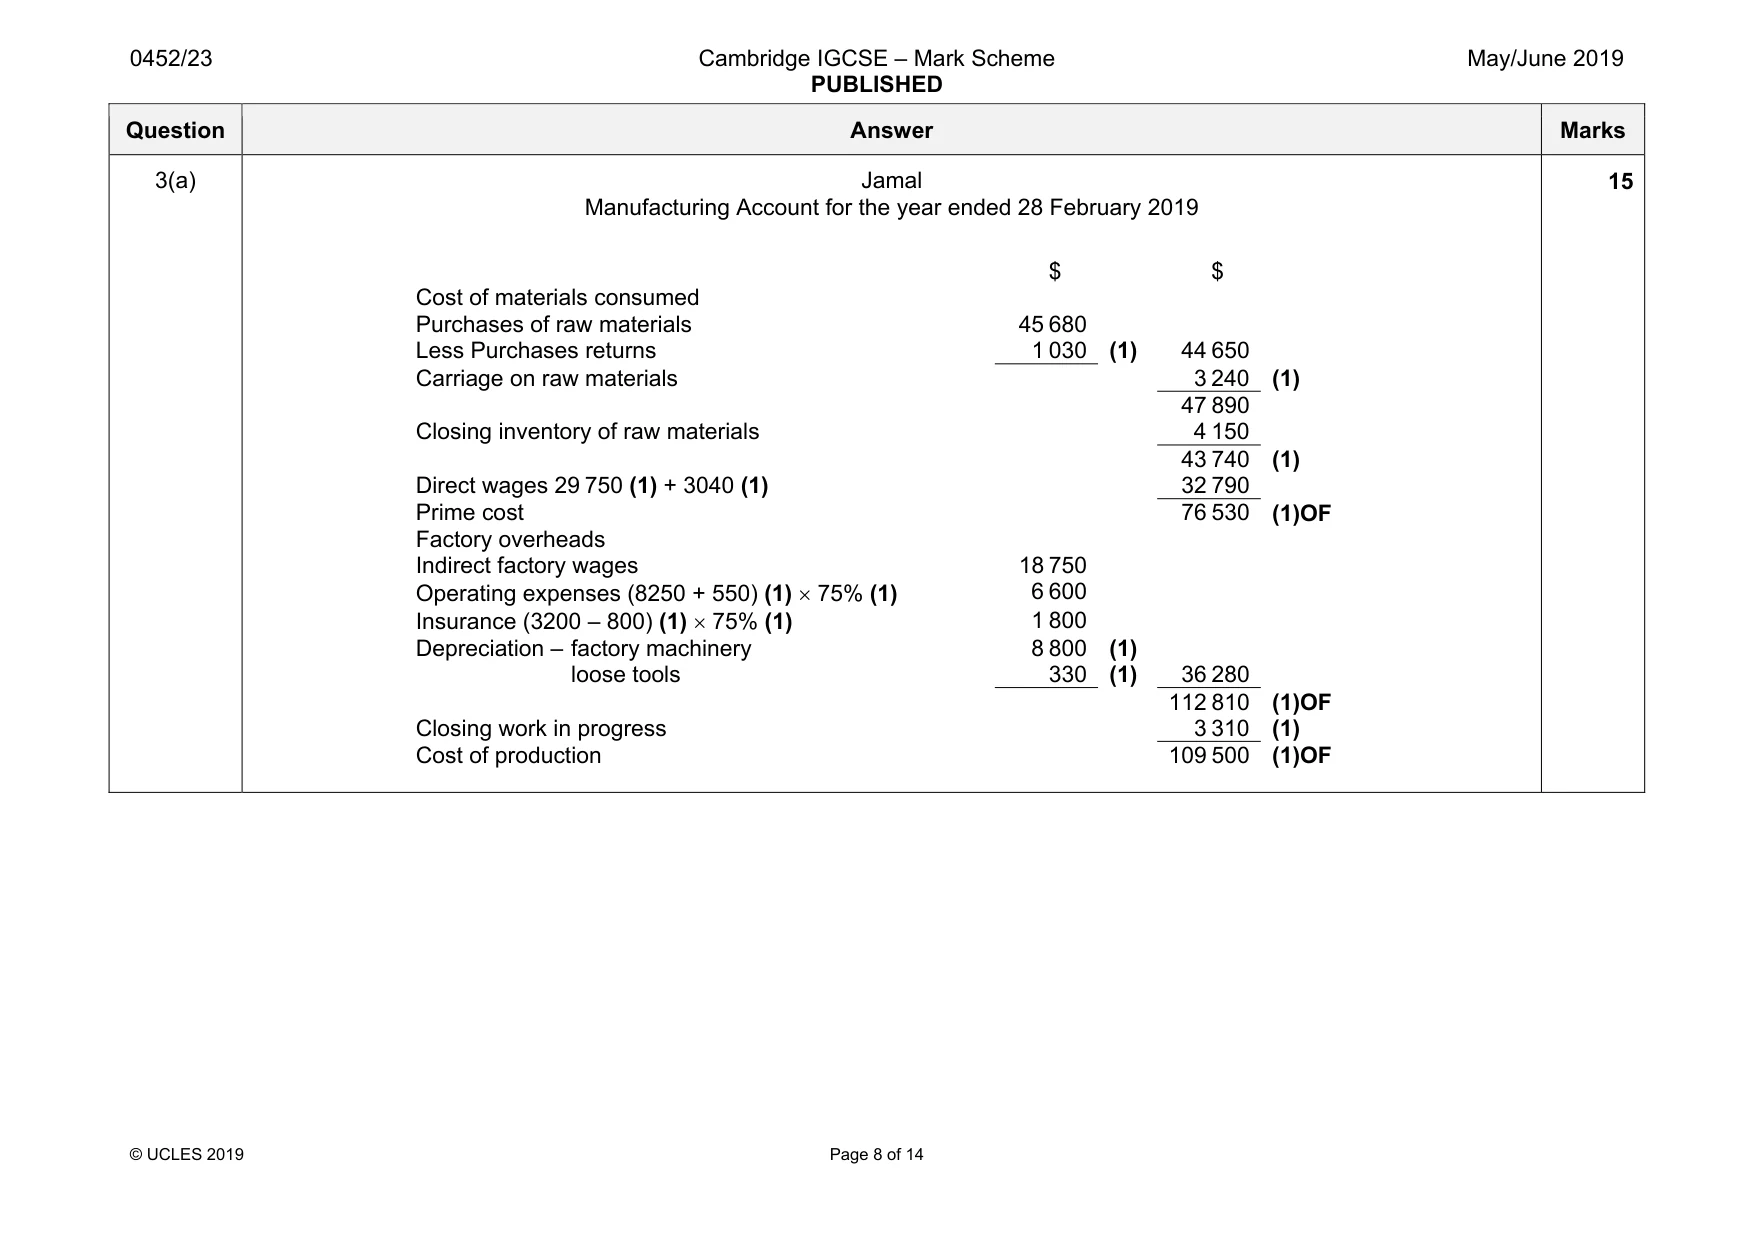
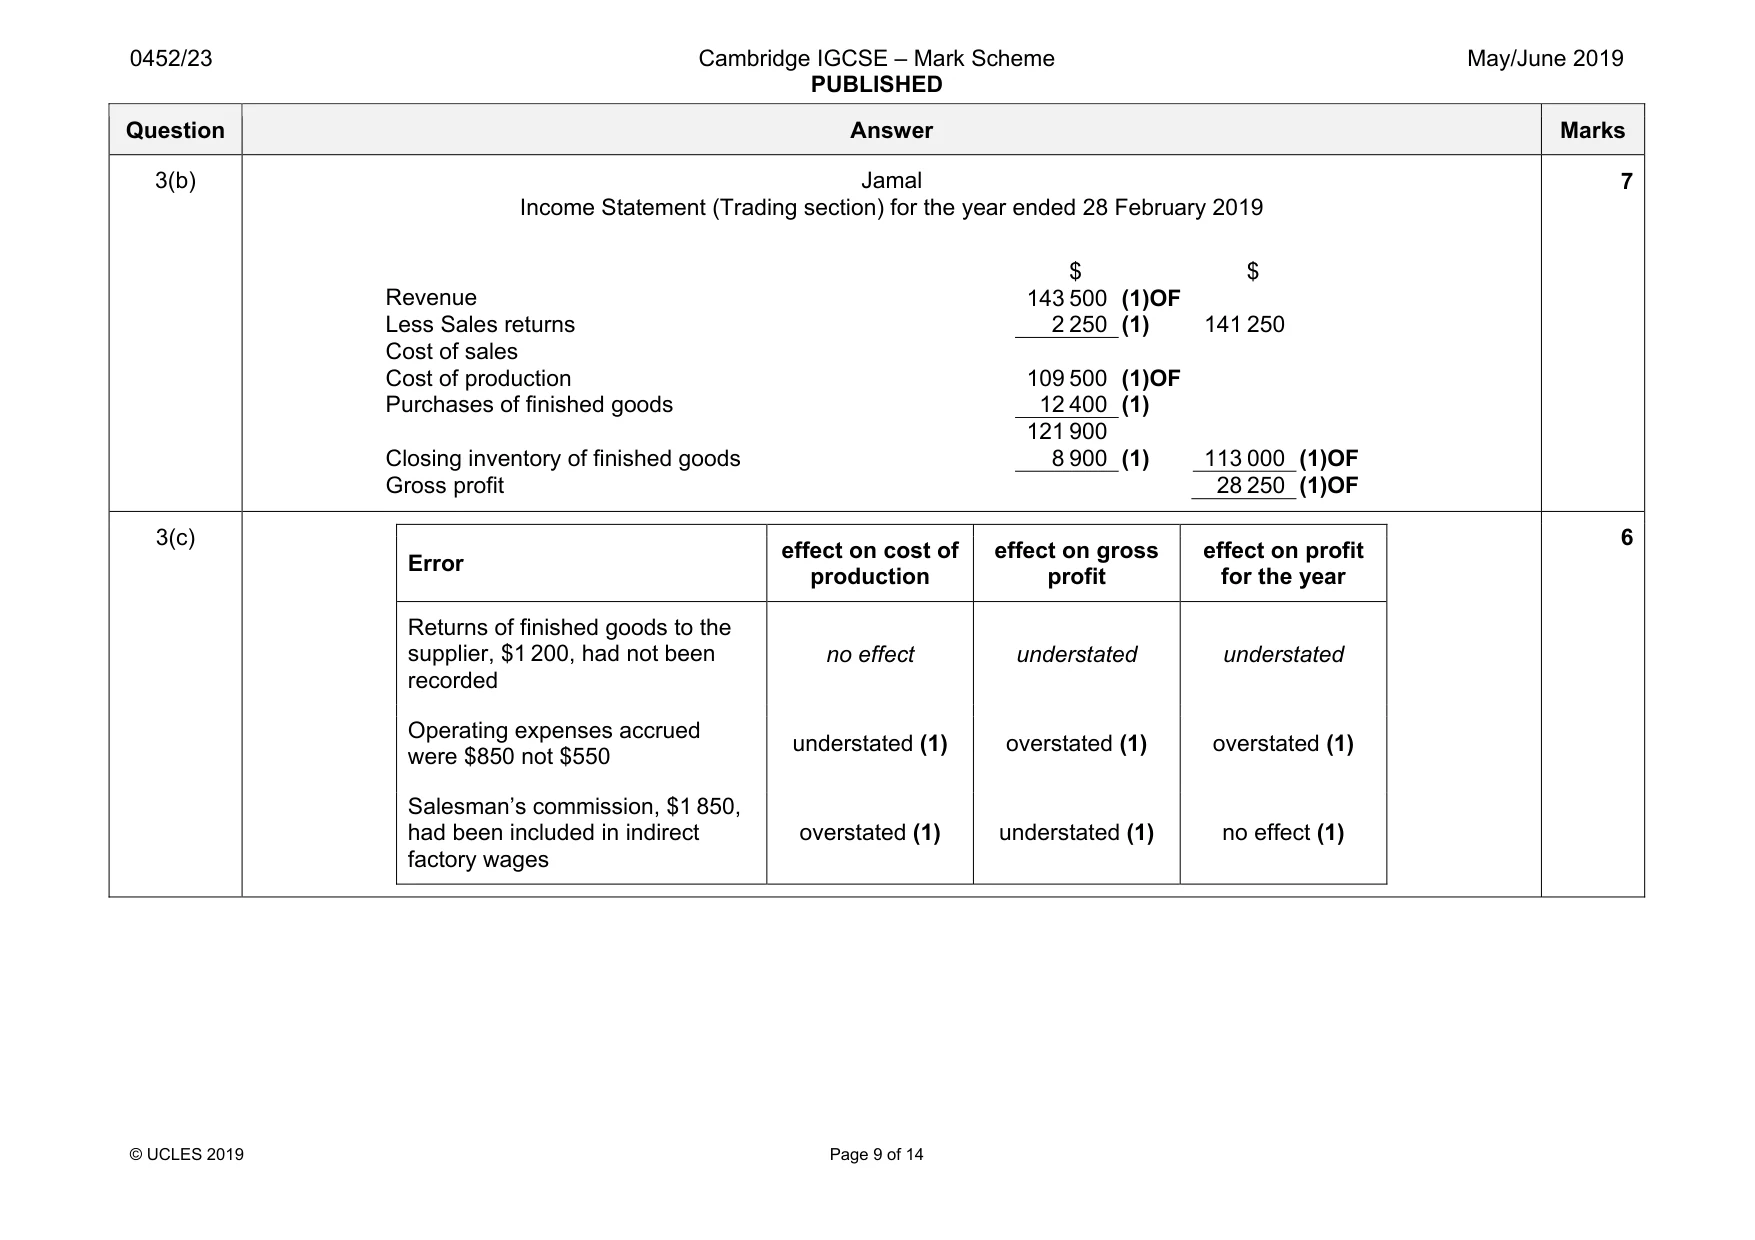
Mark scheme: 3(a) Jamal Manufacturing Account for the year ended 28 February 2019 $00 $00 Cost of materials consumed Purchases of raw materials 45 680 Less Purchases returns 1 030 (1) 44 650 Carriage on raw materials 3 240 (1) 47 890 Closing inventory of raw materials 4 150 43 740 (1) Direct wages 29 750 (1) + 3040 (1) 32 790 Prime cost 76 530 (1)OF Factory overheads Indirect factory wages 18 750 Operating expenses (8250 + 550) (1) × 75% (1) 6 600 Insurance (3200 – 800) (1) × 75% (1) 1 800 Depreciation – factory machinery 8 800 (1) loose tools 330 (1) 36 280 112 810 (1)OF Closing work in progress 3 310 (1) Cost of production 109 500 (1)OF 15 Question Answer Marks 3(b) Jamal Income Statement (Trading section) for the year ended 28 February 2019 $00 $00 Revenue 143 500 (1)OF Less Sales returns 2 250 (1) 141 250 Cost of sales Cost of production 109 500 (1)OF Purchases of finished goods 12 400 (1) 121 900 Closing inventory of finished goods 8 900 (1) 113 000 (1)OF Gross profit 28 250 (1)OF 7 3(c) Error effect on cost of production effect on gross profit effect on profit for the year Returns of finished goods to the supplier, $1 200, had not been recorded no effect understated understated Operating expenses accrued were $850 not $550 understated (1) overstated (1) overstated (1) Salesman’s commission, $1 850, had been included in indirect factory wages overstated (1) understated (1) no effect (1) 6
Q4 · Shen is a retailer of men’s clothes
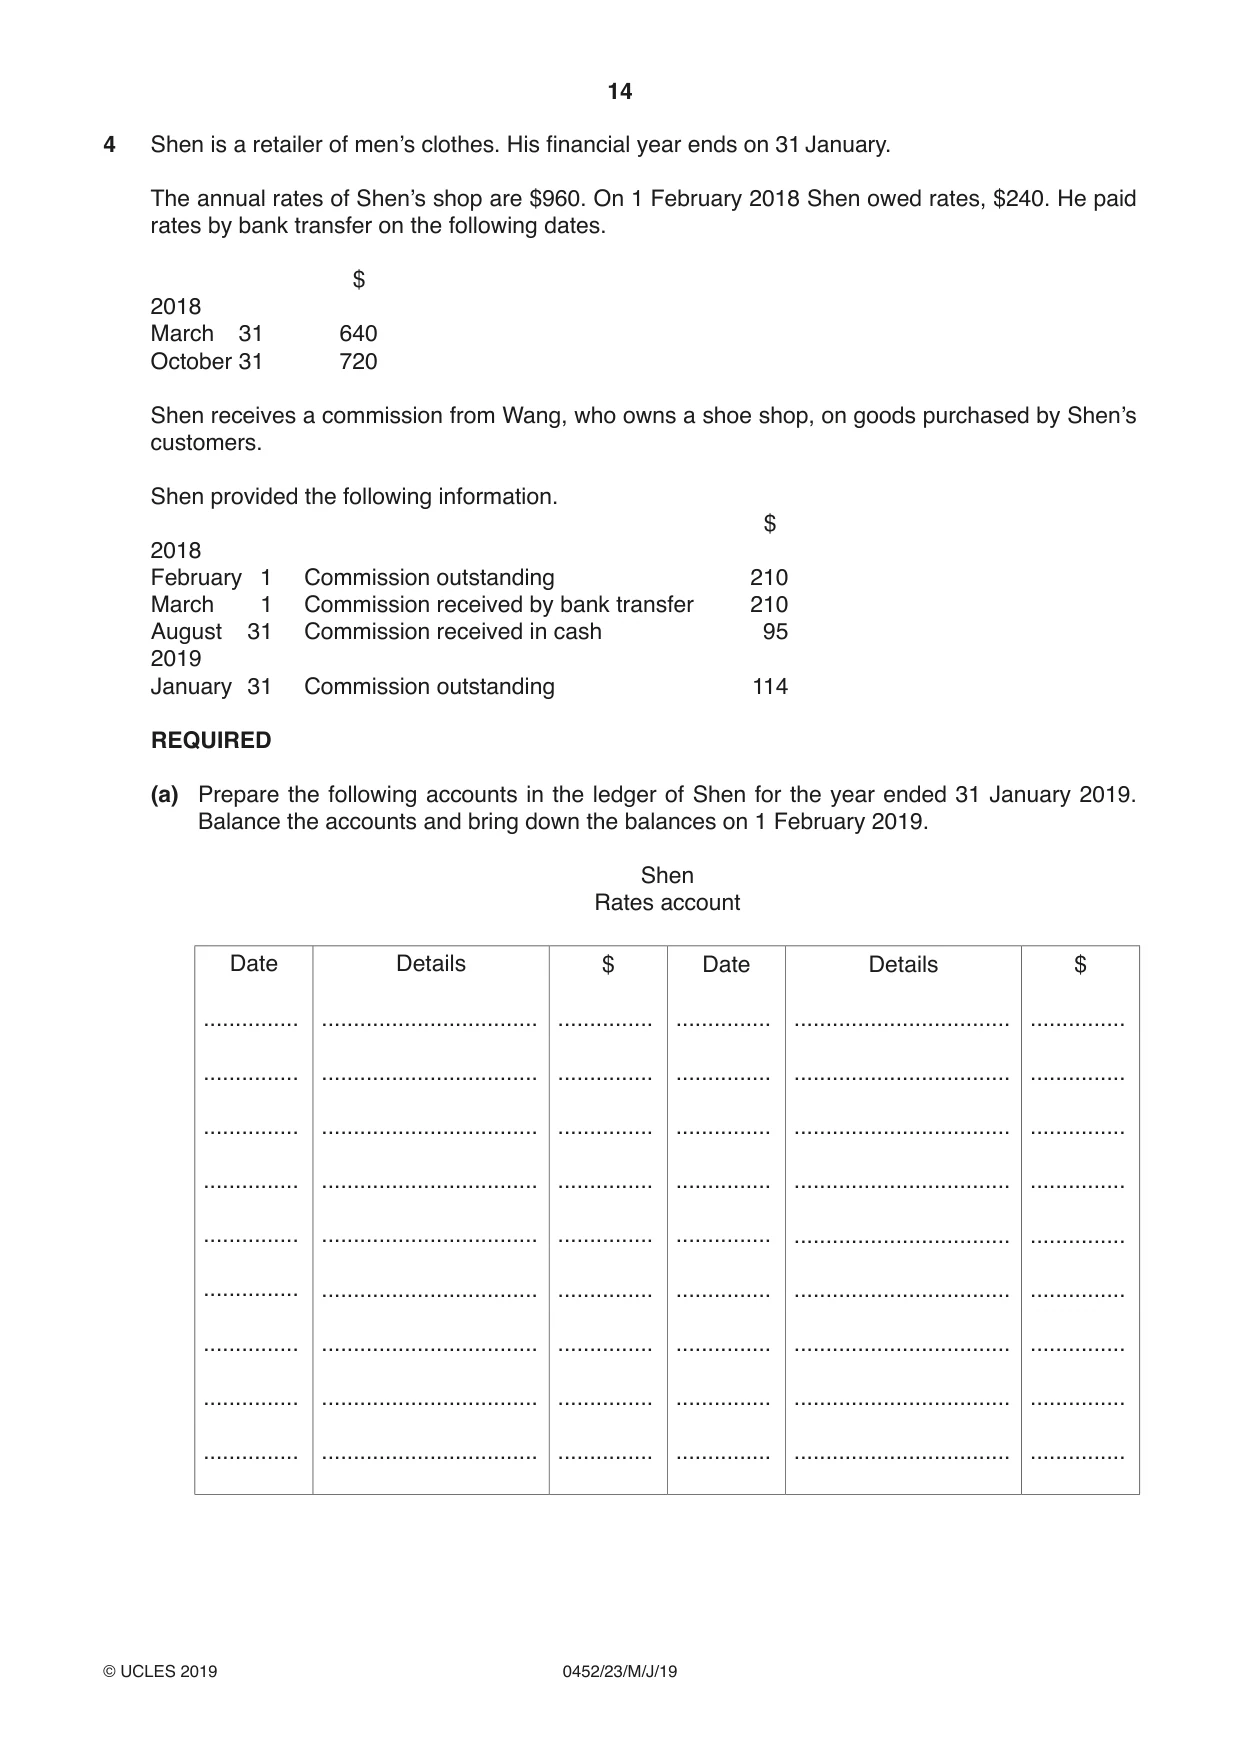
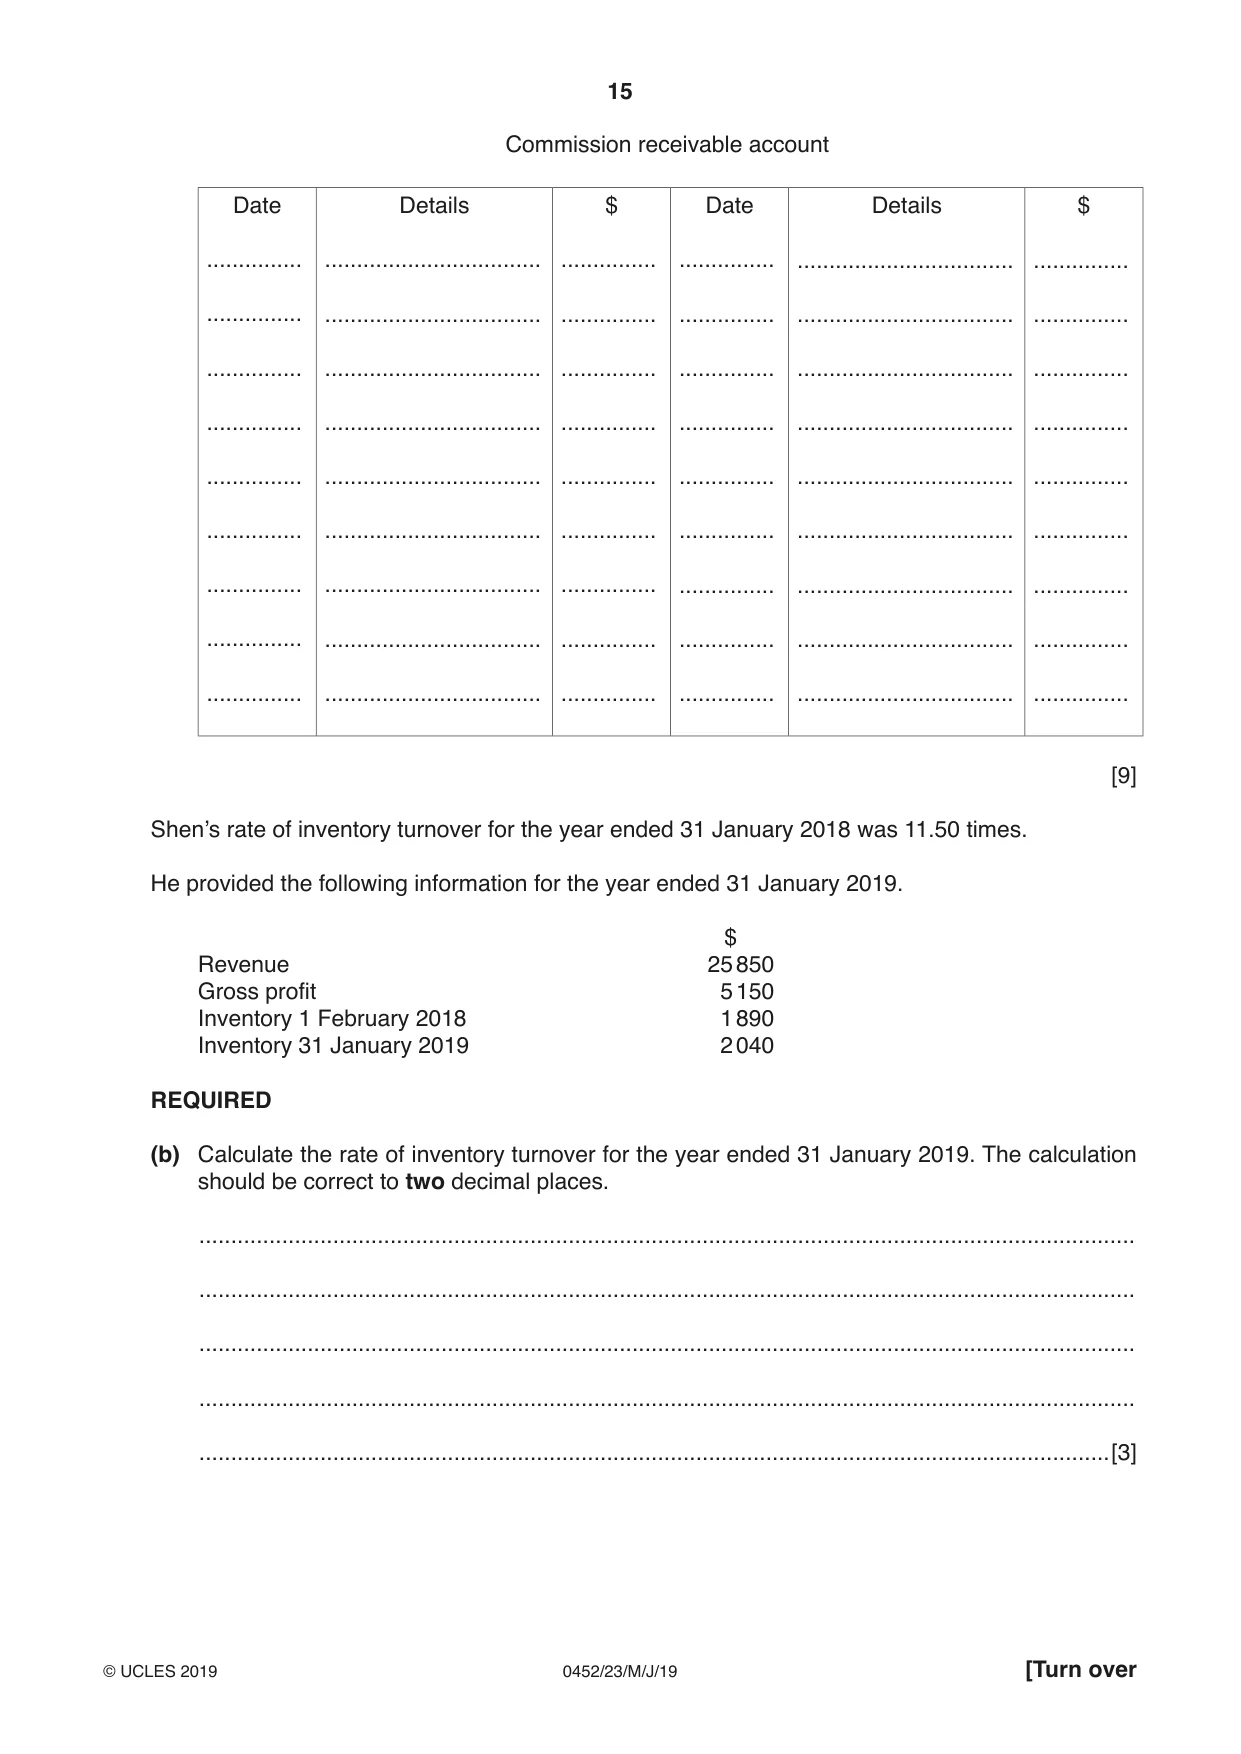
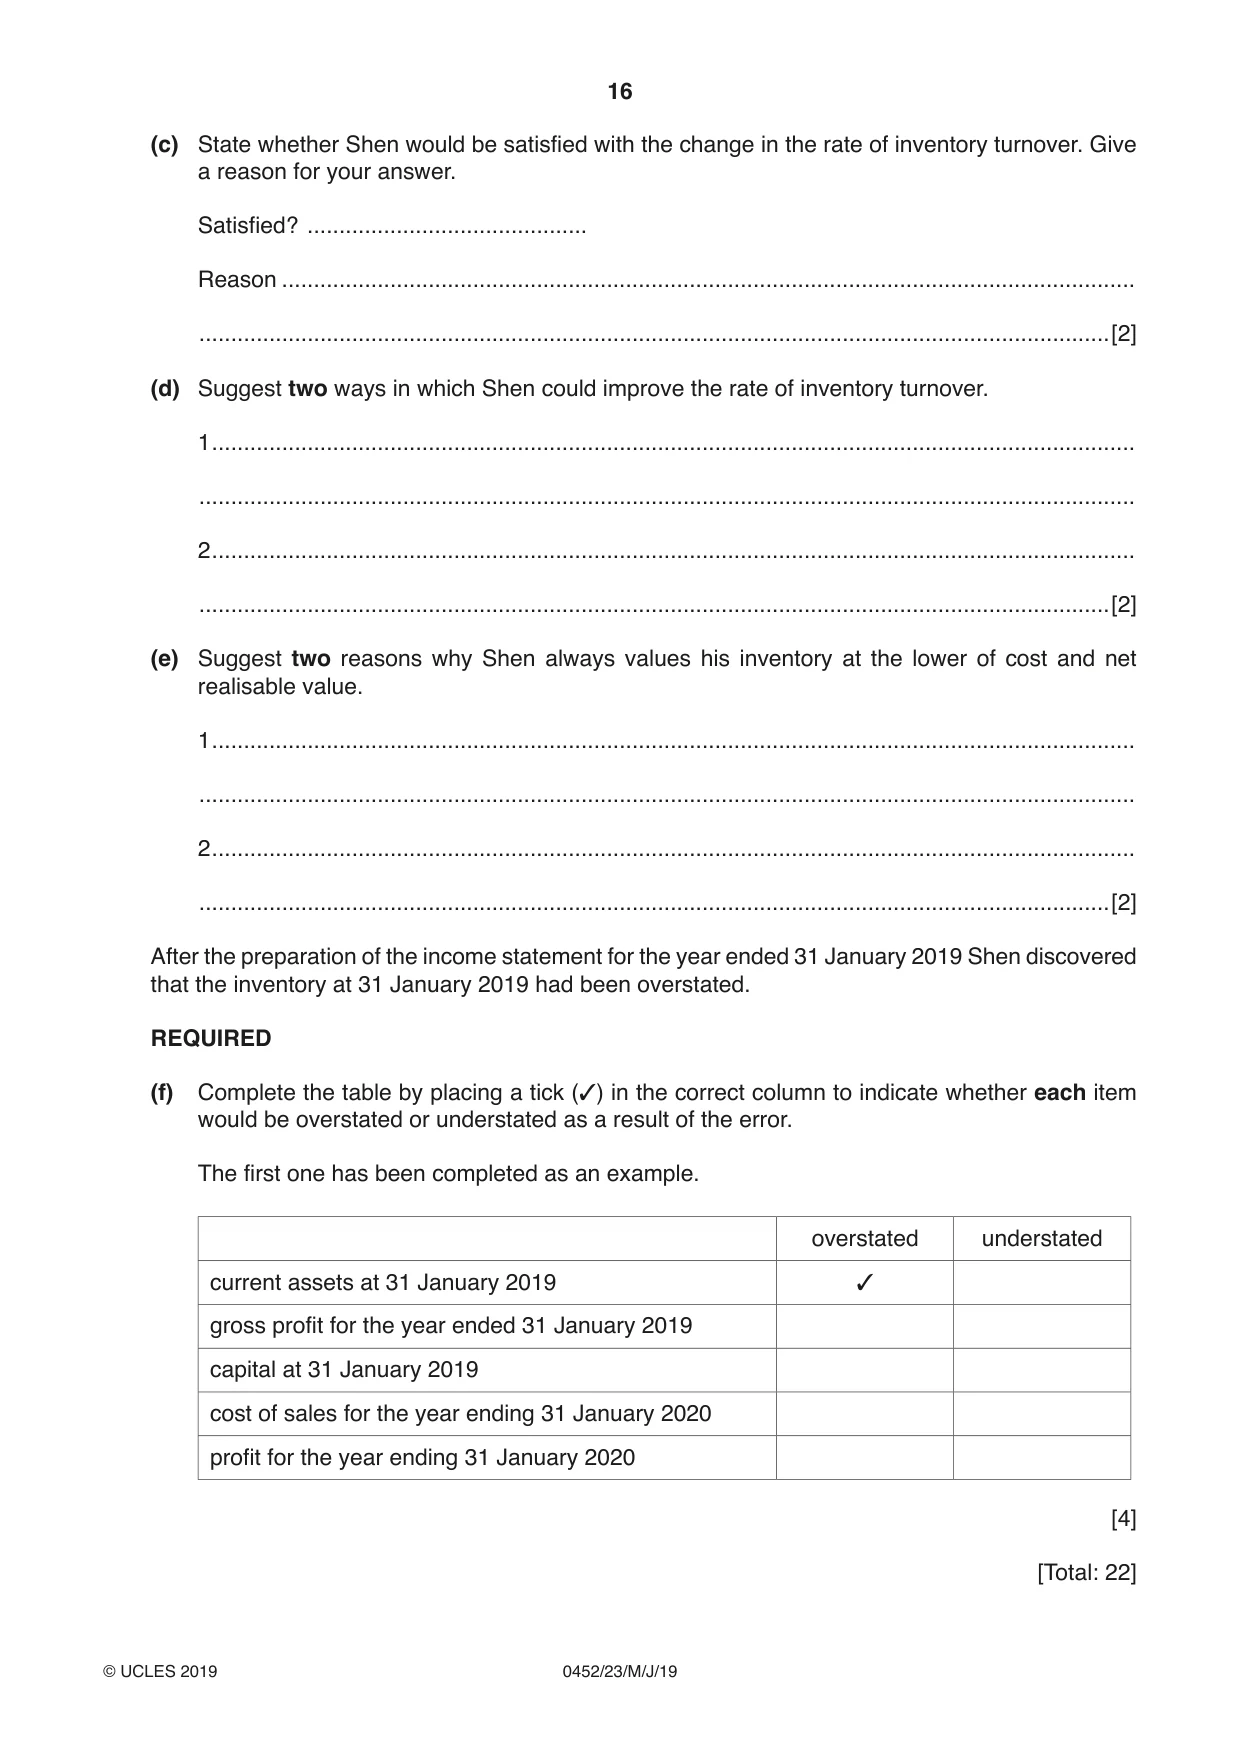
4 Shen is a retailer of men’s clothes. His financial year ends on 31 January. The annual rates of Shen’s shop are $960. On 1 February 2018 Shen owed rates, $240. He paid rates by bank transfer on the following dates. $ 2018 March 31 640 October 31 720 Shen receives a commission from Wang, who owns a shoe shop, on goods purchased by Shen’s customers. Shen provided the following information. $ 2018 February 1 Commission outstanding 210 March 1 Commission received by bank transfer 210 August 31 Commission received in cash 95 2019 January 31 Commission outstanding 114 REQUIRED (a) Prepare the following accounts in the ledger of Shen for the year ended 31 January 2019. Balance the accounts and bring down the balances on 1 February 2019. Shen Rates account Date Details $ Date Details $ ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... Commission receivable account Date Details $ Date Details $ ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... ............... .................................. ............... [9] Shen’s rate of inventory turnover for the year ended 31 January 2018 was 11.50 times. He provided the following information for the year ended 31 January 2019. $ Revenue 25 850 Gross profit 5 150 Inventory 1 February 2018 1 890 Inventory 31 January 2019 2 040 REQUIRED (b) Calculate the rate of inventory turnover for the year ended 31 January 2019. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[3] (c) State whether Shen would be satisfied with the change in the rate of inventory turnover. Give a reason for your answer. Satisfied? ............................................ Reason ...................................................................................................................................... ...............................................................................................................................................[2] (d) Suggest two ways in which Shen could improve the rate of inventory turnover. 1 ................................................................................................................................................. ................................................................................................................................................... 2 ................................................................................................................................................. ...............................................................................................................................................[2] (e) Suggest two reasons why Shen always values his inventory at the lower of cost and net realisable value. 1 ................................................................................................................................................. ................................................................................................................................................... 2 ................................................................................................................................................. ...............................................................................................................................................[2] After the preparation of the income statement for the year ended 31 January 2019 Shen discovered that the inventory at 31 January 2019 had been overstated. REQUIRED (f) Complete the table by placing a tick (✓) in the correct column to indicate whether each item would be overstated or understated as a result of the error. The first one has been completed as an example. overstated understated ✓ current assets at 31 January 2019 gross profit for the year ended 31 January 2019 capital at 31 January 2019 cost of sales for the year ending 31 January 2020 profit for the year ending 31 January 2020 [4] [Total: 22]
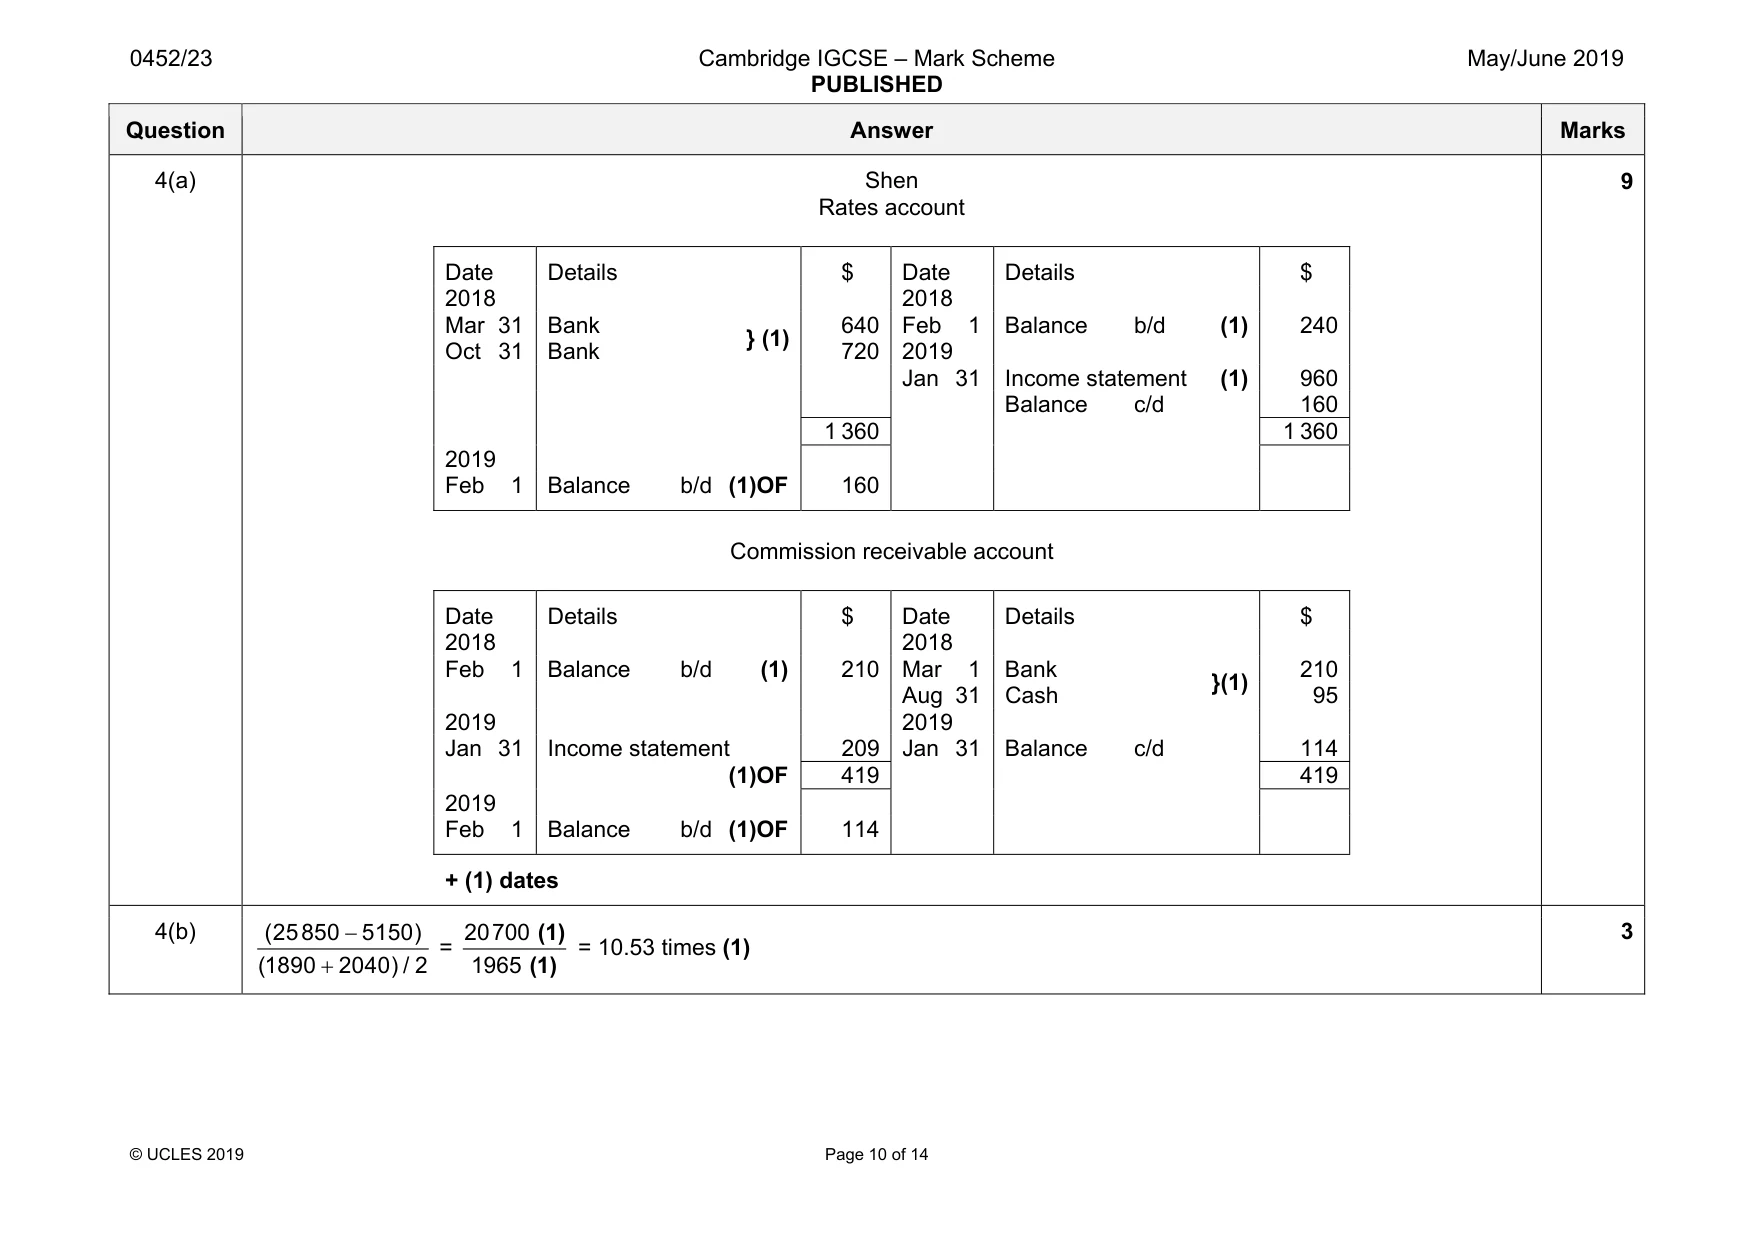
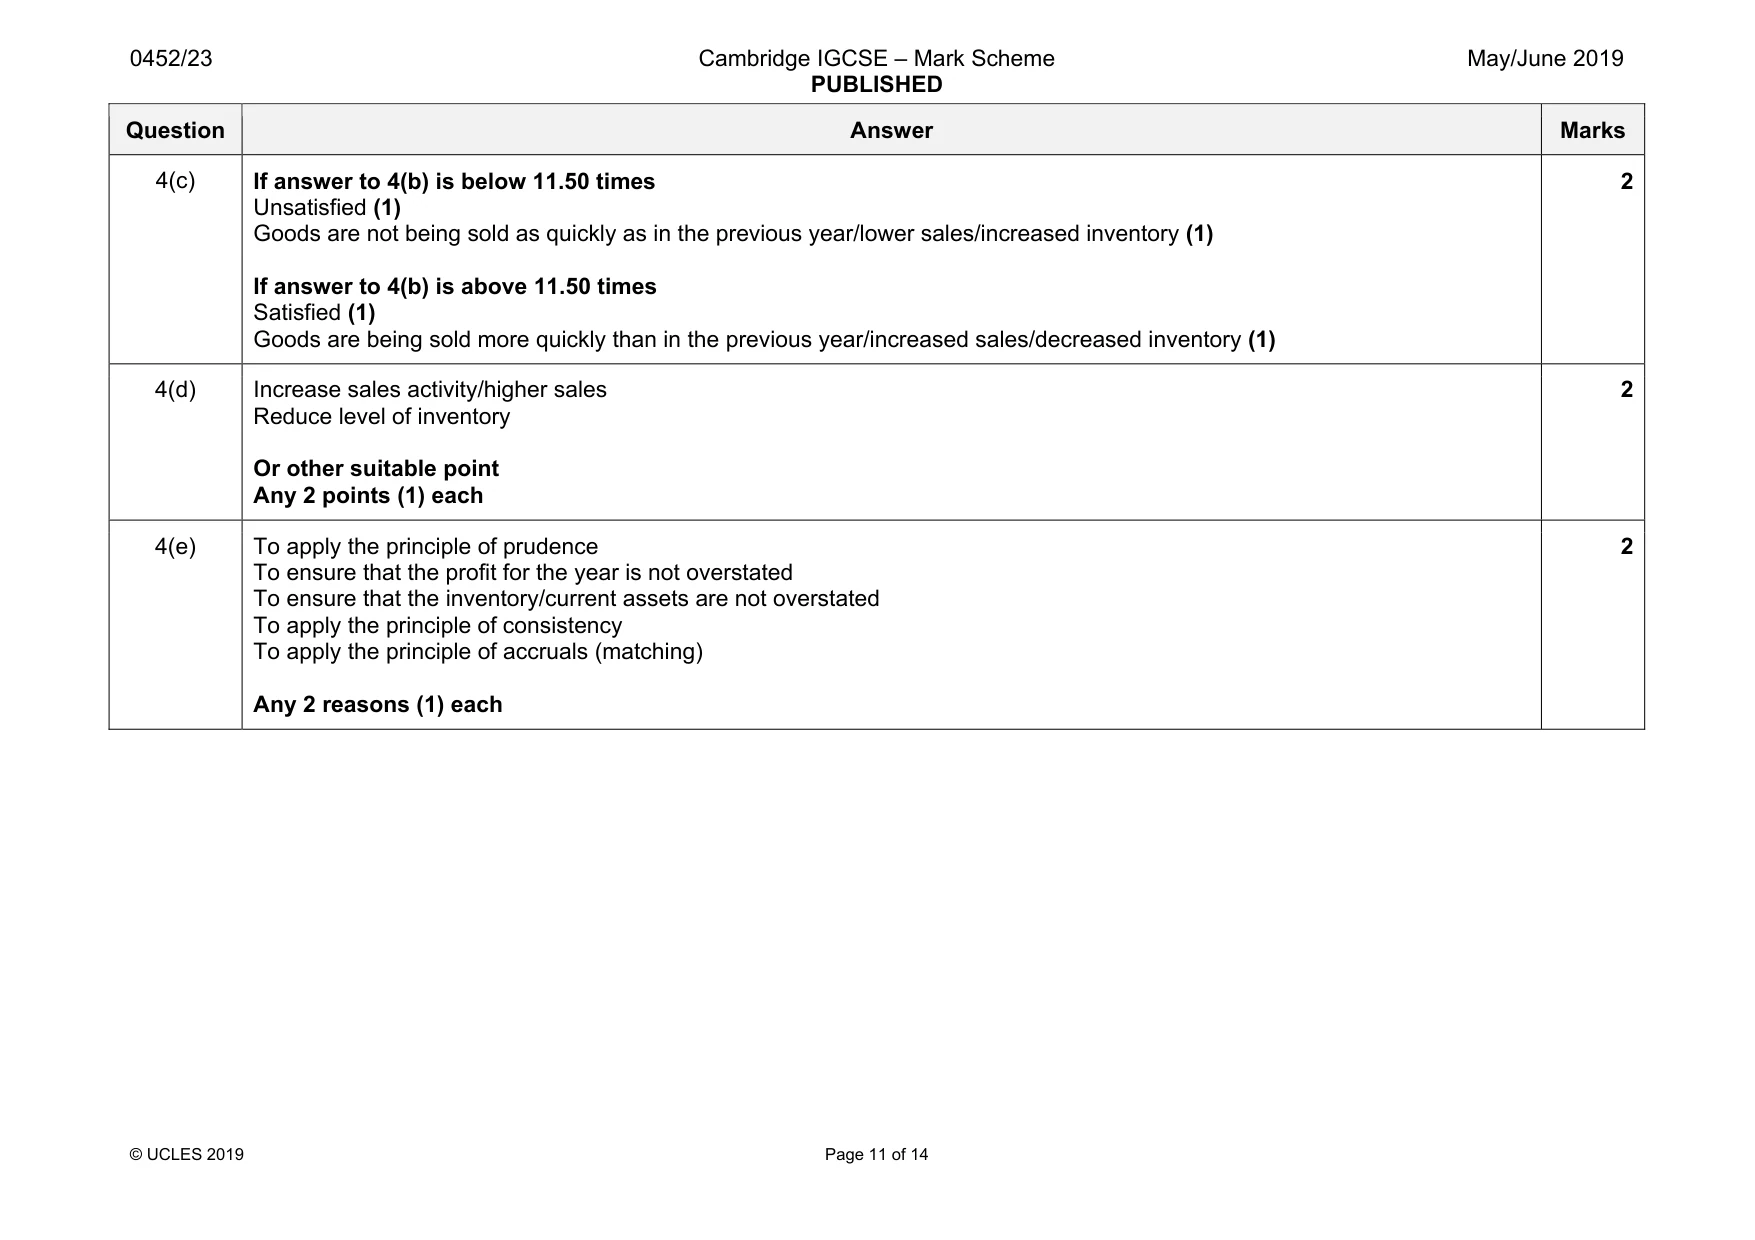
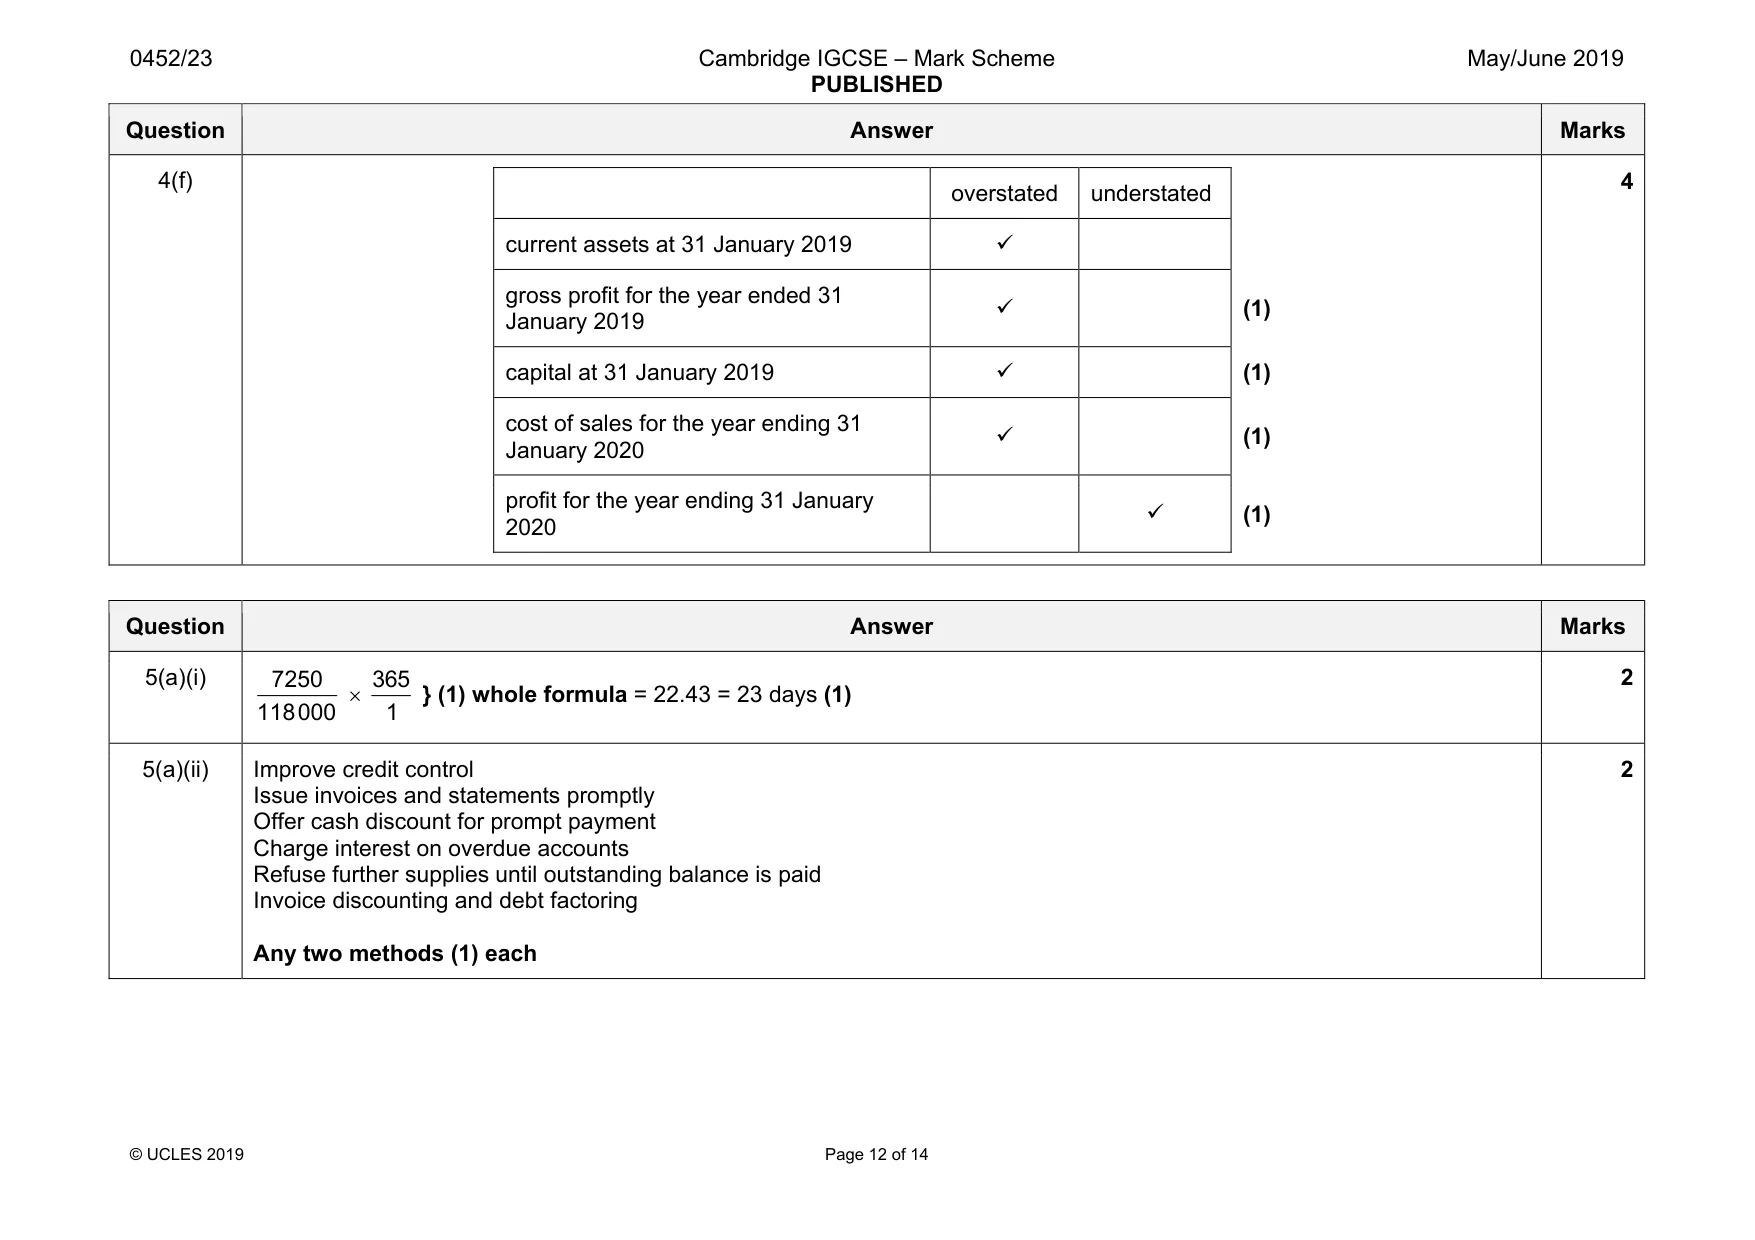
Mark scheme: 4(a) Shen Rates account Date Details $00 Date Details $00 2018 2018 Mar 31 Bank } (1) 640 Feb 1 Balance b/d (1) 240 Oct 31 Bank 720 2019 Jan 31 Income statement (1) 960 Balance c/d 160 1 360 1 360 2019 Feb 1 Balance b/d (1)OF 160 Commission receivable account Date Details $00 Date Details $00 2018 2018 Feb 1 Balance b/d (1) 210 Mar 1 Bank }(1) 210 Aug 31 Cash 95 2019 2019 Jan 31 Income statement 209 Jan 31 Balance c/d 114 (1)OF 419 419 2019 Feb 1 Balance b/d (1)OF 114 + (1) dates 9 4(b) (25850 5150) (1890 2040) / 2 − + = 20700 1965 (1) (1) = 10.53 times (1) 3 Question Answer Marks 4(c) If answer to 4(b) is below 11.50 times Unsatisfied (1) Goods are not being sold as quickly as in the previous year/lower sales/increased inventory (1) If answer to 4(b) is above 11.50 times Satisfied (1) Goods are being sold more quickly than in the previous year/increased sales/decreased inventory (1) 2 4(d) Increase sales activity/higher sales Reduce level of inventory Or other suitable point Any 2 points (1) each 2 4(e) To apply the principle of prudence To ensure that the profit for the year is not overstated To ensure that the inventory/current assets are not overstated To apply the principle of consistency To apply the principle of accruals (matching) Any 2 reasons (1) each 2 Question Answer Marks 4(f) overstated understated current assets at 31 January 2019 9 gross profit for the year ended 31 January 2019 9 (1) capital at 31 January 2019 9 (1) cost of sales for the year ending 31 January 2020 9 (1) profit for the year ending 31 January 2020 9 (1) 4
Q5 · Myra is a trader
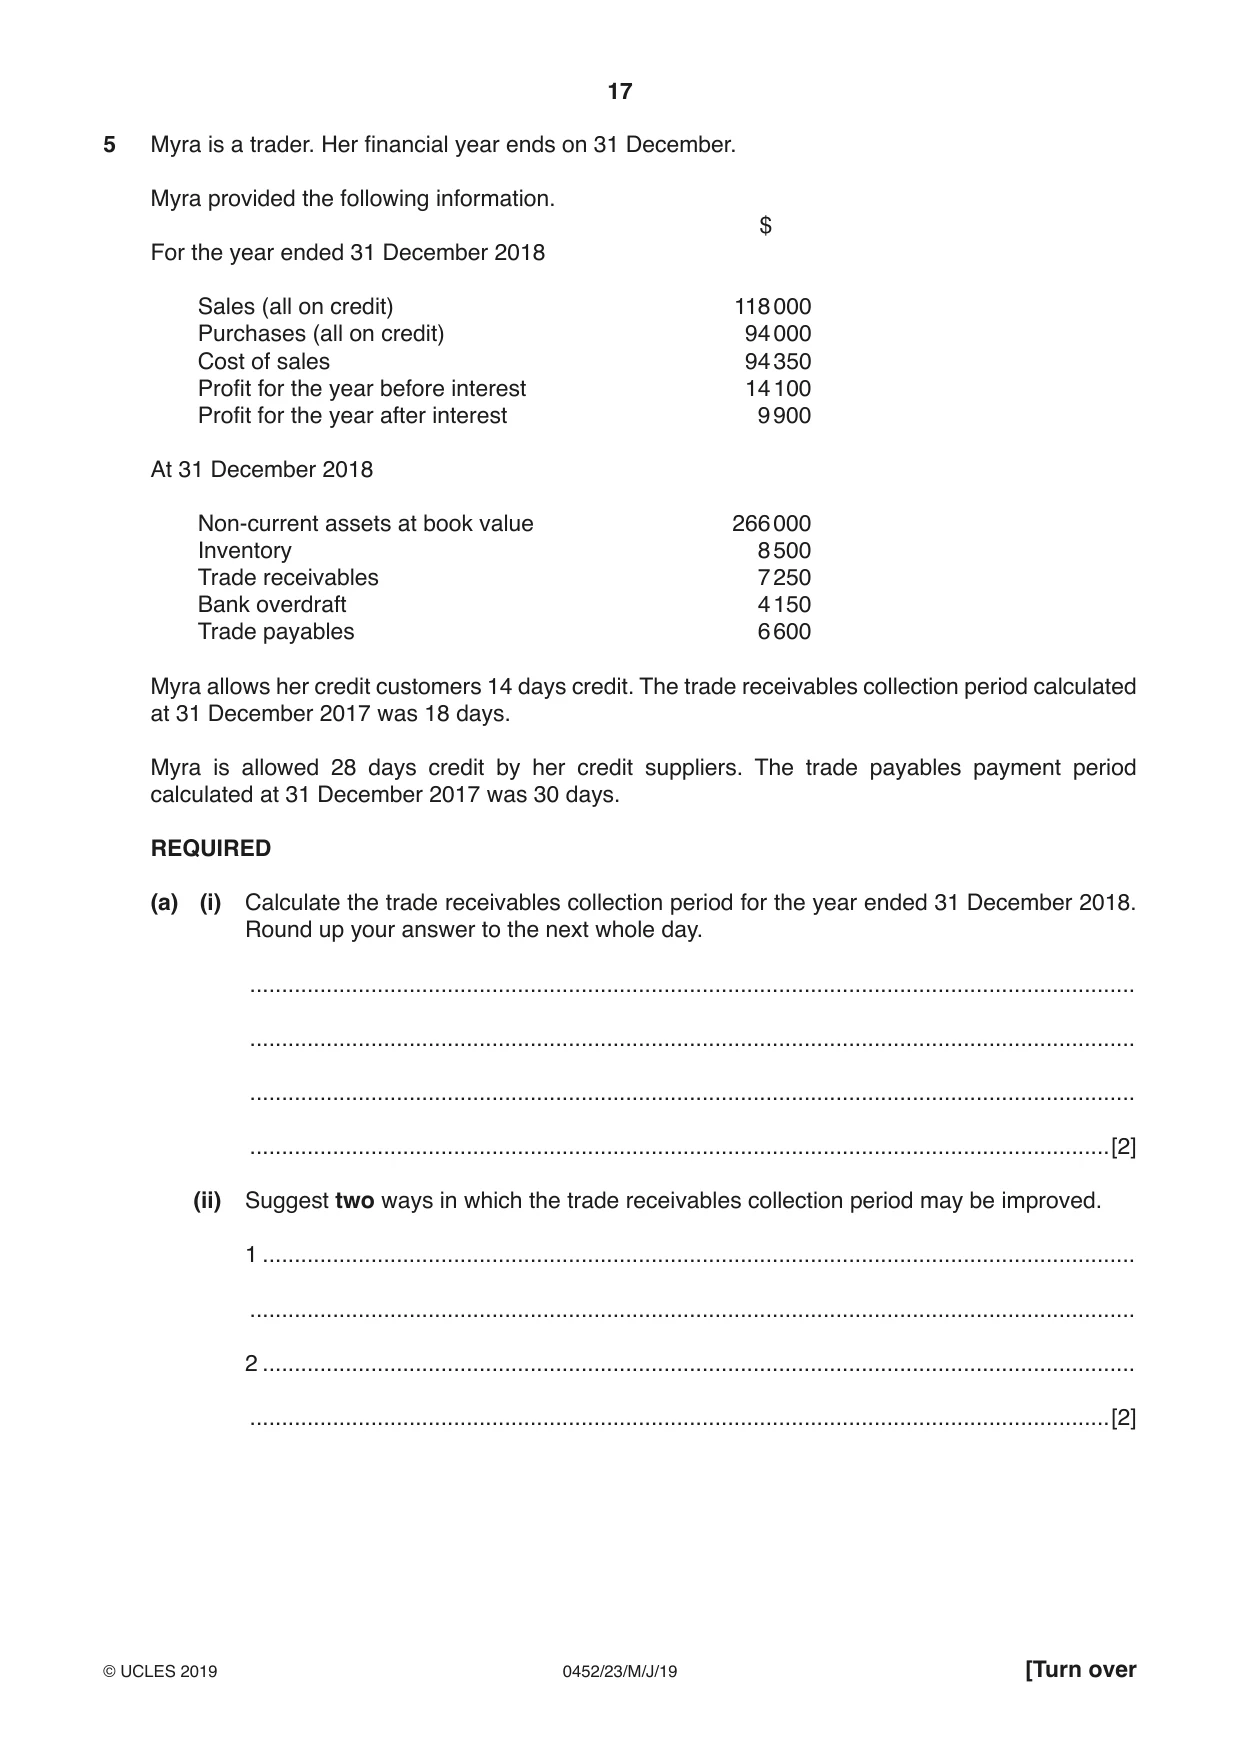
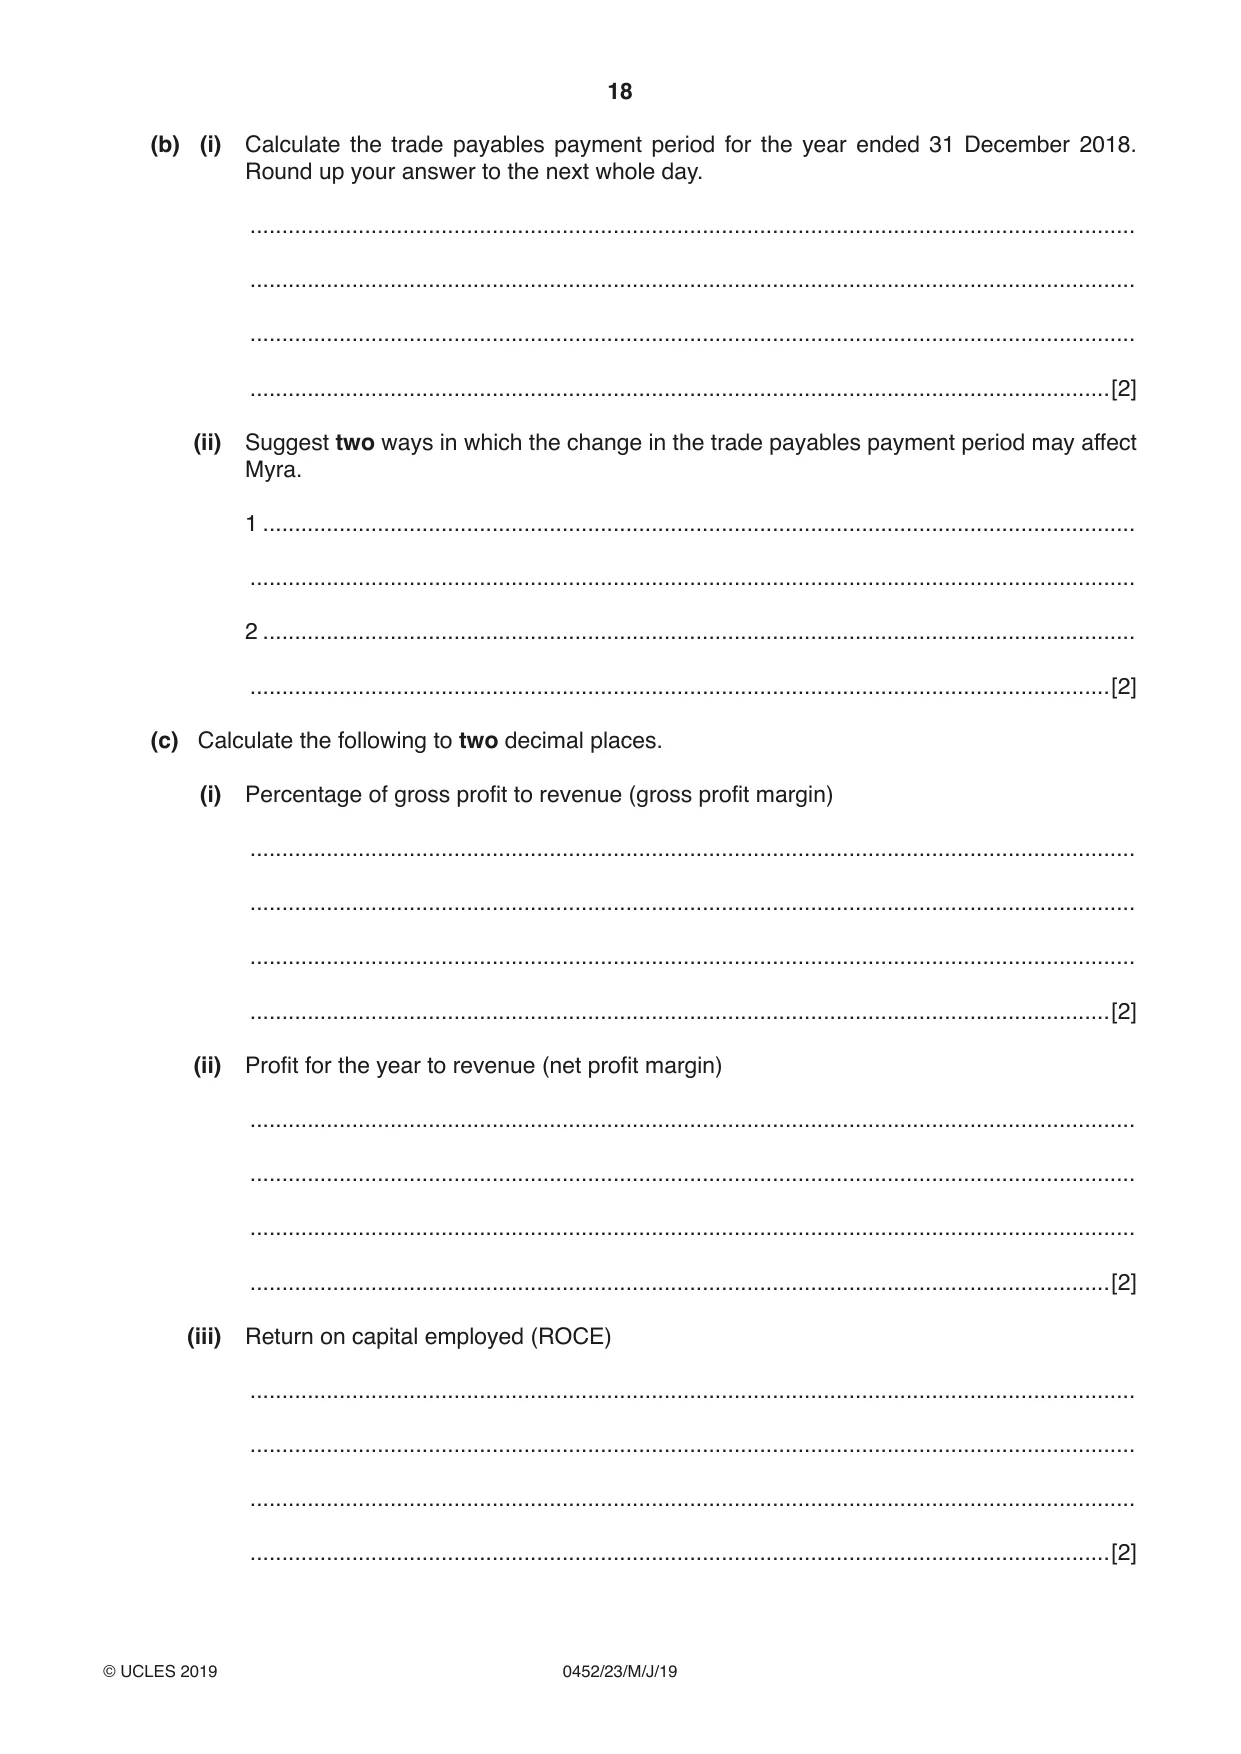
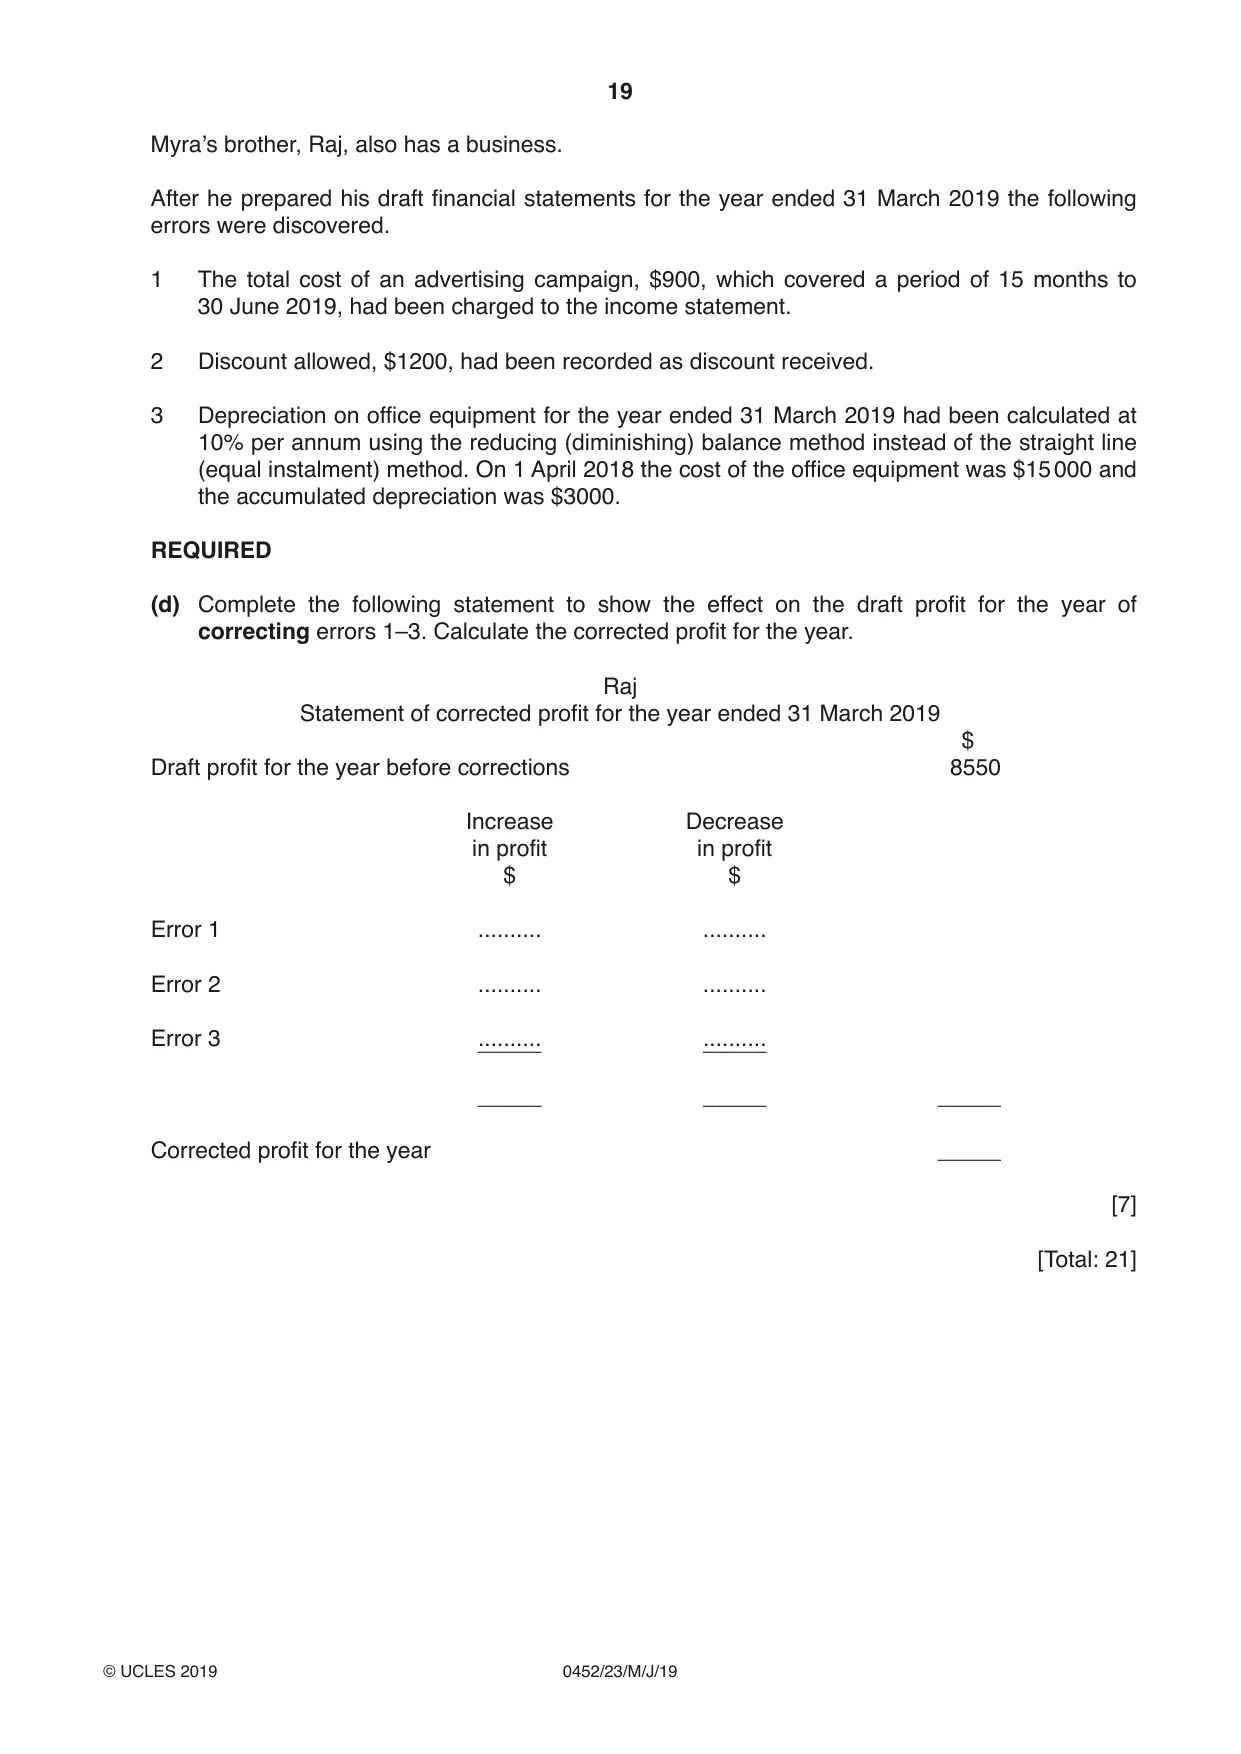
5 Myra is a trader. Her financial year ends on 31 December. Myra provided the following information. $ For the year ended 31 December 2018 Sales (all on credit) 118 000 Purchases (all on credit) 94 000 Cost of sales 94 350 Profit for the year before interest 14 100 Profit for the year after interest 9 900 At 31 December 2018 Non-current assets at book value 266 000 Inventory 8 500 Trade receivables 7 250 Bank overdraft 4 150 Trade payables 6 600 Myra allows her credit customers 14 days credit. The trade receivables collection period calculated at 31 December 2017 was 18 days. Myra is allowed 28 days credit by her credit suppliers. The trade payables payment period calculated at 31 December 2017 was 30 days. REQUIRED (a) (i) Calculate the trade receivables collection period for the year ended 31 December 2018. Round up your answer to the next whole day. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Suggest two ways in which the trade receivables collection period may be improved. 1 ......................................................................................................................................... ........................................................................................................................................... 2 ......................................................................................................................................... .......................................................................................................................................[2] (b) (i) Calculate the trade payables payment period for the year ended 31 December 2018. Round up your answer to the next whole day. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Suggest two ways in which the change in the trade payables payment period may affect Myra. 1 ......................................................................................................................................... ........................................................................................................................................... 2 ......................................................................................................................................... .......................................................................................................................................[2] (c) Calculate the following to two decimal places. (i) Percentage of gross profit to revenue (gross profit margin) ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Profit for the year to revenue (net profit margin) ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (iii) Return on capital employed (ROCE) ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] Myra’s brother, Raj, also has a business. After he prepared his draft financial statements for the year ended 31 March 2019 the following errors were discovered. 1 The total cost of an advertising campaign, $900, which covered a period of 15 months to 30 June 2019, had been charged to the income statement. 2 Discount allowed, $1200, had been recorded as discount received. 3 Depreciation on office equipment for the year ended 31 March 2019 had been calculated at 10% per annum using the reducing (diminishing) balance method instead of the straight line (equal instalment) method. On 1 April 2018 the cost of the office equipment was $15 000 and the accumulated depreciation was $3000. REQUIRED (d) Complete the following statement to show the effect on the draft profit for the year of correcting errors 1–3. Calculate the corrected profit for the year. Raj Statement of corrected profit for the year ended 31 March 2019 $ Draft profit for the year before corrections 8550 Increase Decrease in profit in profit $ $ Error 1 .......... .......... Error 2 .......... .......... Error 3 _____.......... _____.......... _____ _____ _____ Corrected profit for the year _____ [7] [Total: 21]
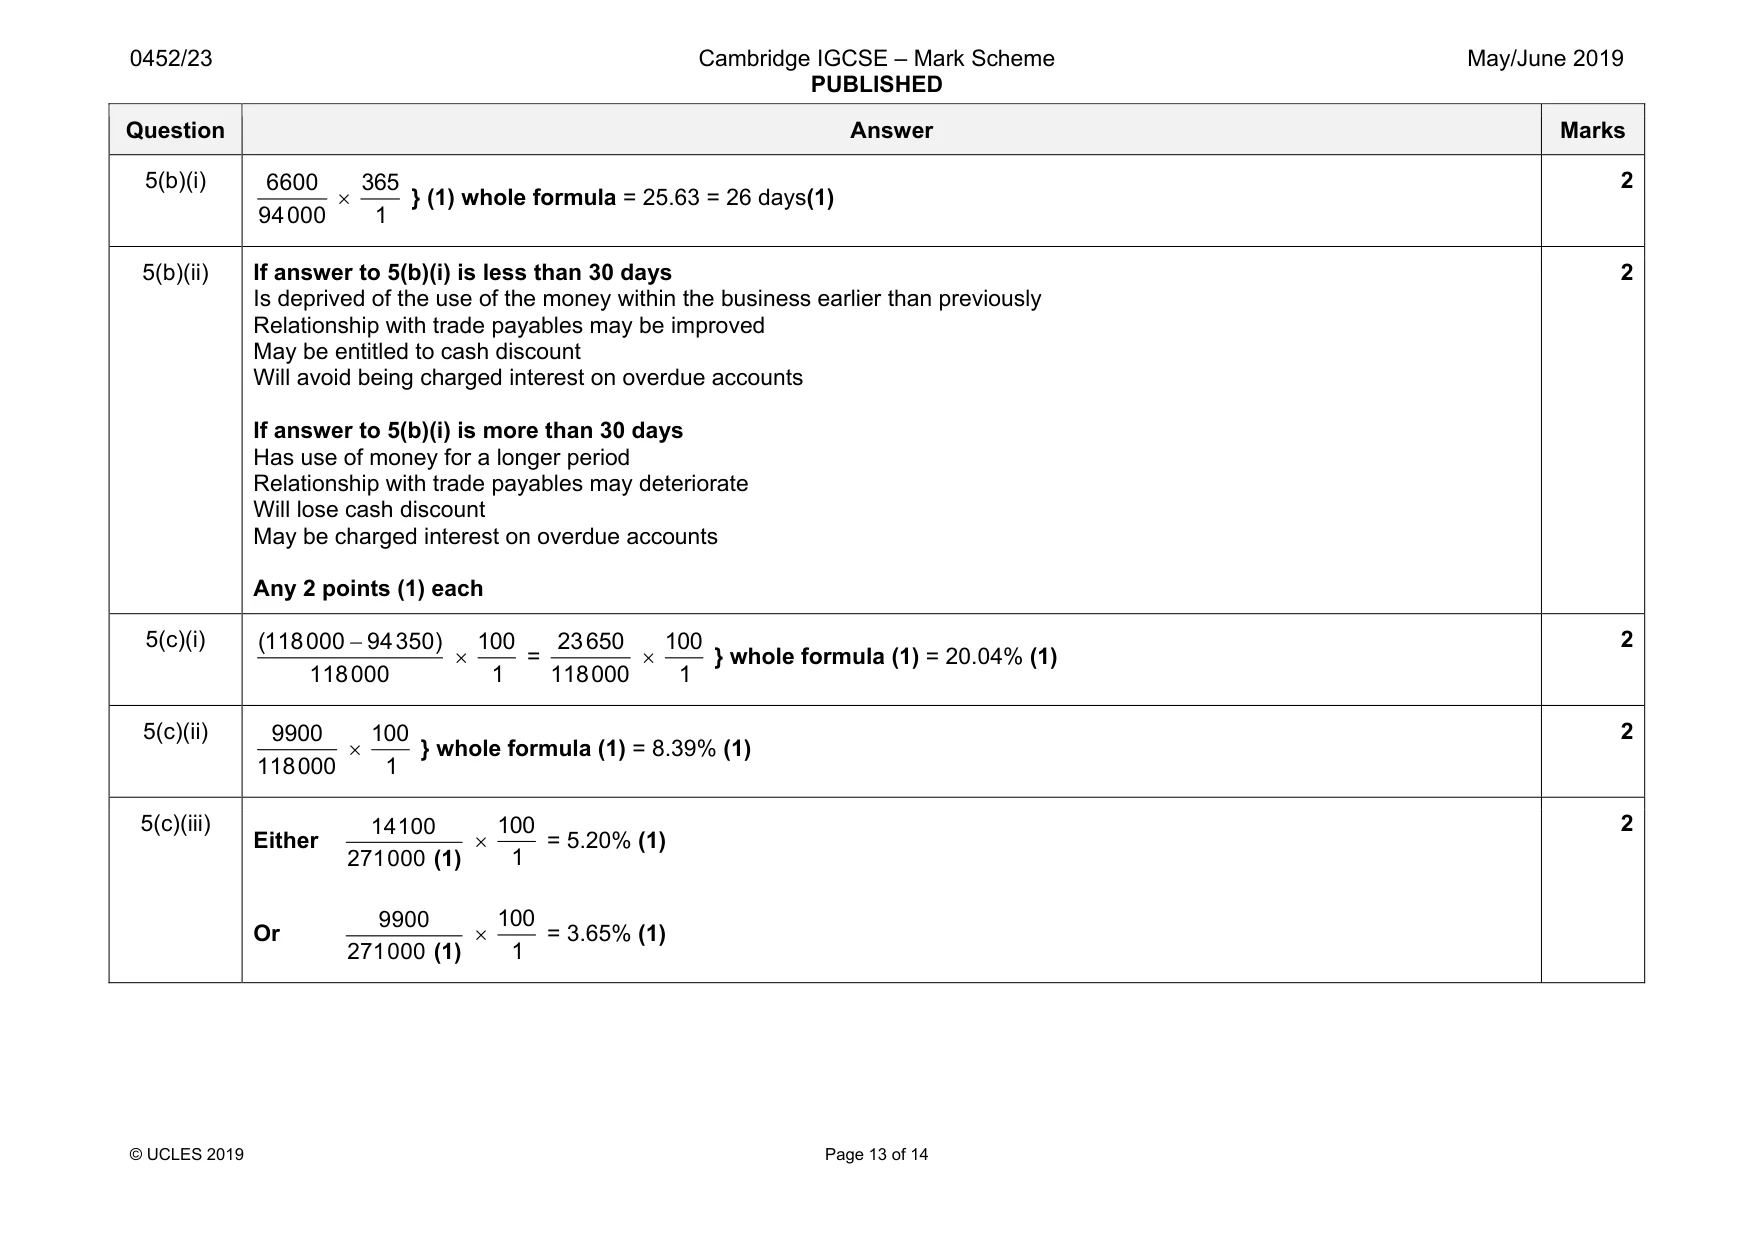
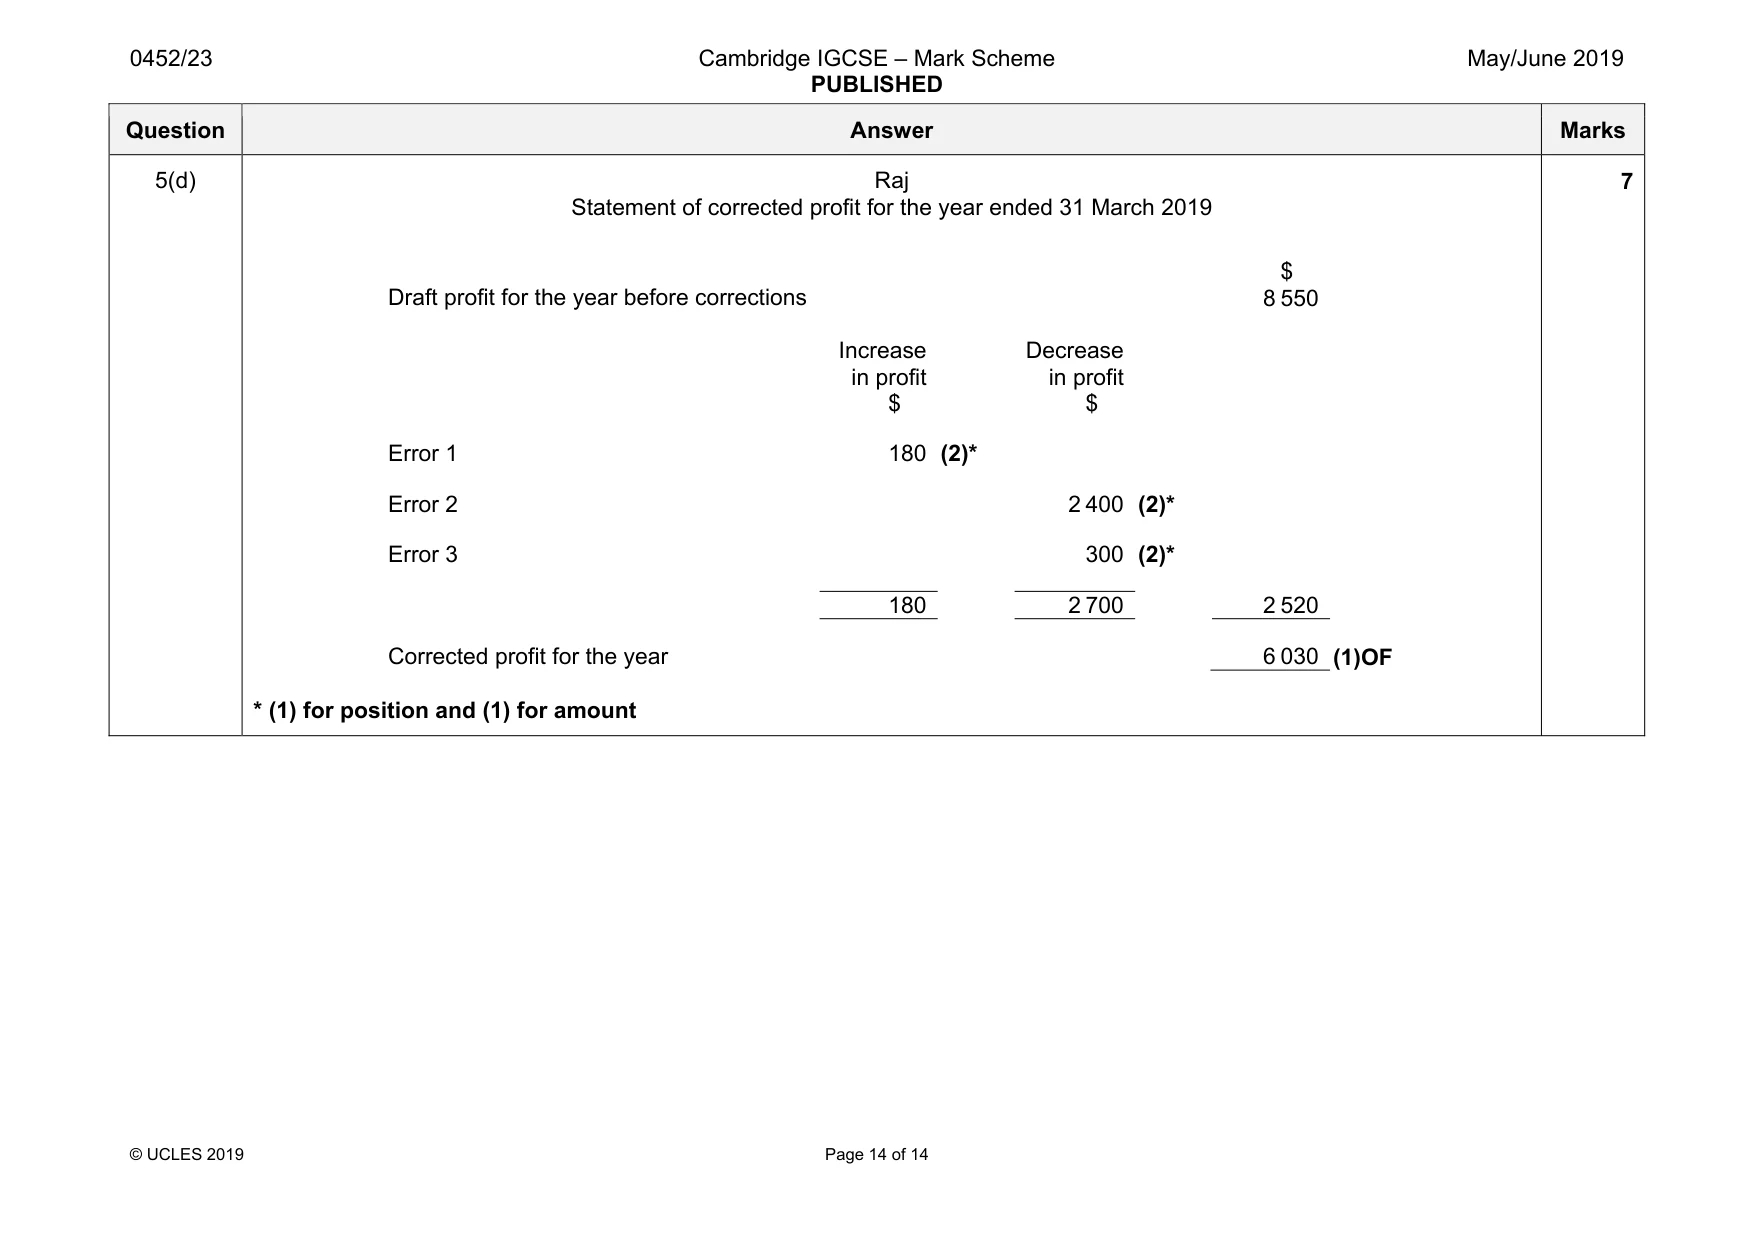
Mark scheme: 5(a)(i) 7250 118000 × 365 1 } (1) whole formula = 22.43 = 23 days (1) 2 5(a)(ii) Improve credit control Issue invoices and statements promptly Offer cash discount for prompt payment Charge interest on overdue accounts Refuse further supplies until outstanding balance is paid Invoice discounting and debt factoring Any two methods (1) each 2 Question Answer Marks 5(b)(i) 6600 94000 × 365 1 } (1) whole formula = 25.63 = 26 days(1) 2 5(b)(ii) If answer to 5(b)(i) is less than 30 days Is deprived of the use of the money within the business earlier than previously Relationship with trade payables may be improved May be entitled to cash discount Will avoid being charged interest on overdue accounts If answer to 5(b)(i) is more than 30 days Has use of money for a longer period Relationship with trade payables may deteriorate Will lose cash discount May be charged interest on overdue accounts Any 2 points (1) each 2 5(c)(i) (118000 94350) 118000 − × 100 1 = 23650 118000 × 100 1 } whole formula (1) = 20.04% (1) 2 5(c)(ii) 9900 118000 × 100 1 } whole formula (1) = 8.39% (1) 2 5(c)(iii) Either 14100 271000 (1) × 100 1 = 5.20% (1) Or 9900 271000 (1) × 100 1 = 3.65% (1) 2 Question Answer Marks 5(d) Raj Statement of corrected profit for the year ended 31 March 2019 $00 Draft profit for the year before corrections 8 550 Increase in profit Decrease in profit $00 $00 Error 1 180 (2)* Error 2 2 400 (2)* Error 3 300 (2)* 180 2 700 2 520 Corrected profit for the year 6 030 (1)OF * (1) for position and (1) for amount 7
More questions on Calculation and understanding of accounting ratios
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2019 May/June, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.