Cambridge IGCSE Accounting 0452 — 2019 May/June Paper 2 · Variant 1
0452/21/M/J/19 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Sabelo is a trader
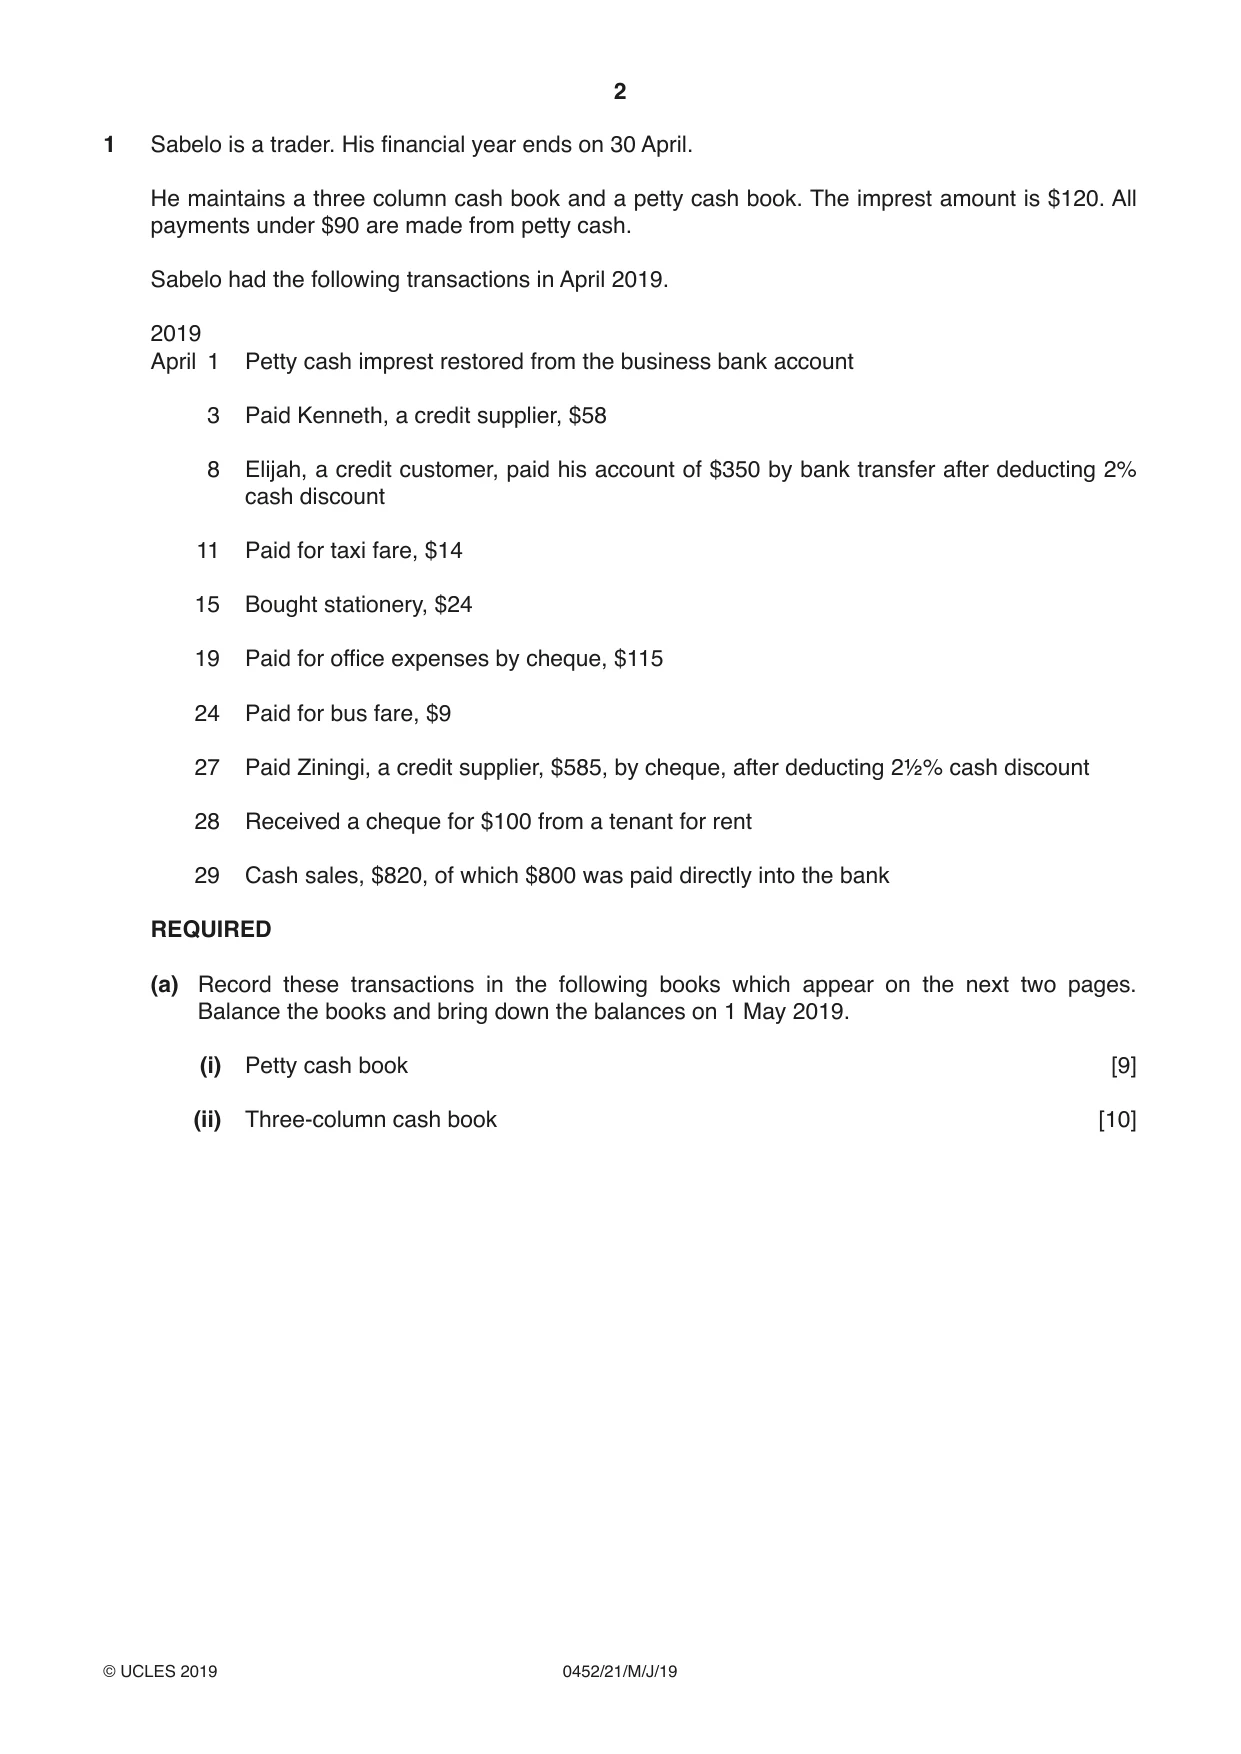
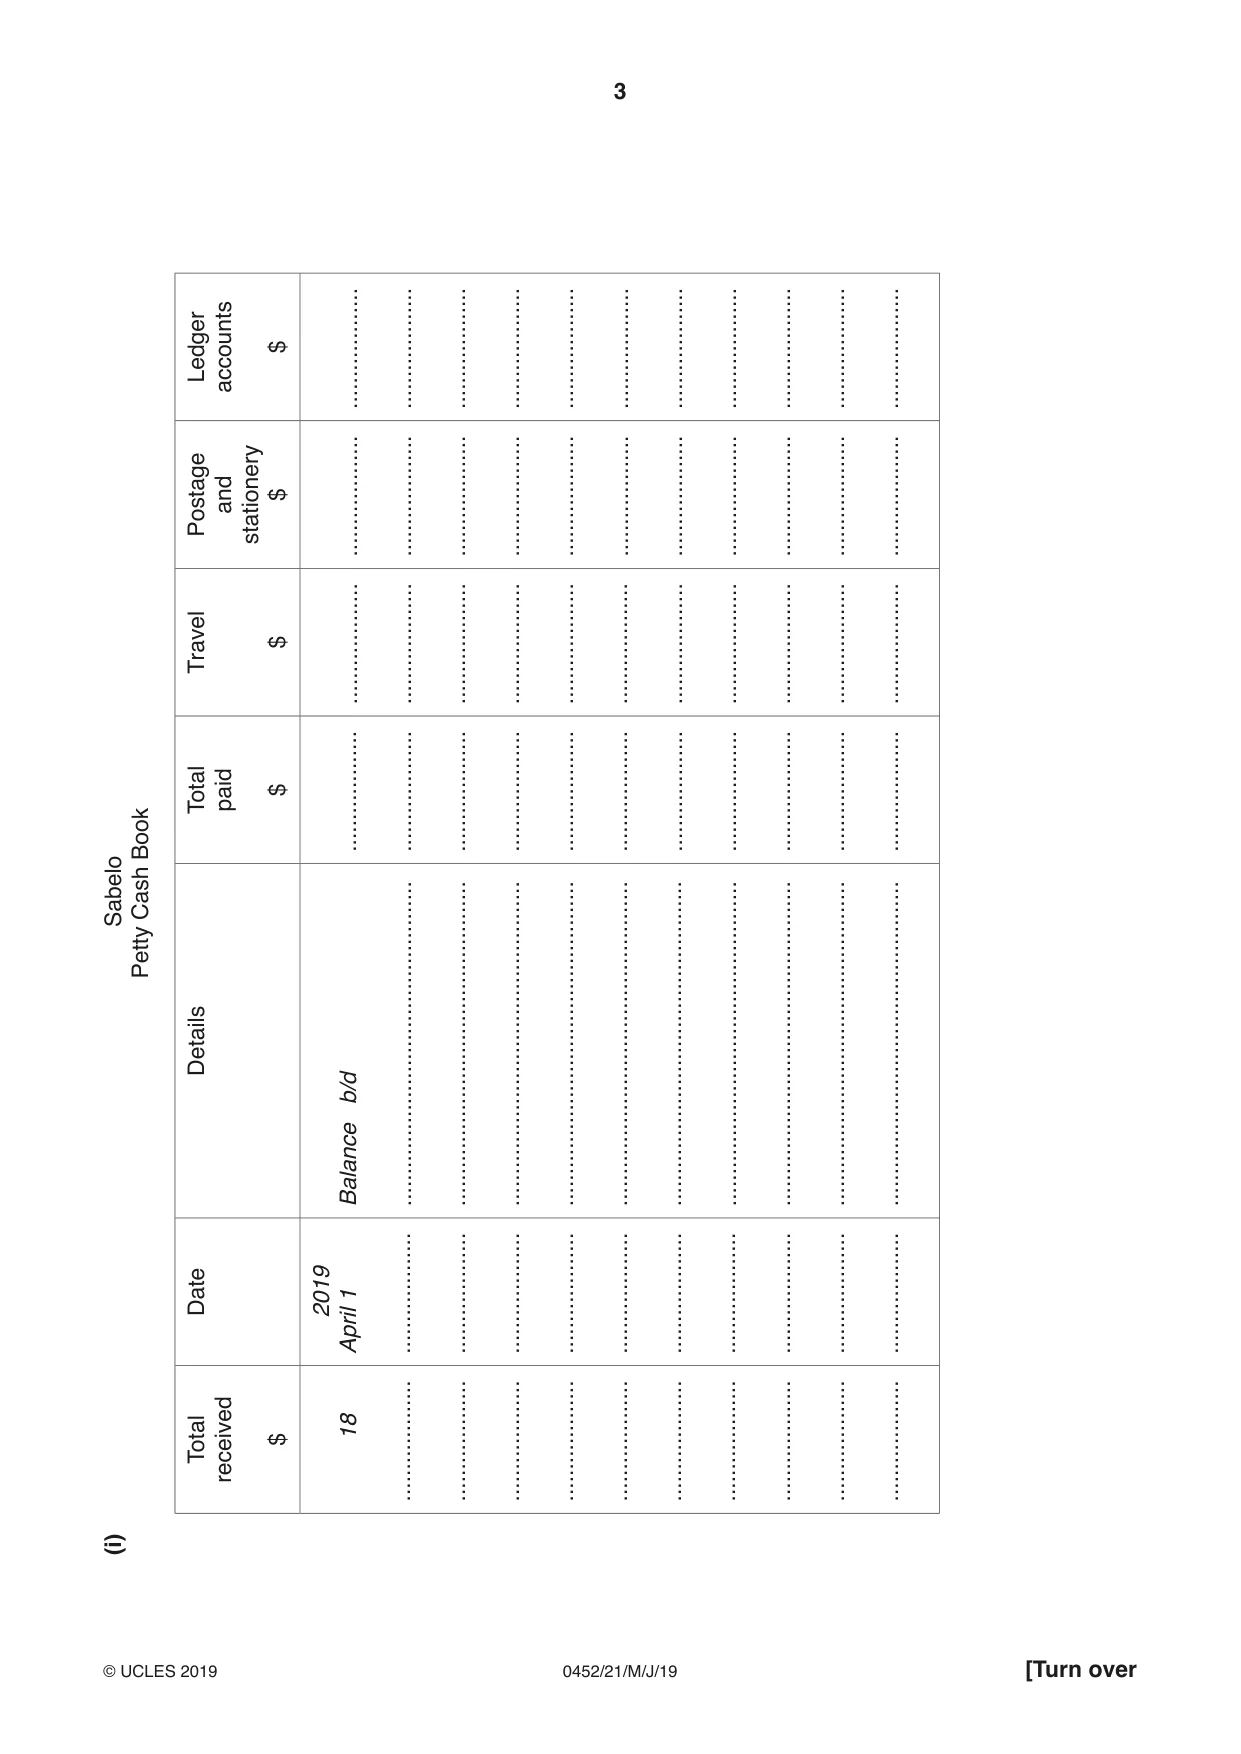
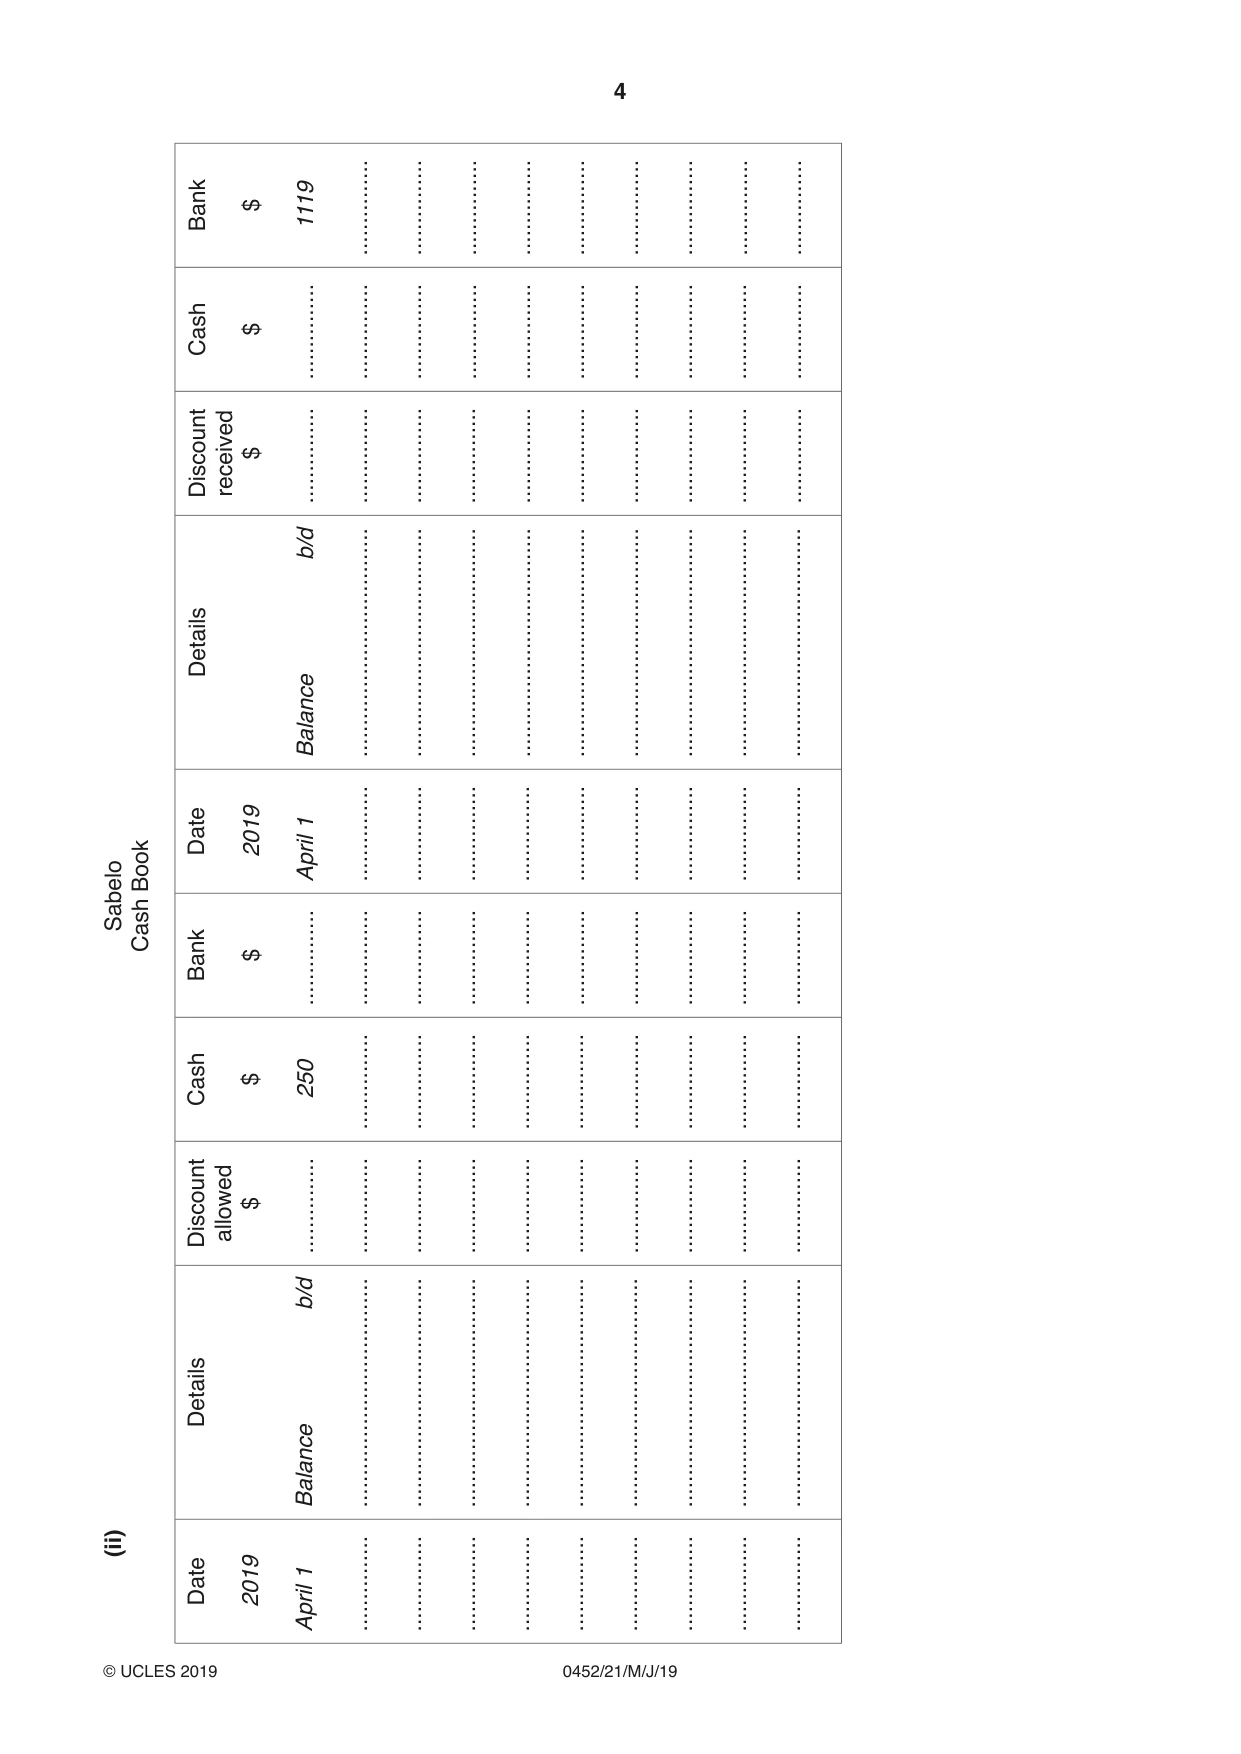
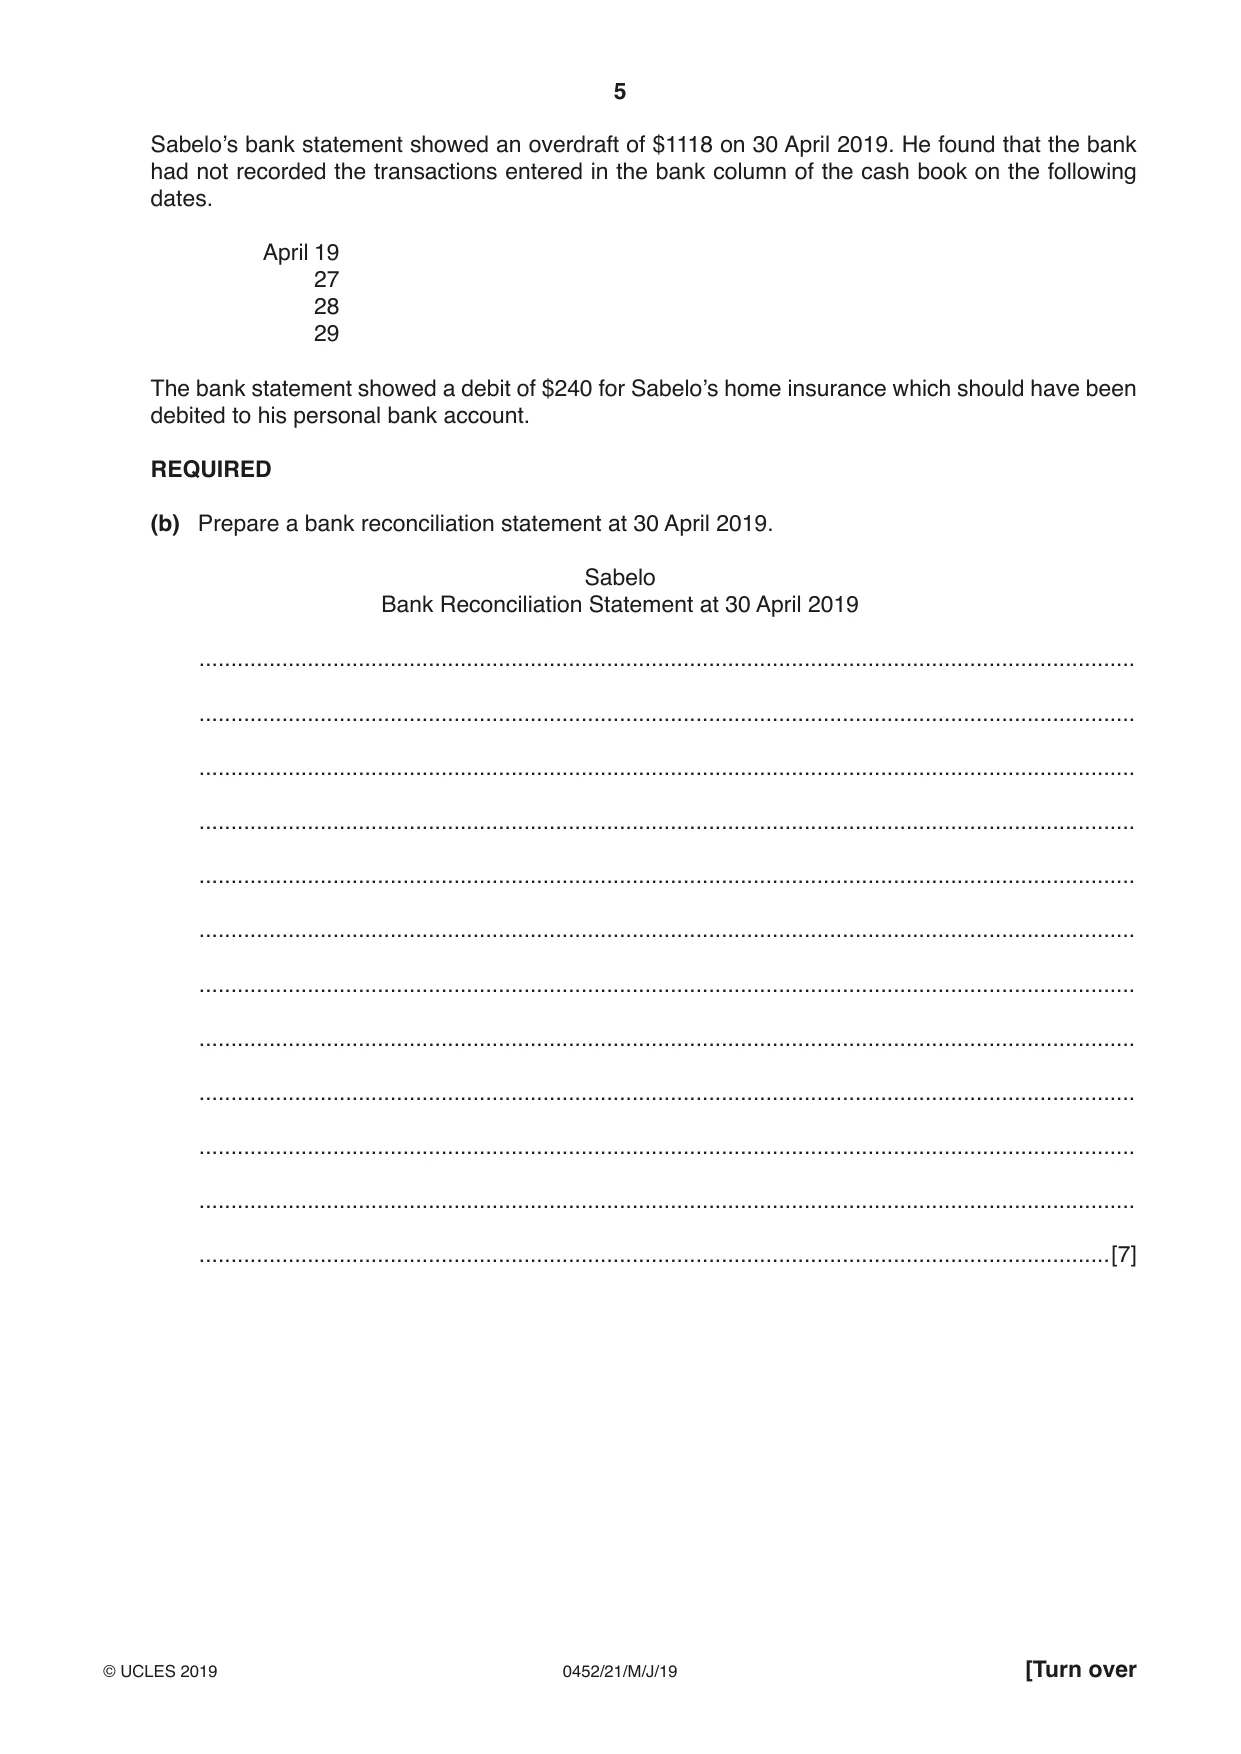
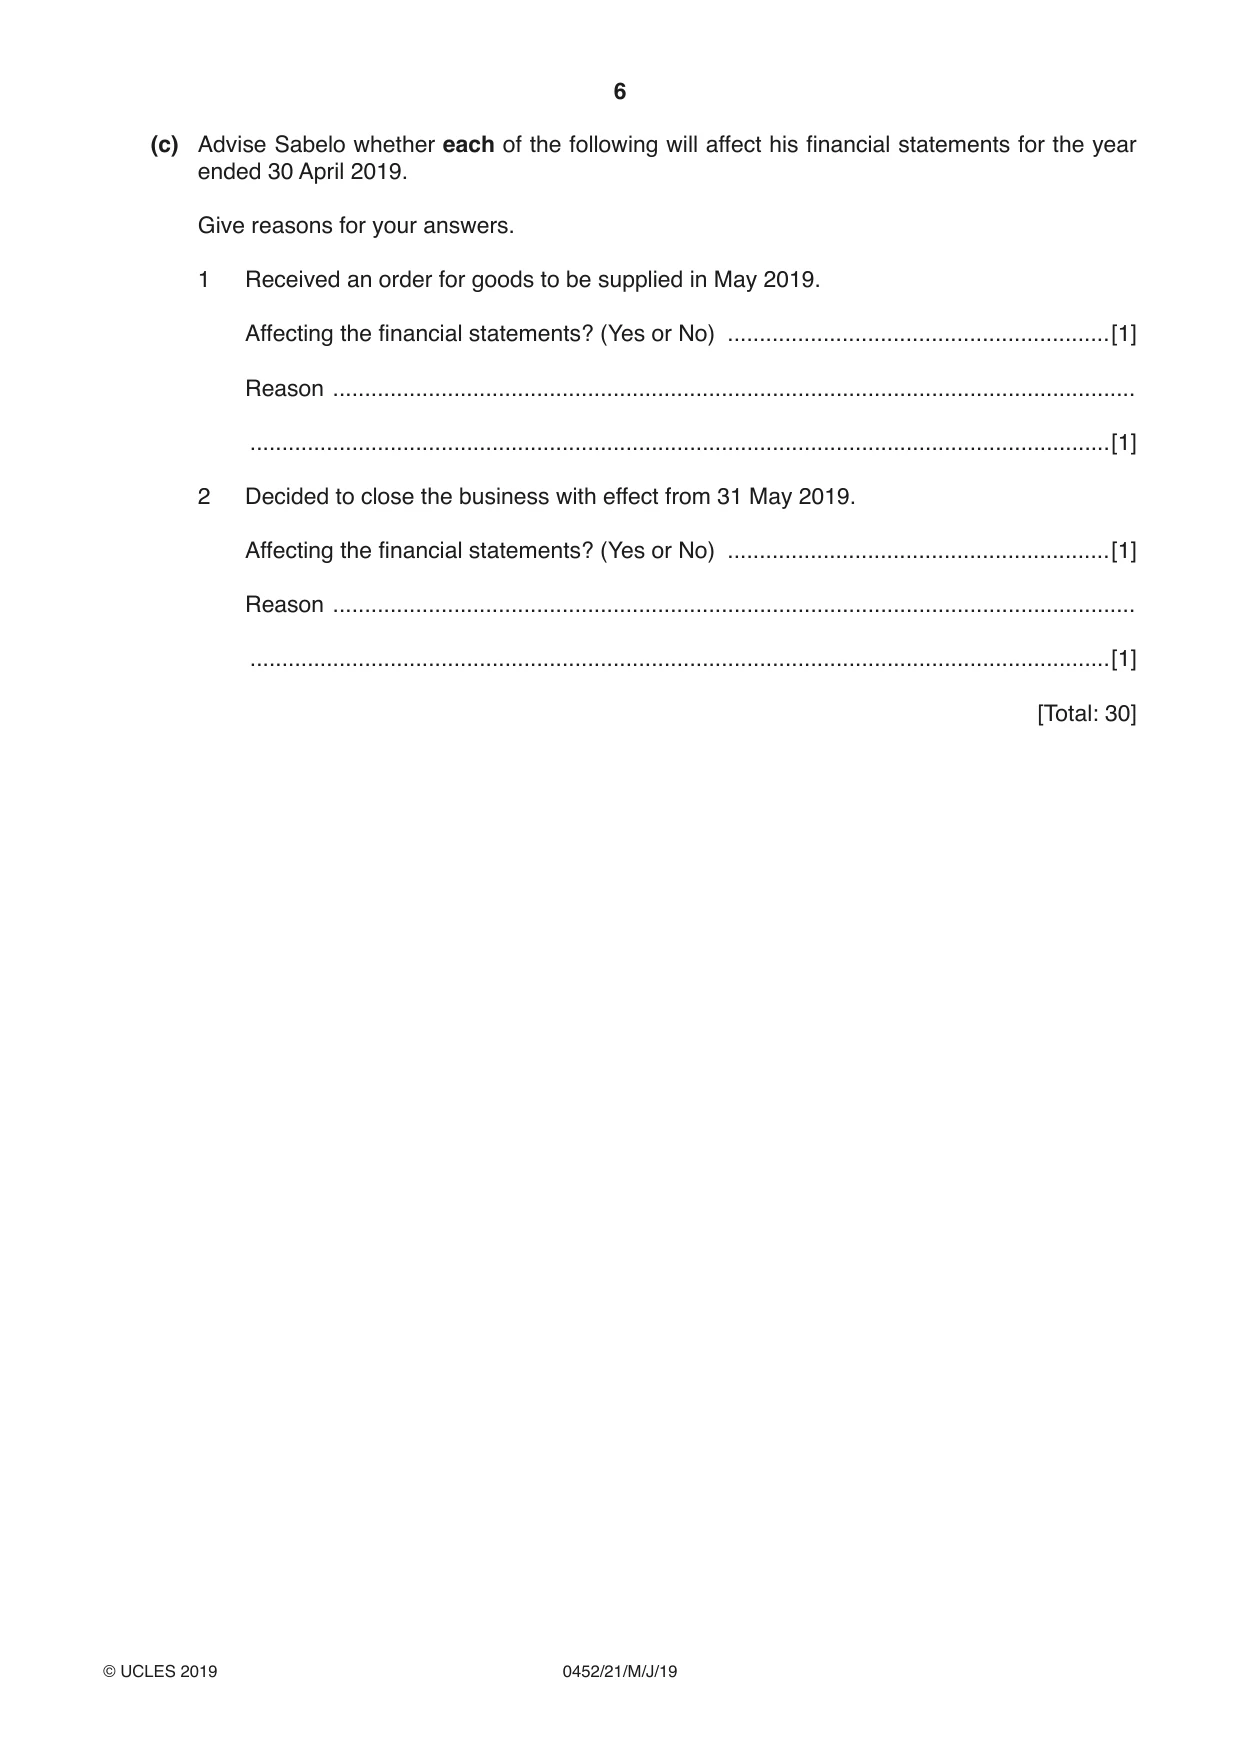
1 Sabelo is a trader. His financial year ends on 30 April. He maintains a three column cash book and a petty cash book. The imprest amount is $120. All payments under $90 are made from petty cash. Sabelo had the following transactions in April 2019. 2019 April 1 Petty cash imprest restored from the business bank account 3 Paid Kenneth, a credit supplier, $58 8 Elijah, a credit customer, paid his account of $350 by bank transfer after deducting 2% cash discount 11 Paid for taxi fare, $14 15 Bought stationery, $24 19 Paid for office expenses by cheque, $115 24 Paid for bus fare, $9 27 Paid Ziningi, a credit supplier, $585, by cheque, after deducting 2½% cash discount 28 Received a cheque for $100 from a tenant for rent 29 Cash sales, $820, of which $800 was paid directly into the bank REQUIRED (a) Record these transactions in the following books which appear on the next two pages. Balance the books and bring down the balances on 1 May 2019. (i) Petty cash book [9] (ii) Three-column cash book [10] $ Ledger accounts ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... $ and Postage stationery ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... $ Travel ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... $ Totalpaid ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... Book CashSabelo Petty Details b/d Balance ................................................... ................................................... ................................................... ................................................... ................................................... ................................................... ................................................... ................................................... ................................................... ................................................... 1 Date 2019 April ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... 18 $ Total received ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... $ Bank 1119 ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Cash ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountreceived ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... b/d Details Balance .................................... .................................... .................................... .................................... .................................... .................................... .................................... .................................... .................................... 1 Date 2019 April ............... ............... ............... ............... ............... ............... ............... ............... ............... Book Sabelo Cash $ Bank ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ 250 Cash ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountallowed ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... b/d Details Balance .................................... .................................... .................................... .................................... .................................... .................................... .................................... .................................... .................................... Sabelo’s bank statement showed an overdraft of $1118 on 30 April 2019. He found that the bank had not recorded the transactions entered in the bank column of the cash book on the following dates. April 19 27 28 29 The bank statement showed a debit of $240 for Sabelo’s home insurance which should have been debited to his personal bank account. REQUIRED (b) Prepare a bank reconciliation statement at 30 April 2019. Sabelo Bank Reconciliation Statement at 30 April 2019 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[7] (c) Advise Sabelo whether each of the following will affect his financial statements for the year ended 30 April 2019. Give reasons for your answers. 1 Received an order for goods to be supplied in May 2019. Affecting the financial statements? (Yes or No) ............................................................[1] Reason .............................................................................................................................. .......................................................................................................................................[1] 2 Decided to close the business with effect from 31 May 2019. Affecting the financial statements? (Yes or No) ............................................................[1] Reason .............................................................................................................................. .......................................................................................................................................[1] [Total: 30]
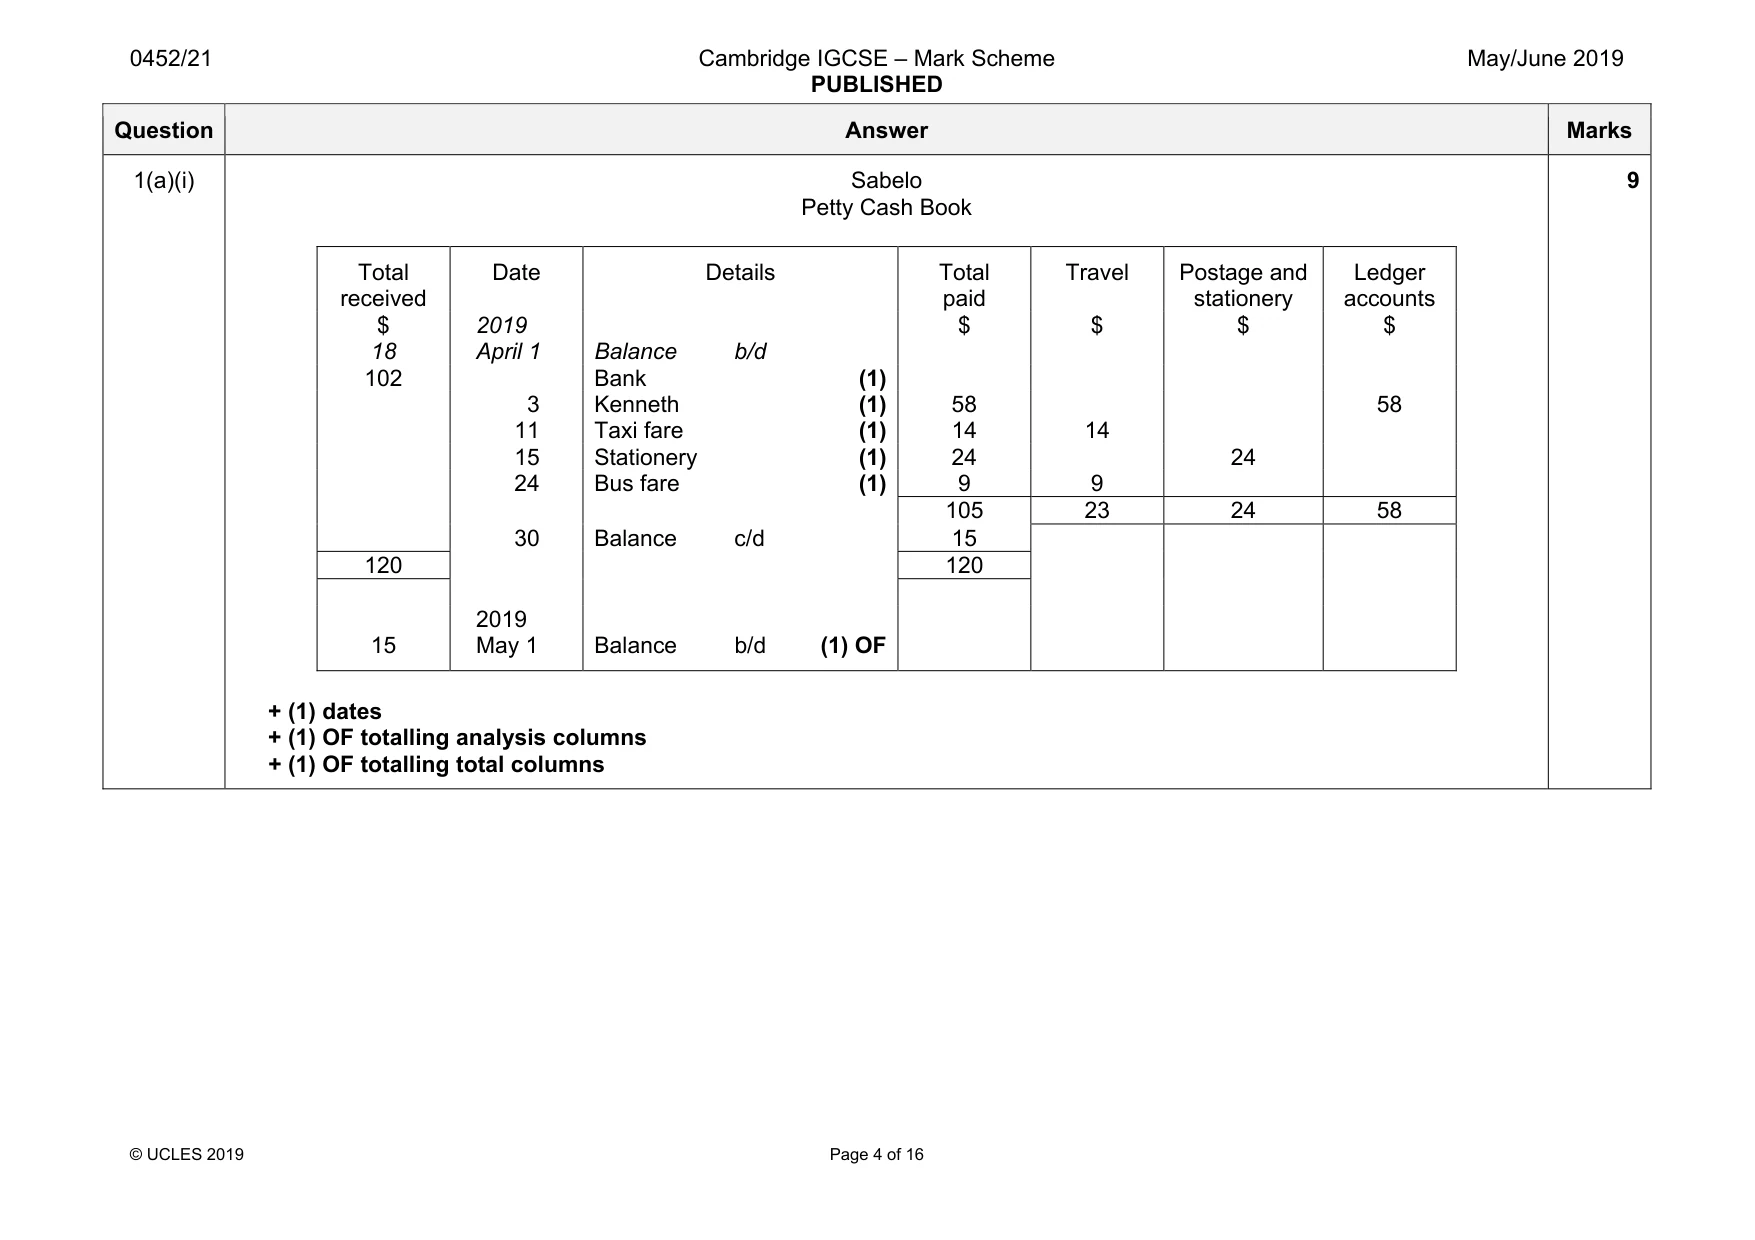
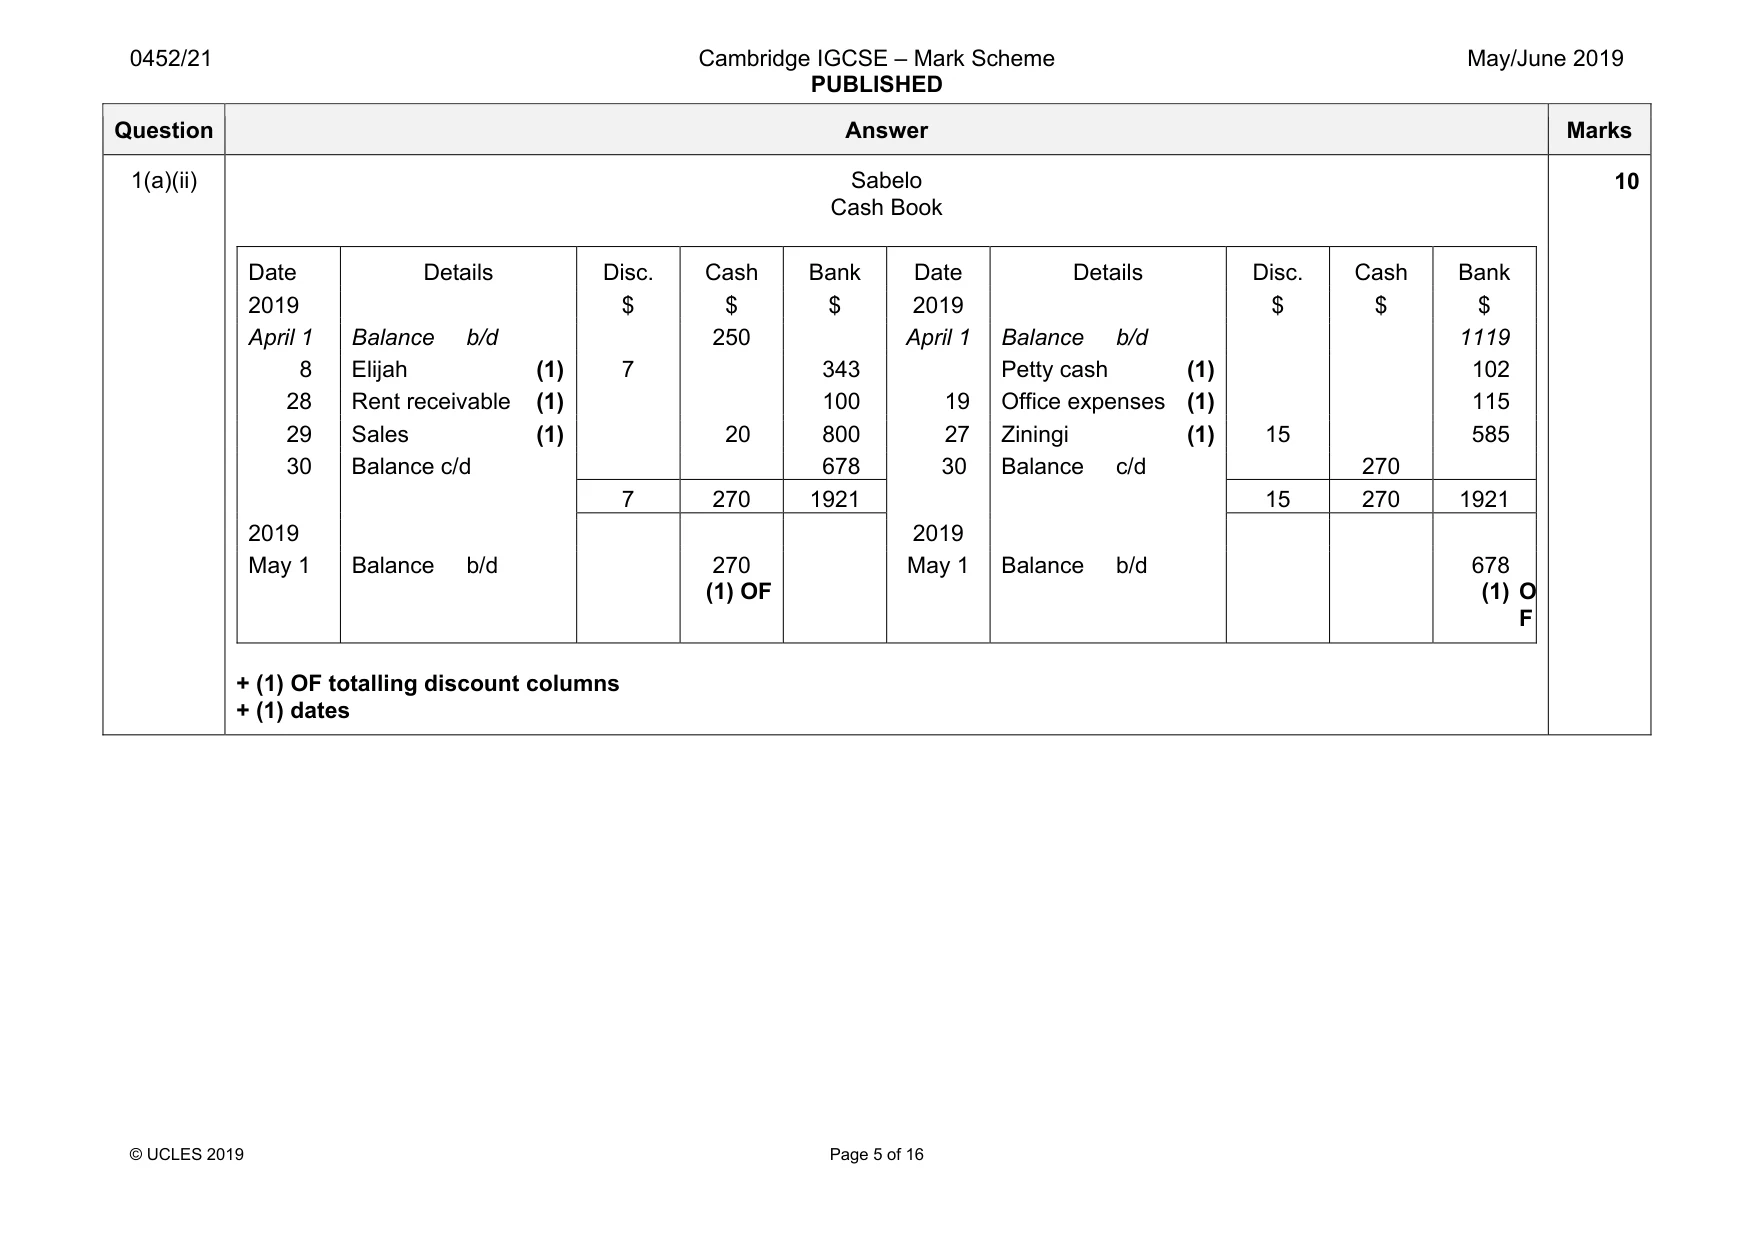
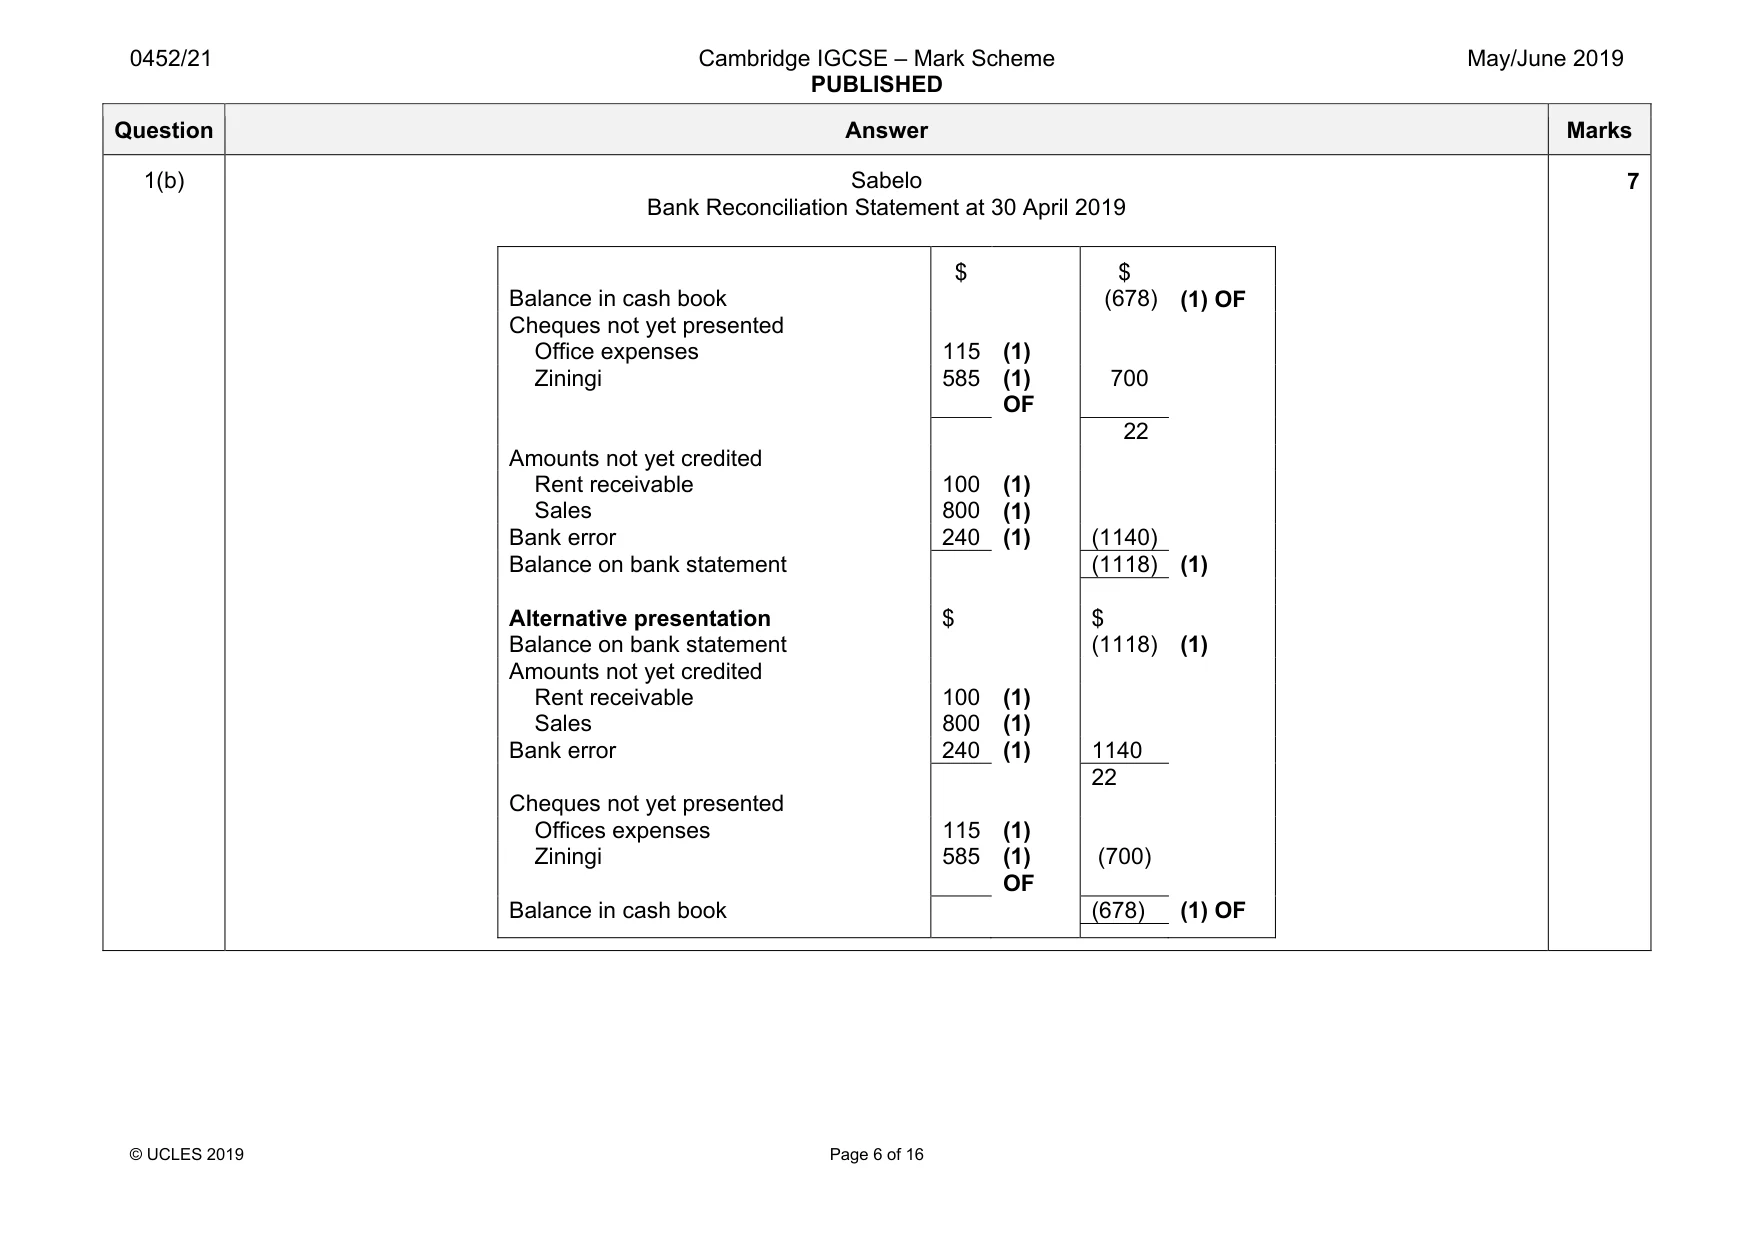
Mark scheme: 1(a)(i) Sabelo Petty Cash Book Total received Date Details Total paid Travel Postage and stationery Ledger accounts $ 2019 $ $ $ $ 18 April 1 Balance b/d 102 Bank (1) 3 Kenneth (1) 58 58 11 Taxi fare (1) 14 14 15 Stationery (1) 24 24 24 Bus fare (1) 9 9 105 23 24 58 30 Balance c/d 15 120 120 2019 15 May 1 Balance b/d (1) OF + (1) dates + (1) OF totalling analysis columns + (1) OF totalling total columns 9 Question Answer Marks 1(a)(ii) Sabelo Cash Book Date Details Disc. Cash Bank Date Details Disc. Cash Bank 2019 $ $ $ 2019 $ $ $ April 1 Balance b/d 250 April 1 Balance b/d 1119 8 Elijah (1) 7 343 Petty cash (1) 102 28 Rent receivable (1) 100 19 Office expenses (1) 115 29 Sales (1) 20 800 27 Ziningi (1) 15 585 30 Balance c/d 678 30 Balance c/d 270 7 270 1921 15 270 1921 2019 2019 May 1 Balance b/d 270 May 1 Balance b/d 678 (1) OF (1) O F + (1) OF totalling discount columns + (1) dates 10 Question Answer Marks 1(b) Sabelo Bank Reconciliation Statement at 30 April 2019 $ $ Balance in cash book (678) (1) OF Cheques not yet presented Office expenses 115 (1) Ziningi 585 (1) OF 700 22 Amounts not yet credited Rent receivable 100 (1) Sales 800 (1) Bank error 240 (1) (1140) Balance on bank statement (1118) (1) Alternative presentation $ $ Balance on bank statement (1118) (1) Amounts not yet credited Rent receivable 100 (1) Sales 800 (1) Bank error 240 (1) 1140 22 Cheques not yet presented Offices expenses 115 (1) Ziningi 585 (1) OF (700) Balance in cash book (678) (1) OF 7 Question Answer Marks 1(c) 1 No (1) Either Application of the realisation principle (1) OR Revenue is recognised when the legal liability to pay passes to the customer (not when goods are ordered) so no entry will be made when an order is received (1) 2 Yes (1) Either Application of the going concern principle (1) Or When it is known that the business is going to be discontinued it may be necessary to adjust the value of some assets to their expected sale values (1) 4
Q2 · Jade is a customer of Adil
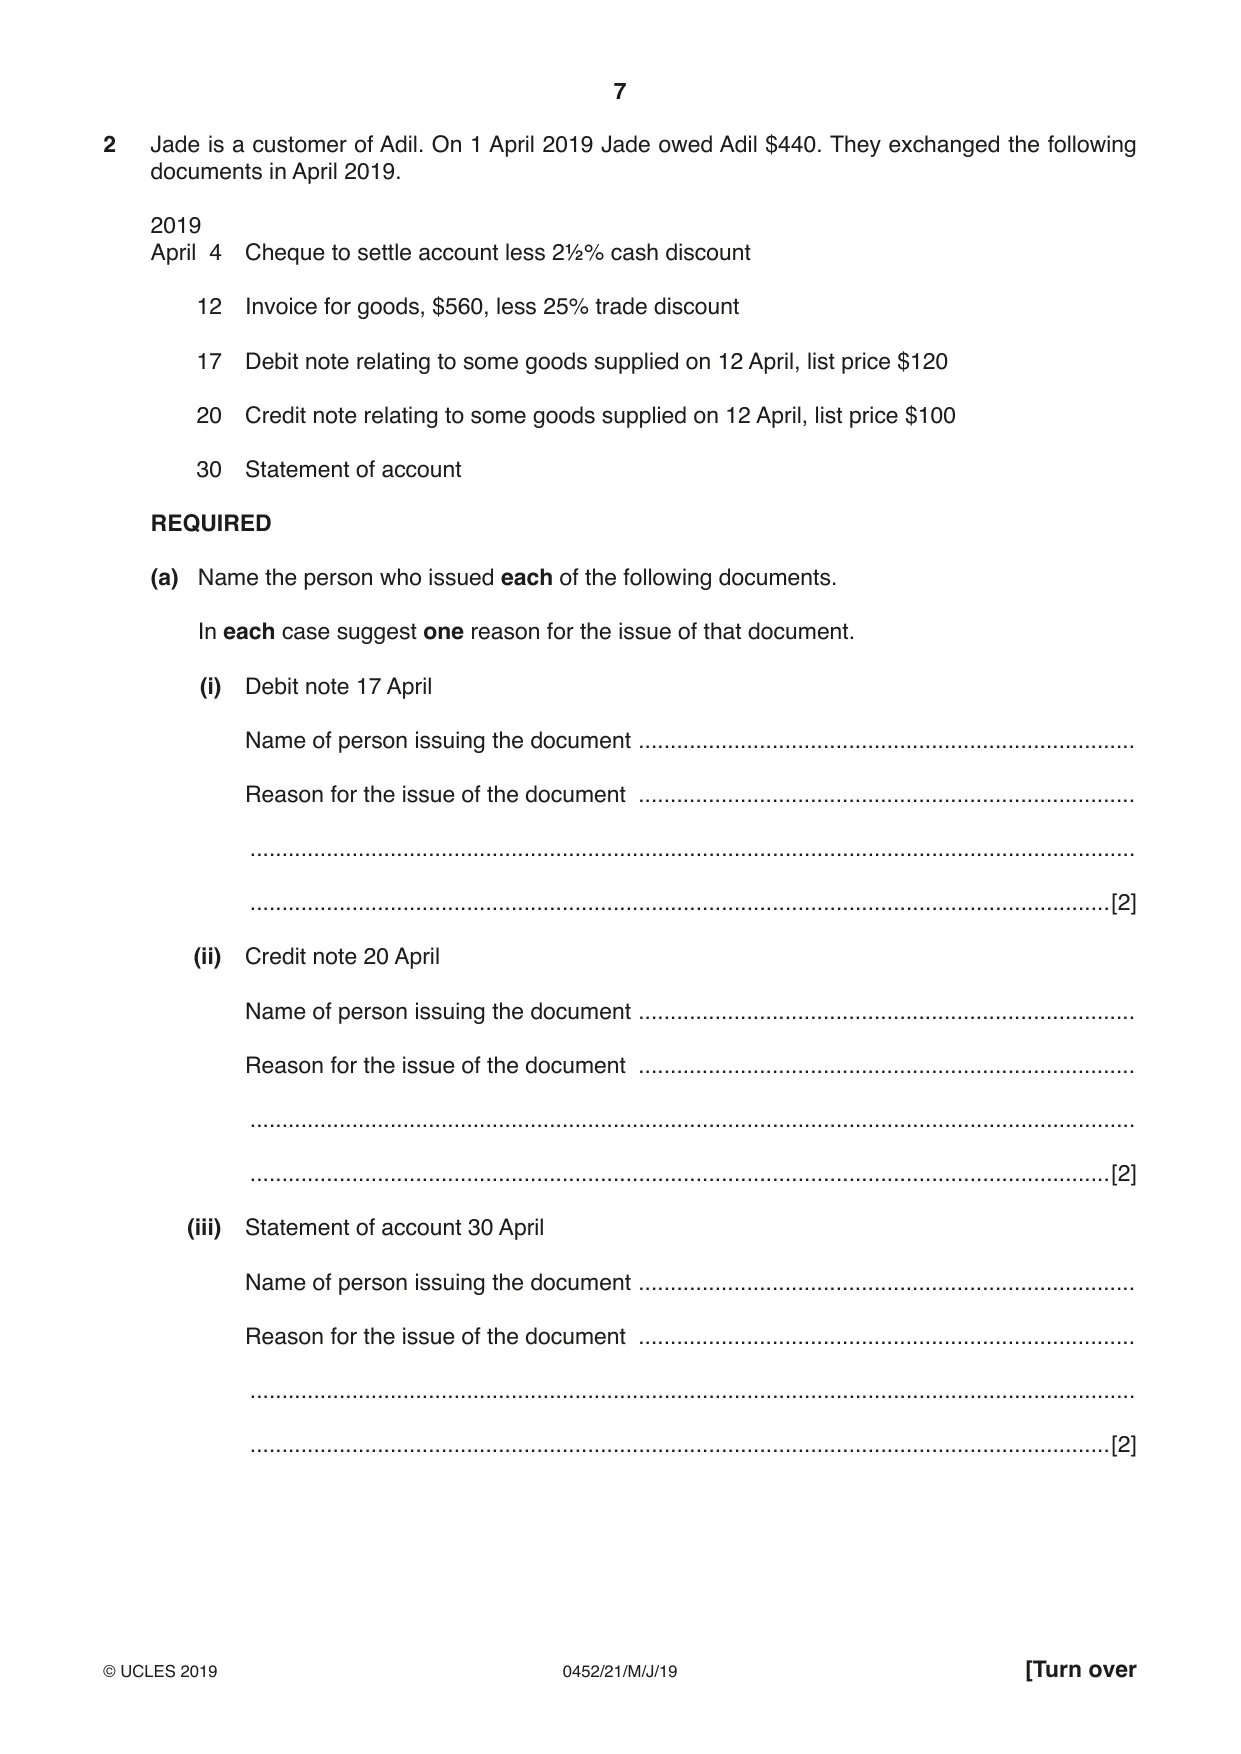
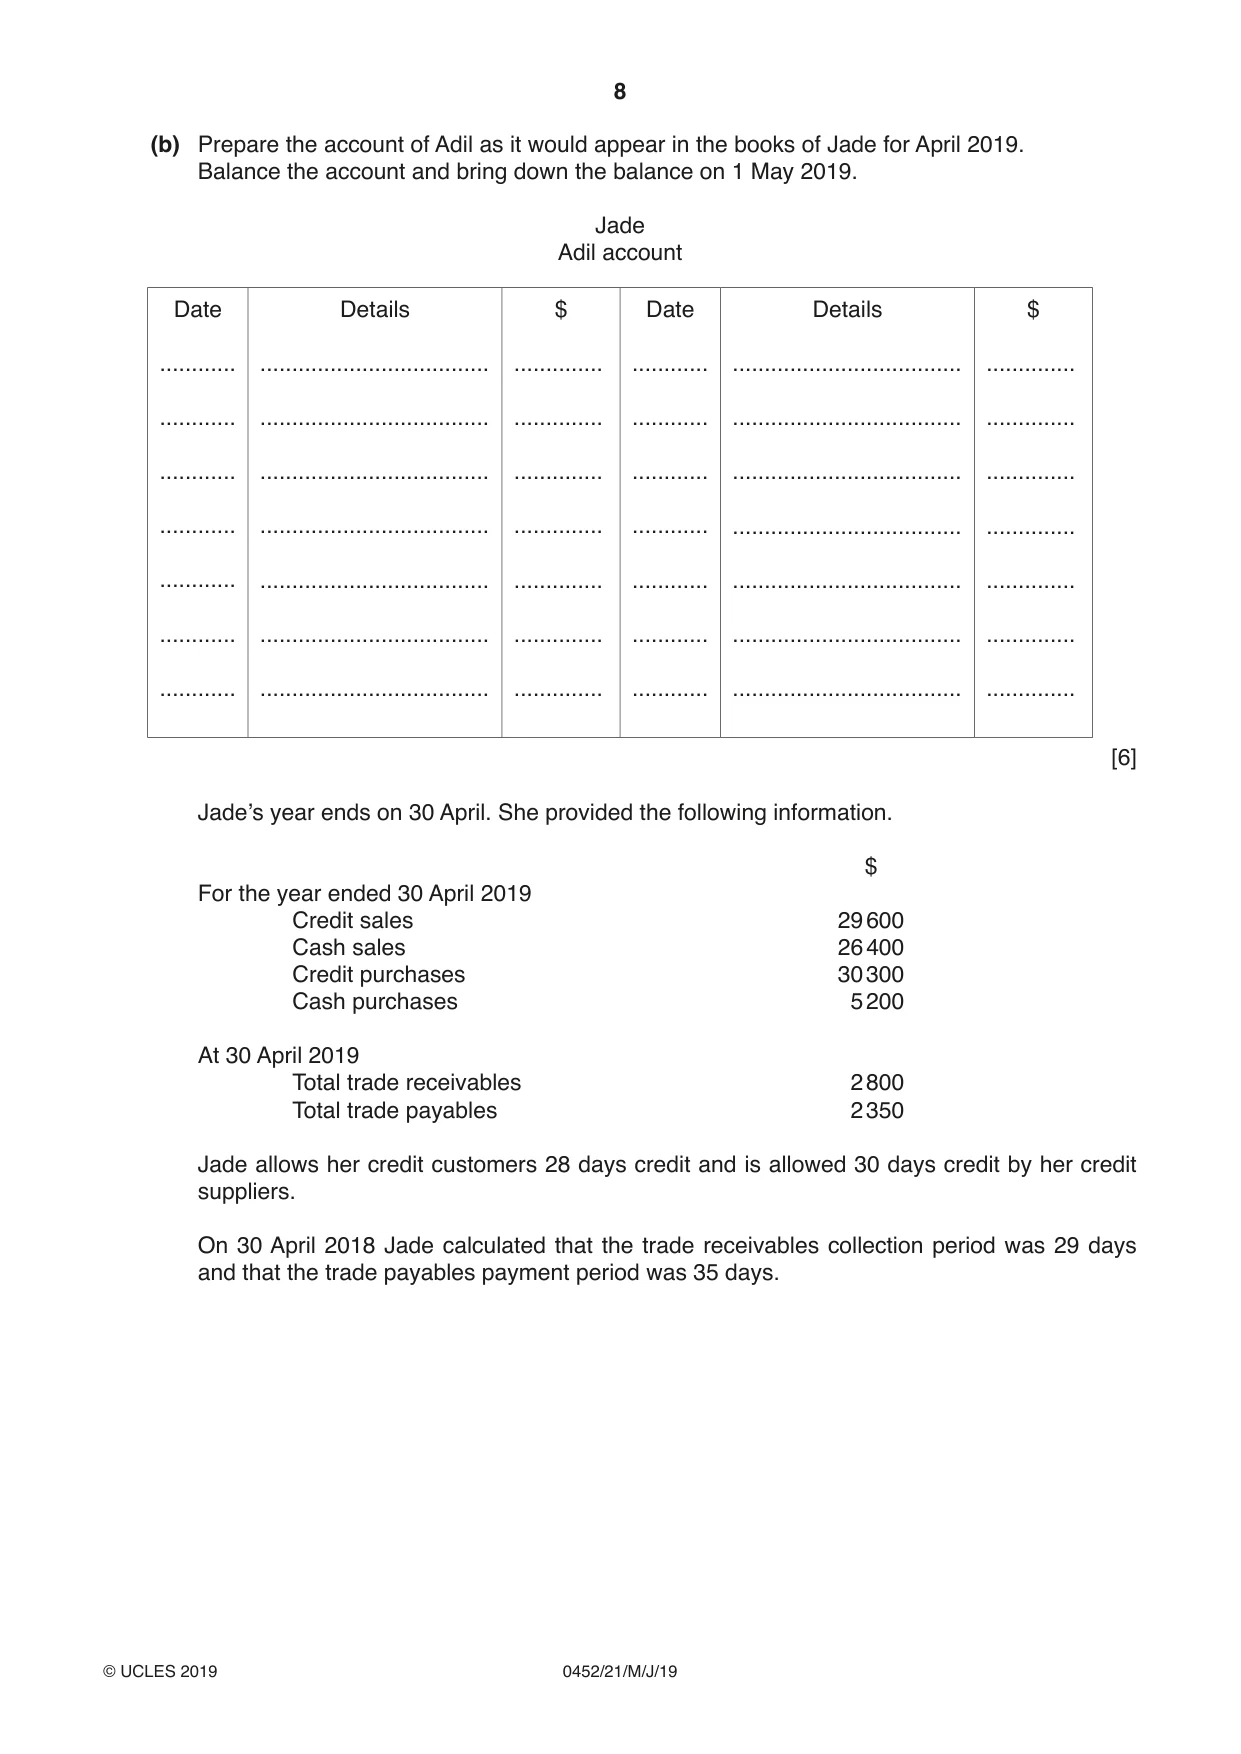
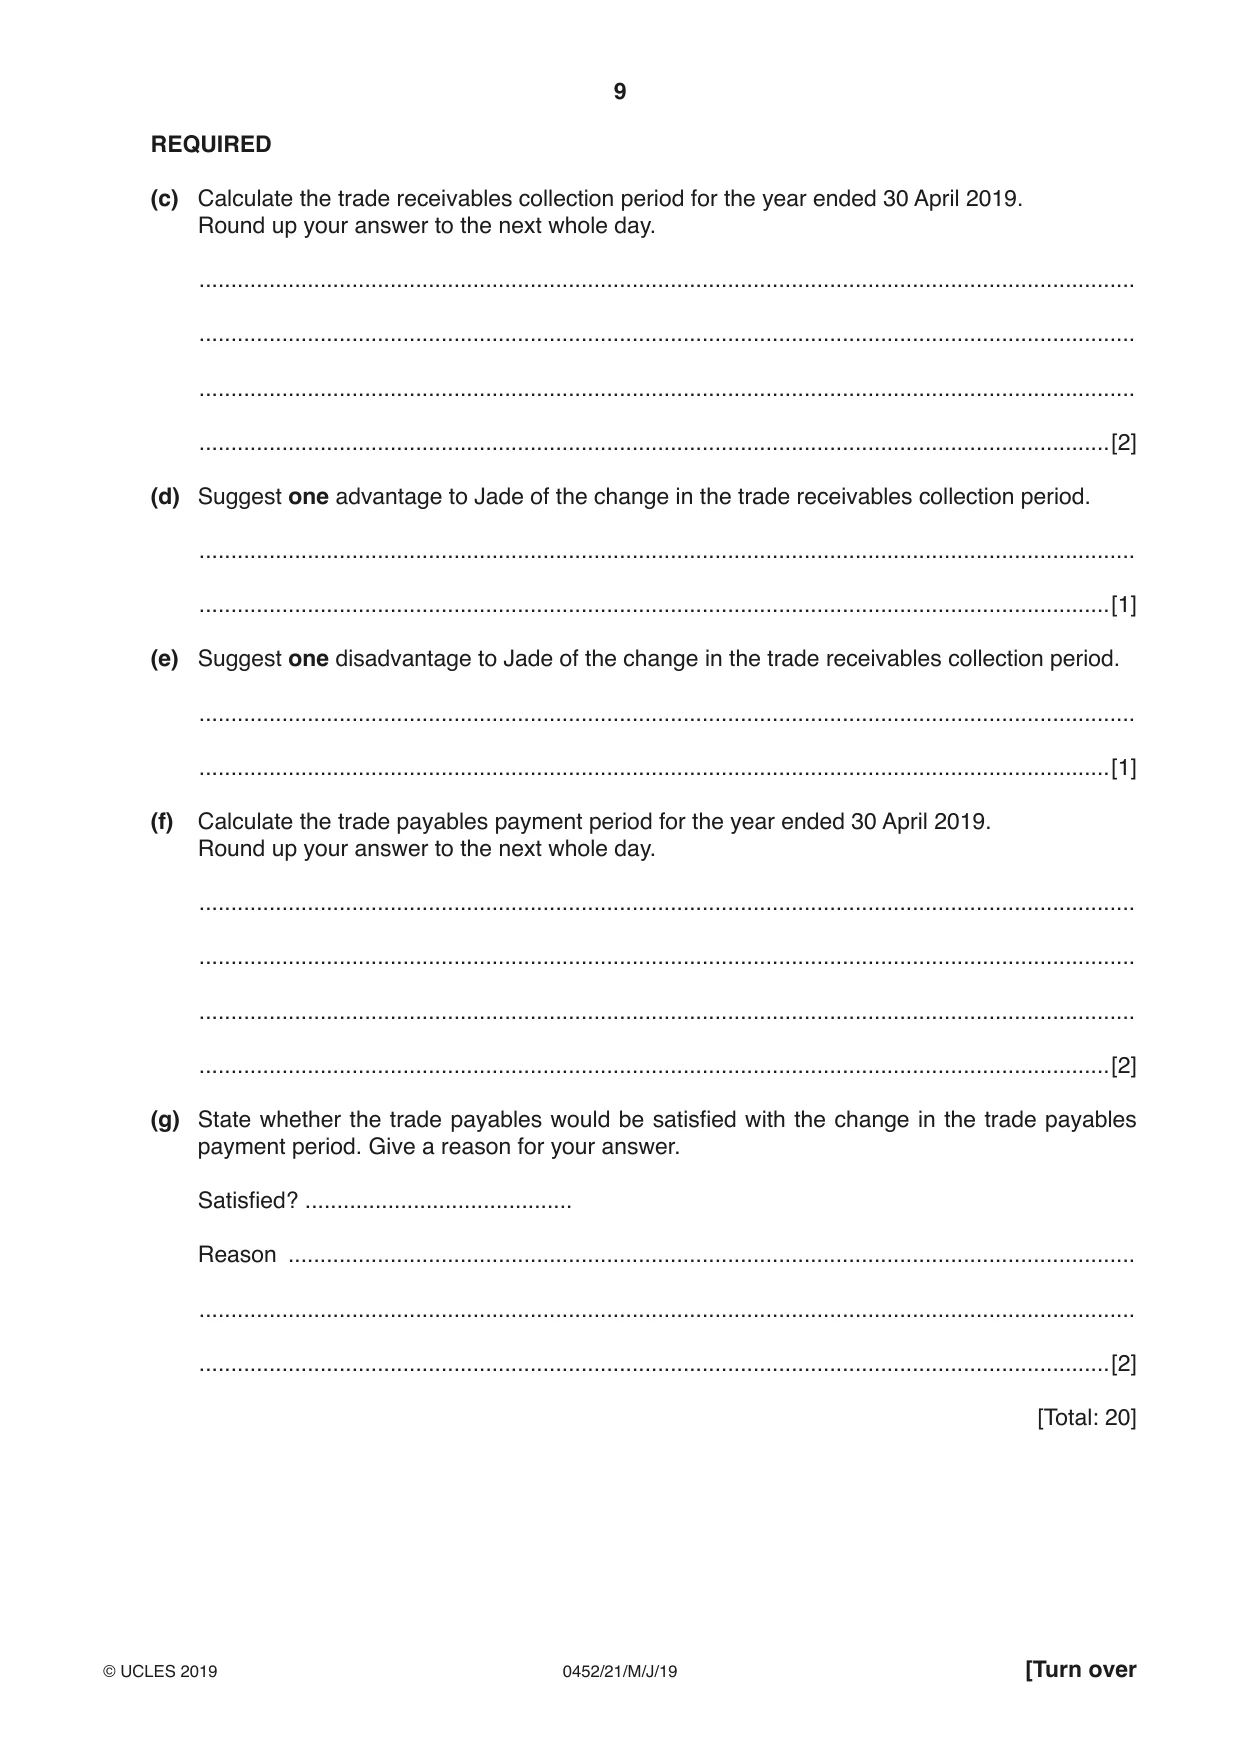
2 Jade is a customer of Adil. On 1 April 2019 Jade owed Adil $440. They exchanged the following documents in April 2019. 2019 April 4 Cheque to settle account less 2½% cash discount 12 Invoice for goods, $560, less 25% trade discount 17 Debit note relating to some goods supplied on 12 April, list price $120 20 Credit note relating to some goods supplied on 12 April, list price $100 30 Statement of account REQUIRED (a) Name the person who issued each of the following documents. In each case suggest one reason for the issue of that document. (i) Debit note 17 April Name of person issuing the document .............................................................................. Reason for the issue of the document .............................................................................. ........................................................................................................................................... .......................................................................................................................................[2] (ii) Credit note 20 April Name of person issuing the document .............................................................................. Reason for the issue of the document .............................................................................. ........................................................................................................................................... .......................................................................................................................................[2] (iii) Statement of account 30 April Name of person issuing the document .............................................................................. Reason for the issue of the document .............................................................................. ........................................................................................................................................... .......................................................................................................................................[2] (b) Prepare the account of Adil as it would appear in the books of Jade for April 2019. Balance the account and bring down the balance on 1 May 2019. Jade Adil account Date Details $ Date Details $ ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. [6] Jade’s year ends on 30 April. She provided the following information. $ For the year ended 30 April 2019 Credit sales 29 600 Cash sales 26 400 Credit purchases 30 300 Cash purchases 5 200 At 30 April 2019 Total trade receivables 2 800 Total trade payables 2 350 Jade allows her credit customers 28 days credit and is allowed 30 days credit by her credit suppliers. On 30 April 2018 Jade calculated that the trade receivables collection period was 29 days and that the trade payables payment period was 35 days. REQUIRED (c) Calculate the trade receivables collection period for the year ended 30 April 2019. Round up your answer to the next whole day. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (d) Suggest one advantage to Jade of the change in the trade receivables collection period. ................................................................................................................................................... ...............................................................................................................................................[1] (e) Suggest one disadvantage to Jade of the change in the trade receivables collection period. ................................................................................................................................................... ...............................................................................................................................................[1] (f) Calculate the trade payables payment period for the year ended 30 April 2019. Round up your answer to the next whole day. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (g) State whether the trade payables would be satisfied with the change in the trade payables payment period. Give a reason for your answer. Satisfied? .......................................... Reason ..................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] [Total: 20]
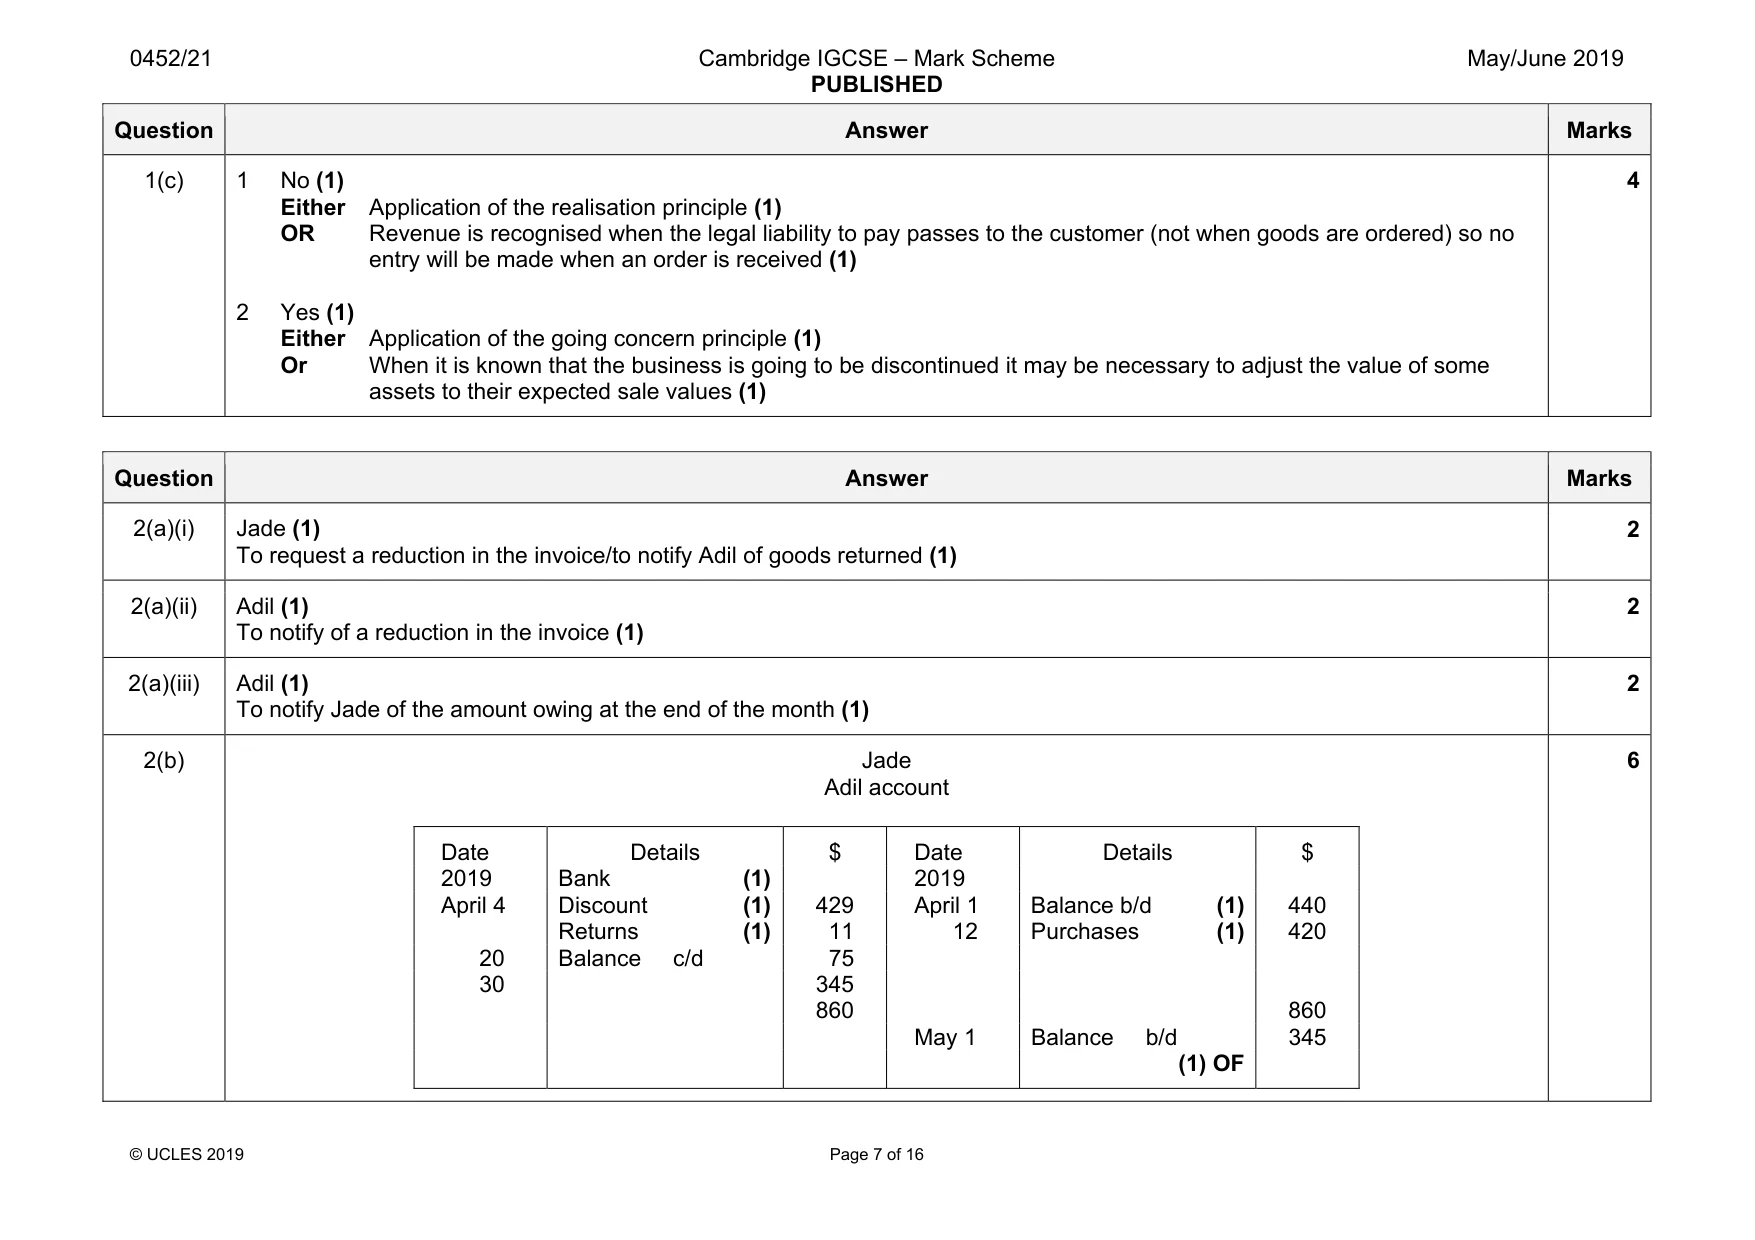
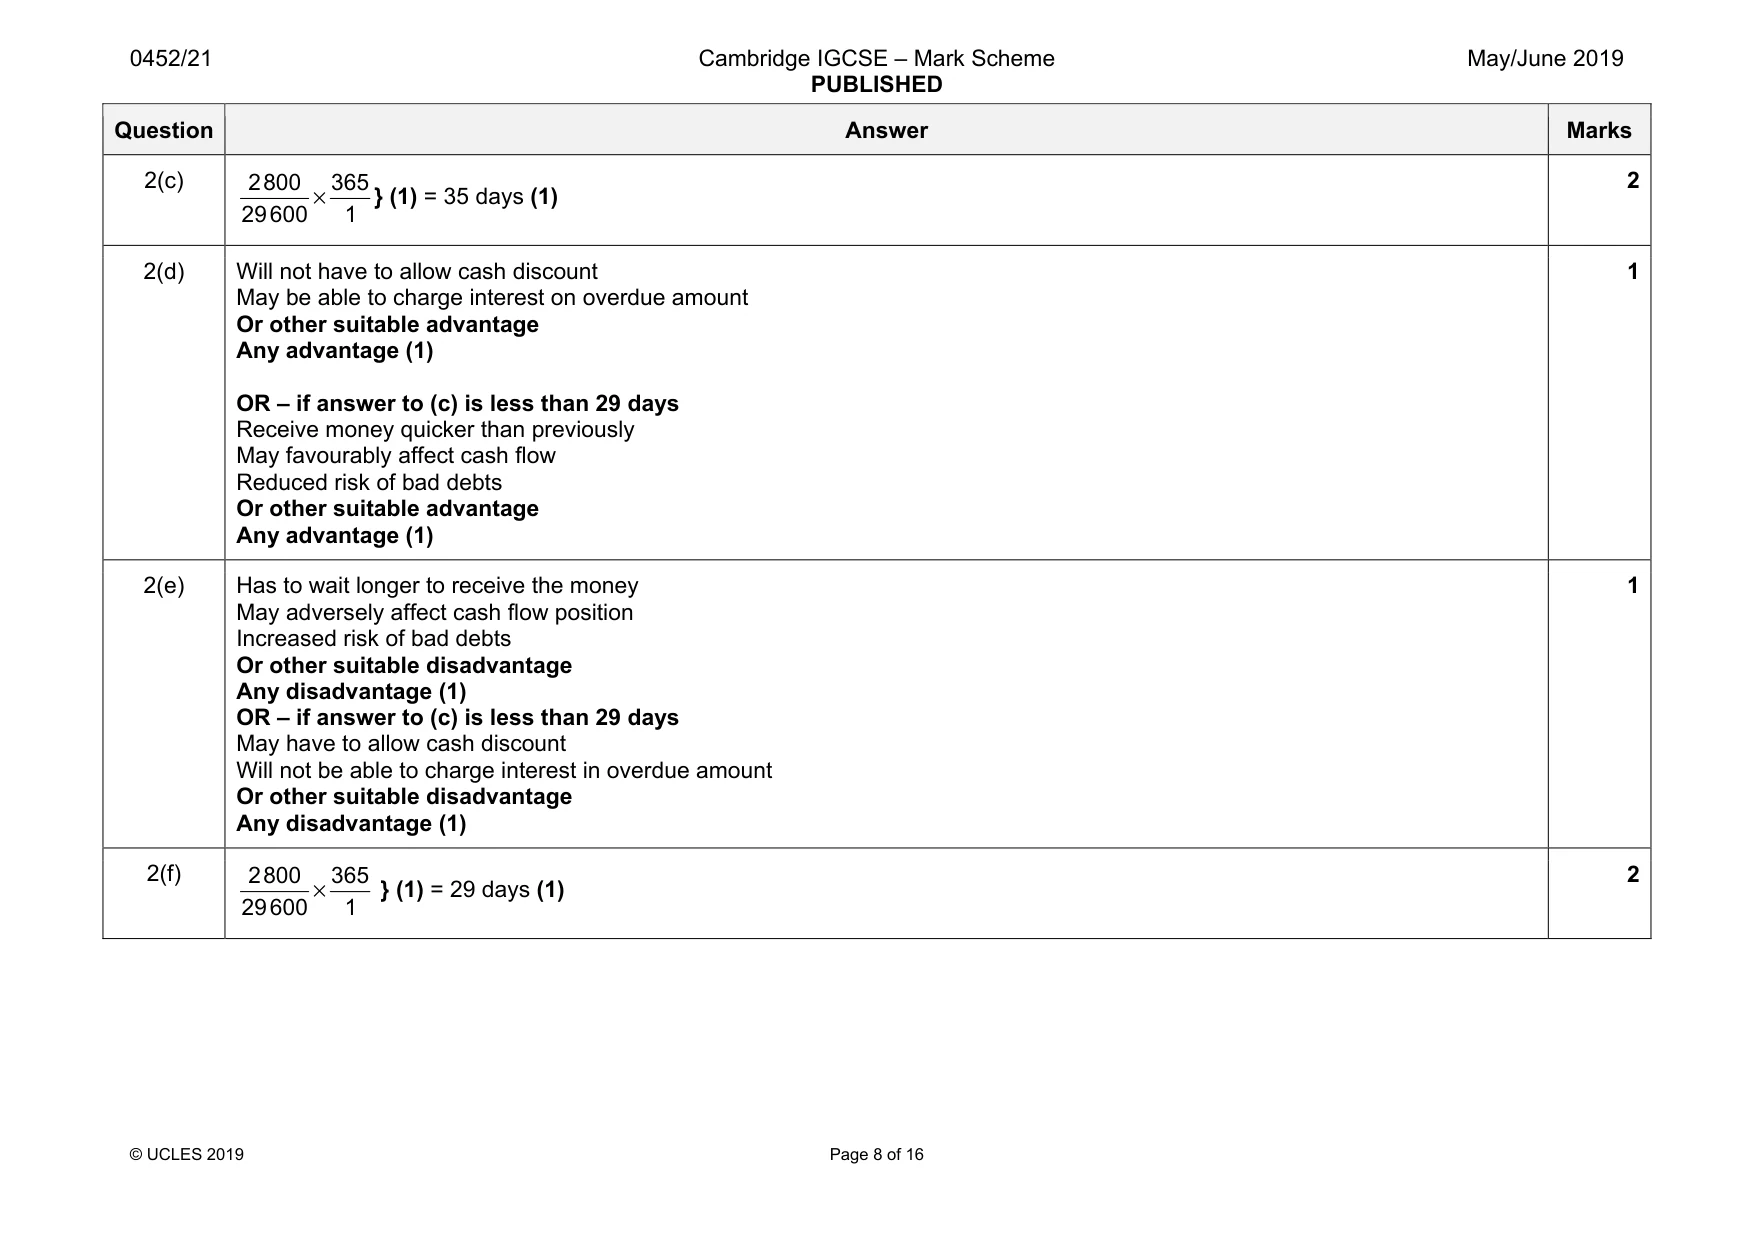
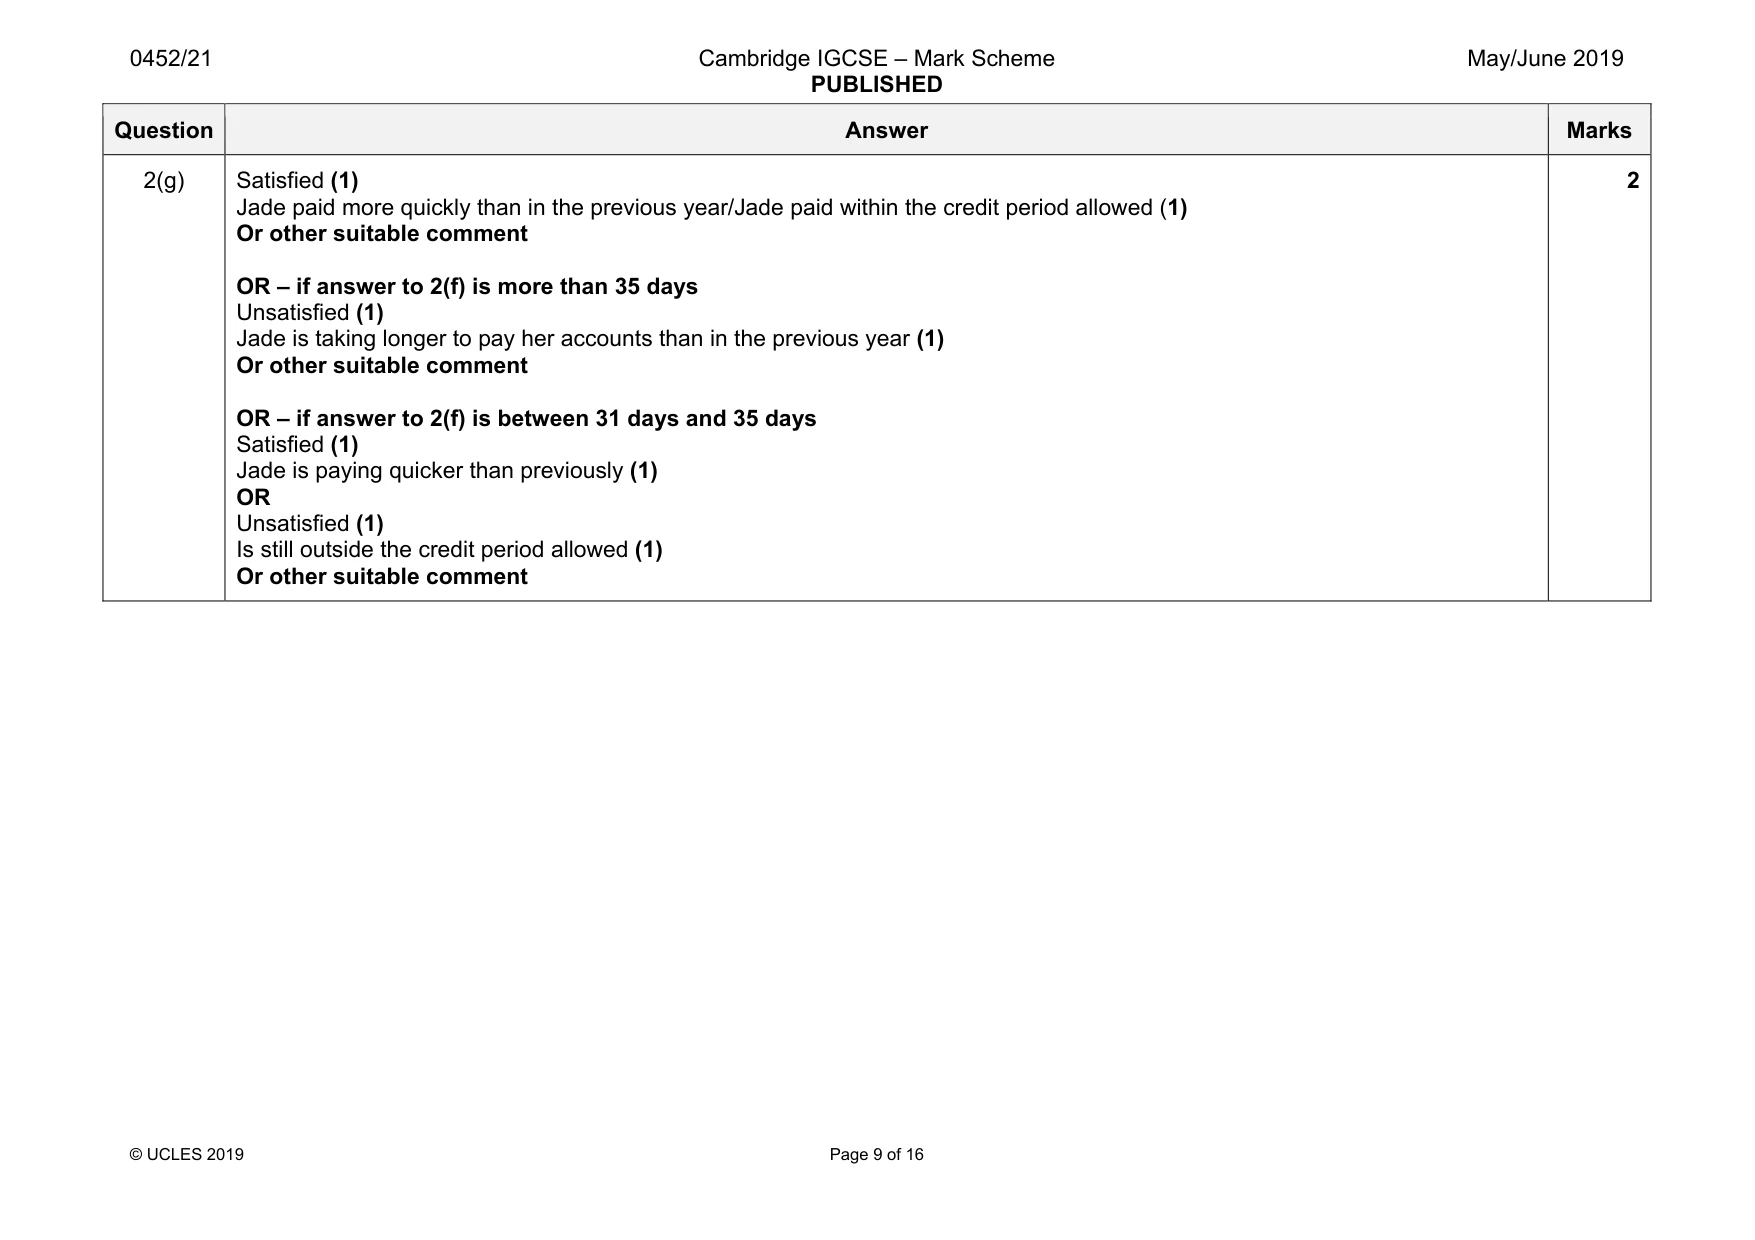
Mark scheme: 2(a)(i) Jade (1) To request a reduction in the invoice/to notify Adil of goods returned (1) 2 2(a)(ii) Adil (1) To notify of a reduction in the invoice (1) 2 2(a)(iii) Adil (1) To notify Jade of the amount owing at the end of the month (1) 2 2(b) Jade Adil account Date Details $ Date Details $ 2019 Bank (1) 2019 April 4 Discount (1) 429 April 1 Balance b/d (1) 440 Returns (1) 11 12 Purchases (1) 420 20 Balance c/d 75 30 345 860 860 May 1 Balance b/d 345 (1) OF 6 Question Answer Marks 2(c) 2800 365 29600 1 × } (1) = 35 days (1) 2 2(d) Will not have to allow cash discount May be able to charge interest on overdue amount Or other suitable advantage Any advantage (1) OR – if answer to (c) is less than 29 days Receive money quicker than previously May favourably affect cash flow Reduced risk of bad debts Or other suitable advantage Any advantage (1) 1 2(e) Has to wait longer to receive the money May adversely affect cash flow position Increased risk of bad debts Or other suitable disadvantage Any disadvantage (1) OR – if answer to (c) is less than 29 days May have to allow cash discount Will not be able to charge interest in overdue amount Or other suitable disadvantage Any disadvantage (1) 1 2(f) 2800 365 29600 1 × } (1) = 29 days (1) 2 Question Answer Marks 2(g) Satisfied (1) Jade paid more quickly than in the previous year/Jade paid within the credit period allowed (1) Or other suitable comment OR – if answer to 2(f) is more than 35 days Unsatisfied (1) Jade is taking longer to pay her accounts than in the previous year (1) Or other suitable comment OR – if answer to 2(f) is between 31 days and 35 days Satisfied (1) Jade is paying quicker than previously (1) OR Unsatisfied (1) Is still outside the credit period allowed (1) Or other suitable comment 2
Q3 · Min started a business selling office machinery on 1 January 2018
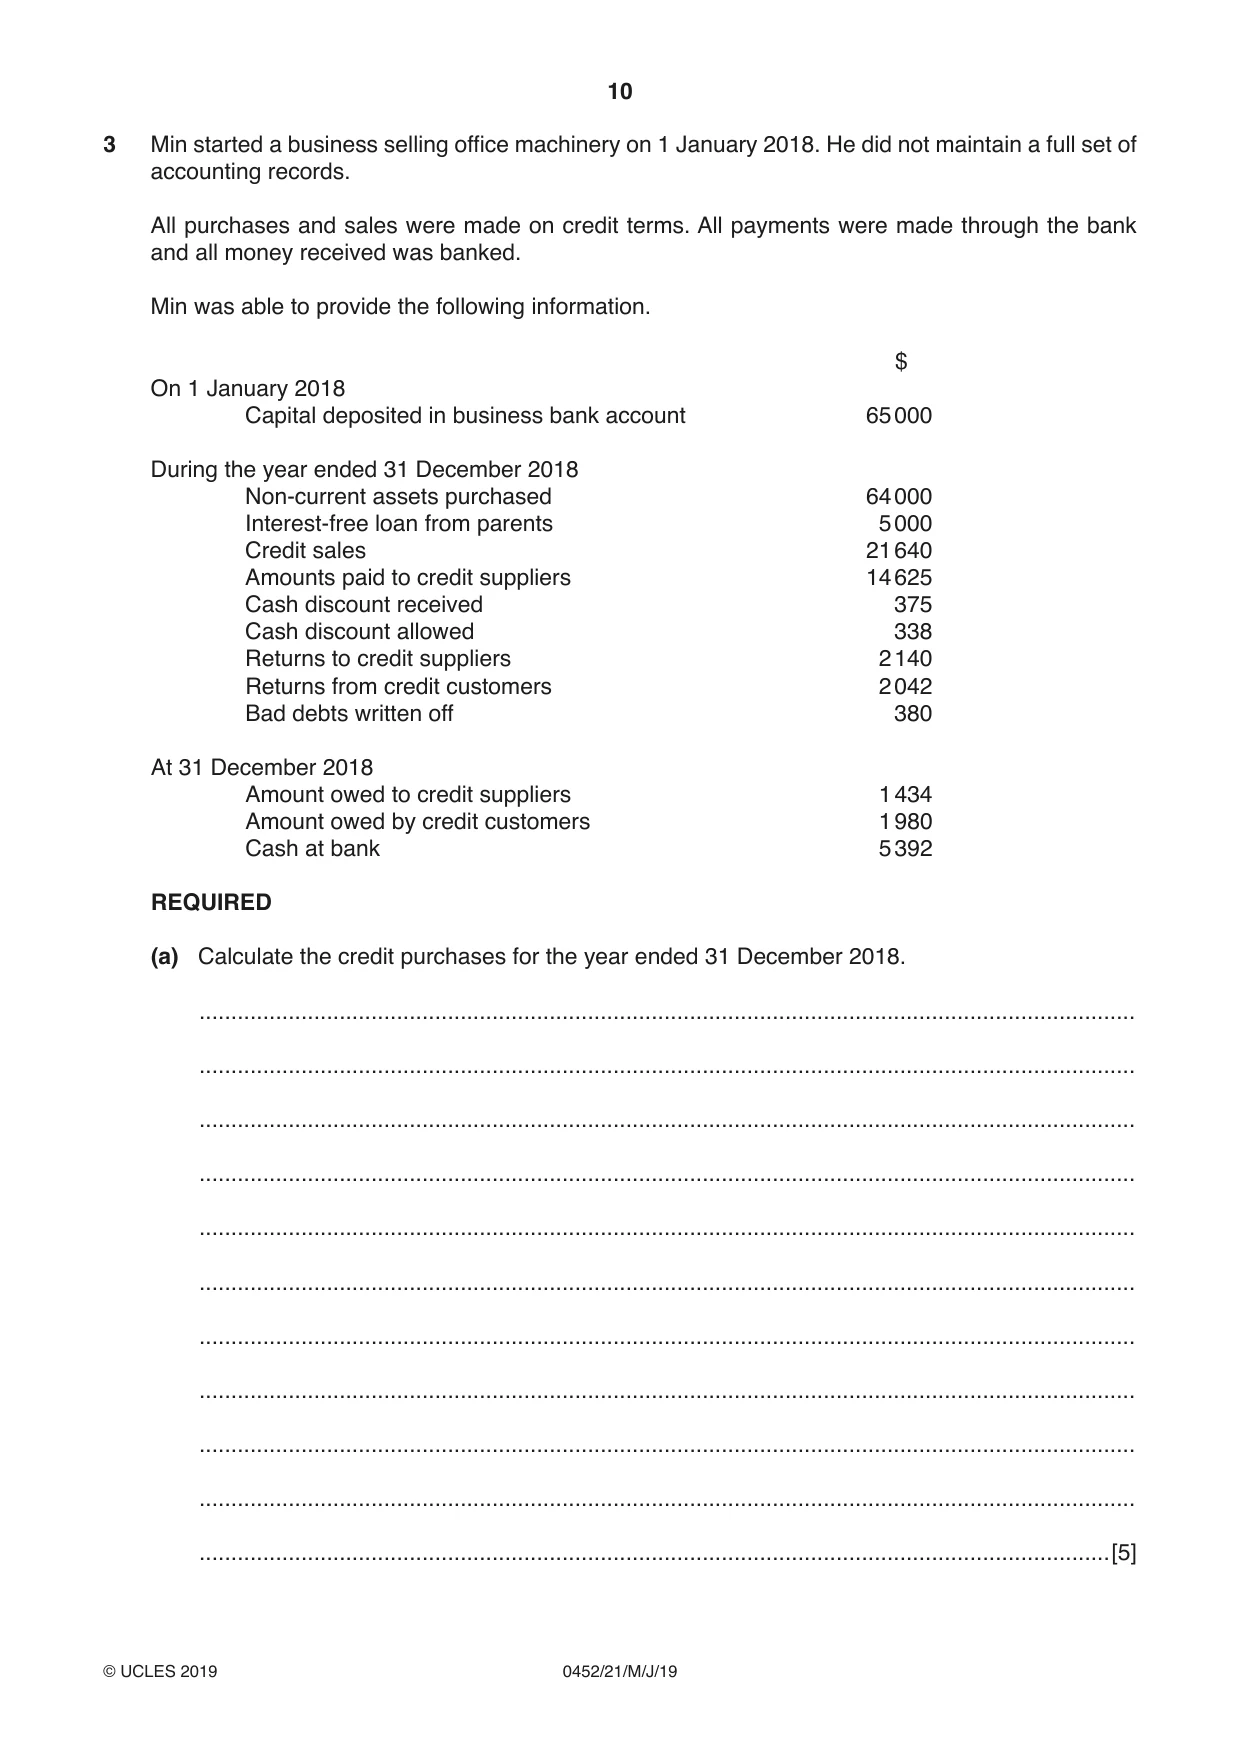
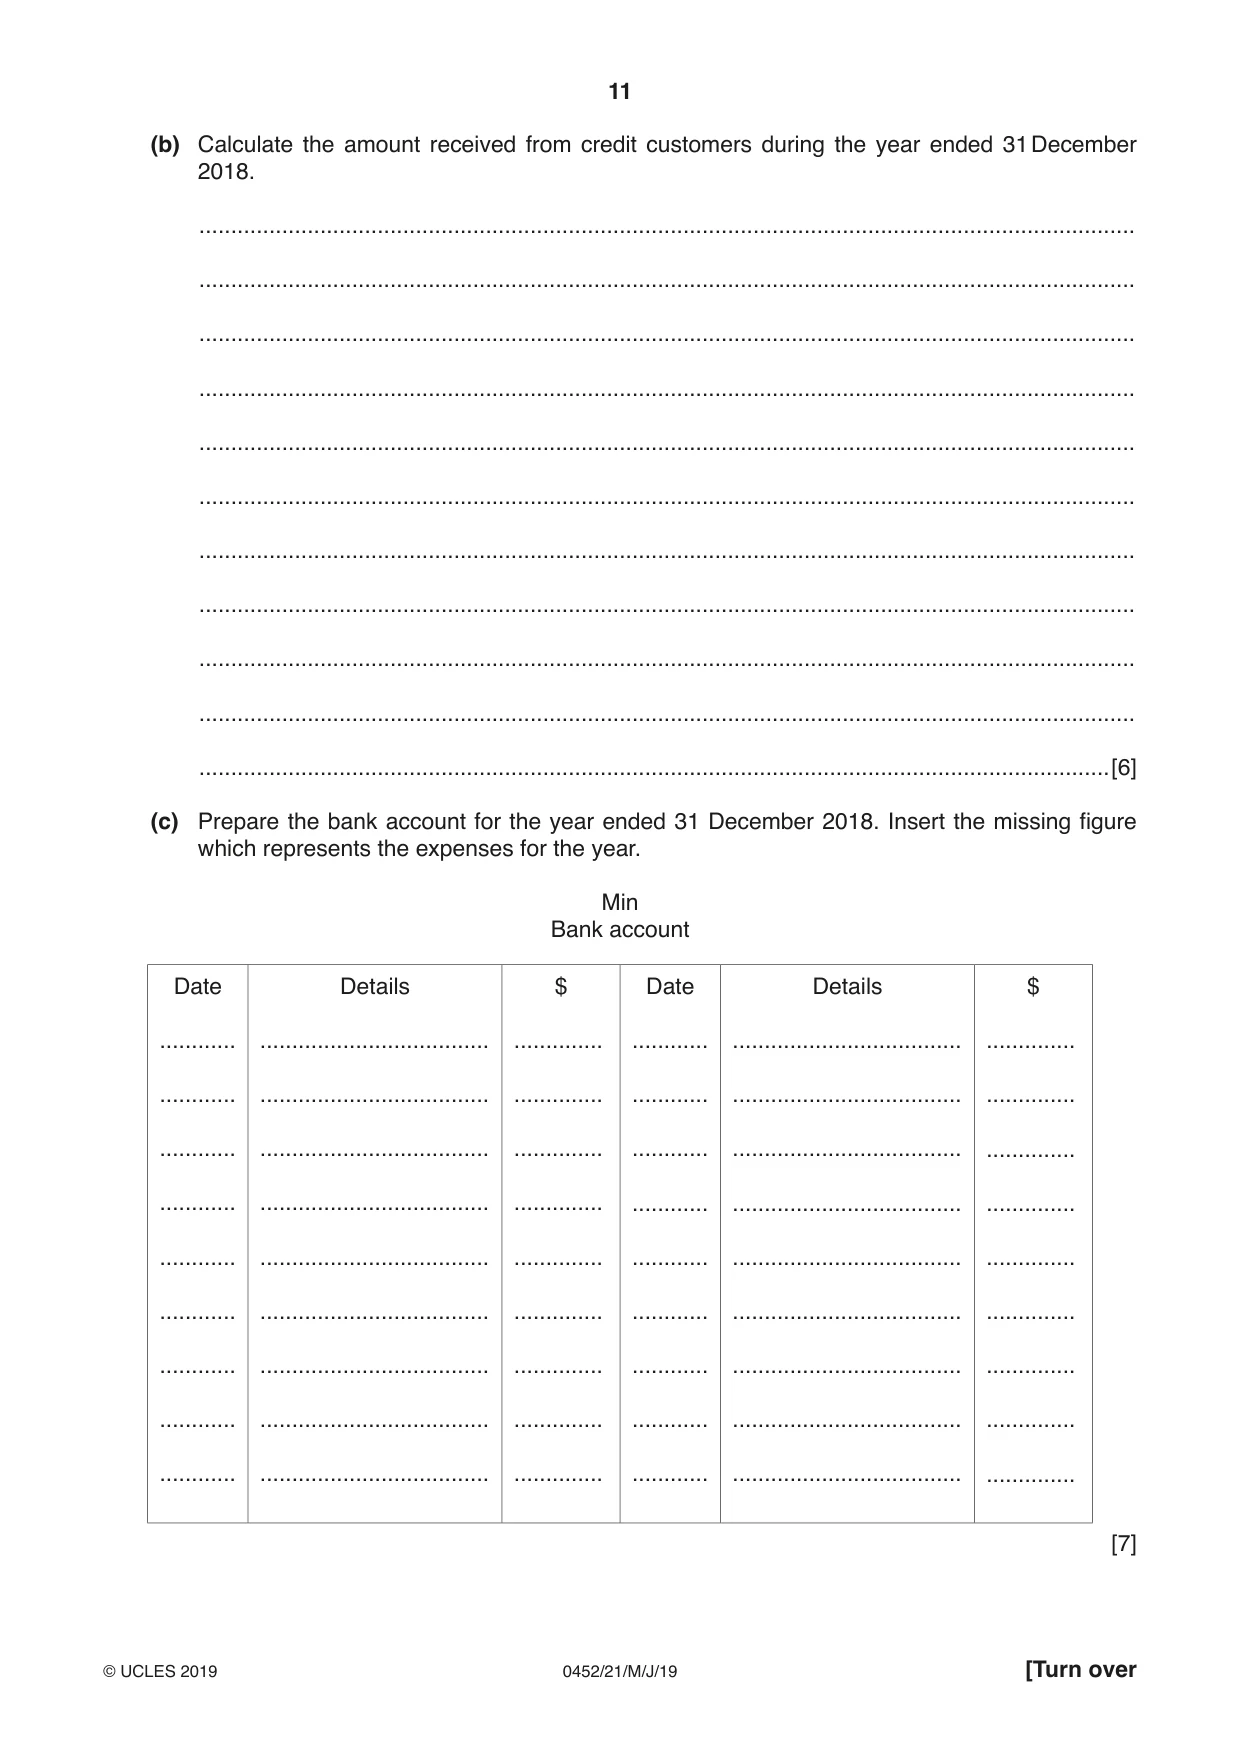
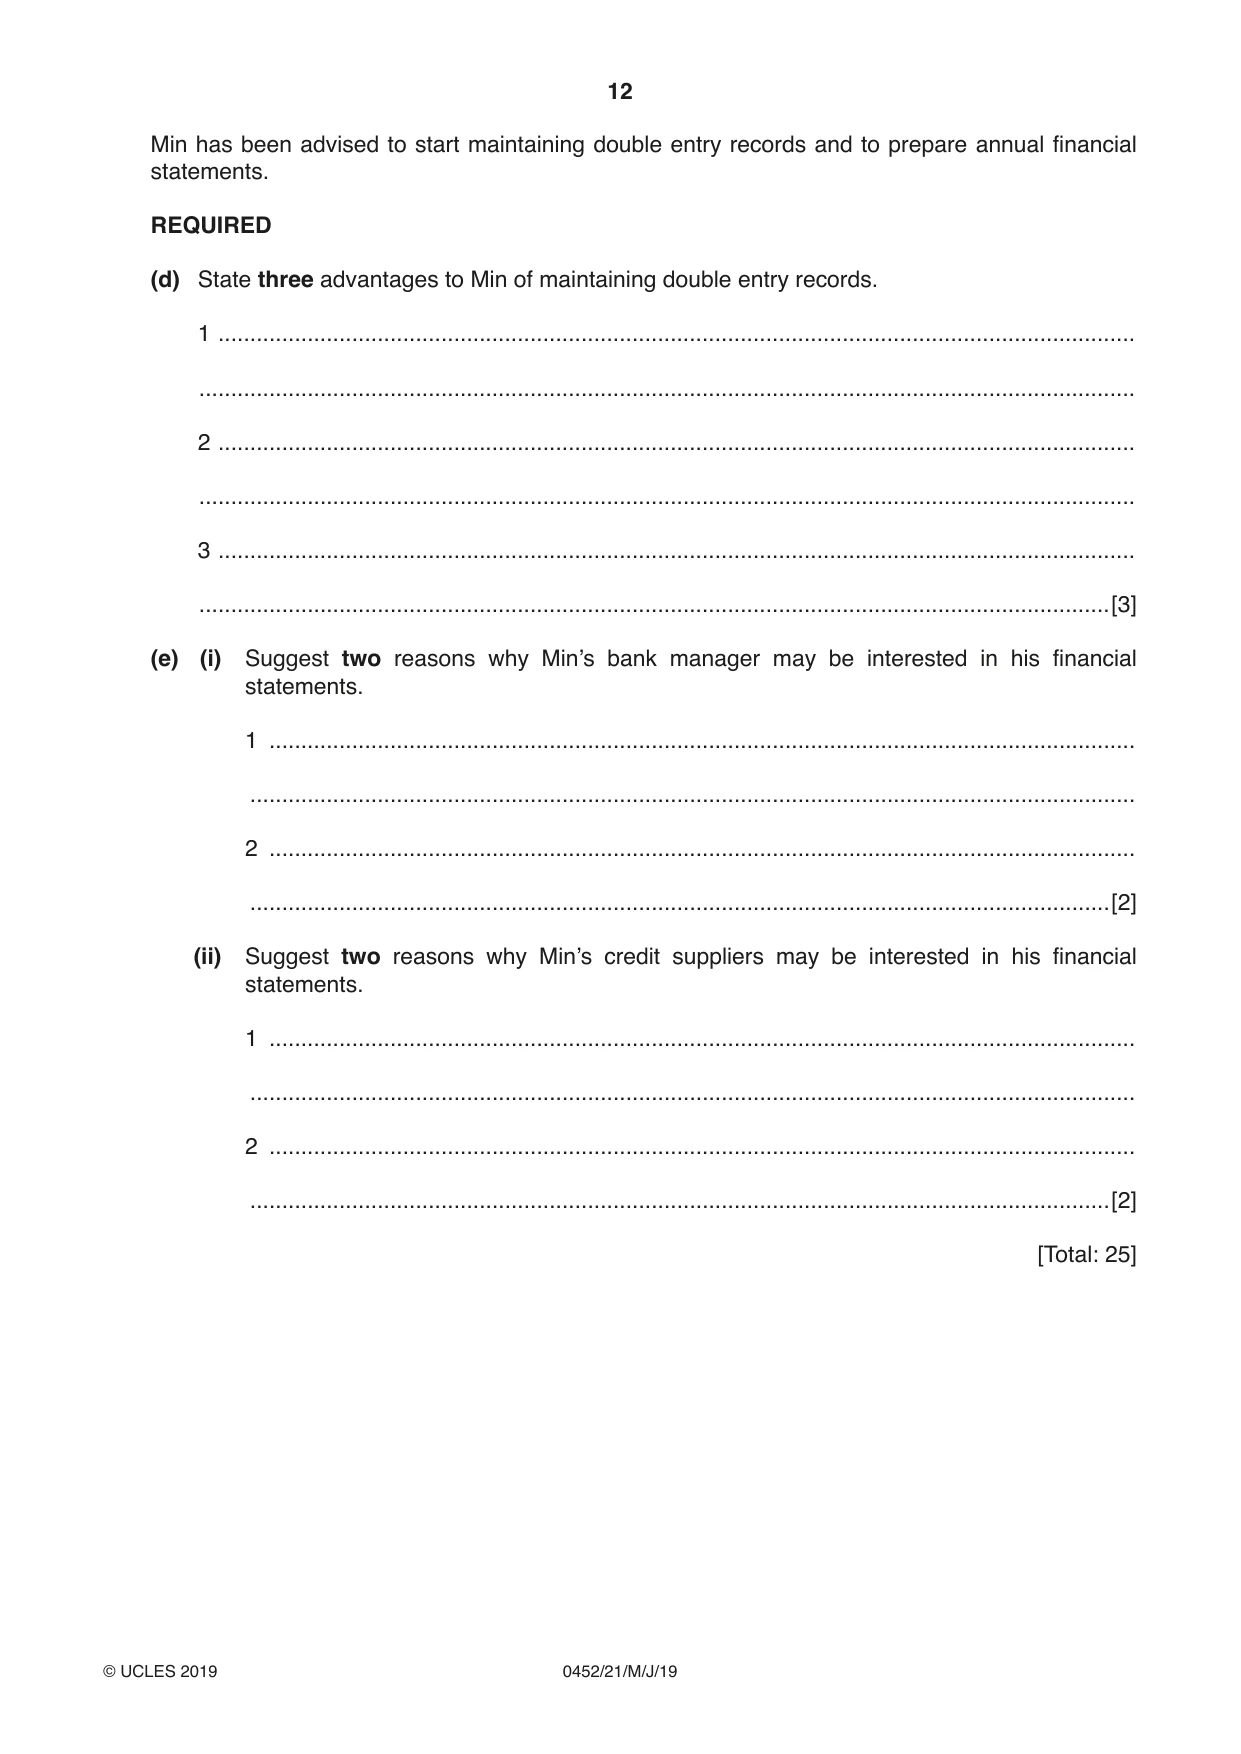
3 Min started a business selling office machinery on 1 January 2018. He did not maintain a full set of accounting records. All purchases and sales were made on credit terms. All payments were made through the bank and all money received was banked. Min was able to provide the following information. $ On 1 January 2018 Capital deposited in business bank account 65 000 During the year ended 31 December 2018 Non-current assets purchased 64 000 Interest-free loan from parents 5 000 Credit sales 21 640 Amounts paid to credit suppliers 14 625 Cash discount received 375 Cash discount allowed 338 Returns to credit suppliers 2 140 Returns from credit customers 2 042 Bad debts written off 380 At 31 December 2018 Amount owed to credit suppliers 1 434 Amount owed by credit customers 1 980 Cash at bank 5 392 REQUIRED (a) Calculate the credit purchases for the year ended 31 December 2018. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[5] (b) Calculate the amount received from credit customers during the year ended 31 December 2018. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[6] (c) Prepare the bank account for the year ended 31 December 2018. Insert the missing figure which represents the expenses for the year. Min Bank account Date Details $ Date Details $ ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. [7] Min has been advised to start maintaining double entry records and to prepare annual financial statements. REQUIRED (d) State three advantages to Min of maintaining double entry records. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ...............................................................................................................................................[3] (e) (i) Suggest two reasons why Min’s bank manager may be interested in his financial statements. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ .......................................................................................................................................[2] (ii) Suggest two reasons why Min’s credit suppliers may be interested in his financial statements. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ .......................................................................................................................................[2] [Total: 25] PLEASE TURN OVER
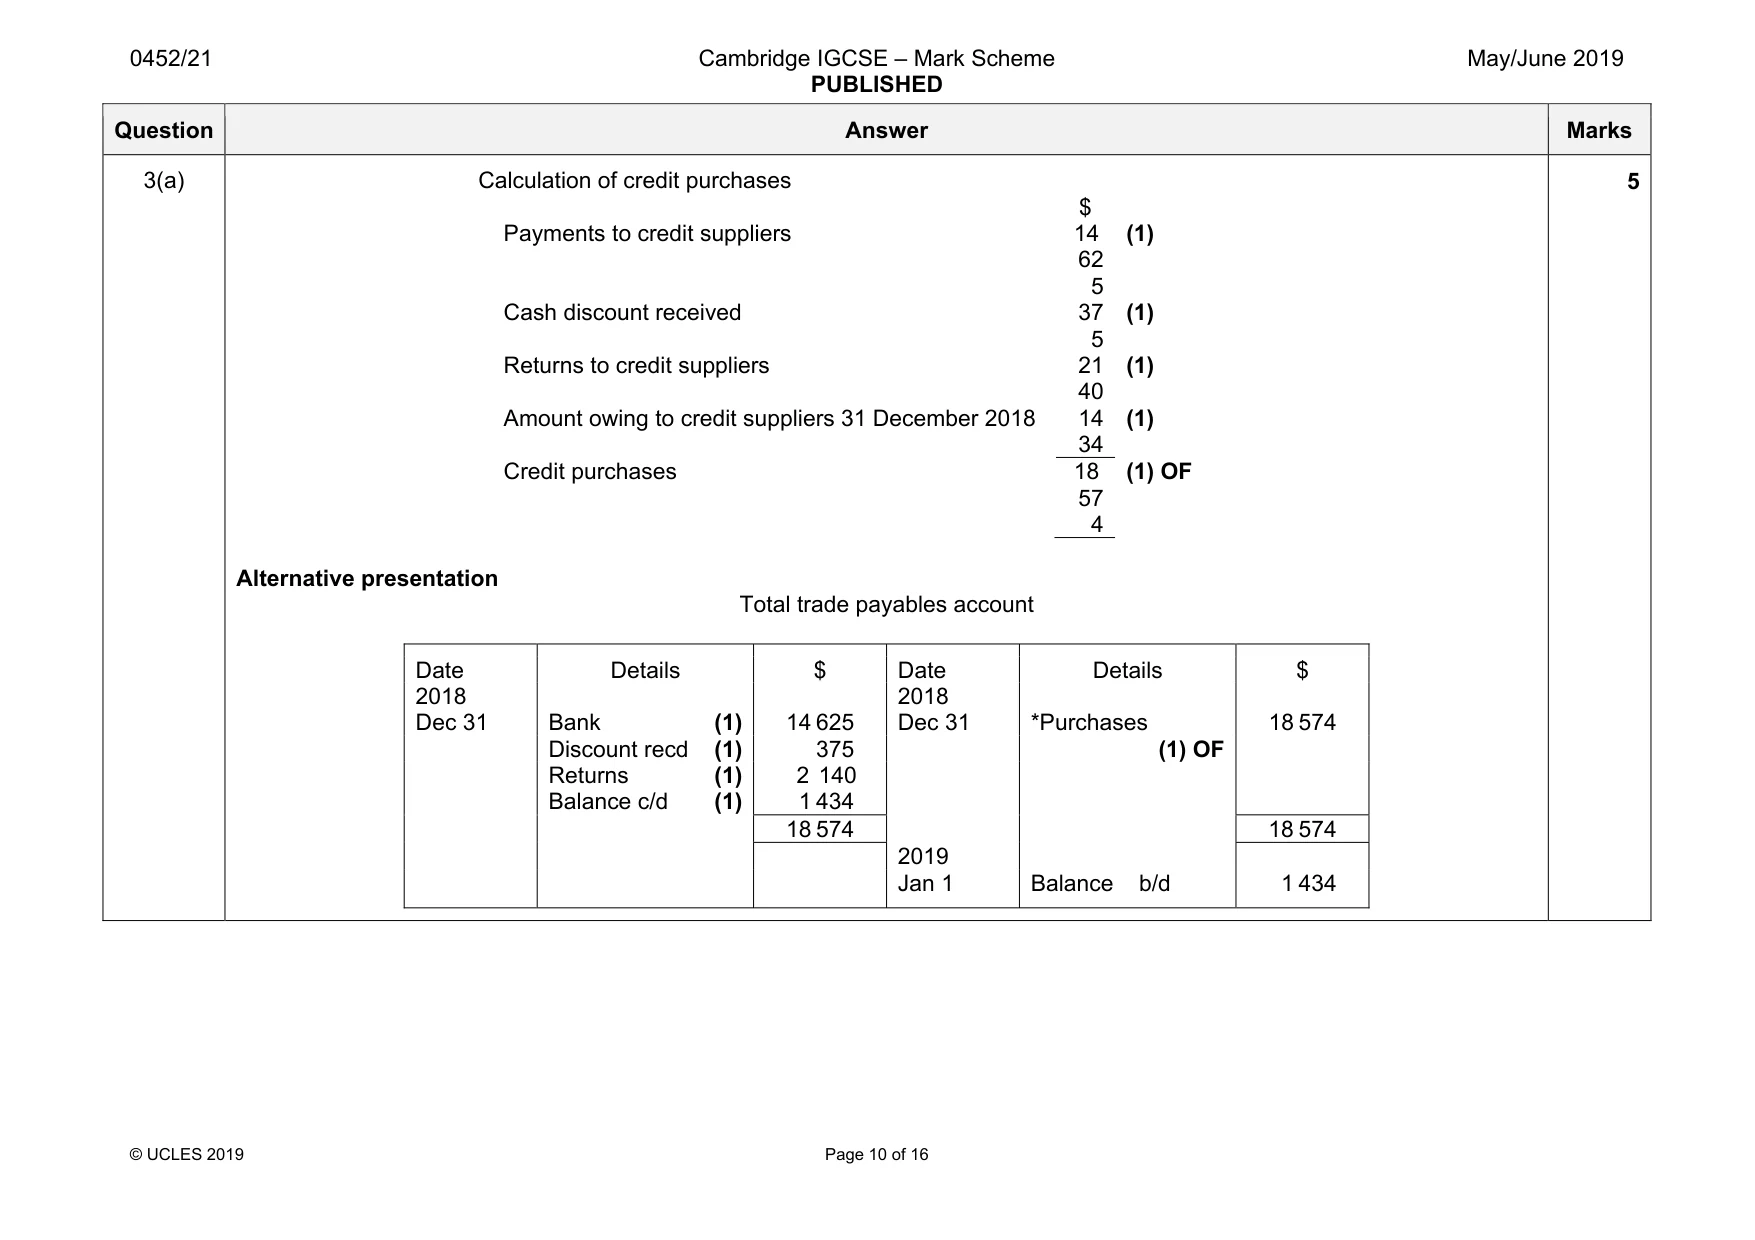
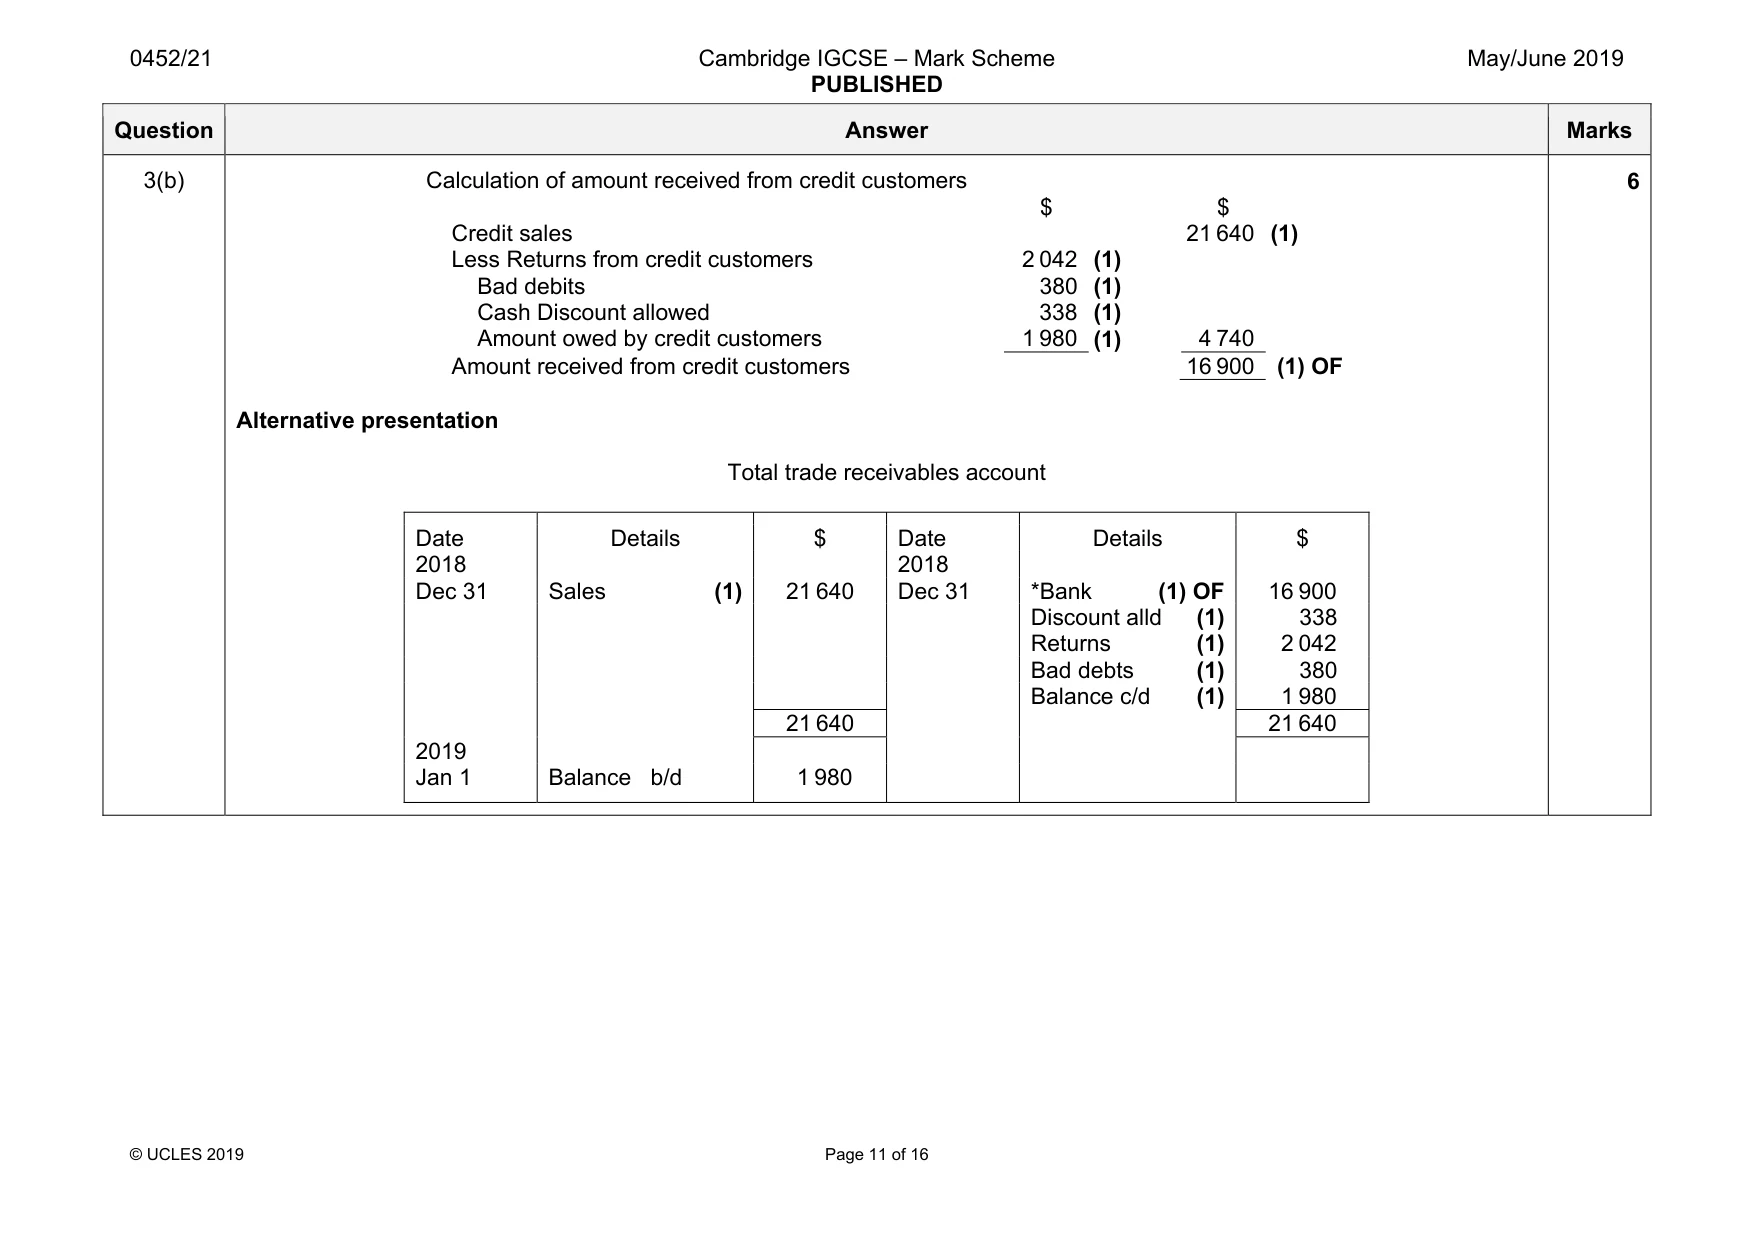
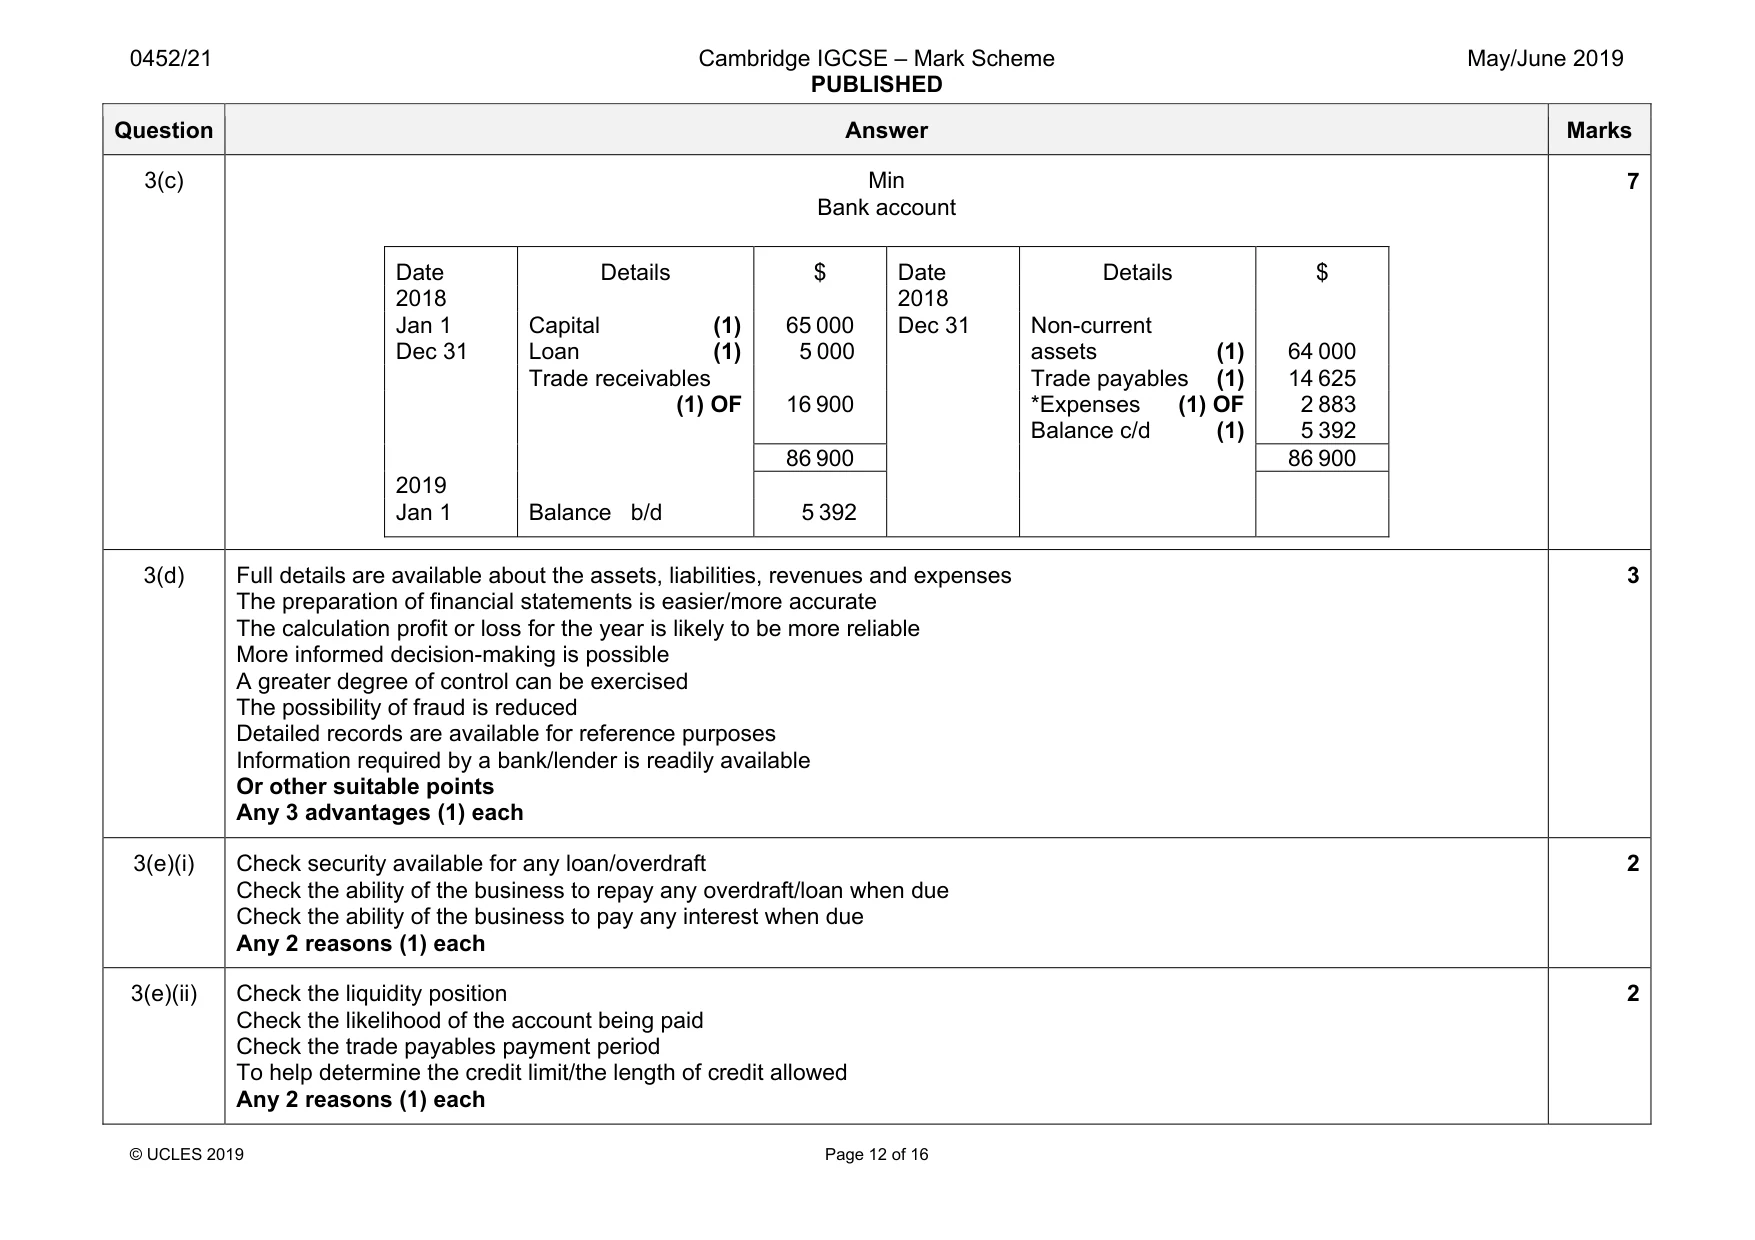
Mark scheme: 3(a) Calculation of credit purchases $ Payments to credit suppliers 14 62 5 (1) Cash discount received 37 5 (1) Returns to credit suppliers 21 40 (1) Amount owing to credit suppliers 31 December 2018 14 34 (1) Credit purchases 18 57 4 (1) OF Alternative presentation Total trade payables account Date Details $ Date Details $ 2018 2018 Dec 31 Bank (1) 14 625 Dec 31 *Purchases 18 574 Discount recd (1) 375 (1) OF Returns (1) 2 140 Balance c/d (1) 1 434 18 574 18 574 2019 Jan 1 Balance b/d 1 434 5 Question Answer Marks 3(b) Calculation of amount received from credit customers $ $ Credit sales 21 640 (1) Less Returns from credit customers 2 042 (1) Bad debits 380 (1) Cash Discount allowed 338 (1) Amount owed by credit customers 1 980 (1) 4 740 Amount received from credit customers 16 900 (1) OF Alternative presentation Total trade receivables account Date Details $ Date Details $ 2018 2018 Dec 31 Sales (1) 21 640 Dec 31 *Bank (1) OF 16 900 Discount alld (1) 338 Returns (1) 2 042 Bad debts (1) 380 Balance c/d (1) 1 980 21 640 21 640 2019 Jan 1 Balance b/d 1 980 6 Question Answer Marks 3(c) Min Bank account Date Details $ Date Details $ 2018 2018 Jan 1 Capital (1) 65 000 Dec 31 Non-current Dec 31 Loan (1) 5 000 assets (1) 64 000 Trade receivables Trade payables (1) 14 625 (1) OF 16 900 *Expenses (1) OF 2 883 Balance c/d (1) 5 392 86 900 86 900 2019 Jan 1 Balance b/d 5 392 7 3(d) Full details are available about the assets, liabilities, revenues and expenses The preparation of financial statements is easier/more accurate The calculation profit or loss for the year is likely to be more reliable More informed decision-making is possible A greater degree of control can be exercised The possibility of fraud is reduced Detailed records are available for reference purposes Information required by a bank/lender is readily available Or other suitable points Any 3 advantages (1) each 3 3(e)(i) Check security available for any loan/overdraft Check the ability of the business to repay any overdraft/loan when due Check the ability of the business to pay any interest when due Any 2 reasons (1) each 2 3(e)(ii) Check the liquidity position Check the likelihood of the account being paid Check the trade payables payment period To help determine the credit limit/the length of credit allowed Any 2 reasons (1) each 2
Q4 · Liam and Mia are in partnership
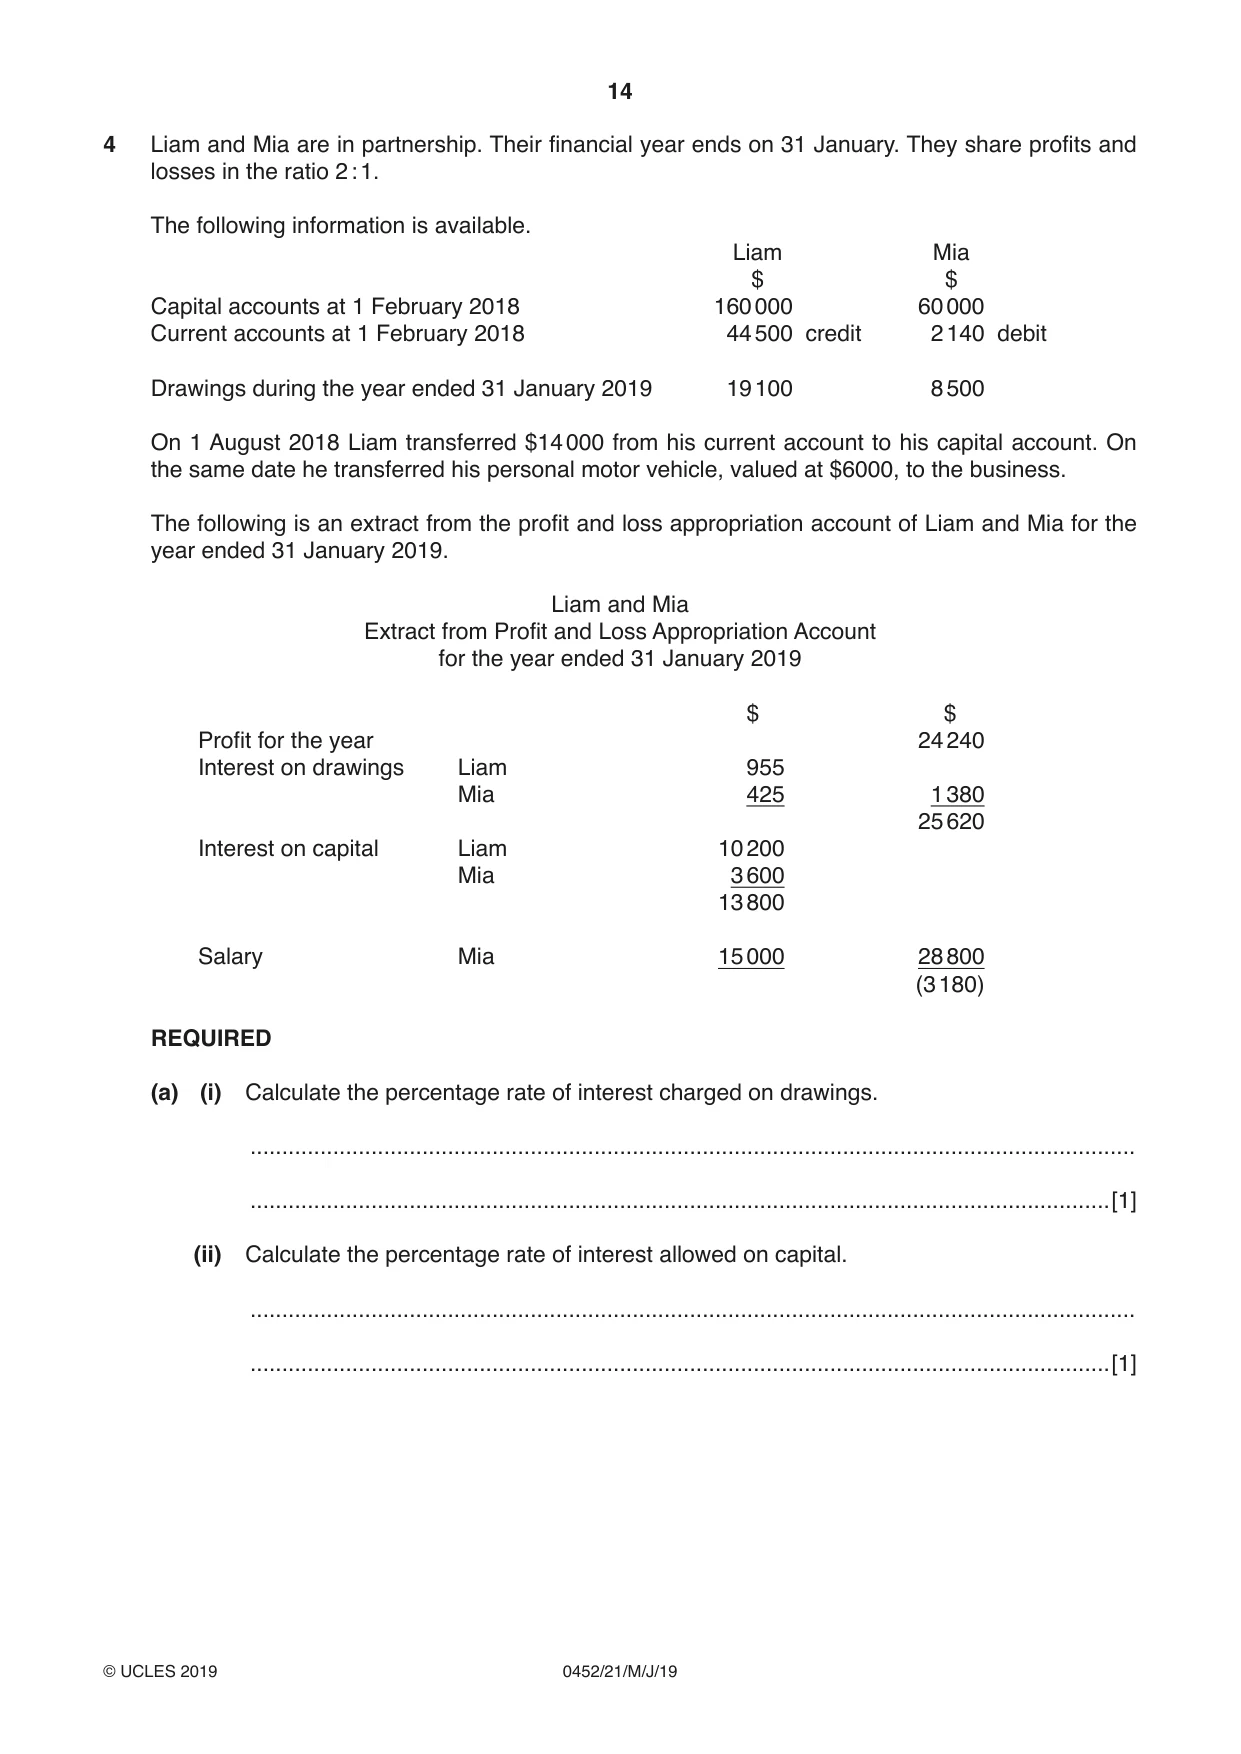
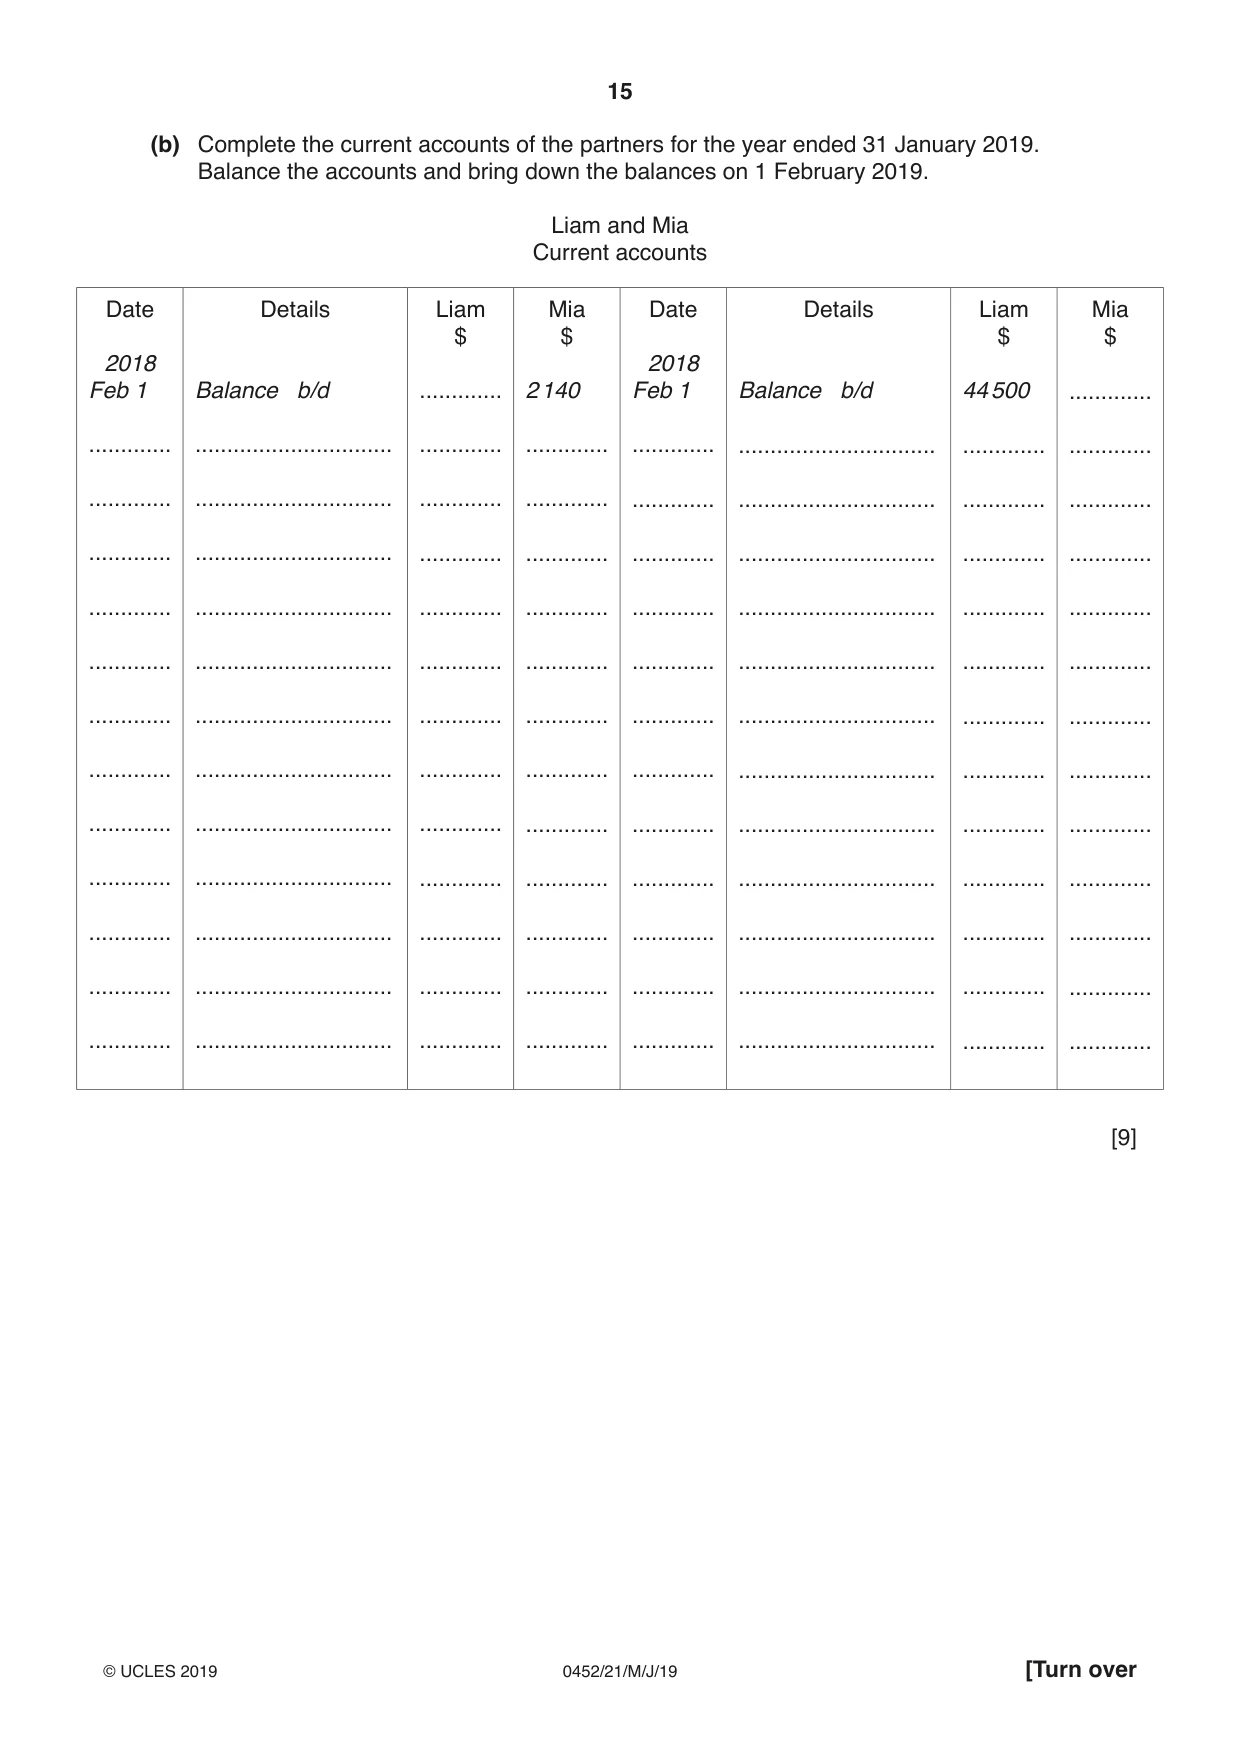
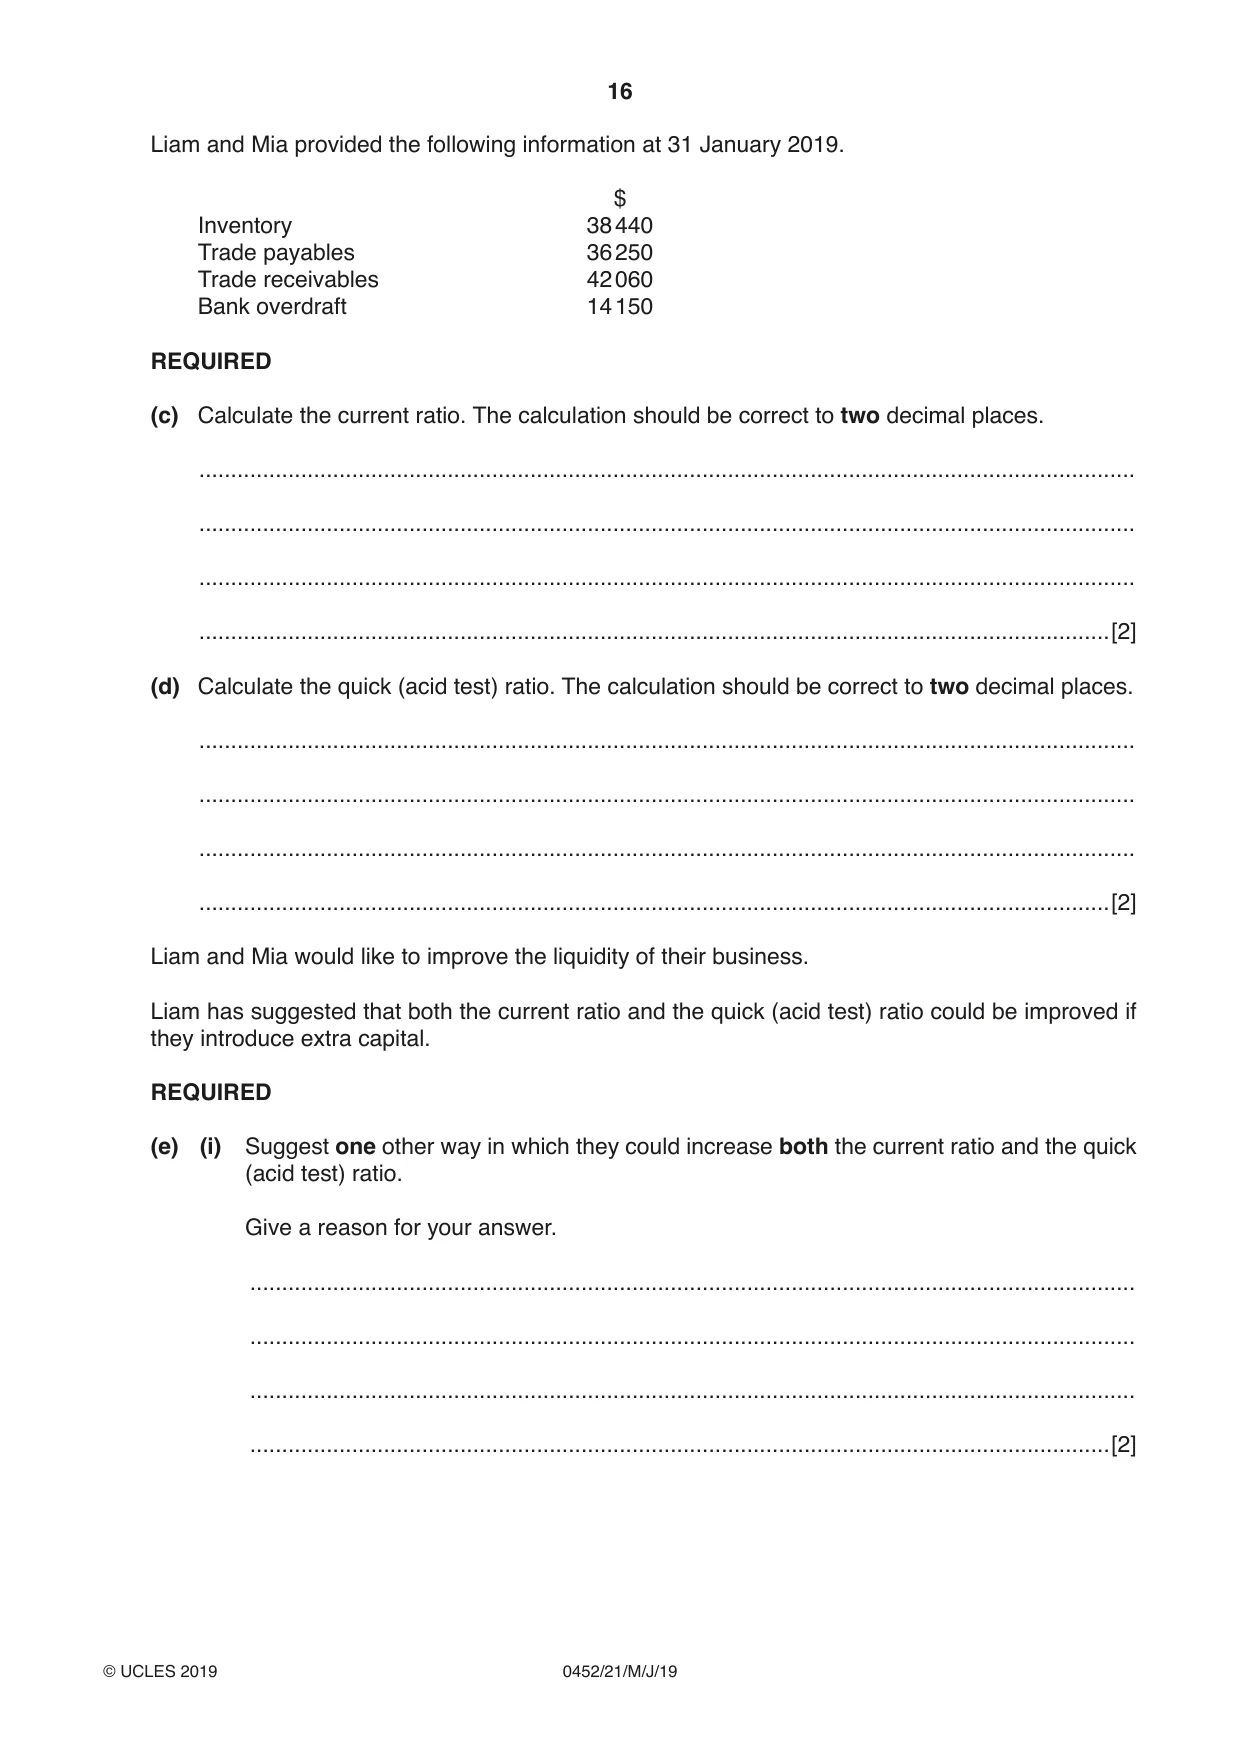
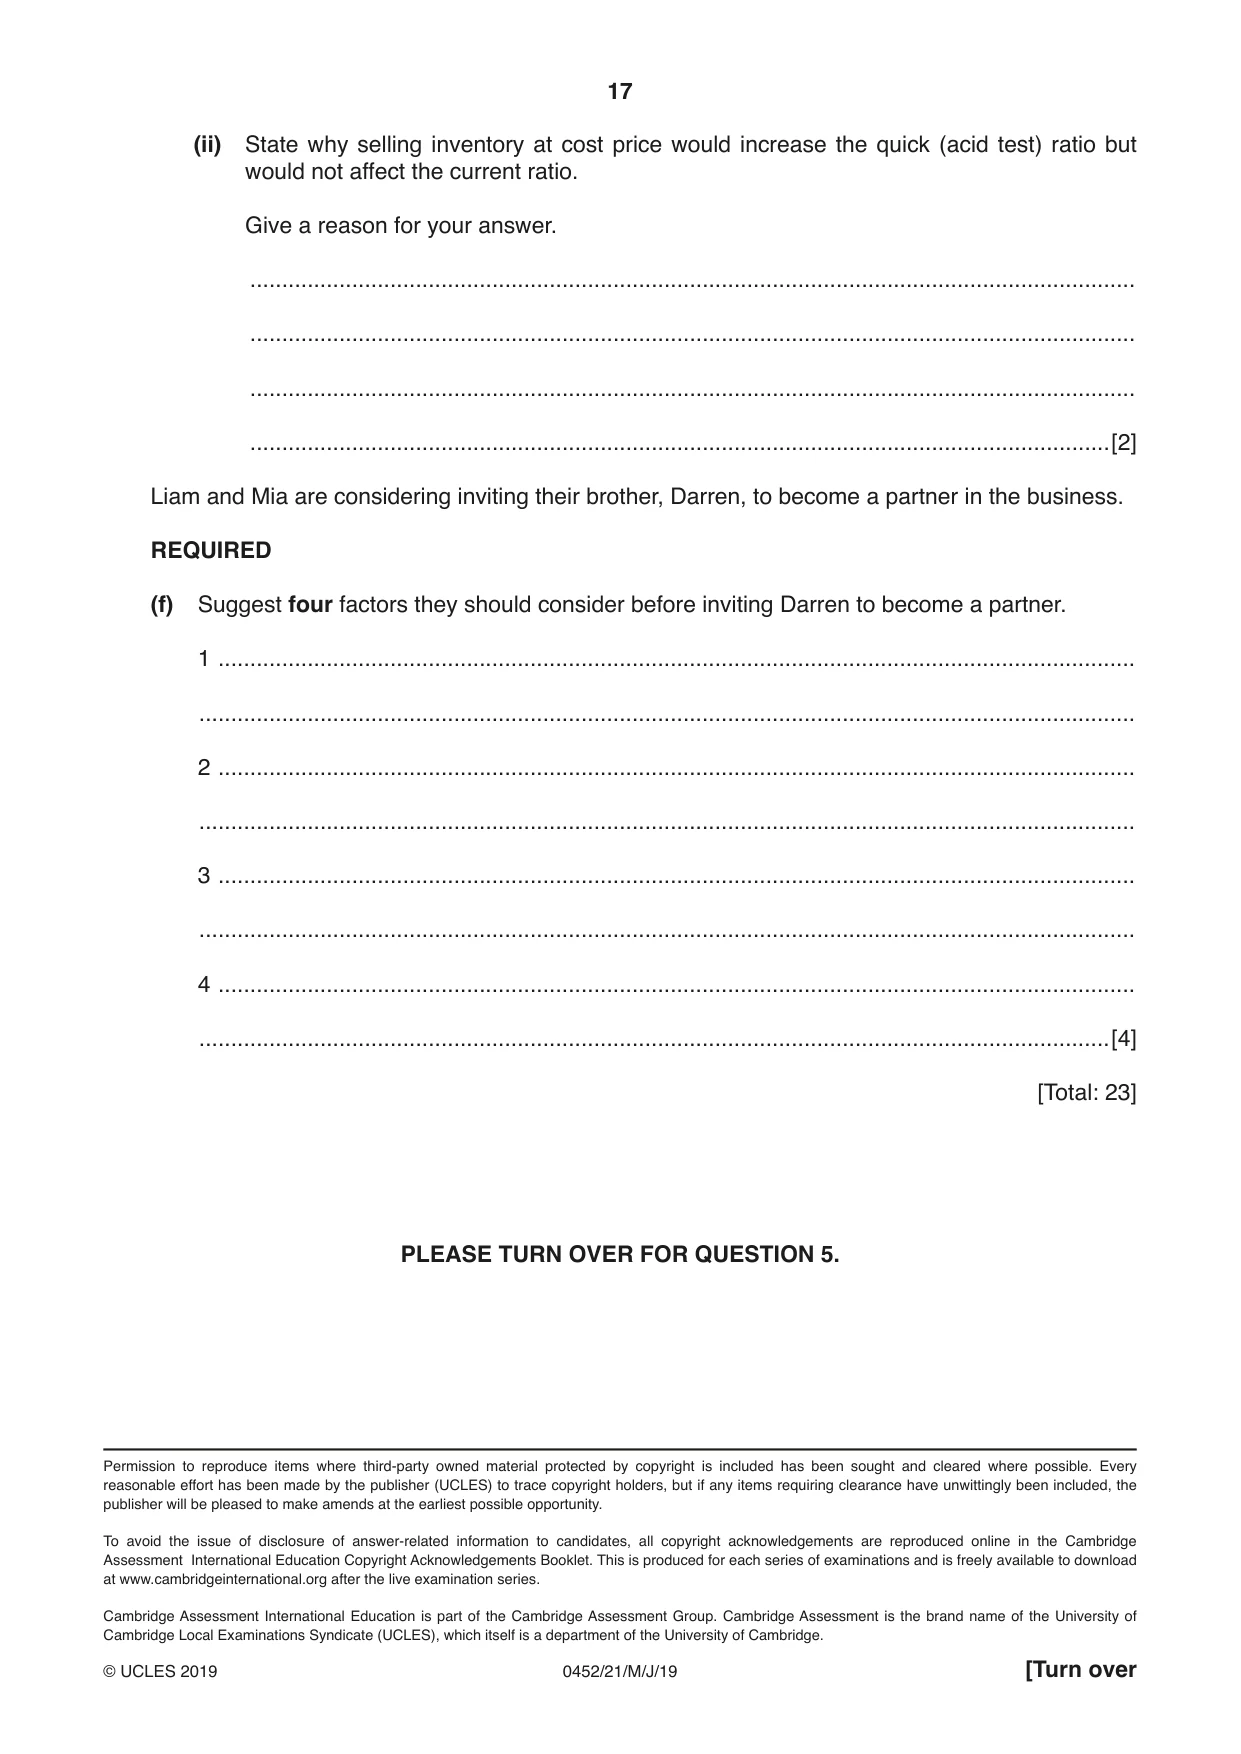
4 Liam and Mia are in partnership. Their financial year ends on 31 January. They share profits and losses in the ratio 2 : 1. The following information is available. Liam Mia $ $ Capital accounts at 1 February 2018 160 000 60 000 Current accounts at 1 February 2018 44 500 credit 2 140 debit Drawings during the year ended 31 January 2019 19 100 8 500 On 1 August 2018 Liam transferred $14 000 from his current account to his capital account. On the same date he transferred his personal motor vehicle, valued at $6000, to the business. The following is an extract from the profit and loss appropriation account of Liam and Mia for the year ended 31 January 2019. Liam and Mia Extract from Profit and Loss Appropriation Account for the year ended 31 January 2019 $ $ Profit for the year 24 240 Interest on drawings Liam 955 Mia 425 1 380 25 620 Interest on capital Liam 10 200 Mia 3 600 13 800 Salary Mia 15 000 28 800 (3 180) REQUIRED (a) (i) Calculate the percentage rate of interest charged on drawings. ........................................................................................................................................... .......................................................................................................................................[1] (ii) Calculate the percentage rate of interest allowed on capital. ........................................................................................................................................... .......................................................................................................................................[1] (b) Complete the current accounts of the partners for the year ended 31 January 2019. Balance the accounts and bring down the balances on 1 February 2019. Liam and Mia Current accounts Date Details Liam Mia Date Details Liam Mia $ $ $ $ 2018 2018 Feb 1 Balance b/d ............. 2 140 Feb 1 Balance b/d 44 500 ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. ............. ............................... ............. ............. [9] Liam and Mia provided the following information at 31 January 2019. $ Inventory 38 440 Trade payables 36 250 Trade receivables 42 060 Bank overdraft 14 150 REQUIRED (c) Calculate the current ratio. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (d) Calculate the quick (acid test) ratio. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] Liam and Mia would like to improve the liquidity of their business. Liam has suggested that both the current ratio and the quick (acid test) ratio could be improved if they introduce extra capital. REQUIRED (e) (i) Suggest one other way in which they could increase both the current ratio and the quick (acid test) ratio. Give a reason for your answer. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) State why selling inventory at cost price would increase the quick (acid test) ratio but would not affect the current ratio. Give a reason for your answer. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] Liam and Mia are considering inviting their brother, Darren, to become a partner in the business. REQUIRED (f) Suggest four factors they should consider before inviting Darren to become a partner. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... 4 ................................................................................................................................................ ...............................................................................................................................................[4] [Total: 23] PLEASE TURN OVER FOR QUESTION 5.
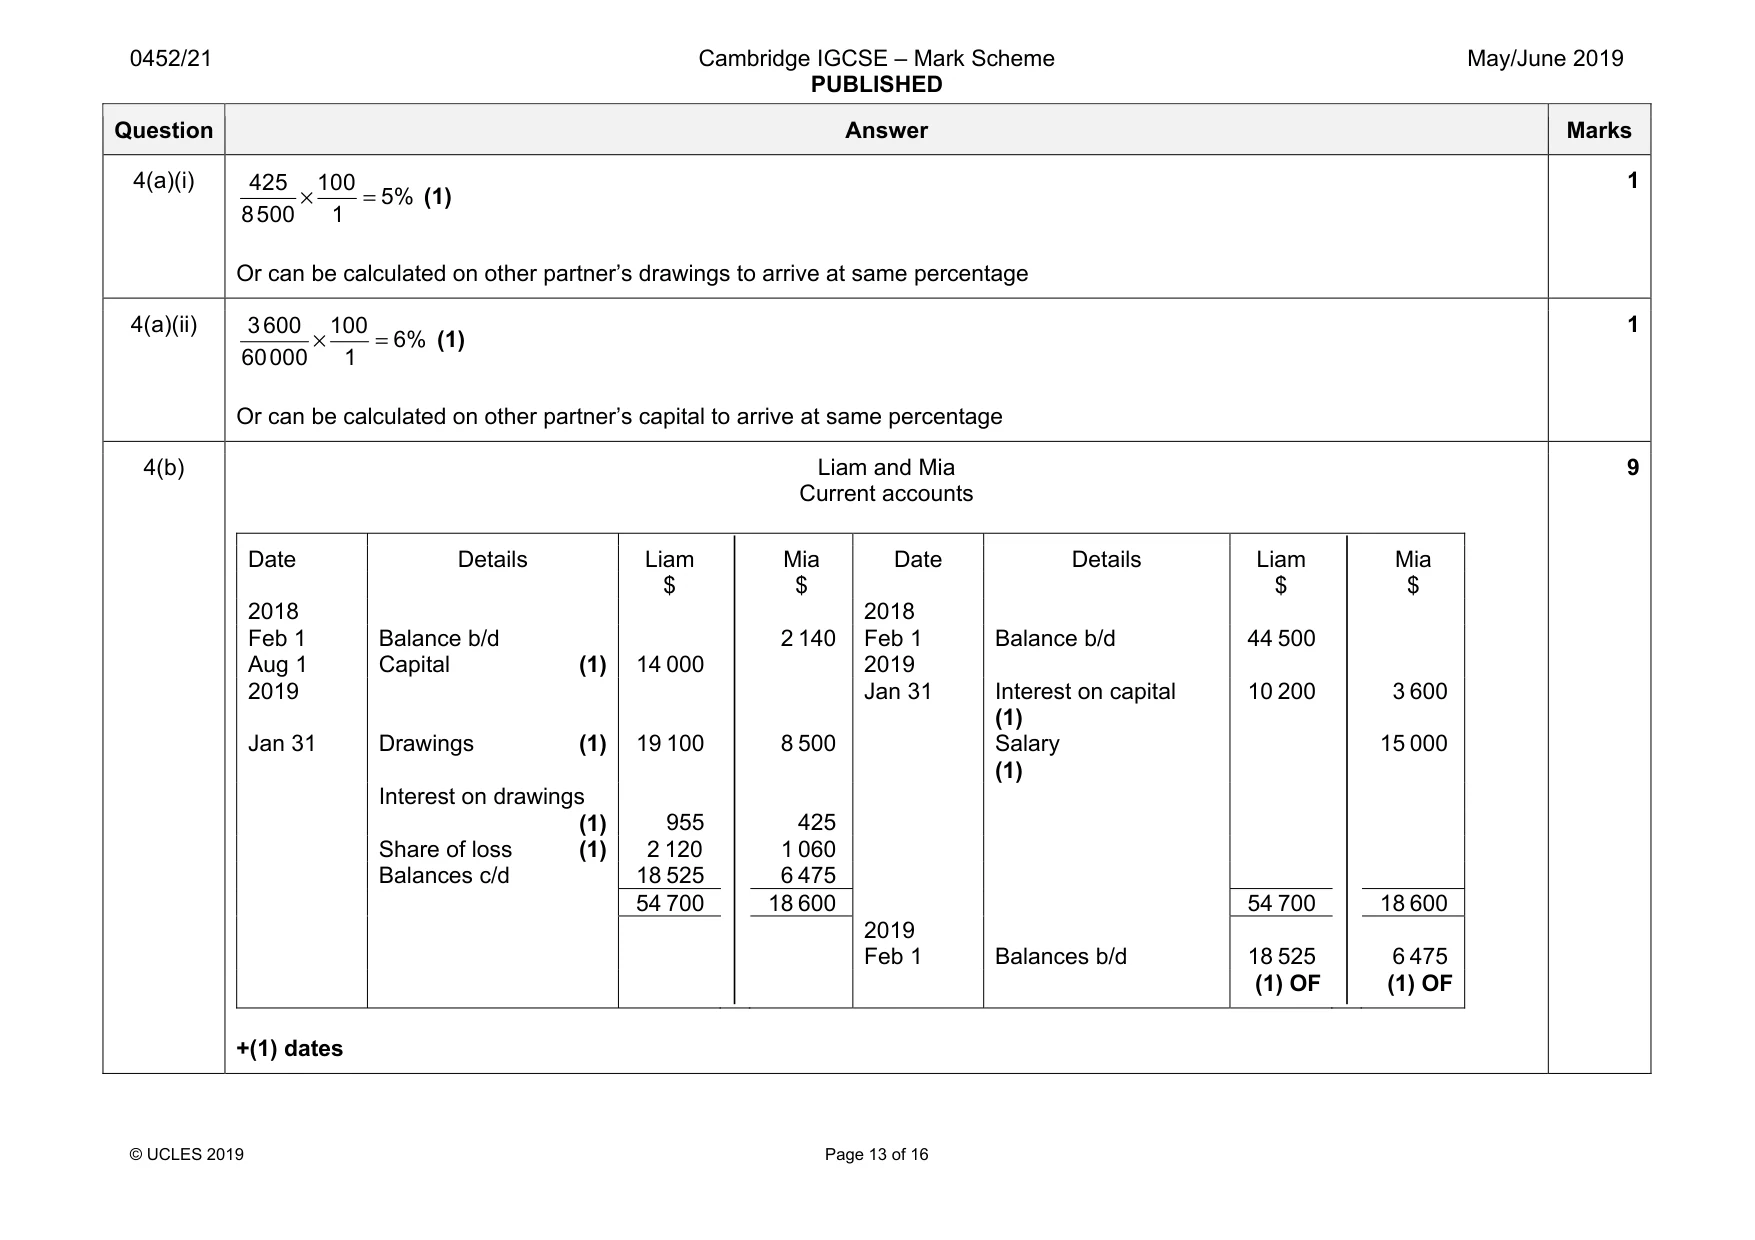
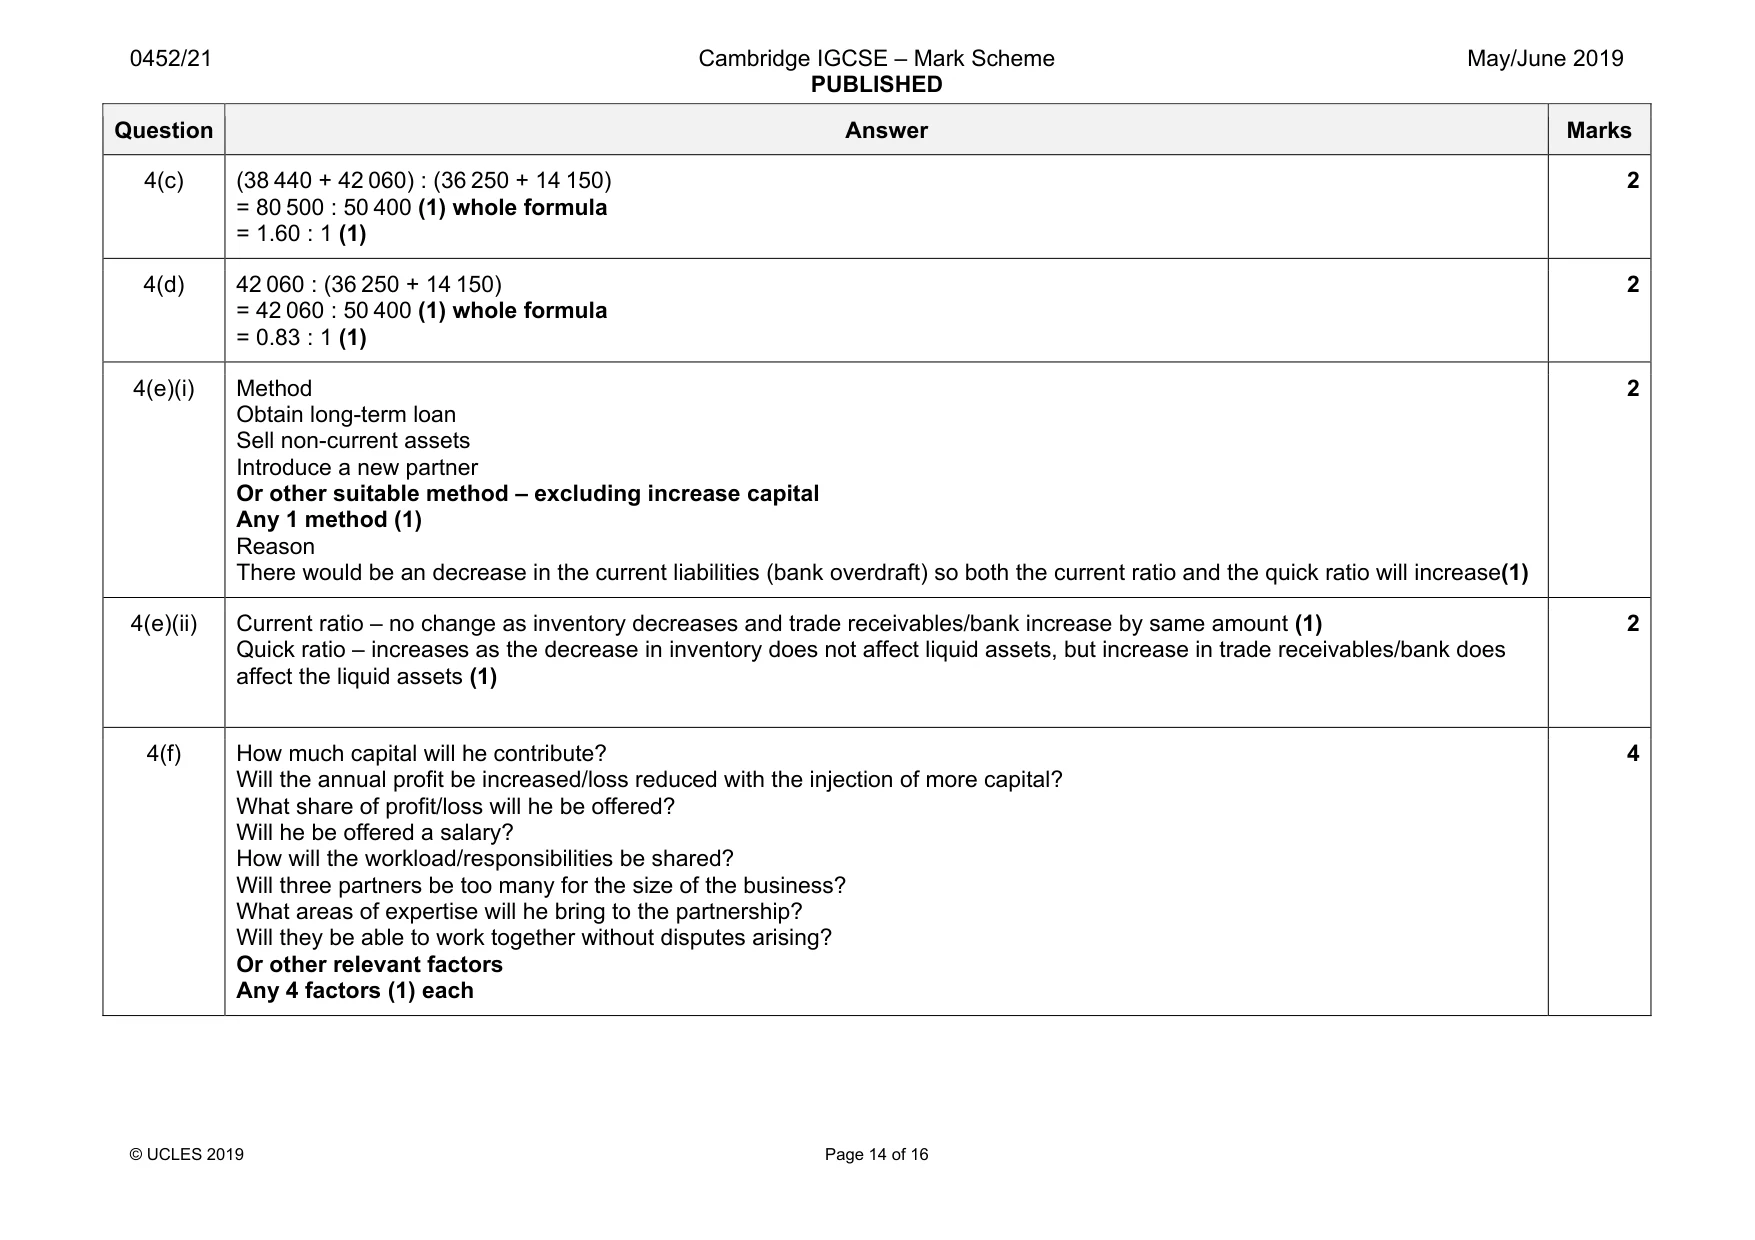
Mark scheme: 4(a)(i) 425 100 5% 8500 1 × = (1) Or can be calculated on other partner’s drawings to arrive at same percentage 1 4(a)(ii) 3600 100 6% 60000 1 × = (1) Or can be calculated on other partner’s capital to arrive at same percentage 1 4(b) Liam and Mia Current accounts Date Details Liam Mia Date Details Liam Mia $ $ $ $ 2018 2018 Feb 1 Balance b/d 2 140 Feb 1 Balance b/d 44 500 Aug 1 Capital (1) 14 000 2019 2019 Jan 31 Interest on capital (1) 10 200 3 600 Jan 31 Drawings (1) 19 100 8 500 Salary (1) 15 000 Interest on drawings (1) 955 425 Share of loss (1) 2 120 1 060 Balances c/d 18 525 6 475 54 700 18 600 54 700 18 600 2019 Feb 1 Balances b/d 18 525 6 475 (1) OF (1) OF +(1) dates 9 Question Answer Marks 4(c) (38 440 + 42 060) : (36 250 + 14 150) = 80 500 : 50 400 (1) whole formula = 1.60 : 1 (1) 2 4(d) 42 060 : (36 250 + 14 150) = 42 060 : 50 400 (1) whole formula = 0.83 : 1 (1) 2 4(e)(i) Method Obtain long-term loan Sell non-current assets Introduce a new partner Or other suitable method – excluding increase capital Any 1 method (1) Reason There would be an decrease in the current liabilities (bank overdraft) so both the current ratio and the quick ratio will increase(1) 2 4(e)(ii) Current ratio – no change as inventory decreases and trade receivables/bank increase by same amount (1) Quick ratio – increases as the decrease in inventory does not affect liquid assets, but increase in trade receivables/bank does affect the liquid assets (1) 2 4(f) How much capital will he contribute? Will the annual profit be increased/loss reduced with the injection of more capital? What share of profit/loss will he be offered? Will he be offered a salary? How will the workload/responsibilities be shared? Will three partners be too many for the size of the business? What areas of expertise will he bring to the partnership? Will they be able to work together without disputes arising? Or other relevant factors Any 4 factors (1) each 4
Q5 · Nadia is a trader
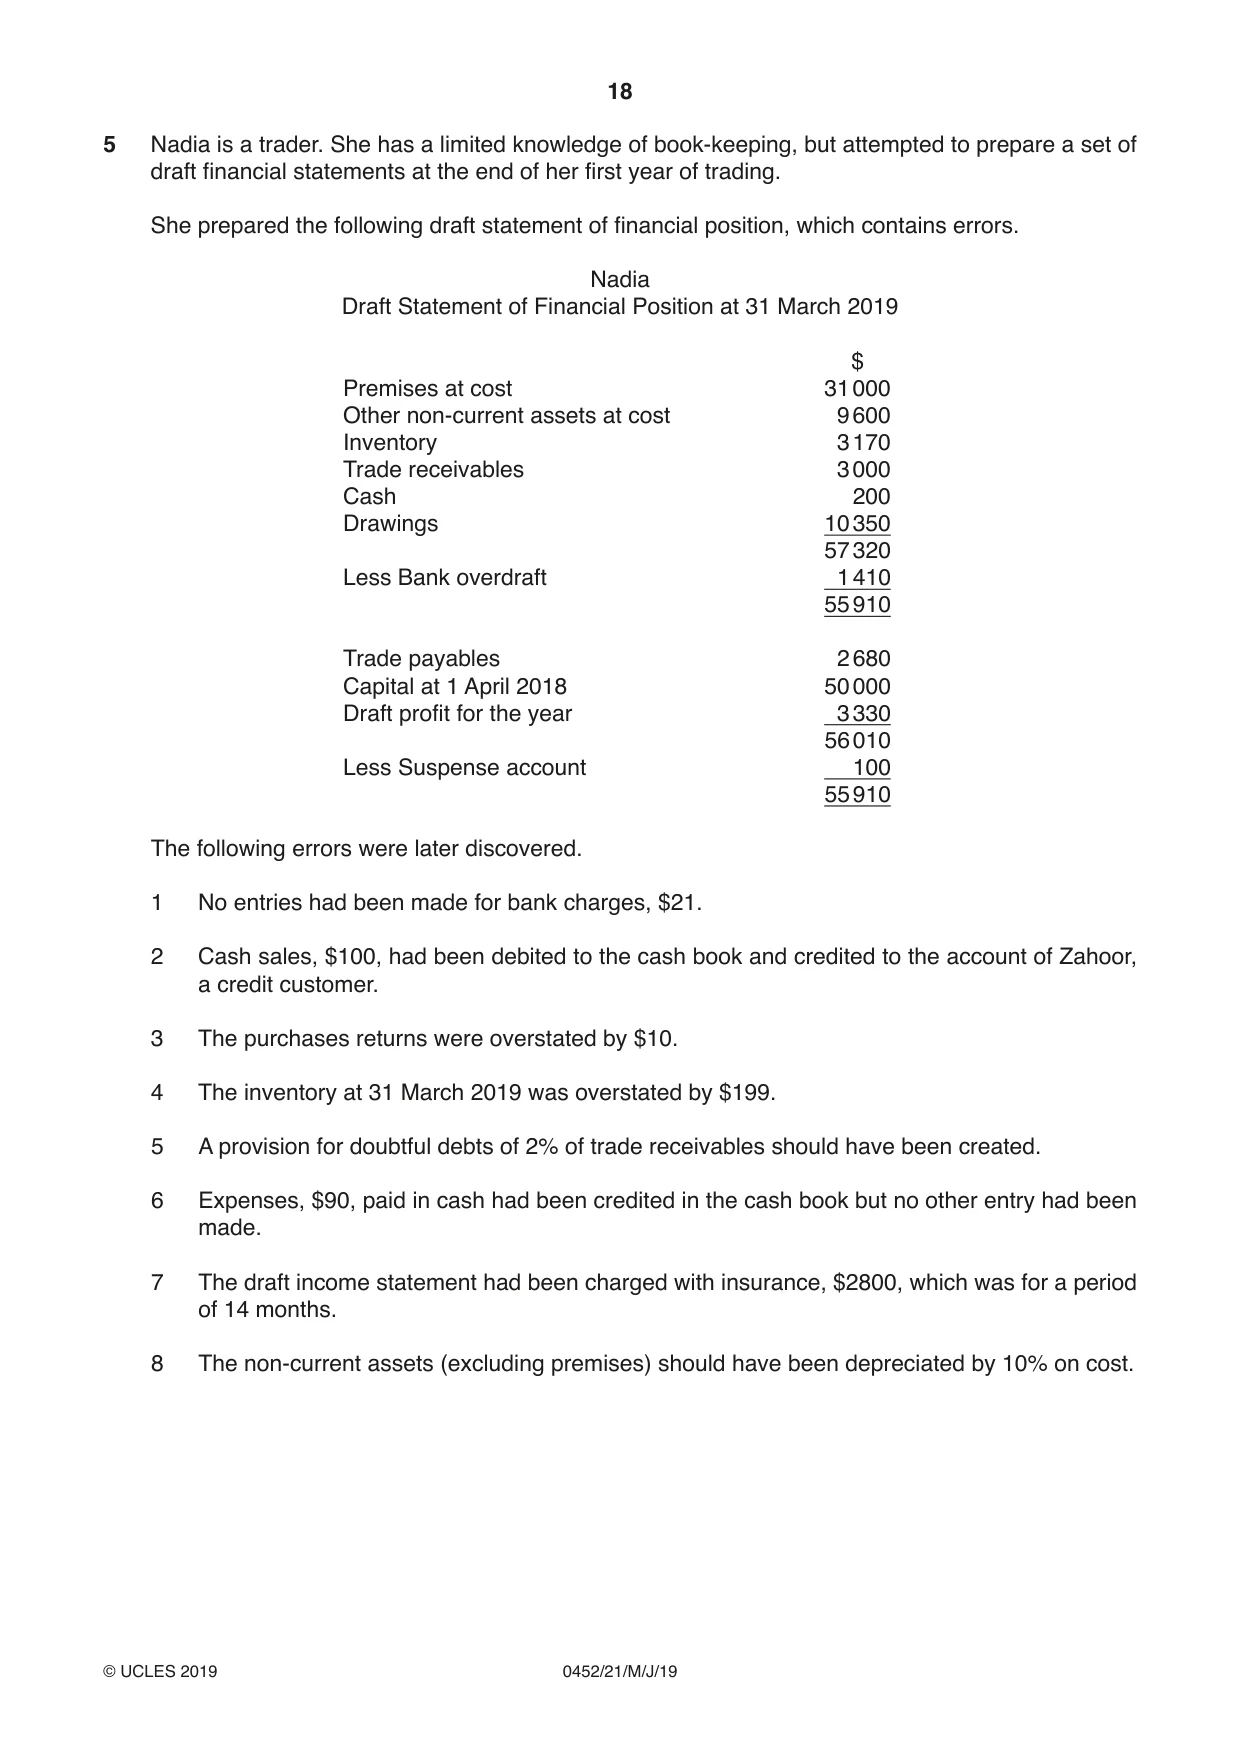
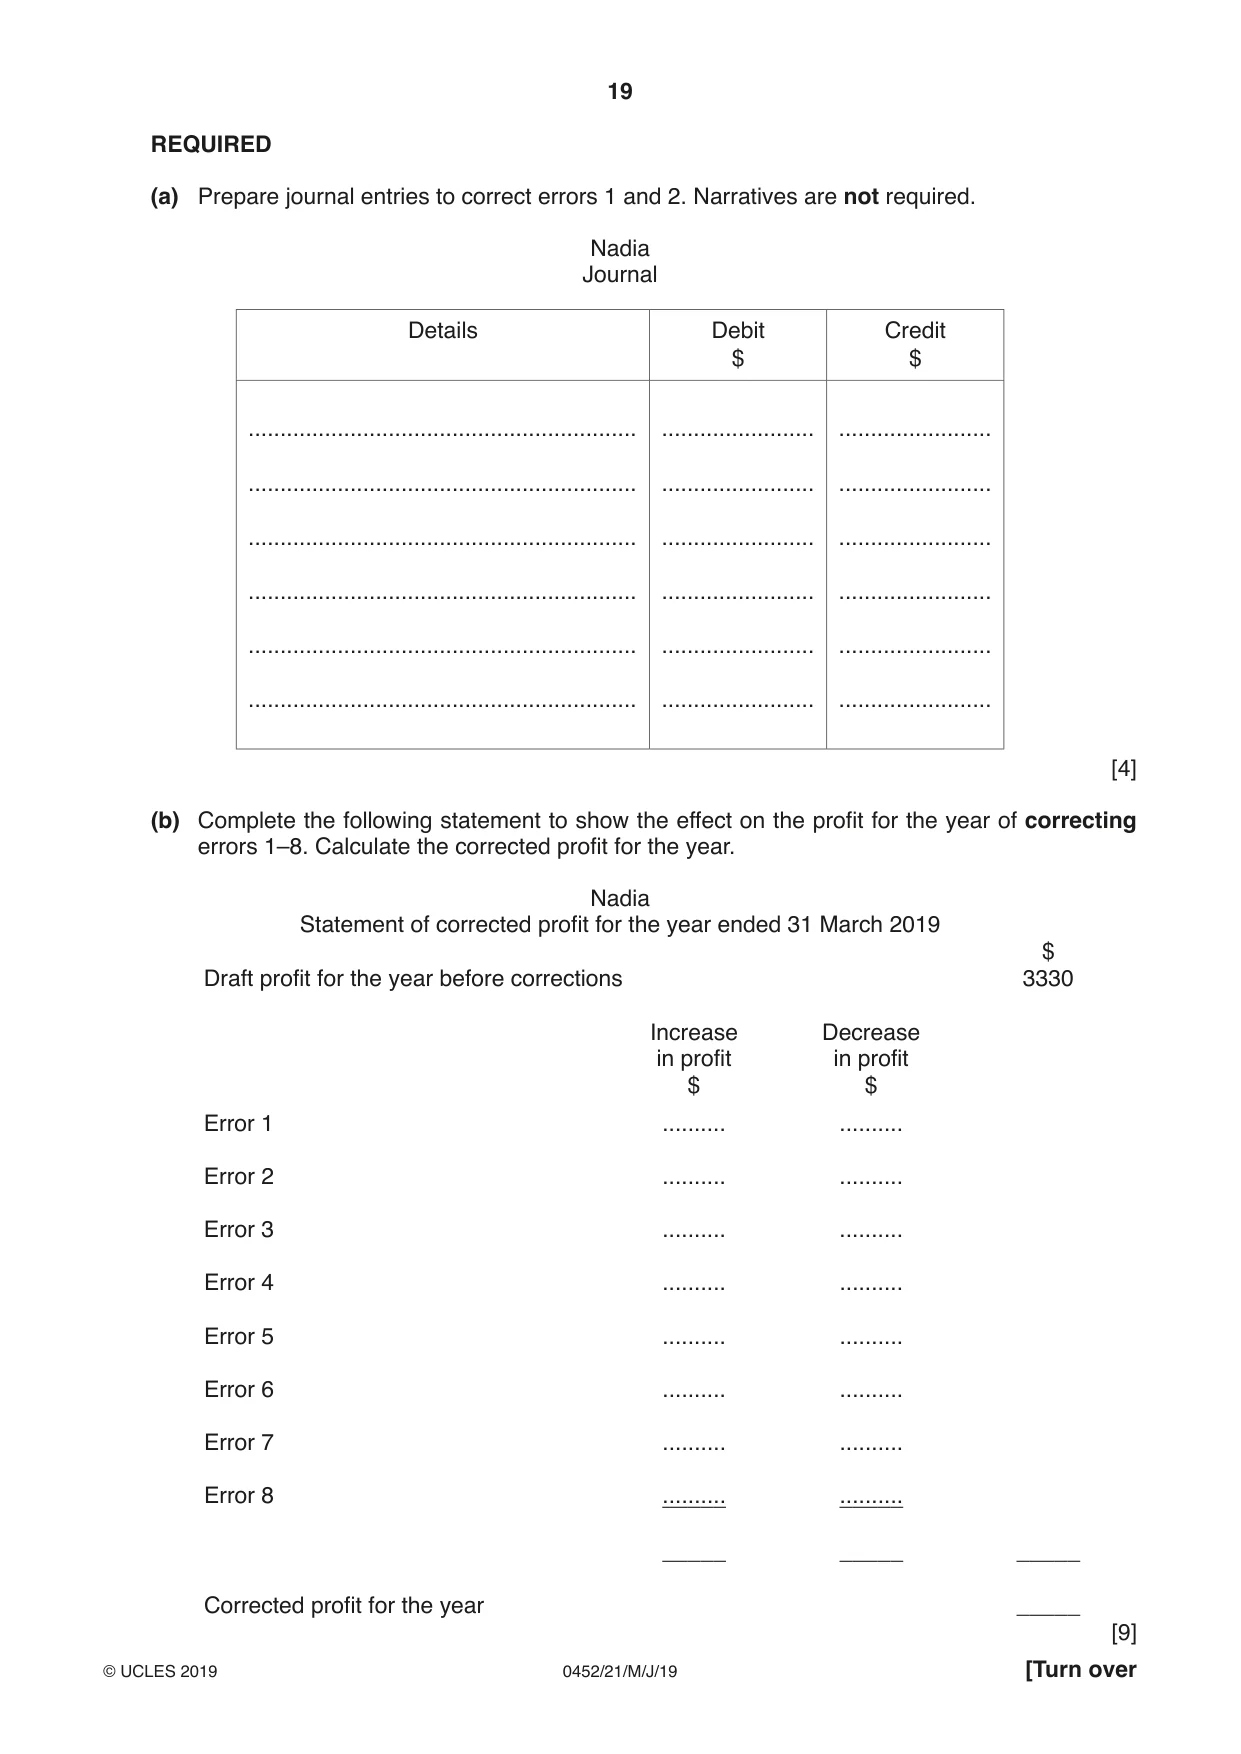
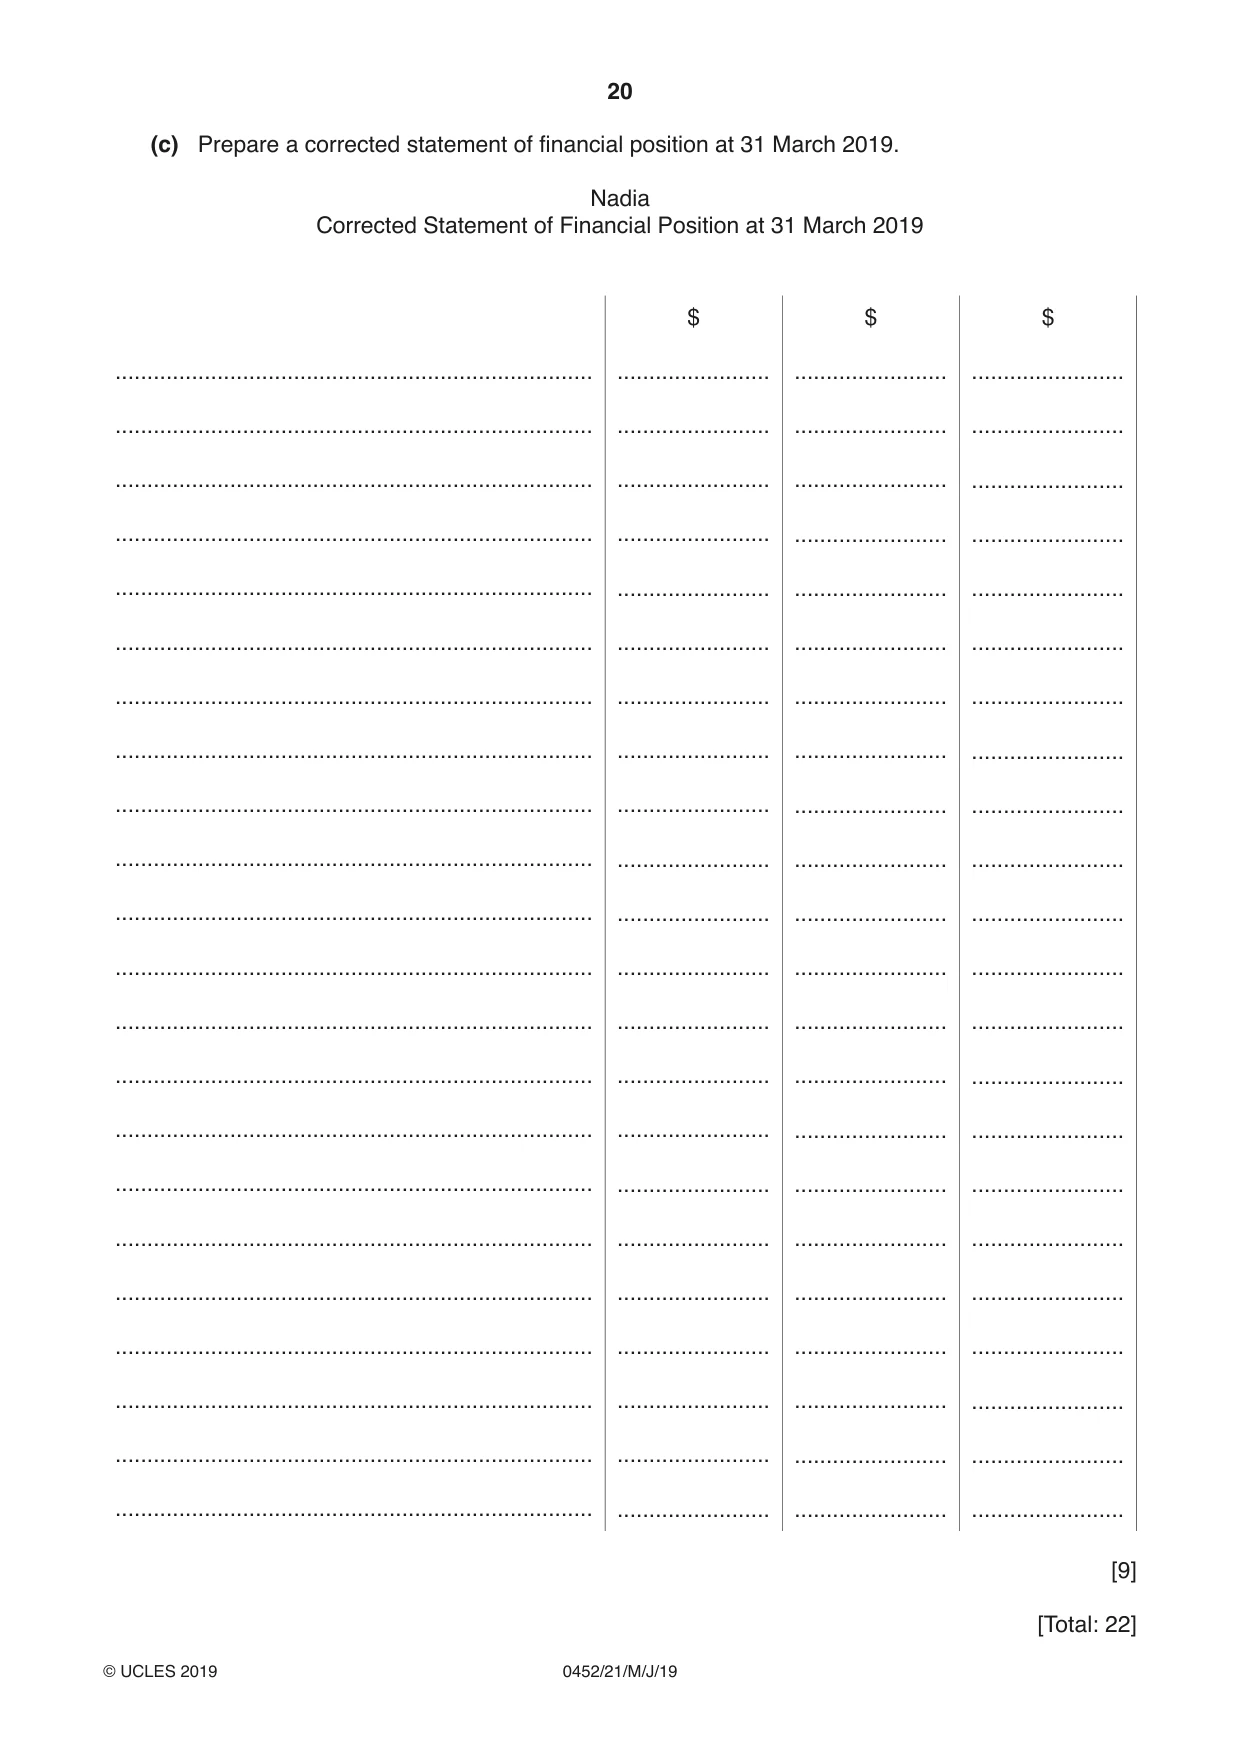
5 Nadia is a trader. She has a limited knowledge of book-keeping, but attempted to prepare a set of draft financial statements at the end of her first year of trading. She prepared the following draft statement of financial position, which contains errors. Nadia Draft Statement of Financial Position at 31 March 2019 $ Premises at cost 31 000 Other non-current assets at cost 9 600 Inventory 3 170 Trade receivables 3 000 Cash 200 Drawings 10 350 57 320 Less Bank overdraft 1 410 55 910 Trade payables 2 680 Capital at 1 April 2018 50 000 Draft profit for the year 3 330 56 010 Less Suspense account 100 55 910 The following errors were later discovered. 1 No entries had been made for bank charges, $21. 2 Cash sales, $100, had been debited to the cash book and credited to the account of Zahoor, a credit customer. 3 The purchases returns were overstated by $10. 4 The inventory at 31 March 2019 was overstated by $199. 5 A provision for doubtful debts of 2% of trade receivables should have been created. 6 Expenses, $90, paid in cash had been credited in the cash book but no other entry had been made. 7 The draft income statement had been charged with insurance, $2800, which was for a period of 14 months. 8 The non-current assets (excluding premises) should have been depreciated by 10% on cost. REQUIRED (a) Prepare journal entries to correct errors 1 and 2. Narratives are not required. Nadia Journal Details Debit Credit $ $ ............................................................. ........................ ........................ ............................................................. ........................ ........................ ............................................................. ........................ ........................ ............................................................. ........................ ........................ ............................................................. ........................ ........................ ............................................................. ........................ ........................ [4] (b) Complete the following statement to show the effect on the profit for the year of correcting errors 1–8. Calculate the corrected profit for the year. Nadia Statement of corrected profit for the year ended 31 March 2019 $ Draft profit for the year before corrections 3330 Increase Decrease in profit in profit $ $ Error 1 .......... .......... Error 2 .......... .......... Error 3 .......... .......... Error 4 .......... .......... Error 5 .......... .......... Error 6 .......... .......... Error 7 .......... .......... Error 8 _____.......... _____.......... _____ _____ _____ Corrected profit for the year _____ [9] l position at 31 dia cial Position at $ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................
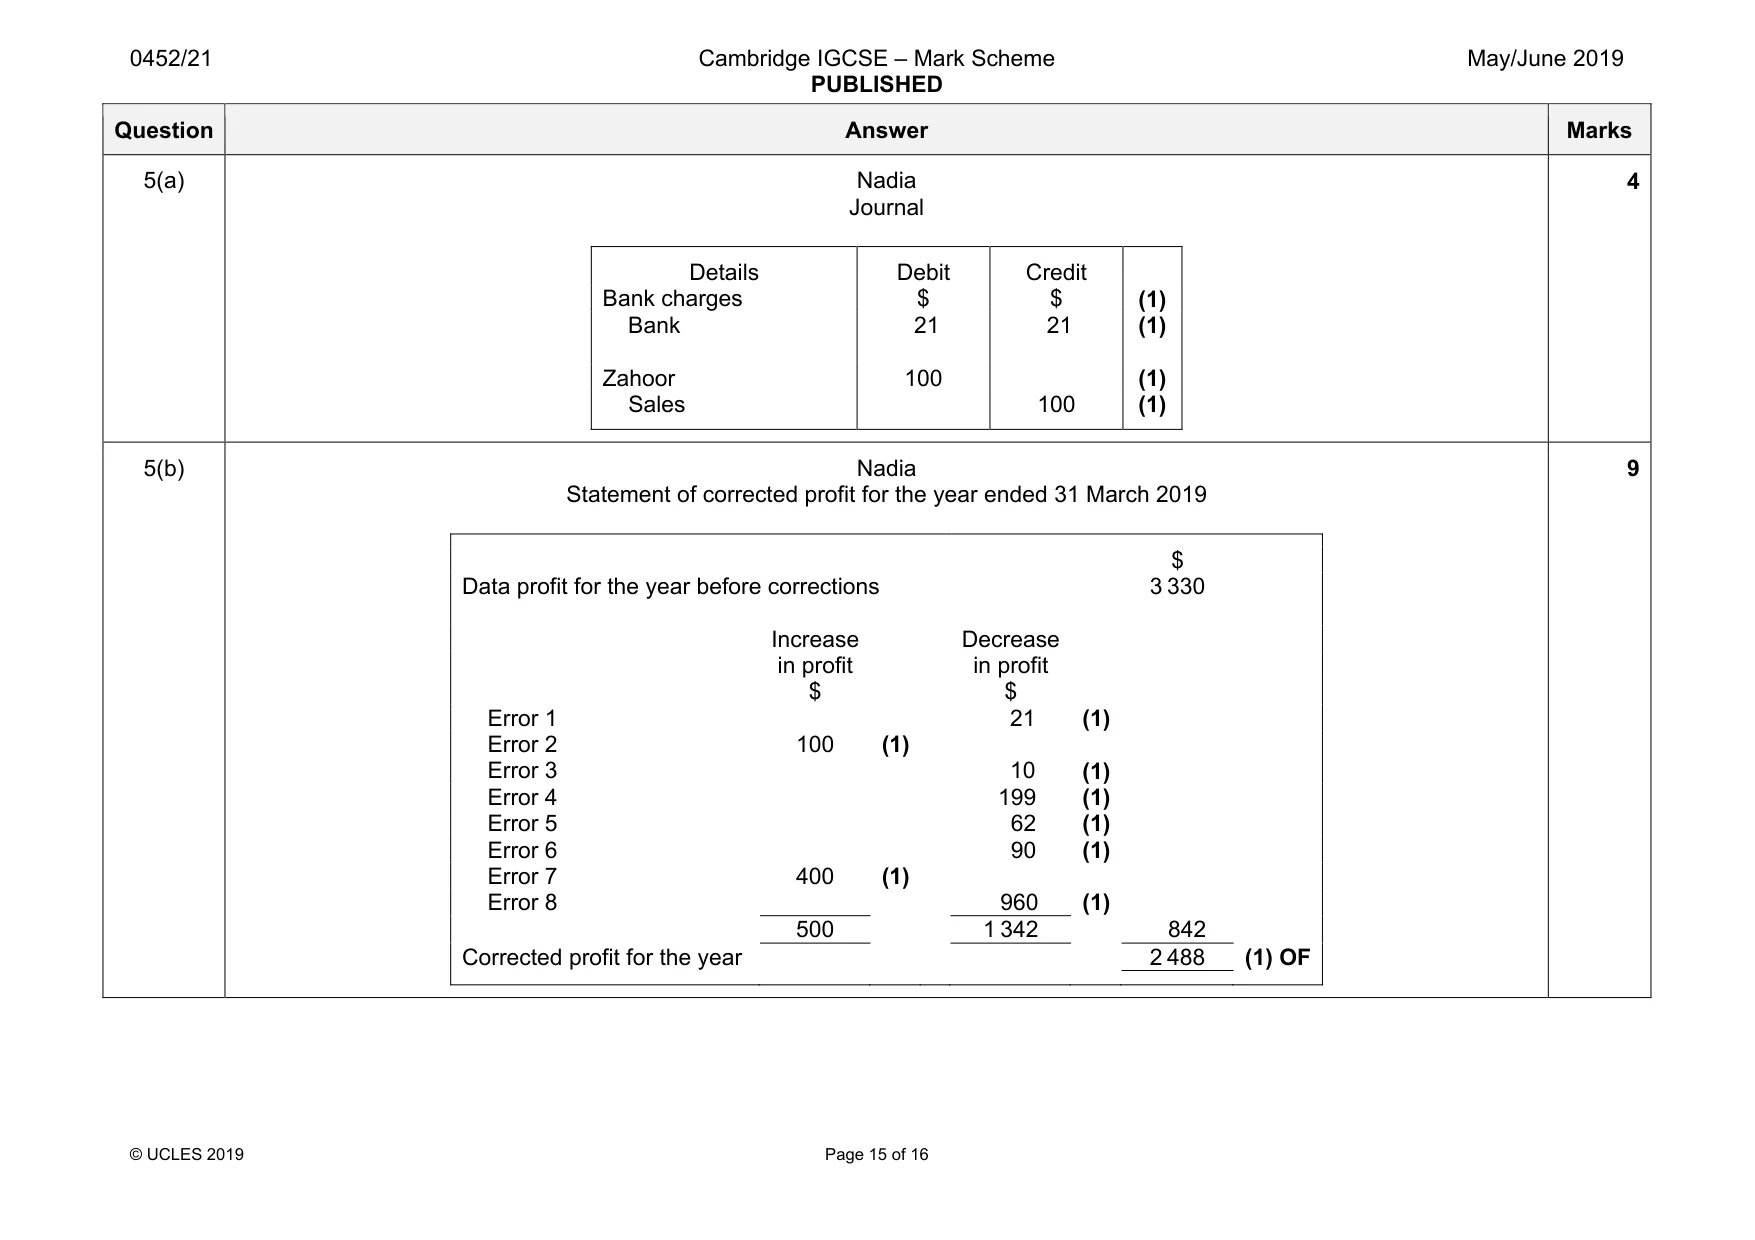
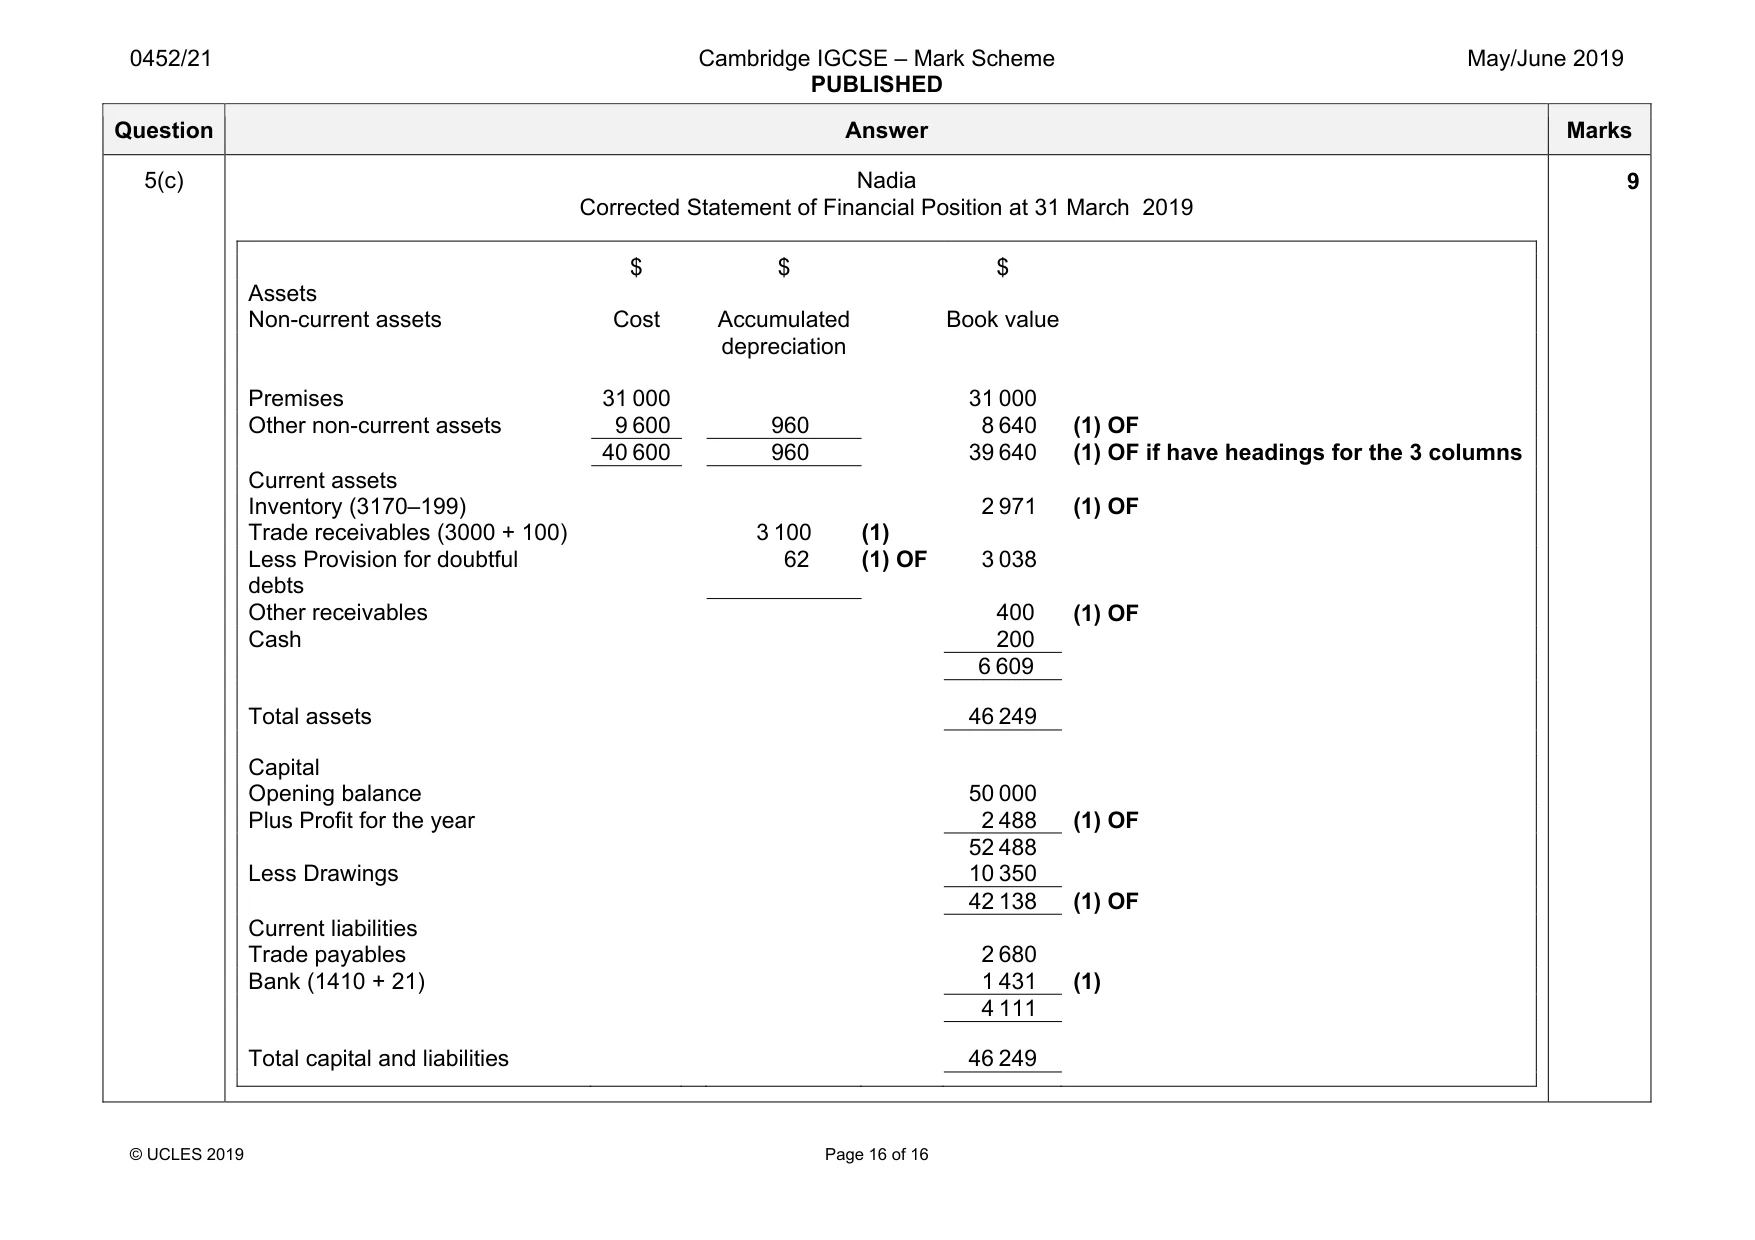
Mark scheme: 5(a) Nadia Journal Details Debit Credit Bank charges $ $ (1) Bank 21 21 (1) Zahoor 100 (1) Sales 100 (1) 4 5(b) Nadia Statement of corrected profit for the year ended 31 March 2019 $ Data profit for the year before corrections 3 330 Increase Decrease in profit in profit $ $ Error 1 21 (1) Error 2 100 (1) Error 3 10 (1) Error 4 199 (1) Error 5 62 (1) Error 6 90 (1) Error 7 400 (1) Error 8 960 (1) 500 1 342 842 Corrected profit for the year 2 488 (1) OF 9 Question Answer Marks 5(c) Nadia Corrected Statement of Financial Position at 31 March 2019 $ $ $ Assets Non-current assets Cost Accumulated Book value depreciation Premises 31 000 31 000 Other non-current assets 9 600 960 8 640 (1) OF 40 600 960 39 640 (1) OF if have headings for the 3 columns Current assets Inventory (3170–199) 2 971 (1) OF Trade receivables (3000 + 100) 3 100 (1) Less Provision for doubtful debts 62 (1) OF 3 038 Other receivables 400 (1) OF Cash 200 6 609 Total assets 46 249 Capital Opening balance 50 000 Plus Profit for the year 2 488 (1) OF 52 488 Less Drawings 10 350 42 138 (1) OF Current liabilities Trade payables 2 680 Bank (1410 + 21) 1 431 (1) 4 111 Total capital and liabilities 46 249 9
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2019 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.