Cambridge IGCSE Accounting 0452 — 2025 May/June Paper 2 · Variant 1
0452/21/M/J/25 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme18 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Anika started in business on 1 March 2024, but she did not start to keep full…
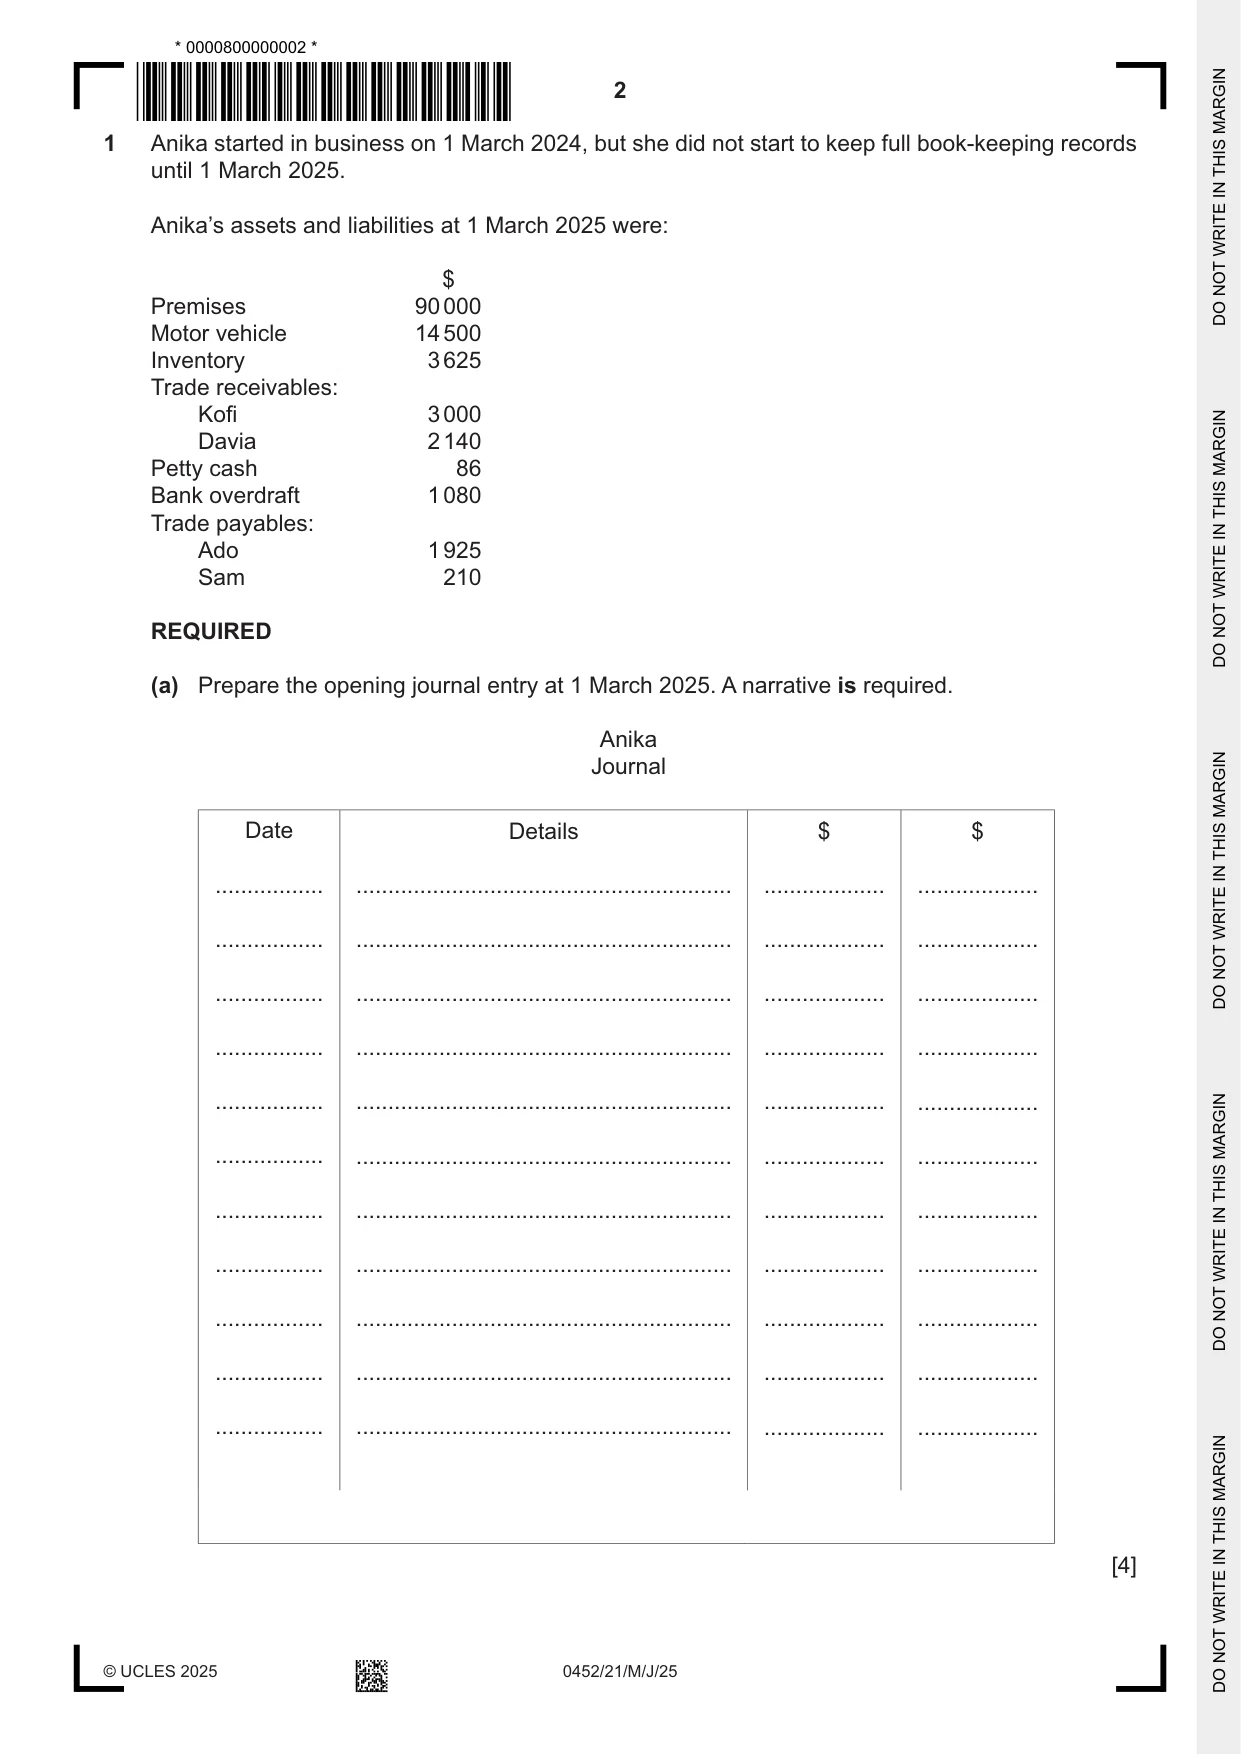
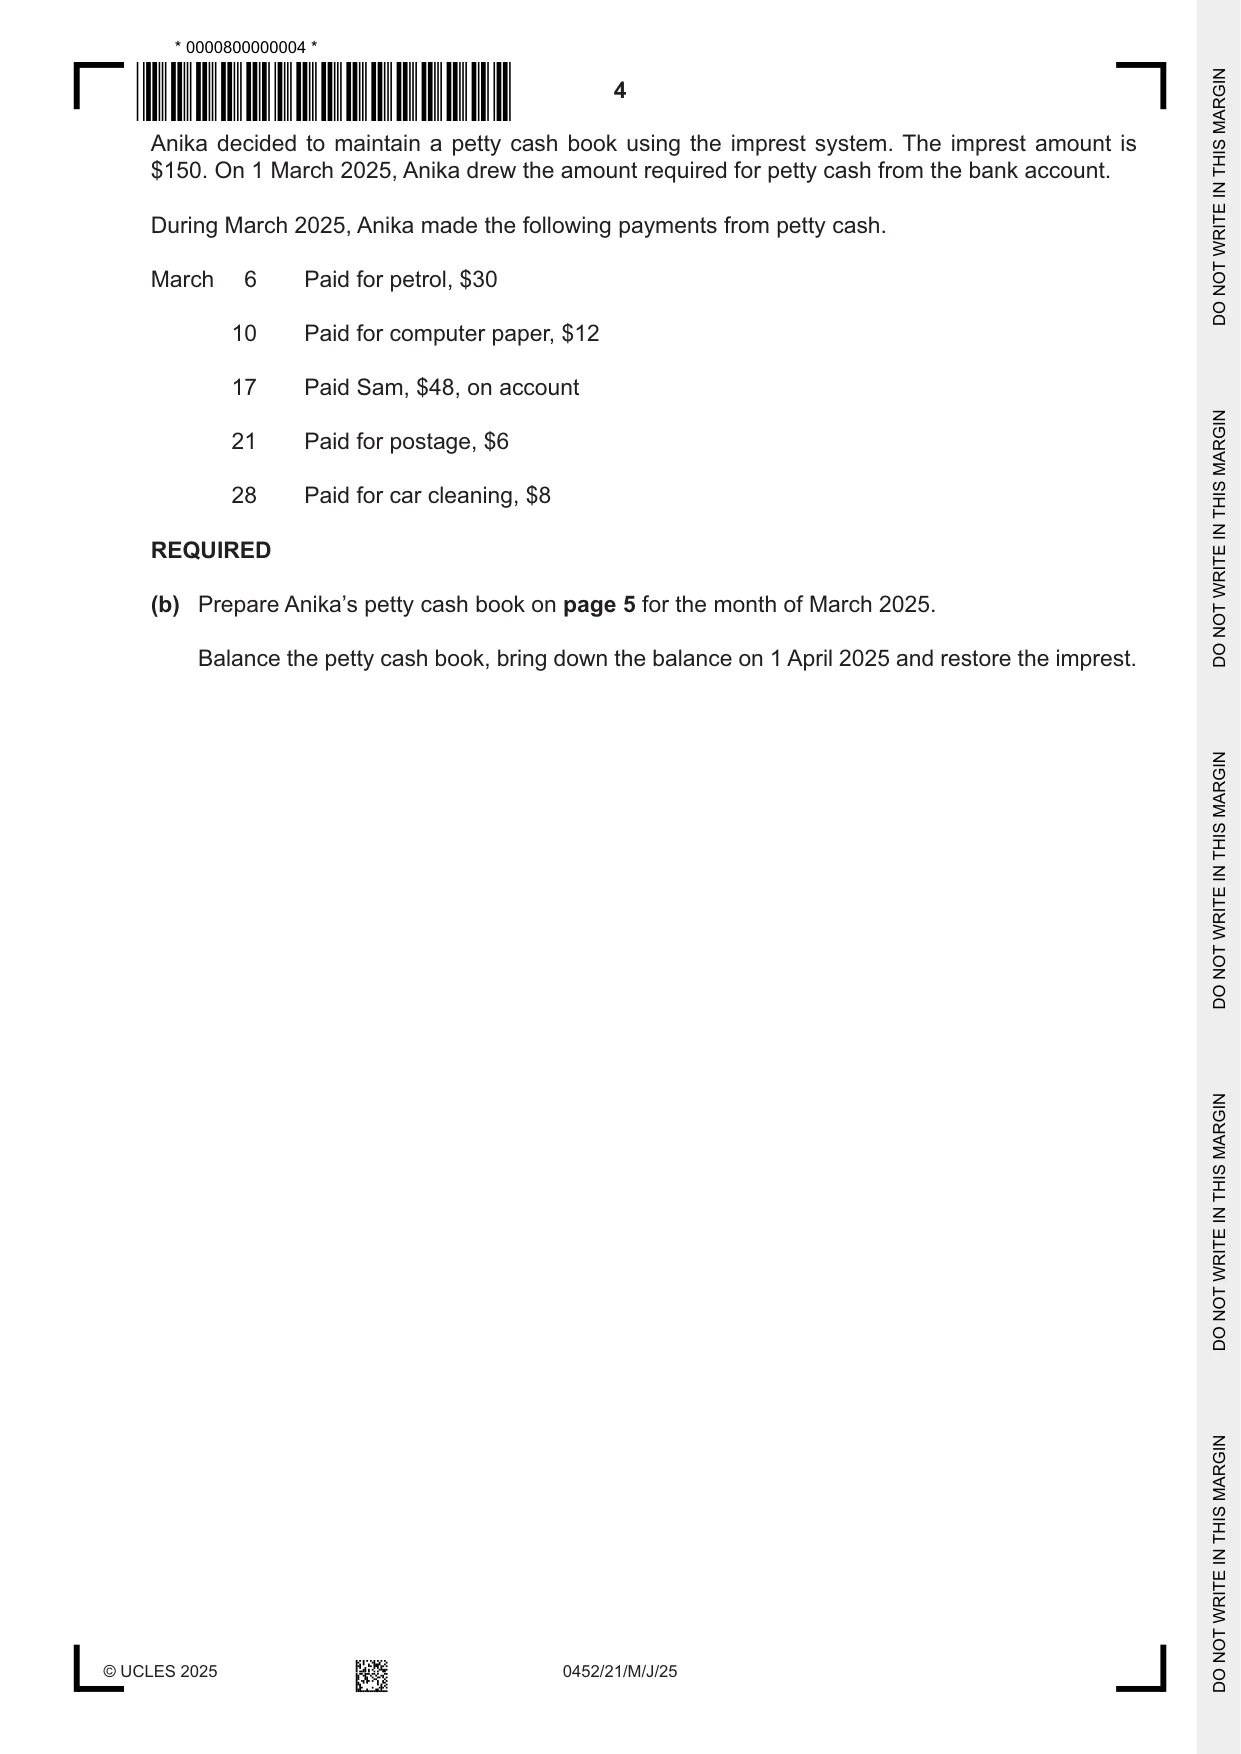
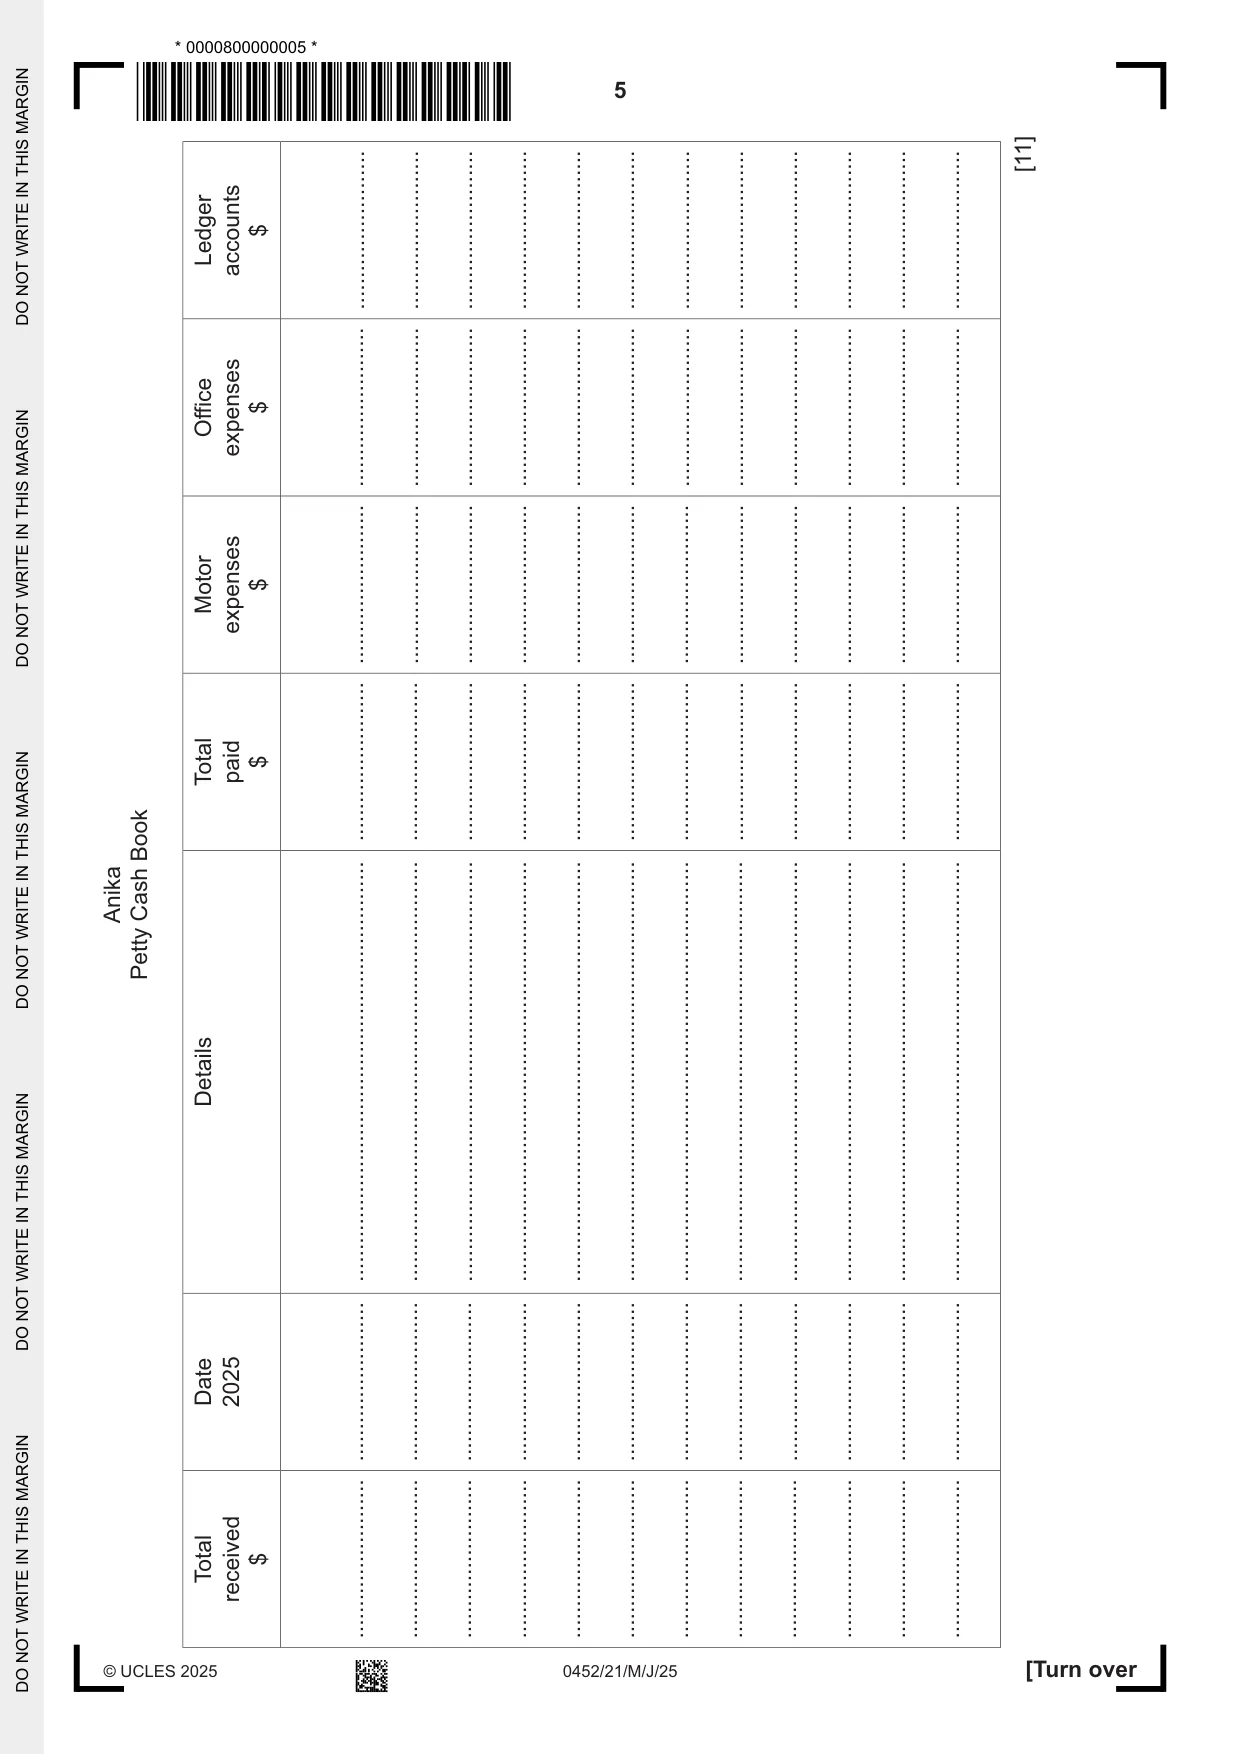
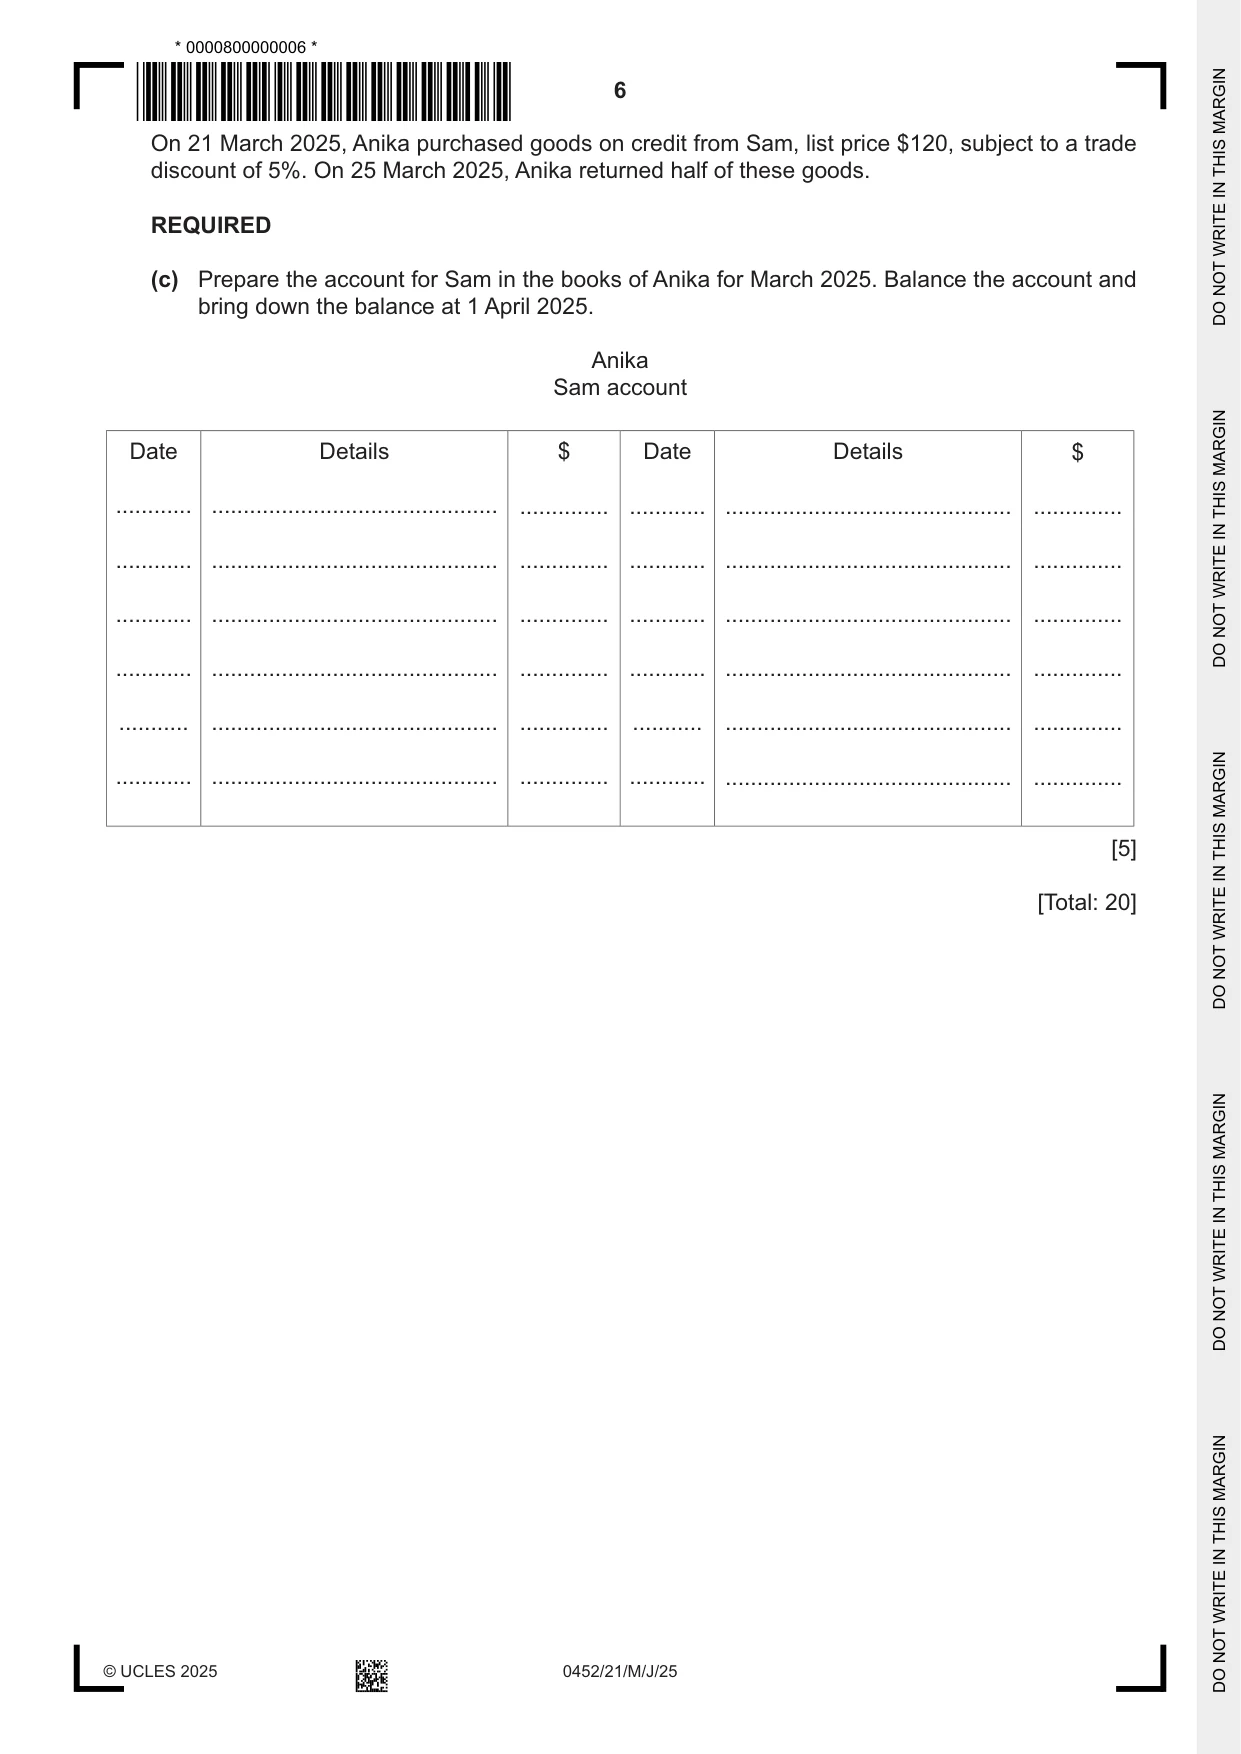
1 Anika started in business on 1 March 2024, but she did not start to keep full book-keeping records until 1 March 2025. Anika’s assets and liabilities at 1 March 2025 were: $ Premises 90 000 Motor vehicle 14 500 Inventory 3 625 Trade receivables: Kofi 3 000 Davia 2 140 Petty cash 86 Bank overdraft 1 080 Trade payables: Ado 1 925 Sam 210 REQUIRED (a) Prepare the opening journal entry at 1 March 2025. A narrative is required. Anika Journal Date Details $ $ ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... ................. ........................................................... ................... ................... [4] Question 1 continues on page 4. Anika decided to maintain a petty cash book using the imprest system. The imprest amount is $150. On 1 March 2025, Anika drew the amount required for petty cash from the bank account. During March 2025, Anika made the following payments from petty cash. March 6 Paid for petrol, $30 10 Paid for computer paper, $12 17 Paid Sam, $48, on account 21 Paid for postage, $6 28 Paid for car cleaning, $8 REQUIRED (b) Prepare Anika’s petty cash book on page 5 for the month of March 2025. Balance the petty cash book, bring down the balance on 1 April 2025 and restore the imprest. [11] $ Ledger accounts ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... $ Office expenses ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... $ Motor expenses ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... $ Total paid ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... Book Anika Cash Petty Details .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. .................................................................. Date 2025 ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... ......................... On 21 March 2025, Anika purchased goods on credit from Sam, list price $120, subject to a trade discount of 5%. On 25 March 2025, Anika returned half of these goods. REQUIRED (c) Prepare the account for Sam in the books of Anika for March 2025. Balance the account and bring down the balance at 1 April 2025. Anika Sam account Date Details $ Date Details $ ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ........... ............................................. .............. ........... ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. [5] [Total: 20]
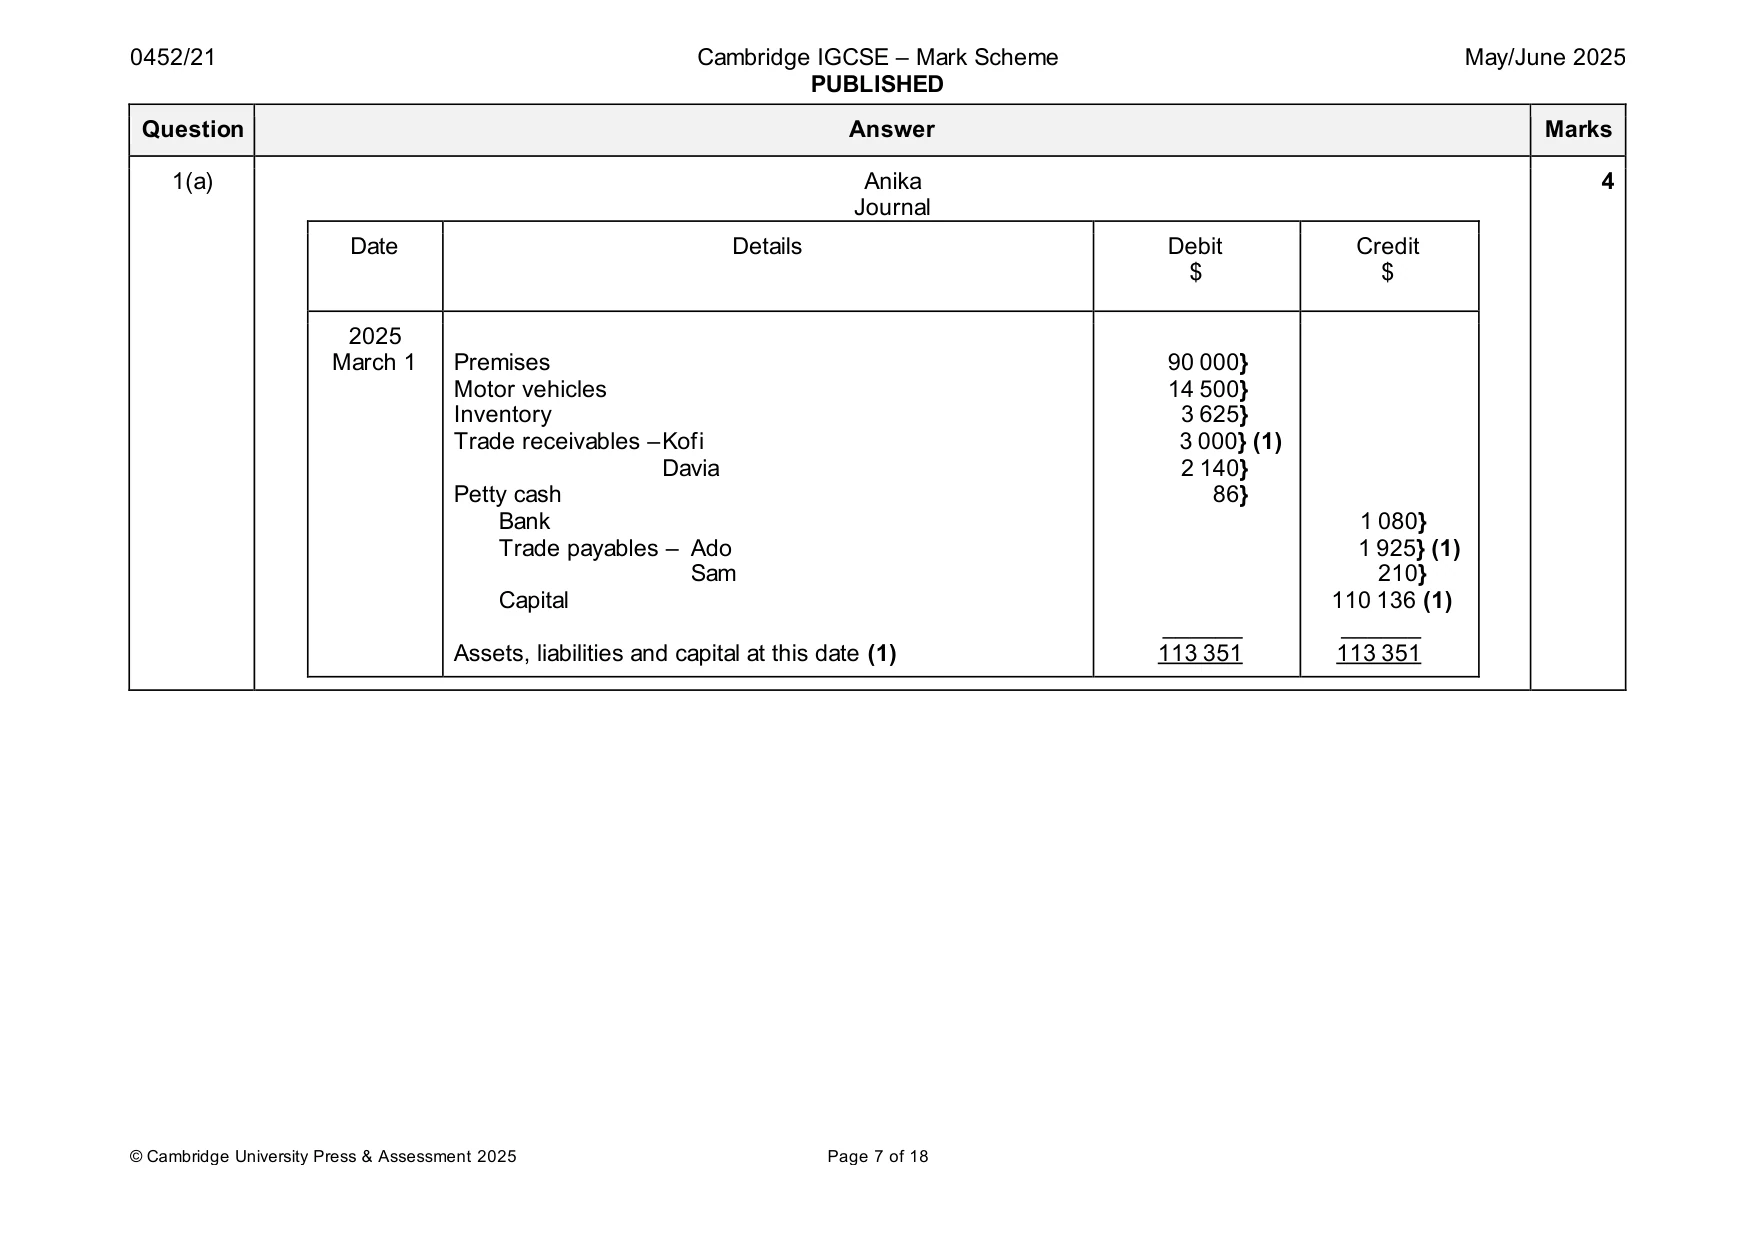
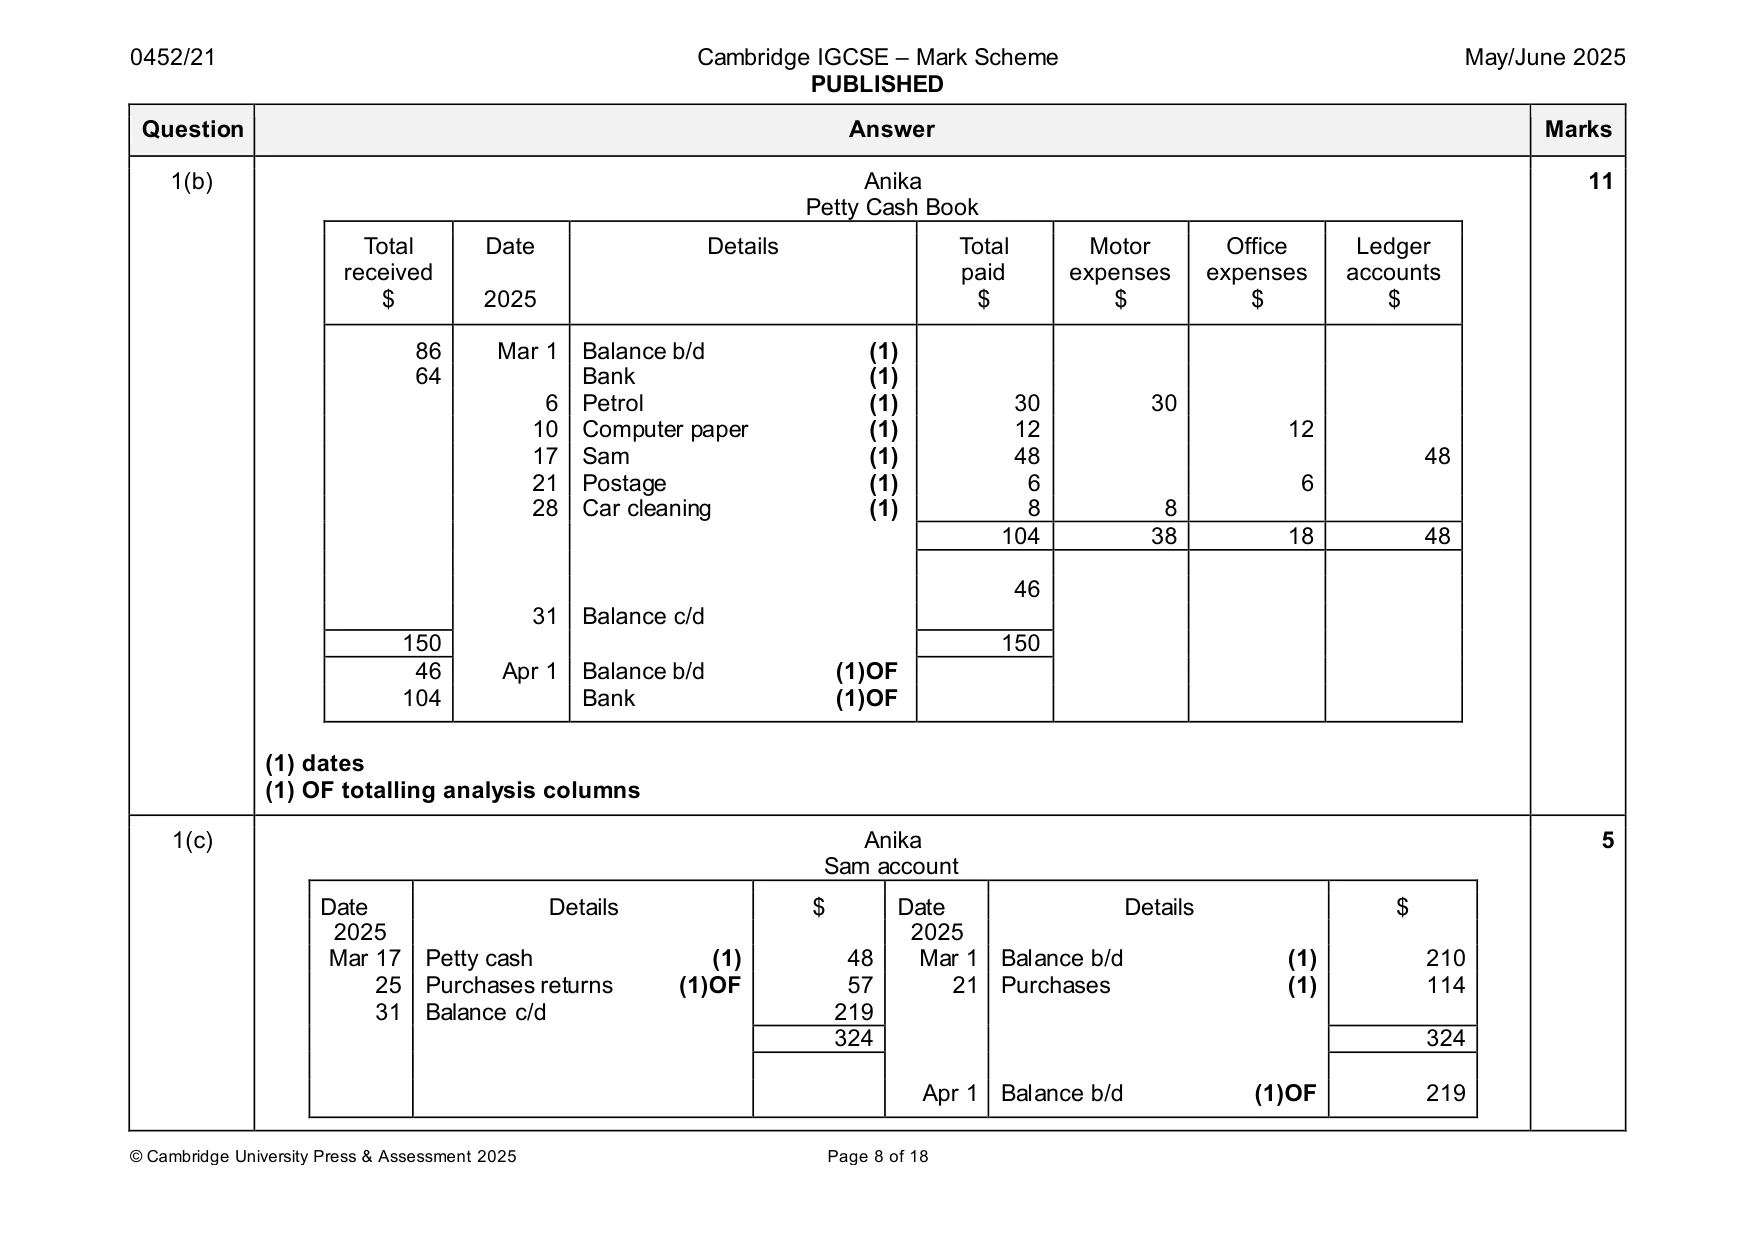
Mark scheme: Question Answer Marks 1(a) Anika 4 Journal Date Details Debit Credit $ $ 2025 March 1 Premises 90 000} Motor vehicles 14 500} Inventory 3 625} Trade receivables – Kofi 3 000} (1) Davia 2 140} Petty cash 86} Bank 1 080} Trade payables – Ado 1 925} (1) Sam 210} Capital 110 136 (1) ______ ______ Assets, liabilities and capital at this date (1) 113 351 113 351 1(b) Anika 11 Petty Cash Book Total Date Details Total Motor Office Ledger received paid expenses expenses accounts $ 2025 $ $ $ $ 86 Mar 1 Balance b/d (1) 64 Bank (1) 6 Petrol (1) 30 30 10 Computer paper (1) 12 12 17 Sam (1) 48 48 21 Postage (1) 6 6 28 Car cleaning (1) 8 8 104 38 18 48 46 31 Balance c/d 150 150 46 Apr 1 Balance b/d (1)OF 104 Bank (1)OF (1) dates (1) OF totalling analysis columns 1(c) Anika 5 Sam account Date Details $ Date Details $ 2025 2025 Mar 17 Petty cash (1) 48 Mar 1 Balance b/d (1) 210 25 Purchases returns (1)OF 57 21 Purchases (1) 114 31 Balance c/d 219 324 324 Apr 1 Balance b/d (1)OF 219
Q2 · Mo is a farmer
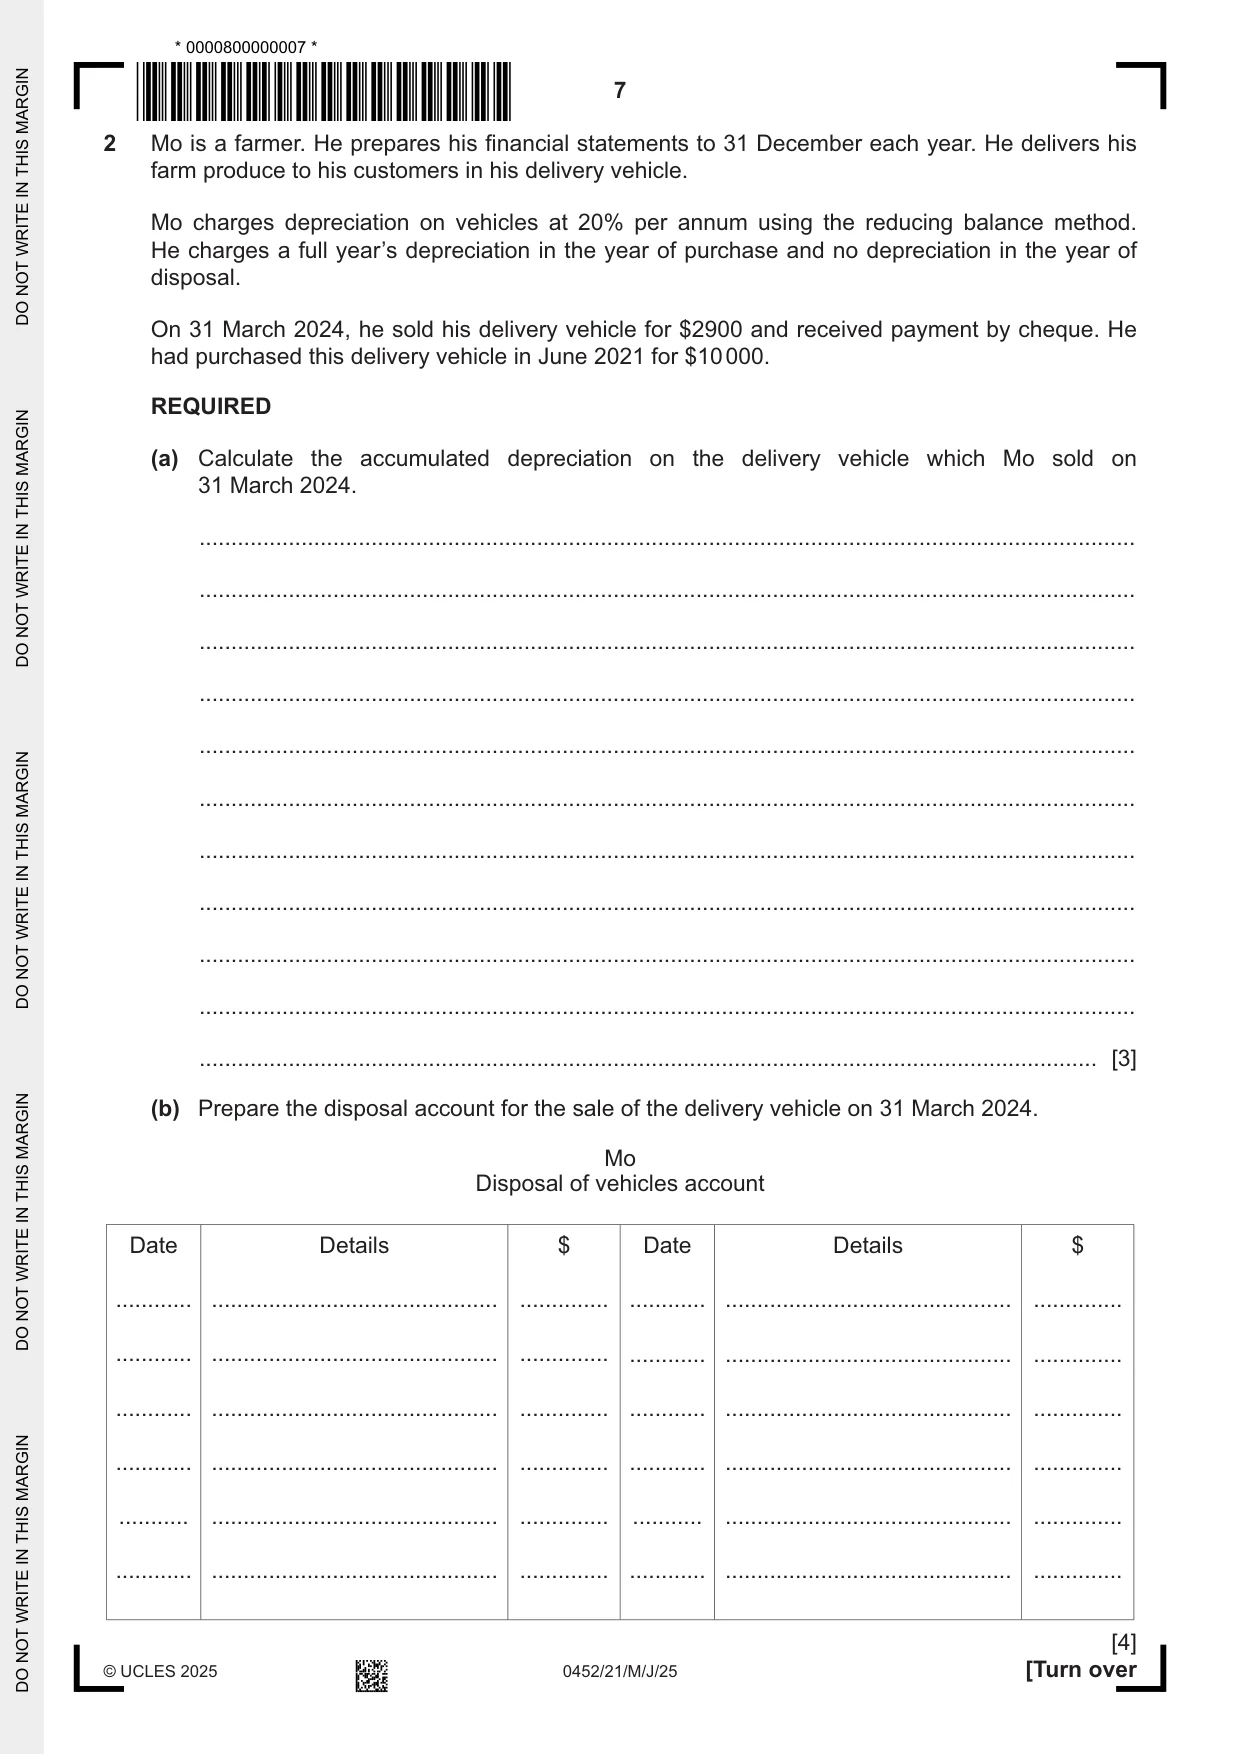
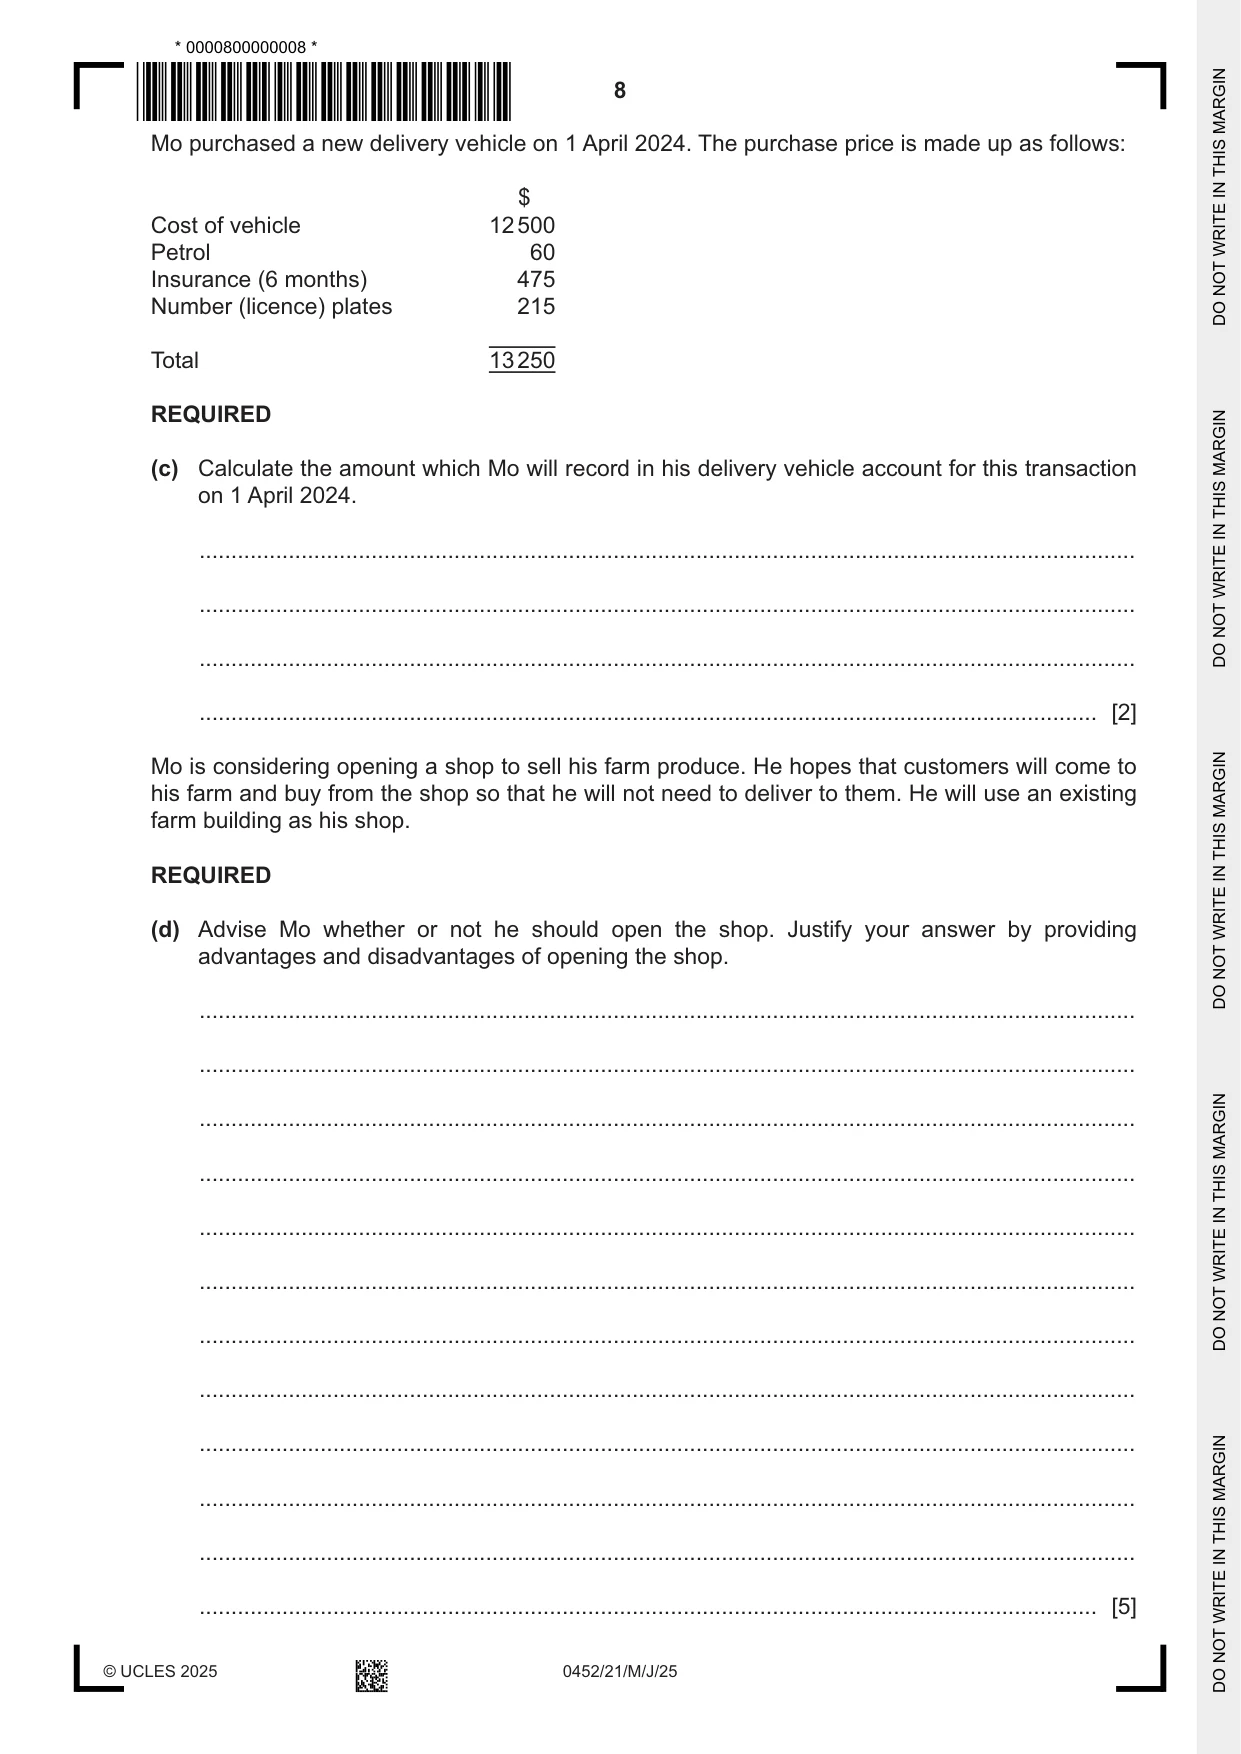
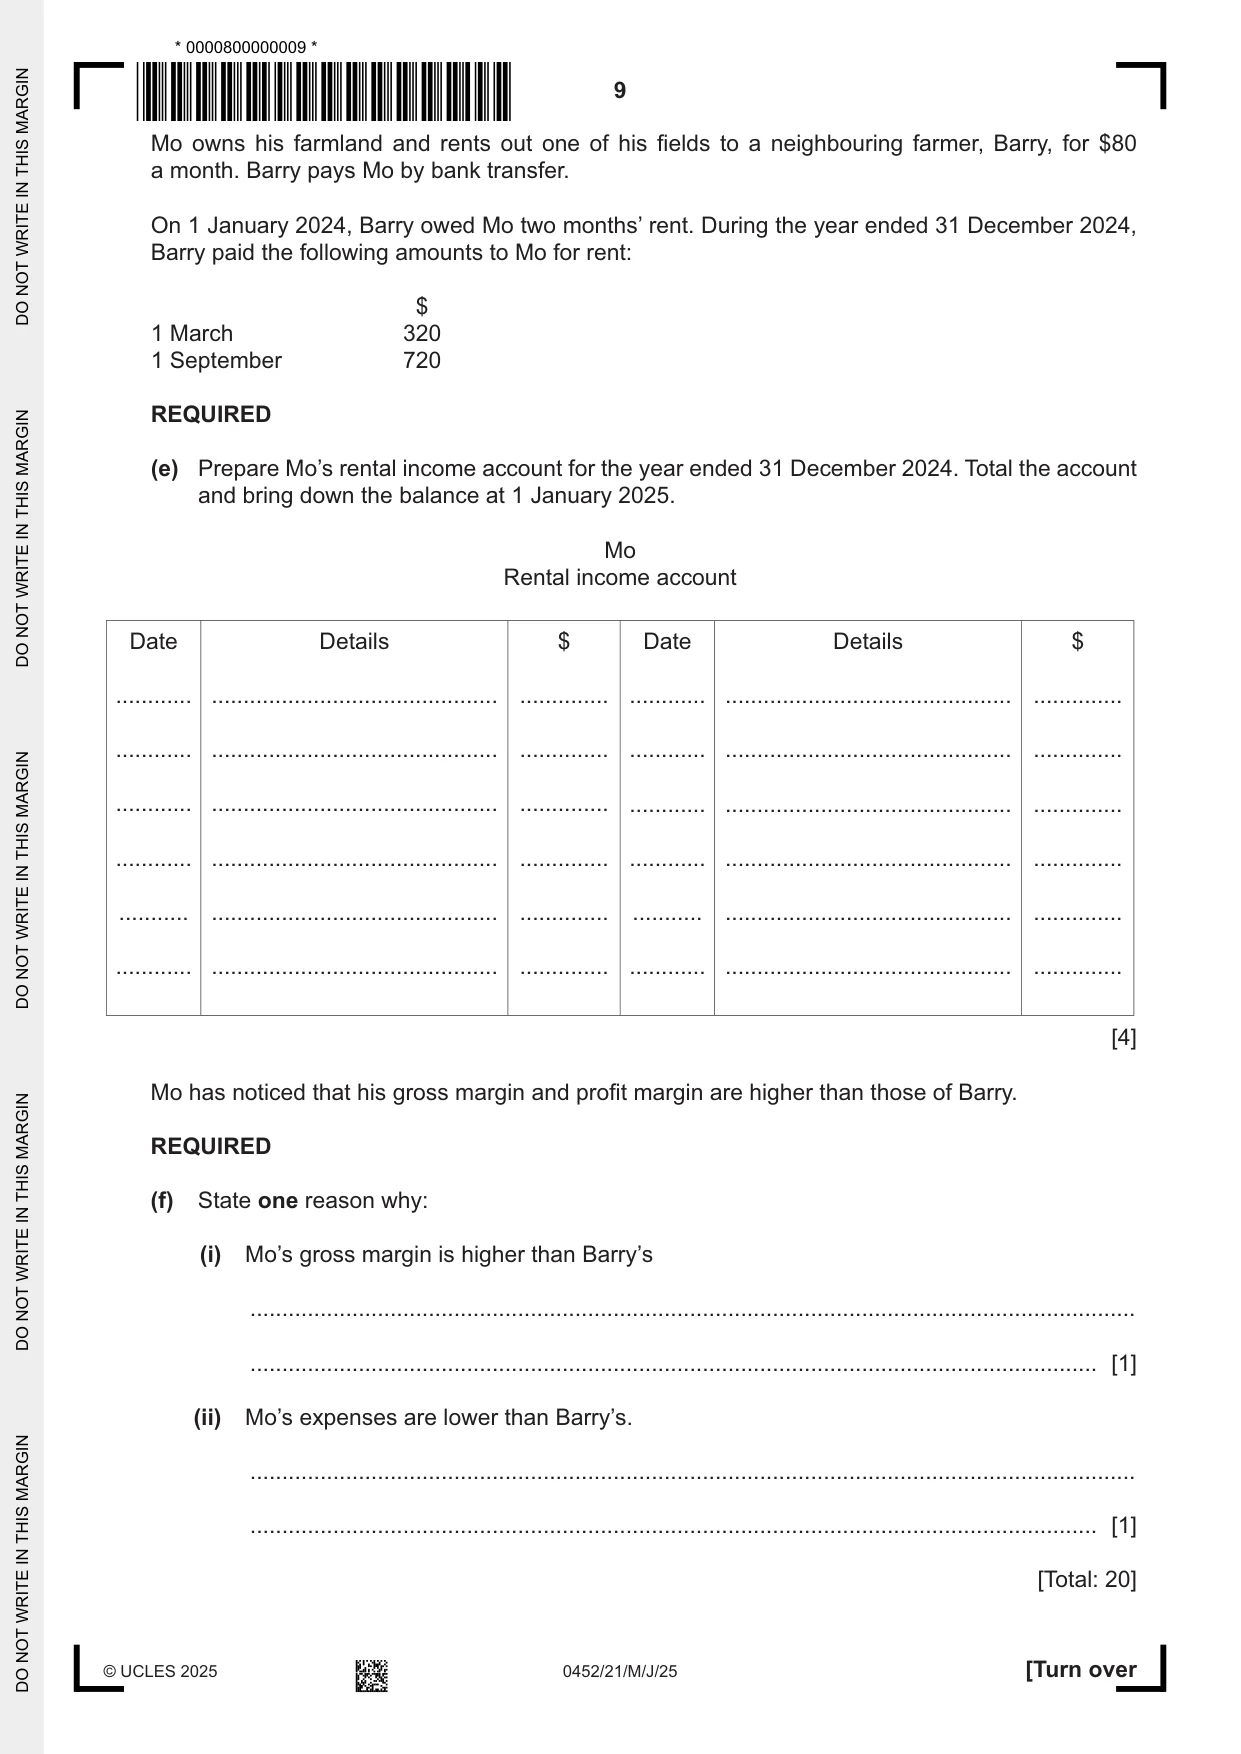
2 Mo is a farmer. He prepares his financial statements to 31 December each year. He delivers his farm produce to his customers in his delivery vehicle. Mo charges depreciation on vehicles at 20% per annum using the reducing balance method. He charges a full year’s depreciation in the year of purchase and no depreciation in the year of disposal. On 31 March 2024, he sold his delivery vehicle for $2900 and received payment by cheque. He had purchased this delivery vehicle in June 2021 for $10 000. REQUIRED (a) Calculate the accumulated depreciation on the delivery vehicle which Mo sold on 31 March 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Prepare the disposal account for the sale of the delivery vehicle on 31 March 2024. Mo Disposal of vehicles account Date Details $ Date Details $ ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ........... ............................................. .............. ........... ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. [4] Mo purchased a new delivery vehicle on 1 April 2024. The purchase price is made up as follows: $ Cost of vehicle 12 500 Petrol 60 Insurance (6 months) 475 Number (licence) plates 215 Total 13 250 REQUIRED (c) Calculate the amount which Mo will record in his delivery vehicle account for this transaction on 1 April 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Mo is considering opening a shop to sell his farm produce. He hopes that customers will come to his farm and buy from the shop so that he will not need to deliver to them. He will use an existing farm building as his shop. REQUIRED (d) Advise Mo whether or not he should open the shop. Justify your answer by providing advantages and disadvantages of opening the shop. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Mo owns his farmland and rents out one of his fields to a neighbouring farmer, Barry, for $80 a month. Barry pays Mo by bank transfer. On 1 January 2024, Barry owed Mo two months’ rent. During the year ended 31 December 2024, Barry paid the following amounts to Mo for rent: $ 1 March 320 1 September 720 REQUIRED (e) Prepare Mo’s rental income account for the year ended 31 December 2024. Total the account and bring down the balance at 1 January 2025. Mo Rental income account Date Details $ Date Details $ ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ........... ............................................. .............. ........... ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. [4] Mo has noticed that his gross margin and profit margin are higher than those of Barry. REQUIRED (f) State one reason why: (i) Mo’s gross margin is higher than Barry’s ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Mo’s expenses are lower than Barry’s. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
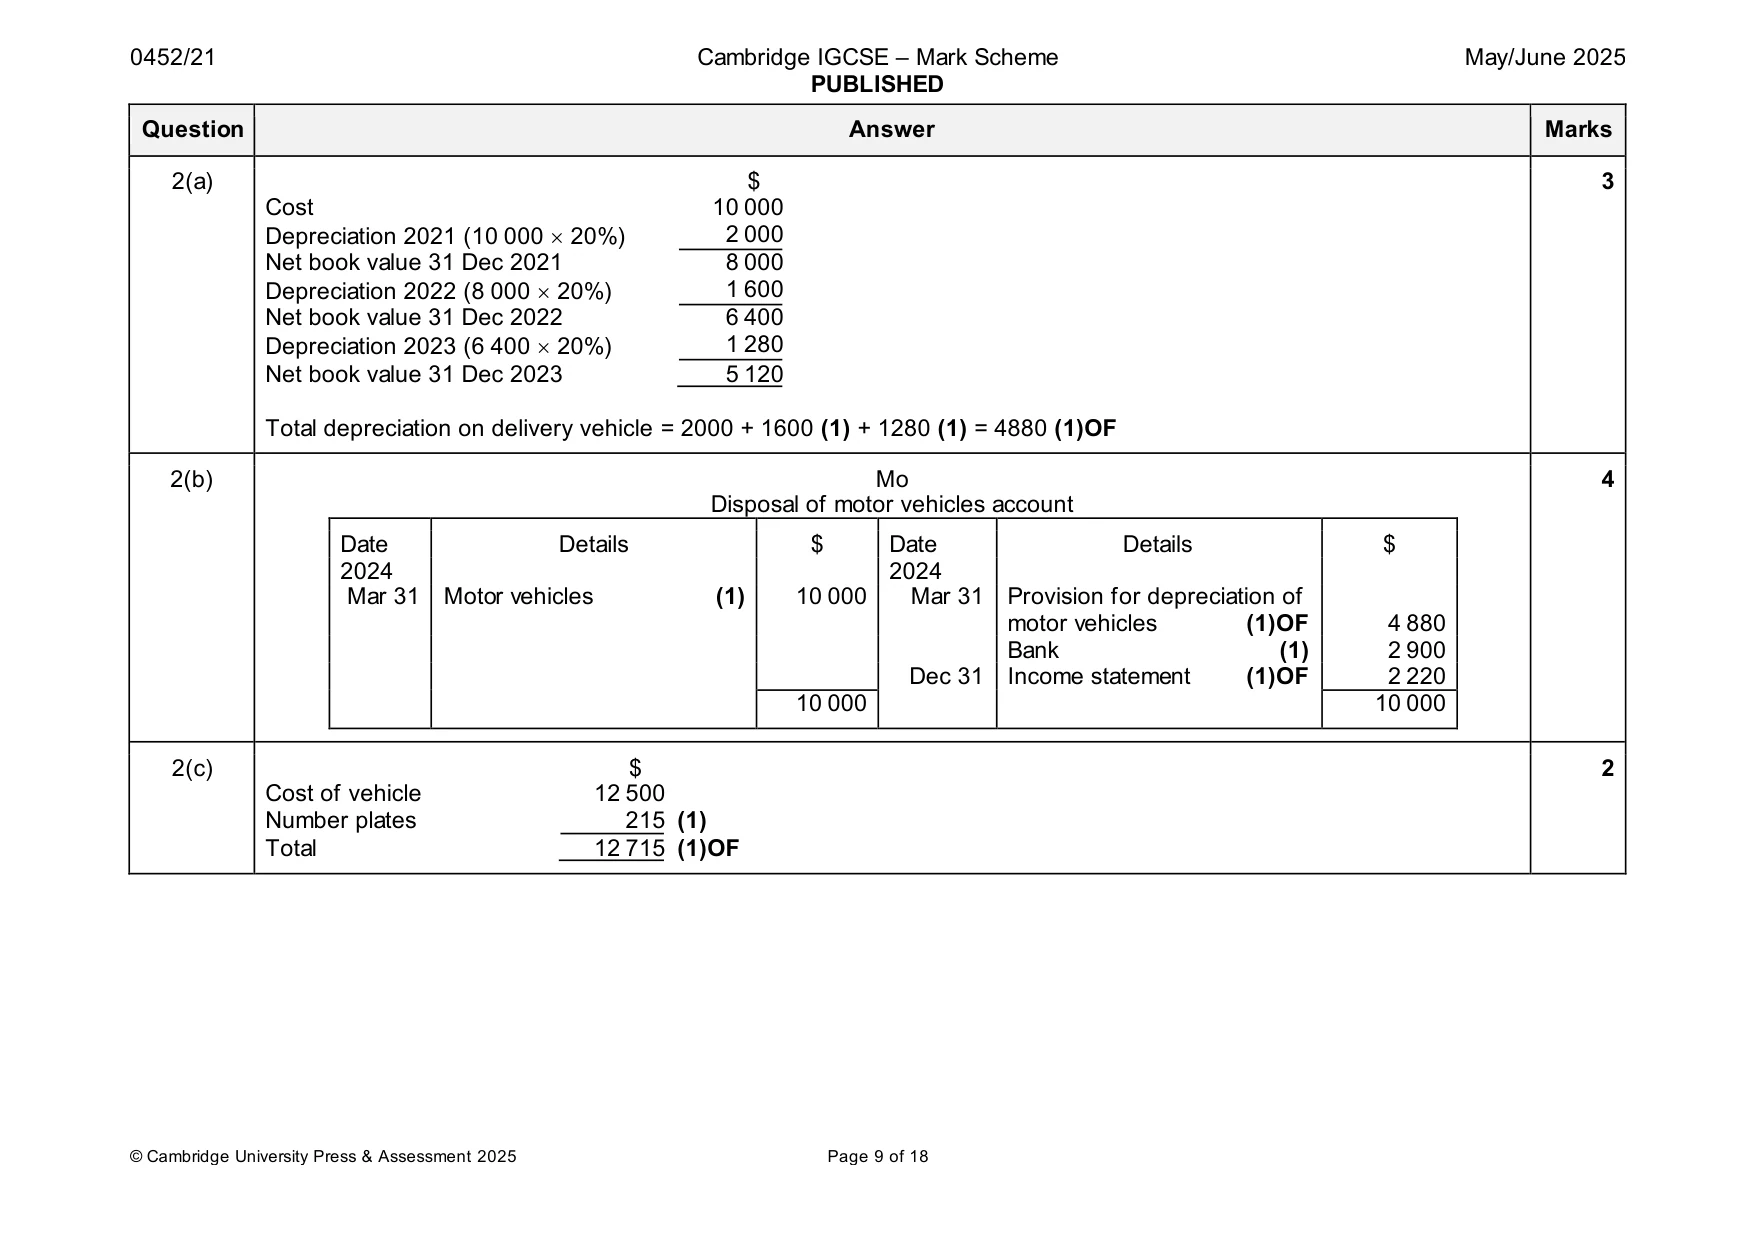
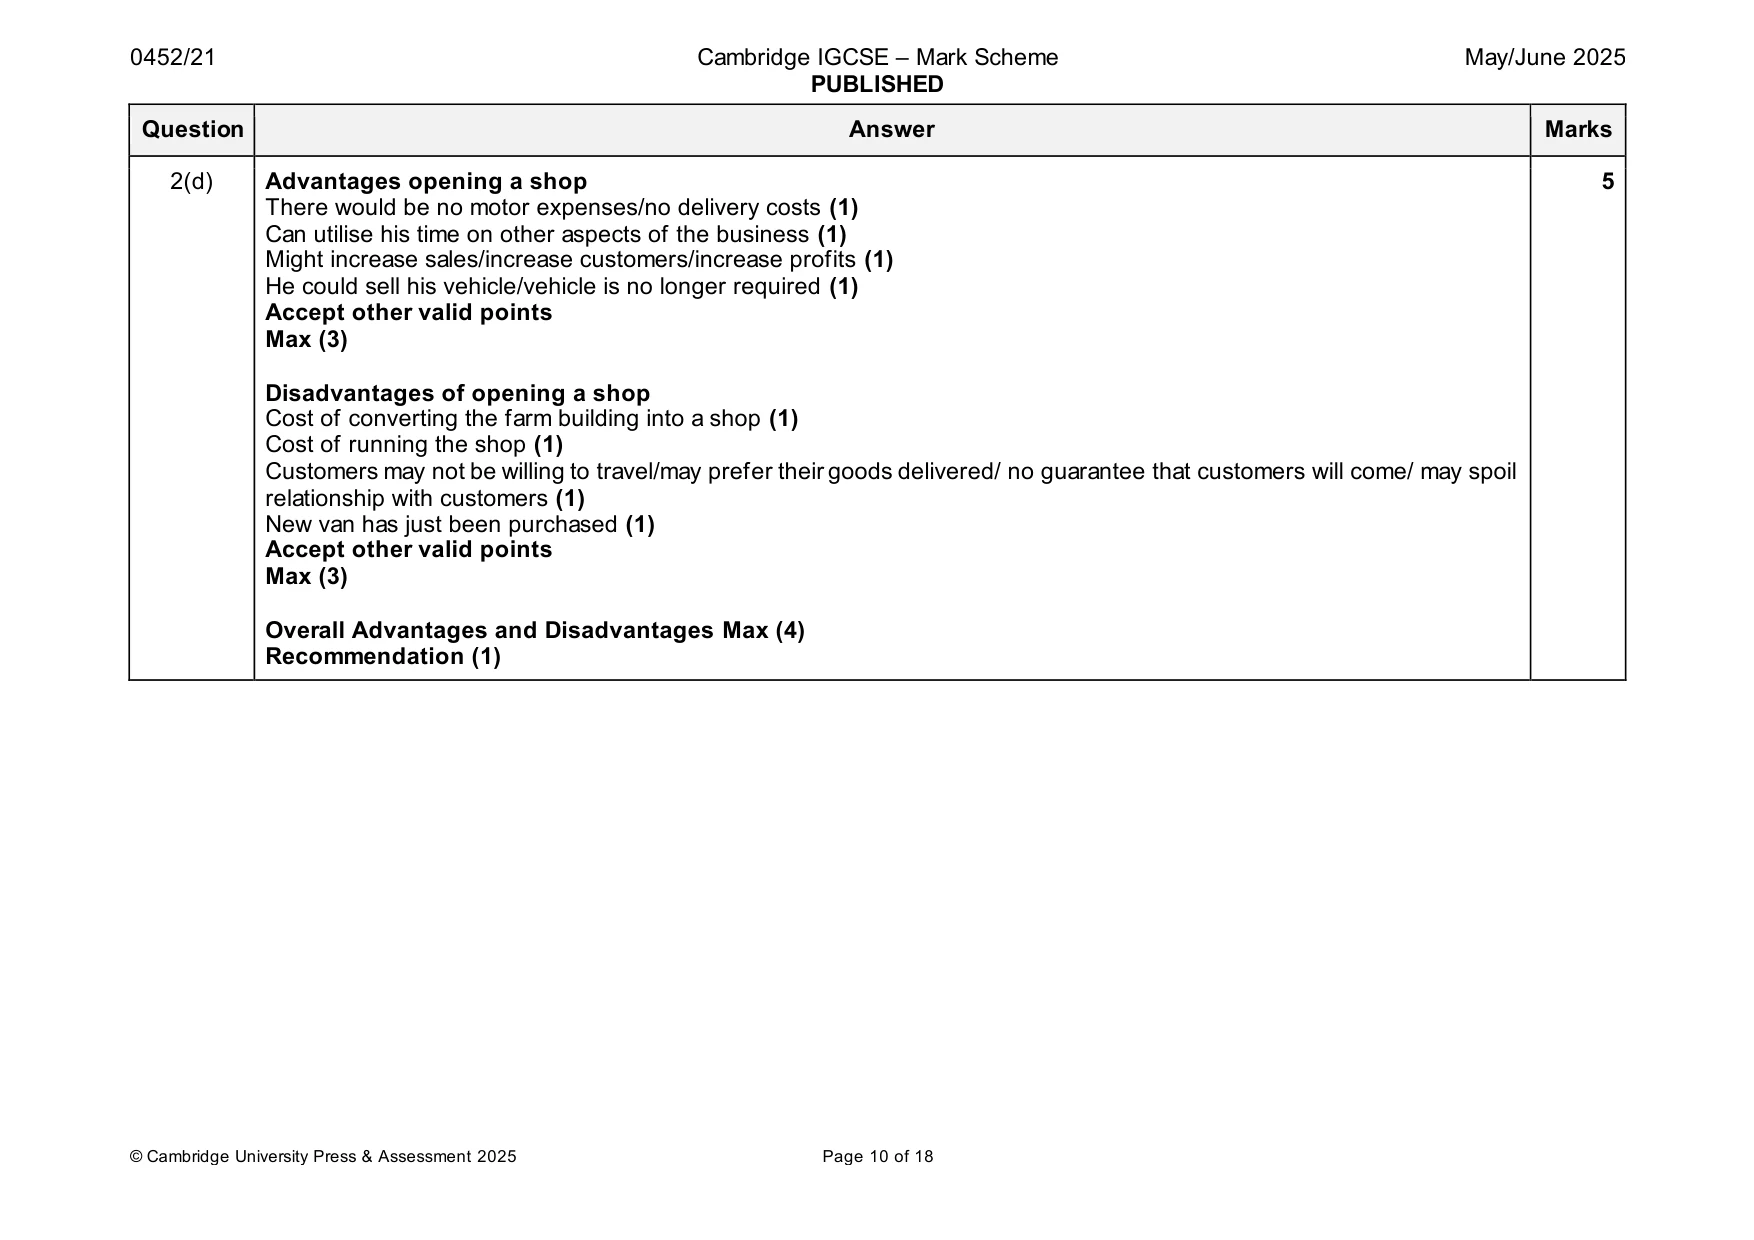
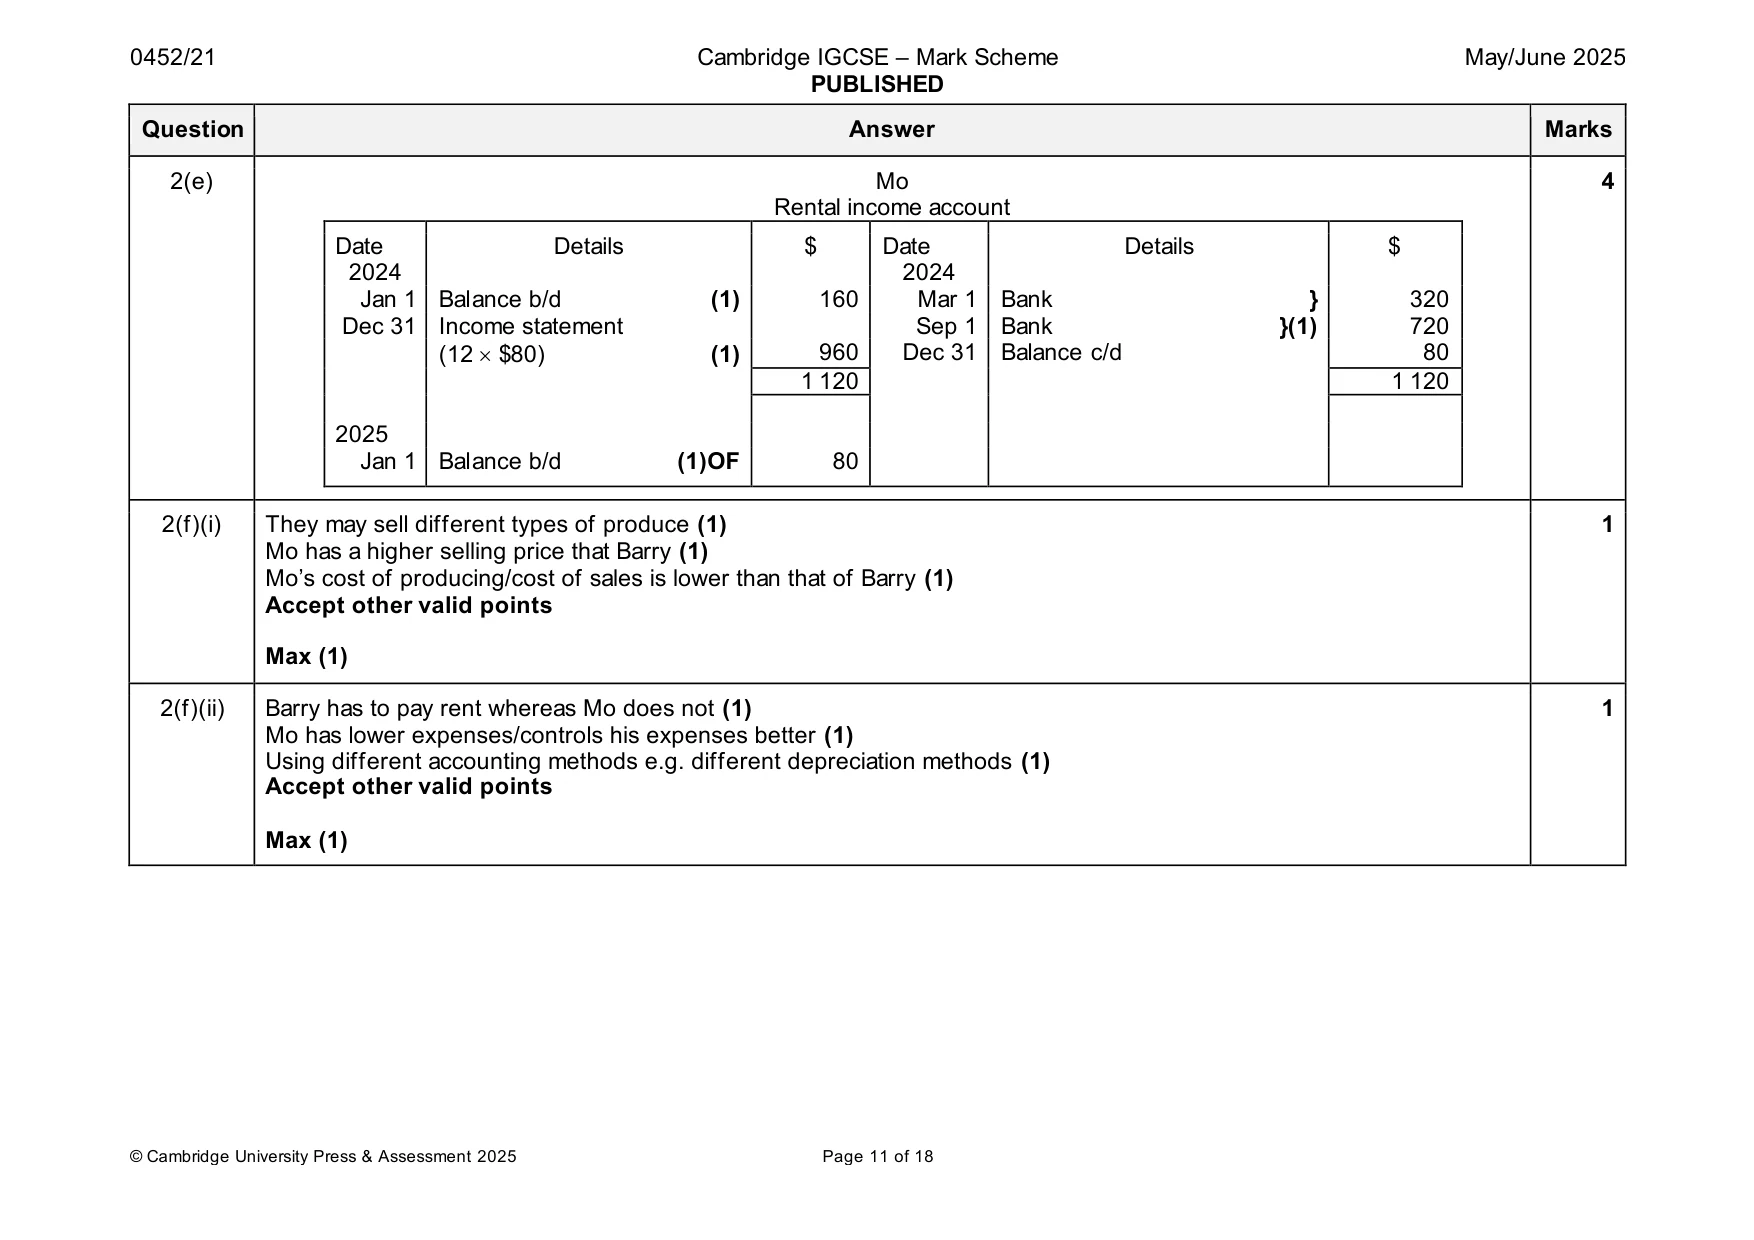
Mark scheme: 2(a) $ 3 Cost 10 000 Depreciation 2021 (10 000 20%) 2 000 Net book value 31 Dec 2021 8 000 Depreciation 2022 (8 000 20%) 1 600 Net book value 31 Dec 2022 6 400 Depreciation 2023 (6 400 20%) 1 280 Net book value 31 Dec 2023 5 120 Total depreciation on delivery vehicle = 2000 + 1600 (1) + 1280 (1) = 4880 (1)OF 2(b) Mo 4 Disposal of motor vehicles account Date Details $ Date Details $ 2024 2024 Mar 31 Motor vehicles (1) 10 000 Mar 31 Provision for depreciation of motor vehicles (1)OF 4 880 Bank (1) 2 900 Dec 31 Income statement (1)OF 2 220 10 000 10 000 2(c) $ 2 Cost of vehicle 12 500 Number plates 215 (1) Total 12 715 (1)OF 2(d) Advantages opening a shop 5 There would be no motor expenses/no delivery costs (1) Can utilise his time on other aspects of the business (1) Might increase sales/increase customers/increase profits (1) He could sell his vehicle/vehicle is no longer required (1) Accept other valid points Max (3) Disadvantages of opening a shop Cost of converting the farm building into a shop (1) Cost of running the shop (1) Customers may not be willing to travel/may prefer their goods delivered/ no guarantee that customers will come/ may spoil relationship with customers (1) New van has just been purchased (1) Accept other valid points Max (3) Overall Advantages and Disadvantages Max (4) Recommendation (1) 2(e) Mo 4 Rental income account Date Details $ Date Details $ 2024 2024 Jan 1 Balance b/d (1) 160 Mar 1 Bank } 320 Dec 31 Income statement Sep 1 Bank }(1) 720 (12 $80) (1) 960 Dec 31 Balance c/d 80 1 120 1 120 2025 Jan 1 Balance b/d (1)OF 80 2(f)(i) They may sell different types of produce (1) 1 Mo has a higher selling price that Barry (1) Mo’s cost of producing/cost of sales is lower than that of Barry (1) Accept other valid points Max (1) 2(f)(ii) Barry has to pay rent whereas Mo does not (1) 1 Mo has lower expenses/controls his expenses better (1) Using different accounting methods e.g. different depreciation methods (1) Accept other valid points Max (1)
More questions on Accounting for depreciation and disposal of non-current assets
Q3 · Nabil prepared a trial balance at 30 April 2025
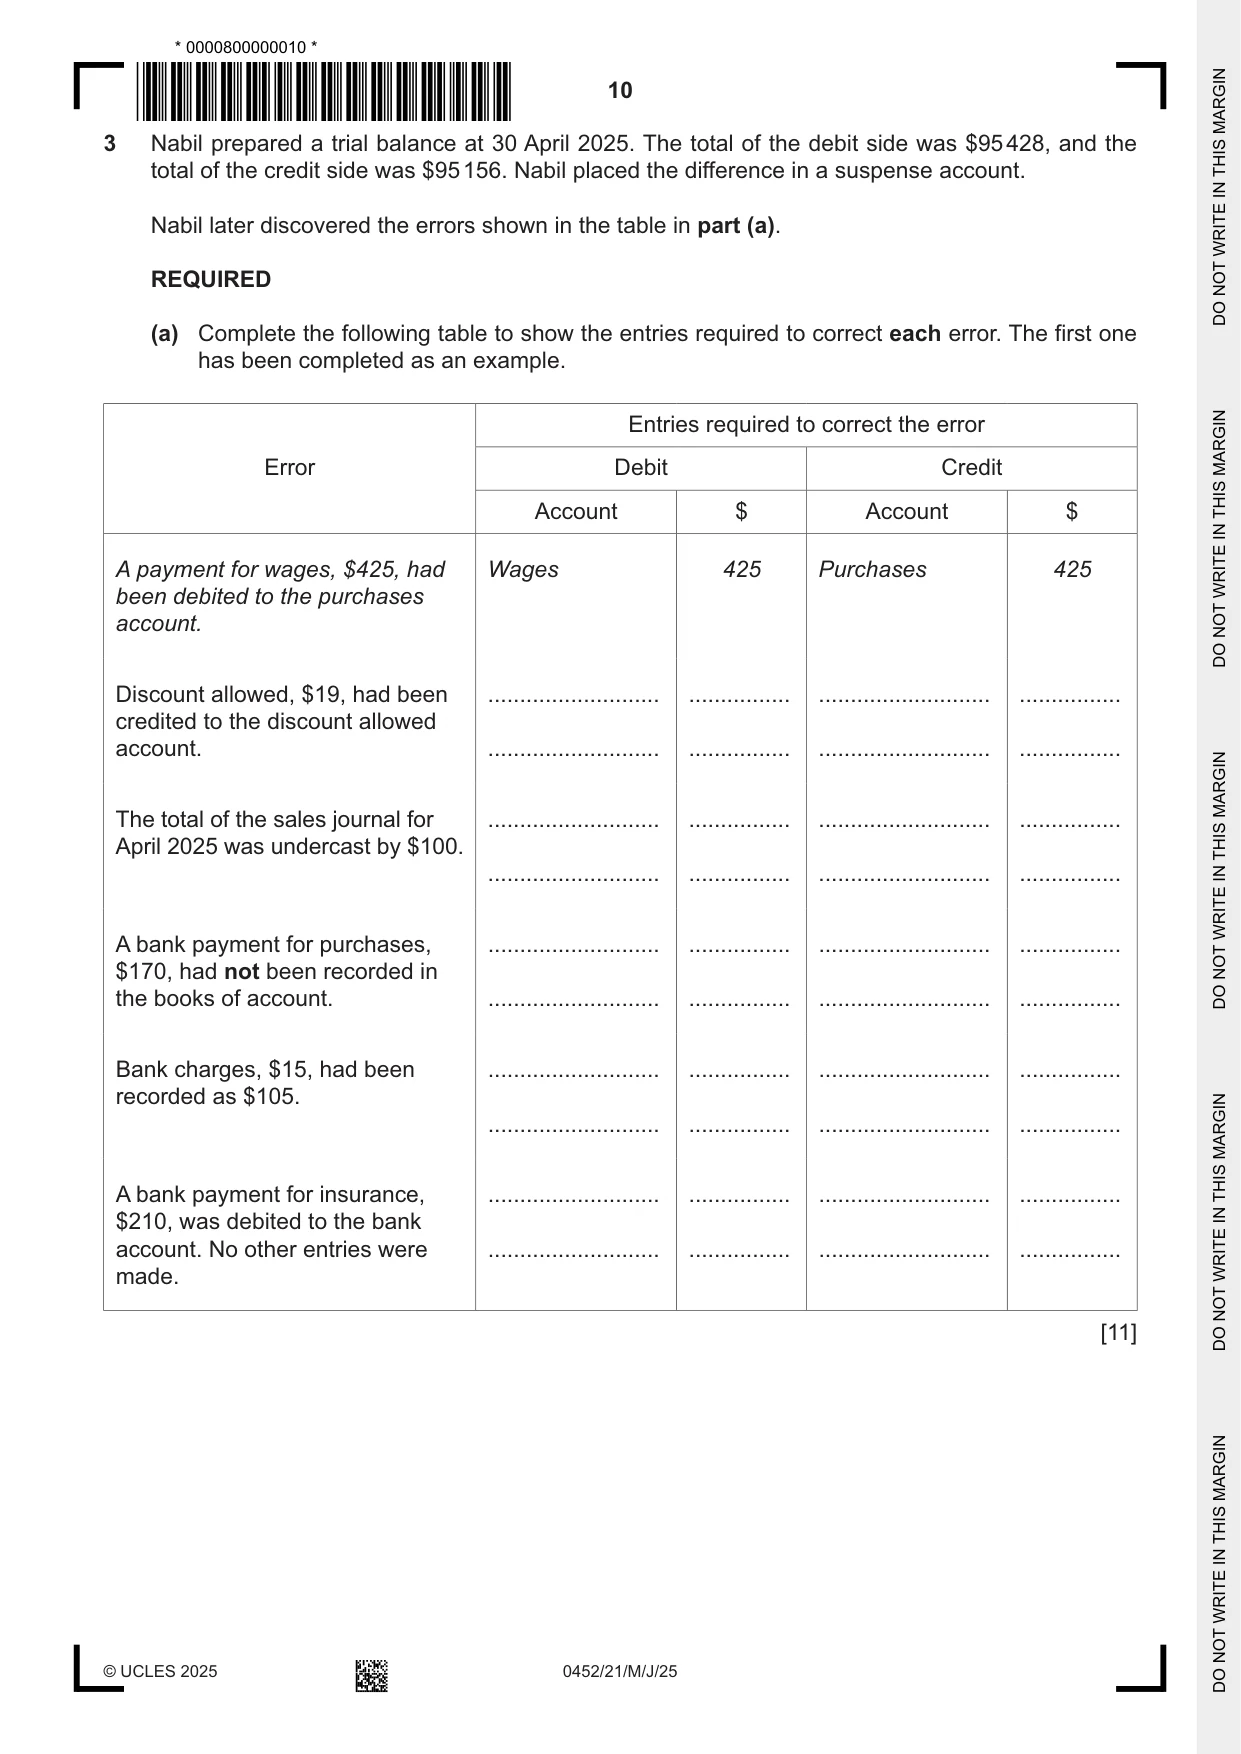
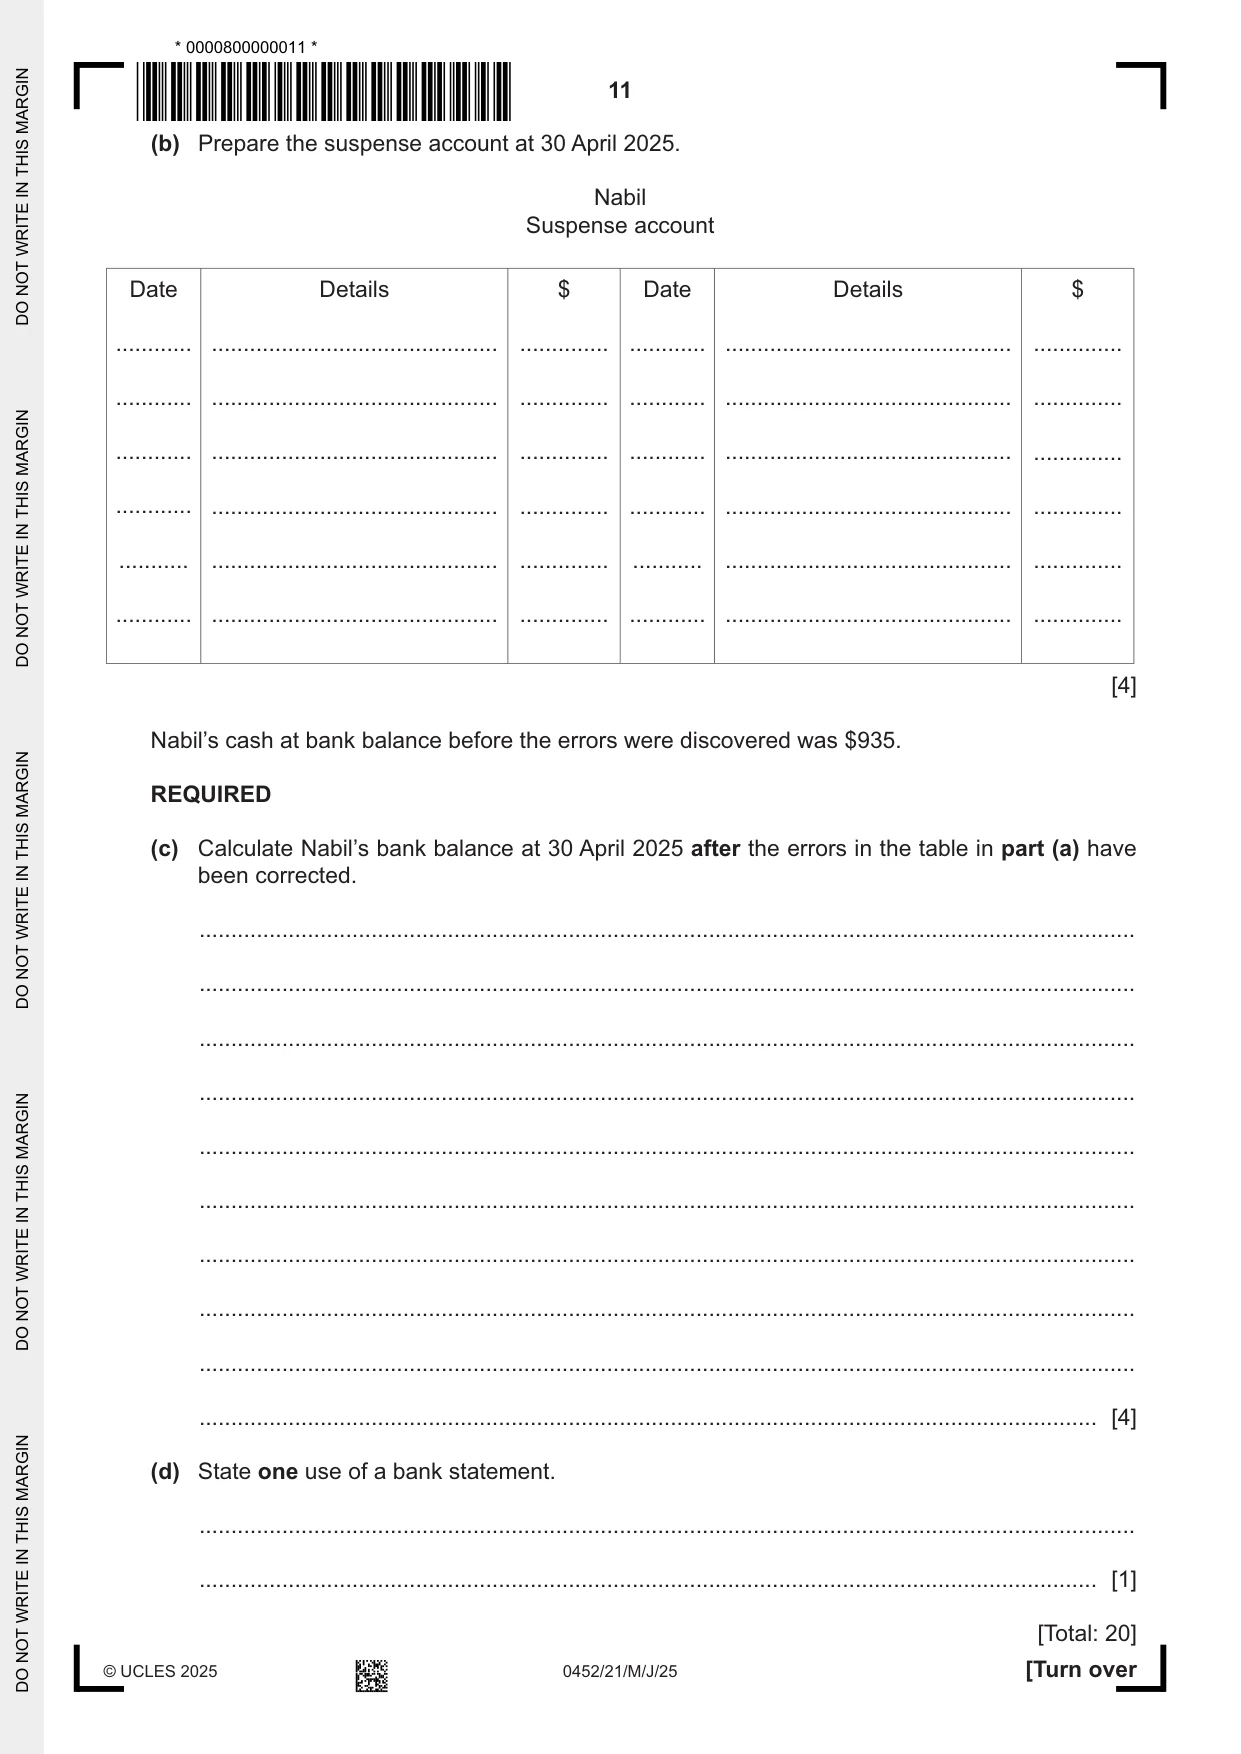
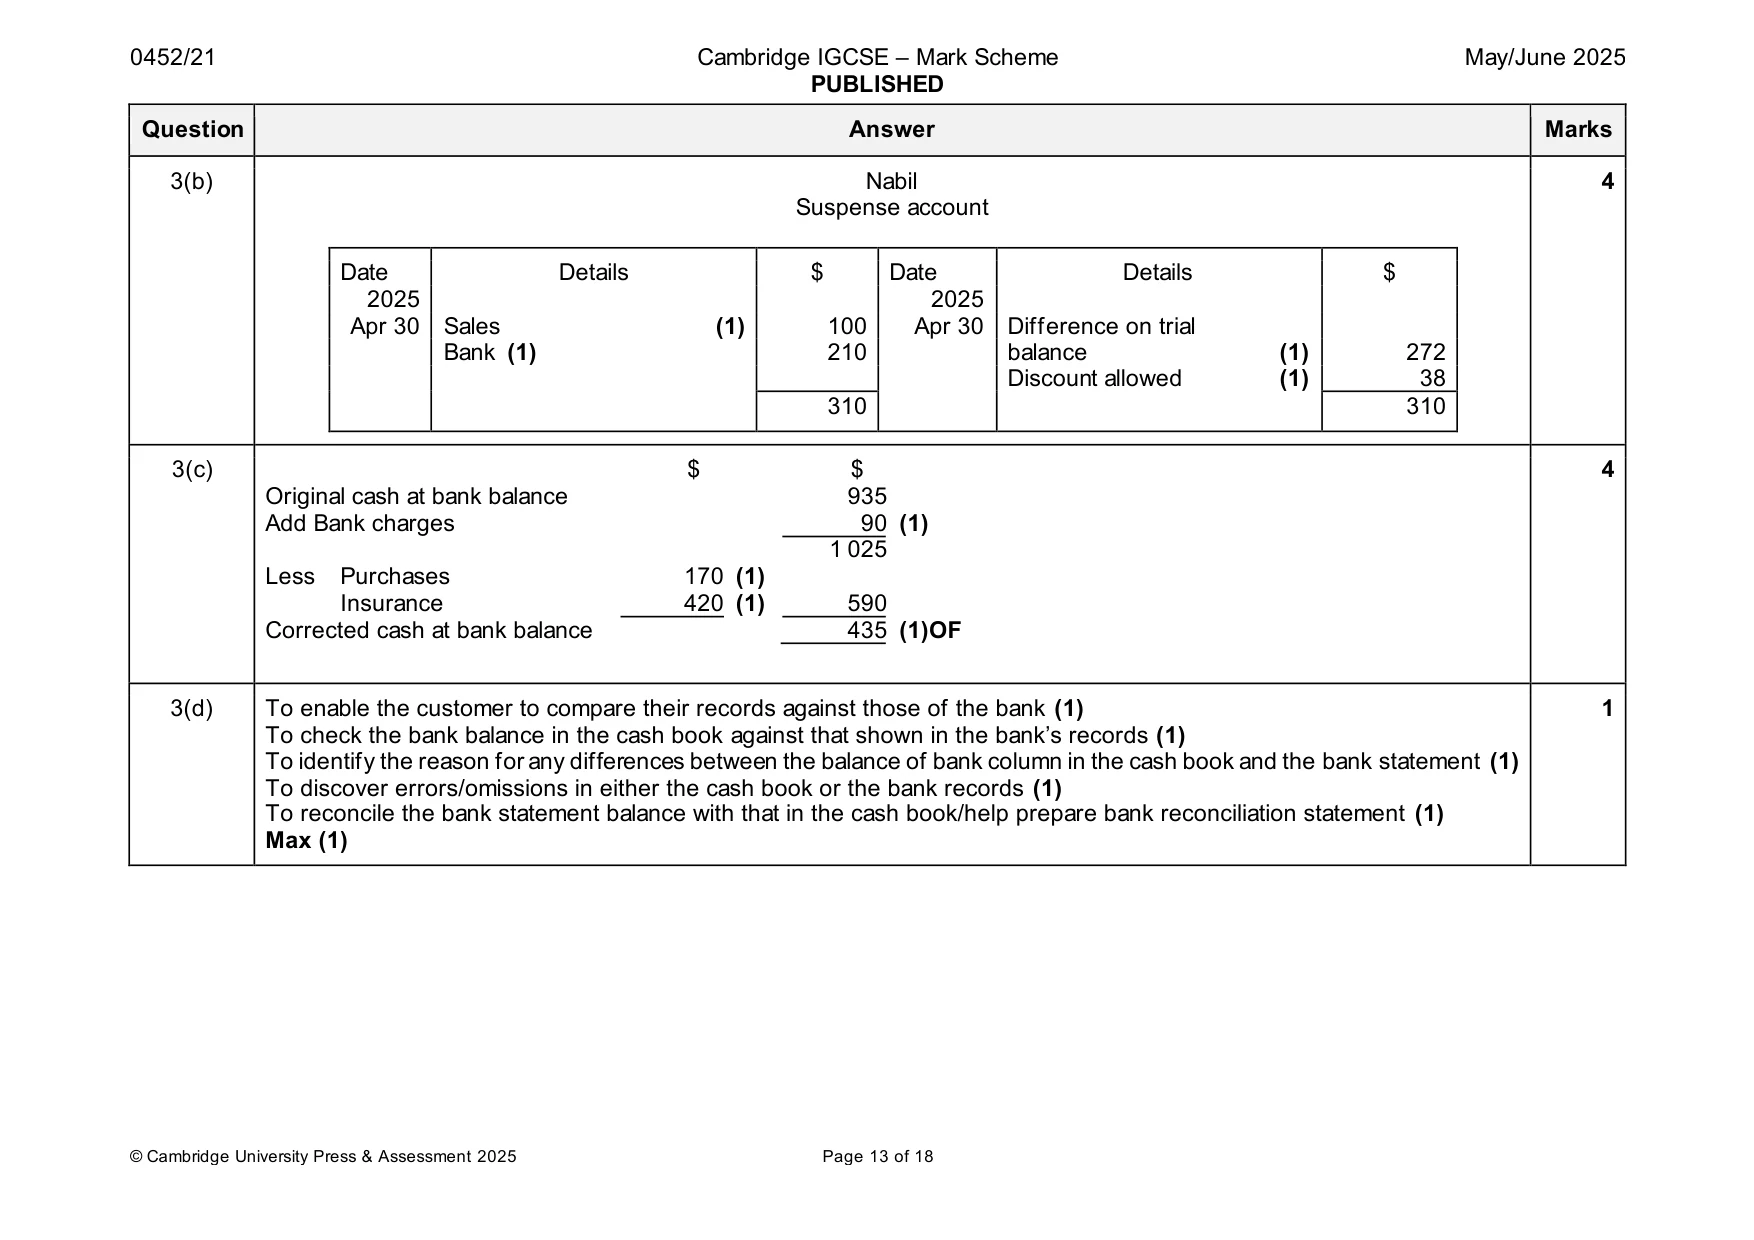
3 Nabil prepared a trial balance at 30 April 2025. The total of the debit side was $95 428, and the total of the credit side was $95 156. Nabil placed the difference in a suspense account. Nabil later discovered the errors shown in the table in part (a). REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for wages, $425, had Wages 425 Purchases 425 been debited to the purchases account. Discount allowed, $19, had been ........................... ................ ........................... ................ credited to the discount allowed account. ........................... ................ ........................... ................ The total of the sales journal for ........................... ................ ........................... ................ April 2025 was undercast by $100. ........................... ................ ........................... ................ A bank payment for purchases, ........................... ................ ........................... ................ $170, had not been recorded in the books of account. ........................... ................ ........................... ................ Bank charges, $15, had been ........................... ................ ........................... ................ recorded as $105. ........................... ................ ........................... ................ A bank payment for insurance, ........................... ................ ........................... ................ $210, was debited to the bank account. No other entries were ........................... ................ ........................... ................ made. [11] (b) Prepare the suspense account at 30 April 2025. Nabil Suspense account Date Details $ Date Details $ ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. ........... ............................................. .............. ........... ............................................. .............. ............ ............................................. .............. ............ ............................................. .............. [4] Nabil’s cash at bank balance before the errors were discovered was $935. REQUIRED (c) Calculate Nabil’s bank balance at 30 April 2025 after the errors in the table in part (a) have been corrected. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (d) State one use of a bank statement. ................................................................................................................................................... ............................................................................................................................................. [1] [Total: 20]
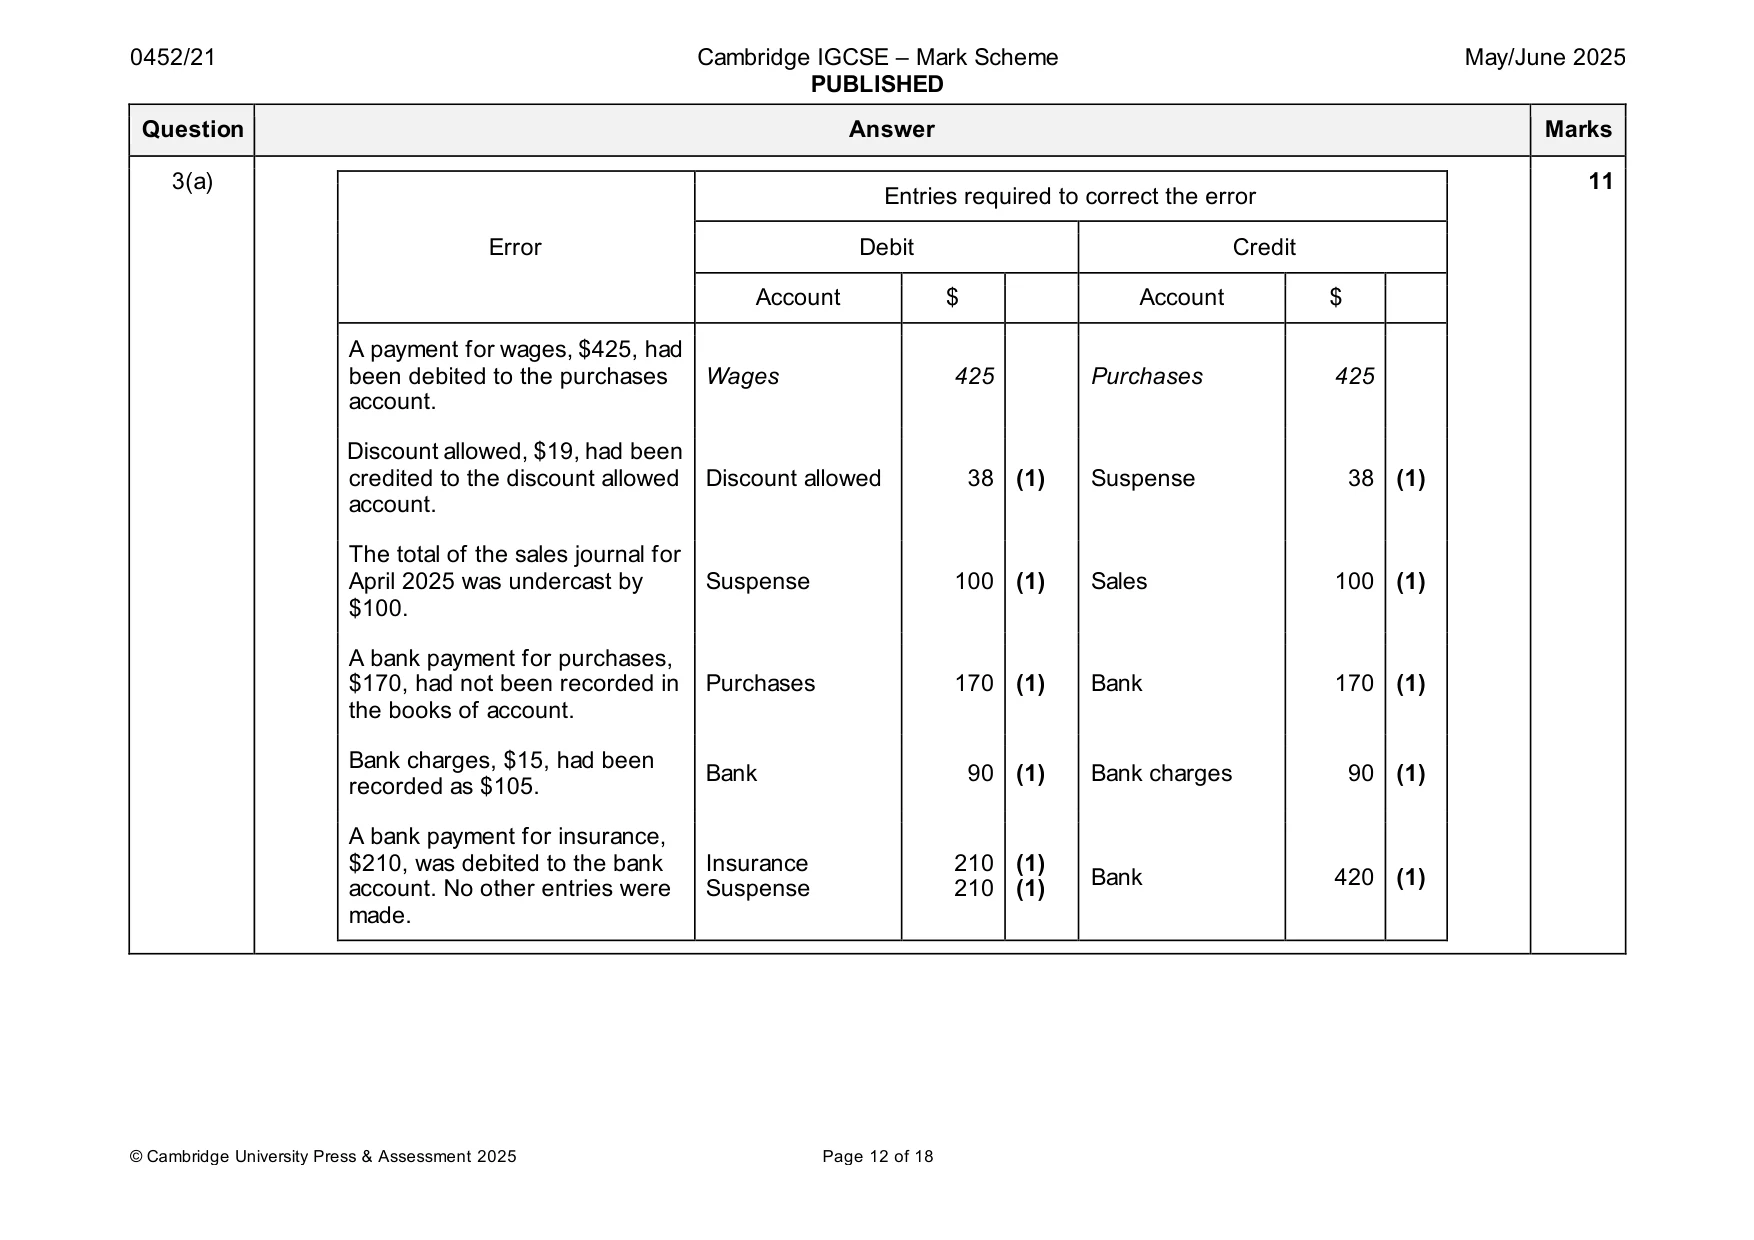
Mark scheme: 3(a) 11 Entries required to correct the error Error Debit Credit Account $ Account $ A payment for wages, $425, had been debited to the purchases Wages 425 Purchases 425 account. Discount allowed, $19, had been credited to the discount allowed Discount allowed 38 (1) Suspense 38 (1) account. The total of the sales journal for April 2025 was undercast by Suspense 100 (1) Sales 100 (1) $100. A bank payment for purchases, $170, had not been recorded in Purchases 170 (1) Bank 170 (1) the books of account. Bank charges, $15, had been Bank 90 (1) Bank charges 90 (1) recorded as $105. A bank payment for insurance, $210, was debited to the bank Insurance 210 (1) Bank 420 (1) account. No other entries were Suspense 210 (1) made. 3(b) Nabil 4 Suspense account Date Details $ Date Details $ 2025 2025 Apr 30 Sales (1) 100 Apr 30 Difference on trial Bank (1) 210 balance (1) 272 Discount allowed (1) 38 310 310 3(c) $ $ 4 Original cash at bank balance 935 Add Bank charges 90 (1) 1 025 Less Purchases 170 (1) Insurance 420 (1) 590 Corrected cash at bank balance 435 (1)OF 3(d) To enable the customer to compare their records against those of the bank (1) 1 To check the bank balance in the cash book against that shown in the bank’s records (1) To identify the reason for any differences between the balance of bank column in the cash book and the bank statement (1) To discover errors/omissions in either the cash book or the bank records (1) To reconcile the bank statement balance with that in the cash book/help prepare bank reconciliation statement (1) Max (1)
Q4 · H Limited prepares its financial statements to 30 April each year
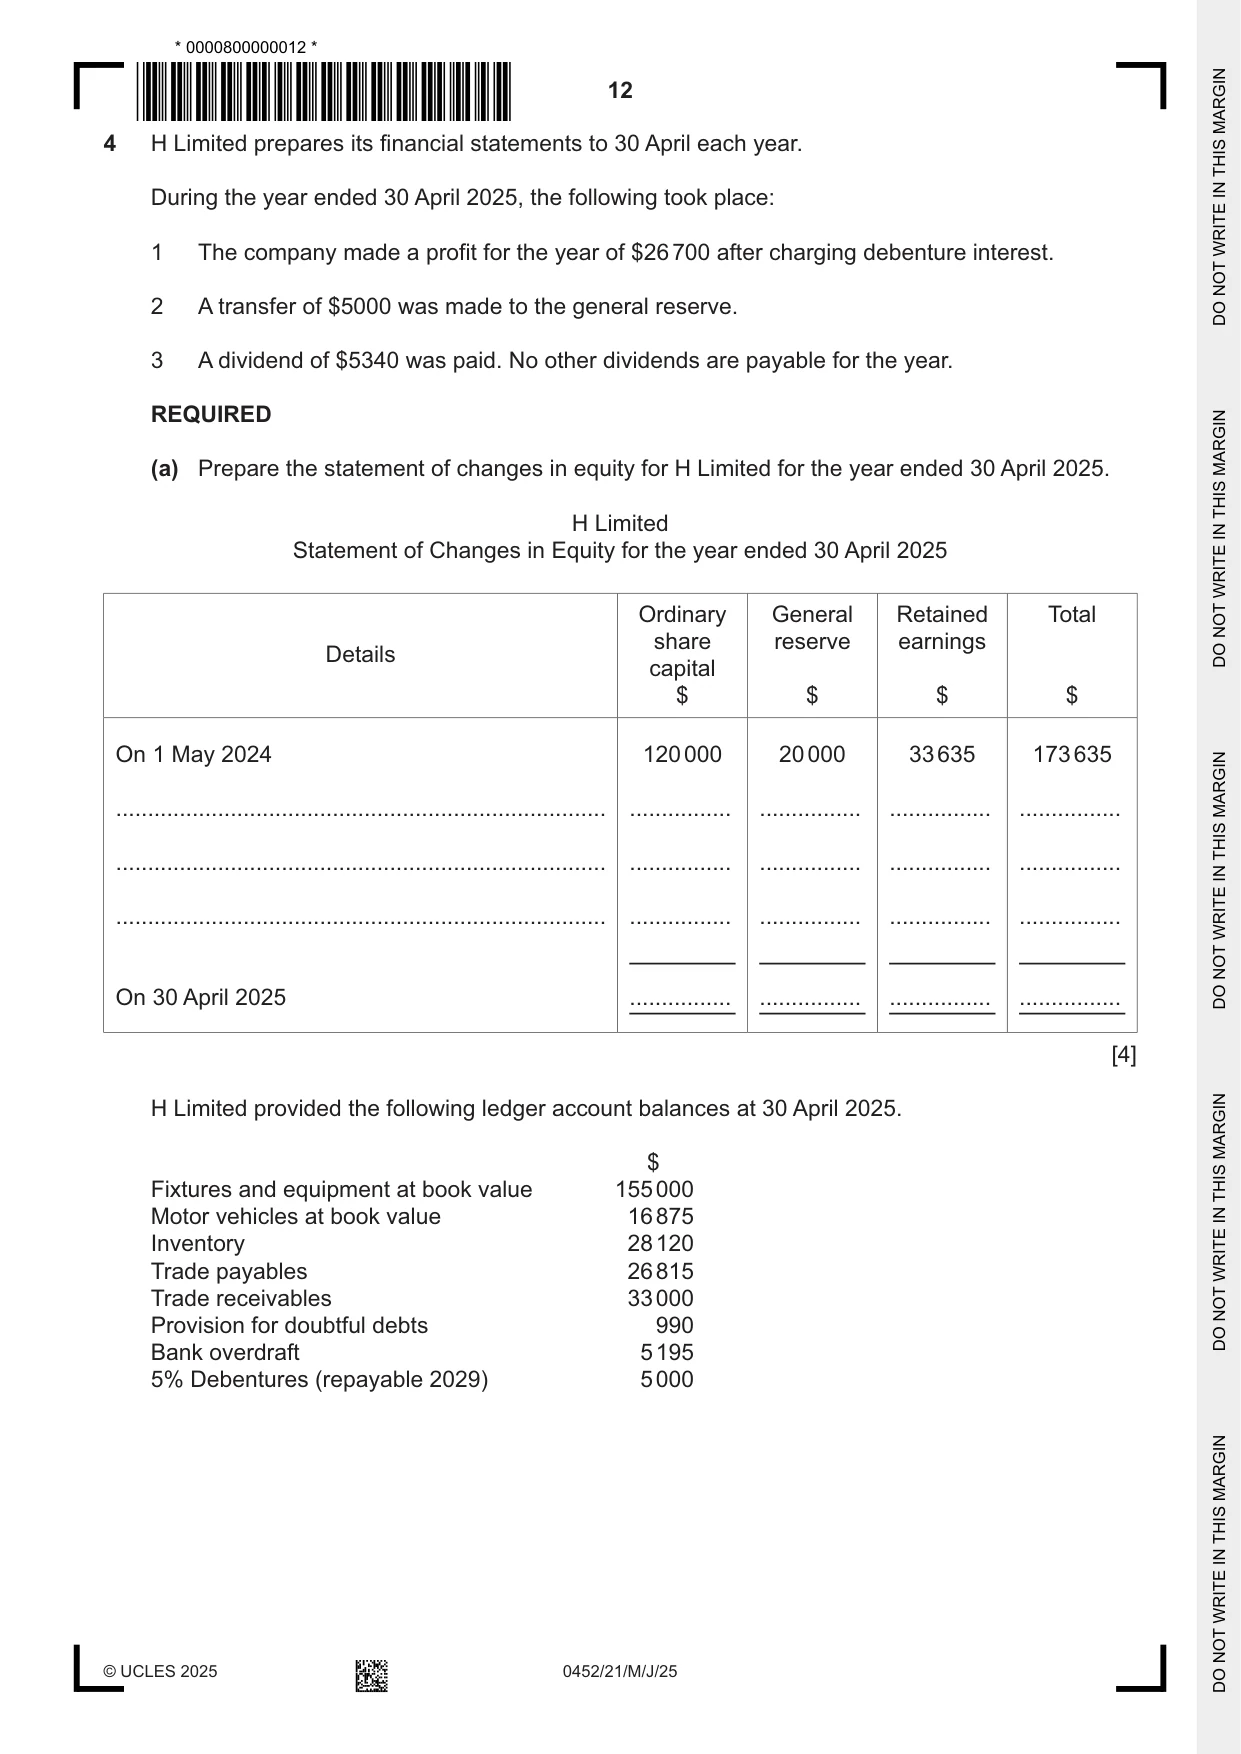
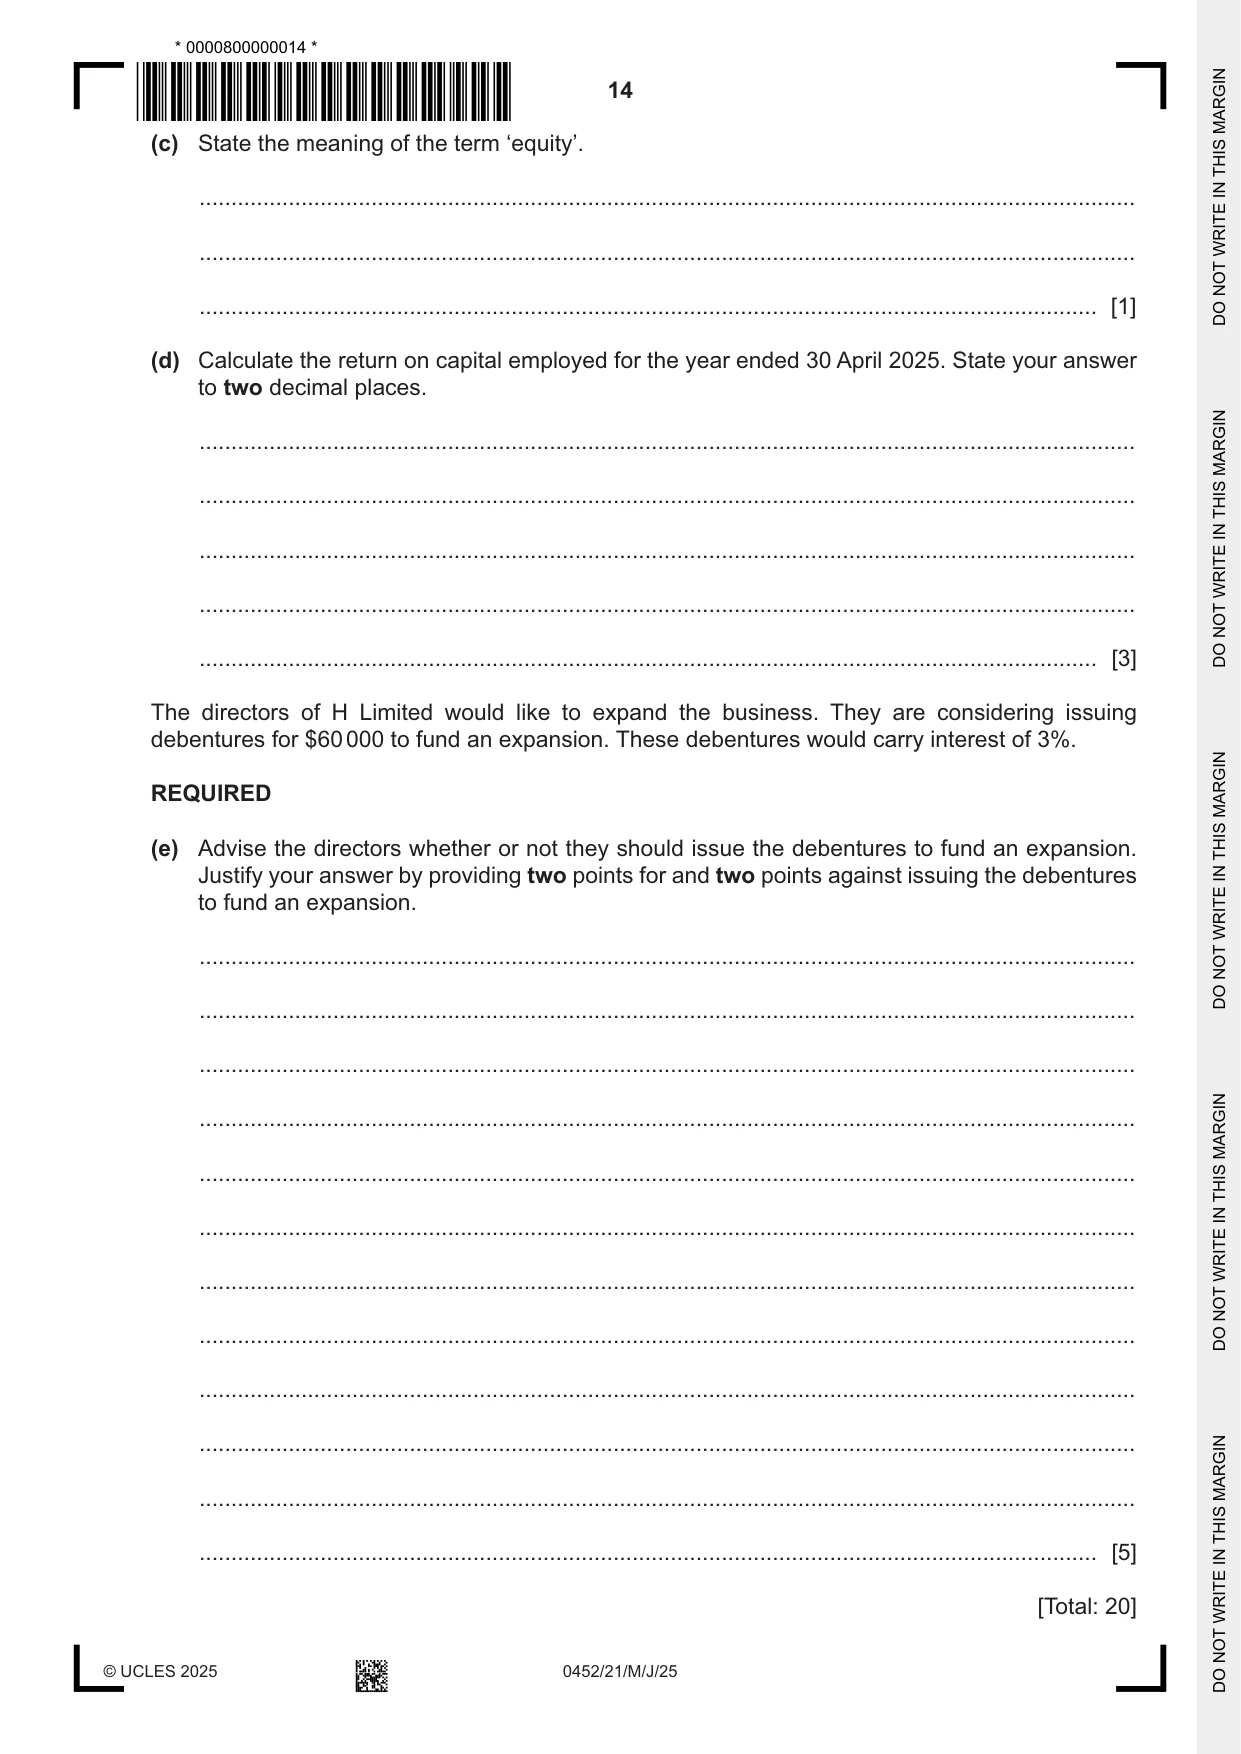
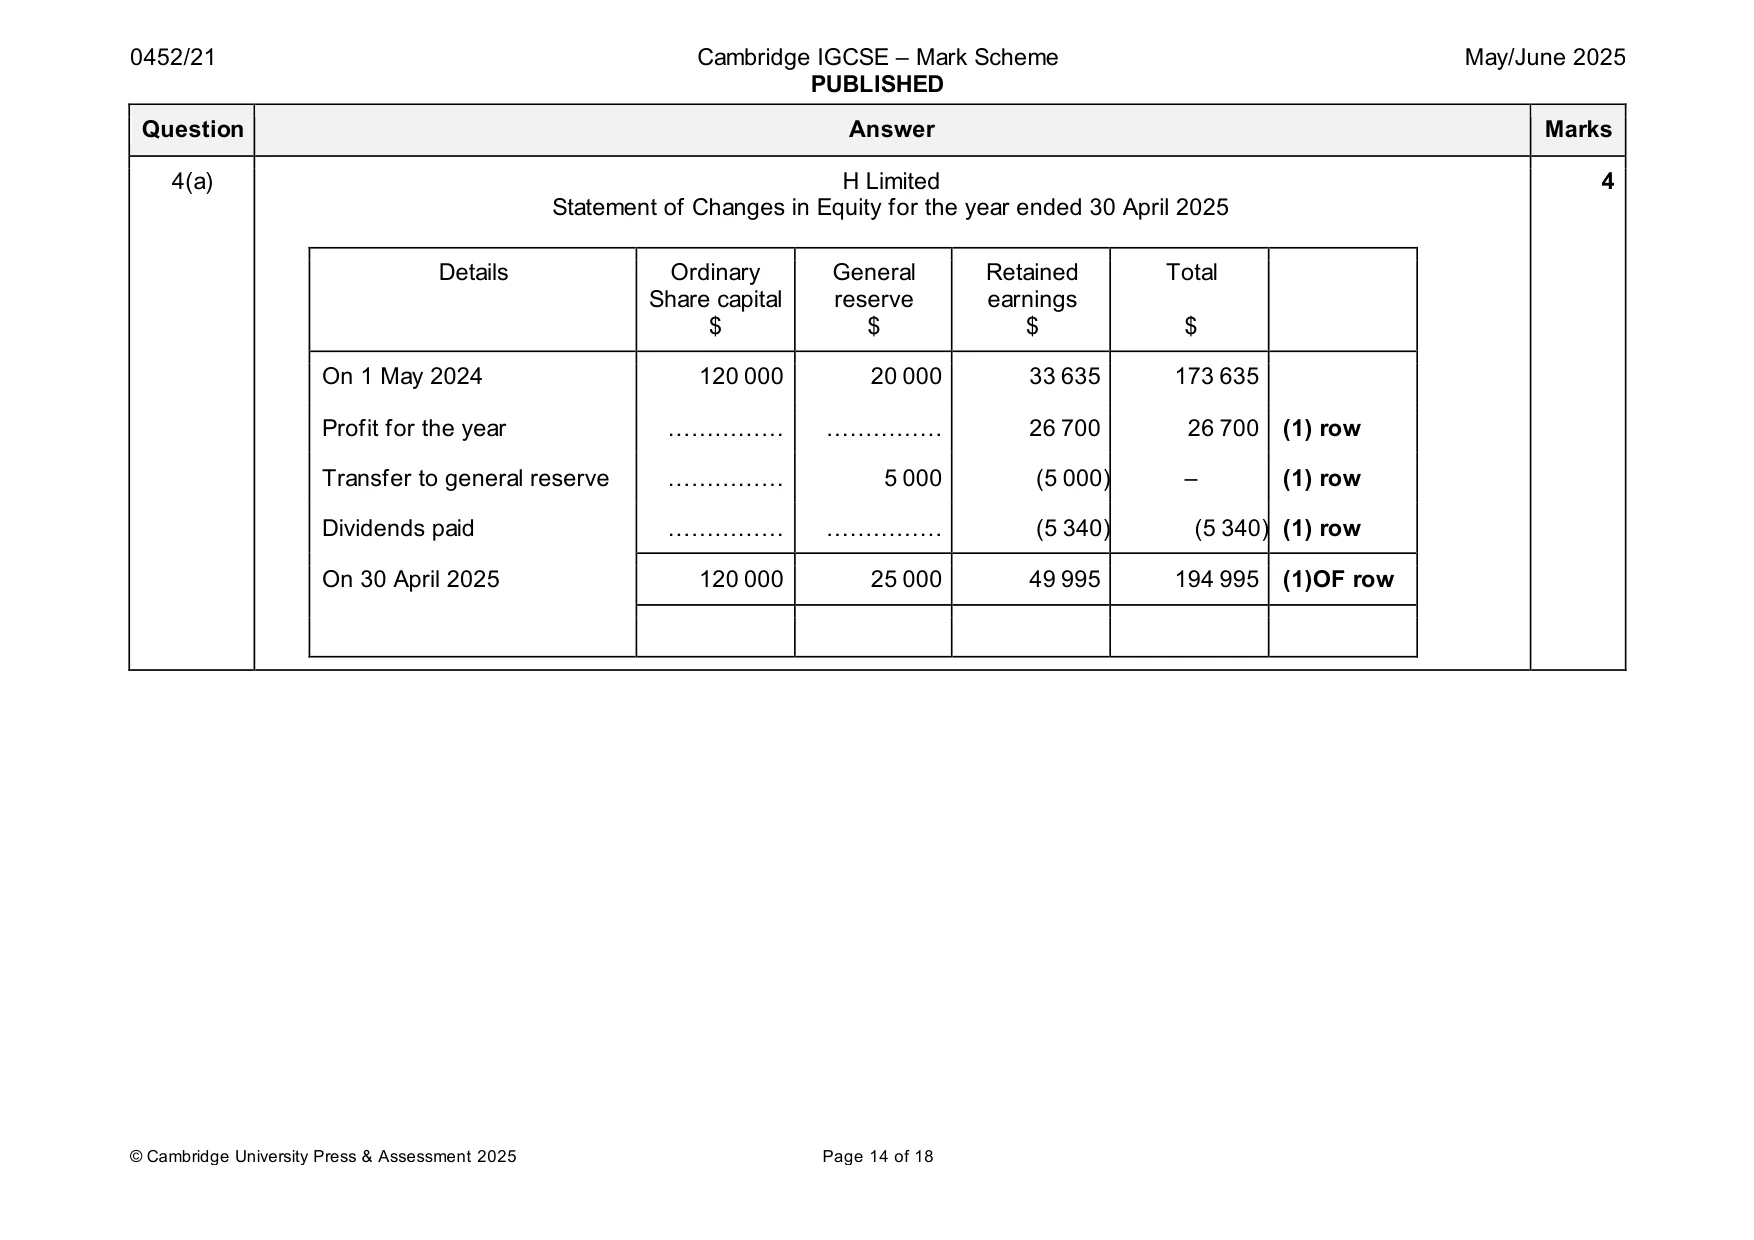
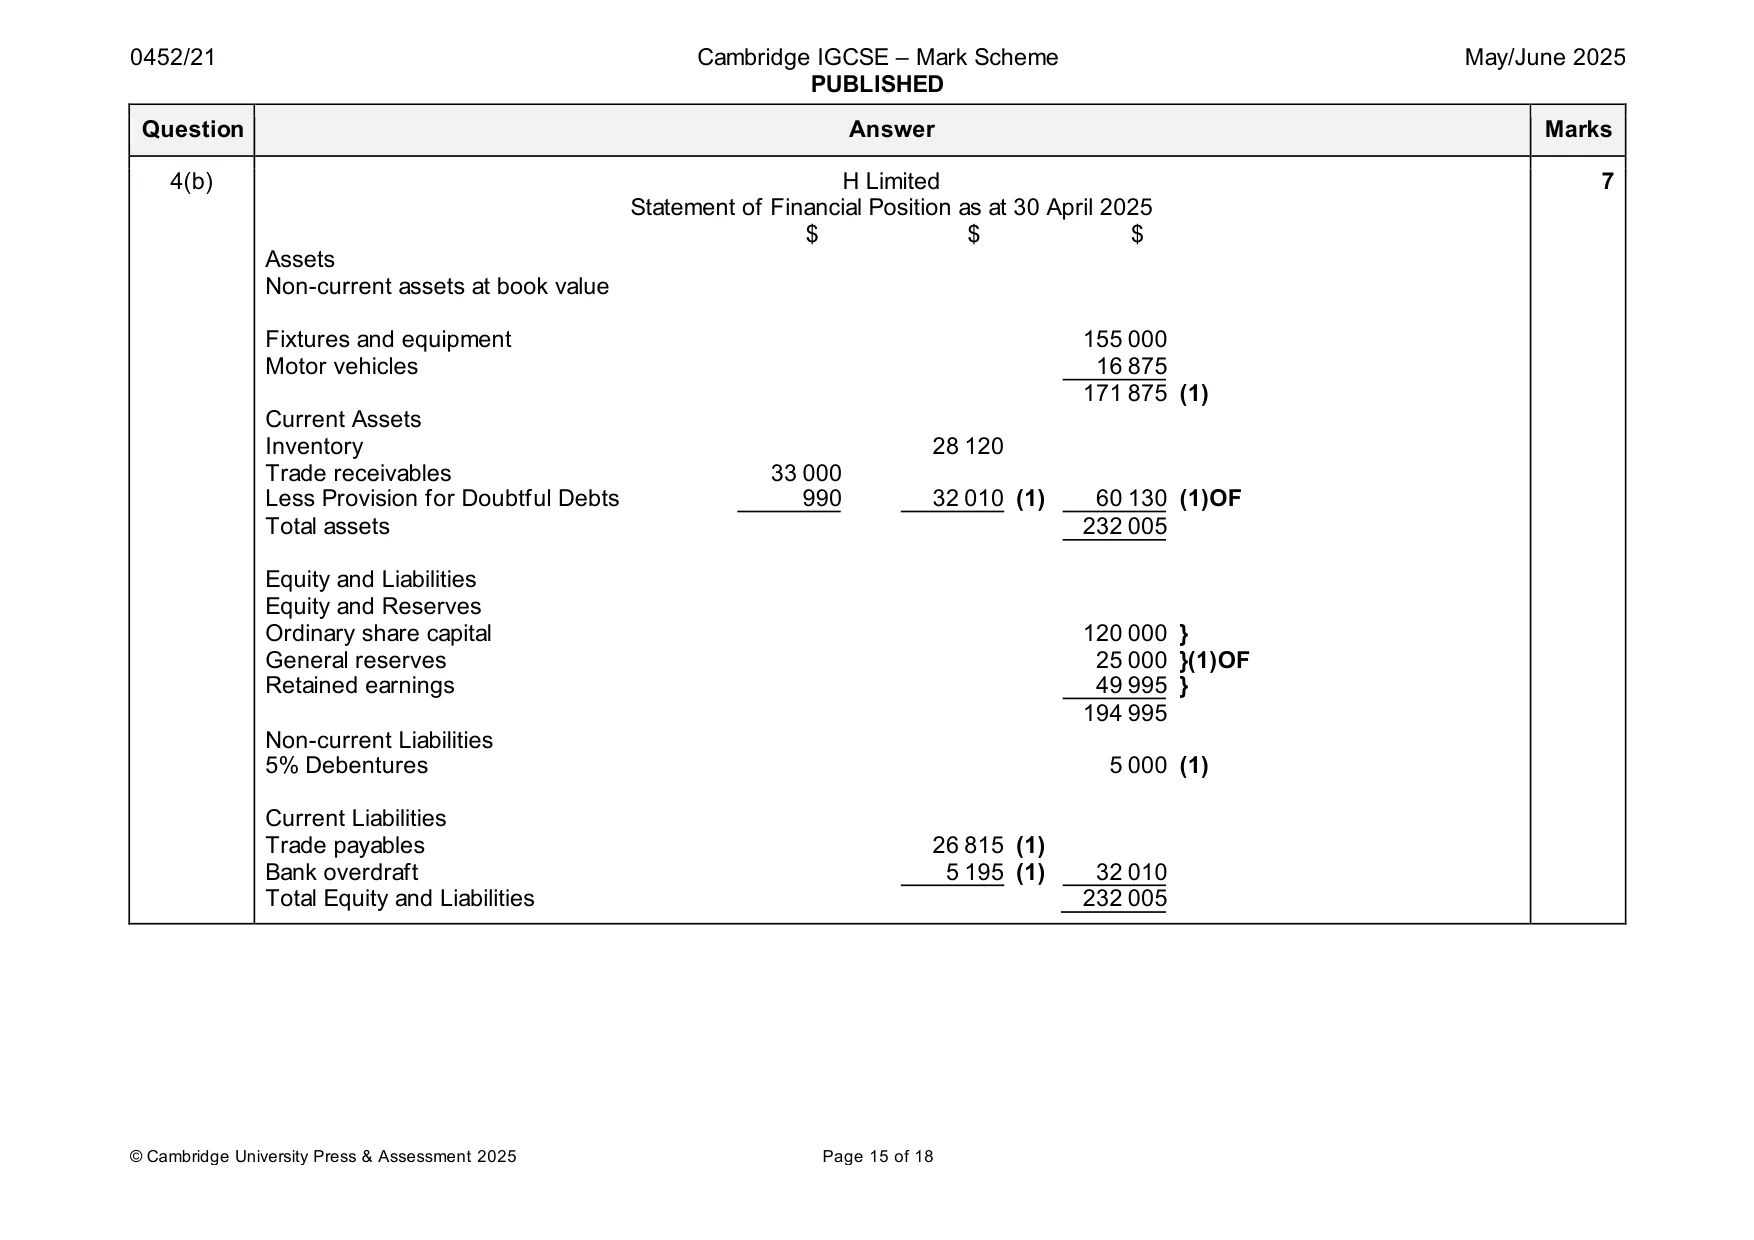
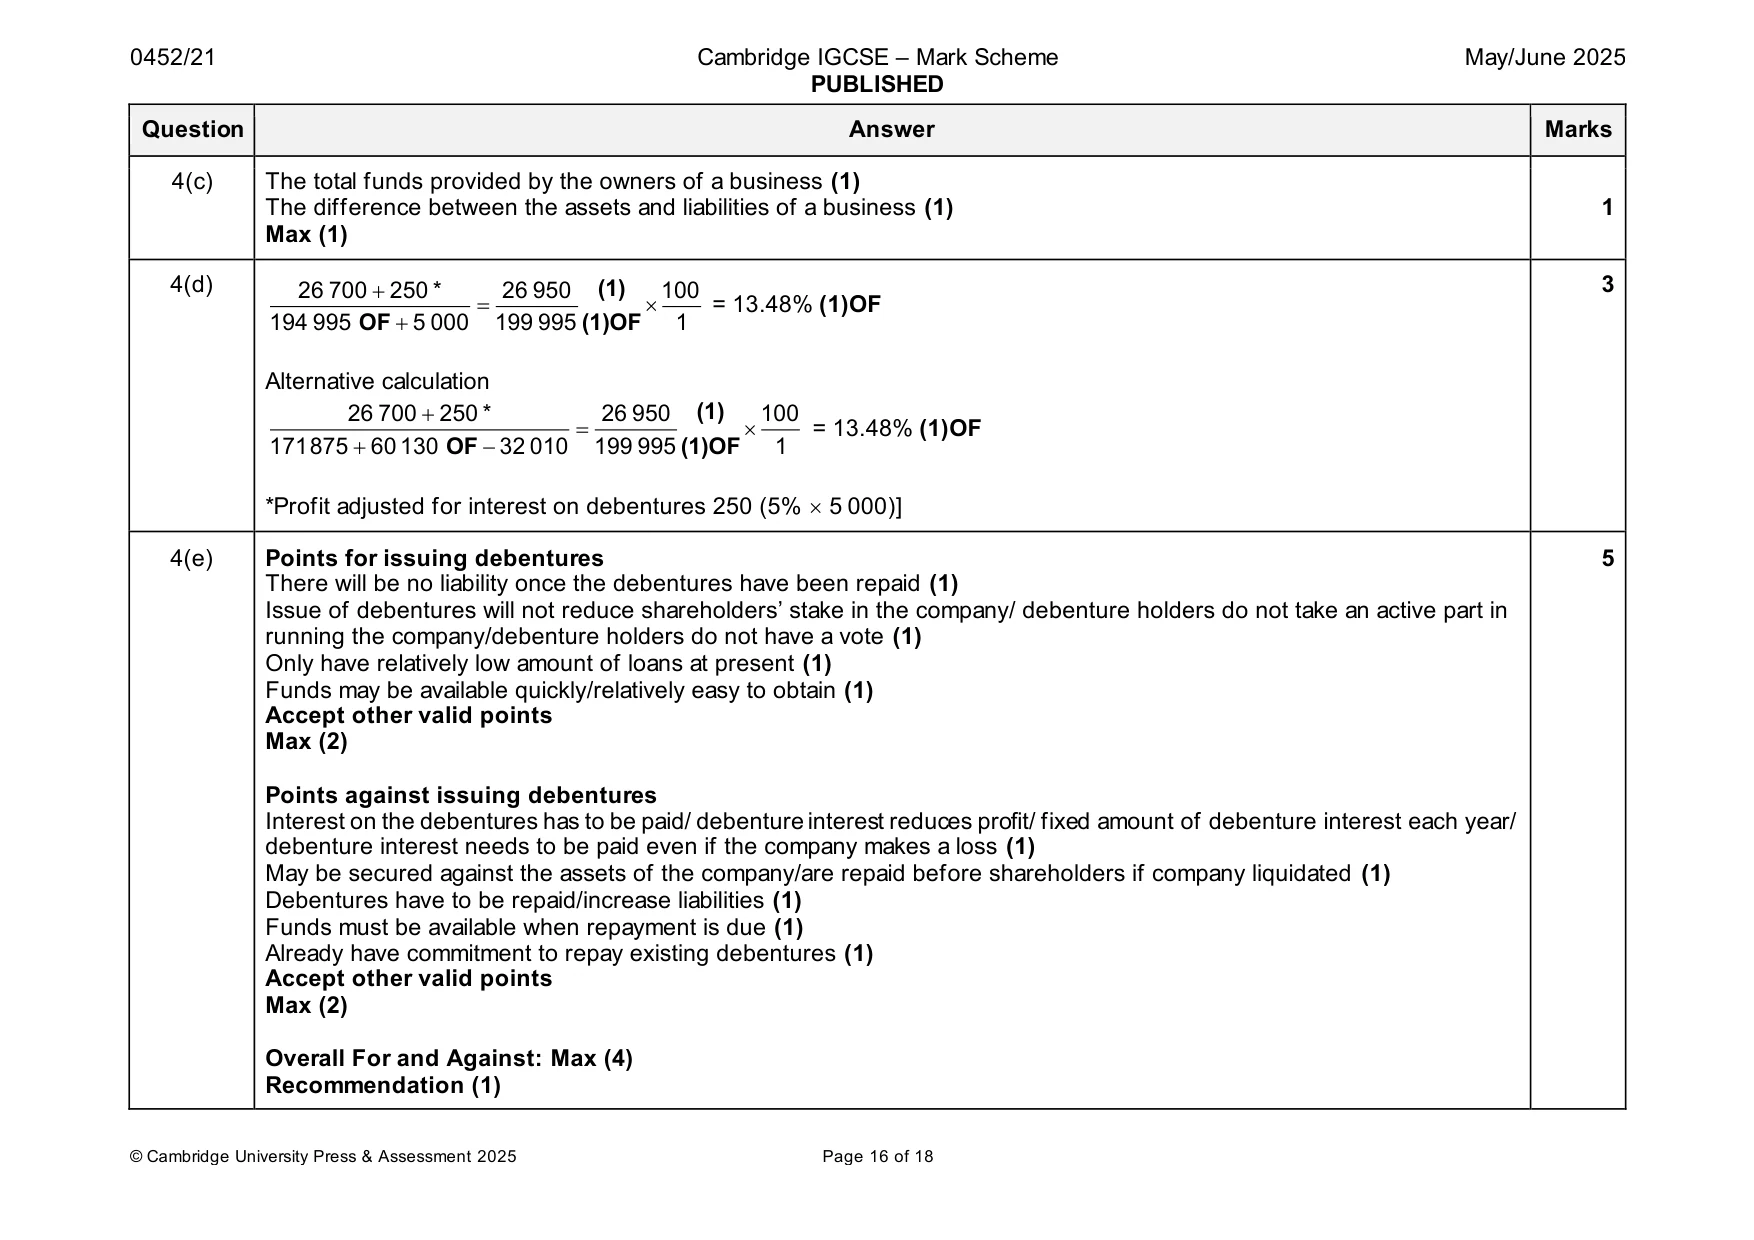
4 H Limited prepares its financial statements to 30 April each year. During the year ended 30 April 2025, the following took place: 1 The company made a profit for the year of $26 700 after charging debenture interest. 2 A transfer of $5000 was made to the general reserve. 3 A dividend of $5340 was paid. No other dividends are payable for the year. REQUIRED (a) Prepare the statement of changes in equity for H Limited for the year ended 30 April 2025. H Limited Statement of Changes in Equity for the year ended 30 April 2025 Ordinary General Retained Total share reserve earnings Details capital $ $ $ $ On 1 May 2024 120 000 20 000 33 635 173 635 ............................................................................. ................ ................ ................ ................ ............................................................................. ................ ................ ................ ................ ............................................................................. ................ ................ ................ ................ On 30 April 2025 ................ ................ ................ ................ [4] H Limited provided the following ledger account balances at 30 April 2025. $ Fixtures and equipment at book value 155 000 Motor vehicles at book value 16 875 Inventory 28 120 Trade payables 26 815 Trade receivables 33 000 Provision for doubtful debts 990 Bank overdraft 5 195 5% Debentures (repayable 2029) 5 000 REQUIRED (b) Prepare the statement of financial position for H Limited at 30 H Limited Statement of Financial Position at 30 Ap ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. (c) State the meaning of the term ‘equity’. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] (d) Calculate the return on capital employed for the year ended 30 April 2025. State your answer to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] The directors of H Limited would like to expand the business. They are considering issuing debentures for $60 000 to fund an expansion. These debentures would carry interest of 3%. REQUIRED (e) Advise the directors whether or not they should issue the debentures to fund an expansion. Justify your answer by providing two points for and two points against issuing the debentures to fund an expansion. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] Question 5 starts on page 16.
Mark scheme: 4(a) H Limited 4 Statement of Changes in Equity for the year ended 30 April 2025 Details Ordinary General Retained Total Share capital reserve earnings $ $ $ $ On 1 May 2024 120 000 20 000 33 635 173 635 Profit for the year …………… …………… 26 700 26 700 (1) row Transfer to general reserve …………… 5 000 (5 000) – (1) row Dividends paid …………… …………… (5 340) (5 340) (1) row On 30 April 2025 120 000 25 000 49 995 194 995 (1)OF row 4(b) H Limited 7 Statement of Financial Position as at 30 April 2025 $ $ $ Assets Non-current assets at book value Fixtures and equipment 155 000 Motor vehicles 16 875 171 875 (1) Current Assets Inventory 28 120 Trade receivables 33 000 Less Provision for Doubtful Debts 990 32 010 (1) 60 130 (1)OF Total assets 232 005 Equity and Liabilities Equity and Reserves Ordinary share capital 120 000 } General reserves 25 000 }(1)OF Retained earnings 49 995 } 194 995 Non-current Liabilities 5% Debentures 5 000 (1) Current Liabilities Trade payables 26 815 (1) Bank overdraft 5 195 (1) 32 010 Total Equity and Liabilities 232 005 4(c) The total funds provided by the owners of a business (1) The difference between the assets and liabilities of a business (1) 1 Max (1) 4(d) 26 700 + 250 * 26 950 (1) 100 3 = = 13.48% (1)OF 194 995 OF + 5 000 199 995 (1)OF 1 Alternative calculation 26 700 + 250 * 26 950 (1) 100 = = 13.48% (1)OF 171875 + 60 130 OF − 32 010 199 995 (1)OF 1 *Profit adjusted for interest on debentures 250 (5% 5 000)] 4(e) Points for issuing debentures 5 There will be no liability once the debentures have been repaid (1) Issue of debentures will not reduce shareholders’ stake in the company/ debenture holders do not take an active part in running the company/debenture holders do not have a vote (1) Only have relatively low amount of loans at present (1) Funds may be available quickly/relatively easy to obtain (1) Accept other valid points Max (2) Points against issuing debentures Interest on the debentures has to be paid/ debenture interest reduces profit/ fixed amount of debenture interest each year/ debenture interest needs to be paid even if the company makes a loss (1) May be secured against the assets of the company/are repaid before shareholders if company liquidated (1) Debentures have to be repaid/increase liabilities (1) Funds must be available when repayment is due (1) Already have commitment to repay existing debentures (1) Accept other valid points Max (2) Overall For and Against: Max (4) Recommendation (1)
Q5 · Grace owns a factory which makes shoes
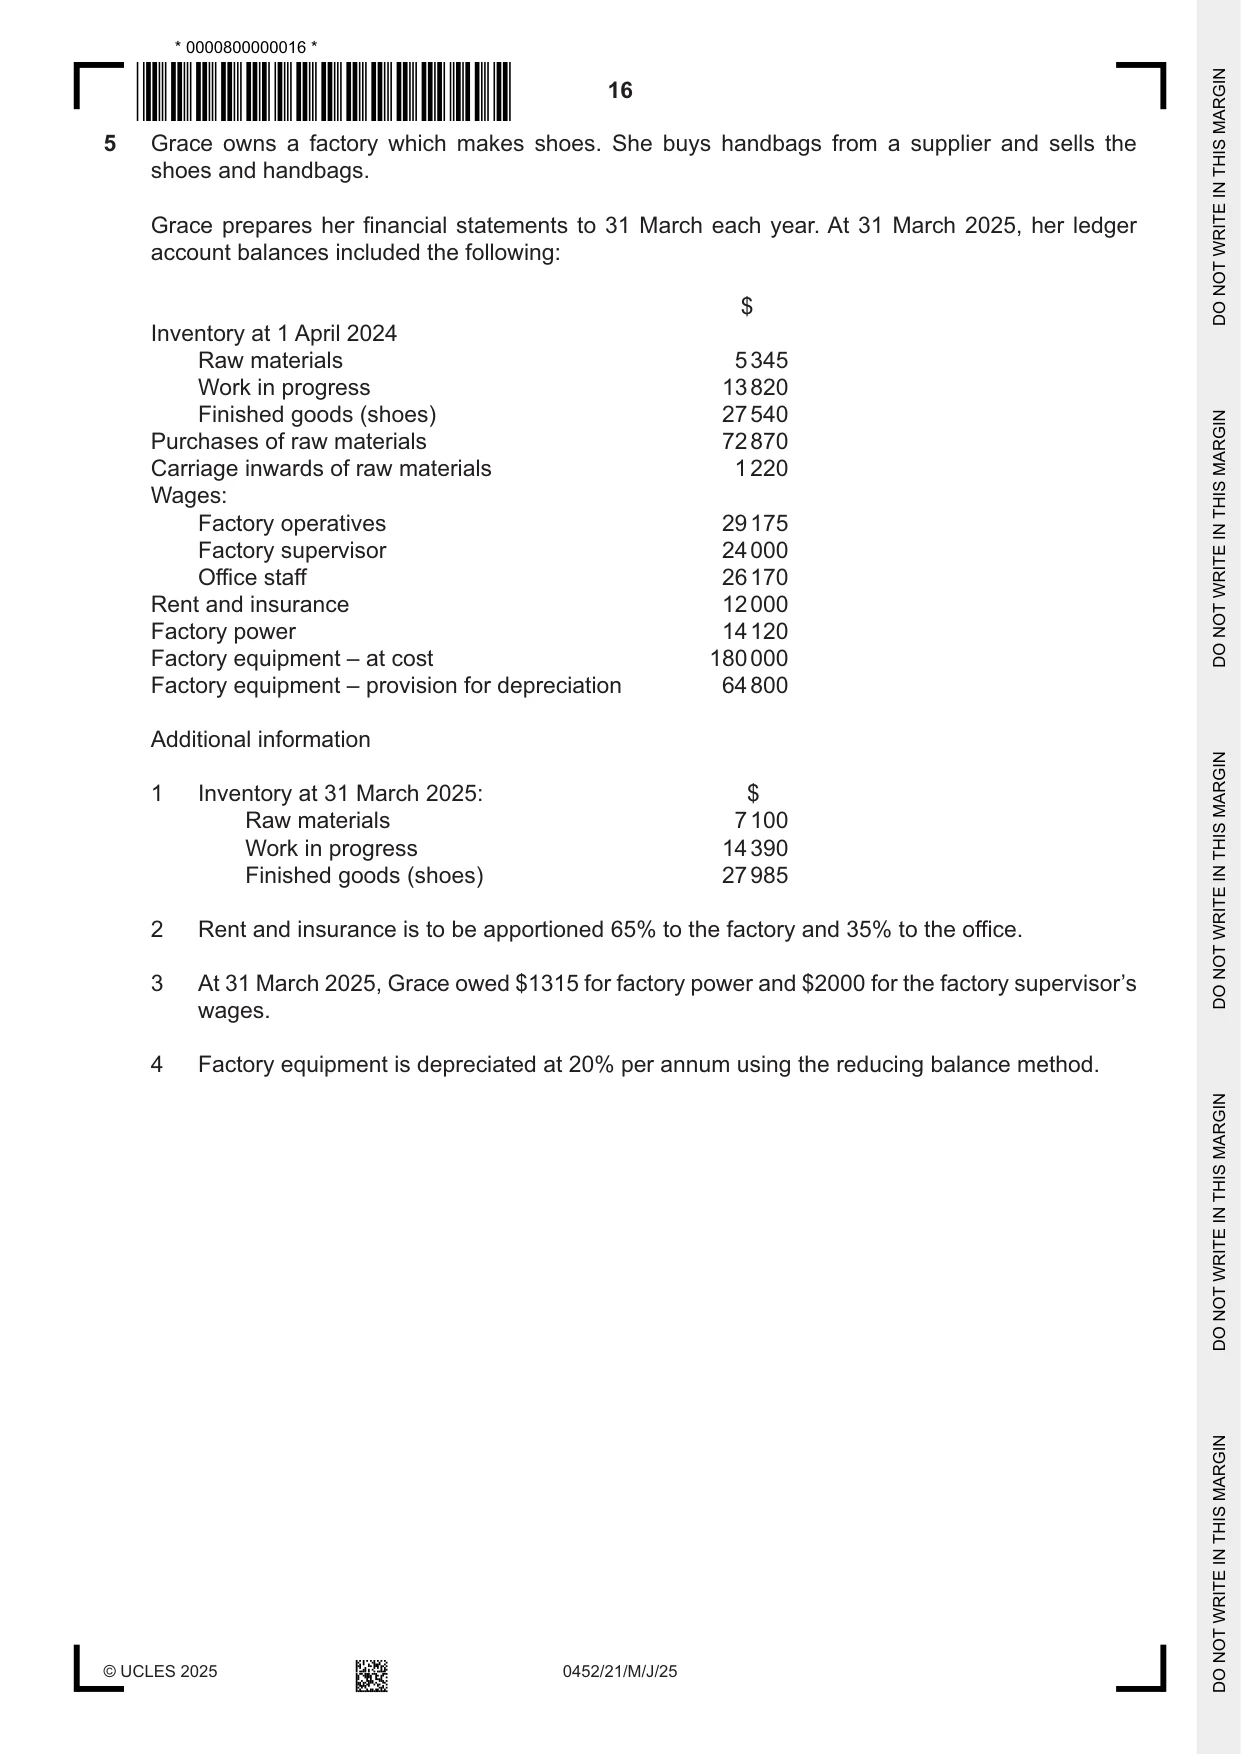
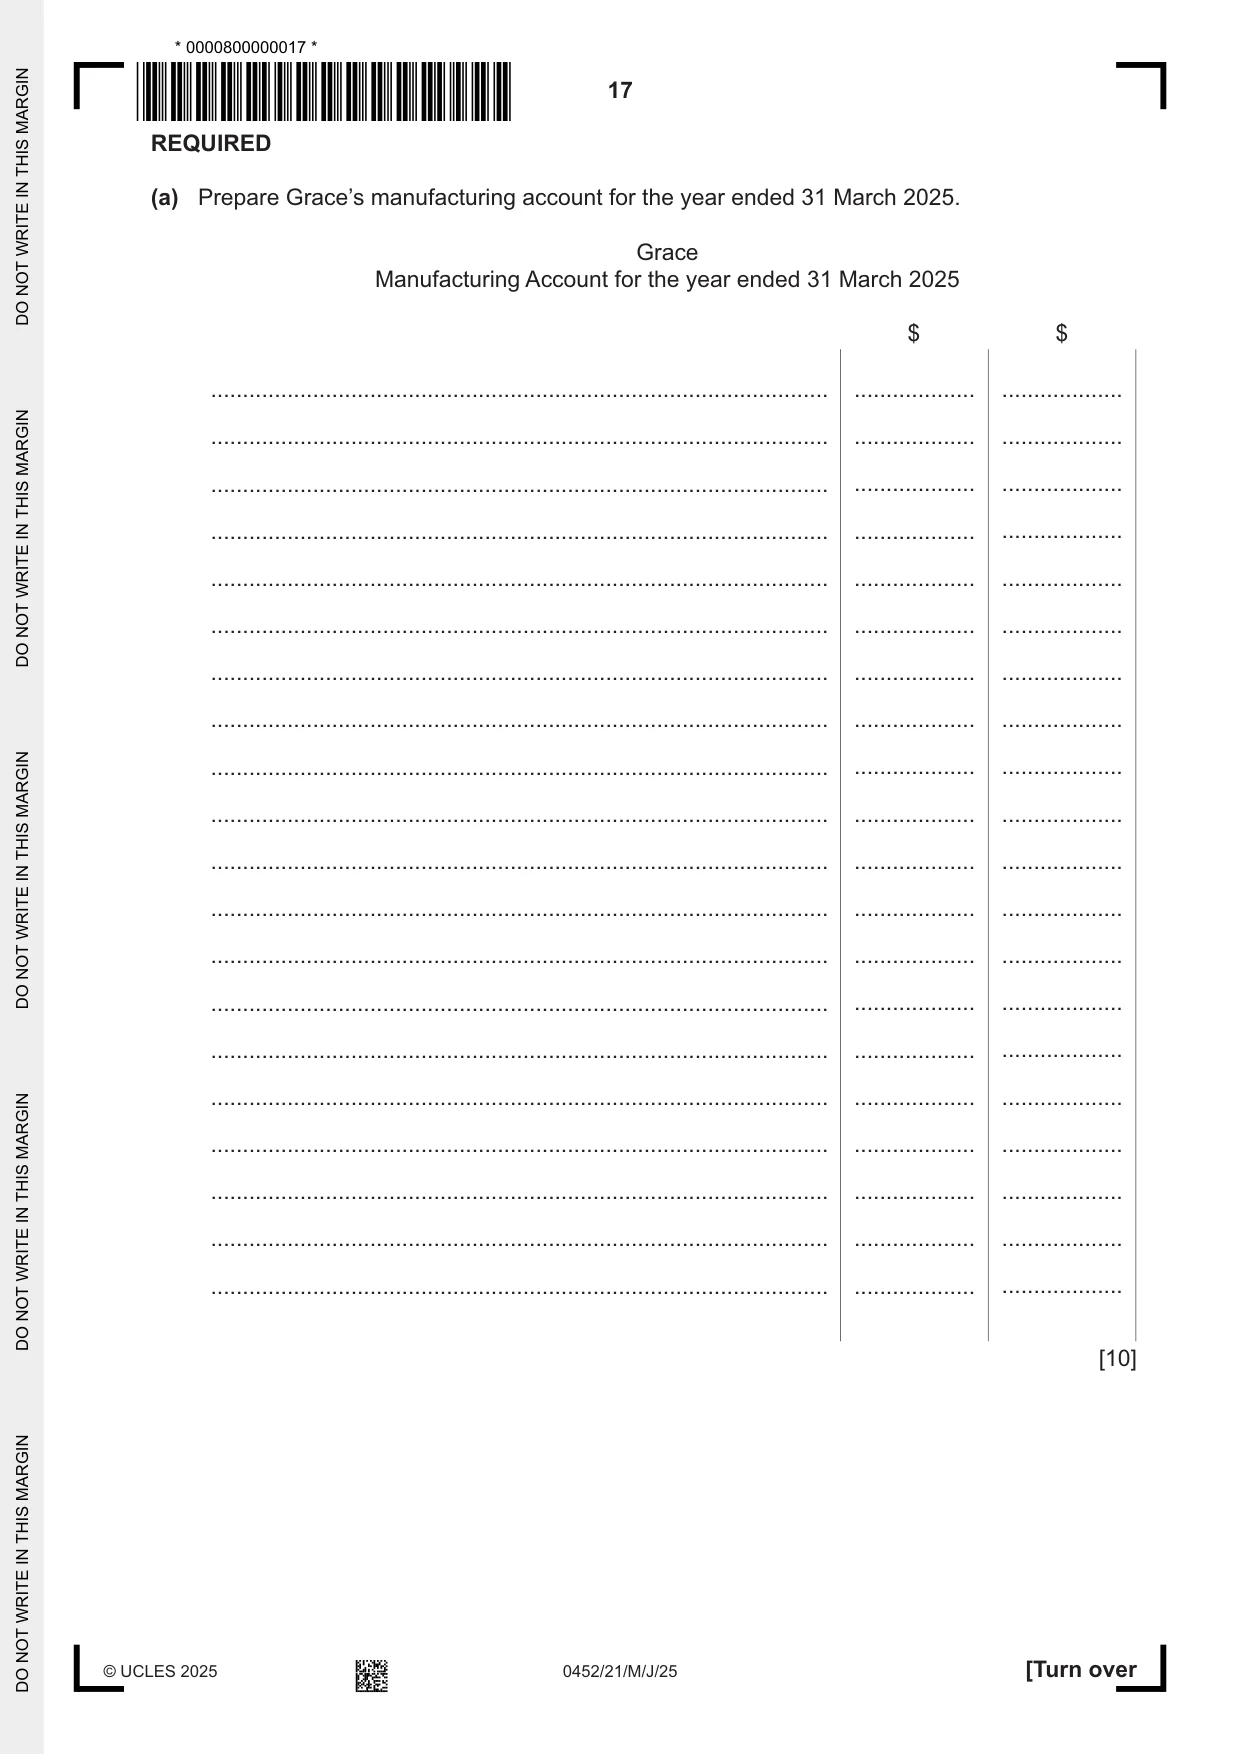
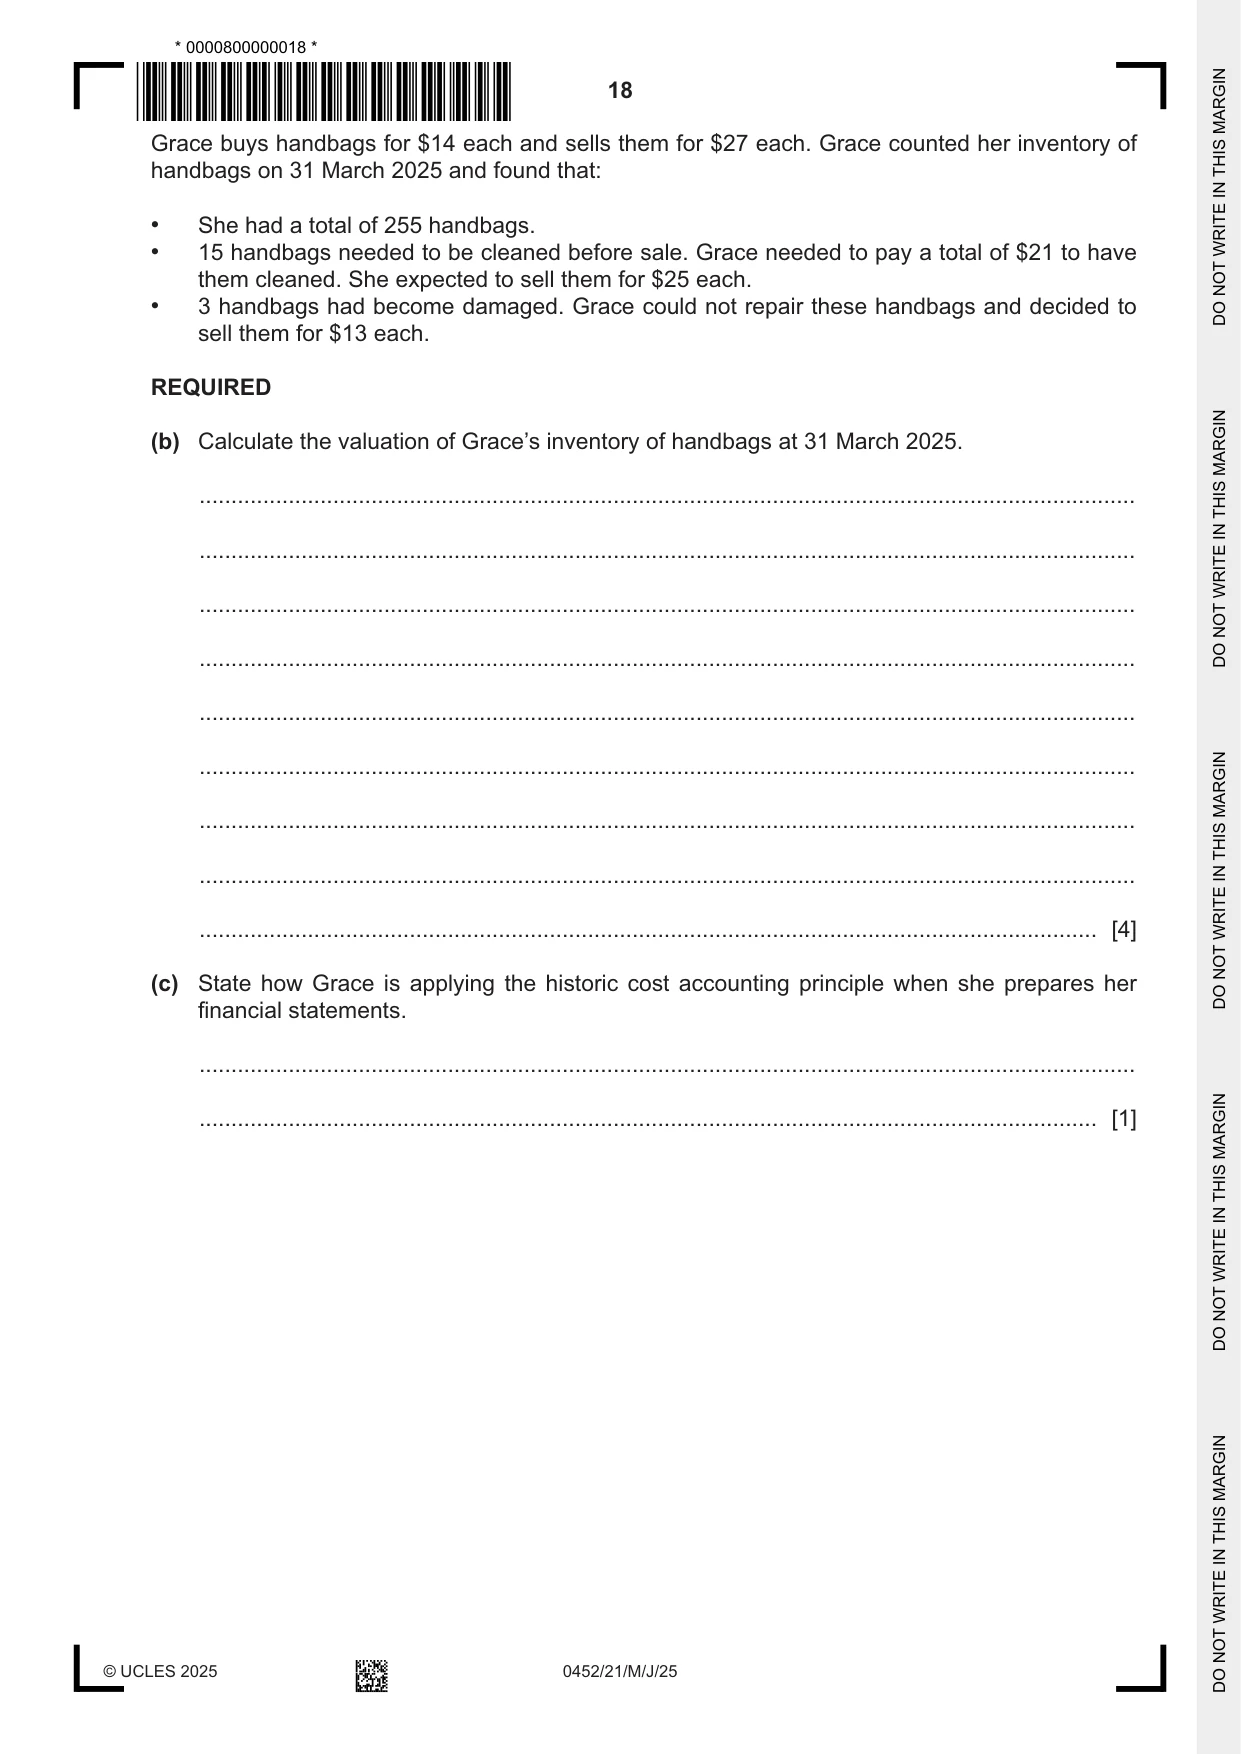
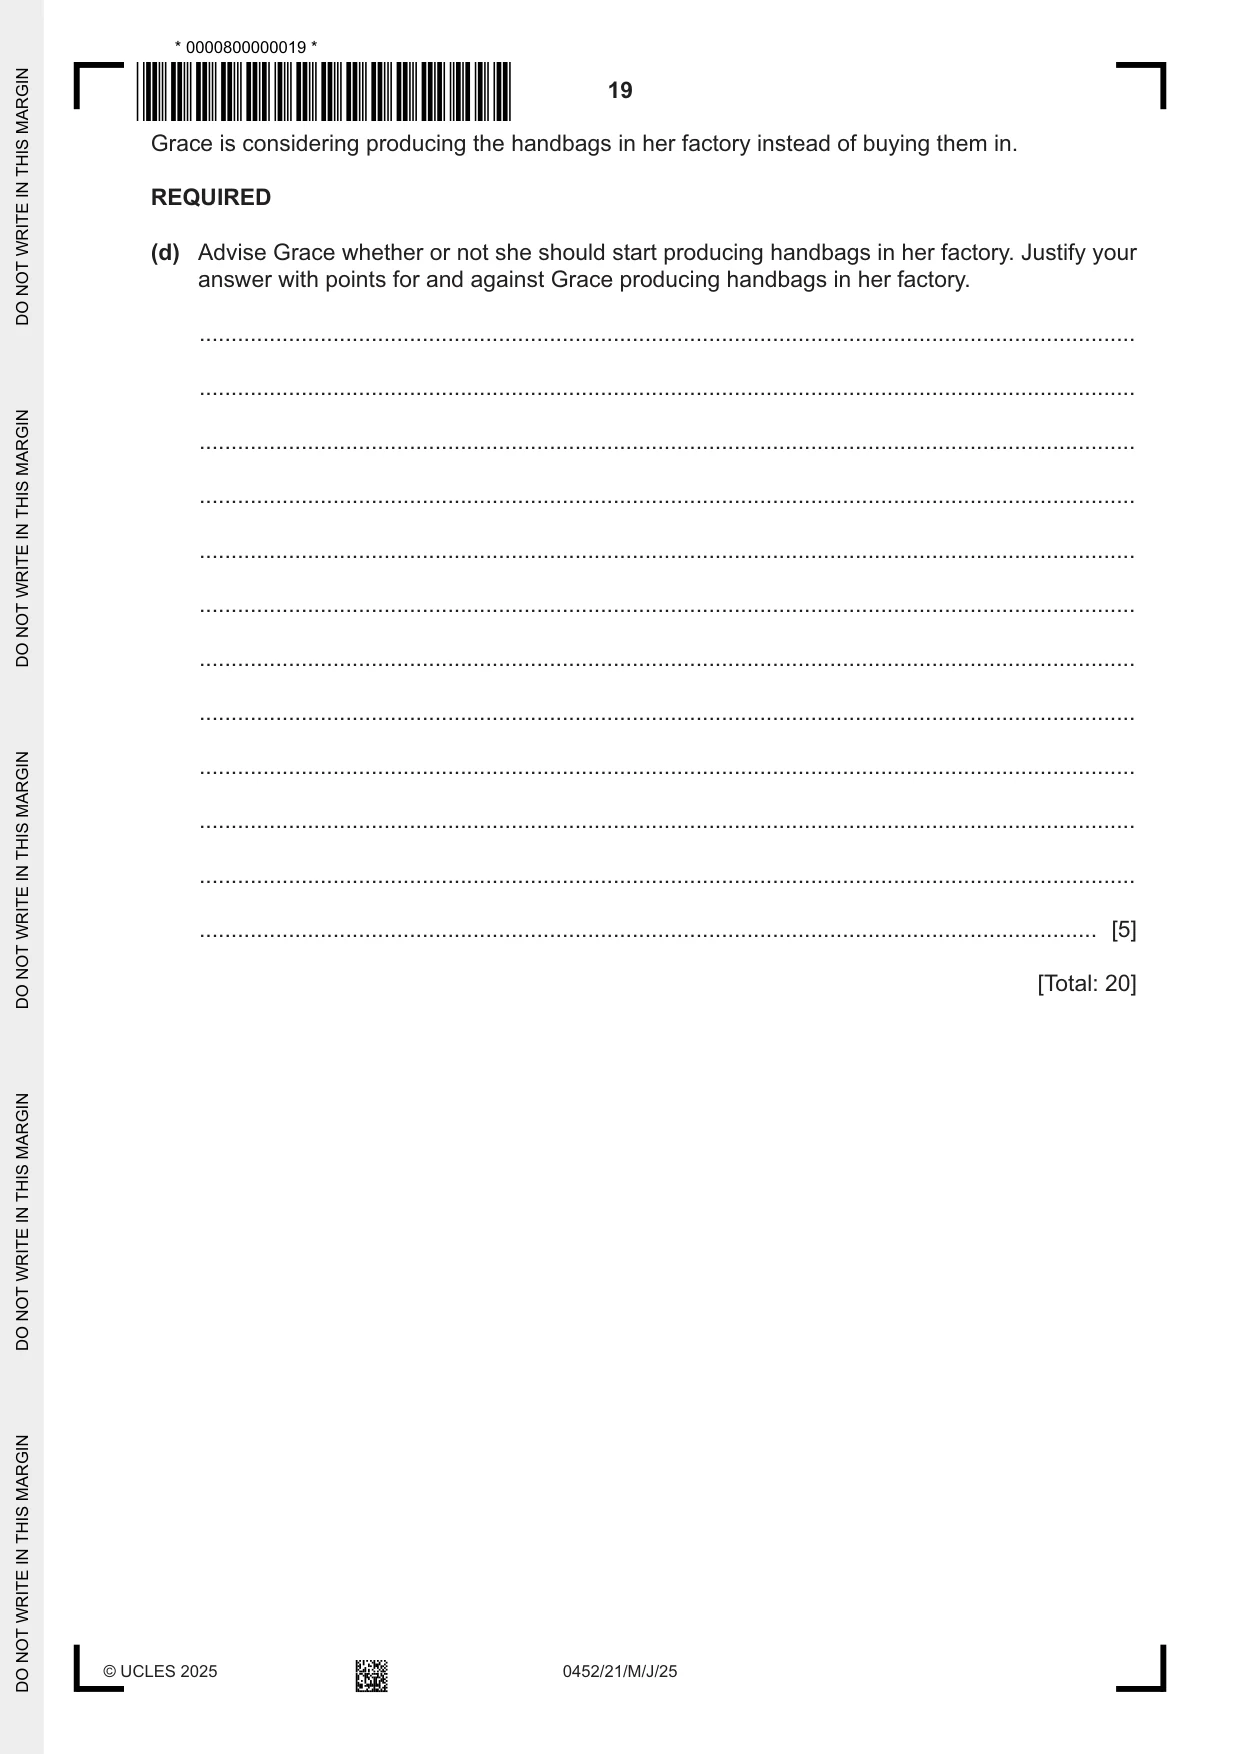
5 Grace owns a factory which makes shoes. She buys handbags from a supplier and sells the shoes and handbags. Grace prepares her financial statements to 31 March each year. At 31 March 2025, her ledger account balances included the following: $ Inventory at 1 April 2024 Raw materials 5 345 Work in progress 13 820 Finished goods (shoes) 27 540 Purchases of raw materials 72 870 Carriage inwards of raw materials 1 220 Wages: Factory operatives 29 175 Factory supervisor 24 000 Office staff 26 170 Rent and insurance 12 000 Factory power 14 120 Factory equipment – at cost 180 000 Factory equipment – provision for depreciation 64 800 Additional information 1 Inventory at 31 March 2025: $ Raw materials 7 100 Work in progress 14 390 Finished goods (shoes) 27 985 2 Rent and insurance is to be apportioned 65% to the factory and 35% to the office. 3 At 31 March 2025, Grace owed $1315 for factory power and $2000 for the factory supervisor’s wages. 4 Factory equipment is depreciated at 20% per annum using the reducing balance method. REQUIRED (a) Prepare Grace’s manufacturing account for the year ended 31 March 2025. Grace Manufacturing Account for the year ended 31 March 2025 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [10] Grace buys handbags for $14 each and sells them for $27 each. Grace counted her inventory of handbags on 31 March 2025 and found that: • She had a total of 255 handbags. • 15 handbags needed to be cleaned before sale. Grace needed to pay a total of $21 to have them cleaned. She expected to sell them for $25 each. • 3 handbags had become damaged. Grace could not repair these handbags and decided to sell them for $13 each. REQUIRED (b) Calculate the valuation of Grace’s inventory of handbags at 31 March 2025. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) State how Grace is applying the historic cost accounting principle when she prepares her financial statements. ................................................................................................................................................... ............................................................................................................................................. [1]
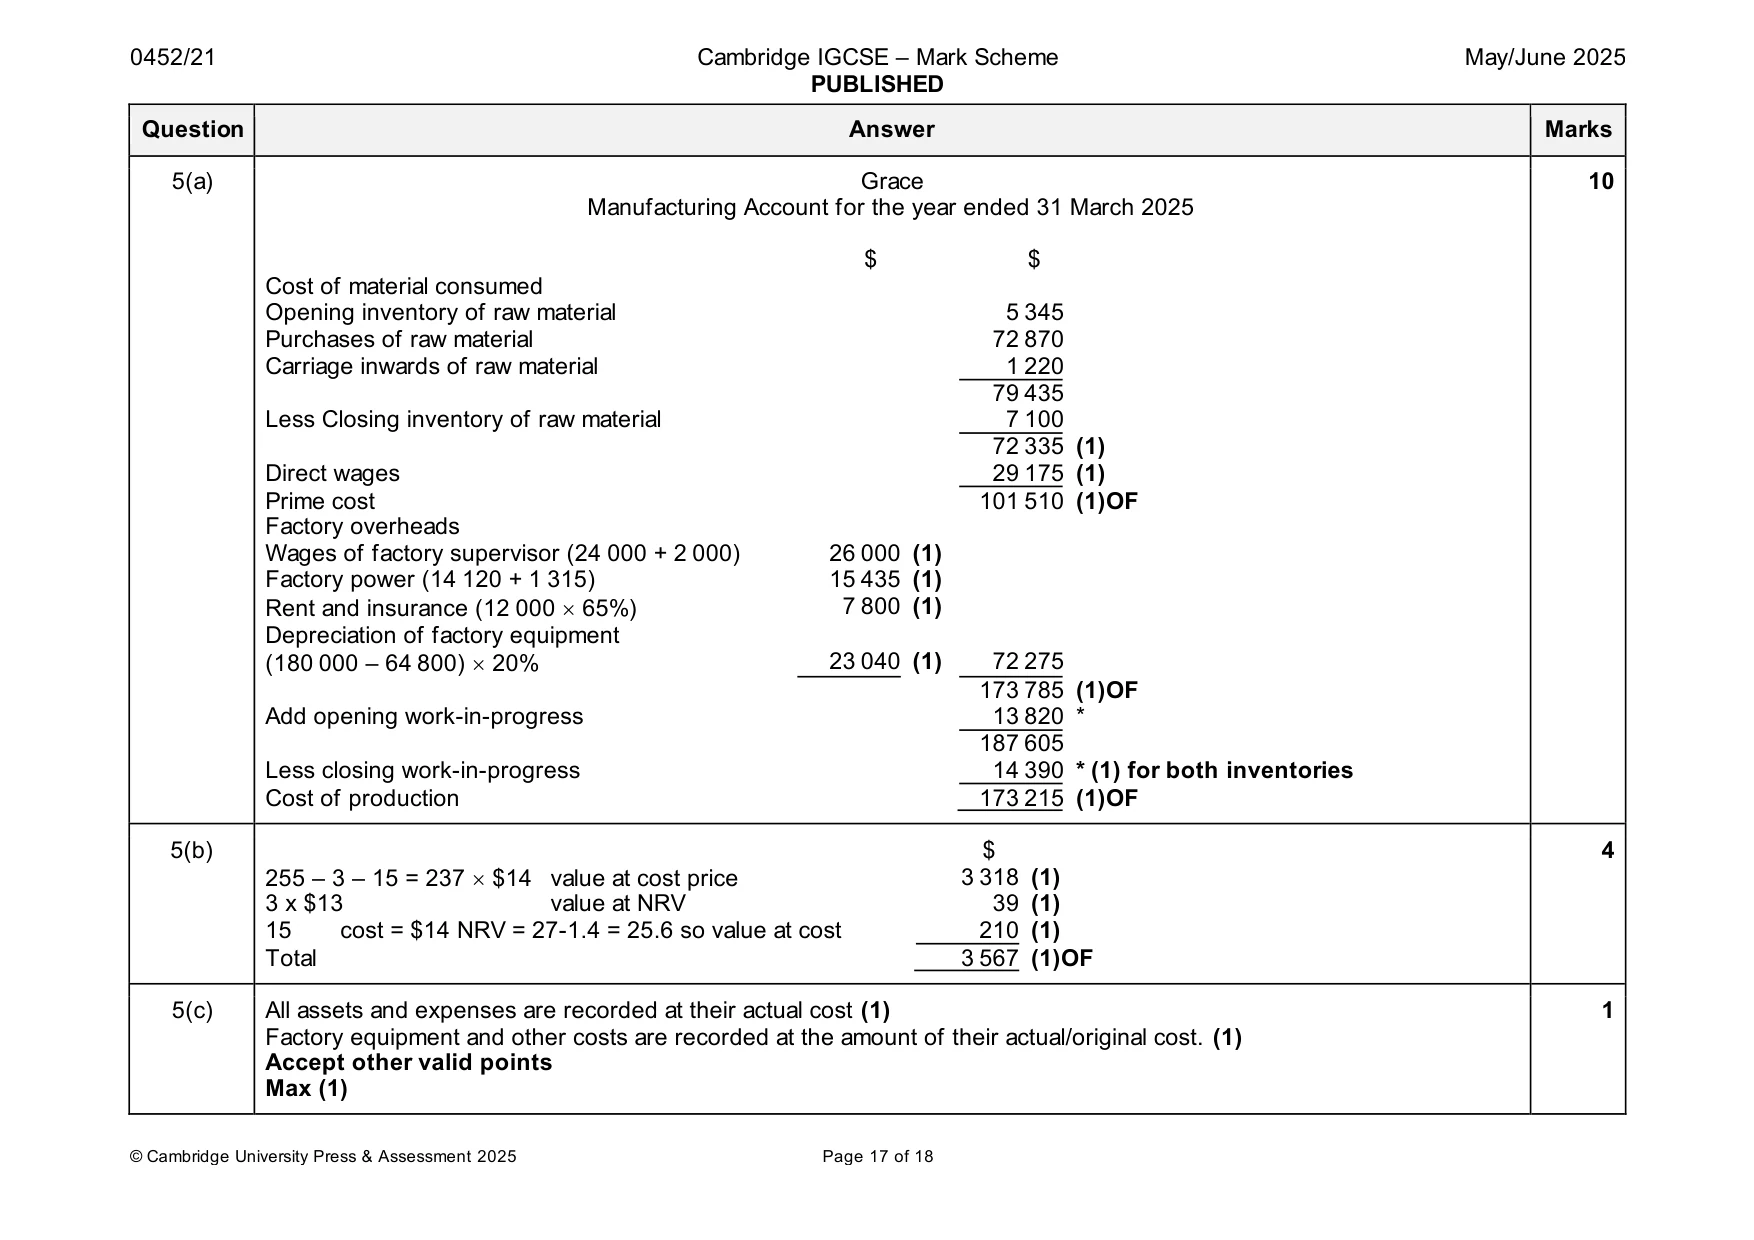
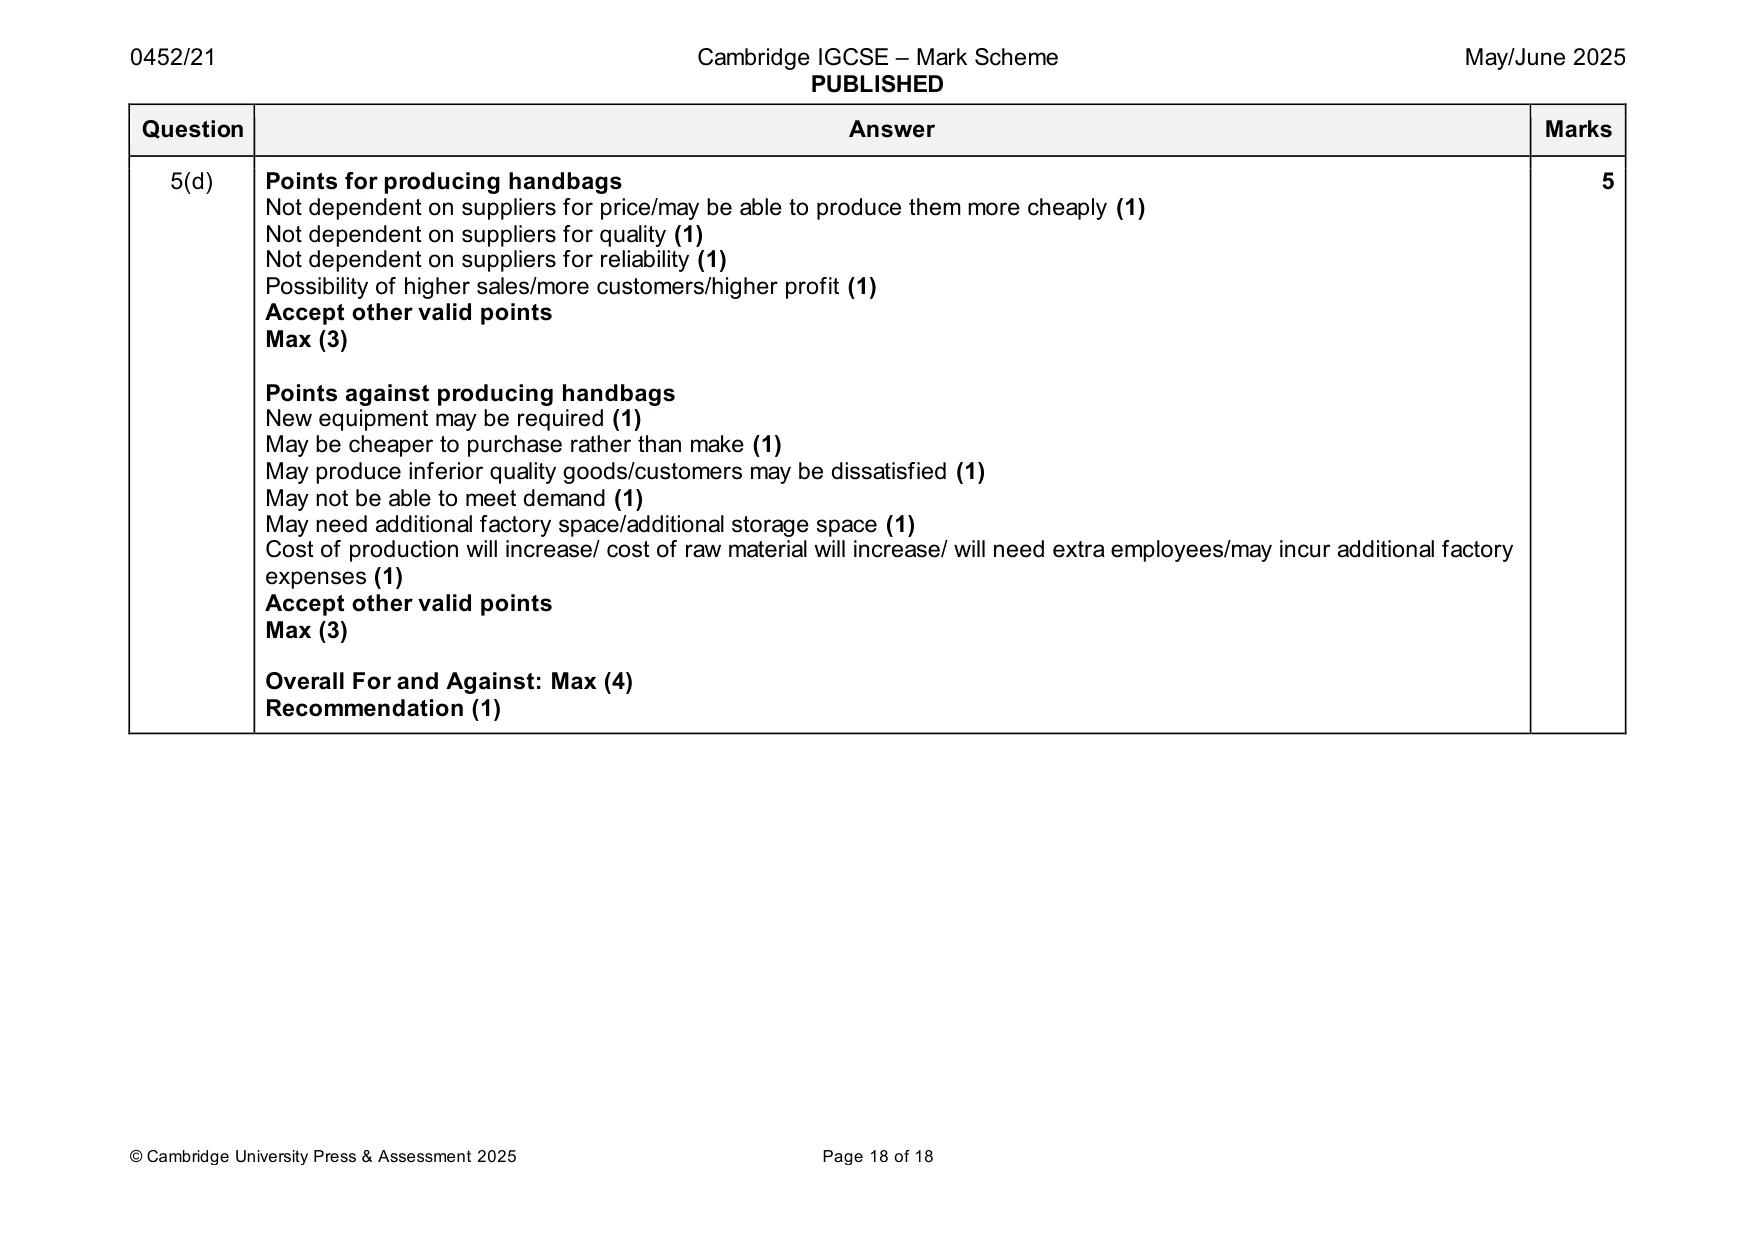
Mark scheme: 5(a) Grace 10 Manufacturing Account for the year ended 31 March 2025 $ $ Cost of material consumed Opening inventory of raw material 5 345 Purchases of raw material 72 870 Carriage inwards of raw material 1 220 79 435 Less Closing inventory of raw material 7 100 72 335 (1) Direct wages 29 175 (1) Prime cost 101 510 (1)OF Factory overheads Wages of factory supervisor (24 000 + 2 000) 26 000 (1) Factory power (14 120 + 1 315) 15 435 (1) Rent and insurance (12 000 65%) 7 800 (1) Depreciation of factory equipment (180 000 – 64 800) 20% 23 040 (1) 72 275 173 785 (1)OF Add opening work-in-progress 13 820 * 187 605 Less closing work-in-progress 14 390 * (1) for both inventories Cost of production 173 215 (1)OF 5(b) $ 4 255 – 3 – 15 = 237 $14 value at cost price 3 318 (1) 3 x $13 value at NRV 39 (1) 15 cost = $14 NRV = 27-1.4 = 25.6 so value at cost 210 (1) Total 3 567 (1)OF 5(c) All assets and expenses are recorded at their actual cost (1) 1 Factory equipment and other costs are recorded at the amount of their actual/original cost. (1) Accept other valid points Max (1) 5(d) Points for producing handbags 5 Not dependent on suppliers for price/may be able to produce them more cheaply (1) Not dependent on suppliers for quality (1) Not dependent on suppliers for reliability (1) Possibility of higher sales/more customers/higher profit (1) Accept other valid points Max (3) Points against producing handbags New equipment may be required (1) May be cheaper to purchase rather than make (1) May produce inferior quality goods/customers may be dissatisfied (1) May not be able to meet demand (1) May need additional factory space/additional storage space (1) Cost of production will increase/ cost of raw material will increase/ will need extra employees/may incur additional factory expenses (1) Accept other valid points Max (3) Overall For and Against: Max (4) Recommendation (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.