Cambridge IGCSE Accounting 0452 — 2023 May/June Paper 2 · Variant 1
0452/21/M/J/23 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages

Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Shvan maintains a petty cash book using the imprest system
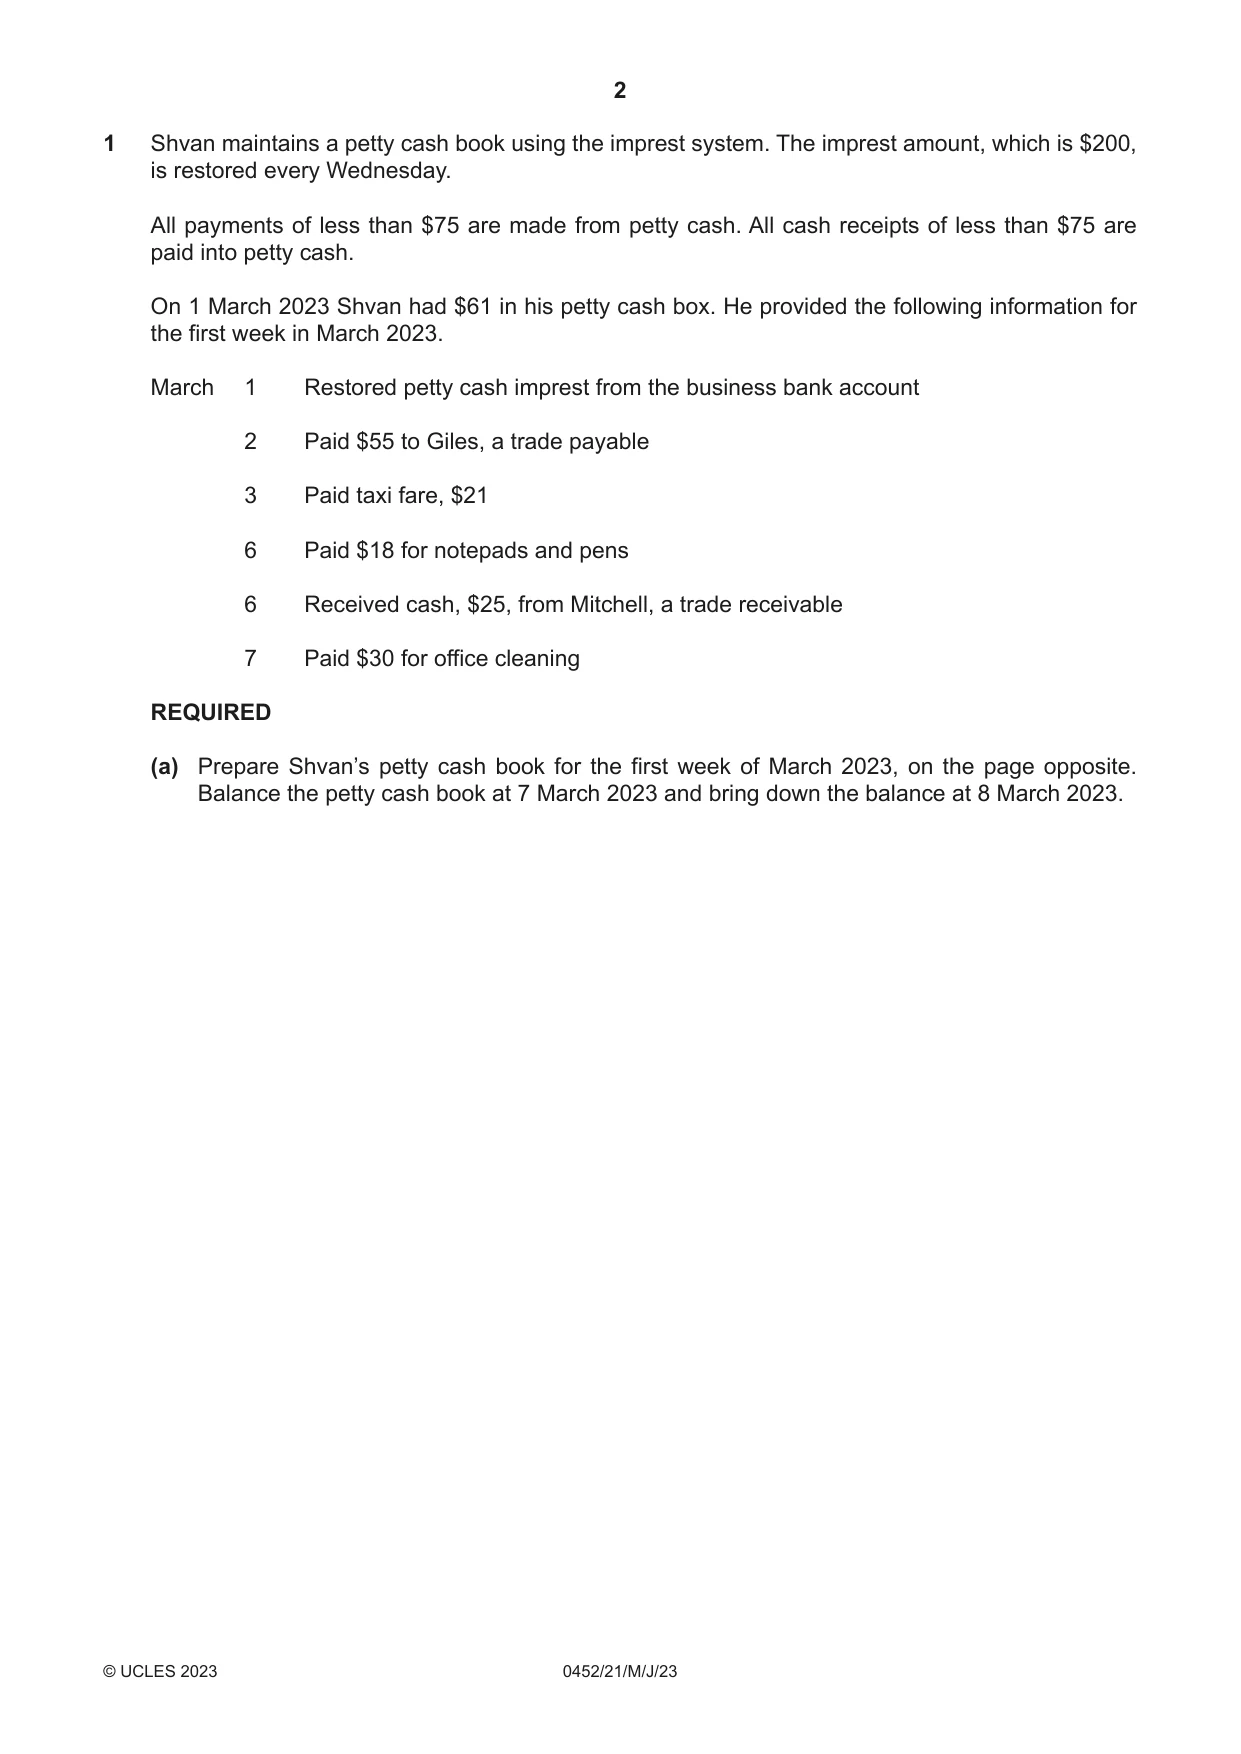
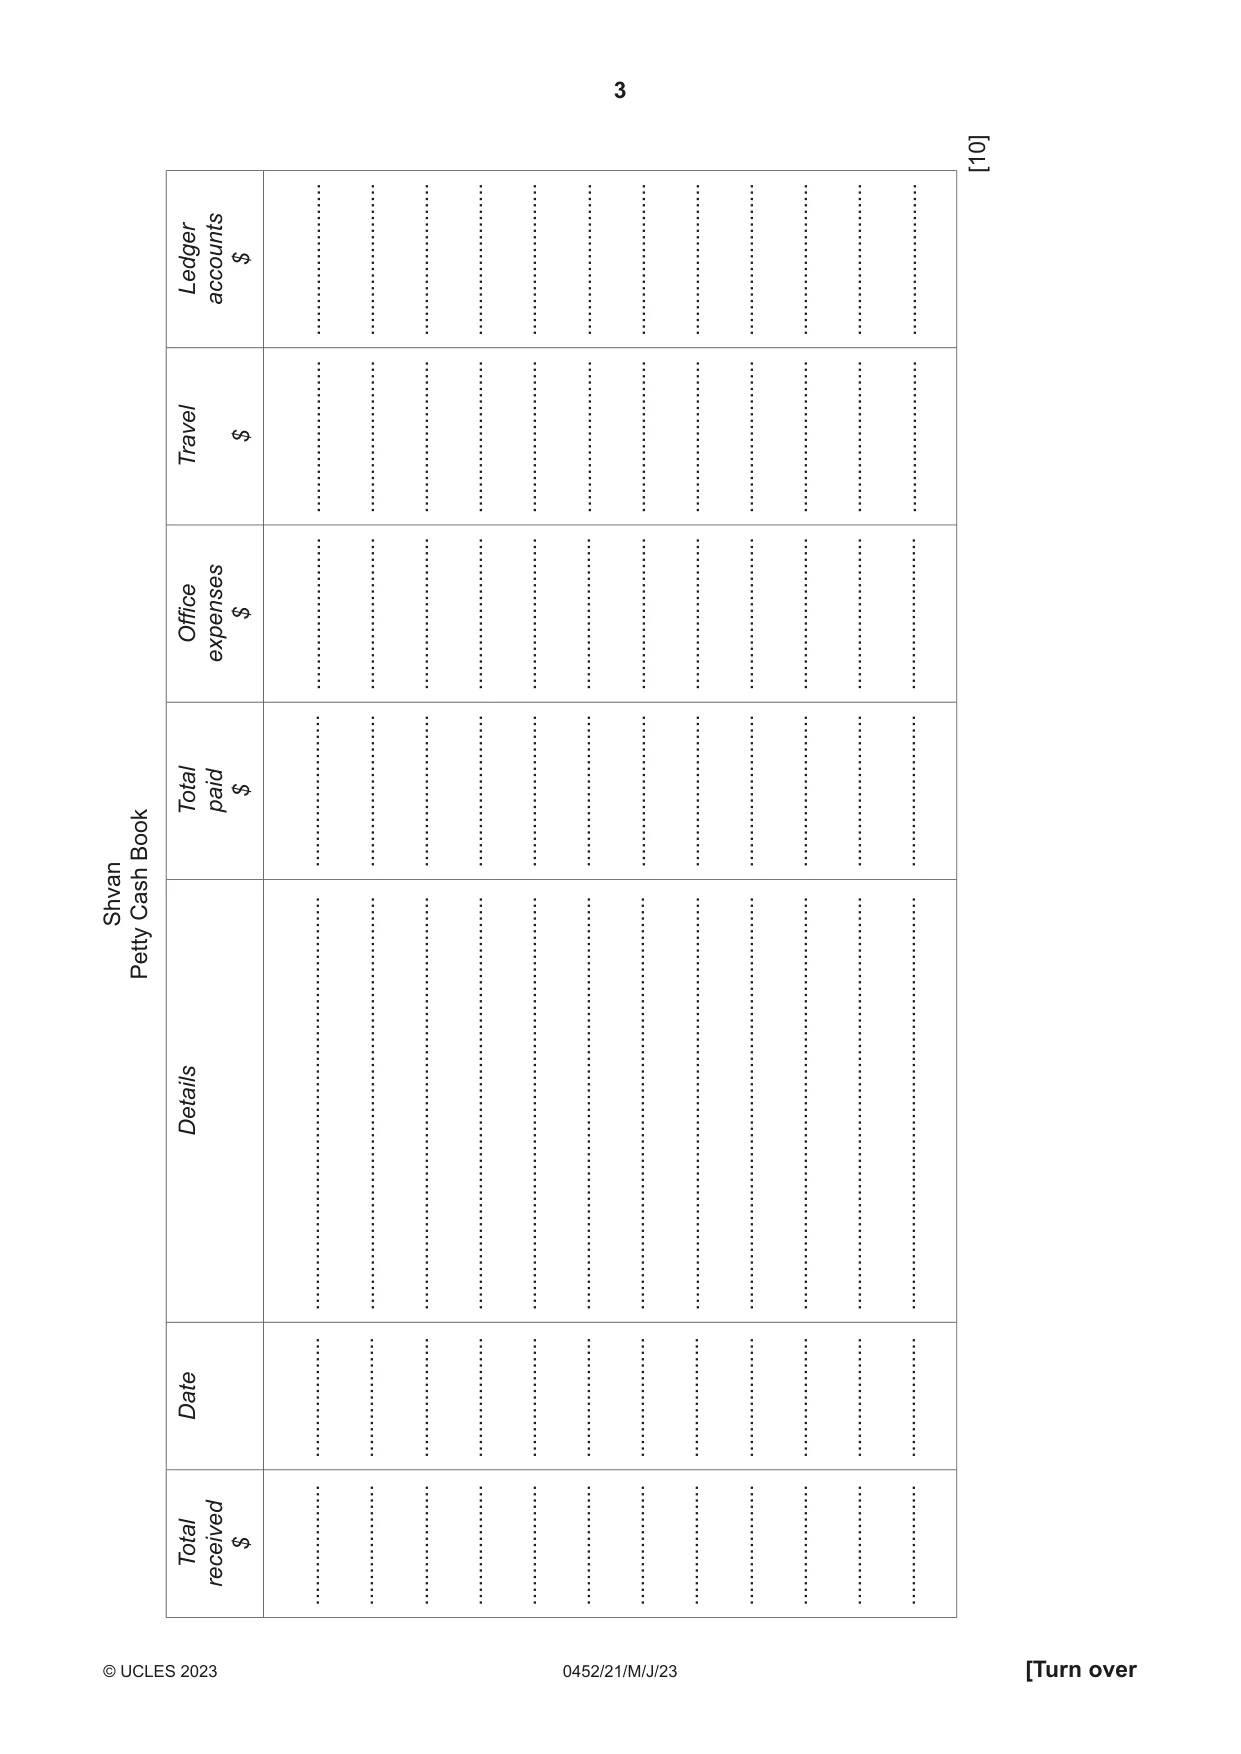
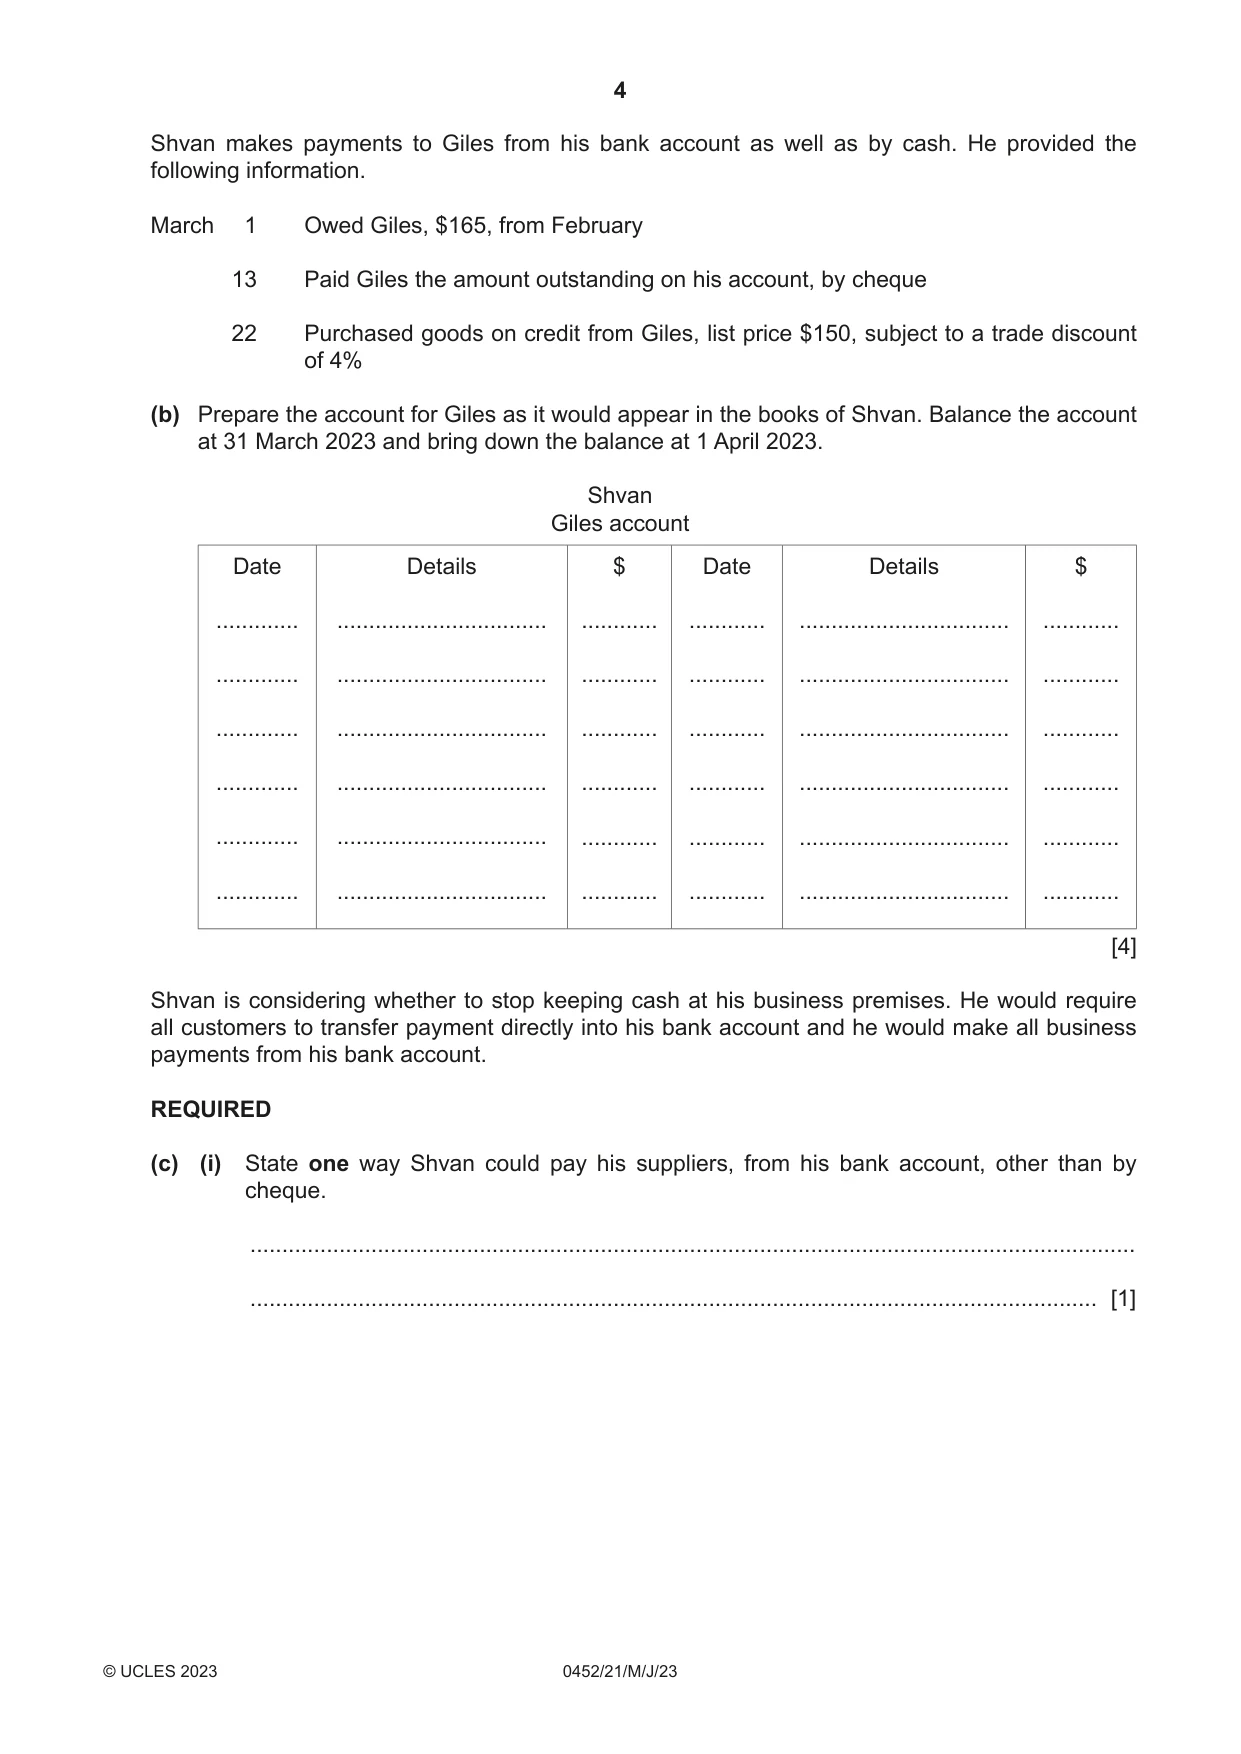
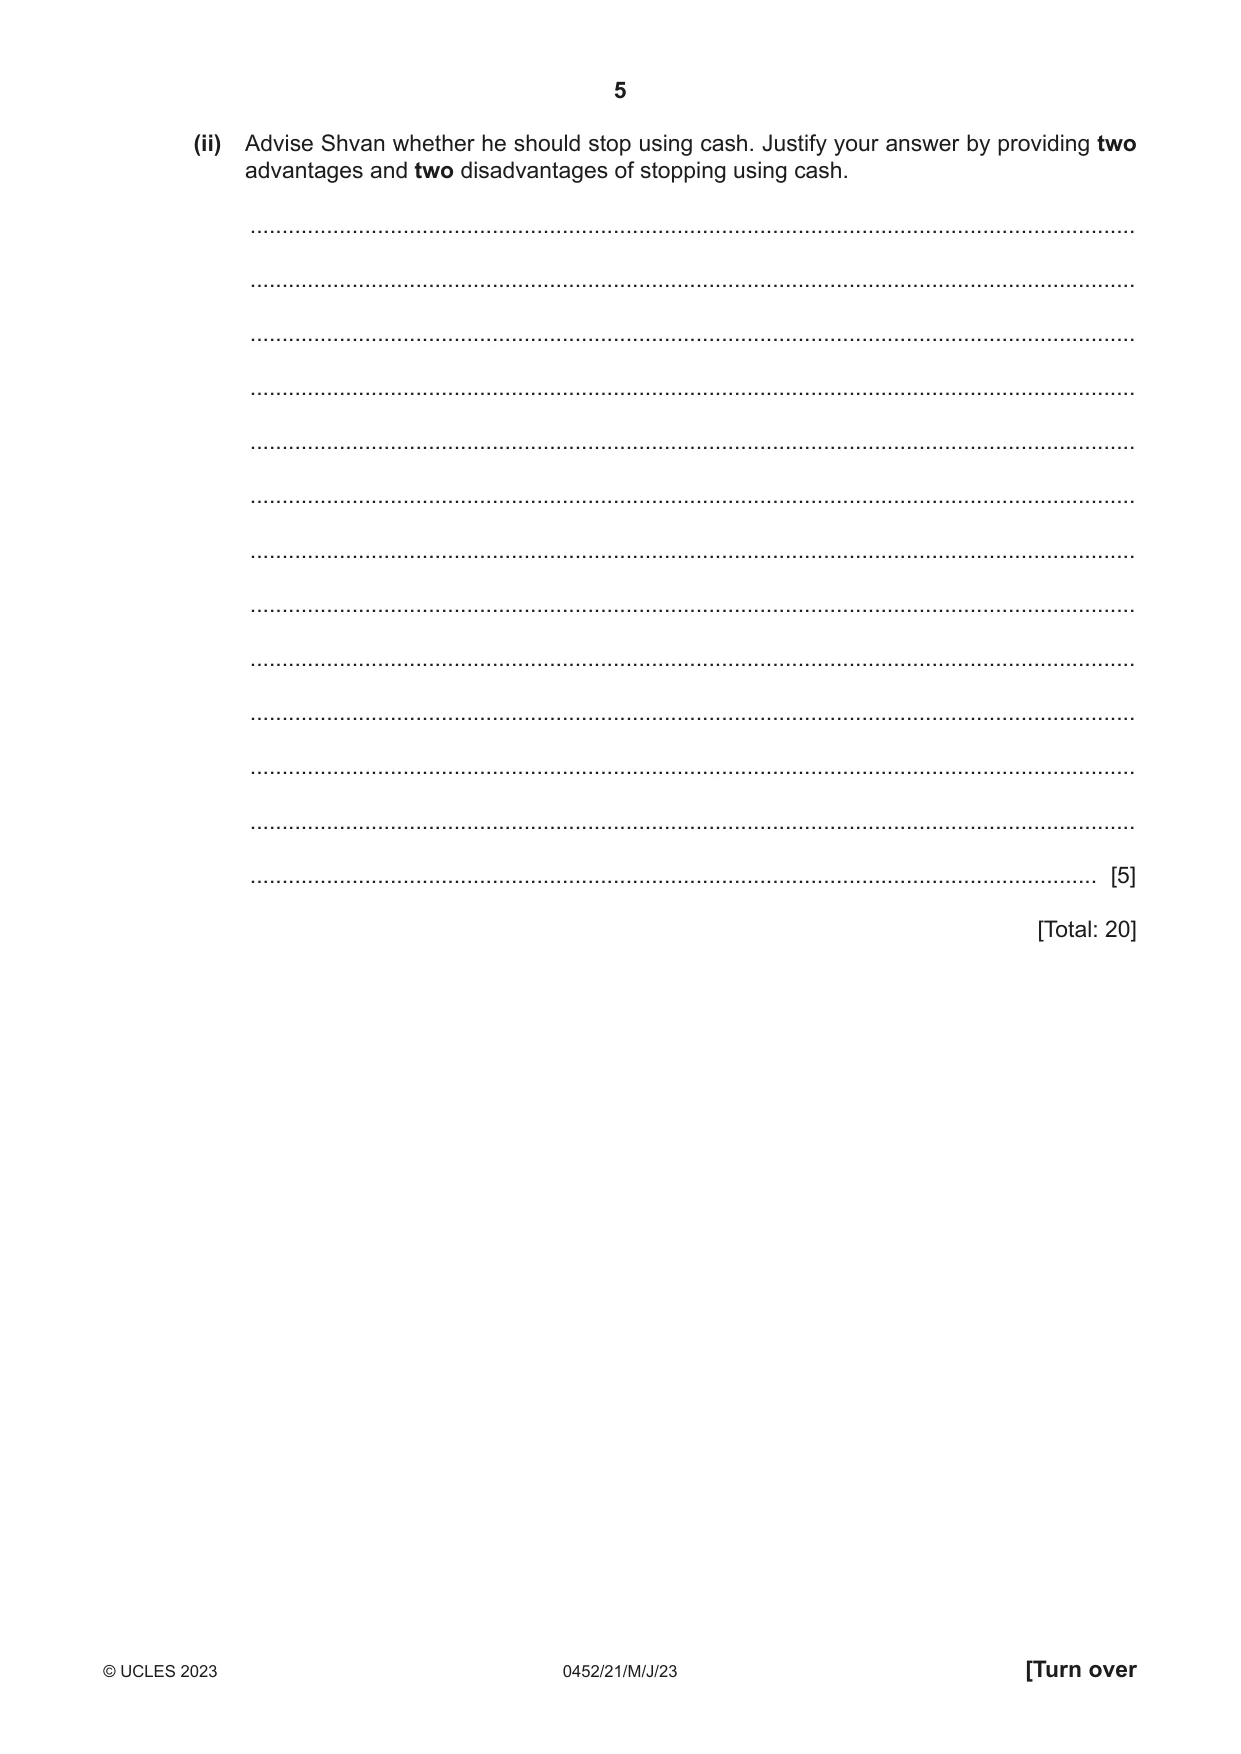
1 Shvan maintains a petty cash book using the imprest system. The imprest amount, which is $200, is restored every Wednesday. All payments of less than $75 are made from petty cash. All cash receipts of less than $75 are paid into petty cash. On 1 March 2023 Shvan had $61 in his petty cash box. He provided the following information for the first week in March 2023. March 1 Restored petty cash imprest from the business bank account 2 Paid $55 to Giles, a trade payable 3 Paid taxi fare, $21 6 Paid $18 for notepads and pens 6 Received cash, $25, from Mitchell, a trade receivable 7 Paid $30 for office cleaning REQUIRED (a) Prepare Shvan’s petty cash book for the first week of March 2023, on the page opposite. Balance the petty cash book at 7 March 2023 and bring down the balance at 8 March 2023. [10] $ Ledger accounts ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Travel ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Office expenses ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Totalpaid Book ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ShvanCash Petty Details ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. ................................................................. Date ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... $ Total received ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... Shvan makes payments to Giles from his bank account as well as by cash. He provided the following information. March 1 Owed Giles, $165, from February 13 Paid Giles the amount outstanding on his account, by cheque 22 Purchased goods on credit from Giles, list price $150, subject to a trade discount of 4% (b) Prepare the account for Giles as it would appear in the books of Shvan. Balance the account at 31 March 2023 and bring down the balance at 1 April 2023. Shvan Giles account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [4] Shvan is considering whether to stop keeping cash at his business premises. He would require all customers to transfer payment directly into his bank account and he would make all business payments from his bank account. REQUIRED (c) (i) State one way Shvan could pay his suppliers, from his bank account, other than by cheque. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Advise Shvan whether he should stop using cash. Justify your answer by providing two advantages and two disadvantages of stopping using cash. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [5] [Total: 20]
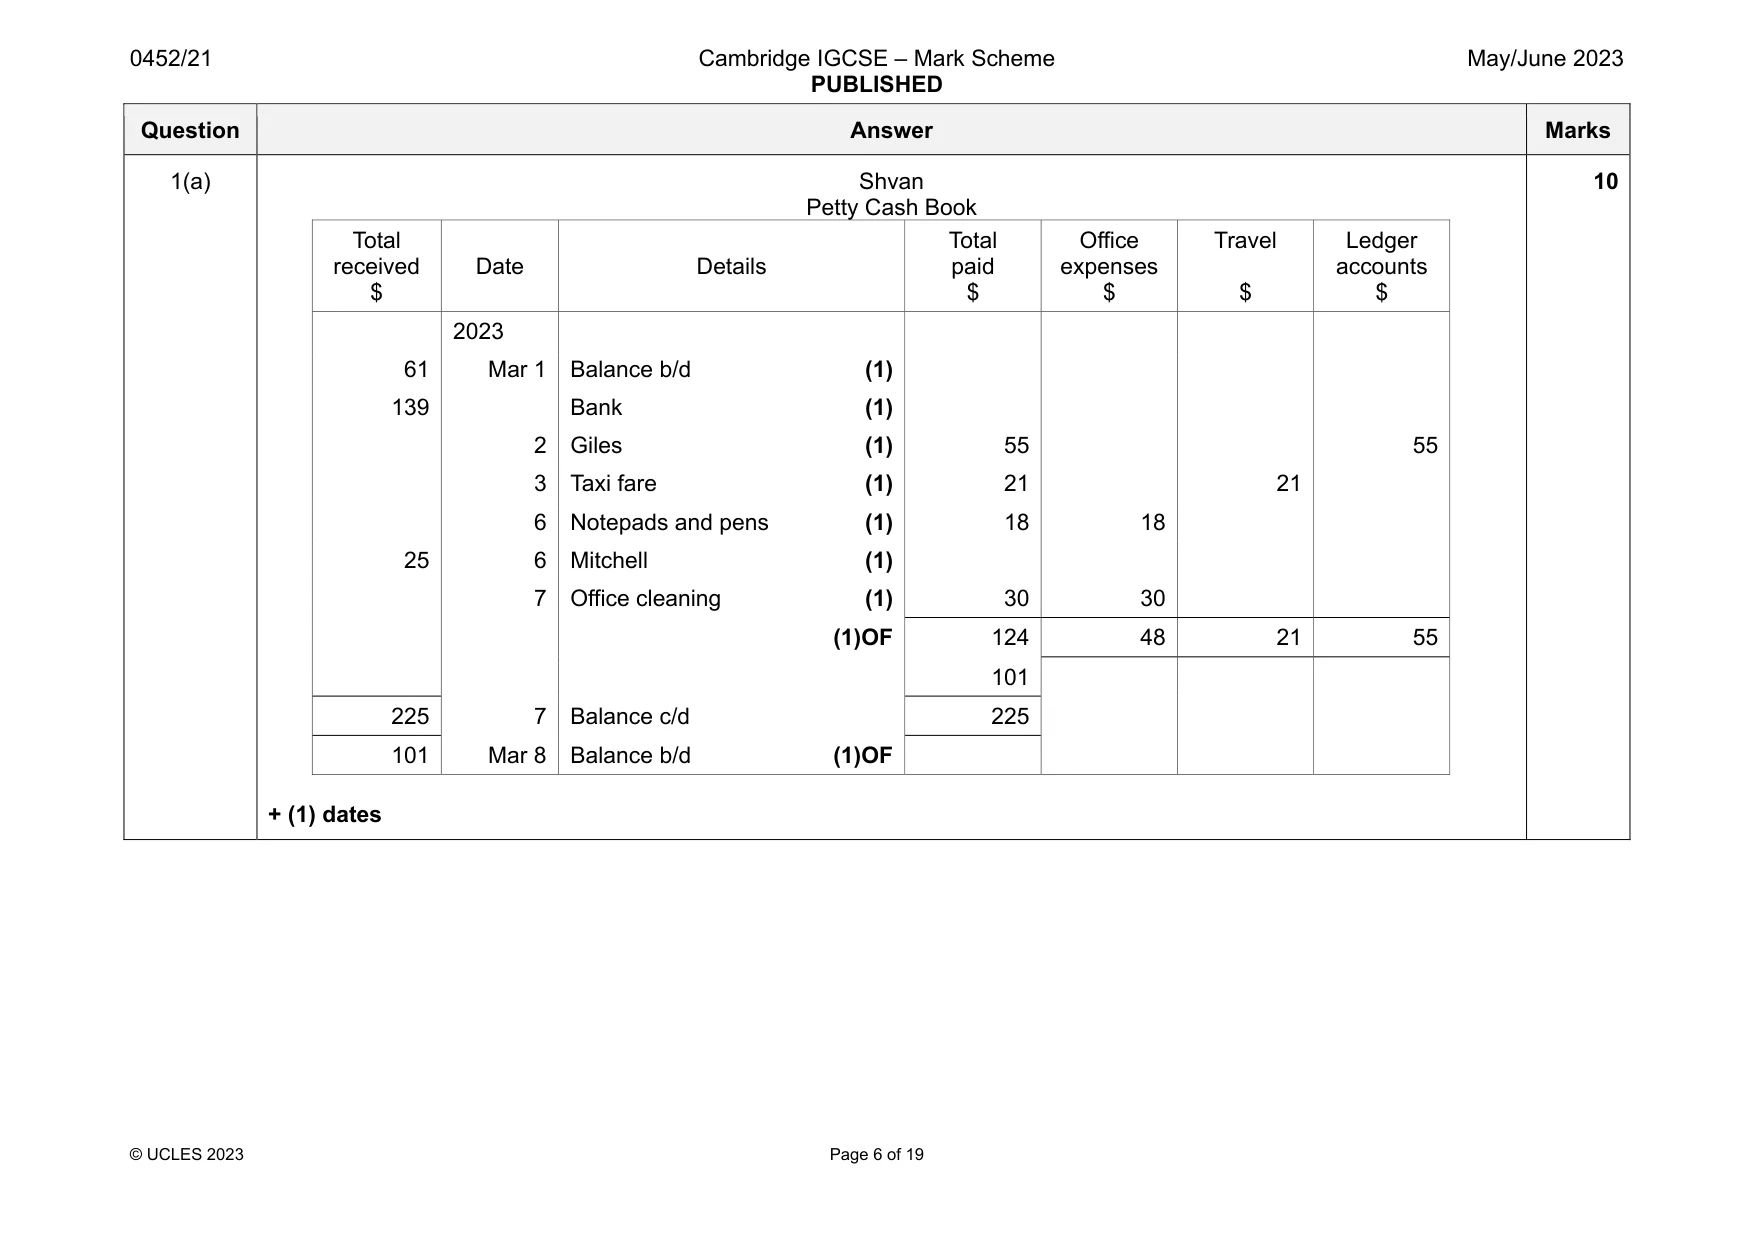
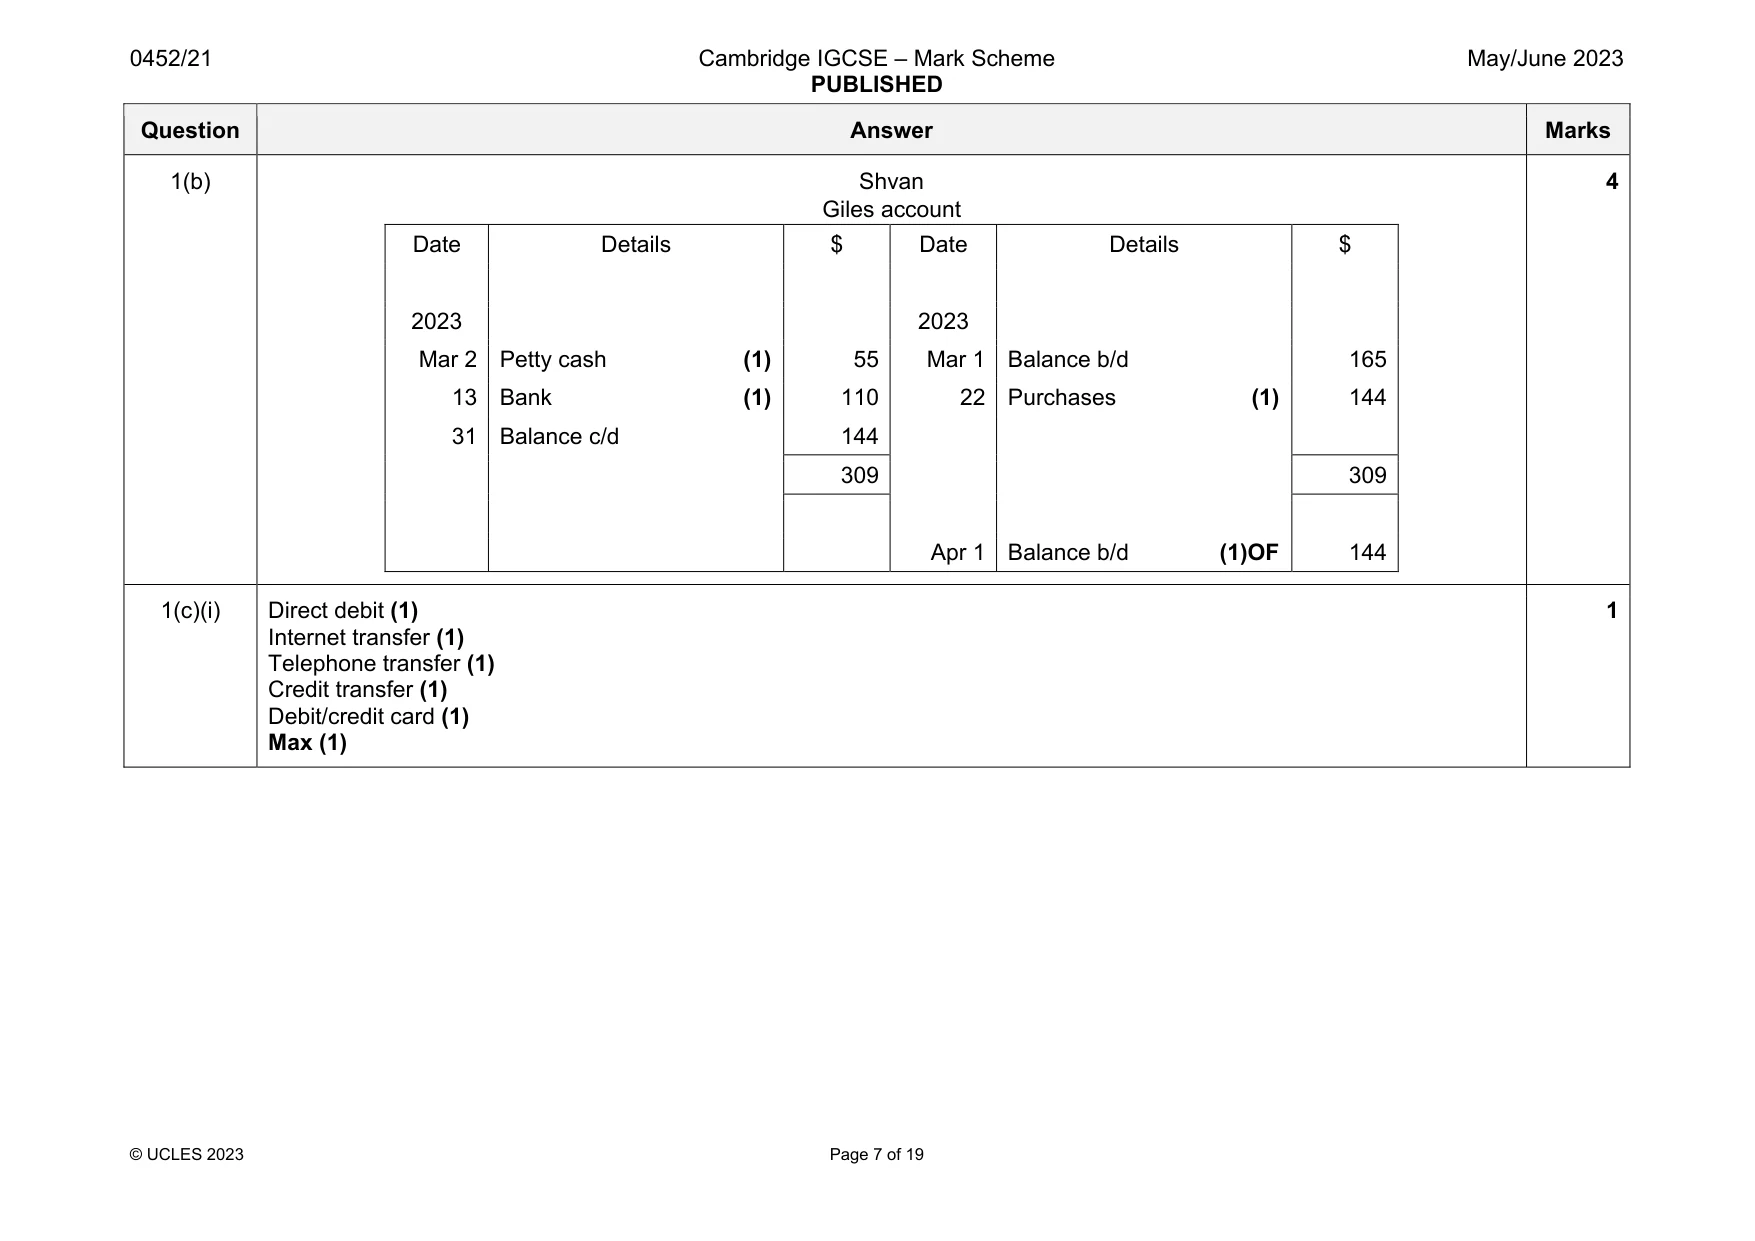
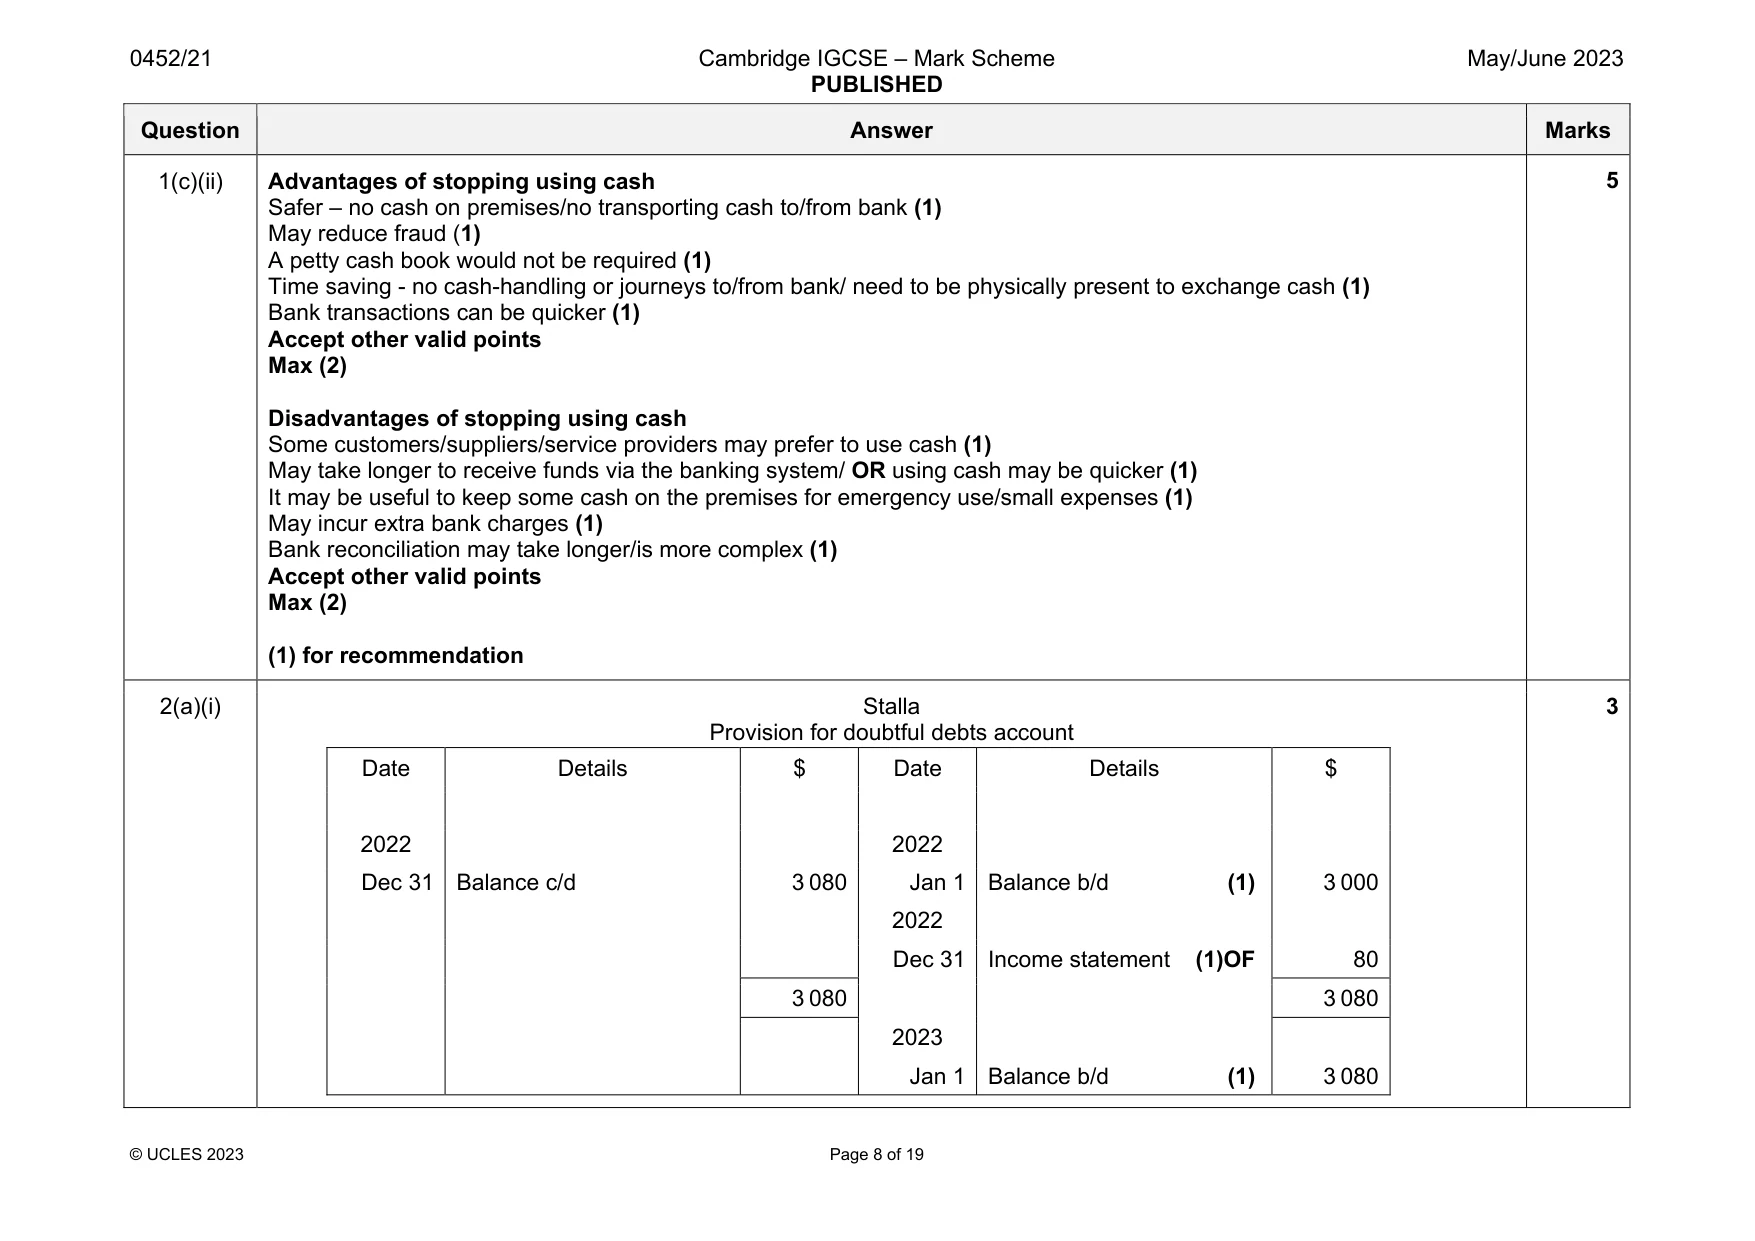
Mark scheme: 1(a) Shvan Petty Cash Book Total received $ Date Details Total paid $ Office expenses $ Travel $ Ledger accounts $ 2023 61 Mar 1 Balance b/d (1) 139 Bank (1) 2 Giles (1) 55 55 3 Taxi fare (1) 21 21 6 Notepads and pens (1) 18 18 25 6 Mitchell (1) 7 Office cleaning (1) 30 30 (1)OF 124 48 21 55 101 225 7 Balance c/d 225 101 Mar 8 Balance b/d (1)OF + (1) dates 10 Question Answer Marks 1(b) Shvan Giles account Date Details $ Date Details $ 2023 2023 Mar 2 Petty cash (1) 55 Mar 1 Balance b/d 165 13 Bank (1) 110 22 Purchases (1) 144 31 Balance c/d 144 309 309 Apr 1 Balance b/d (1)OF 144 4 1(c)(i) Direct debit (1) Internet transfer (1) Telephone transfer (1) Credit transfer (1) Debit/credit card (1) Max (1) 1 Question Answer Marks 1(c)(ii) Advantages of stopping using cash Safer – no cash on premises/no transporting cash to/from bank (1) May reduce fraud (1) A petty cash book would not be required (1) Time saving - no cash-handling or journeys to/from bank/ need to be physically present to exchange cash (1) Bank transactions can be quicker (1) Accept other valid points Max (2) Disadvantages of stopping using cash Some customers/suppliers/service providers may prefer to use cash (1) May take longer to receive funds via the banking system/ OR using cash may be quicker (1) It may be useful to keep some cash on the premises for emergency use/small expenses (1) May incur extra bank charges (1) Bank reconciliation may take longer/is more complex (1) Accept other valid points Max (2) (1) for recommendation 5
Q2 · Stalla is a sole trader who sells on credit
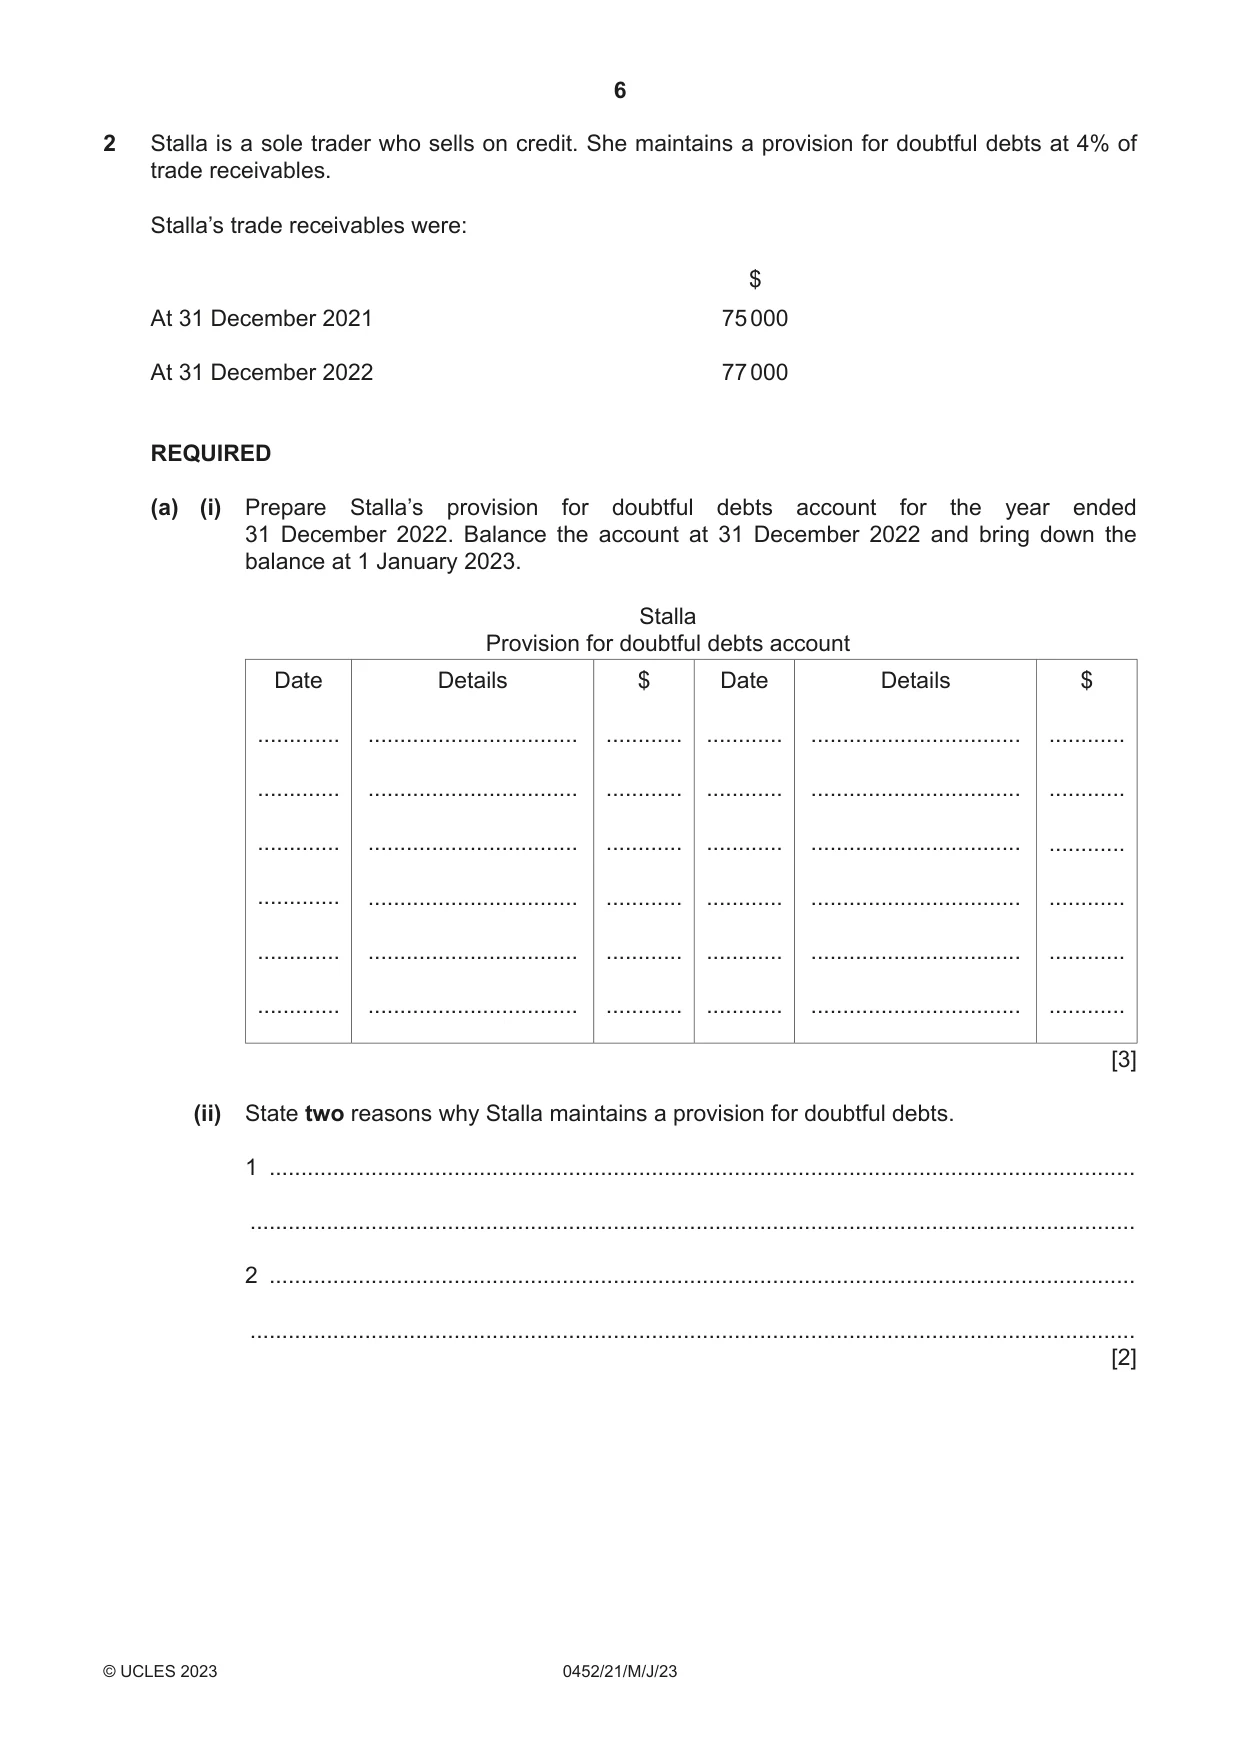
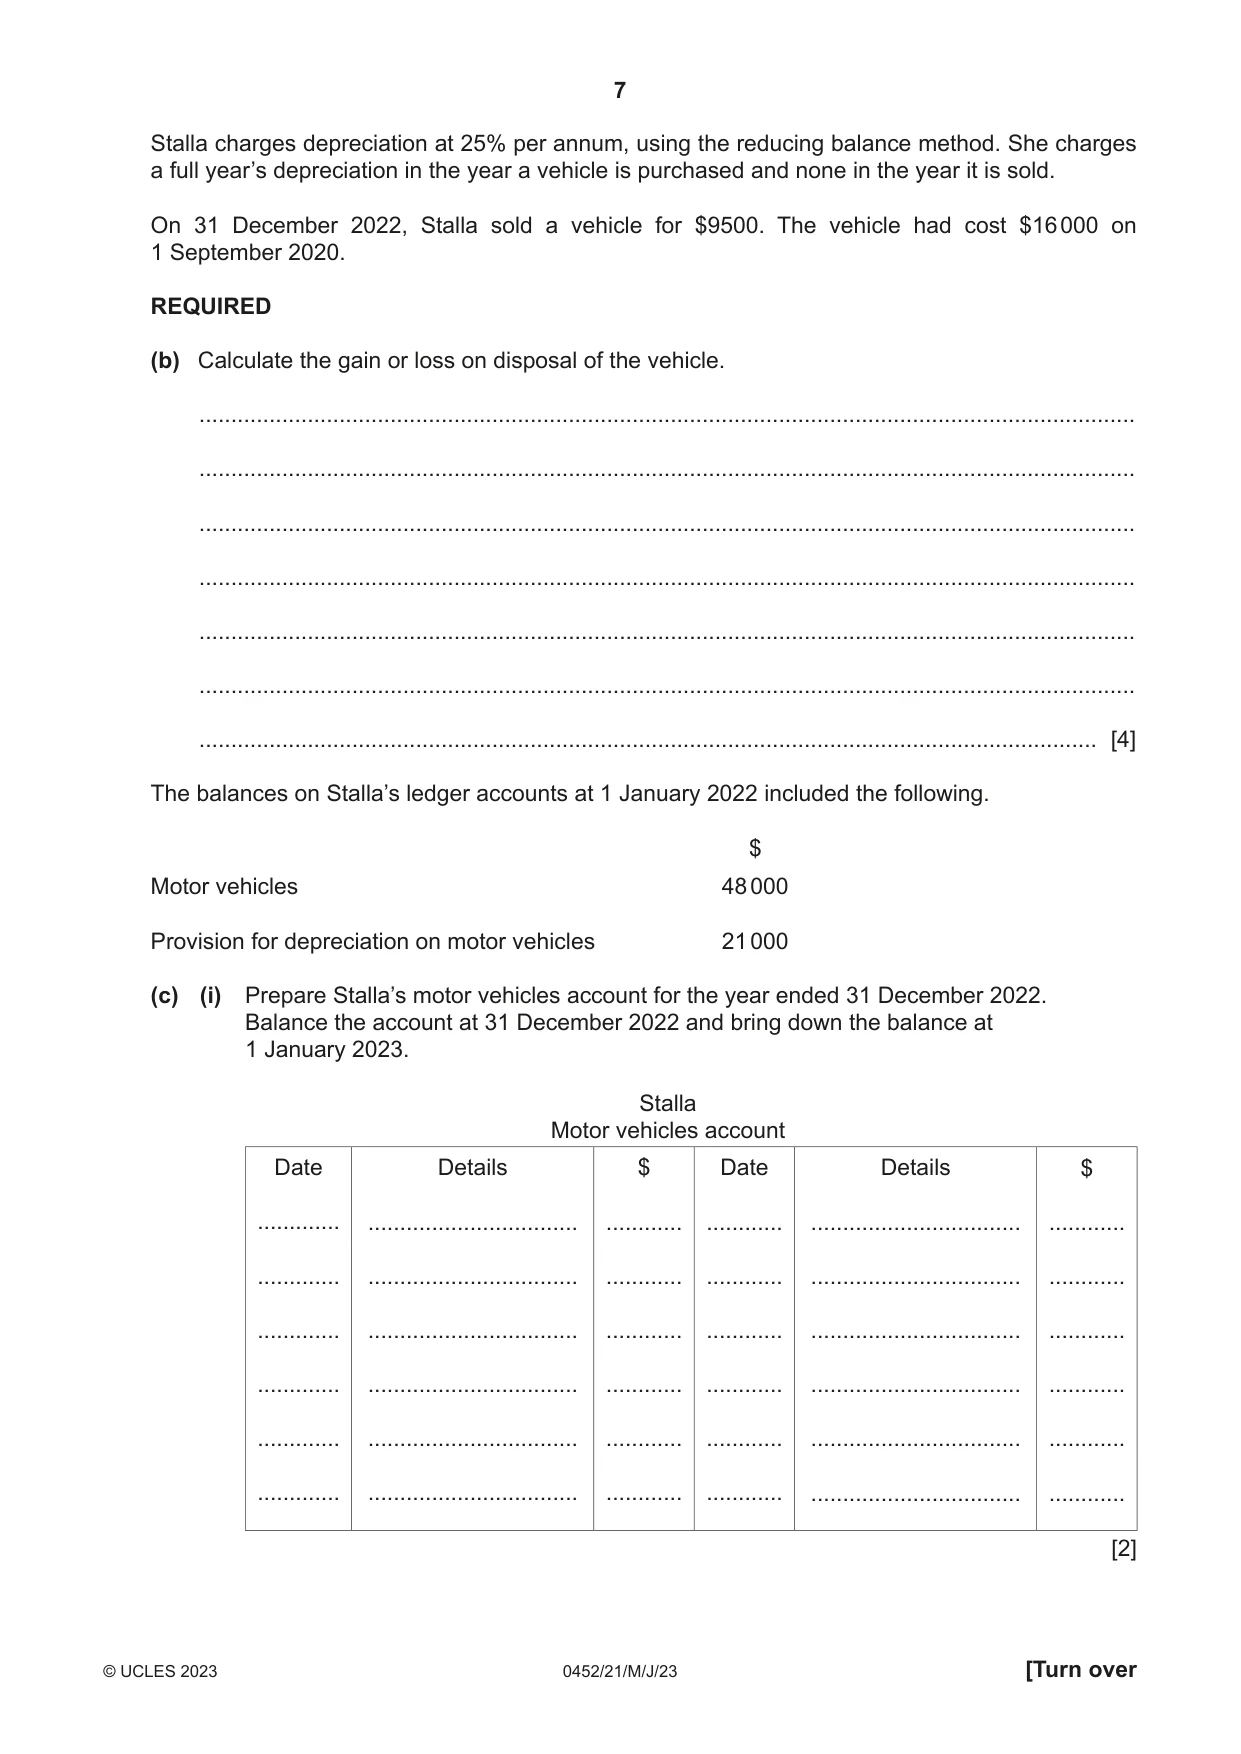
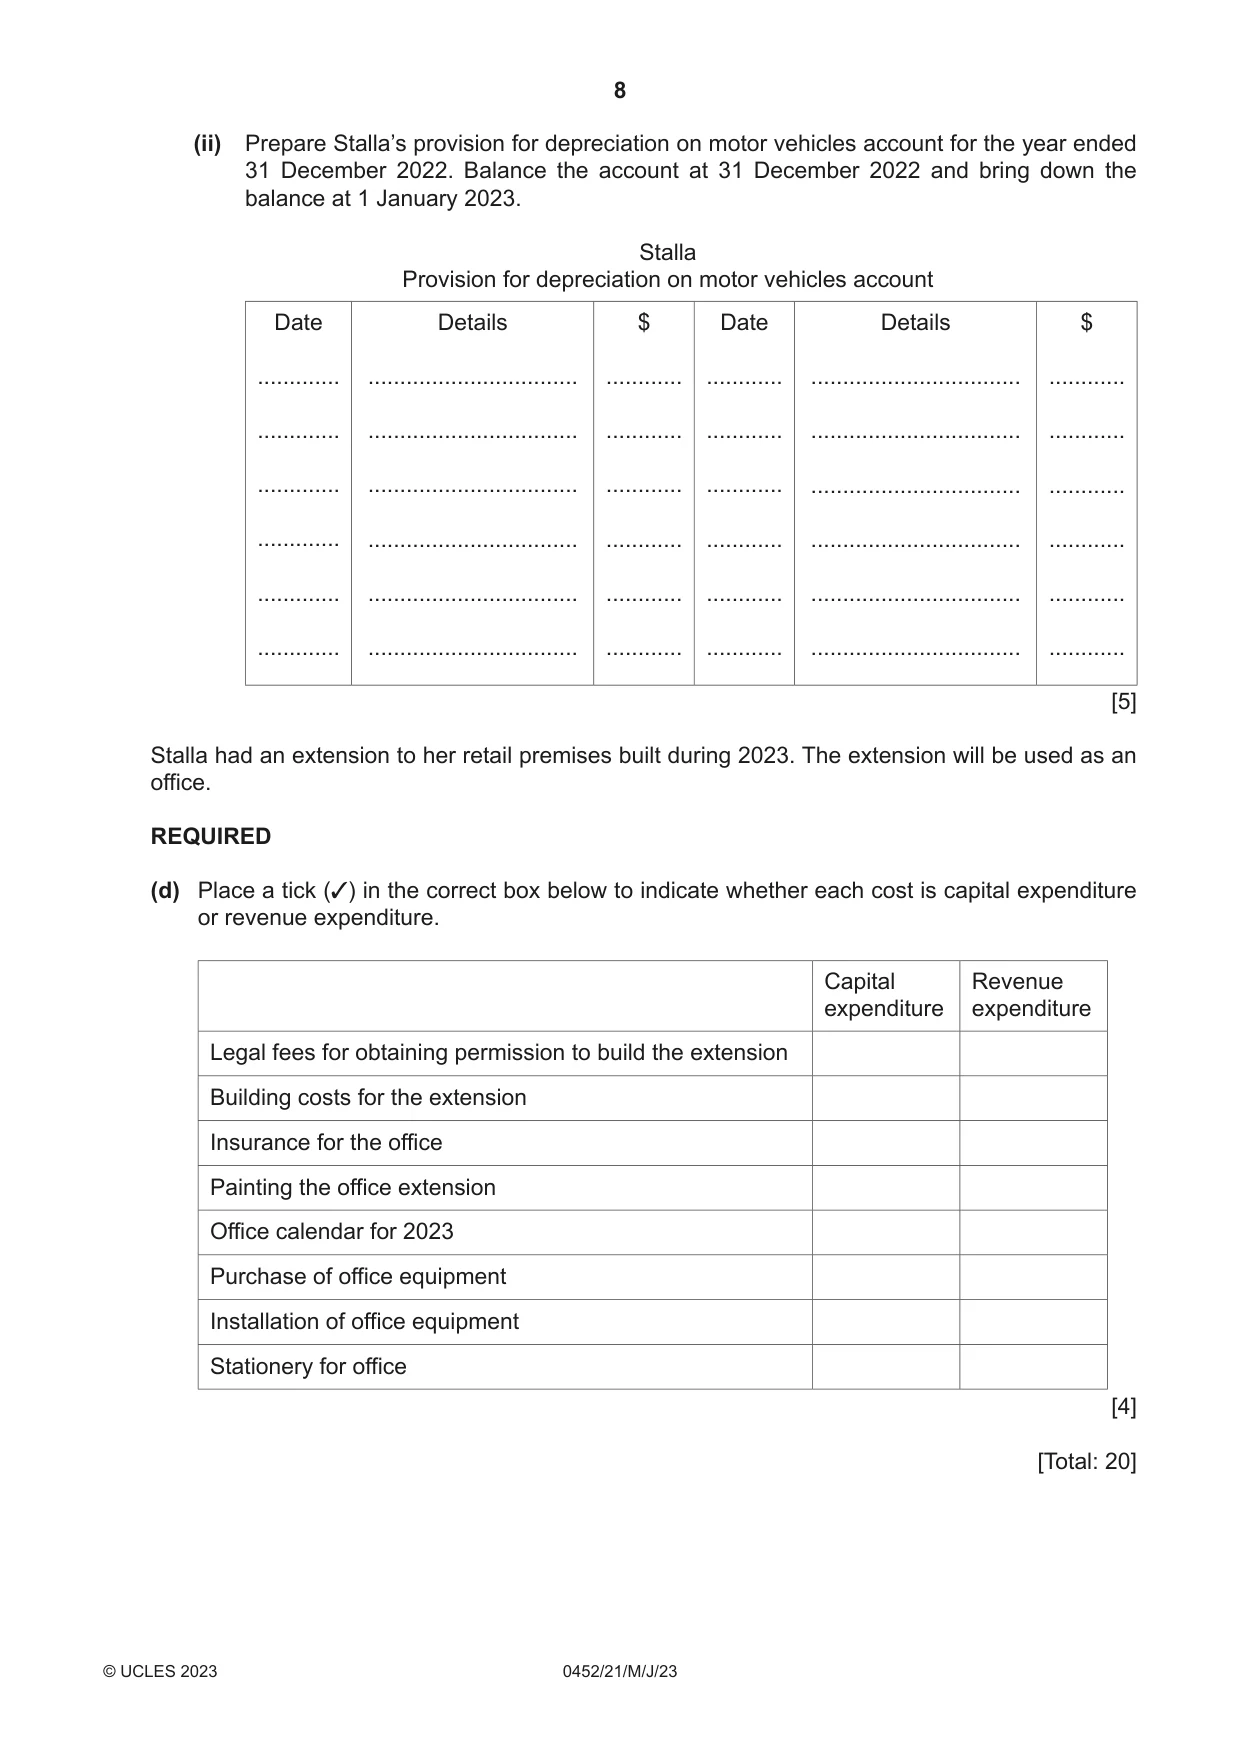
2 Stalla is a sole trader who sells on credit. She maintains a provision for doubtful debts at 4% of trade receivables. Stalla’s trade receivables were: $ At 31 December 2021 75 000 At 31 December 2022 77 000 REQUIRED (a) (i) Prepare Stalla’s provision for doubtful debts account for the year ended 31 December 2022. Balance the account at 31 December 2022 and bring down the balance at 1 January 2023. Stalla Provision for doubtful debts account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [3] (ii) State two reasons why Stalla maintains a provision for doubtful debts. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] Stalla charges depreciation at 25% per annum, using the reducing balance method. She charges a full year’s depreciation in the year a vehicle is purchased and none in the year it is sold. On 31 December 2022, Stalla sold a vehicle for $9500. The vehicle had cost $16 000 on 1 September 2020. REQUIRED (b) Calculate the gain or loss on disposal of the vehicle. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] The balances on Stalla’s ledger accounts at 1 January 2022 included the following. $ Motor vehicles 48 000 Provision for depreciation on motor vehicles 21 000 (c) (i) Prepare Stalla’s motor vehicles account for the year ended 31 December 2022. Balance the account at 31 December 2022 and bring down the balance at 1 January 2023. Stalla Motor vehicles account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [2] (ii) Prepare Stalla’s provision for depreciation on motor vehicles account for the year ended 31 December 2022. Balance the account at 31 December 2022 and bring down the balance at 1 January 2023. Stalla Provision for depreciation on motor vehicles account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [5] Stalla had an extension to her retail premises built during 2023. The extension will be used as an office. REQUIRED (d) Place a tick (3) in the correct box below to indicate whether each cost is capital expenditure or revenue expenditure. Capital Revenue expenditure expenditure Legal fees for obtaining permission to build the extension Building costs for the extension Insurance for the office Painting the office extension Office calendar for 2023 Purchase of office equipment Installation of office equipment Stationery for office [4] [Total: 20]
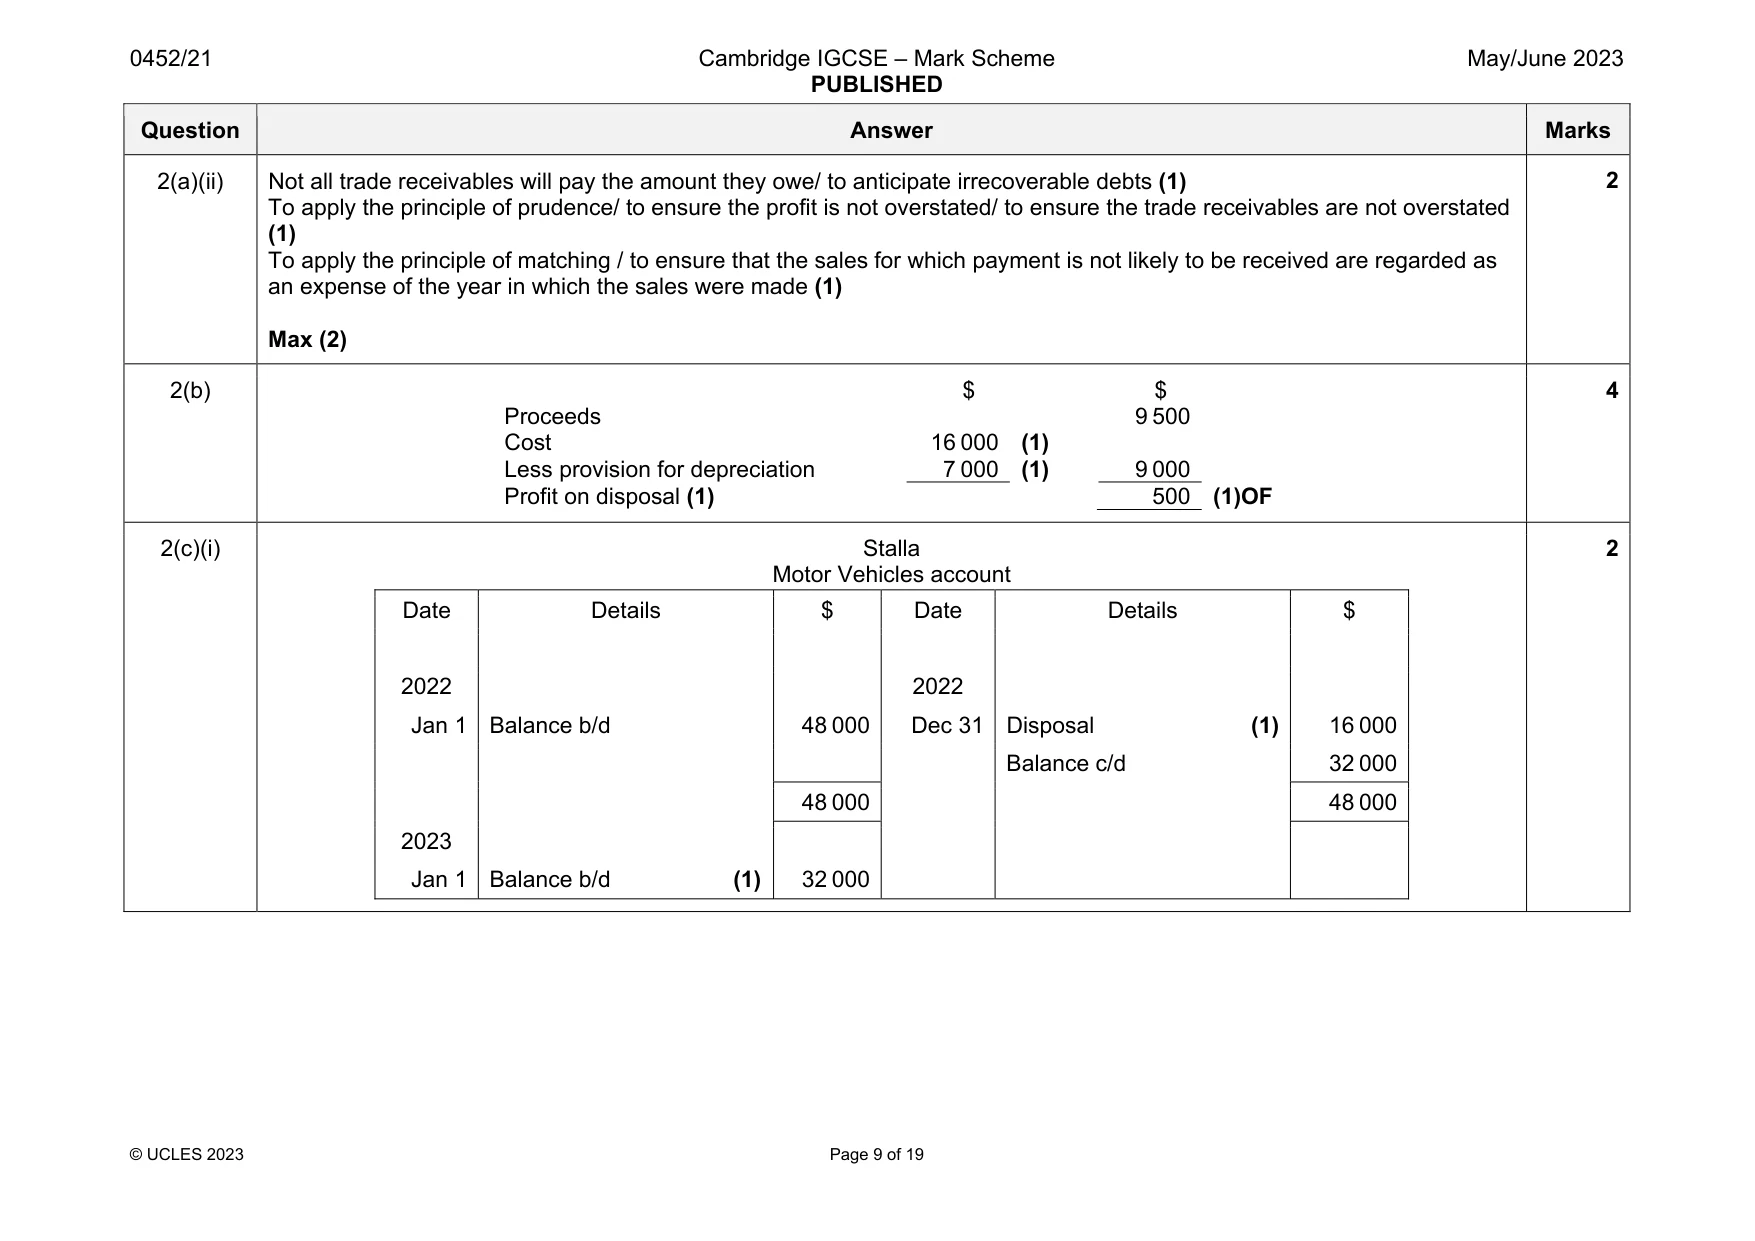
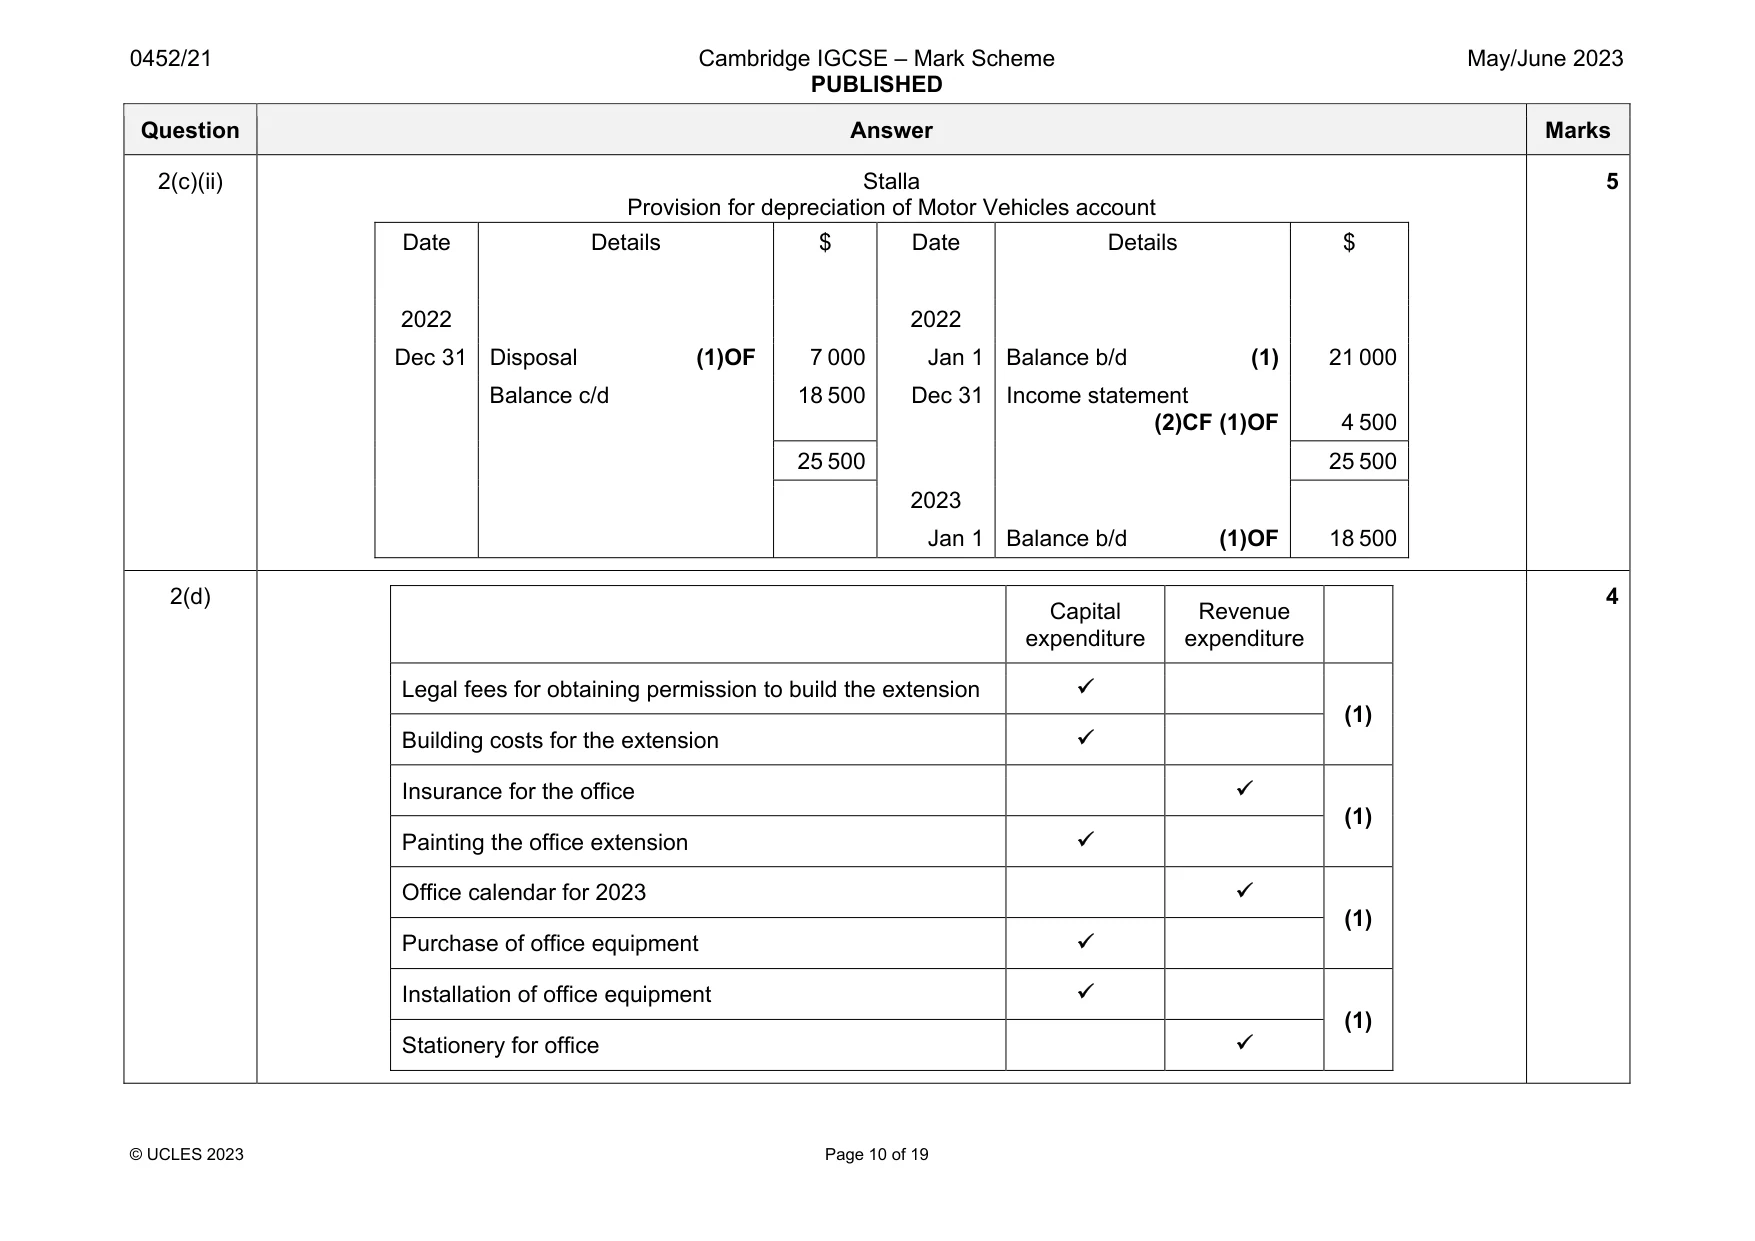
Mark scheme: 2(a)(i) Stalla Provision for doubtful debts account Date Details $ Date Details $ 2022 2022 Dec 31 Balance c/d 3 080 Jan 1 Balance b/d (1) 3 000 2022 Dec 31 Income statement (1)OF 80 3 080 3 080 2023 Jan 1 Balance b/d (1) 3 080 3 Question Answer Marks 2(a)(ii) Not all trade receivables will pay the amount they owe/ to anticipate irrecoverable debts (1) To apply the principle of prudence/ to ensure the profit is not overstated/ to ensure the trade receivables are not overstated (1) To apply the principle of matching / to ensure that the sales for which payment is not likely to be received are regarded as an expense of the year in which the sales were made (1) Max (2) 2 2(b) $ $ Proceeds 9 500 Cost 16 000 (1) Less provision for depreciation 7 000 (1) 9 000 Profit on disposal (1) 500 (1)OF 4 2(c)(i) Stalla Motor Vehicles account Date Details $ Date Details $ 2022 2022 Jan 1 Balance b/d 48 000 Dec 31 Disposal (1) 16 000 Balance c/d 32 000 48 000 48 000 2023 Jan 1 Balance b/d (1) 32 000 2 Question Answer Marks 2(c)(ii) Stalla Provision for depreciation of Motor Vehicles account Date Details $ Date Details $ 2022 2022 Dec 31 Disposal (1)OF 7 000 Jan 1 Balance b/d (1) 21 000 Balance c/d 18 500 Dec 31 Income statement (2)CF (1)OF 4 500 25 500 25 500 2023 Jan 1 Balance b/d (1)OF 18 500 5 2(d) Capital expenditure Revenue expenditure Legal fees for obtaining permission to build the extension (1) Building costs for the extension Insurance for the office (1) Painting the office extension Office calendar for 2023 (1) Purchase of office equipment Installation of office equipment (1) Stationery for office 4
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q3 · Eshe is a trader
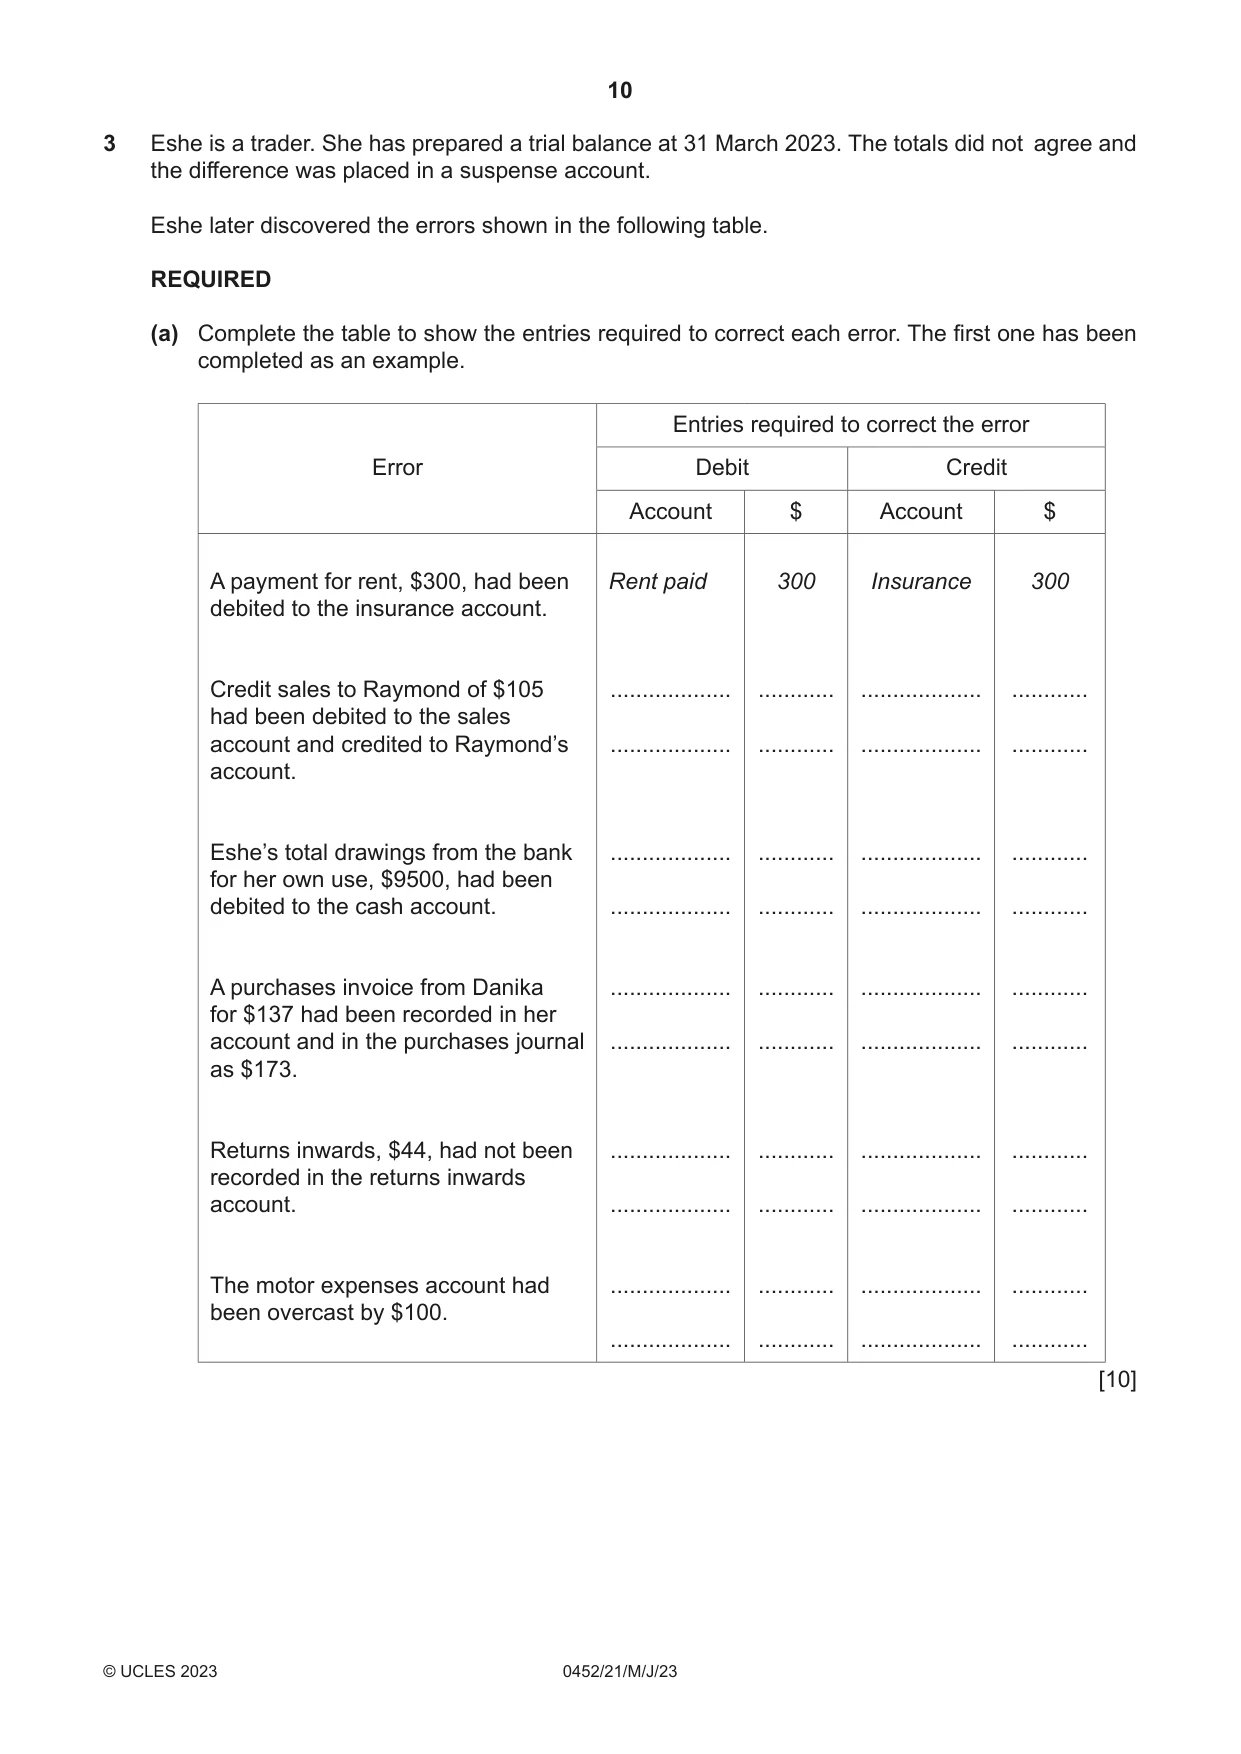
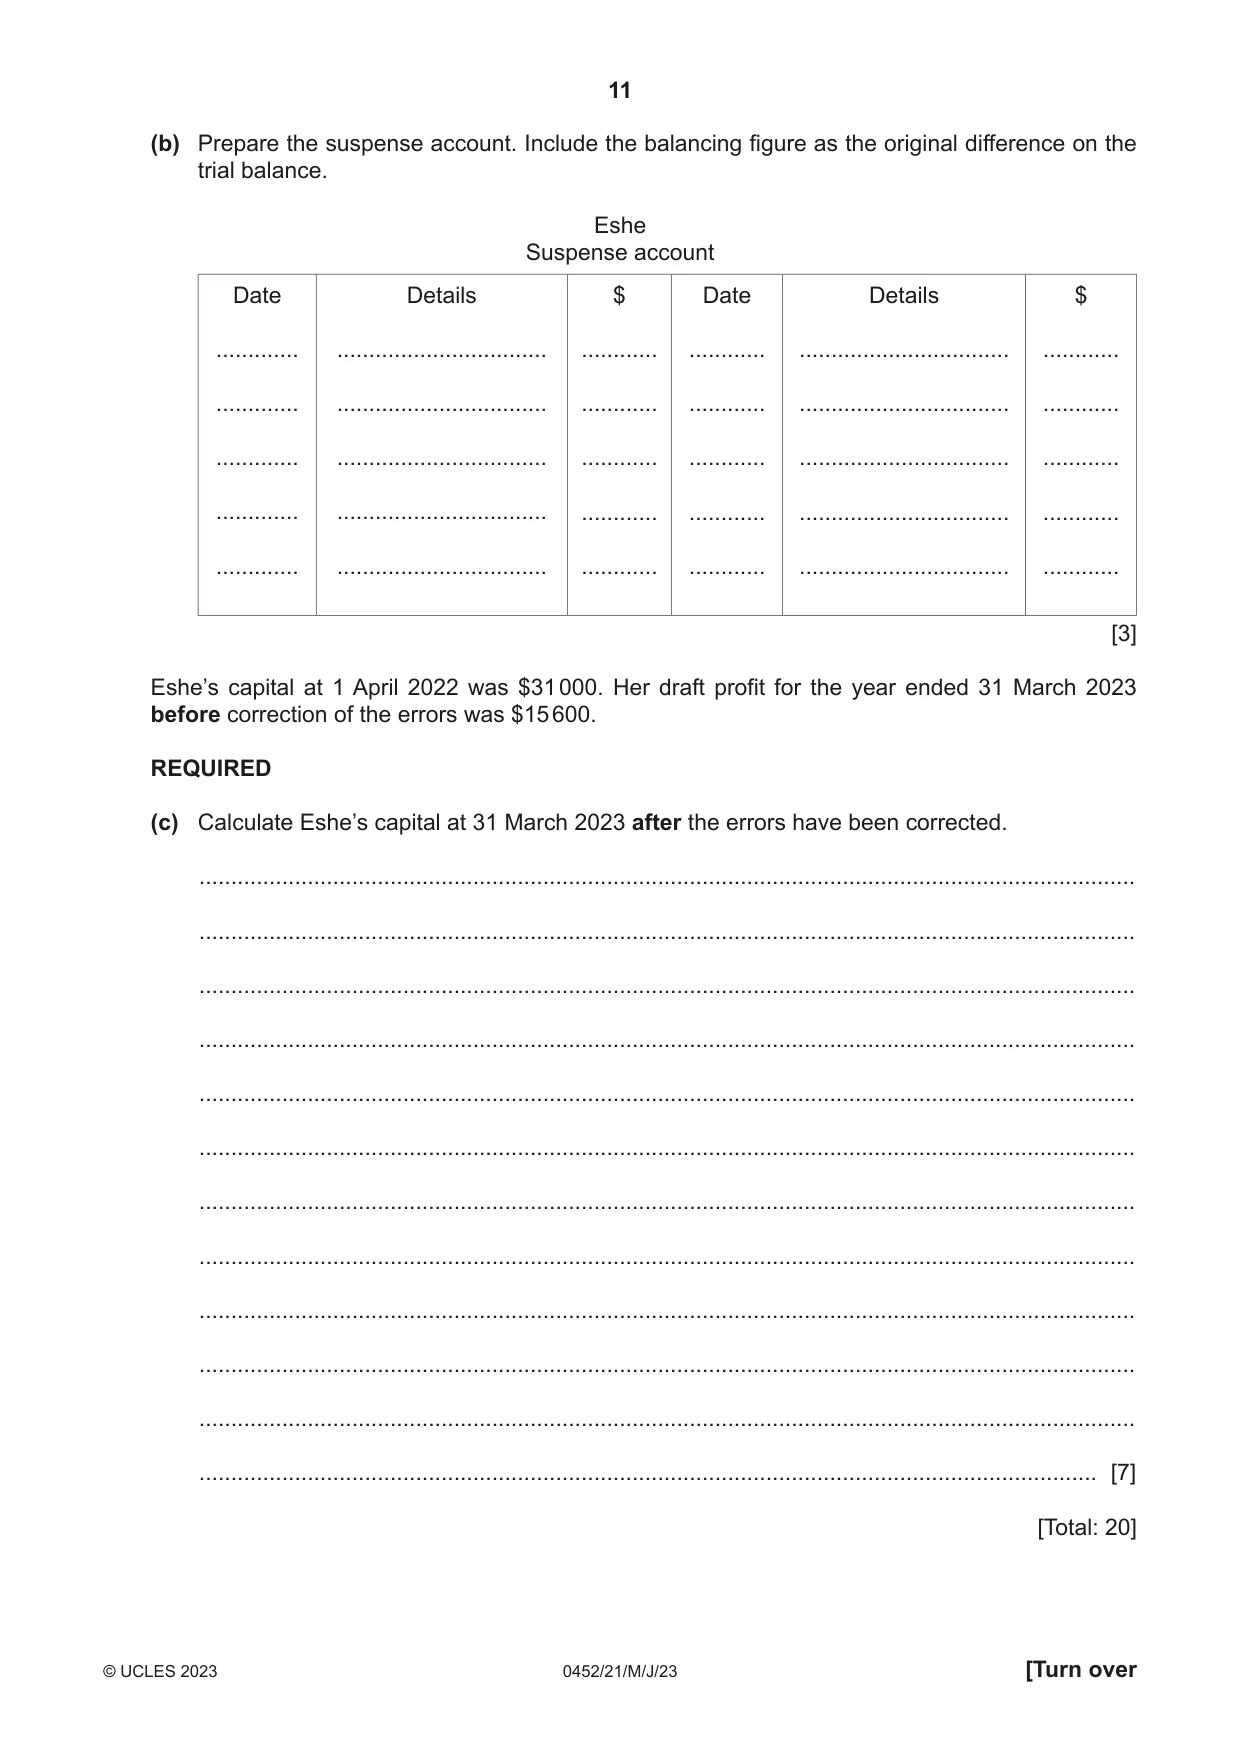
3 Eshe is a trader. She has prepared a trial balance at 31 March 2023. The totals did not agree and the difference was placed in a suspense account. Eshe later discovered the errors shown in the following table. REQUIRED (a) Complete the table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for rent, $300, had been Rent paid 300 Insurance 300 debited to the insurance account. Credit sales to Raymond of $105 ................... ............ ................... ............ had been debited to the sales account and credited to Raymond’s ................... ............ ................... ............ account. Eshe’s total drawings from the bank ................... ............ ................... ............ for her own use, $9500, had been debited to the cash account. ................... ............ ................... ............ A purchases invoice from Danika ................... ............ ................... ............ for $137 had been recorded in her account and in the purchases journal ................... ............ ................... ............ as $173. Returns inwards, $44, had not been ................... ............ ................... ............ recorded in the returns inwards account. ................... ............ ................... ............ The motor expenses account had ................... ............ ................... ............ been overcast by $100. ................... ............ ................... ............ [10] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Eshe Suspense account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [3] Eshe’s capital at 1 April 2022 was $31 000. Her draft profit for the year ended 31 March 2023 before correction of the errors was $15 600. REQUIRED (c) Calculate Eshe’s capital at 31 March 2023 after the errors have been corrected. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 20]
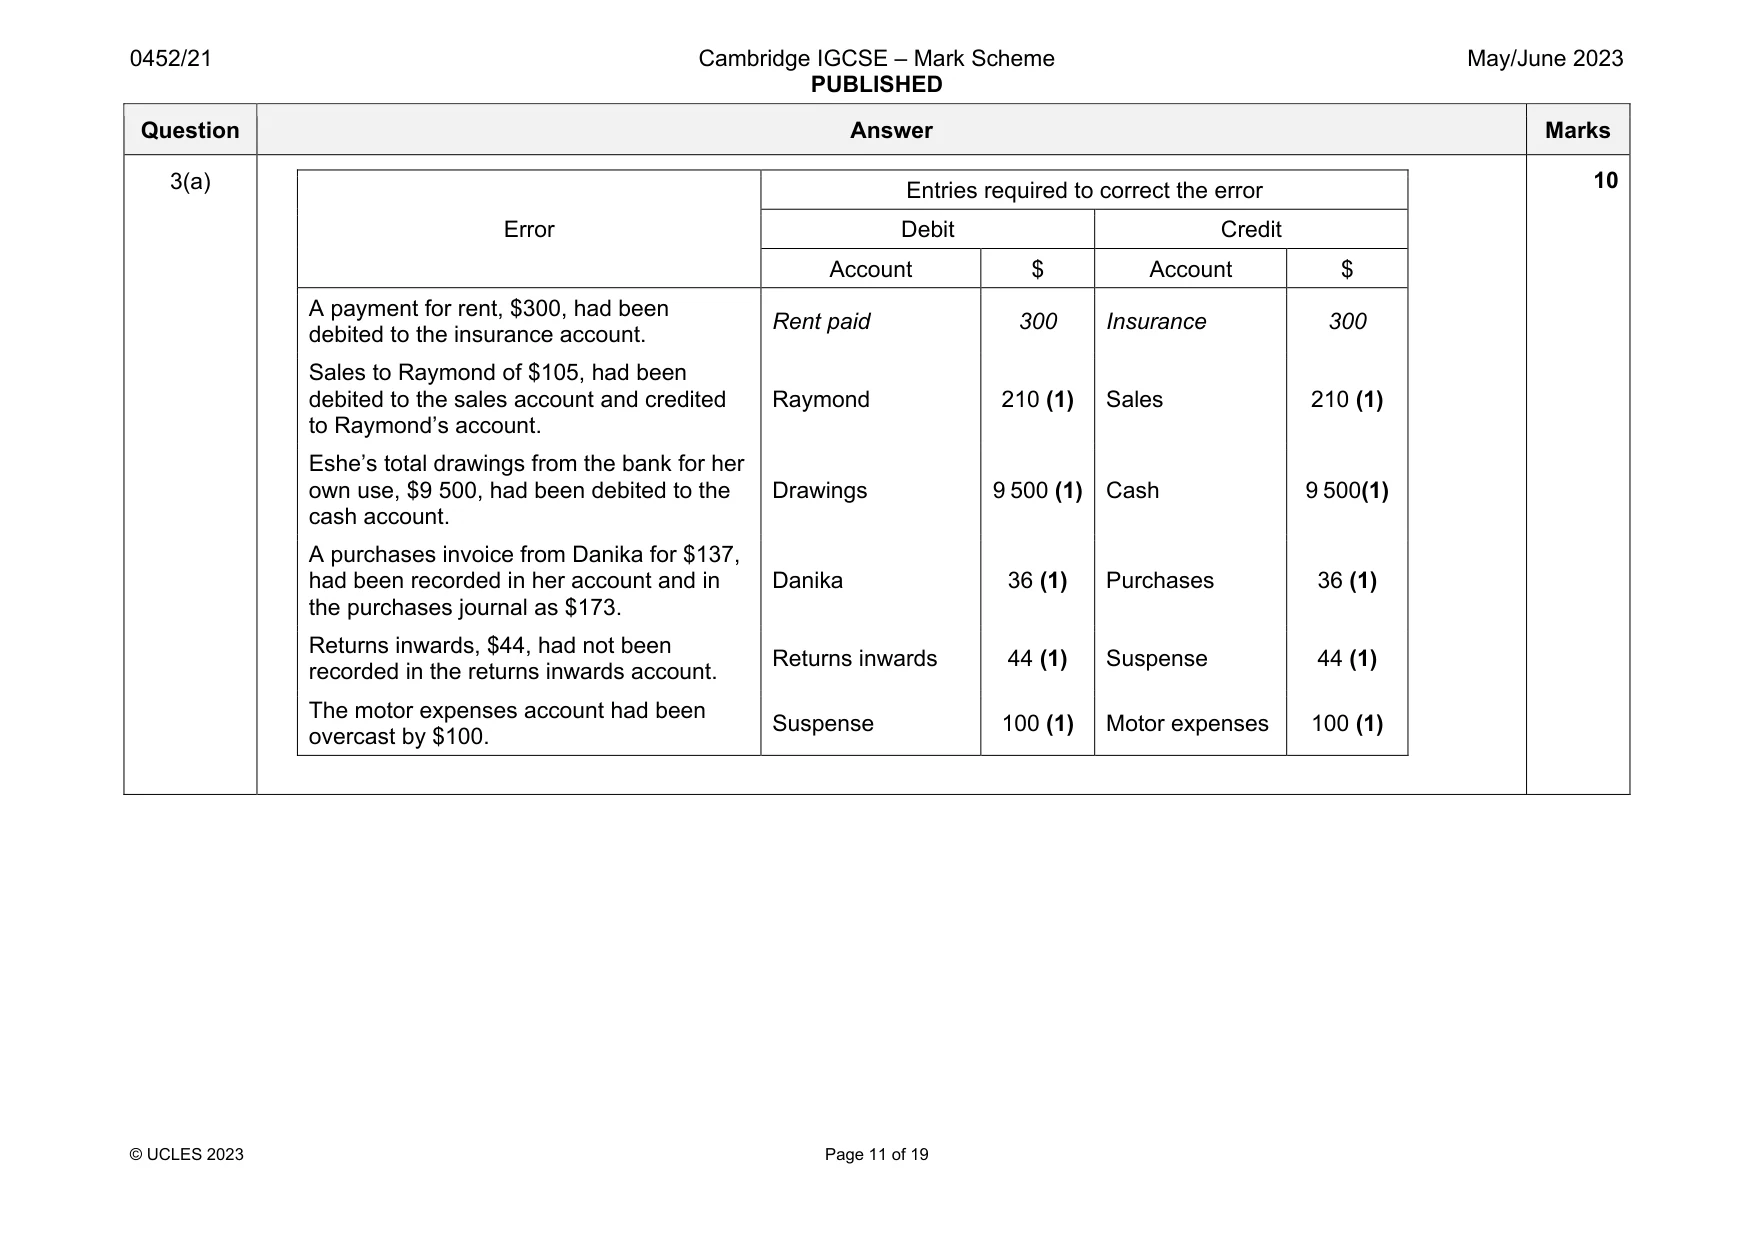
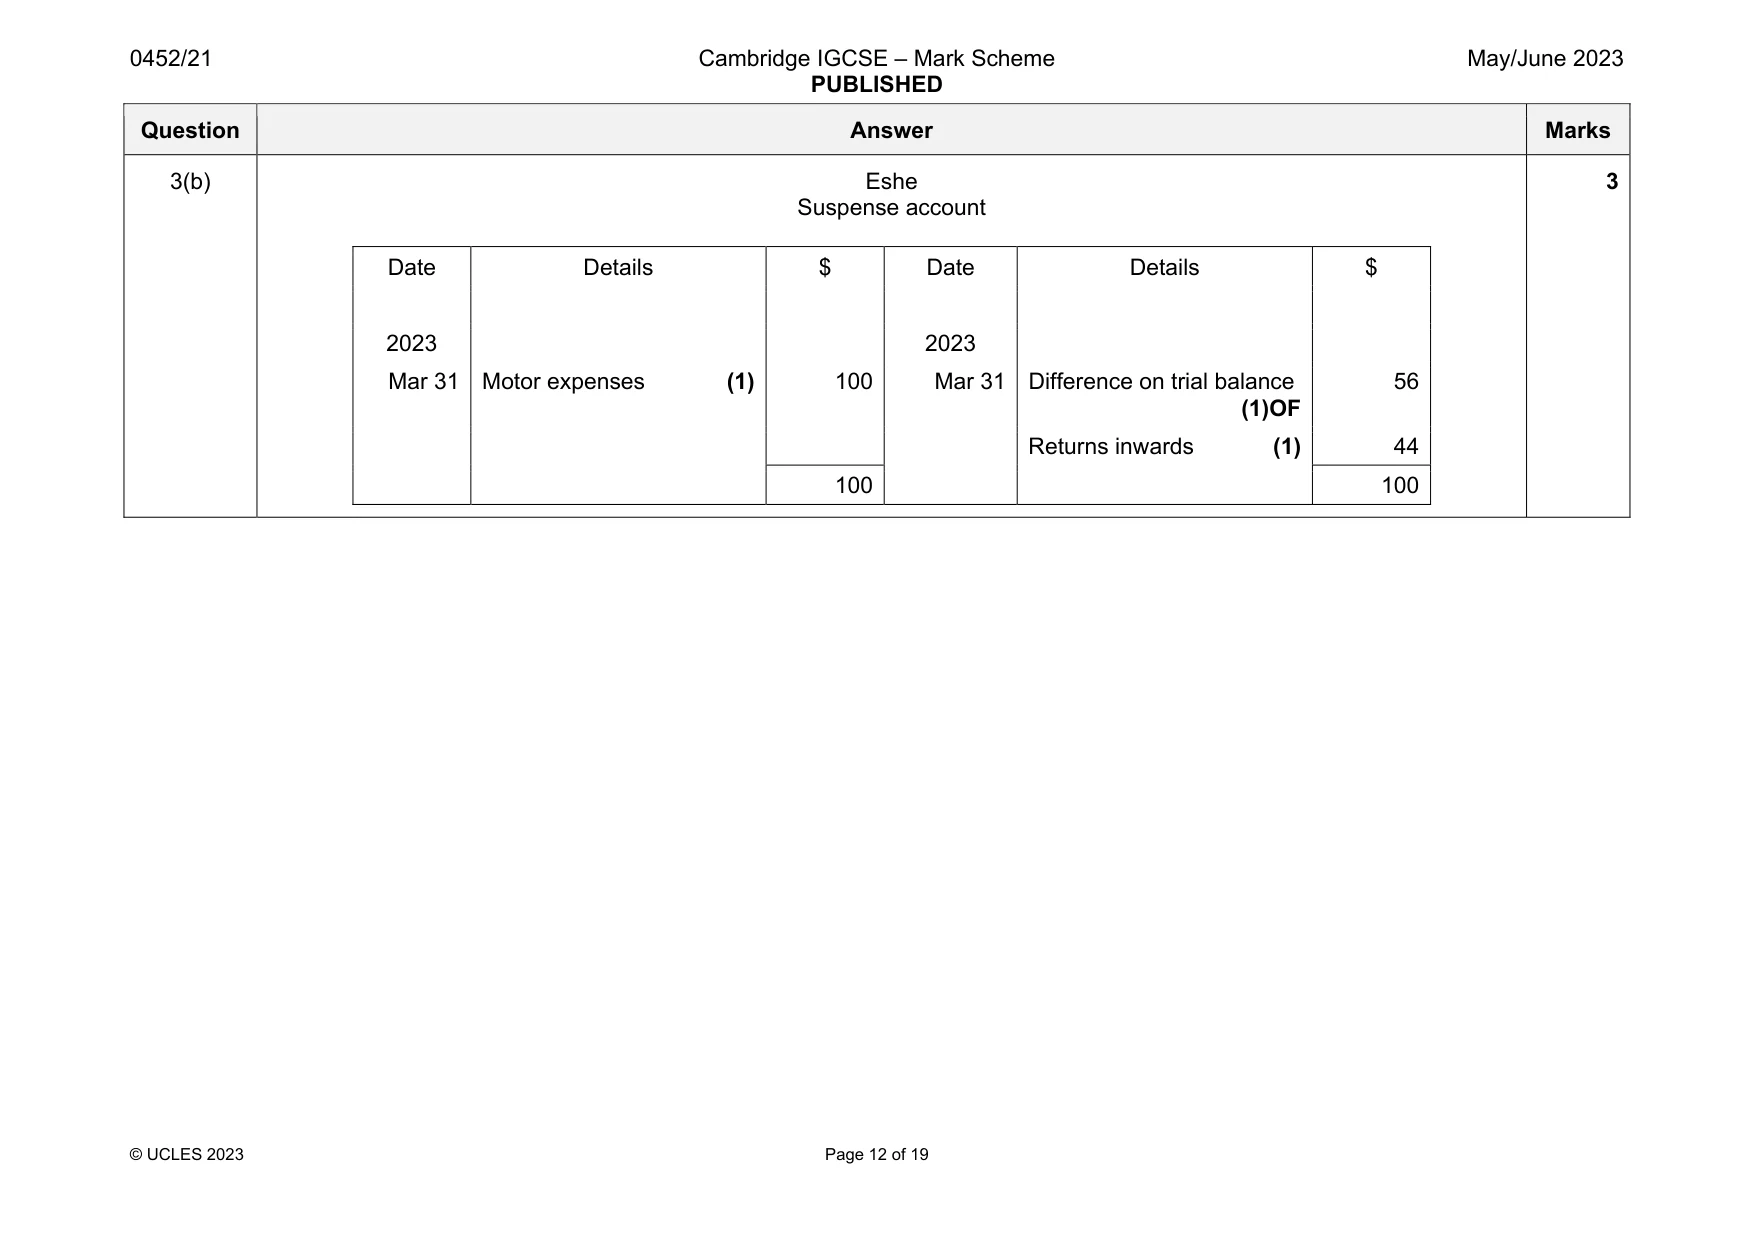
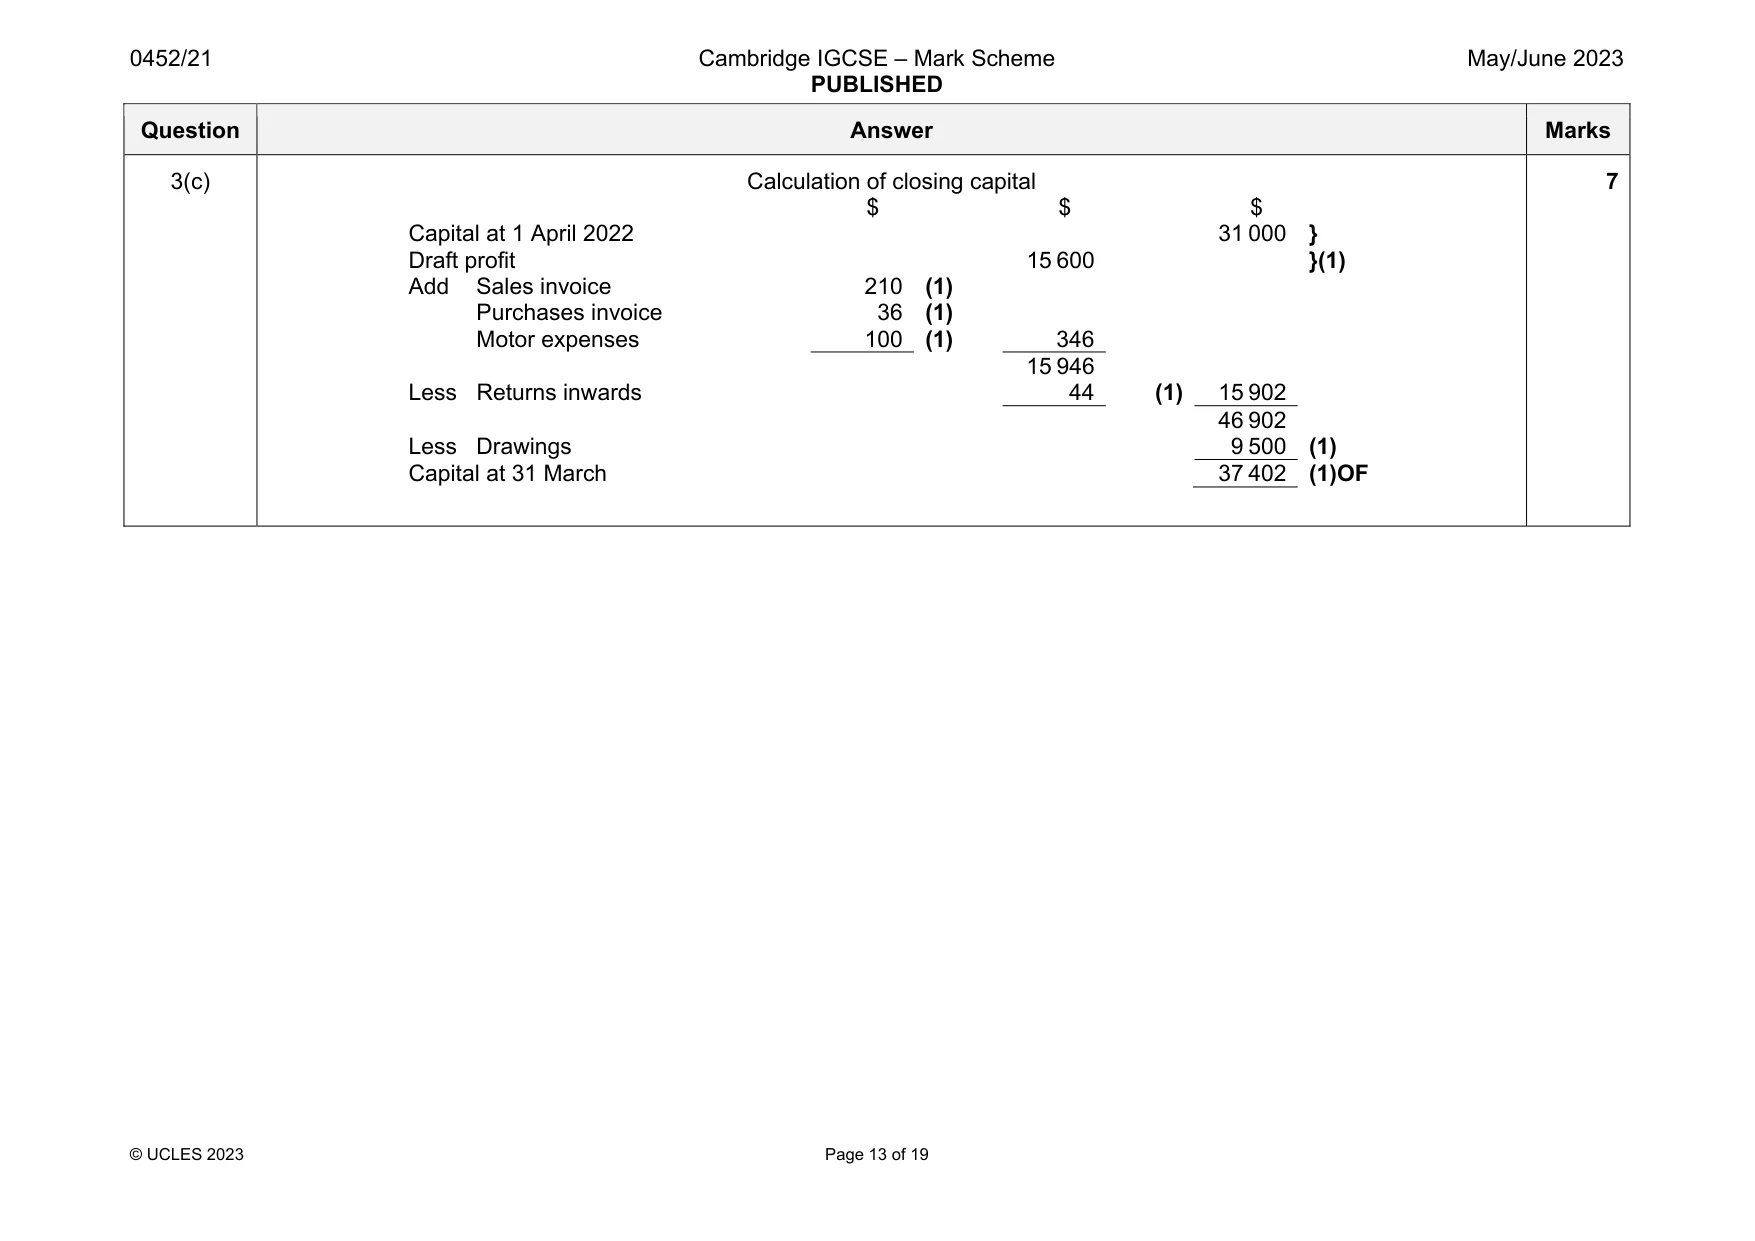
Mark scheme: 3(a) Error Entries required to correct the error Debit Credit Account $ Account $ A payment for rent, $300, had been debited to the insurance account. Rent paid 300 Insurance 300 Sales to Raymond of $105, had been debited to the sales account and credited to Raymond’s account. Raymond 210 (1) Sales 210 (1) Eshe’s total drawings from the bank for her own use, $9 500, had been debited to the cash account. Drawings 9 500 (1) Cash 9 500(1) A purchases invoice from Danika for $137, had been recorded in her account and in the purchases journal as $173. Danika 36 (1) Purchases 36 (1) Returns inwards, $44, had not been recorded in the returns inwards account. Returns inwards 44 (1) Suspense 44 (1) The motor expenses account had been overcast by $100. Suspense 100 (1) Motor expenses 100 (1) Question Answer Marks 3(b) Eshe Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Motor expenses (1) 100 Mar 31 Difference on trial balance (1)OF 56 Returns inwards (1) 44 100 100 3 Question Answer Marks 3(c) Calculation of closing capital $ $ $ Capital at 1 April 2022 31 000 } Draft profit 15 600 }(1) Add Sales invoice 210 (1) Purchases invoice 36 (1) Motor expenses 100 (1) 346 15 946 Less Returns inwards 44 (1) 15 902 46 902 Less Drawings 9 500 (1) Capital at 31 March 37 402 (1)OF 7
Q4 · Salman owns a footwear factory
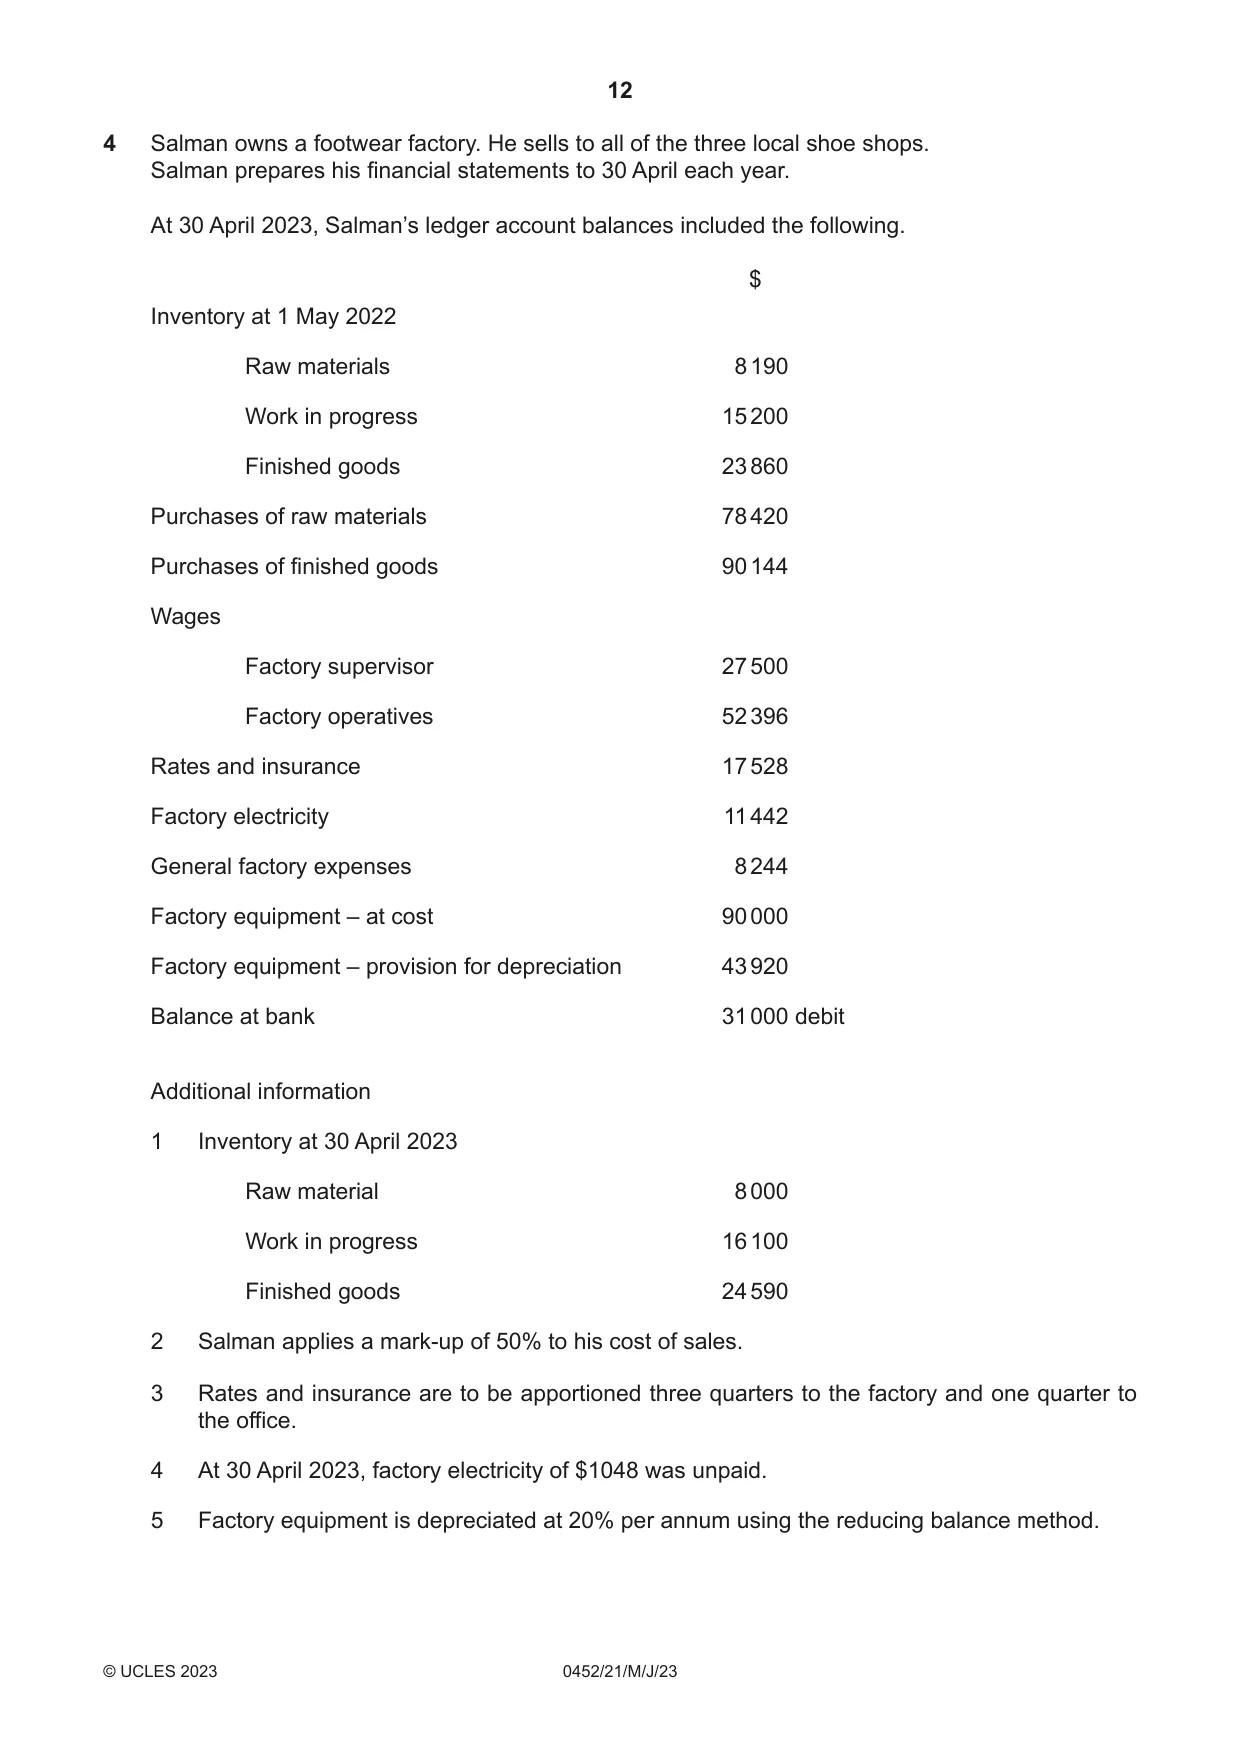
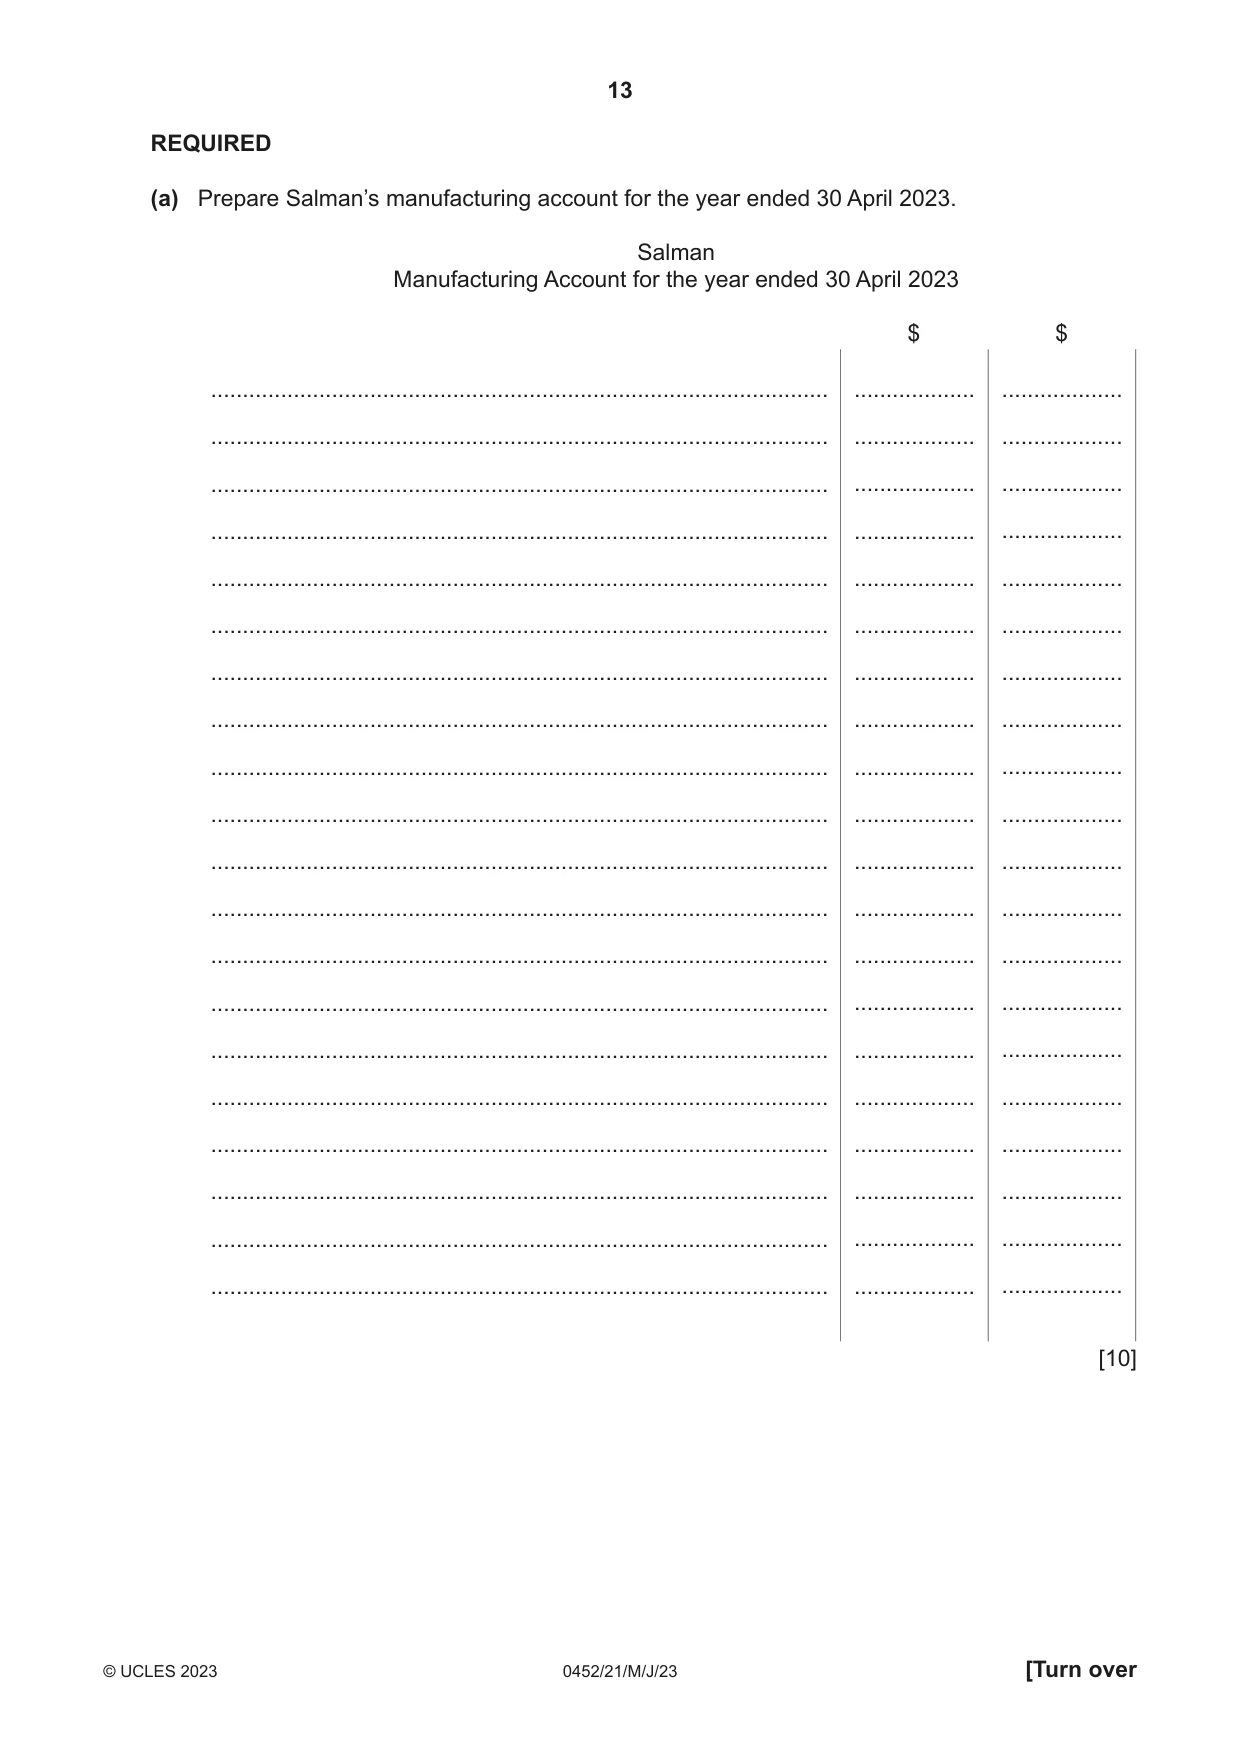
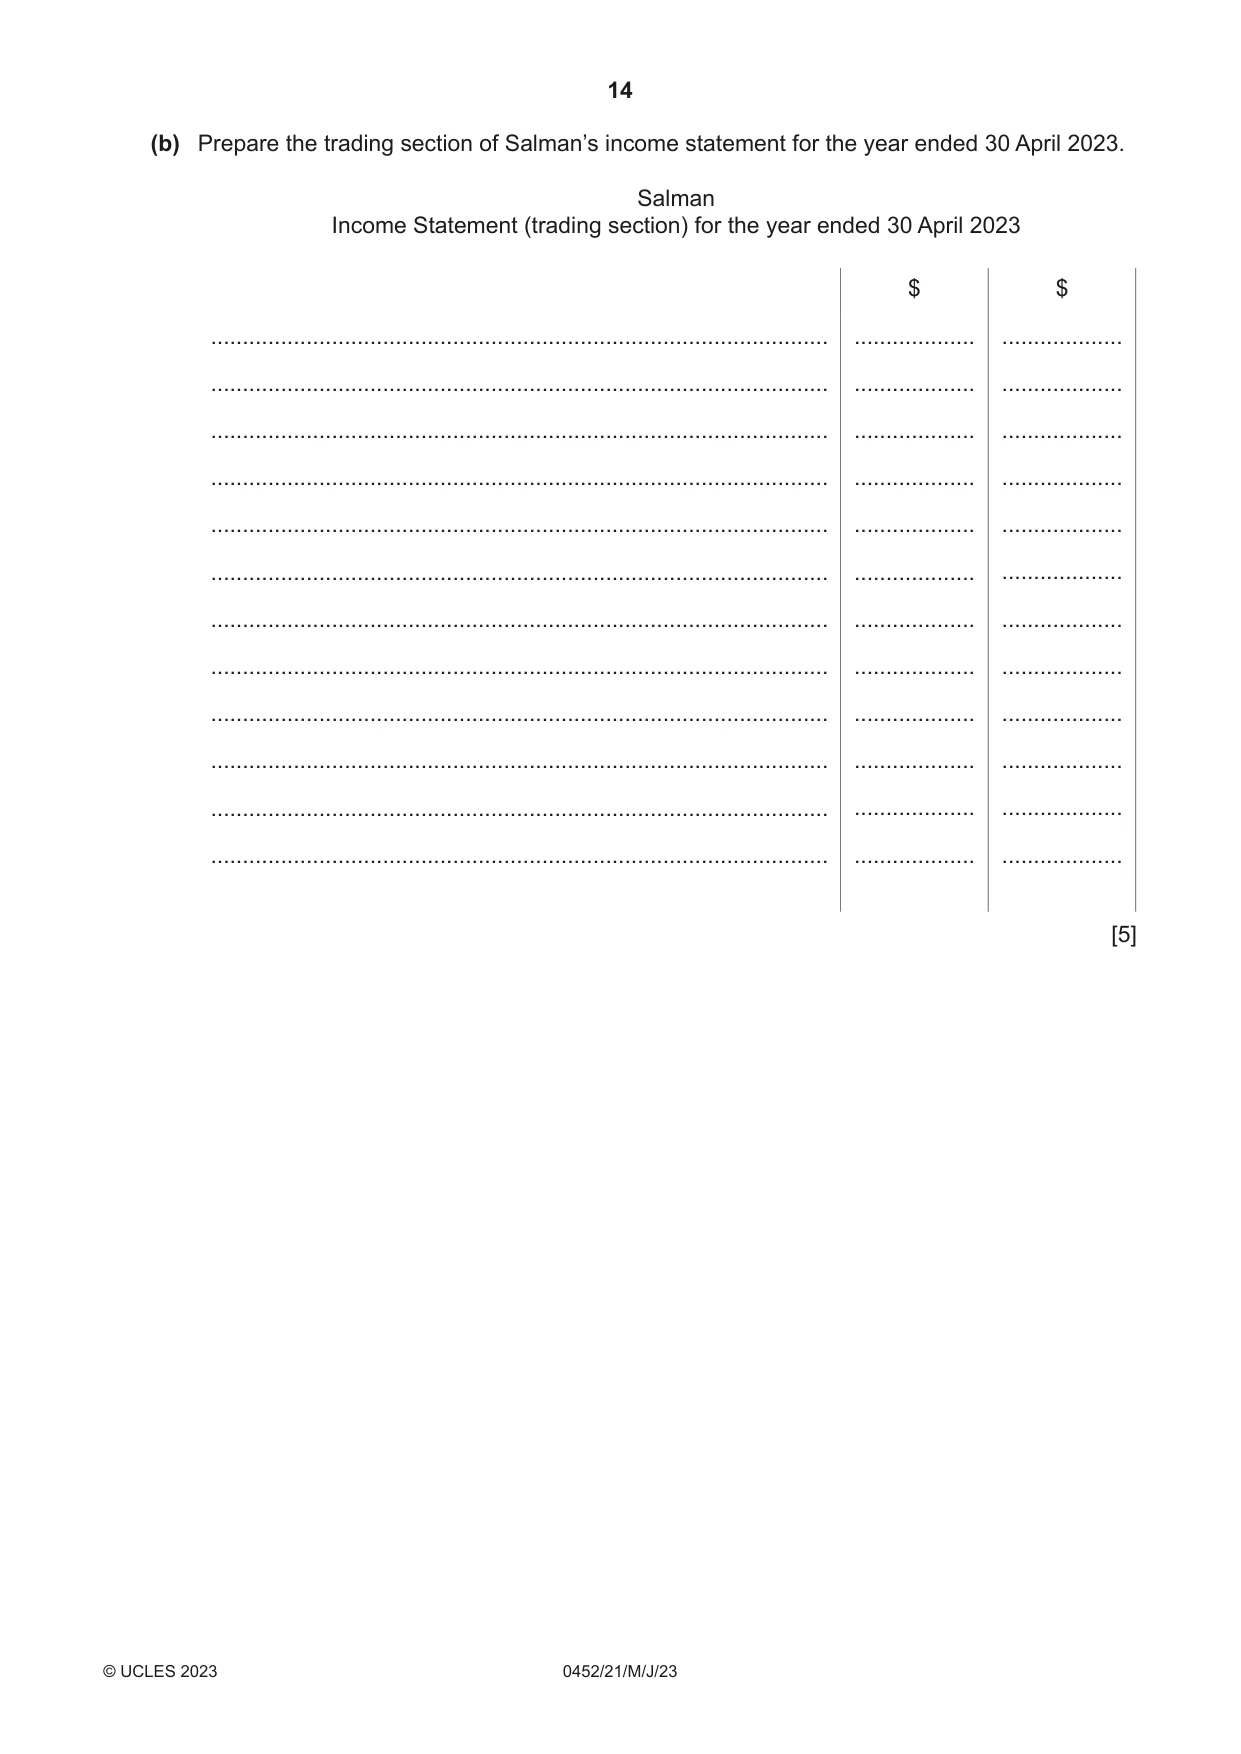
4 Salman owns a footwear factory. He sells to all of the three local shoe shops. Salman prepares his financial statements to 30 April each year. At 30 April 2023, Salman’s ledger account balances included the following. $ Inventory at 1 May 2022 Raw materials 8 190 Work in progress 15 200 Finished goods 23 860 Purchases of raw materials 78 420 Purchases of finished goods 90 144 Wages Factory supervisor 27 500 Factory operatives 52 396 Rates and insurance 17 528 Factory electricity 11 442 General factory expenses 8 244 Factory equipment – at cost 90 000 Factory equipment – provision for depreciation 43 920 Balance at bank 31 000 debit Additional information 1 Inventory at 30 April 2023 Raw material 8 000 Work in progress 16 100 Finished goods 24 590 2 Salman applies a mark-up of 50% to his cost of sales. 3 Rates and insurance are to be apportioned three quarters to the factory and one quarter to the office. 4 At 30 April 2023, factory electricity of $1048 was unpaid. 5 Factory equipment is depreciated at 20% per annum using the reducing balance method. REQUIRED (a) Prepare Salman’s manufacturing account for the year ended 30 April 2023. Salman Manufacturing Account for the year ended 30 April 2023 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [10] (b) Prepare the trading section of Salman’s income statement for the year ended 30 April 2023. Salman Income Statement (trading section) for the year ended 30 April 2023 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [5] Salman is considering converting some of his office space into additional factory capacity. (c) Advise Salman whether he should convert some of his premises from office use to factory use. Justify your answer by providing arguments for and against this conversion of office space into additional factory capacity. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
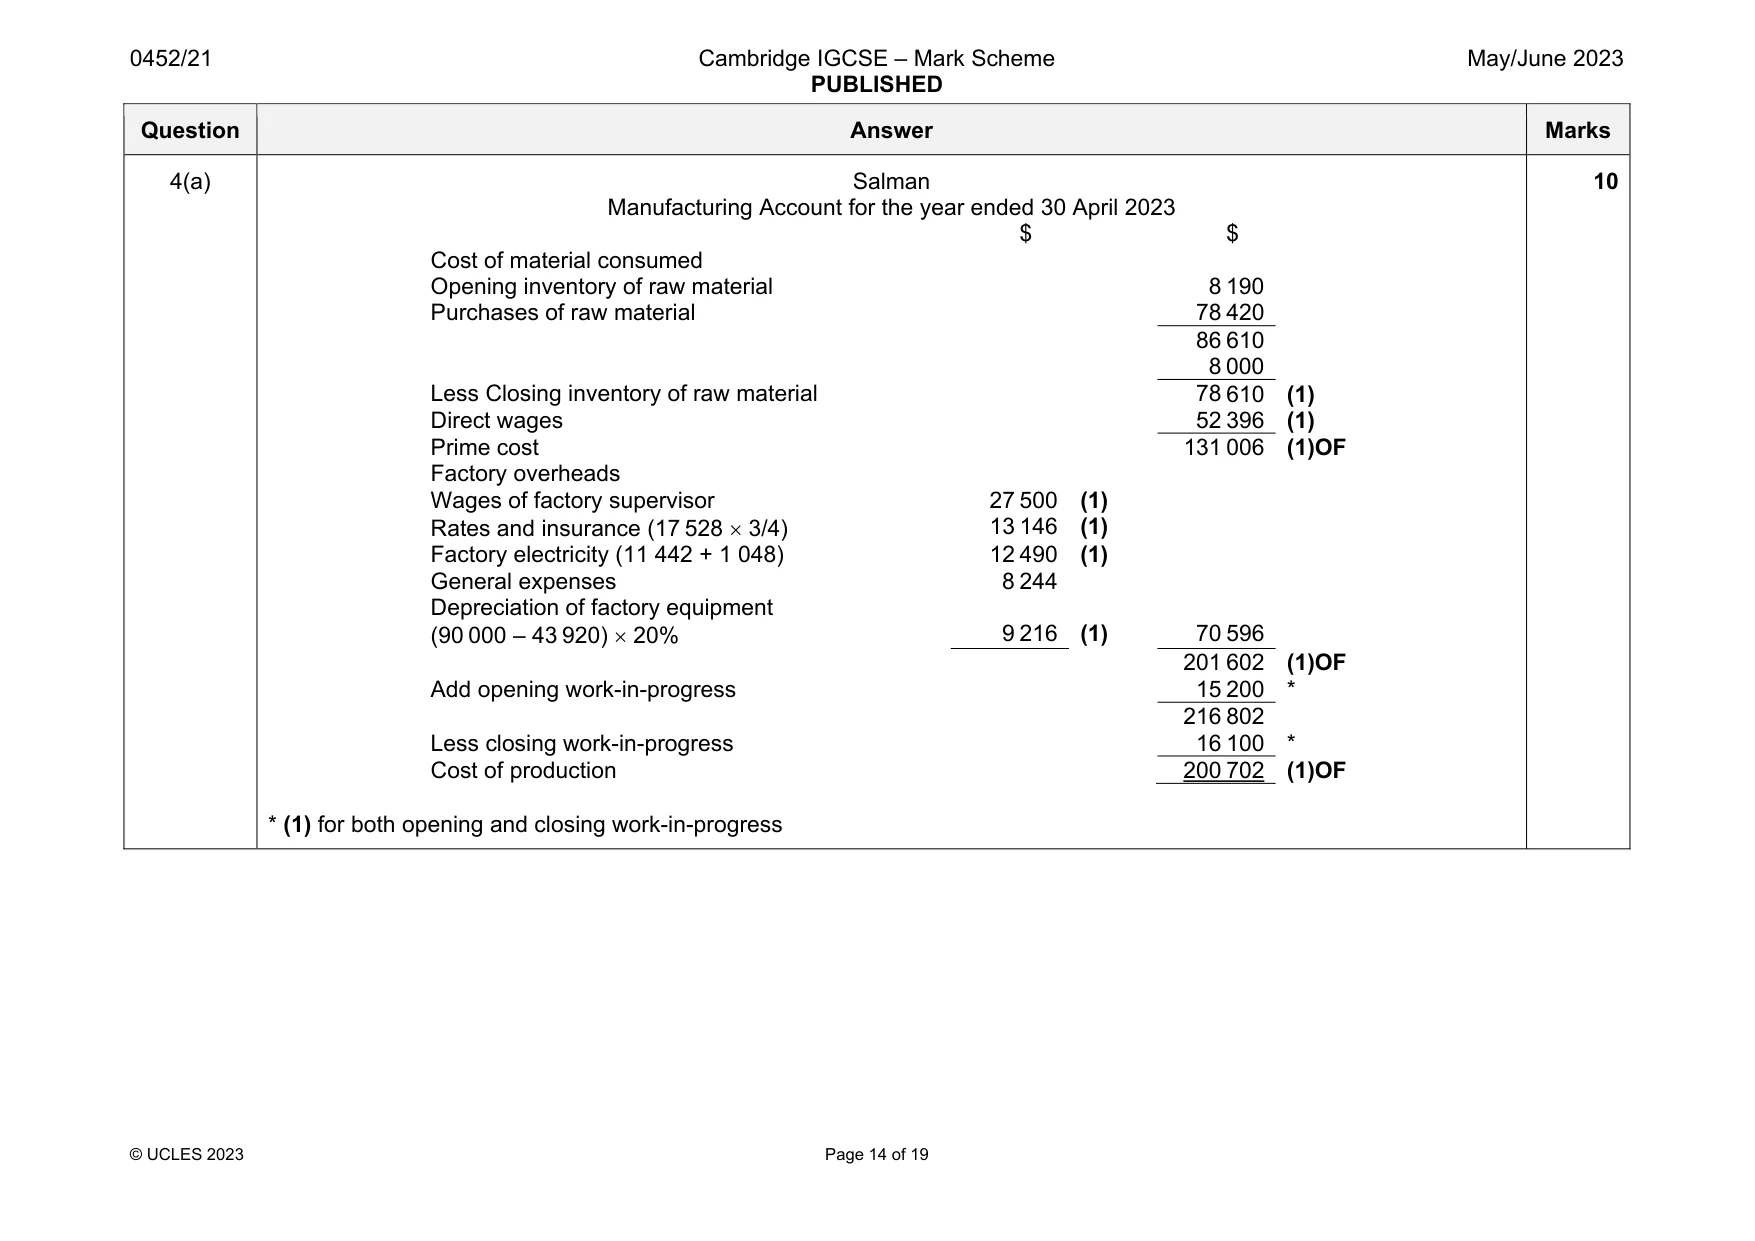
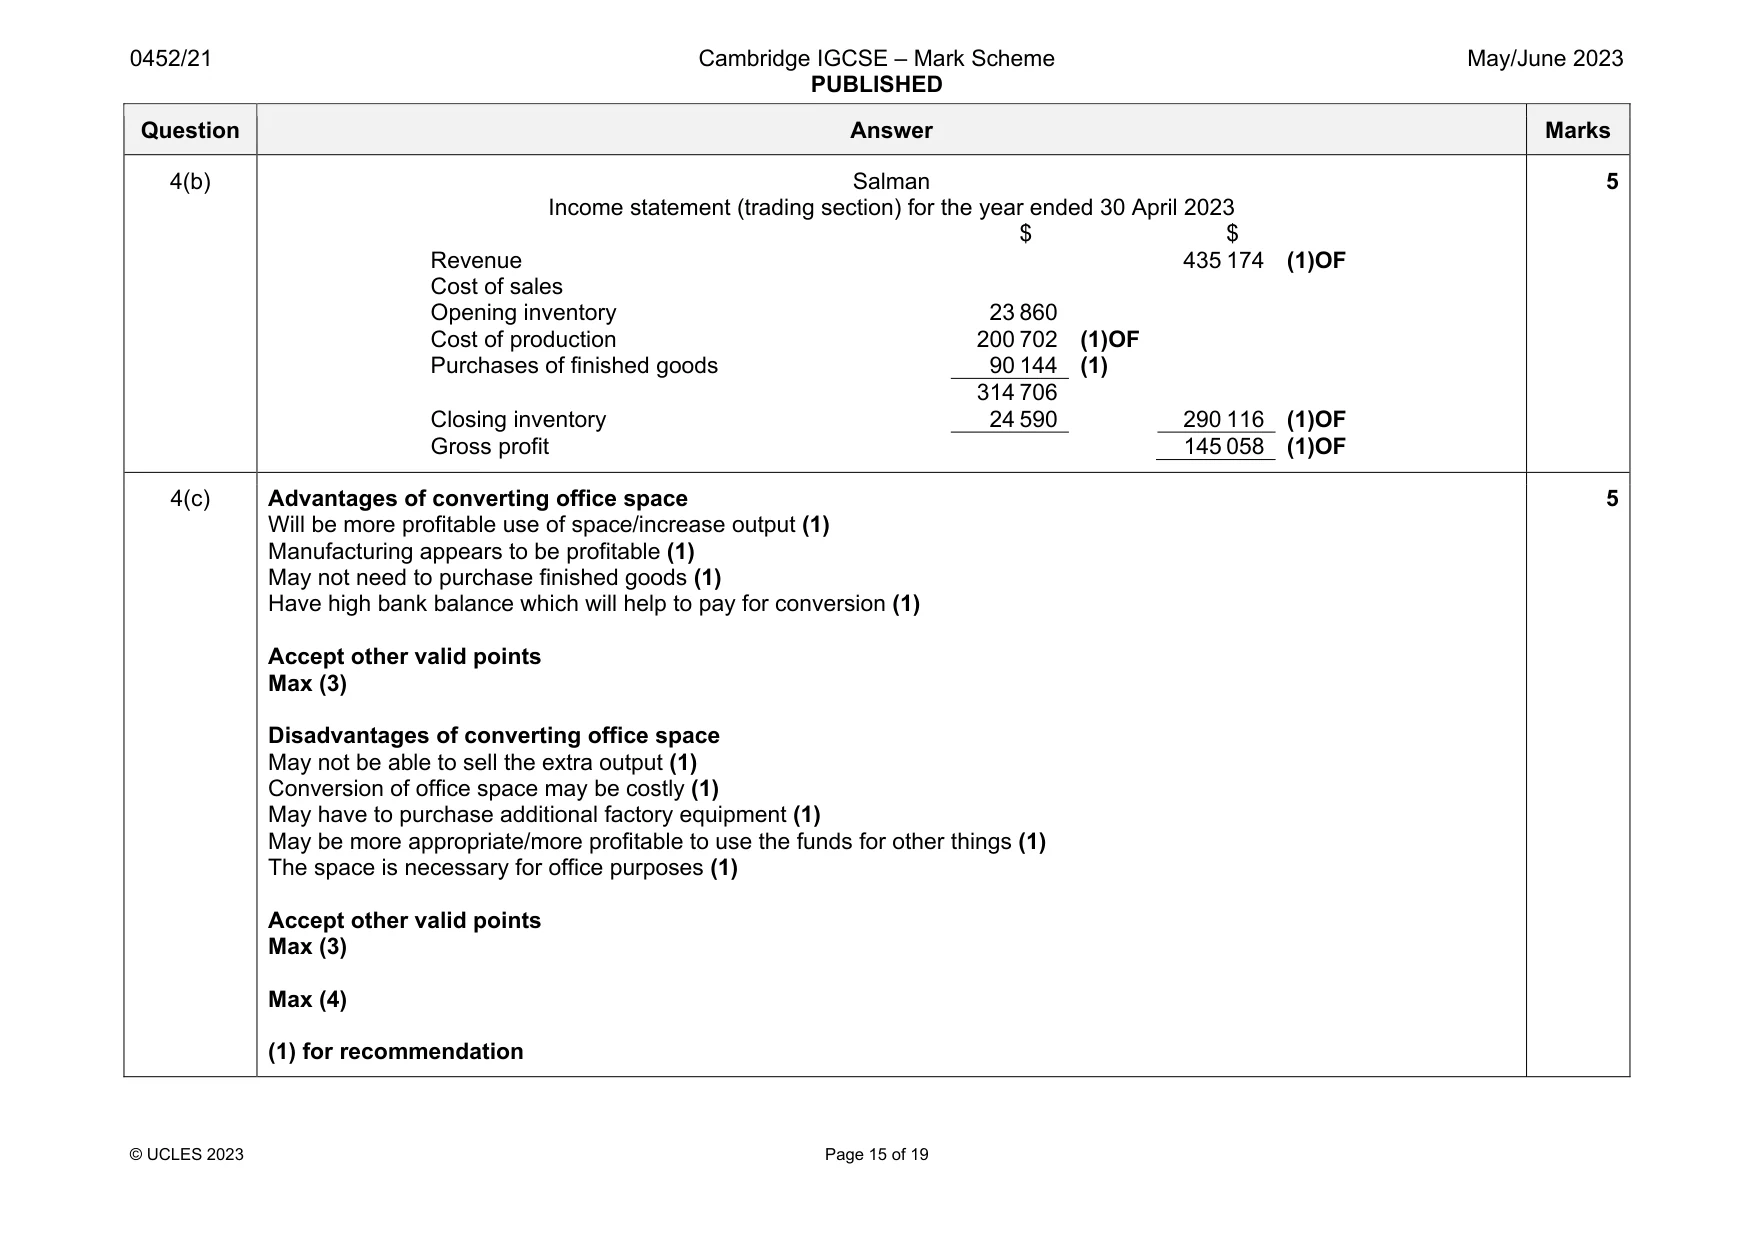
Mark scheme: 4(a) Salman Manufacturing Account for the year ended 30 April 2023 $ $ Cost of material consumed Opening inventory of raw material 8 190 Purchases of raw material 78 420 86 610 8 000 Less Closing inventory of raw material 78 610 (1) Direct wages 52 396 (1) Prime cost 131 006 (1)OF Factory overheads Wages of factory supervisor 27 500 (1) Rates and insurance (17 528 3/4) 13 146 (1) Factory electricity (11 442 + 1 048) 12 490 (1) General expenses 8 244 Depreciation of factory equipment (90 000 – 43 920) 20% 9 216 (1) 70 596 201 602 (1)OF Add opening work-in-progress 15 200 * 216 802 Less closing work-in-progress 16 100 * Cost of production 200 702 (1)OF * (1) for both opening and closing work-in-progress 10 Question Answer Marks 4(b) Salman Income statement (trading section) for the year ended 30 April 2023 $ $ Revenue 435 174 (1)OF Cost of sales Opening inventory 23 860 Cost of production 200 702 (1)OF Purchases of finished goods 90 144 (1) 314 706 Closing inventory 24 590 290 116 (1)OF Gross profit 145 058 (1)OF 5 4(c) Advantages of converting office space Will be more profitable use of space/increase output (1) Manufacturing appears to be profitable (1) May not need to purchase finished goods (1) Have high bank balance which will help to pay for conversion (1) Accept other valid points Max (3) Disadvantages of converting office space May not be able to sell the extra output (1) Conversion of office space may be costly (1) May have to purchase additional factory equipment (1) May be more appropriate/more profitable to use the funds for other things (1) The space is necessary for office purposes (1) Accept other valid points Max (3) Max (4) (1) for recommendation 5
Q5 · Q Limited prepares its financial statements to 31 March each year
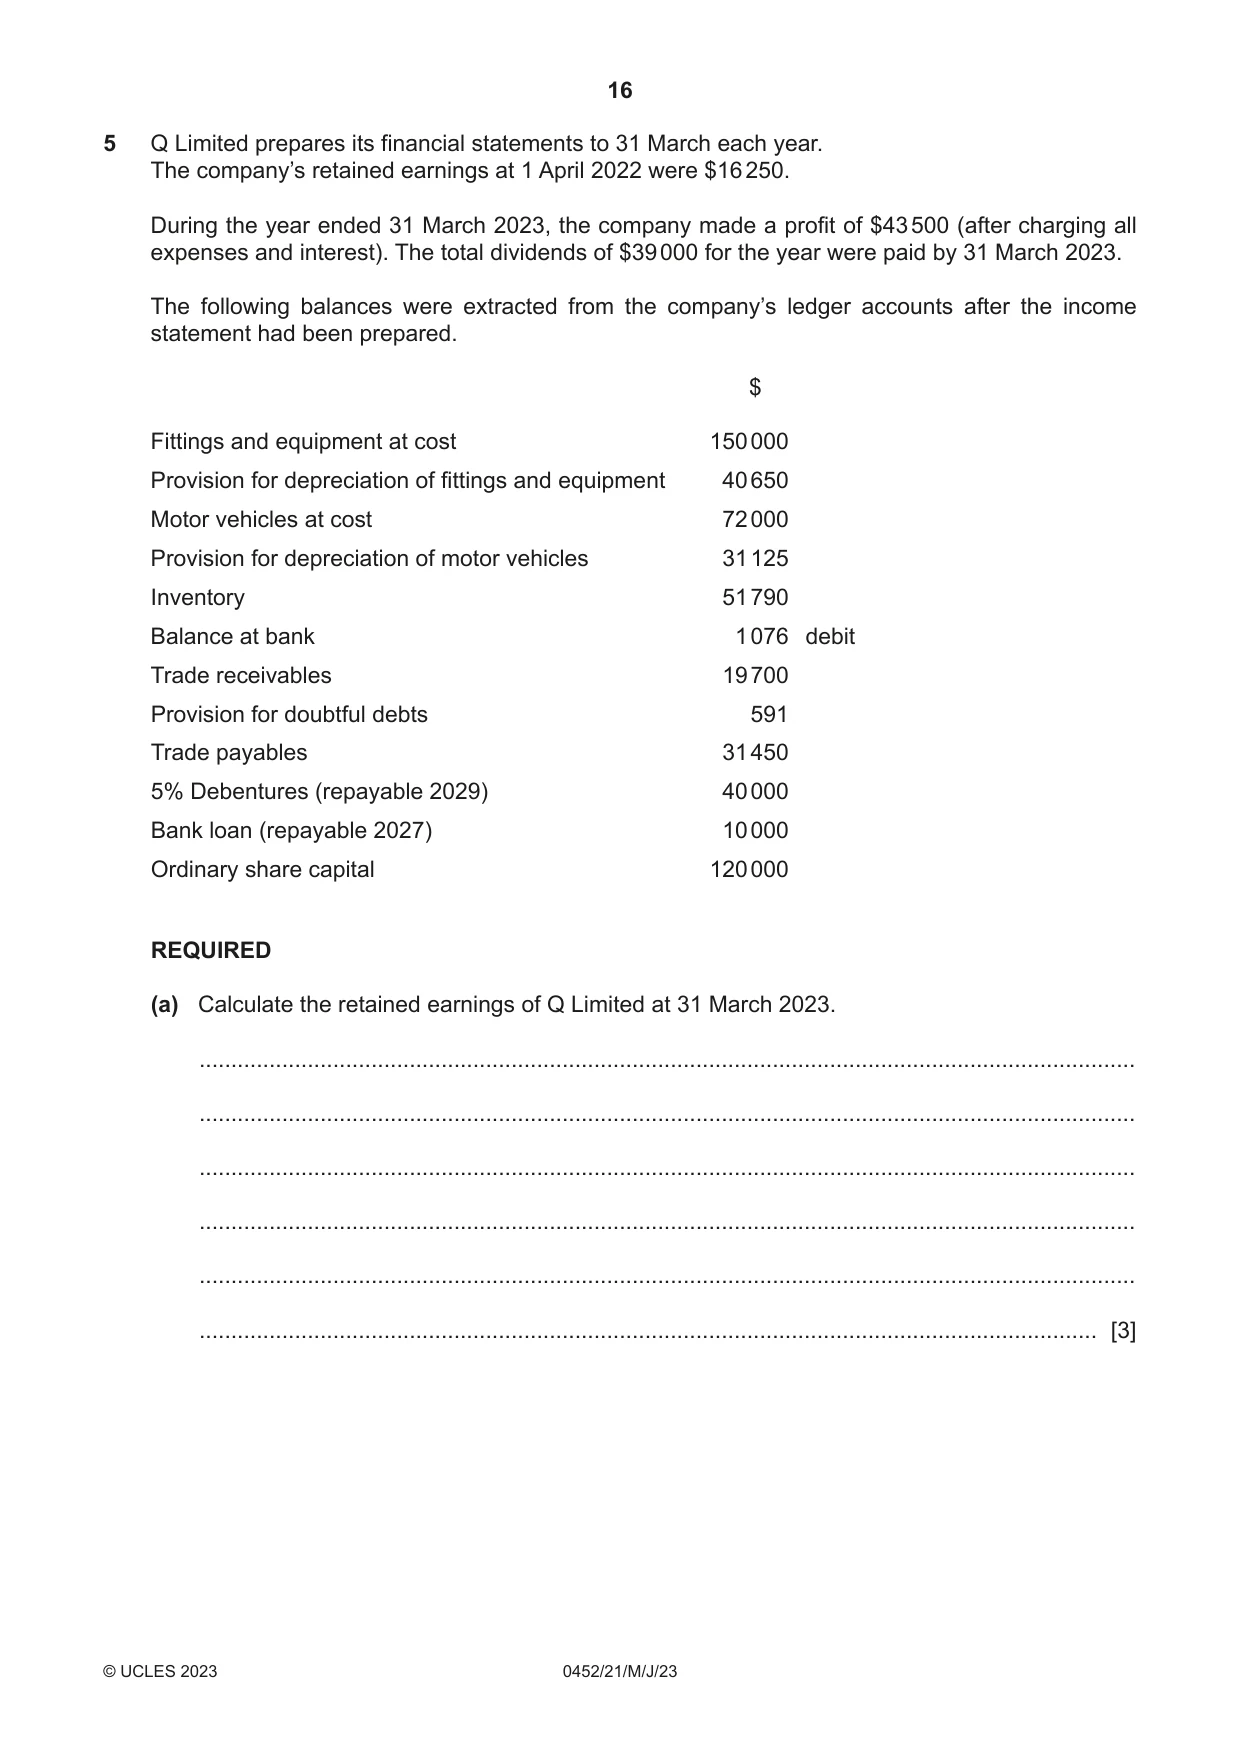
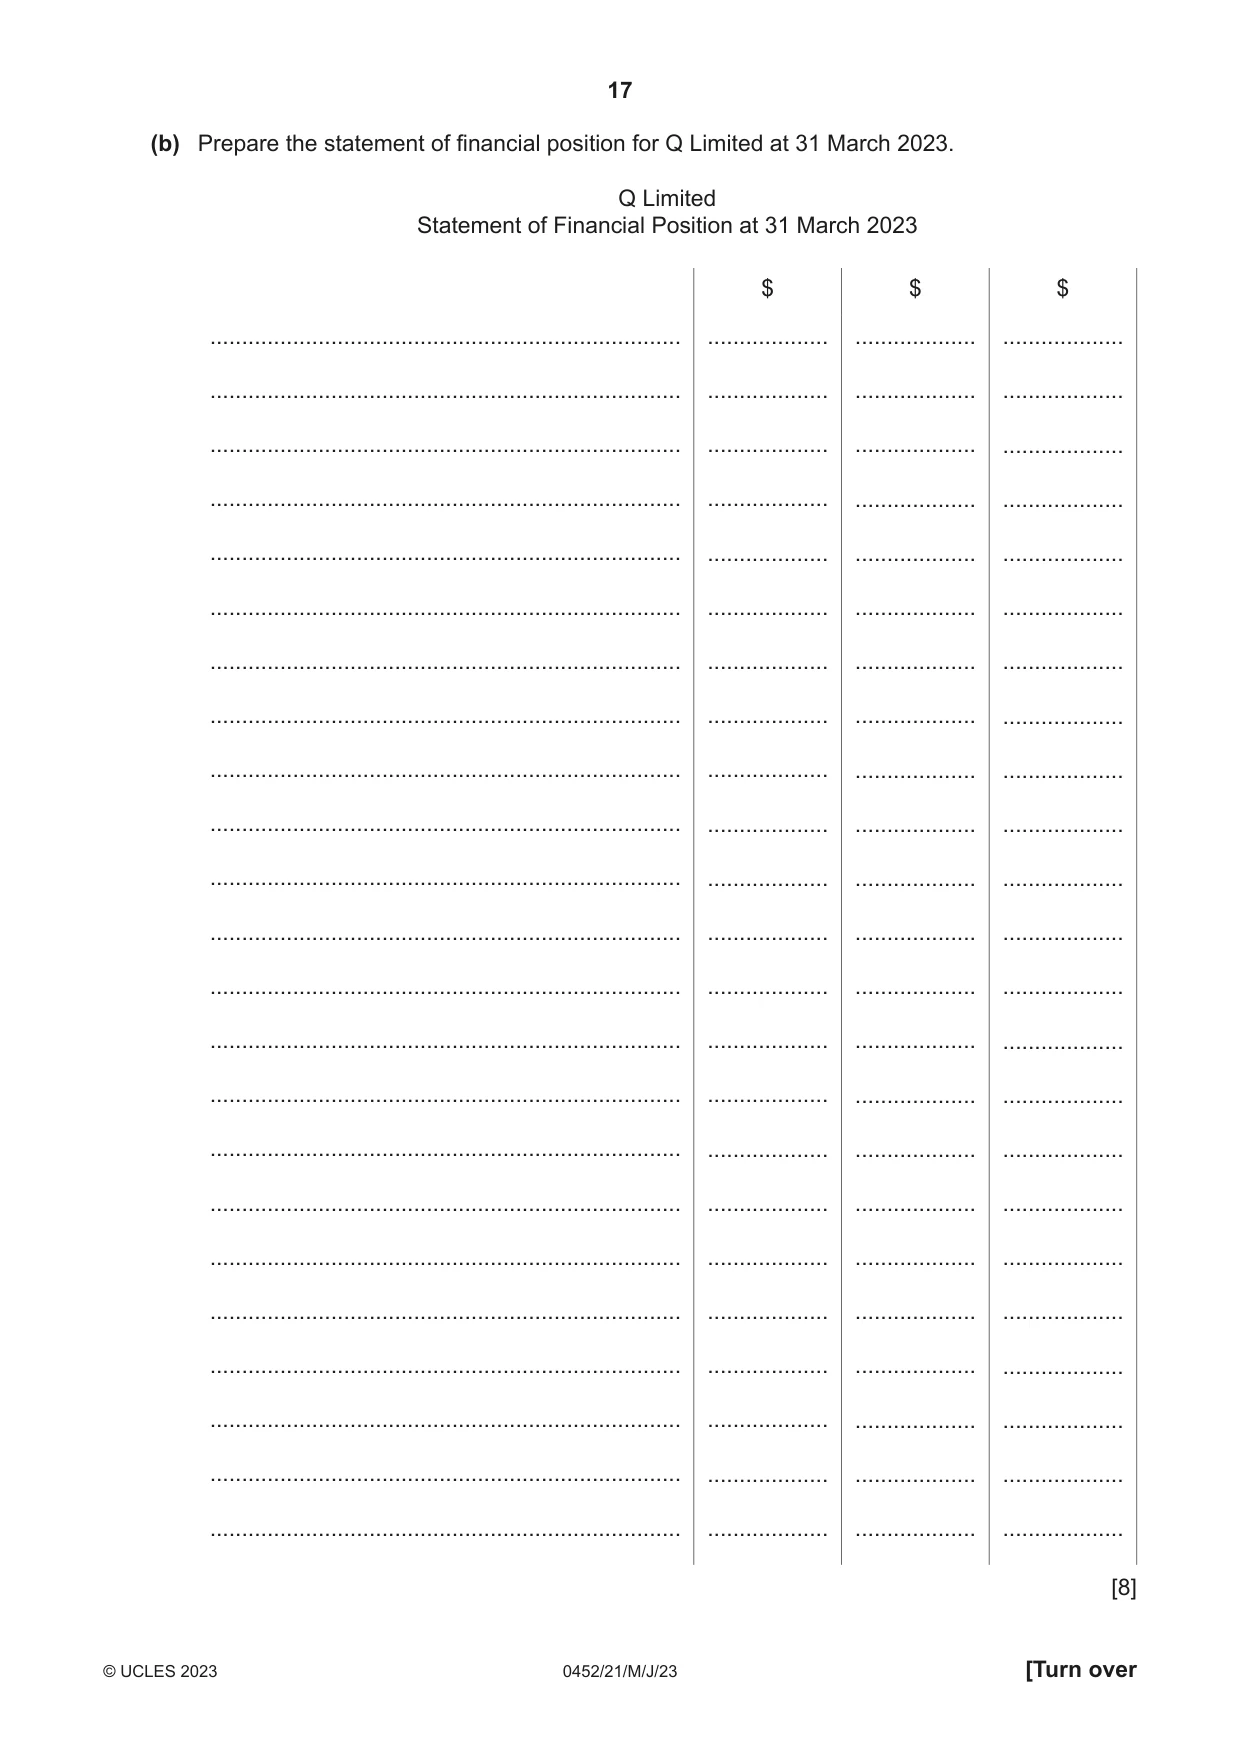
5 Q Limited prepares its financial statements to 31 March each year. The company’s retained earnings at 1 April 2022 were $16 250. During the year ended 31 March 2023, the company made a profit of $43 500 (after charging all expenses and interest). The total dividends of $39 000 for the year were paid by 31 March 2023. The following balances were extracted from the company’s ledger accounts after the income statement had been prepared. $ Fittings and equipment at cost 150 000 Provision for depreciation of fittings and equipment 40 650 Motor vehicles at cost 72 000 Provision for depreciation of motor vehicles 31 125 Inventory 51 790 Balance at bank 1 076 debit Trade receivables 19 700 Provision for doubtful debts 591 Trade payables 31 450 5% Debentures (repayable 2029) 40 000 Bank loan (repayable 2027) 10 000 Ordinary share capital 120 000 REQUIRED (a) Calculate the retained earnings of Q Limited at 31 March 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Prepare the statement of financial position for Q Q Limi Statement of Financial Pos .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... (c) Calculate the liquid (acid test) ratio to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] The directors (who are also the shareholders) would like to expand the company and wish to borrow $50 000 to fund the expansion. They are considering whether to issue further ordinary shares or to request another long-term bank loan. REQUIRED (d) (i) Suggest two reasons why although the company has made a profit, there is little cash available in the bank account to fund the expansion. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (ii) Advise the directors whether they should fund the expansion by issuing ordinary shares or requesting a bank loan. Justify your answer. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [5] [Total: 20]
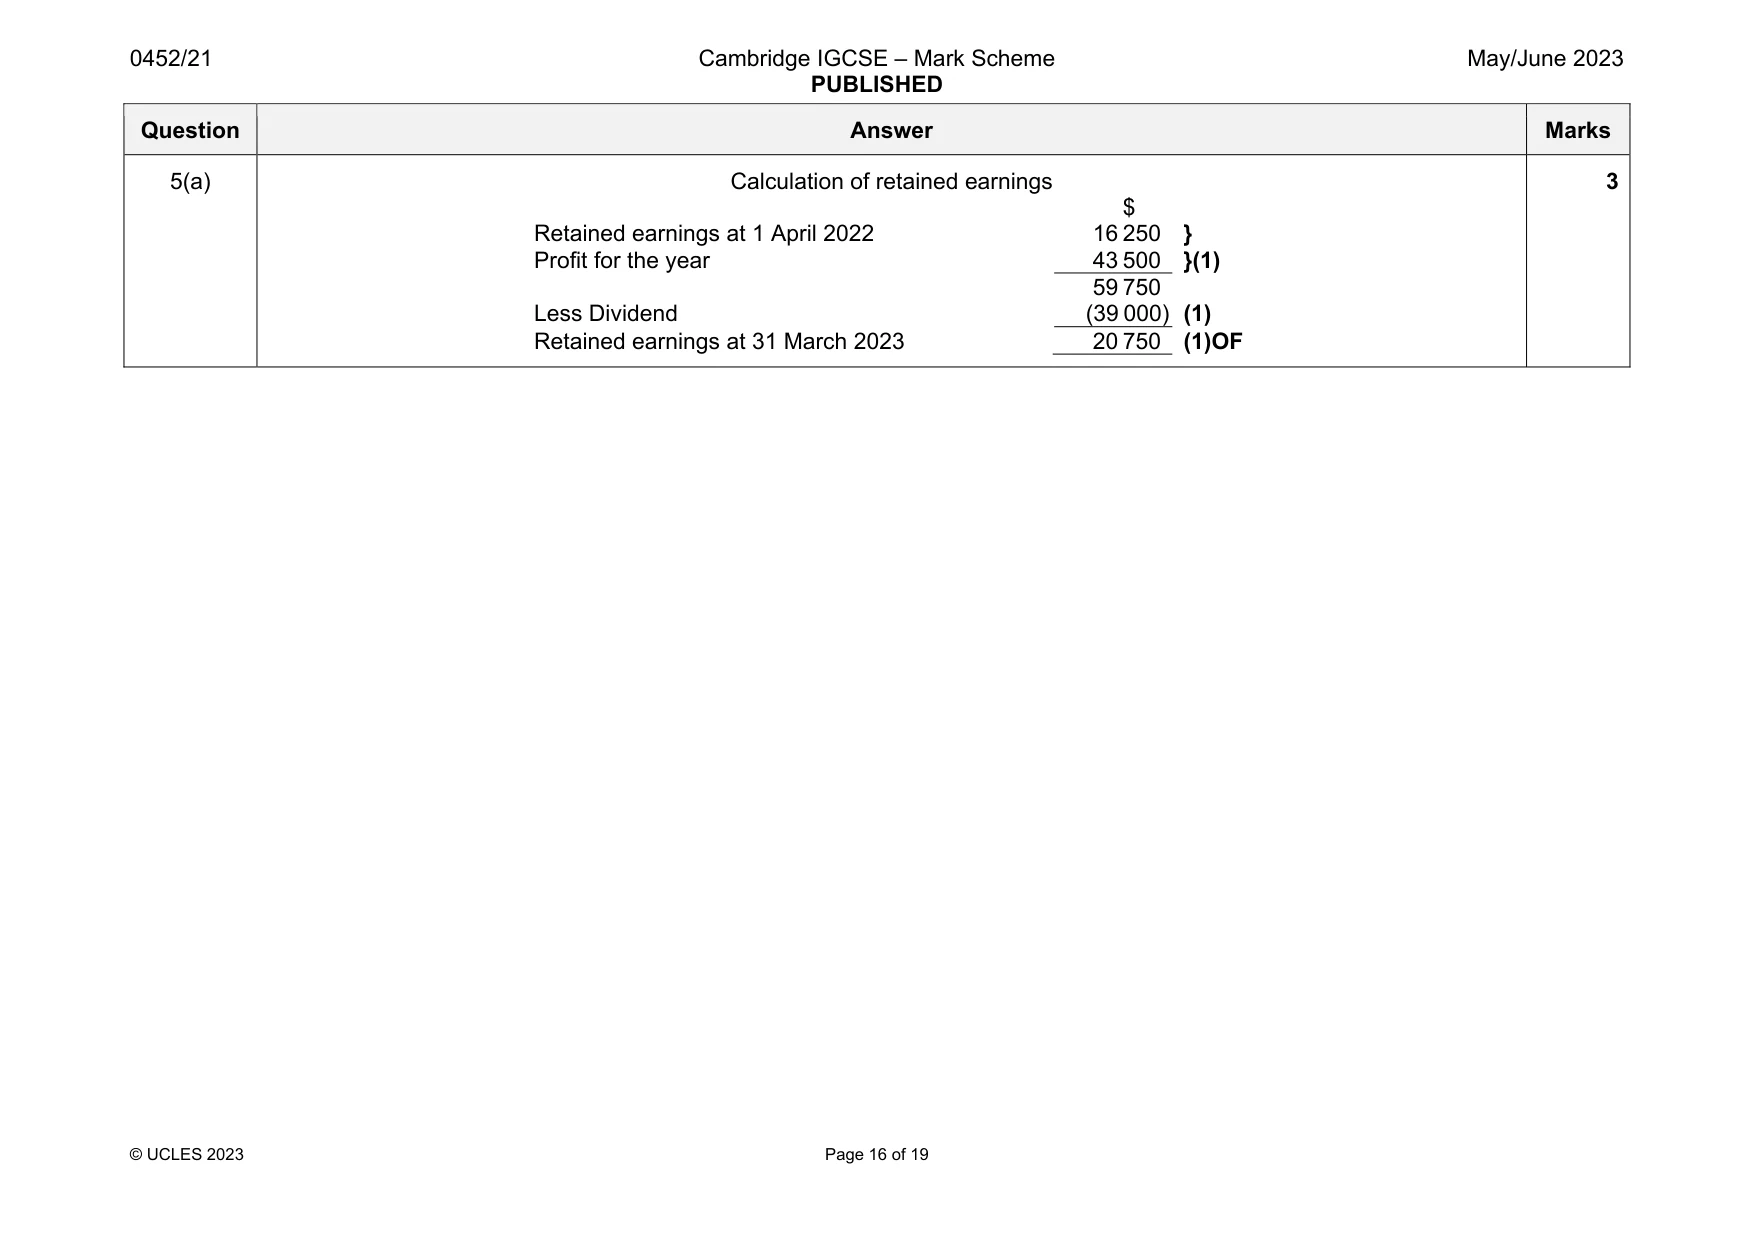
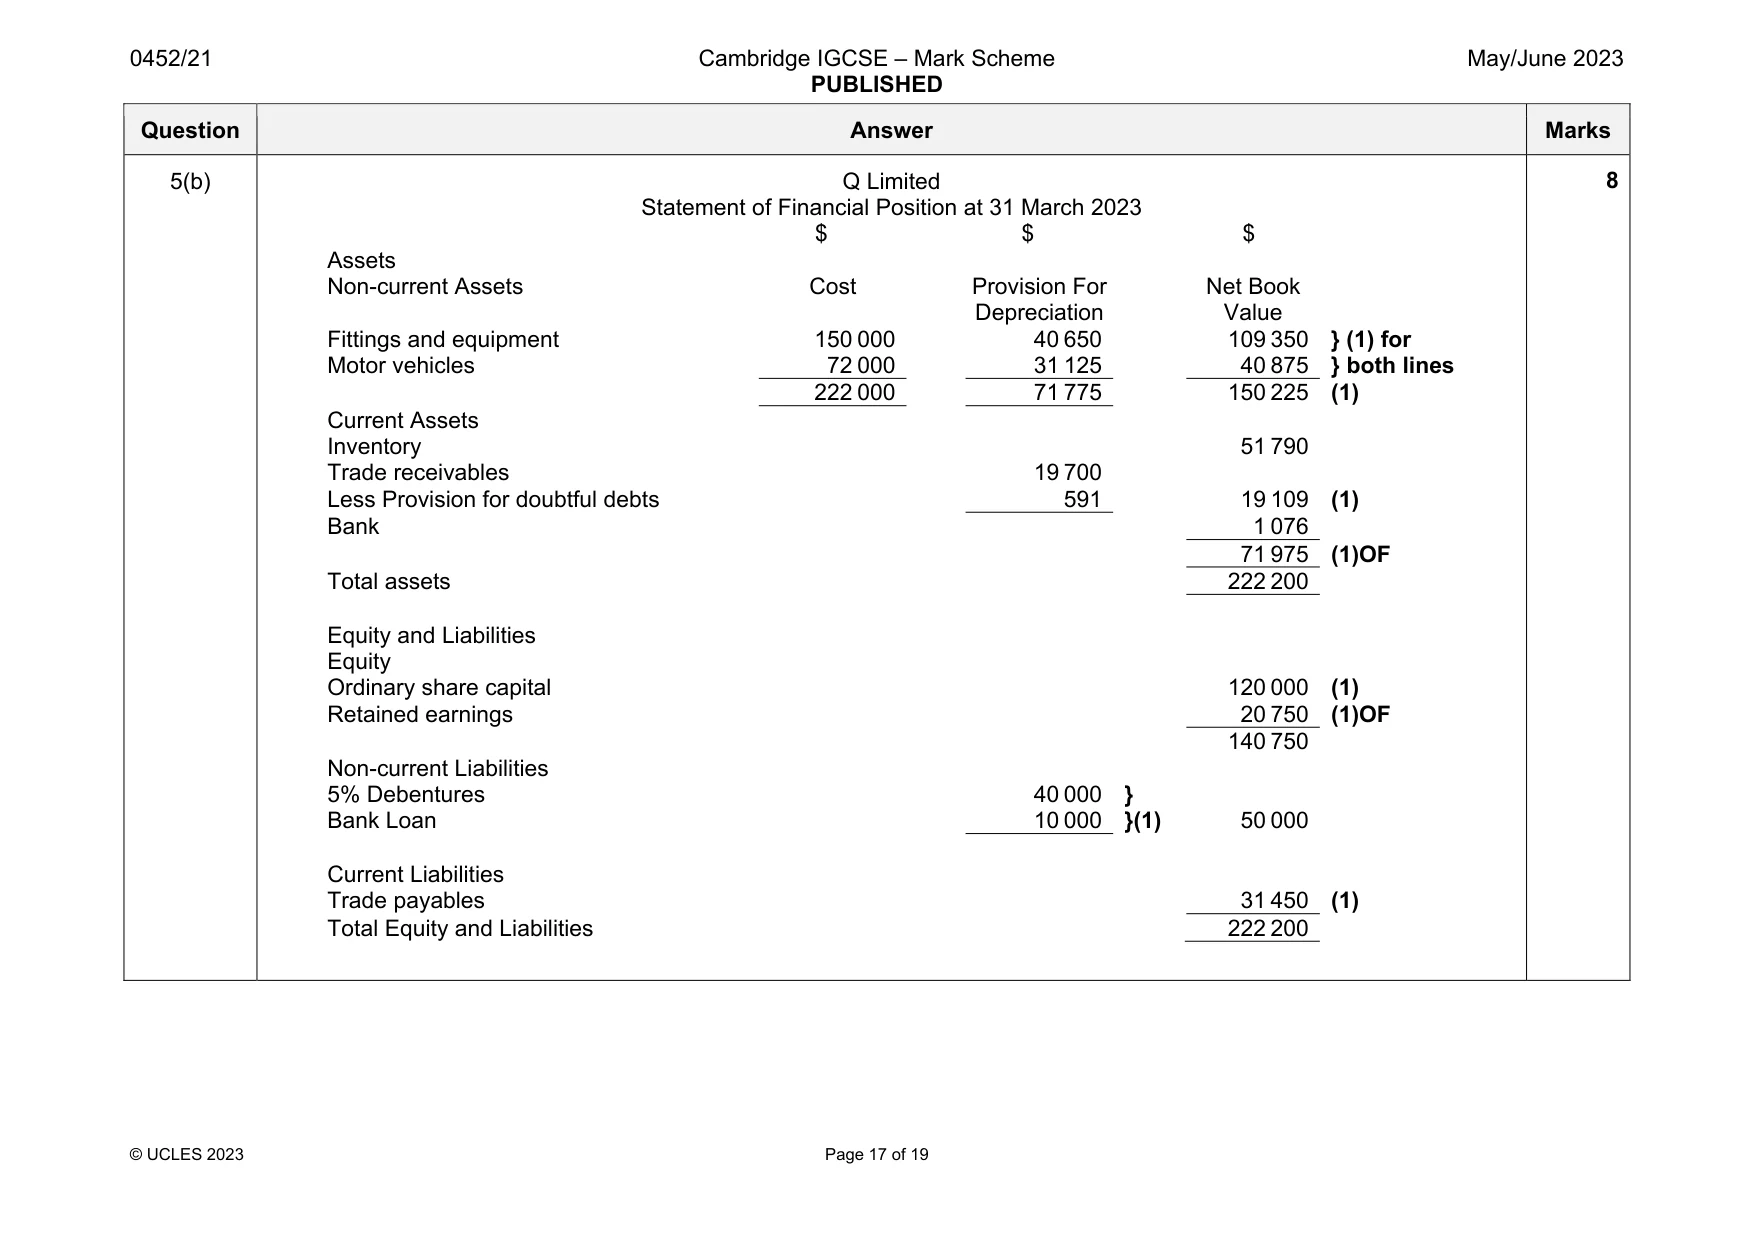
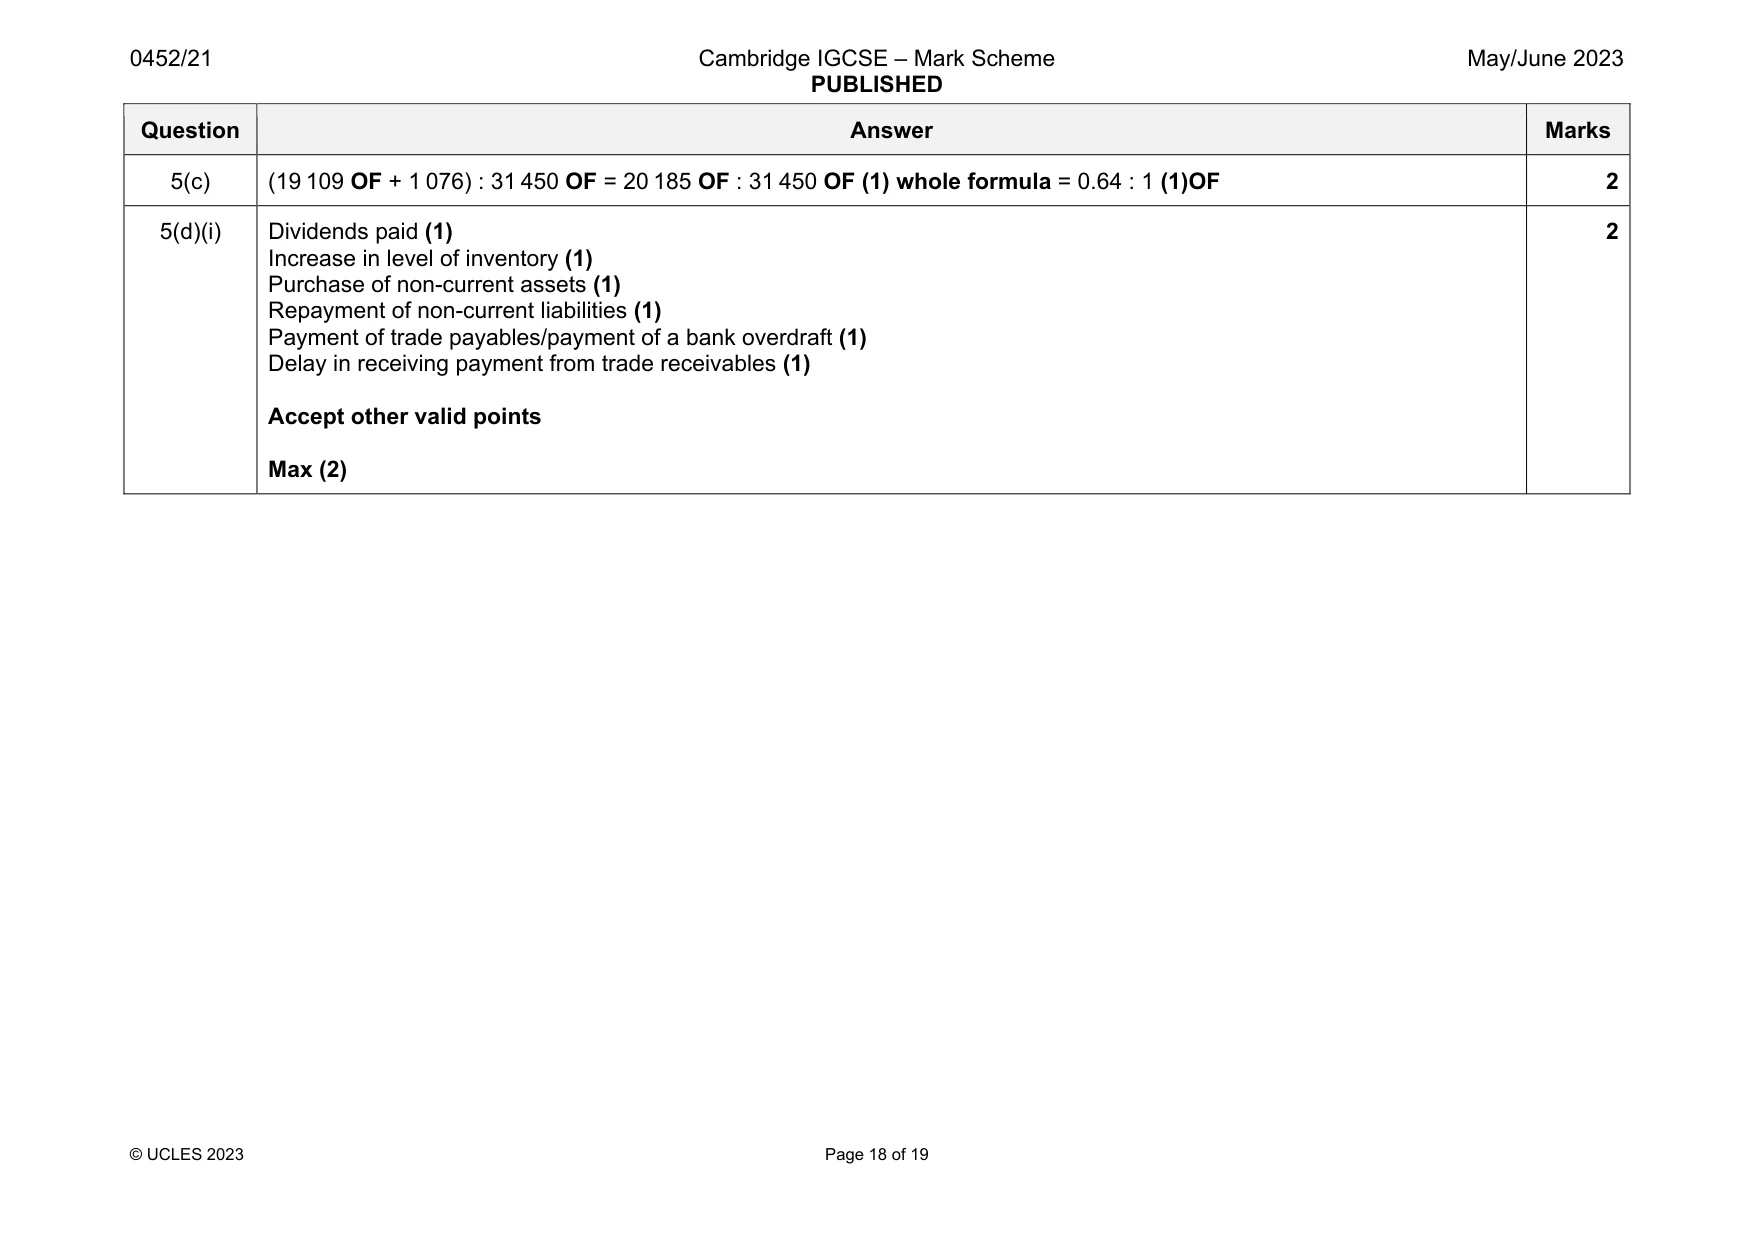
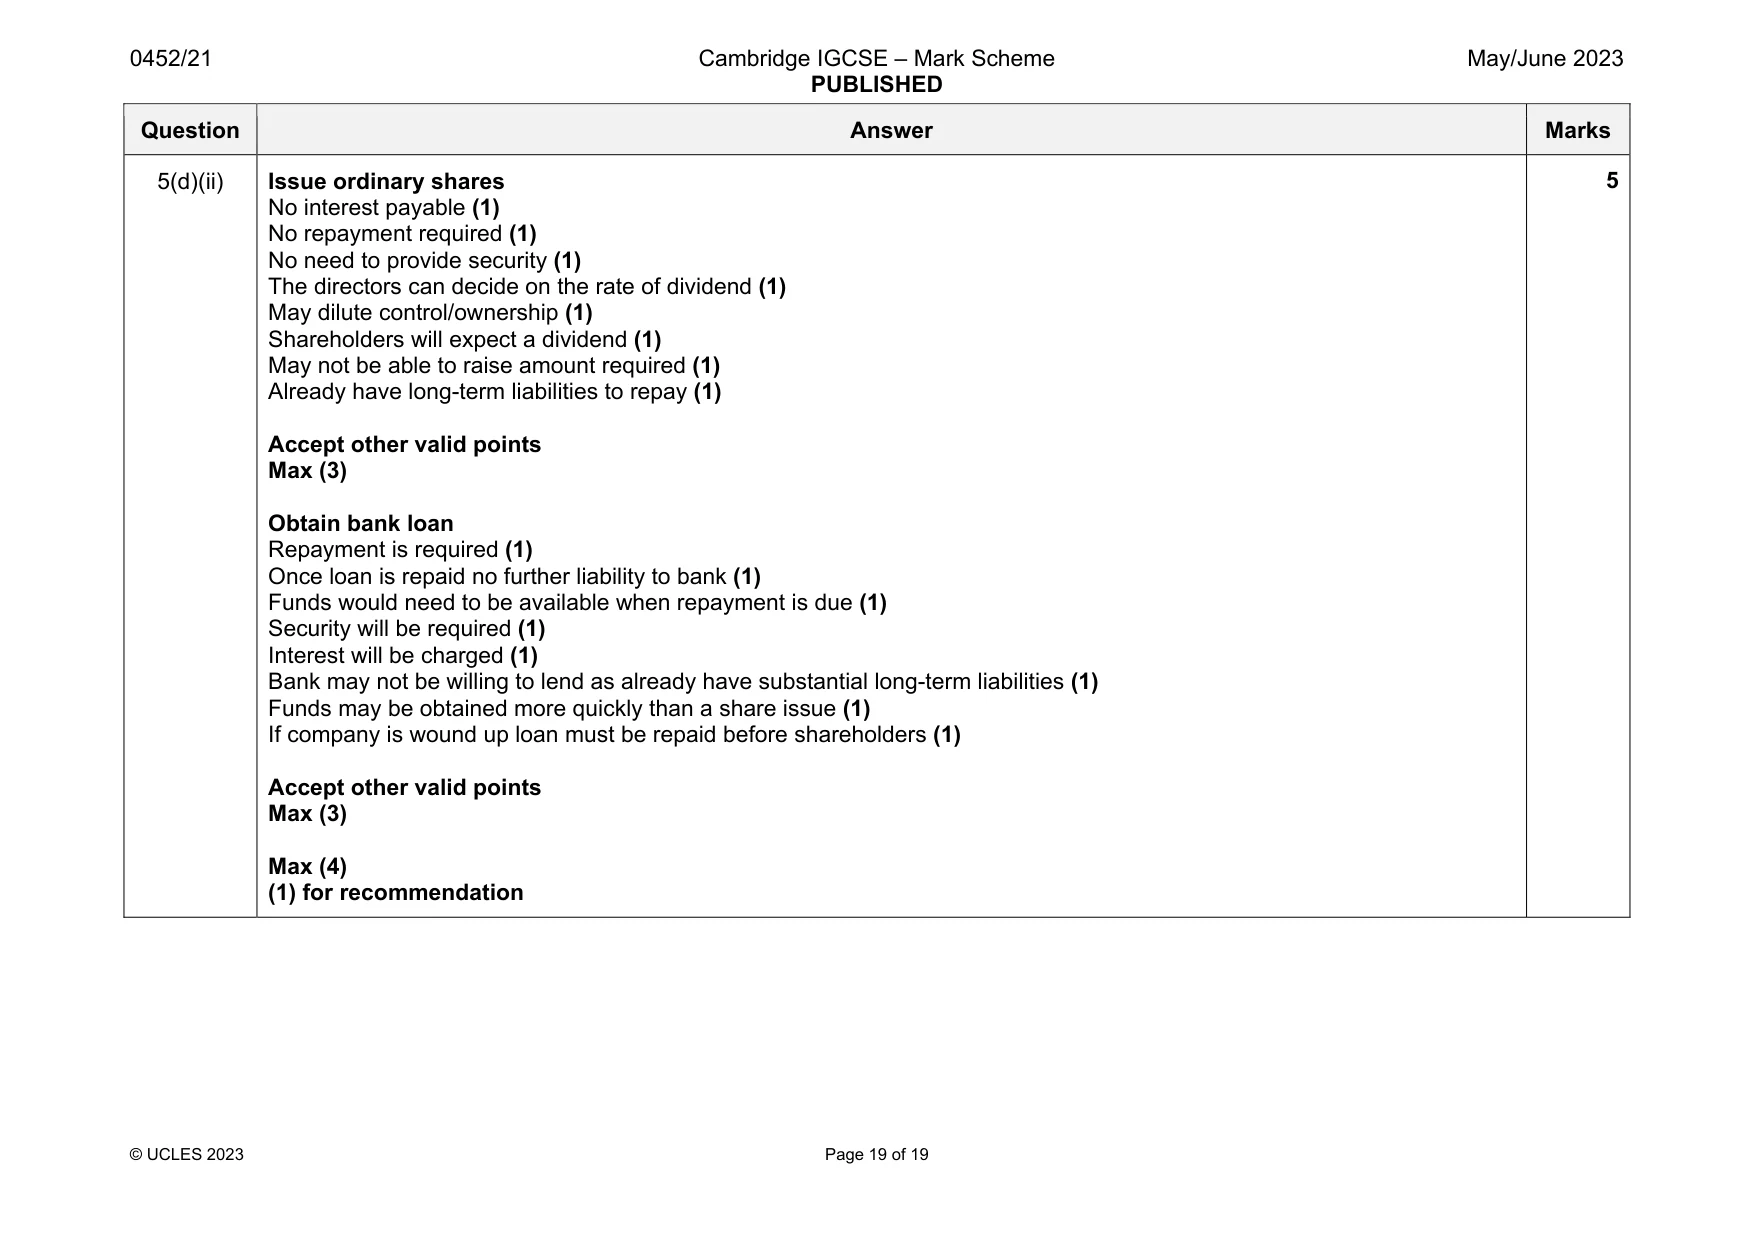
Mark scheme: 5(a) Calculation of retained earnings $ Retained earnings at 1 April 2022 16 250 } Profit for the year 43 500 }(1) 59 750 Less Dividend (39 000) (1) Retained earnings at 31 March 2023 20 750 (1)OF 3 Question Answer Marks 5(b) Q Limited Statement of Financial Position at 31 March 2023 $ $ $ Assets Non-current Assets Cost Provision For Depreciation Net Book Value Fittings and equipment 150 000 40 650 109 350 } (1) for Motor vehicles 72 000 31 125 40 875 } both lines 222 000 71 775 150 225 (1) Current Assets Inventory 51 790 Trade receivables 19 700 Less Provision for doubtful debts 591 19 109 (1) Bank 1 076 71 975 (1)OF Total assets 222 200 Equity and Liabilities Equity Ordinary share capital 120 000 (1) Retained earnings 20 750 (1)OF 140 750 Non-current Liabilities 5% Debentures 40 000 } Bank Loan 10 000 }(1) 50 000 Current Liabilities Trade payables 31 450 (1) Total Equity and Liabilities 222 200 8 Question Answer Marks 5(c) (19 109 OF + 1 076) : 31 450 OF = 20 185 OF : 31 450 OF (1) whole formula = 0.64 : 1 (1)OF 2 5(d)(i) Dividends paid (1) Increase in level of inventory (1) Purchase of non-current assets (1) Repayment of non-current liabilities (1) Payment of trade payables/payment of a bank overdraft (1) Delay in receiving payment from trade receivables (1) Accept other valid points Max (2) 2 Question Answer Marks 5(d)(ii) Issue ordinary shares No interest payable (1) No repayment required (1) No need to provide security (1) The directors can decide on the rate of dividend (1) May dilute control/ownership (1) Shareholders will expect a dividend (1) May not be able to raise amount required (1) Already have long-term liabilities to repay (1) Accept other valid points Max (3) Obtain bank loan Repayment is required (1) Once loan is repaid no further liability to bank (1) Funds would need to be available when repayment is due (1) Security will be required (1) Interest will be charged (1) Bank may not be willing to lend as already have substantial long-term liabilities (1) Funds may be obtained more quickly than a share issue (1) If company is wound up loan must be repaid before shareholders (1) Accept other valid points Max (3) Max (4) (1) for recommendation 5
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.