Cambridge IGCSE Accounting 0452 — 2024 May/June Paper 2 · Variant 1
0452/21/M/J/24 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Addo is a trader who only sells on credit
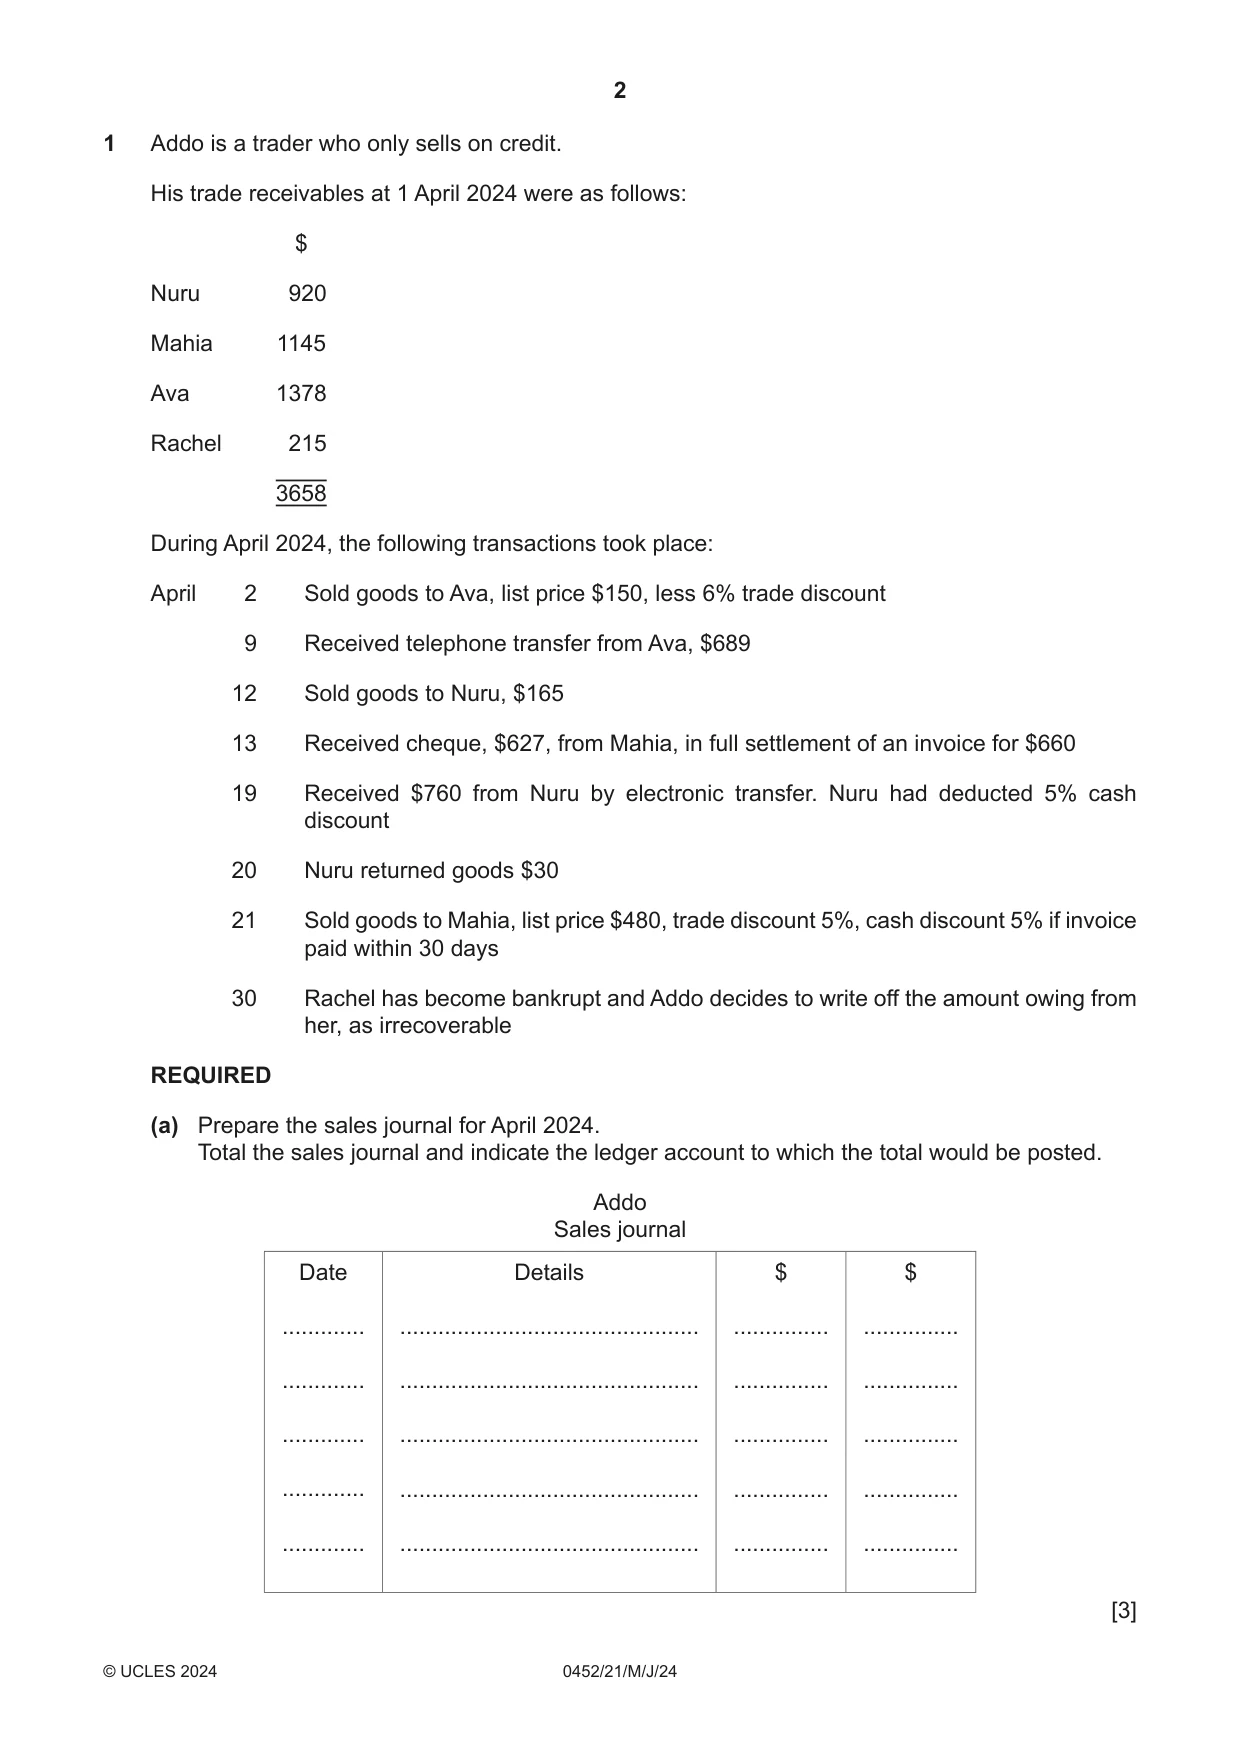
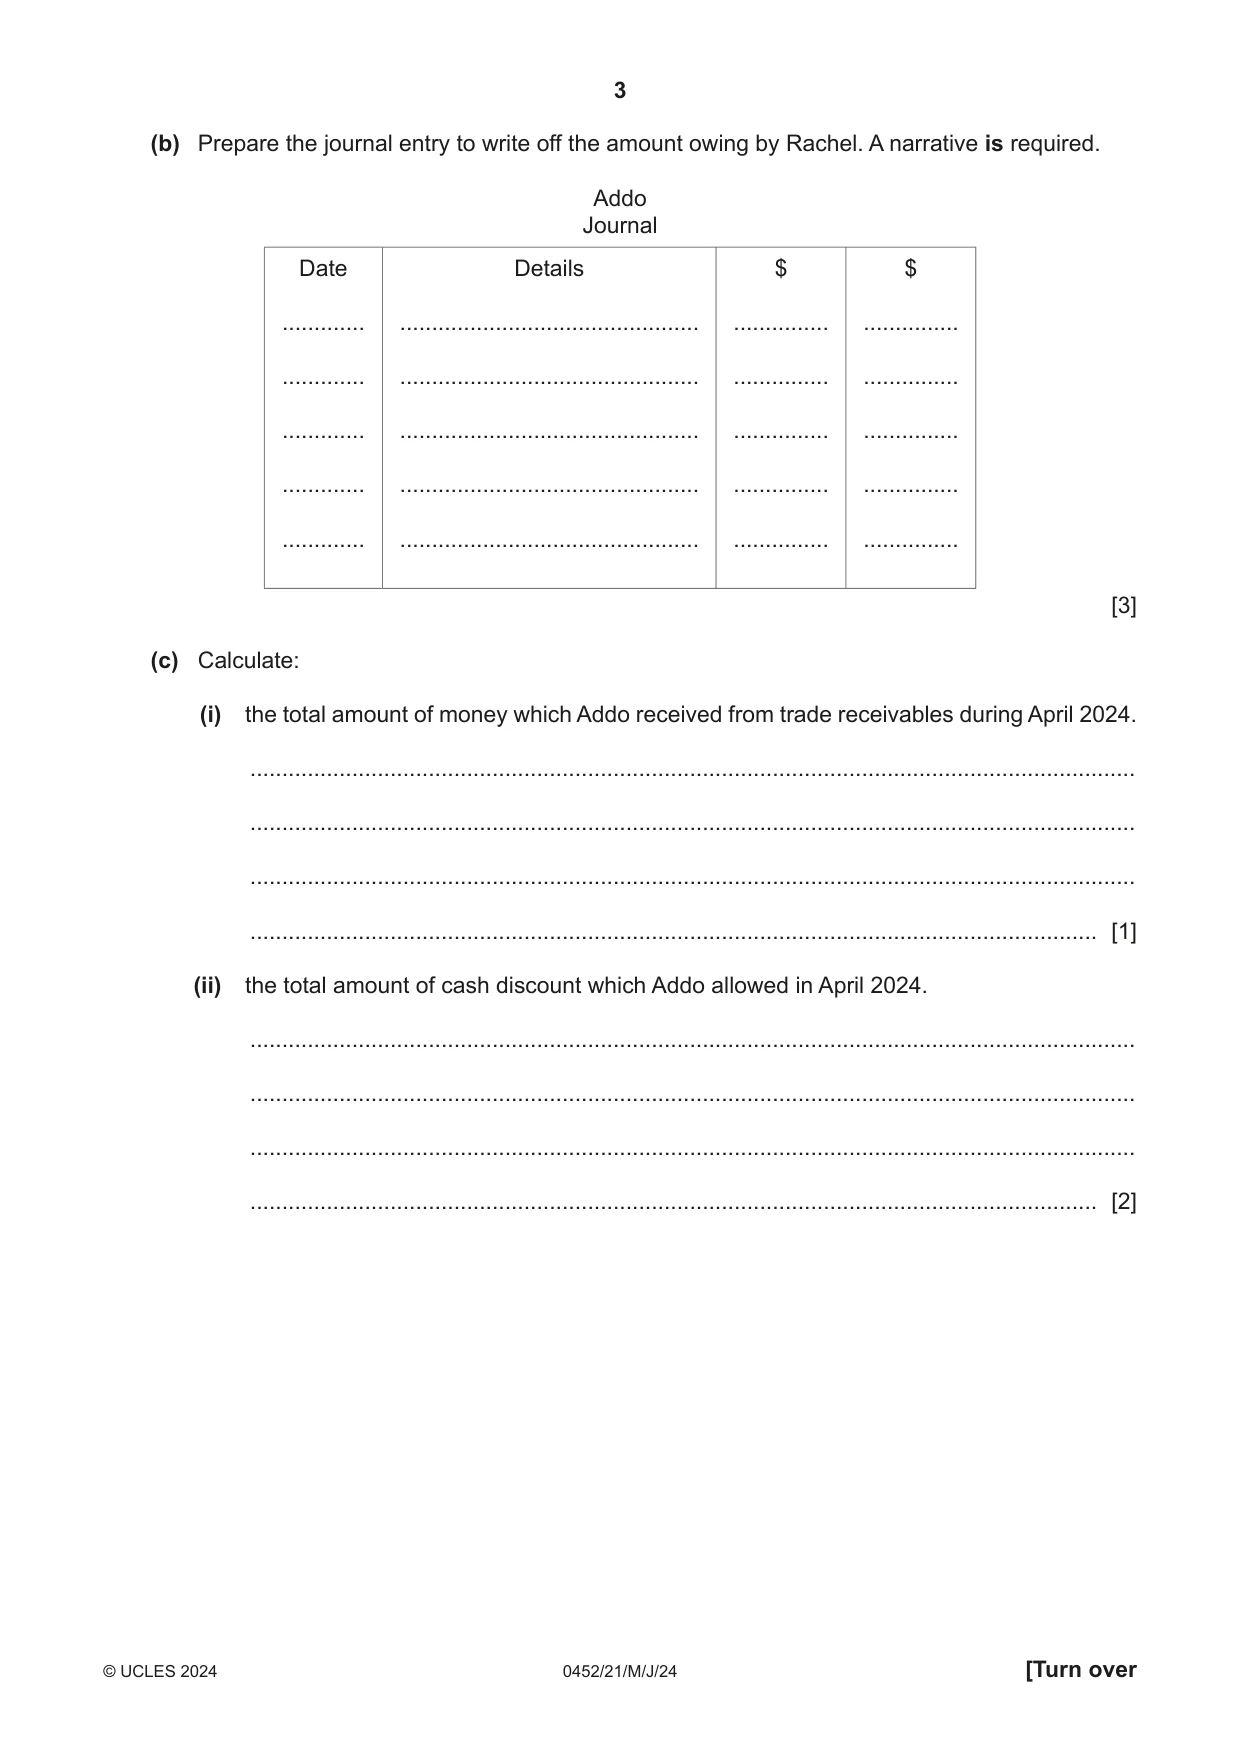
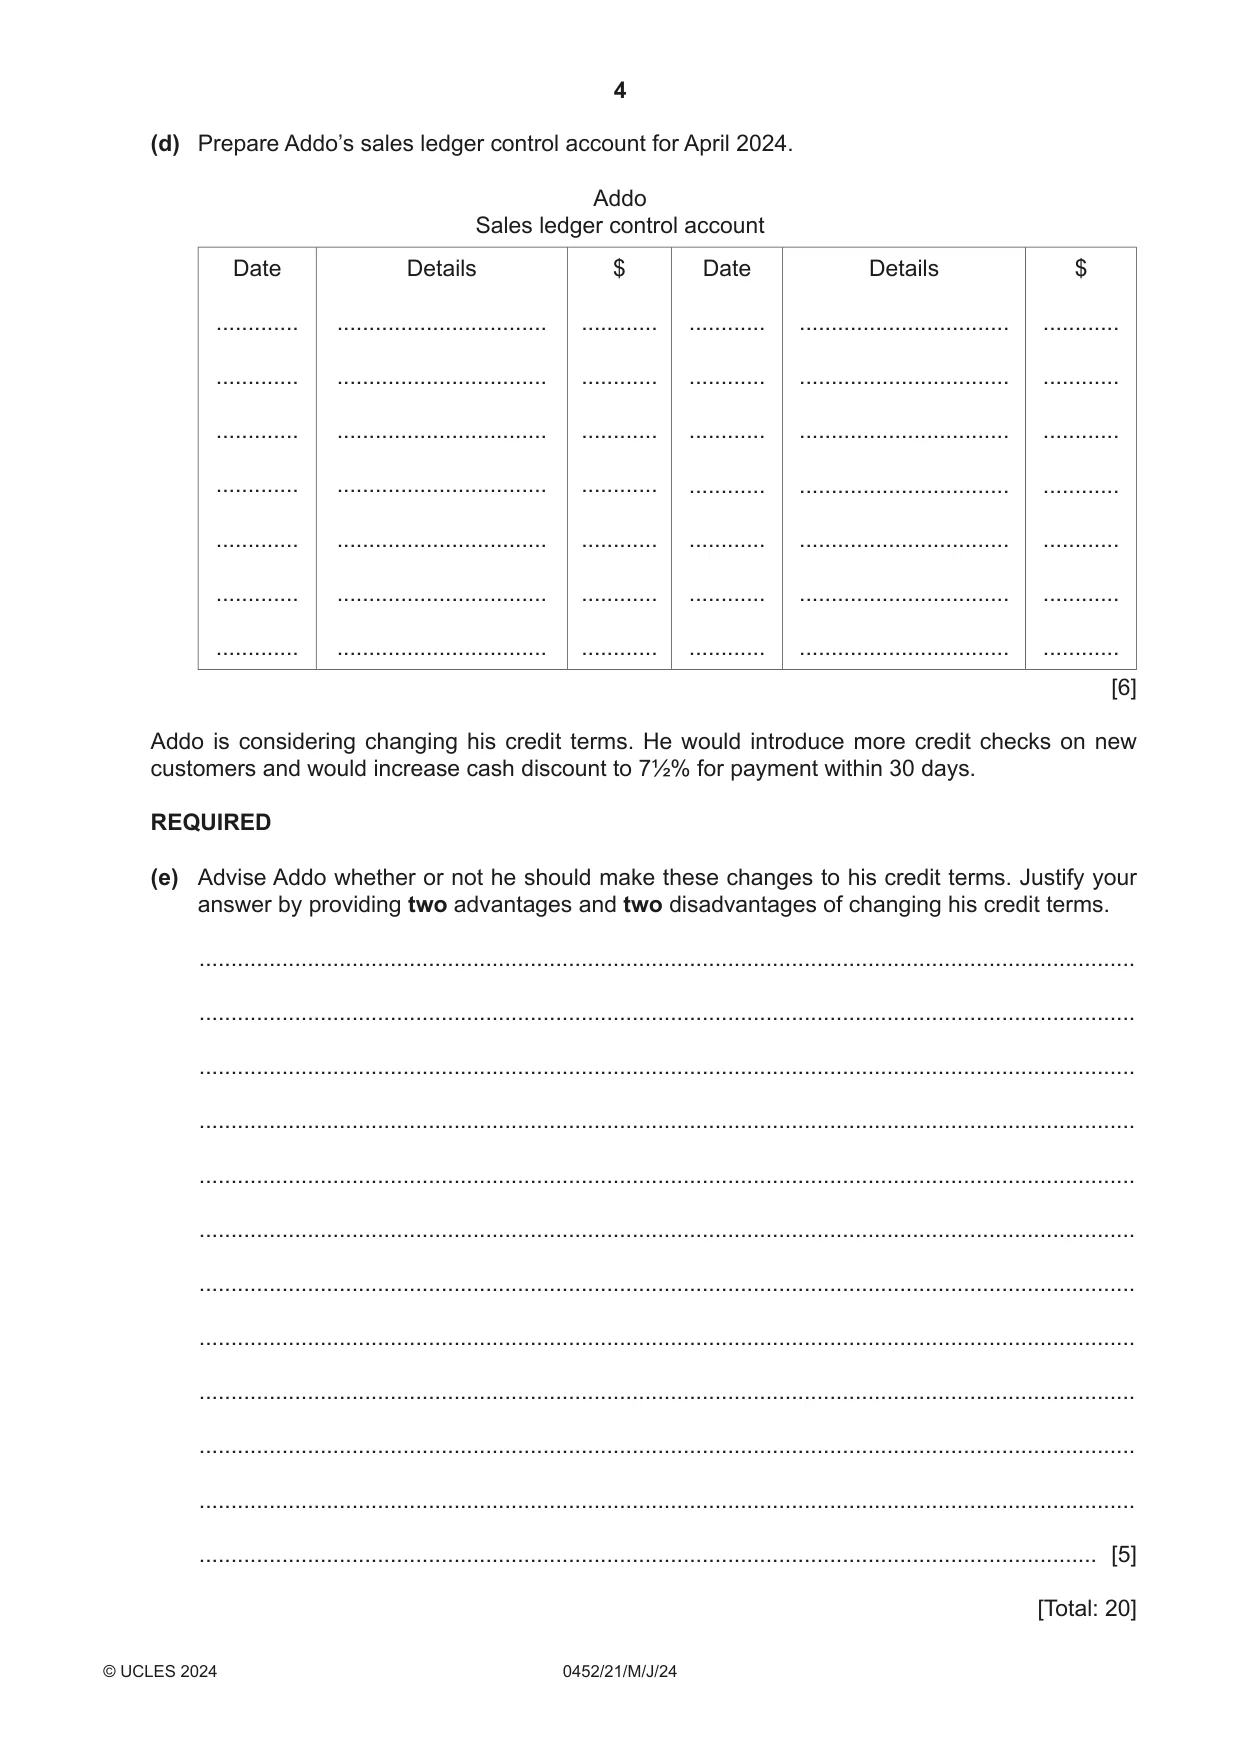
1 Addo is a trader who only sells on credit. His trade receivables at 1 April 2024 were as follows: $ Nuru 920 Mahia 1145 Ava 1378 Rachel 215 3658 During April 2024, the following transactions took place: April 2 Sold goods to Ava, list price $150, less 6% trade discount 9 Received telephone transfer from Ava, $689 12 Sold goods to Nuru, $165 13 Received cheque, $627, from Mahia, in full settlement of an invoice for $660 19 Received $760 from Nuru by electronic transfer. Nuru had deducted 5% cash discount 20 Nuru returned goods $30 21 Sold goods to Mahia, list price $480, trade discount 5%, cash discount 5% if invoice paid within 30 days 30 Rachel has become bankrupt and Addo decides to write off the amount owing from her, as irrecoverable REQUIRED (a) Prepare the sales journal for April 2024. Total the sales journal and indicate the ledger account to which the total would be posted. Addo Sales journal Date Details $ $ ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... [3] (b) Prepare the journal entry to write off the amount owing by Rachel. A narrative is required. Addo Journal Date Details $ $ ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... ............. ............................................... ............... ............... [3] (c) Calculate: (i) the total amount of money which Addo received from trade receivables during April 2024. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [1] (ii) the total amount of cash discount which Addo allowed in April 2024. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (d) Prepare Addo’s sales ledger control account for April 2024. Addo Sales ledger control account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [6] Addo is considering changing his credit terms. He would introduce more credit checks on new customers and would increase cash discount to 7½% for payment within 30 days. REQUIRED (e) Advise Addo whether or not he should make these changes to his credit terms. Justify your answer by providing two advantages and two disadvantages of changing his credit terms. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
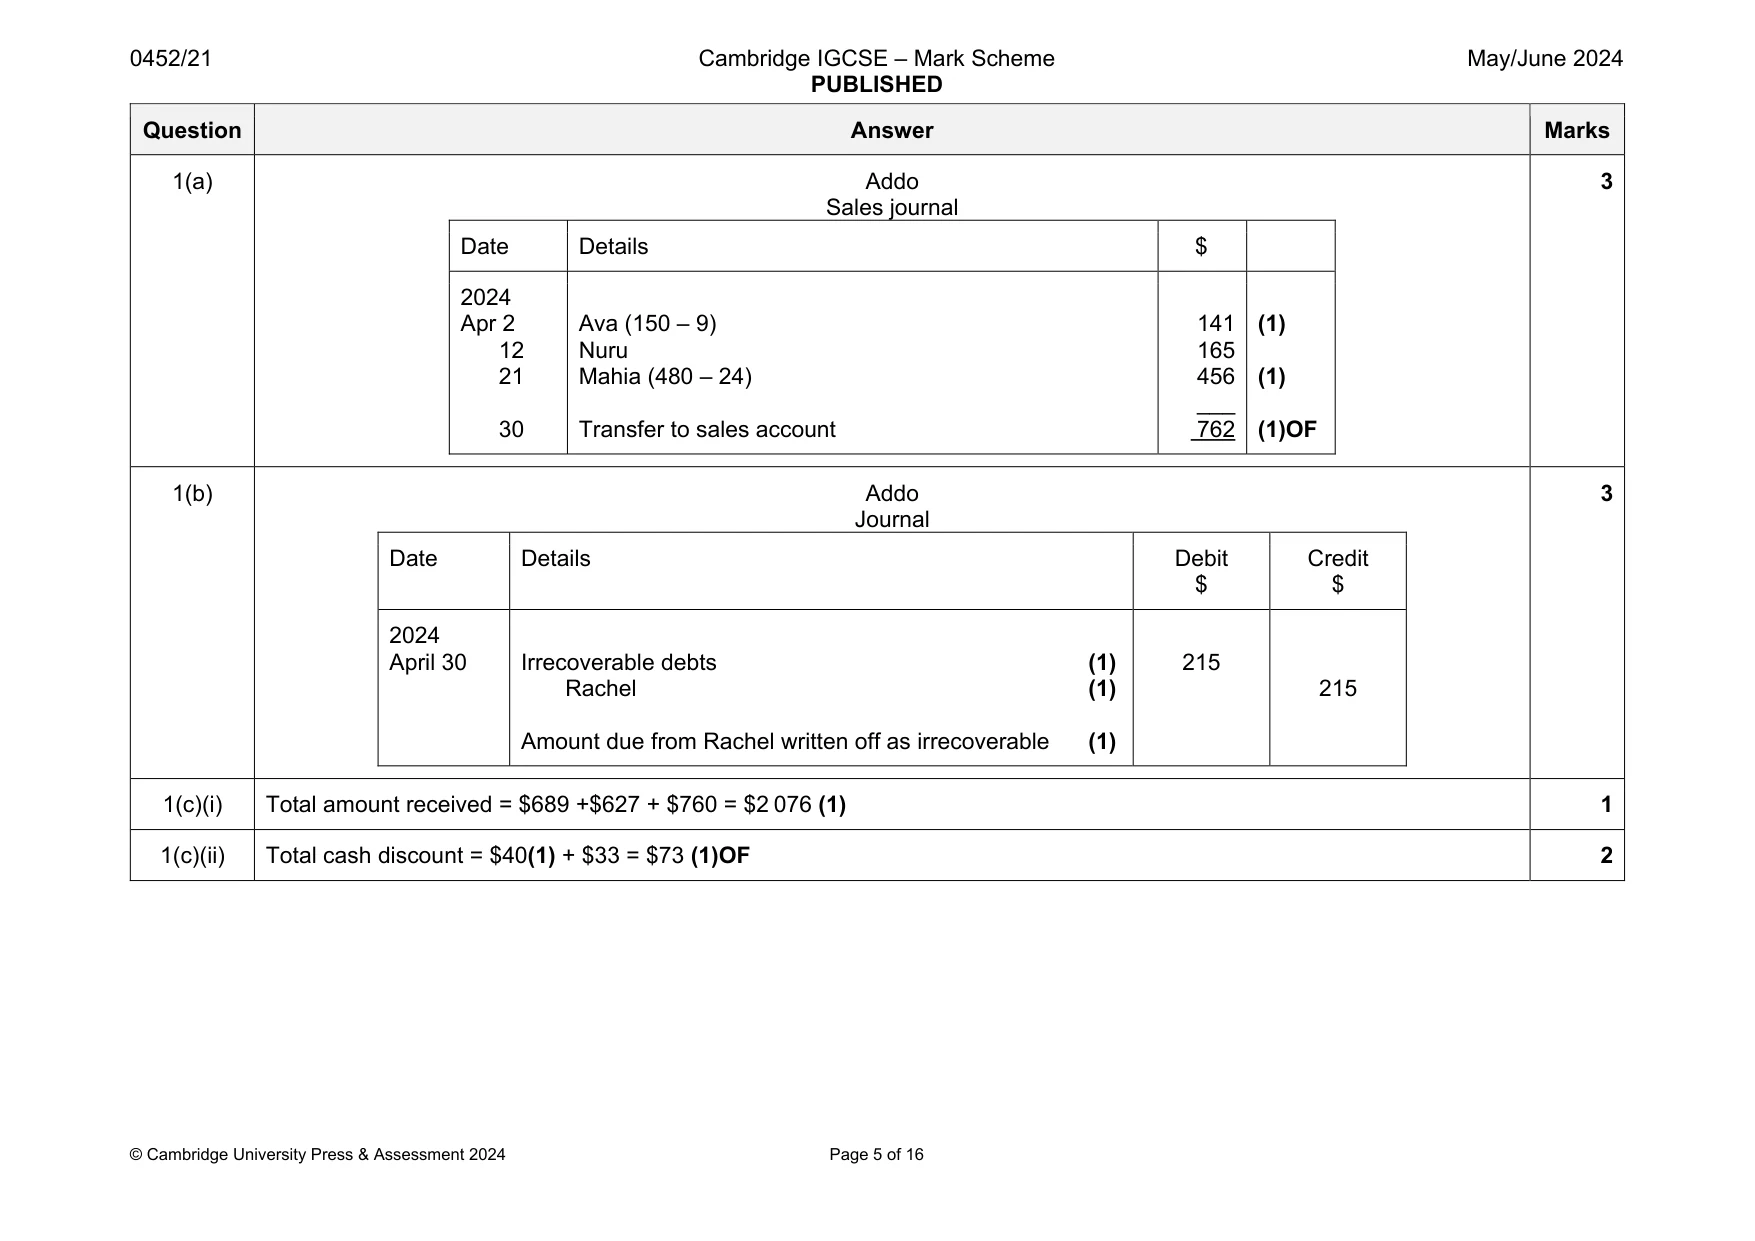
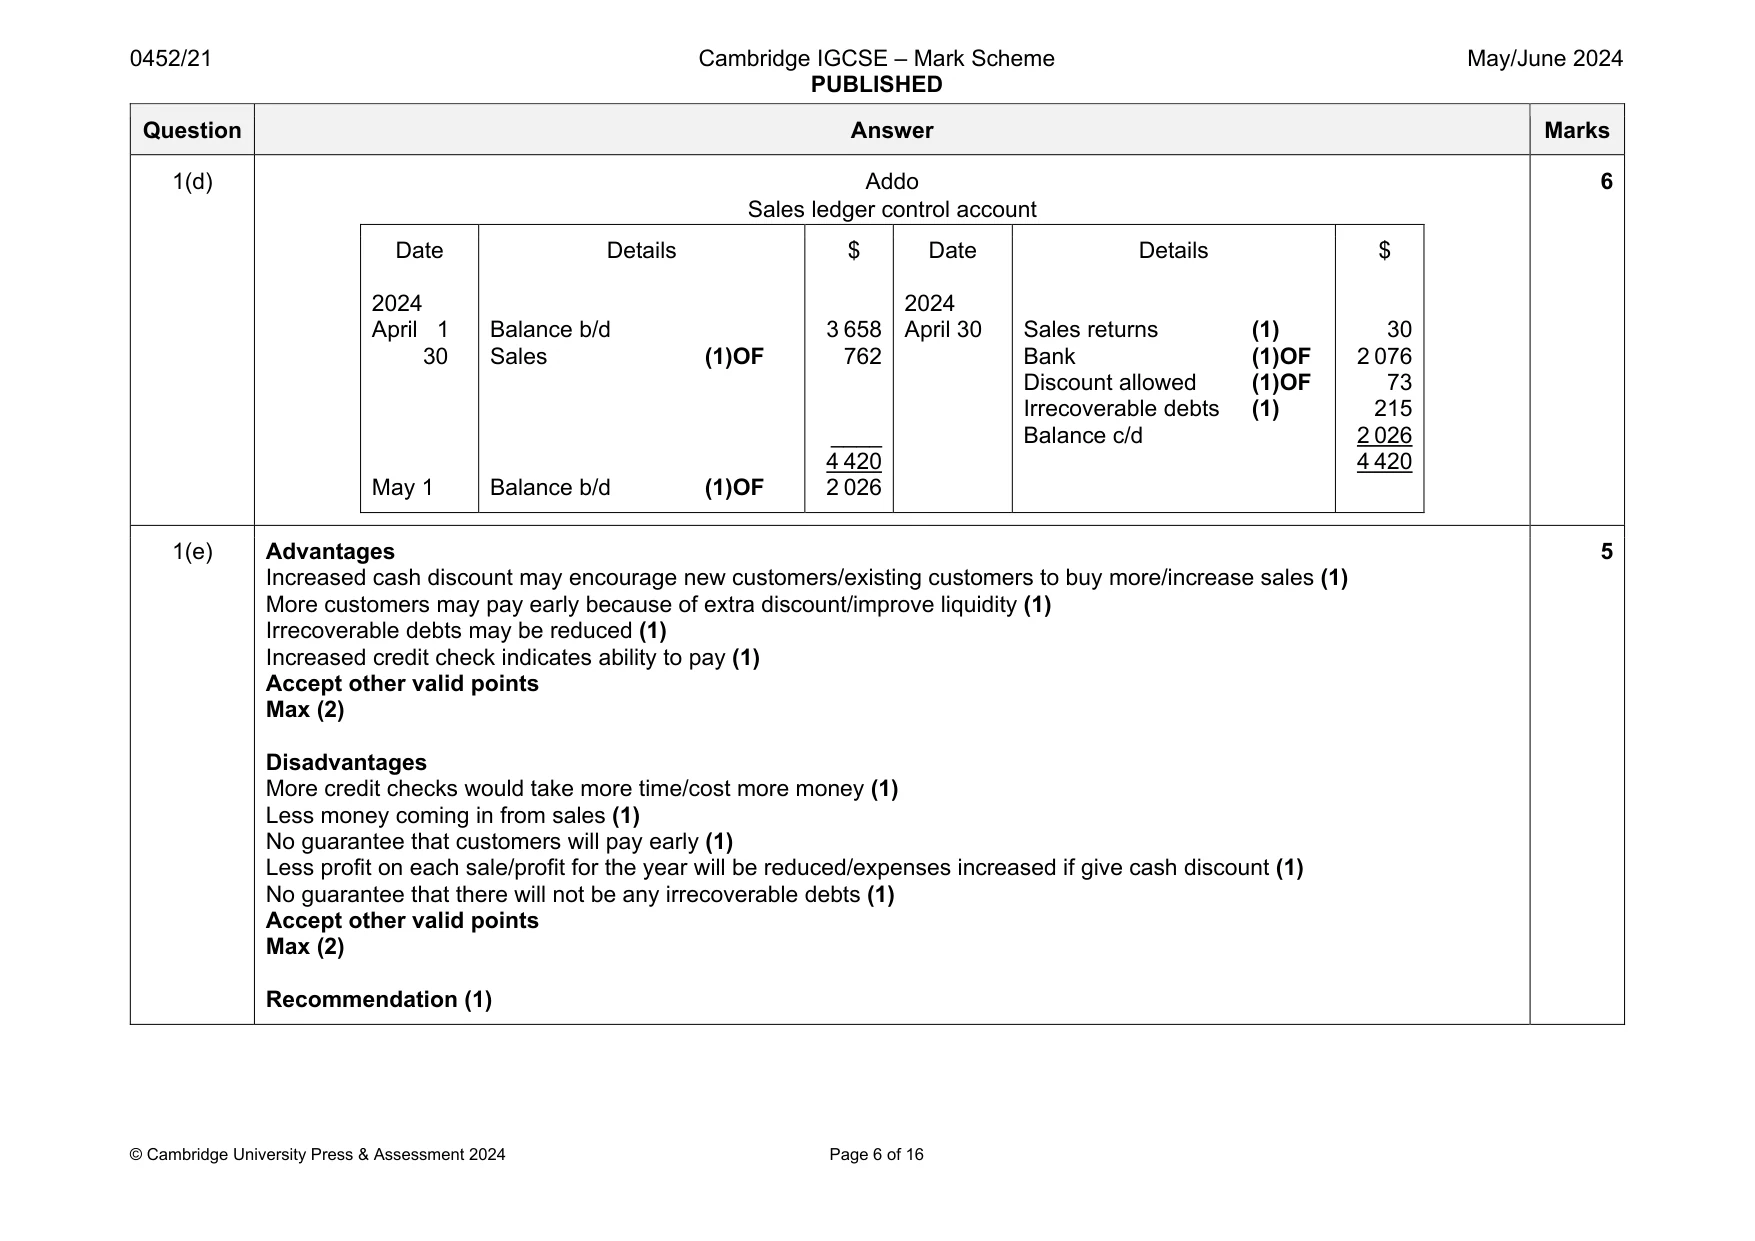
Mark scheme: 1(a) Addo Sales journal Date Details $ 2024 Apr 2 12 21 30 Ava (150 – 9) Nuru Mahia (480 – 24) Transfer to sales account 141 165 456 ___ 762 (1) (1) (1)OF 3 1(b) Addo Journal Date Details Debit $ Credit $ 2024 April 30 Irrecoverable debts (1) Rachel (1) Amount due from Rachel written off as irrecoverable (1) 215 215 3 1(c)(i) Total amount received = $689 +$627 + $760 = $2 076 (1) 1 1(c)(ii) Total cash discount = $40(1) + $33 = $73 (1)OF 2 Question Answer Marks 1(d) Addo Sales ledger control account Date 2024 April 1 30 May 1 Details Balance b/d Sales (1)OF Balance b/d (1)OF $ 3 658 762 ____ 4 420 2 026 Date 2024 April 30 Details Sales returns (1) Bank (1)OF Discount allowed (1)OF Irrecoverable debts (1) Balance c/d $ 30 2 076 73 215 2 026 4 420 6 1(e) Advantages Increased cash discount may encourage new customers/existing customers to buy more/increase sales (1) More customers may pay early because of extra discount/improve liquidity (1) Irrecoverable debts may be reduced (1) Increased credit check indicates ability to pay (1) Accept other valid points Max (2) Disadvantages More credit checks would take more time/cost more money (1) Less money coming in from sales (1) No guarantee that customers will pay early (1) Less profit on each sale/profit for the year will be reduced/expenses increased if give cash discount (1) No guarantee that there will not be any irrecoverable debts (1) Accept other valid points Max (2) Recommendation (1) 5
Q2 · Paul is a trader
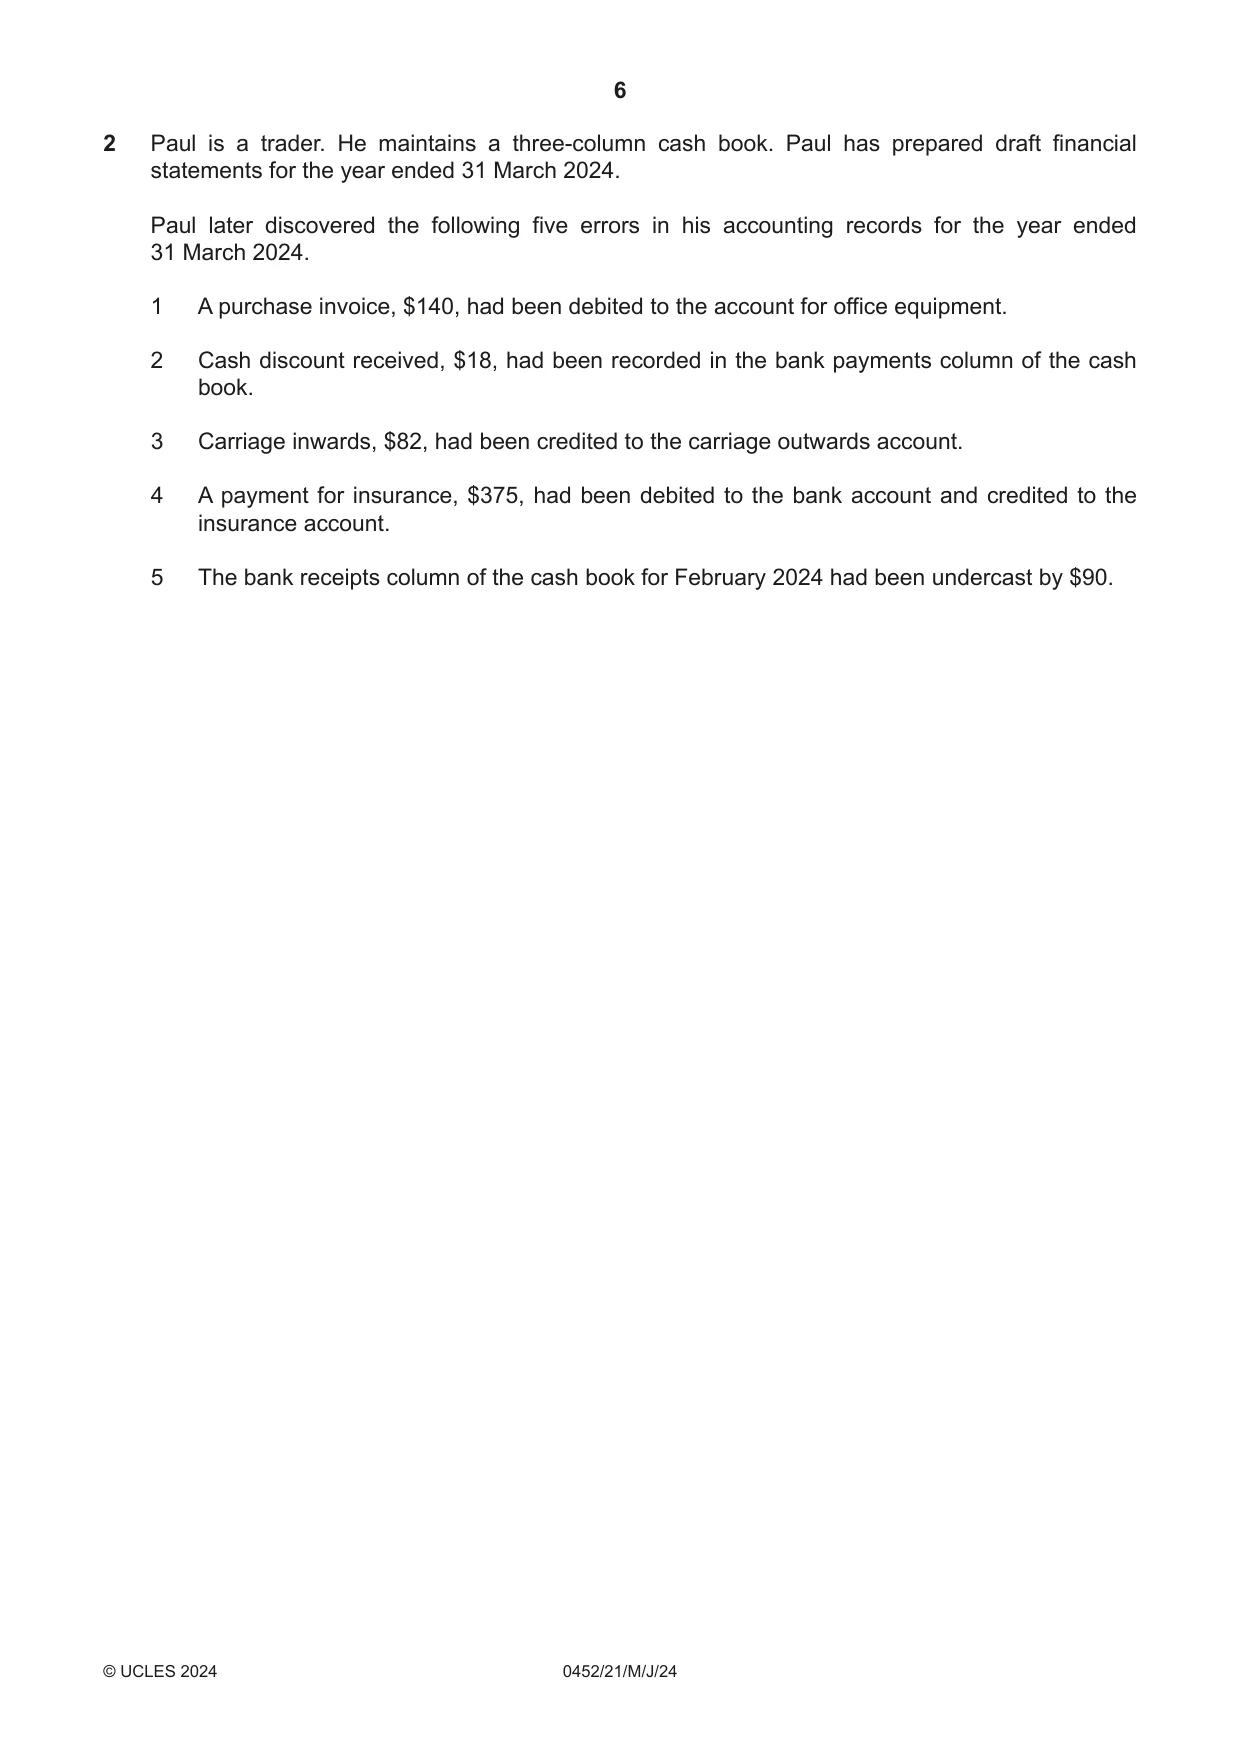
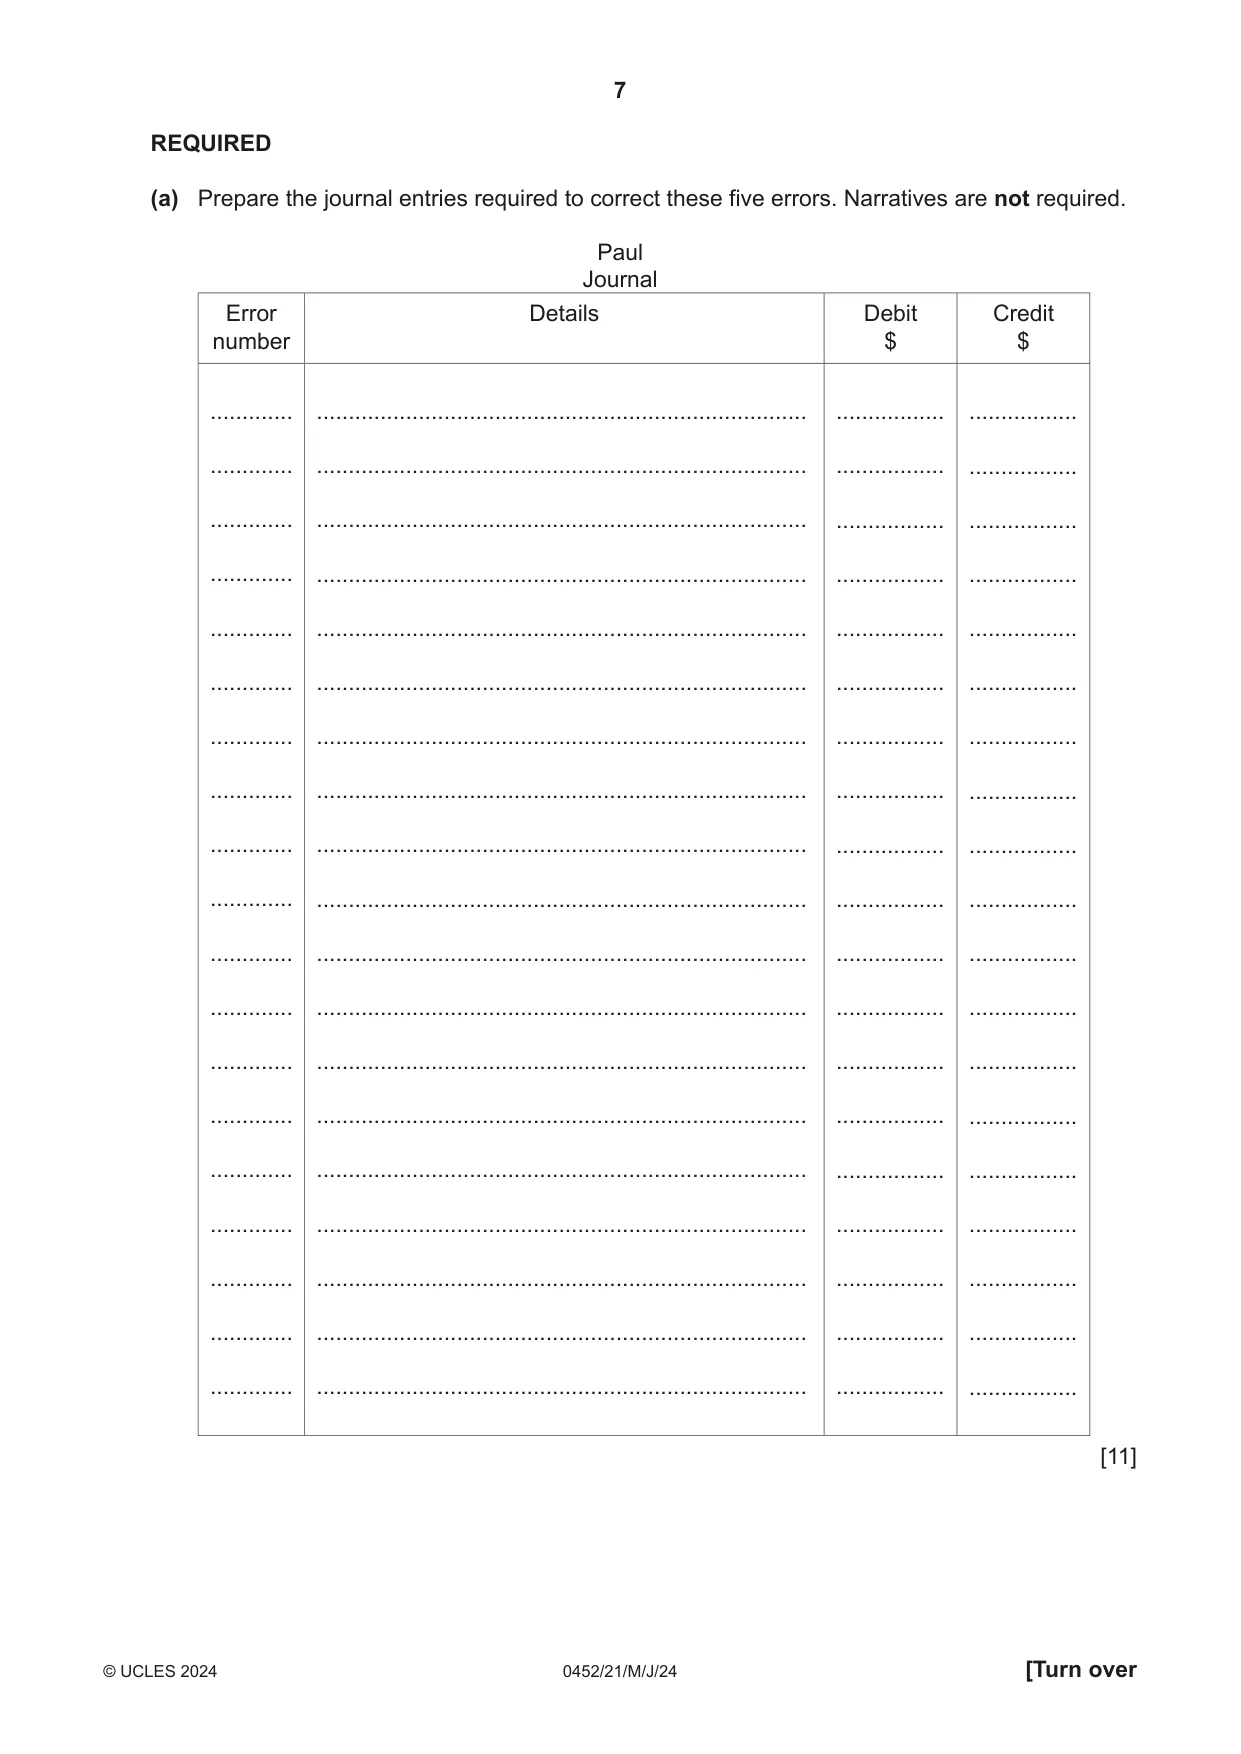
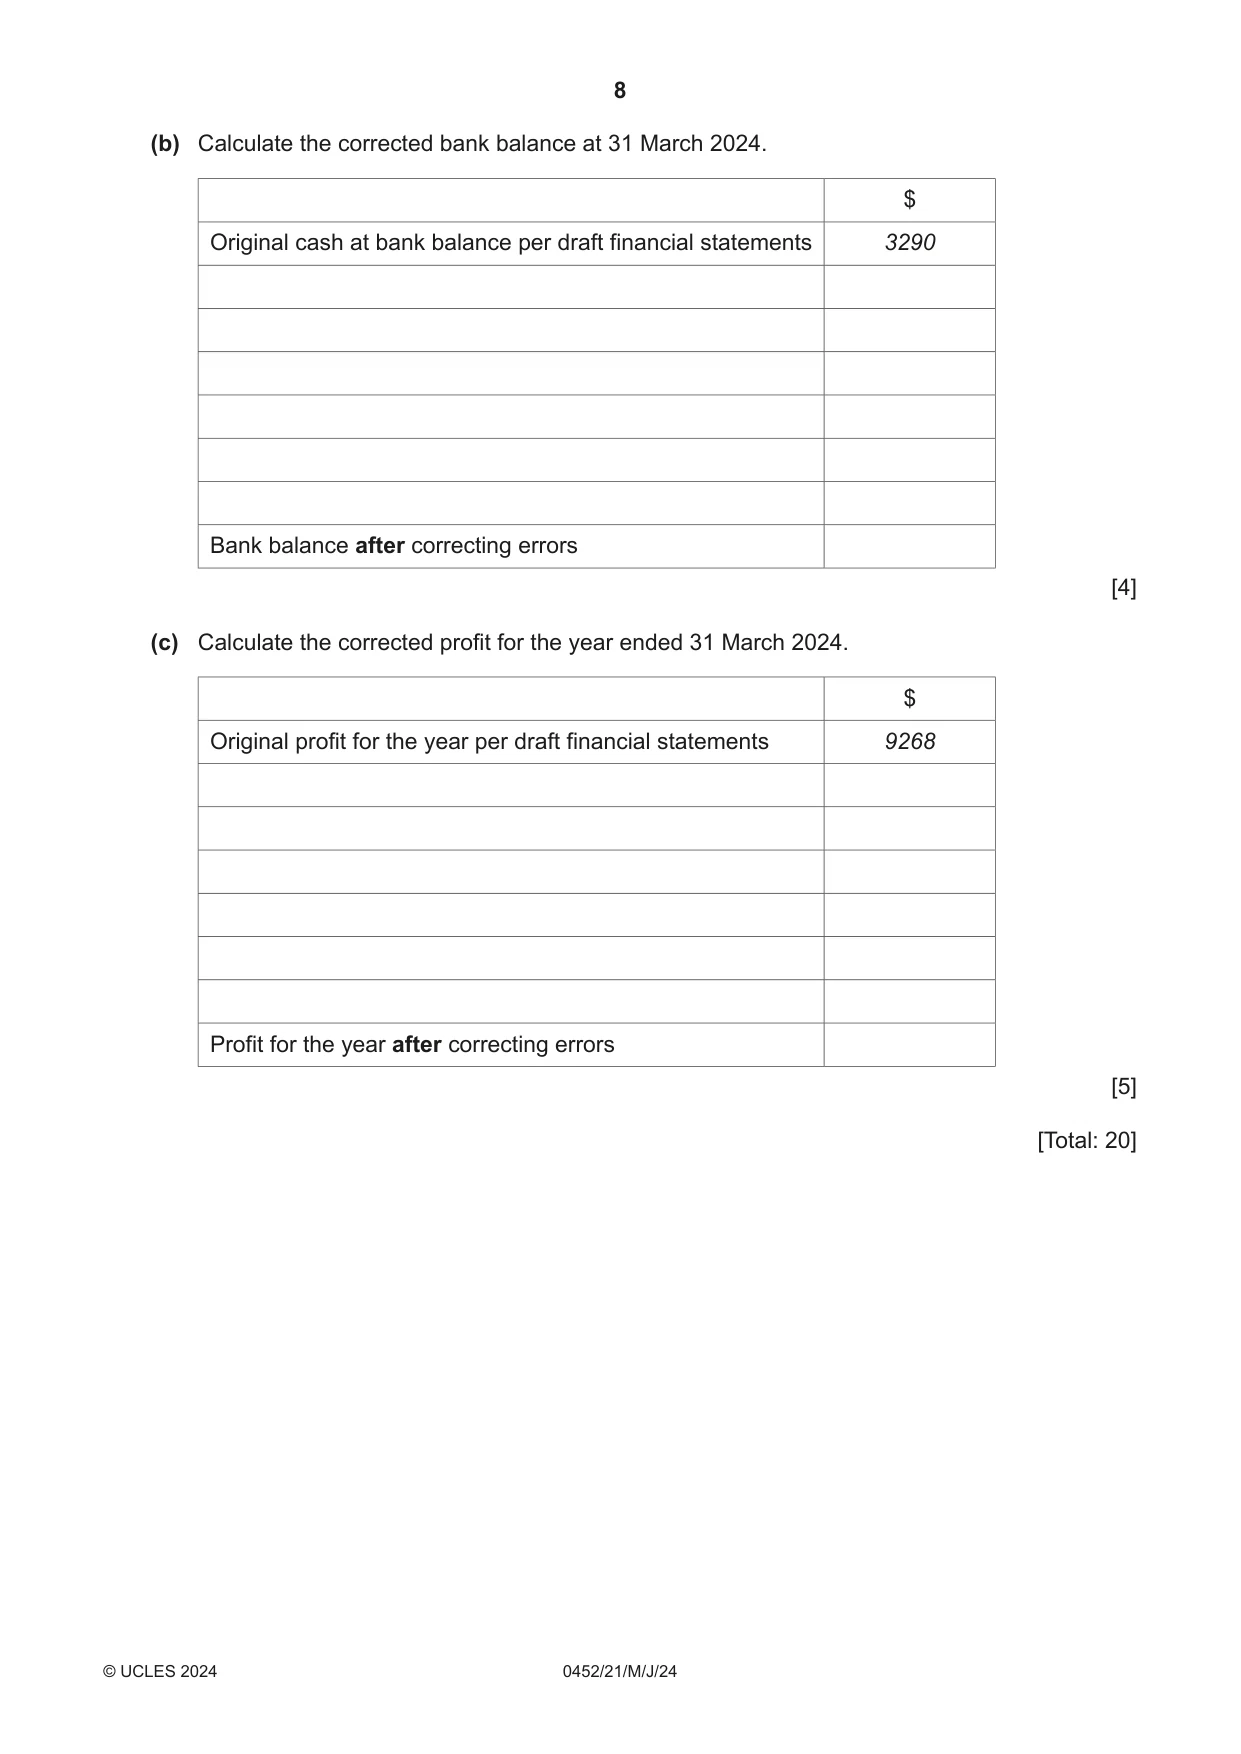
2 Paul is a trader. He maintains a three-column cash book. Paul has prepared draft financial statements for the year ended 31 March 2024. Paul later discovered the following five errors in his accounting records for the year ended 31 March 2024. 1 A purchase invoice, $140, had been debited to the account for office equipment. 2 Cash discount received, $18, had been recorded in the bank payments column of the cash book. 3 Carriage inwards, $82, had been credited to the carriage outwards account. 4 A payment for insurance, $375, had been debited to the bank account and credited to the insurance account. 5 The bank receipts column of the cash book for February 2024 had been undercast by $90. journal entries required to correct these five error Paul Journal Details ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. ............................................................................. (b) Calculate the corrected bank balance at 31 March 2024. $ Original cash at bank balance per draft financial statements 3290 Bank balance after correcting errors [4] (c) Calculate the corrected profit for the year ended 31 March 2024. $ Original profit for the year per draft financial statements 9268 Profit for the year after correcting errors [5] [Total: 20]
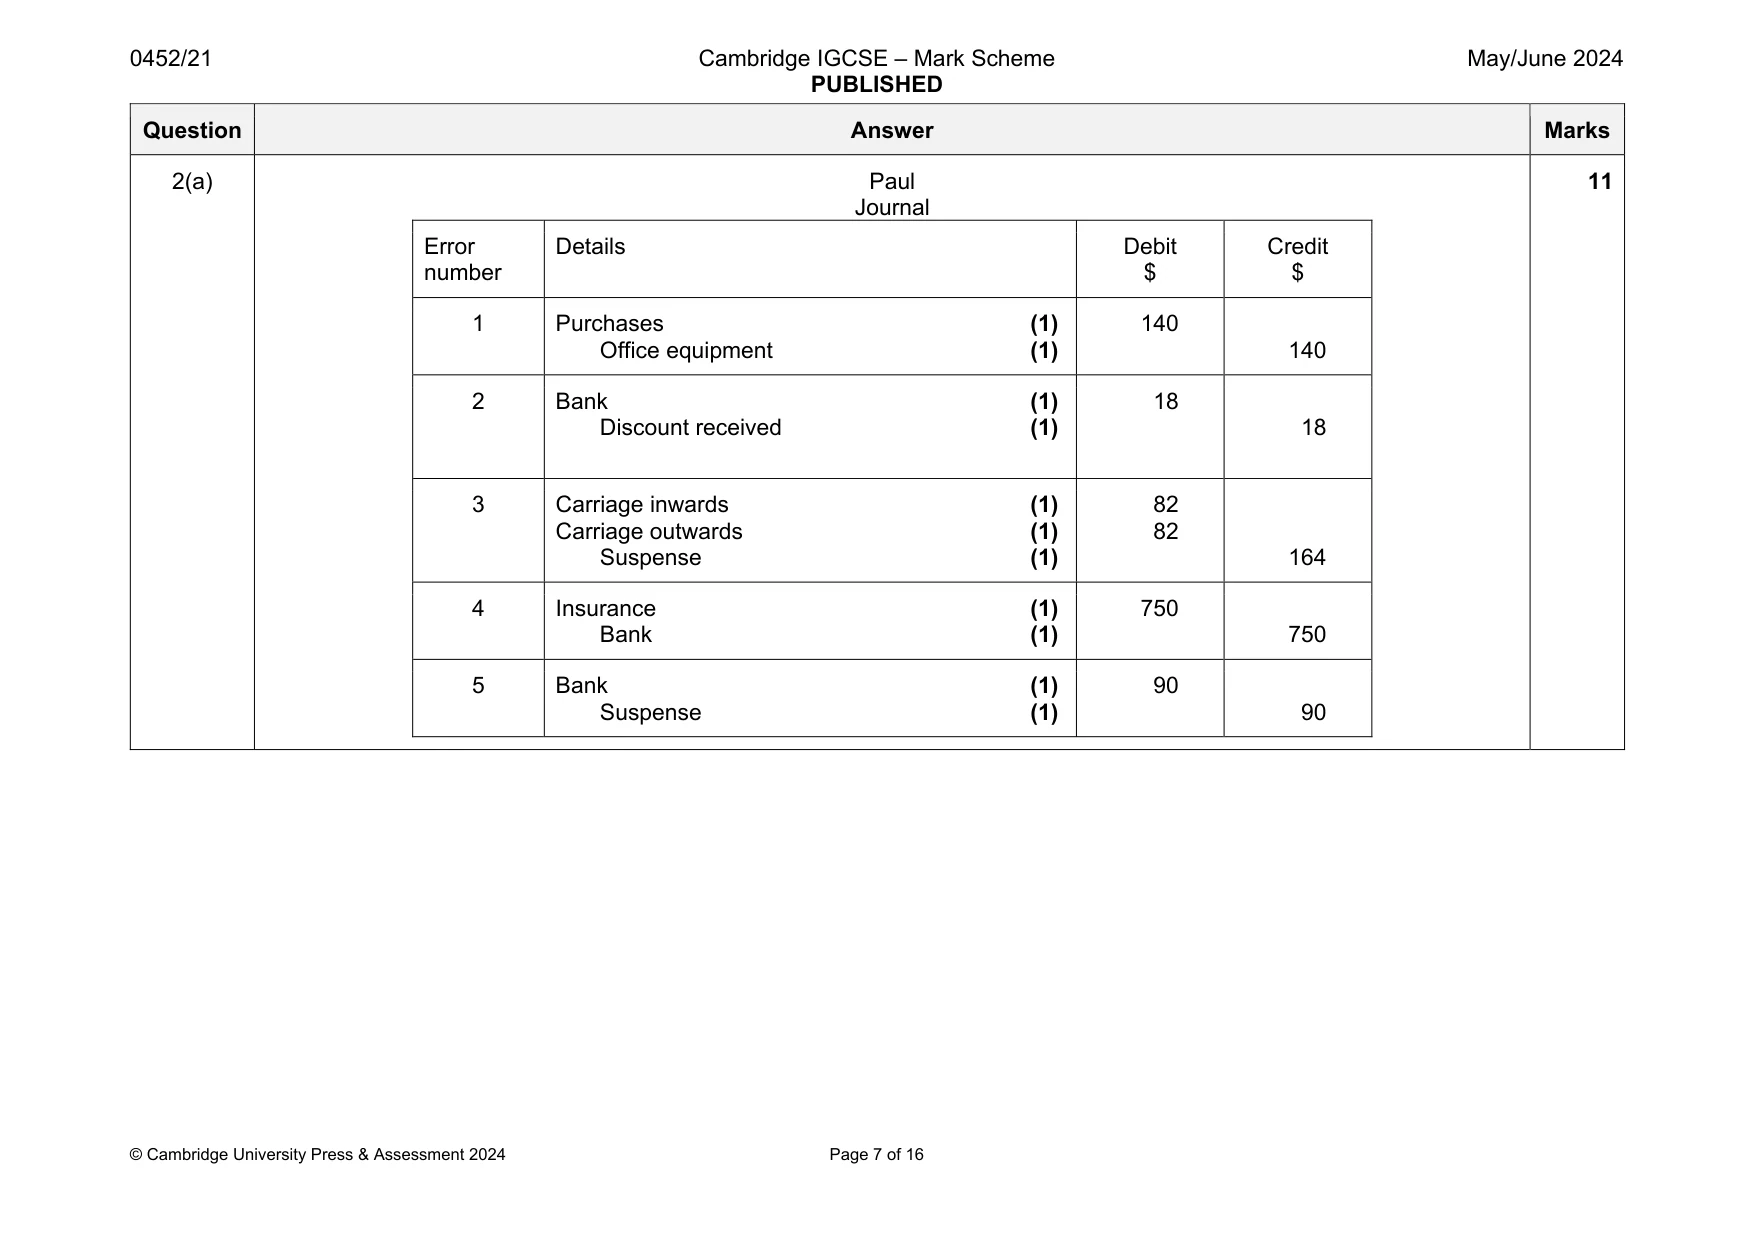
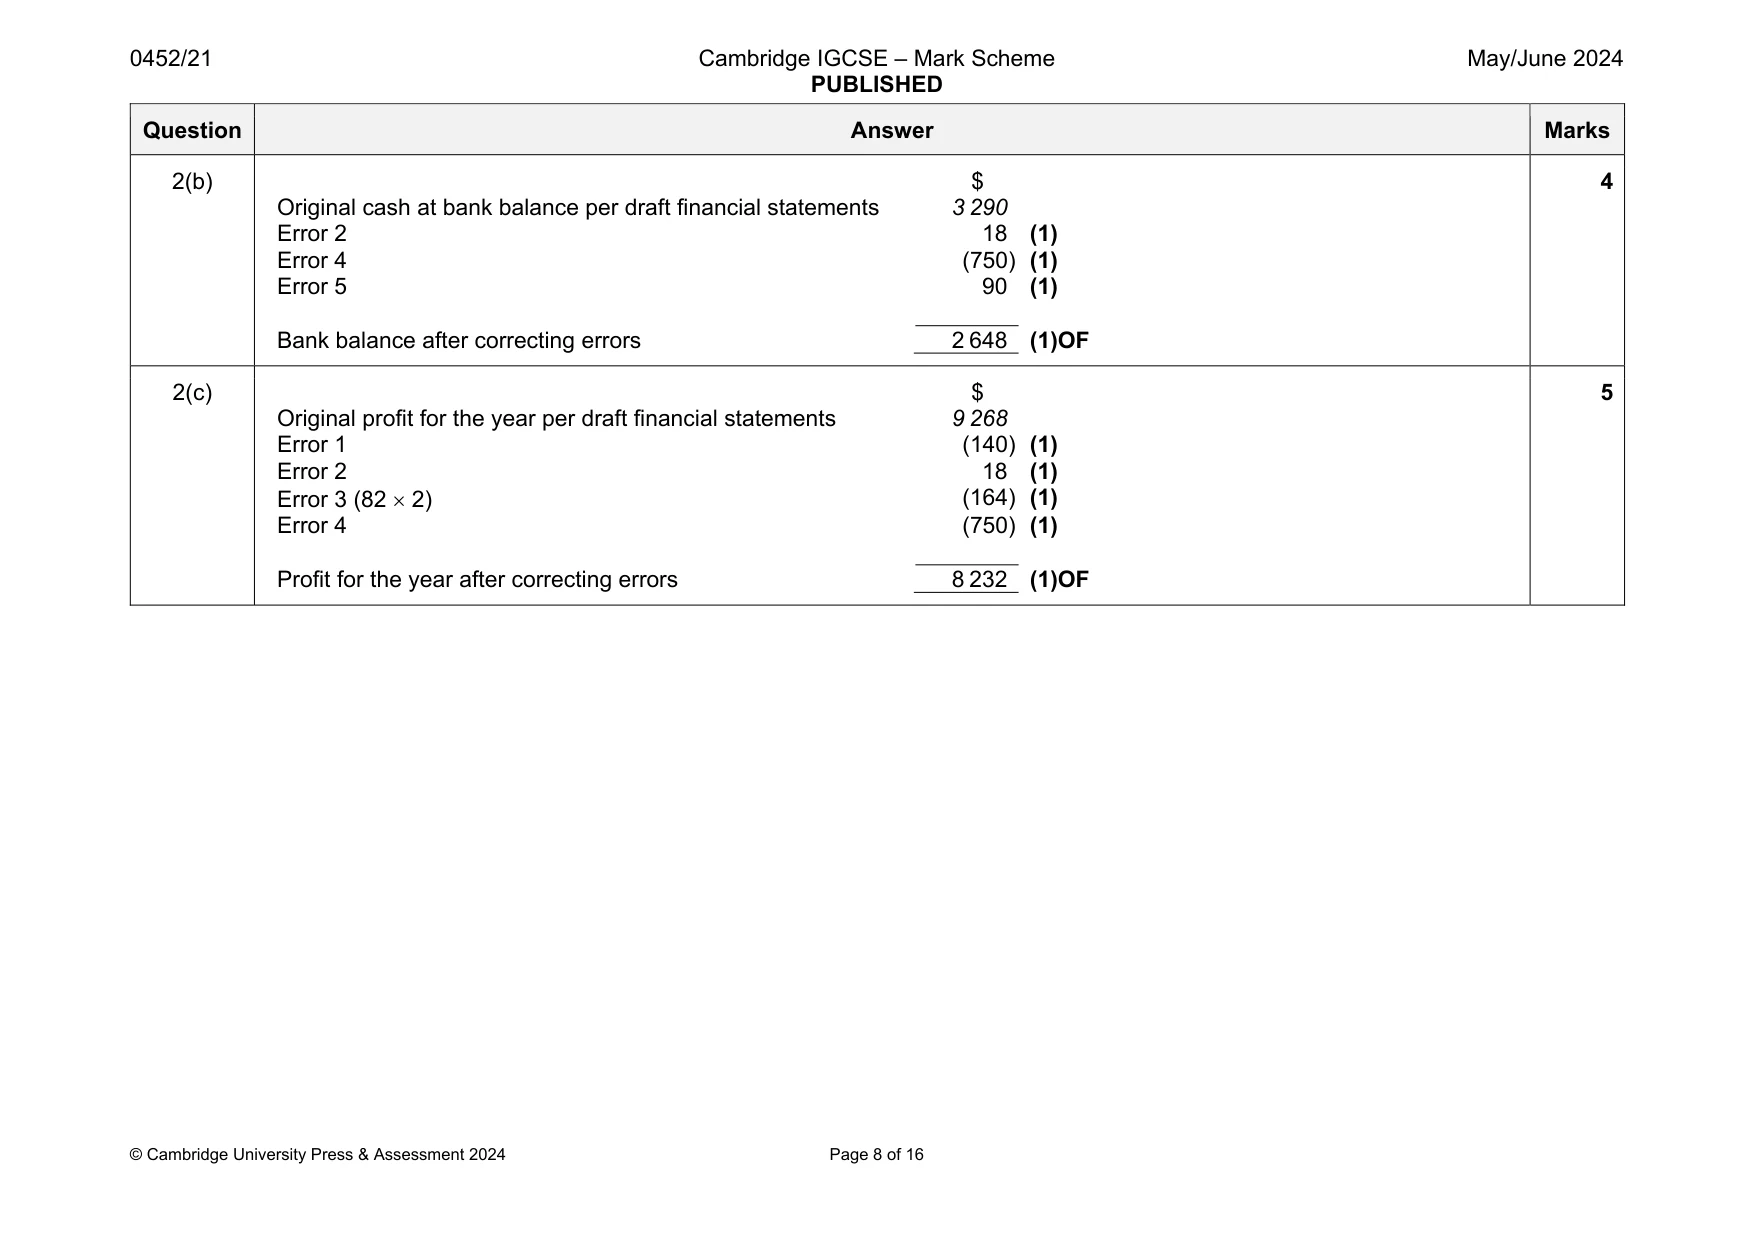
Mark scheme: 2(a) Paul Journal Error number Details Debit $ Credit $ 1 Purchases (1) Office equipment (1) 140 140 2 Bank (1) Discount received (1) 18 18 3 Carriage inwards (1) Carriage outwards (1) Suspense (1) 82 82 164 4 Insurance (1) Bank (1) 750 750 5 Bank (1) Suspense (1) 90 90 11 Question Answer Marks 2(b) $ Original cash at bank balance per draft financial statements 3 290 Error 2 18 (1) Error 4 (750) (1) Error 5 90 (1) Bank balance after correcting errors 2 648 (1)OF 4 2(c) $ Original profit for the year per draft financial statements 9 268 Error 1 (140) (1) Error 2 18 (1) Error 3 (82 2) (164) (1) Error 4 (750) (1) Profit for the year after correcting errors 8 232 (1)OF 5
Q3 · Zahra and Panya are the shareholders and directors of Q Limited
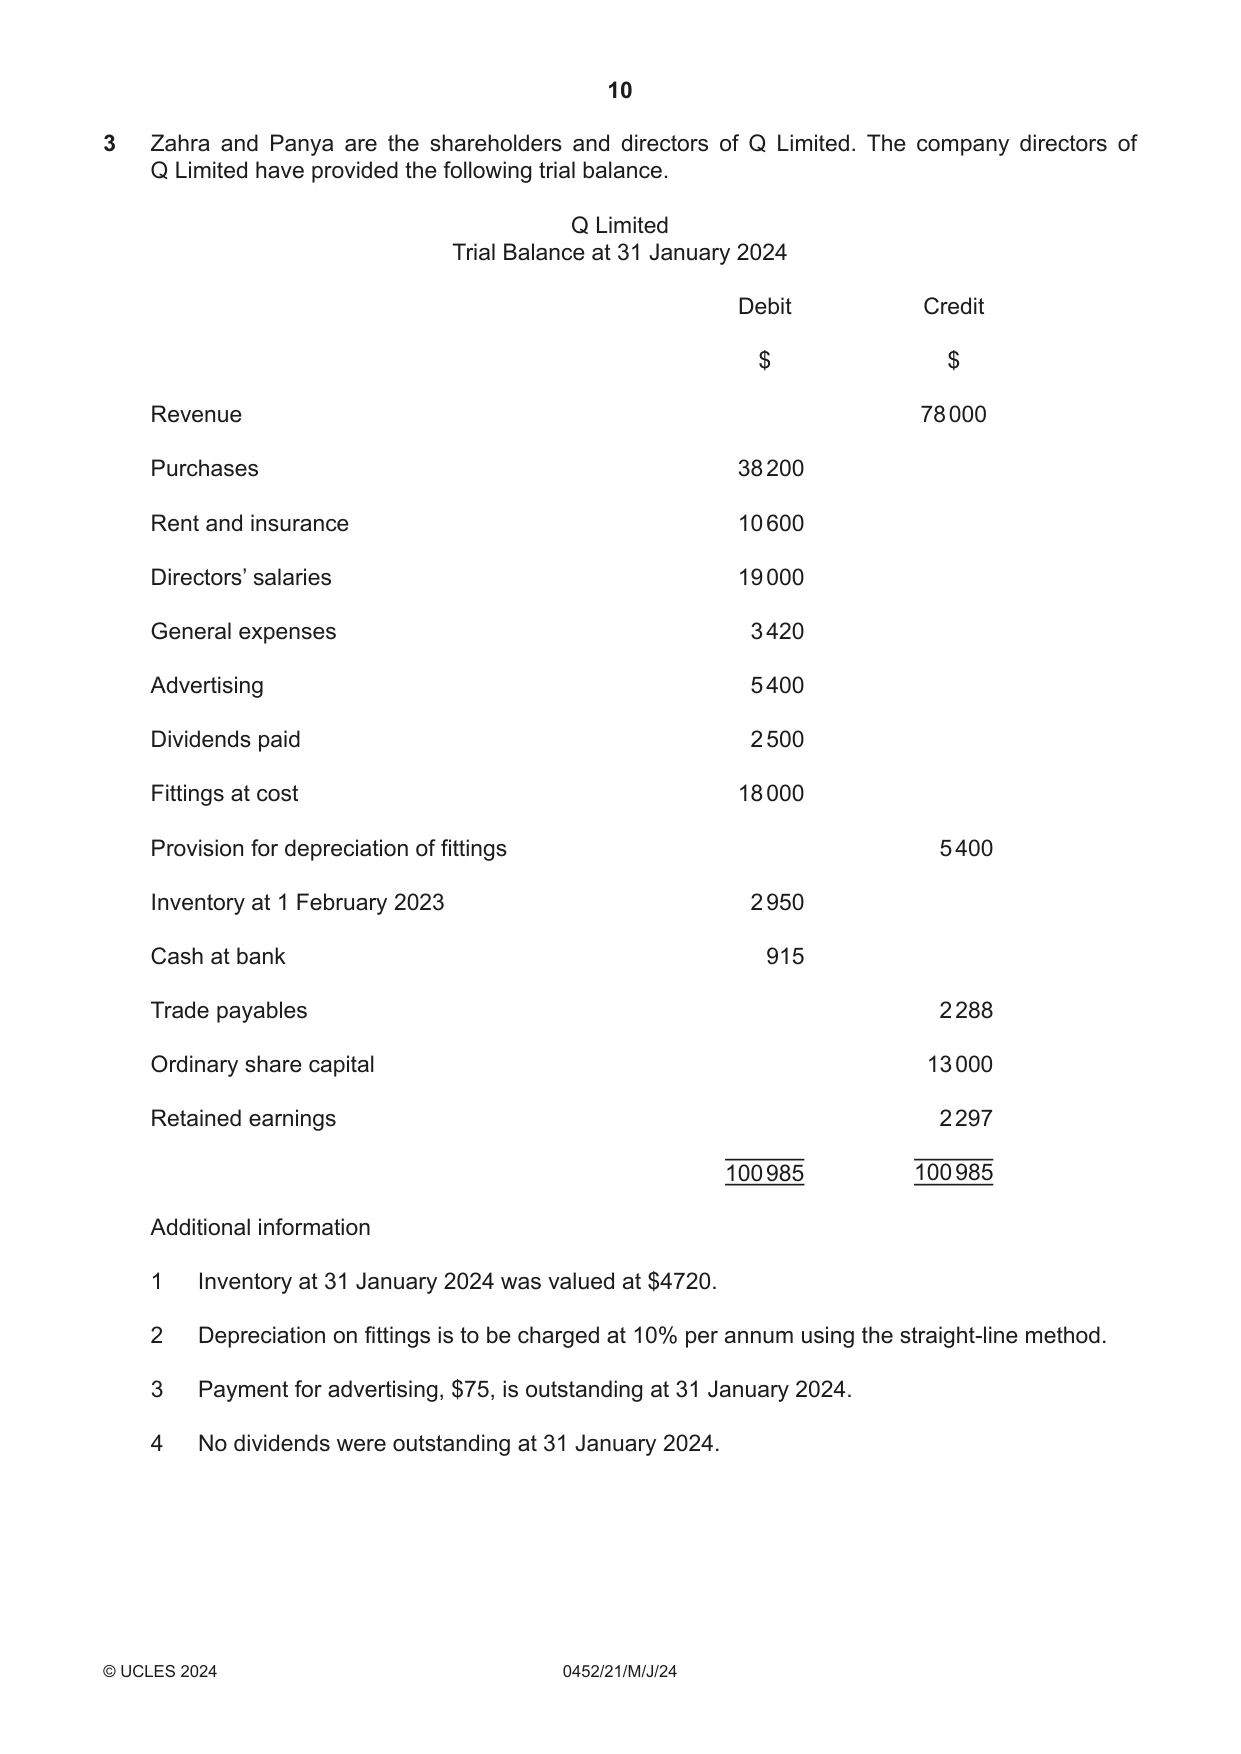
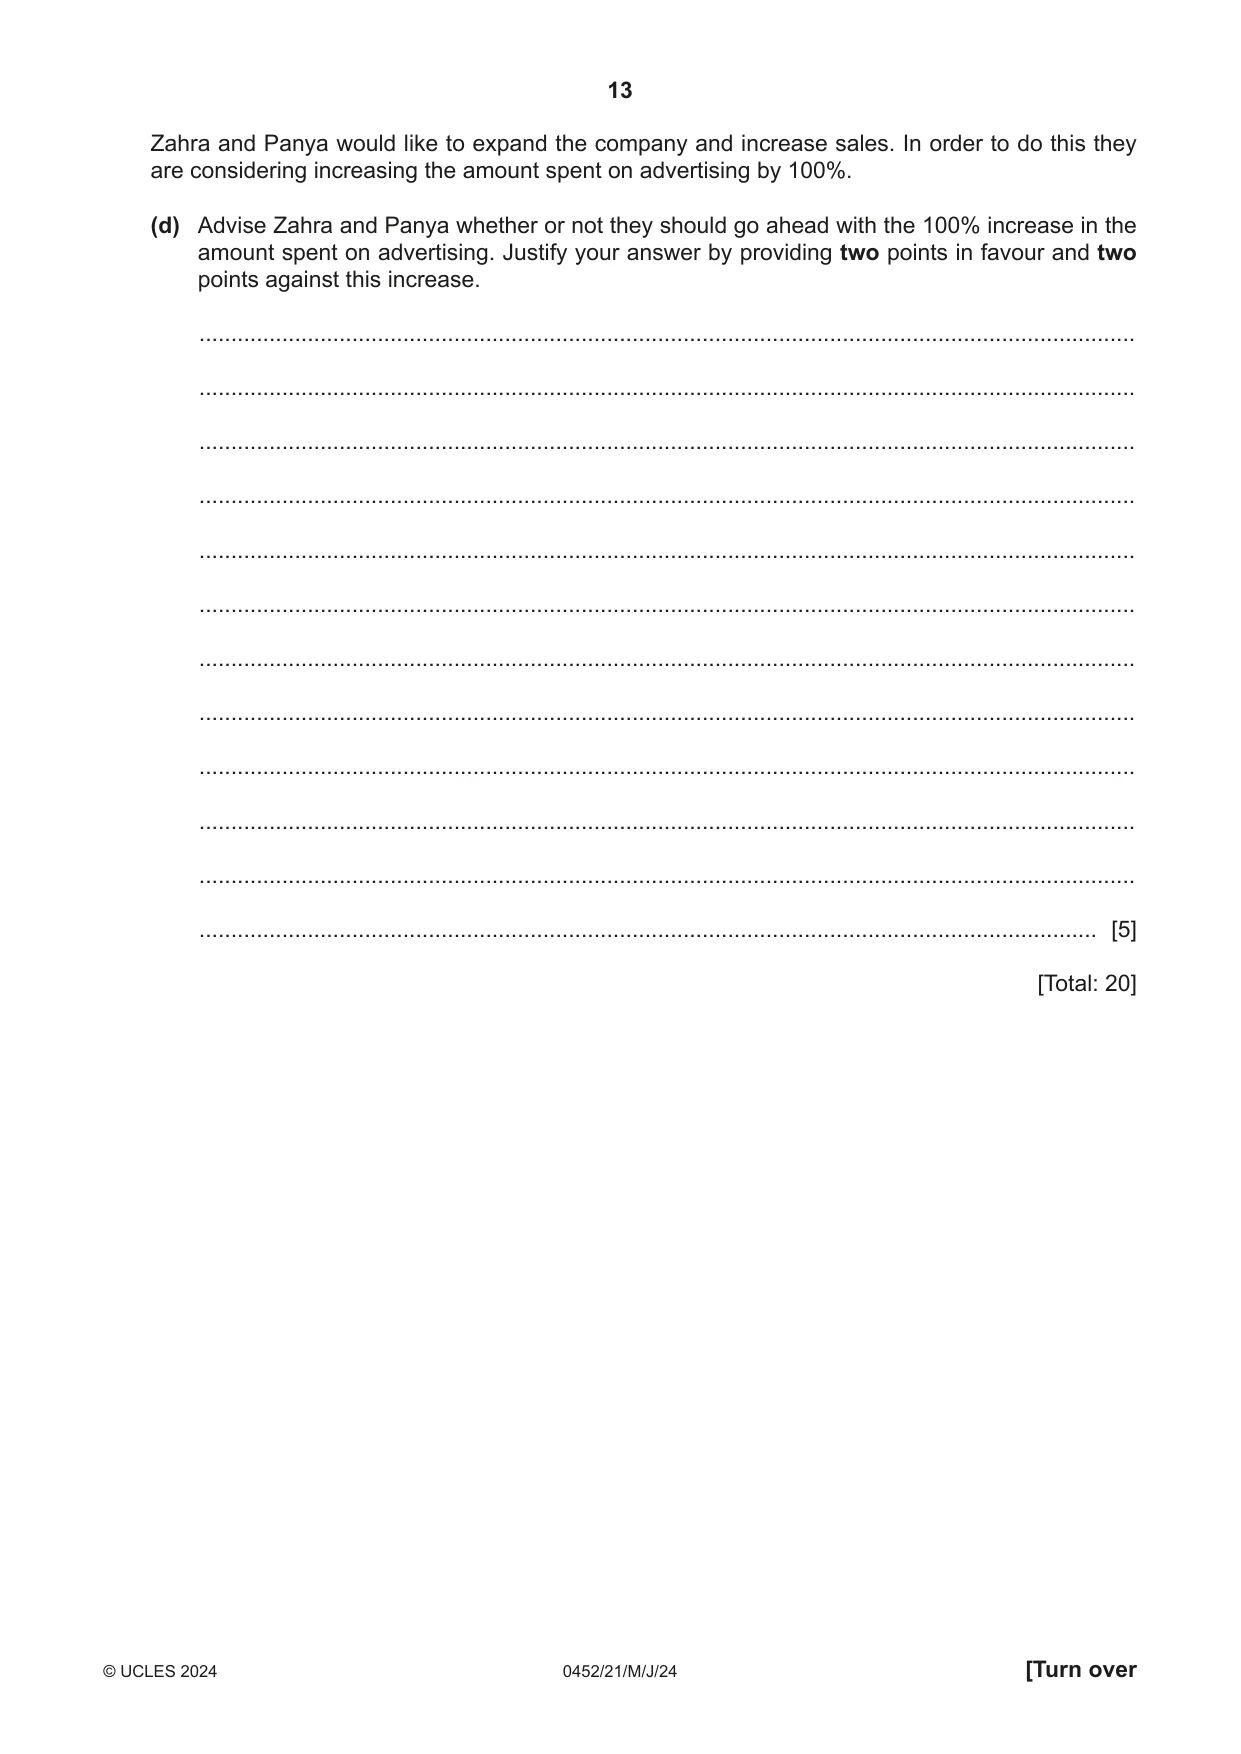
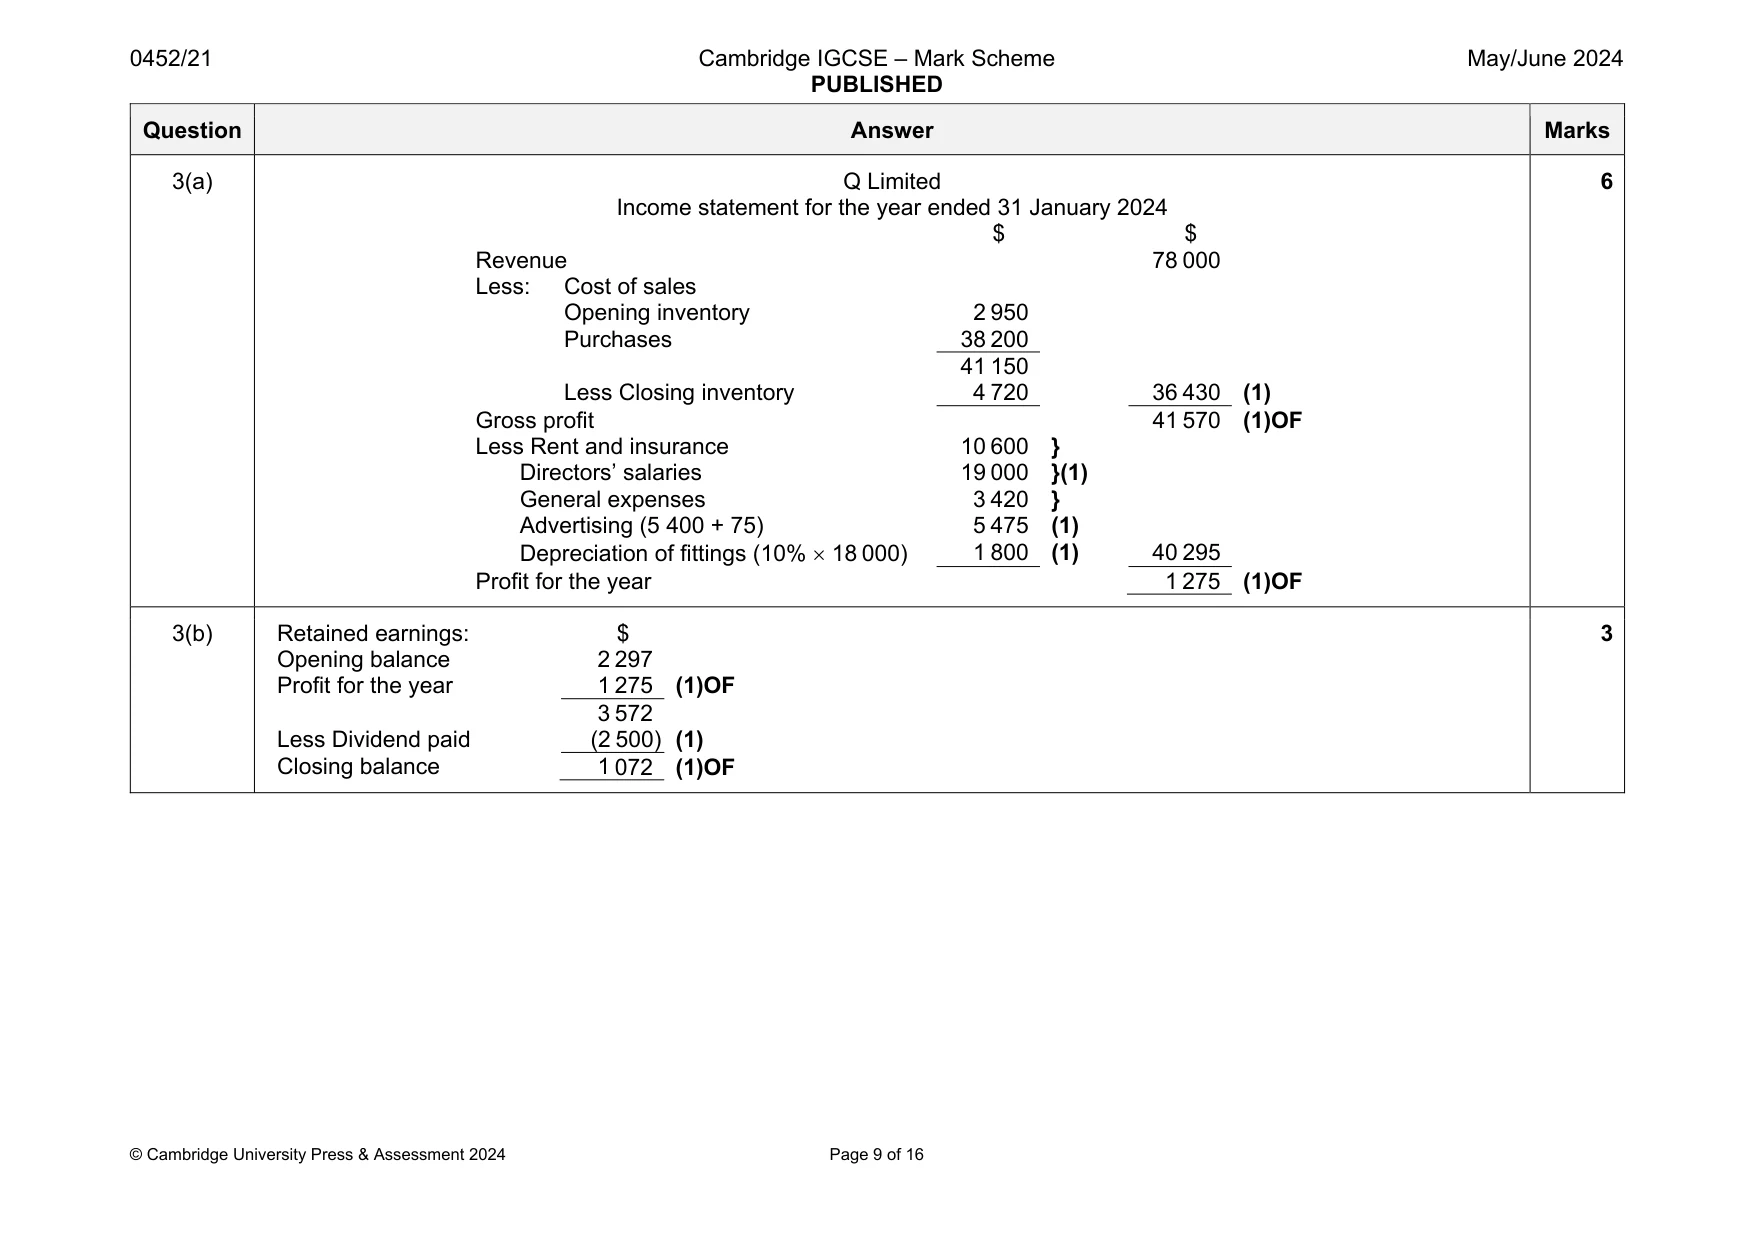
3 Zahra and Panya are the shareholders and directors of Q Limited. The company directors of Q Limited have provided the following trial balance. Q Limited Trial Balance at 31 January 2024 Debit Credit $ $ Revenue 78 000 Purchases 38 200 Rent and insurance 10 600 Directors’ salaries 19 000 General expenses 3 420 Advertising 5 400 Dividends paid 2 500 Fittings at cost 18 000 Provision for depreciation of fittings 5 400 Inventory at 1 February 2023 2 950 Cash at bank 915 Trade payables 2 288 Ordinary share capital 13 000 Retained earnings 2 297 100 985 100 985 Additional information 1 Inventory at 31 January 2024 was valued at $4720. 2 Depreciation on fittings is to be charged at 10% per annum using the straight-line method. 3 Payment for advertising, $75, is outstanding at 31 January 2024. 4 No dividends were outstanding at 31 January 2024. REQUIRED (a) Prepare the income statement for Q Limited for the year ended 31 January 2024. Q Limited Income statement for the year ended 31 January 2024 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [6] (b) Calculate the retained earnings at 31 January 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (c) Prepare the statement of financial position for Q Limited at 31 January 2024. Q Limited Statement of financial position at 31 January 2024 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [6] Zahra and Panya would like to expand the company and increase sales. In order to do this they are considering increasing the amount spent on advertising by 100%. (d) Advise Zahra and Panya whether or not they should go ahead with the 100% increase in the amount spent on advertising. Justify your answer by providing two points in favour and two points against this increase. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
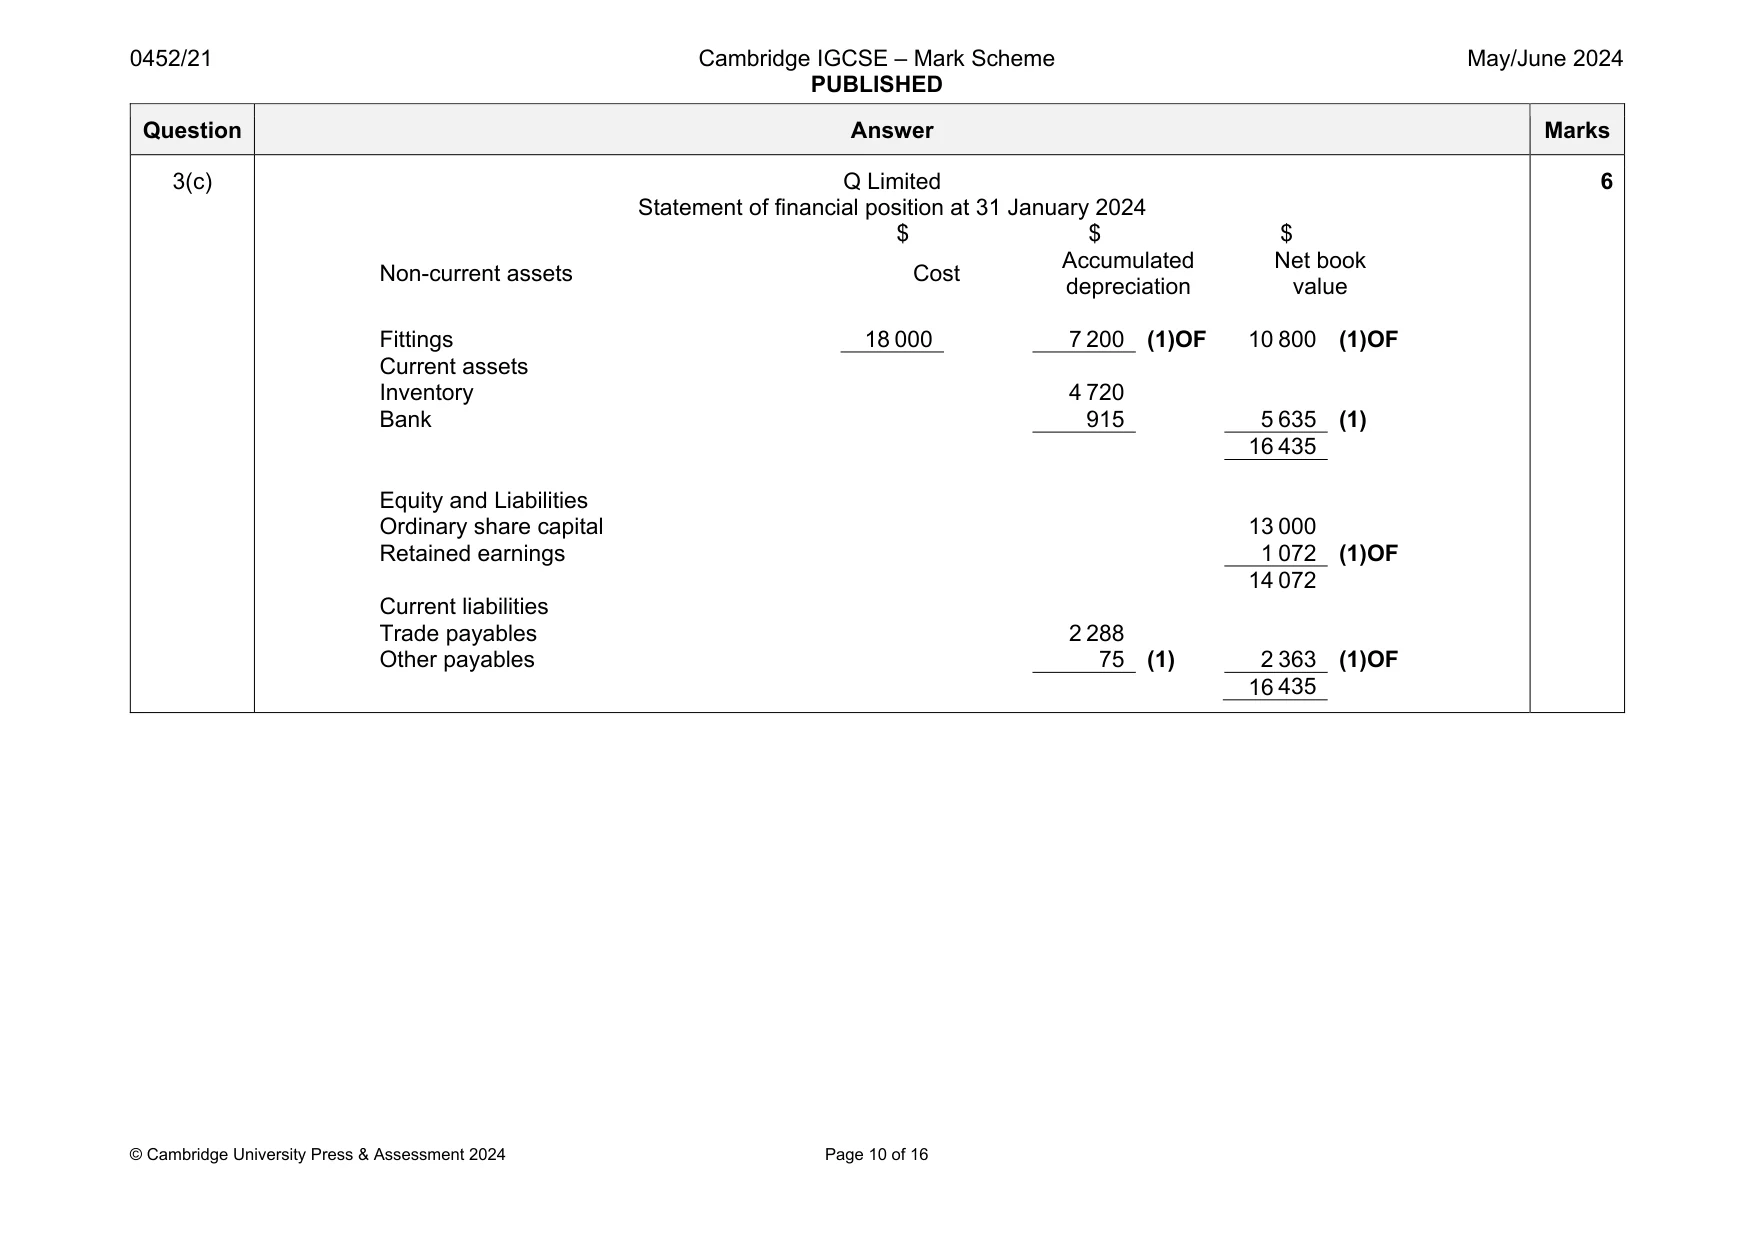
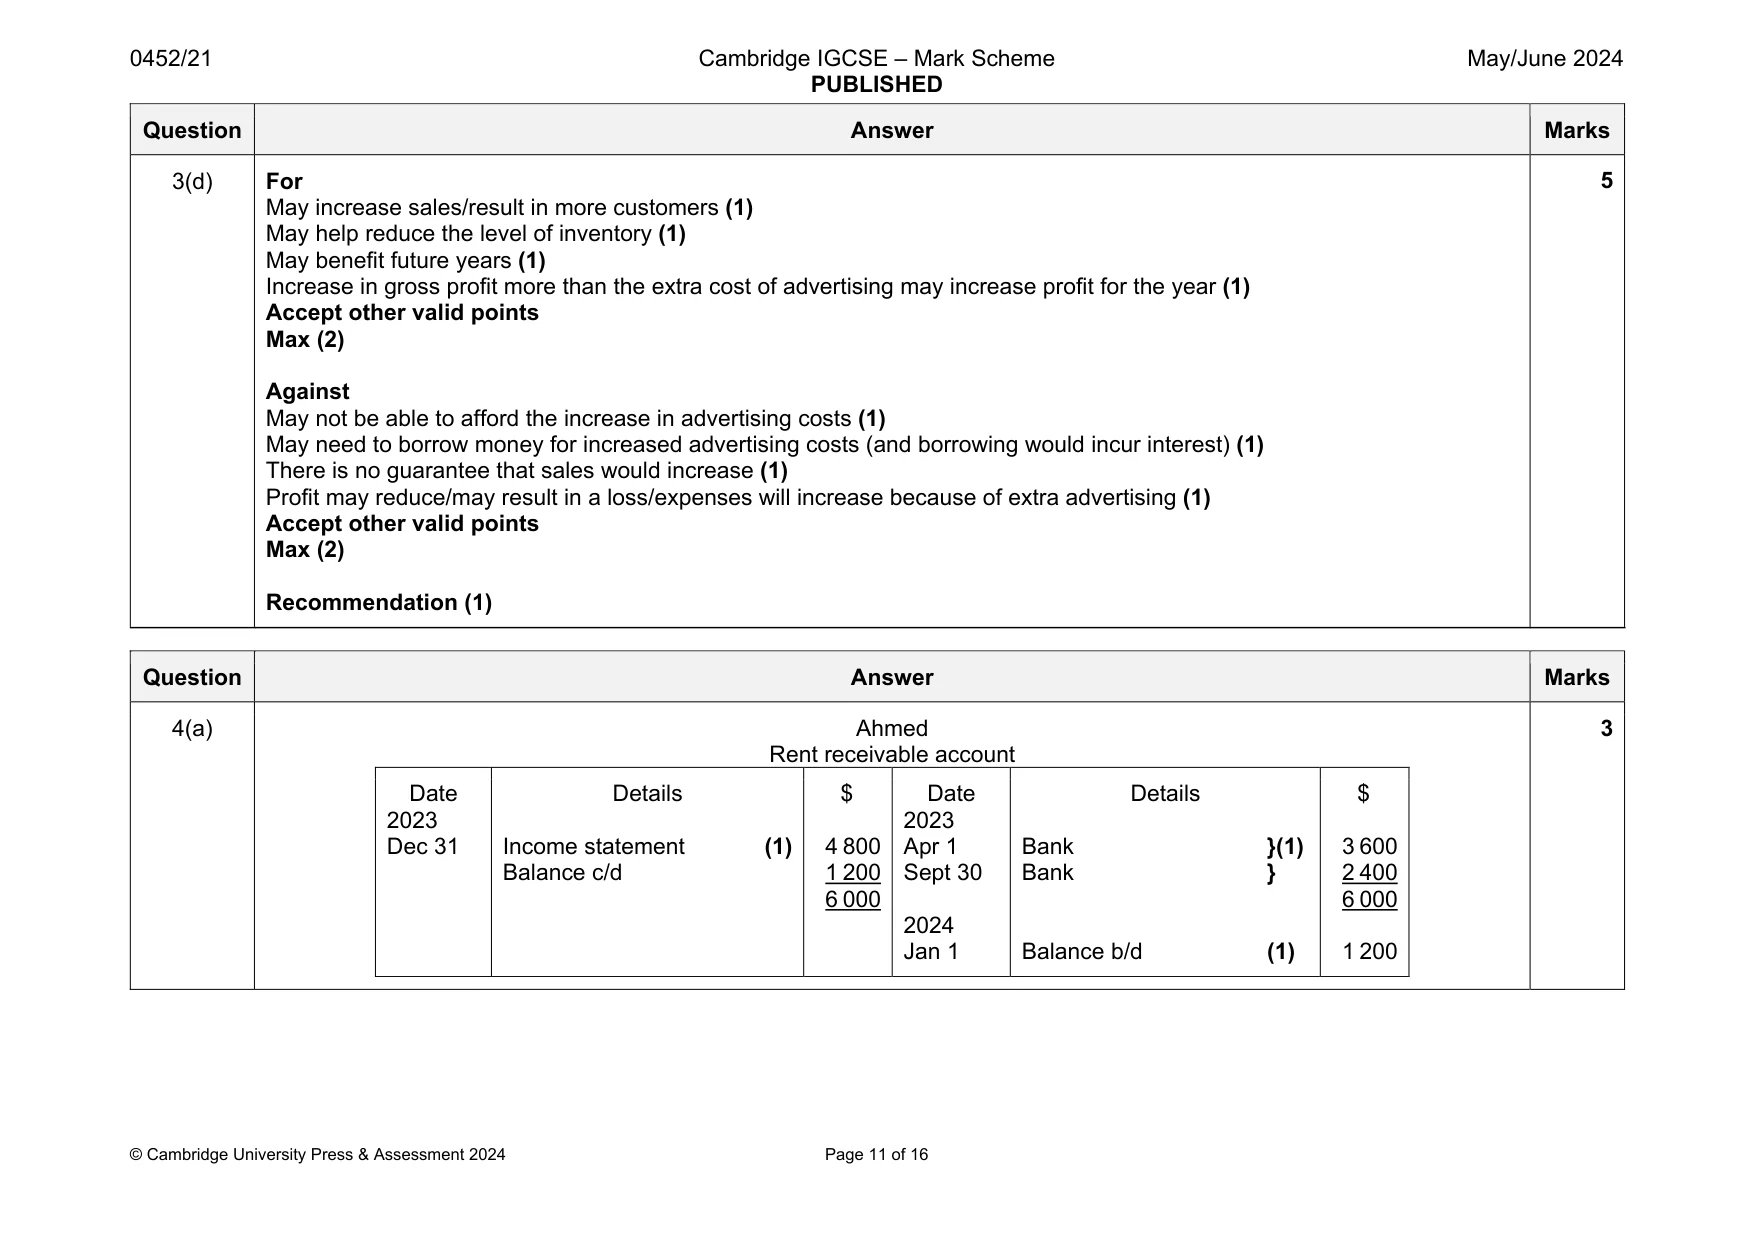
Mark scheme: 3(a) Q Limited Income statement for the year ended 31 January 2024 $ $ Revenue 78 000 Less: Cost of sales Opening inventory 2 950 Purchases 38 200 41 150 Less Closing inventory 4 720 36 430 (1) Gross profit 41 570 (1)OF Less Rent and insurance 10 600 } Directors’ salaries 19 000 }(1) General expenses 3 420 } Advertising (5 400 + 75) 5 475 (1) Depreciation of fittings (10% 18 000) 1 800 (1) 40 295 Profit for the year 1 275 (1)OF 6 3(b) Retained earnings: $ Opening balance 2 297 Profit for the year 1 275 (1)OF 3 572 Less Dividend paid (2 500) (1) Closing balance 1 072 (1)OF 3 Question Answer Marks 3(c) Q Limited Statement of financial position at 31 January 2024 $ $ $ Non-current assets Cost Accumulated depreciation Net book value Fittings 18 000 7 200 (1)OF 10 800 (1)OF Current assets Inventory 4 720 Bank 915 5 635 (1) 16 435 Equity and Liabilities Ordinary share capital 13 000 Retained earnings 1 072 (1)OF 14 072 Current liabilities Trade payables 2 288 Other payables 75 (1) 2 363 (1)OF 16 435 6 Question Answer Marks 3(d) For May increase sales/result in more customers (1) May help reduce the level of inventory (1) May benefit future years (1) Increase in gross profit more than the extra cost of advertising may increase profit for the year (1) Accept other valid points Max (2) Against May not be able to afford the increase in advertising costs (1) May need to borrow money for increased advertising costs (and borrowing would incur interest) (1) There is no guarantee that sales would increase (1) Profit may reduce/may result in a loss/expenses will increase because of extra advertising (1) Accept other valid points Max (2) Recommendation (1) 5
Q4 · Ahmed owns a trading business
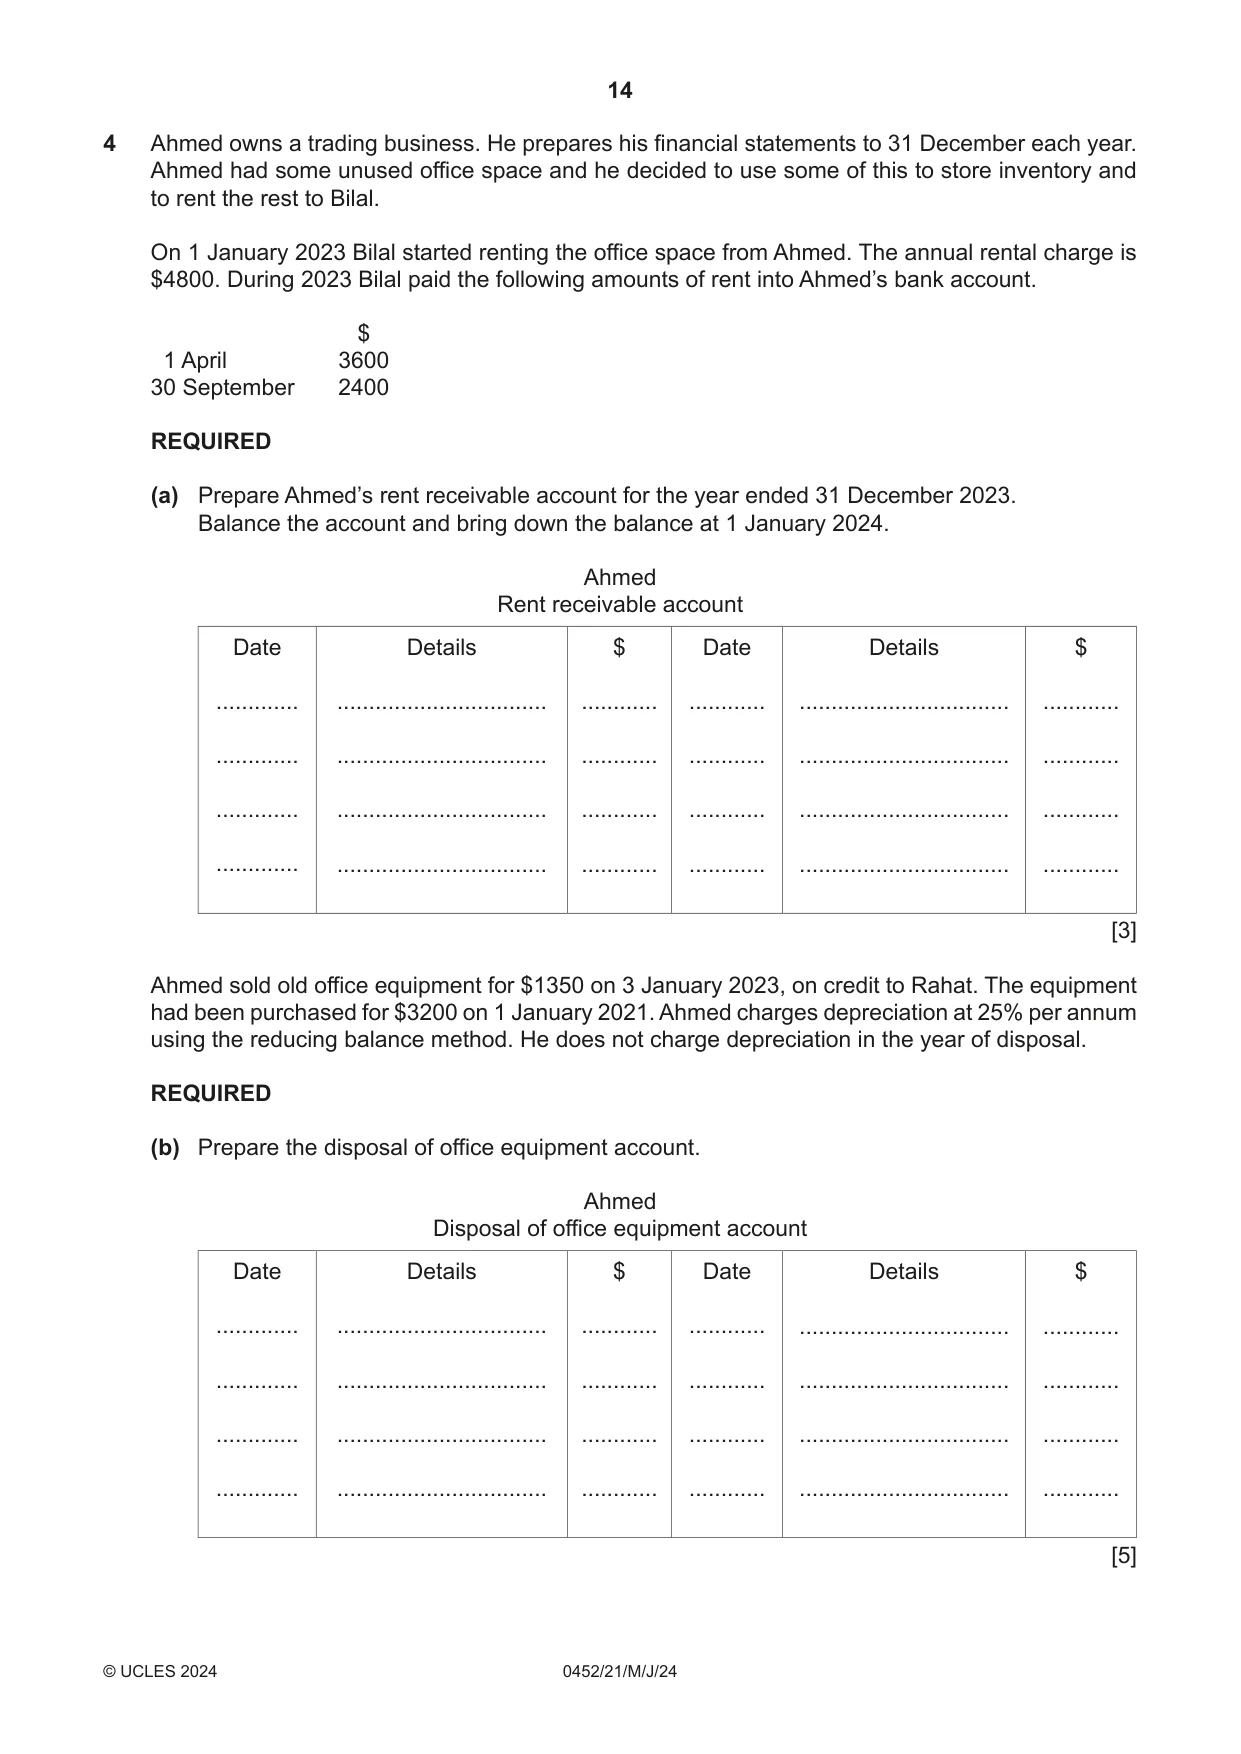
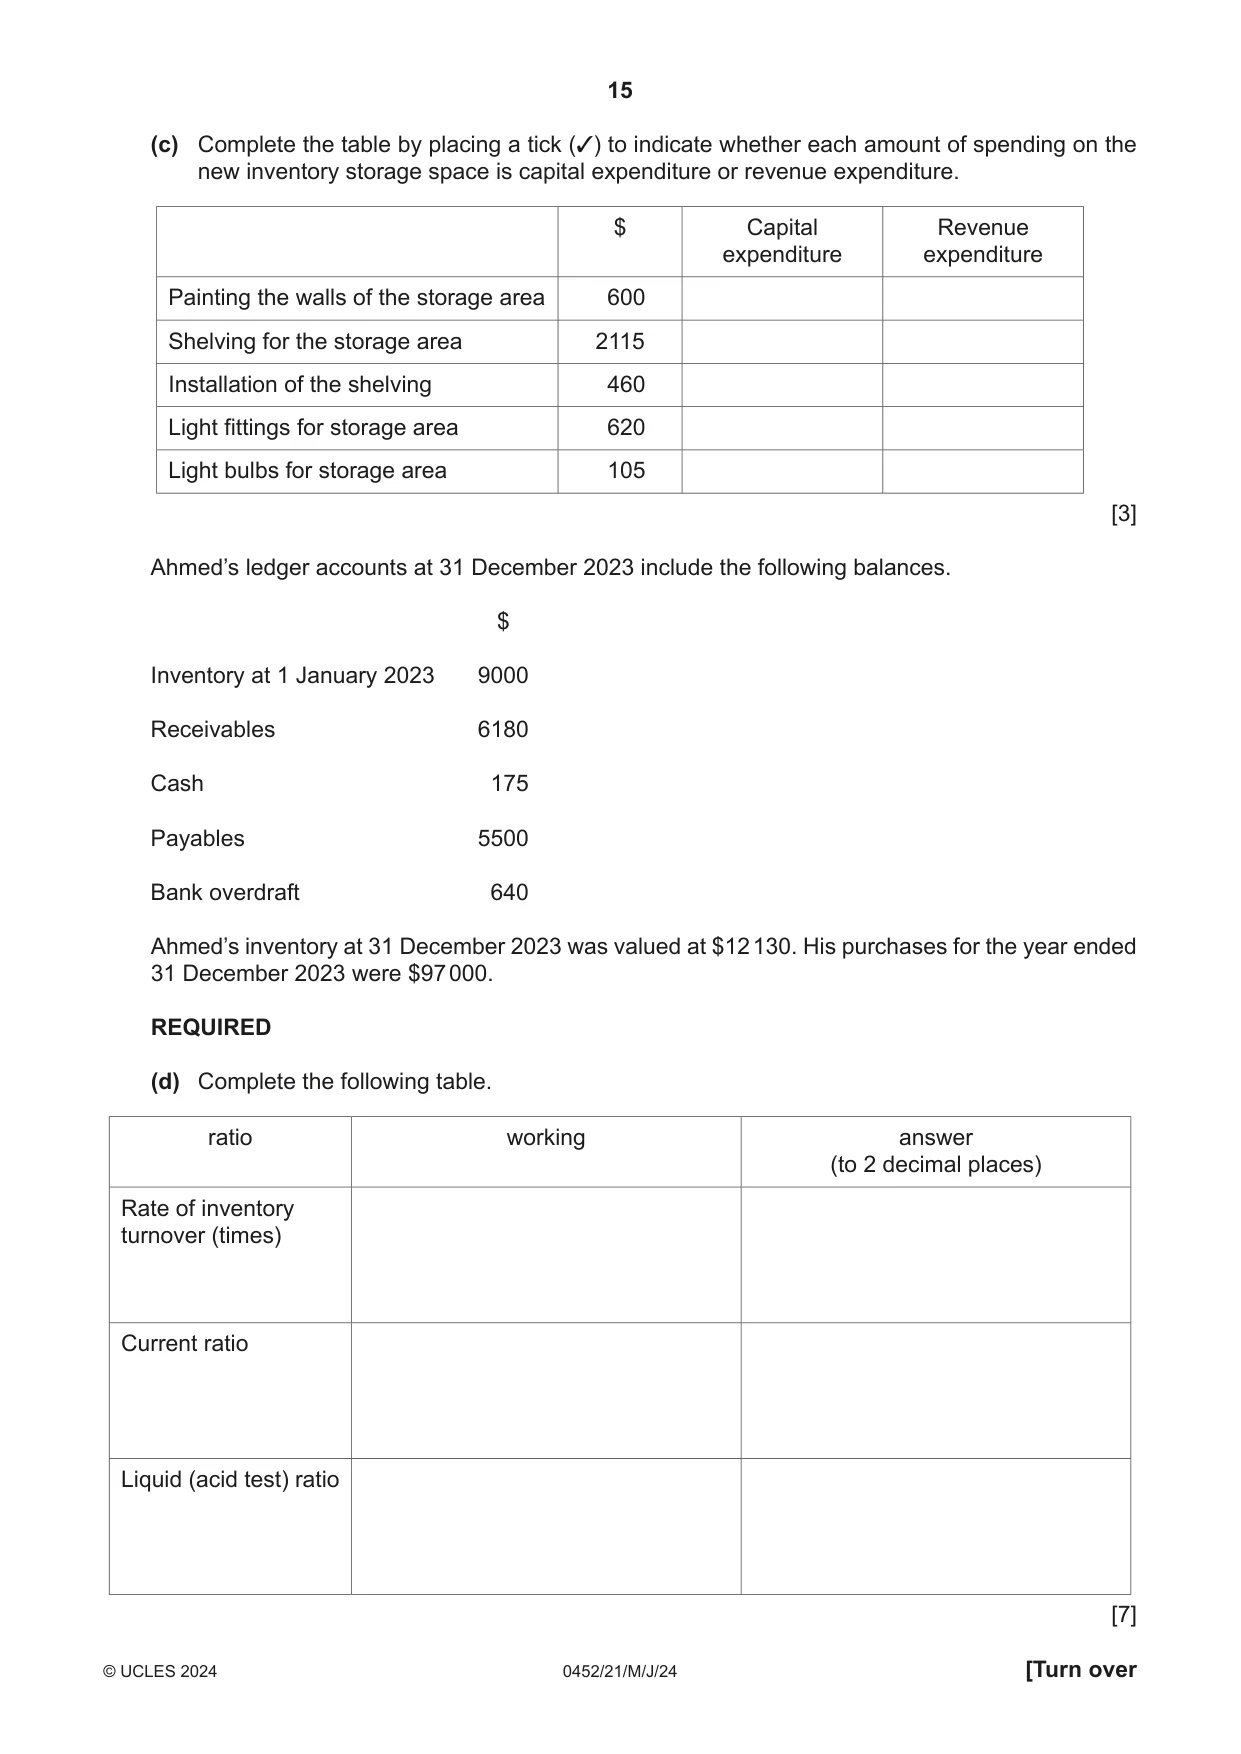
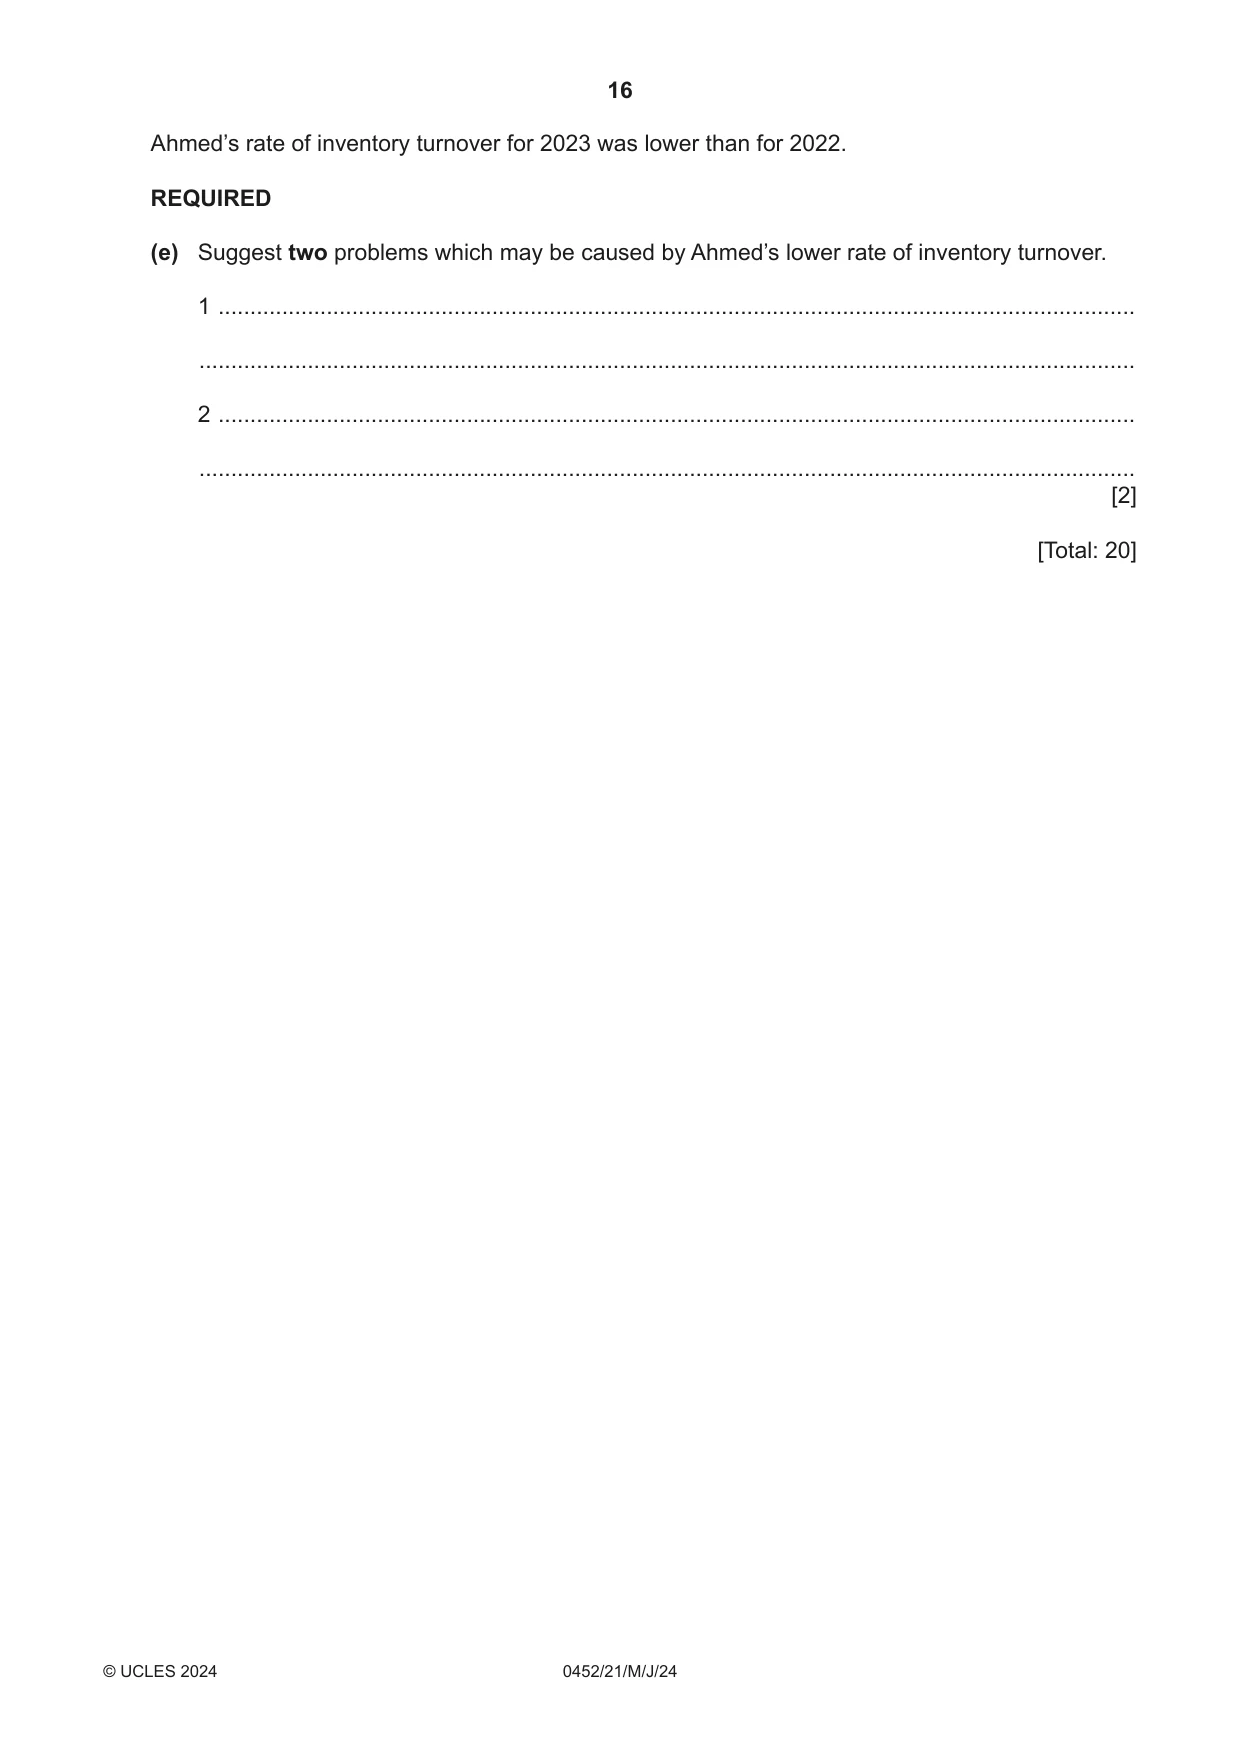
4 Ahmed owns a trading business. He prepares his financial statements to 31 December each year. Ahmed had some unused office space and he decided to use some of this to store inventory and to rent the rest to Bilal. On 1 January 2023 Bilal started renting the office space from Ahmed. The annual rental charge is $4800. During 2023 Bilal paid the following amounts of rent into Ahmed’s bank account. $ 1 April 3600 30 September 2400 REQUIRED (a) Prepare Ahmed’s rent receivable account for the year ended 31 December 2023. Balance the account and bring down the balance at 1 January 2024. Ahmed Rent receivable account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [3] Ahmed sold old office equipment for $1350 on 3 January 2023, on credit to Rahat. The equipment had been purchased for $3200 on 1 January 2021. Ahmed charges depreciation at 25% per annum using the reducing balance method. He does not charge depreciation in the year of disposal. REQUIRED (b) Prepare the disposal of office equipment account. Ahmed Disposal of office equipment account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [5] (c) Complete the table by placing a tick (✓) to indicate whether each amount of spending on the new inventory storage space is capital expenditure or revenue expenditure. $ Capital Revenue expenditure expenditure Painting the walls of the storage area 600 Shelving for the storage area 2115 Installation of the shelving 460 Light fittings for storage area 620 Light bulbs for storage area 105 [3] Ahmed’s ledger accounts at 31 December 2023 include the following balances. $ Inventory at 1 January 2023 9000 Receivables 6180 Cash 175 Payables 5500 Bank overdraft 640 Ahmed’s inventory at 31 December 2023 was valued at $12 130. His purchases for the year ended 31 December 2023 were $97 000. REQUIRED (d) Complete the following table. ratio working answer (to 2 decimal places) Rate of inventory turnover (times) Current ratio Liquid (acid test) ratio [7] Ahmed’s rate of inventory turnover for 2023 was lower than for 2022. REQUIRED (e) Suggest two problems which may be caused by Ahmed’s lower rate of inventory turnover. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 20]
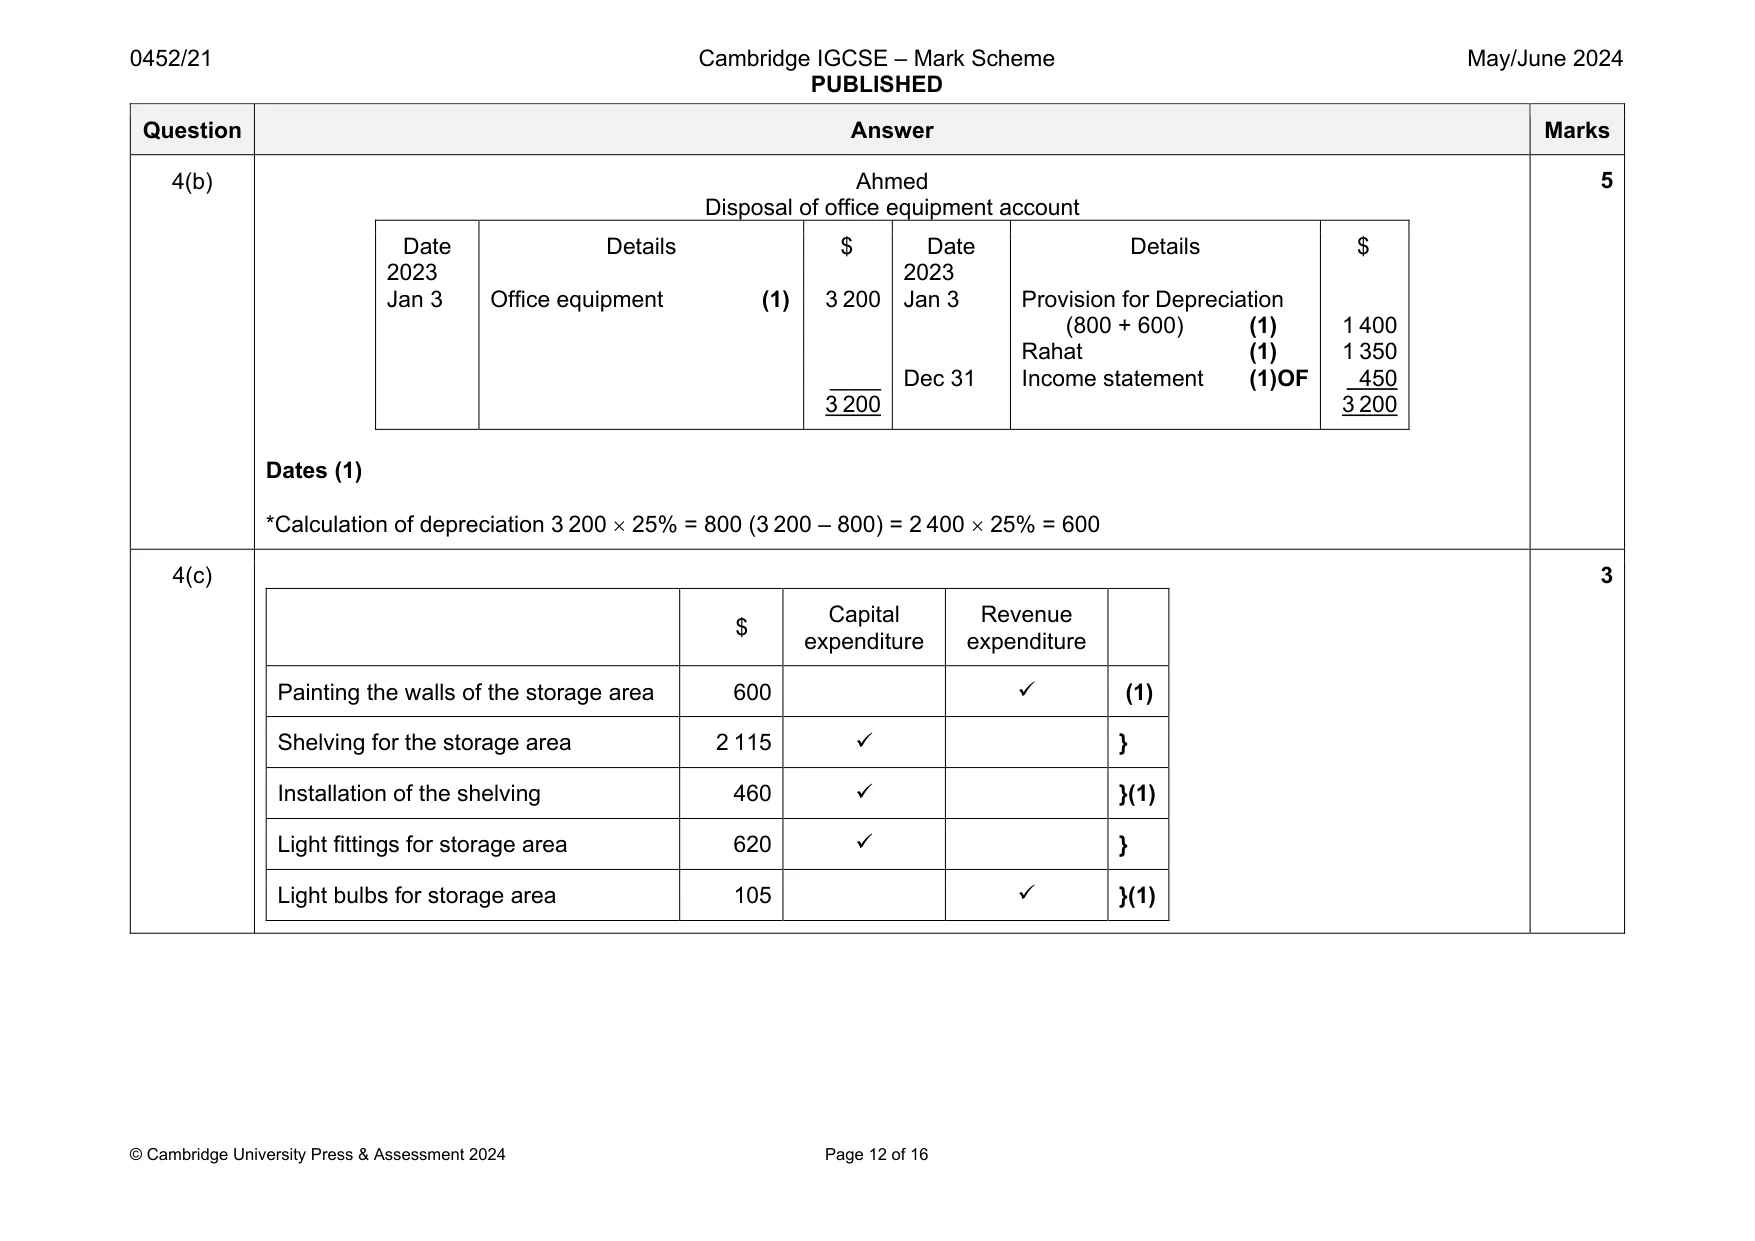
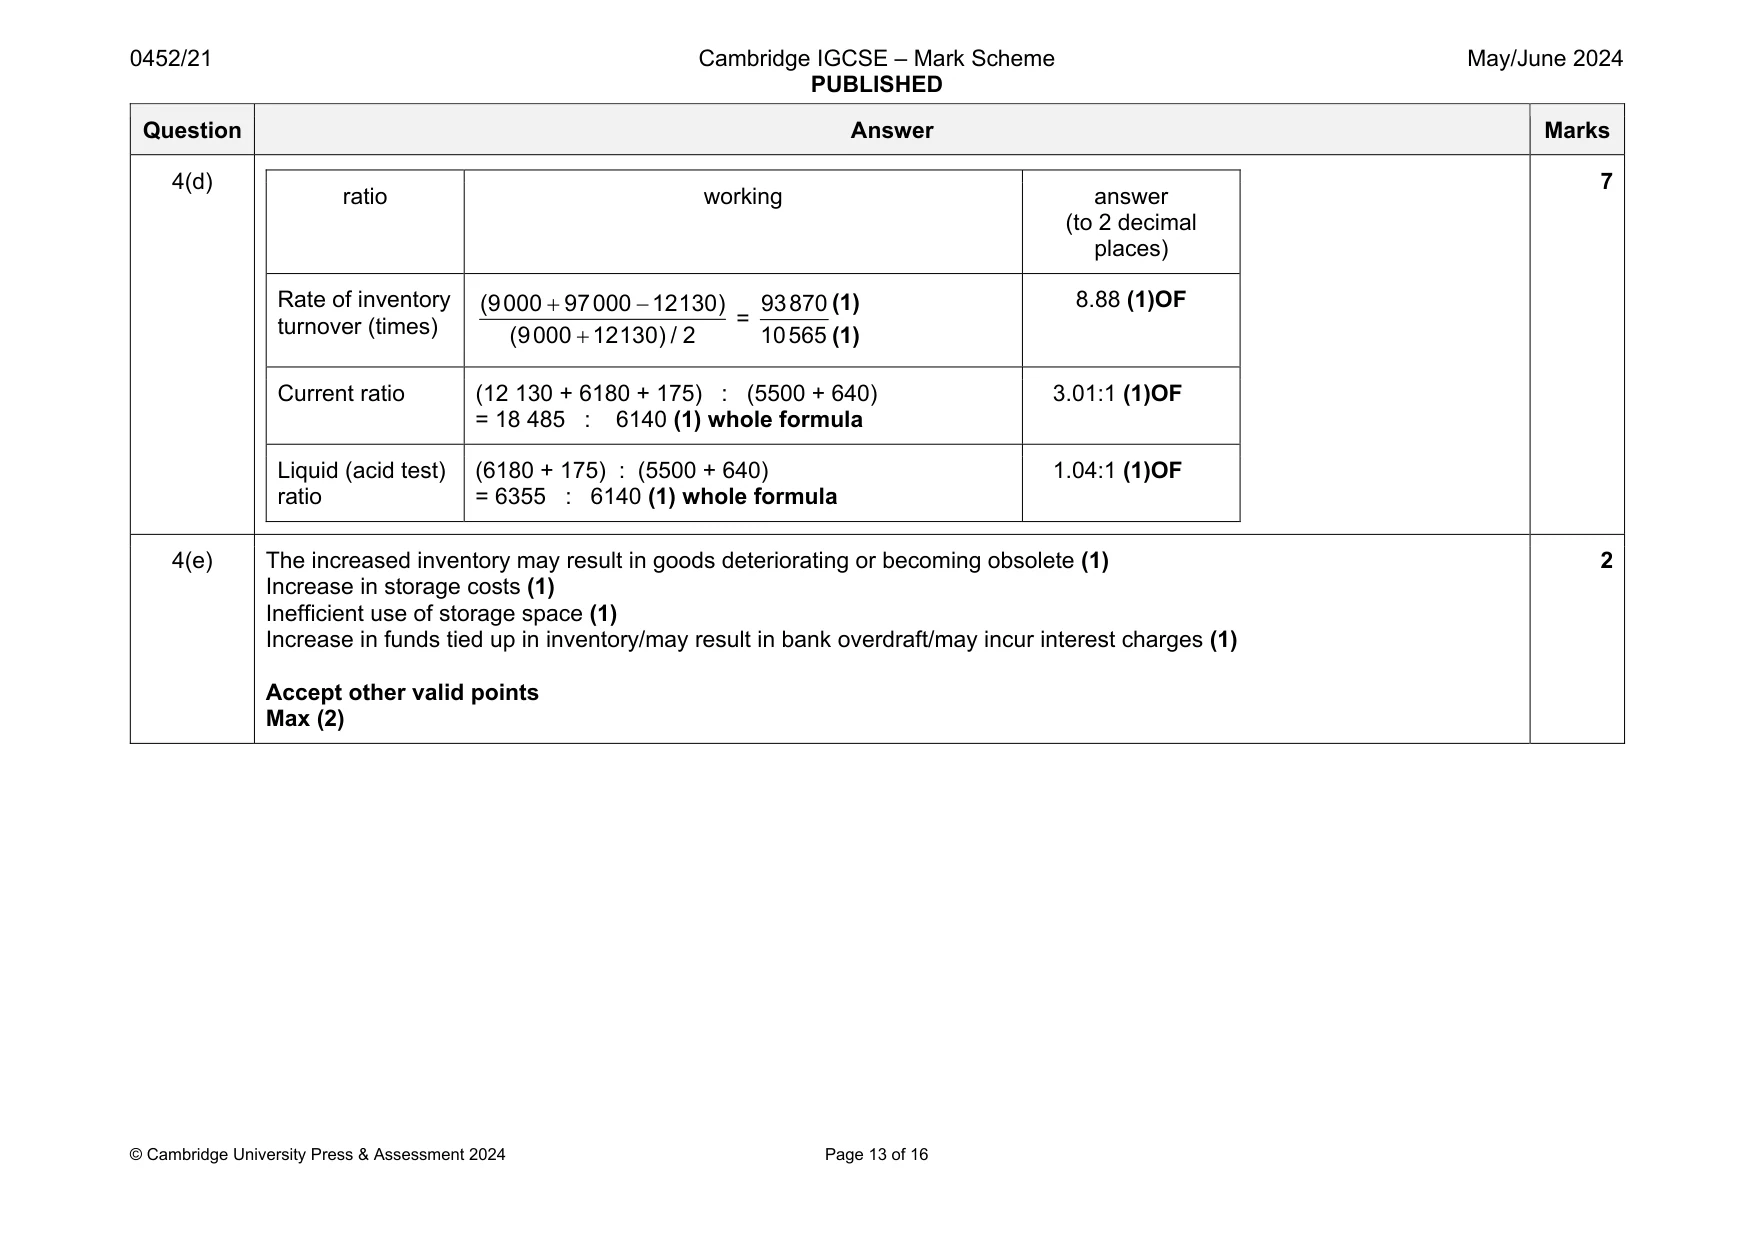
Mark scheme: 4(a) Ahmed Rent receivable account Date 2023 Dec 31 Details Income statement (1) Balance c/d $ 4 800 1 200 6 000 Date 2023 Apr 1 Sept 30 2024 Jan 1 Details Bank }(1) Bank } Balance b/d (1) $ 3 600 2 400 6 000 1 200 3 Question Answer Marks 4(b) Ahmed Disposal of office equipment account Date 2023 Jan 3 Details Office equipment (1) $ 3 200 ____ 3 200 Date 2023 Jan 3 Dec 31 Details Provision for Depreciation (800 + 600) (1) Rahat (1) Income statement (1)OF $ 1 400 1 350 450 3 200 Dates (1) *Calculation of depreciation 3 200 25% = 800 (3 200 – 800) = 2 400 25% = 600 5 4(c) $ Capital expenditure Revenue expenditure Painting the walls of the storage area 600 (1) Shelving for the storage area 2 115 } Installation of the shelving 460 }(1) Light fittings for storage area 620 } Light bulbs for storage area 105 }(1) 3 Question Answer Marks 4(d) ratio working answer (to 2 decimal places) Rate of inventory turnover (times) (9000 97000 12130) (9000 12130) / 2 = 93870 10565 (1) (1) 8.88 (1)OF Current ratio (12 130 + 6180 + 175) : (5500 + 640) = 18 485 : 6140 (1) whole formula 3.01:1 (1)OF Liquid (acid test) ratio (6180 + 175) : (5500 + 640) = 6355 : 6140 (1) whole formula 1.04:1 (1)OF 7 4(e) The increased inventory may result in goods deteriorating or becoming obsolete (1) Increase in storage costs (1) Inefficient use of storage space (1) Increase in funds tied up in inventory/may result in bank overdraft/may incur interest charges (1) Accept other valid points Max (2) 2
More questions on Calculation and understanding of accounting ratios
Q5 · Stella started in business as a retailer on 1 April 2023
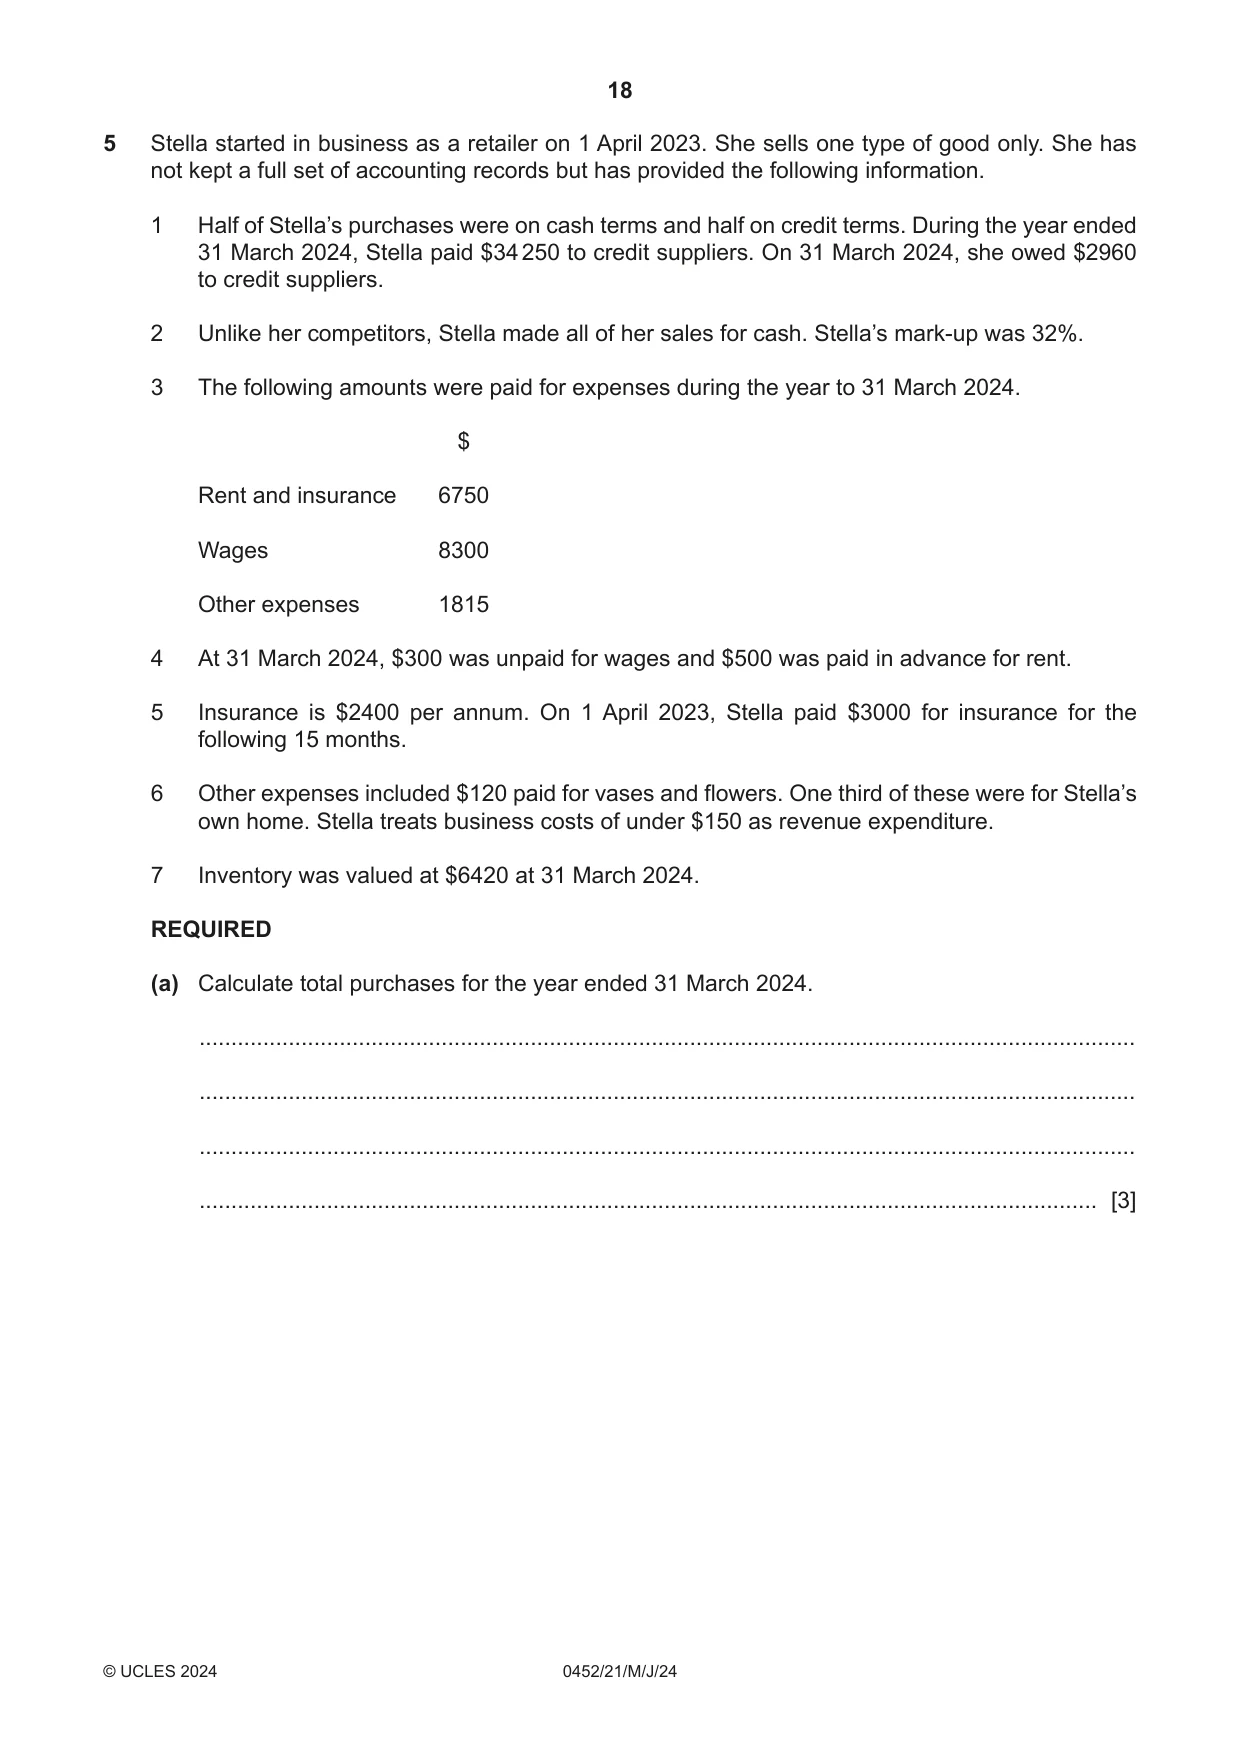
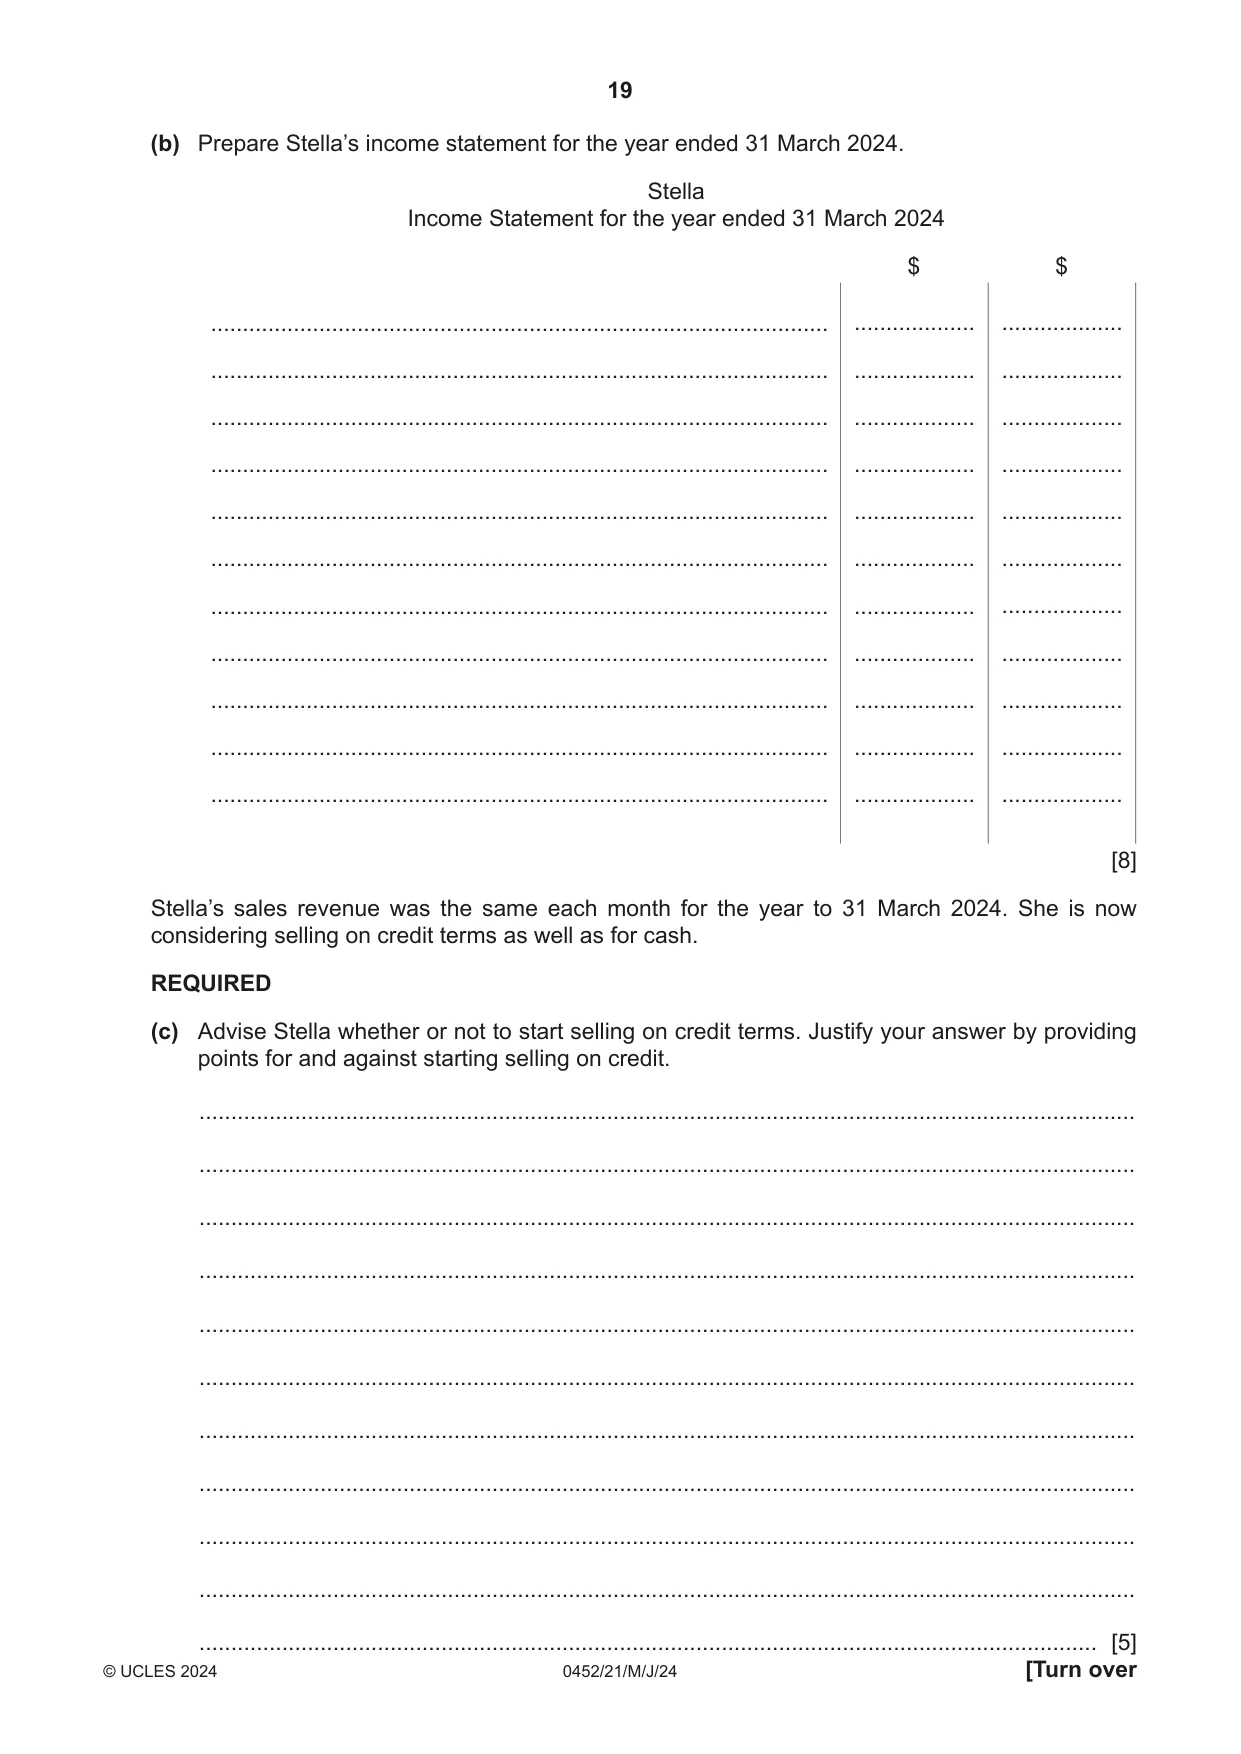
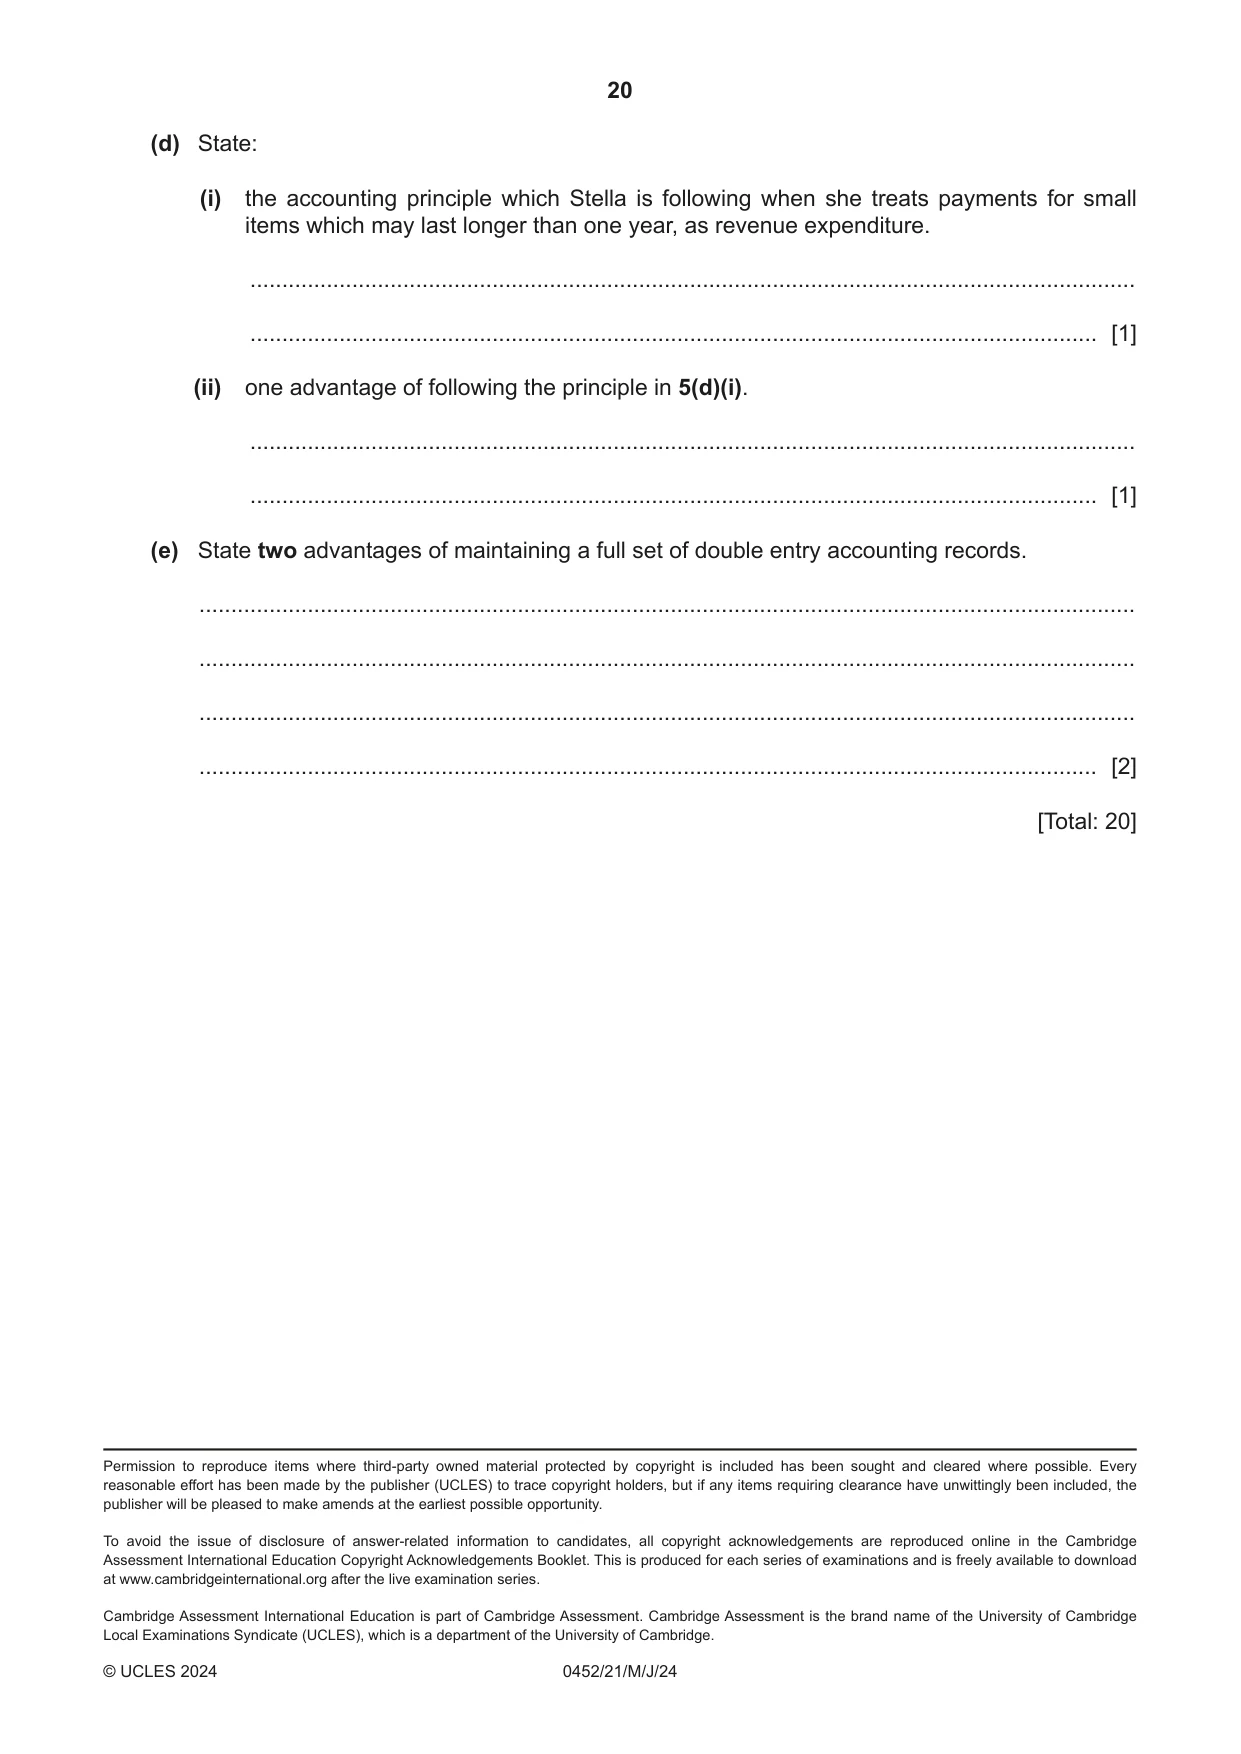
5 Stella started in business as a retailer on 1 April 2023. She sells one type of good only. She has not kept a full set of accounting records but has provided the following information. 1 Half of Stella’s purchases were on cash terms and half on credit terms. During the year ended 31 March 2024, Stella paid $34 250 to credit suppliers. On 31 March 2024, she owed $2960 to credit suppliers. 2 Unlike her competitors, Stella made all of her sales for cash. Stella’s mark-up was 32%. 3 The following amounts were paid for expenses during the year to 31 March 2024. $ Rent and insurance 6750 Wages 8300 Other expenses 1815 4 At 31 March 2024, $300 was unpaid for wages and $500 was paid in advance for rent. 5 Insurance is $2400 per annum. On 1 April 2023, Stella paid $3000 for insurance for the following 15 months. 6 Other expenses included $120 paid for vases and flowers. One third of these were for Stella’s own home. Stella treats business costs of under $150 as revenue expenditure. 7 Inventory was valued at $6420 at 31 March 2024. REQUIRED (a) Calculate total purchases for the year ended 31 March 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Prepare Stella’s income statement for the year ended 31 March 2024. Stella Income Statement for the year ended 31 March 2024 $ $ ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... ................................................................................................. ................... ................... [8] Stella’s sales revenue was the same each month for the year to 31 March 2024. She is now considering selling on credit terms as well as for cash. REQUIRED (c) Advise Stella whether or not to start selling on credit terms. Justify your answer by providing points for and against starting selling on credit. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State: (i) the accounting principle which Stella is following when she treats payments for small items which may last longer than one year, as revenue expenditure. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) one advantage of following the principle in 5(d)(i). ........................................................................................................................................... ..................................................................................................................................... [1] (e) State two advantages of maintaining a full set of double entry accounting records. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 20]
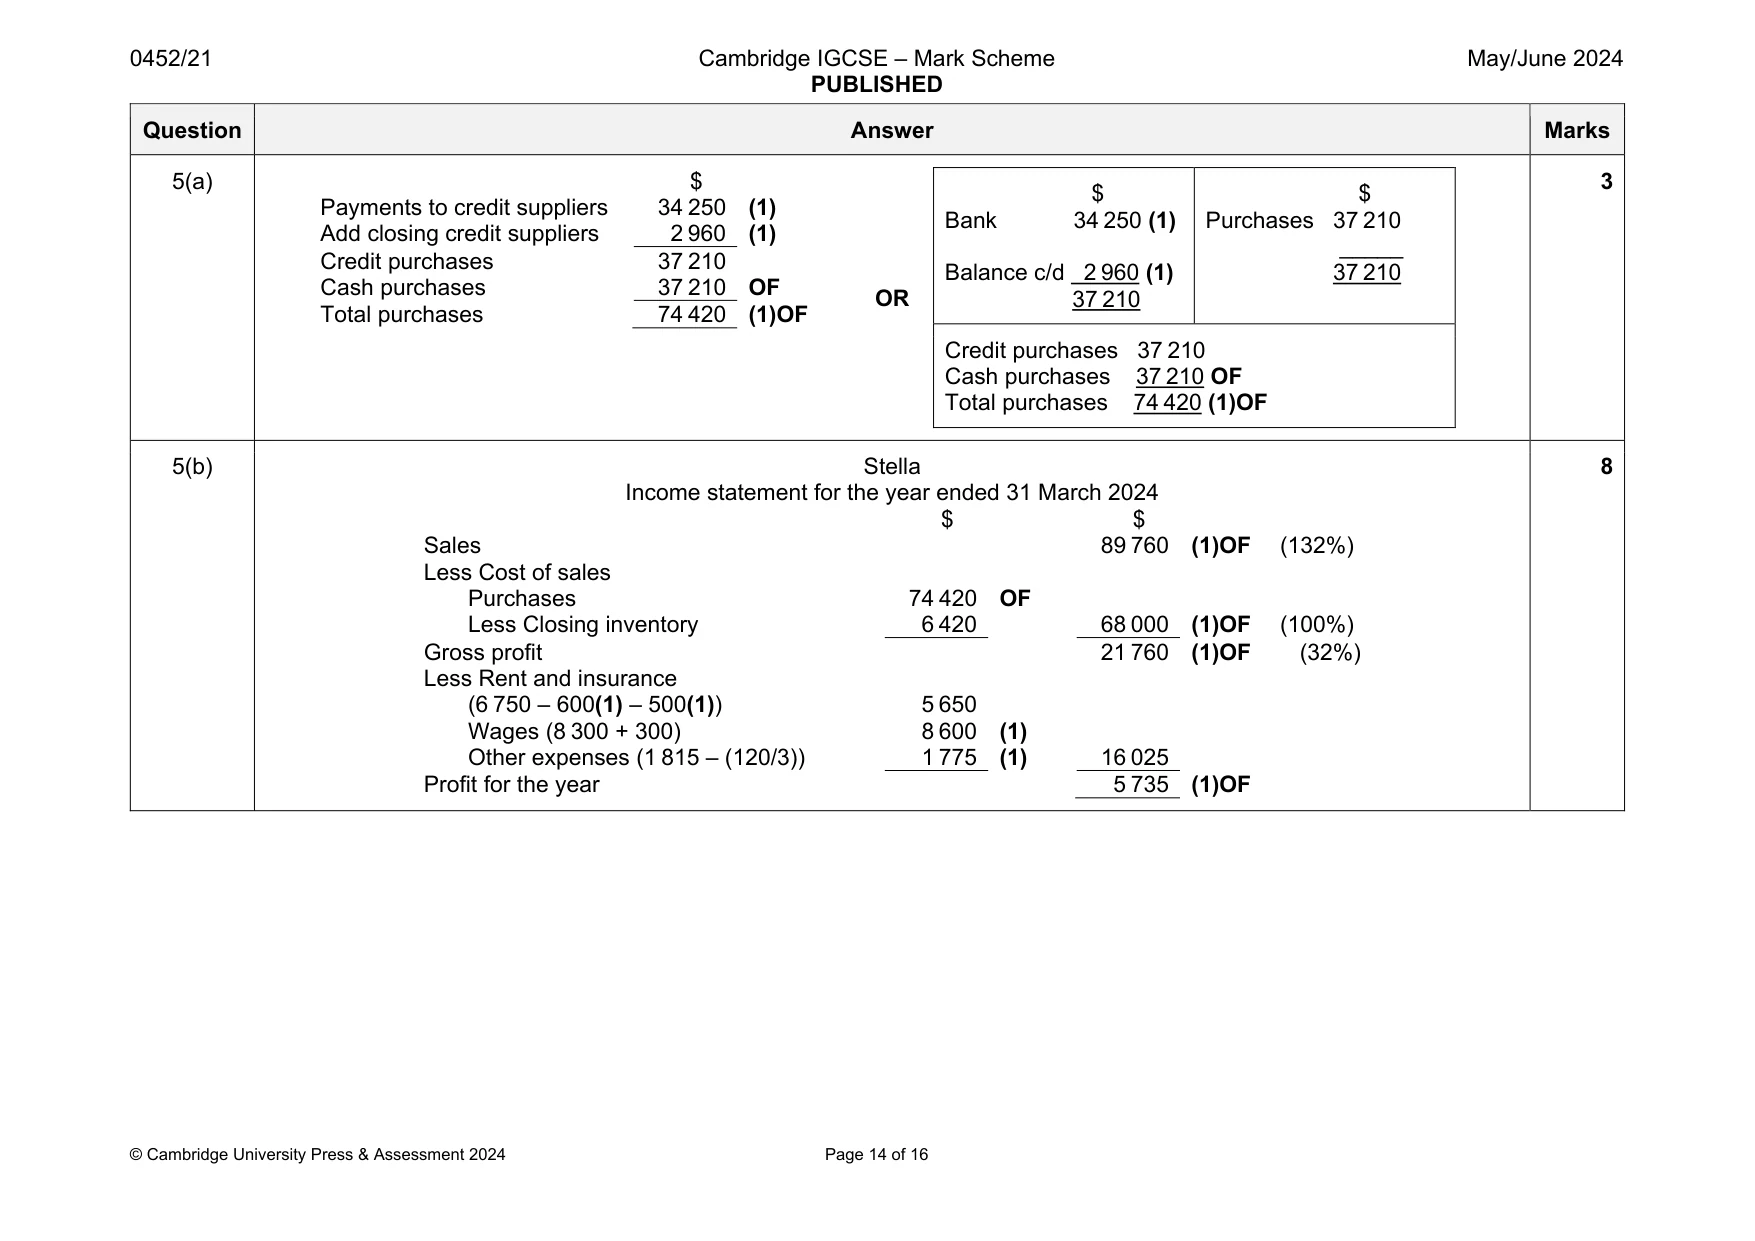
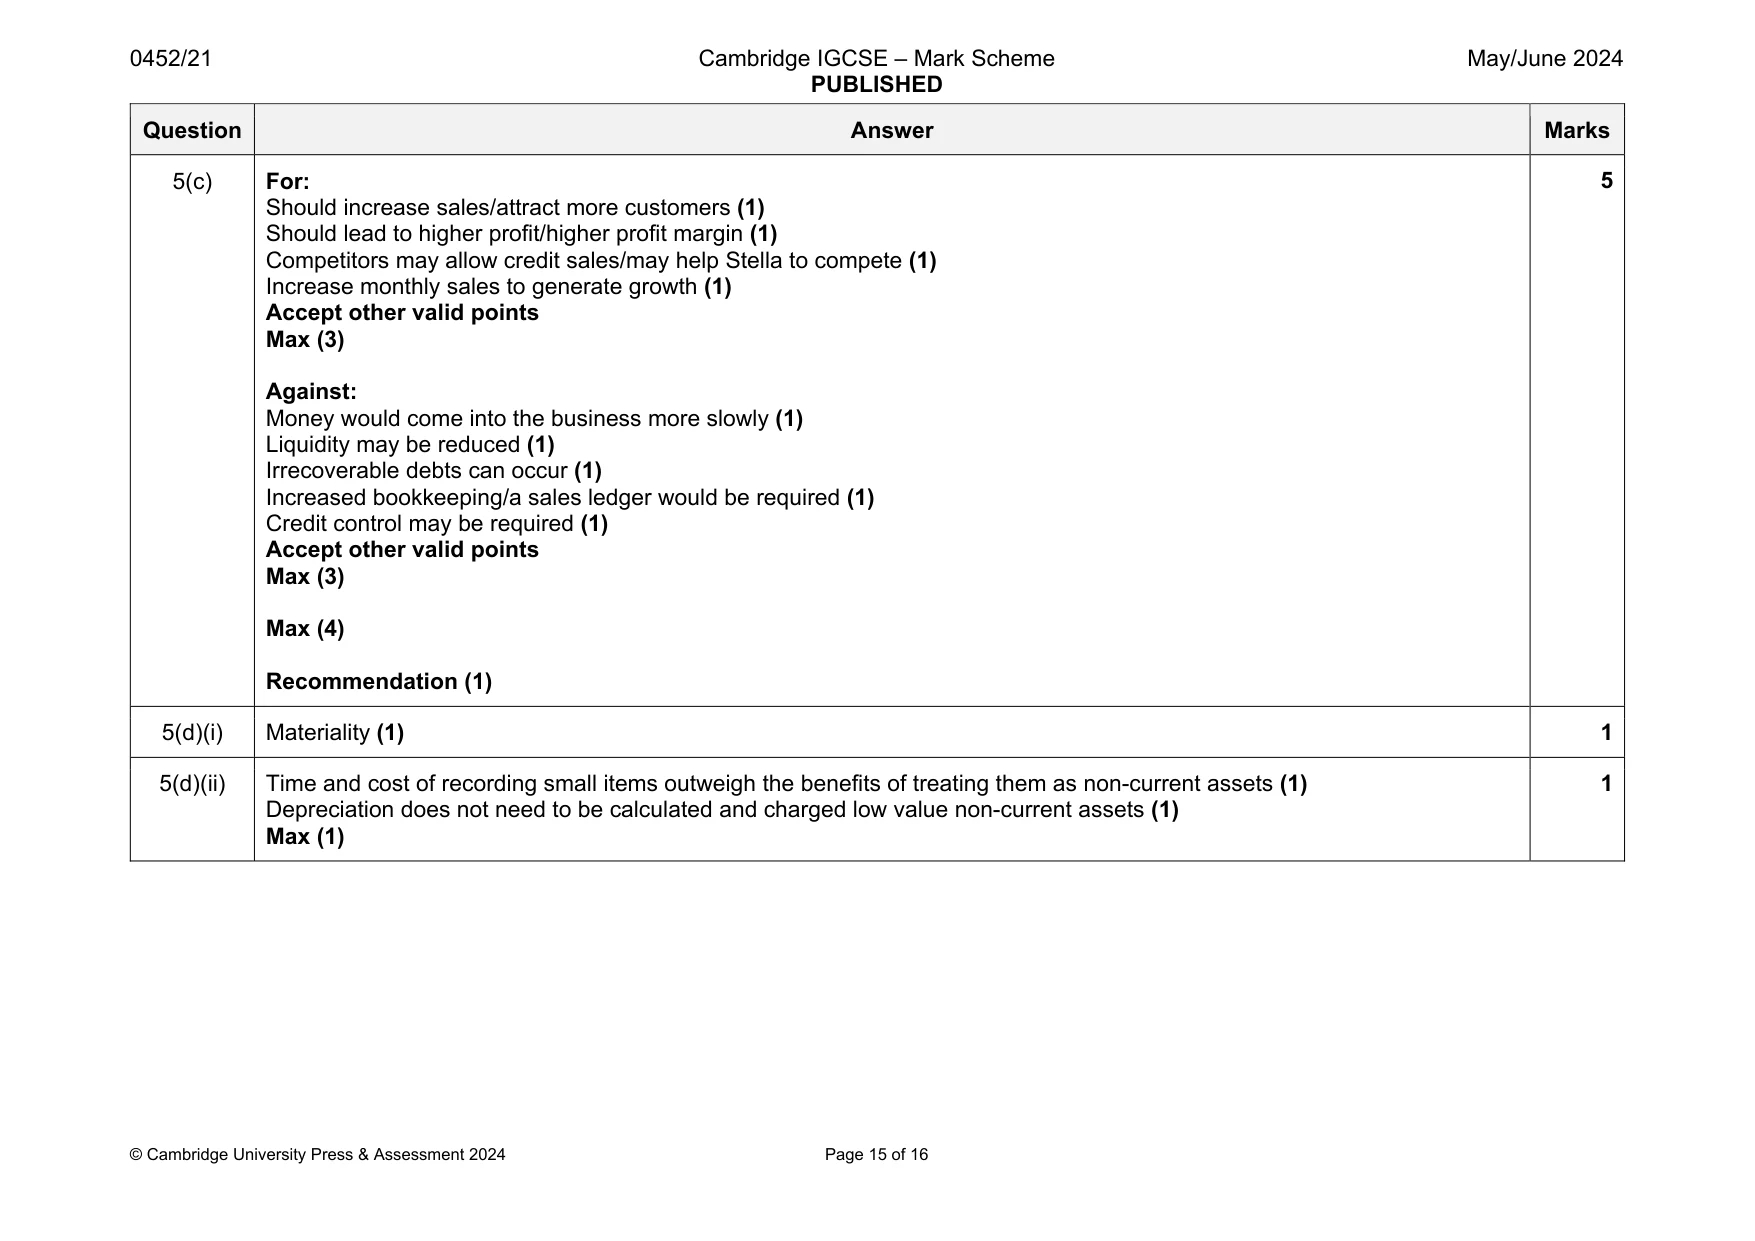
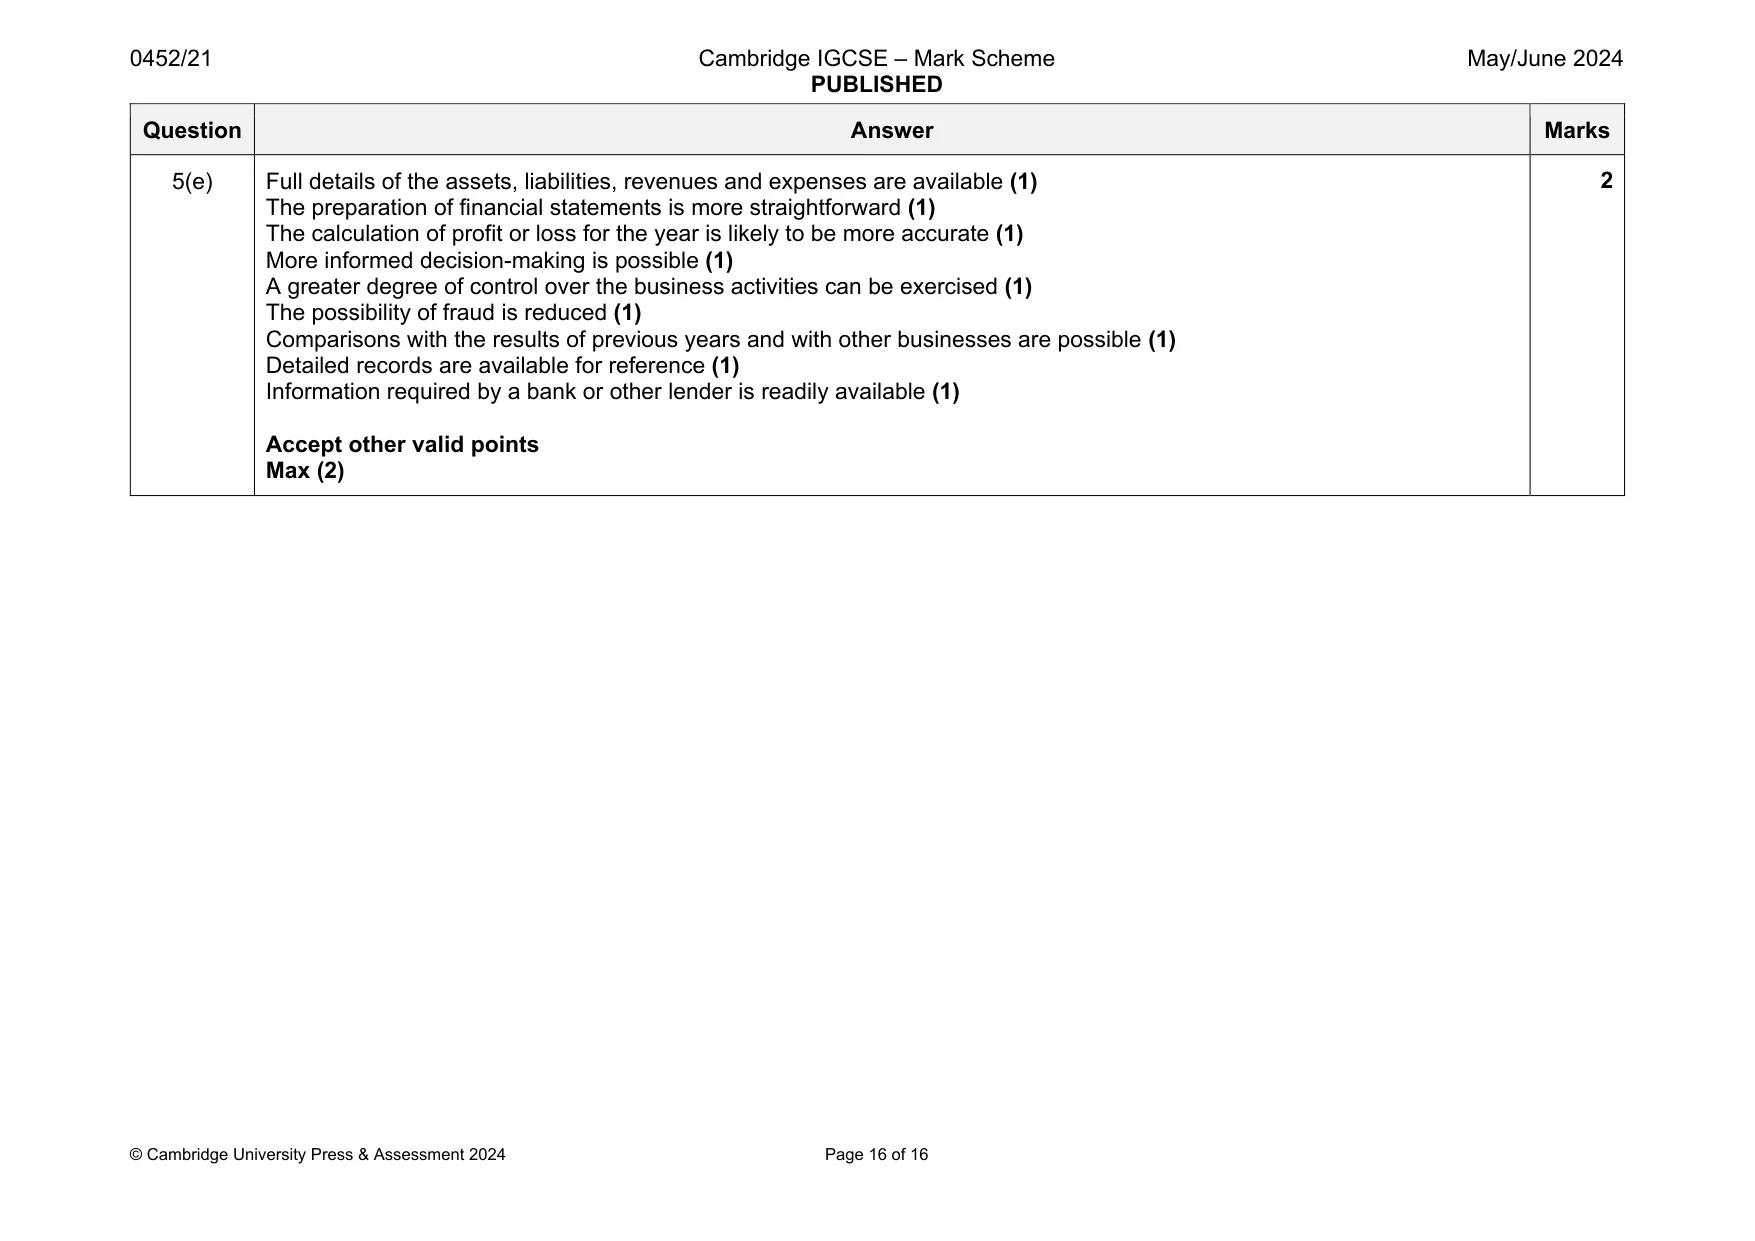
Mark scheme: 5(a) $ Payments to credit suppliers 34 250 (1) Add closing credit suppliers 2 960 (1) Credit purchases 37 210 Cash purchases 37 210 OF Total purchases 74 420 (1)OF OR $ Bank 34 250 (1) Balance c/d 2 960 (1) 37 210 $ Purchases 37 210 _____ 37 210 Credit purchases 37 210 Cash purchases 37 210 OF Total purchases 74 420 (1)OF 3 5(b) Stella Income statement for the year ended 31 March 2024 $ $ Sales 89 760 (1)OF (132%) Less Cost of sales Purchases 74 420 OF Less Closing inventory 6 420 68 000 (1)OF (100%) Gross profit 21 760 (1)OF (32%) Less Rent and insurance (6 750 – 600(1) – 500(1)) 5 650 Wages (8 300 + 300) 8 600 (1) Other expenses (1 815 – (120/3)) 1 775 (1) 16 025 Profit for the year 5 735 (1)OF 8 Question Answer Marks 5(c) For: Should increase sales/attract more customers (1) Should lead to higher profit/higher profit margin (1) Competitors may allow credit sales/may help Stella to compete (1) Increase monthly sales to generate growth (1) Accept other valid points Max (3) Against: Money would come into the business more slowly (1) Liquidity may be reduced (1) Irrecoverable debts can occur (1) Increased bookkeeping/a sales ledger would be required (1) Credit control may be required (1) Accept other valid points Max (3) Max (4) Recommendation (1) 5 5(d)(i) Materiality (1) 1 5(d)(ii) Time and cost of recording small items outweigh the benefits of treating them as non-current assets (1) Depreciation does not need to be calculated and charged low value non-current assets (1) Max (1) 1 Question Answer Marks 5(e) Full details of the assets, liabilities, revenues and expenses are available (1) The preparation of financial statements is more straightforward (1) The calculation of profit or loss for the year is likely to be more accurate (1) More informed decision-making is possible (1) A greater degree of control over the business activities can be exercised (1) The possibility of fraud is reduced (1) Comparisons with the results of previous years and with other businesses are possible (1) Detailed records are available for reference (1) Information required by a bank or other lender is readily available (1) Accept other valid points Max (2) 2
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.