Cambridge IGCSE Accounting 0452 — 2018 Oct/Nov Paper 2 · Variant 1
0452/21/O/N/18 · 6 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Thato opened a wholesale shoe business on 1 August 2018
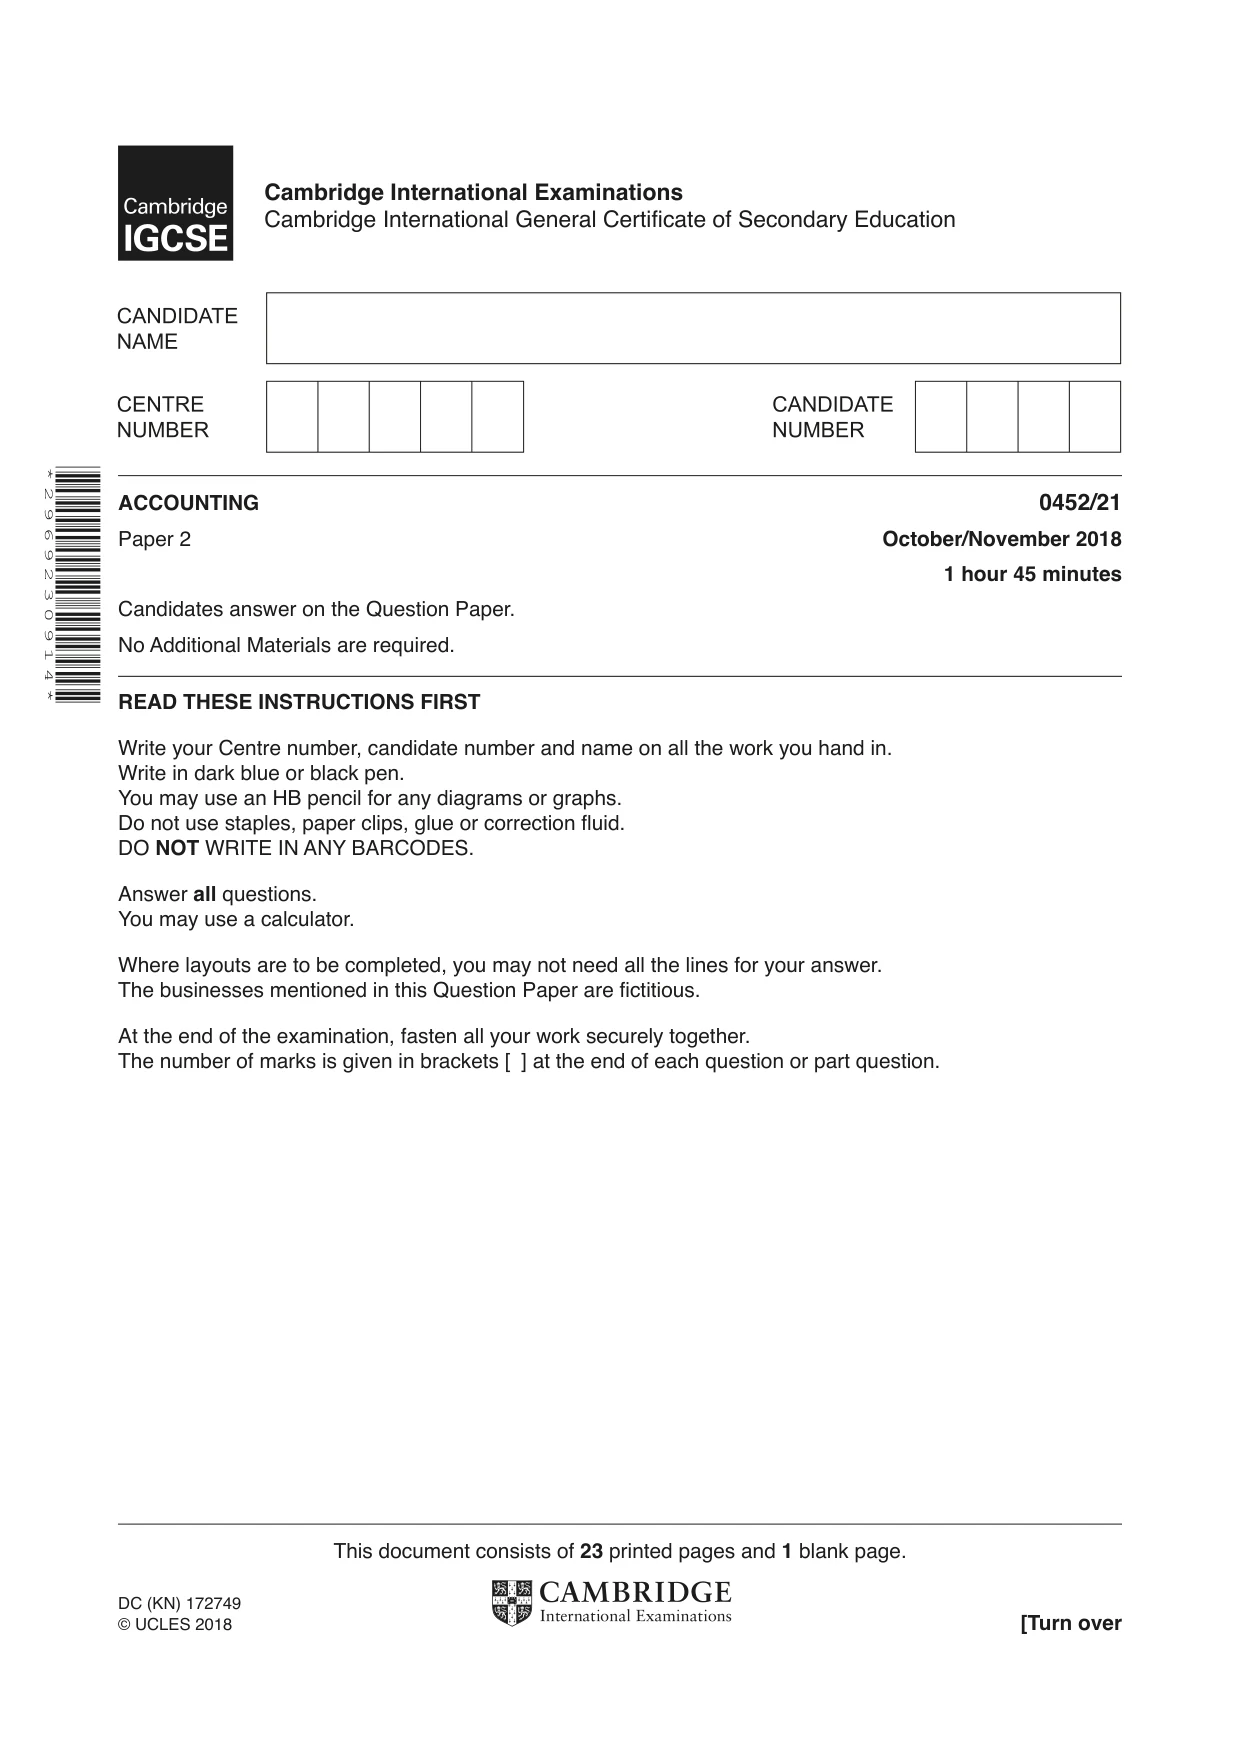
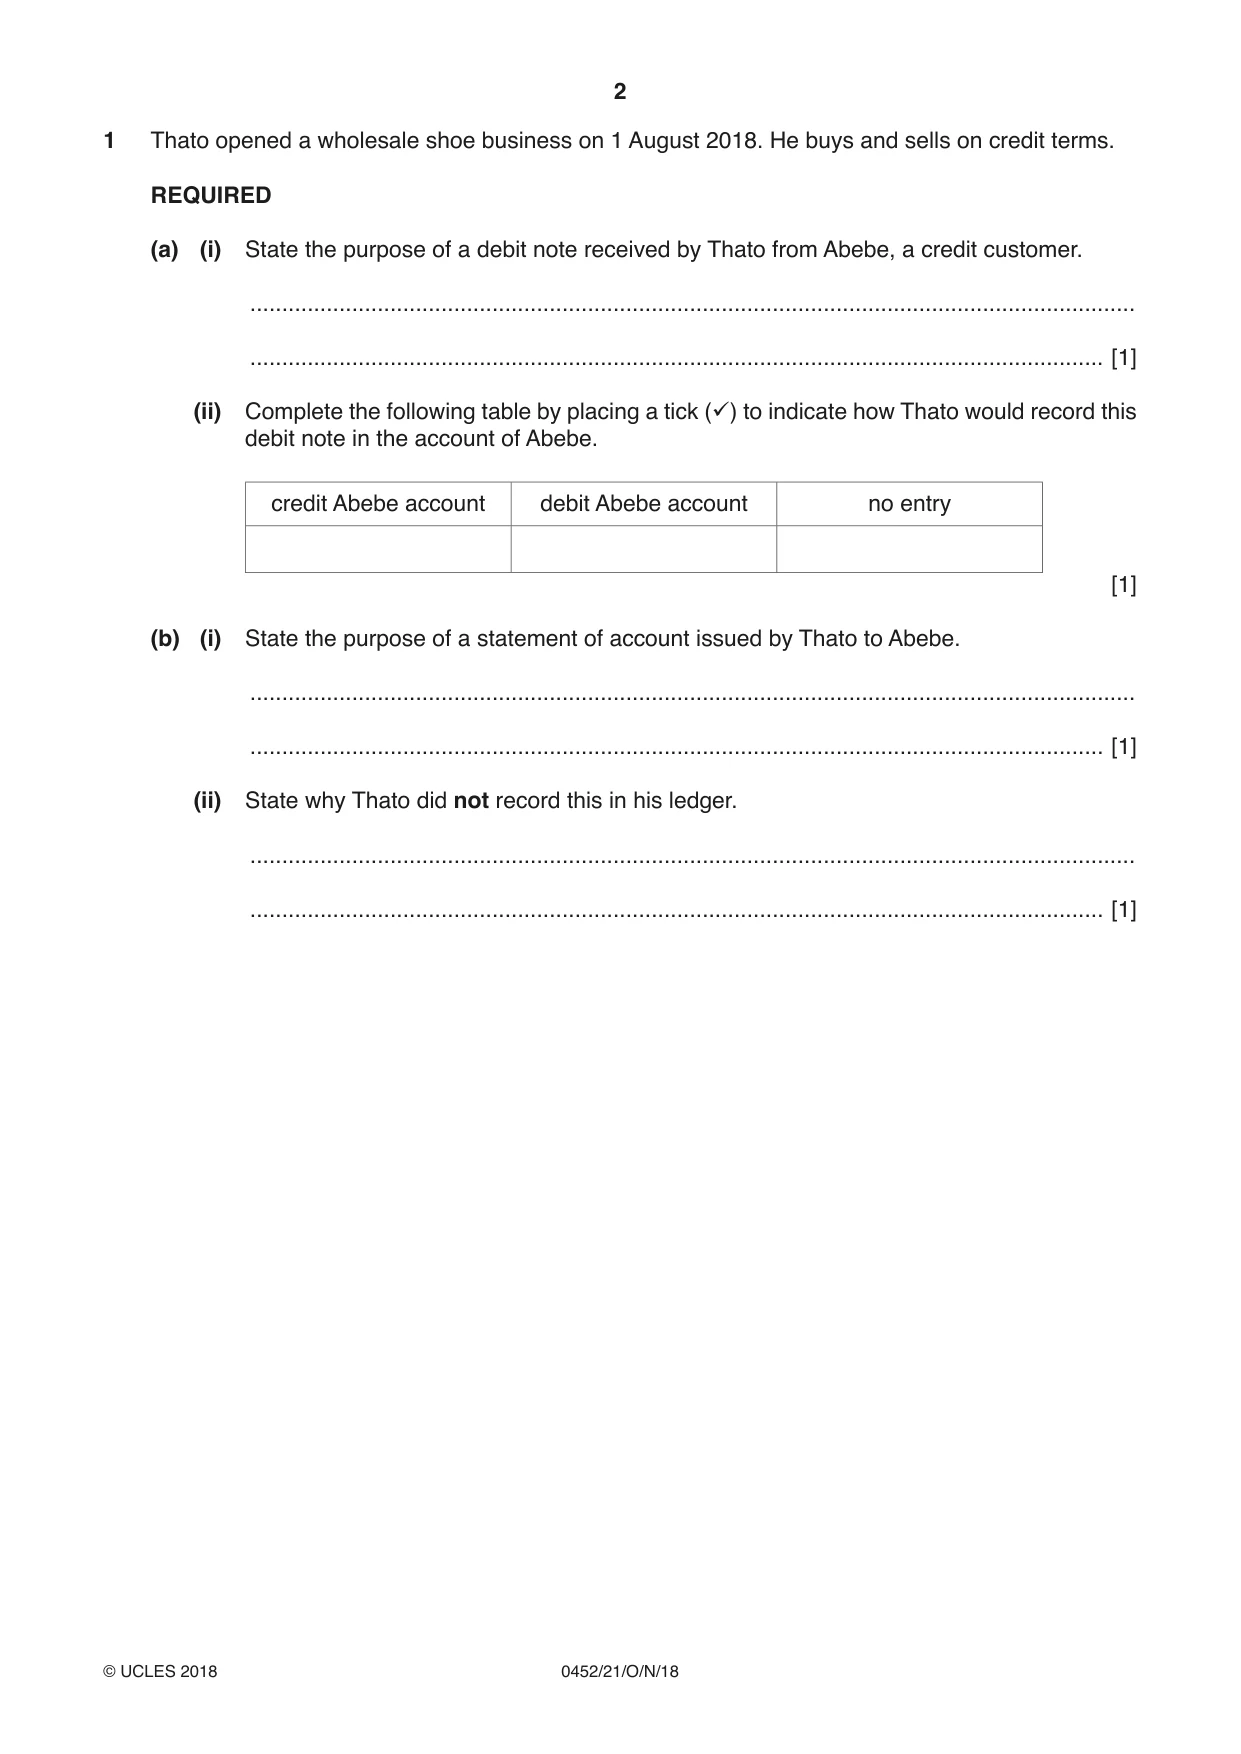
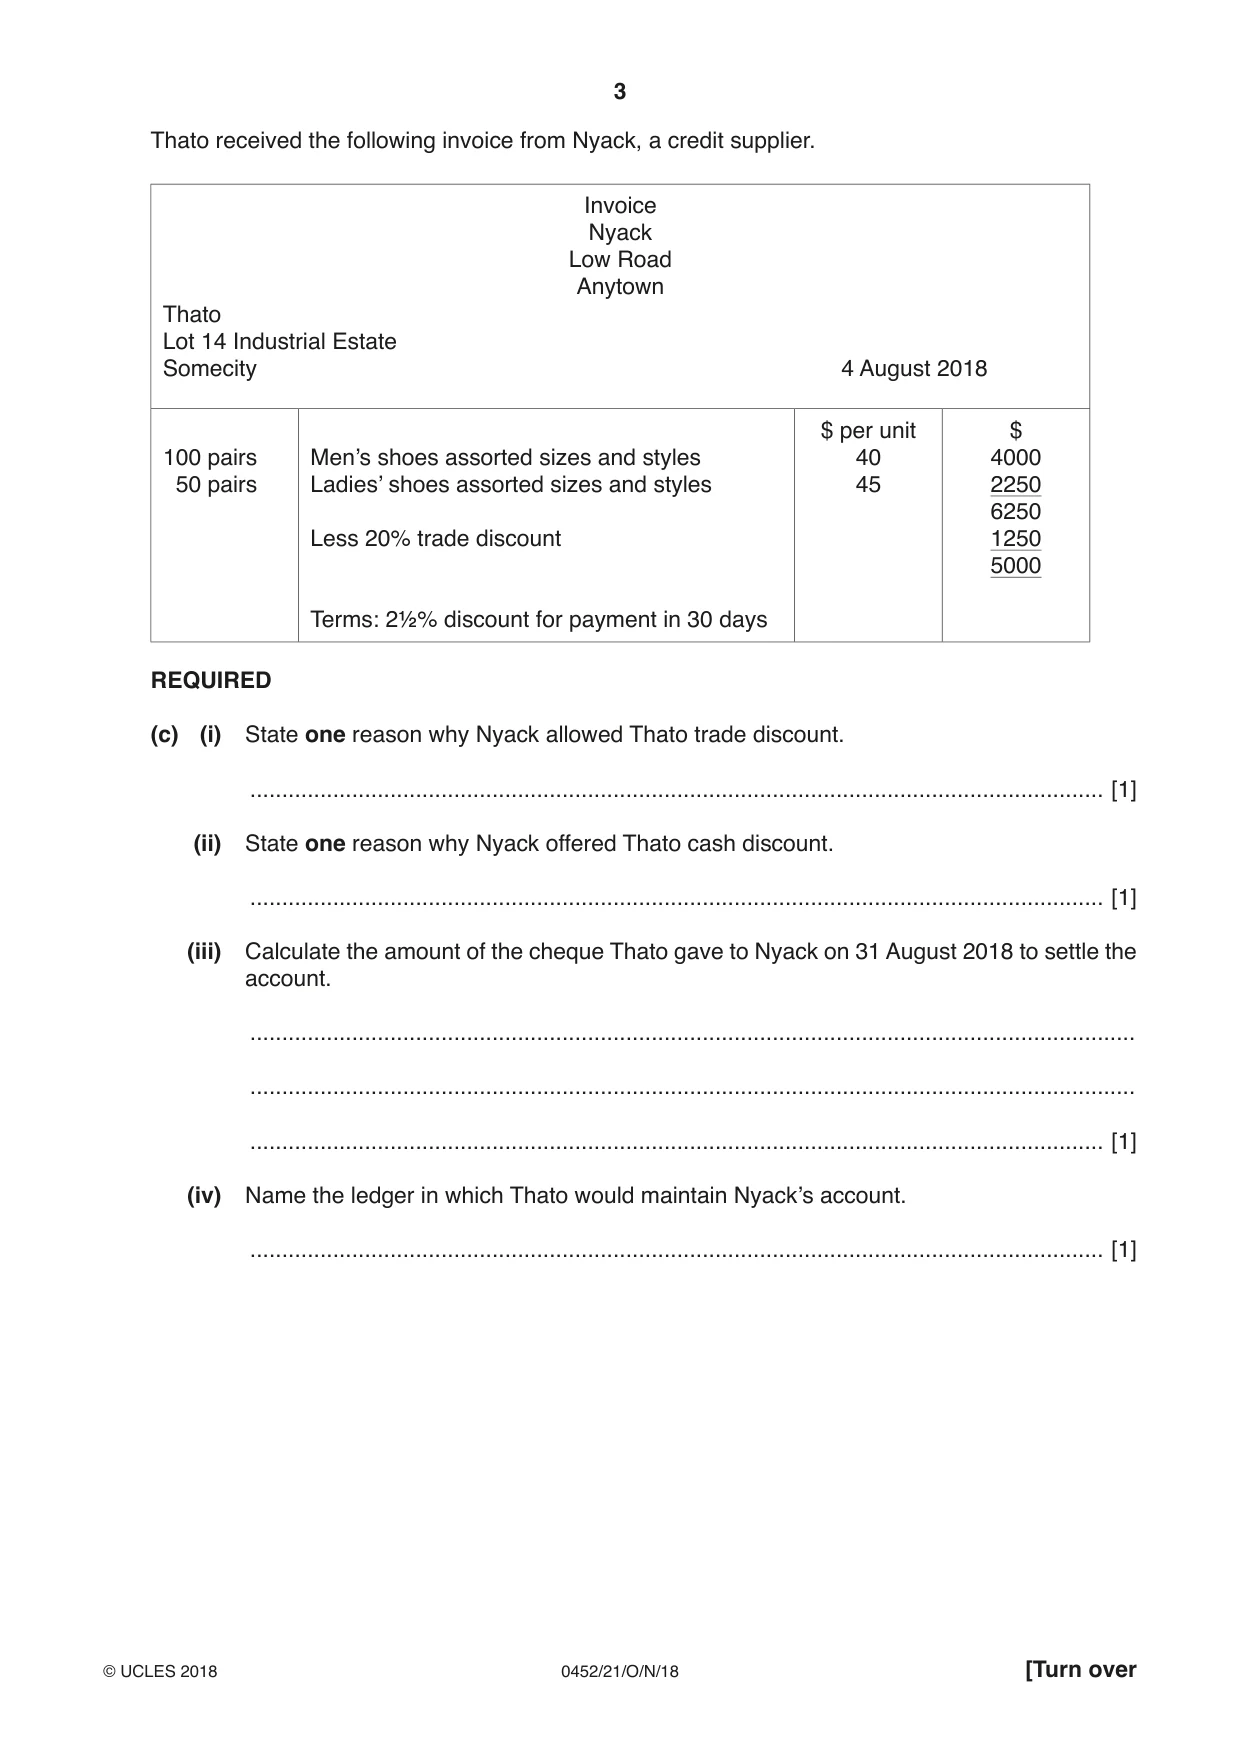
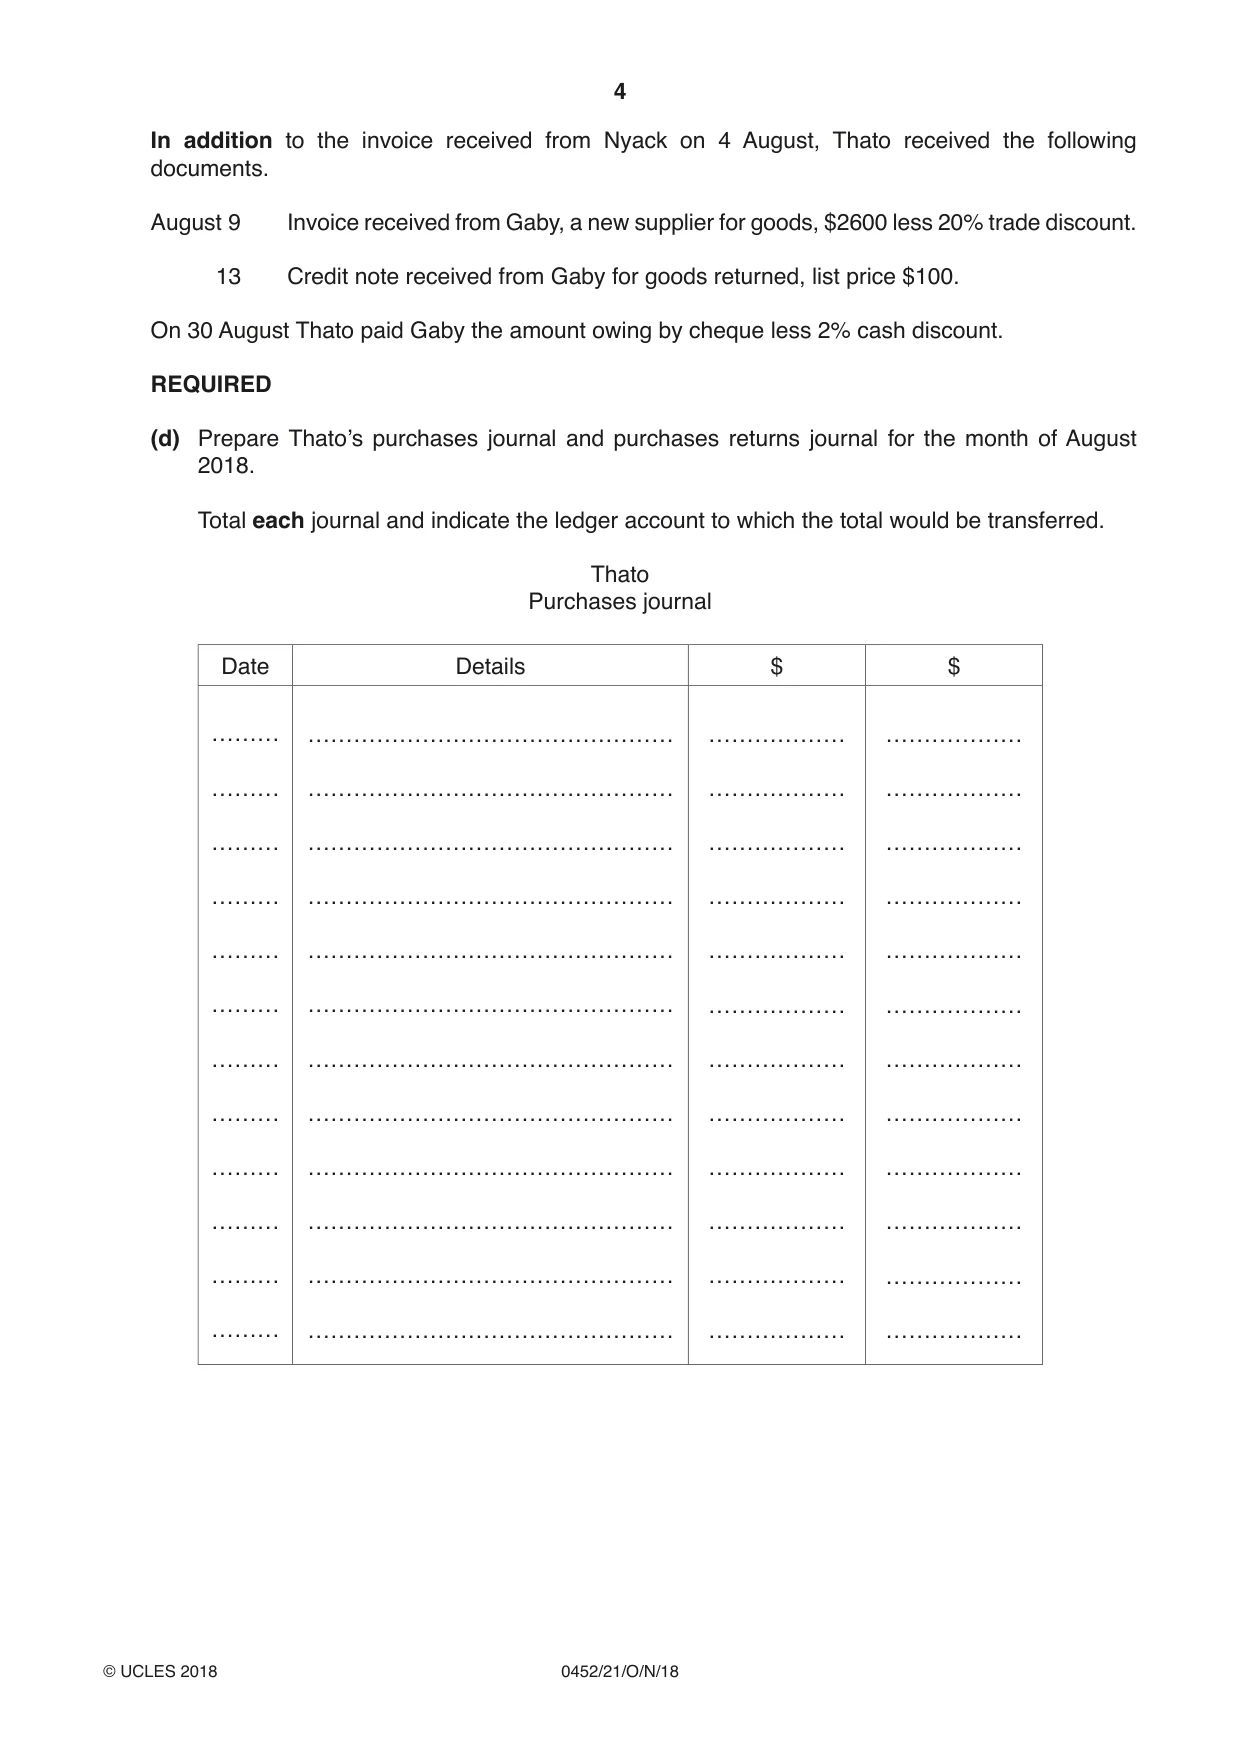
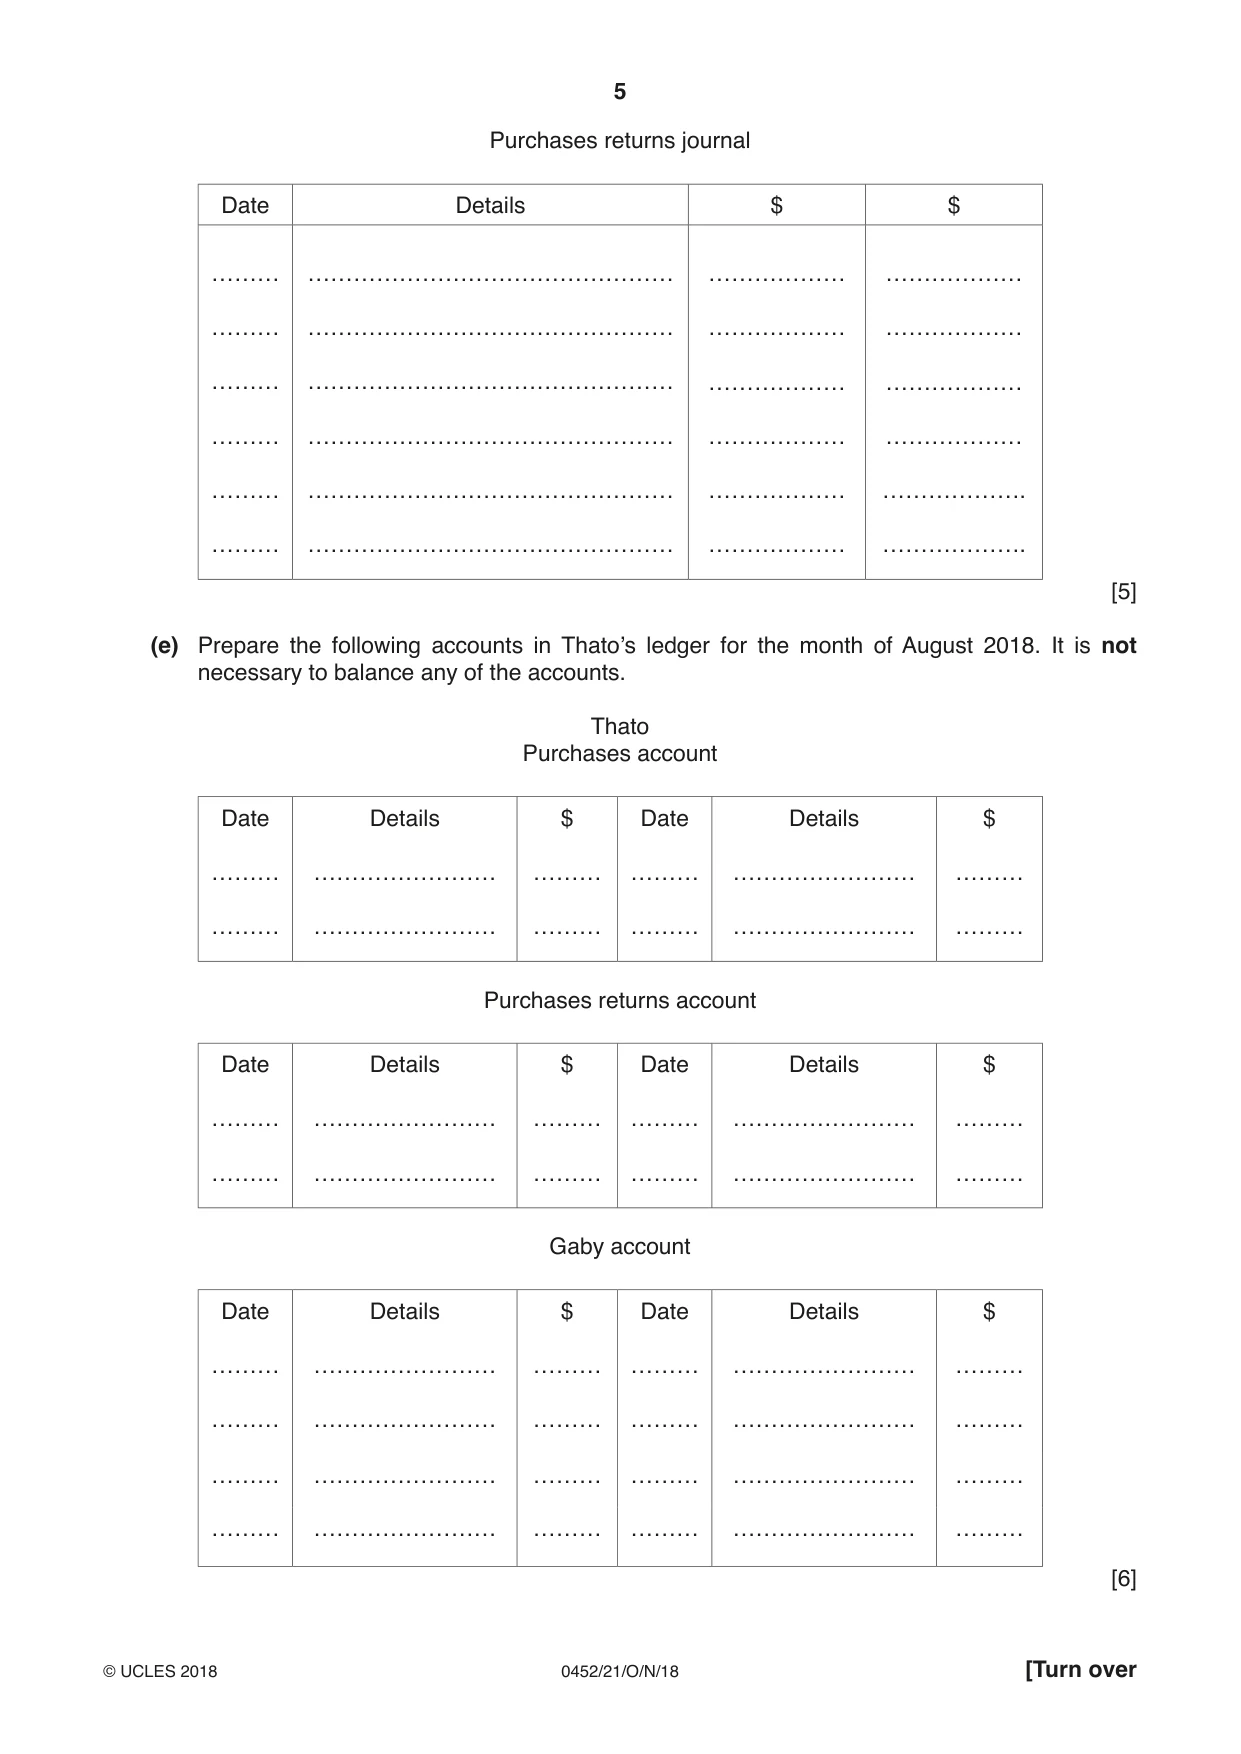
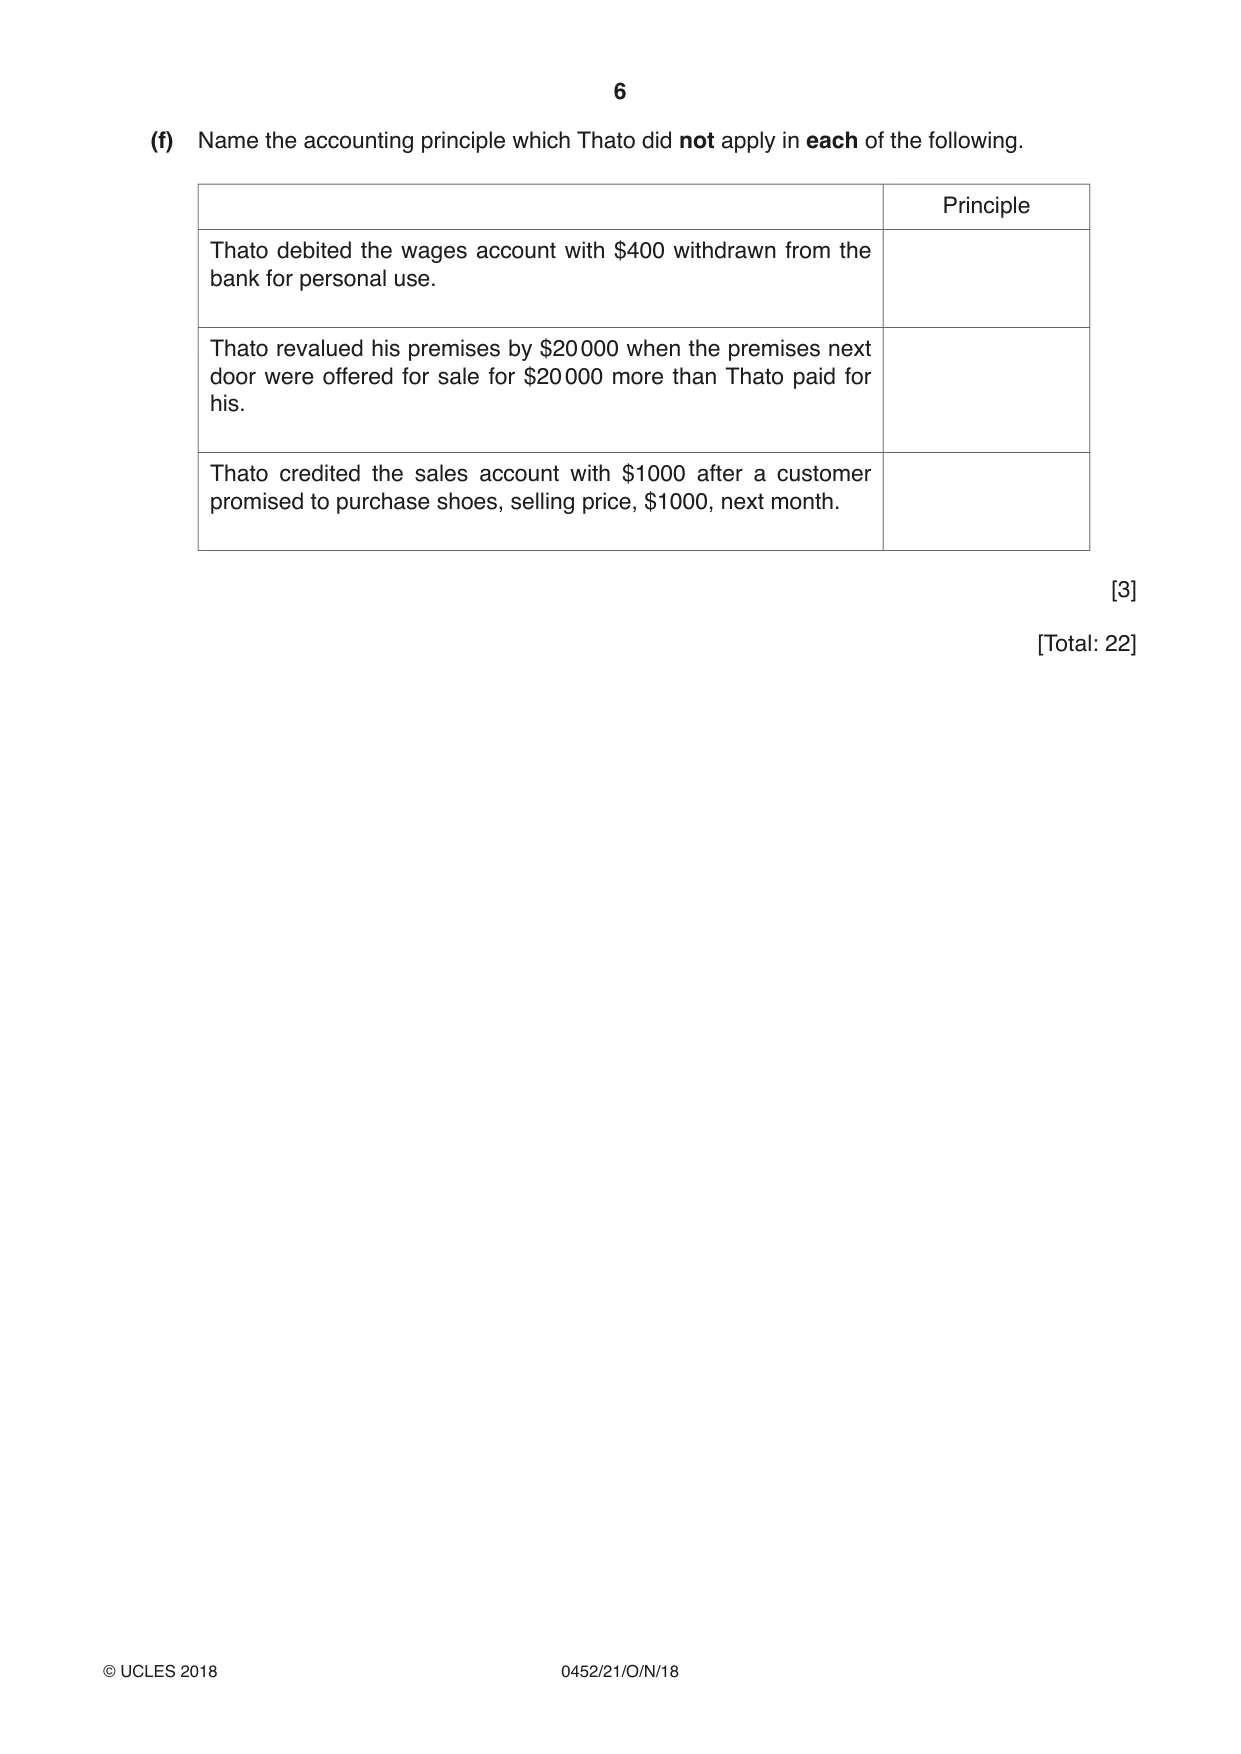
1 Thato opened a wholesale shoe business on 1 August 2018. He buys and sells on credit terms. REQUIRED (a) (i) State the purpose of a debit note received by Thato from Abebe, a credit customer. ........................................................................................................................................... ...................................................................................................................................... [1] (ii) Complete the following table by placing a tick () to indicate how Thato would record this debit note in the account of Abebe. credit Abebe account debit Abebe account no entry [1] (b) (i) State the purpose of a statement of account issued by Thato to Abebe. ........................................................................................................................................... ...................................................................................................................................... [1] (ii) State why Thato did not record this in his ledger. ........................................................................................................................................... ...................................................................................................................................... [1] Thato received the following invoice from Nyack, a credit supplier. Invoice Nyack Low Road Anytown Thato Lot 14 Industrial Estate Somecity 4 August 2018 $ per unit $ 100 pairs Men’s shoes assorted sizes and styles 40 4000 50 pairs Ladies’ shoes assorted sizes and styles 45 2250 6250 Less 20% trade discount 1250 5000 Terms: 2½% discount for payment in 30 days REQUIRED (c) (i) State one reason why Nyack allowed Thato trade discount. ...................................................................................................................................... [1] (ii) State one reason why Nyack offered Thato cash discount. ...................................................................................................................................... [1] (iii) Calculate the amount of the cheque Thato gave to Nyack on 31 August 2018 to settle the account. ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [1] (iv) Name the ledger in which Thato would maintain Nyack’s account. ...................................................................................................................................... [1] In addition to the invoice received from Nyack on 4 August, Thato received the following documents. August 9 Invoice received from Gaby, a new supplier for goods, $2600 less 20% trade discount. 13 Credit note received from Gaby for goods returned, list price $100. On 30 August Thato paid Gaby the amount owing by cheque less 2% cash discount. REQUIRED (d) Prepare Thato’s purchases journal and purchases returns journal for the month of August 2018. Total each journal and indicate the ledger account to which the total would be transferred. Thato Purchases journal Date Details $ $ ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… Purchases returns journal Date Details $ $ ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ……………… ……… ……………… ………………. ……… ……………… ………………. [5] (e) Prepare the following accounts in Thato’s ledger for the month of August 2018. It is not necessary to balance any of the accounts. Thato Purchases account Date Details $ Date Details $ ……… ……… ……… ……… ……… ……… ……… ……… Purchases returns account Date Details $ Date Details $ ……… ……… ……… ……… ……… ……… ……… ……… Gaby account Date Details $ Date Details $ ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… [6] (f) Name the accounting principle which Thato did not apply in each of the following. Principle Thato debited the wages account with $400 withdrawn from the bank for personal use. Thato revalued his premises by $20 000 when the premises next door were offered for sale for $20 000 more than Thato paid for his. Thato credited the sales account with $1000 after a customer promised to purchase shoes, selling price, $1000, next month. [3] [Total: 22]
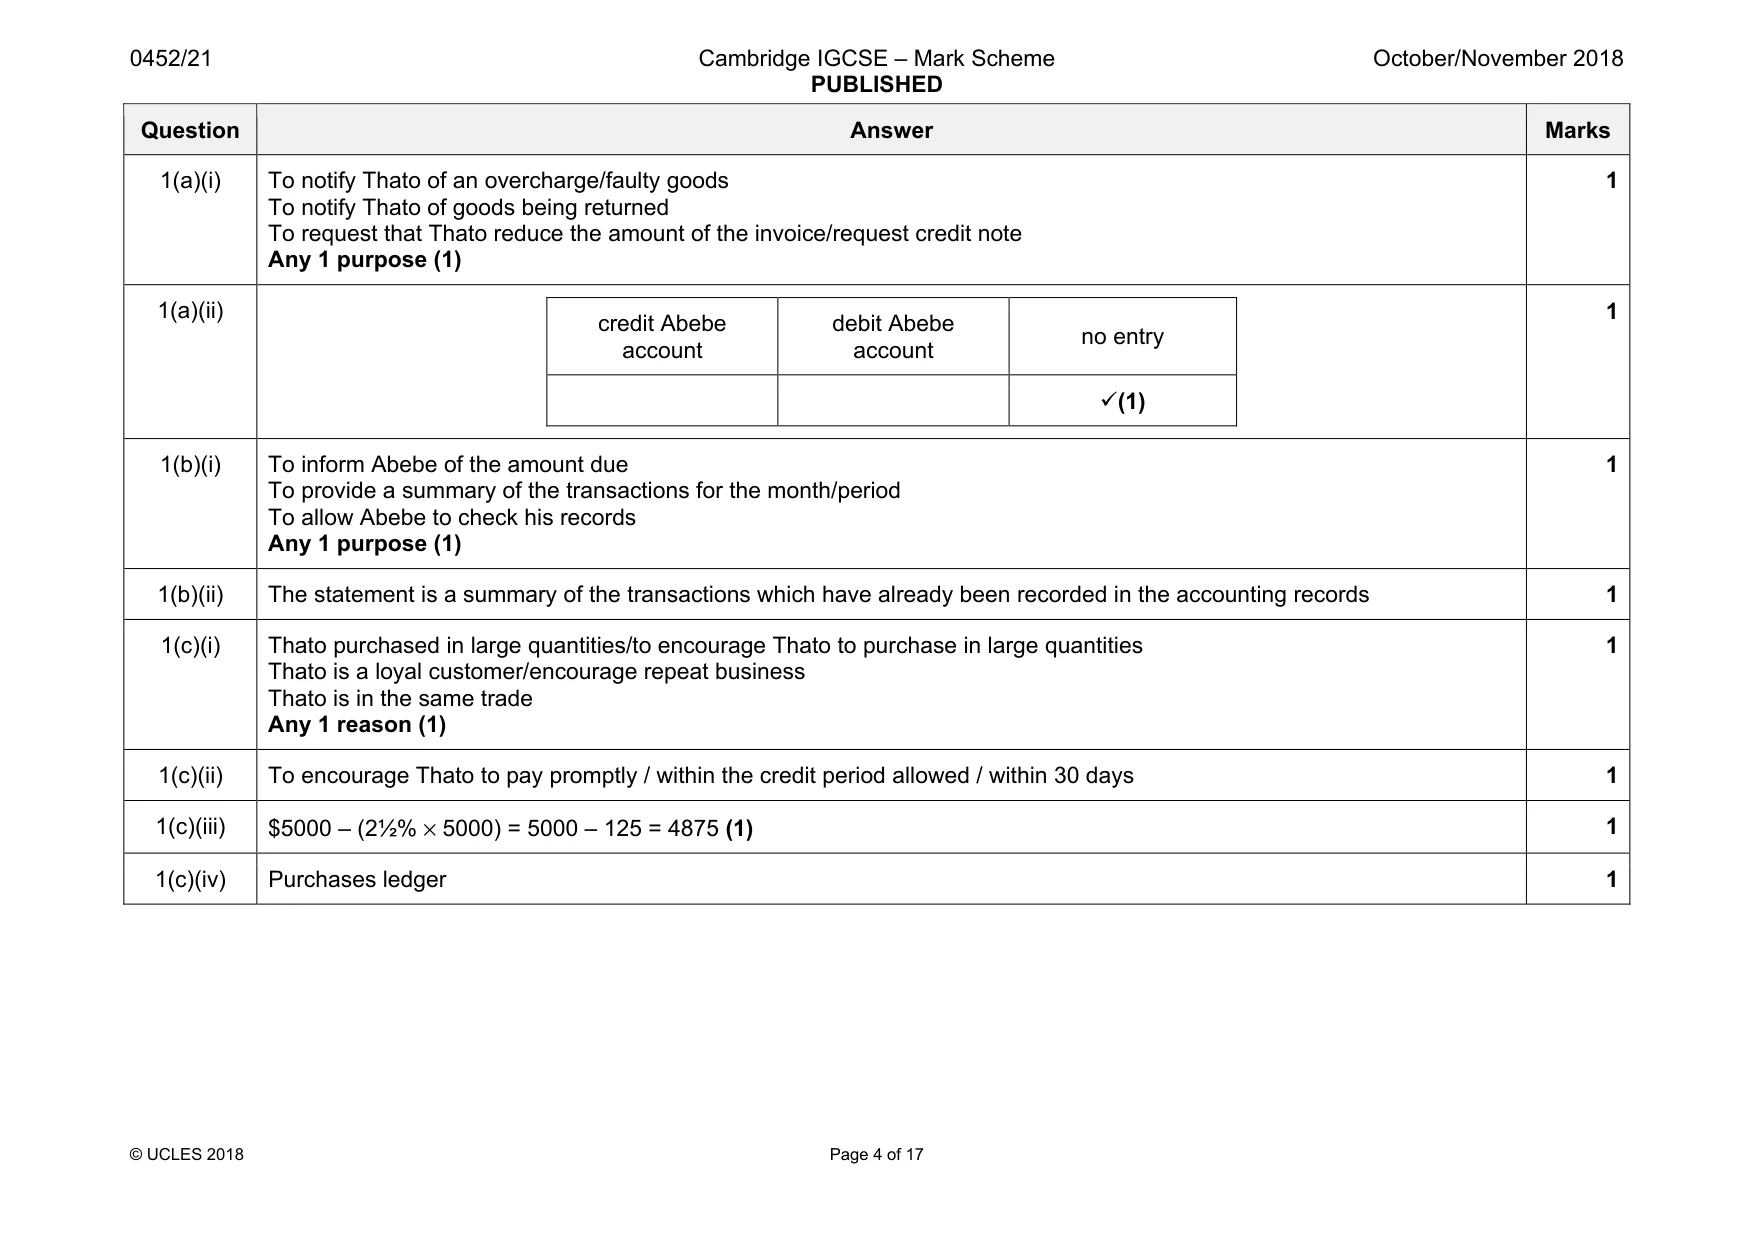
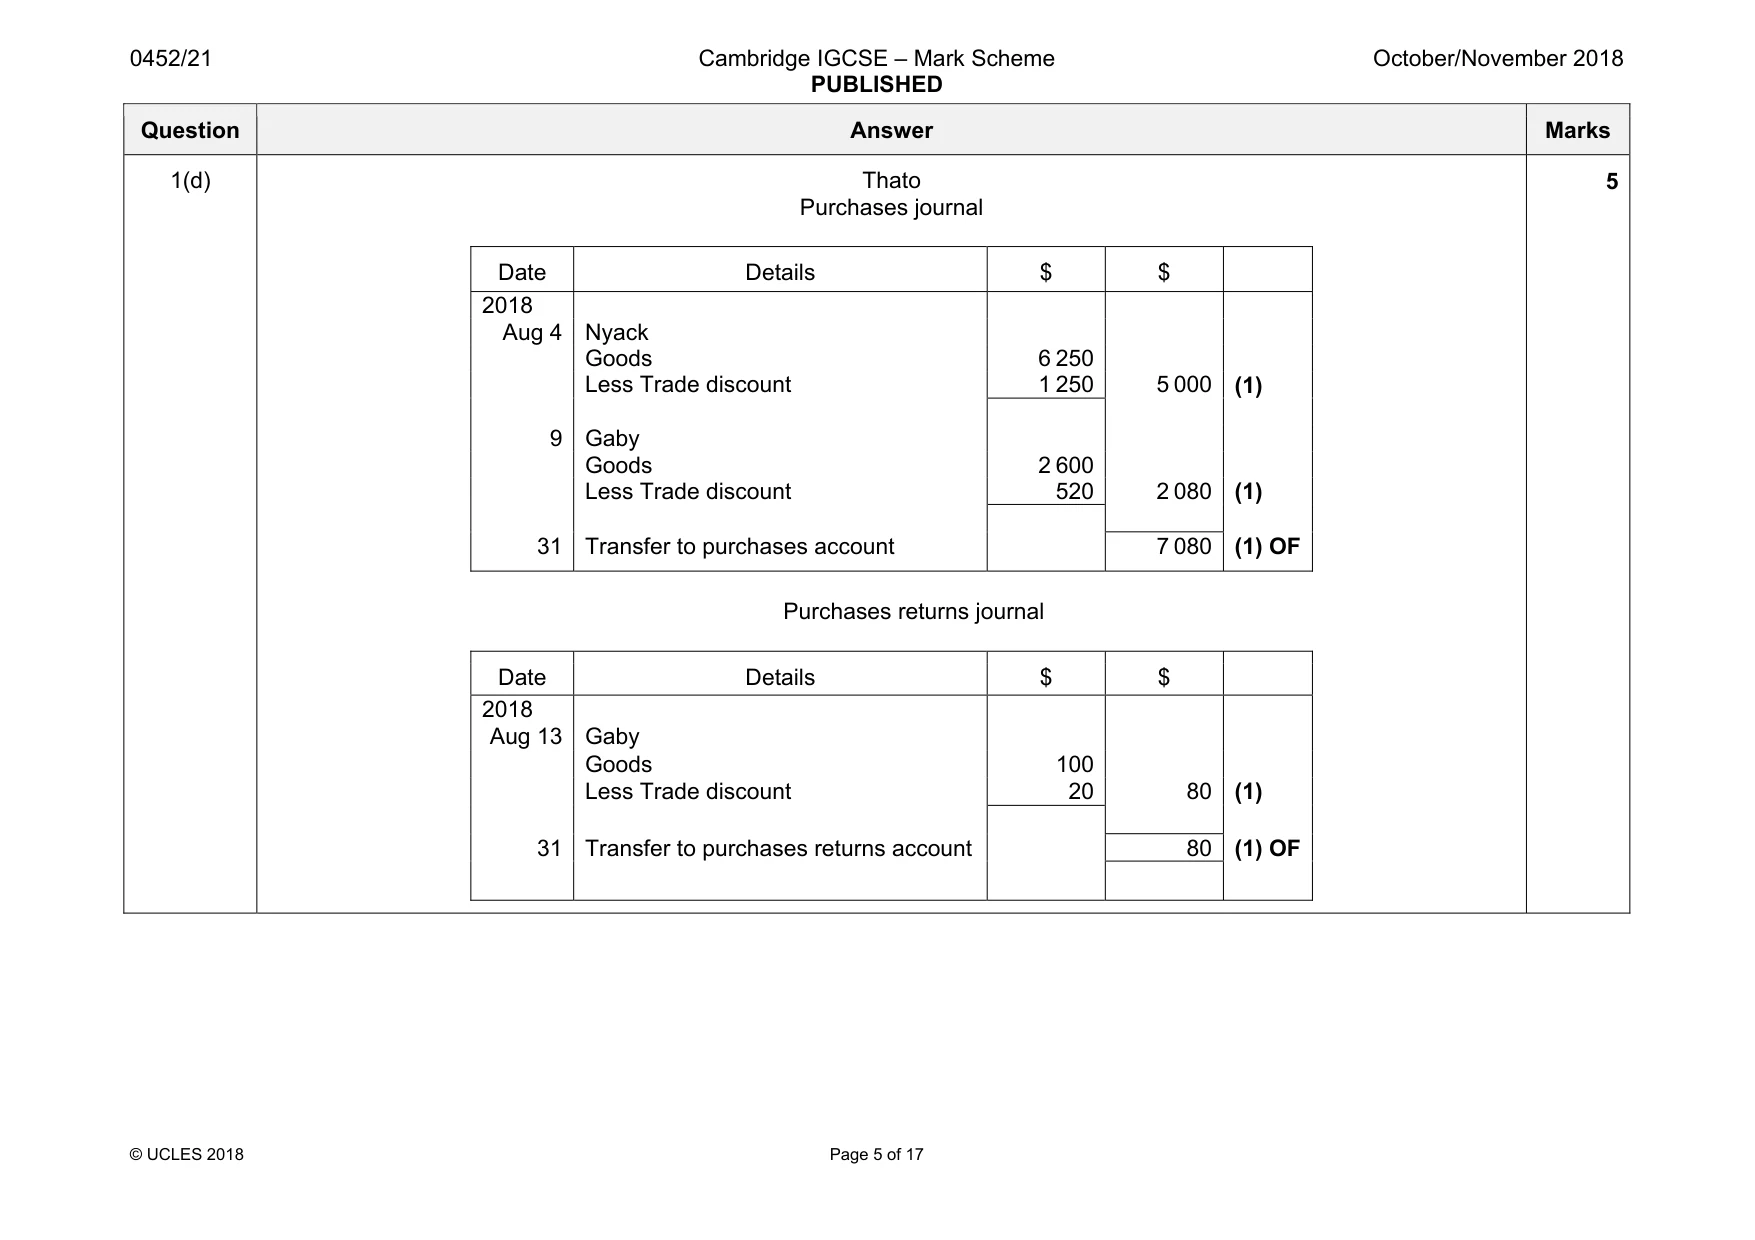
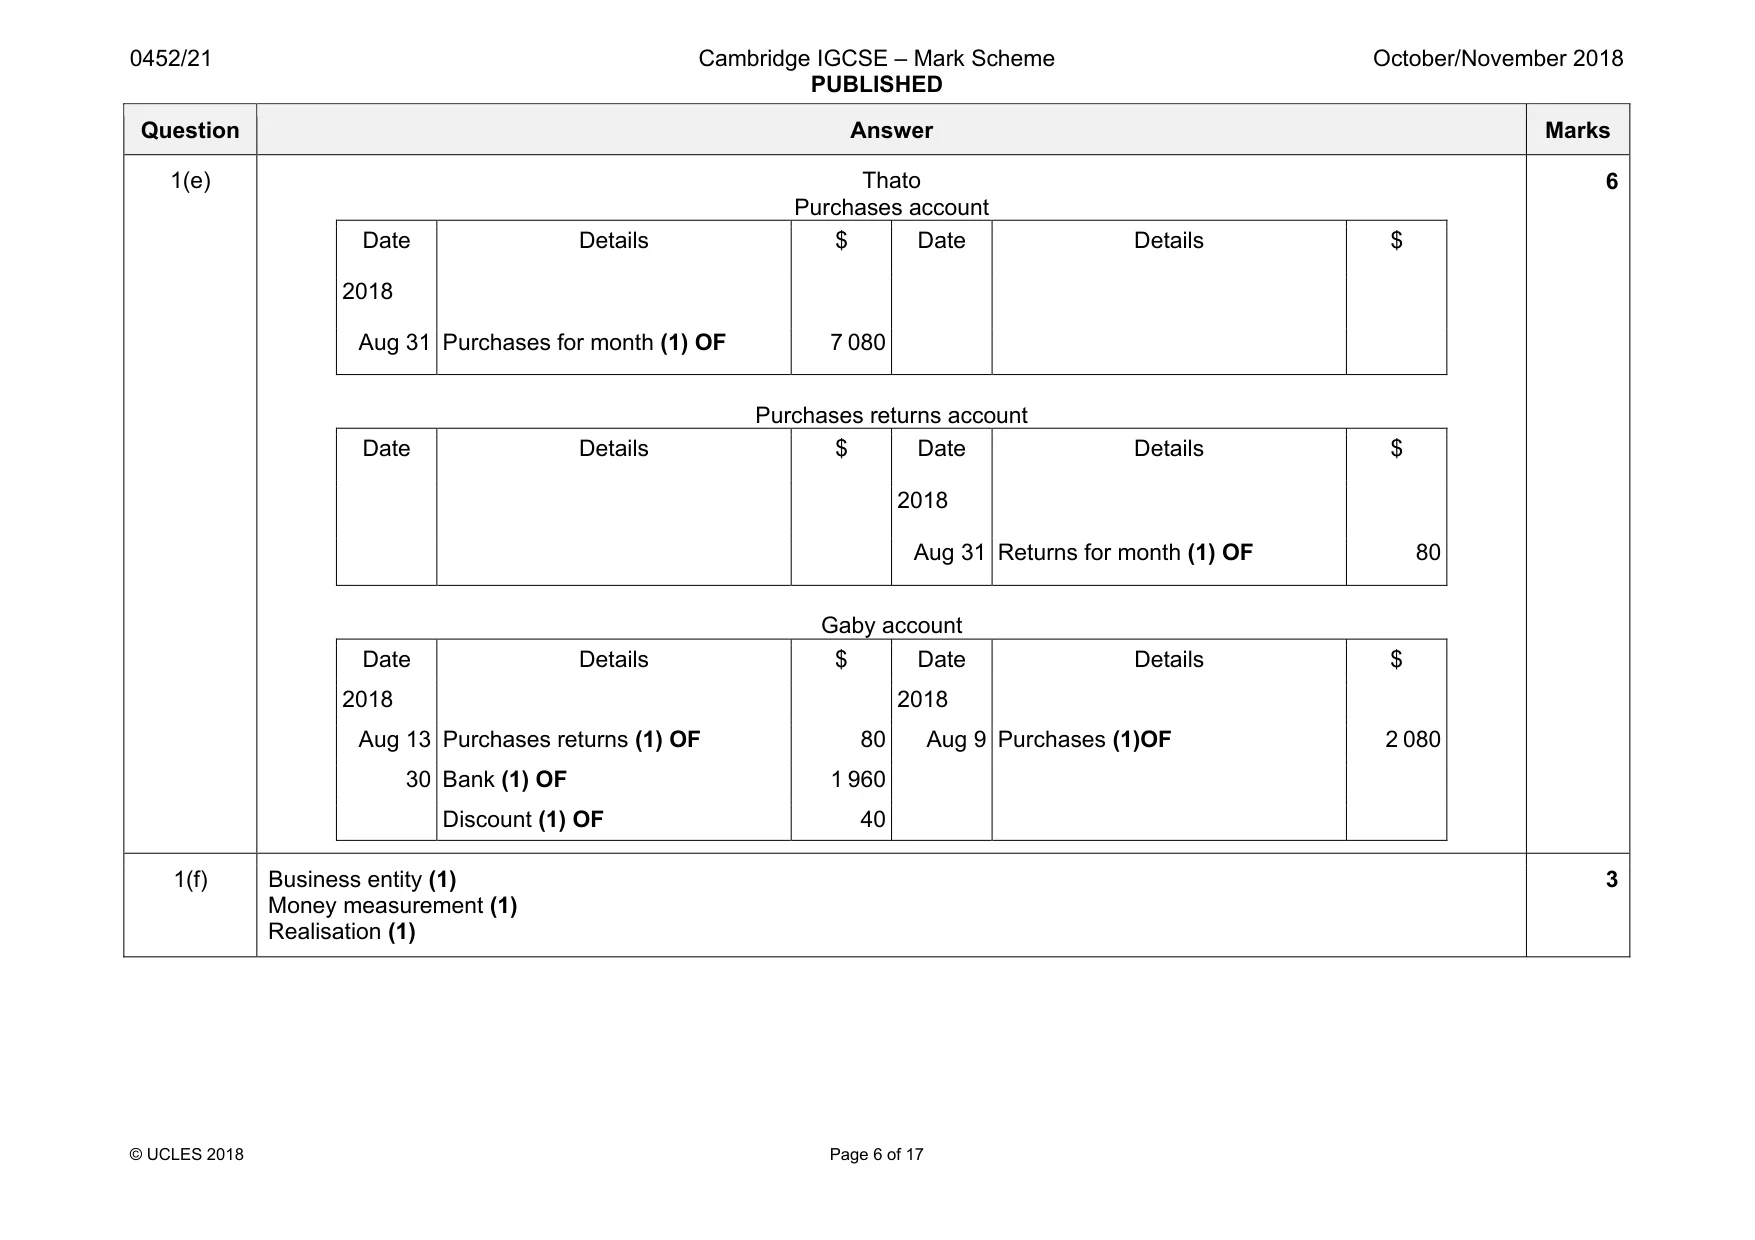
Mark scheme: 1(a)(i) To notify Thato of an overcharge/faulty goods To notify Thato of goods being returned To request that Thato reduce the amount of the invoice/request credit note Any 1 purpose (1) 1 1(a)(ii) credit Abebe account debit Abebe account no entry 9(1) 1 1(b)(i) To inform Abebe of the amount due To provide a summary of the transactions for the month/period To allow Abebe to check his records Any 1 purpose (1) 1 1(b)(ii) The statement is a summary of the transactions which have already been recorded in the accounting records 1 1(c)(i) Thato purchased in large quantities/to encourage Thato to purchase in large quantities Thato is a loyal customer/encourage repeat business Thato is in the same trade Any 1 reason (1) 1 1(c)(ii) To encourage Thato to pay promptly / within the credit period allowed / within 30 days 1 1(c)(iii) $5000 – (2½% × 5000) = 5000 – 125 = 4875 (1) 1 1(c)(iv) Purchases ledger 1 Question Answer Marks 1(d) Thato Purchases journal Date Details $ $ 2018 Aug 4 Nyack Goods 6 250 Less Trade discount 1 250 5 000 (1) 9 Gaby Goods 2 600 Less Trade discount 520 2 080 (1) 31 Transfer to purchases account 7 080 (1) OF Purchases returns journal Date Details $ $ 2018 Aug 13 Gaby Goods 100 Less Trade discount 20 80 (1) 31 Transfer to purchases returns account 80 (1) OF 5 Question Answer Marks 1(e) Thato Purchases account Date Details $ Date Details $ 2018 Aug 31 Purchases for month (1) OF 7 080 Purchases returns account Date Details $ Date Details $ 2018 Aug 31 Returns for month (1) OF 80 Gaby account Date Details $ Date Details $ 2018 2018 Aug 13 Purchases returns (1) OF 80 Aug 9 Purchases (1)OF 2 080 30 Bank (1) OF 1 960 Discount (1) OF 40 6 1(f) Business entity (1) Money measurement (1) Realisation (1) 3
Q2 · Sara maintains a petty cash book
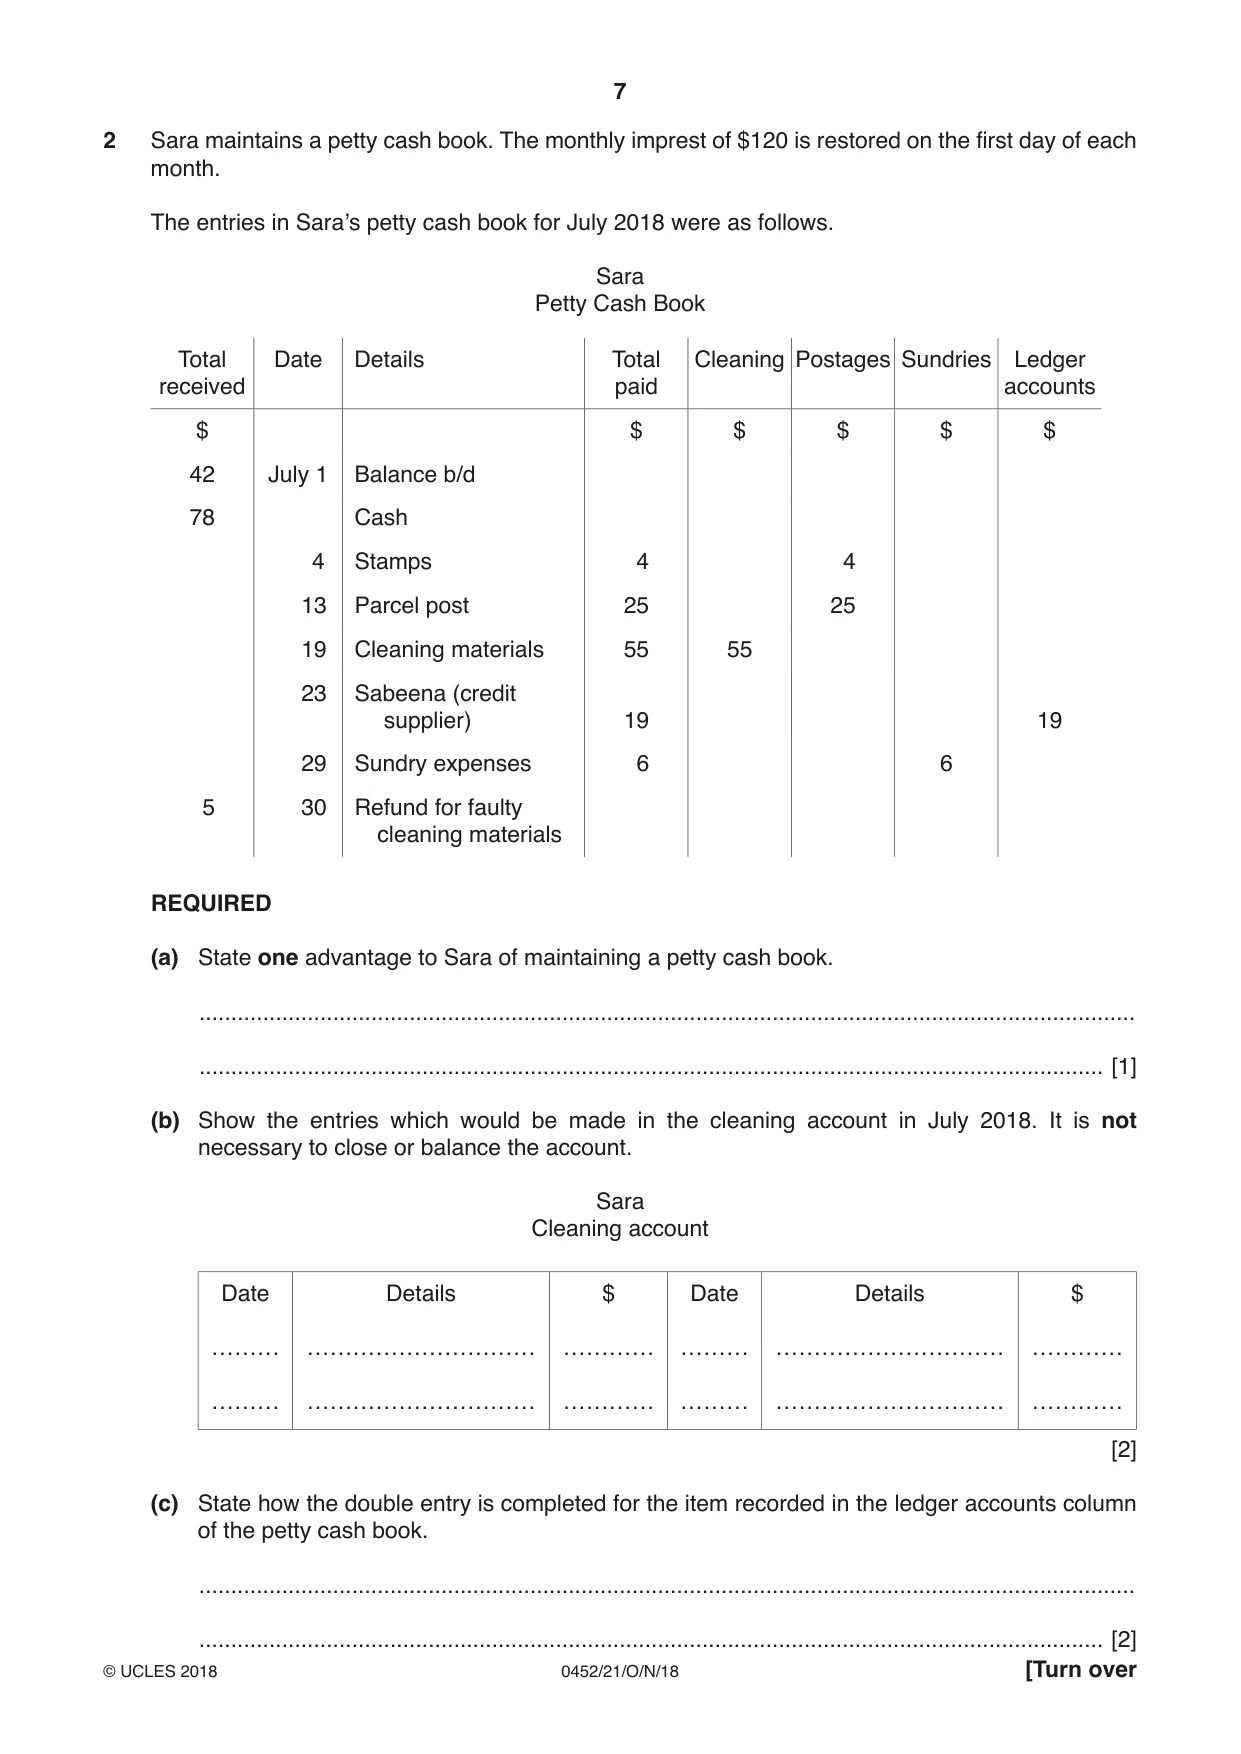
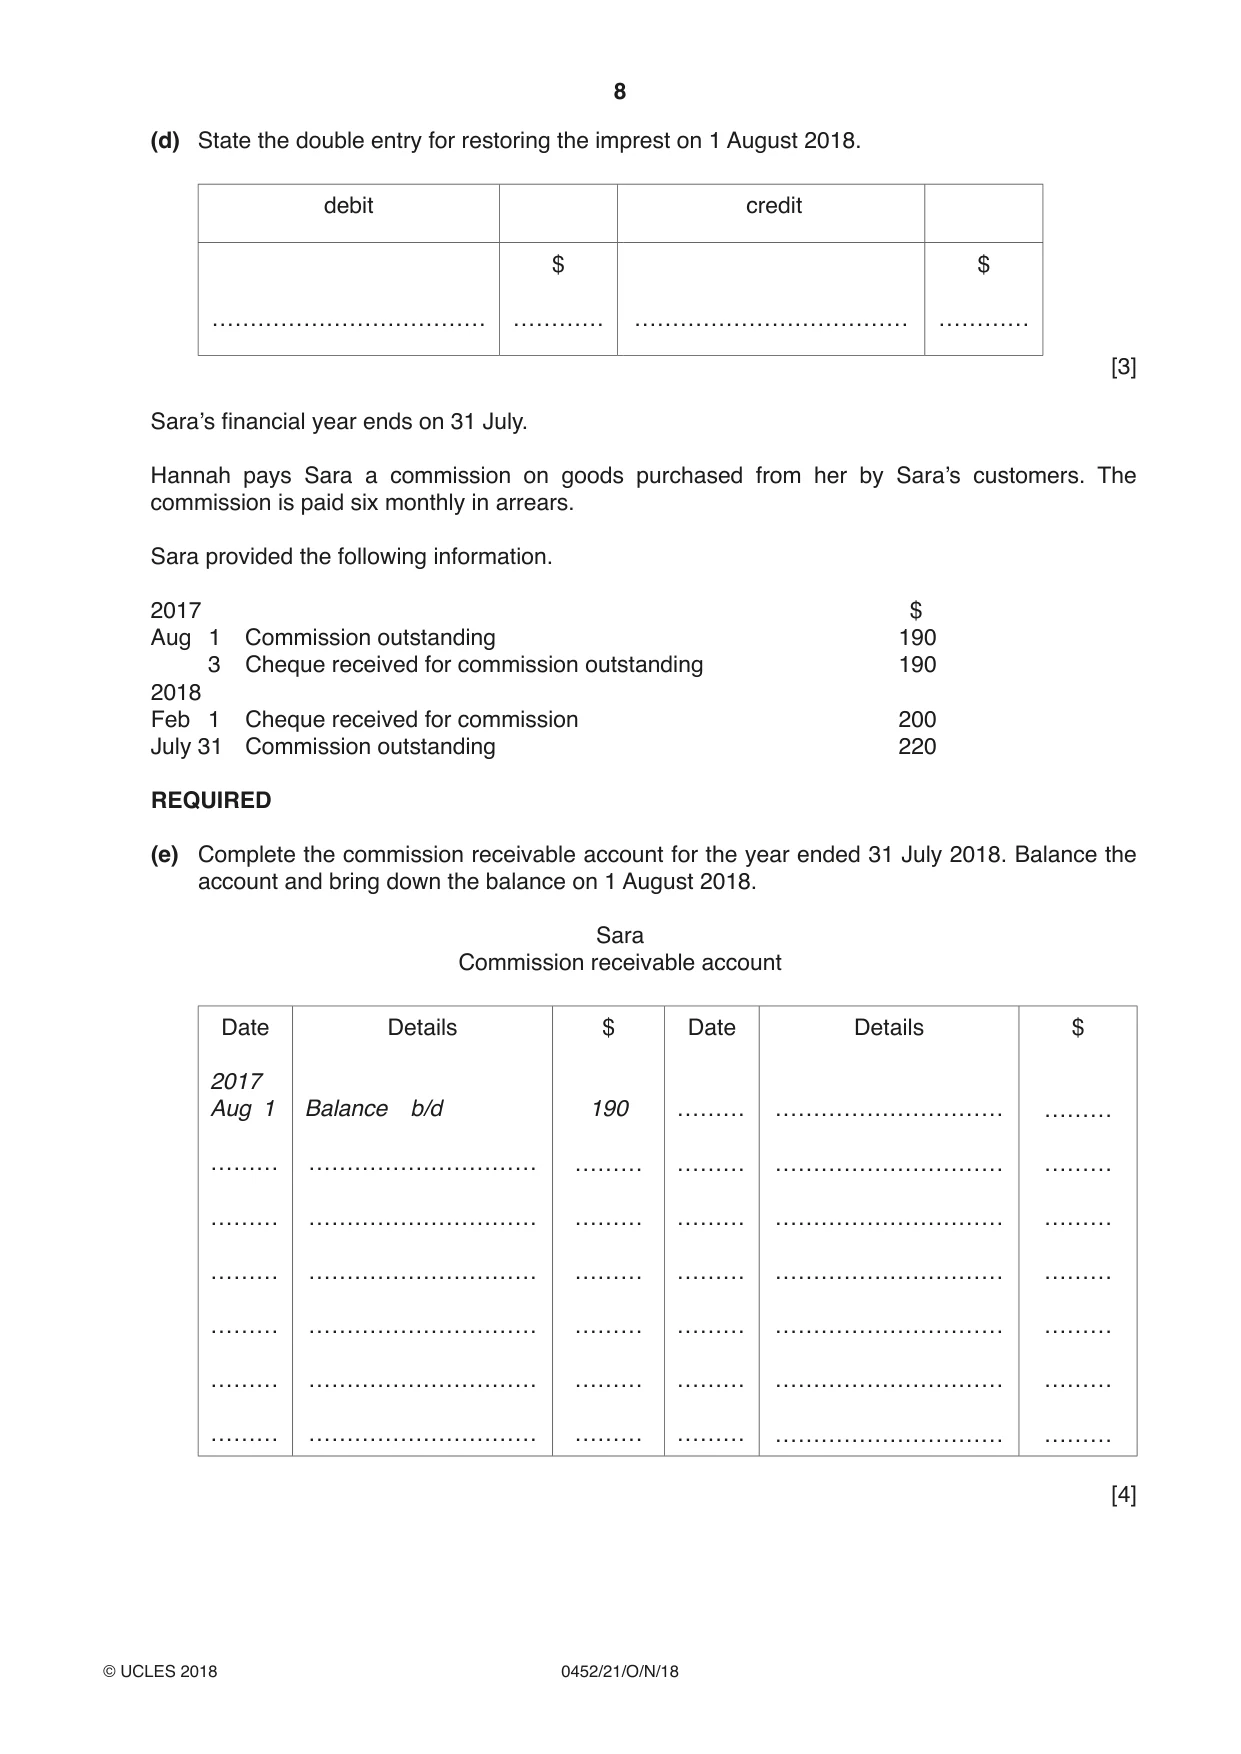
2 Sara maintains a petty cash book. The monthly imprest of $120 is restored on the first day of each month. The entries in Sara’s petty cash book for July 2018 were as follows. Sara Petty Cash Book Total Date Details Total Cleaning Postages Sundries Ledger received paid accounts $ $ $ $ $ $ 42 July 1 Balance b/d 78 Cash 4 Stamps 4 4 13 Parcel post 25 25 19 Cleaning materials 55 55 23 Sabeena (credit supplier) 19 19 29 Sundry expenses 6 6 5 30 Refund for faulty cleaning materials REQUIRED (a) State one advantage to Sara of maintaining a petty cash book. ................................................................................................................................................... .............................................................................................................................................. [1] (b) Show the entries which would be made in the cleaning account in July 2018. It is not necessary to close or balance the account. Sara Cleaning account Date Details $ Date Details $ ……… ………… ……… ………… ……… ………… ……… ………… [2] (c) State how the double entry is completed for the item recorded in the ledger accounts column of the petty cash book. ................................................................................................................................................... (d) State the double entry for restoring the imprest on 1 August 2018. debit credit $ $ ………… ………… [3] Sara’s financial year ends on 31 July. Hannah pays Sara a commission on goods purchased from her by Sara’s customers. The commission is paid six monthly in arrears. Sara provided the following information. 2017 $
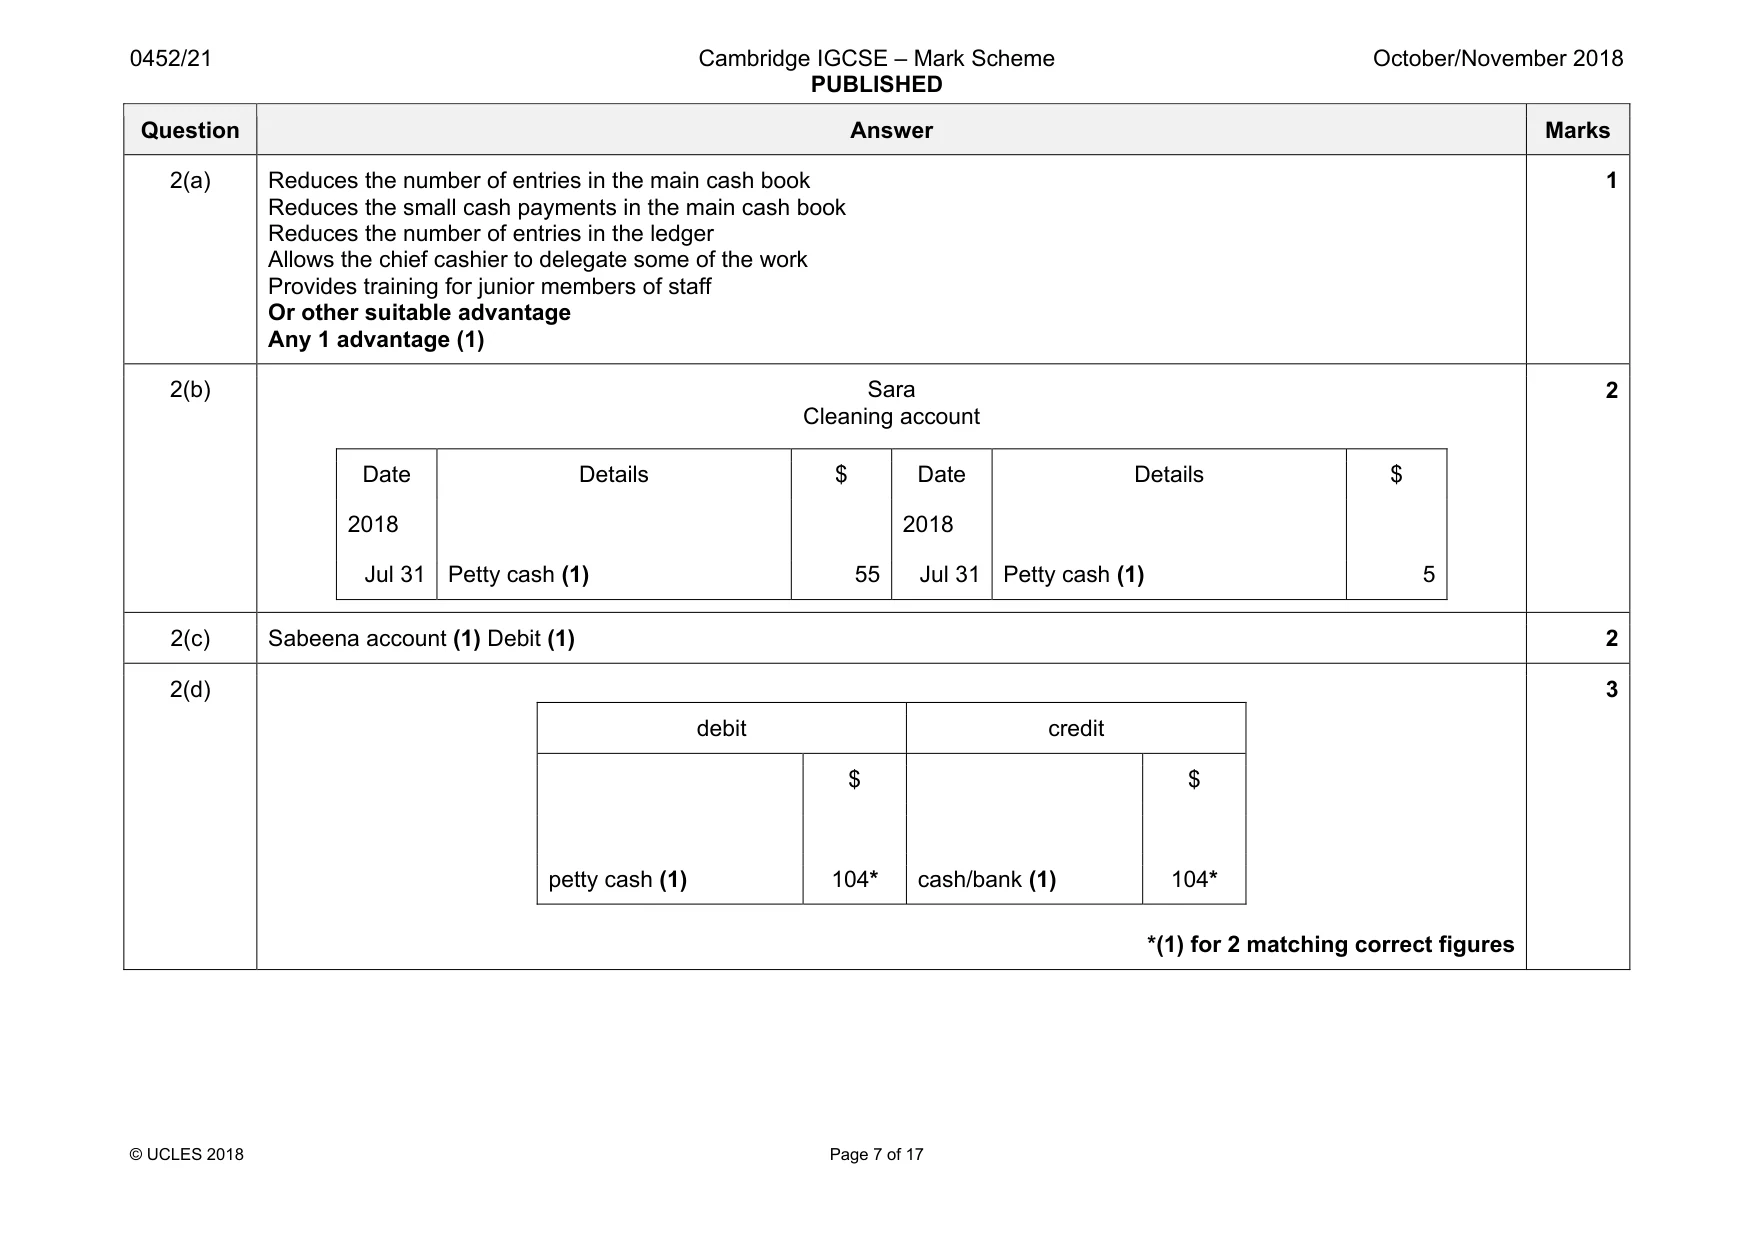
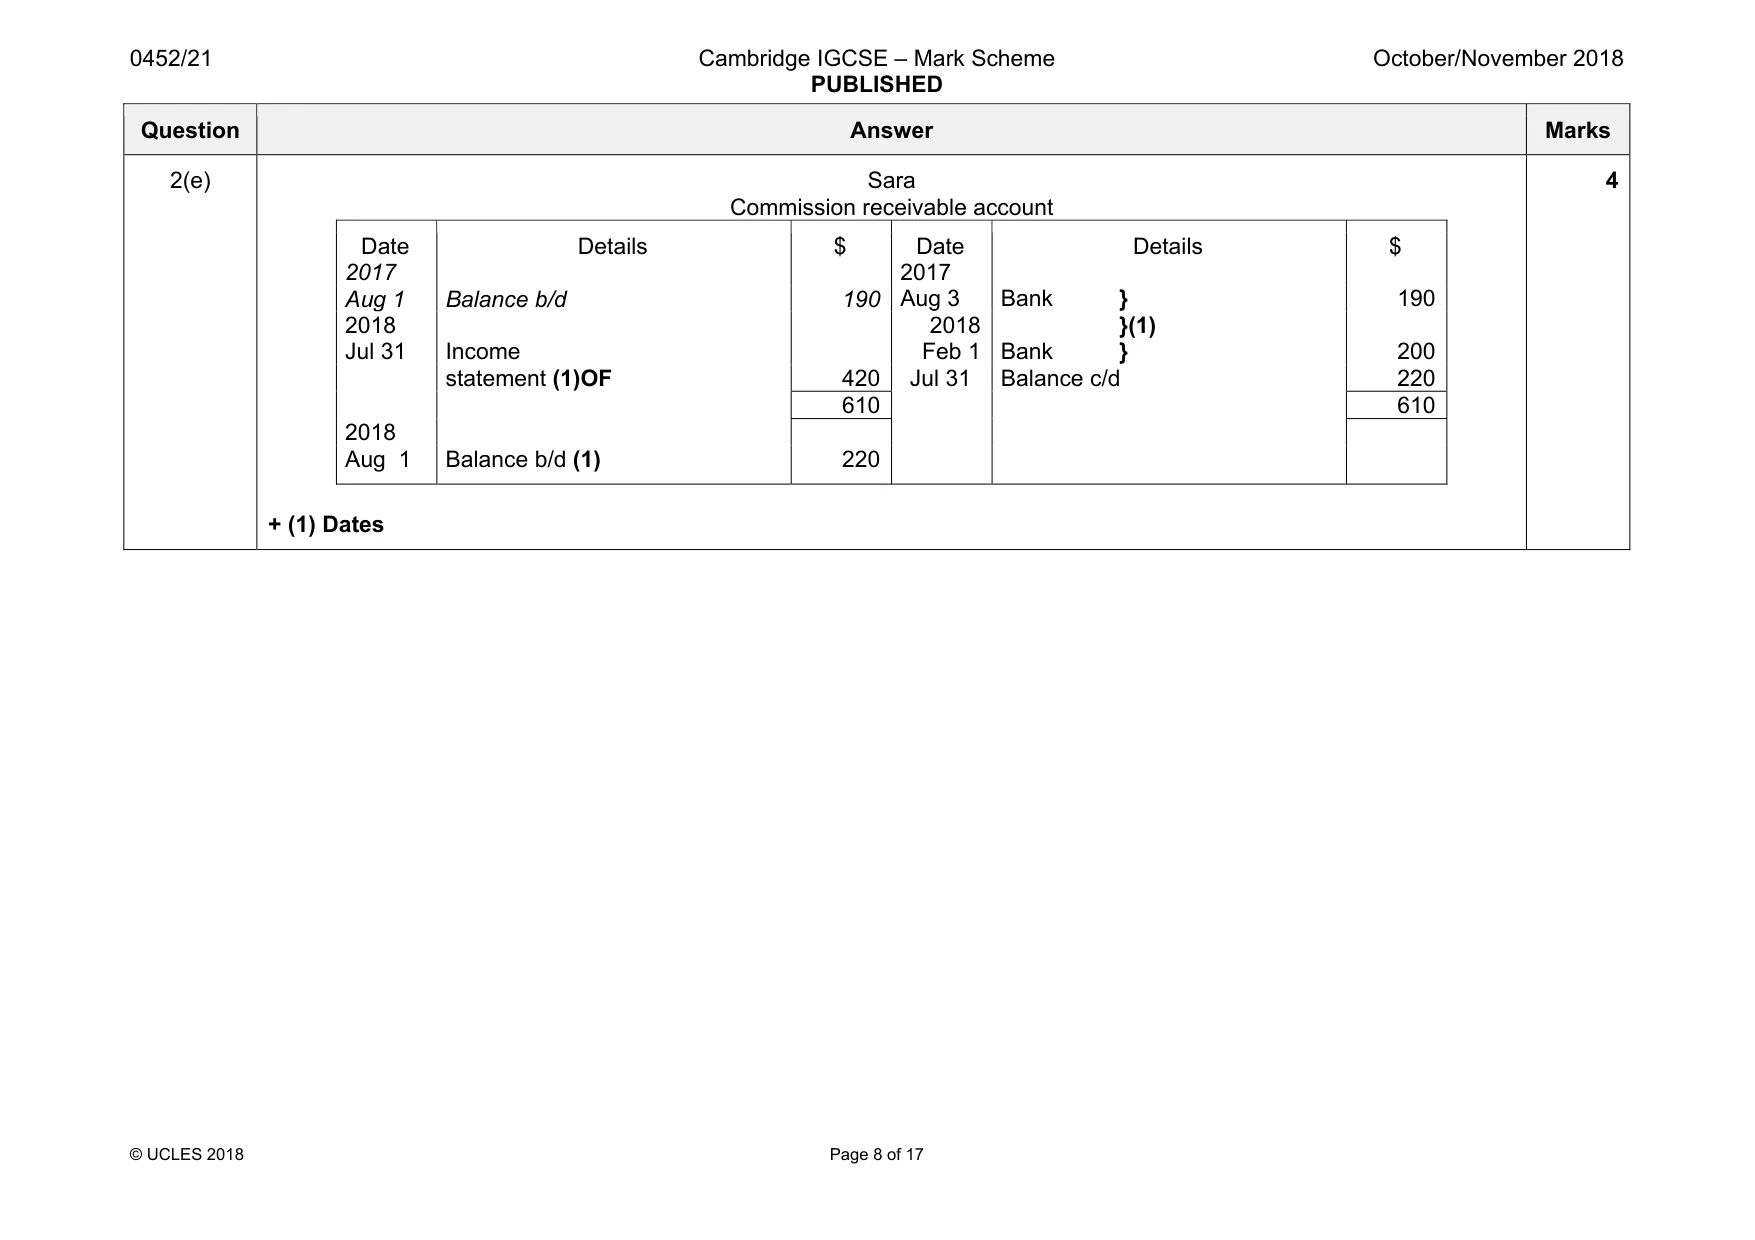
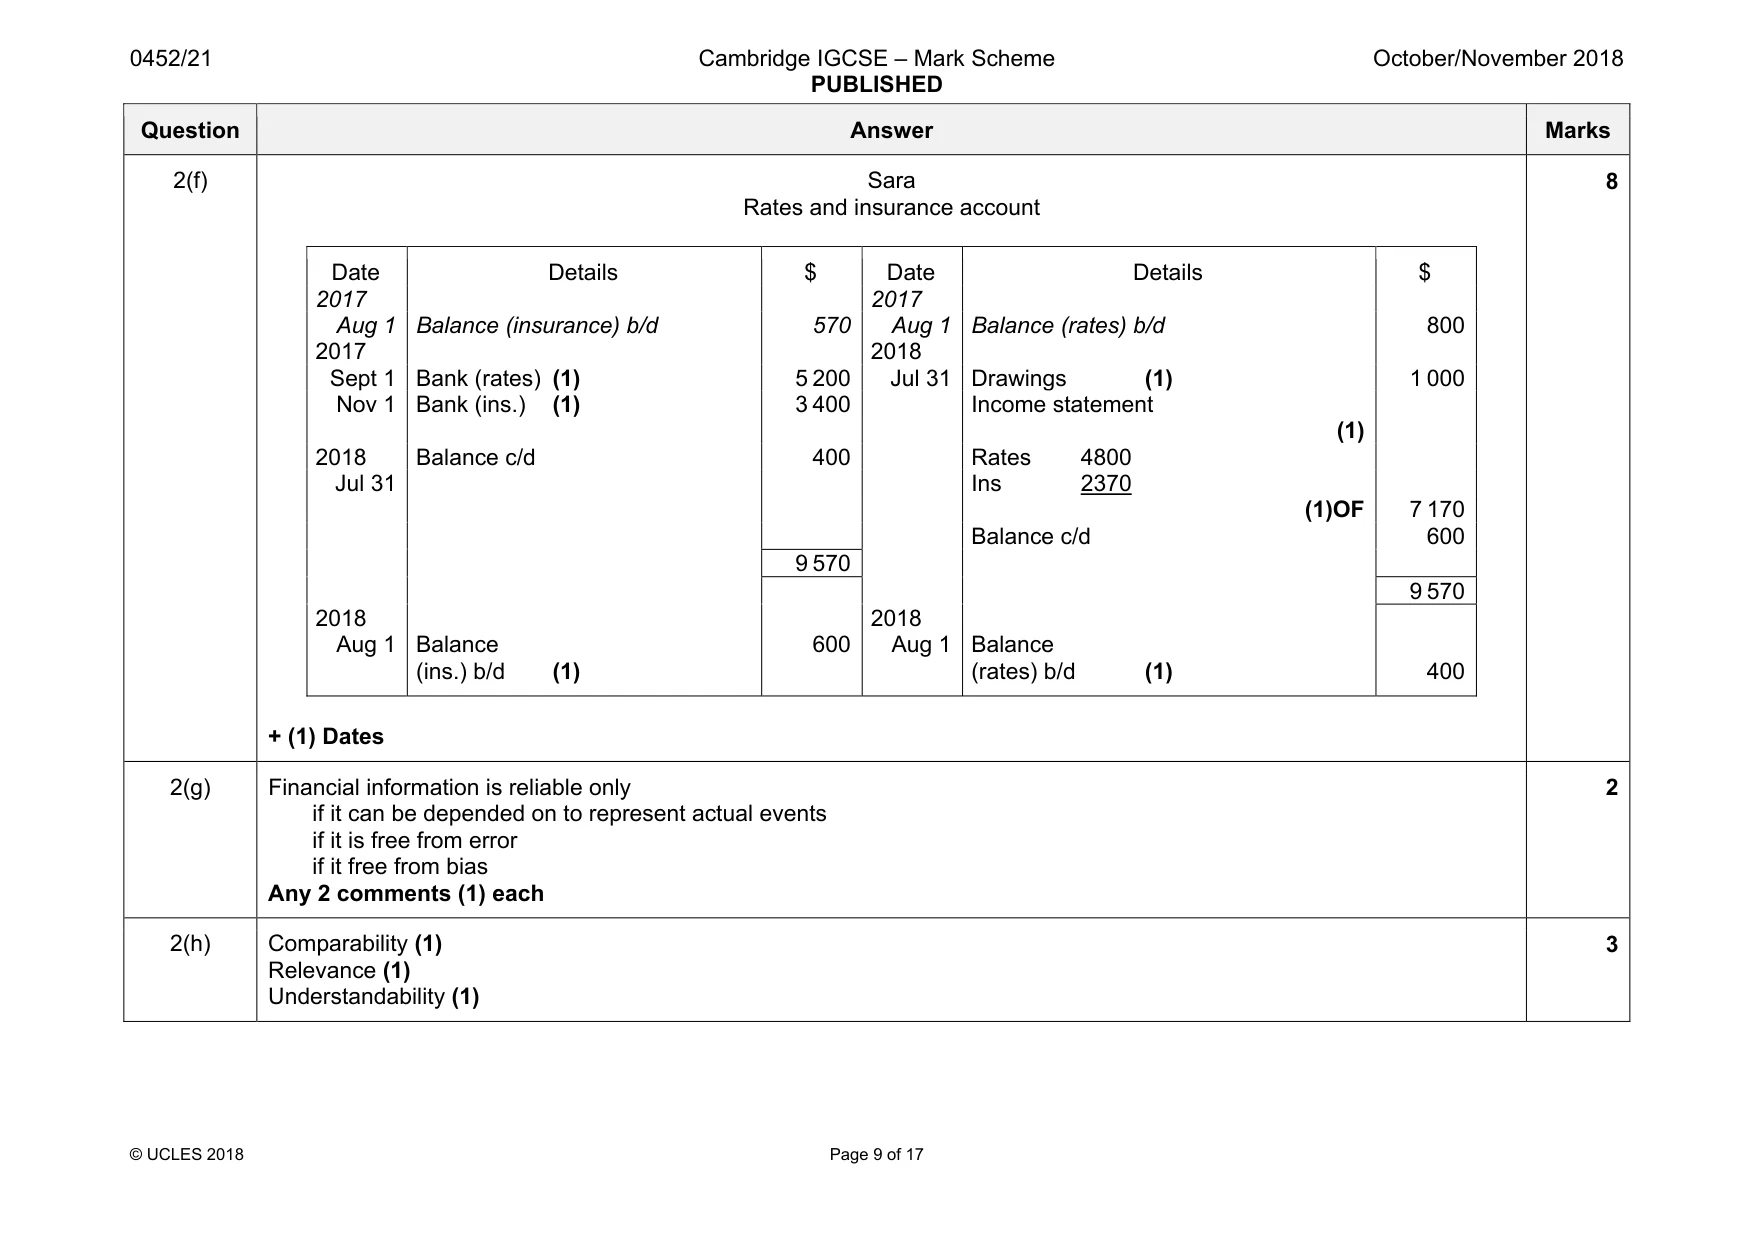
Mark scheme: 2(a) Reduces the number of entries in the main cash book Reduces the small cash payments in the main cash book Reduces the number of entries in the ledger Allows the chief cashier to delegate some of the work Provides training for junior members of staff Or other suitable advantage Any 1 advantage (1) 1 2(b) Sara Cleaning account Date Details $ Date Details $ 2018 2018 Jul 31 Petty cash (1) 55 Jul 31 Petty cash (1) 5 2 2(c) Sabeena account (1) Debit (1) 2 2(d) debit credit $ $ petty cash (1) 104* cash/bank (1) 104* *(1) for 2 matching correct figures 3 Question Answer Marks 2(e) Sara Commission receivable account Date Details $ Date Details $ 2017 2017 Aug 1 Balance b/d 190 Aug 3 Bank } 190 2018 2018 }(1) Jul 31 Income Feb 1 Bank } 200 statement (1)OF 420 Jul 31 Balance c/d 220 610 610 2018 Aug 1 Balance b/d (1) 220 + (1) Dates 4 Question Answer Marks 2(f) Sara Rates and insurance account Date Details $ Date Details $ 2017 2017 Aug 1 Balance (insurance) b/d 570 Aug 1 Balance (rates) b/d 800 2017 2018 Sept 1 Bank (rates) (1) 5 200 Jul 31 Drawings (1) 1 000 Nov 1 Bank (ins.) (1) 3 400 Income statement (1) 2018 Balance c/d 400 Rates 4800 Jul 31 Ins 2370 (1)OF 7 170 Balance c/d 600 9 570 9 570 2018 2018 Aug 1 Balance (ins.) b/d (1) 600 Aug 1 Balance (rates) b/d (1) 400 + (1) Dates 8 2(g) Financial information is reliable only if it can be depended on to represent actual events if it is free from error if it free from bias Any 2 comments (1) each 2 2(h) Comparability (1) Relevance (1) Understandability (1) 3
Q3 · Cheque received for commission outstanding 190 2018 Feb 1 Cheque received for commission…
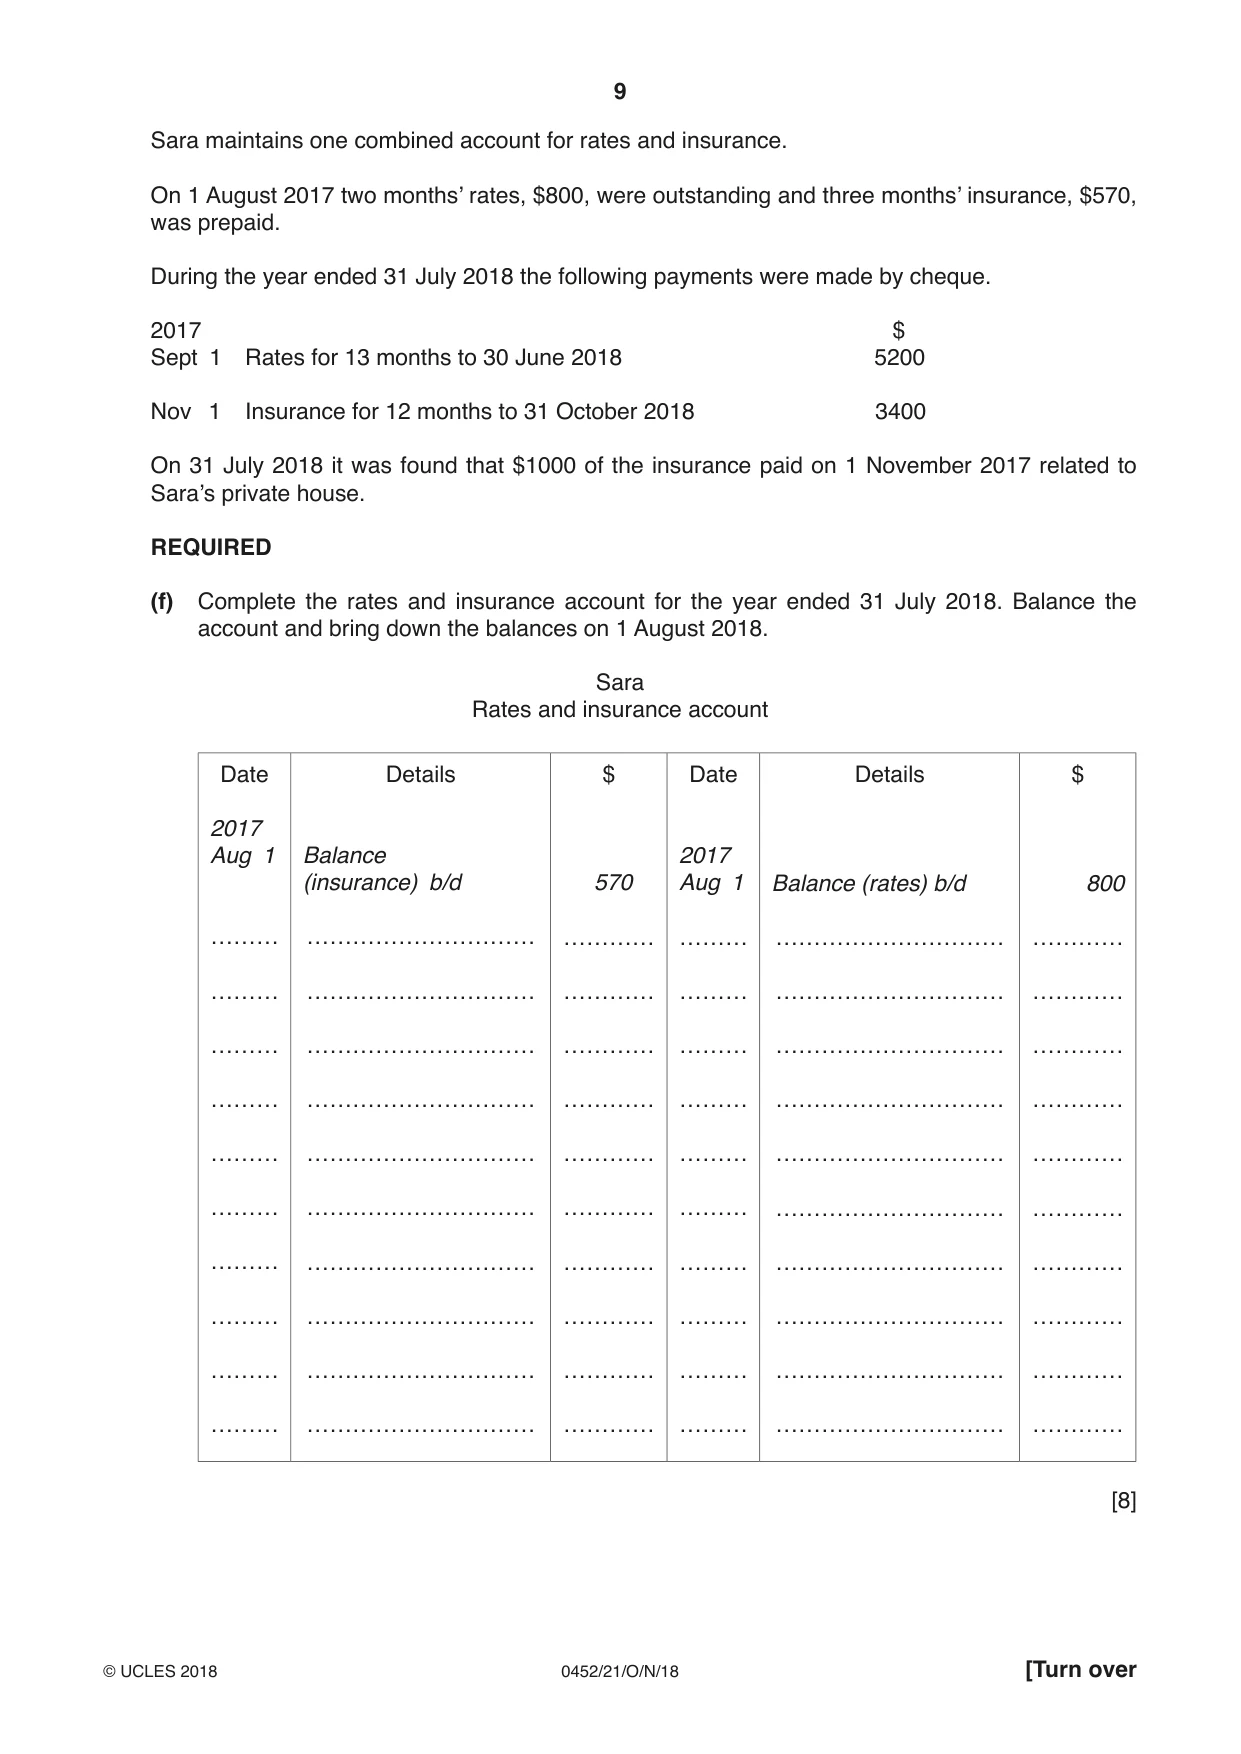
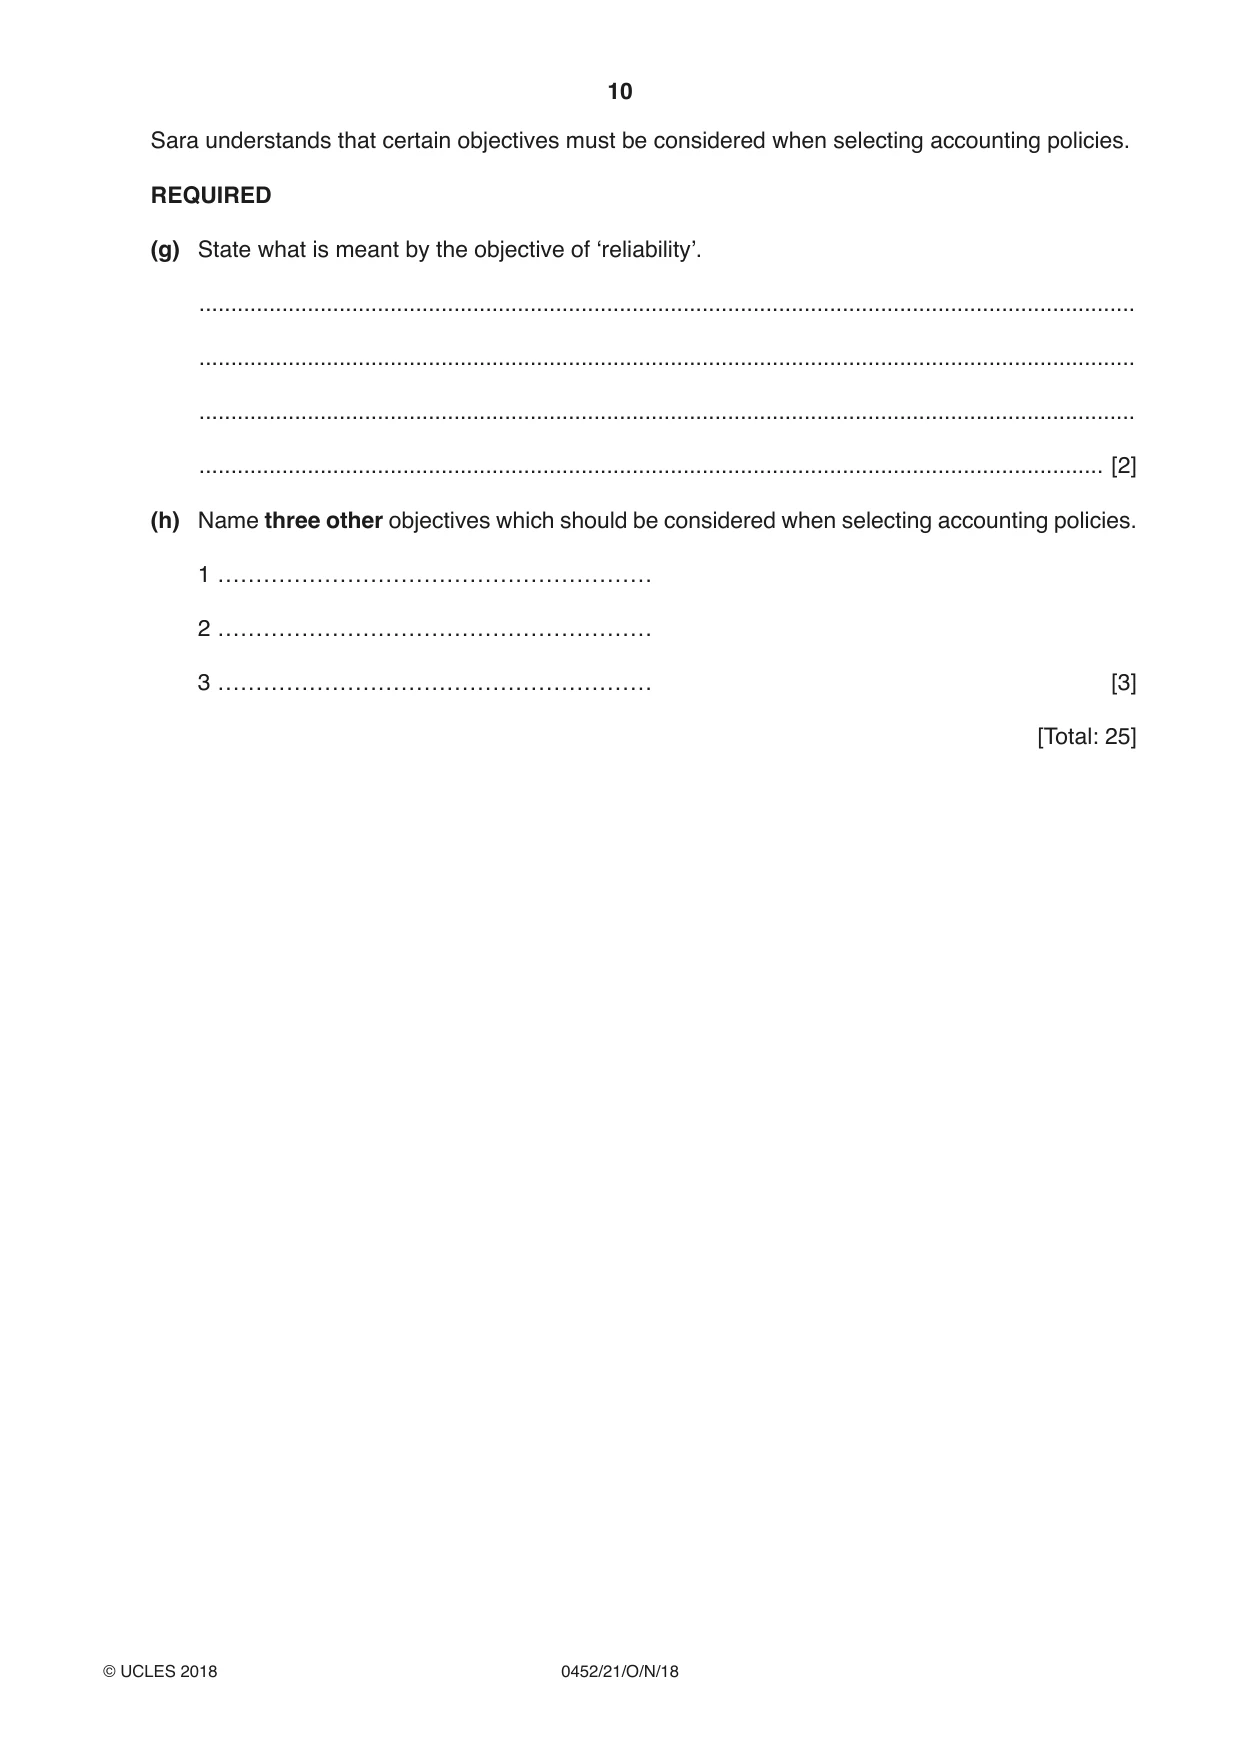
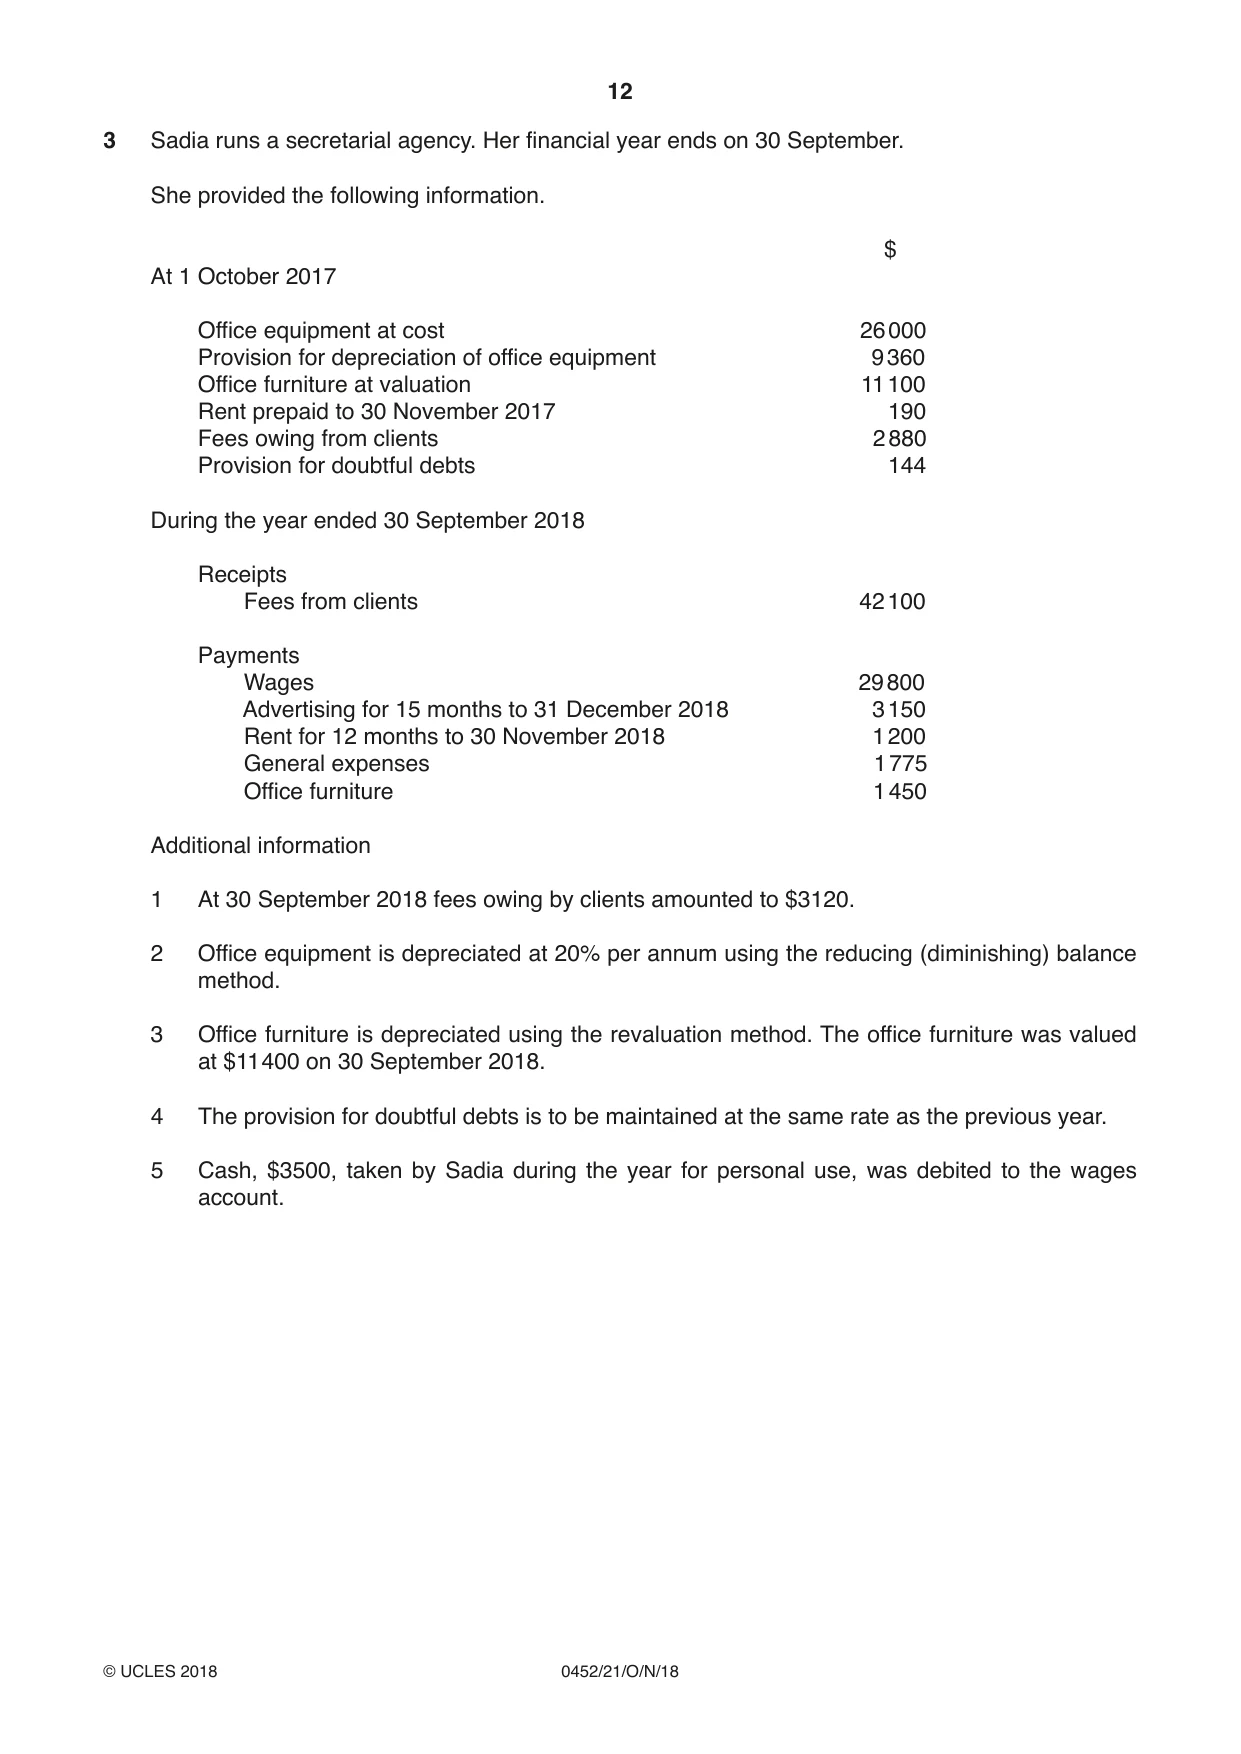
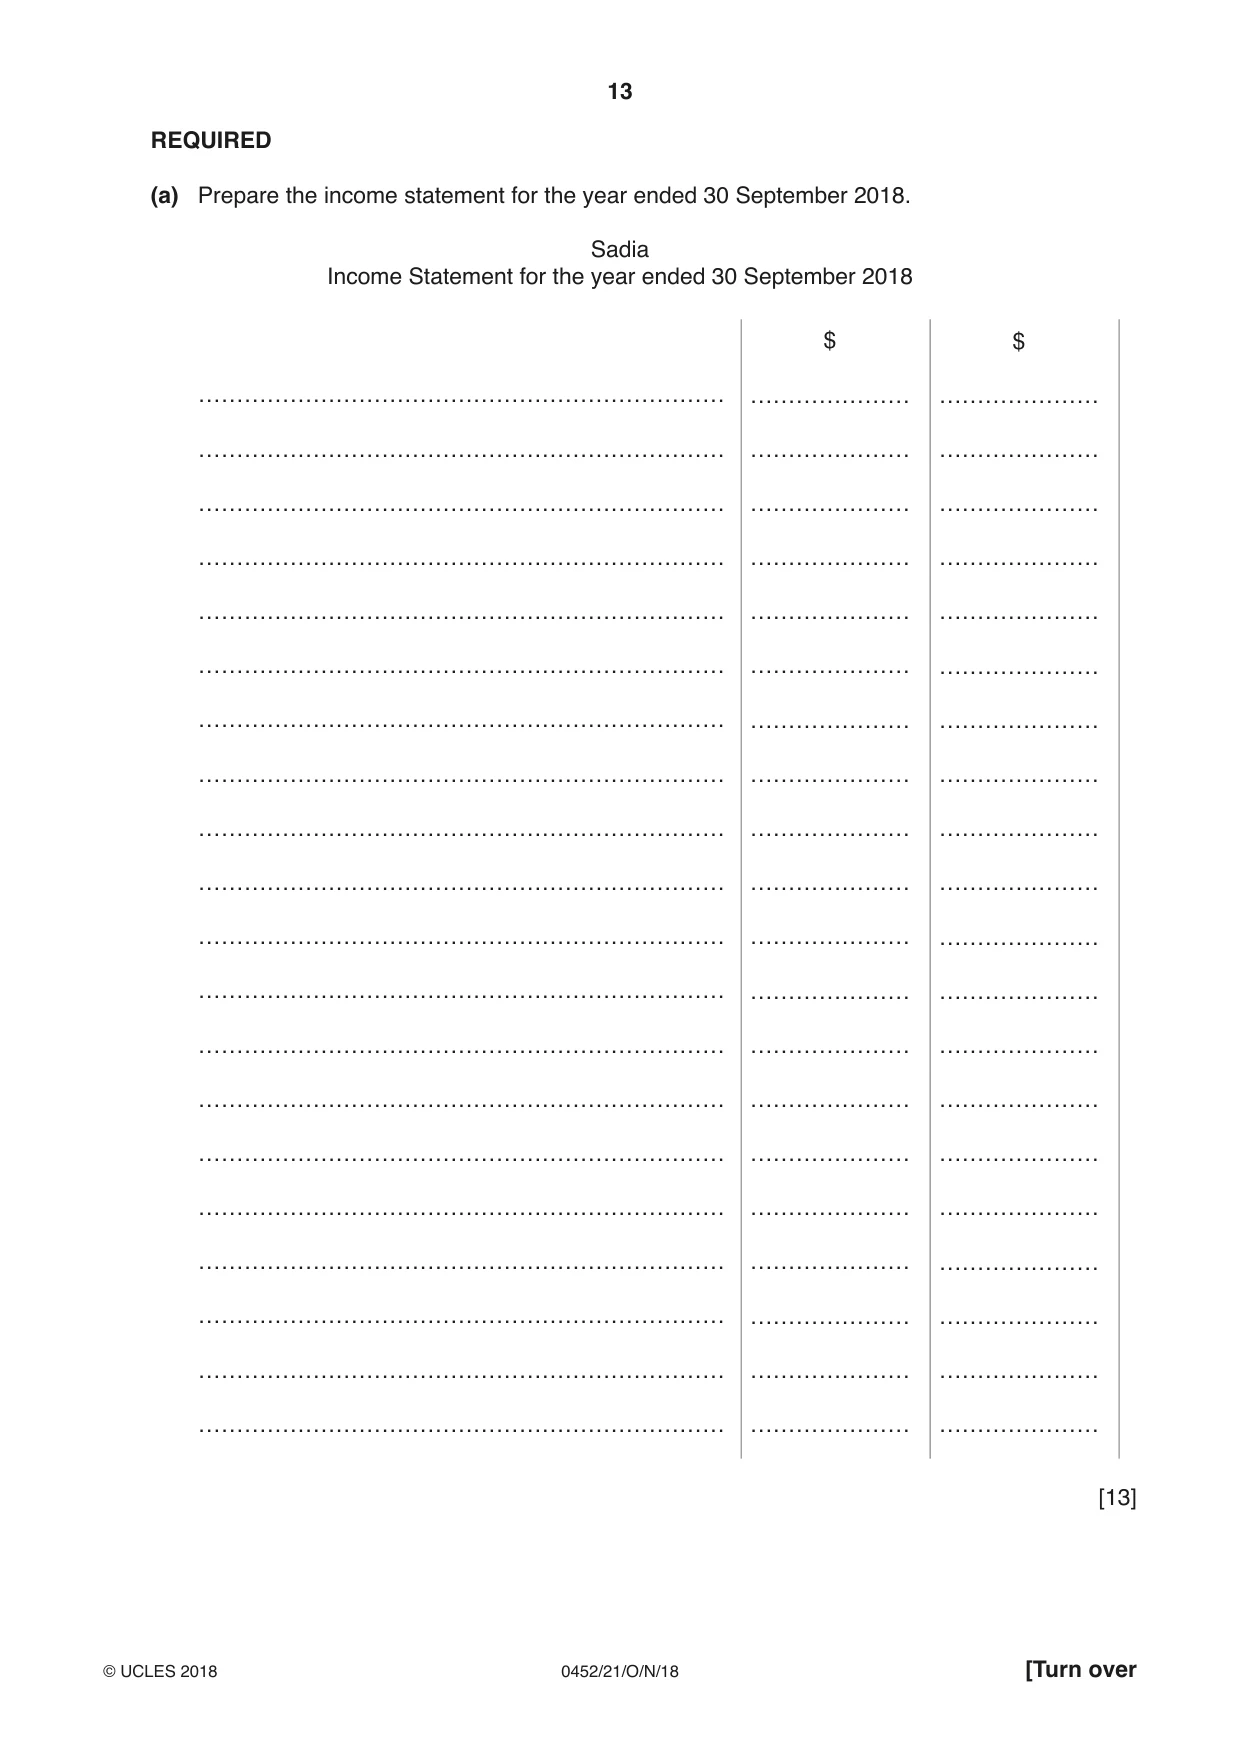
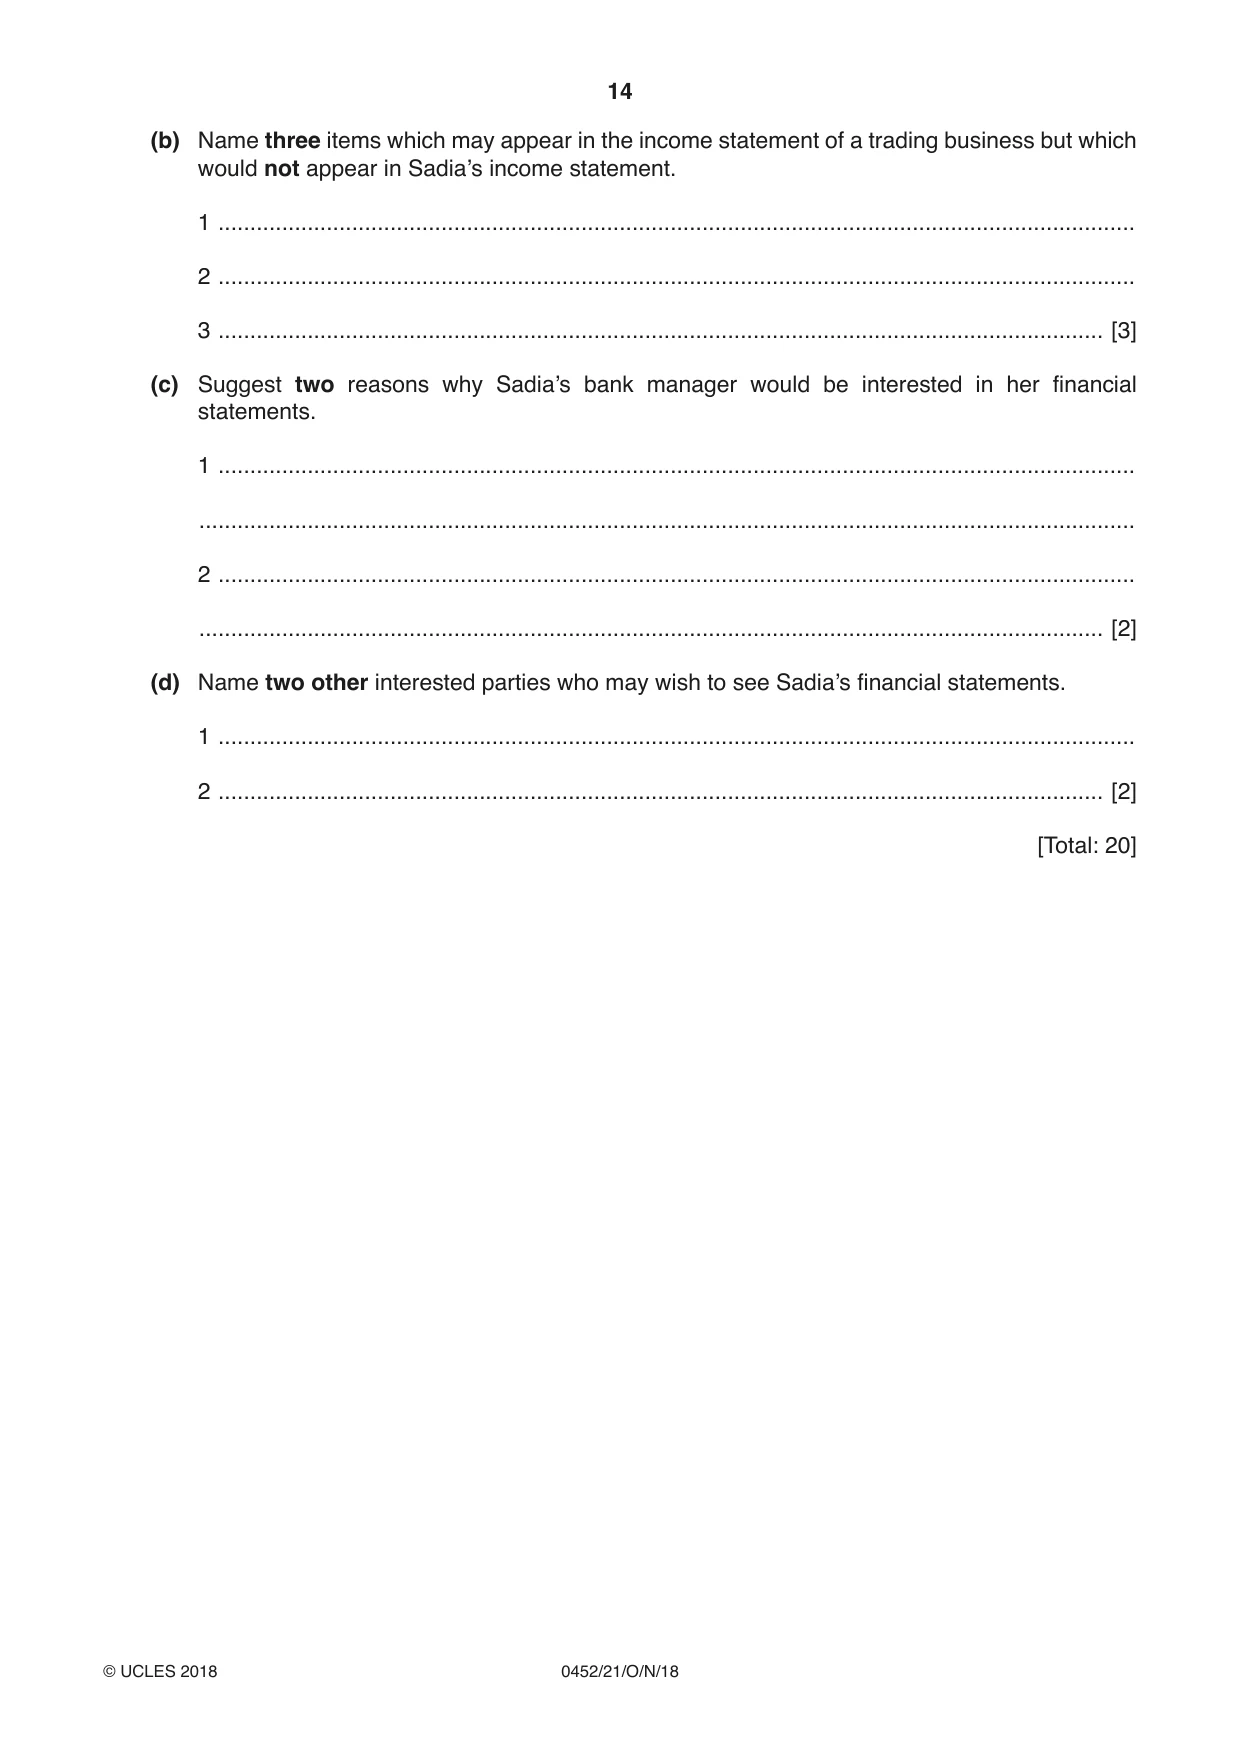
3 Cheque received for commission outstanding 190 2018 Feb 1 Cheque received for commission 200 July 31 Commission outstanding 220 REQUIRED (e) Complete the commission receivable account for the year ended 31 July 2018. Balance the account and bring down the balance on 1 August 2018. Sara Commission receivable account Date Details $ Date Details $ 2017 Aug 1 Balance b/d 190 ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… ……… [4] Sara maintains one combined account for rates and insurance. On 1 August 2017 two months’ rates, $800, were outstanding and three months’ insurance, $570, was prepaid. During the year ended 31 July 2018 the following payments were made by cheque. 2017 $ Sept 1 Rates for 13 months to 30 June 2018 5200 Nov 1 Insurance for 12 months to 31 October 2018 3400 On 31 July 2018 it was found that $1000 of the insurance paid on 1 November 2017 related to Sara’s private house. REQUIRED (f) Complete the rates and insurance account for the year ended 31 July 2018. Balance the account and bring down the balances on 1 August 2018. Sara Rates and insurance account Date Details $ Date Details $ 2017 Aug 1 Balance 2017 (insurance) b/d 570 Aug 1 Balance (rates) b/d 800 ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… ……… ………… [8] Sara understands that certain objectives must be considered when selecting accounting policies. REQUIRED (g) State what is meant by the objective of ‘reliability’. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (h) Name three other objectives which should be considered when selecting accounting policies. [3] [Total: 25] PLEASE TURN OVER 3 Sadia runs a secretarial agency. Her financial year ends on 30 September. She provided the following information. $ At 1 October 2017 Office equipment at cost 26 000 Provision for depreciation of office equipment 9 360 Office furniture at valuation 11 100 Rent prepaid to 30 November 2017 190 Fees owing from clients 2 880 Provision for doubtful debts 144 During the year ended 30 September 2018 Receipts Fees from clients 42 100 Payments Wages 29 800 Advertising for 15 months to 31 December 2018 3 150 Rent for 12 months to 30 November 2018 1 200 General expenses 1 775 Office furniture 1 450 Additional information 1 At 30 September 2018 fees owing by clients amounted to $3120. 2 Office equipment is depreciated at 20% per annum using the reducing (diminishing) balance method. 3 Office furniture is depreciated using the revaluation method. The office furniture was valued at $11 400 on 30 September 2018. 4 The provision for doubtful debts is to be maintained at the same rate as the previous year. 5 Cash, $3500, taken by Sadia during the year for personal use, was debited to the wages account. REQUIRED (a) Prepare the income statement for the year ended 30 Sadia Income Statement for the year ended 30 (b) Name three items which may appear in the income statement of a trading business but which would not appear in Sadia’s income statement. 1 ................................................................................................................................................ 2 ................................................................................................................................................ 3 ........................................................................................................................................... [3] (c) Suggest two reasons why Sadia’s bank manager would be interested in her financial statements. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (d) Name two other interested parties who may wish to see Sadia’s financial statements. 1 ................................................................................................................................................ 2 ........................................................................................................................................... [2] [Total: 20]
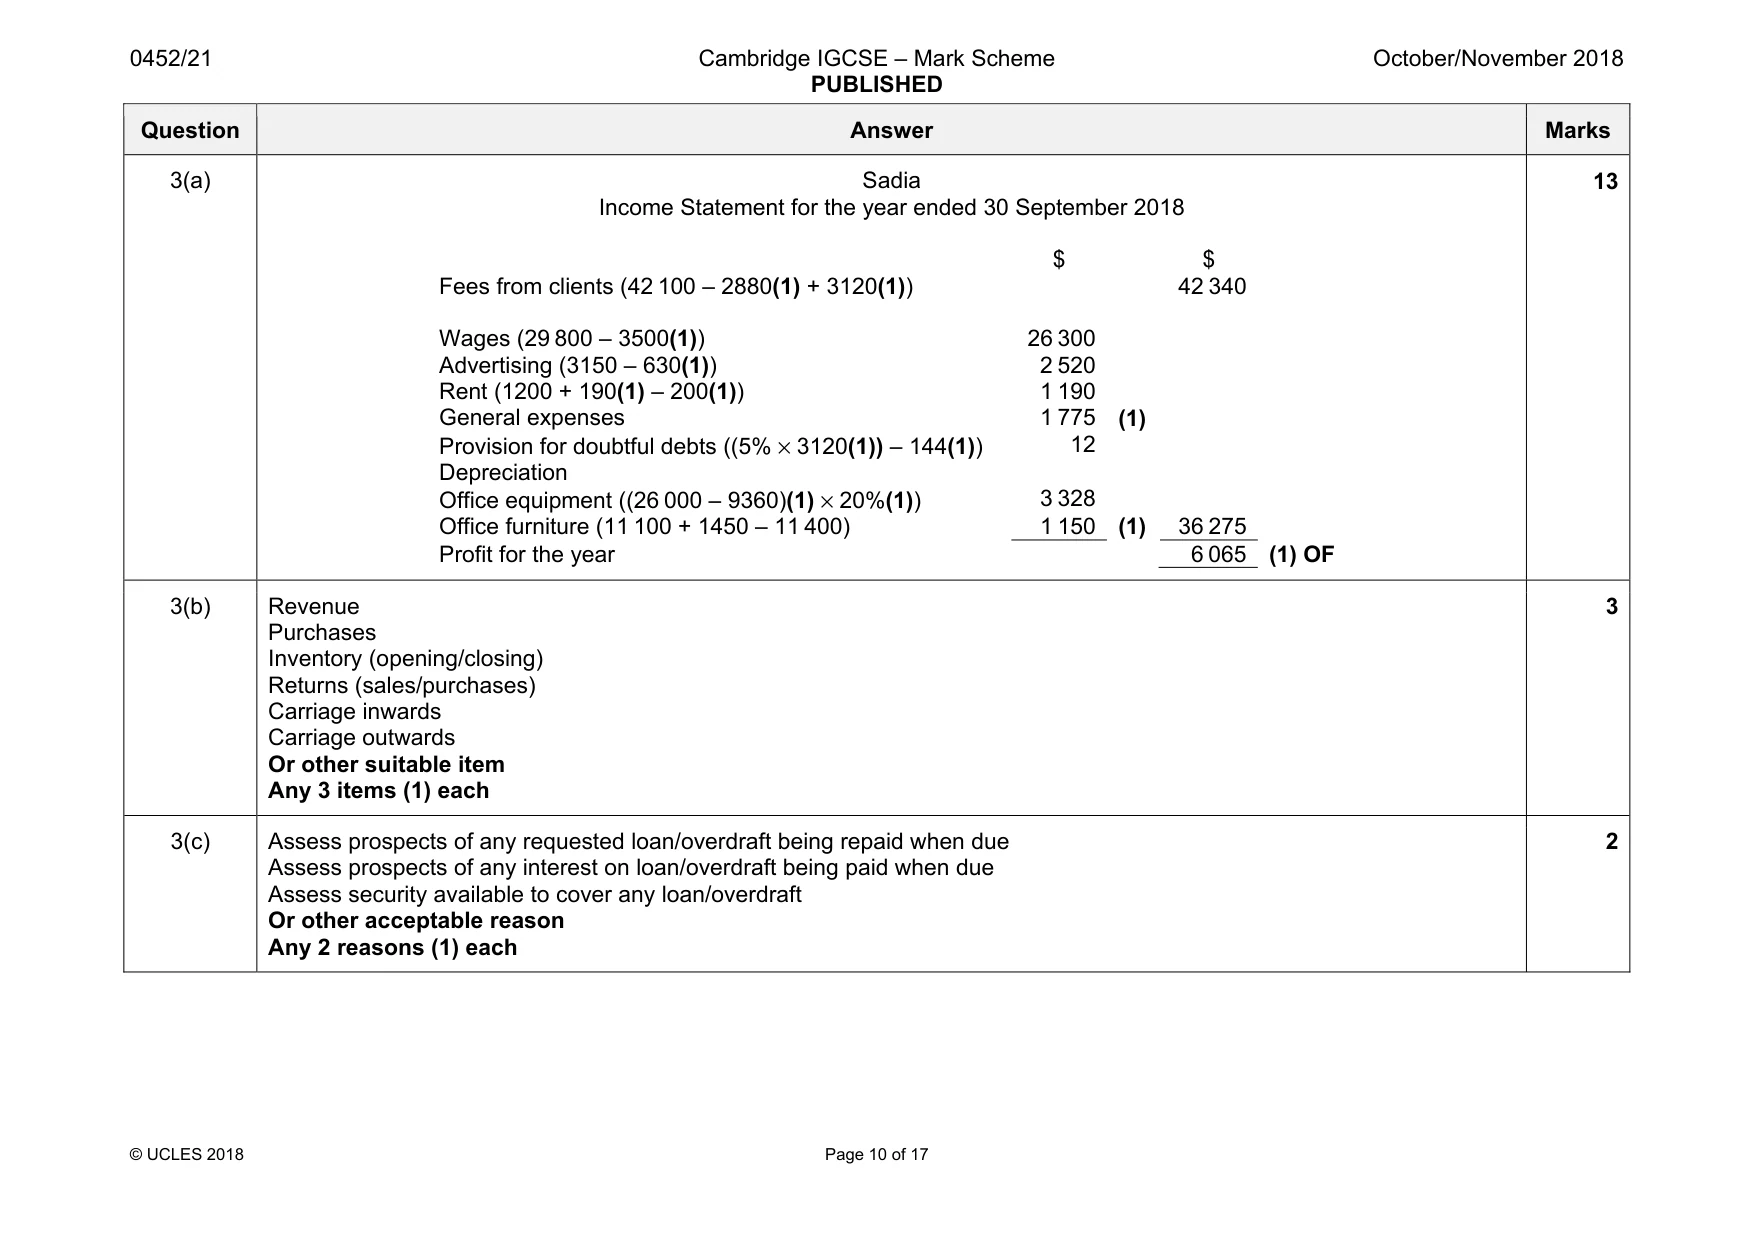
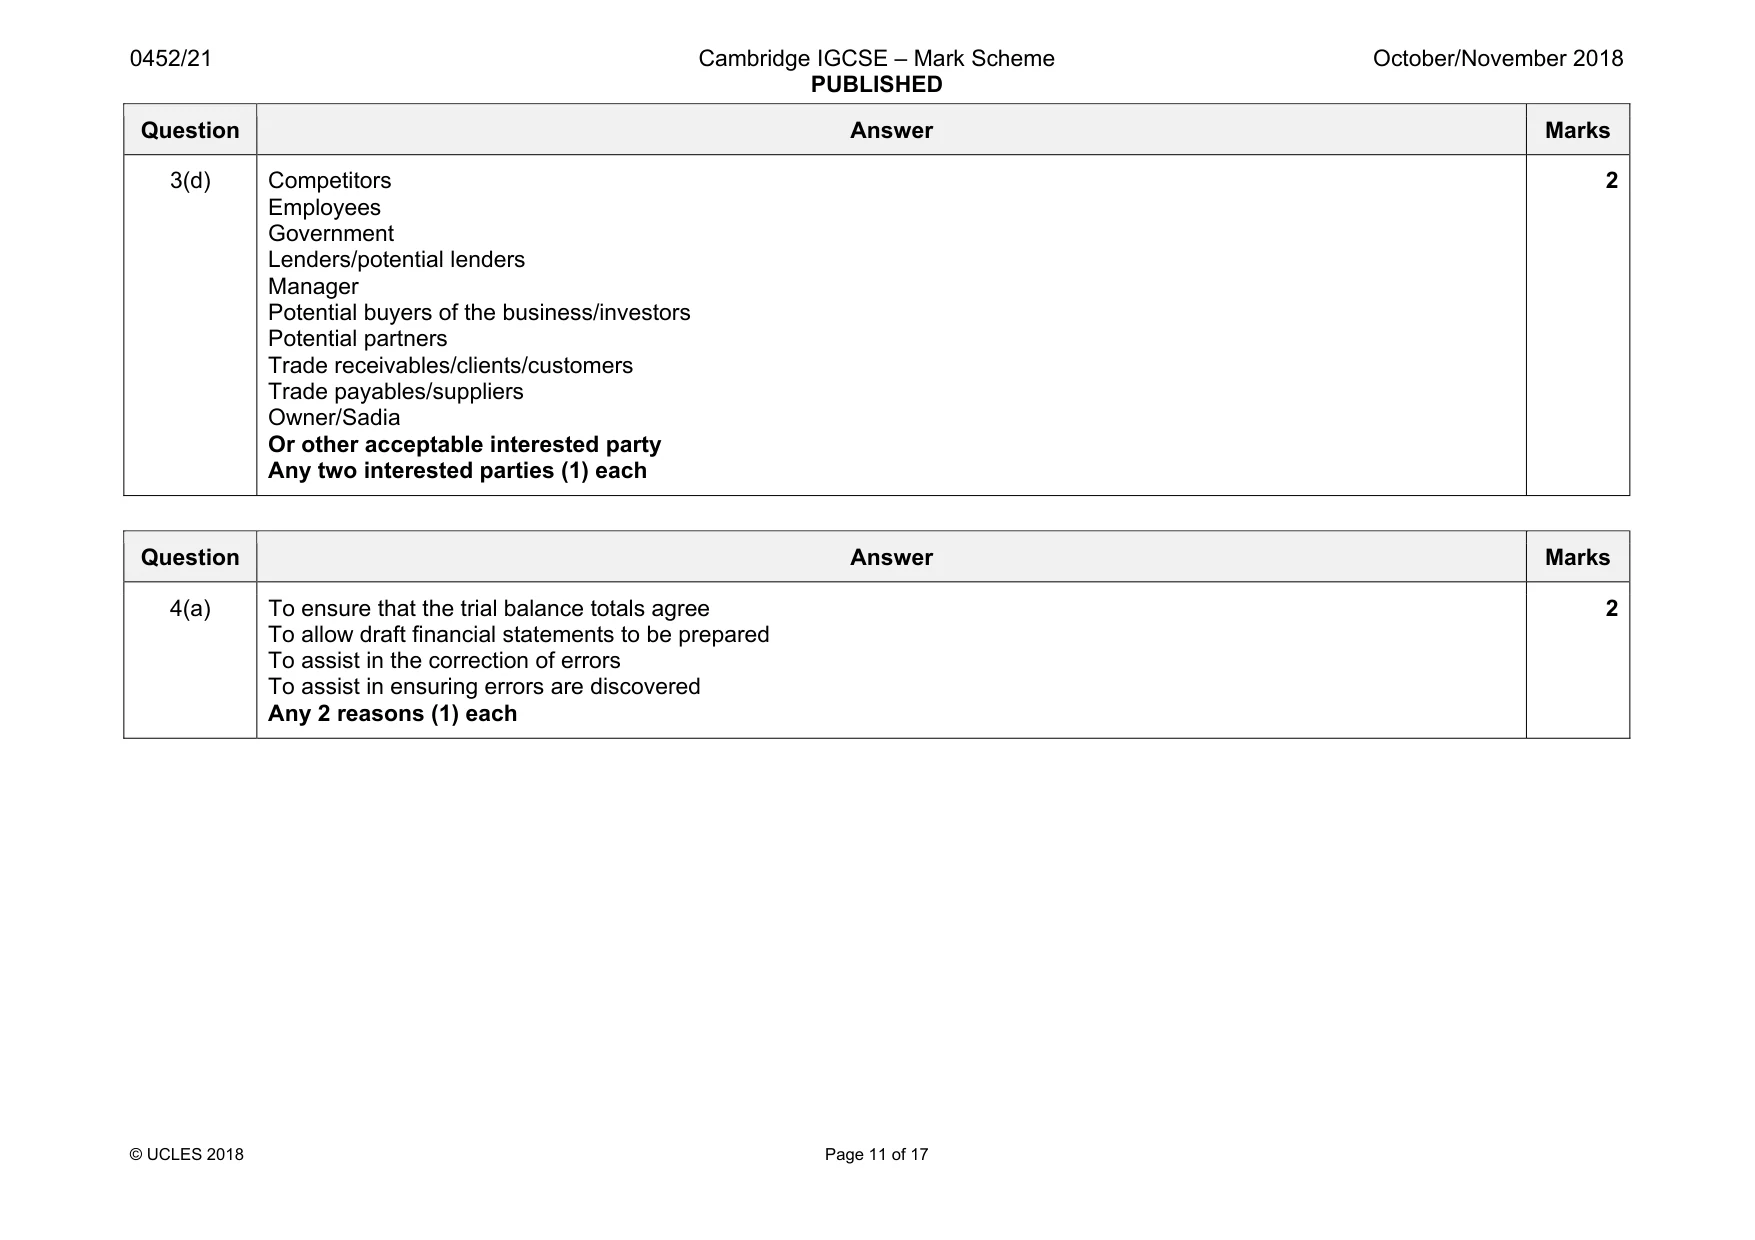
Mark scheme: 3(a) Sadia Income Statement for the year ended 30 September 2018 $ $ Fees from clients (42 100 – 2880(1) + 3120(1)) 42 340 Wages (29 800 – 3500(1)) 26 300 Advertising (3150 – 630(1)) 2 520 Rent (1200 + 190(1) – 200(1)) 1 190 General expenses 1 775 (1) Provision for doubtful debts ((5% × 3120(1)) – 144(1)) 12 Depreciation Office equipment ((26 000 – 9360)(1) × 20%(1)) 3 328 Office furniture (11 100 + 1450 – 11 400) 1 150 (1) 36 275 Profit for the year 6 065 (1) OF 13 3(b) Revenue Purchases Inventory (opening/closing) Returns (sales/purchases) Carriage inwards Carriage outwards Or other suitable item Any 3 items (1) each 3 3(c) Assess prospects of any requested loan/overdraft being repaid when due Assess prospects of any interest on loan/overdraft being paid when due Assess security available to cover any loan/overdraft Or other acceptable reason Any 2 reasons (1) each 2 Question Answer Marks 3(d) Competitors Employees Government Lenders/potential lenders Manager Potential buyers of the business/investors Potential partners Trade receivables/clients/customers Trade payables/suppliers Owner/Sadia Or other acceptable interested party Any two interested parties (1) each 2
Q4 · Rizwan is a motor trader
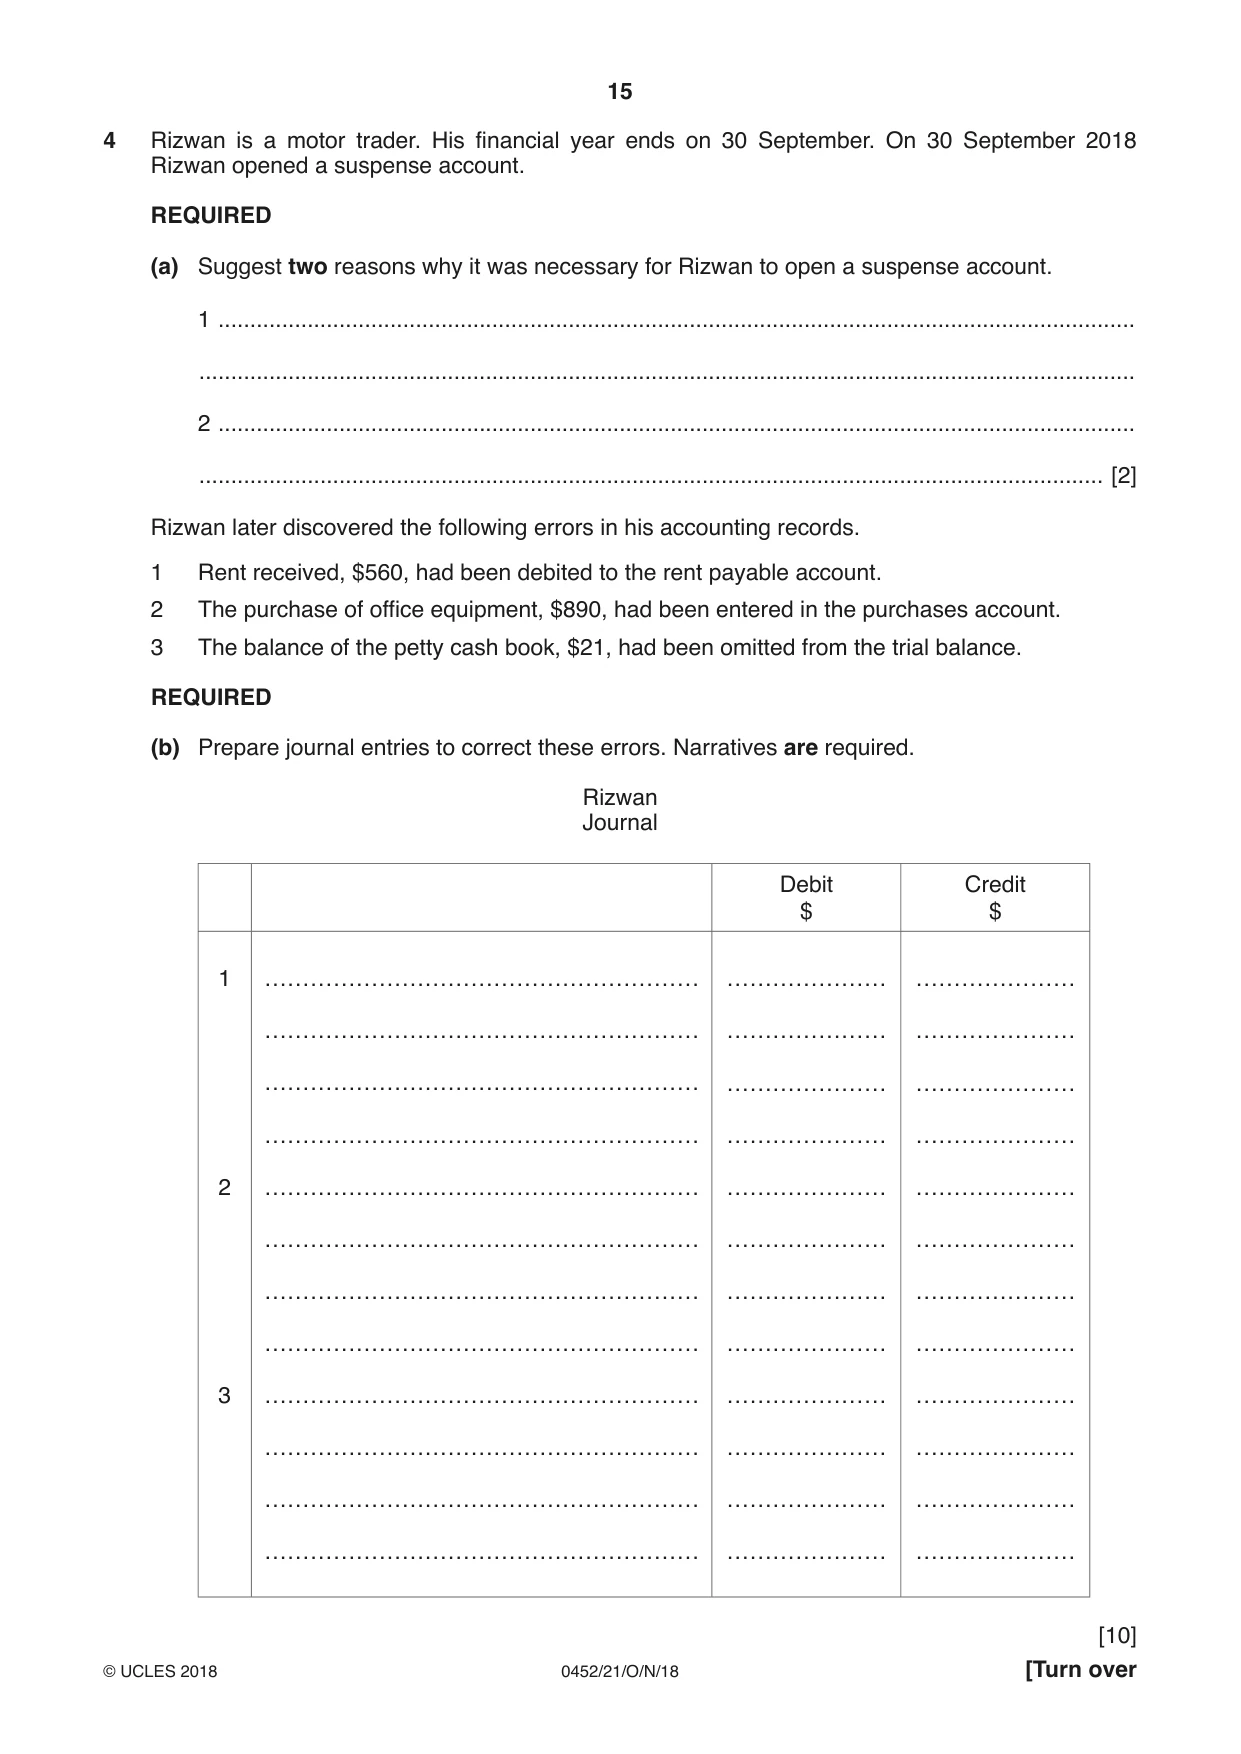
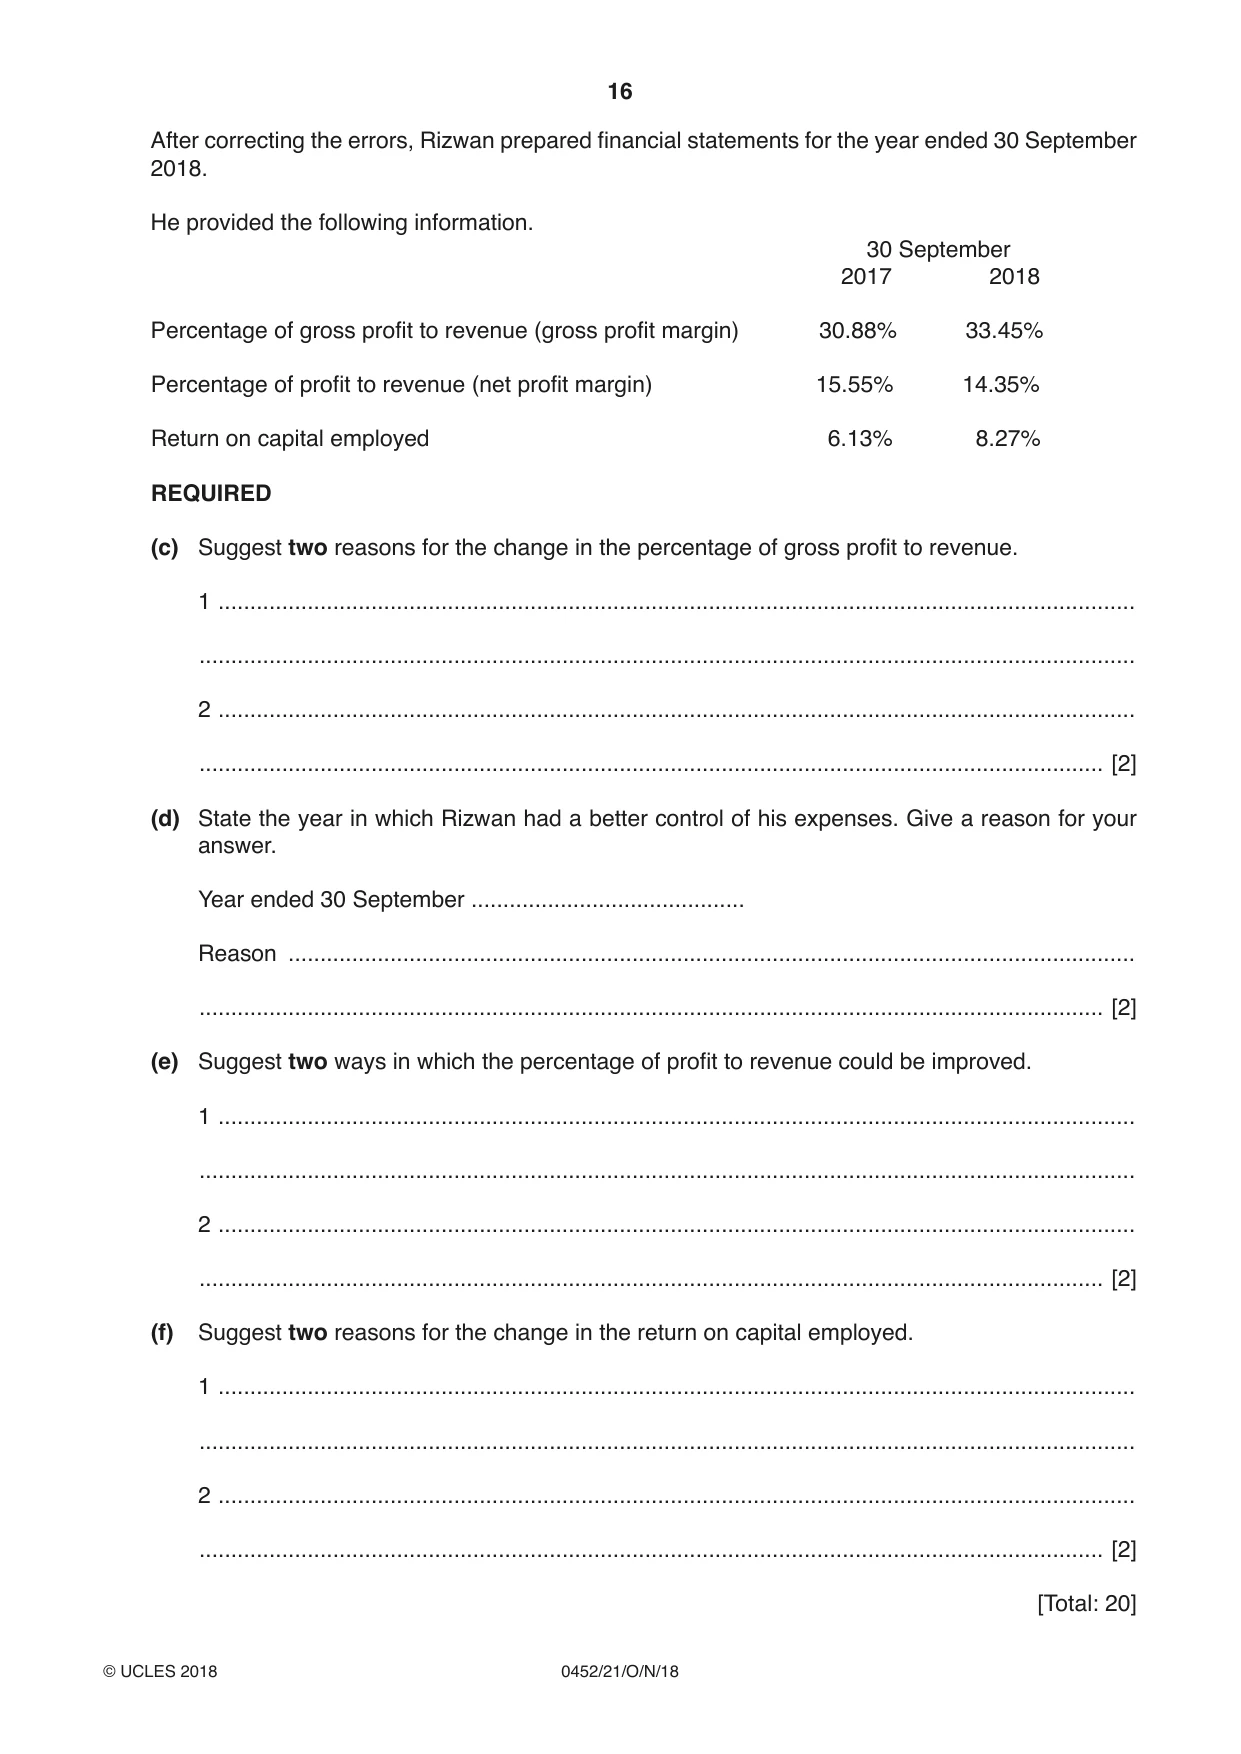
4 Rizwan is a motor trader. His financial year ends on 30 September. On 30 September 2018 Rizwan opened a suspense account. REQUIRED (a) Suggest two reasons why it was necessary for Rizwan to open a suspense account. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] Rizwan later discovered the following errors in his accounting records. 1 Rent received, $560, had been debited to the rent payable account. 2 The purchase of office equipment, $890, had been entered in the purchases account. 3 The balance of the petty cash book, $21, had been omitted from the trial balance. REQUIRED (b) Prepare journal entries to correct these errors. Narratives are required. Rizwan Journal Debit Credit $ $ 1 ………………… ………………… ………………… ………………… ………………… ………………… ………………… ………………… 2 ………………… ………………… ………………… ………………… ………………… ………………… ………………… ………………… 3 ………………… ………………… ………………… ………………… ………………… ………………… ………………… ………………… [10] After correcting the errors, Rizwan prepared financial statements for the year ended 30 September 2018. He provided the following information. 30 September 2017 2018 Percentage of gross profit to revenue (gross profit margin) 30.88% 33.45% Percentage of profit to revenue (net profit margin) 15.55% 14.35% Return on capital employed 6.13% 8.27% REQUIRED (c) Suggest two reasons for the change in the percentage of gross profit to revenue. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (d) State the year in which Rizwan had a better control of his expenses. Give a reason for your answer. Year ended 30 September ........................................... Reason ..................................................................................................................................... .............................................................................................................................................. [2] (e) Suggest two ways in which the percentage of profit to revenue could be improved. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (f) Suggest two reasons for the change in the return on capital employed. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] [Total: 20] PLEASE TURN OVER
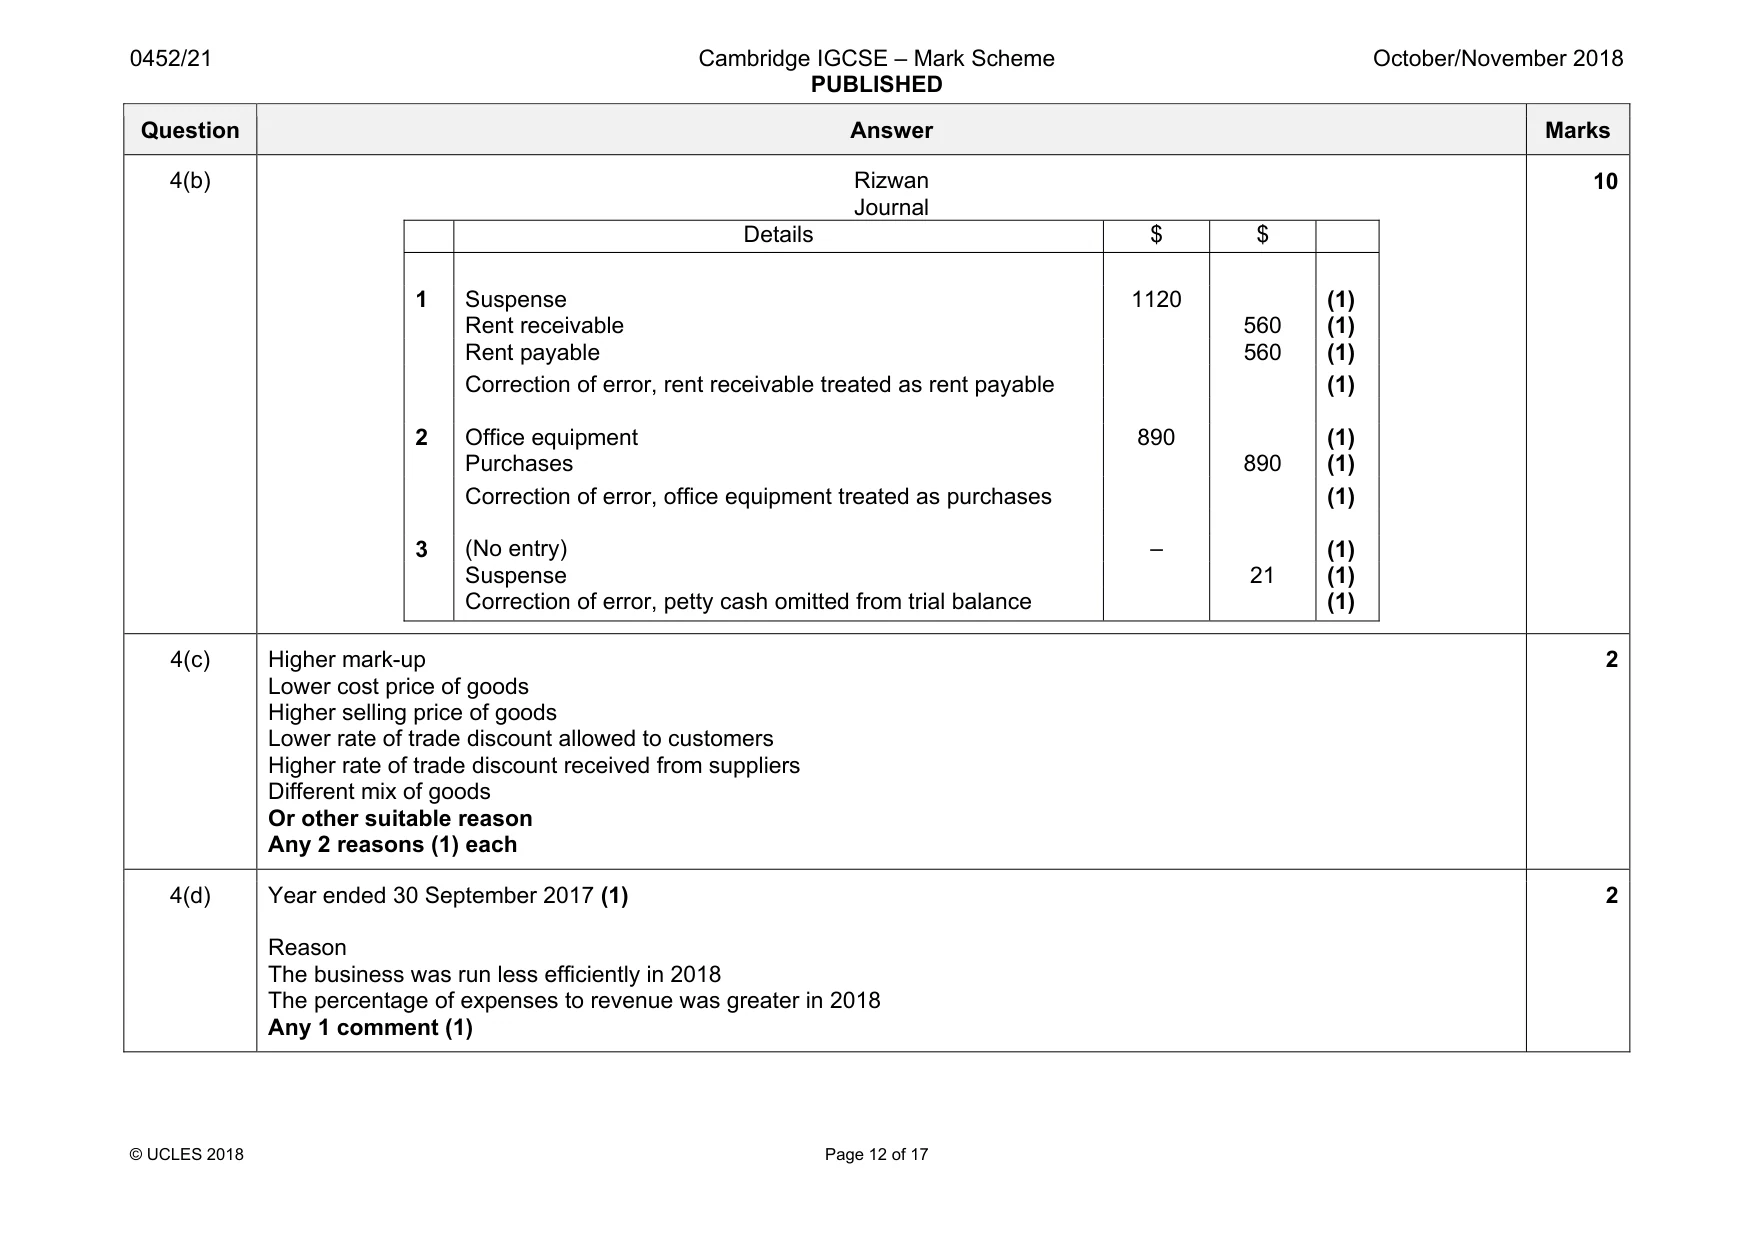
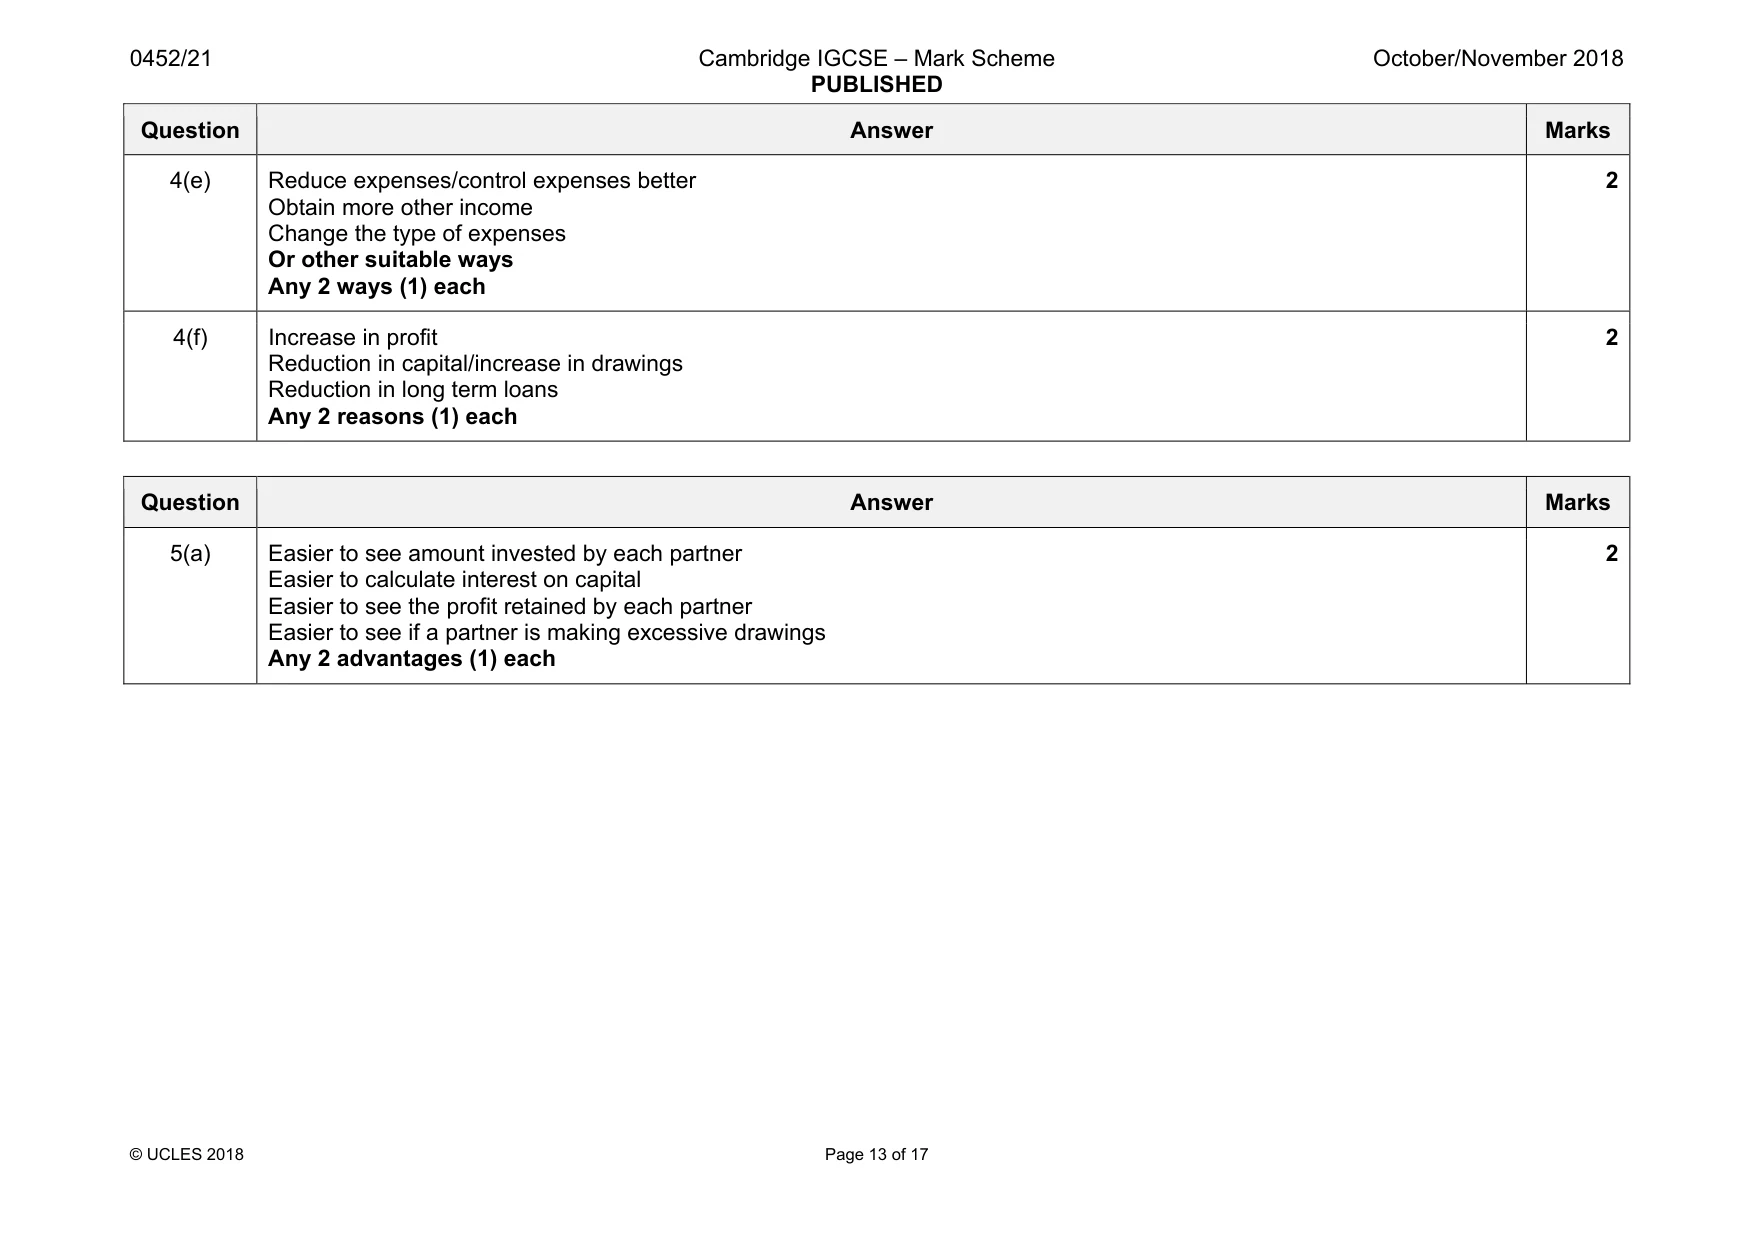
Mark scheme: 4(a) To ensure that the trial balance totals agree To allow draft financial statements to be prepared To assist in the correction of errors To assist in ensuring errors are discovered Any 2 reasons (1) each 2 Question Answer Marks 4(b) Rizwan Journal Details $ $ 1 Suspense 1120 (1) Rent receivable 560 (1) Rent payable 560 (1) Correction of error, rent receivable treated as rent payable (1) 2 Office equipment 890 (1) Purchases 890 (1) Correction of error, office equipment treated as purchases (1) 3 (No entry) – (1) Suspense 21 (1) Correction of error, petty cash omitted from trial balance (1) 10 4(c) Higher mark-up Lower cost price of goods Higher selling price of goods Lower rate of trade discount allowed to customers Higher rate of trade discount received from suppliers Different mix of goods Or other suitable reason Any 2 reasons (1) each 2 4(d) Year ended 30 September 2017 (1) Reason The business was run less efficiently in 2018 The percentage of expenses to revenue was greater in 2018 Any 1 comment (1) 2 Question Answer Marks 4(e) Reduce expenses/control expenses better Obtain more other income Change the type of expenses Or other suitable ways Any 2 ways (1) each 2 4(f) Increase in profit Reduction in capital/increase in drawings Reduction in long term loans Any 2 reasons (1) each 2
Q5 · Mark and Ella are in partnership
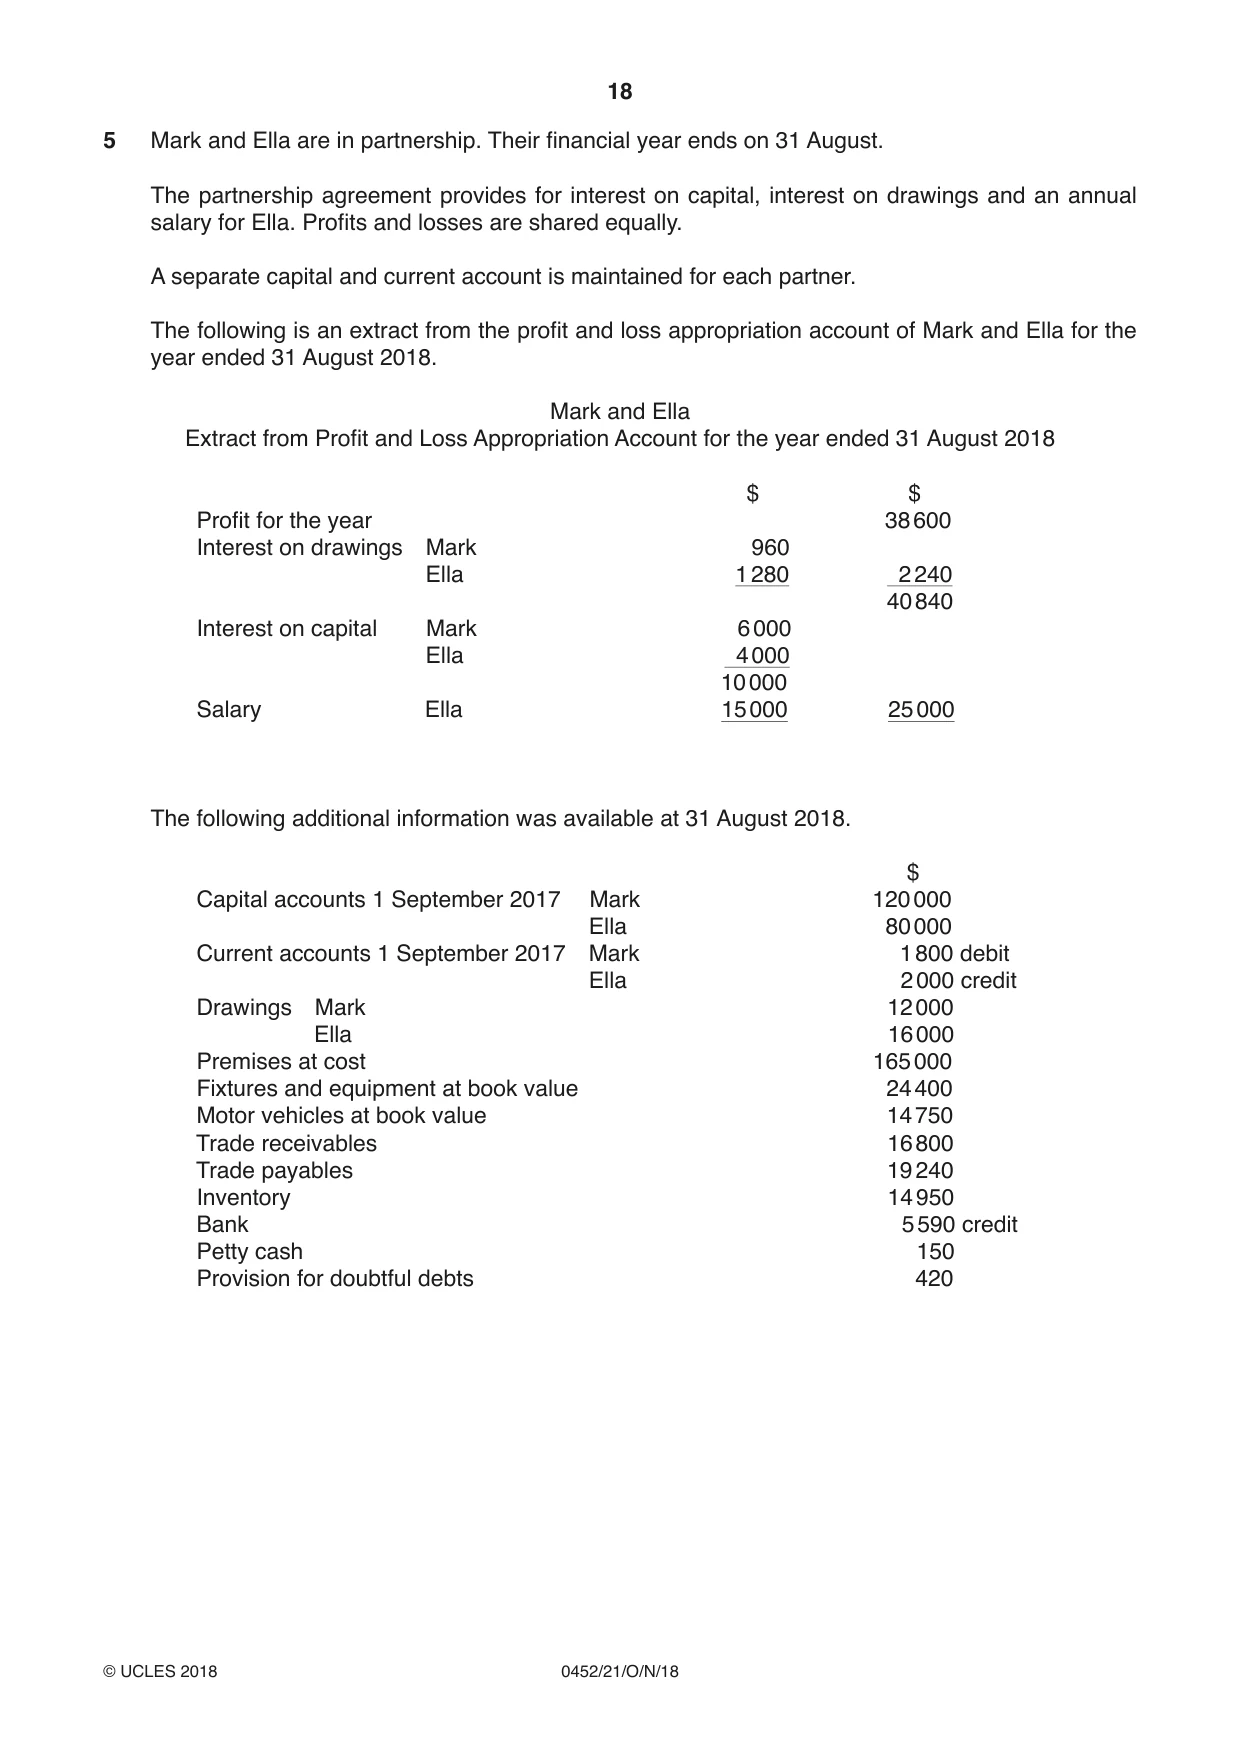
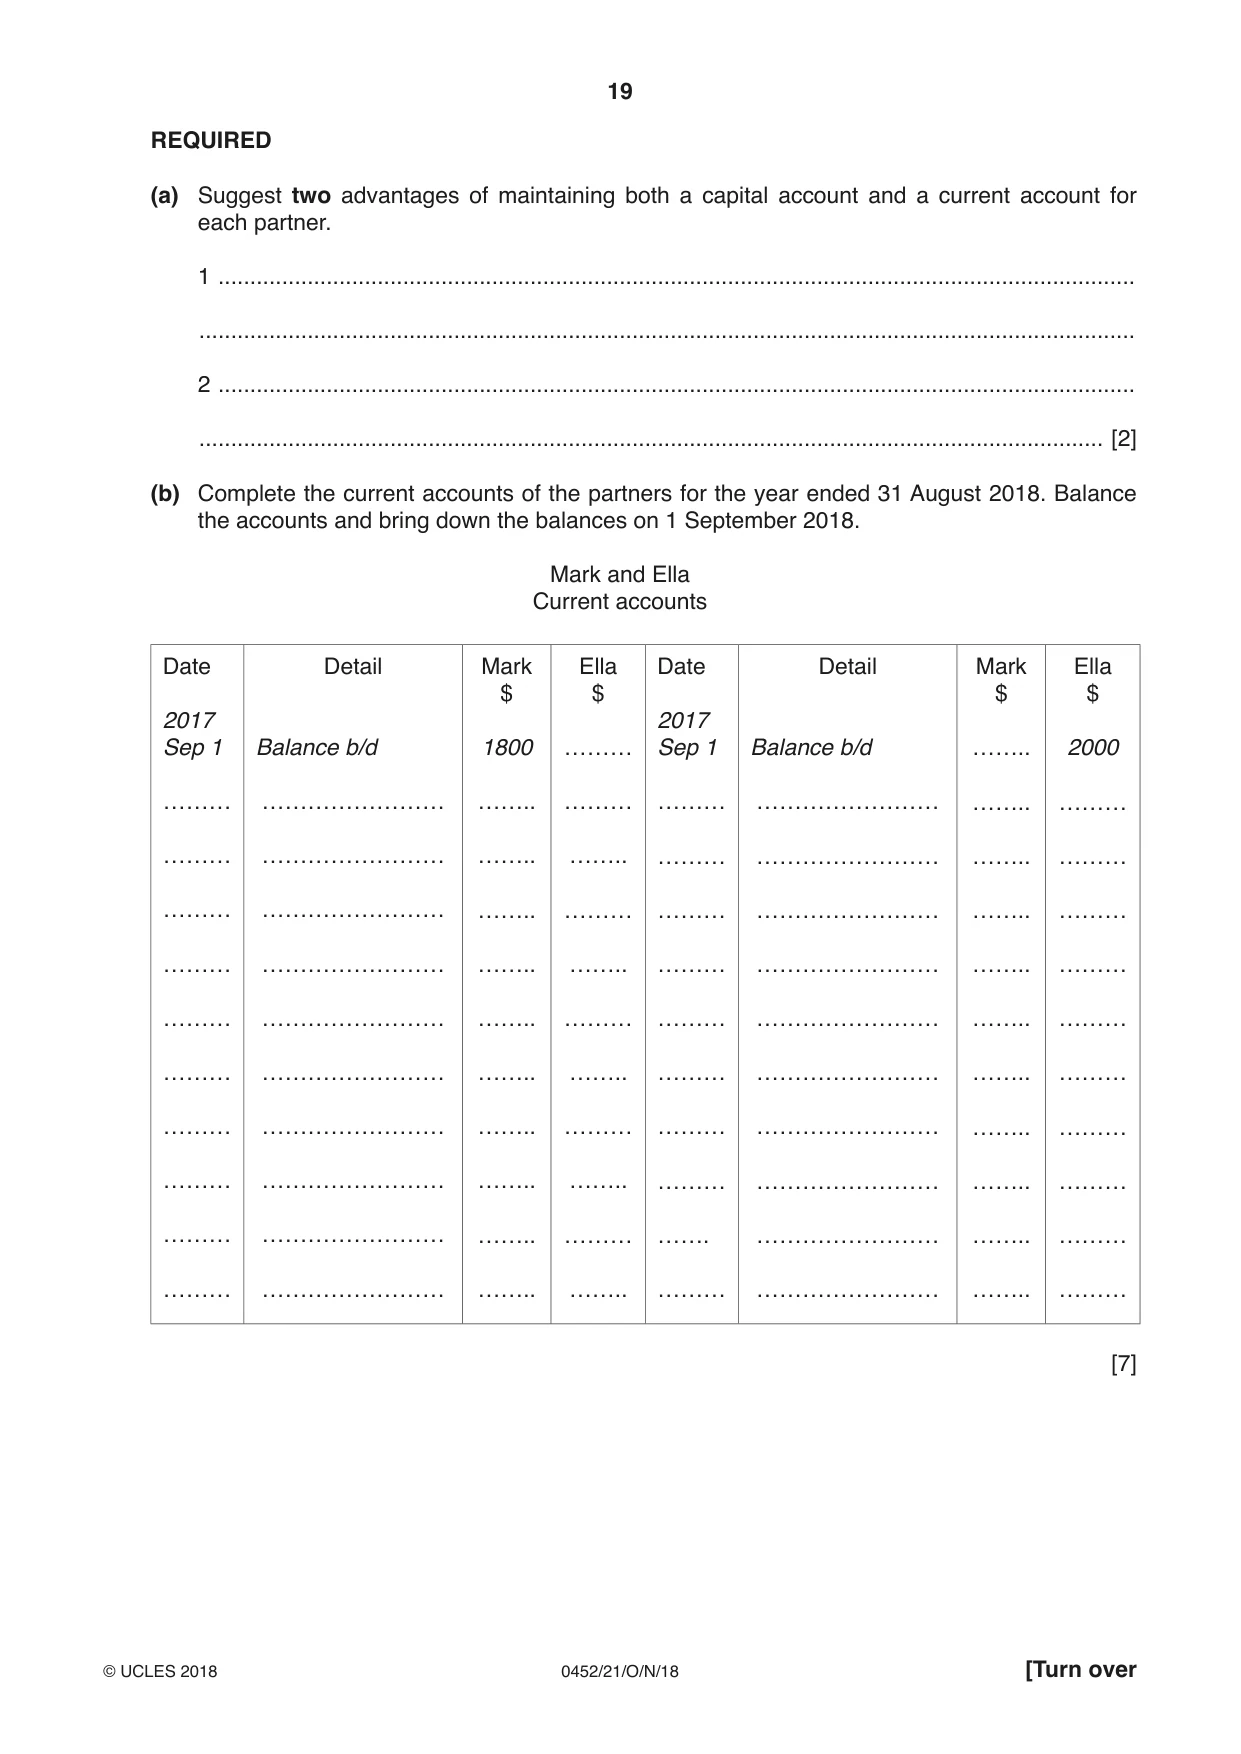
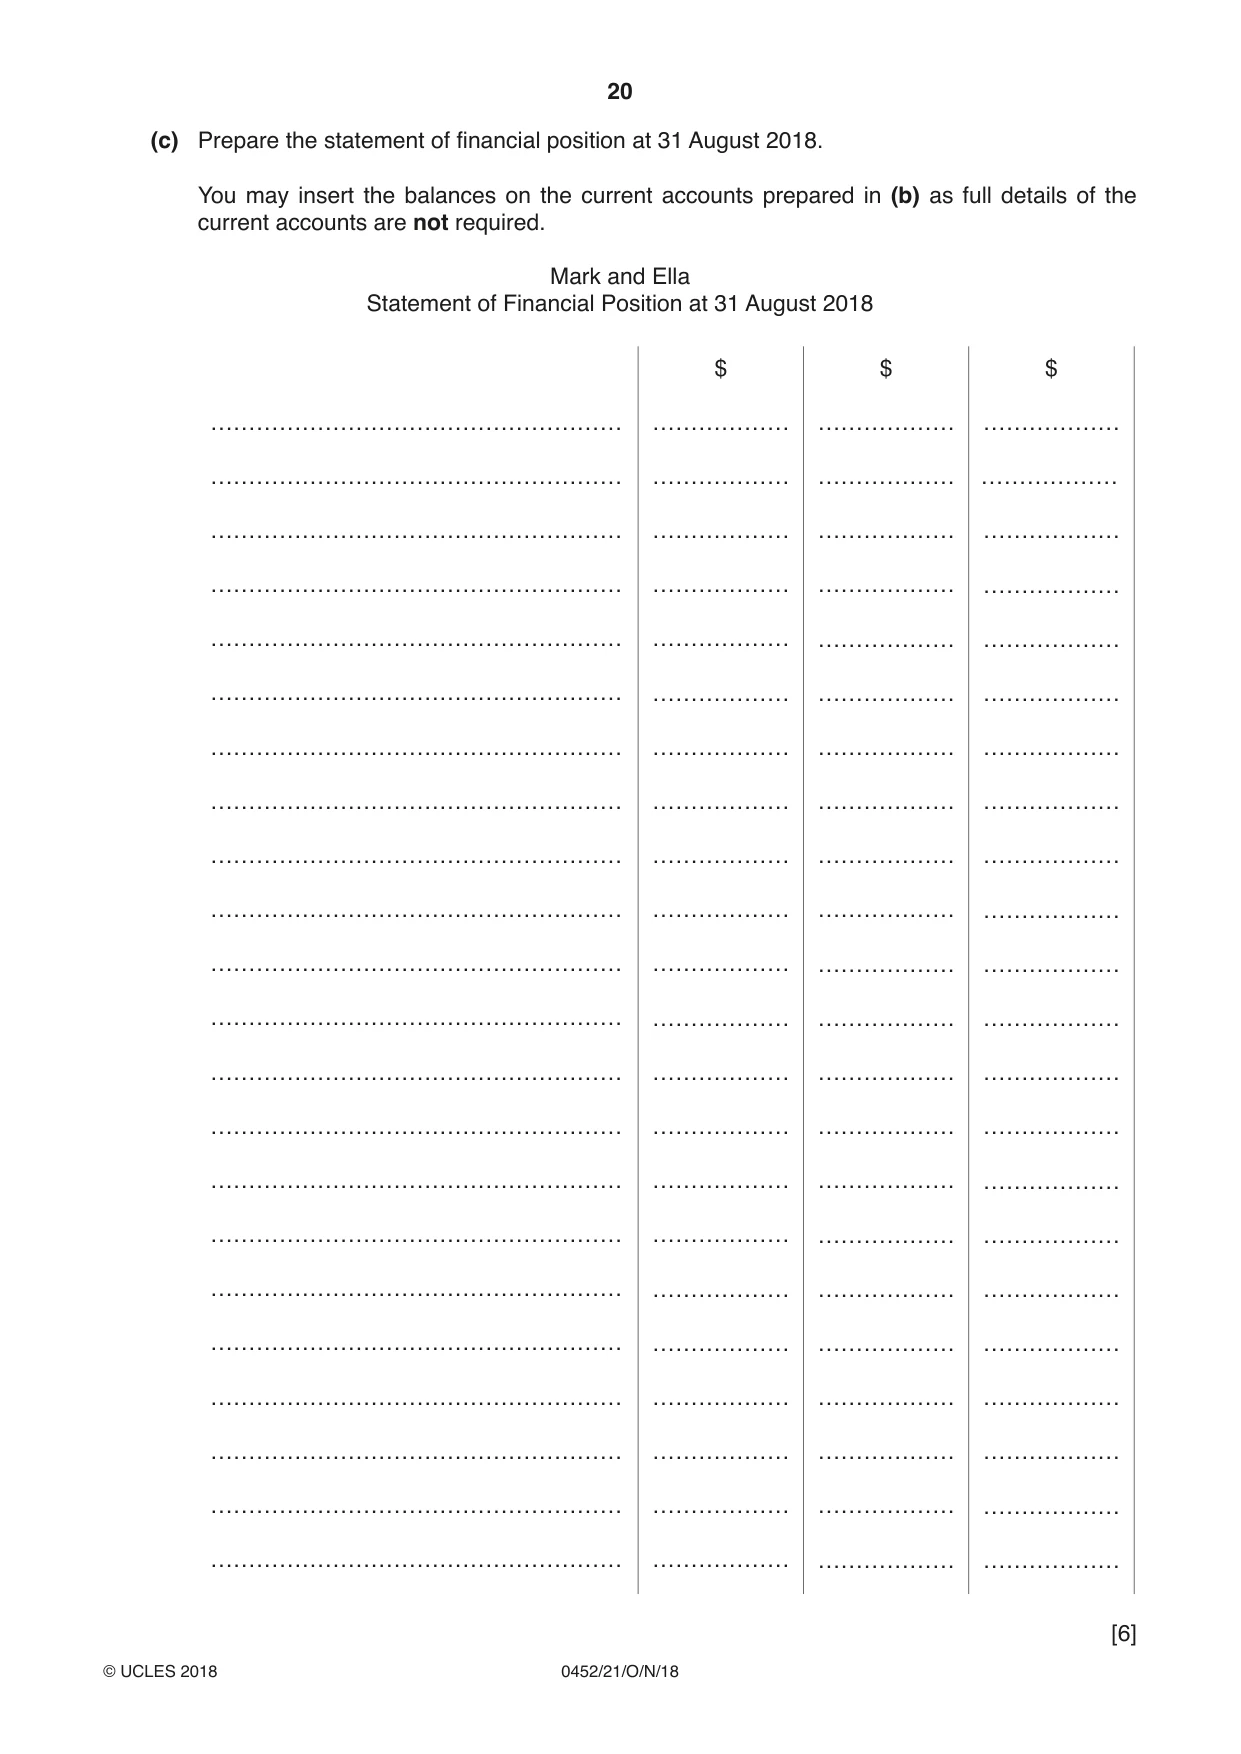
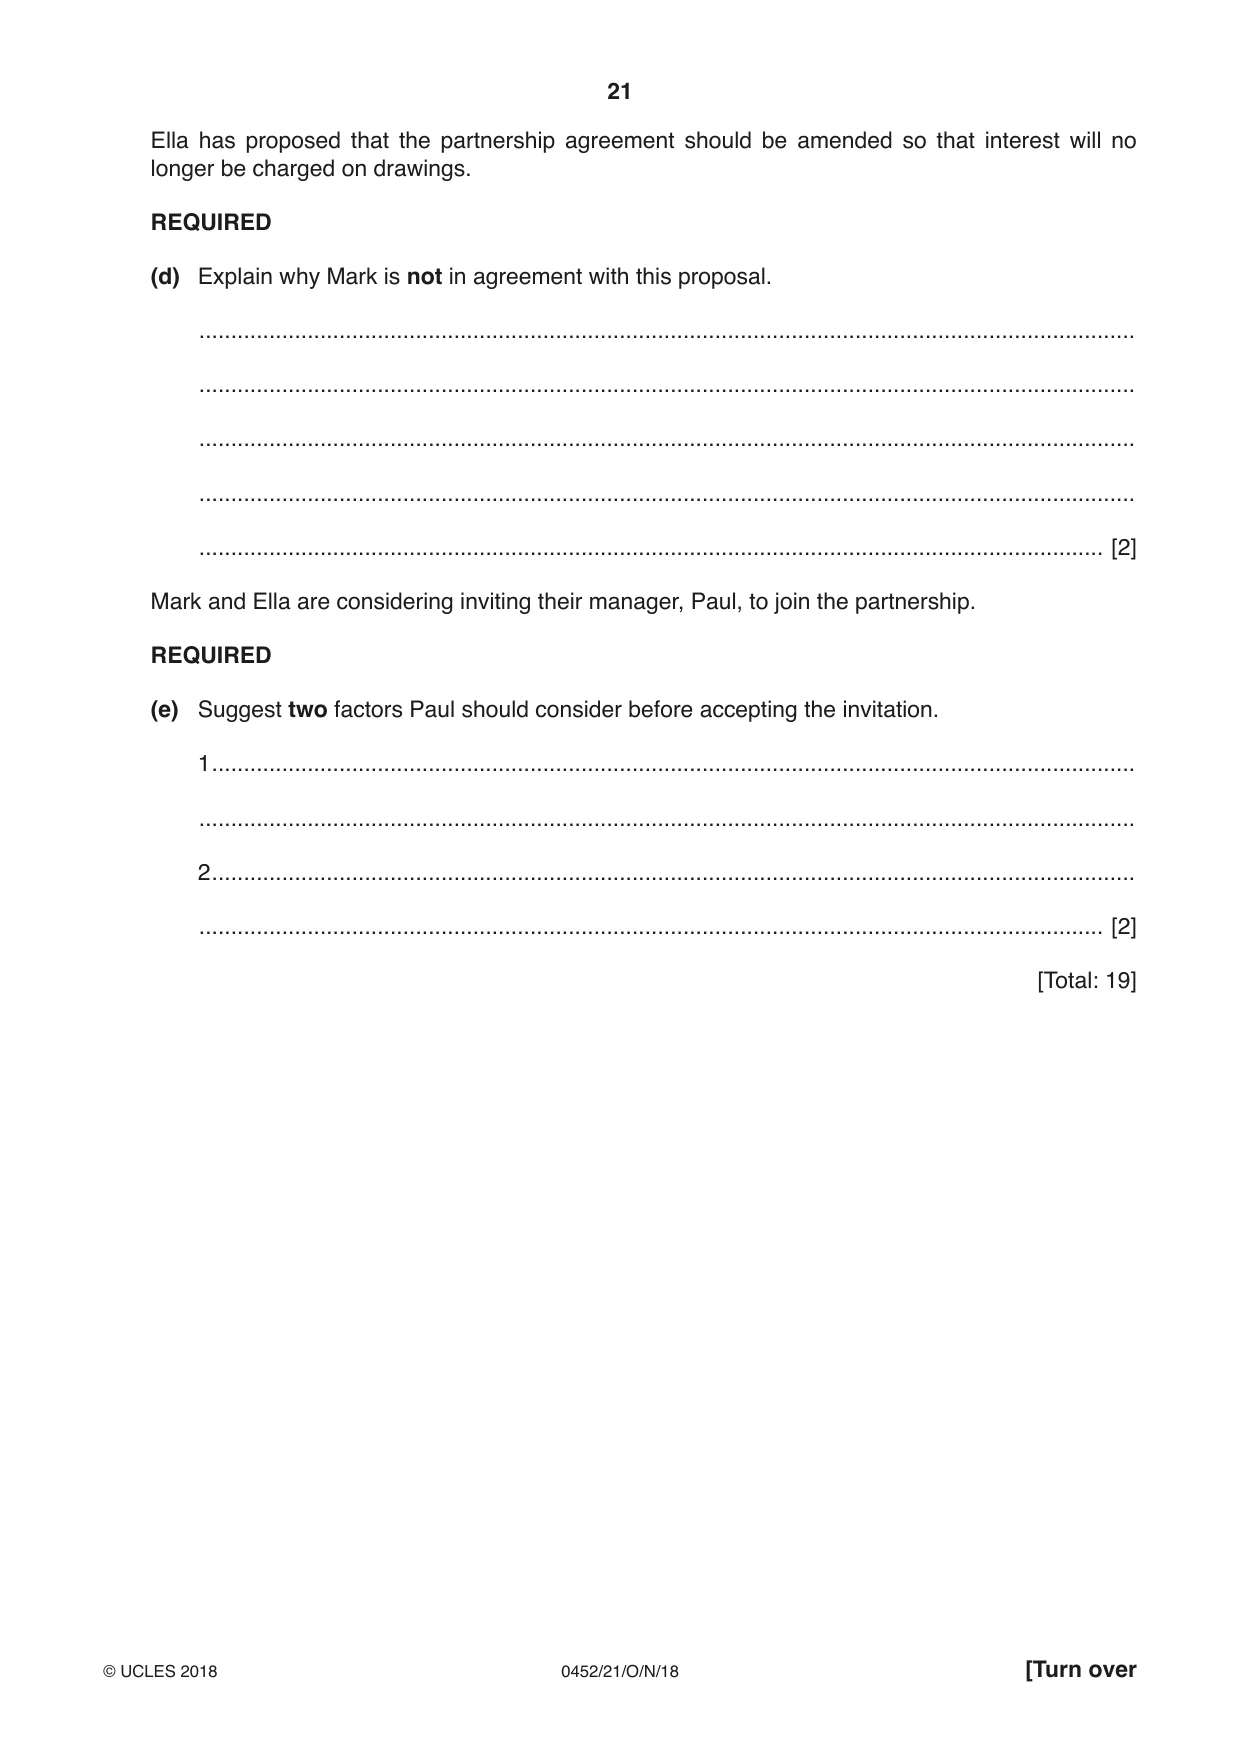
5 Mark and Ella are in partnership. Their financial year ends on 31 August. The partnership agreement provides for interest on capital, interest on drawings and an annual salary for Ella. Profits and losses are shared equally. A separate capital and current account is maintained for each partner. The following is an extract from the profit and loss appropriation account of Mark and Ella for the year ended 31 August 2018. Mark and Ella Extract from Profit and Loss Appropriation Account for the year ended 31 August 2018 $ $ Profit for the year 38 600 Interest on drawings Mark 960 Ella 1 280 2 240 40 840 Interest on capital Mark 6 000 Ella 4 000 10 000 Salary Ella 15 000 25 000 The following additional information was available at 31 August 2018. $ Capital accounts 1 September 2017 Mark 120 000 Ella 80 000 Current accounts 1 September 2017 Mark 1 800 debit Ella 2 000 credit Drawings Mark 12 000 Ella 16 000 Premises at cost 165 000 Fixtures and equipment at book value 24 400 Motor vehicles at book value 14 750 Trade receivables 16 800 Trade payables 19 240 Inventory 14 950 Bank 5 590 credit Petty cash 150 Provision for doubtful debts 420 REQUIRED (a) Suggest two advantages of maintaining both a capital account and a current account for each partner. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (b) Complete the current accounts of the partners for the year ended 31 August 2018. Balance the accounts and bring down the balances on 1 September 2018. Mark and Ella Current accounts Date Detail Mark Ella Date Detail Mark Ella $ $ $ $ 2017 2017 Sep 1 Balance b/d 1800 ……… Sep 1 Balance b/d …….. 2000 ……… …….. ……… ……… …….. ……… ……… …….. …….. ……… …….. ……… ……… …….. ……… ……… …….. ……… ……… …….. …….. ……… …….. ……… ……… …….. ……… ……… …….. ……… ……… …….. …….. ……… …….. ……… ……… …….. ……… ……… …….. ……… ……… …….. …….. ……… …….. ……… ……… …….. ……… ……. …….. ……… ……… …….. …….. ……… …….. ……… [7] (c) Prepare the statement of financial position You may insert the balances on the curre current accounts are not required. Mark an Statement of Financial Po Ella has proposed that the partnership agreement should be amended so that interest will no longer be charged on drawings. REQUIRED (d) Explain why Mark is not in agreement with this proposal. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] Mark and Ella are considering inviting their manager, Paul, to join the partnership. REQUIRED (e) Suggest two factors Paul should consider before accepting the invitation. 1 ................................................................................................................................................. ................................................................................................................................................... 2 ................................................................................................................................................. .............................................................................................................................................. [2] [Total: 19]
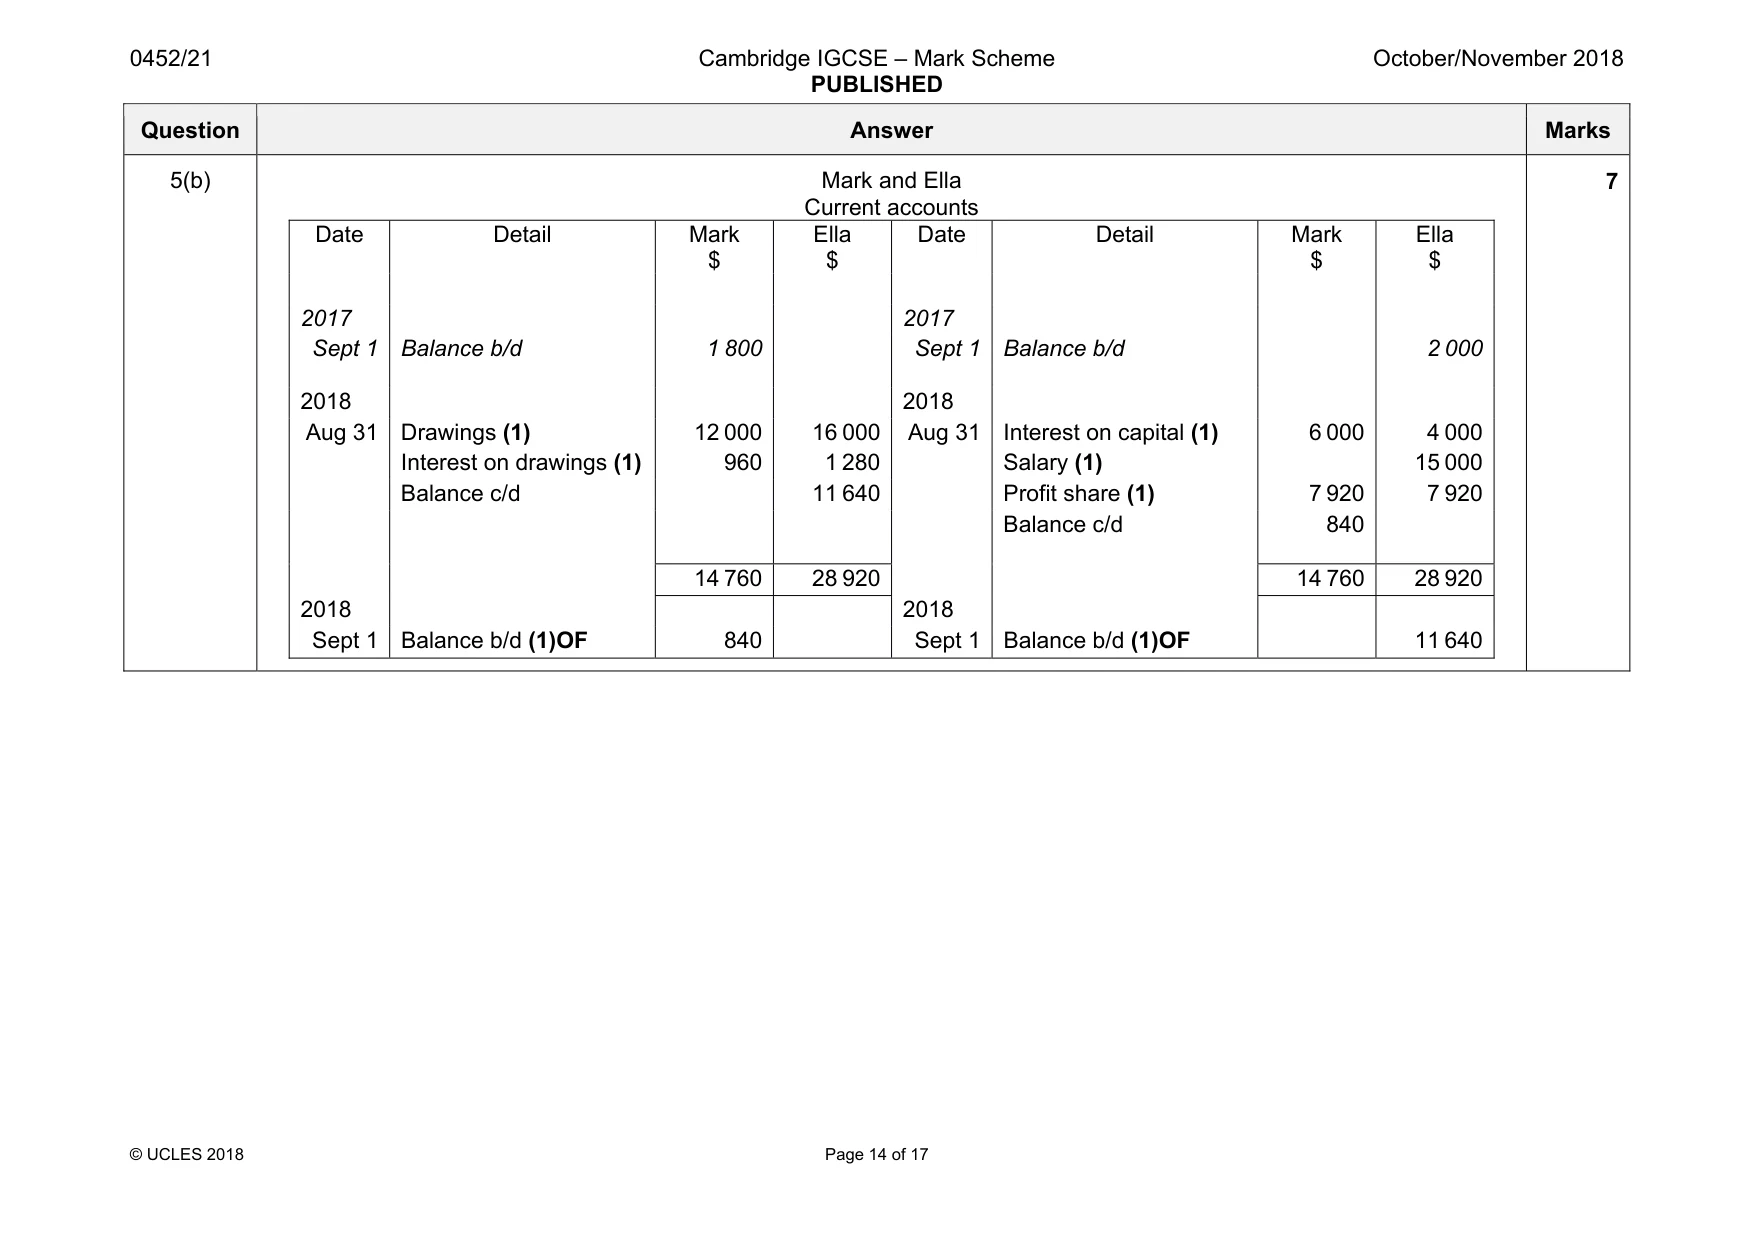
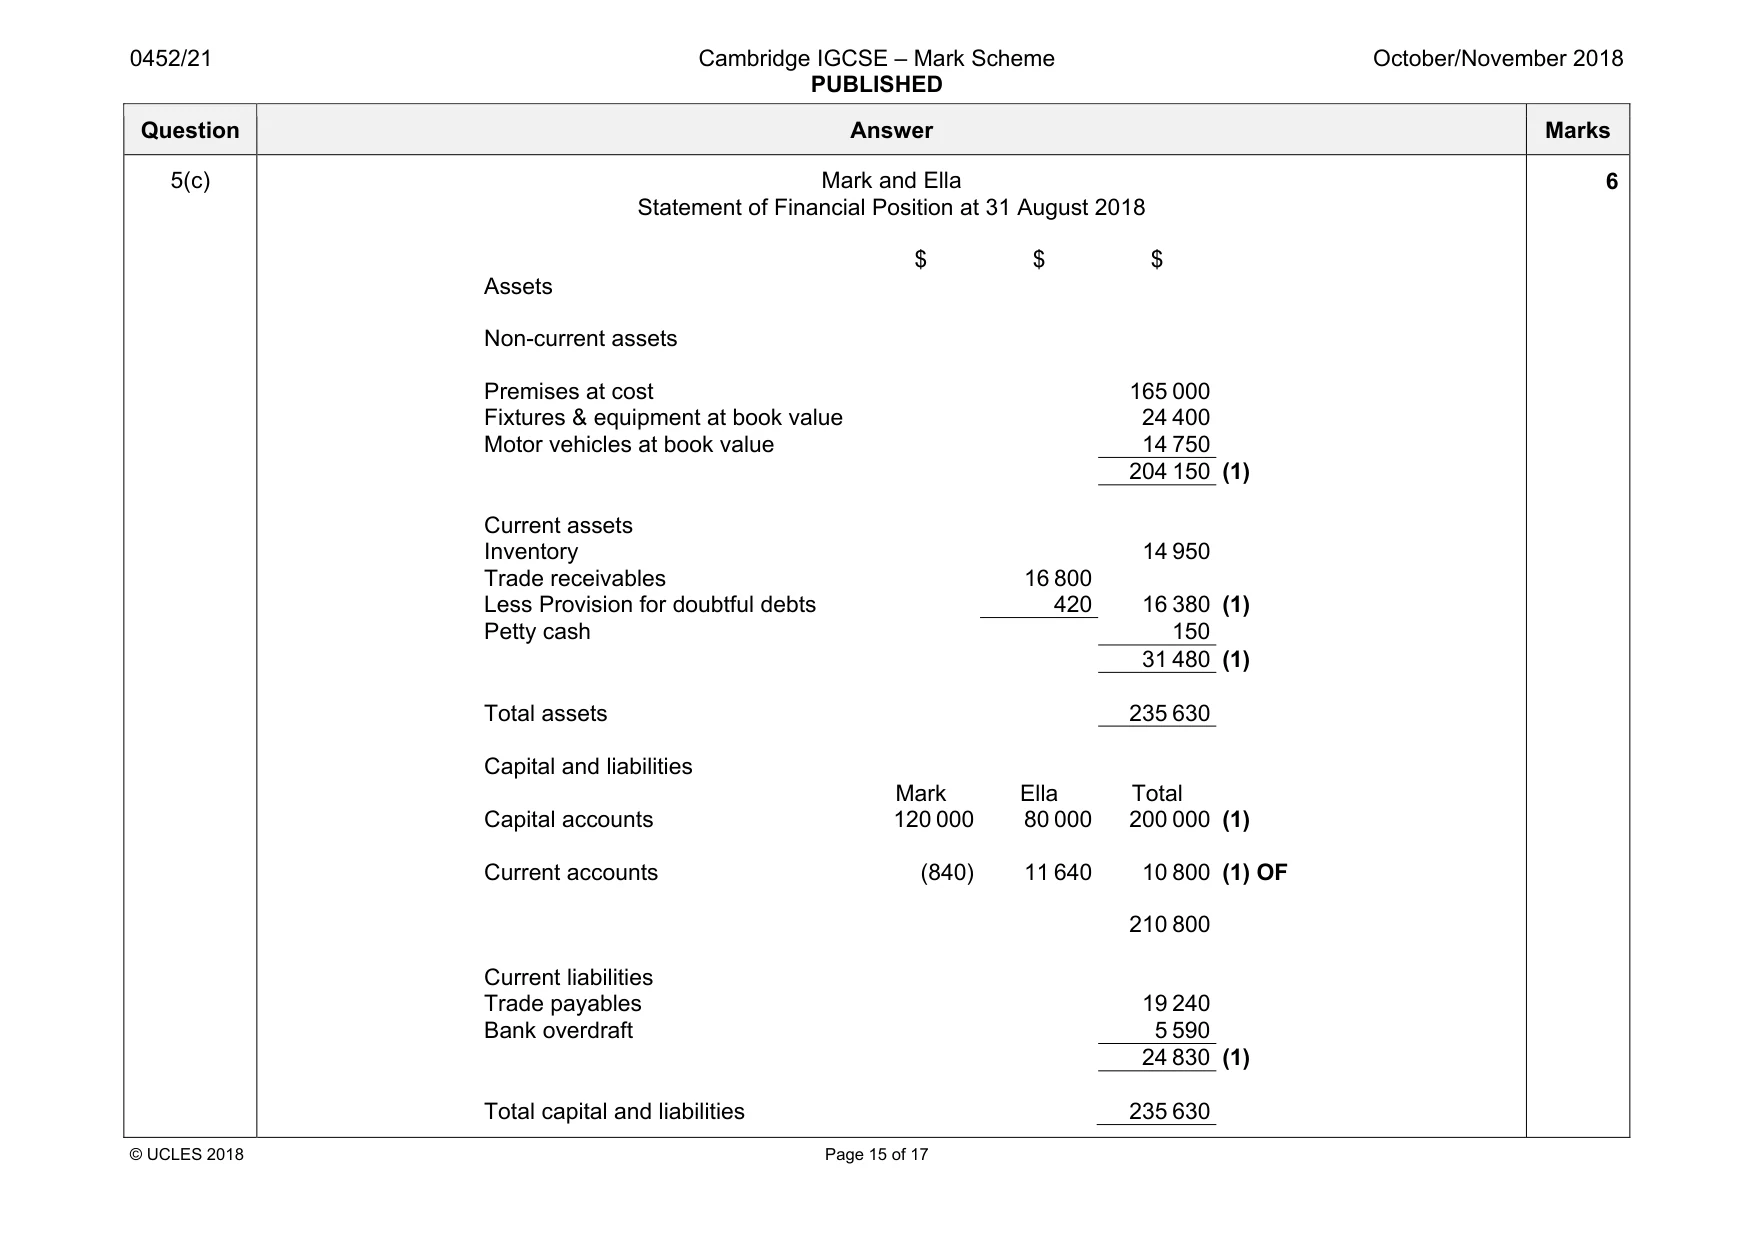
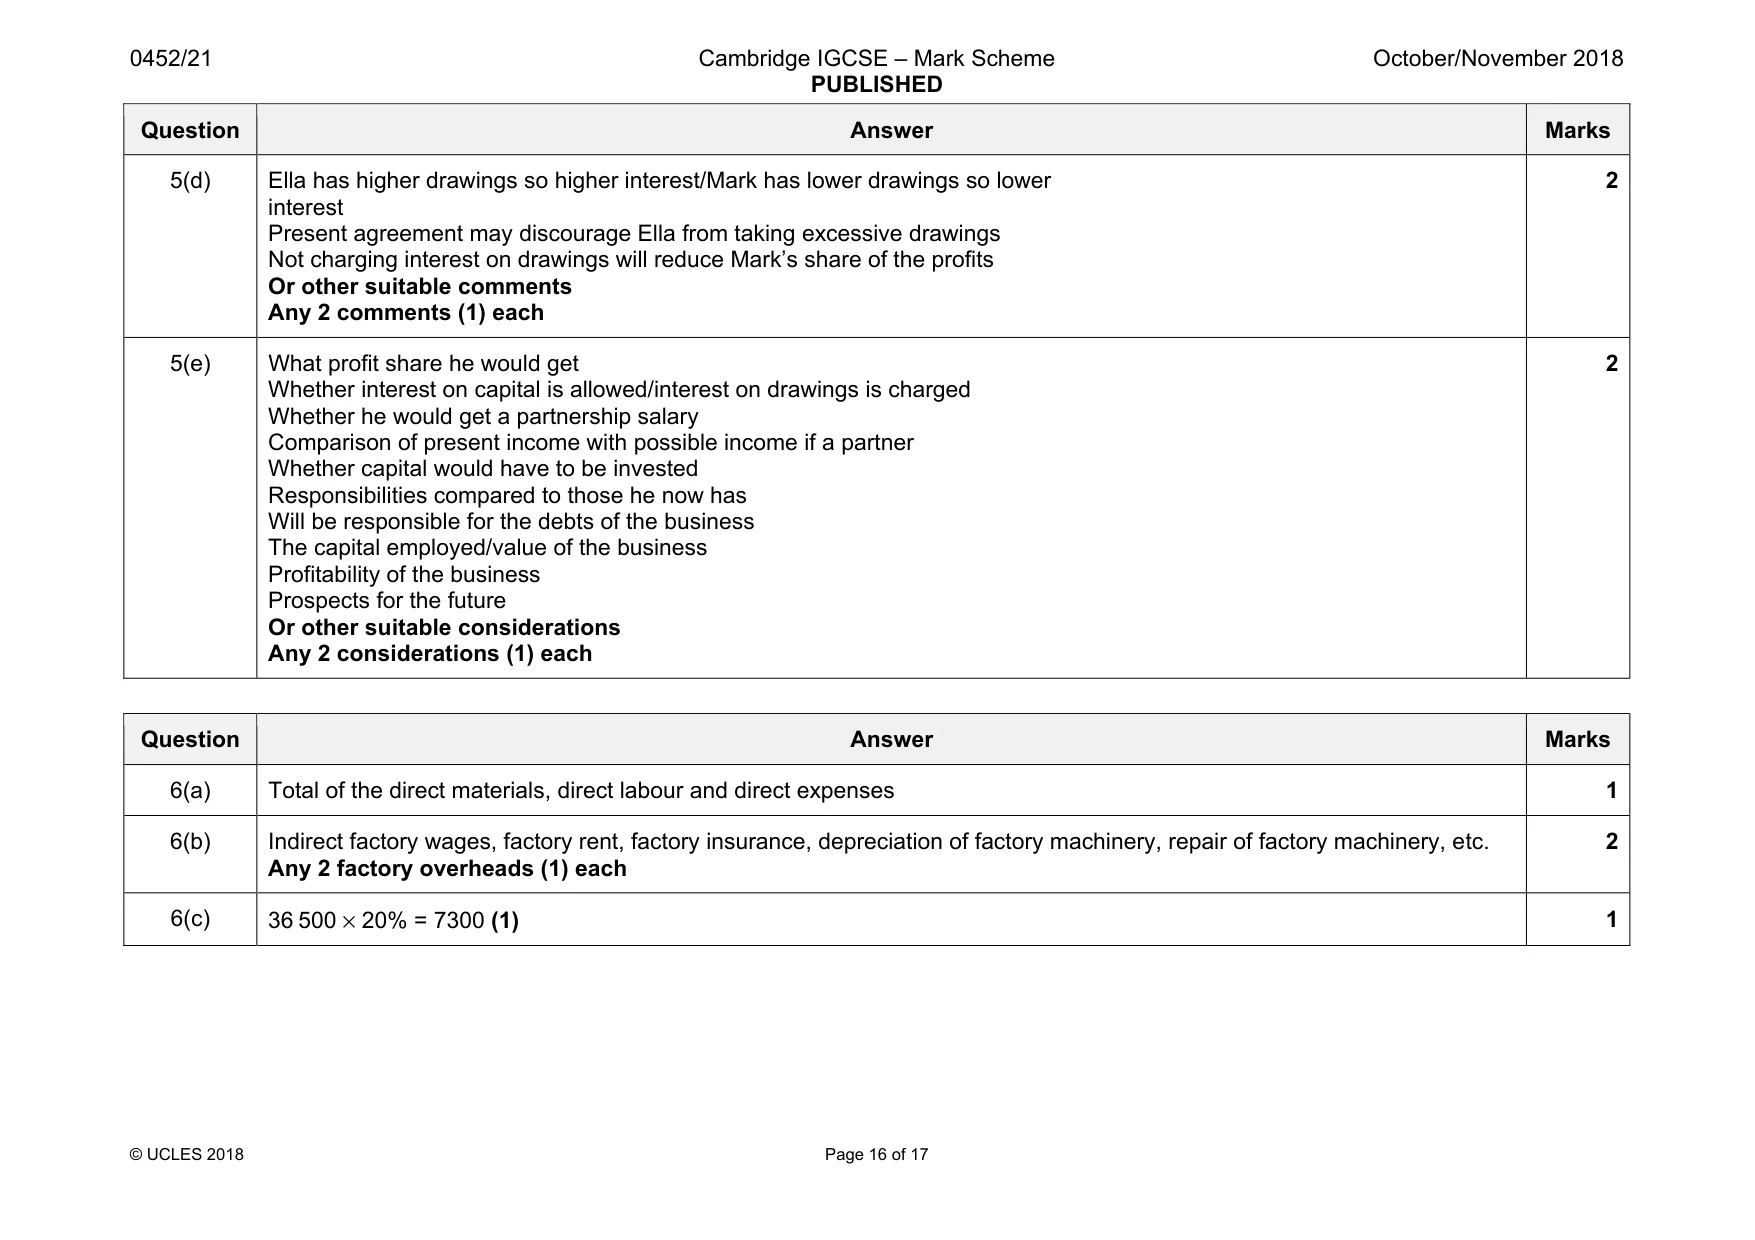
Mark scheme: 5(a) Easier to see amount invested by each partner Easier to calculate interest on capital Easier to see the profit retained by each partner Easier to see if a partner is making excessive drawings Any 2 advantages (1) each 2 Question Answer Marks 5(b) Mark and Ella Current accounts Date Detail Mark $ Ella $ Date Detail Mark $ Ella $ 2017 2017 Sept 1 Balance b/d 1 800 Sept 1 Balance b/d 2 000 2018 2018 Aug 31 Drawings (1) 12 000 16 000 Aug 31 Interest on capital (1) 6 000 4 000 Interest on drawings (1) 960 1 280 Salary (1) 15 000 Balance c/d 11 640 Profit share (1) 7 920 7 920 Balance c/d 840 14 760 28 920 14 760 28 920 2018 2018 Sept 1 Balance b/d (1)OF 840 Sept 1 Balance b/d (1)OF 11 640 7 Question Answer Marks 5(c) Mark and Ella Statement of Financial Position at 31 August 2018 $ $ $ Assets Non-current assets Premises at cost 165 000 Fixtures & equipment at book value 24 400 Motor vehicles at book value 14 750 204 150 (1) Current assets Inventory 14 950 Trade receivables 16 800 Less Provision for doubtful debts 420 16 380 (1) Petty cash 150 31 480 (1) Total assets 235 630 Capital and liabilities Mark Ella Total Capital accounts 120 000 80 000 200 000 (1) Current accounts (840) 11 640 10 800 (1) OF 210 800 Current liabilities Trade payables 19 240 Bank overdraft 5 590 24 830 (1) Total capital and liabilities 235 630 6 Question Answer Marks 5(d) Ella has higher drawings so higher interest/Mark has lower drawings so lower interest Present agreement may discourage Ella from taking excessive drawings Not charging interest on drawings will reduce Mark’s share of the profits Or other suitable comments Any 2 comments (1) each 2 5(e) What profit share he would get Whether interest on capital is allowed/interest on drawings is charged Whether he would get a partnership salary Comparison of present income with possible income if a partner Whether capital would have to be invested Responsibilities compared to those he now has Will be responsible for the debts of the business The capital employed/value of the business Profitability of the business Prospects for the future Or other suitable considerations Any 2 considerations (1) each 2
Q6 · Josef manufactures computer accessories
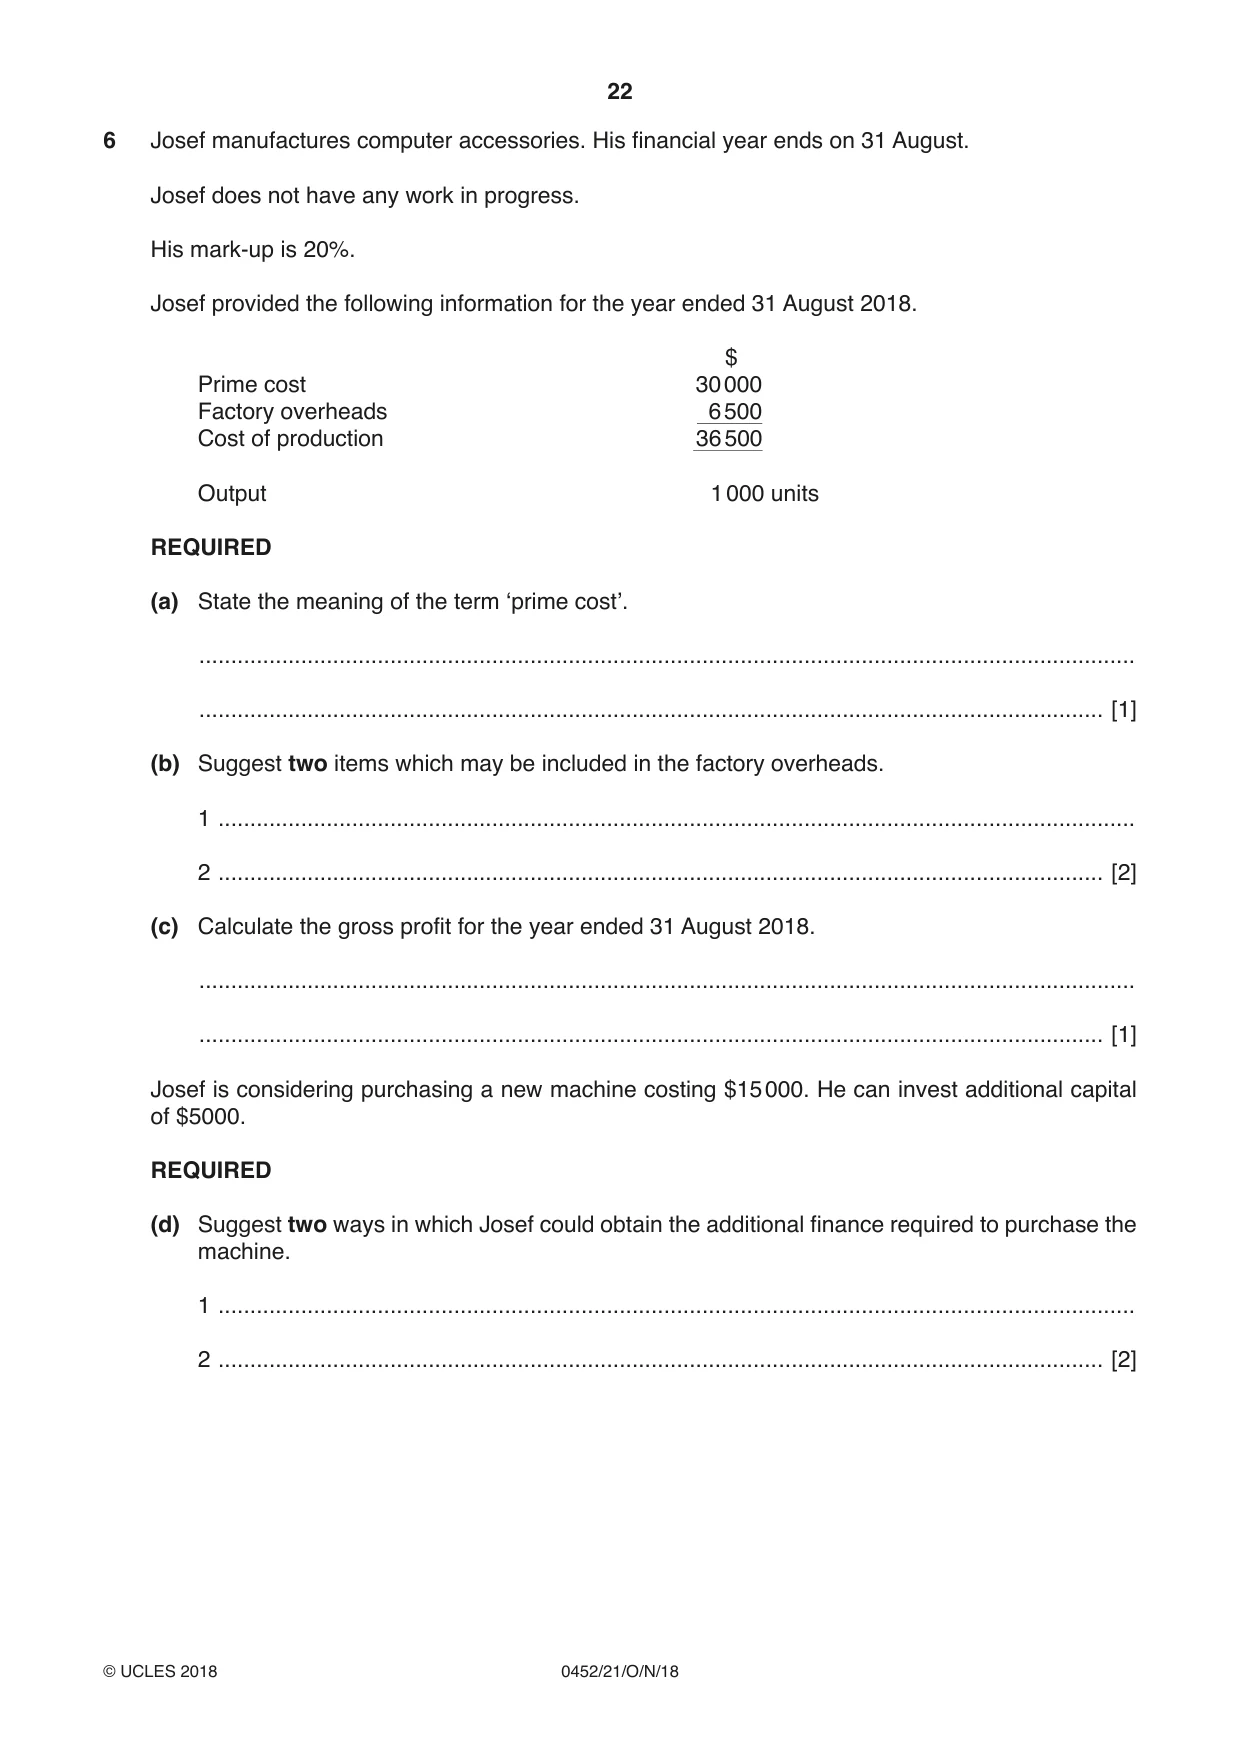
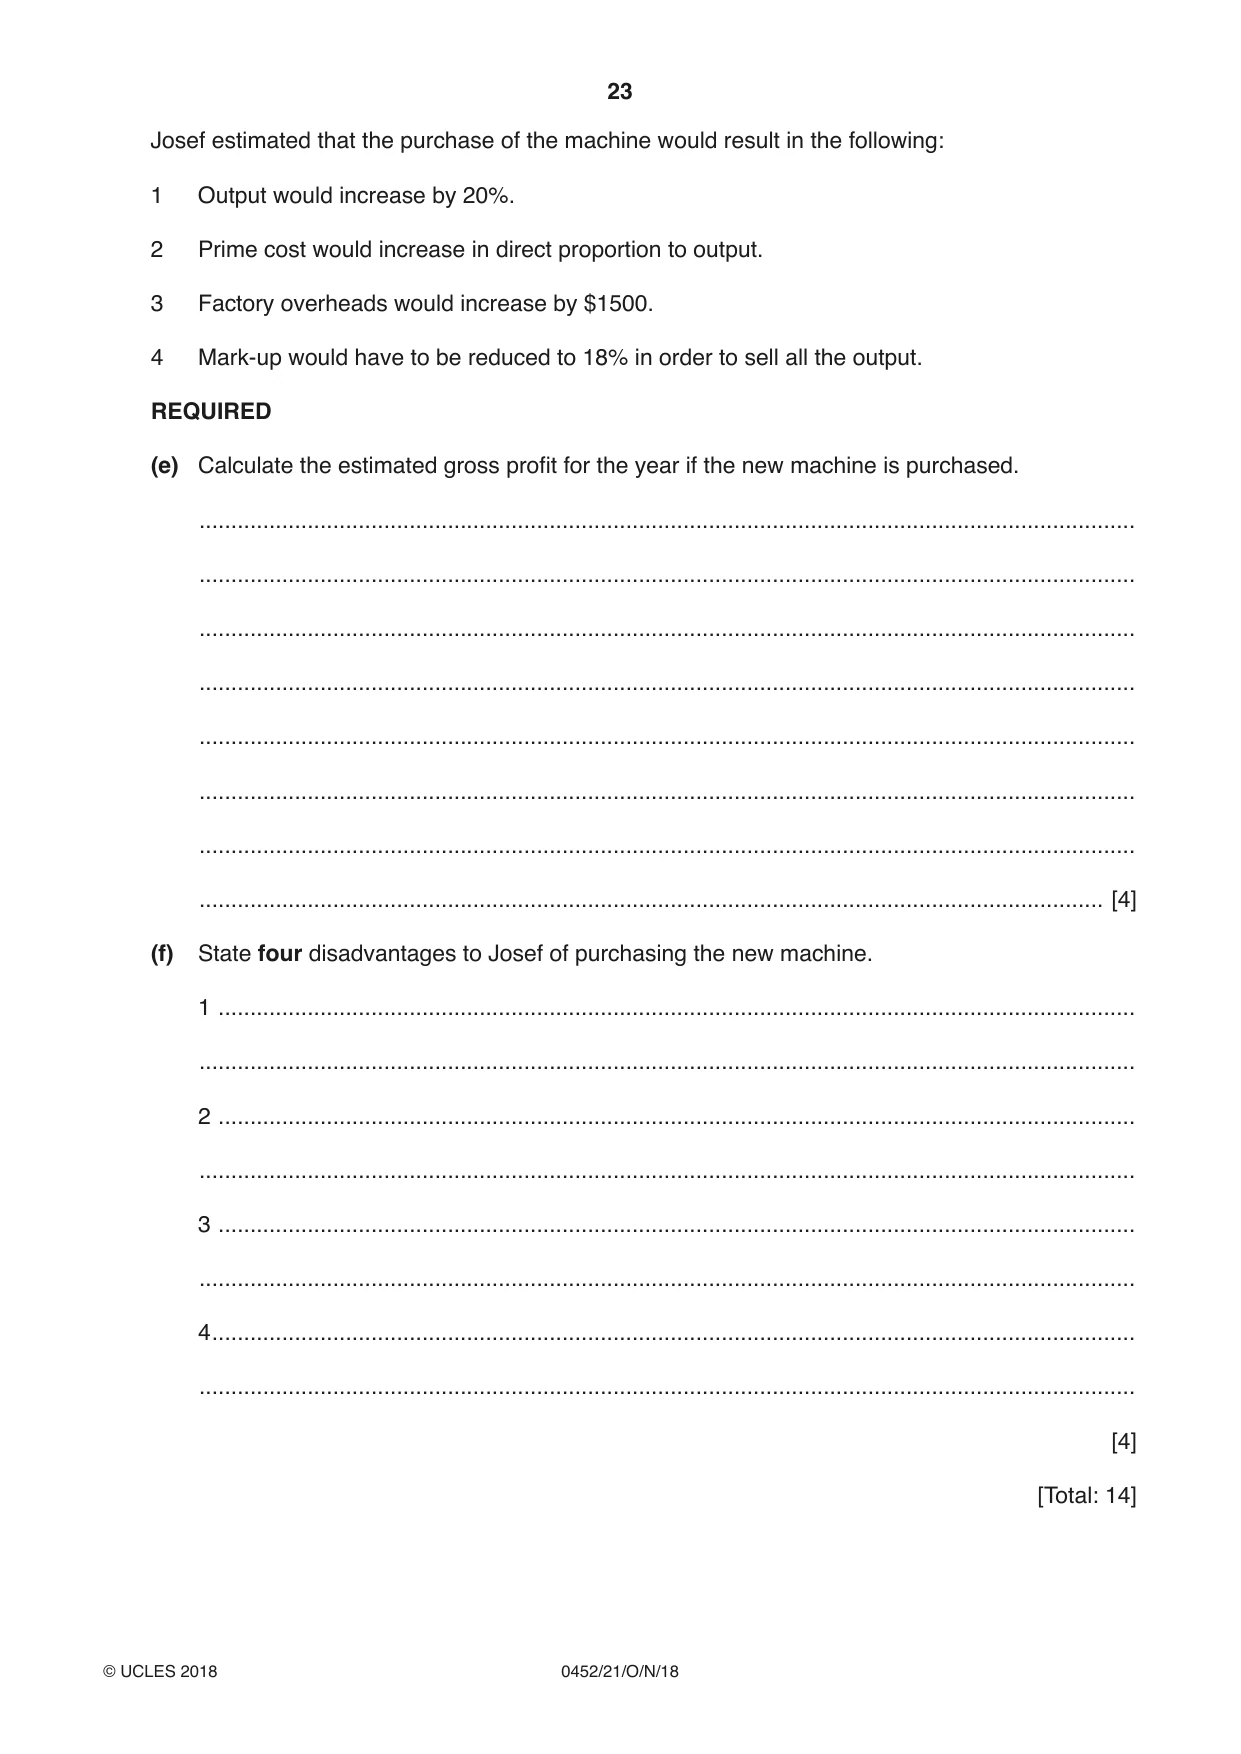
6 Josef manufactures computer accessories. His financial year ends on 31 August. Josef does not have any work in progress. His mark-up is 20%. Josef provided the following information for the year ended 31 August 2018. $ Prime cost 30 000 Factory overheads 6 500 Cost of production 36 500 Output 1 000 units REQUIRED (a) State the meaning of the term ‘prime cost’. ................................................................................................................................................... .............................................................................................................................................. [1] (b) Suggest two items which may be included in the factory overheads. 1 ................................................................................................................................................ 2 ........................................................................................................................................... [2] (c) Calculate the gross profit for the year ended 31 August 2018. ................................................................................................................................................... .............................................................................................................................................. [1] Josef is considering purchasing a new machine costing $15 000. He can invest additional capital of $5000. REQUIRED (d) Suggest two ways in which Josef could obtain the additional finance required to purchase the machine. 1 ................................................................................................................................................ 2 ........................................................................................................................................... [2] Josef estimated that the purchase of the machine would result in the following: 1 Output would increase by 20%. 2 Prime cost would increase in direct proportion to output. 3 Factory overheads would increase by $1500. 4 Mark-up would have to be reduced to 18% in order to sell all the output. REQUIRED (e) Calculate the estimated gross profit for the year if the new machine is purchased. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [4] (f) State four disadvantages to Josef of purchasing the new machine. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... 4 ................................................................................................................................................. ................................................................................................................................................... [4] [Total: 14]
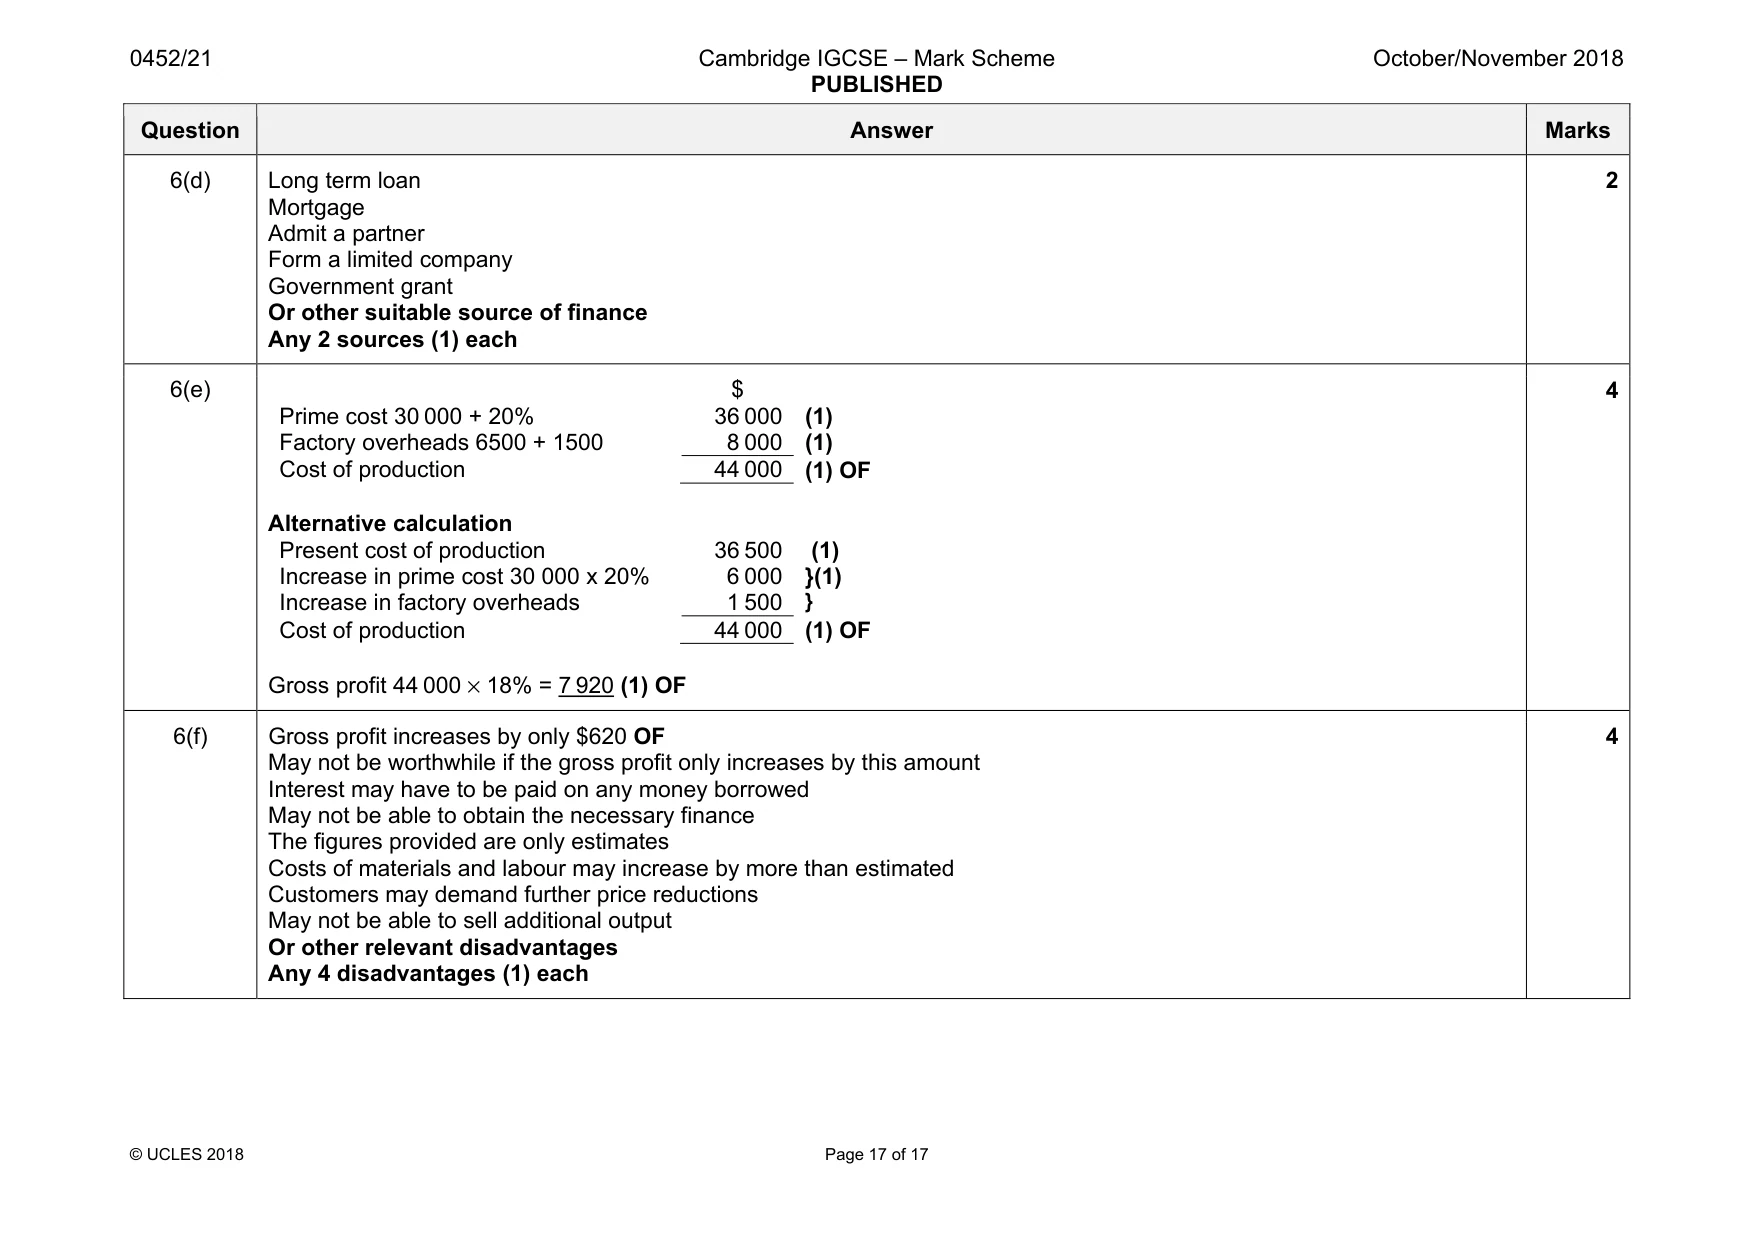
Mark scheme: 6(a) Total of the direct materials, direct labour and direct expenses 1 6(b) Indirect factory wages, factory rent, factory insurance, depreciation of factory machinery, repair of factory machinery, etc. Any 2 factory overheads (1) each 2 6(c) 36 500 × 20% = 7300 (1) 1 Question Answer Marks 6(d) Long term loan Mortgage Admit a partner Form a limited company Government grant Or other suitable source of finance Any 2 sources (1) each 2 6(e) $ Prime cost 30 000 + 20% 36 000 (1) Factory overheads 6500 + 1500 8 000 (1) Cost of production 44 000 (1) OF Alternative calculation Present cost of production 36 500 (1) Increase in prime cost 30 000 x 20% 6 000 }(1) Increase in factory overheads 1 500 } Cost of production 44 000 (1) OF Gross profit 44 000 × 18% = 7 920 (1) OF 4 6(f) Gross profit increases by only $620 OF May not be worthwhile if the gross profit only increases by this amount Interest may have to be paid on any money borrowed May not be able to obtain the necessary finance The figures provided are only estimates Costs of materials and labour may increase by more than estimated Customers may demand further price reductions May not be able to sell additional output Or other relevant disadvantages Any 4 disadvantages (1) each 4
More questions on Calculation and understanding of accounting ratios
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2018 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.