Cambridge IGCSE Accounting 0452 — 2017 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/17 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme12 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Saffie is a trader
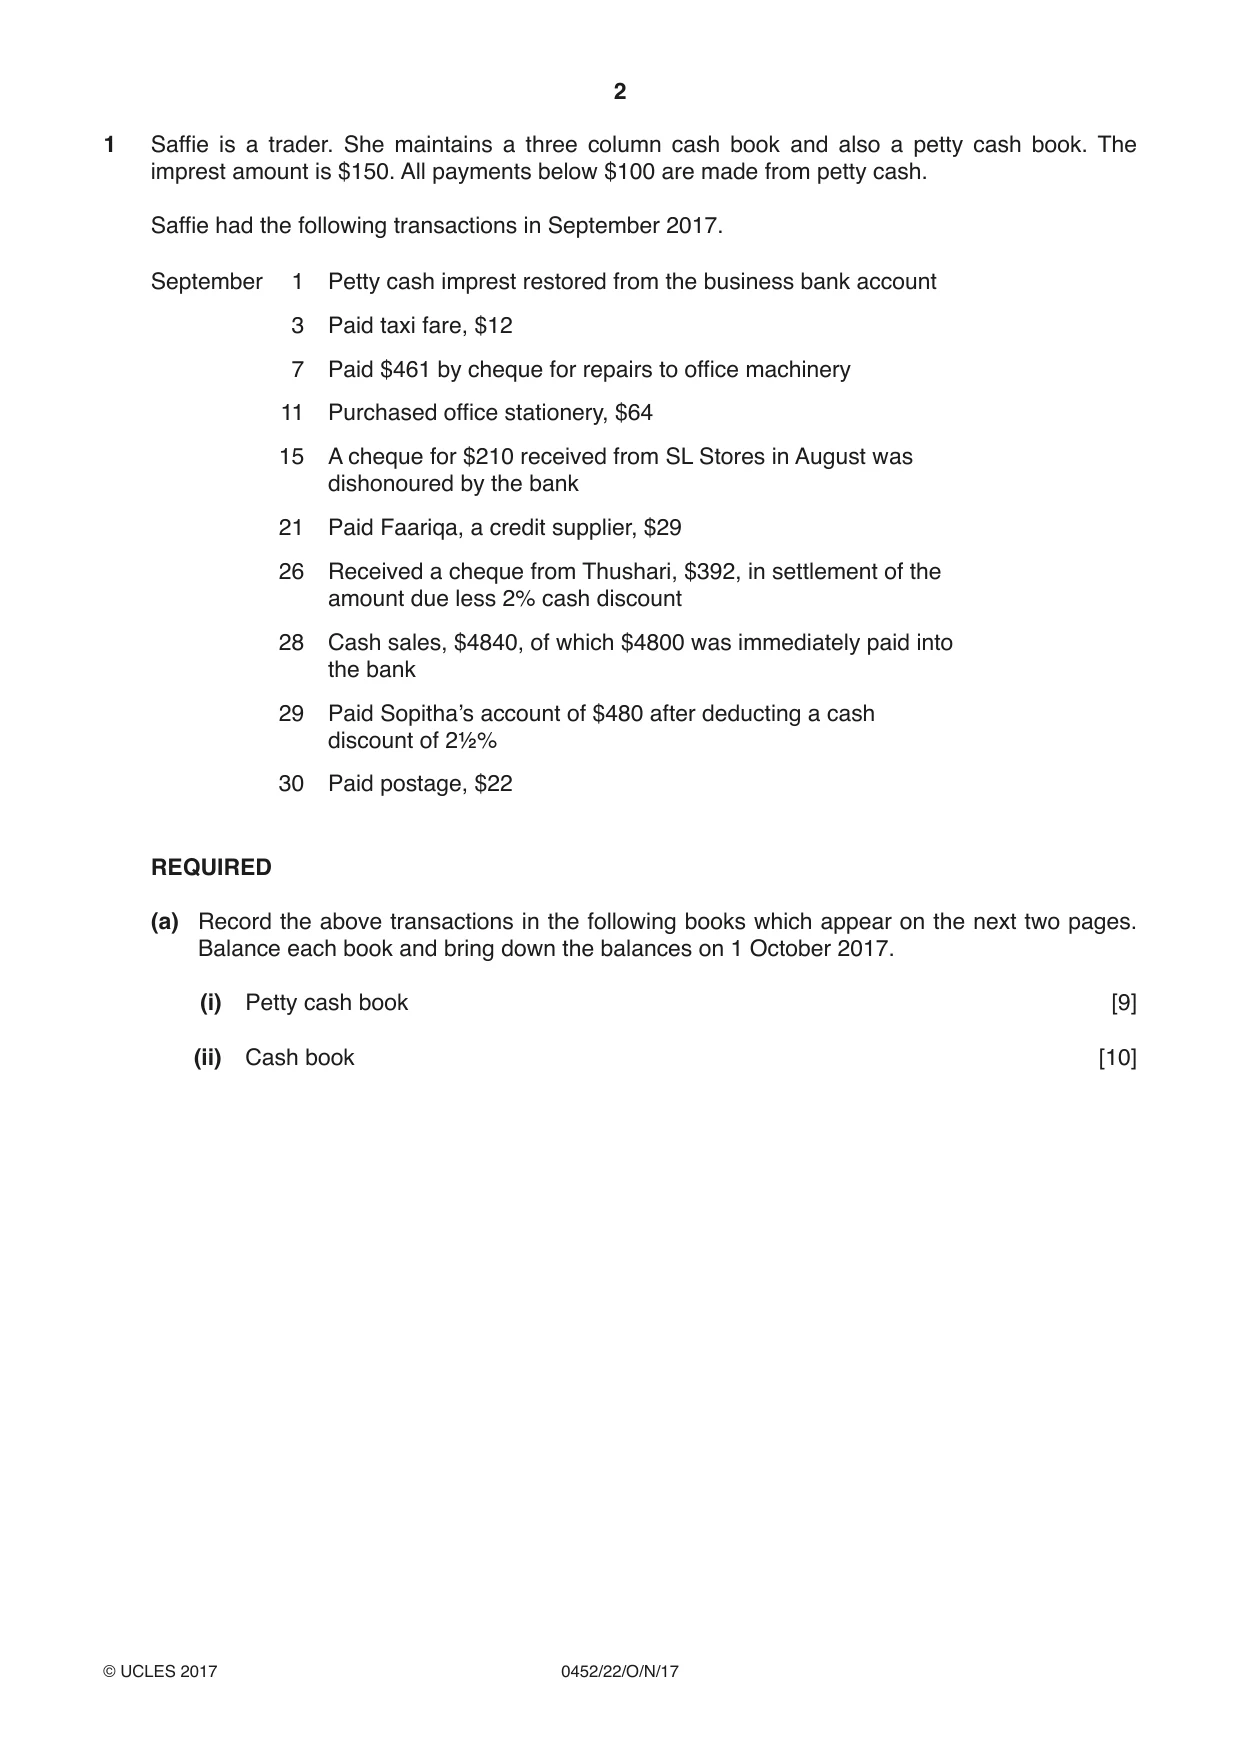
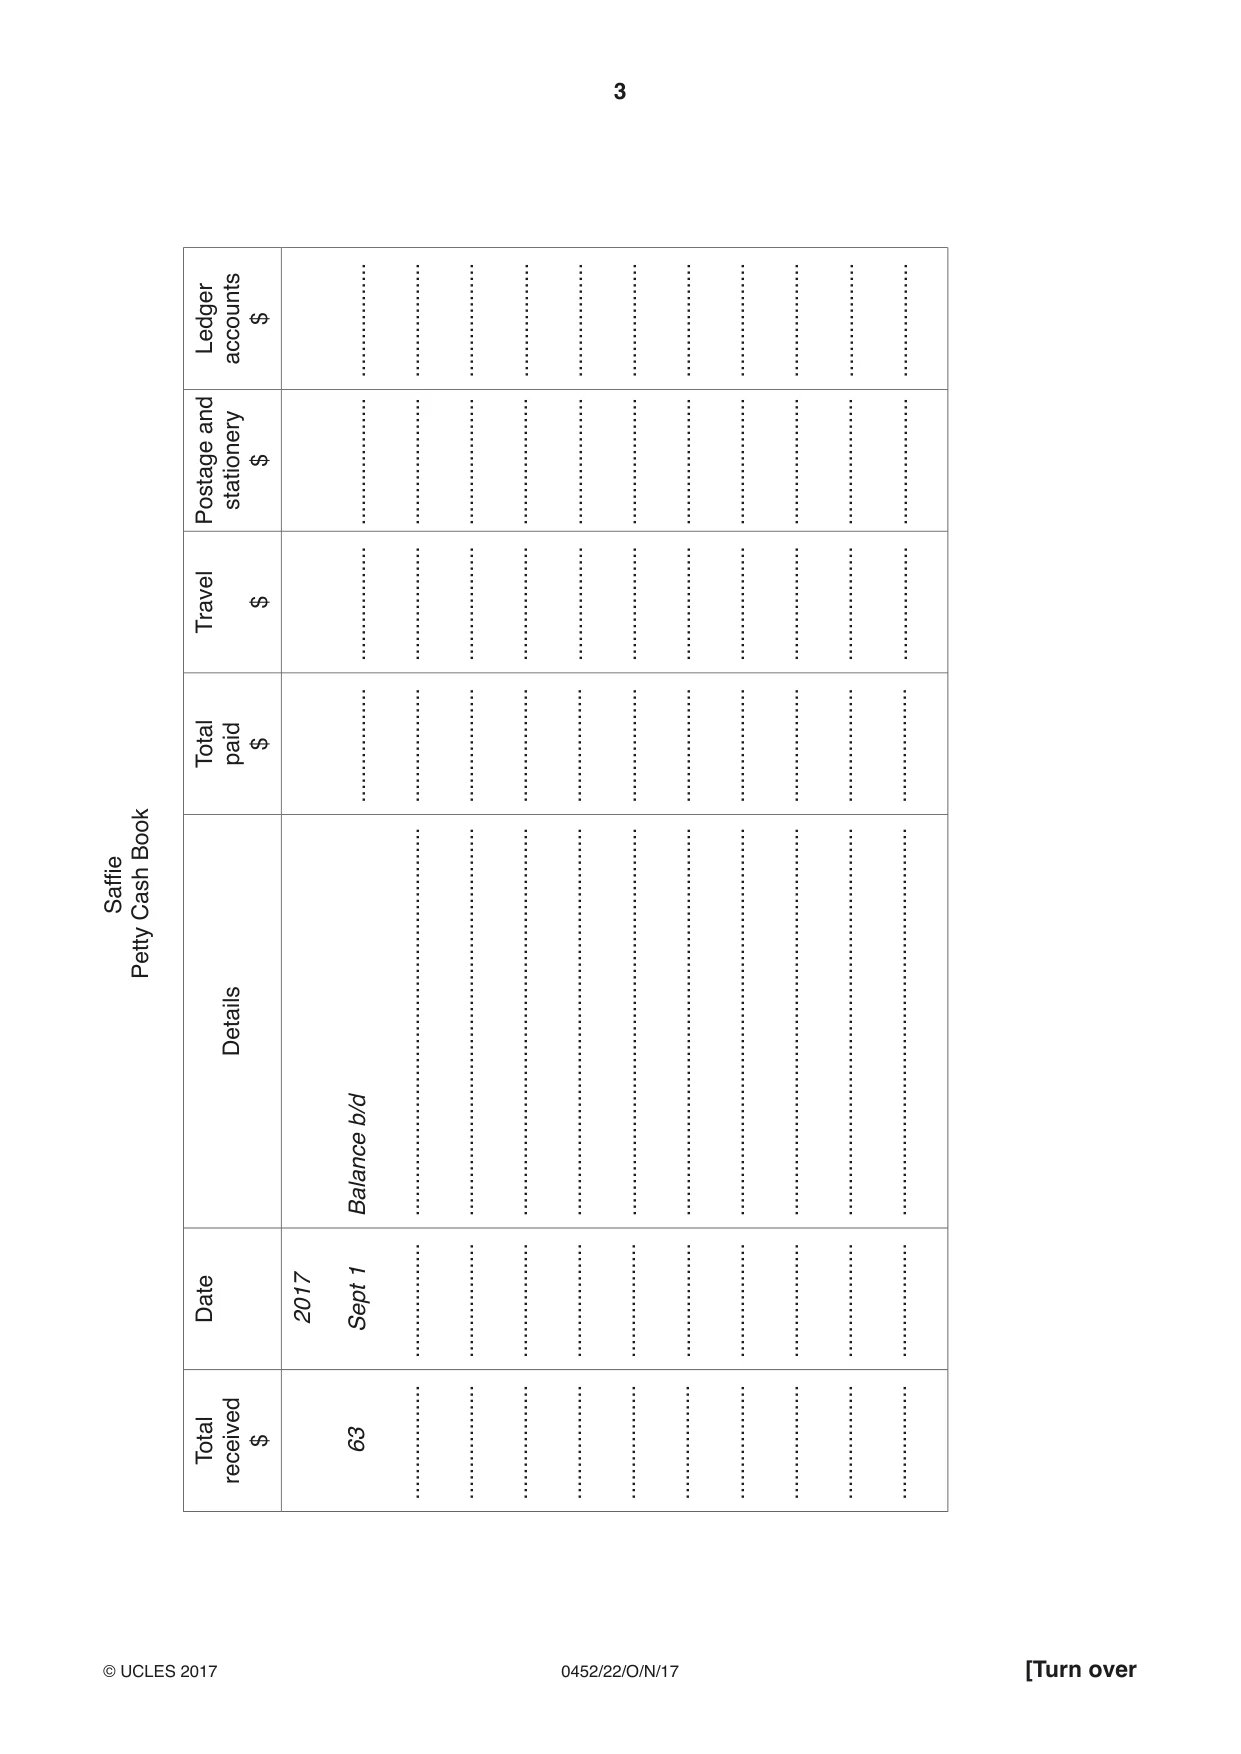
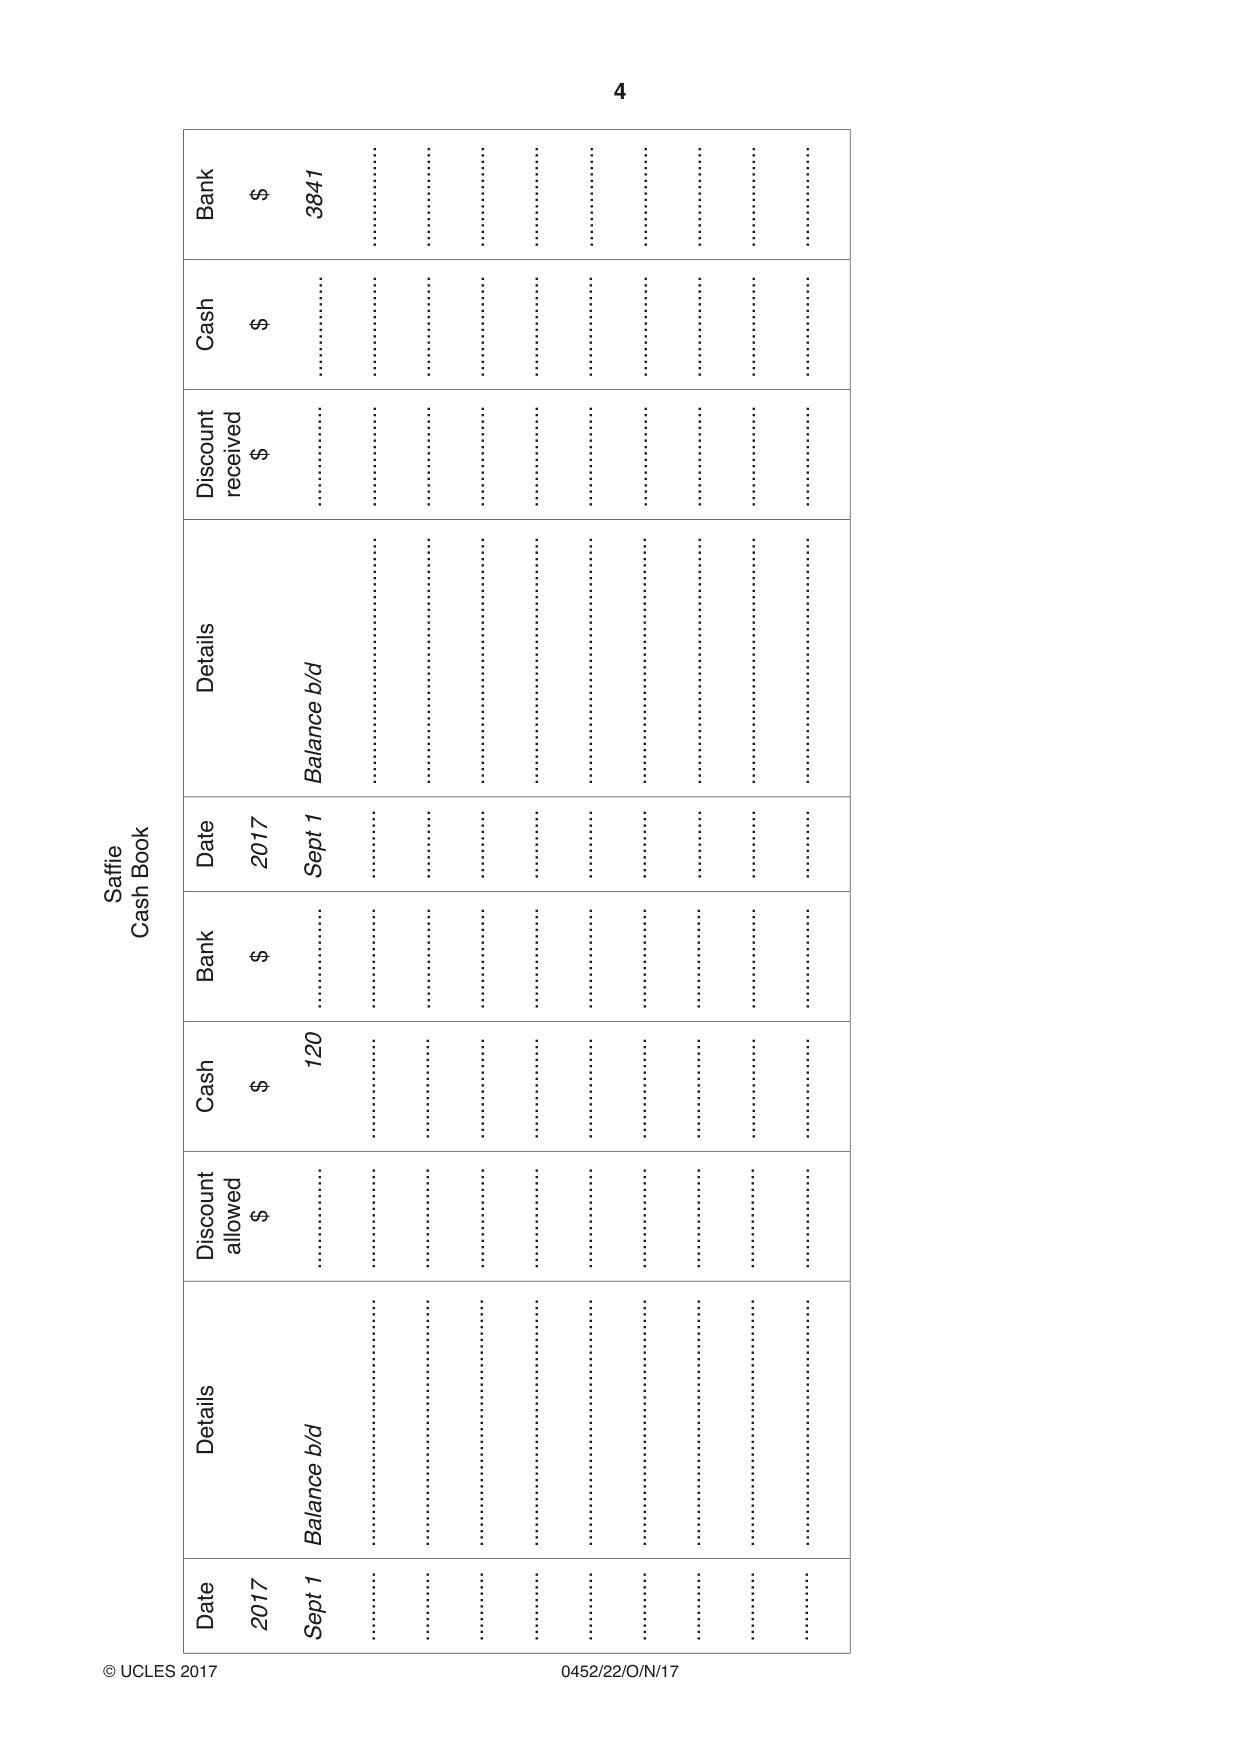
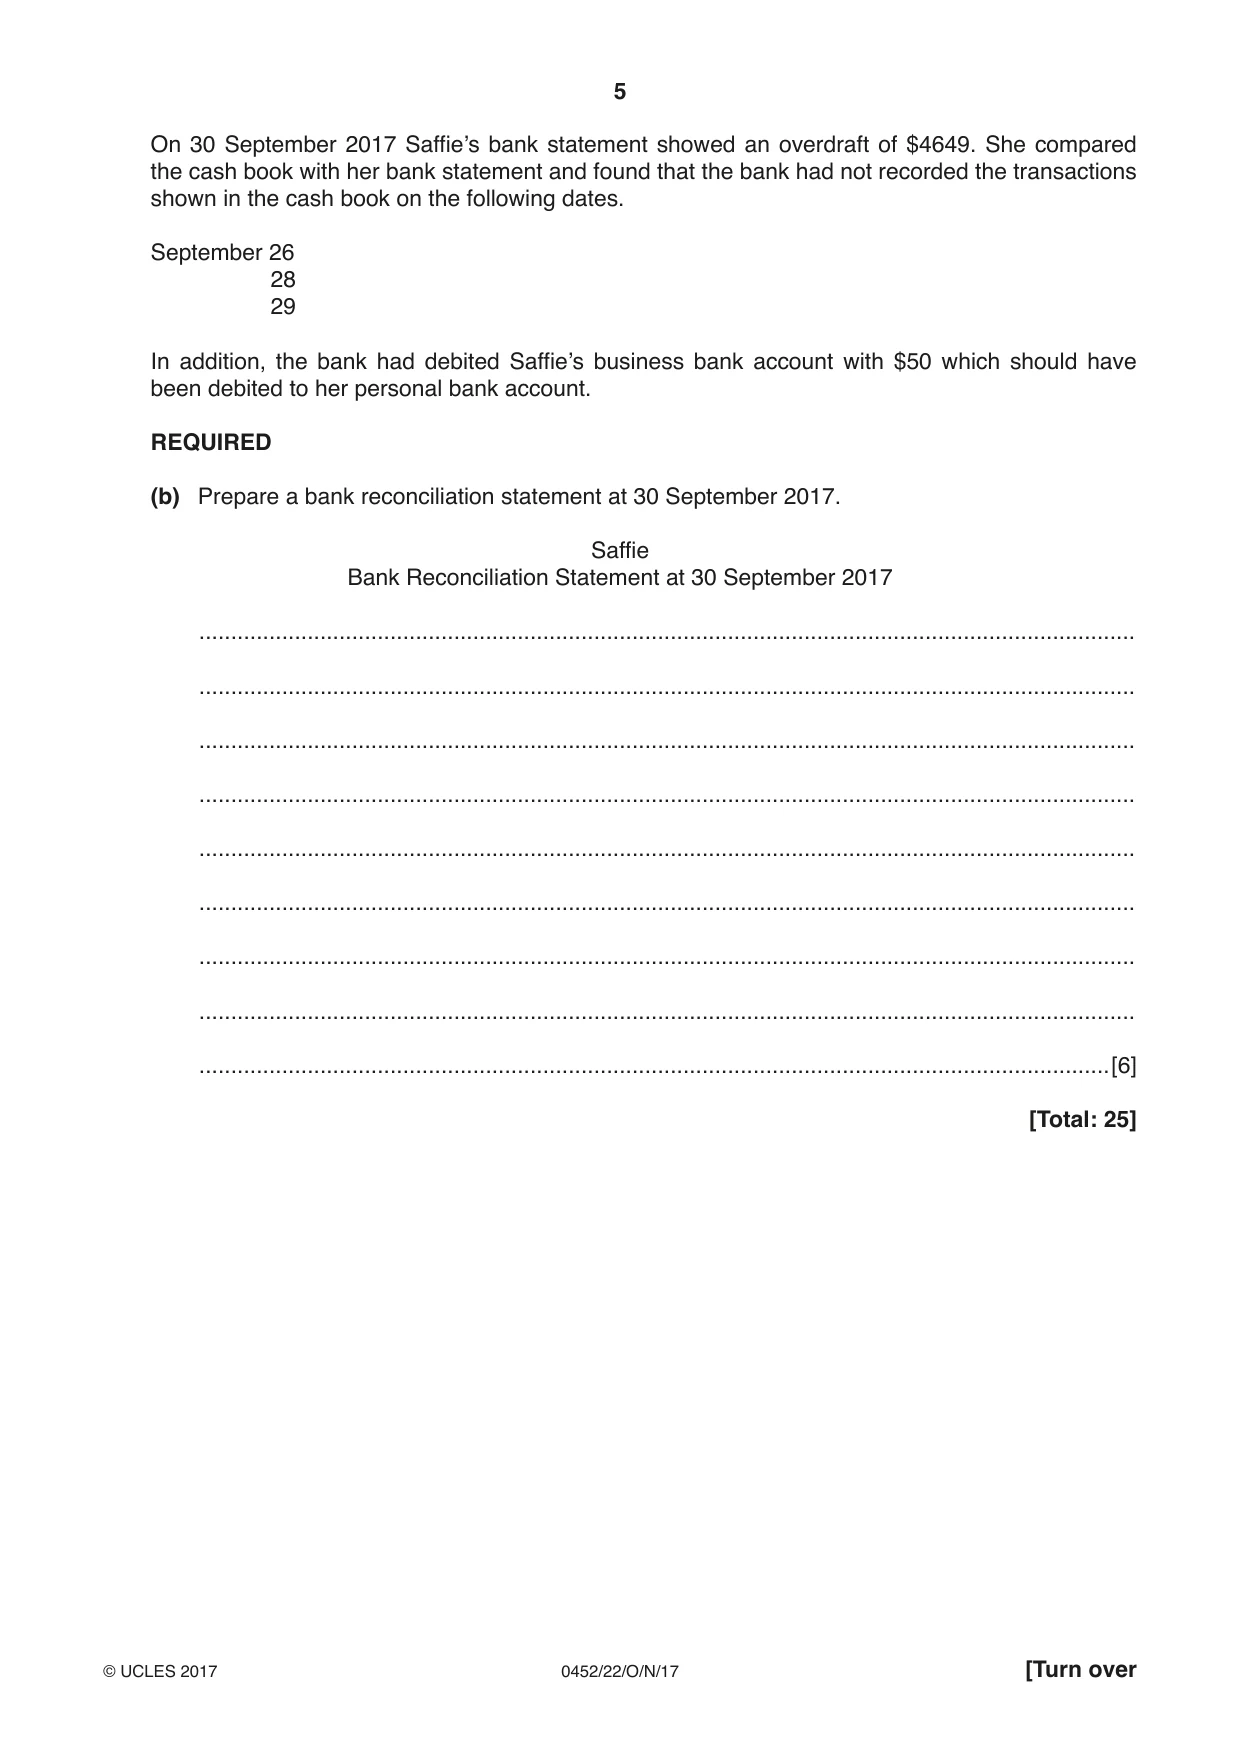
1 Saffie is a trader. She maintains a three column cash book and also a petty cash book. The imprest amount is $150. All payments below $100 are made from petty cash. Saffie had the following transactions in September 2017. September 1 Petty cash imprest restored from the business bank account 3 Paid taxi fare, $12 7 Paid $461 by cheque for repairs to office machinery 11 Purchased office stationery, $64 15 A cheque for $210 received from SL Stores in August was dishonoured by the bank 21 Paid Faariqa, a credit supplier, $29 26 Received a cheque from Thushari, $392, in settlement of the amount due less 2% cash discount 28 Cash sales, $4840, of which $4800 was immediately paid into the bank 29 Paid Sopitha’s account of $480 after deducting a cash discount of 2½% 30 Paid postage, $22 REQUIRED (a) Record the above transactions in the following books which appear on the next two pages. Balance each book and bring down the balances on 1 October 2017. (i) Petty cash book [9] (ii) Cash book [10] $ Ledger accounts .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. and $ stationery Postage .................... .................... .................... .................... .................... .................... .................... .................... .................... .................... .................... $ Travel .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. $ Totalpaid .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. Book Saffie Cash Petty Details b/d Balance ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. ............................................................. 1 Date 2017 Sept .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. $ 63 Total received .................. .................. .................. .................. .................. .................. .................. .................. .................. .................. $ Bank 3841 ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Cash ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Discountreceived ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ Details b/d Balance ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... 1 Date 2017 Book Sept ........... ........... ........... ........... ........... ........... ........... ........... ...........Saffie Cash $ Bank ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ 120 $ Cash ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Discountallowed ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ Details b/d Balance ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... On 30 September 2017 Saffie’s bank statement showed an overdraft of $4649. She compared the cash book with her bank statement and found that the bank had not recorded the transactions shown in the cash book on the following dates. September 26 28 29 In addition, the bank had debited Saffie’s business bank account with $50 which should have been debited to her personal bank account. REQUIRED (b) Prepare a bank reconciliation statement at 30 September 2017. Saffie Bank Reconciliation Statement at 30 September 2017 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[6] [Total: 25]
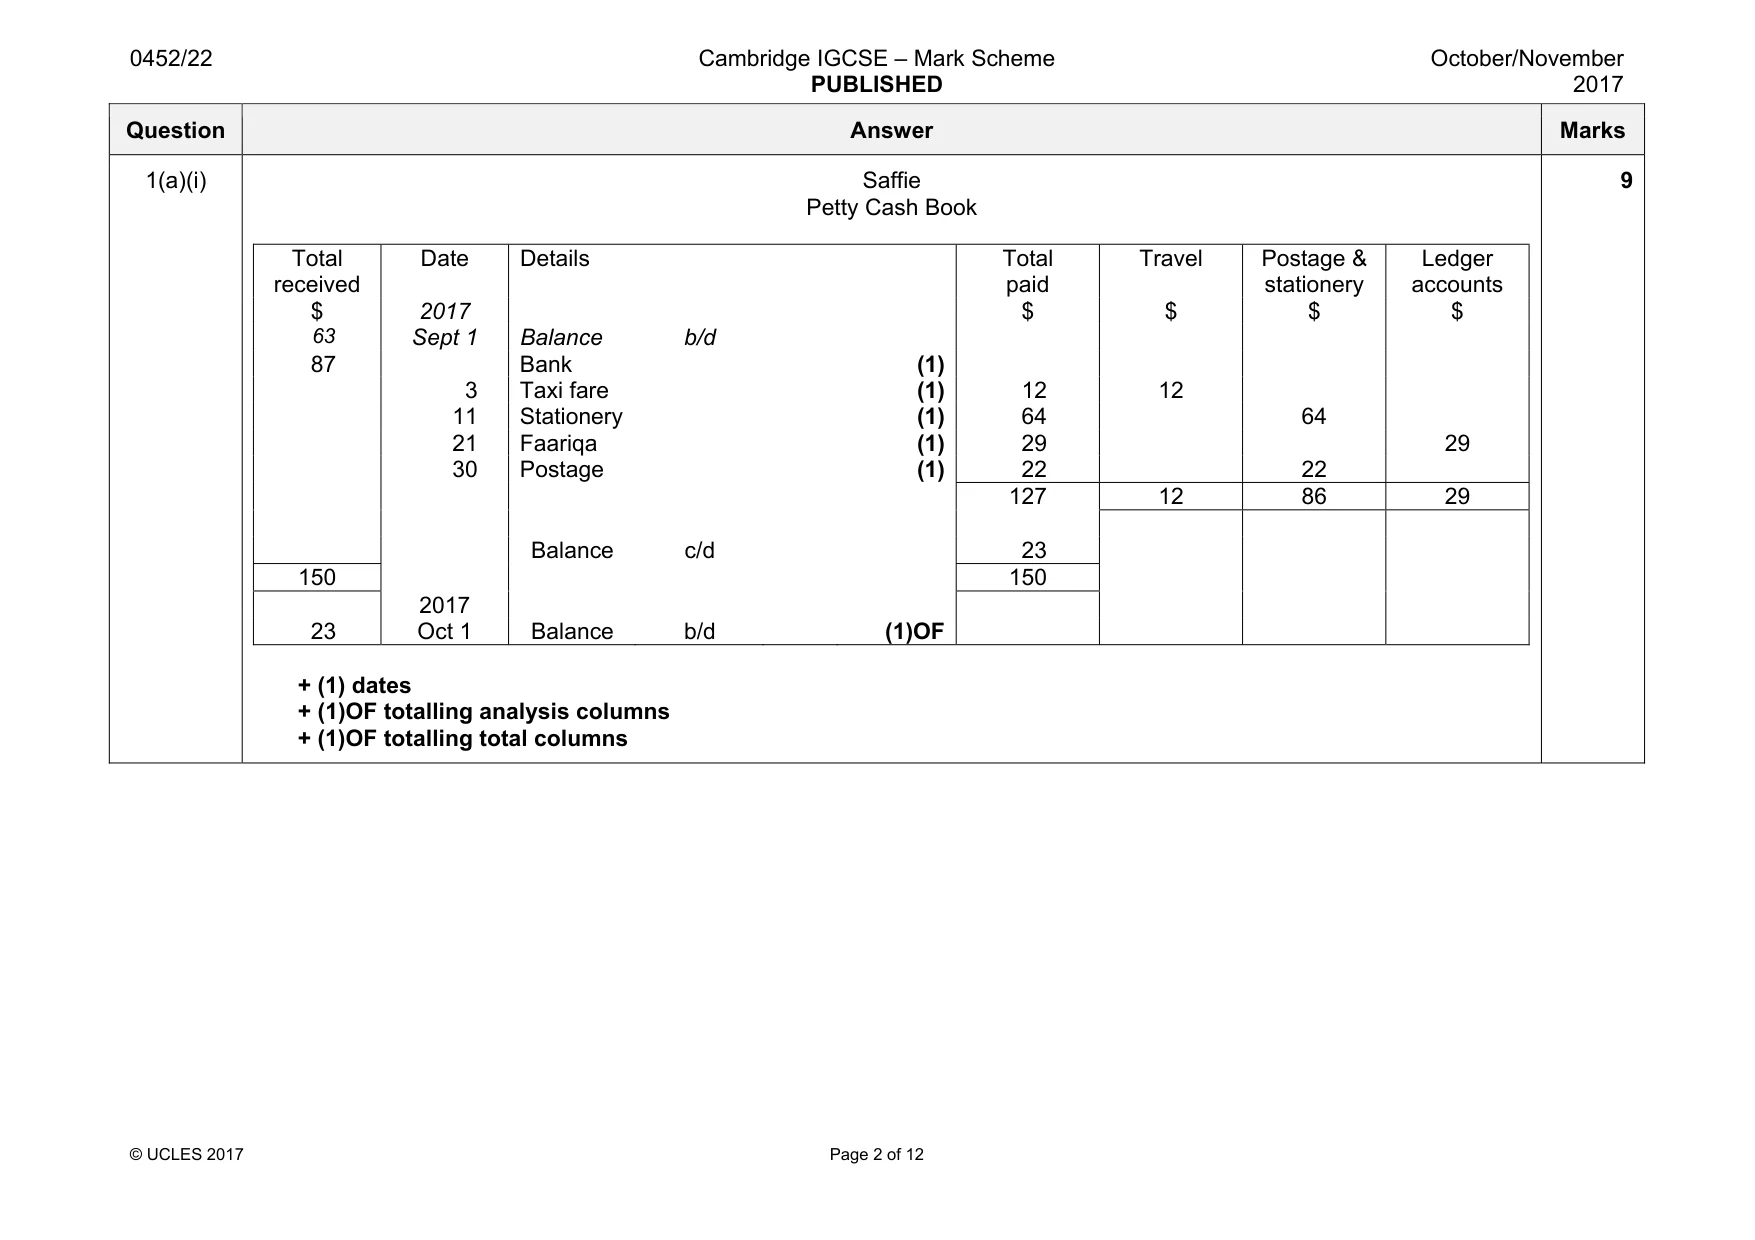
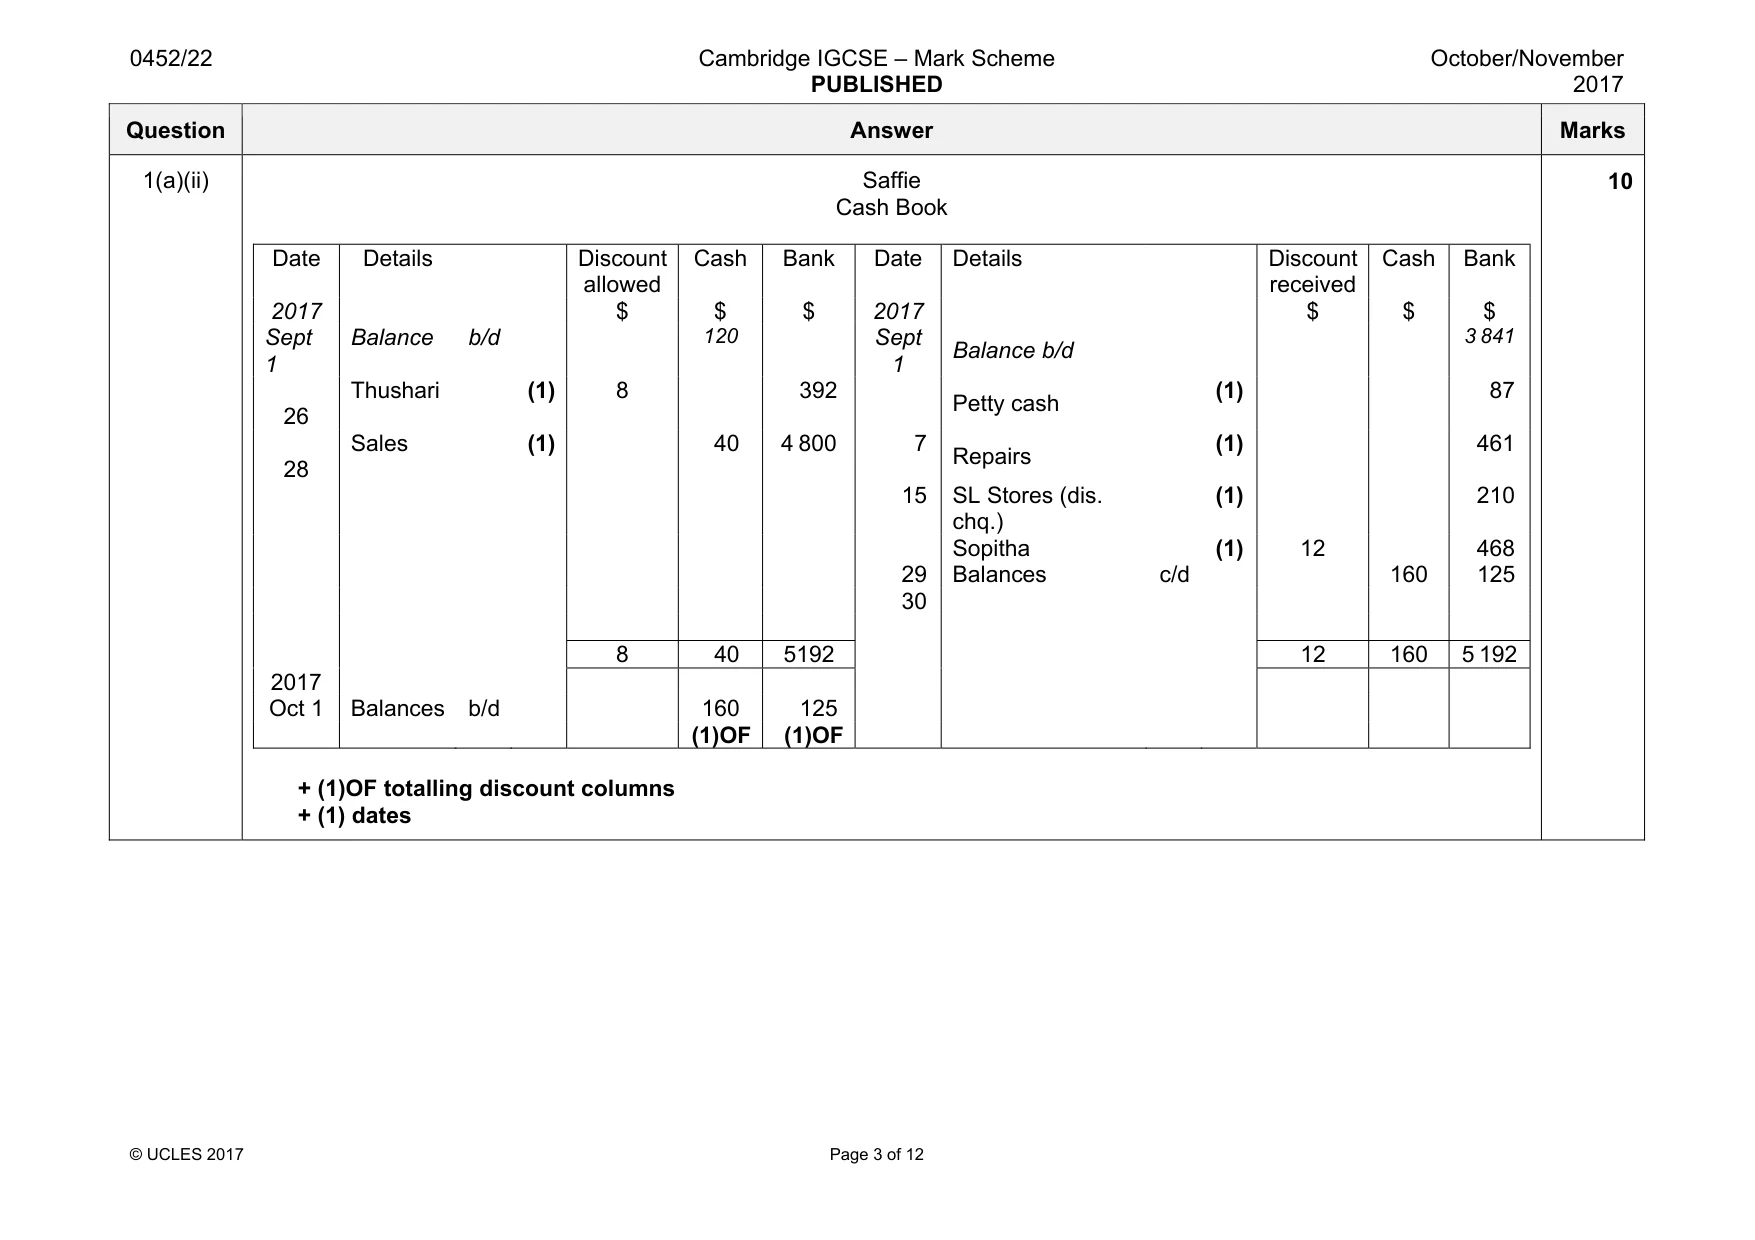
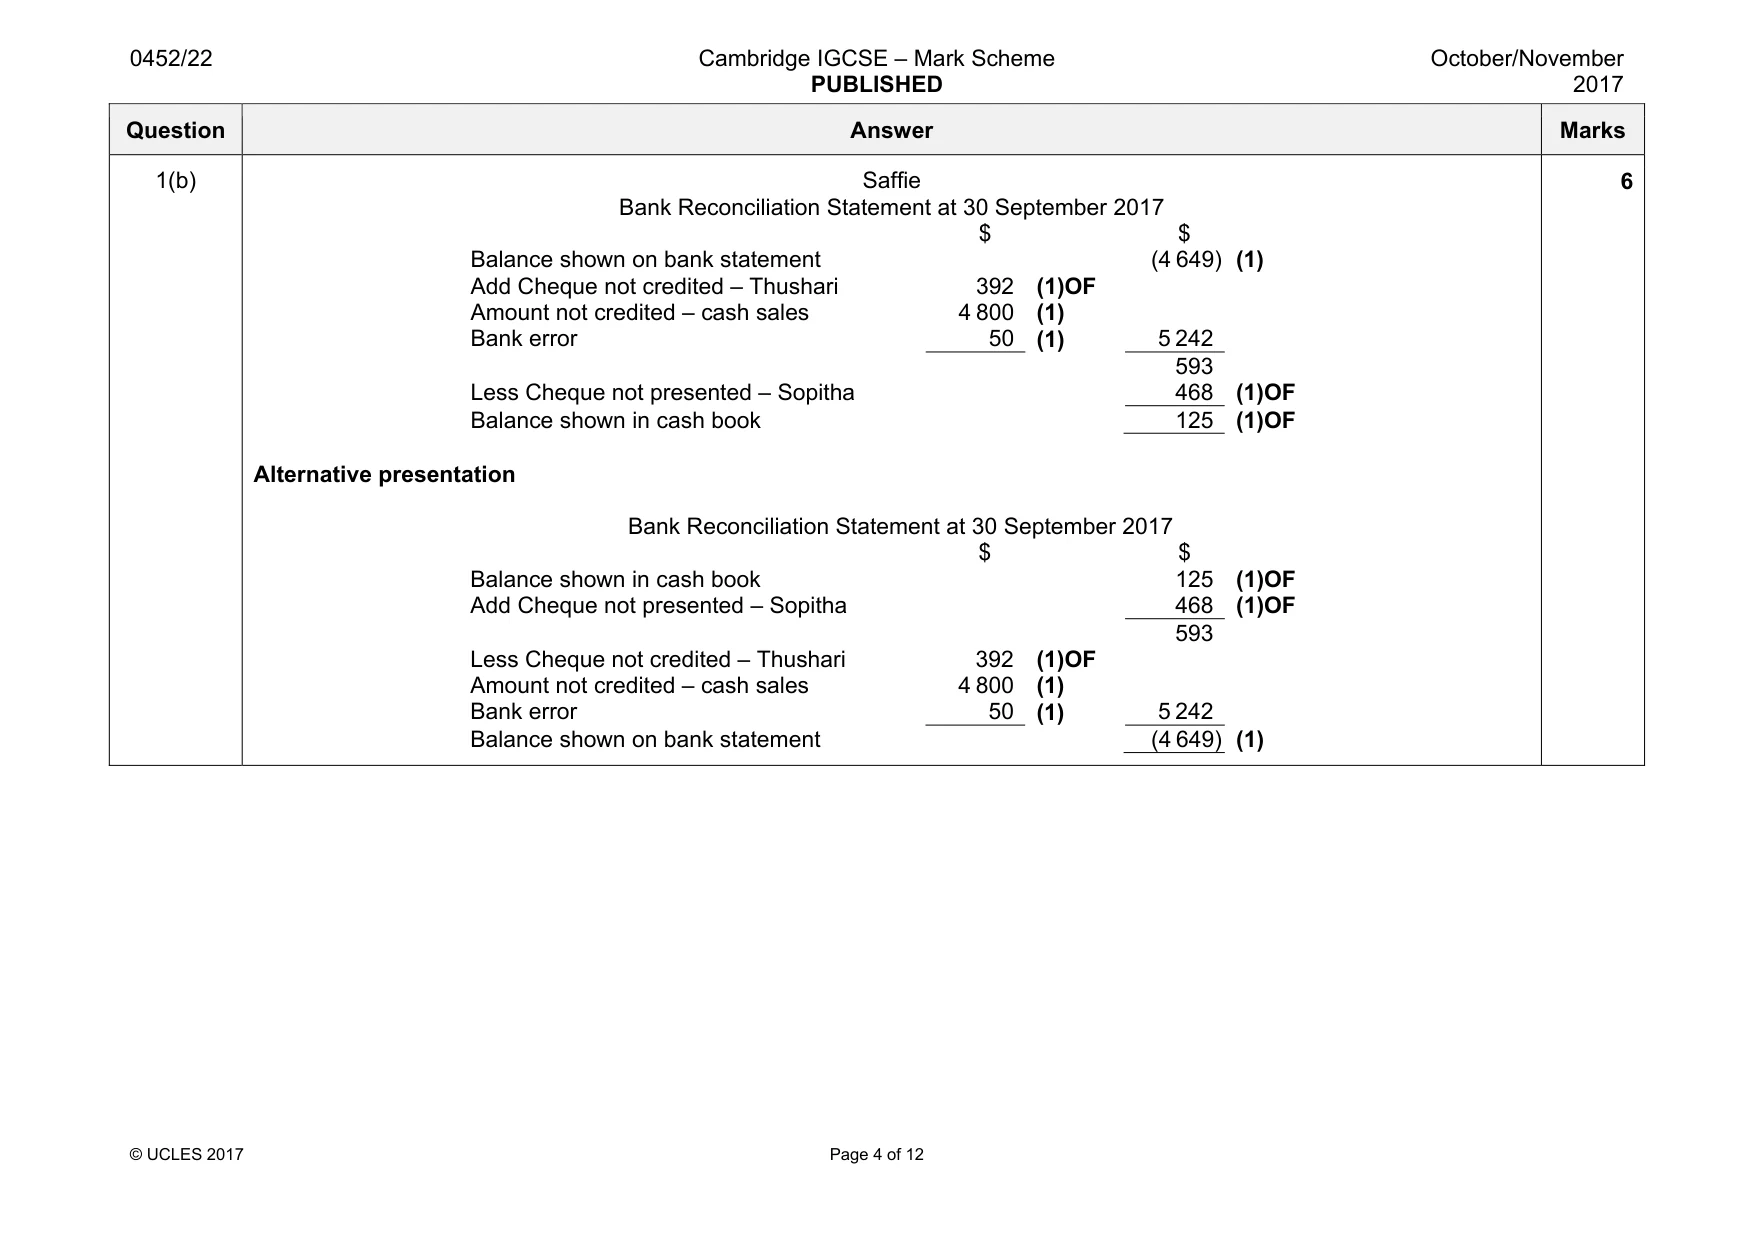
Mark scheme: 1(a)(i) Saffie Petty Cash Book Total received Date Details Total paid Travel Postage & stationery Ledger accounts $ 2017 $ $ $ $ 63 Sept 1 Balance b/d 87 Bank (1) 3 Taxi fare (1) 12 12 11 Stationery (1) 64 64 21 Faariqa (1) 29 29 30 Postage (1) 22 22 127 12 86 29 Balance c/d 23 150 150 2017 23 Oct 1 Balance b/d (1)OF + (1) dates + (1)OF totalling analysis columns + (1)OF totalling total columns 9 Question Answer Marks 1(a)(ii) Saffie Cash Book Date Details Discount allowed Cash Bank Date Details Discount received Cash Bank 2017 $ $ $ 2017 $ $ $ Sept 1 Balance b/d 120 Sept 1 Balance b/d 3 841 26 Thushari (1) 8 392 Petty cash (1) 87 28 Sales (1) 40 4 800 7 Repairs (1) 461 15 SL Stores (dis. chq.) (1) 210 Sopitha (1) 12 468 29 Balances c/d 160 125 30 8 40 5192 12 160 5 192 2017 Oct 1 Balances b/d 160 125 (1)OF (1)OF + (1)OF totalling discount columns + (1) dates 10 Question Answer Marks 1(b) Saffie Bank Reconciliation Statement at 30 September 2017 $ $ Balance shown on bank statement (4 649) (1) Add Cheque not credited – Thushari 392 (1)OF Amount not credited – cash sales 4 800 (1) Bank error 50 (1) 5 242 593 Less Cheque not presented – Sopitha 468 (1)OF Balance shown in cash book 125 (1)OF Alternative presentation Bank Reconciliation Statement at 30 September 2017 $ $ Balance shown in cash book 125 (1)OF Add Cheque not presented – Sopitha 468 (1)OF 593 Less Cheque not credited – Thushari 392 (1)OF Amount not credited – cash sales 4 800 (1) Bank error 50 (1) 5 242 Balance shown on bank statement (4 649) (1) 6
Q2 · Mustafa opened a garment factory on 1 August 2016
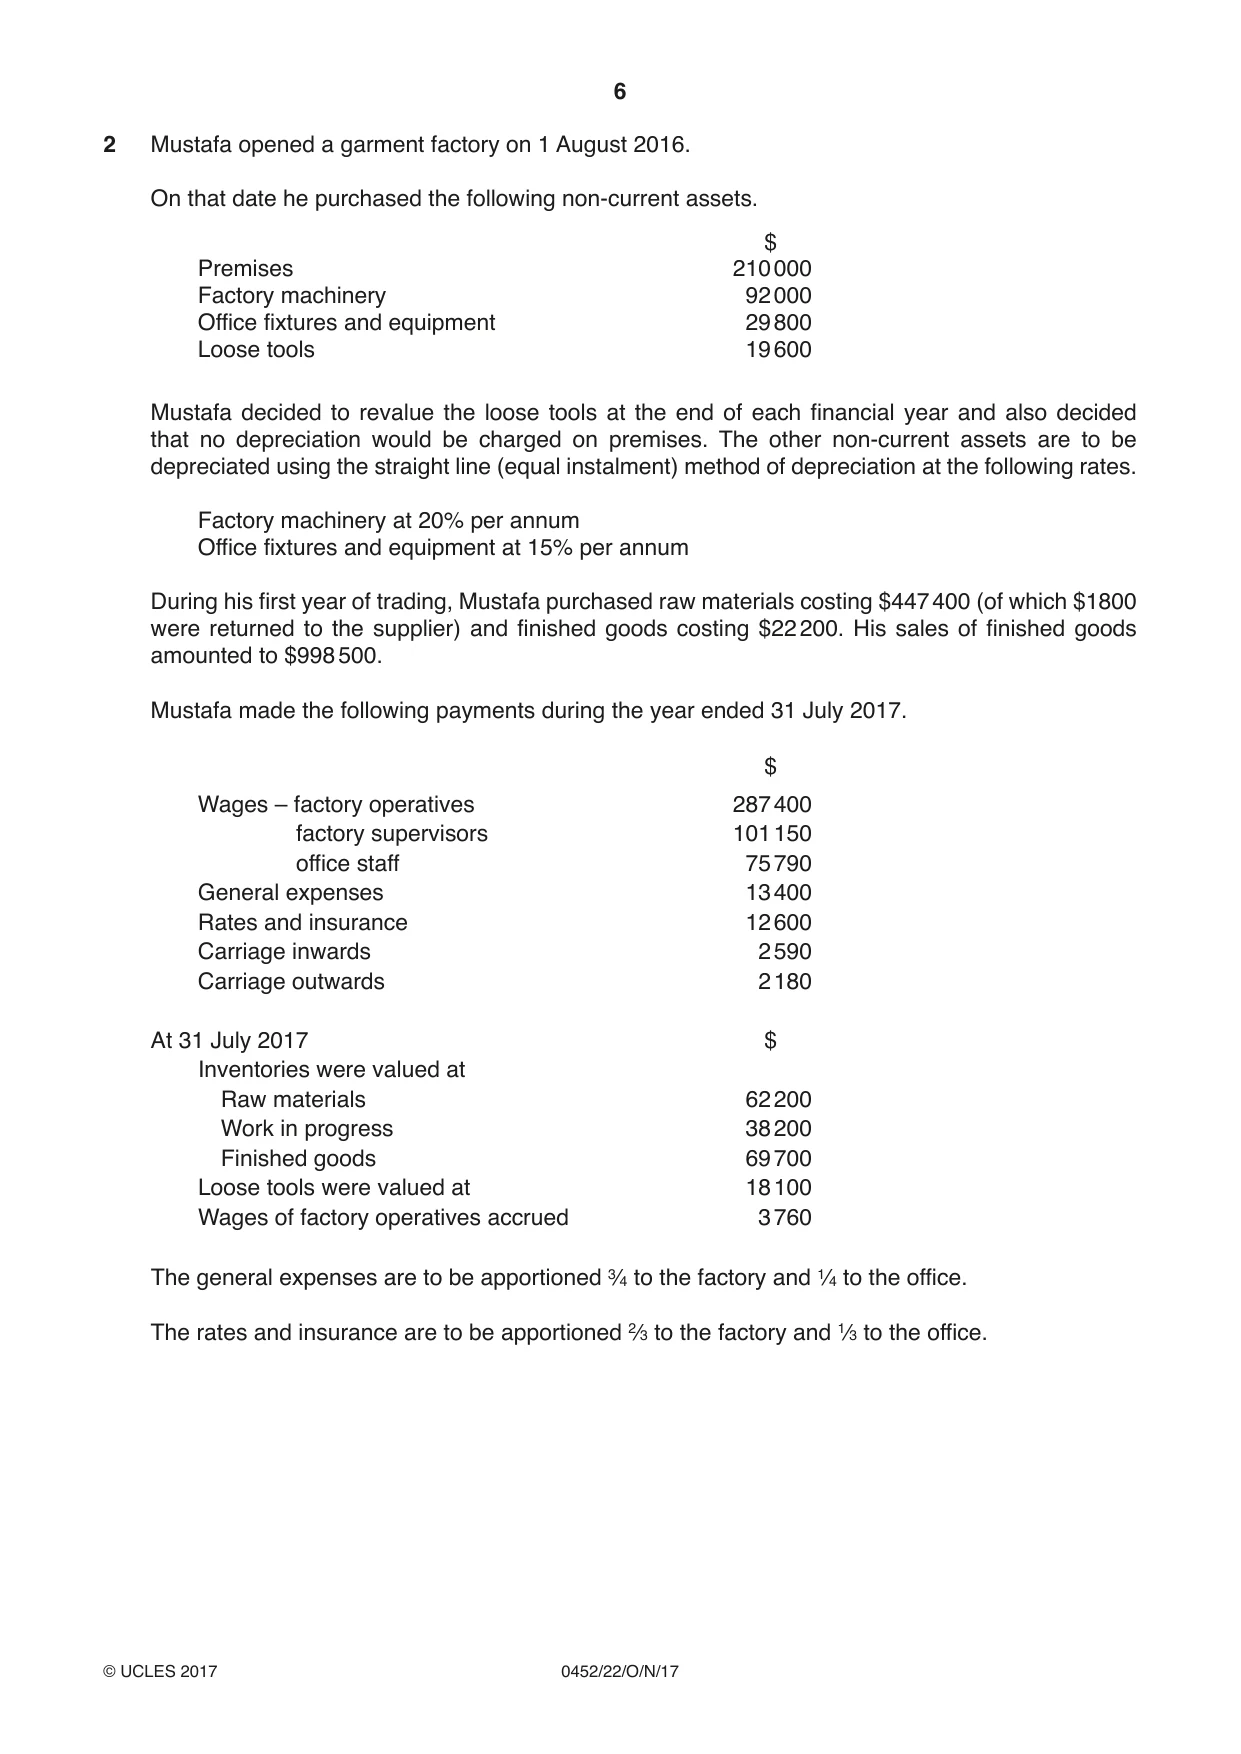
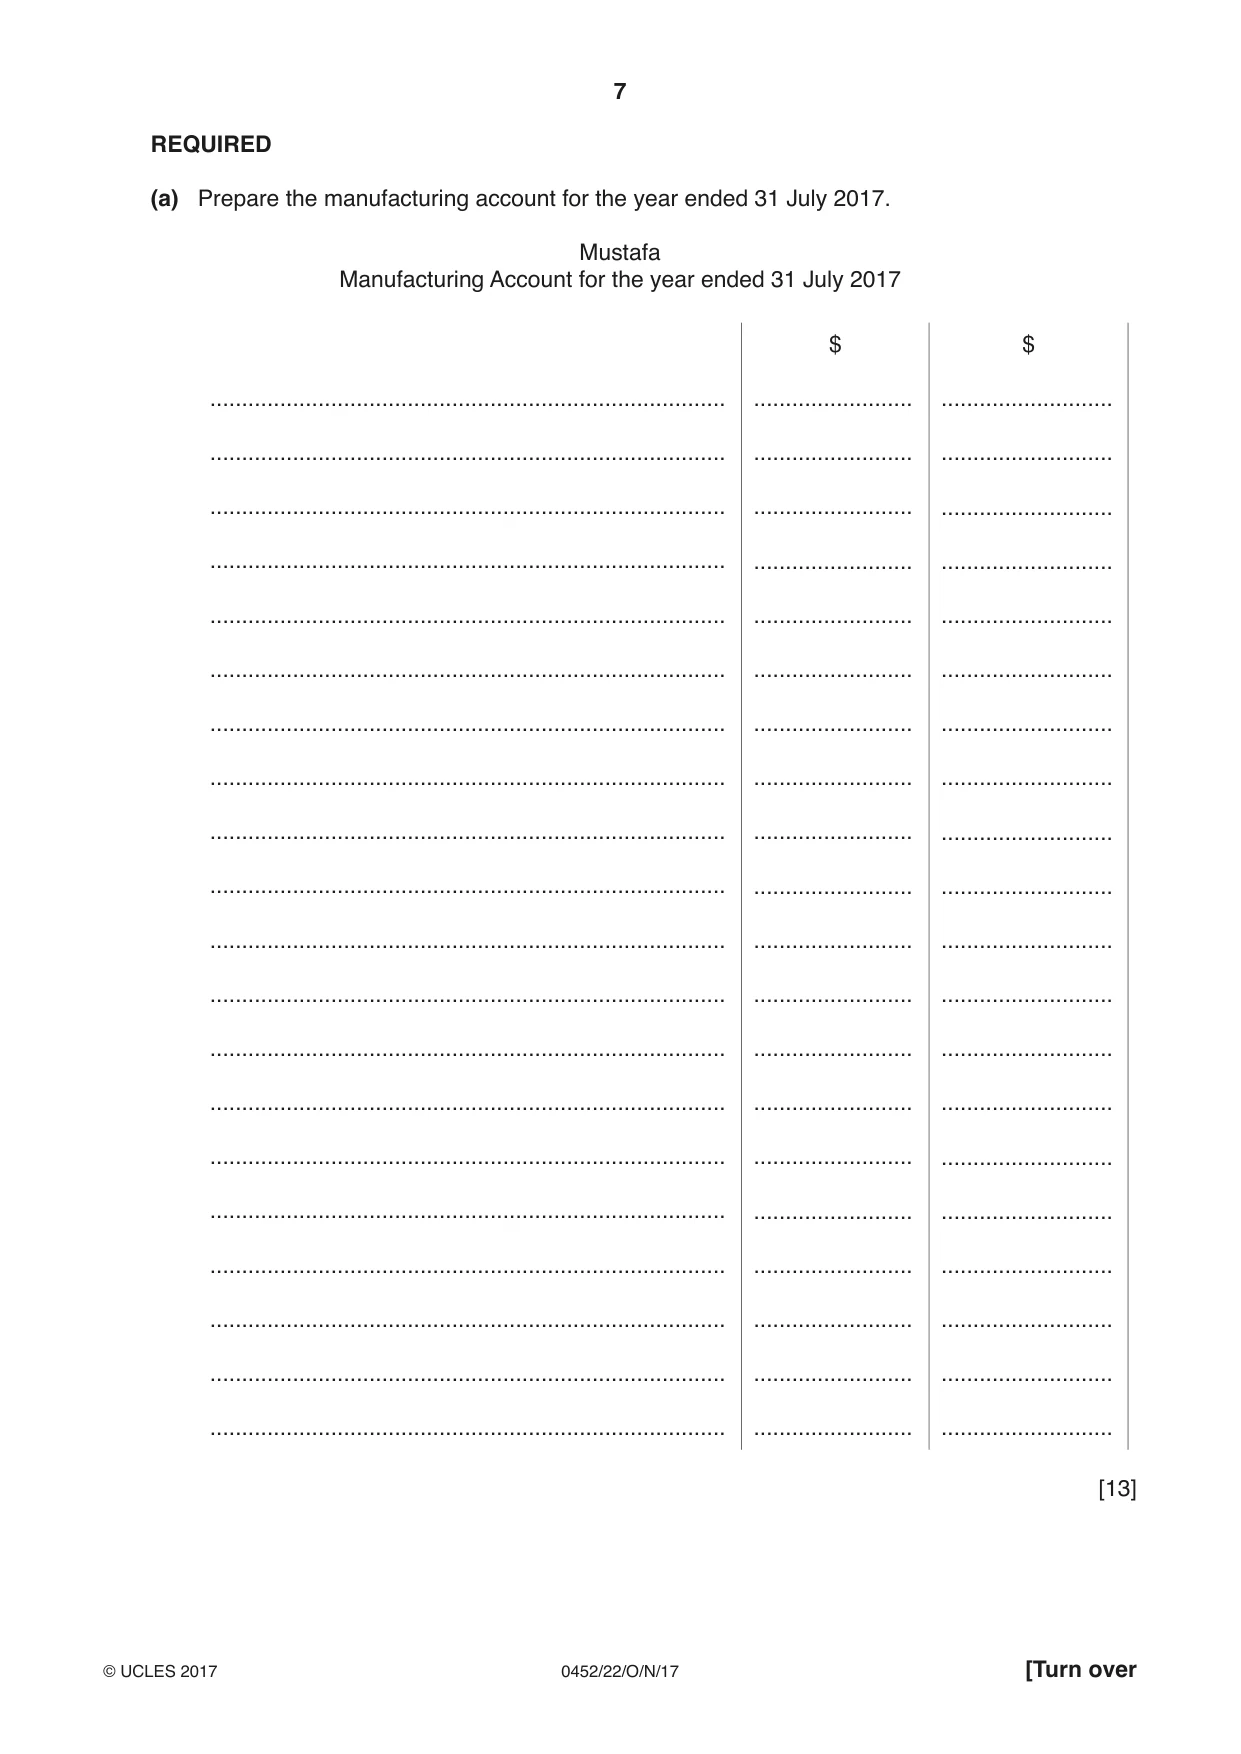
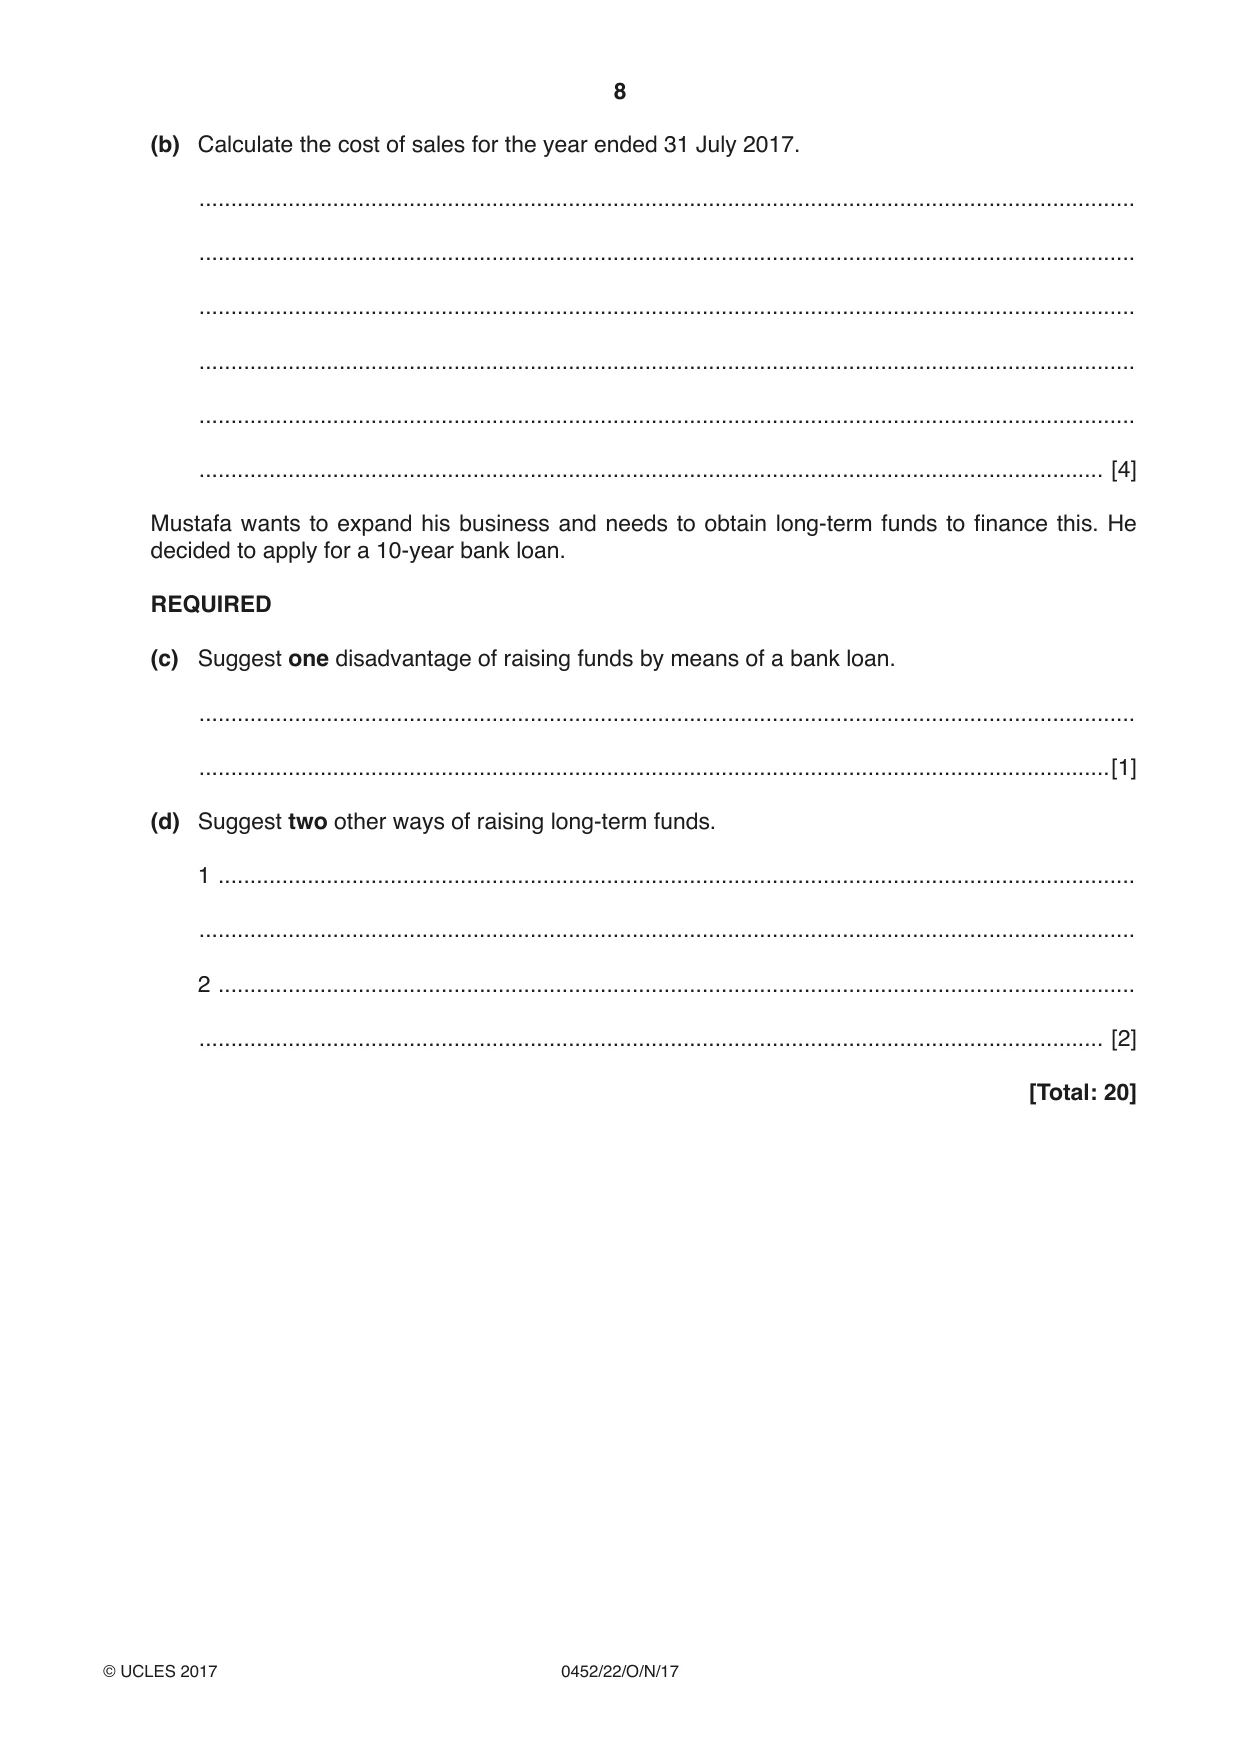
2 Mustafa opened a garment factory on 1 August 2016. On that date he purchased the following non-current assets. $ Premises 210 000 Factory machinery 92 000 Office fixtures and equipment 29 800 Loose tools 19 600 Mustafa decided to revalue the loose tools at the end of each financial year and also decided that no depreciation would be charged on premises. The other non-current assets are to be depreciated using the straight line (equal instalment) method of depreciation at the following rates. Factory machinery at 20% per annum Office fixtures and equipment at 15% per annum During his first year of trading, Mustafa purchased raw materials costing $447 400 (of which $1800 were returned to the supplier) and finished goods costing $22 200. His sales of finished goods amounted to $998 500. Mustafa made the following payments during the year ended 31 July 2017. $ Wages – factory operatives 287 400 factory supervisors 101 150 office staff 75 790 General expenses 13 400 Rates and insurance 12 600 Carriage inwards 2 590 Carriage outwards 2 180 At 31 July 2017 $ Inventories were valued at Raw materials 62 200 Work in progress 38 200 Finished goods 69 700 Loose tools were valued at 18 100 Wages of factory operatives accrued 3 760 The general expenses are to be apportioned 3⁄4 to the factory and 1⁄4 to the office. The rates and insurance are to be apportioned 2⁄3 to the factory and 1⁄3 to the office. REQUIRED (a) Prepare the manufacturing account for the year ende Mustafa Manufacturing Account for the year en ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. (b) Calculate the cost of sales for the year ended 31 July 2017. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [4] Mustafa wants to expand his business and needs to obtain long-term funds to finance this. He decided to apply for a 10-year bank loan. REQUIRED (c) Suggest one disadvantage of raising funds by means of a bank loan. ................................................................................................................................................... ...............................................................................................................................................[1] (d) Suggest two other ways of raising long-term funds. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] [Total: 20] Question 3 is on the next page.
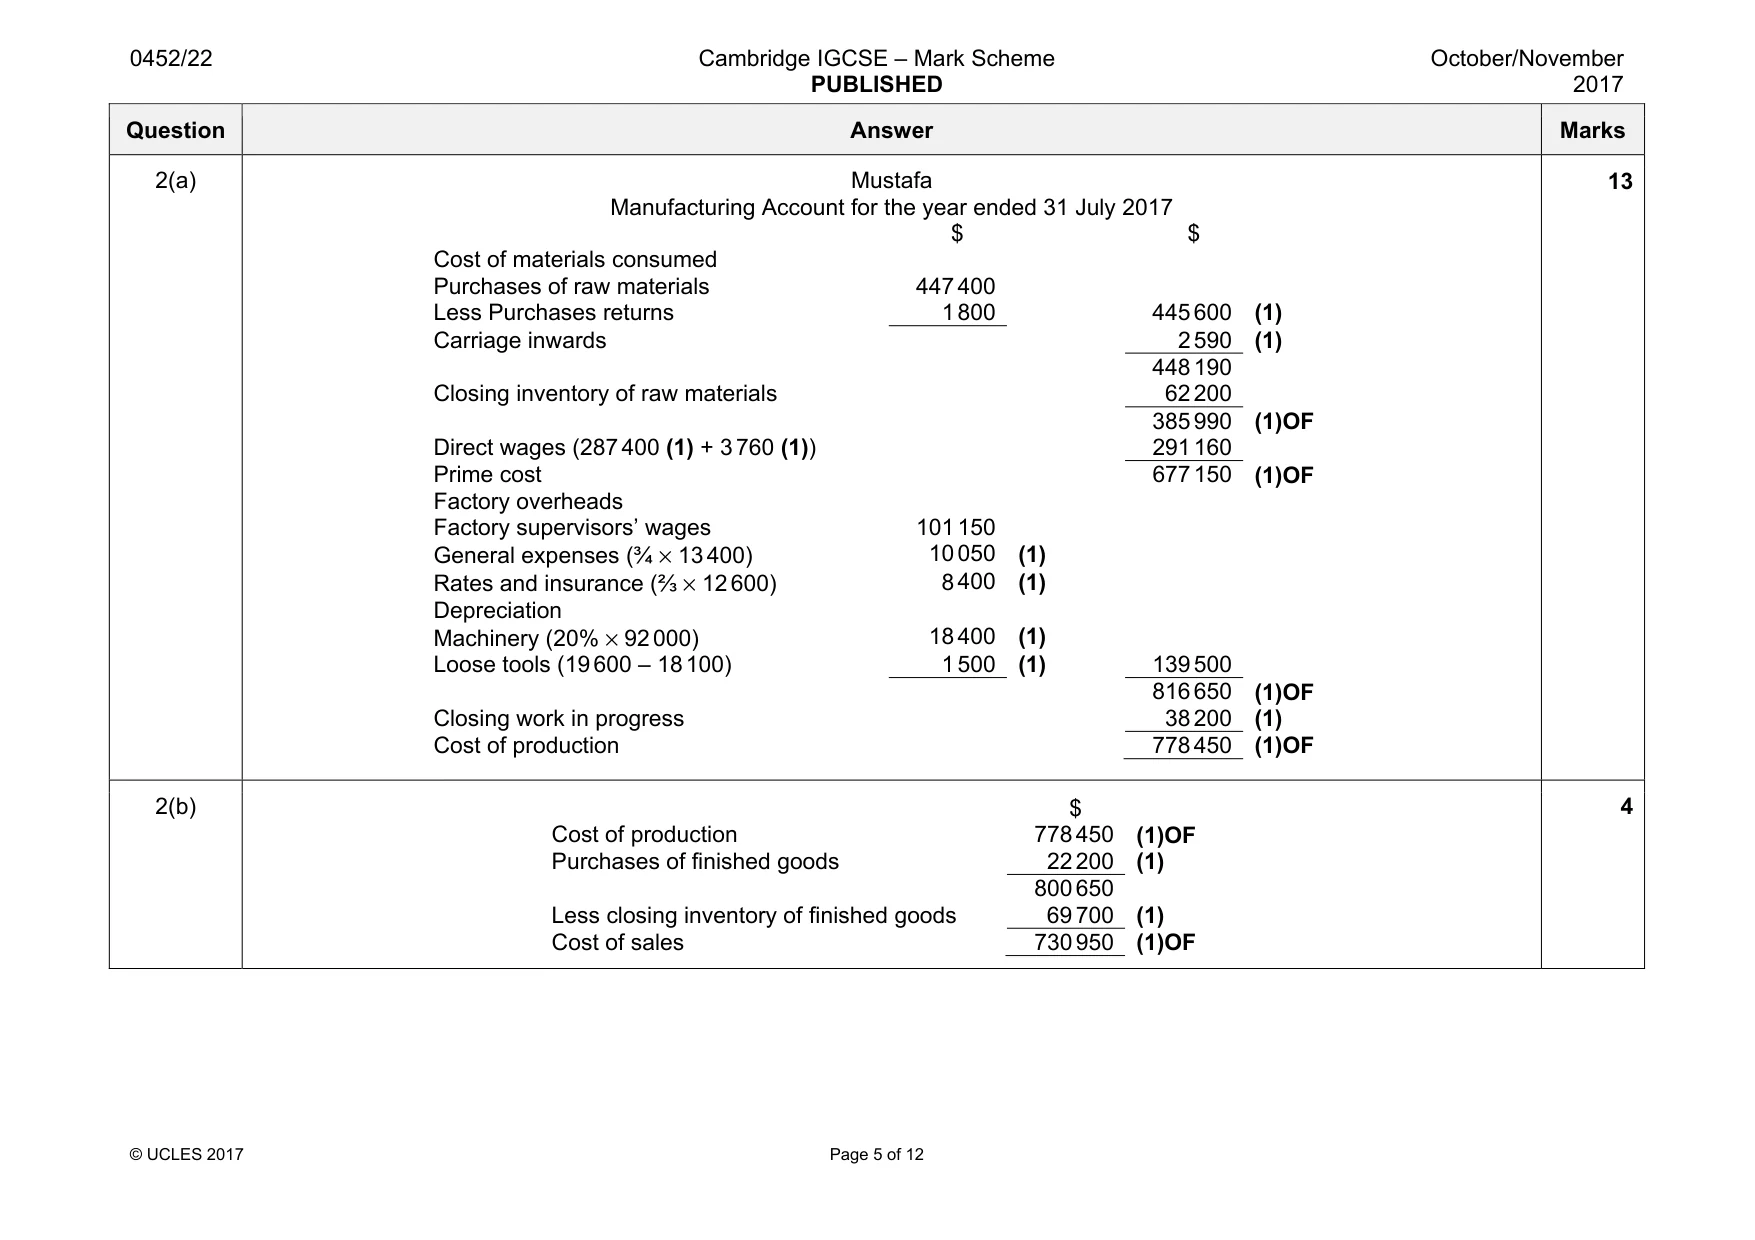
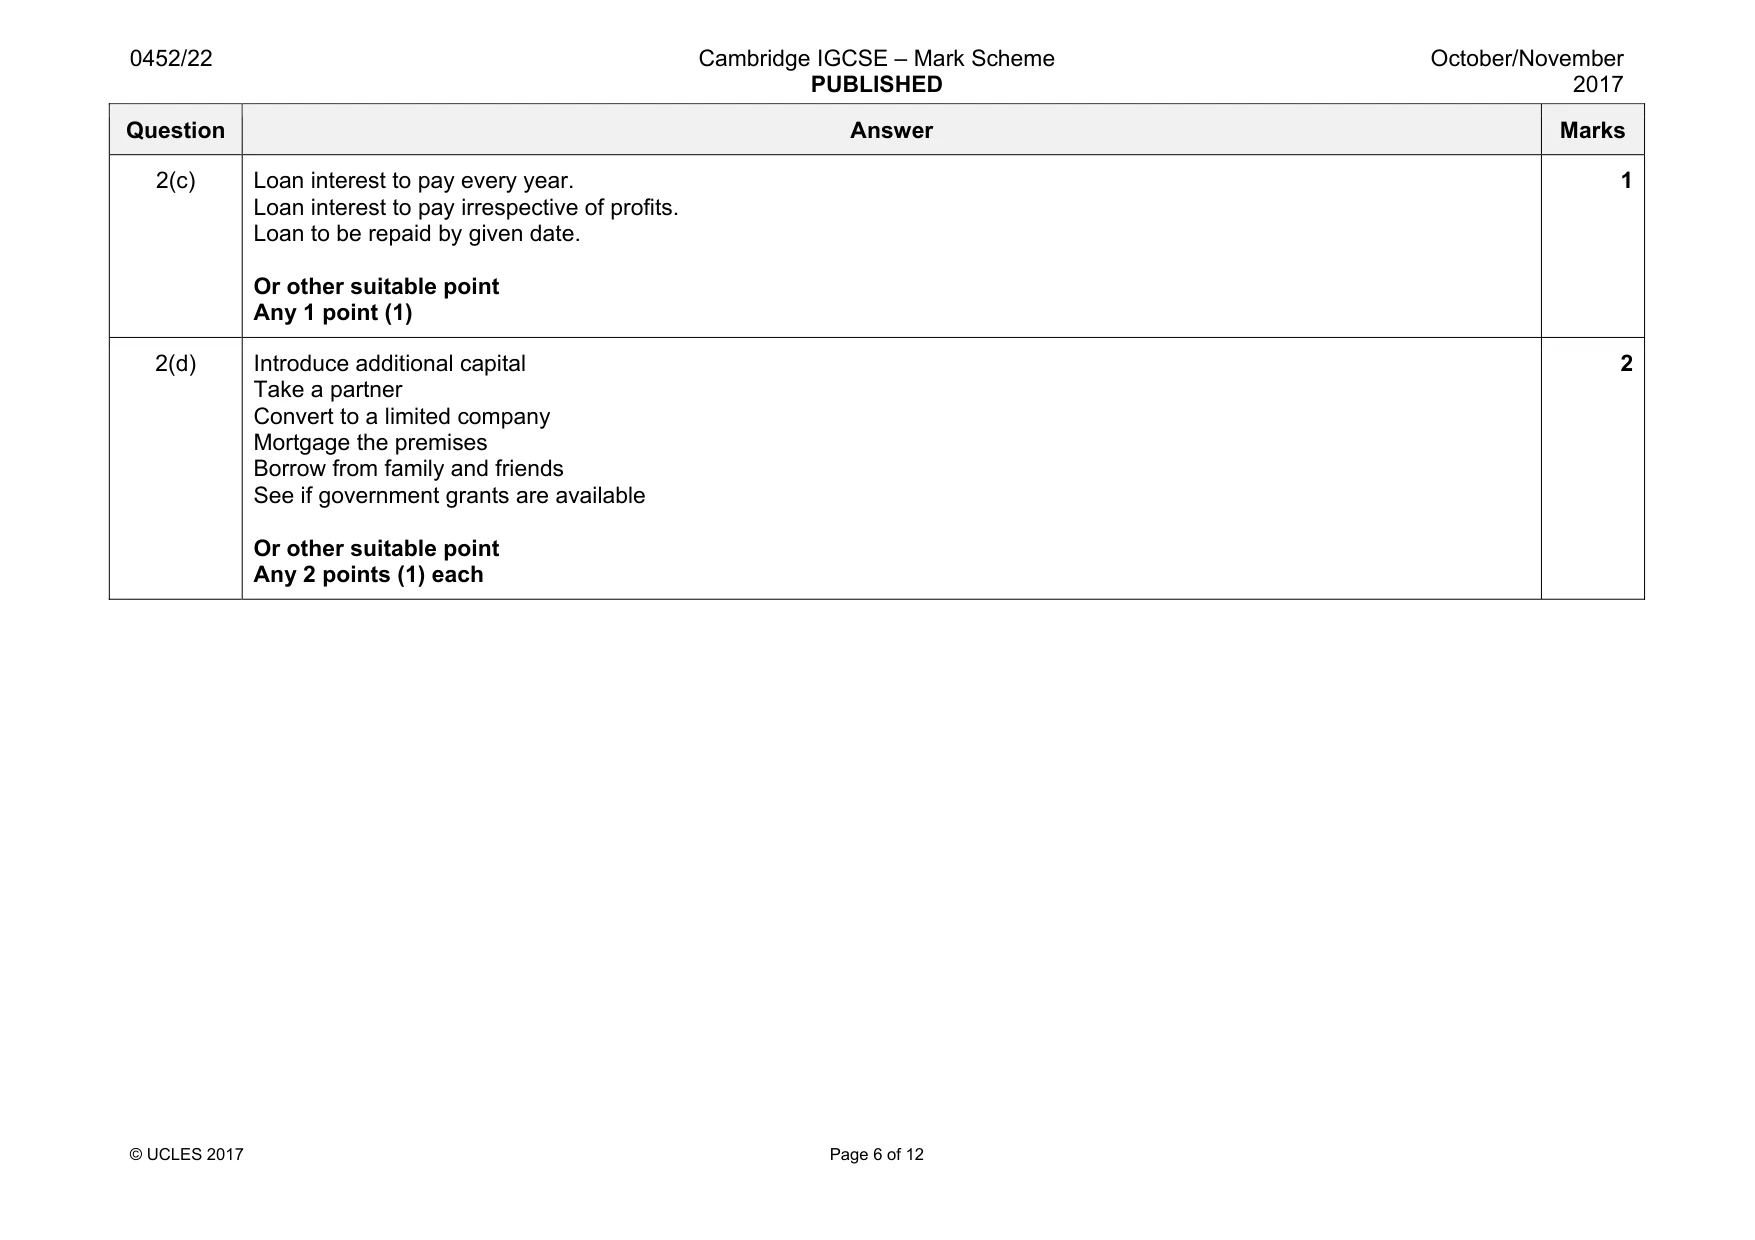
Mark scheme: 2(a) Mustafa Manufacturing Account for the year ended 31 July 2017 $ $ Cost of materials consumed Purchases of raw materials 447 400 Less Purchases returns 1 800 445 600 (1) Carriage inwards 2 590 (1) 448 190 Closing inventory of raw materials 62 200 385 990 (1)OF Direct wages (287 400 (1) + 3 760 (1)) 291 160 Prime cost 677 150 (1)OF Factory overheads Factory supervisors’ wages 101 150 General expenses (¾ × 13 400) 10 050 (1) Rates and insurance (⅔ × 12 600) 8 400 (1) Depreciation Machinery (20% × 92 000) 18 400 (1) Loose tools (19 600 – 18 100) 1 500 (1) 139 500 816 650 (1)OF Closing work in progress 38 200 (1) Cost of production 778 450 (1)OF 13 2(b) $ Cost of production 778 450 (1)OF Purchases of finished goods 22 200 (1) 800 650 Less closing inventory of finished goods 69 700 (1) Cost of sales 730 950 (1)OF 4 Question Answer Marks 2(c) Loan interest to pay every year. Loan interest to pay irrespective of profits. Loan to be repaid by given date. Or other suitable point Any 1 point (1) 1 2(d) Introduce additional capital Take a partner Convert to a limited company Mortgage the premises Borrow from family and friends See if government grants are available Or other suitable point Any 2 points (1) each 2
Q3 · Zikri is a retailer
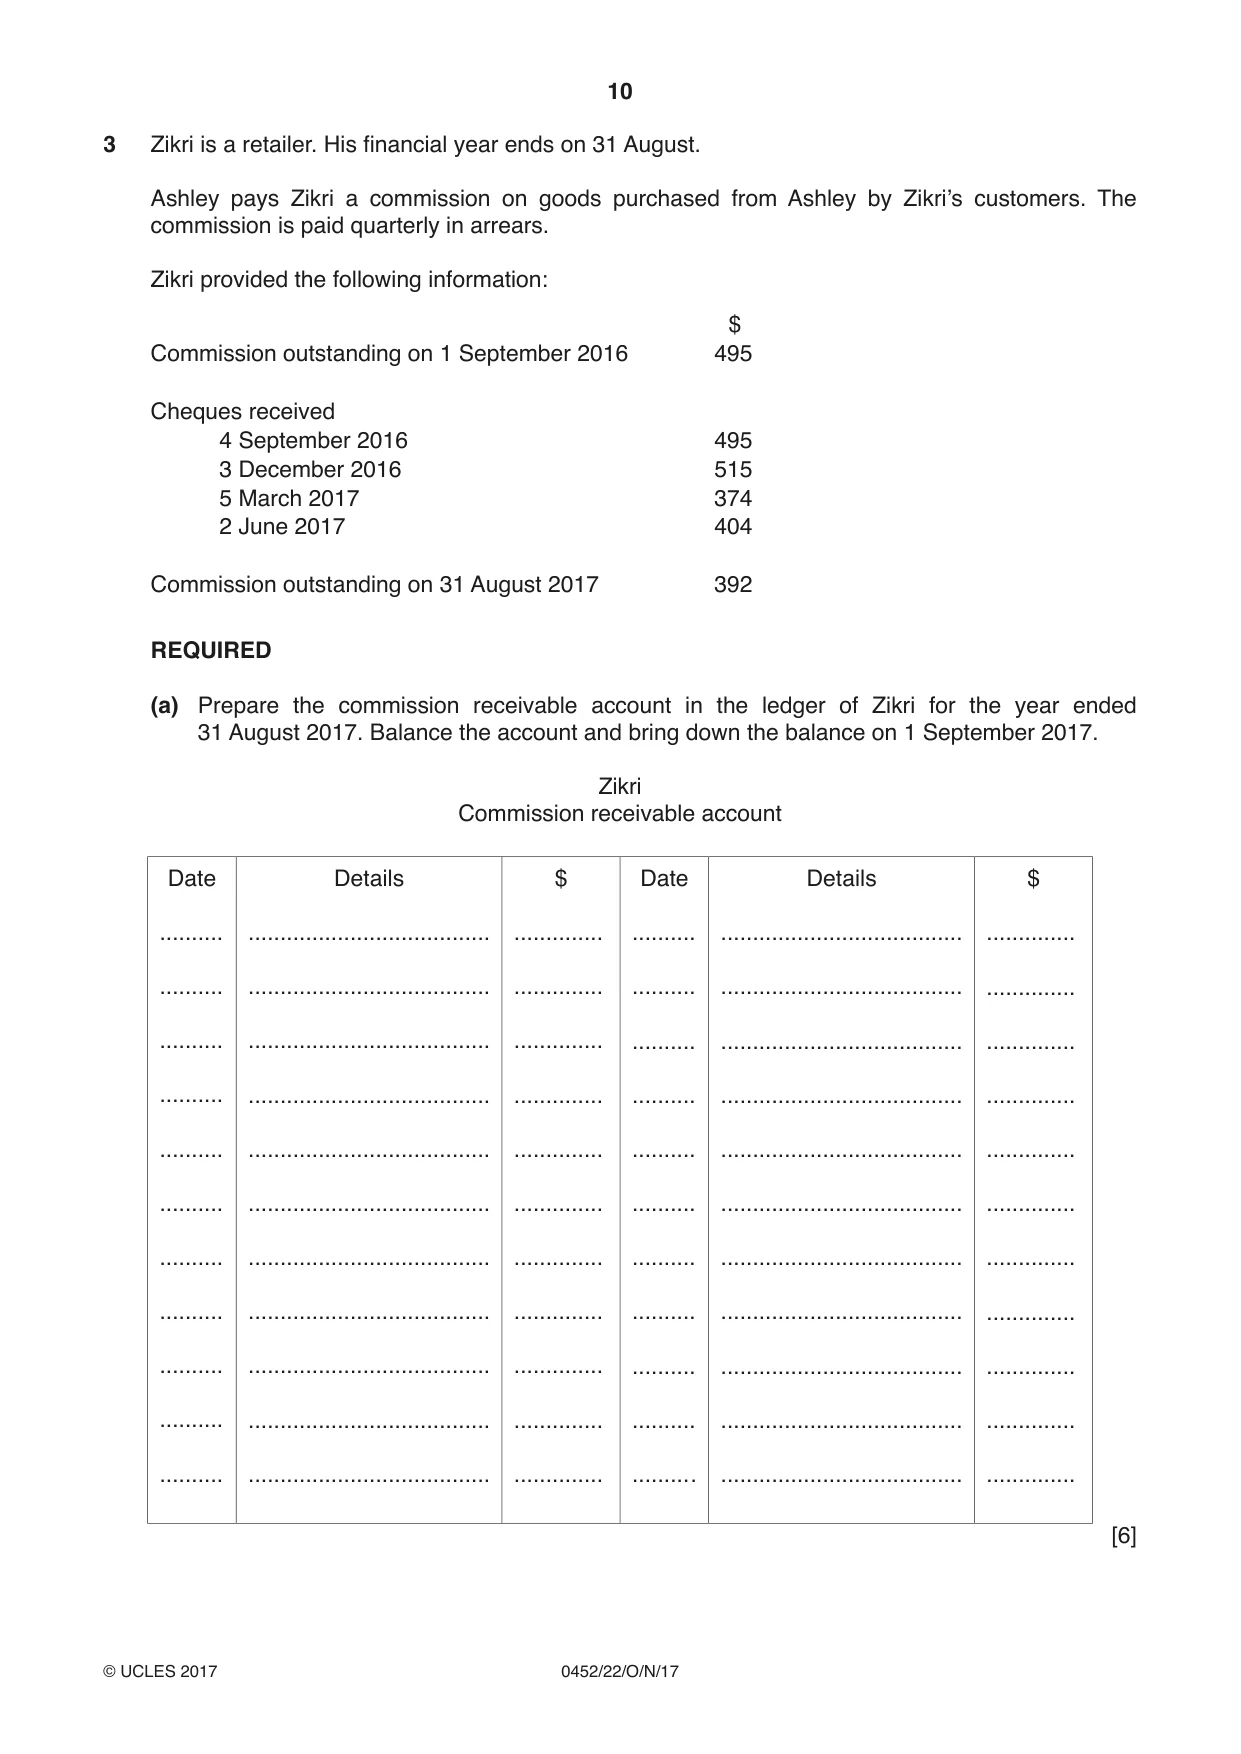
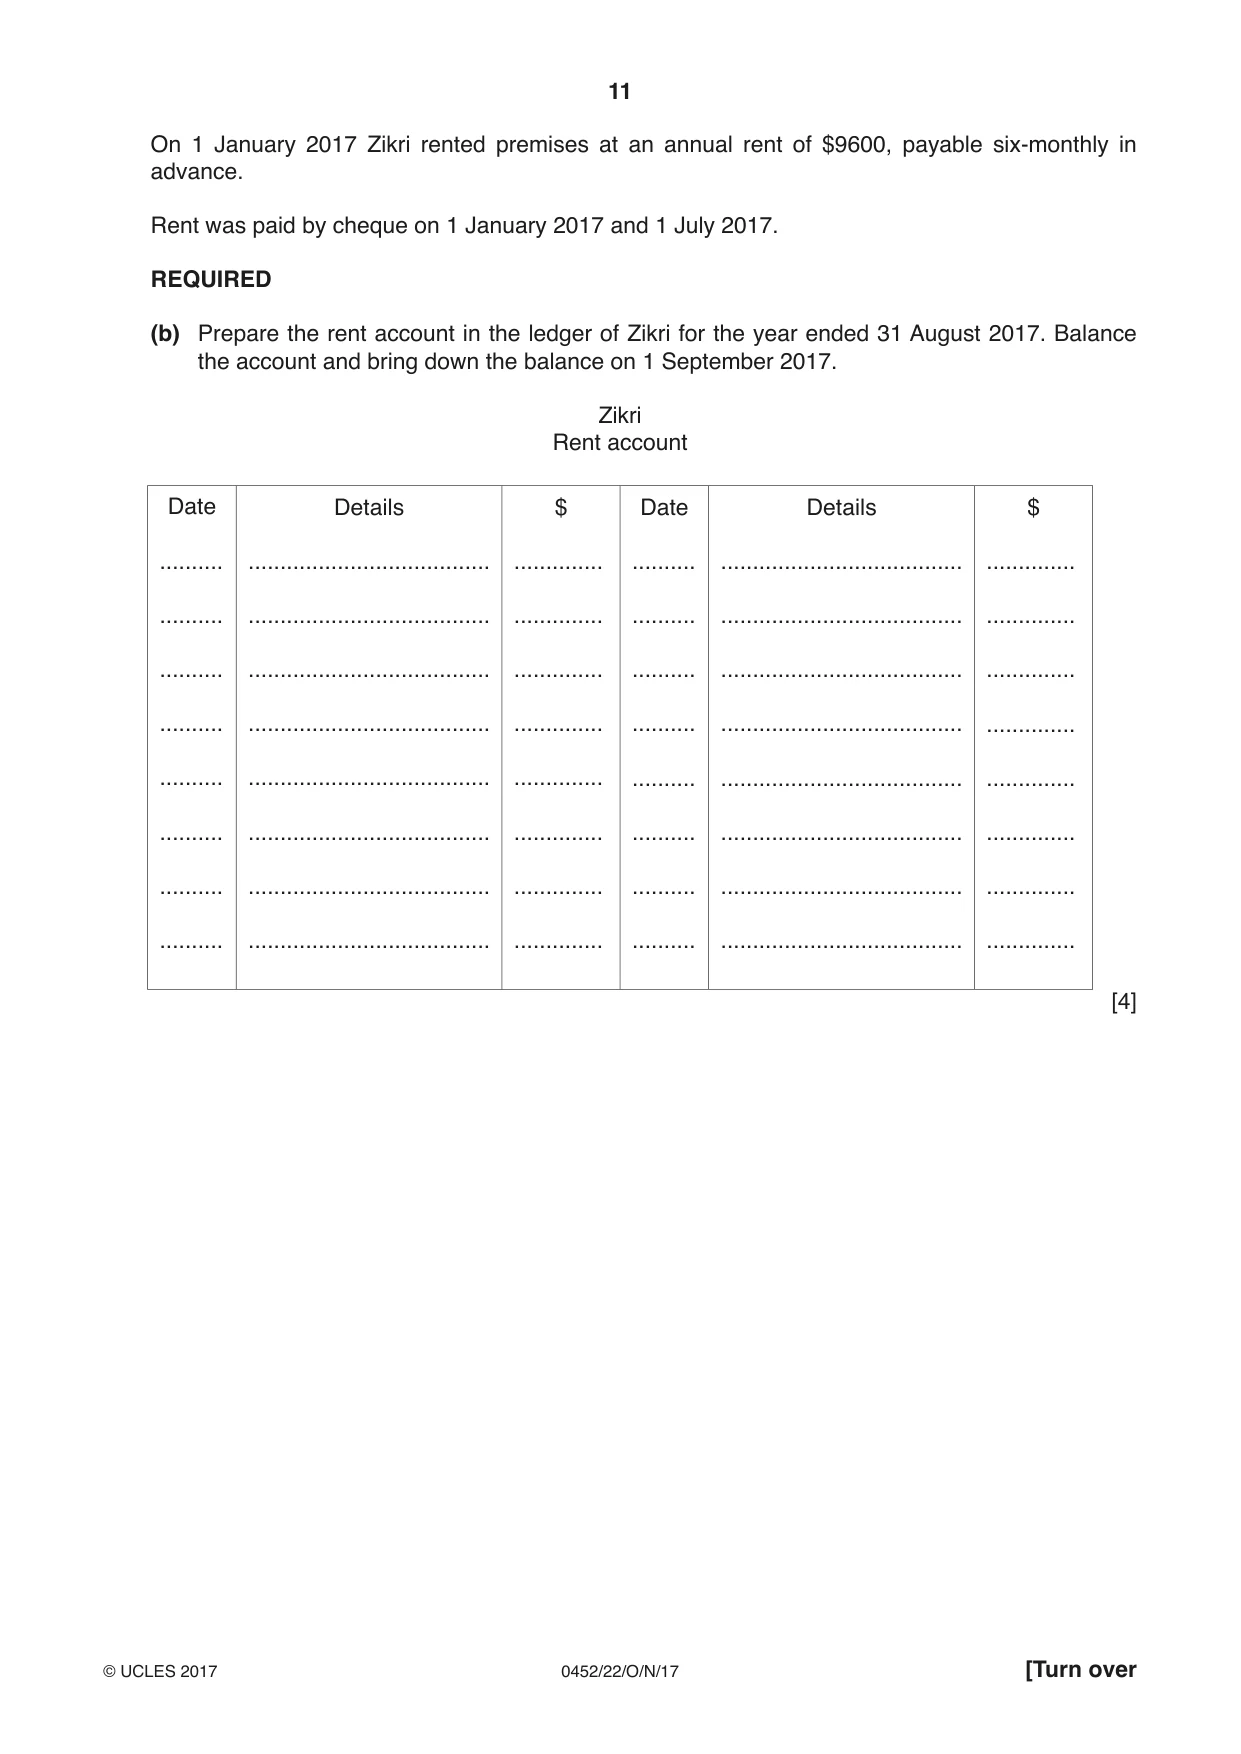
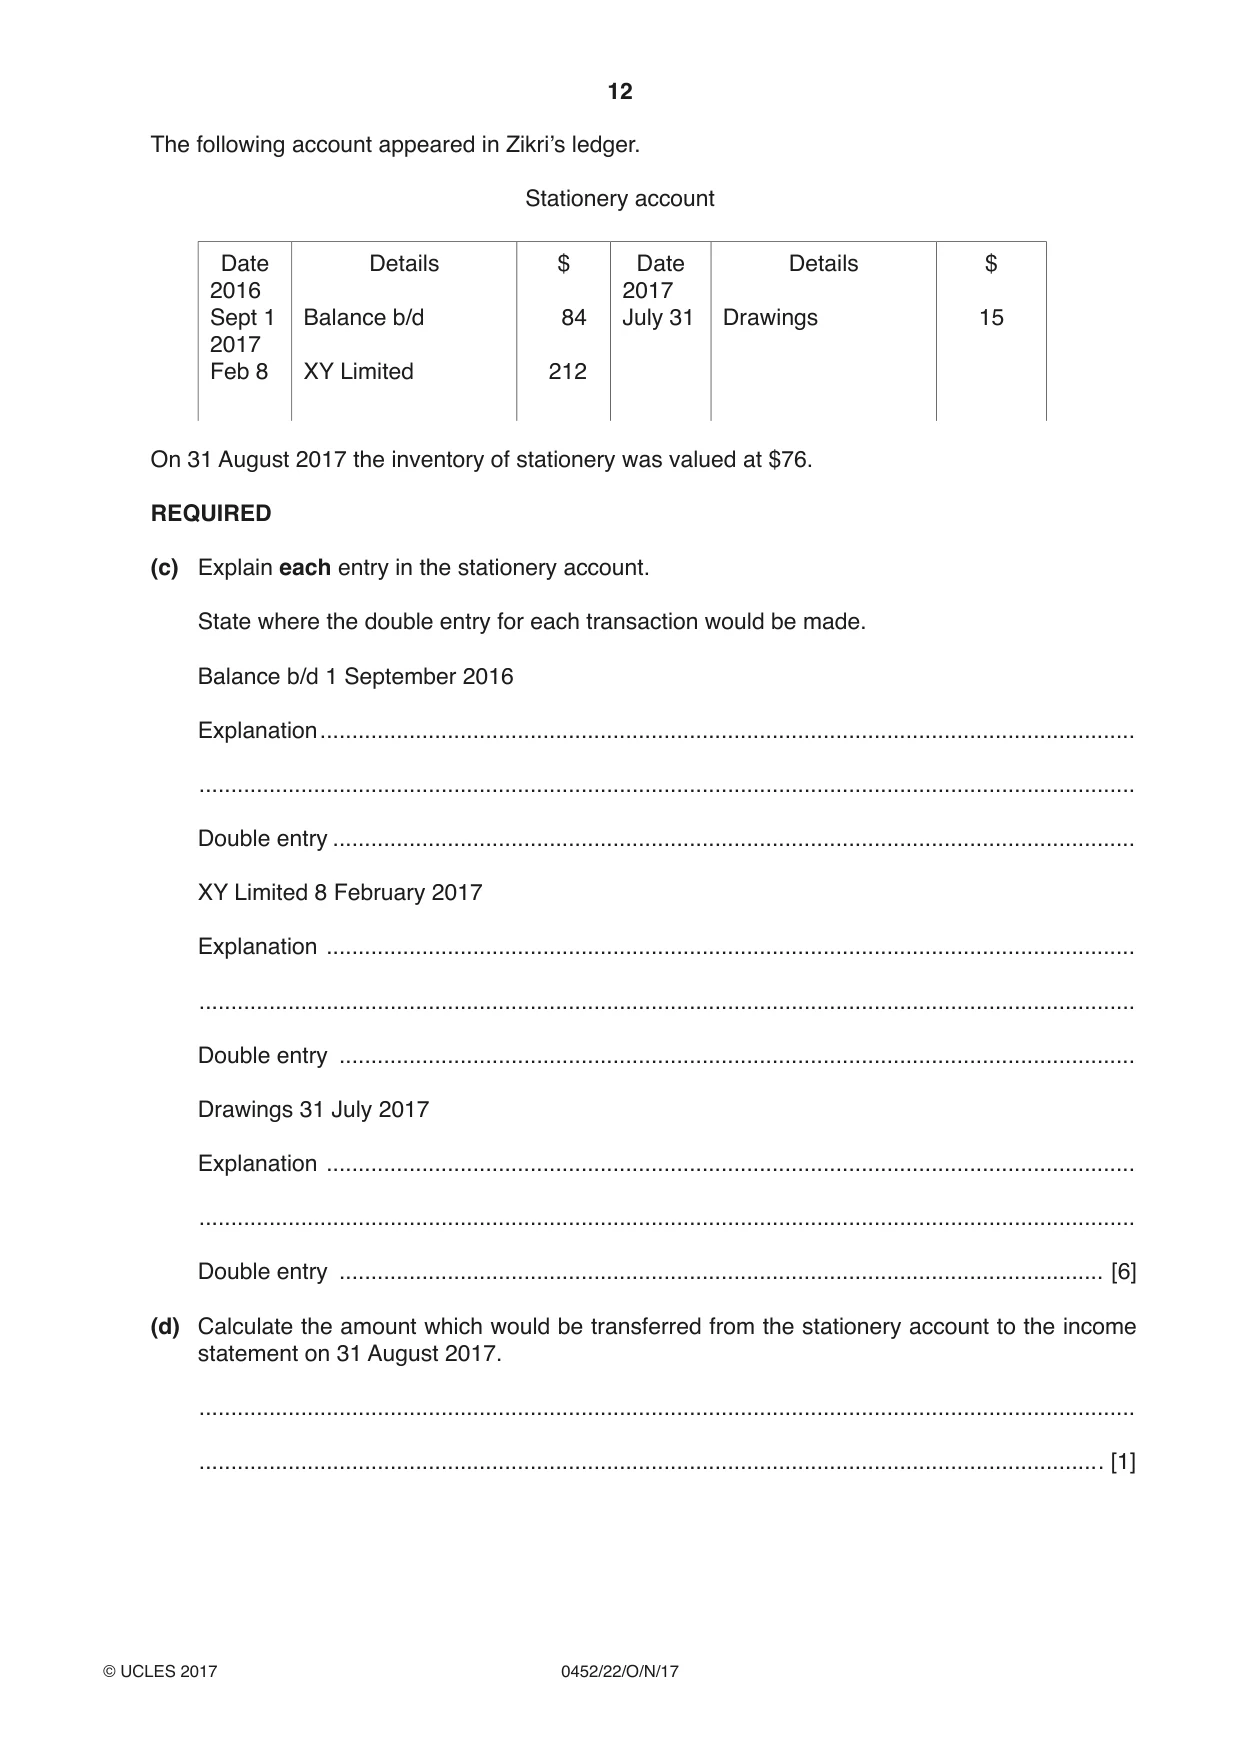
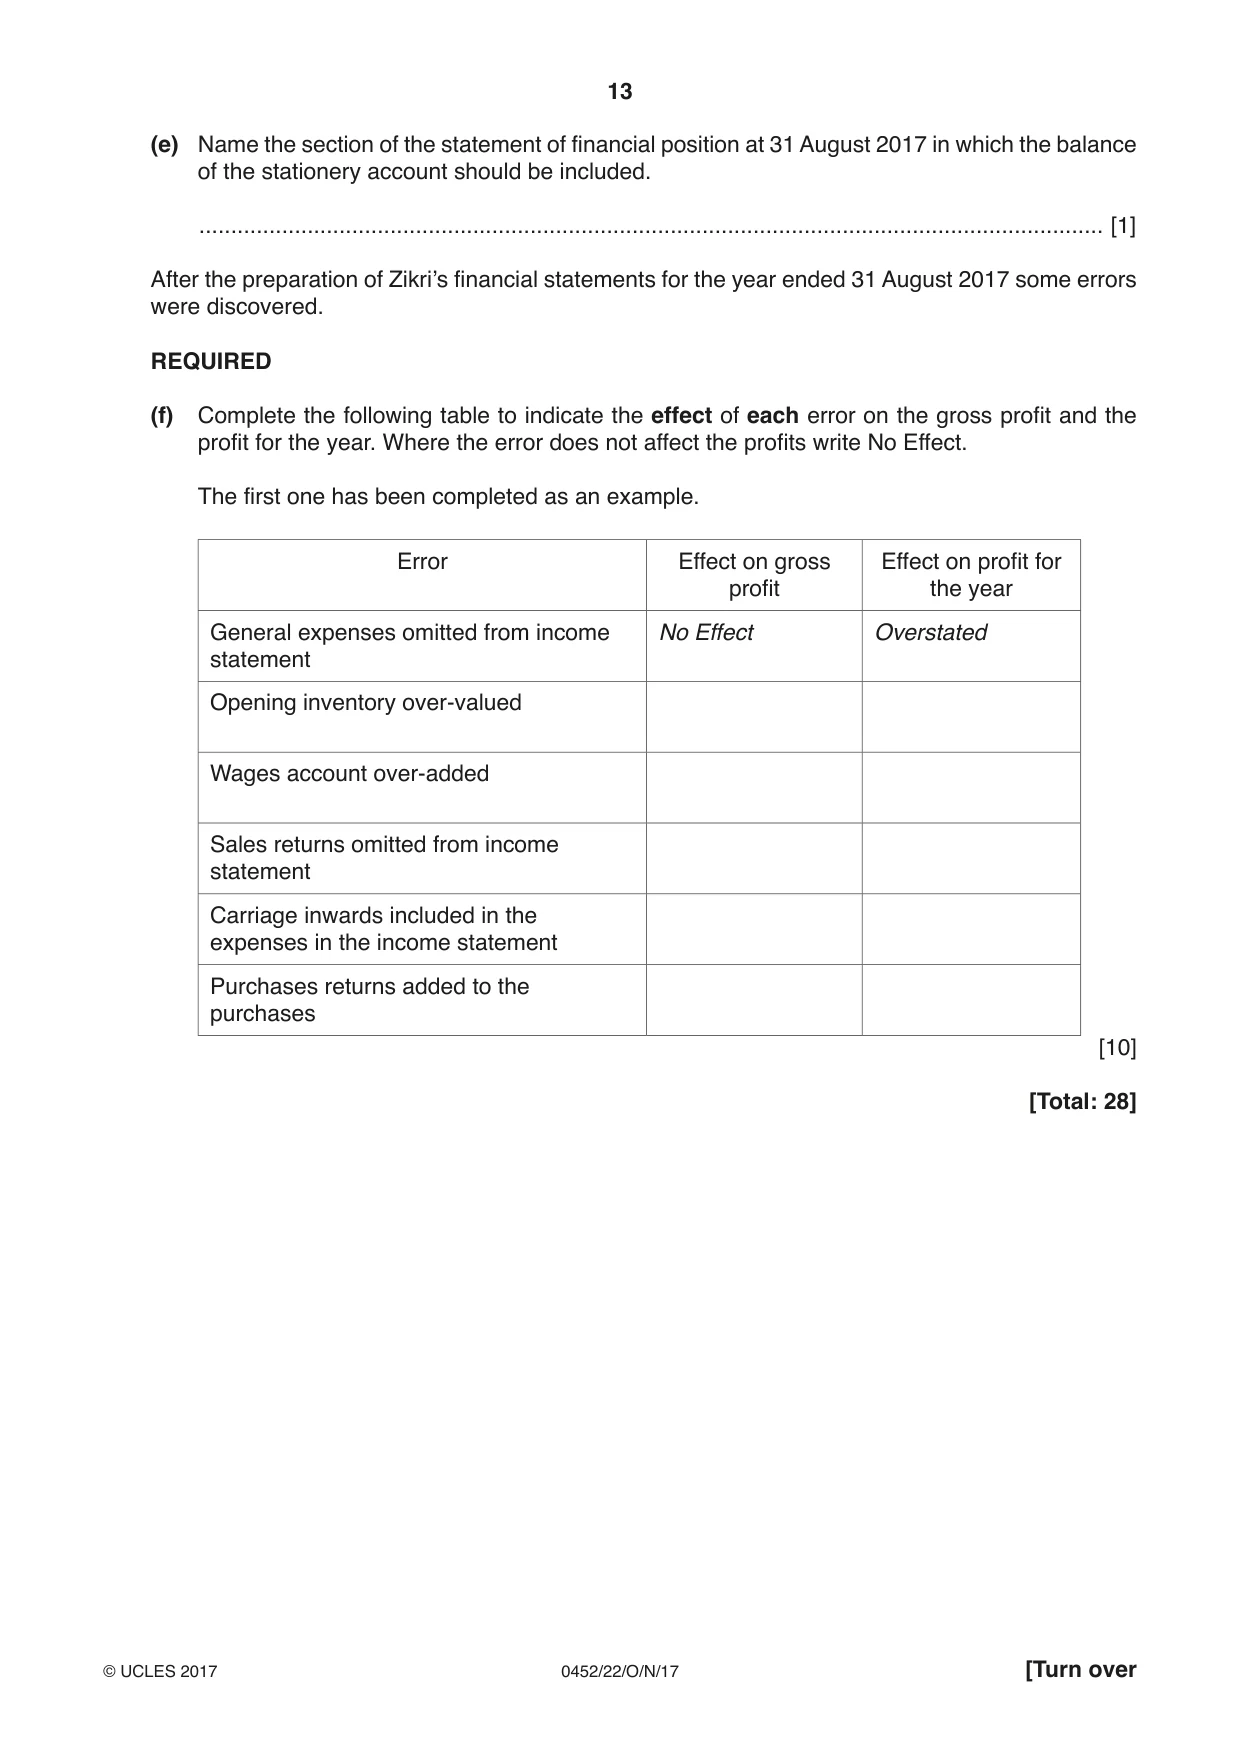
3 Zikri is a retailer. His financial year ends on 31 August. Ashley pays Zikri a commission on goods purchased from Ashley by Zikri’s customers. The commission is paid quarterly in arrears. Zikri provided the following information: $ Commission outstanding on 1 September 2016 495 Cheques received 4 September 2016 495 3 December 2016 515 5 March 2017 374 2 June 2017 404 Commission outstanding on 31 August 2017 392 REQUIRED (a) Prepare the commission receivable account in the ledger of Zikri for the year ended 31 August 2017. Balance the account and bring down the balance on 1 September 2017. Zikri Commission receivable account Date Details $ Date Details $ .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. [6] On 1 January 2017 Zikri rented premises at an annual rent of $9600, payable six-monthly in advance. Rent was paid by cheque on 1 January 2017 and 1 July 2017. REQUIRED (b) Prepare the rent account in the ledger of Zikri for the year ended 31 August 2017. Balance the account and bring down the balance on 1 September 2017. Zikri Rent account Date Details $ Date Details $ .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. .......... ...................................... .............. [4] The following account appeared in Zikri’s ledger. Stationery account Date Details $ Date Details $ 2016 2017 Sept 1 Balance b/d 84 July 31 Drawings 15 2017 Feb 8 XY Limited 212 On 31 August 2017 the inventory of stationery was valued at $76. REQUIRED (c) Explain each entry in the stationery account. State where the double entry for each transaction would be made. Balance b/d 1 September 2016 Explanation ................................................................................................................................ ................................................................................................................................................... Double entry .............................................................................................................................. XY Limited 8 February 2017 Explanation ............................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. Drawings 31 July 2017 Explanation ............................................................................................................................... ................................................................................................................................................... Double entry ........................................................................................................................ [6] (d) Calculate the amount which would be transferred from the stationery account to the income statement on 31 August 2017. ................................................................................................................................................... .............................................................................................................................................. [1] (e) Name the section of the statement of financial position at 31 August 2017 in which the balance of the stationery account should be included. .............................................................................................................................................. [1] After the preparation of Zikri’s financial statements for the year ended 31 August 2017 some errors were discovered. REQUIRED (f) Complete the following table to indicate the effect of each error on the gross profit and the profit for the year. Where the error does not affect the profits write No Effect. The first one has been completed as an example. Error Effect on gross Effect on profit for profit the year General expenses omitted from income No Effect Overstated statement Opening inventory over-valued Wages account over-added Sales returns omitted from income statement Carriage inwards included in the expenses in the income statement Purchases returns added to the purchases [10] [Total: 28]
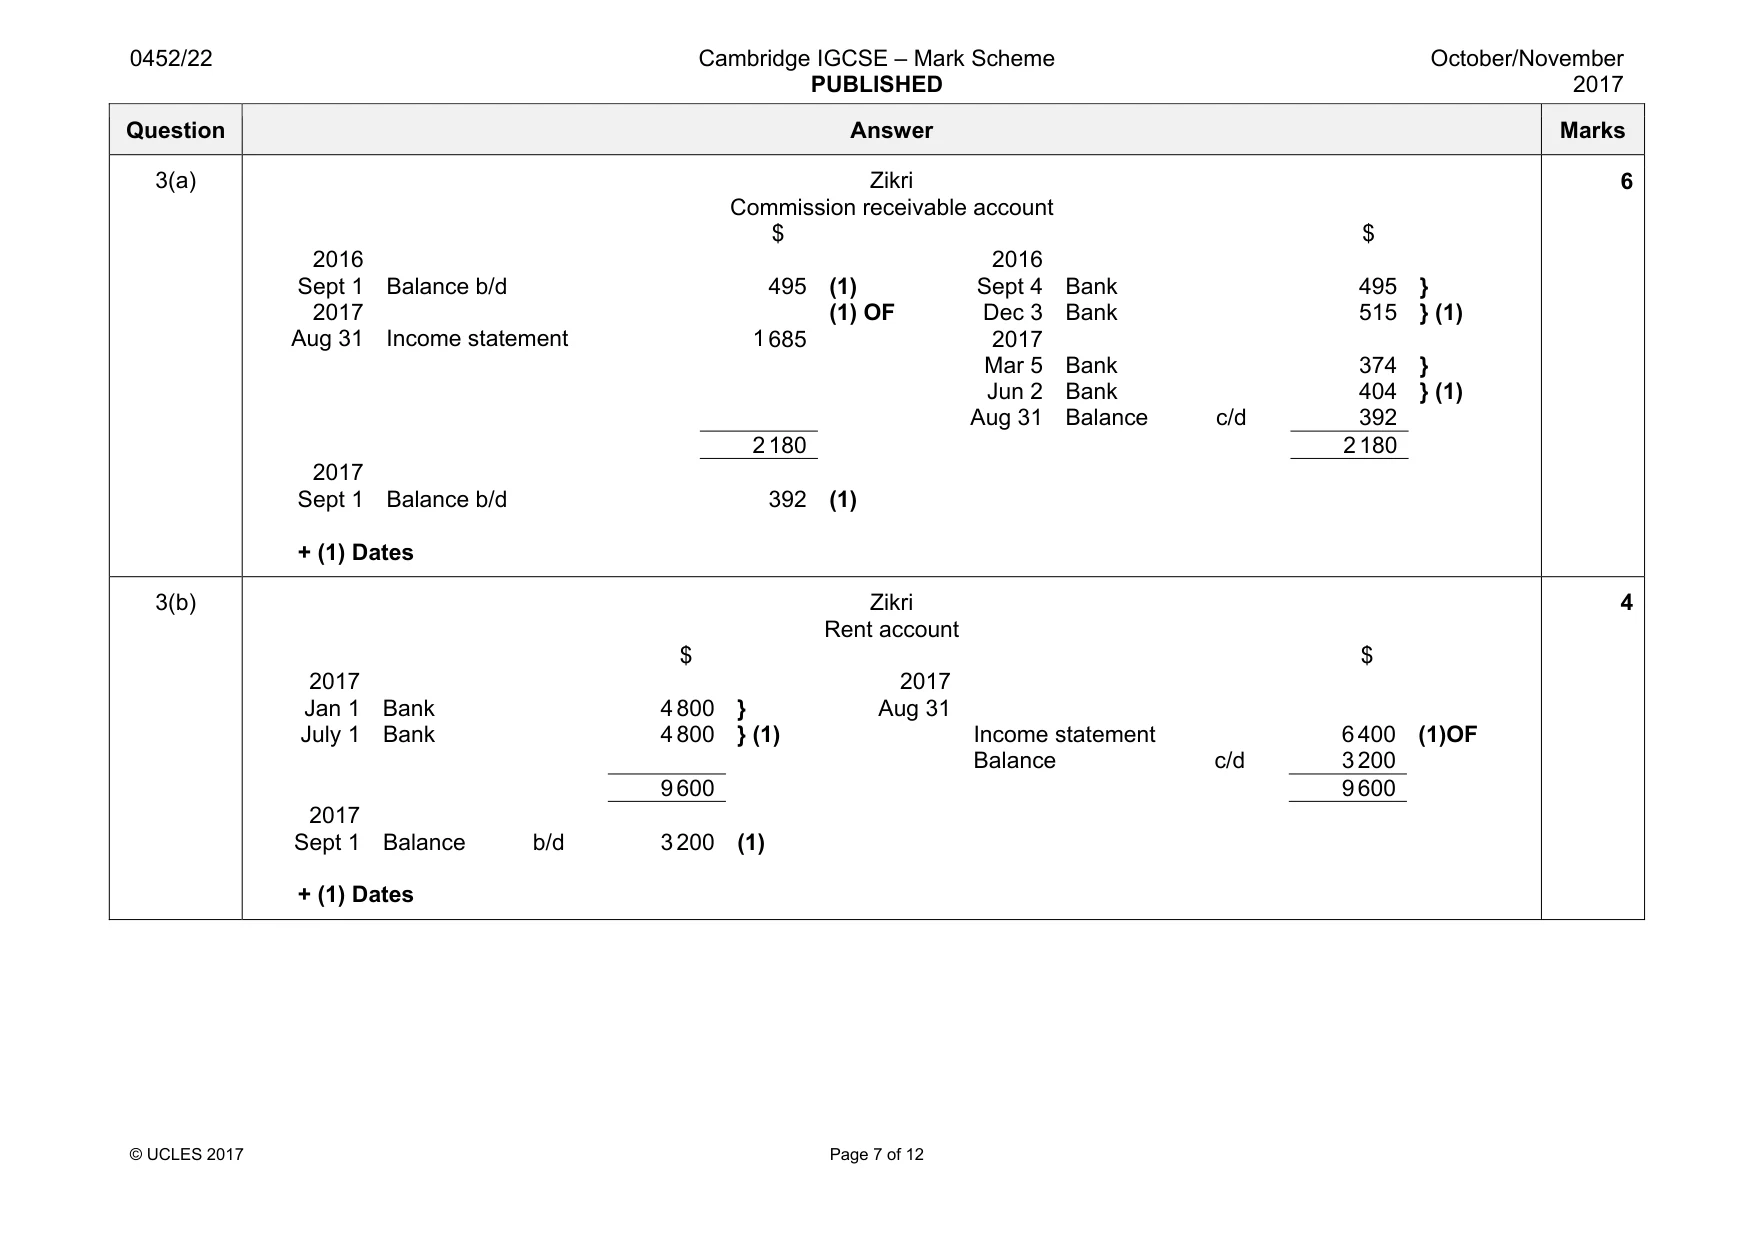
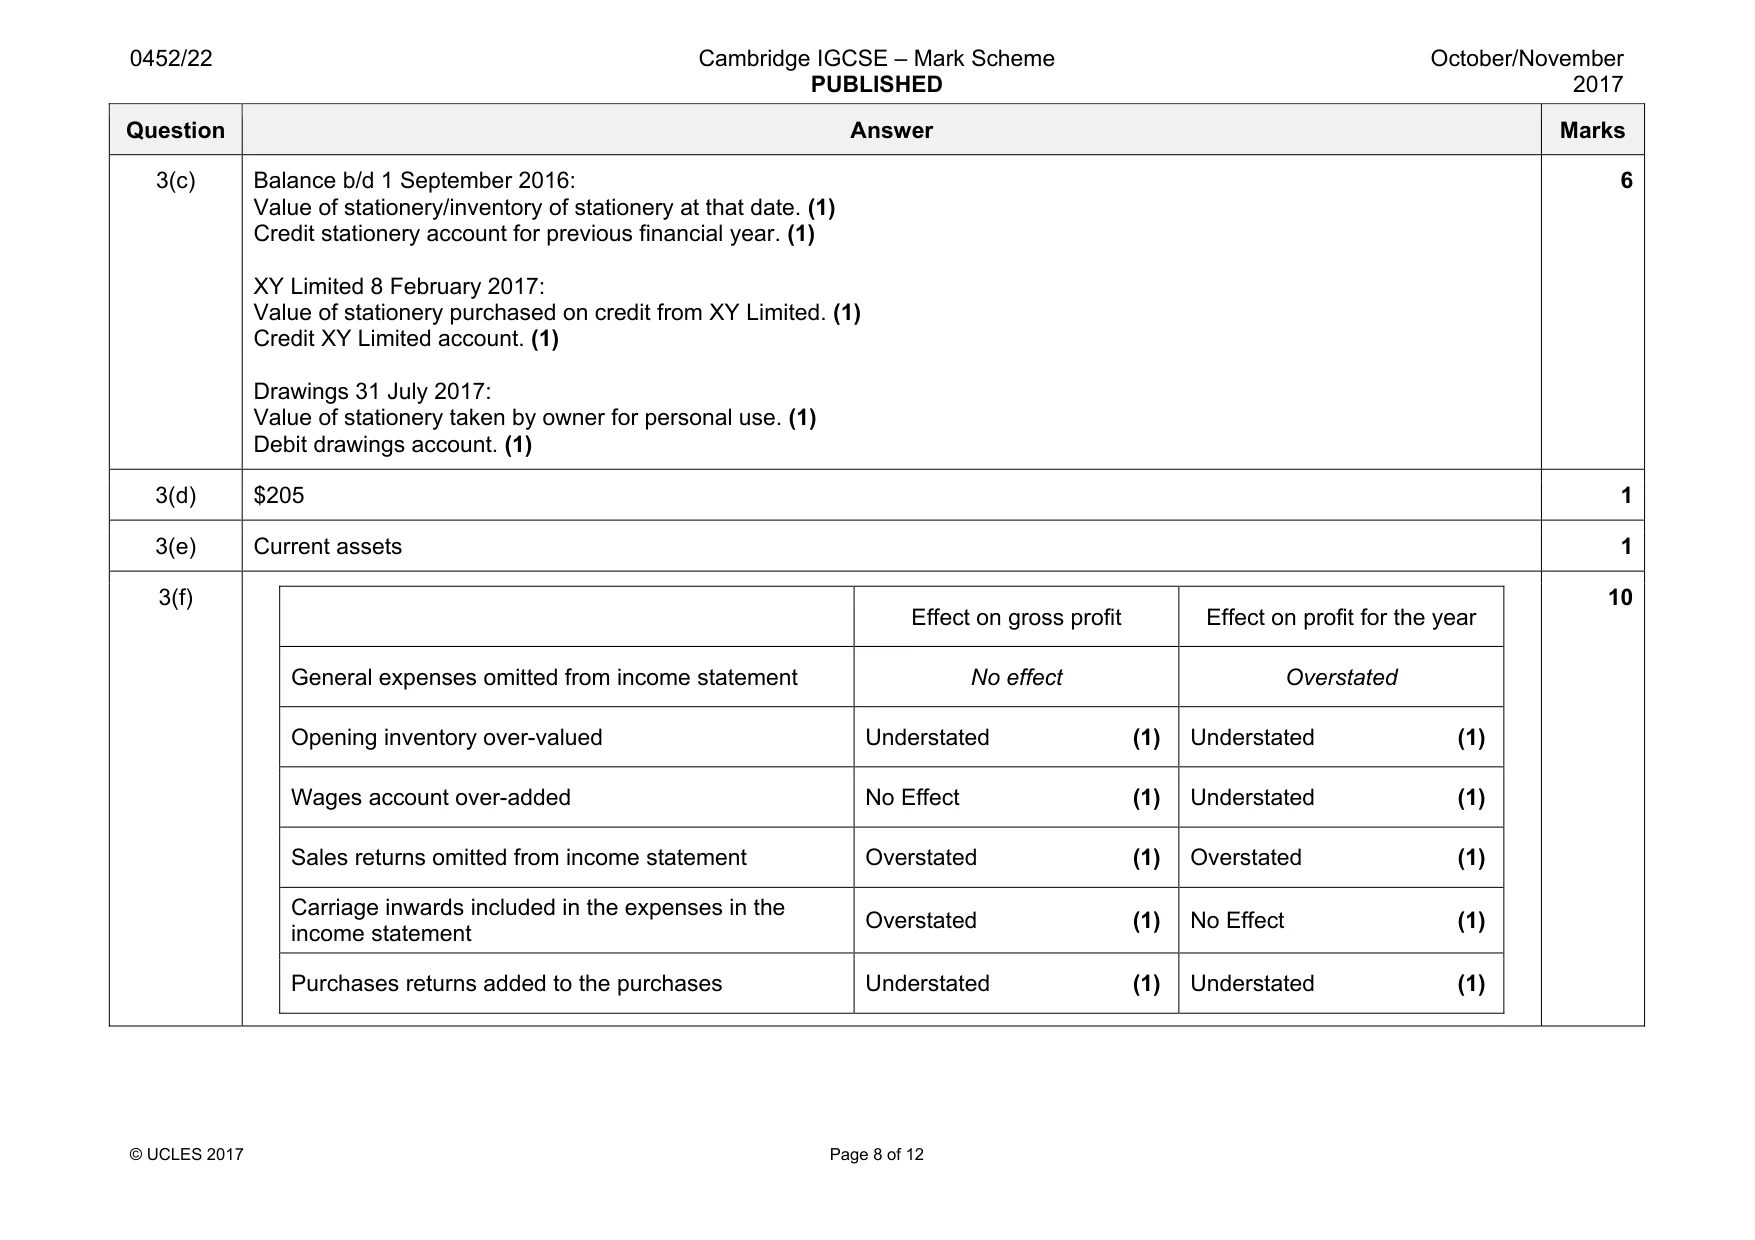
Mark scheme: 3(a) Zikri Commission receivable account $ $ 2016 2016 Sept 1 Balance b/d 495 (1) Sept 4 Bank 495 } 2017 (1) OF Dec 3 Bank 515 } (1) Aug 31 Income statement 1 685 2017 Mar 5 Bank 374 } Jun 2 Bank 404 } (1) Aug 31 Balance c/d 392 2 180 2 180 2017 Sept 1 Balance b/d 392 (1) + (1) Dates 6 3(b) Zikri Rent account $ $ 2017 2017 Jan 1 Bank 4 800 } Aug 31 July 1 Bank 4 800 } (1) Income statement 6 400 (1)OF Balance c/d 3 200 9 600 9 600 2017 Sept 1 Balance b/d 3 200 (1) + (1) Dates 4 Question Answer Marks 3(c) Balance b/d 1 September 2016: Value of stationery/inventory of stationery at that date. (1) Credit stationery account for previous financial year. (1) XY Limited 8 February 2017: Value of stationery purchased on credit from XY Limited. (1) Credit XY Limited account. (1) Drawings 31 July 2017: Value of stationery taken by owner for personal use. (1) Debit drawings account. (1) 6 3(d) $205 1 3(e) Current assets 1 3(f) Effect on gross profit Effect on profit for the year General expenses omitted from income statement No effect Overstated Opening inventory over-valued Understated (1) Understated (1) Wages account over-added No Effect (1) Understated (1) Sales returns omitted from income statement Overstated (1) Overstated (1) Carriage inwards included in the expenses in the income statement Overstated (1) No Effect (1) Purchases returns added to the purchases Understated (1) Understated (1) 10
Q4 · Rashida is a wholesaler
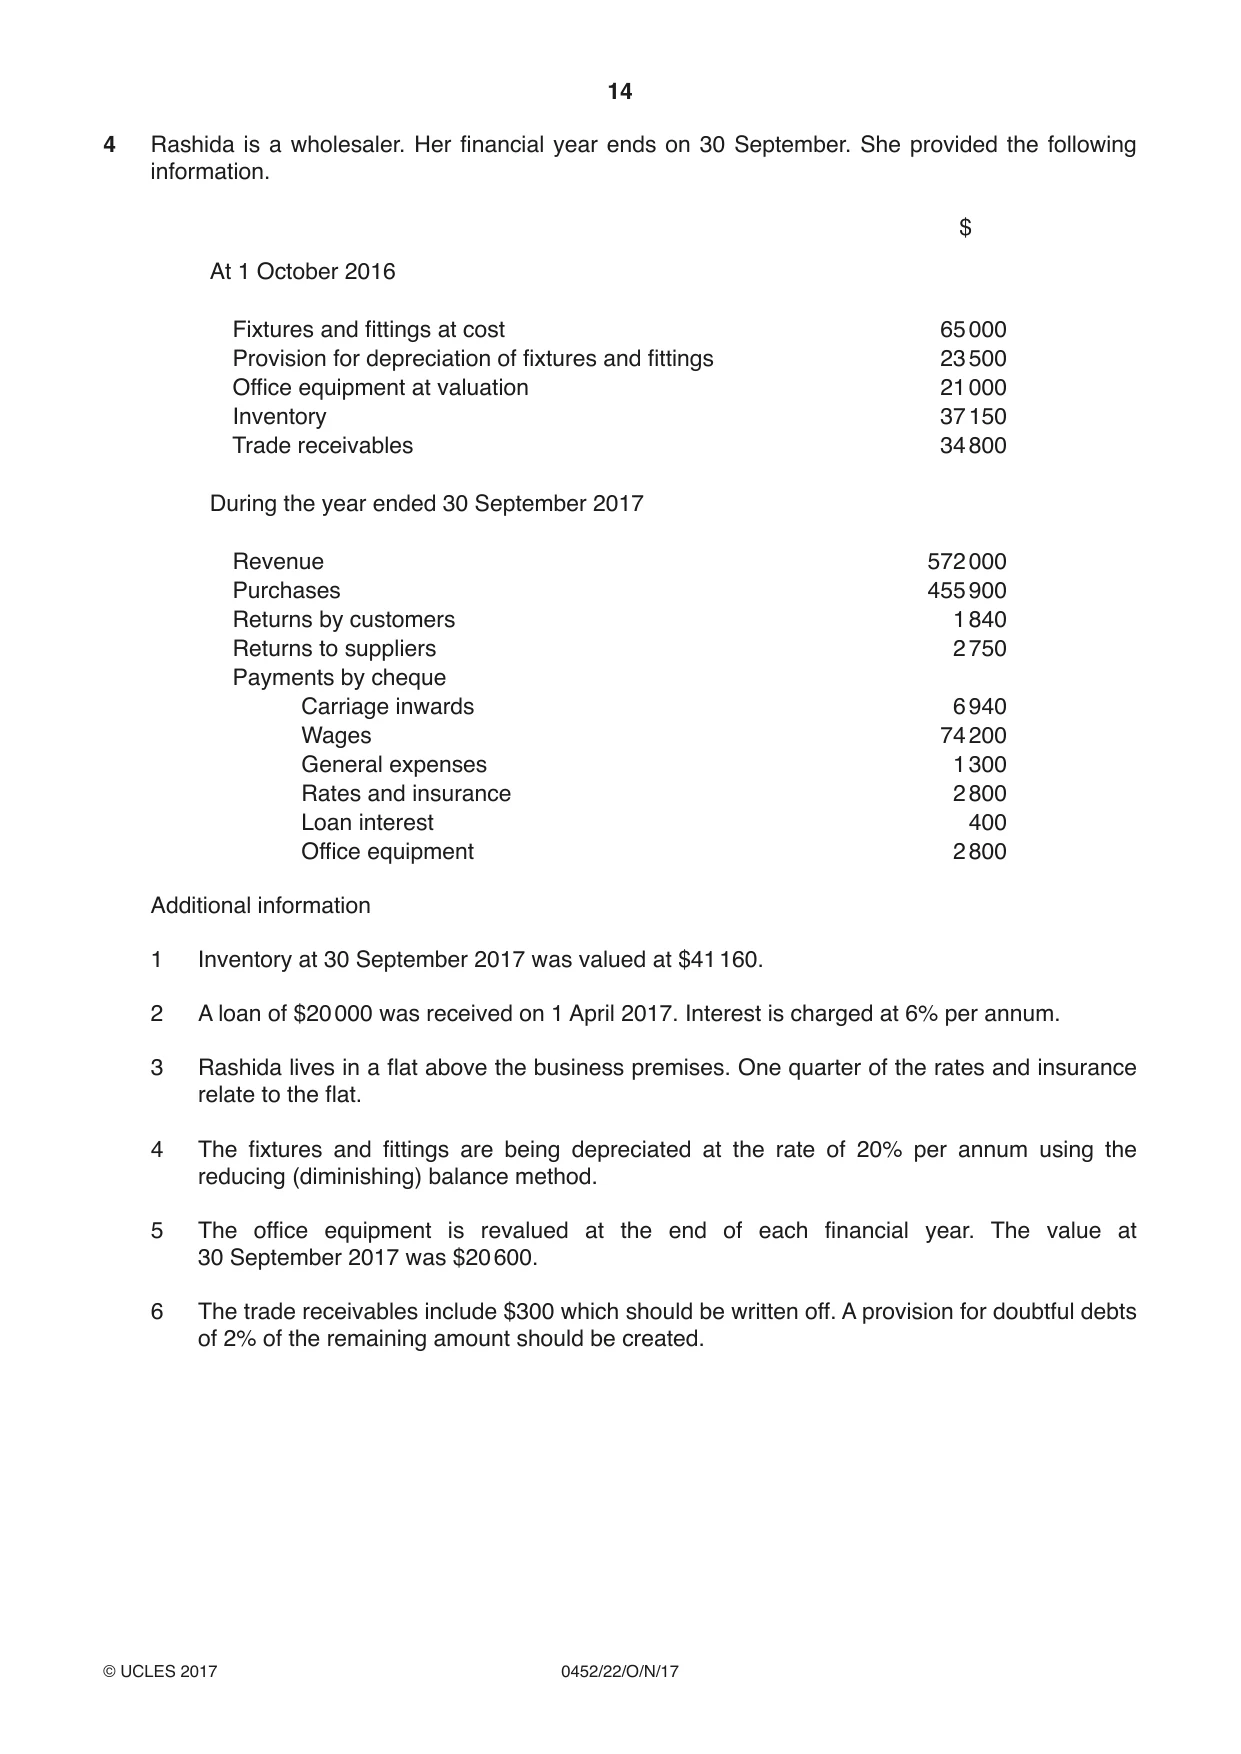
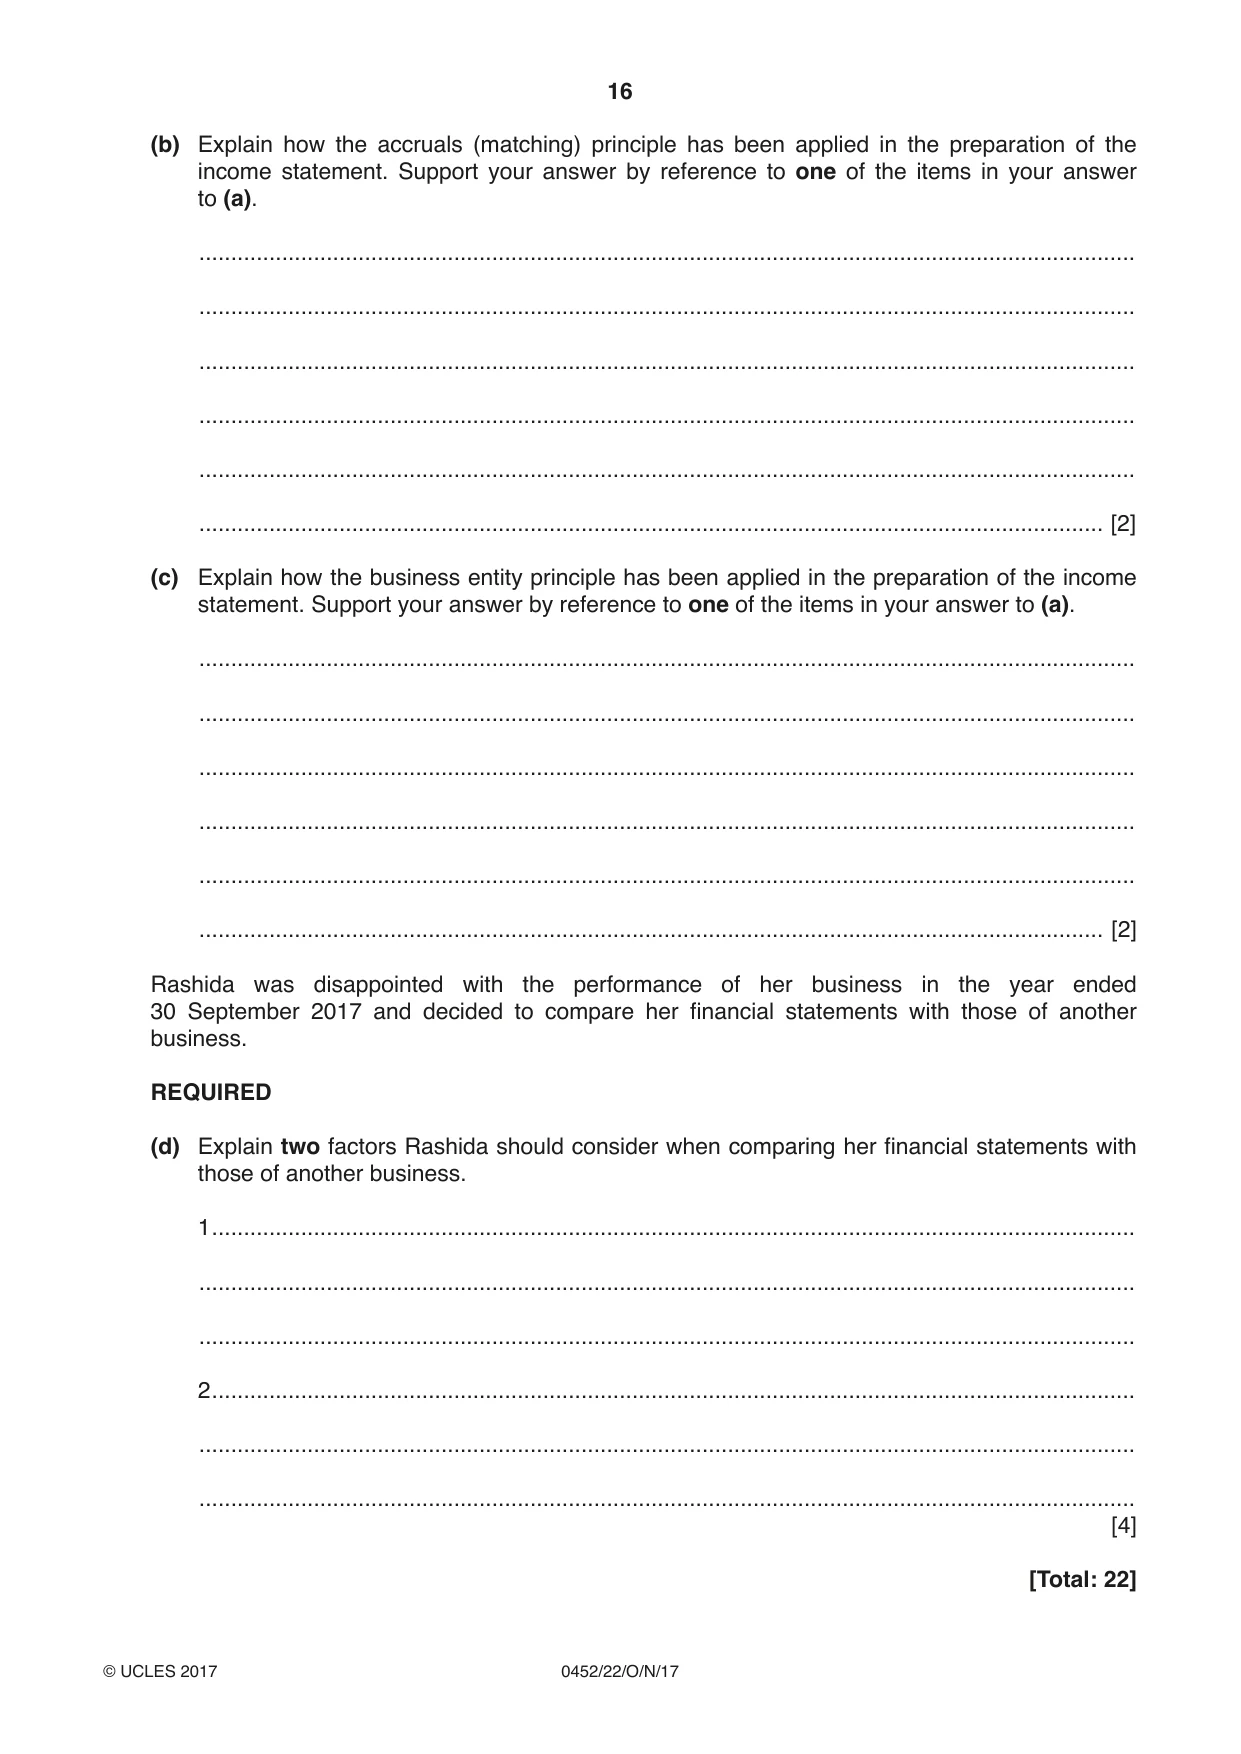
4 Rashida is a wholesaler. Her financial year ends on 30 September. She provided the following information. $ At 1 October 2016 Fixtures and fittings at cost 65 000 Provision for depreciation of fixtures and fittings 23 500 Office equipment at valuation 21 000 Inventory 37 150 Trade receivables 34 800 During the year ended 30 September 2017 Revenue 572 000 Purchases 455 900 Returns by customers 1 840 Returns to suppliers 2 750 Payments by cheque Carriage inwards 6 940 Wages 74 200 General expenses 1 300 Rates and insurance 2 800 Loan interest 400 Office equipment 2 800 Additional information 1 Inventory at 30 September 2017 was valued at $41 160. 2 A loan of $20 000 was received on 1 April 2017. Interest is charged at 6% per annum. 3 Rashida lives in a flat above the business premises. One quarter of the rates and insurance relate to the flat. 4 The fixtures and fittings are being depreciated at the rate of 20% per annum using the reducing (diminishing) balance method. 5 The office equipment is revalued at the end of each financial year. The value at 30 September 2017 was $20 600. 6 The trade receivables include $300 which should be written off. A provision for doubtful debts of 2% of the remaining amount should be created. REQUIRED (a) Prepare the income statement for the year ended 3 Rashida Income Statement for the year ended 3 ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... (b) Explain how the accruals (matching) principle has been applied in the preparation of the income statement. Support your answer by reference to one of the items in your answer to (a). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (c) Explain how the business entity principle has been applied in the preparation of the income statement. Support your answer by reference to one of the items in your answer to (a). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] Rashida was disappointed with the performance of her business in the year ended 30 September 2017 and decided to compare her financial statements with those of another business. REQUIRED (d) Explain two factors Rashida should consider when comparing her financial statements with those of another business. 1 ................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... [4] [Total: 22]
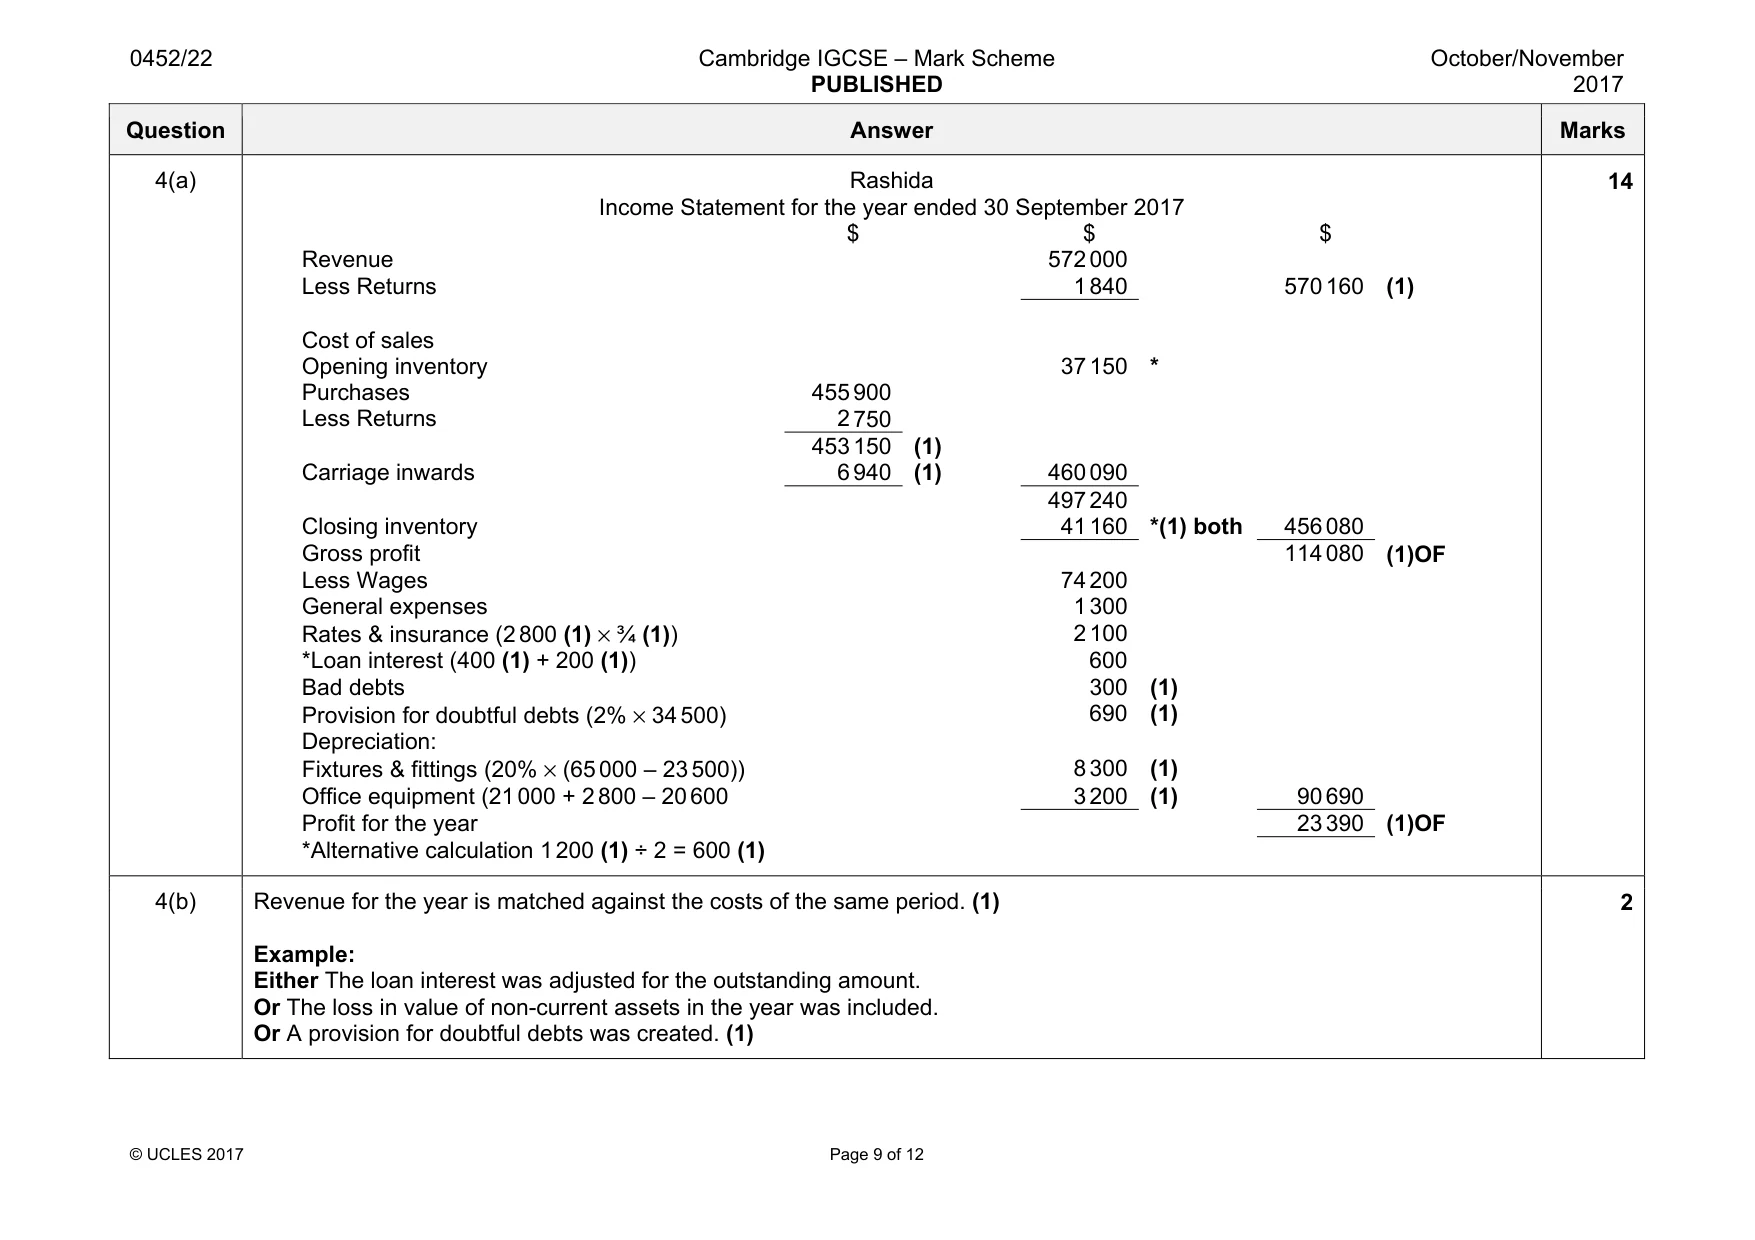
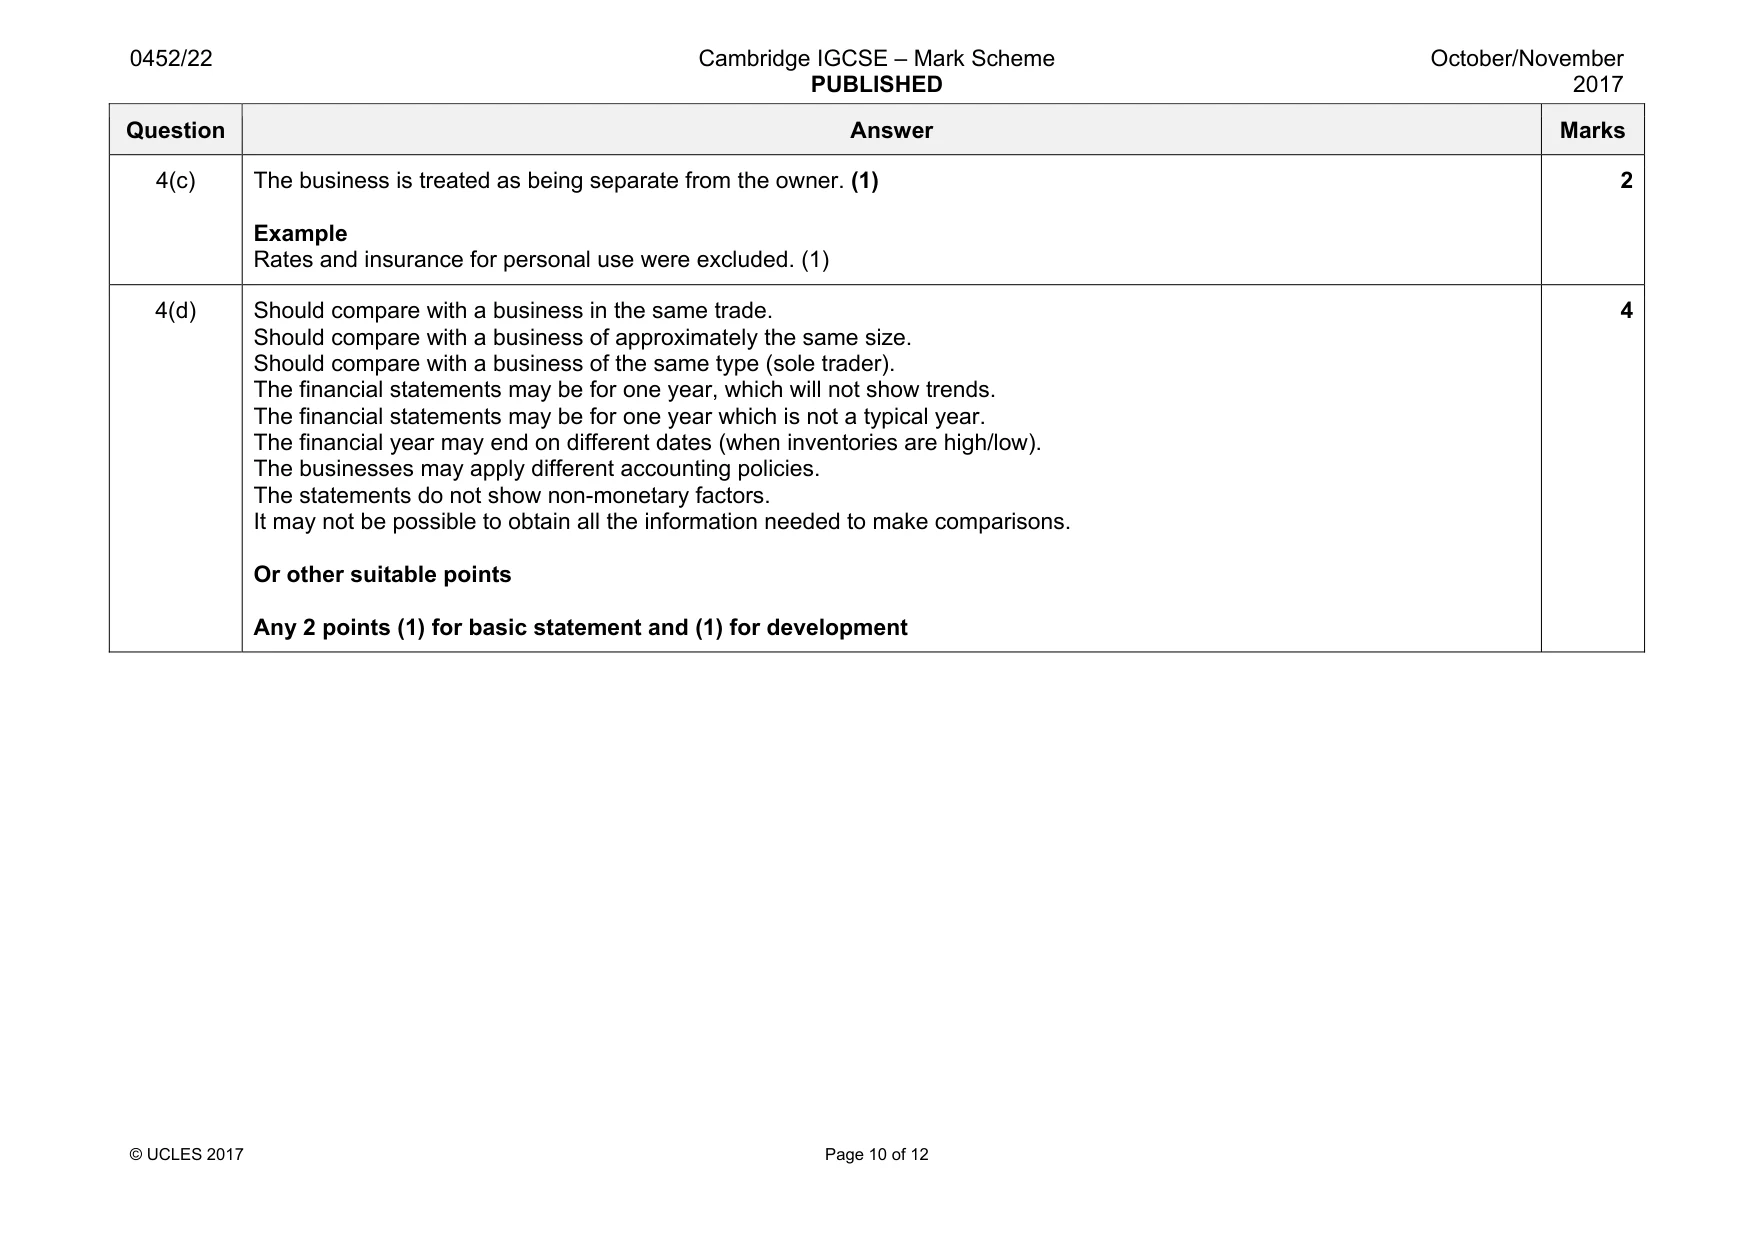
Mark scheme: 4(a) Rashida Income Statement for the year ended 30 September 2017 $ $ $ Revenue 572 000 Less Returns 1 840 570 160 (1) Cost of sales Opening inventory 37 150 * Purchases 455 900 Less Returns 2 750 453 150 (1) Carriage inwards 6 940 (1) 460 090 497 240 Closing inventory 41 160 *(1) both 456 080 Gross profit 114 080 (1)OF Less Wages 74 200 General expenses 1 300 Rates & insurance (2 800 (1) × ¾ (1)) 2 100 *Loan interest (400 (1) + 200 (1)) 600 Bad debts 300 (1) Provision for doubtful debts (2% × 34 500) 690 (1) Depreciation: Fixtures & fittings (20% × (65 000 – 23 500)) 8 300 (1) Office equipment (21 000 + 2 800 – 20 600 3 200 (1) 90 690 Profit for the year 23 390 (1)OF *Alternative calculation 1 200 (1) ÷ 2 = 600 (1) 14 4(b) Revenue for the year is matched against the costs of the same period. (1) Example: Either The loan interest was adjusted for the outstanding amount. Or The loss in value of non-current assets in the year was included. Or A provision for doubtful debts was created. (1) 2 Question Answer Marks 4(c) The business is treated as being separate from the owner. (1) Example Rates and insurance for personal use were excluded. (1) 2 4(d) Should compare with a business in the same trade. Should compare with a business of approximately the same size. Should compare with a business of the same type (sole trader). The financial statements may be for one year, which will not show trends. The financial statements may be for one year which is not a typical year. The financial year may end on different dates (when inventories are high/low). The businesses may apply different accounting policies. The statements do not show non-monetary factors. It may not be possible to obtain all the information needed to make comparisons. Or other suitable points Any 2 points (1) for basic statement and (1) for development 4
Q5 · Ben opened a retail store on 1 April 2017
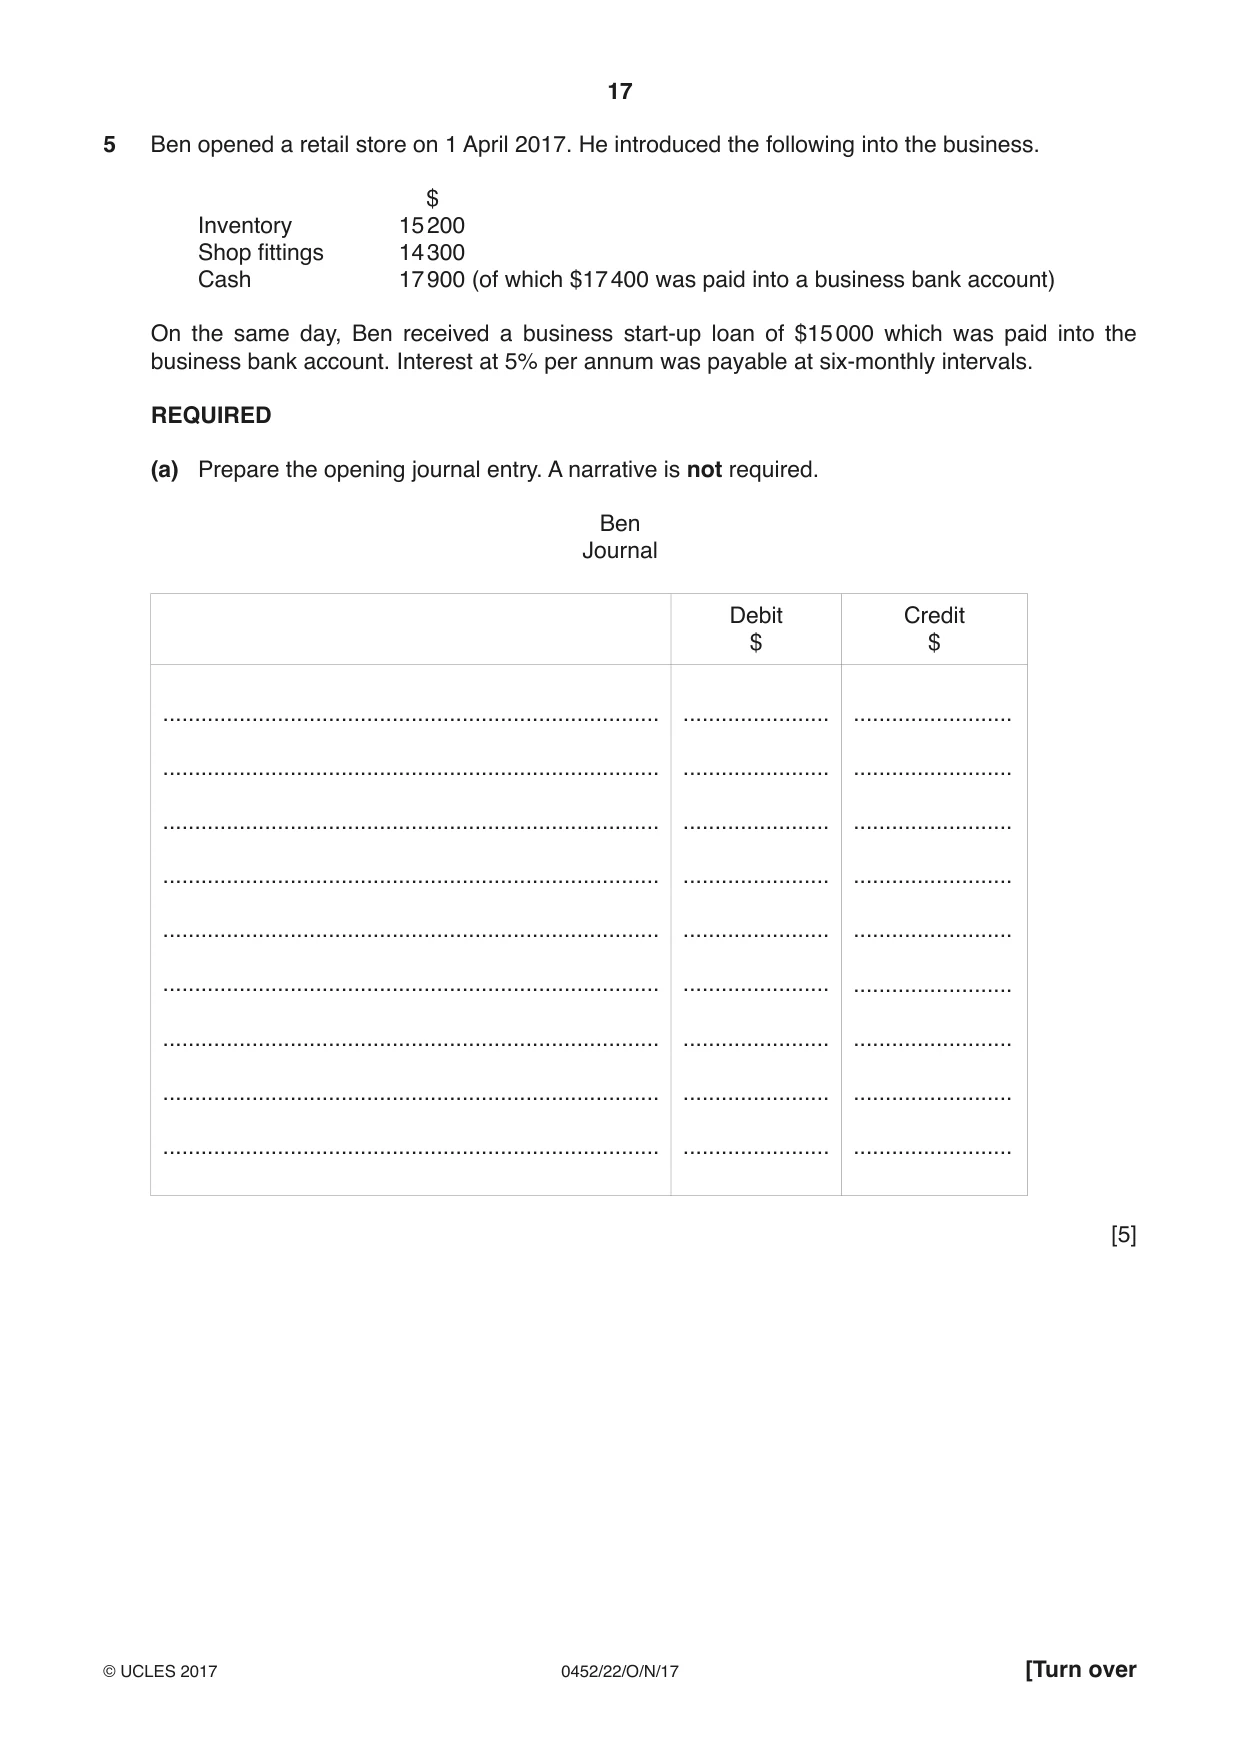
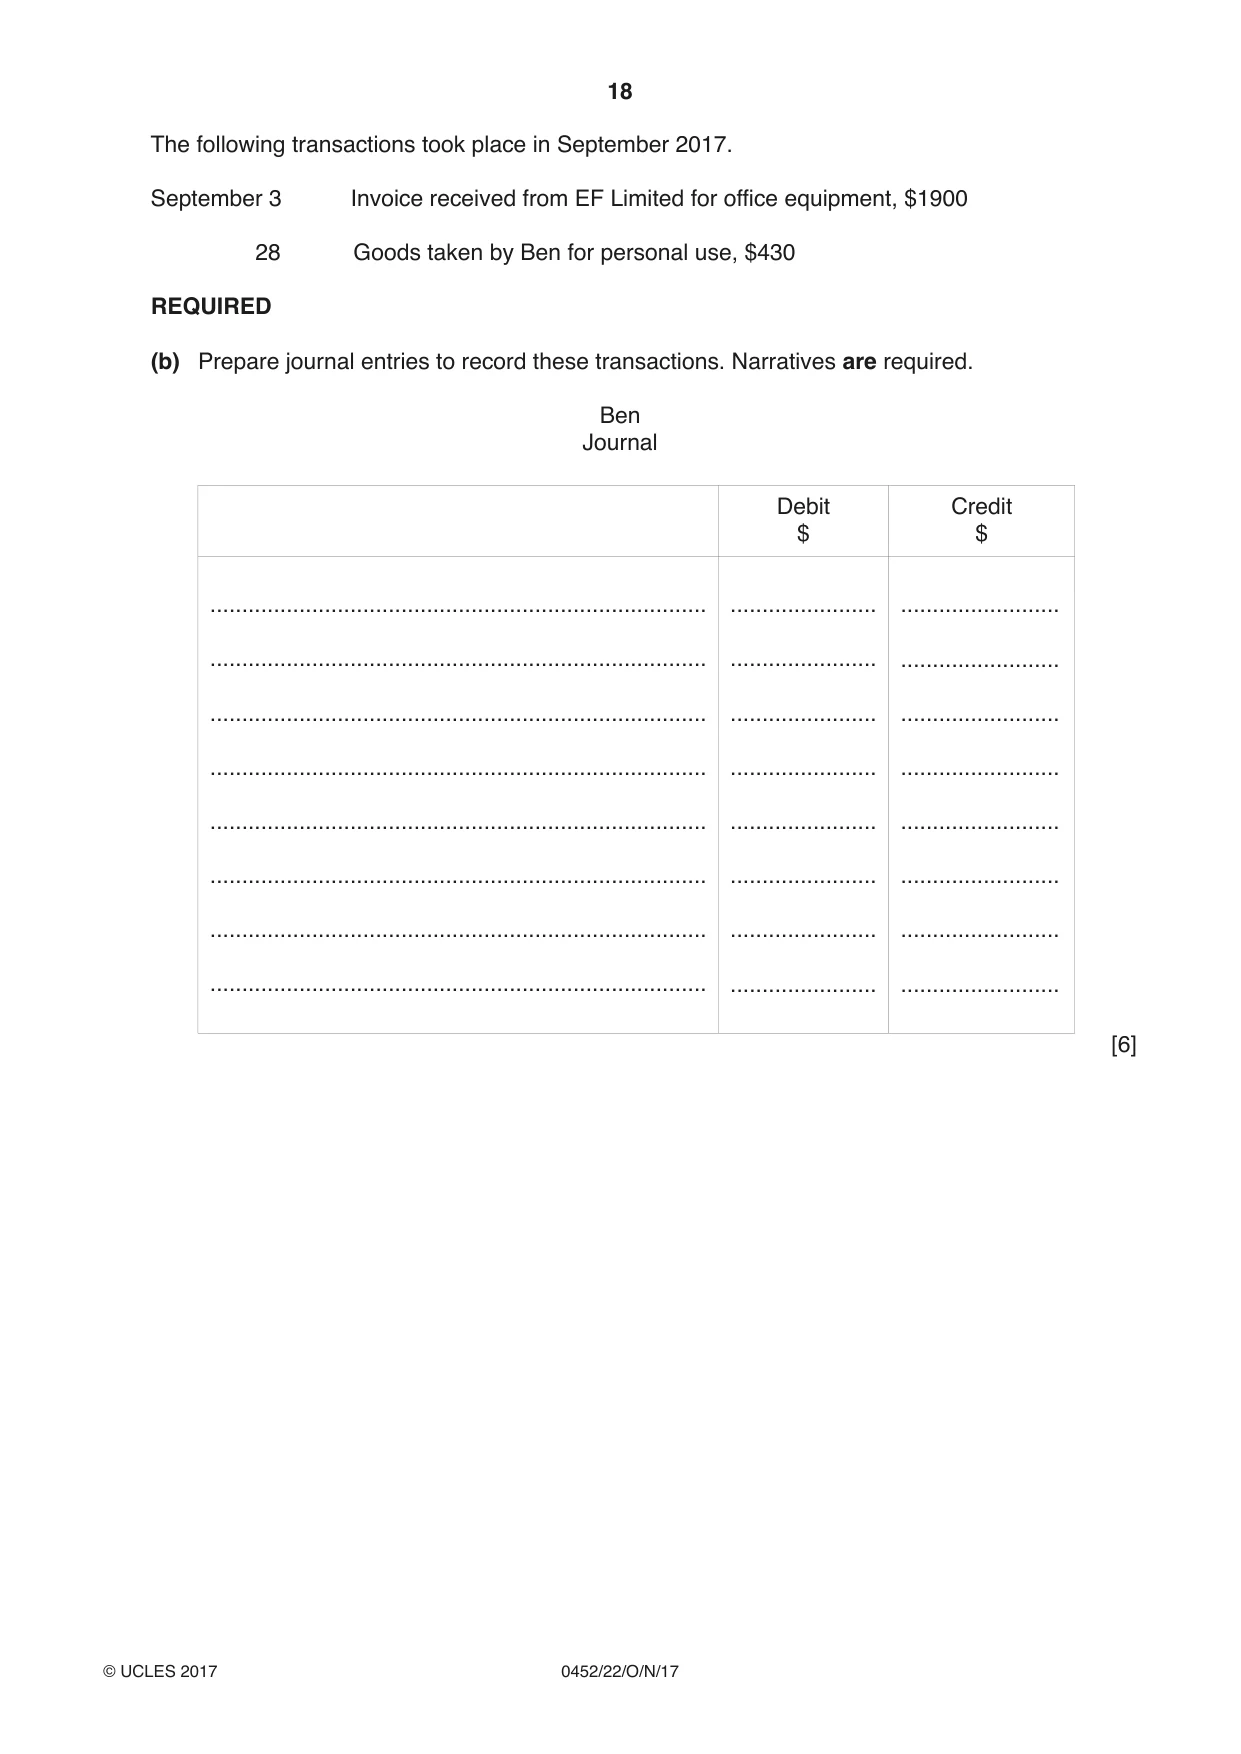
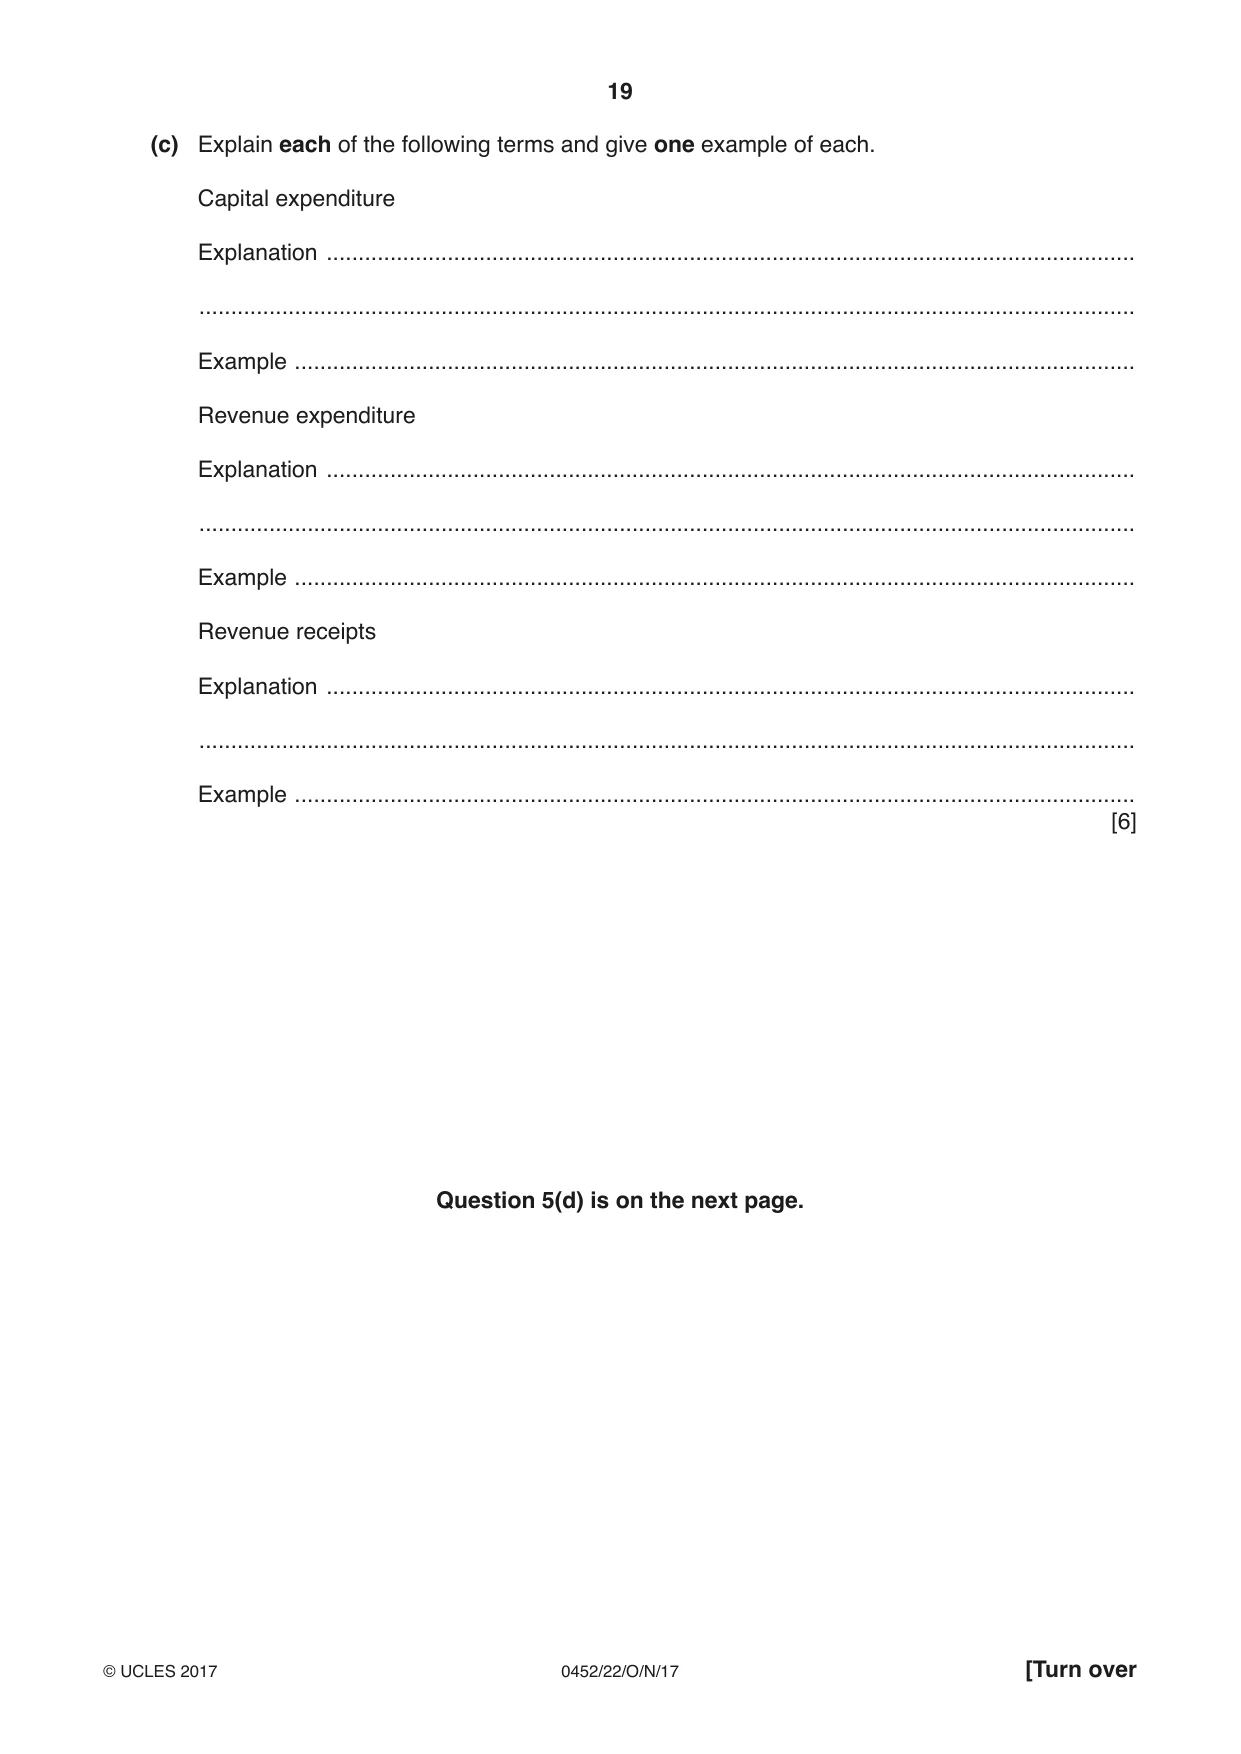
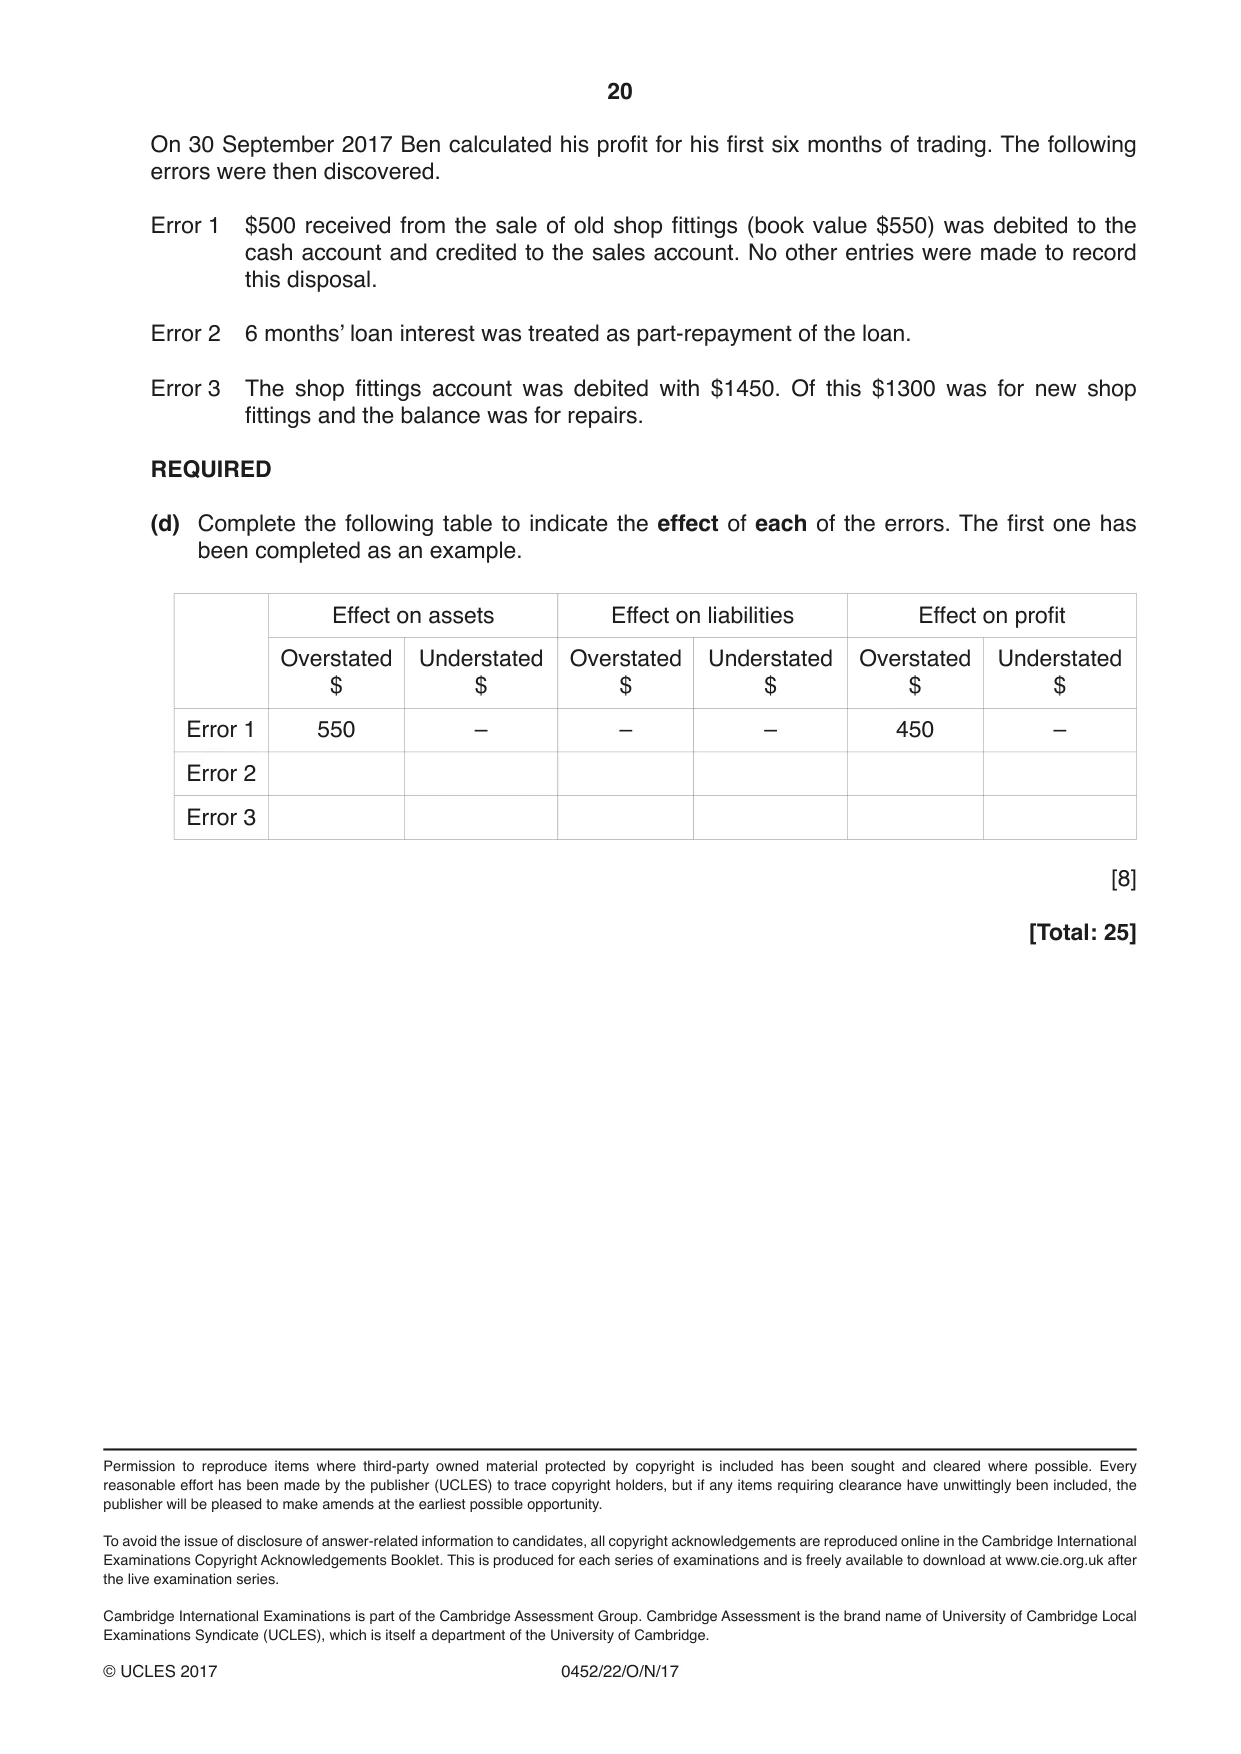
5 Ben opened a retail store on 1 April 2017. He introduced the following into the business. $ Inventory 15 200 Shop fittings 14 300 Cash 17 900 (of which $17 400 was paid into a business bank account) On the same day, Ben received a business start-up loan of $15 000 which was paid into the business bank account. Interest at 5% per annum was payable at six-monthly intervals. REQUIRED (a) Prepare the opening journal entry. A narrative is not required. Ben Journal Debit Credit $ $ .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... [5] The following transactions took place in September 2017. September 3 Invoice received from EF Limited for office equipment, $1900 28 Goods taken by Ben for personal use, $430 REQUIRED (b) Prepare journal entries to record these transactions. Narratives are required. Ben Journal Debit Credit $ $ .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... .............................................................................. ....................... ......................... [6] (c) Explain each of the following terms and give one example of each. Capital expenditure Explanation ............................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... Revenue expenditure Explanation ............................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... Revenue receipts Explanation ............................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... [6] Question 5(d) is on the next page.
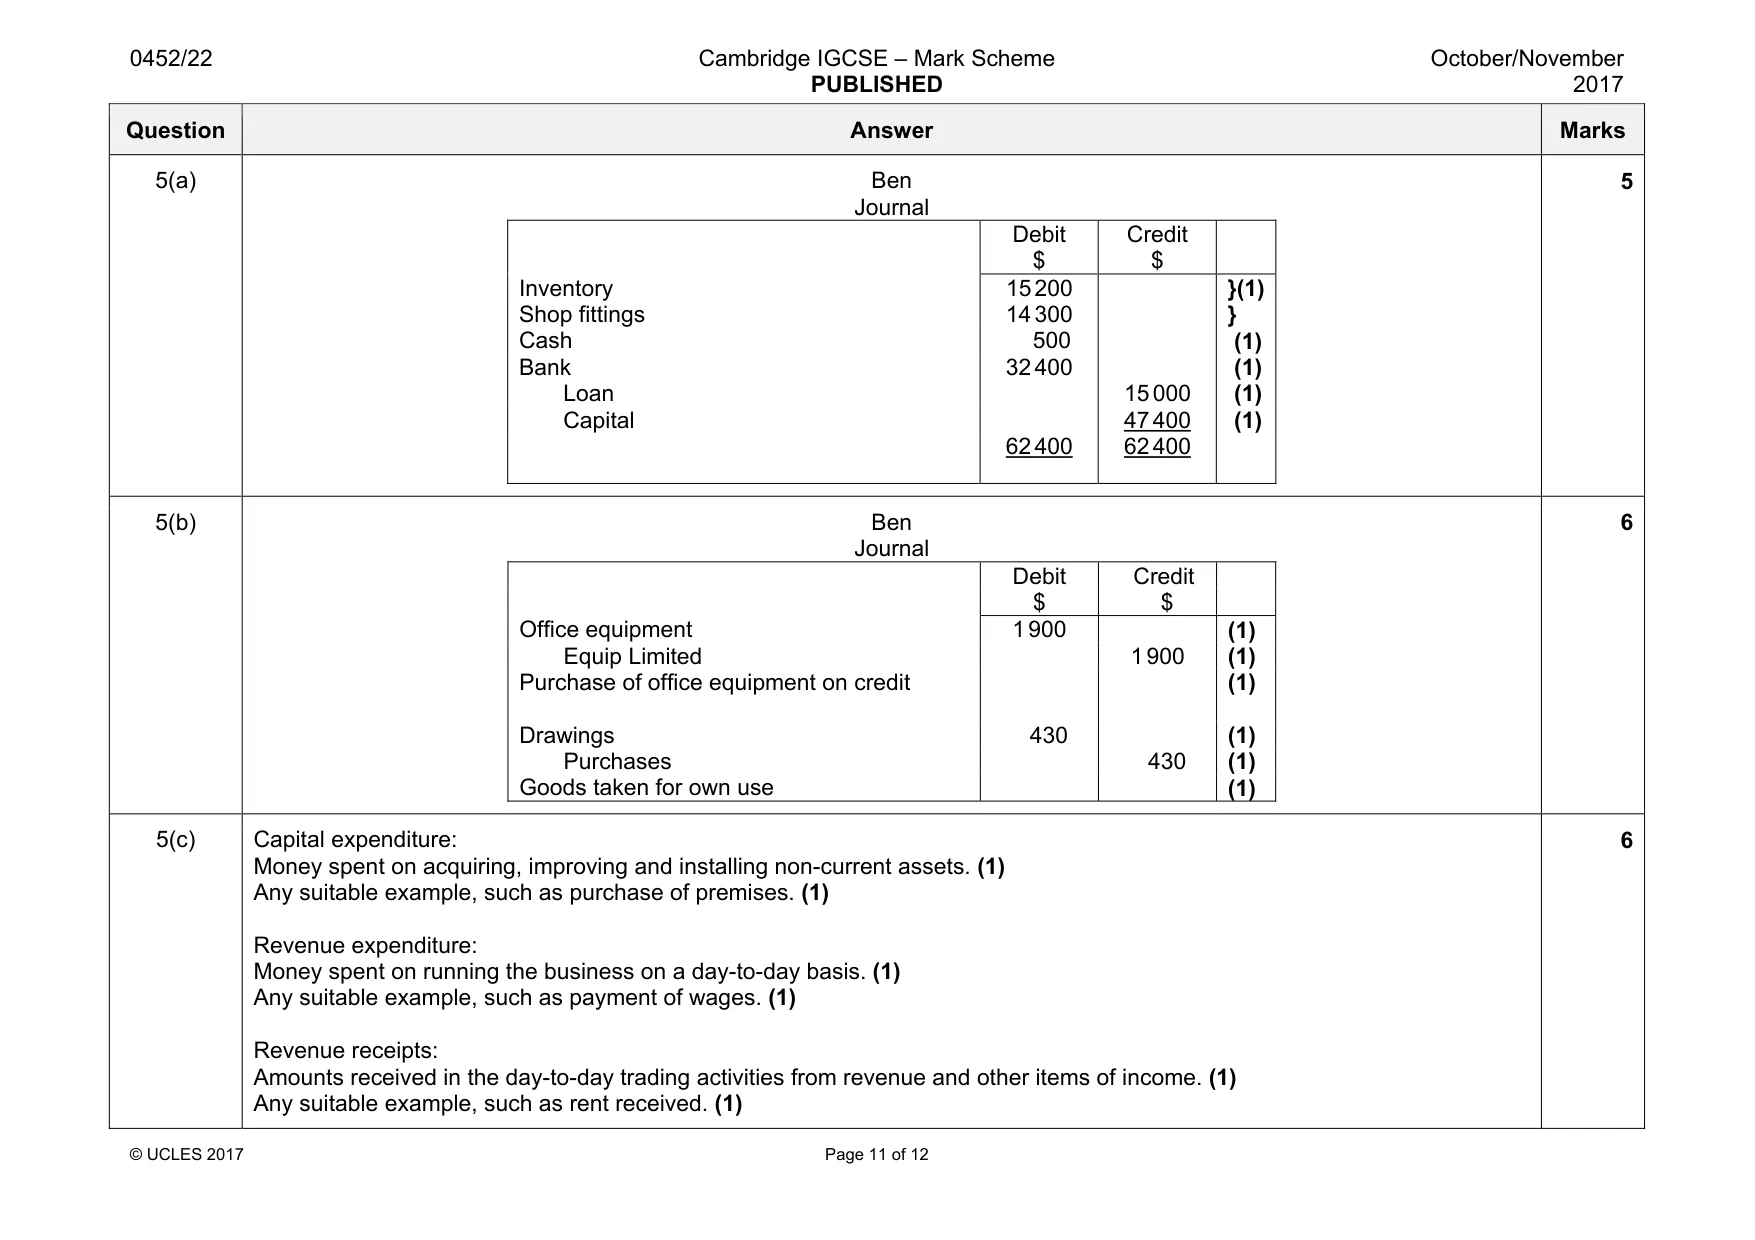
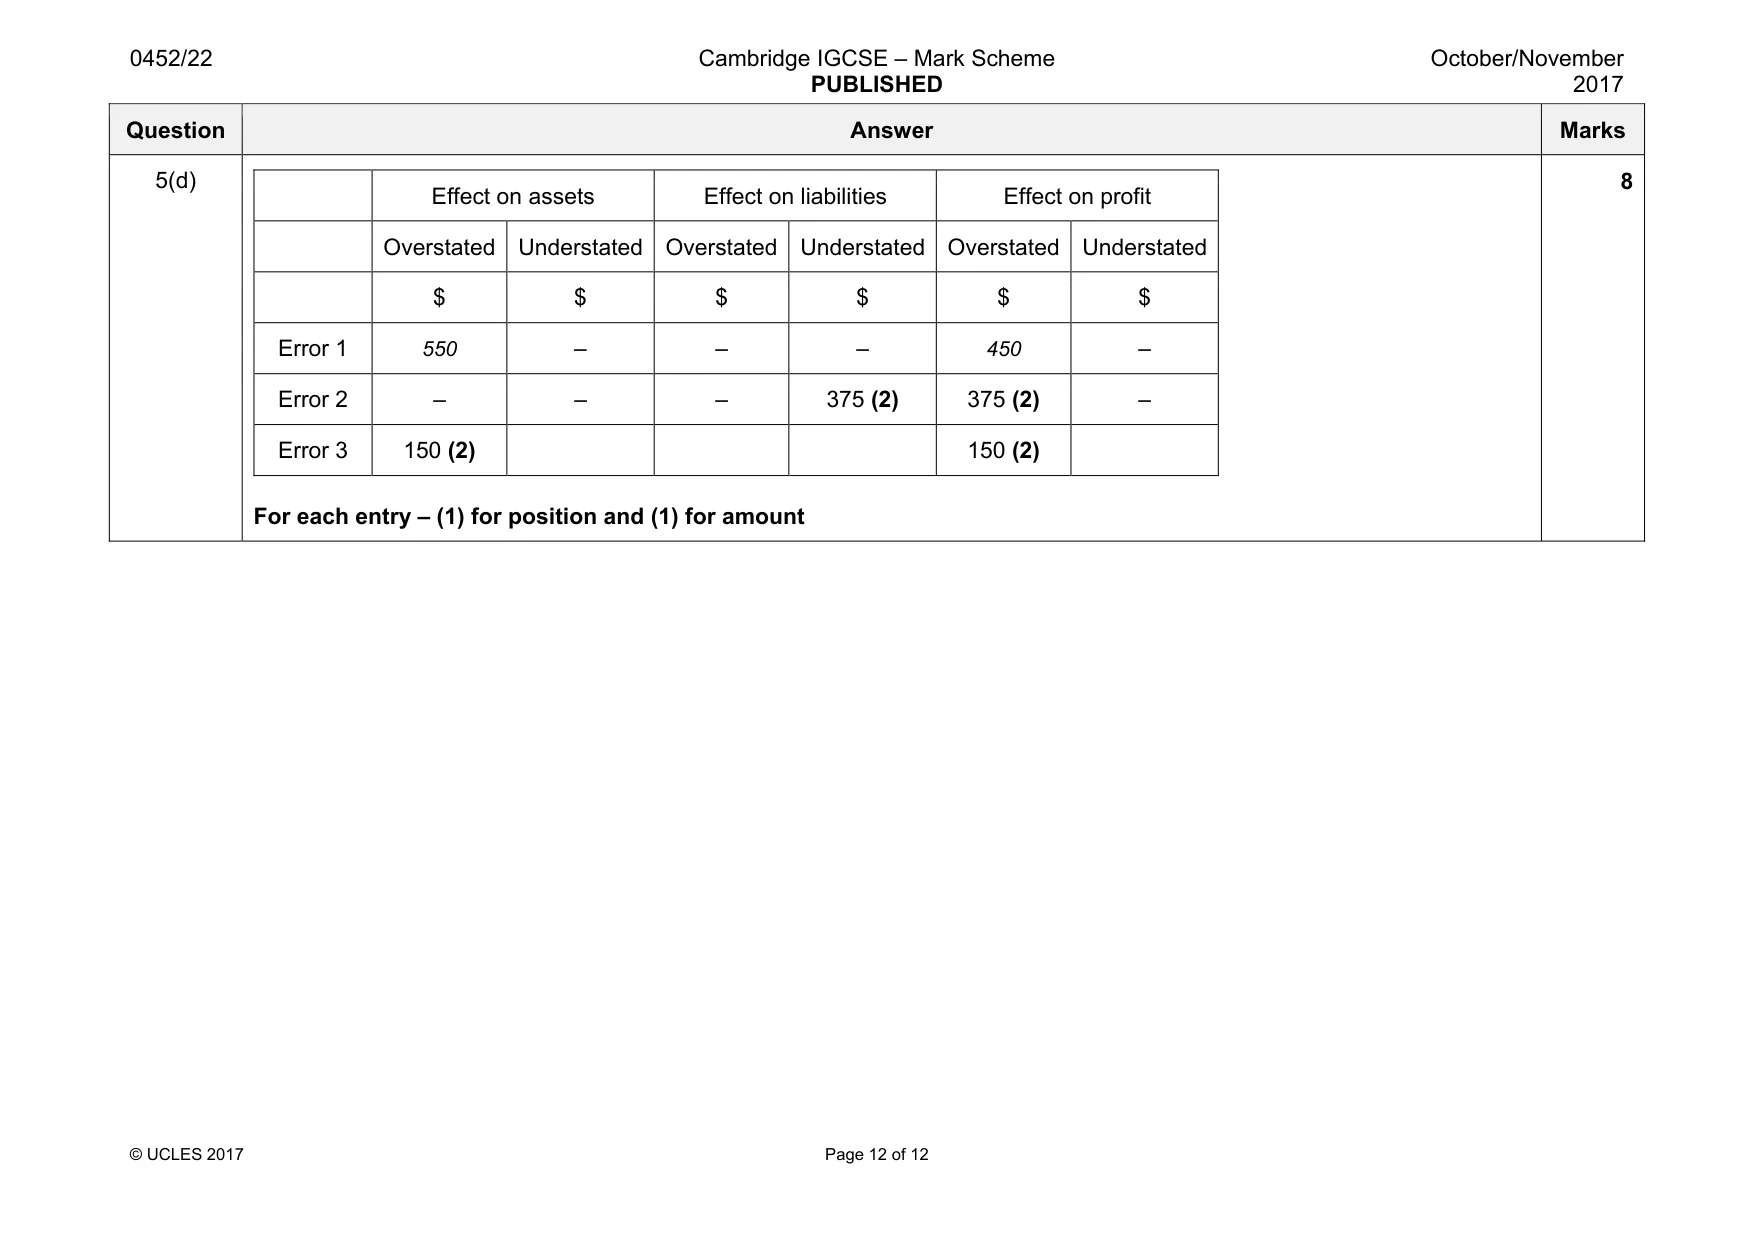
Mark scheme: 5(a) Ben Journal Debit Credit $ $ Inventory 15 200 }(1) Shop fittings 14 300 } Cash 500 (1) Bank 32 400 (1) Loan 15 000 (1) Capital 47 400 (1) 62 400 62 400 5 5(b) Ben Journal Debit Credit $ $ Office equipment 1 900 (1) Equip Limited 1 900 (1) Purchase of office equipment on credit (1) Drawings 430 (1) Purchases 430 (1) Goods taken for own use (1) 6 5(c) Capital expenditure: Money spent on acquiring, improving and installing non-current assets. (1) Any suitable example, such as purchase of premises. (1) Revenue expenditure: Money spent on running the business on a day-to-day basis. (1) Any suitable example, such as payment of wages. (1) Revenue receipts: Amounts received in the day-to-day trading activities from revenue and other items of income. (1) Any suitable example, such as rent received. (1) 6 Question Answer Marks 5(d) Effect on assets Effect on liabilities Effect on profit Overstated Understated Overstated Understated Overstated Understated $ $ $ $ $ $ Error 1 550 – – – 450 – Error 2 – – – 375 (2) 375 (2) – Error 3 150 (2) 150 (2) For each entry – (1) for position and (1) for amount 8
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2017 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.