Cambridge IGCSE Accounting 0452 — 2017 Oct/Nov Paper 2 · Variant 1
0452/21/O/N/17 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Zodwa is a trader
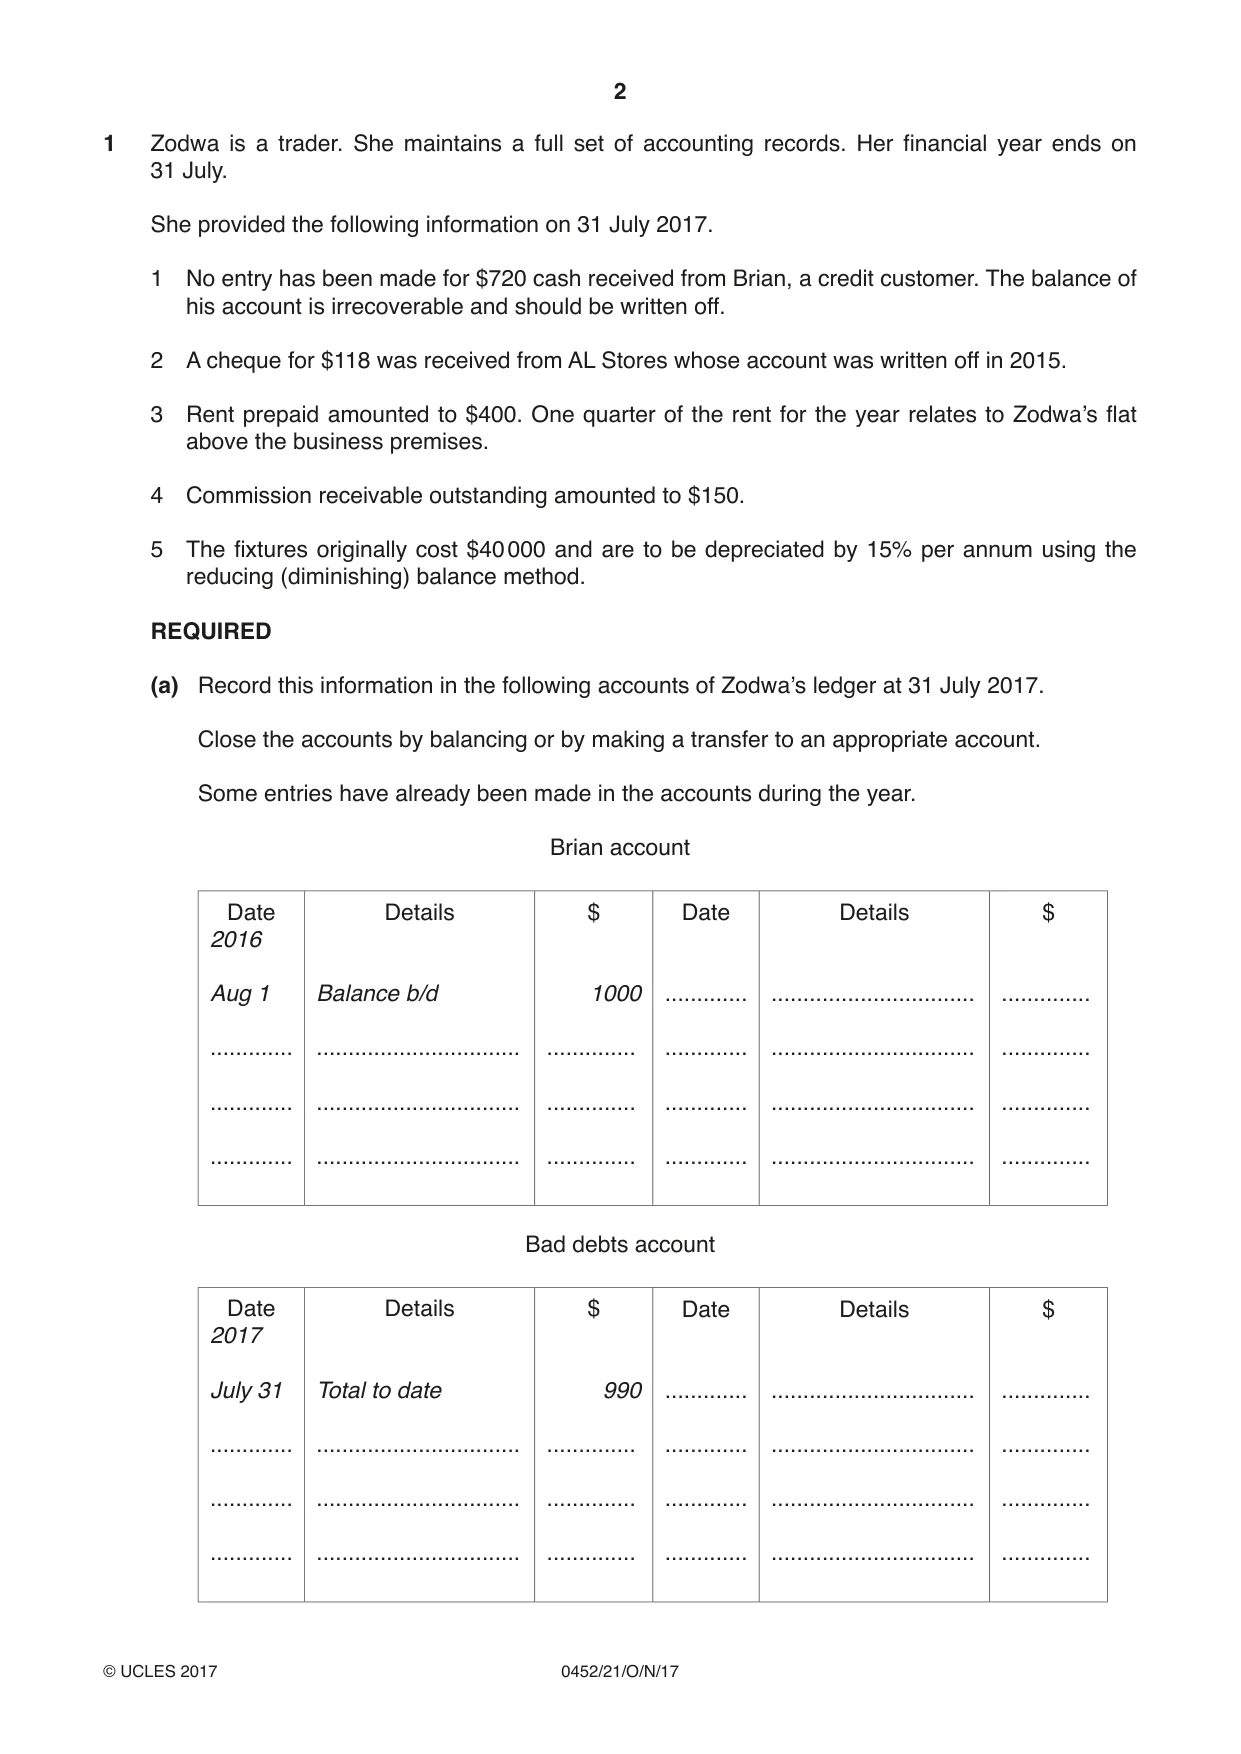
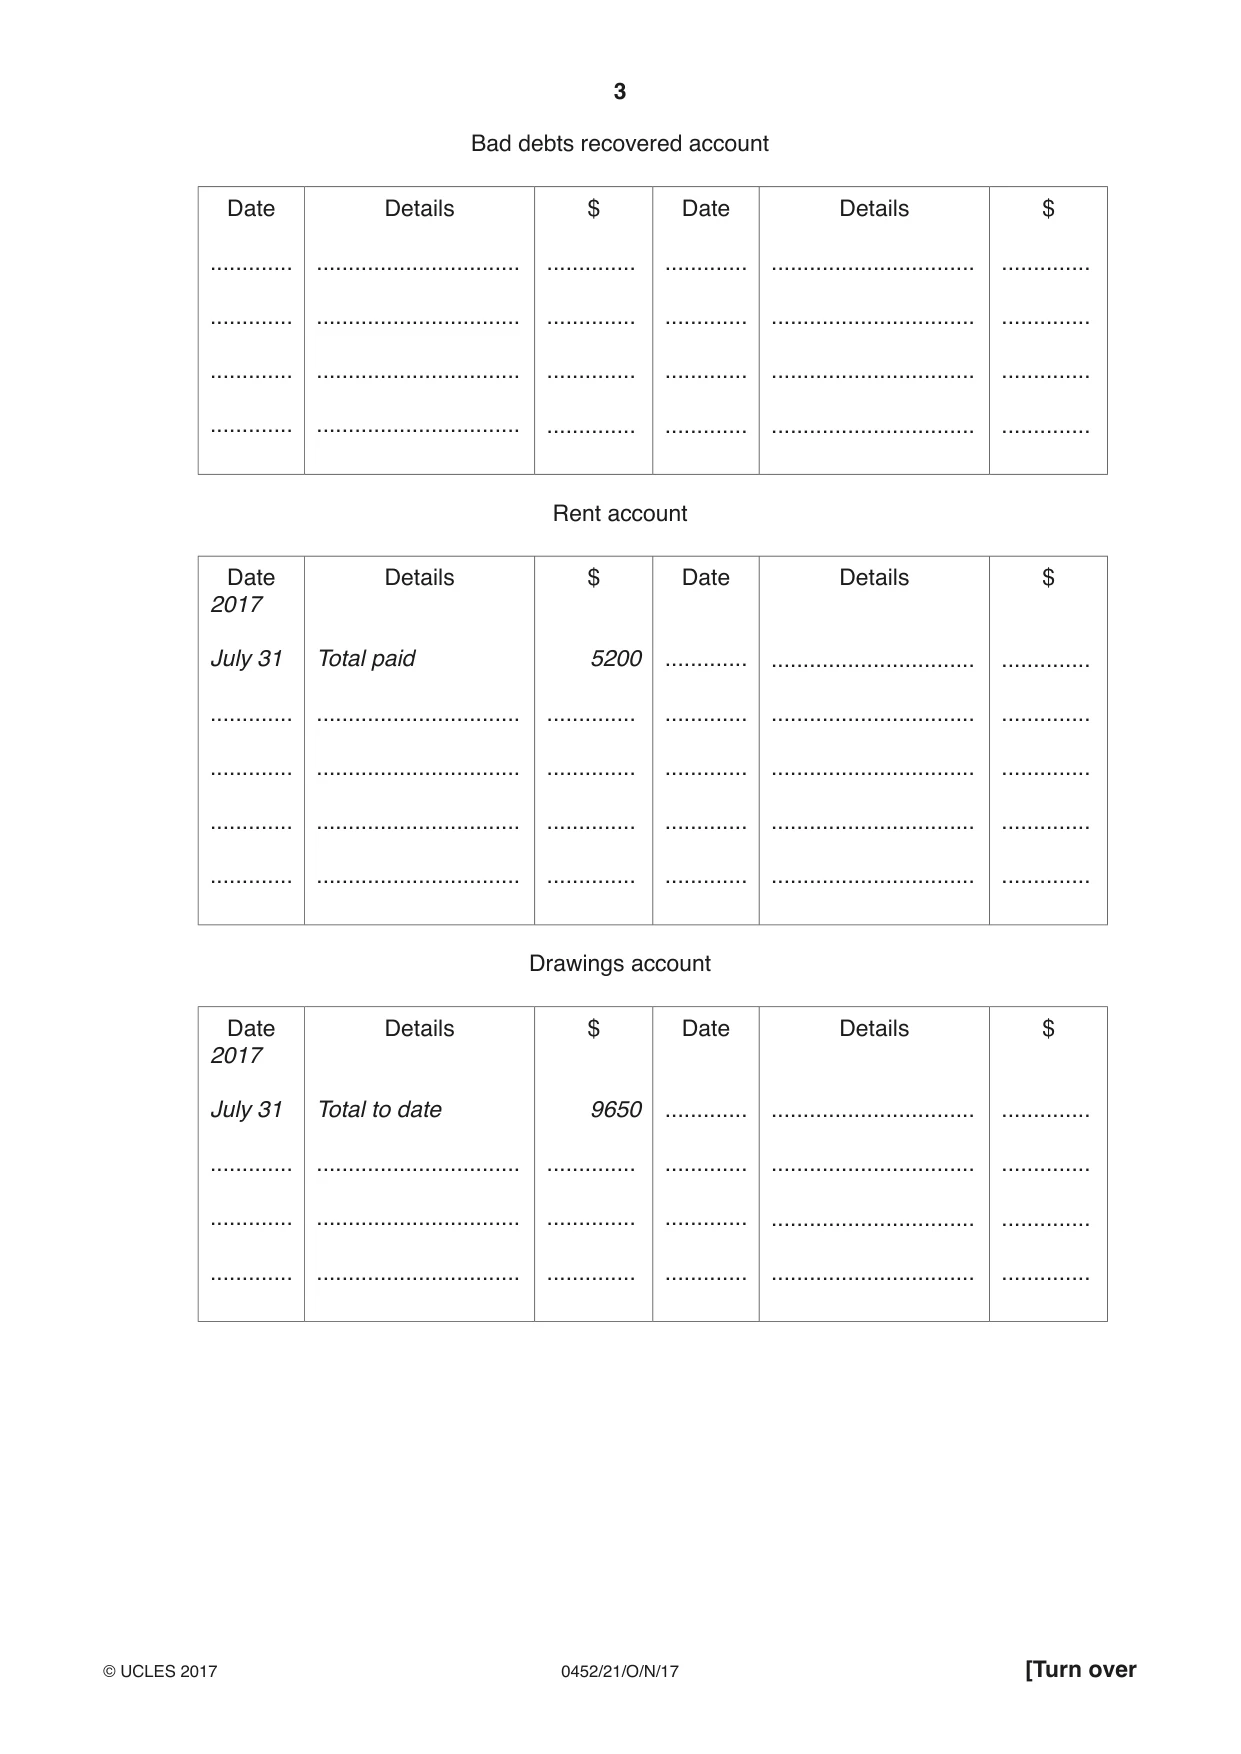
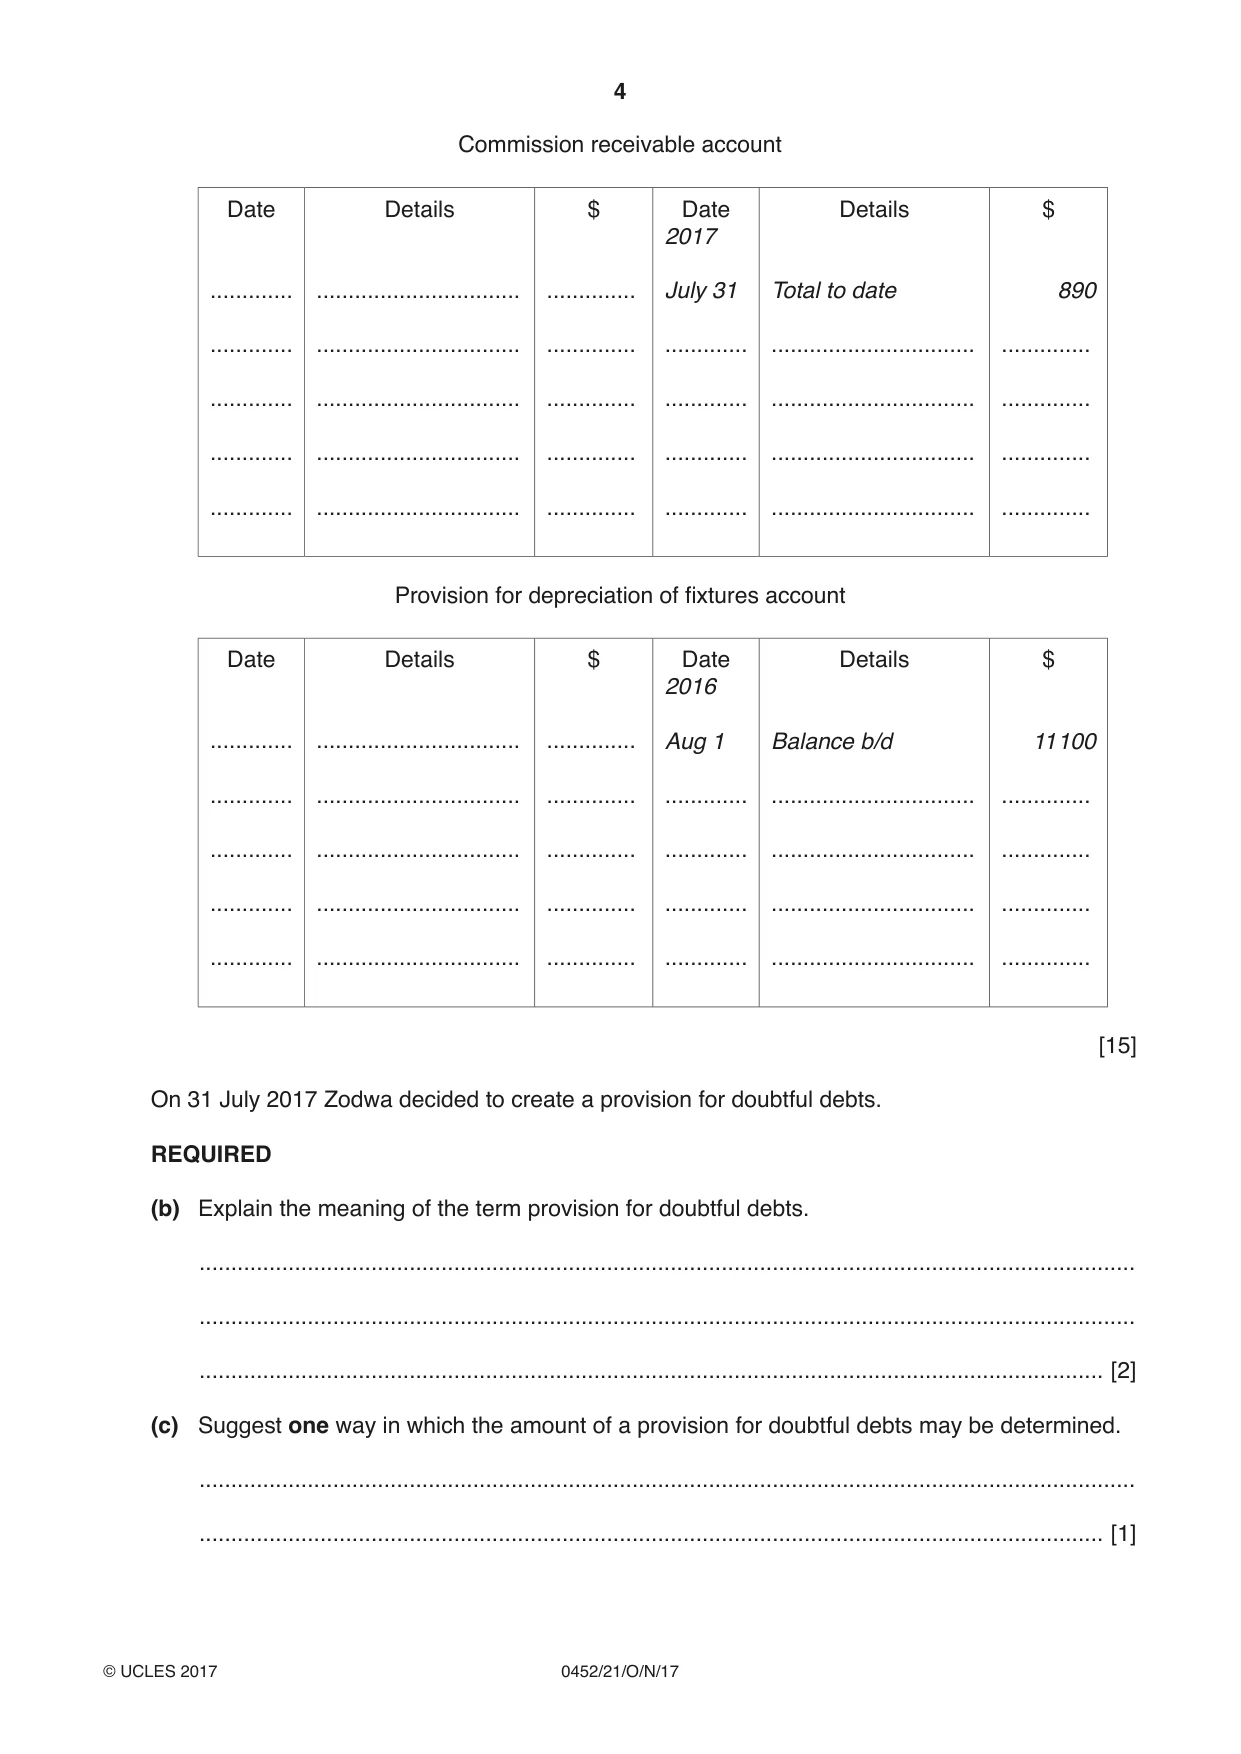
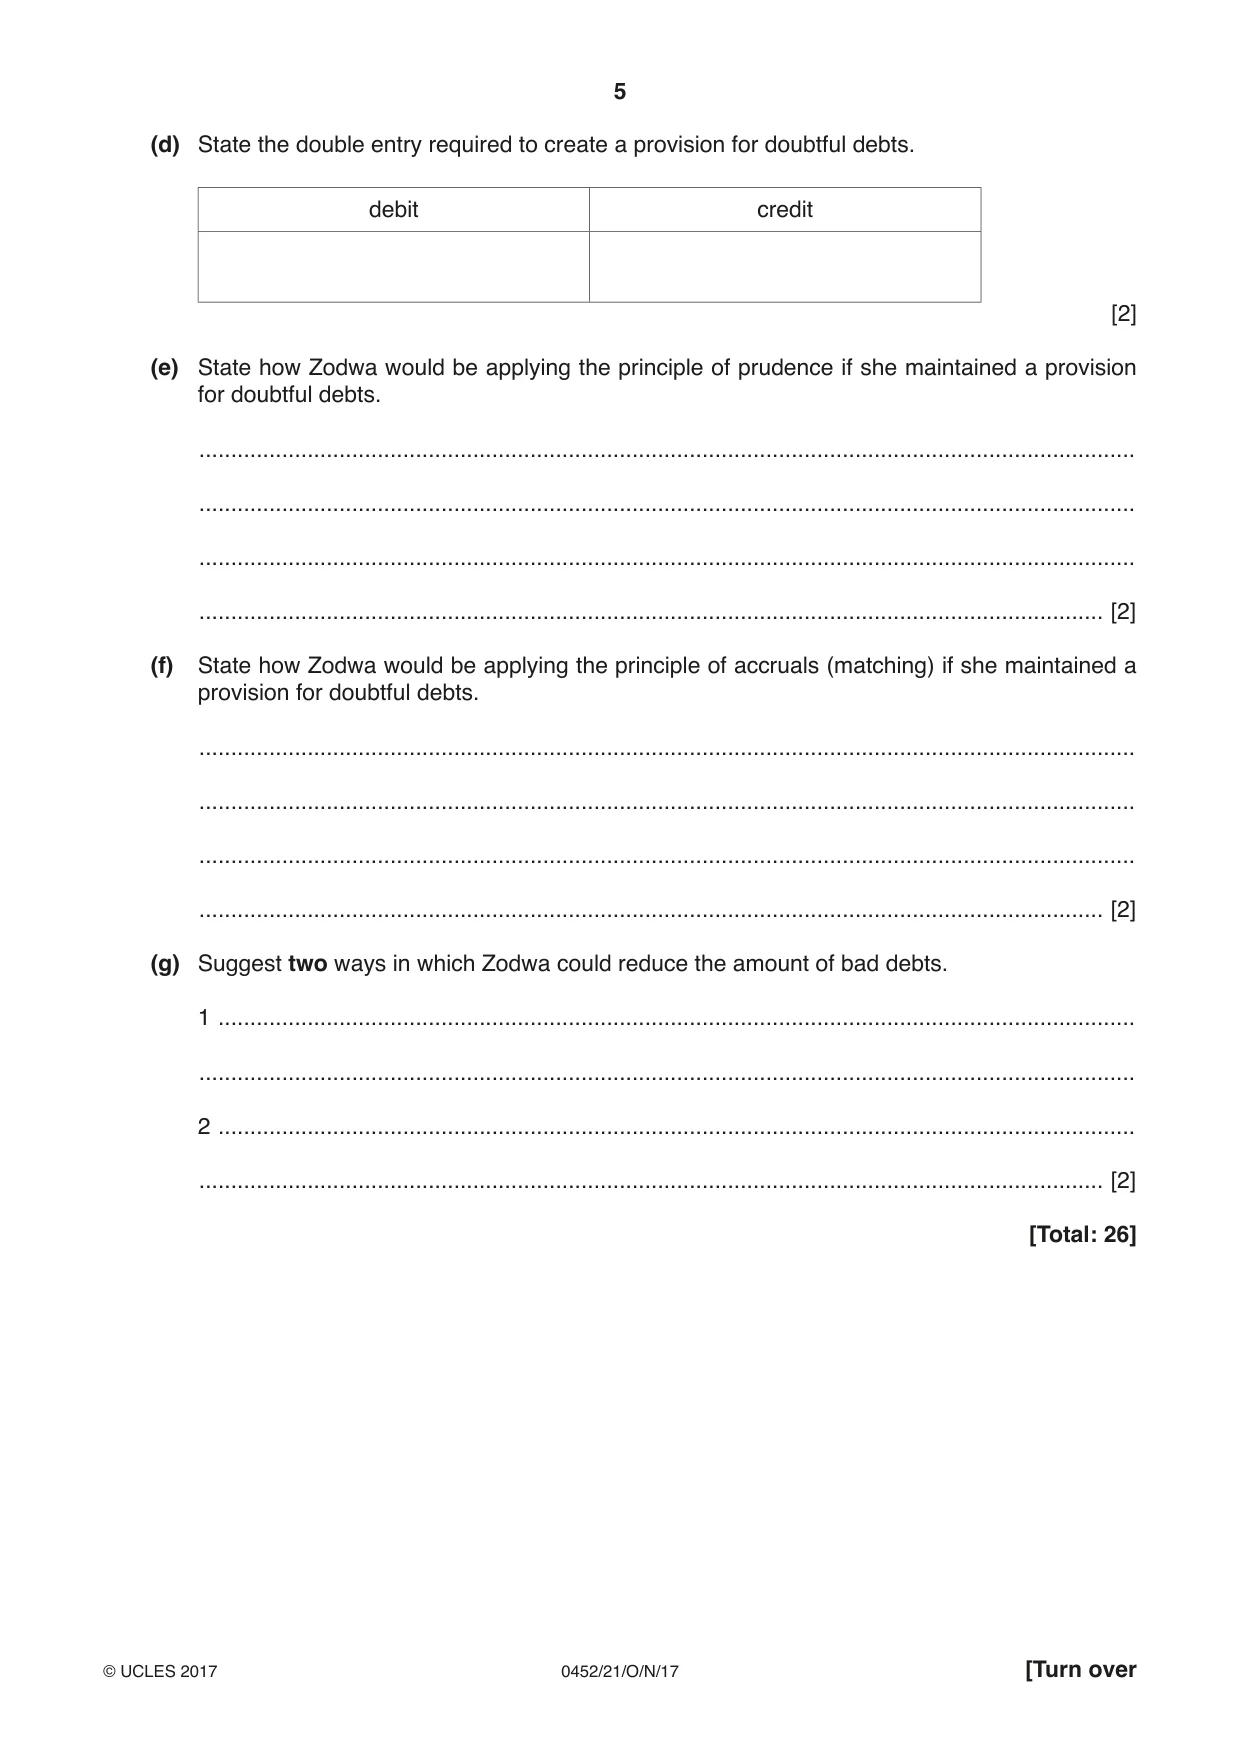
1 Zodwa is a trader. She maintains a full set of accounting records. Her financial year ends on 31 July. She provided the following information on 31 July 2017. 1 No entry has been made for $720 cash received from Brian, a credit customer. The balance of his account is irrecoverable and should be written off. 2 A cheque for $118 was received from AL Stores whose account was written off in 2015. 3 Rent prepaid amounted to $400. One quarter of the rent for the year relates to Zodwa’s flat above the business premises. 4 Commission receivable outstanding amounted to $150. 5 The fixtures originally cost $40 000 and are to be depreciated by 15% per annum using the reducing (diminishing) balance method. REQUIRED (a) Record this information in the following accounts of Zodwa’s ledger at 31 July 2017. Close the accounts by balancing or by making a transfer to an appropriate account. Some entries have already been made in the accounts during the year. Brian account Date Details $ Date Details $ 2016 Aug 1 Balance b/d 1000 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Bad debts account Date Details $ Date Details $ 2017 July 31 Total to date 990 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Bad debts recovered account Date Details $ Date Details $ ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Rent account Date Details $ Date Details $ 2017 July 31 Total paid 5200 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Drawings account Date Details $ Date Details $ 2017 July 31 Total to date 9650 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Commission receivable account Date Details $ Date Details $ 2017 ............. ................................ .............. July 31 Total to date 890 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. Provision for depreciation of fixtures account Date Details $ Date Details $ 2016 ............. ................................ .............. Aug 1 Balance b/d 11 100 ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. ............. ................................ .............. [15] On 31 July 2017 Zodwa decided to create a provision for doubtful debts. REQUIRED (b) Explain the meaning of the term provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (c) Suggest one way in which the amount of a provision for doubtful debts may be determined. ................................................................................................................................................... .............................................................................................................................................. [1] (d) State the double entry required to create a provision for doubtful debts. debit credit [2] (e) State how Zodwa would be applying the principle of prudence if she maintained a provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (f) State how Zodwa would be applying the principle of accruals (matching) if she maintained a provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (g) Suggest two ways in which Zodwa could reduce the amount of bad debts. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] [Total: 26]
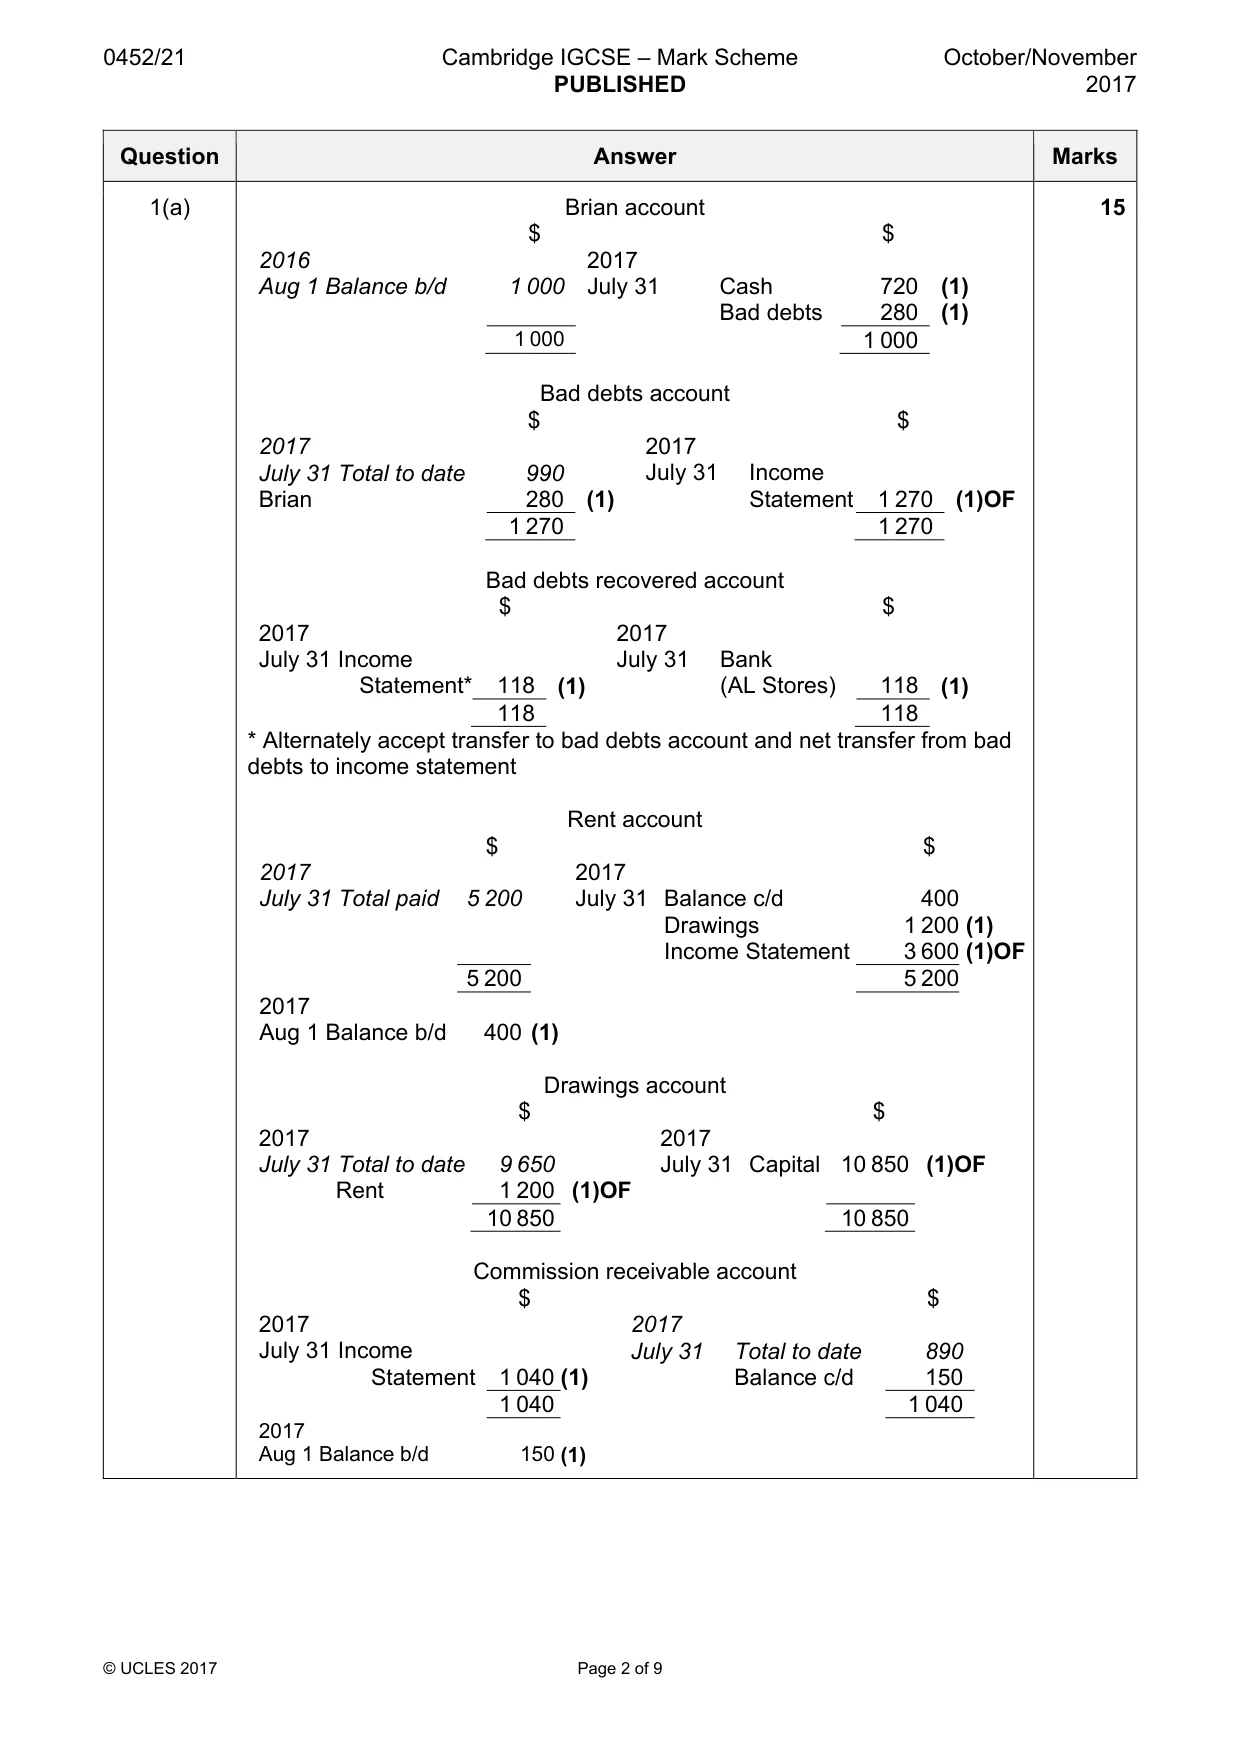
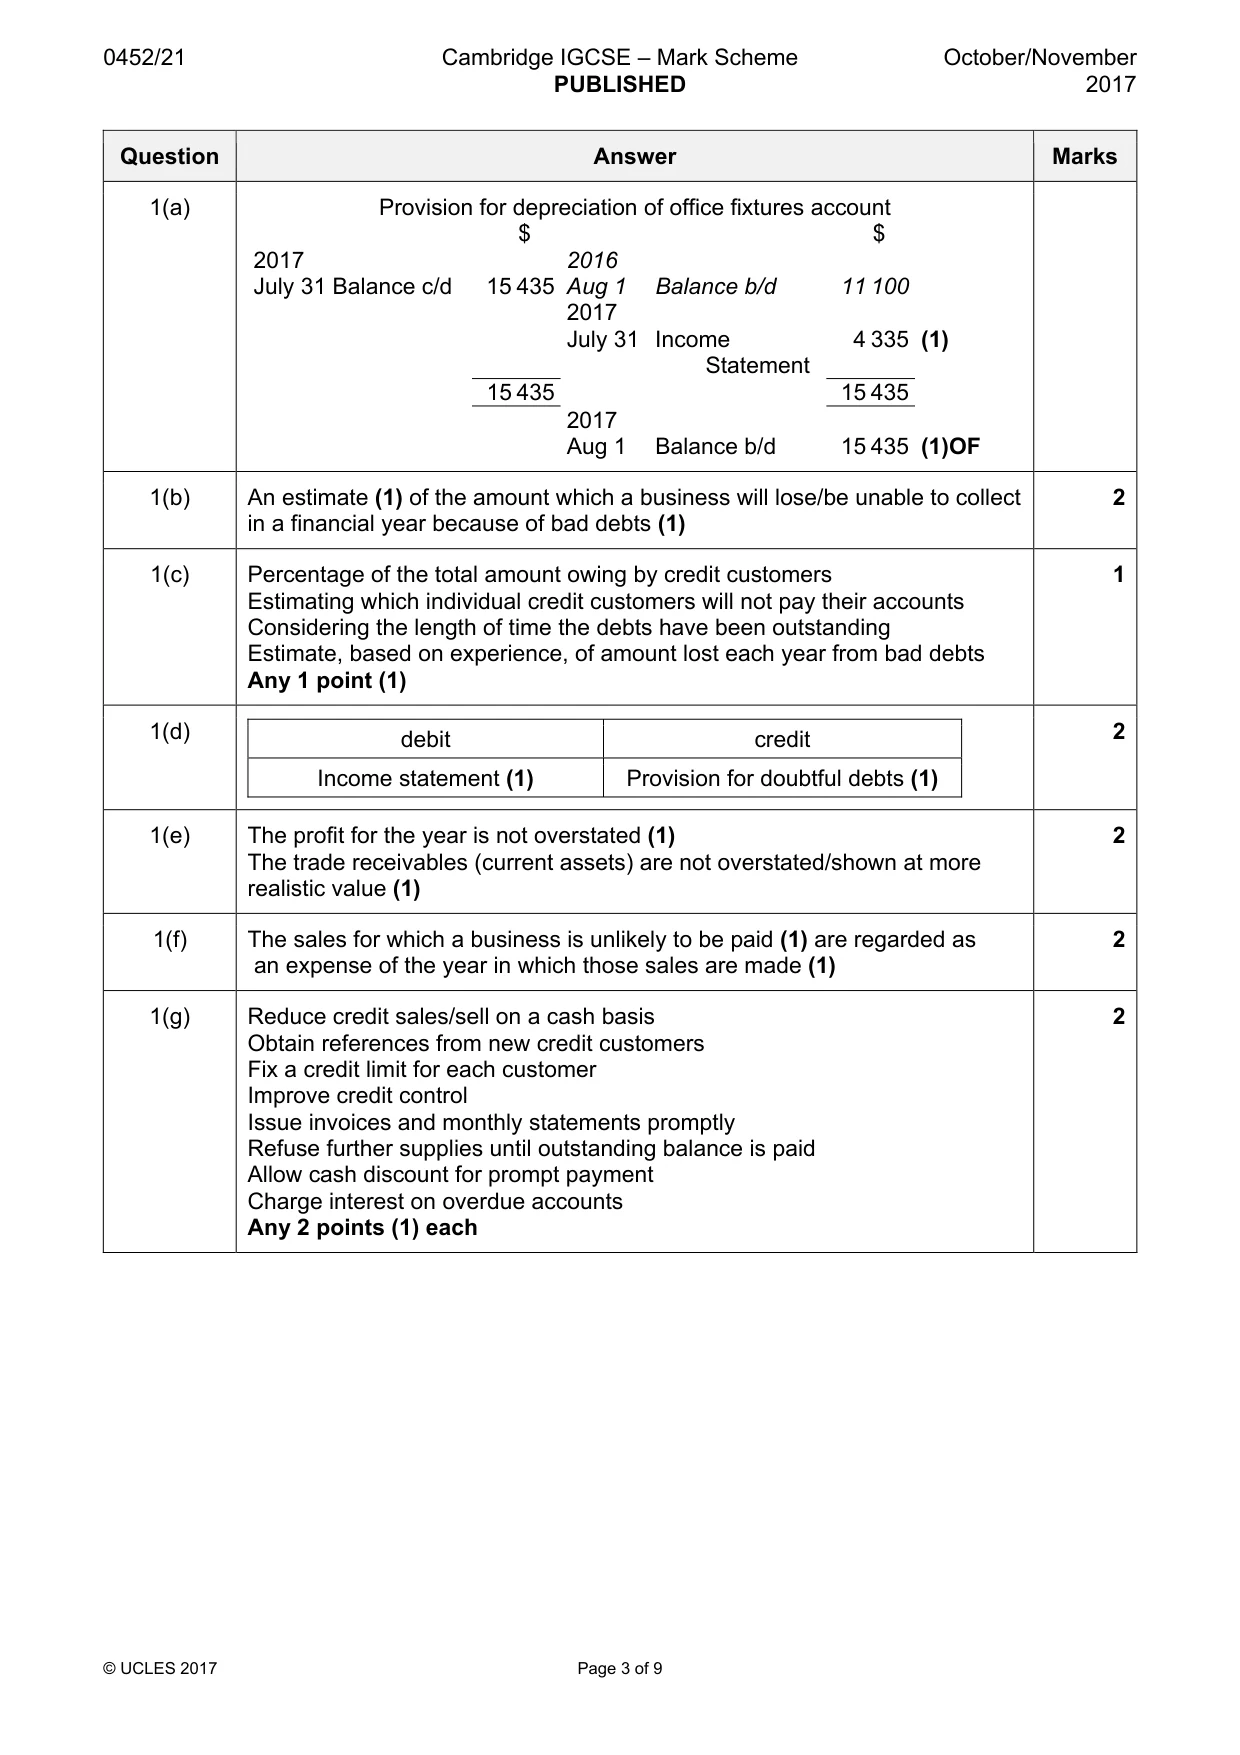
Mark scheme: Question Answer Marks 1(a) Brian account 15 $ $ 2016 2017 Aug 1 Balance b/d 1 000 July 31 Cash 720 (1) Bad debts 280 (1) 1 000 1 000 Bad debts account $ $ 2017 2017 July 31 Total to date 990 July 31 Income Brian 280 (1) Statement 1 270 (1)OF 1 270 1 270 Bad debts recovered account $ $ 2017 2017 July 31 Income July 31 Bank Statement* 118 (1) (AL Stores) 118 (1) 118 118 * Alternately accept transfer to bad debts account and net transfer from bad debts to income statement Rent account $ $ 2017 2017 July 31 Total paid 5 200 July 31 Balance c/d 400 Drawings 1 200 (1) Income Statement 3 600 (1)OF 5 200 5 200 2017 Aug 1 Balance b/d 400 (1) Drawings account $ $ 2017 2017 July 31 Total to date 9 650 July 31 Capital 10 850 (1)OF Rent 1 200 (1)OF 10 850 10 850 Commission receivable account $ $ 2017 2017 July 31 Income July 31 Total to date 890 Statement 1 040 (1) Balance c/d 150 1 040 1 040 2017 Aug 1 Balance b/d 150 (1) 1(a) Provision for depreciation of office fixtures account $ $ 2017 2016 July 31 Balance c/d 15 435 Aug 1 Balance b/d 11 100 2017 July 31 Income 4 335 (1) Statement 15 435 15 435 2017 Aug 1 Balance b/d 15 435 (1)OF 1(b) An estimate (1) of the amount which a business will lose/be unable to collect 2 in a financial year because of bad debts (1) 1(c) Percentage of the total amount owing by credit customers 1 Estimating which individual credit customers will not pay their accounts Considering the length of time the debts have been outstanding Estimate, based on experience, of amount lost each year from bad debts Any 1 point (1) 1(d) 2 debit credit Income statement (1) Provision for doubtful debts (1) 1(e) The profit for the year is not overstated (1) 2 The trade receivables (current assets) are not overstated/shown at more realistic value (1) 1(f) The sales for which a business is unlikely to be paid (1) are regarded as 2 an expense of the year in which those sales are made (1) 1(g) Reduce credit sales/sell on a cash basis 2 Obtain references from new credit customers Fix a credit limit for each customer Improve credit control Issue invoices and monthly statements promptly Refuse further supplies until outstanding balance is paid Allow cash discount for prompt payment Charge interest on overdue accounts Any 2 points (1) each
Q2 · Mahendra’s financial year ends on 31 August
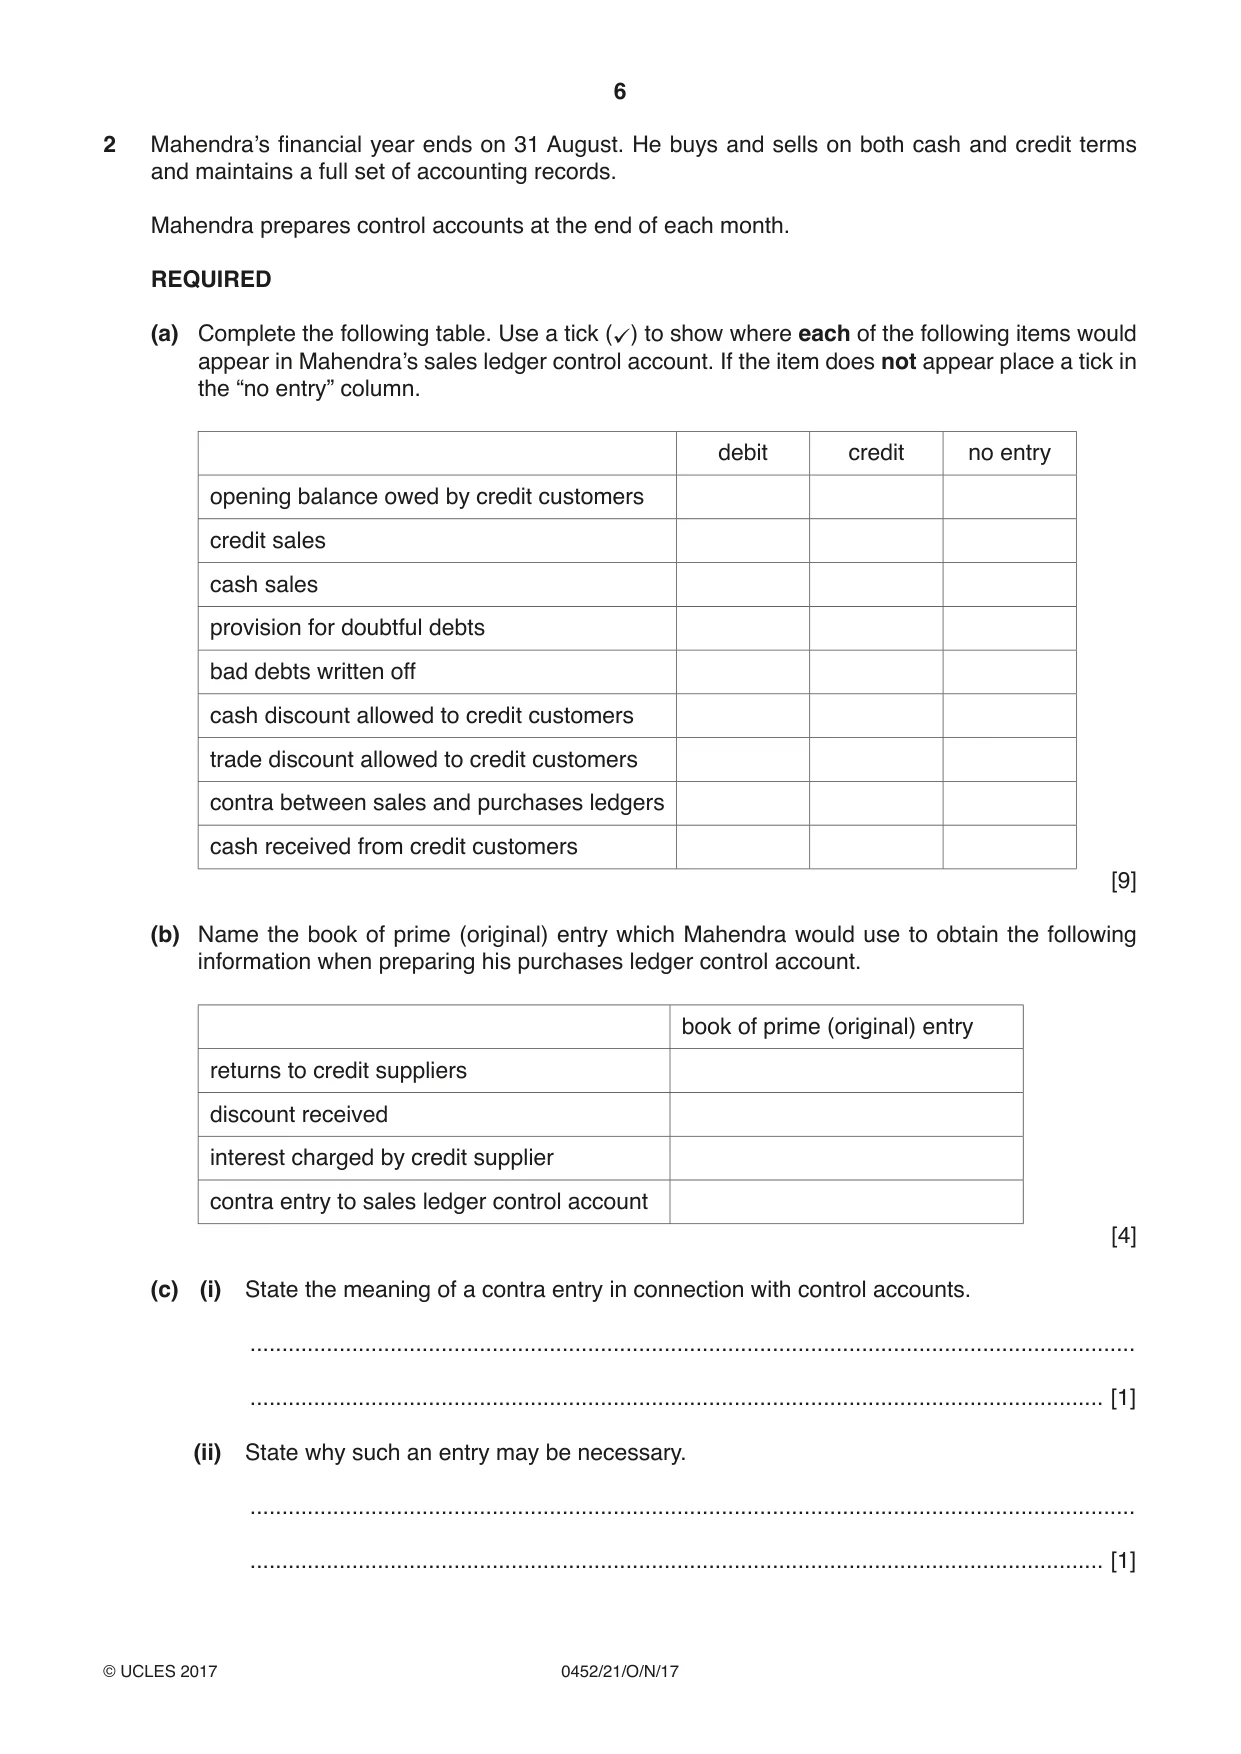
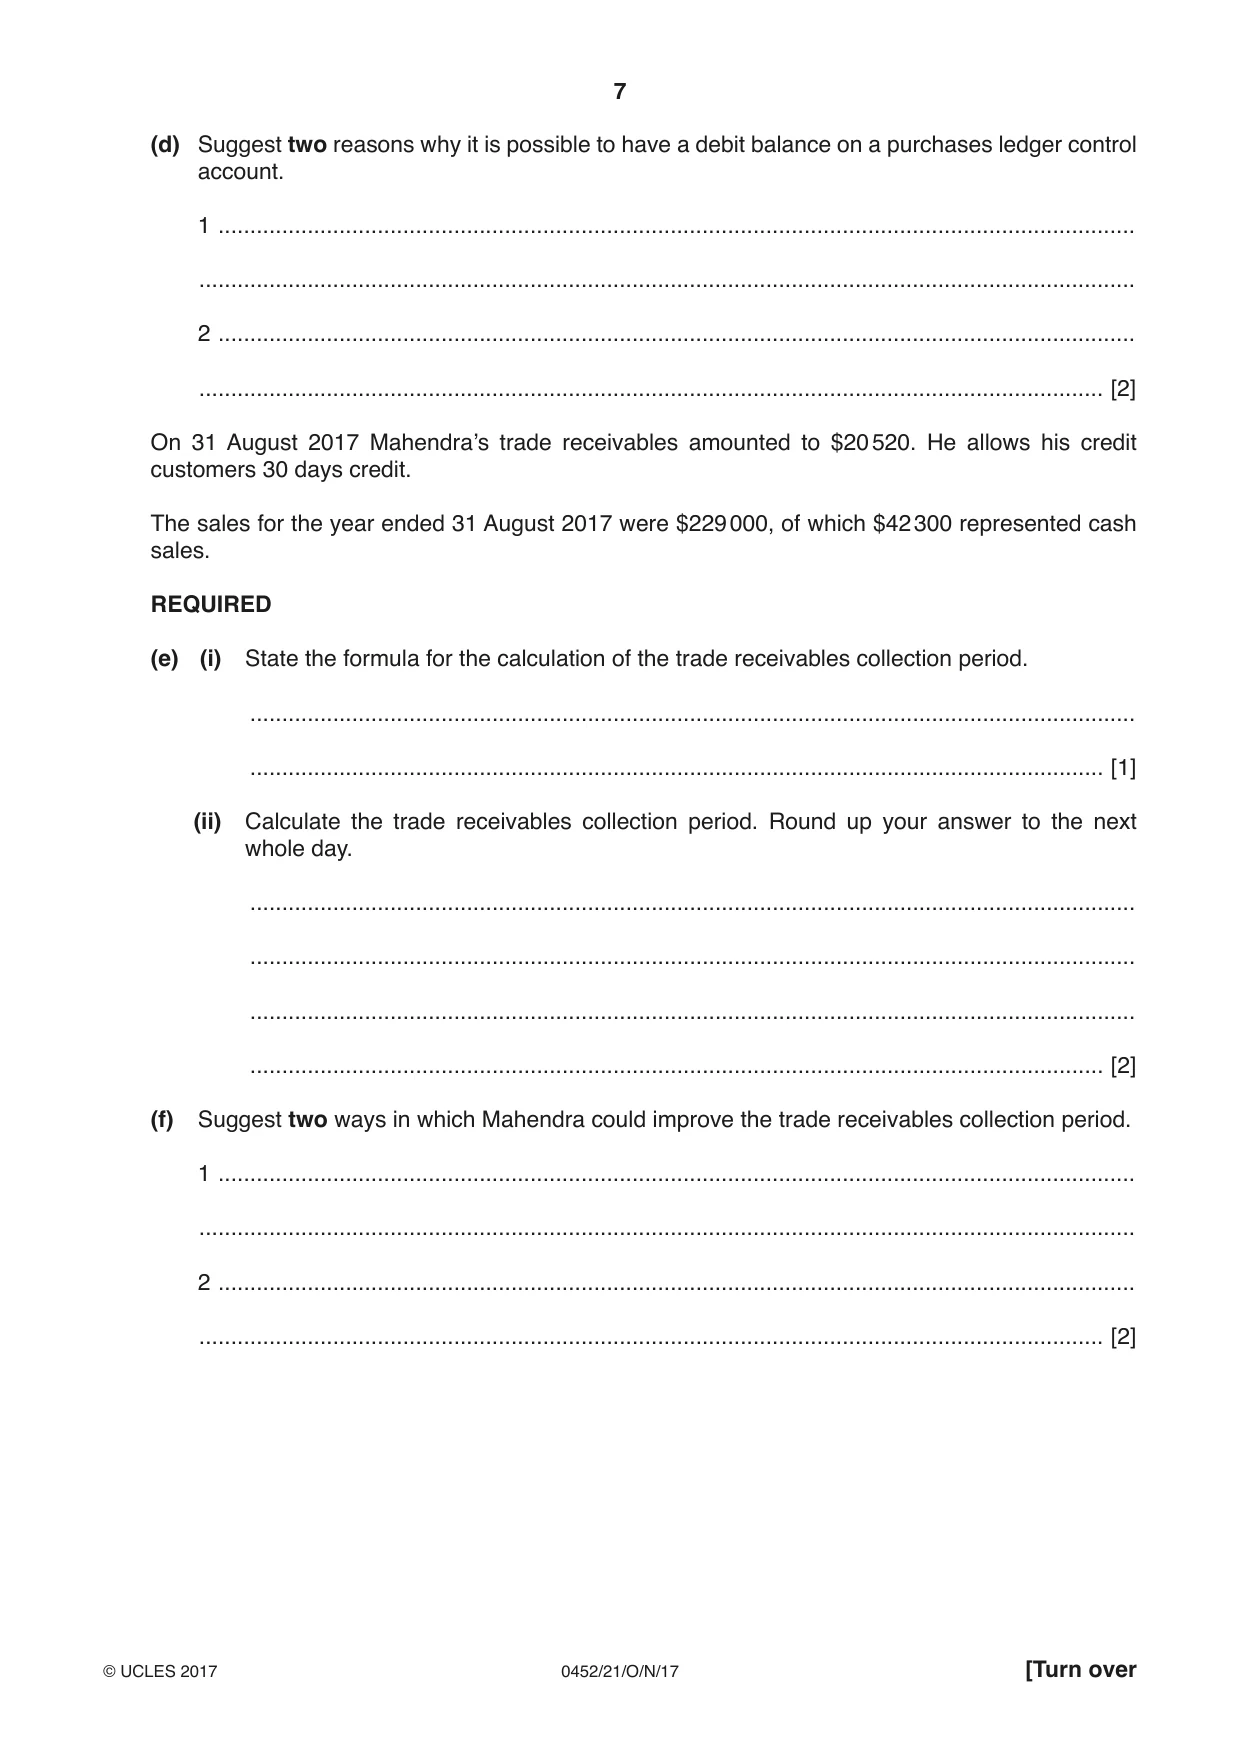
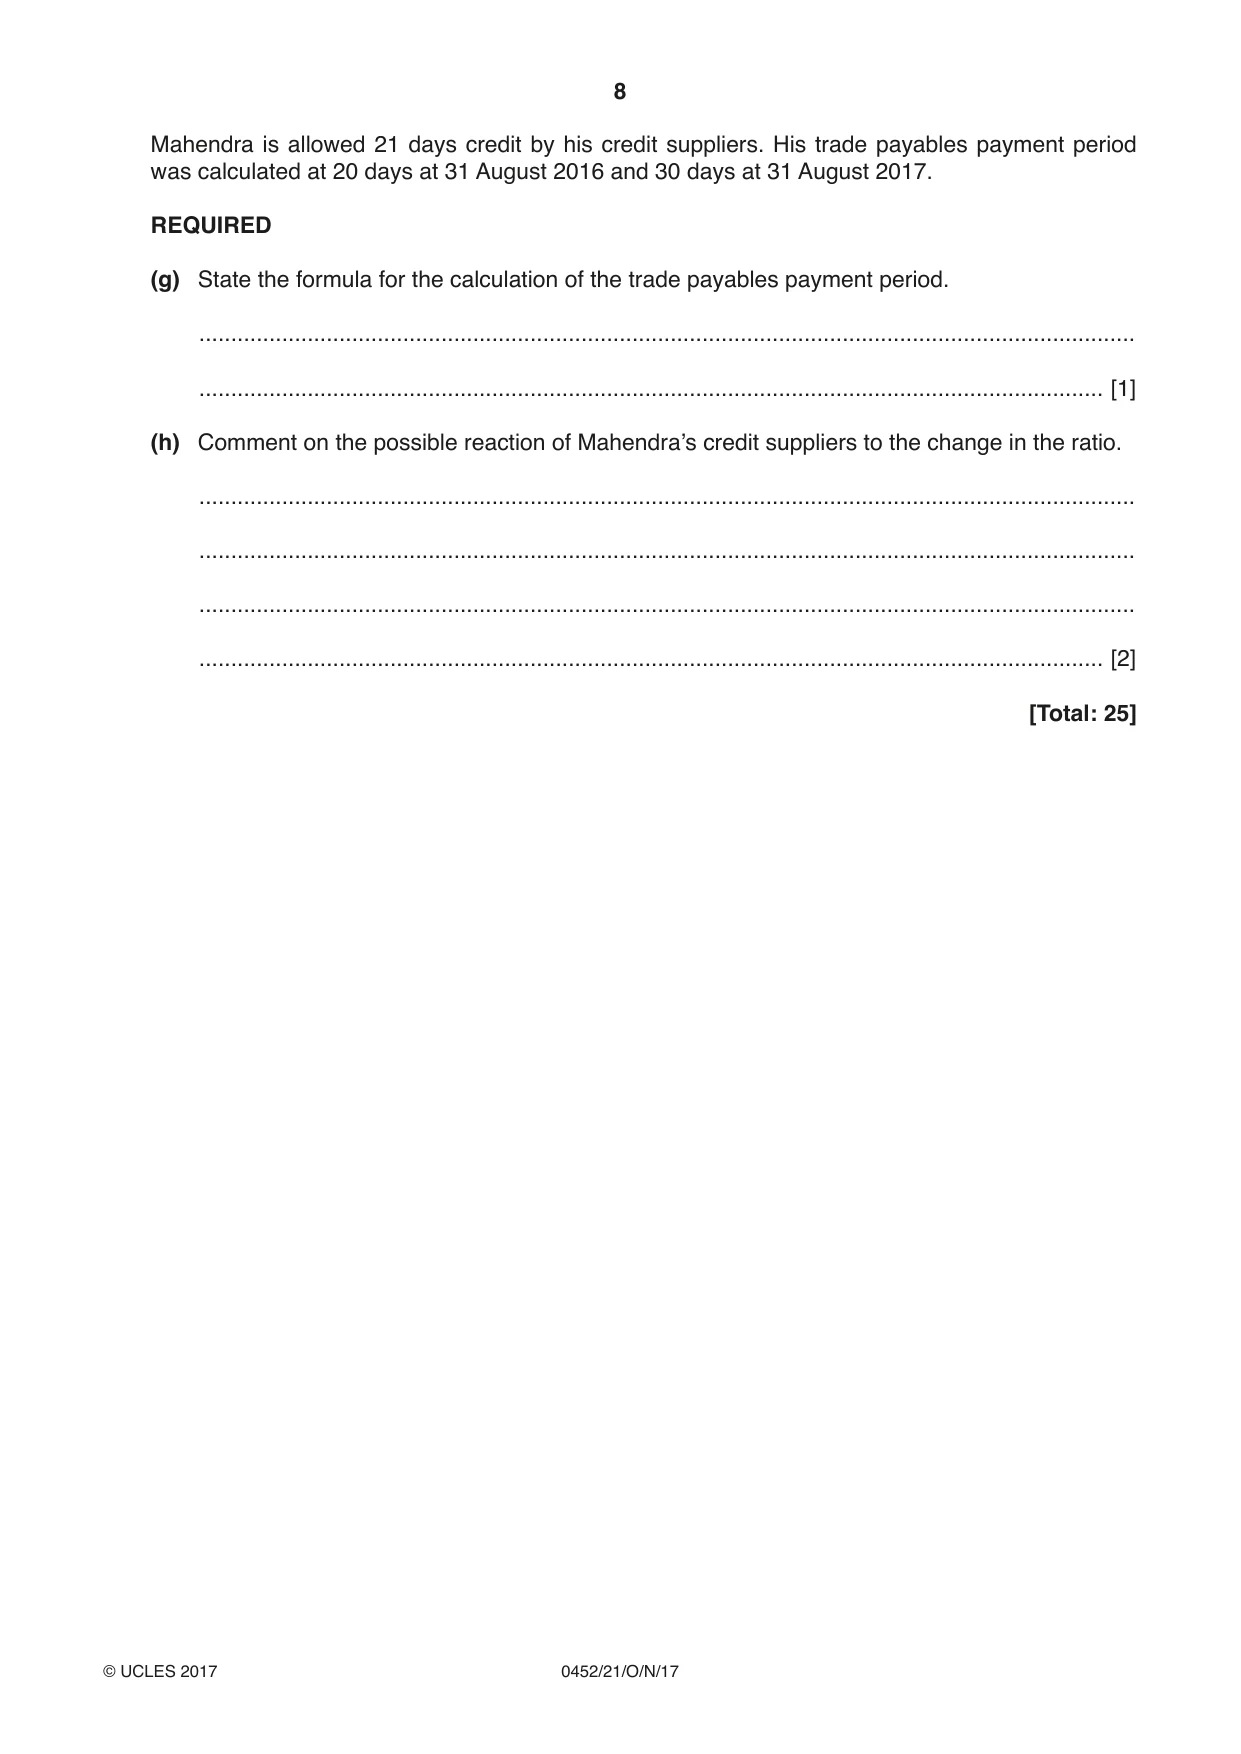
2 Mahendra’s financial year ends on 31 August. He buys and sells on both cash and credit terms and maintains a full set of accounting records. Mahendra prepares control accounts at the end of each month. REQUIRED (a) Complete the following table. Use a tick () to show where each of the following items would appear in Mahendra’s sales ledger control account. If the item does not appear place a tick in the “no entry” column. debit credit no entry opening balance owed by credit customers credit sales cash sales provision for doubtful debts bad debts written off cash discount allowed to credit customers trade discount allowed to credit customers contra between sales and purchases ledgers cash received from credit customers [9] (b) Name the book of prime (original) entry which Mahendra would use to obtain the following information when preparing his purchases ledger control account. book of prime (original) entry returns to credit suppliers discount received interest charged by credit supplier contra entry to sales ledger control account [4] (c) (i) State the meaning of a contra entry in connection with control accounts. ........................................................................................................................................... ...................................................................................................................................... [1] (ii) State why such an entry may be necessary. ........................................................................................................................................... ...................................................................................................................................... [1] (d) Suggest two reasons why it is possible to have a debit balance on a purchases ledger control account. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] On 31 August 2017 Mahendra’s trade receivables amounted to $20 520. He allows his credit customers 30 days credit. The sales for the year ended 31 August 2017 were $229 000, of which $42 300 represented cash sales. REQUIRED (e) (i) State the formula for the calculation of the trade receivables collection period. ........................................................................................................................................... ...................................................................................................................................... [1] (ii) Calculate the trade receivables collection period. Round up your answer to the next whole day. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] (f) Suggest two ways in which Mahendra could improve the trade receivables collection period. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] Mahendra is allowed 21 days credit by his credit suppliers. His trade payables payment period was calculated at 20 days at 31 August 2016 and 30 days at 31 August 2017. REQUIRED (g) State the formula for the calculation of the trade payables payment period. ................................................................................................................................................... .............................................................................................................................................. [1] (h) Comment on the possible reaction of Mahendra’s credit suppliers to the change in the ratio. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] [Total: 25] Question 3 is on the next page.
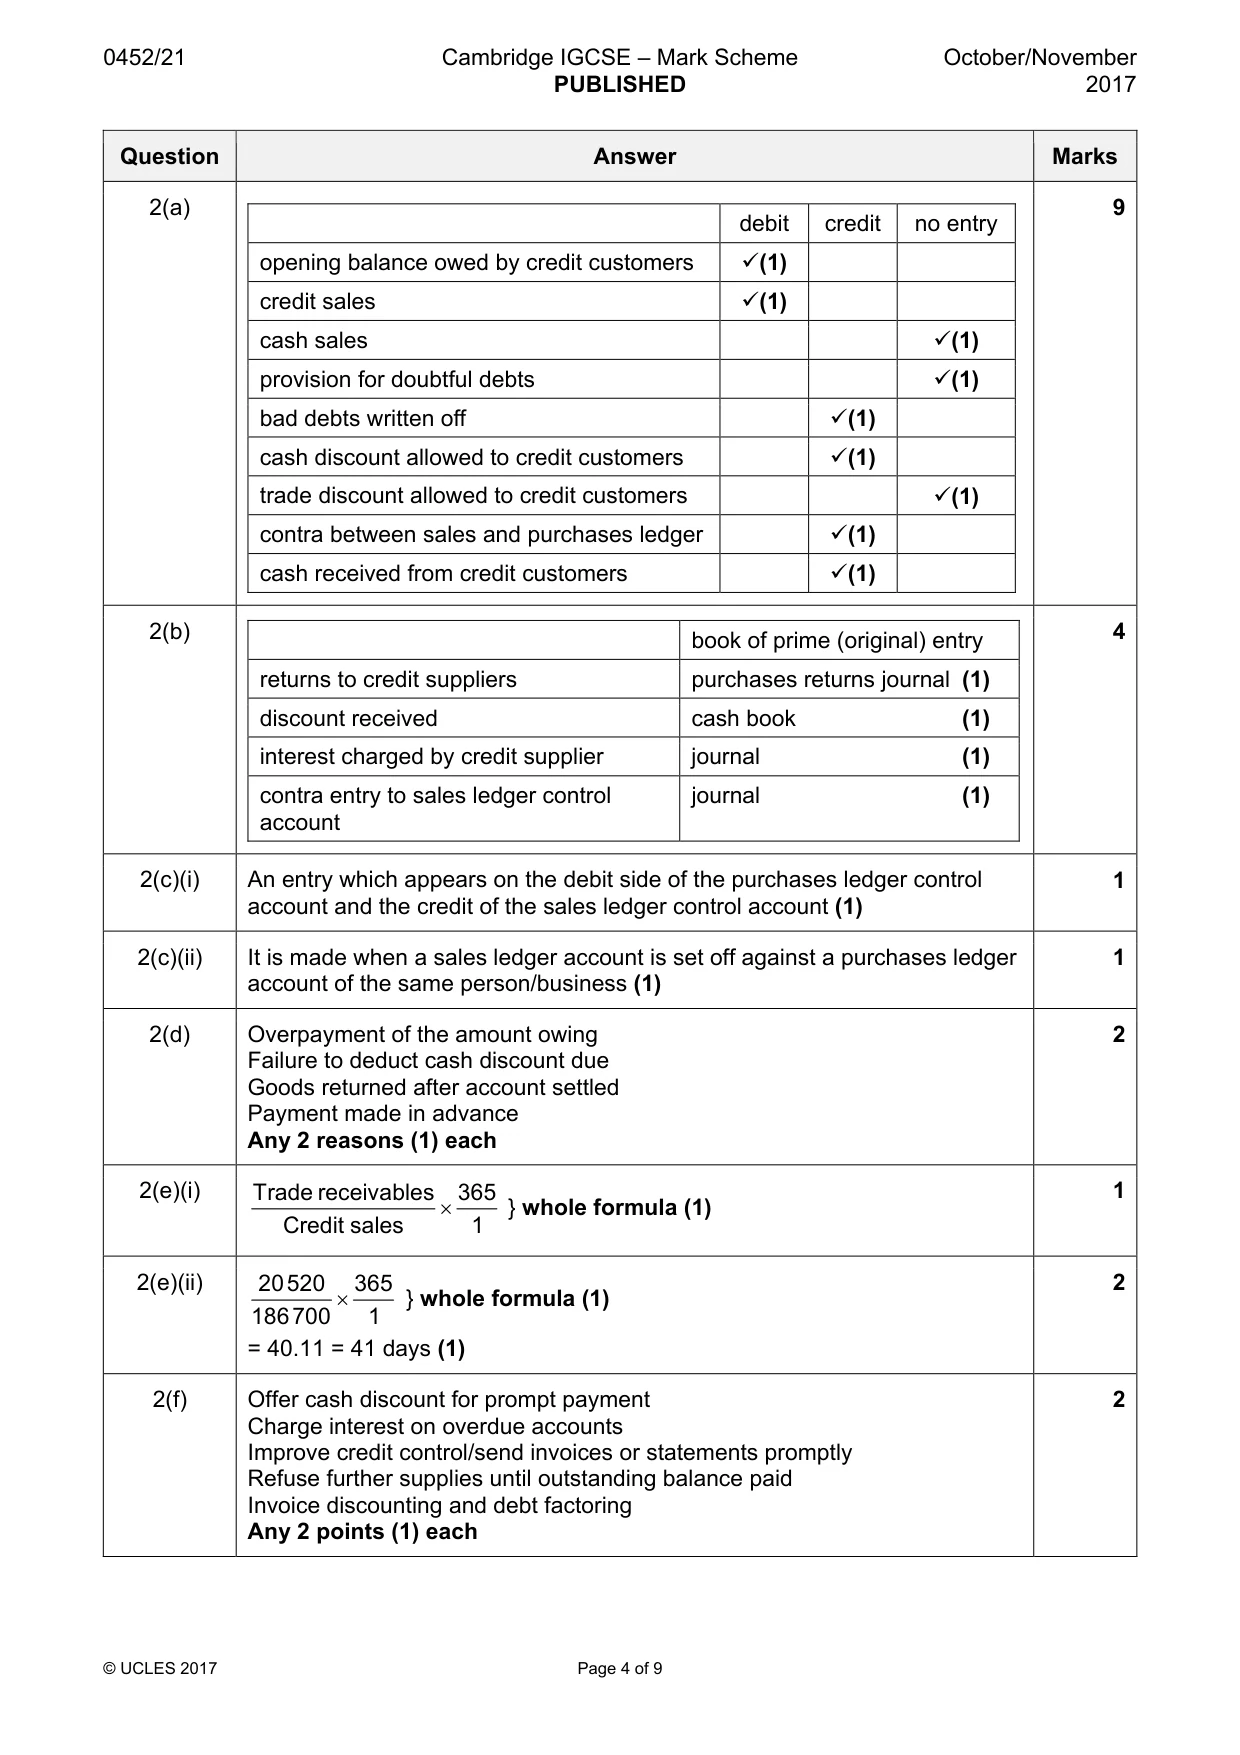
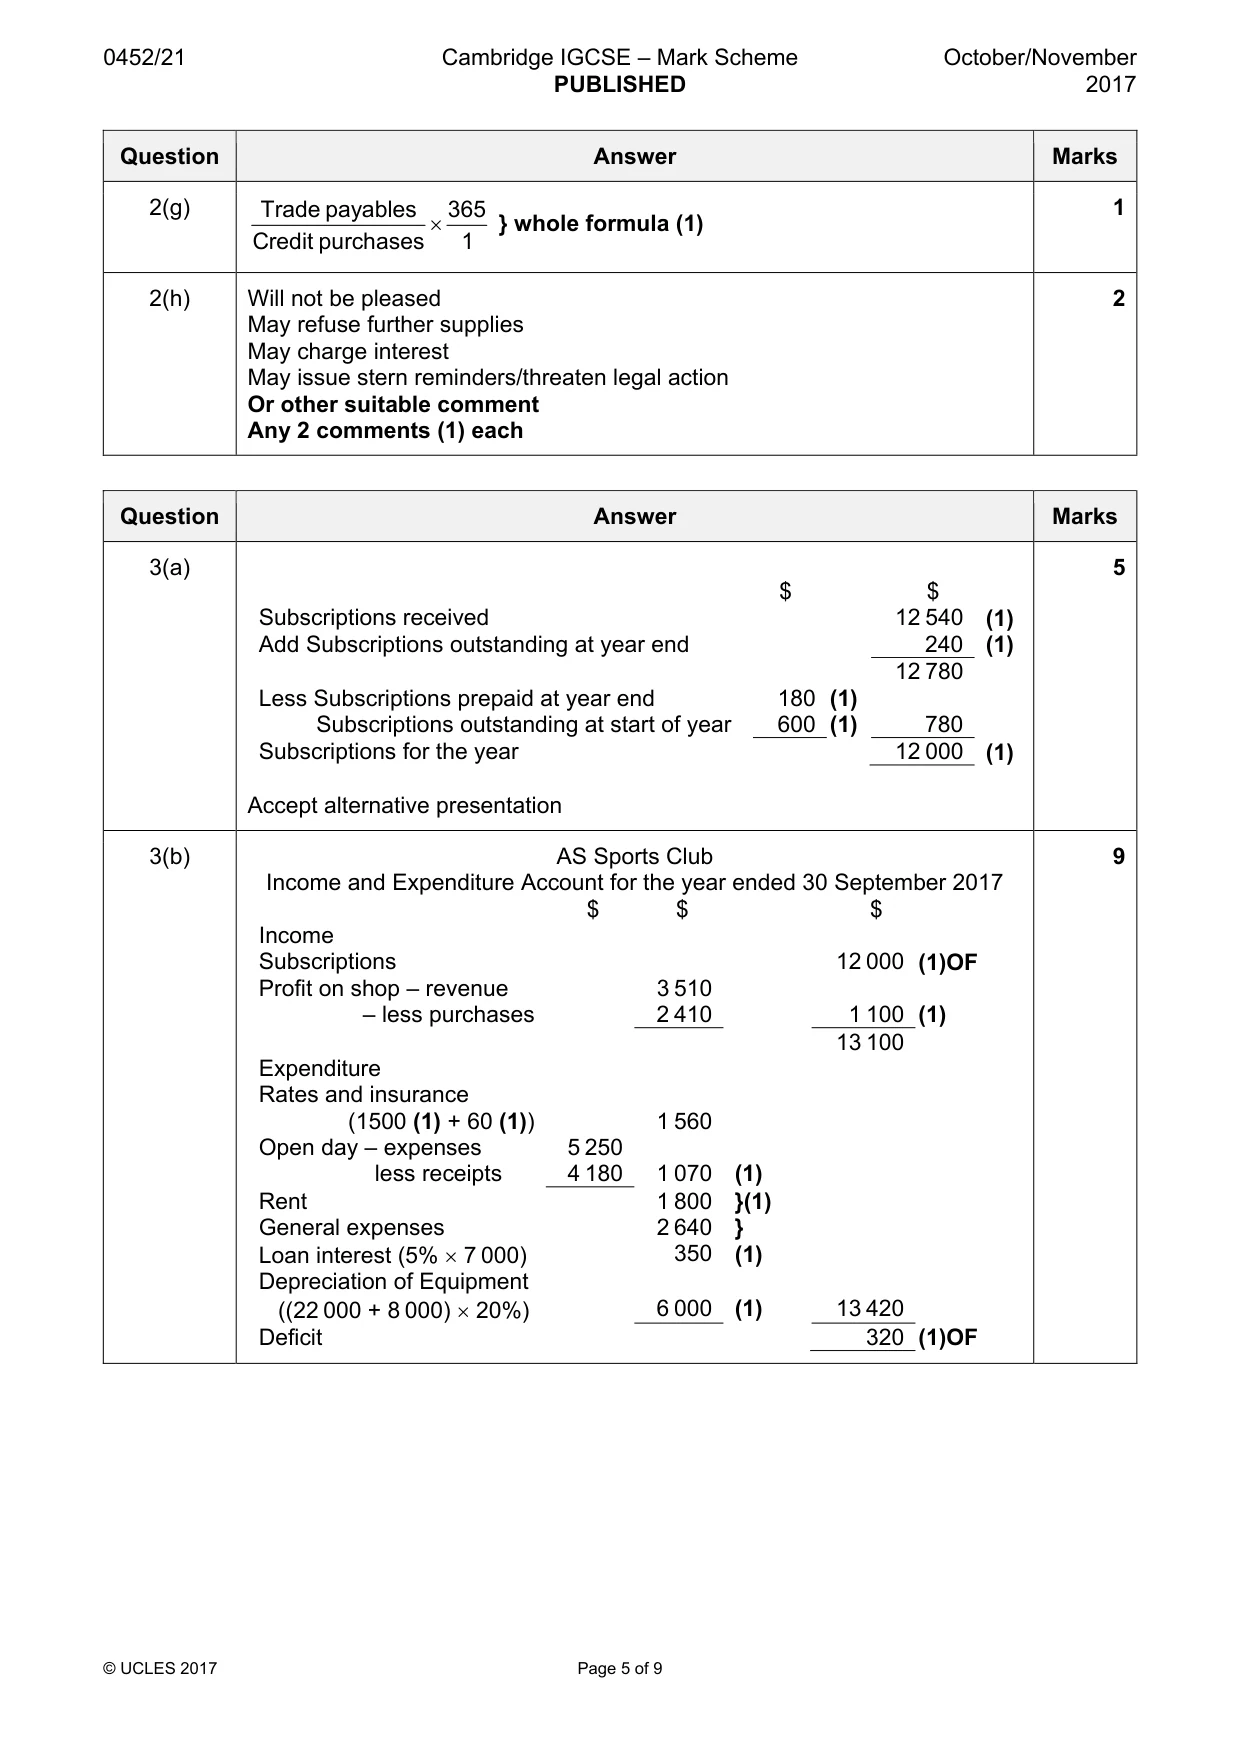
Mark scheme: 2(a) 9 debit credit no entry opening balance owed by credit customers 9(1) credit sales 9(1) cash sales 9(1) provision for doubtful debts 9(1) bad debts written off 9(1) cash discount allowed to credit customers 9(1) trade discount allowed to credit customers 9(1) contra between sales and purchases ledger 9(1) cash received from credit customers 9(1) 2(b) 4 book of prime (original) entry returns to credit suppliers purchases returns journal (1) discount received cash book (1) interest charged by credit supplier journal (1) contra entry to sales ledger control journal (1) account 2(c)(i) An entry which appears on the debit side of the purchases ledger control 1 account and the credit of the sales ledger control account (1) 2(c)(ii) It is made when a sales ledger account is set off against a purchases ledger 1 account of the same person/business (1) 2(d) Overpayment of the amount owing 2 Failure to deduct cash discount due Goods returned after account settled Payment made in advance Any 2 reasons (1) each 2(e)(i) Trade receivables 365 1 × } whole formula (1) Credit sales 1 2(e)(ii) 20520 365 2 × } whole formula (1) 186700 1 = 40.11 = 41 days (1) 2(f) Offer cash discount for prompt payment 2 Charge interest on overdue accounts Improve credit control/send invoices or statements promptly Refuse further supplies until outstanding balance paid Invoice discounting and debt factoring Any 2 points (1) each 2(g) Trade payables 365 1 × } whole formula (1) Credit purchases 1 2(h) Will not be pleased 2 May refuse further supplies May charge interest May issue stern reminders/threaten legal action Or other suitable comment Any 2 comments (1) each
Q3 · The financial year of the AS Sports Club ends on 30 September
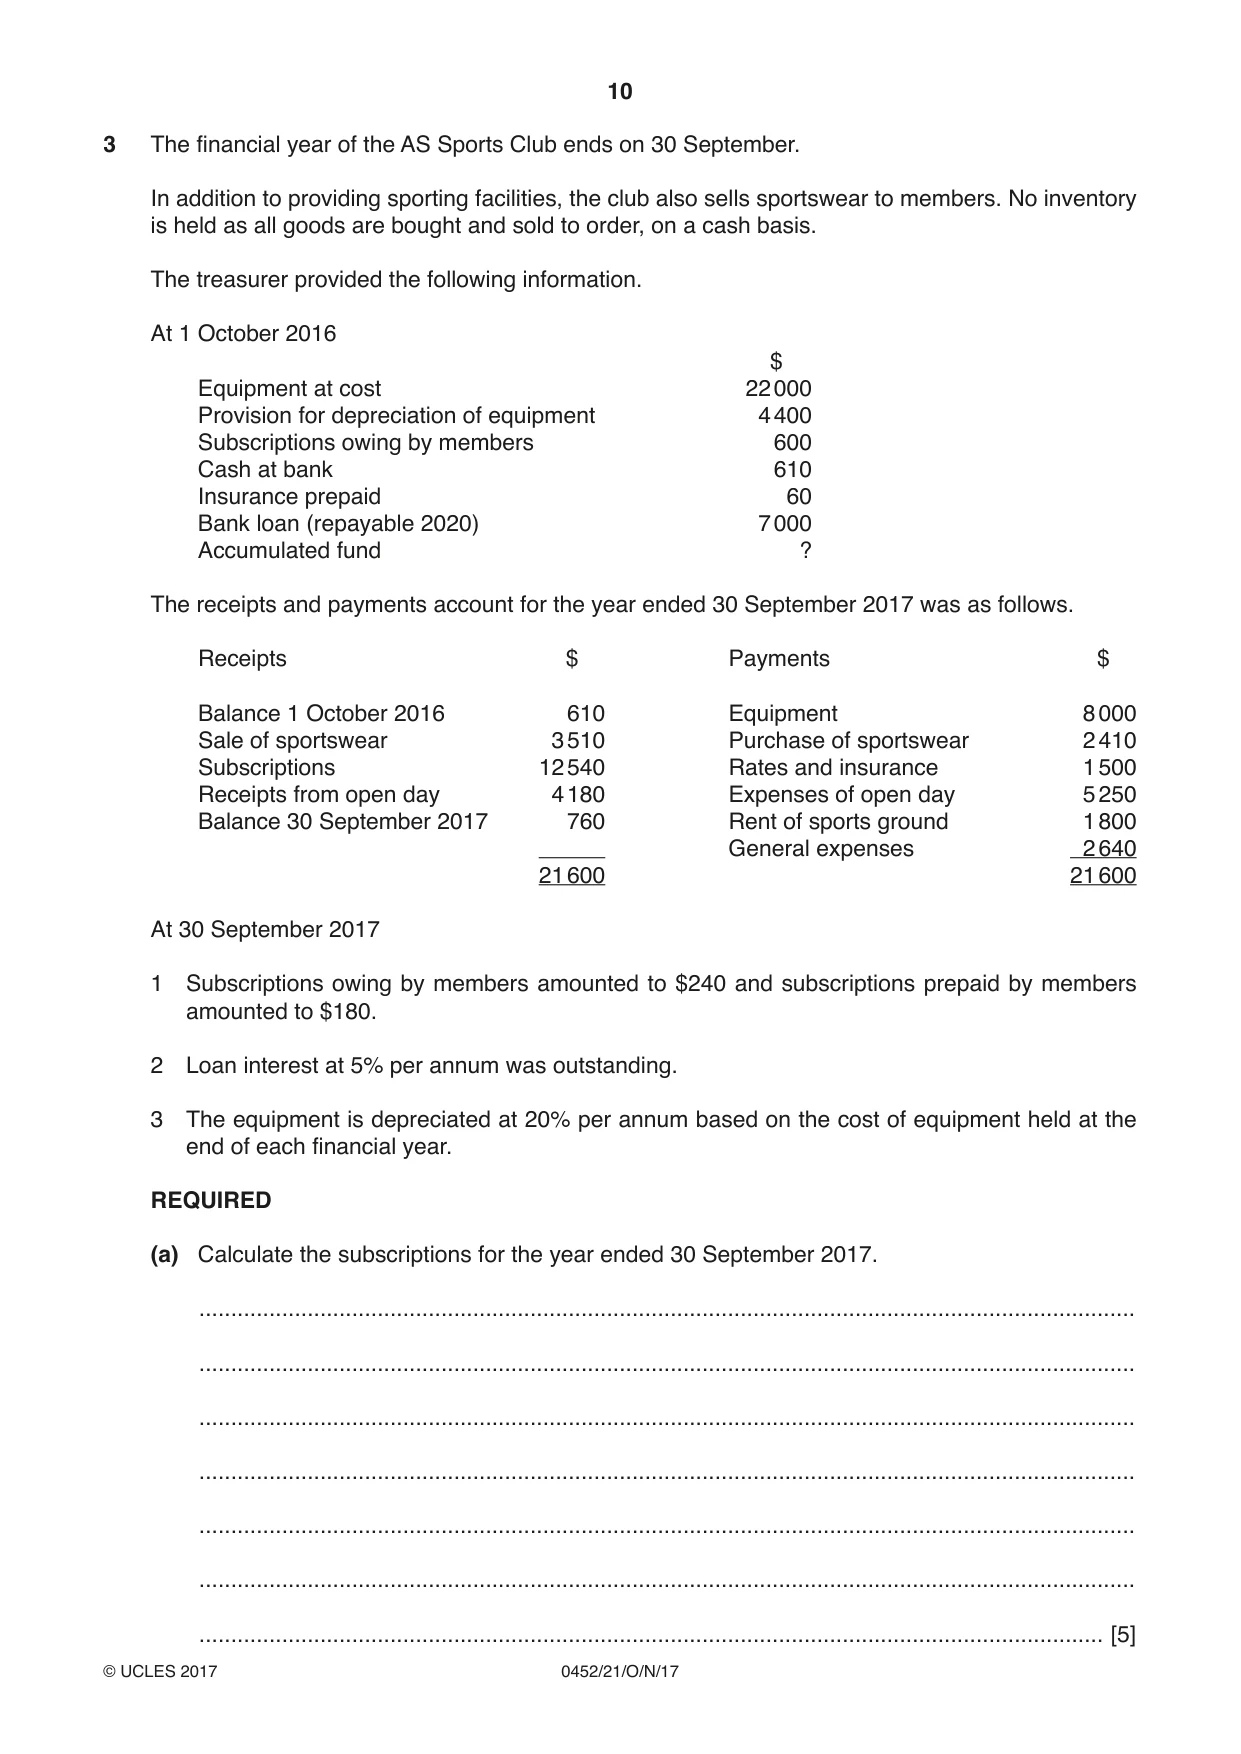
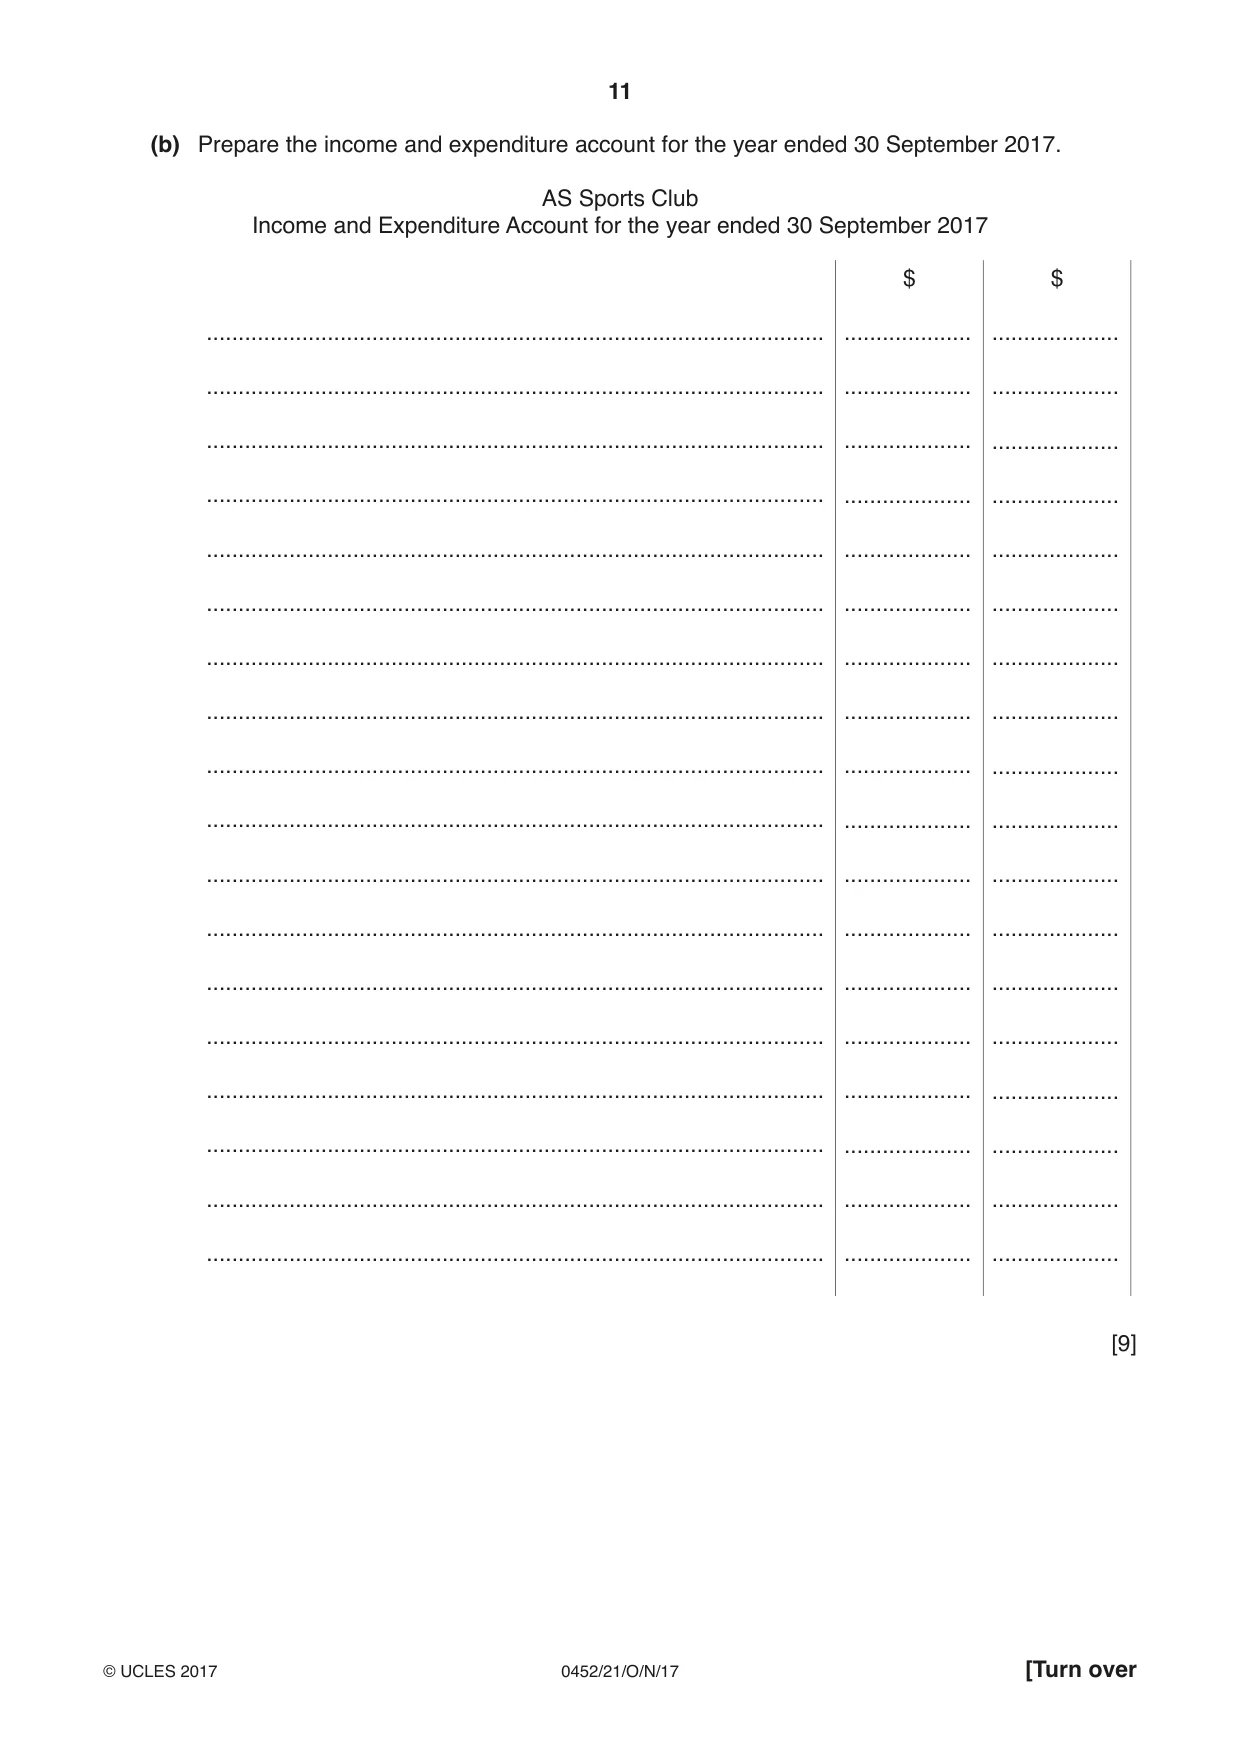
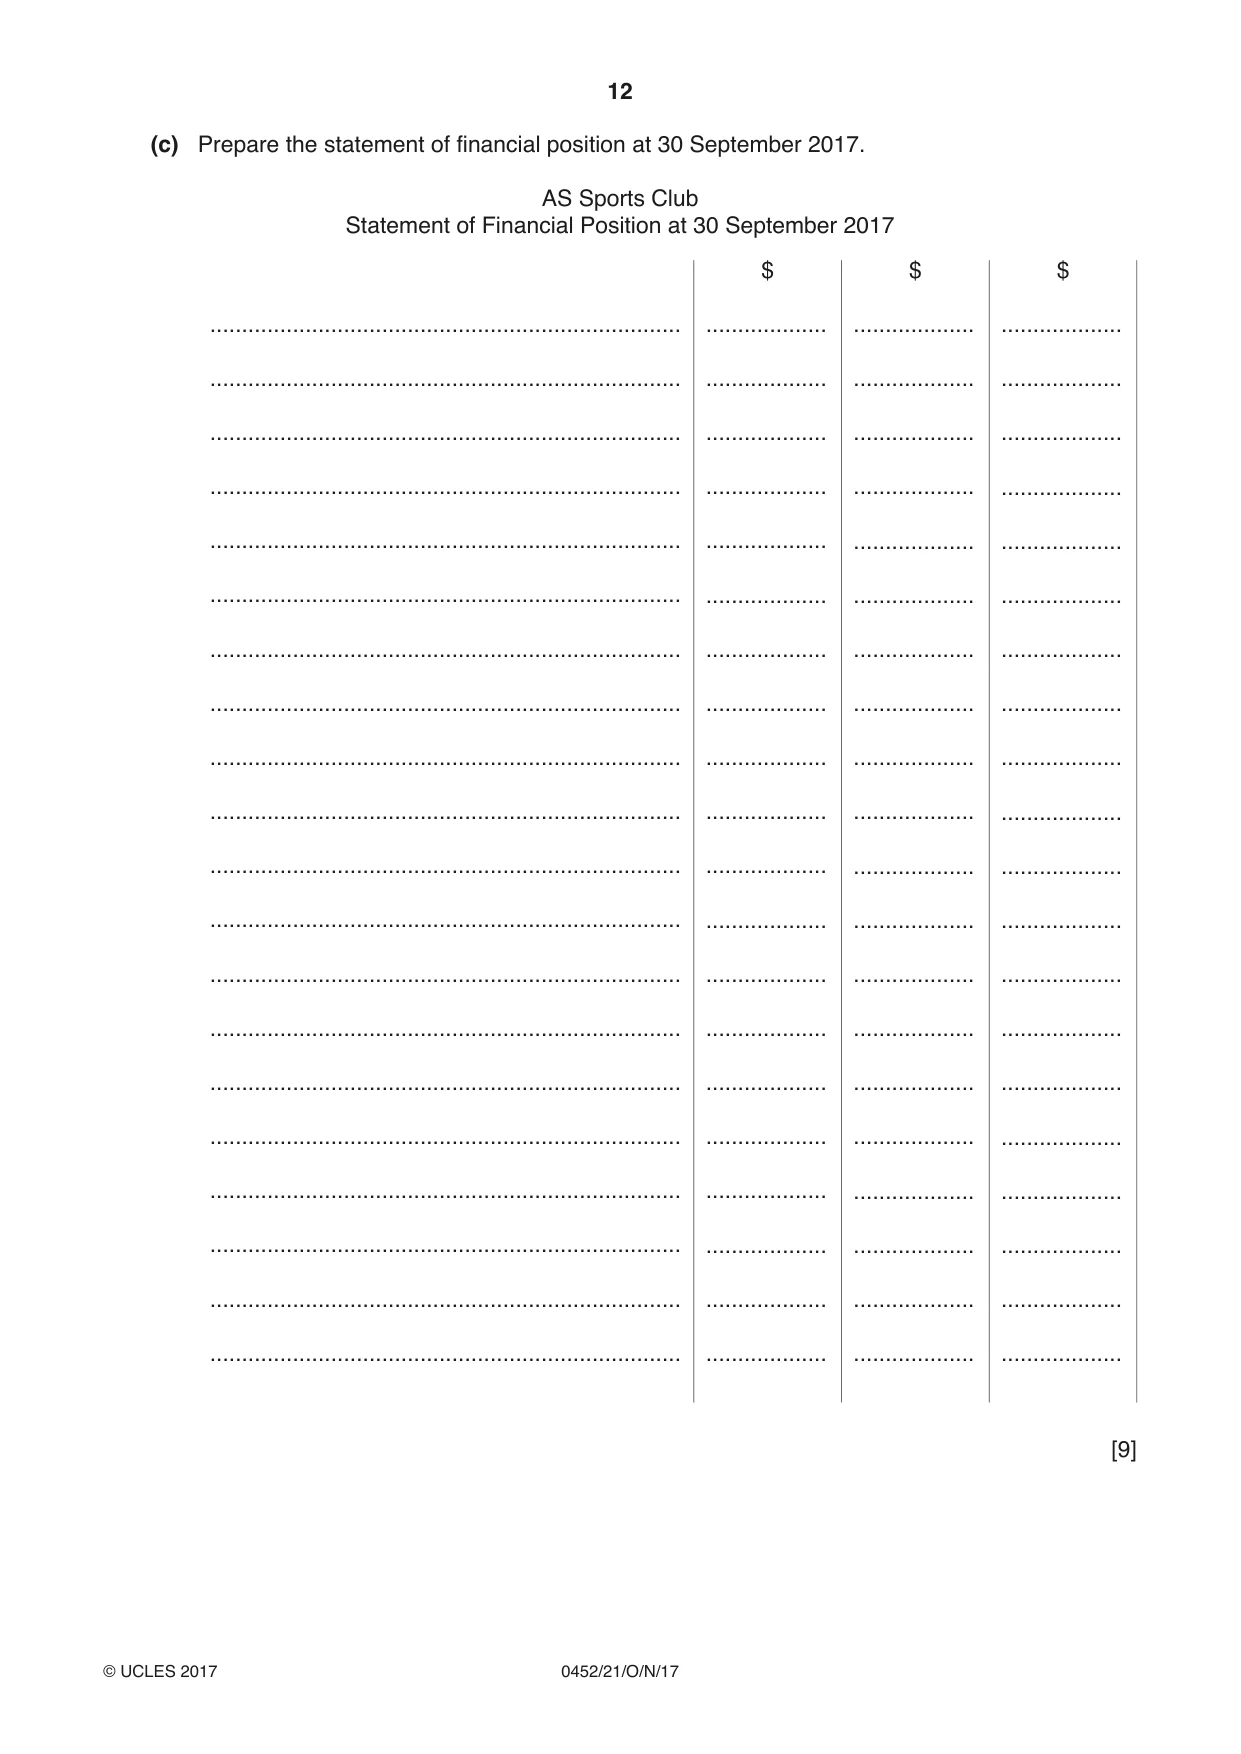
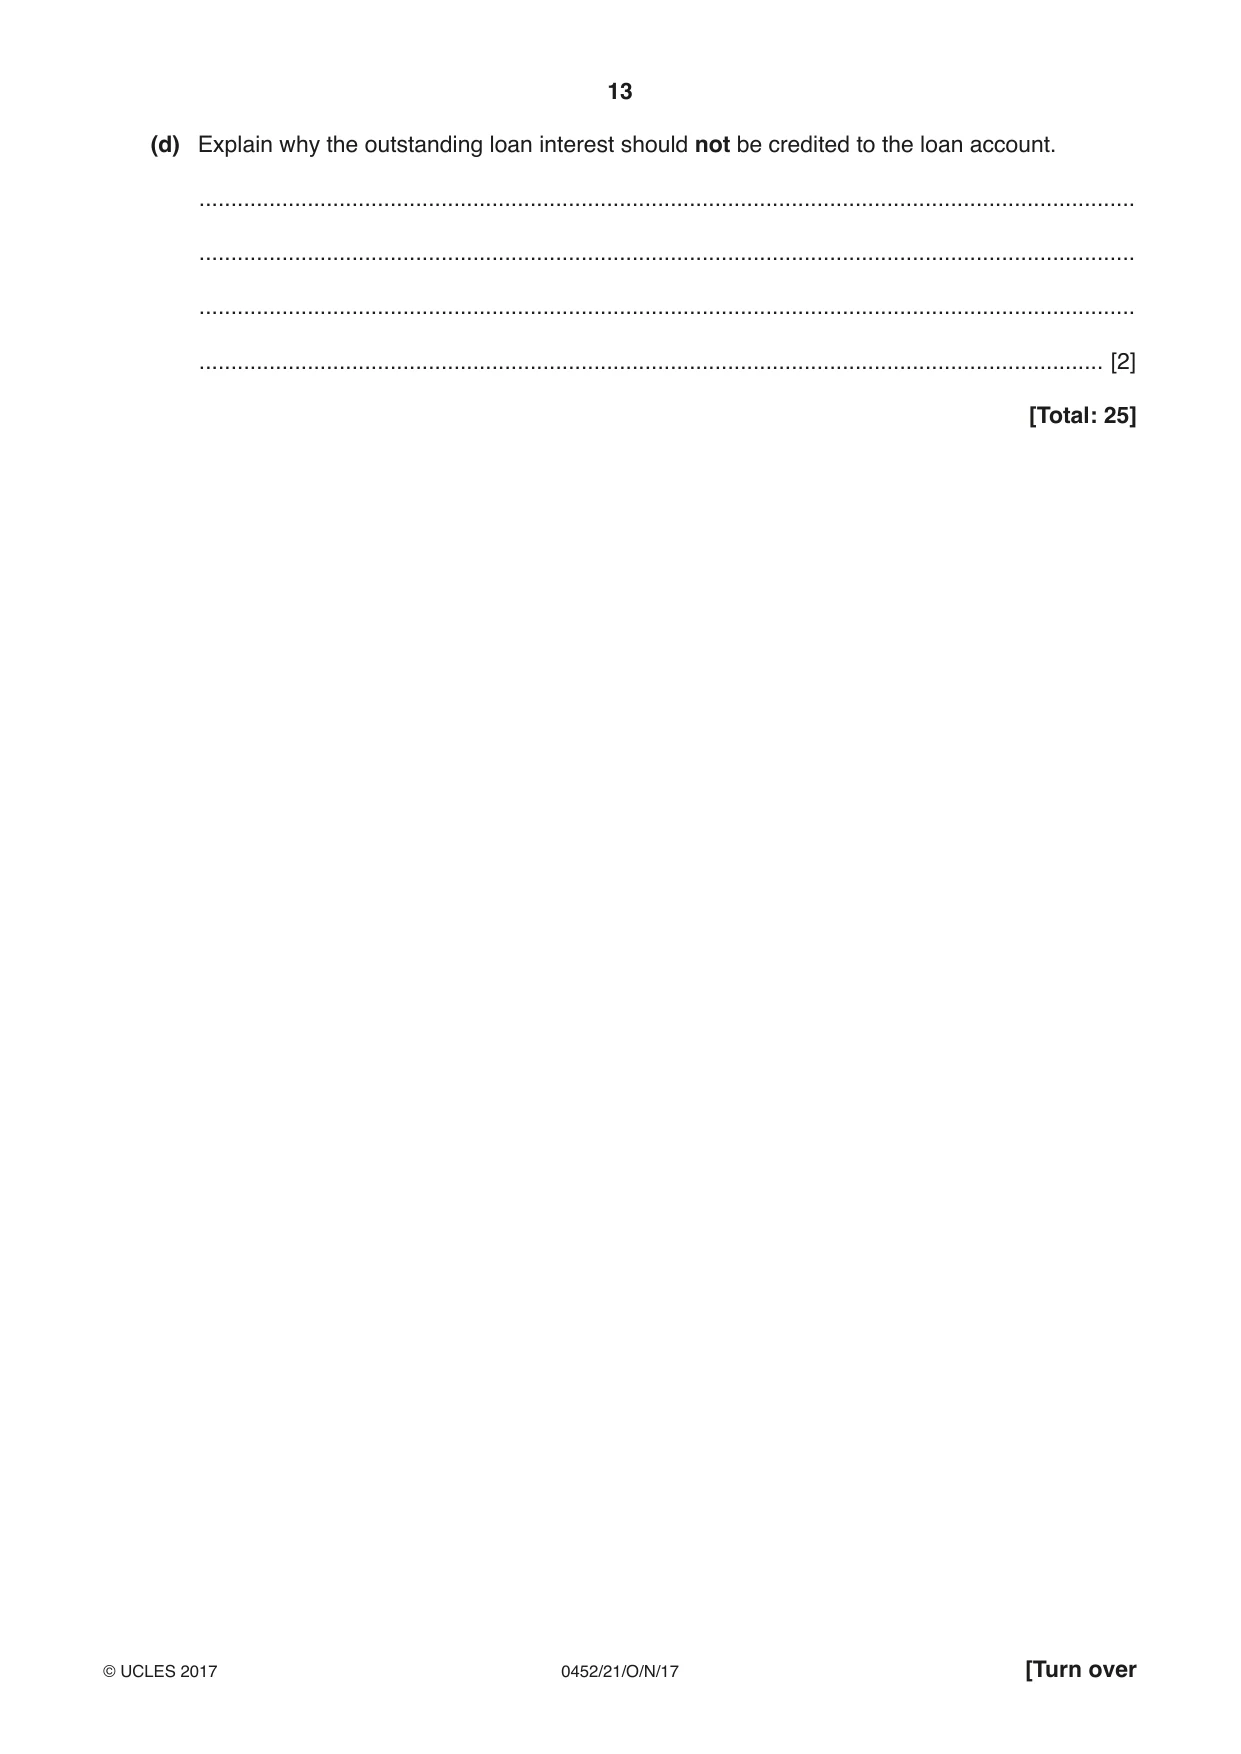
3 The financial year of the AS Sports Club ends on 30 September. In addition to providing sporting facilities, the club also sells sportswear to members. No inventory is held as all goods are bought and sold to order, on a cash basis. The treasurer provided the following information. At 1 October 2016 $ Equipment at cost 22 000 Provision for depreciation of equipment 4 400 Subscriptions owing by members 600 Cash at bank 610 Insurance prepaid 60 Bank loan (repayable 2020) 7 000 Accumulated fund ? The receipts and payments account for the year ended 30 September 2017 was as follows. Receipts $ Payments $ Balance 1 October 2016 610 Equipment 8 000 Sale of sportswear 3 510 Purchase of sportswear 2 410 Subscriptions 12 540 Rates and insurance 1 500 Receipts from open day 4 180 Expenses of open day 5 250 Balance 30 September 2017 760 Rent of sports ground 1 800 General expenses 2 640 21 600 21 600 At 30 September 2017 1 Subscriptions owing by members amounted to $240 and subscriptions prepaid by members amounted to $180. 2 Loan interest at 5% per annum was outstanding. 3 The equipment is depreciated at 20% per annum based on the cost of equipment held at the end of each financial year. REQUIRED (a) Calculate the subscriptions for the year ended 30 September 2017. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] (b) Prepare the income and expenditure account for the year ended 30 September 2017. AS Sports Club Income and Expenditure Account for the year ended 30 September 2017 $ $ ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... ................................................................................................. .................... .................... [9] (c) Prepare the statement of financial position at 30 AS Sports Clu Statement of Financial Position at .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... .......................................................................... (d) Explain why the outstanding loan interest should not be credited to the loan account. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] [Total: 25]
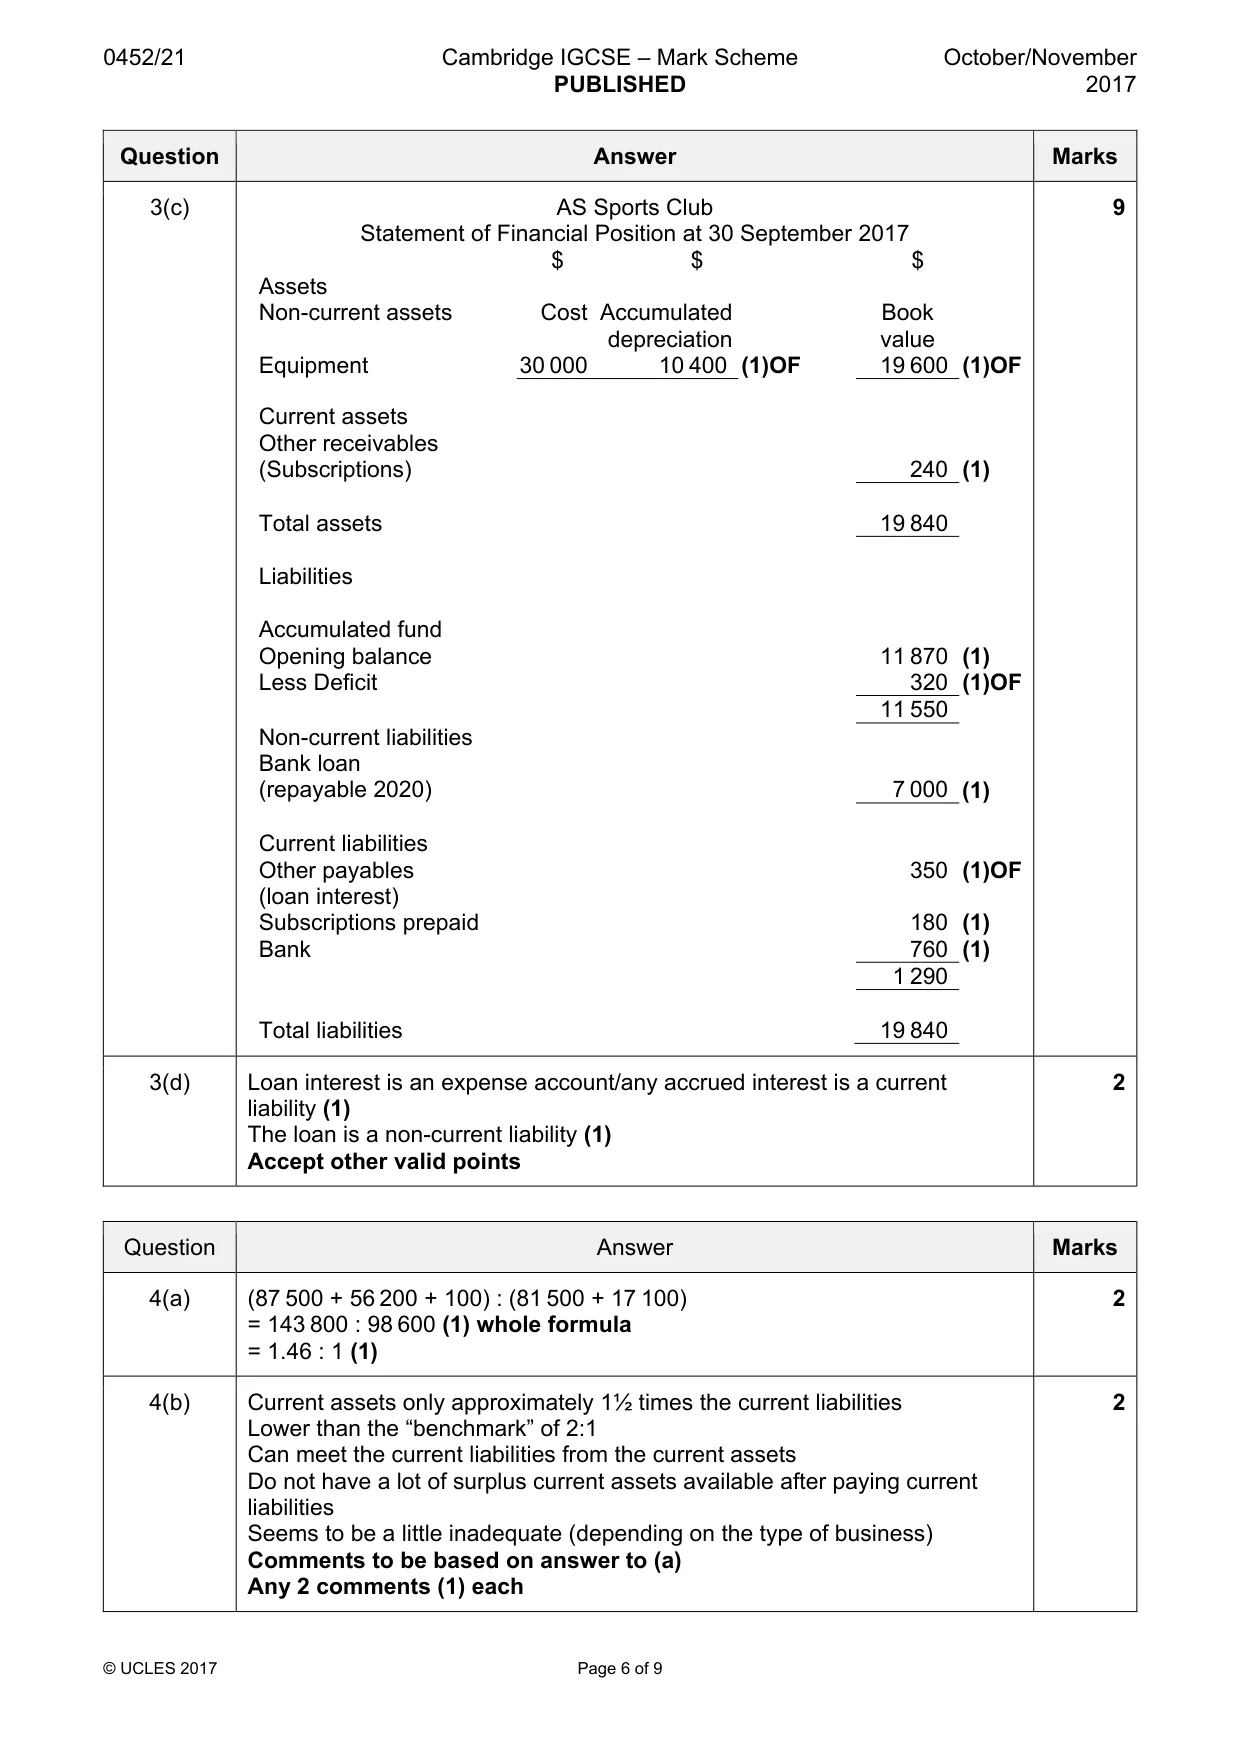
Mark scheme: 3(a) 5 $ $ Subscriptions received 12 540 (1) Add Subscriptions outstanding at year end 240 (1) 12 780 Less Subscriptions prepaid at year end 180 (1) Subscriptions outstanding at start of year 600 (1) 780 Subscriptions for the year 12 000 (1) Accept alternative presentation 3(b) AS Sports Club 9 Income and Expenditure Account for the year ended 30 September 2017 $ $ $ Income Subscriptions 12 000 (1)OF Profit on shop – revenue 3 510 – less purchases 2 410 1 100 (1) 13 100 Expenditure Rates and insurance (1500 (1) + 60 (1)) 1 560 Open day – expenses 5 250 less receipts 4 180 1 070 (1) Rent 1 800 }(1) General expenses 2 640 } Loan interest (5% × 7 000) 350 (1) Depreciation of Equipment ((22 000 + 8 000) × 20%) 6 000 (1) 13 420 Deficit 320 (1)OF 3(c) AS Sports Club 9 Statement of Financial Position at 30 September 2017 $ $ $ Assets Non-current assets Cost Accumulated Book depreciation value Equipment 30 000 10 400 (1)OF 19 600 (1)OF Current assets Other receivables (Subscriptions) 240 (1) Total assets 19 840 Liabilities Accumulated fund Opening balance 11 870 (1) Less Deficit 320 (1)OF 11 550 Non-current liabilities Bank loan (repayable 2020) 7 000 (1) Current liabilities Other payables 350 (1)OF (loan interest) Subscriptions prepaid 180 (1) Bank 760 (1) 1 290 Total liabilities 19 840 3(d) Loan interest is an expense account/any accrued interest is a current 2 liability (1) The loan is a non-current liability (1) Accept other valid points
Q4 · Hanif’s financial year ends on 31 July
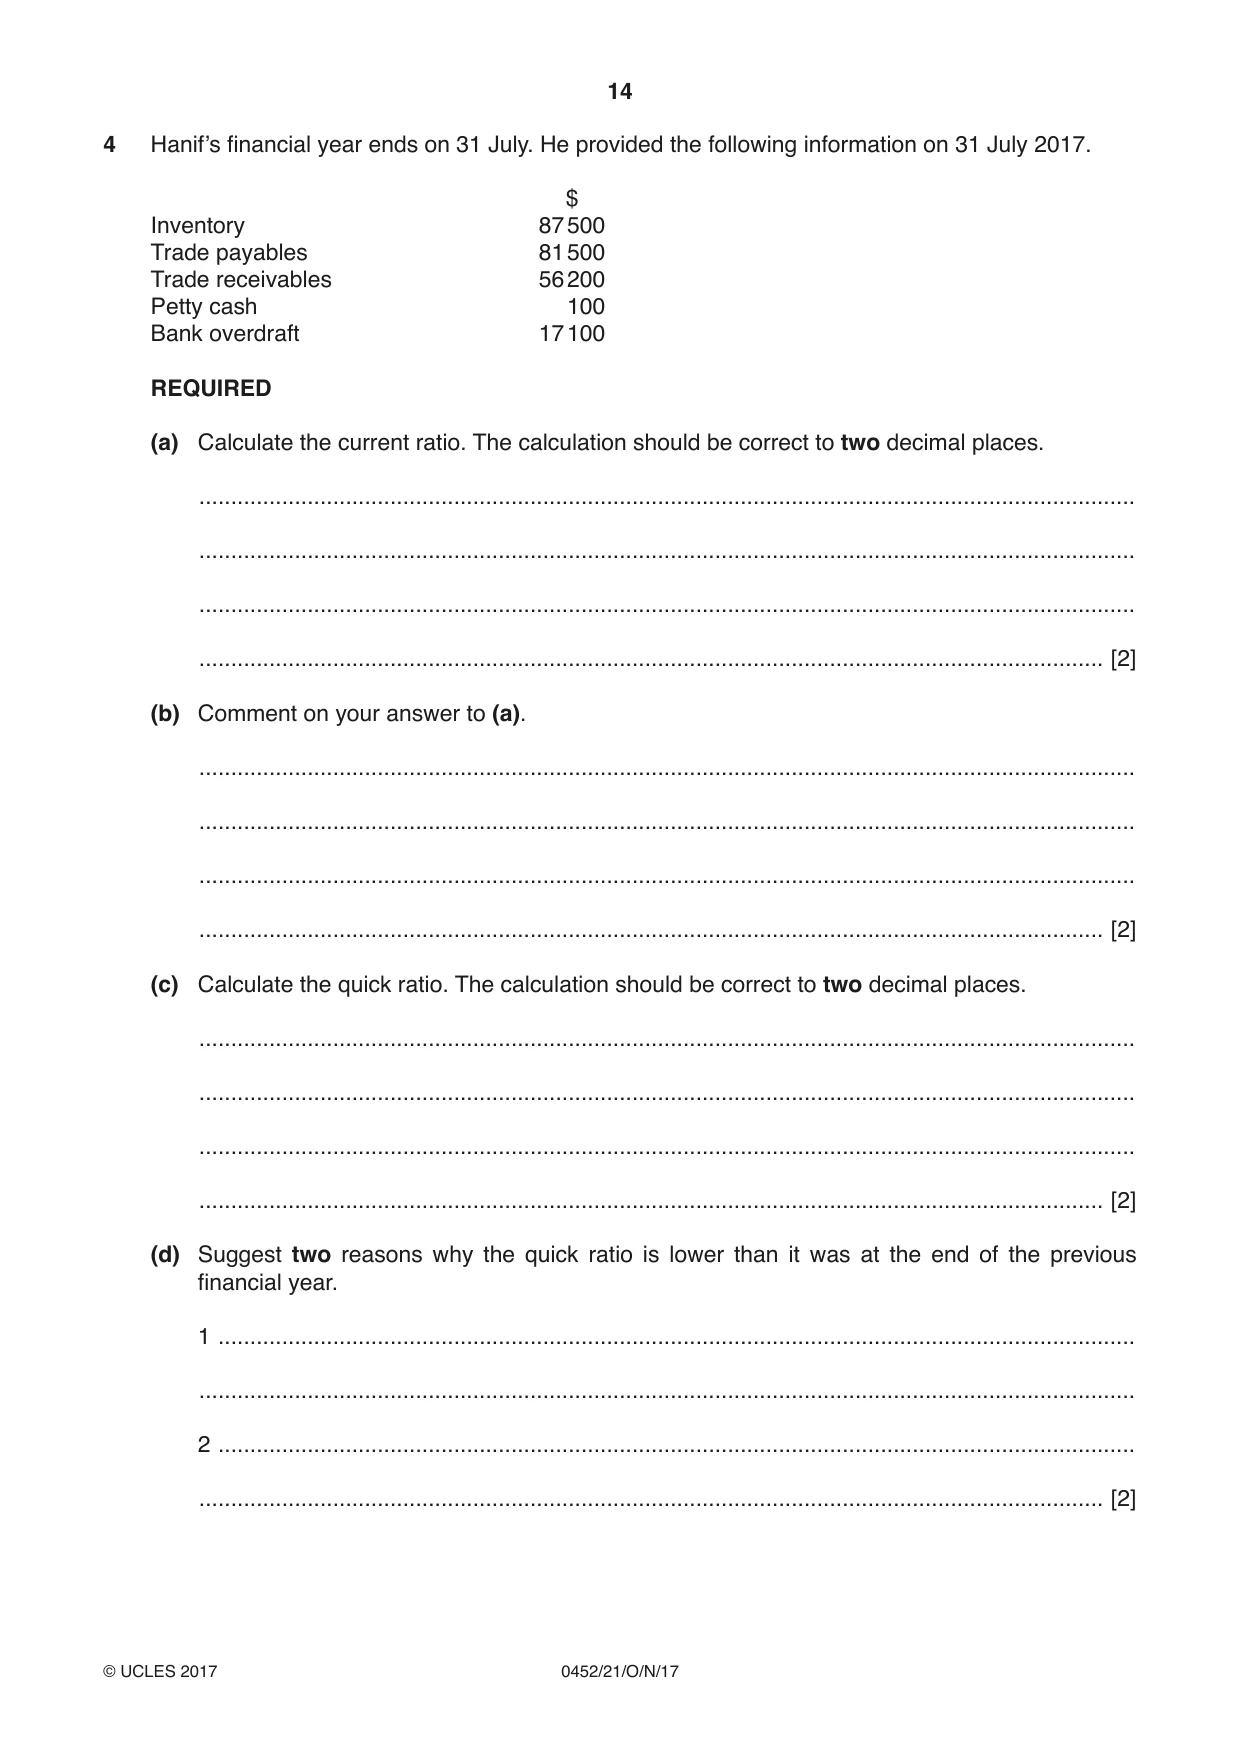
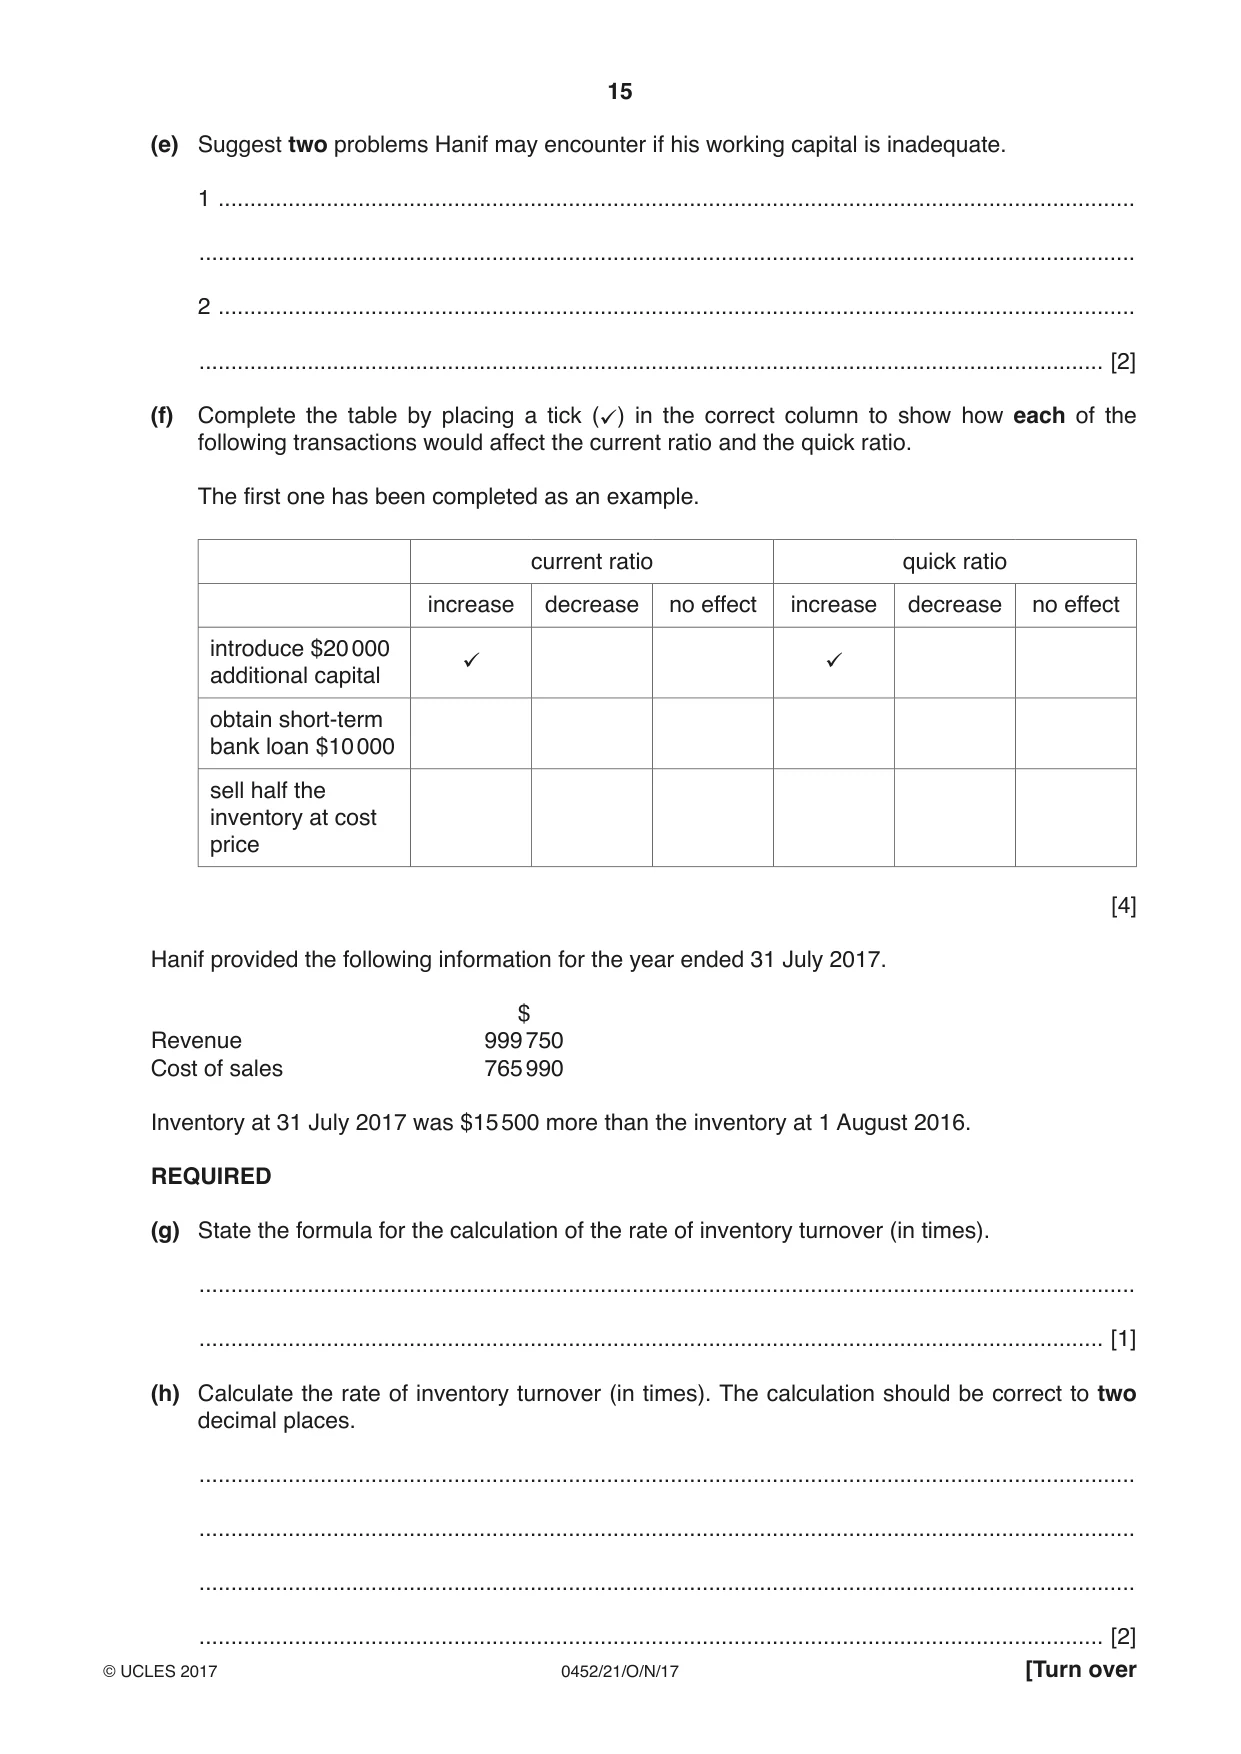
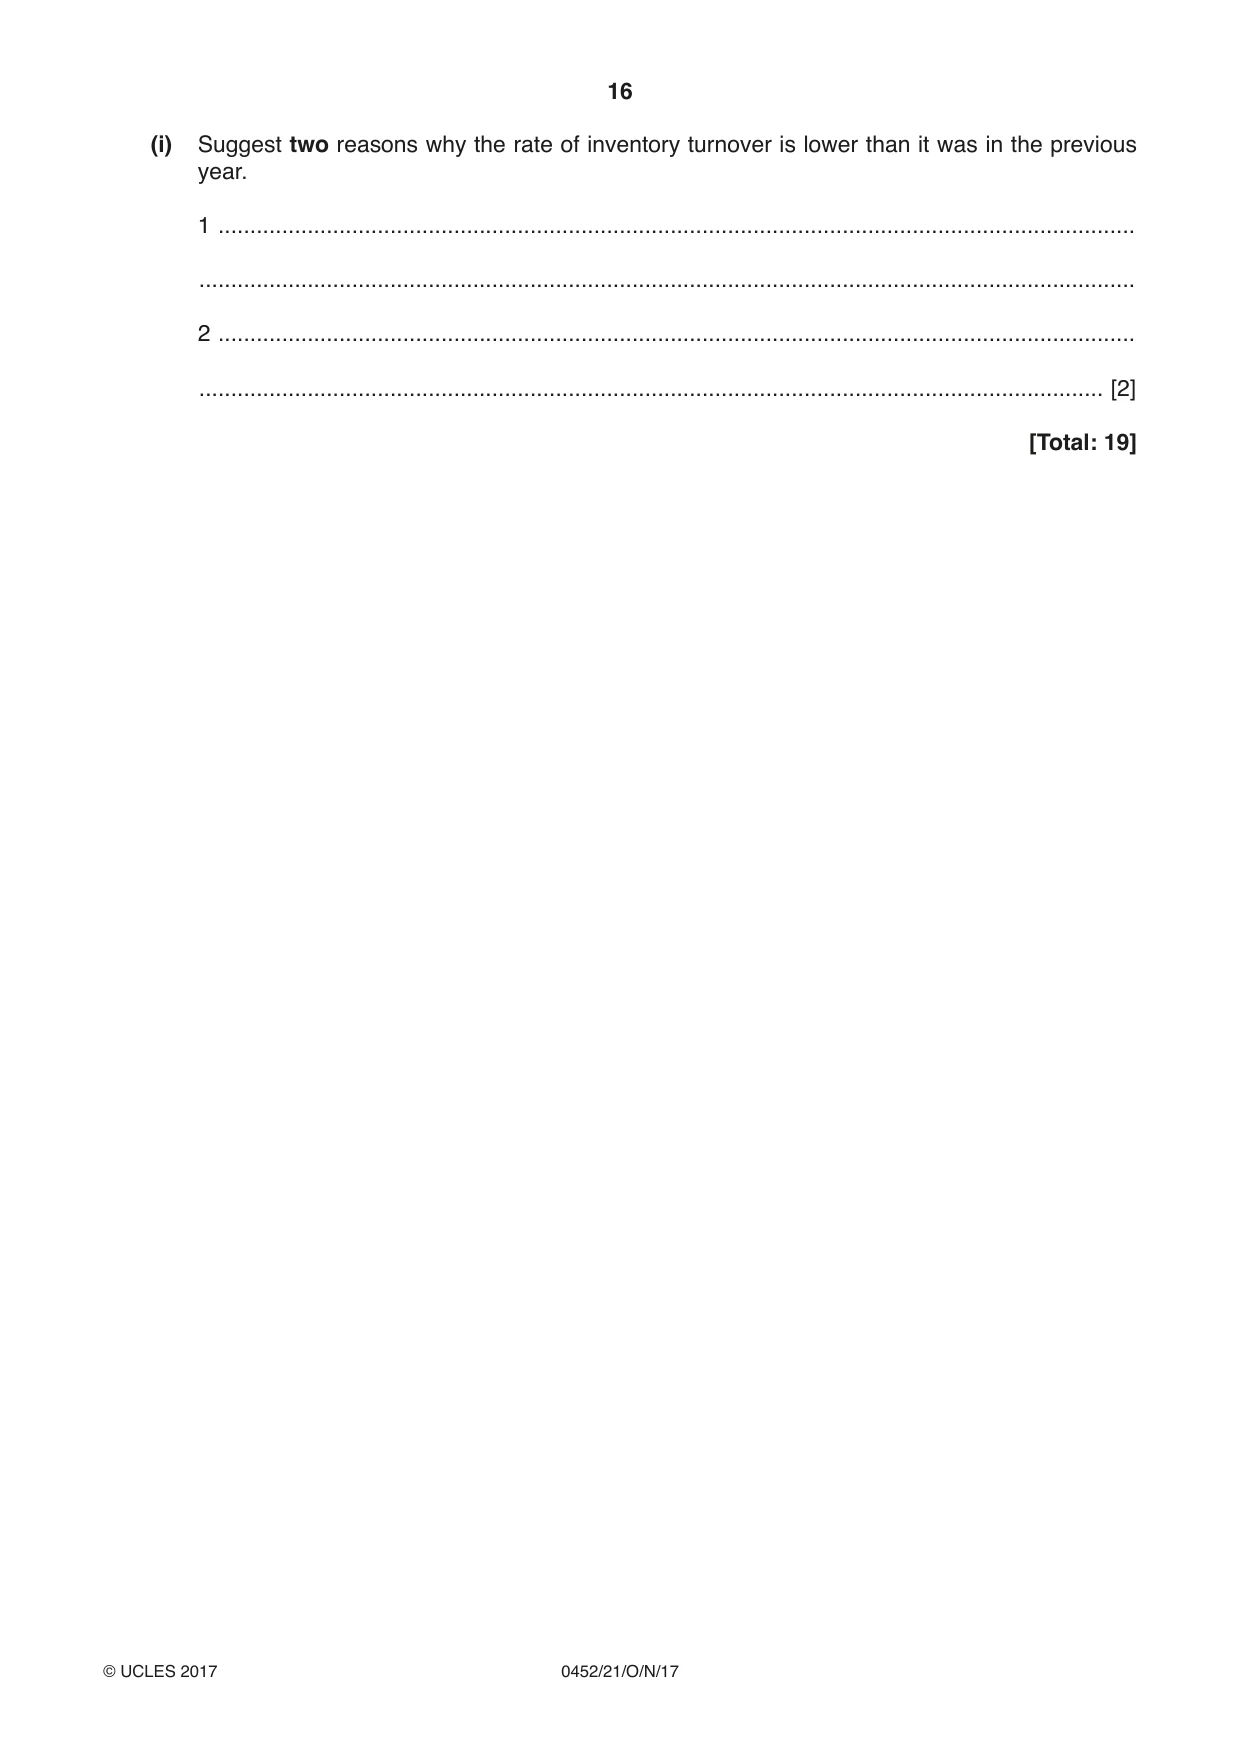
4 Hanif’s financial year ends on 31 July. He provided the following information on 31 July 2017. $ Inventory 87 500 Trade payables 81 500 Trade receivables 56 200 Petty cash 100 Bank overdraft 17 100 REQUIRED (a) Calculate the current ratio. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (b) Comment on your answer to (a). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (c) Calculate the quick ratio. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (d) Suggest two reasons why the quick ratio is lower than it was at the end of the previous financial year. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (e) Suggest two problems Hanif may encounter if his working capital is inadequate. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (f) Complete the table by placing a tick () in the correct column to show how each of the following transactions would affect the current ratio and the quick ratio. The first one has been completed as an example. current ratio quick ratio increase decrease no effect increase decrease no effect introduce $20 000 additional capital obtain short-term bank loan $10 000 sell half the inventory at cost price [4] Hanif provided the following information for the year ended 31 July 2017. $ Revenue 999 750 Cost of sales 765 990 Inventory at 31 July 2017 was $15 500 more than the inventory at 1 August 2016. REQUIRED (g) State the formula for the calculation of the rate of inventory turnover (in times). ................................................................................................................................................... .............................................................................................................................................. [1] (h) Calculate the rate of inventory turnover (in times). The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... (i) Suggest two reasons why the rate of inventory turnover is lower than it was in the previous year. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] [Total: 19] Question 5 is on the next page.
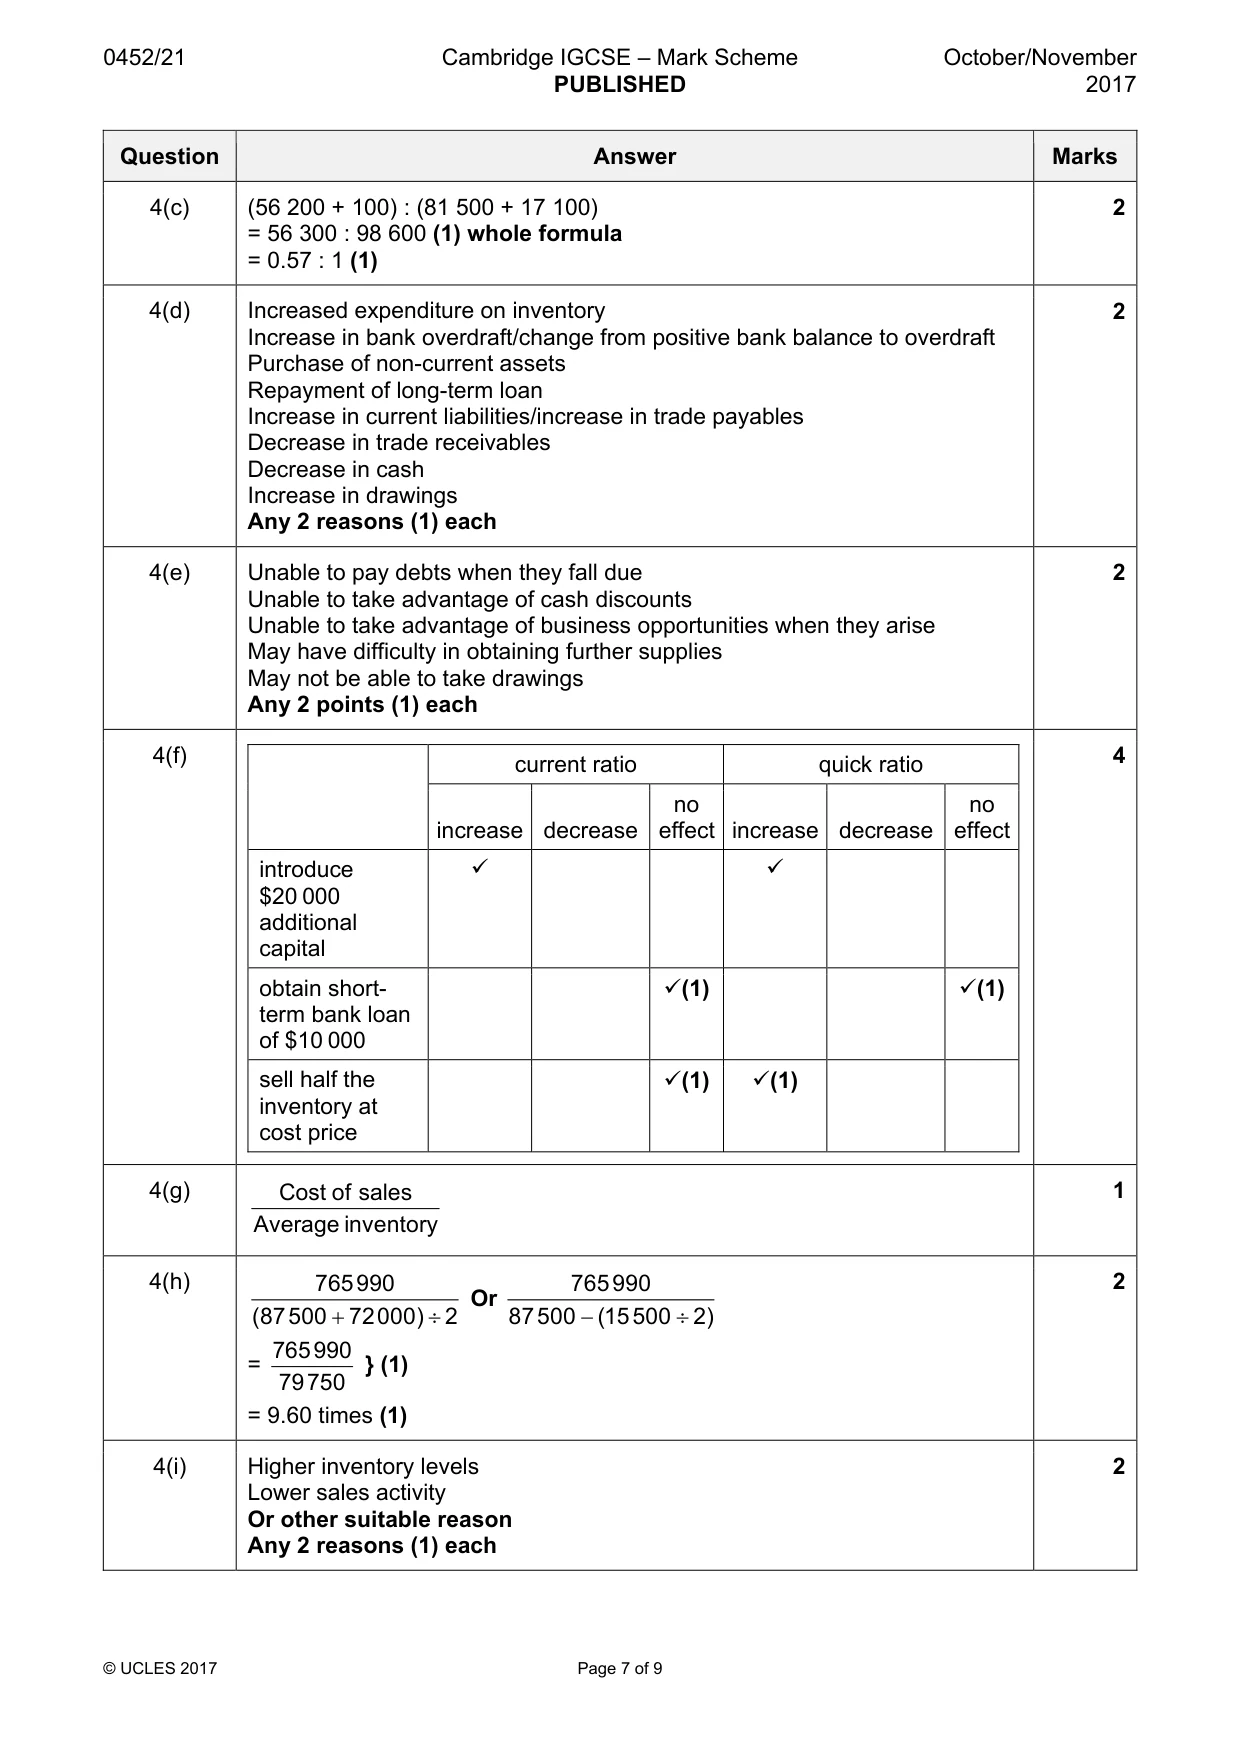
Mark scheme: 4(a) (87 500 + 56 200 + 100) : (81 500 + 17 100) 2 = 143 800 : 98 600 (1) whole formula = 1.46 : 1 (1) 4(b) Current assets only approximately 1½ times the current liabilities 2 Lower than the “benchmark” of 2:1 Can meet the current liabilities from the current assets Do not have a lot of surplus current assets available after paying current liabilities Seems to be a little inadequate (depending on the type of business) Comments to be based on answer to (a) Any 2 comments (1) each 4(c) (56 200 + 100) : (81 500 + 17 100) 2 = 56 300 : 98 600 (1) whole formula = 0.57 : 1 (1) 4(d) Increased expenditure on inventory 2 Increase in bank overdraft/change from positive bank balance to overdraft Purchase of non-current assets Repayment of long-term loan Increase in current liabilities/increase in trade payables Decrease in trade receivables Decrease in cash Increase in drawings Any 2 reasons (1) each 4(e) Unable to pay debts when they fall due 2 Unable to take advantage of cash discounts Unable to take advantage of business opportunities when they arise May have difficulty in obtaining further supplies May not be able to take drawings Any 2 points (1) each 4(f) 4 current ratio quick ratio no no increase decrease effect increase decrease effect introduce 9 9 $20 000 additional capital obtain short- 9(1) 9(1) term bank loan of $10 000 sell half the 9(1) 9(1) inventory at cost price 4(g) Cost of sales 1 Average inventory 4(h) 765990 765990 2 Or (87500 + 72000) ÷ 2 87500 − (15500 ÷ 2) 765990 = } (1) 79750 = 9.60 times (1) 4(i) Higher inventory levels 2 Lower sales activity Or other suitable reason Any 2 reasons (1) each
More questions on Calculation and understanding of accounting ratios
Q5 · The financial year of CP Limited ends on 30 September
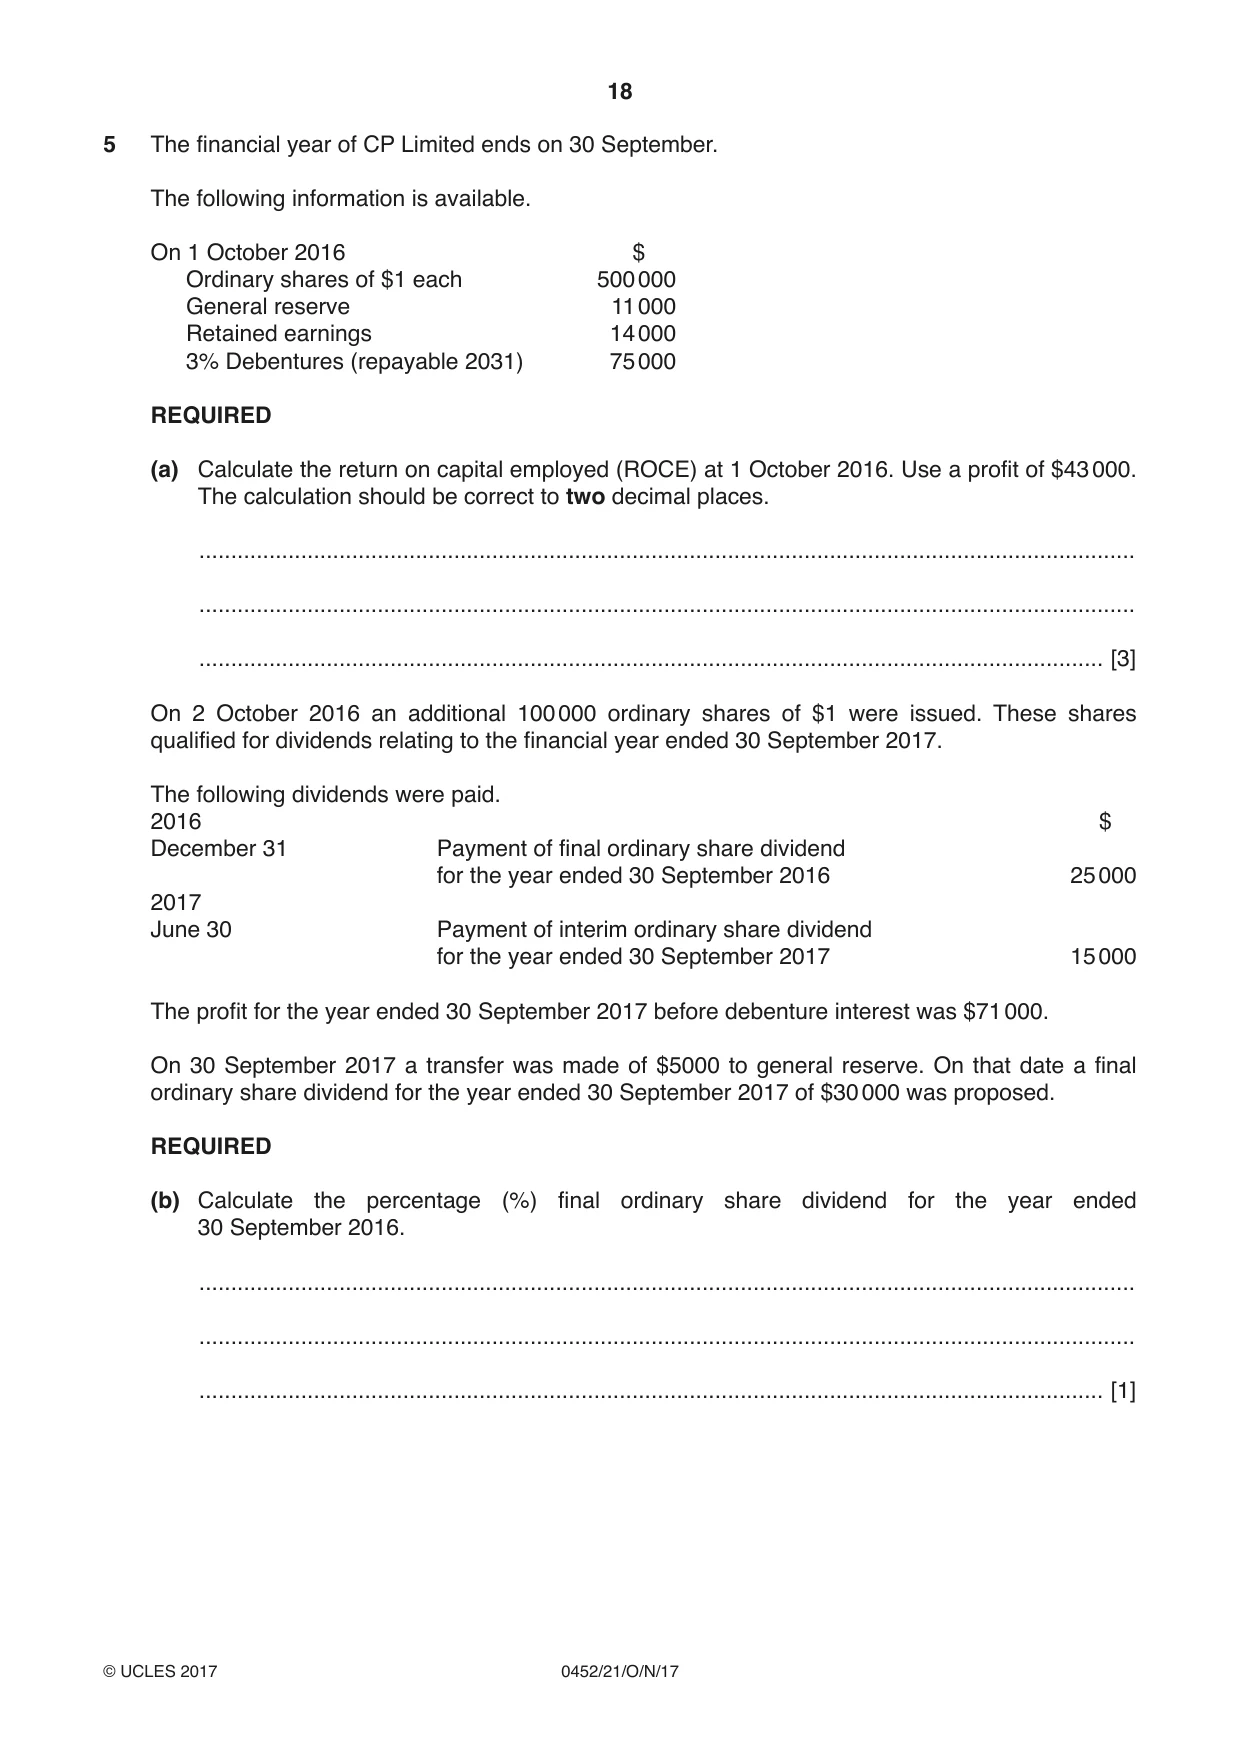
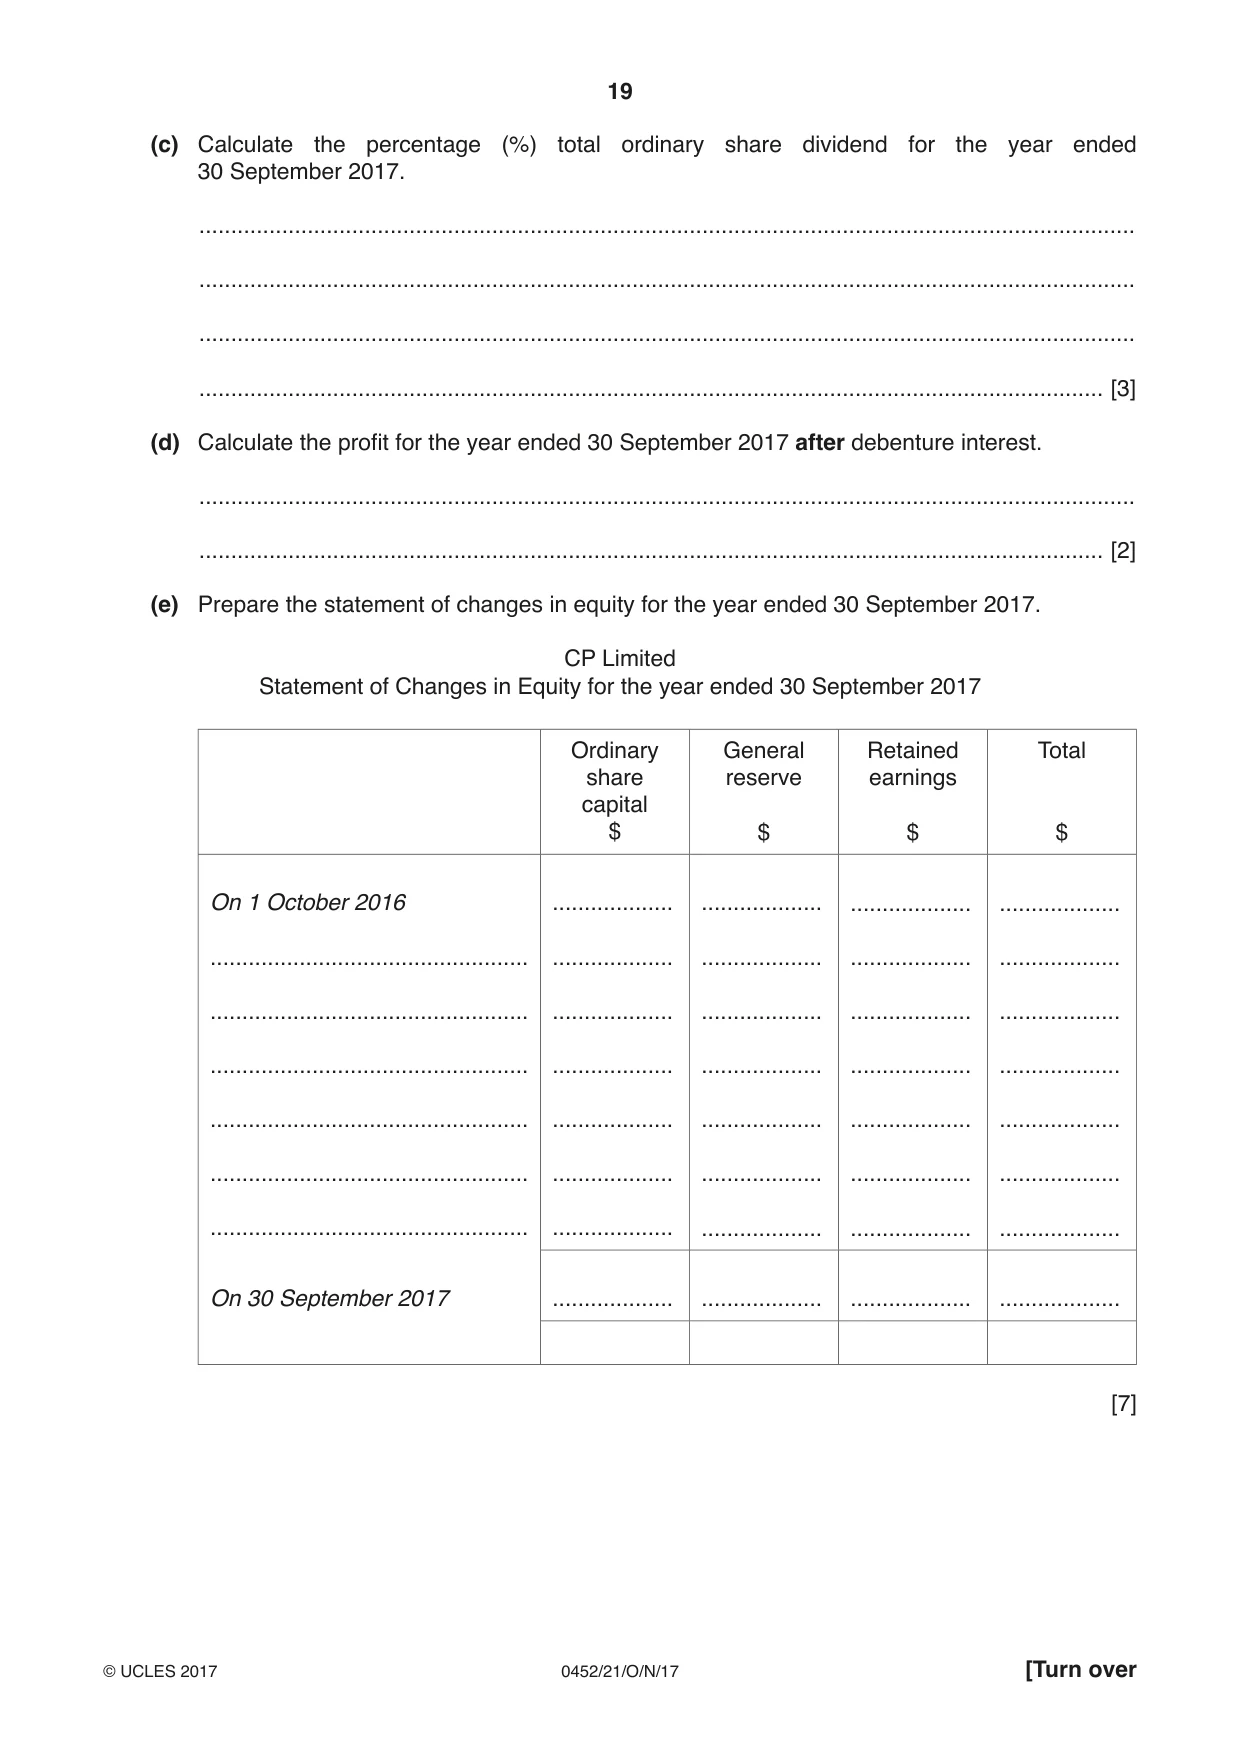
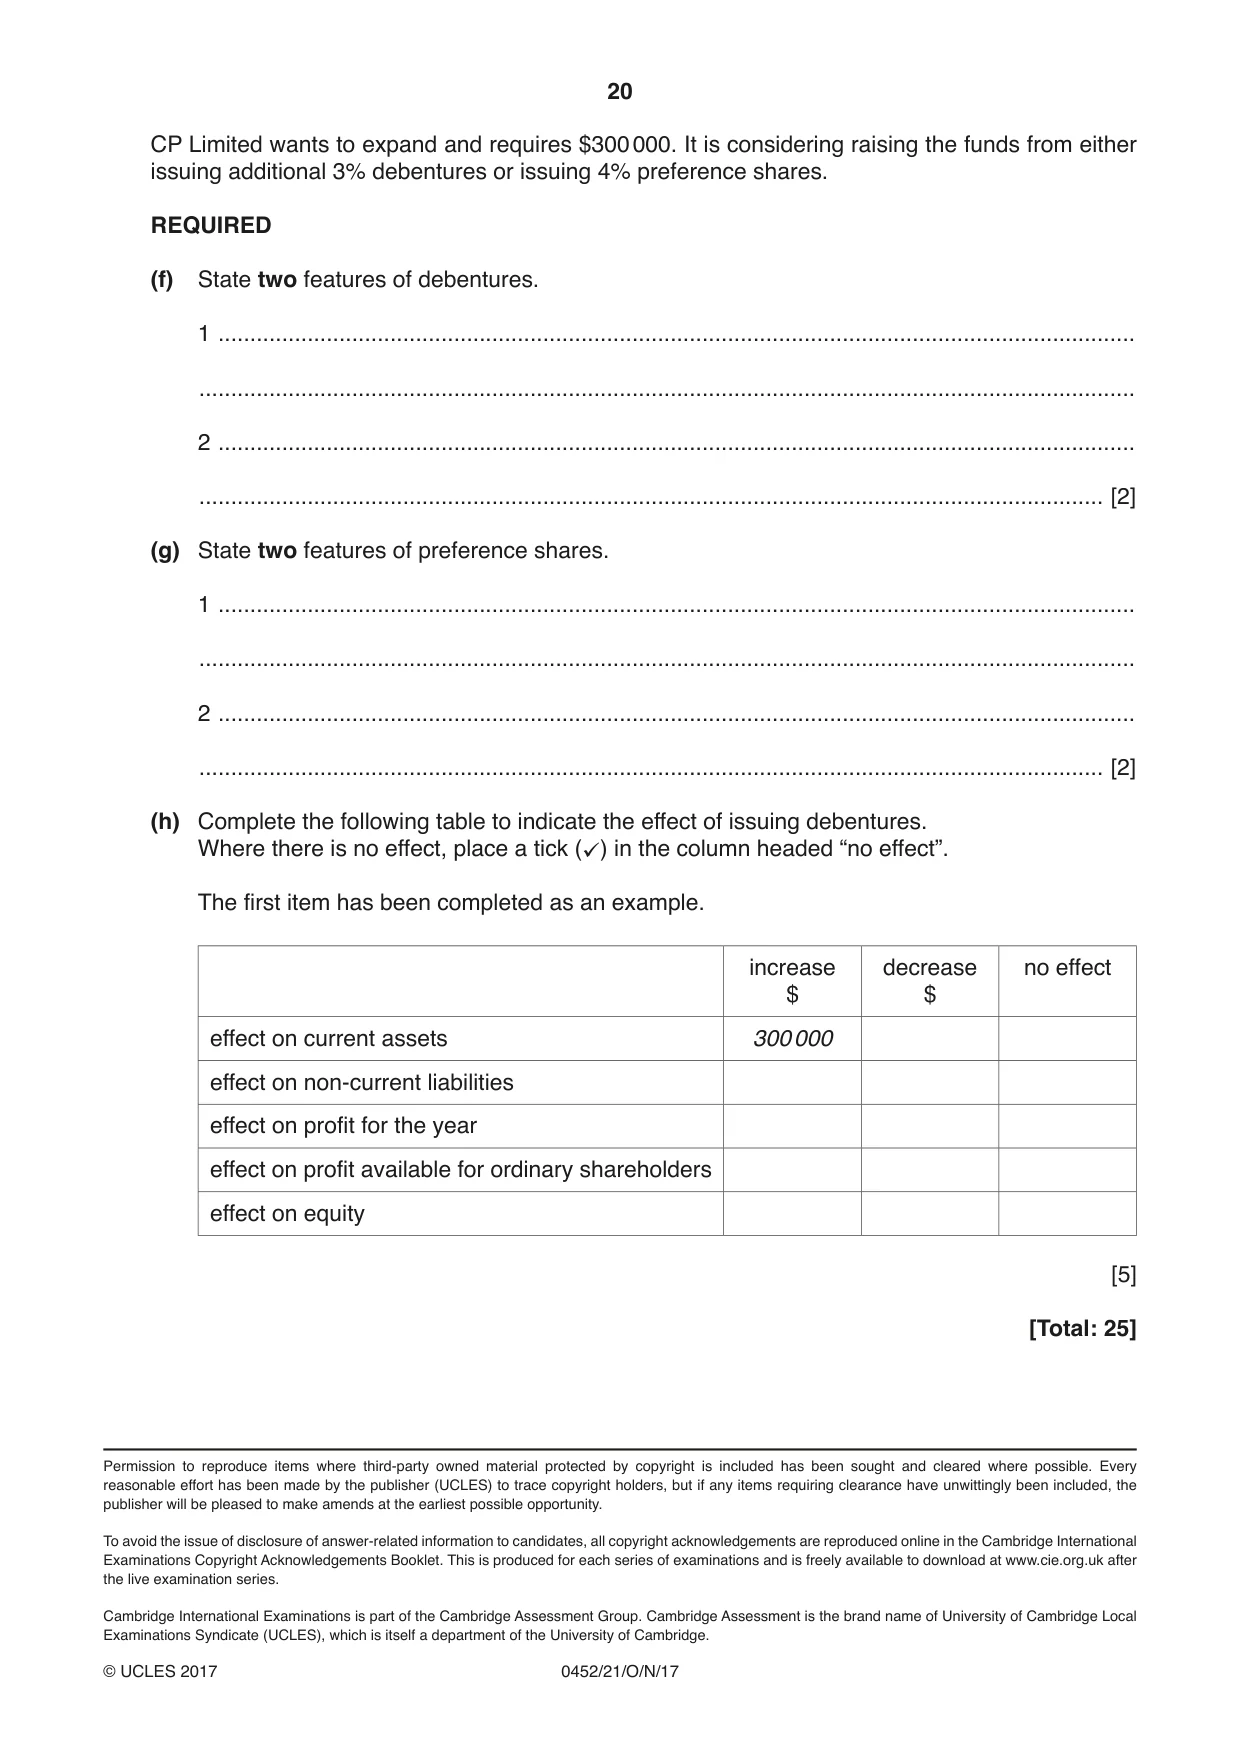
5 The financial year of CP Limited ends on 30 September. The following information is available. On 1 October 2016 $ Ordinary shares of $1 each 500 000 General reserve 11 000 Retained earnings 14 000 3% Debentures (repayable 2031) 75 000 REQUIRED (a) Calculate the return on capital employed (ROCE) at 1 October 2016. Use a profit of $43 000. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [3] On 2 October 2016 an additional 100 000 ordinary shares of $1 were issued. These shares qualified for dividends relating to the financial year ended 30 September 2017. The following dividends were paid. 2016 $ December 31 Payment of final ordinary share dividend for the year ended 30 September 2016 25 000 2017 June 30 Payment of interim ordinary share dividend for the year ended 30 September 2017 15 000 The profit for the year ended 30 September 2017 before debenture interest was $71 000. On 30 September 2017 a transfer was made of $5000 to general reserve. On that date a final ordinary share dividend for the year ended 30 September 2017 of $30 000 was proposed. REQUIRED (b) Calculate the percentage (%) final ordinary share dividend for the year ended 30 September 2016. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [1] (c) Calculate the percentage (%) total ordinary share dividend for the year ended 30 September 2017. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [3] (d) Calculate the profit for the year ended 30 September 2017 after debenture interest. ................................................................................................................................................... .............................................................................................................................................. [2] (e) Prepare the statement of changes in equity for the year ended 30 September 2017. CP Limited Statement of Changes in Equity for the year ended 30 September 2017 Ordinary General Retained Total share reserve earnings capital $ $ $ $ On 1 October 2016 ................... ................... ................... ................... .................................................. ................... ................... ................... ................... .................................................. ................... ................... ................... ................... .................................................. ................... ................... ................... ................... .................................................. ................... ................... ................... ................... .................................................. ................... ................... ................... ................... .................................................. ................... ................... ................... ................... On 30 September 2017 ................... ................... ................... ................... [7] CP Limited wants to expand and requires $300 000. It is considering raising the funds from either issuing additional 3% debentures or issuing 4% preference shares. REQUIRED (f) State two features of debentures. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (g) State two features of preference shares. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (h) Complete the following table to indicate the effect of issuing debentures. Where there is no effect, place a tick () in the column headed “no effect”. The first item has been completed as an example. increase decrease no effect $ $ effect on current assets 300 000 effect on non-current liabilities effect on profit for the year effect on profit available for ordinary shareholders effect on equity [5] [Total: 25]
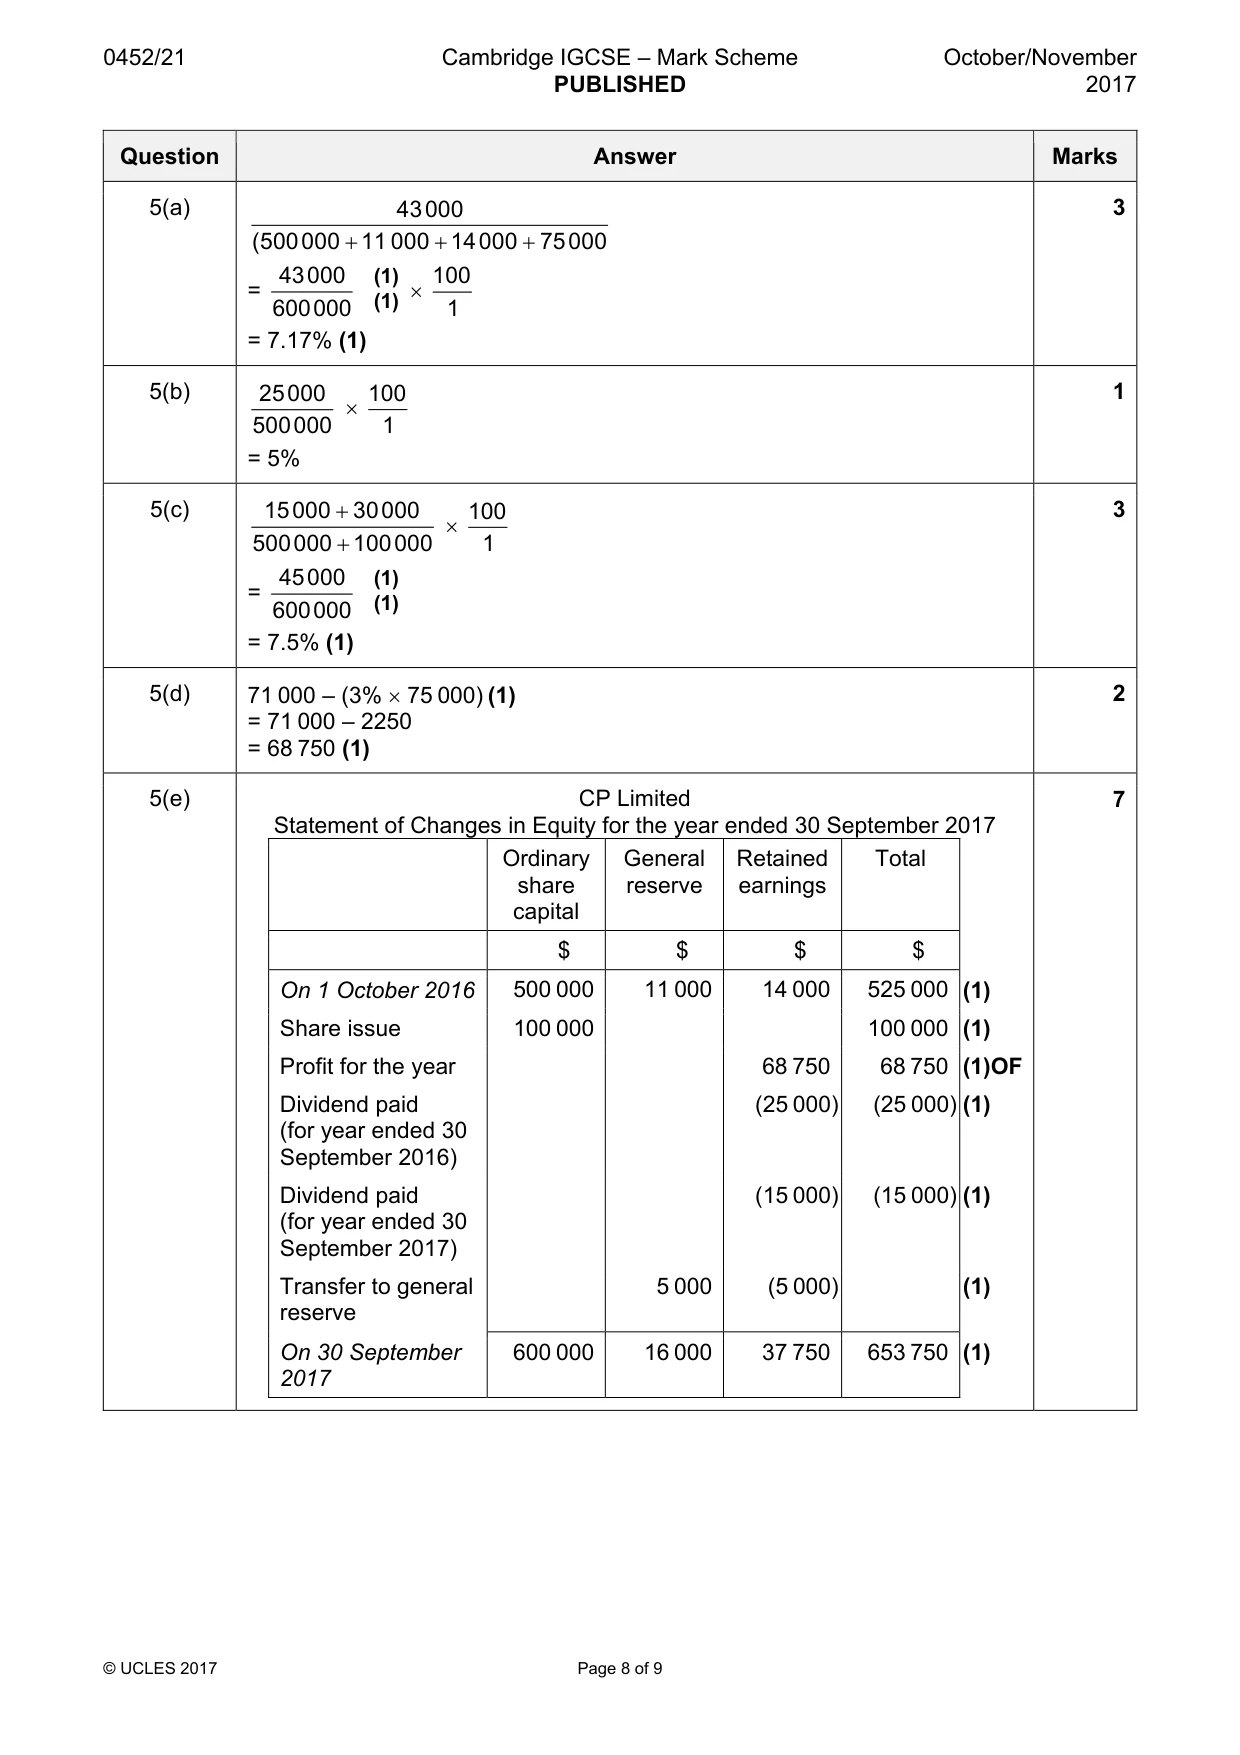
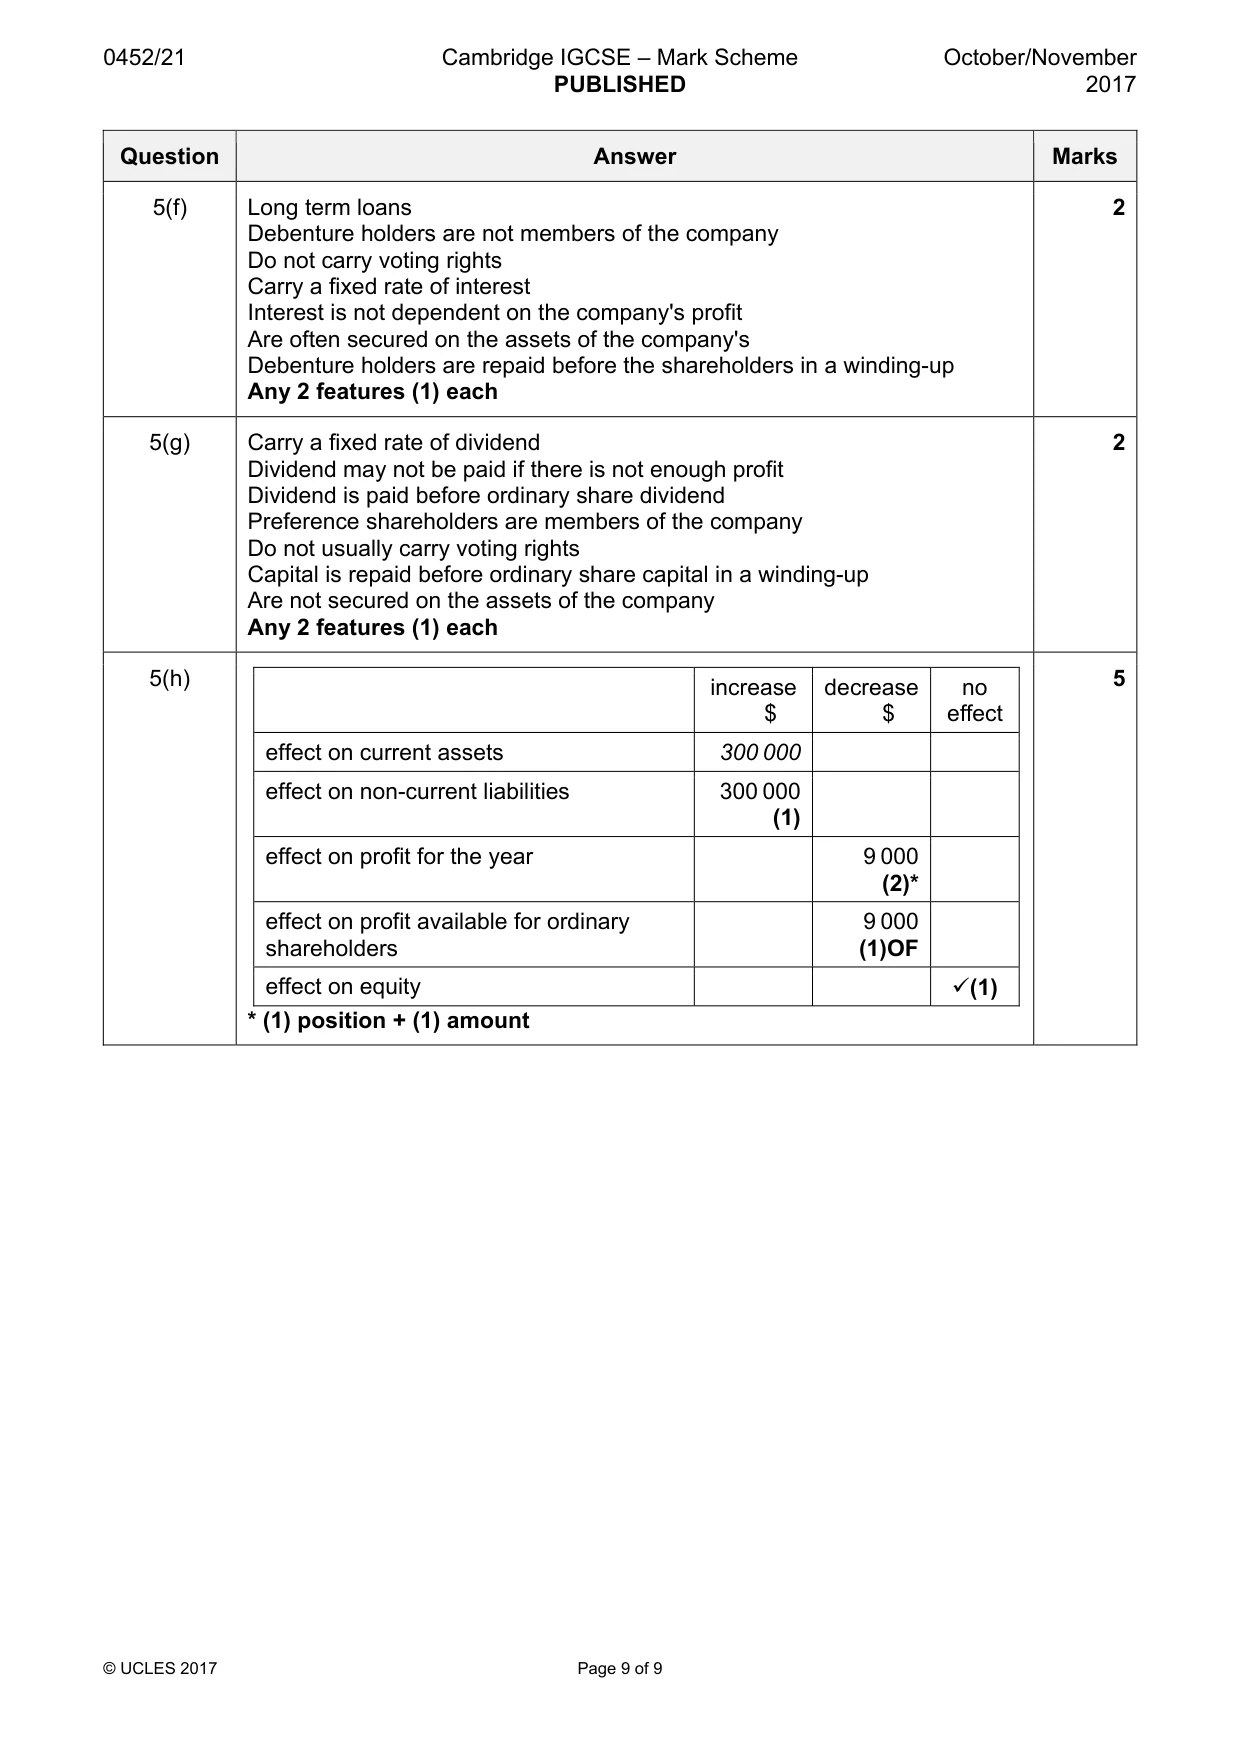
Mark scheme: 5(a) 43000 3 (500000 + 11 000 + 14000 + 75000 43000 (1) 100 = × 600000 (1) 1 = 7.17% (1) 5(b) 25000 100 1 × 500000 1 = 5% 5(c) 15000 + 30000 100 3 × 500000 + 100000 1 45000 (1) = 600000 (1) = 7.5% (1) 5(d) 71 000 – (3% × 75 000) (1) 2 = 71 000 – 2250 = 68 750 (1) 5(e) CP Limited 7 Statement of Changes in Equity for the year ended 30 September 2017 Ordinary General Retained Total share reserve earnings capital $ $ $ $ On 1 October 2016 500 000 11 000 14 000 525 000 (1) Share issue 100 000 100 000 (1) Profit for the year 68 750 68 750 (1)OF Dividend paid (25 000) (25 000) (1) (for year ended 30 September 2016) Dividend paid (15 000) (15 000) (1) (for year ended 30 September 2017) Transfer to general 5 000 (5 000) (1) reserve On 30 September 600 000 16 000 37 750 653 750 (1) 2017 5(f) Long term loans 2 Debenture holders are not members of the company Do not carry voting rights Carry a fixed rate of interest Interest is not dependent on the company's profit Are often secured on the assets of the company's Debenture holders are repaid before the shareholders in a winding-up Any 2 features (1) each 5(g) Carry a fixed rate of dividend 2 Dividend may not be paid if there is not enough profit Dividend is paid before ordinary share dividend Preference shareholders are members of the company Do not usually carry voting rights Capital is repaid before ordinary share capital in a winding-up Are not secured on the assets of the company Any 2 features (1) each 5(h) 5 increase decrease no $ $ effect effect on current assets 300 000 effect on non-current liabilities 300 000 (1) effect on profit for the year 9 000 (2)* effect on profit available for ordinary 9 000 shareholders (1)OF effect on equity 9(1) * (1) position + (1) amount
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2017 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.