Cambridge IGCSE Accounting 0452 — 2017 May/June Paper 2 · Variant 3
0452/23/M/J/17 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme12 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Shiromi is a trader in office equipment
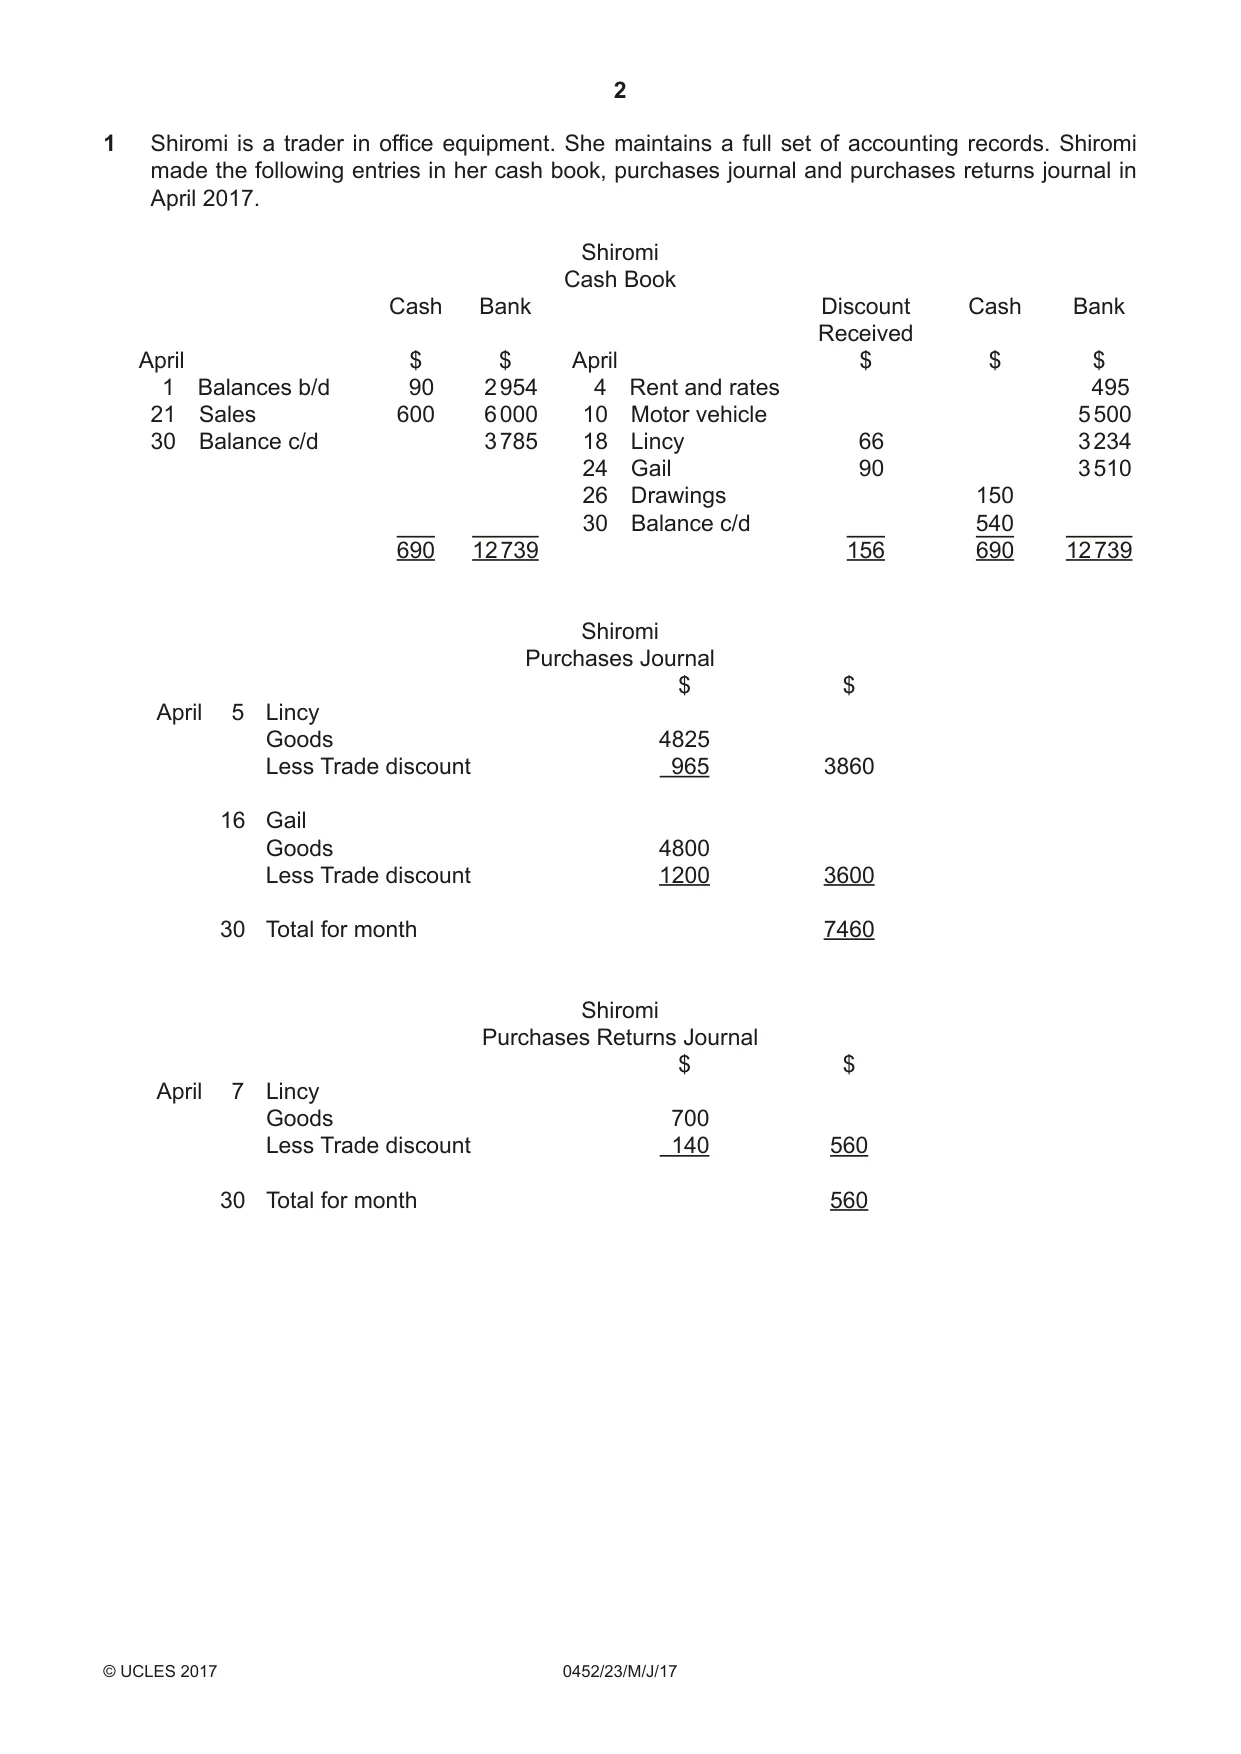
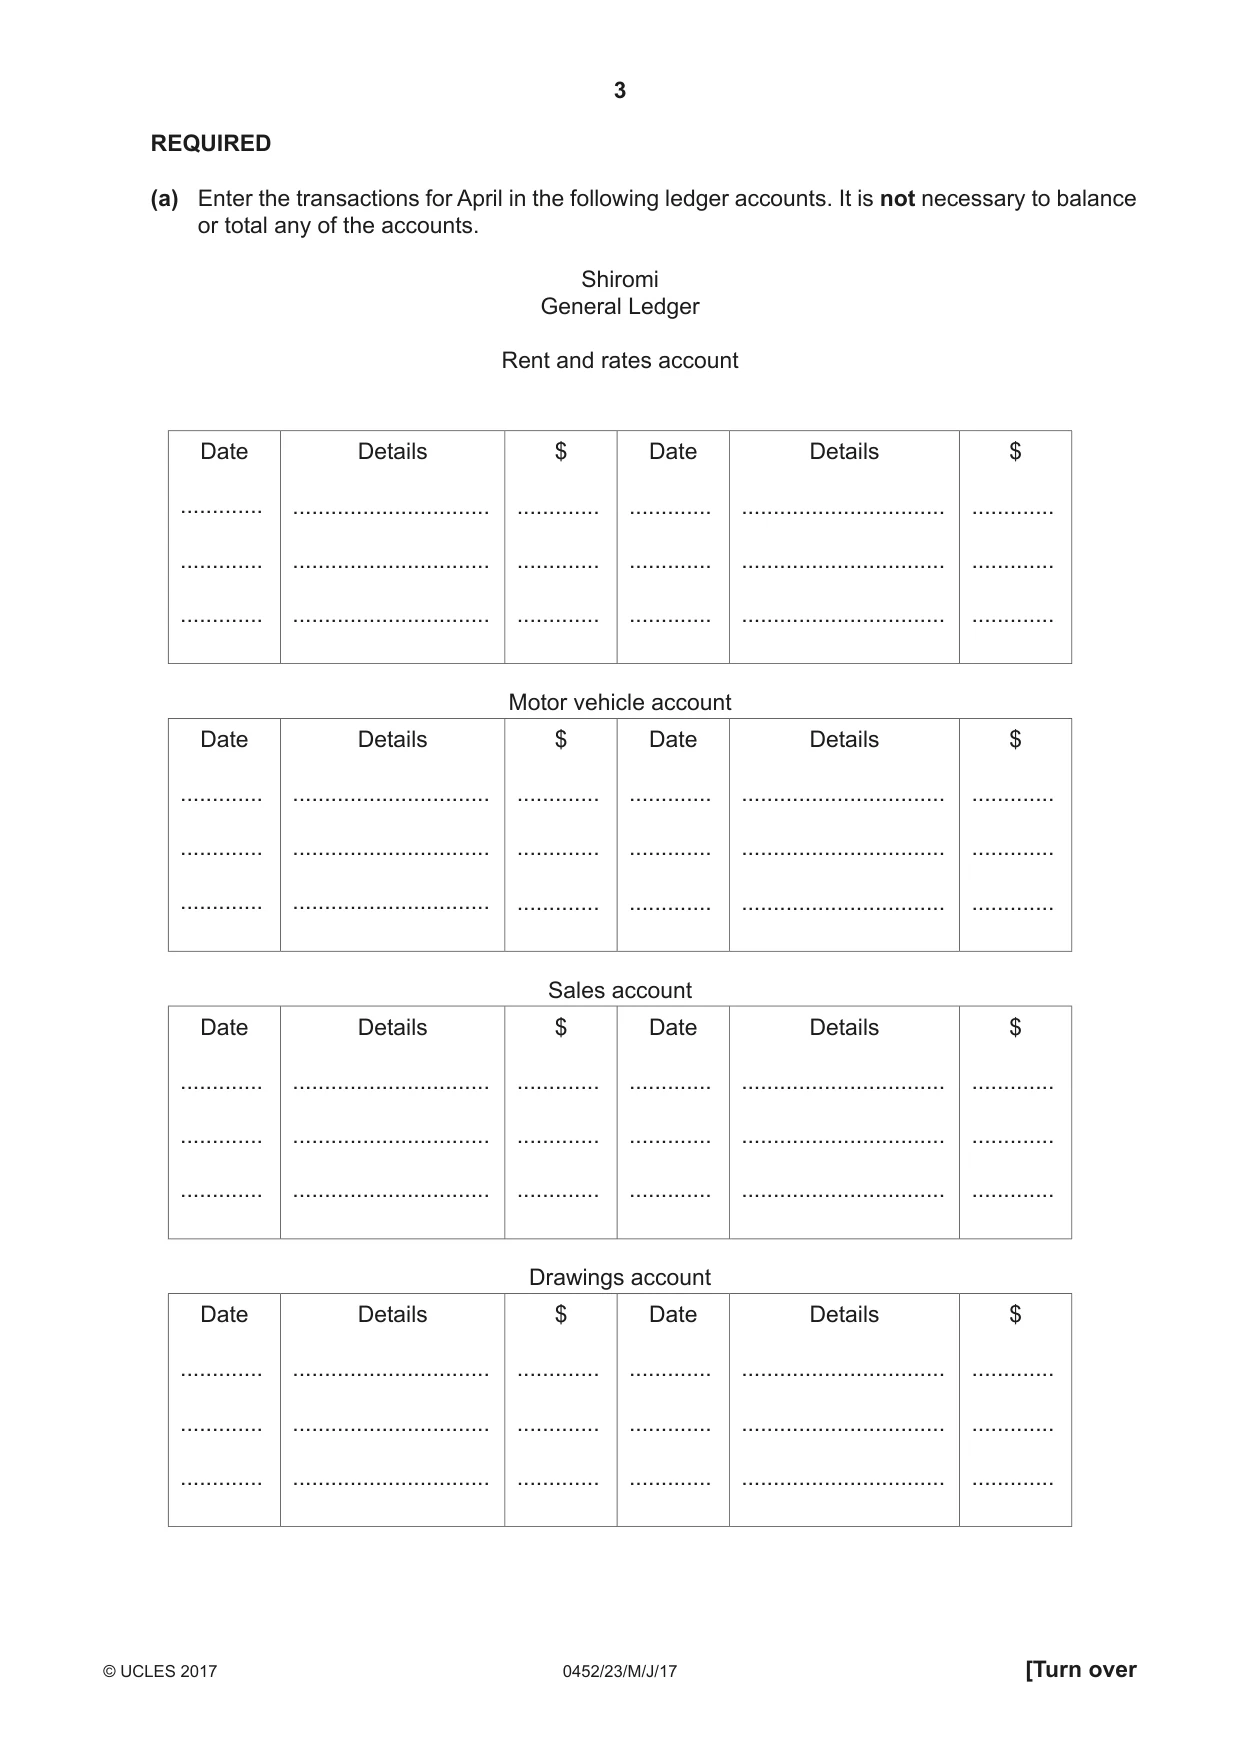
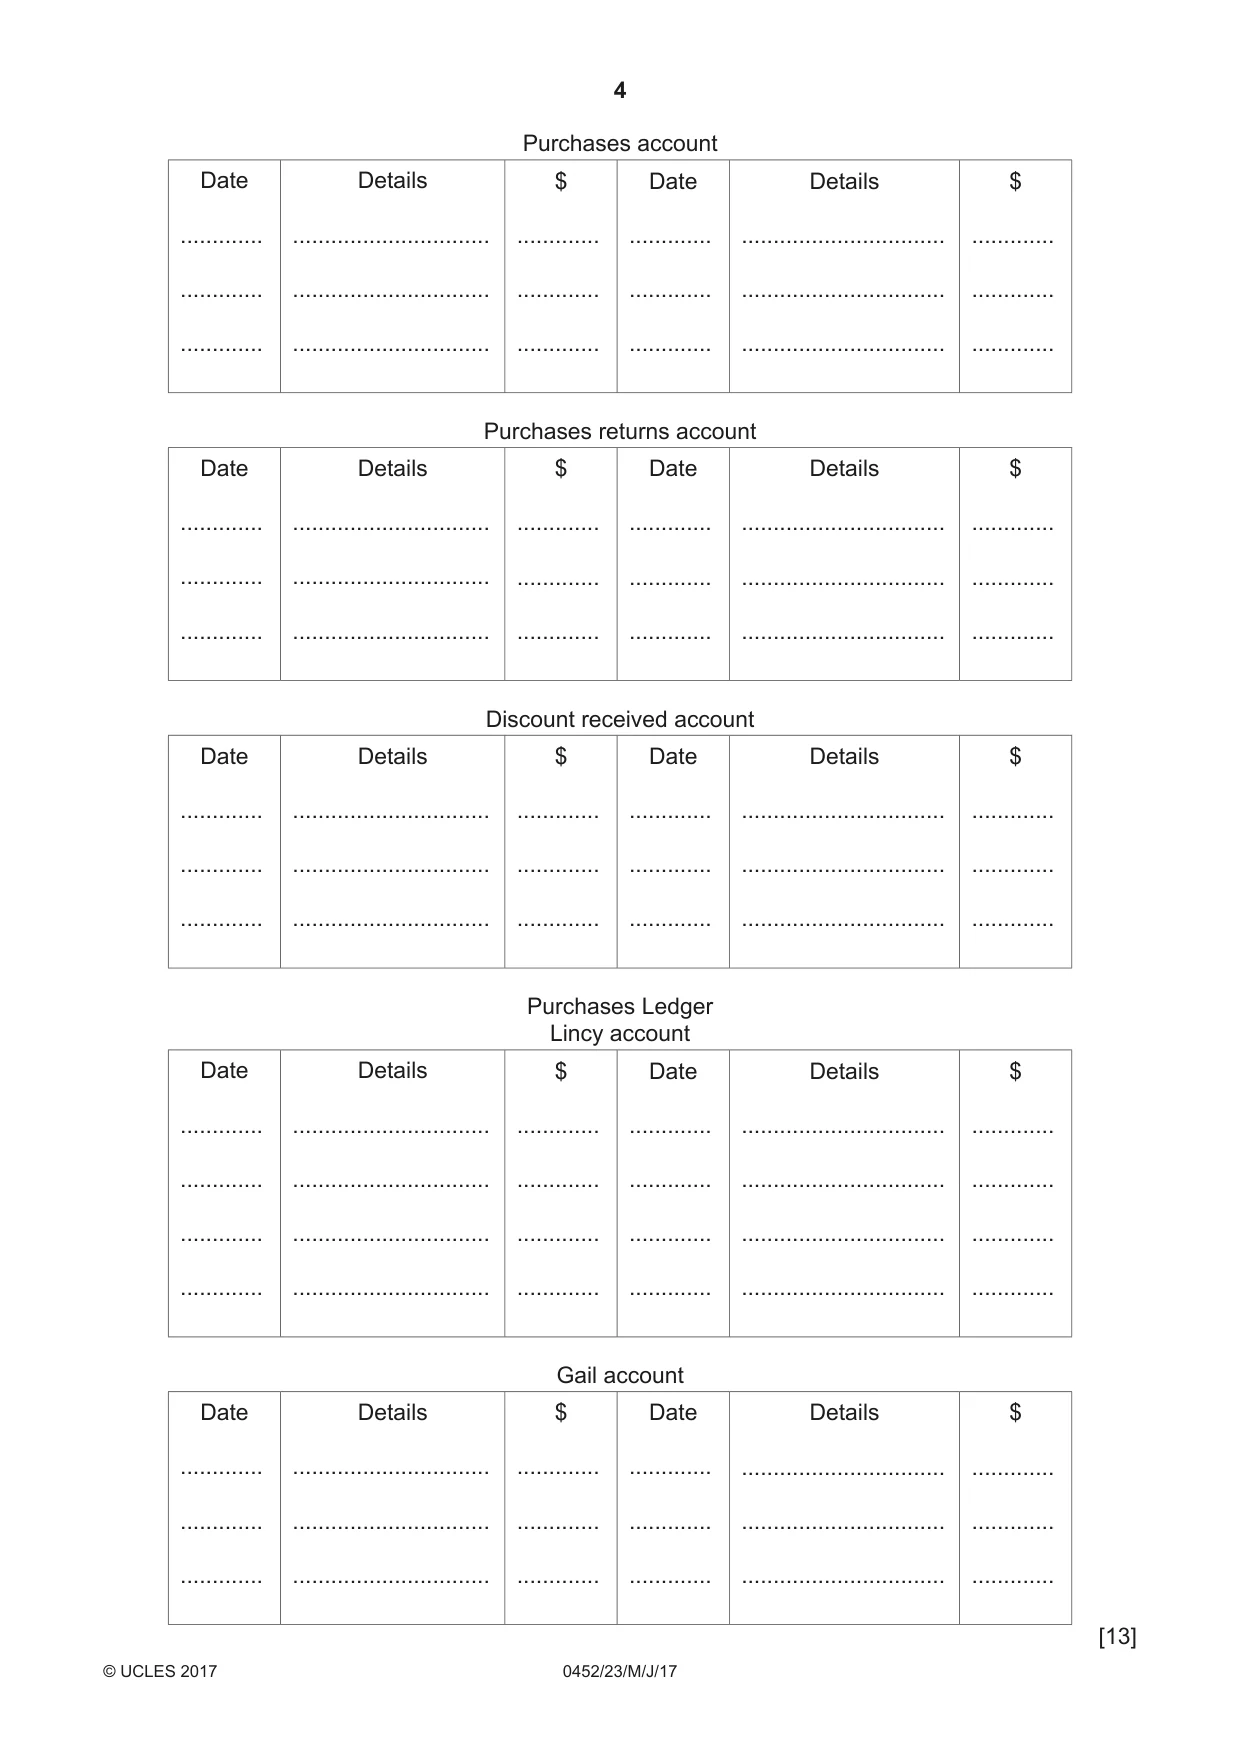
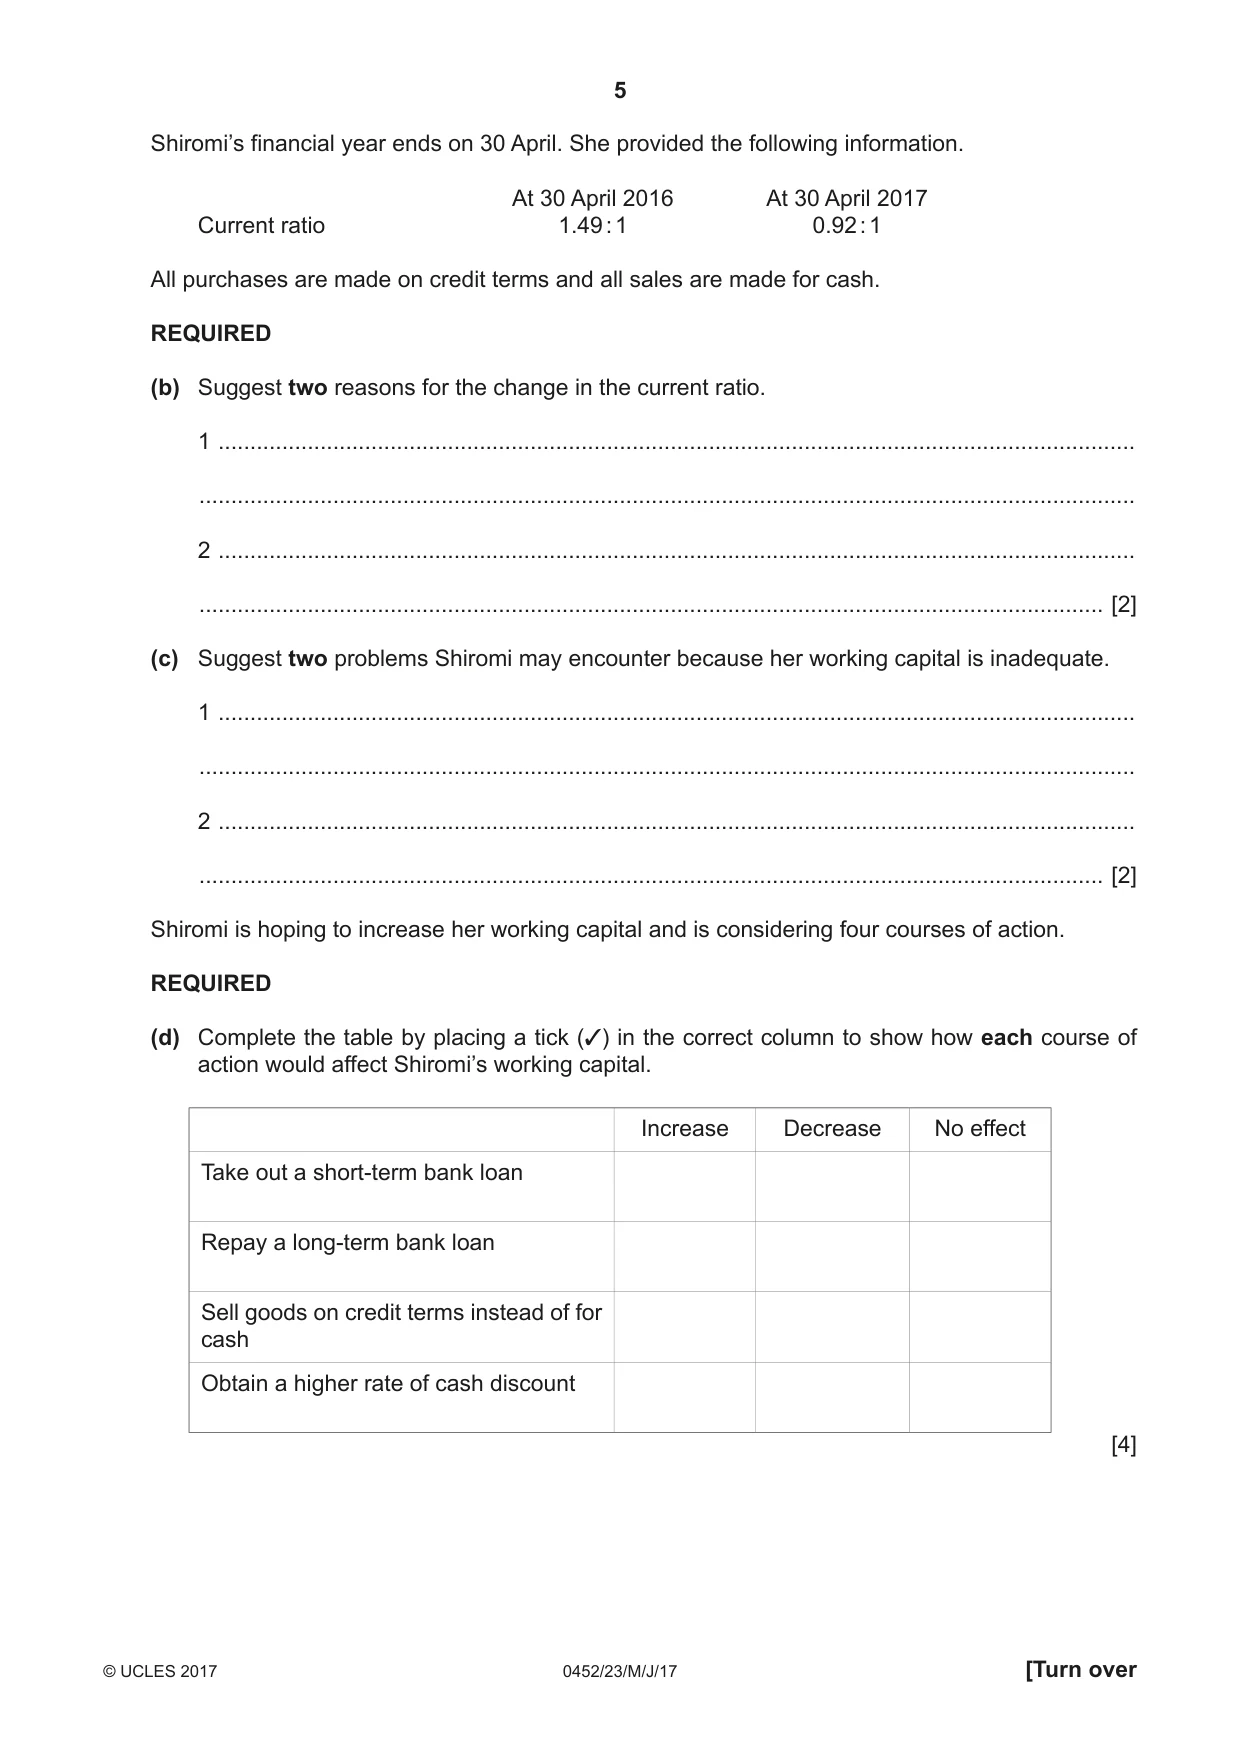
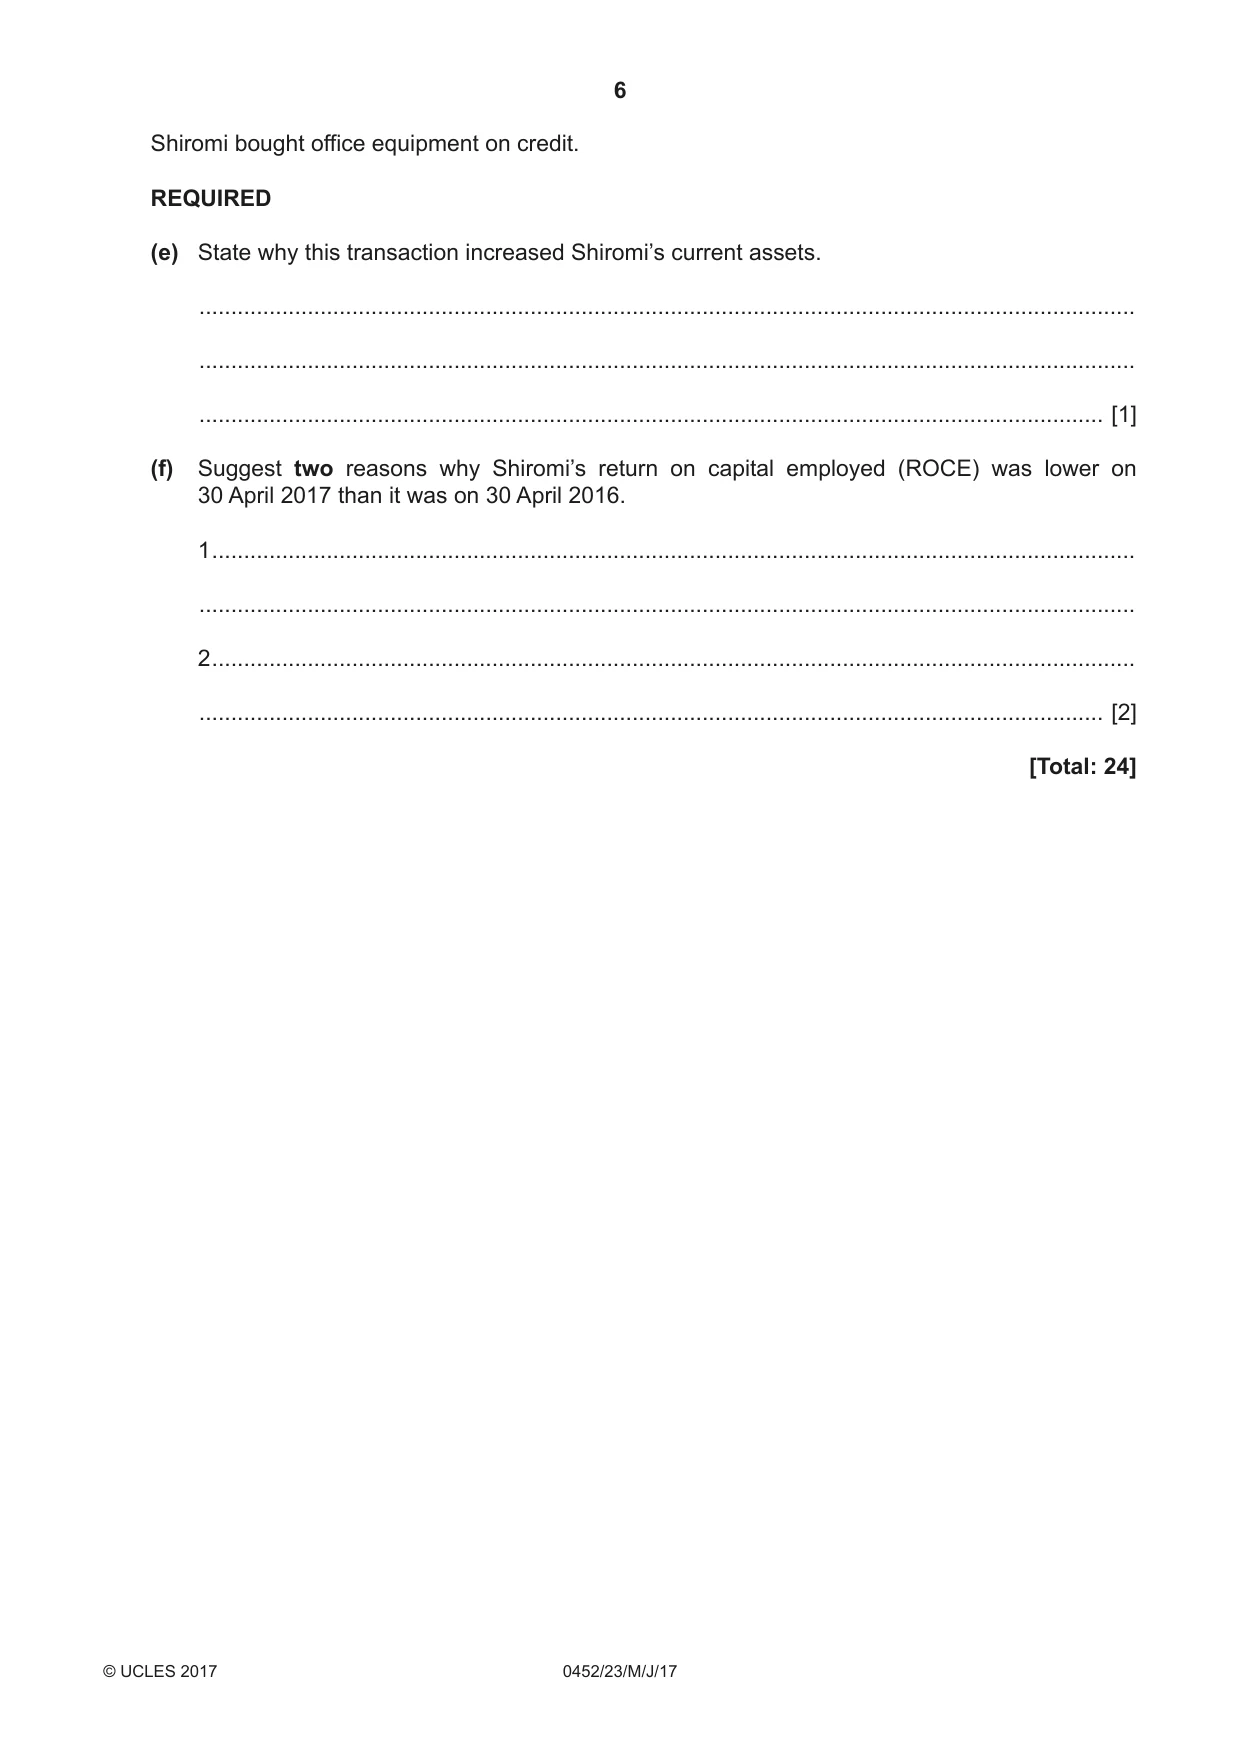
1 Shiromi is a trader in office equipment. She maintains a full set of accounting records. Shiromi made the following entries in her cash book, purchases journal and purchases returns journal in April 2017. Shiromi Cash Book Cash Bank Discount Cash Bank Received April $ $ April $ $ $ 1 Balances b/d 90 2 954 4 Rent and rates 495 21 Sales 600 6 000 10 Motor vehicle 5 500 30 Balance c/d 3 785 18 Lincy 66 3 234 24 Gail 90 3 510 26 Drawings 150 30 Balance c/d 540 690 12 739 156 690 12 739 Shiromi Purchases Journal $ $ April 5 Lincy Goods 4825 Less Trade discount 965 3860 16 Gail Goods 4800 Less Trade discount 1200 3600 30 Total for month 7460 Shiromi Purchases Returns Journal $ $ April 7 Lincy Goods 700 Less Trade discount 140 560 30 Total for month 560 REQUIRED (a) Enter the transactions for April in the following ledger accounts. It is not necessary to balance or total any of the accounts. Shiromi General Ledger Rent and rates account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Motor vehicle account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Sales account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Drawings account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Purchases account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Purchases returns account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Discount received account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Purchases Ledger Lincy account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. Gail account Date Details $ Date Details $ ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. ............. ............................... ............. ............. ................................ ............. [13] Shiromi’s financial year ends on 30 April. She provided the following information. At 30 April 2016 At 30 April 2017 Current ratio 1.49 : 1 0.92 : 1 All purchases are made on credit terms and all sales are made for cash. REQUIRED (b) Suggest two reasons for the change in the current ratio. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (c) Suggest two problems Shiromi may encounter because her working capital is inadequate. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] Shiromi is hoping to increase her working capital and is considering four courses of action. REQUIRED (d) Complete the table by placing a tick (✓) in the correct column to show how each course of action would affect Shiromi’s working capital. Increase Decrease No effect Take out a short-term bank loan Repay a long-term bank loan Sell goods on credit terms instead of for cash Obtain a higher rate of cash discount [4] Shiromi bought office equipment on credit. REQUIRED (e) State why this transaction increased Shiromi’s current assets. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [1] (f) Suggest two reasons why Shiromi’s return on capital employed (ROCE) was lower on 30 April 2017 than it was on 30 April 2016. 1 ................................................................................................................................................. ................................................................................................................................................... 2 ................................................................................................................................................. .............................................................................................................................................. [2] [Total: 24]
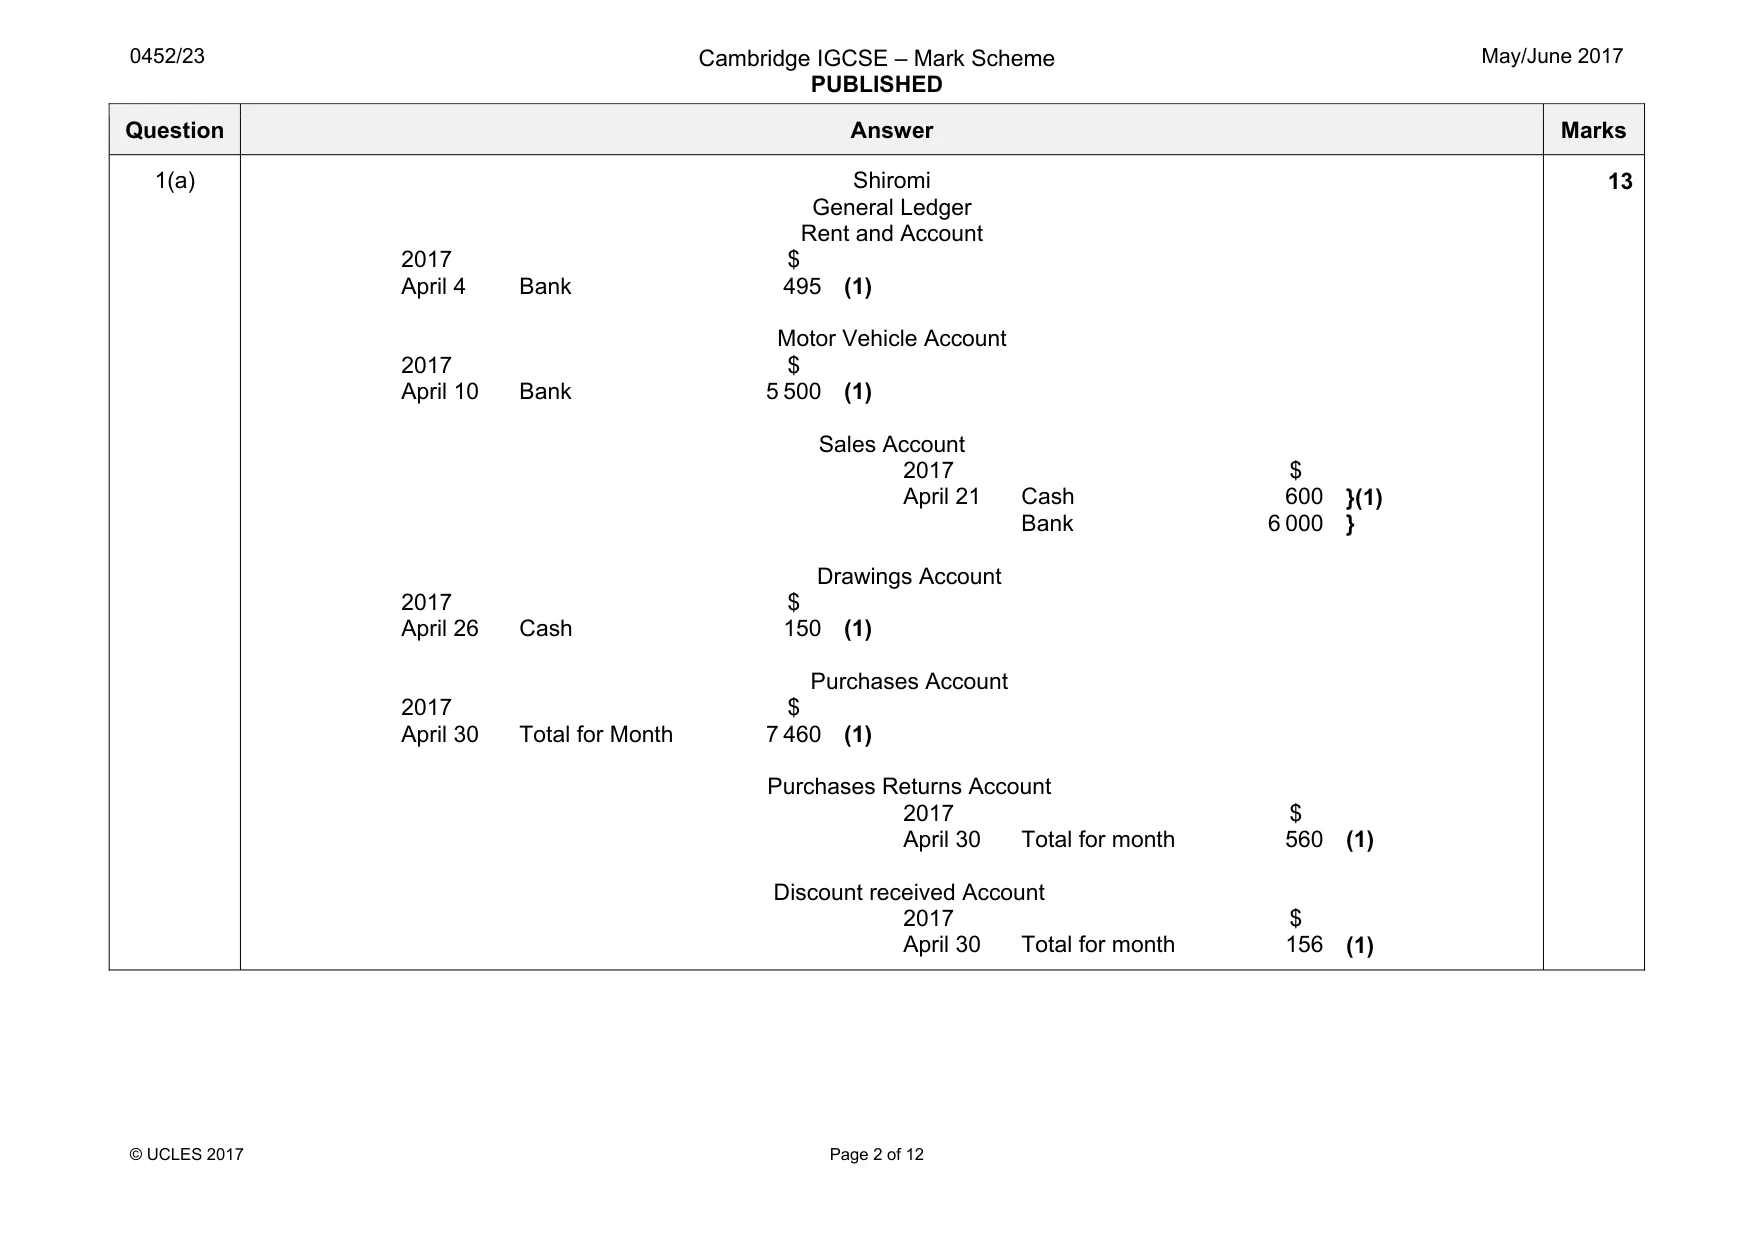
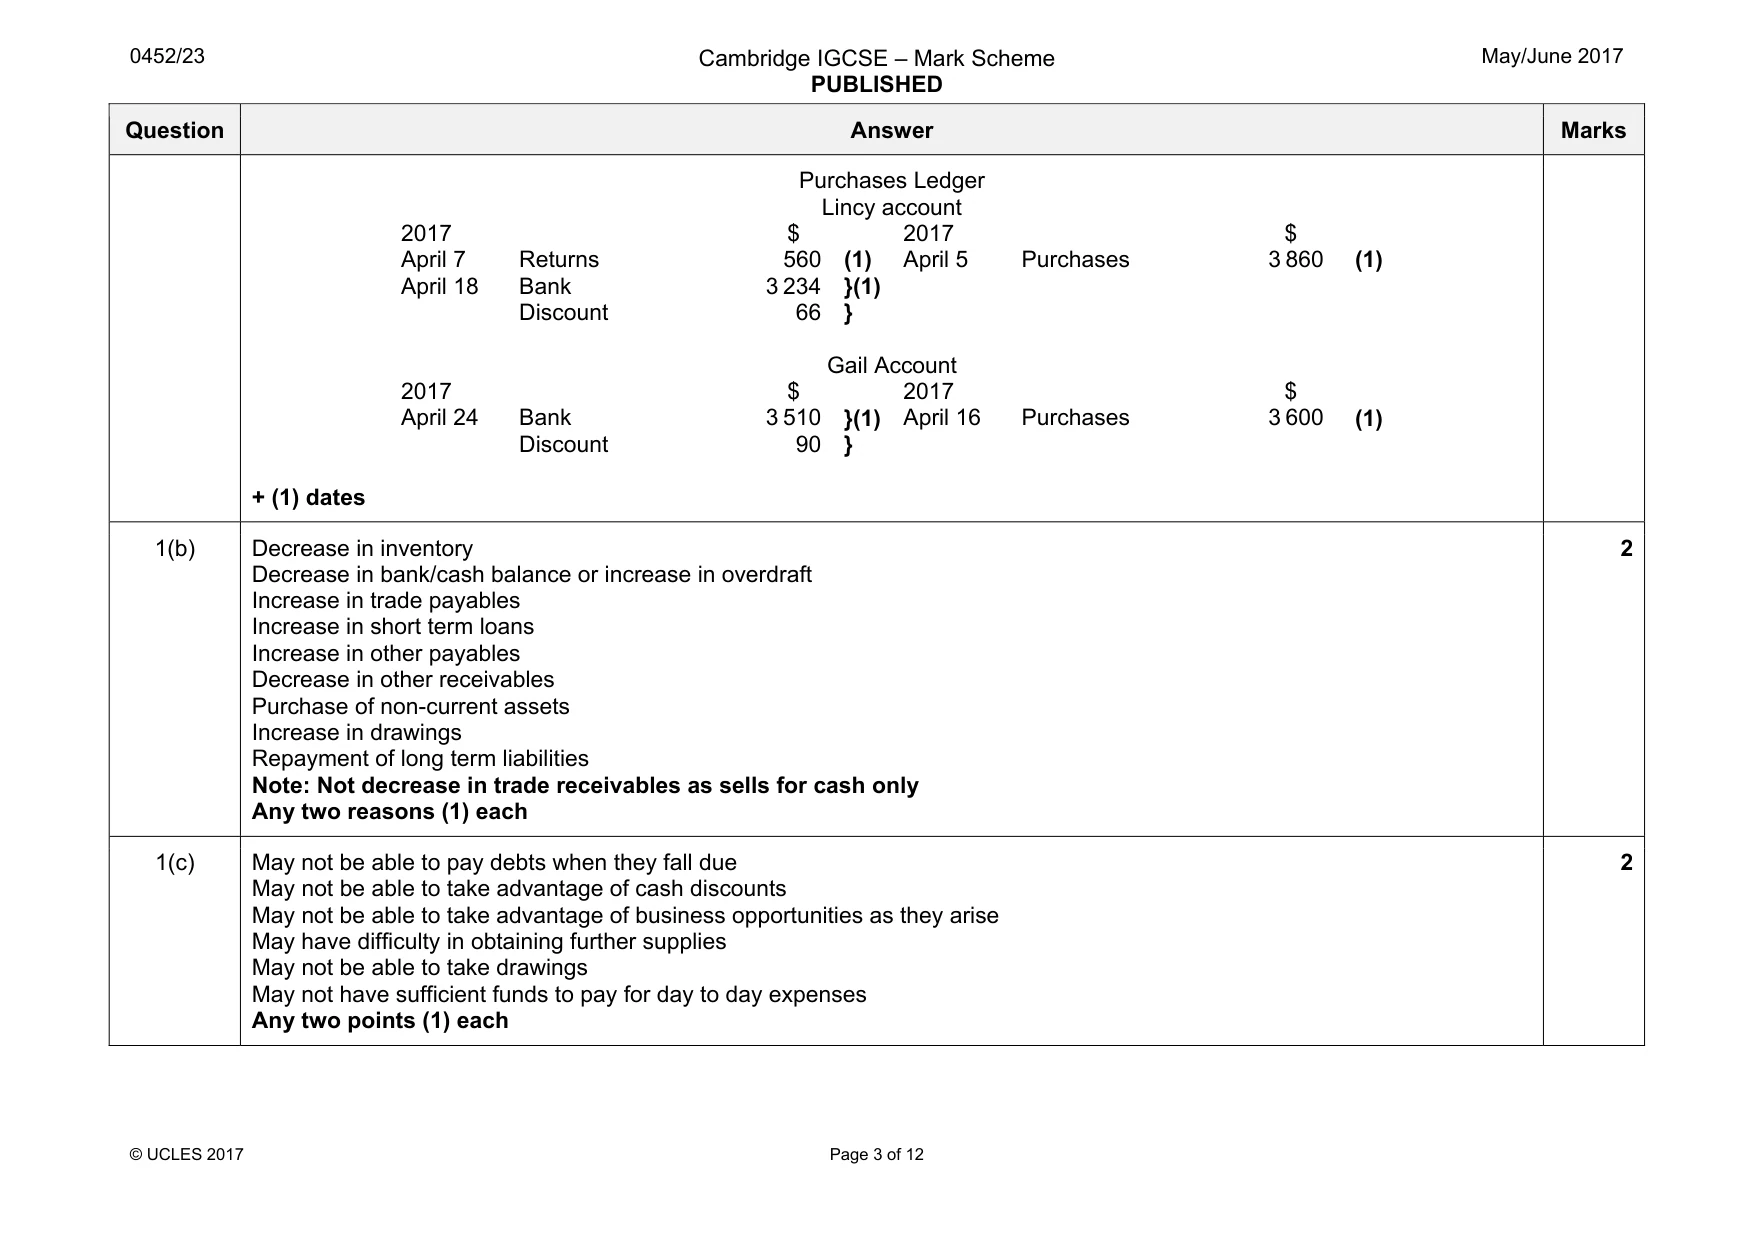
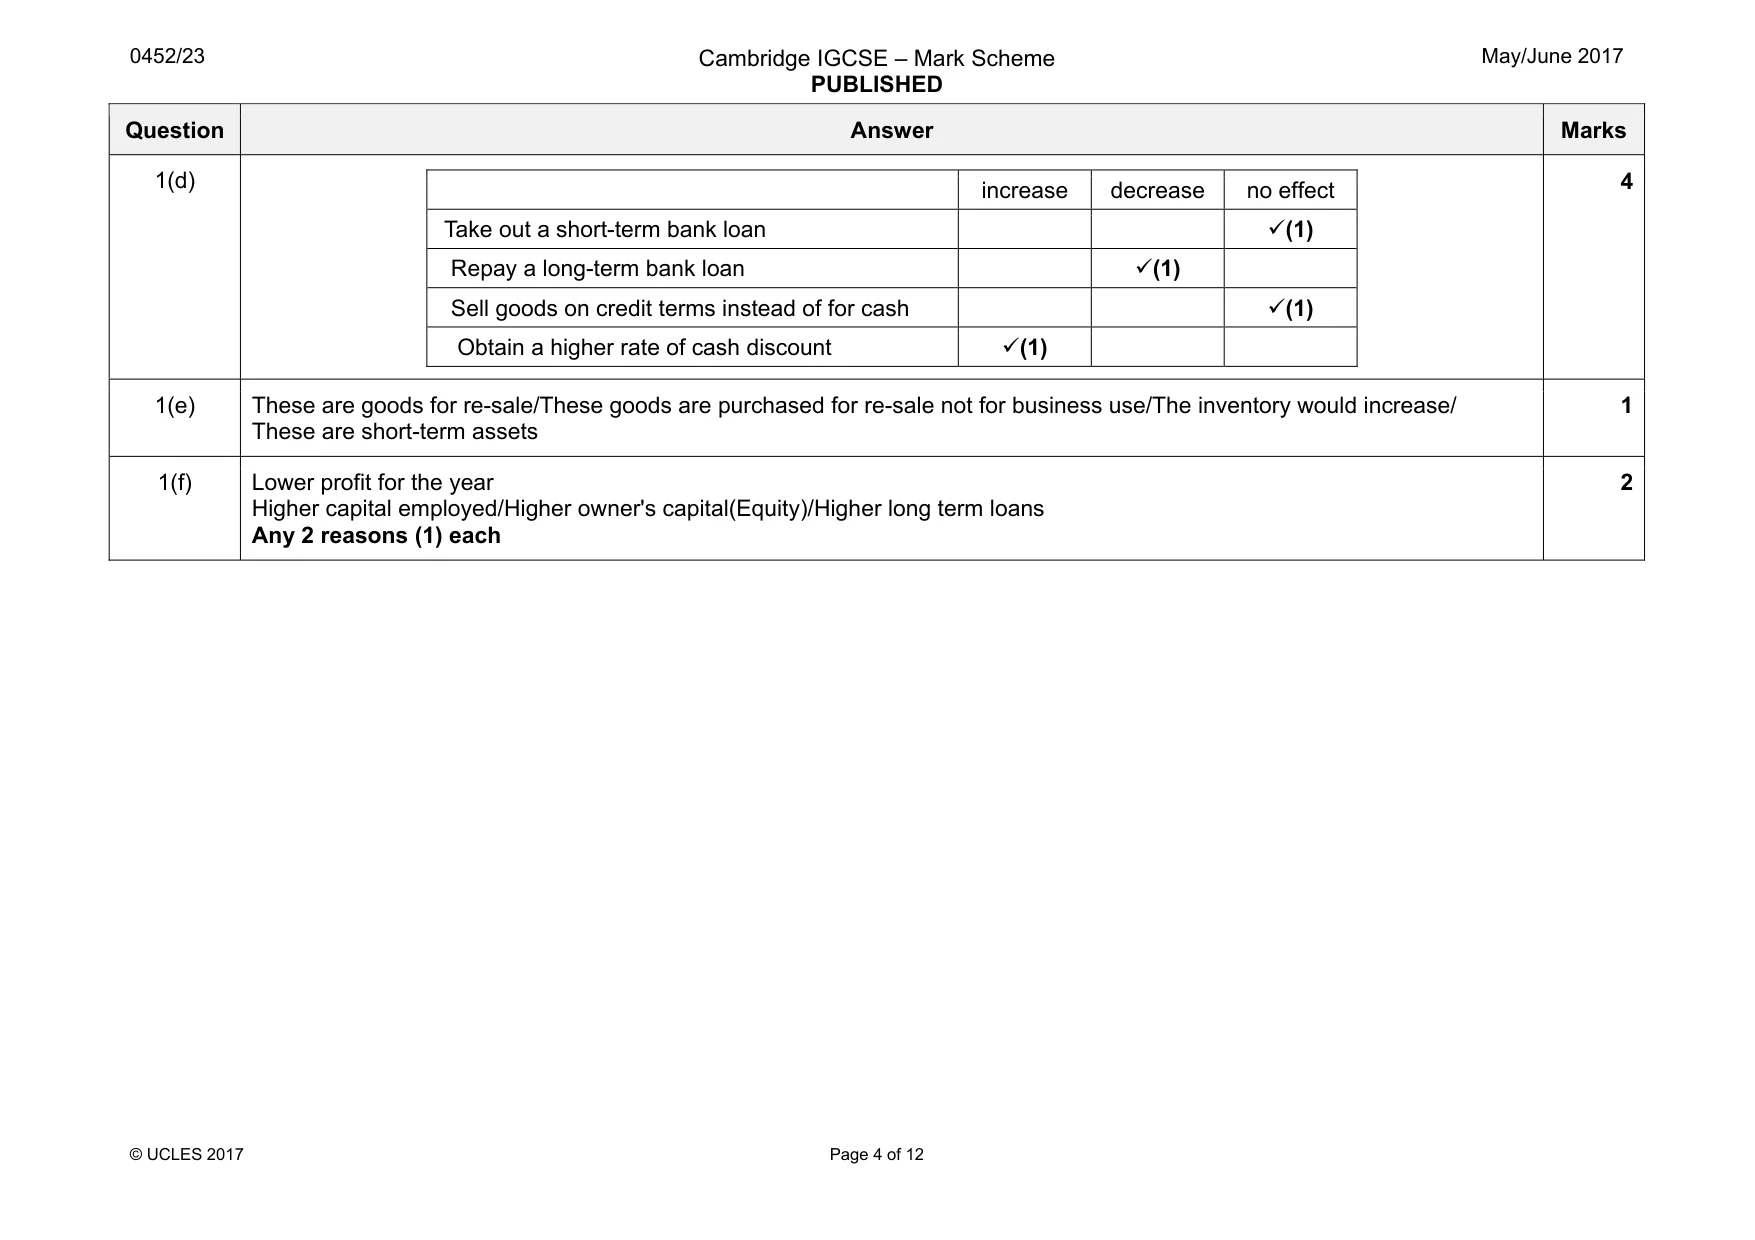
Mark scheme: 1(a) Shiromi General Ledger Rent and Account 2017 $ April 4 Bank 495 (1) Motor Vehicle Account 2017 $ April 10 Bank 5 500 (1) Sales Account 2017 $ April 21 Cash 600 }(1) Bank 6 000 } Drawings Account 2017 $ April 26 Cash 150 (1) Purchases Account 2017 $ April 30 Total for Month 7 460 (1) Purchases Returns Account 2017 $ April 30 Total for month 560 (1) Discount received Account 2017 $ April 30 Total for month 156 (1) 13 Question Answer Marks Purchases Ledger Lincy account 2017 $ 2017 $ April 7 Returns 560 (1) April 5 Purchases 3 860 (1) April 18 Bank 3 234 }(1) Discount 66 } Gail Account 2017 $ 2017 $ April 24 Bank 3 510 }(1) April 16 Purchases 3 600 (1) Discount 90 } + (1) dates 1(b) Decrease in inventory Decrease in bank/cash balance or increase in overdraft Increase in trade payables Increase in short term loans Increase in other payables Decrease in other receivables Purchase of non-current assets Increase in drawings Repayment of long term liabilities Note: Not decrease in trade receivables as sells for cash only Any two reasons (1) each 2 1(c) May not be able to pay debts when they fall due May not be able to take advantage of cash discounts May not be able to take advantage of business opportunities as they arise May have difficulty in obtaining further supplies May not be able to take drawings May not have sufficient funds to pay for day to day expenses Any two points (1) each 2 Question Answer Marks 1(d) increase decrease no effect Take out a short-term bank loan 9(1) Repay a long-term bank loan 9(1) Sell goods on credit terms instead of for cash 9(1) Obtain a higher rate of cash discount 9(1) 4 1(e) These are goods for re-sale/These goods are purchased for re-sale not for business use/The inventory would increase/ These are short-term assets 1 1(f) Lower profit for the year Higher capital employed/Higher owner's capital(Equity)/Higher long term loans Any 2 reasons (1) each 2
Q2 · Waheed is a trader
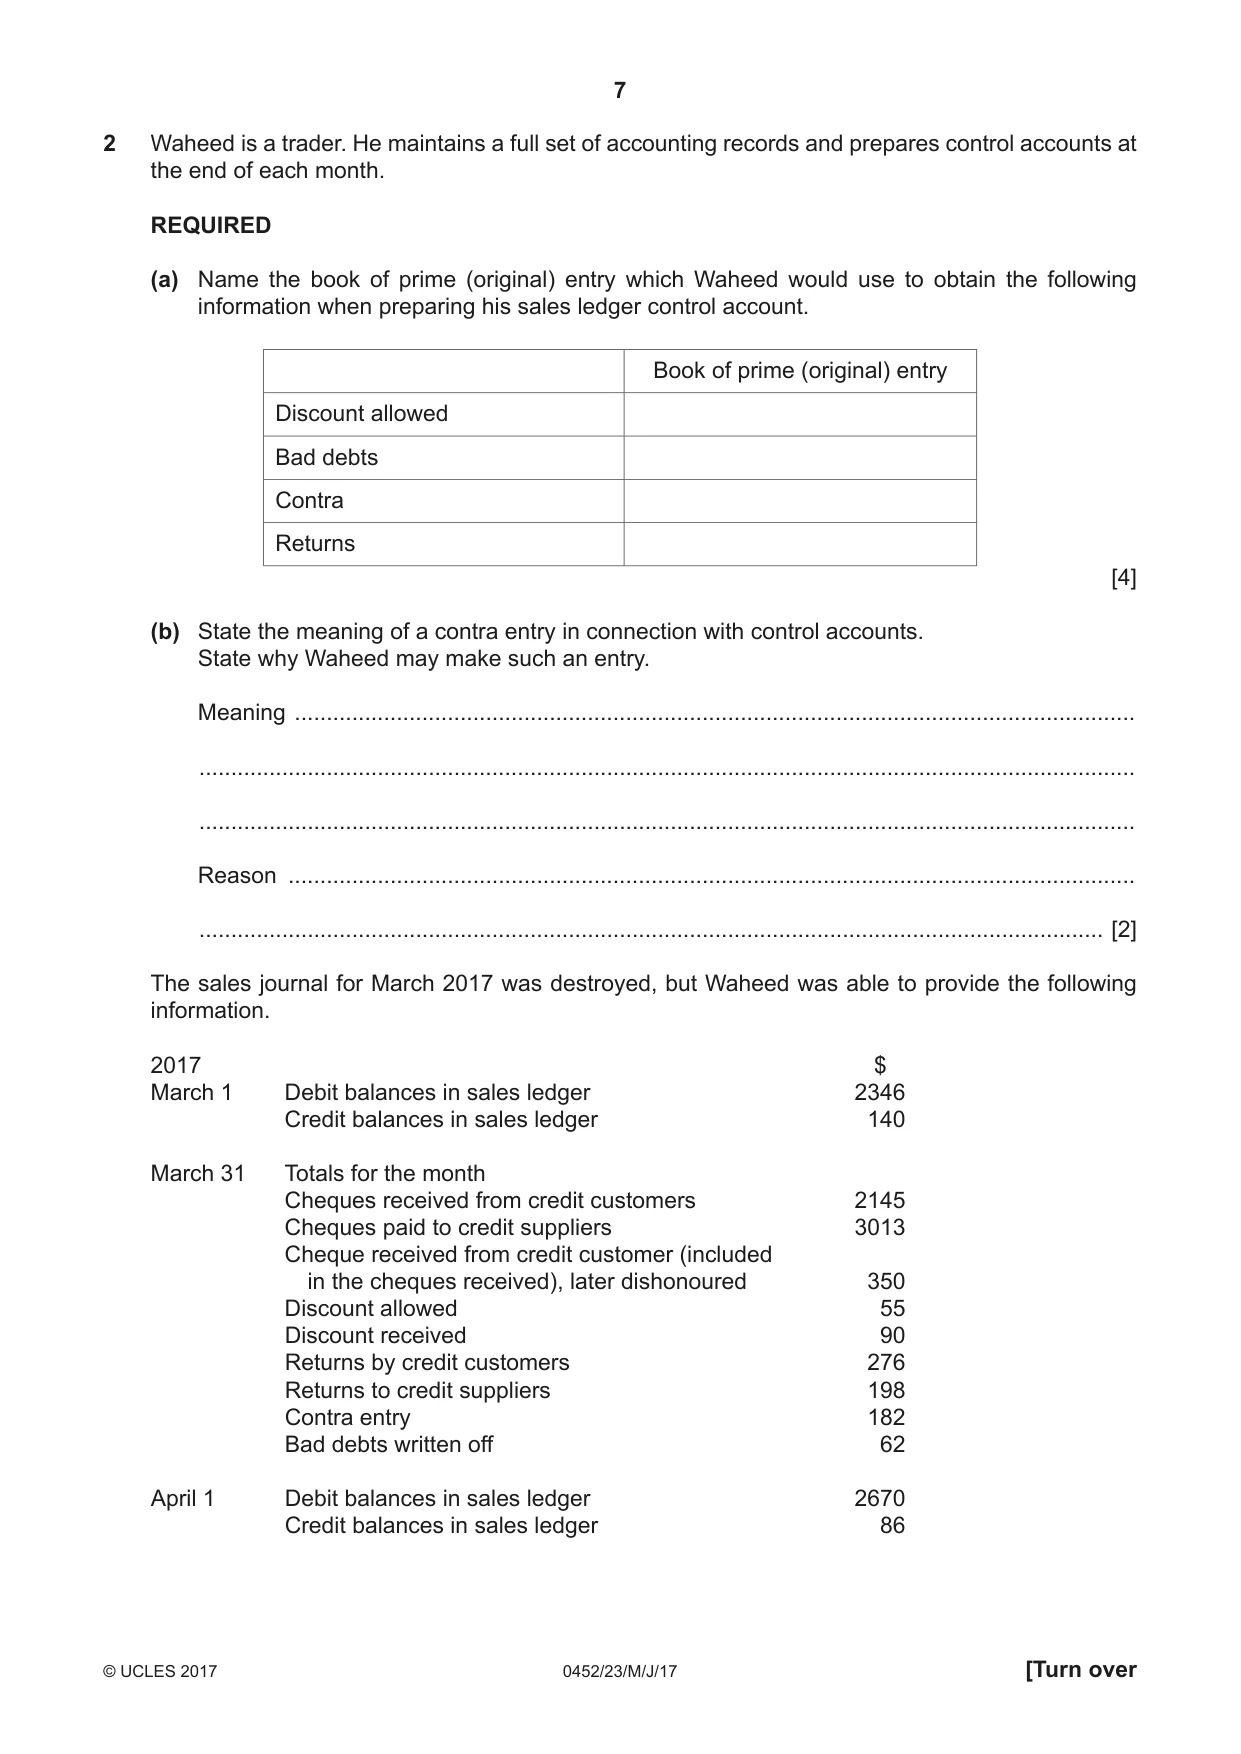
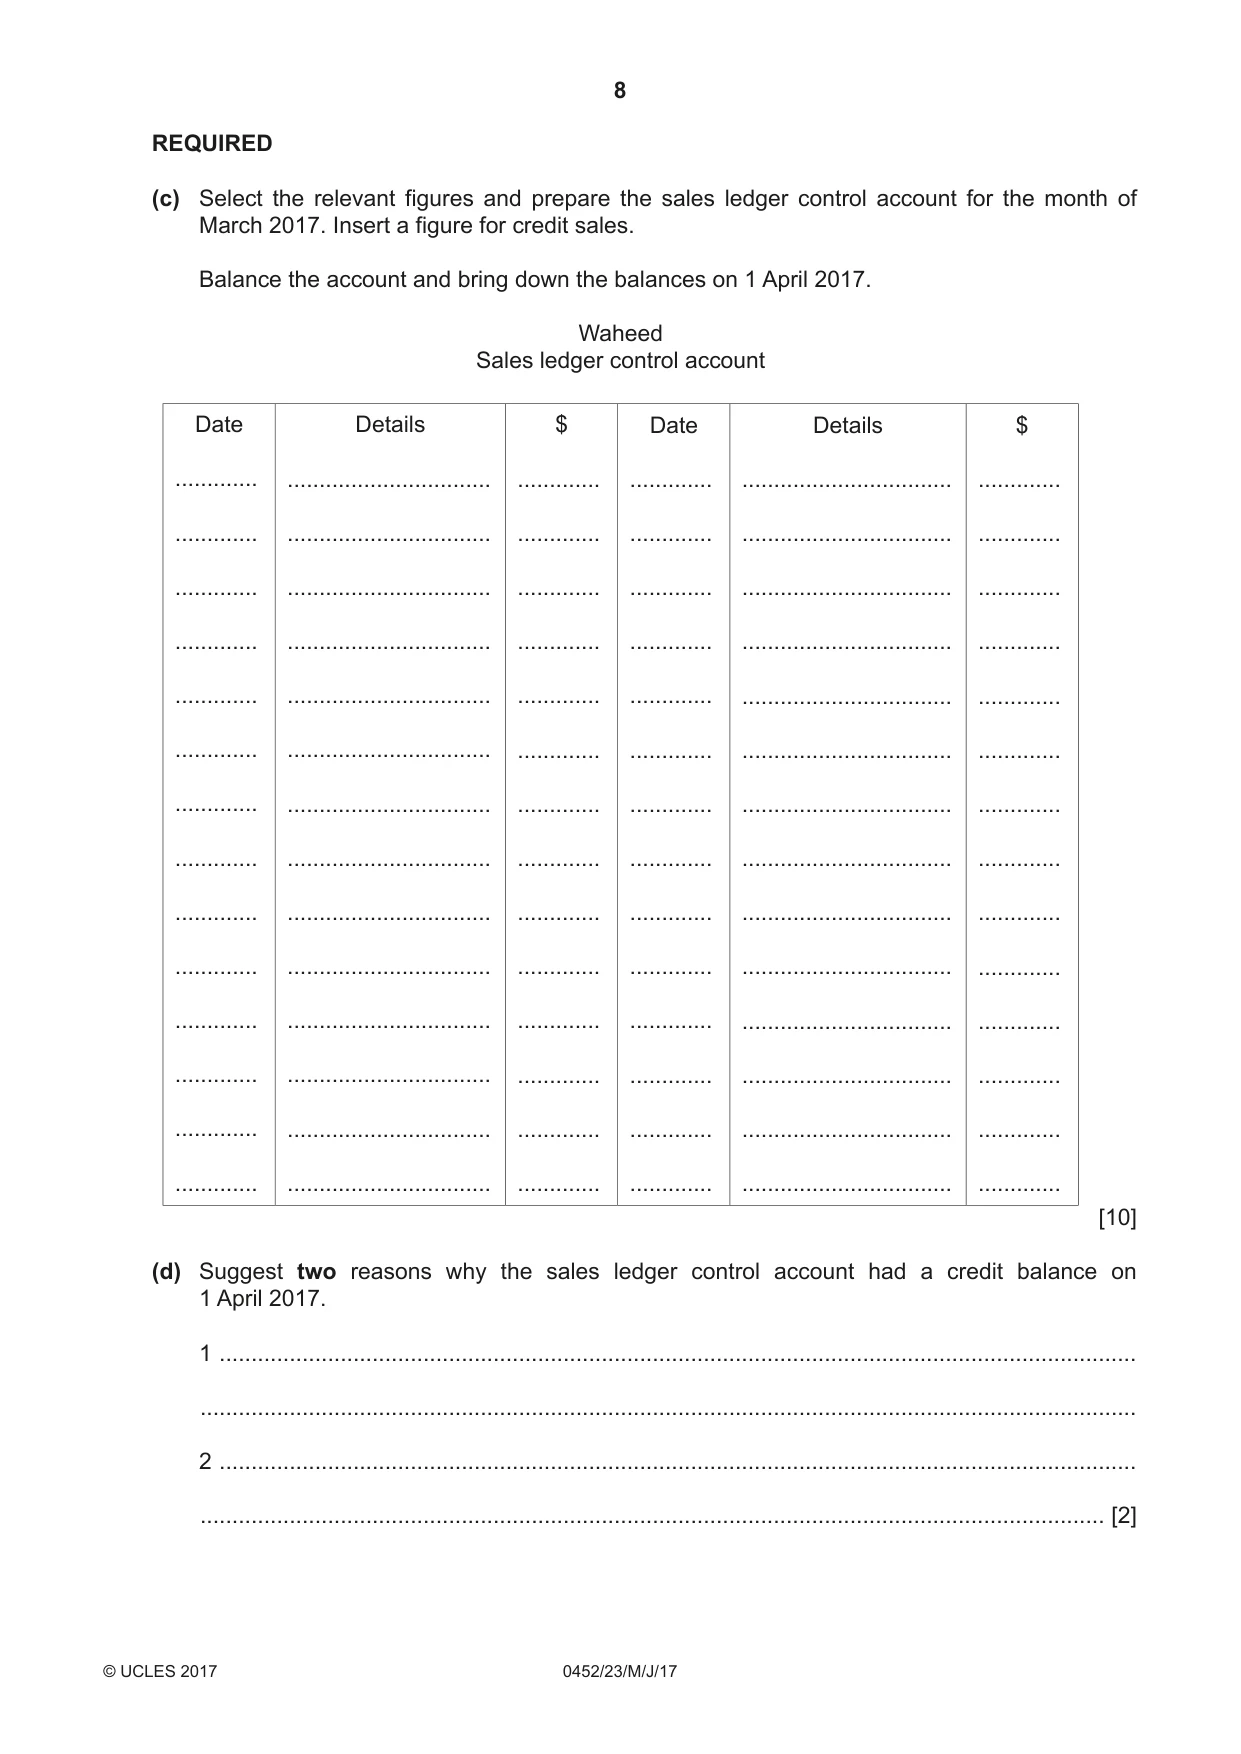
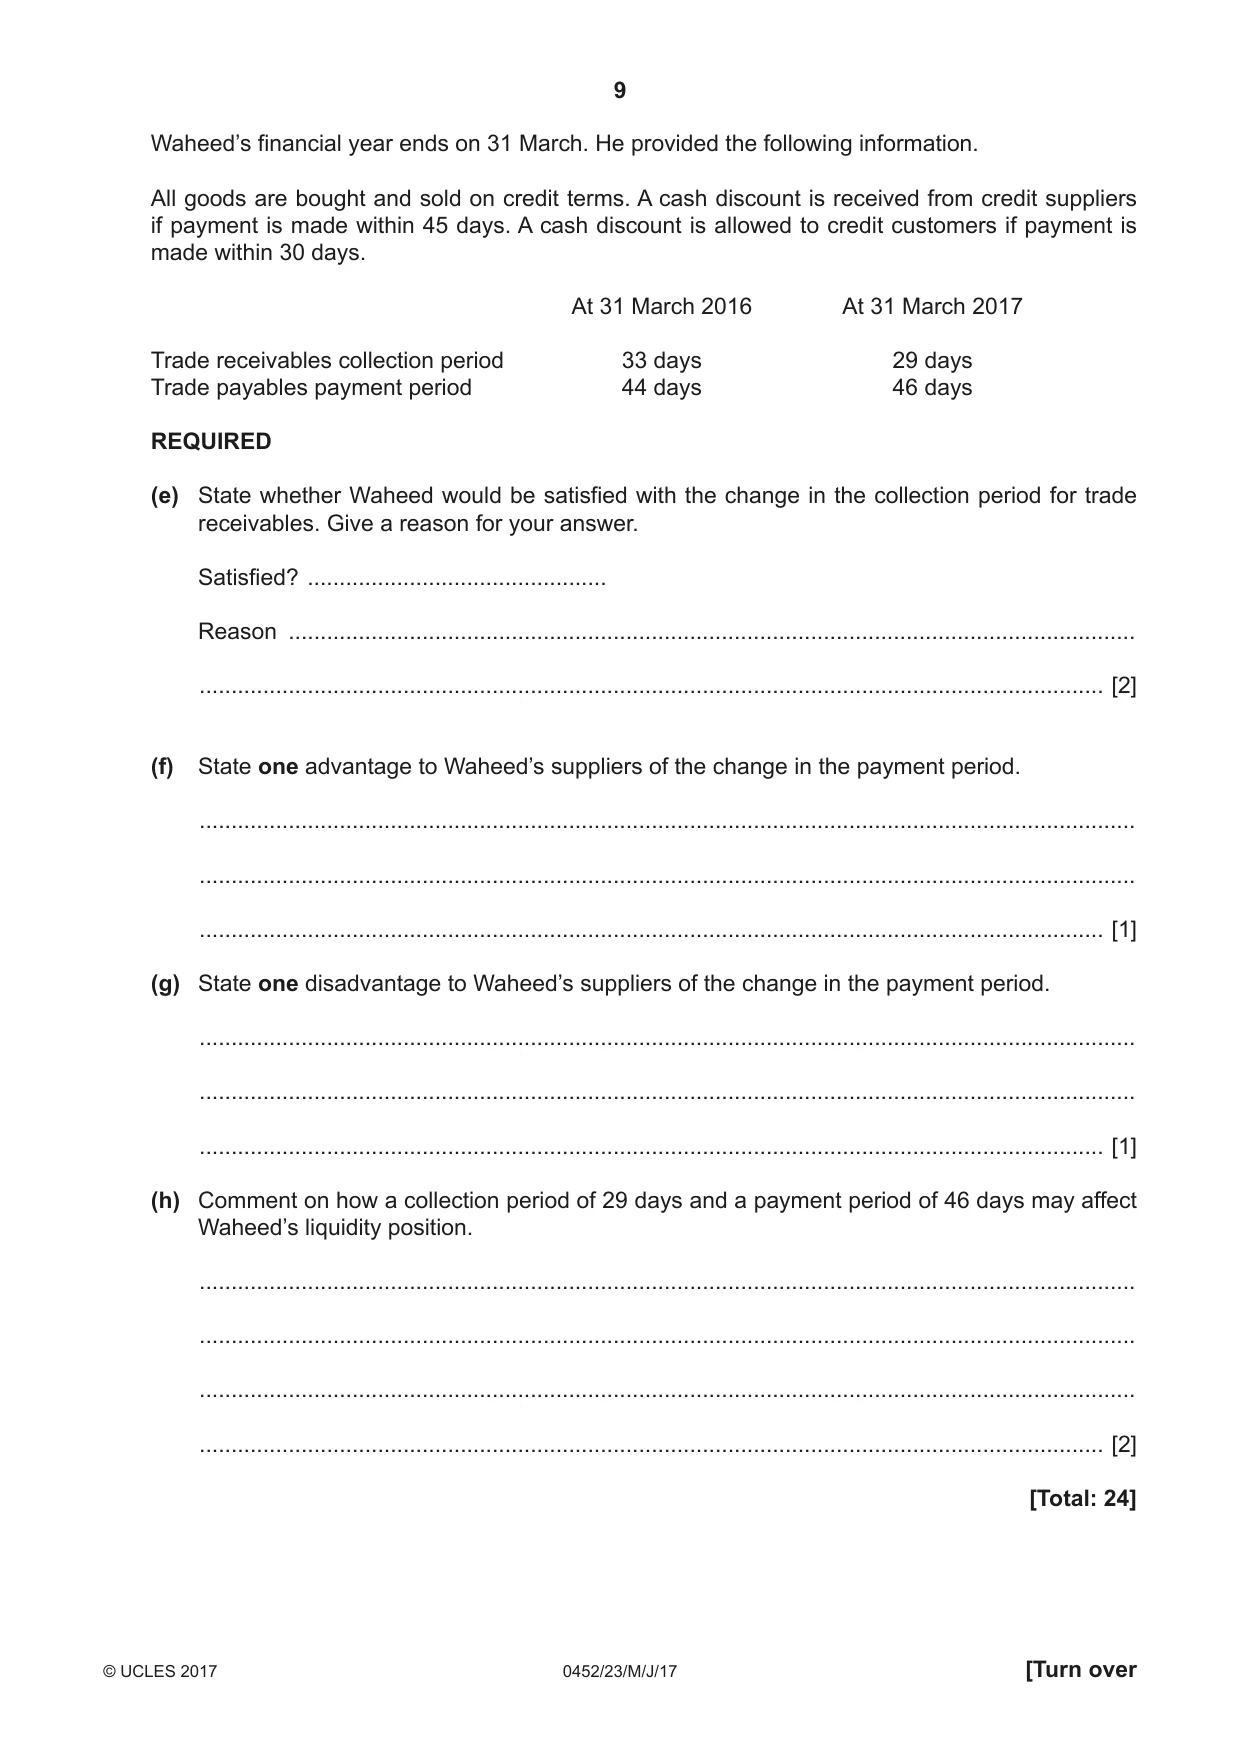
2 Waheed is a trader. He maintains a full set of accounting records and prepares control accounts at the end of each month. REQUIRED (a) Name the book of prime (original) entry which Waheed would use to obtain the following information when preparing his sales ledger control account. Book of prime (original) entry Discount allowed Bad debts Contra Returns [4] (b) State the meaning of a contra entry in connection with control accounts. State why Waheed may make such an entry. Meaning .................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Reason ..................................................................................................................................... .............................................................................................................................................. [2] The sales journal for March 2017 was destroyed, but Waheed was able to provide the following information. 2017 $ March 1 Debit balances in sales ledger 2346 Credit balances in sales ledger 140 March 31 Totals for the month Cheques received from credit customers 2145 Cheques paid to credit suppliers 3013 Cheque received from credit customer (included in the cheques received), later dishonoured 350 Discount allowed 55 Discount received 90 Returns by credit customers 276 Returns to credit suppliers 198 Contra entry 182 Bad debts written off 62 April 1 Debit balances in sales ledger 2670 Credit balances in sales ledger 86 REQUIRED (c) Select the relevant figures and prepare the sales ledger control account for the month of March 2017. Insert a figure for credit sales. Balance the account and bring down the balances on 1 April 2017. Waheed Sales ledger control account Date Details $ Date Details $ ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. [10] (d) Suggest two reasons why the sales ledger control account had a credit balance on 1 April 2017. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] Waheed’s financial year ends on 31 March. He provided the following information. All goods are bought and sold on credit terms. A cash discount is received from credit suppliers if payment is made within 45 days. A cash discount is allowed to credit customers if payment is made within 30 days. At 31 March 2016 At 31 March 2017 Trade receivables collection period 33 days 29 days Trade payables payment period 44 days 46 days REQUIRED (e) State whether Waheed would be satisfied with the change in the collection period for trade receivables. Give a reason for your answer. Satisfied? ............................................... Reason ..................................................................................................................................... .............................................................................................................................................. [2] (f) State one advantage to Waheed’s suppliers of the change in the payment period. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [1] (g) State one disadvantage to Waheed’s suppliers of the change in the payment period. ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [1] (h) Comment on how a collection period of 29 days and a payment period of 46 days may affect Waheed’s liquidity position. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] [Total: 24]
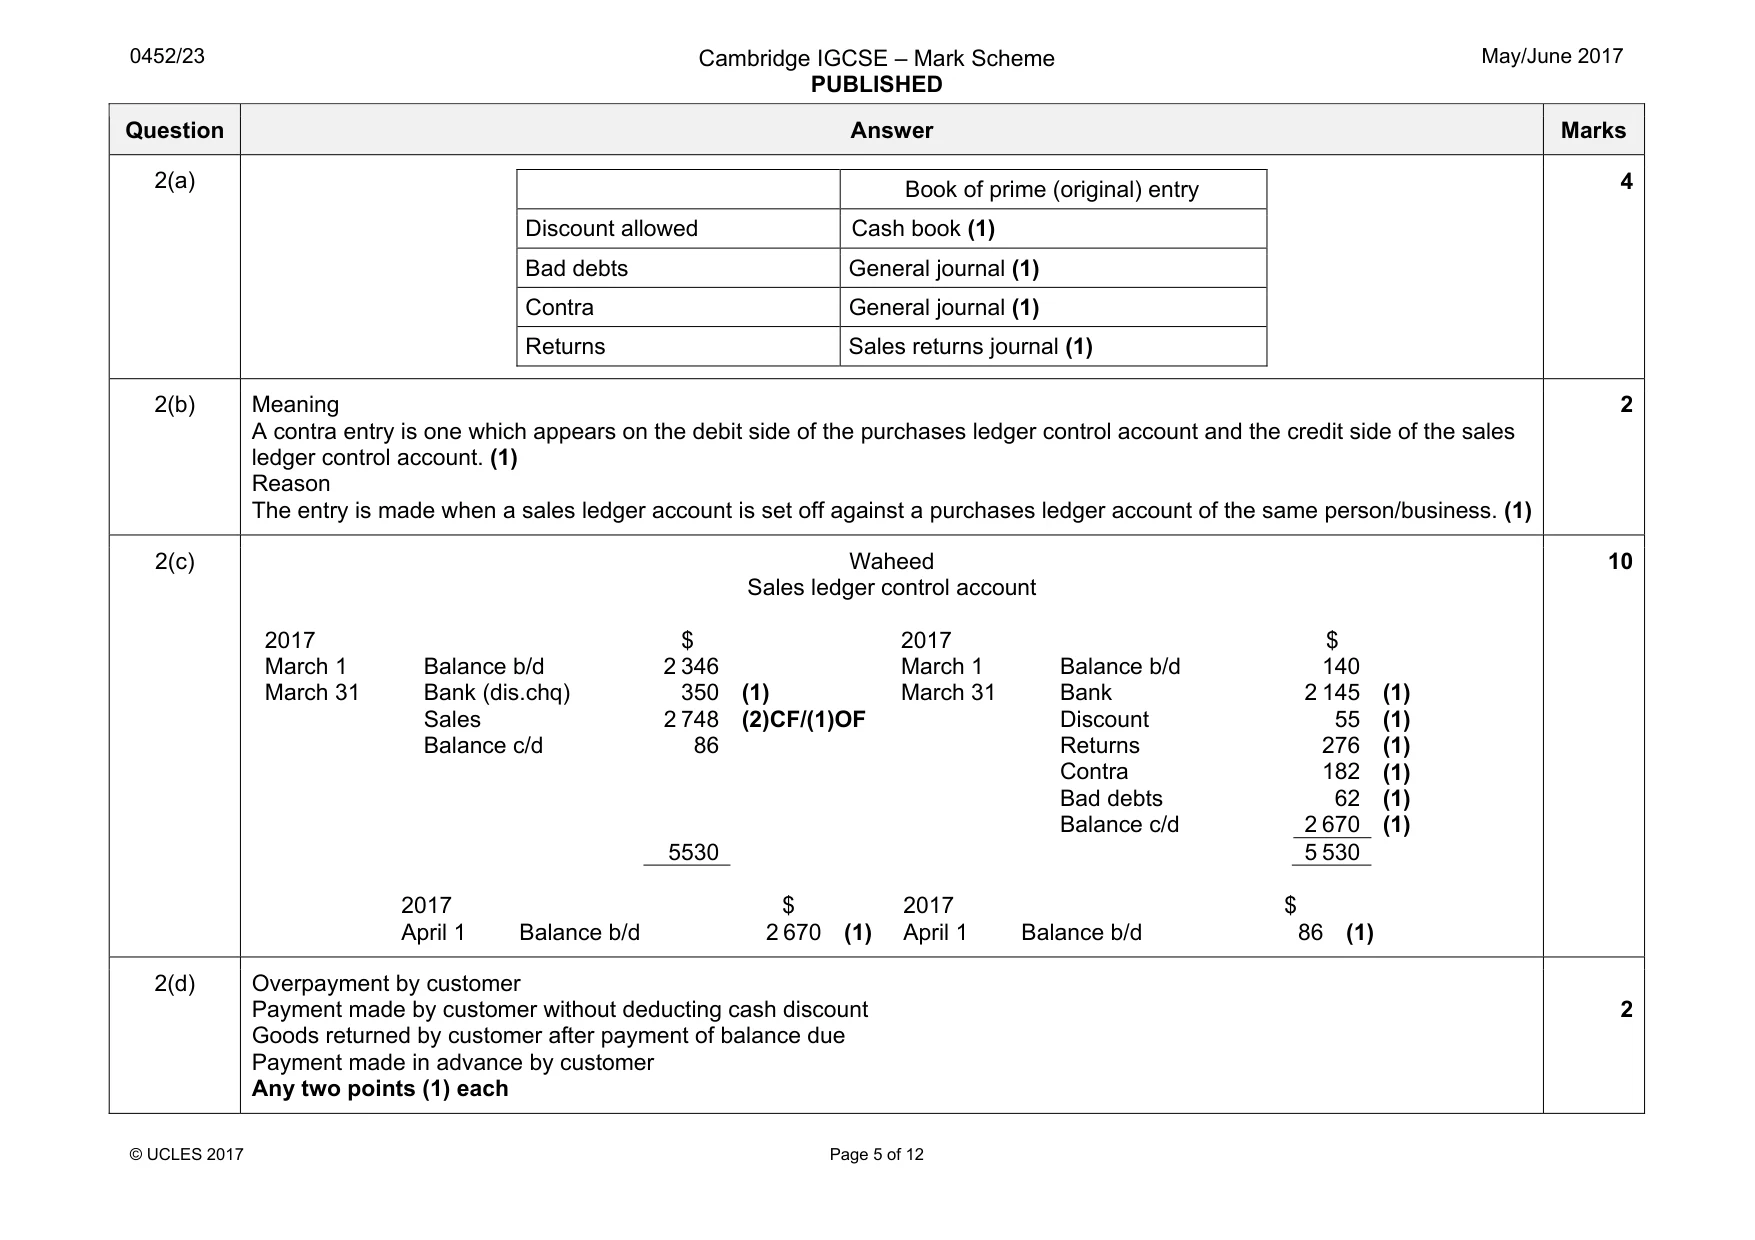
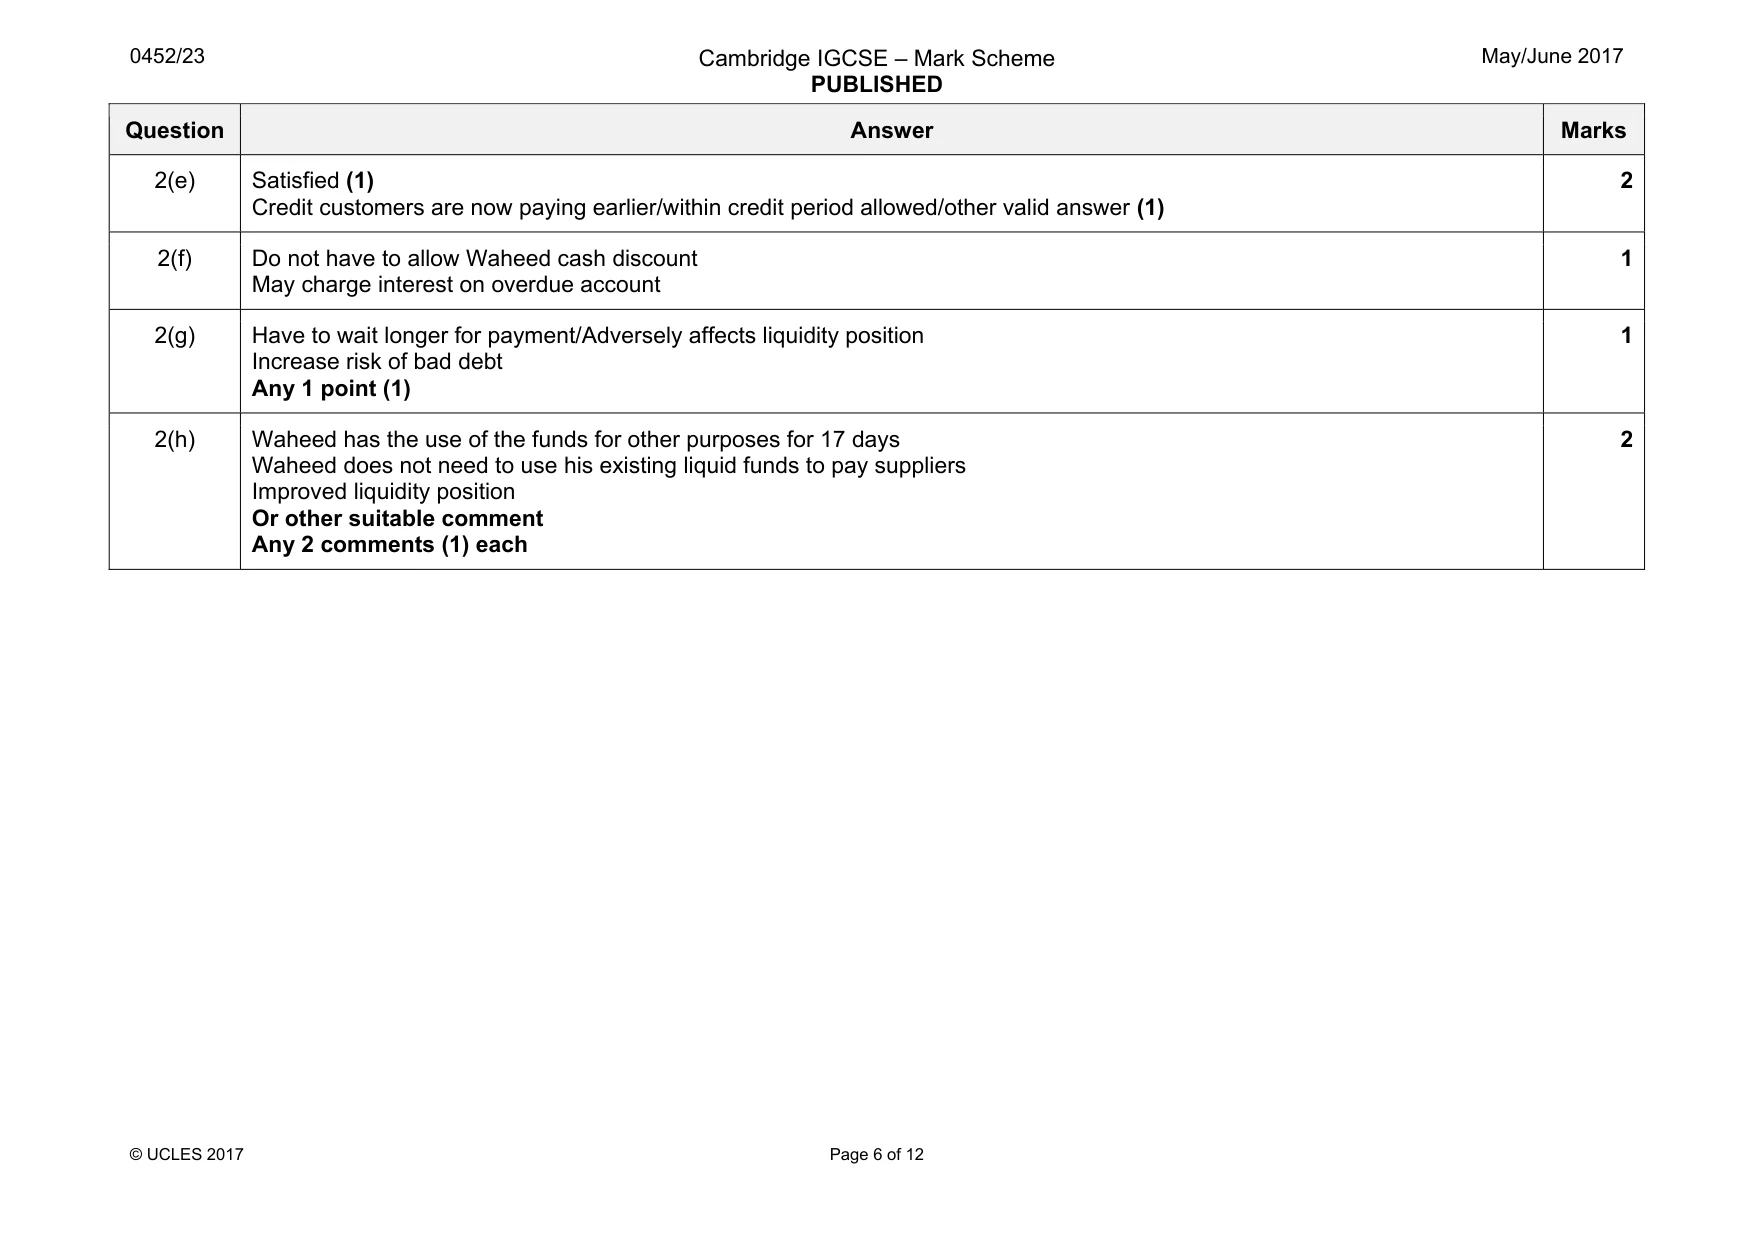
Mark scheme: 2(a) Book of prime (original) entry Discount allowed Cash book (1) Bad debts General journal (1) Contra General journal (1) Returns Sales returns journal (1) 4 2(b) Meaning A contra entry is one which appears on the debit side of the purchases ledger control account and the credit side of the sales ledger control account. (1) Reason The entry is made when a sales ledger account is set off against a purchases ledger account of the same person/business. (1) 2 2(c) Waheed Sales ledger control account 2017 $ 2017 $ March 1 Balance b/d 2 346 March 1 Balance b/d 140 March 31 Bank (dis.chq) 350 (1) March 31 Bank 2 145 (1) Sales 2 748 (2)CF/(1)OF Discount 55 (1) Balance c/d 86 Returns 276 (1) Contra 182 (1) Bad debts 62 (1) Balance c/d 2 670 (1) 5530 5 530 2017 $ 2017 $ April 1 Balance b/d 2 670 (1) April 1 Balance b/d 86 (1) 10 2(d) Overpayment by customer Payment made by customer without deducting cash discount Goods returned by customer after payment of balance due Payment made in advance by customer Any two points (1) each 2 Question Answer Marks 2(e) Satisfied (1) Credit customers are now paying earlier/within credit period allowed/other valid answer (1) 2 2(f) Do not have to allow Waheed cash discount May charge interest on overdue account 1 2(g) Have to wait longer for payment/Adversely affects liquidity position Increase risk of bad debt Any 1 point (1) 1 2(h) Waheed has the use of the funds for other purposes for 17 days Waheed does not need to use his existing liquid funds to pay suppliers Improved liquidity position Or other suitable comment Any 2 comments (1) each 2
Q3 · The A1 Sports Club was formed some years ago
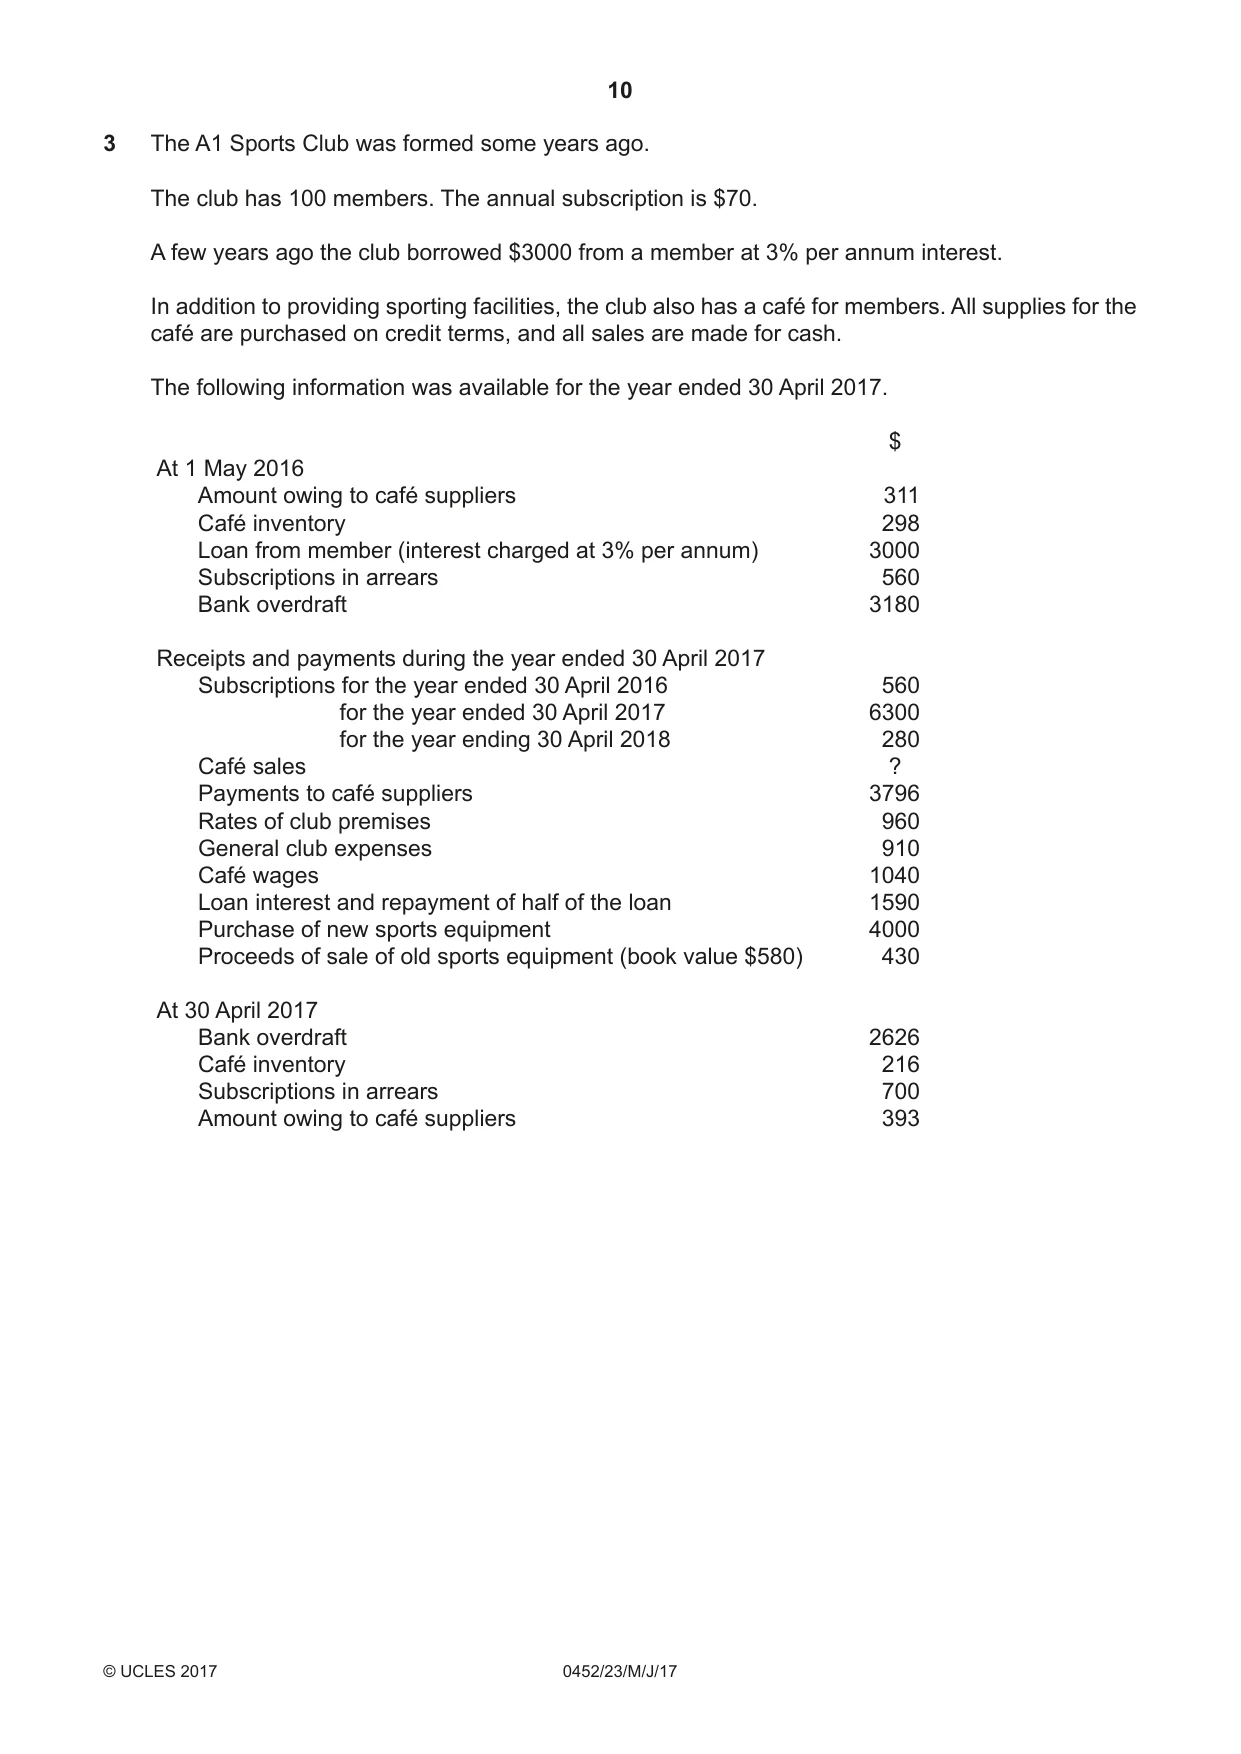
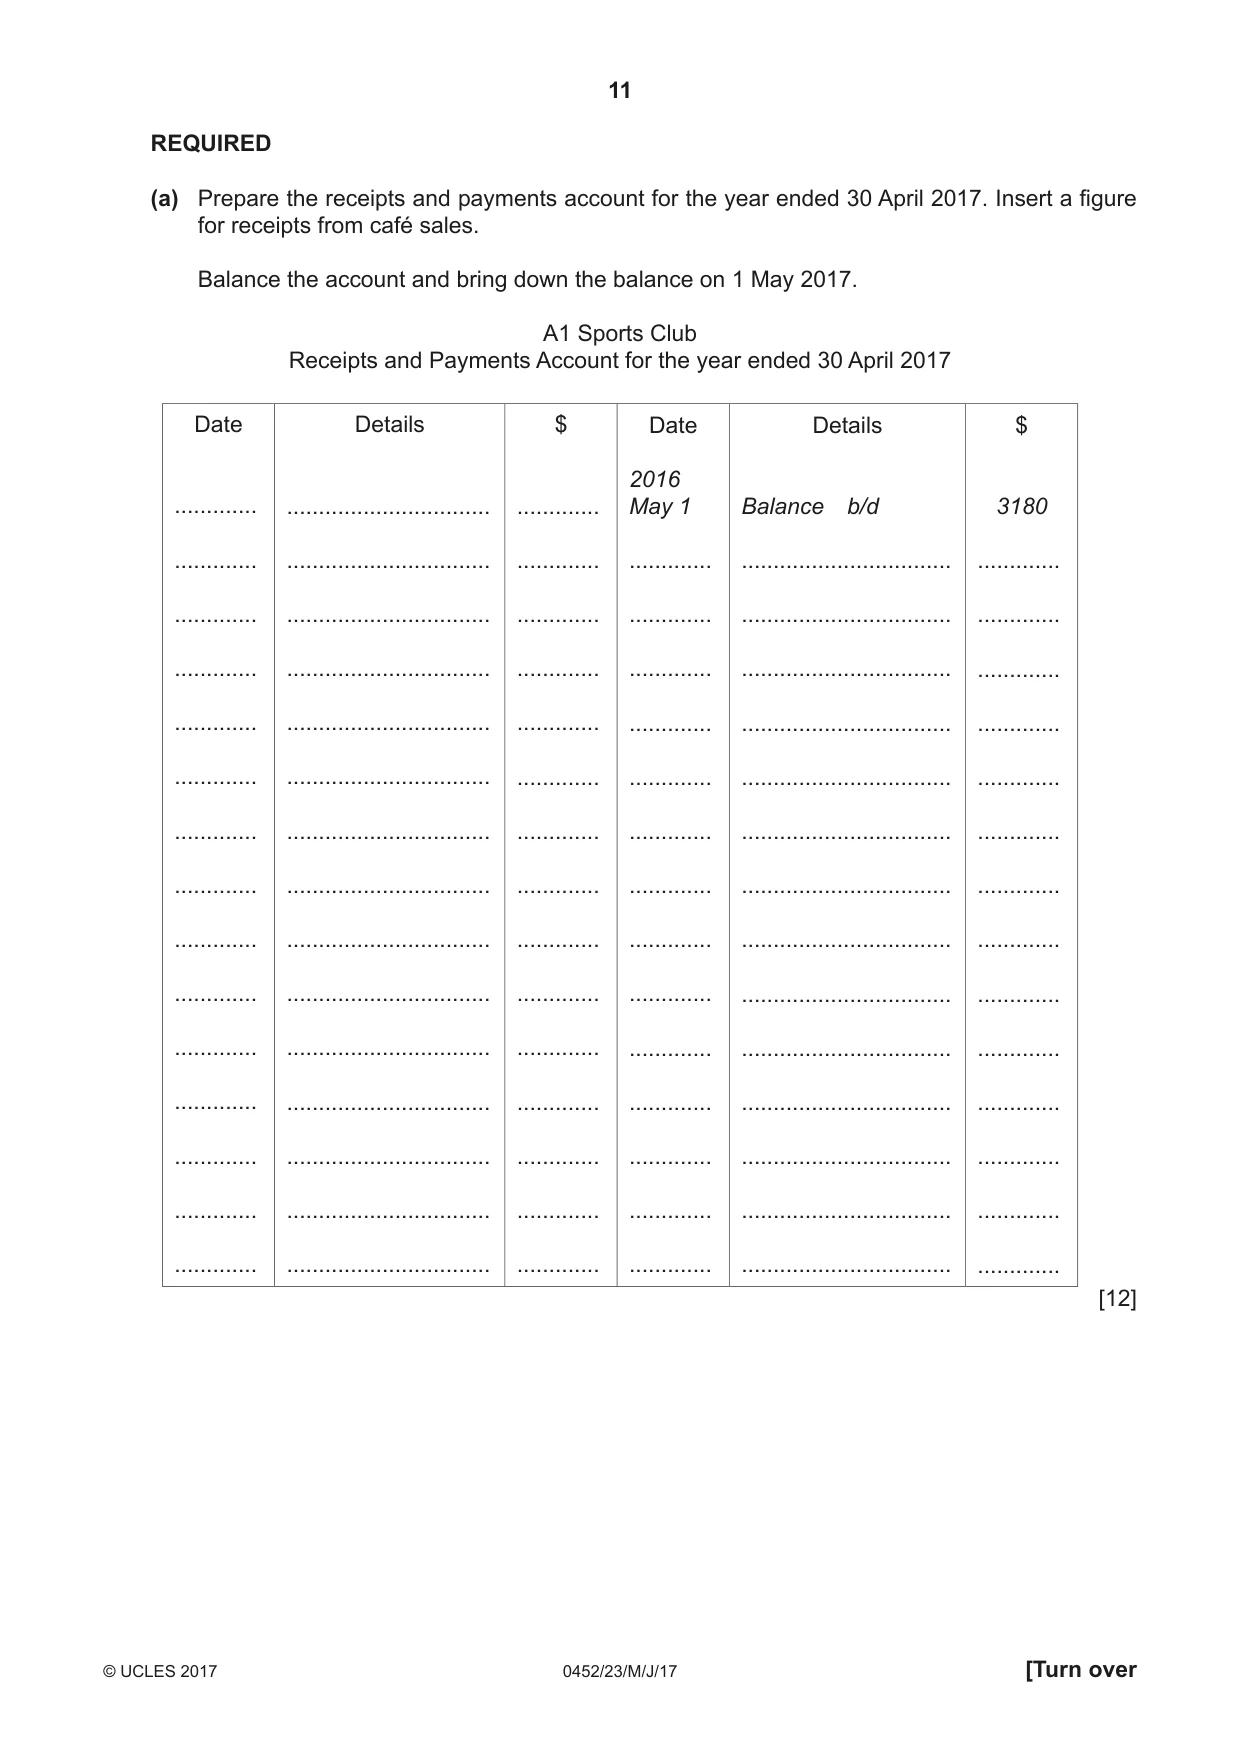
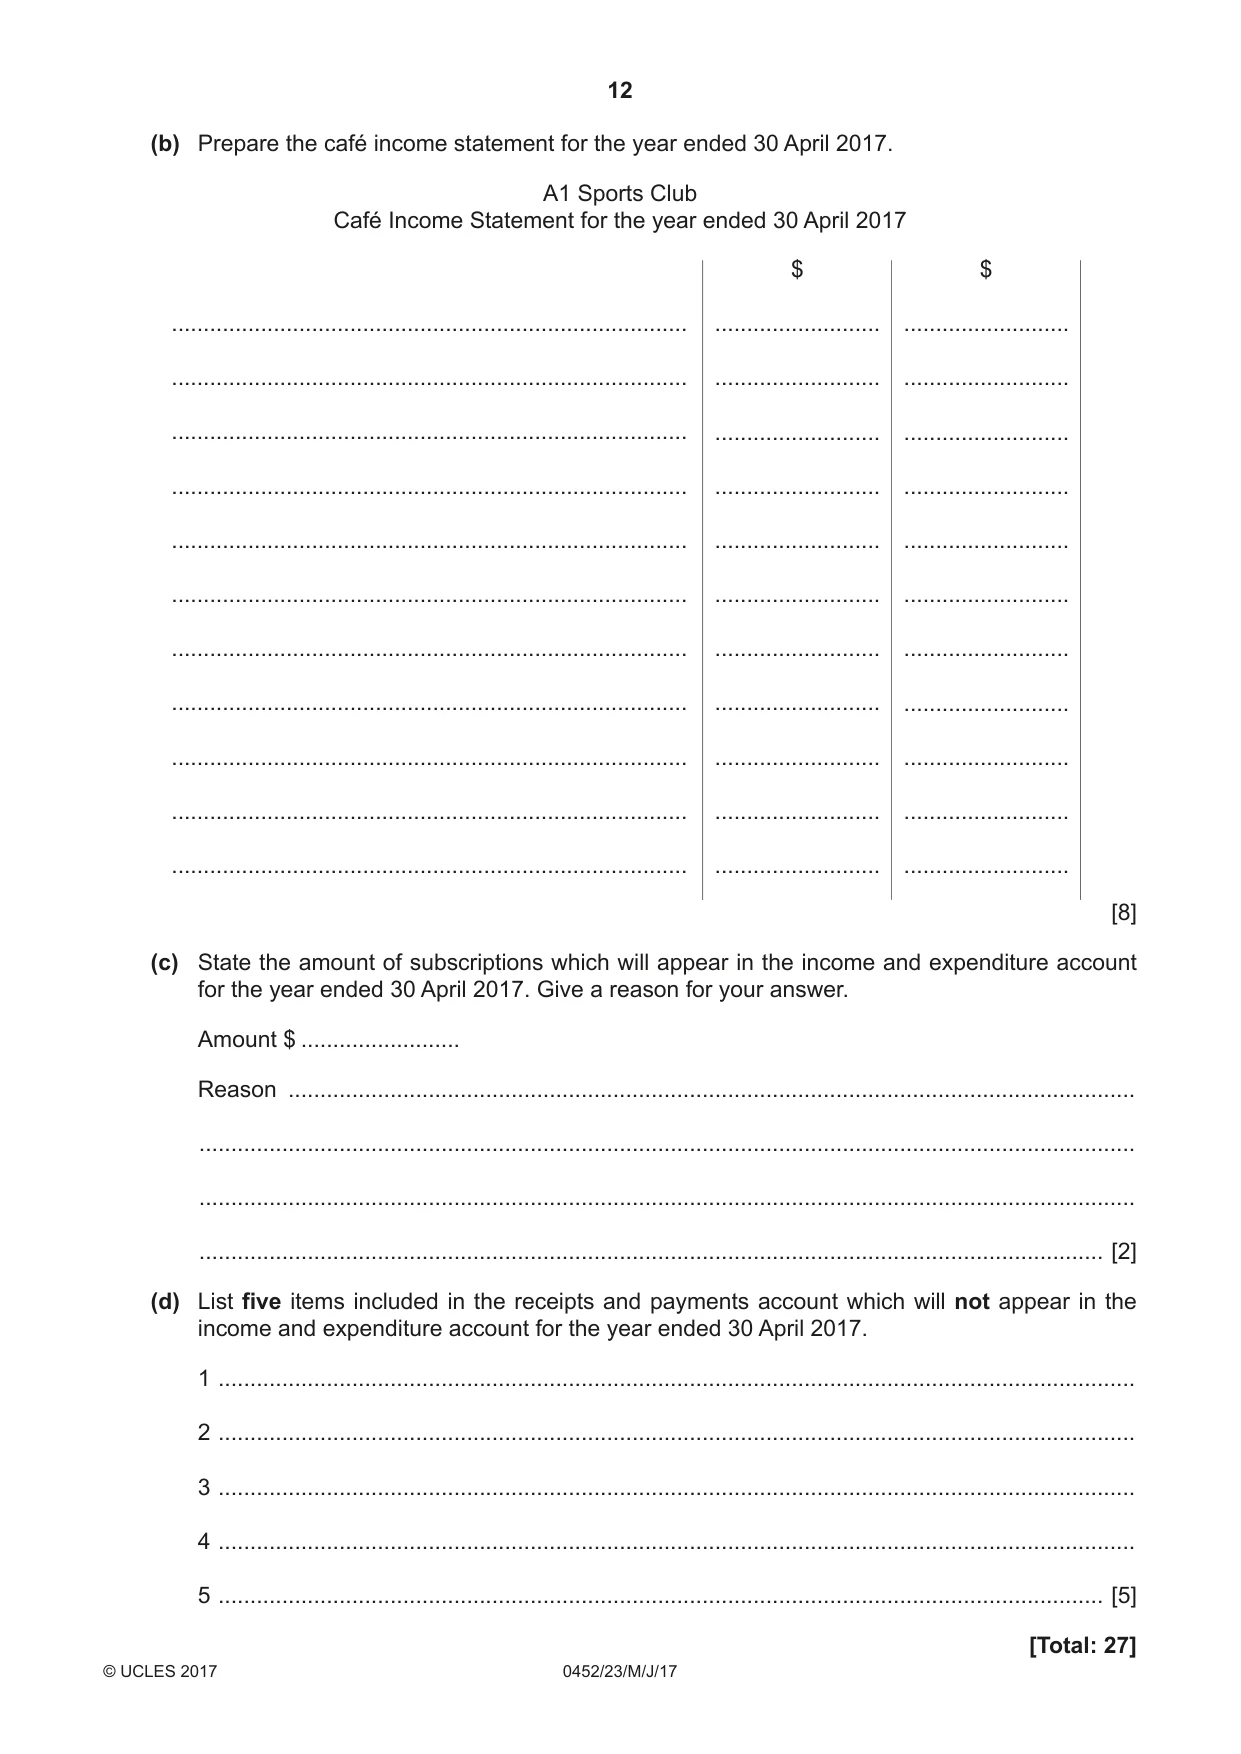
3 The A1 Sports Club was formed some years ago. The club has 100 members. The annual subscription is $70. A few years ago the club borrowed $3000 from a member at 3% per annum interest. In addition to providing sporting facilities, the club also has a café for members. All supplies for the café are purchased on credit terms, and all sales are made for cash. The following information was available for the year ended 30 April 2017. $ At 1 May 2016 Amount owing to café suppliers 311 Café inventory 298 Loan from member (interest charged at 3% per annum) 3000 Subscriptions in arrears 560 Bank overdraft 3180 Receipts and payments during the year ended 30 April 2017 Subscriptions for the year ended 30 April 2016 560 for the year ended 30 April 2017 6300 for the year ending 30 April 2018 280 Café sales ? Payments to café suppliers 3796 Rates of club premises 960 General club expenses 910 Café wages 1040 Loan interest and repayment of half of the loan 1590 Purchase of new sports equipment 4000 Proceeds of sale of old sports equipment (book value $580) 430 At 30 April 2017 Bank overdraft 2626 Café inventory 216 Subscriptions in arrears 700 Amount owing to café suppliers 393 REQUIRED (a) Prepare the receipts and payments account for the year ended 30 April 2017. Insert a figure for receipts from café sales. Balance the account and bring down the balance on 1 May 2017. A1 Sports Club Receipts and Payments Account for the year ended 30 April 2017 Date Details $ Date Details $ 2016 ............. ................................ ............. May 1 Balance b/d 3180 ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. [12] (b) Prepare the café income statement for the year ended 30 April 2017. A1 Sports Club Café Income Statement for the year ended 30 April 2017 $ $ ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... ................................................................................. .......................... .......................... [8] (c) State the amount of subscriptions which will appear in the income and expenditure account for the year ended 30 April 2017. Give a reason for your answer. Amount $ ......................... Reason ..................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (d) List five items included in the receipts and payments account which will not appear in the income and expenditure account for the year ended 30 April 2017. 1 ................................................................................................................................................ 2 ................................................................................................................................................ 3 ................................................................................................................................................ 4 ................................................................................................................................................ 5 ........................................................................................................................................... [5] [Total: 27] Question 4 is on the next page.
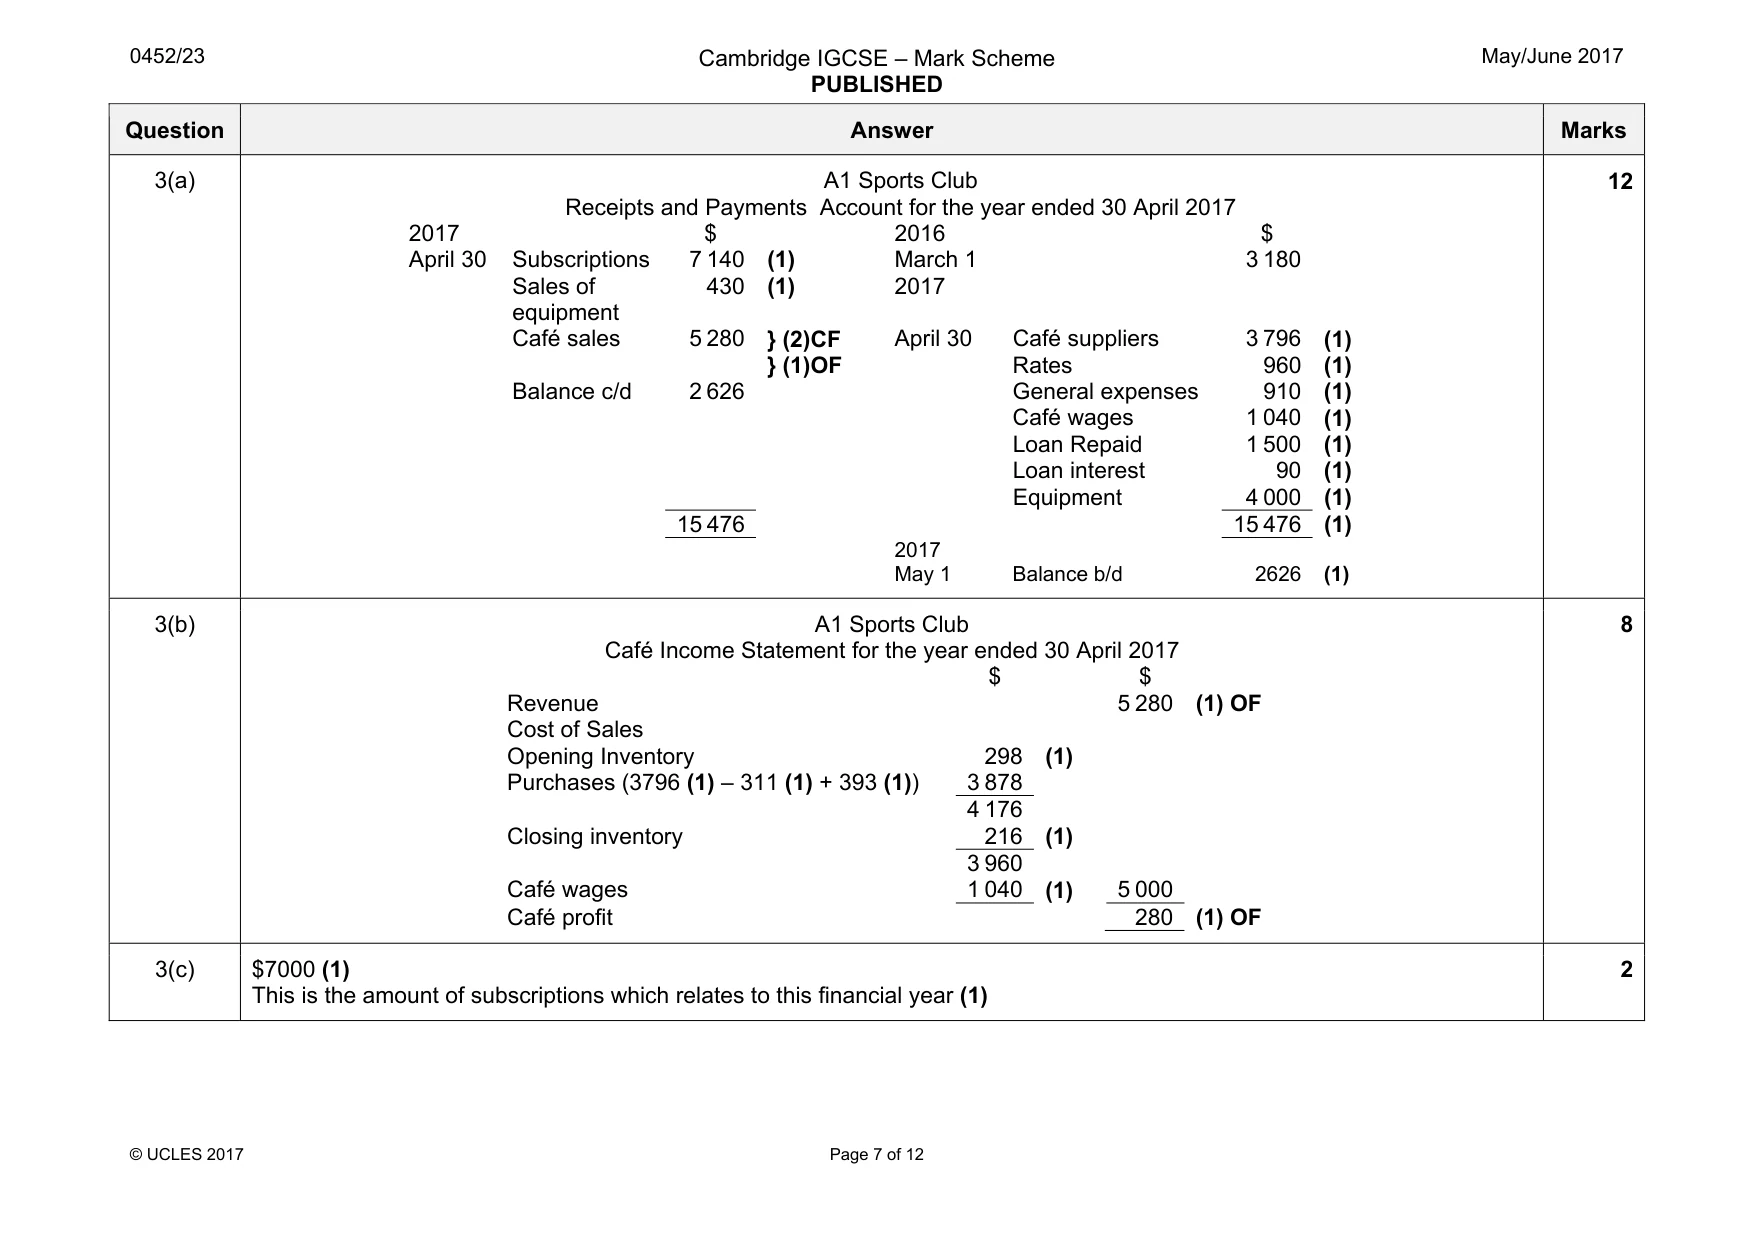
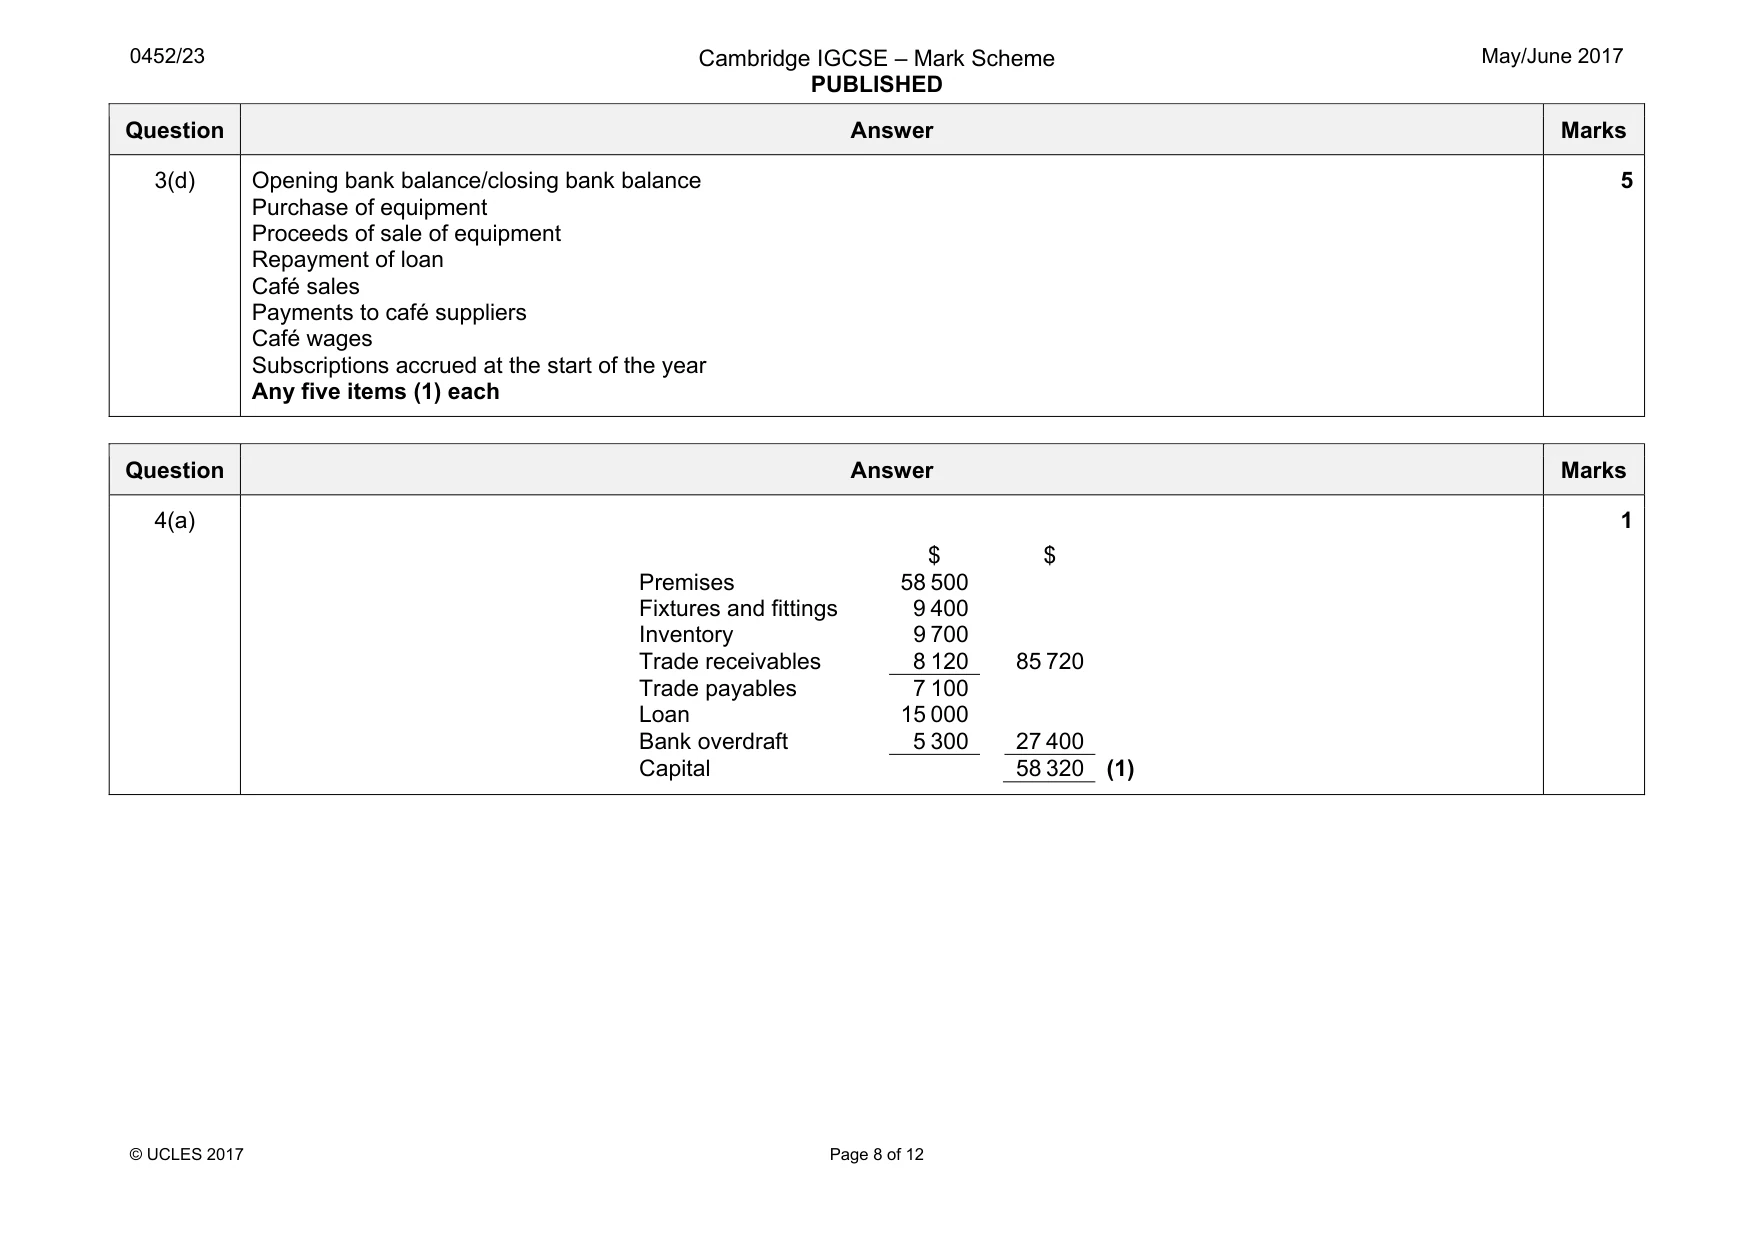
Mark scheme: 3(a) A1 Sports Club Receipts and Payments Account for the year ended 30 April 2017 2017 $ 2016 $ April 30 Subscriptions 7 140 (1) March 1 3 180 Sales of equipment 430 (1) 2017 Café sales 5 280 } (2)CF April 30 Café suppliers 3 796 (1) } (1)OF Rates 960 (1) Balance c/d 2 626 General expenses 910 (1) Café wages 1 040 (1) Loan Repaid 1 500 (1) Loan interest 90 (1) Equipment 4 000 (1) 15 476 15 476 (1) 2017 May 1 Balance b/d 2626 (1) 12 3(b) A1 Sports Club Café Income Statement for the year ended 30 April 2017 $ $ Revenue 5 280 (1) OF Cost of Sales Opening Inventory 298 (1) Purchases (3796 (1) – 311 (1) + 393 (1)) 3 878 4 176 Closing inventory 216 (1) 3 960 Café wages 1 040 (1) 5 000 Café profit 280 (1) OF 8 3(c) $7000 (1) This is the amount of subscriptions which relates to this financial year (1) 2 Question Answer Marks 3(d) Opening bank balance/closing bank balance Purchase of equipment Proceeds of sale of equipment Repayment of loan Café sales Payments to café suppliers Café wages Subscriptions accrued at the start of the year Any five items (1) each 5
Q4 · Virat is a trader
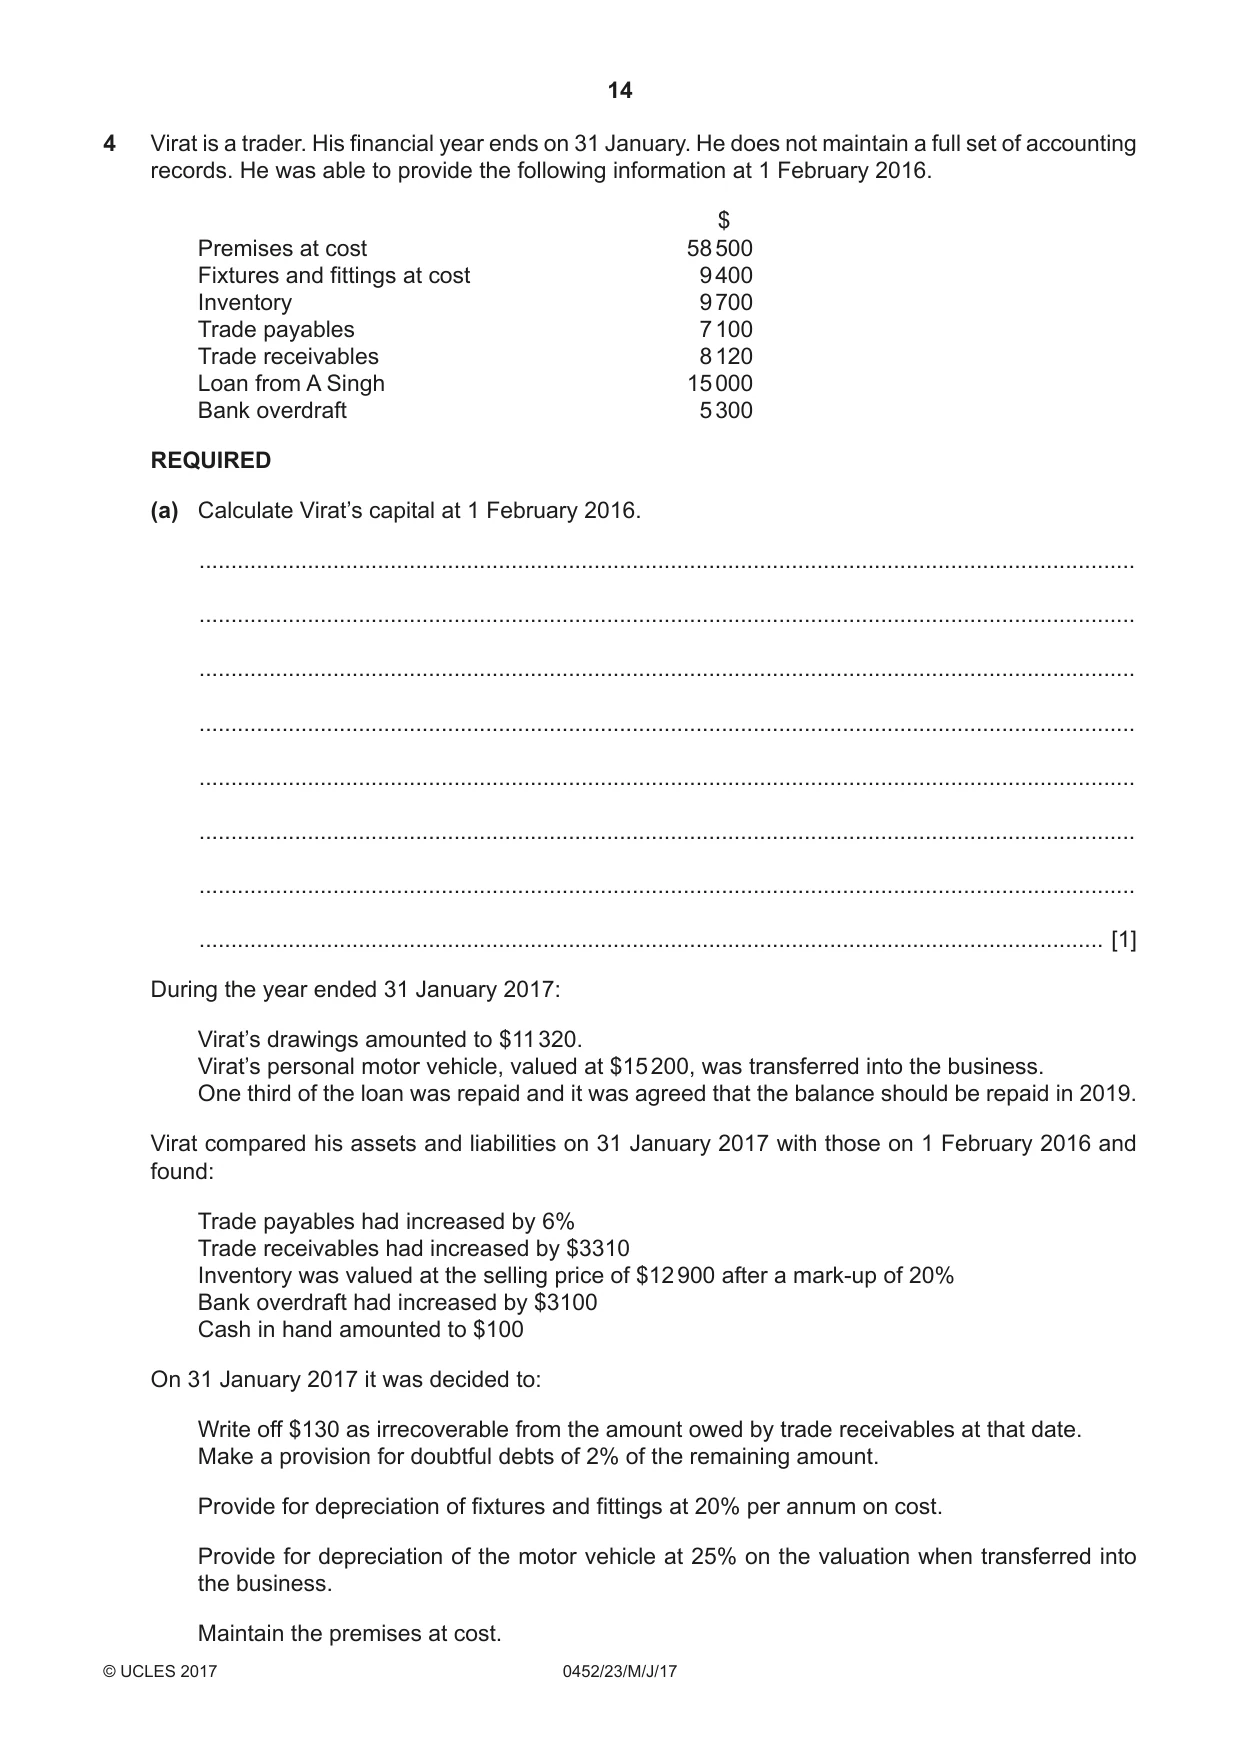
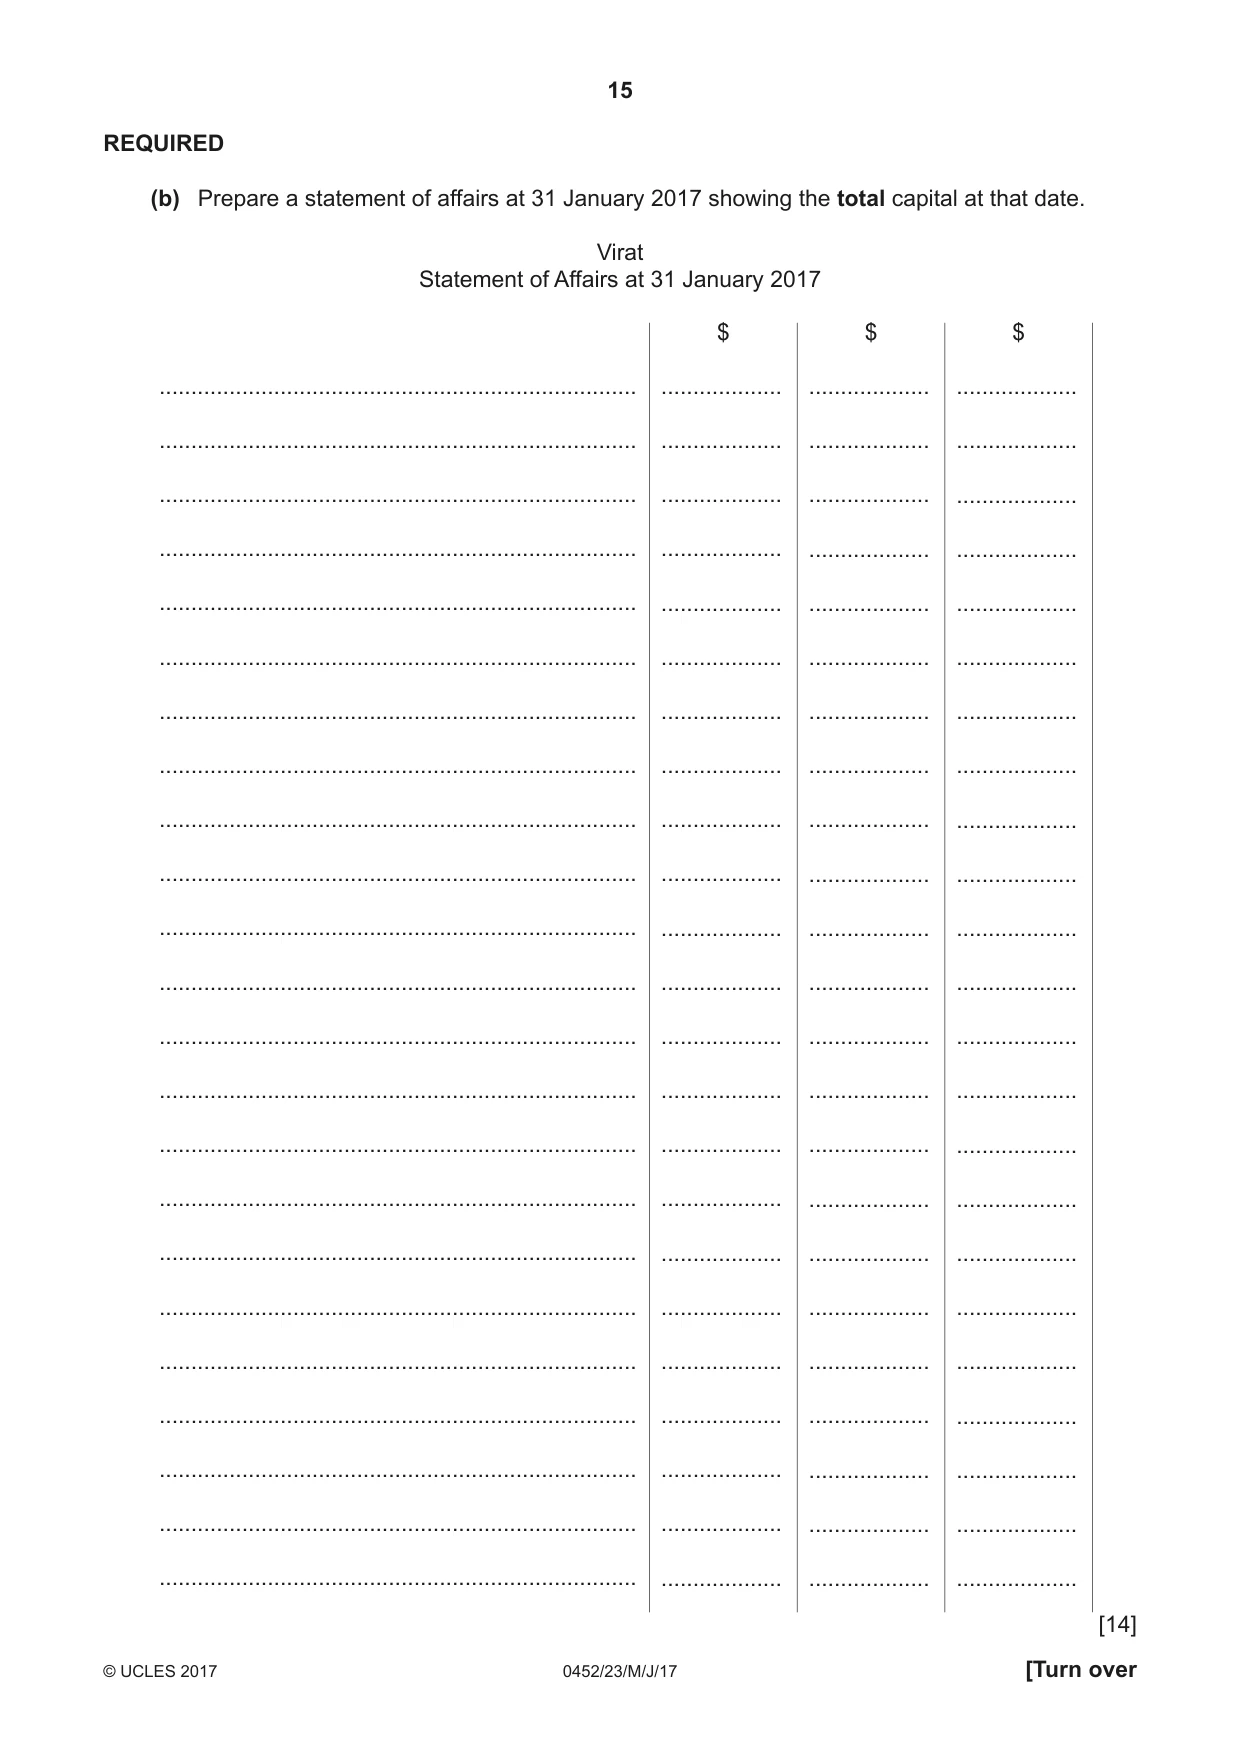
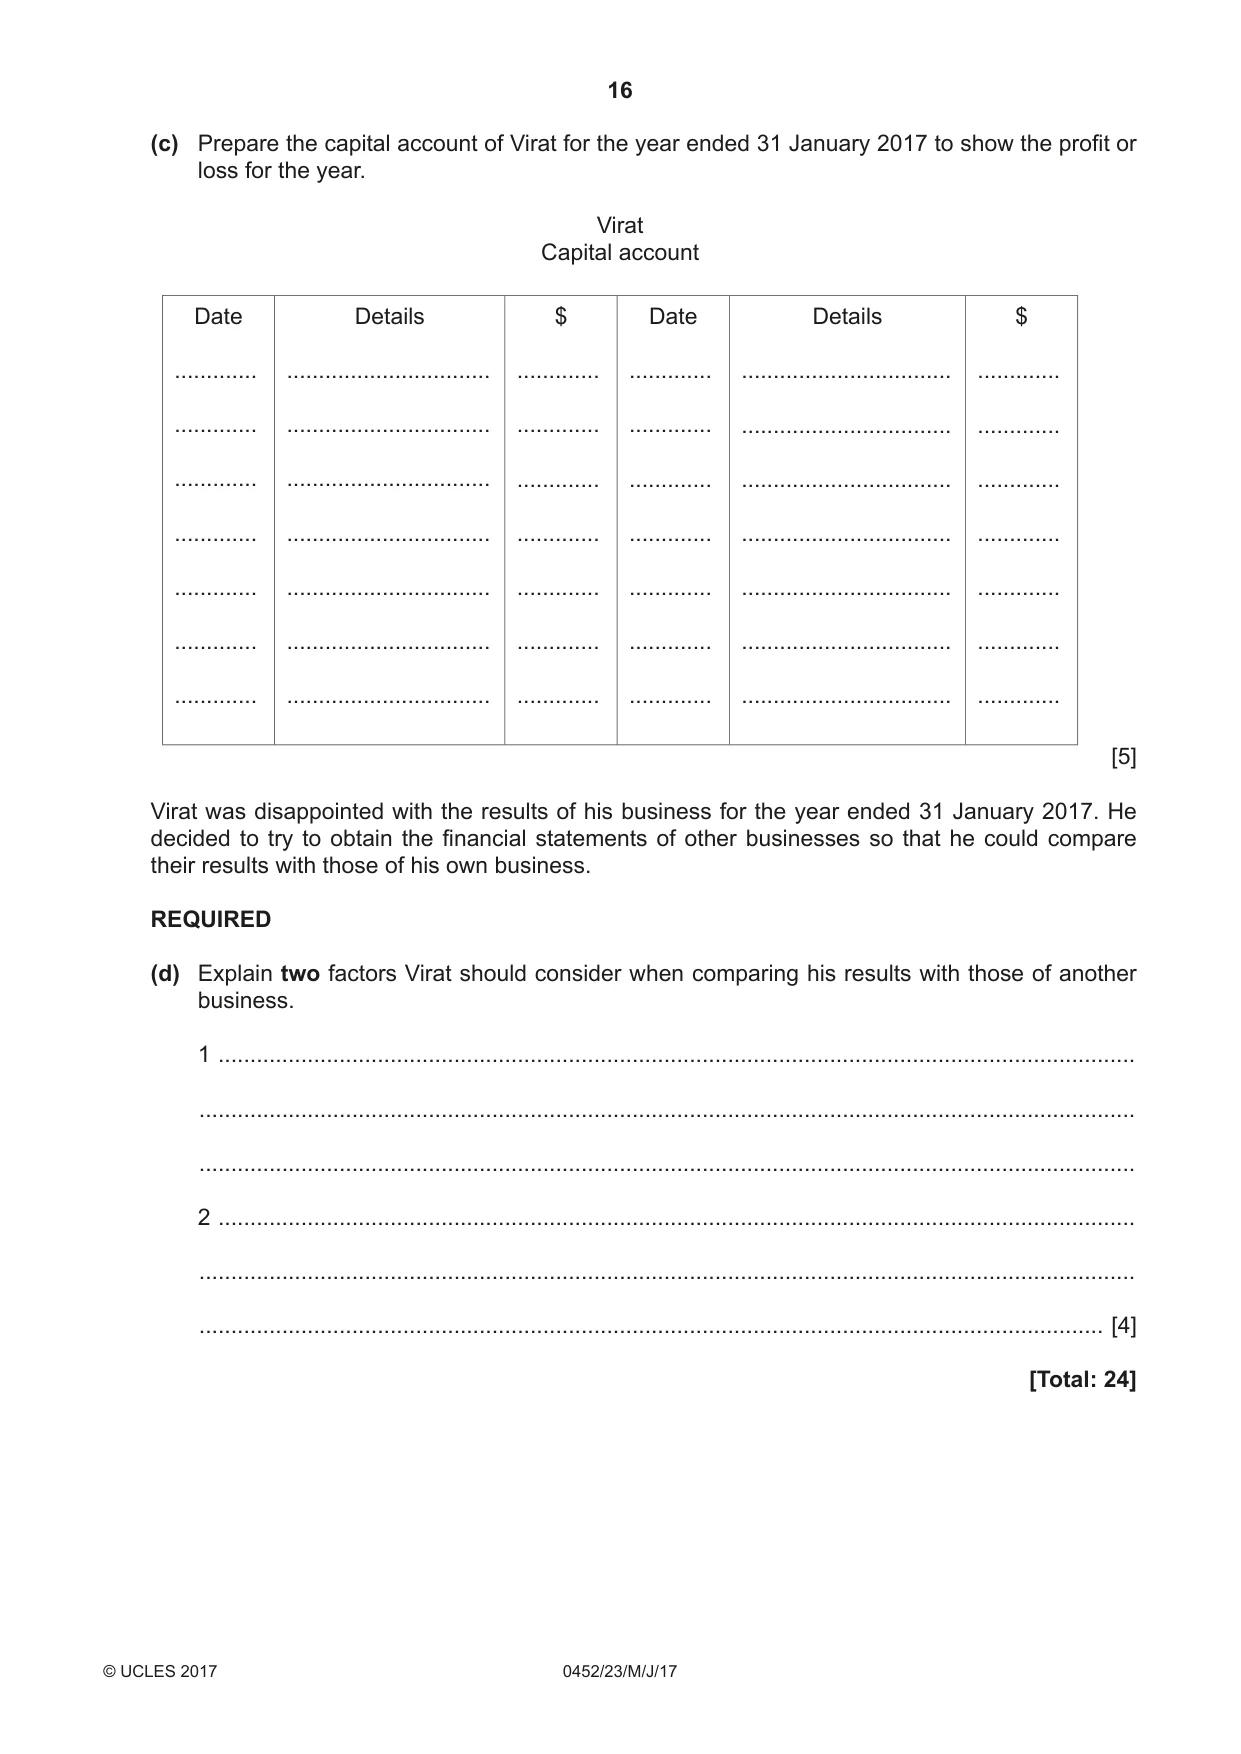
4 Virat is a trader. His financial year ends on 31 January. He does not maintain a full set of accounting records. He was able to provide the following information at 1 February 2016. $ Premises at cost 58 500 Fixtures and fittings at cost 9 400 Inventory 9 700 Trade payables 7 100 Trade receivables 8 120 Loan from A Singh 15 000 Bank overdraft 5 300 REQUIRED (a) Calculate Virat’s capital at 1 February 2016. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [1] During the year ended 31 January 2017: Virat’s drawings amounted to $11 320. Virat’s personal motor vehicle, valued at $15 200, was transferred into the business. One third of the loan was repaid and it was agreed that the balance should be repaid in 2019. Virat compared his assets and liabilities on 31 January 2017 with those on 1 February 2016 and found: Trade payables had increased by 6% Trade receivables had increased by $3310 Inventory was valued at the selling price of $12 900 after a mark-up of 20% Bank overdraft had increased by $3100 Cash in hand amounted to $100 On 31 January 2017 it was decided to: Write off $130 as irrecoverable from the amount owed by trade receivables at that date. Make a provision for doubtful debts of 2% of the remaining amount. Provide for depreciation of fixtures and fittings at 20% per annum on cost. Provide for depreciation of the motor vehicle at 25% on the valuation when transferred into the business. Maintain the premises at cost. REQUIRED (b) Prepare a statement of affairs at 31 January Virat Statement of Affairs at ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... (c) Prepare the capital account of Virat for the year ended 31 January 2017 to show the profit or loss for the year. Virat Capital account Date Details $ Date Details $ ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. [5] Virat was disappointed with the results of his business for the year ended 31 January 2017. He decided to try to obtain the financial statements of other businesses so that he could compare their results with those of his own business. REQUIRED (d) Explain two factors Virat should consider when comparing his results with those of another business. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... .............................................................................................................................................. [4] [Total: 24] Question 5 is on the next page.
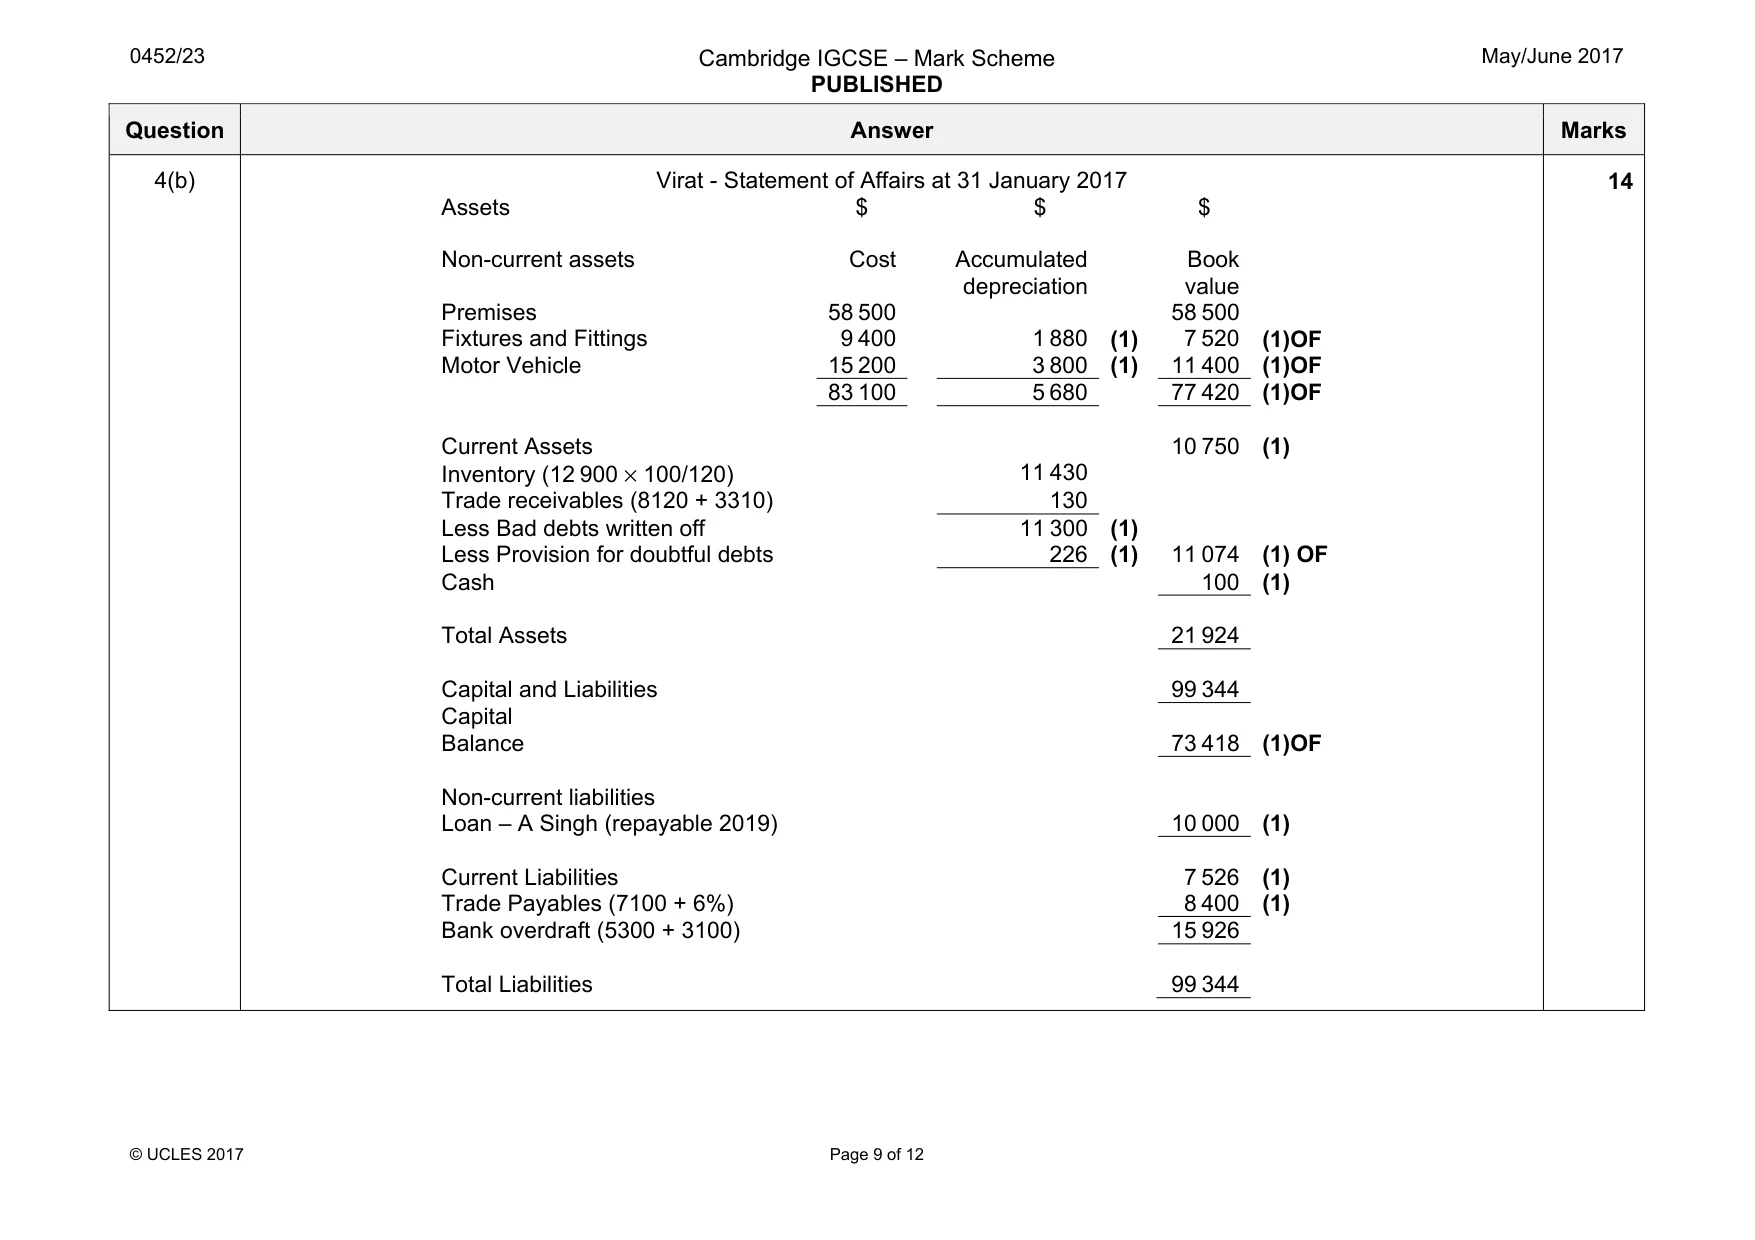
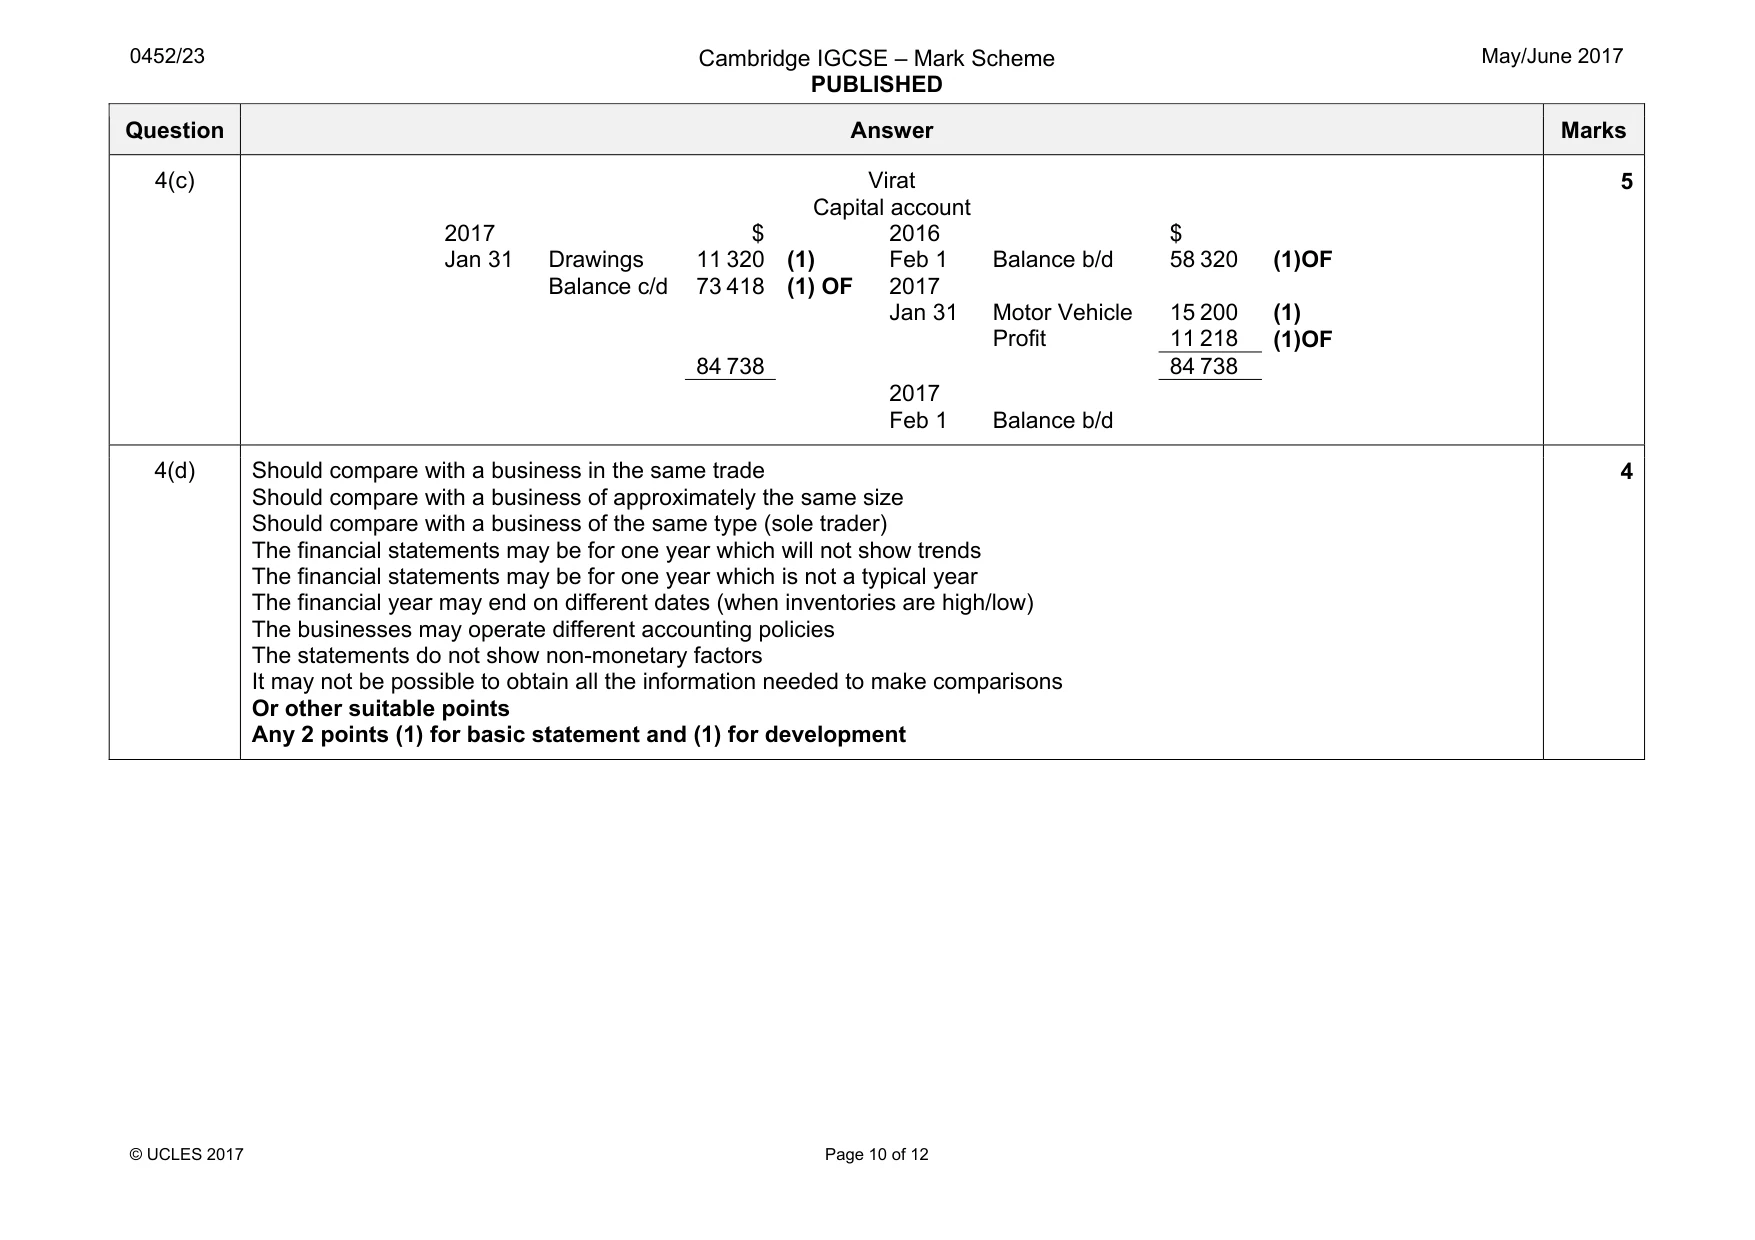
Mark scheme: 4(a) $ $ Premises 58 500 Fixtures and fittings 9 400 Inventory 9 700 Trade receivables 8 120 85 720 Trade payables 7 100 Loan 15 000 Bank overdraft 5 300 27 400 Capital 58 320 (1) 1 Question Answer Marks 4(b) Virat - Statement of Affairs at 31 January 2017 Assets $ $ $ Non-current assets Cost Accumulated Book depreciation value Premises 58 500 58 500 Fixtures and Fittings 9 400 1 880 (1) 7 520 (1)OF Motor Vehicle 15 200 3 800 (1) 11 400 (1)OF 83 100 5 680 77 420 (1)OF Current Assets 10 750 (1) Inventory (12 900 × 100/120) 11 430 Trade receivables (8120 + 3310) 130 Less Bad debts written off 11 300 (1) Less Provision for doubtful debts 226 (1) 11 074 (1) OF Cash 100 (1) Total Assets 21 924 Capital and Liabilities 99 344 Capital Balance 73 418 (1)OF Non-current liabilities Loan – A Singh (repayable 2019) 10 000 (1) Current Liabilities 7 526 (1) Trade Payables (7100 + 6%) 8 400 (1) Bank overdraft (5300 + 3100) 15 926 Total Liabilities 99 344 14 Question Answer Marks 4(c) Virat Capital account 2017 $ 2016 $ Jan 31 Drawings 11 320 (1) Feb 1 Balance b/d 58 320 (1)OF Balance c/d 73 418 (1) OF 2017 Jan 31 Motor Vehicle 15 200 (1) Profit 11 218 (1)OF 84 738 84 738 2017 Feb 1 Balance b/d 5 4(d) Should compare with a business in the same trade Should compare with a business of approximately the same size Should compare with a business of the same type (sole trader) The financial statements may be for one year which will not show trends The financial statements may be for one year which is not a typical year The financial year may end on different dates (when inventories are high/low) The businesses may operate different accounting policies The statements do not show non-monetary factors It may not be possible to obtain all the information needed to make comparisons Or other suitable points Any 2 points (1) for basic statement and (1) for development 4
Q5 · Heng is a wholesaler
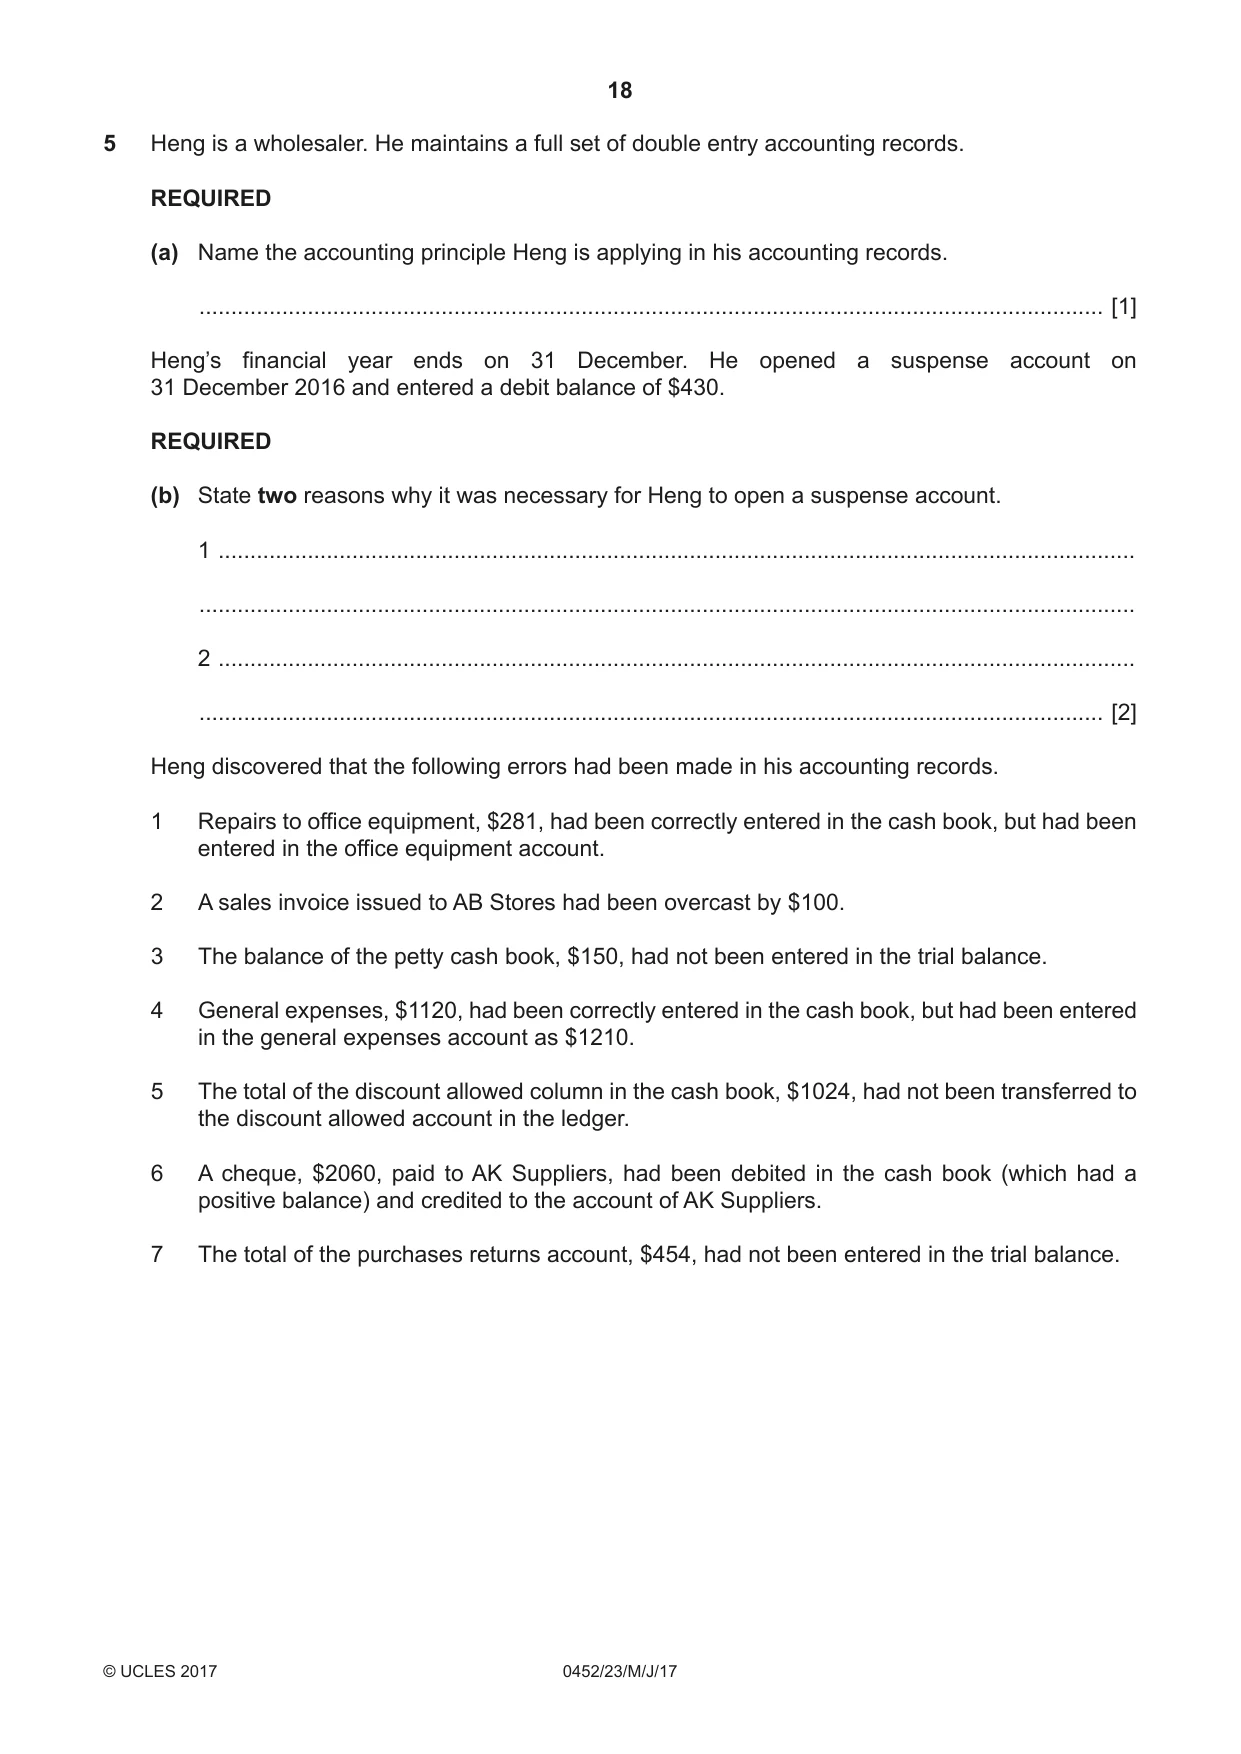
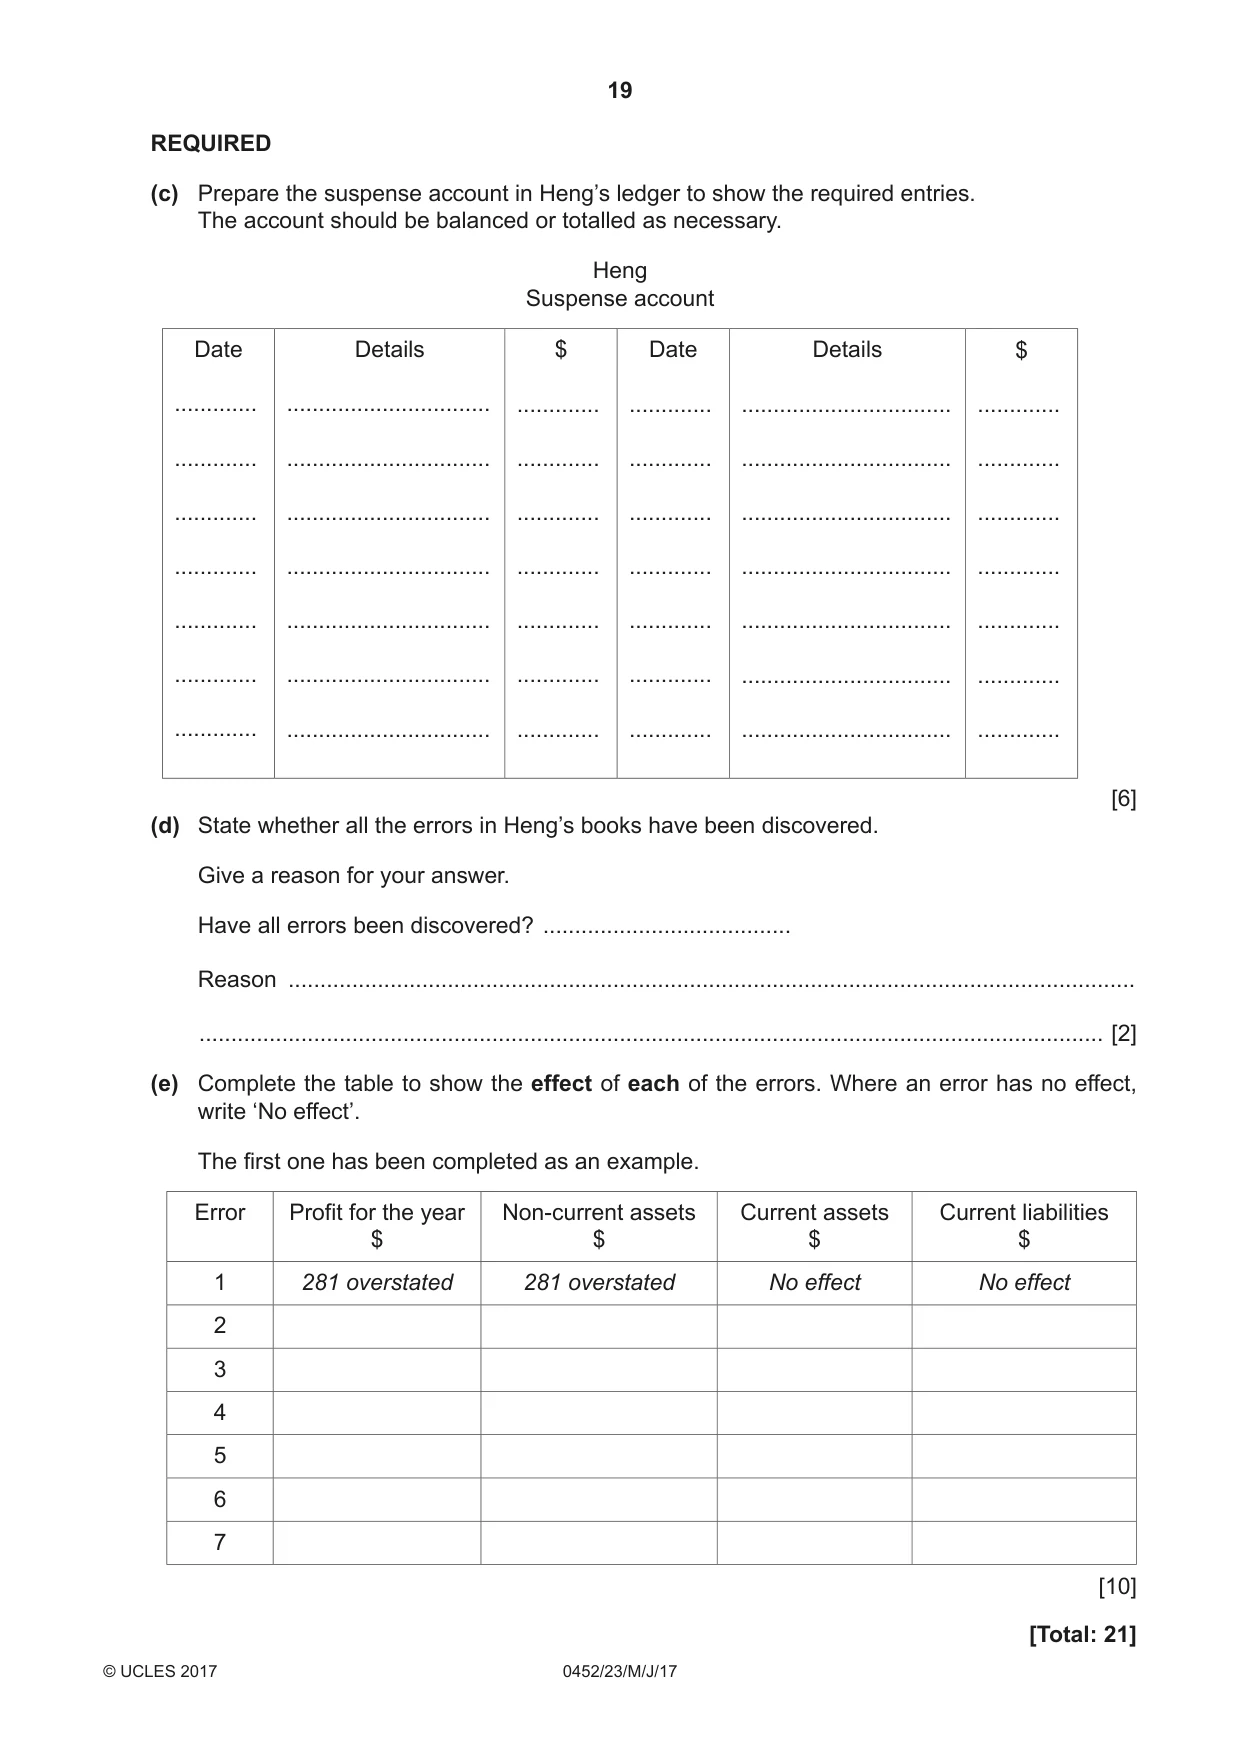
5 Heng is a wholesaler. He maintains a full set of double entry accounting records. REQUIRED (a) Name the accounting principle Heng is applying in his accounting records. .............................................................................................................................................. [1] Heng’s financial year ends on 31 December. He opened a suspense account on 31 December 2016 and entered a debit balance of $430. REQUIRED (b) State two reasons why it was necessary for Heng to open a suspense account. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] Heng discovered that the following errors had been made in his accounting records. 1 Repairs to office equipment, $281, had been correctly entered in the cash book, but had been entered in the office equipment account. 2 A sales invoice issued to AB Stores had been overcast by $100. 3 The balance of the petty cash book, $150, had not been entered in the trial balance. 4 General expenses, $1120, had been correctly entered in the cash book, but had been entered in the general expenses account as $1210. 5 The total of the discount allowed column in the cash book, $1024, had not been transferred to the discount allowed account in the ledger. 6 A cheque, $2060, paid to AK Suppliers, had been debited in the cash book (which had a positive balance) and credited to the account of AK Suppliers. 7 The total of the purchases returns account, $454, had not been entered in the trial balance. REQUIRED (c) Prepare the suspense account in Heng’s ledger to show the required entries. The account should be balanced or totalled as necessary. Heng Suspense account Date Details $ Date Details $ ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. ............. ................................ ............. ............. ................................. ............. [6] (d) State whether all the errors in Heng’s books have been discovered. Give a reason for your answer. Have all errors been discovered? ....................................... Reason ..................................................................................................................................... .............................................................................................................................................. [2] (e) Complete the table to show the effect of each of the errors. Where an error has no effect, write ‘No effect’. The first one has been completed as an example. Error Profit for the year Non-current assets Current assets Current liabilities $ $ $ $ 1 281 overstated 281 overstated No effect No effect 2 3 4 5 6 7 [10]
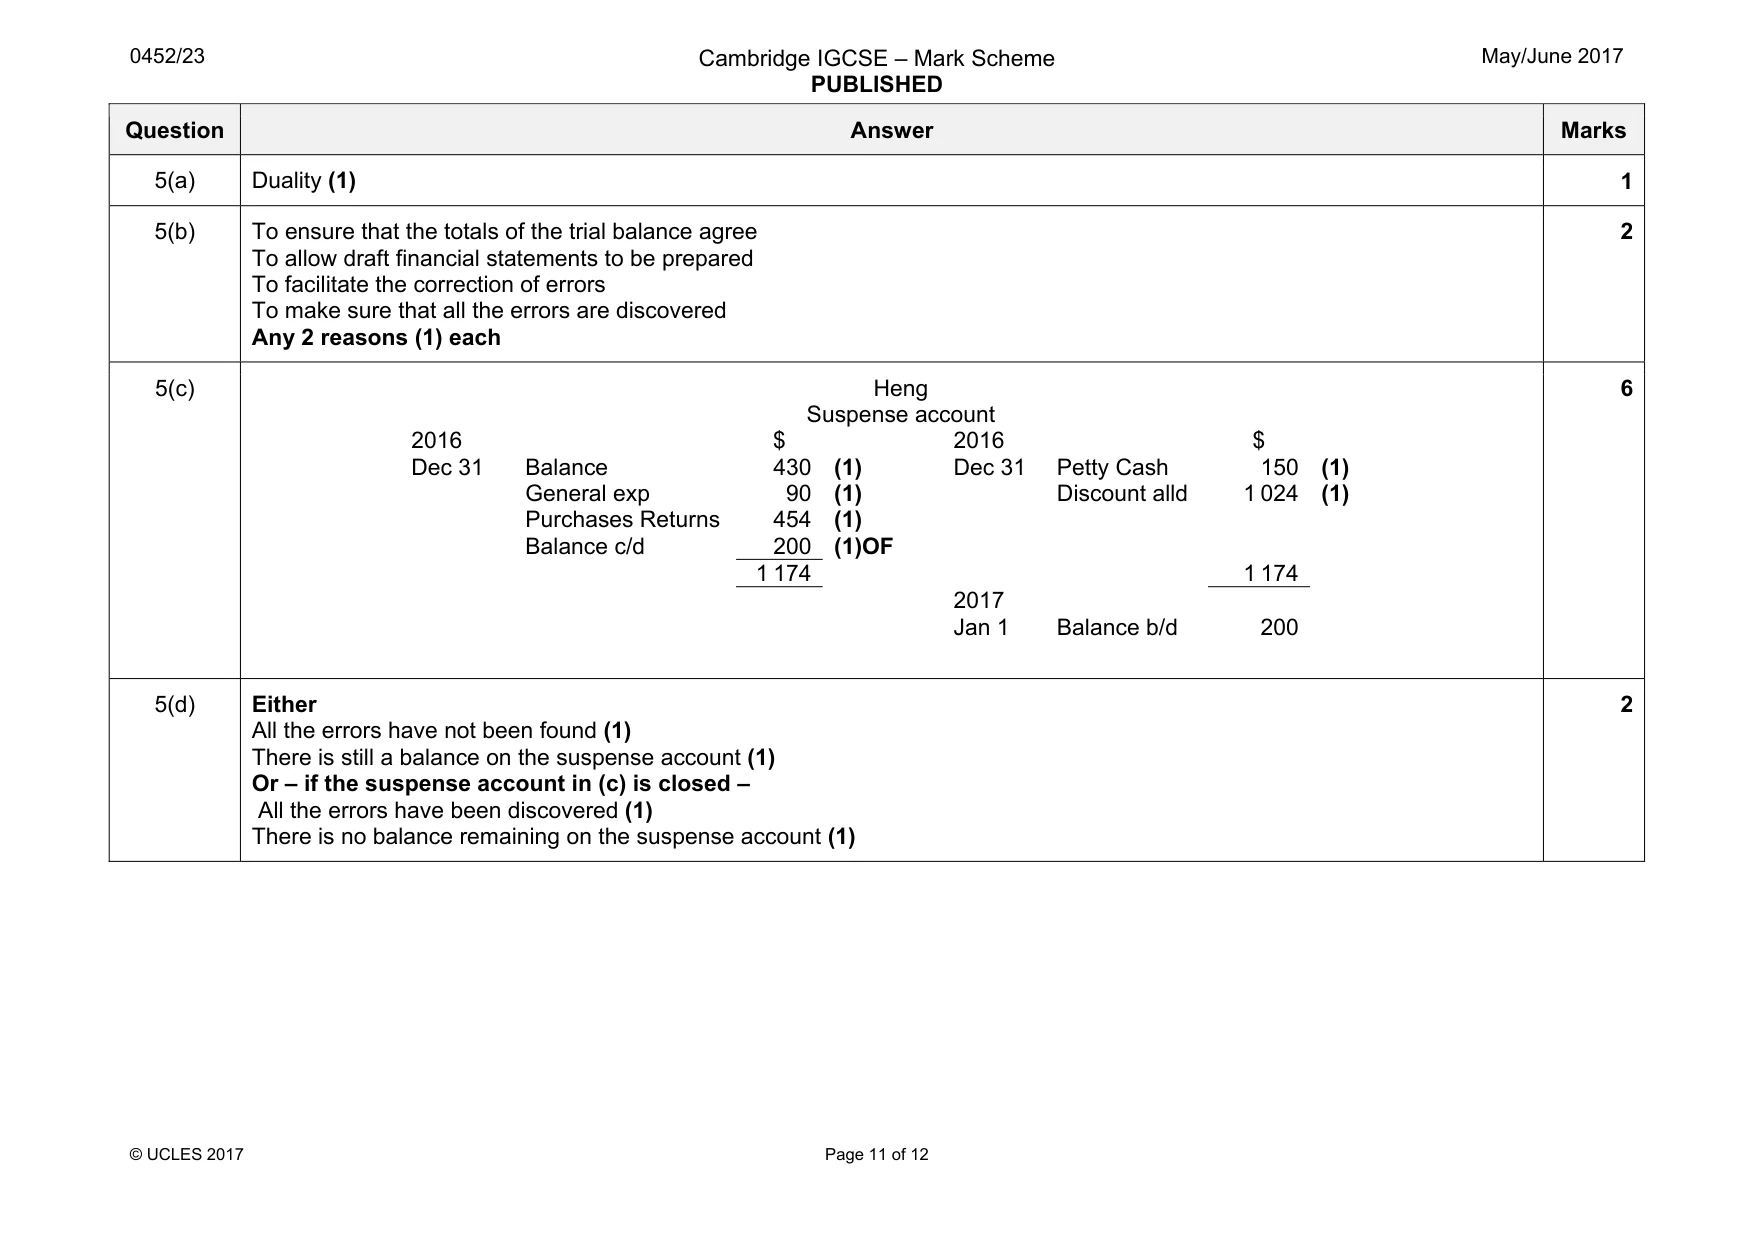
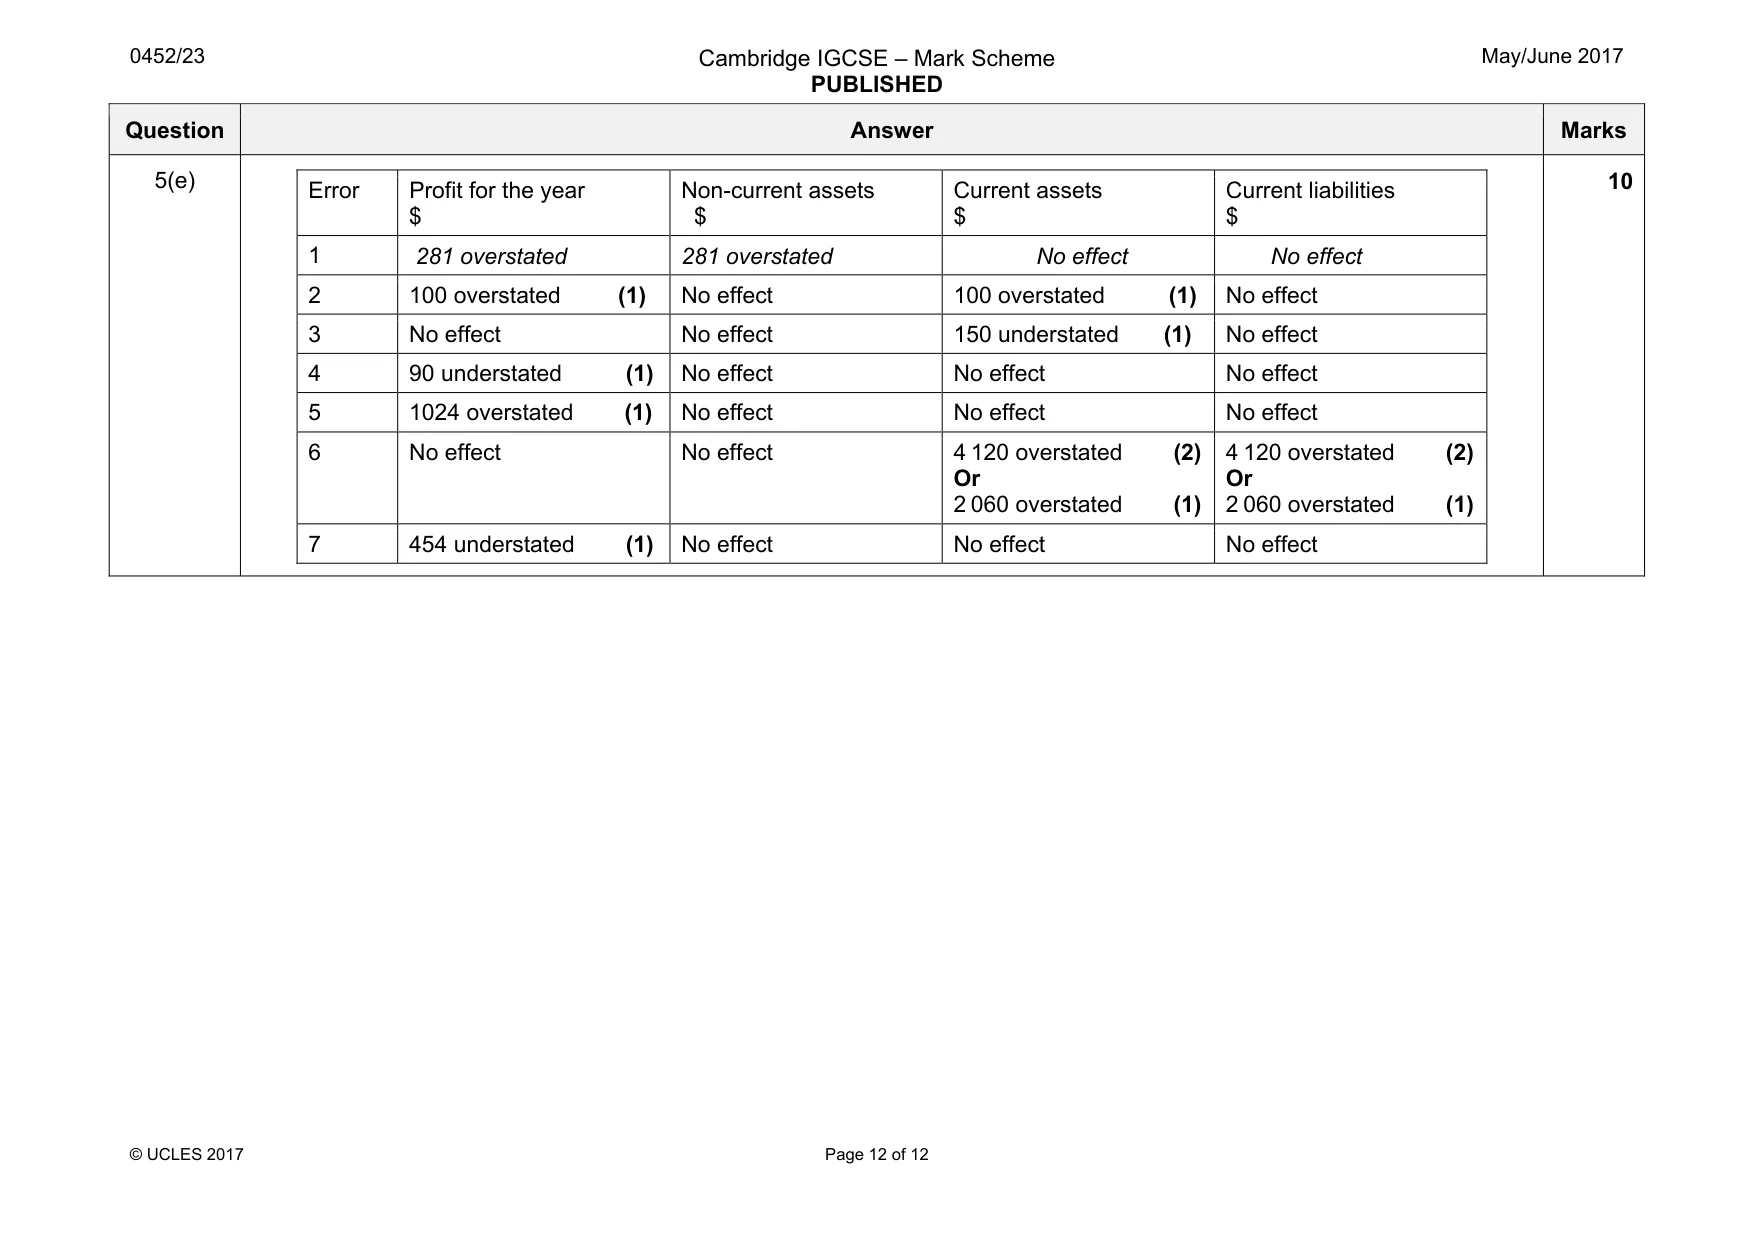
Mark scheme: 5(a) Duality (1) 1 5(b) To ensure that the totals of the trial balance agree To allow draft financial statements to be prepared To facilitate the correction of errors To make sure that all the errors are discovered Any 2 reasons (1) each 2 5(c) Heng Suspense account 2016 $ 2016 $ Dec 31 Balance 430 (1) Dec 31 Petty Cash 150 (1) General exp 90 (1) Discount alld 1 024 (1) Purchases Returns 454 (1) Balance c/d 200 (1)OF 1 174 1 174 2017 Jan 1 Balance b/d 200 6 5(d) Either All the errors have not been found (1) There is still a balance on the suspense account (1) Or – if the suspense account in (c) is closed – All the errors have been discovered (1) There is no balance remaining on the suspense account (1) 2 Question Answer Marks 5(e) Error Profit for the year $ Non-current assets $ Current assets $ Current liabilities $ 1 281 overstated 281 overstated No effect No effect 2 100 overstated (1) No effect 100 overstated (1) No effect 3 No effect No effect 150 understated (1) No effect 4 90 understated (1) No effect No effect No effect 5 1024 overstated (1) No effect No effect No effect 6 No effect No effect 4 120 overstated (2) Or 2 060 overstated (1) 4 120 overstated (2) Or 2 060 overstated (1) 7 454 understated (1) No effect No effect No effect 10
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2017 May/June, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.