Cambridge IGCSE Accounting 0452 — 2017 May/June Paper 2 · Variant 1
0452/21/M/J/17 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme13 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Amjad is a furniture wholesaler
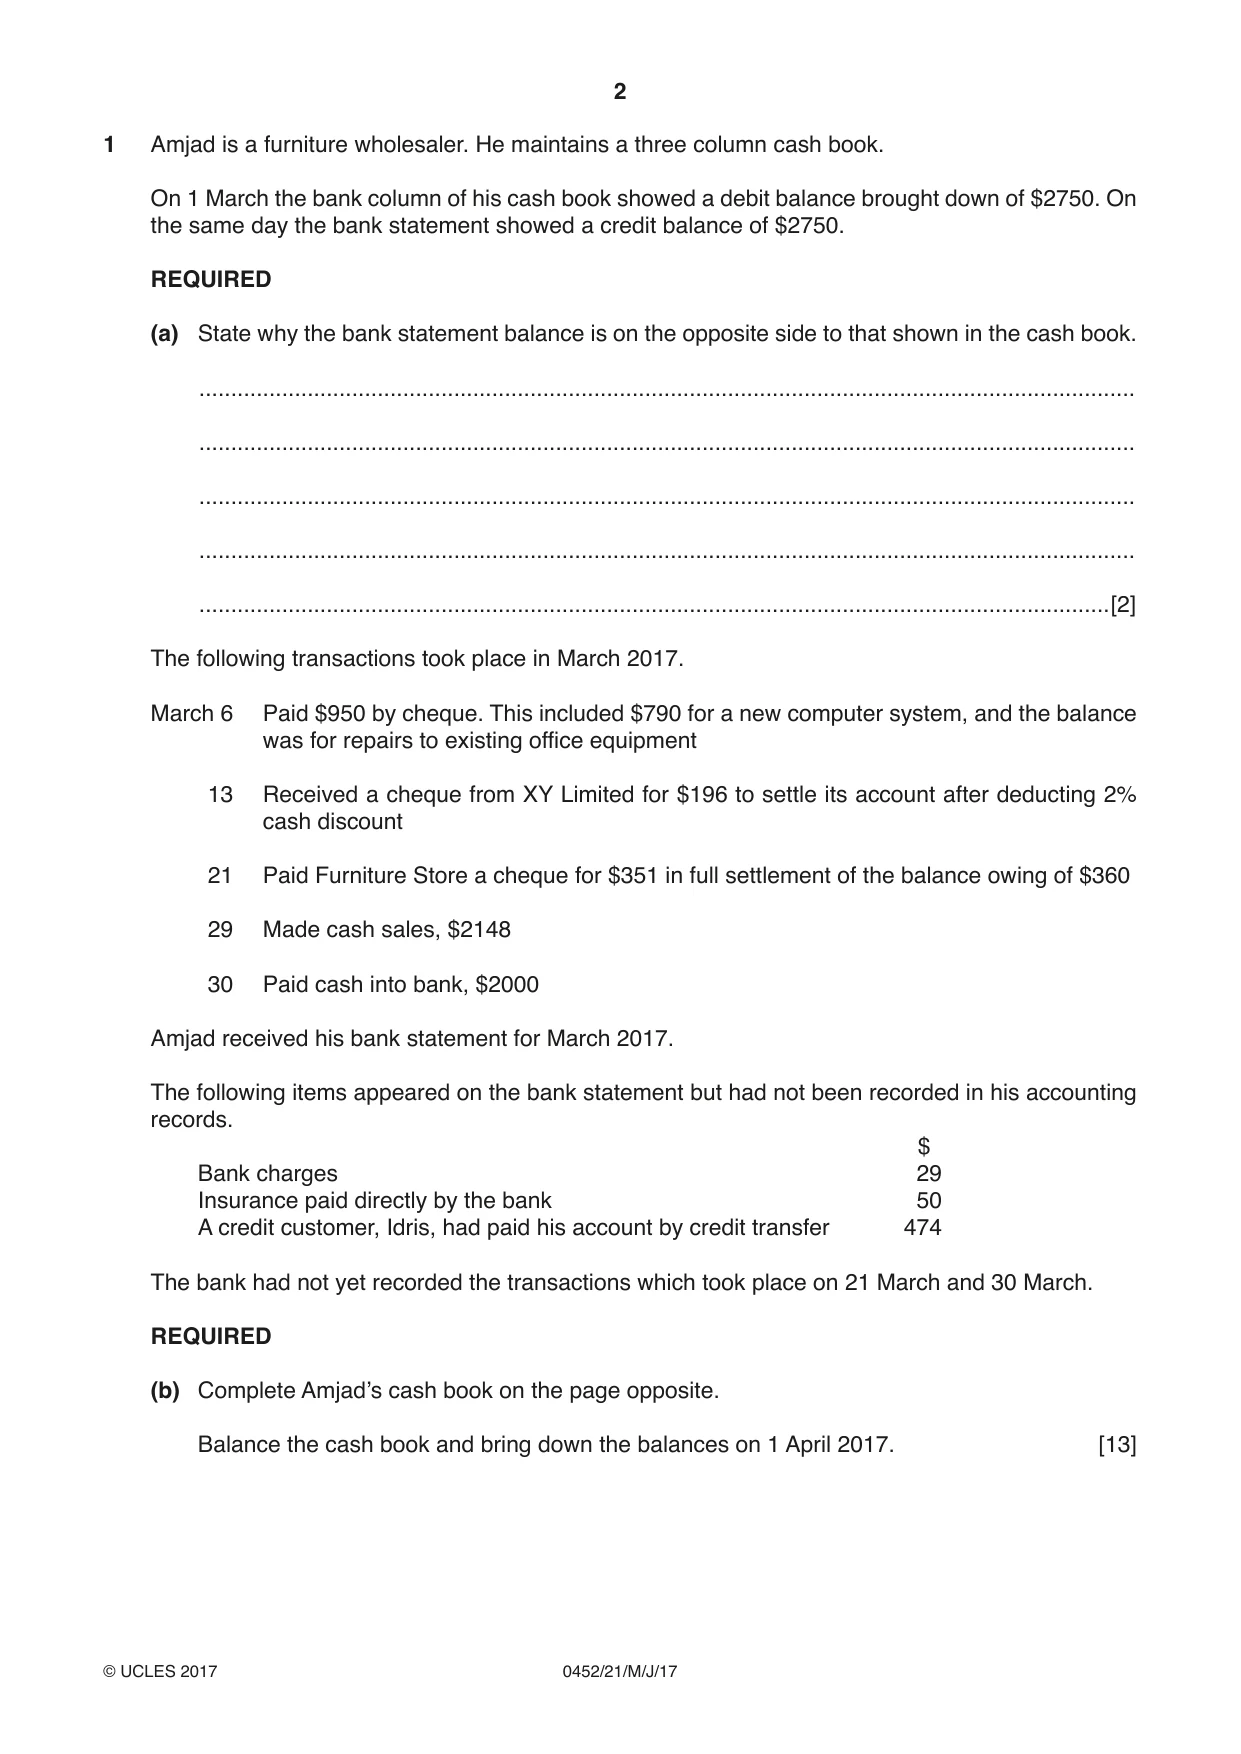
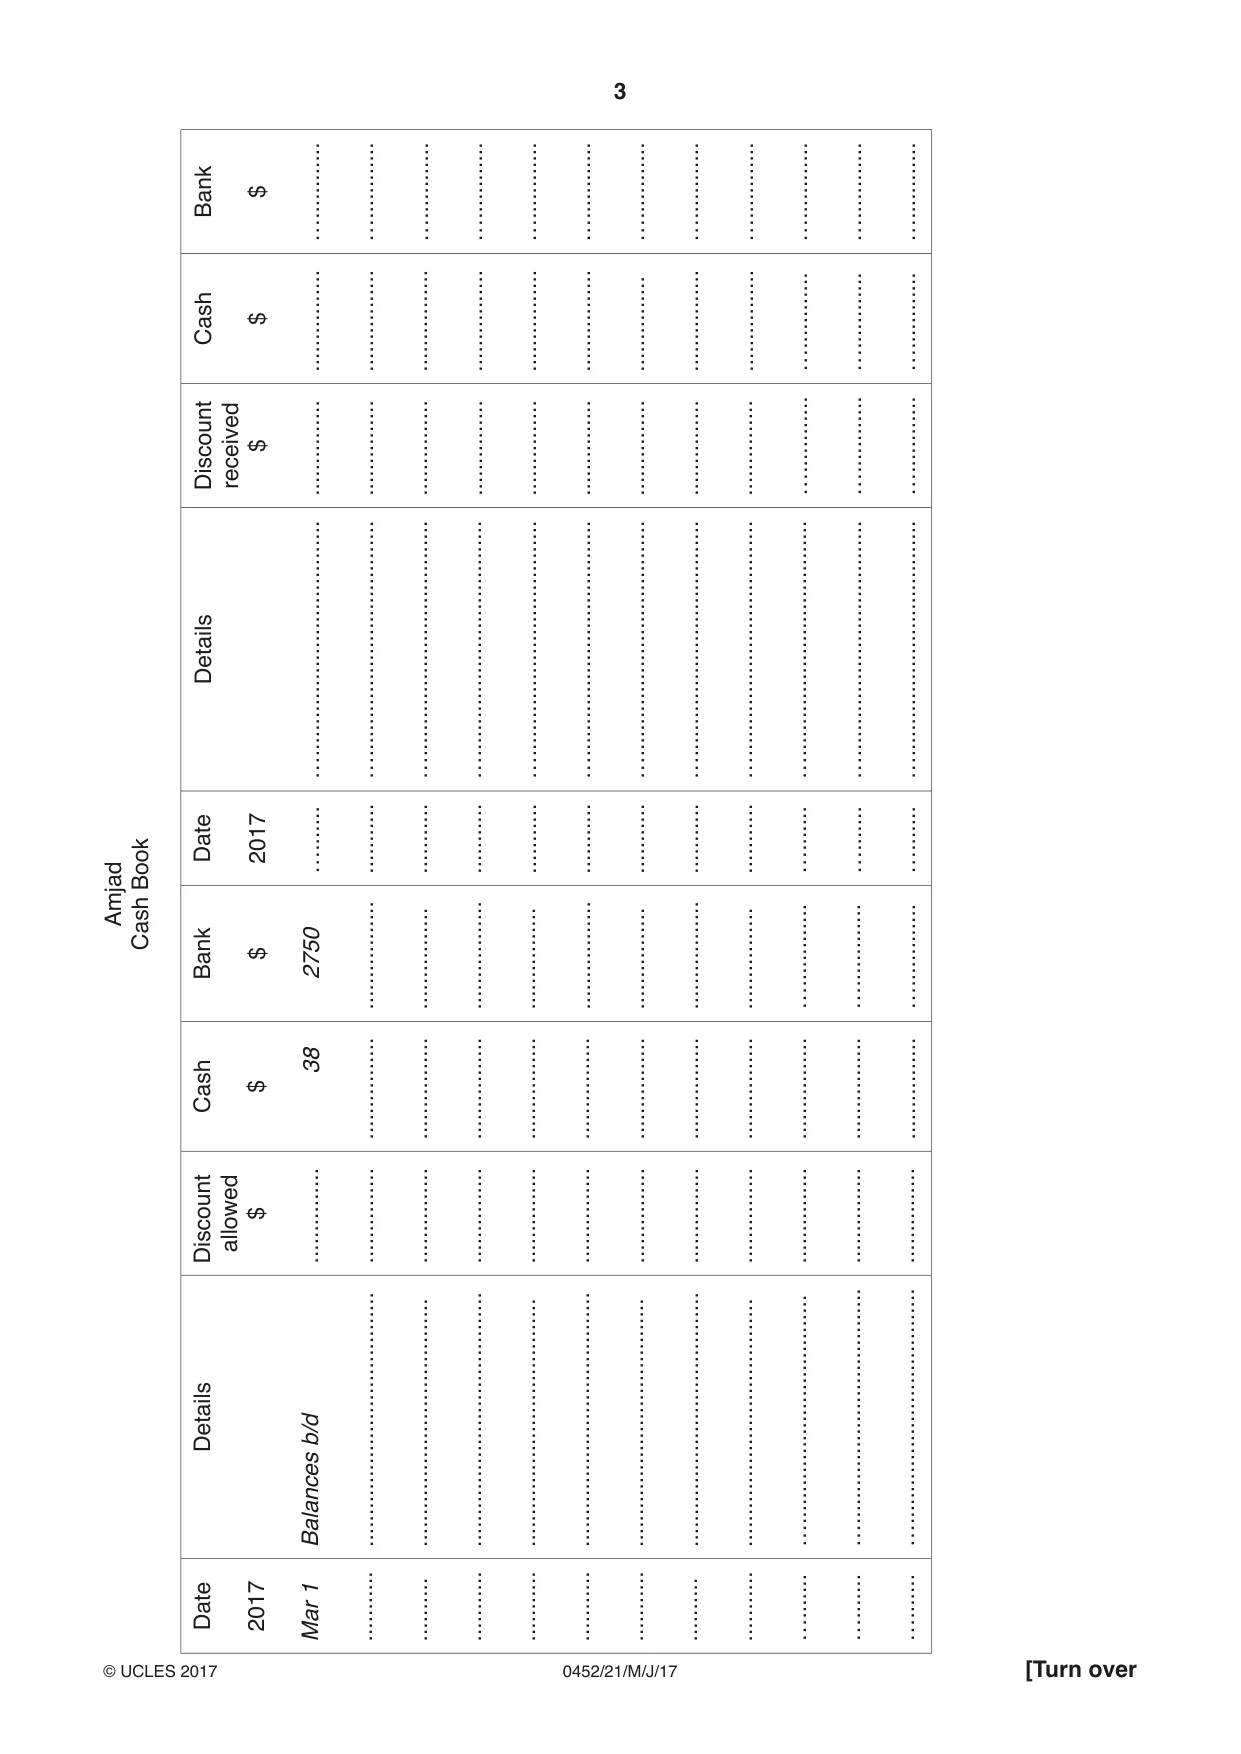
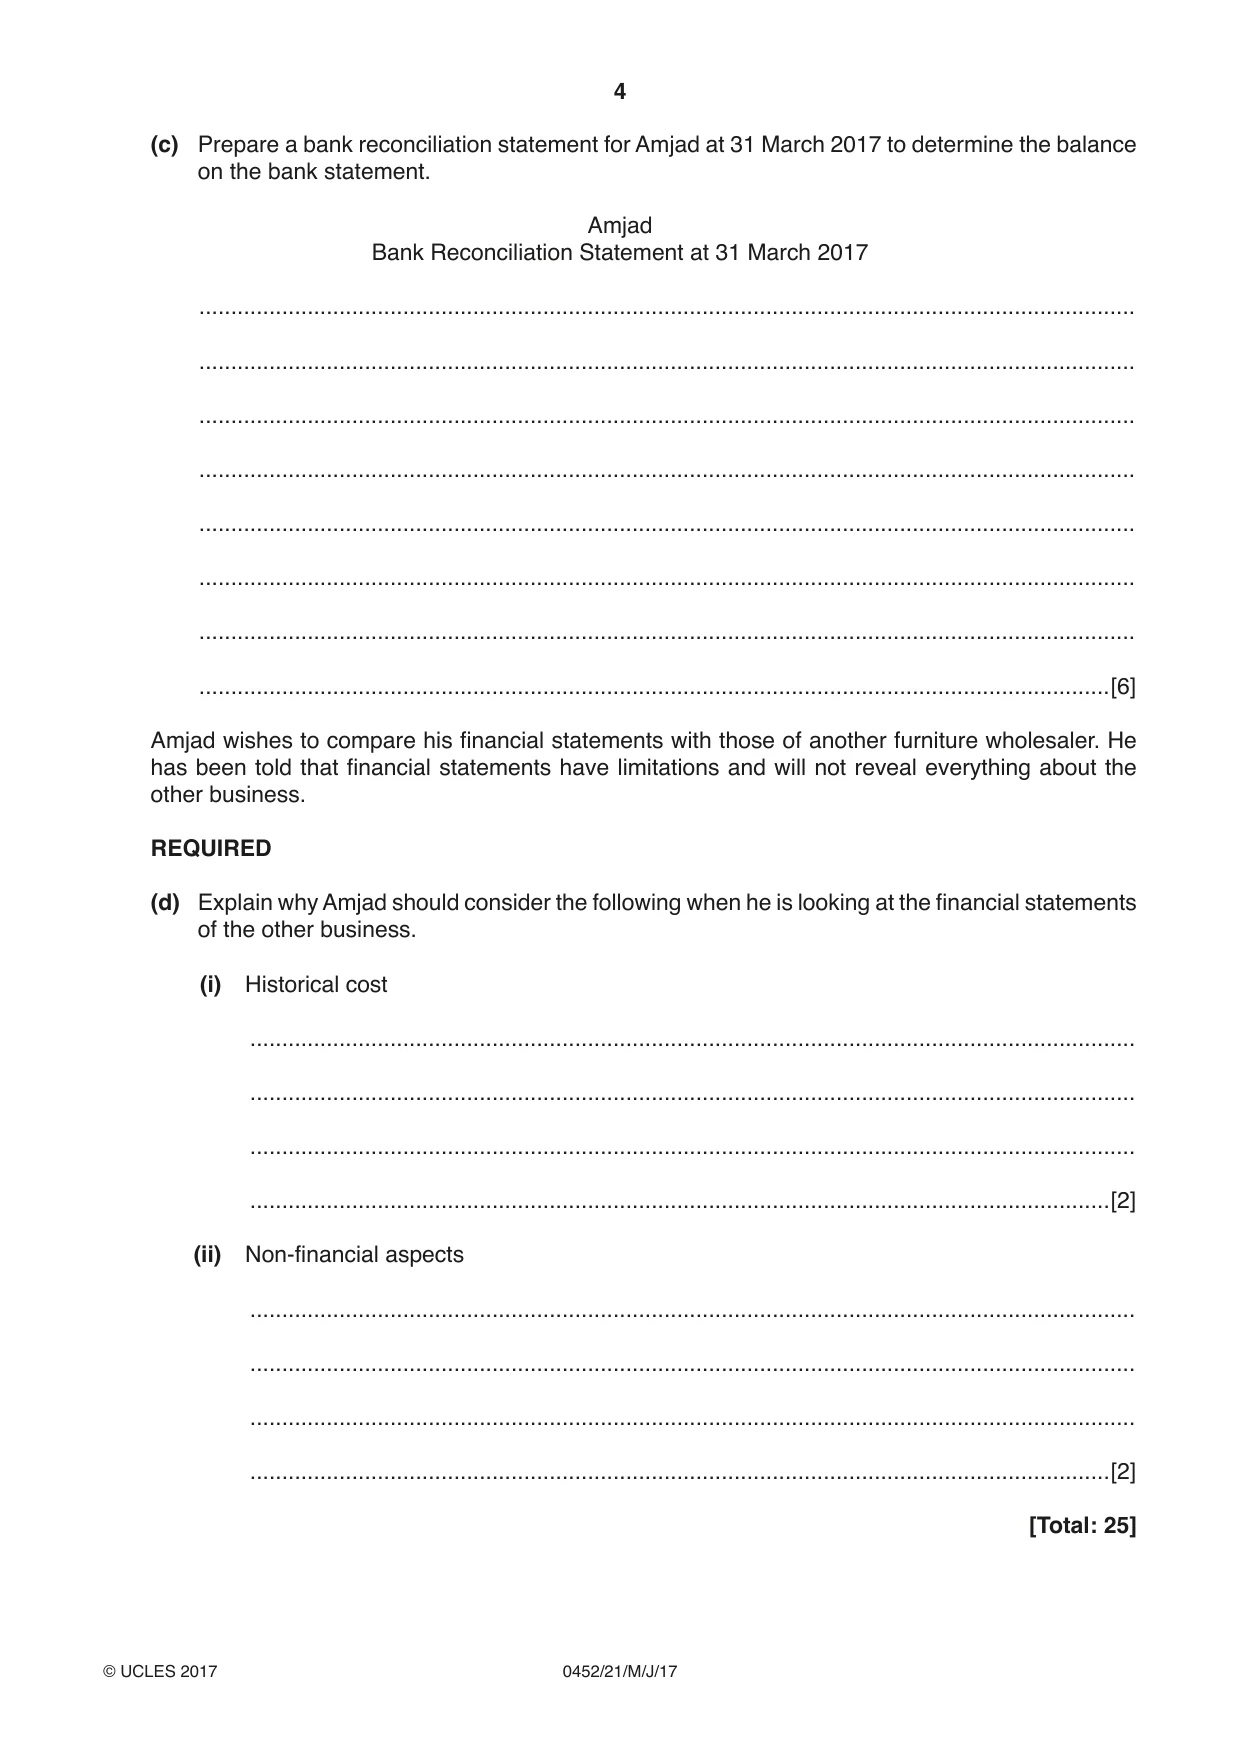
1 Amjad is a furniture wholesaler. He maintains a three column cash book. On 1 March the bank column of his cash book showed a debit balance brought down of $2750. On the same day the bank statement showed a credit balance of $2750. REQUIRED (a) State why the bank statement balance is on the opposite side to that shown in the cash book. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] The following transactions took place in March 2017. March 6 Paid $950 by cheque. This included $790 for a new computer system, and the balance was for repairs to existing office equipment 13 Received a cheque from XY Limited for $196 to settle its account after deducting 2% cash discount 21 Paid Furniture Store a cheque for $351 in full settlement of the balance owing of $360 29 Made cash sales, $2148 30 Paid cash into bank, $2000 Amjad received his bank statement for March 2017. The following items appeared on the bank statement but had not been recorded in his accounting records. $ Bank charges 29 Insurance paid directly by the bank 50 A credit customer, Idris, had paid his account by credit transfer 474 The bank had not yet recorded the transactions which took place on 21 March and 30 March. REQUIRED (b) Complete Amjad’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 April 2017. [13] $ Bank …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ Cash ................ ................ ................ ................ ................ ................ ............... ................ ................ …............ …............ …............ $ Discountreceived ............... ............... ............... ............... ............... ............... ............... ............... ............... …............ …............ …............ Details …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... …..................................... Date 2017 …....... ........... ........... ........... ........... ........... ........... ........... ........... …....... …....... …....... Book Amjad Cash $ Bank 2750 ................. ................ ................. ................ ................. ................ ................. ................ …............. …............. …............. 38 $ Cash ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Discountallowed ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... Details b/d Balances ........................................ ....................................... ........................................ ....................................... ........................................ ....................................... ........................................ ....................................... ….................................... …..................................... …..................................... (c) Prepare a bank reconciliation statement for Amjad at 31 March 2017 to determine the balance on the bank statement. Amjad Bank Reconciliation Statement at 31 March 2017 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[6] Amjad wishes to compare his financial statements with those of another furniture wholesaler. He has been told that financial statements have limitations and will not reveal everything about the other business. REQUIRED (d) Explain why Amjad should consider the following when he is looking at the financial statements of the other business. (i) Historical cost ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Non-financial aspects ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] [Total: 25] Question 2 is on the next page.
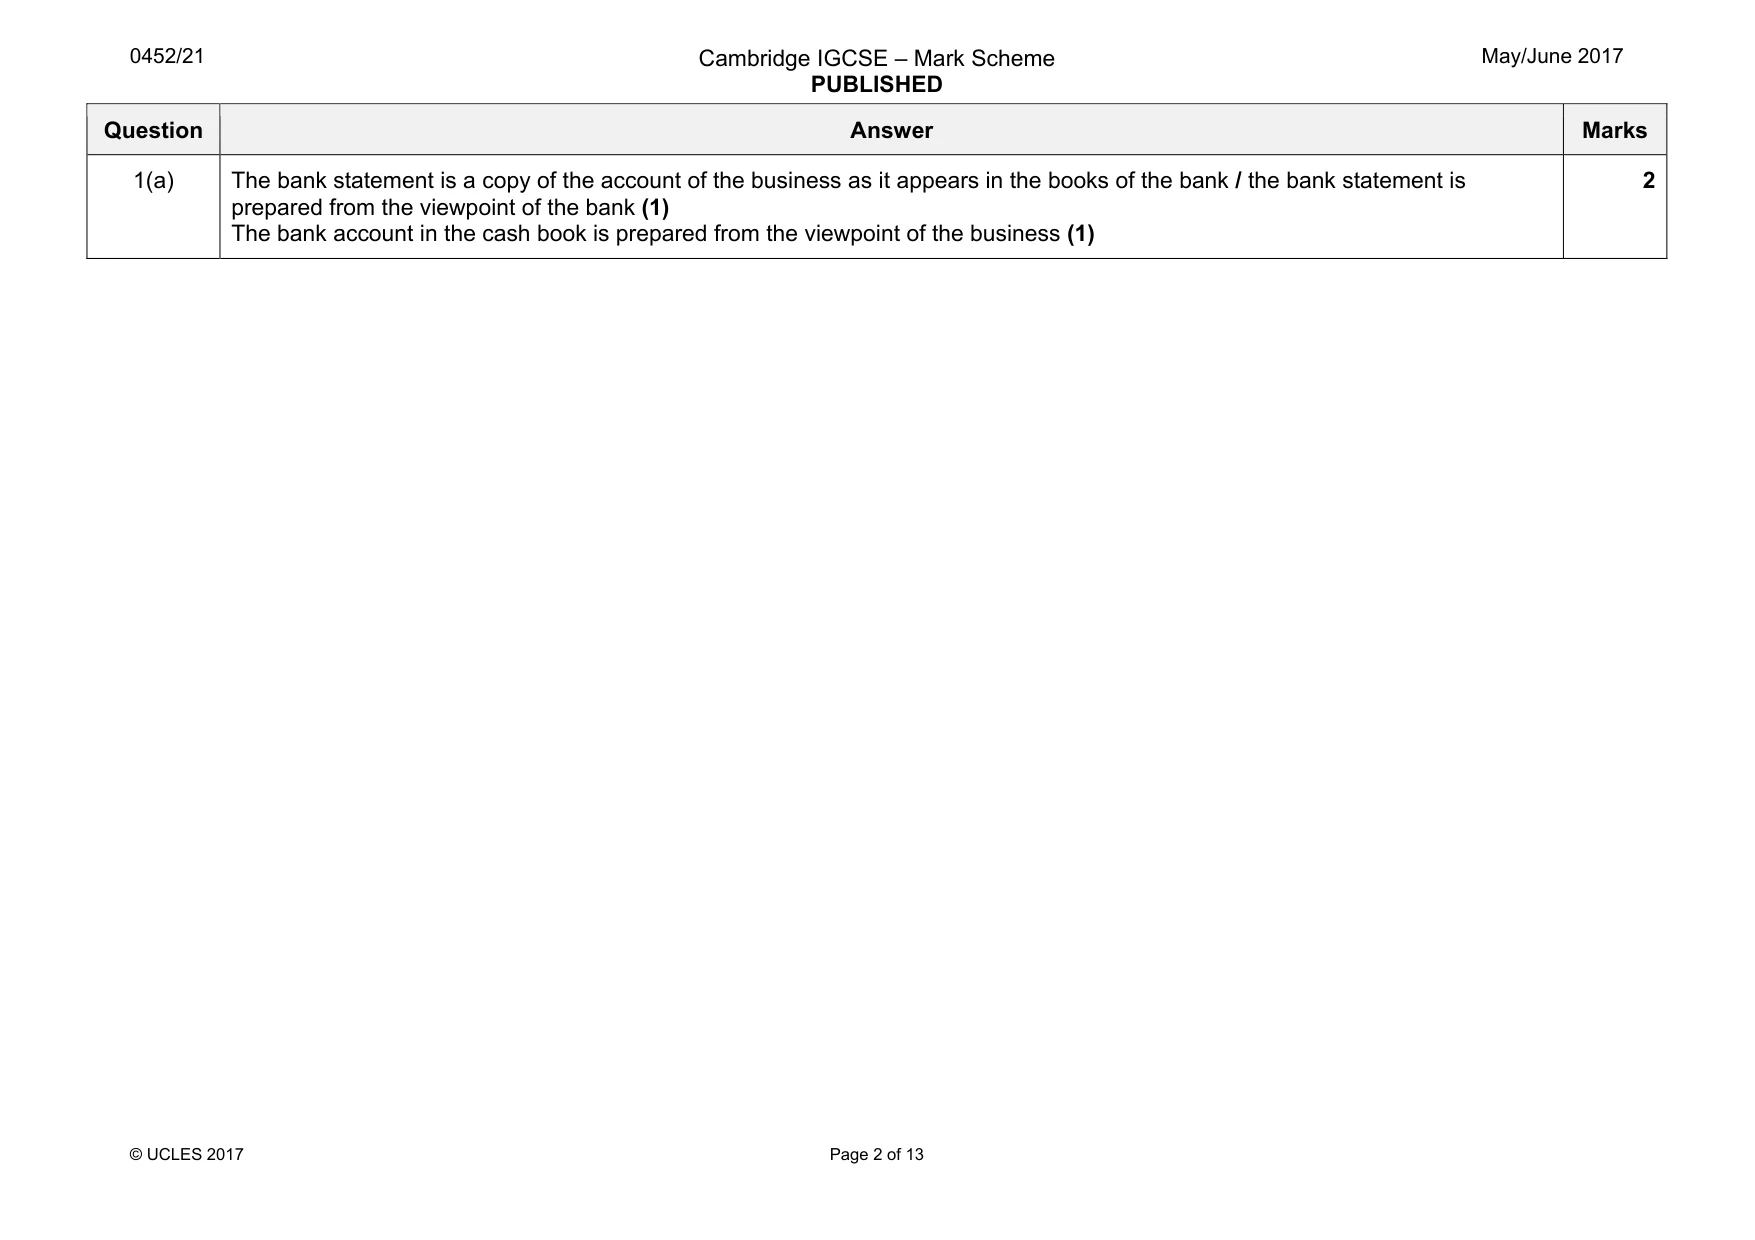
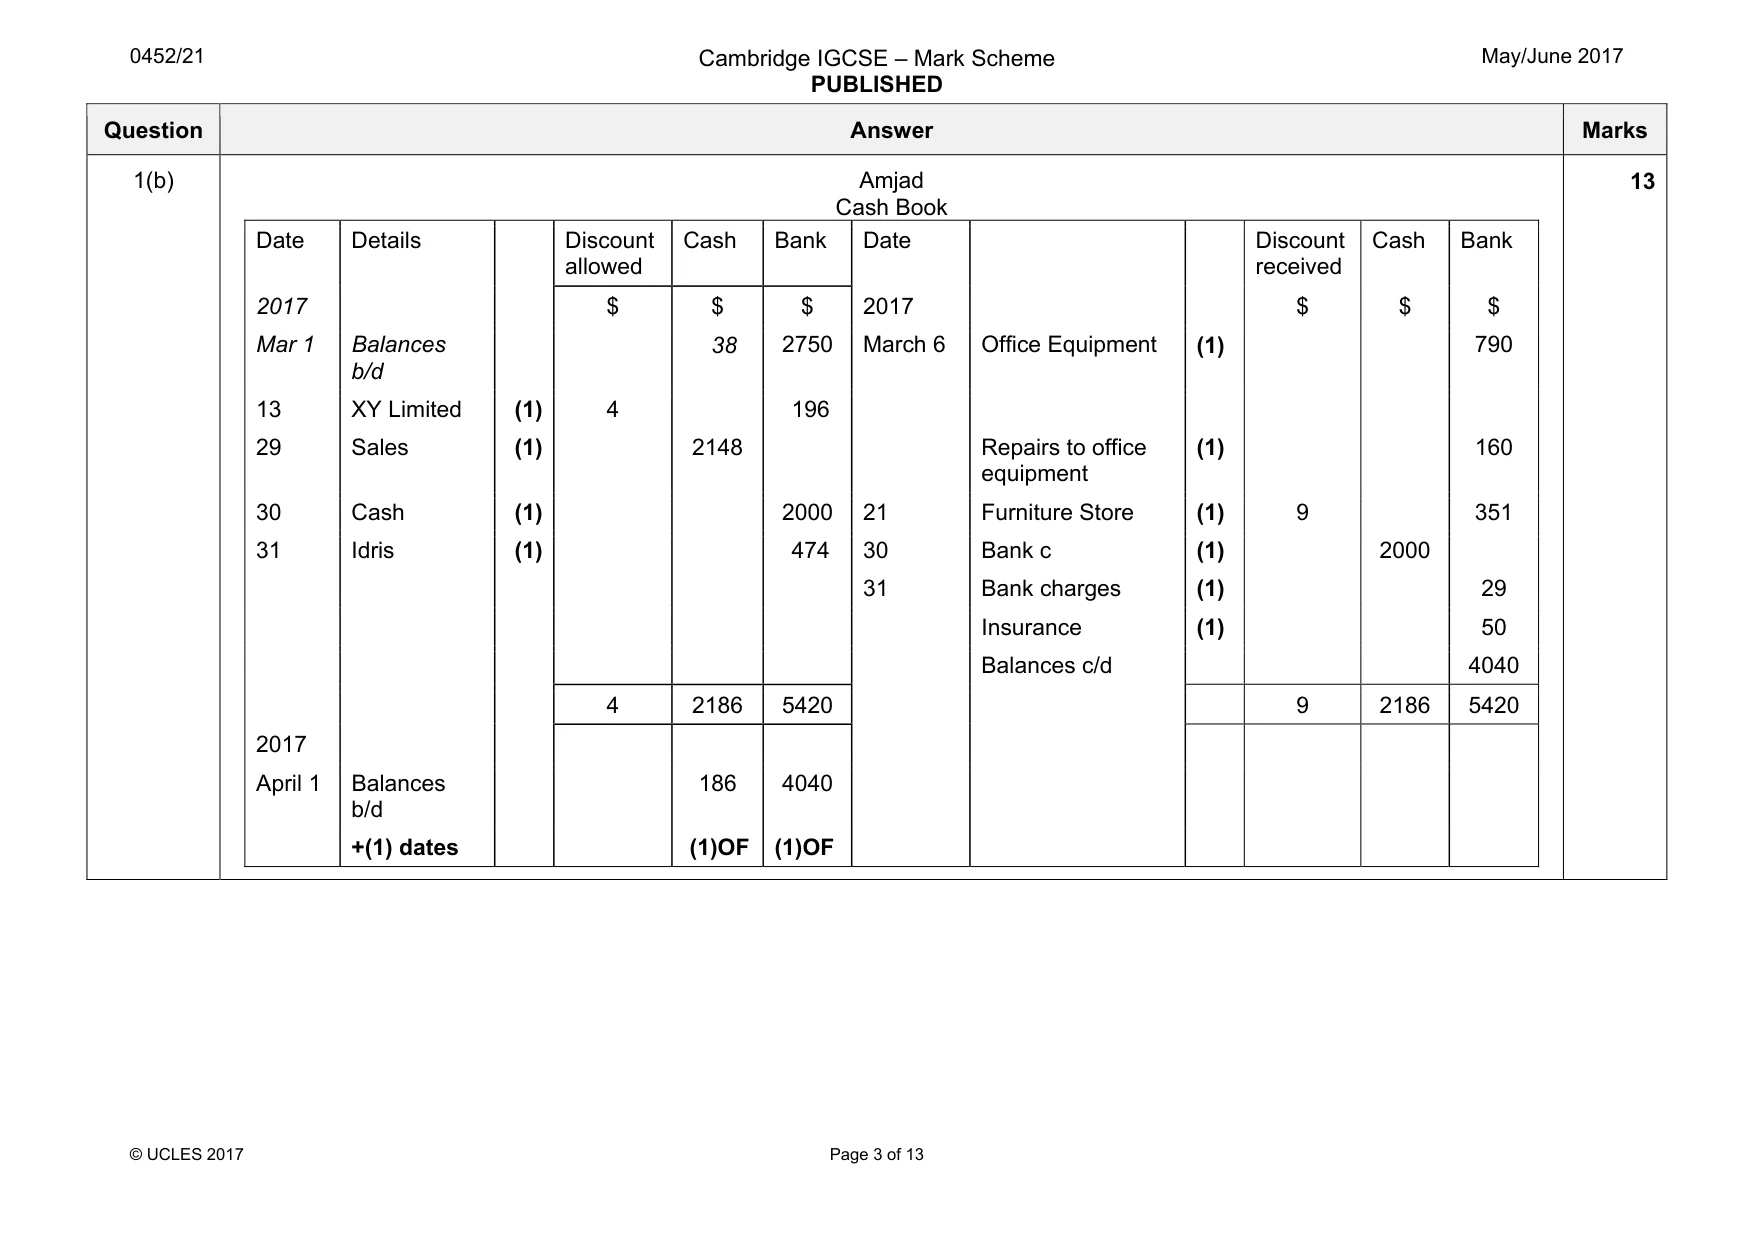
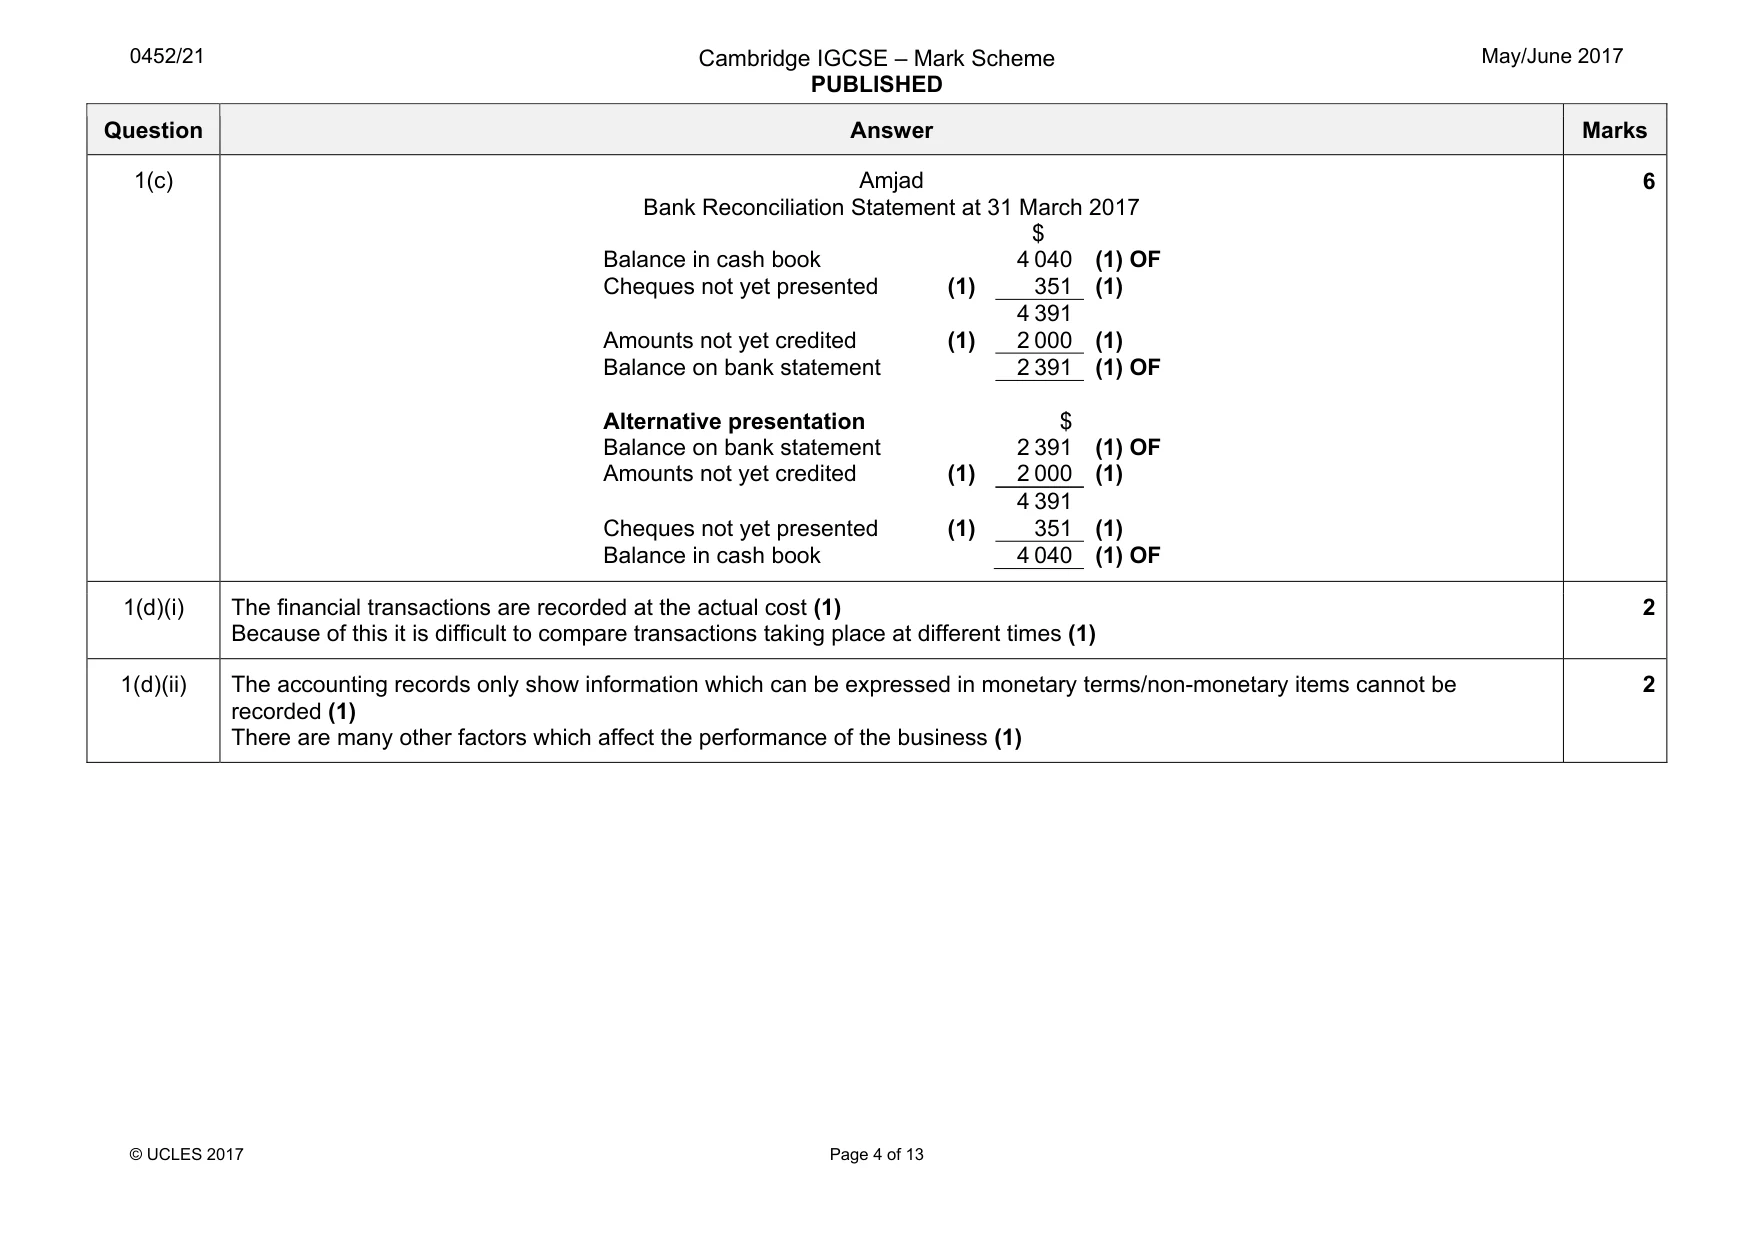
Mark scheme: 1(a) The bank statement is a copy of the account of the business as it appears in the books of the bank / the bank statement is prepared from the viewpoint of the bank (1) The bank account in the cash book is prepared from the viewpoint of the business (1) 2 Question Answer Marks 1(b) Amjad Cash Book Date Details Discount allowed Cash Bank Date Discount received Cash Bank 2017 $ $ $ 2017 $ $ $ Mar 1 Balances b/d 38 2750 March 6 Office Equipment (1) 790 13 XY Limited (1) 4 196 29 Sales (1) 2148 Repairs to office equipment (1) 160 30 Cash (1) 2000 21 Furniture Store (1) 9 351 31 Idris (1) 474 30 Bank c (1) 2000 31 Bank charges (1) 29 Insurance (1) 50 Balances c/d 4040 4 2186 5420 9 2186 5420 2017 April 1 Balances b/d 186 4040 +(1) dates (1)OF (1)OF 13 Question Answer Marks 1(c) Amjad Bank Reconciliation Statement at 31 March 2017 $ Balance in cash book 4 040 (1) OF Cheques not yet presented (1) 351 (1) 4 391 Amounts not yet credited (1) 2 000 (1) Balance on bank statement 2 391 (1) OF Alternative presentation $ Balance on bank statement 2 391 (1) OF Amounts not yet credited (1) 2 000 (1) 4 391 Cheques not yet presented (1) 351 (1) Balance in cash book 4 040 (1) OF 6 1(d)(i) The financial transactions are recorded at the actual cost (1) Because of this it is difficult to compare transactions taking place at different times (1) 2 1(d)(ii) The accounting records only show information which can be expressed in monetary terms/non-monetary items cannot be recorded (1) There are many other factors which affect the performance of the business (1) 2
Q2 · Harum is a trader
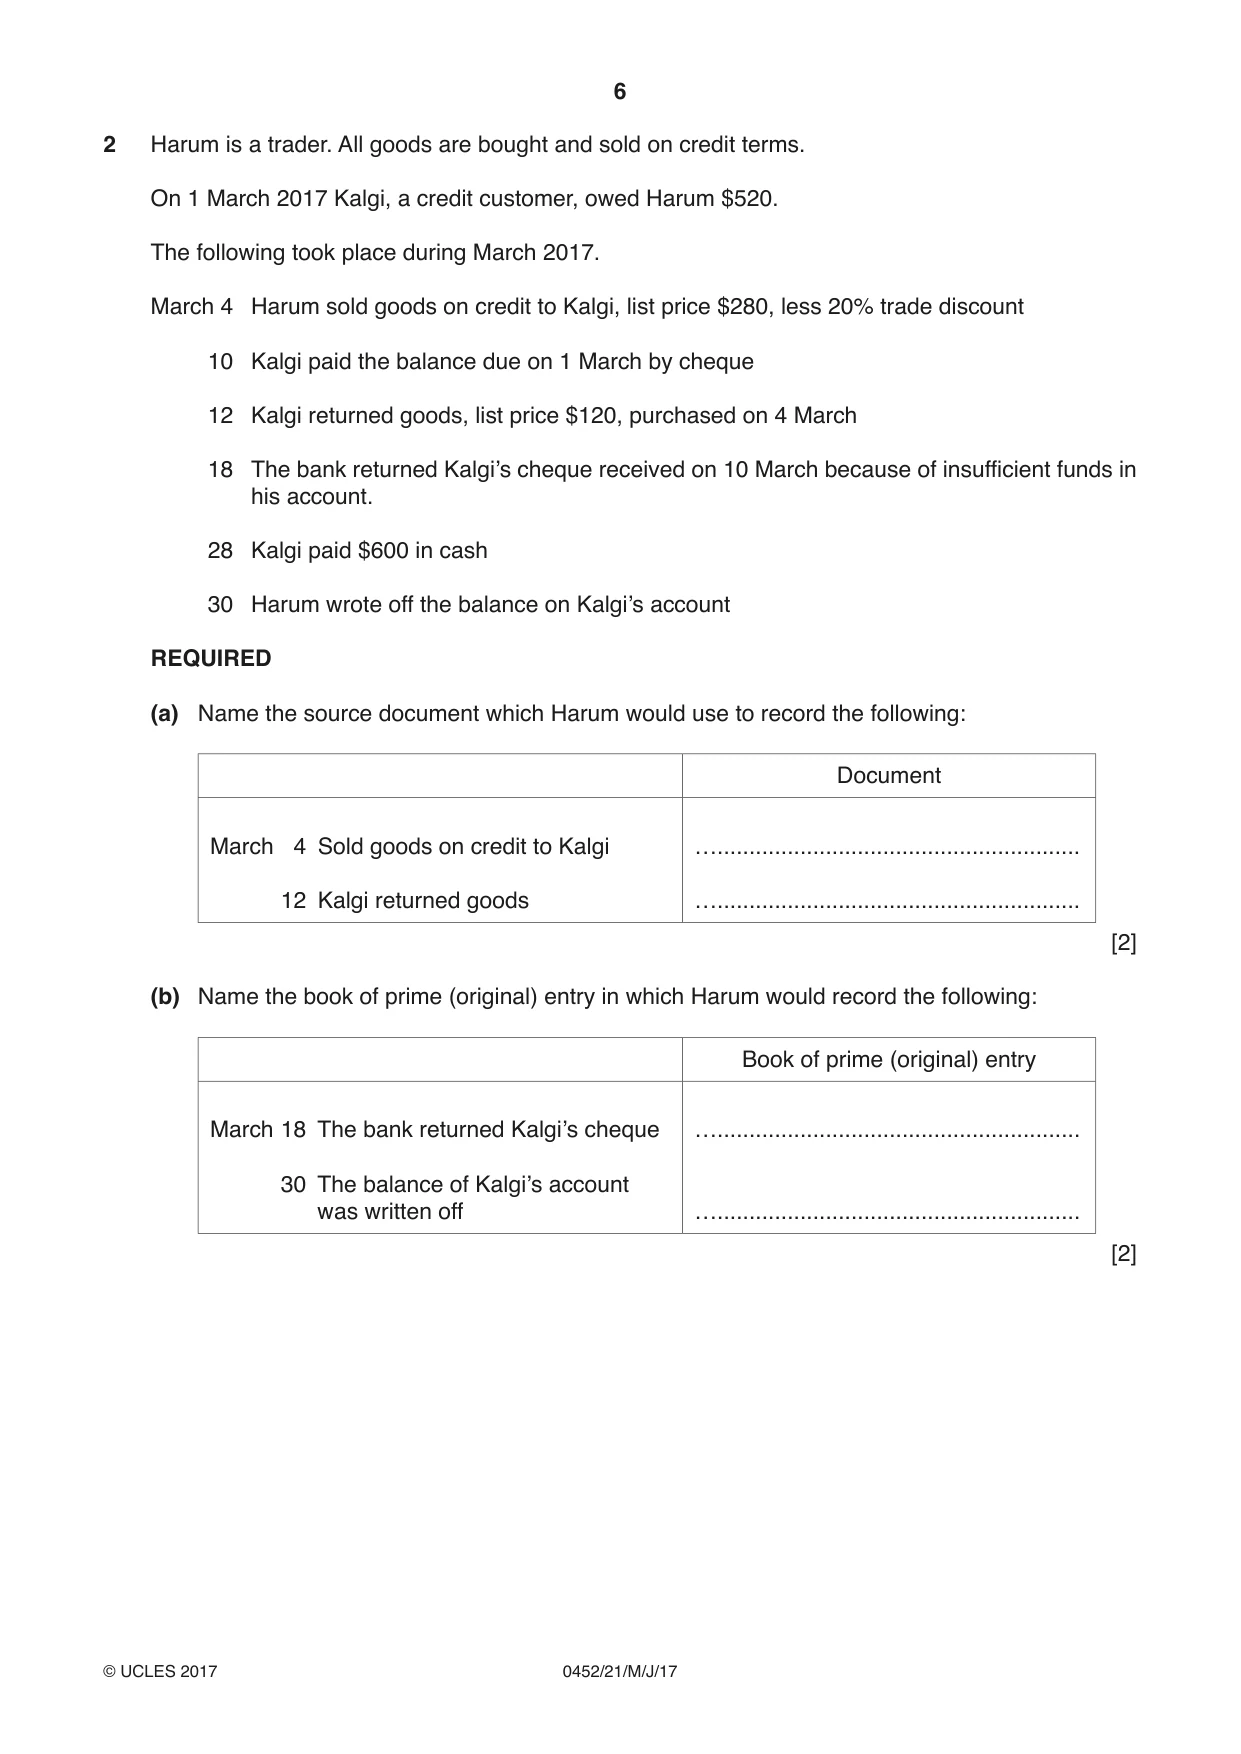
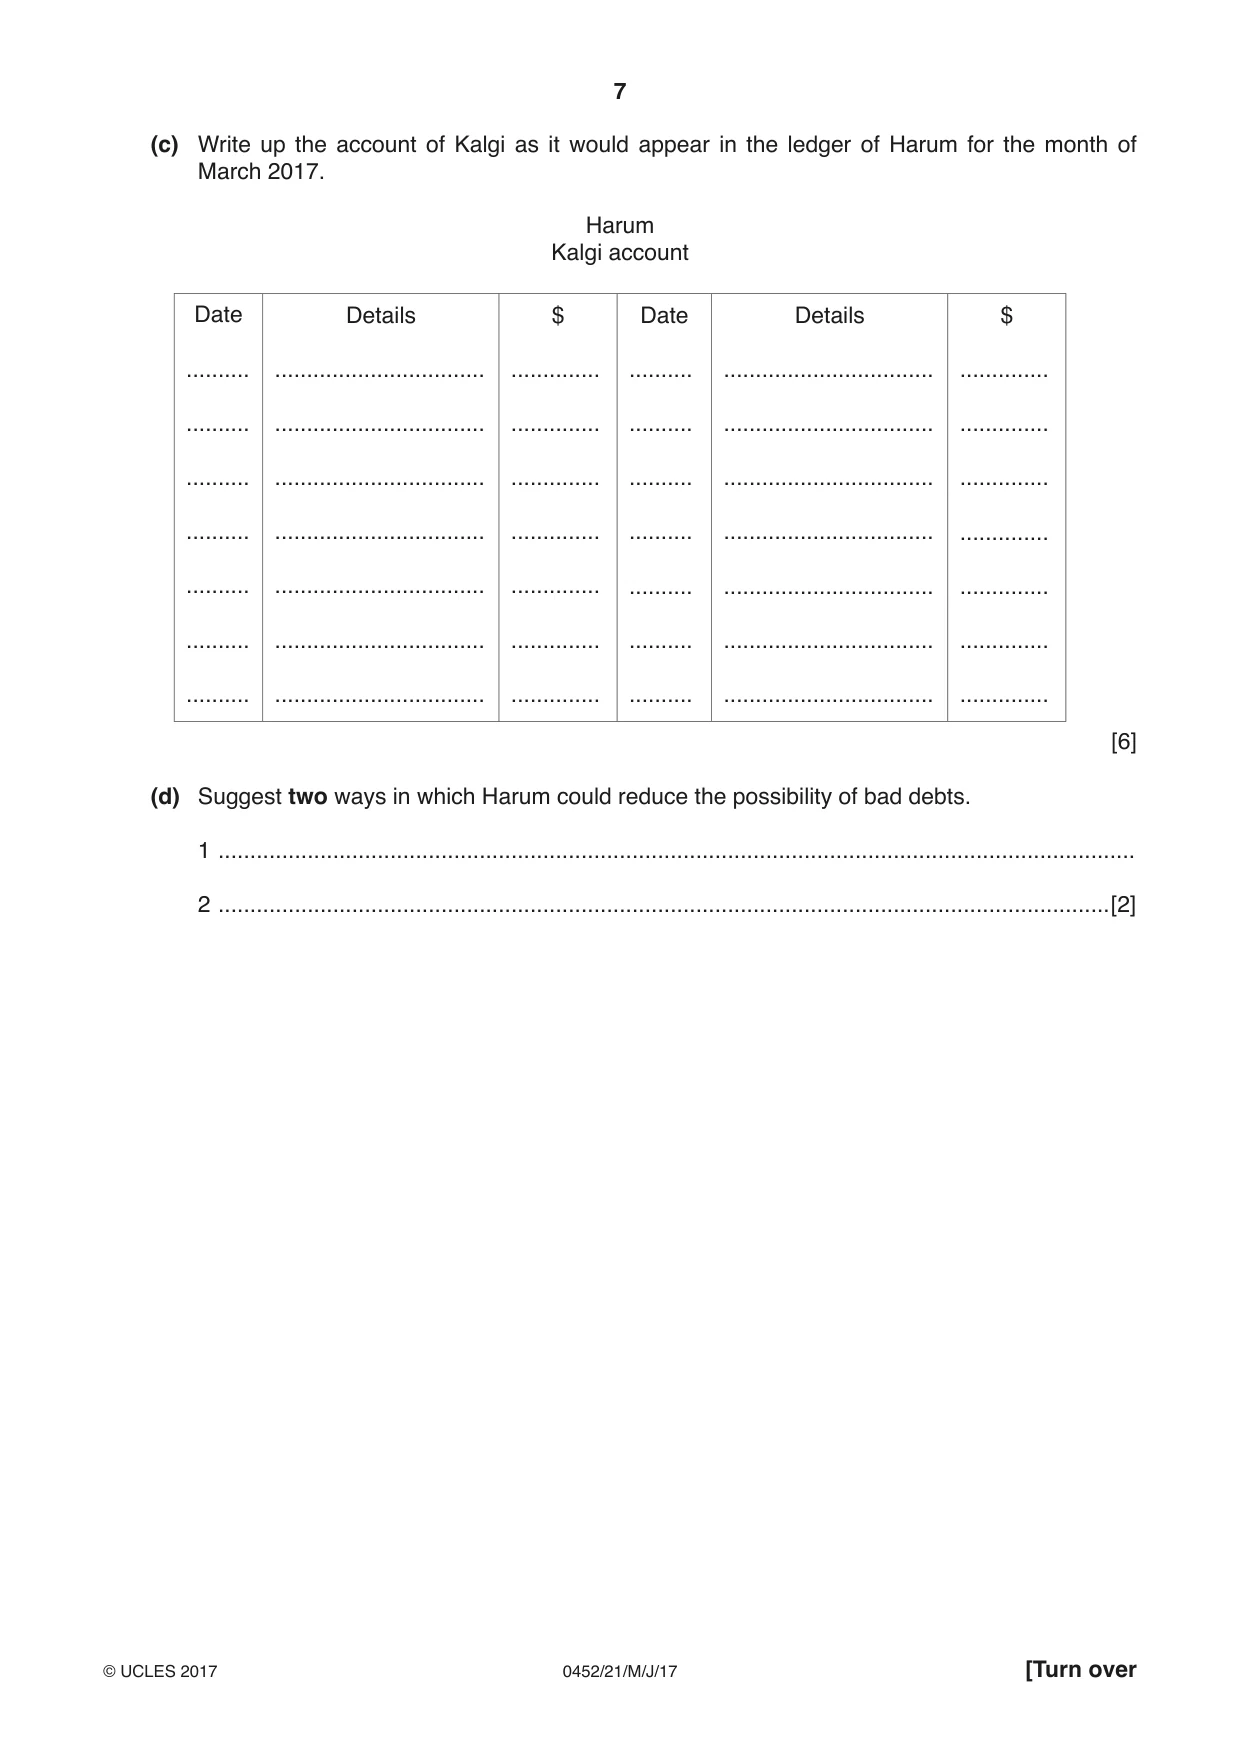
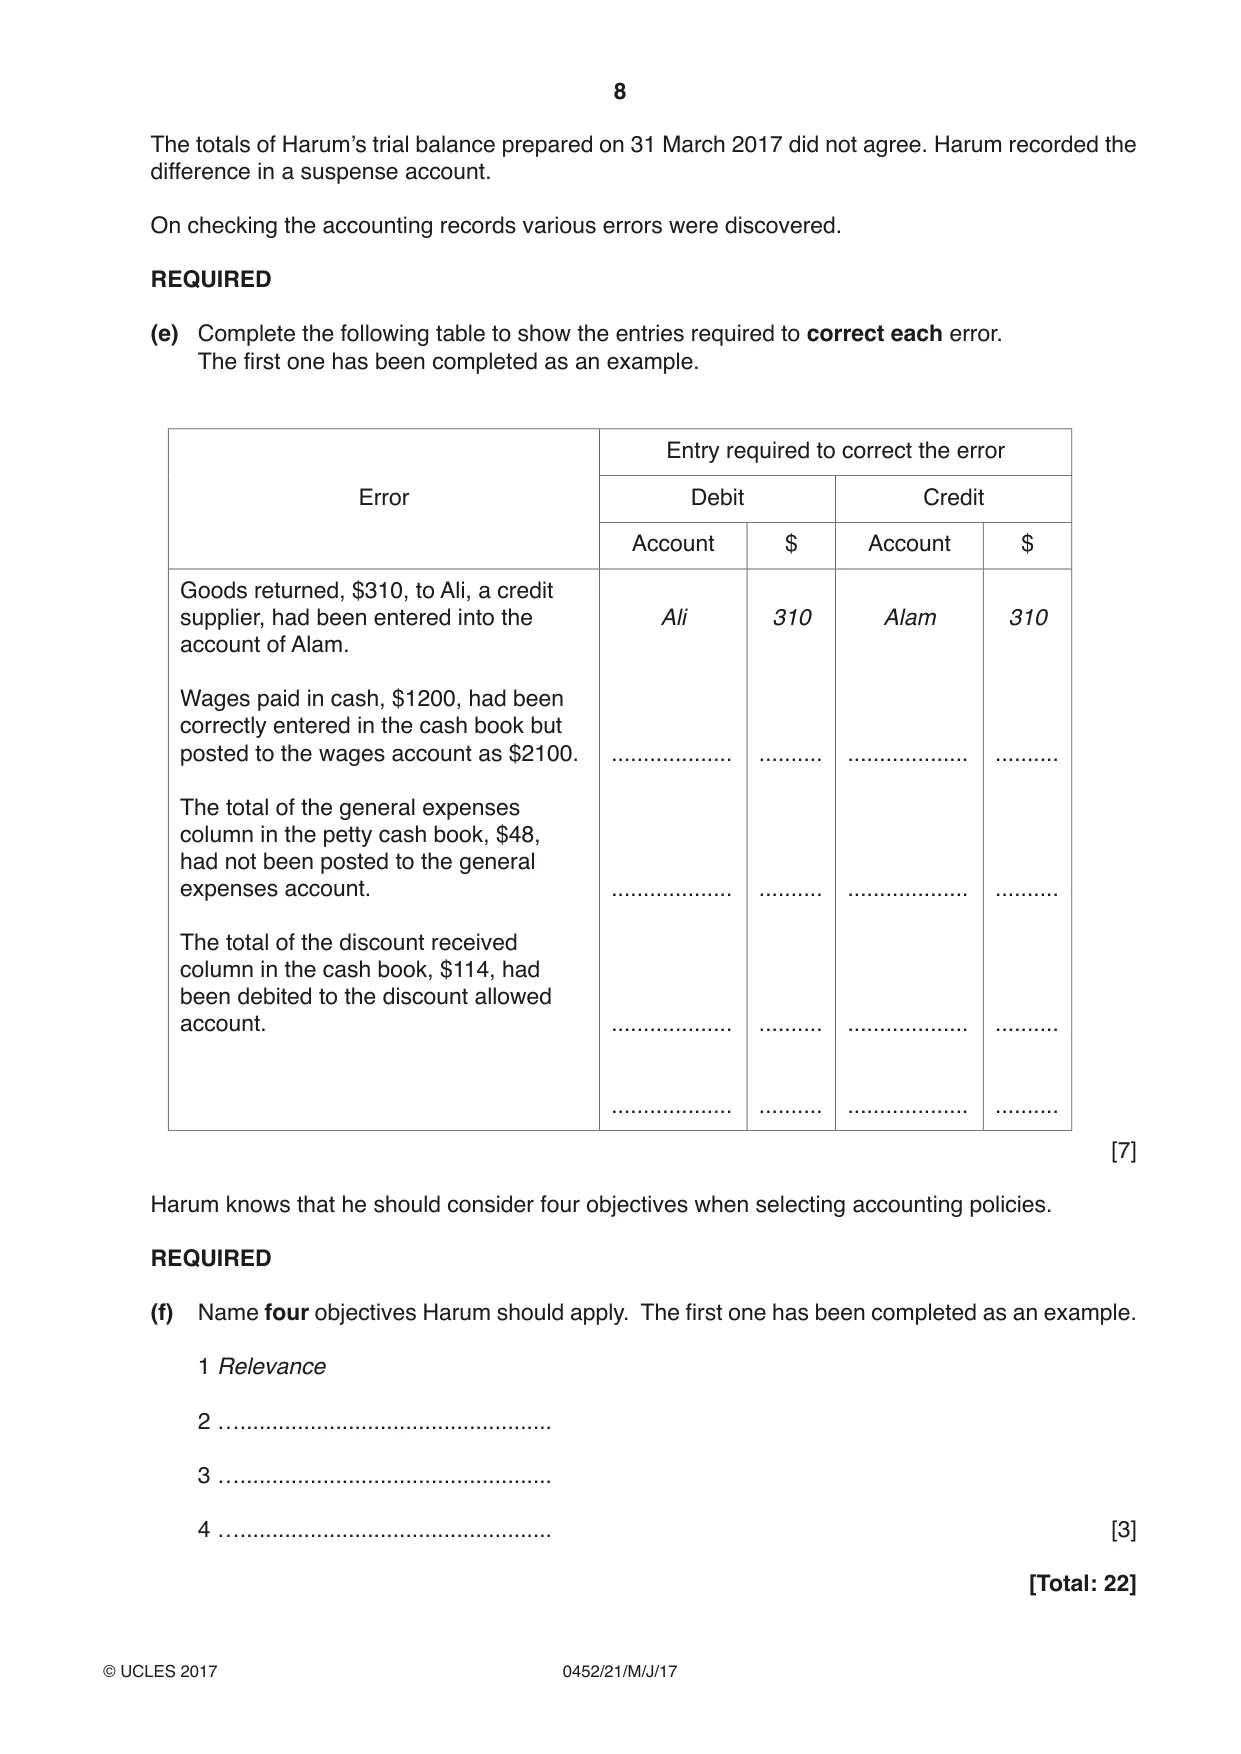
2 Harum is a trader. All goods are bought and sold on credit terms. On 1 March 2017 Kalgi, a credit customer, owed Harum $520. The following took place during March 2017. March 4 Harum sold goods on credit to Kalgi, list price $280, less 20% trade discount 10 Kalgi paid the balance due on 1 March by cheque 12 Kalgi returned goods, list price $120, purchased on 4 March 18 The bank returned Kalgi’s cheque received on 10 March because of insufficient funds in his account. 28 Kalgi paid $600 in cash 30 Harum wrote off the balance on Kalgi’s account REQUIRED (a) Name the source document which Harum would use to record the following: Document March 4 Sold goods on credit to Kalgi …......................................................... 12 Kalgi returned goods …......................................................... [2] (b) Name the book of prime (original) entry in which Harum would record the following: Book of prime (original) entry March 18 The bank returned Kalgi’s cheque …......................................................... 30 The balance of Kalgi’s account was written off …......................................................... [2] (c) Write up the account of Kalgi as it would appear in the ledger of Harum for the month of March 2017. Harum Kalgi account Date Details $ Date Details $ .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. [6] (d) Suggest two ways in which Harum could reduce the possibility of bad debts. 1 ................................................................................................................................................ 2 ............................................................................................................................................[2] The totals of Harum’s trial balance prepared on 31 March 2017 did not agree. Harum recorded the difference in a suspense account. On checking the accounting records various errors were discovered. REQUIRED (e) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entry required to correct the error Error Debit Credit Account $ Account $ Goods returned, $310, to Ali, a credit supplier, had been entered into the Ali 310 Alam 310 account of Alam. Wages paid in cash, $1200, had been correctly entered in the cash book but posted to the wages account as $2100. ................... .......... ................... .......... The total of the general expenses column in the petty cash book, $48, had not been posted to the general expenses account. ................... .......... ................... .......... The total of the discount received column in the cash book, $114, had been debited to the discount allowed account. ................... .......... ................... .......... ................... .......... ................... .......... [7] Harum knows that he should consider four objectives when selecting accounting policies. REQUIRED (f) Name four objectives Harum should apply. The first one has been completed as an example. 1 Relevance 2 …................................................. 3 …................................................. 4 …................................................. [3] [Total: 22] Question 3 is on the next page.
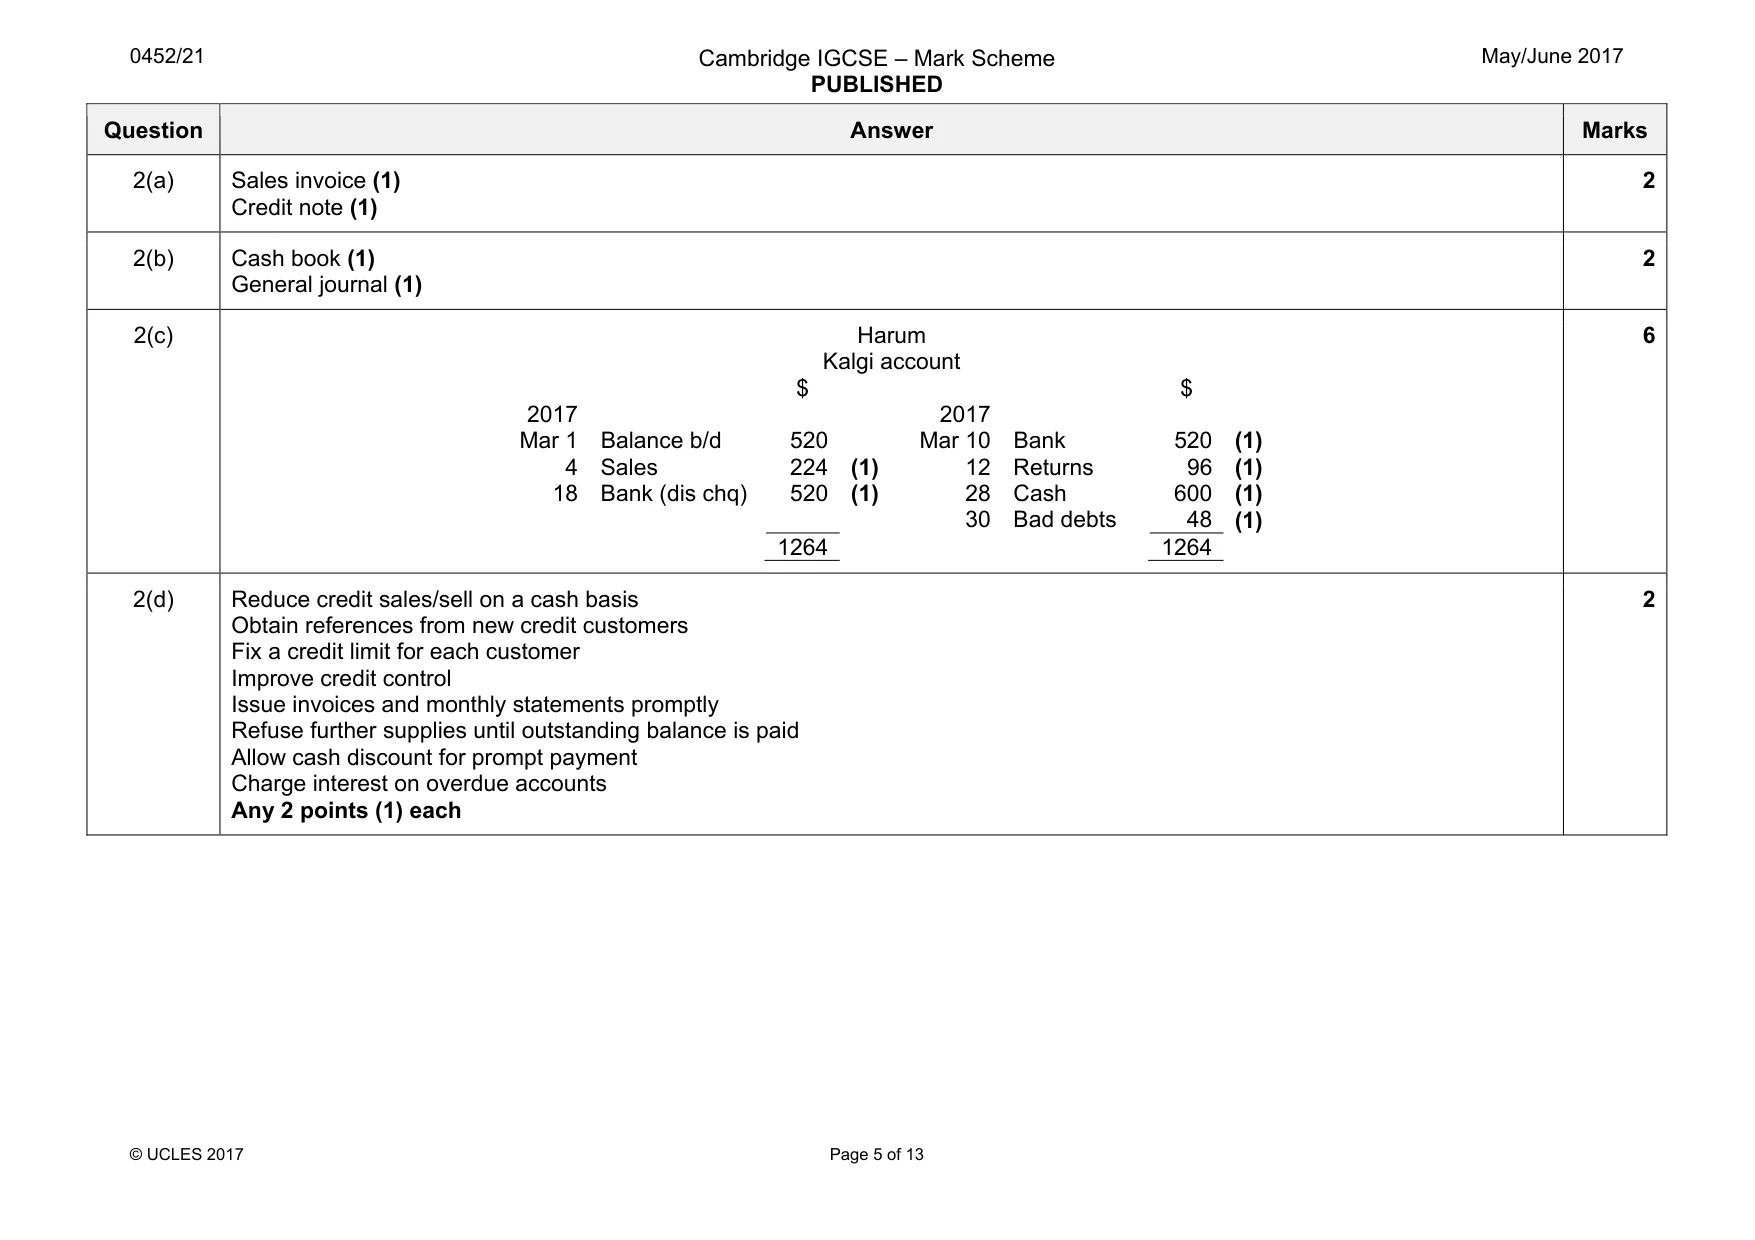
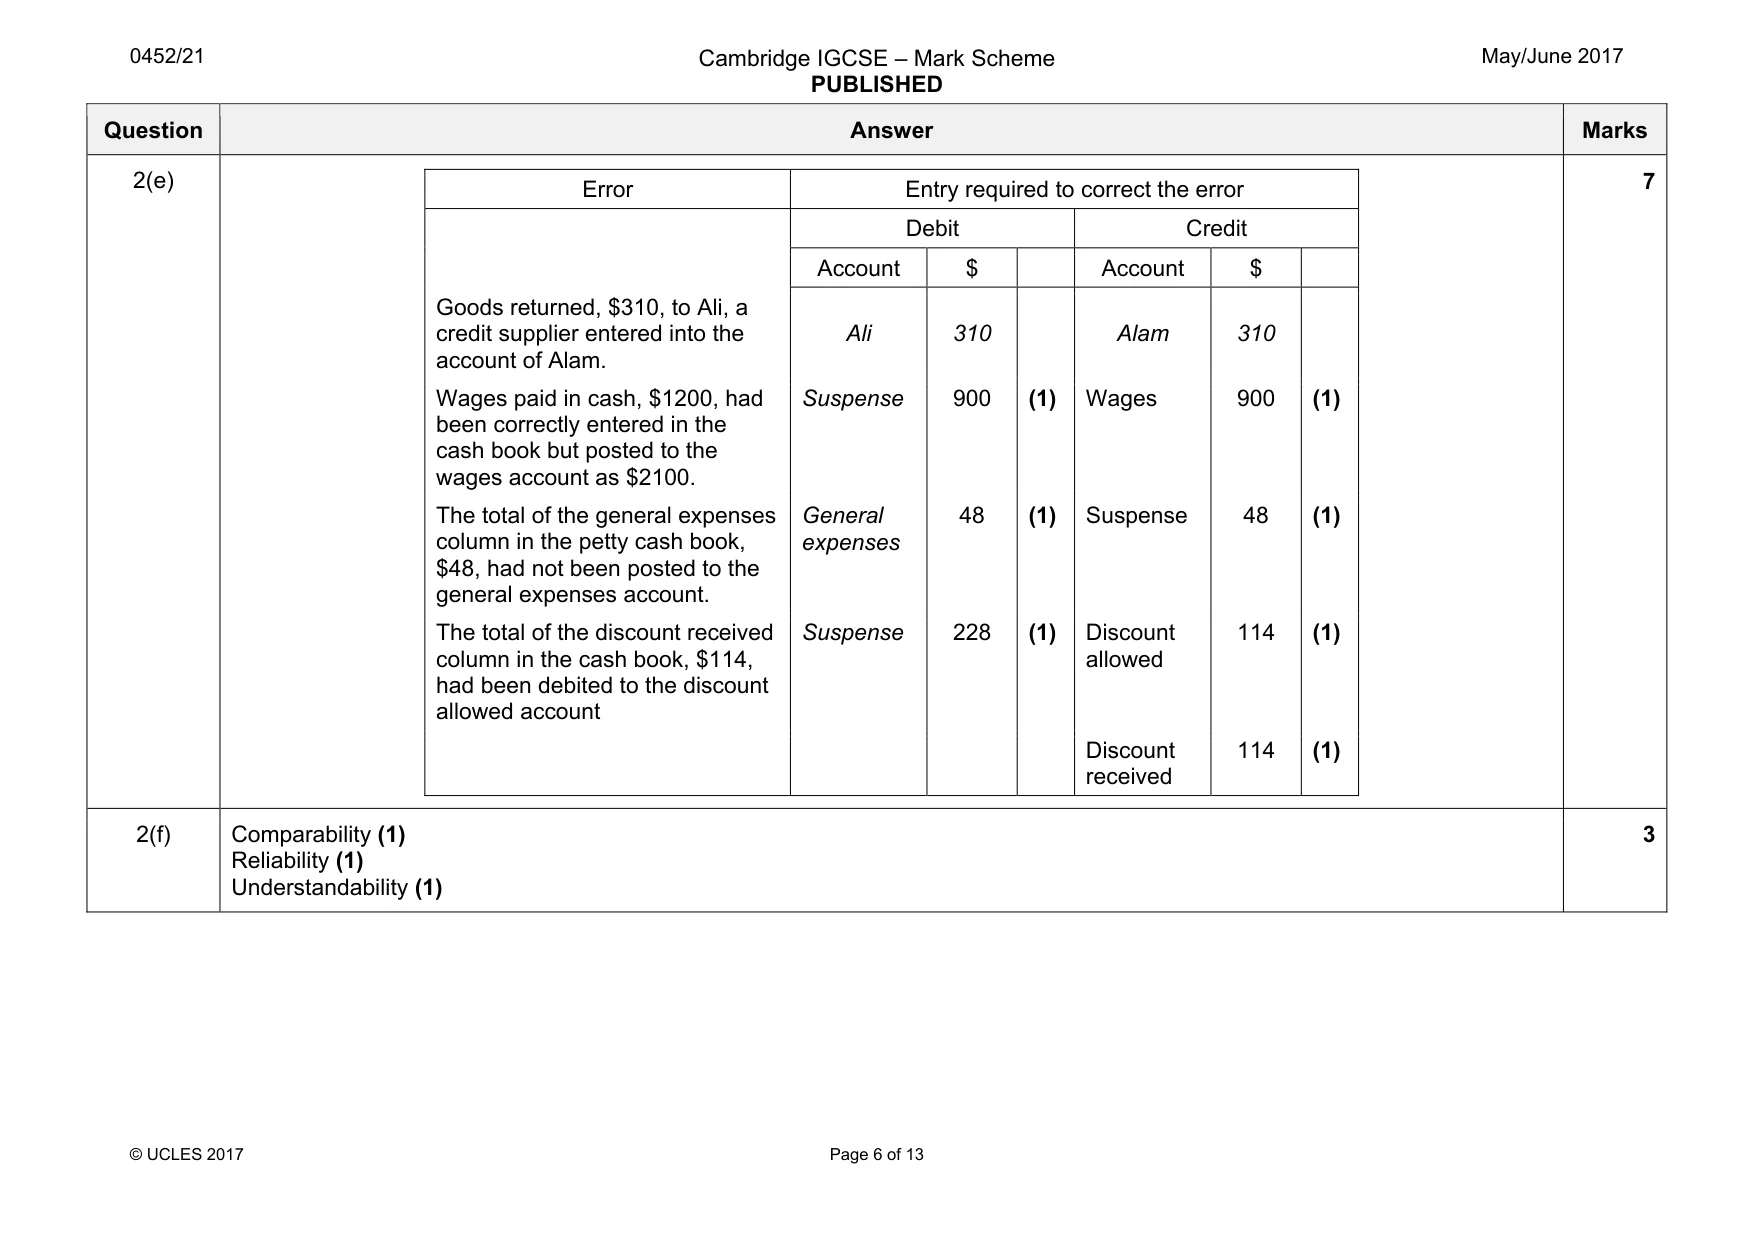
Mark scheme: 2(a) Sales invoice (1) Credit note (1) 2 2(b) Cash book (1) General journal (1) 2 2(c) Harum Kalgi account $ $ 2017 2017 Mar 1 Balance b/d 520 Mar 10 Bank 520 (1) 4 Sales 224 (1) 12 Returns 96 (1) 18 Bank (dis chq) 520 (1) 28 Cash 600 (1) 30 Bad debts 48 (1) 1264 1264 6 2(d) Reduce credit sales/sell on a cash basis Obtain references from new credit customers Fix a credit limit for each customer Improve credit control Issue invoices and monthly statements promptly Refuse further supplies until outstanding balance is paid Allow cash discount for prompt payment Charge interest on overdue accounts Any 2 points (1) each 2 Question Answer Marks 2(e) Error Entry required to correct the error Debit Credit Account $ Account $ Goods returned, $310, to Ali, a credit supplier entered into the account of Alam. Ali 310 Alam 310 Wages paid in cash, $1200, had been correctly entered in the cash book but posted to the wages account as $2100. Suspense 900 (1) Wages 900 (1) The total of the general expenses column in the petty cash book, $48, had not been posted to the general expenses account. General expenses 48 (1) Suspense 48 (1) The total of the discount received column in the cash book, $114, had been debited to the discount allowed account Suspense 228 (1) Discount allowed 114 (1) Discount received 114 (1) 7 2(f) Comparability (1) Reliability (1) Understandability (1) 3
Q3 · Meena and Rafah are in partnership
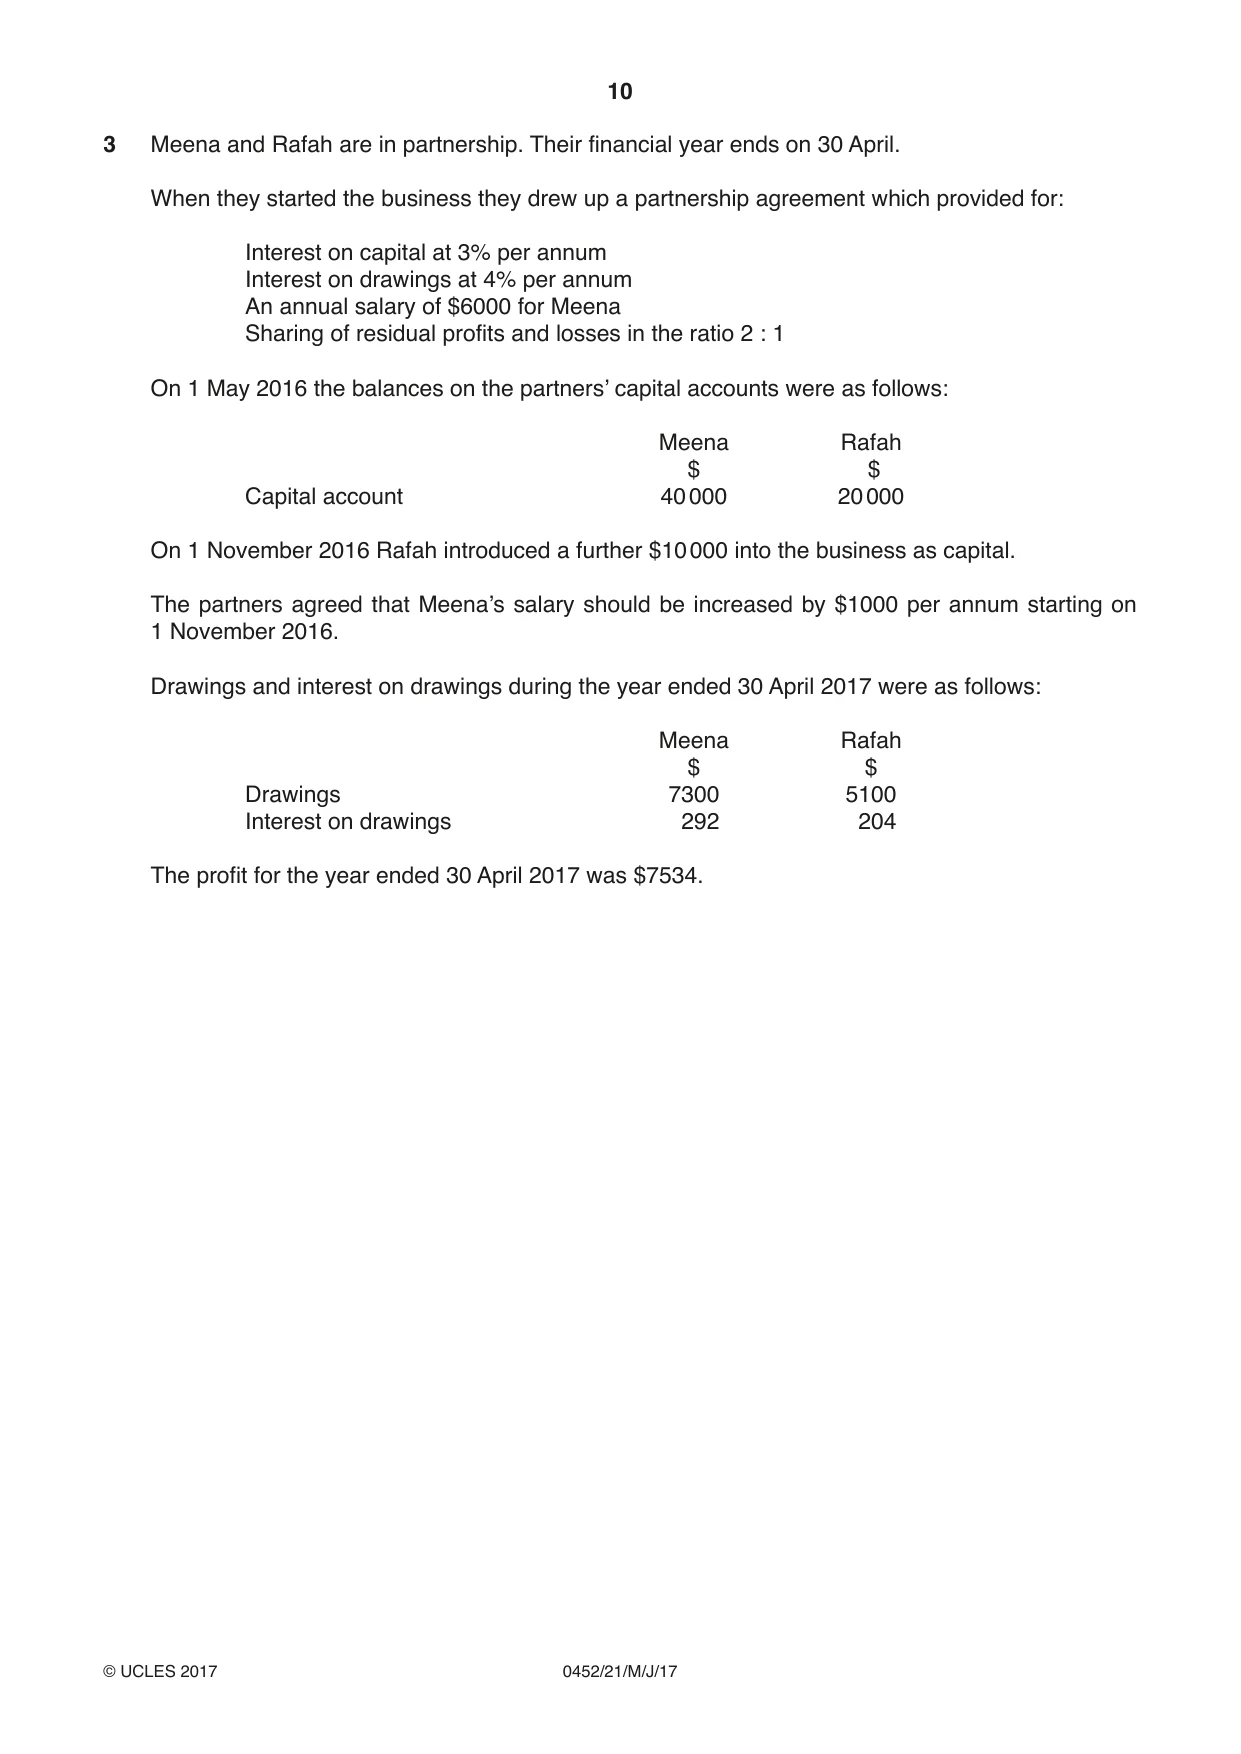
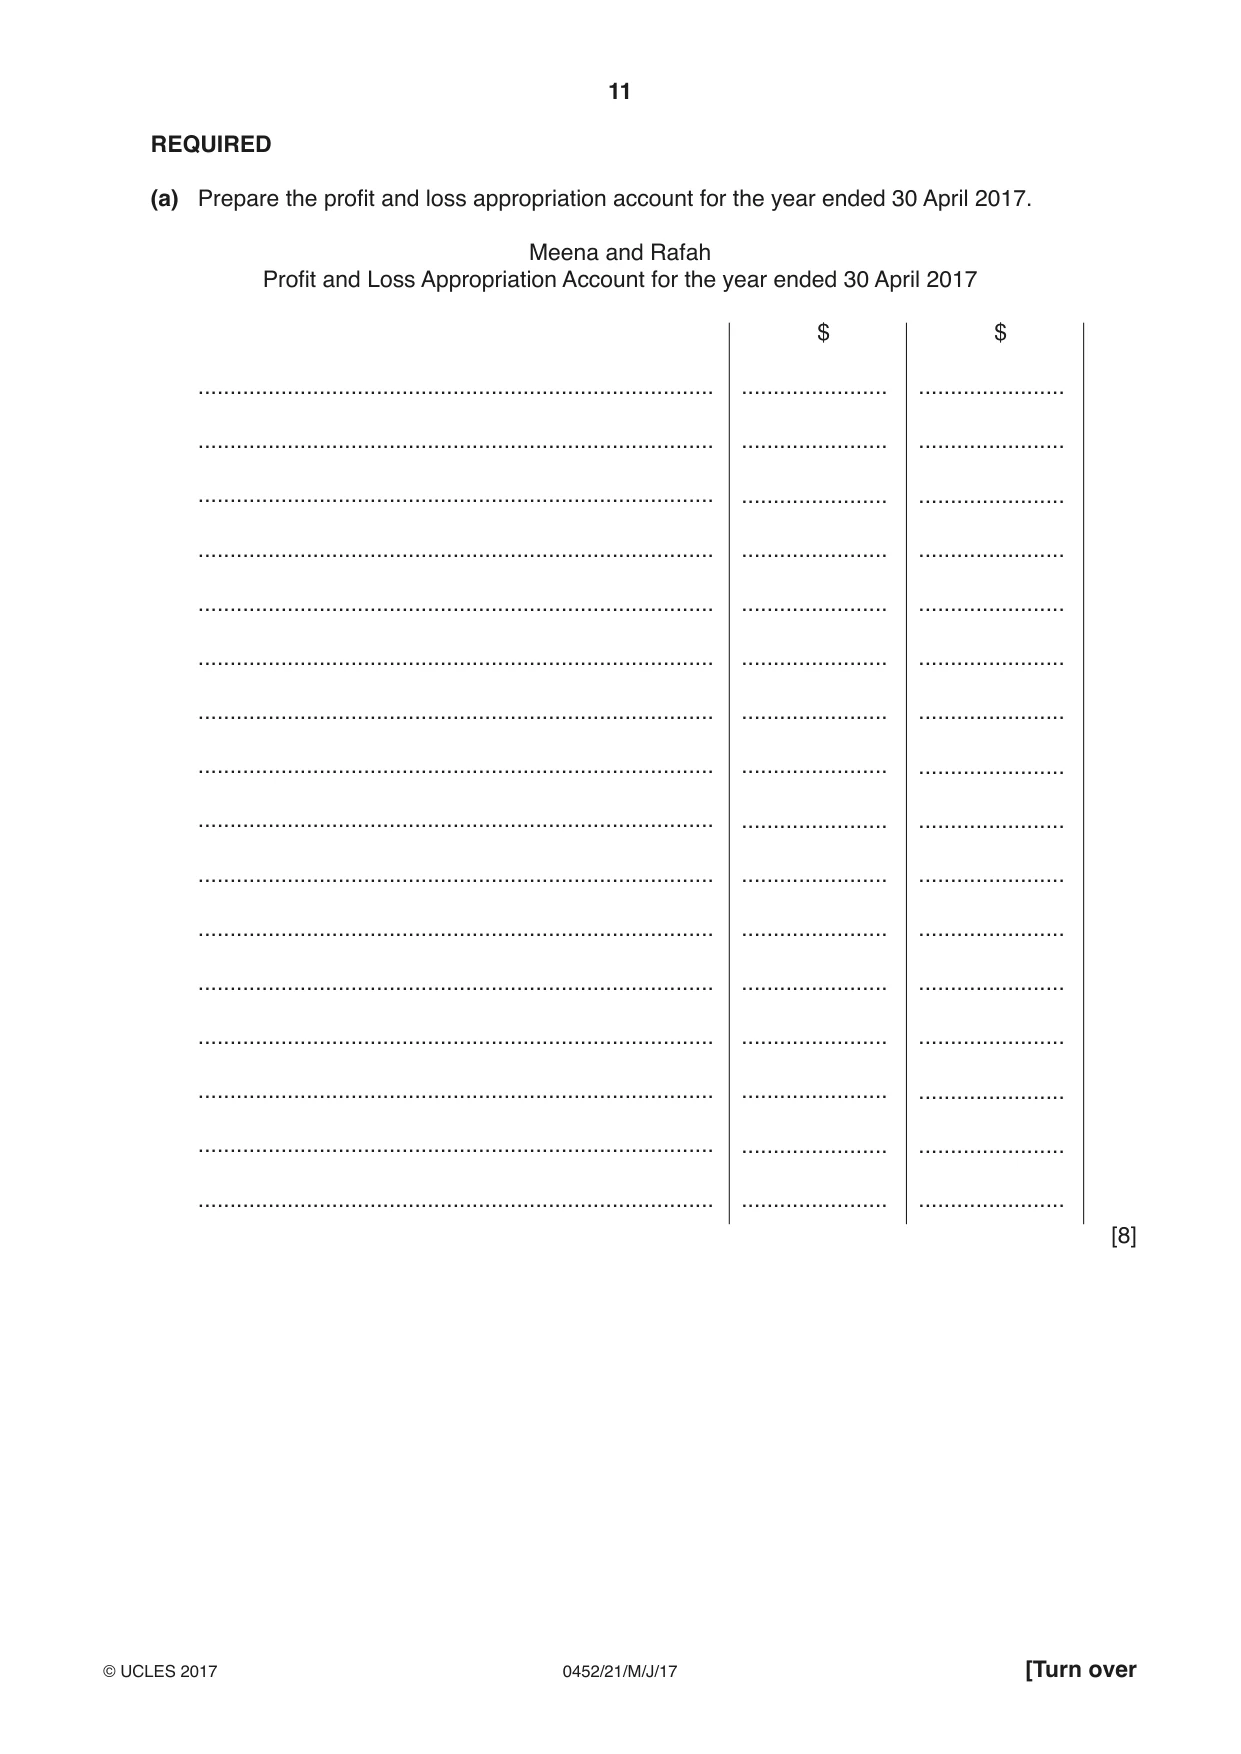
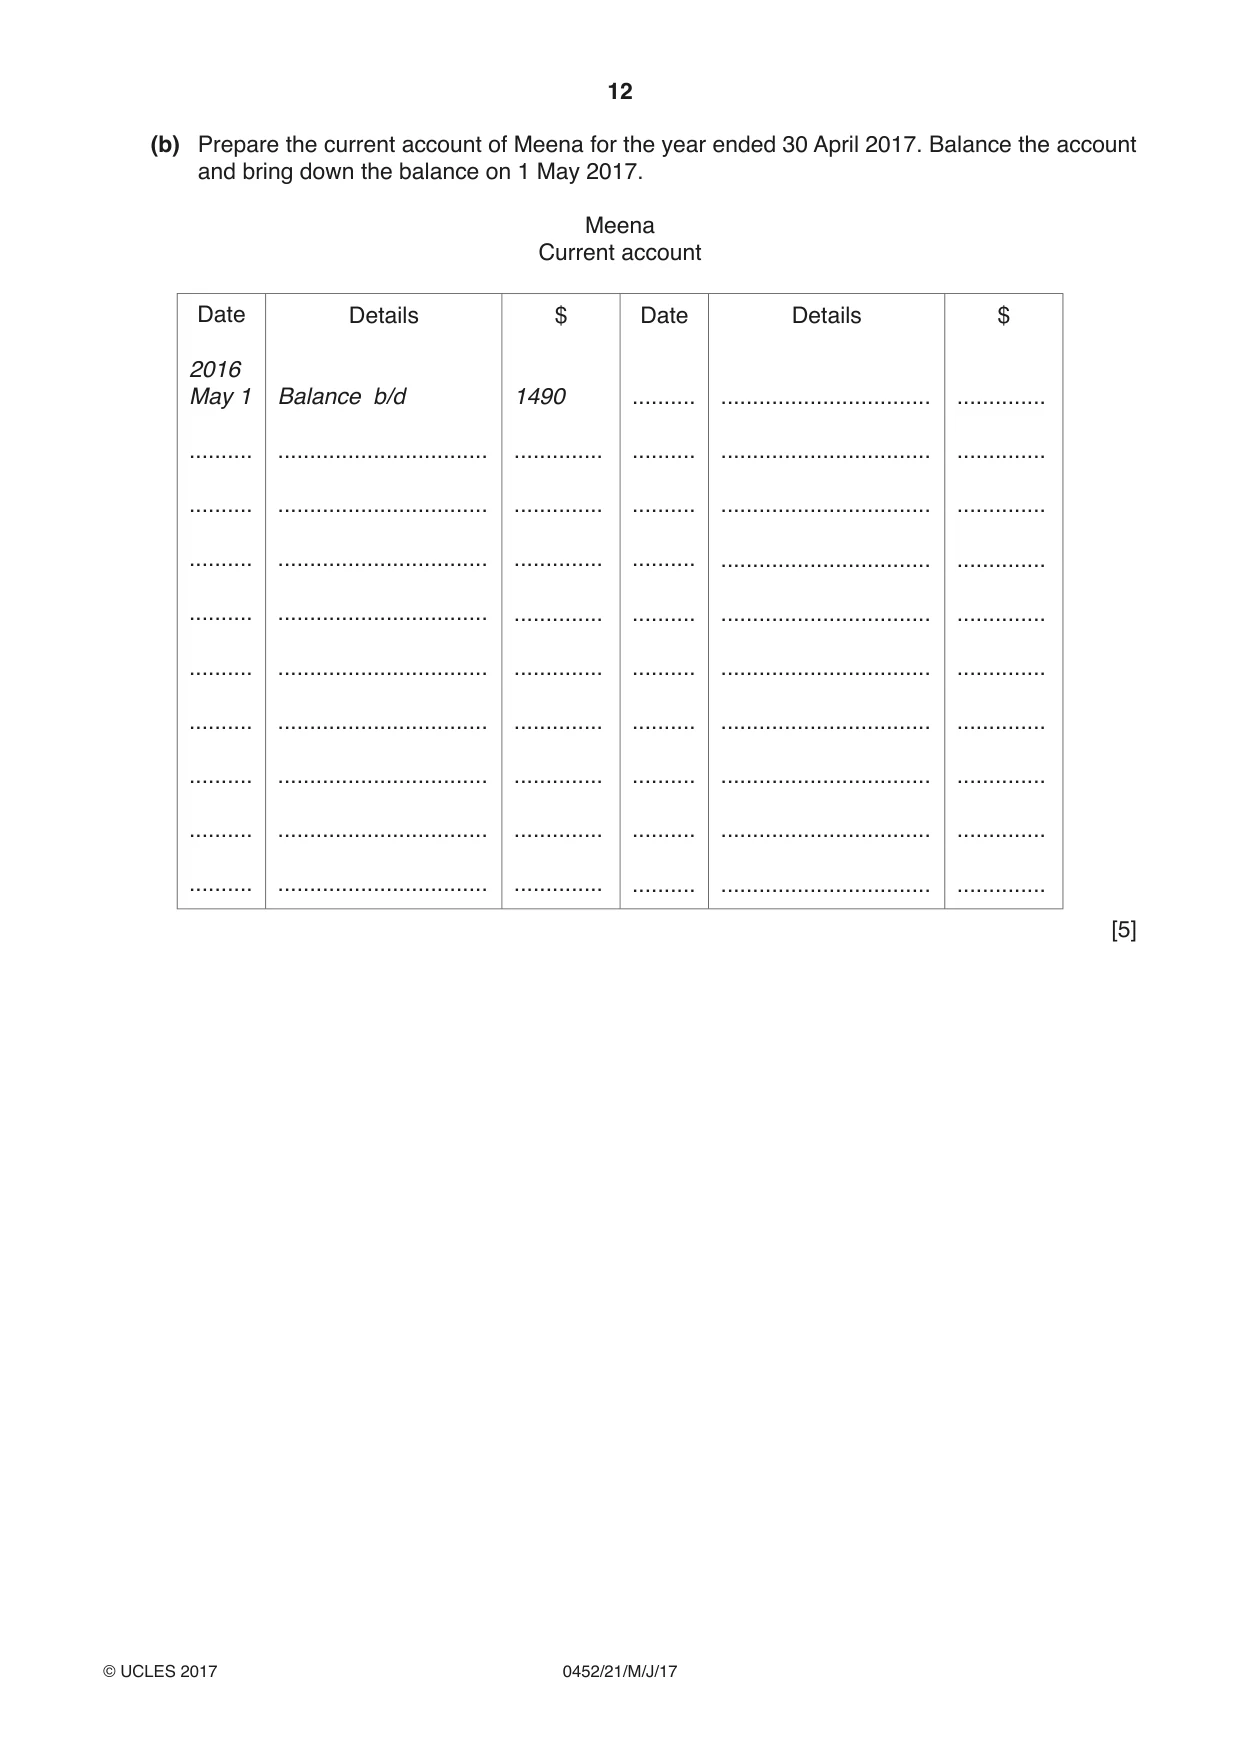
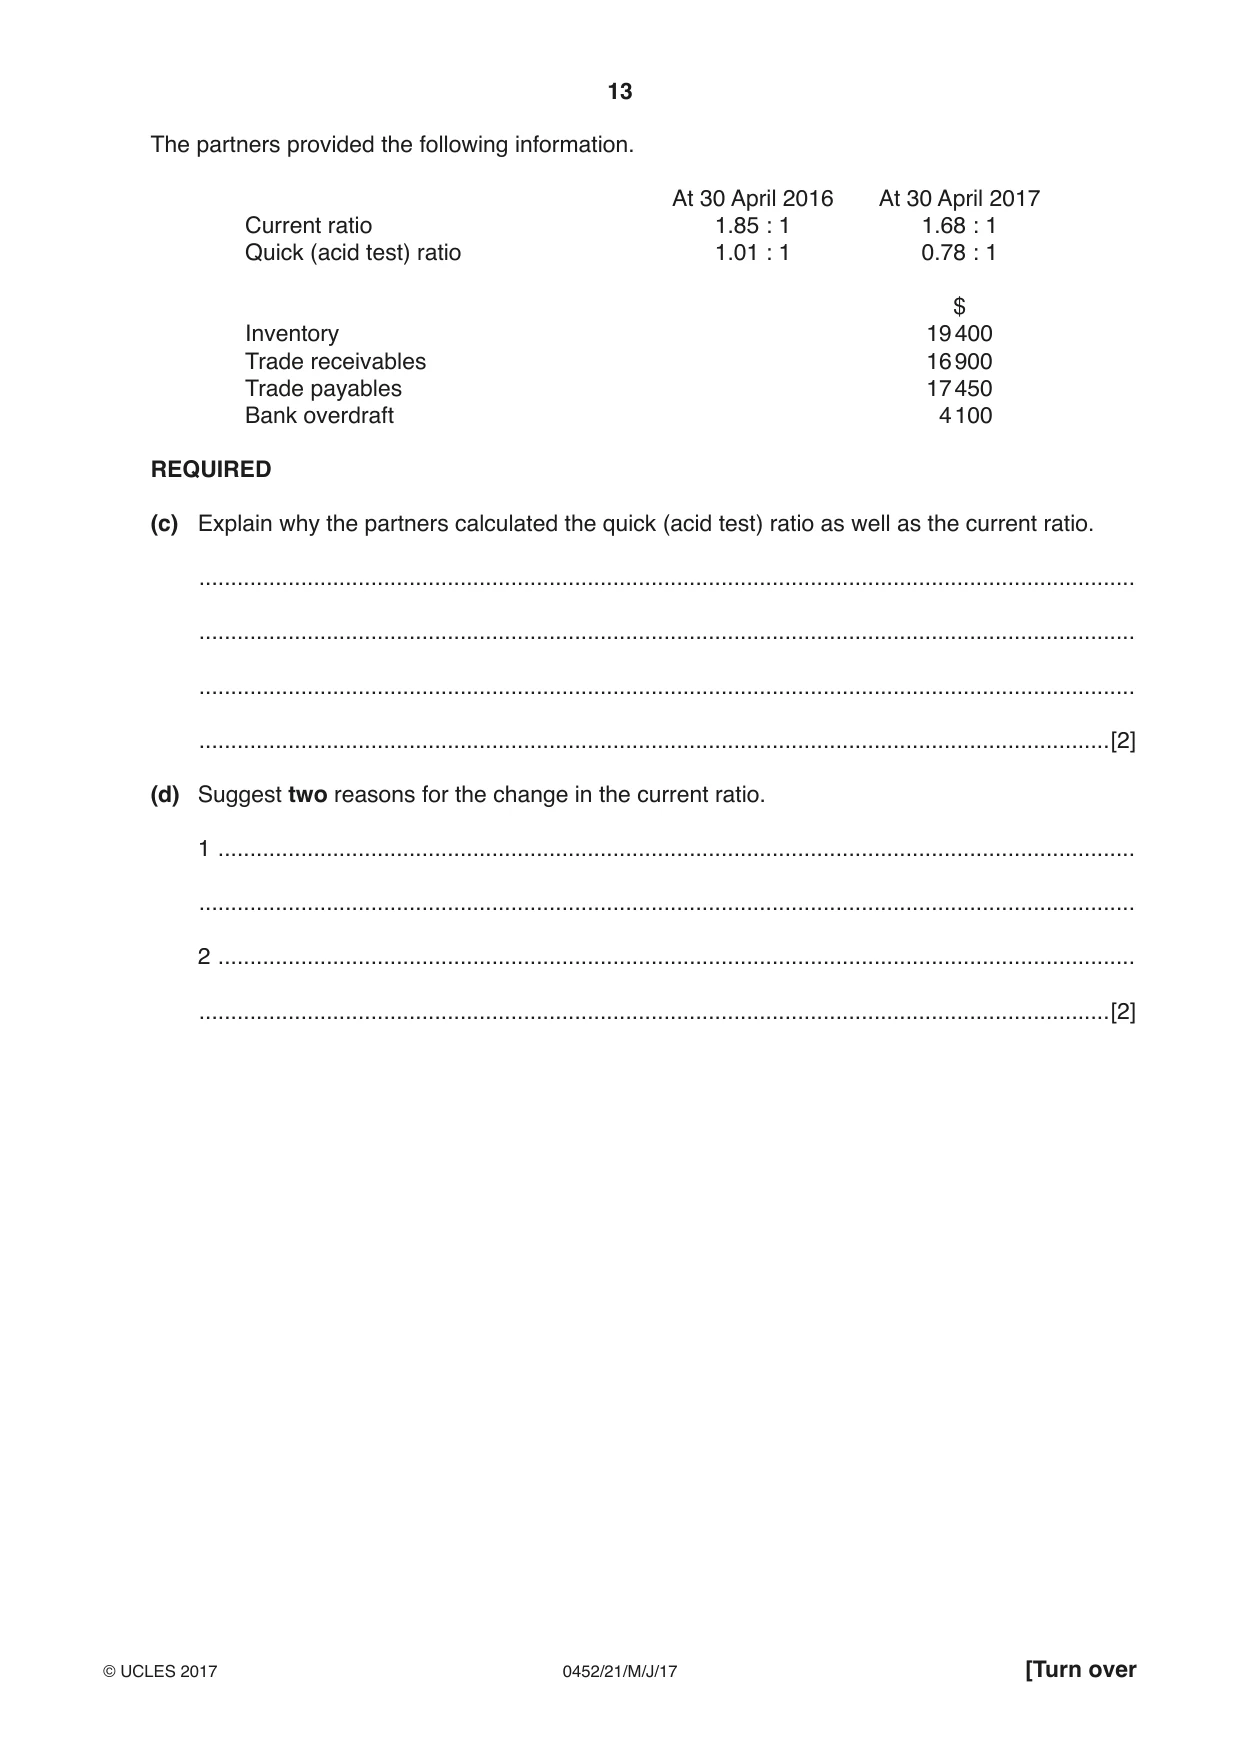
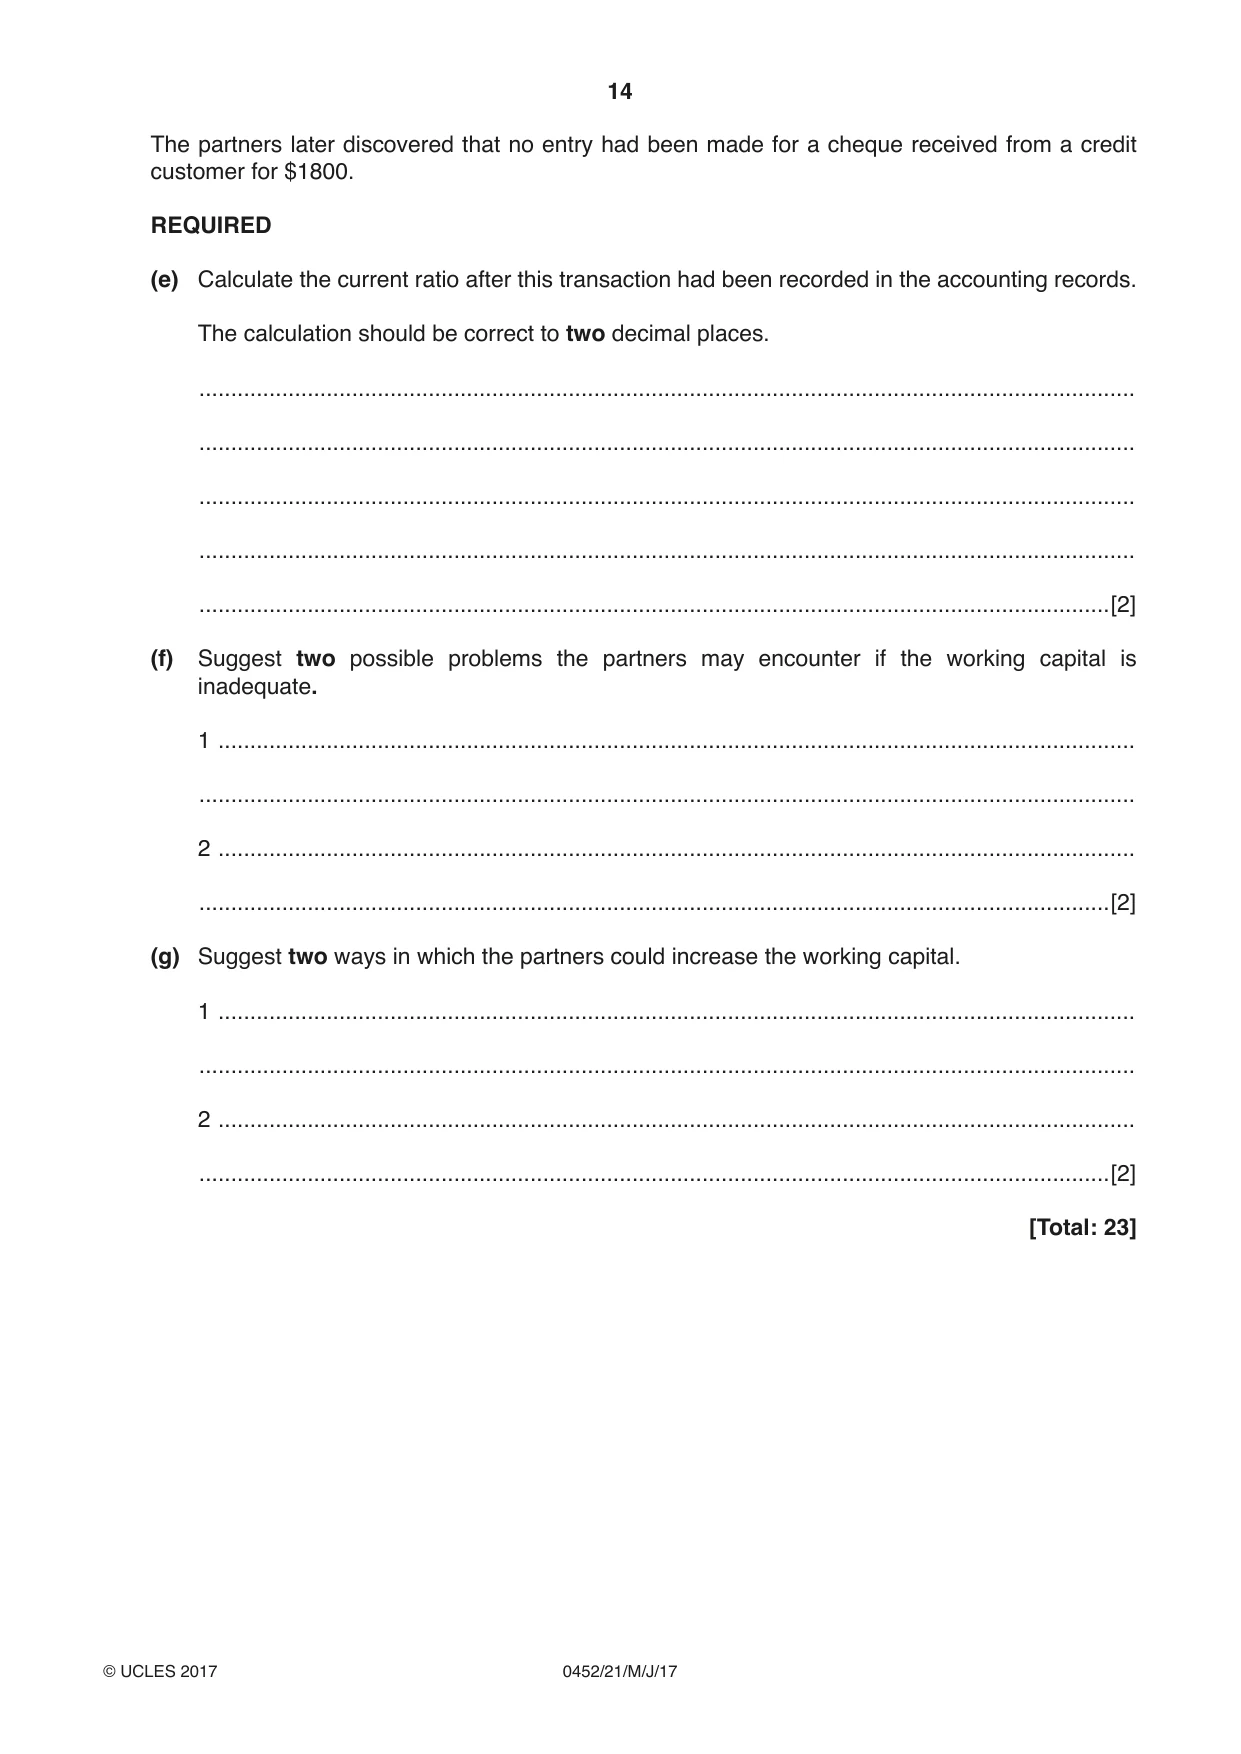
3 Meena and Rafah are in partnership. Their financial year ends on 30 April. When they started the business they drew up a partnership agreement which provided for: Interest on capital at 3% per annum Interest on drawings at 4% per annum An annual salary of $6000 for Meena Sharing of residual profits and losses in the ratio 2 : 1 On 1 May 2016 the balances on the partners’ capital accounts were as follows: Meena Rafah $ $ Capital account 40 000 20 000 On 1 November 2016 Rafah introduced a further $10 000 into the business as capital. The partners agreed that Meena’s salary should be increased by $1000 per annum starting on 1 November 2016. Drawings and interest on drawings during the year ended 30 April 2017 were as follows: Meena Rafah $ $ Drawings 7300 5100 Interest on drawings 292 204 The profit for the year ended 30 April 2017 was $7534. REQUIRED (a) Prepare the profit and loss appropriation account for the year ended 30 April 2017. Meena and Rafah Profit and Loss Appropriation Account for the year ended 30 April 2017 $ $ ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... ................................................................................. ....................... ....................... [8] (b) Prepare the current account of Meena for the year ended 30 April 2017. Balance the account and bring down the balance on 1 May 2017. Meena Current account Date Details $ Date Details $ 2016 May 1 Balance b/d 1490 .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. [5] The partners provided the following information. At 30 April 2016 At 30 April 2017 Current ratio 1.85 : 1 1.68 : 1 Quick (acid test) ratio 1.01 : 1 0.78 : 1 $ Inventory 19 400 Trade receivables 16 900 Trade payables 17 450 Bank overdraft 4 100 REQUIRED (c) Explain why the partners calculated the quick (acid test) ratio as well as the current ratio. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (d) Suggest two reasons for the change in the current ratio. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] The partners later discovered that no entry had been made for a cheque received from a credit customer for $1800. REQUIRED (e) Calculate the current ratio after this transaction had been recorded in the accounting records. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (f) Suggest two possible problems the partners may encounter if the working capital is inadequate. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] (g) Suggest two ways in which the partners could increase the working capital. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] [Total: 23]
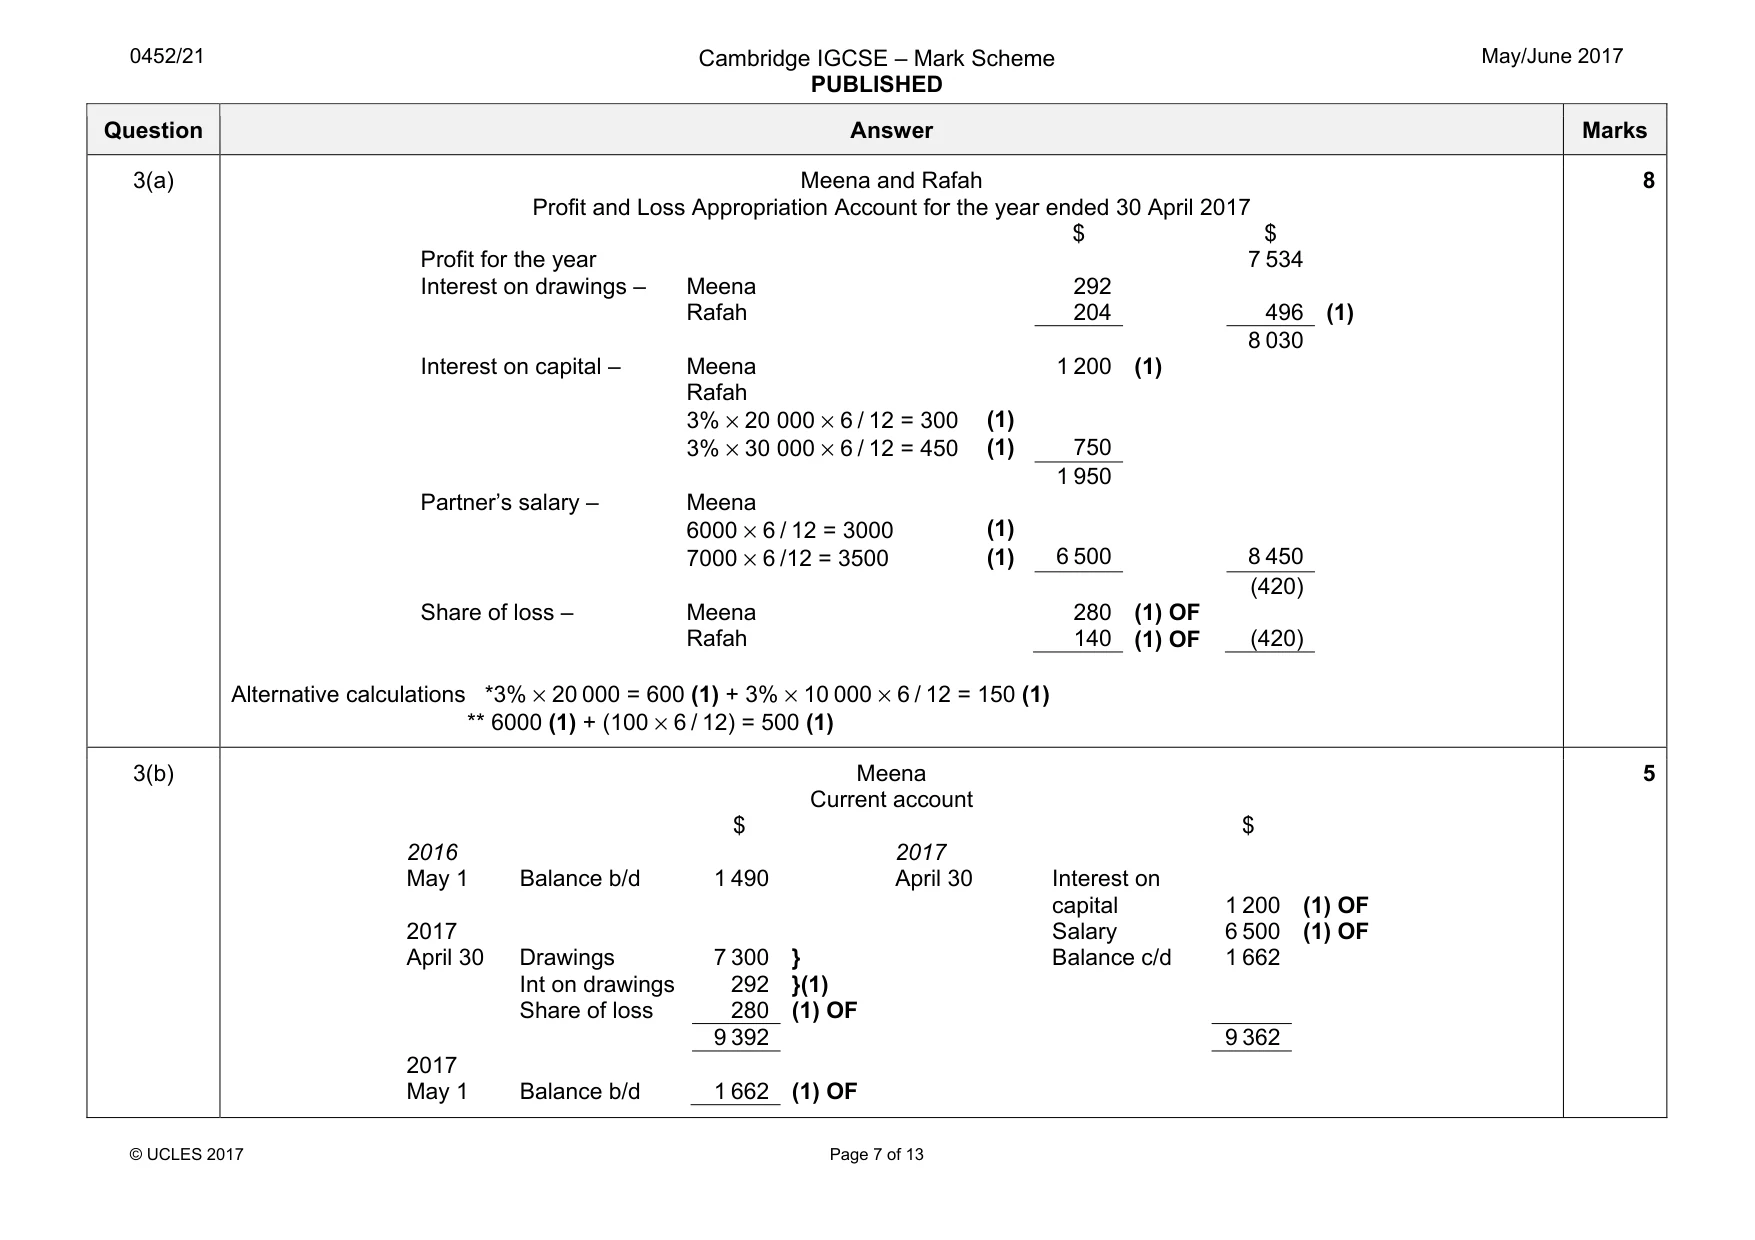
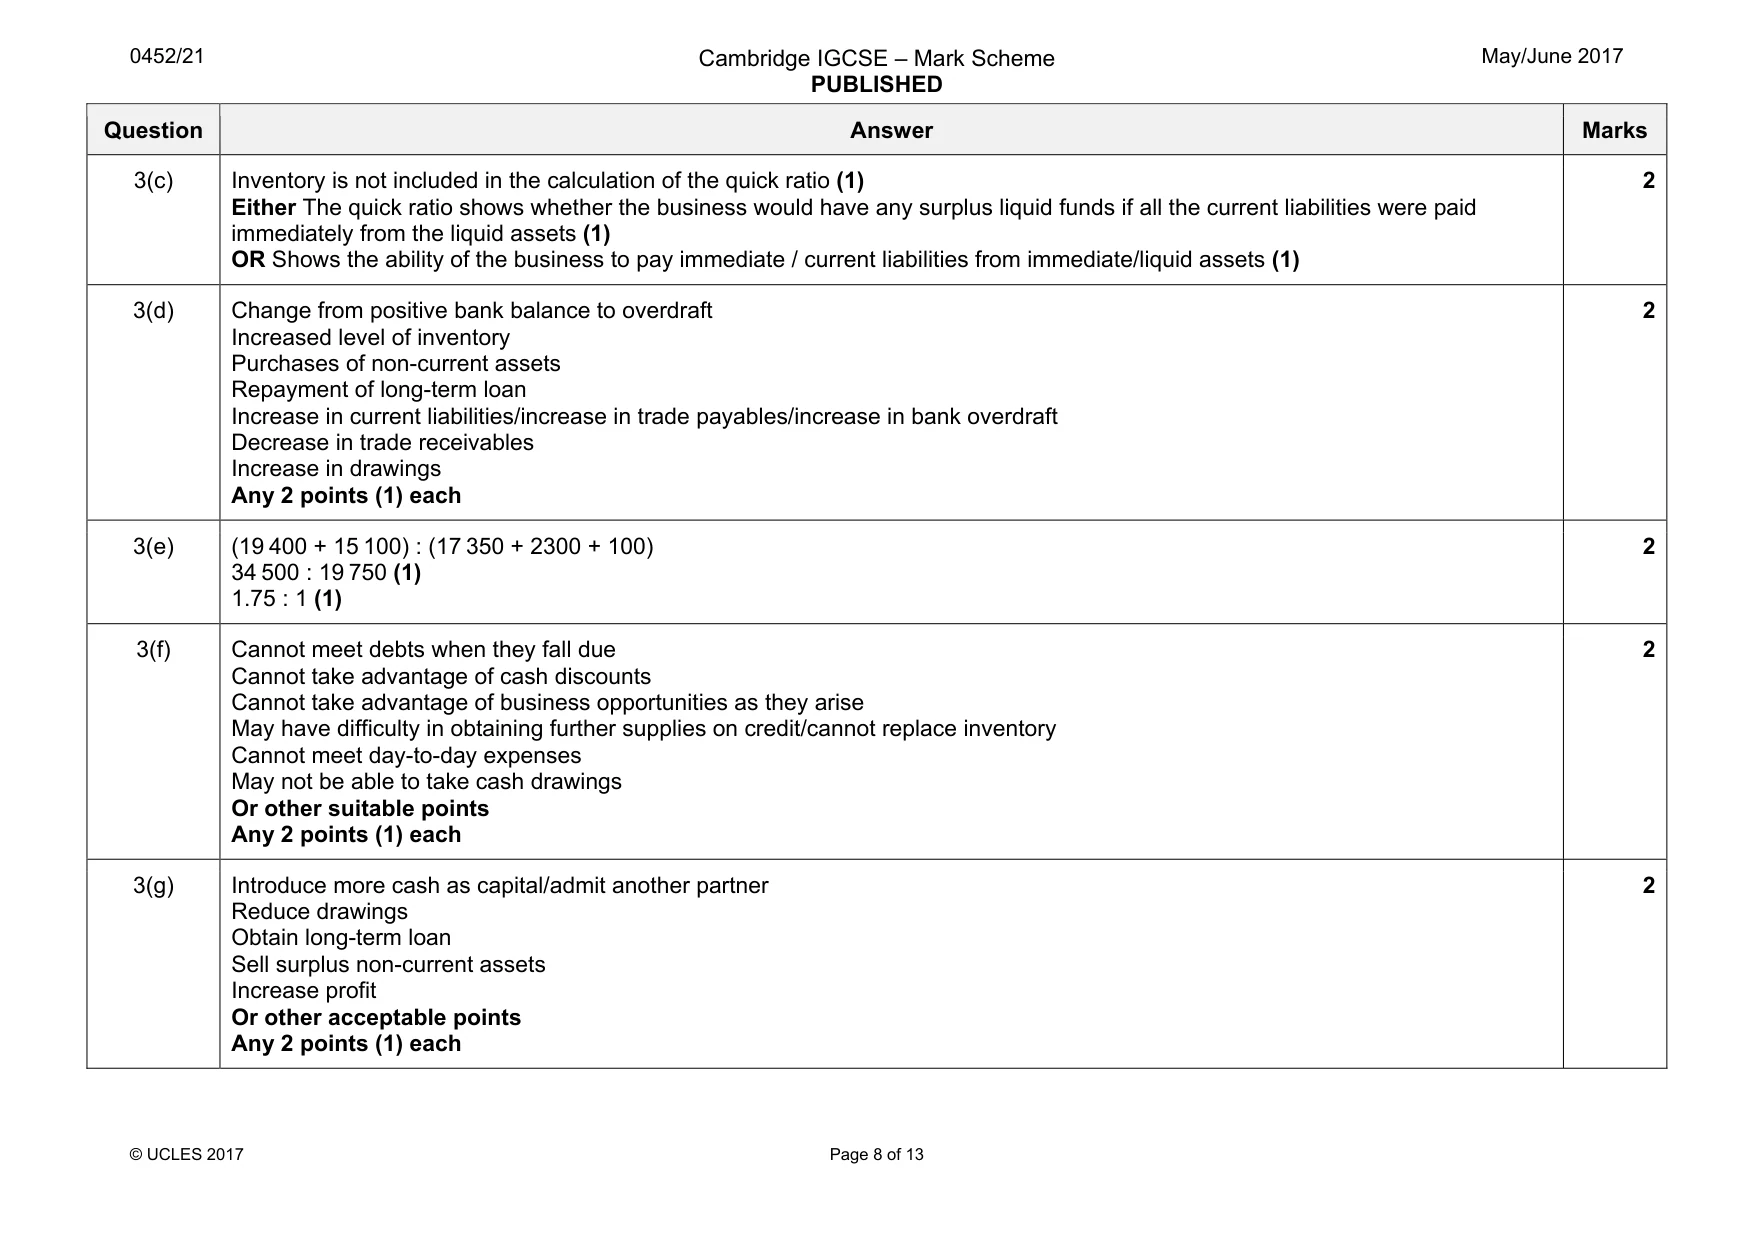
Mark scheme: 3(a) Meena and Rafah Profit and Loss Appropriation Account for the year ended 30 April 2017 $ $ Profit for the year 7 534 Interest on drawings – Meena 292 Rafah 204 496 (1) 8 030 Interest on capital – Meena 1 200 (1) Rafah 3% × 20 000 × 6 / 12 = 300 (1) 3% × 30 000 × 6 / 12 = 450 (1) 750 1 950 Partner’s salary – Meena 6000 × 6 / 12 = 3000 (1) 7000 × 6 /12 = 3500 (1) 6 500 8 450 (420) Share of loss – Meena 280 (1) OF Rafah 140 (1) OF (420) Alternative calculations *3% × 20 000 = 600 (1) + 3% × 10 000 × 6 / 12 = 150 (1) ** 6000 (1) + (100 × 6 / 12) = 500 (1) 8 3(b) Meena Current account $ $ 2016 2017 May 1 Balance b/d 1 490 April 30 Interest on capital 1 200 (1) OF 2017 Salary 6 500 (1) OF April 30 Drawings 7 300 } Balance c/d 1 662 Int on drawings 292 }(1) Share of loss 280 (1) OF 9 392 9 362 2017 May 1 Balance b/d 1 662 (1) OF 5 Question Answer Marks 3(c) Inventory is not included in the calculation of the quick ratio (1) Either The quick ratio shows whether the business would have any surplus liquid funds if all the current liabilities were paid immediately from the liquid assets (1) OR Shows the ability of the business to pay immediate / current liabilities from immediate/liquid assets (1) 2 3(d) Change from positive bank balance to overdraft Increased level of inventory Purchases of non-current assets Repayment of long-term loan Increase in current liabilities/increase in trade payables/increase in bank overdraft Decrease in trade receivables Increase in drawings Any 2 points (1) each 2 3(e) (19 400 + 15 100) : (17 350 + 2300 + 100) 34 500 : 19 750 (1) 1.75 : 1 (1) 2 3(f) Cannot meet debts when they fall due Cannot take advantage of cash discounts Cannot take advantage of business opportunities as they arise May have difficulty in obtaining further supplies on credit/cannot replace inventory Cannot meet day-to-day expenses May not be able to take cash drawings Or other suitable points Any 2 points (1) each 2 3(g) Introduce more cash as capital/admit another partner Reduce drawings Obtain long-term loan Sell surplus non-current assets Increase profit Or other acceptable points Any 2 points (1) each 2
Q4 · The financial year of Msamati Manufacturing ends on 31 January
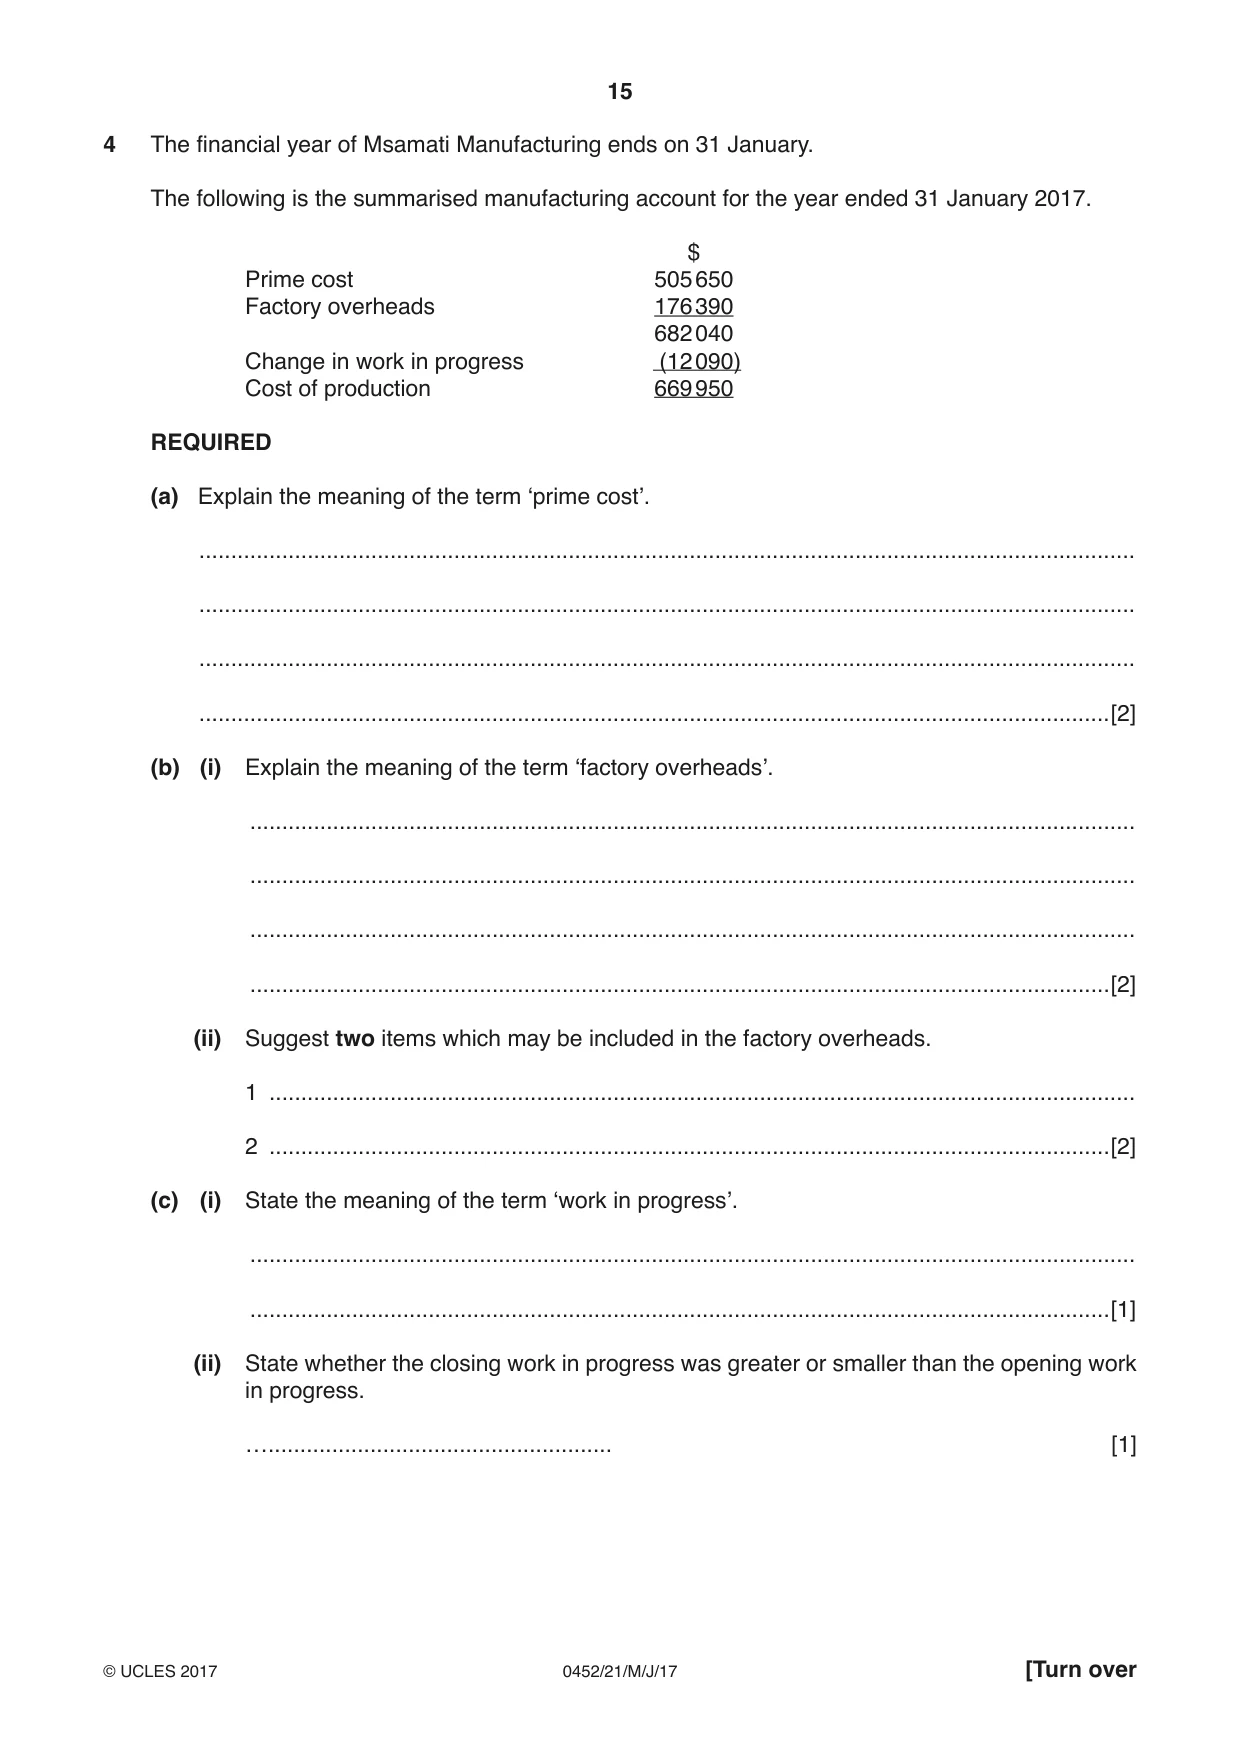
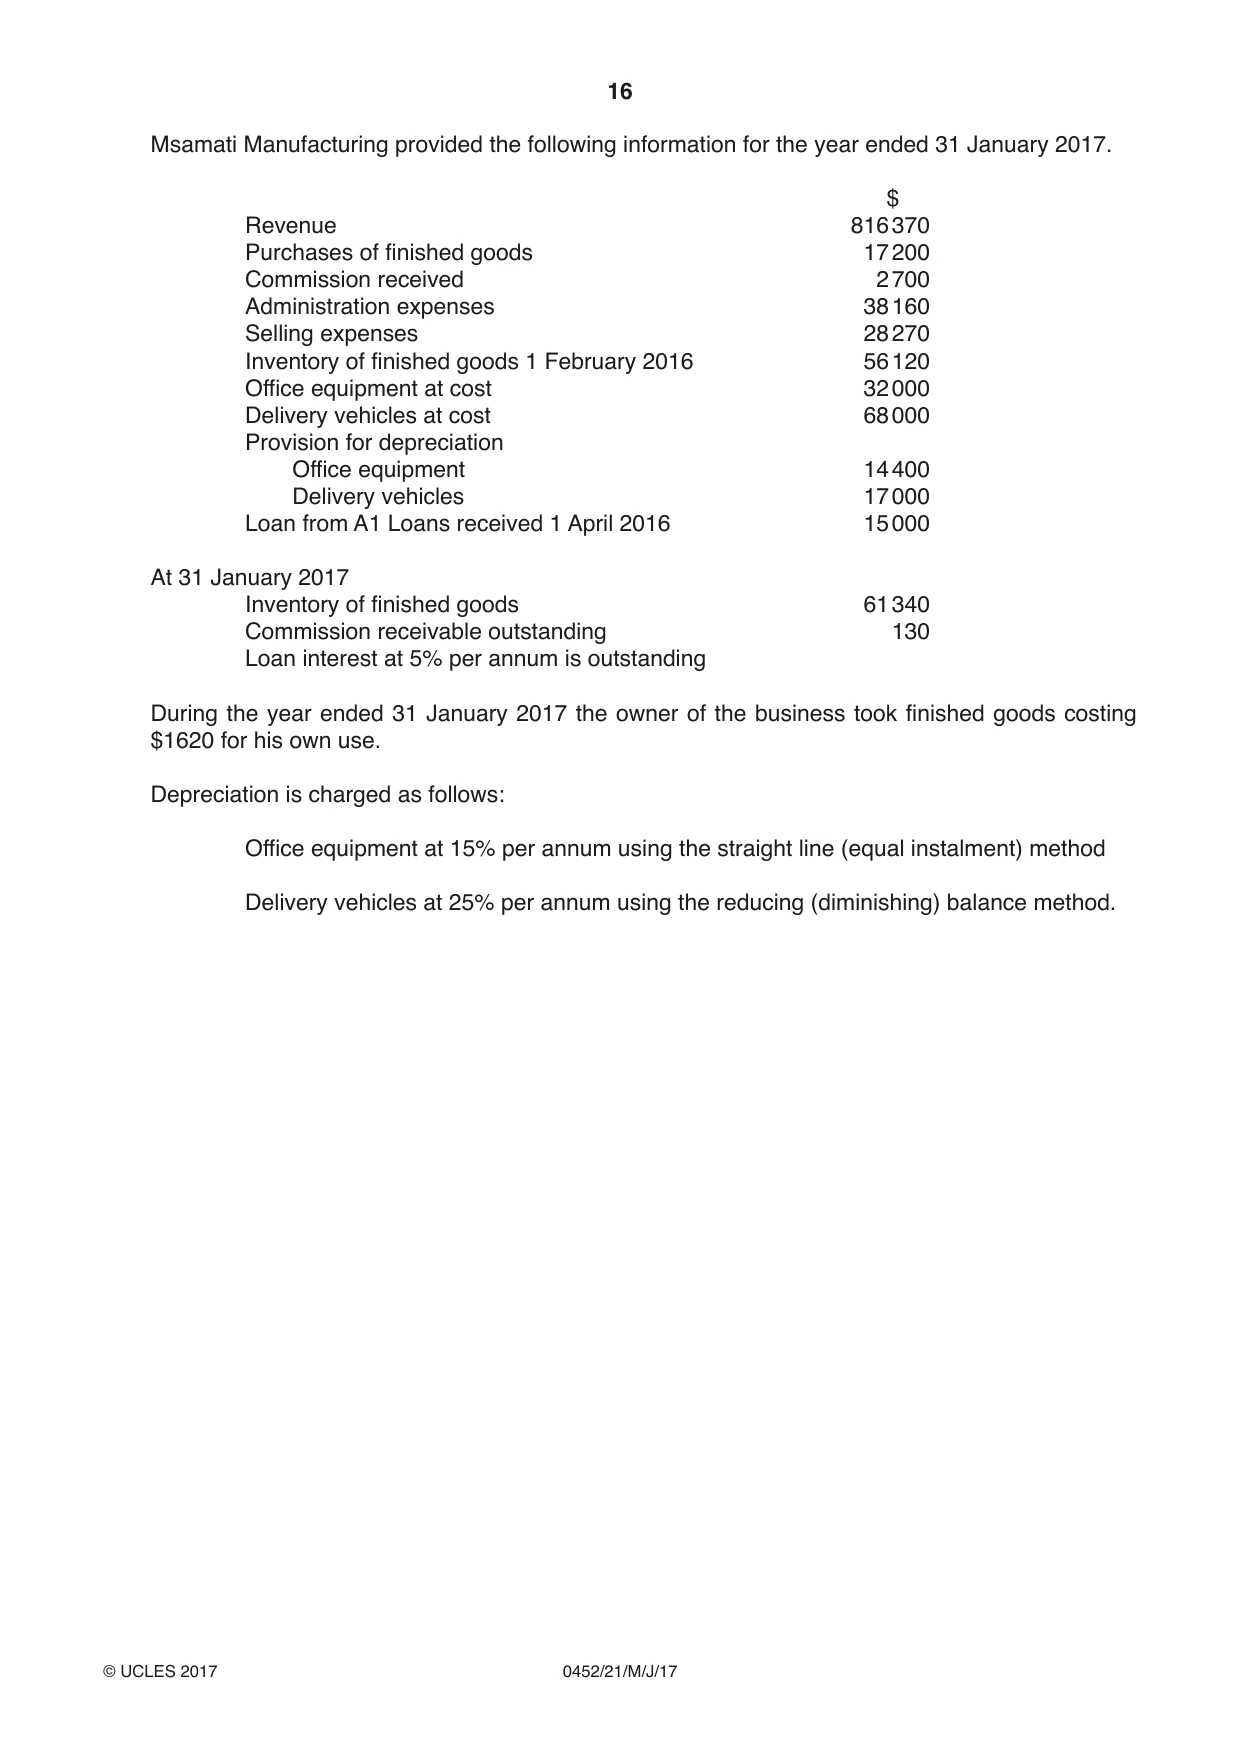
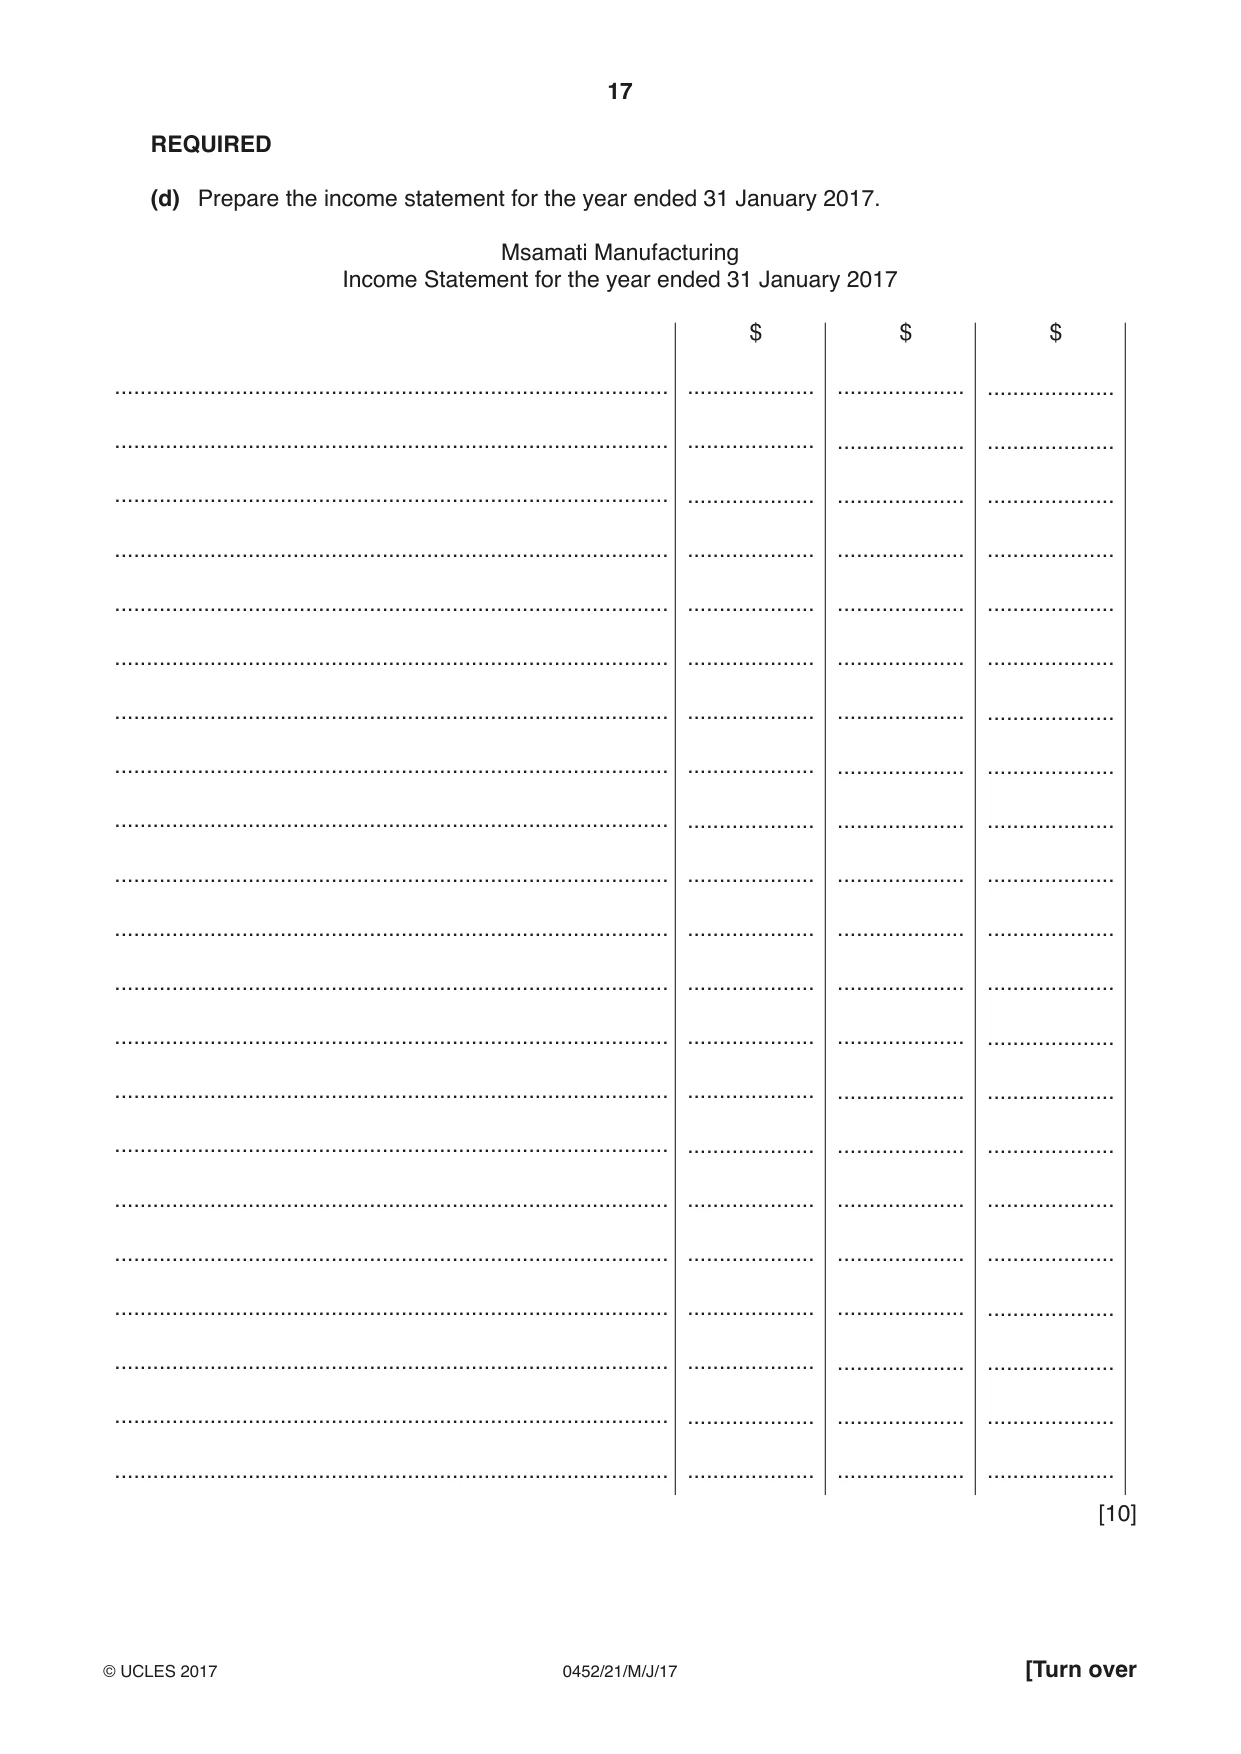
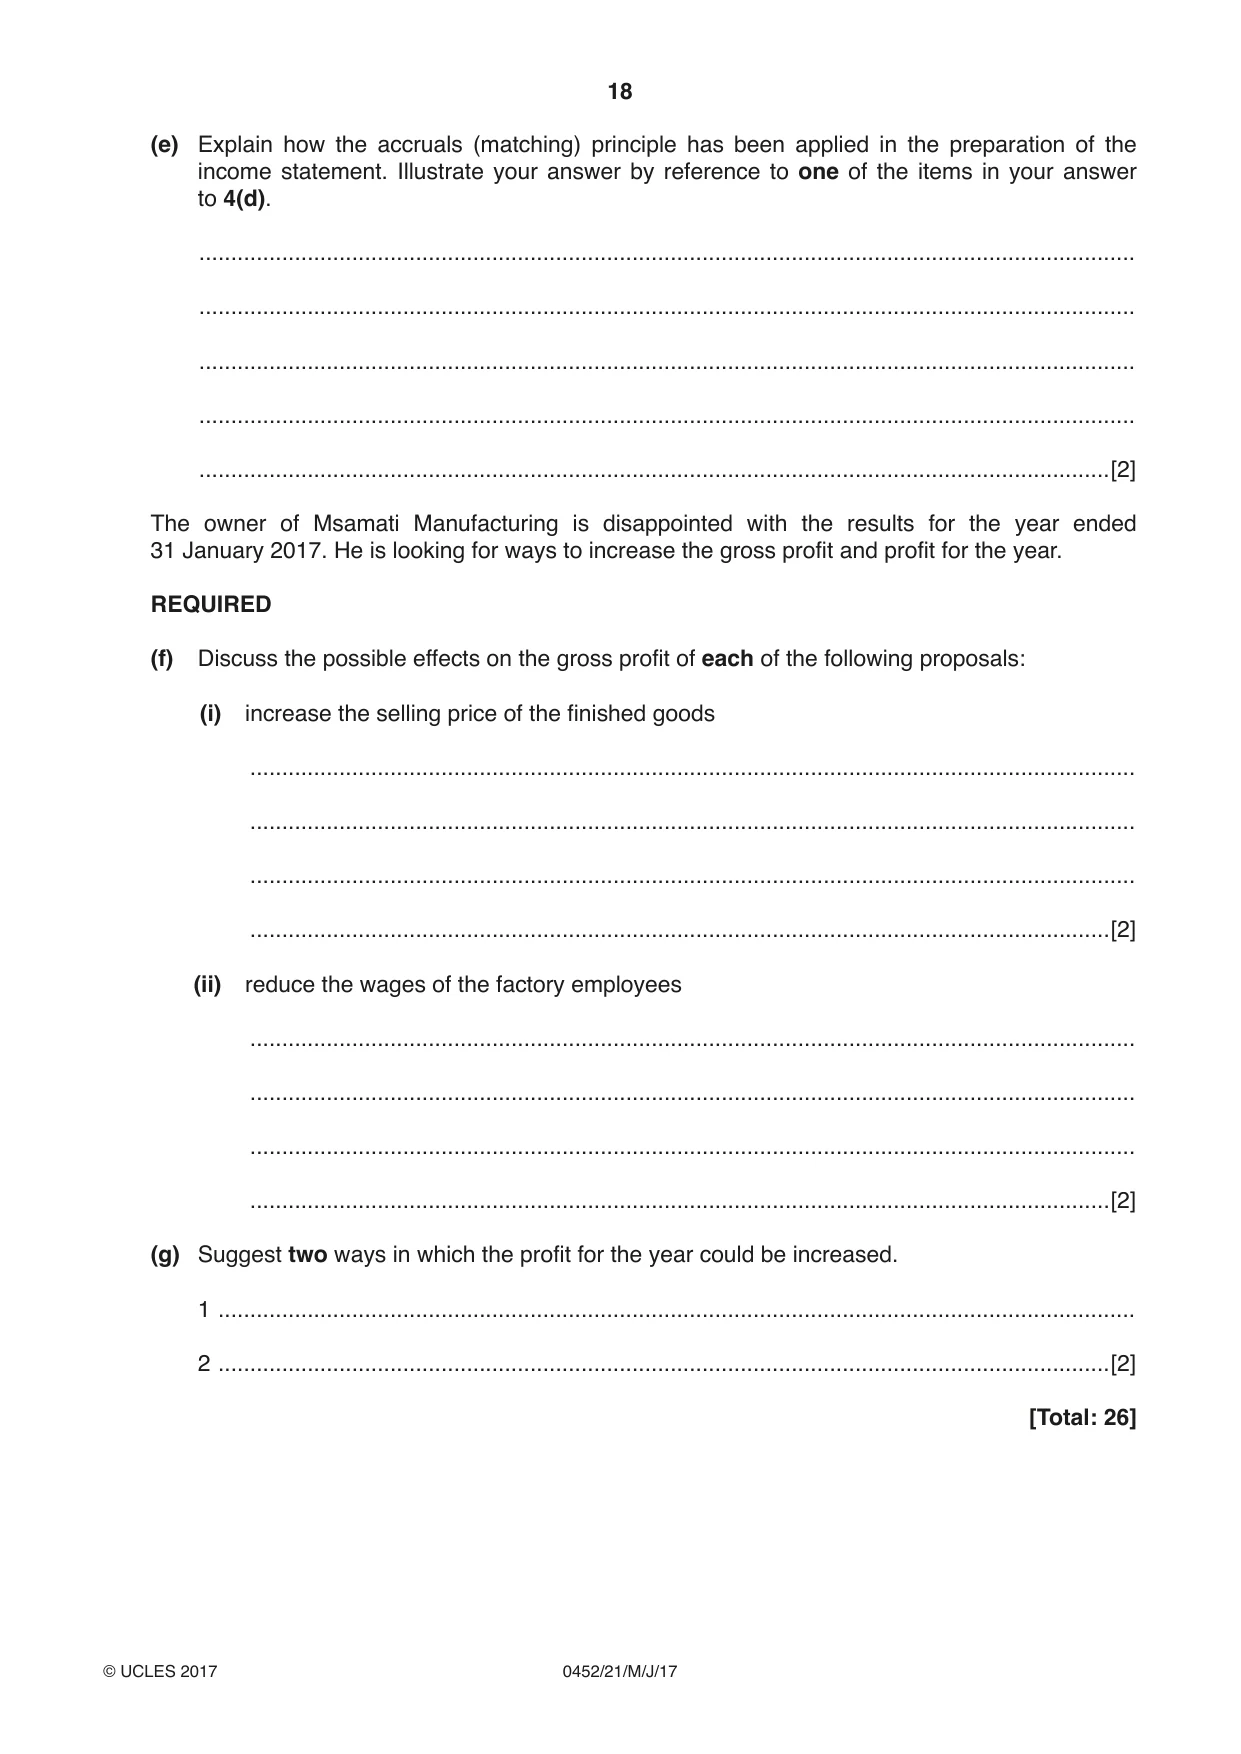
4 The financial year of Msamati Manufacturing ends on 31 January. The following is the summarised manufacturing account for the year ended 31 January 2017. $ Prime cost 505 650 Factory overheads 176 390 682 040 Change in work in progress (12 090) Cost of production 669 950 REQUIRED (a) Explain the meaning of the term ‘prime cost’. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (b) (i) Explain the meaning of the term ‘factory overheads’. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Suggest two items which may be included in the factory overheads. 1 ........................................................................................................................................ 2 ....................................................................................................................................[2] (c) (i) State the meaning of the term ‘work in progress’. ........................................................................................................................................... .......................................................................................................................................[1] (ii) State whether the closing work in progress was greater or smaller than the opening work in progress. …...................................................... [1] Msamati Manufacturing provided the following information for the year ended 31 January 2017. $ Revenue 816 370 Purchases of finished goods 17 200 Commission received 2 700 Administration expenses 38 160 Selling expenses 28 270 Inventory of finished goods 1 February 2016 56 120 Office equipment at cost 32 000 Delivery vehicles at cost 68 000 Provision for depreciation Office equipment 14 400 Delivery vehicles 17 000 Loan from A1 Loans received 1 April 2016 15 000 At 31 January 2017 Inventory of finished goods 61 340 Commission receivable outstanding 130 Loan interest at 5% per annum is outstanding During the year ended 31 January 2017 the owner of the business took finished goods costing $1620 for his own use. Depreciation is charged as follows: Office equipment at 15% per annum using the straight line (equal instalment) method Delivery vehicles at 25% per annum using the reducing (diminishing) balance method. REQUIRED (d) Prepare the income statement for the year end Msamati Manufa Income Statement for the year e ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... ....................................................................................... (e) Explain how the accruals (matching) principle has been applied in the preparation of the income statement. Illustrate your answer by reference to one of the items in your answer to 4(d). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] The owner of Msamati Manufacturing is disappointed with the results for the year ended 31 January 2017. He is looking for ways to increase the gross profit and profit for the year. REQUIRED (f) Discuss the possible effects on the gross profit of each of the following proposals: (i) increase the selling price of the finished goods ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) reduce the wages of the factory employees ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (g) Suggest two ways in which the profit for the year could be increased. 1 ................................................................................................................................................ 2 ............................................................................................................................................[2] [Total: 26] Question 5 is on the next page.
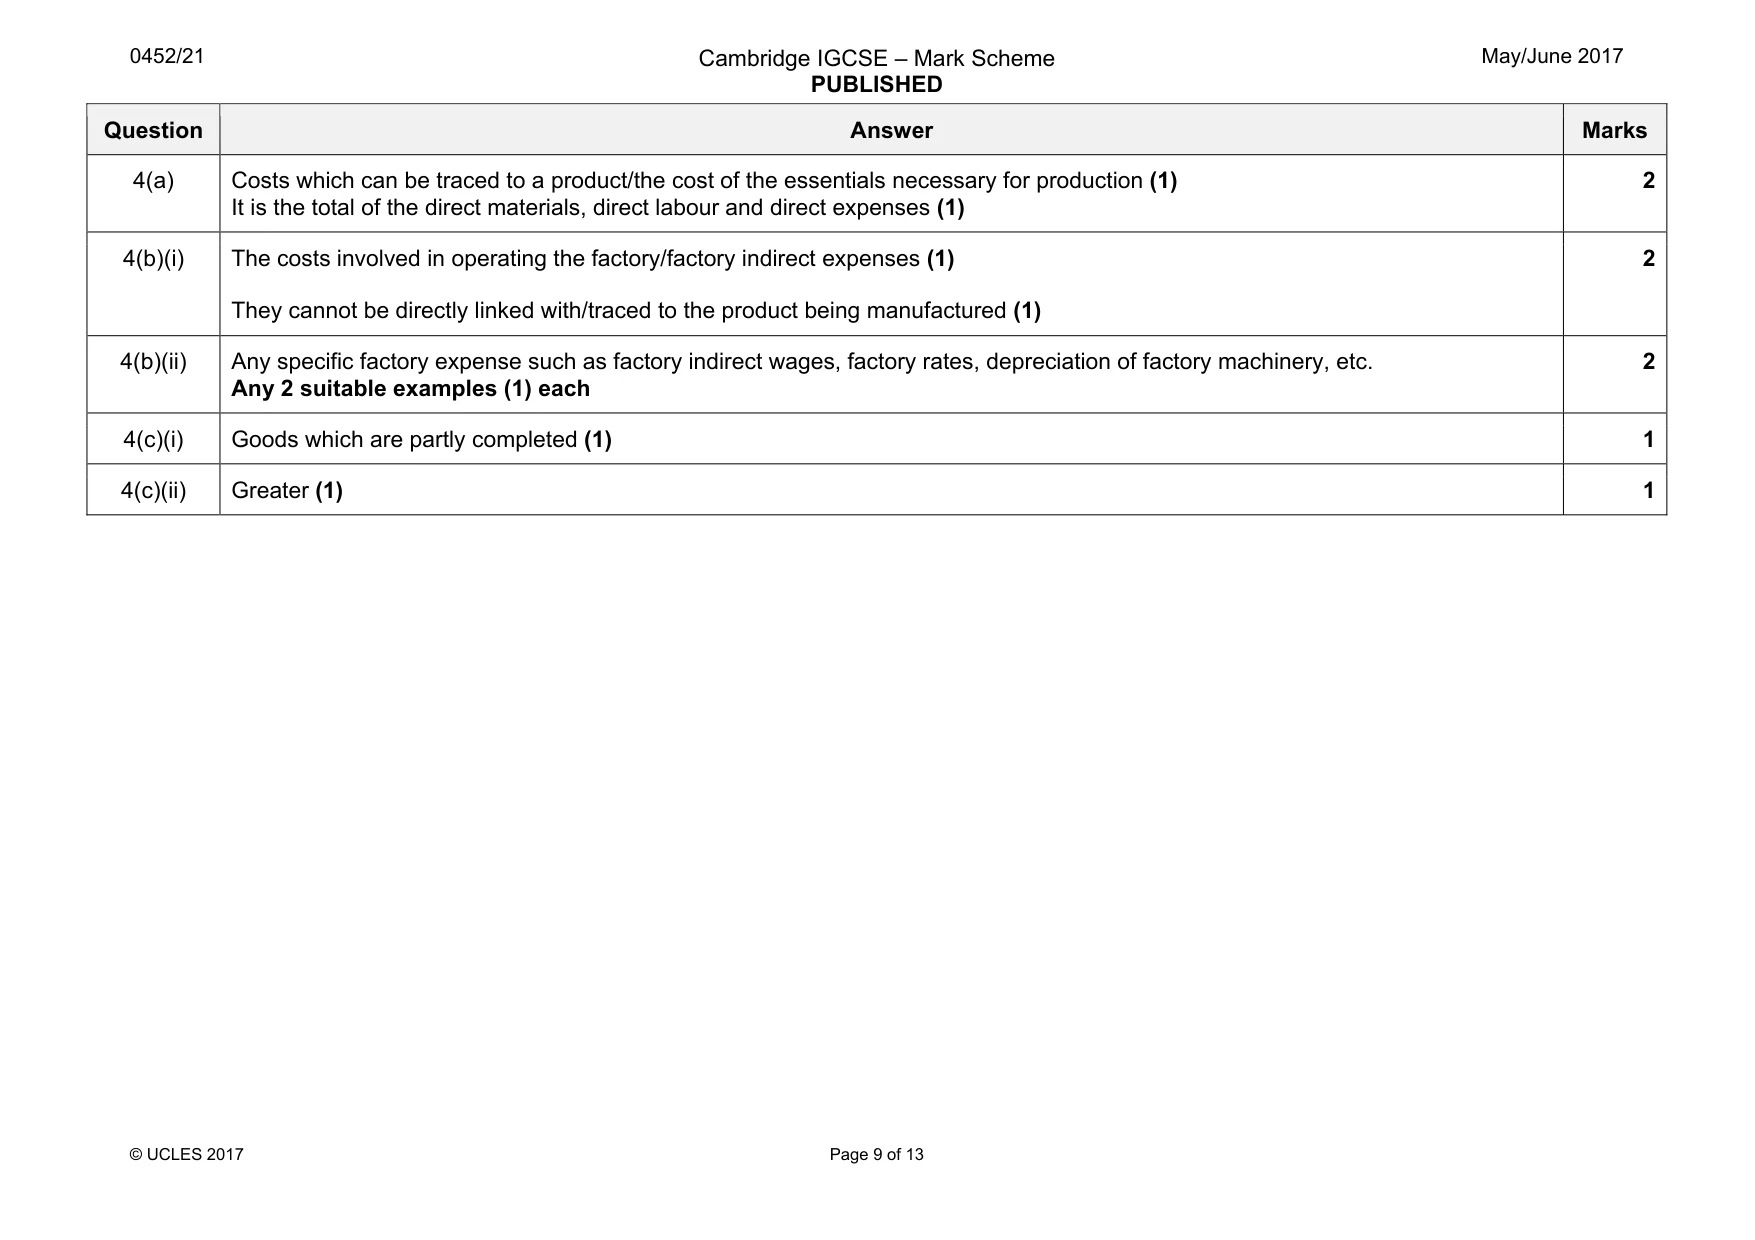
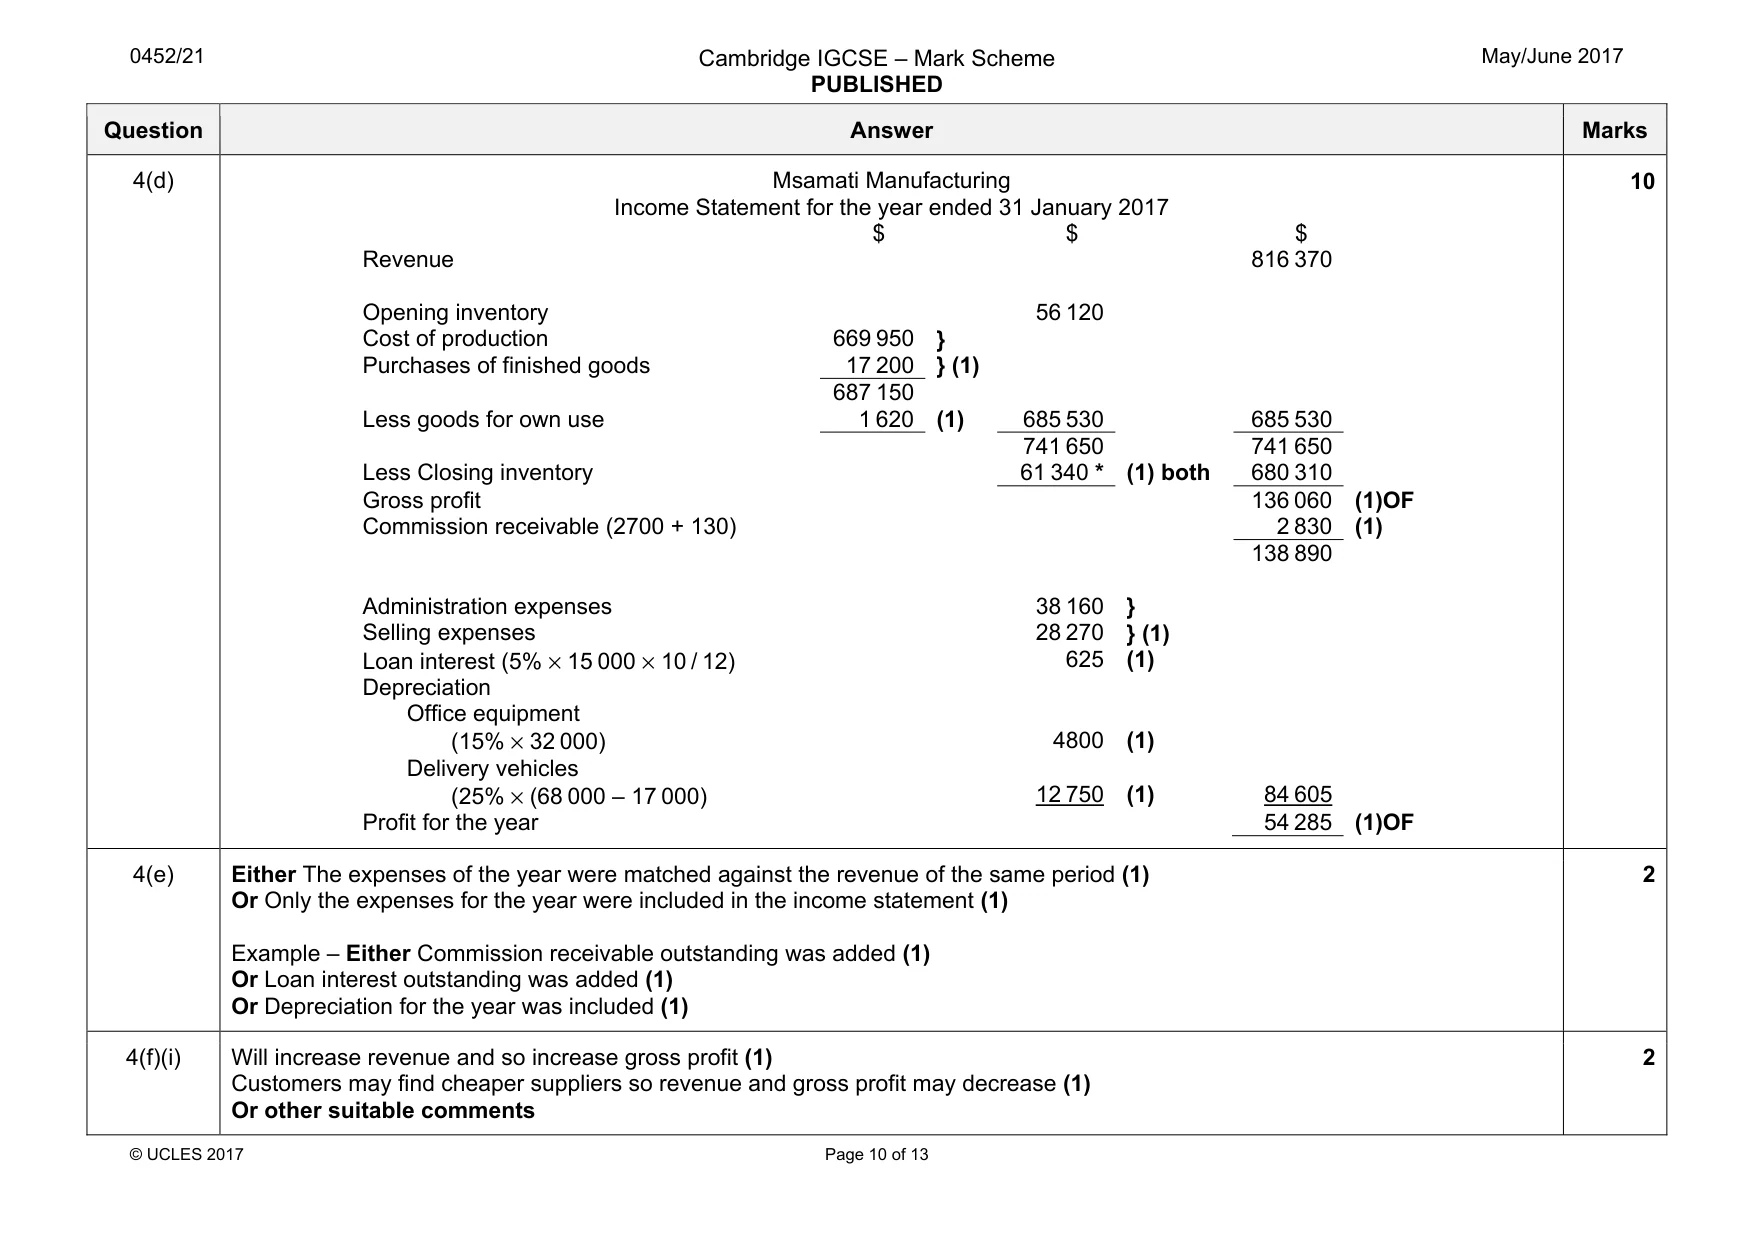
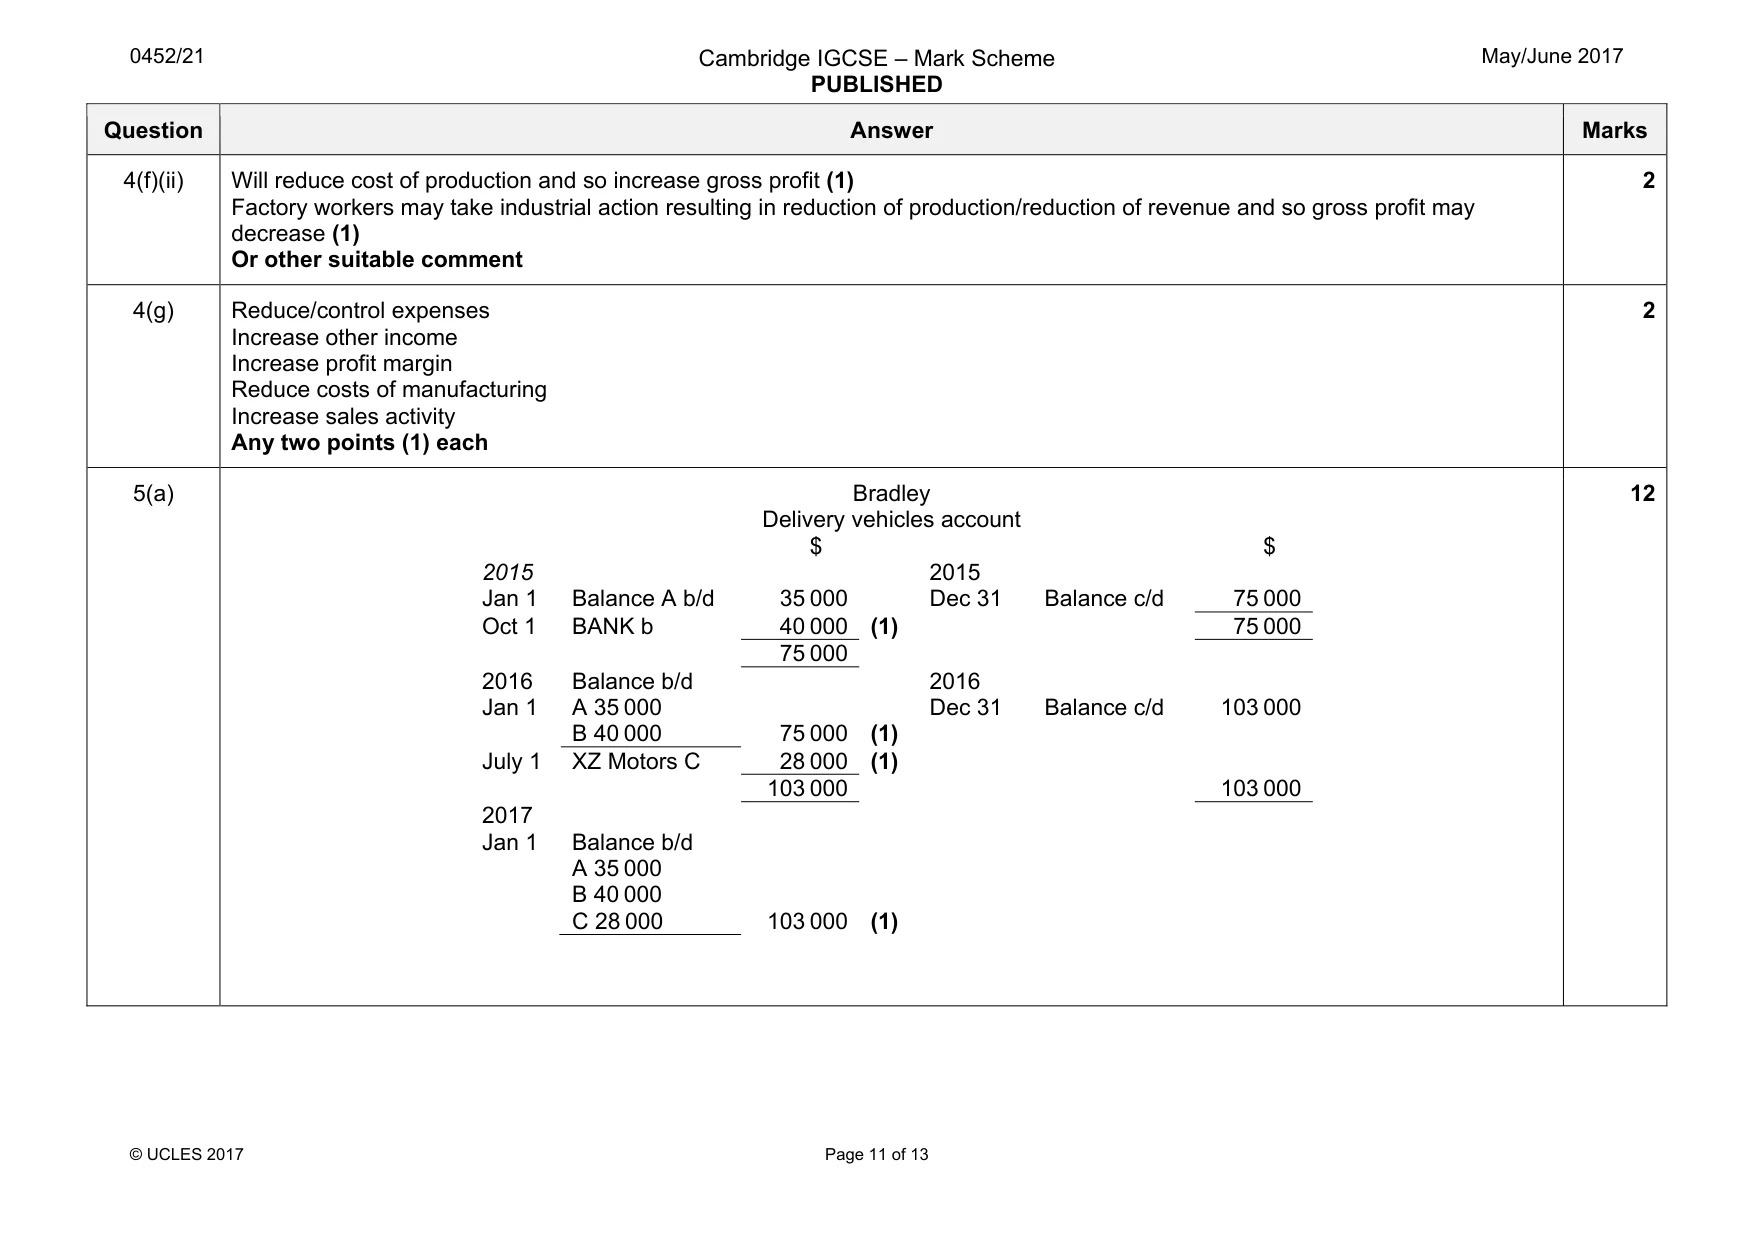
Mark scheme: 4(a) Costs which can be traced to a product/the cost of the essentials necessary for production (1) It is the total of the direct materials, direct labour and direct expenses (1) 2 4(b)(i) The costs involved in operating the factory/factory indirect expenses (1) They cannot be directly linked with/traced to the product being manufactured (1) 2 4(b)(ii) Any specific factory expense such as factory indirect wages, factory rates, depreciation of factory machinery, etc. Any 2 suitable examples (1) each 2 4(c)(i) Goods which are partly completed (1) 1 4(c)(ii) Greater (1) 1 Question Answer Marks 4(d) Msamati Manufacturing Income Statement for the year ended 31 January 2017 $ $ $ Revenue 816 370 Opening inventory 56 120 Cost of production 669 950 } Purchases of finished goods 17 200 } (1) 687 150 Less goods for own use 1 620 (1) 685 530 685 530 741 650 741 650 Less Closing inventory 61 340 * (1) both 680 310 Gross profit 136 060 (1)OF Commission receivable (2700 + 130) 2 830 (1) 138 890 Administration expenses 38 160 } Selling expenses 28 270 } (1) Loan interest (5% × 15 000 × 10 / 12) 625 (1) Depreciation Office equipment (15% × 32 000) 4800 (1) Delivery vehicles (25% × (68 000 – 17 000) 12 750 (1) 84 605 Profit for the year 54 285 (1)OF 10 4(e) Either The expenses of the year were matched against the revenue of the same period (1) Or Only the expenses for the year were included in the income statement (1) Example – Either Commission receivable outstanding was added (1) Or Loan interest outstanding was added (1) Or Depreciation for the year was included (1) 2 4(f)(i) Will increase revenue and so increase gross profit (1) Customers may find cheaper suppliers so revenue and gross profit may decrease (1) Or other suitable comments 2 Question Answer Marks 4(f)(ii) Will reduce cost of production and so increase gross profit (1) Factory workers may take industrial action resulting in reduction of production/reduction of revenue and so gross profit may decrease (1) Or other suitable comment 2 4(g) Reduce/control expenses Increase other income Increase profit margin Reduce costs of manufacturing Increase sales activity Any two points (1) each 2
Q5 · Bradley is a wholesaler
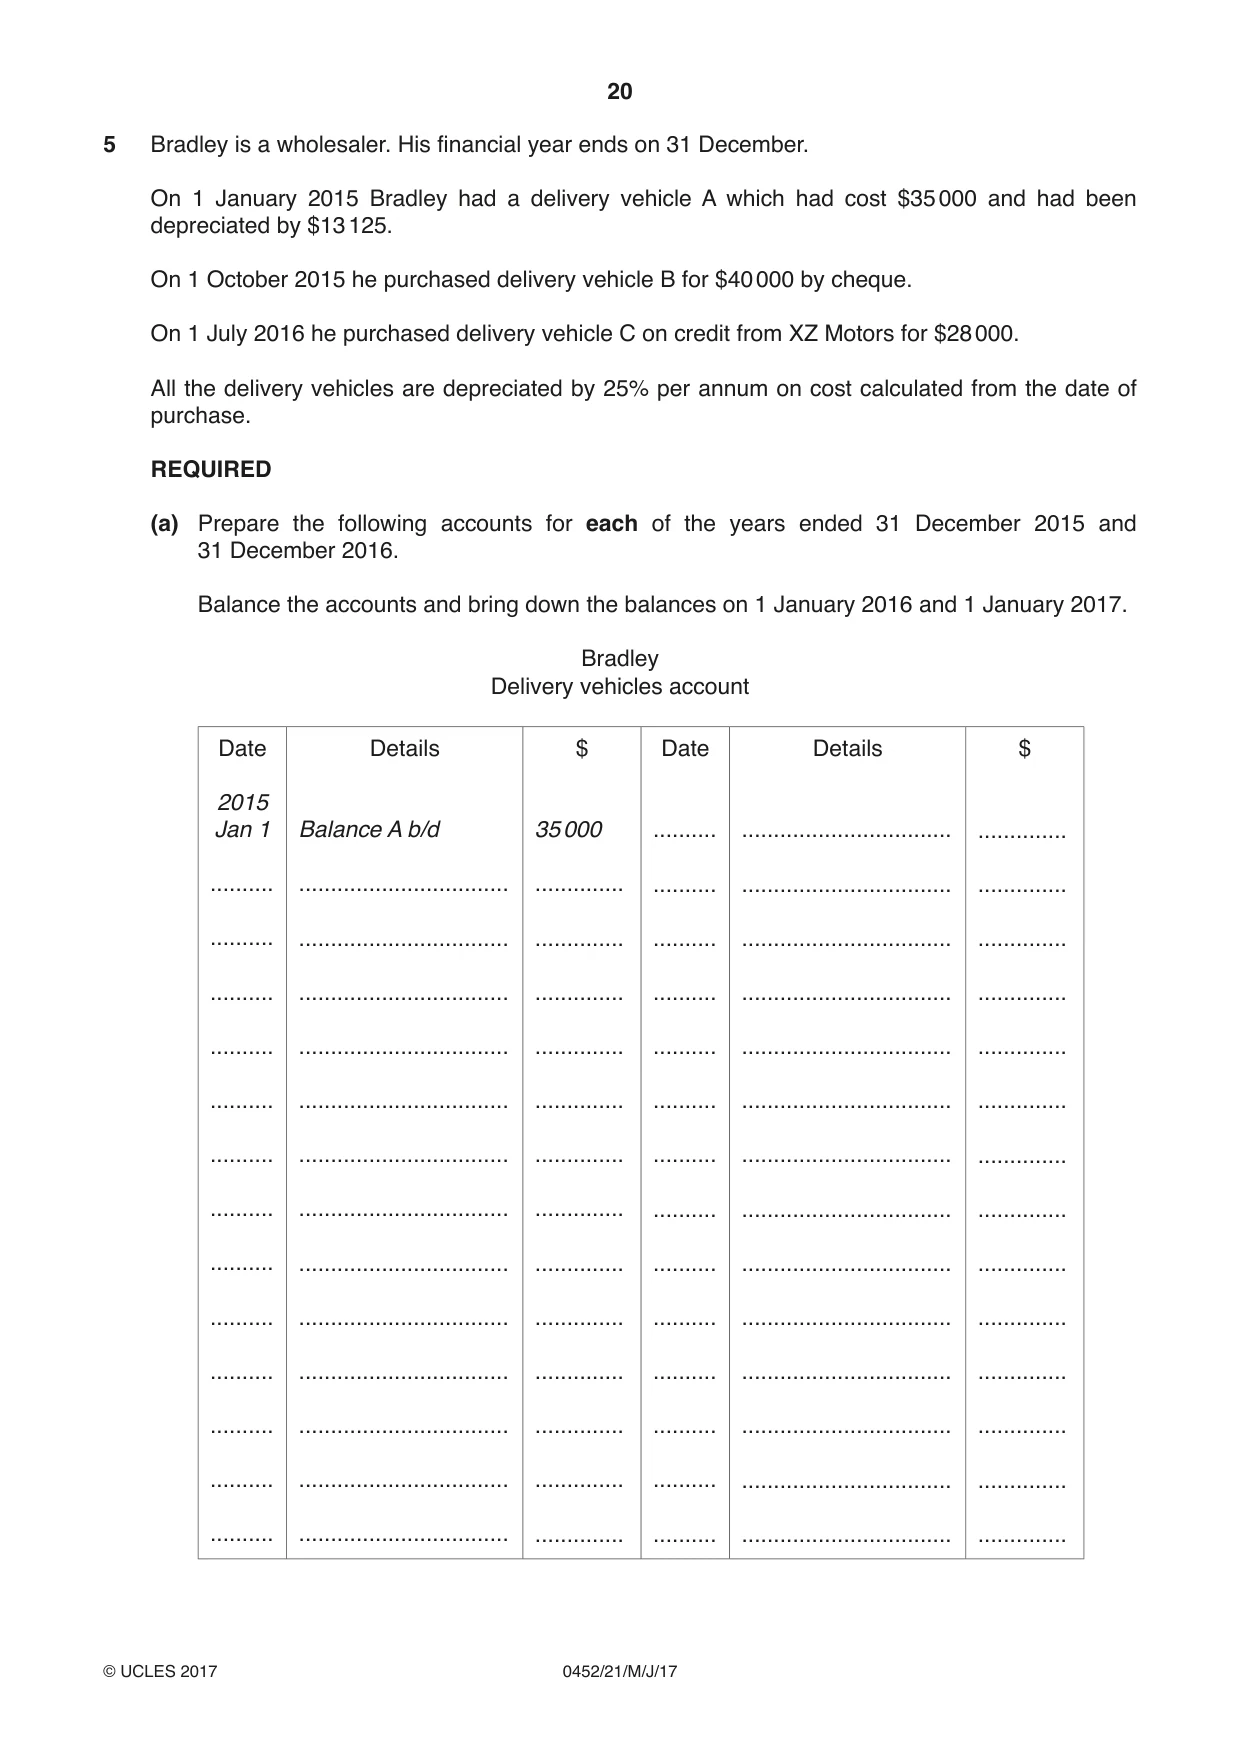
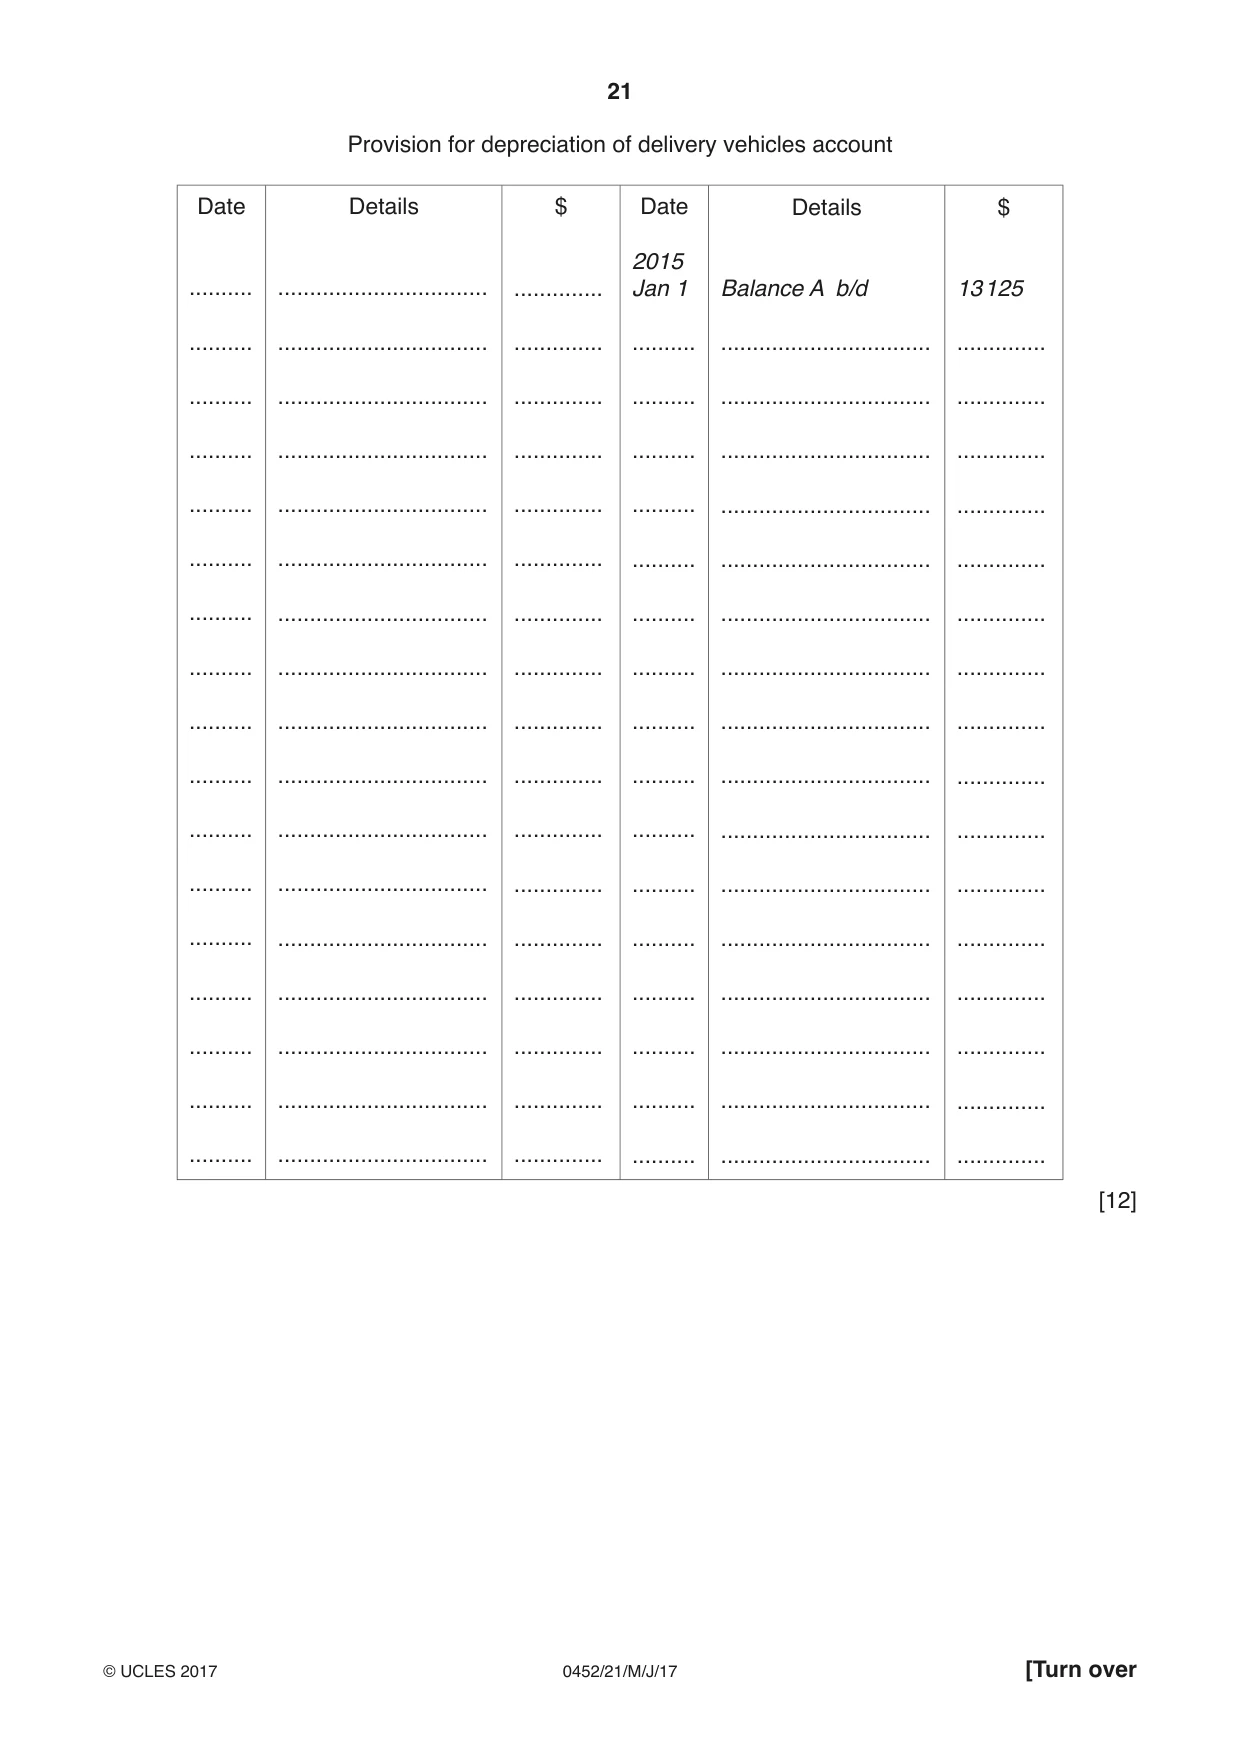
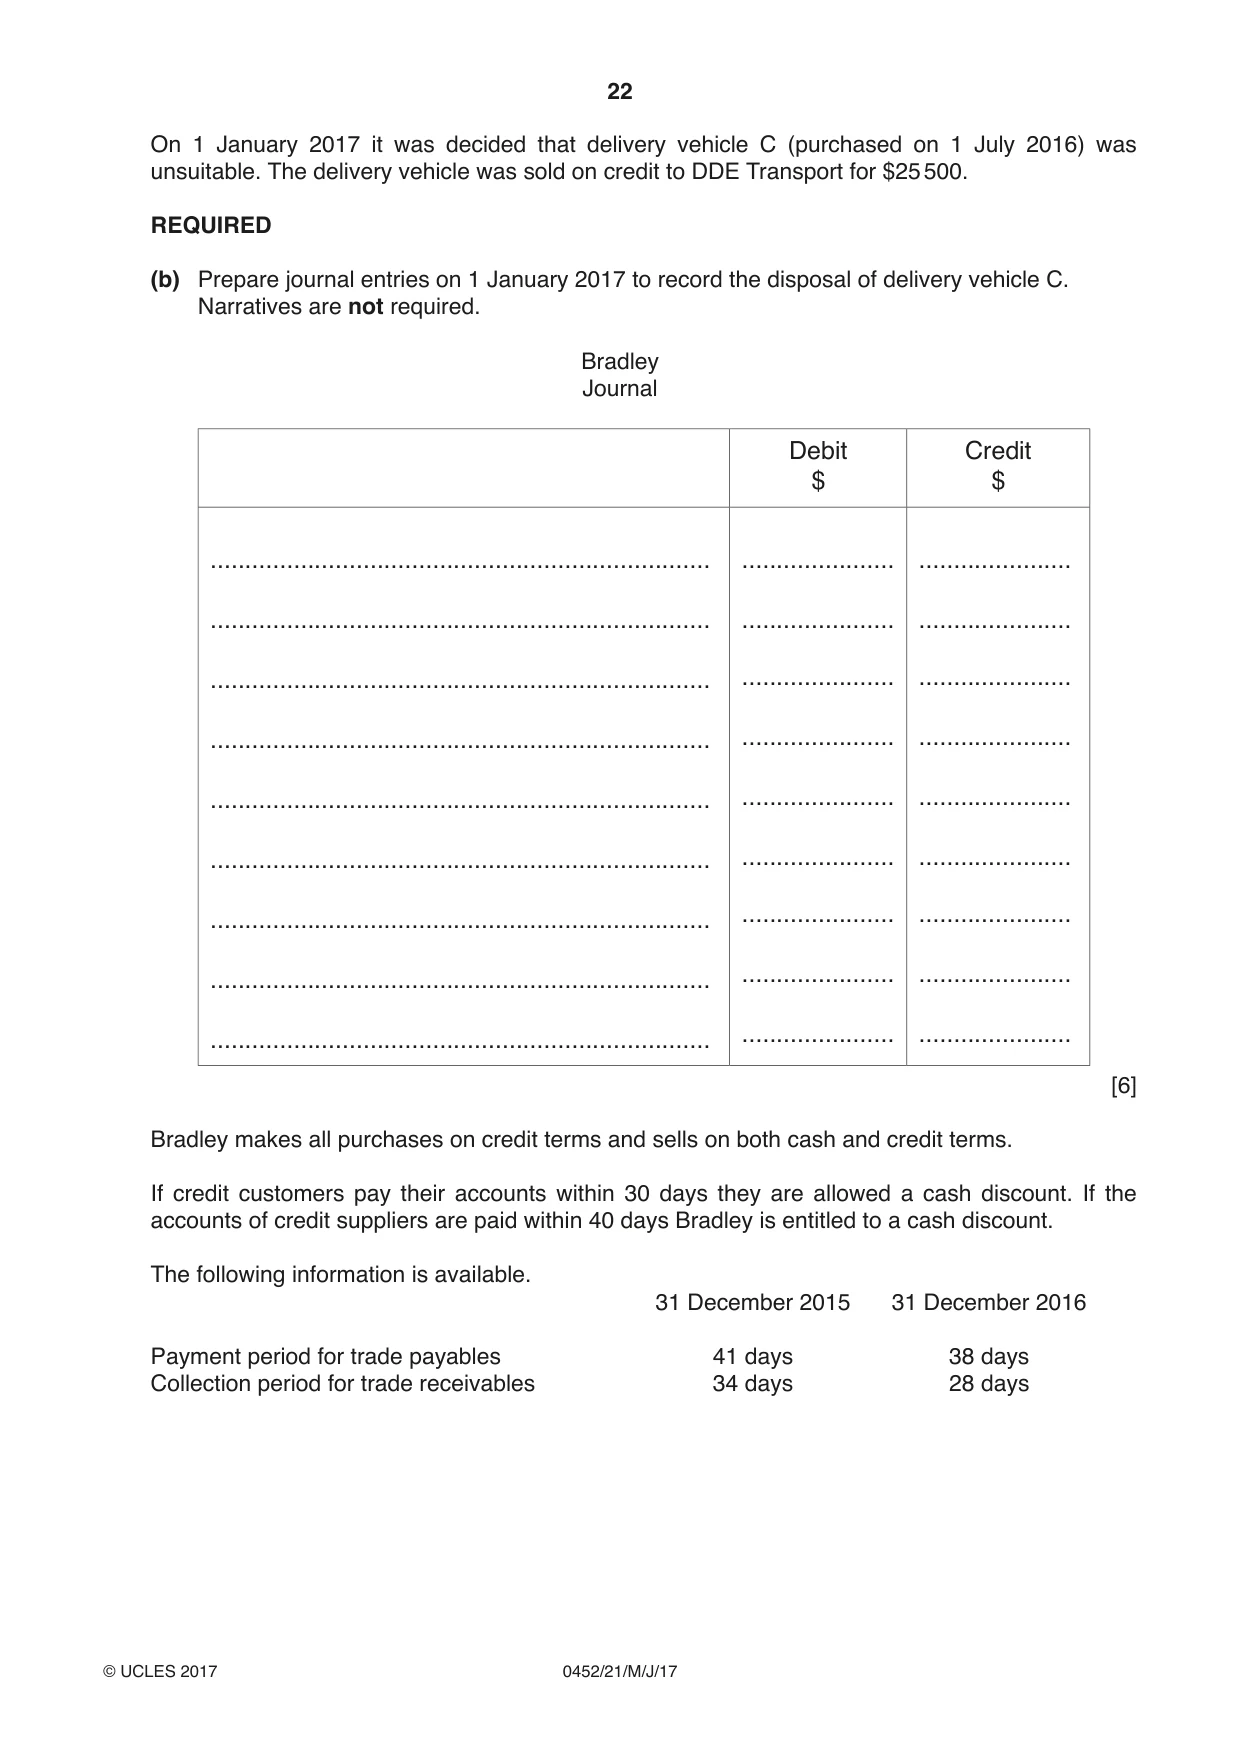
5 Bradley is a wholesaler. His financial year ends on 31 December. On 1 January 2015 Bradley had a delivery vehicle A which had cost $35 000 and had been depreciated by $13 125. On 1 October 2015 he purchased delivery vehicle B for $40 000 by cheque. On 1 July 2016 he purchased delivery vehicle C on credit from XZ Motors for $28 000. All the delivery vehicles are depreciated by 25% per annum on cost calculated from the date of purchase. REQUIRED (a) Prepare the following accounts for each of the years ended 31 December 2015 and 31 December 2016. Balance the accounts and bring down the balances on 1 January 2016 and 1 January 2017. Bradley Delivery vehicles account Date Details $ Date Details $ 2015 Jan 1 Balance A b/d 35 000 .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. Provision for depreciation of delivery vehicles account Date Details $ Date Details $ 2015 .......... ................................. .............. Jan 1 Balance A b/d 13125 .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. .......... ................................. .............. [12] On 1 January 2017 it was decided that delivery vehicle C (purchased on 1 July 2016) was unsuitable. The delivery vehicle was sold on credit to DDE Transport for $25 500. REQUIRED (b) Prepare journal entries on 1 January 2017 to record the disposal of delivery vehicle C. Narratives are not required. Bradley Journal Debit Credit $ $ ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... ........................................................................ ...................... ...................... [6] Bradley makes all purchases on credit terms and sells on both cash and credit terms. If credit customers pay their accounts within 30 days they are allowed a cash discount. If the accounts of credit suppliers are paid within 40 days Bradley is entitled to a cash discount. The following information is available. 31 December 2015 31 December 2016 Payment period for trade payables 41 days 38 days Collection period for trade receivables 34 days 28 days
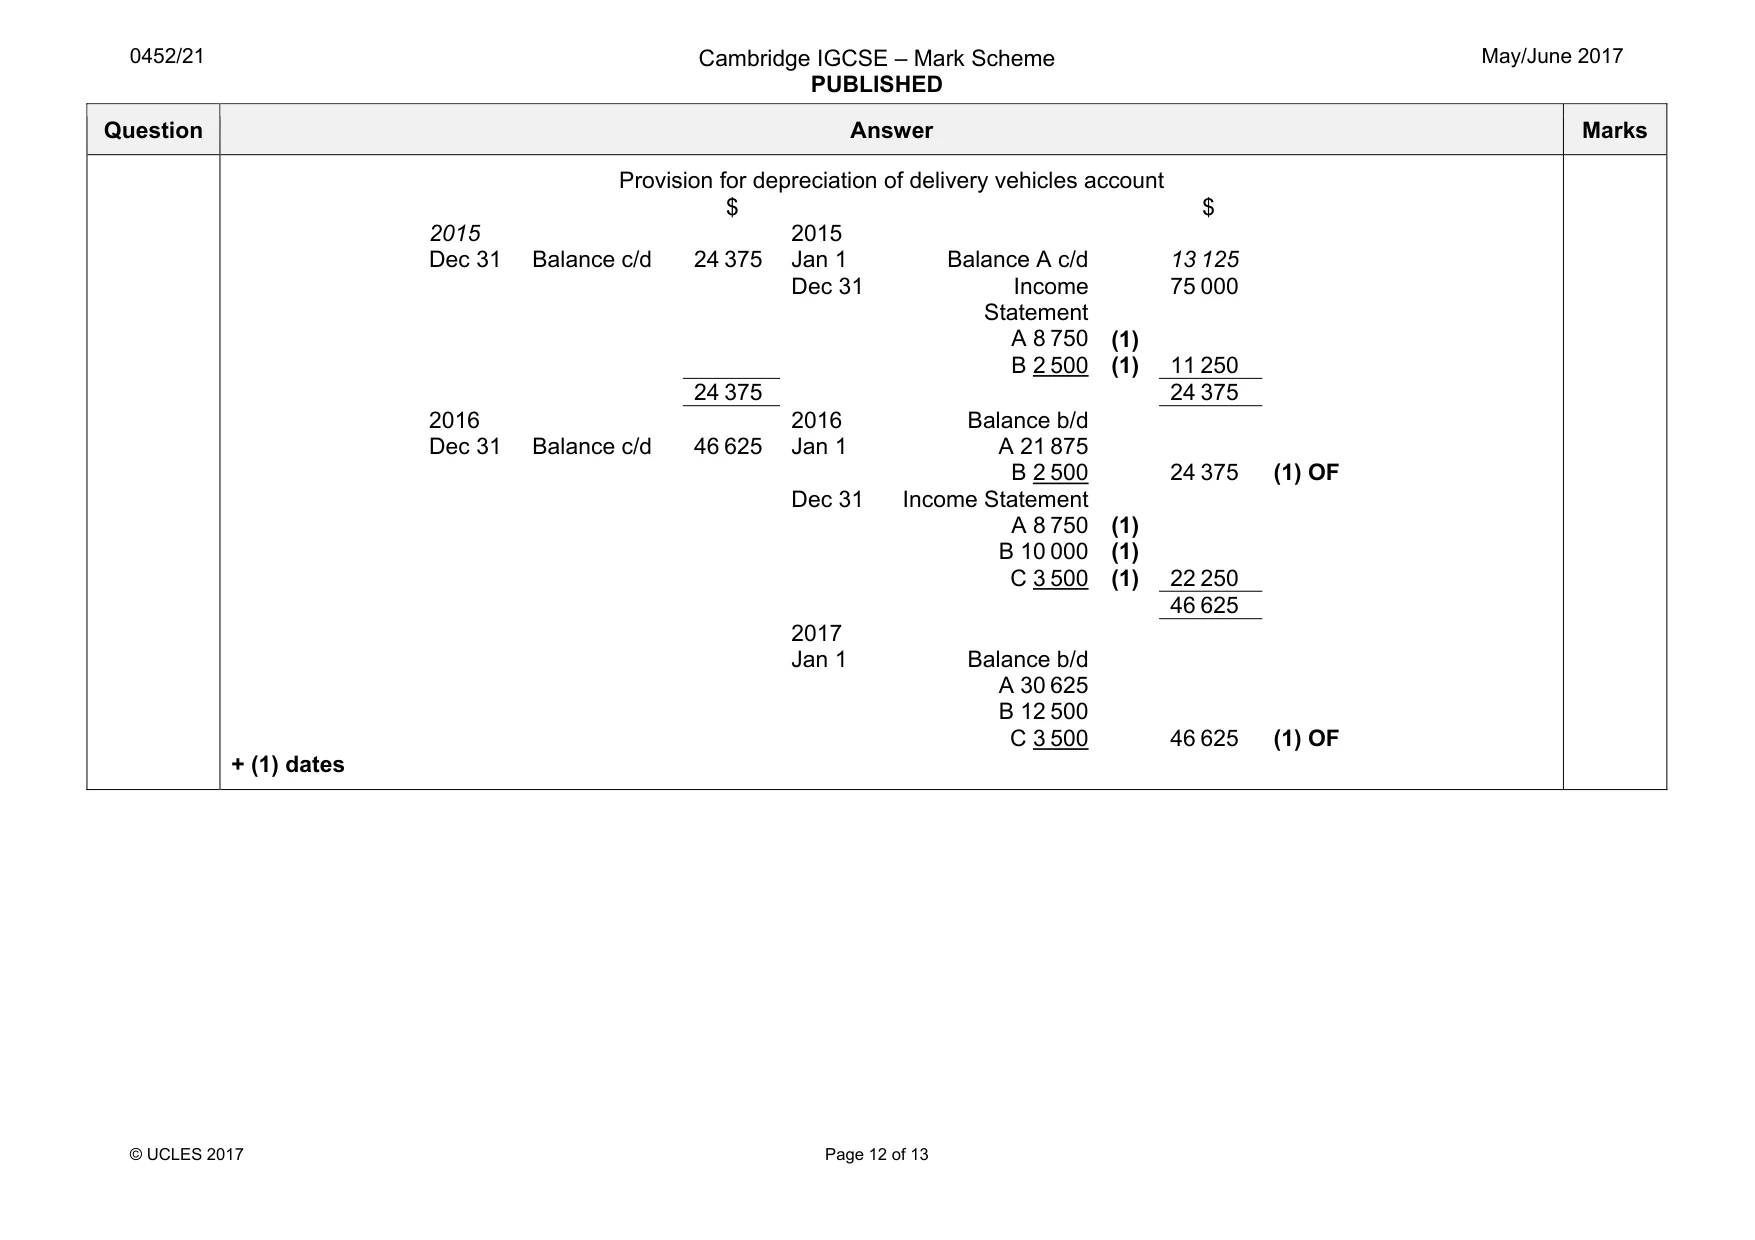
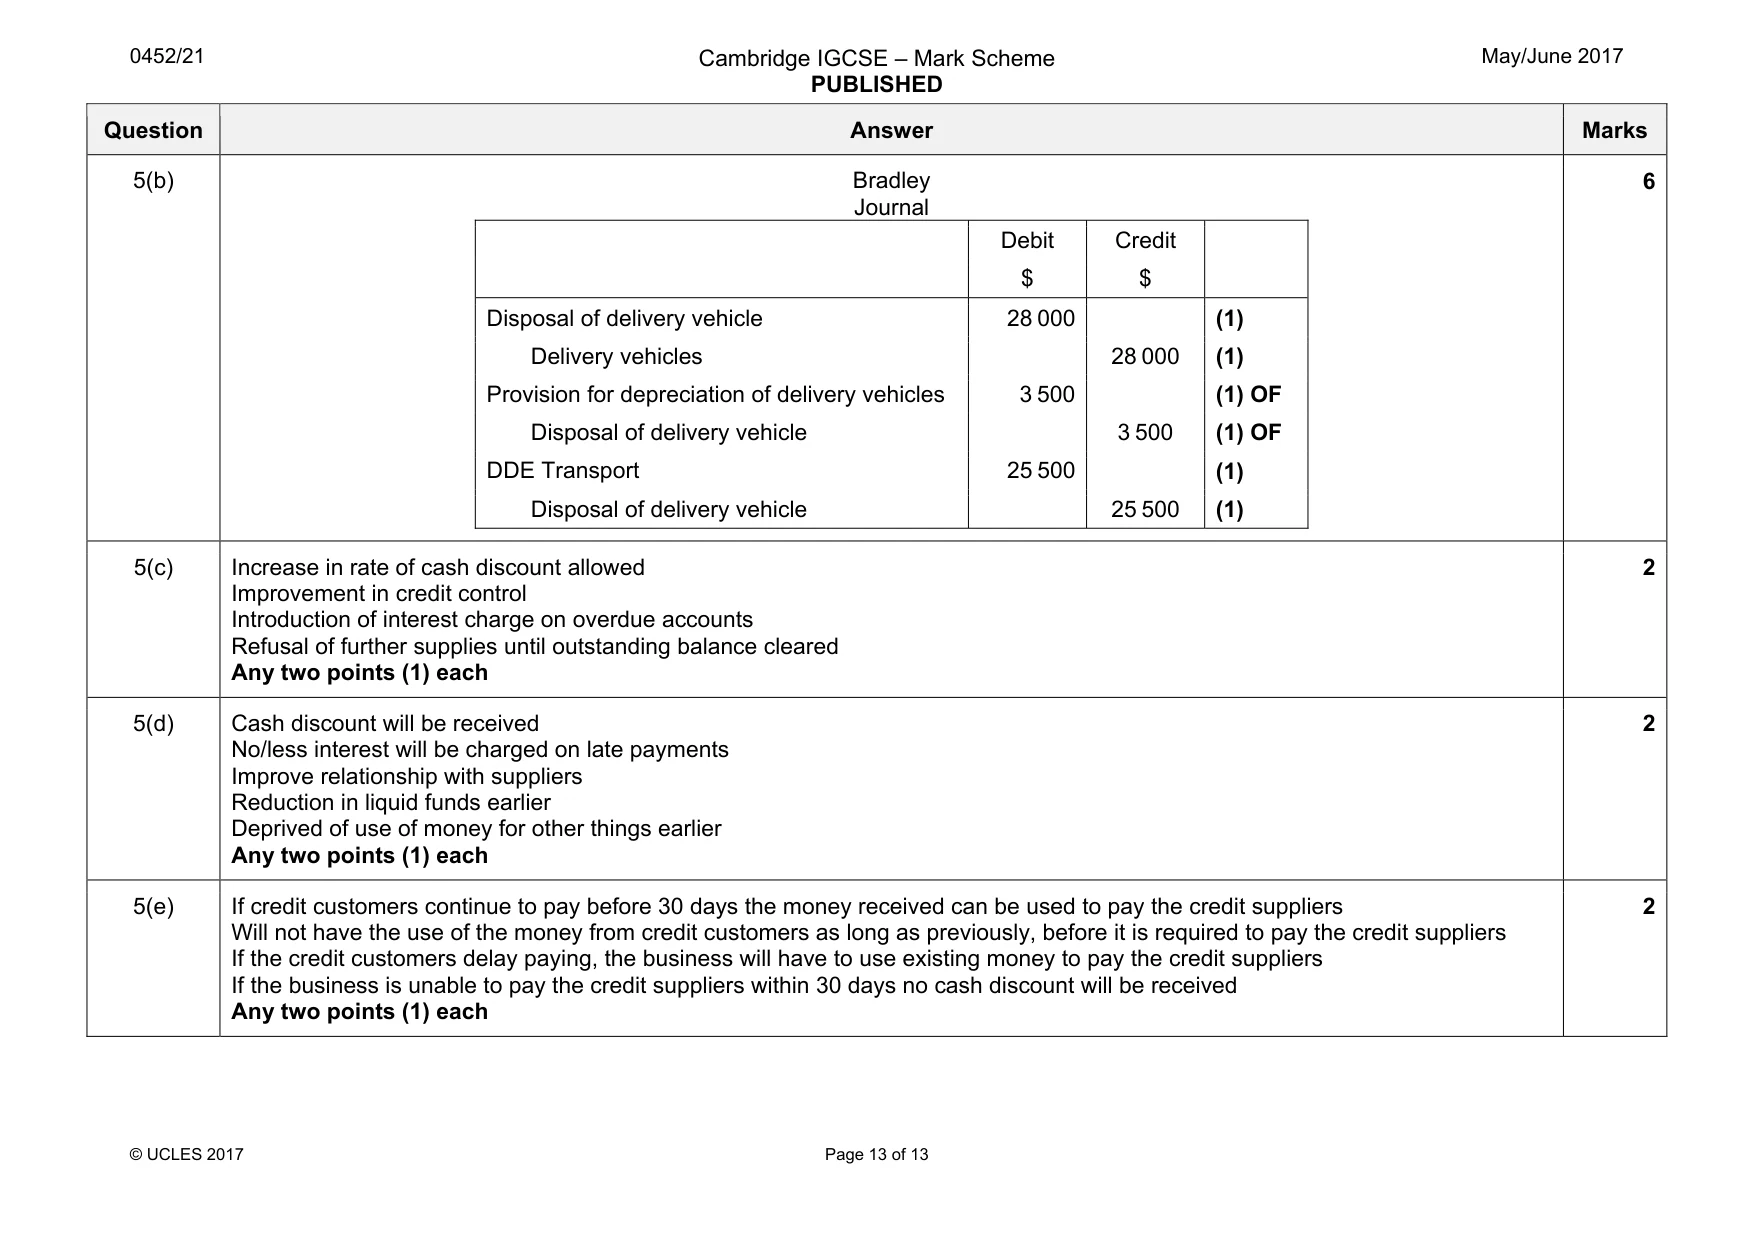
Mark scheme: 5(a) Bradley Delivery vehicles account $ $ 2015 2015 Jan 1 Balance A b/d 35 000 Dec 31 Balance c/d 75 000 Oct 1 BANK b 40 000 (1) 75 000 75 000 2016 Balance b/d 2016 Jan 1 A 35 000 Dec 31 Balance c/d 103 000 B 40 000 75 000 (1) July 1 XZ Motors C 28 000 (1) 103 000 103 000 2017 Jan 1 Balance b/d A 35 000 B 40 000 C 28 000 103 000 (1) 12 Question Answer Marks Provision for depreciation of delivery vehicles account $ $ 2015 2015 Dec 31 Balance c/d 24 375 Jan 1 Balance A c/d 13 125 Dec 31 Income 75 000 Statement A 8 750 (1) B 2 500 (1) 11 250 24 375 24 375 2016 2016 Balance b/d Dec 31 Balance c/d 46 625 Jan 1 A 21 875 B 2 500 24 375 (1) OF Dec 31 Income Statement A 8 750 (1) B 10 000 (1) C 3 500 (1) 22 250 46 625 2017 Jan 1 Balance b/d A 30 625 B 12 500 C 3 500 46 625 (1) OF + (1) dates Question Answer Marks 5(b) Bradley Journal Debit Credit $ $ Disposal of delivery vehicle 28 000 (1) Delivery vehicles 28 000 (1) Provision for depreciation of delivery vehicles 3 500 (1) OF Disposal of delivery vehicle 3 500 (1) OF DDE Transport 25 500 (1) Disposal of delivery vehicle 25 500 (1) 6 5(c) Increase in rate of cash discount allowed Improvement in credit control Introduction of interest charge on overdue accounts Refusal of further supplies until outstanding balance cleared Any two points (1) each 2 5(d) Cash discount will be received No/less interest will be charged on late payments Improve relationship with suppliers Reduction in liquid funds earlier Deprived of use of money for other things earlier Any two points (1) each 2 5(e) If credit customers continue to pay before 30 days the money received can be used to pay the credit suppliers Will not have the use of the money from credit customers as long as previously, before it is required to pay the credit suppliers If the credit customers delay paying, the business will have to use existing money to pay the credit suppliers If the business is unable to pay the credit suppliers within 30 days no cash discount will be received Any two points (1) each 2
More questions on Accounting for depreciation and disposal of non-current assets
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2017 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.