Cambridge IGCSE Accounting 0452 — 2016 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/16 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
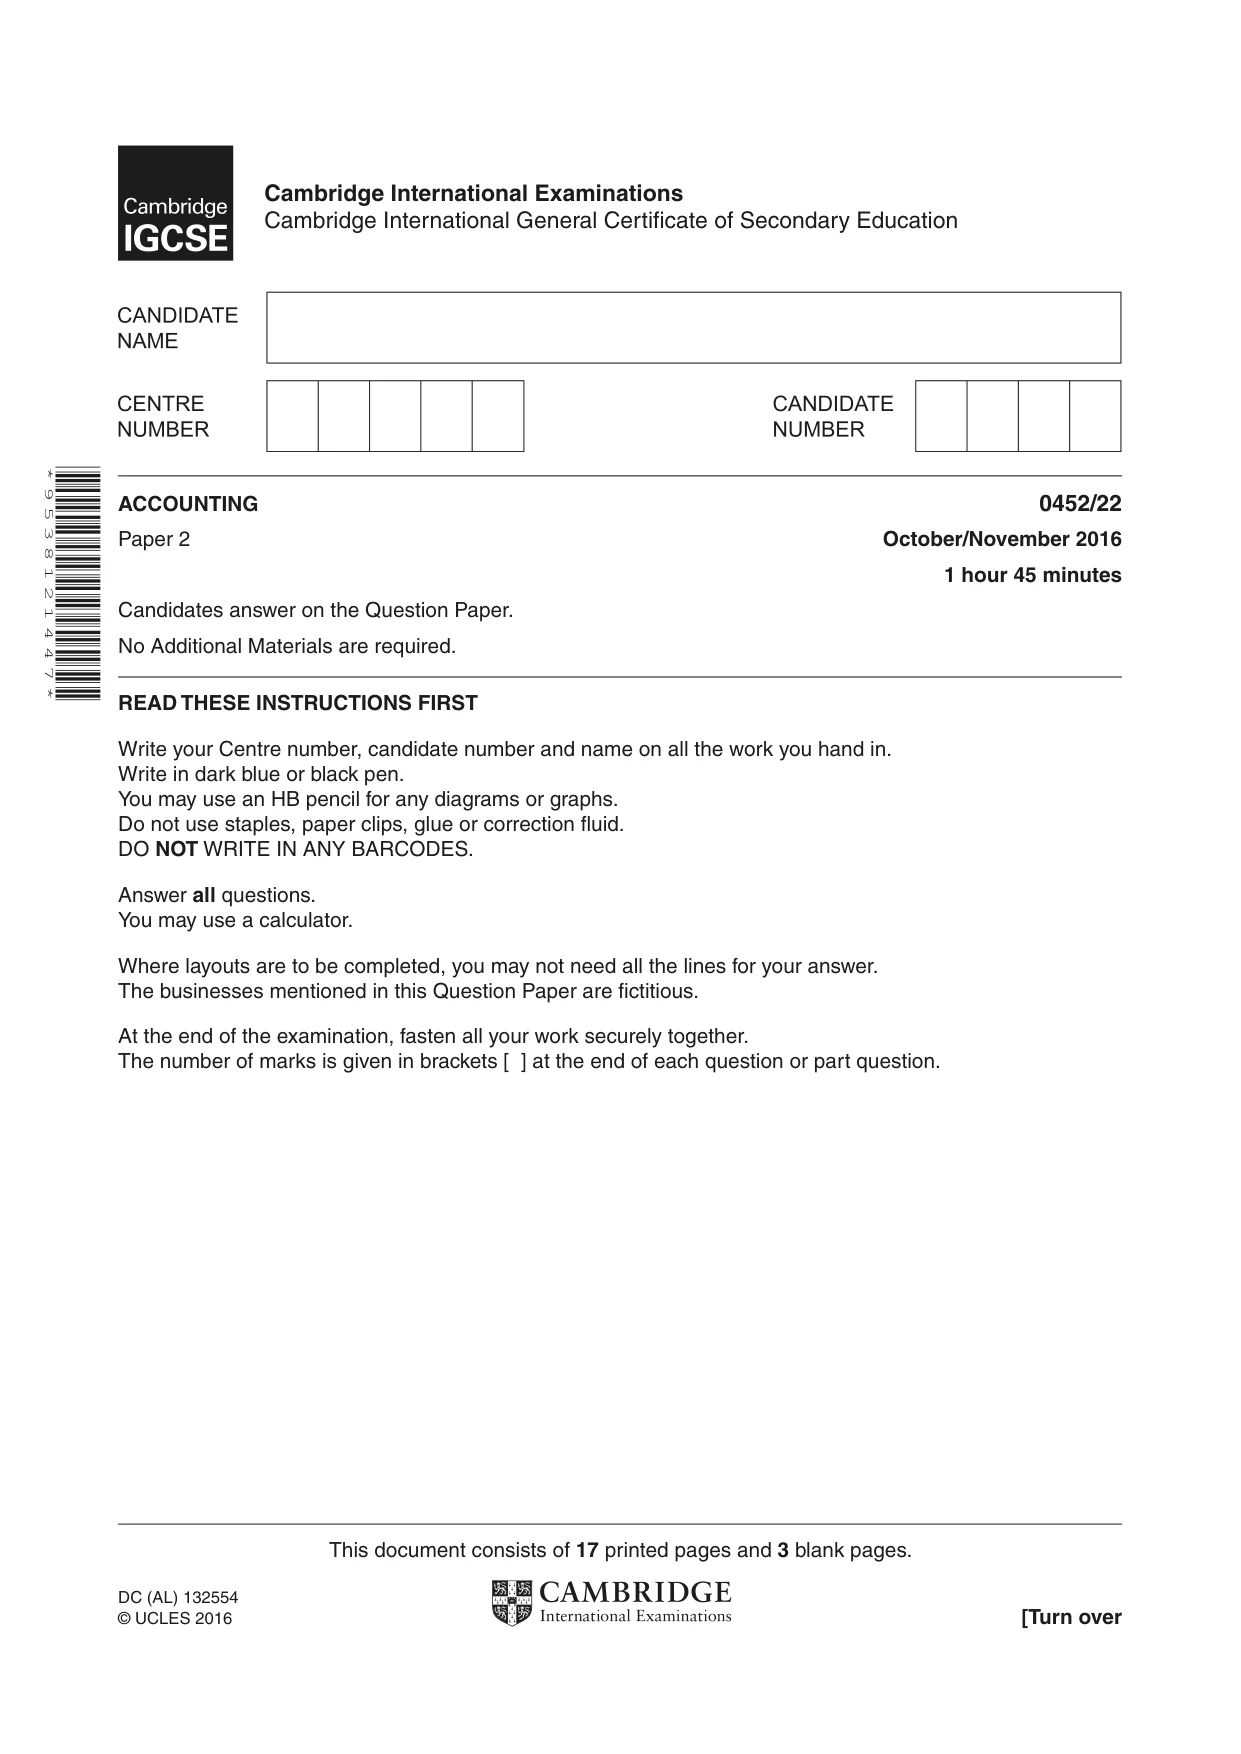
This document consists of 17 printed pages and 3 blank pages. DC (AL) 132554 © UCLES 2016 [Turn over Cambridge International Examinations Cambridge International General Certificate of Secondary Education * 9 5 3 8 1 2 1 4 4 7 * ACCOUNTING 0452/22 Paper 2 October/November 2016 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use an HB pencil for any diagrams or graphs. Do not use staples, paper clips, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
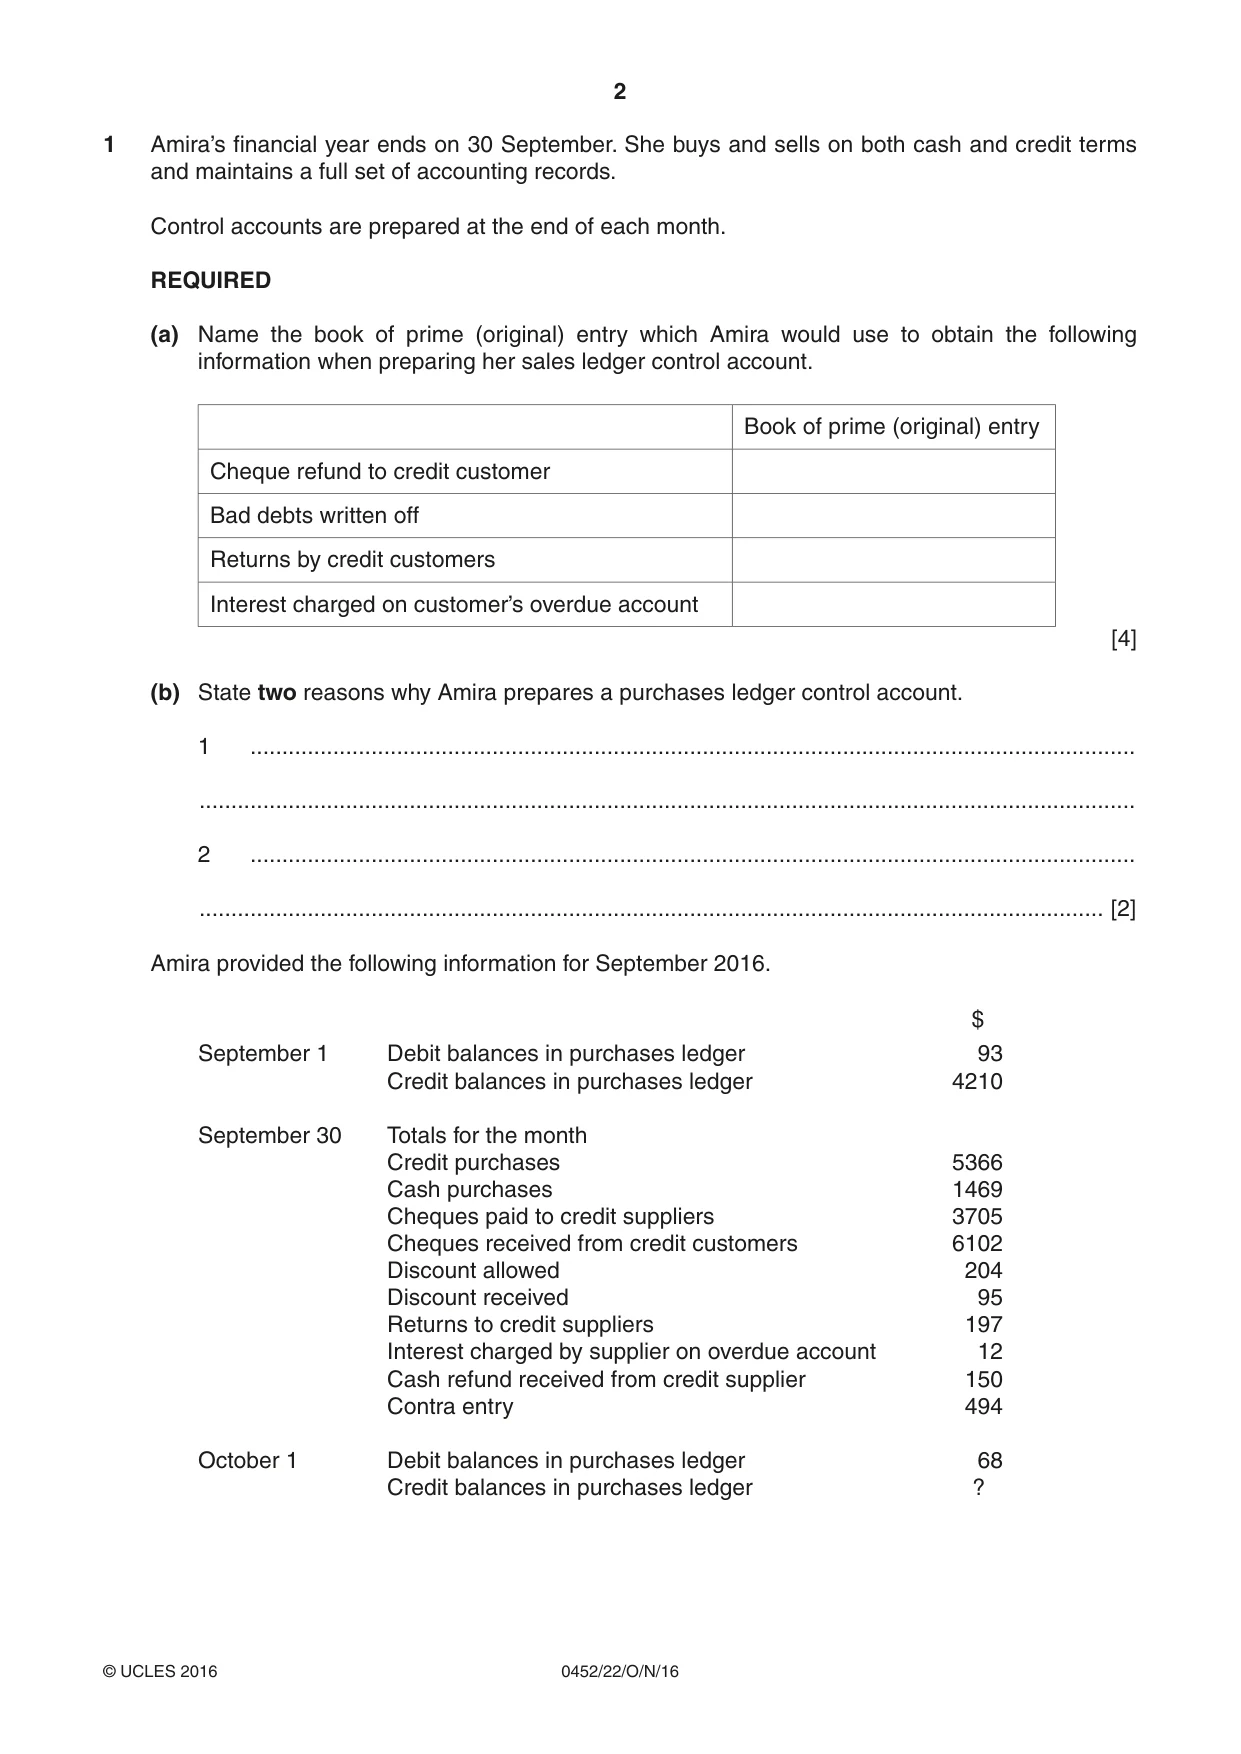
2 0452/22/O/N/16 © UCLES 2016 1 Amira’s financial year ends on 30 September. She buys and sells on both cash and credit terms and maintains a full set of accounting records. Control accounts are prepared at the end of each month. REQUIRED (a) Name the book of prime (original) entry which Amira would use to obtain the following information when preparing her sales ledger control account. Book of prime (original) entry Cheque refund to credit customer Bad debts written off Returns by credit customers Interest charged on customer’s overdue account [4] (b) State two reasons why Amira prepares a purchases ledger control account. 1 … … 2 … … [2] Amira provided the following information for September 2016. $ September 1 Debit balances in purchases ledger 93 Credit balances in purchases ledger 4210 September 30 Totals for the month Credit purchases 5366 Cash purchases 1469 Cheques paid to credit suppliers 3705 Cheques received from credit customers 6102 Discount allowed 204 Discount received 95 Returns to credit suppliers 197 Interest charged by supplier on overdue account 12 Cash refund received from credit supplier 150 Contra entry 494 October 1 Debit balances in purchases ledger 68 Credit balances in purchases ledger ?
Question paper, page 3
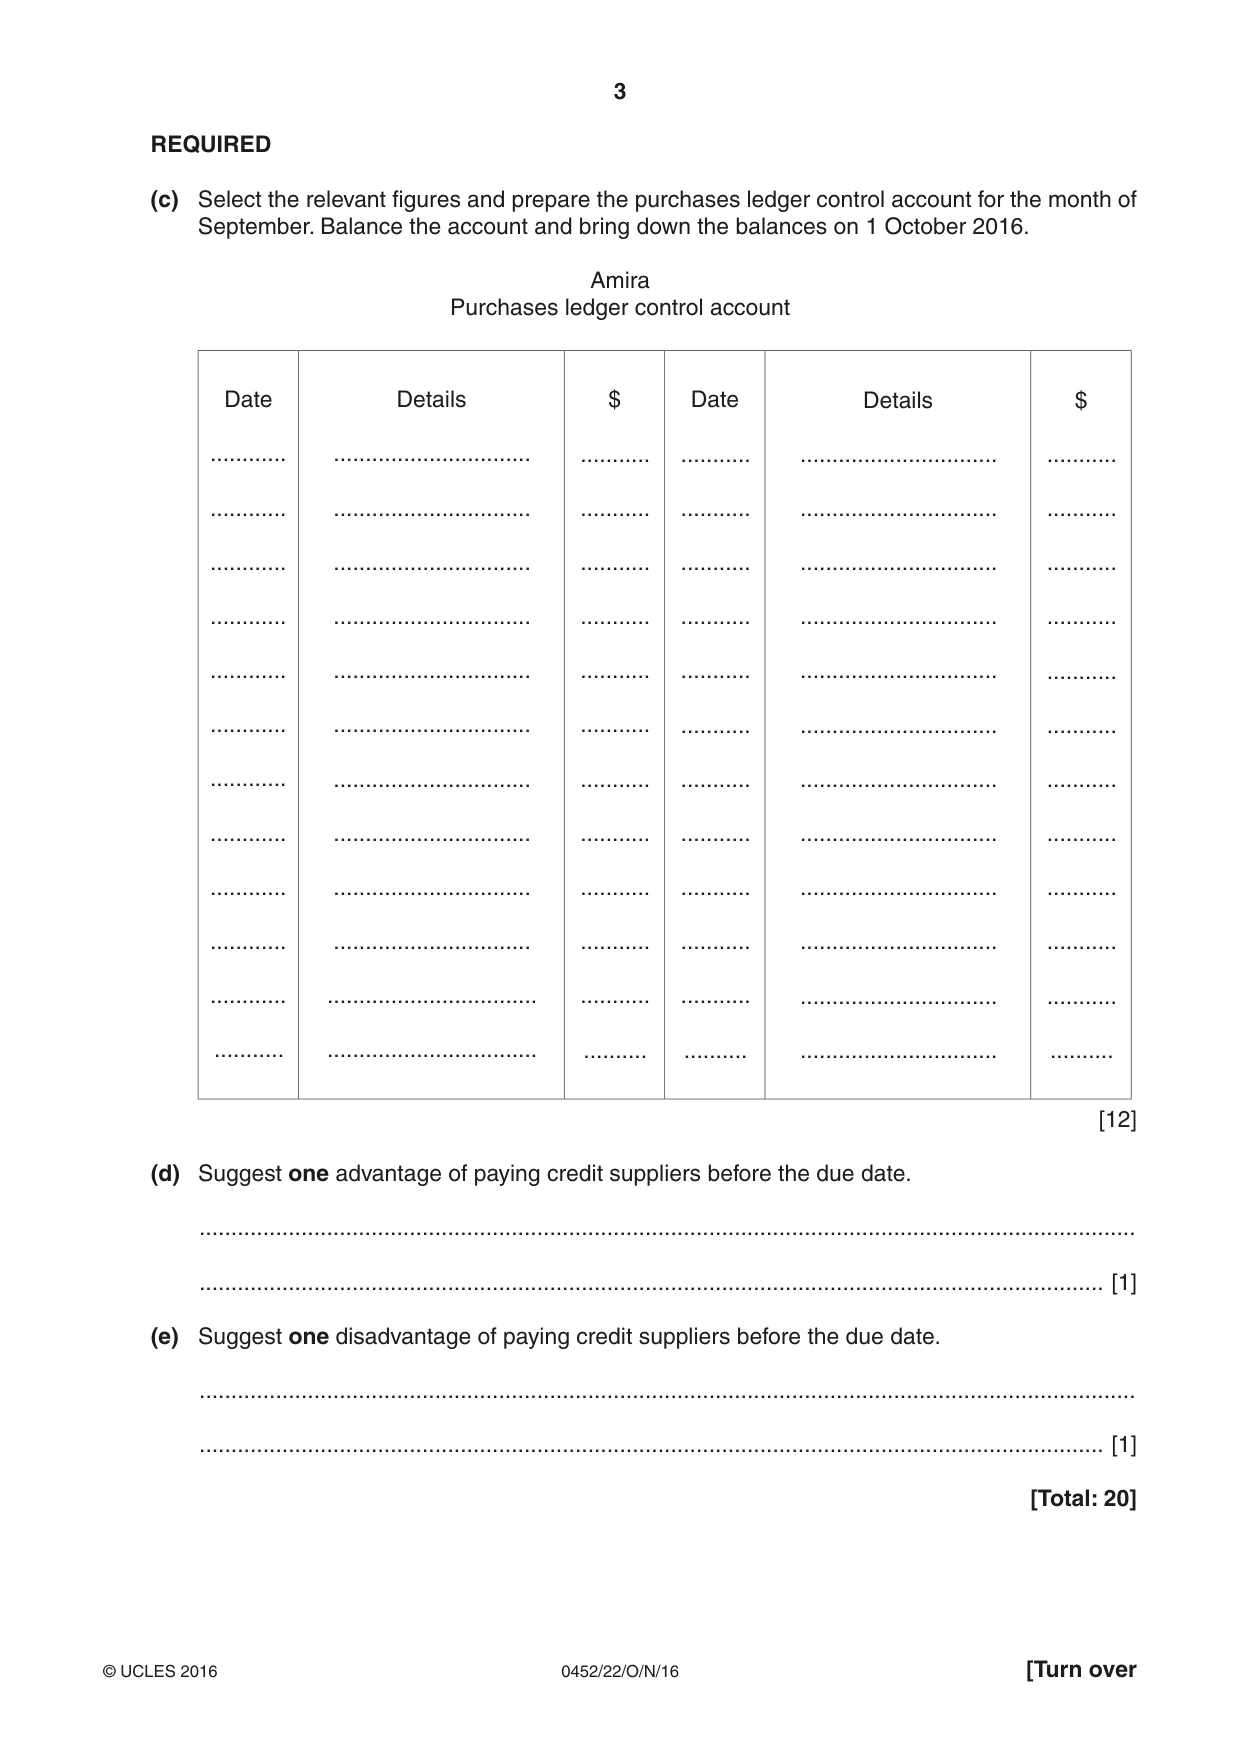
3 0452/22/O/N/16 © UCLES 2016 [Turn over REQUIRED (c) Select the relevant figures and prepare the purchases ledger control account for the month of September. Balance the account and bring down the balances on 1 October 2016. Amira Purchases ledger control account Date … … … … … … … … … … … … Details … … … … … … … … … … … … $ … … … … … … … … … … … … Date … … … … … … … … … … … … Details … … … … … … … … … … … … $ … … … … … … … … … … … … [12] (d) Suggest one advantage of paying credit suppliers before the due date. … … [1] (e) Suggest one disadvantage of paying credit suppliers before the due date. … … [1] [Total: 20]
Question paper, page 4
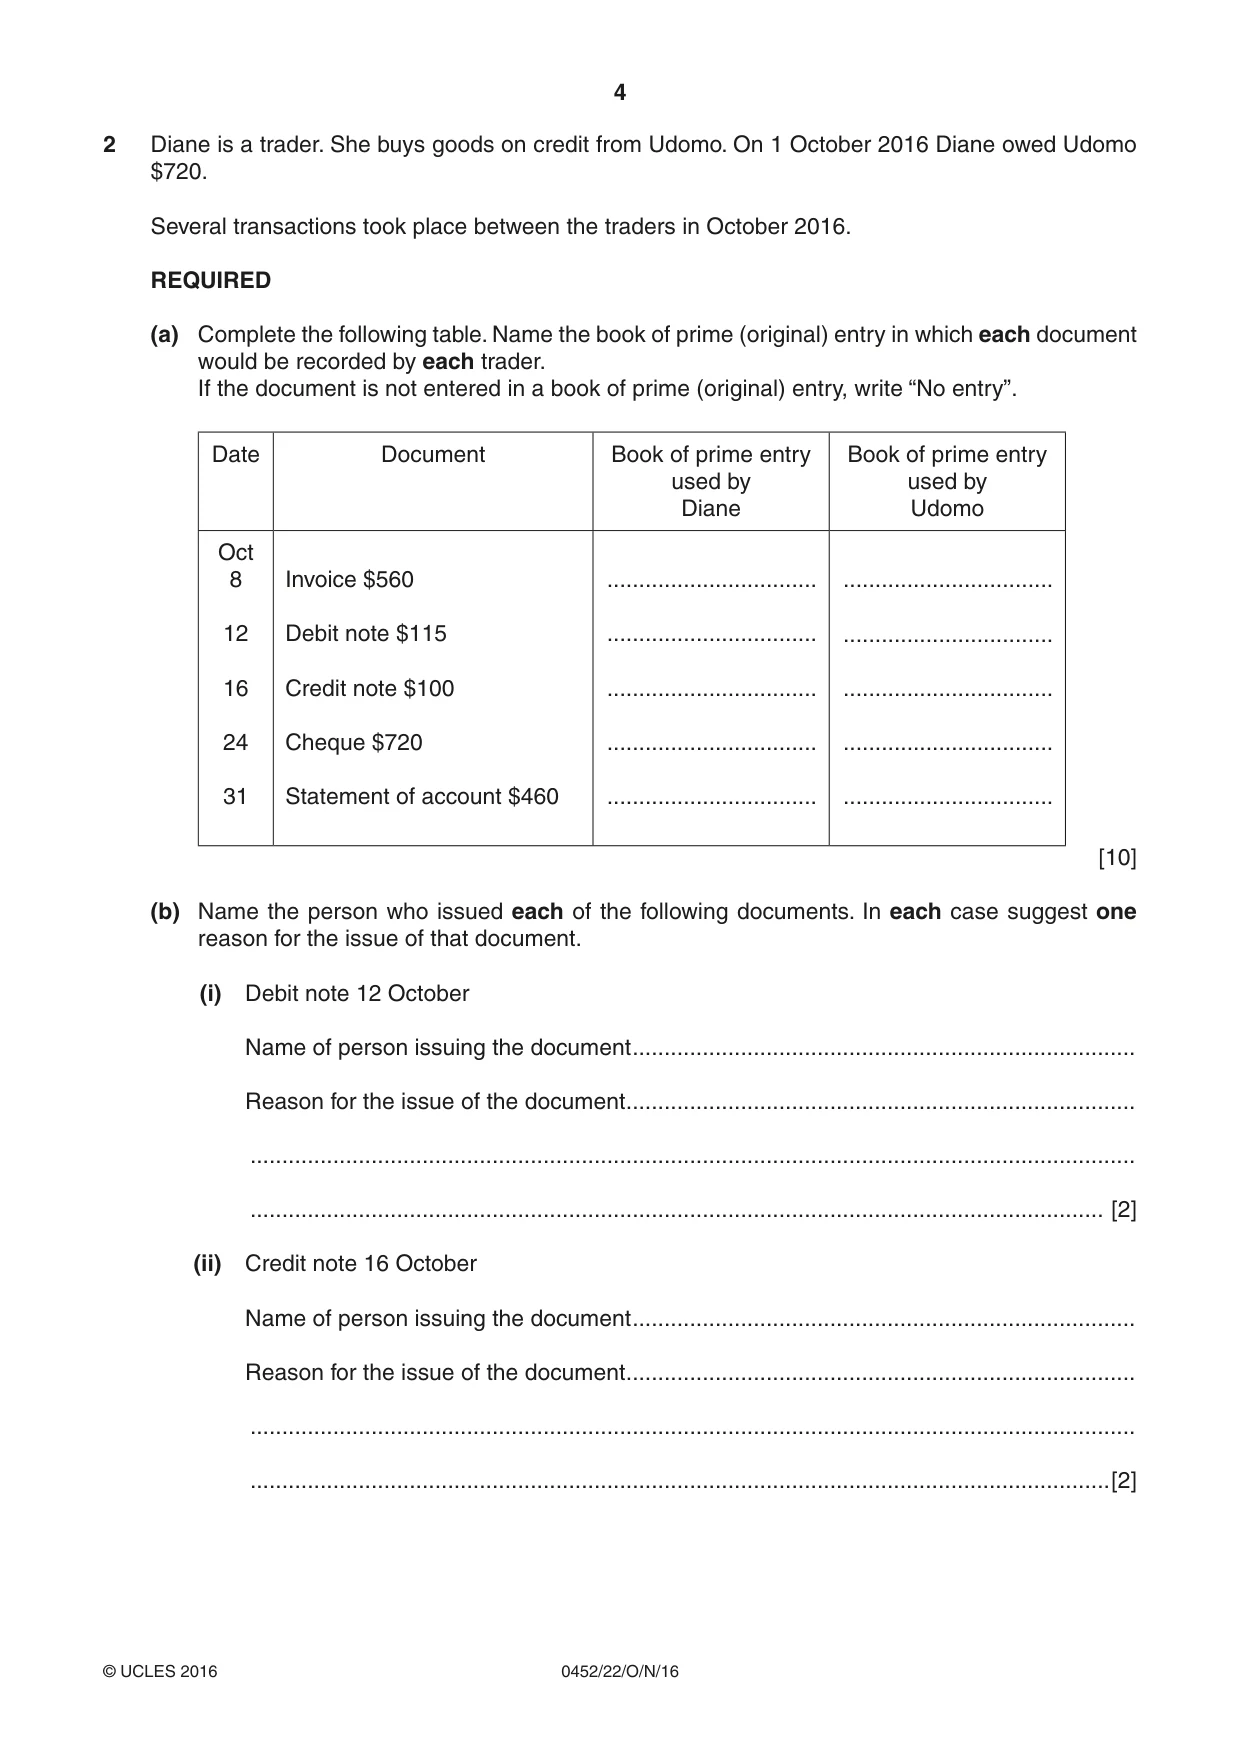
4 0452/22/O/N/16 © UCLES 2016 2 Diane is a trader. She buys goods on credit from Udomo. On 1 October 2016 Diane owed Udomo $720. Several transactions took place between the traders in October 2016. REQUIRED (a) Complete the following table. Name the book of prime (original) entry in which each document would be recorded by each trader. If the document is not entered in a book of prime (original) entry, write “No entry”. Date Document Book of prime entry used by Diane Book of prime entry used by Udomo Oct 8 12 16 24 31 Invoice $560 Debit note $115 Credit note $100 Cheque $720 Statement of account $460 … … … … … … … … … … [10] (b) Name the person who issued each of the following documents. In each case suggest one reason for the issue of that document. (i) Debit note 12 October Name of person issuing the document … Reason for the issue of the document … … … [2] (ii) Credit note 16 October Name of person issuing the document … Reason for the issue of the document … … …[2]
Question paper, page 5
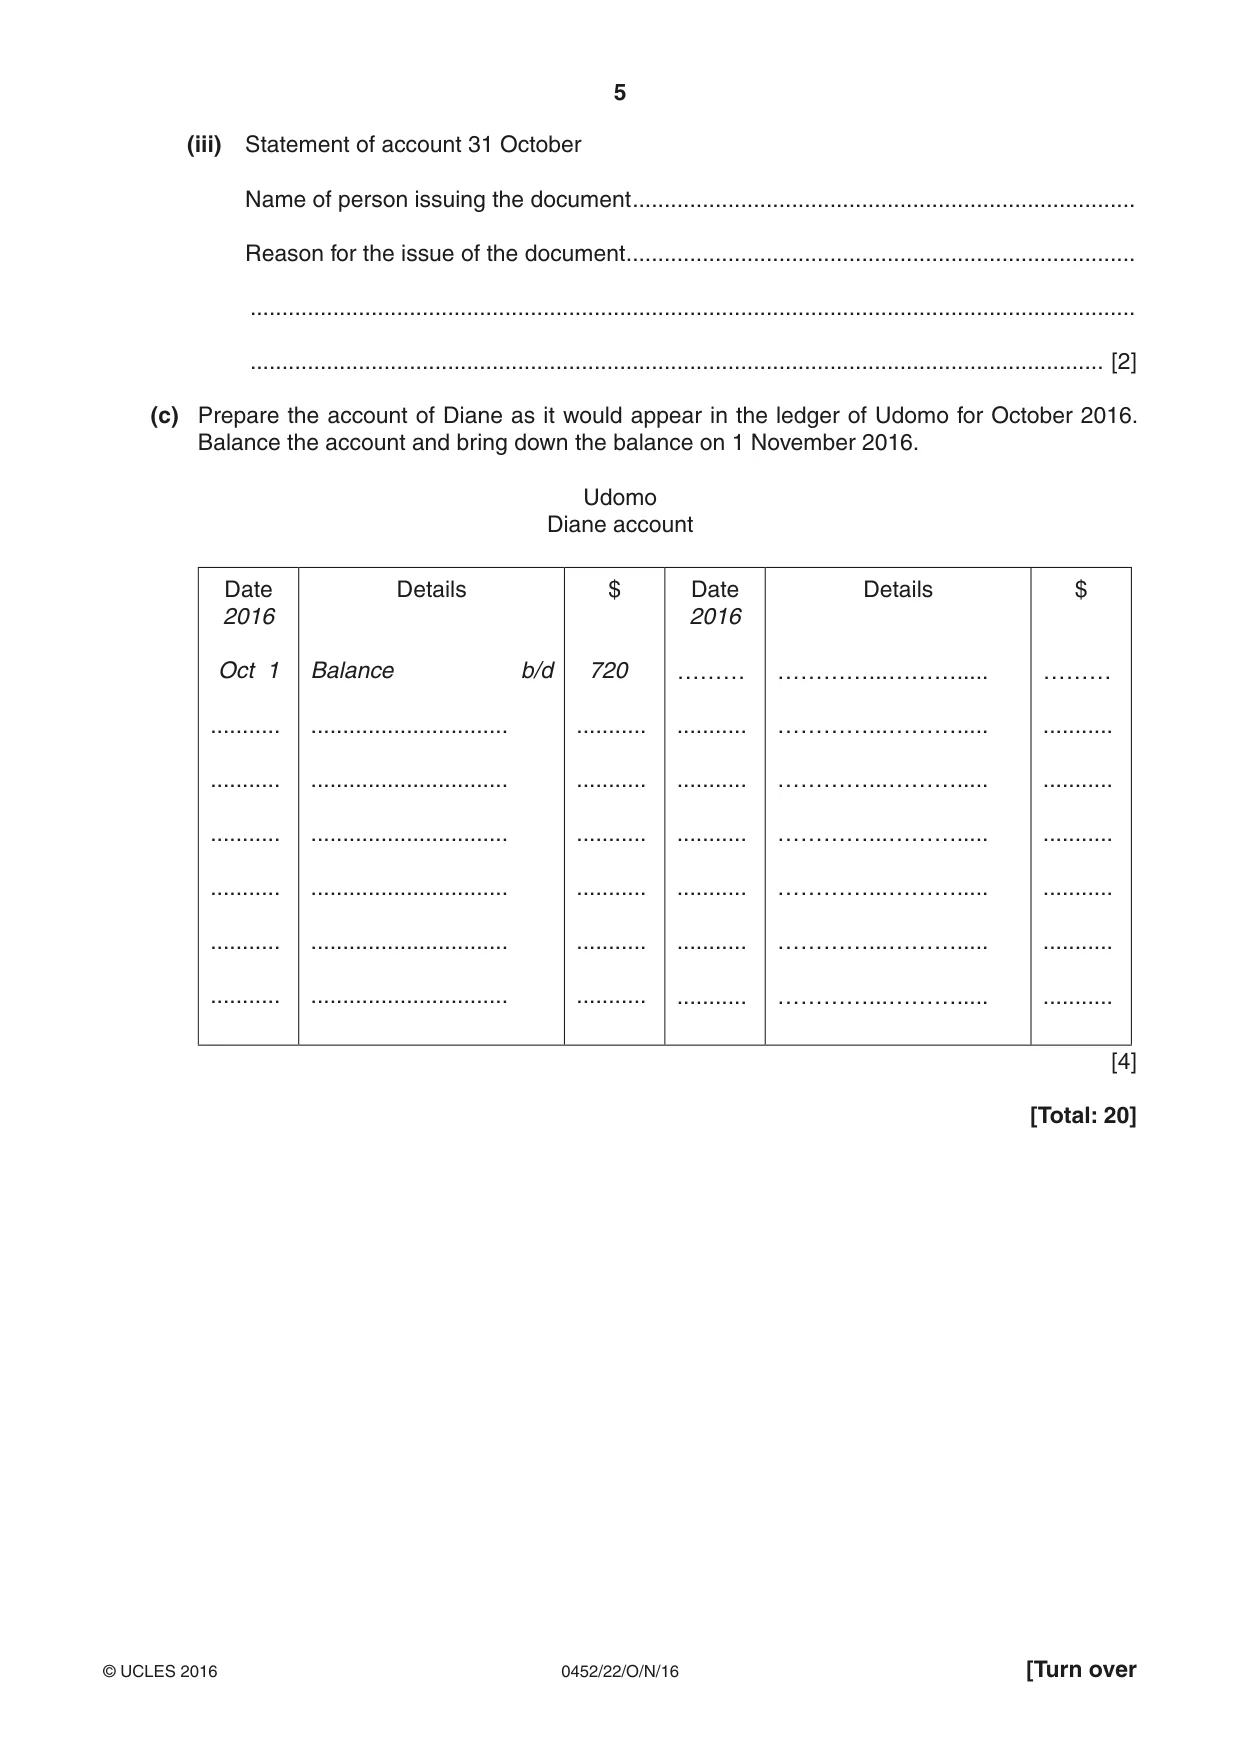
5 0452/22/O/N/16 © UCLES 2016 [Turn over (iii) Statement of account 31 October Name of person issuing the document … Reason for the issue of the document … … … [2] (c) Prepare the account of Diane as it would appear in the ledger of Udomo for October 2016. Balance the account and bring down the balance on 1 November 2016. Udomo Diane account Date 2016 Oct 1 … … … … … … Details Balance b/d … … … … … … $ 720 … … … … … … Date 2016 ……… … … … … … … Details …………...………… …………...………… …………...………… …………...………… …………...………… …………...………… …………...………… $ ……… … … … … … … [4] [Total: 20]
Question paper, page 6
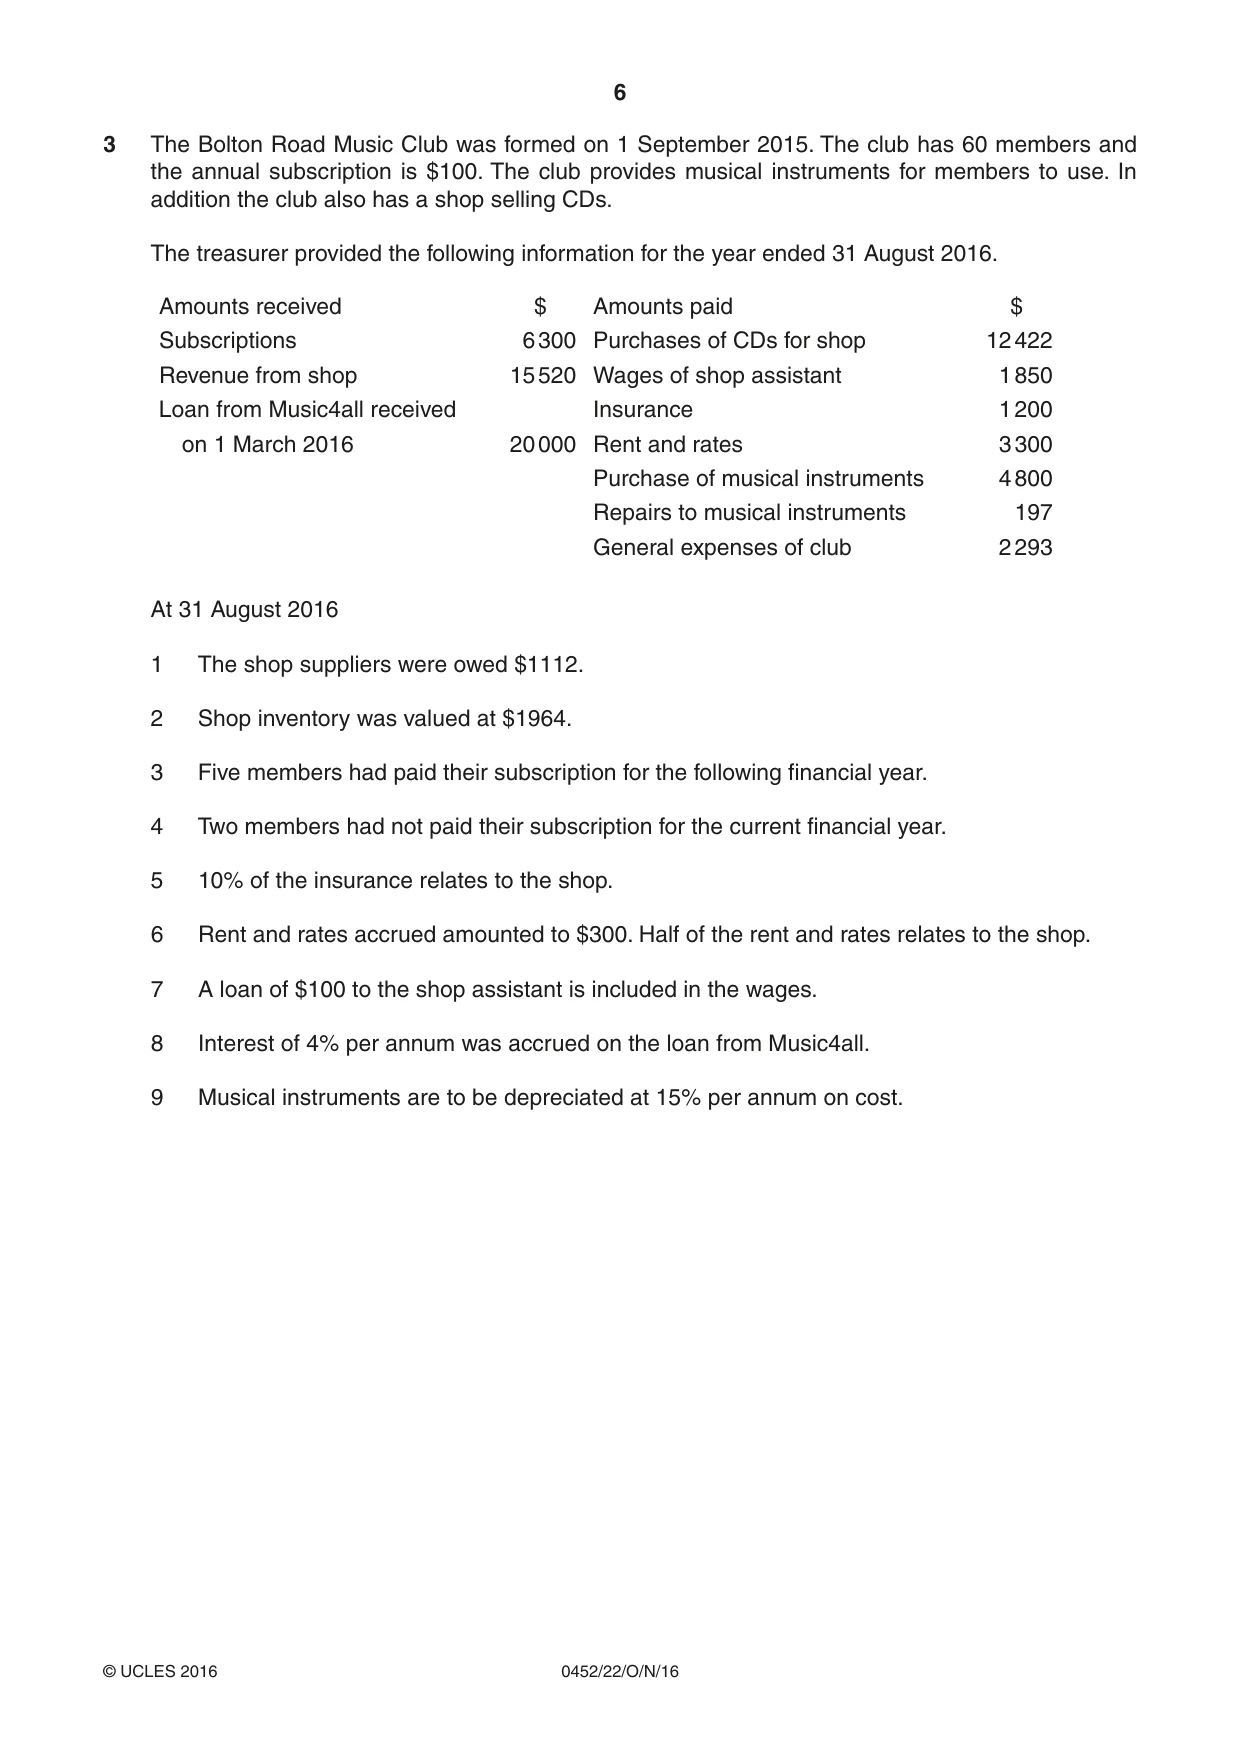
6 0452/22/O/N/16 © UCLES 2016 3 The Bolton Road Music Club was formed on 1 September 2015. The club has 60 members and the annual subscription is $100. The club provides musical instruments for members to use. In addition the club also has a shop selling CDs. The treasurer provided the following information for the year ended 31 August 2016. Amounts received $ Amounts paid $ Subscriptions 6 300 Purchases of CDs for shop 12 422 Revenue from shop 15 520 Wages of shop assistant 1 850 Loan from Music4all received Insurance 1 200 on 1 March 2016 20 000 Rent and rates 3 300 Purchase of musical instruments 4 800 Repairs to musical instruments 197 General expenses of club 2 293 At 31 August 2016 1 The shop suppliers were owed $1112. 2 Shop inventory was valued at $1964. 3 Five members had paid their subscription for the following financial year. 4 Two members had not paid their subscription for the current financial year. 5 10% of the insurance relates to the shop. 6 Rent and rates accrued amounted to $300. Half of the rent and rates relates to the shop. 7 A loan of $100 to the shop assistant is included in the wages. 8 Interest of 4% per annum was accrued on the loan from Music4all. 9 Musical instruments are to be depreciated at 15% per annum on cost.
Question paper, page 7
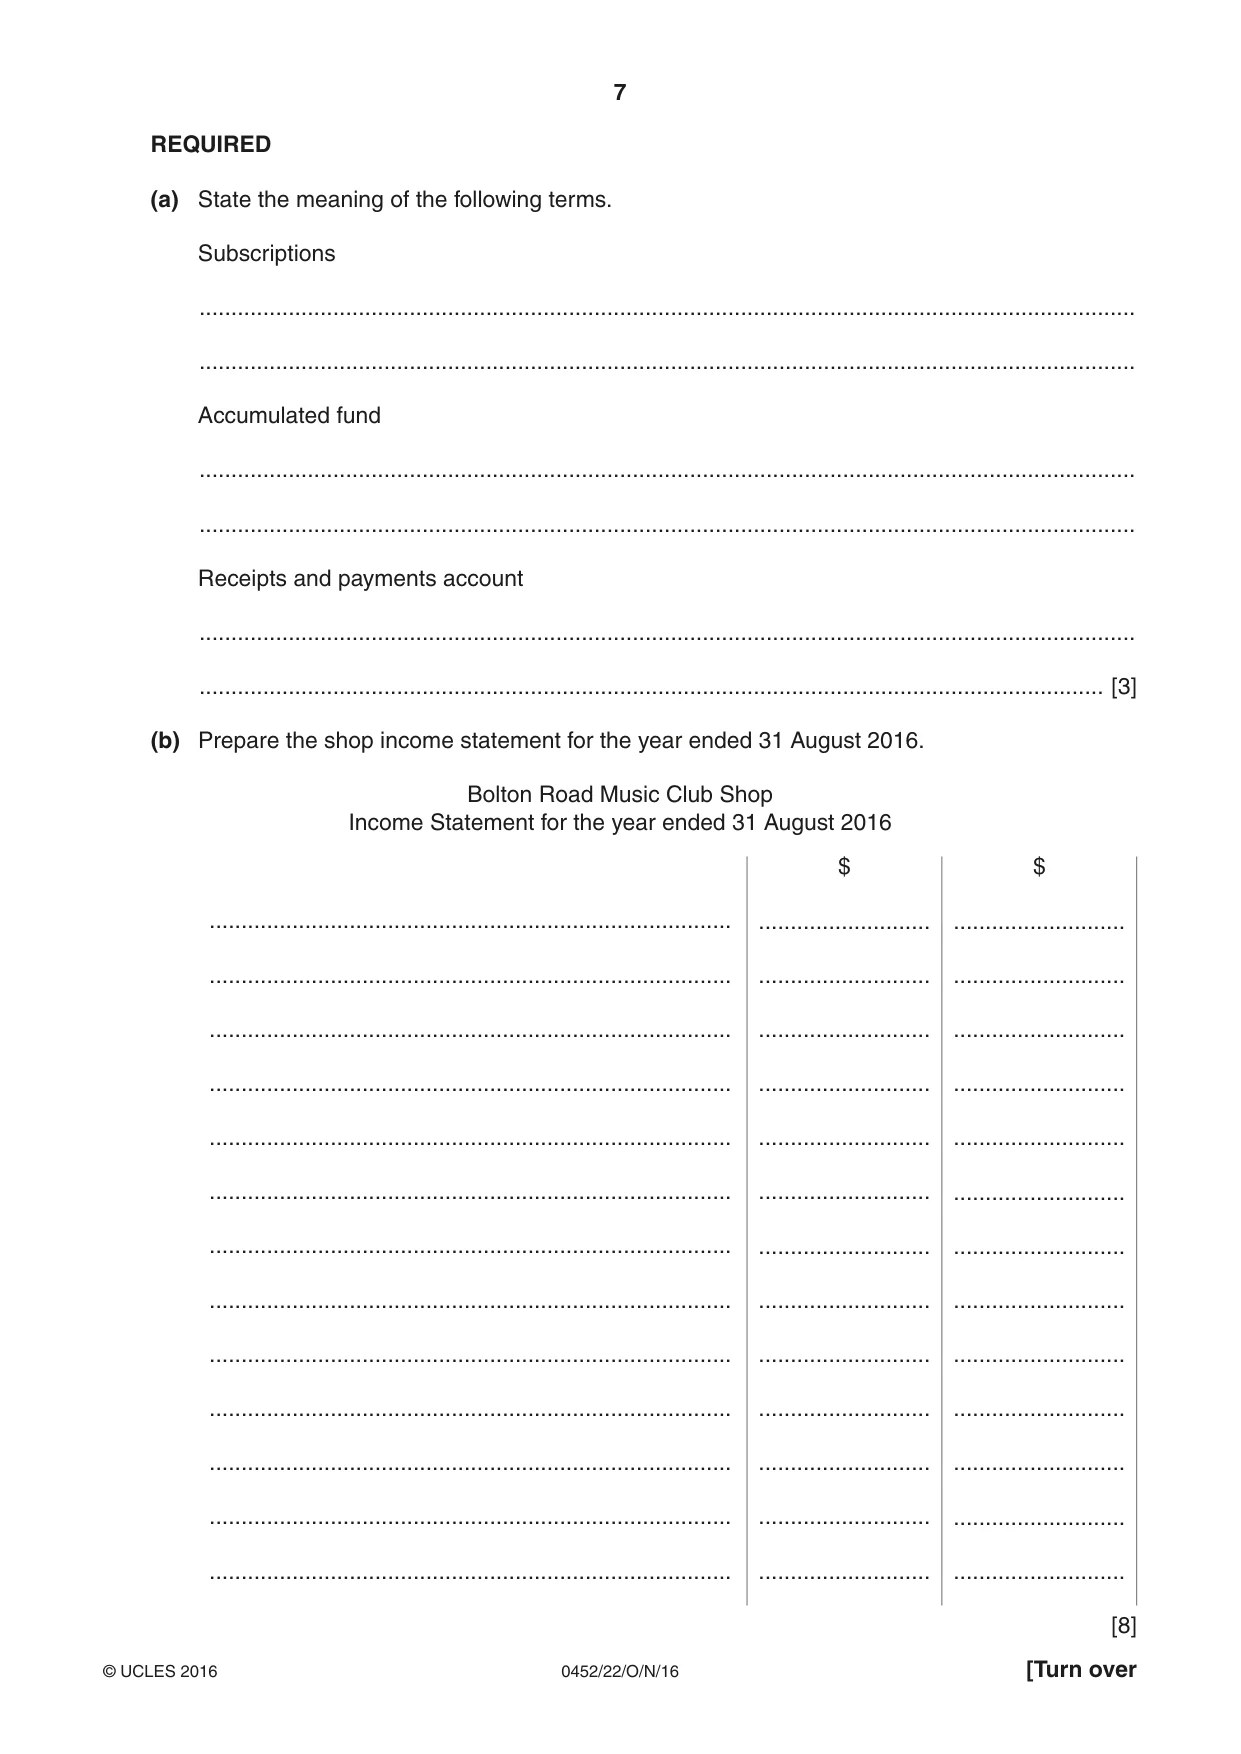
7 0452/22/O/N/16 © UCLES 2016 [Turn over REQUIRED (a) State the meaning of the following terms. Subscriptions … … Accumulated fund … … Receipts and payments account … … [3] (b) Prepare the shop income statement for the year ended 31 August 2016. Bolton Road Music Club Shop Income Statement for the year ended 31 August 2016 … … … … … … … … … … … … … $ … … … … … … … … … … … … … $ … … … … … … … … … … … … … [8]
Question paper, page 8
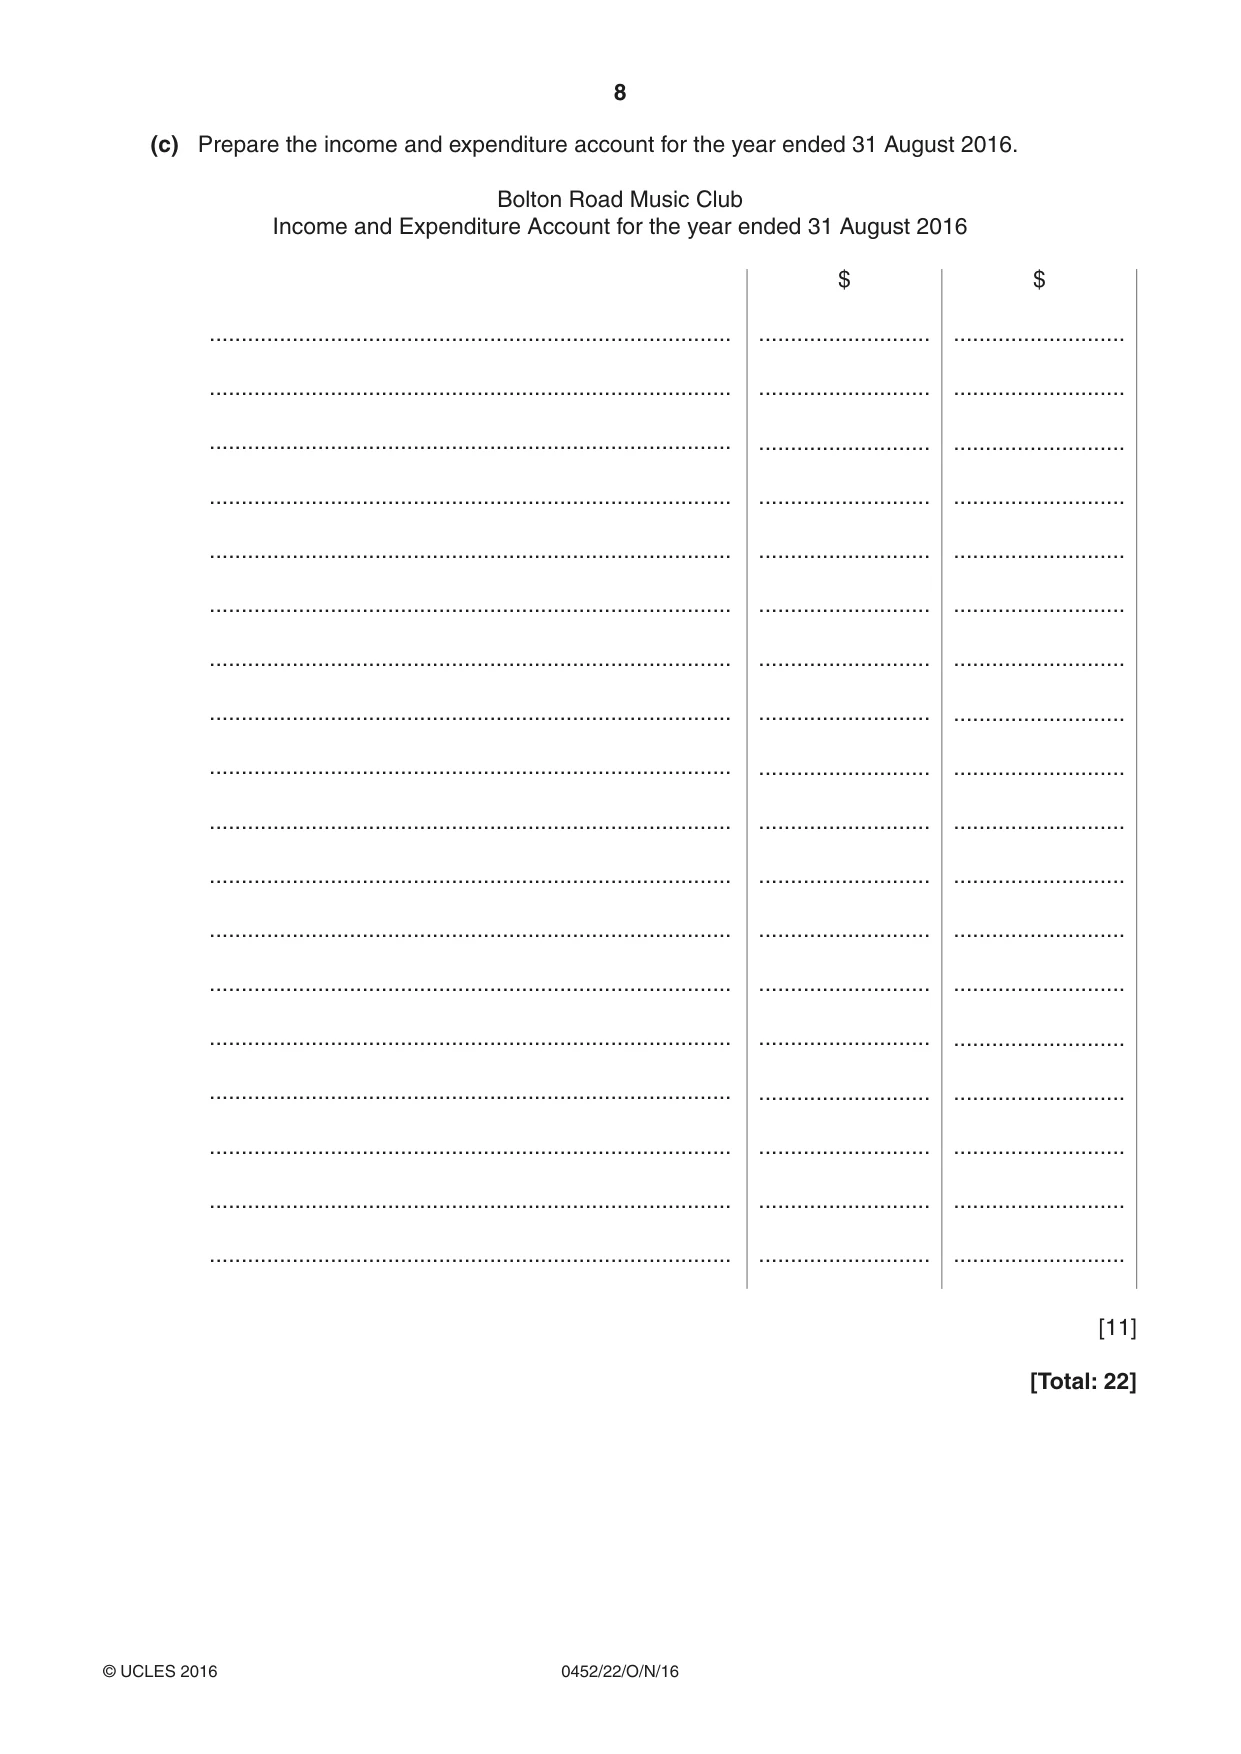
8 0452/22/O/N/16 © UCLES 2016 (c) Prepare the income and expenditure account for the year ended 31 August 2016. Bolton Road Music Club Income and Expenditure Account for the year ended 31 August 2016 … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … [11] [Total: 22]
Question paper, page 9
9 0452/22/O/N/16 © UCLES 2016 [Turn over Question 4 is on the next page.
Question paper, page 10
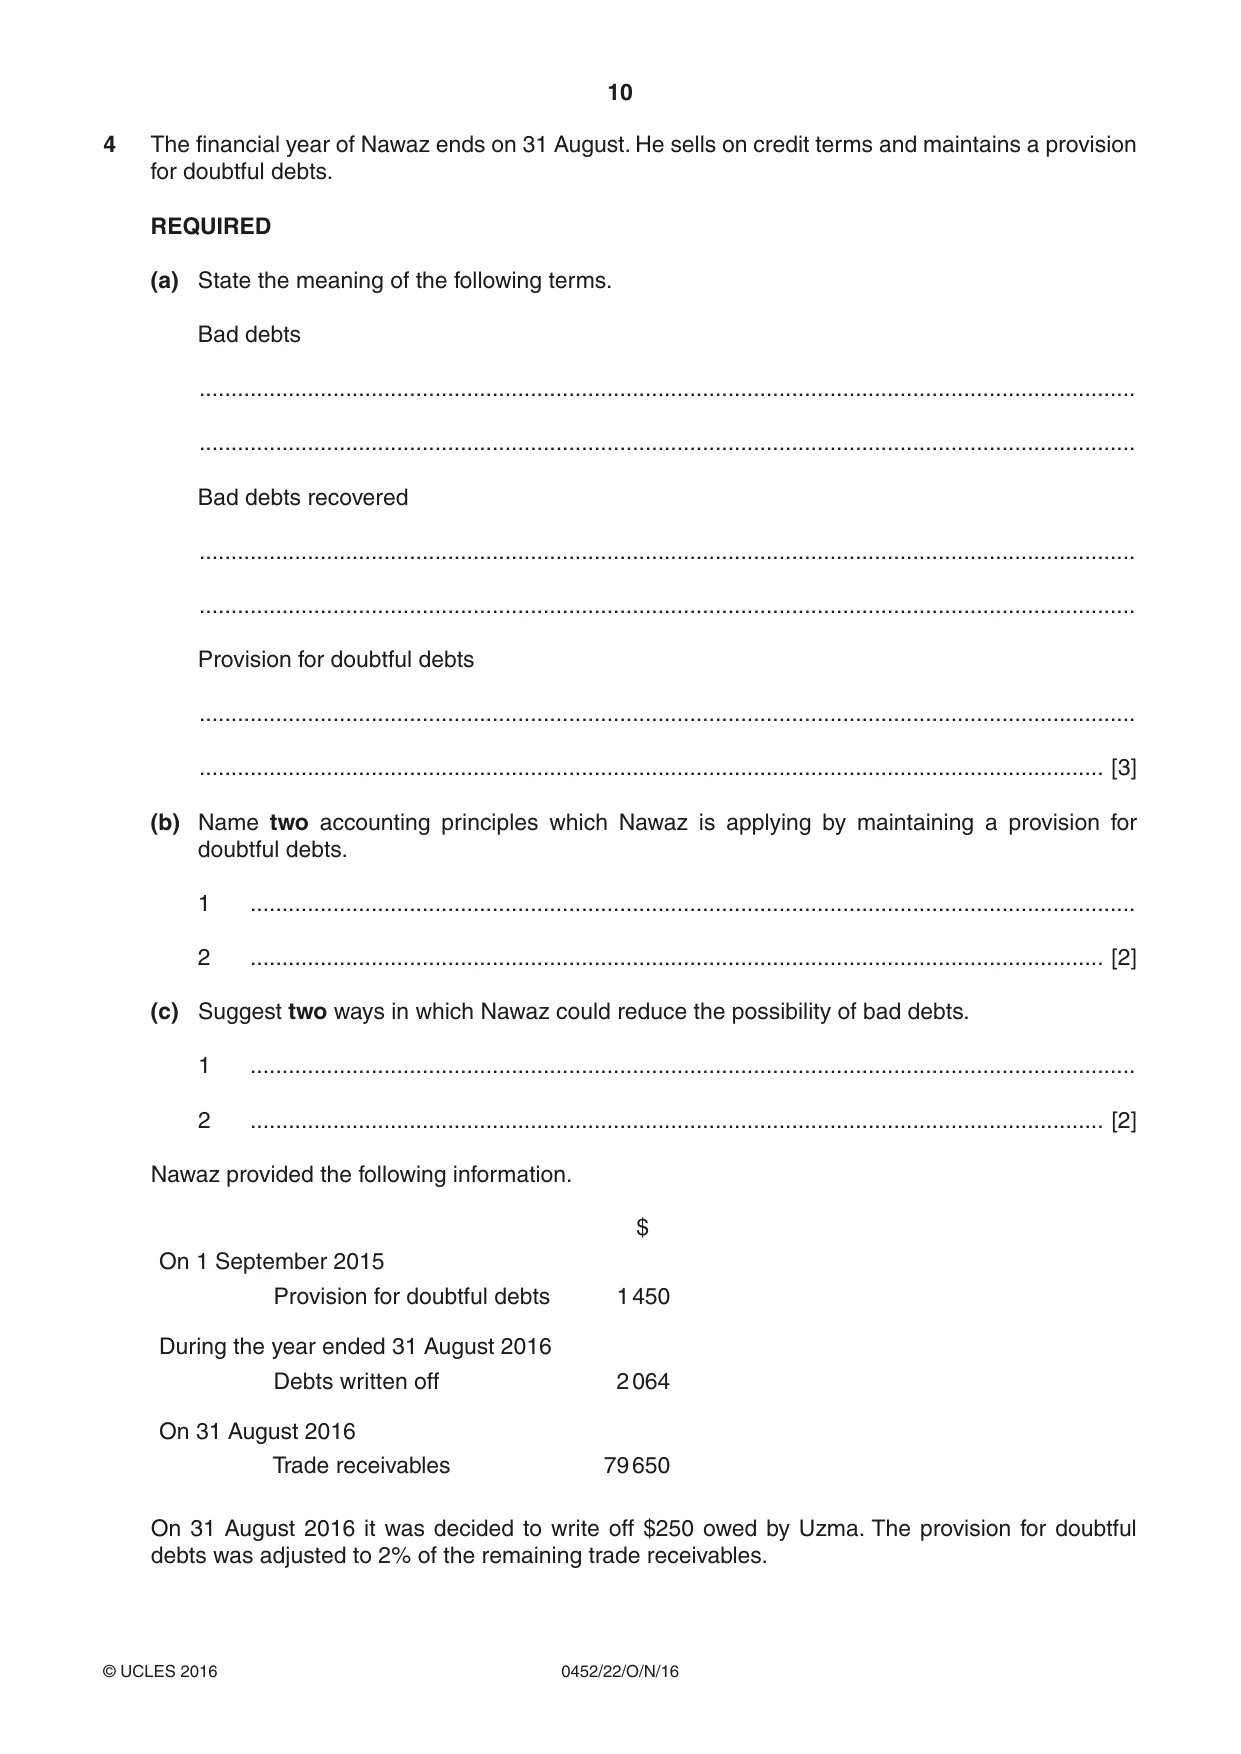
10 0452/22/O/N/16 © UCLES 2016 4 The financial year of Nawaz ends on 31 August. He sells on credit terms and maintains a provision for doubtful debts. REQUIRED (a) State the meaning of the following terms. Bad debts … … Bad debts recovered … … Provision for doubtful debts … … [3] (b) Name two accounting principles which Nawaz is applying by maintaining a provision for doubtful debts. 1 … 2 … [2] (c) Suggest two ways in which Nawaz could reduce the possibility of bad debts. 1 … 2 … [2] Nawaz provided the following information. $ On 1 September 2015 Provision for doubtful debts 1 450 During the year ended 31 August 2016 Debts written off 2 064 On 31 August 2016 Trade receivables 79 650 On 31 August 2016 it was decided to write off $250 owed by Uzma. The provision for doubtful debts was adjusted to 2% of the remaining trade receivables.
Question paper, page 11
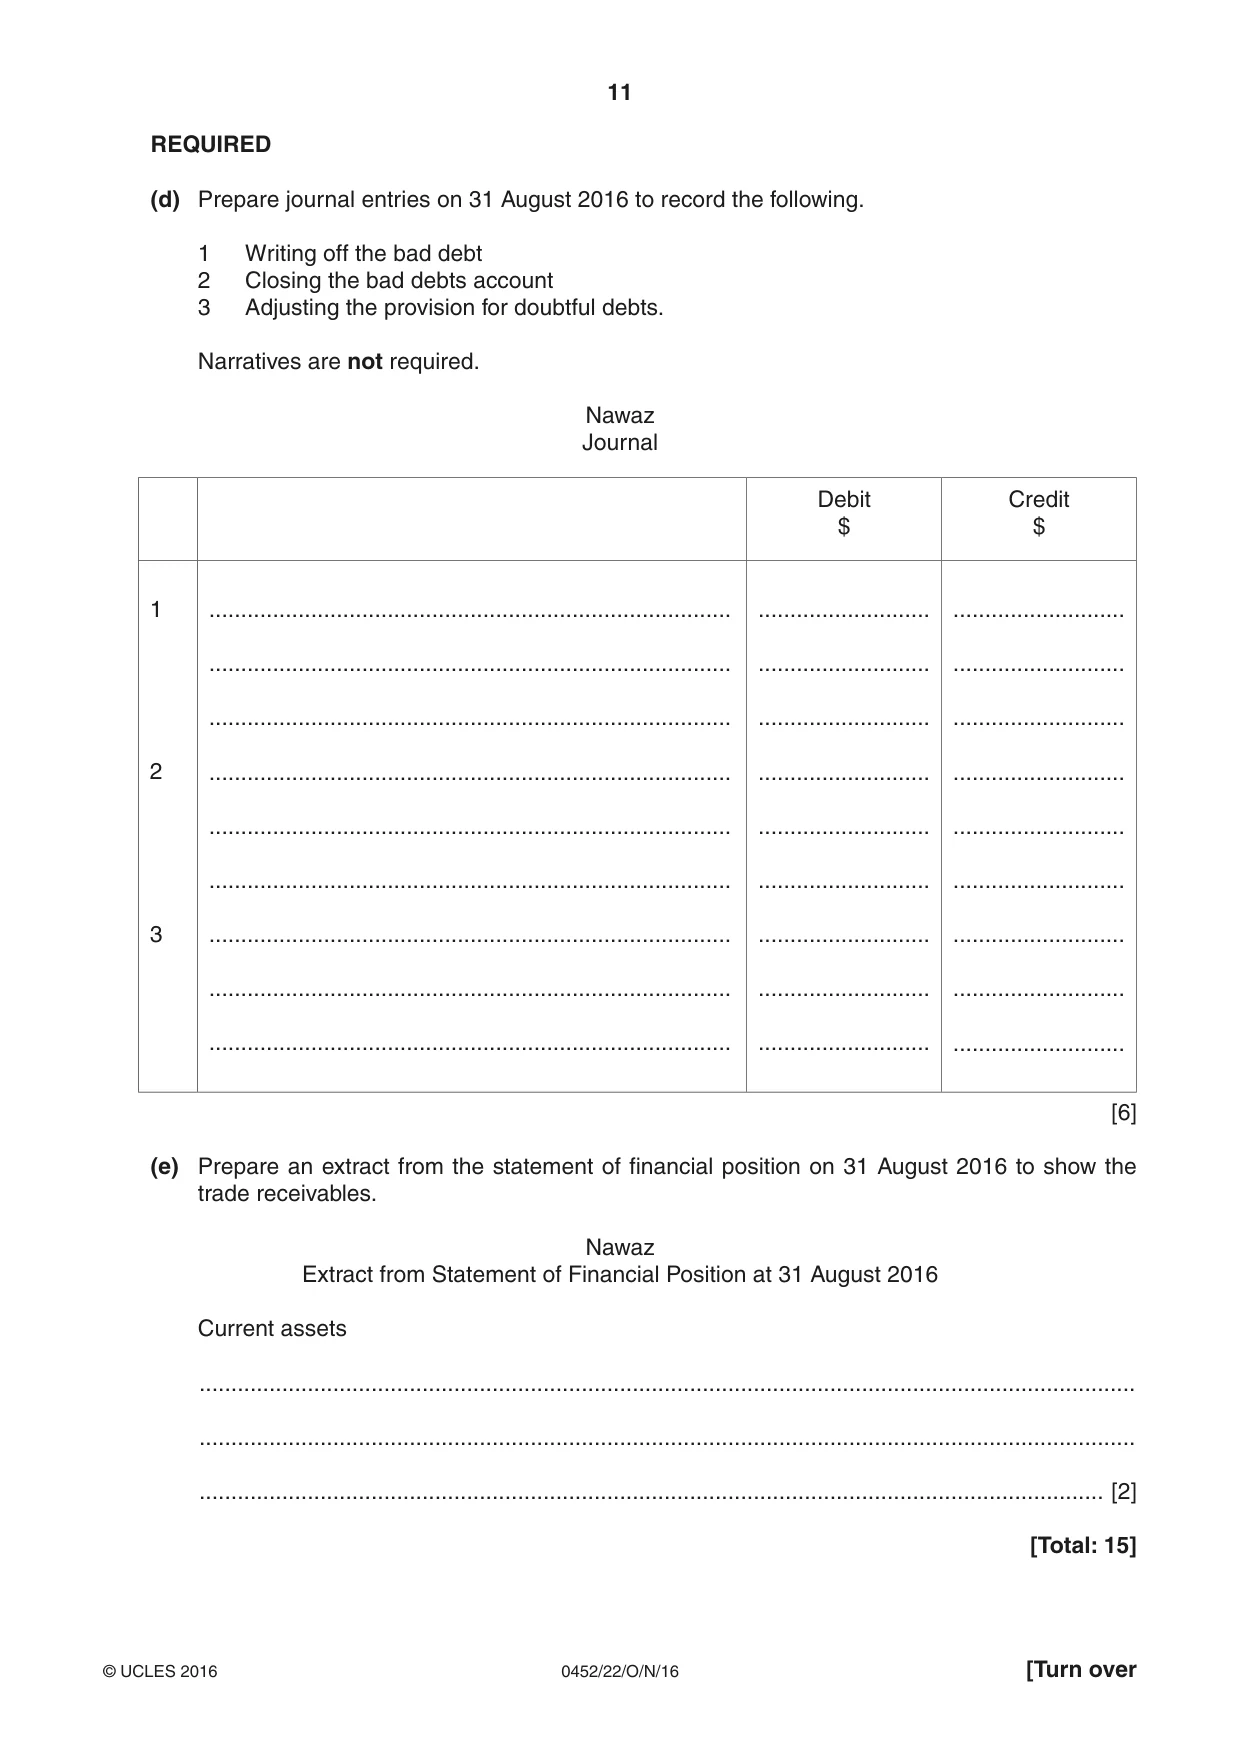
11 0452/22/O/N/16 © UCLES 2016 [Turn over REQUIRED (d) Prepare journal entries on 31 August 2016 to record the following. 1 Writing off the bad debt 2 Closing the bad debts account 3 Adjusting the provision for doubtful debts. Narratives are not required. Nawaz Journal Debit $ Credit $ 1 2 3 … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] (e) Prepare an extract from the statement of financial position on 31 August 2016 to show the trade receivables. Nawaz Extract from Statement of Financial Position at 31 August 2016 Current assets … … … [2] [Total: 15]
Question paper, page 12
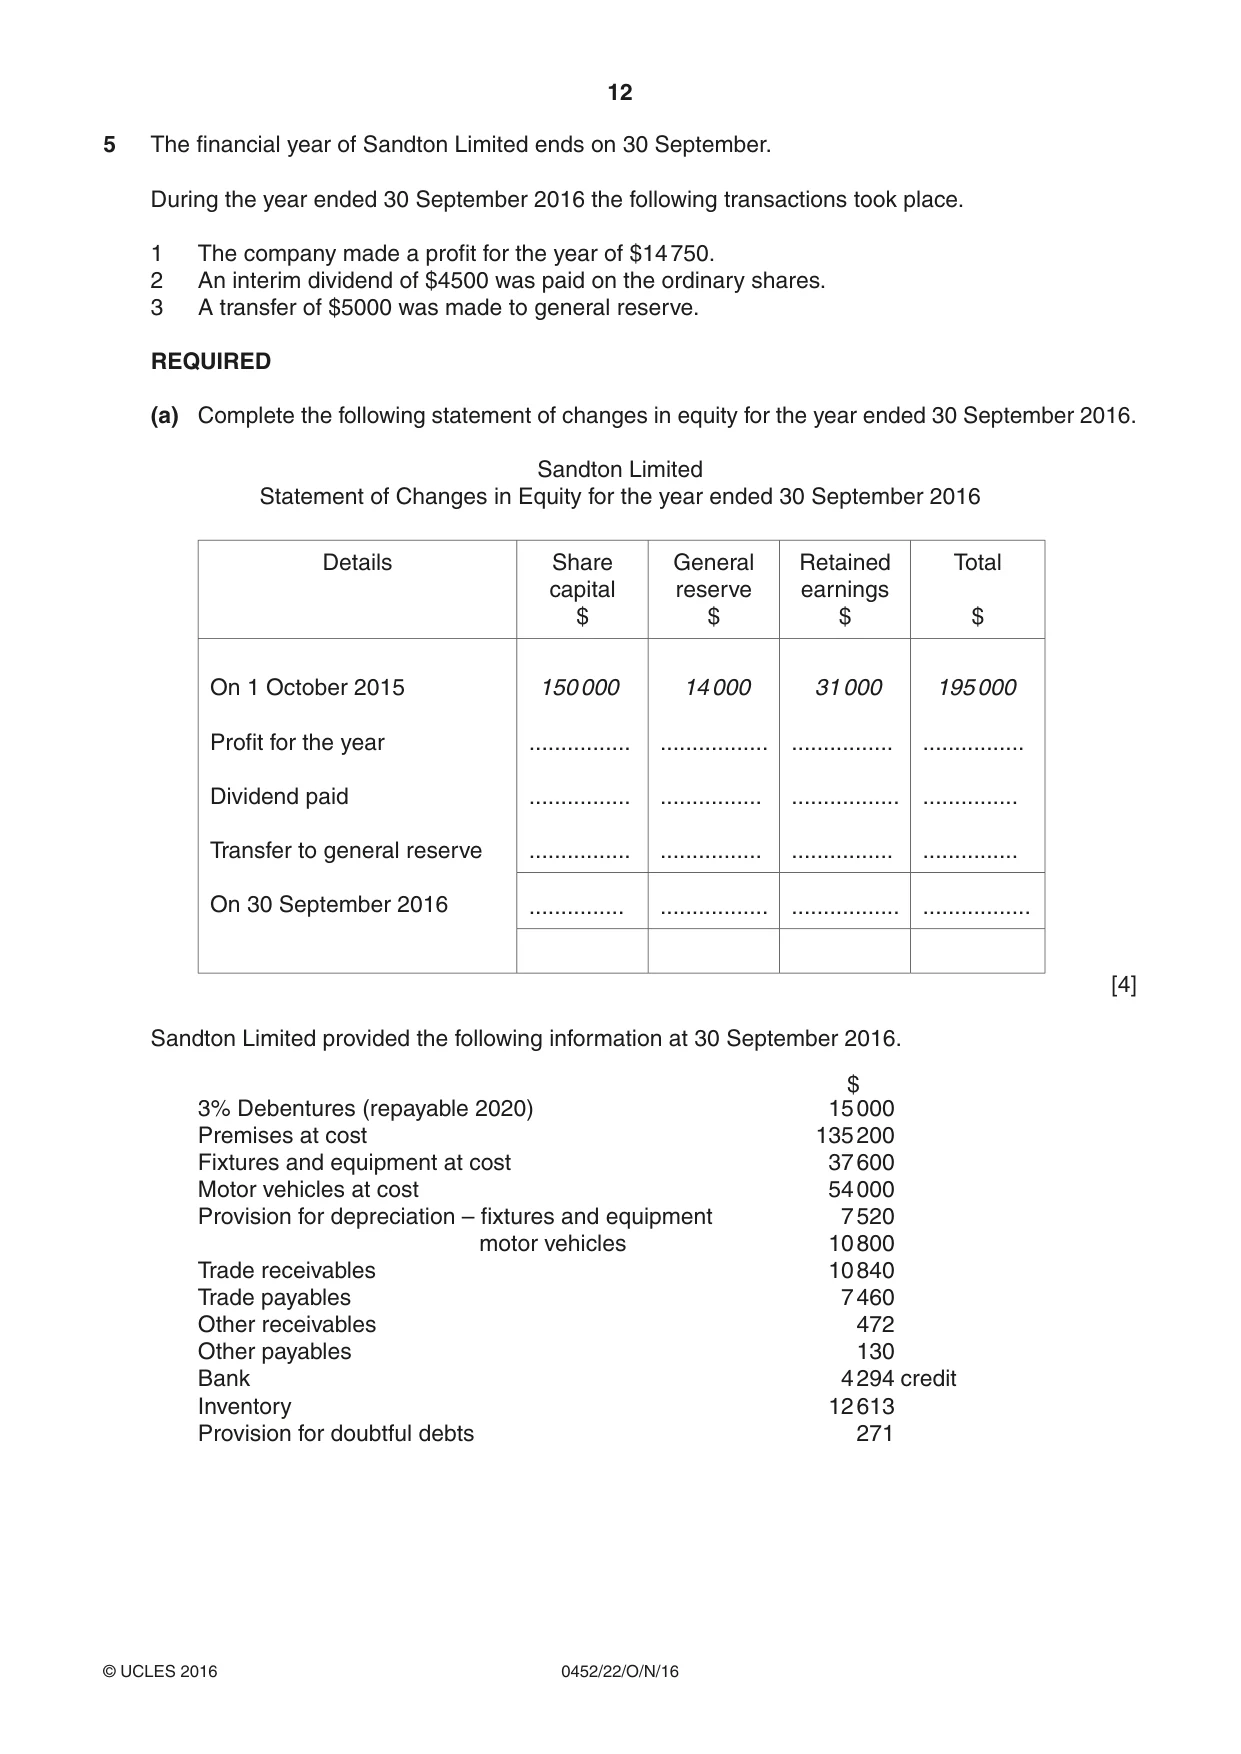
12 0452/22/O/N/16 © UCLES 2016 5 The financial year of Sandton Limited ends on 30 September. During the year ended 30 September 2016 the following transactions took place. 1 The company made a profit for the year of $14 750. 2 An interim dividend of $4500 was paid on the ordinary shares. 3 A transfer of $5000 was made to general reserve. REQUIRED (a) Complete the following statement of changes in equity for the year ended 30 September 2016. Sandton Limited Statement of Changes in Equity for the year ended 30 September 2016 Details Share capital $ General reserve $ Retained earnings $ Total $ On 1 October 2015 Profit for the year Dividend paid Transfer to general reserve On 30 September 2016 150 000 … … … 14 000 … … … 31 000 … … … 195 000 … … … … … … … [4] Sandton Limited provided the following information at 30 September 2016. $ 3% Debentures (repayable 2020) 15 000 Premises at cost 135 200 Fixtures and equipment at cost 37 600 Motor vehicles at cost 54 000 Provision for depreciation – fixtures and equipment 7 520 motor vehicles 10 800 Trade receivables 10 840 Trade payables 7 460 Other receivables 472 Other payables 130 Bank 4 294 credit Inventory 12 613 Provision for doubtful debts 271
Question paper, page 13
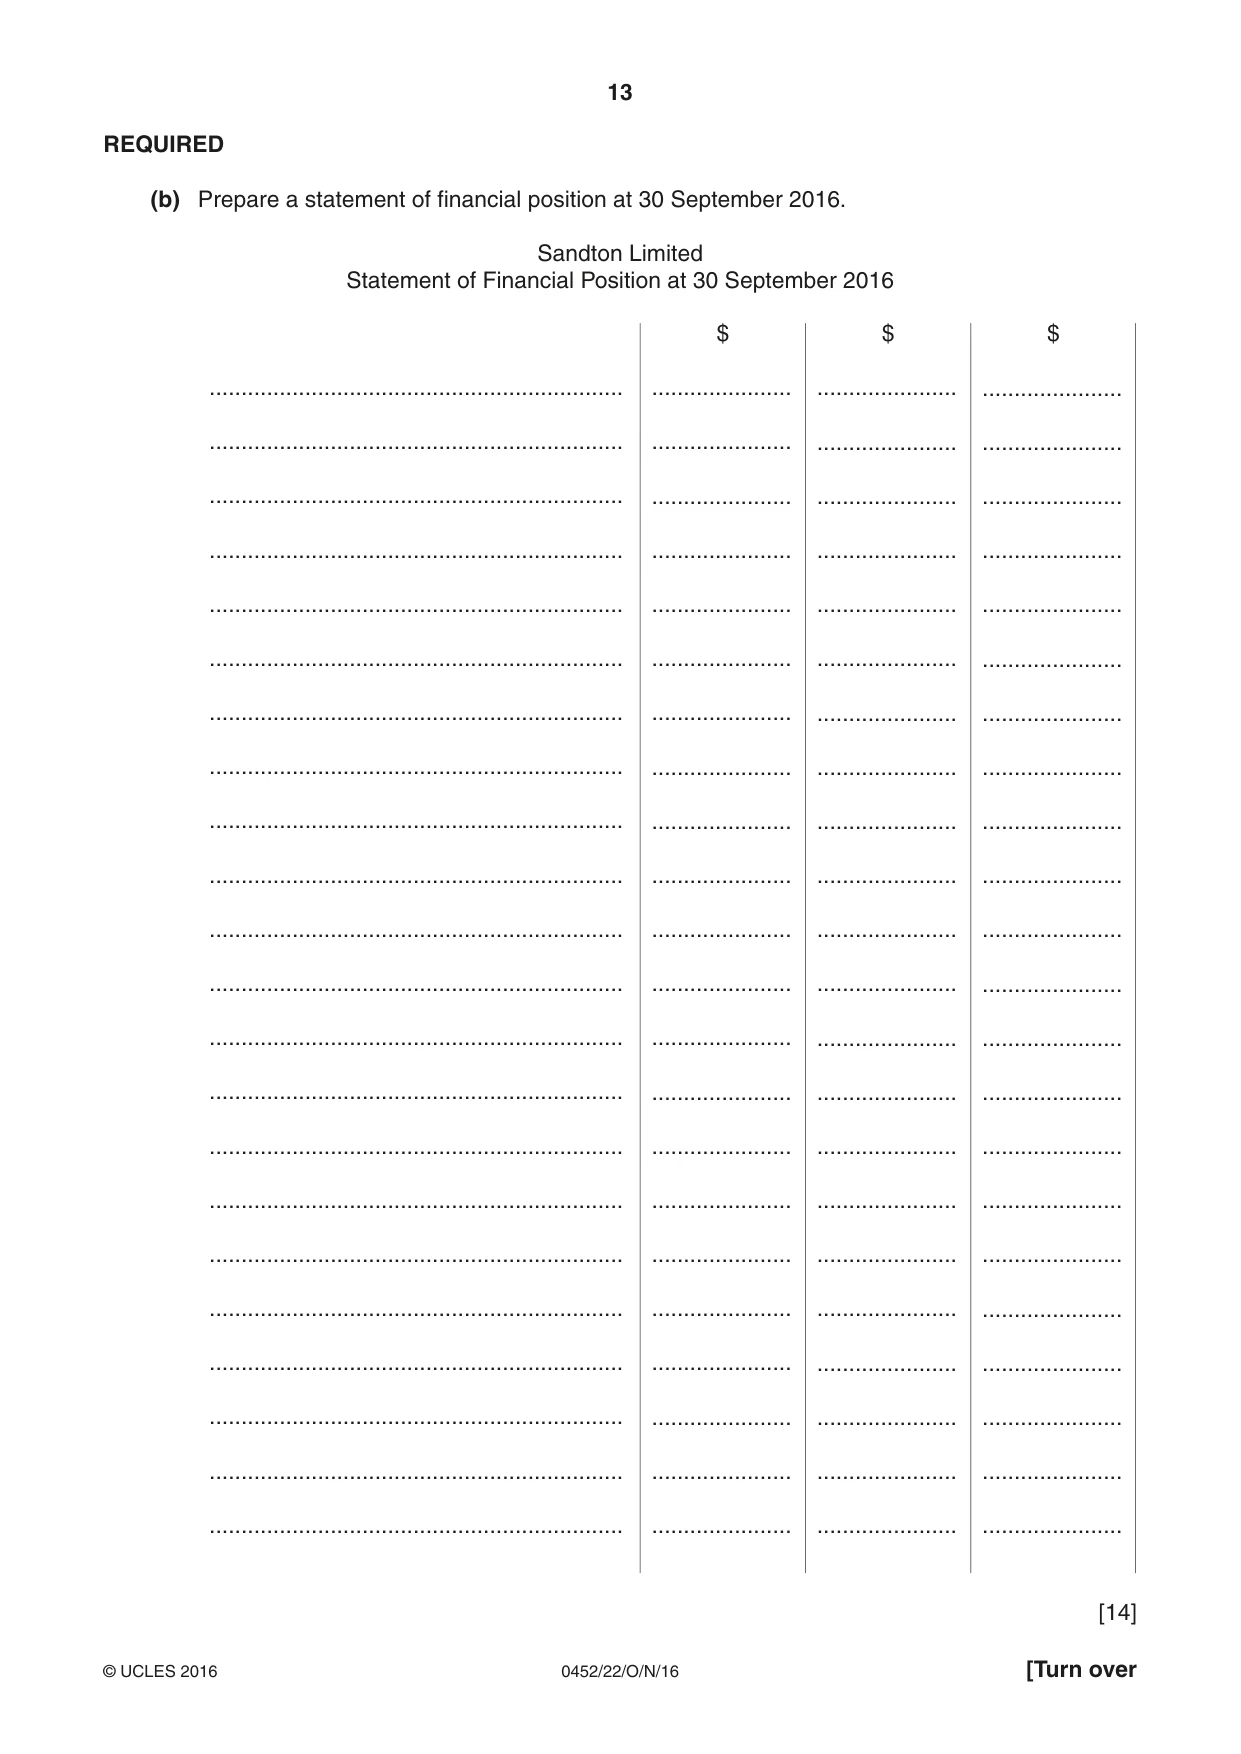
13 0452/22/O/N/16 © UCLES 2016 [Turn over REQUIRED (b) Prepare a statement of financial position at 30 September 2016. Sandton Limited Statement of Financial Position at 30 September 2016 … … … … … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … … … … … [14]
Question paper, page 14
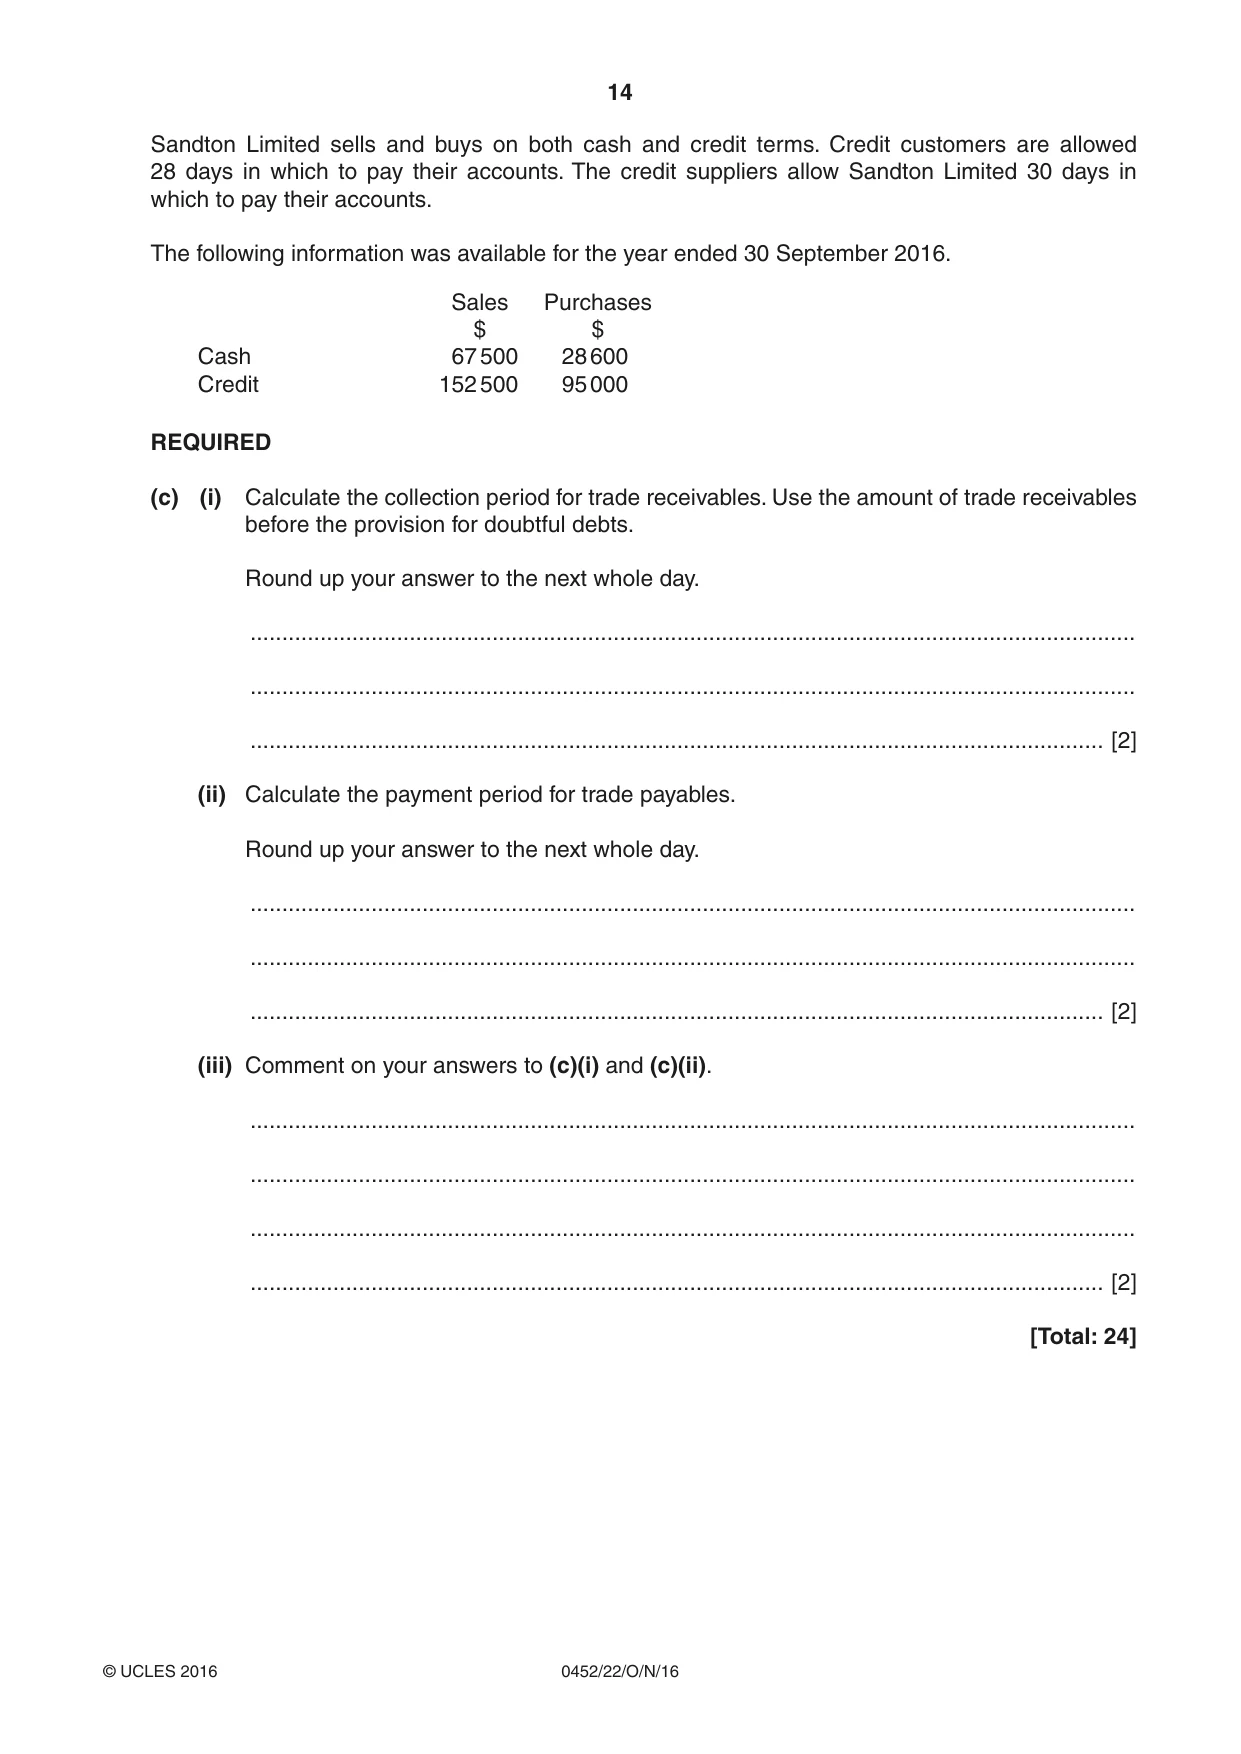
14 0452/22/O/N/16 © UCLES 2016 Sandton Limited sells and buys on both cash and credit terms. Credit customers are allowed 28 days in which to pay their accounts. The credit suppliers allow Sandton Limited 30 days in which to pay their accounts. The following information was available for the year ended 30 September 2016. Sales Purchases $ $ Cash 67 500 28 600 Credit 152 500 95 000 REQUIRED (c) (i) Calculate the collection period for trade receivables. Use the amount of trade receivables before the provision for doubtful debts. Round up your answer to the next whole day. … … … [2] (ii) Calculate the payment period for trade payables. Round up your answer to the next whole day. … … … [2] (iii) Comment on your answers to (c)(i) and (c)(ii). … … … … [2] [Total: 24]
Question paper, page 15
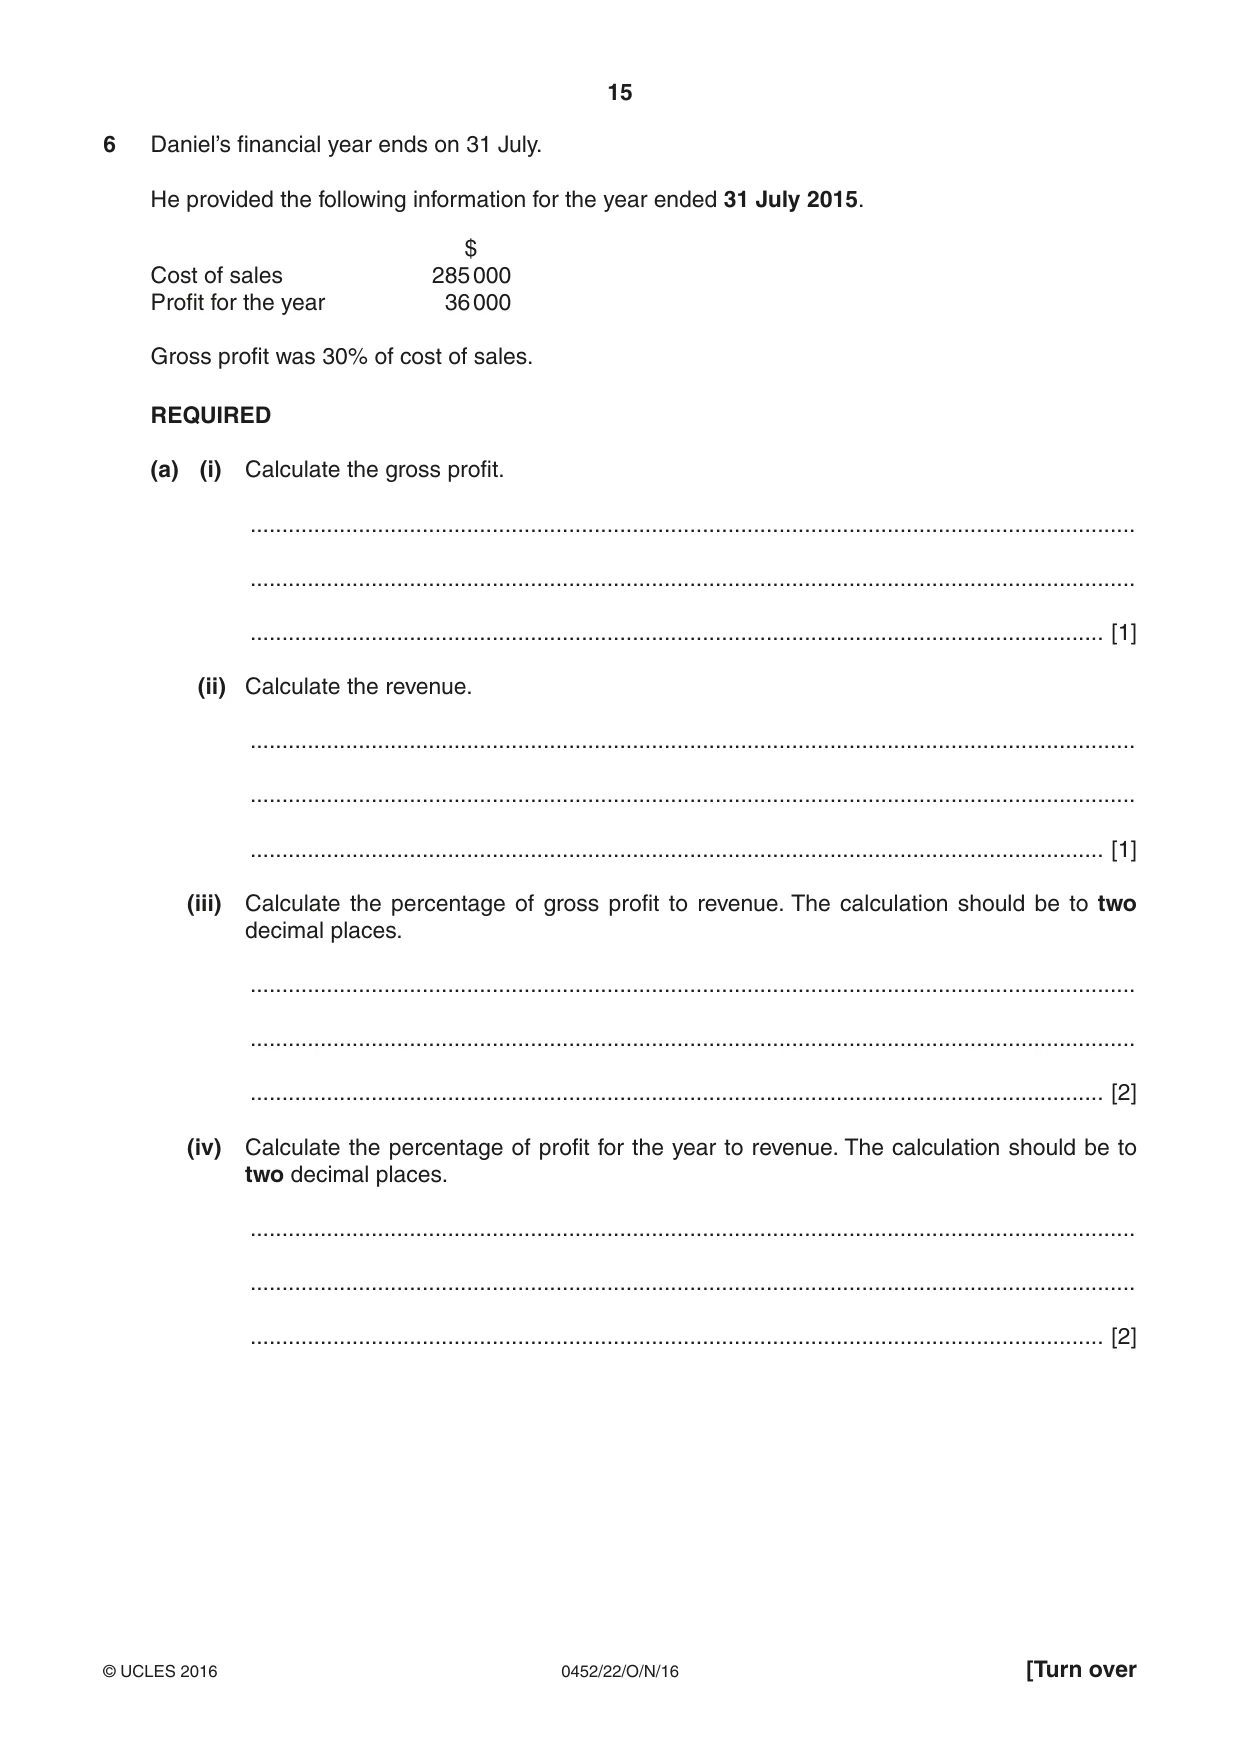
15 0452/22/O/N/16 © UCLES 2016 [Turn over 6 Daniel’s financial year ends on 31 July. He provided the following information for the year ended 31 July 2015. $ Cost of sales 285 000 Profit for the year 36 000 Gross profit was 30% of cost of sales. REQUIRED (a) (i) Calculate the gross profit. … … … [1] (ii) Calculate the revenue. … … … [1] (iii) Calculate the percentage of gross profit to revenue. The calculation should be to two decimal places. … … … [2] (iv) Calculate the percentage of profit for the year to revenue. The calculation should be to two decimal places. … … … [2]
Question paper, page 16
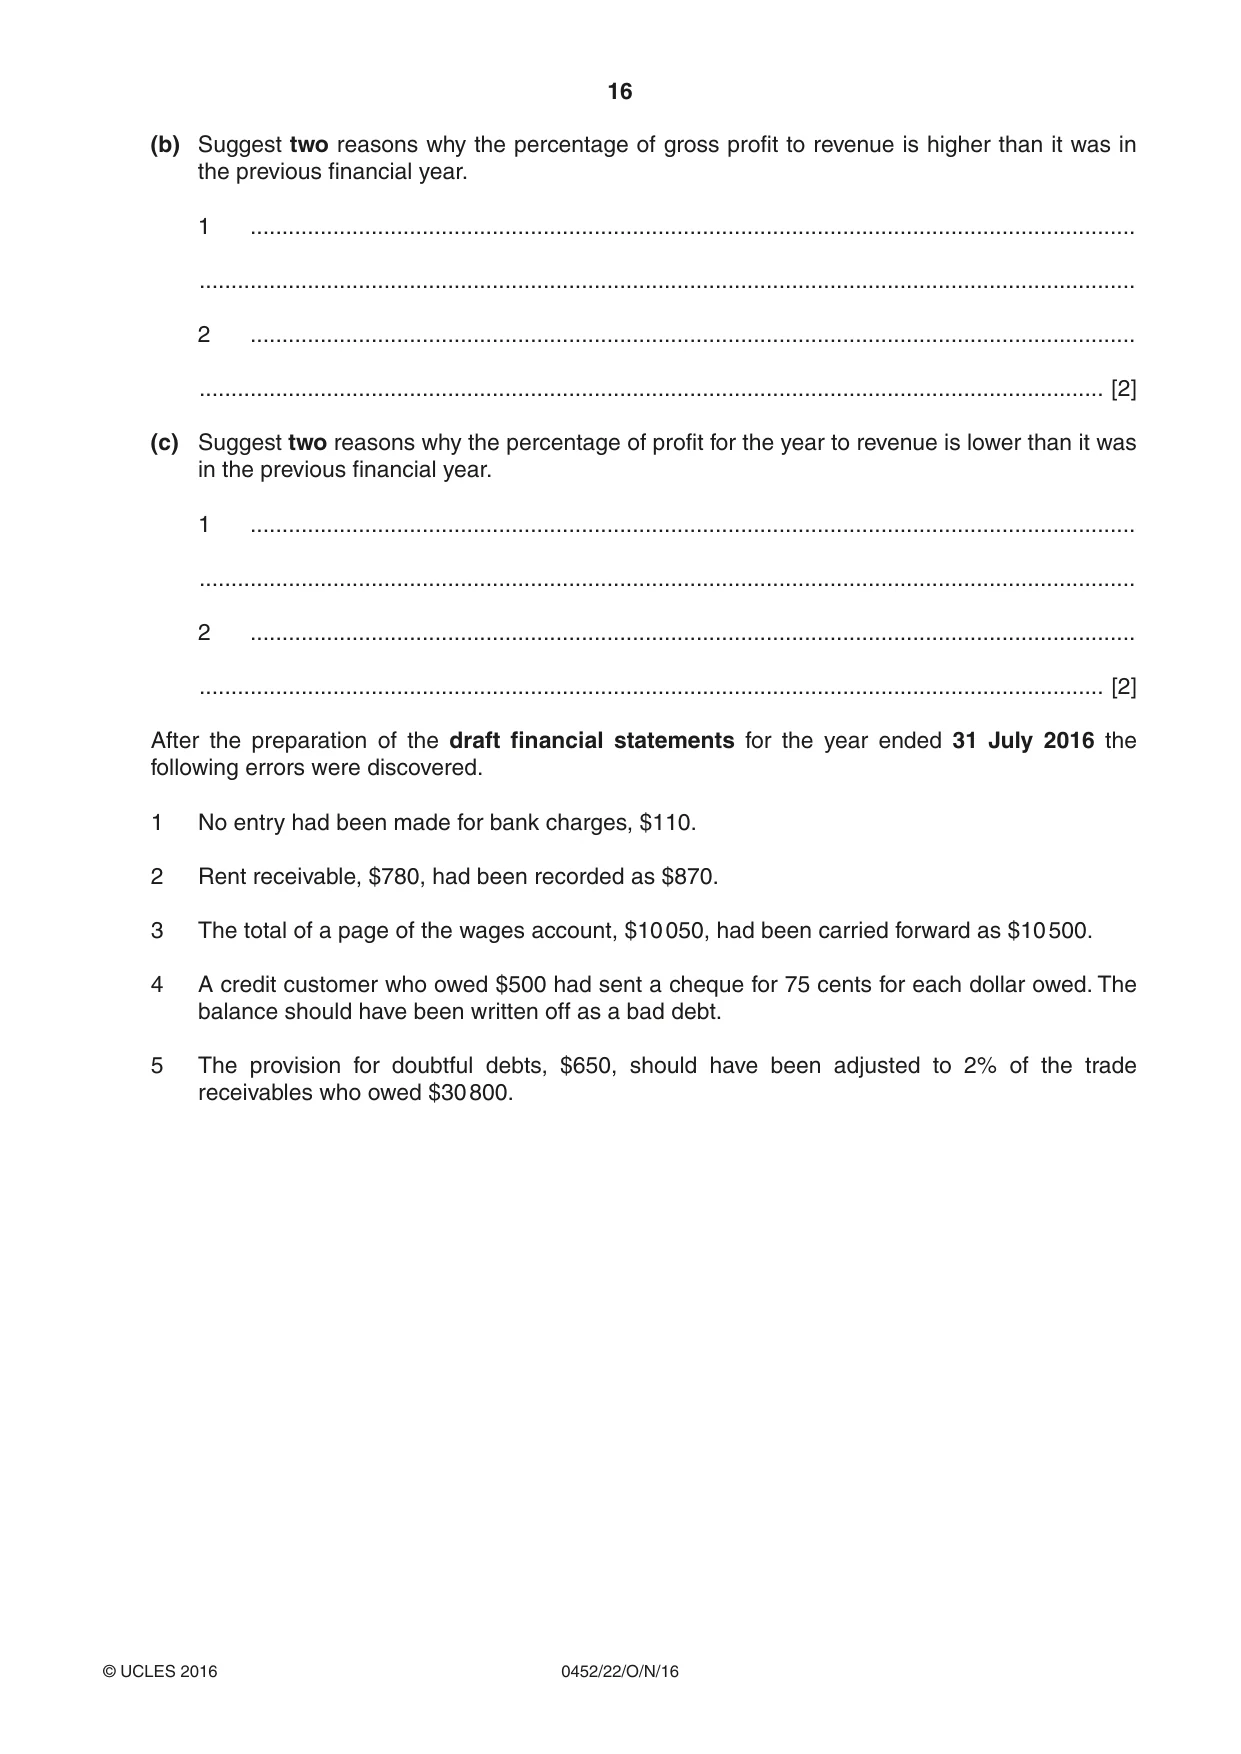
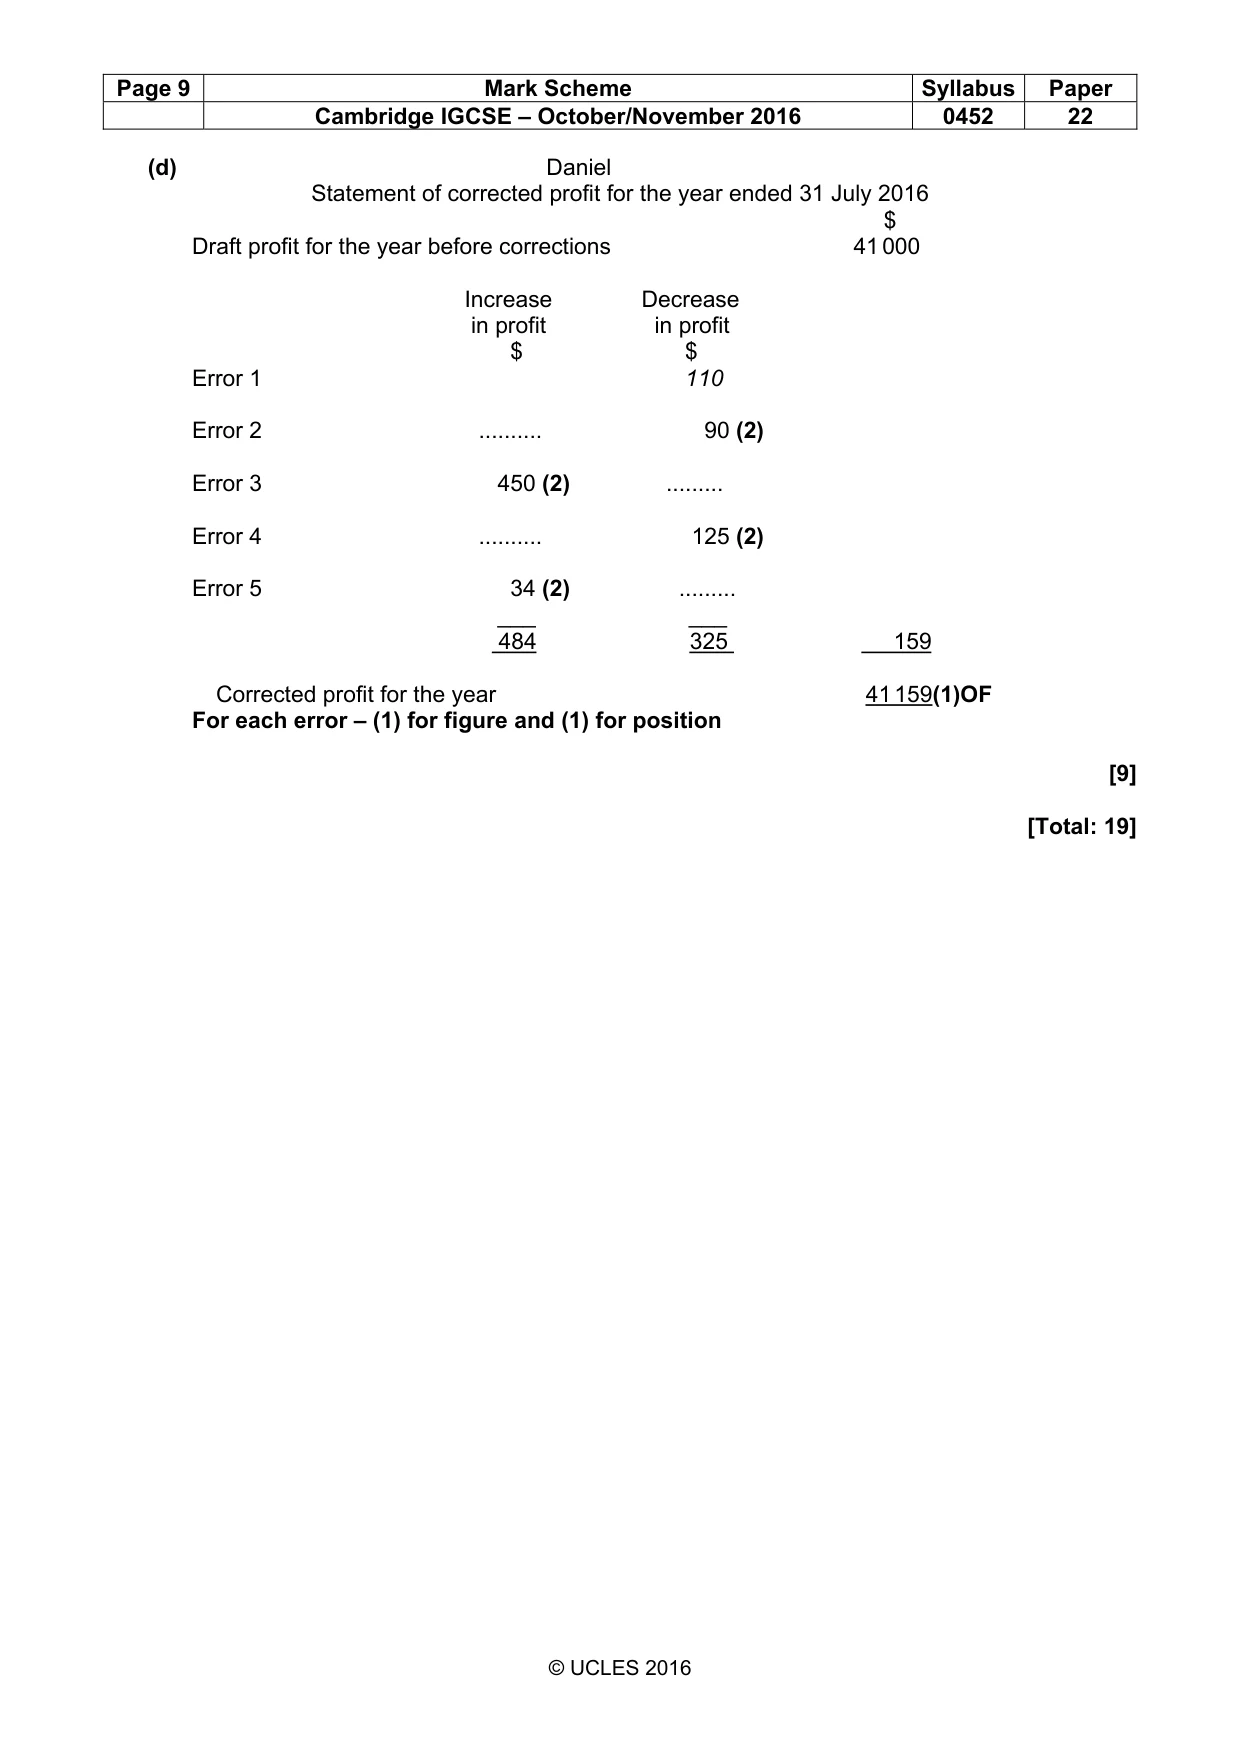
16 0452/22/O/N/16 © UCLES 2016 (b) Suggest two reasons why the percentage of gross profit to revenue is higher than it was in the previous financial year. 1 … … 2 … … [2] (c) Suggest two reasons why the percentage of profit for the year to revenue is lower than it was in the previous financial year. 1 … … 2 … … [2] After the preparation of the draft financial statements for the year ended 31 July 2016 the following errors were discovered. 1 No entry had been made for bank charges, $110. 2 Rent receivable, $780, had been recorded as $870. 3 The total of a page of the wages account, $10 050, had been carried forward as $10 500. 4 A credit customer who owed $500 had sent a cheque for 75 cents for each dollar owed. The balance should have been written off as a bad debt. 5 The provision for doubtful debts, $650, should have been adjusted to 2% of the trade receivables who owed $30 800.
Question paper, page 17
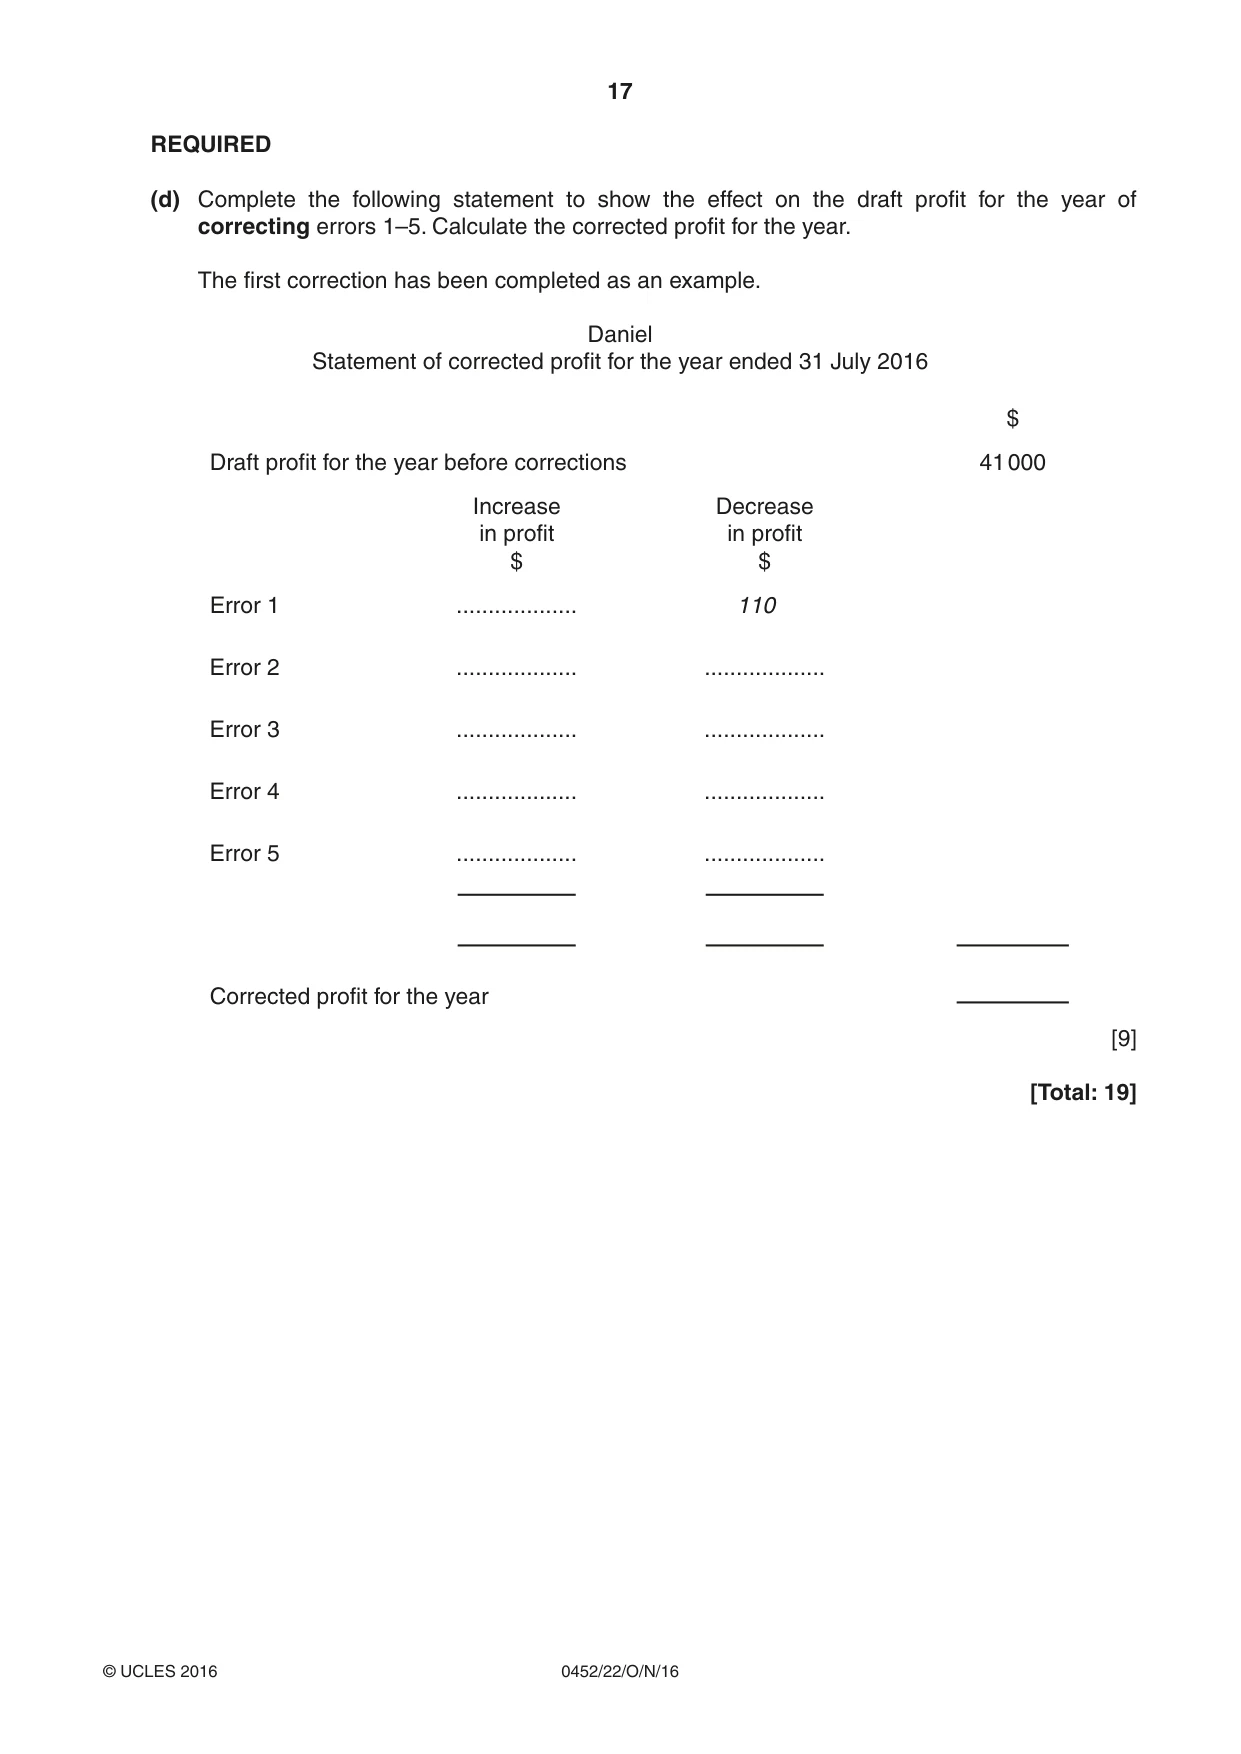
17 0452/22/O/N/16 © UCLES 2016 REQUIRED (d) Complete the following statement to show the effect on the draft profit for the year of correcting errors 1–5. Calculate the corrected profit for the year. The first correction has been completed as an example. Daniel Statement of corrected profit for the year ended 31 July 2016 $ Draft profit for the year before corrections 41 000 Increase in profit $ Decrease in profit $ Error 1 … 110 Error 2 … … Error 3 … … Error 4 … … Error 5 … … Corrected profit for the year [9] [Total: 19]
Question paper, page 18
18 0452/22/O/N/16 © UCLES 2016 BLANK PAGE
Question paper, page 19
19 0452/22/O/N/16 © UCLES 2016 BLANK PAGE
Question paper, page 20
20 0452/22/O/N/16 © UCLES 2016 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge International Examinations Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cie.org.uk after the live examination series. Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
® IGCSE is the registered trademark of Cambridge International Examinations. This document consists of 9 printed pages. © UCLES 2016 [Turn over Cambridge International Examinations Cambridge International General Certificate of Secondary Education ACCOUNTING 0452/22 Paper 2 October/November 2016 MARK SCHEME Maximum Mark: 120 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2016 series for most Cambridge IGCSE®, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
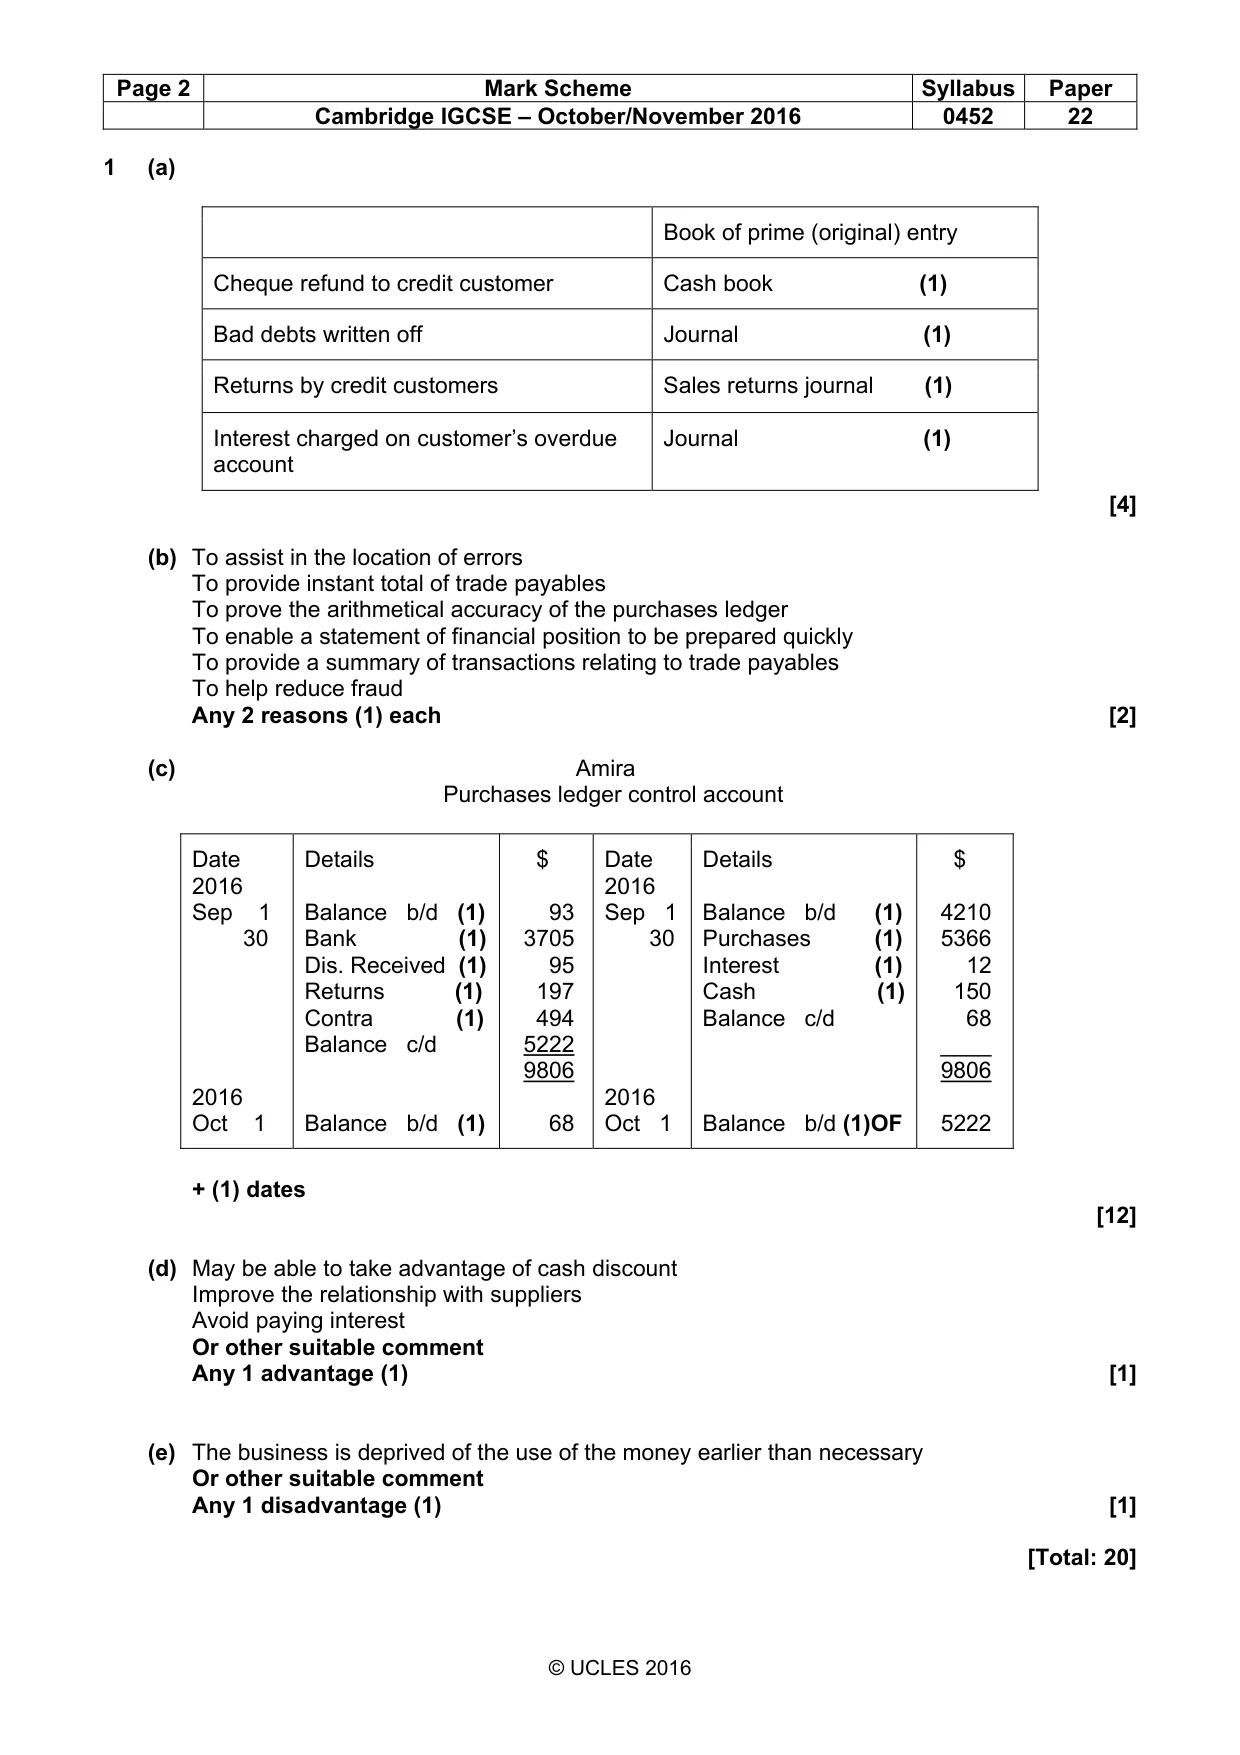
Page 2 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 1 (a) Book of prime (original) entry Cheque refund to credit customer Cash book (1) Bad debts written off Journal (1) Returns by credit customers Sales returns journal (1) Interest charged on customer’s overdue account Journal (1) [4] (b) To assist in the location of errors To provide instant total of trade payables To prove the arithmetical accuracy of the purchases ledger To enable a statement of financial position to be prepared quickly To provide a summary of transactions relating to trade payables To help reduce fraud Any 2 reasons (1) each [2] (c) Amira Purchases ledger control account Date 2016 Sep 1 30 2016 Oct 1 Details Balance b/d (1) Bank (1) Dis. Received (1) Returns (1) Contra (1) Balance c/d Balance b/d (1) $ 93 3705 95 197 494 5222 9806 68 Date 2016 Sep 1 30 2016 Oct 1 Details Balance b/d (1) Purchases (1) Interest (1) Cash (1) Balance c/d Balance b/d (1)OF $ 4210 5366 12 150 68 ____ 9806 5222 + (1) dates [12] (d) May be able to take advantage of cash discount Improve the relationship with suppliers Avoid paying interest Or other suitable comment Any 1 advantage (1) [1] (e) The business is deprived of the use of the money earlier than necessary Or other suitable comment Any 1 disadvantage (1) [1] [Total: 20]
Mark scheme, page 3
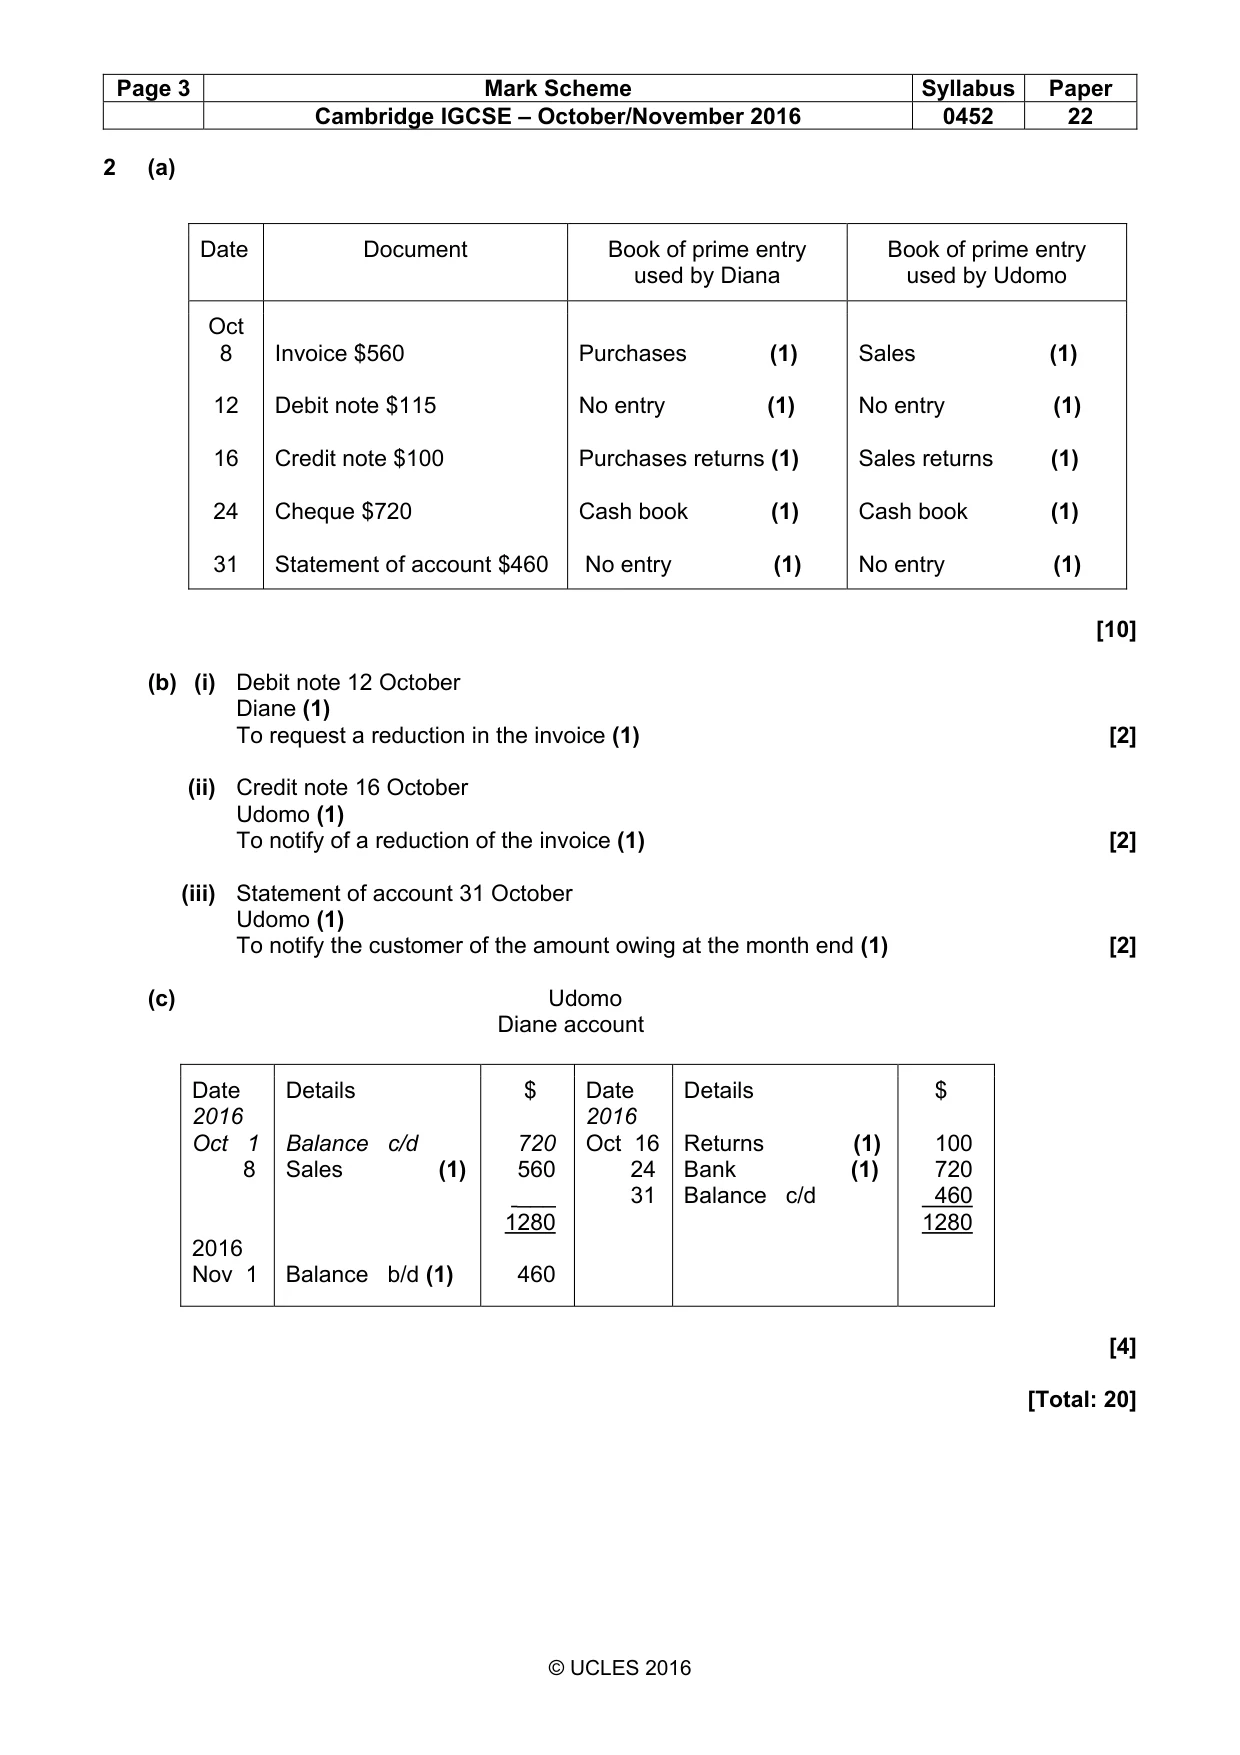
Page 3 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 2 (a) [10] (b) (i) Debit note 12 October Diane (1) To request a reduction in the invoice (1) [2] (ii) Credit note 16 October Udomo (1) To notify of a reduction of the invoice (1) [2] (iii) Statement of account 31 October Udomo (1) To notify the customer of the amount owing at the month end (1) [2] (c) Udomo Diane account Date 2016 Oct 1 8 2016 Nov 1 Details Balance c/d Sales (1) Balance b/d (1) $ 720 560 ___ 1280 460 Date 2016 Oct 16 24 31 Details Returns (1) Bank (1) Balance c/d $ 100 720 460 1280 [4] [Total: 20] Date Document Book of prime entry used by Diana Book of prime entry used by Udomo Oct 8 12 16 24 31 Invoice $560 Debit note $115 Credit note $100 Cheque $720 Statement of account $460 Purchases (1) No entry (1) Purchases returns (1) Cash book (1) No entry (1) Sales (1) No entry (1) Sales returns (1) Cash book (1) No entry (1)
Mark scheme, page 4
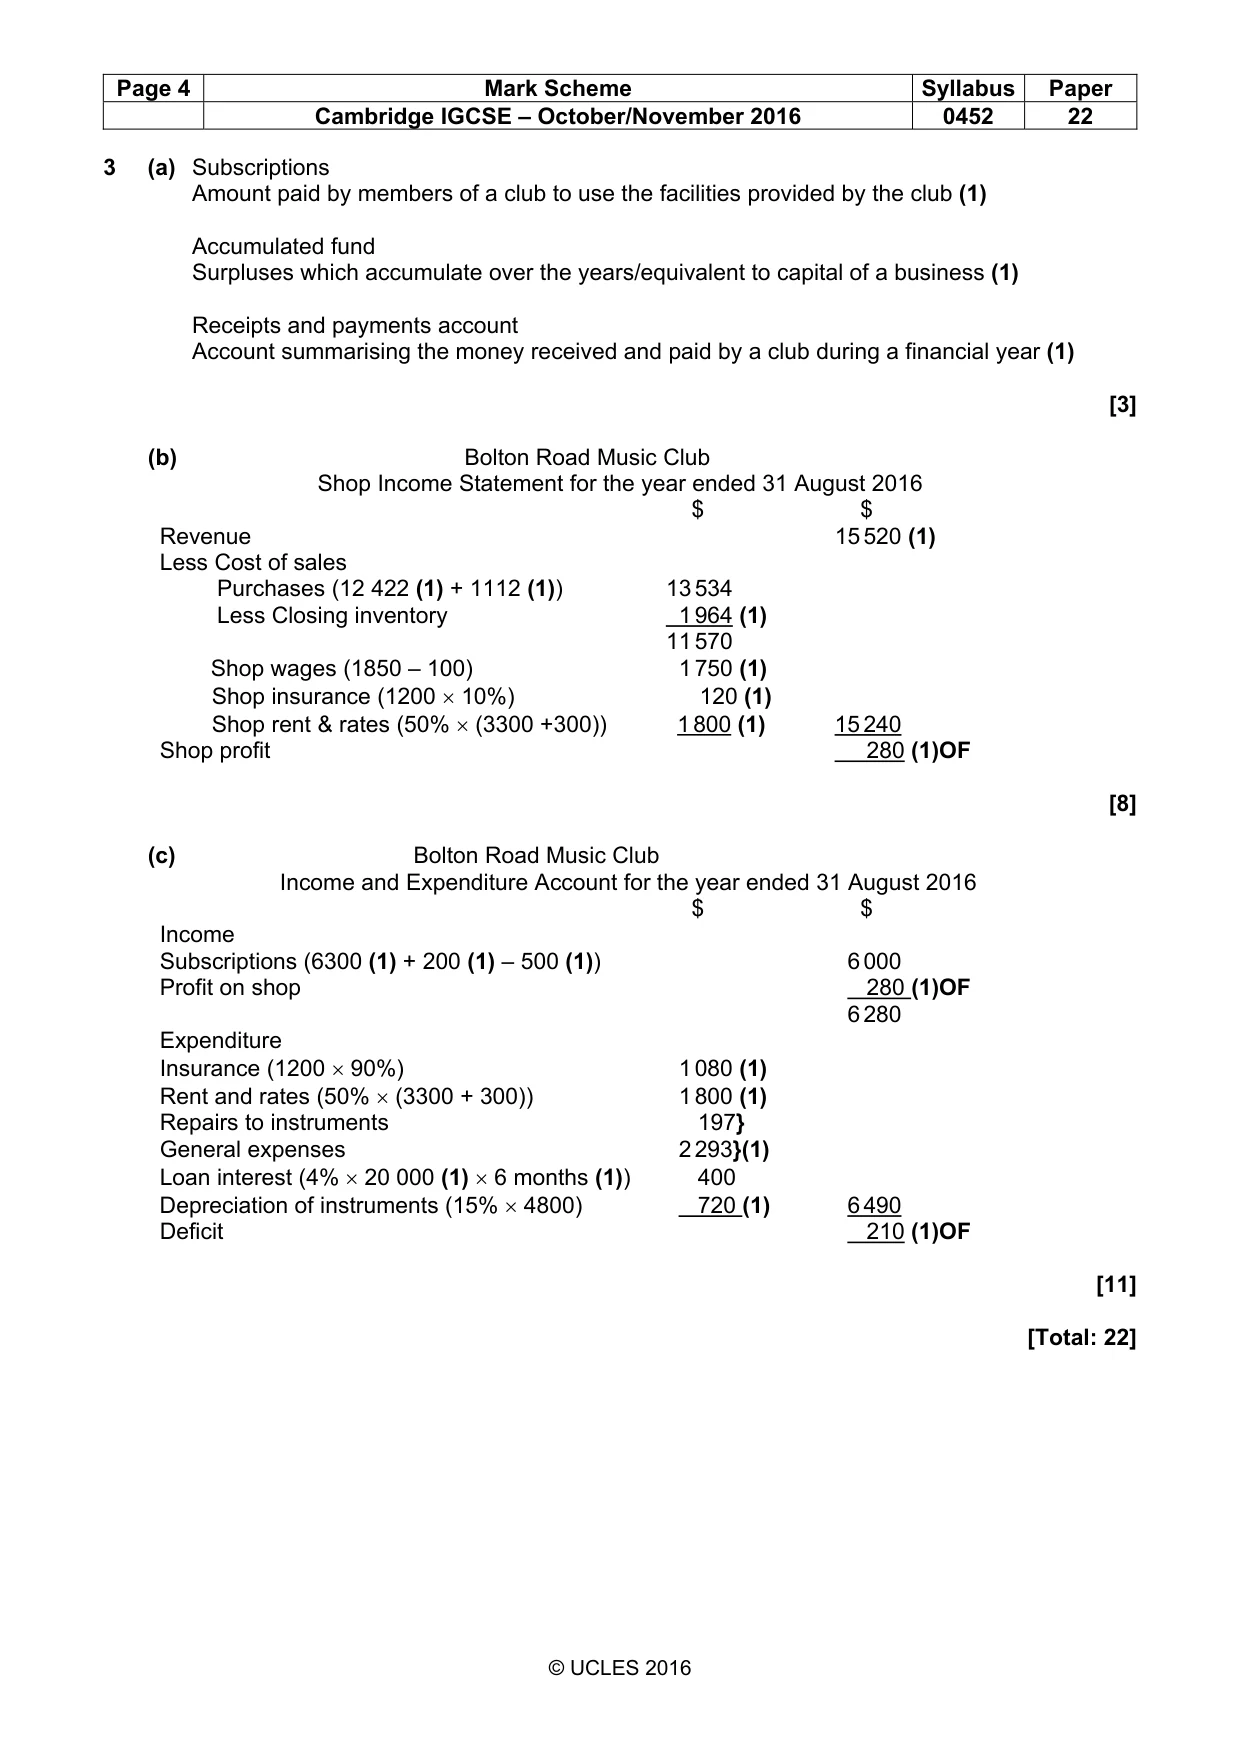
Page 4 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 3 (a) Subscriptions Amount paid by members of a club to use the facilities provided by the club (1) Accumulated fund Surpluses which accumulate over the years/equivalent to capital of a business (1) Receipts and payments account Account summarising the money received and paid by a club during a financial year (1) [3] (b) Bolton Road Music Club Shop Income Statement for the year ended 31 August 2016 $ $ Revenue 15 520 (1) Less Cost of sales Purchases (12 422 (1) + 1112 (1)) 13 534 Less Closing inventory 1 964 (1) 11 570 Shop wages (1850 – 100) 1 750 (1) Shop insurance (1200 × 10%) 120 (1) Shop rent & rates (50% × (3300 +300)) 1 800 (1) 15 240 Shop profit 280 (1)OF [8] (c) Bolton Road Music Club Income and Expenditure Account for the year ended 31 August 2016 $ $ Income Subscriptions (6300 (1) + 200 (1) – 500 (1)) 6 000 Profit on shop 280 (1)OF 6 280 Expenditure Insurance (1200 × 90%) 1 080 (1) Rent and rates (50% × (3300 + 300)) 1 800 (1) Repairs to instruments 197} General expenses 2 293}(1) Loan interest (4% × 20 000 (1) × 6 months (1)) 400 Depreciation of instruments (15% × 4800) 720 (1) 6 490 Deficit 210 (1)OF [11] [Total: 22]
Mark scheme, page 5
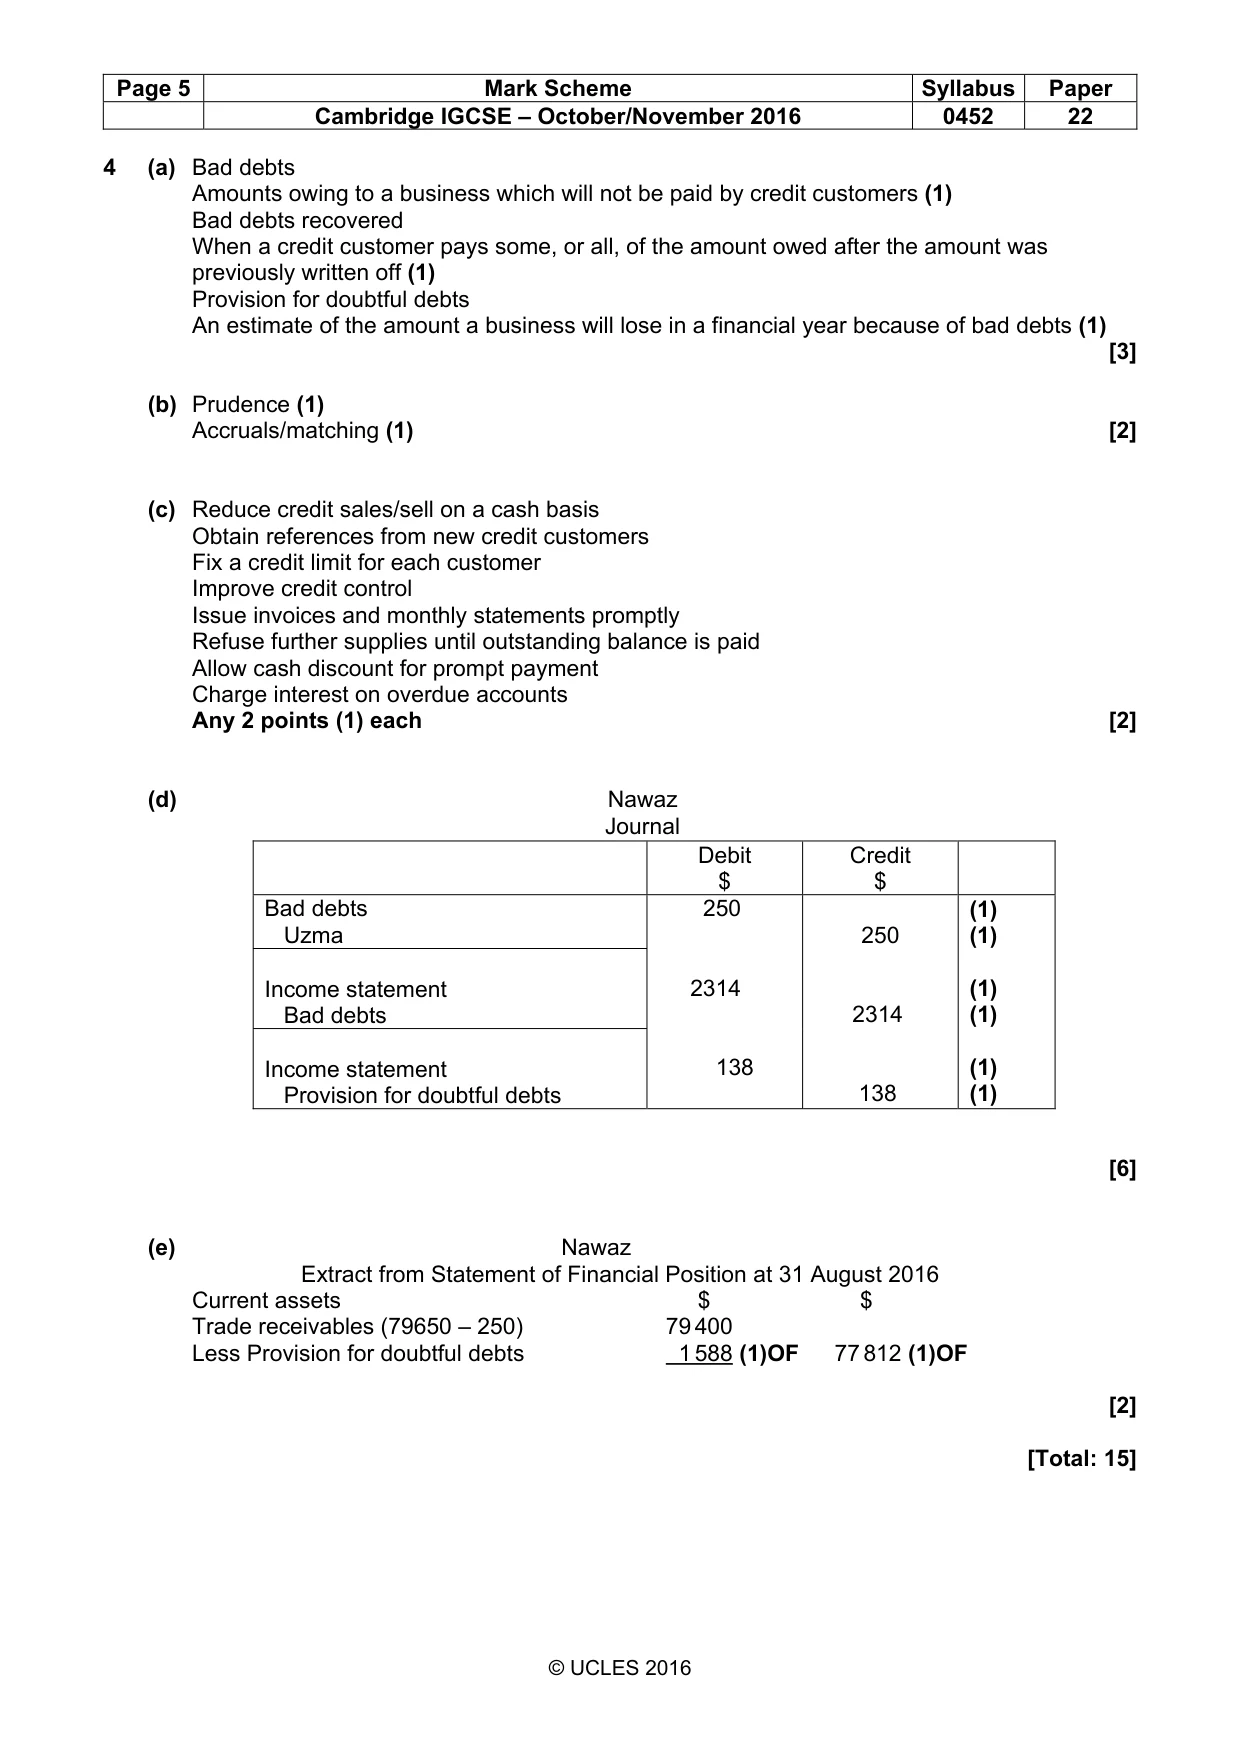
Page 5 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 4 (a) Bad debts Amounts owing to a business which will not be paid by credit customers (1) Bad debts recovered When a credit customer pays some, or all, of the amount owed after the amount was previously written off (1) Provision for doubtful debts An estimate of the amount a business will lose in a financial year because of bad debts (1) [3] (b) Prudence (1) Accruals/matching (1) [2] (c) Reduce credit sales/sell on a cash basis Obtain references from new credit customers Fix a credit limit for each customer Improve credit control Issue invoices and monthly statements promptly Refuse further supplies until outstanding balance is paid Allow cash discount for prompt payment Charge interest on overdue accounts Any 2 points (1) each [2] (d) Nawaz Journal [6] (e) Nawaz Extract from Statement of Financial Position at 31 August 2016 Current assets $ $ Trade receivables (79650 – 250) 79 400 Less Provision for doubtful debts 1 588 (1)OF 77 812 (1)OF [2] [Total: 15] Debit $ Credit $ Bad debts Uzma 250 2314 138 250 2314 138 (1) (1) (1) (1) (1) (1) Income statement Bad debts Income statement Provision for doubtful debts
Mark scheme, page 6
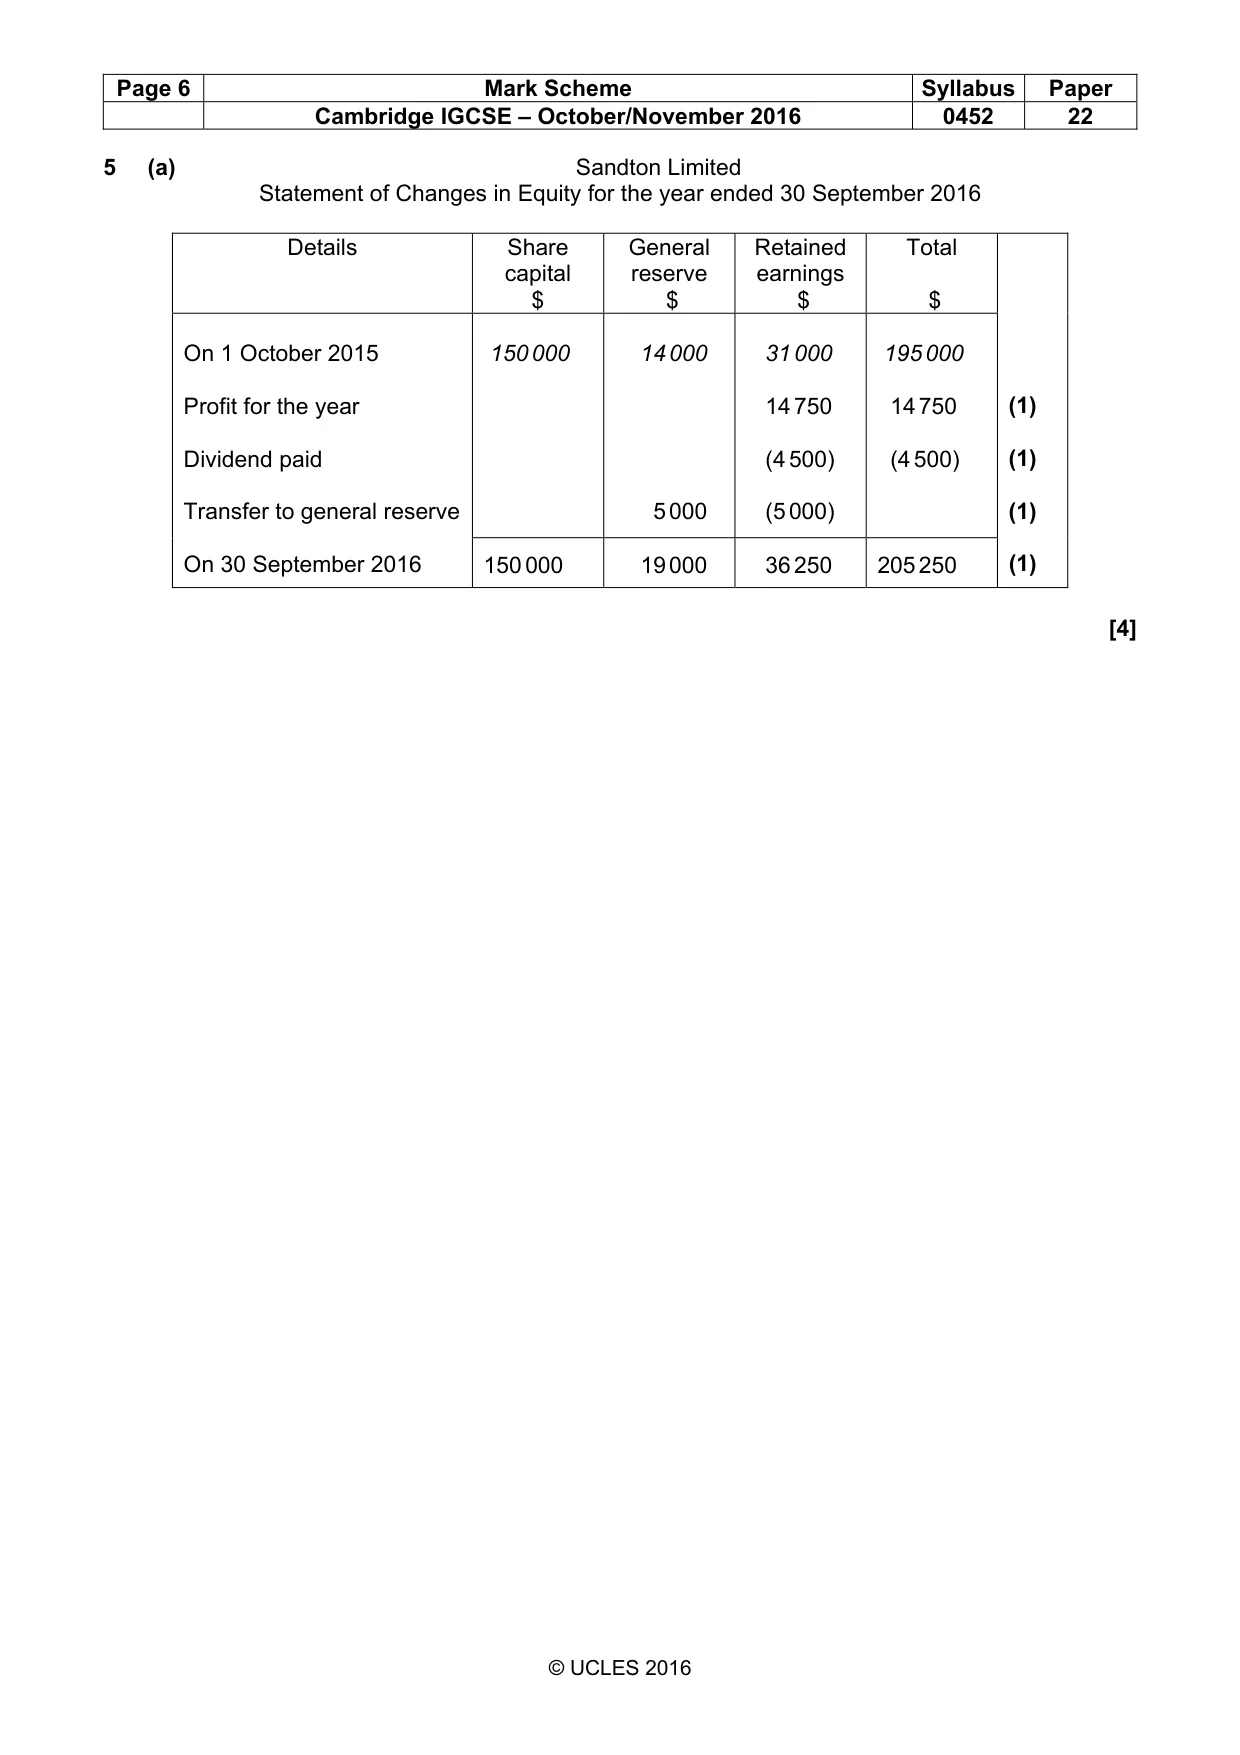
Page 6 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 5 (a) Sandton Limited Statement of Changes in Equity for the year ended 30 September 2016 Details Share capital $ General reserve $ Retained earnings $ Total $ (1) (1) (1) (1) On 1 October 2015 Profit for the year Dividend paid Transfer to general reserve On 30 September 2016 150 000 14 000 5 000 31 000 14 750 (4 500) (5 000) 195 000 14 750 (4 500) 150 000 19 000 36 250 205 250 [4]
Mark scheme, page 7
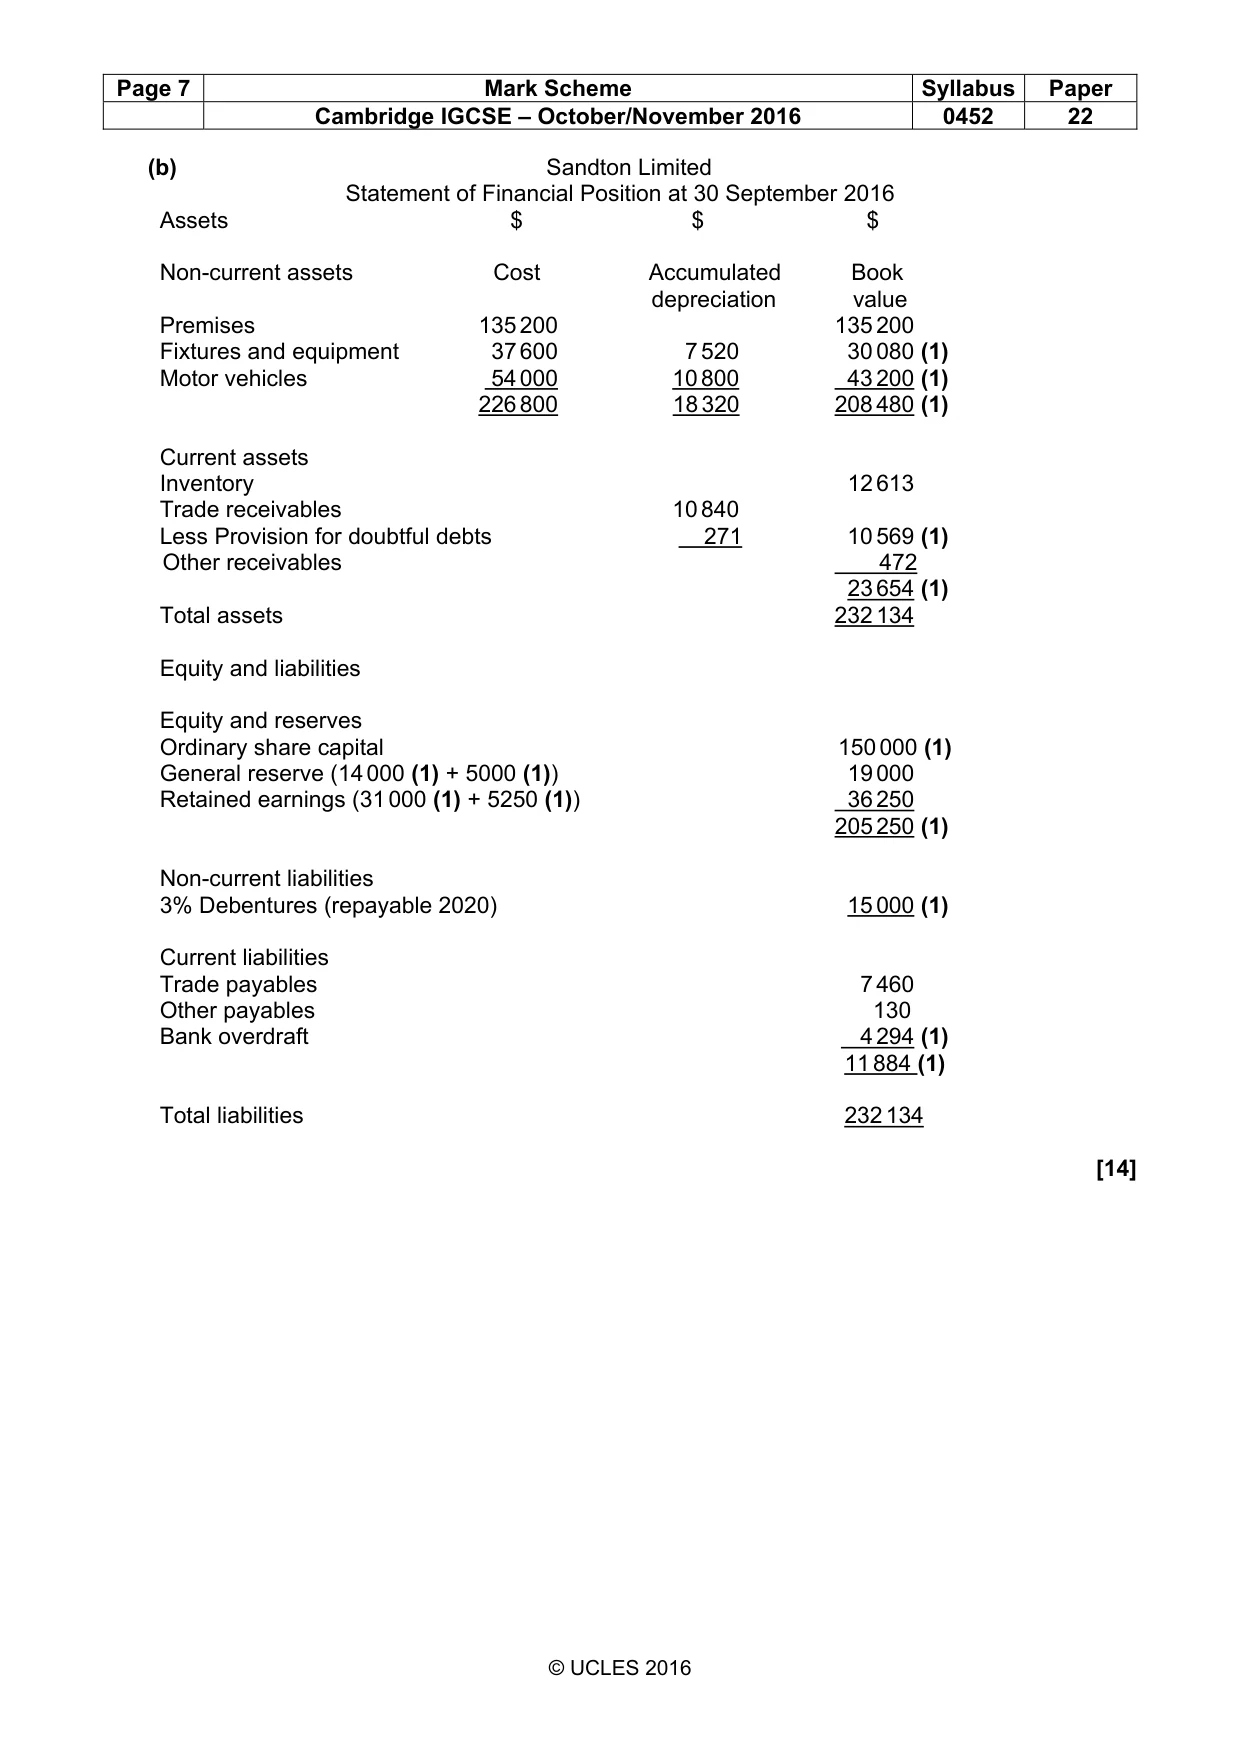
Page 7 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 (b) Sandton Limited Statement of Financial Position at 30 September 2016 Assets $ $ $ Non-current assets Cost Accumulated Book depreciation value Premises 135 200 135 200 Fixtures and equipment 37 600 7 520 30 080 (1) Motor vehicles 54 000 10 800 43 200 (1) 226 800 18 320 208 480 (1) Current assets Inventory 12 613 Trade receivables 10 840 Less Provision for doubtful debts 271 10 569 (1) Other receivables 472 23 654 (1) Total assets 232 134 Equity and liabilities Equity and reserves Ordinary share capital 150 000 (1) General reserve (14 000 (1) + 5000 (1)) 19 000 Retained earnings (31 000 (1) + 5250 (1)) 36 250 205 250 (1) Non-current liabilities 3% Debentures (repayable 2020) 15 000 (1) Current liabilities Trade payables 7 460 Other payables 130 Bank overdraft 4 294 (1) 11 884 (1) Total liabilities 232 134 [14]
Mark scheme, page 8
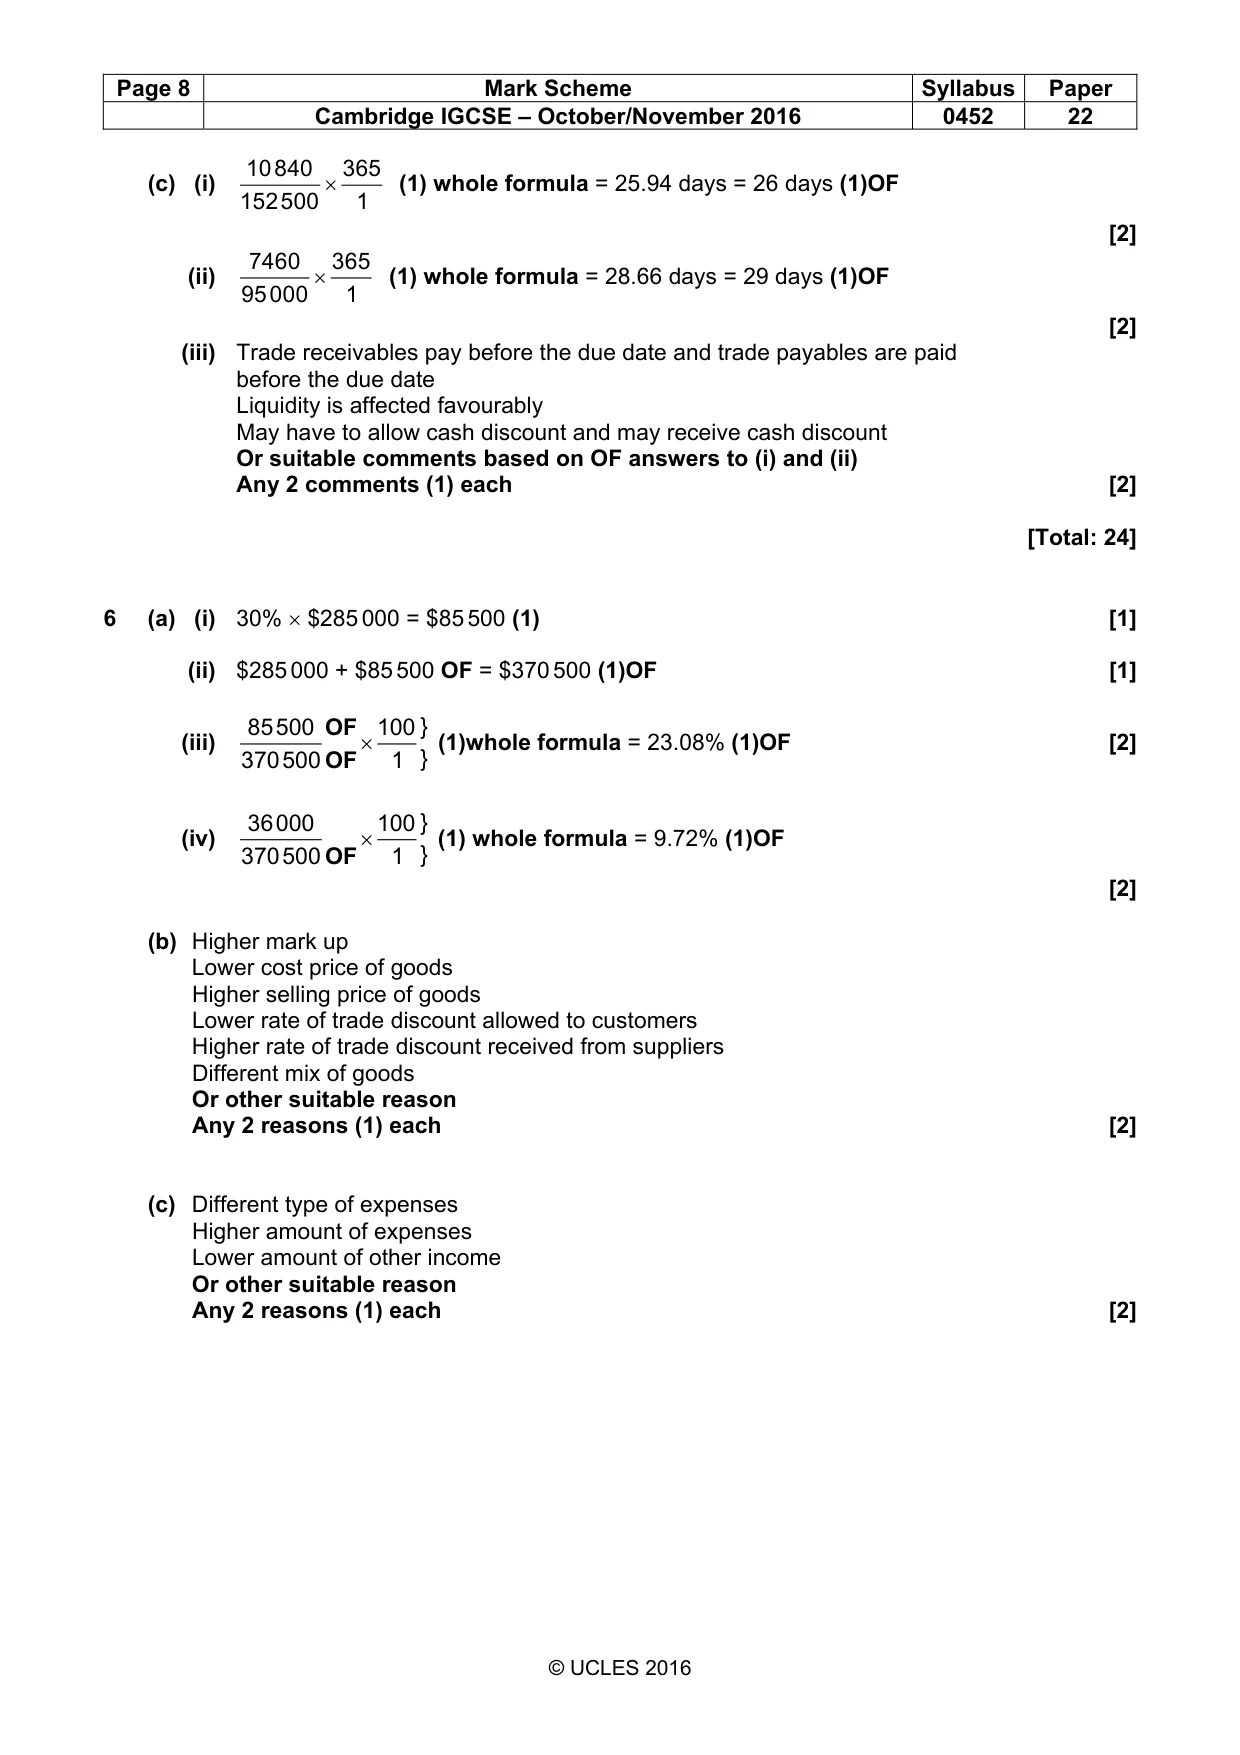
Page 8 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 (c) (i) 10840 365 152500 1 × (1) whole formula = 25.94 days = 26 days (1)OF [2] (ii) 7460 365 95000 1 × (1) whole formula = 28.66 days = 29 days (1)OF [2] (iii) Trade receivables pay before the due date and trade payables are paid before the due date Liquidity is affected favourably May have to allow cash discount and may receive cash discount Or suitable comments based on OF answers to (i) and (ii) Any 2 comments (1) each [2] [Total: 24] 6 (a) (i) 30% × $285 000 = $85 500 (1) [1] (ii) $285 000 + $85 500 OF = $370 500 (1)OF [1] (iii) } 85500 100 } 370500 1 × OF OF (1)whole formula = 23.08% (1)OF [2] (iv) } 36000 100 } 370500 1 × OF (1) whole formula = 9.72% (1)OF [2] (b) Higher mark up Lower cost price of goods Higher selling price of goods Lower rate of trade discount allowed to customers Higher rate of trade discount received from suppliers Different mix of goods Or other suitable reason Any 2 reasons (1) each [2] (c) Different type of expenses Higher amount of expenses Lower amount of other income Or other suitable reason Any 2 reasons (1) each [2]
Mark scheme, page 9
Page 9 Mark Scheme Syllabus Paper Cambridge IGCSE – October/November 2016 0452 22 © UCLES 2016 (d) Daniel Statement of corrected profit for the year ended 31 July 2016 $ Draft profit for the year before corrections 41 000 Increase Decrease in profit in profit $ $ Error 1 110 Error 2 … 90 (2) Error 3 450 (2) … Error 4 … 125 (2) Error 5 34 (2) … ___ ___ 484 325 159 Corrected profit for the year 41 159(1)OF For each error – (1) for figure and (1) for position [9] [Total: 19]
What you needed in this session
Cambridge’s own grade thresholds for 2016 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.