Cambridge IGCSE Accounting 0452 — 2013 Oct/Nov Paper 1 · Variant 2
0452/12/O/N/13 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper1 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/12 Paper 1 October/November 2013 This Question Paper is not currently available, but will be uploaded here as soon as possible. www.theallpapers.com
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the October/November 2013 series 0452 ACCOUNTING 0452/12 Paper 1, maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2013 series for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level components and some Ordinary Level components.
Mark scheme, page 2
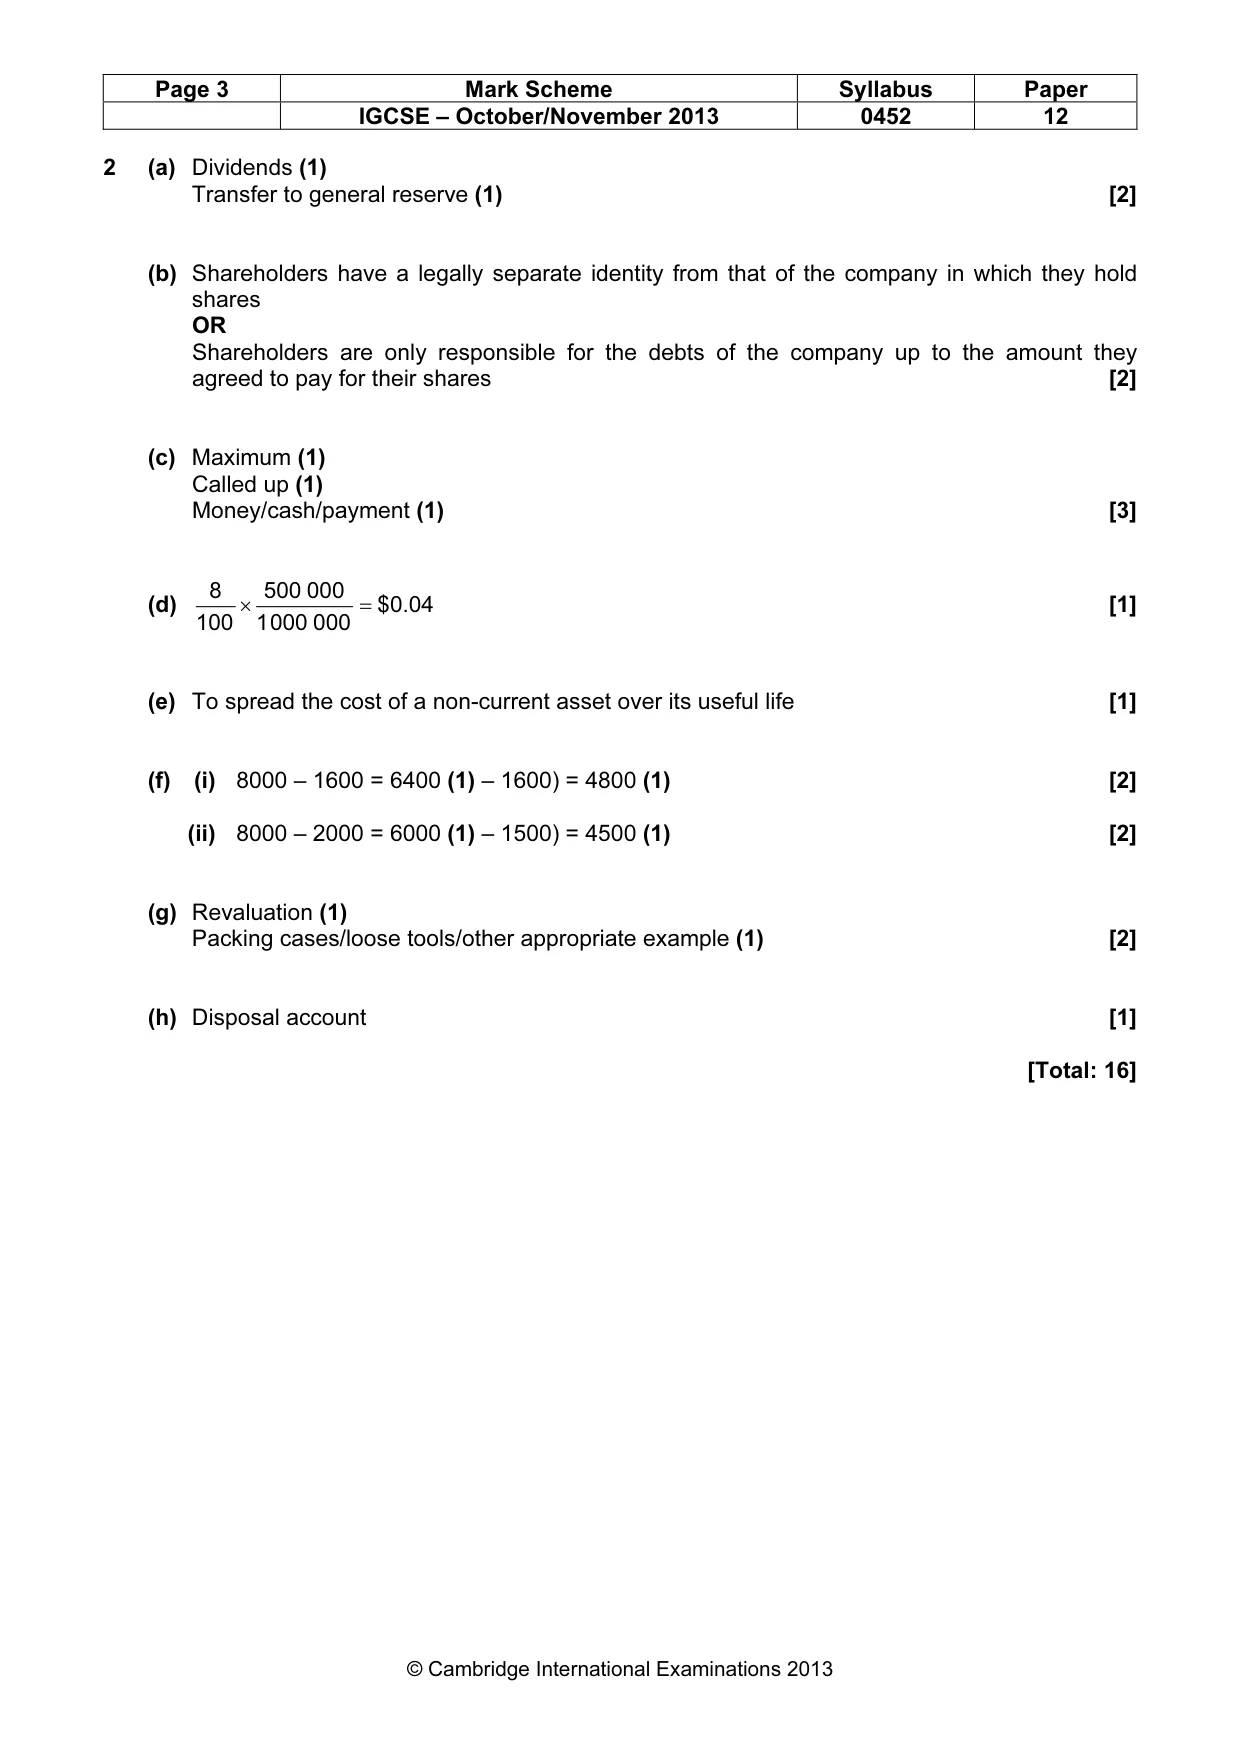
Page 2 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 1 (a) D (b) D (c) D (d) B (e) A (f) B (g) C (h) A (i) A (j) C (1) mark each [Total: 10]
Mark scheme, page 3
Page 3 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 2 (a) Dividends (1) Transfer to general reserve (1) [2] (b) Shareholders have a legally separate identity from that of the company in which they hold shares OR Shareholders are only responsible for the debts of the company up to the amount they agreed to pay for their shares [2] (c) Maximum (1) Called up (1) Money/cash/payment (1) [3] (d) $0.04 000 000 1 000 500 100 8 = × [1] (e) To spread the cost of a non-current asset over its useful life [1] (f) (i) 8000 – 1600 = 6400 (1) – 1600) = 4800 (1) [2] (ii) 8000 – 2000 = 6000 (1) – 1500) = 4500 (1) [2] (g) Revaluation (1) Packing cases/loose tools/other appropriate example (1) [2] (h) Disposal account [1] [Total: 16]
Mark scheme, page 4
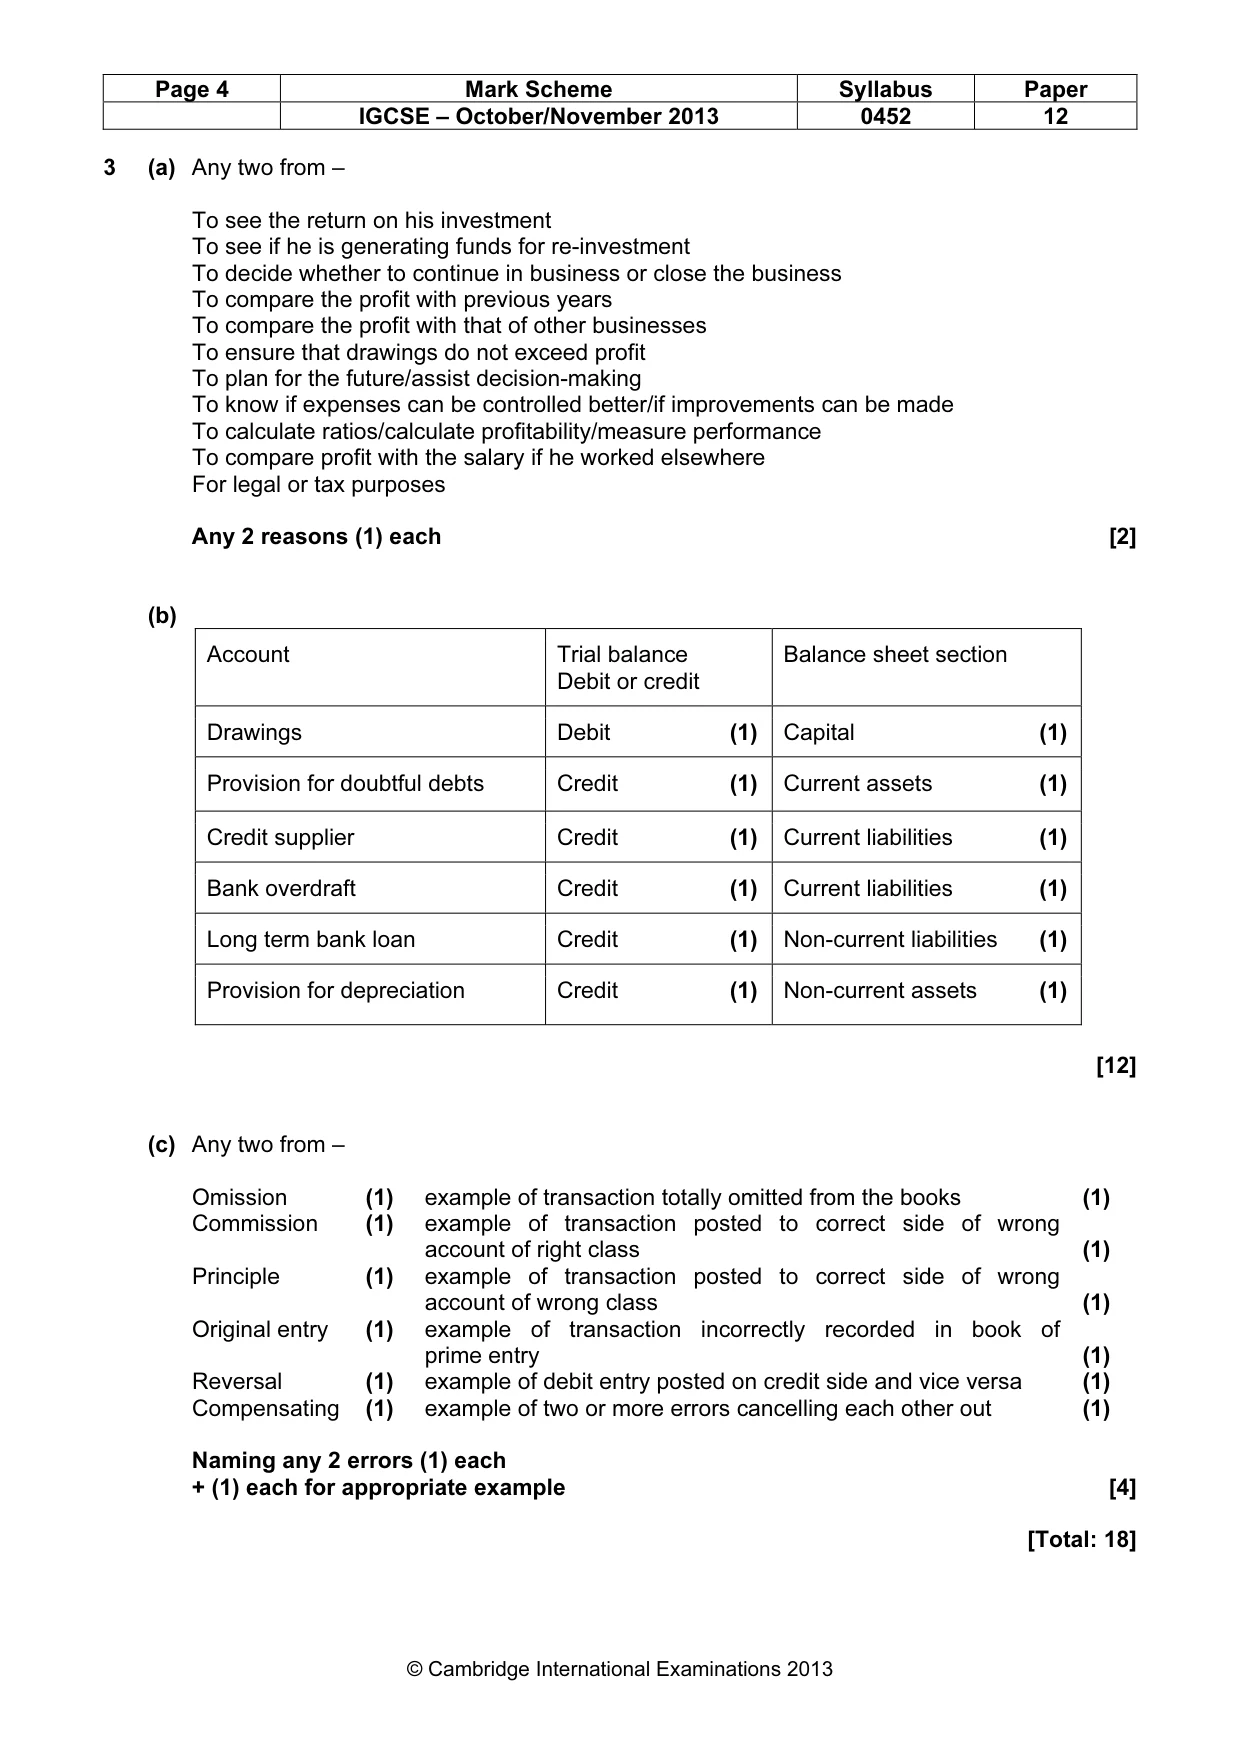
Page 4 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 3 (a) Any two from – To see the return on his investment To see if he is generating funds for re-investment To decide whether to continue in business or close the business To compare the profit with previous years To compare the profit with that of other businesses To ensure that drawings do not exceed profit To plan for the future/assist decision-making To know if expenses can be controlled better/if improvements can be made To calculate ratios/calculate profitability/measure performance To compare profit with the salary if he worked elsewhere For legal or tax purposes Any 2 reasons (1) each [2] (b) Account Trial balance Debit or credit Balance sheet section Drawings Debit (1) Capital (1) Provision for doubtful debts Credit (1) Current assets (1) Credit supplier Credit (1) Current liabilities (1) Bank overdraft Credit (1) Current liabilities (1) Long term bank loan Credit (1) Non-current liabilities (1) Provision for depreciation Credit (1) Non-current assets (1) [12] (c) Any two from – Omission (1) example of transaction totally omitted from the books (1) Commission (1) example of transaction posted to correct side of wrong account of right class (1) Principle (1) example of transaction posted to correct side of wrong account of wrong class (1) Original entry (1) example of transaction incorrectly recorded in book of prime entry (1) Reversal (1) example of debit entry posted on credit side and vice versa (1) Compensating (1) example of two or more errors cancelling each other out (1) Naming any 2 errors (1) each + (1) each for appropriate example [4] [Total: 18]
Mark scheme, page 5
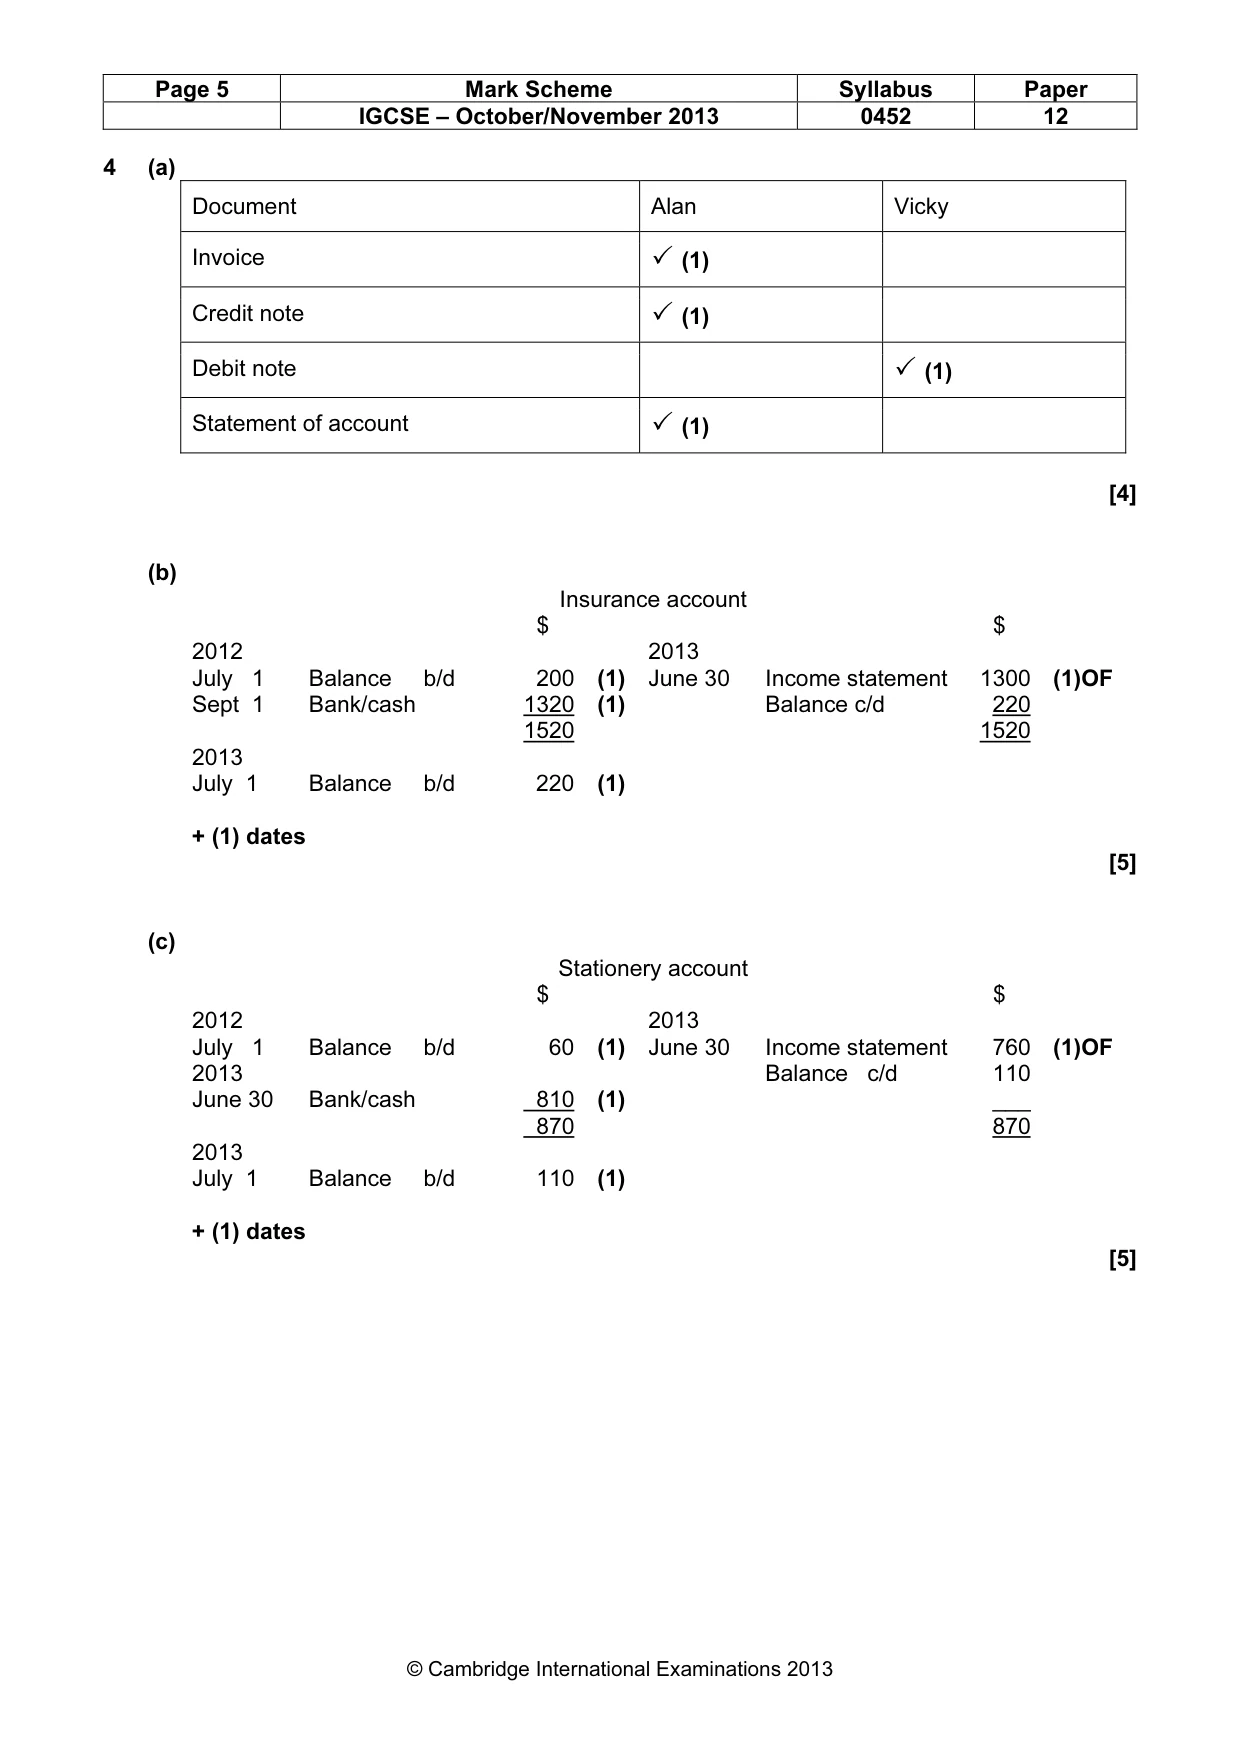
Page 5 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 4 (a) Document Alan Vicky Invoice ✓(1) Credit note ✓(1) Debit note ✓ (1) Statement of account ✓(1) [4] (b) Insurance account $ $ 2012 2013 July 1 Balance b/d 200 (1) June 30 Income statement 1300 (1)OF Sept 1 Bank/cash 1320 (1) Balance c/d 220 1520 1520 2013 July 1 Balance b/d 220 (1) + (1) dates [5] (c) Stationery account $ $ 2012 2013 July 1 Balance b/d 60 (1) June 30 Income statement 760 (1)OF 2013 Balance c/d 110 June 30 Bank/cash 810 (1) ___ 870 870 2013 July 1 Balance b/d 110 (1) + (1) dates [5]
Mark scheme, page 6
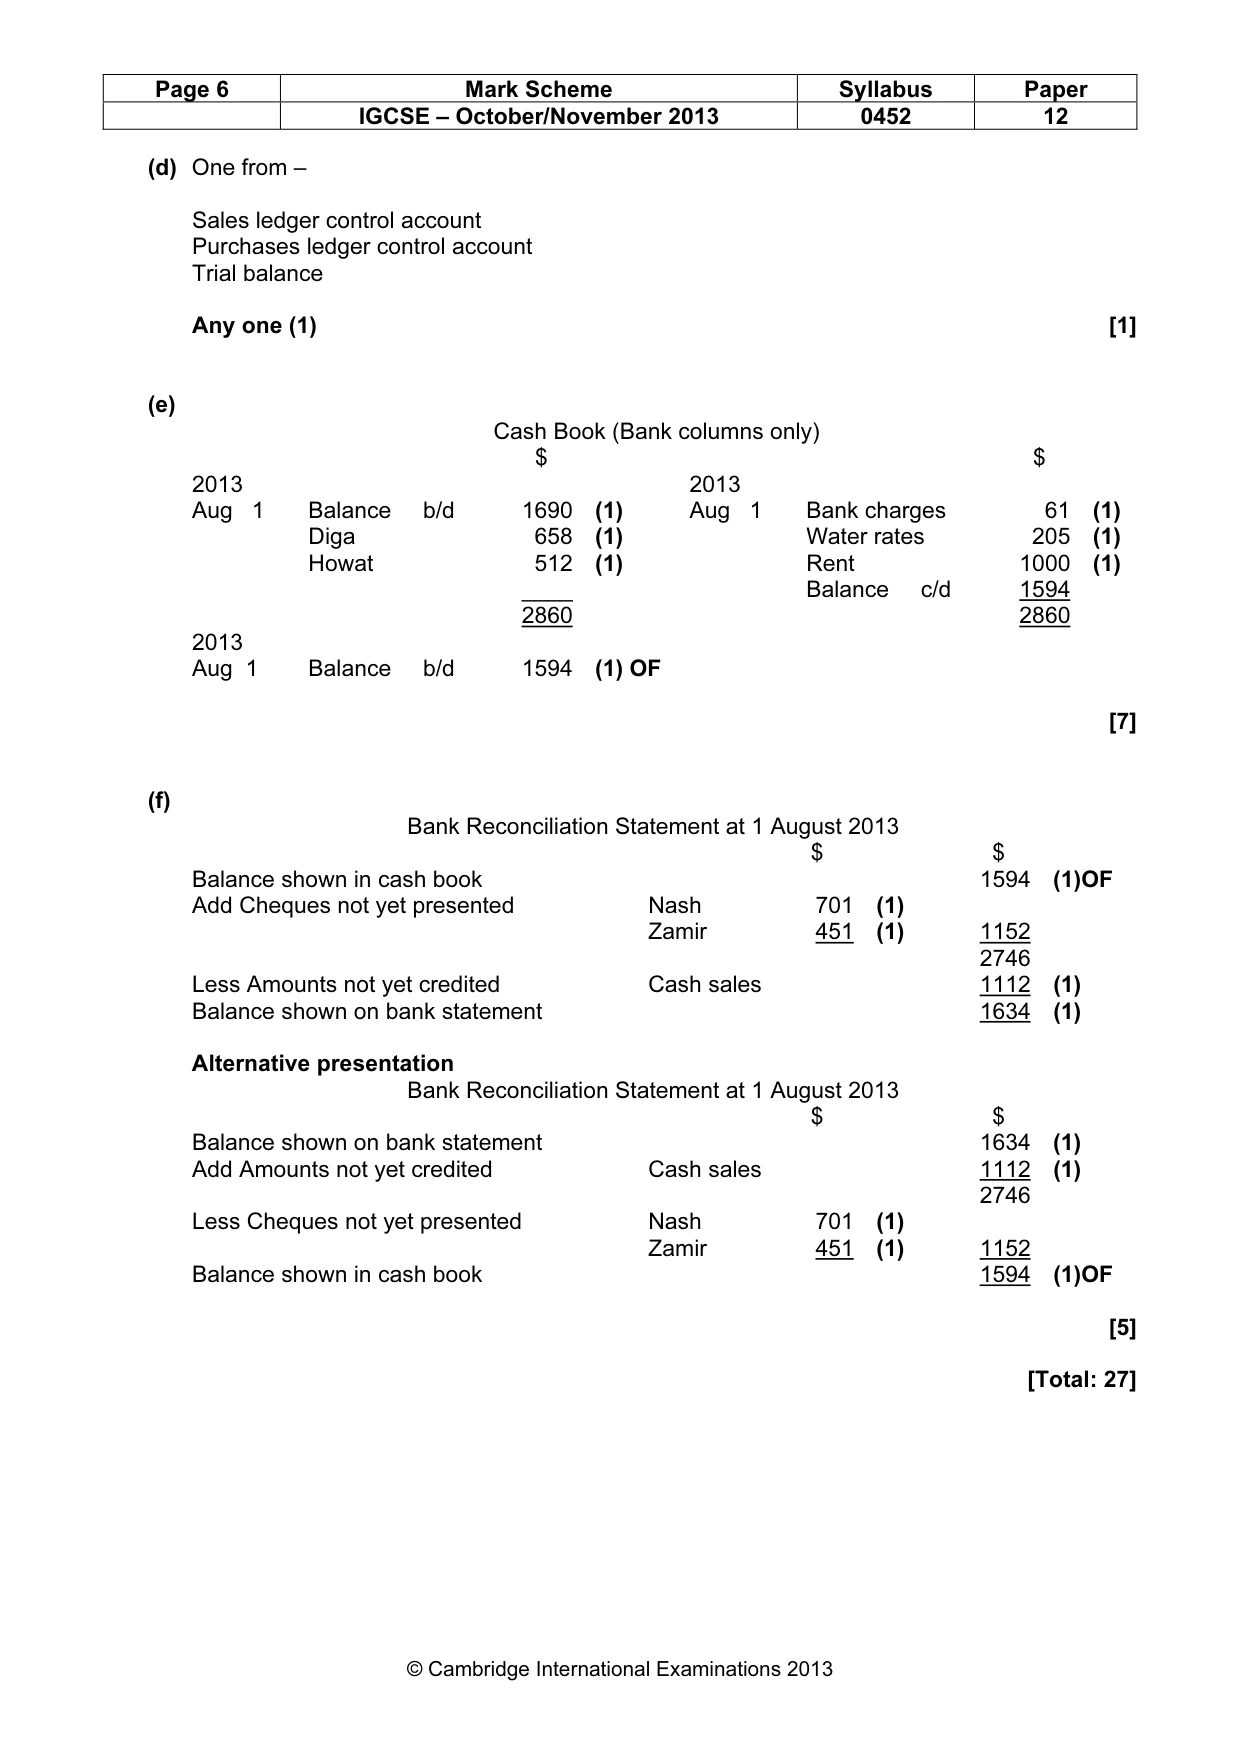
Page 6 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 (d) One from – Sales ledger control account Purchases ledger control account Trial balance Any one (1) [1] (e) Cash Book (Bank columns only) $ $ 2013 2013 Aug 1 Balance b/d 1690 (1) Aug 1 Bank charges 61 (1) Diga 658 (1) Water rates 205 (1) Howat 512 (1) Rent 1000 (1) ____ Balance c/d 1594 2860 2860 2013 Aug 1 Balance b/d 1594 (1) OF [7] (f) Bank Reconciliation Statement at 1 August 2013 $ $ Balance shown in cash book 1594 (1)OF Add Cheques not yet presented Nash 701 (1) Zamir 451 (1) 1152 2746 Less Amounts not yet credited Cash sales 1112 (1) Balance shown on bank statement 1634 (1) Alternative presentation Bank Reconciliation Statement at 1 August 2013 $ $ Balance shown on bank statement 1634 (1) Add Amounts not yet credited Cash sales 1112 (1) 2746 Less Cheques not yet presented Nash 701 (1) Zamir 451 (1) 1152 Balance shown in cash book 1594 (1)OF [5] [Total: 27]
Mark scheme, page 7
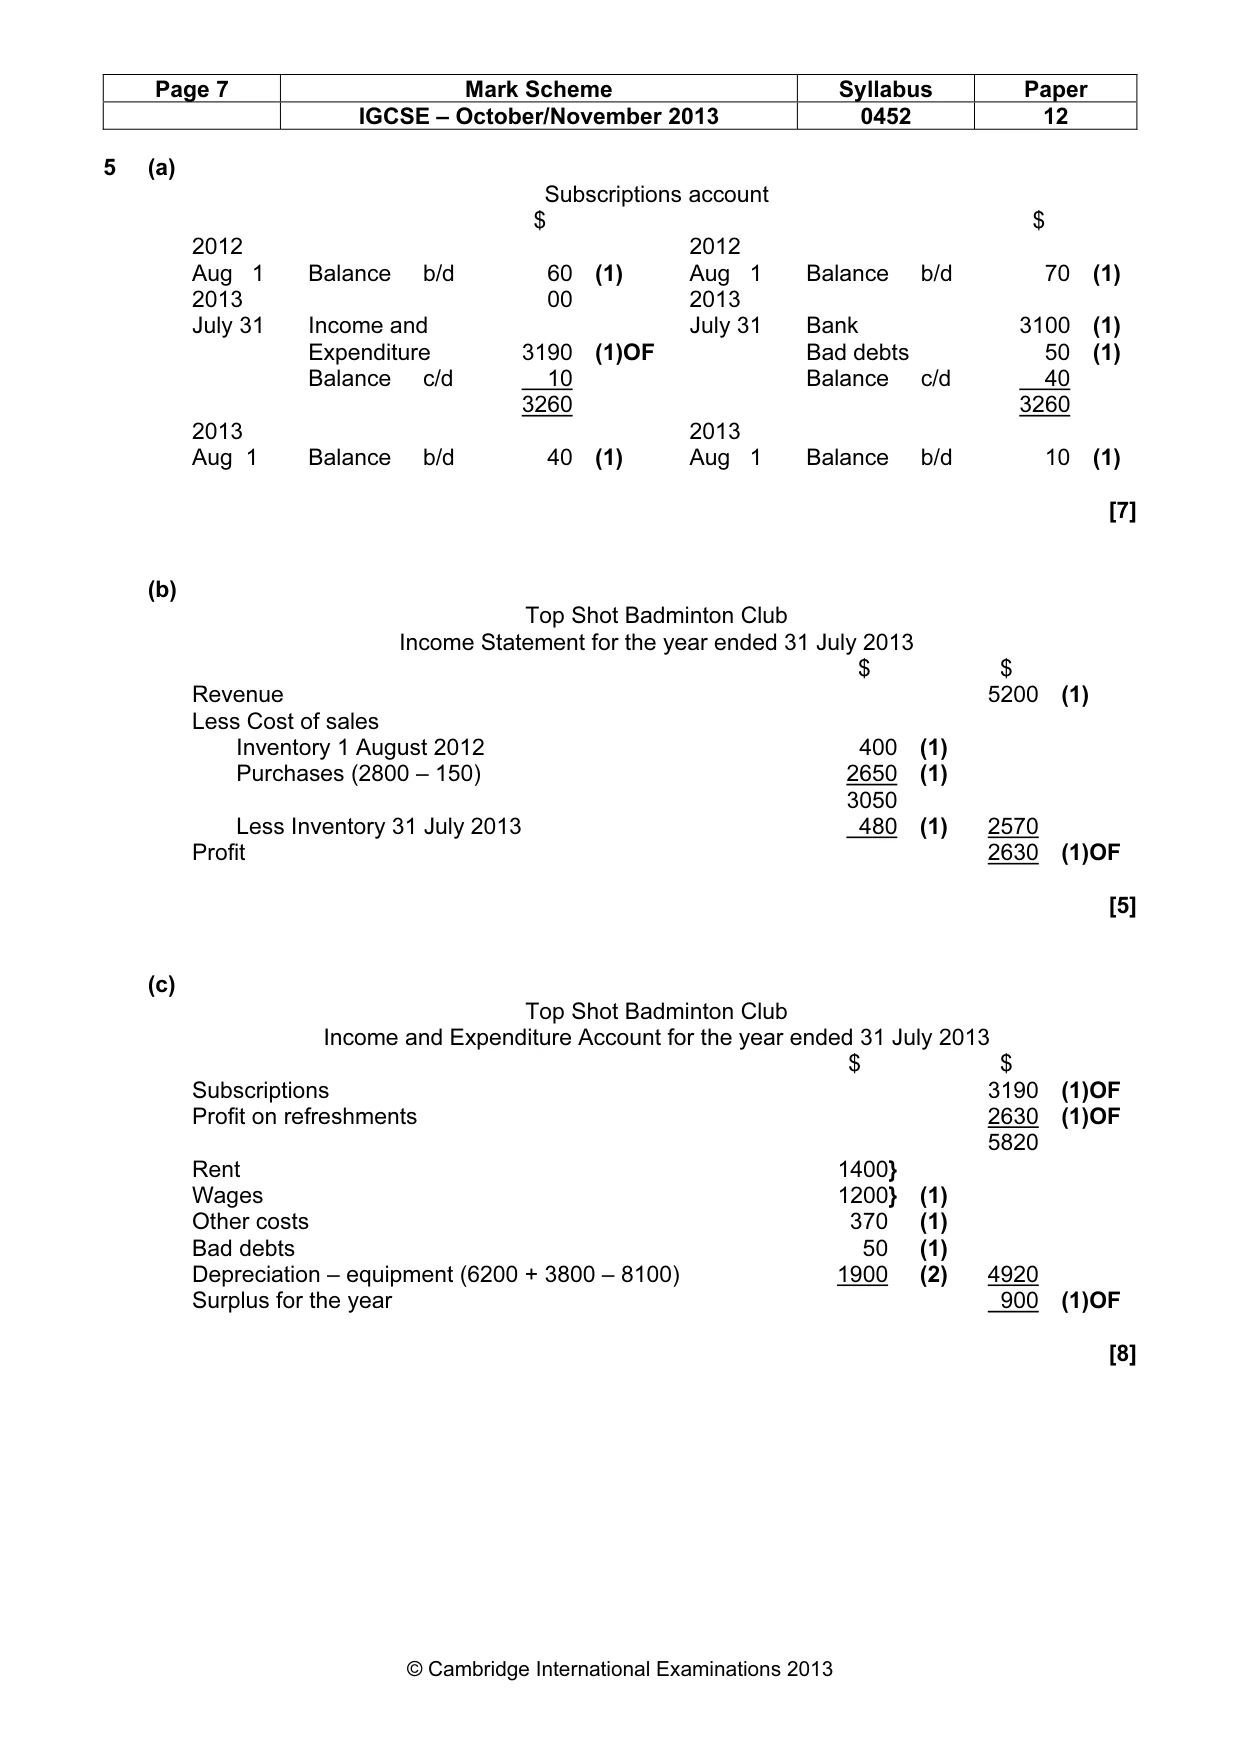
Page 7 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 5 (a) Subscriptions account $ $ 2012 2012 Aug 1 Balance b/d 60 (1) Aug 1 Balance b/d 70 (1) 2013 00 2013 July 31 Income and July 31 Bank 3100 (1) Expenditure 3190 (1)OF Bad debts 50 (1) Balance c/d 10 Balance c/d 40 3260 3260 2013 2013 Aug 1 Balance b/d 40 (1) Aug 1 Balance b/d 10 (1) [7] (b) Top Shot Badminton Club Income Statement for the year ended 31 July 2013 $ $ Revenue 5200 (1) Less Cost of sales Inventory 1 August 2012 400 (1) Purchases (2800 – 150) 2650 (1) 3050 Less Inventory 31 July 2013 480 (1) 2570 Profit 2630 (1)OF [5] (c) Top Shot Badminton Club Income and Expenditure Account for the year ended 31 July 2013 $ $ Subscriptions 3190 (1)OF Profit on refreshments 2630 (1)OF 5820 Rent 1400} Wages 1200} (1) Other costs 370 (1) Bad debts 50 (1) Depreciation – equipment (6200 + 3800 – 8100) 1900 (2) 4920 Surplus for the year 900 (1)OF [8]
Mark scheme, page 8
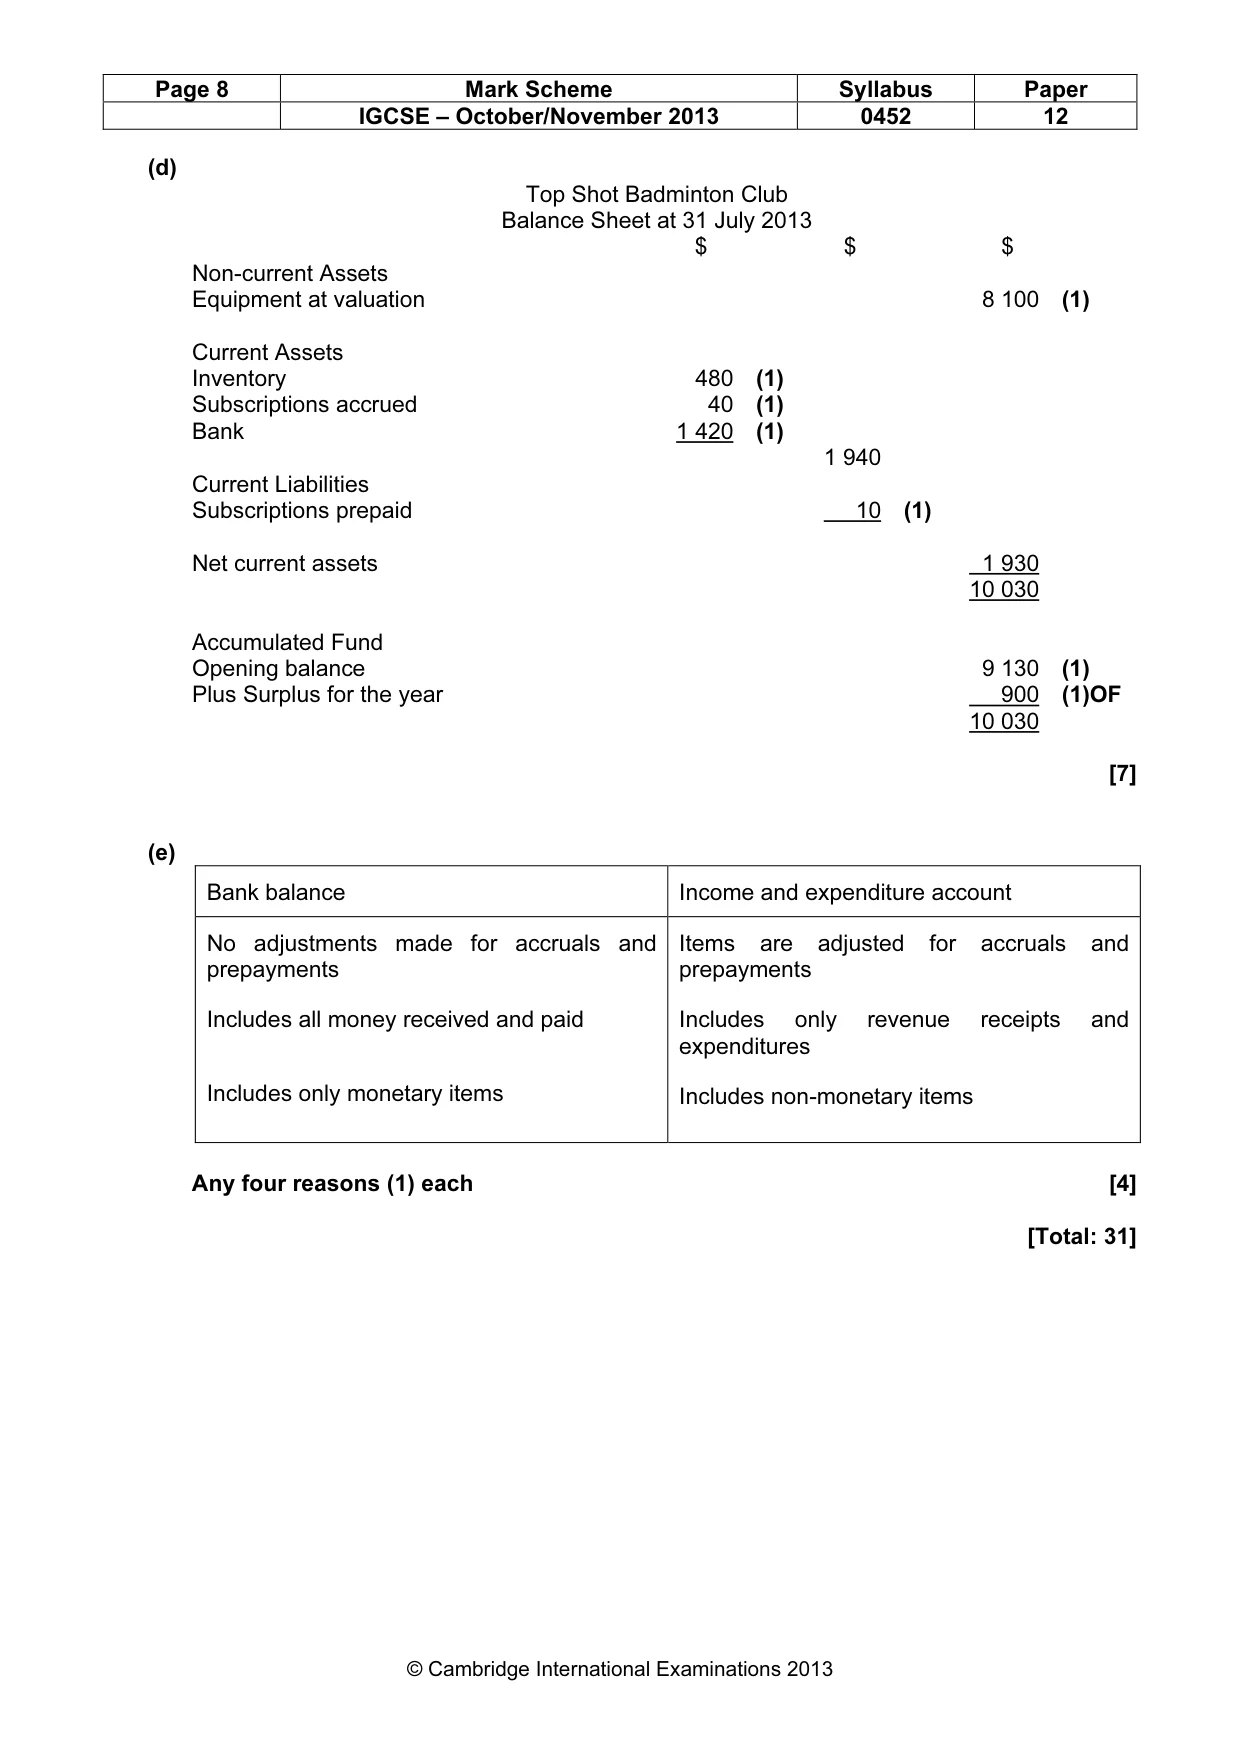
Page 8 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 (d) Top Shot Badminton Club Balance Sheet at 31 July 2013 $ $ $ Non-current Assets Equipment at valuation 8 100 (1) Current Assets Inventory 480 (1) Subscriptions accrued 40 (1) Bank 1 420 (1) 1 940 Current Liabilities Subscriptions prepaid 10 (1) Net current assets 1 930 10 030 Accumulated Fund Opening balance 9 130 (1) Plus Surplus for the year 900 (1)OF 10 030 [7] (e) Bank balance Income and expenditure account No adjustments made for accruals and prepayments Includes all money received and paid Includes only monetary items Items are adjusted for accruals and prepayments Includes only revenue receipts and expenditures Includes non-monetary items Any four reasons (1) each [4] [Total: 31]
Mark scheme, page 9
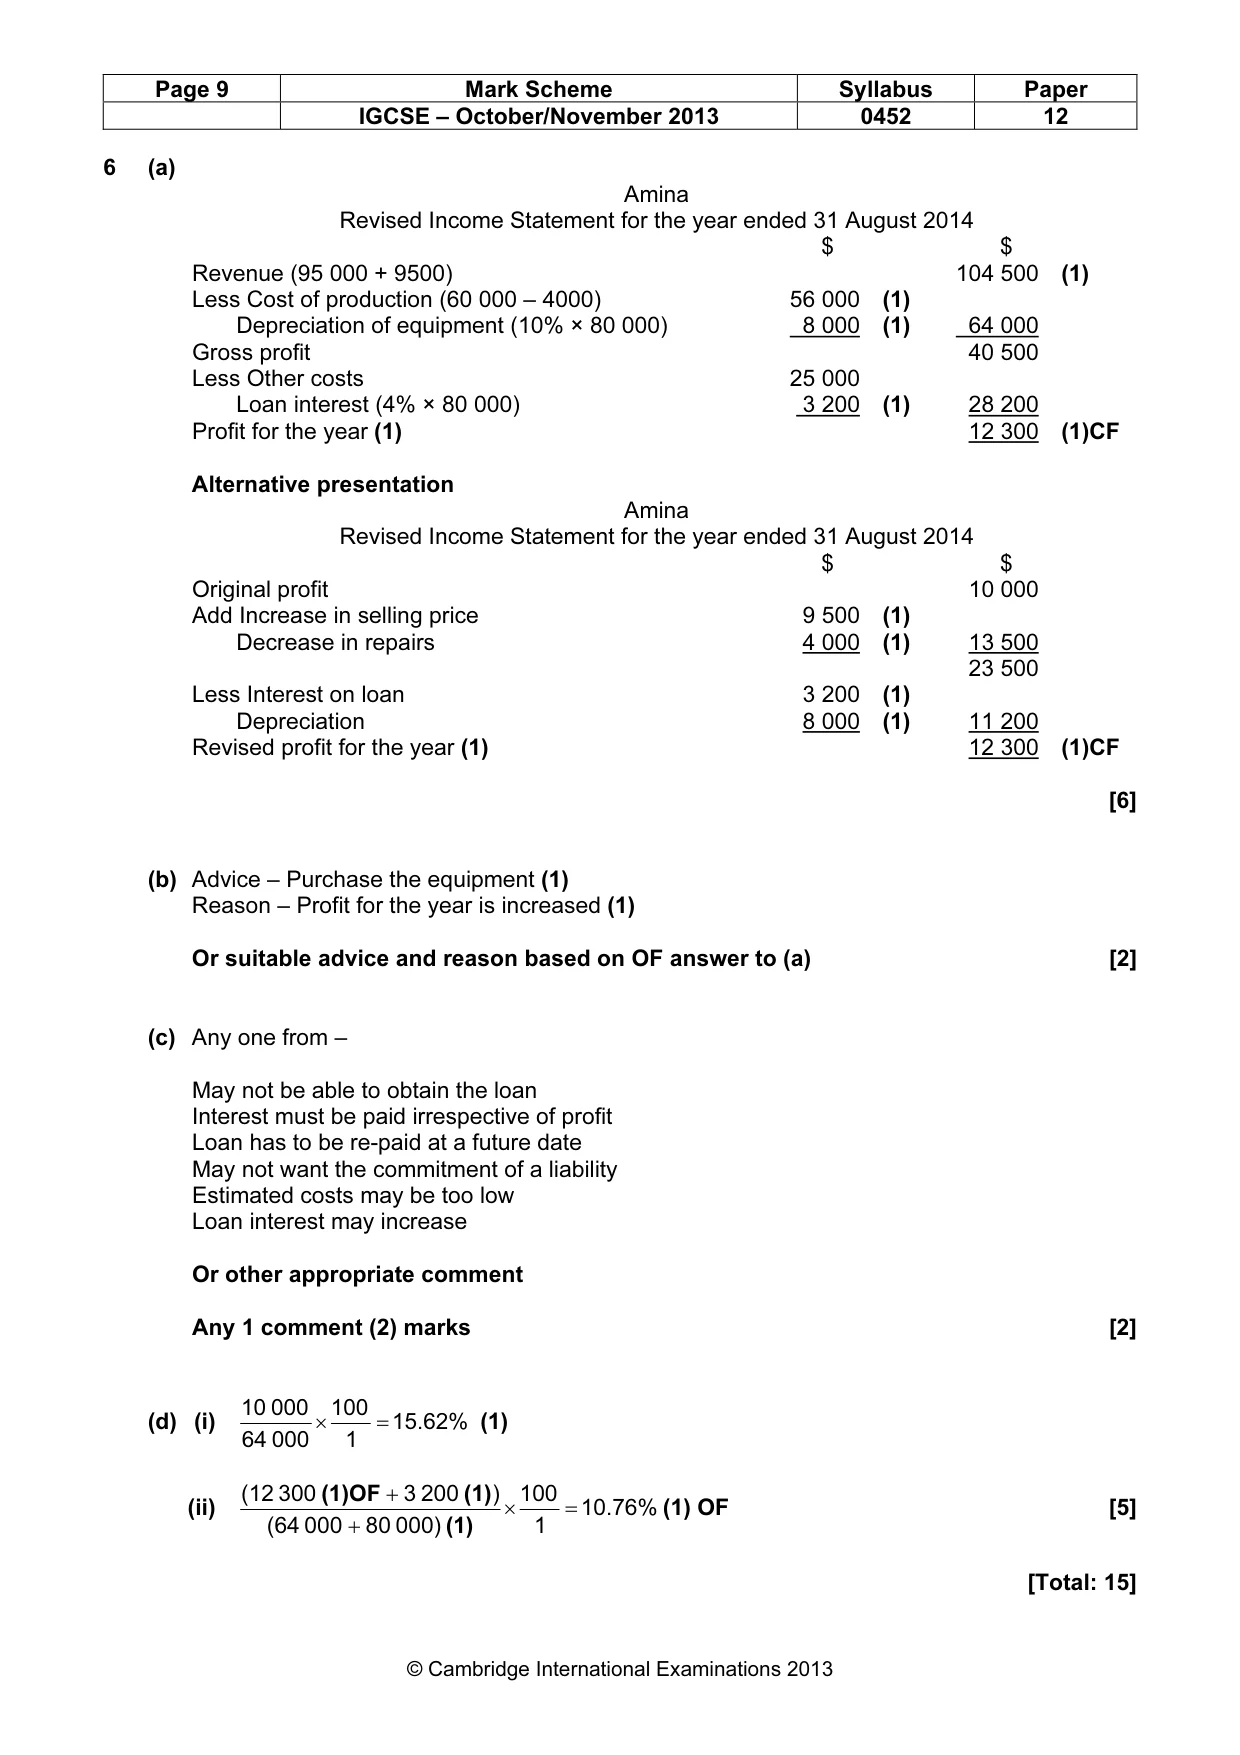
Page 9 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 12 © Cambridge International Examinations 2013 6 (a) Amina Revised Income Statement for the year ended 31 August 2014 $ $ Revenue (95 000 + 9500) 104 500 (1) Less Cost of production (60 000 – 4000) 56 000 (1) Depreciation of equipment (10% × 80 000) 8 000 (1) 64 000 Gross profit 40 500 Less Other costs 25 000 Loan interest (4% × 80 000) 3 200 (1) 28 200 Profit for the year (1) 12 300 (1)CF Alternative presentation Amina Revised Income Statement for the year ended 31 August 2014 $ $ Original profit 10 000 Add Increase in selling price 9 500 (1) Decrease in repairs 4 000 (1) 13 500 23 500 Less Interest on loan 3 200 (1) Depreciation 8 000 (1) 11 200 Revised profit for the year (1) 12 300 (1)CF [6] (b) Advice – Purchase the equipment (1) Reason – Profit for the year is increased (1) Or suitable advice and reason based on OF answer to (a) [2] (c) Any one from – May not be able to obtain the loan Interest must be paid irrespective of profit Loan has to be re-paid at a future date May not want the commitment of a liability Estimated costs may be too low Loan interest may increase Or other appropriate comment Any 1 comment (2) marks [2] (d) (i) 15.62% 1 100 000 64 000 10 = × (1) (ii) 10.76% 1 100 000) 80 000 (64 ) 200 3 300 (12 = × + + (1) (1) (1)OF (1) OF [5] [Total: 15]
What you needed in this session
Cambridge’s own grade thresholds for 2013 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.