Cambridge IGCSE Accounting 0452 — 2013 May/June Paper 2 · Variant 3
0452/23/M/J/13 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme11 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 20 printed pages. IB13 06_0452_23/2RP © UCLES 2013 [Turn over *0945197922* UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/23 Paper 2 May/June 2013 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for any diagrams or graphs. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
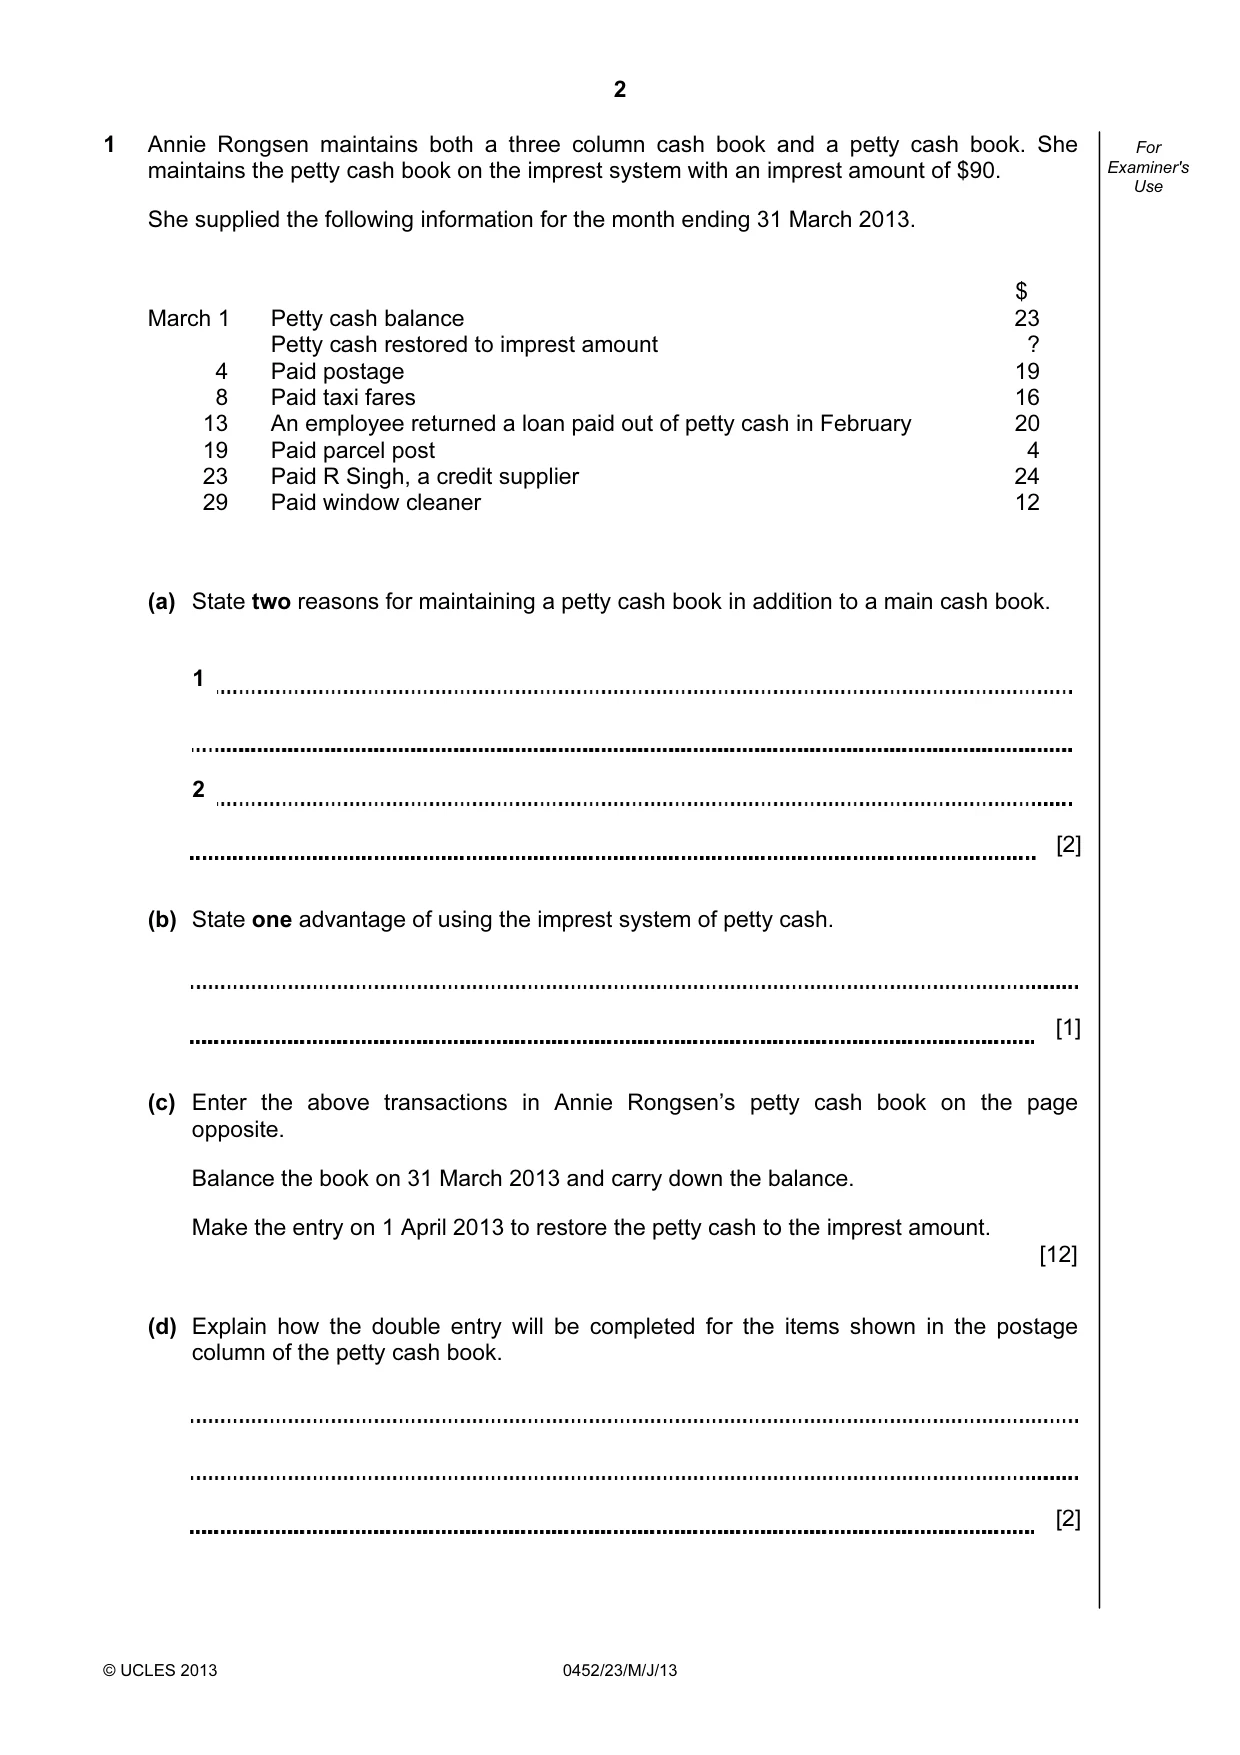
Question paper, page 2
2 © UCLES 2013 0452/23/M/J/13 For Examiner's Use 1 Annie Rongsen maintains both a three column cash book and a petty cash book. She maintains the petty cash book on the imprest system with an imprest amount of $90. She supplied the following information for the month ending 31 March 2013. $ March 1 Petty cash balance 23 Petty cash restored to imprest amount ? 4 Paid postage 19 8 Paid taxi fares 16 13 An employee returned a loan paid out of petty cash in February 20 19 Paid parcel post 4 23 Paid R Singh, a credit supplier 24 29 Paid window cleaner 12 (a) State two reasons for maintaining a petty cash book in addition to a main cash book. 1 2 [2] (b) State one advantage of using the imprest system of petty cash. [1] (c) Enter the above transactions in Annie Rongsen’s petty cash book on the page opposite. Balance the book on 31 March 2013 and carry down the balance. Make the entry on 1 April 2013 to restore the petty cash to the imprest amount. [12] (d) Explain how the double entry will be completed for the items shown in the postage column of the petty cash book. [2]
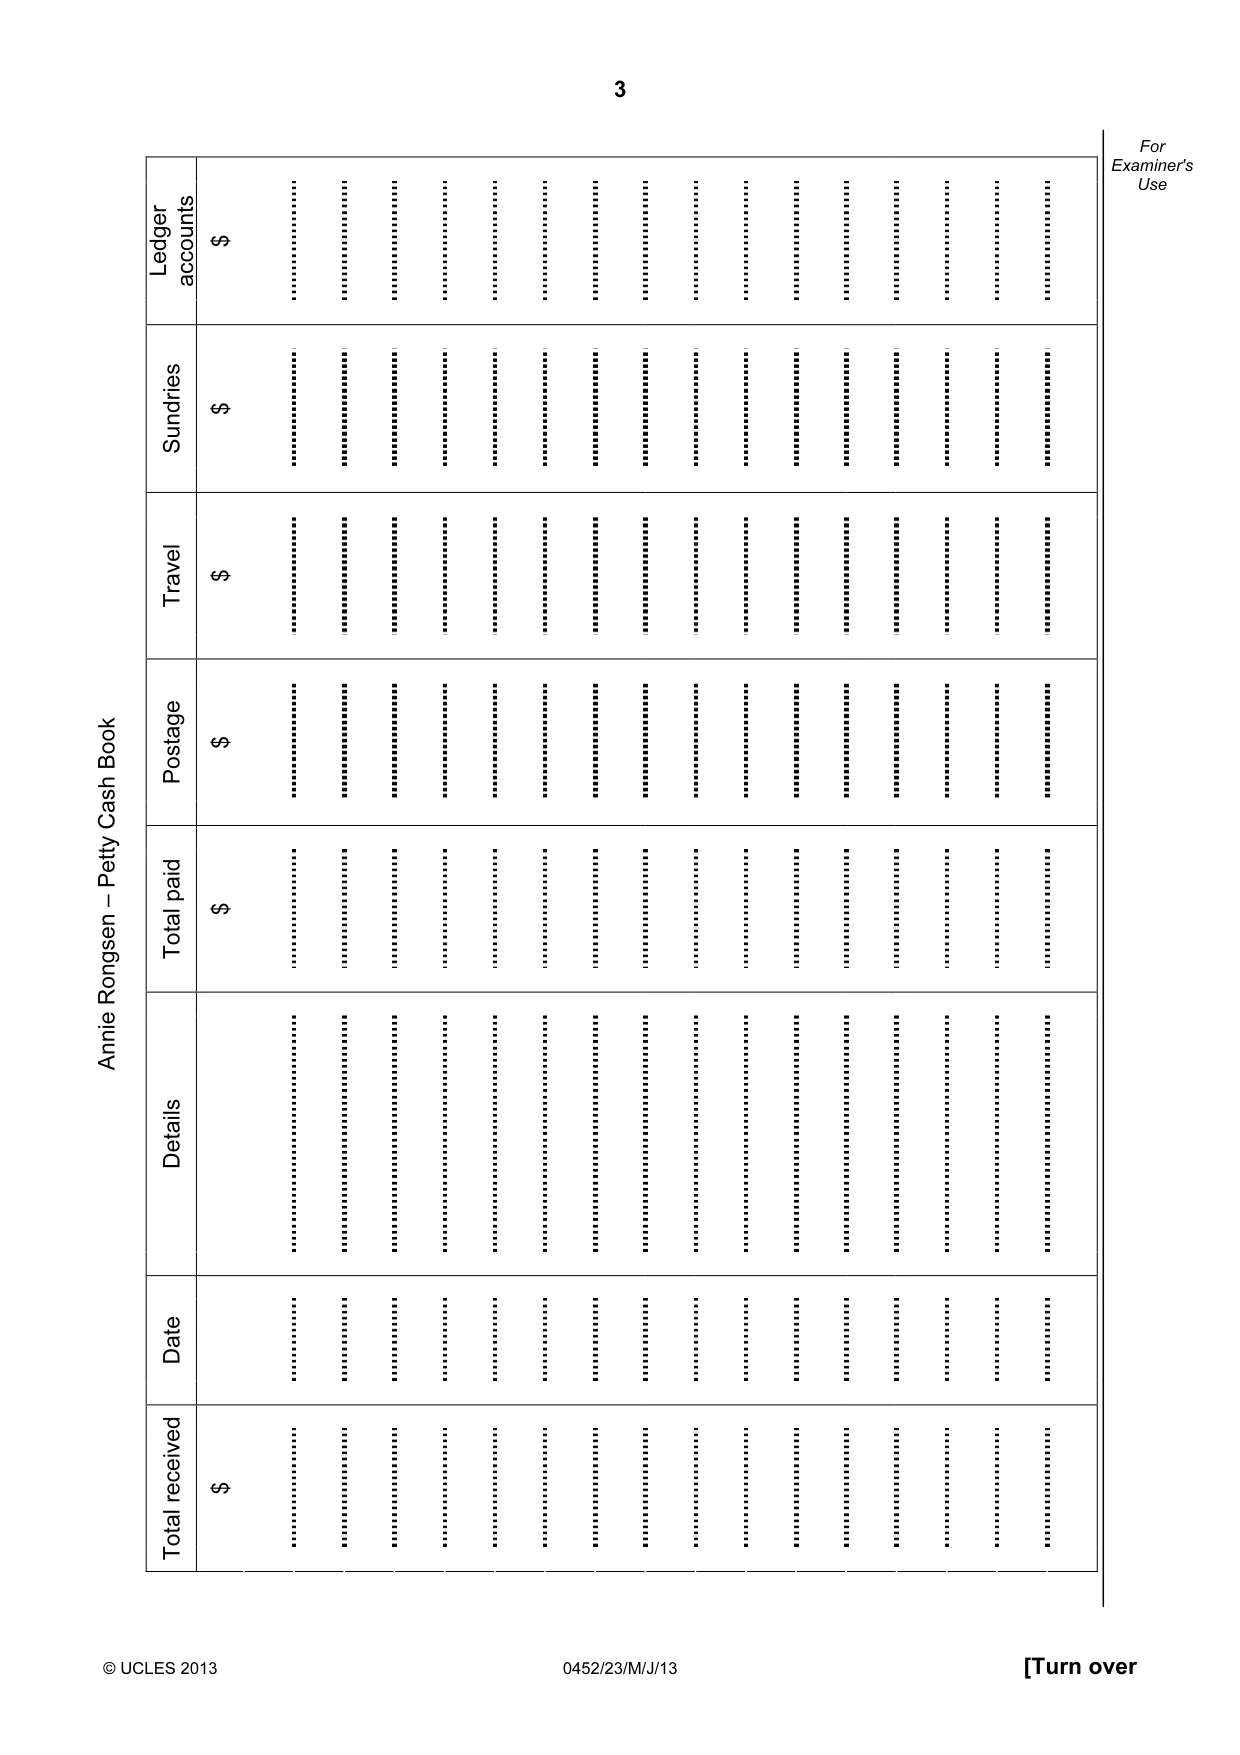
Question paper, page 3
3 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use Ledger accounts $ Sundries $ Travel $ Postage $ Total paid $ Details Date Annie Rongsen – Petty Cash Book Total received $
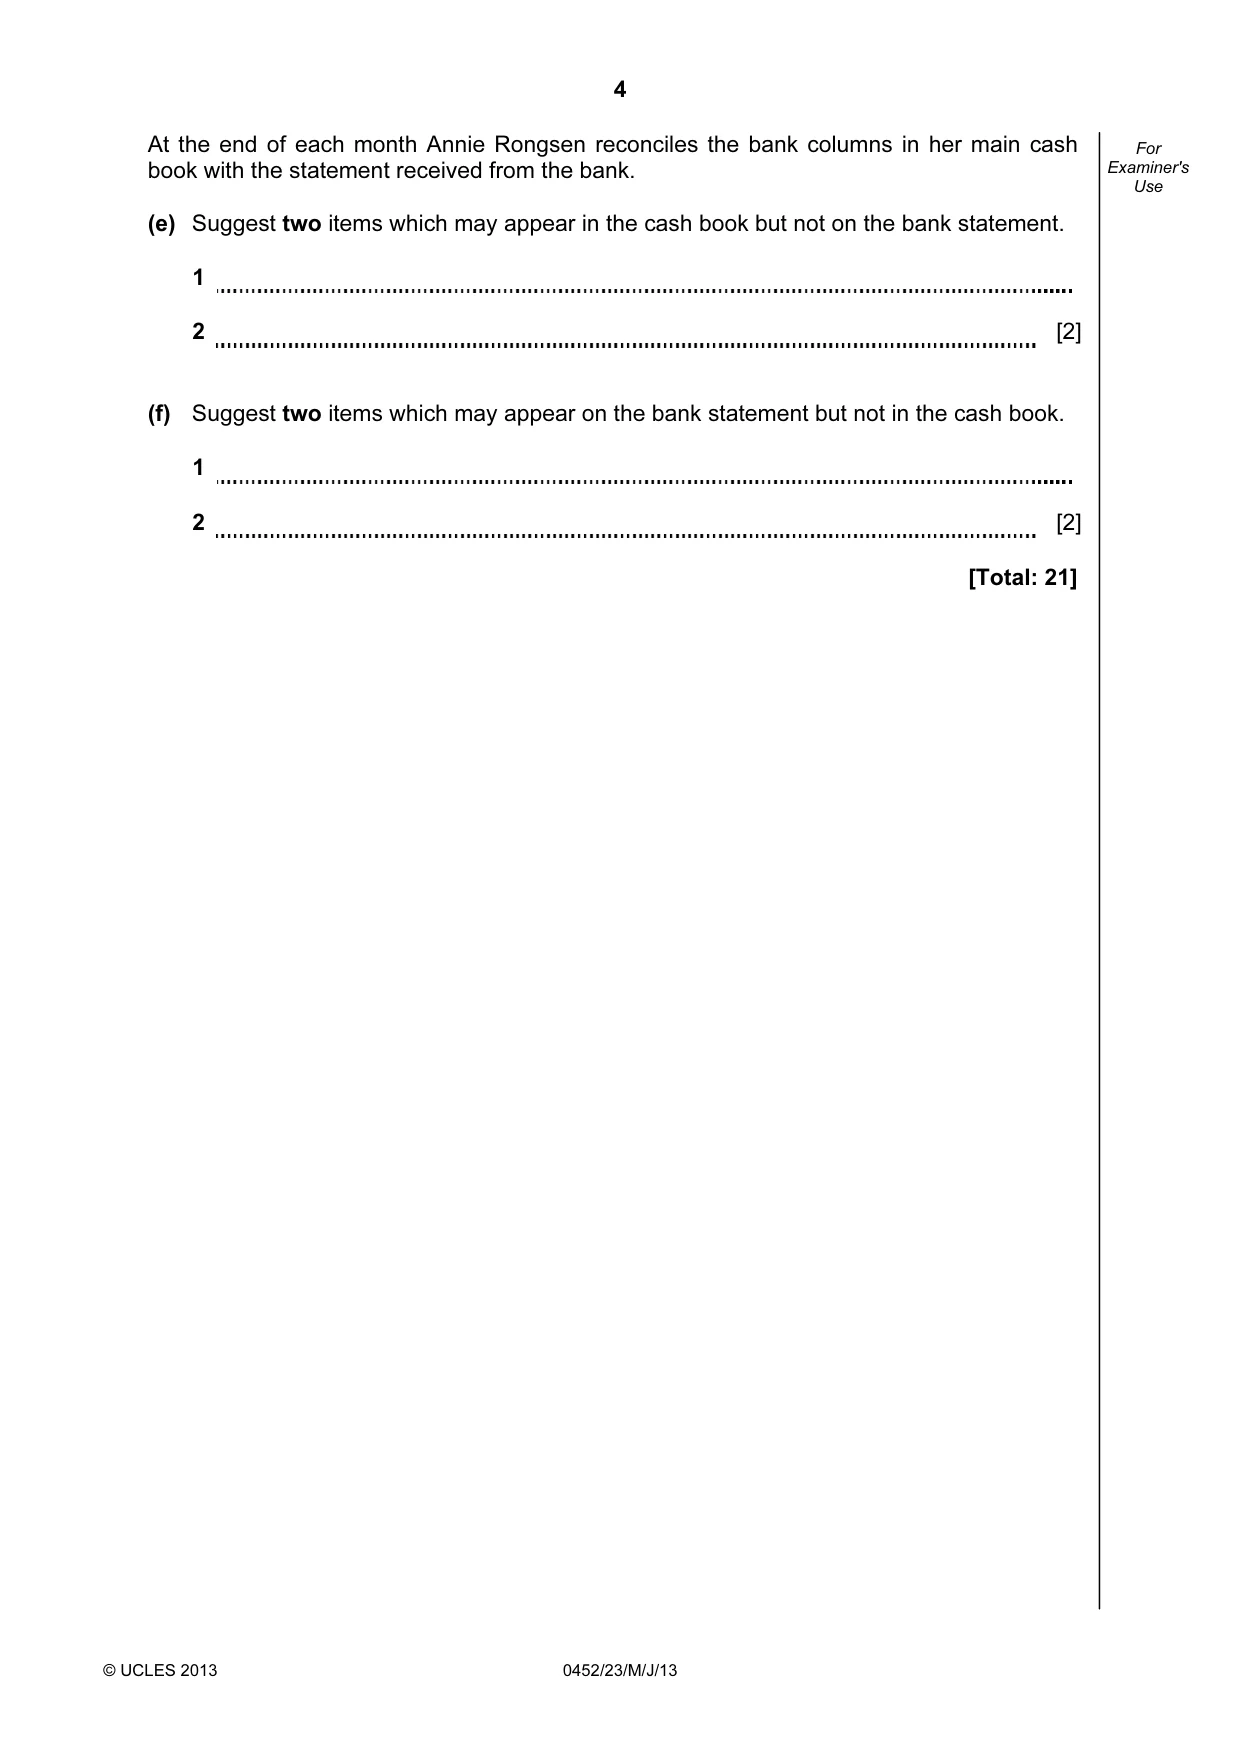
Question paper, page 4
4 © UCLES 2013 0452/23/M/J/13 For Examiner's Use At the end of each month Annie Rongsen reconciles the bank columns in her main cash book with the statement received from the bank. (e) Suggest two items which may appear in the cash book but not on the bank statement. 1 2 [2] (f) Suggest two items which may appear on the bank statement but not in the cash book. 1 2 [2] [Total: 21]
Question paper, page 5
5 © UCLES 2013 0452/23/M/J/13 [Turn over Question 2 is on the next page.
Question paper, page 6
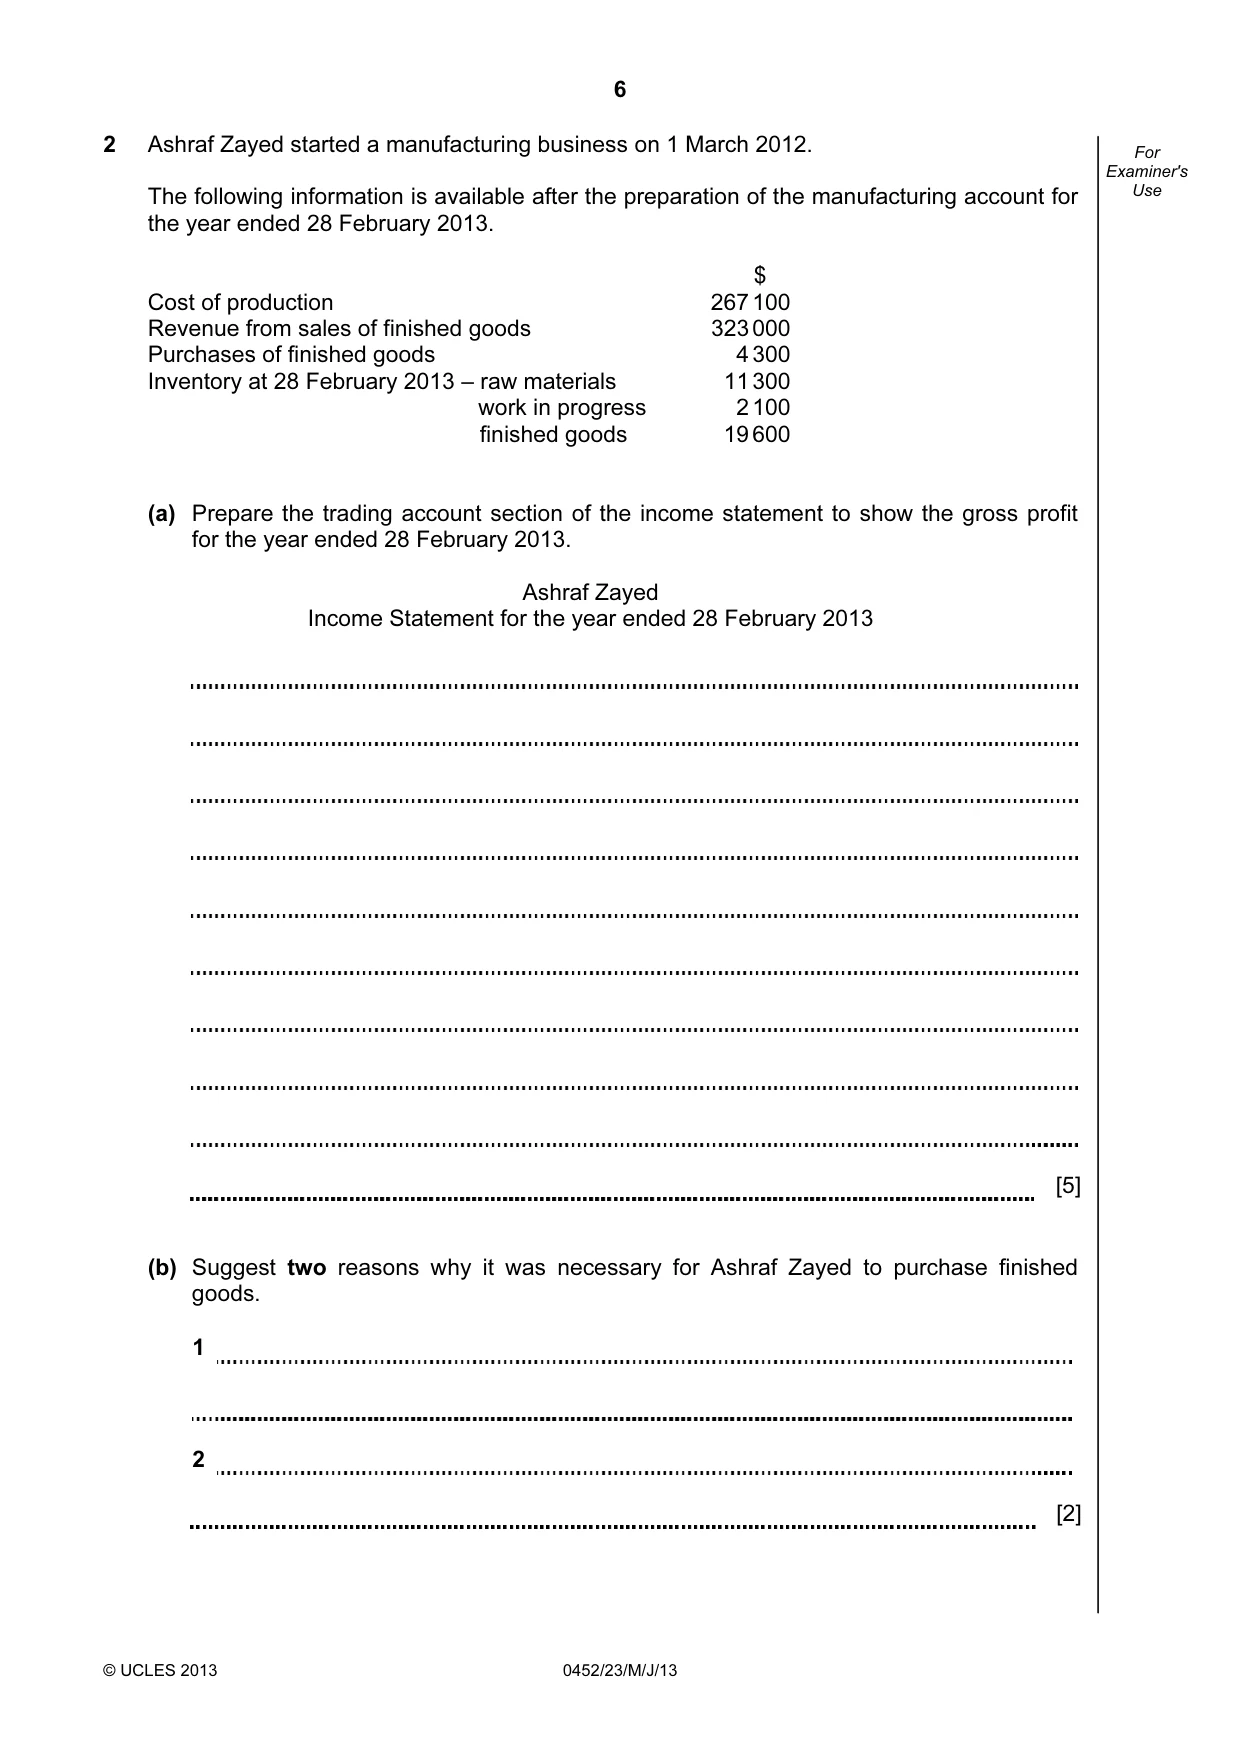
6 © UCLES 2013 0452/23/M/J/13 For Examiner's Use 2 Ashraf Zayed started a manufacturing business on 1 March 2012. The following information is available after the preparation of the manufacturing account for the year ended 28 February 2013. $ Cost of production 267 100 Revenue from sales of finished goods 323 000 Purchases of finished goods 4 300 Inventory at 28 February 2013 – raw materials 11 300 work in progress 2 100 finished goods 19 600 (a) Prepare the trading account section of the income statement to show the gross profit for the year ended 28 February 2013. Ashraf Zayed Income Statement for the year ended 28 February 2013 [5] (b) Suggest two reasons why it was necessary for Ashraf Zayed to purchase finished goods. 1 2 [2]
Question paper, page 7
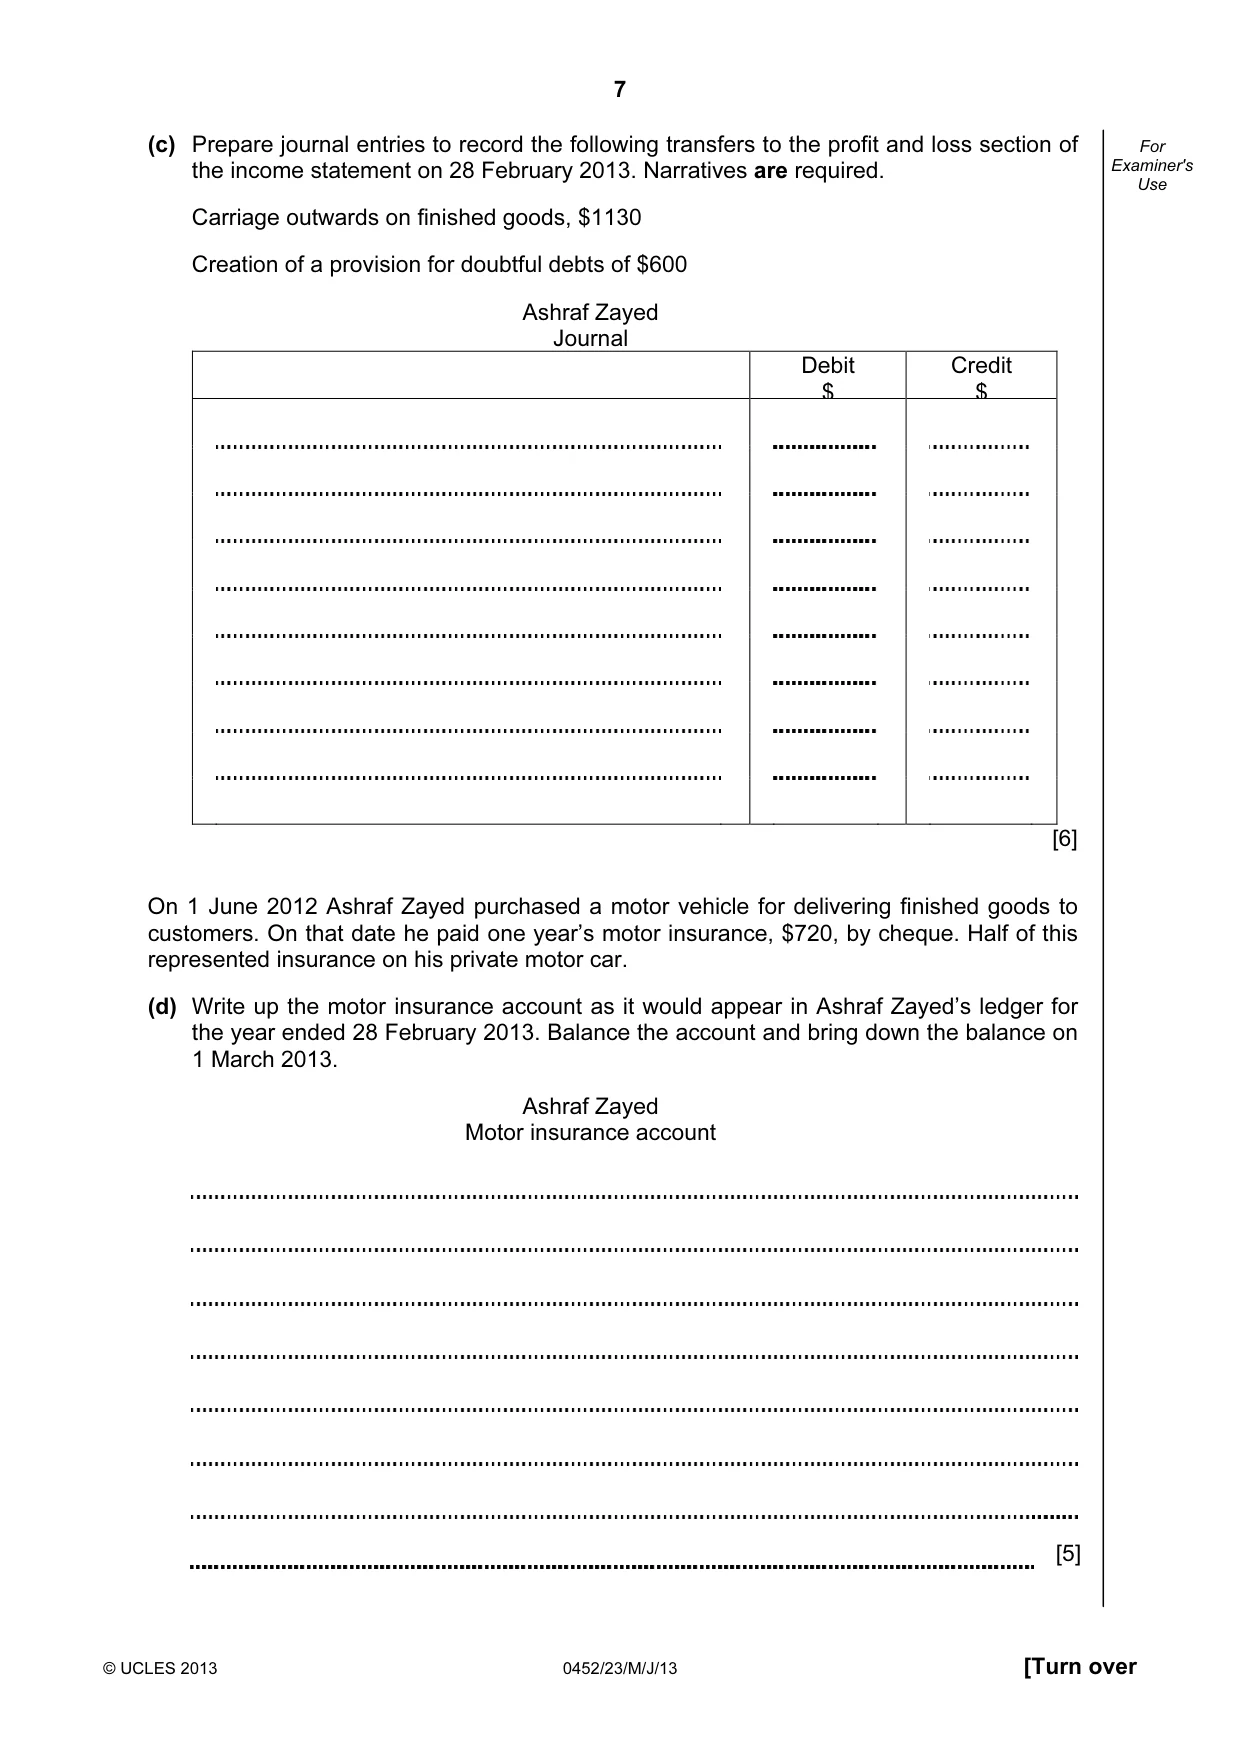
7 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use (c) Prepare journal entries to record the following transfers to the profit and loss section of the income statement on 28 February 2013. Narratives are required. Carriage outwards on finished goods, $1130 Creation of a provision for doubtful debts of $600 Ashraf Zayed Journal Debit $ Credit $ [6] On 1 June 2012 Ashraf Zayed purchased a motor vehicle for delivering finished goods to customers. On that date he paid one year’s motor insurance, $720, by cheque. Half of this represented insurance on his private motor car. (d) Write up the motor insurance account as it would appear in Ashraf Zayed’s ledger for the year ended 28 February 2013. Balance the account and bring down the balance on 1 March 2013. Ashraf Zayed Motor insurance account [5]
Question paper, page 8
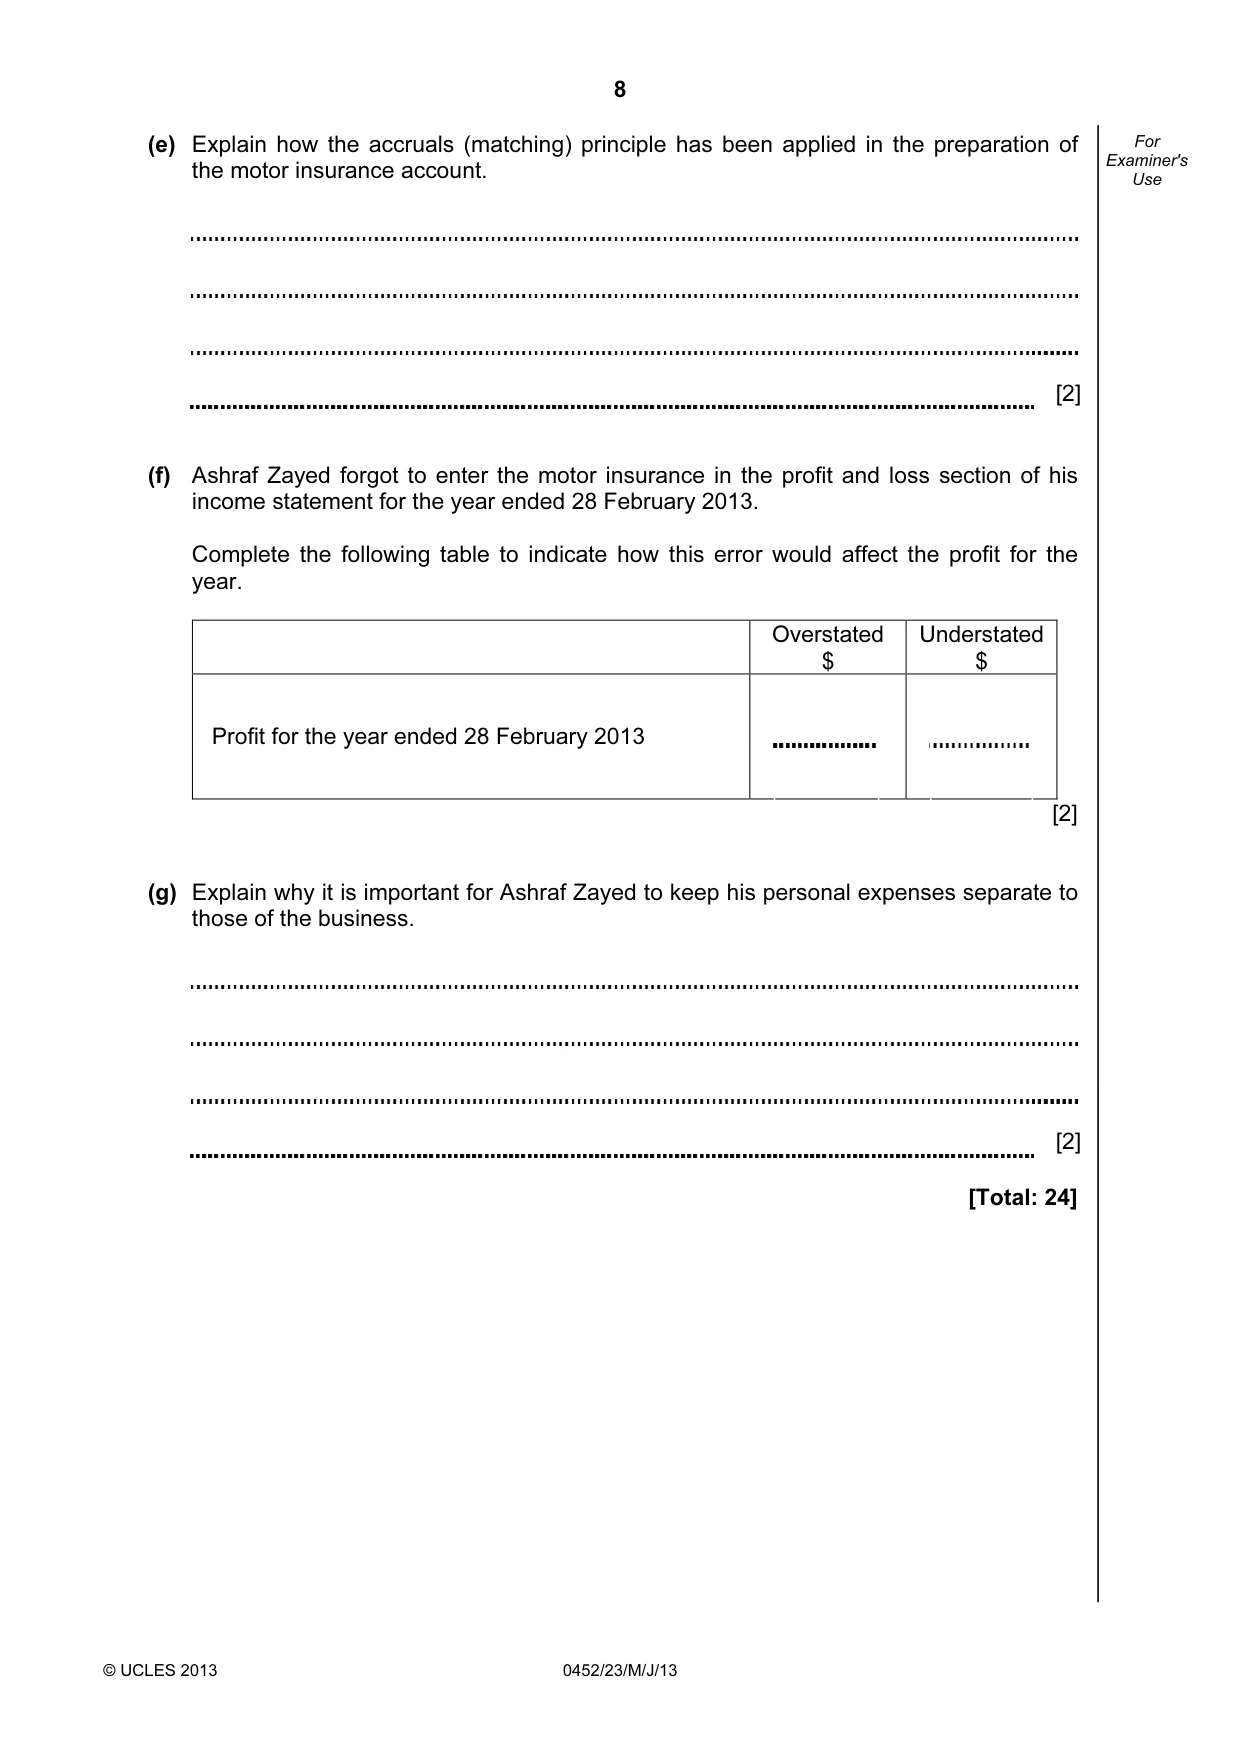
8 © UCLES 2013 0452/23/M/J/13 For Examiner's Use (e) Explain how the accruals (matching) principle has been applied in the preparation of the motor insurance account. [2] (f) Ashraf Zayed forgot to enter the motor insurance in the profit and loss section of his income statement for the year ended 28 February 2013. Complete the following table to indicate how this error would affect the profit for the year. Overstated $ Understated $ Profit for the year ended 28 February 2013 [2] (g) Explain why it is important for Ashraf Zayed to keep his personal expenses separate to those of the business. [2] [Total: 24]
Question paper, page 9
9 © UCLES 2013 0452/23/M/J/13 [Turn over Question 3 is on the next page.
Question paper, page 10
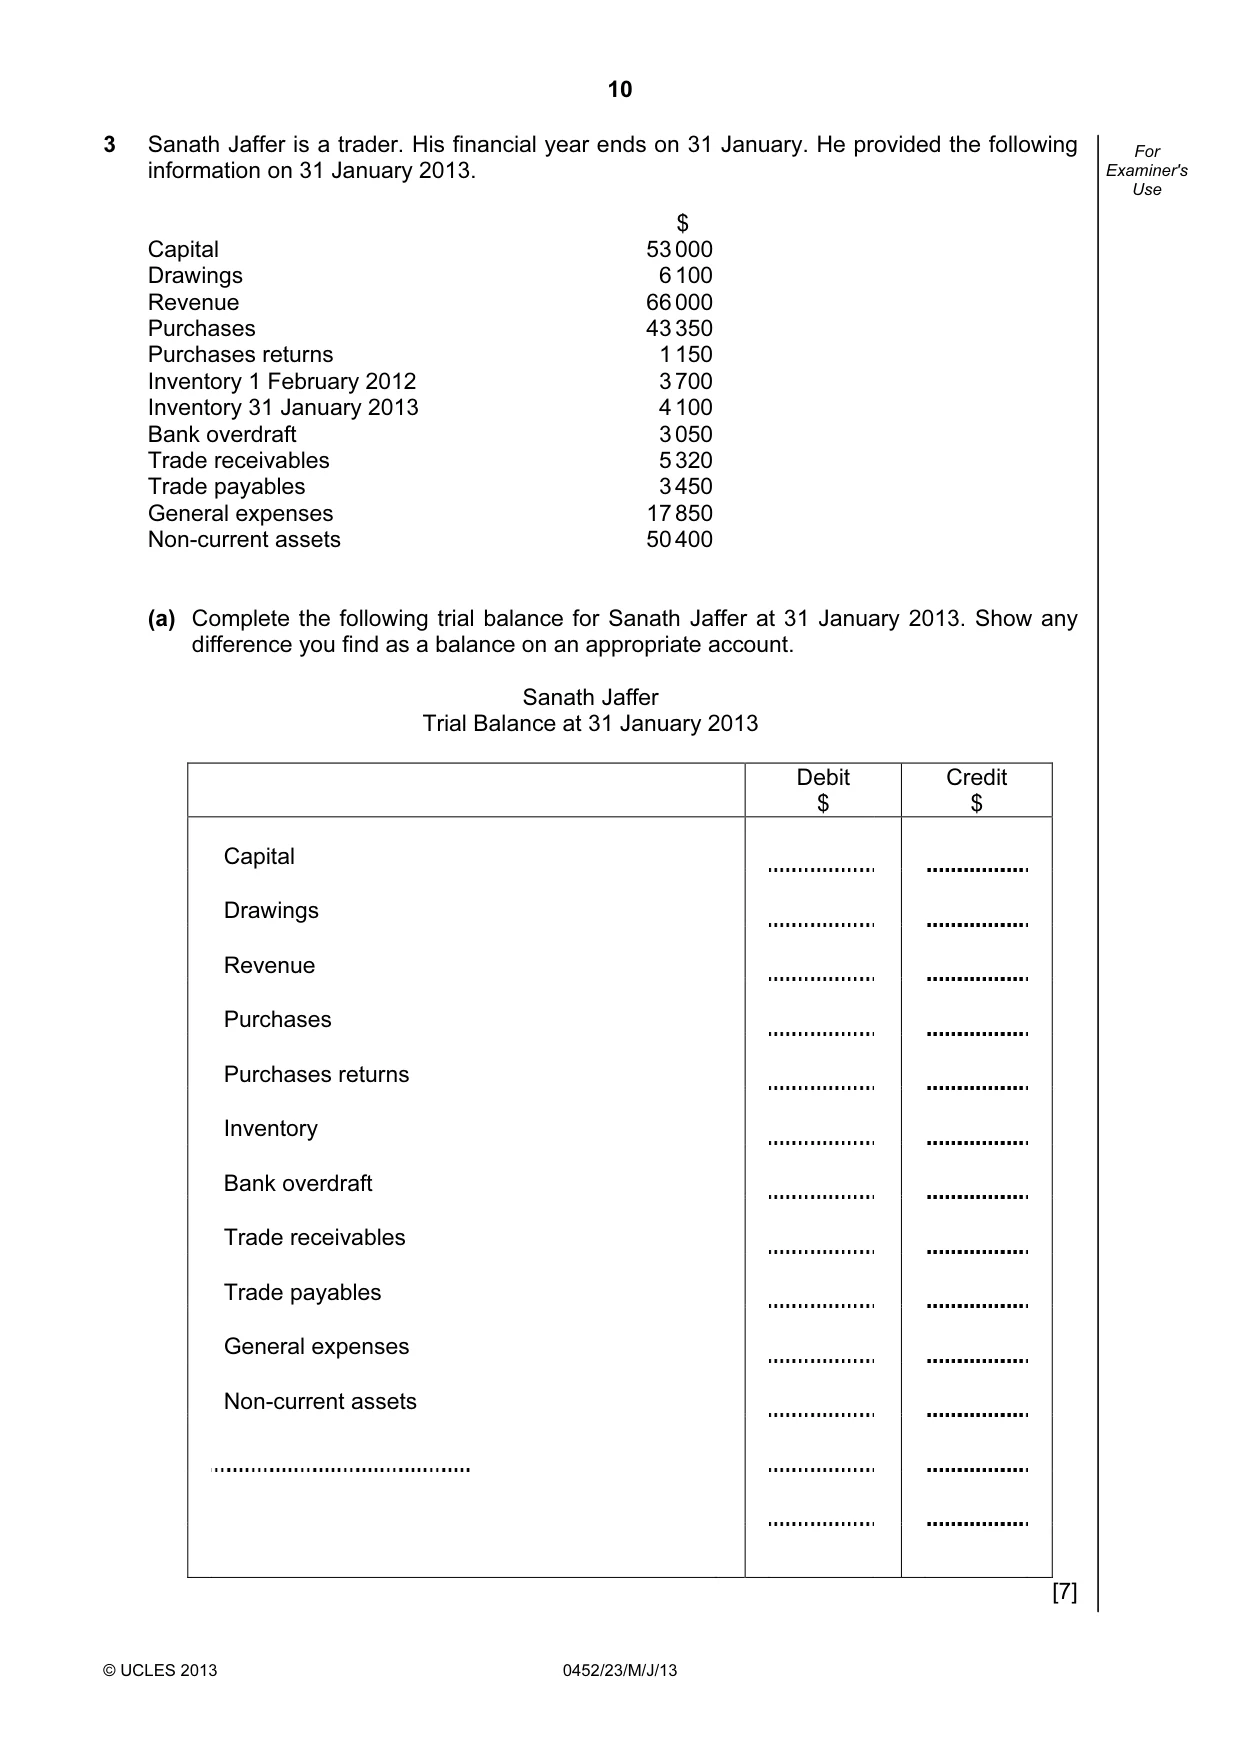
10 © UCLES 2013 0452/23/M/J/13 For Examiner's Use 3 Sanath Jaffer is a trader. His financial year ends on 31 January. He provided the following information on 31 January 2013. $ Capital 53 000 Drawings 6 100 Revenue 66 000 Purchases 43 350 Purchases returns 1 150 Inventory 1 February 2012 3 700 Inventory 31 January 2013 4 100 Bank overdraft 3 050 Trade receivables 5 320 Trade payables 3 450 General expenses 17 850 Non-current assets 50 400 (a) Complete the following trial balance for Sanath Jaffer at 31 January 2013. Show any difference you find as a balance on an appropriate account. Sanath Jaffer Trial Balance at 31 January 2013 Debit $ Credit $ Capital Drawings Revenue Purchases Purchases returns Inventory Bank overdraft Trade receivables Trade payables General expenses Non-current assets [7]
Question paper, page 11
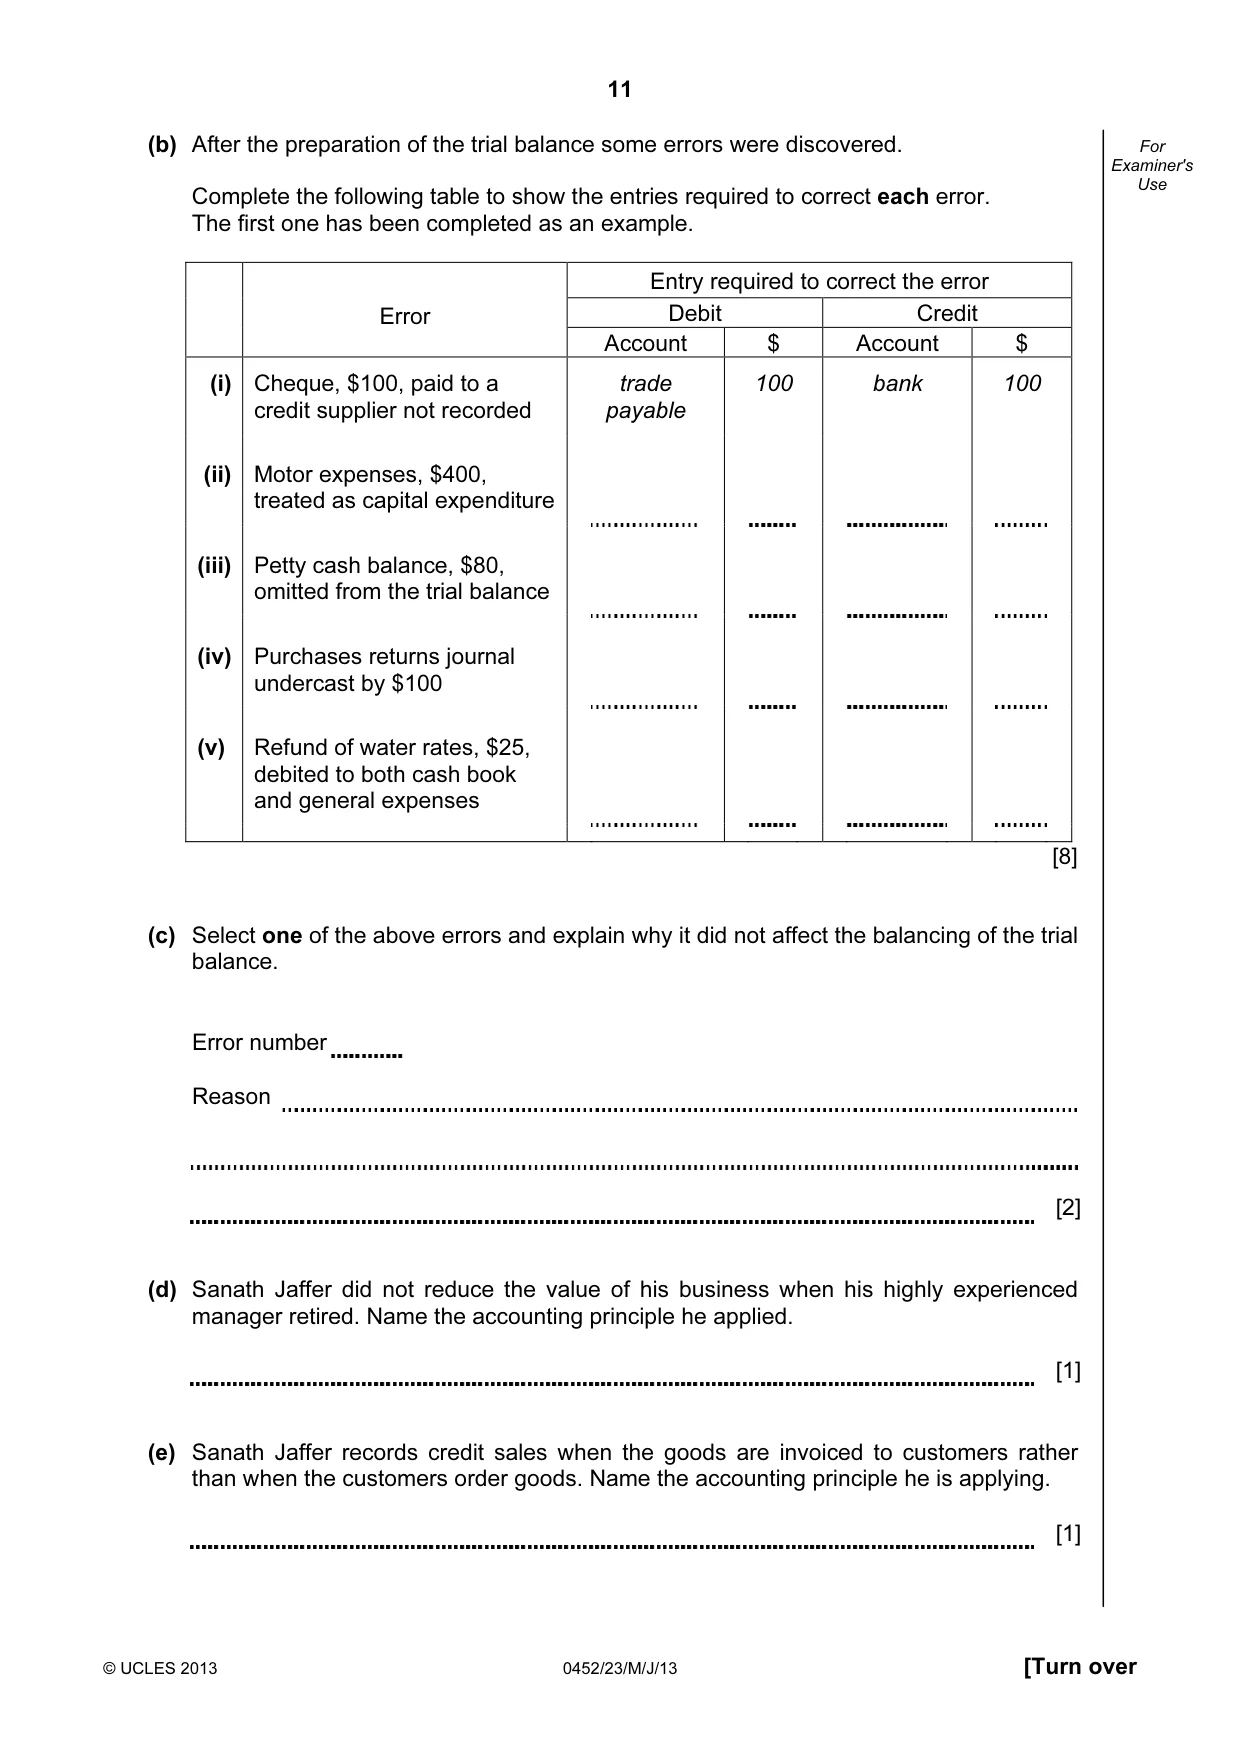
11 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use (b) After the preparation of the trial balance some errors were discovered. Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entry required to correct the error Debit Credit Error Account $ Account $ (i) Cheque, $100, paid to a credit supplier not recorded trade payable 100 bank 100 (ii) Motor expenses, $400, treated as capital expenditure (iii) Petty cash balance, $80, omitted from the trial balance (iv) Purchases returns journal undercast by $100 (v) Refund of water rates, $25, debited to both cash book and general expenses [8] (c) Select one of the above errors and explain why it did not affect the balancing of the trial balance. Error number Reason [2] (d) Sanath Jaffer did not reduce the value of his business when his highly experienced manager retired. Name the accounting principle he applied. [1] (e) Sanath Jaffer records credit sales when the goods are invoiced to customers rather than when the customers order goods. Name the accounting principle he is applying. [1]
Question paper, page 12
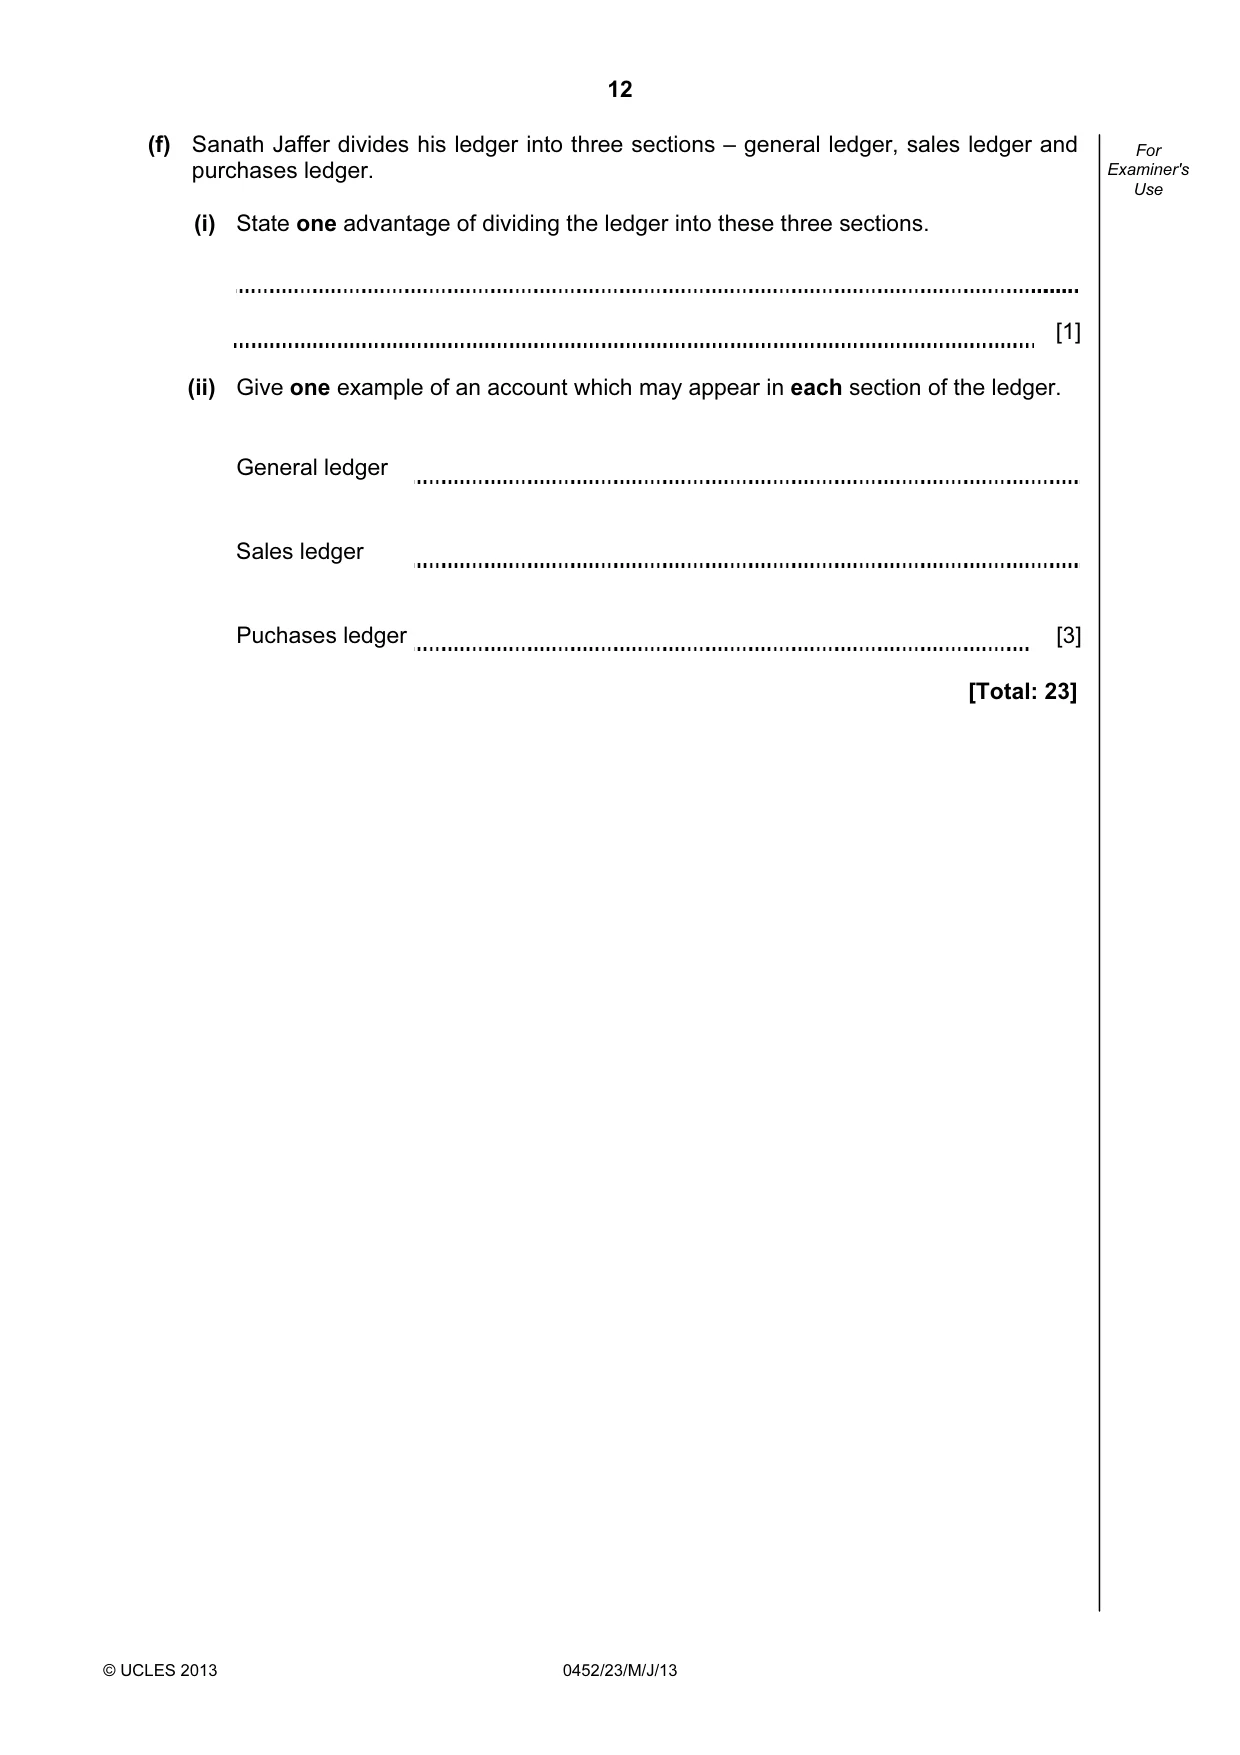
12 © UCLES 2013 0452/23/M/J/13 For Examiner's Use (f) Sanath Jaffer divides his ledger into three sections – general ledger, sales ledger and purchases ledger. (i) State one advantage of dividing the ledger into these three sections. [1] (ii) Give one example of an account which may appear in each section of the ledger. General ledger Sales ledger Puchases ledger [3] [Total: 23]
Question paper, page 13
13 © UCLES 2013 0452/23/M/J/13 [Turn over Question 4 is on the next page.
Question paper, page 14
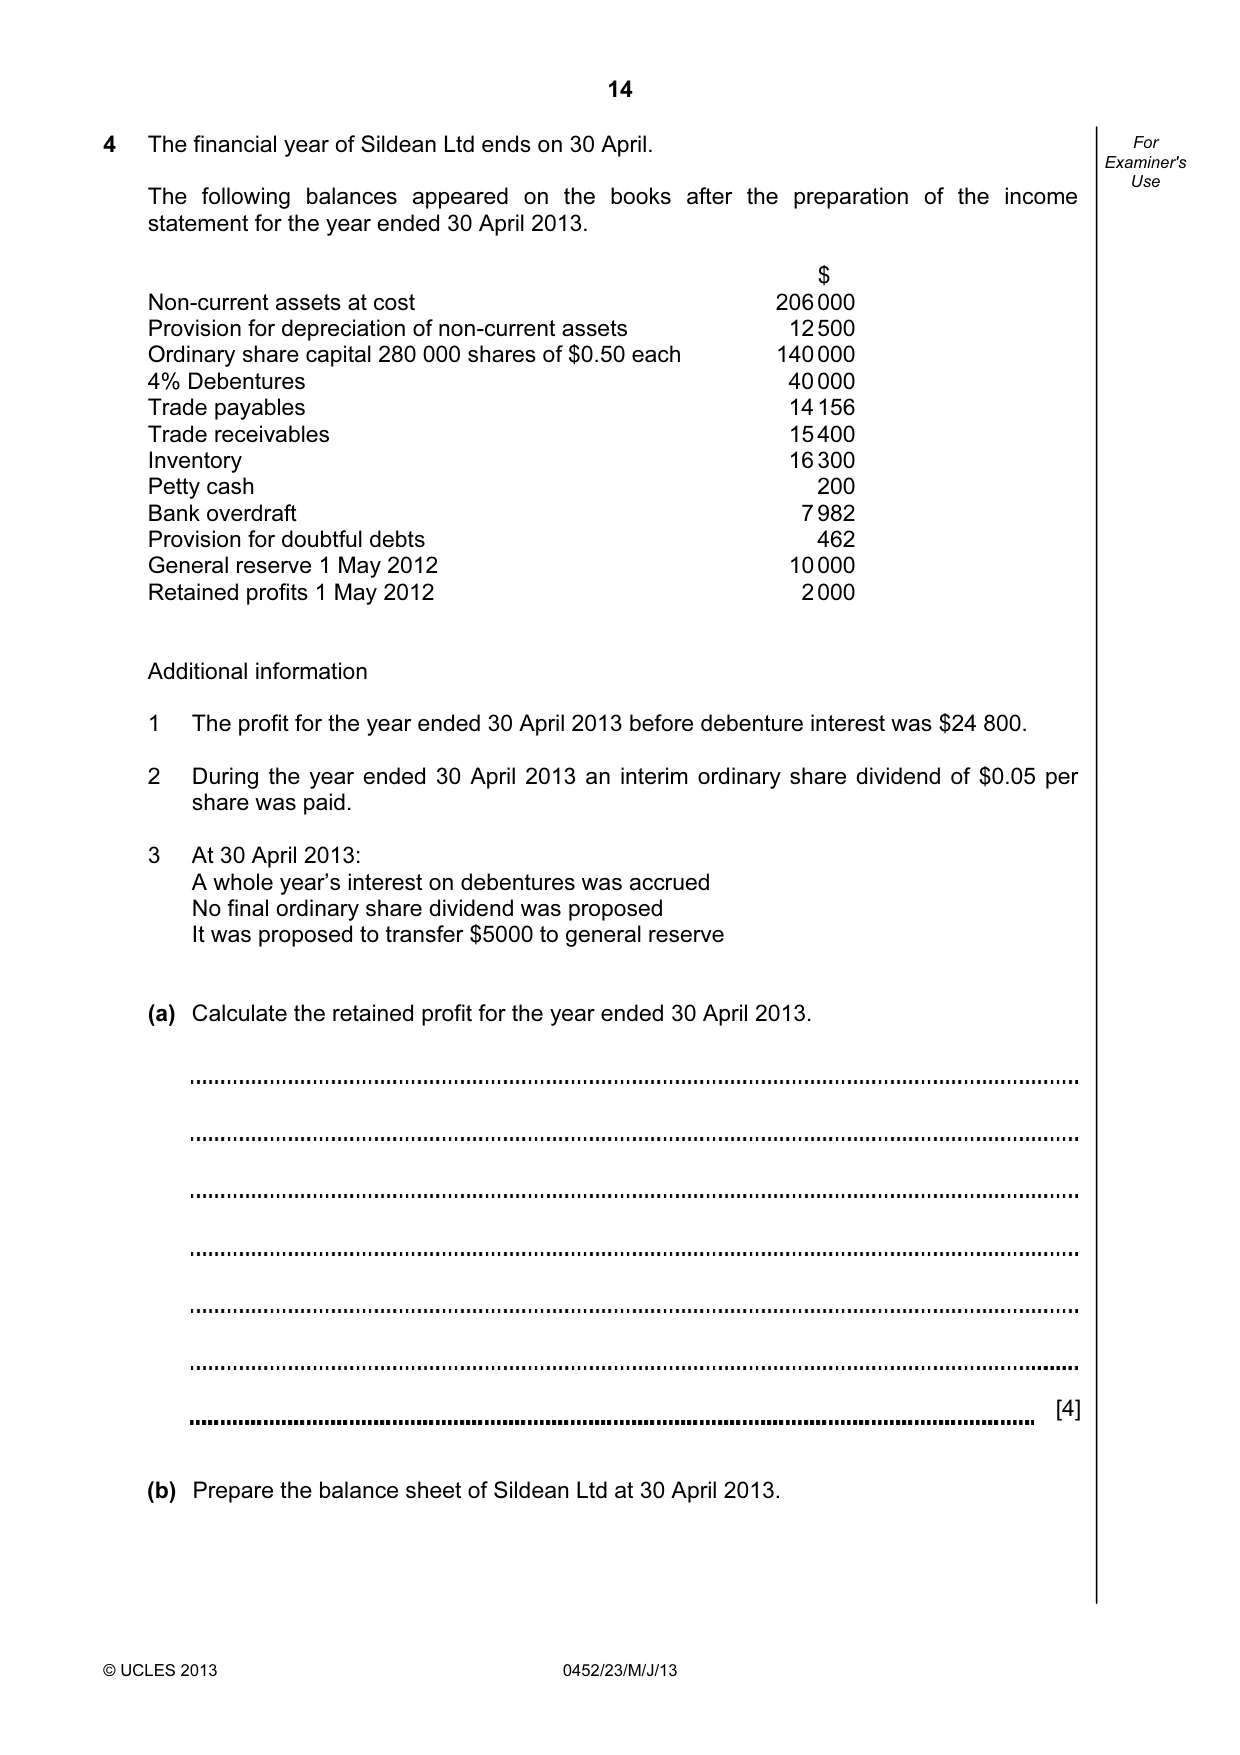
14 © UCLES 2013 0452/23/M/J/13 For Examiner's Use 4 The financial year of Sildean Ltd ends on 30 April. The following balances appeared on the books after the preparation of the income statement for the year ended 30 April 2013. $ Non-current assets at cost 206 000 Provision for depreciation of non-current assets 12 500 Ordinary share capital 280 000 shares of $0.50 each 140 000 4% Debentures 40 000 Trade payables 14 156 Trade receivables 15 400 Inventory 16 300 Petty cash 200 Bank overdraft 7 982 Provision for doubtful debts 462 General reserve 1 May 2012 10 000 Retained profits 1 May 2012 2 000 Additional information 1 The profit for the year ended 30 April 2013 before debenture interest was $24 800. 2 During the year ended 30 April 2013 an interim ordinary share dividend of $0.05 per share was paid. 3 At 30 April 2013: A whole year’s interest on debentures was accrued No final ordinary share dividend was proposed It was proposed to transfer $5000 to general reserve (a) Calculate the retained profit for the year ended 30 April 2013. [4] (b) Prepare the balance sheet of Sildean Ltd at 30 April 2013.
Question paper, page 15
15 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use Sildean Ltd Balance Sheet at 30 April 2013 [10]
Question paper, page 16
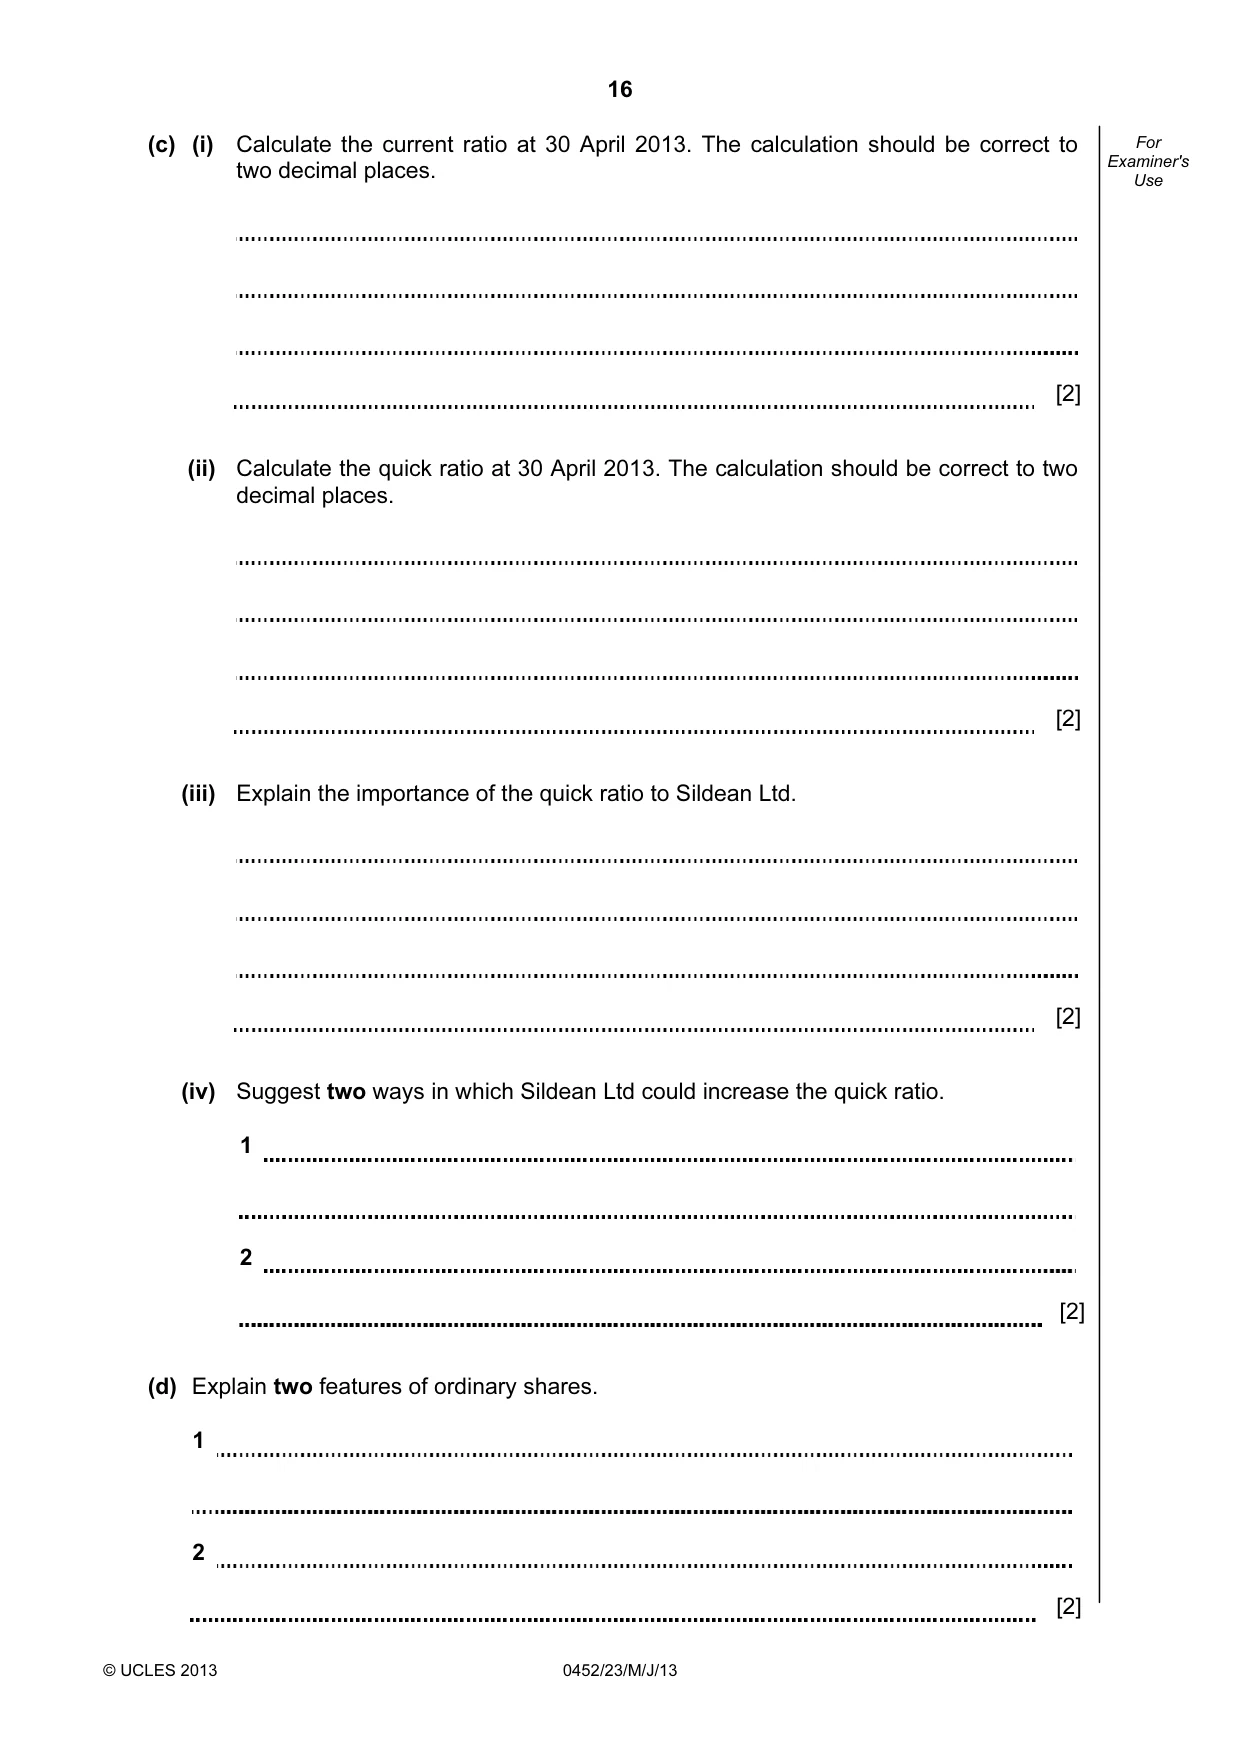
16 © UCLES 2013 0452/23/M/J/13 For Examiner's Use (c) (i) Calculate the current ratio at 30 April 2013. The calculation should be correct to two decimal places. [2] (ii) Calculate the quick ratio at 30 April 2013. The calculation should be correct to two decimal places. [2] (iii) Explain the importance of the quick ratio to Sildean Ltd. [2] (iv) Suggest two ways in which Sildean Ltd could increase the quick ratio. 1 2 [2] (d) Explain two features of ordinary shares. 1 2 [2]
Question paper, page 17
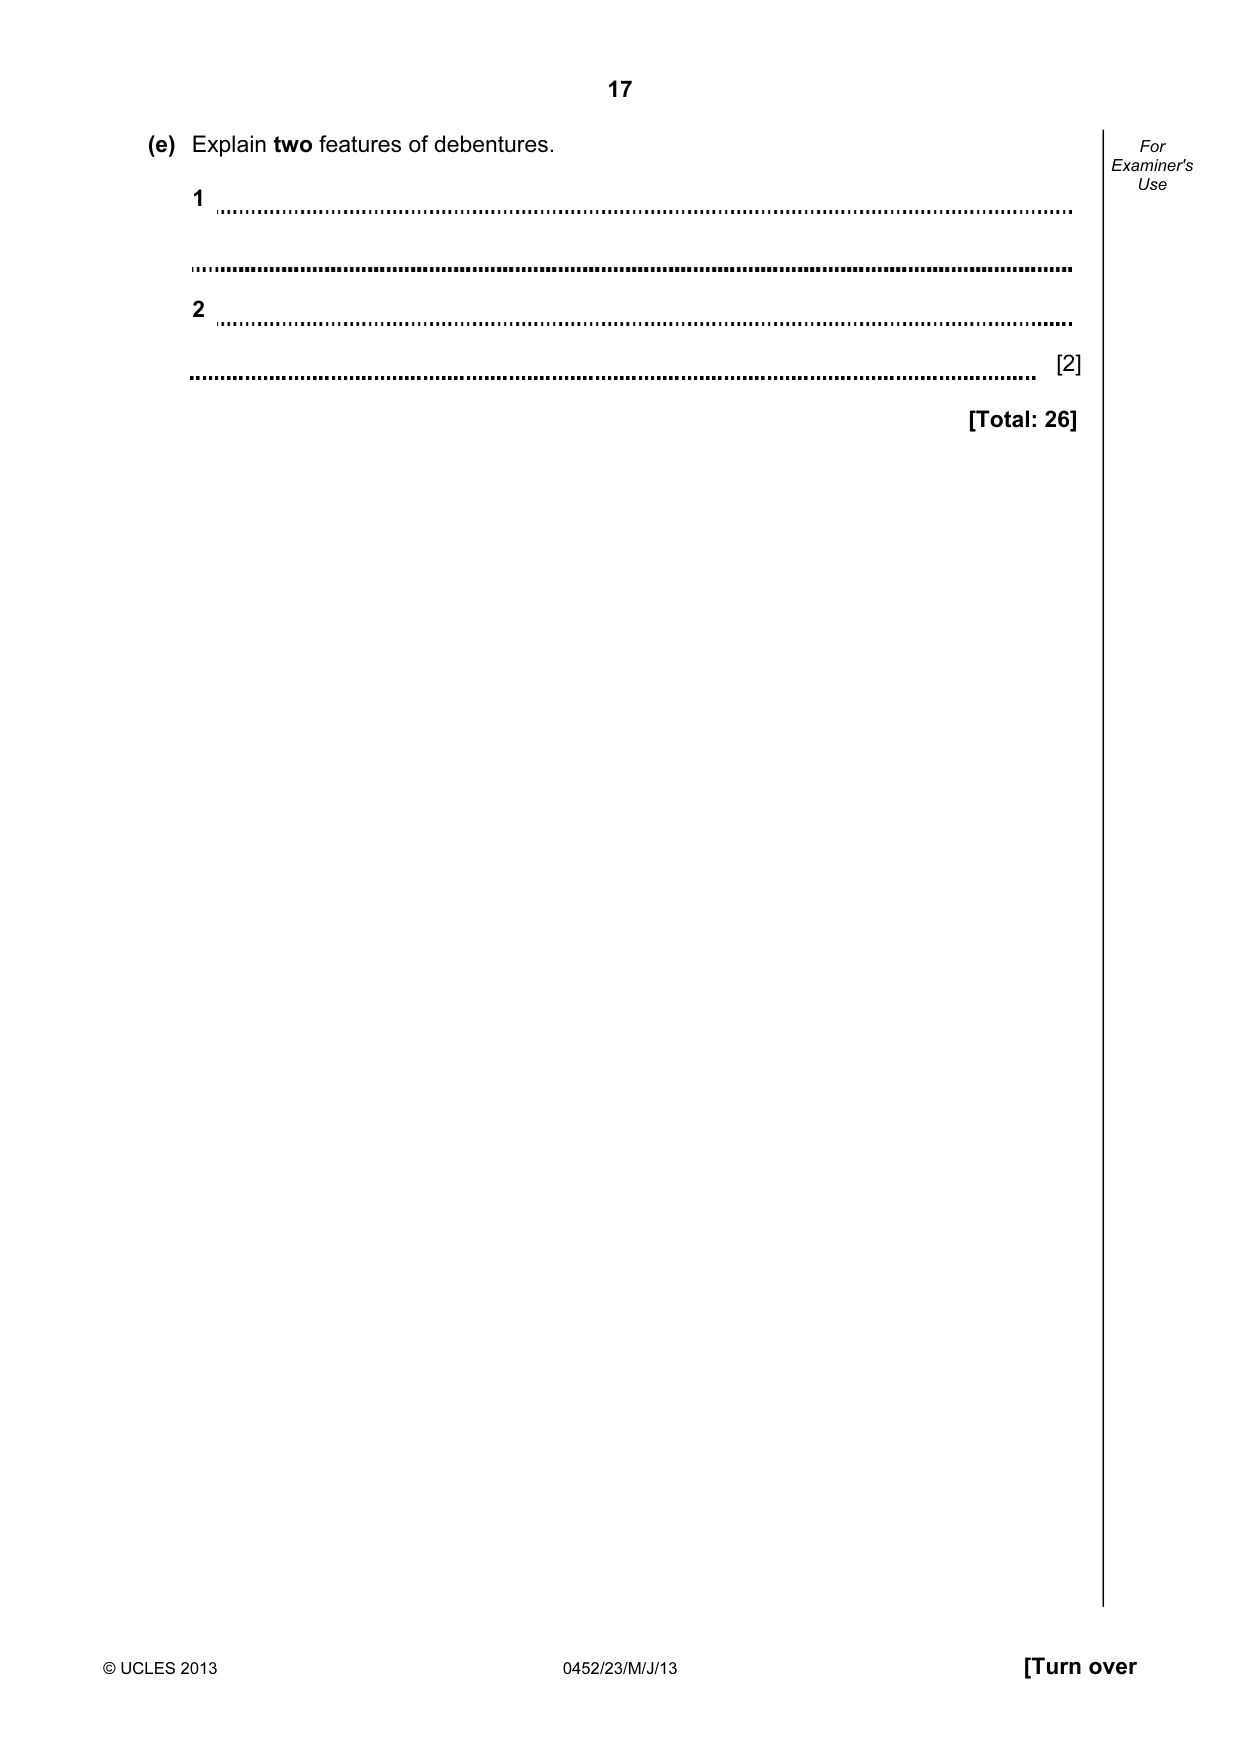
17 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use (e) Explain two features of debentures. 1 2 [2] [Total: 26]
Question paper, page 18
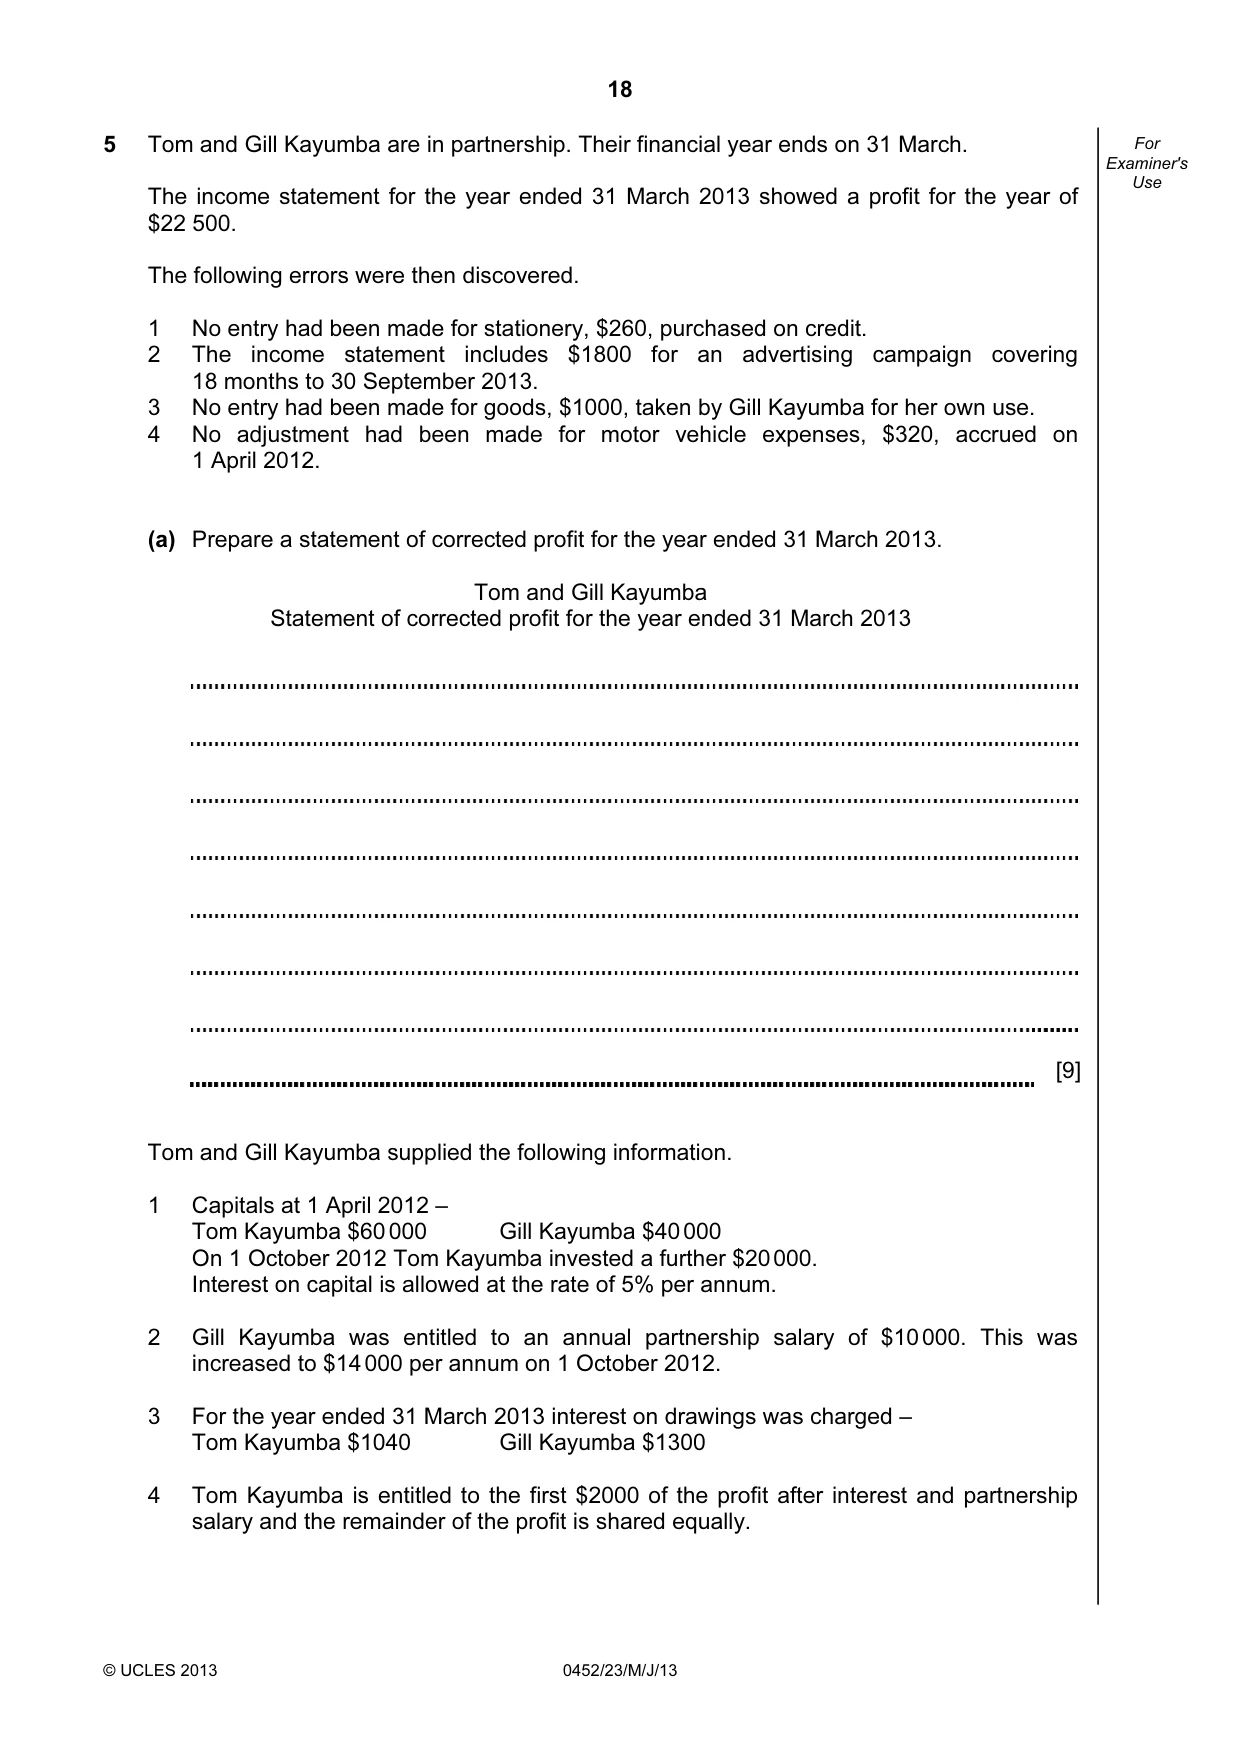
18 © UCLES 2013 0452/23/M/J/13 For Examiner's Use 5 Tom and Gill Kayumba are in partnership. Their financial year ends on 31 March. The income statement for the year ended 31 March 2013 showed a profit for the year of $22 500. The following errors were then discovered. 1 No entry had been made for stationery, $260, purchased on credit. 2 The income statement includes $1800 for an advertising campaign covering 18 months to 30 September 2013. 3 No entry had been made for goods, $1000, taken by Gill Kayumba for her own use. 4 No adjustment had been made for motor vehicle expenses, $320, accrued on 1 April 2012. (a) Prepare a statement of corrected profit for the year ended 31 March 2013. Tom and Gill Kayumba Statement of corrected profit for the year ended 31 March 2013 [9] Tom and Gill Kayumba supplied the following information. 1 Capitals at 1 April 2012 – Tom Kayumba $60 000 Gill Kayumba $40 000 On 1 October 2012 Tom Kayumba invested a further $20 000. Interest on capital is allowed at the rate of 5% per annum. 2 Gill Kayumba was entitled to an annual partnership salary of $10 000. This was increased to $14 000 per annum on 1 October 2012. 3 For the year ended 31 March 2013 interest on drawings was charged – Tom Kayumba $1040 Gill Kayumba $1300 4 Tom Kayumba is entitled to the first $2000 of the profit after interest and partnership salary and the remainder of the profit is shared equally.
Question paper, page 19
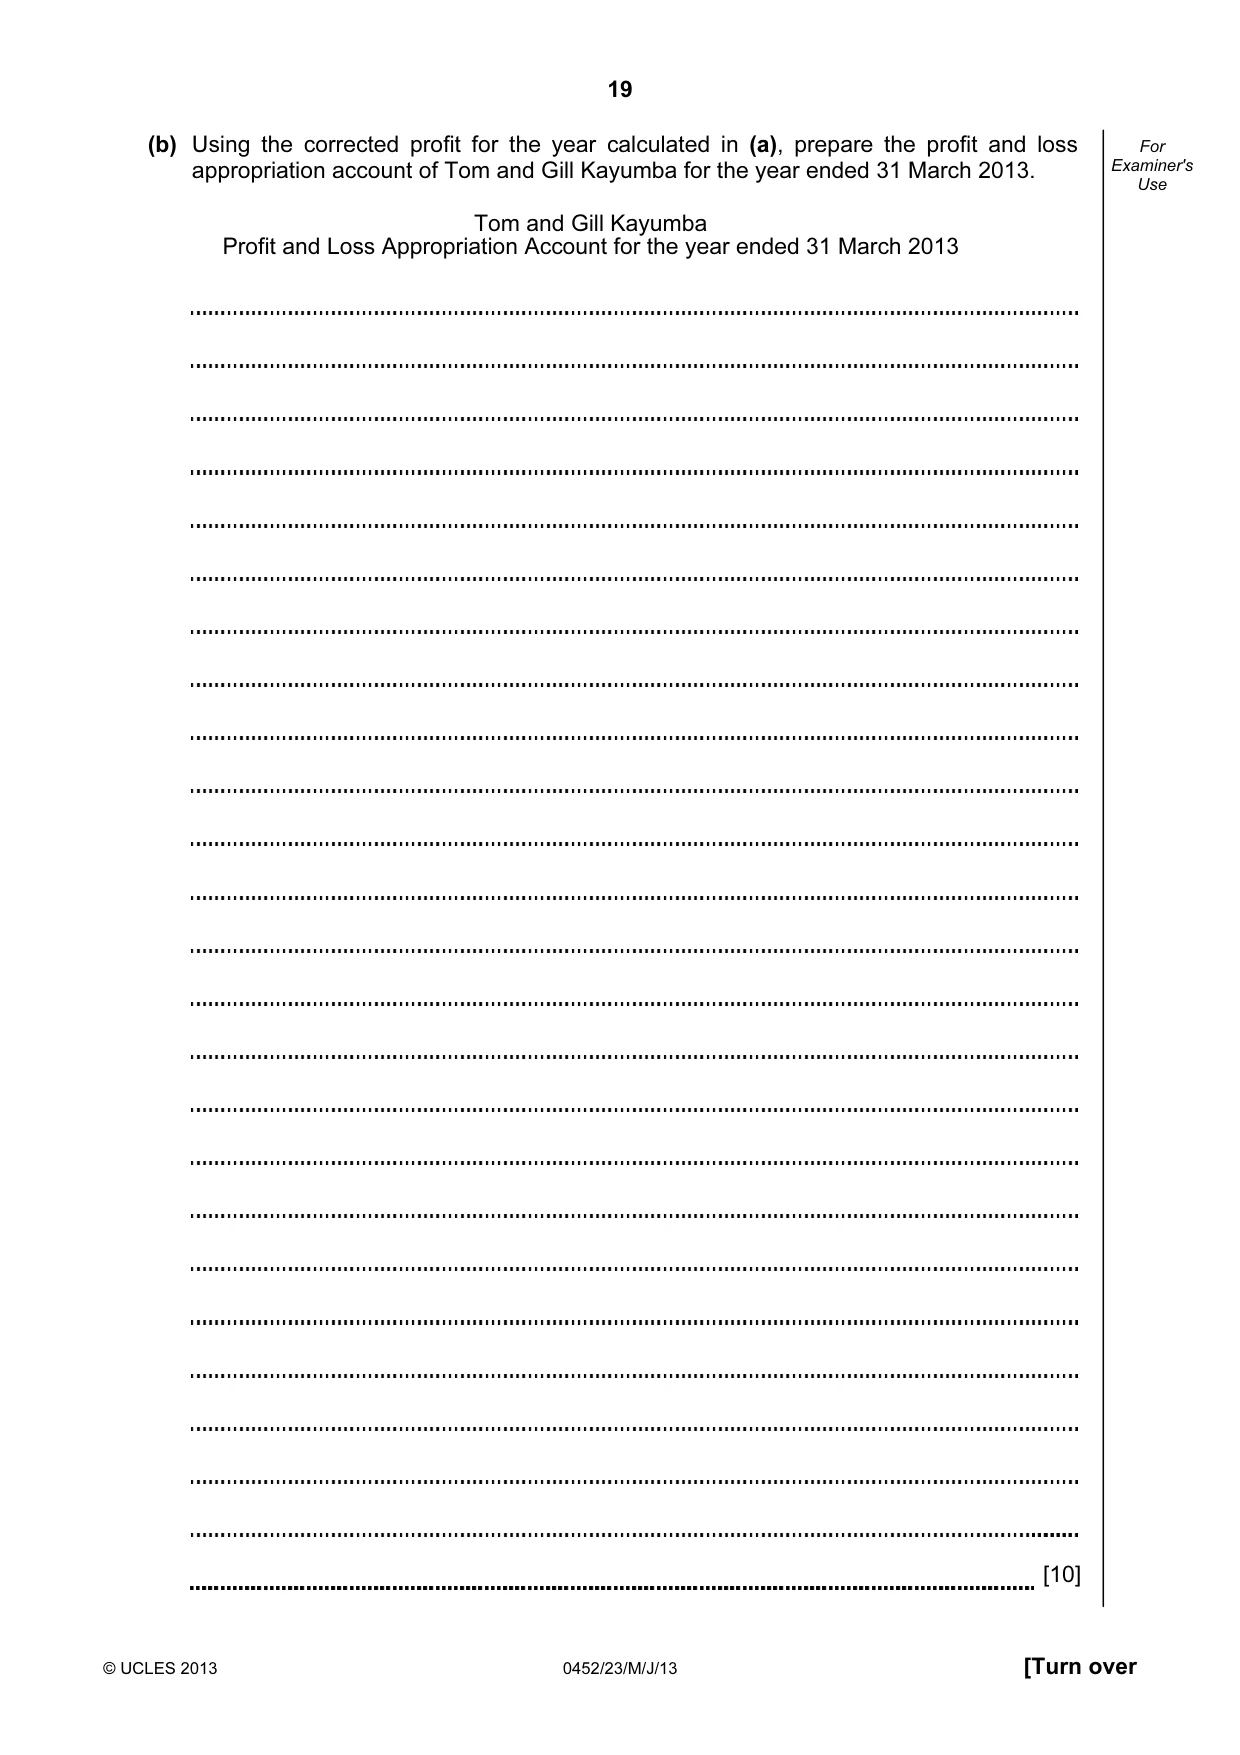
19 © UCLES 2013 0452/23/M/J/13 [Turn over For Examiner's Use (b) Using the corrected profit for the year calculated in (a), prepare the profit and loss appropriation account of Tom and Gill Kayumba for the year ended 31 March 2013. Tom and Gill Kayumba Profit and Loss Appropriation Account for the year ended 31 March 2013 [10]
Question paper, page 20
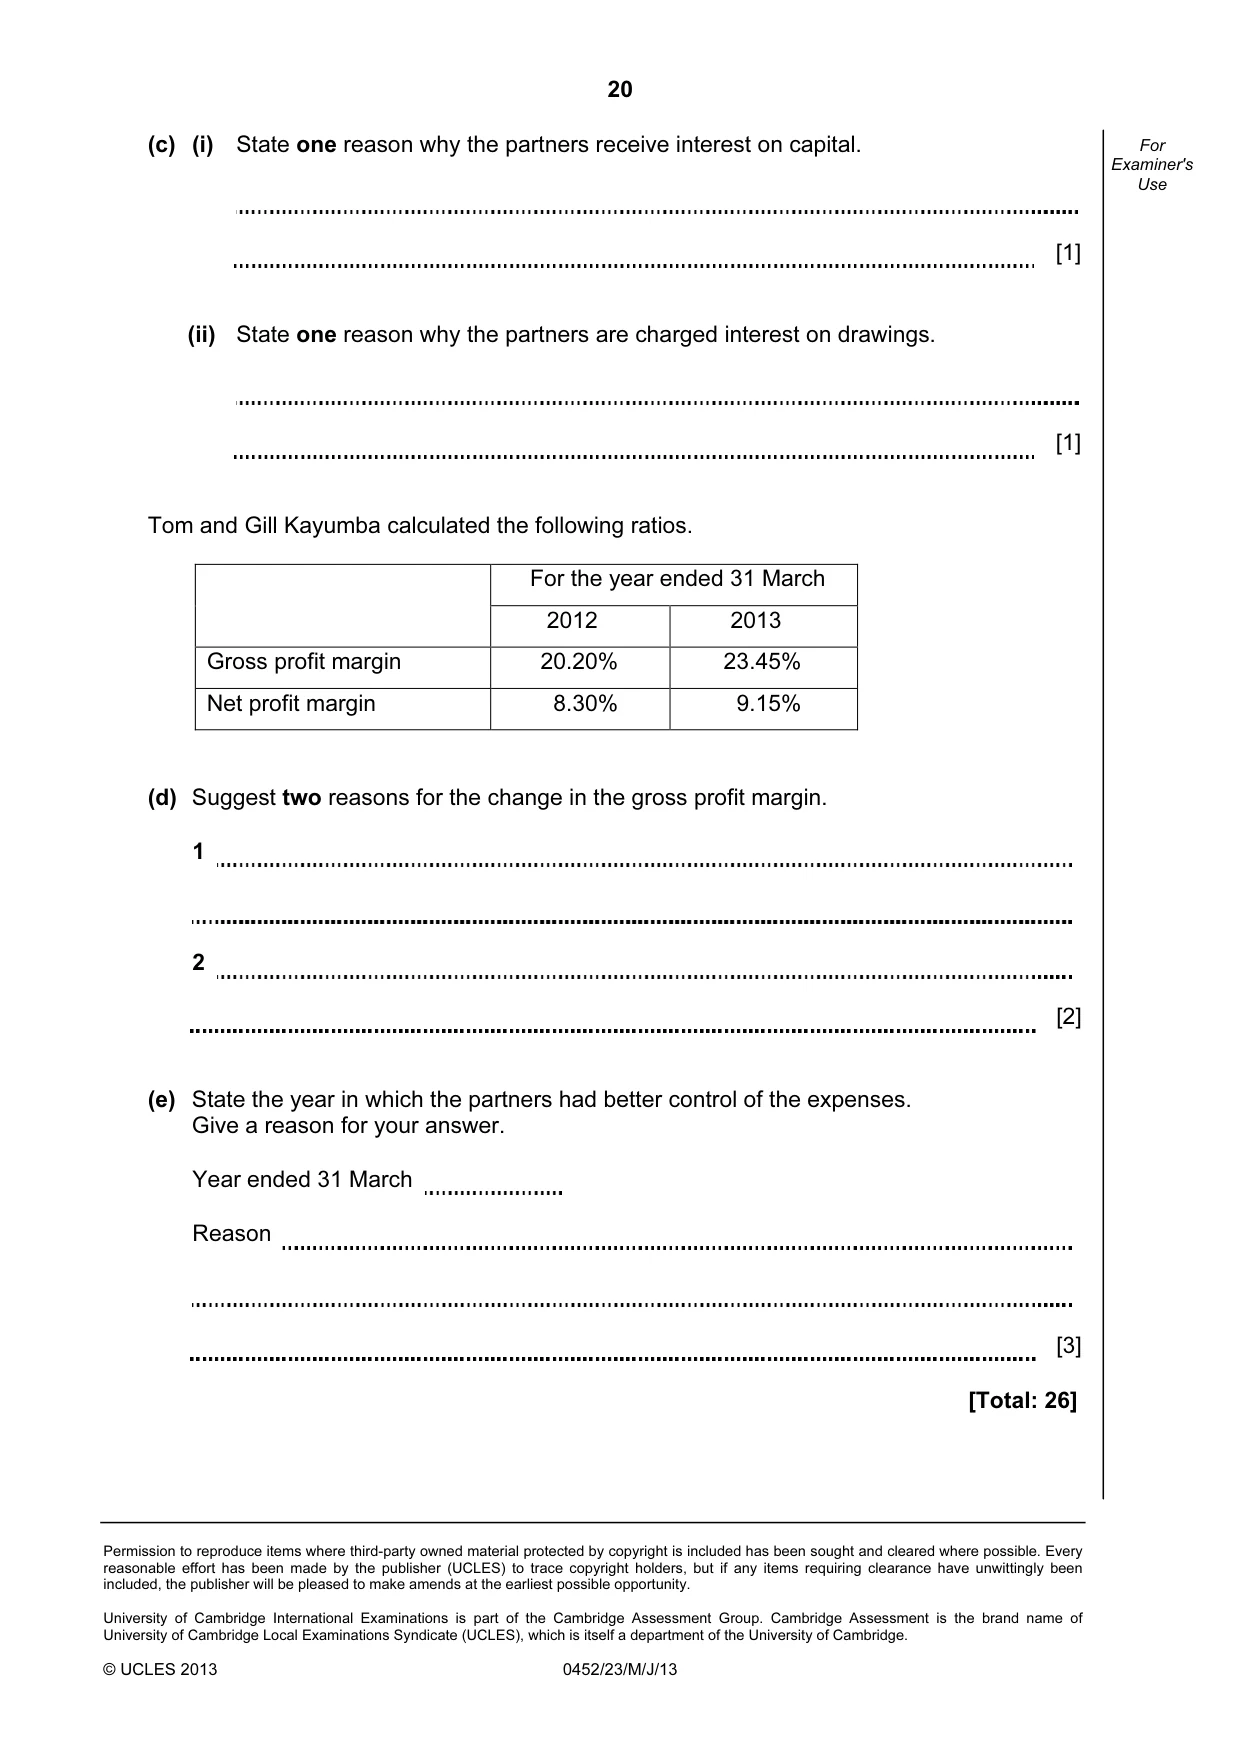
20 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2013 0452/23/M/J/13 For Examiner's Use (c) (i) State one reason why the partners receive interest on capital. [1] (ii) State one reason why the partners are charged interest on drawings. [1] Tom and Gill Kayumba calculated the following ratios. For the year ended 31 March 2012 2013 Gross profit margin 20.20% 23.45% Net profit margin 8.30% 9.15% (d) Suggest two reasons for the change in the gross profit margin. 1 2 [2] (e) State the year in which the partners had better control of the expenses. Give a reason for your answer. Year ended 31 March Reason [3] [Total: 26]
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the May/June 2013 series 0452 ACCOUNTING 0452/23 Paper 2, maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the May/June 2013 series for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level components and some Ordinary Level components.
Mark scheme, page 2
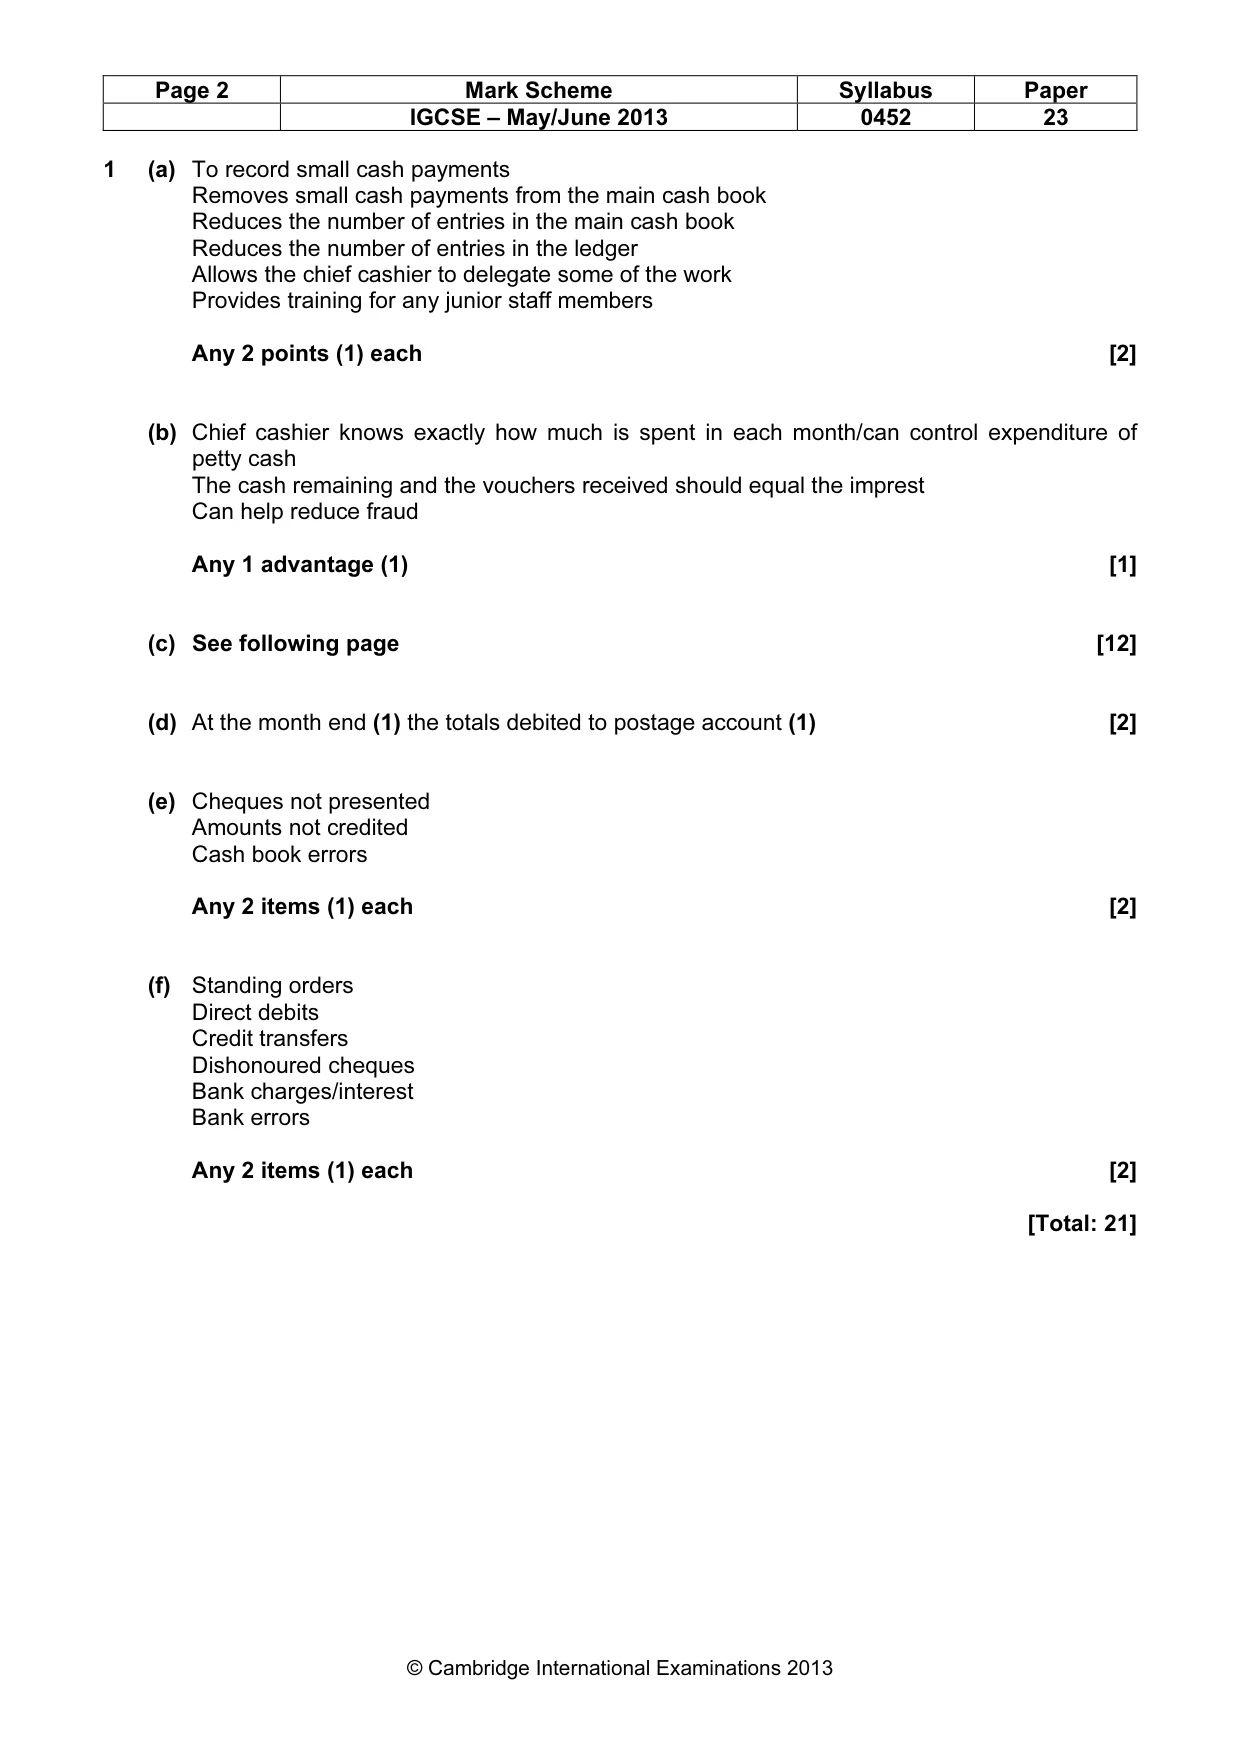
Page 2 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 1 (a) To record small cash payments Removes small cash payments from the main cash book Reduces the number of entries in the main cash book Reduces the number of entries in the ledger Allows the chief cashier to delegate some of the work Provides training for any junior staff members Any 2 points (1) each [2] (b) Chief cashier knows exactly how much is spent in each month/can control expenditure of petty cash The cash remaining and the vouchers received should equal the imprest Can help reduce fraud Any 1 advantage (1) [1] (c) See following page [12] (d) At the month end (1) the totals debited to postage account (1) [2] (e) Cheques not presented Amounts not credited Cash book errors Any 2 items (1) each [2] (f) Standing orders Direct debits Credit transfers Dishonoured cheques Bank charges/interest Bank errors Any 2 items (1) each [2] [Total: 21]
Mark scheme, page 3
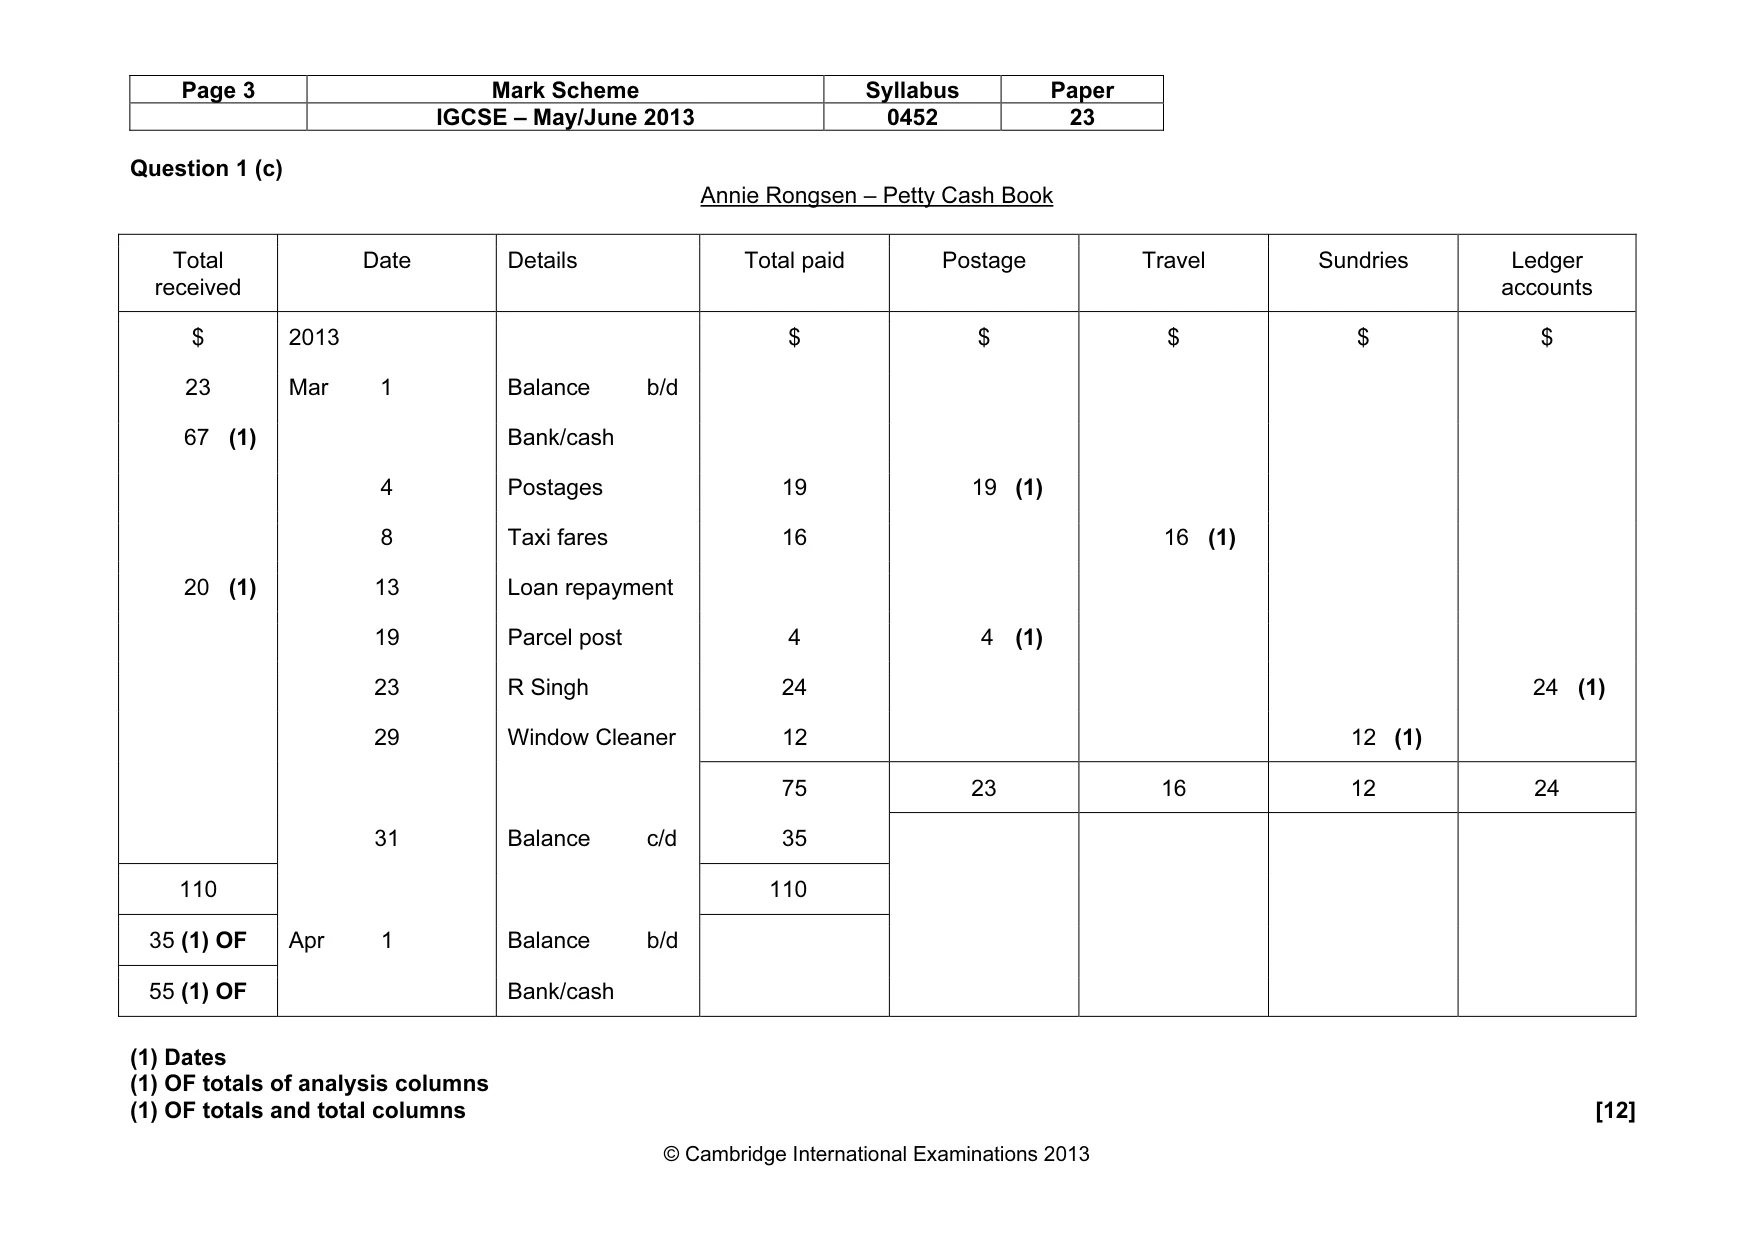
Page 3 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 Question 1 (c) Annie Rongsen – Petty Cash Book Total received Date Details Total paid Postage Travel Sundries Ledger accounts $ 2013 $ $ $ $ $ 23 Mar 1 Balance b/d 67 (1) Bank/cash 4 Postages 19 19 (1) 8 Taxi fares 16 16 (1) 20 (1) 13 Loan repayment 19 Parcel post 4 4 (1) 23 R Singh 24 24 (1) 29 Window Cleaner 12 12 (1) 75 23 16 12 24 31 Balance c/d 35 110 110 35 (1) OF Apr 1 Balance b/d 55 (1) OF Bank/cash (1) Dates (1) OF totals of analysis columns (1) OF totals and total columns [12]
Mark scheme, page 4
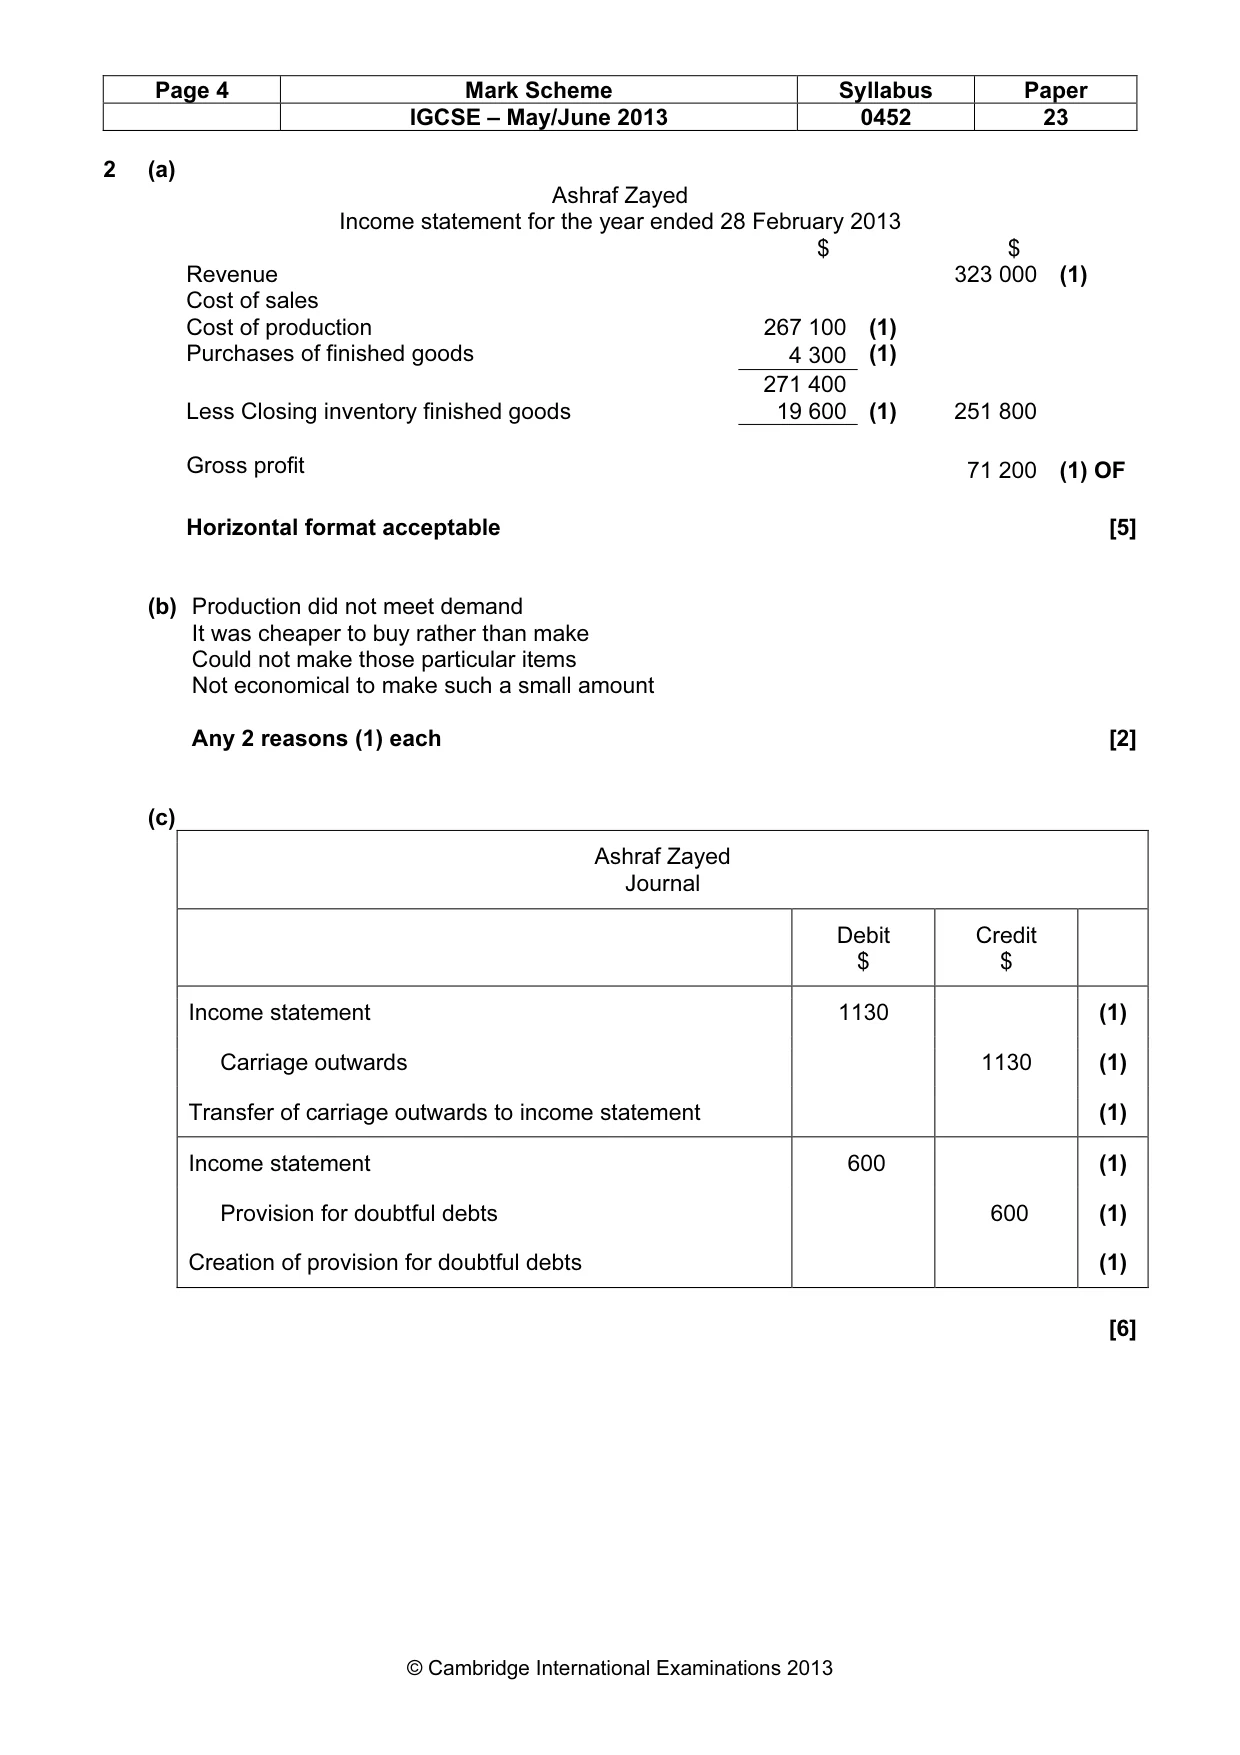
Page 4 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 2 (a) Ashraf Zayed Income statement for the year ended 28 February 2013 $ $ Revenue 323 000 (1) Cost of sales Cost of production 267 100 (1) Purchases of finished goods 4 300 (1) 271 400 Less Closing inventory finished goods 19 600 (1) 251 800 Gross profit 71 200 (1) OF Horizontal format acceptable [5] (b) Production did not meet demand It was cheaper to buy rather than make Could not make those particular items Not economical to make such a small amount Any 2 reasons (1) each [2] (c) Ashraf Zayed Journal Debit $ Credit $ Income statement 1130 (1) Carriage outwards 1130 (1) Transfer of carriage outwards to income statement (1) Income statement 600 (1) Provision for doubtful debts 600 (1) Creation of provision for doubtful debts (1) [6]
Mark scheme, page 5
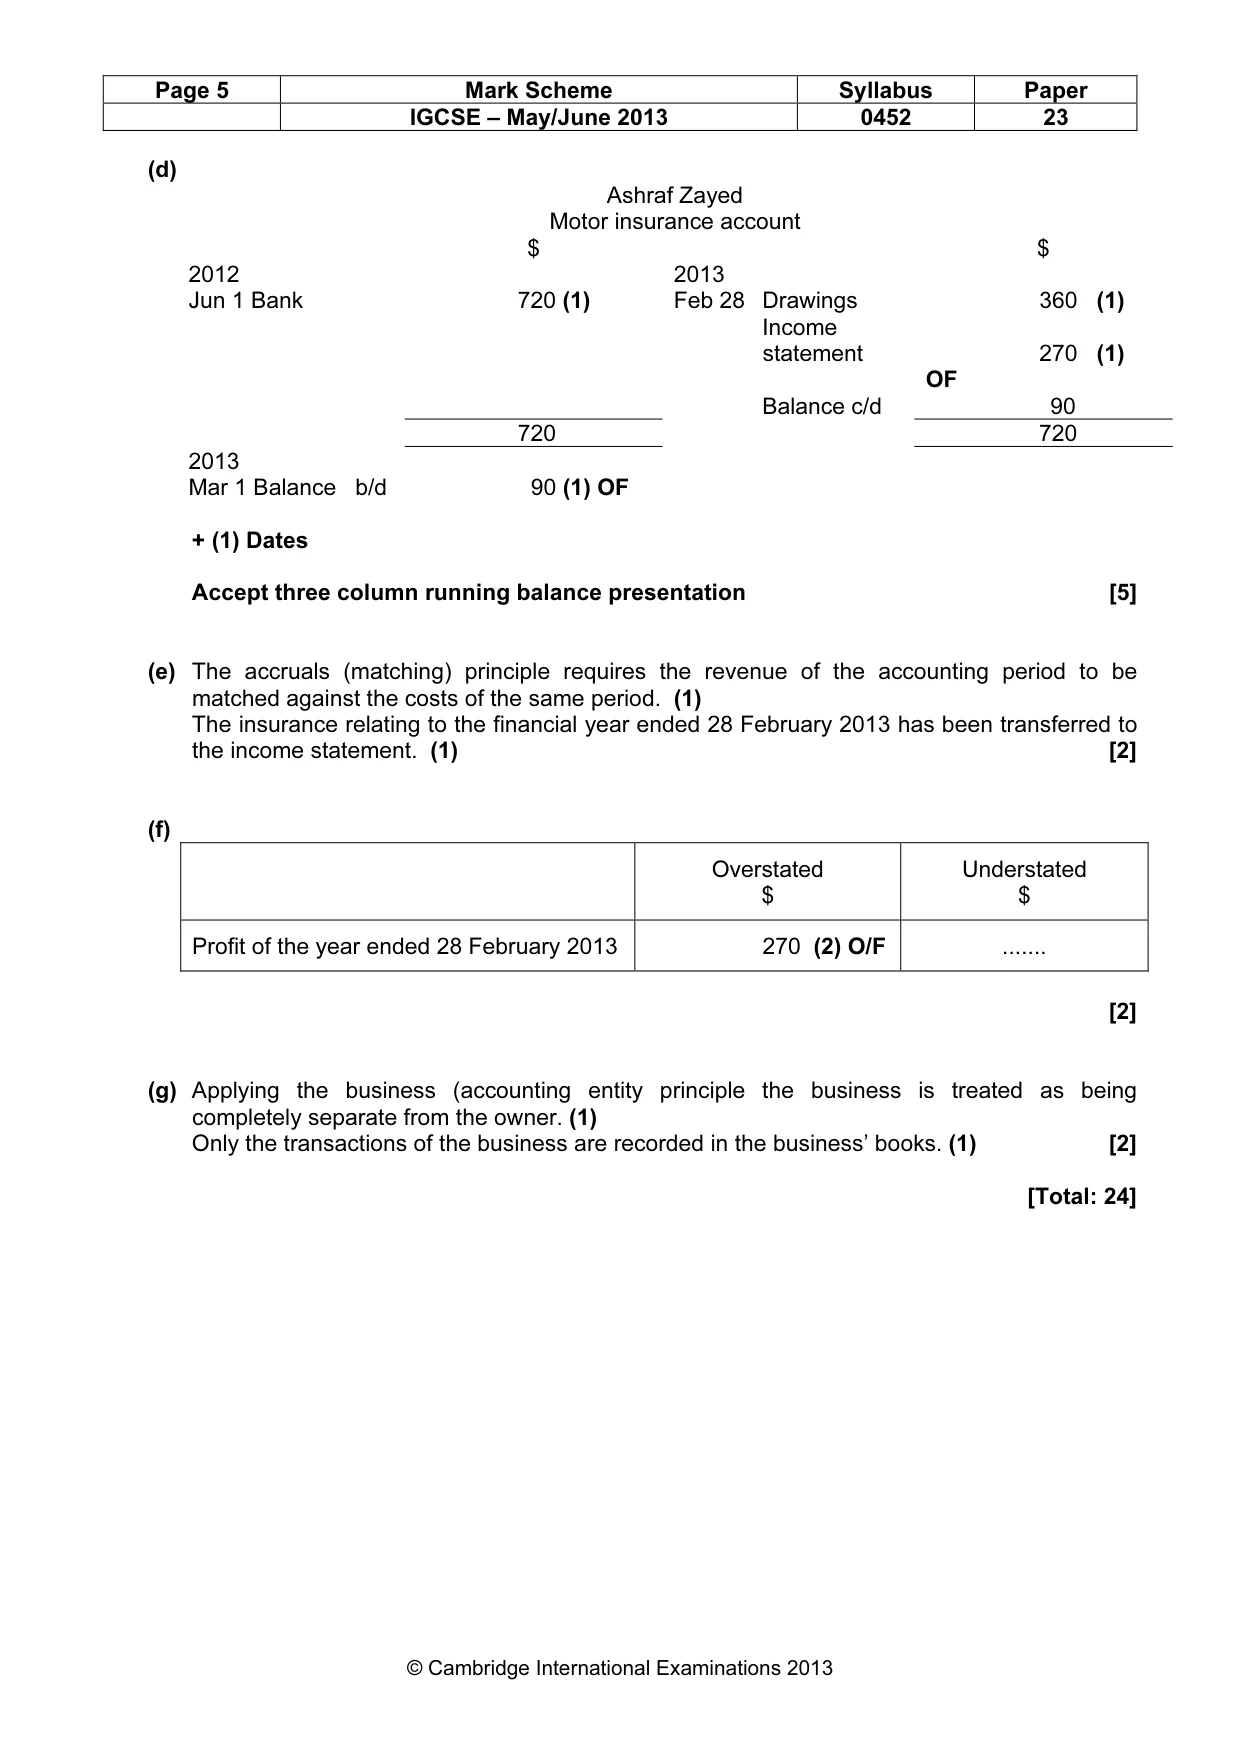
Page 5 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 (d) Ashraf Zayed Motor insurance account $ $ 2012 2013 Jun 1 Bank 720 (1) Feb 28 Drawings 360 (1) Income statement 270 (1) OF Balance c/d 90 720 720 2013 Mar 1 Balance b/d 90 (1) OF + (1) Dates Accept three column running balance presentation [5] (e) The accruals (matching) principle requires the revenue of the accounting period to be matched against the costs of the same period. (1) The insurance relating to the financial year ended 28 February 2013 has been transferred to the income statement. (1) [2] (f) Overstated $ Understated $ Profit of the year ended 28 February 2013 270 (2) O/F … [2] (g) Applying the business (accounting entity principle the business is treated as being completely separate from the owner. (1) Only the transactions of the business are recorded in the business’ books. (1) [2] [Total: 24]
Mark scheme, page 6
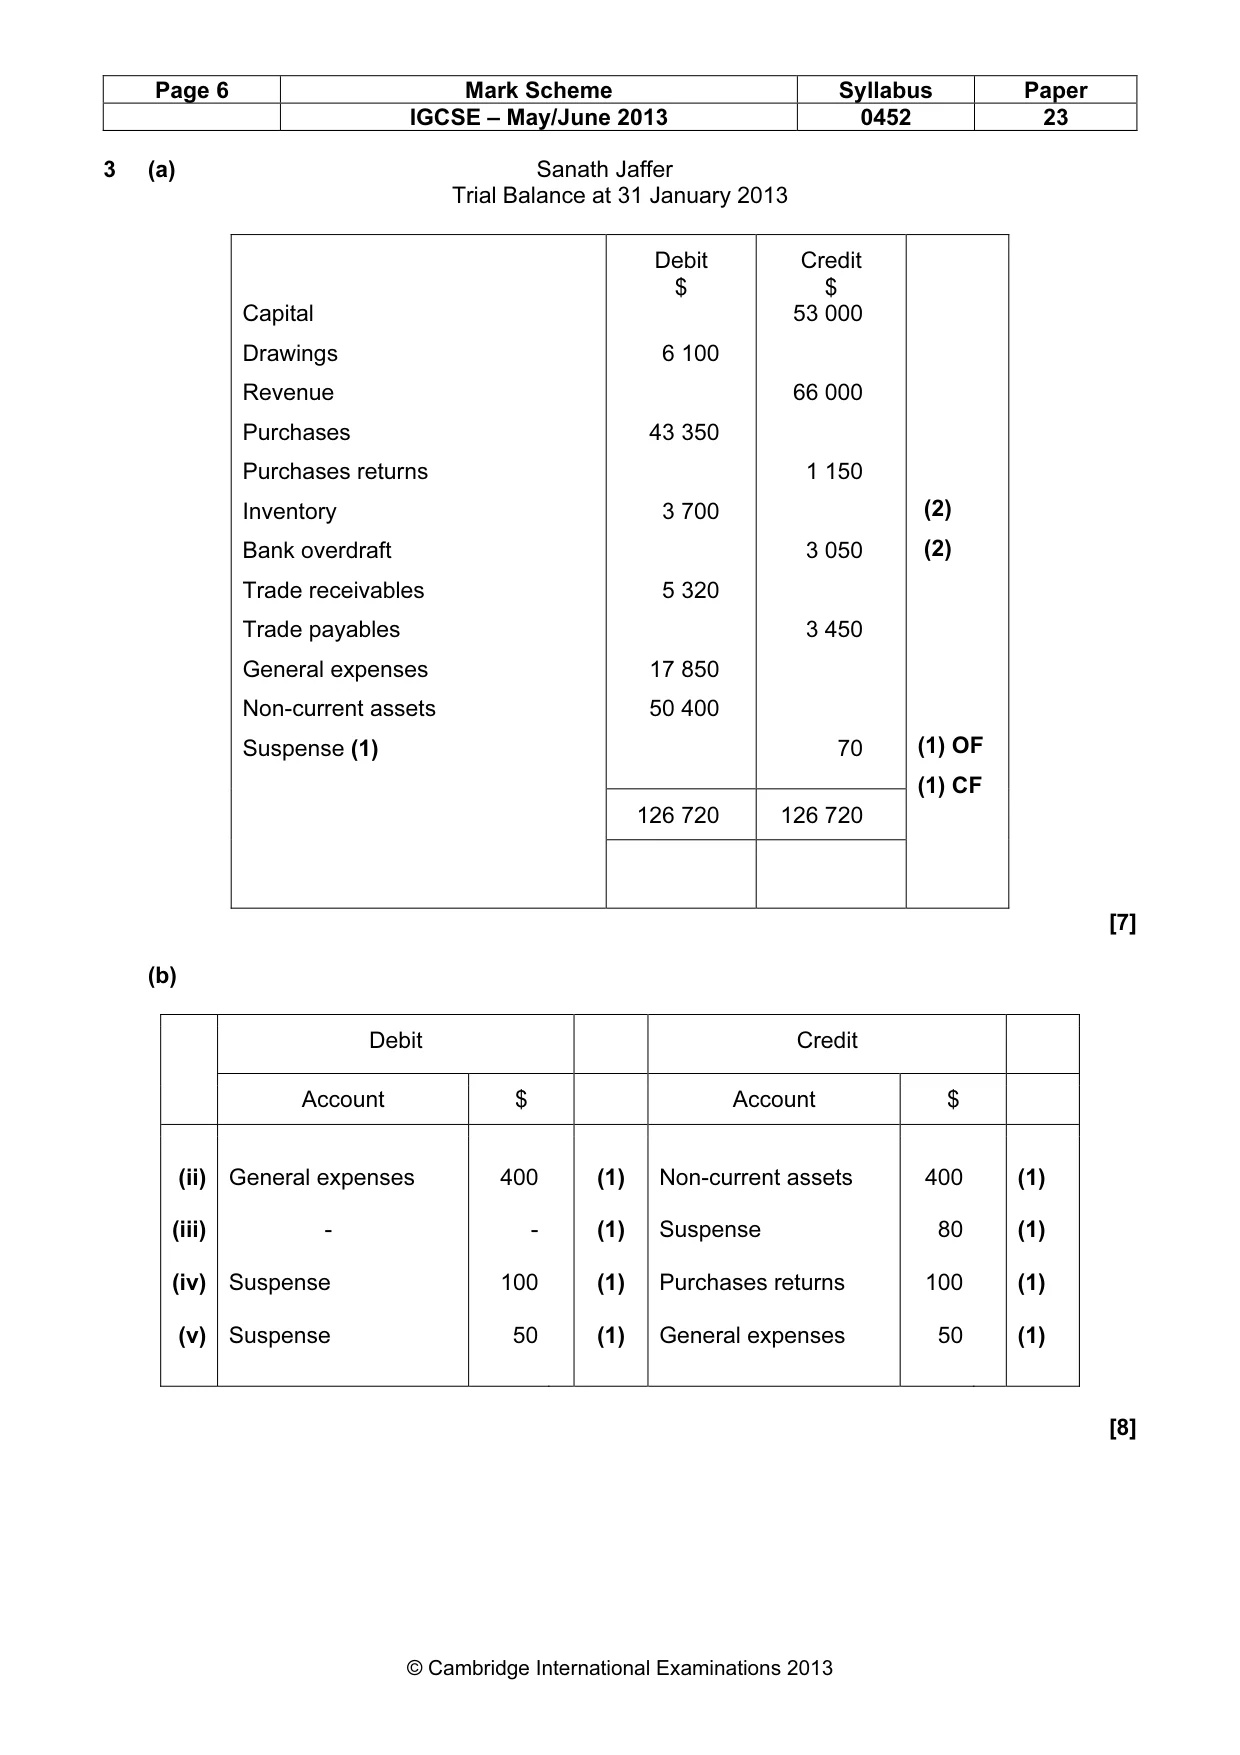
Page 6 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 3 (a) Sanath Jaffer Trial Balance at 31 January 2013 Capital Drawings Revenue Purchases Purchases returns Inventory Bank overdraft Trade receivables Trade payables General expenses Non-current assets Suspense (1) Debit $ 6 100 43 350 3 700 5 320 17 850 50 400 Credit $ 53 000 66 000 1 150 3 050 3 450 70 (2) (2) (1) OF (1) CF 126 720 126 720 [7] (b) Debit Credit Account $ Account $ (ii) (iii) (iv) (v) General expenses - Suspense Suspense 400 - 100 50 (1) (1) (1) (1) Non-current assets Suspense Purchases returns General expenses 400 80 100 50 (1) (1) (1) (1) [8]
Mark scheme, page 7
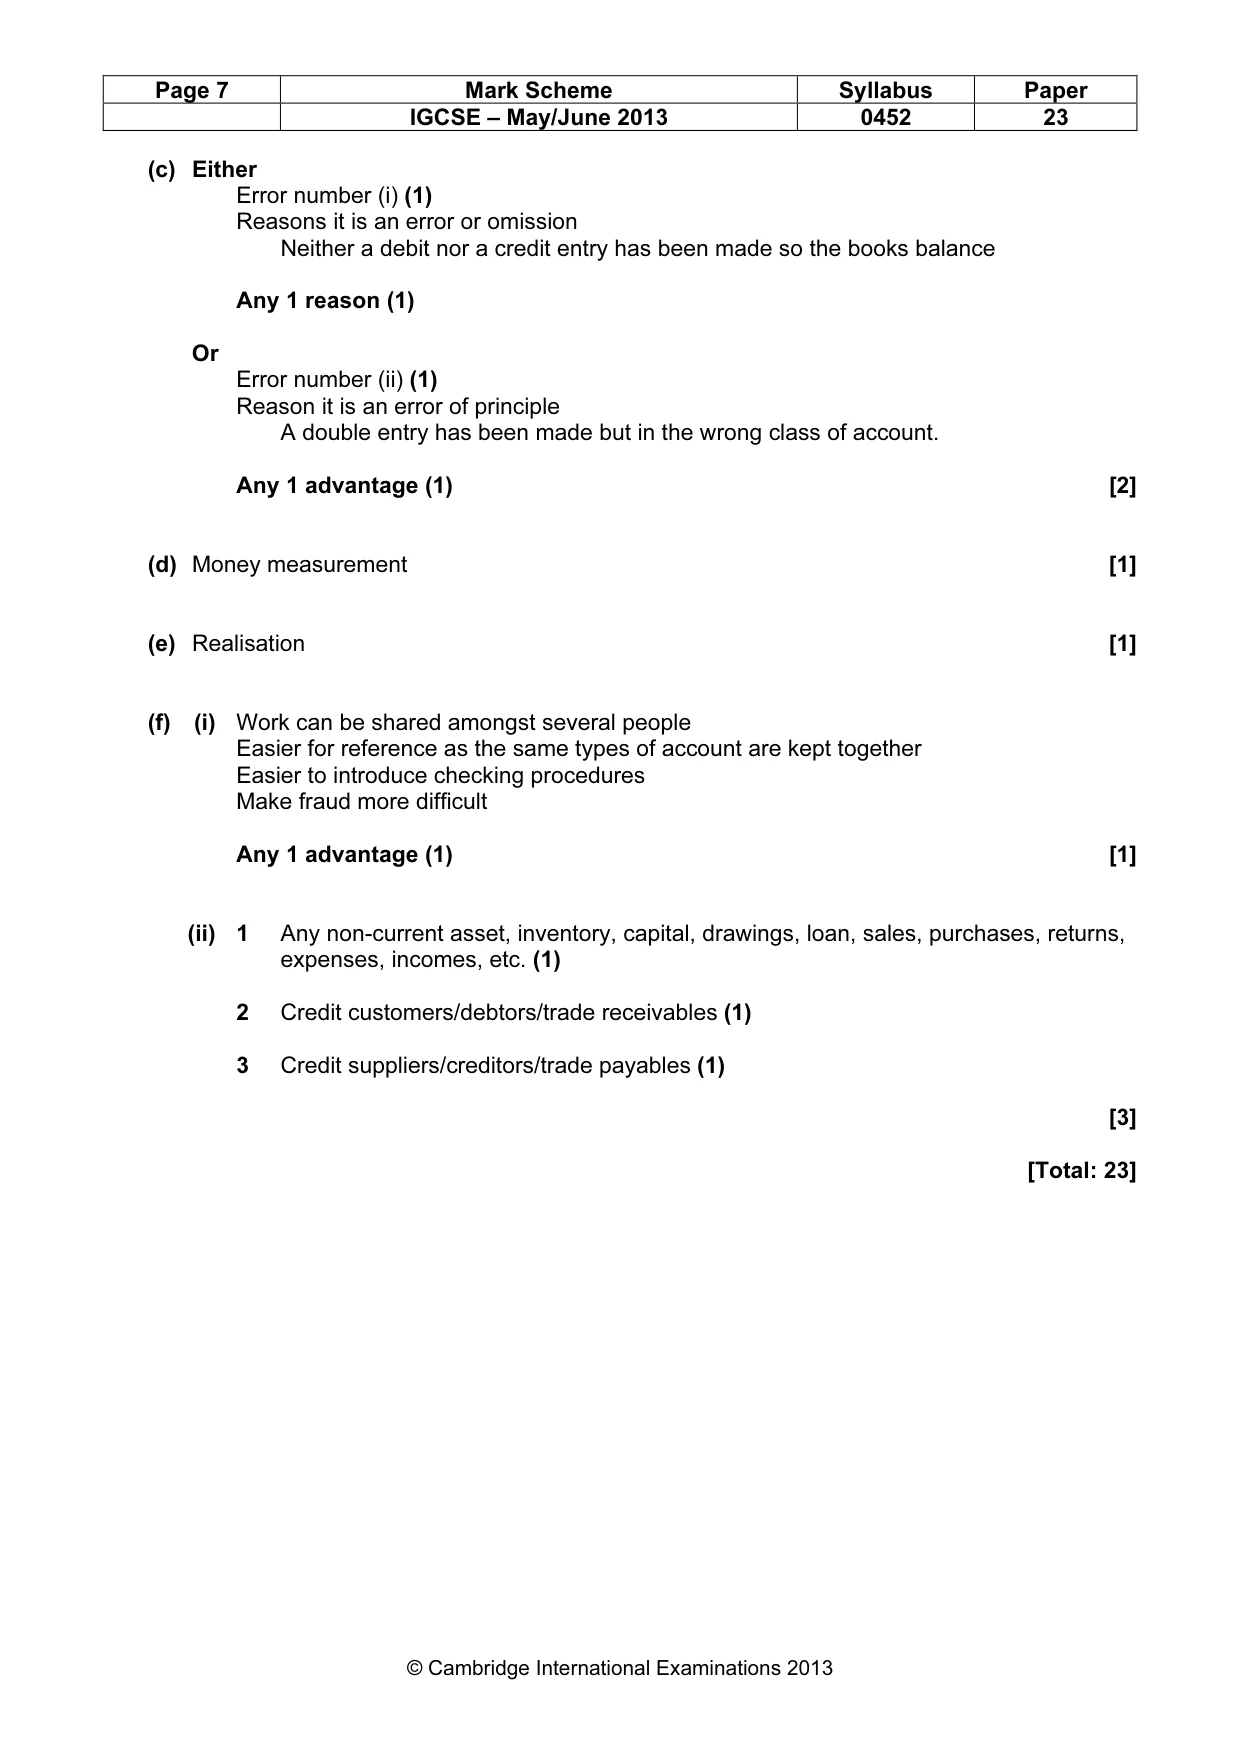
Page 7 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 (c) Either Error number (i) (1) Reasons it is an error or omission Neither a debit nor a credit entry has been made so the books balance Any 1 reason (1) Or Error number (ii) (1) Reason it is an error of principle A double entry has been made but in the wrong class of account. Any 1 advantage (1) [2] (d) Money measurement [1] (e) Realisation [1] (f) (i) Work can be shared amongst several people Easier for reference as the same types of account are kept together Easier to introduce checking procedures Make fraud more difficult Any 1 advantage (1) [1] (ii) 1 Any non-current asset, inventory, capital, drawings, loan, sales, purchases, returns, expenses, incomes, etc. (1) 2 Credit customers/debtors/trade receivables (1) 3 Credit suppliers/creditors/trade payables (1) [3] [Total: 23]
Mark scheme, page 8
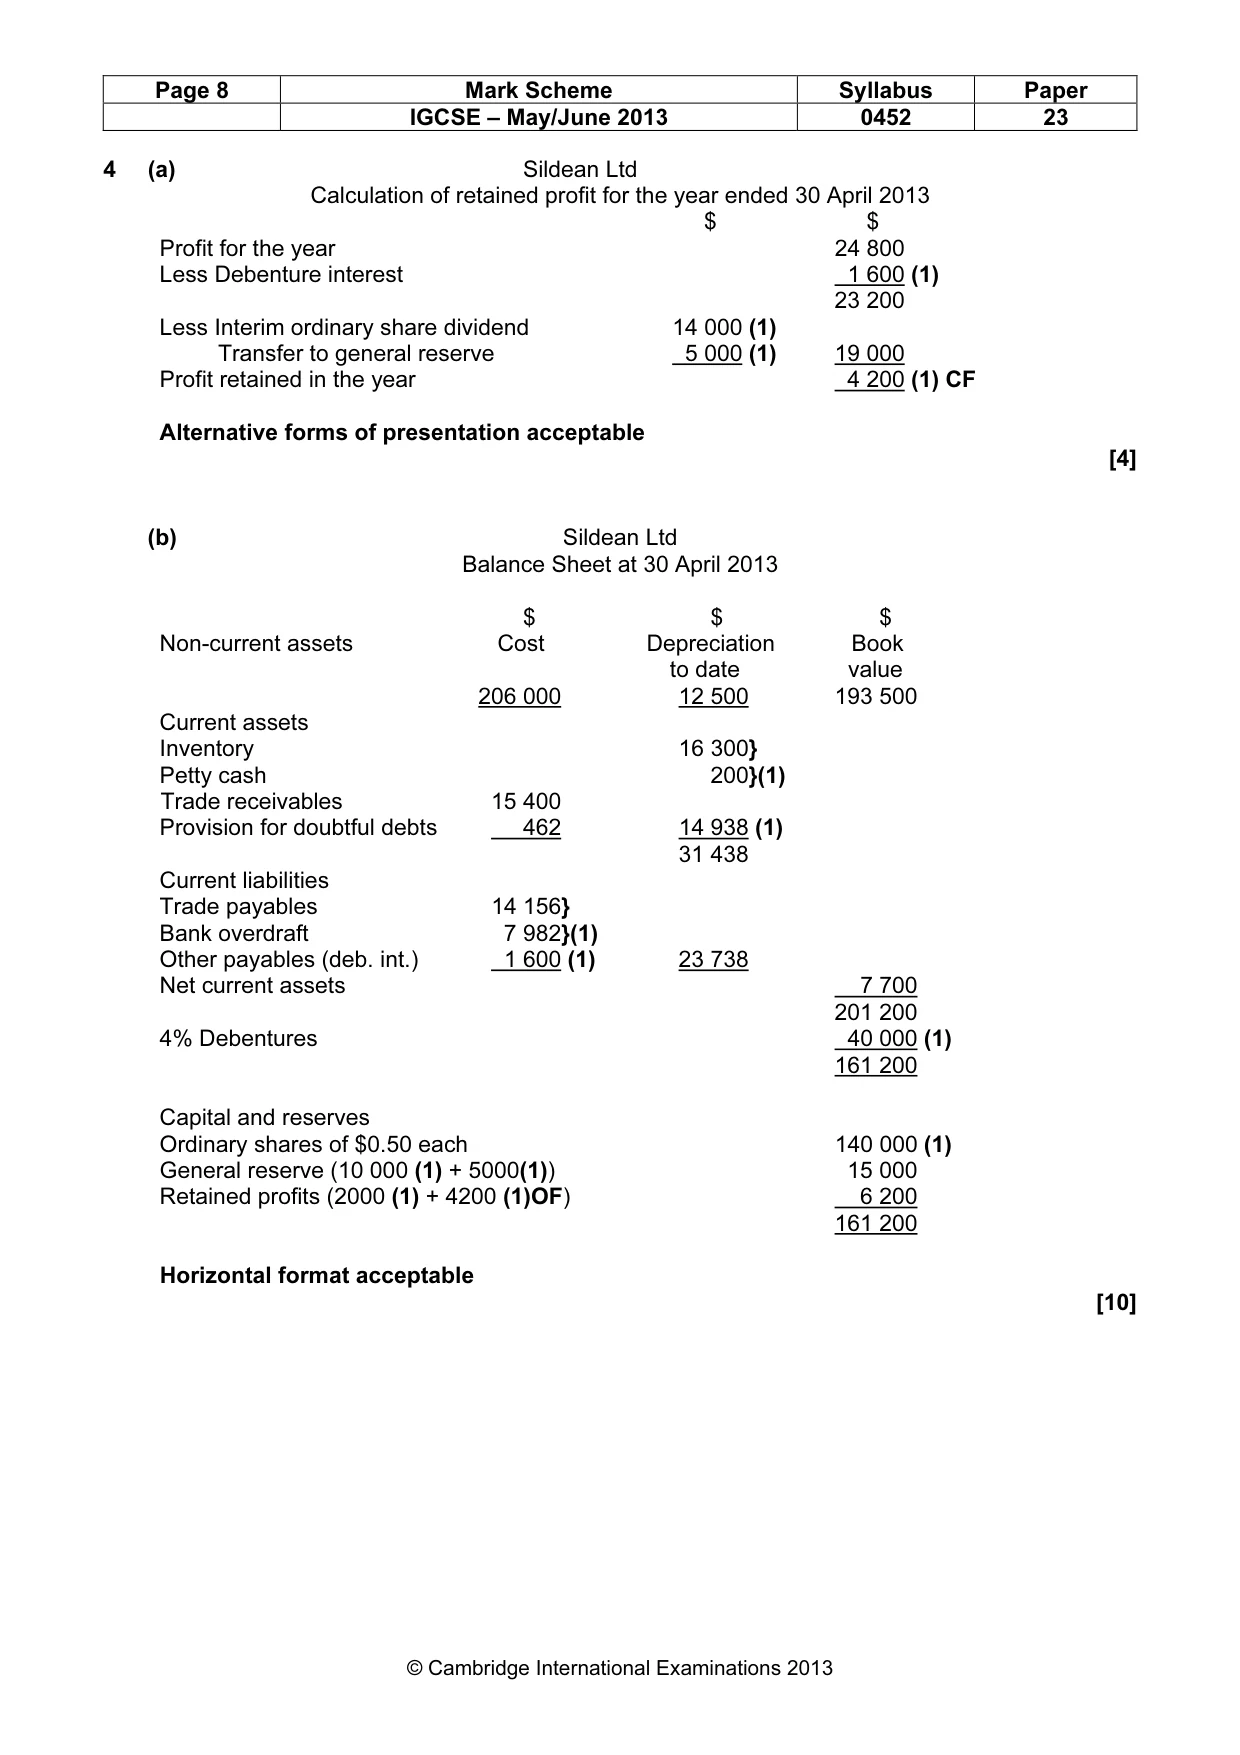
Page 8 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 4 (a) Sildean Ltd Calculation of retained profit for the year ended 30 April 2013 $ $ Profit for the year 24 800 Less Debenture interest 1 600 (1) 23 200 Less Interim ordinary share dividend 14 000 (1) Transfer to general reserve 5 000 (1) 19 000 Profit retained in the year 4 200 (1) CF Alternative forms of presentation acceptable [4] (b) Sildean Ltd Balance Sheet at 30 April 2013 $ $ $ Non-current assets Cost Depreciation Book to date value 206 000 12 500 193 500 Current assets Inventory 16 300} Petty cash 200}(1) Trade receivables 15 400 Provision for doubtful debts 462 14 938 (1) 31 438 Current liabilities Trade payables 14 156} Bank overdraft 7 982}(1) Other payables (deb. int.) 1 600 (1) 23 738 Net current assets 7 700 201 200 4% Debentures 40 000 (1) 161 200 Capital and reserves Ordinary shares of $0.50 each 140 000 (1) General reserve (10 000 (1) + 5000(1)) 15 000 Retained profits (2000 (1) + 4200 (1)OF) 6 200 161 200 Horizontal format acceptable [10]
Mark scheme, page 9
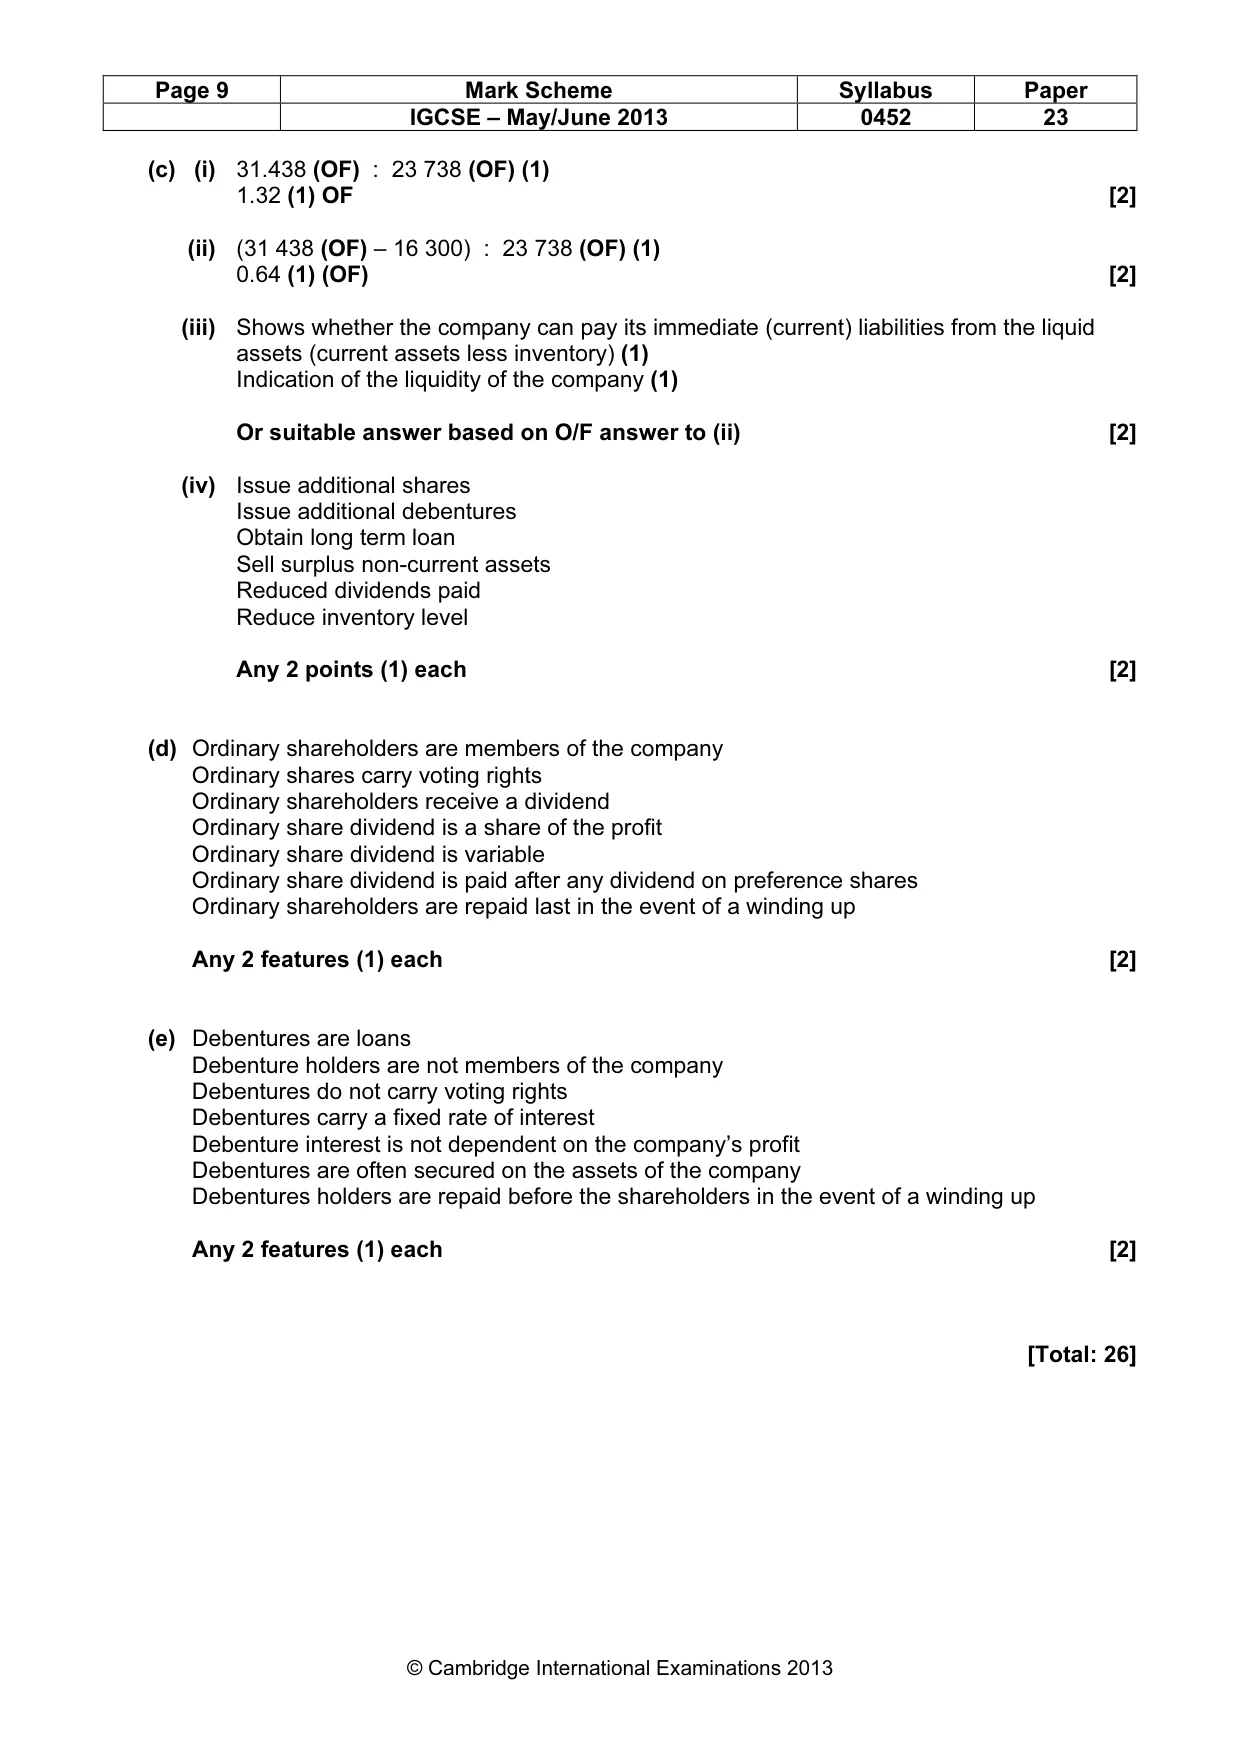
Page 9 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 (c) (i) 31.438 (OF) : 23 738 (OF) (1) 1.32 (1) OF [2] (ii) (31 438 (OF) – 16 300) : 23 738 (OF) (1) 0.64 (1) (OF) [2] (iii) Shows whether the company can pay its immediate (current) liabilities from the liquid assets (current assets less inventory) (1) Indication of the liquidity of the company (1) Or suitable answer based on O/F answer to (ii) [2] (iv) Issue additional shares Issue additional debentures Obtain long term loan Sell surplus non-current assets Reduced dividends paid Reduce inventory level Any 2 points (1) each [2] (d) Ordinary shareholders are members of the company Ordinary shares carry voting rights Ordinary shareholders receive a dividend Ordinary share dividend is a share of the profit Ordinary share dividend is variable Ordinary share dividend is paid after any dividend on preference shares Ordinary shareholders are repaid last in the event of a winding up Any 2 features (1) each [2] (e) Debentures are loans Debenture holders are not members of the company Debentures do not carry voting rights Debentures carry a fixed rate of interest Debenture interest is not dependent on the company’s profit Debentures are often secured on the assets of the company Debentures holders are repaid before the shareholders in the event of a winding up Any 2 features (1) each [2] [Total: 26]
Mark scheme, page 10
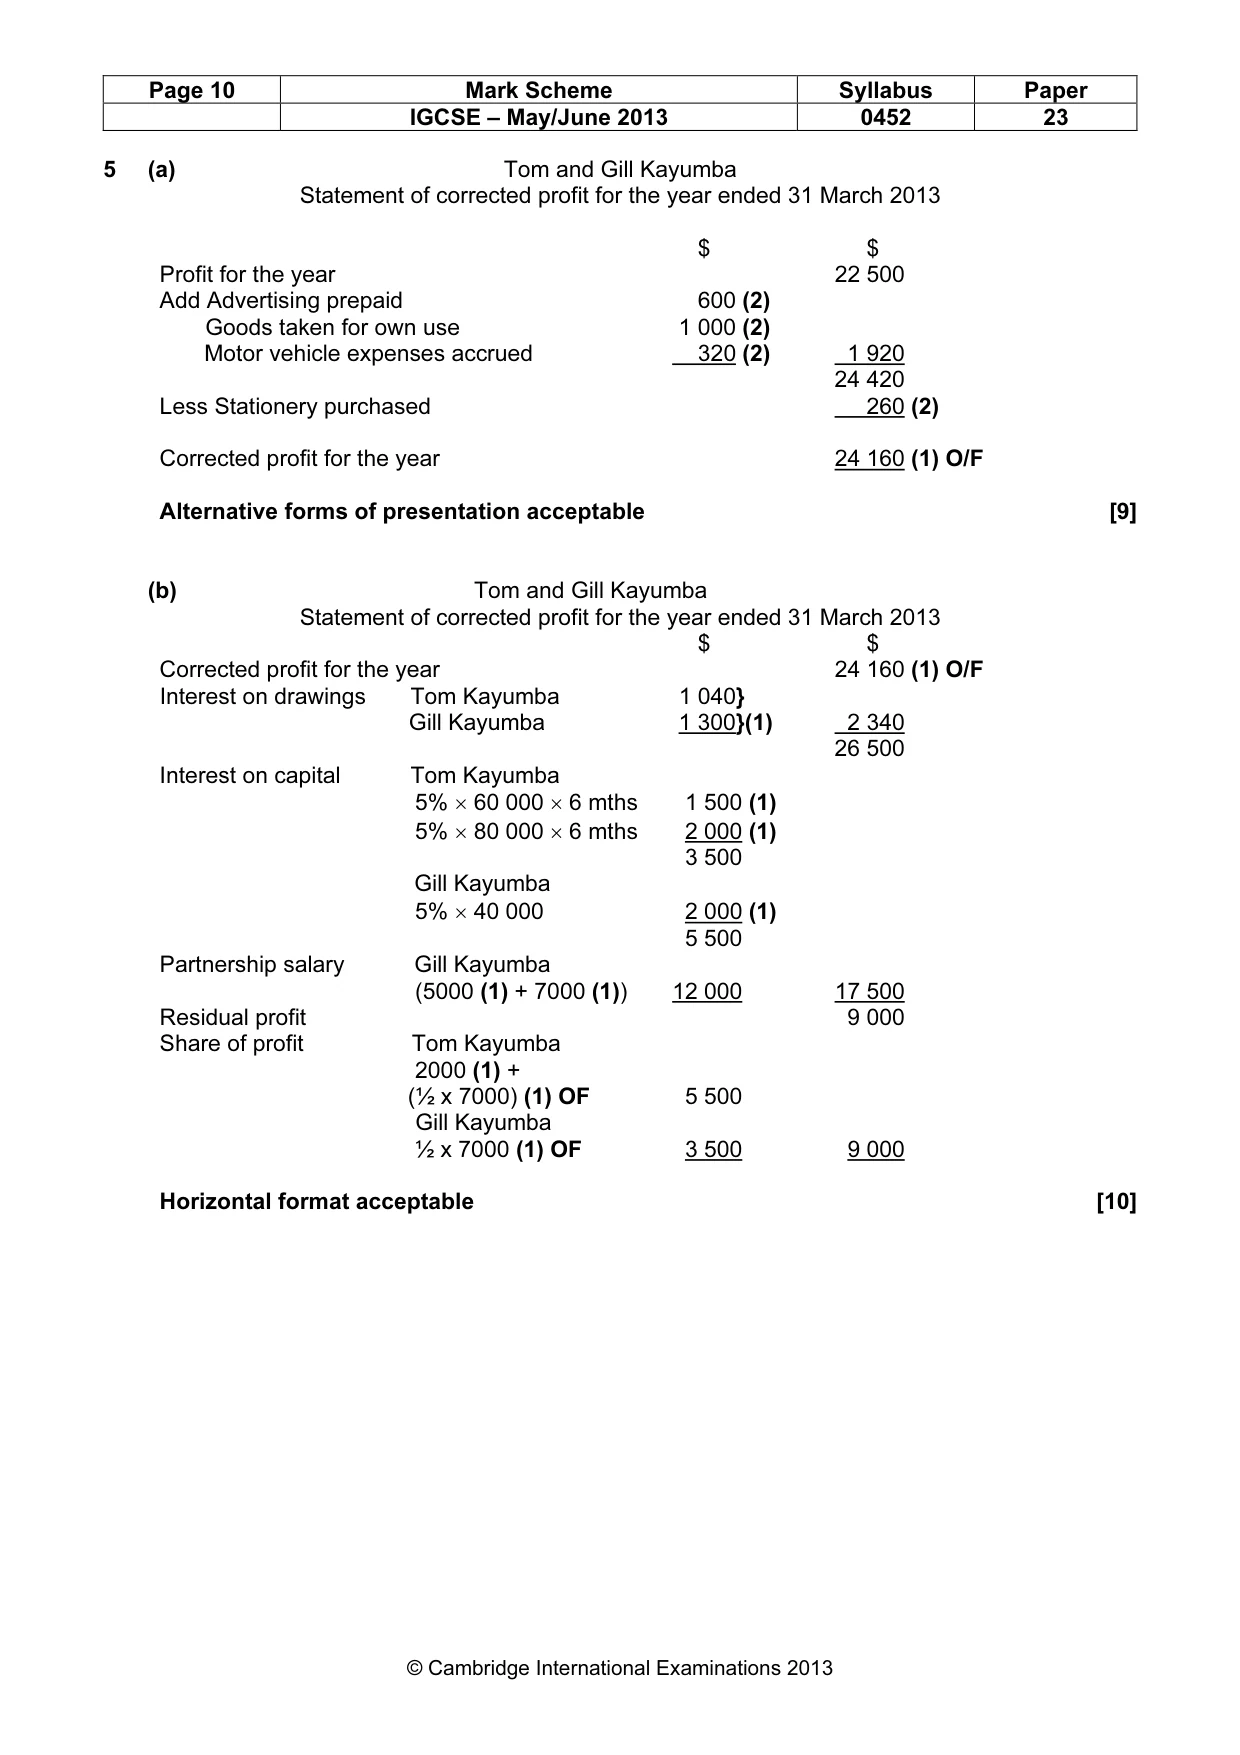
Page 10 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 5 (a) Tom and Gill Kayumba Statement of corrected profit for the year ended 31 March 2013 $ $ Profit for the year 22 500 Add Advertising prepaid 600 (2) Goods taken for own use 1 000 (2) Motor vehicle expenses accrued 320 (2) 1 920 24 420 Less Stationery purchased 260 (2) Corrected profit for the year 24 160 (1) O/F Alternative forms of presentation acceptable [9] (b) Tom and Gill Kayumba Statement of corrected profit for the year ended 31 March 2013 $ $ Corrected profit for the year 24 160 (1) O/F Interest on drawings Tom Kayumba 1 040} Gill Kayumba 1 300}(1) 2 340 26 500 Interest on capital Tom Kayumba 5% × 60 000 × 6 mths 1 500 (1) 5% × 80 000 × 6 mths 2 000 (1) 3 500 Gill Kayumba 5% × 40 000 2 000 (1) 5 500 Partnership salary Gill Kayumba (5000 (1) + 7000 (1)) 12 000 17 500 Residual profit 9 000 Share of profit Tom Kayumba 2000 (1) + (½ x 7000) (1) OF 5 500 Gill Kayumba ½ x 7000 (1) OF 3 500 9 000 Horizontal format acceptable [10]
Mark scheme, page 11
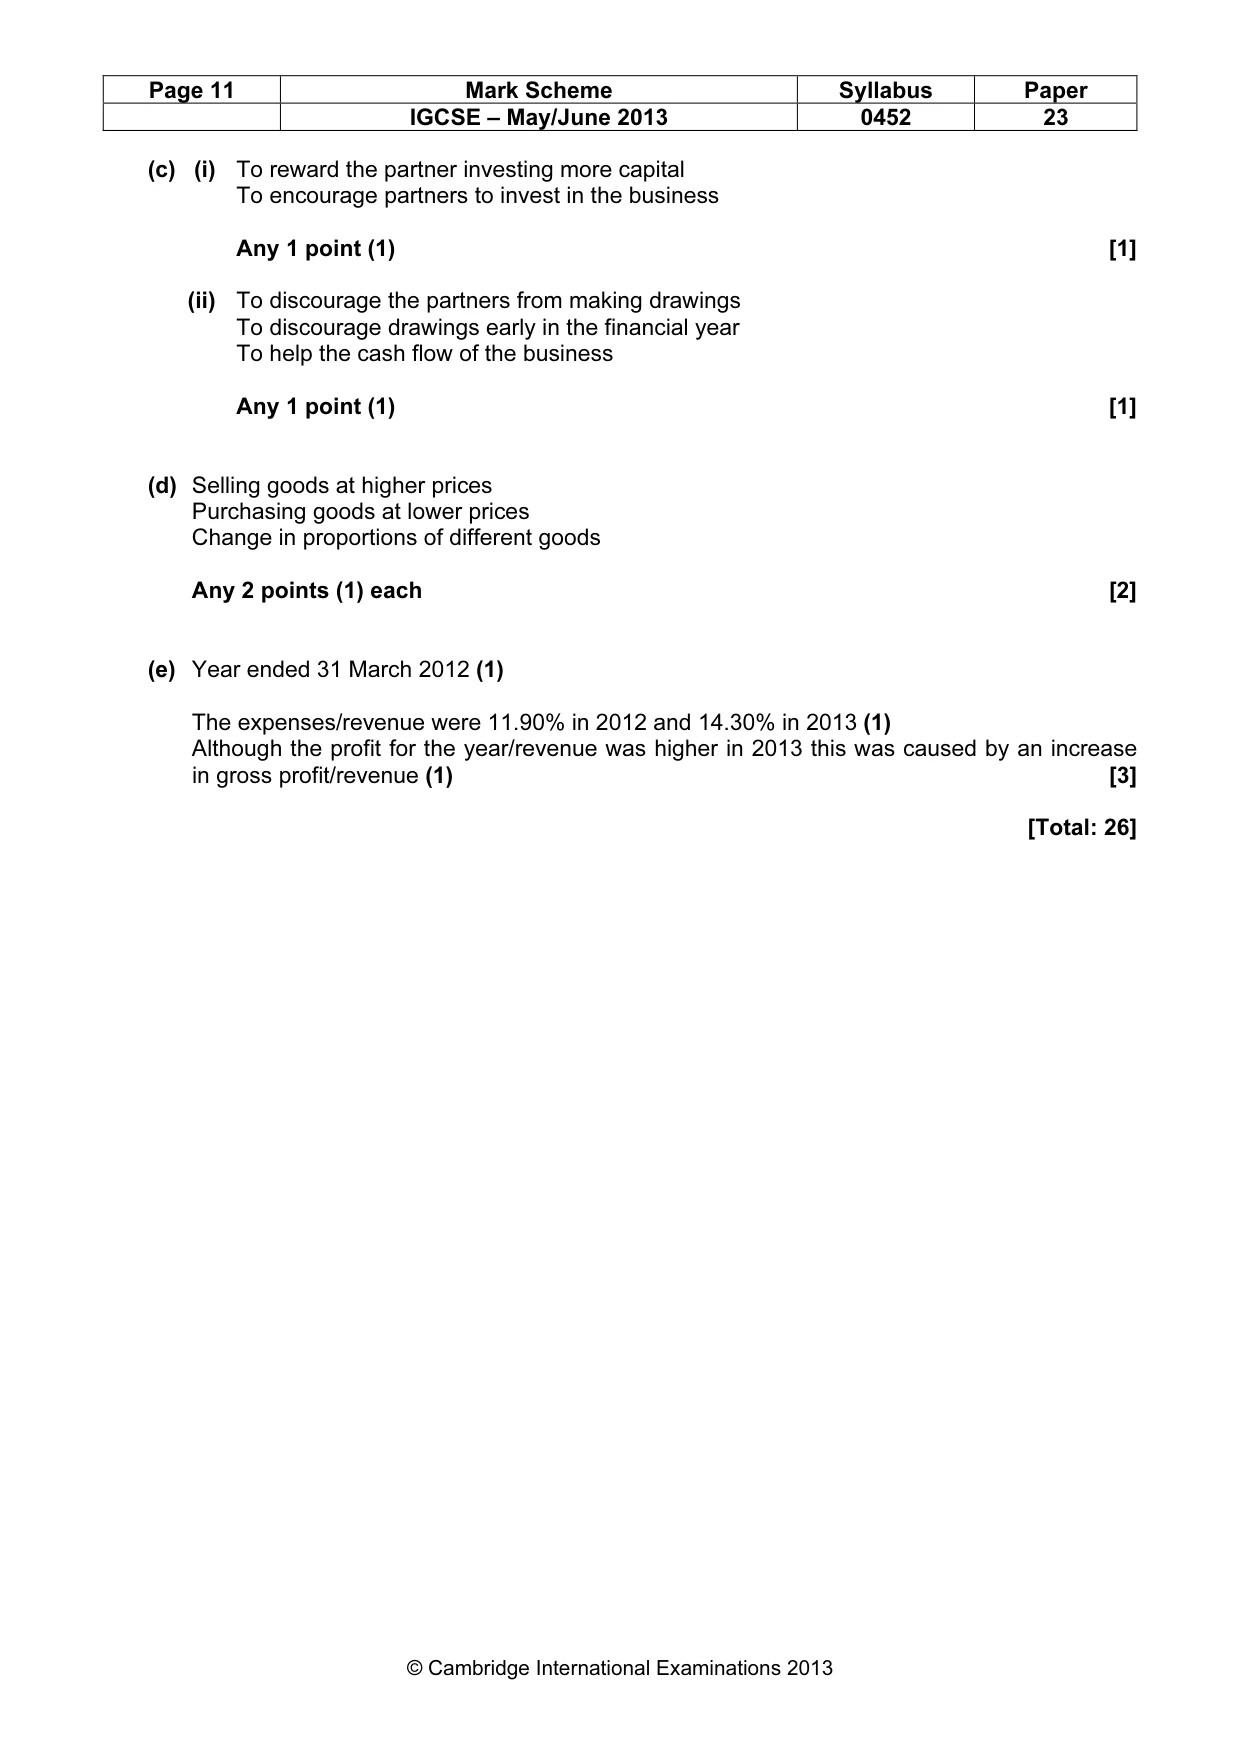
Page 11 Mark Scheme Syllabus Paper IGCSE – May/June 2013 0452 23 © Cambridge International Examinations 2013 (c) (i) To reward the partner investing more capital To encourage partners to invest in the business Any 1 point (1) [1] (ii) To discourage the partners from making drawings To discourage drawings early in the financial year To help the cash flow of the business Any 1 point (1) [1] (d) Selling goods at higher prices Purchasing goods at lower prices Change in proportions of different goods Any 2 points (1) each [2] (e) Year ended 31 March 2012 (1) The expenses/revenue were 11.90% in 2012 and 14.30% in 2013 (1) Although the profit for the year/revenue was higher in 2013 this was caused by an increase in gross profit/revenue (1) [3] [Total: 26]
What you needed in this session
Cambridge’s own grade thresholds for 2013 May/June, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.