Cambridge IGCSE Accounting 0452 — 2012 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/12 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages

Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 16 printed pages. IB12 11_0452_22/RP © UCLES 2012 [Turn over *1478344099* For Examiner's Use 1 2 3 4 5 Total UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/22 Paper 2 October/November 2012 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for any diagrams or graphs. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
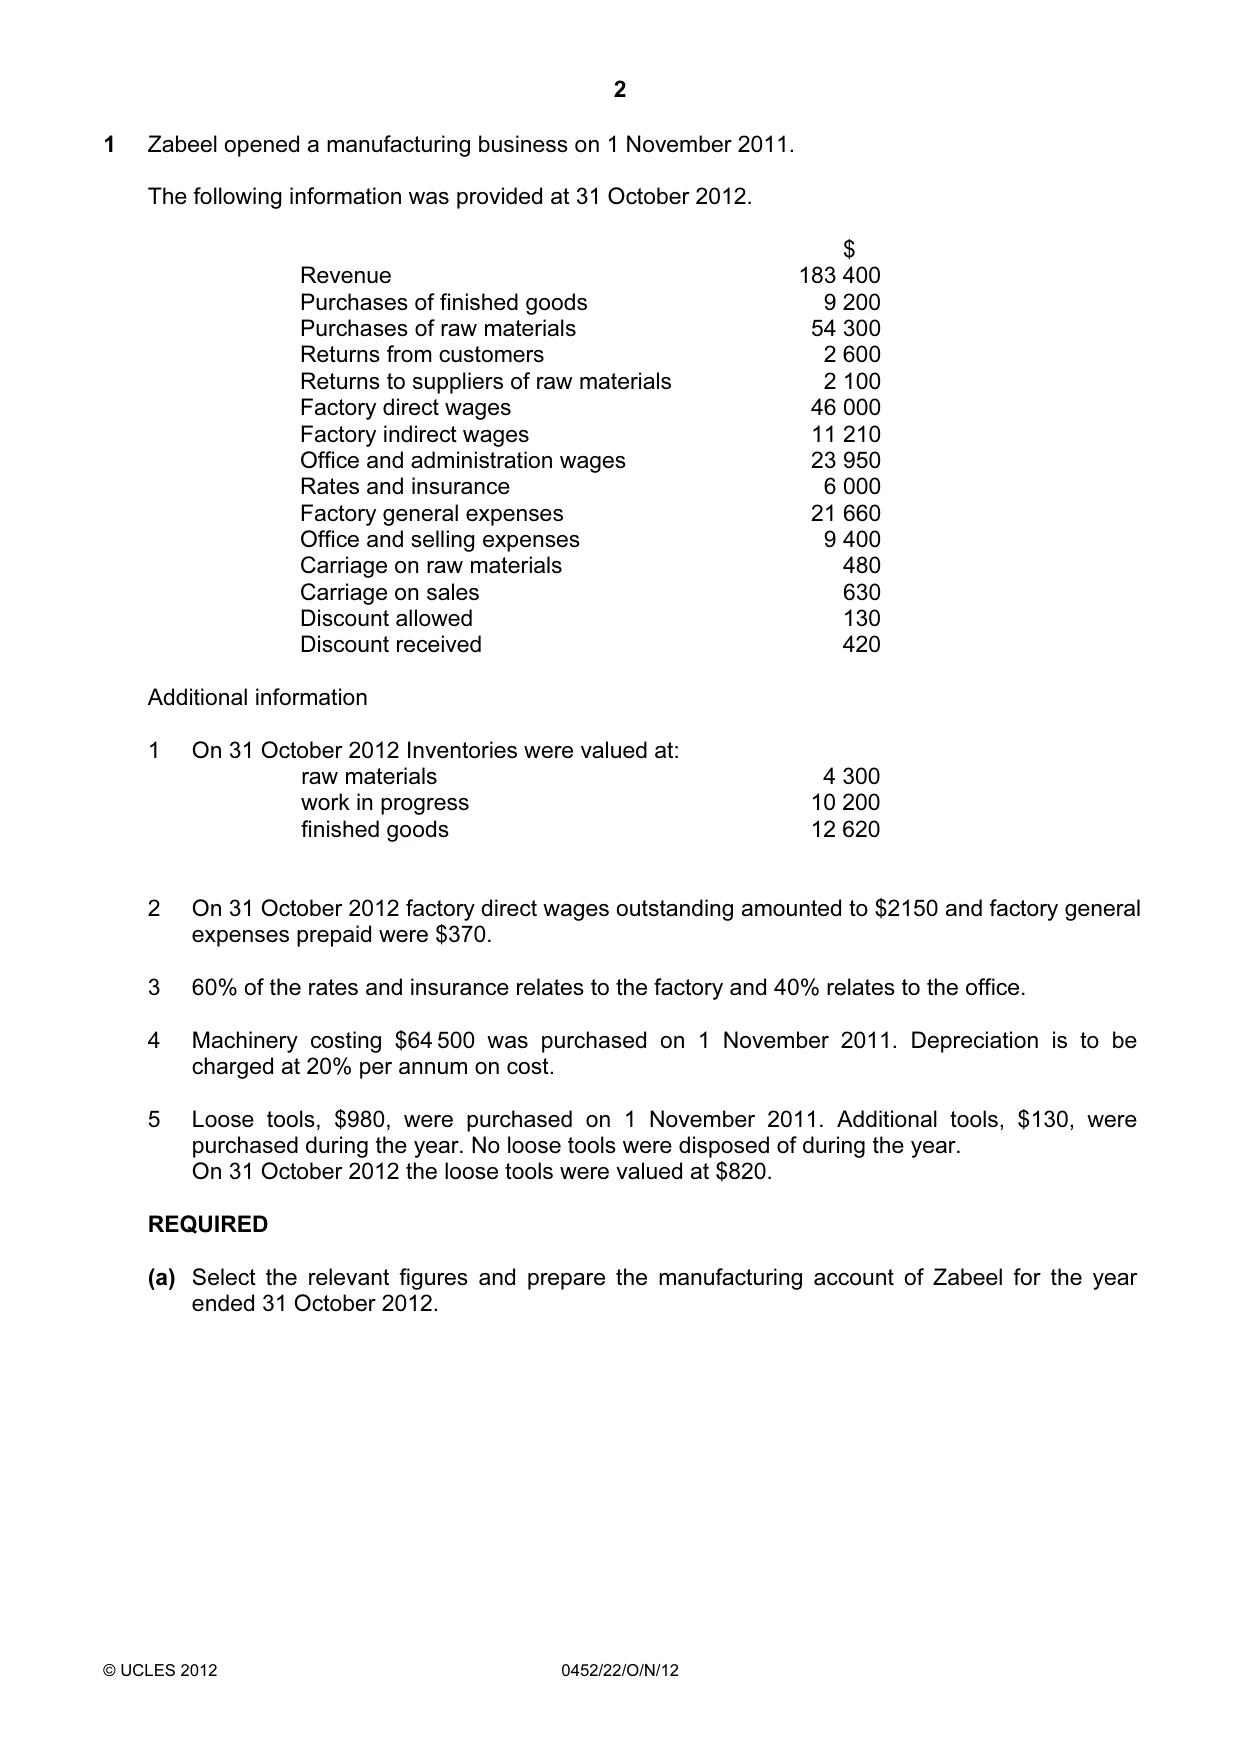
Question paper, page 2
2 © UCLES 2012 0452/22/O/N/12 1 Zabeel opened a manufacturing business on 1 November 2011. The following information was provided at 31 October 2012. $ Revenue 183 400 Purchases of finished goods 9 200 Purchases of raw materials 54 300 Returns from customers 2 600 Returns to suppliers of raw materials 2 100 Factory direct wages 46 000 Factory indirect wages 11 210 Office and administration wages 23 950 Rates and insurance 6 000 Factory general expenses 21 660 Office and selling expenses 9 400 Carriage on raw materials 480 Carriage on sales 630 Discount allowed 130 Discount received 420 Additional information 1 On 31 October 2012 Inventories were valued at: raw materials 4 300 work in progress 10 200 finished goods 12 620 2 On 31 October 2012 factory direct wages outstanding amounted to $2150 and factory general expenses prepaid were $370. 3 60% of the rates and insurance relates to the factory and 40% relates to the office. 4 Machinery costing $64 500 was purchased on 1 November 2011. Depreciation is to be charged at 20% per annum on cost. 5 Loose tools, $980, were purchased on 1 November 2011. Additional tools, $130, were purchased during the year. No loose tools were disposed of during the year. On 31 October 2012 the loose tools were valued at $820. REQUIRED (a) Select the relevant figures and prepare the manufacturing account of Zabeel for the year ended 31 October 2012.
Question paper, page 3
3 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use Zabeel Manufacturing account for the year ended 31 October 2012 [14]
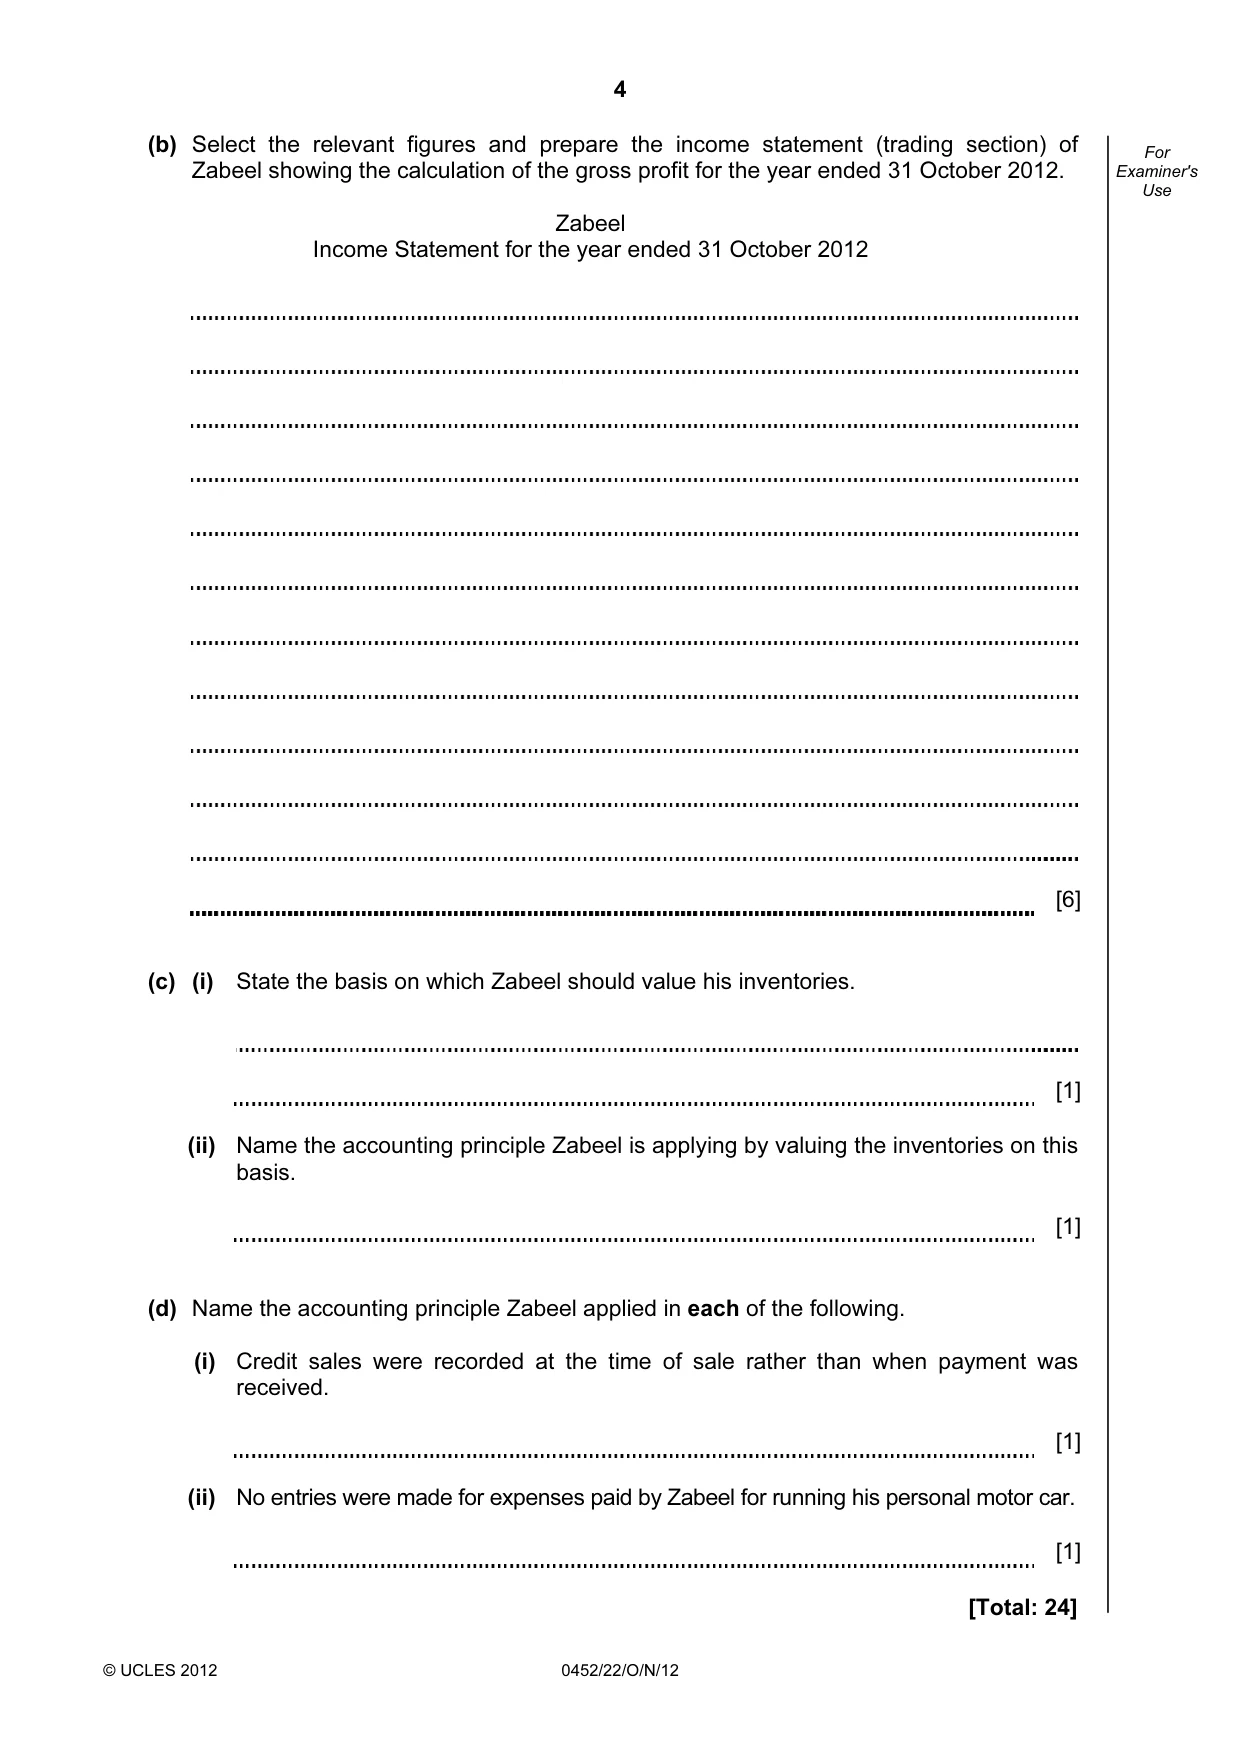
Question paper, page 4
4 © UCLES 2012 0452/22/O/N/12 For Examiner's Use (b) Select the relevant figures and prepare the income statement (trading section) of Zabeel showing the calculation of the gross profit for the year ended 31 October 2012. Zabeel Income Statement for the year ended 31 October 2012 [6] (c) (i) State the basis on which Zabeel should value his inventories. [1] (ii) Name the accounting principle Zabeel is applying by valuing the inventories on this basis. [1] (d) Name the accounting principle Zabeel applied in each of the following. (i) Credit sales were recorded at the time of sale rather than when payment was received. [1] (ii) No entries were made for expenses paid by Zabeel for running his personal motor car. [1] [Total: 24]
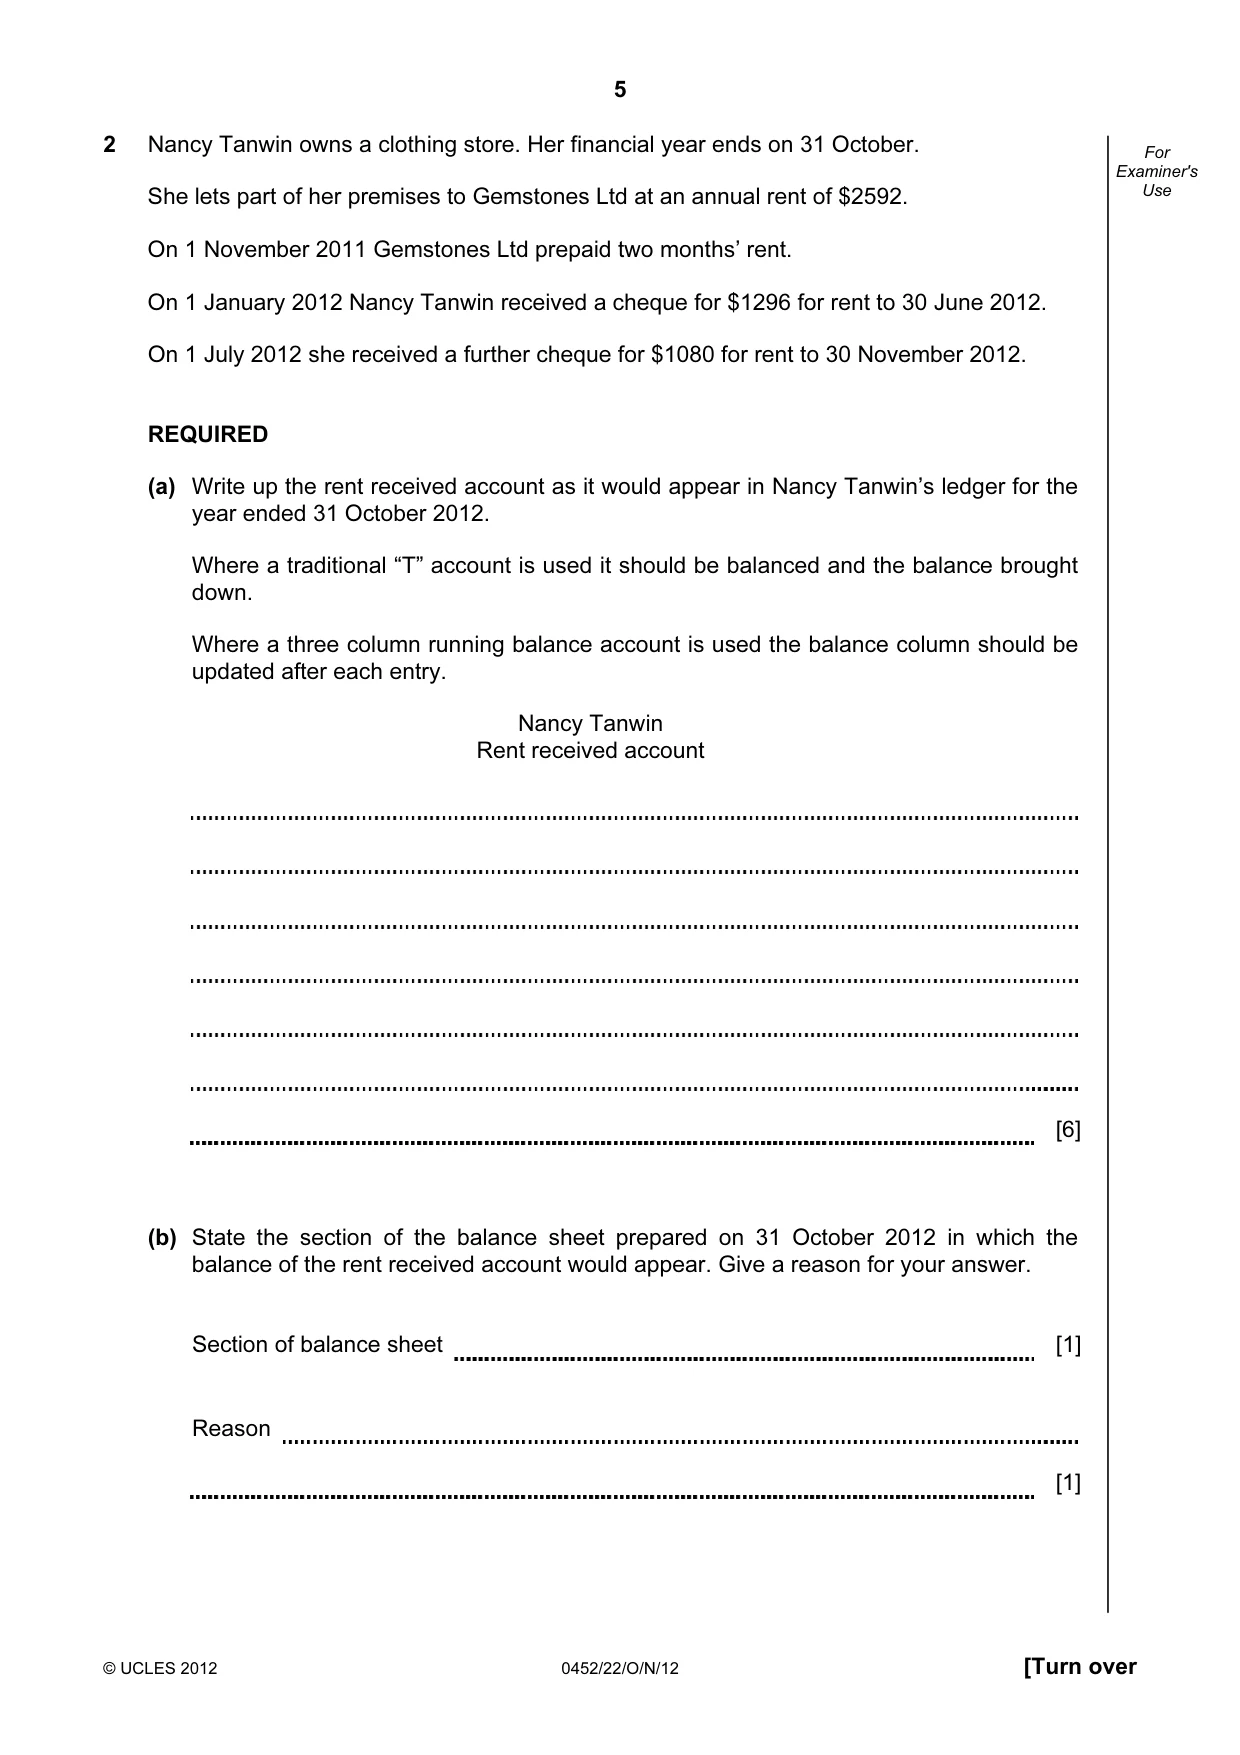
Question paper, page 5
5 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use 2 Nancy Tanwin owns a clothing store. Her financial year ends on 31 October. She lets part of her premises to Gemstones Ltd at an annual rent of $2592. On 1 November 2011 Gemstones Ltd prepaid two months’ rent. On 1 January 2012 Nancy Tanwin received a cheque for $1296 for rent to 30 June 2012. On 1 July 2012 she received a further cheque for $1080 for rent to 30 November 2012. REQUIRED (a) Write up the rent received account as it would appear in Nancy Tanwin’s ledger for the year ended 31 October 2012. Where a traditional “T” account is used it should be balanced and the balance brought down. Where a three column running balance account is used the balance column should be updated after each entry. Nancy Tanwin Rent received account [6] (b) State the section of the balance sheet prepared on 31 October 2012 in which the balance of the rent received account would appear. Give a reason for your answer. Section of balance sheet [1] Reason [1]
Question paper, page 6
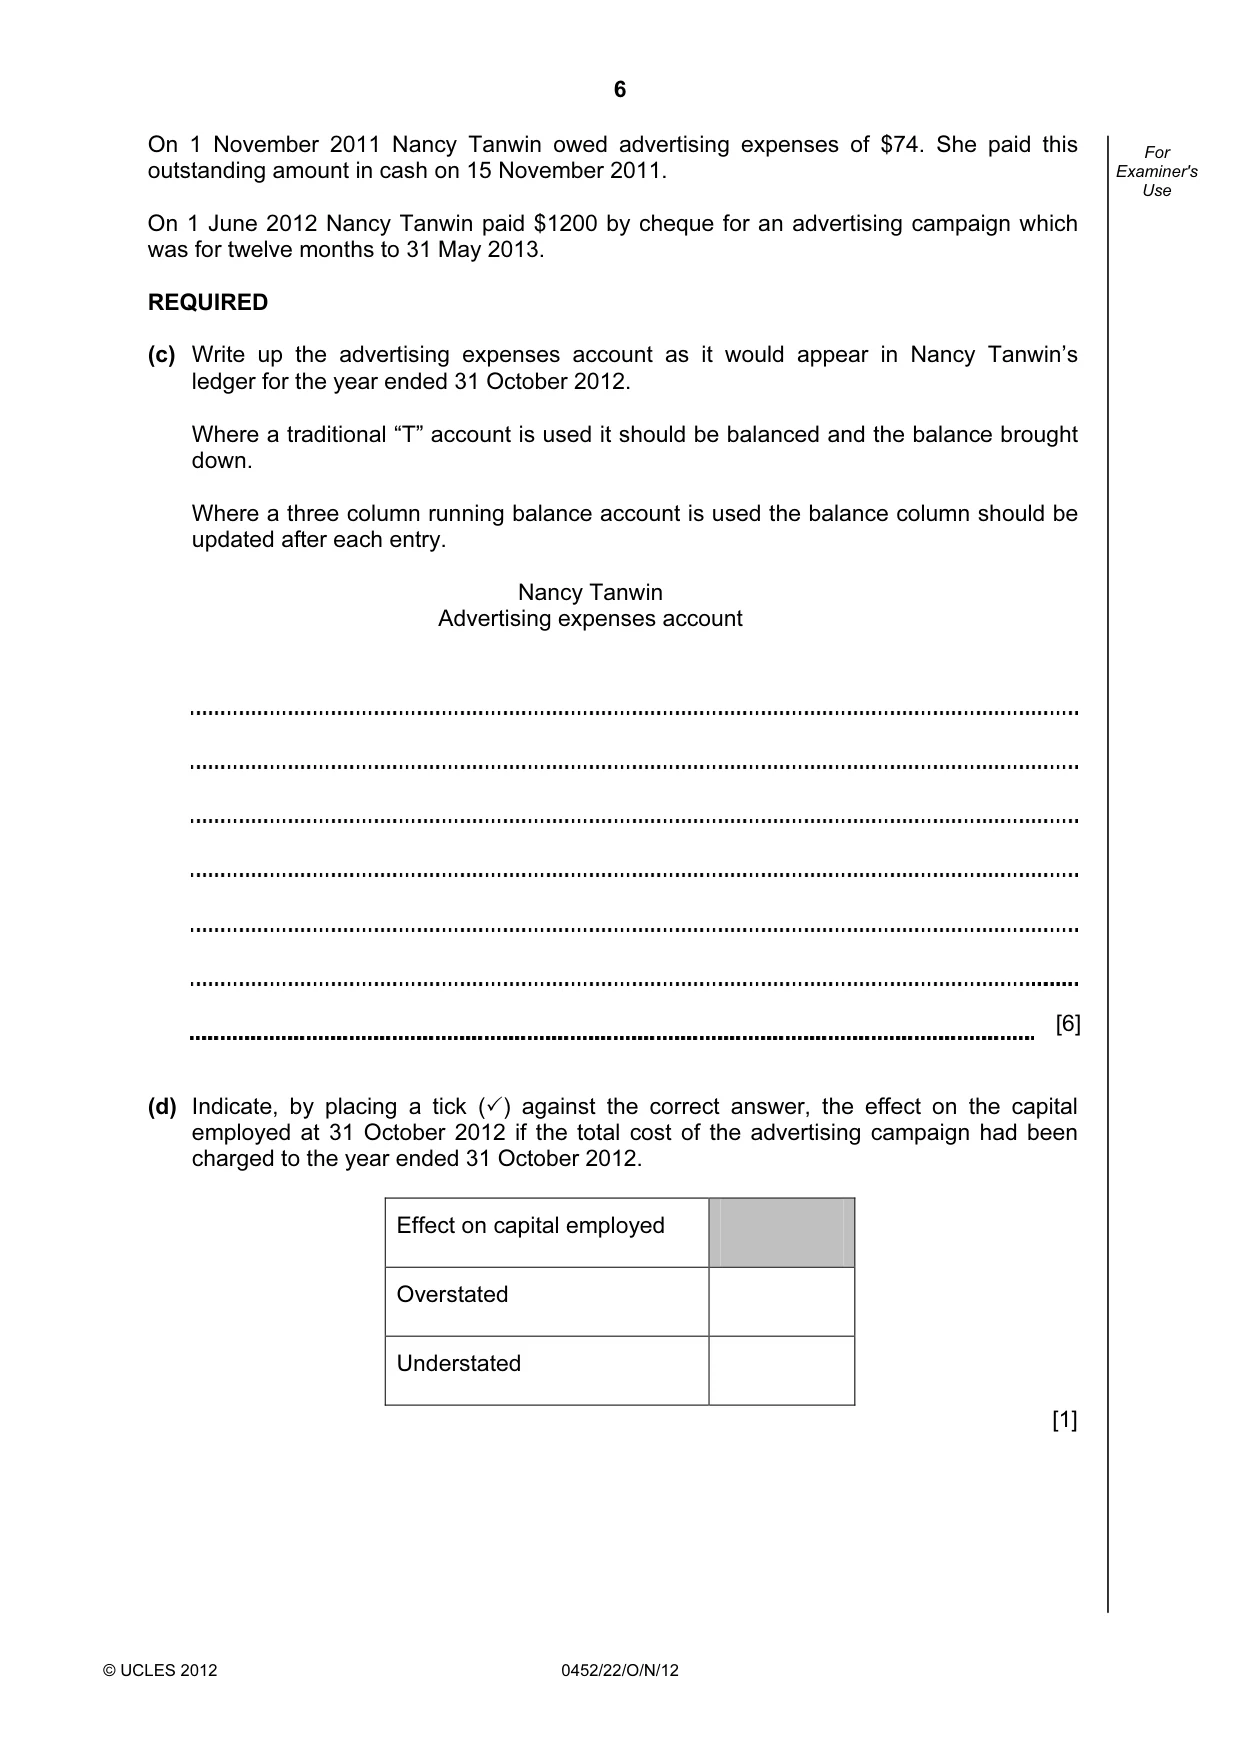
6 © UCLES 2012 0452/22/O/N/12 For Examiner's Use On 1 November 2011 Nancy Tanwin owed advertising expenses of $74. She paid this outstanding amount in cash on 15 November 2011. On 1 June 2012 Nancy Tanwin paid $1200 by cheque for an advertising campaign which was for twelve months to 31 May 2013. REQUIRED (c) Write up the advertising expenses account as it would appear in Nancy Tanwin’s ledger for the year ended 31 October 2012. Where a traditional “T” account is used it should be balanced and the balance brought down. Where a three column running balance account is used the balance column should be updated after each entry. Nancy Tanwin Advertising expenses account [6] (d) Indicate, by placing a tick (✓) against the correct answer, the effect on the capital employed at 31 October 2012 if the total cost of the advertising campaign had been charged to the year ended 31 October 2012. Effect on capital employed Overstated Understated [1]
Question paper, page 7
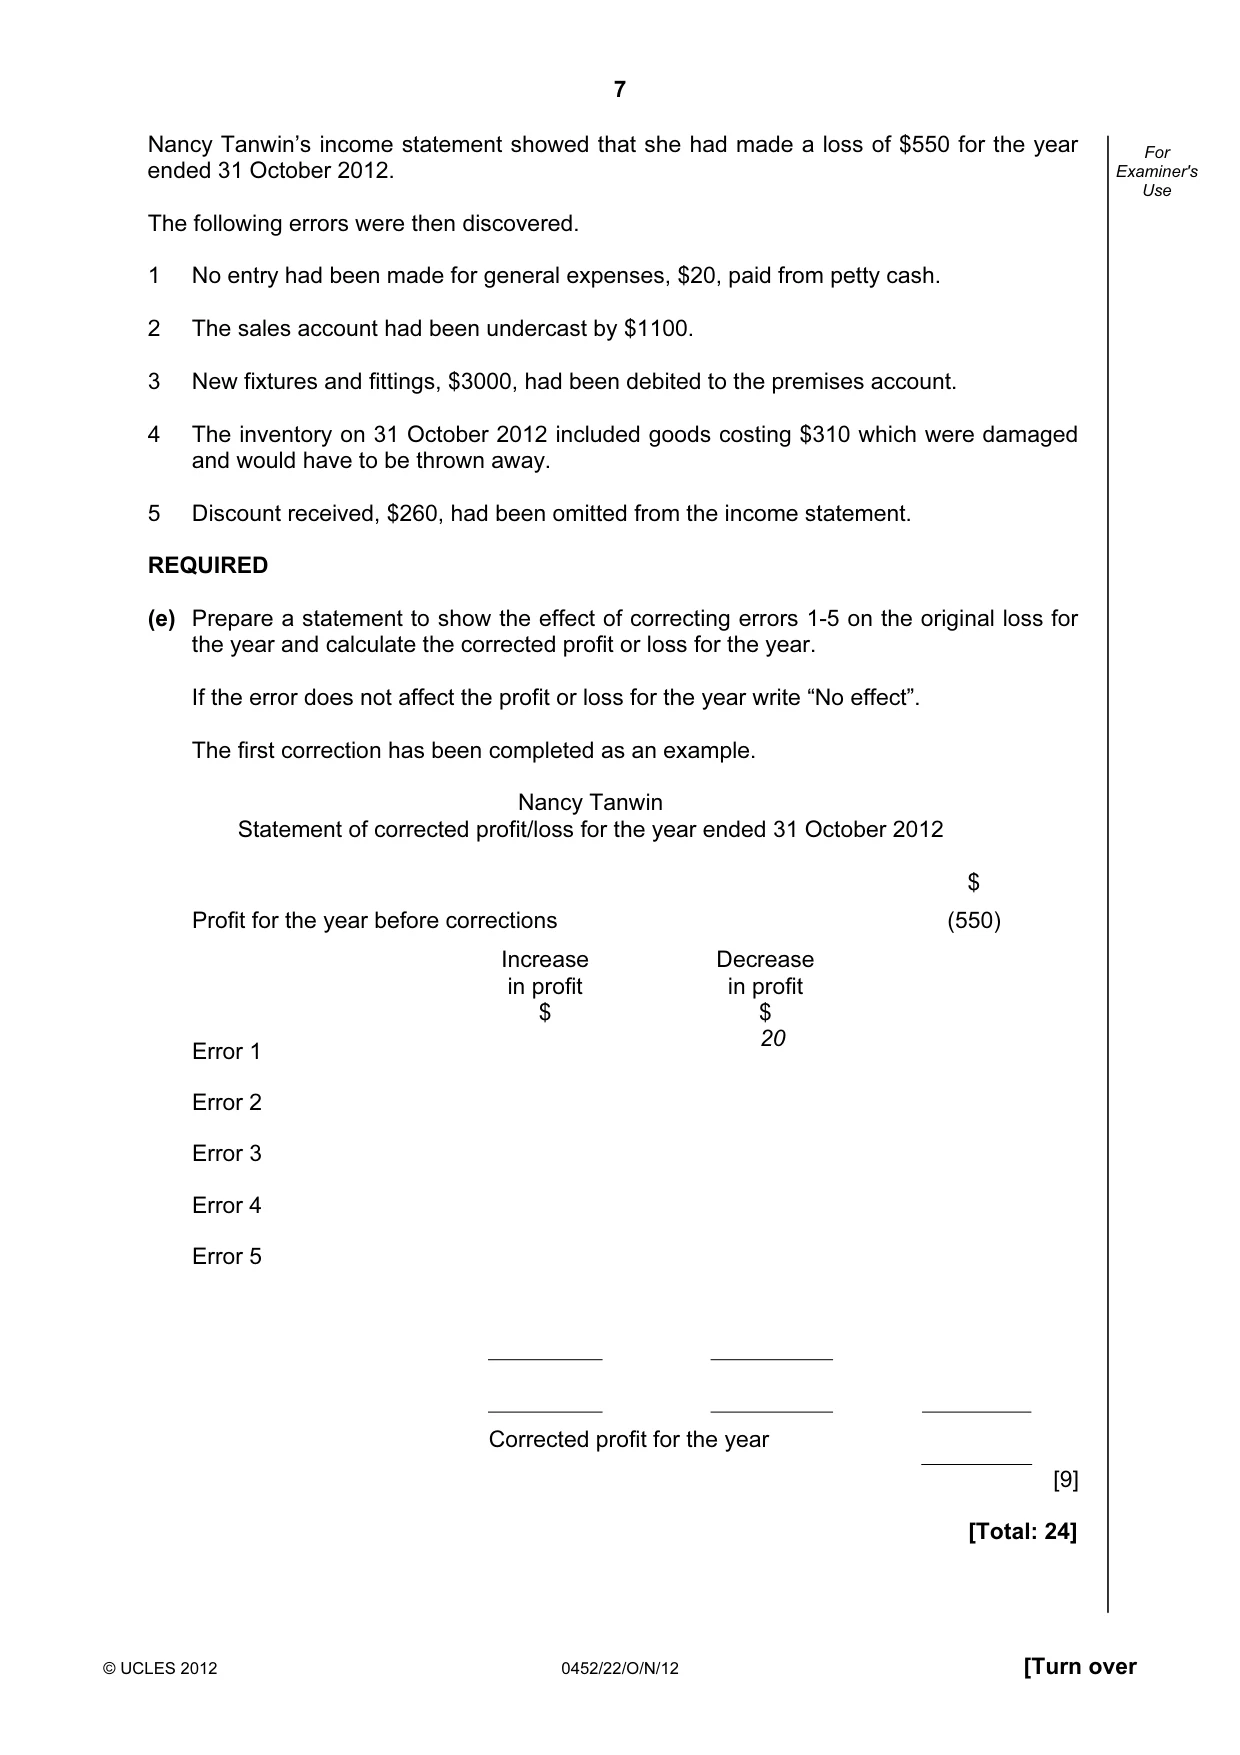
7 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use Nancy Tanwin’s income statement showed that she had made a loss of $550 for the year ended 31 October 2012. The following errors were then discovered. 1 No entry had been made for general expenses, $20, paid from petty cash. 2 The sales account had been undercast by $1100. 3 New fixtures and fittings, $3000, had been debited to the premises account. 4 The inventory on 31 October 2012 included goods costing $310 which were damaged and would have to be thrown away. 5 Discount received, $260, had been omitted from the income statement. REQUIRED (e) Prepare a statement to show the effect of correcting errors 1-5 on the original loss for the year and calculate the corrected profit or loss for the year. If the error does not affect the profit or loss for the year write “No effect”. The first correction has been completed as an example. Nancy Tanwin Statement of corrected profit/loss for the year ended 31 October 2012 $ Profit for the year before corrections (550) Increase in profit Decrease in profit $ $ Error 1 20 Error 2 Error 3 Error 4 Error 5 Corrected profit for the year [9] [Total: 24]
Question paper, page 8
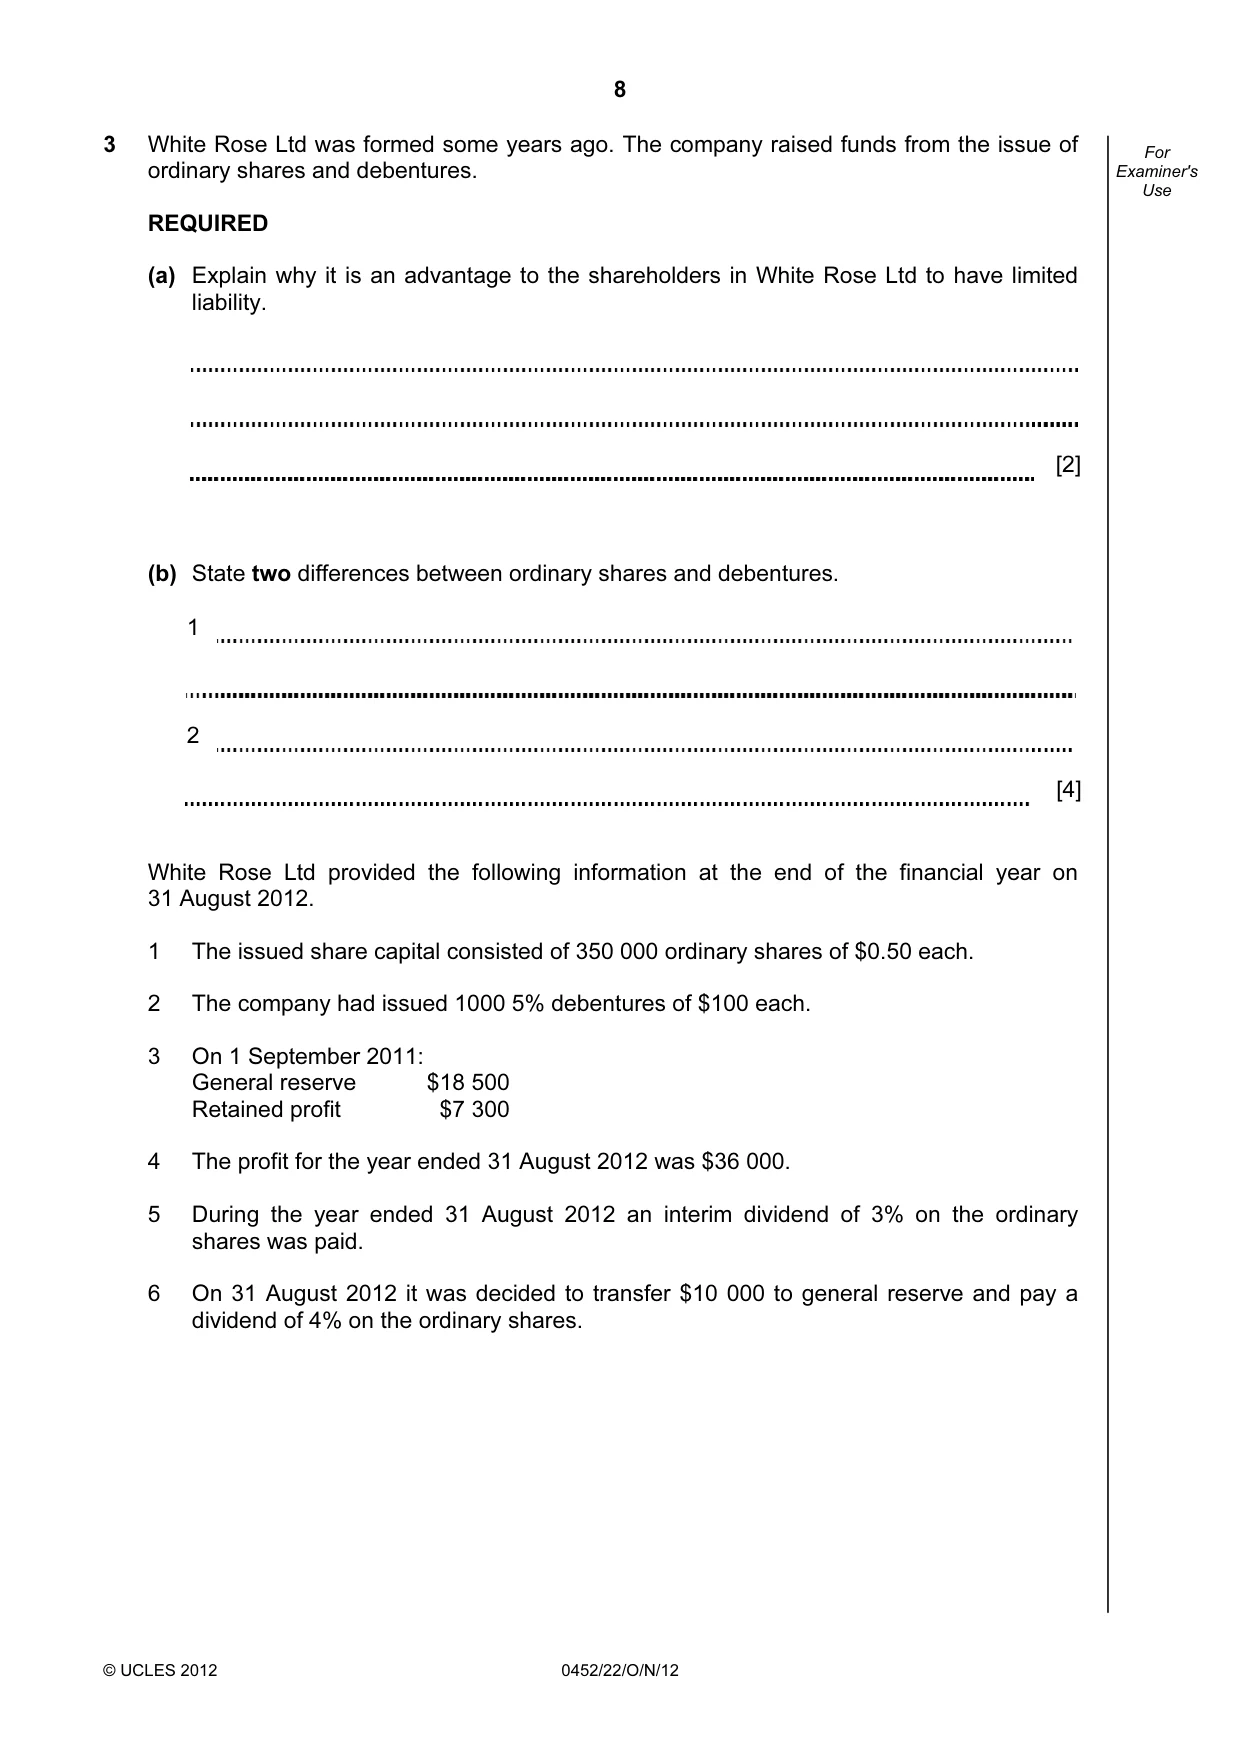
8 © UCLES 2012 0452/22/O/N/12 For Examiner's Use 3 White Rose Ltd was formed some years ago. The company raised funds from the issue of ordinary shares and debentures. REQUIRED (a) Explain why it is an advantage to the shareholders in White Rose Ltd to have limited liability. [2] (b) State two differences between ordinary shares and debentures. 1 2 [4] White Rose Ltd provided the following information at the end of the financial year on 31 August 2012. 1 The issued share capital consisted of 350 000 ordinary shares of $0.50 each. 2 The company had issued 1000 5% debentures of $100 each. 3 On 1 September 2011: General reserve $18 500 Retained profit $7 300 4 The profit for the year ended 31 August 2012 was $36 000. 5 During the year ended 31 August 2012 an interim dividend of 3% on the ordinary shares was paid. 6 On 31 August 2012 it was decided to transfer $10 000 to general reserve and pay a dividend of 4% on the ordinary shares.
Question paper, page 9
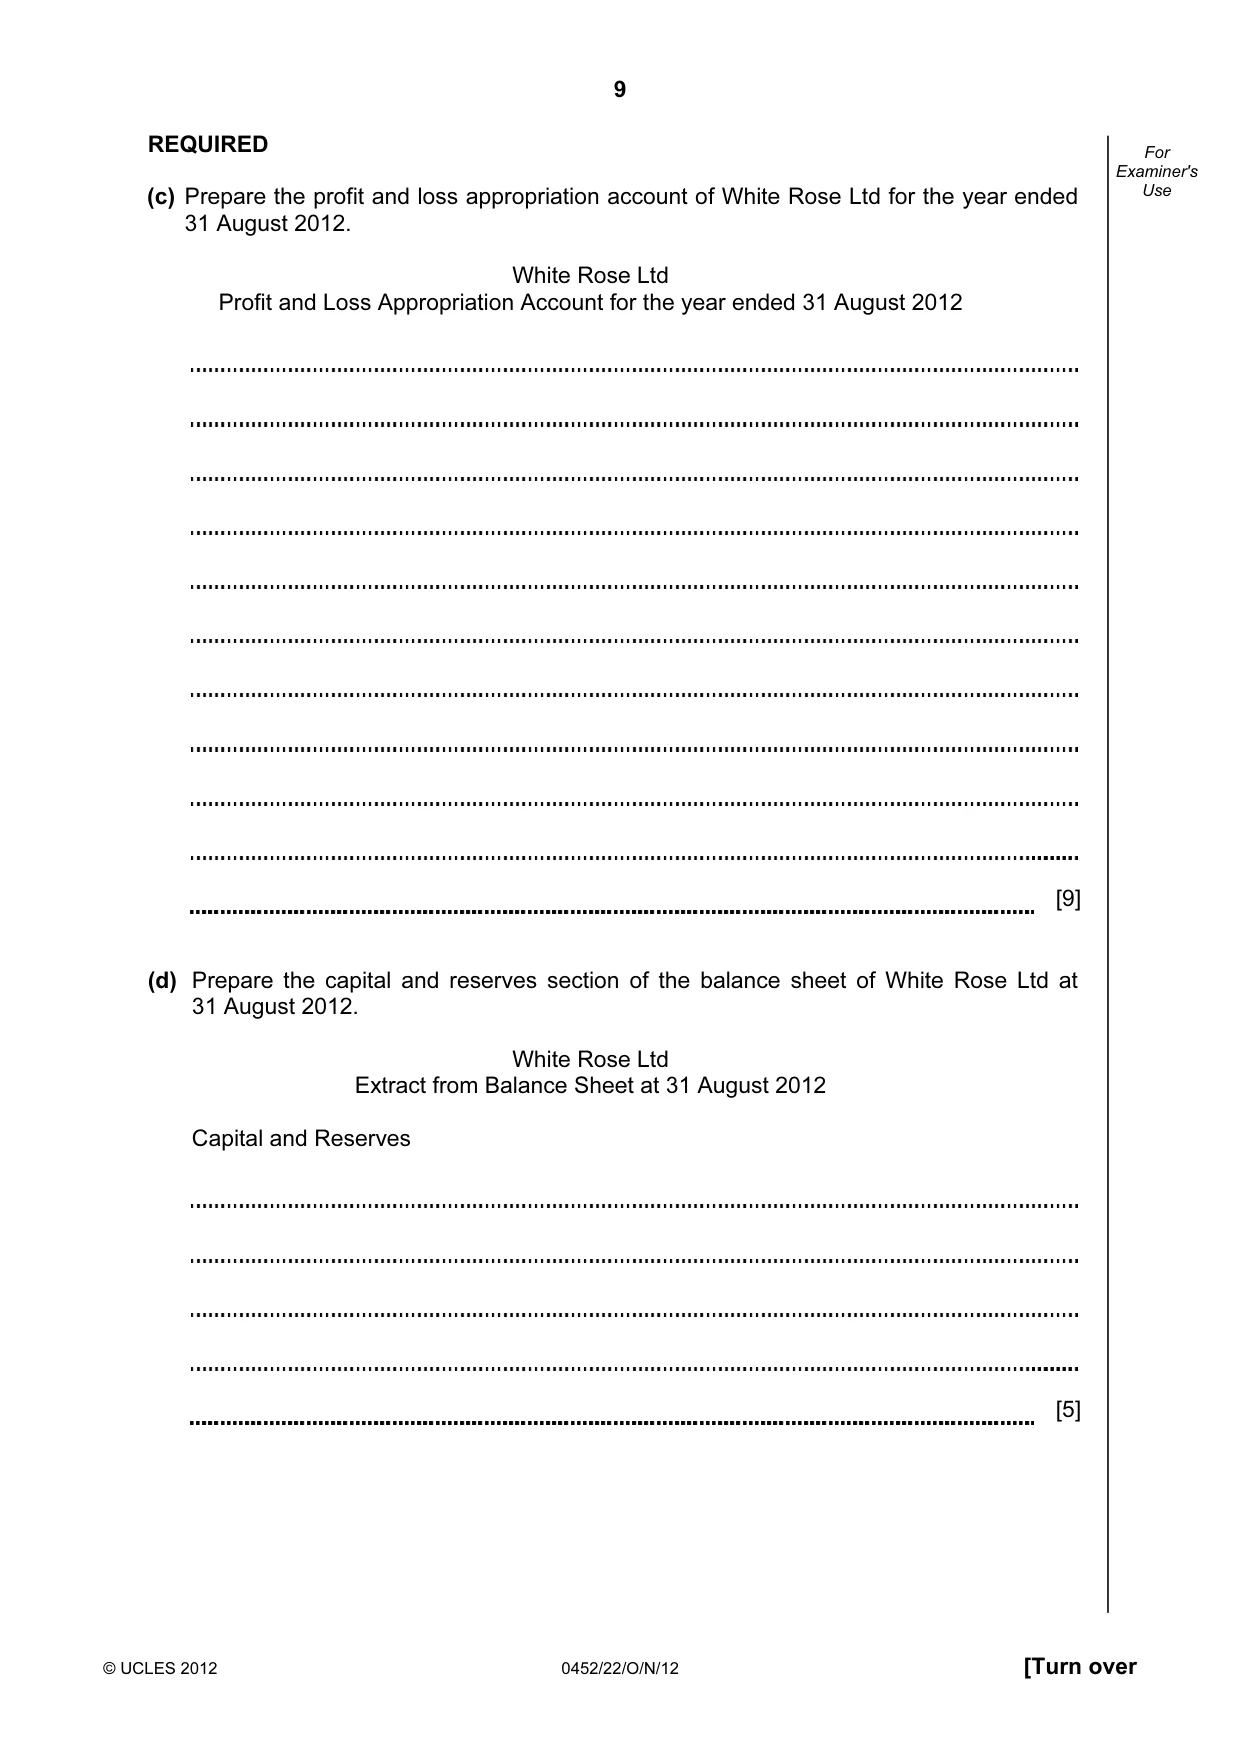
9 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use REQUIRED (c) Prepare the profit and loss appropriation account of White Rose Ltd for the year ended 31 August 2012. White Rose Ltd Profit and Loss Appropriation Account for the year ended 31 August 2012 [9] (d) Prepare the capital and reserves section of the balance sheet of White Rose Ltd at 31 August 2012. White Rose Ltd Extract from Balance Sheet at 31 August 2012 Capital and Reserves [5]
Question paper, page 10
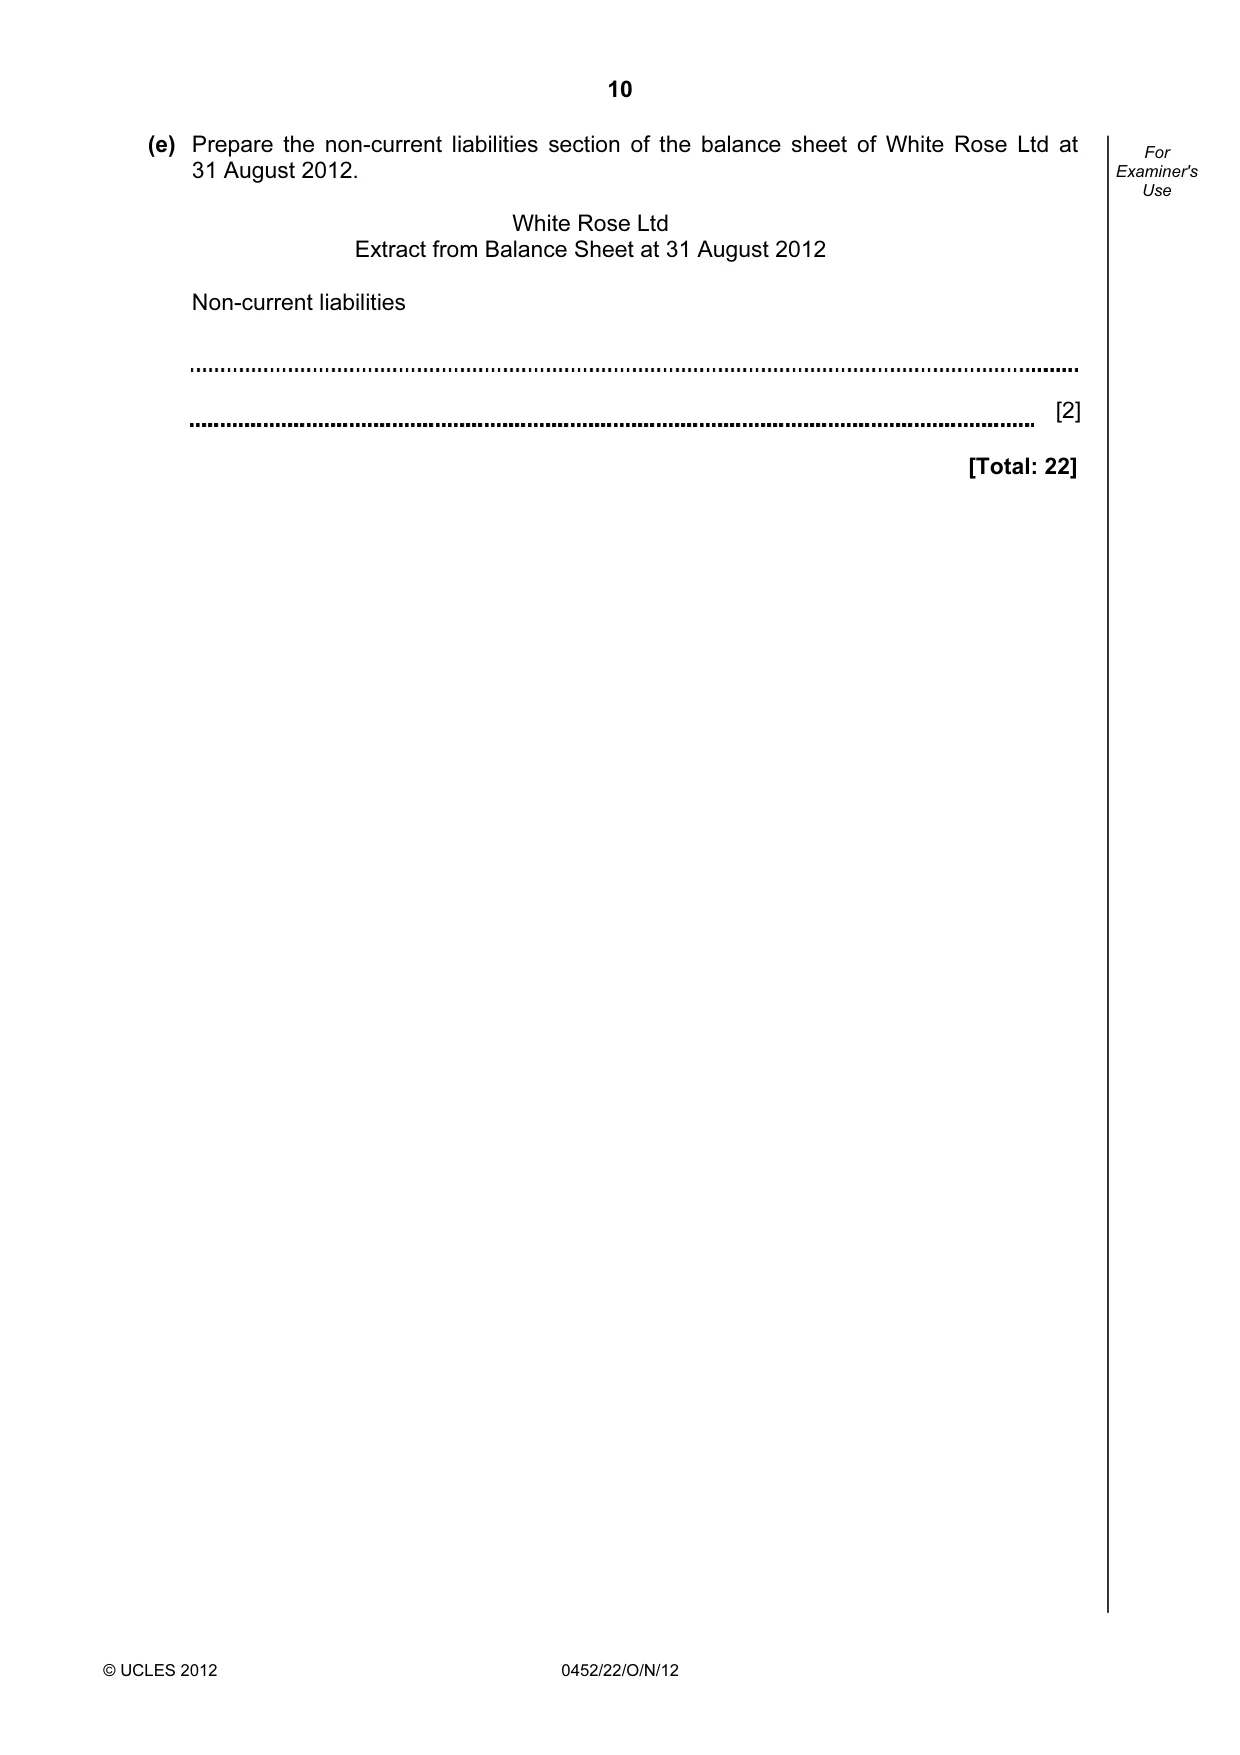
10 © UCLES 2012 0452/22/O/N/12 For Examiner's Use (e) Prepare the non-current liabilities section of the balance sheet of White Rose Ltd at 31 August 2012. White Rose Ltd Extract from Balance Sheet at 31 August 2012 Non-current liabilities [2] [Total: 22]
Question paper, page 11
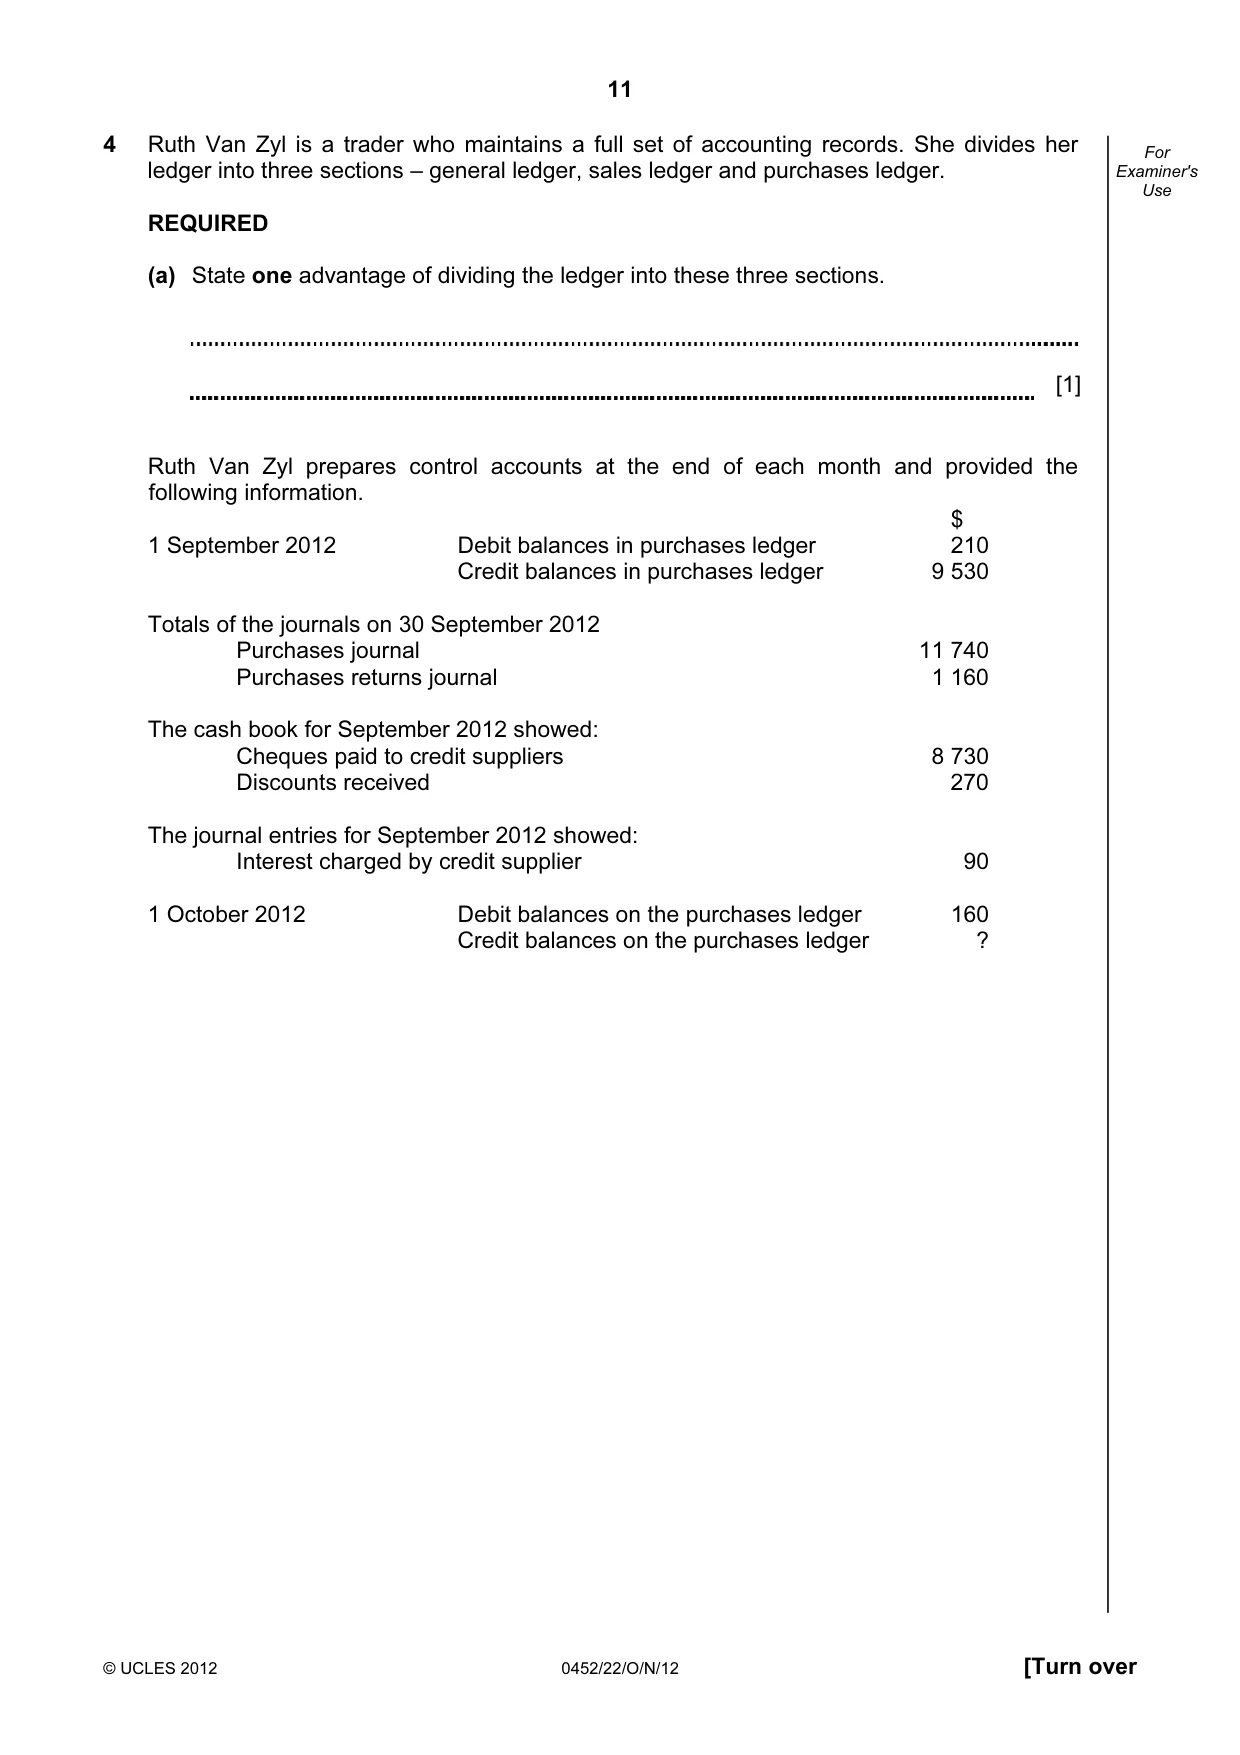
11 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use 4 Ruth Van Zyl is a trader who maintains a full set of accounting records. She divides her ledger into three sections – general ledger, sales ledger and purchases ledger. REQUIRED (a) State one advantage of dividing the ledger into these three sections. [1] Ruth Van Zyl prepares control accounts at the end of each month and provided the following information. $ 1 September 2012 Debit balances in purchases ledger 210 Credit balances in purchases ledger 9 530 Totals of the journals on 30 September 2012 Purchases journal 11 740 Purchases returns journal 1 160 The cash book for September 2012 showed: Cheques paid to credit suppliers 8 730 Discounts received 270 The journal entries for September 2012 showed: Interest charged by credit supplier 90 1 October 2012 Debit balances on the purchases ledger 160 Credit balances on the purchases ledger ?
Question paper, page 12
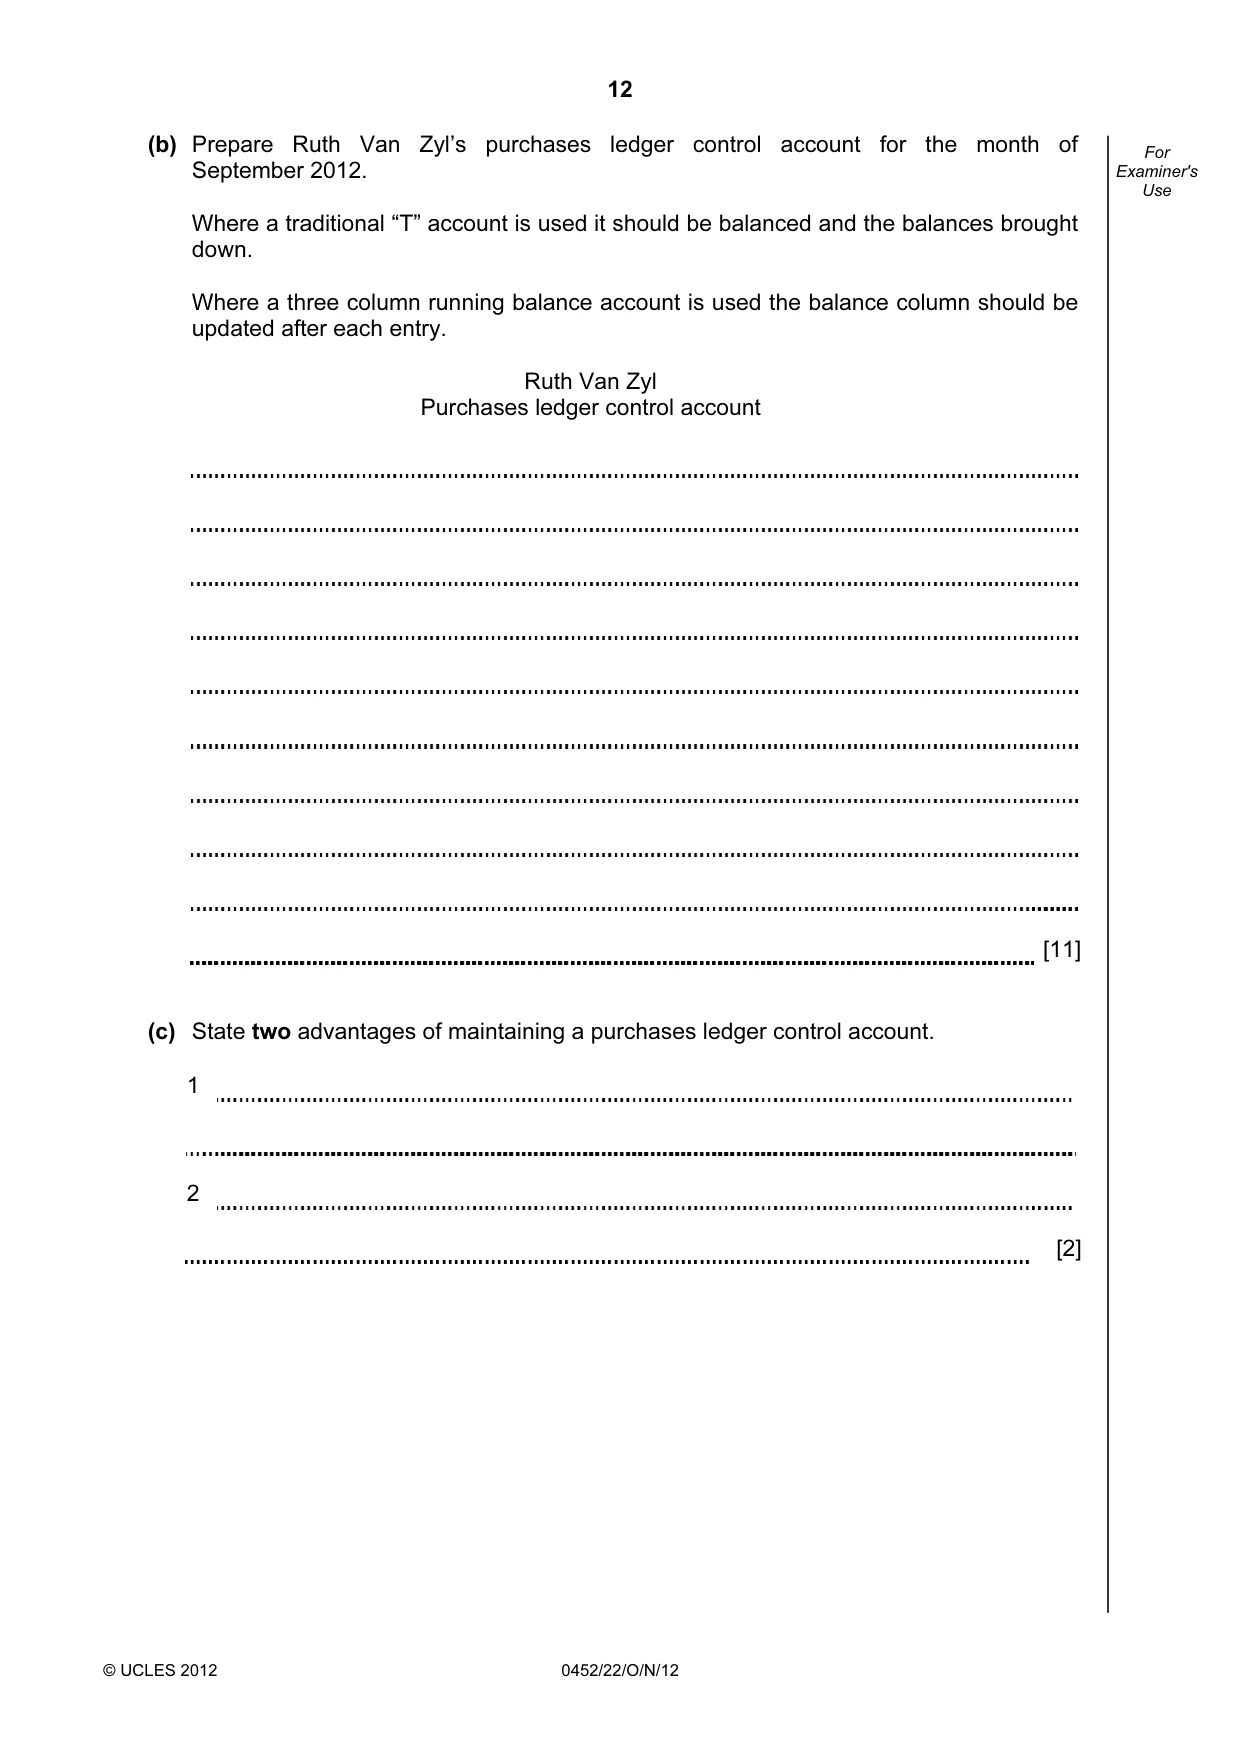
12 © UCLES 2012 0452/22/O/N/12 For Examiner's Use (b) Prepare Ruth Van Zyl’s purchases ledger control account for the month of September 2012. Where a traditional “T” account is used it should be balanced and the balances brought down. Where a three column running balance account is used the balance column should be updated after each entry. Ruth Van Zyl Purchases ledger control account [11] (c) State two advantages of maintaining a purchases ledger control account. 1 2 [2]
Question paper, page 13
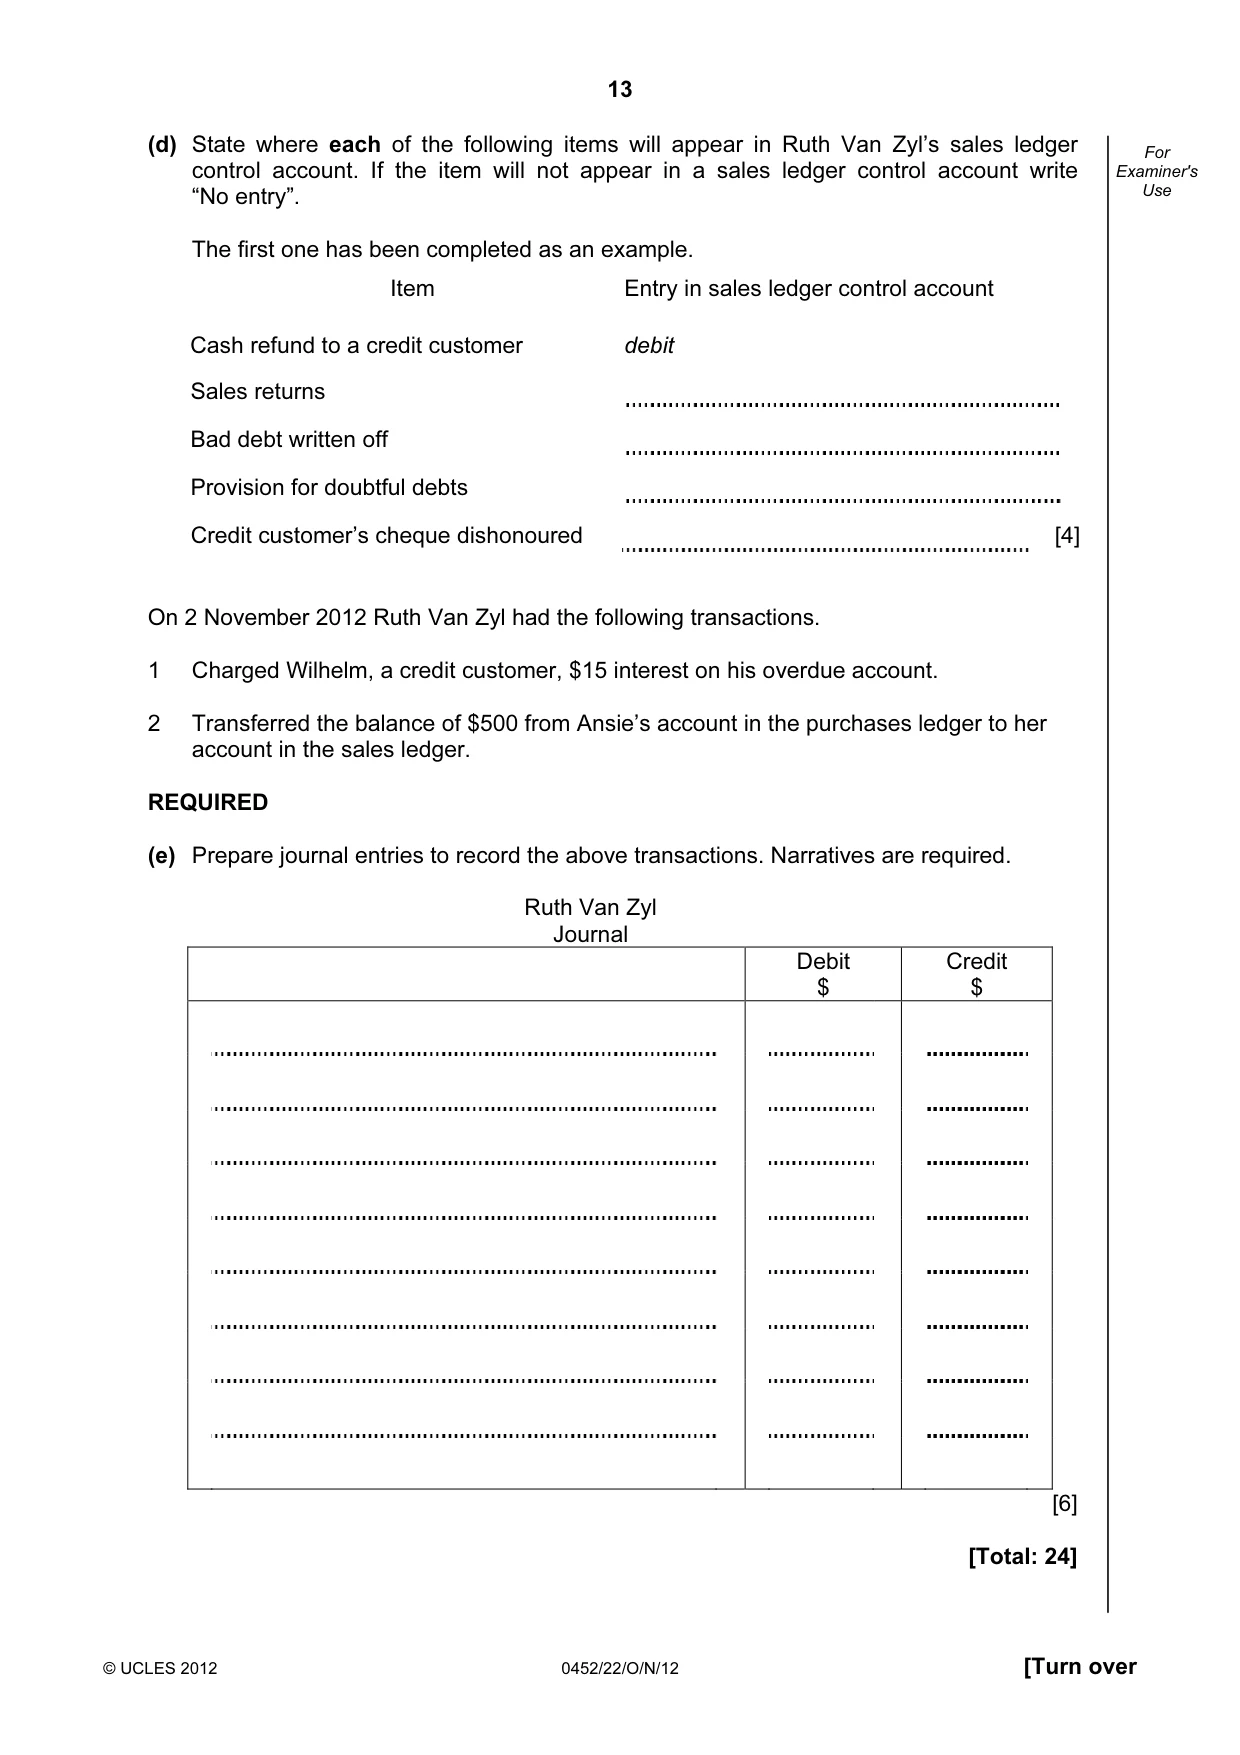
13 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use (d) State where each of the following items will appear in Ruth Van Zyl’s sales ledger control account. If the item will not appear in a sales ledger control account write “No entry”. The first one has been completed as an example. Item Entry in sales ledger control account Cash refund to a credit customer debit Sales returns Bad debt written off Provision for doubtful debts Credit customer’s cheque dishonoured [4] On 2 November 2012 Ruth Van Zyl had the following transactions. 1 Charged Wilhelm, a credit customer, $15 interest on his overdue account. 2 Transferred the balance of $500 from Ansie’s account in the purchases ledger to her account in the sales ledger. REQUIRED (e) Prepare journal entries to record the above transactions. Narratives are required. Ruth Van Zyl Journal Debit $ Credit $ [6] [Total: 24]
Question paper, page 14
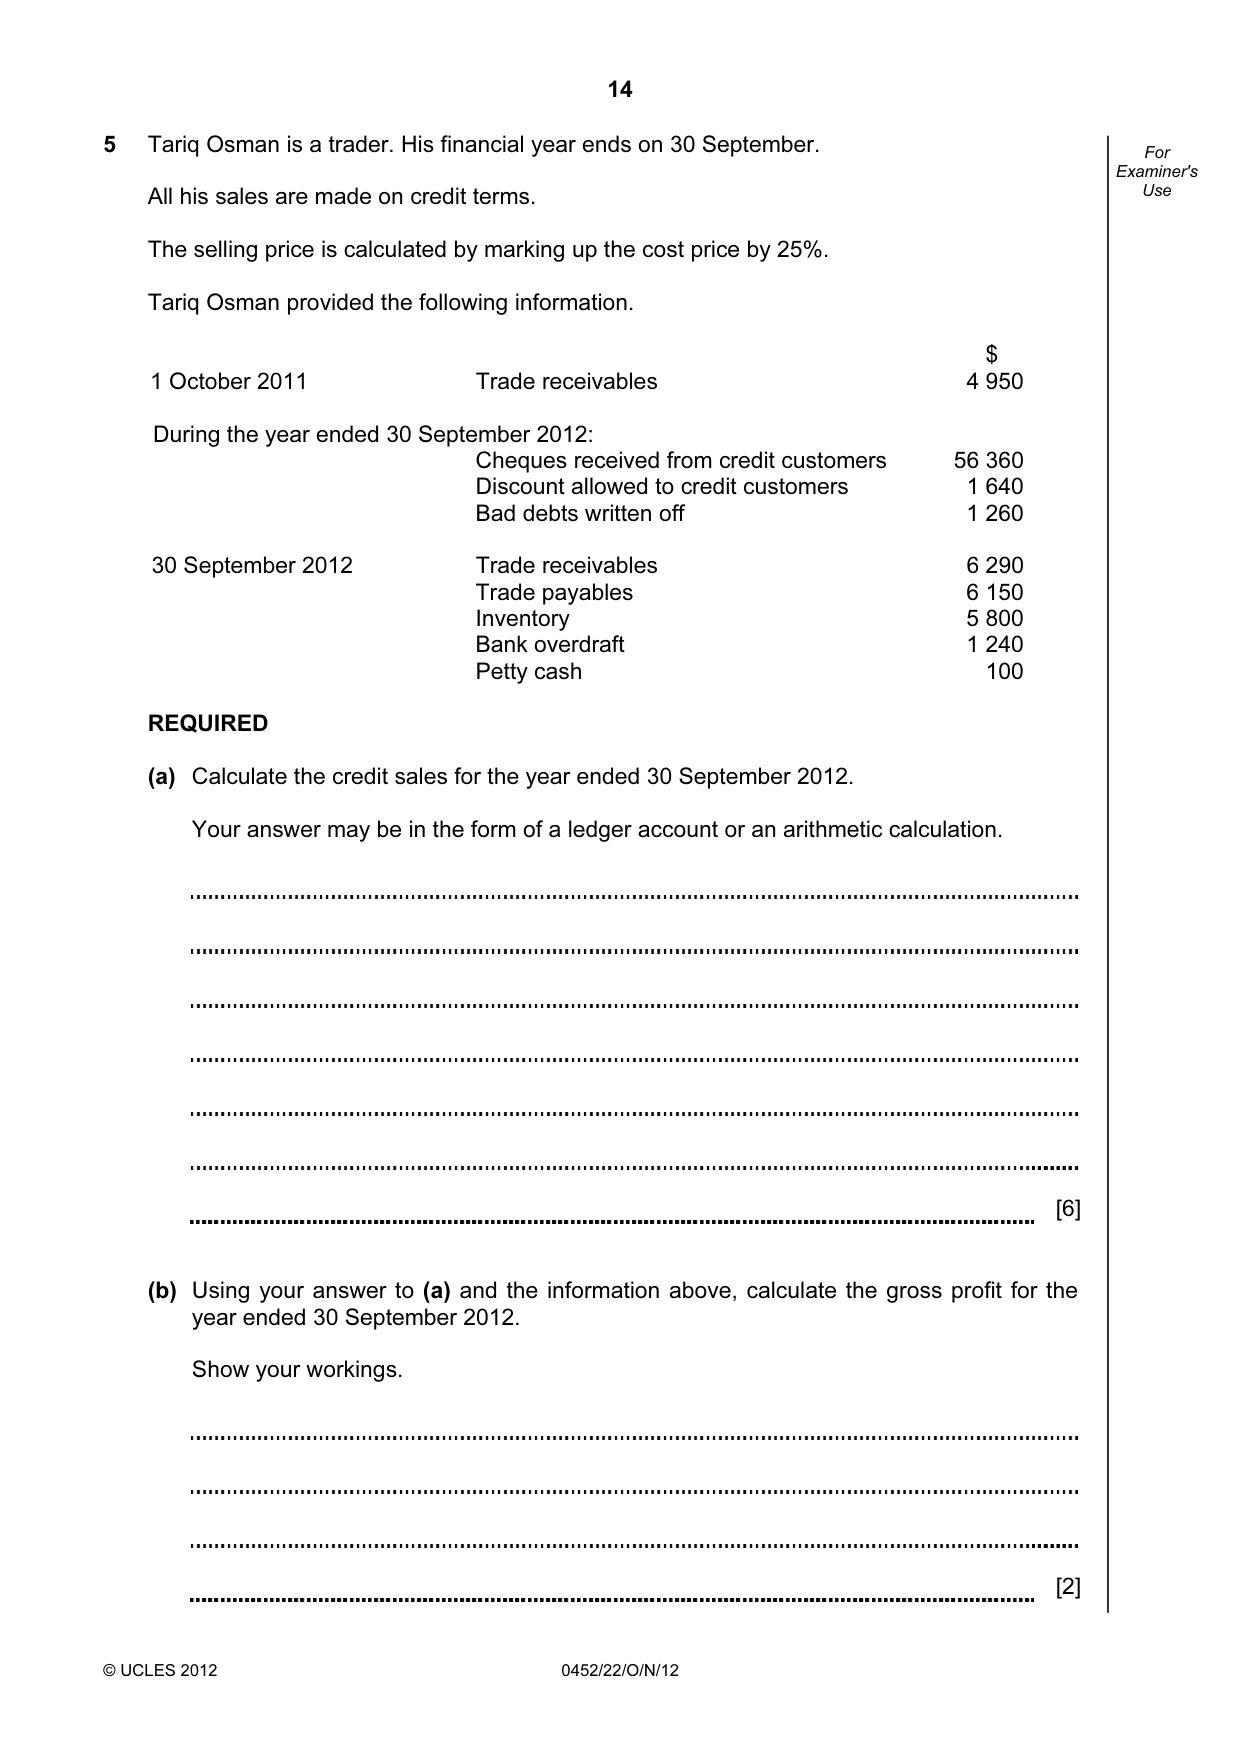
14 © UCLES 2012 0452/22/O/N/12 For Examiner's Use 5 Tariq Osman is a trader. His financial year ends on 30 September. All his sales are made on credit terms. The selling price is calculated by marking up the cost price by 25%. Tariq Osman provided the following information. $ 1 October 2011 Trade receivables 4 950 During the year ended 30 September 2012: Cheques received from credit customers 56 360 Discount allowed to credit customers 1 640 Bad debts written off 1 260 30 September 2012 Trade receivables 6 290 Trade payables 6 150 Inventory 5 800 Bank overdraft 1 240 Petty cash 100 REQUIRED (a) Calculate the credit sales for the year ended 30 September 2012. Your answer may be in the form of a ledger account or an arithmetic calculation. [6] (b) Using your answer to (a) and the information above, calculate the gross profit for the year ended 30 September 2012. Show your workings. [2]
Question paper, page 15
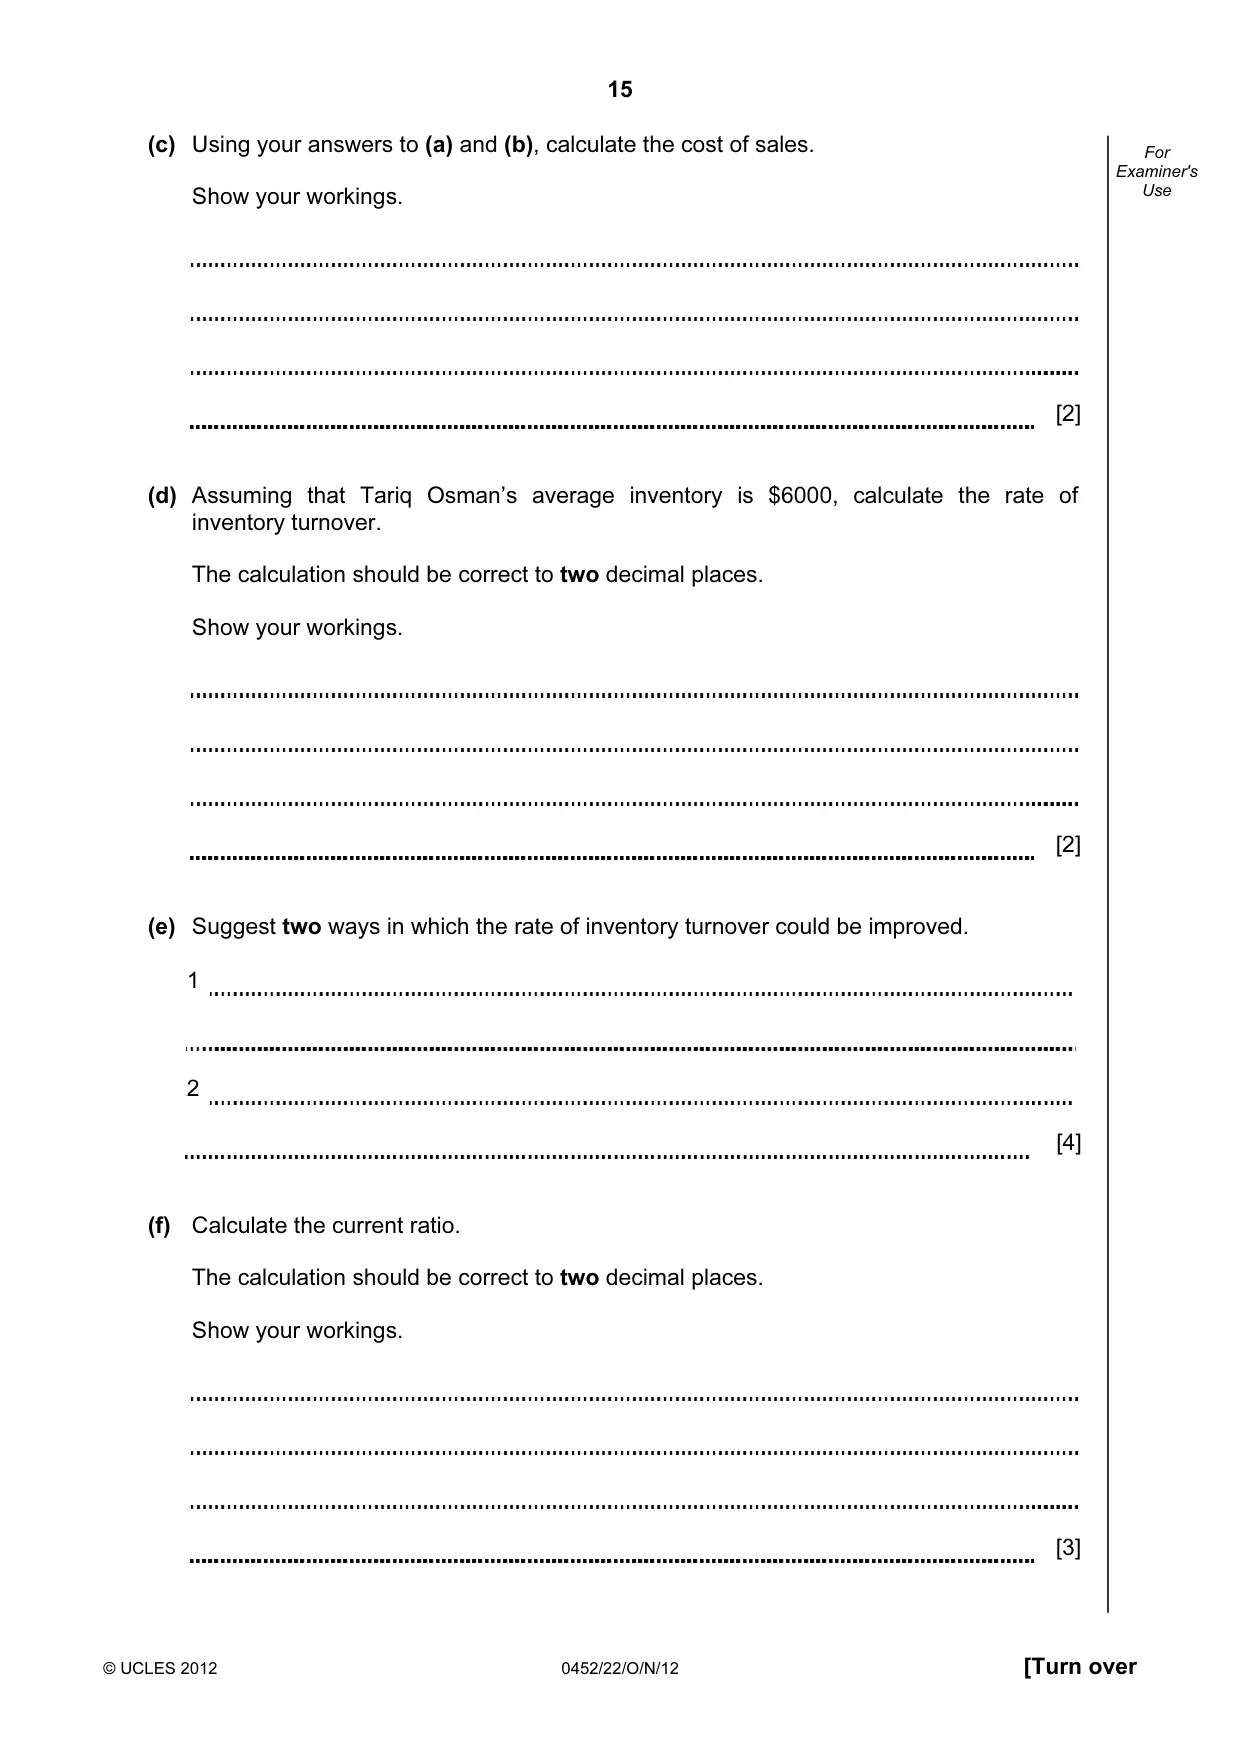
15 © UCLES 2012 0452/22/O/N/12 [Turn over For Examiner's Use (c) Using your answers to (a) and (b), calculate the cost of sales. Show your workings. [2] (d) Assuming that Tariq Osman’s average inventory is $6000, calculate the rate of inventory turnover. The calculation should be correct to two decimal places. Show your workings. [2] (e) Suggest two ways in which the rate of inventory turnover could be improved. 1 2 [4] (f) Calculate the current ratio. The calculation should be correct to two decimal places. Show your workings. [3]
Question paper, page 16
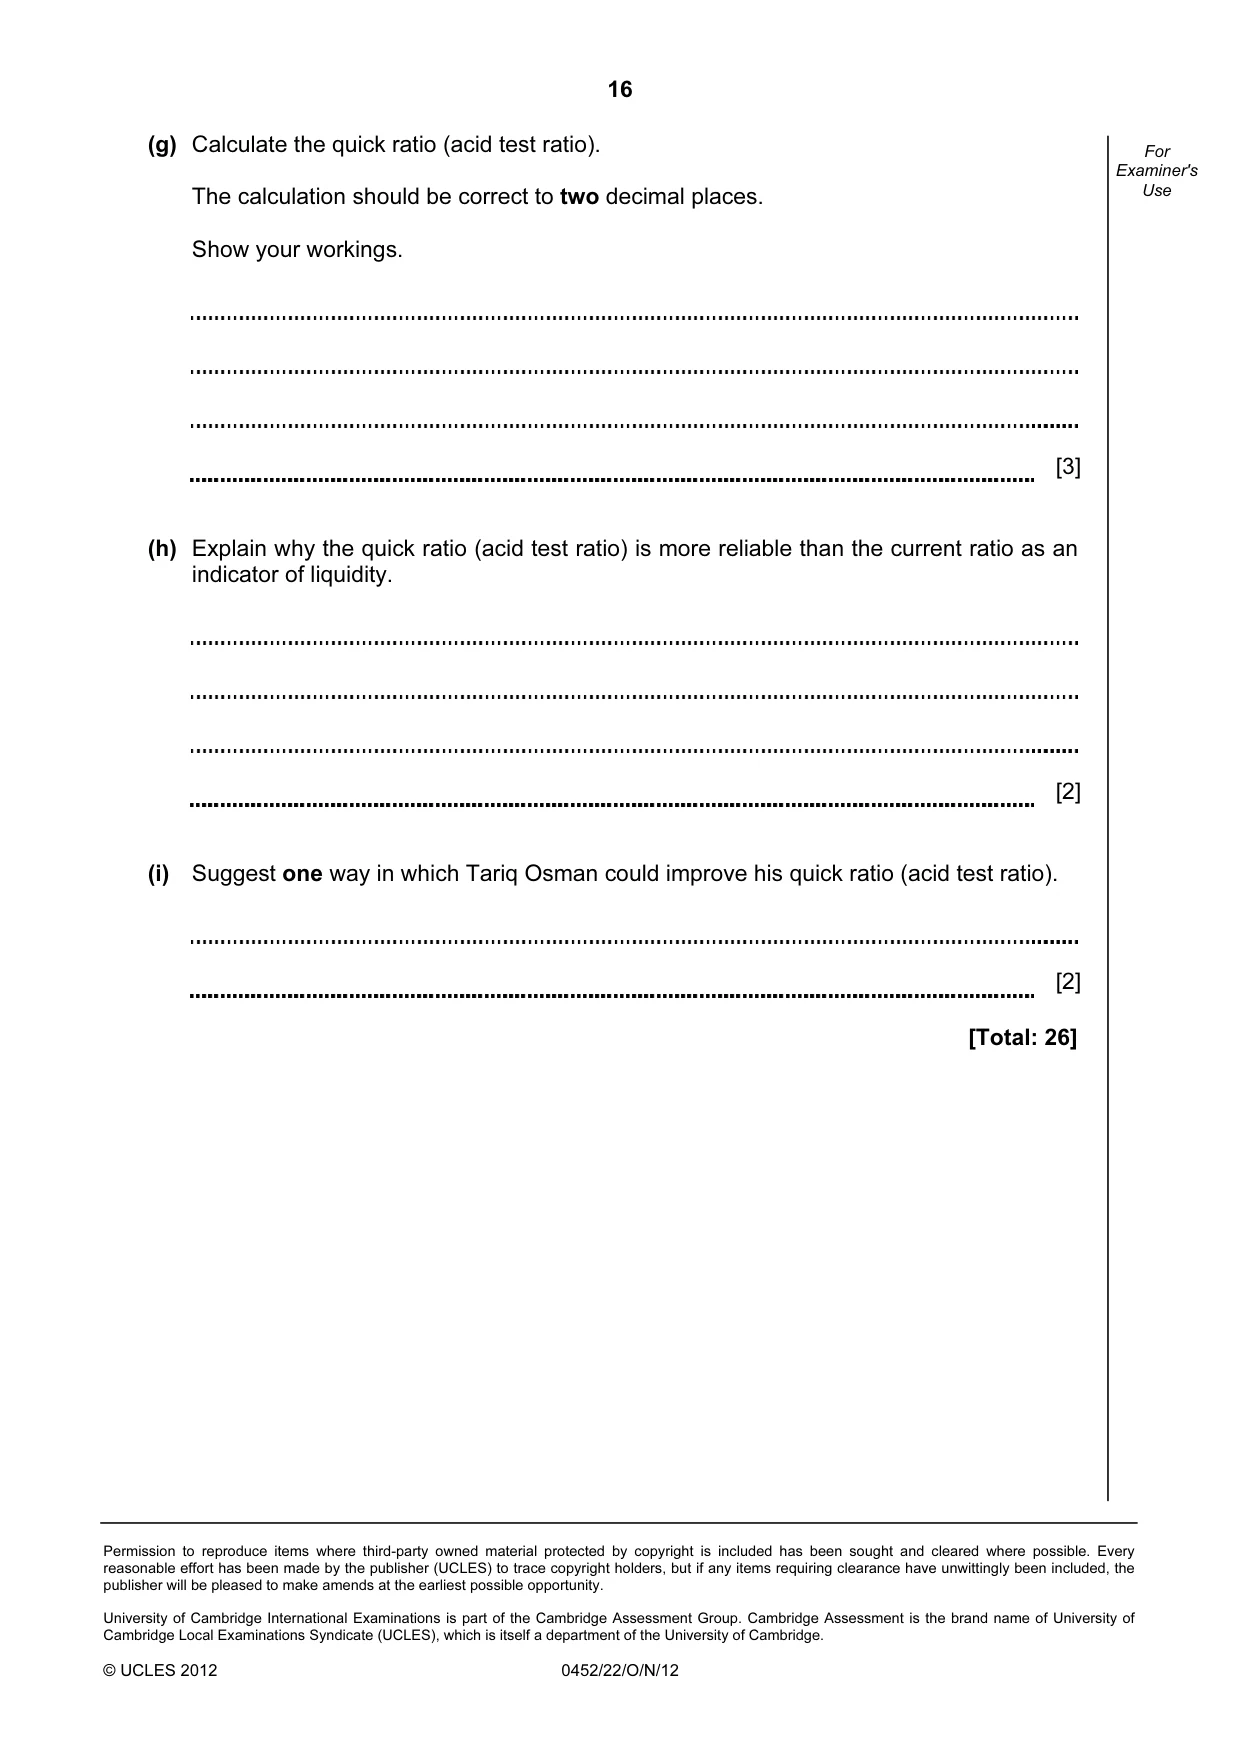
16 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2012 0452/22/O/N/12 For Examiner's Use (g) Calculate the quick ratio (acid test ratio). The calculation should be correct to two decimal places. Show your workings. [3] (h) Explain why the quick ratio (acid test ratio) is more reliable than the current ratio as an indicator of liquidity. [2] (i) Suggest one way in which Tariq Osman could improve his quick ratio (acid test ratio). [2] [Total: 26]
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the October/November 2012 series 0452 ACCOUNTING 0452/22 Paper 2, maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2012 series for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level components and some Ordinary Level components.
Mark scheme, page 2
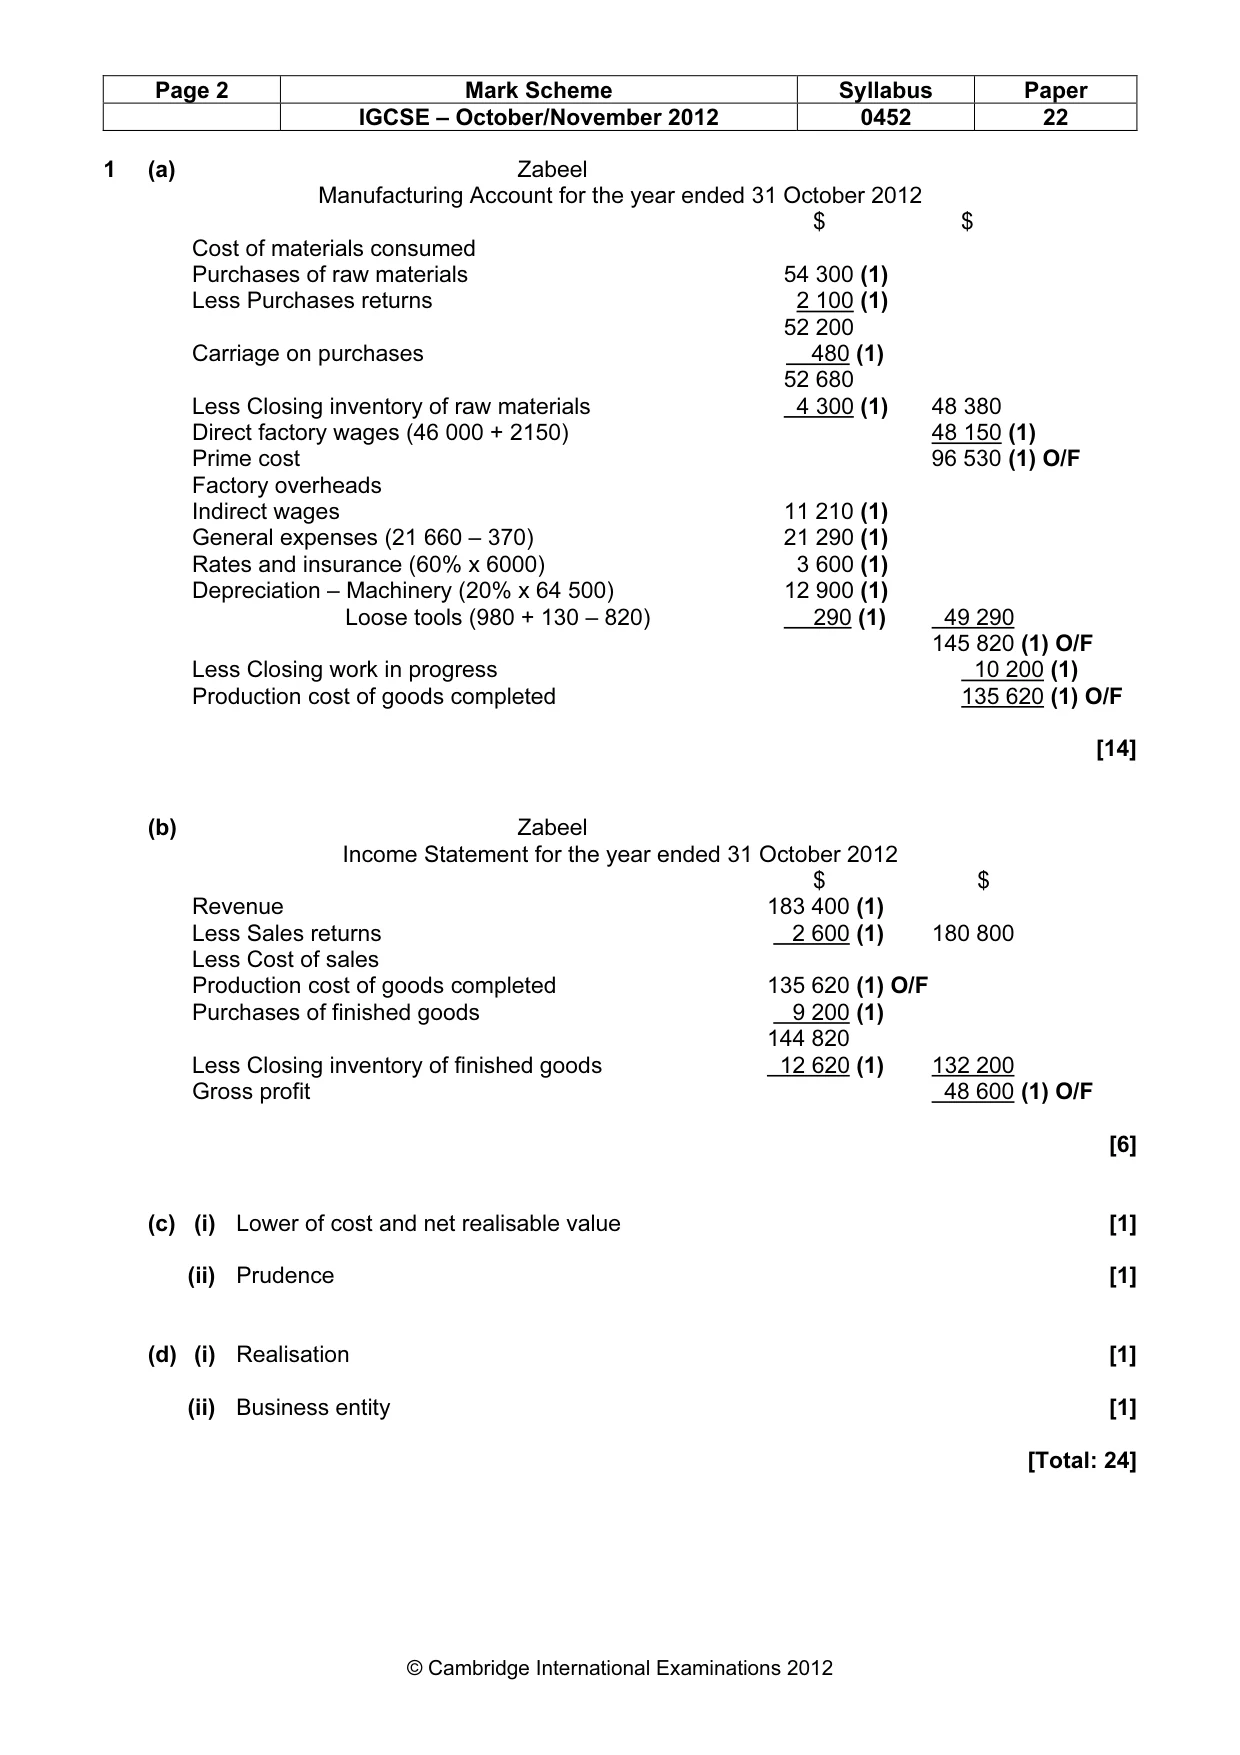
Page 2 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 1 (a) Zabeel Manufacturing Account for the year ended 31 October 2012 $ $ Cost of materials consumed Purchases of raw materials 54 300 (1) Less Purchases returns 2 100 (1) 52 200 Carriage on purchases 480 (1) 52 680 Less Closing inventory of raw materials 4 300 (1) 48 380 Direct factory wages (46 000 + 2150) 48 150 (1) Prime cost 96 530 (1) O/F Factory overheads Indirect wages 11 210 (1) General expenses (21 660 – 370) 21 290 (1) Rates and insurance (60% x 6000) 3 600 (1) Depreciation – Machinery (20% x 64 500) 12 900 (1) Loose tools (980 + 130 – 820) 290 (1) 49 290 145 820 (1) O/F Less Closing work in progress 10 200 (1) Production cost of goods completed 135 620 (1) O/F [14] (b) Zabeel Income Statement for the year ended 31 October 2012 $ $ Revenue 183 400 (1) Less Sales returns 2 600 (1) 180 800 Less Cost of sales Production cost of goods completed 135 620 (1) O/F Purchases of finished goods 9 200 (1) 144 820 Less Closing inventory of finished goods 12 620 (1) 132 200 Gross profit 48 600 (1) O/F [6] (c) (i) Lower of cost and net realisable value [1] (ii) Prudence [1] (d) (i) Realisation [1] (ii) Business entity [1] [Total: 24]
Mark scheme, page 3
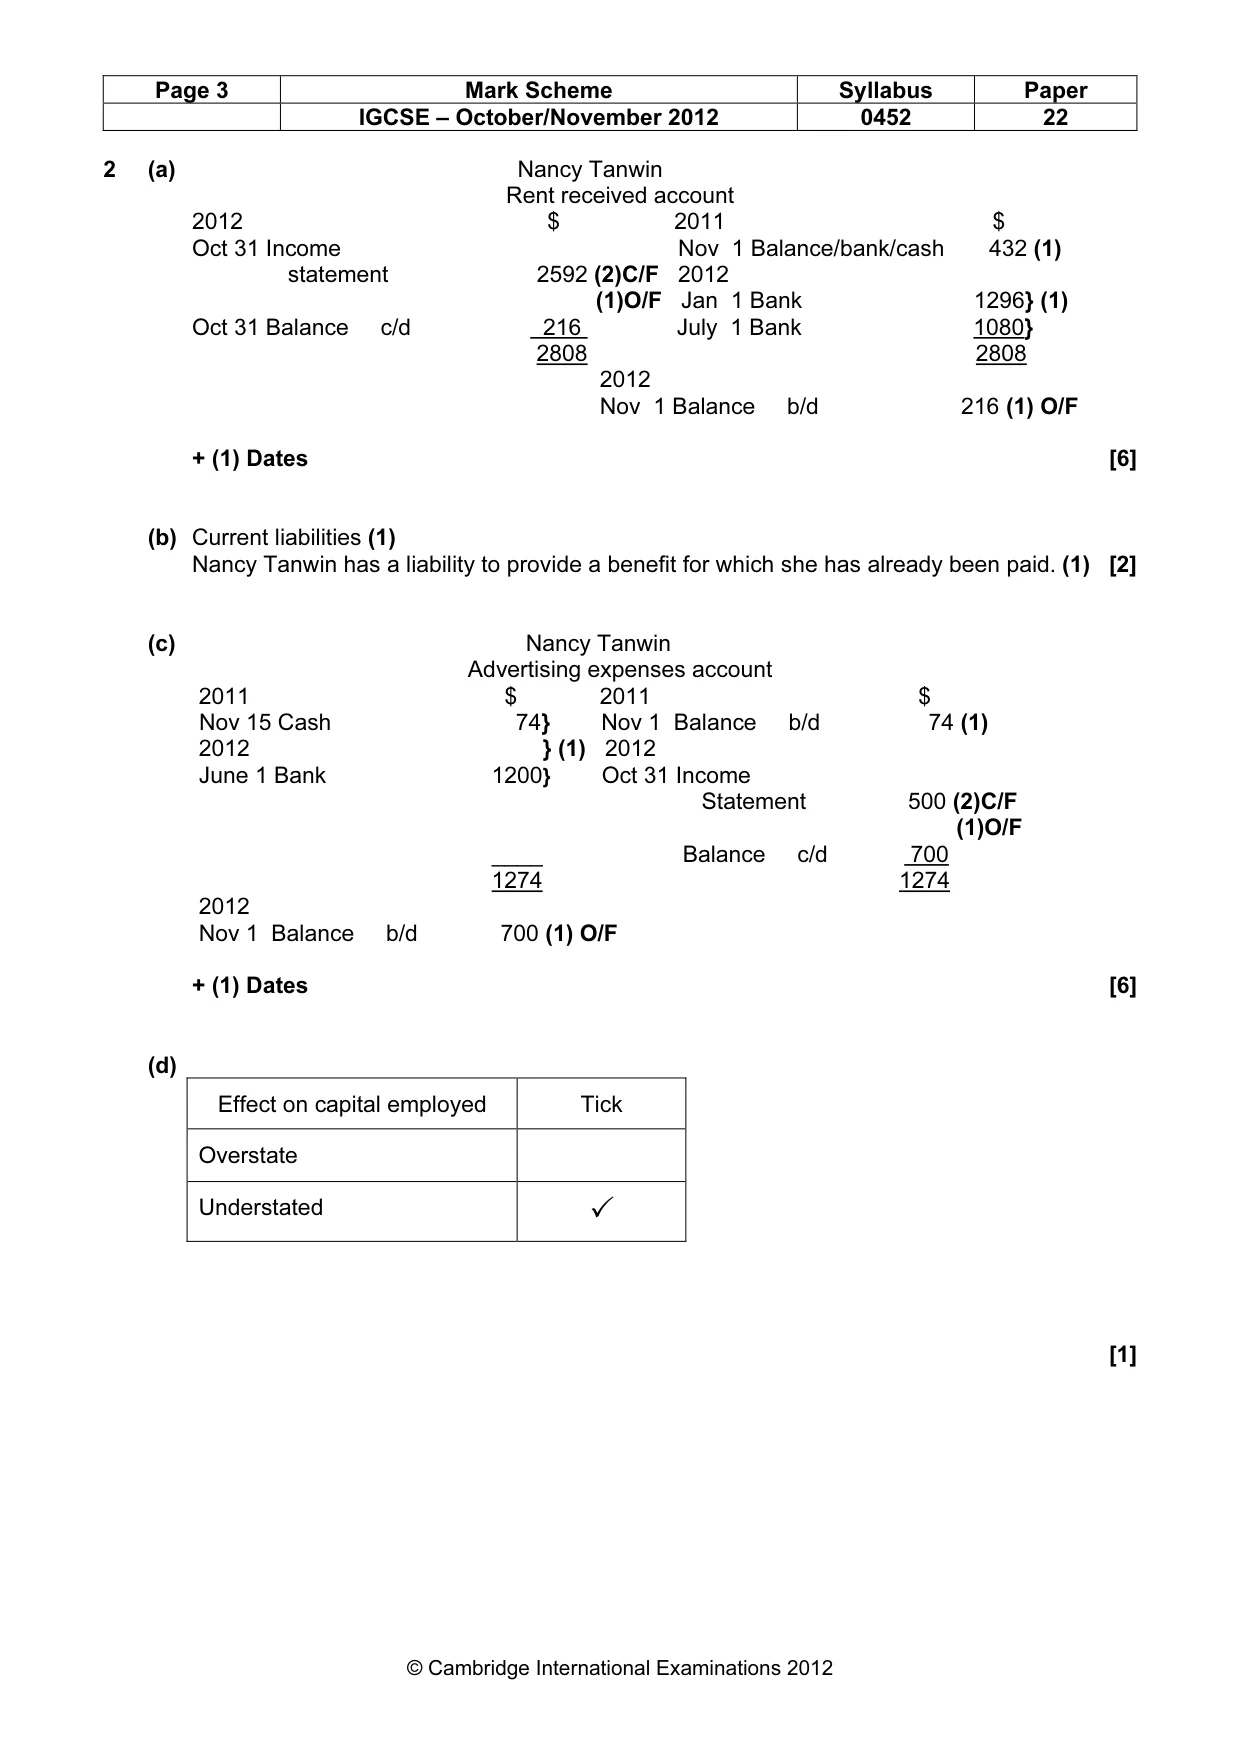
Page 3 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 2 (a) Nancy Tanwin Rent received account 2012 $ 2011 $ Oct 31 Income Nov 1 Balance/bank/cash 432 (1) statement 2592 (2)C/F 2012 (1)O/F Jan 1 Bank 1296} (1) Oct 31 Balance c/d 216 July 1 Bank 1080} 2808 2808 2012 Nov 1 Balance b/d 216 (1) O/F + (1) Dates [6] (b) Current liabilities (1) Nancy Tanwin has a liability to provide a benefit for which she has already been paid. (1) [2] (c) Nancy Tanwin Advertising expenses account 2011 $ 2011 $ Nov 15 Cash 74} Nov 1 Balance b/d 74 (1) 2012 } (1) 2012 June 1 Bank 1200} Oct 31 Income Statement 500 (2)C/F (1)O/F ____ Balance c/d 700 1274 1274 2012 Nov 1 Balance b/d 700 (1) O/F + (1) Dates [6] (d) [1] Effect on capital employed Tick Overstate Understated ✓
Mark scheme, page 4
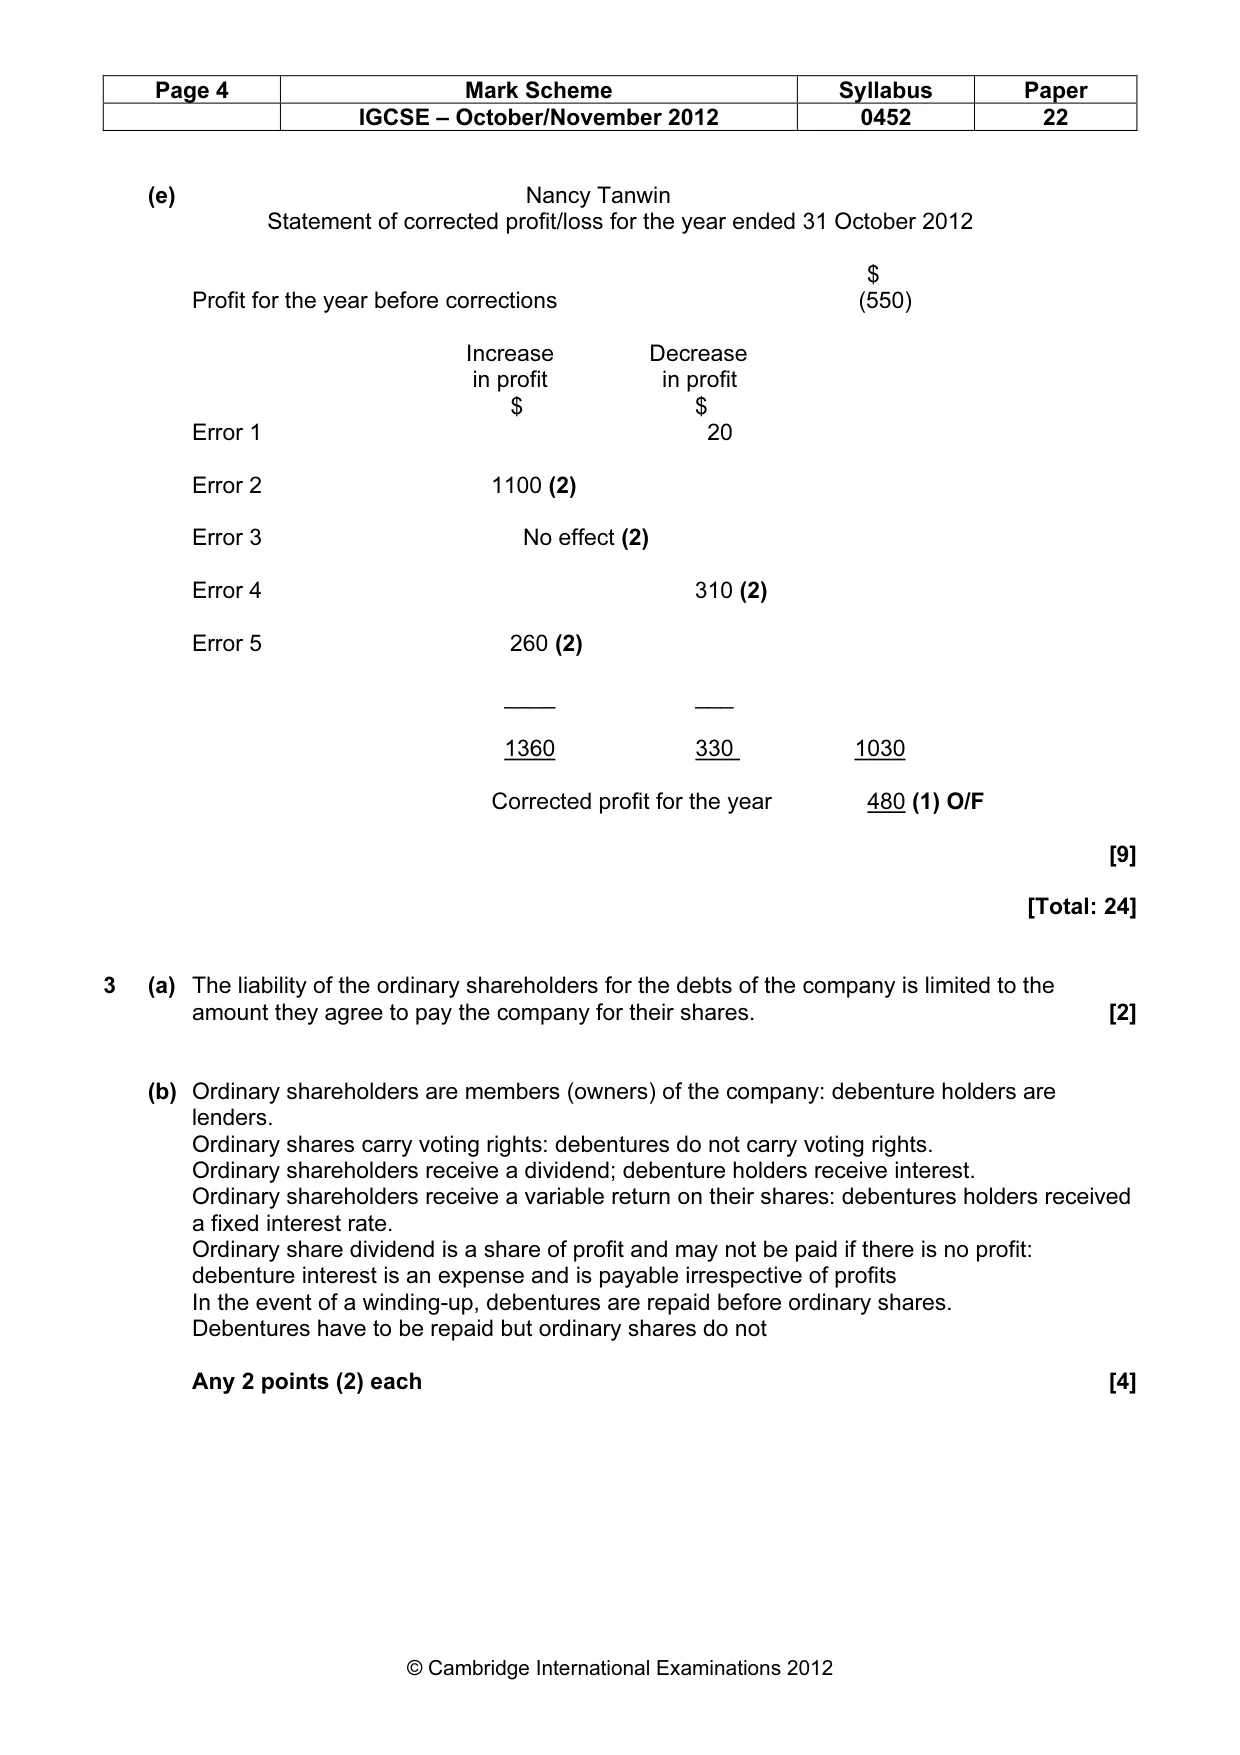
Page 4 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 (e) Nancy Tanwin Statement of corrected profit/loss for the year ended 31 October 2012 $ Profit for the year before corrections (550) Increase Decrease in profit in profit $ $ Error 1 20 Error 2 1100 (2) Error 3 No effect (2) Error 4 310 (2) Error 5 260 (2) ____ ___ 1360 330 1030 Corrected profit for the year 480 (1) O/F [9] [Total: 24] 3 (a) The liability of the ordinary shareholders for the debts of the company is limited to the amount they agree to pay the company for their shares. [2] (b) Ordinary shareholders are members (owners) of the company: debenture holders are lenders. Ordinary shares carry voting rights: debentures do not carry voting rights. Ordinary shareholders receive a dividend; debenture holders receive interest. Ordinary shareholders receive a variable return on their shares: debentures holders received a fixed interest rate. Ordinary share dividend is a share of profit and may not be paid if there is no profit: debenture interest is an expense and is payable irrespective of profits In the event of a winding-up, debentures are repaid before ordinary shares. Debentures have to be repaid but ordinary shares do not Any 2 points (2) each [4]
Mark scheme, page 5
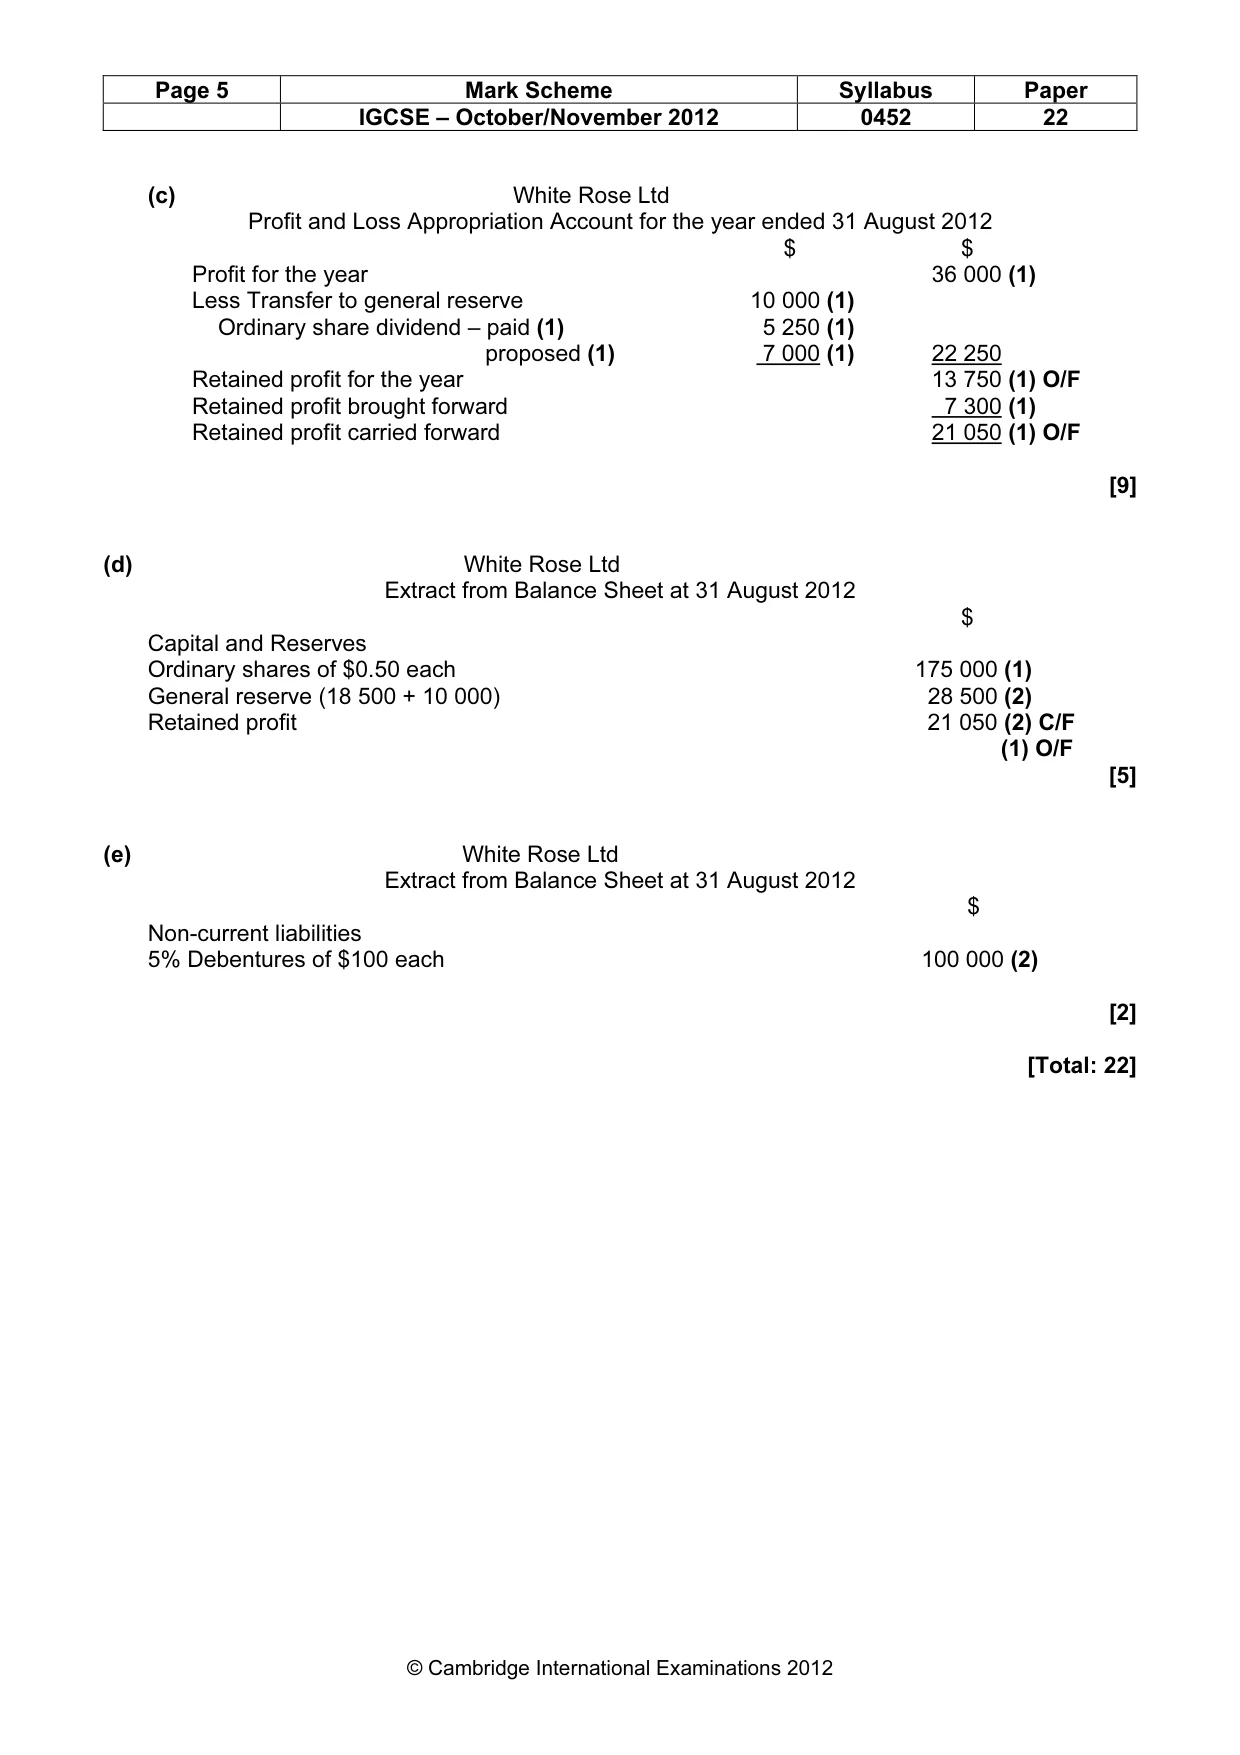
Page 5 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 (c) White Rose Ltd Profit and Loss Appropriation Account for the year ended 31 August 2012 $ $ Profit for the year 36 000 (1) Less Transfer to general reserve 10 000 (1) Ordinary share dividend – paid (1) 5 250 (1) proposed (1) 7 000 (1) 22 250 Retained profit for the year 13 750 (1) O/F Retained profit brought forward 7 300 (1) Retained profit carried forward 21 050 (1) O/F [9] (d) White Rose Ltd Extract from Balance Sheet at 31 August 2012 $ Capital and Reserves Ordinary shares of $0.50 each 175 000 (1) General reserve (18 500 + 10 000) 28 500 (2) Retained profit 21 050 (2) C/F (1) O/F [5] (e) White Rose Ltd Extract from Balance Sheet at 31 August 2012 $ Non-current liabilities 5% Debentures of $100 each 100 000 (2) [2] [Total: 22]
Mark scheme, page 6
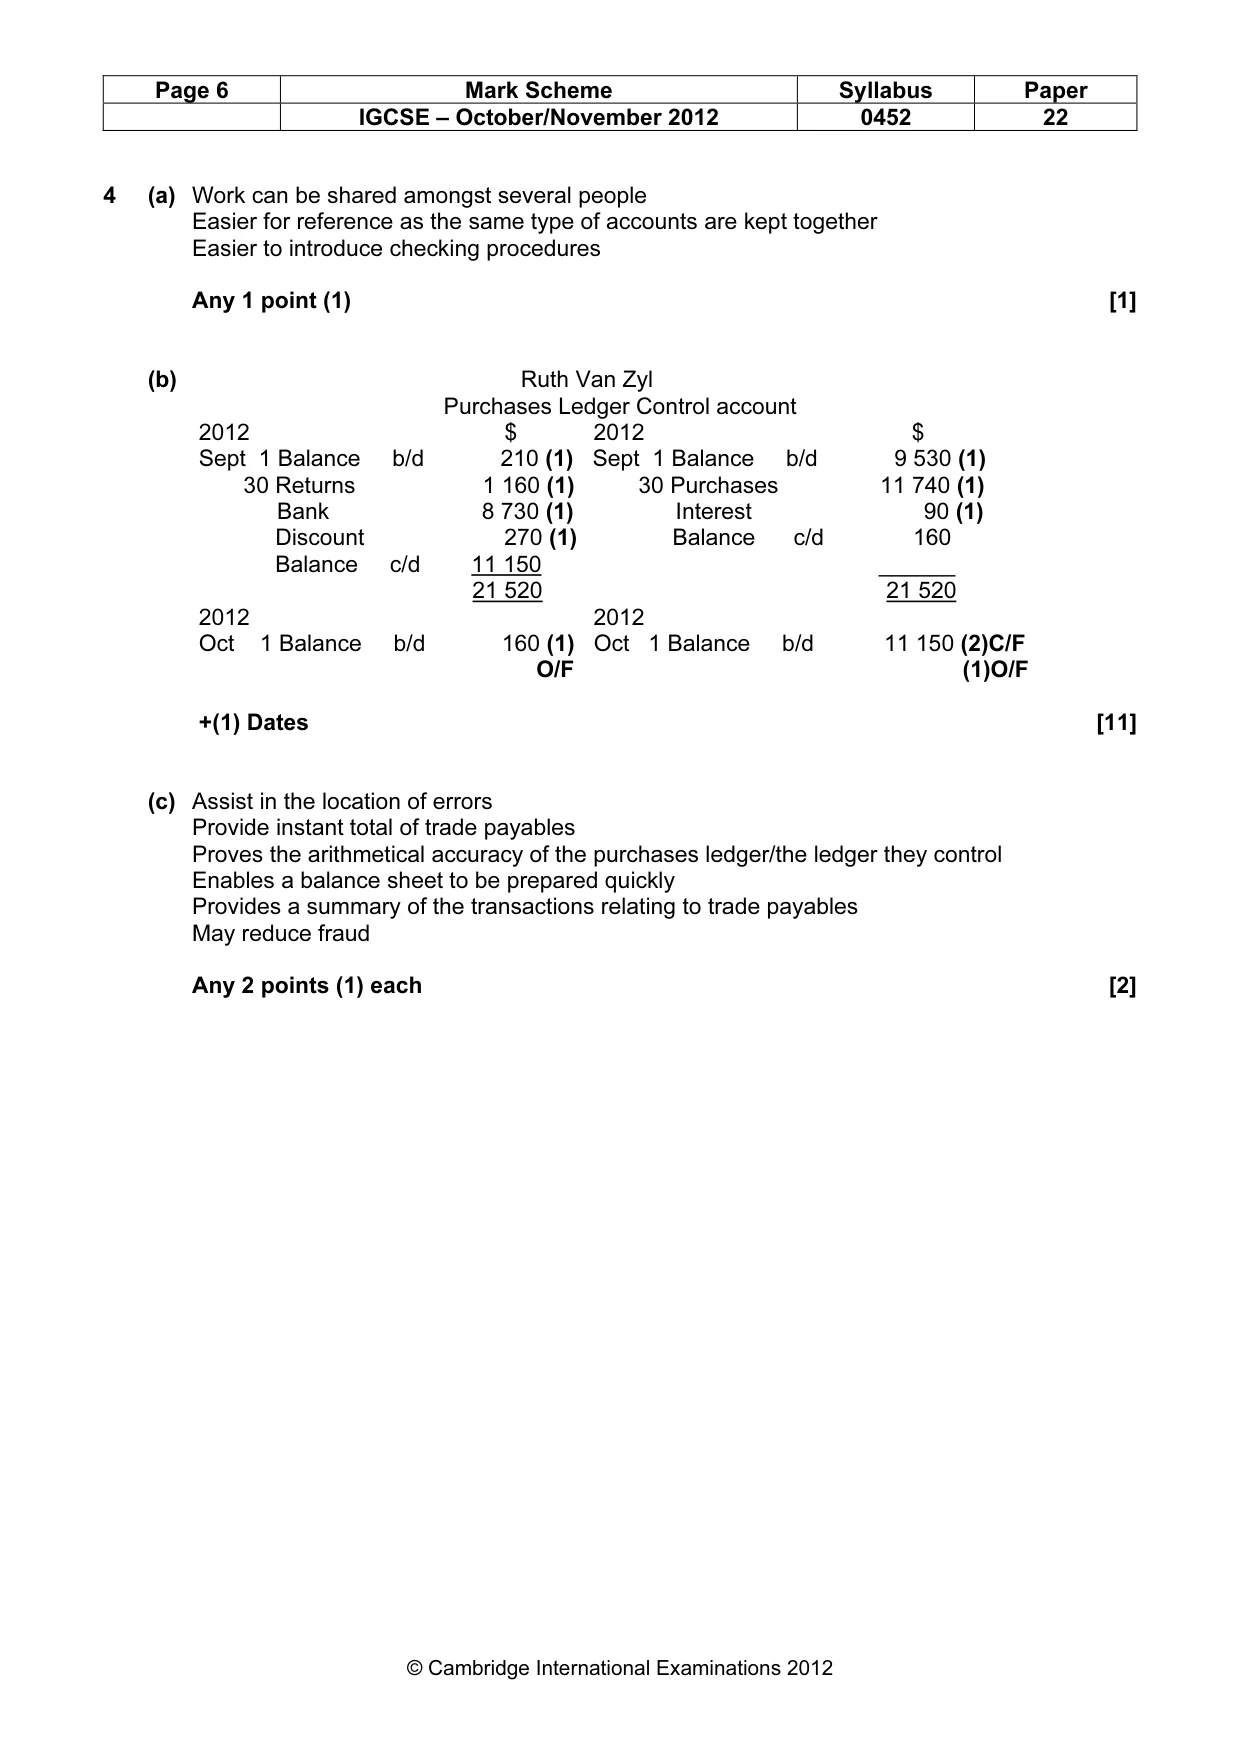
Page 6 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 4 (a) Work can be shared amongst several people Easier for reference as the same type of accounts are kept together Easier to introduce checking procedures Any 1 point (1) [1] (b) Ruth Van Zyl Purchases Ledger Control account 2012 $ 2012 $ Sept 1 Balance b/d 210 (1) Sept 1 Balance b/d 9 530 (1) 30 Returns 1 160 (1) 30 Purchases 11 740 (1) Bank 8 730 (1) Interest 90 (1) Discount 270 (1) Balance c/d 160 Balance c/d 11 150 ______ 21 520 21 520 2012 2012 Oct 1 Balance b/d 160 (1) Oct 1 Balance b/d 11 150 (2)C/F O/F (1)O/F +(1) Dates [11] (c) Assist in the location of errors Provide instant total of trade payables Proves the arithmetical accuracy of the purchases ledger/the ledger they control Enables a balance sheet to be prepared quickly Provides a summary of the transactions relating to trade payables May reduce fraud Any 2 points (1) each [2]
Mark scheme, page 7
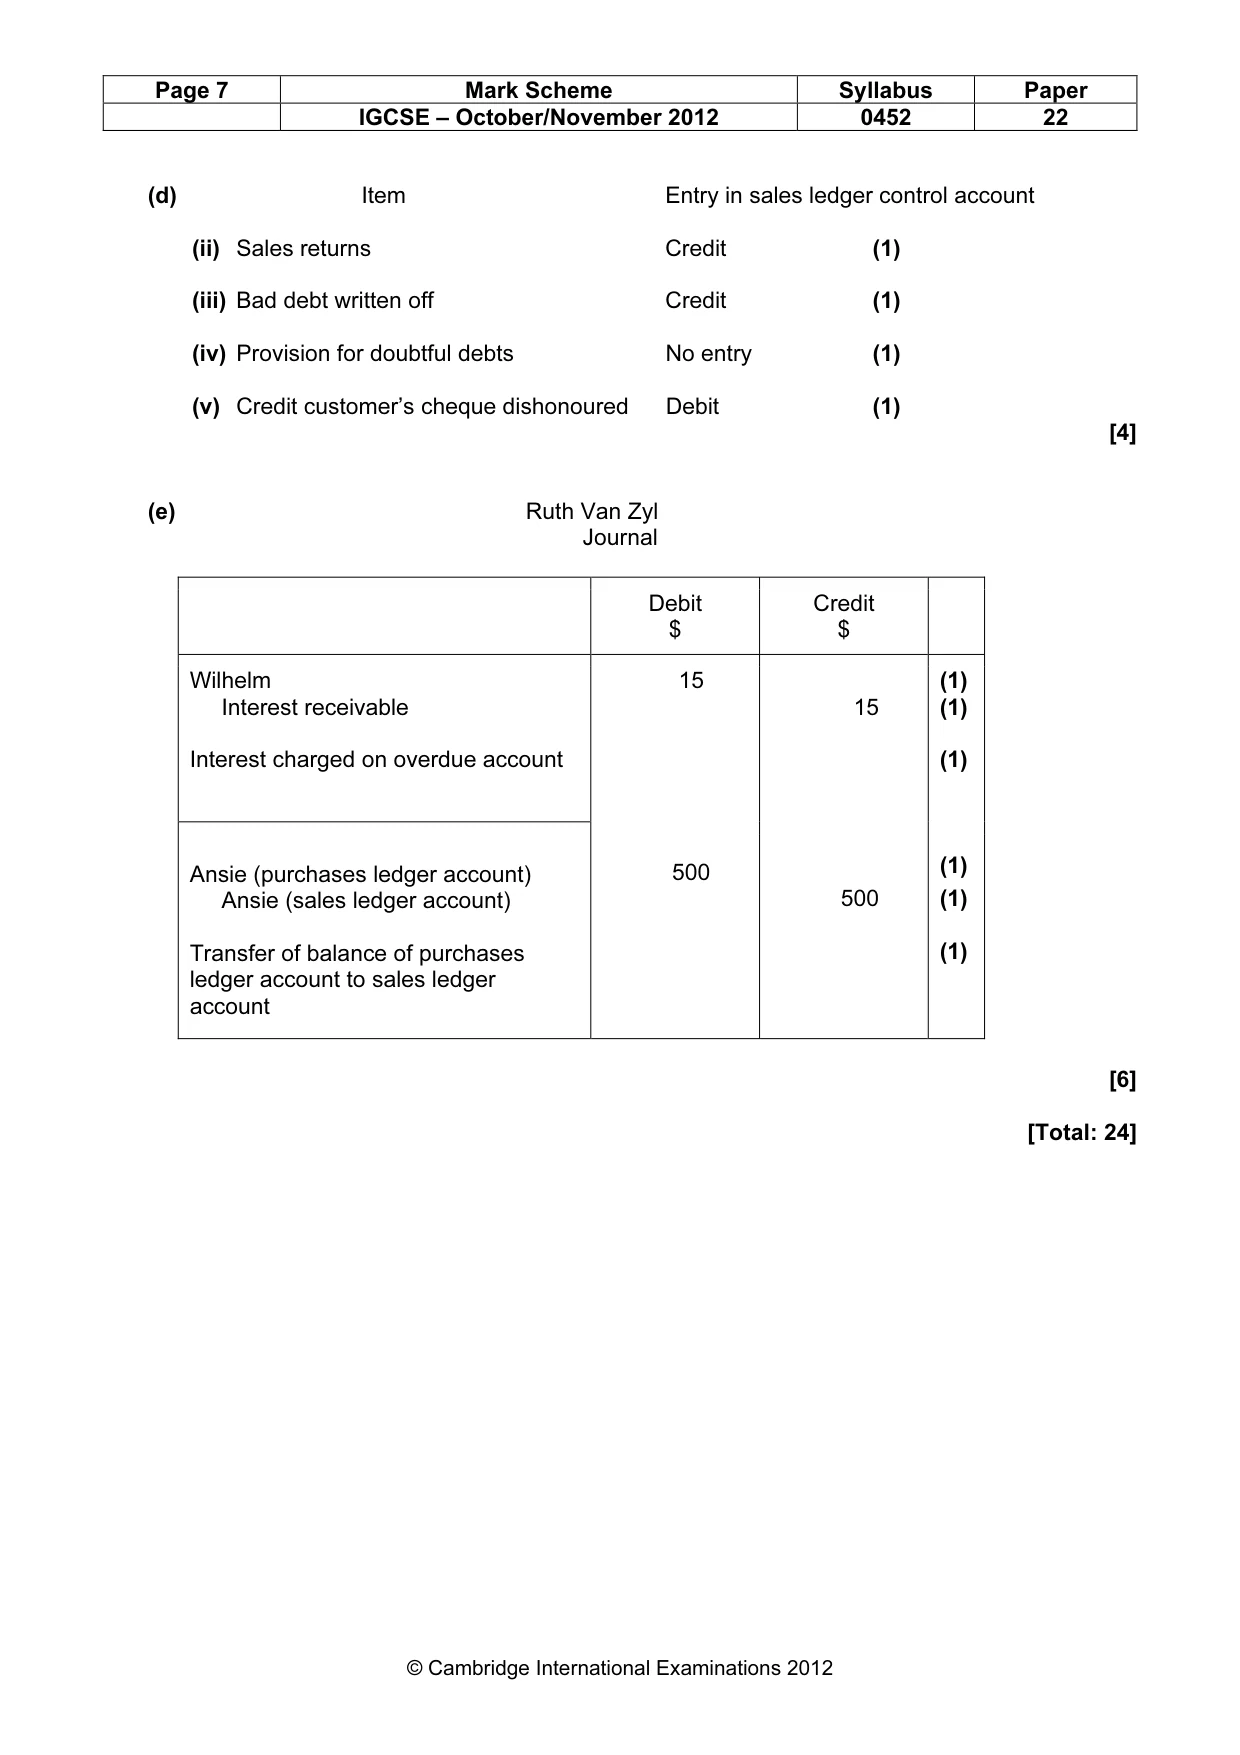
Page 7 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 (d) Item Entry in sales ledger control account (ii) Sales returns Credit (1) (iii) Bad debt written off Credit (1) (iv) Provision for doubtful debts No entry (1) (v) Credit customer’s cheque dishonoured Debit (1) [4] (e) Ruth Van Zyl Journal Debit $ Credit $ Wilhelm Interest receivable Interest charged on overdue account Ansie (purchases ledger account) Ansie (sales ledger account) Transfer of balance of purchases ledger account to sales ledger account 15 500 15 500 (1) (1) (1) (1) (1) (1) [6] [Total: 24]
Mark scheme, page 8
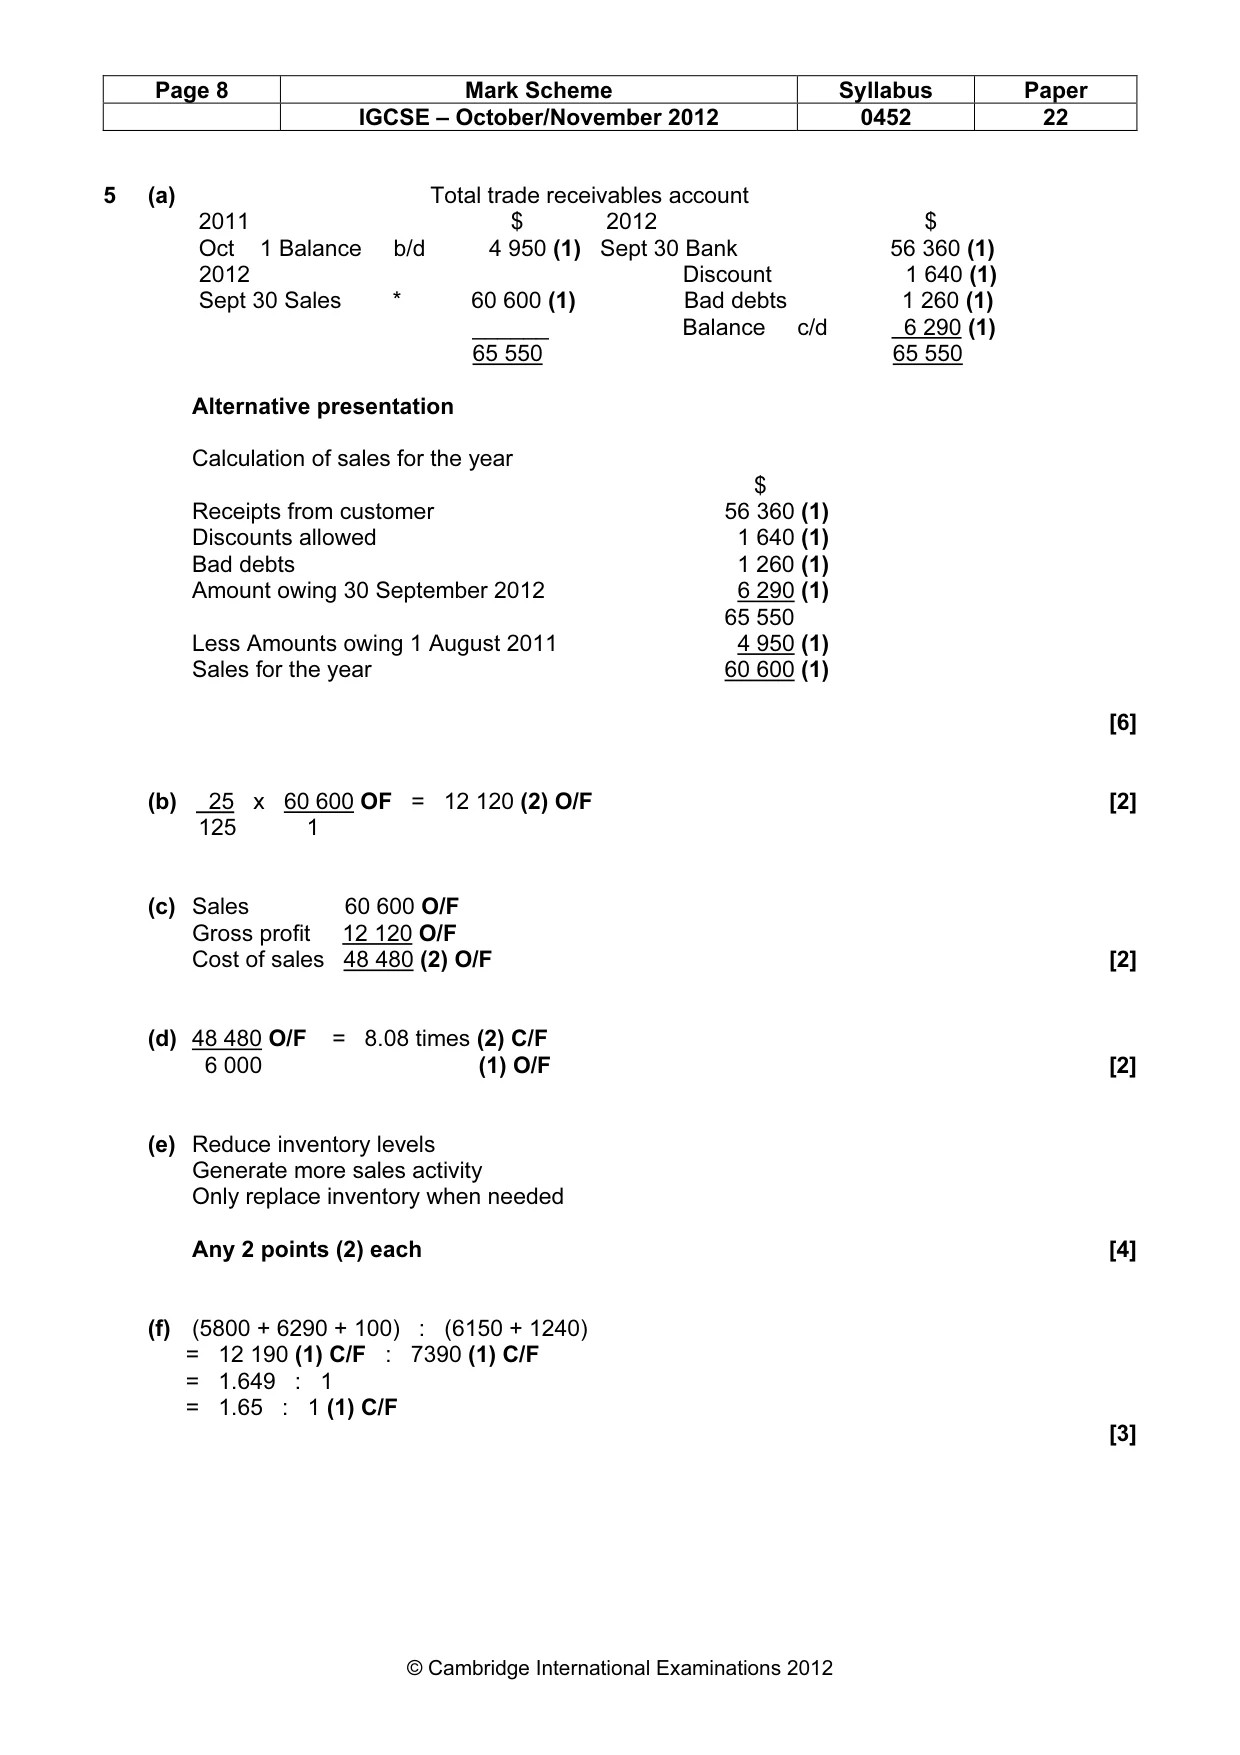
Page 8 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 5 (a) Total trade receivables account 2011 $ 2012 $ Oct 1 Balance b/d 4 950 (1) Sept 30 Bank 56 360 (1) 2012 Discount 1 640 (1) Sept 30 Sales * 60 600 (1) Bad debts 1 260 (1) ______ Balance c/d 6 290 (1) 65 550 65 550 Alternative presentation Calculation of sales for the year $ Receipts from customer 56 360 (1) Discounts allowed 1 640 (1) Bad debts 1 260 (1) Amount owing 30 September 2012 6 290 (1) 65 550 Less Amounts owing 1 August 2011 4 950 (1) Sales for the year 60 600 (1) [6] (b) 25 x 60 600 OF = 12 120 (2) O/F [2] 125 1 (c) Sales 60 600 O/F Gross profit 12 120 O/F Cost of sales 48 480 (2) O/F [2] (d) 48 480 O/F = 8.08 times (2) C/F 6 000 (1) O/F [2] (e) Reduce inventory levels Generate more sales activity Only replace inventory when needed Any 2 points (2) each [4] (f) (5800 + 6290 + 100) : (6150 + 1240) = 12 190 (1) C/F : 7390 (1) C/F = 1.649 : 1 = 1.65 : 1 (1) C/F [3]
Mark scheme, page 9
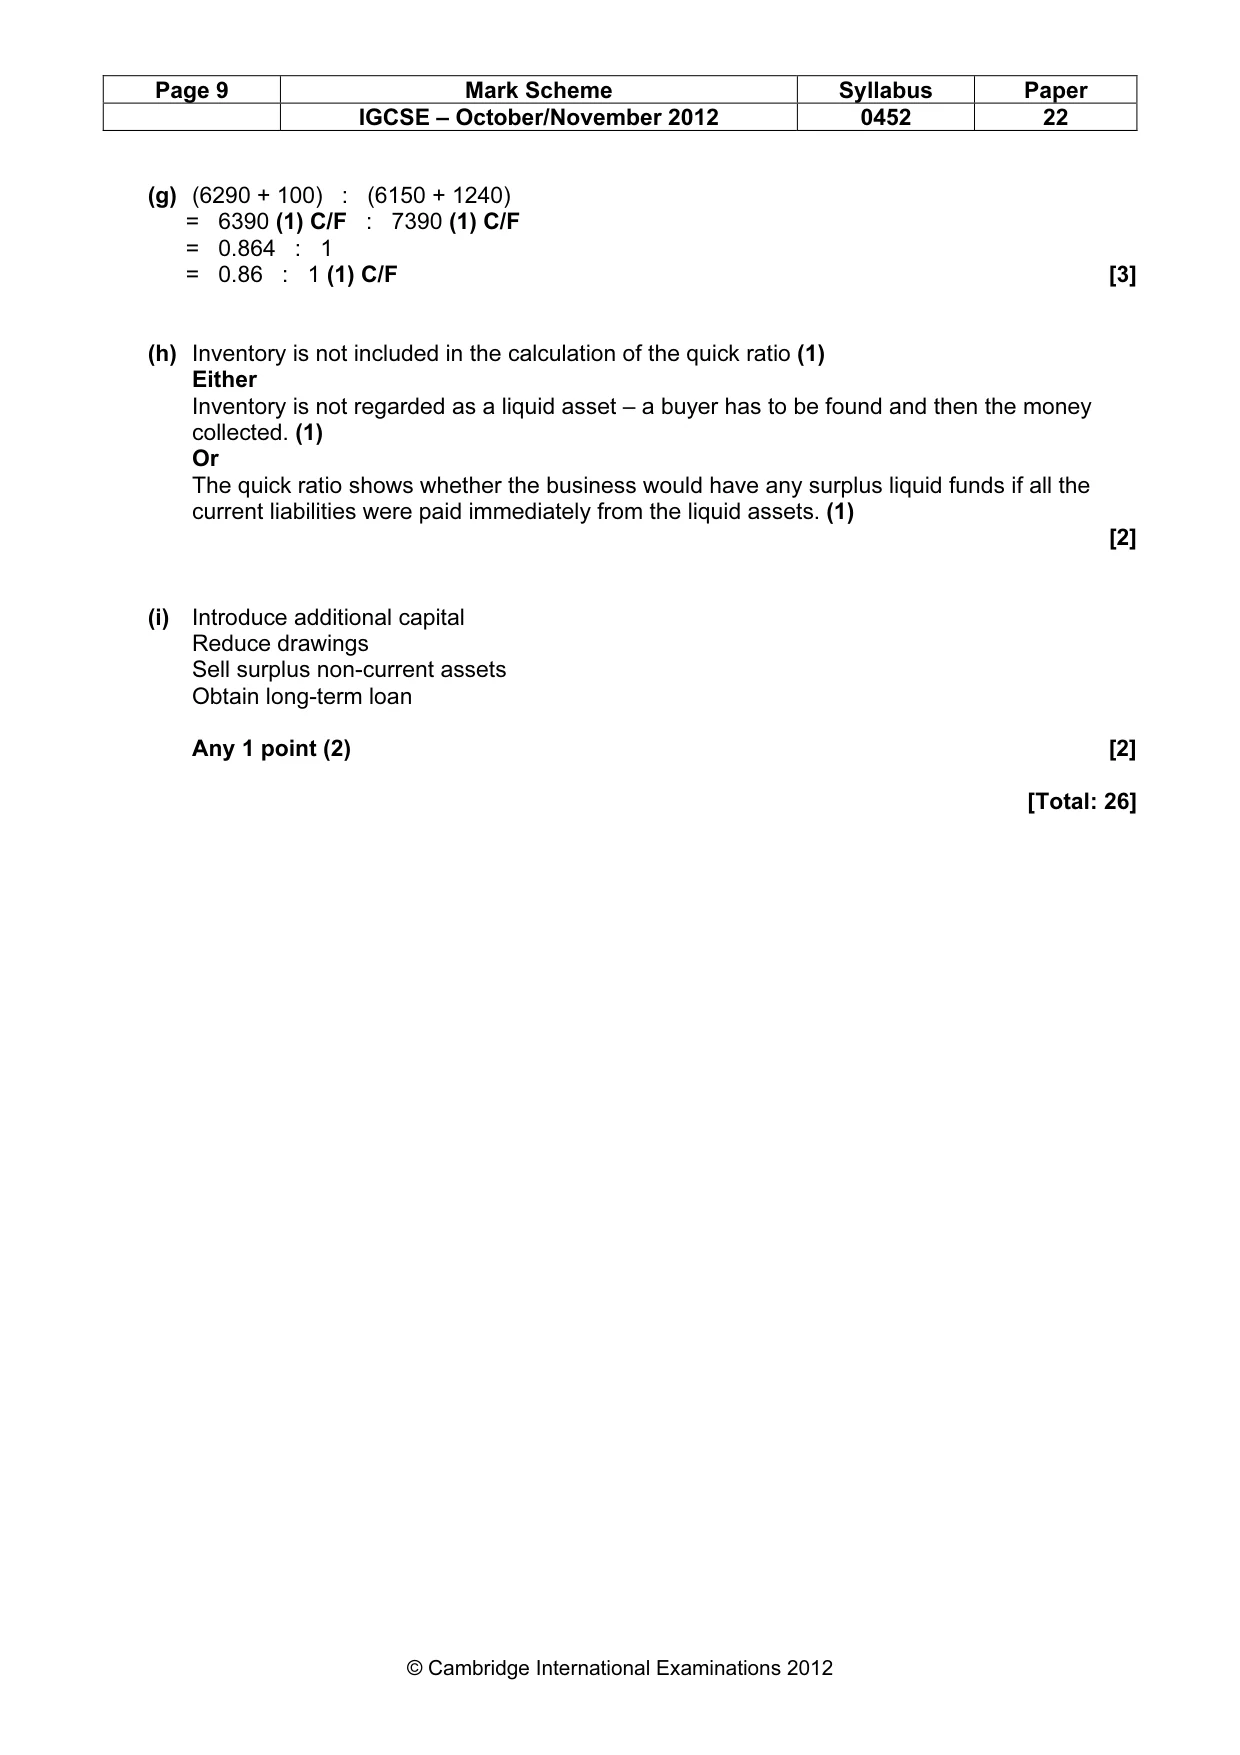
Page 9 Mark Scheme Syllabus Paper IGCSE – October/November 2012 0452 22 © Cambridge International Examinations 2012 (g) (6290 + 100) : (6150 + 1240) = 6390 (1) C/F : 7390 (1) C/F = 0.864 : 1 = 0.86 : 1 (1) C/F [3] (h) Inventory is not included in the calculation of the quick ratio (1) Either Inventory is not regarded as a liquid asset – a buyer has to be found and then the money collected. (1) Or The quick ratio shows whether the business would have any surplus liquid funds if all the current liabilities were paid immediately from the liquid assets. (1) [2] (i) Introduce additional capital Reduce drawings Sell surplus non-current assets Obtain long-term loan Any 1 point (2) [2] [Total: 26]
What you needed in this session
Cambridge’s own grade thresholds for 2012 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.