Cambridge IGCSE Accounting 0452 — 2011 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/11 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
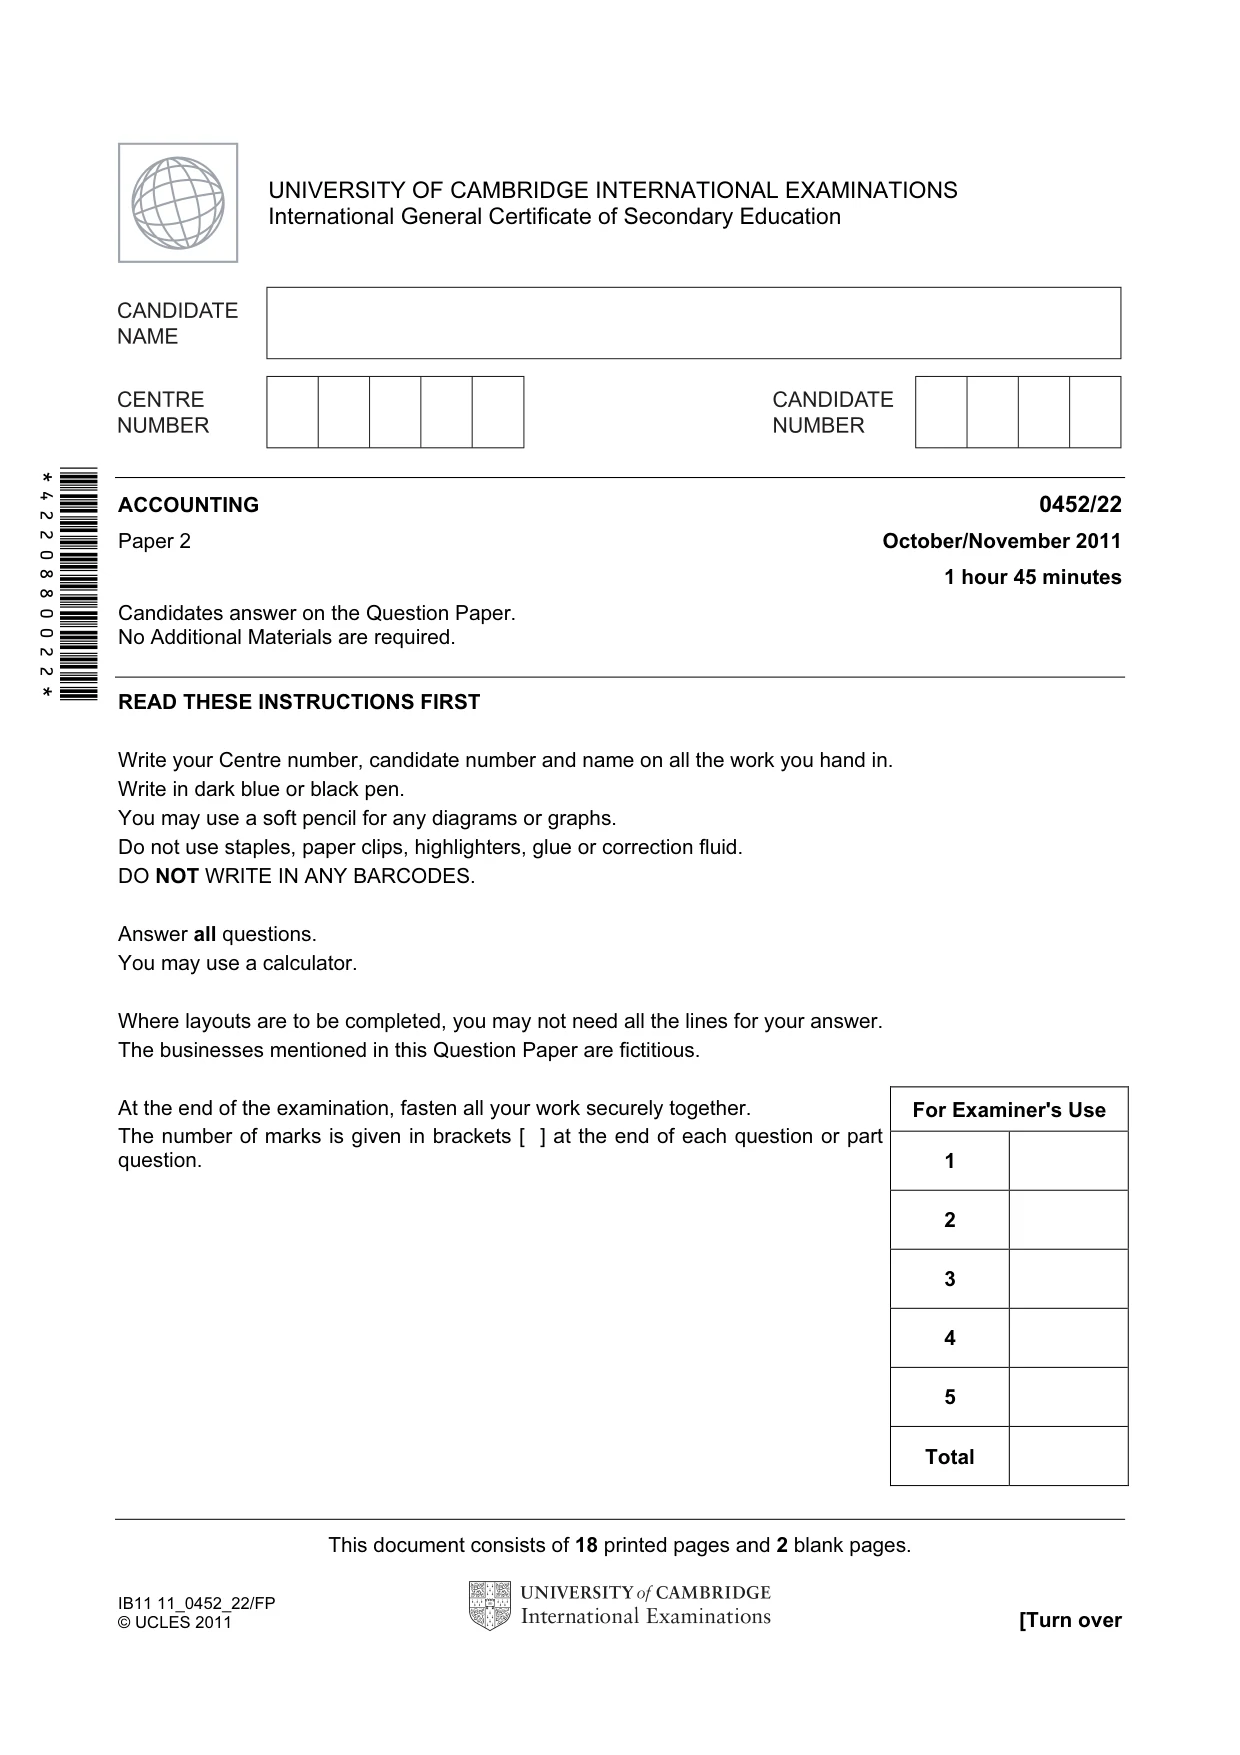
This document consists of 18 printed pages and 2 blank pages. IB11 11_0452_22/FP © UCLES 2011 [Turn over *4220880022* For Examiner's Use 1 2 3 4 5 Total UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/22 Paper 2 October/November 2011 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for any diagrams or graphs. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
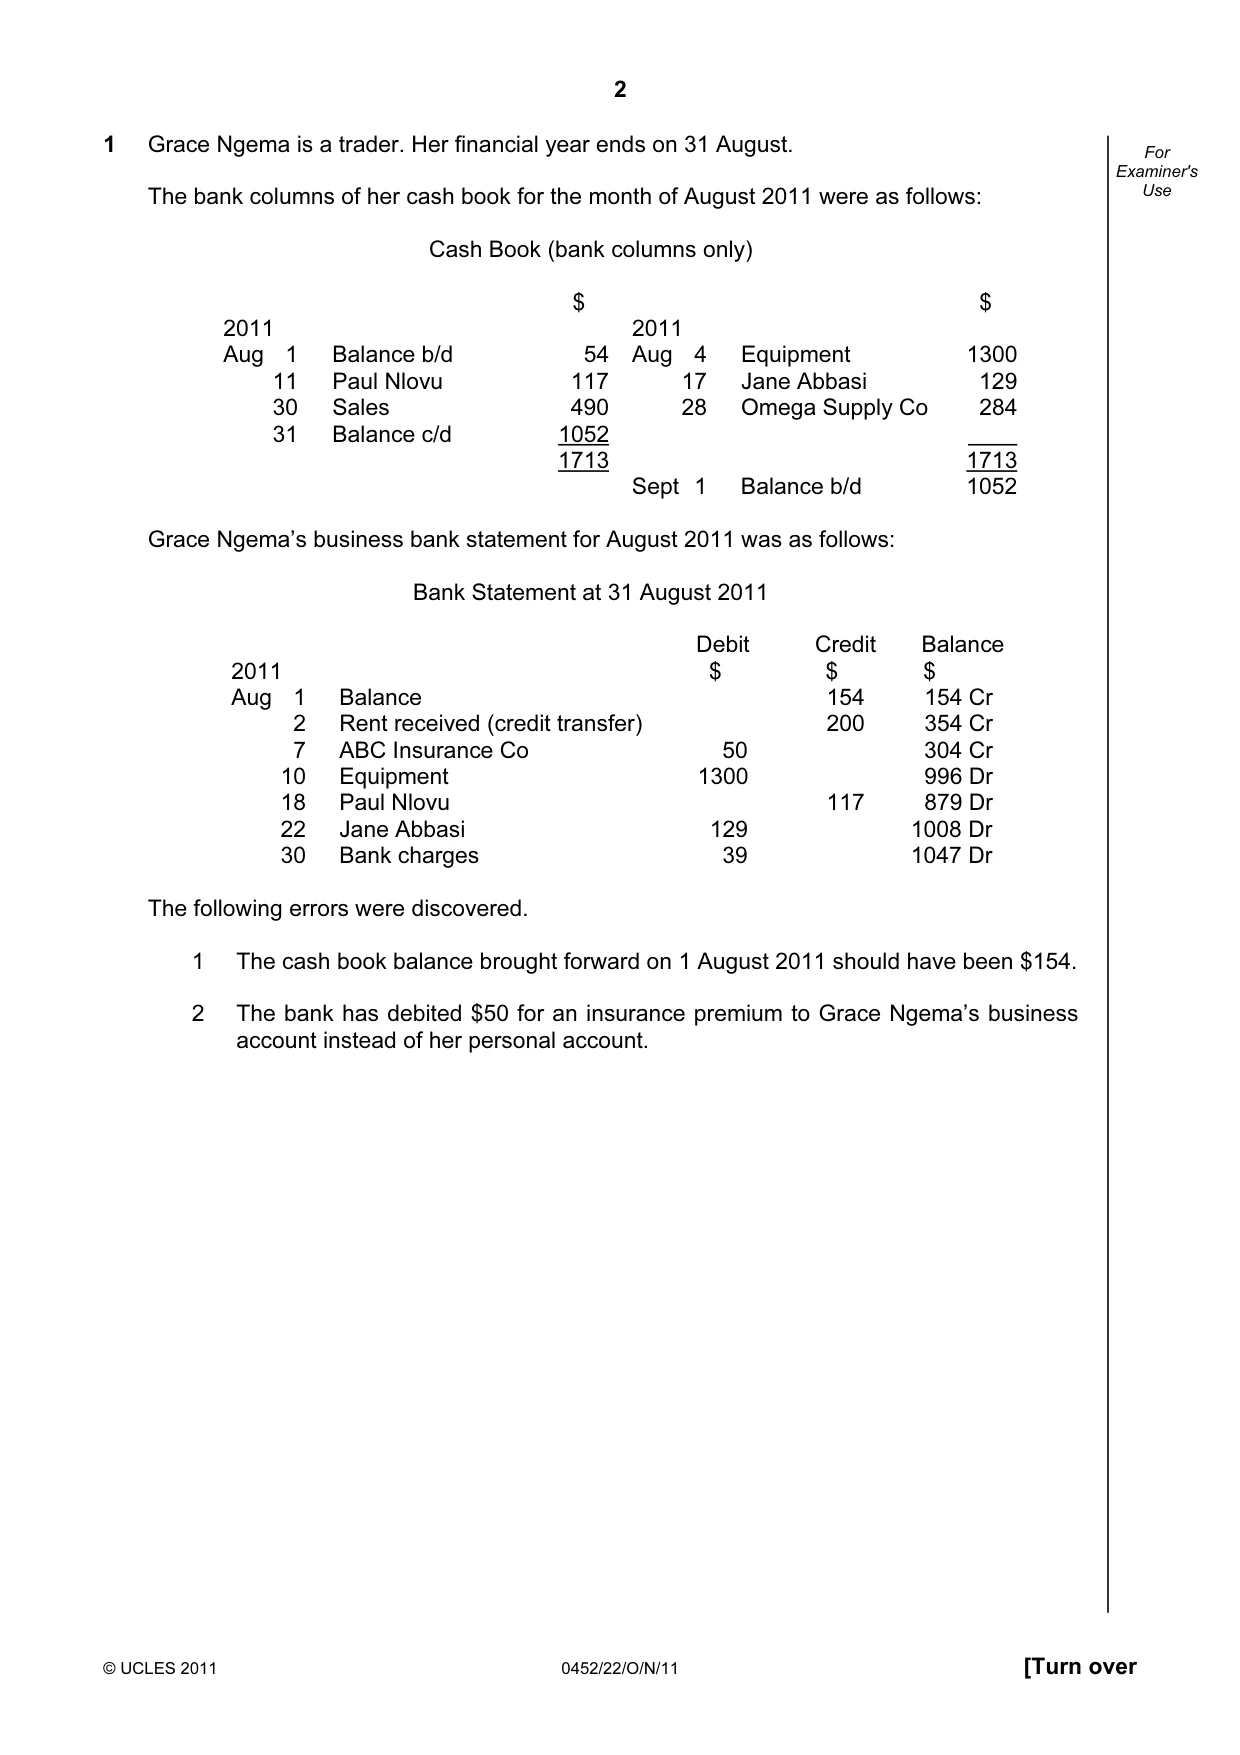
2 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use 1 Grace Ngema is a trader. Her financial year ends on 31 August. The bank columns of her cash book for the month of August 2011 were as follows: Cash Book (bank columns only) $ $ 2011 2011 Aug 1 Balance b/d 54 Aug 4 Equipment 1300 11 Paul Nlovu 117 17 Jane Abbasi 129 30 Sales 490 28 Omega Supply Co 284 31 Balance c/d 1052 1713 1713 Sept 1 Balance b/d 1052 Grace Ngema’s business bank statement for August 2011 was as follows: Bank Statement at 31 August 2011 Debit Credit Balance 2011 $ $ $ Aug 1 Balance 154 154 Cr 2 Rent received (credit transfer) 200 354 Cr 7 ABC Insurance Co 50 304 Cr 10 Equipment 1300 996 Dr 18 Paul Nlovu 117 879 Dr 22 Jane Abbasi 129 1008 Dr 30 Bank charges 39 1047 Dr The following errors were discovered. 1 The cash book balance brought forward on 1 August 2011 should have been $154. 2 The bank has debited $50 for an insurance premium to Grace Ngema’s business account instead of her personal account.
Question paper, page 3
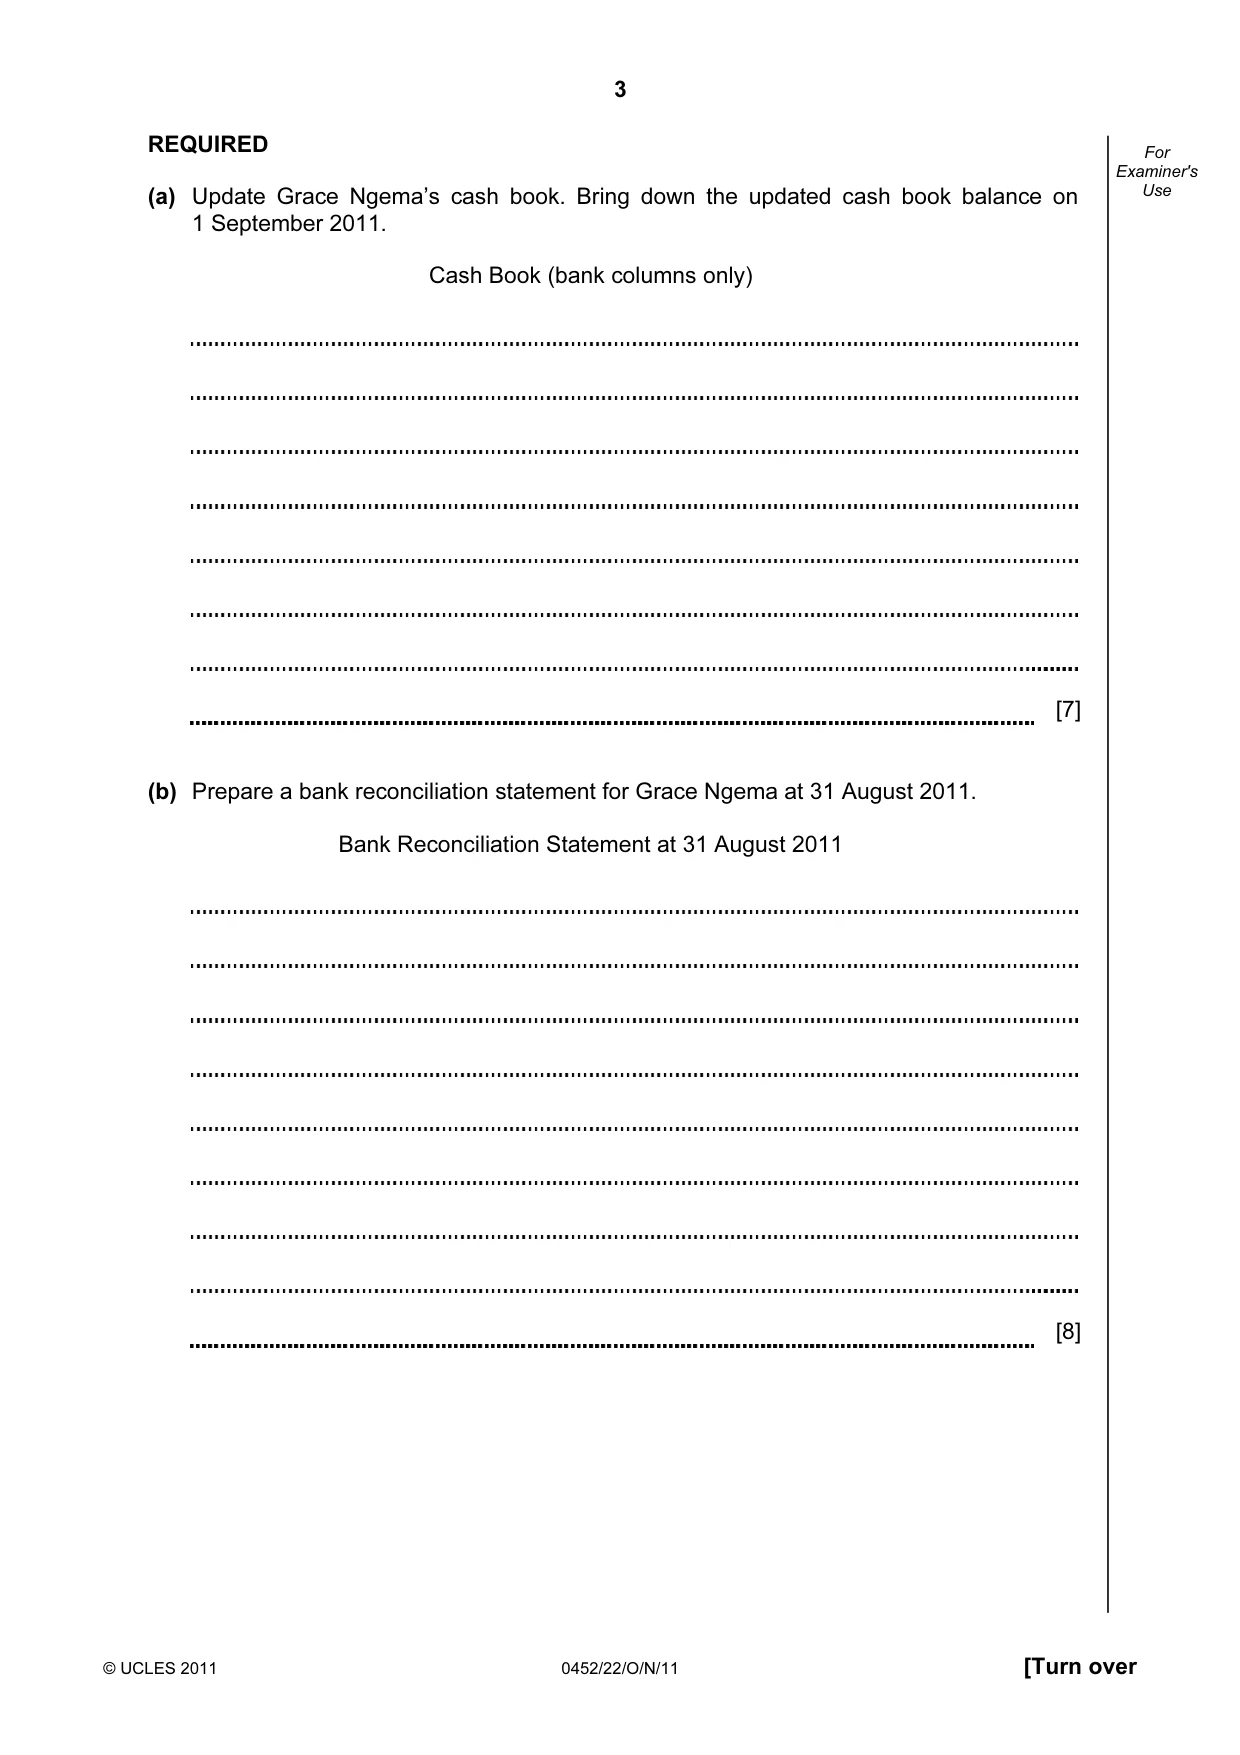
3 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use REQUIRED (a) Update Grace Ngema’s cash book. Bring down the updated cash book balance on 1 September 2011. Cash Book (bank columns only) [7] (b) Prepare a bank reconciliation statement for Grace Ngema at 31 August 2011. Bank Reconciliation Statement at 31 August 2011 [8]
Question paper, page 4
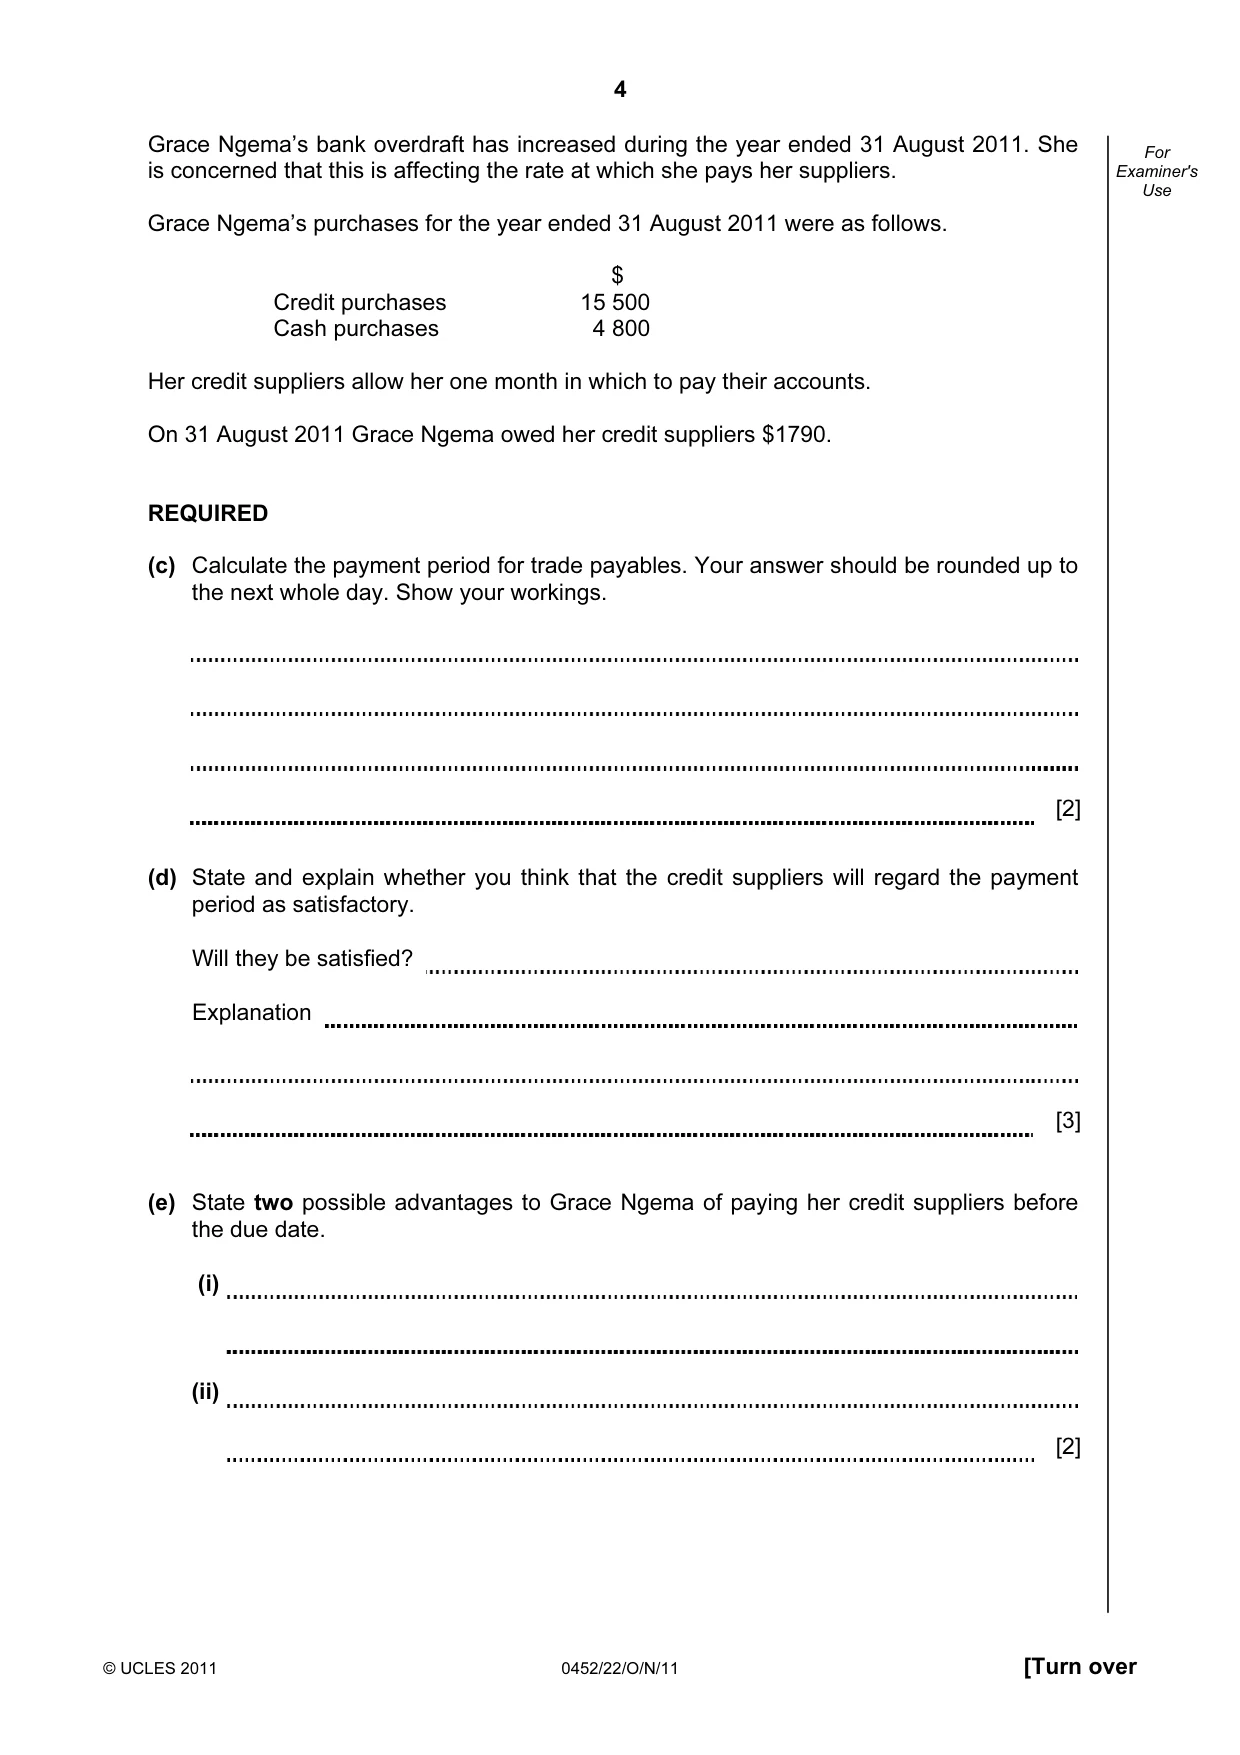
4 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use Grace Ngema’s bank overdraft has increased during the year ended 31 August 2011. She is concerned that this is affecting the rate at which she pays her suppliers. Grace Ngema’s purchases for the year ended 31 August 2011 were as follows. $ Credit purchases 15 500 Cash purchases 4 800 Her credit suppliers allow her one month in which to pay their accounts. On 31 August 2011 Grace Ngema owed her credit suppliers $1790. REQUIRED (c) Calculate the payment period for trade payables. Your answer should be rounded up to the next whole day. Show your workings. [2] (d) State and explain whether you think that the credit suppliers will regard the payment period as satisfactory. Will they be satisfied? Explanation [3] (e) State two possible advantages to Grace Ngema of paying her credit suppliers before the due date. (i) (ii) [2]
Question paper, page 5
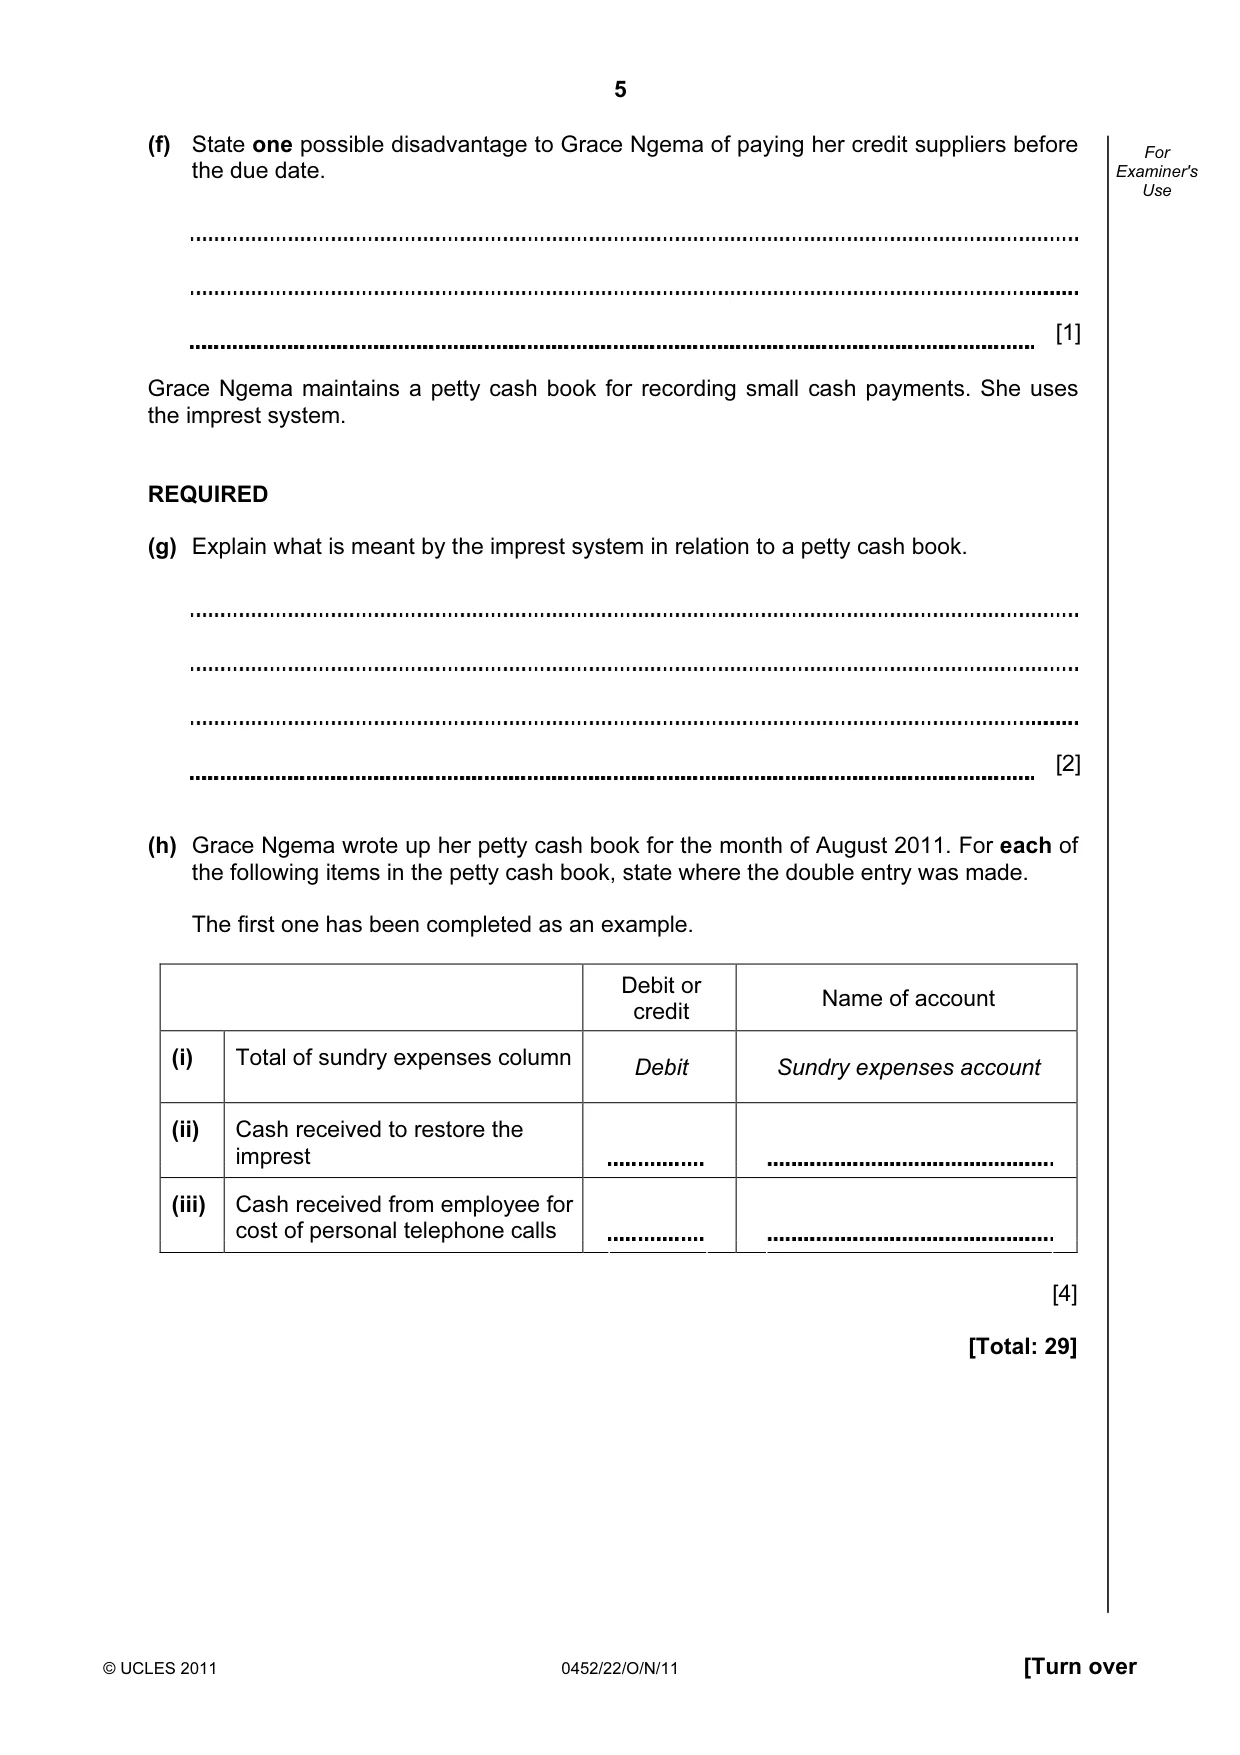
5 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use (f) State one possible disadvantage to Grace Ngema of paying her credit suppliers before the due date. [1] Grace Ngema maintains a petty cash book for recording small cash payments. She uses the imprest system. REQUIRED (g) Explain what is meant by the imprest system in relation to a petty cash book. [2] (h) Grace Ngema wrote up her petty cash book for the month of August 2011. For each of the following items in the petty cash book, state where the double entry was made. The first one has been completed as an example. Debit or credit Name of account (i) Total of sundry expenses column Debit Sundry expenses account (ii) Cash received to restore the imprest (iii) Cash received from employee for cost of personal telephone calls [4] [Total: 29]
Question paper, page 6
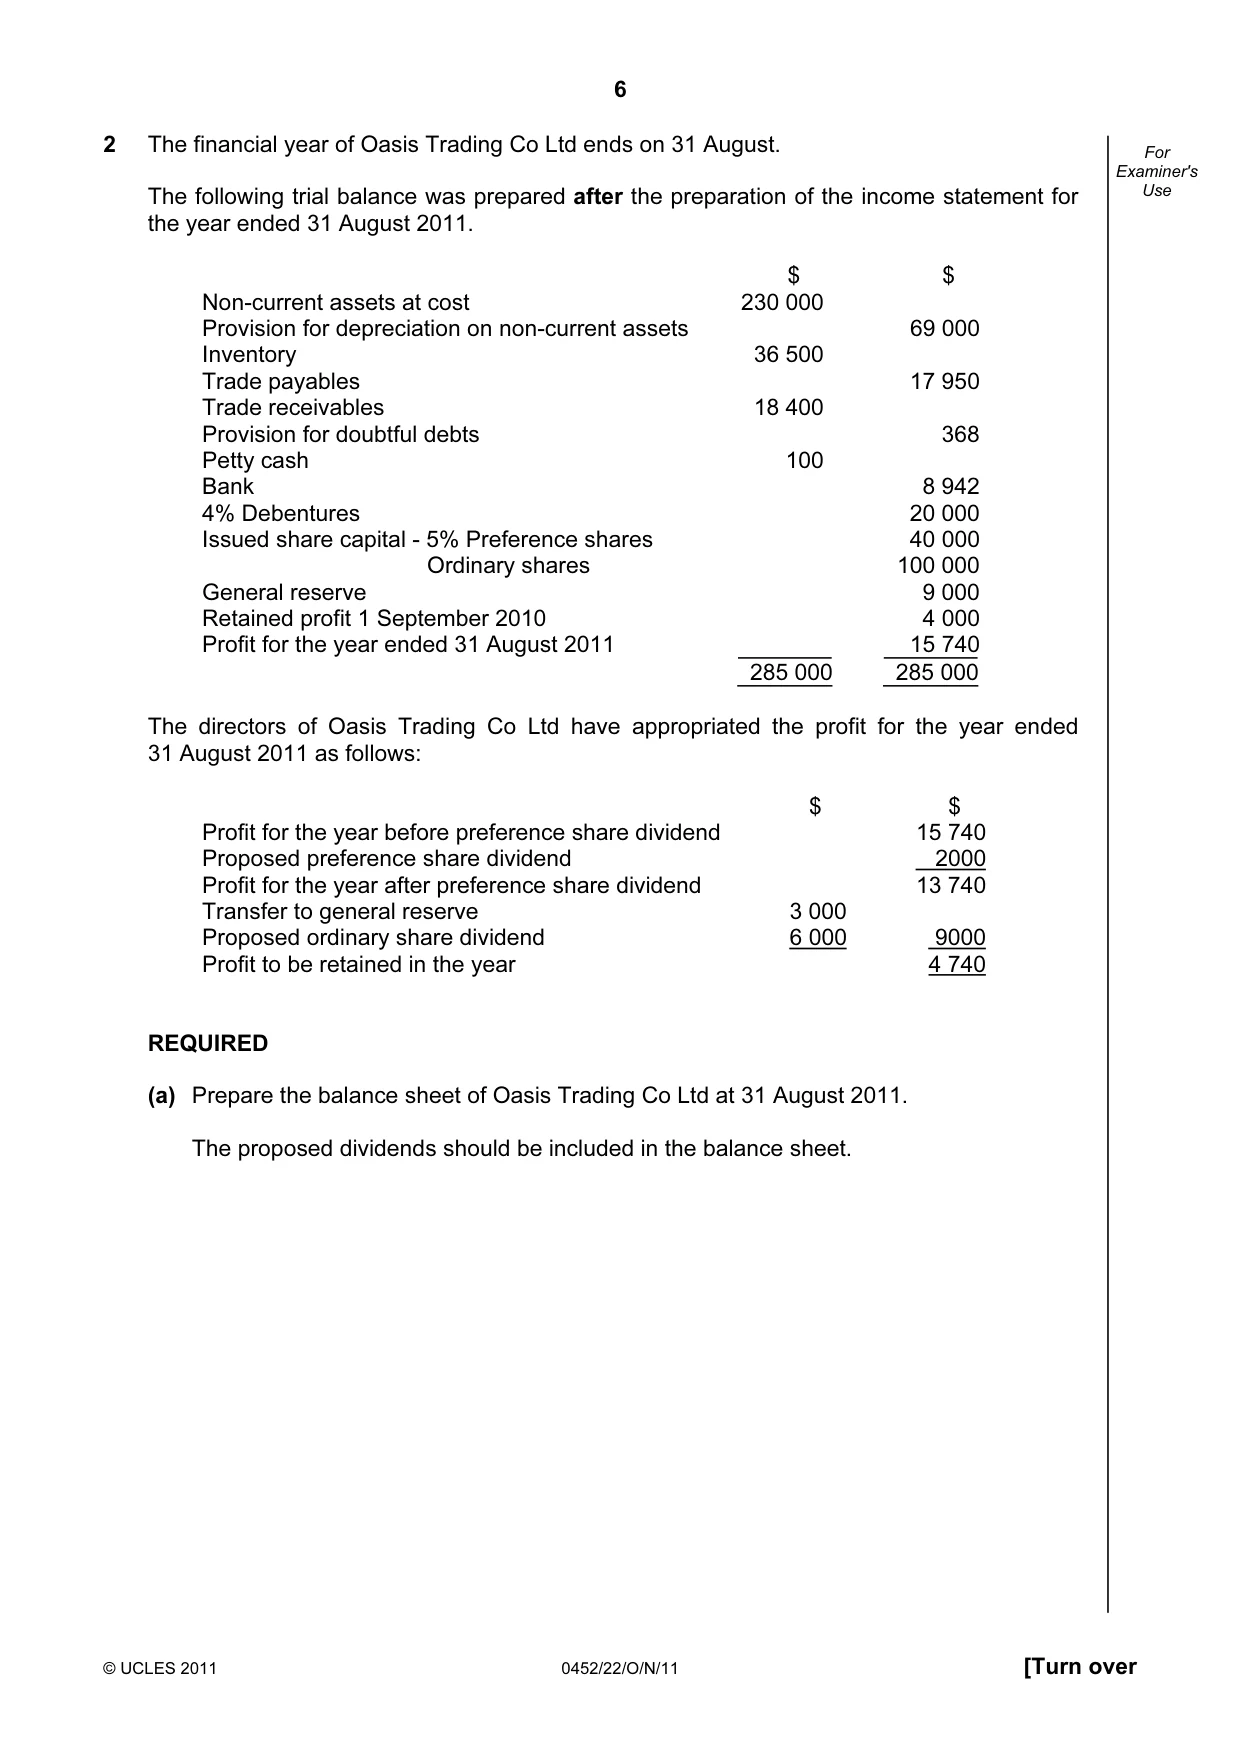
6 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use 2 The financial year of Oasis Trading Co Ltd ends on 31 August. The following trial balance was prepared after the preparation of the income statement for the year ended 31 August 2011. $ $ Non-current assets at cost 230 000 Provision for depreciation on non-current assets 69 000 Inventory 36 500 Trade payables 17 950 Trade receivables 18 400 Provision for doubtful debts 368 Petty cash 100 Bank 8 942 4% Debentures 20 000 Issued share capital - 5% Preference shares 40 000 Ordinary shares 100 000 General reserve 9 000 Retained profit 1 September 2010 4 000 Profit for the year ended 31 August 2011 15 740 285 000 285 000 The directors of Oasis Trading Co Ltd have appropriated the profit for the year ended 31 August 2011 as follows: $ $ Profit for the year before preference share dividend 15 740 Proposed preference share dividend 2000 Profit for the year after preference share dividend 13 740 Transfer to general reserve 3 000 Proposed ordinary share dividend 6 000 9000 Profit to be retained in the year 4 740 REQUIRED (a) Prepare the balance sheet of Oasis Trading Co Ltd at 31 August 2011. The proposed dividends should be included in the balance sheet.
Question paper, page 7
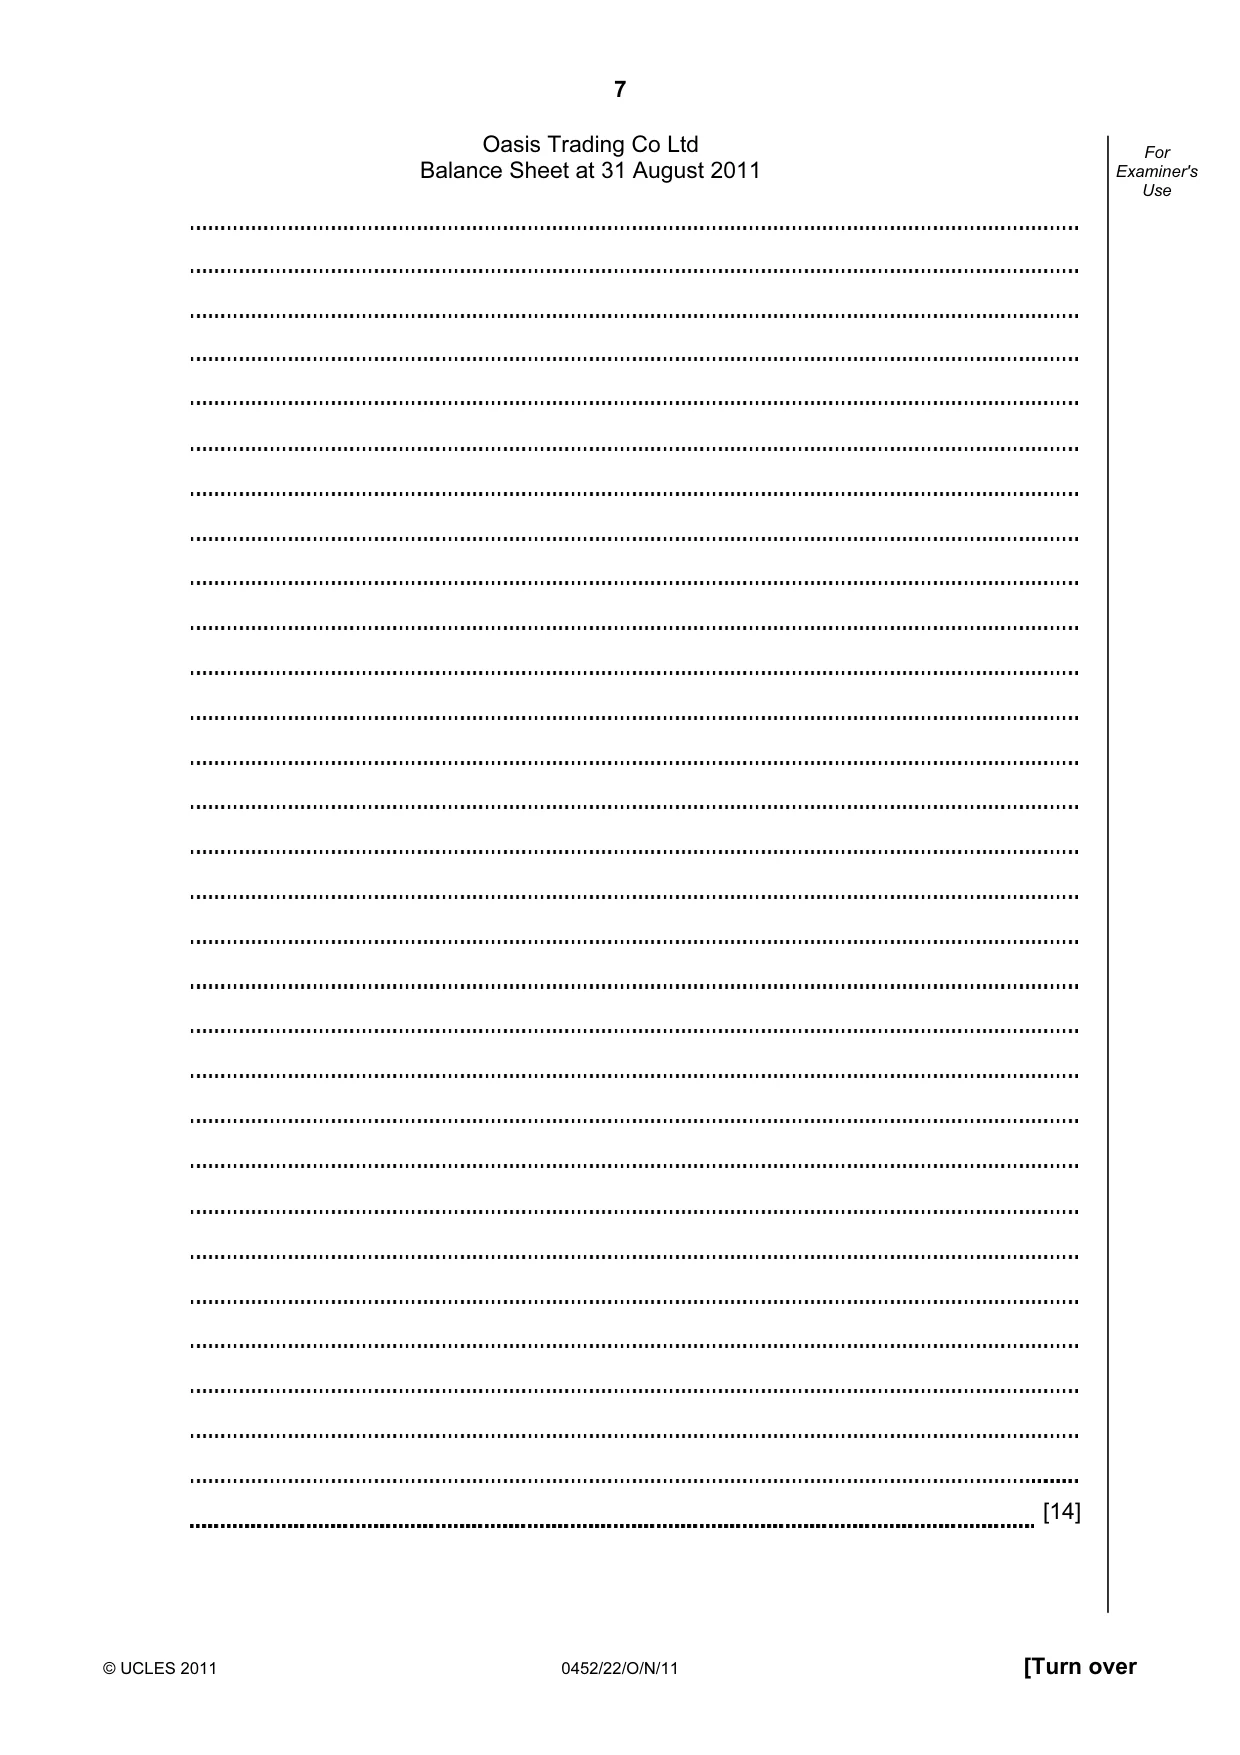
7 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use Oasis Trading Co Ltd Balance Sheet at 31 August 2011 [14]
Question paper, page 8
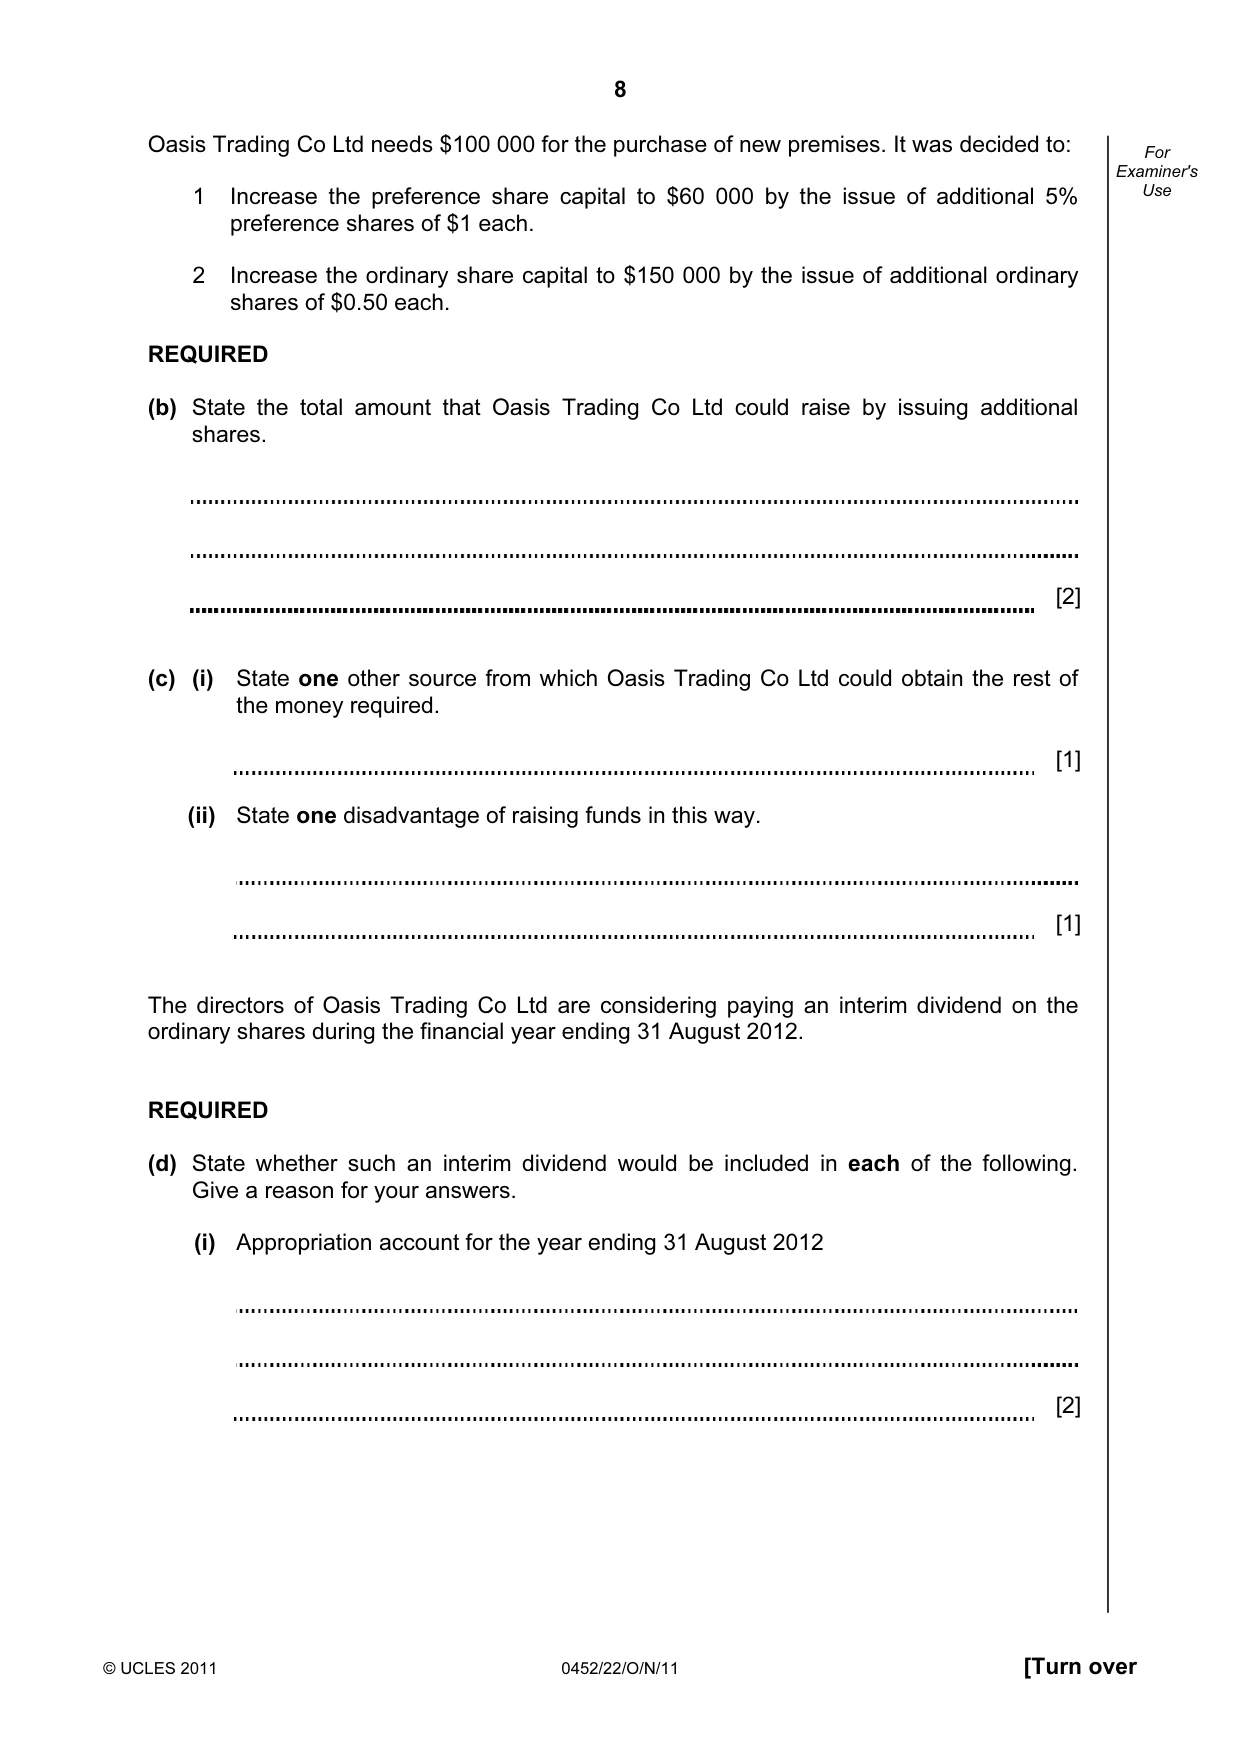
8 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use Oasis Trading Co Ltd needs $100 000 for the purchase of new premises. It was decided to: 1 Increase the preference share capital to $60 000 by the issue of additional 5% preference shares of $1 each. 2 Increase the ordinary share capital to $150 000 by the issue of additional ordinary shares of $0.50 each. REQUIRED (b) State the total amount that Oasis Trading Co Ltd could raise by issuing additional shares. [2] (c) (i) State one other source from which Oasis Trading Co Ltd could obtain the rest of the money required. [1] (ii) State one disadvantage of raising funds in this way. [1] The directors of Oasis Trading Co Ltd are considering paying an interim dividend on the ordinary shares during the financial year ending 31 August 2012. REQUIRED (d) State whether such an interim dividend would be included in each of the following. Give a reason for your answers. (i) Appropriation account for the year ending 31 August 2012 [2]
Question paper, page 9
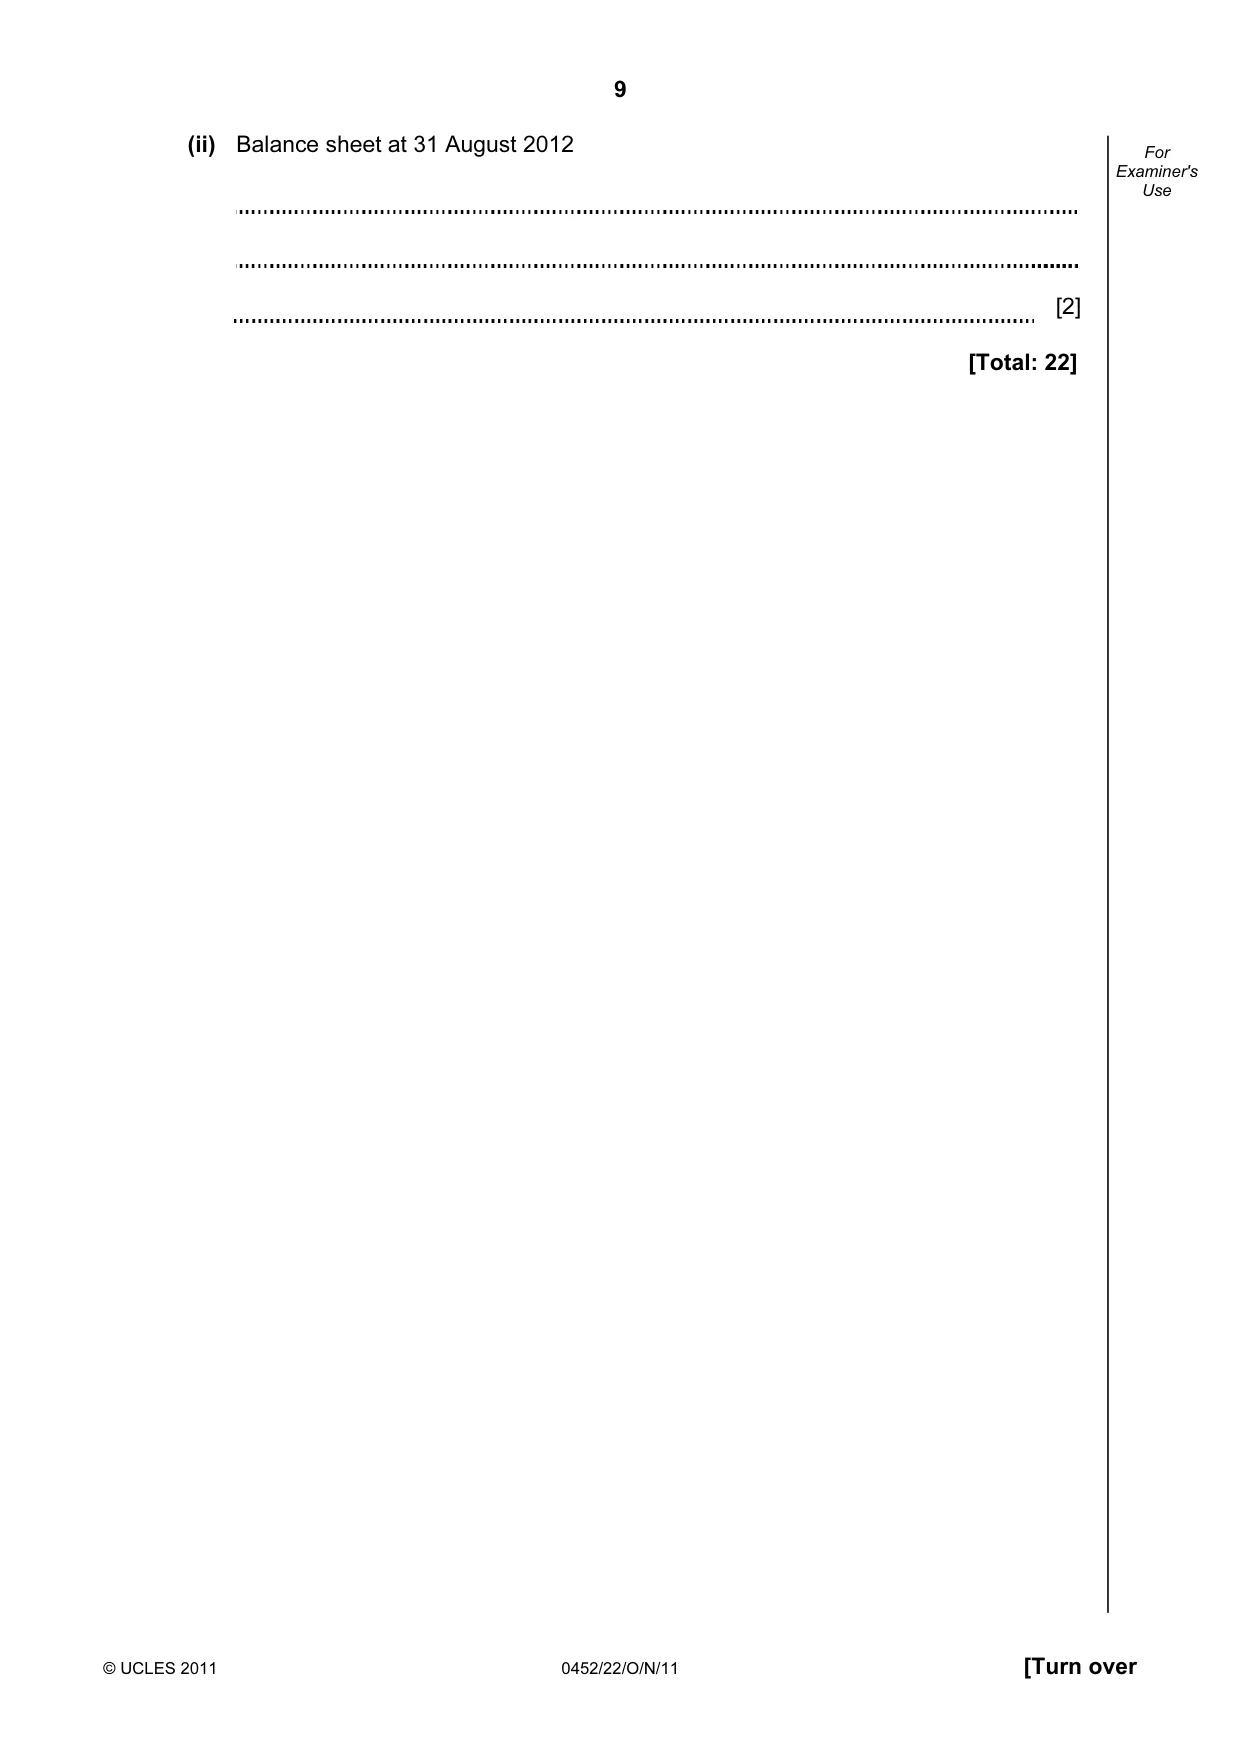
9 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use (ii) Balance sheet at 31 August 2012 [2] [Total: 22]
Question paper, page 10
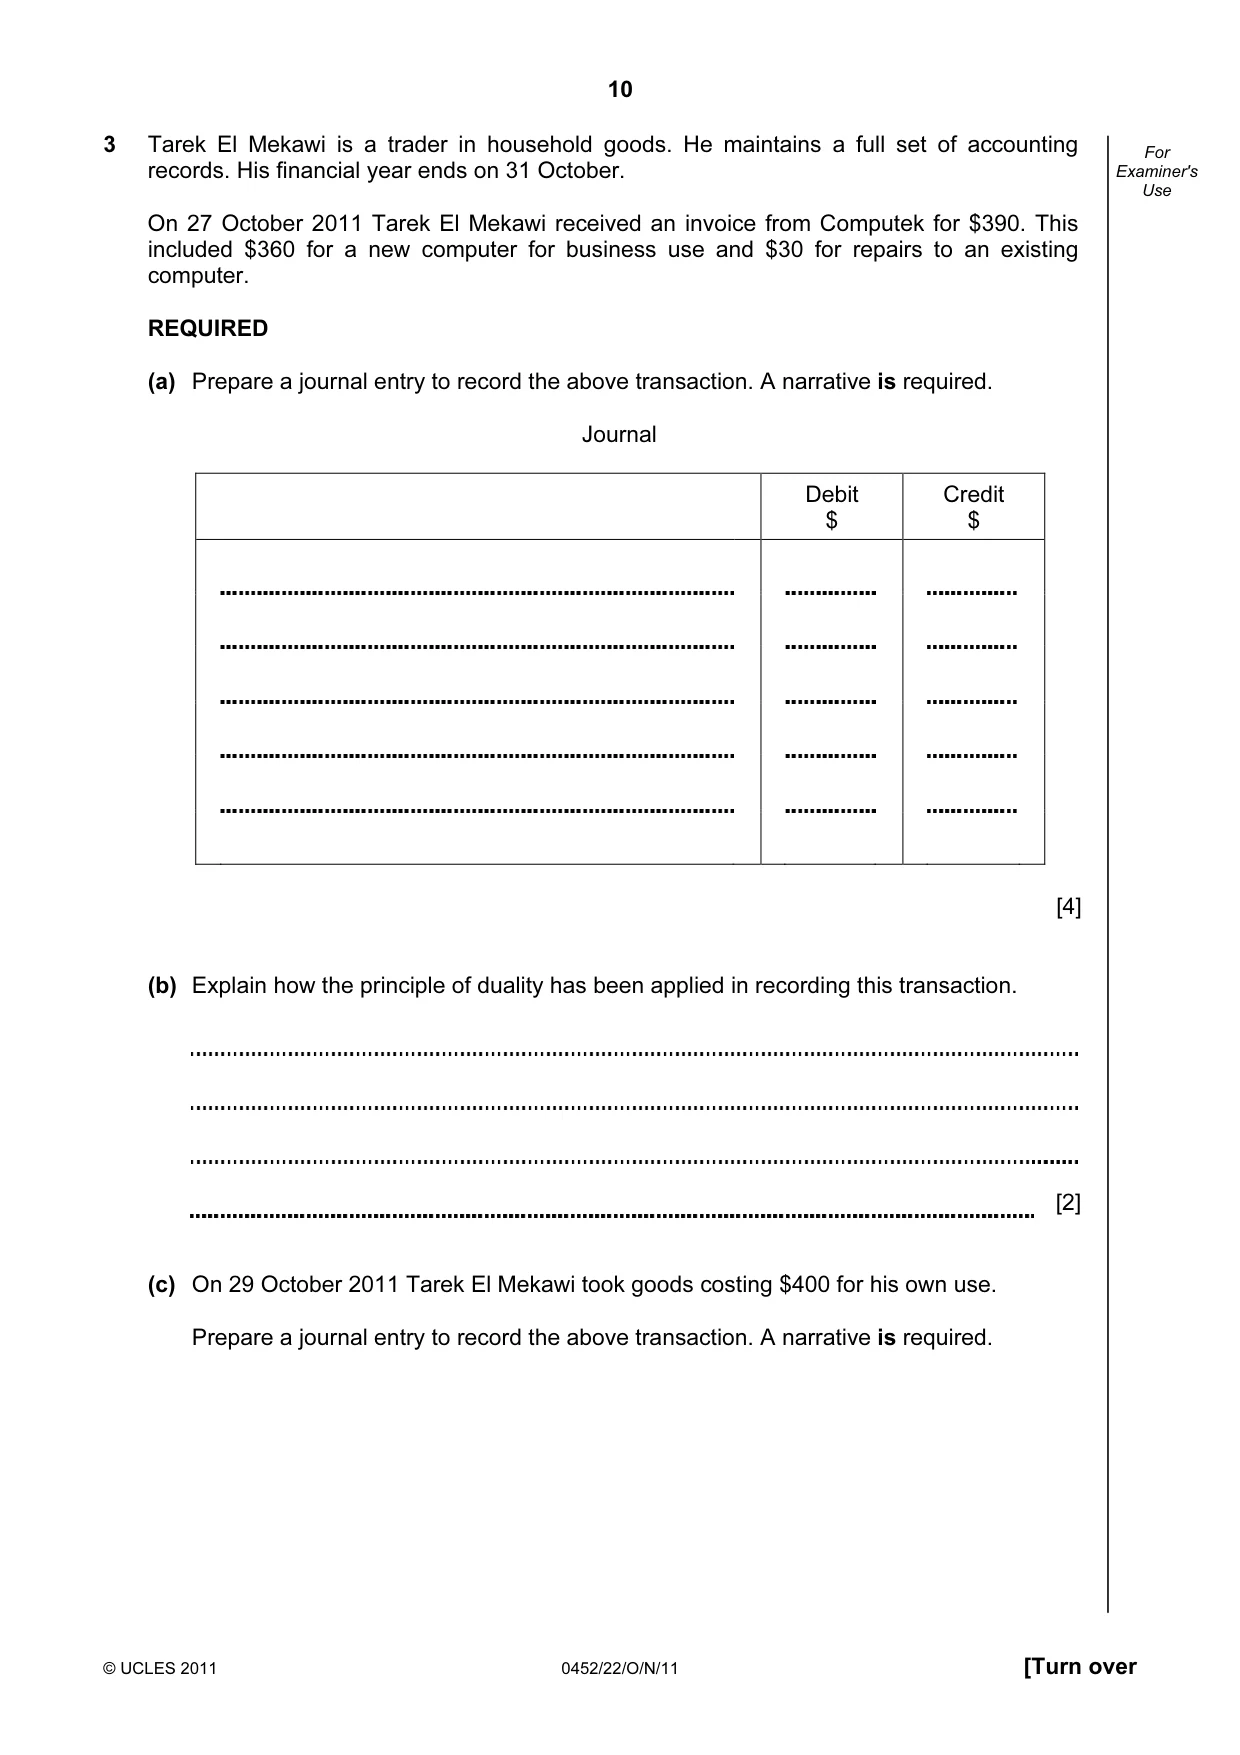
10 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use 3 Tarek El Mekawi is a trader in household goods. He maintains a full set of accounting records. His financial year ends on 31 October. On 27 October 2011 Tarek El Mekawi received an invoice from Computek for $390. This included $360 for a new computer for business use and $30 for repairs to an existing computer. REQUIRED (a) Prepare a journal entry to record the above transaction. A narrative is required. Journal Debit $ Credit $ [4] (b) Explain how the principle of duality has been applied in recording this transaction. [2] (c) On 29 October 2011 Tarek El Mekawi took goods costing $400 for his own use. Prepare a journal entry to record the above transaction. A narrative is required.
Question paper, page 11
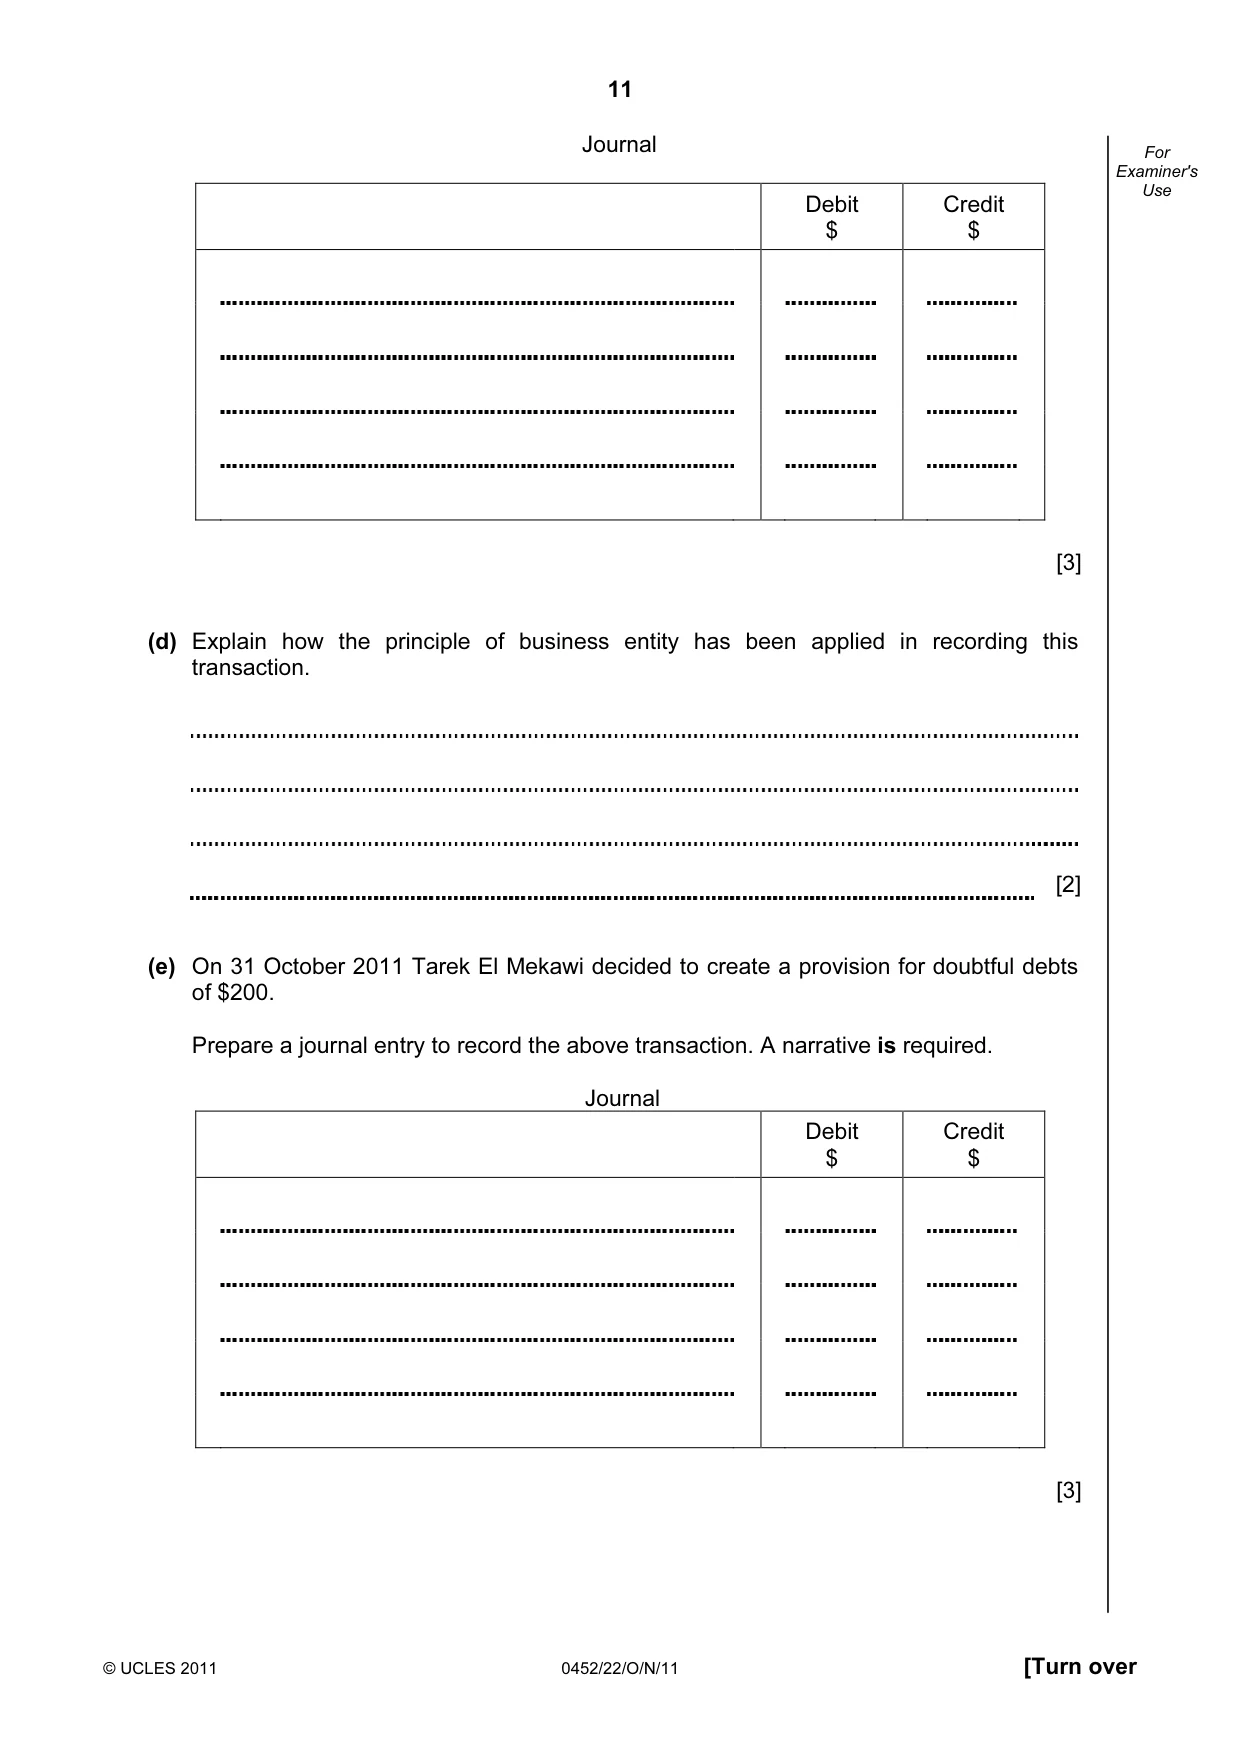
11 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use Journal Debit $ Credit $ [3] (d) Explain how the principle of business entity has been applied in recording this transaction. [2] (e) On 31 October 2011 Tarek El Mekawi decided to create a provision for doubtful debts of $200. Prepare a journal entry to record the above transaction. A narrative is required. Journal Debit $ Credit $ [3]
Question paper, page 12
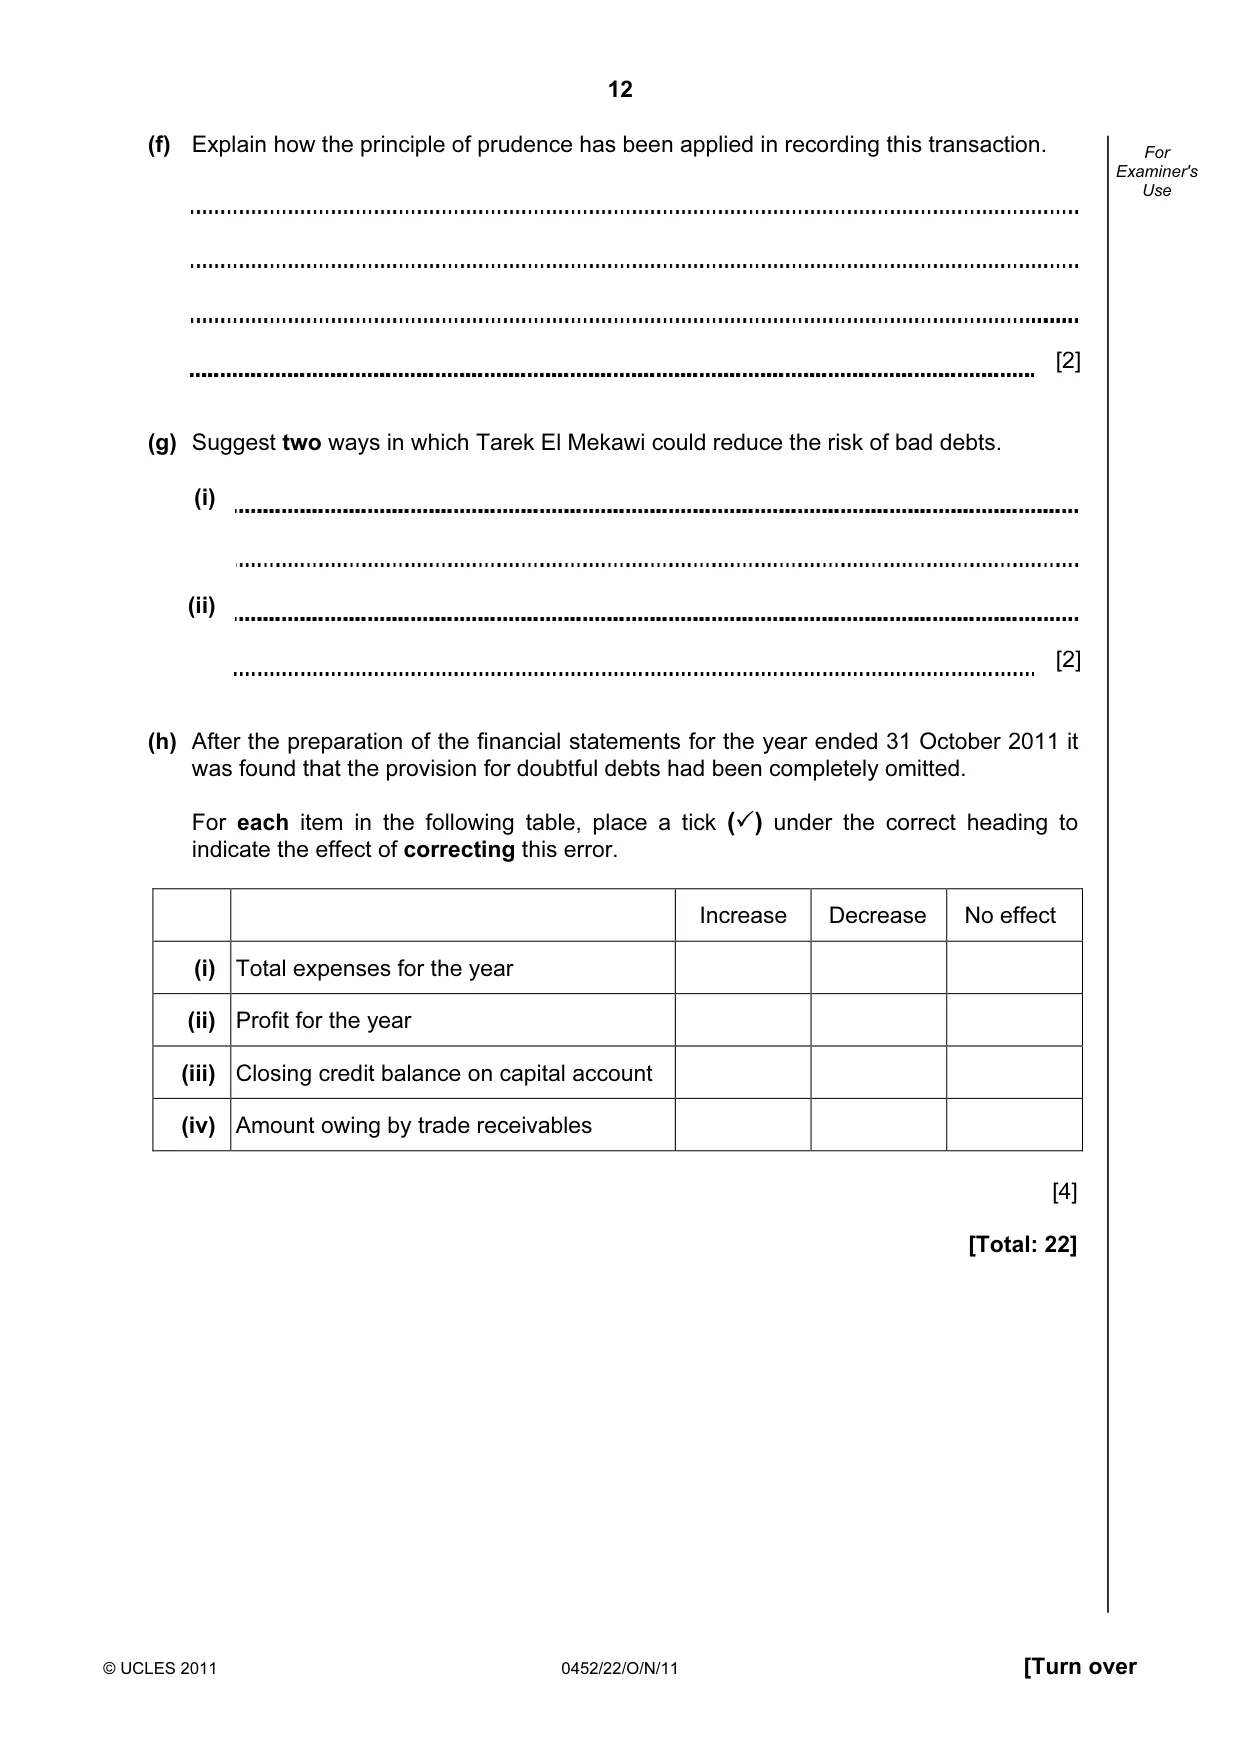
12 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use (f) Explain how the principle of prudence has been applied in recording this transaction. [2] (g) Suggest two ways in which Tarek El Mekawi could reduce the risk of bad debts. (i) (ii) [2] (h) After the preparation of the financial statements for the year ended 31 October 2011 it was found that the provision for doubtful debts had been completely omitted. For each item in the following table, place a tick (✓) under the correct heading to indicate the effect of correcting this error. Increase Decrease No effect (i) Total expenses for the year (ii) Profit for the year (iii) Closing credit balance on capital account (iv) Amount owing by trade receivables [4] [Total: 22]
Question paper, page 13
13 © UCLES 2011 0452/22/O/N/11 [Turn over Question 4 is on the next page.
Question paper, page 14
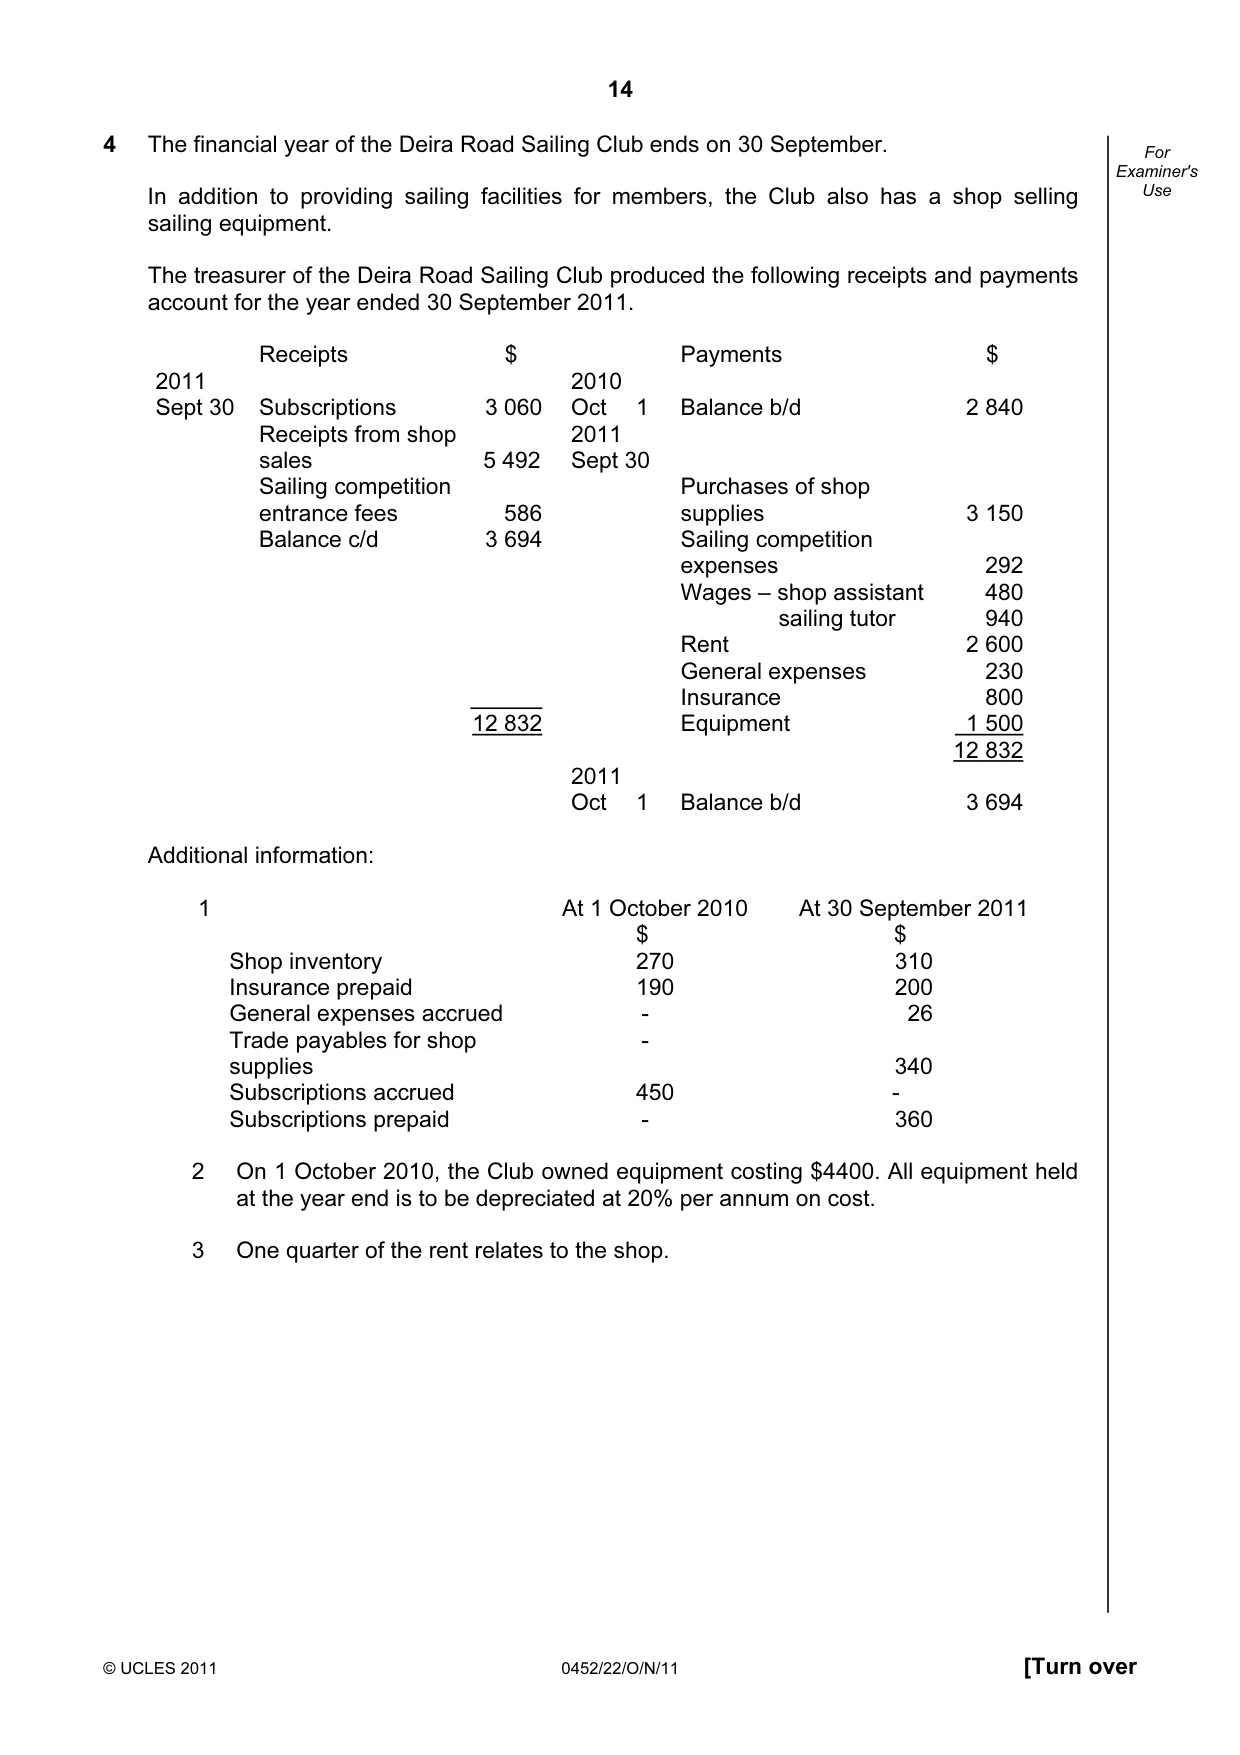
14 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use 4 The financial year of the Deira Road Sailing Club ends on 30 September. In addition to providing sailing facilities for members, the Club also has a shop selling sailing equipment. The treasurer of the Deira Road Sailing Club produced the following receipts and payments account for the year ended 30 September 2011. Receipts $ Payments $ 2011 2010 Sept 30 Subscriptions 3 060 Oct 1 Balance b/d 2 840 Receipts from shop sales 5 492 2011 Sept 30 Sailing competition entrance fees 586 Purchases of shop supplies 3 150 Balance c/d 3 694 Sailing competition expenses 292 Wages – shop assistant 480 sailing tutor 940 Rent 2 600 General expenses 230 Insurance 800 12 832 Equipment 1 500 12 832 2011 Oct 1 Balance b/d 3 694 Additional information: 1 At 1 October 2010 At 30 September 2011 $ $ Shop inventory 270 310 Insurance prepaid 190 200 General expenses accrued - 26 Trade payables for shop supplies - 340 Subscriptions accrued 450 - Subscriptions prepaid - 360 2 On 1 October 2010, the Club owned equipment costing $4400. All equipment held at the year end is to be depreciated at 20% per annum on cost. 3 One quarter of the rent relates to the shop.
Question paper, page 15
15 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use REQUIRED (a) Prepare the shop income statement of the Deira Road Sailing Club for the year ended 30 September 2011. Deira Road Sailing Club Shop Income Statement for the year ended 30 September 2011 [8]
Question paper, page 16
16 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use (b) Prepare the income and expenditure account of the Deira Road Sailing Club for the year ended 30 September 2011. Deira Road Sailing Club Income and Expenditure Account for the year ended 30 September 2011 [16] [Total: 24]
Question paper, page 17
17 © UCLES 2011 0452/22/O/N/11 [Turn over Question 5 is on the next page
Question paper, page 18
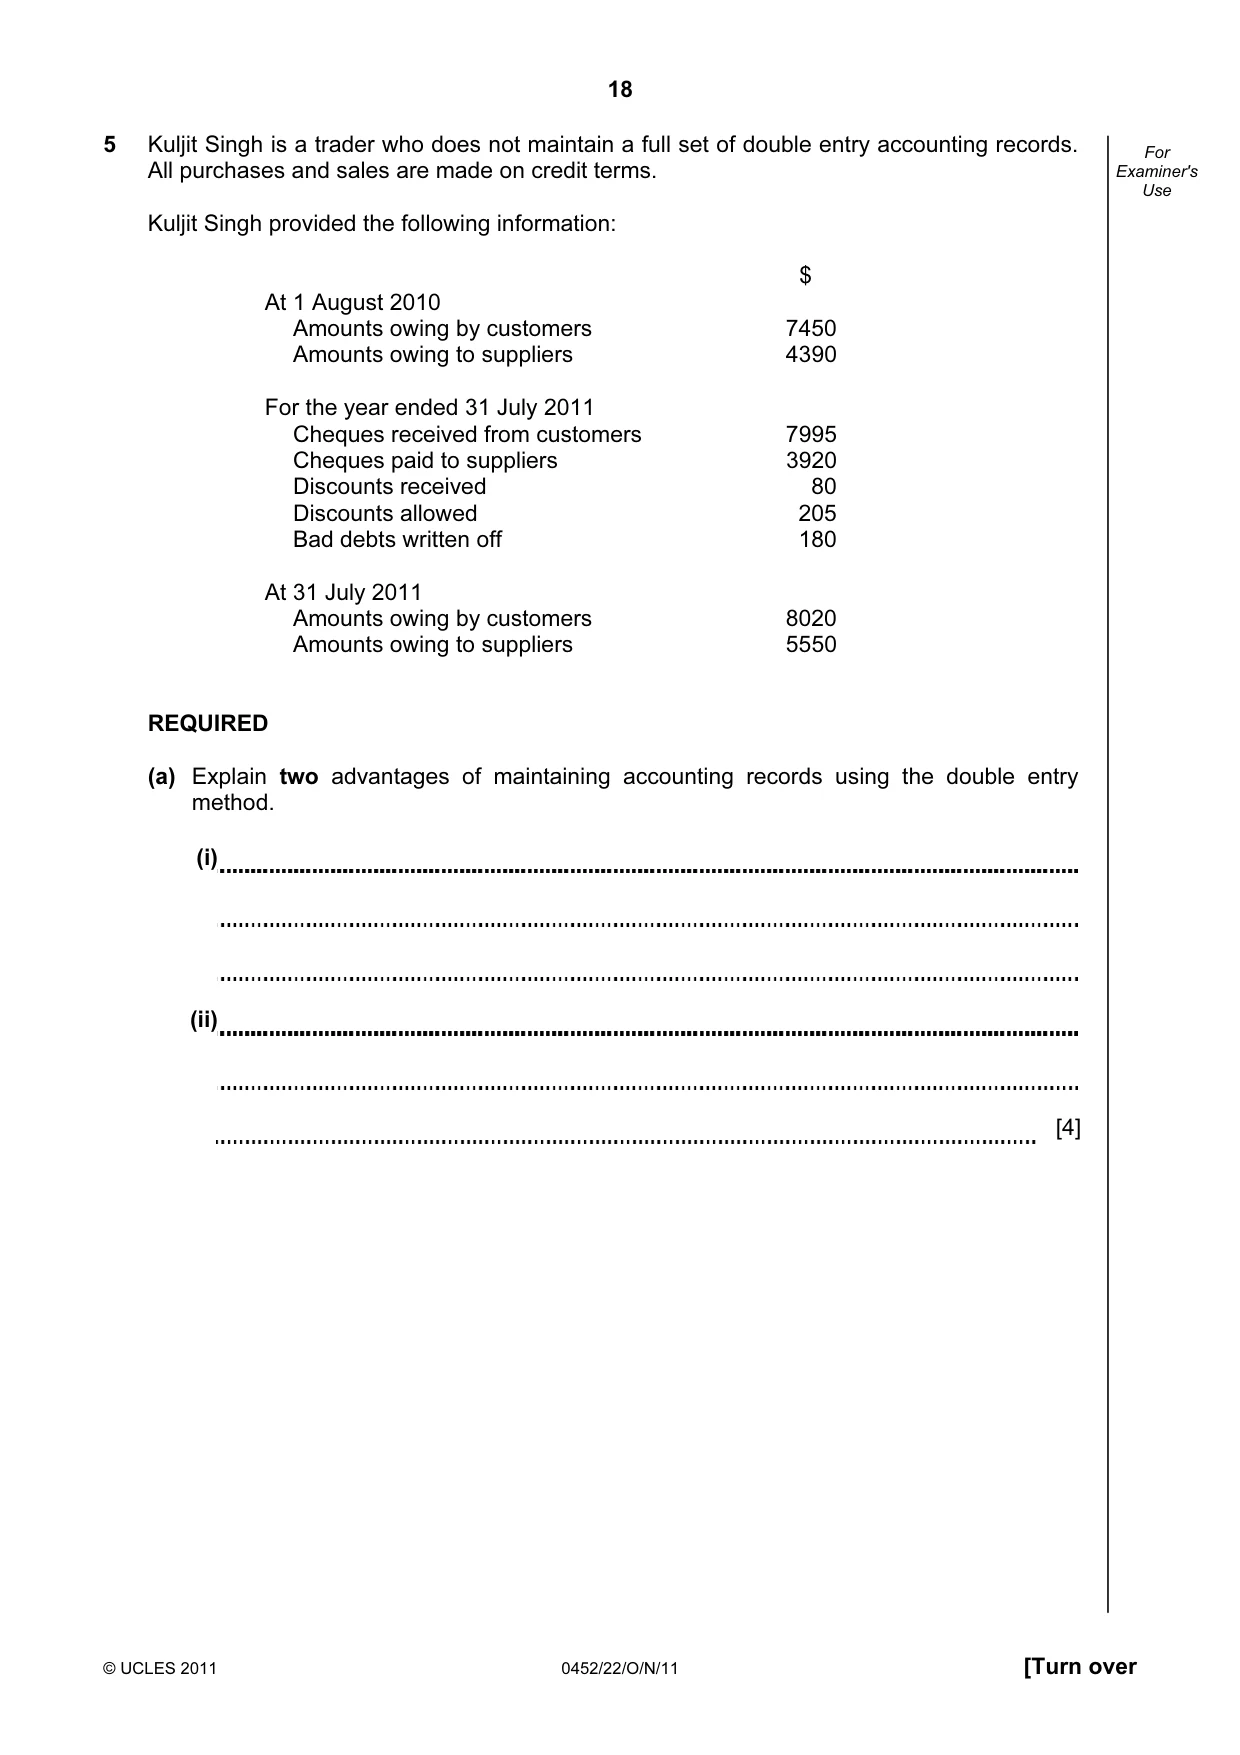
18 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use 5 Kuljit Singh is a trader who does not maintain a full set of double entry accounting records. All purchases and sales are made on credit terms. Kuljit Singh provided the following information: $ At 1 August 2010 Amounts owing by customers 7450 Amounts owing to suppliers 4390 For the year ended 31 July 2011 Cheques received from customers 7995 Cheques paid to suppliers 3920 Discounts received 80 Discounts allowed 205 Bad debts written off 180 At 31 July 2011 Amounts owing by customers 8020 Amounts owing to suppliers 5550 REQUIRED (a) Explain two advantages of maintaining accounting records using the double entry method. (i) (ii) [4]
Question paper, page 19
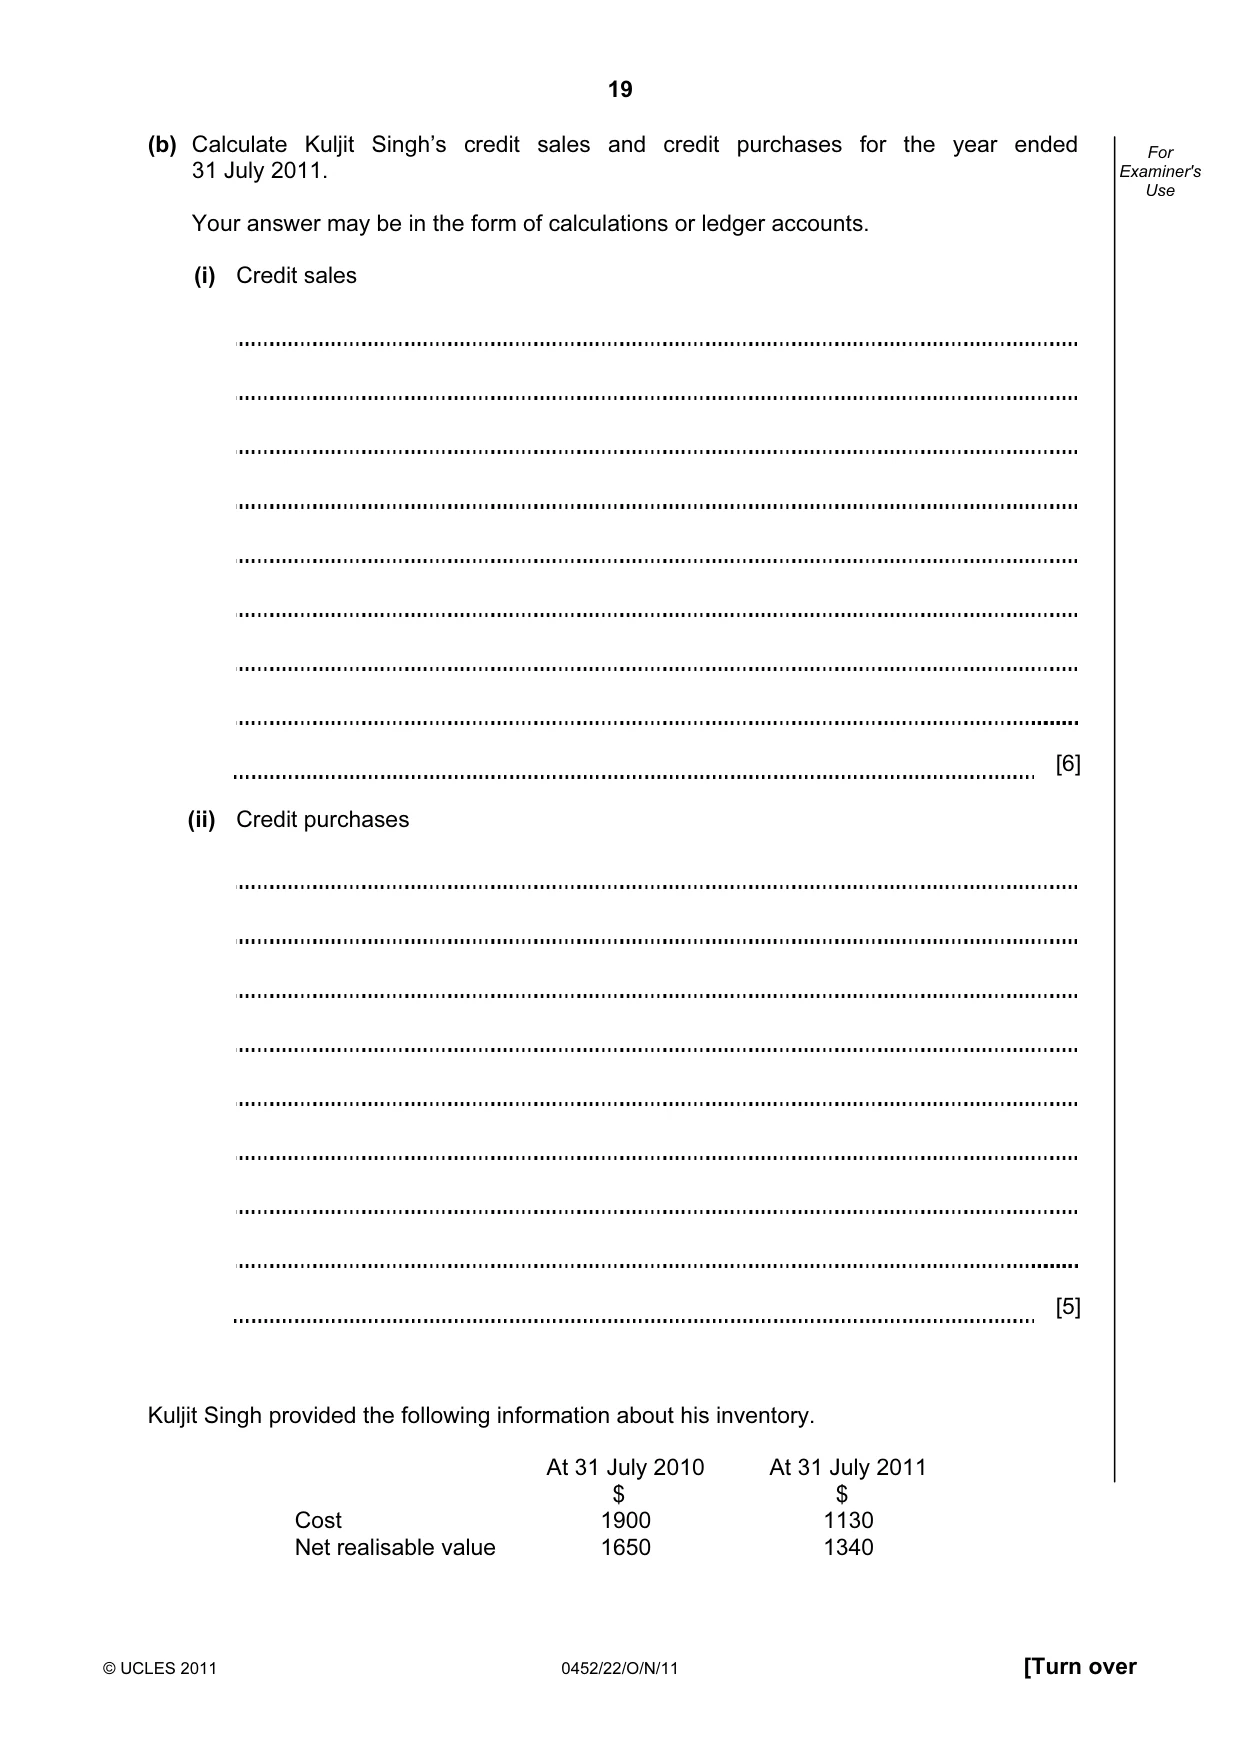
19 © UCLES 2011 0452/22/O/N/11 [Turn over For Examiner's Use (b) Calculate Kuljit Singh’s credit sales and credit purchases for the year ended 31 July 2011. Your answer may be in the form of calculations or ledger accounts. (i) Credit sales [6] (ii) Credit purchases [5] Kuljit Singh provided the following information about his inventory. At 31 July 2010 At 31 July 2011 $ $ Cost 1900 1130 Net realisable value 1650 1340
Question paper, page 20
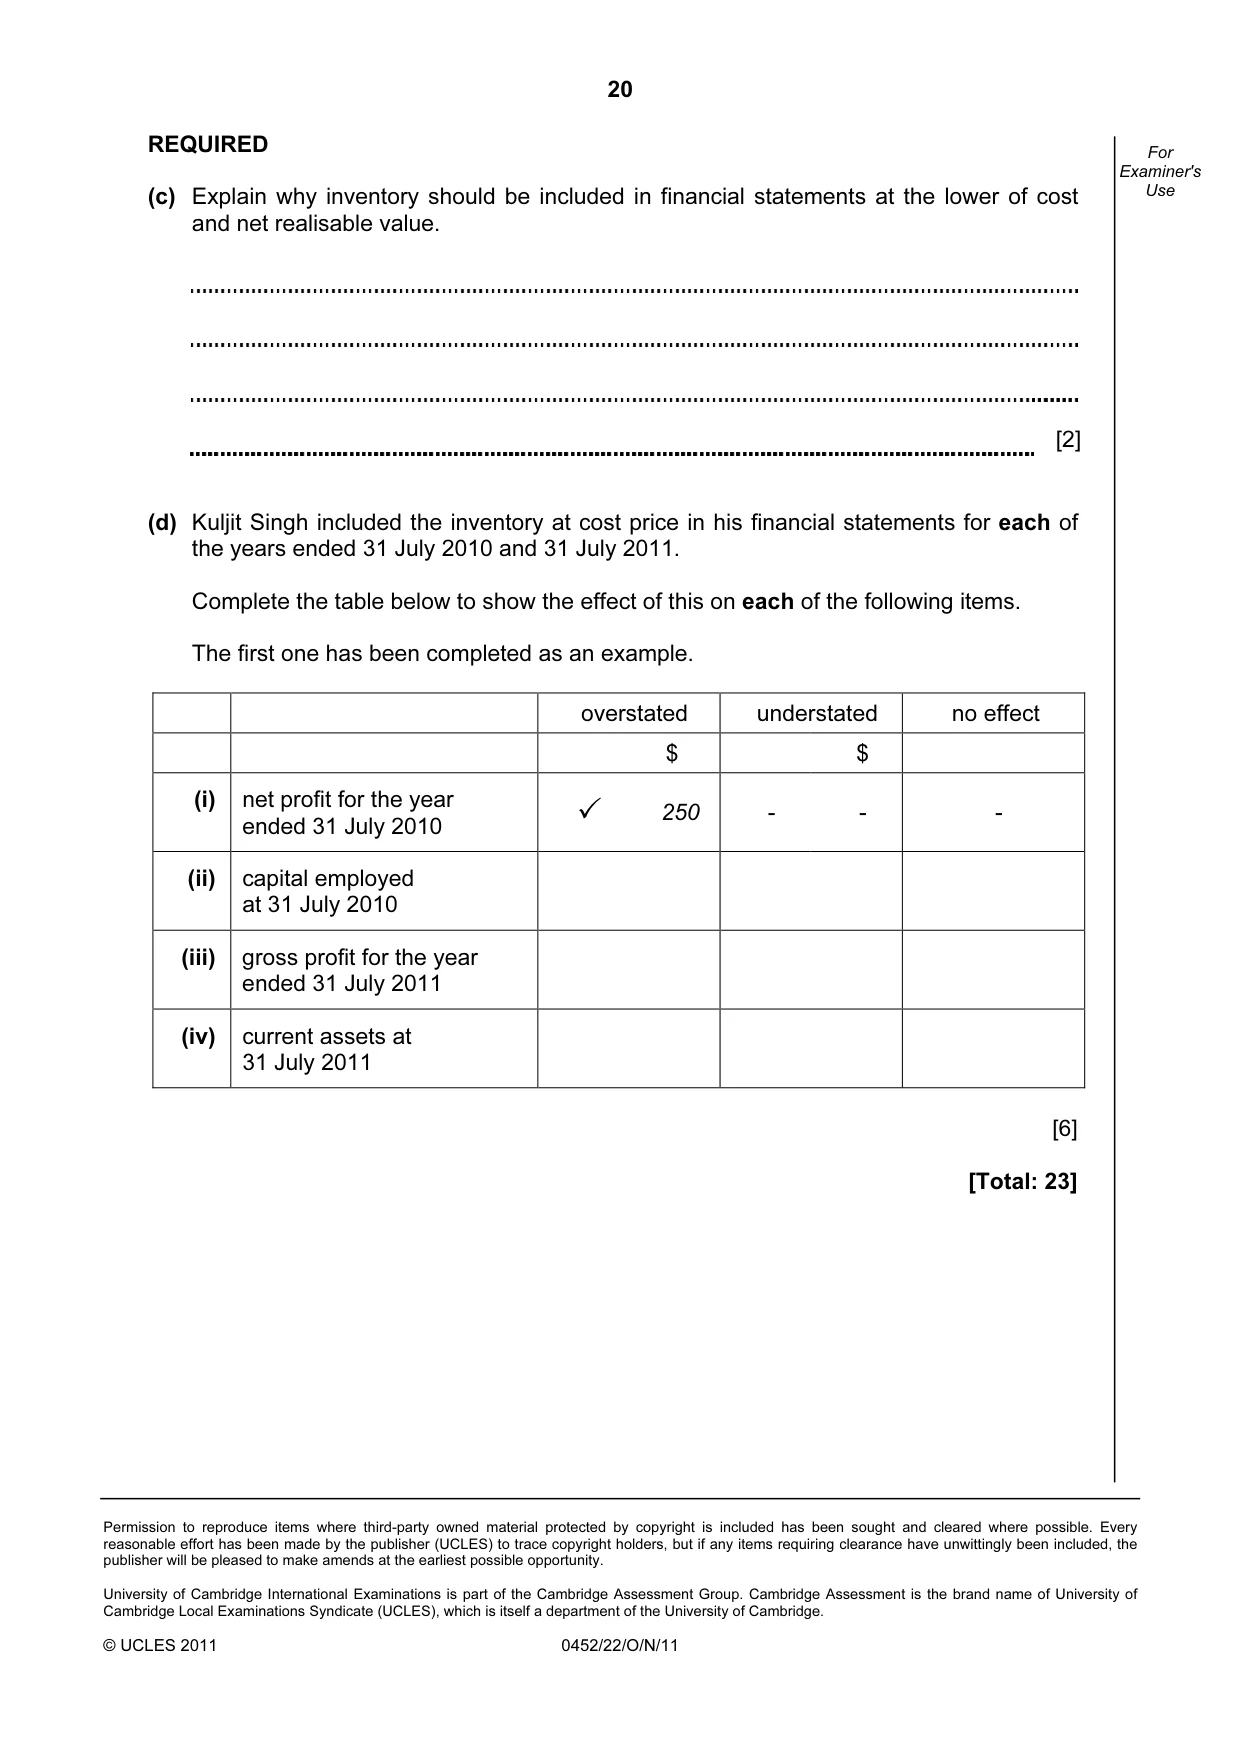
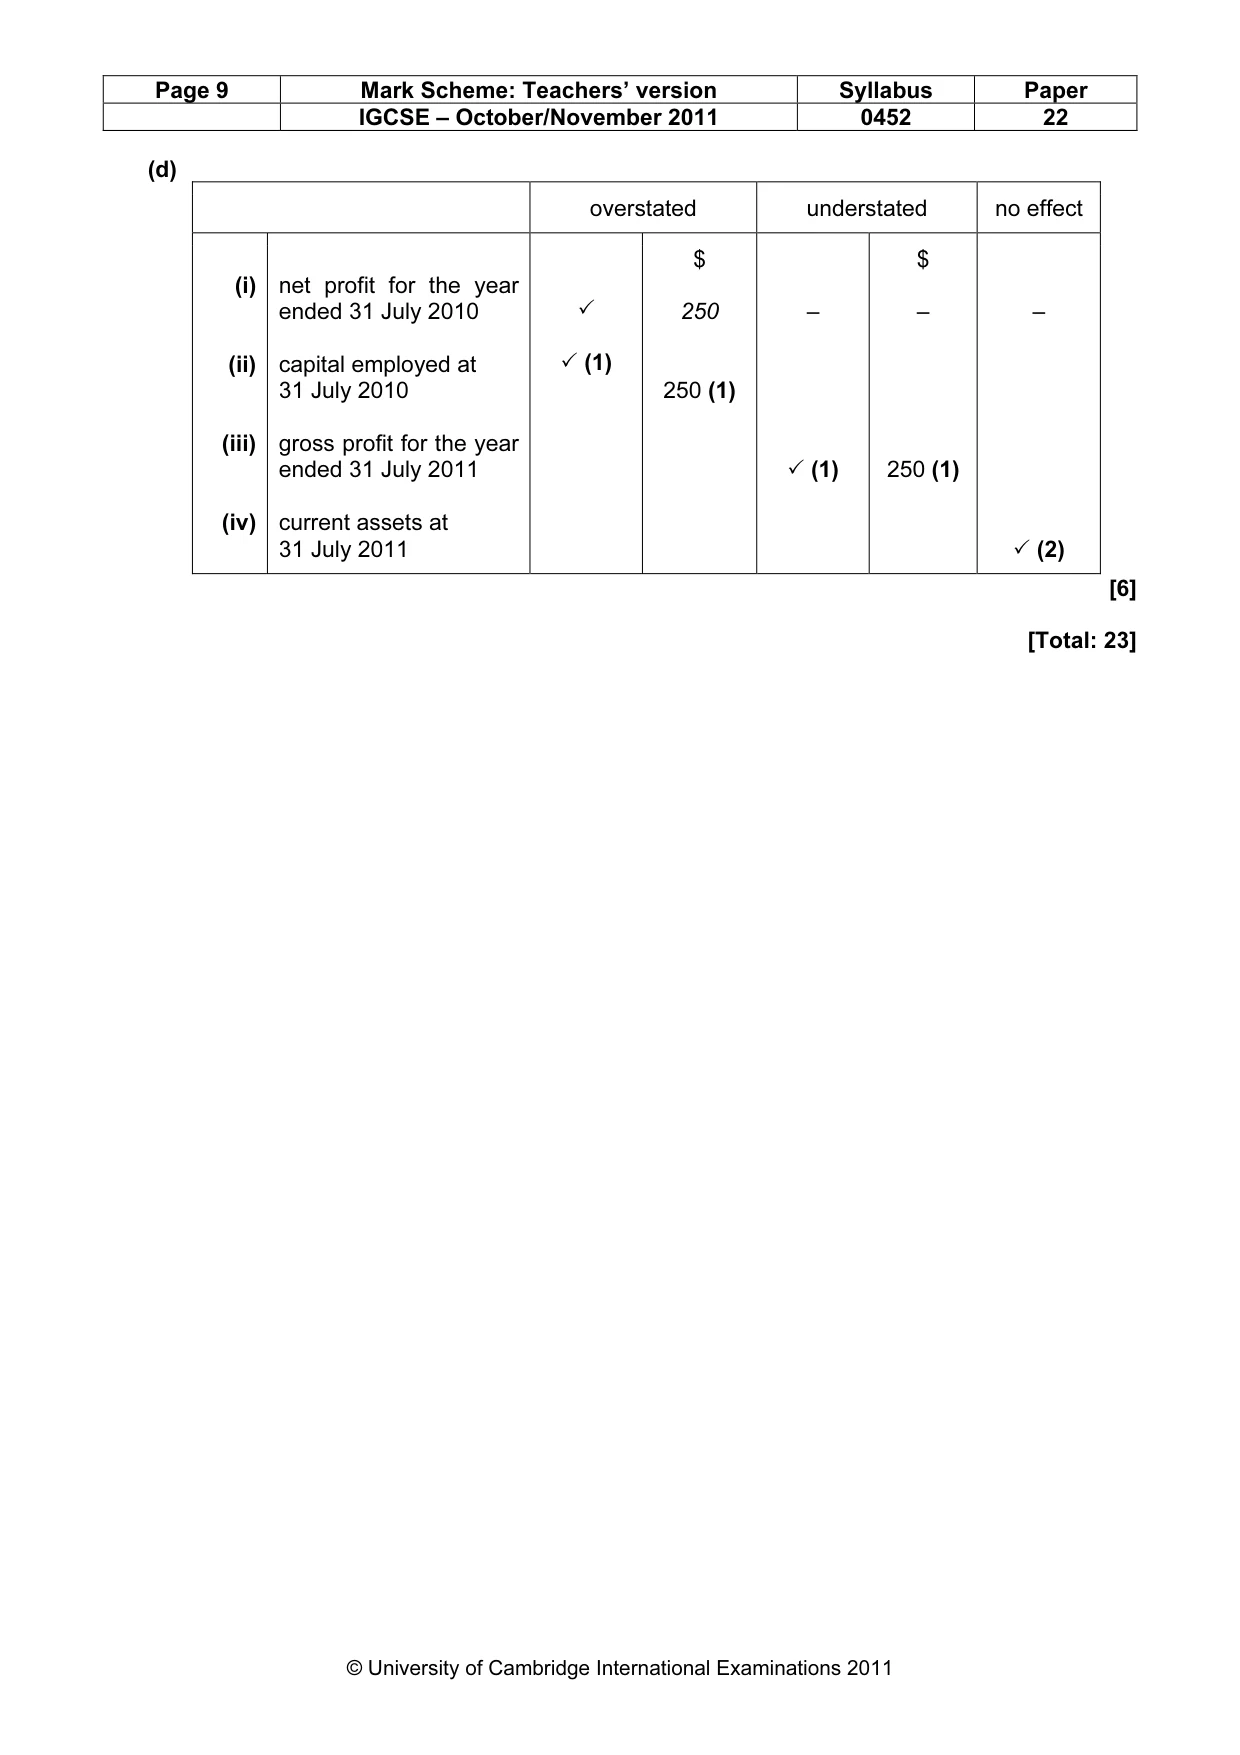
20 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2011 0452/22/O/N/11 For Examiner's Use REQUIRED (c) Explain why inventory should be included in financial statements at the lower of cost and net realisable value. [2] (d) Kuljit Singh included the inventory at cost price in his financial statements for each of the years ended 31 July 2010 and 31 July 2011. Complete the table below to show the effect of this on each of the following items. The first one has been completed as an example. overstated understated no effect $ $ (i) net profit for the year ended 31 July 2010 ✓ 250 - - - (ii) capital employed at 31 July 2010 (iii) gross profit for the year ended 31 July 2011 (iv) current assets at 31 July 2011 [6] [Total: 23]
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the October/November 2011 question paper for the guidance of teachers 0452 ACCOUNTING 0452/22 Paper 2, maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes must be read in conjunction with the question papers and the report on the examination. • Cambridge will not enter into discussions or correspondence in connection with these mark schemes. Cambridge is publishing the mark schemes for the October/November 2011 question papers for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses.
Mark scheme, page 2
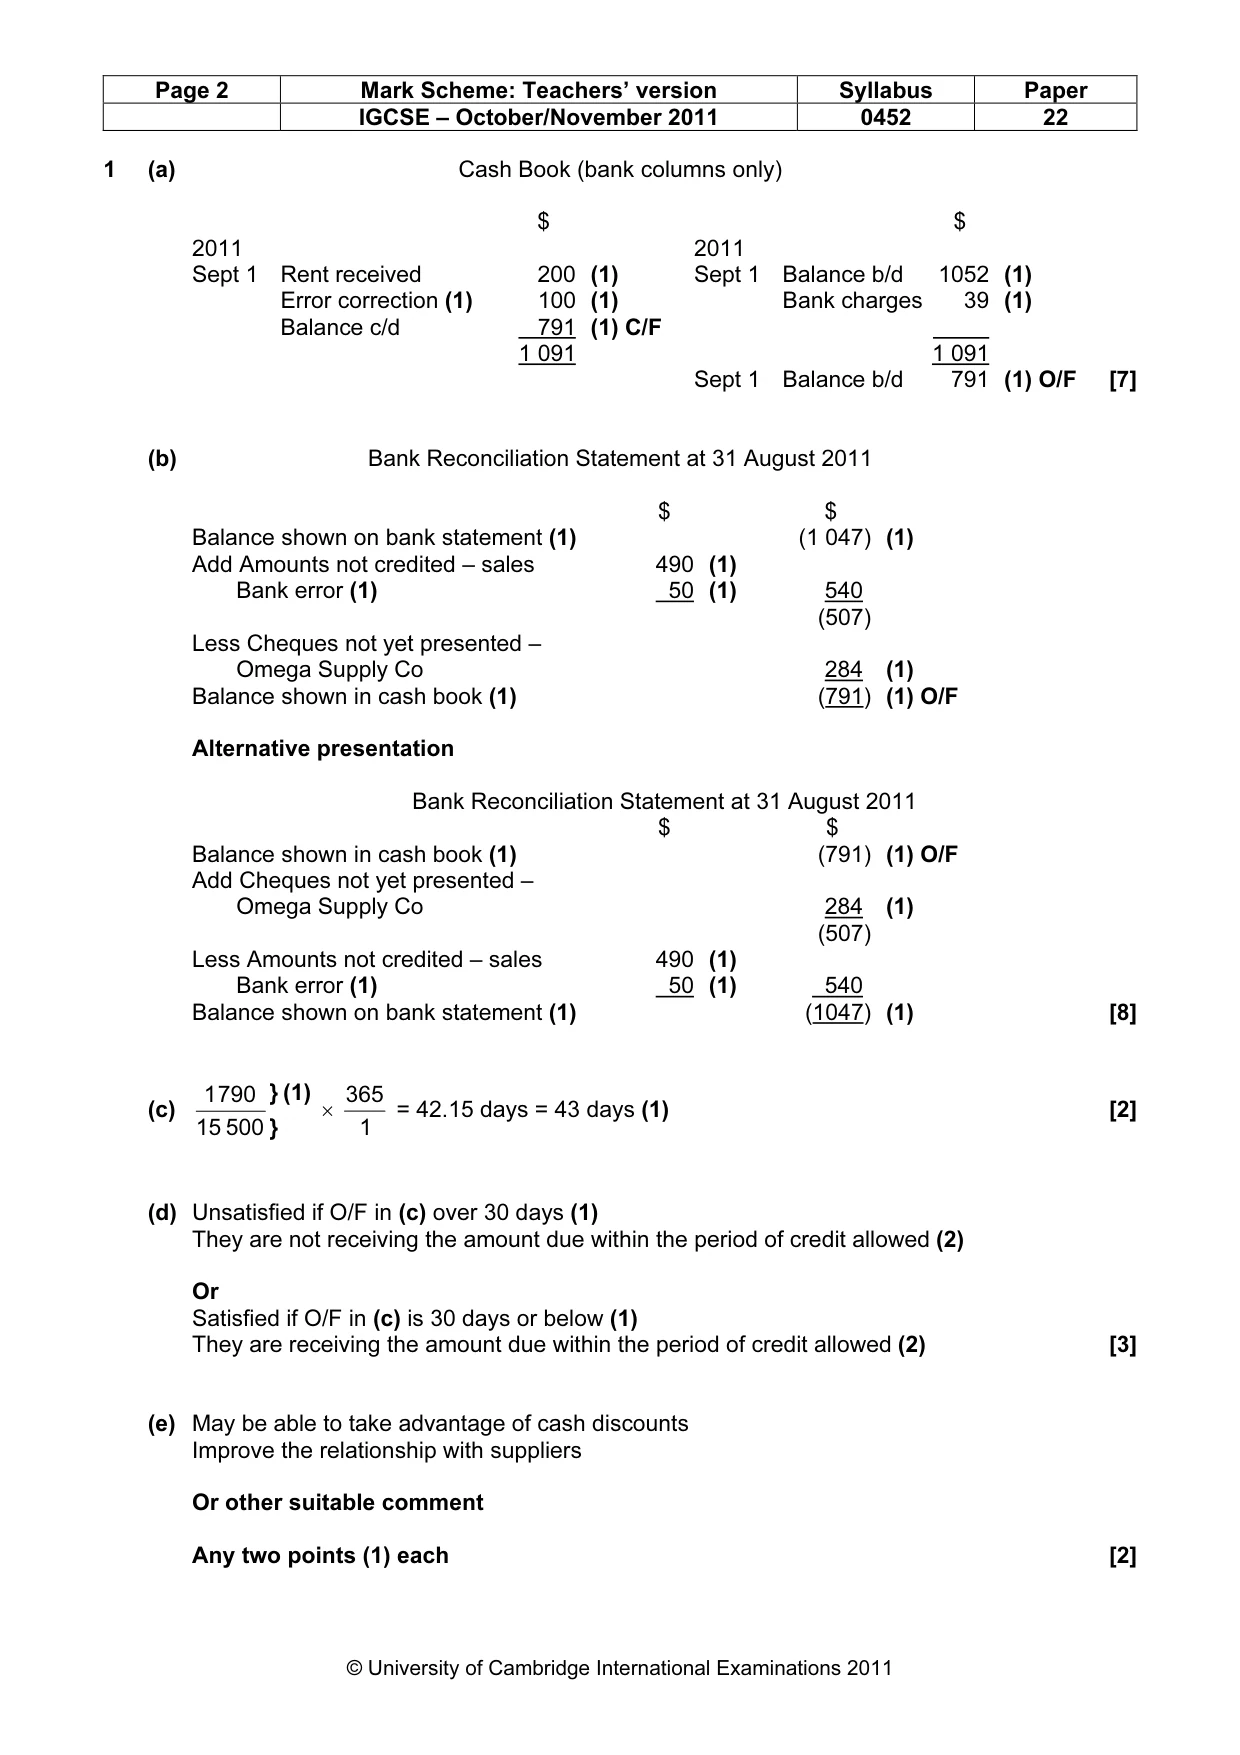
Page 2 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 1 (a) Cash Book (bank columns only) $ $ 2011 2011 Sept 1 Rent received 200 (1) Sept 1 Balance b/d 1052 (1) Error correction (1) 100 (1) Bank charges 39 (1) Balance c/d 791 (1) C/F 1 091 1 091 Sept 1 Balance b/d 791 (1) O/F [7] (b) Bank Reconciliation Statement at 31 August 2011 $ $ Balance shown on bank statement (1) (1 047) (1) Add Amounts not credited – sales 490 (1) Bank error (1) 50 (1) 540 (507) Less Cheques not yet presented – Omega Supply Co 284 (1) Balance shown in cash book (1) (791) (1) O/F Alternative presentation Bank Reconciliation Statement at 31 August 2011 $ $ Balance shown in cash book (1) (791) (1) O/F Add Cheques not yet presented – Omega Supply Co 284 (1) (507) Less Amounts not credited – sales 490 (1) Bank error (1) 50 (1) 540 Balance shown on bank statement (1) (1047) (1) [8] (c) } (1) } 500 15 790 1 × 1 365 = 42.15 days = 43 days (1) [2] (d) Unsatisfied if O/F in (c) over 30 days (1) They are not receiving the amount due within the period of credit allowed (2) Or Satisfied if O/F in (c) is 30 days or below (1) They are receiving the amount due within the period of credit allowed (2) [3] (e) May be able to take advantage of cash discounts Improve the relationship with suppliers Or other suitable comment Any two points (1) each [2]
Mark scheme, page 3
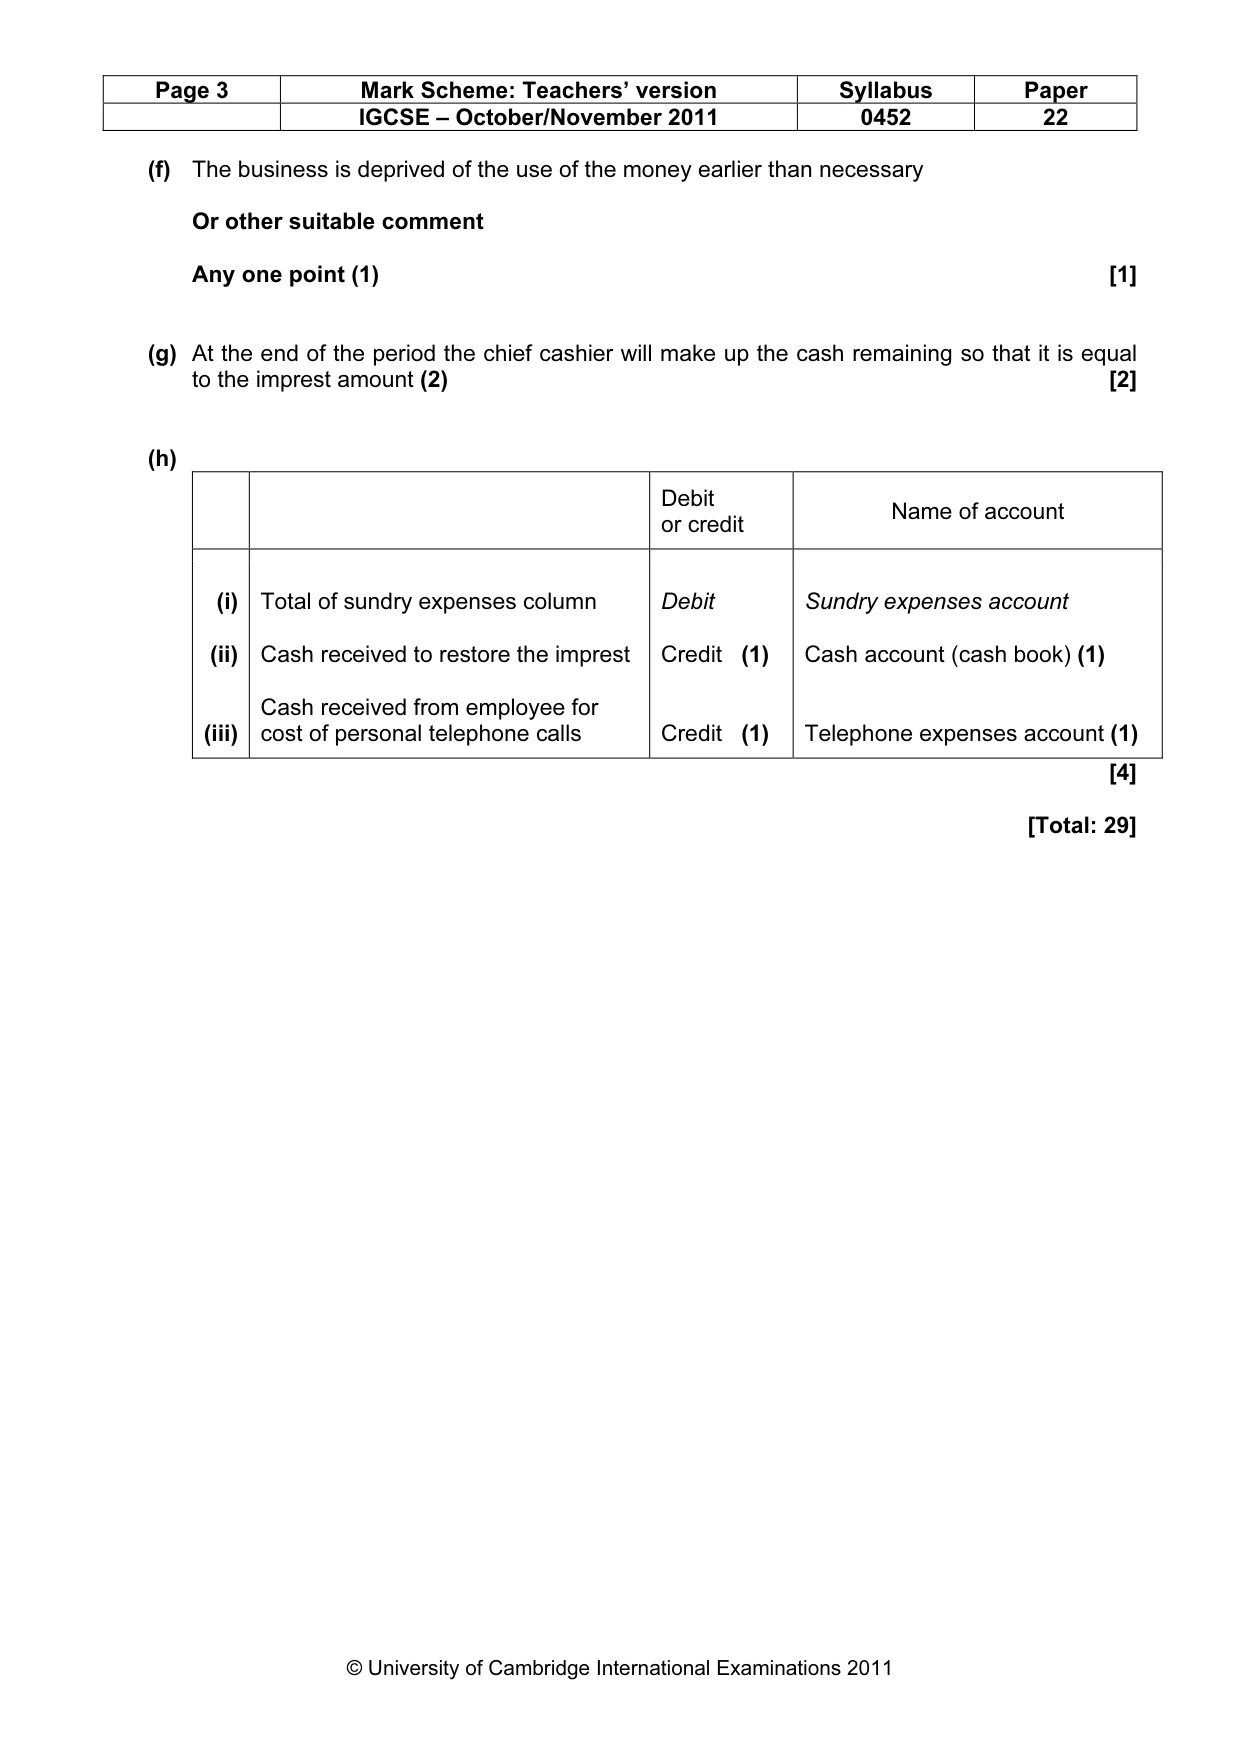
Page 3 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 (f) The business is deprived of the use of the money earlier than necessary Or other suitable comment Any one point (1) [1] (g) At the end of the period the chief cashier will make up the cash remaining so that it is equal to the imprest amount (2) [2] (h) Debit or credit Name of account (i) (ii) (iii) Total of sundry expenses column Cash received to restore the imprest Cash received from employee for cost of personal telephone calls Debit Credit (1) Credit (1) Sundry expenses account Cash account (cash book) (1) Telephone expenses account (1) [4] [Total: 29]
Mark scheme, page 4
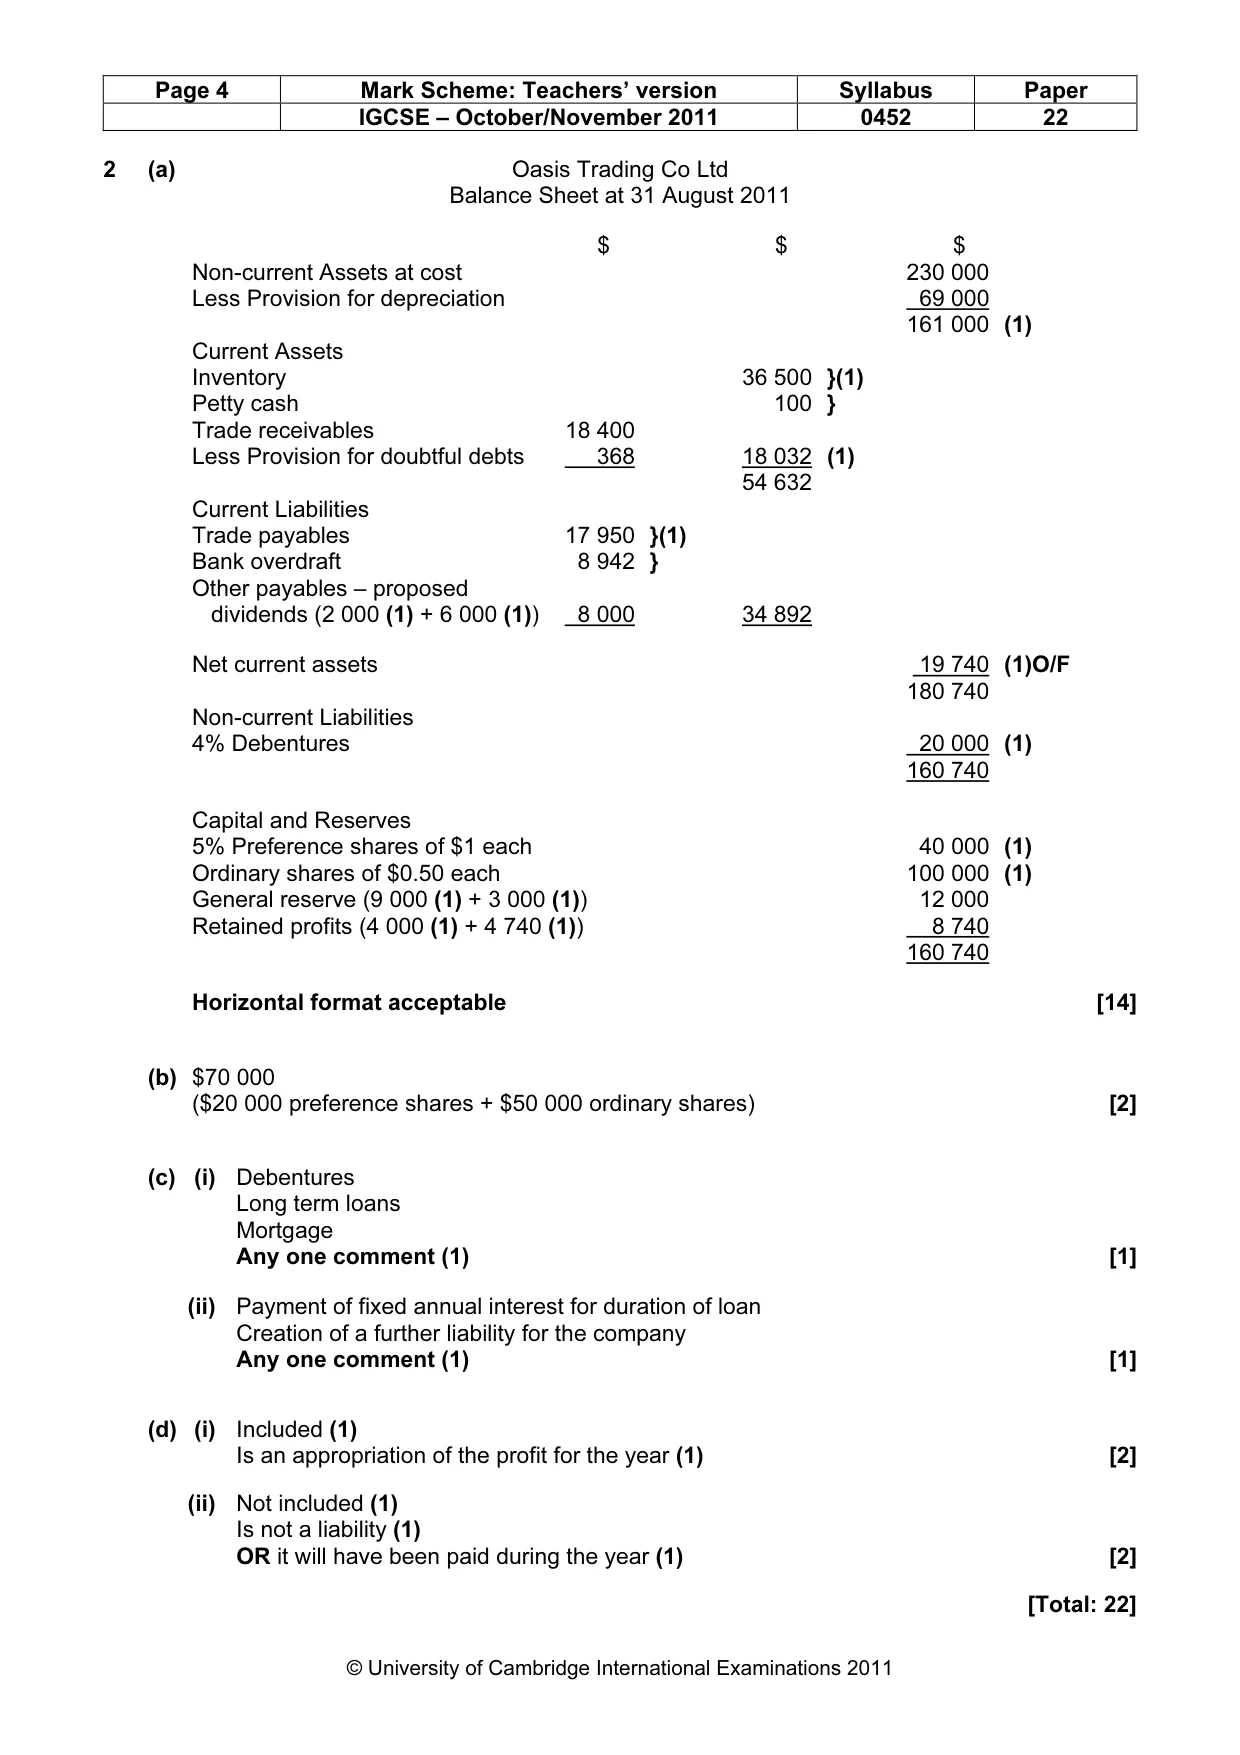
Page 4 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 2 (a) Oasis Trading Co Ltd Balance Sheet at 31 August 2011 $ $ $ Non-current Assets at cost 230 000 Less Provision for depreciation 69 000 161 000 (1) Current Assets Inventory 36 500 }(1) Petty cash 100 } Trade receivables 18 400 Less Provision for doubtful debts 368 18 032 (1) 54 632 Current Liabilities Trade payables 17 950 }(1) Bank overdraft 8 942 } Other payables – proposed dividends (2 000 (1) + 6 000 (1)) 8 000 34 892 Net current assets 19 740 (1)O/F 180 740 Non-current Liabilities 4% Debentures 20 000 (1) 160 740 Capital and Reserves 5% Preference shares of $1 each 40 000 (1) Ordinary shares of $0.50 each 100 000 (1) General reserve (9 000 (1) + 3 000 (1)) 12 000 Retained profits (4 000 (1) + 4 740 (1)) 8 740 160 740 Horizontal format acceptable [14] (b) $70 000 ($20 000 preference shares + $50 000 ordinary shares) [2] (c) (i) Debentures Long term loans Mortgage Any one comment (1) [1] (ii) Payment of fixed annual interest for duration of loan Creation of a further liability for the company Any one comment (1) [1] (d) (i) Included (1) Is an appropriation of the profit for the year (1) [2] (ii) Not included (1) Is not a liability (1) OR it will have been paid during the year (1) [2] [Total: 22]
Mark scheme, page 5
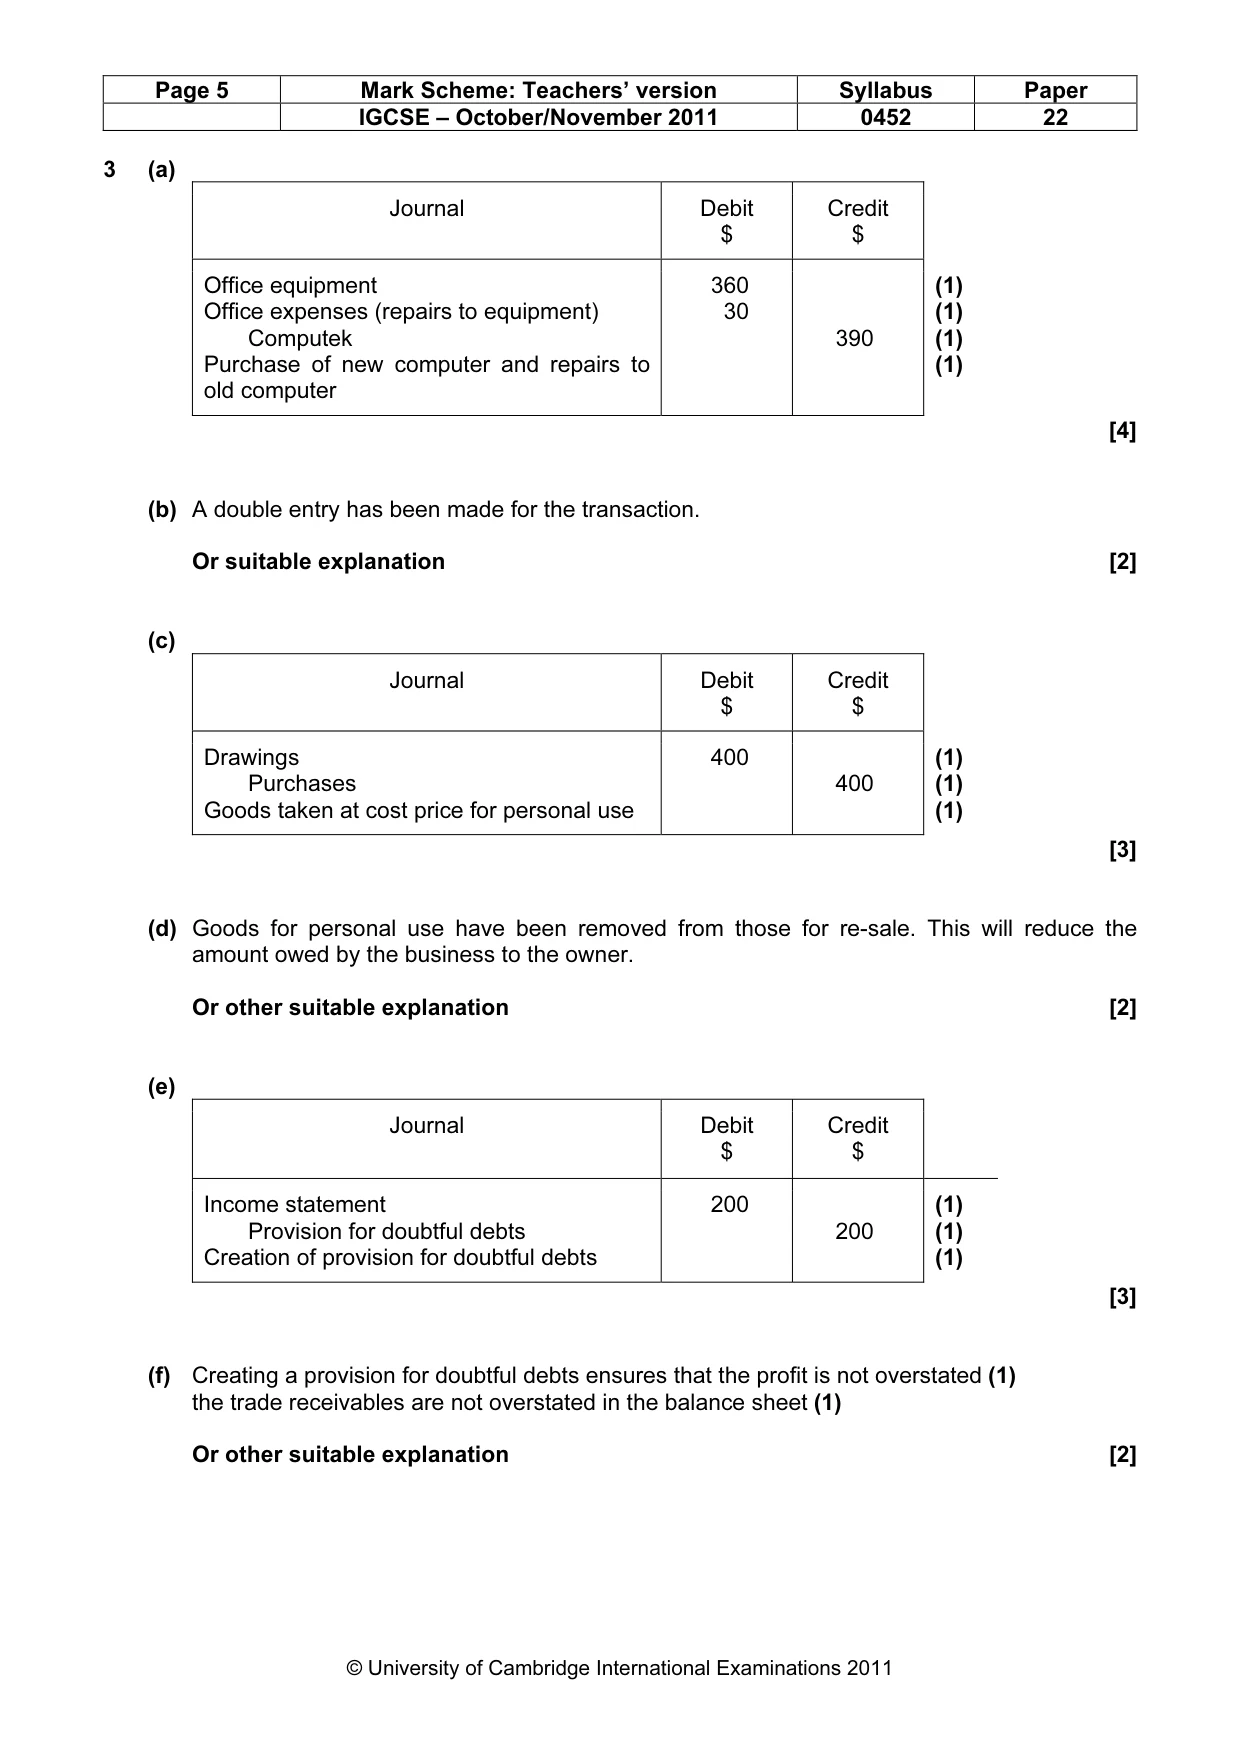
Page 5 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 3 (a) Journal Debit $ Credit $ Office equipment Office expenses (repairs to equipment) Computek Purchase of new computer and repairs to old computer 360 30 390 (1) (1) (1) (1) [4] (b) A double entry has been made for the transaction. Or suitable explanation [2] (c) Journal Debit $ Credit $ Drawings Purchases Goods taken at cost price for personal use 400 400 (1) (1) (1) [3] (d) Goods for personal use have been removed from those for re-sale. This will reduce the amount owed by the business to the owner. Or other suitable explanation [2] (e) Journal Debit $ Credit $ Income statement Provision for doubtful debts Creation of provision for doubtful debts 200 200 (1) (1) (1) [3] (f) Creating a provision for doubtful debts ensures that the profit is not overstated (1) the trade receivables are not overstated in the balance sheet (1) Or other suitable explanation [2]
Mark scheme, page 6
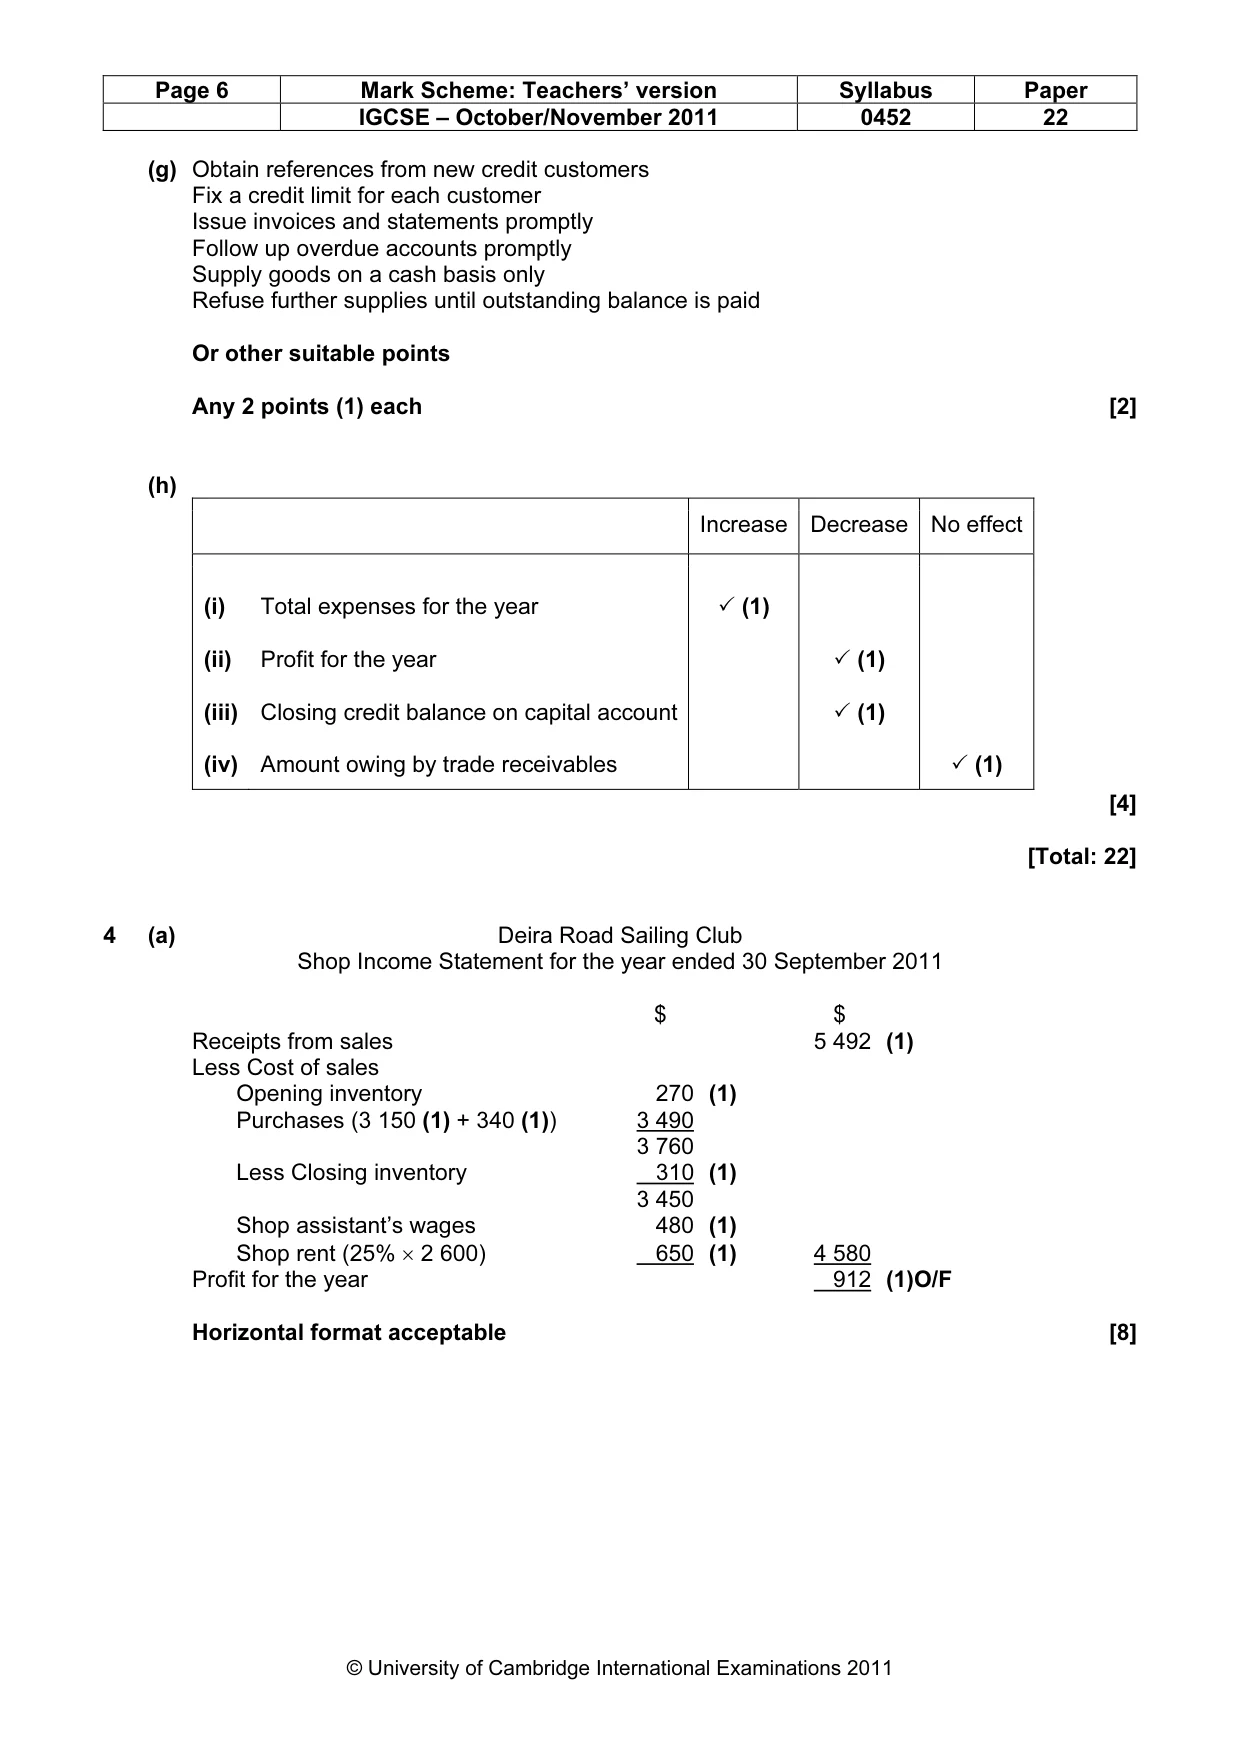
Page 6 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 (g) Obtain references from new credit customers Fix a credit limit for each customer Issue invoices and statements promptly Follow up overdue accounts promptly Supply goods on a cash basis only Refuse further supplies until outstanding balance is paid Or other suitable points Any 2 points (1) each [2] (h) Increase Decrease No effect (i) (ii) (iii) (iv) Total expenses for the year Profit for the year Closing credit balance on capital account Amount owing by trade receivables ✓ (1) ✓ (1) ✓ (1) ✓ (1) [4] [Total: 22] 4 (a) Deira Road Sailing Club Shop Income Statement for the year ended 30 September 2011 $ $ Receipts from sales 5 492 (1) Less Cost of sales Opening inventory 270 (1) Purchases (3 150 (1) + 340 (1)) 3 490 3 760 Less Closing inventory 310 (1) 3 450 Shop assistant’s wages 480 (1) Shop rent (25% × 2 600) 650 (1) 4 580 Profit for the year 912 (1)O/F Horizontal format acceptable [8]
Mark scheme, page 7
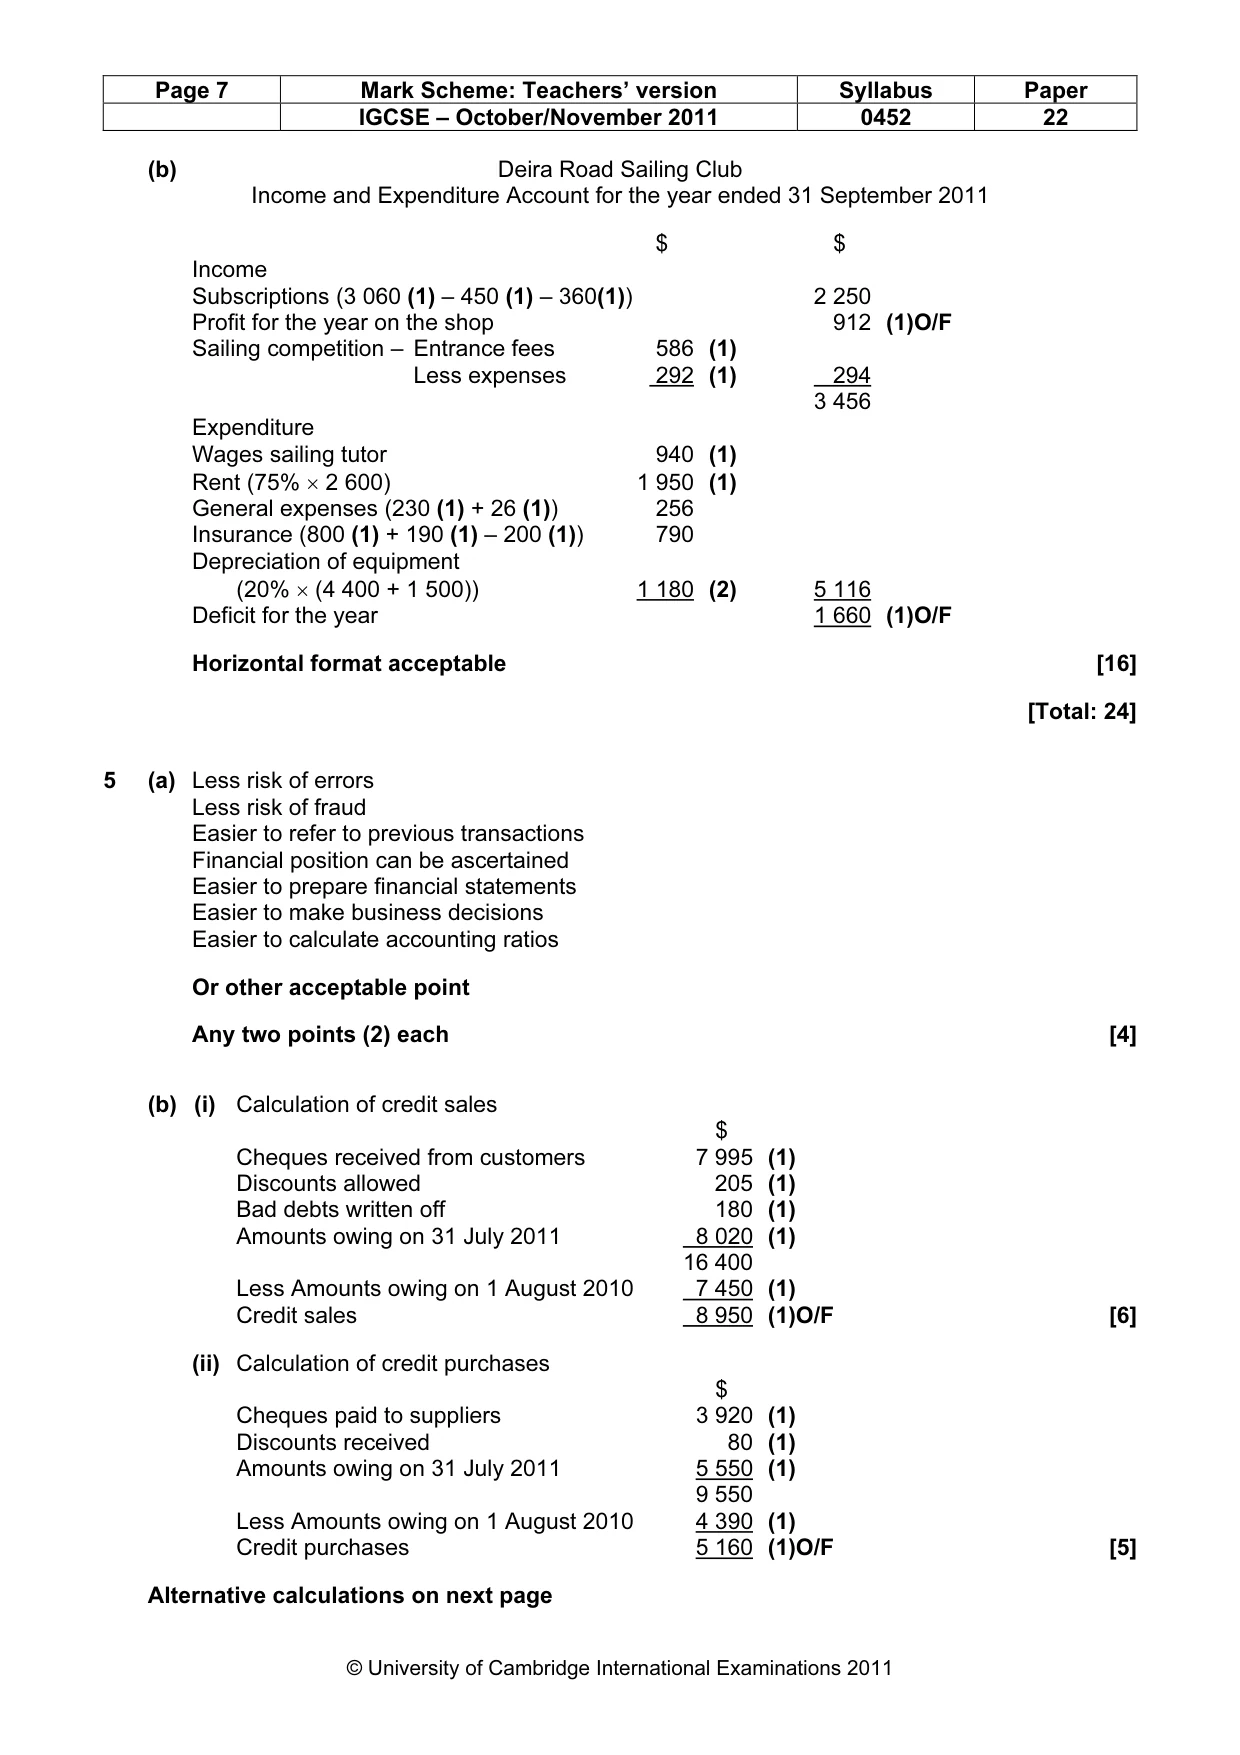
Page 7 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 (b) Deira Road Sailing Club Income and Expenditure Account for the year ended 31 September 2011 $ $ Income Subscriptions (3 060 (1) – 450 (1) – 360(1)) 2 250 Profit for the year on the shop 912 (1)O/F Sailing competition – Entrance fees 586 (1) Less expenses 292 (1) 294 3 456 Expenditure Wages sailing tutor 940 (1) Rent (75% × 2 600) 1 950 (1) General expenses (230 (1) + 26 (1)) 256 Insurance (800 (1) + 190 (1) – 200 (1)) 790 Depreciation of equipment (20% × (4 400 + 1 500)) 1 180 (2) 5 116 Deficit for the year 1 660 (1)O/F Horizontal format acceptable [16] [Total: 24] 5 (a) Less risk of errors Less risk of fraud Easier to refer to previous transactions Financial position can be ascertained Easier to prepare financial statements Easier to make business decisions Easier to calculate accounting ratios Or other acceptable point Any two points (2) each [4] (b) (i) Calculation of credit sales $ Cheques received from customers 7 995 (1) Discounts allowed 205 (1) Bad debts written off 180 (1) Amounts owing on 31 July 2011 8 020 (1) 16 400 Less Amounts owing on 1 August 2010 7 450 (1) Credit sales 8 950 (1)O/F [6] (ii) Calculation of credit purchases $ Cheques paid to suppliers 3 920 (1) Discounts received 80 (1) Amounts owing on 31 July 2011 5 550 (1) 9 550 Less Amounts owing on 1 August 2010 4 390 (1) Credit purchases 5 160 (1)O/F [5] Alternative calculations on next page
Mark scheme, page 8
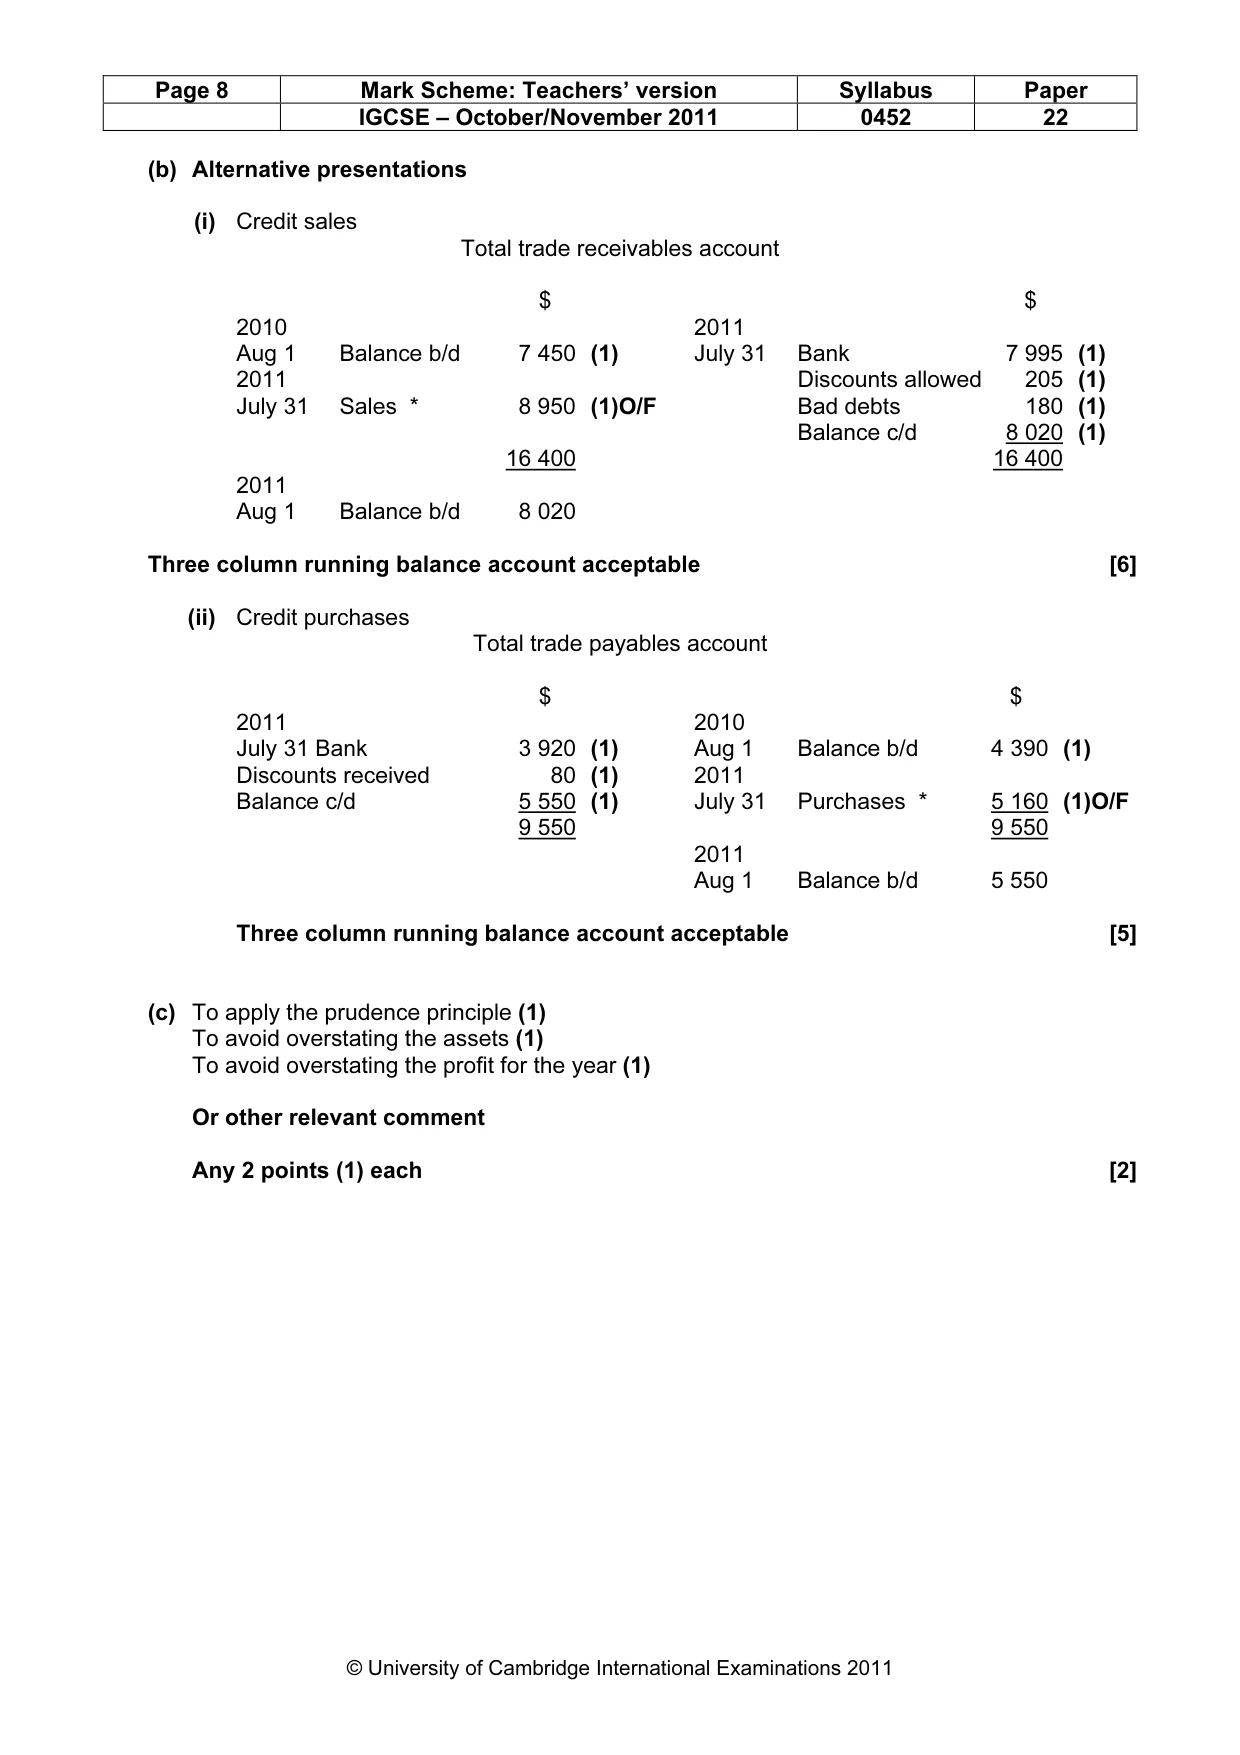
Page 8 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 (b) Alternative presentations (i) Credit sales Total trade receivables account $ $ 2010 2011 Aug 1 Balance b/d 7 450 (1) July 31 Bank 7 995 (1) 2011 Discounts allowed 205 (1) July 31 Sales * 8 950 (1)O/F Bad debts 180 (1) Balance c/d 8 020 (1) 16 400 16 400 2011 Aug 1 Balance b/d 8 020 Three column running balance account acceptable [6] (ii) Credit purchases Total trade payables account $ $ 2011 2010 July 31 Bank 3 920 (1) Aug 1 Balance b/d 4 390 (1) Discounts received 80 (1) 2011 Balance c/d 5 550 (1) July 31 Purchases * 5 160 (1)O/F 9 550 9 550 2011 Aug 1 Balance b/d 5 550 Three column running balance account acceptable [5] (c) To apply the prudence principle (1) To avoid overstating the assets (1) To avoid overstating the profit for the year (1) Or other relevant comment Any 2 points (1) each [2]
Mark scheme, page 9
Page 9 Mark Scheme: Teachers’ version Syllabus Paper IGCSE – October/November 2011 0452 22 © University of Cambridge International Examinations 2011 (d) overstated understated no effect (i) (ii) (iii) (iv) net profit for the year ended 31 July 2010 capital employed at 31 July 2010 gross profit for the year ended 31 July 2011 current assets at 31 July 2011 ✓ ✓ (1) $ 250 250 (1) – ✓ (1) $ – 250 (1) – ✓ (2) [6] [Total: 23]
What you needed in this session
Cambridge’s own grade thresholds for 2011 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.