Cambridge IGCSE Accounting 0452 — 2022 Oct/Nov Paper 2 · Variant 1
0452/21/O/N/22 · 6 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme18 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Anika owns property which she rents out to university students
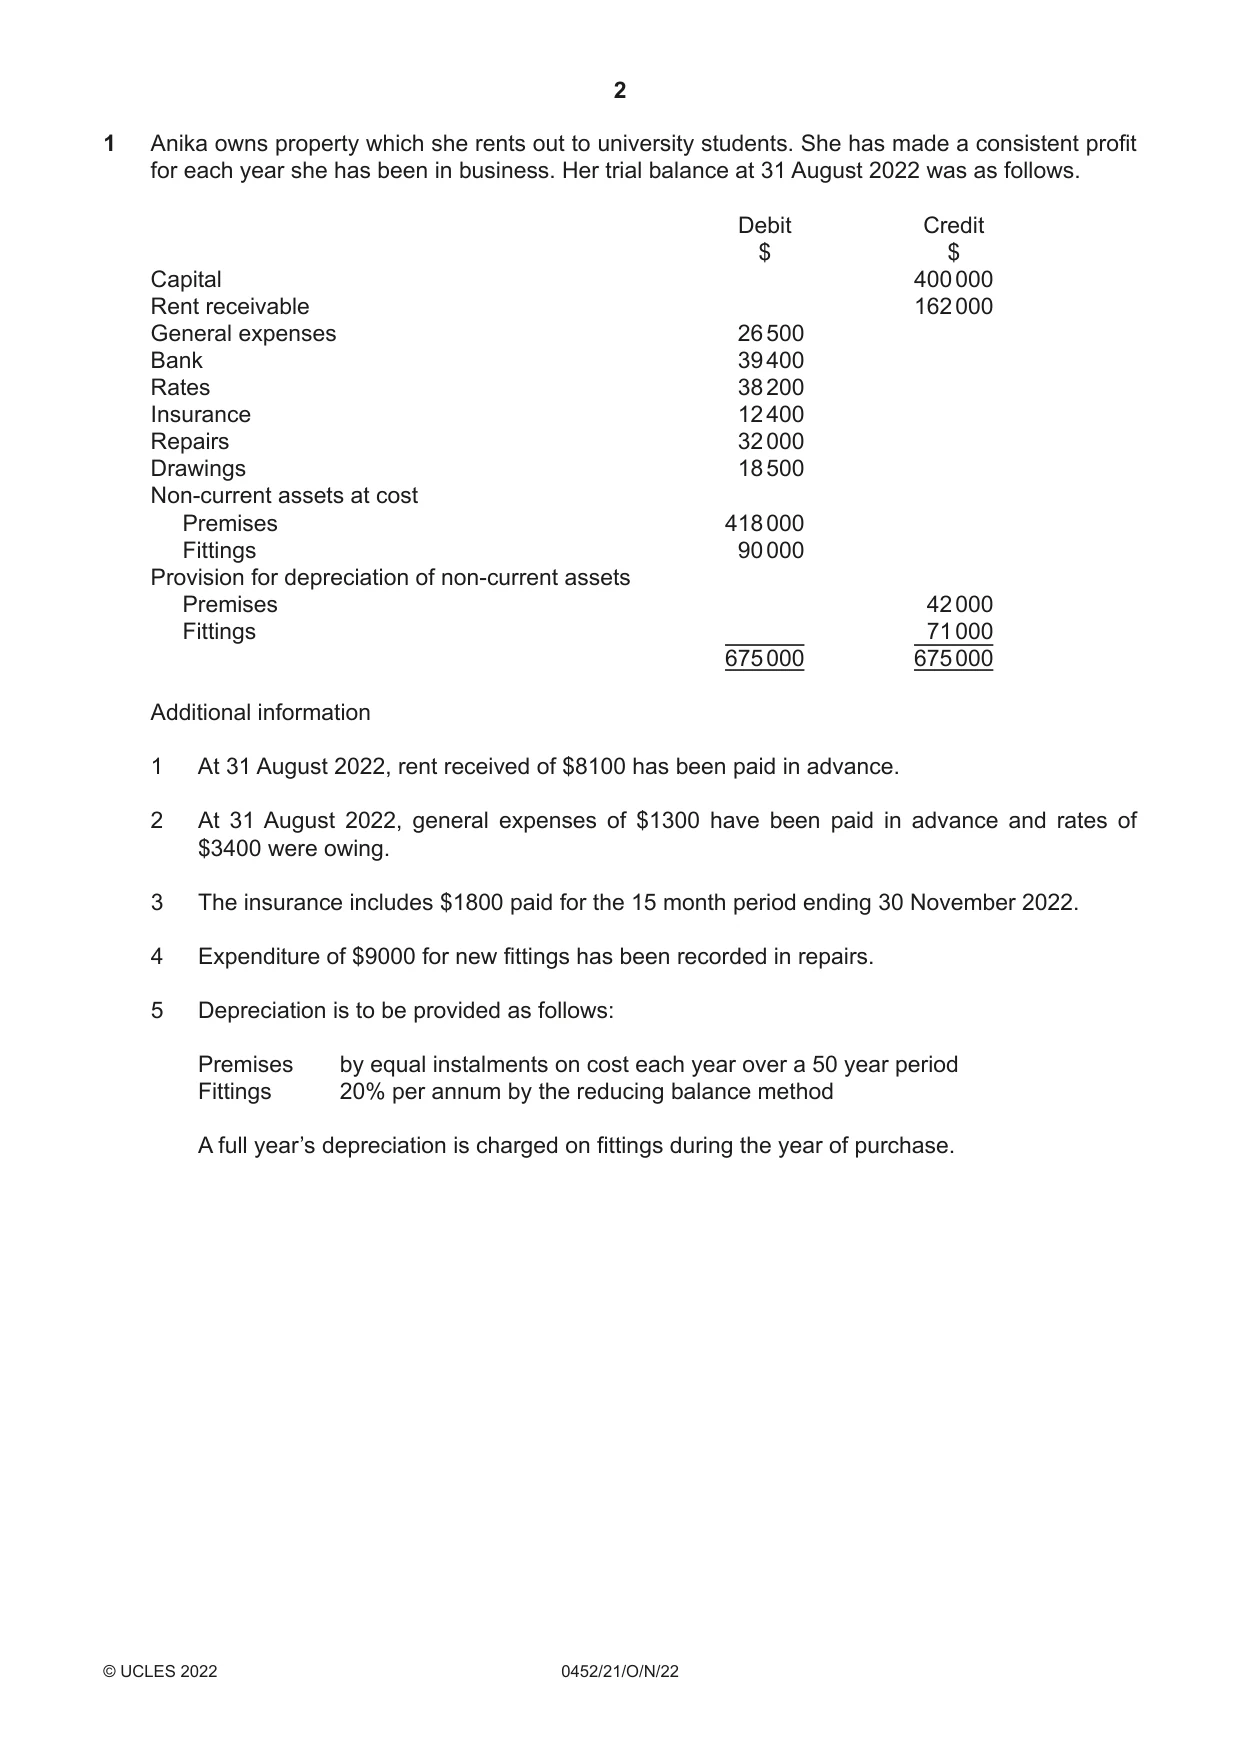
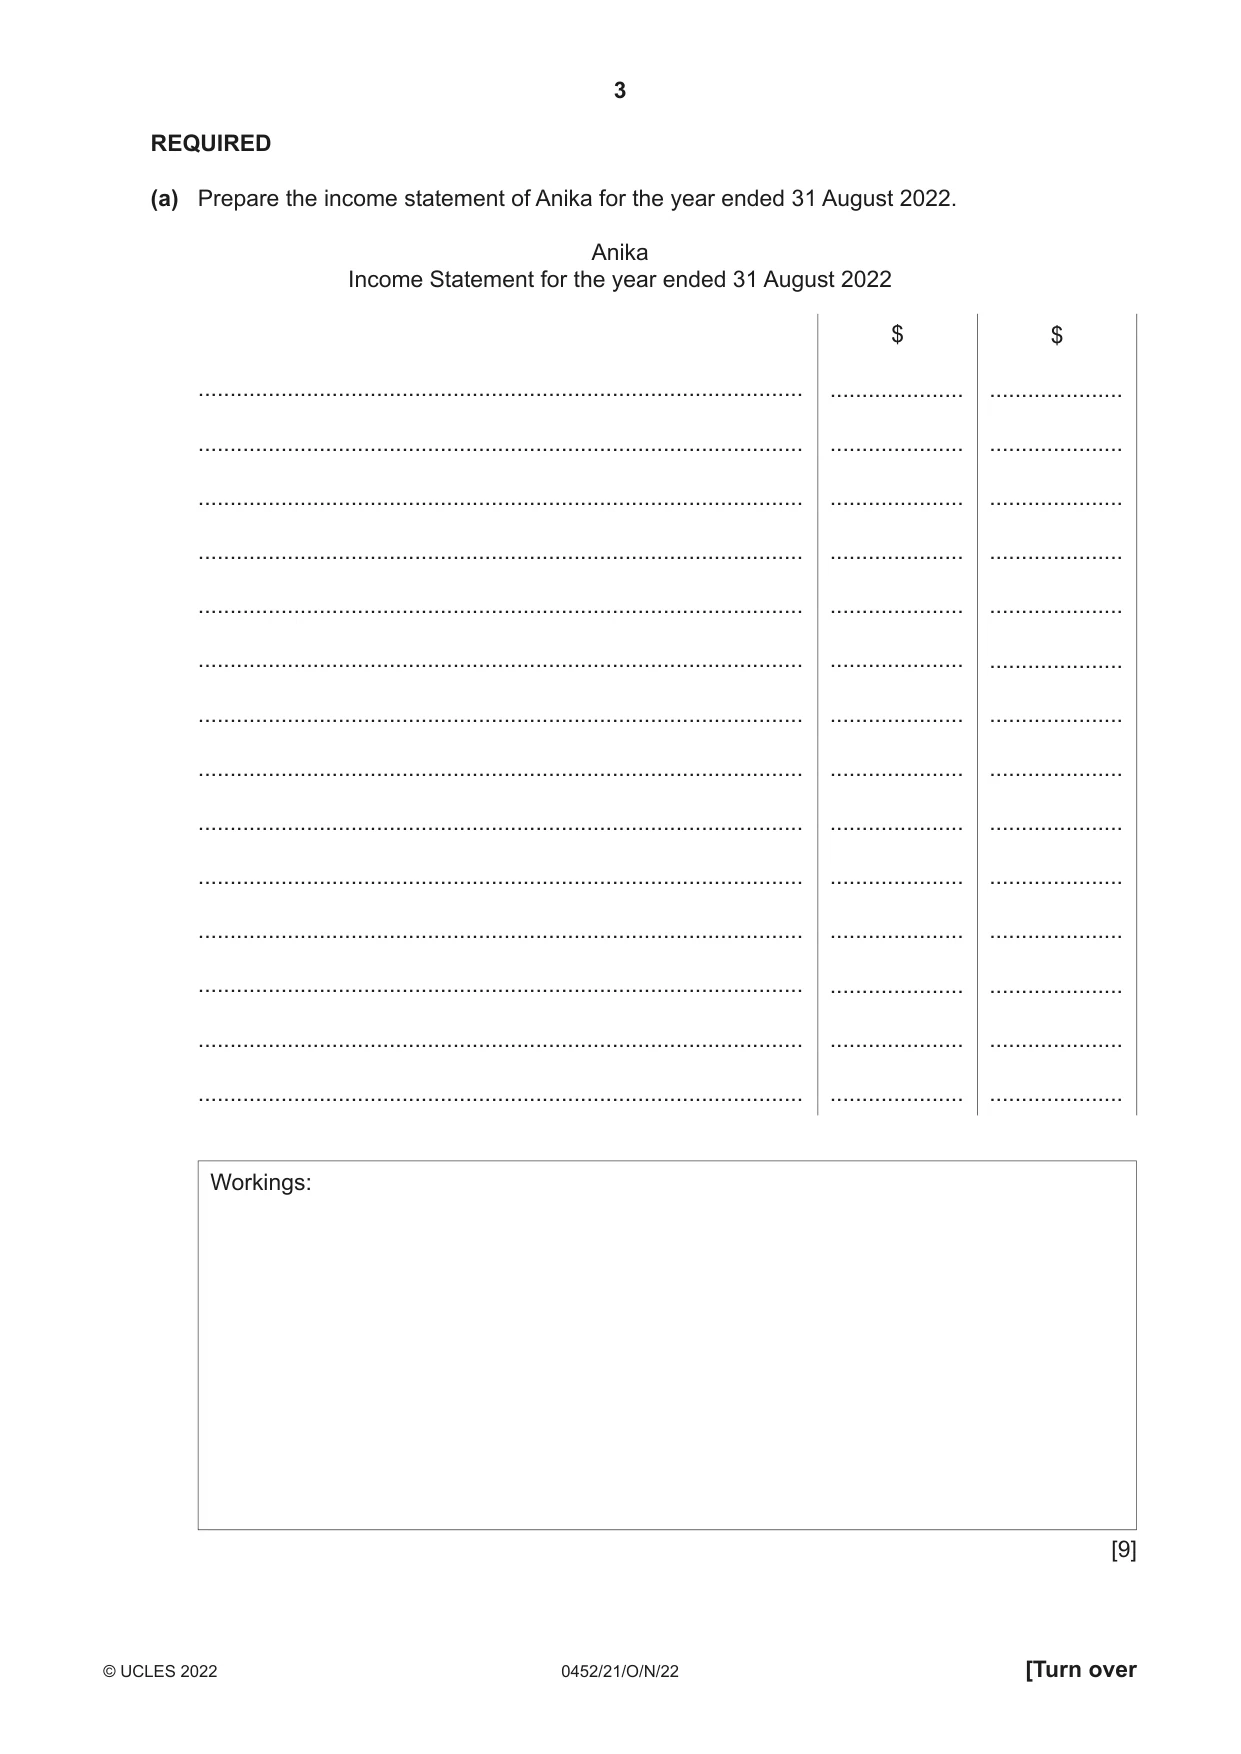
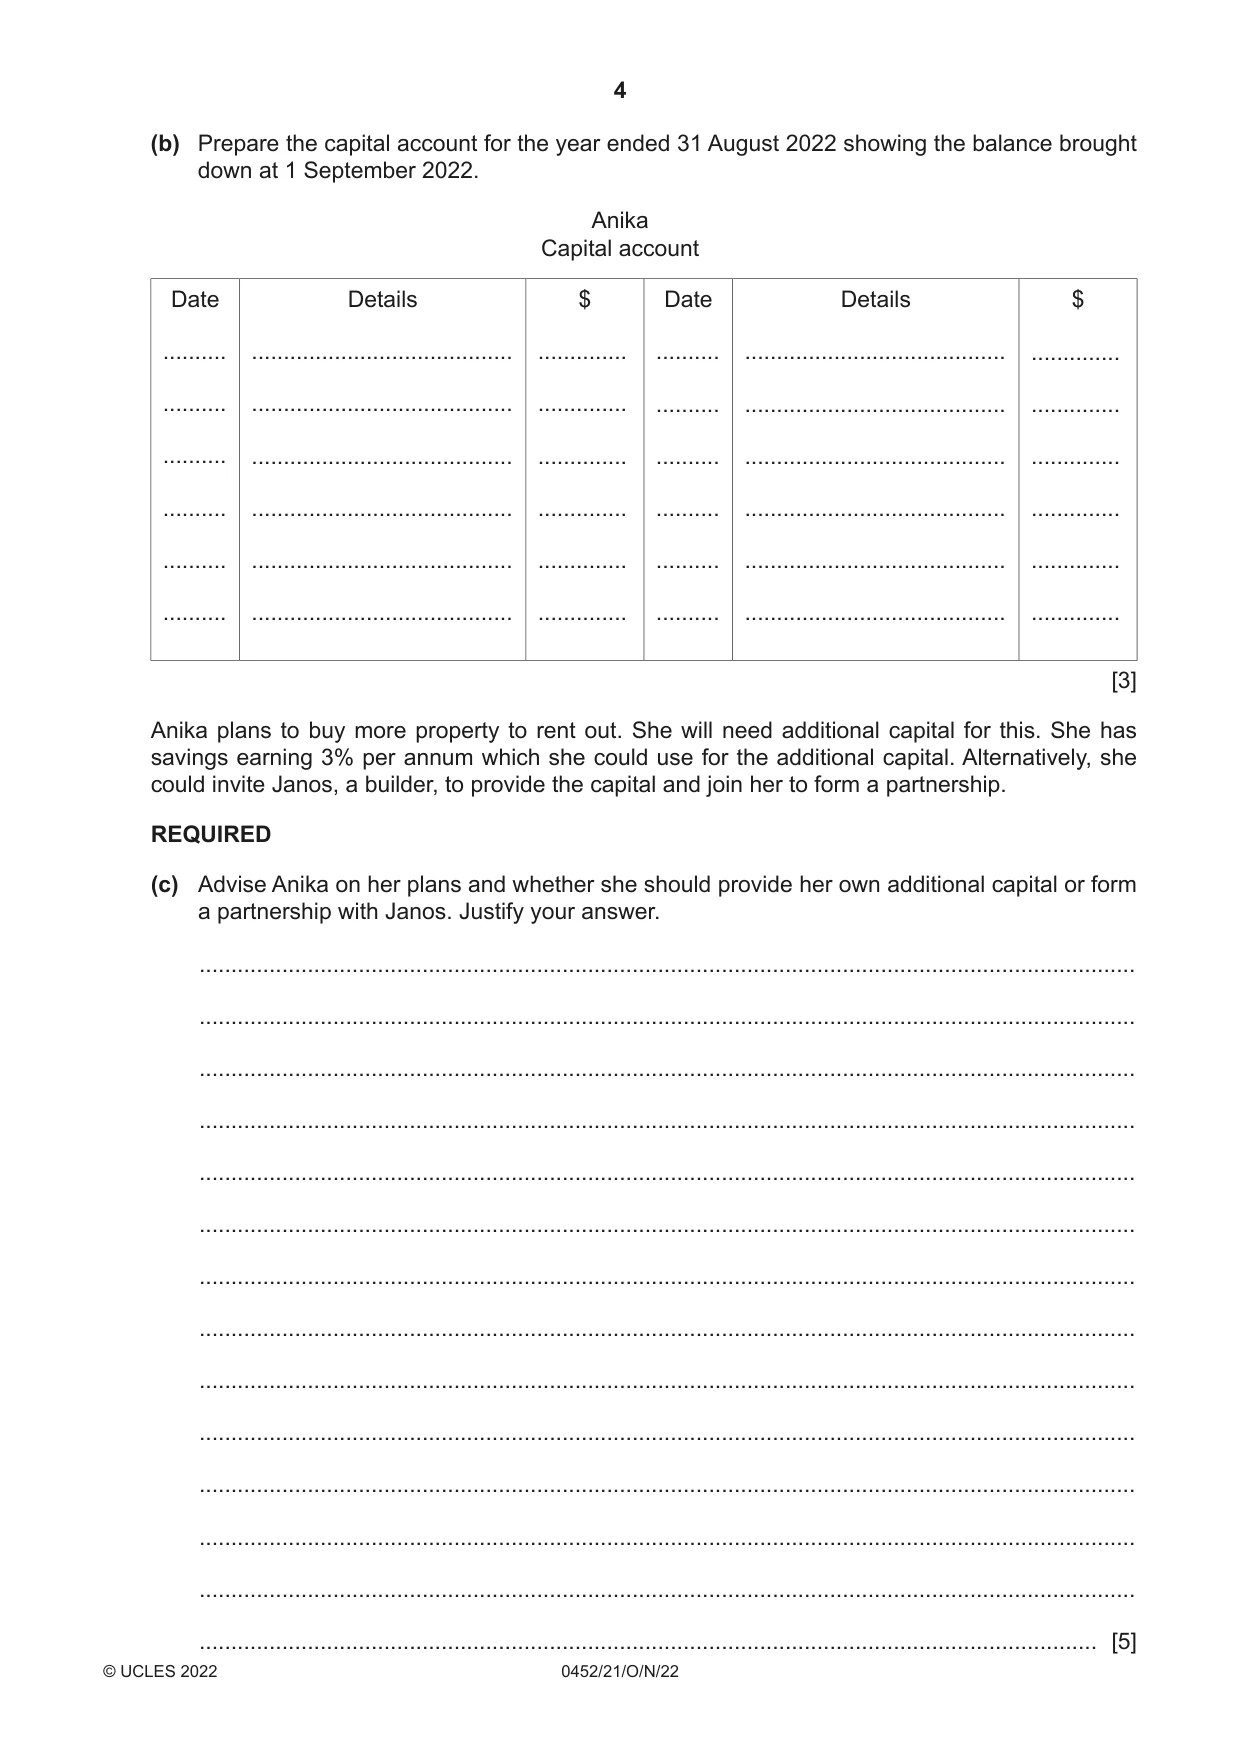
1 Anika owns property which she rents out to university students. She has made a consistent profit for each year she has been in business. Her trial balance at 31 August 2022 was as follows. Debit Credit $ $ Capital 400 000 Rent receivable 162 000 General expenses 26 500 Bank 39 400 Rates 38 200 Insurance 12 400 Repairs 32 000 Drawings 18 500 Non-current assets at cost Premises 418 000 Fittings 90 000 Provision for depreciation of non-current assets Premises 42 000 Fittings 71 000 675 000 675 000 Additional information 1 At 31 August 2022, rent received of $8100 has been paid in advance. 2 At 31 August 2022, general expenses of $1300 have been paid in advance and rates of $3400 were owing. 3 The insurance includes $1800 paid for the 15 month period ending 30 November 2022. 4 Expenditure of $9000 for new fittings has been recorded in repairs. 5 Depreciation is to be provided as follows: Premises by equal instalments on cost each year over a 50 year period Fittings 20% per annum by the reducing balance method A full year’s depreciation is charged on fittings during the year of purchase. REQUIRED (a) Prepare the income statement of Anika for the year ended 31 August 2022. Anika Income Statement for the year ended 31 August 2022 $ $ ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... Workings: [9] (b) Prepare the capital account for the year ended 31 August 2022 showing the balance brought down at 1 September 2022. Anika Capital account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [3] Anika plans to buy more property to rent out. She will need additional capital for this. She has savings earning 3% per annum which she could use for the additional capital. Alternatively, she could invite Janos, a builder, to provide the capital and join her to form a partnership. REQUIRED (c) Advise Anika on her plans and whether she should provide her own additional capital or form a partnership with Janos. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) Explain to Anika the difference between capital expenditure and revenue expenditure. Why is this difference between the two important when preparing the financial statements? ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] [Total: 20]
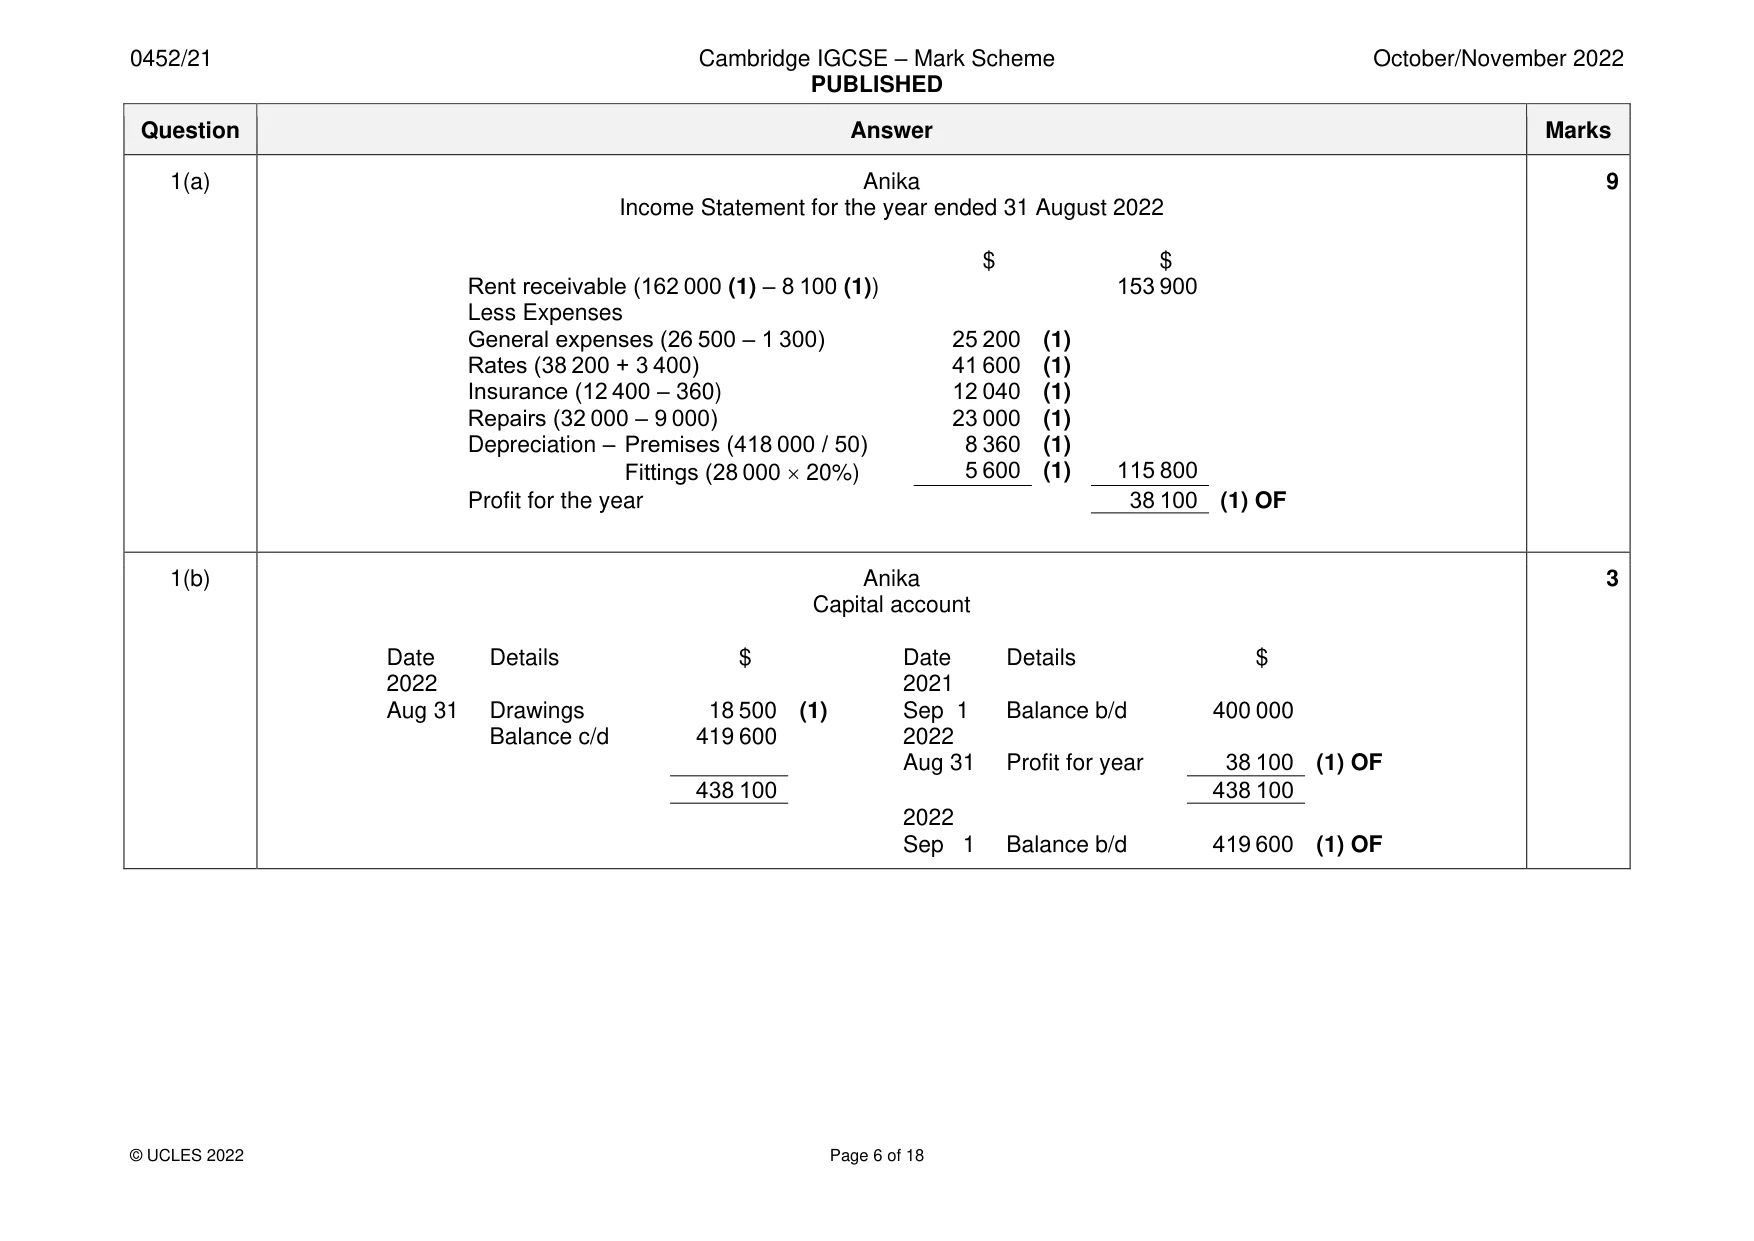
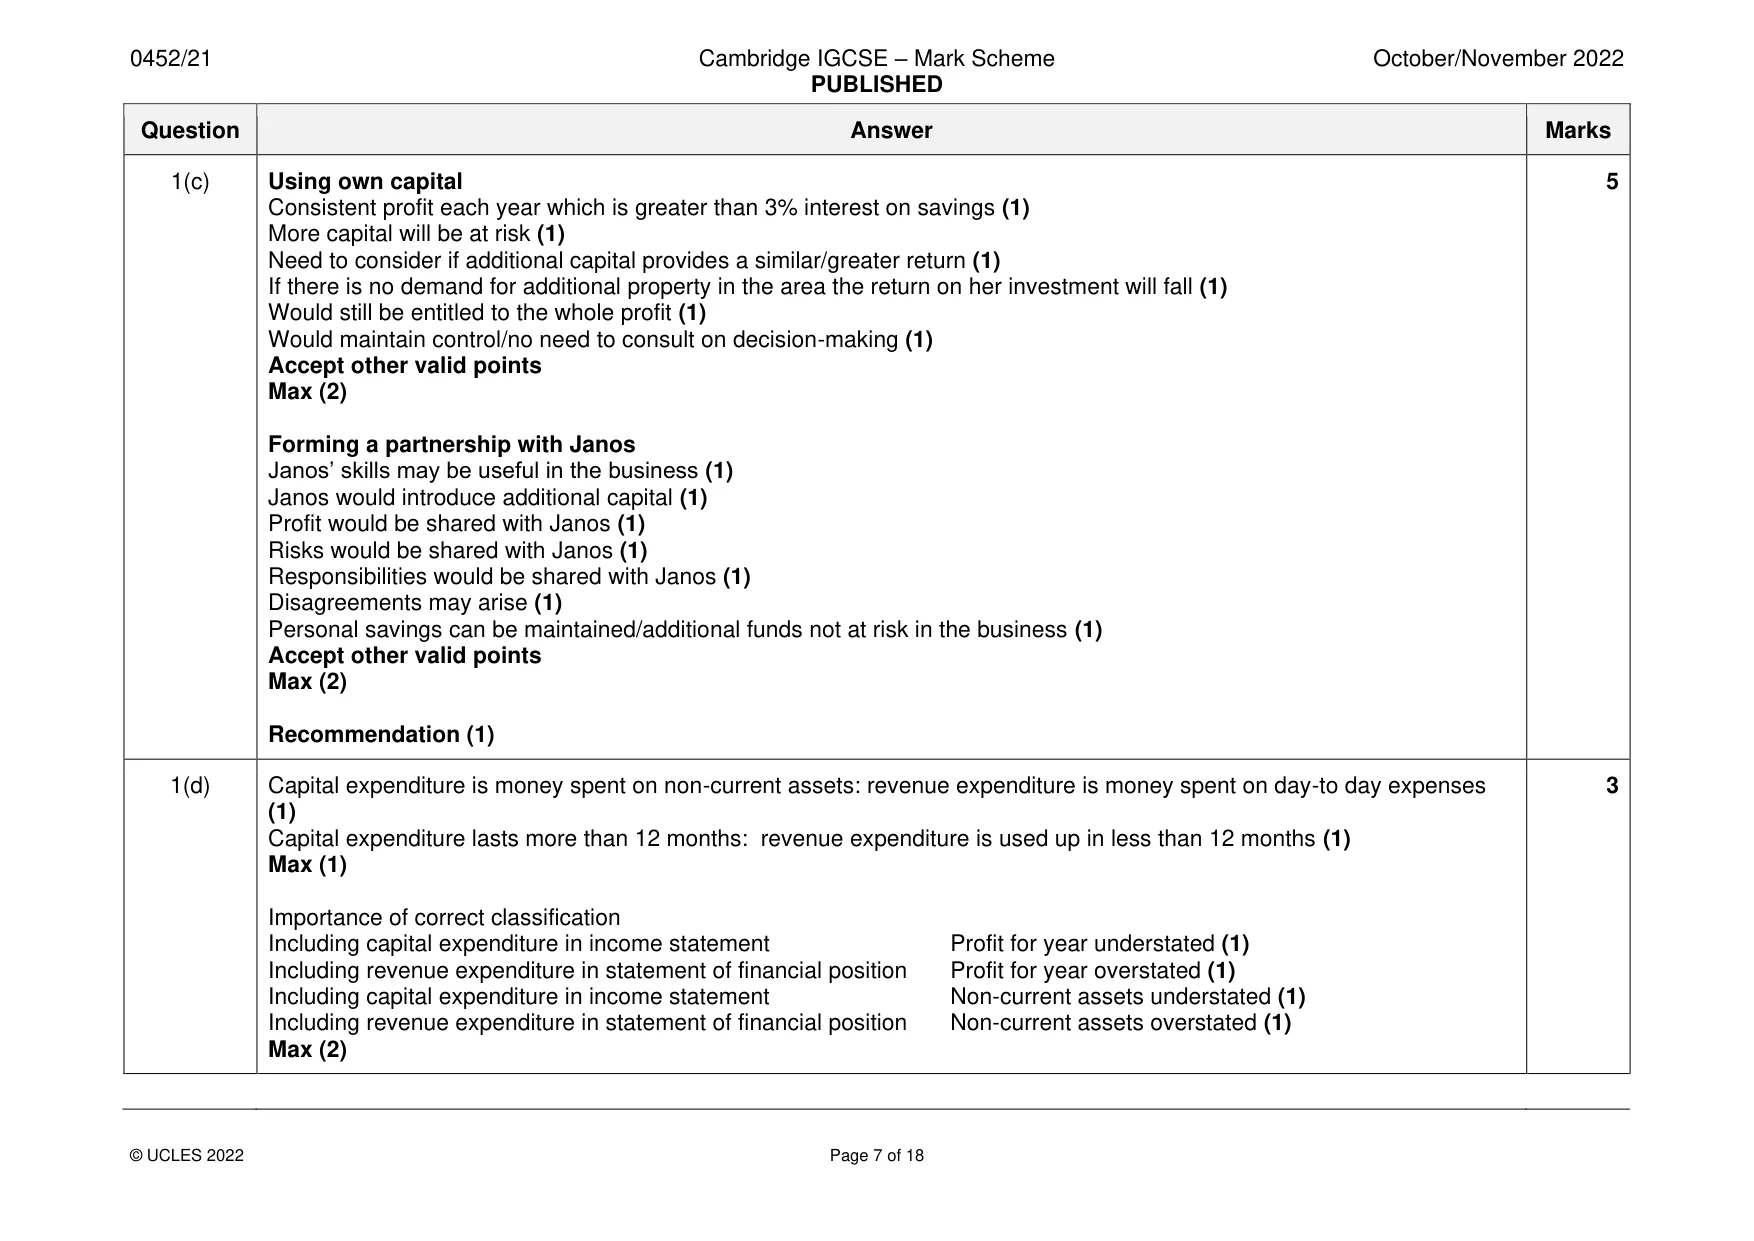
Mark scheme: Question Answer Marks 1(a) Anika 9 Income Statement for the year ended 31 August 2022 $ $ Rent receivable (162 000 (1) – 8 100 (1)) 153 900 Less Expenses General expenses (26 500 – 1 300) 25 200 (1) Rates (38 200 + 3 400) 41 600 (1) Insurance (12 400 – 360) 12 040 (1) Repairs (32 000 – 9 000) 23 000 (1) Depreciation – Premises (418 000 / 50) 8 360 (1) Fittings (28 000 20%) 5 600 (1) 115 800 Profit for the year 38 100 (1) OF 1(b) Anika 3 Capital account Date Details $ Date Details $ 2022 2021 Aug 31 Drawings 18 500 (1) Sep 1 Balance b/d 400 000 Balance c/d 419 600 2022 Aug 31 Profit for year 38 100 (1) OF 438 100 438 100 2022 Sep 1 Balance b/d 419 600 (1) OF 1(c) Using own capital 5 Consistent profit each year which is greater than 3% interest on savings (1) More capital will be at risk (1) Need to consider if additional capital provides a similar/greater return (1) If there is no demand for additional property in the area the return on her investment will fall (1) Would still be entitled to the whole profit (1) Would maintain control/no need to consult on decision-making (1) Accept other valid points Max (2) Forming a partnership with Janos Janos’ skills may be useful in the business (1) Janos would introduce additional capital (1) Profit would be shared with Janos (1) Risks would be shared with Janos (1) Responsibilities would be shared with Janos (1) Disagreements may arise (1) Personal savings can be maintained/additional funds not at risk in the business (1) Accept other valid points Max (2) Recommendation (1) 1(d) Capital expenditure is money spent on non-current assets: revenue expenditure is money spent on day-to day expenses 3 (1) Capital expenditure lasts more than 12 months: revenue expenditure is used up in less than 12 months (1) Max (1) Importance of correct classification Including capital expenditure in income statement Profit for year understated (1) Including revenue expenditure in statement of financial position Profit for year overstated (1) Including capital expenditure in income statement Non-current assets understated (1) Including revenue expenditure in statement of financial position Non-current assets overstated (1) Max (2)
Q2 · Rasheed started a business on 1 October 2021
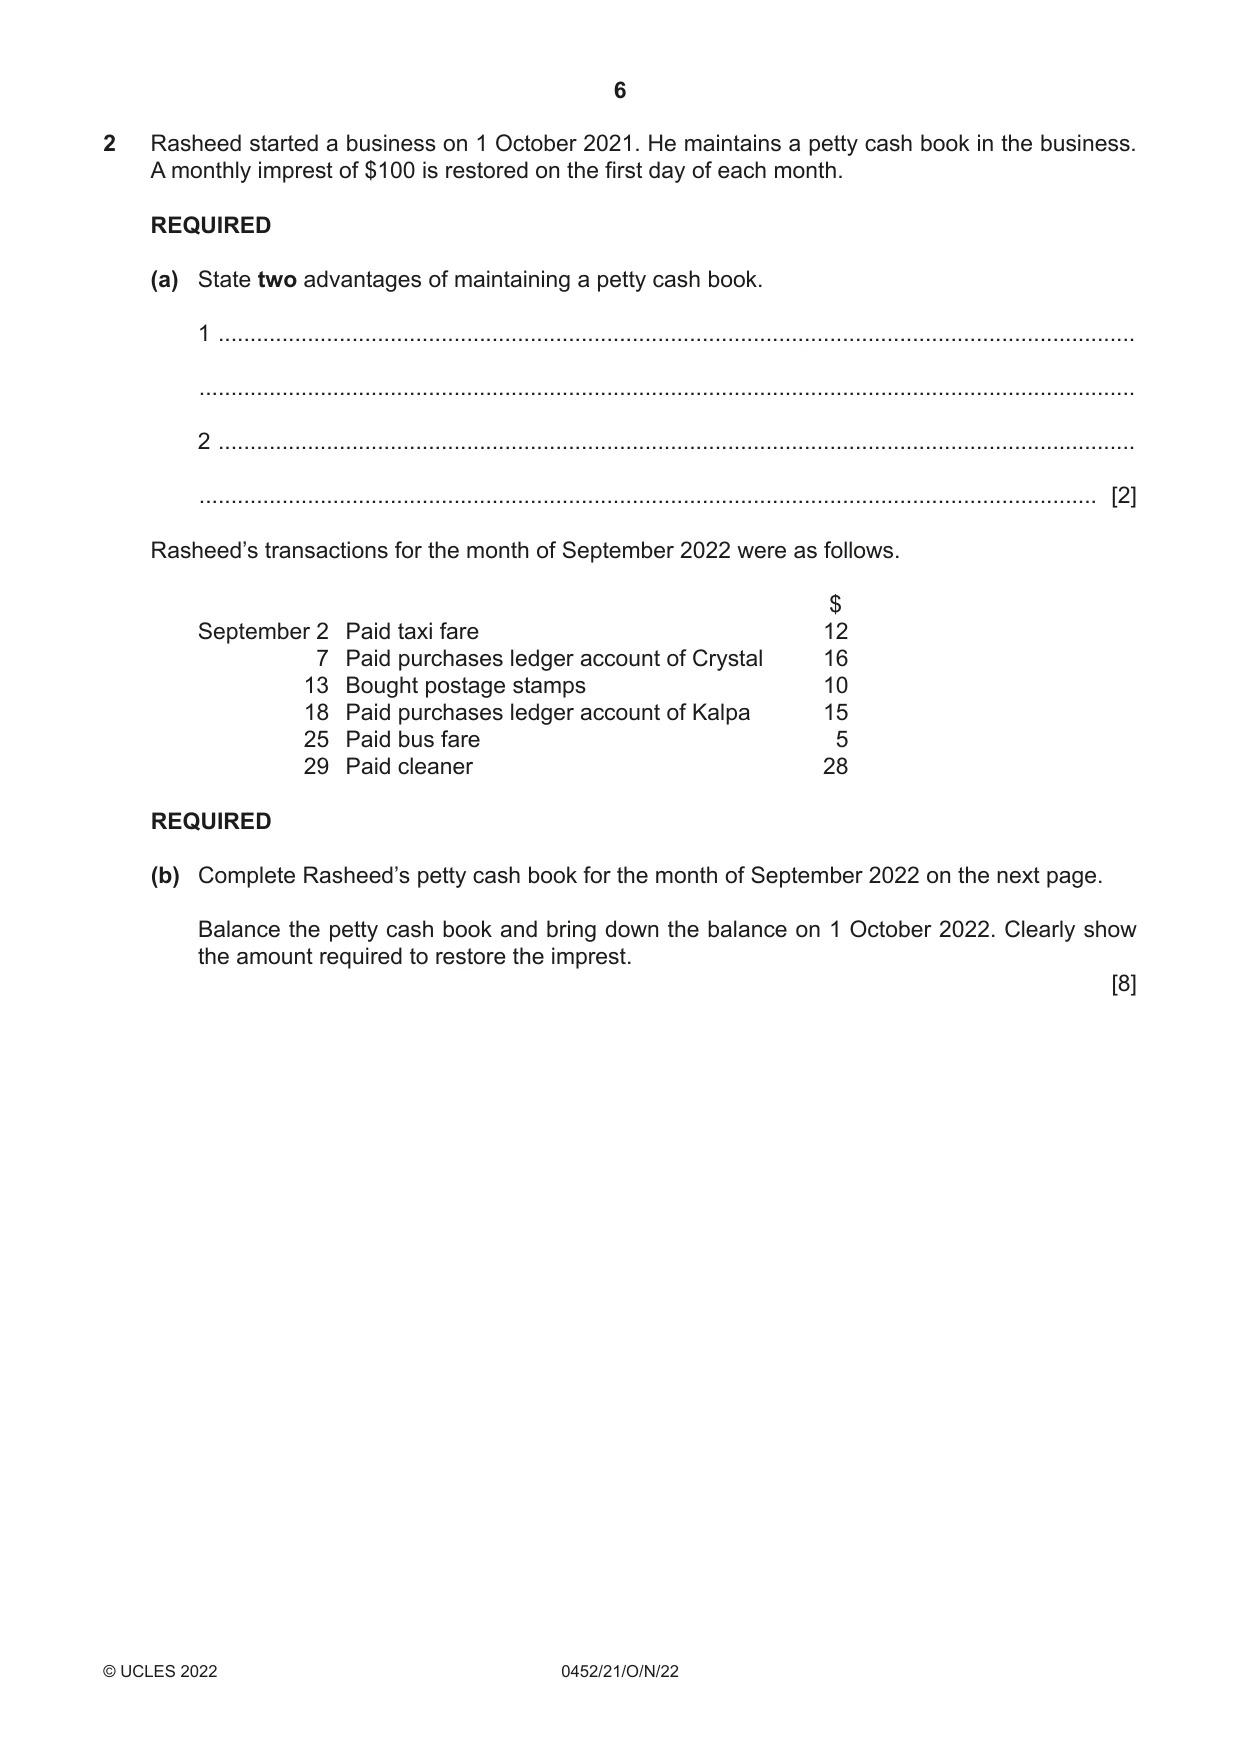
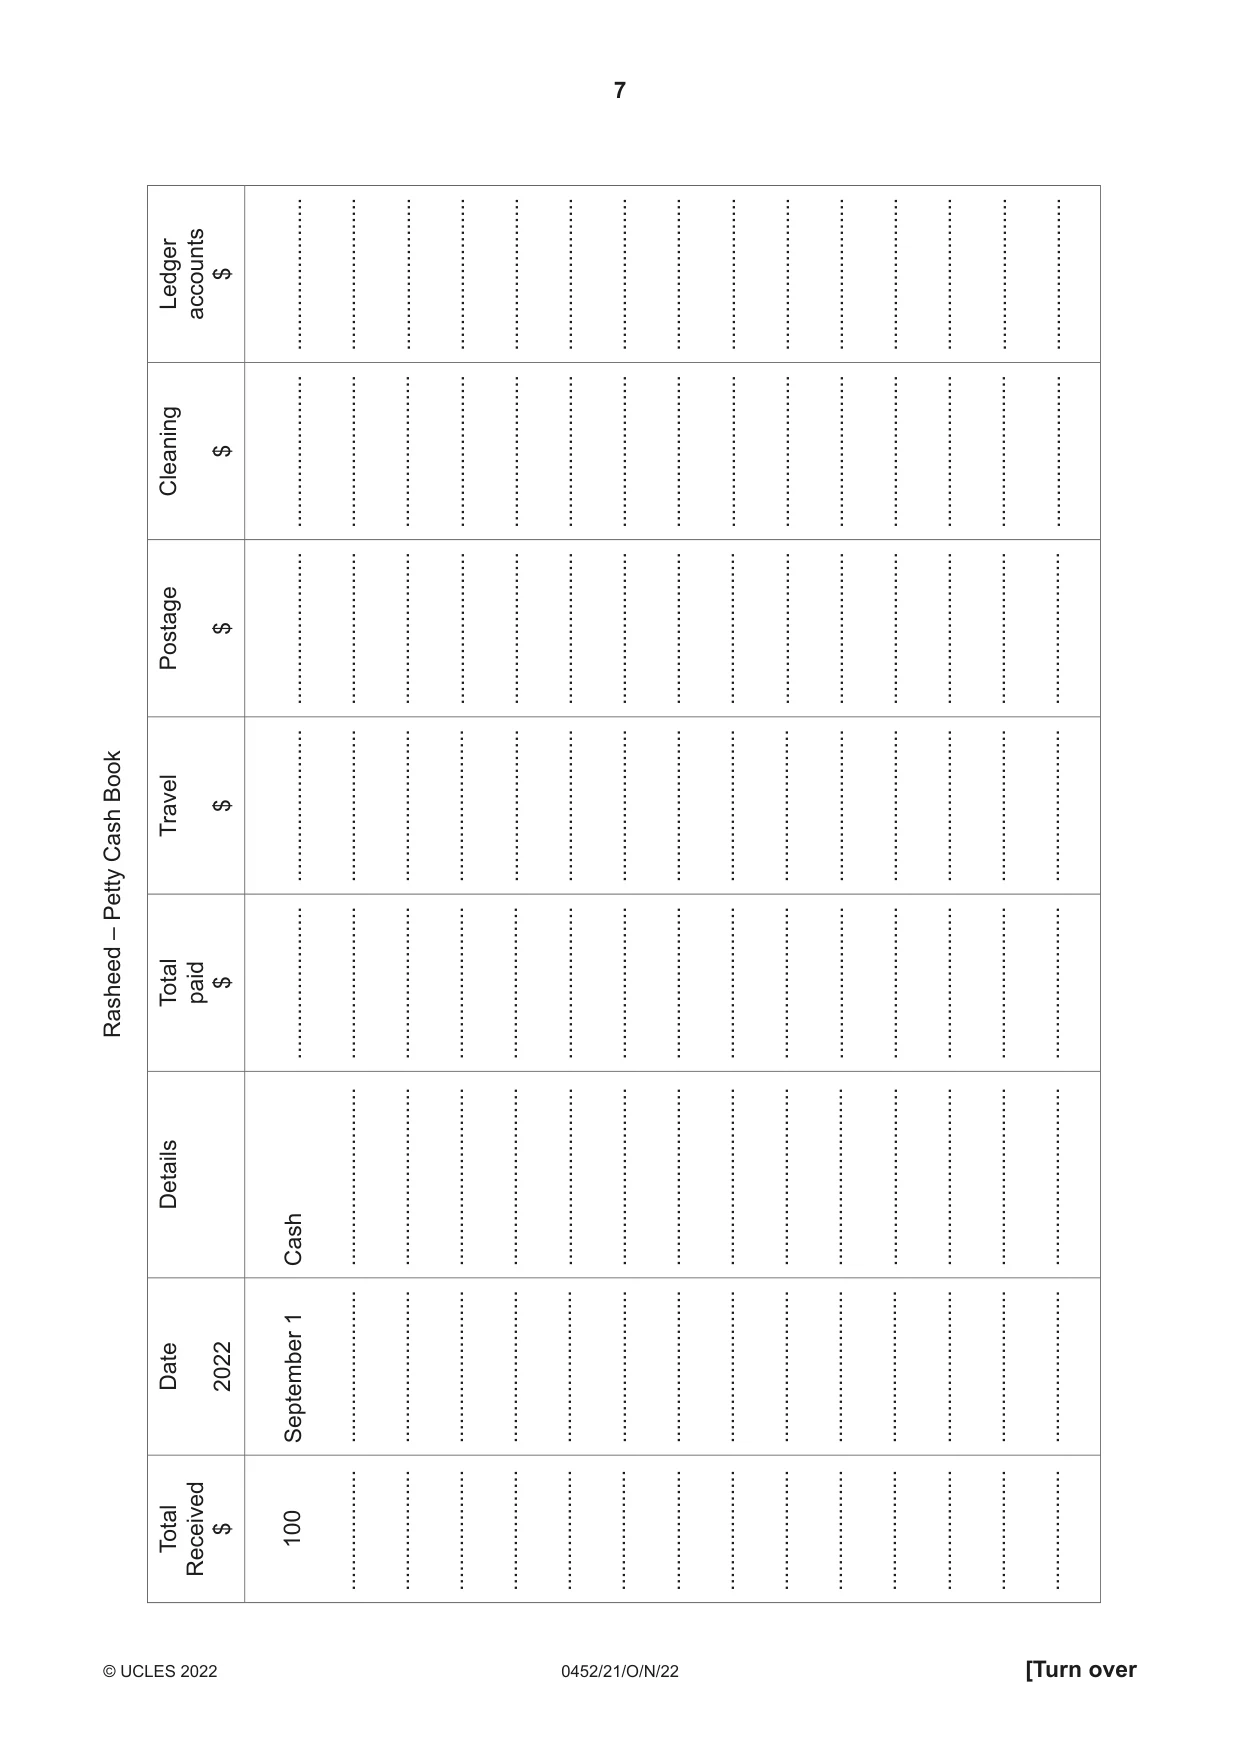
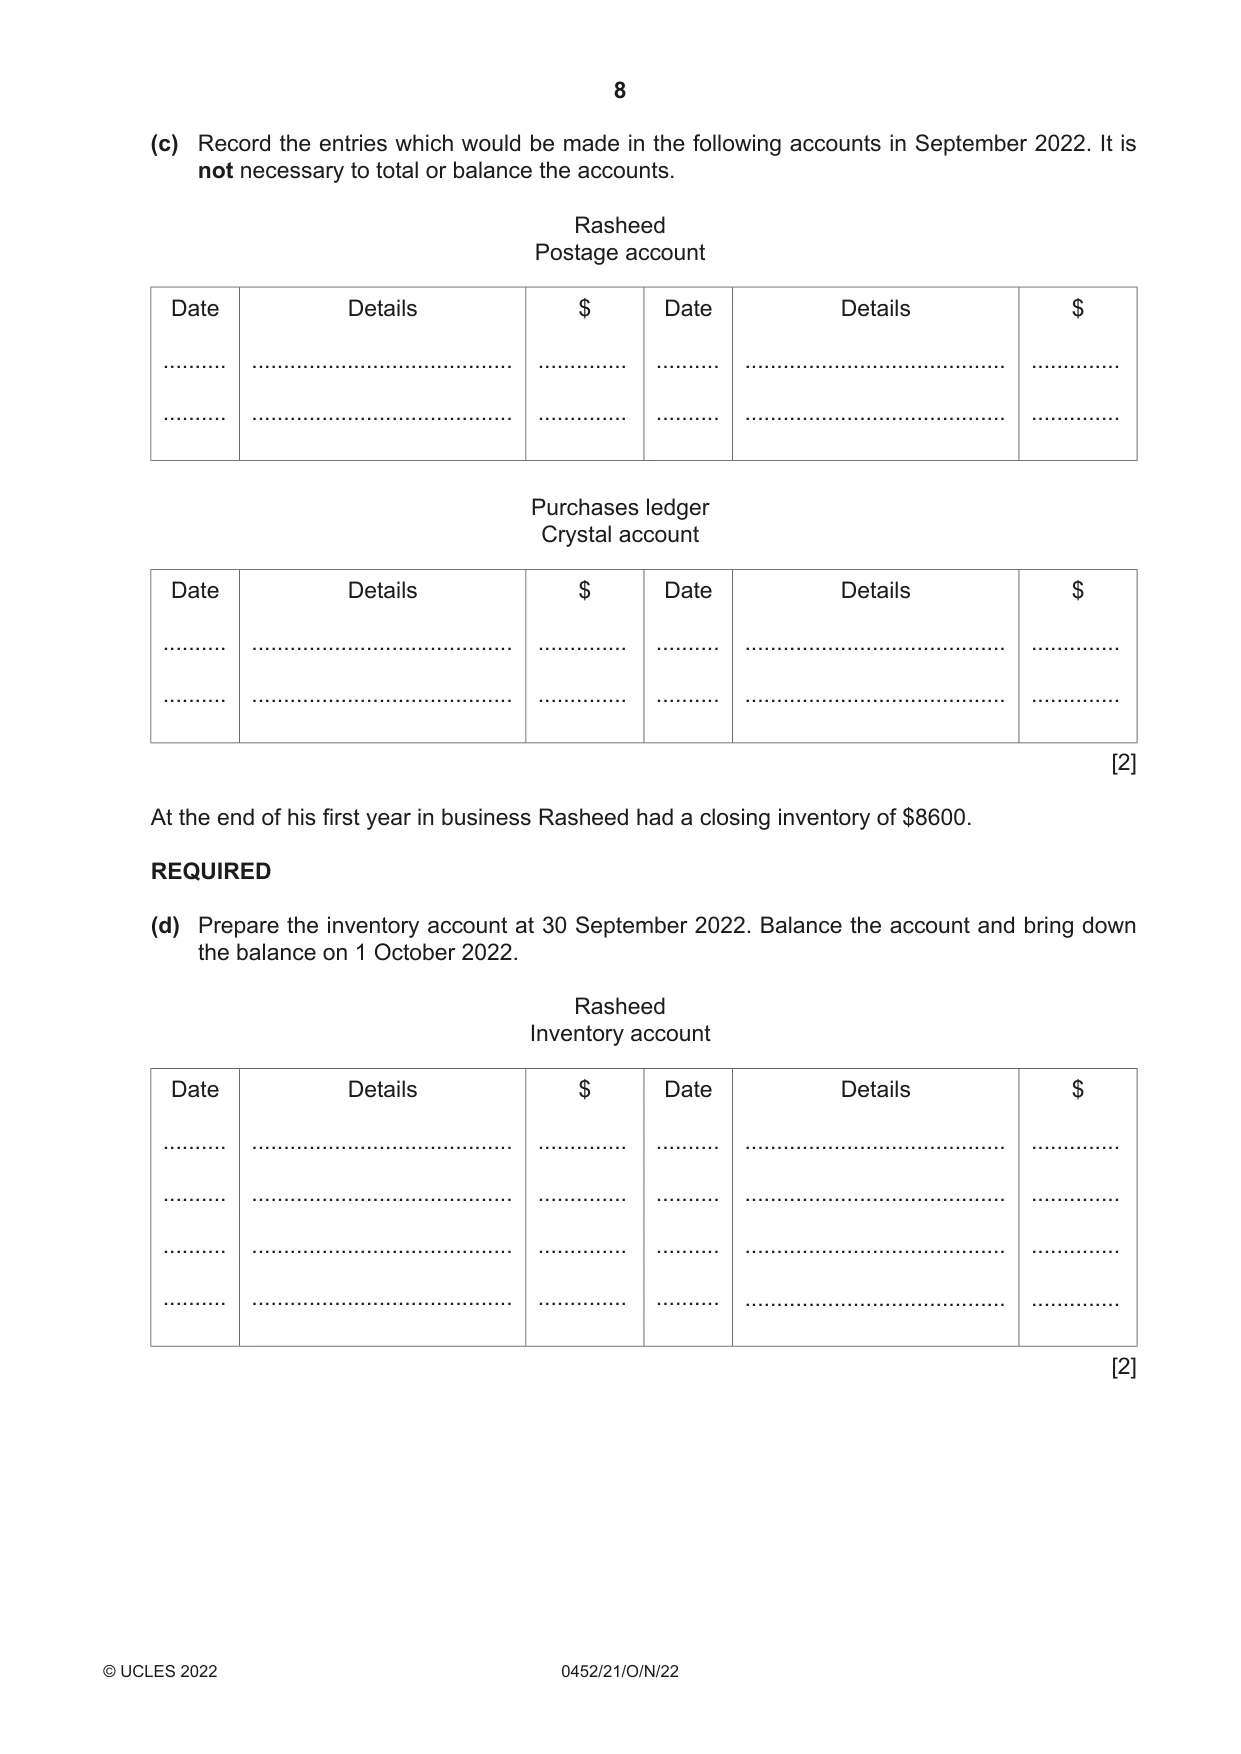
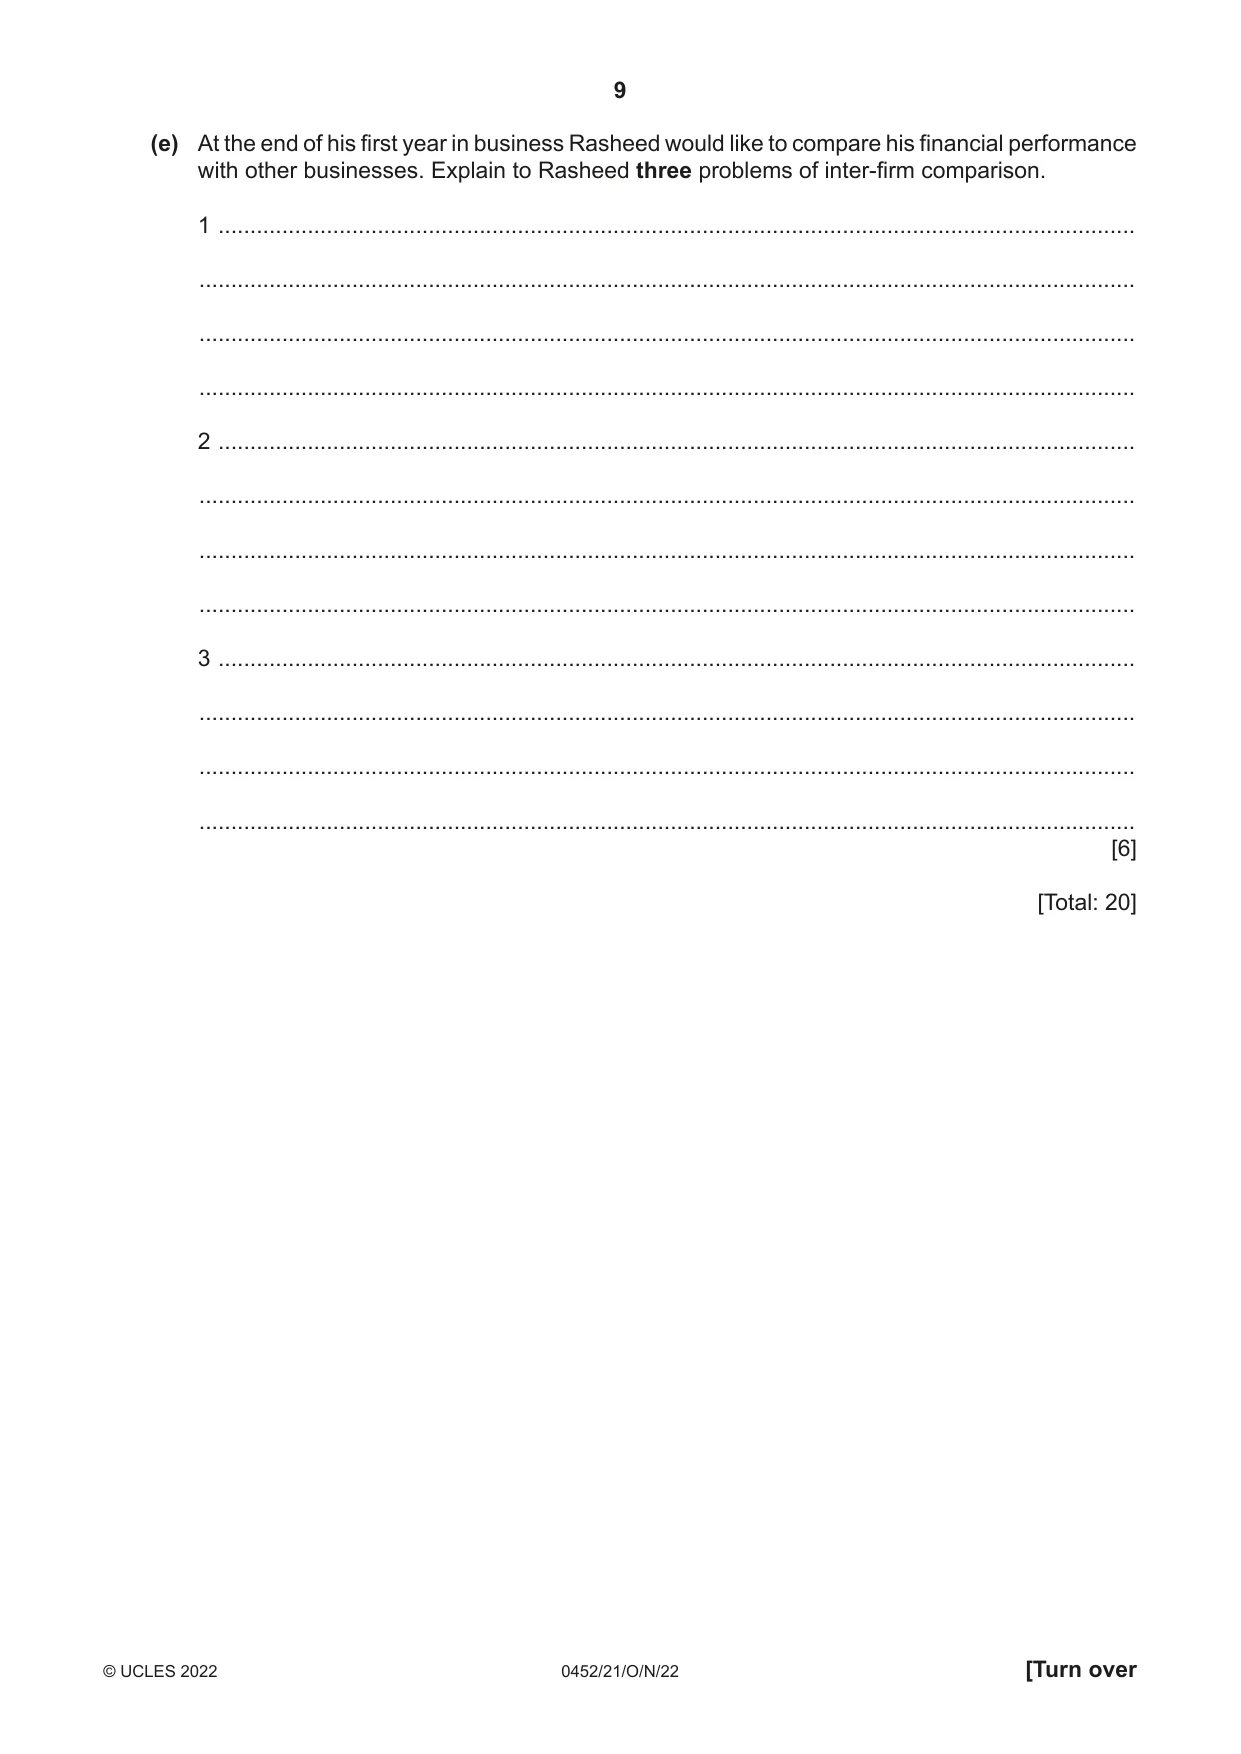
2 Rasheed started a business on 1 October 2021. He maintains a petty cash book in the business. A monthly imprest of $100 is restored on the first day of each month. REQUIRED (a) State two advantages of maintaining a petty cash book. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ............................................................................................................................................. [2] Rasheed’s transactions for the month of September 2022 were as follows. $ September 2 Paid taxi fare 12 7 Paid purchases ledger account of Crystal 16 13 Bought postage stamps 10 18 Paid purchases ledger account of Kalpa 15 25 Paid bus fare 5 29 Paid cleaner 28 REQUIRED (b) Complete Rasheed’s petty cash book for the month of September 2022 on the next page. Balance the petty cash book and bring down the balance on 1 October 2022. Clearly show the amount required to restore the imprest. [8] $ Ledger accounts ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Cleaning ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Postage ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ Book $ TravelCash ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ Petty – $ TotalpaidRasheed ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ Details Cash ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ ............................ 1 Date 2022 September ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ Total 100 Received ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... ................... (c) Record the entries which would be made in the following accounts in September 2022. It is not necessary to total or balance the accounts. Rasheed Postage account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Purchases ledger Crystal account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [2] At the end of his first year in business Rasheed had a closing inventory of $8600. REQUIRED (d) Prepare the inventory account at 30 September 2022. Balance the account and bring down the balance on 1 October 2022. Rasheed Inventory account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [2] (e) At the end of his first year in business Rasheed would like to compare his financial performance with other businesses. Explain to Rasheed three problems of inter-firm comparison. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [6] [Total: 20]
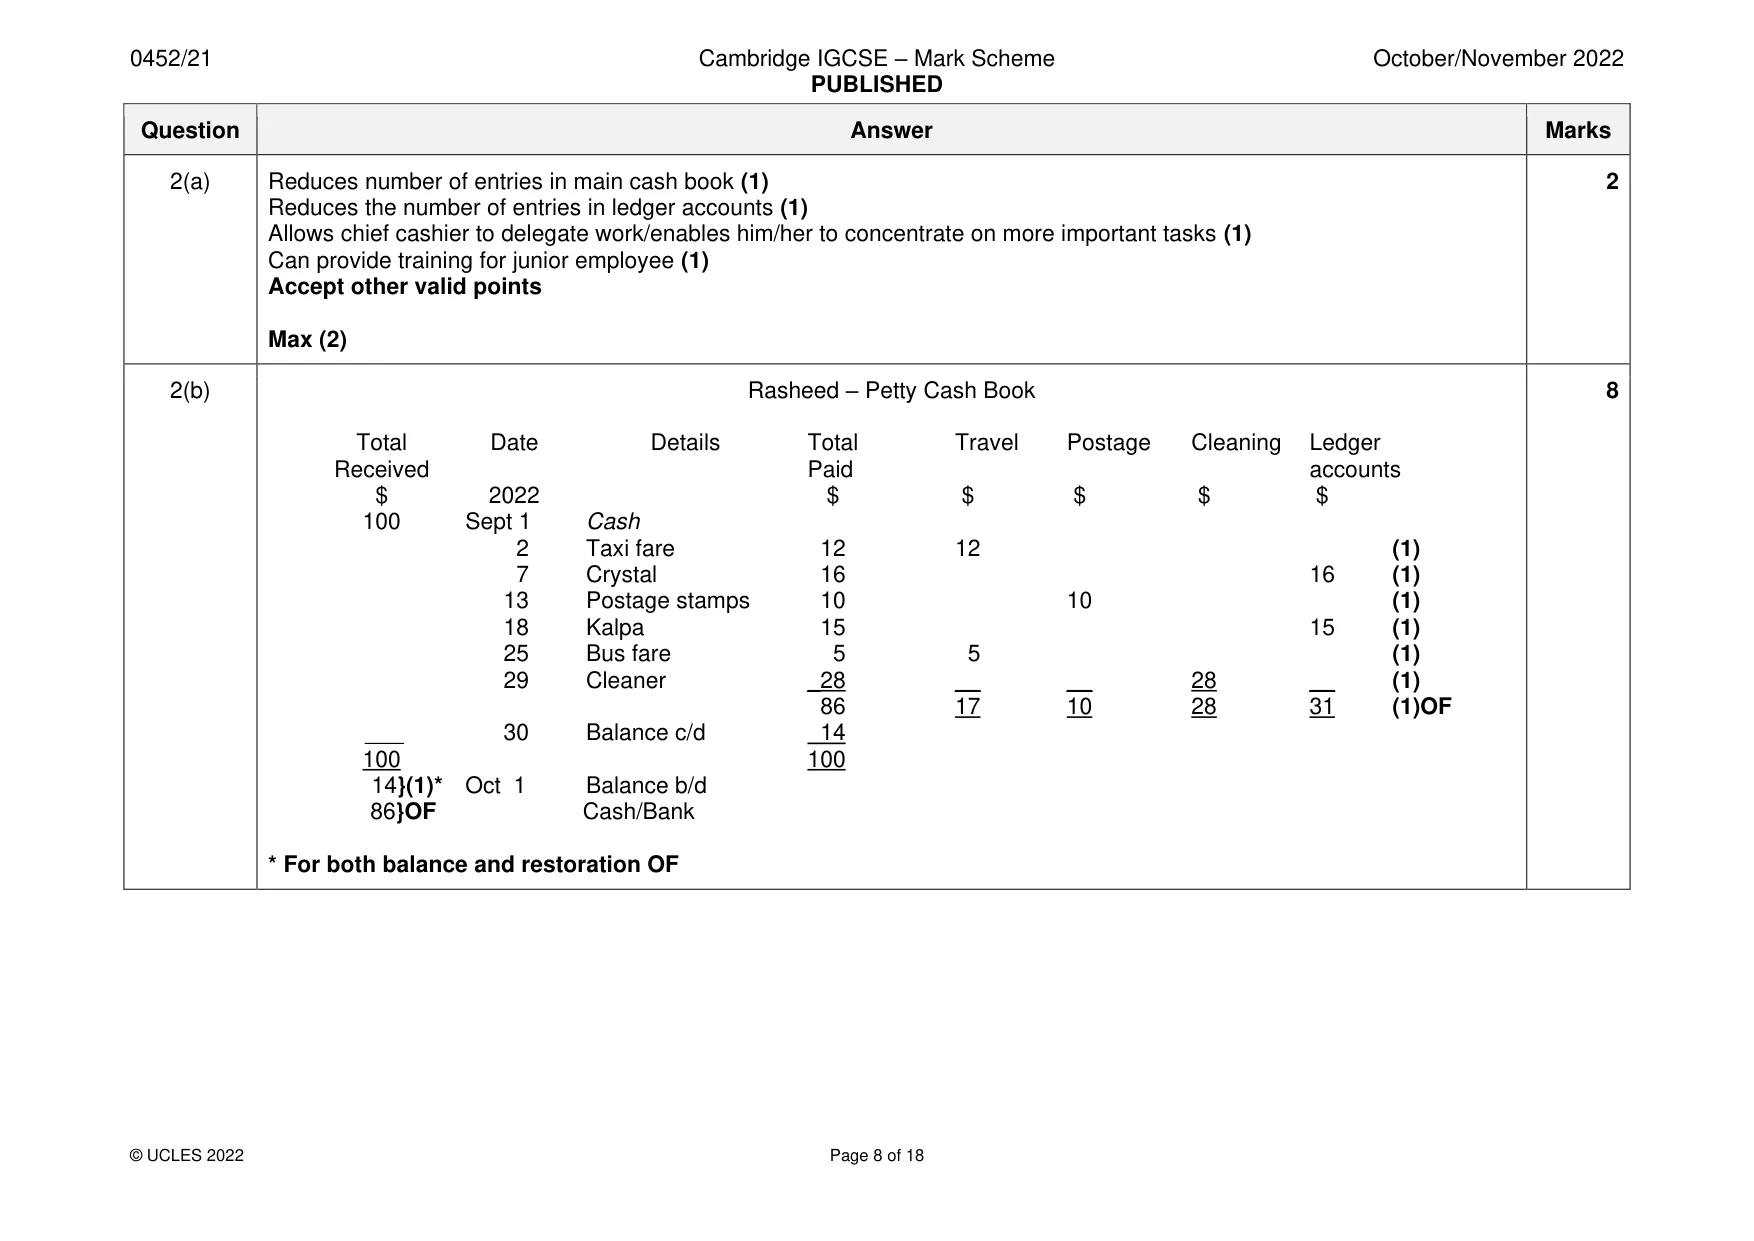
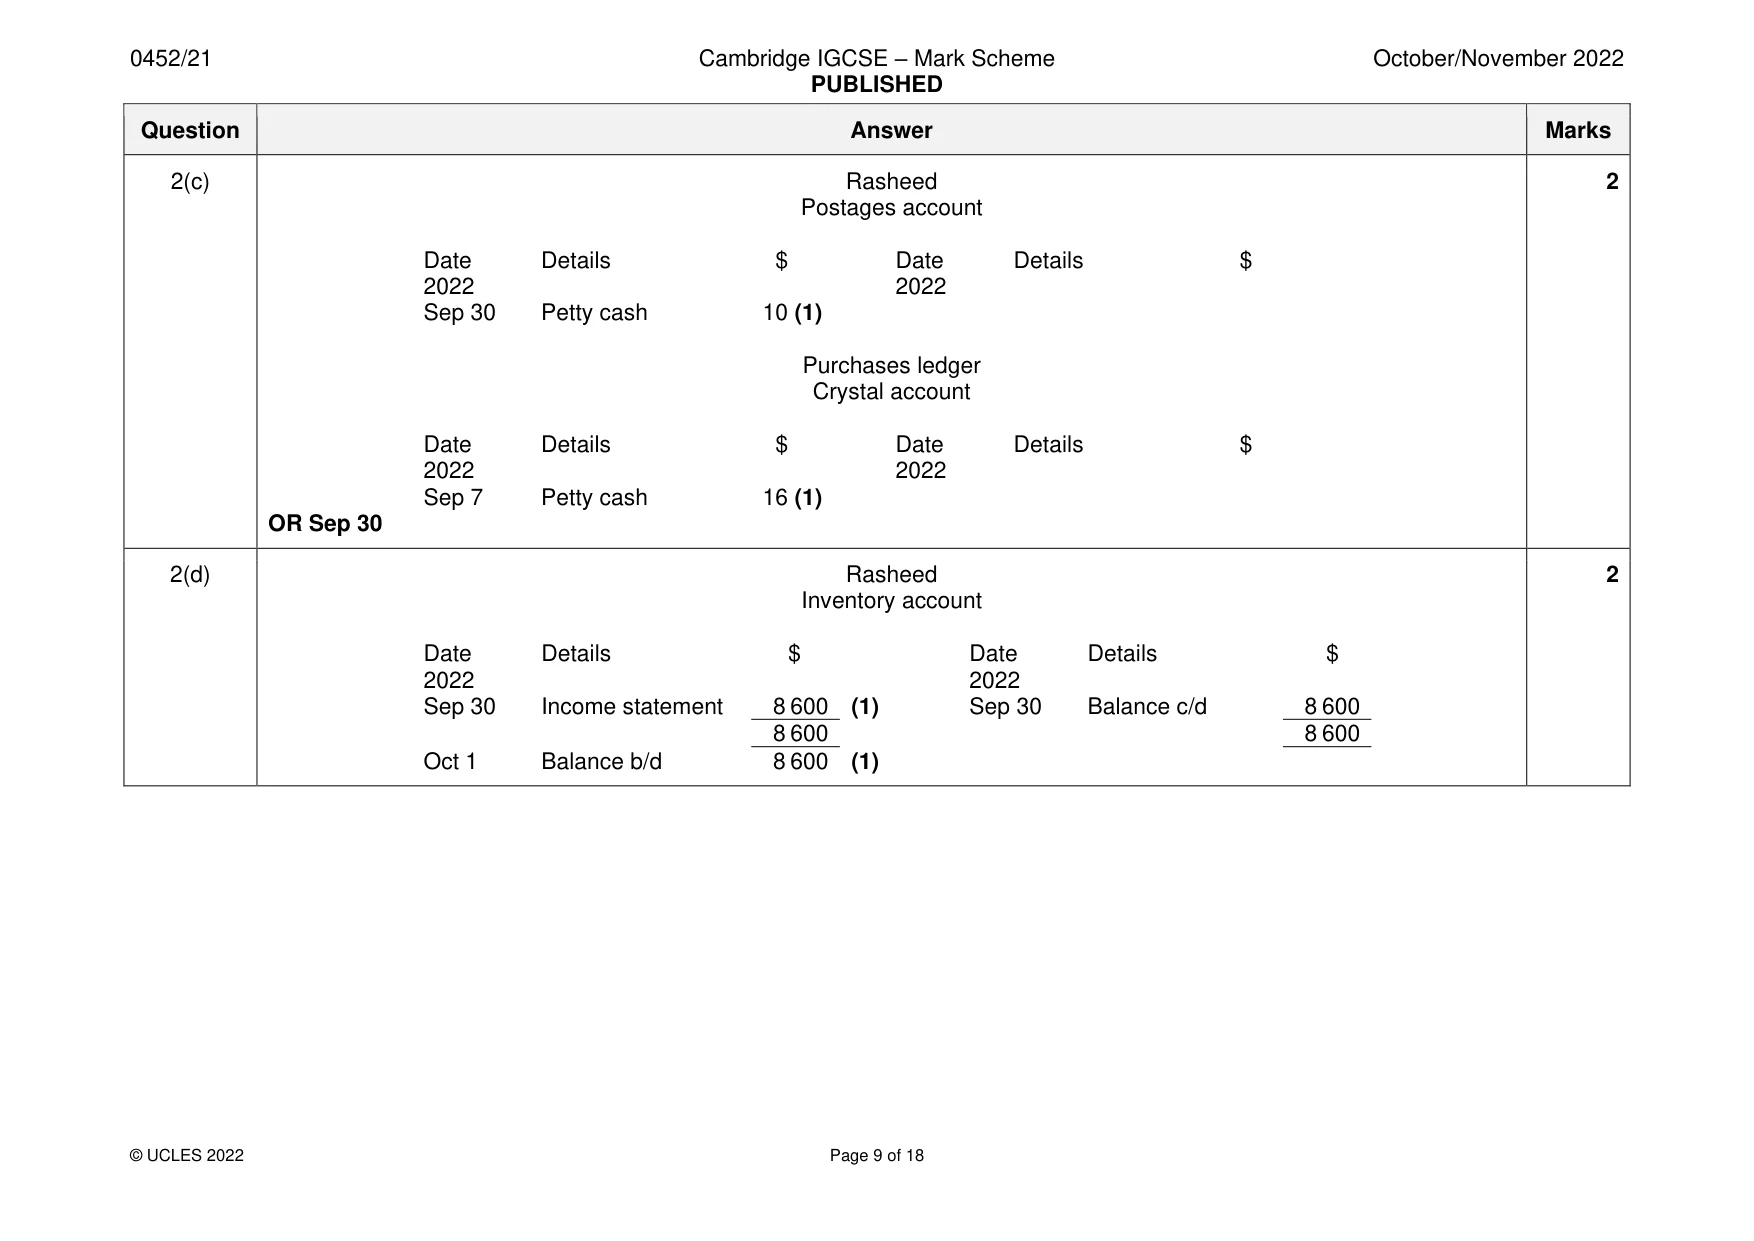
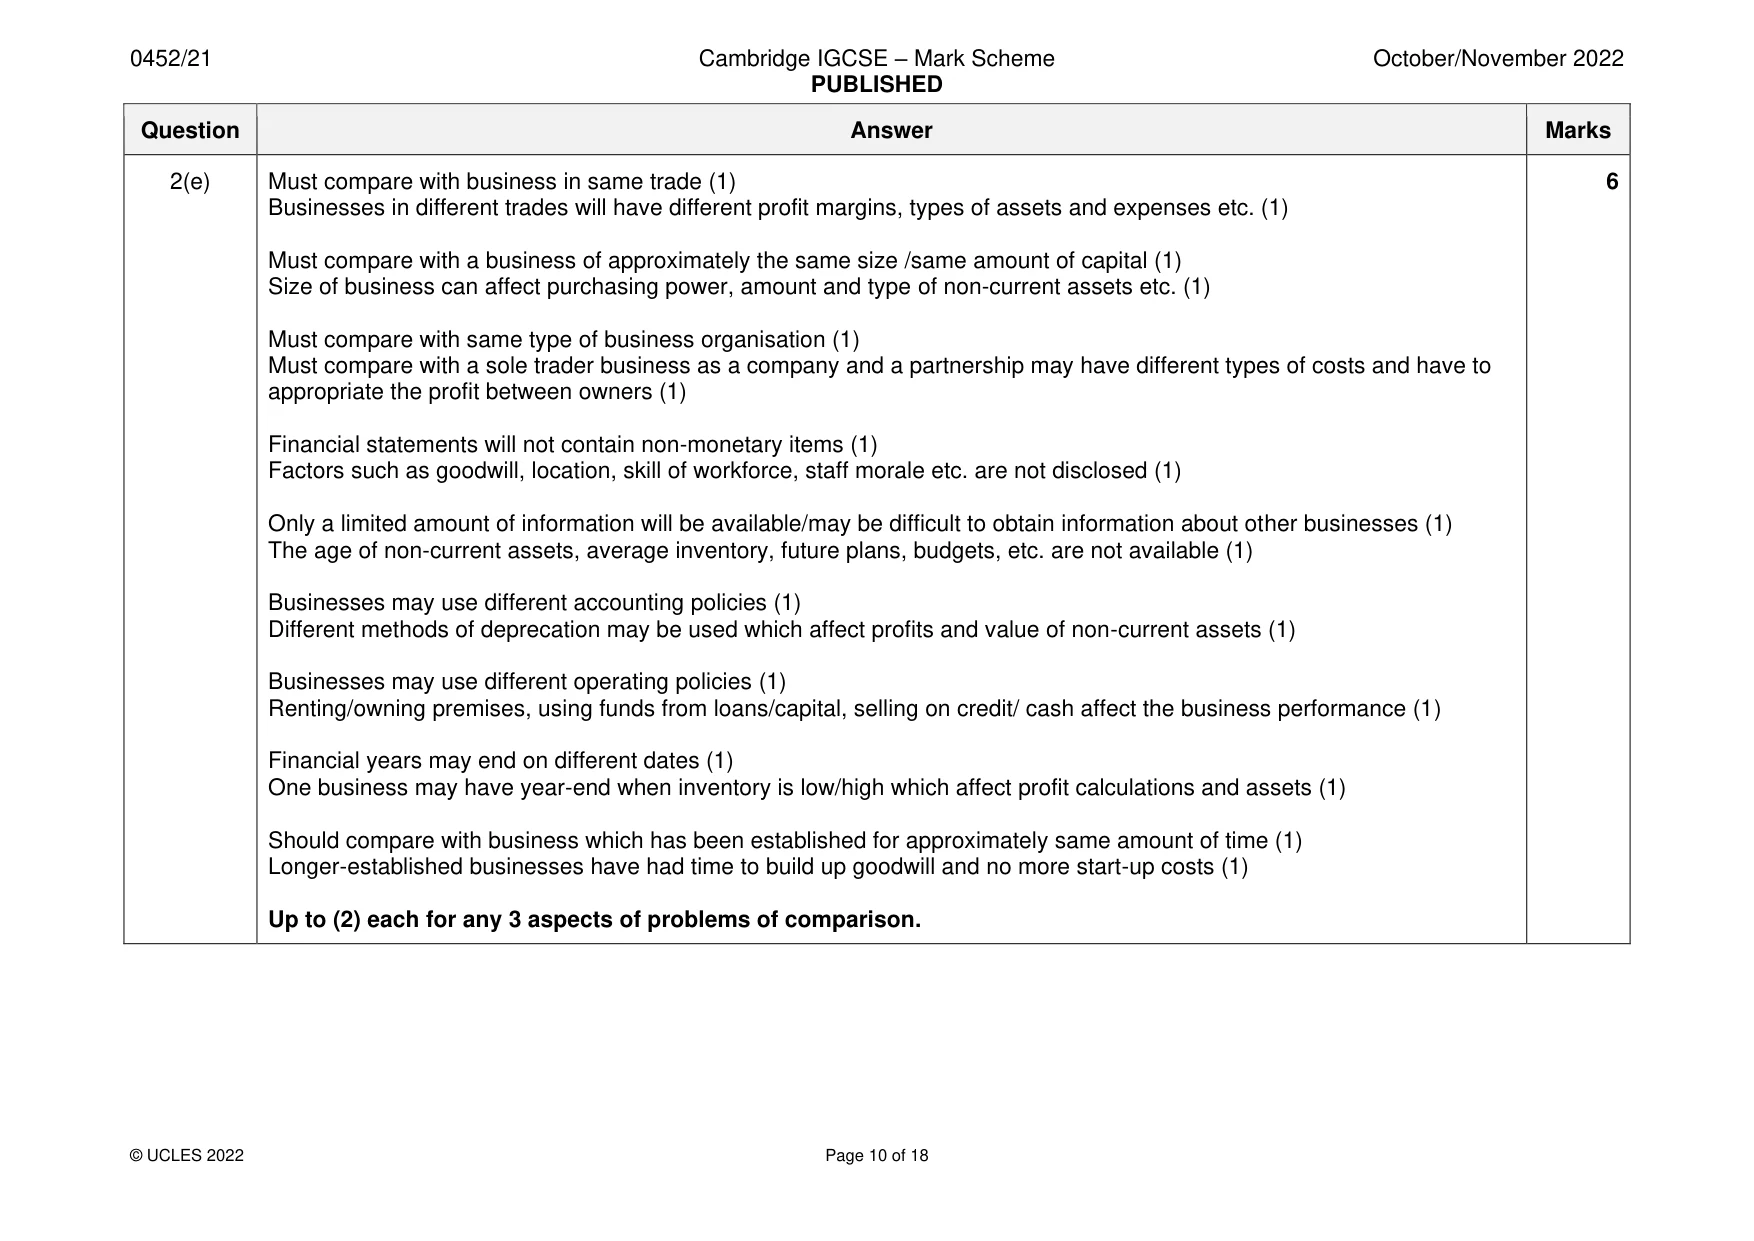
Mark scheme: 2(a) Reduces number of entries in main cash book (1) 2 Reduces the number of entries in ledger accounts (1) Allows chief cashier to delegate work/enables him/her to concentrate on more important tasks (1) Can provide training for junior employee (1) Accept other valid points Max (2) 2(b) Rasheed – Petty Cash Book 8 Total Date Details Total Travel Postage Cleaning Ledger Received Paid accounts $ 2022 $ $ $ $ $ 100 Sept 1 Cash 2 Taxi fare 12 12 (1) 7 Crystal 16 16 (1) 13 Postage stamps 10 10 (1) 18 Kalpa 15 15 (1) 25 Bus fare 5 5 (1) 29 Cleaner _28 __ __ 28 __ (1) 86 17 10 28 31 (1)OF ___ 30 Balance c/d 14 100 100 14}(1)* Oct 1 Balance b/d 86}OF Cash/Bank * For both balance and restoration OF 2(c) Rasheed 2 Postages account Date Details $ Date Details $ 2022 2022 Sep 30 Petty cash 10 (1) Purchases ledger Crystal account Date Details $ Date Details $ 2022 2022 Sep 7 Petty cash 16 (1) OR Sep 30 2(d) Rasheed 2 Inventory account Date Details $ Date Details $ 2022 2022 Sep 30 Income statement 8 600 (1) Sep 30 Balance c/d 8 600 8 600 8 600 Oct 1 Balance b/d 8 600 (1) 2(e) Must compare with business in same trade (1) 6 Businesses in different trades will have different profit margins, types of assets and expenses etc. (1) Must compare with a business of approximately the same size /same amount of capital (1) Size of business can affect purchasing power, amount and type of non-current assets etc. (1) Must compare with same type of business organisation (1) Must compare with a sole trader business as a company and a partnership may have different types of costs and have to appropriate the profit between owners (1) Financial statements will not contain non-monetary items (1) Factors such as goodwill, location, skill of workforce, staff morale etc. are not disclosed (1) Only a limited amount of information will be available/may be difficult to obtain information about other businesses (1) The age of non-current assets, average inventory, future plans, budgets, etc. are not available (1) Businesses may use different accounting policies (1) Different methods of deprecation may be used which affect profits and value of non-current assets (1) Businesses may use different operating policies (1) Renting/owning premises, using funds from loans/capital, selling on credit/ cash affect the business performance (1) Financial years may end on different dates (1) One business may have year-end when inventory is low/high which affect profit calculations and assets (1) Should compare with business which has been established for approximately same amount of time (1) Longer-established businesses have had time to build up goodwill and no more start-up costs (1) Up to (2) each for any 3 aspects of problems of comparison.
Q3 · The following balances have been taken from the accounts of RB, a trader
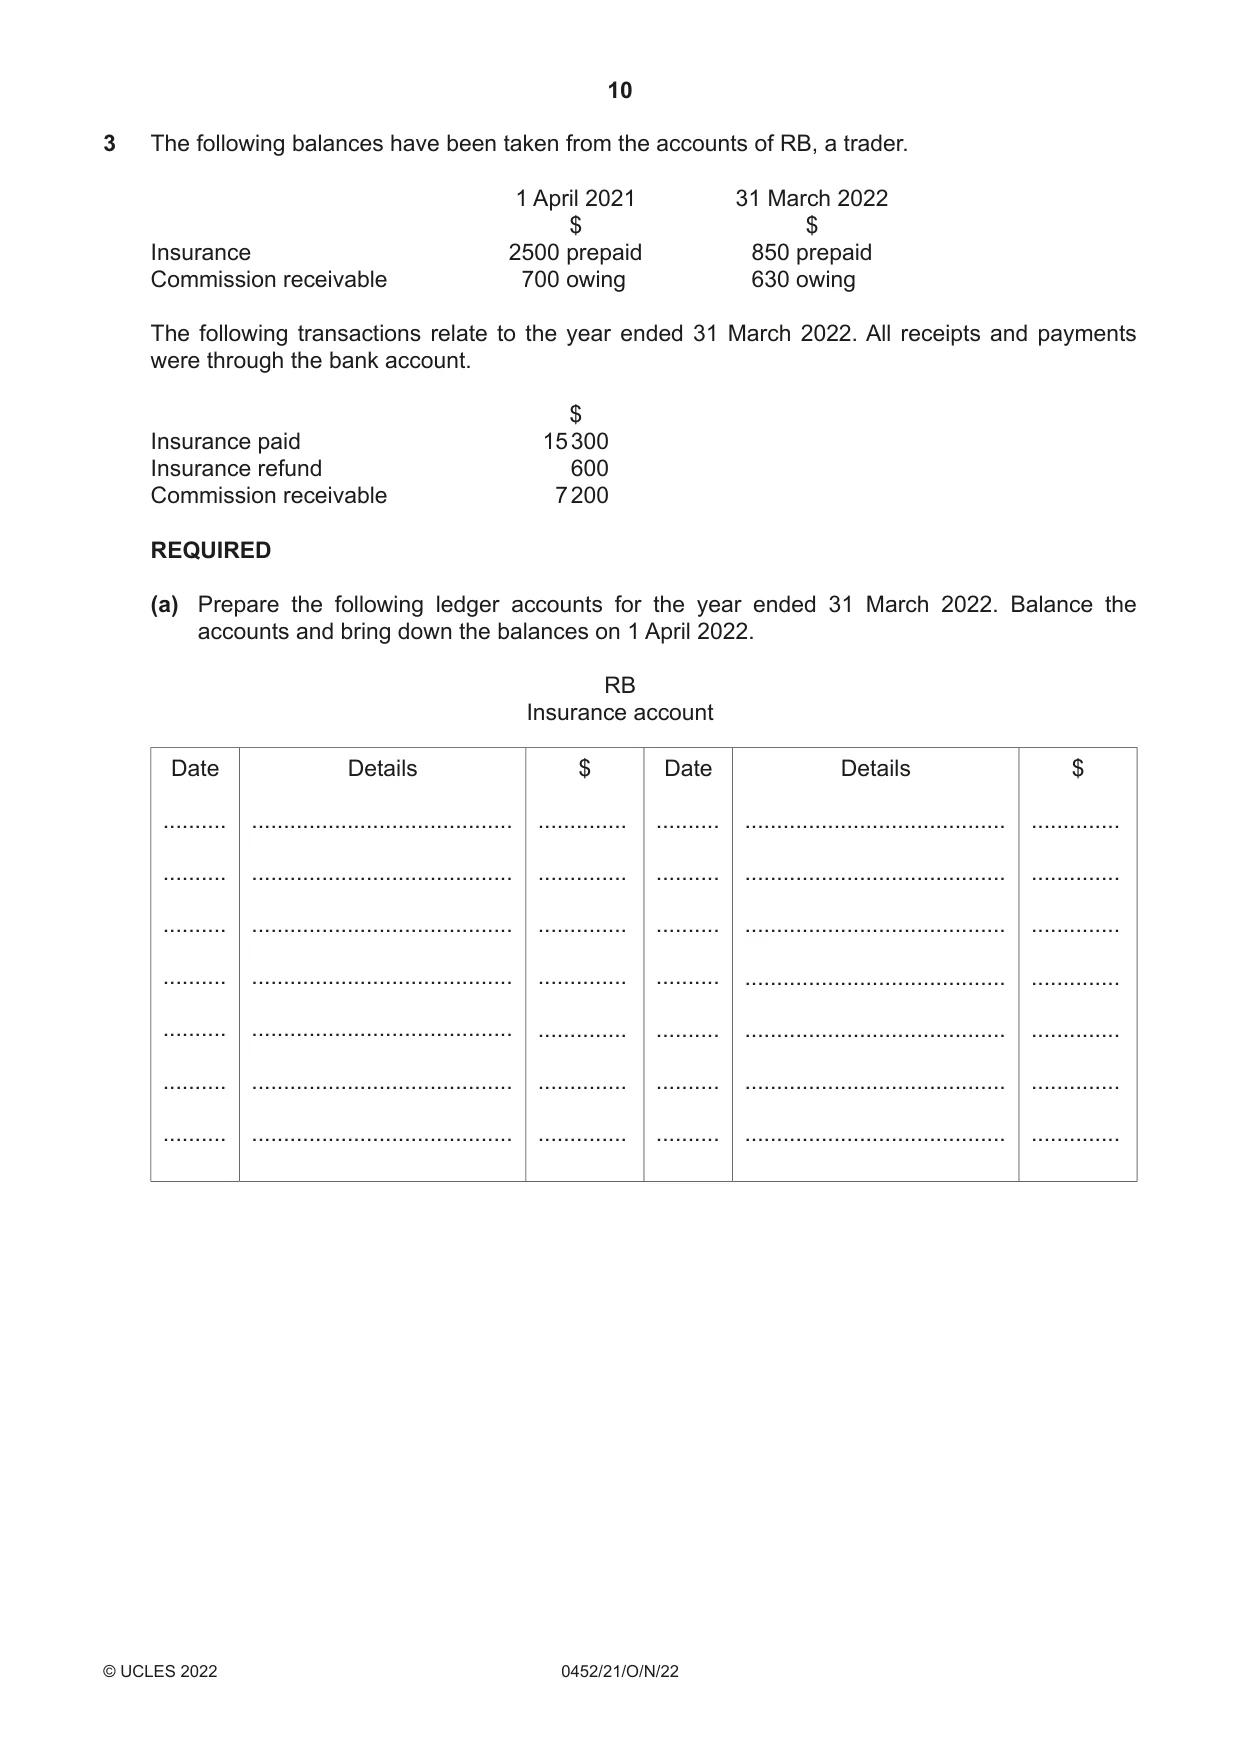
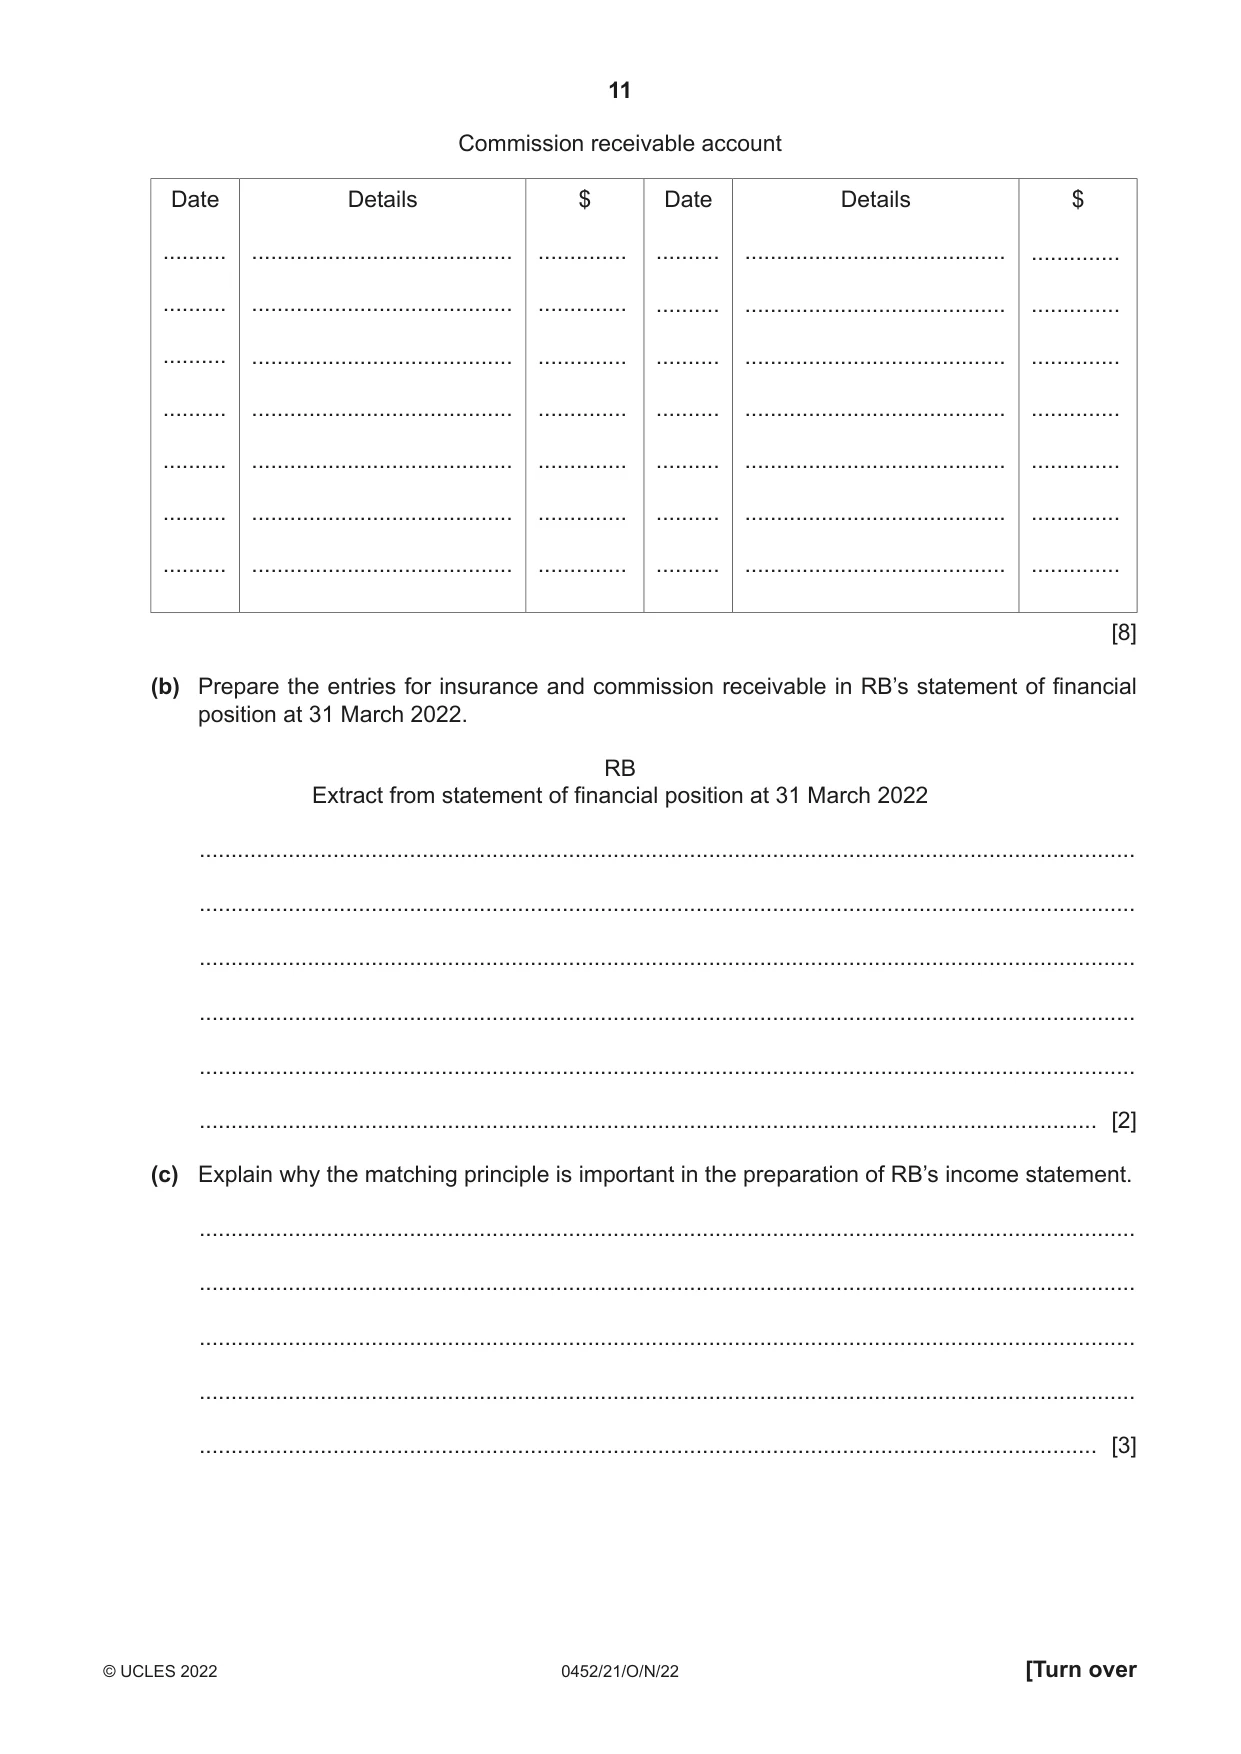
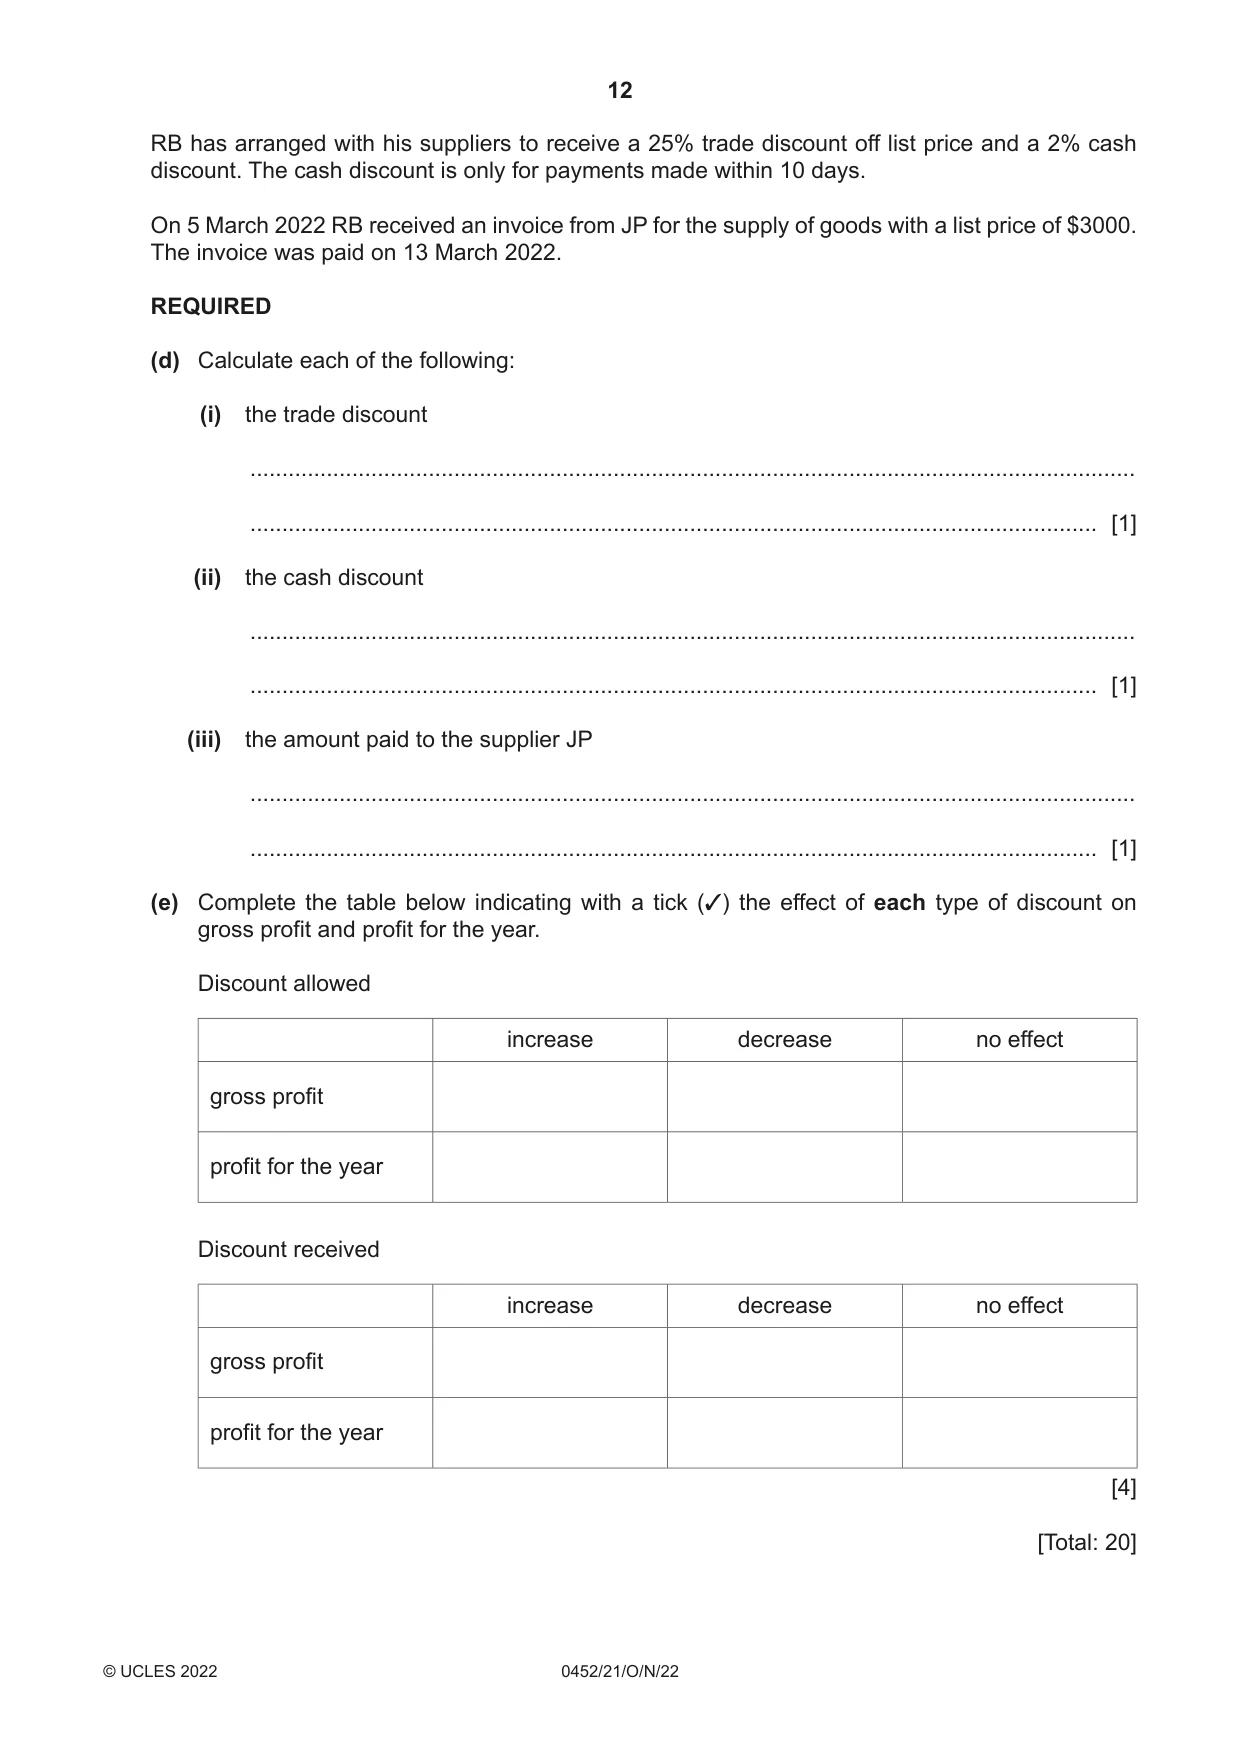
3 The following balances have been taken from the accounts of RB, a trader. 1 April 2021 31 March 2022 $ $ Insurance 2500 prepaid 850 prepaid Commission receivable 700 owing 630 owing The following transactions relate to the year ended 31 March 2022. All receipts and payments were through the bank account. $ Insurance paid 15 300 Insurance refund 600 Commission receivable 7 200 REQUIRED (a) Prepare the following ledger accounts for the year ended 31 March 2022. Balance the accounts and bring down the balances on 1 April 2022. RB Insurance account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Commission receivable account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [8] (b) Prepare the entries for insurance and commission receivable in RB’s statement of financial position at 31 March 2022. RB Extract from statement of financial position at 31 March 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Explain why the matching principle is important in the preparation of RB’s income statement. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] RB has arranged with his suppliers to receive a 25% trade discount off list price and a 2% cash discount. The cash discount is only for payments made within 10 days. On 5 March 2022 RB received an invoice from JP for the supply of goods with a list price of $3000. The invoice was paid on 13 March 2022. REQUIRED (d) Calculate each of the following: (i) the trade discount ........................................................................................................................................... ..................................................................................................................................... [1] (ii) the cash discount ........................................................................................................................................... ..................................................................................................................................... [1] (iii) the amount paid to the supplier JP ........................................................................................................................................... ..................................................................................................................................... [1] (e) Complete the table below indicating with a tick (✓) the effect of each type of discount on gross profit and profit for the year. Discount allowed increase decrease no effect gross profit profit for the year Discount received increase decrease no effect gross profit profit for the year [4] [Total: 20]
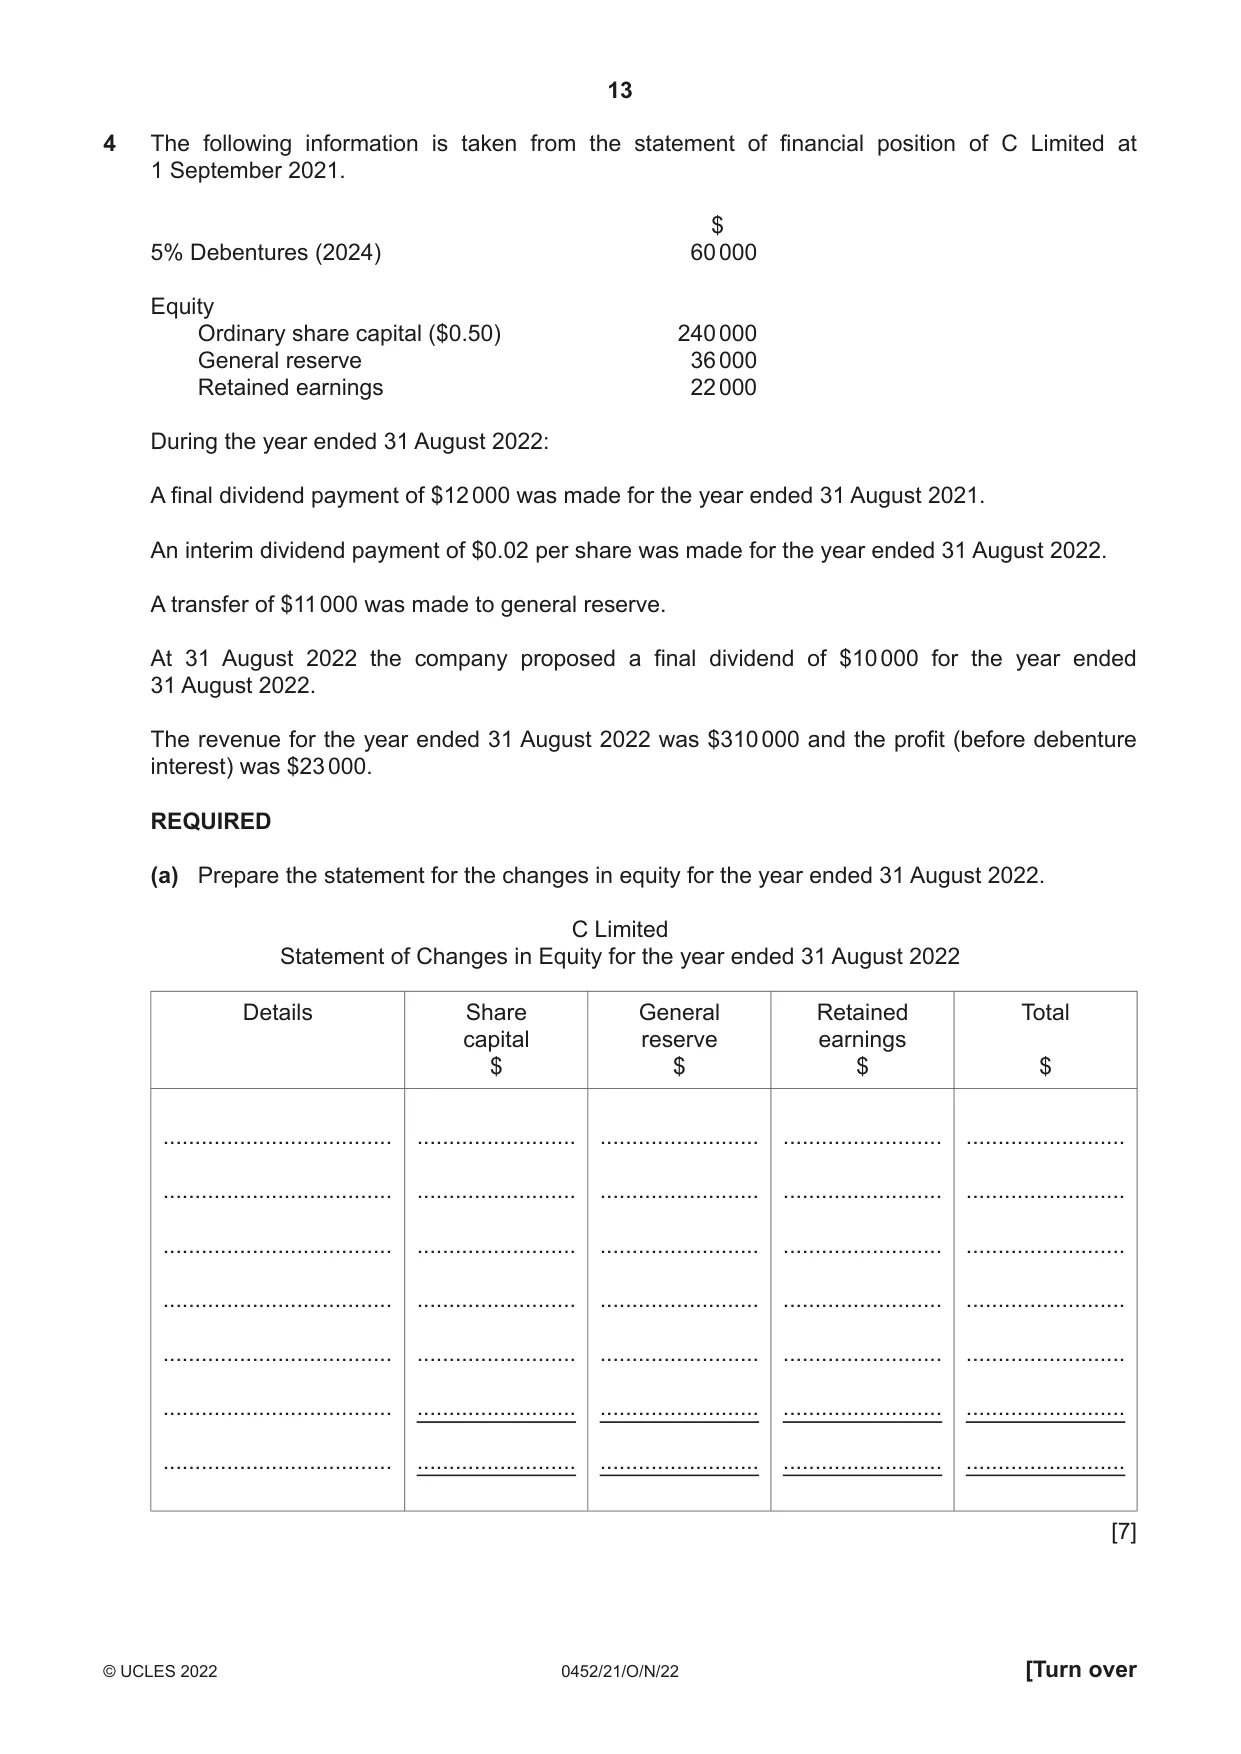
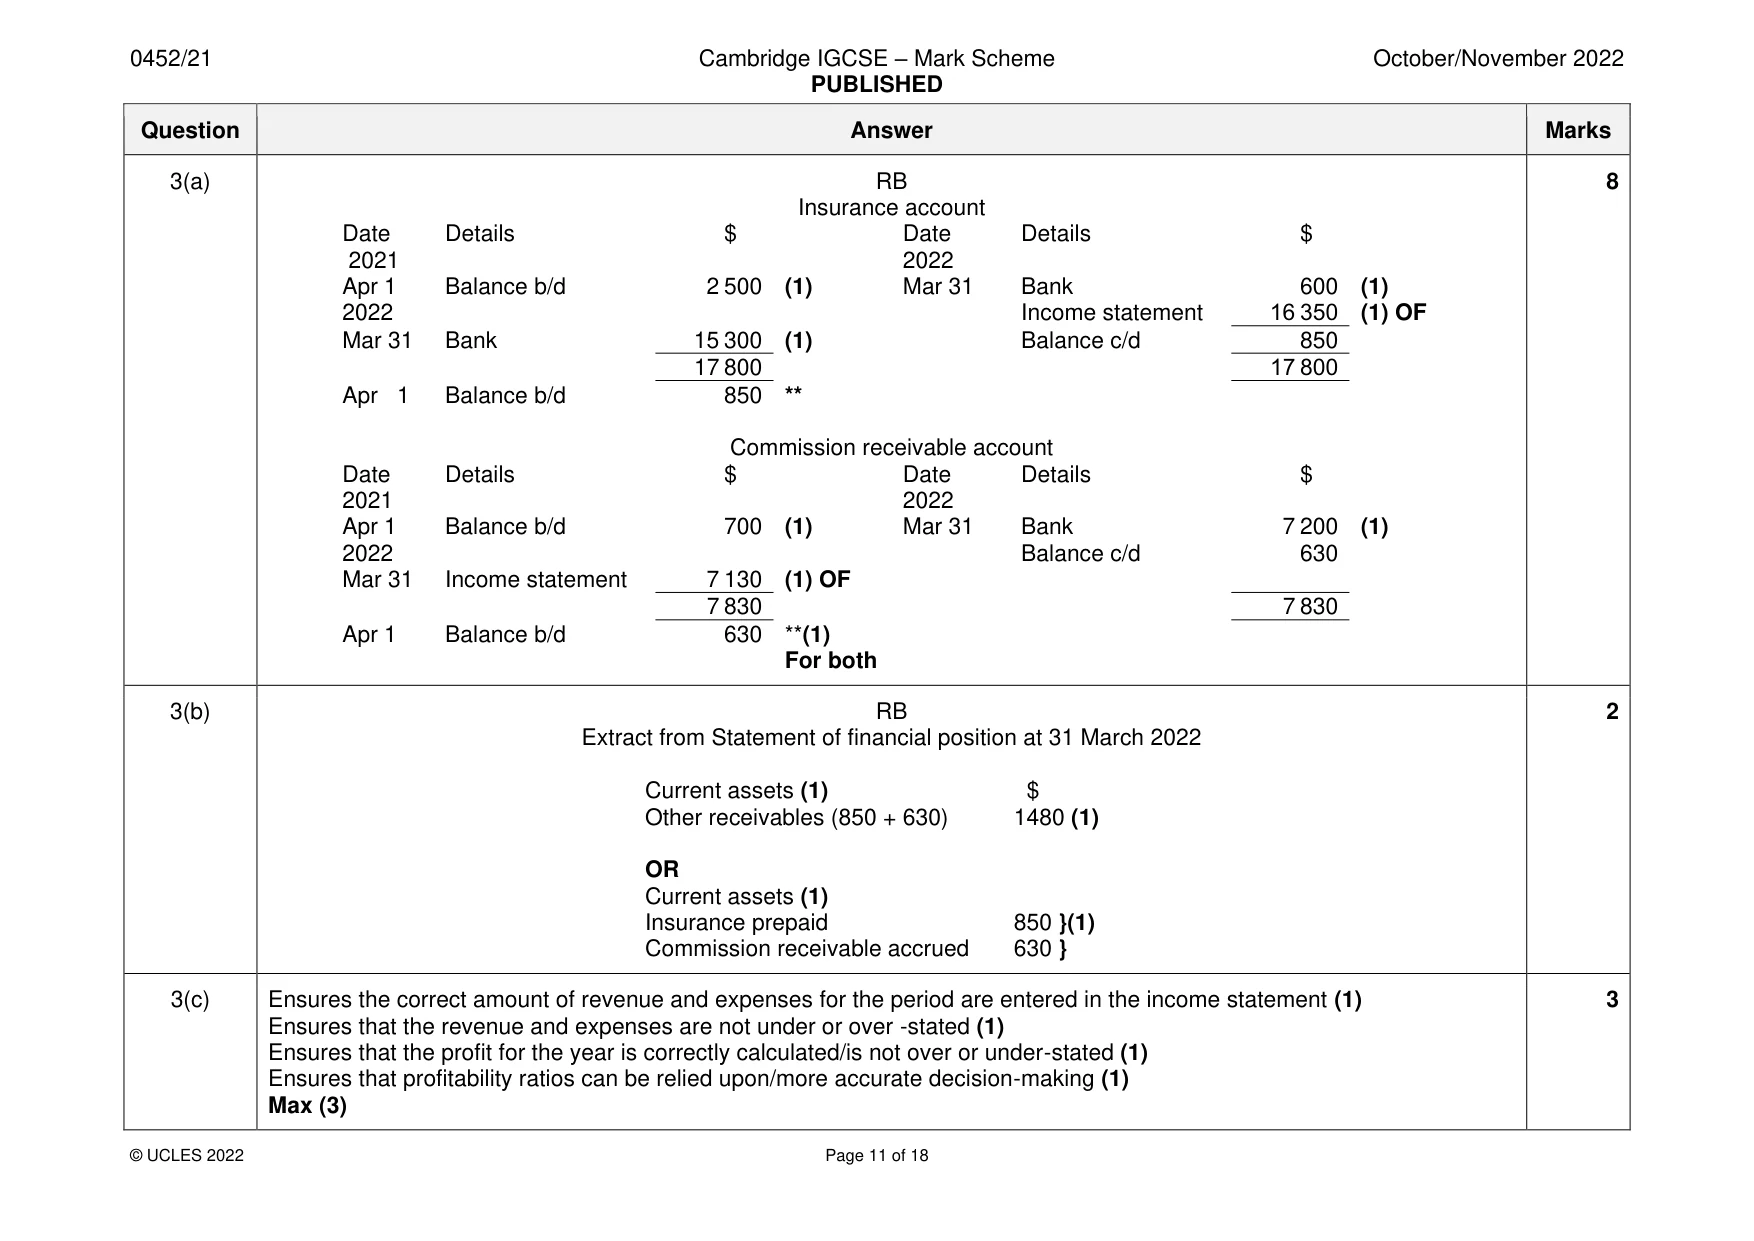
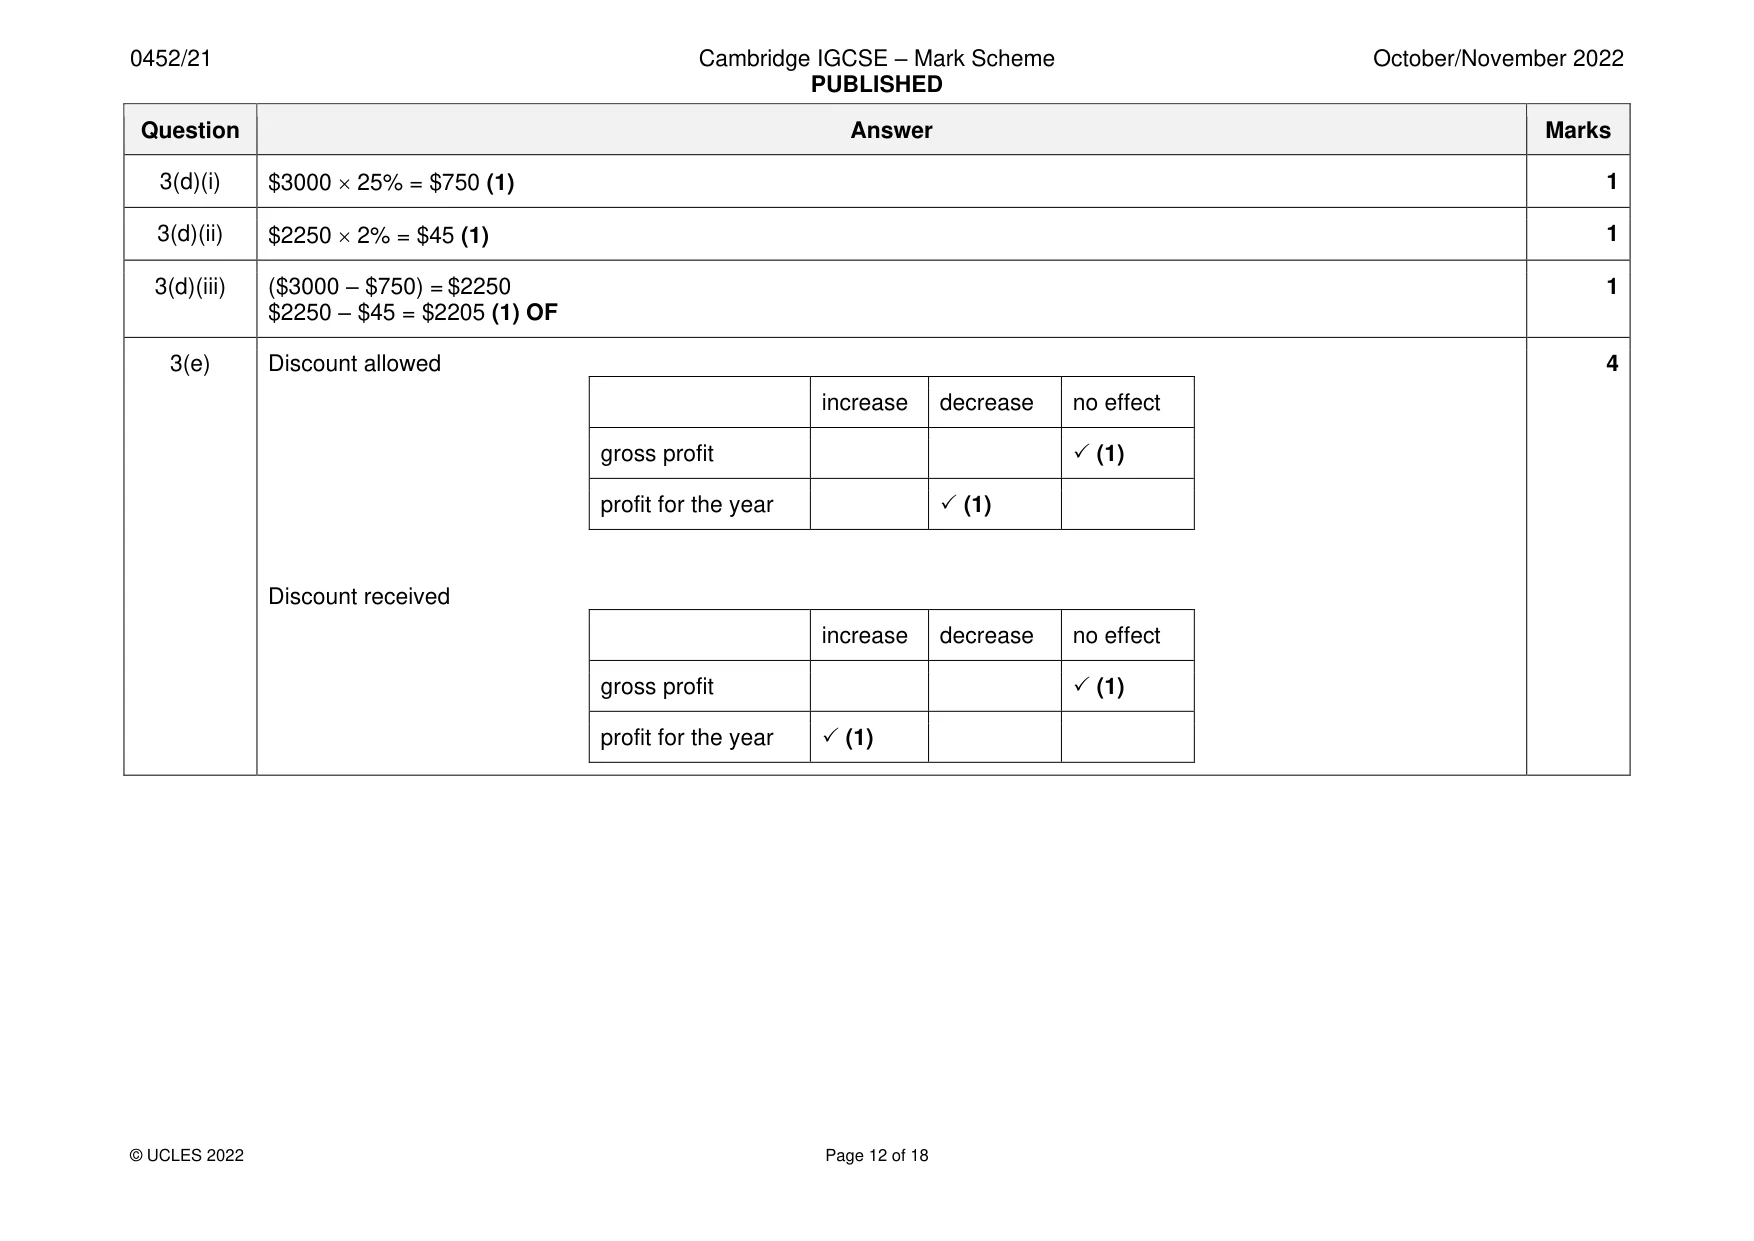
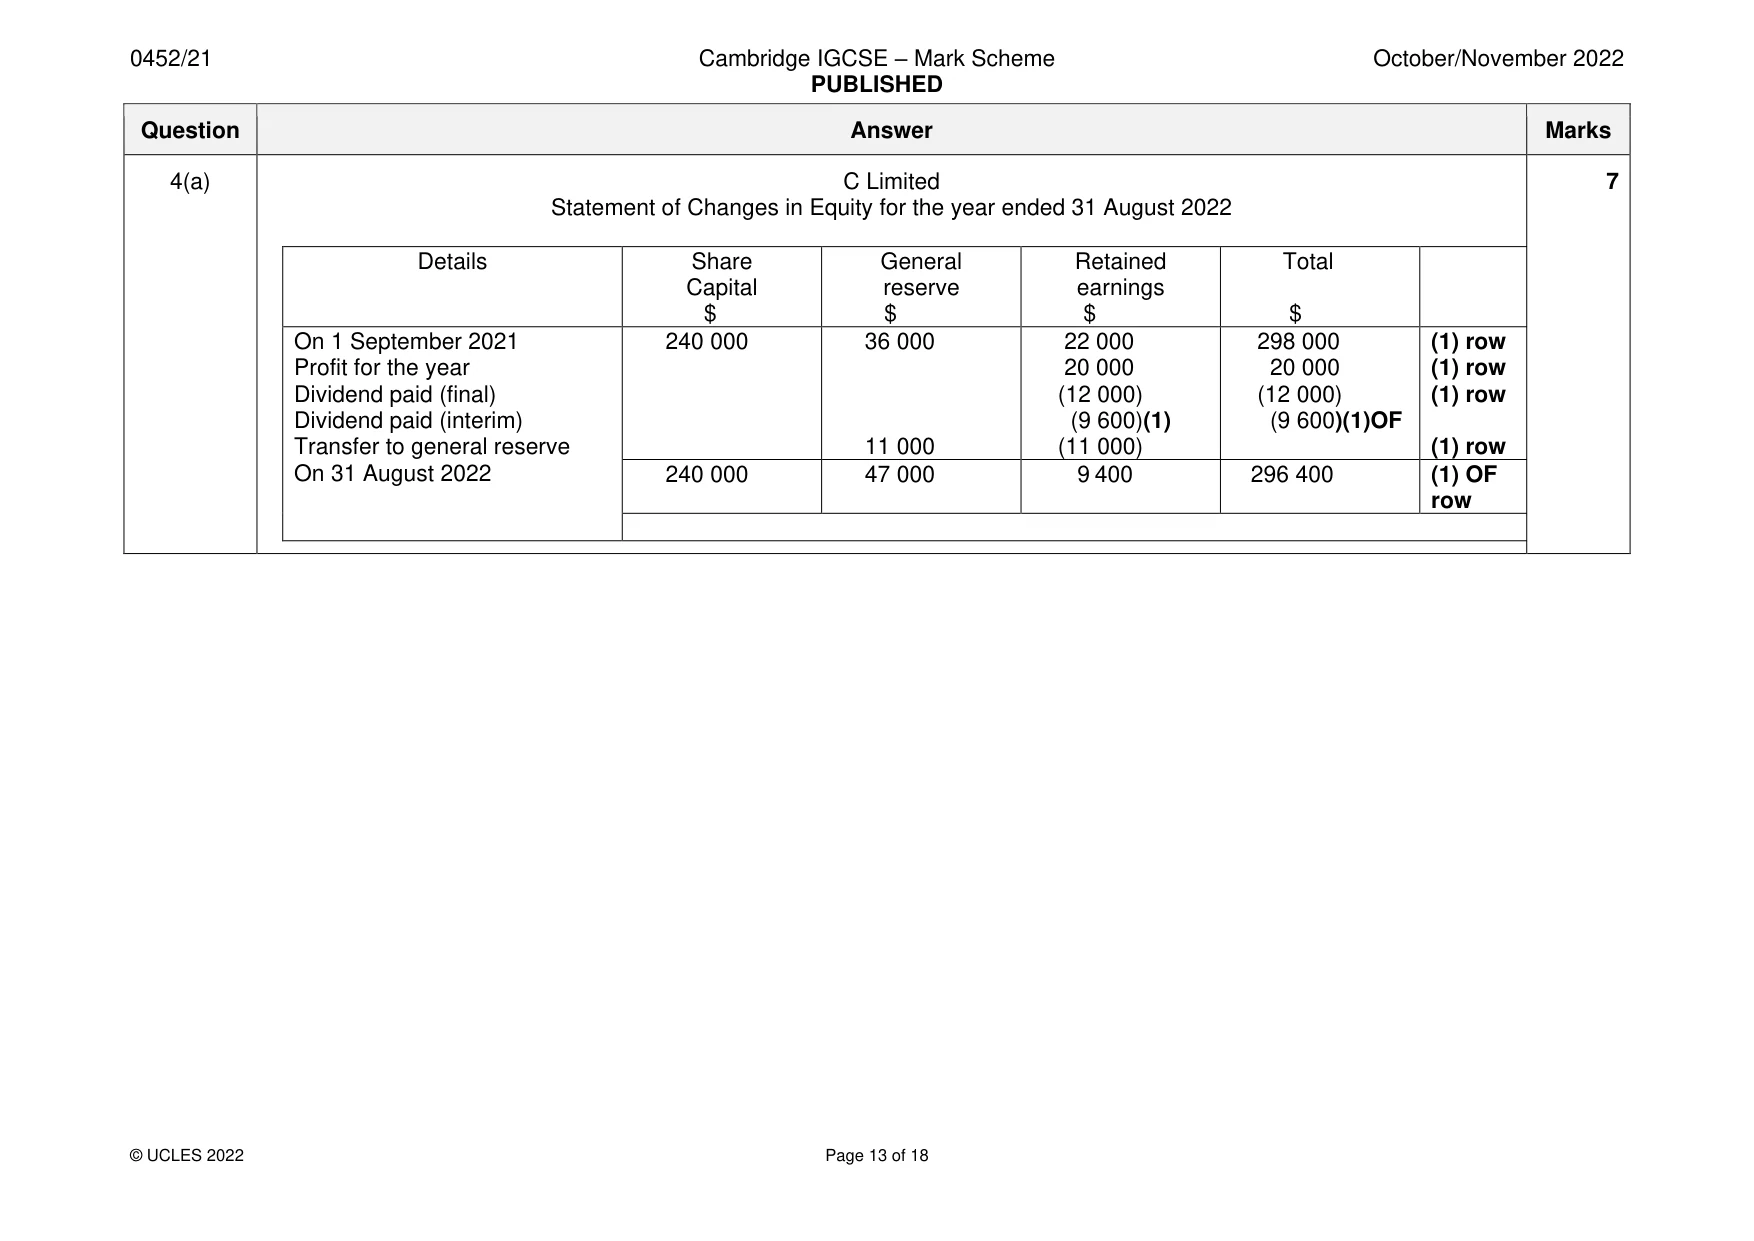
Mark scheme: 3(a) RB 8 Insurance account Date Details $ Date Details $ 2021 2022 Apr 1 Balance b/d 2 500 (1) Mar 31 Bank 600 (1) 2022 Income statement 16 350 (1) OF Mar 31 Bank 15 300 (1) Balance c/d 850 17 800 17 800 Apr 1 Balance b/d 850 ** Commission receivable account Date Details $ Date Details $ 2021 2022 Apr 1 Balance b/d 700 (1) Mar 31 Bank 7 200 (1) 2022 Balance c/d 630 Mar 31 Income statement 7 130 (1) OF 7 830 7 830 Apr 1 Balance b/d 630 **(1) For both 3(b) RB 2 Extract from Statement of financial position at 31 March 2022 Current assets (1) $ Other receivables (850 + 630) 1480 (1) OR Current assets (1) Insurance prepaid 850 }(1) Commission receivable accrued 630 } 3(c) Ensures the correct amount of revenue and expenses for the period are entered in the income statement (1) 3 Ensures that the revenue and expenses are not under or over -stated (1) Ensures that the profit for the year is correctly calculated/is not over or under-stated (1) Ensures that profitability ratios can be relied upon/more accurate decision-making (1) Max (3) 3(d)(i) $3000 25% = $750 (1) 1 3(d)(ii) $2250 2% = $45 (1) 1 3(d)(iii) ($3000 – $750) = $2250 1 $2250 – $45 = $2205 (1) OF 3(e) Discount allowed 4 increase decrease no effect gross profit (1) profit for the year (1) Discount received increase decrease no effect gross profit (1) profit for the year (1) 4(a) C Limited 7 Statement of Changes in Equity for the year ended 31 August 2022 Details Share General Retained Total Capital reserve earnings $ $ $ $ On 1 September 2021 240 000 36 000 22 000 298 000 (1) row Profit for the year 20 000 20 000 (1) row Dividend paid (final) (12 000) (12 000) (1) row Dividend paid (interim) (9 600)(1) (9 600)(1)OF Transfer to general reserve 11 000 (11 000) (1) row On 31 August 2022 240 000 47 000 9 400 296 400 (1) OF row
Q4 · The following information is taken from the statement of financial position of C Limited…
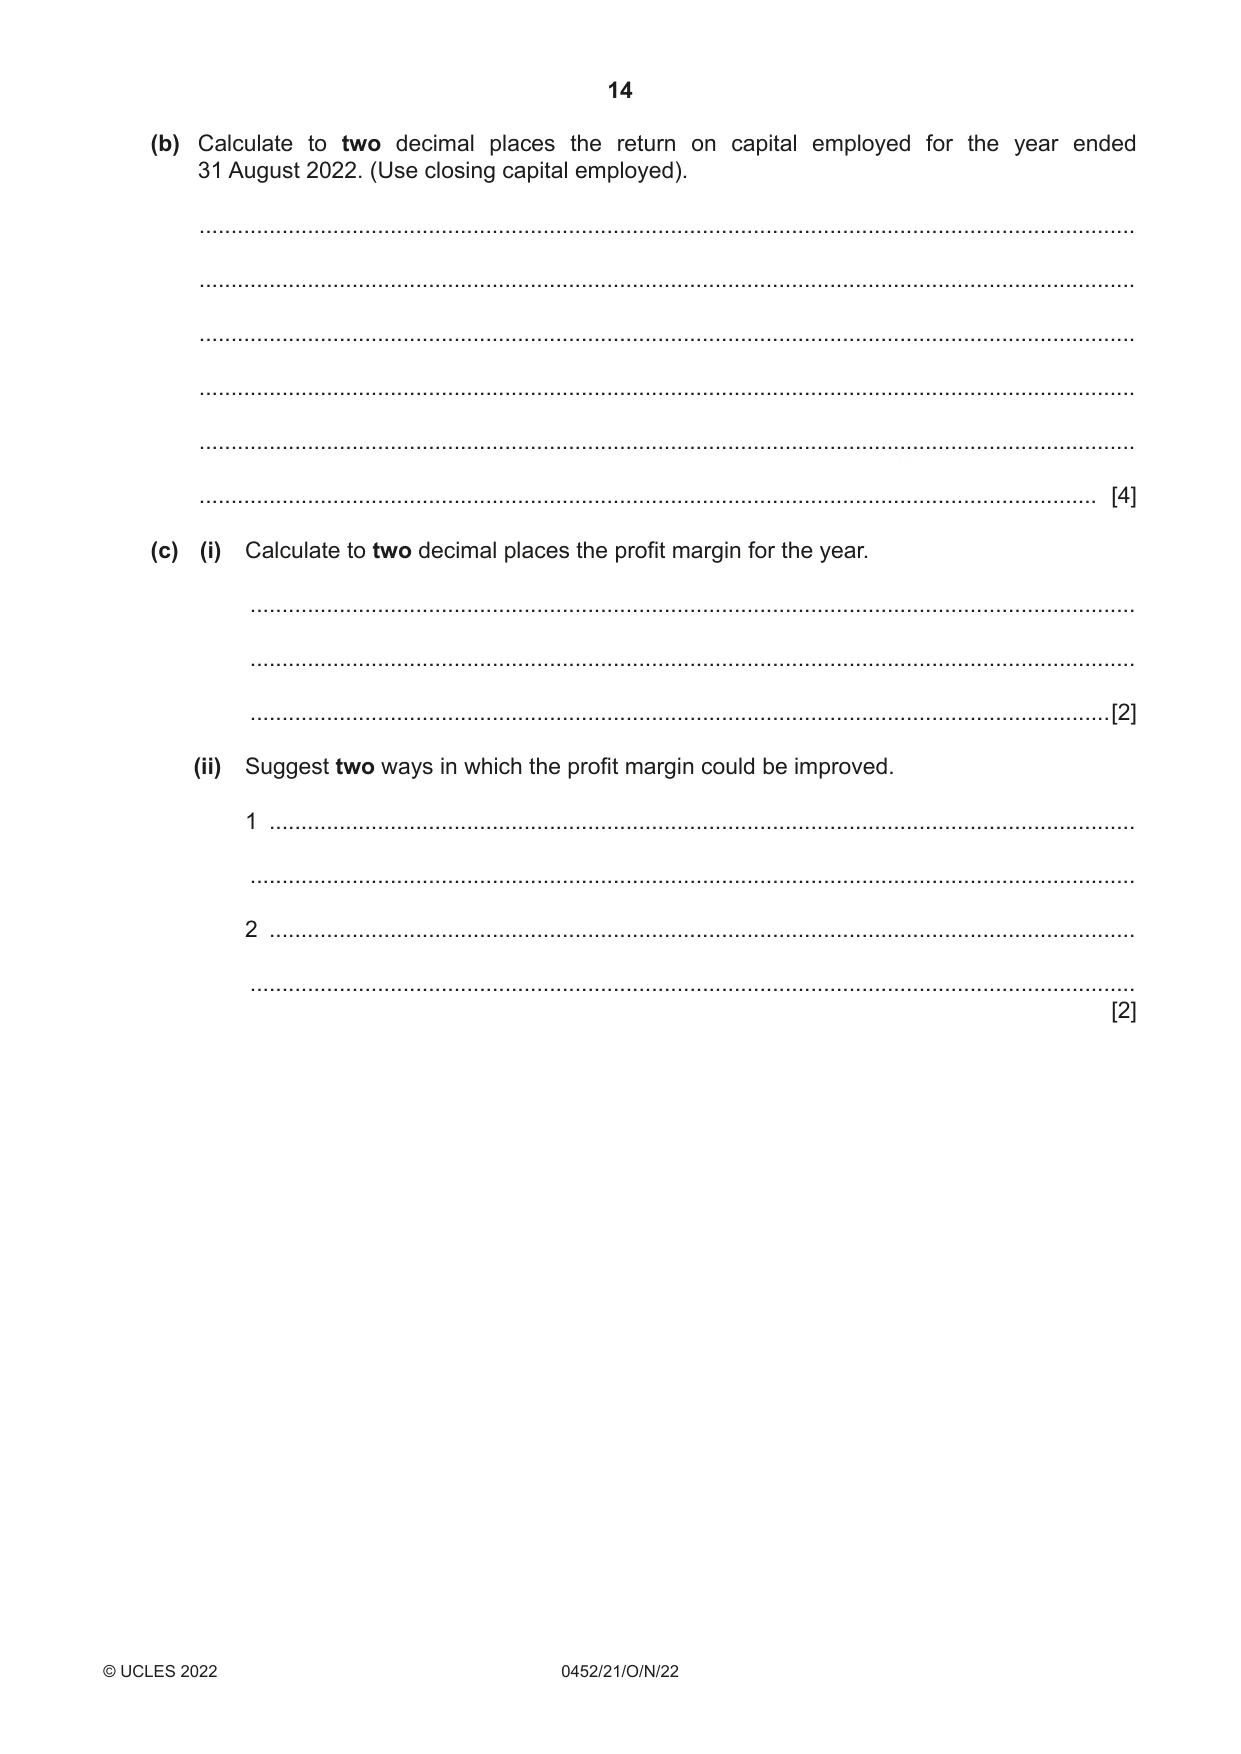
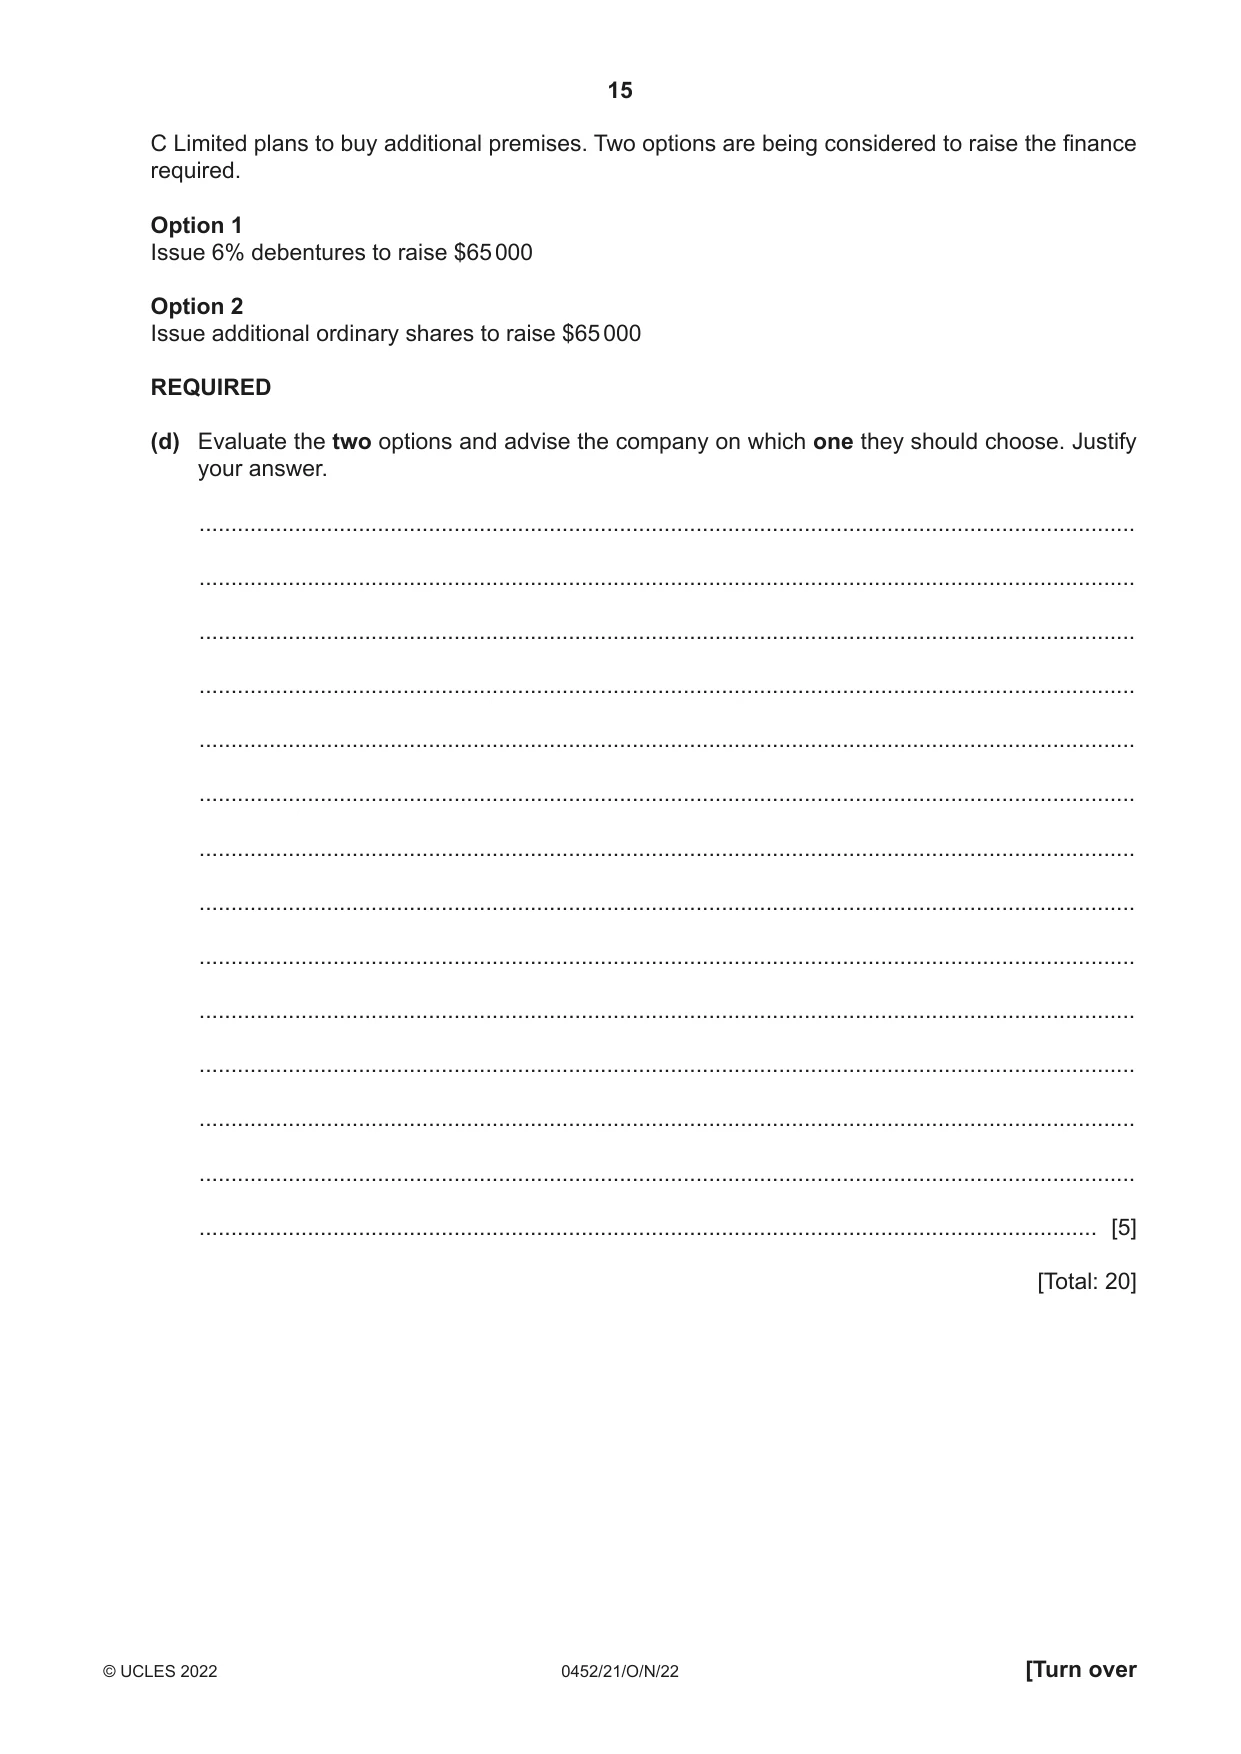
4 The following information is taken from the statement of financial position of C Limited at 1 September 2021. $ 5% Debentures (2024) 60 000 Equity Ordinary share capital ($0.50) 240 000 General reserve 36 000 Retained earnings 22 000 During the year ended 31 August 2022: A final dividend payment of $12 000 was made for the year ended 31 August 2021. An interim dividend payment of $0.02 per share was made for the year ended 31 August 2022. A transfer of $11 000 was made to general reserve. At 31 August 2022 the company proposed a final dividend of $10 000 for the year ended 31 August 2022. The revenue for the year ended 31 August 2022 was $310 000 and the profit (before debenture interest) was $23 000. REQUIRED (a) Prepare the statement for the changes in equity for the year ended 31 August 2022. C Limited Statement of Changes in Equity for the year ended 31 August 2022 Details Share General Retained Total capital reserve earnings $ $ $ $ .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... .................................... ......................... ......................... ......................... ......................... [7] (b) Calculate to two decimal places the return on capital employed for the year ended 31 August 2022. (Use closing capital employed). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) (i) Calculate to two decimal places the profit margin for the year. ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) Suggest two ways in which the profit margin could be improved. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] C Limited plans to buy additional premises. Two options are being considered to raise the finance required. Option 1 Issue 6% debentures to raise $65 000 Option 2 Issue additional ordinary shares to raise $65 000 REQUIRED (d) Evaluate the two options and advise the company on which one they should choose. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
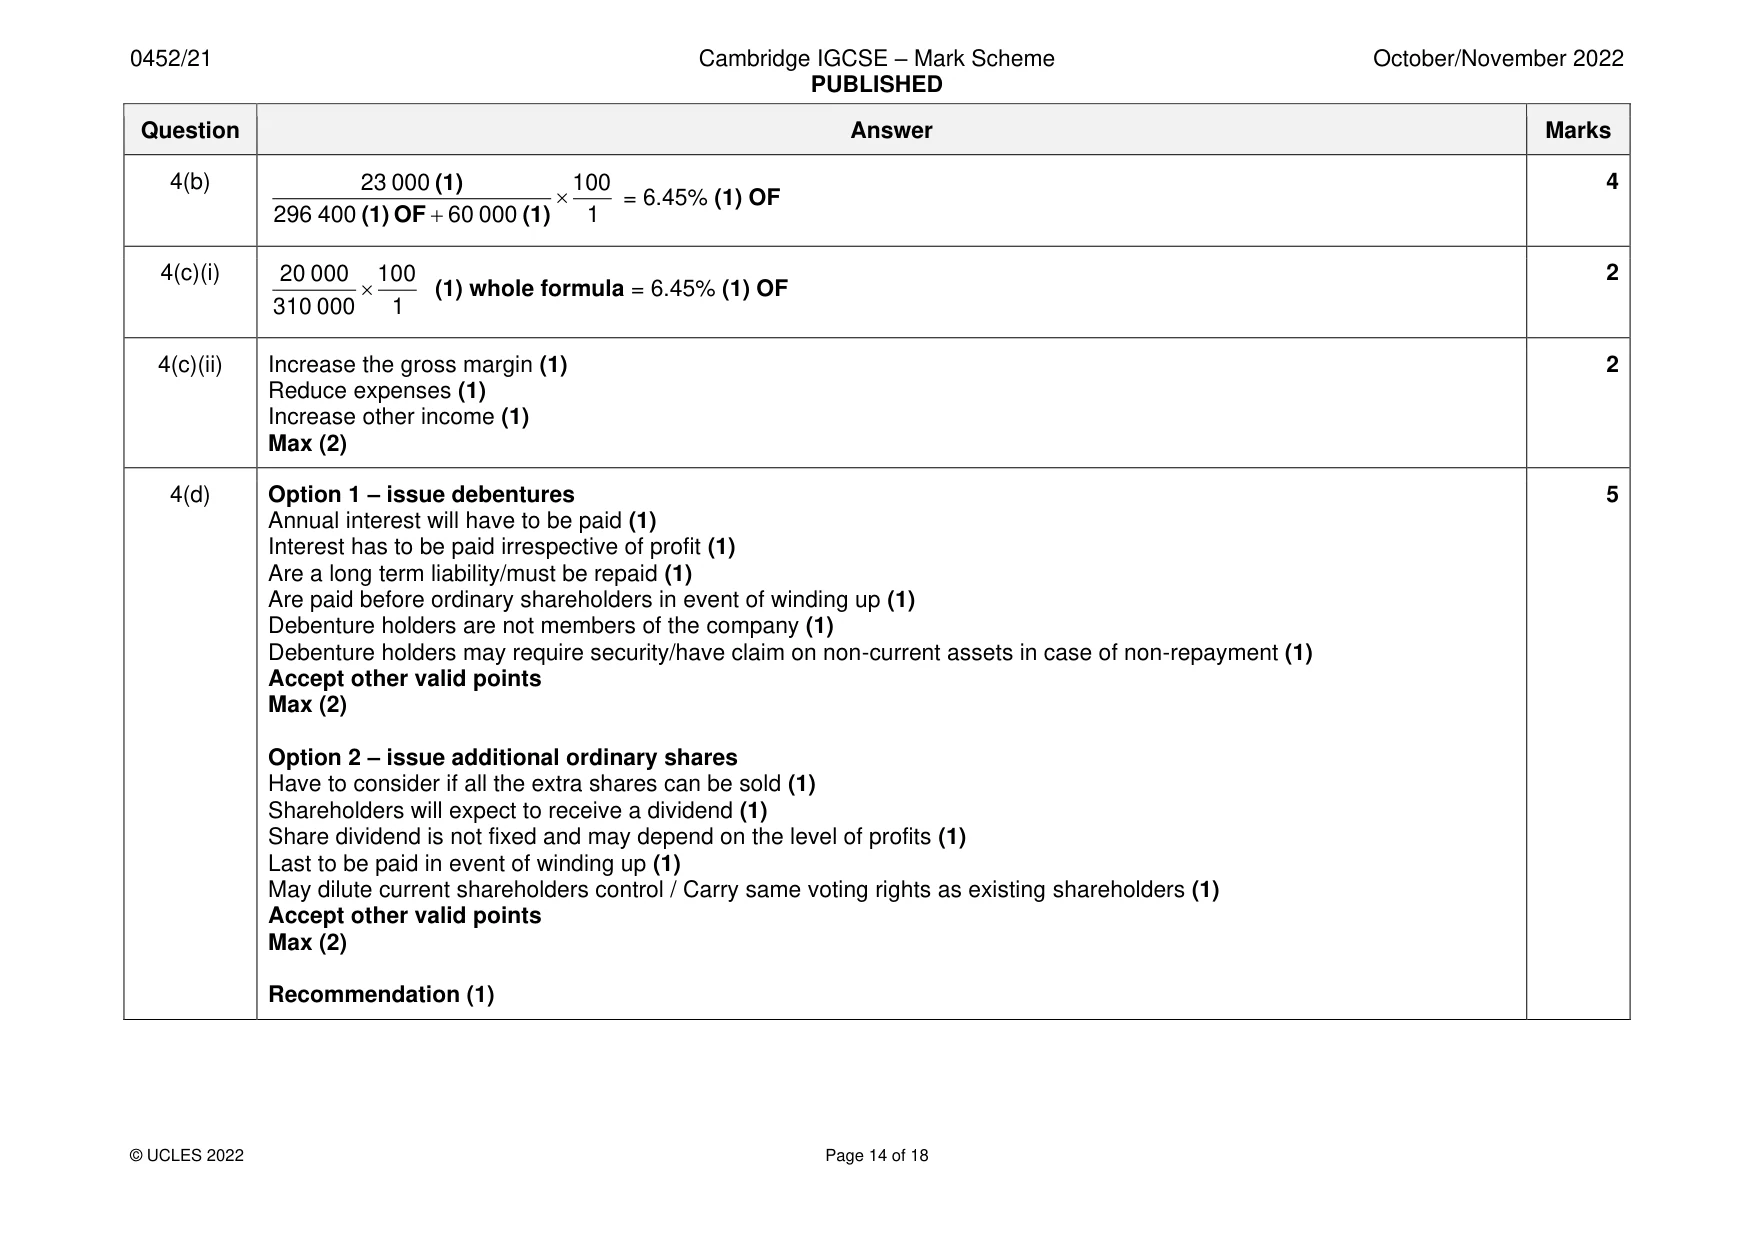
Mark scheme: 4(b) 23 000 (1) 100 4 = 6.45% (1) OF 296 400 (1) OF + 60 000 (1) 1 4(c)(i) 20 000 100 2 (1) whole formula = 6.45% (1) OF 310 000 1 4(c)(ii) Increase the gross margin (1) 2 Reduce expenses (1) Increase other income (1) Max (2) 4(d) Option 1 – issue debentures 5 Annual interest will have to be paid (1) Interest has to be paid irrespective of profit (1) Are a long term liability/must be repaid (1) Are paid before ordinary shareholders in event of winding up (1) Debenture holders are not members of the company (1) Debenture holders may require security/have claim on non-current assets in case of non-repayment (1) Accept other valid points Max (2) Option 2 – issue additional ordinary shares Have to consider if all the extra shares can be sold (1) Shareholders will expect to receive a dividend (1) Share dividend is not fixed and may depend on the level of profits (1) Last to be paid in event of winding up (1) May dilute current shareholders control / Carry same voting rights as existing shareholders (1) Accept other valid points Max (2) Recommendation (1)
Q5 · NT started in business on 1 September 2020
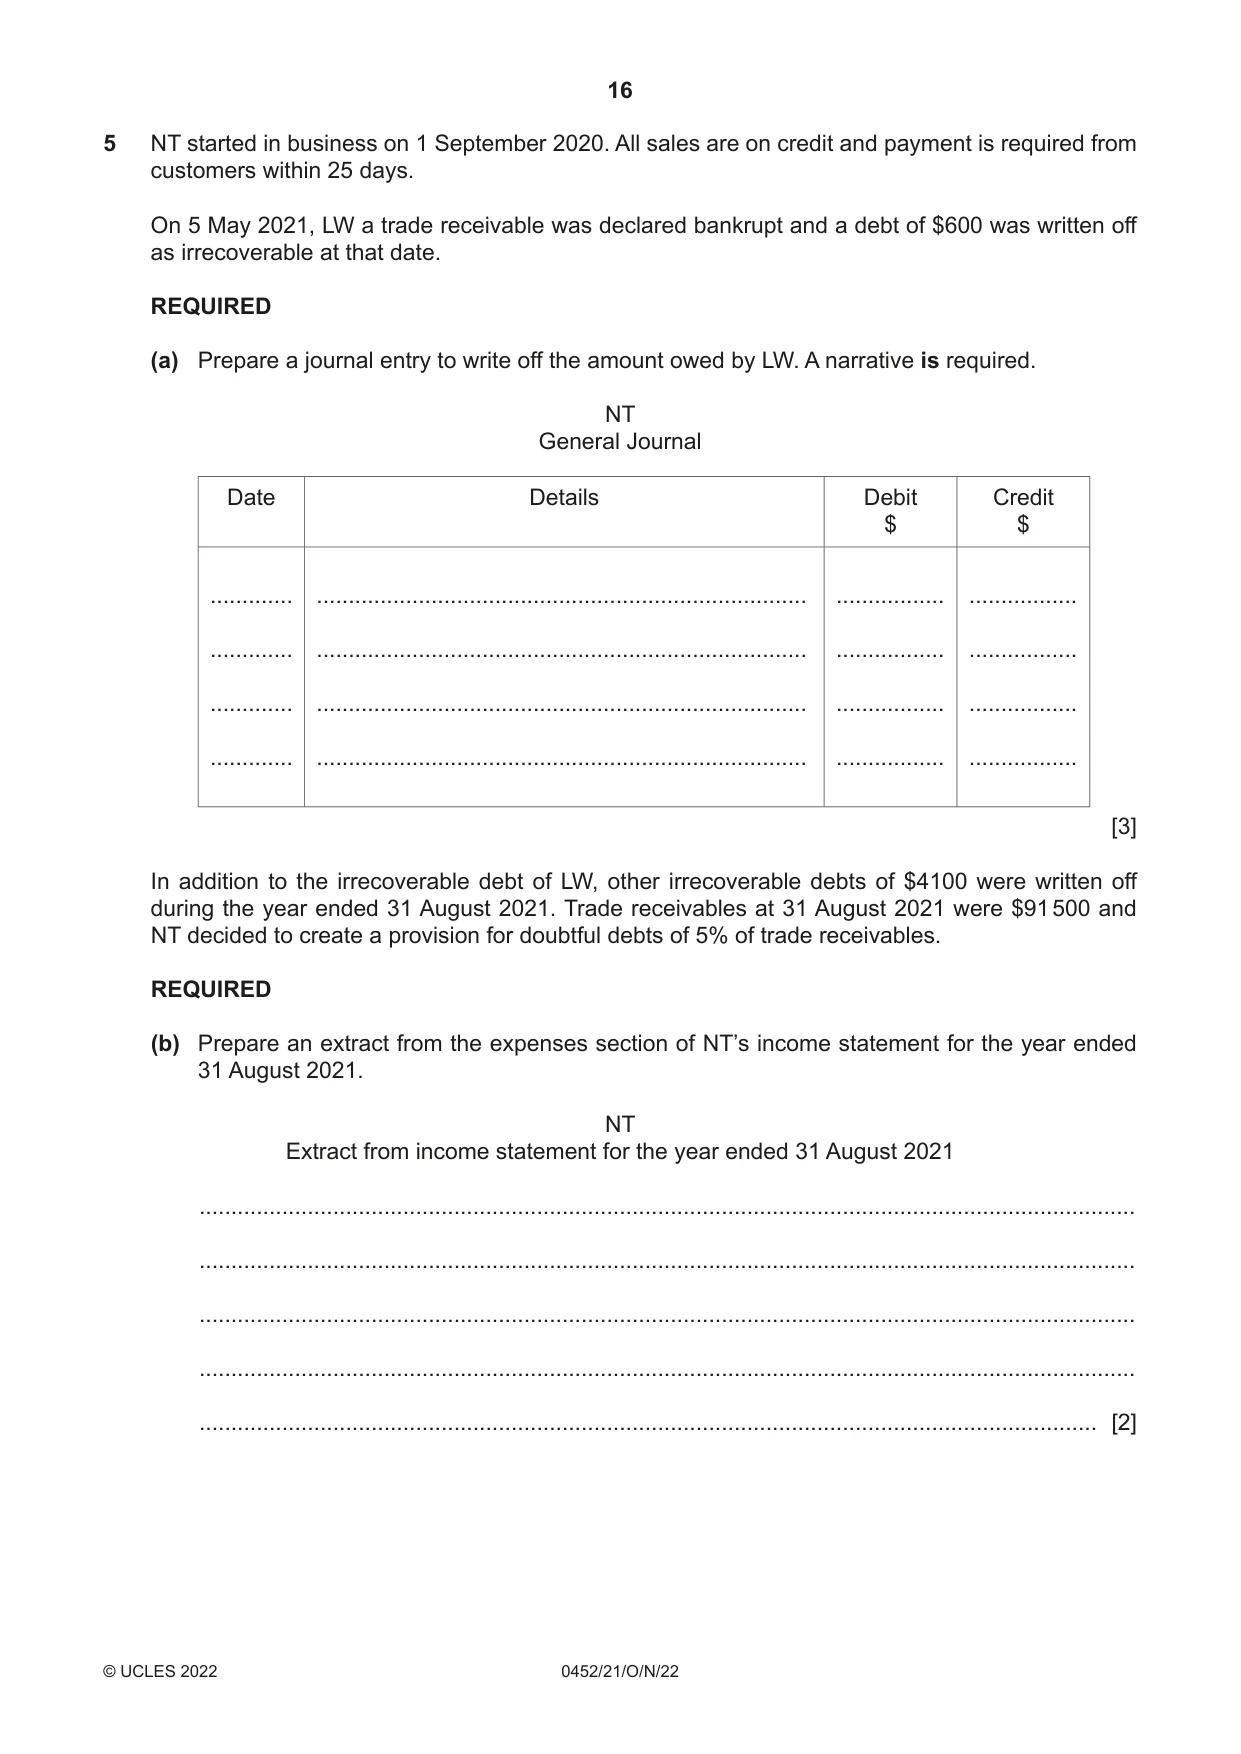
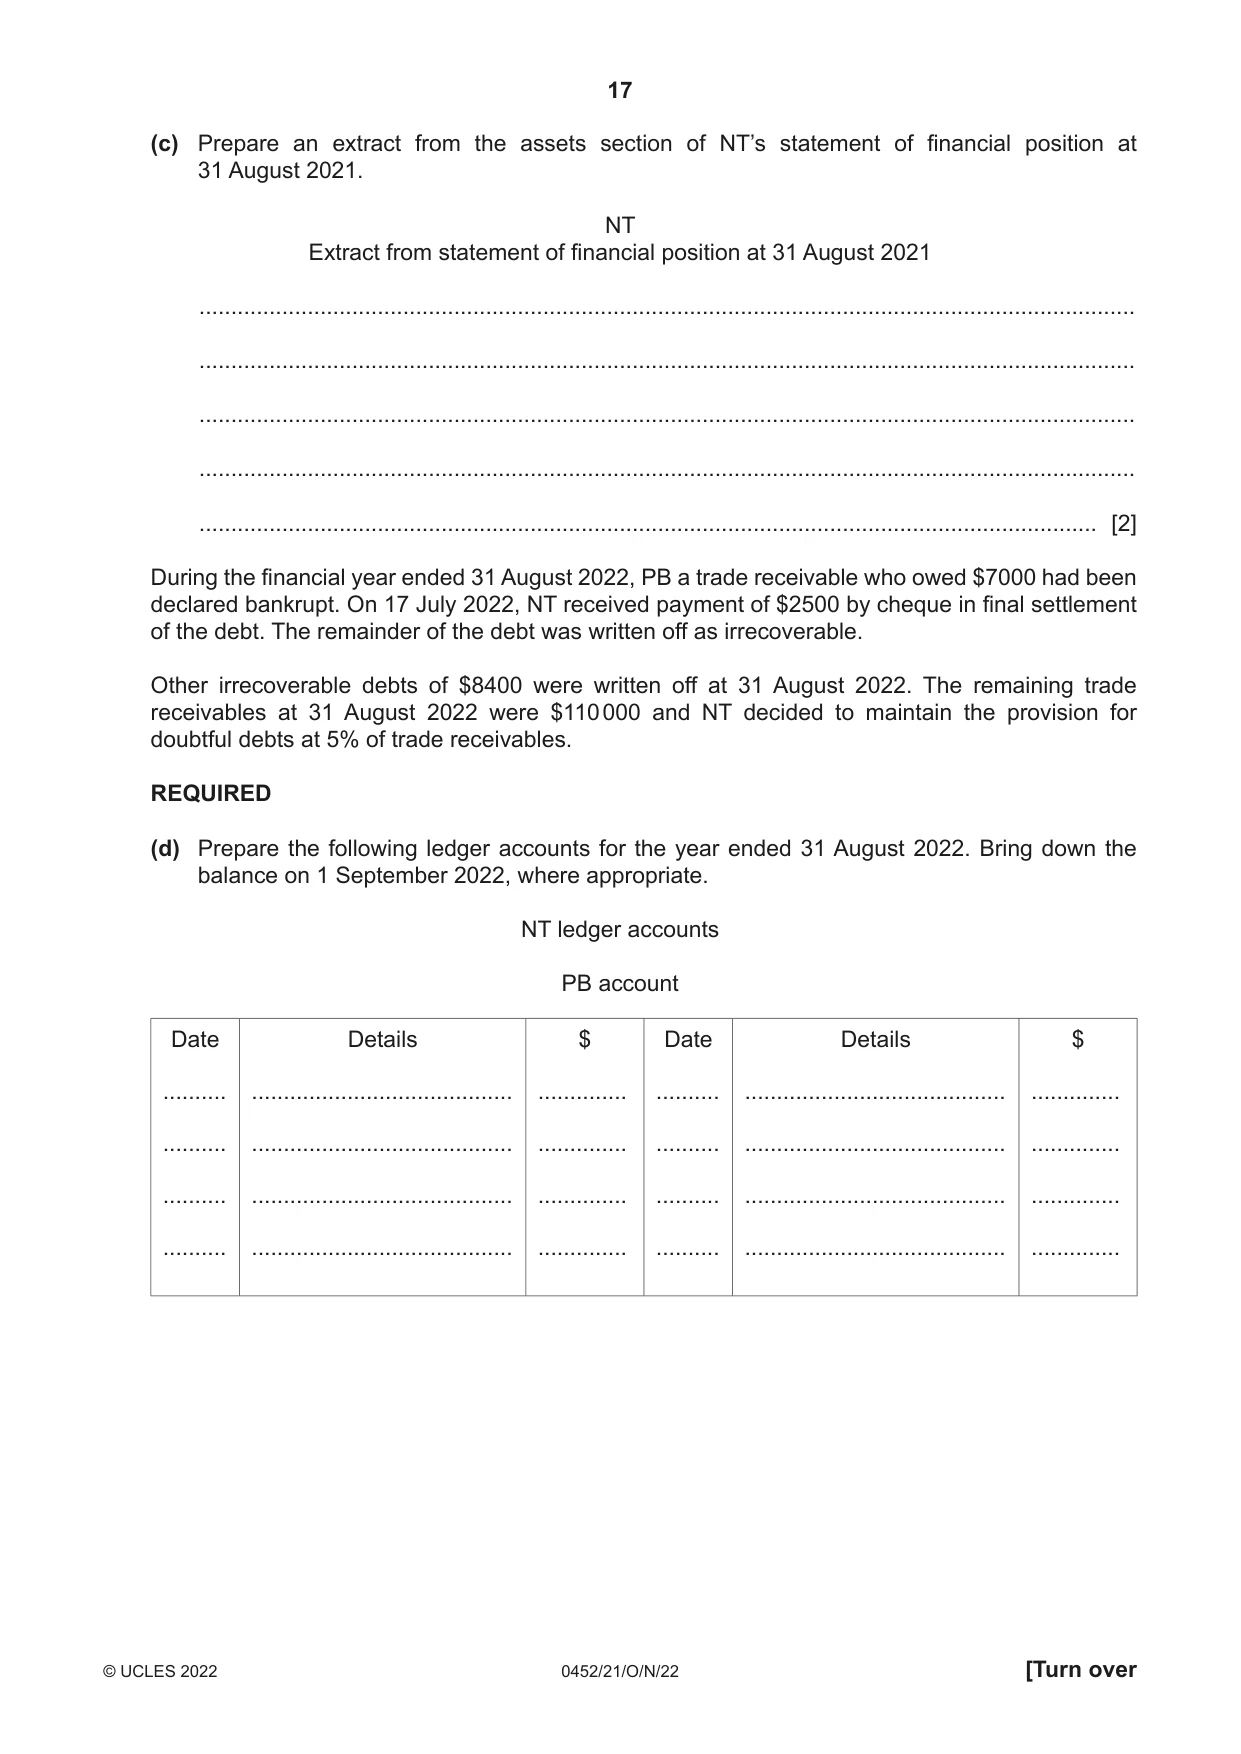
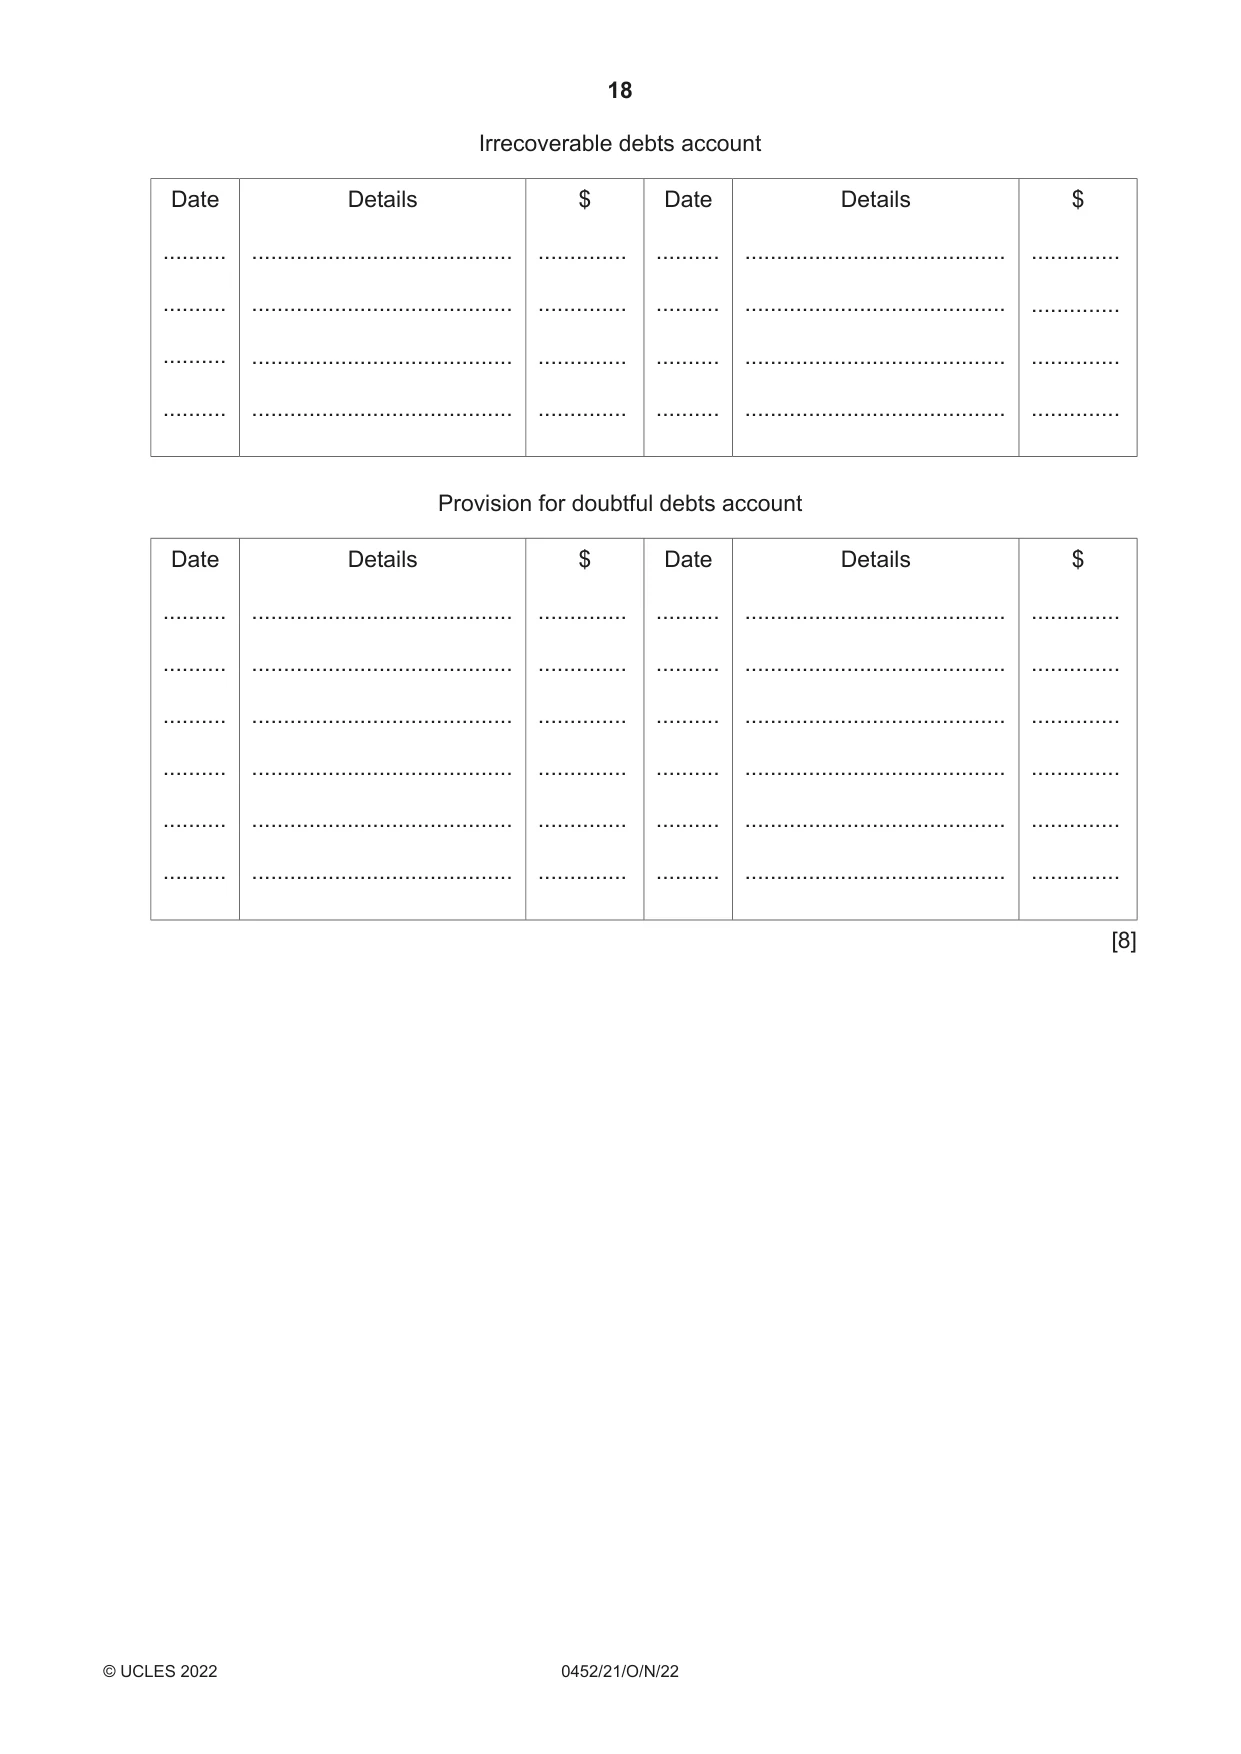
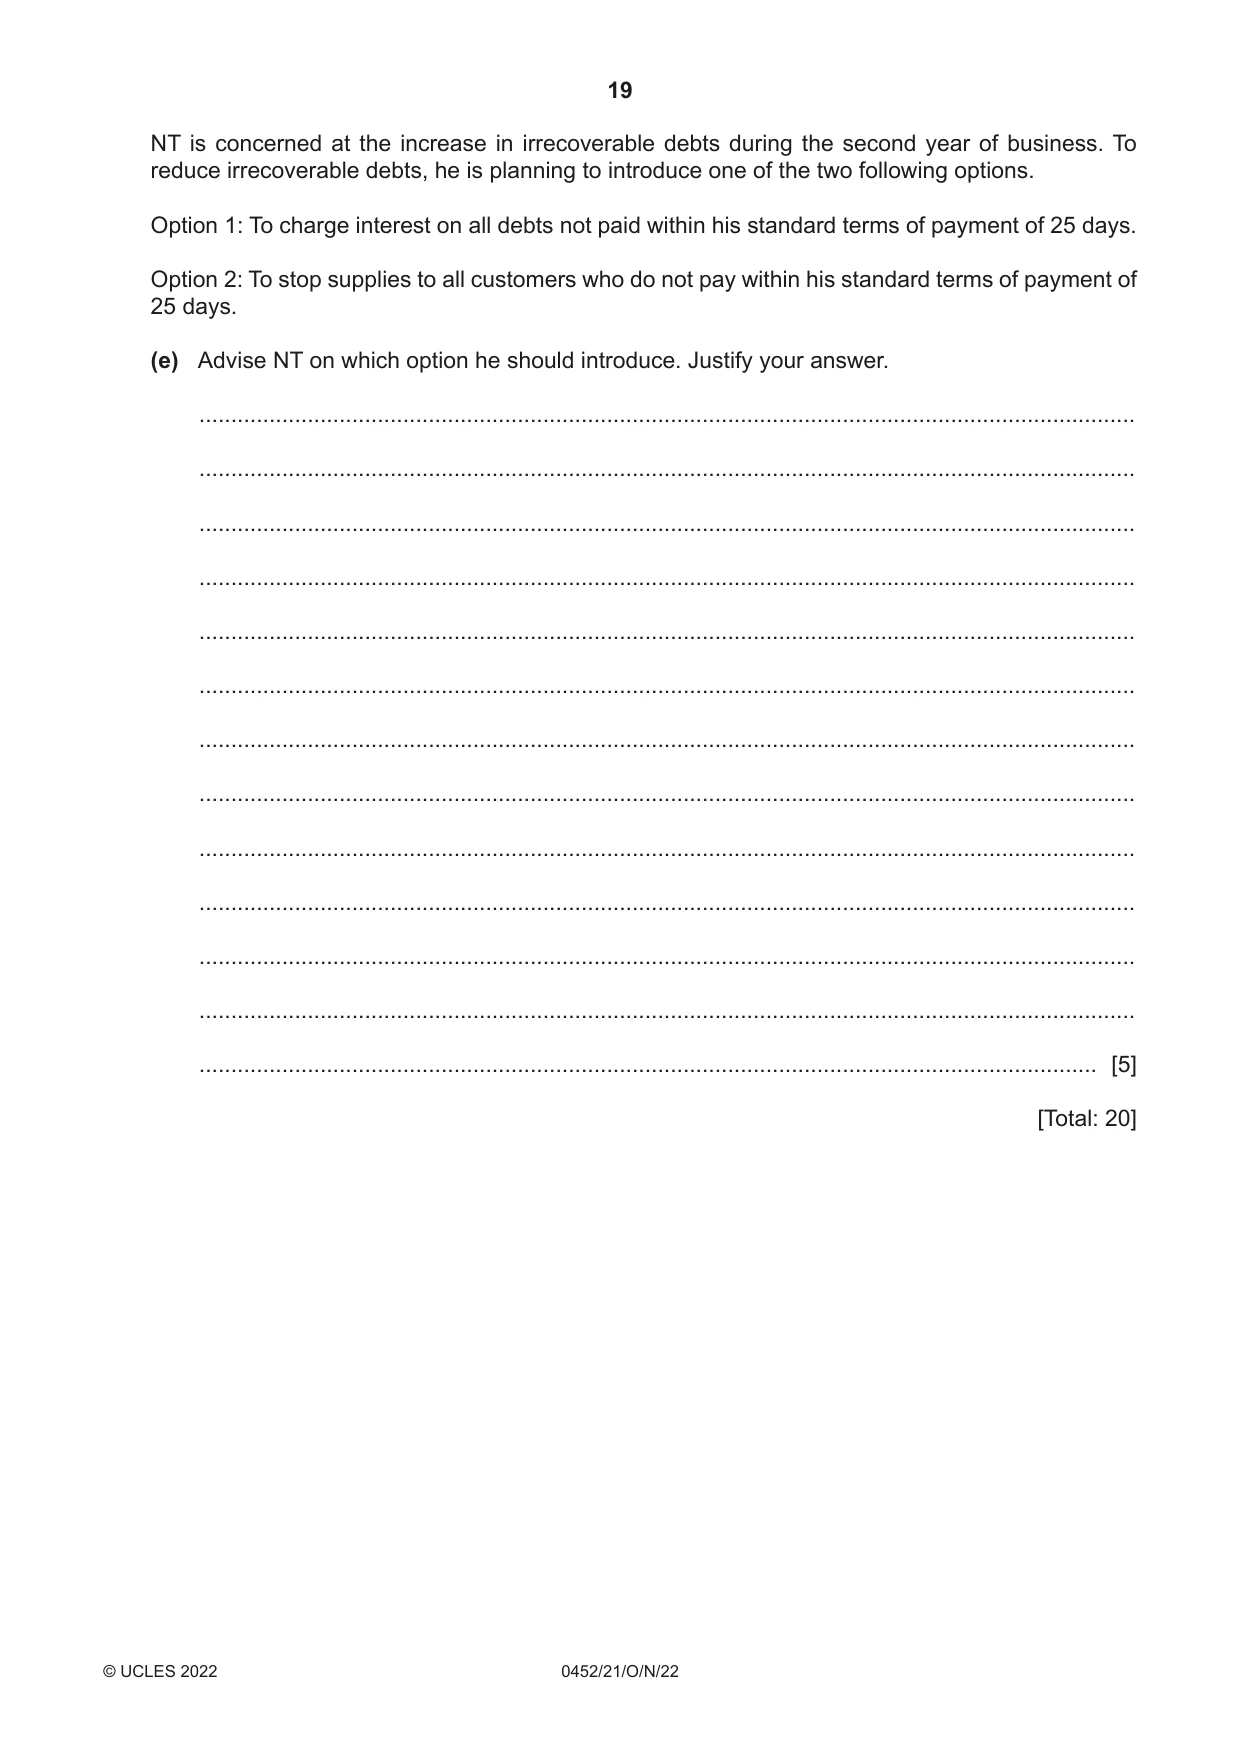
5 NT started in business on 1 September 2020. All sales are on credit and payment is required from customers within 25 days. On 5 May 2021, LW a trade receivable was declared bankrupt and a debt of $600 was written off as irrecoverable at that date. REQUIRED (a) Prepare a journal entry to write off the amount owed by LW. A narrative is required. NT General Journal Date Details Debit Credit $ $ ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. [3] In addition to the irrecoverable debt of LW, other irrecoverable debts of $4100 were written off during the year ended 31 August 2021. Trade receivables at 31 August 2021 were $91 500 and NT decided to create a provision for doubtful debts of 5% of trade receivables. REQUIRED (b) Prepare an extract from the expenses section of NT’s income statement for the year ended 31 August 2021. NT Extract from income statement for the year ended 31 August 2021 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Prepare an extract from the assets section of NT’s statement of financial position at 31 August 2021. NT Extract from statement of financial position at 31 August 2021 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] During the financial year ended 31 August 2022, PB a trade receivable who owed $7000 had been declared bankrupt. On 17 July 2022, NT received payment of $2500 by cheque in final settlement of the debt. The remainder of the debt was written off as irrecoverable. Other irrecoverable debts of $8400 were written off at 31 August 2022. The remaining trade receivables at 31 August 2022 were $110 000 and NT decided to maintain the provision for doubtful debts at 5% of trade receivables. REQUIRED (d) Prepare the following ledger accounts for the year ended 31 August 2022. Bring down the balance on 1 September 2022, where appropriate. NT ledger accounts PB account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Irrecoverable debts account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Provision for doubtful debts account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [8] NT is concerned at the increase in irrecoverable debts during the second year of business. To reduce irrecoverable debts, he is planning to introduce one of the two following options. Option 1: To charge interest on all debts not paid within his standard terms of payment of 25 days. Option 2: To stop supplies to all customers who do not pay within his standard terms of payment of
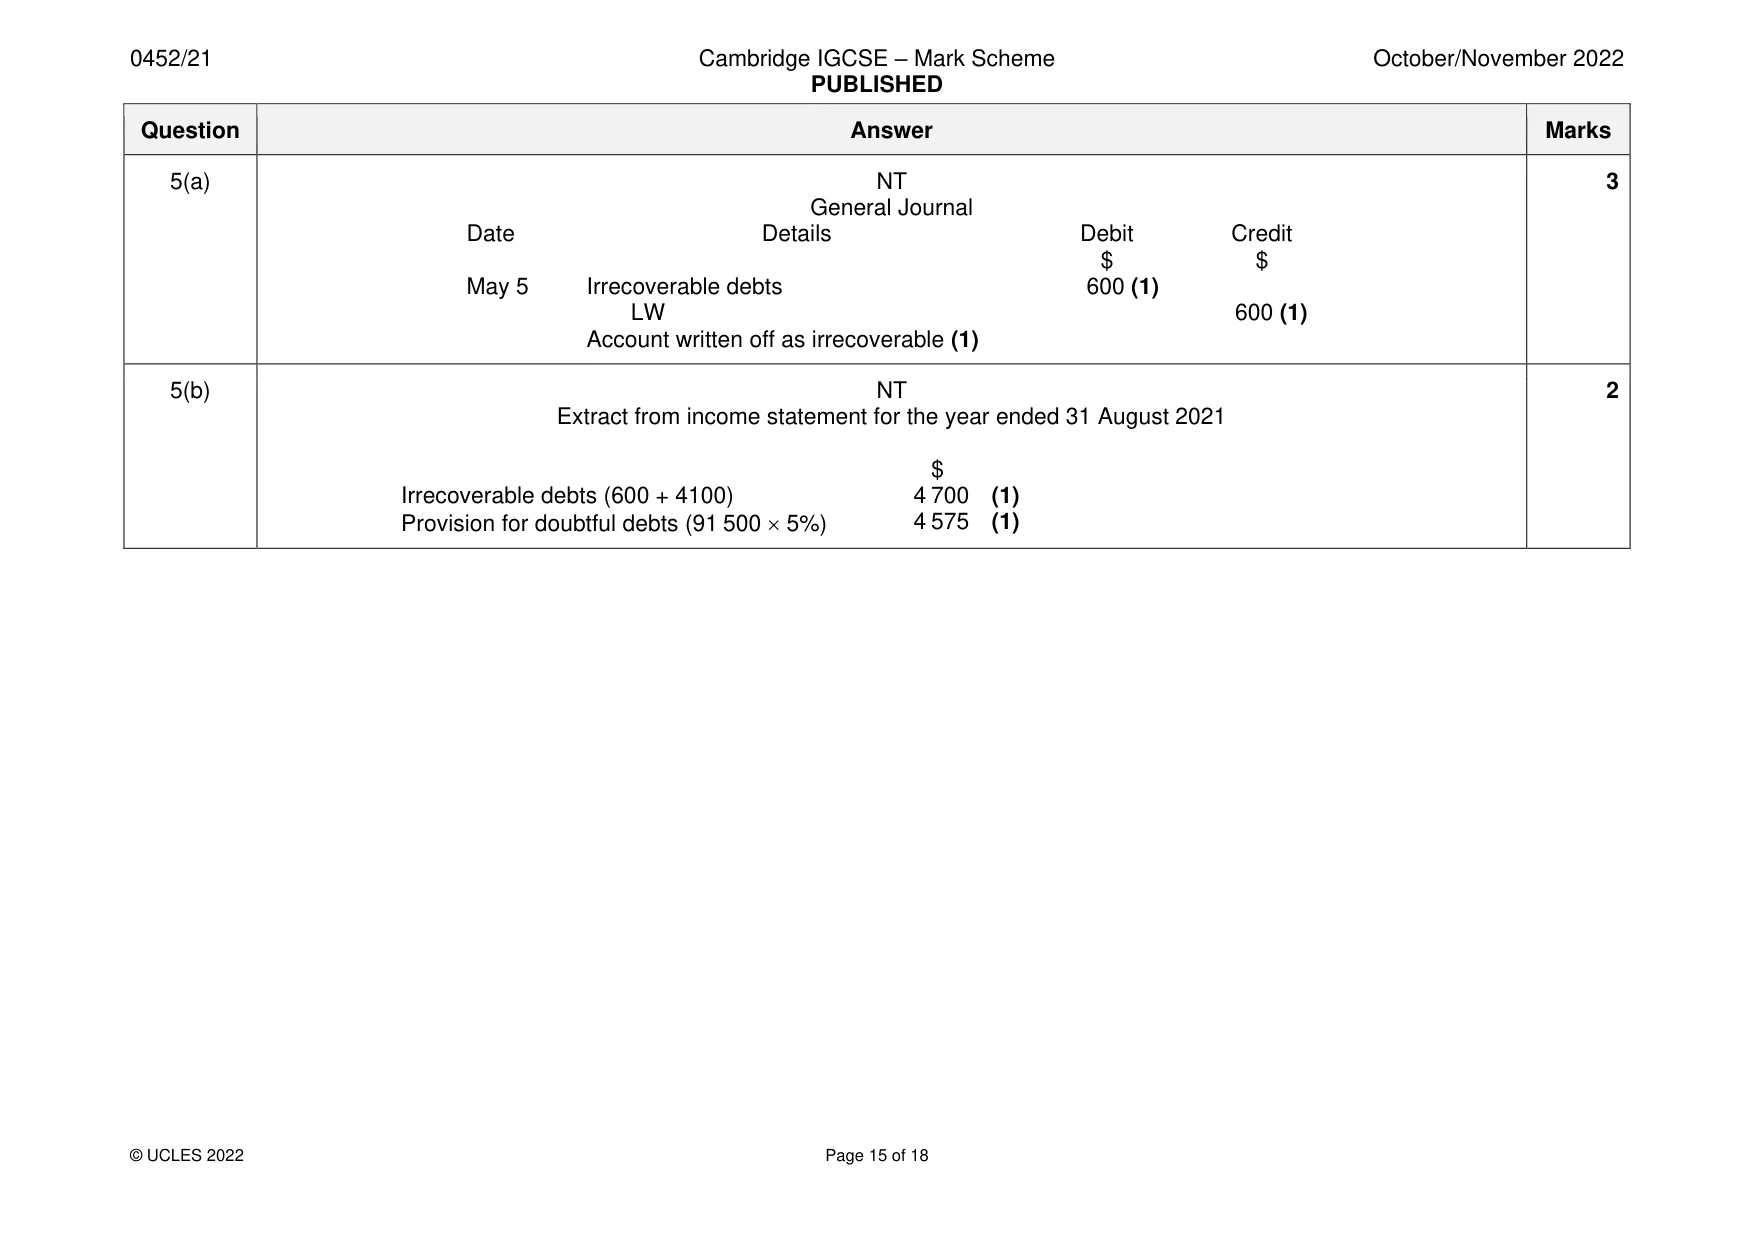
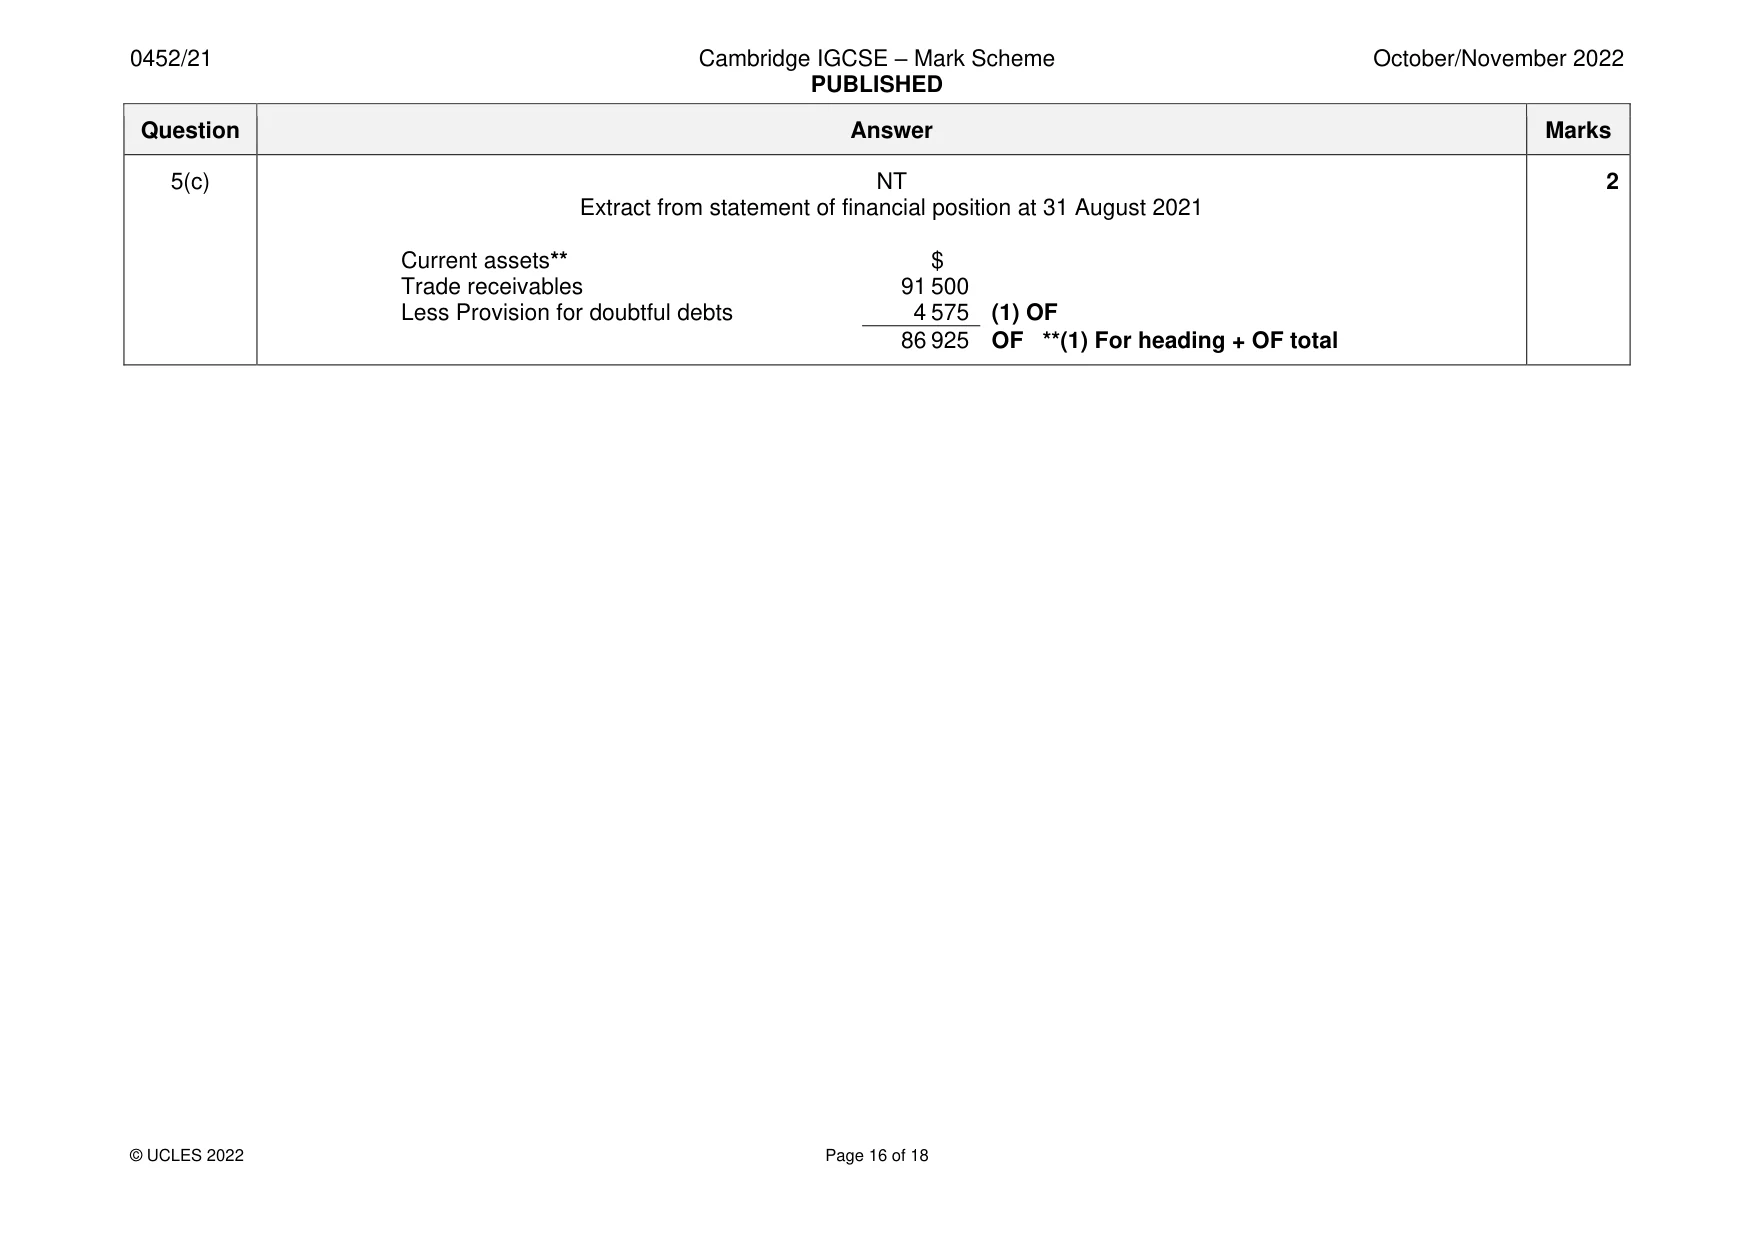
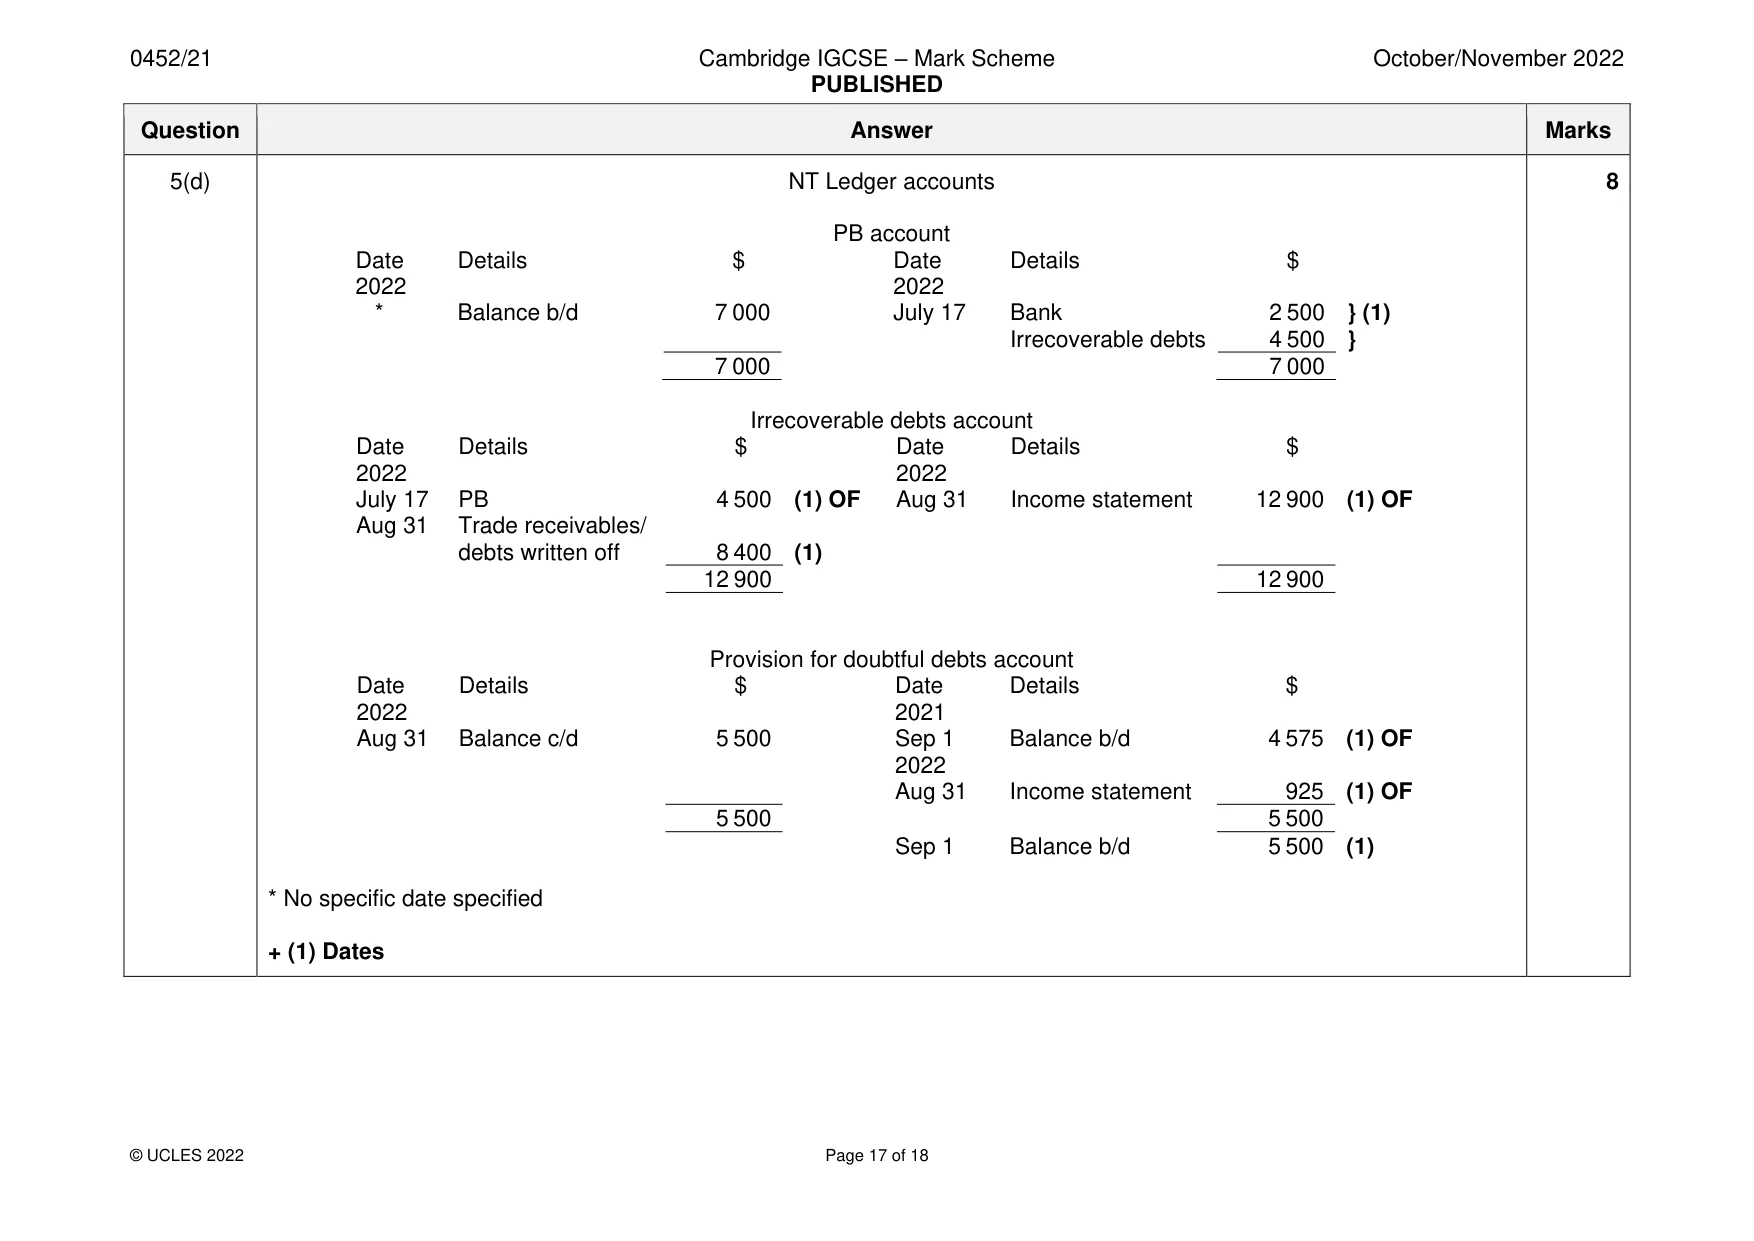
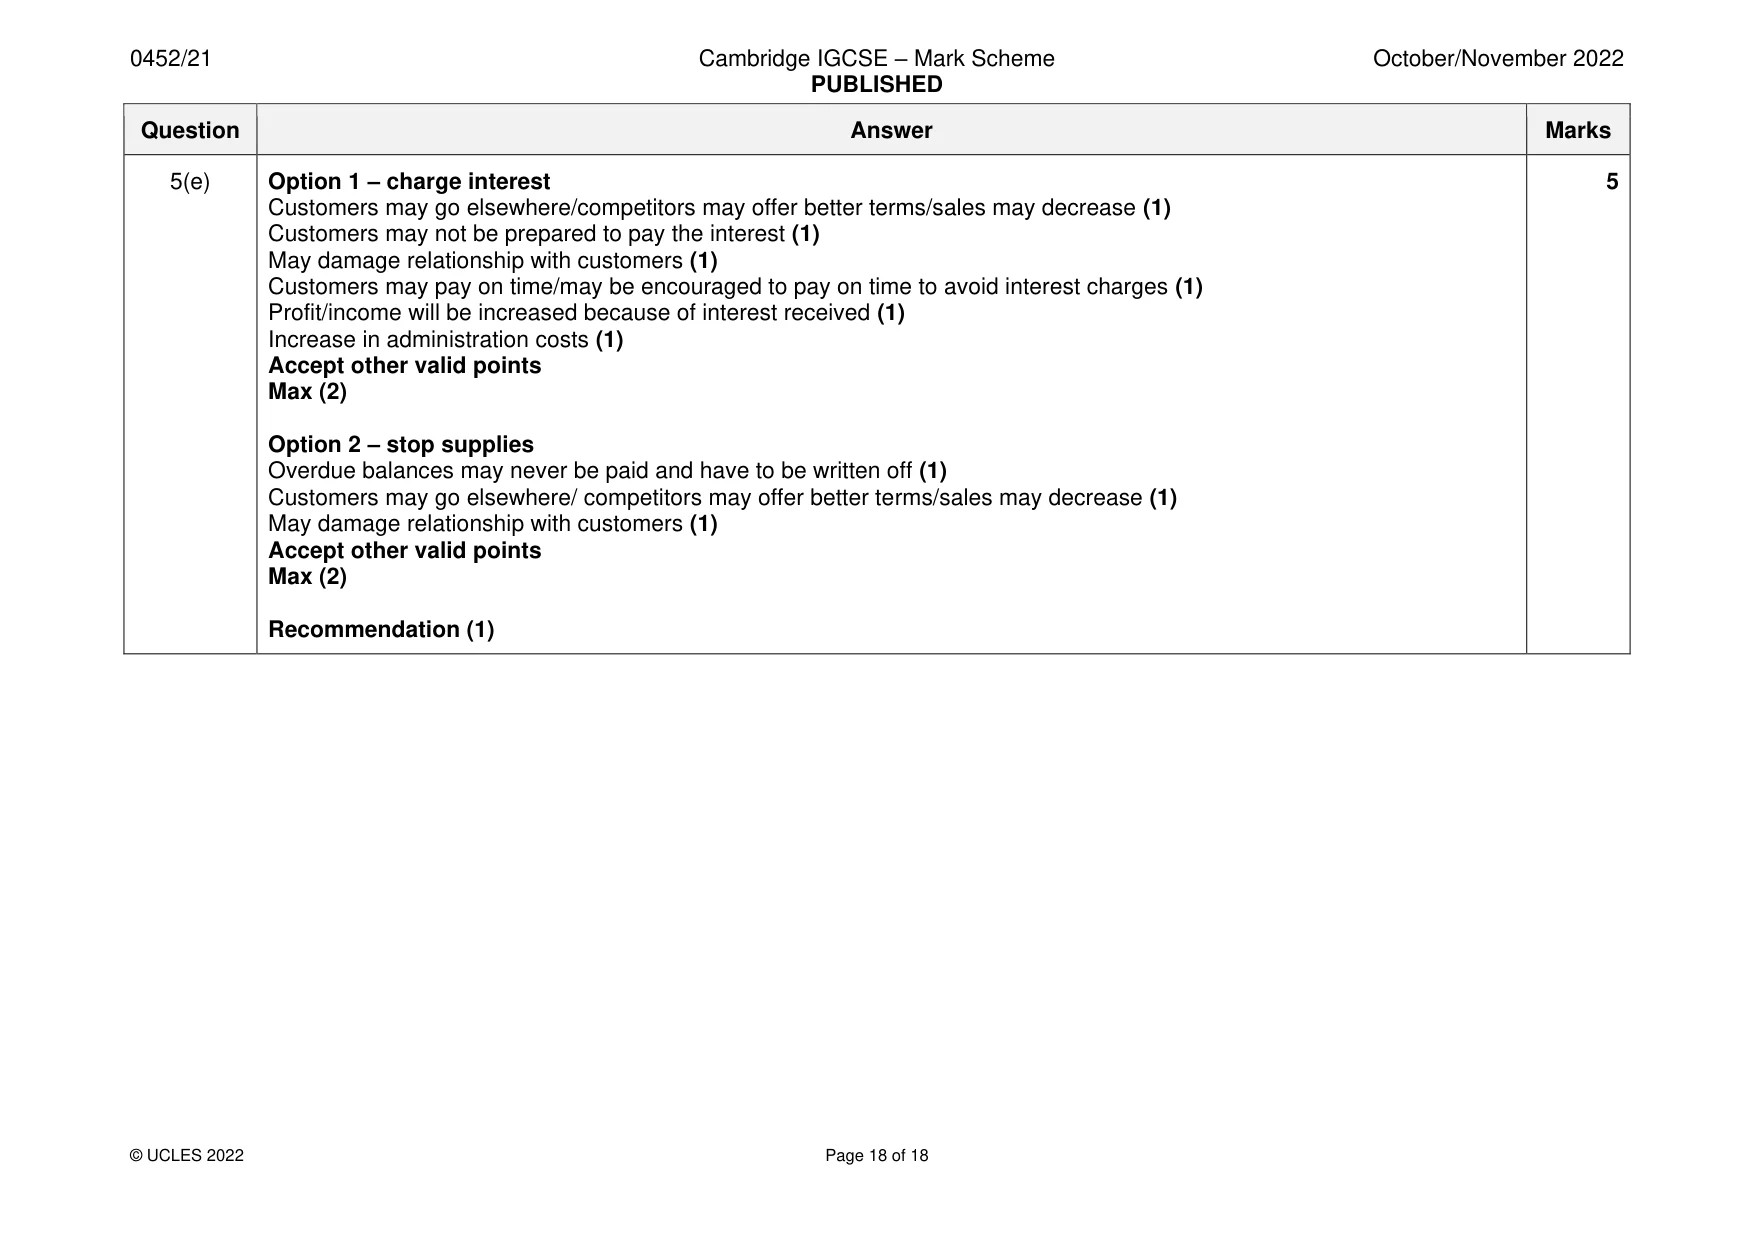
Mark scheme: 5(a) NT 3 General Journal Date Details Debit Credit $ $ May 5 Irrecoverable debts 600 (1) LW 600 (1) Account written off as irrecoverable (1) 5(b) NT 2 Extract from income statement for the year ended 31 August 2021 $ Irrecoverable debts (600 + 4100) 4 700 (1) Provision for doubtful debts (91 500 5%) 4 575 (1) 5(c) NT 2 Extract from statement of financial position at 31 August 2021 Current assets** $ Trade receivables 91 500 Less Provision for doubtful debts 4 575 (1) OF 86 925 OF **(1) For heading + OF total 5(d) NT Ledger accounts 8 PB account Date Details $ Date Details $ 2022 2022 * Balance b/d 7 000 July 17 Bank 2 500 } (1) Irrecoverable debts 4 500 } 7 000 7 000 Irrecoverable debts account Date Details $ Date Details $ 2022 2022 July 17 PB 4 500 (1) OF Aug 31 Income statement 12 900 (1) OF Aug 31 Trade receivables/ debts written off 8 400 (1) 12 900 12 900 Provision for doubtful debts account Date Details $ Date Details $ 2022 2021 Aug 31 Balance c/d 5 500 Sep 1 Balance b/d 4 575 (1) OF 2022 Aug 31 Income statement 925 (1) OF 5 500 5 500 Sep 1 Balance b/d 5 500 (1) * No specific date specified + (1) Dates 5(e) Option 1 – charge interest 5 Customers may go elsewhere/competitors may offer better terms/sales may decrease (1) Customers may not be prepared to pay the interest (1) May damage relationship with customers (1) Customers may pay on time/may be encouraged to pay on time to avoid interest charges (1) Profit/income will be increased because of interest received (1) Increase in administration costs (1) Accept other valid points Max (2) Option 2 – stop supplies Overdue balances may never be paid and have to be written off (1) Customers may go elsewhere/ competitors may offer better terms/sales may decrease (1) May damage relationship with customers (1) Accept other valid points Max (2) Recommendation (1)
More questions on Irrecoverable debts and allowance for irrecoverable debts
Question 25
25 days. (e) Advise NT on which option he should introduce. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.