Cambridge IGCSE Accounting 0452 — 2022 Feb/March Paper 2 · Variant 2
0452/22/F/M/22 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Nazmeen started in business as a hairdresser on 1 January 2022
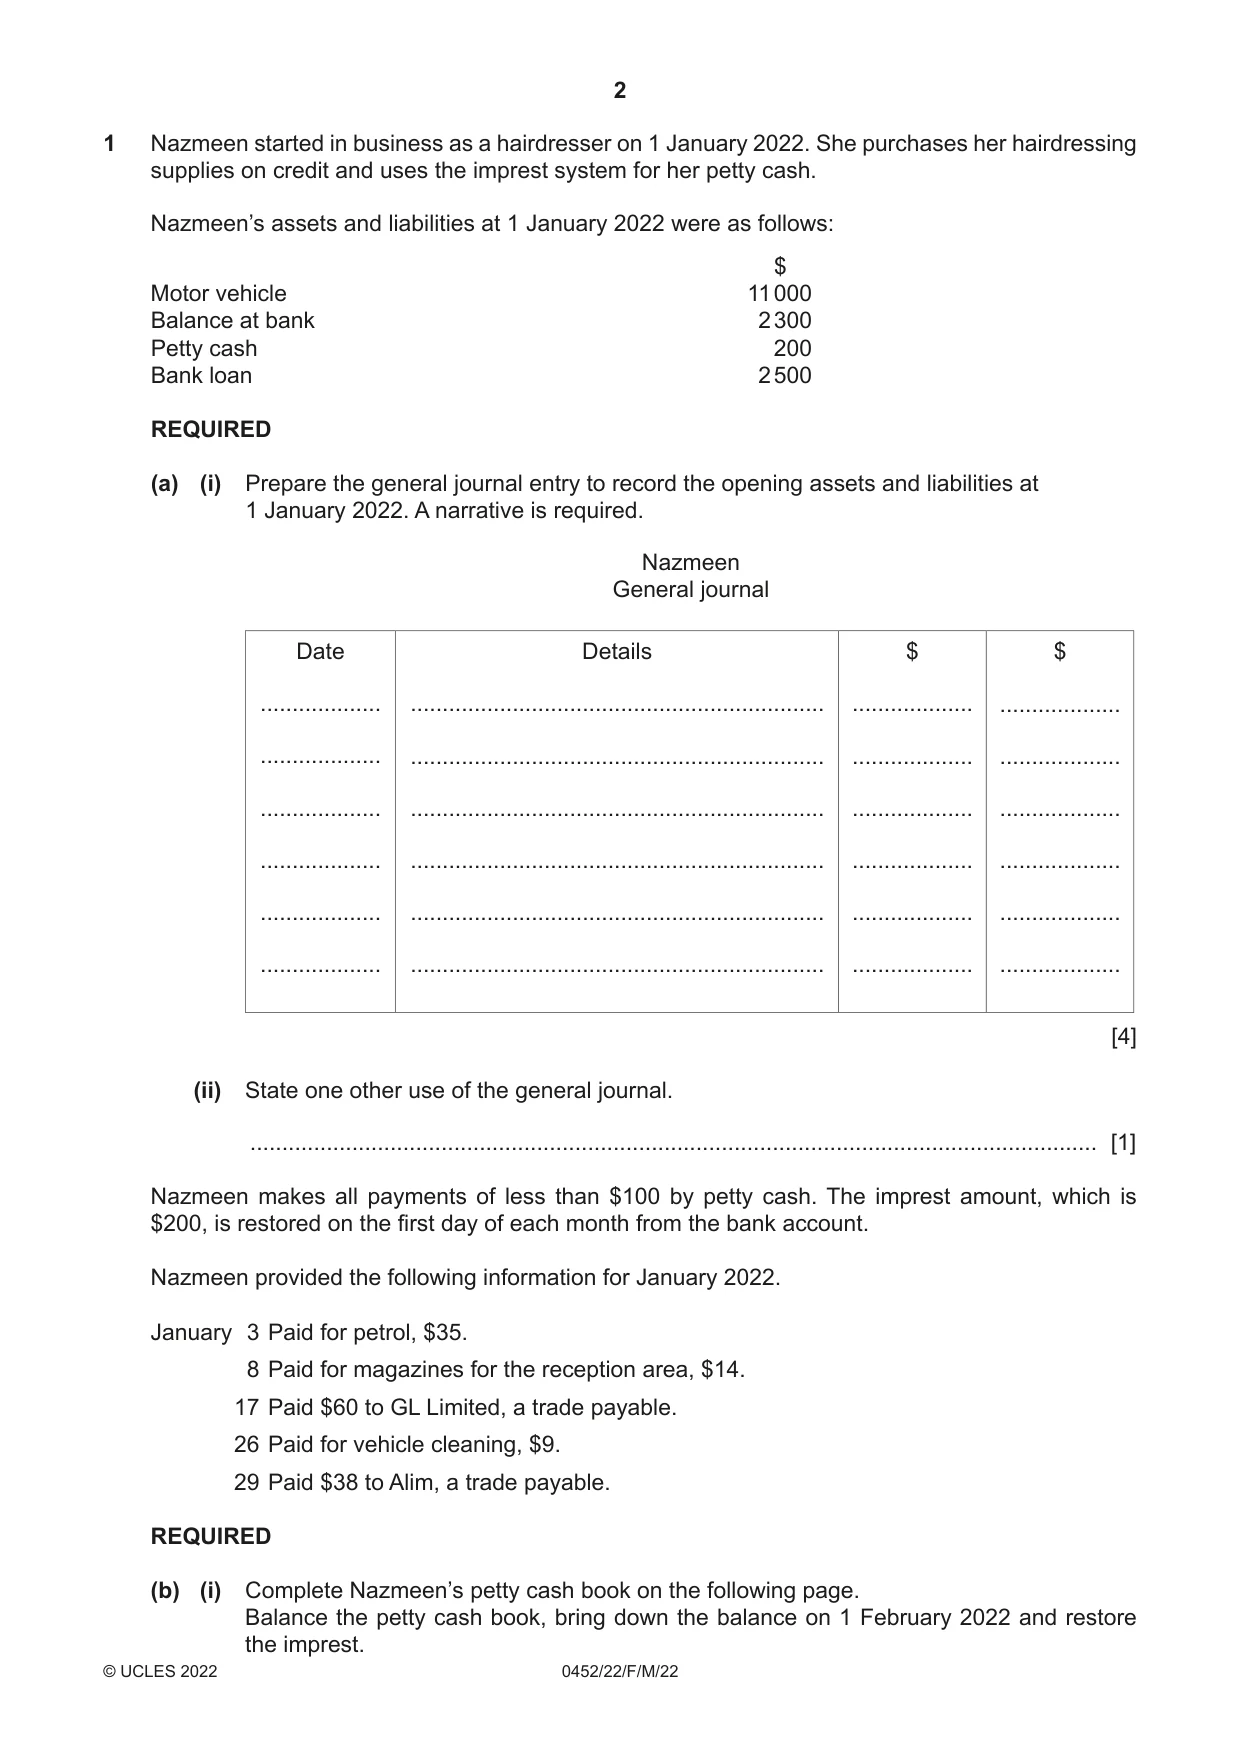
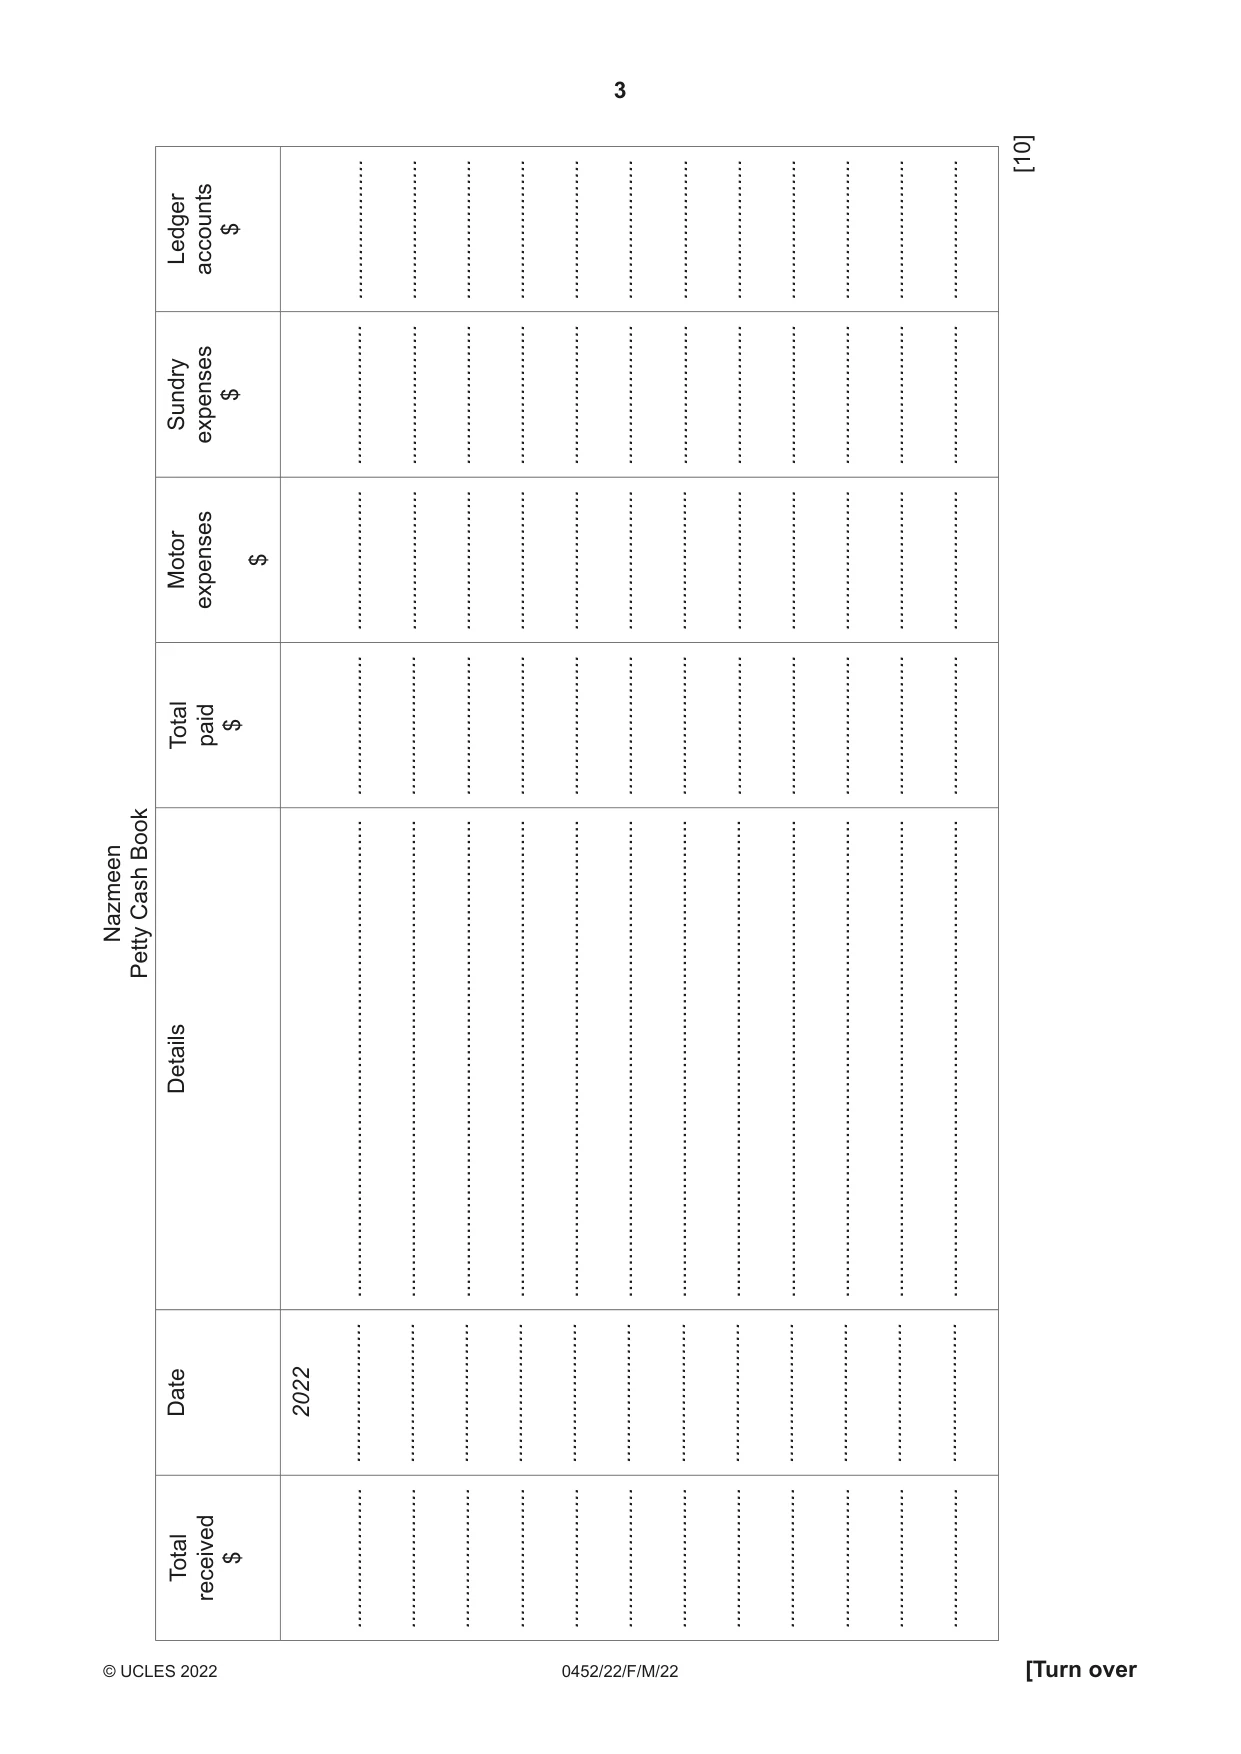
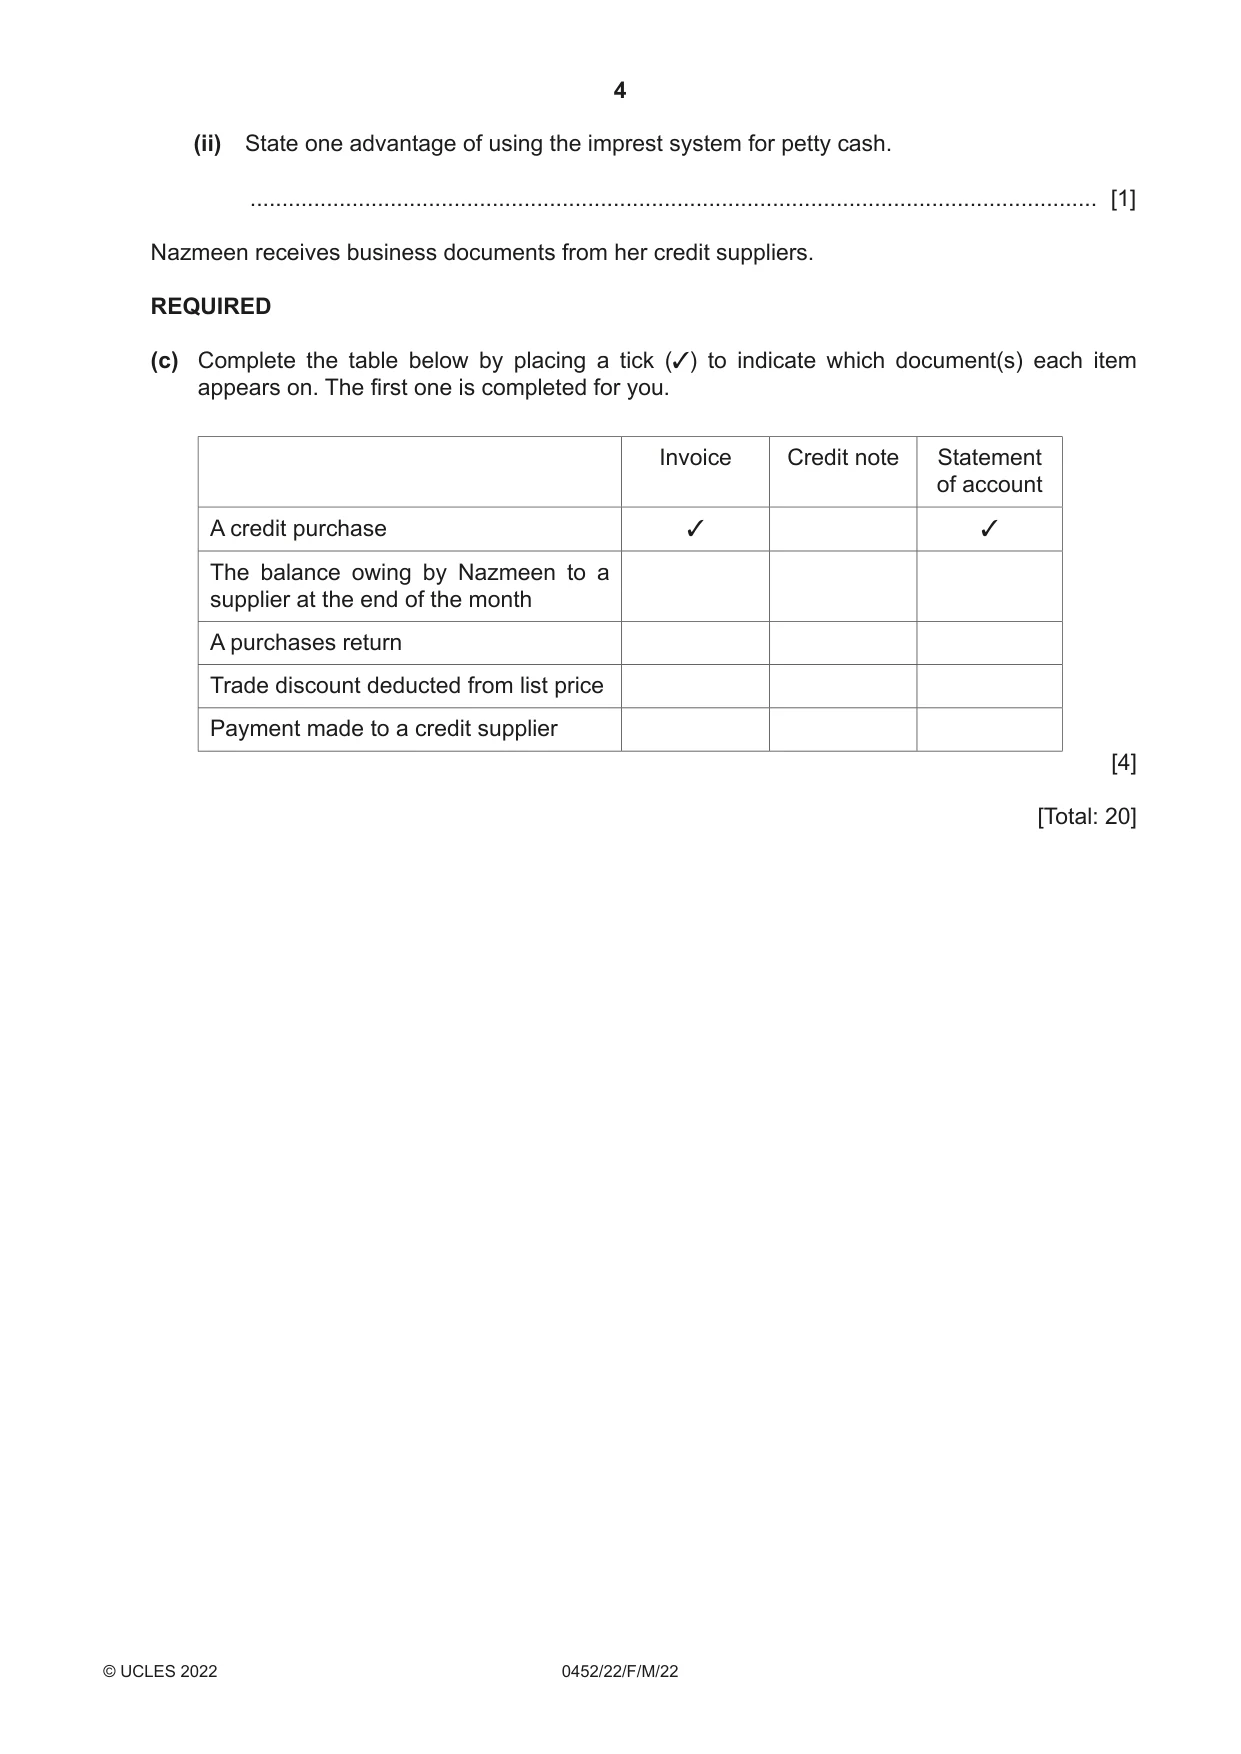
1 Nazmeen started in business as a hairdresser on 1 January 2022. She purchases her hairdressing supplies on credit and uses the imprest system for her petty cash. Nazmeen’s assets and liabilities at 1 January 2022 were as follows: $ Motor vehicle 11 000 Balance at bank 2 300 Petty cash 200 Bank loan 2 500 REQUIRED (a) (i) Prepare the general journal entry to record the opening assets and liabilities at 1 January 2022. A narrative is required. Nazmeen General journal Date Details $ $ ................... ................................................................. ................... ................... ................... ................................................................. ................... ................... ................... ................................................................. ................... ................... ................... ................................................................. ................... ................... ................... ................................................................. ................... ................... ................... ................................................................. ................... ................... [4] (ii) State one other use of the general journal. ..................................................................................................................................... [1] Nazmeen makes all payments of less than $100 by petty cash. The imprest amount, which is $200, is restored on the first day of each month from the bank account. Nazmeen provided the following information for January 2022. January 3 Paid for petrol, $35. 8 Paid for magazines for the reception area, $14. 17 Paid $60 to GL Limited, a trade payable. 26 Paid for vehicle cleaning, $9. 29 Paid $38 to Alim, a trade payable. REQUIRED (b) (i) Complete Nazmeen’s petty cash book on the following page. Balance the petty cash book, bring down the balance on 1 February 2022 and restore the imprest. [10] $ Ledger accounts ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Sundry expenses ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Motor expenses ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Totalpaid ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... Book CashNazmeen Petty Details ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... ........................................................................... Date 2022 ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... (ii) State one advantage of using the imprest system for petty cash. ..................................................................................................................................... [1] Nazmeen receives business documents from her credit suppliers. REQUIRED (c) Complete the table below by placing a tick (3) to indicate which document(s) each item appears on. The first one is completed for you. Invoice Credit note Statement of account A credit purchase 3 3 The balance owing by Nazmeen to a supplier at the end of the month A purchases return Trade discount deducted from list price Payment made to a credit supplier [4] [Total: 20]
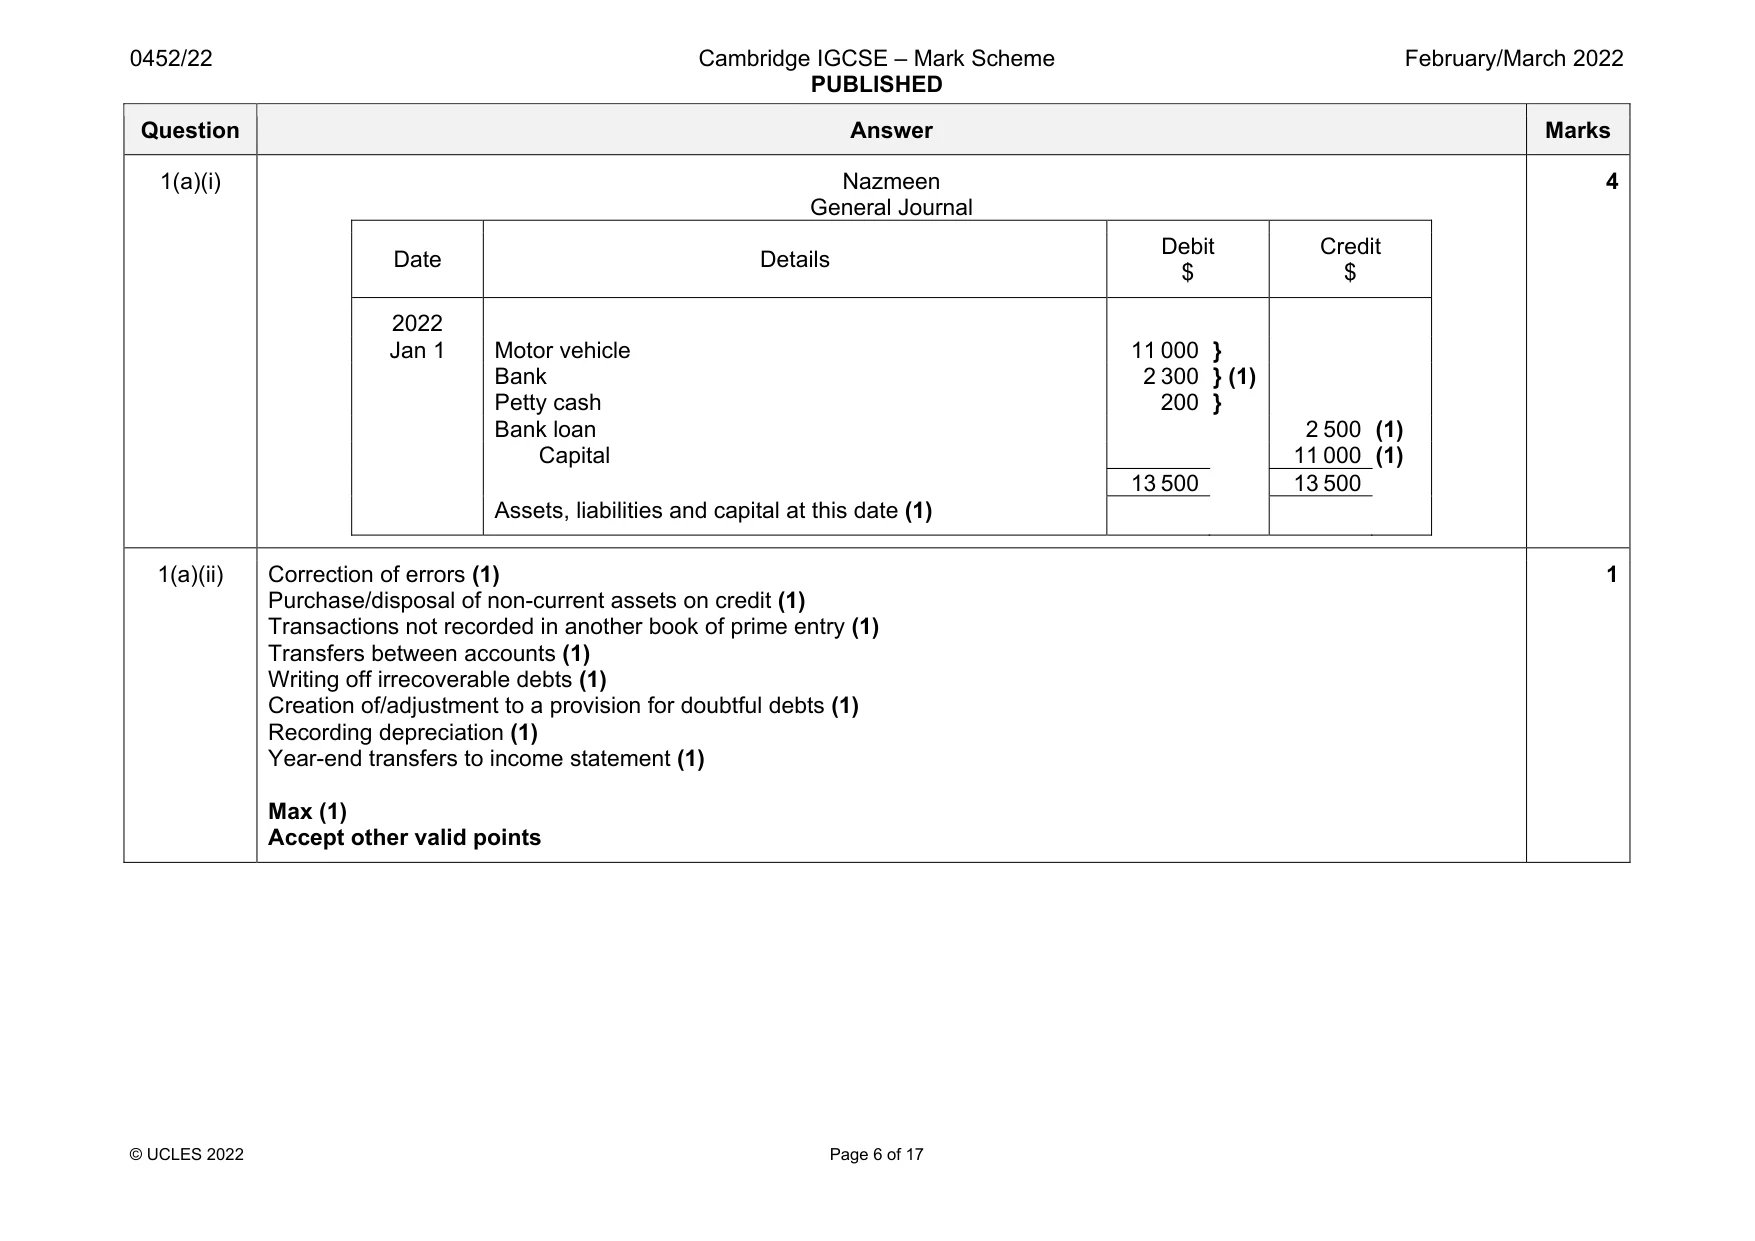
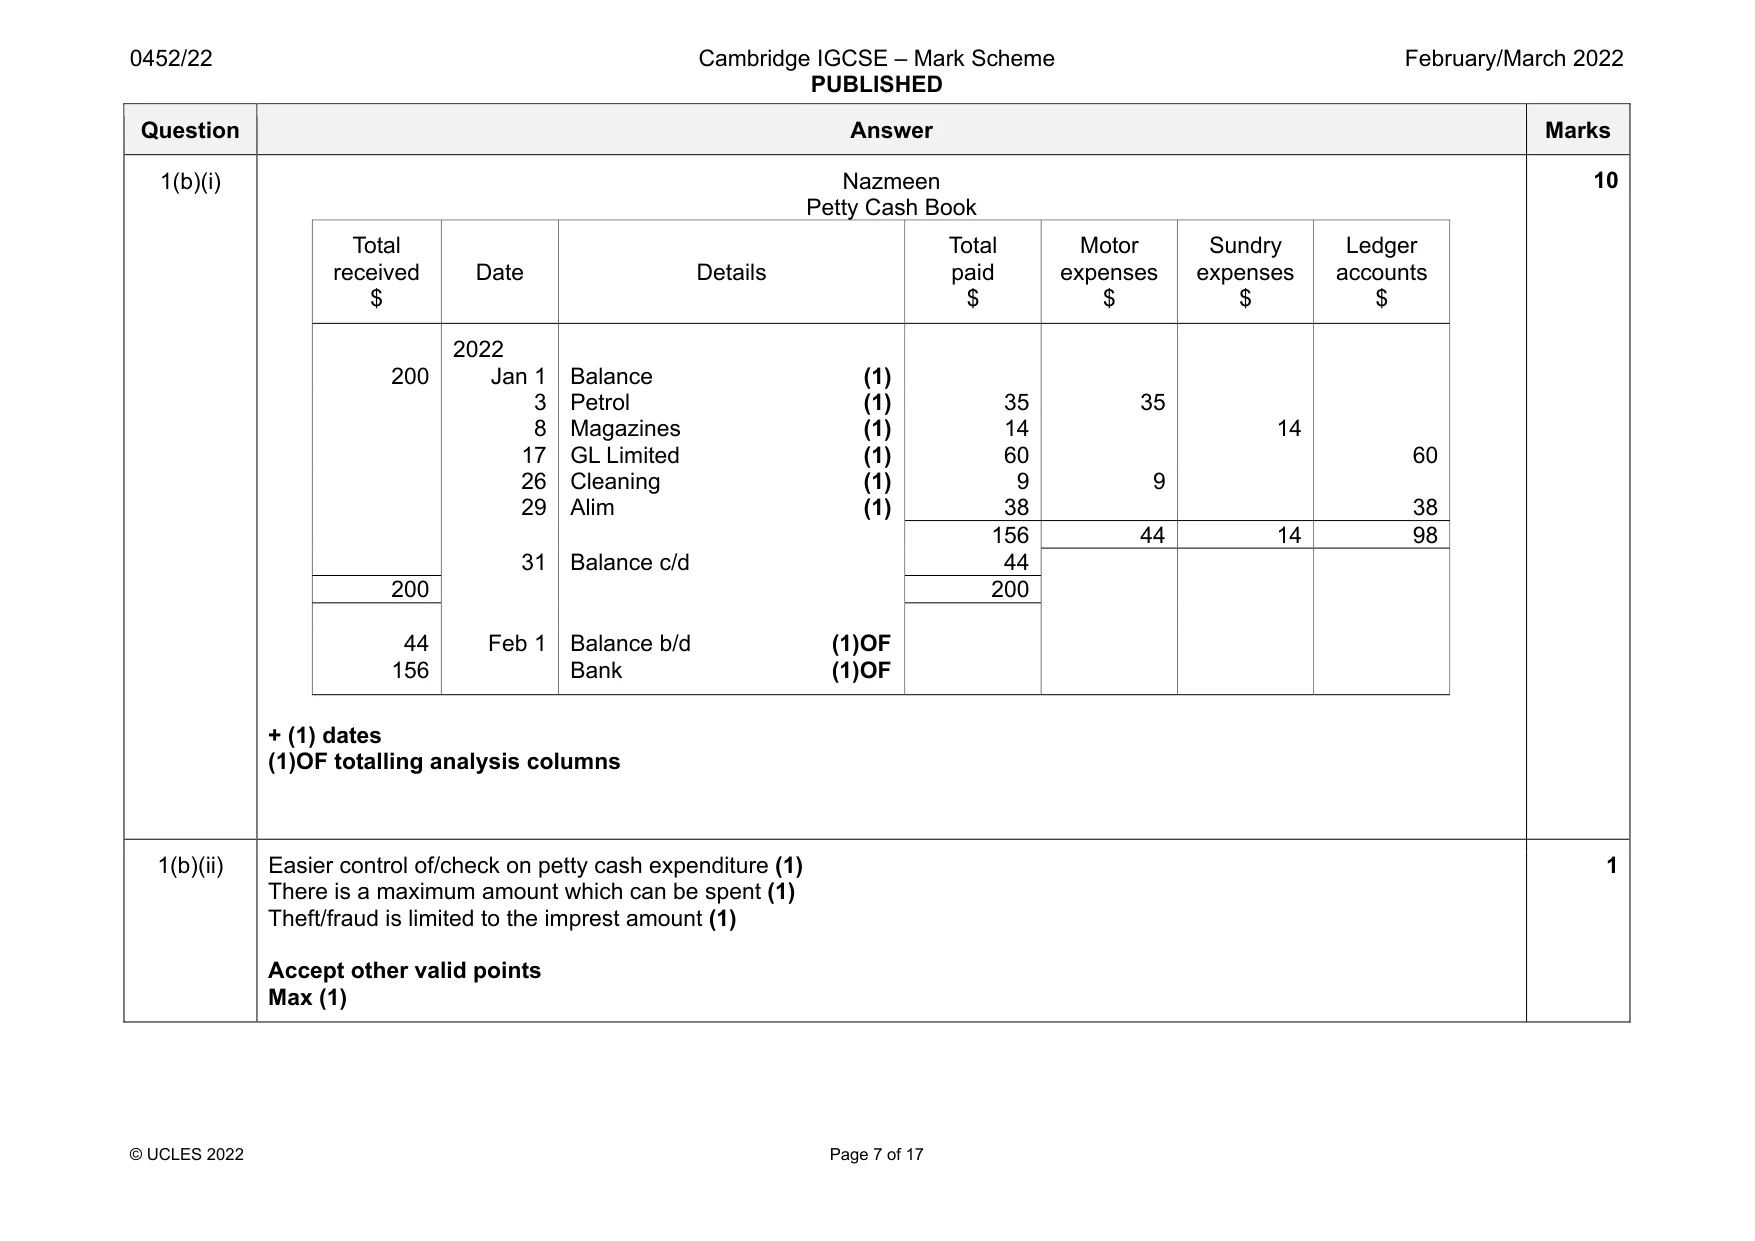
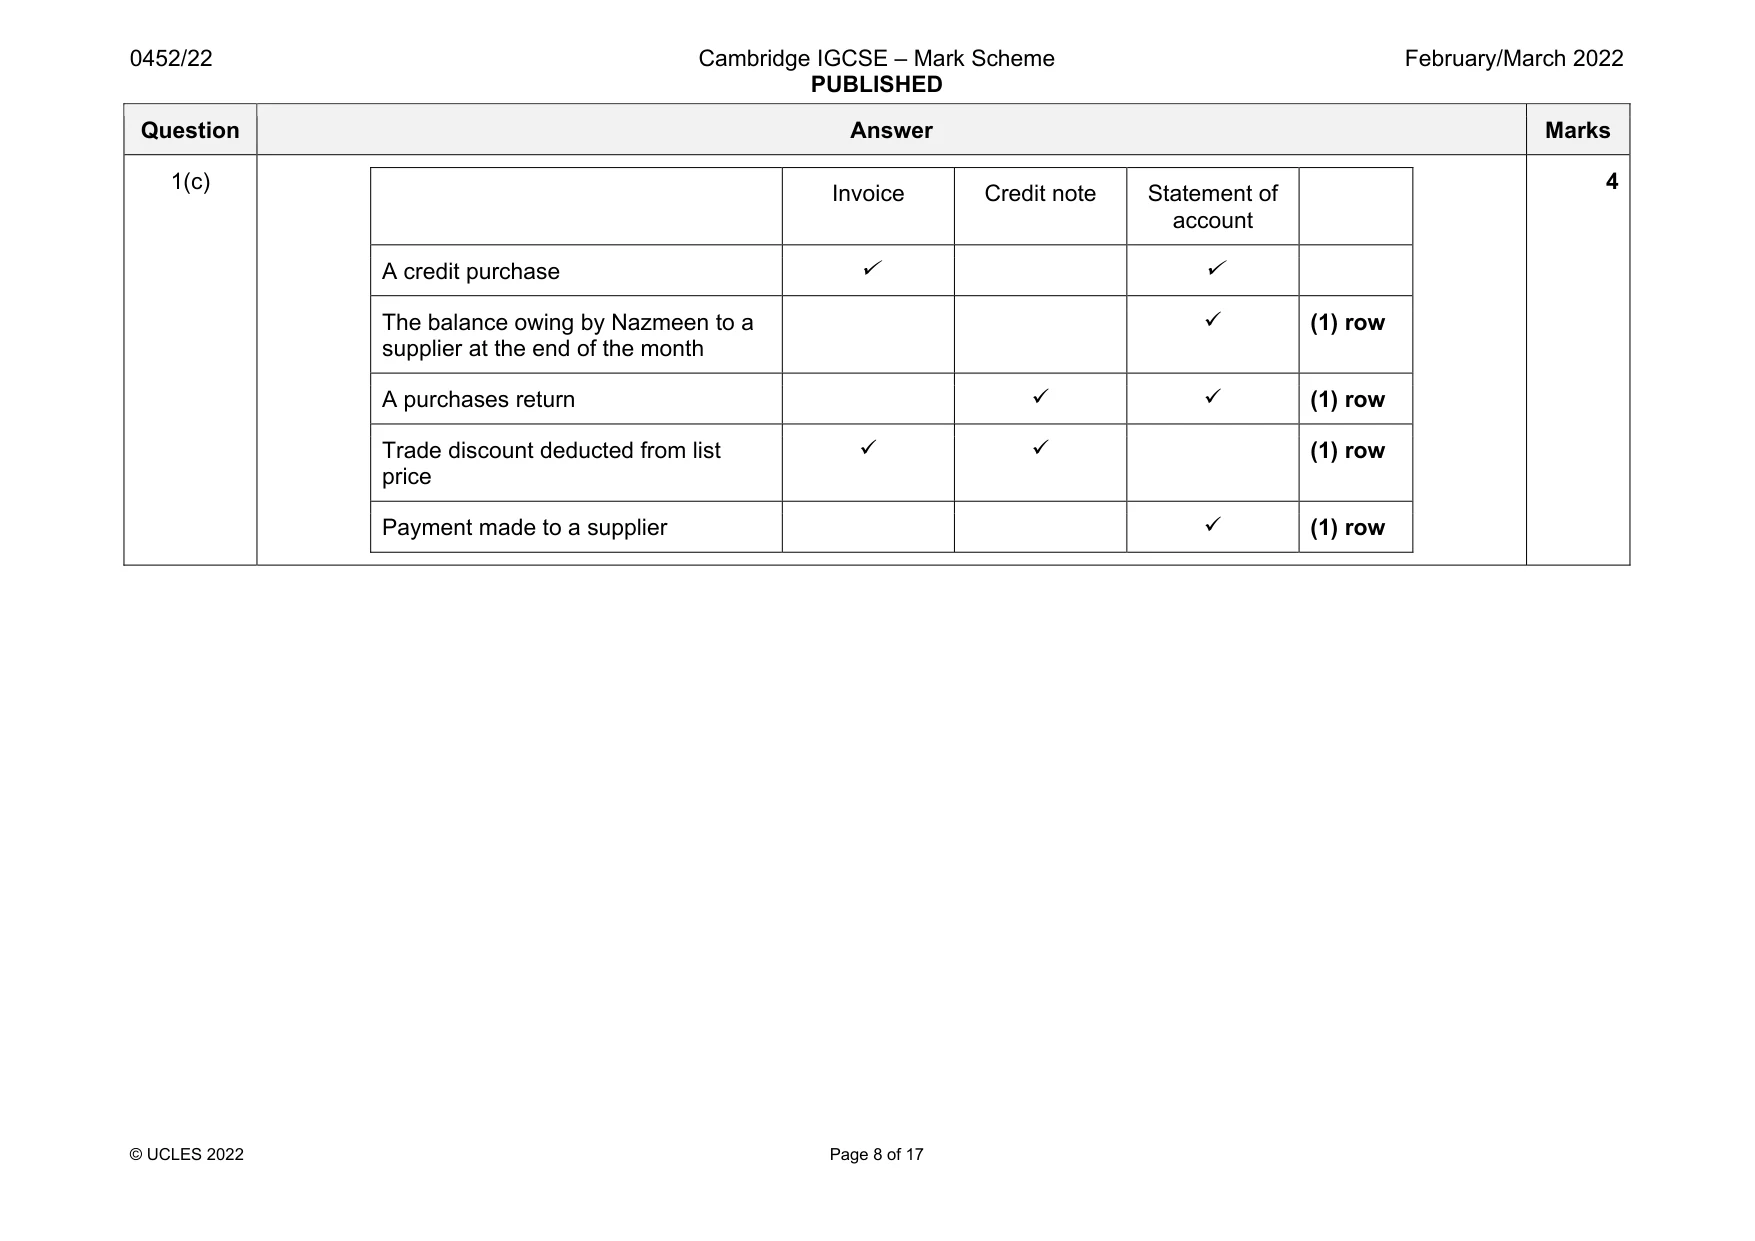
Mark scheme: 1(a)(i) Nazmeen General Journal Date Details Debit $ Credit $ 2022 Jan 1 Motor vehicle 11 000 } Bank 2 300 } (1) Petty cash 200 } Bank loan 2 500 (1) Capital 11 000 (1) 13 500 13 500 Assets, liabilities and capital at this date (1) 4 1(a)(ii) Correction of errors (1) Purchase/disposal of non-current assets on credit (1) Transactions not recorded in another book of prime entry (1) Transfers between accounts (1) Writing off irrecoverable debts (1) Creation of/adjustment to a provision for doubtful debts (1) Recording depreciation (1) Year-end transfers to income statement (1) Max (1) Accept other valid points 1 Question Answer Marks 1(b)(i) Nazmeen Petty Cash Book Total received $ Date Details Total paid $ Motor expenses $ Sundry expenses $ Ledger accounts $ 2022 200 Jan 1 Balance (1) 3 Petrol (1) 35 35 8 Magazines (1) 14 14 17 GL Limited (1) 60 60 26 Cleaning (1) 9 9 29 Alim (1) 38 38 156 44 14 98 31 Balance c/d 44 200 200 44 Feb 1 Balance b/d (1)OF 156 Bank (1)OF + (1) dates (1)OF totalling analysis columns 10 1(b)(ii) Easier control of/check on petty cash expenditure (1) There is a maximum amount which can be spent (1) Theft/fraud is limited to the imprest amount (1) Accept other valid points Max (1) 1 Question Answer Marks 1(c) Invoice Credit note Statement of account A credit purchase The balance owing by Nazmeen to a supplier at the end of the month (1) row A purchases return (1) row Trade discount deducted from list price (1) row Payment made to a supplier (1) row 4
Q2 · Ravi is a trader
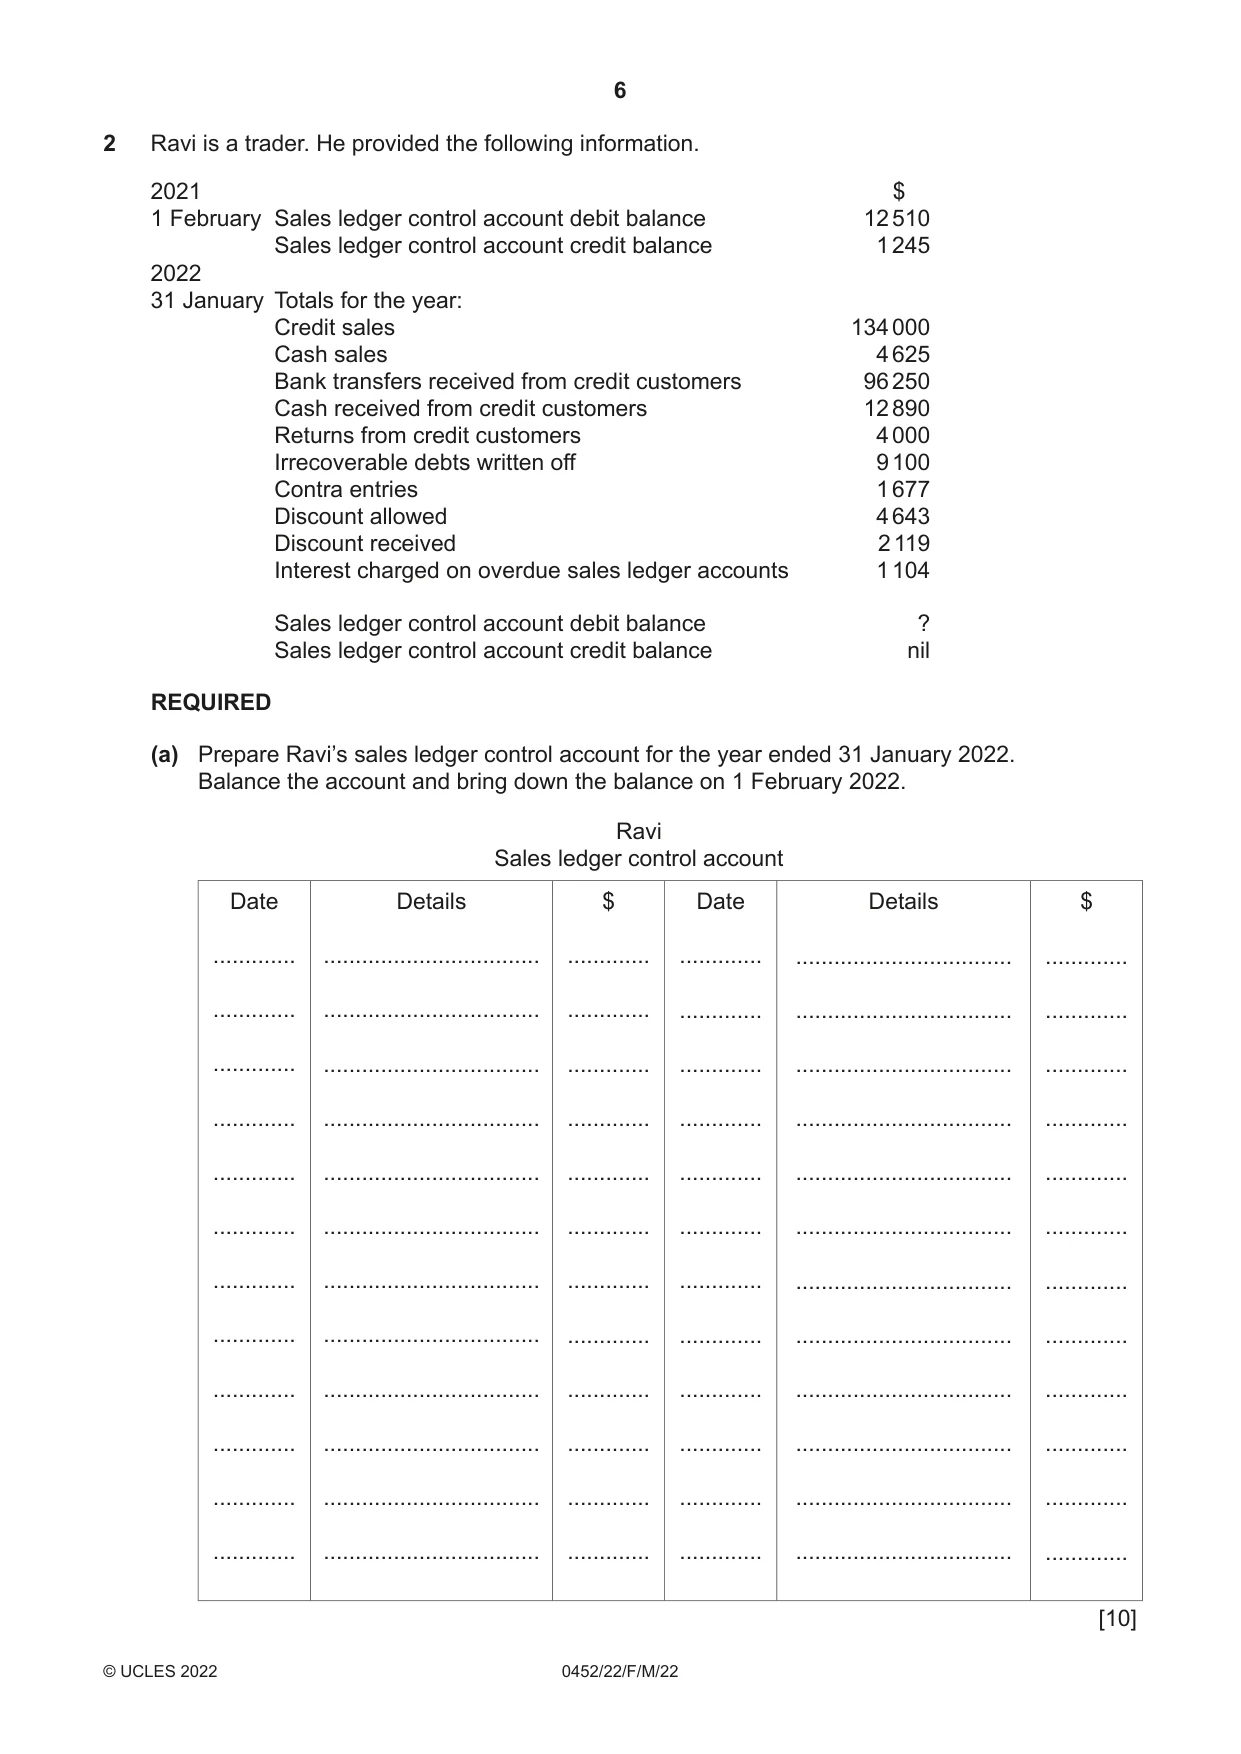
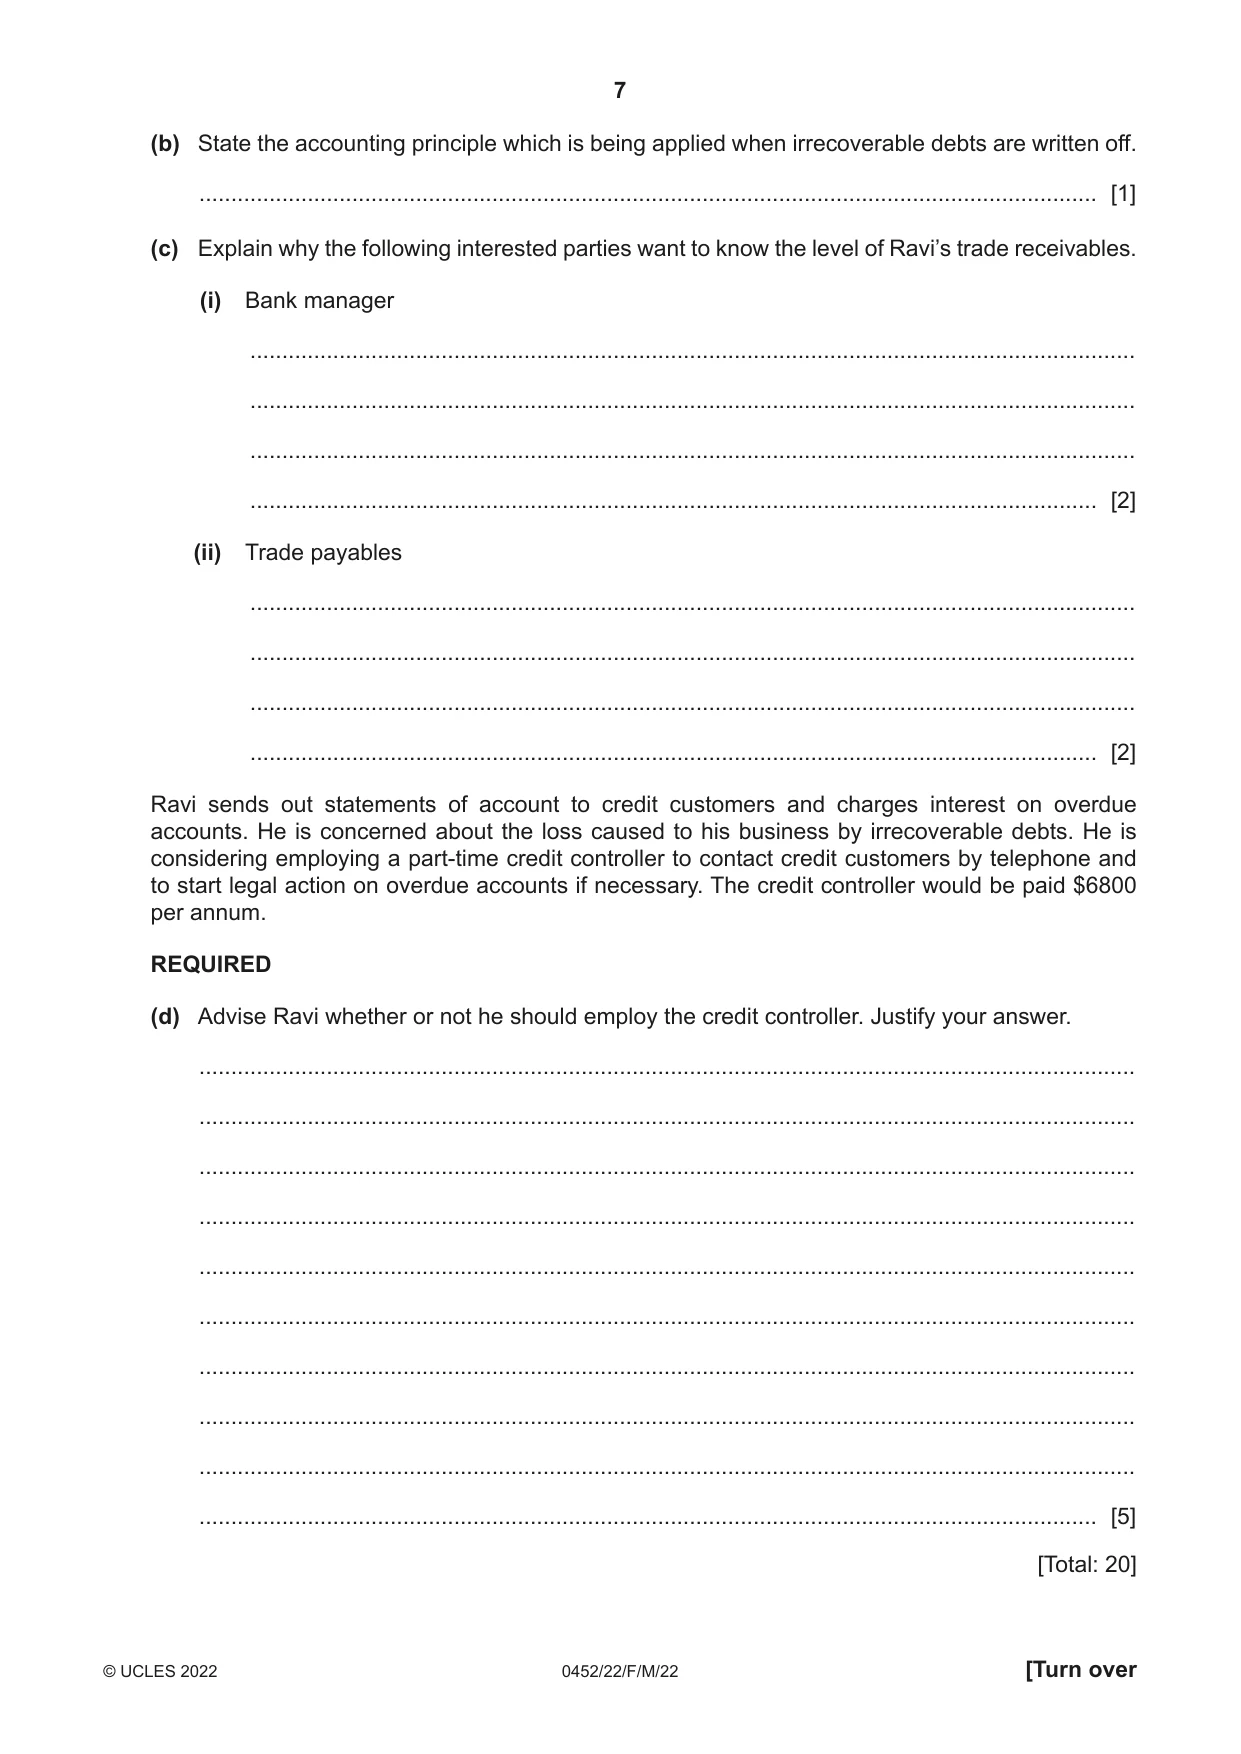
2 Ravi is a trader. He provided the following information. 2021 $ 1 February Sales ledger control account debit balance 12 510 Sales ledger control account credit balance 1 245 2022 31 January Totals for the year: Credit sales 134 000 Cash sales 4 625 Bank transfers received from credit customers 96 250 Cash received from credit customers 12 890 Returns from credit customers 4 000 Irrecoverable debts written off 9 100 Contra entries 1 677 Discount allowed 4 643 Discount received 2 119 Interest charged on overdue sales ledger accounts 1 104 Sales ledger control account debit balance ? Sales ledger control account credit balance nil REQUIRED (a) Prepare Ravi’s sales ledger control account for the year ended 31 January 2022. Balance the account and bring down the balance on 1 February 2022. Ravi Sales ledger control account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [10] (b) State the accounting principle which is being applied when irrecoverable debts are written off. ............................................................................................................................................. [1] (c) Explain why the following interested parties want to know the level of Ravi’s trade receivables. (i) Bank manager ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Trade payables ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Ravi sends out statements of account to credit customers and charges interest on overdue accounts. He is concerned about the loss caused to his business by irrecoverable debts. He is considering employing a part-time credit controller to contact credit customers by telephone and to start legal action on overdue accounts if necessary. The credit controller would be paid $6800 per annum. REQUIRED (d) Advise Ravi whether or not he should employ the credit controller. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
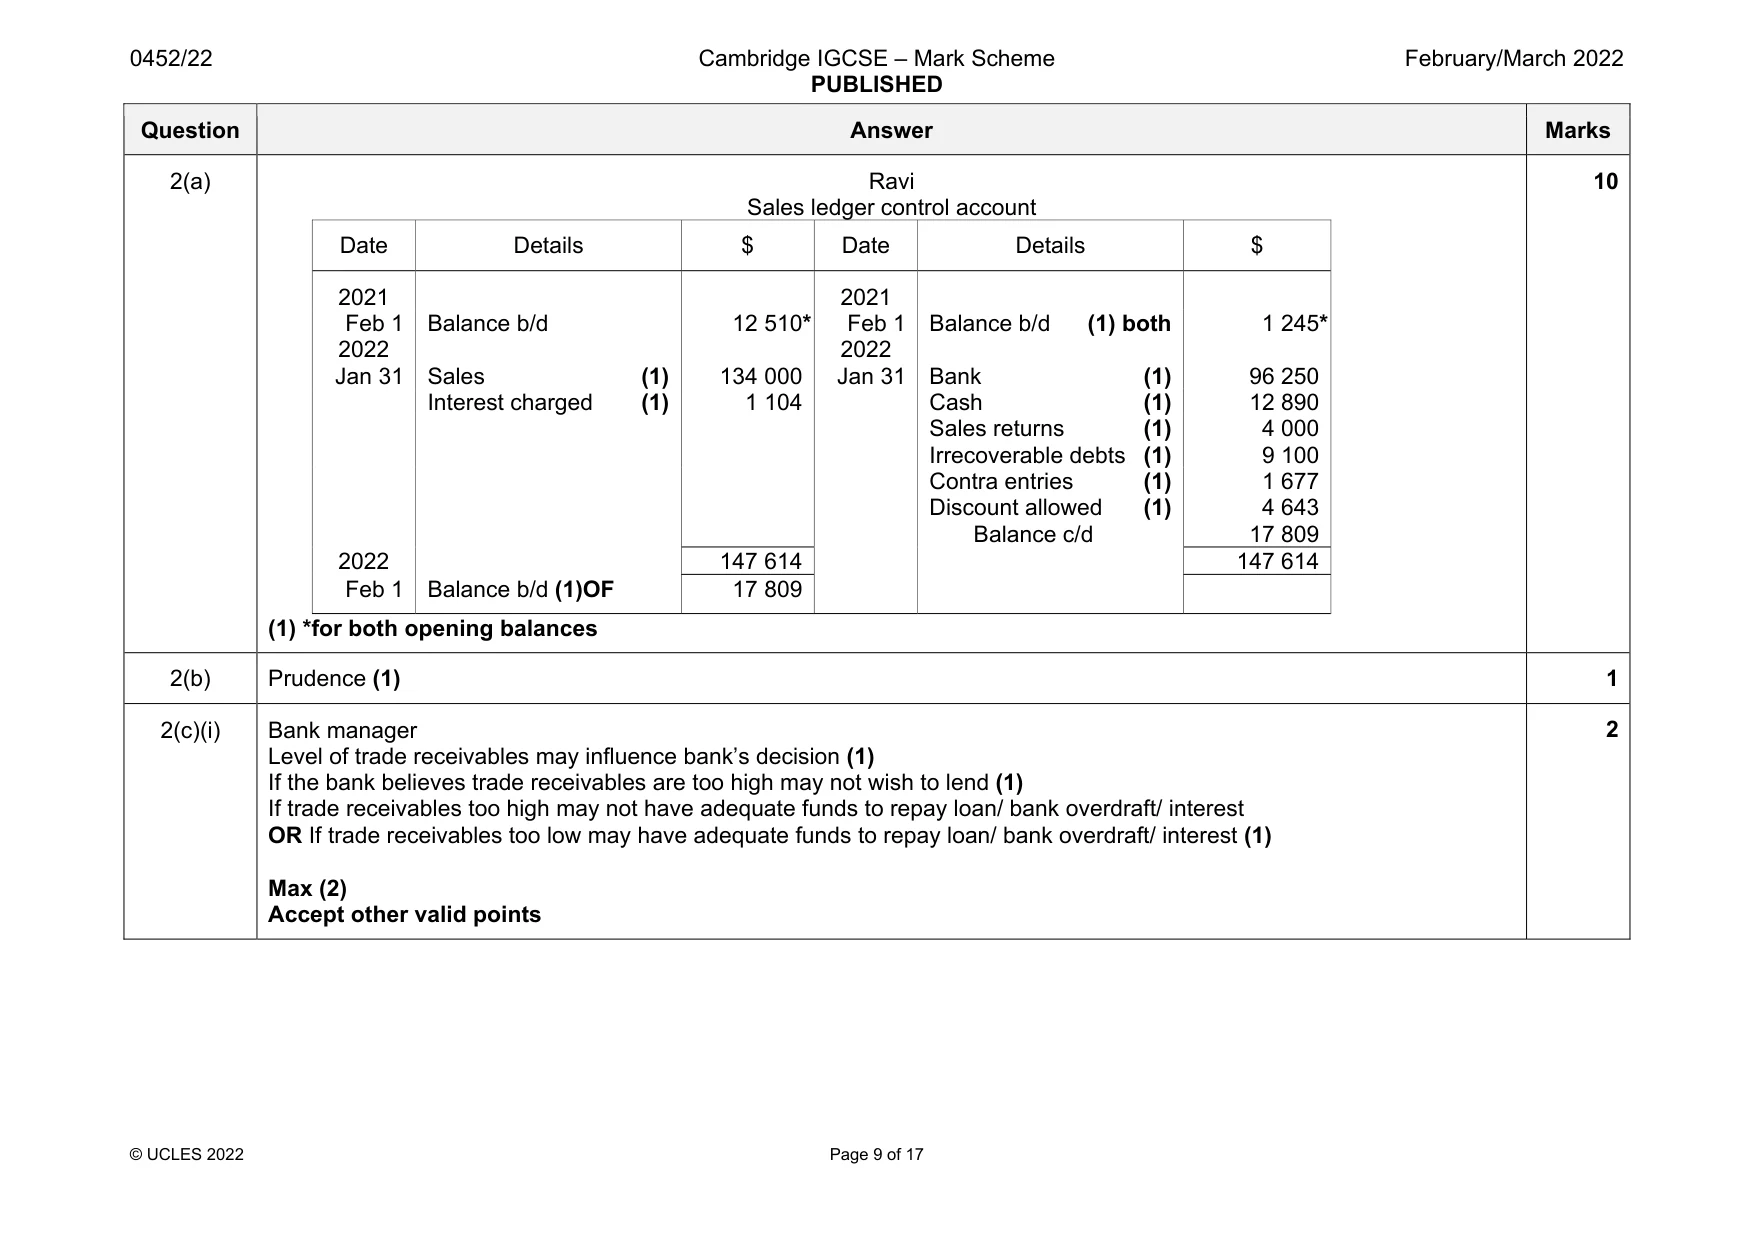
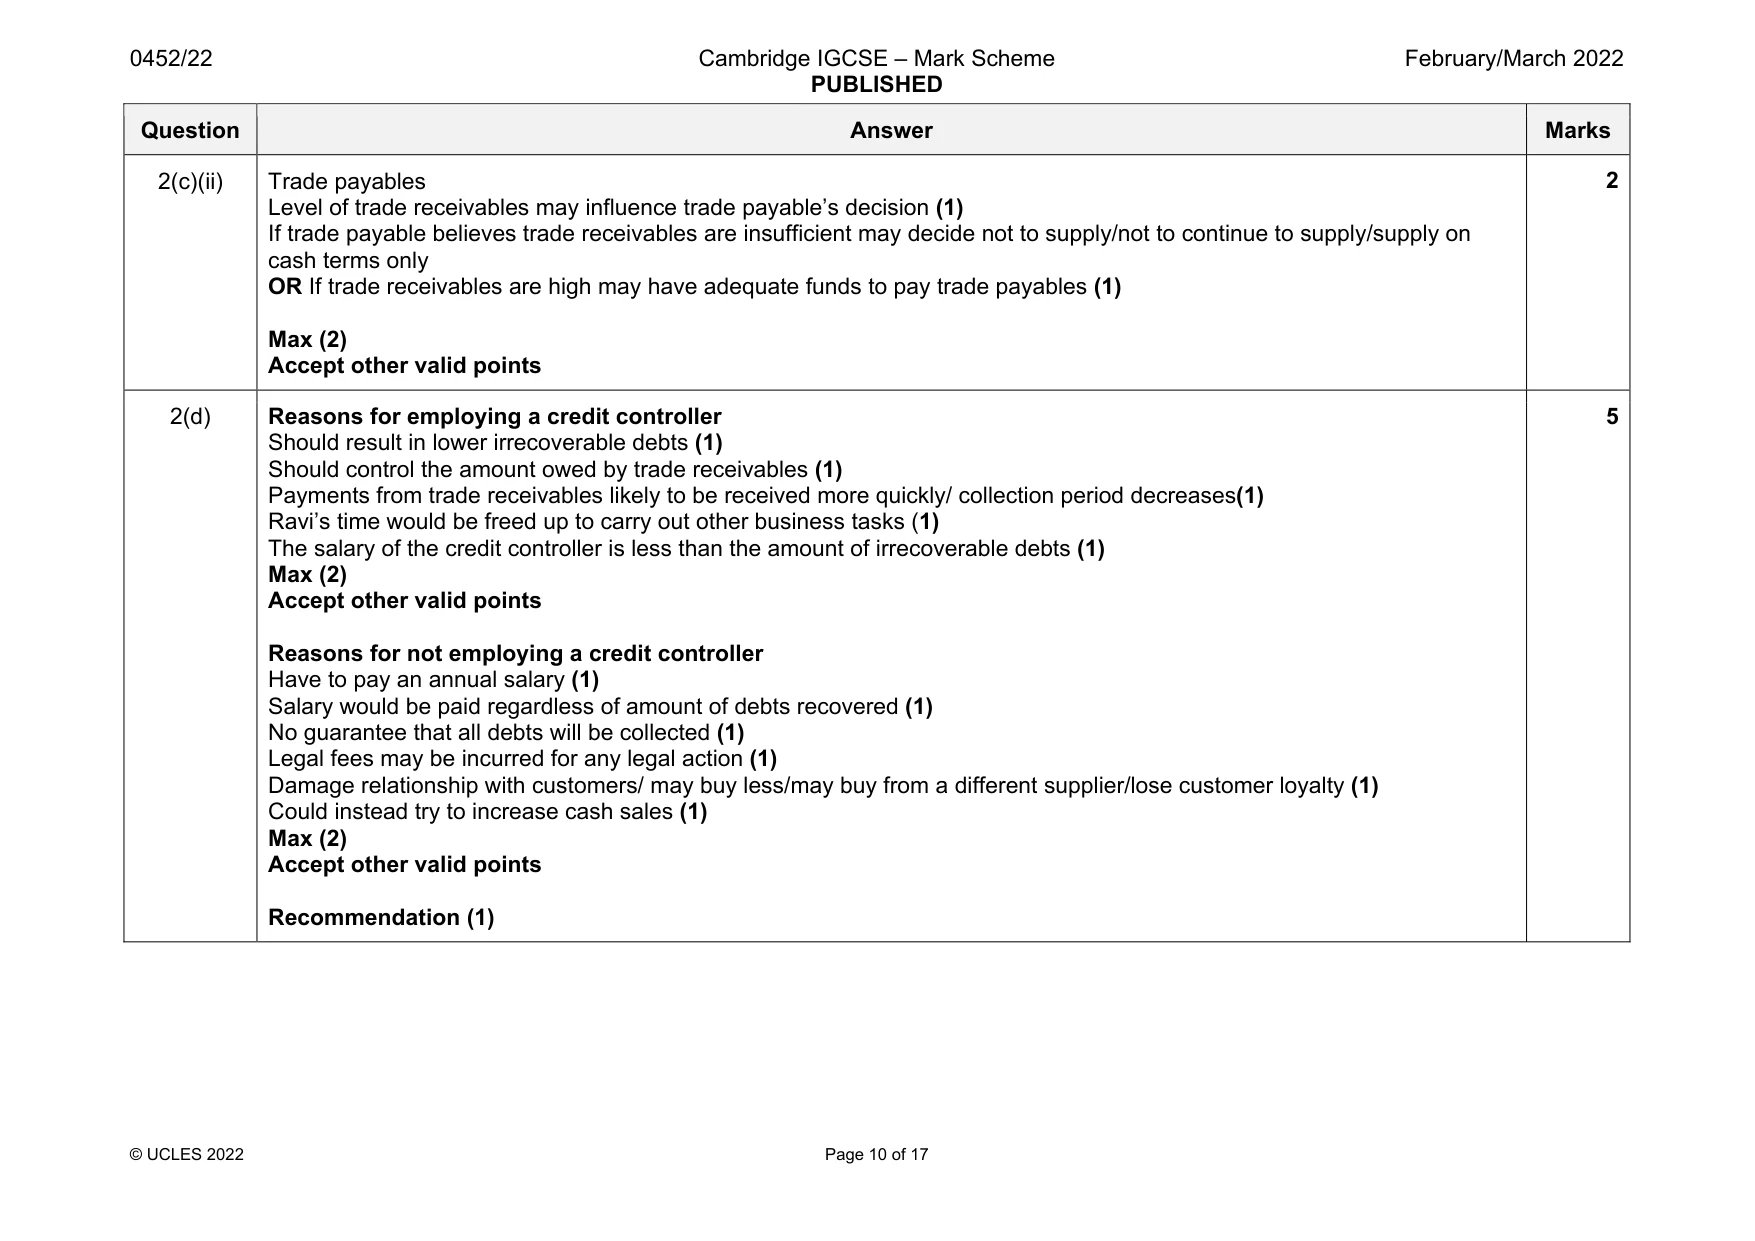
Mark scheme: 2(a) Ravi Sales ledger control account Date Details $ Date Details $ 2021 2021 Feb 1 Balance b/d 12 510* Feb 1 Balance b/d (1) both 1 245* 2022 2022 Jan 31 Sales (1) 134 000 Jan 31 Bank (1) 96 250 Interest charged (1) 1 104 Cash (1) 12 890 Sales returns (1) 4 000 Irrecoverable debts (1) 9 100 Contra entries (1) 1 677 Discount allowed (1) 4 643 Balance c/d 17 809 2022 147 614 147 614 Feb 1 Balance b/d (1)OF 17 809 (1) *for both opening balances 10 2(b) Prudence (1) 1 2(c)(i) Bank manager Level of trade receivables may influence bank’s decision (1) If the bank believes trade receivables are too high may not wish to lend (1) If trade receivables too high may not have adequate funds to repay loan/ bank overdraft/ interest OR If trade receivables too low may have adequate funds to repay loan/ bank overdraft/ interest (1) Max (2) Accept other valid points 2 Question Answer Marks 2(c)(ii) Trade payables Level of trade receivables may influence trade payable’s decision (1) If trade payable believes trade receivables are insufficient may decide not to supply/not to continue to supply/supply on cash terms only OR If trade receivables are high may have adequate funds to pay trade payables (1) Max (2) Accept other valid points 2 2(d) Reasons for employing a credit controller Should result in lower irrecoverable debts (1) Should control the amount owed by trade receivables (1) Payments from trade receivables likely to be received more quickly/ collection period decreases(1) Ravi’s time would be freed up to carry out other business tasks (1) The salary of the credit controller is less than the amount of irrecoverable debts (1) Max (2) Accept other valid points Reasons for not employing a credit controller Have to pay an annual salary (1) Salary would be paid regardless of amount of debts recovered (1) No guarantee that all debts will be collected (1) Legal fees may be incurred for any legal action (1) Damage relationship with customers/ may buy less/may buy from a different supplier/lose customer loyalty (1) Could instead try to increase cash sales (1) Max (2) Accept other valid points Recommendation (1) 5
Q3 · Pari owns a clothing factory
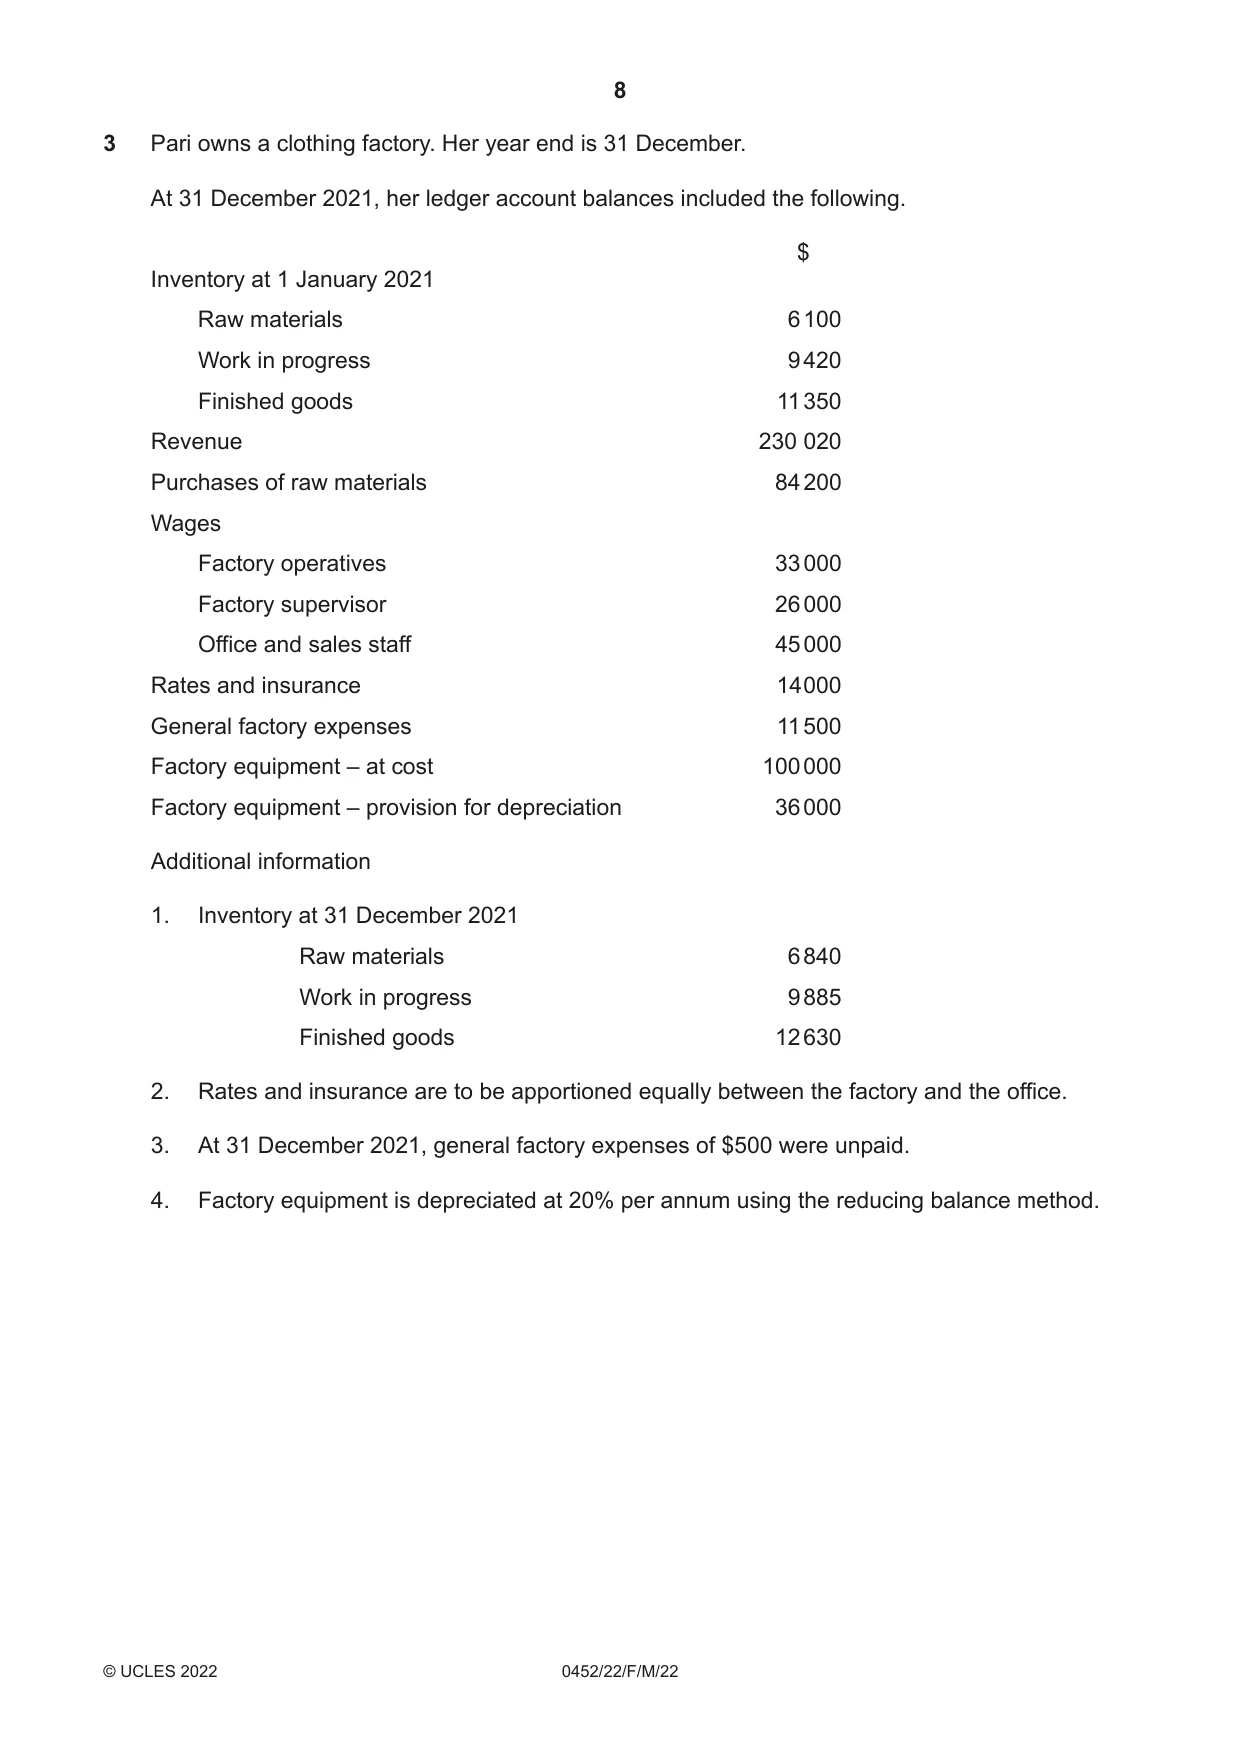
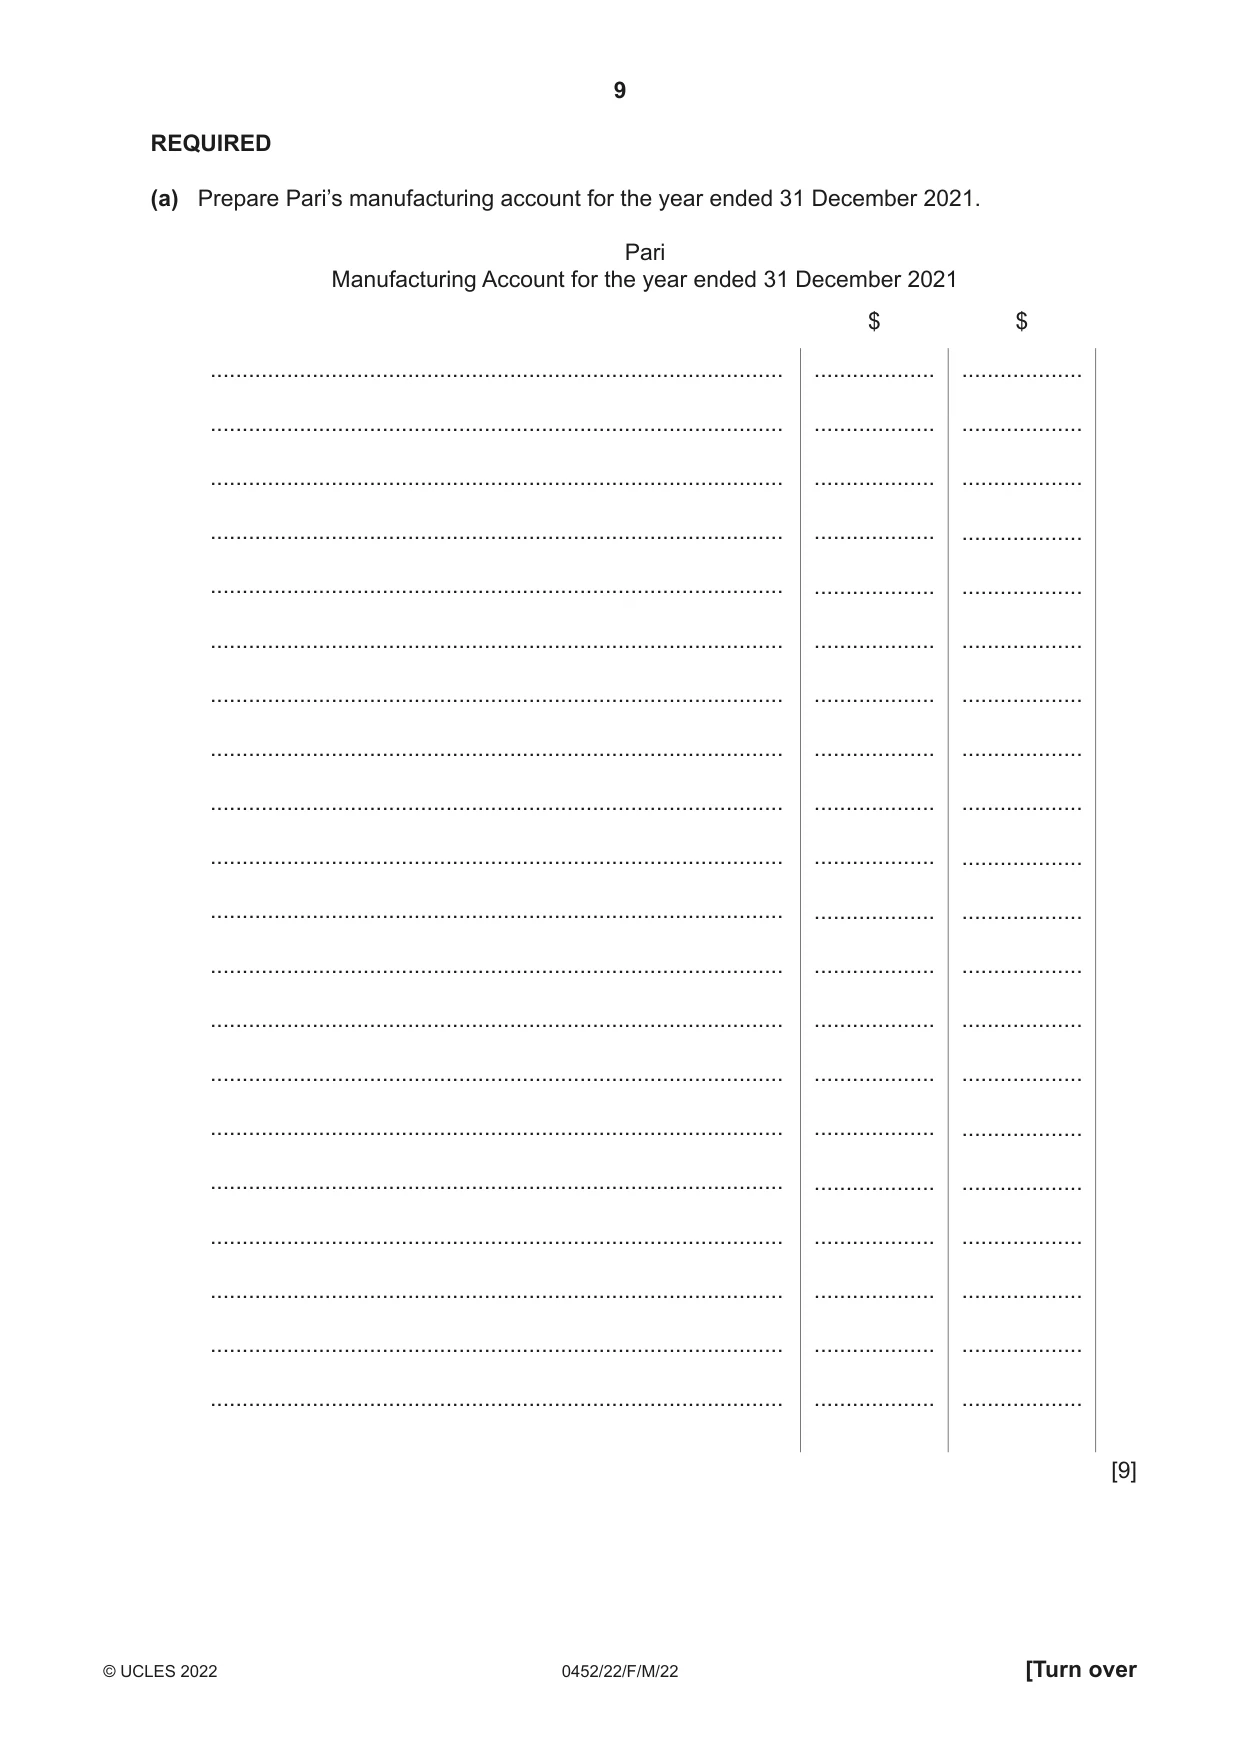
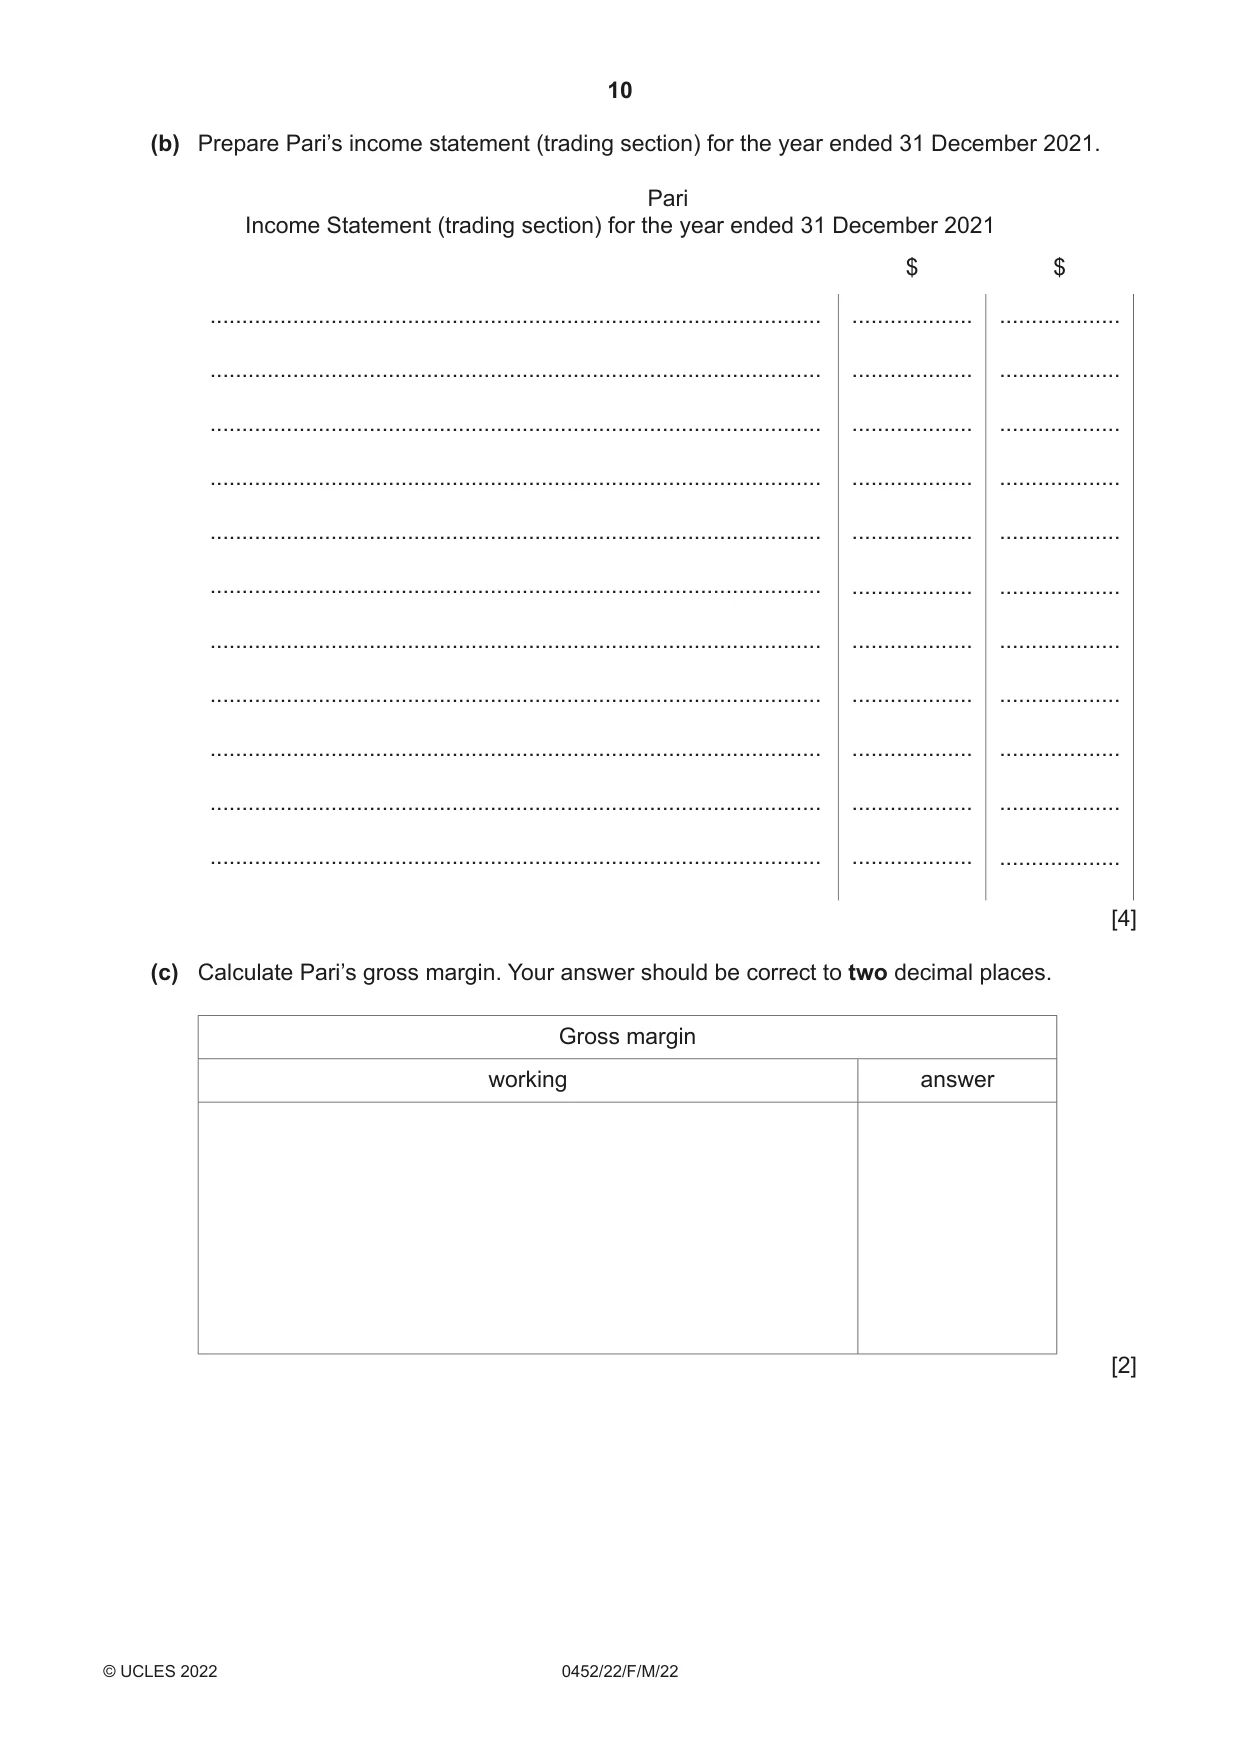
3 Pari owns a clothing factory. Her year end is 31 December. At 31 December 2021, her ledger account balances included the following. $ Inventory at 1 January 2021 Raw materials 6 100 Work in progress 9 420 Finished goods 11 350 Revenue 230 020 Purchases of raw materials 84 200 Wages Factory operatives 33 000 Factory supervisor 26 000 Office and sales staff 45 000 Rates and insurance 14 000 General factory expenses 11 500 Factory equipment – at cost 100 000 Factory equipment – provision for depreciation 36 000 Additional information 1. Inventory at 31 December 2021 Raw materials 6 840 Work in progress 9 885 Finished goods 12 630 2. Rates and insurance are to be apportioned equally between the factory and the office. 3. At 31 December 2021, general factory expenses of $500 were unpaid. 4. Factory equipment is depreciated at 20% per annum using the reducing balance method. REQUIRED (a) Prepare Pari’s manufacturing account for the year ended 3 Pari Manufacturing Account for the year ended 31 .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... (b) Prepare Pari’s income statement (trading section) for the year ended 31 December 2021. Pari Income Statement (trading section) for the year ended 31 December 2021 $ $ ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... ................................................................................................ ................... ................... [4] (c) Calculate Pari’s gross margin. Your answer should be correct to two decimal places. Gross margin working answer [2] Pari is disappointed in her cost of production and gross profit. She is considering buying in her products instead of producing them in her factory. REQUIRED (d) Advise Pari whether or not she should start to buy in her products. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
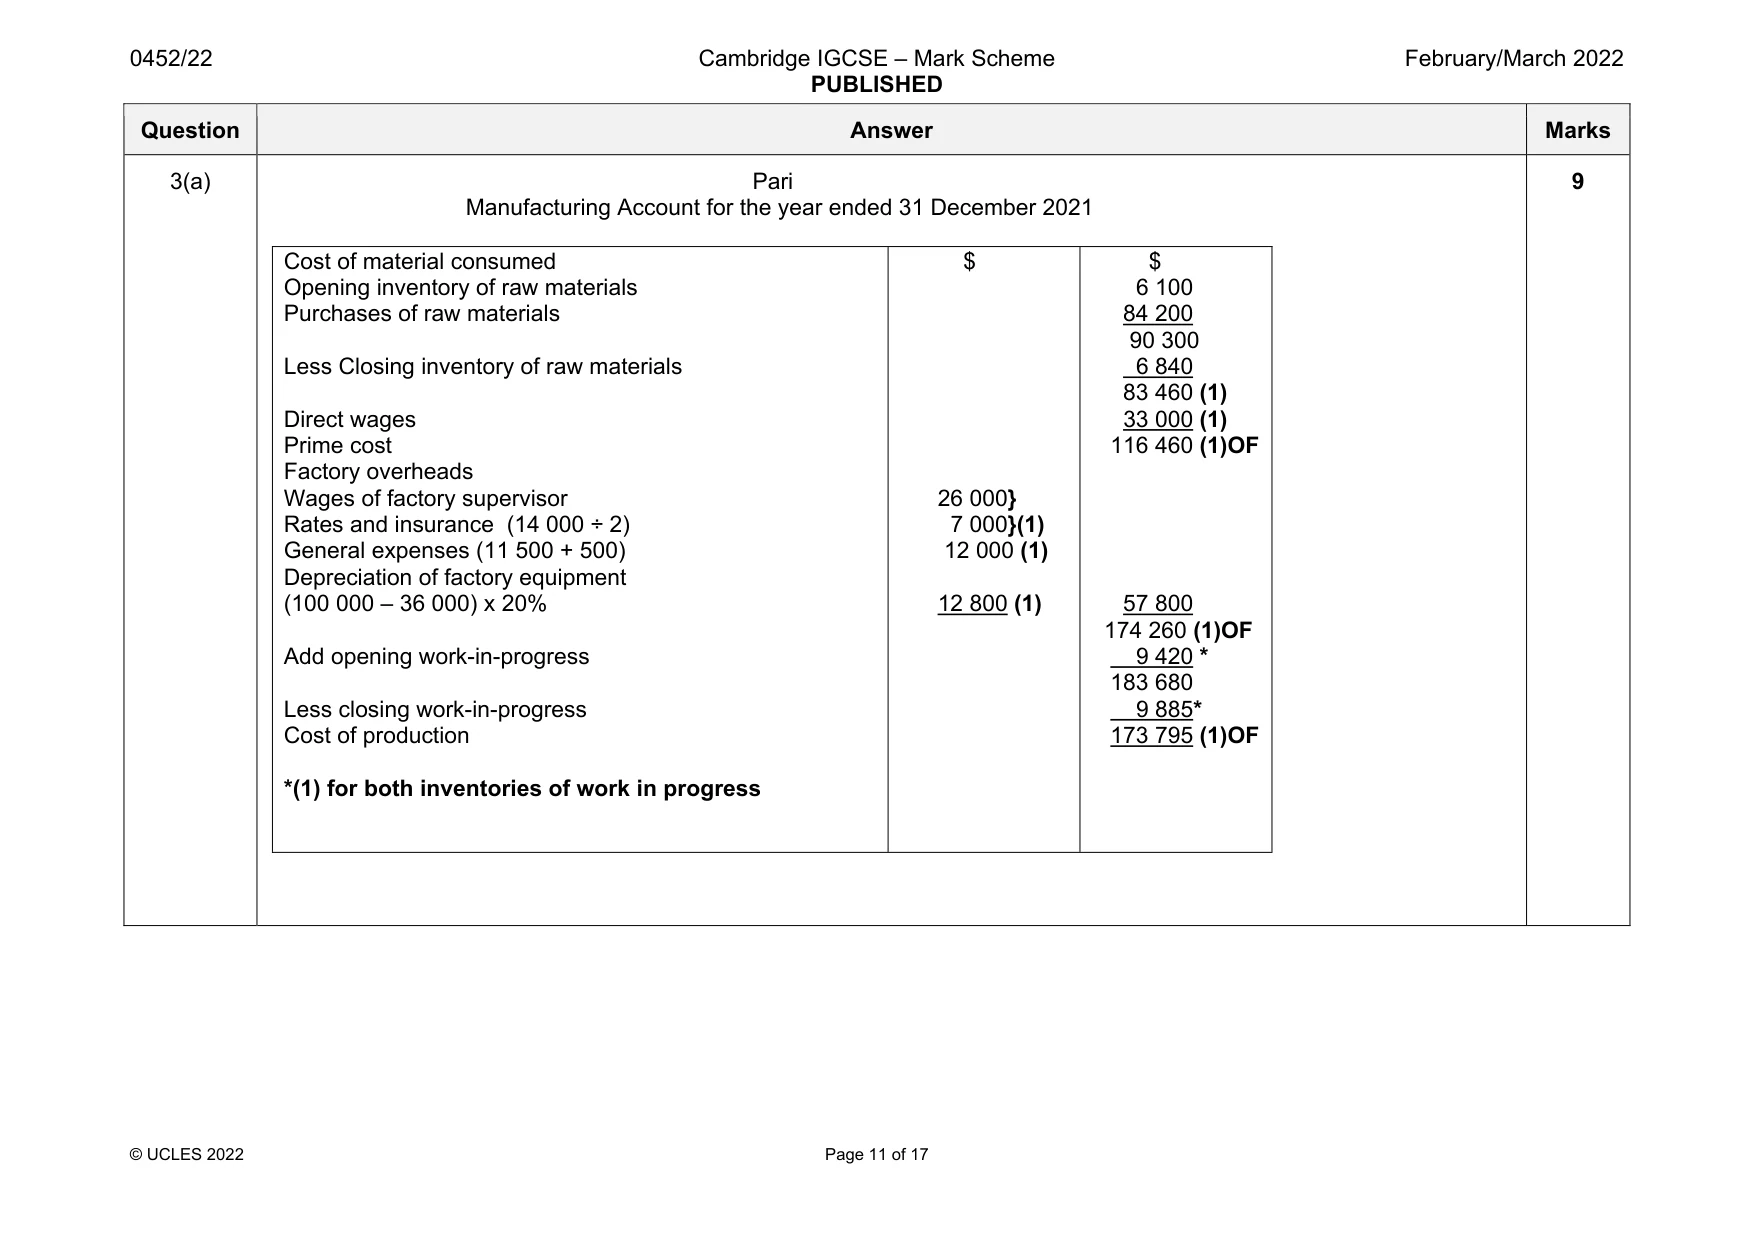
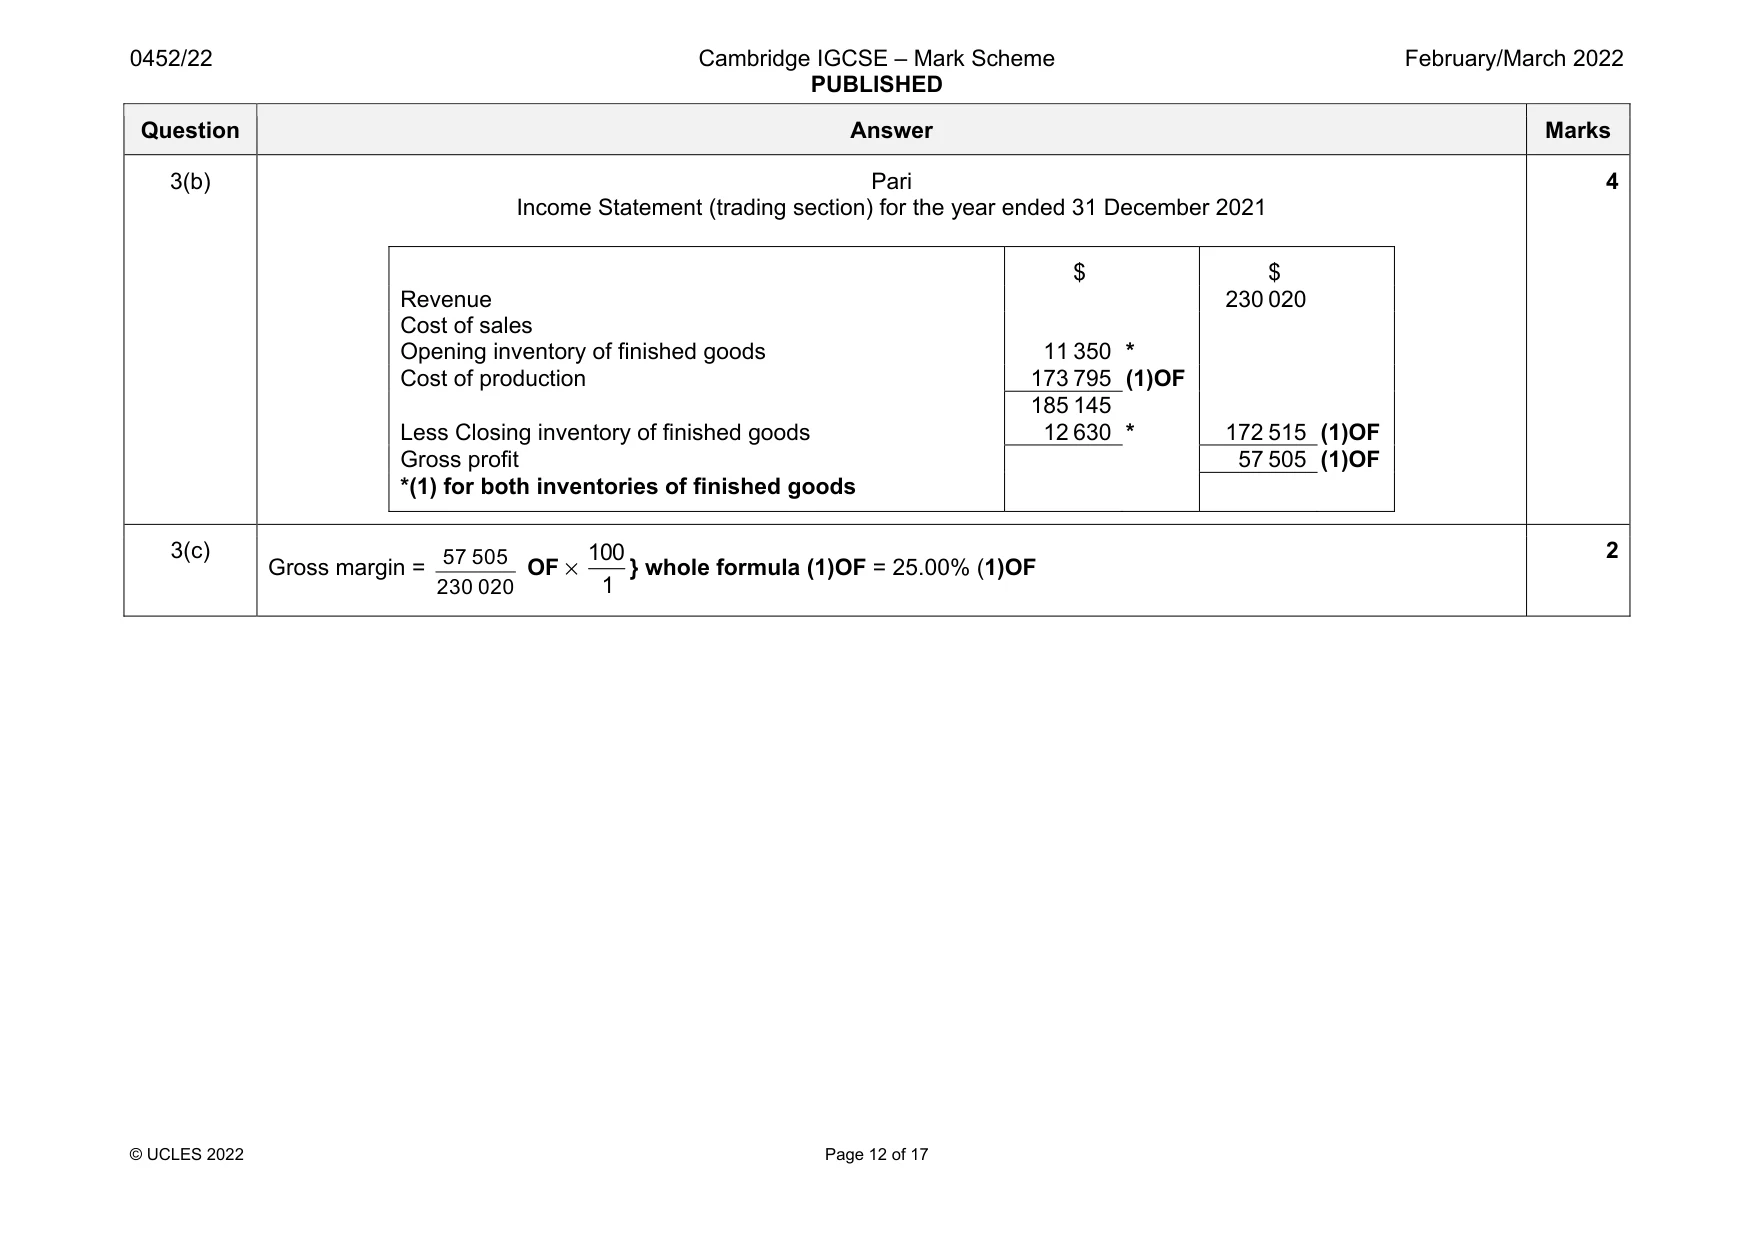
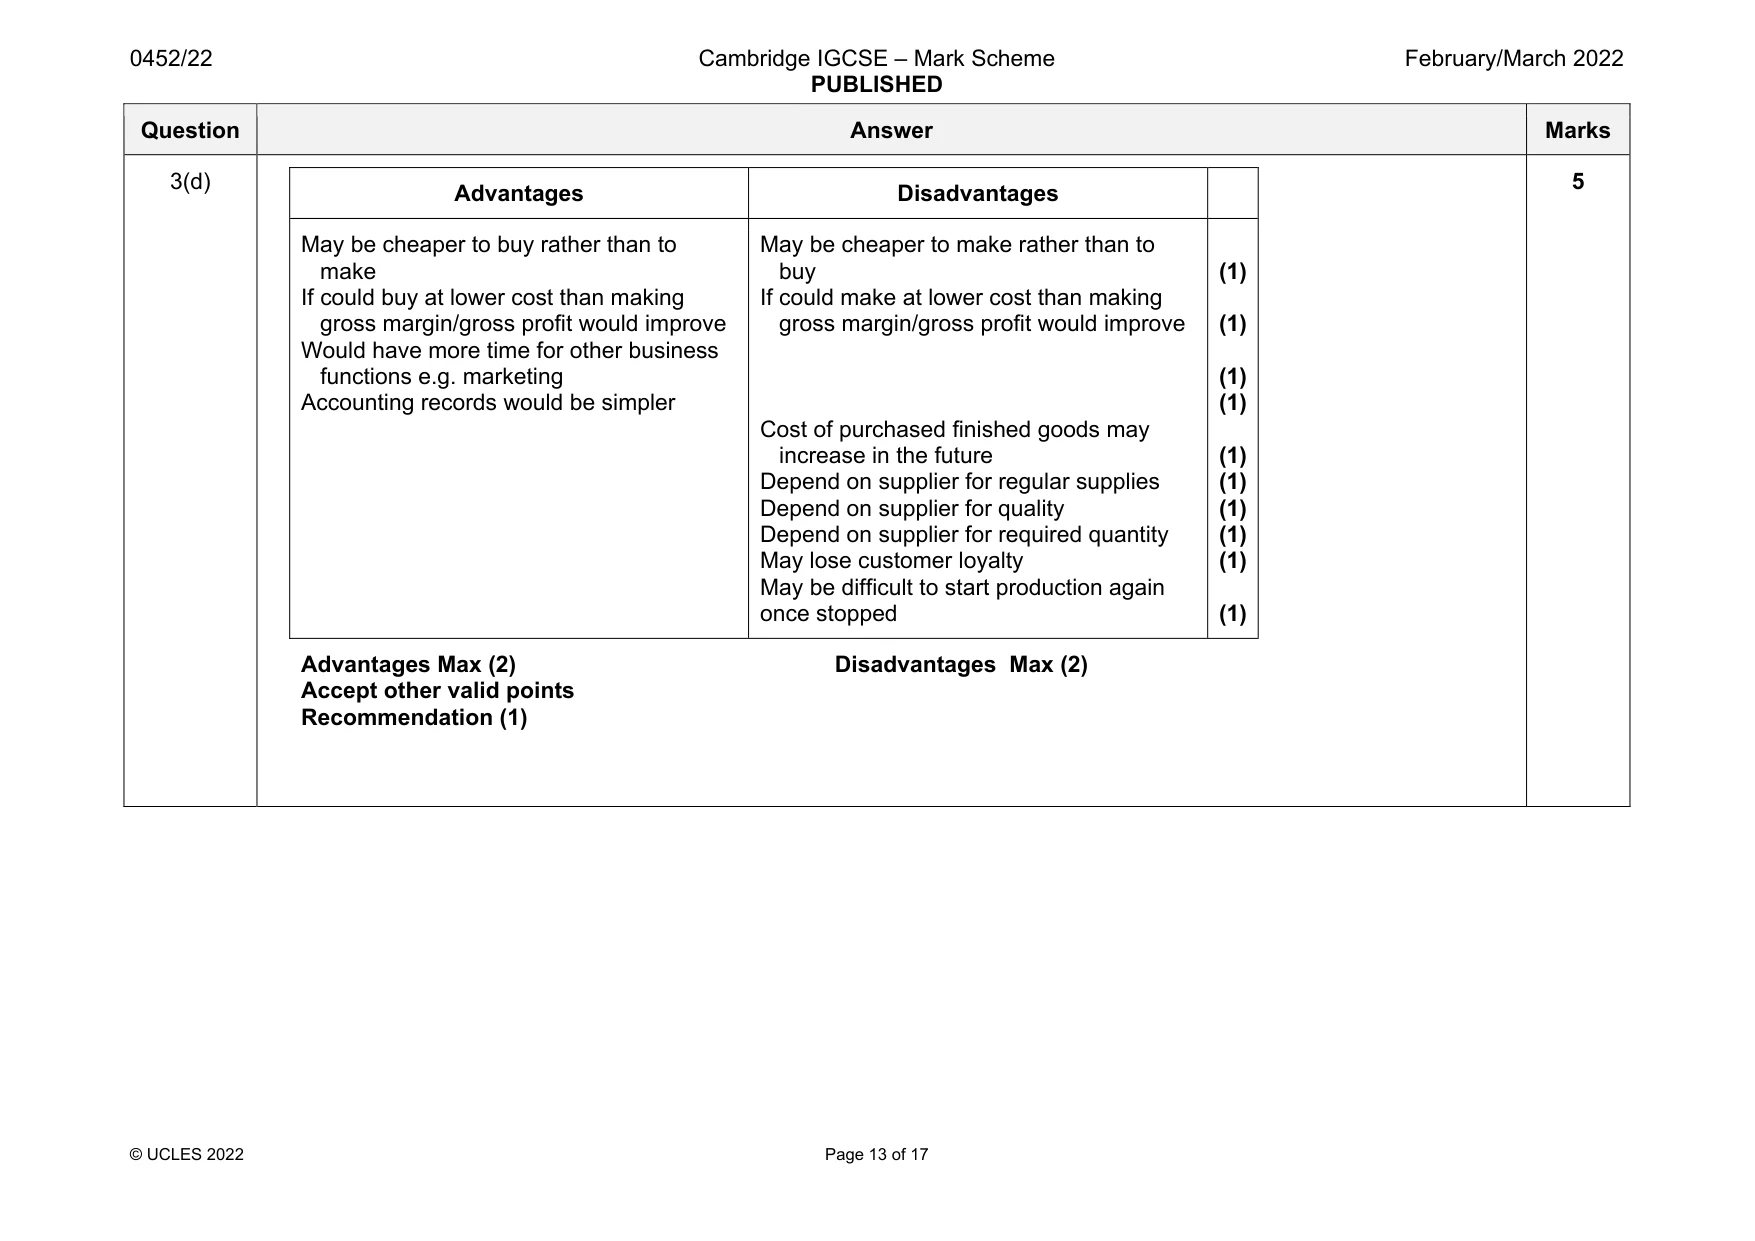
Mark scheme: 3(a) Pari Manufacturing Account for the year ended 31 December 2021 Cost of material consumed Opening inventory of raw materials Purchases of raw materials Less Closing inventory of raw materials Direct wages Prime cost Factory overheads Wages of factory supervisor Rates and insurance (14 000 ÷ 2) General expenses (11 500 + 500) Depreciation of factory equipment (100 000 – 36 000) x 20% Add opening work-in-progress Less closing work-in-progress Cost of production *(1) for both inventories of work in progress $ 26 000} 7 000}(1) 12 000 (1) 12 800 (1) $ 6 100 84 200 90 300 6 840 83 460 (1) 33 000 (1) 116 460 (1)OF 57 800 174 260 (1)OF 9 420 * 183 680 9 885* 173 795 (1)OF 9 Question Answer Marks 3(b) Pari Income Statement (trading section) for the year ended 31 December 2021 $ $ Revenue 230 020 Cost of sales Opening inventory of finished goods 11 350 * Cost of production 173 795 (1)OF 185 145 Less Closing inventory of finished goods 12 630 * 172 515 (1)OF Gross profit 57 505 (1)OF *(1) for both inventories of finished goods 4 3(c) Gross margin = 57 505 230 020 OF × 100 1 } whole formula (1)OF = 25.00% (1)OF 2 Question Answer Marks 3(d) Advantages Disadvantages May be cheaper to buy rather than to make If could buy at lower cost than making gross margin/gross profit would improve Would have more time for other business functions e.g. marketing Accounting records would be simpler May be cheaper to make rather than to buy If could make at lower cost than making gross margin/gross profit would improve Cost of purchased finished goods may increase in the future Depend on supplier for regular supplies Depend on supplier for quality Depend on supplier for required quantity May lose customer loyalty May be difficult to start production again once stopped (1) (1) (1) (1) (1) (1) (1) (1) (1) (1) Advantages Max (2) Disadvantages Max (2) Accept other valid points Recommendation (1) 5
Q4 · Demis is a trader
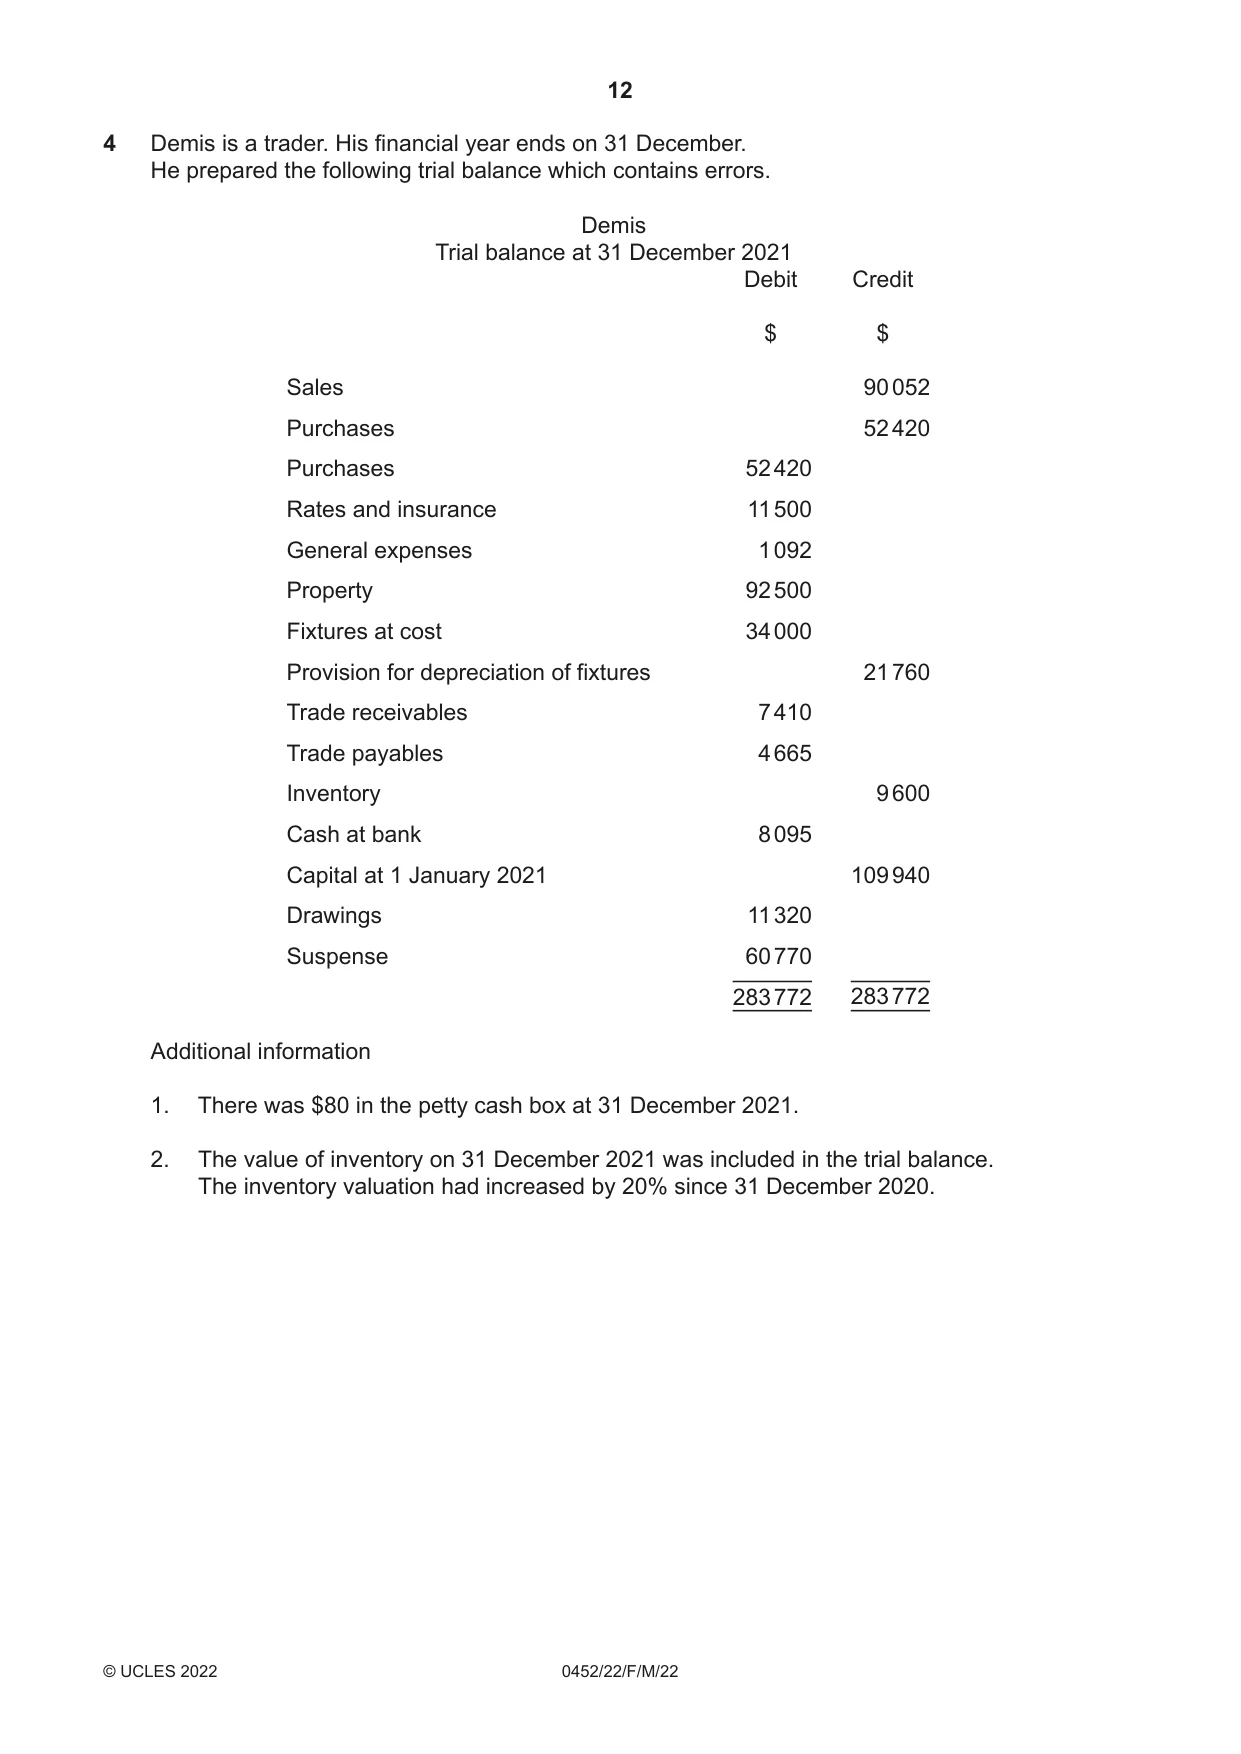
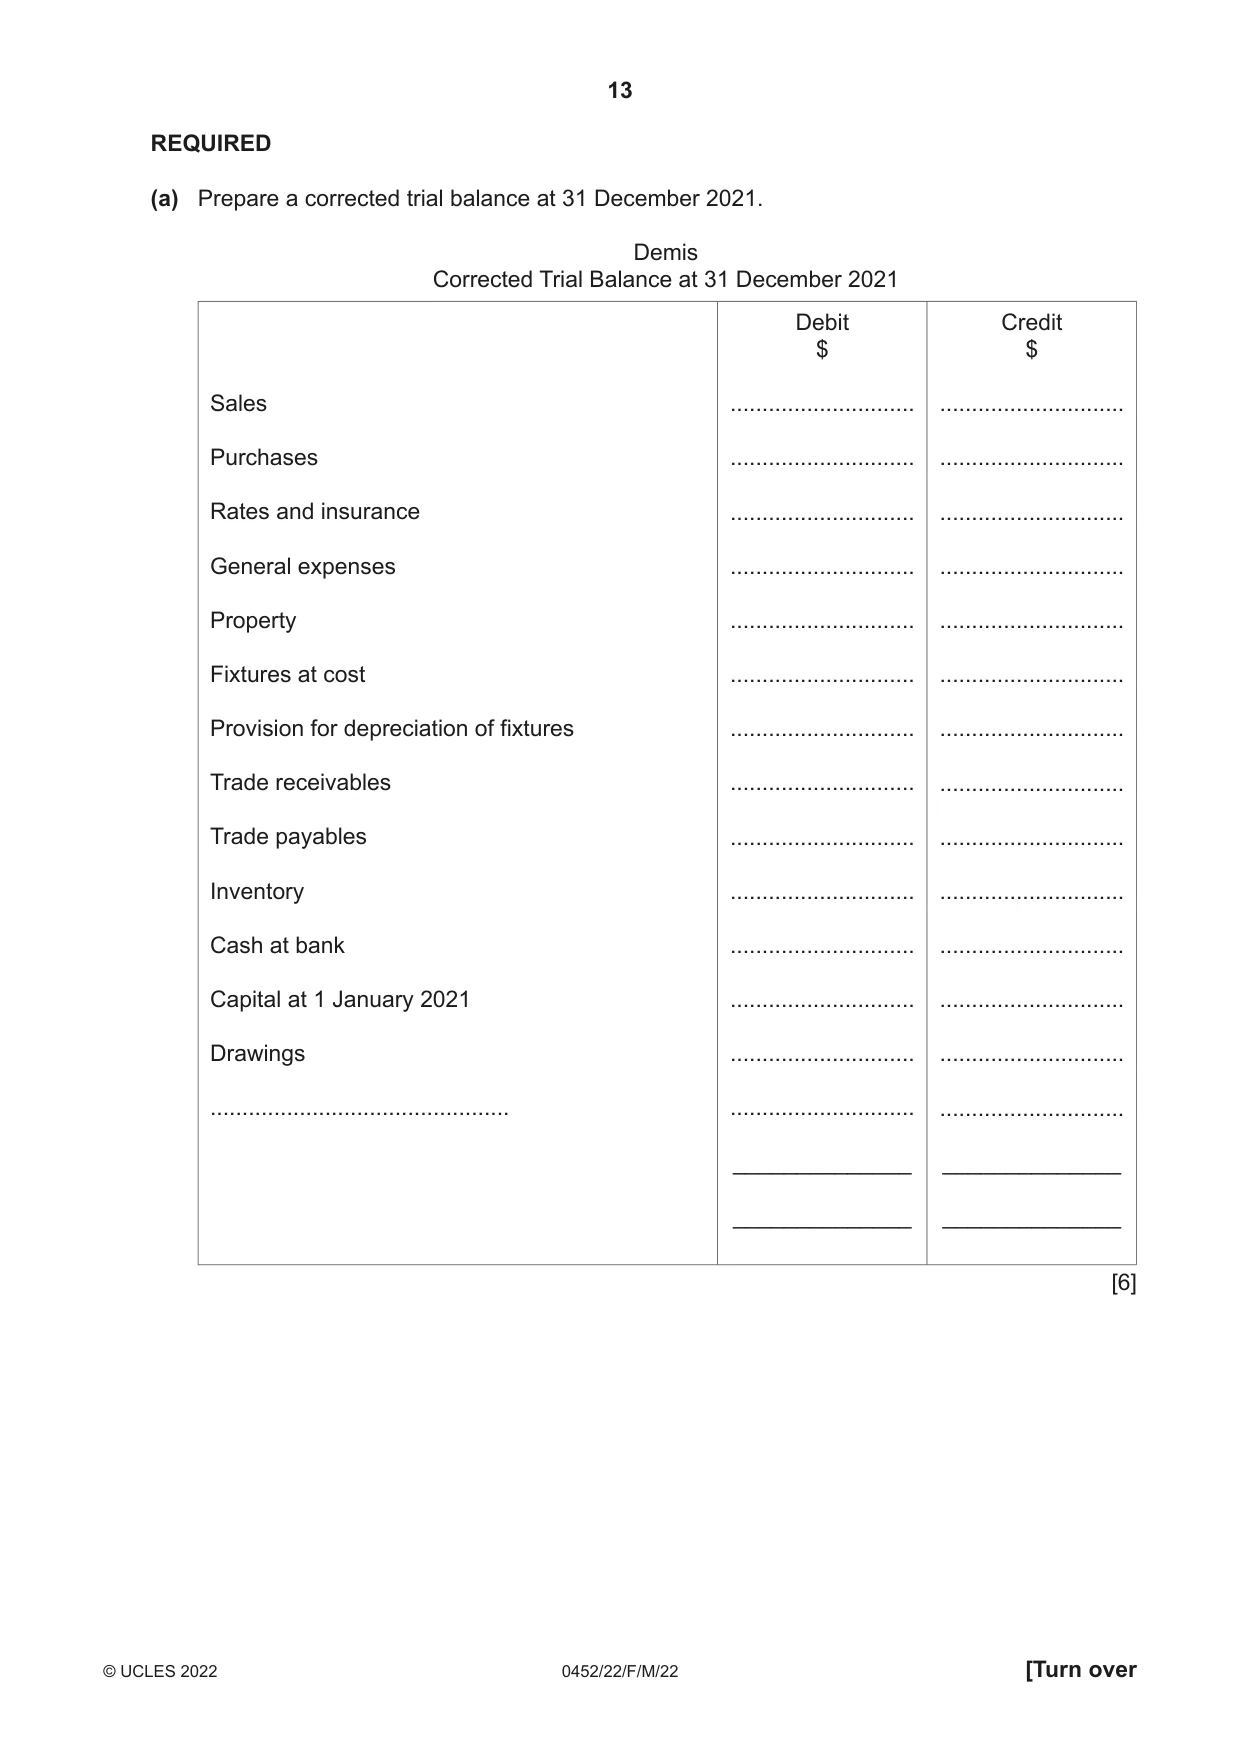
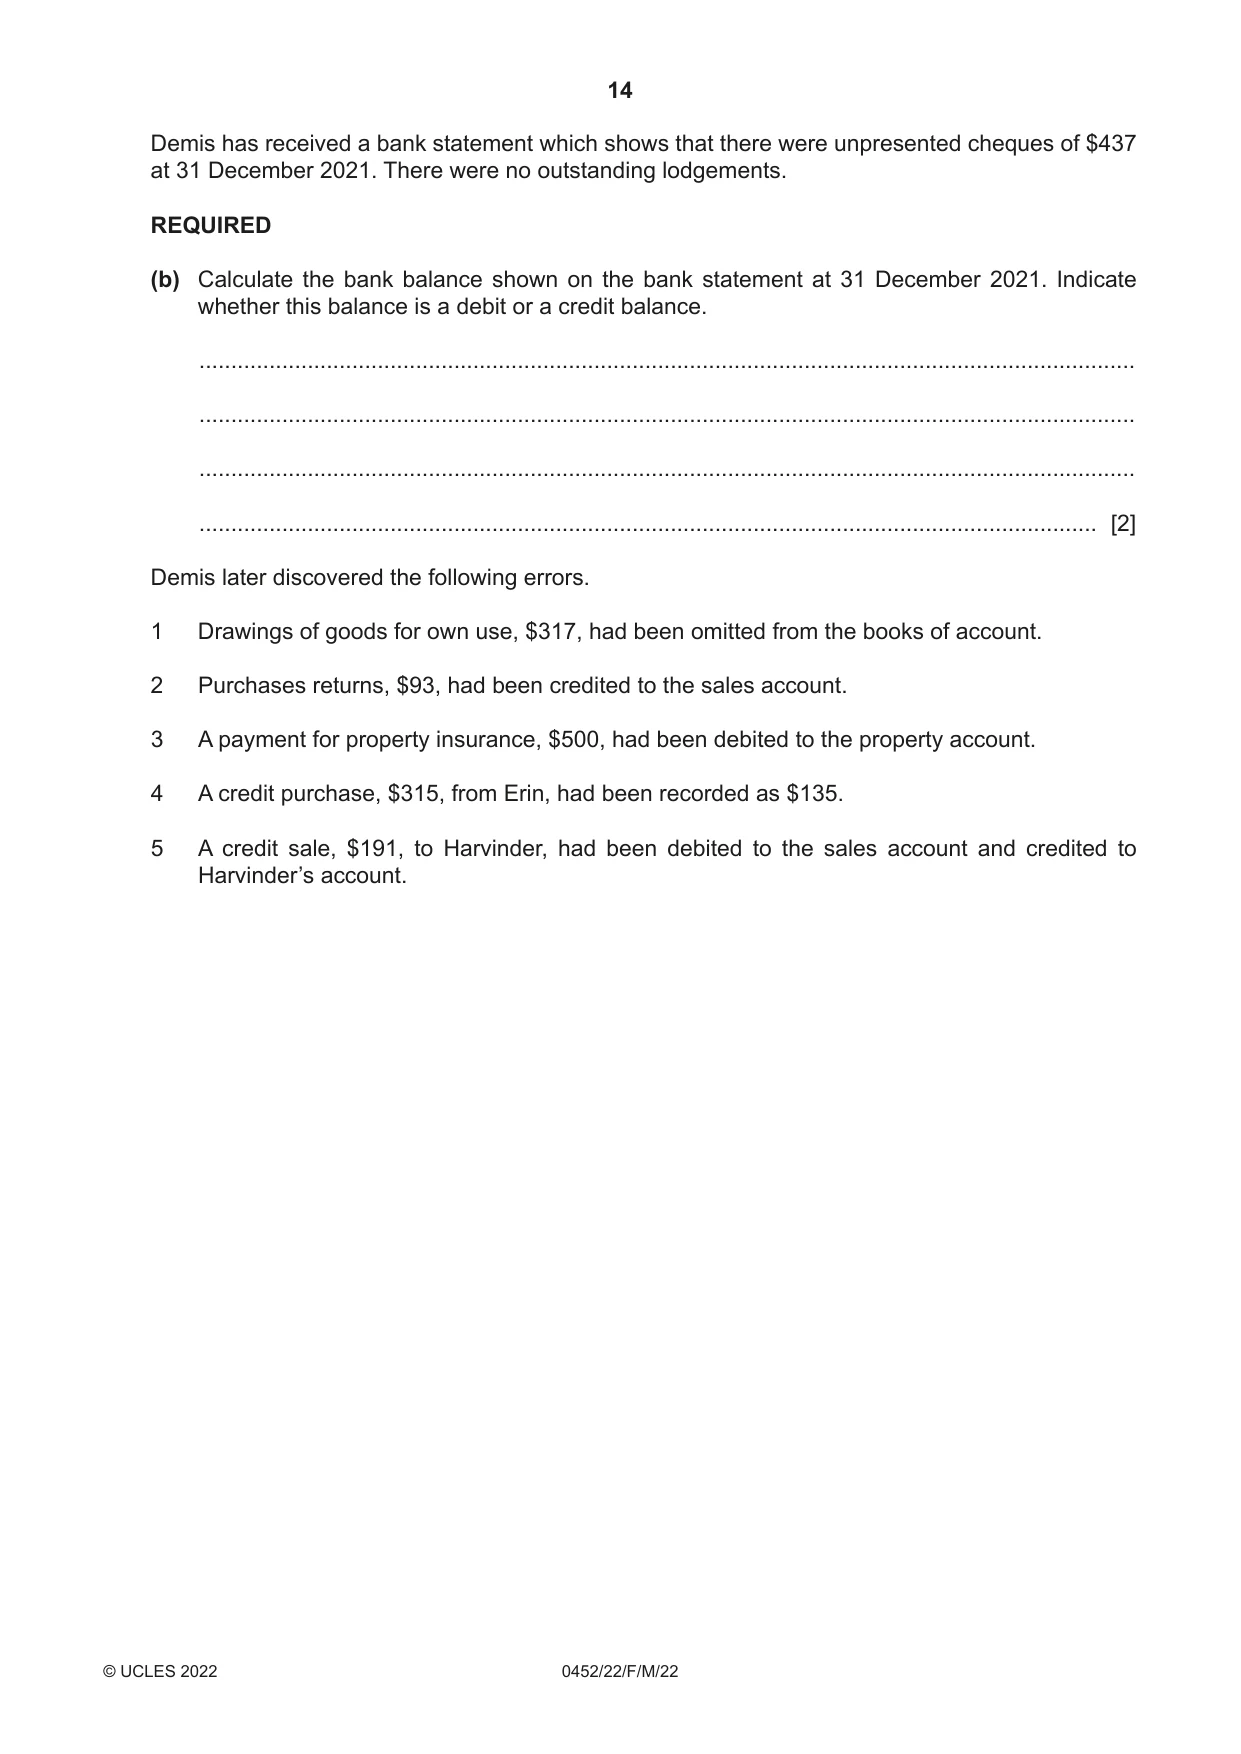
4 Demis is a trader. His financial year ends on 31 December. He prepared the following trial balance which contains errors. Demis Trial balance at 31 December 2021 Debit Credit $ $ Sales 90 052 Purchases 52 420 Purchases 52 420 Rates and insurance 11 500 General expenses 1 092 Property 92 500 Fixtures at cost 34 000 Provision for depreciation of fixtures 21 760 Trade receivables 7 410 Trade payables 4 665 Inventory 9 600 Cash at bank 8 095 Capital at 1 January 2021 109 940 Drawings 11 320 Suspense 60 770 283 772 283 772 Additional information 1. There was $80 in the petty cash box at 31 December 2021. 2. The value of inventory on 31 December 2021 was included in the trial balance. The inventory valuation had increased by 20% since 31 December 2020. REQUIRED (a) Prepare a corrected trial balance at 31 December 2021. Demis Corrected Trial Balance at 31 December 2021 Debit Credit $ $ Sales ............................. ............................. Purchases ............................. ............................. Rates and insurance ............................. ............................. General expenses ............................. ............................. Property ............................. ............................. Fixtures at cost ............................. ............................. Provision for depreciation of fixtures ............................. ............................. Trade receivables ............................. ............................. Trade payables ............................. ............................. Inventory ............................. ............................. Cash at bank ............................. ............................. Capital at 1 January 2021 ............................. ............................. Drawings ............................. ............................. ............................................... ............................. ............................. ______________ ______________ ______________ ______________ [6] Demis has received a bank statement which shows that there were unpresented cheques of $437 at 31 December 2021. There were no outstanding lodgements. REQUIRED (b) Calculate the bank balance shown on the bank statement at 31 December 2021. Indicate whether this balance is a debit or a credit balance. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Demis later discovered the following errors. 1 Drawings of goods for own use, $317, had been omitted from the books of account. 2 Purchases returns, $93, had been credited to the sales account. 3 A payment for property insurance, $500, had been debited to the property account. 4 A credit purchase, $315, from Erin, had been recorded as $135.
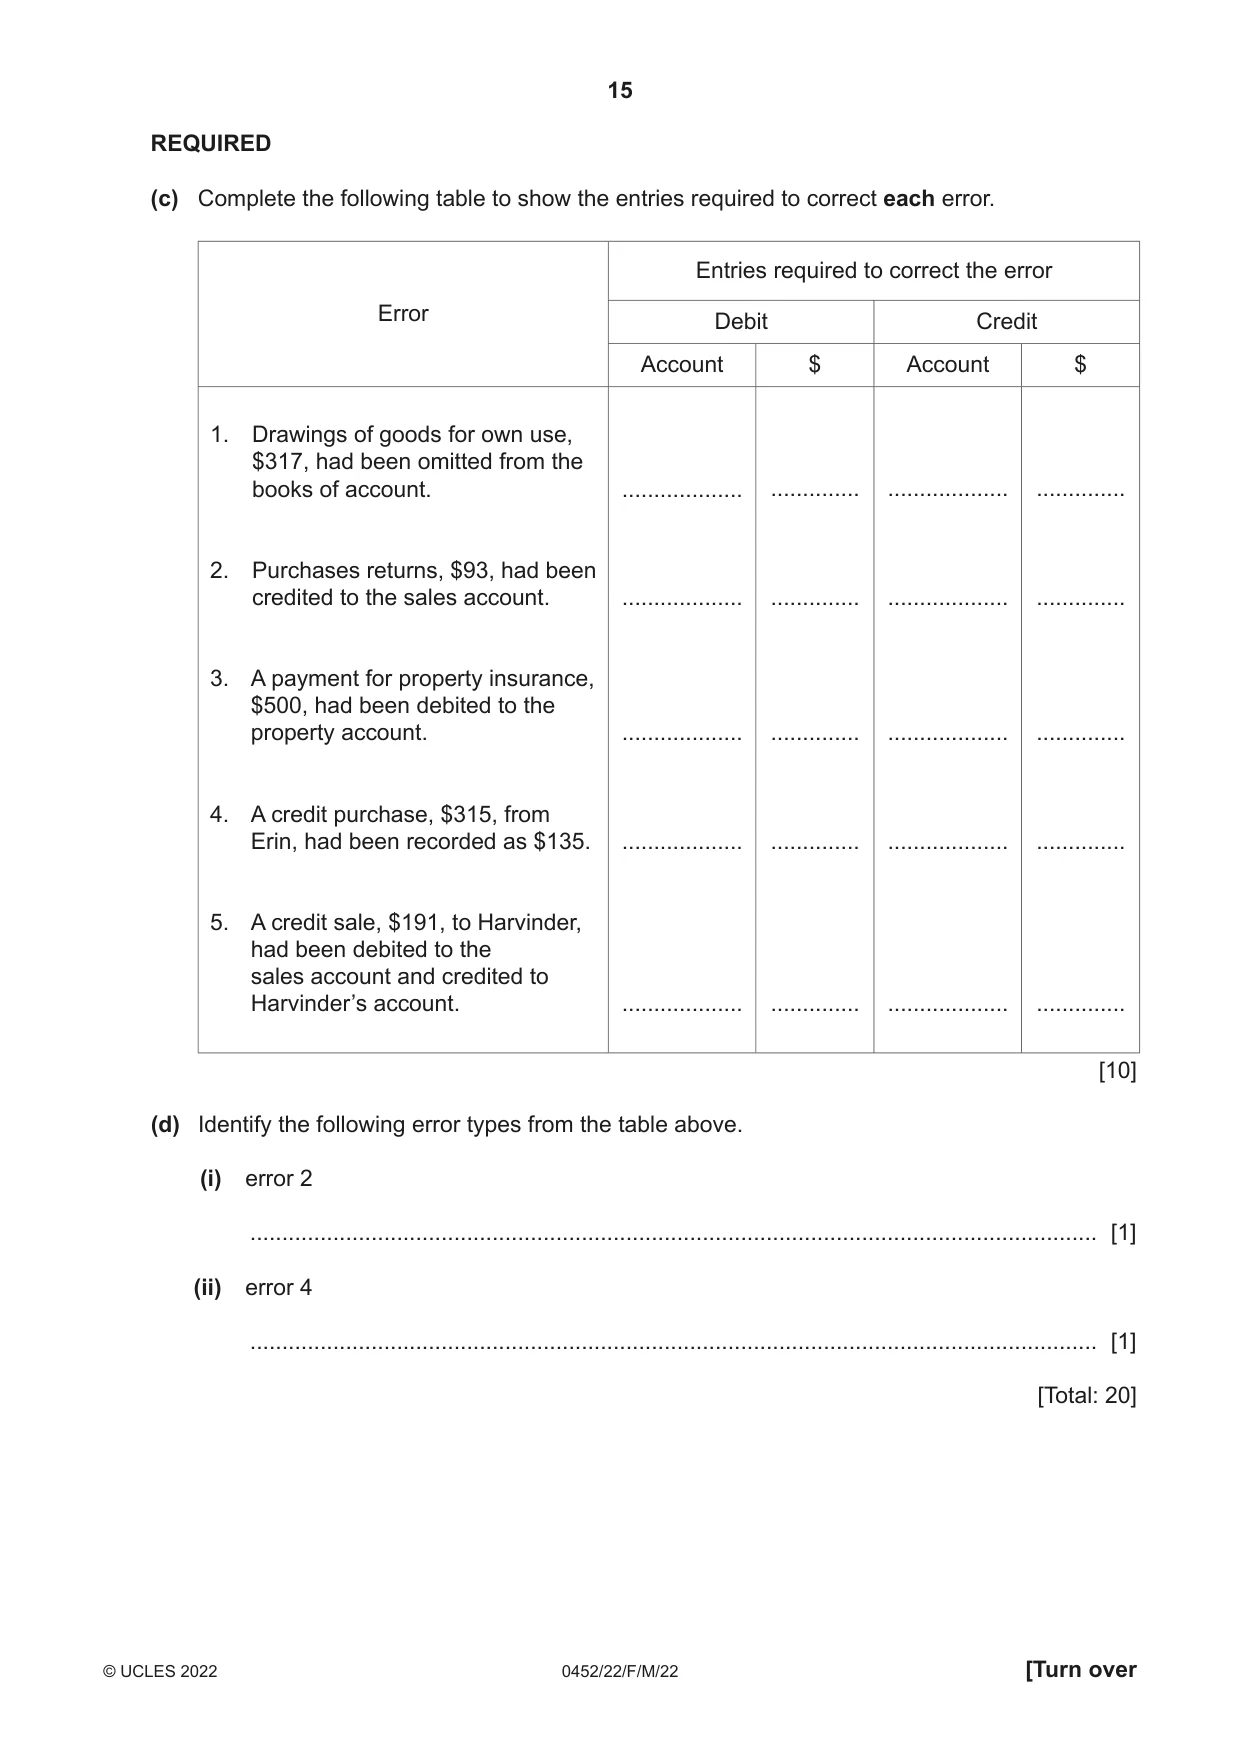
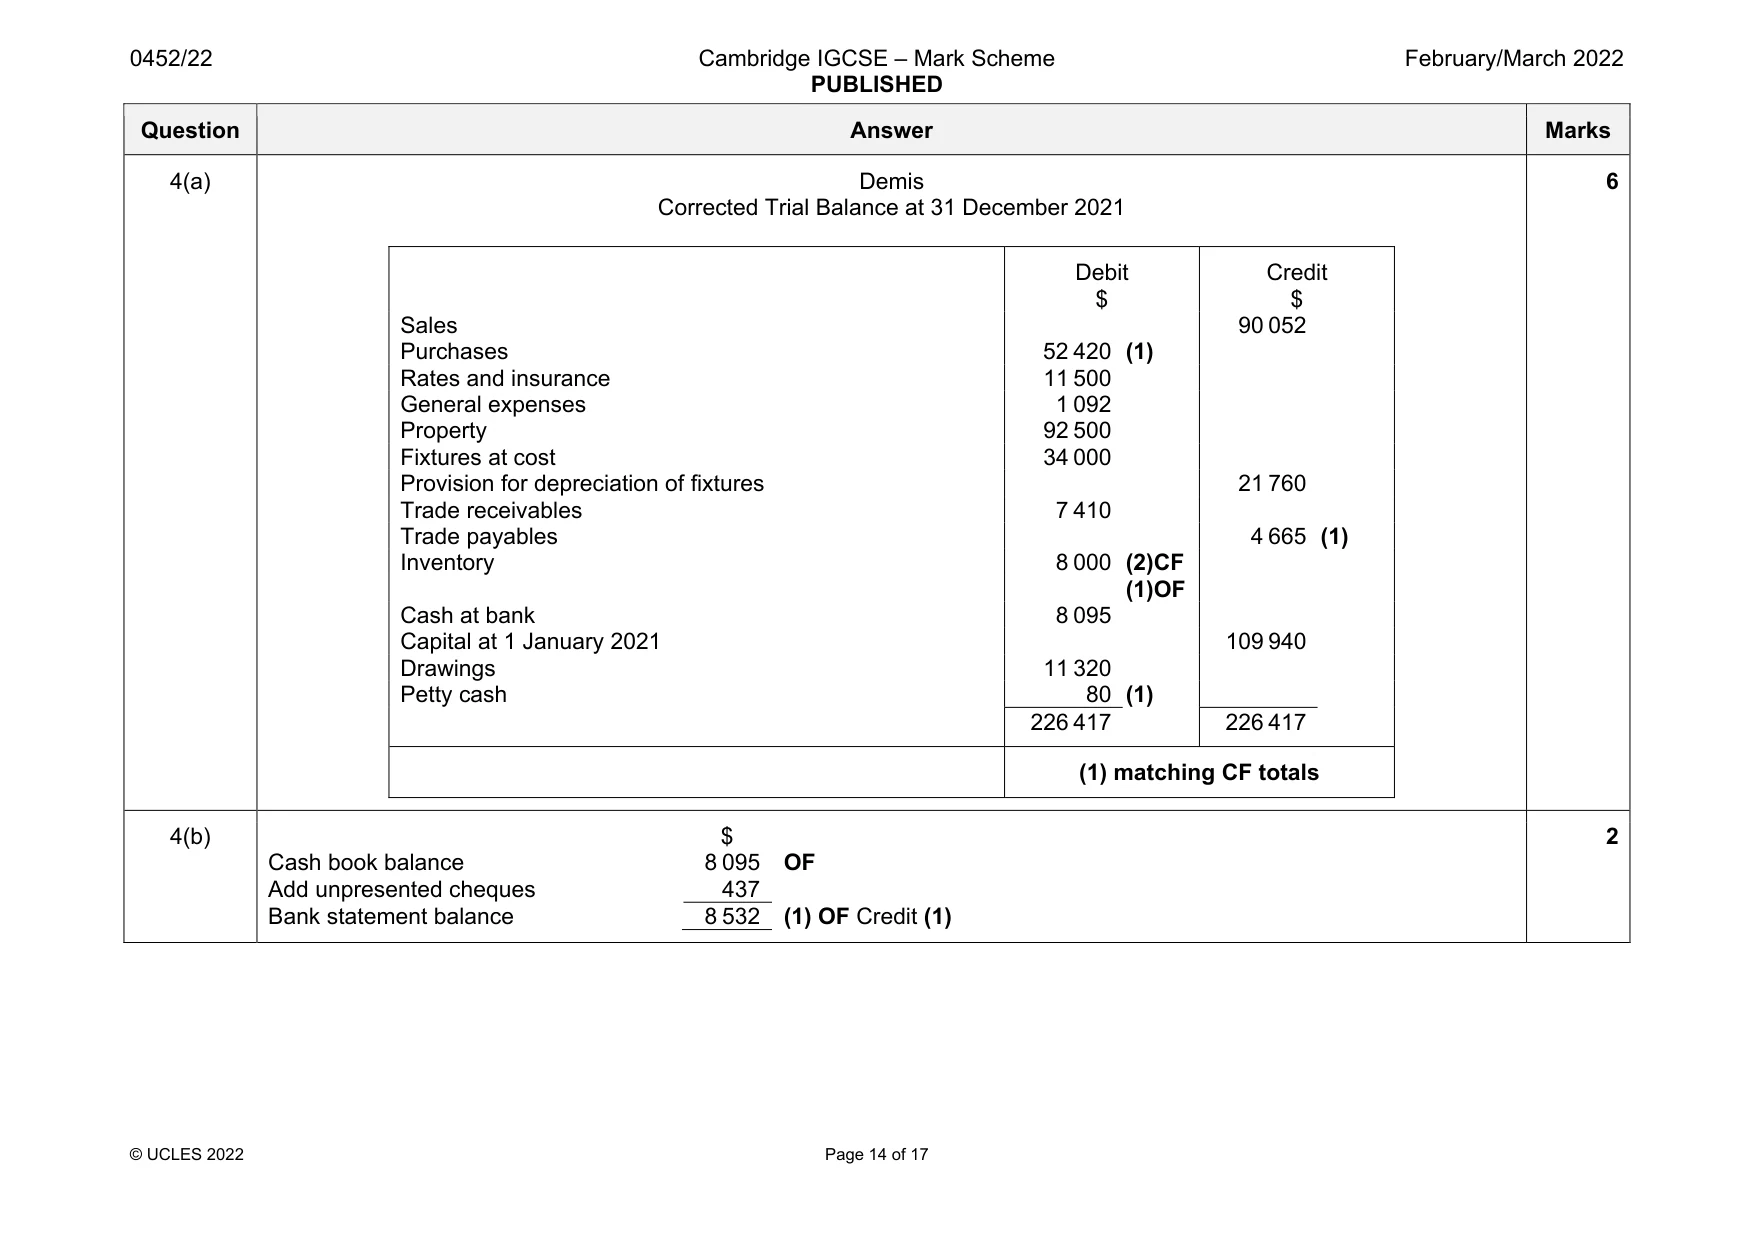
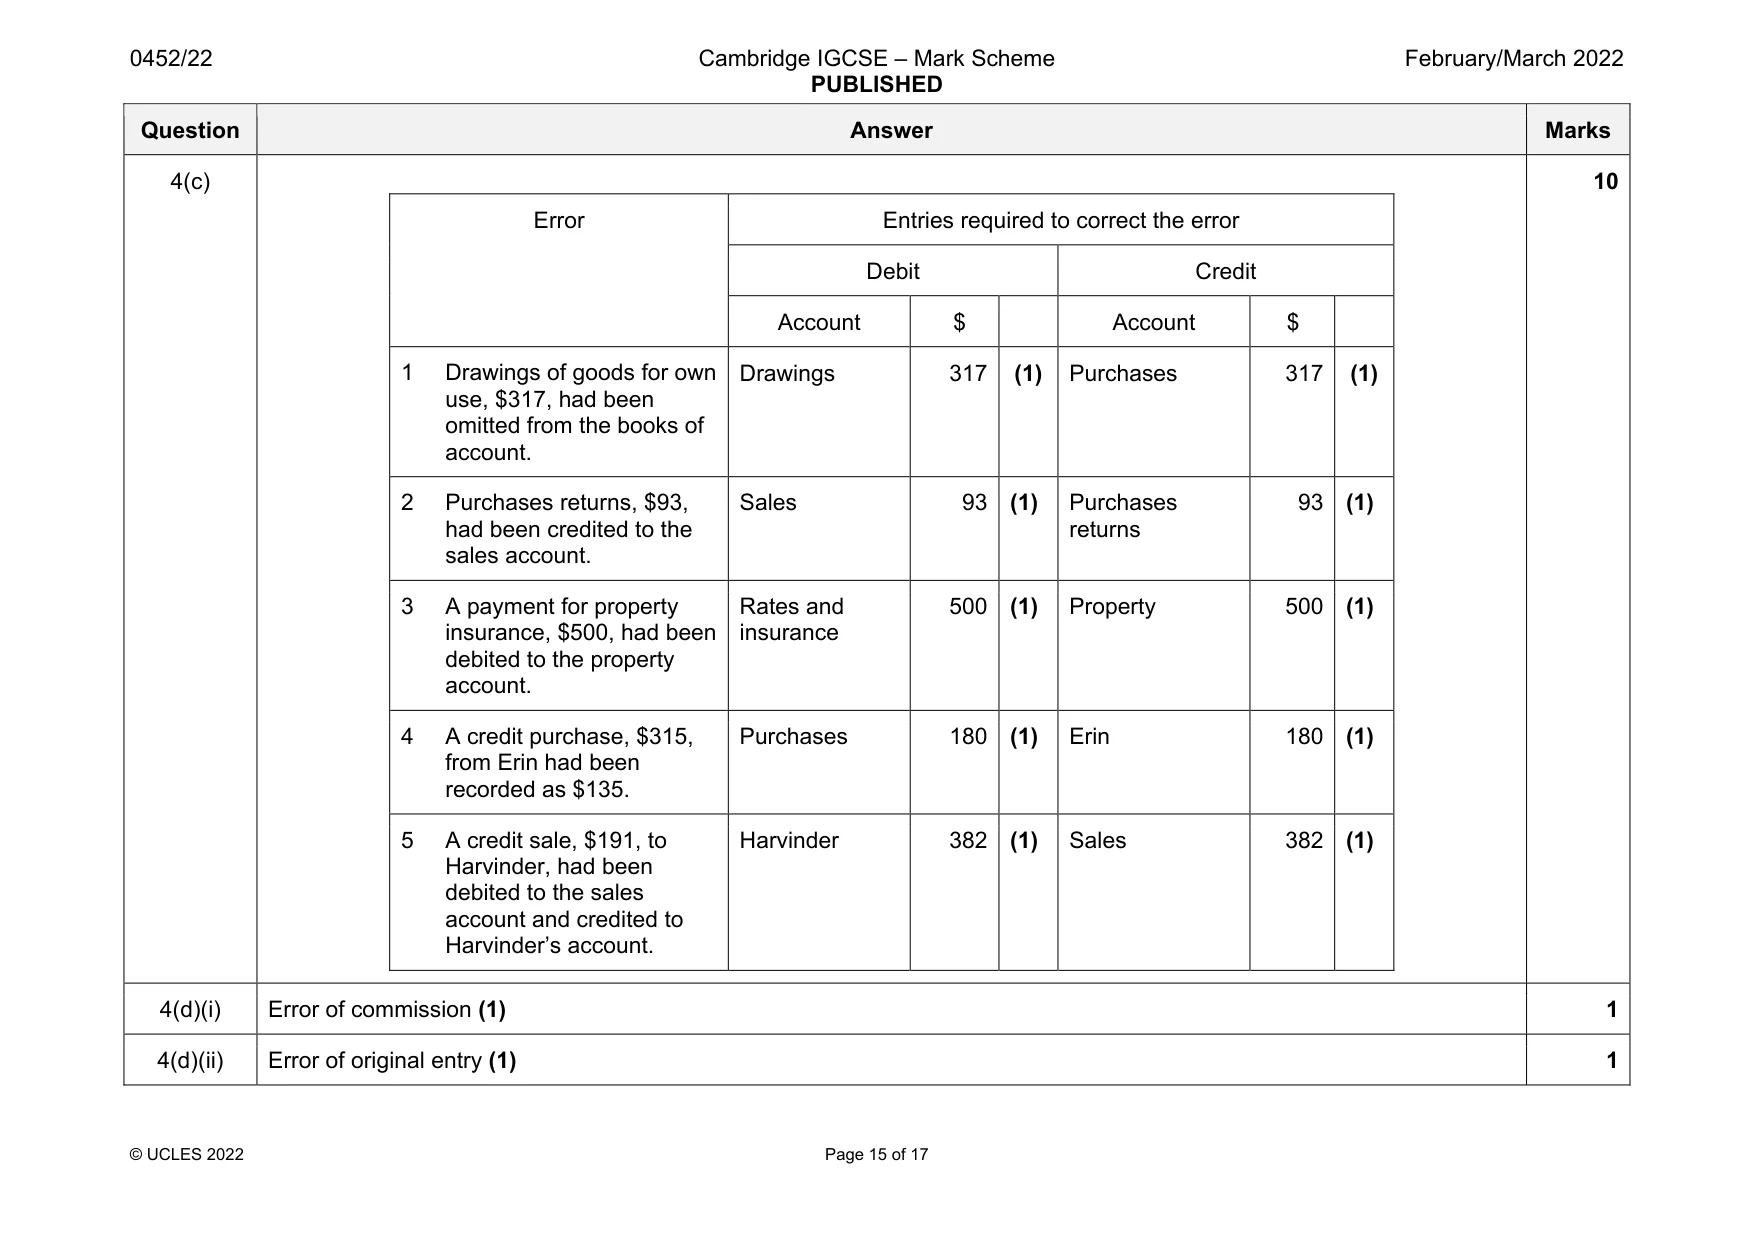
Mark scheme: 4(a) Demis Corrected Trial Balance at 31 December 2021 Debit $ Credit $ Sales 90 052 Purchases 52 420 (1) Rates and insurance 11 500 General expenses 1 092 Property 92 500 Fixtures at cost 34 000 Provision for depreciation of fixtures 21 760 Trade receivables 7 410 Trade payables 4 665 (1) Inventory 8 000 (2)CF (1)OF Cash at bank 8 095 Capital at 1 January 2021 109 940 Drawings 11 320 Petty cash 80 (1) 226 417 226 417 (1) matching CF totals 6 4(b) $ Cash book balance 8 095 OF Add unpresented cheques 437 Bank statement balance 8 532 (1) OF Credit (1) 2 Question Answer Marks 4(c) Error Entries required to correct the error Debit Credit Account $ Account $ 1 Drawings of goods for own use, $317, had been omitted from the books of account. Drawings 317 (1) Purchases 317 (1) 2 Purchases returns, $93, had been credited to the sales account. Sales 93 (1) Purchases returns 93 (1) 3 A payment for property insurance, $500, had been debited to the property account. Rates and insurance 500 (1) Property 500 (1) 4 A credit purchase, $315, from Erin had been recorded as $135. Purchases 180 (1) Erin 180 (1) 5 A credit sale, $191, to Harvinder, had been debited to the sales account and credited to Harvinder’s account. Harvinder 382 (1) Sales 382 (1) 10 4(d)(i) Error of commission (1) 1 4(d)(ii) Error of original entry (1) 1
Q5 · A credit sale, $191, to Harvinder, had been debited to the sales account and credited to…
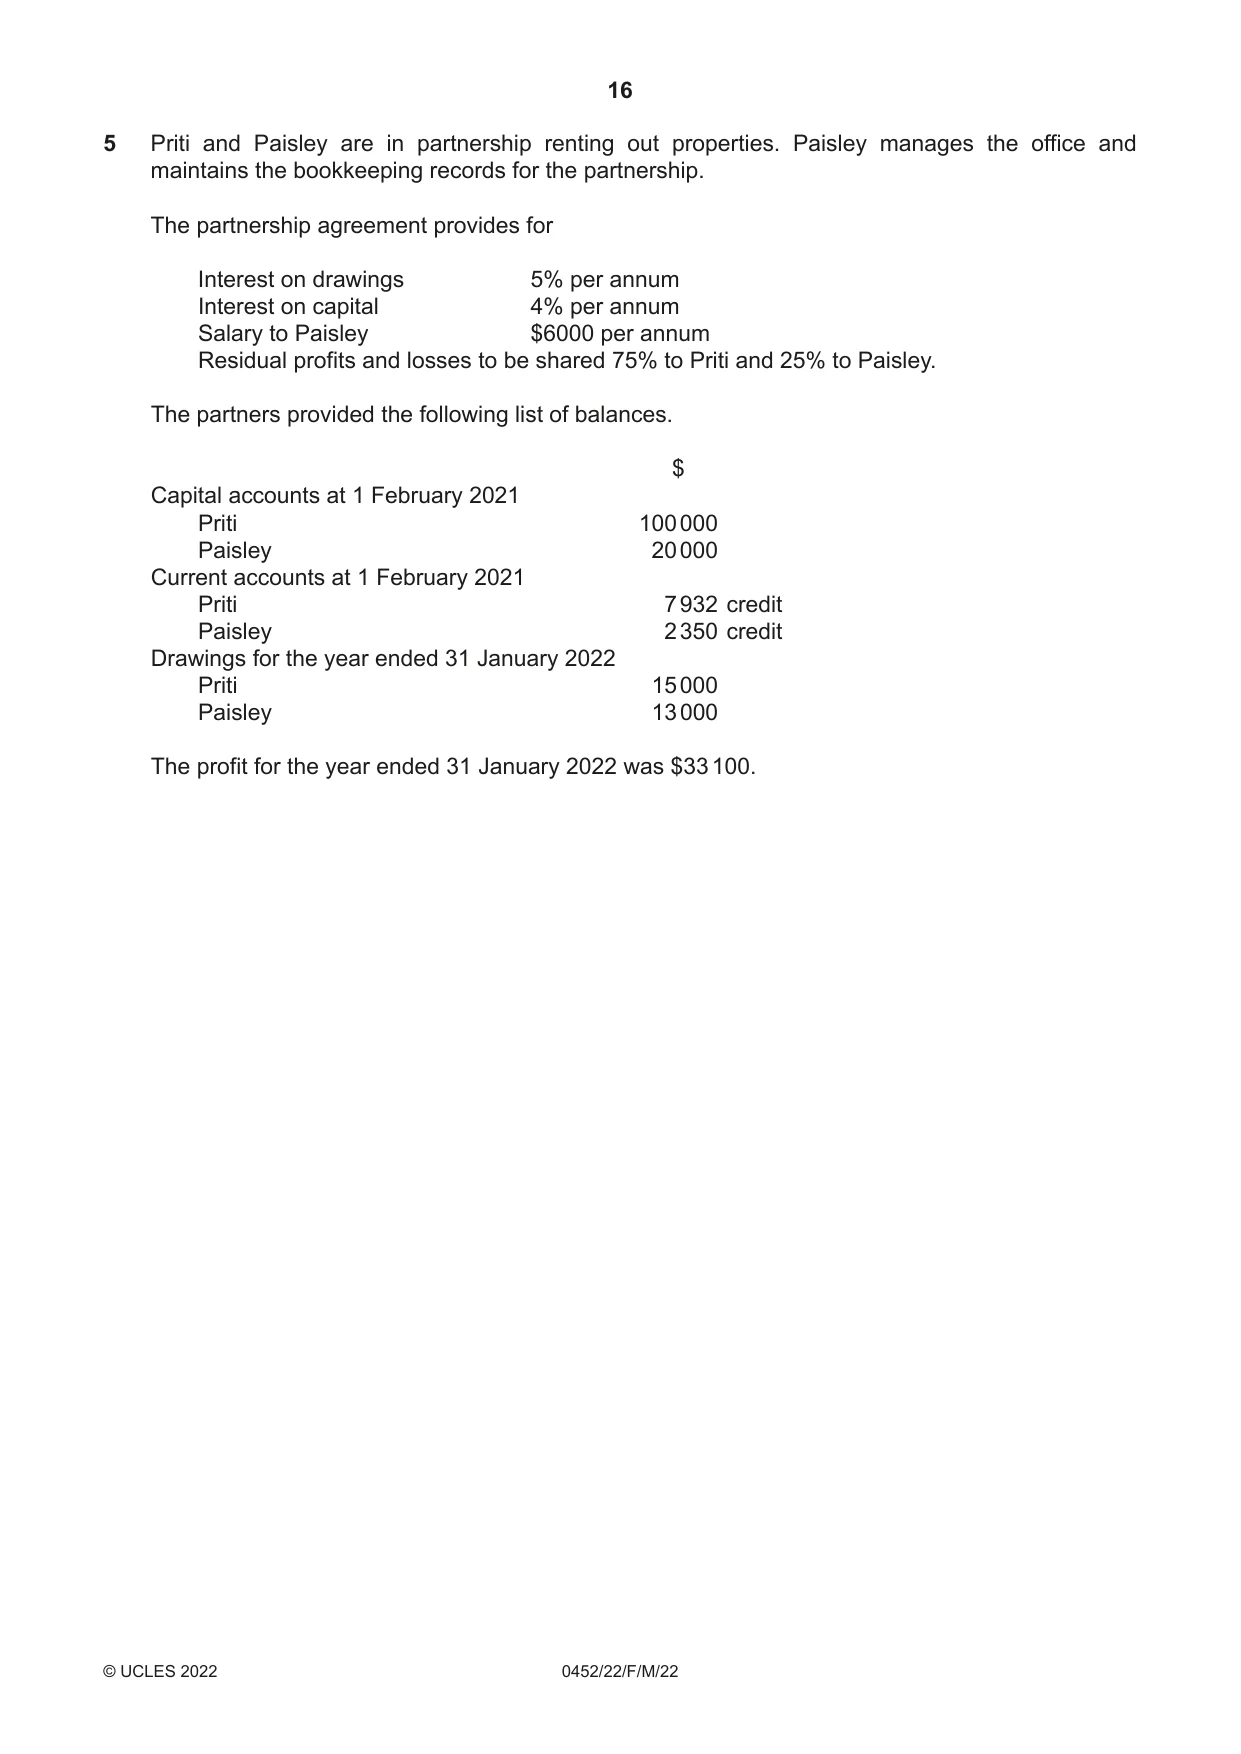
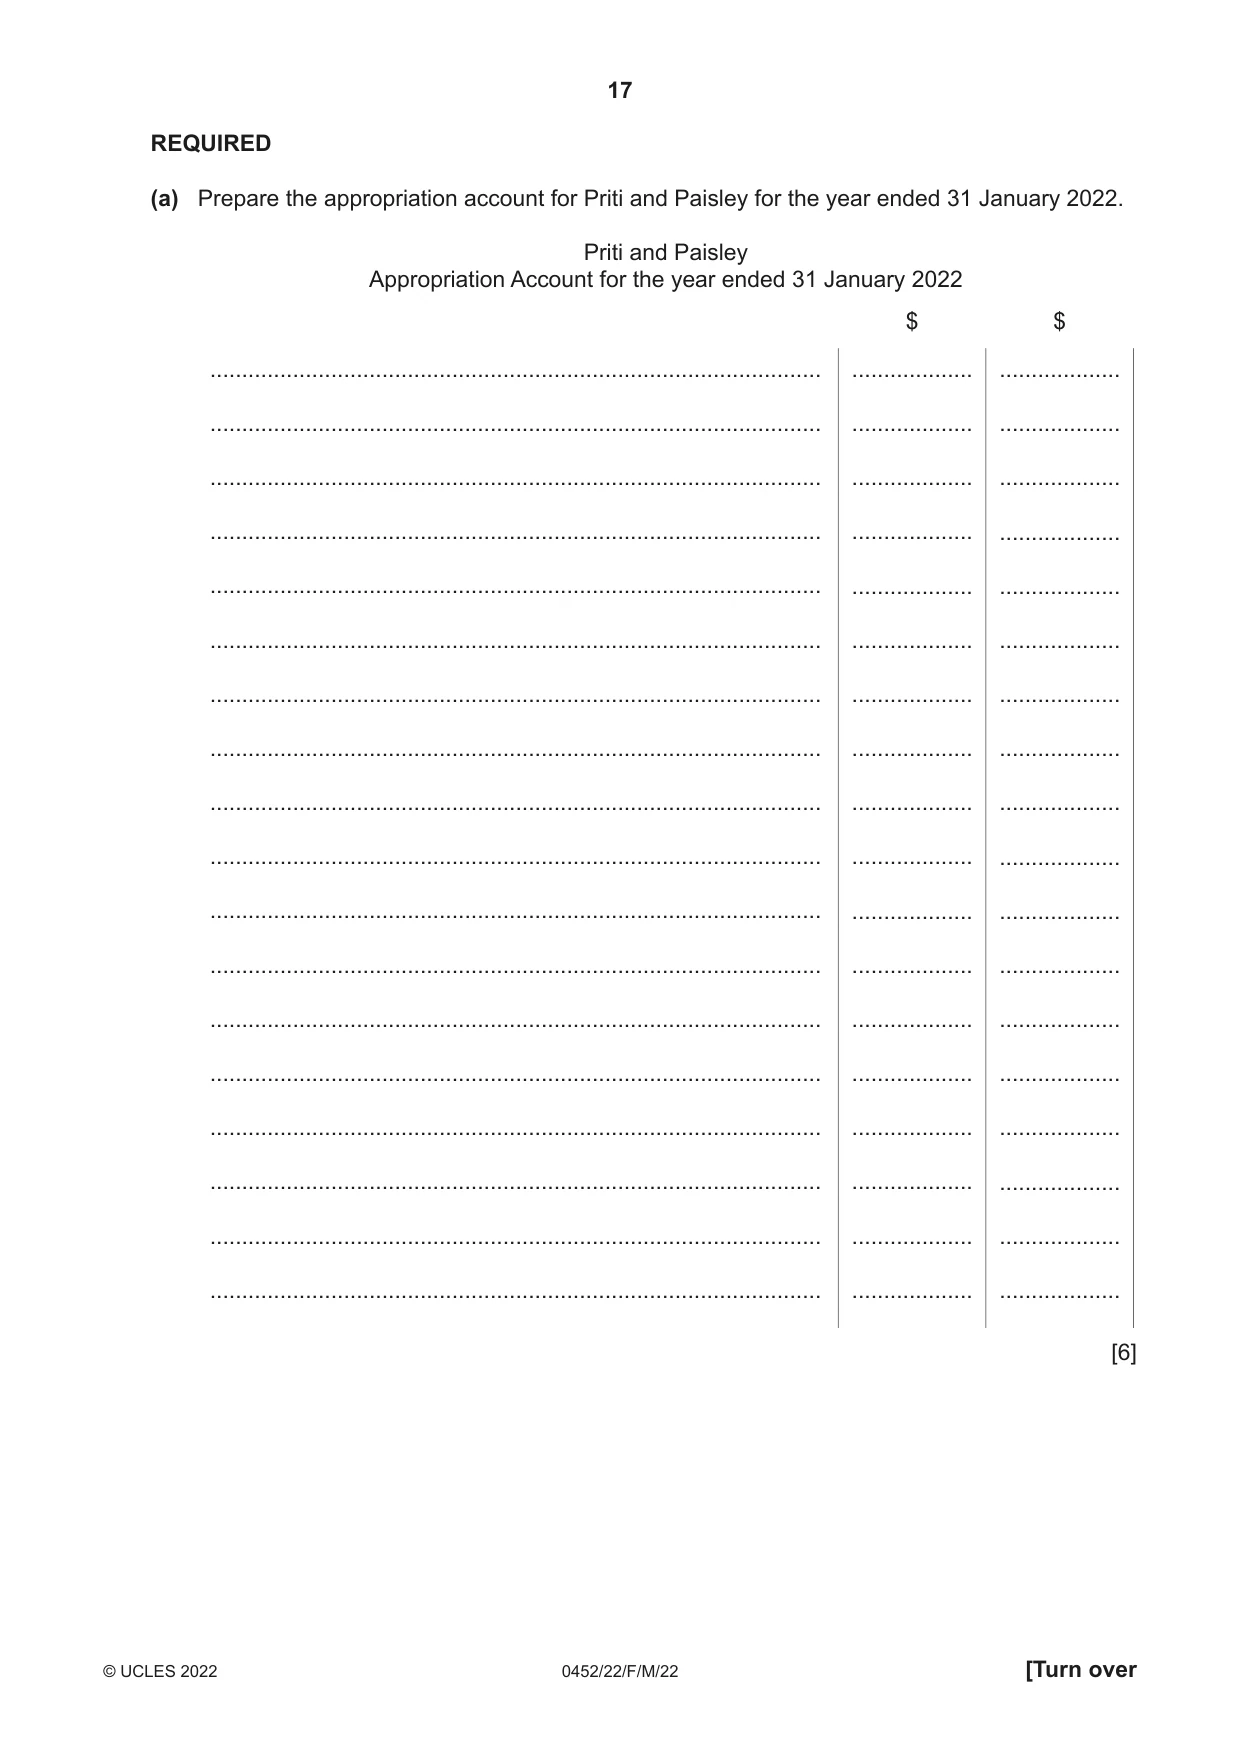
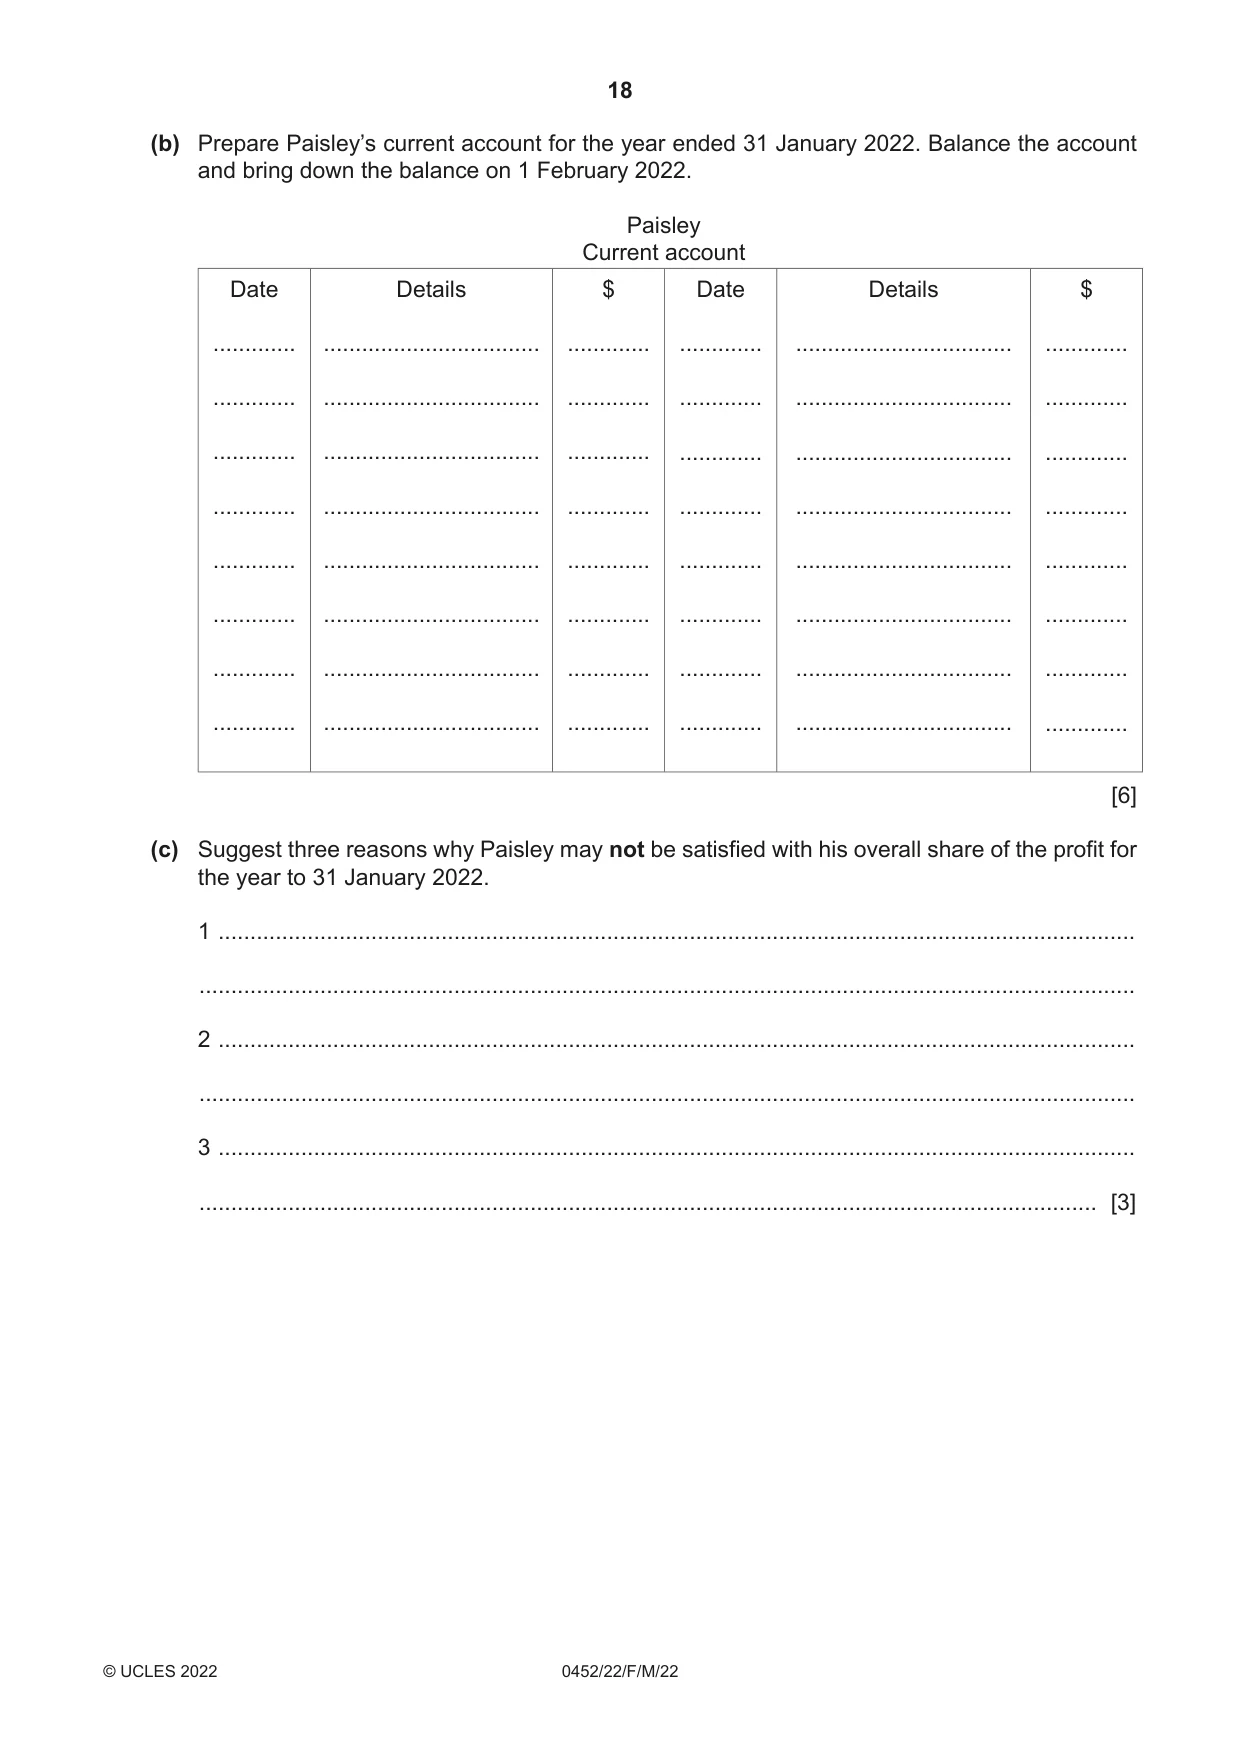
5 A credit sale, $191, to Harvinder, had been debited to the sales account and credited to Harvinder’s account. REQUIRED (c) Complete the following table to show the entries required to correct each error. Entries required to correct the error Error Debit Credit Account $ Account $ 1. Drawings of goods for own use, $317, had been omitted from the books of account. ................... .............. ................... .............. 2. Purchases returns, $93, had been credited to the sales account. ................... .............. ................... .............. 3. A payment for property insurance, $500, had been debited to the property account. ................... .............. ................... .............. 4. A credit purchase, $315, from Erin, had been recorded as $135. ................... .............. ................... .............. 5. A credit sale, $191, to Harvinder, had been debited to the sales account and credited to Harvinder’s account. ................... .............. ................... .............. [10] (d) Identify the following error types from the table above. (i) error 2 ..................................................................................................................................... [1] (ii) error 4 ..................................................................................................................................... [1] [Total: 20] 5 Priti and Paisley are in partnership renting out properties. Paisley manages the office and maintains the bookkeeping records for the partnership. The partnership agreement provides for Interest on drawings 5% per annum Interest on capital 4% per annum Salary to Paisley $6000 per annum Residual profits and losses to be shared 75% to Priti and 25% to Paisley. The partners provided the following list of balances. $ Capital accounts at 1 February 2021 Priti 100 000 Paisley 20 000 Current accounts at 1 February 2021 Priti 7 932 credit Paisley 2 350 credit Drawings for the year ended 31 January 2022 Priti 15 000 Paisley 13 000 The profit for the year ended 31 January 2022 was $33 100.
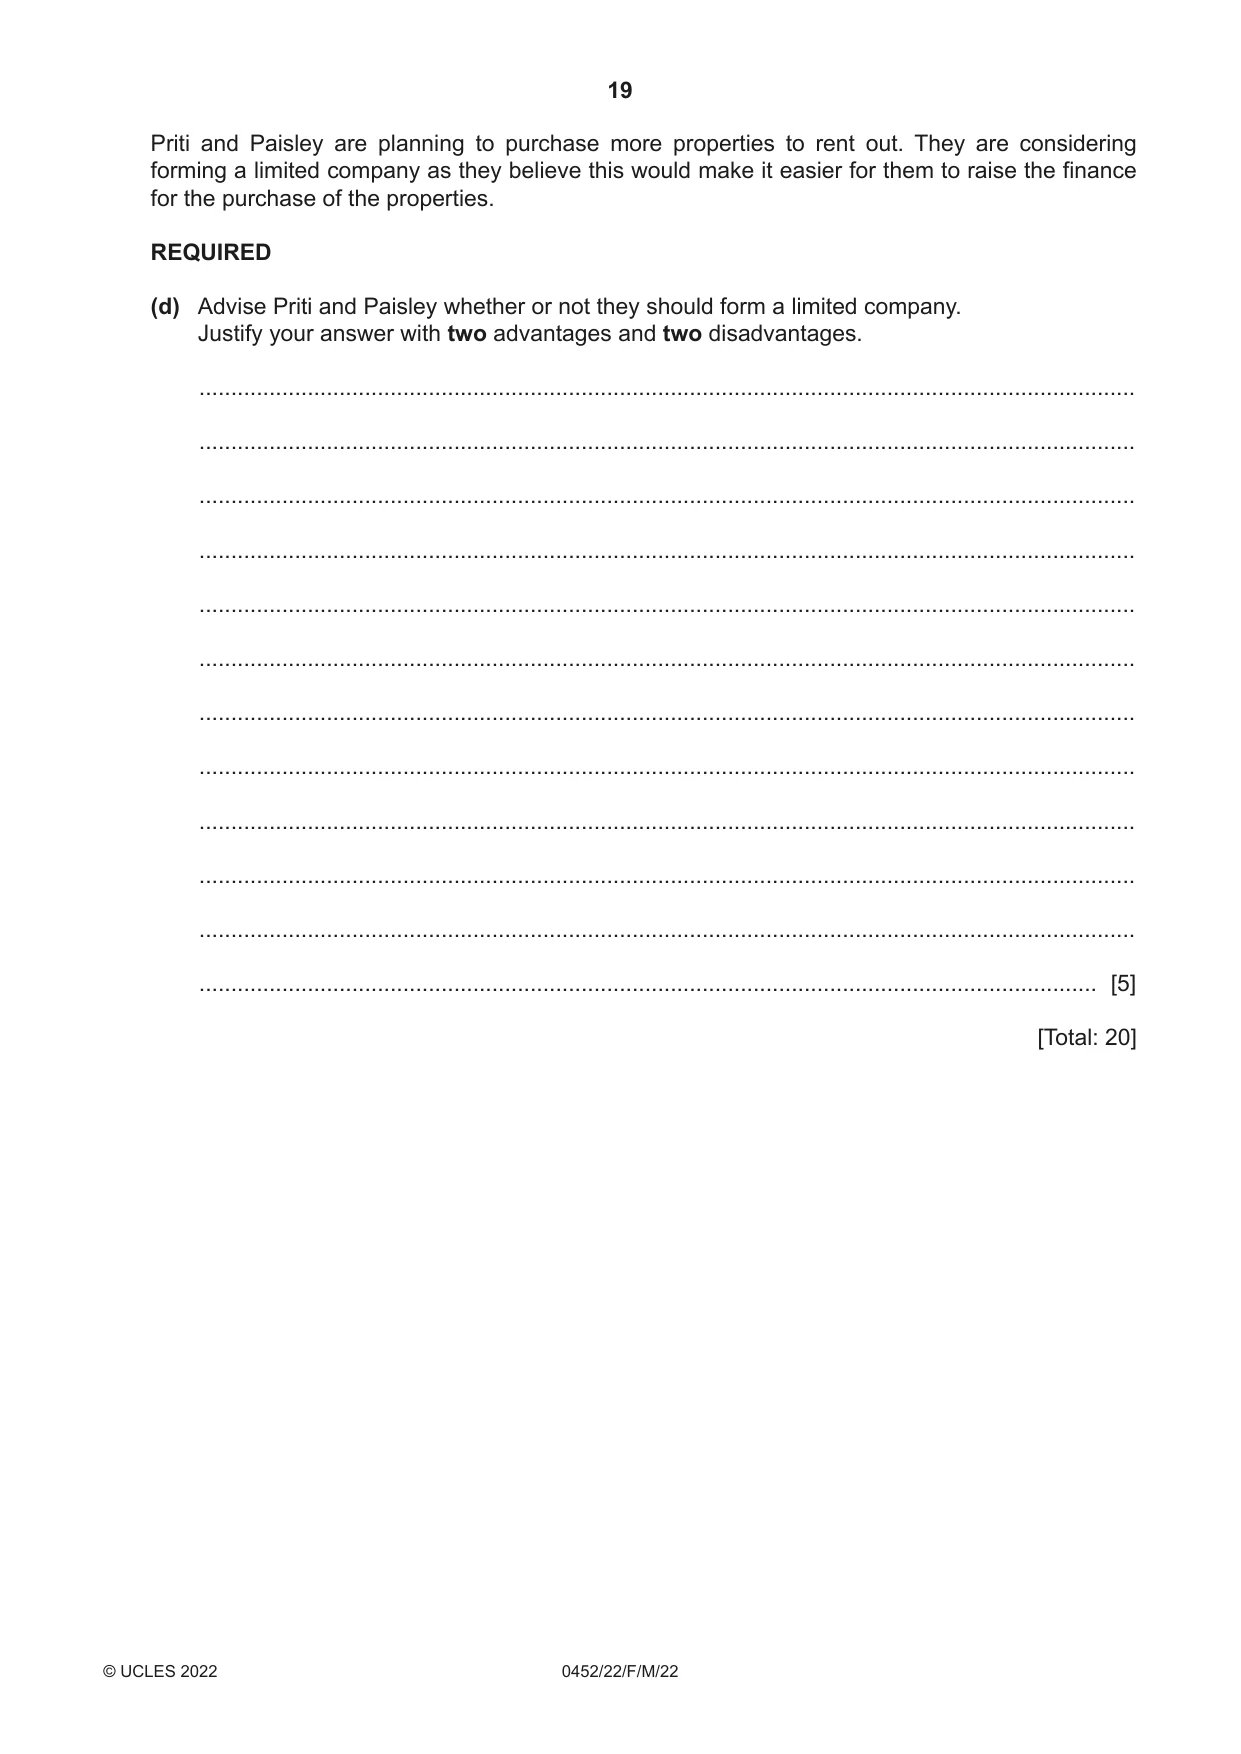
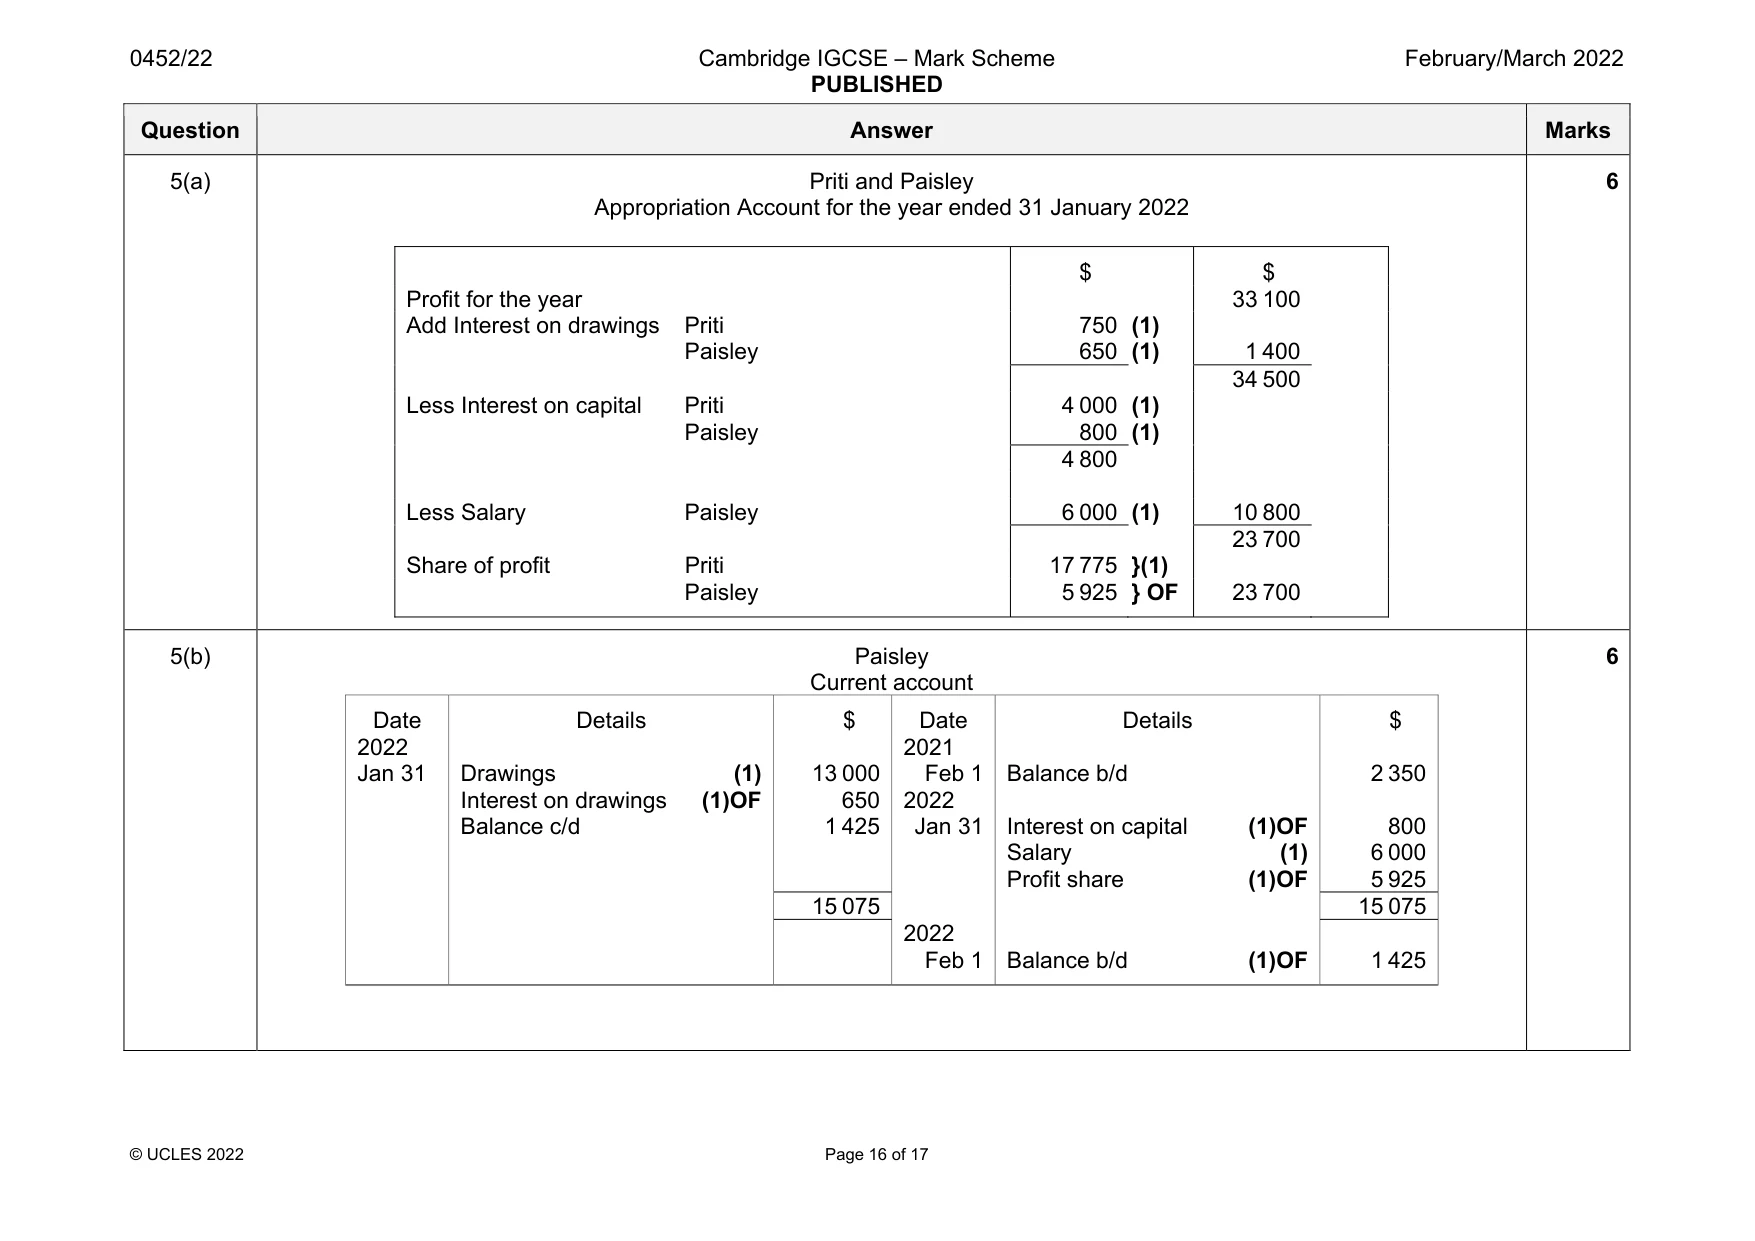
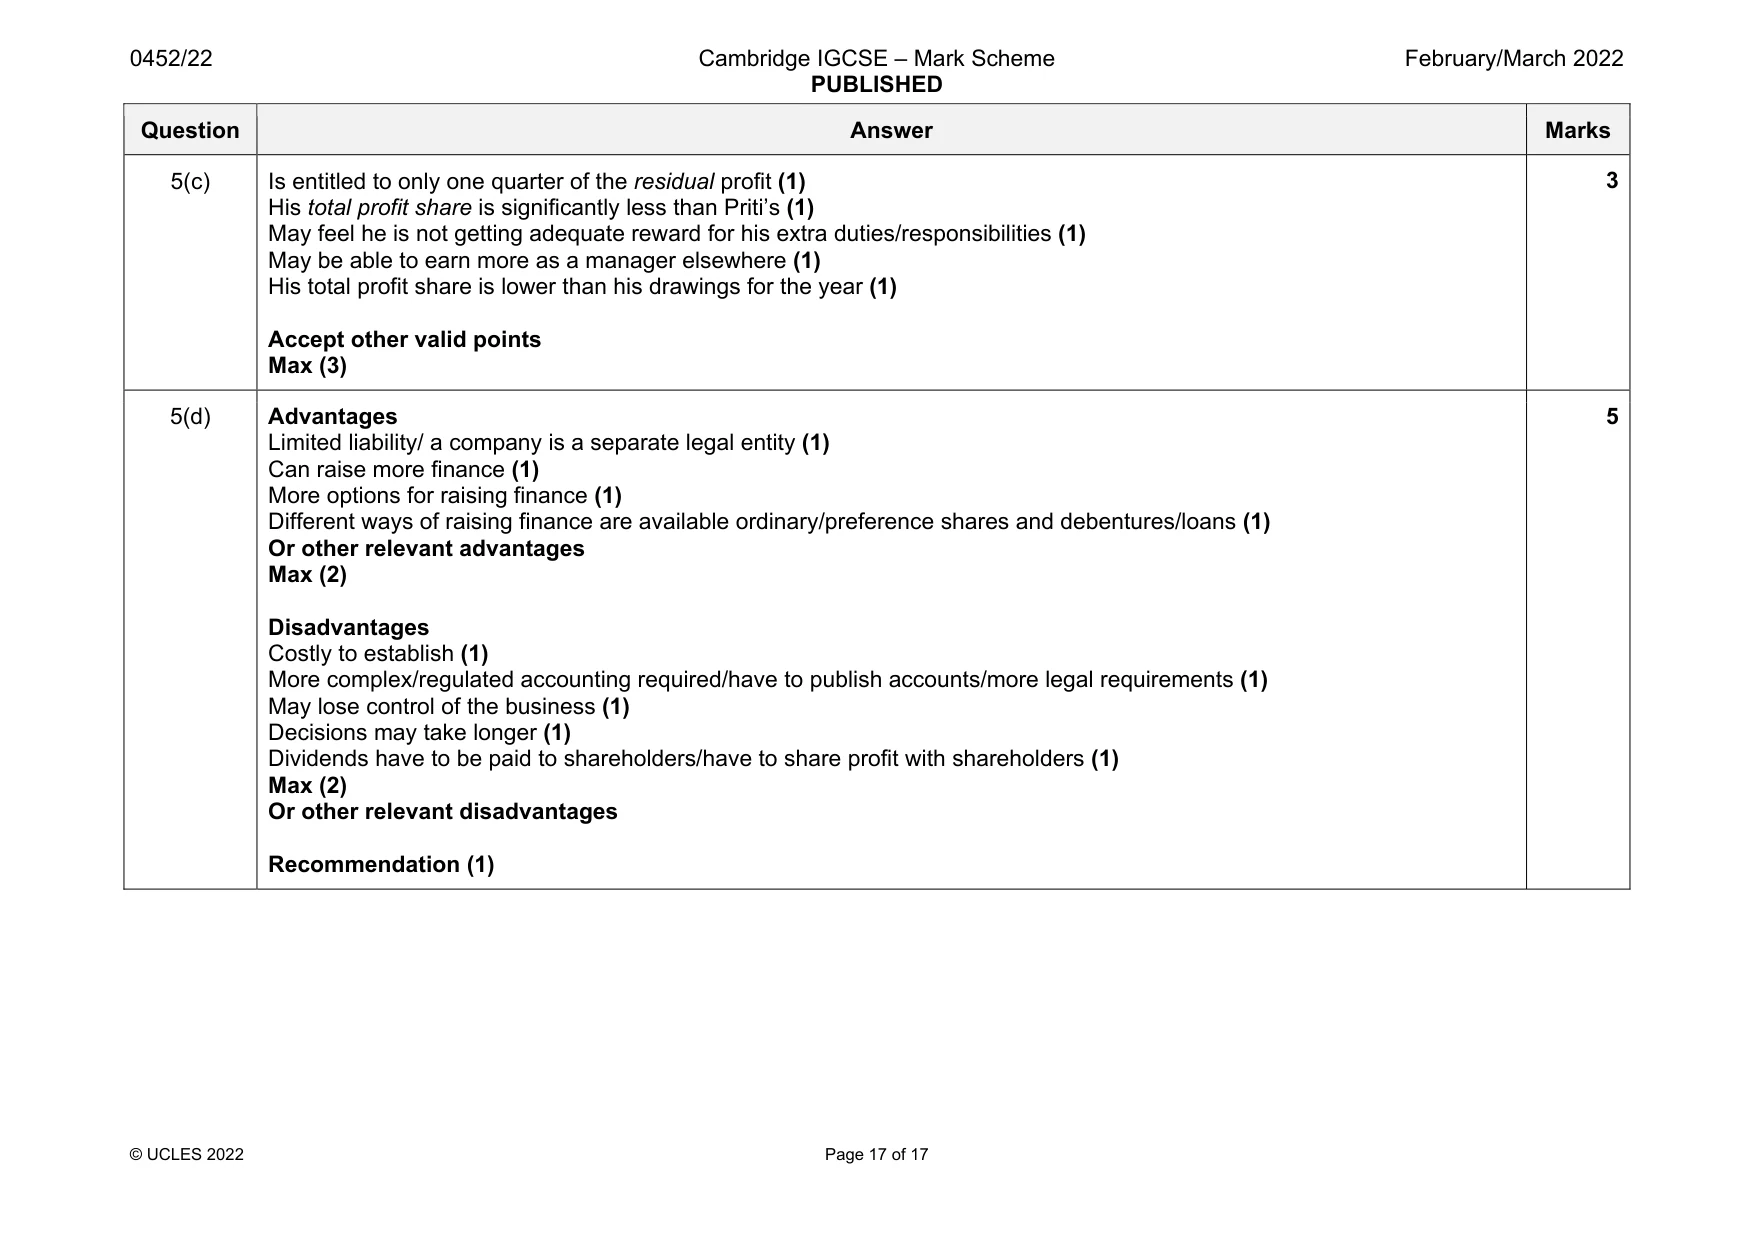
Mark scheme: 5(a) Priti and Paisley Appropriation Account for the year ended 31 January 2022 $ $ Profit for the year 33 100 Add Interest on drawings Priti 750 (1) Paisley 650 (1) 1 400 34 500 Less Interest on capital Priti 4 000 (1) Paisley 800 (1) 4 800 Less Salary Paisley 6 000 (1) 10 800 23 700 Share of profit Priti 17 775 }(1) Paisley 5 925 } OF 23 700 6 5(b) Paisley Current account Date Details $ Date Details $ 2022 2021 Jan 31 Drawings (1) 13 000 Feb 1 Balance b/d 2 350 Interest on drawings (1)OF 650 2022 Balance c/d 1 425 Jan 31 Interest on capital (1)OF 800 Salary (1) 6 000 Profit share (1)OF 5 925 15 075 15 075 2022 Feb 1 Balance b/d (1)OF 1 425 6 Question Answer Marks 5(c) Is entitled to only one quarter of the residual profit (1) His total profit share is significantly less than Priti’s (1) May feel he is not getting adequate reward for his extra duties/responsibilities (1) May be able to earn more as a manager elsewhere (1) His total profit share is lower than his drawings for the year (1) Accept other valid points Max (3) 3 5(d) Advantages Limited liability/ a company is a separate legal entity (1) Can raise more finance (1) More options for raising finance (1) Different ways of raising finance are available ordinary/preference shares and debentures/loans (1) Or other relevant advantages Max (2) Disadvantages Costly to establish (1) More complex/regulated accounting required/have to publish accounts/more legal requirements (1) May lose control of the business (1) Decisions may take longer (1) Dividends have to be paid to shareholders/have to share profit with shareholders (1) Max (2) Or other relevant disadvantages Recommendation (1) 5
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.