Cambridge IGCSE Accounting 0452 — 2021 May/June Paper 2 · Variant 1
0452/21/M/J/21 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme20 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Rahat is a trader
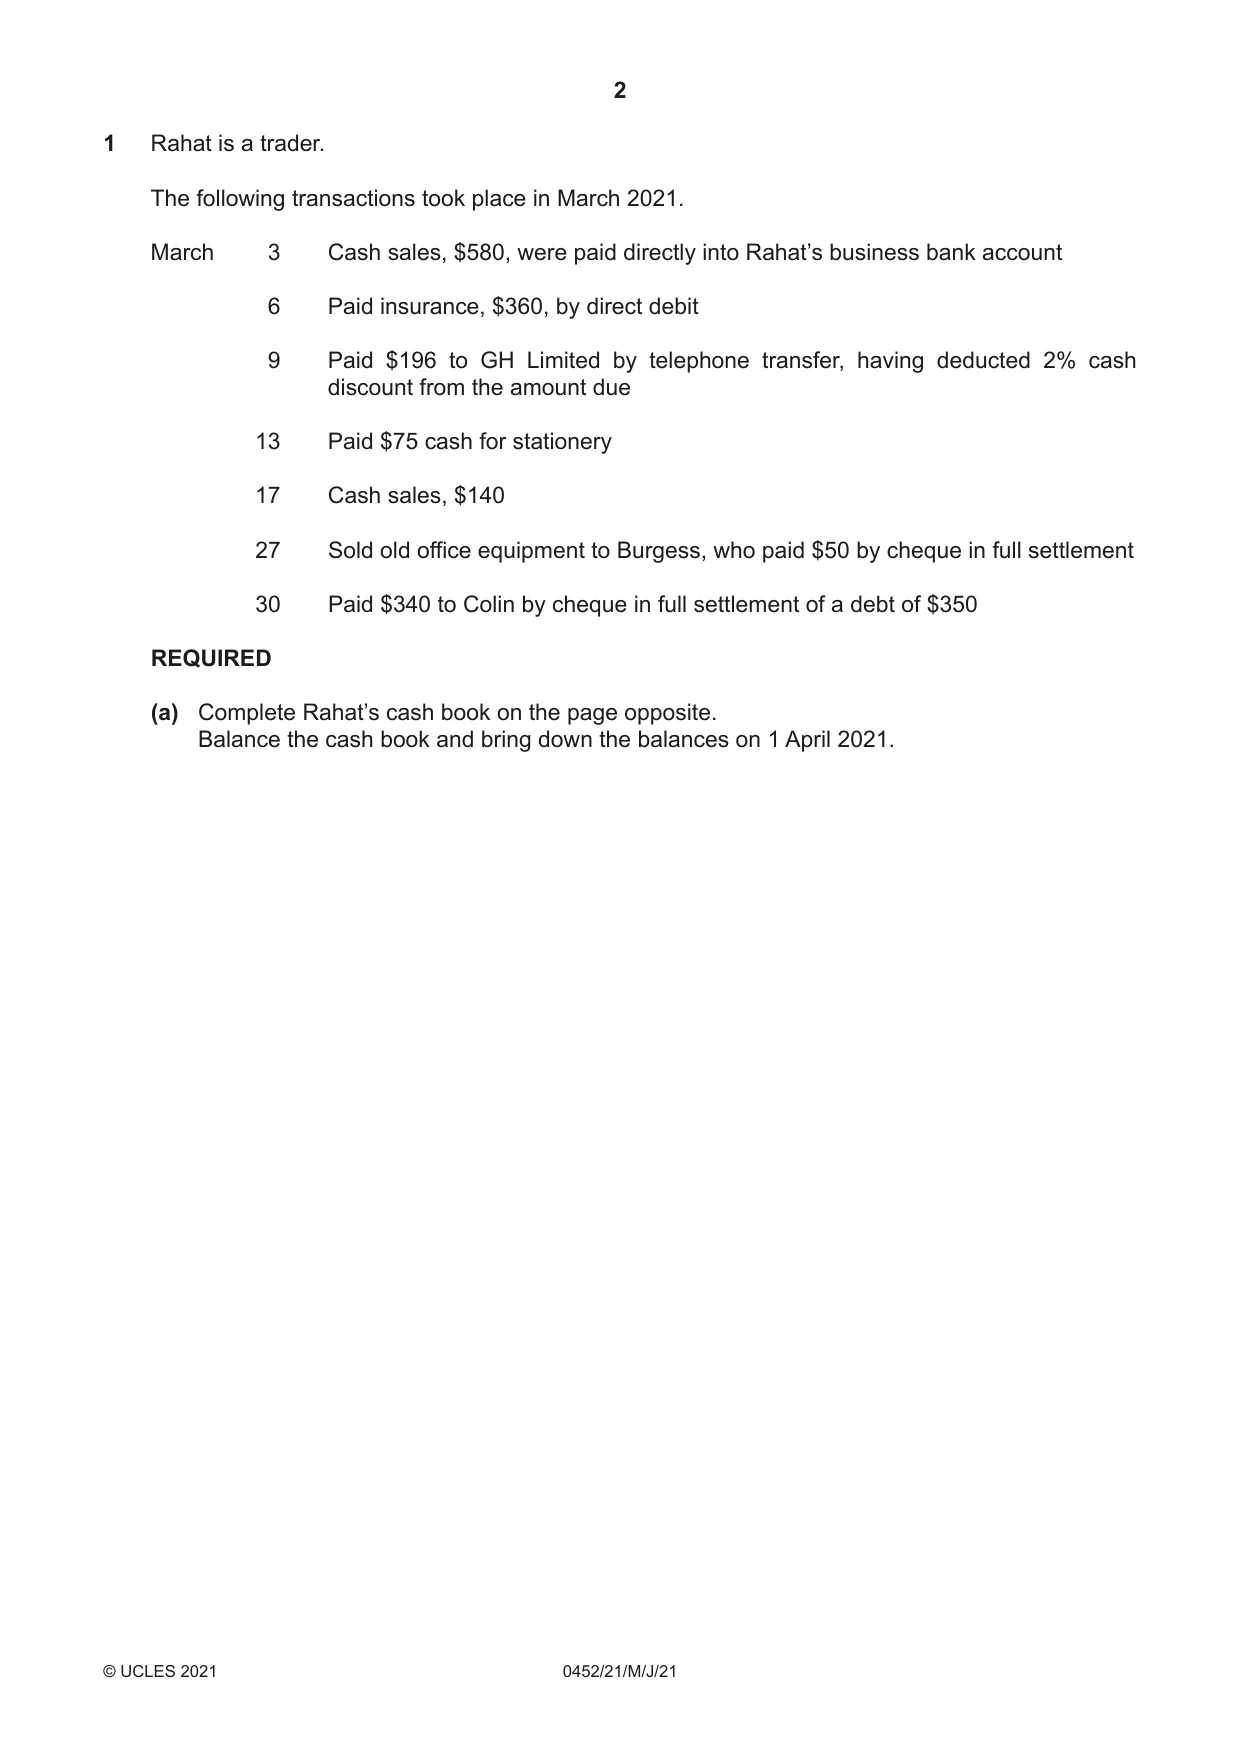
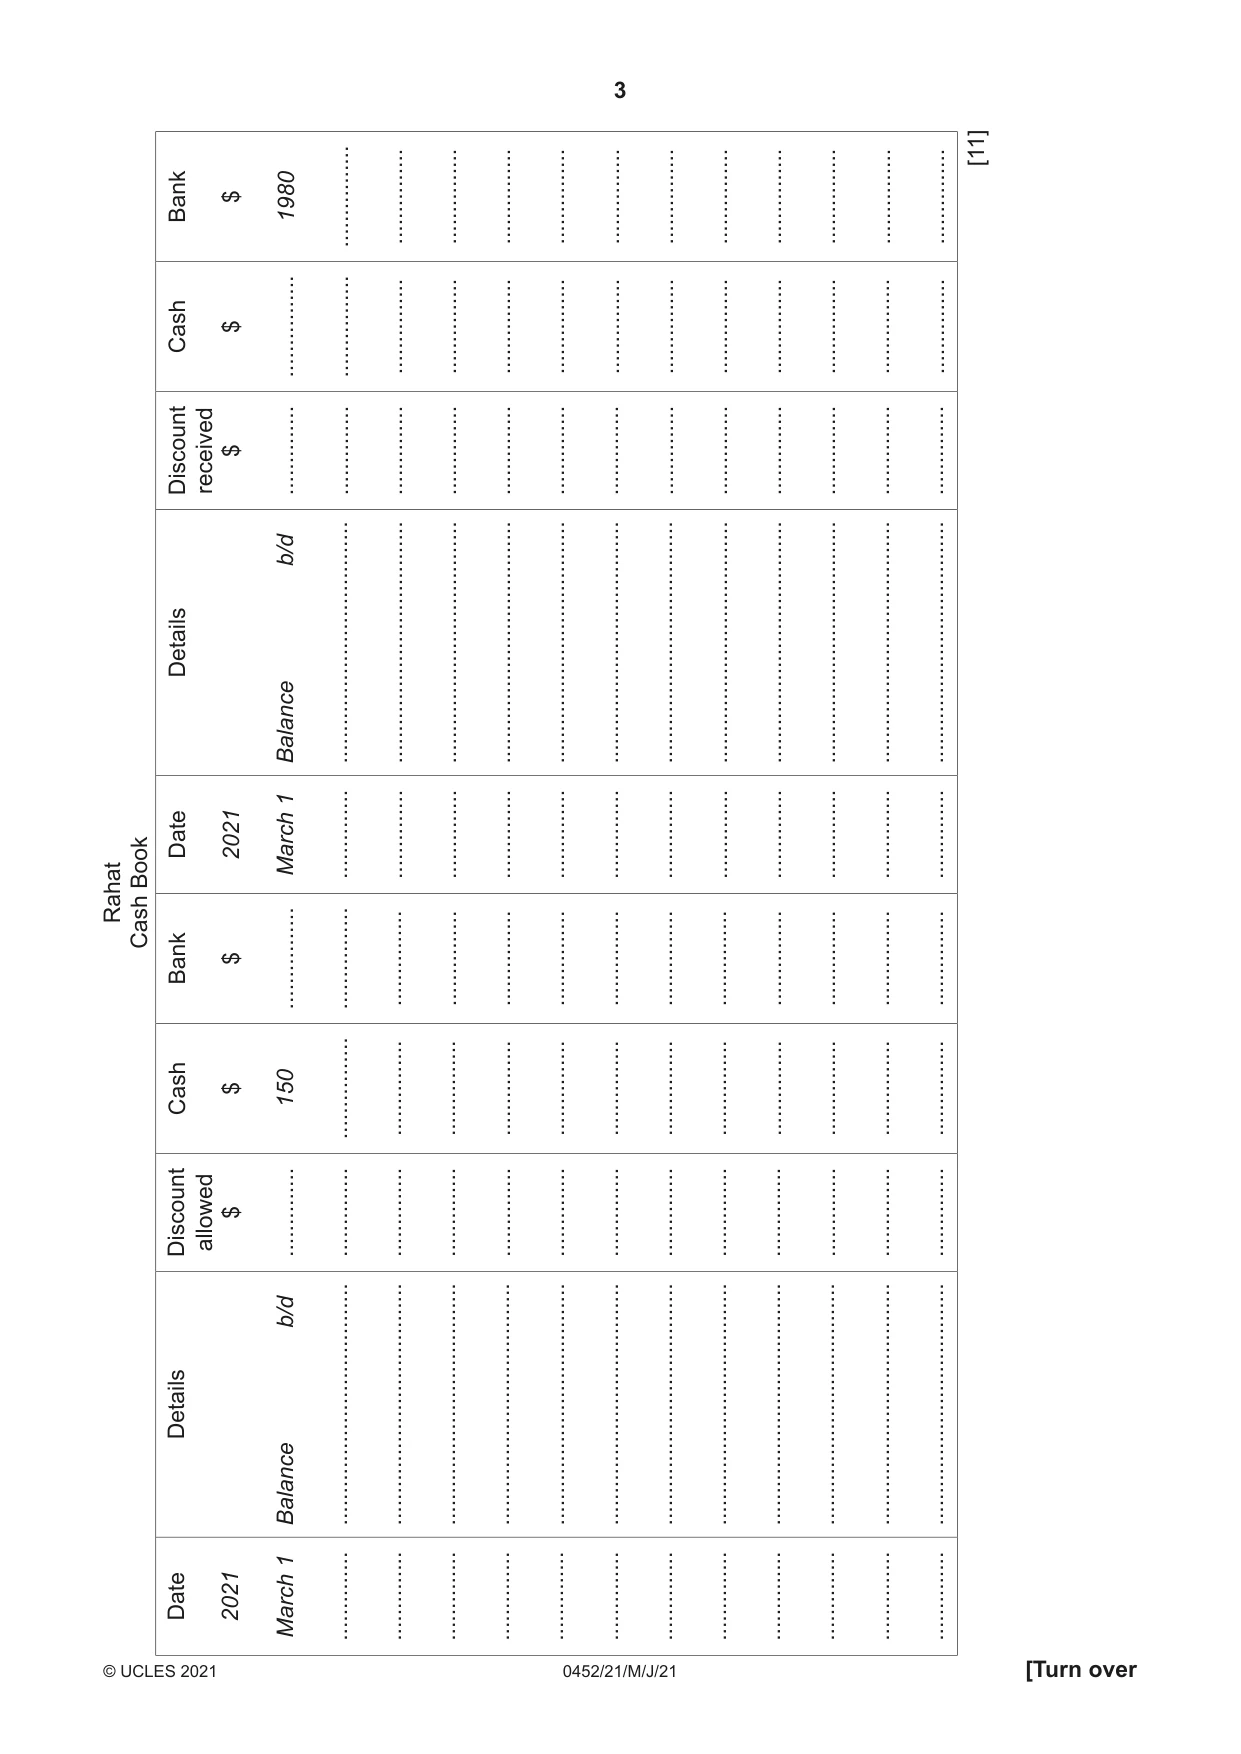
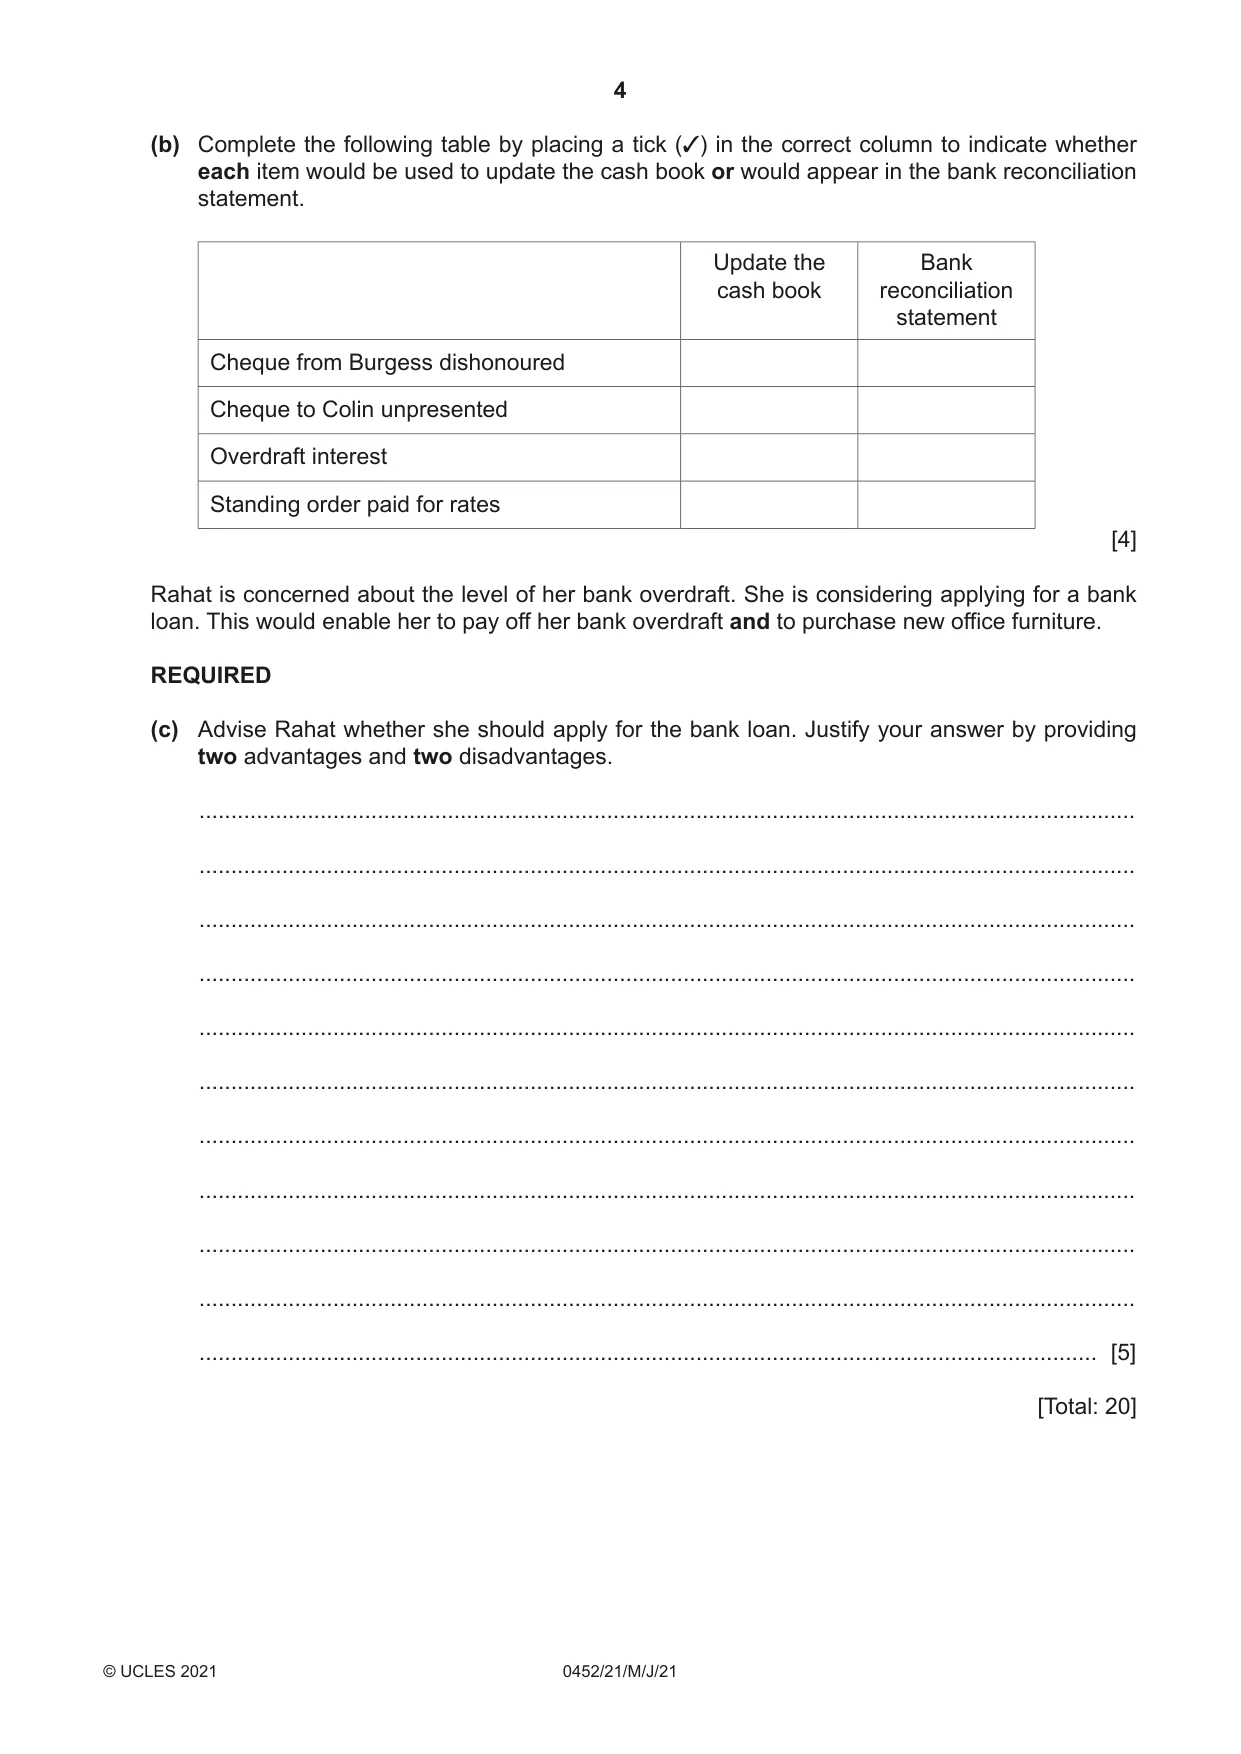
1 Rahat is a trader. The following transactions took place in March 2021. March 3 Cash sales, $580, were paid directly into Rahat’s business bank account 6 Paid insurance, $360, by direct debit 9 Paid $196 to GH Limited by telephone transfer, having deducted 2% cash discount from the amount due 13 Paid $75 cash for stationery 17 Cash sales, $140 27 Sold old office equipment to Burgess, who paid $50 by cheque in full settlement 30 Paid $340 to Colin by cheque in full settlement of a debt of $350 REQUIRED (a) Complete Rahat’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 April 2021. [11] $ Bank 1980 ................ ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Cash ................ ................ ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountreceived .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. b/d Details Balance ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... 1 Date 2021 March .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Book Rahat Cash $ Bank ................ ................ ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ 150 Cash ................ ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... ............... $ Discountallowed .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. b/d Details Balance ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... ...................................... (b) Complete the following table by placing a tick (3) in the correct column to indicate whether each item would be used to update the cash book or would appear in the bank reconciliation statement. Update the Bank cash book reconciliation statement Cheque from Burgess dishonoured Cheque to Colin unpresented Overdraft interest Standing order paid for rates [4] Rahat is concerned about the level of her bank overdraft. She is considering applying for a bank loan. This would enable her to pay off her bank overdraft and to purchase new office furniture. REQUIRED (c) Advise Rahat whether she should apply for the bank loan. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
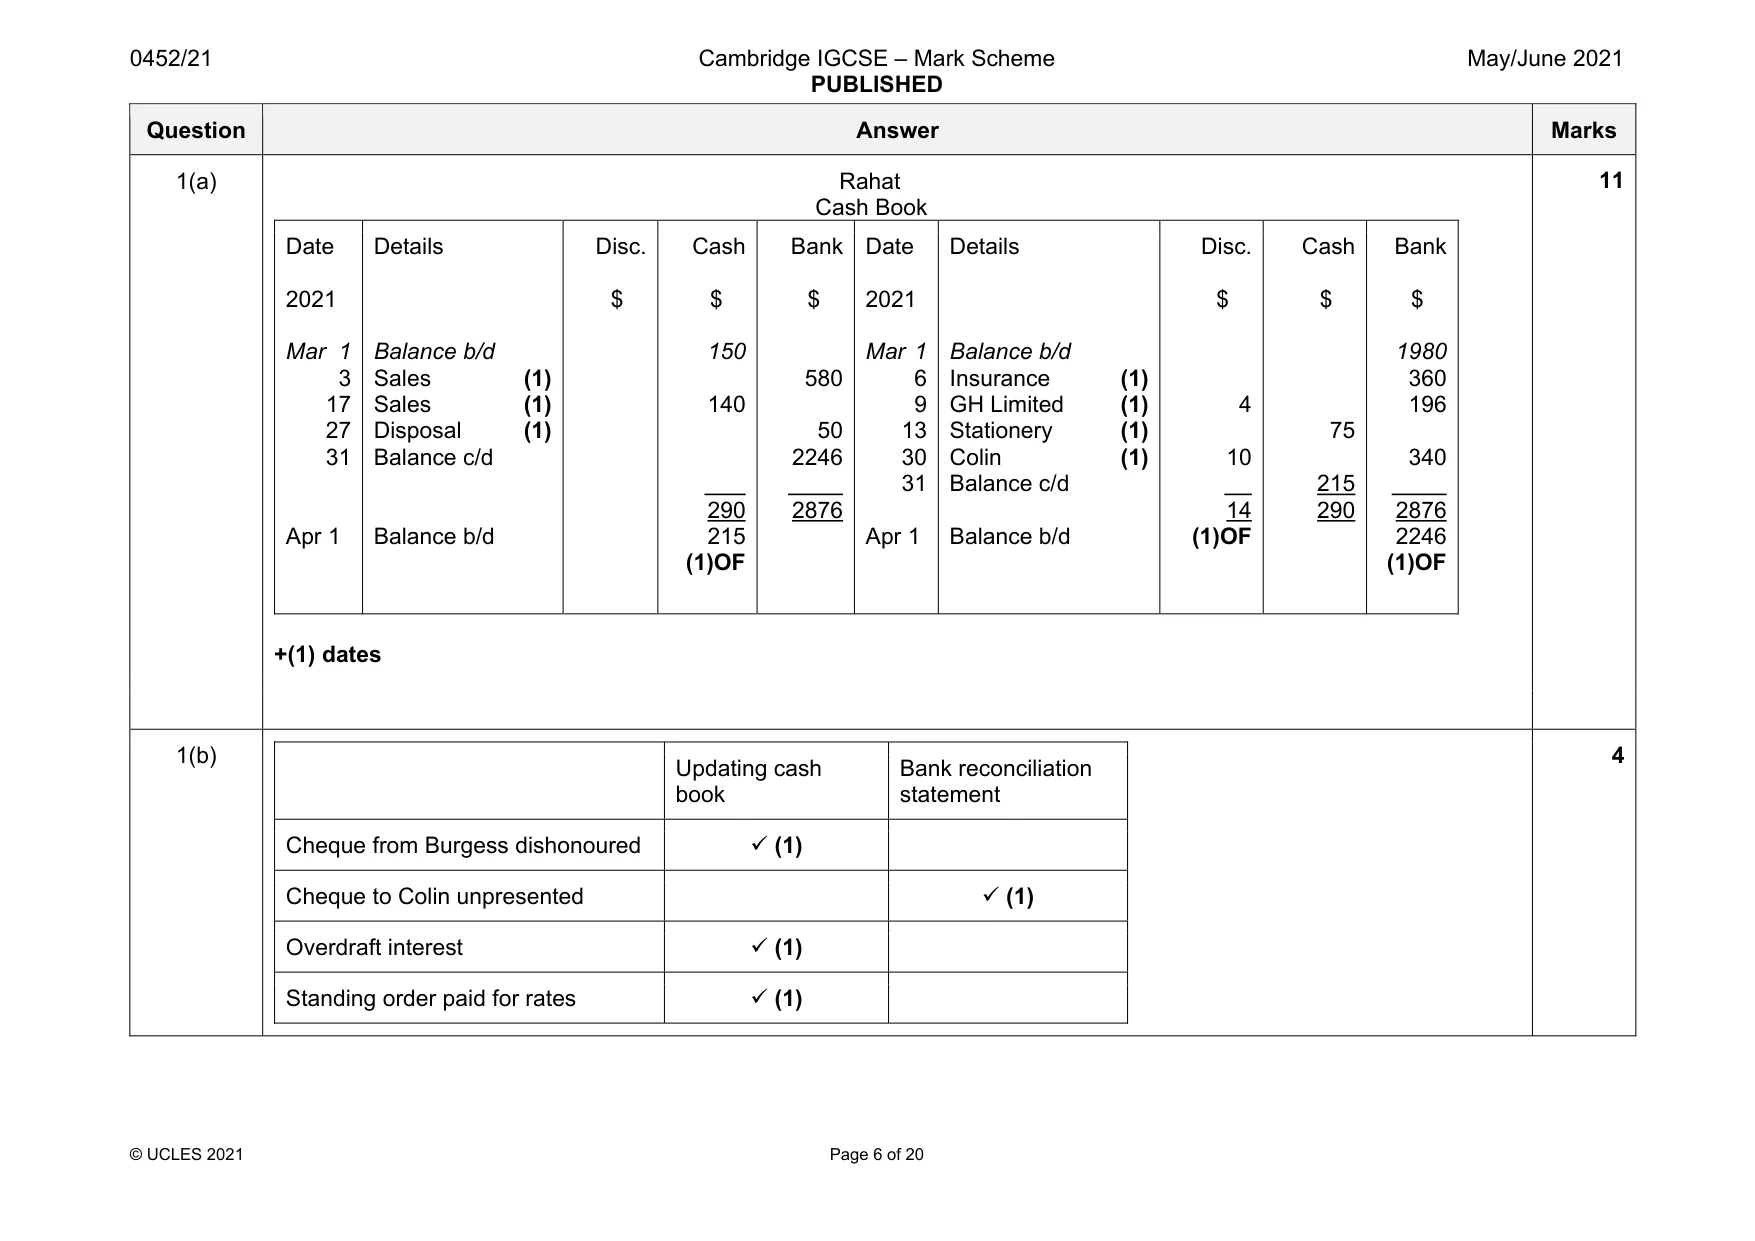
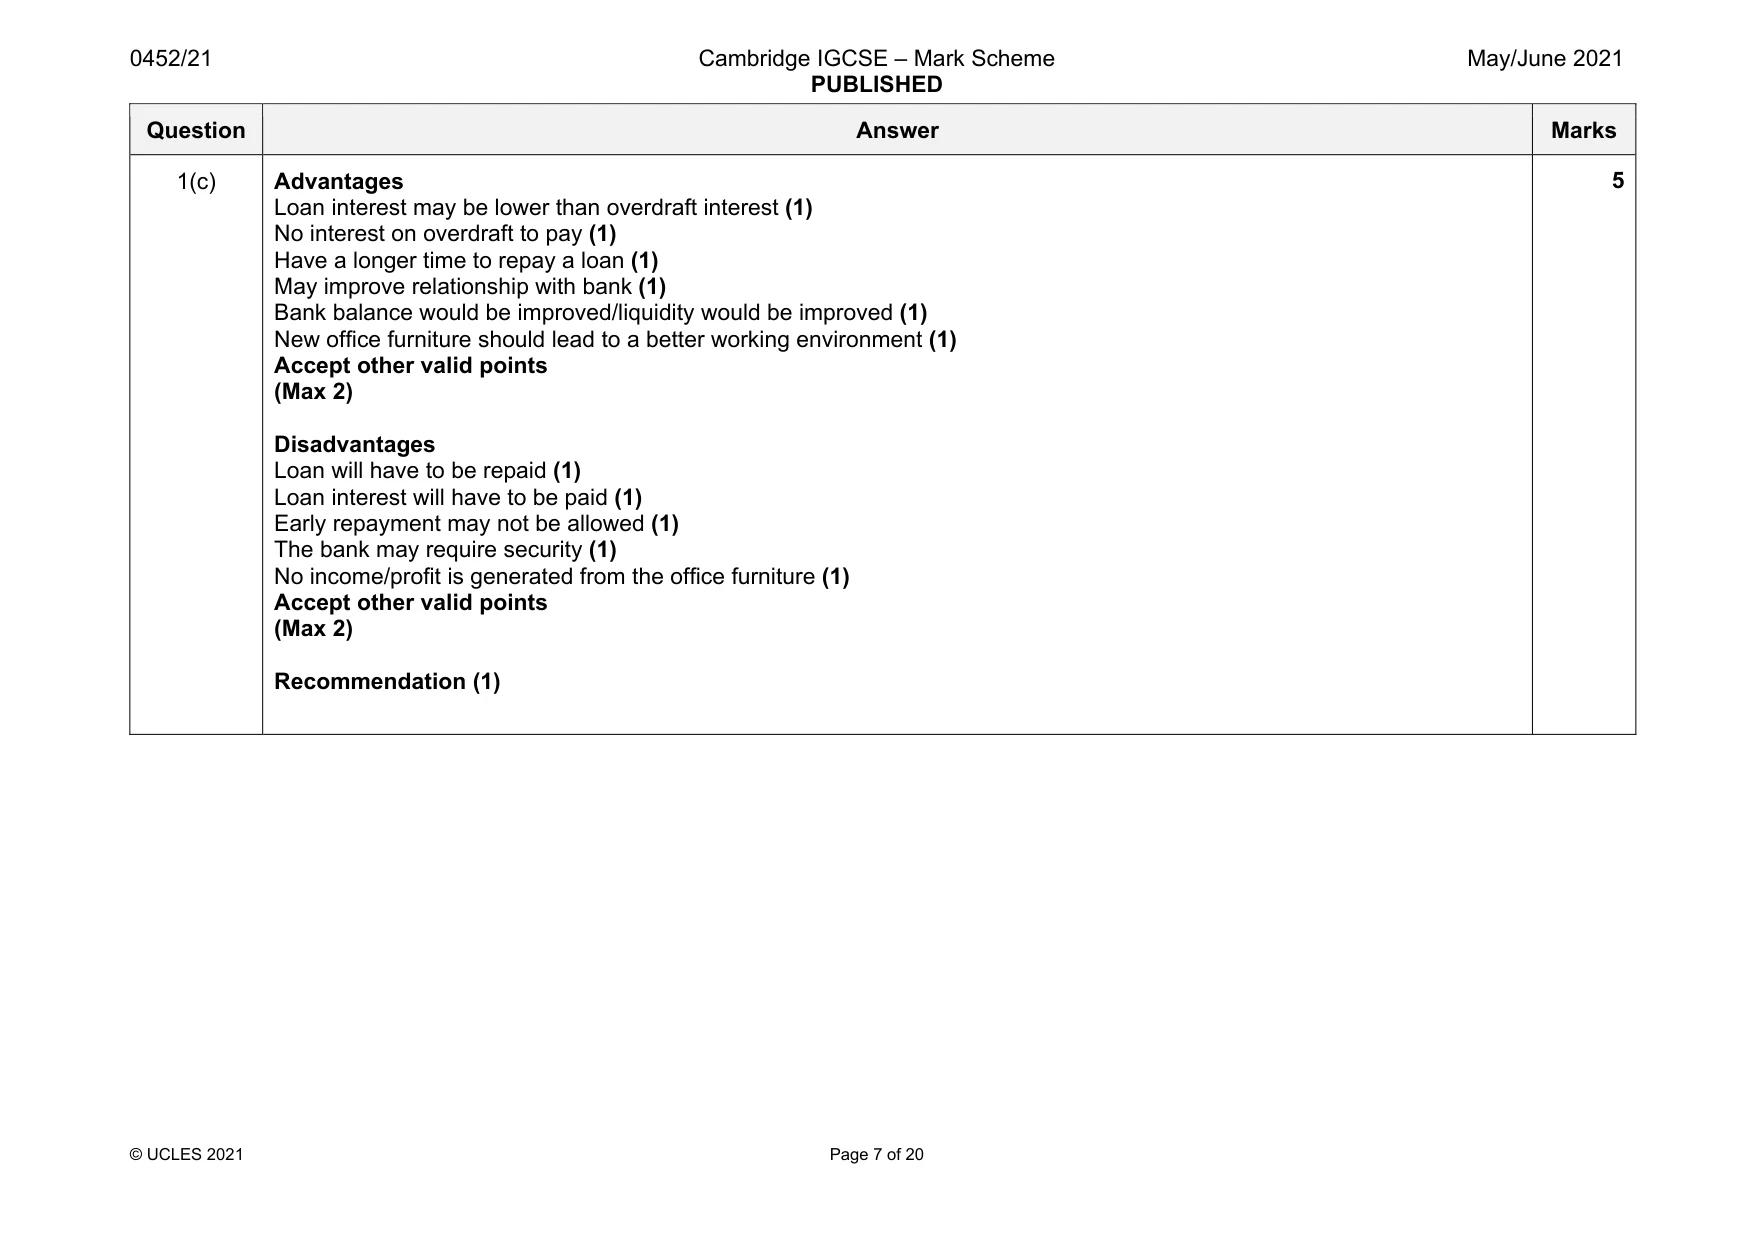
Mark scheme: 1(a) Rahat Cash Book Date 2021 Mar 1 3 17 27 31 Apr 1 Details Balance b/d Sales (1) Sales (1) Disposal (1) Balance c/d Balance b/d Disc. $ Cash $ 150 140 290 215 (1)OF Bank $ 580 50 2246 2876 Date 2021 Mar 1 6 9 13 30 31 Apr 1 Details Balance b/d Insurance (1) GH Limited (1) Stationery (1) Colin (1) Balance c/d Balance b/d Disc. $ 4 10 14 (1)OF Cash $ 75 215 290 Bank $ 1980 360 196 340 2876 2246 (1)OF +(1) dates 1(b) Updating cash book Bank reconciliation statement Cheque from Burgess dishonoured (1) Cheque to Colin unpresented (1) Overdraft interest (1) Standing order paid for rates (1) 4 Question Answer Marks 1(c) Advantages Loan interest may be lower than overdraft interest (1) No interest on overdraft to pay (1) Have a longer time to repay a loan (1) May improve relationship with bank (1) Bank balance would be improved/liquidity would be improved (1) New office furniture should lead to a better working environment (1) Accept other valid points (Max 2) Disadvantages Loan will have to be repaid (1) Loan interest will have to be paid (1) Early repayment may not be allowed (1) The bank may require security (1) No income/profit is generated from the office furniture (1) Accept other valid points (Max 2) Recommendation (1) 5
Q2 · John and Banu are partners
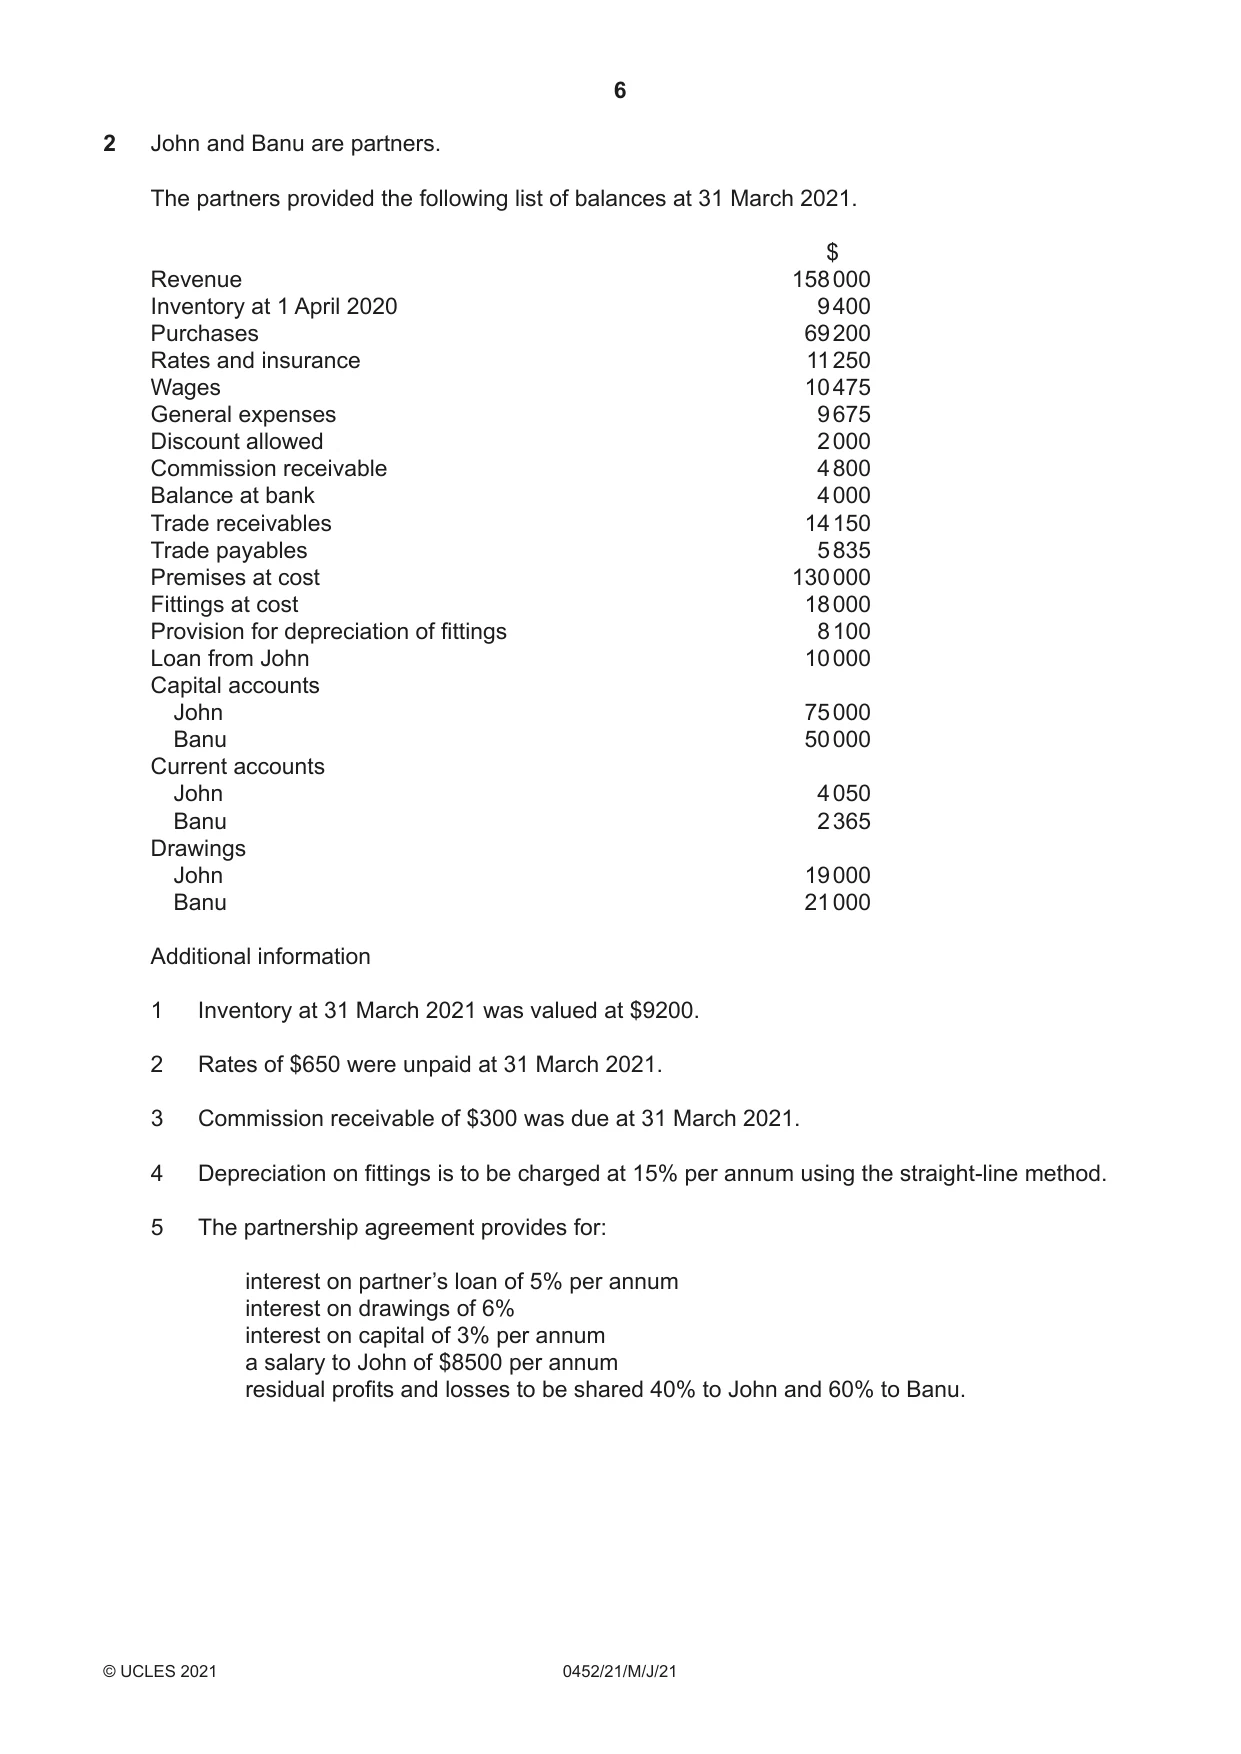
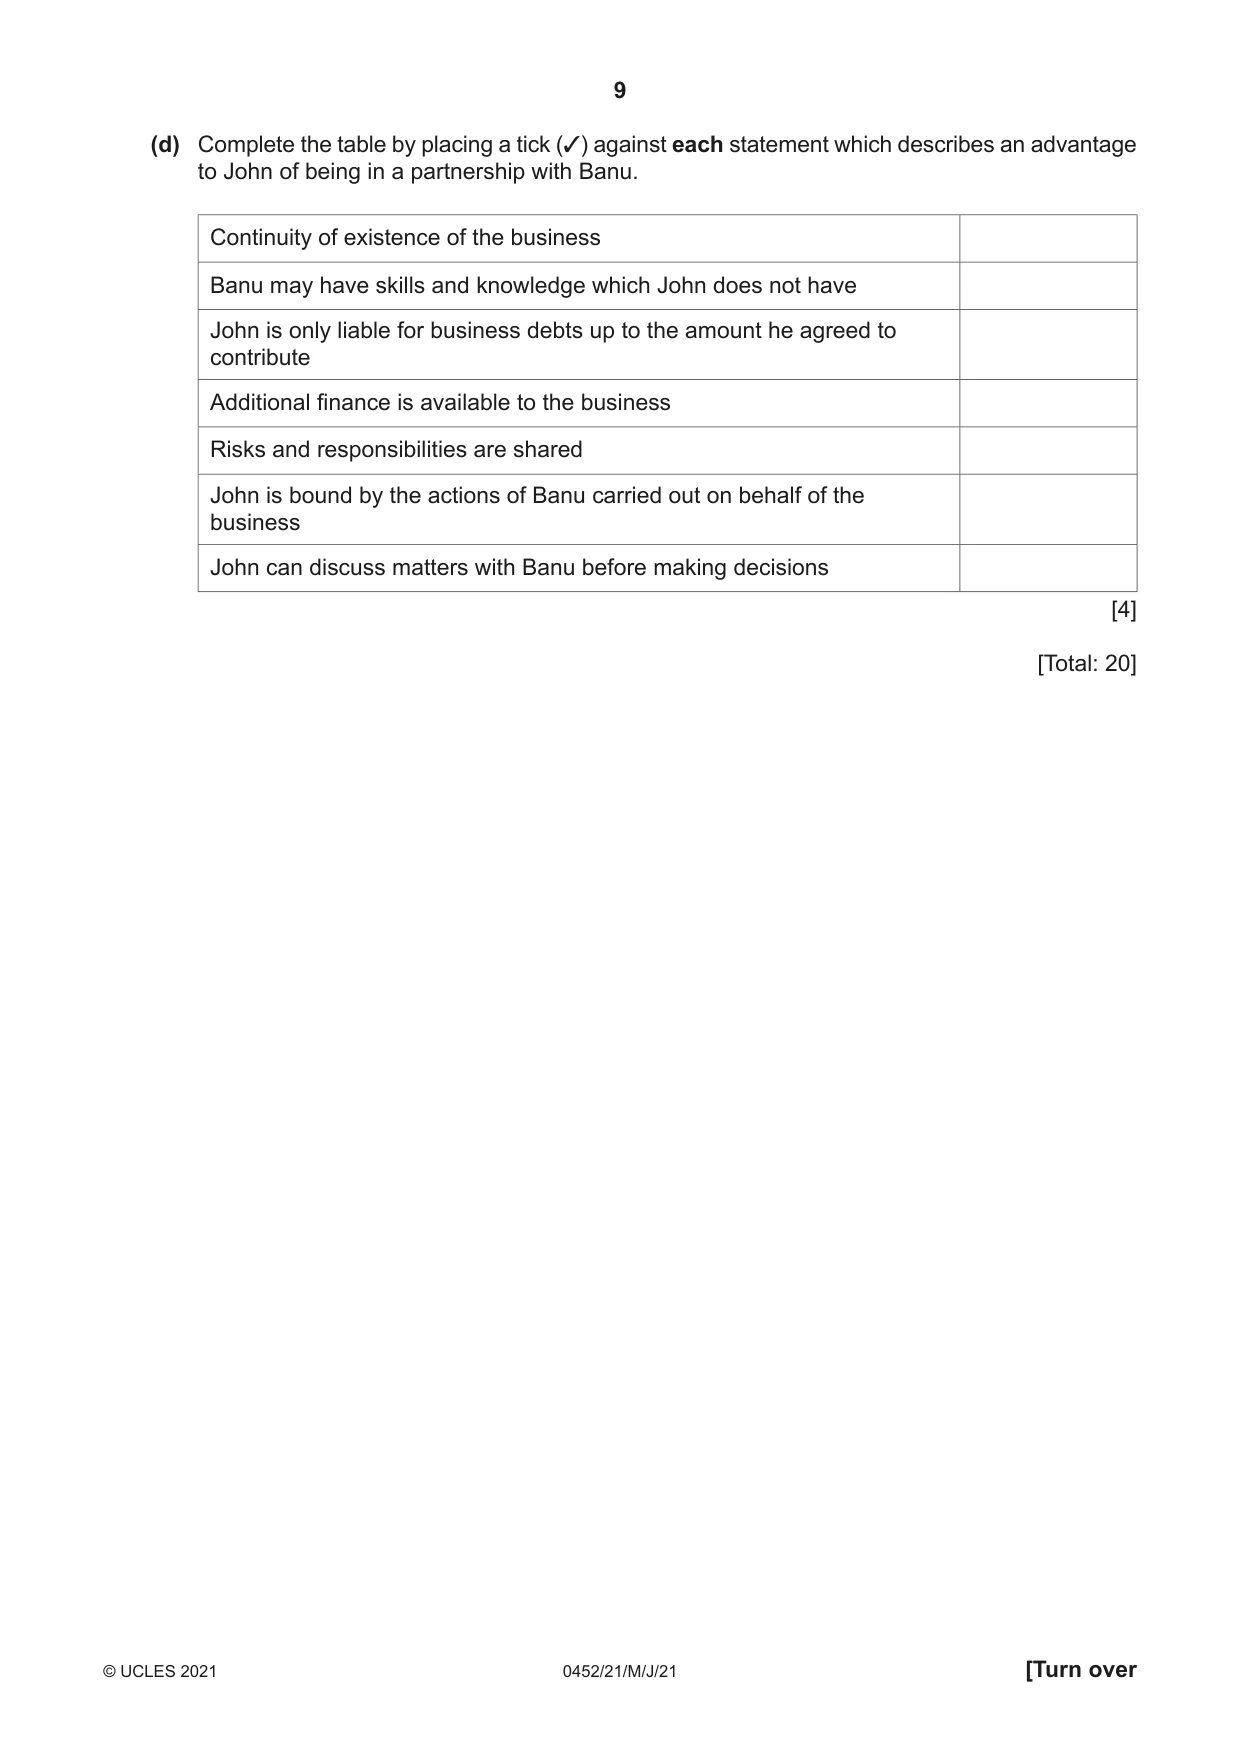
2 John and Banu are partners. The partners provided the following list of balances at 31 March 2021. $ Revenue 158 000 Inventory at 1 April 2020 9 400 Purchases 69 200 Rates and insurance 11 250 Wages 10 475 General expenses 9 675 Discount allowed 2 000 Commission receivable 4 800 Balance at bank 4 000 Trade receivables 14 150 Trade payables 5 835 Premises at cost 130 000 Fittings at cost 18 000 Provision for depreciation of fittings 8 100 Loan from John 10 000 Capital accounts John 75 000 Banu 50 000 Current accounts John 4 050 Banu 2 365 Drawings John 19 000 Banu 21 000 Additional information 1 Inventory at 31 March 2021 was valued at $9200. 2 Rates of $650 were unpaid at 31 March 2021. 3 Commission receivable of $300 was due at 31 March 2021. 4 Depreciation on fittings is to be charged at 15% per annum using the straight-line method. 5 The partnership agreement provides for: interest on partner’s loan of 5% per annum interest on drawings of 6% interest on capital of 3% per annum a salary to John of $8500 per annum residual profits and losses to be shared 40% to John and 60% to Banu. REQUIRED (a) Prepare the income statement for John and Banu for John and Ban Income Statement for the year e ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. (b) Prepare the appropriation account for John and Banu for the year ended 31 March 2021. John and Banu Appropriation Account for the year ended 31 March 2021 $ $ ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... ................................................................................. ........................... ........................... [5] (c) State the purpose of: (i) charging interest on the partners’ drawings ........................................................................................................................................... ..................................................................................................................................... [1] (ii) paying interest on the loan from John. ........................................................................................................................................... ..................................................................................................................................... [1] (d) Complete the table by placing a tick (3) against each statement which describes an advantage to John of being in a partnership with Banu. Continuity of existence of the business Banu may have skills and knowledge which John does not have John is only liable for business debts up to the amount he agreed to contribute Additional finance is available to the business Risks and responsibilities are shared John is bound by the actions of Banu carried out on behalf of the business John can discuss matters with Banu before making decisions [4] [Total: 20]
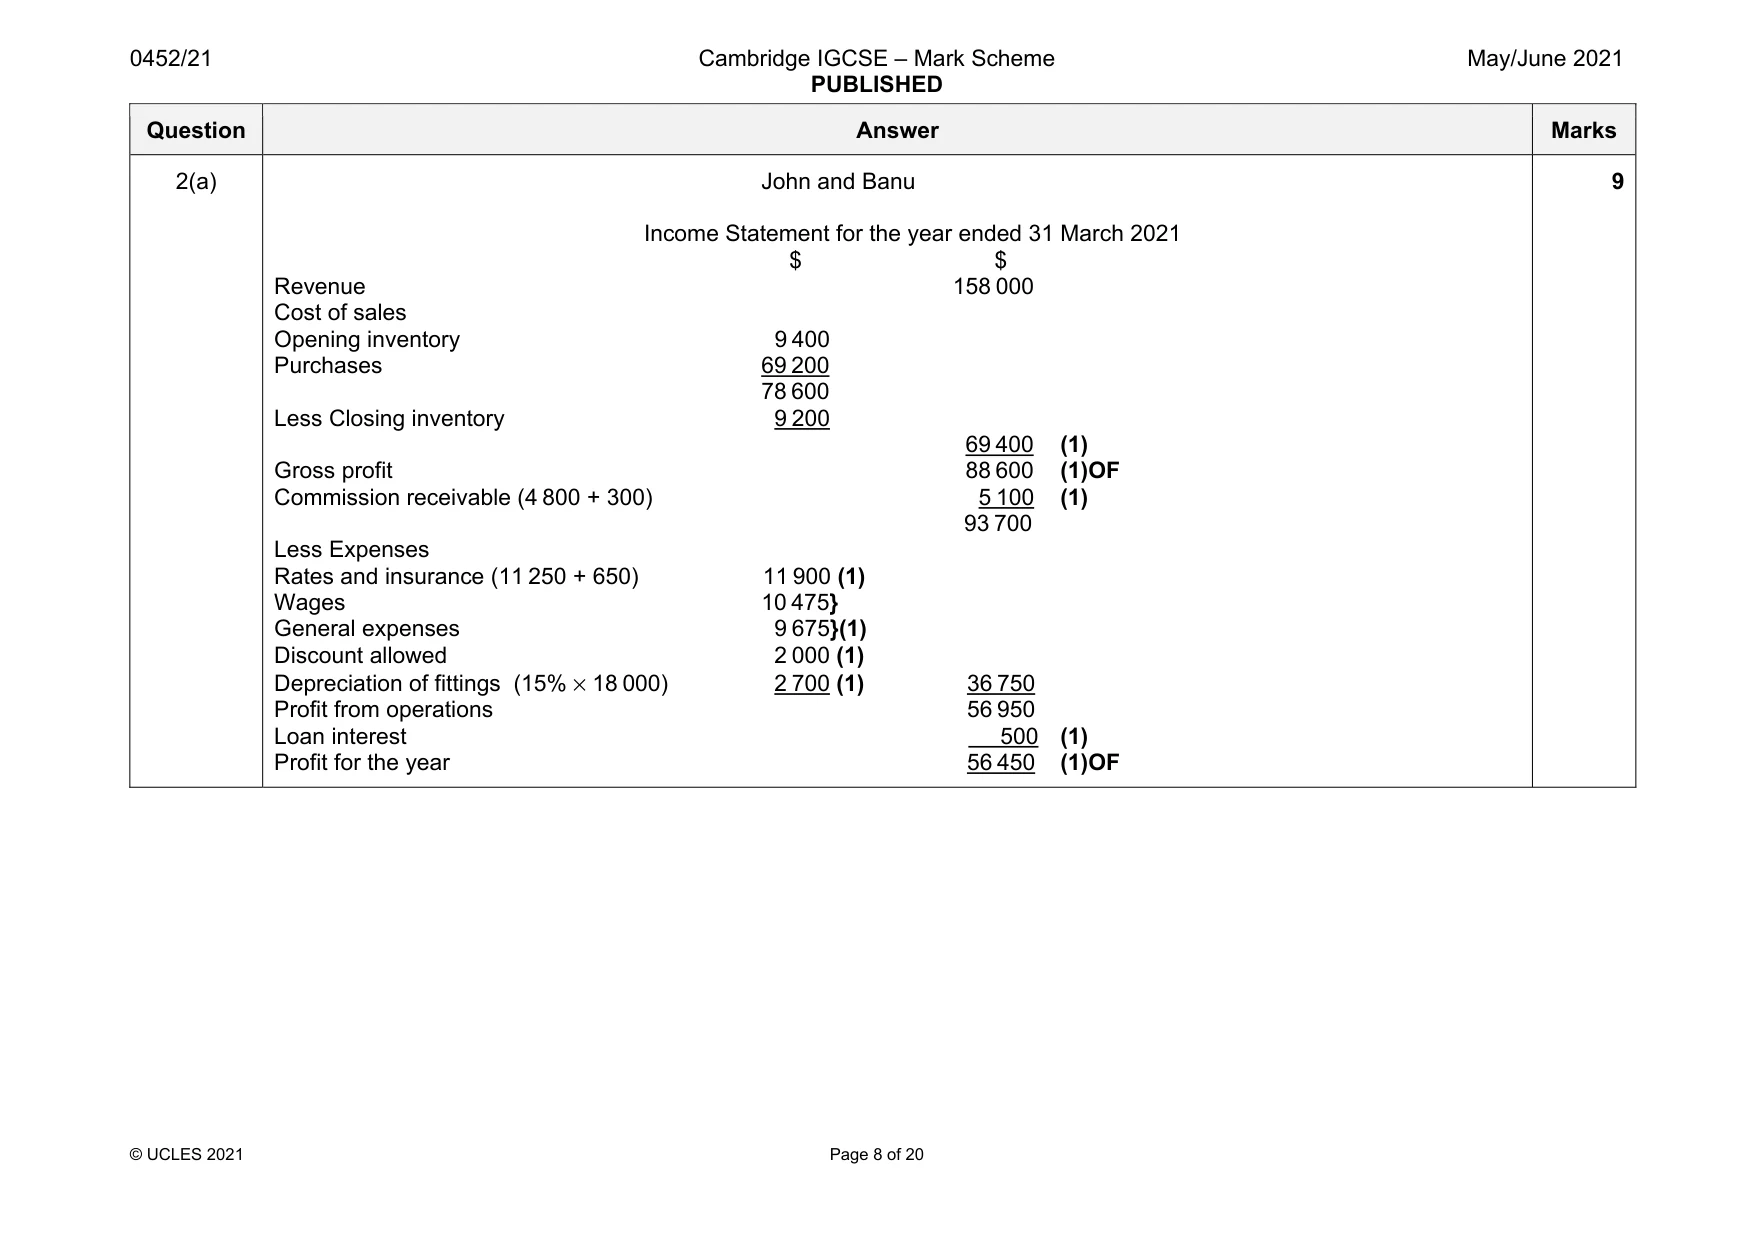
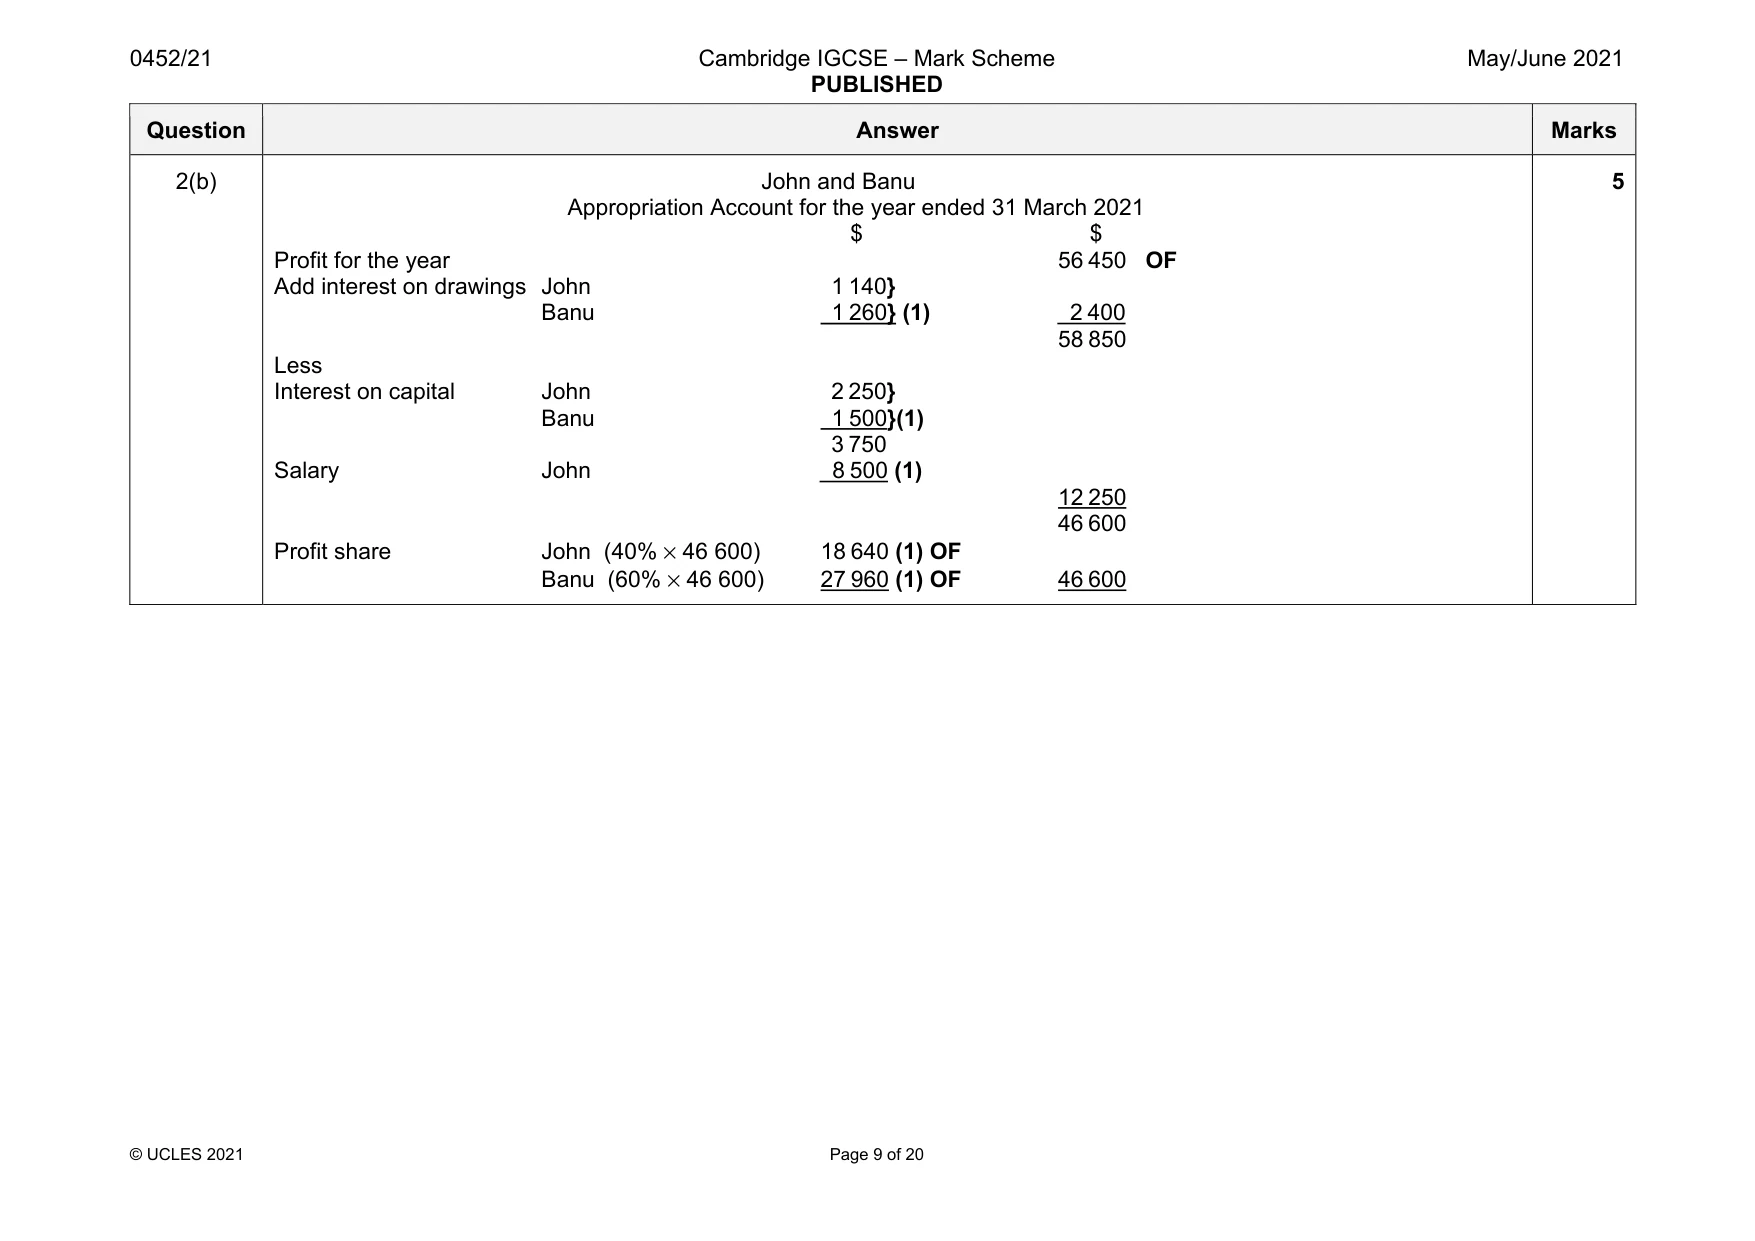
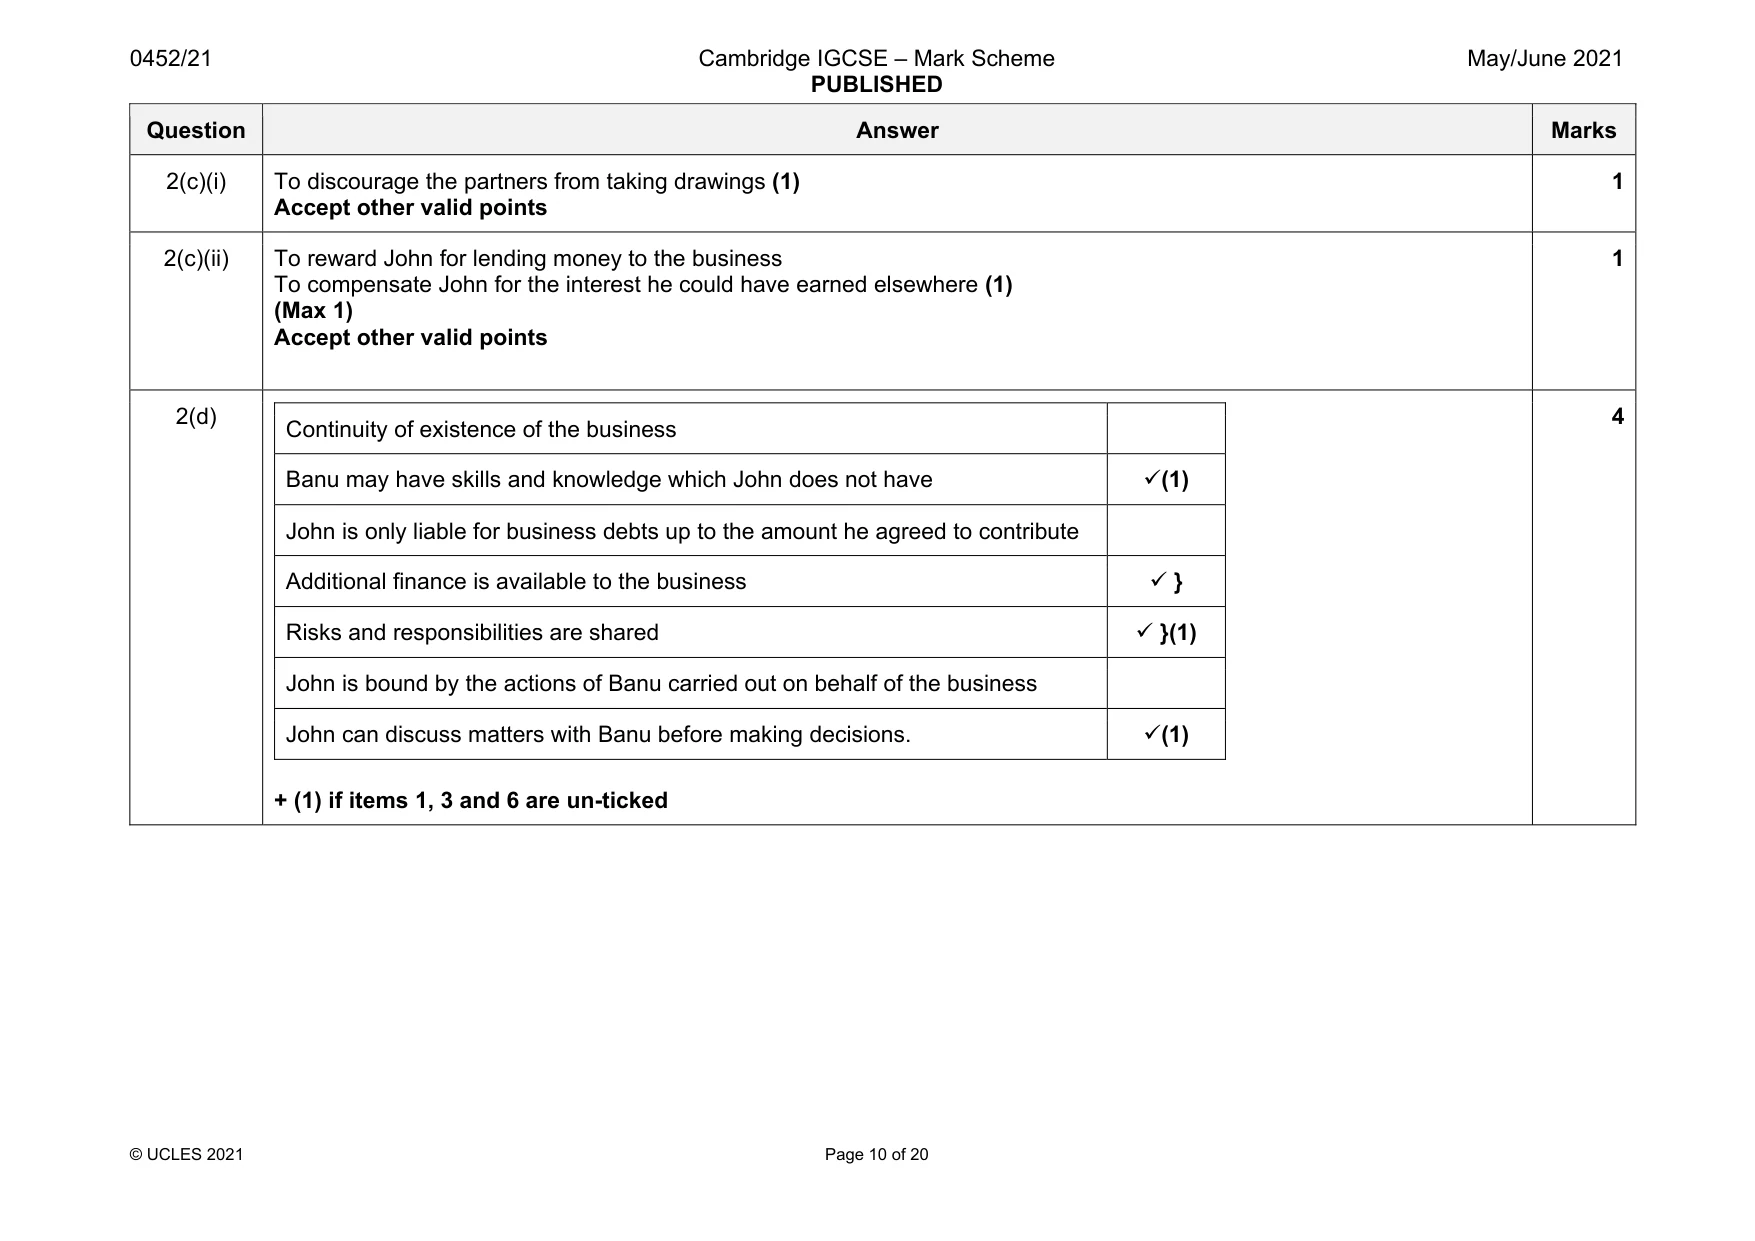
Mark scheme: 2(a) John and Banu Income Statement for the year ended 31 March 2021 $ $ Revenue 158 000 Cost of sales Opening inventory 9 400 Purchases 69 200 78 600 Less Closing inventory 9 200 69 400 (1) Gross profit 88 600 (1)OF Commission receivable (4 800 + 300) 5 100 (1) 93 700 Less Expenses Rates and insurance (11 250 + 650) 11 900 (1) Wages 10 475} General expenses 9 675}(1) Discount allowed 2 000 (1) Depreciation of fittings (15% × 18 000) 2 700 (1) 36 750 Profit from operations 56 950 Loan interest 500 (1) Profit for the year 56 450 (1)OF 9 Question Answer Marks 2(b) John and Banu Appropriation Account for the year ended 31 March 2021 $ $ Profit for the year 56 450 OF Add interest on drawings John 1 140} Banu 1 260} (1) 2 400 58 850 Less Interest on capital John 2 250} Banu 1 500}(1) 3 750 Salary John 8 500 (1) 12 250 46 600 Profit share John (40% × 46 600) 18 640 (1) OF Banu (60% × 46 600) 27 960 (1) OF 46 600 5 Question Answer Marks 2(c)(i) To discourage the partners from taking drawings (1) Accept other valid points 1 2(c)(ii) To reward John for lending money to the business To compensate John for the interest he could have earned elsewhere (1) (Max 1) Accept other valid points 1 2(d) Continuity of existence of the business Banu may have skills and knowledge which John does not have (1) John is only liable for business debts up to the amount he agreed to contribute Additional finance is available to the business } Risks and responsibilities are shared }(1) John is bound by the actions of Banu carried out on behalf of the business John can discuss matters with Banu before making decisions. (1) + (1) if items 1, 3 and 6 are un-ticked 4
Q3 · TC Limited is a manufacturing company
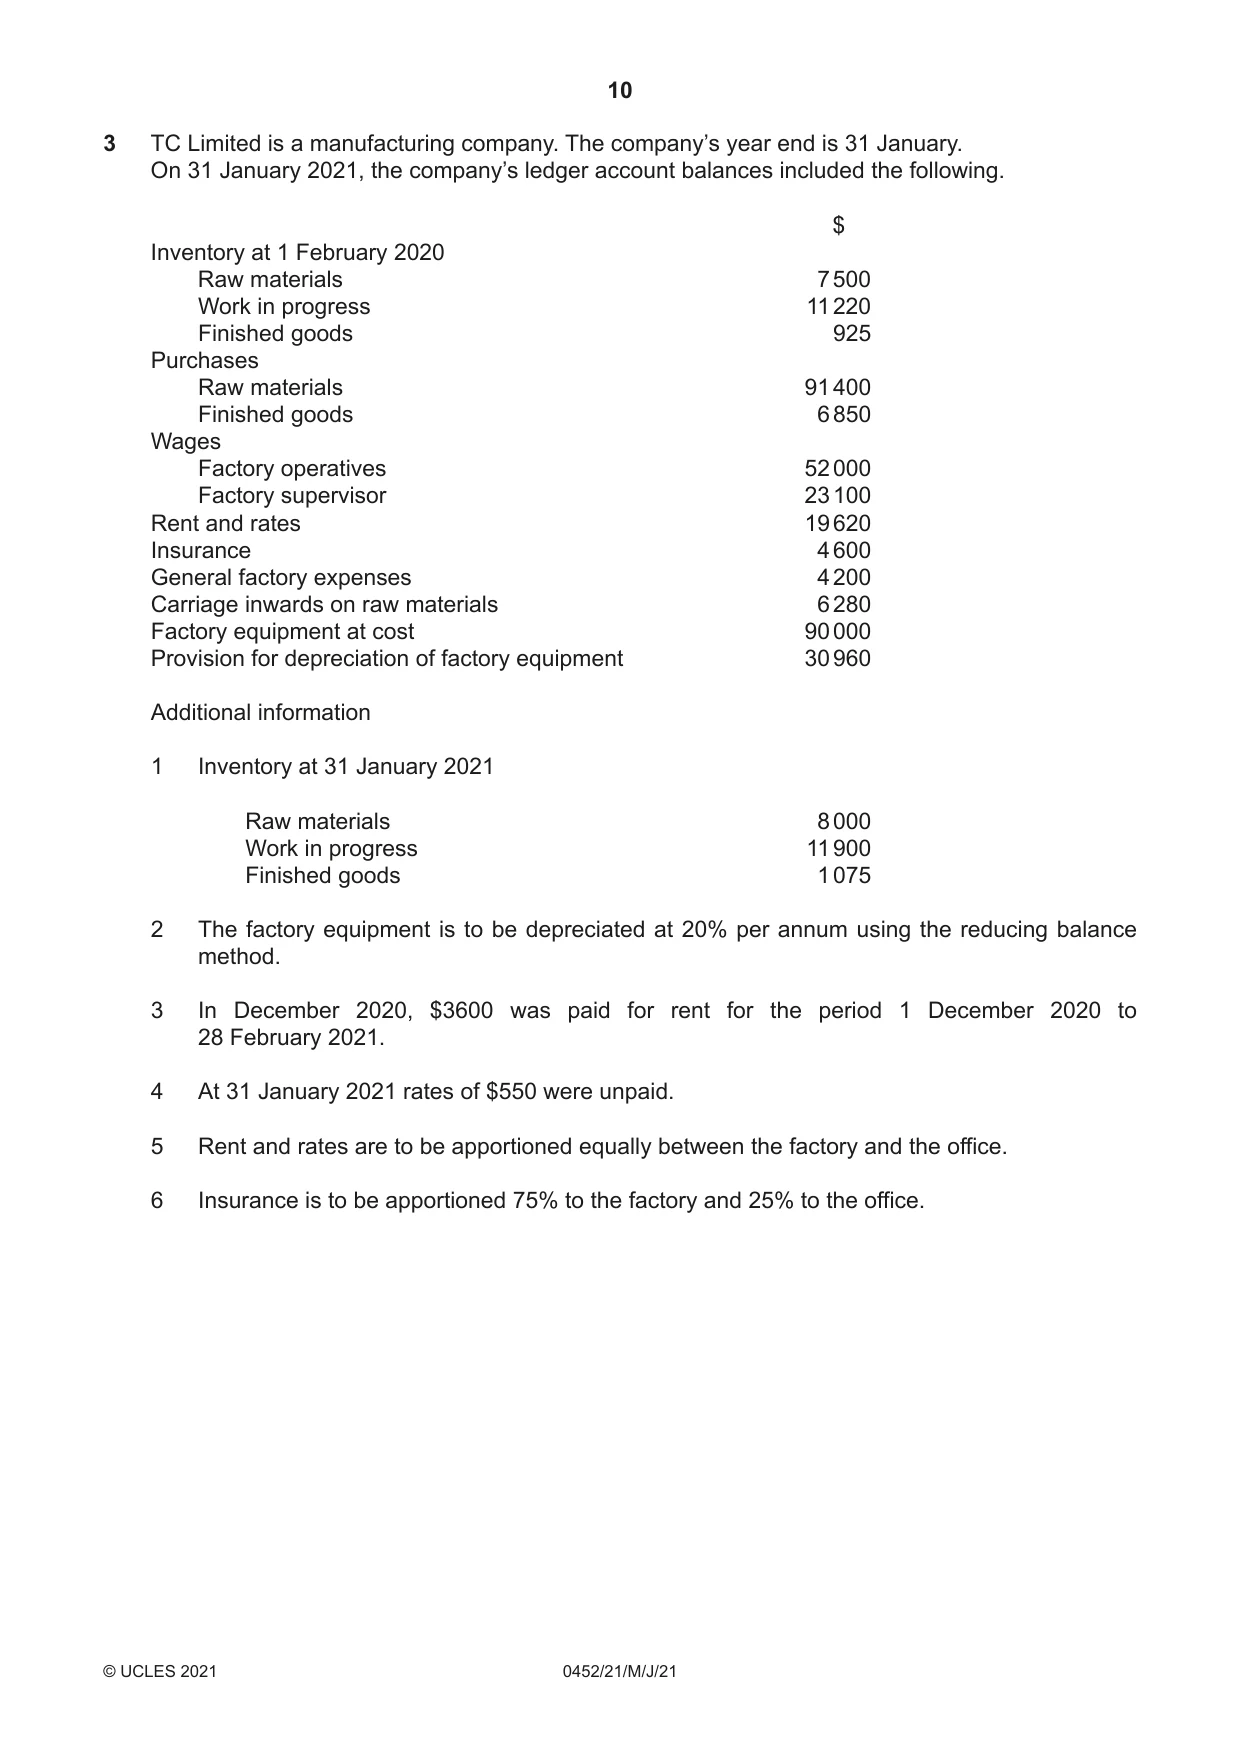
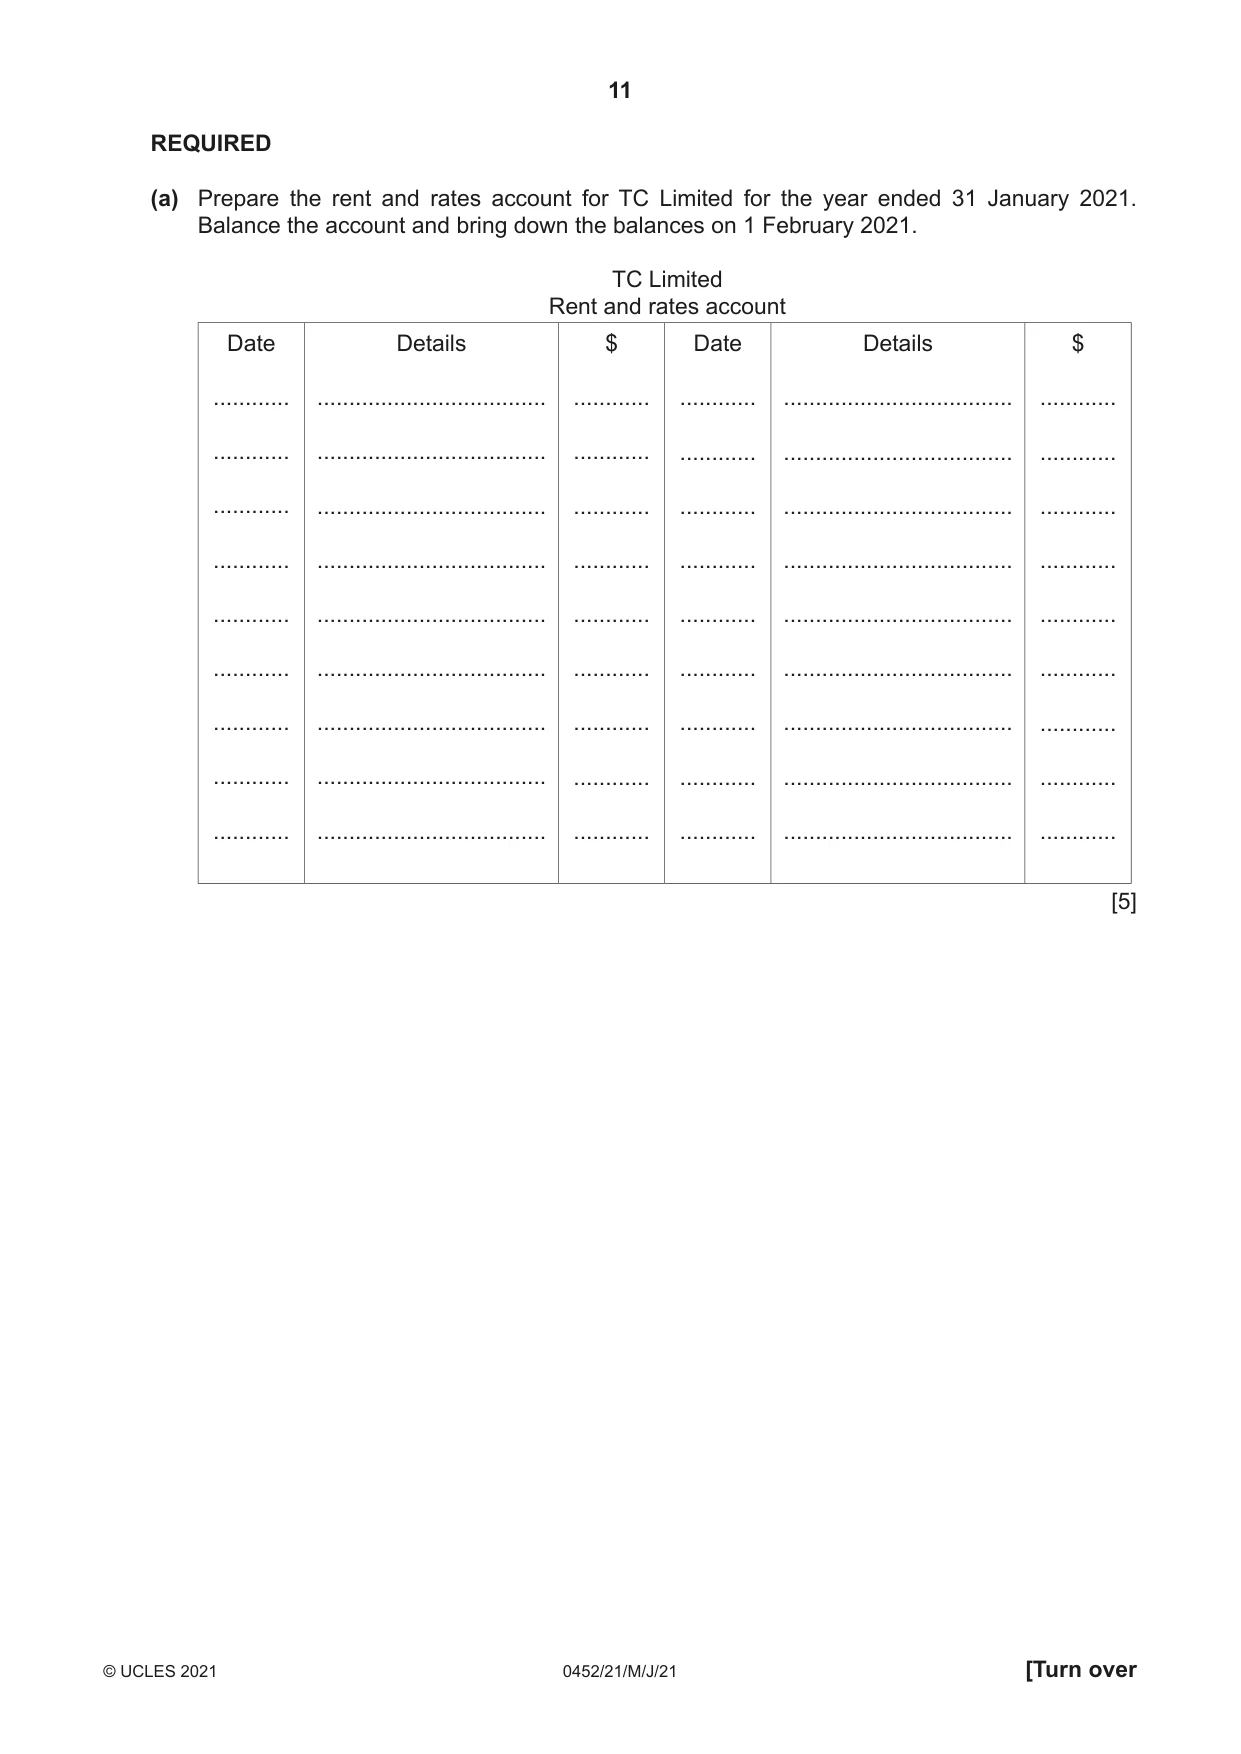
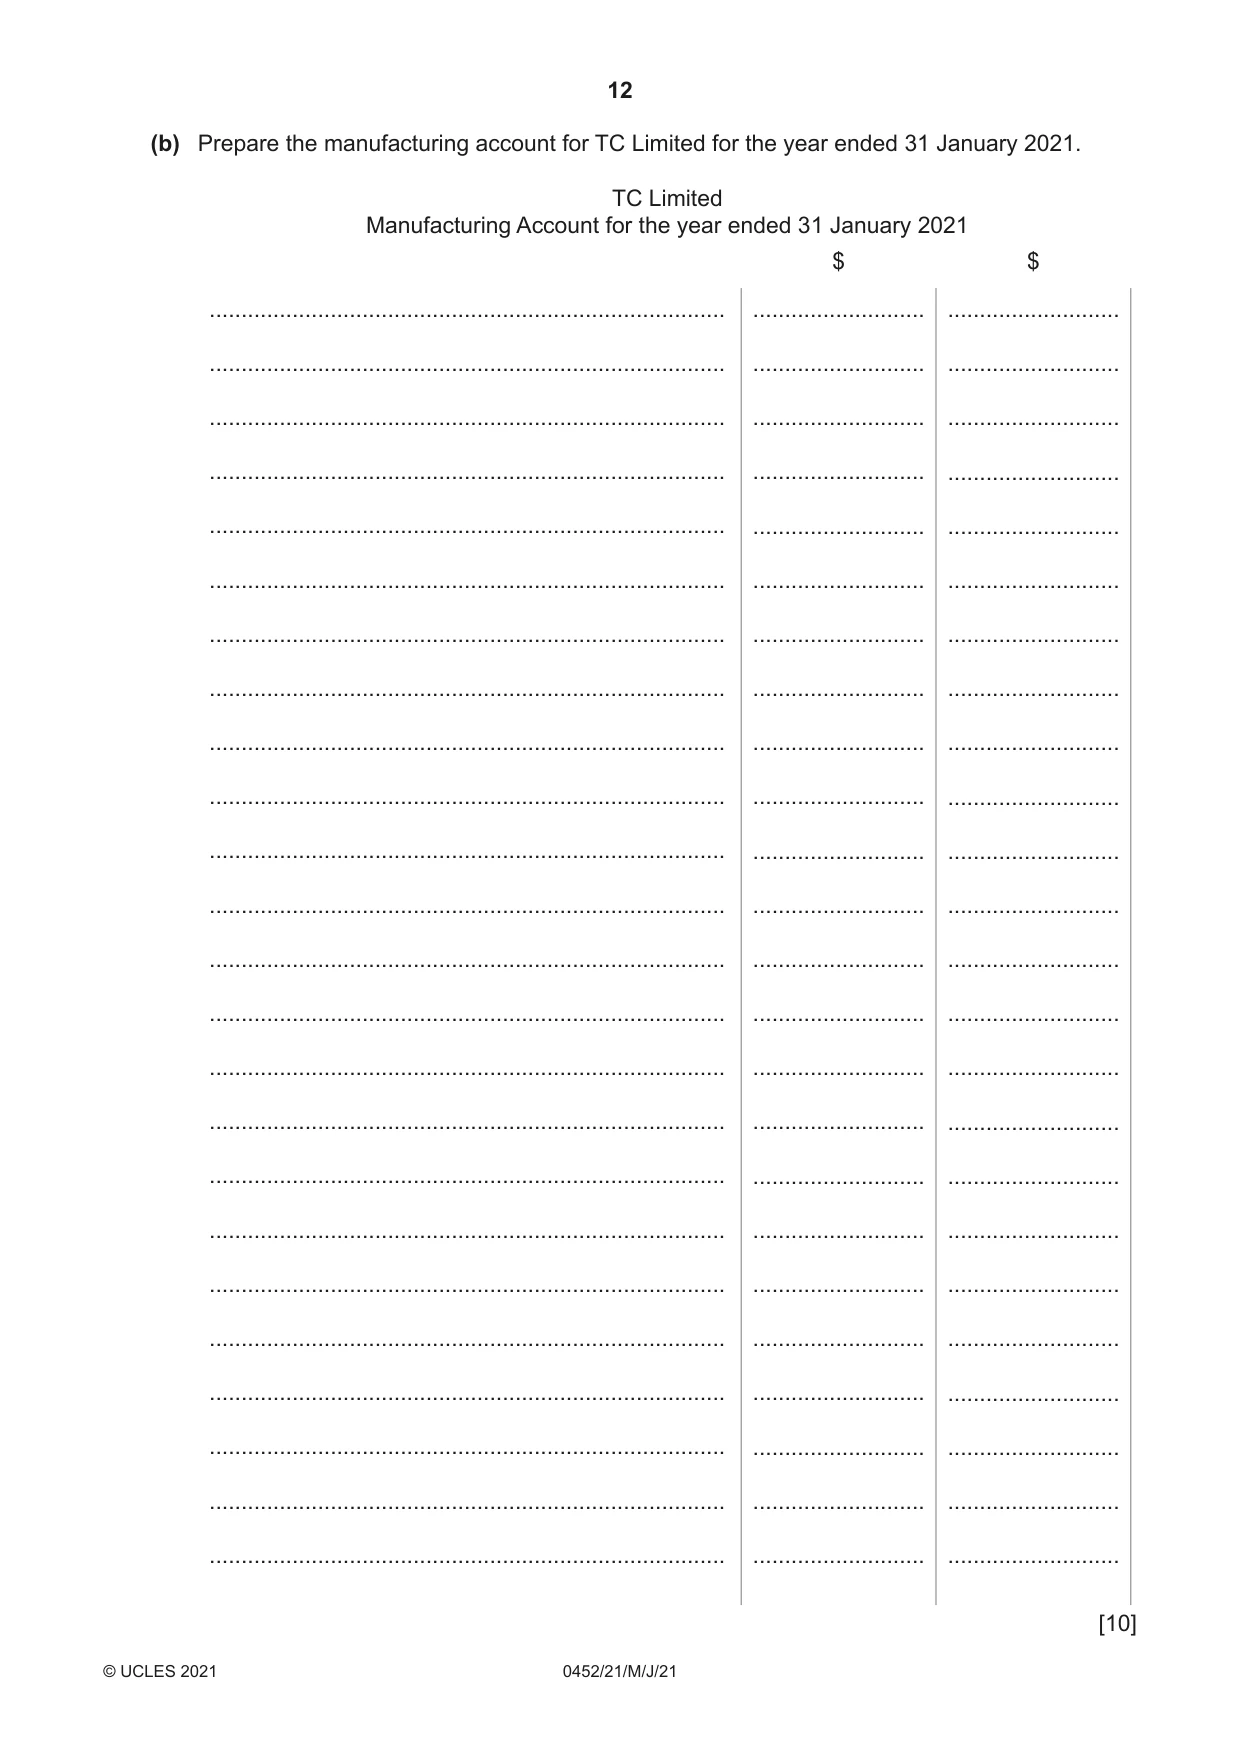
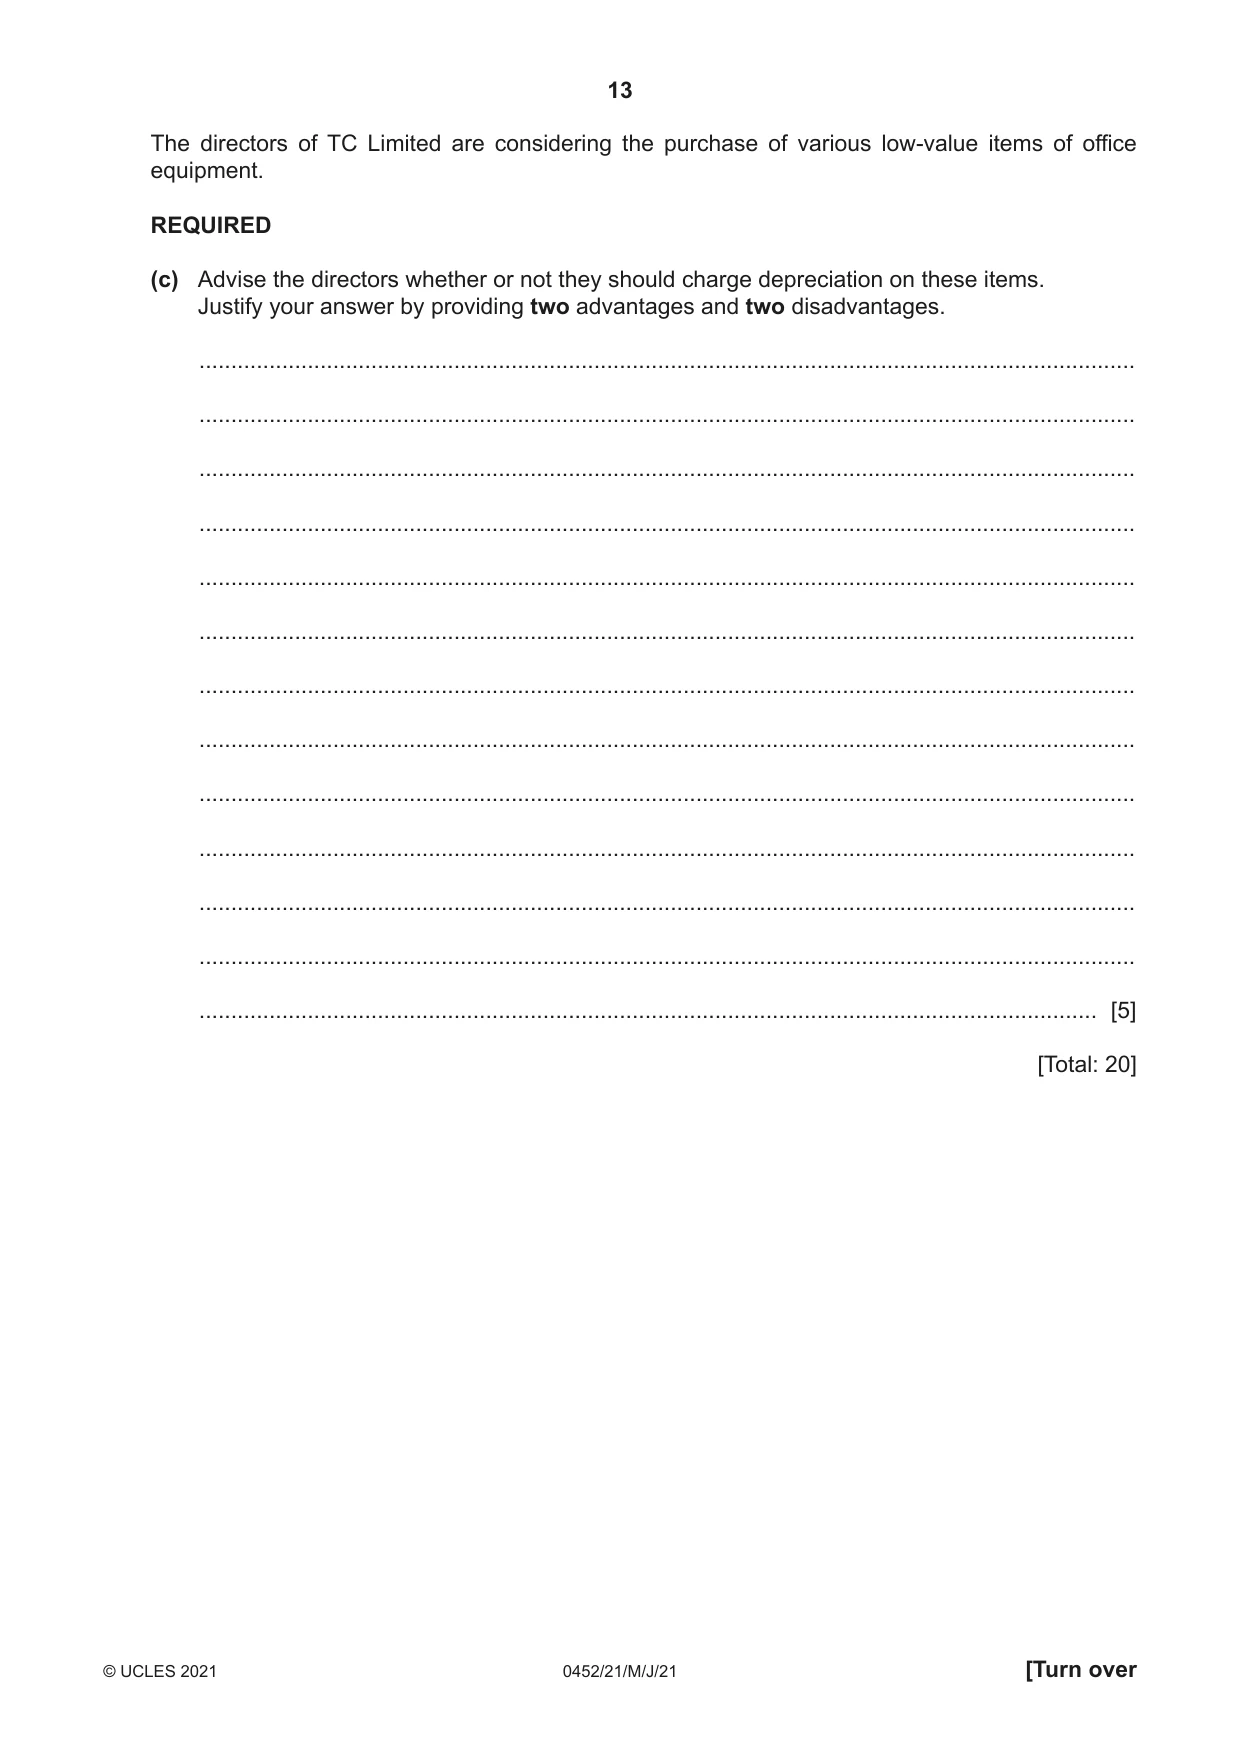
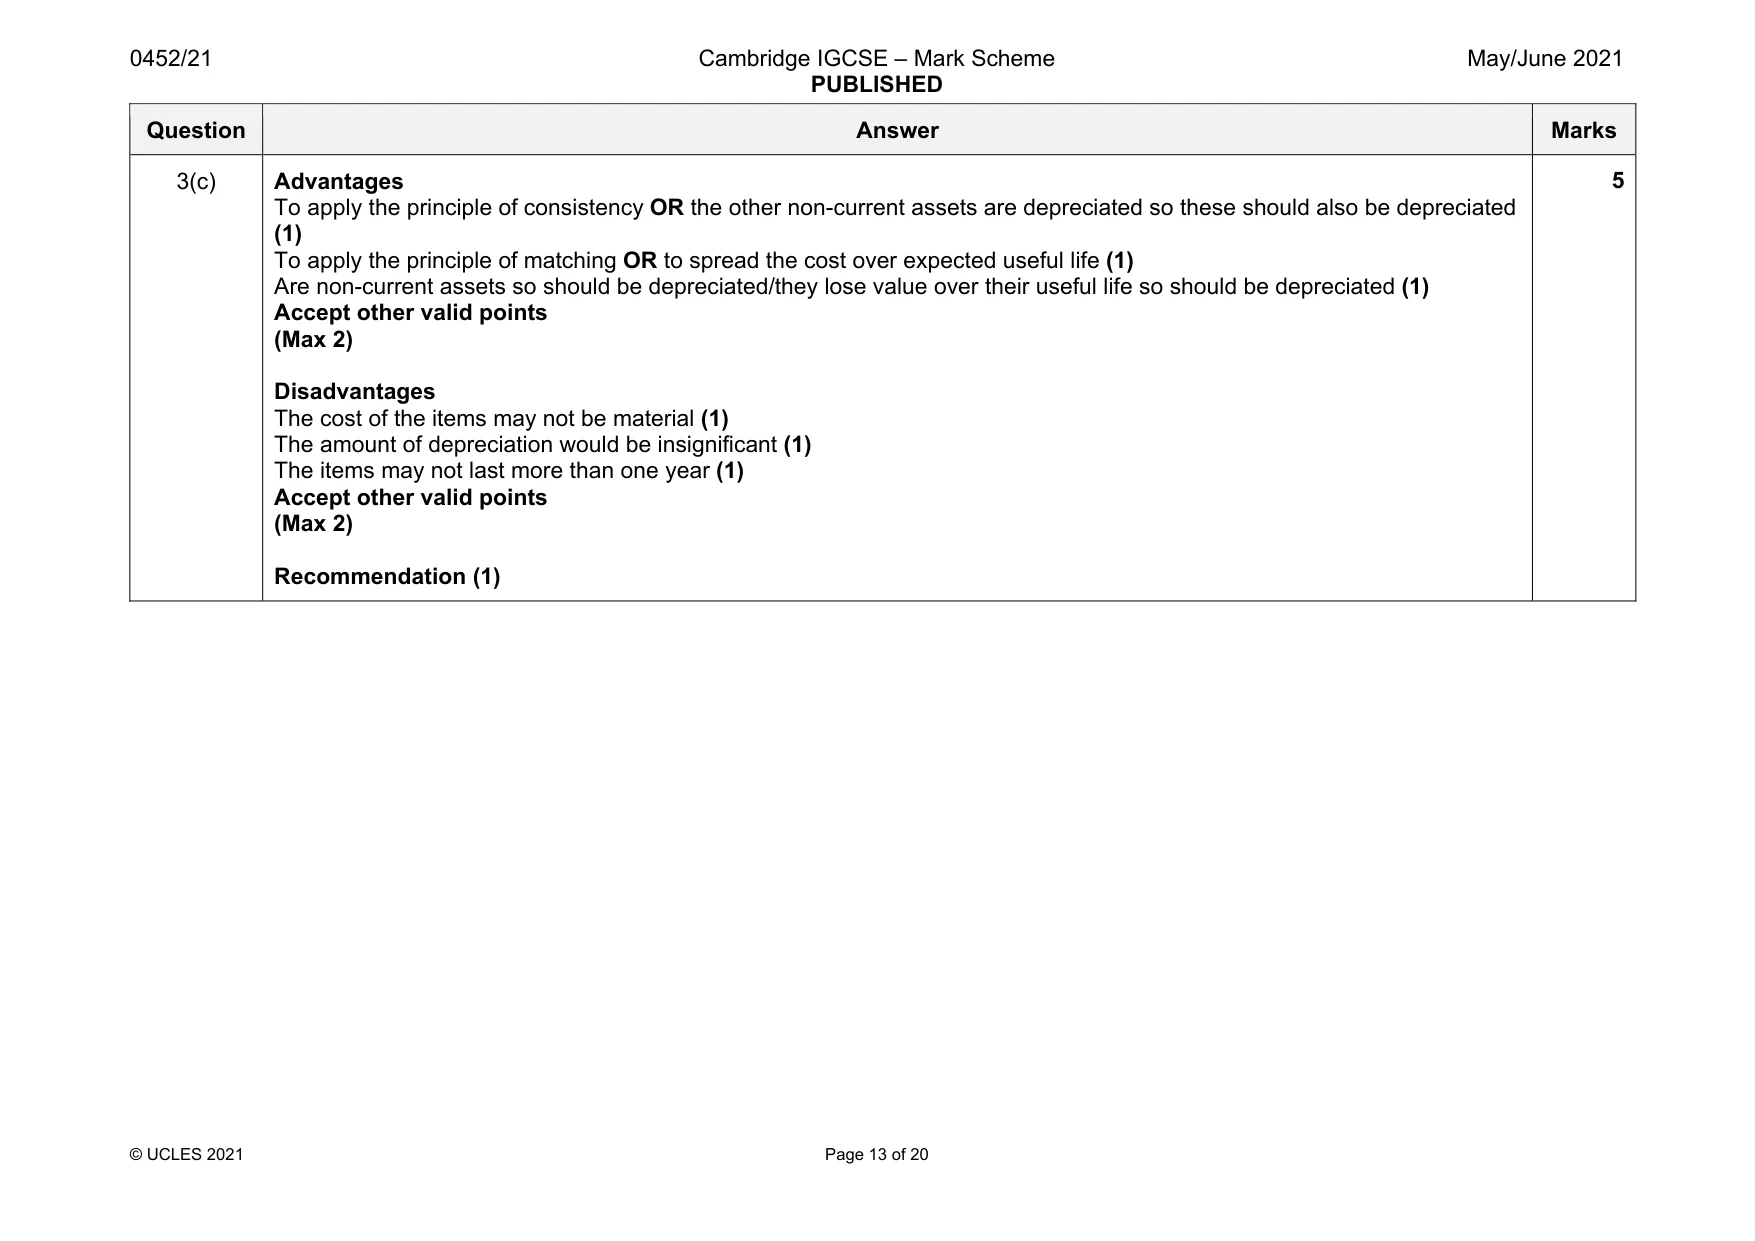
3 TC Limited is a manufacturing company. The company’s year end is 31 January. On 31 January 2021, the company’s ledger account balances included the following. $ Inventory at 1 February 2020 Raw materials 7 500 Work in progress 11 220 Finished goods 925 Purchases Raw materials 91 400 Finished goods 6 850 Wages Factory operatives 52 000 Factory supervisor 23 100 Rent and rates 19 620 Insurance 4 600 General factory expenses 4 200 Carriage inwards on raw materials 6 280 Factory equipment at cost 90 000 Provision for depreciation of factory equipment 30 960 Additional information 1 Inventory at 31 January 2021 Raw materials 8 000 Work in progress 11 900 Finished goods 1 075 2 The factory equipment is to be depreciated at 20% per annum using the reducing balance method. 3 In December 2020, $3600 was paid for rent for the period 1 December 2020 to 28 February 2021. 4 At 31 January 2021 rates of $550 were unpaid. 5 Rent and rates are to be apportioned equally between the factory and the office. 6 Insurance is to be apportioned 75% to the factory and 25% to the office. REQUIRED (a) Prepare the rent and rates account for TC Limited for the year ended 31 January 2021. Balance the account and bring down the balances on 1 February 2021. TC Limited Rent and rates account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ [5] (b) Prepare the manufacturing account for TC Limited fo TC Limited Manufacturing Account for the year ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. The directors of TC Limited are considering the purchase of various low-value items of office equipment. REQUIRED (c) Advise the directors whether or not they should charge depreciation on these items. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
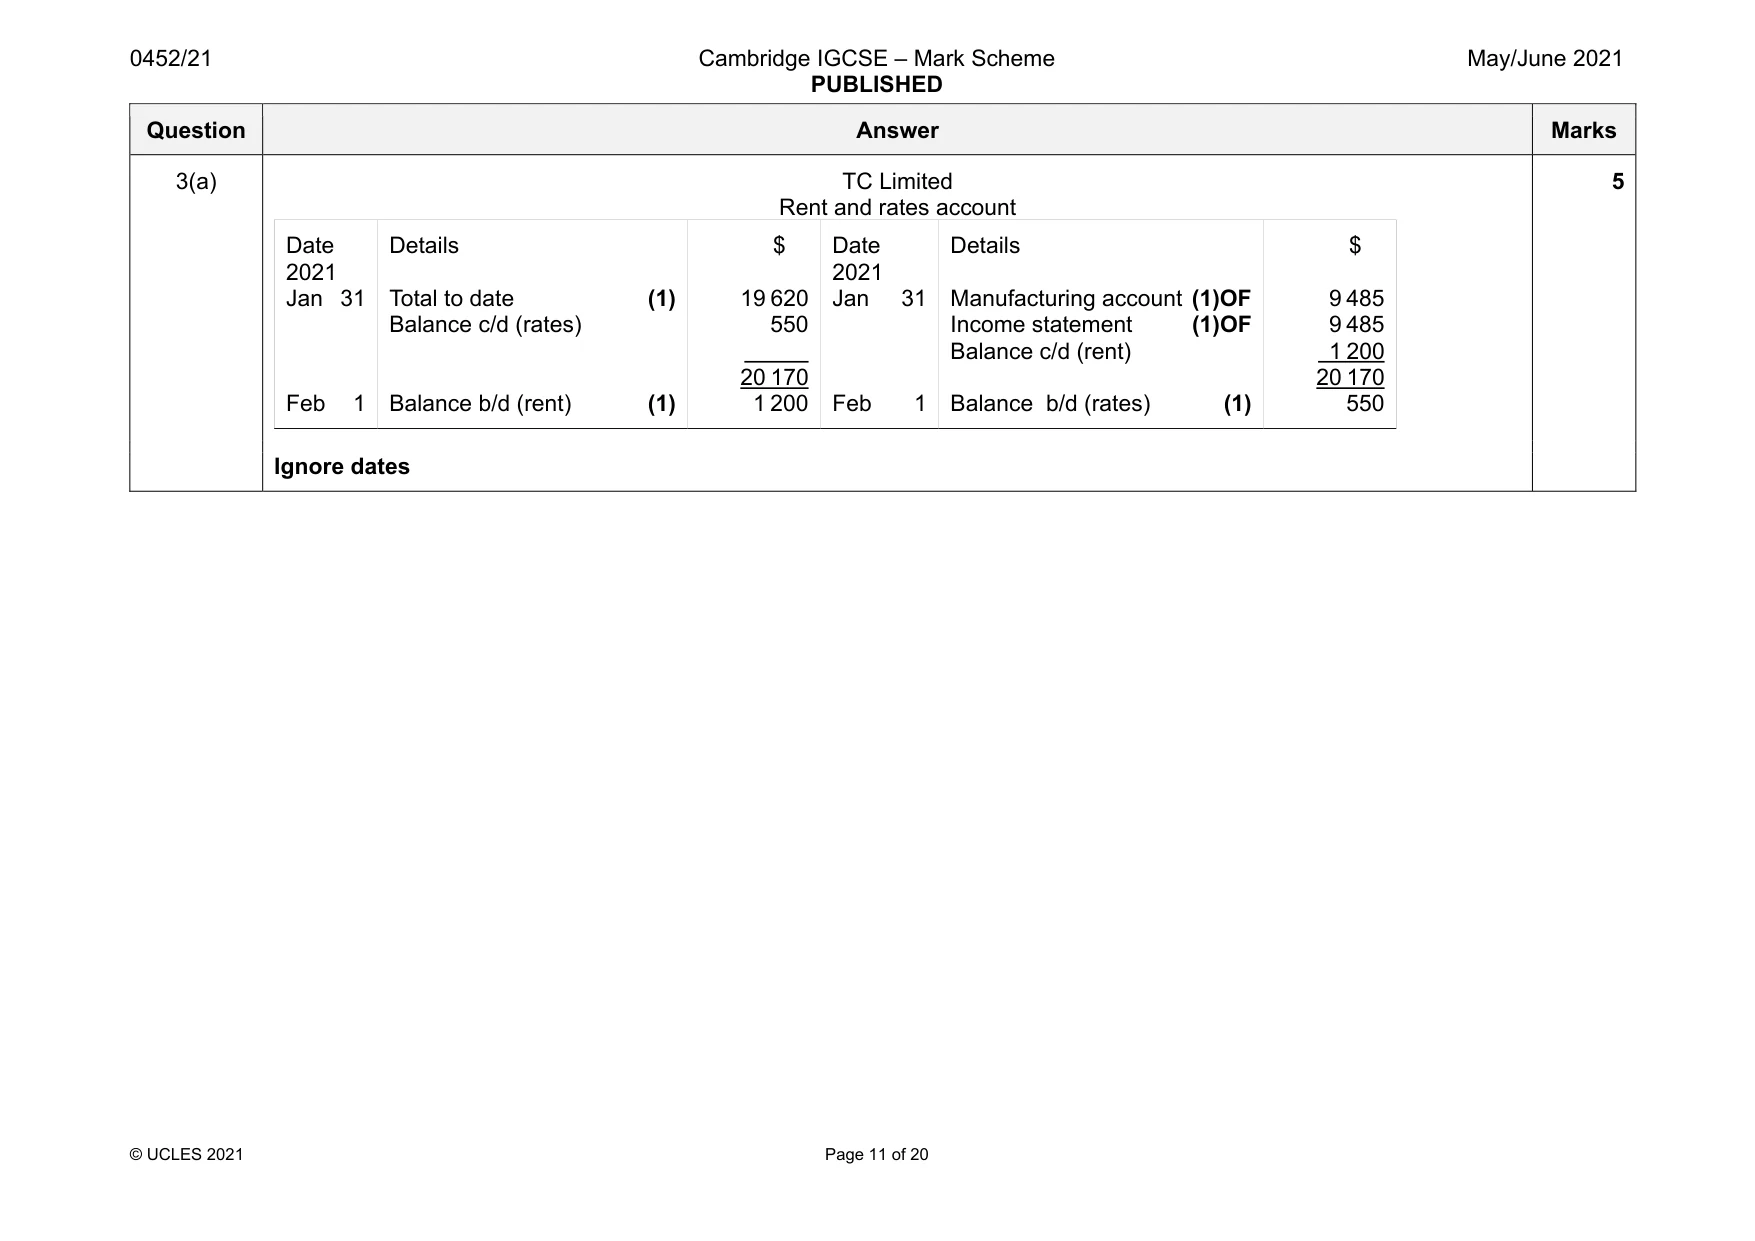
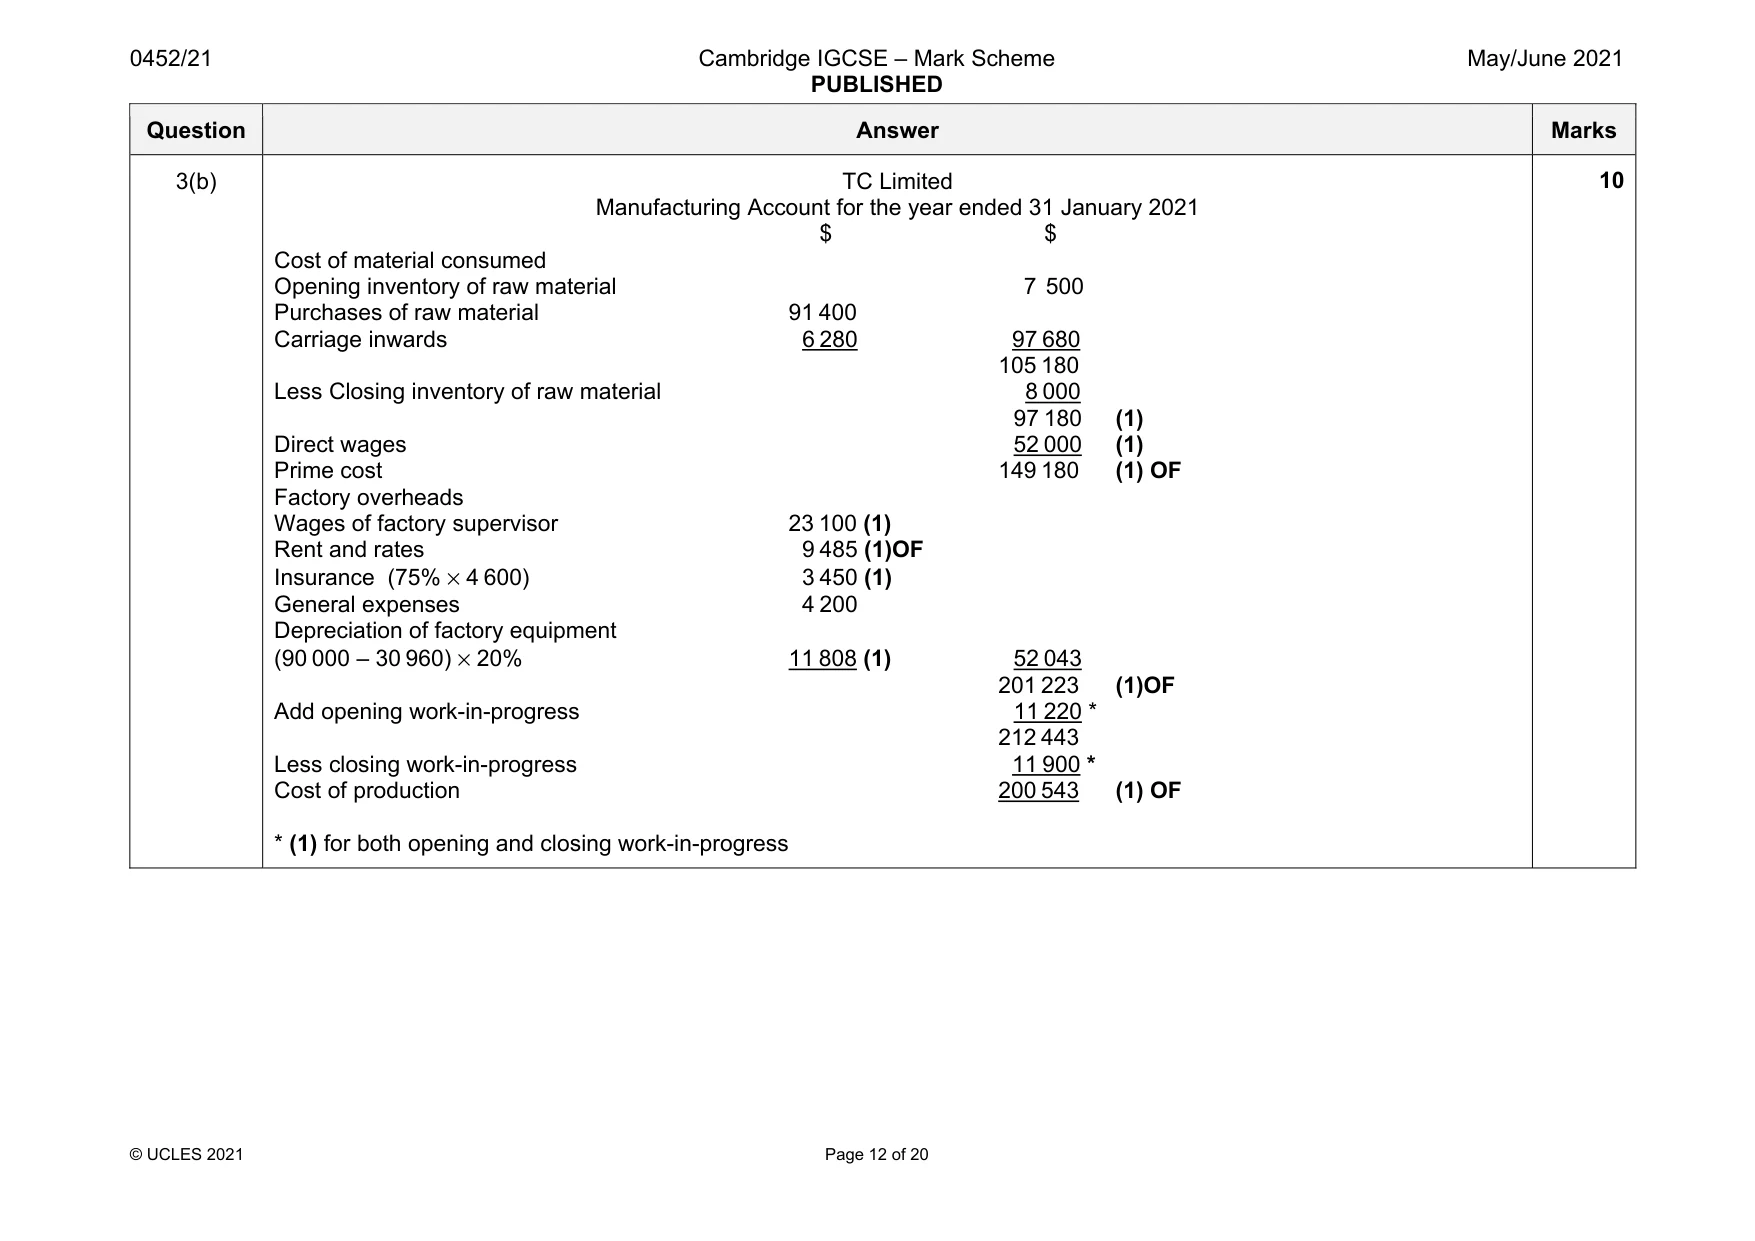
Mark scheme: 3(a) TC Limited Rent and rates account Date 2021 Jan 31 Feb 1 Details Total to date (1) Balance c/d (rates) Balance b/d (rent) (1) $ 19 620 550 20 170 1 200 Date 2021 Jan 31 Feb 1 Details Manufacturing account (1)OF Income statement (1)OF Balance c/d (rent) Balance b/d (rates) (1) $ 9 485 9 485 1 200 20 170 550 5 Ignore dates Question Answer Marks 3(b) TC Limited Manufacturing Account for the year ended 31 January 2021 $ $ Cost of material consumed Opening inventory of raw material 7 500 Purchases of raw material 91 400 Carriage inwards 6 280 97 680 105 180 Less Closing inventory of raw material 8 000 97 180 (1) Direct wages 52 000 (1) Prime cost 149 180 (1) OF Factory overheads Wages of factory supervisor 23 100 (1) Rent and rates 9 485 (1)OF Insurance (75% × 4 600) 3 450 (1) General expenses 4 200 Depreciation of factory equipment (90 000 – 30 960) × 20% 11 808 (1) 52 043 201 223 (1)OF Add opening work-in-progress 11 220 * 212 443 Less closing work-in-progress 11 900 * Cost of production 200 543 (1) OF * (1) for both opening and closing work-in-progress 10 Question Answer Marks 3(c) Advantages To apply the principle of consistency OR the other non-current assets are depreciated so these should also be depreciated (1) To apply the principle of matching OR to spread the cost over expected useful life (1) Are non-current assets so should be depreciated/they lose value over their useful life so should be depreciated (1) Accept other valid points (Max 2) Disadvantages The cost of the items may not be material (1) The amount of depreciation would be insignificant (1) The items may not last more than one year (1) Accept other valid points (Max 2) Recommendation (1) 5
Q4 · Neith is a trader
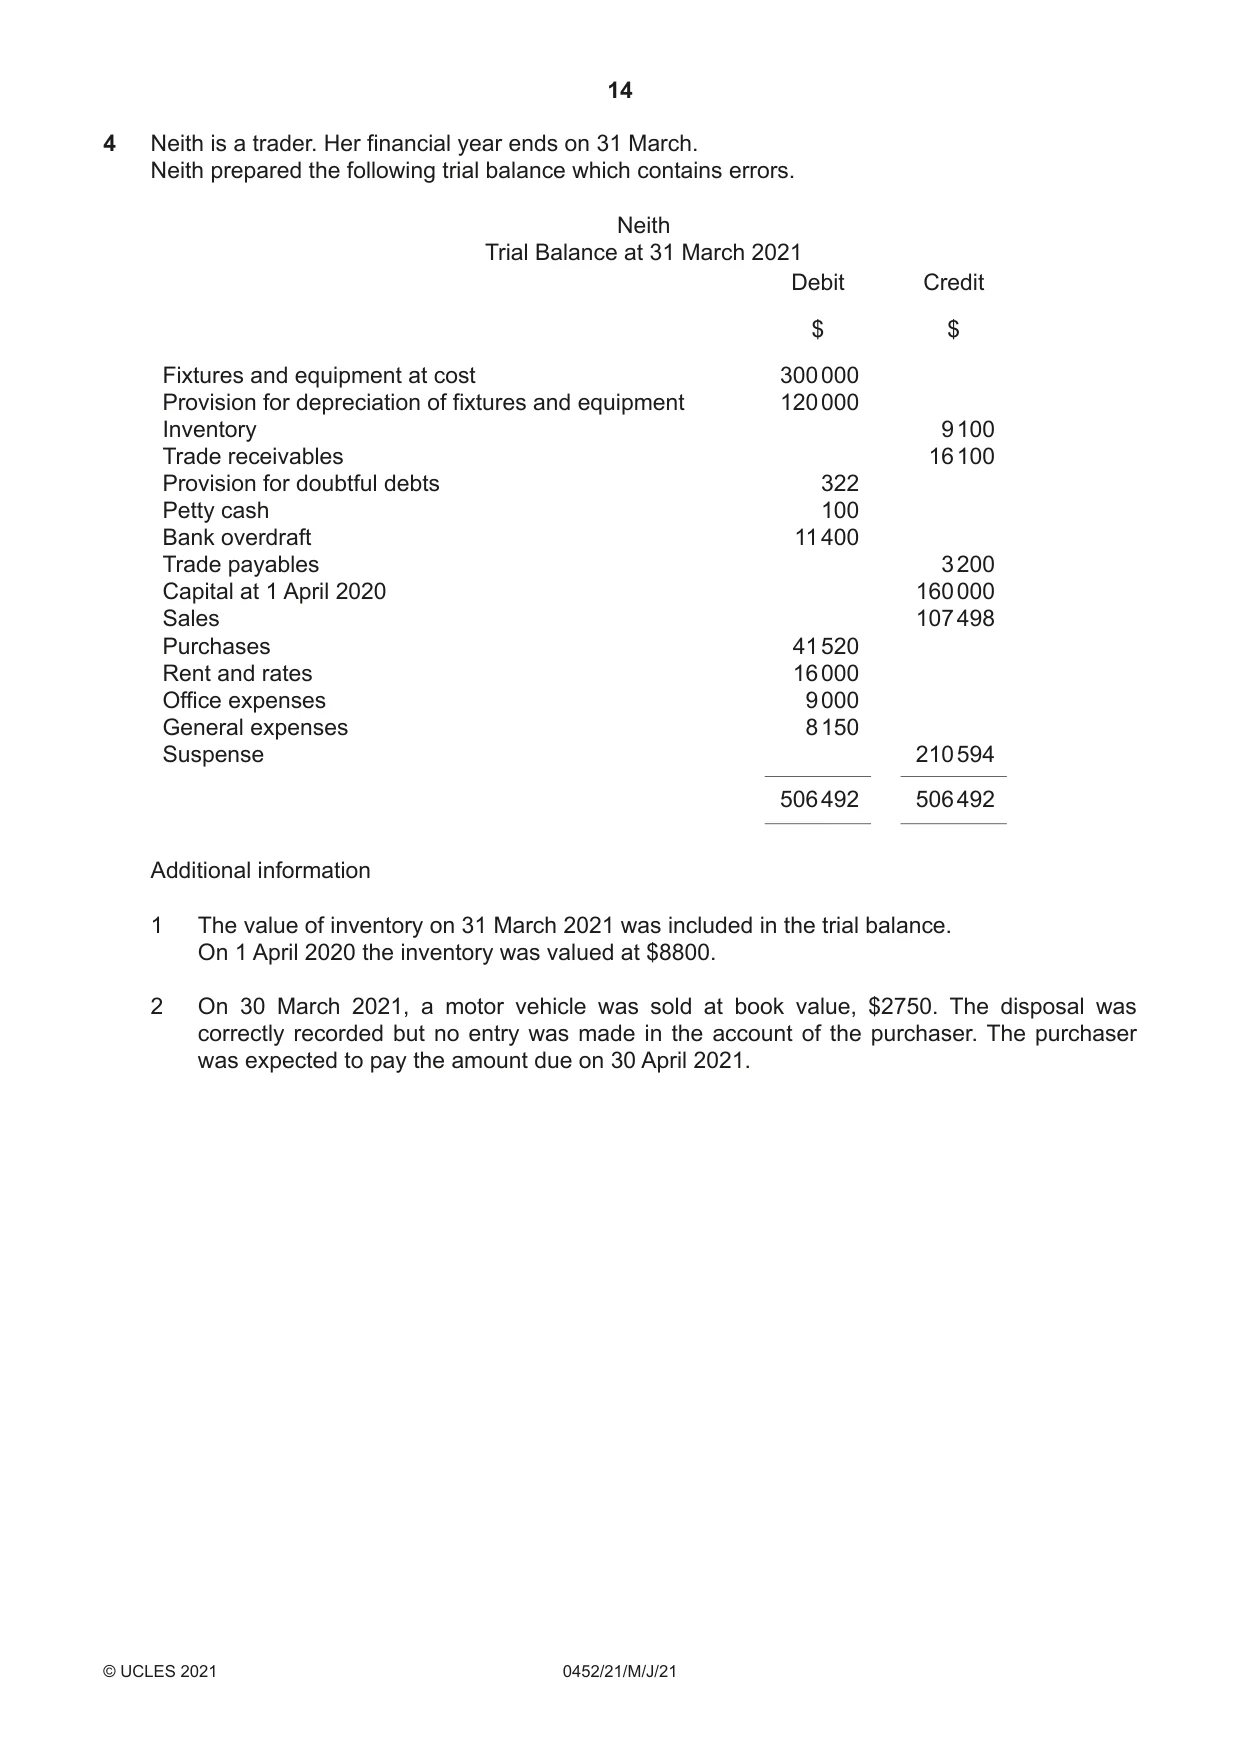
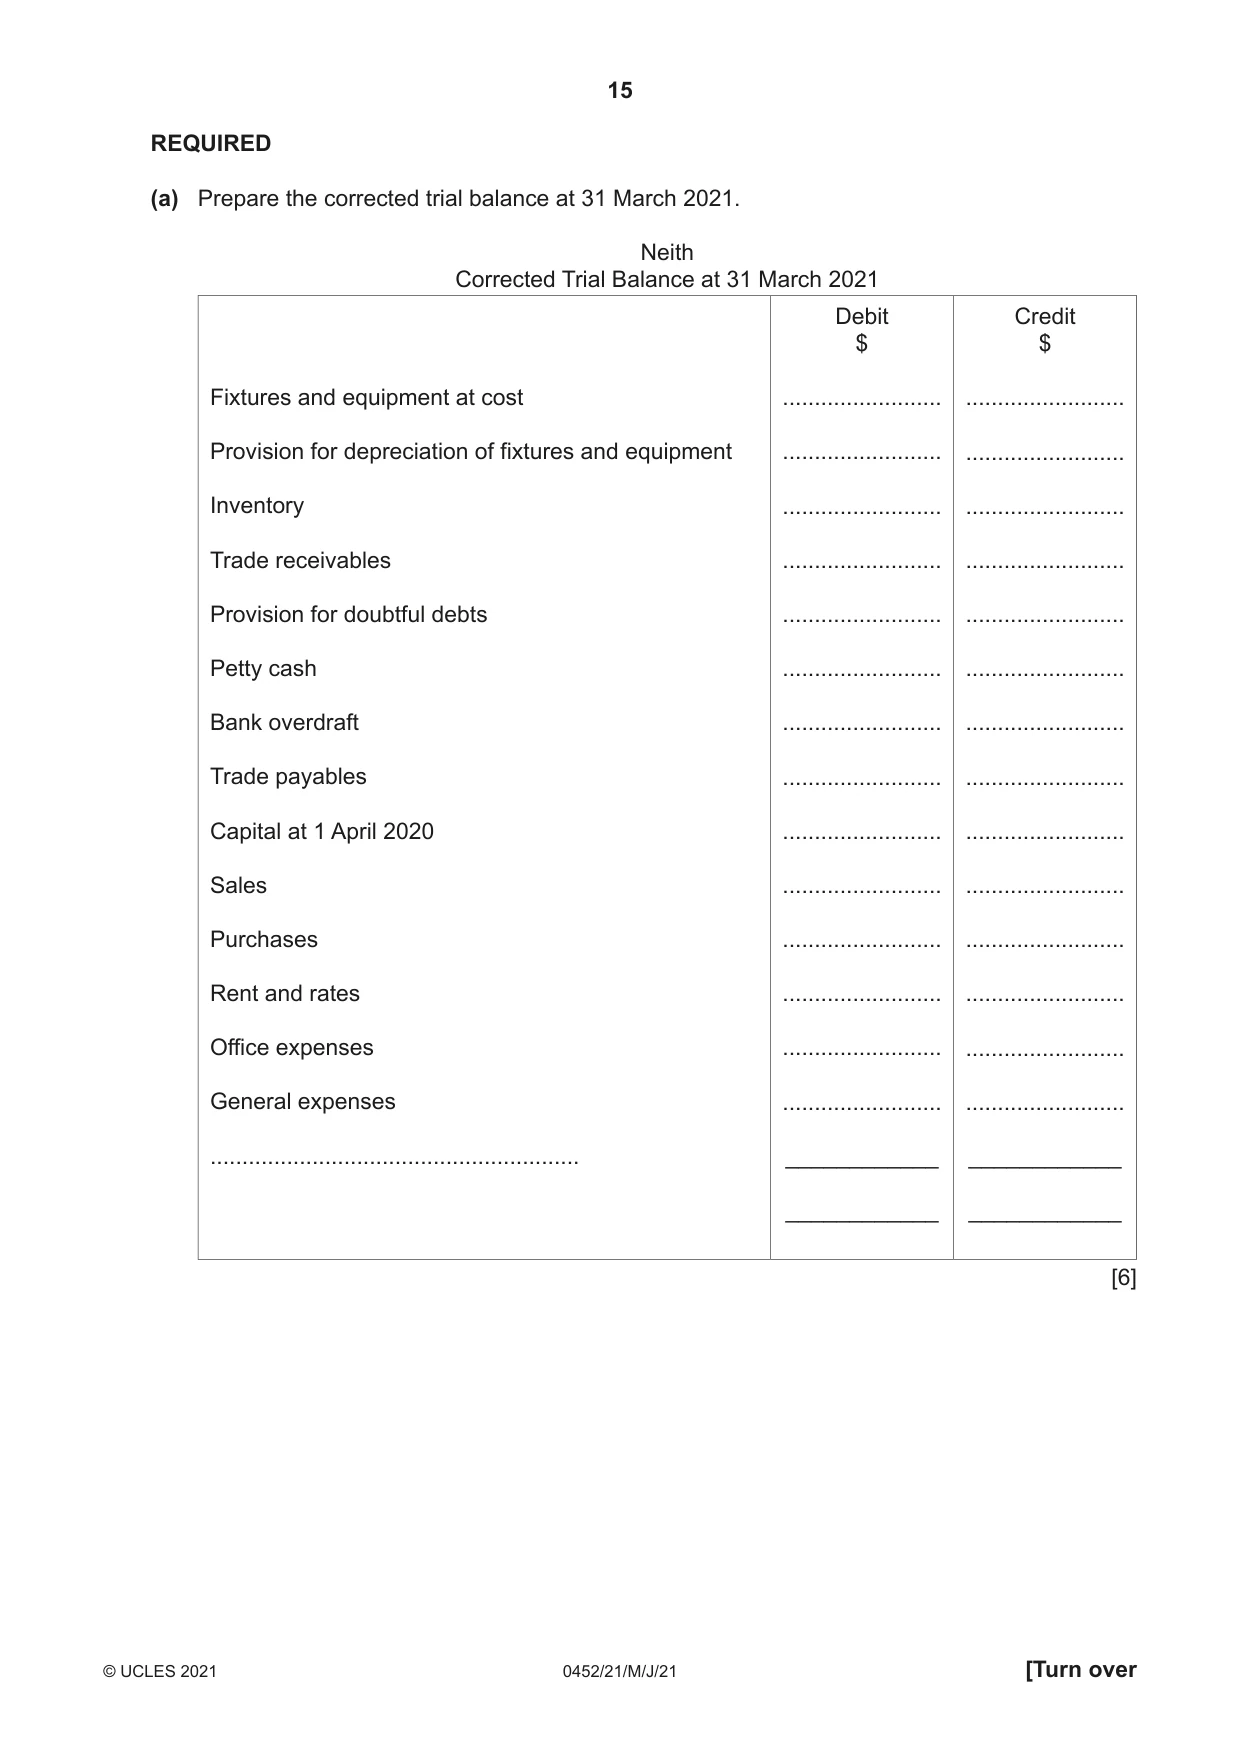
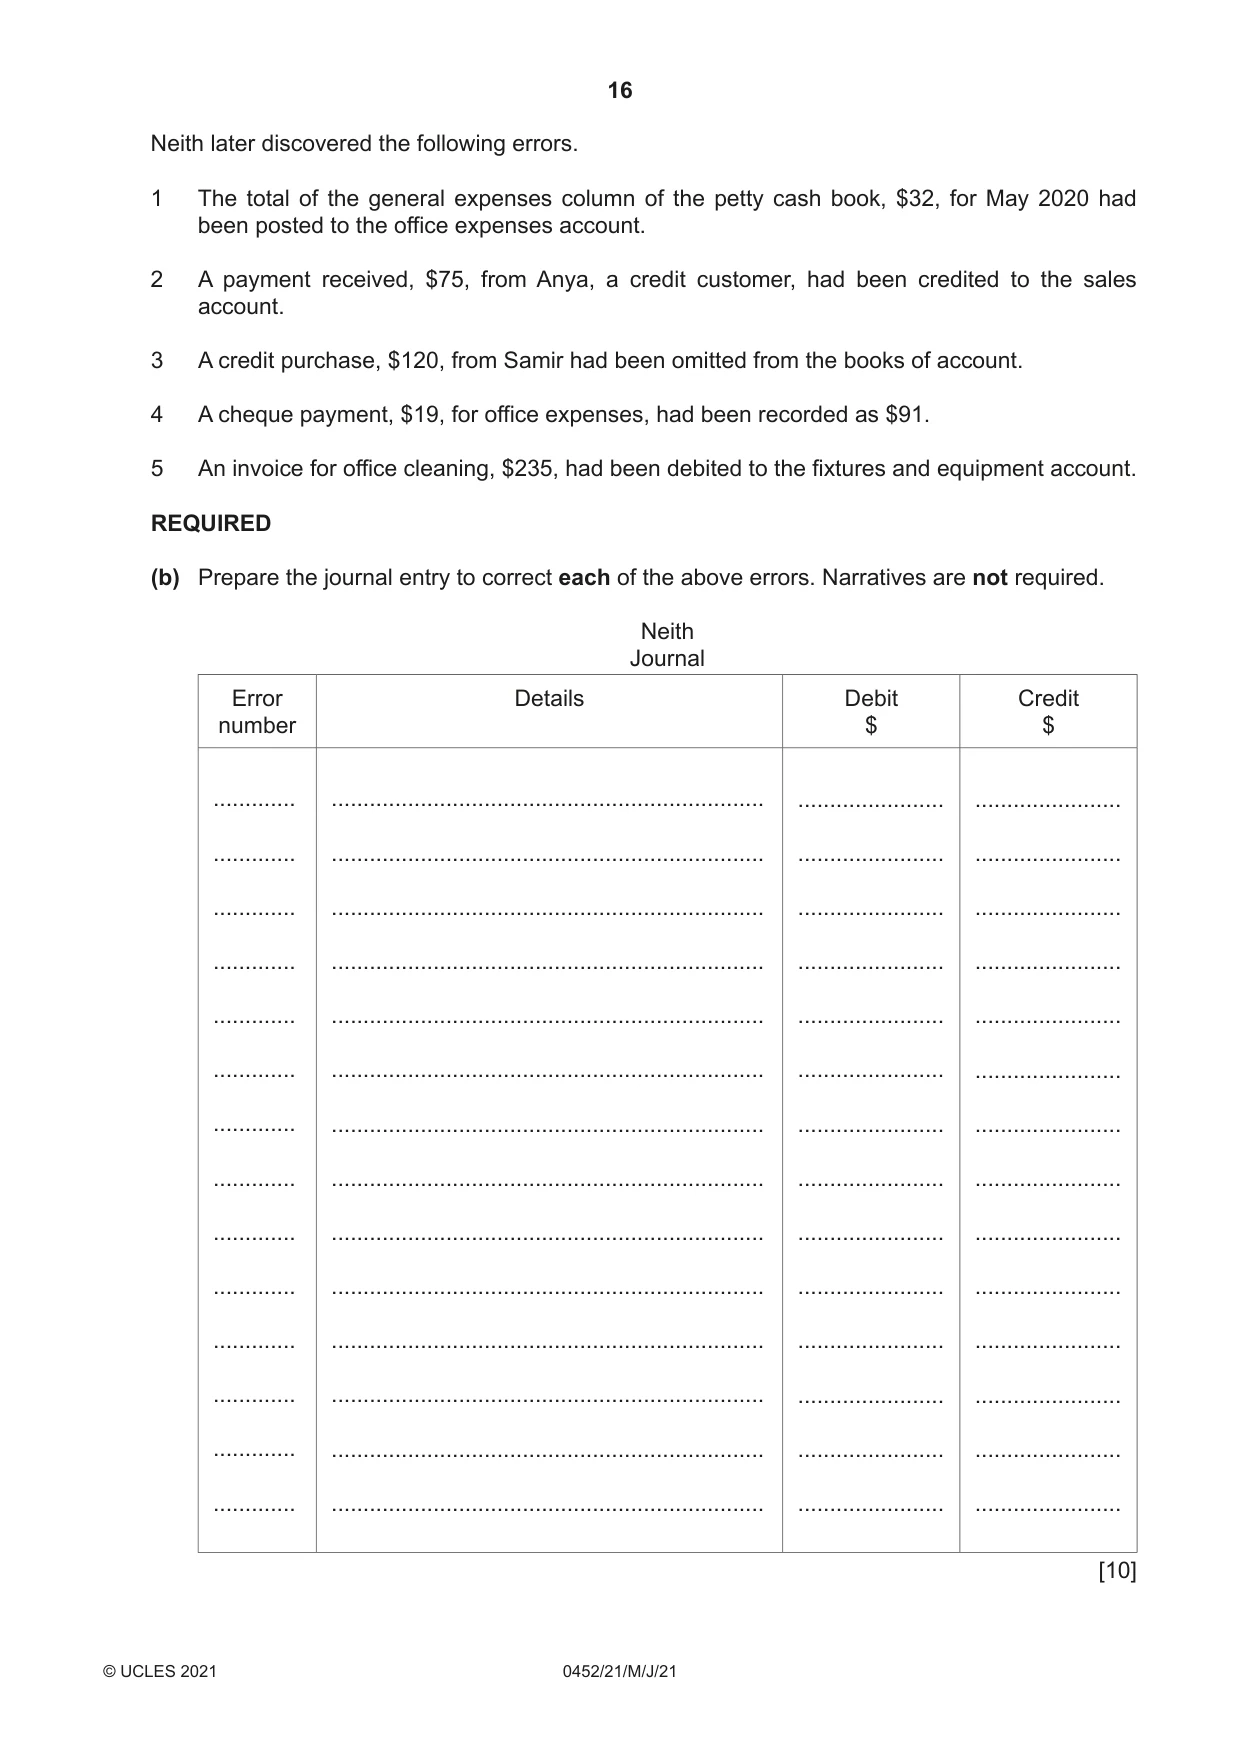
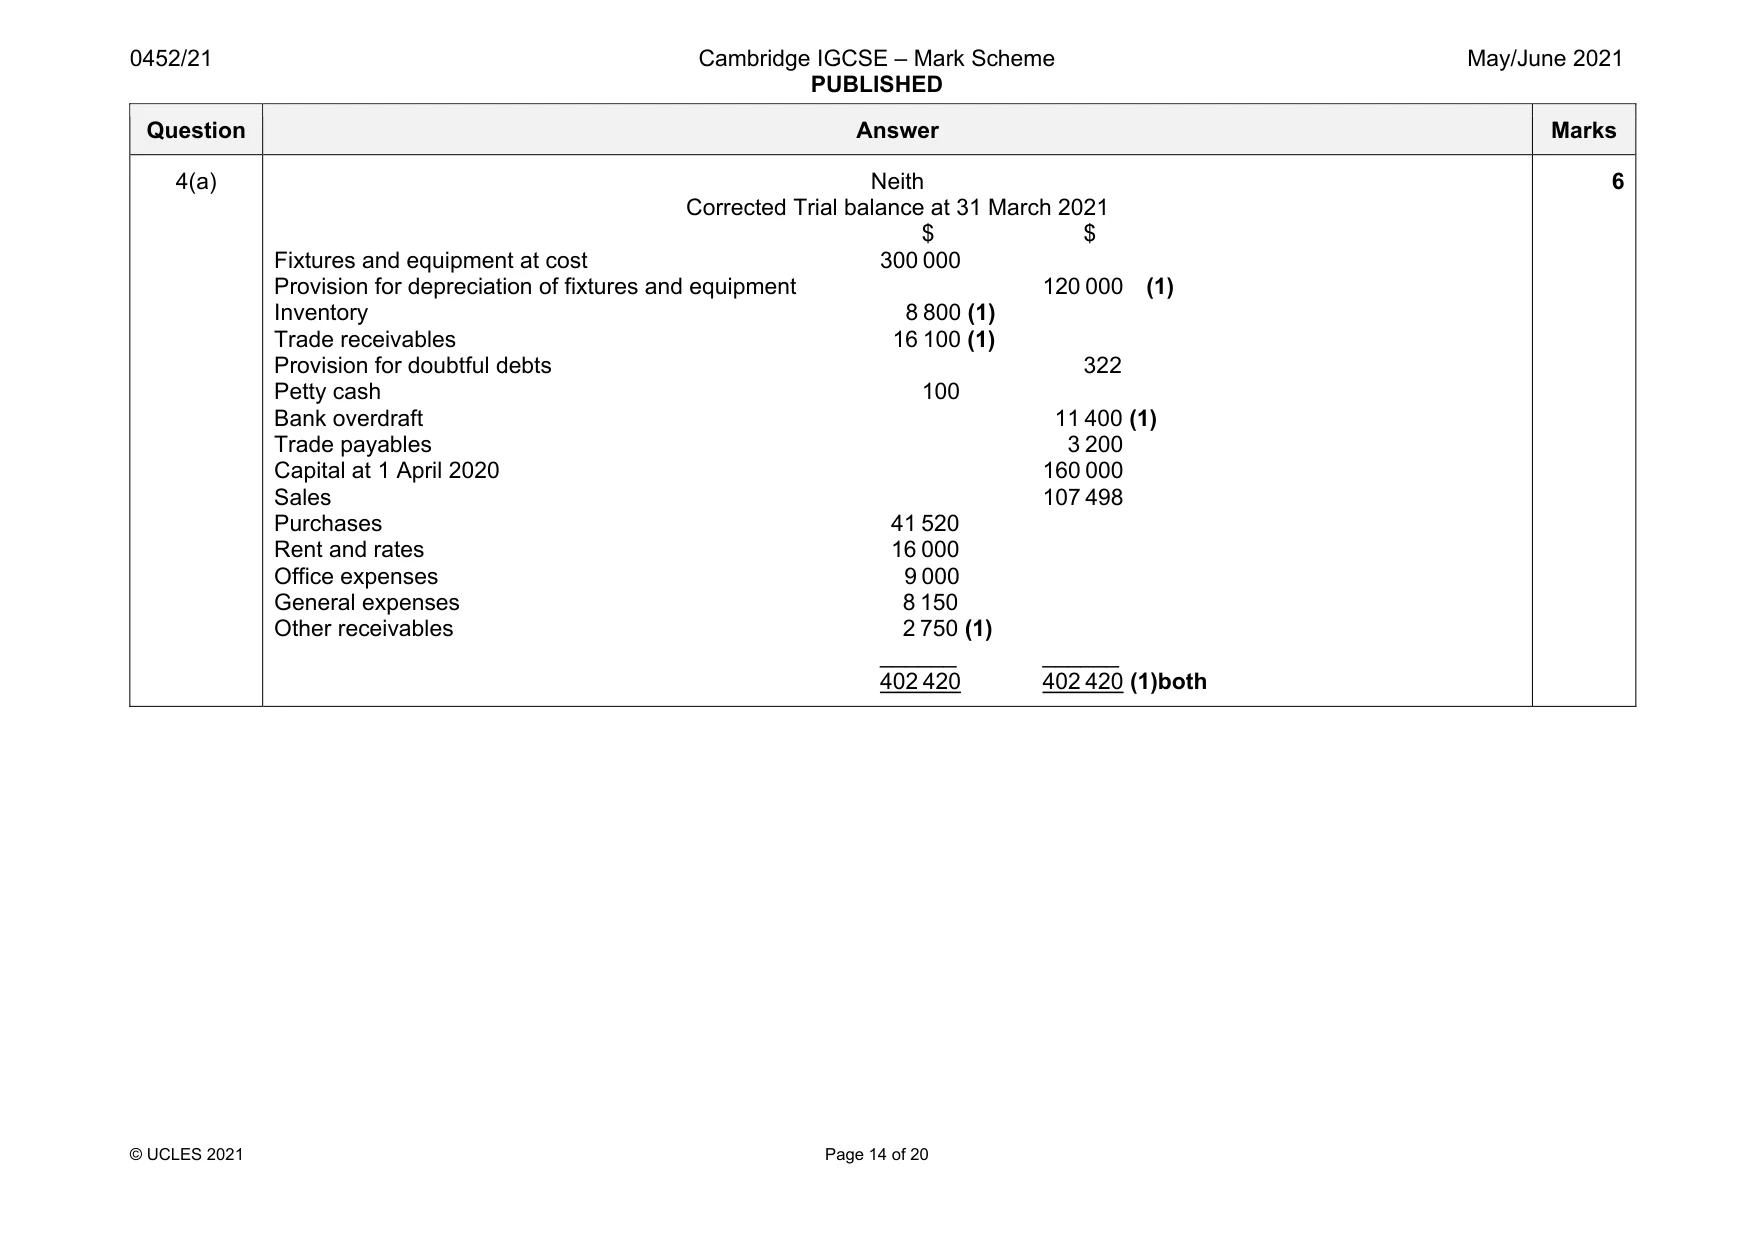
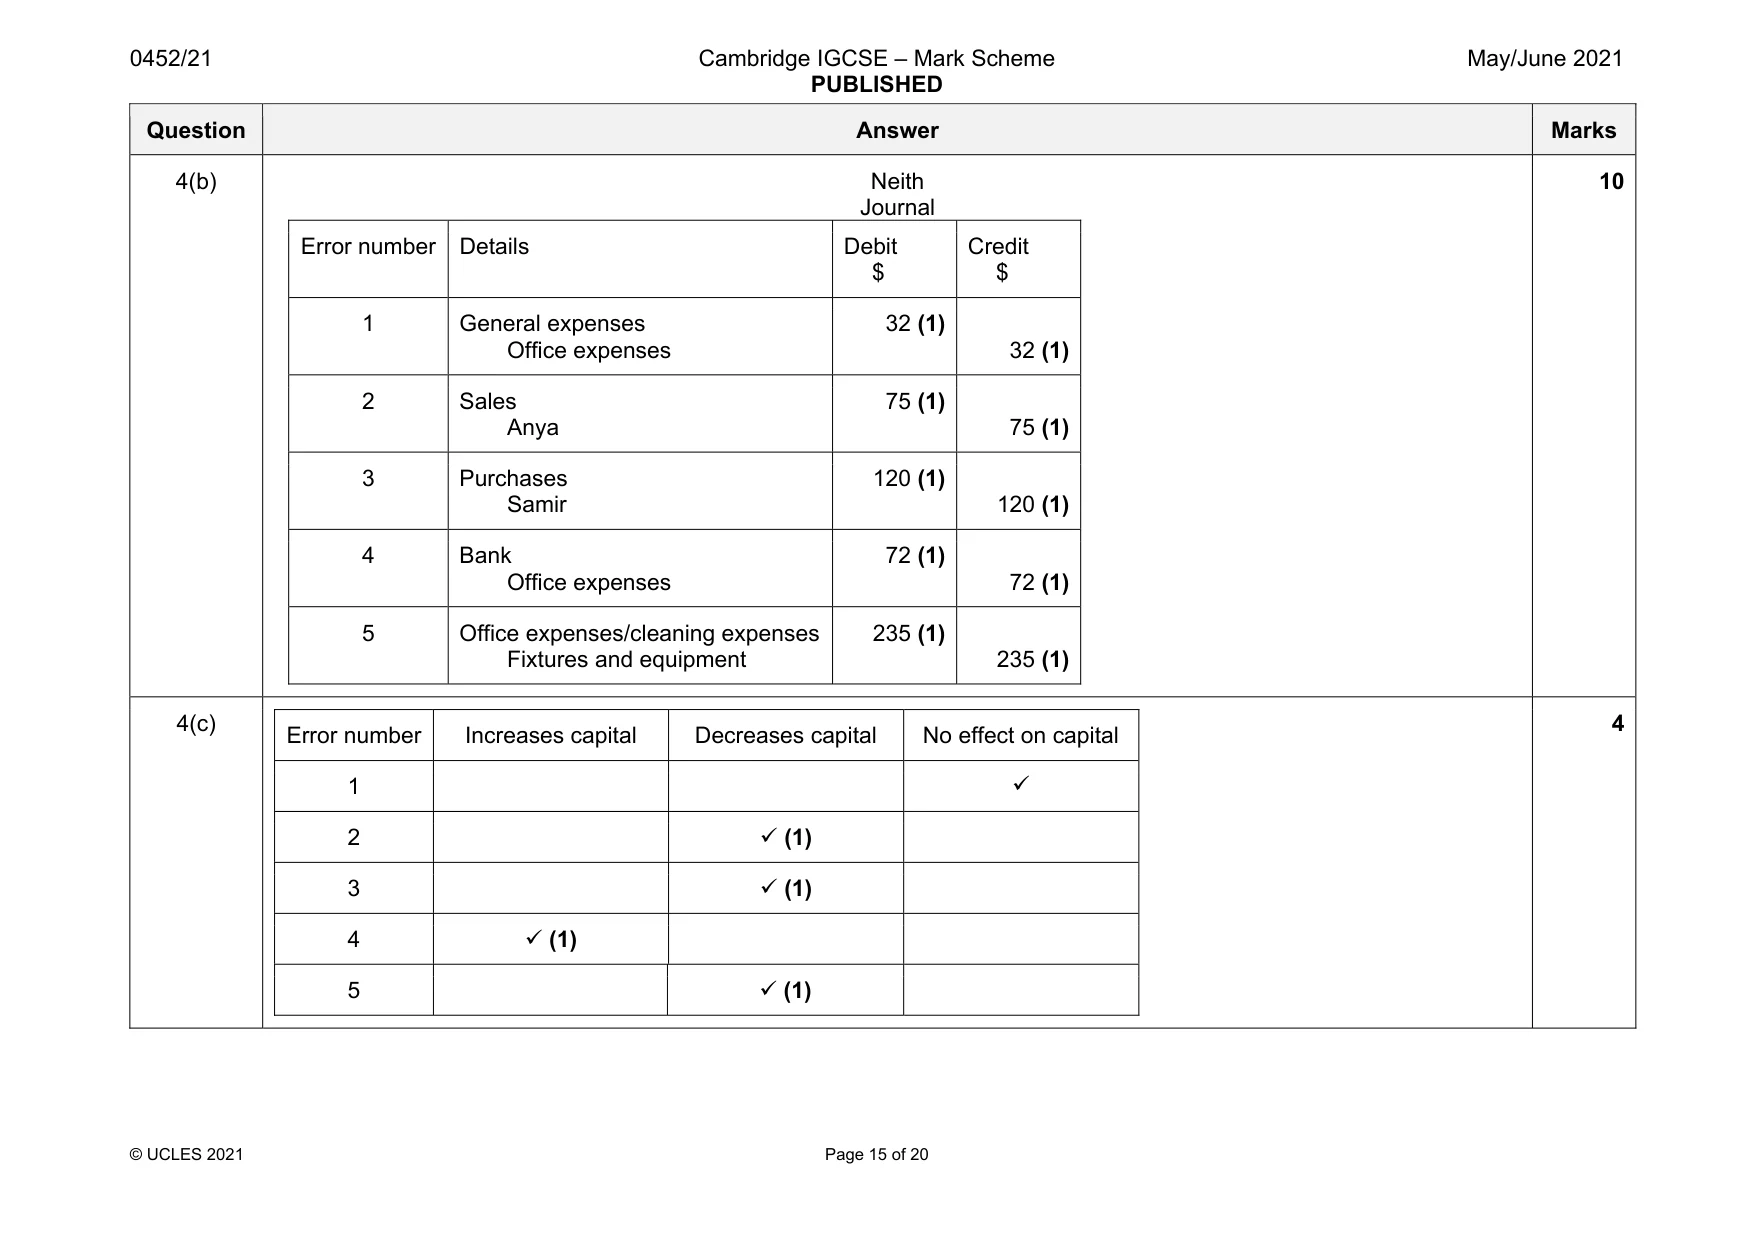
4 Neith is a trader. Her financial year ends on 31 March. Neith prepared the following trial balance which contains errors. Neith Trial Balance at 31 March 2021 Debit Credit $ $ Fixtures and equipment at cost 300 000 Provision for depreciation of fixtures and equipment 120 000 Inventory 9 100 Trade receivables 16 100 Provision for doubtful debts 322 Petty cash 100 Bank overdraft 11 400 Trade payables 3 200 Capital at 1 April 2020 160 000 Sales 107 498 Purchases 41 520 Rent and rates 16 000 Office expenses 9 000 General expenses 8 150 Suspense 210 594 506 492 506 492 Additional information 1 The value of inventory on 31 March 2021 was included in the trial balance. On 1 April 2020 the inventory was valued at $8800. 2 On 30 March 2021, a motor vehicle was sold at book value, $2750. The disposal was correctly recorded but no entry was made in the account of the purchaser. The purchaser was expected to pay the amount due on 30 April 2021. REQUIRED (a) Prepare the corrected trial balance at 31 March 2021. Neith Corrected Trial Balance at 31 March 2021 Debit Credit $ $ Fixtures and equipment at cost ......................... ......................... Provision for depreciation of fixtures and equipment ......................... ......................... Inventory ......................... ......................... Trade receivables ......................... ......................... Provision for doubtful debts ......................... ......................... Petty cash ......................... ......................... Bank overdraft ......................... ......................... Trade payables ......................... ......................... Capital at 1 April 2020 ......................... ......................... Sales ......................... ......................... Purchases ......................... ......................... Rent and rates ......................... ......................... Office expenses ......................... ......................... General expenses ......................... ......................... .......................................................... ____________ ____________ ____________ ____________ [6] Neith later discovered the following errors. 1 The total of the general expenses column of the petty cash book, $32, for May 2020 had been posted to the office expenses account. 2 A payment received, $75, from Anya, a credit customer, had been credited to the sales account. 3 A credit purchase, $120, from Samir had been omitted from the books of account. 4 A cheque payment, $19, for office expenses, had been recorded as $91.
Mark scheme: 4(a) Neith Corrected Trial balance at 31 March 2021 $ $ Fixtures and equipment at cost 300 000 Provision for depreciation of fixtures and equipment 120 000 (1) Inventory 8 800 (1) Trade receivables 16 100 (1) Provision for doubtful debts 322 Petty cash 100 Bank overdraft 11 400 (1) Trade payables 3 200 Capital at 1 April 2020 160 000 Sales 107 498 Purchases 41 520 Rent and rates 16 000 Office expenses 9 000 General expenses 8 150 Other receivables 2 750 (1) ______ ______ 402 420 402 420 (1)both 6 Question Answer Marks 4(b) Neith Journal Error number Details Debit $ Credit $ 1 General expenses Office expenses 32 (1) 32 (1) 2 Sales Anya 75 (1) 75 (1) 3 Purchases Samir 120 (1) 120 (1) 4 Bank Office expenses 72 (1) 72 (1) 5 Office expenses/cleaning expenses Fixtures and equipment 235 (1) 235 (1) 10 4(c) Error number Increases capital Decreases capital No effect on capital 1 2 (1) 3 (1) 4 (1) 5 (1) 4
Q5 · An invoice for office cleaning, $235, had been debited to the fixtures and equipment…
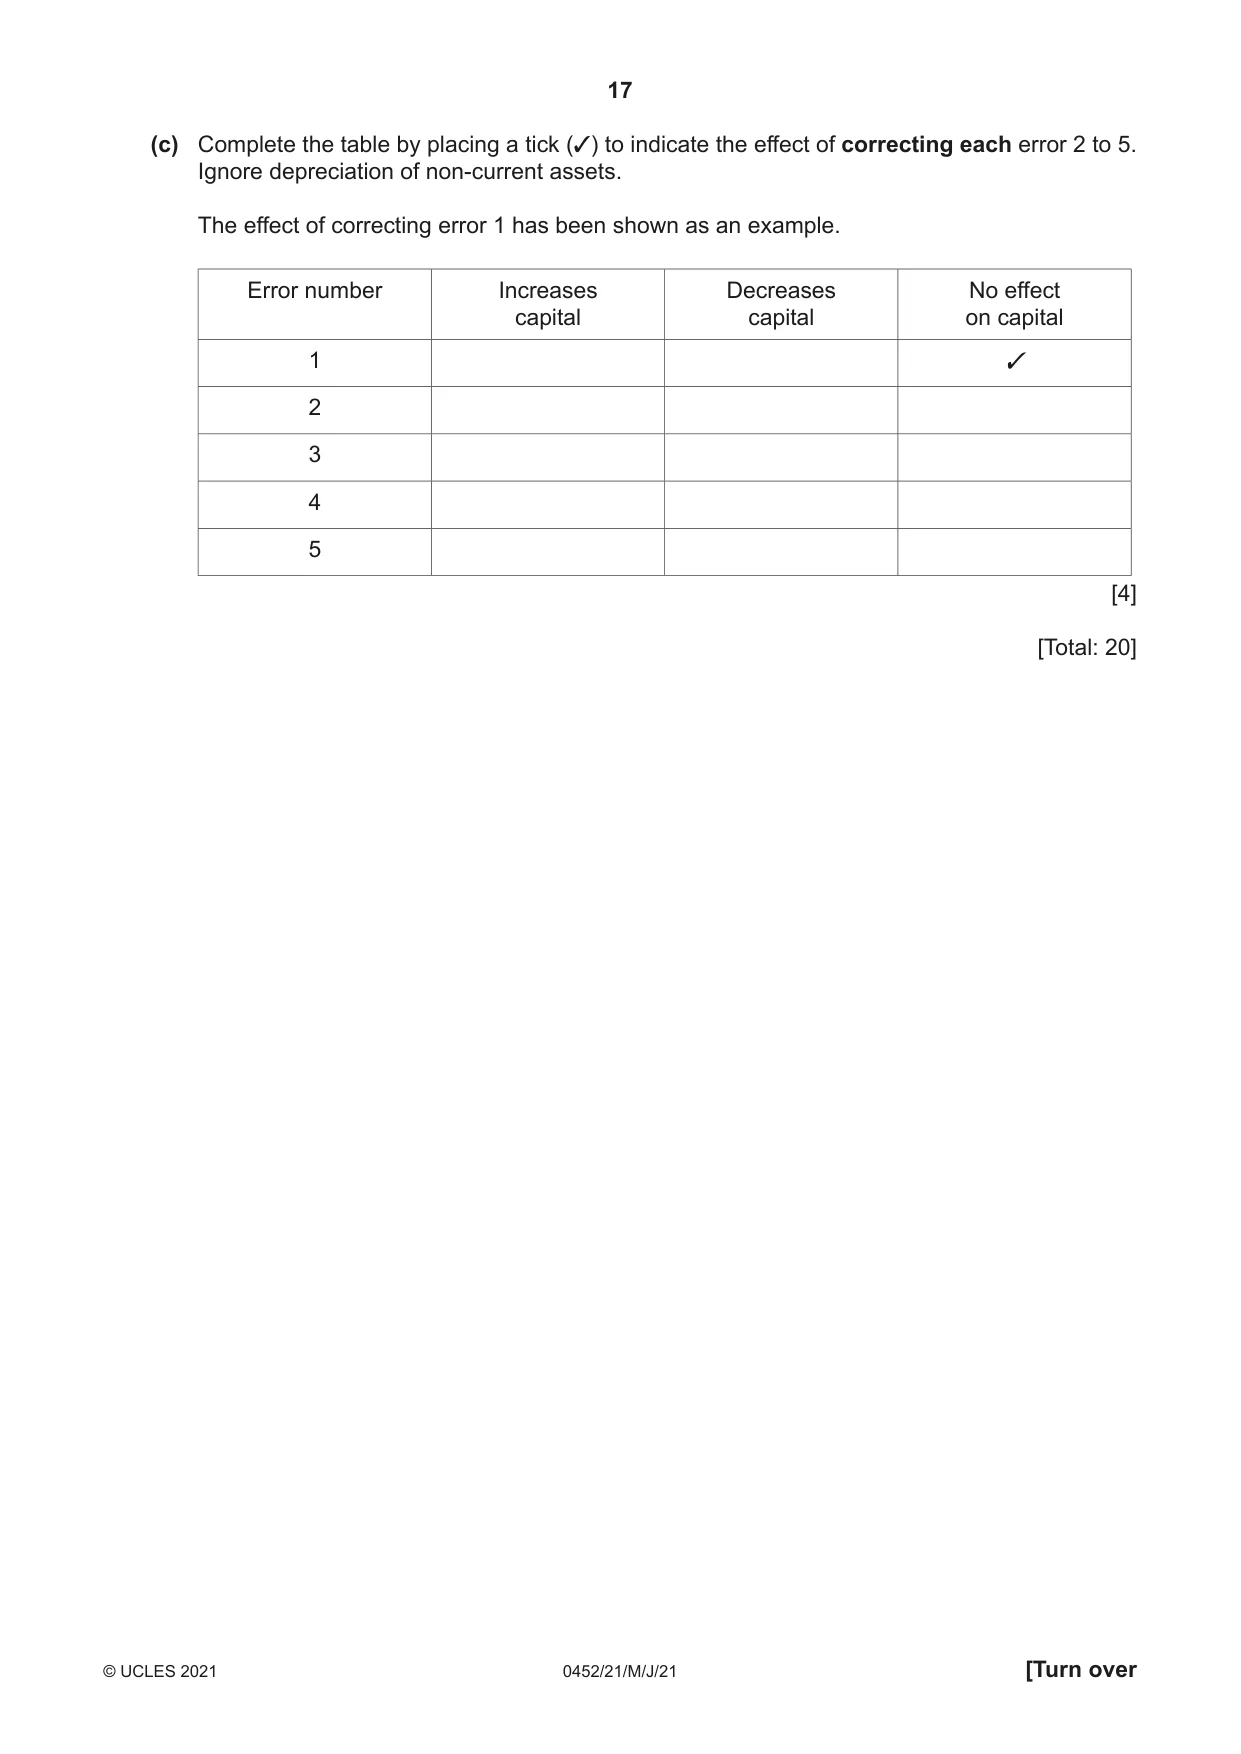
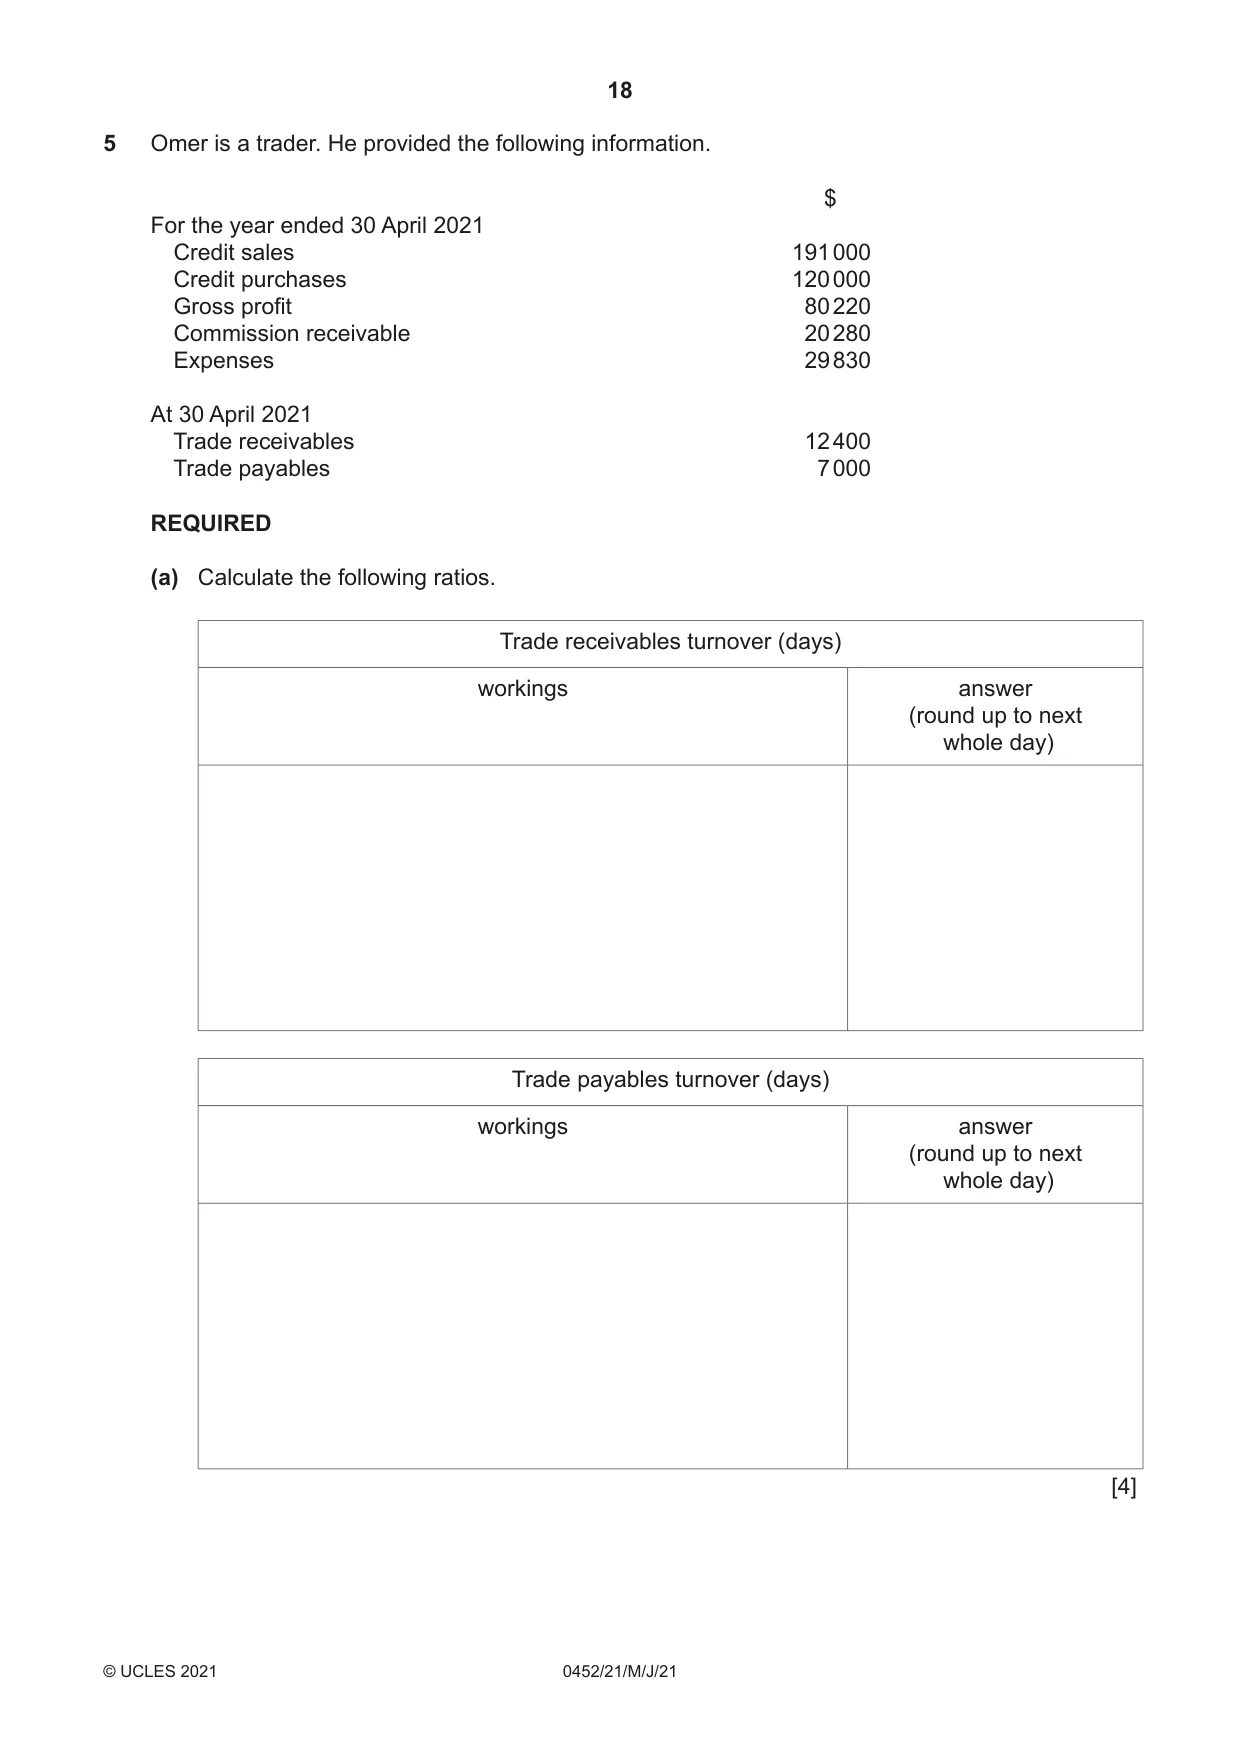
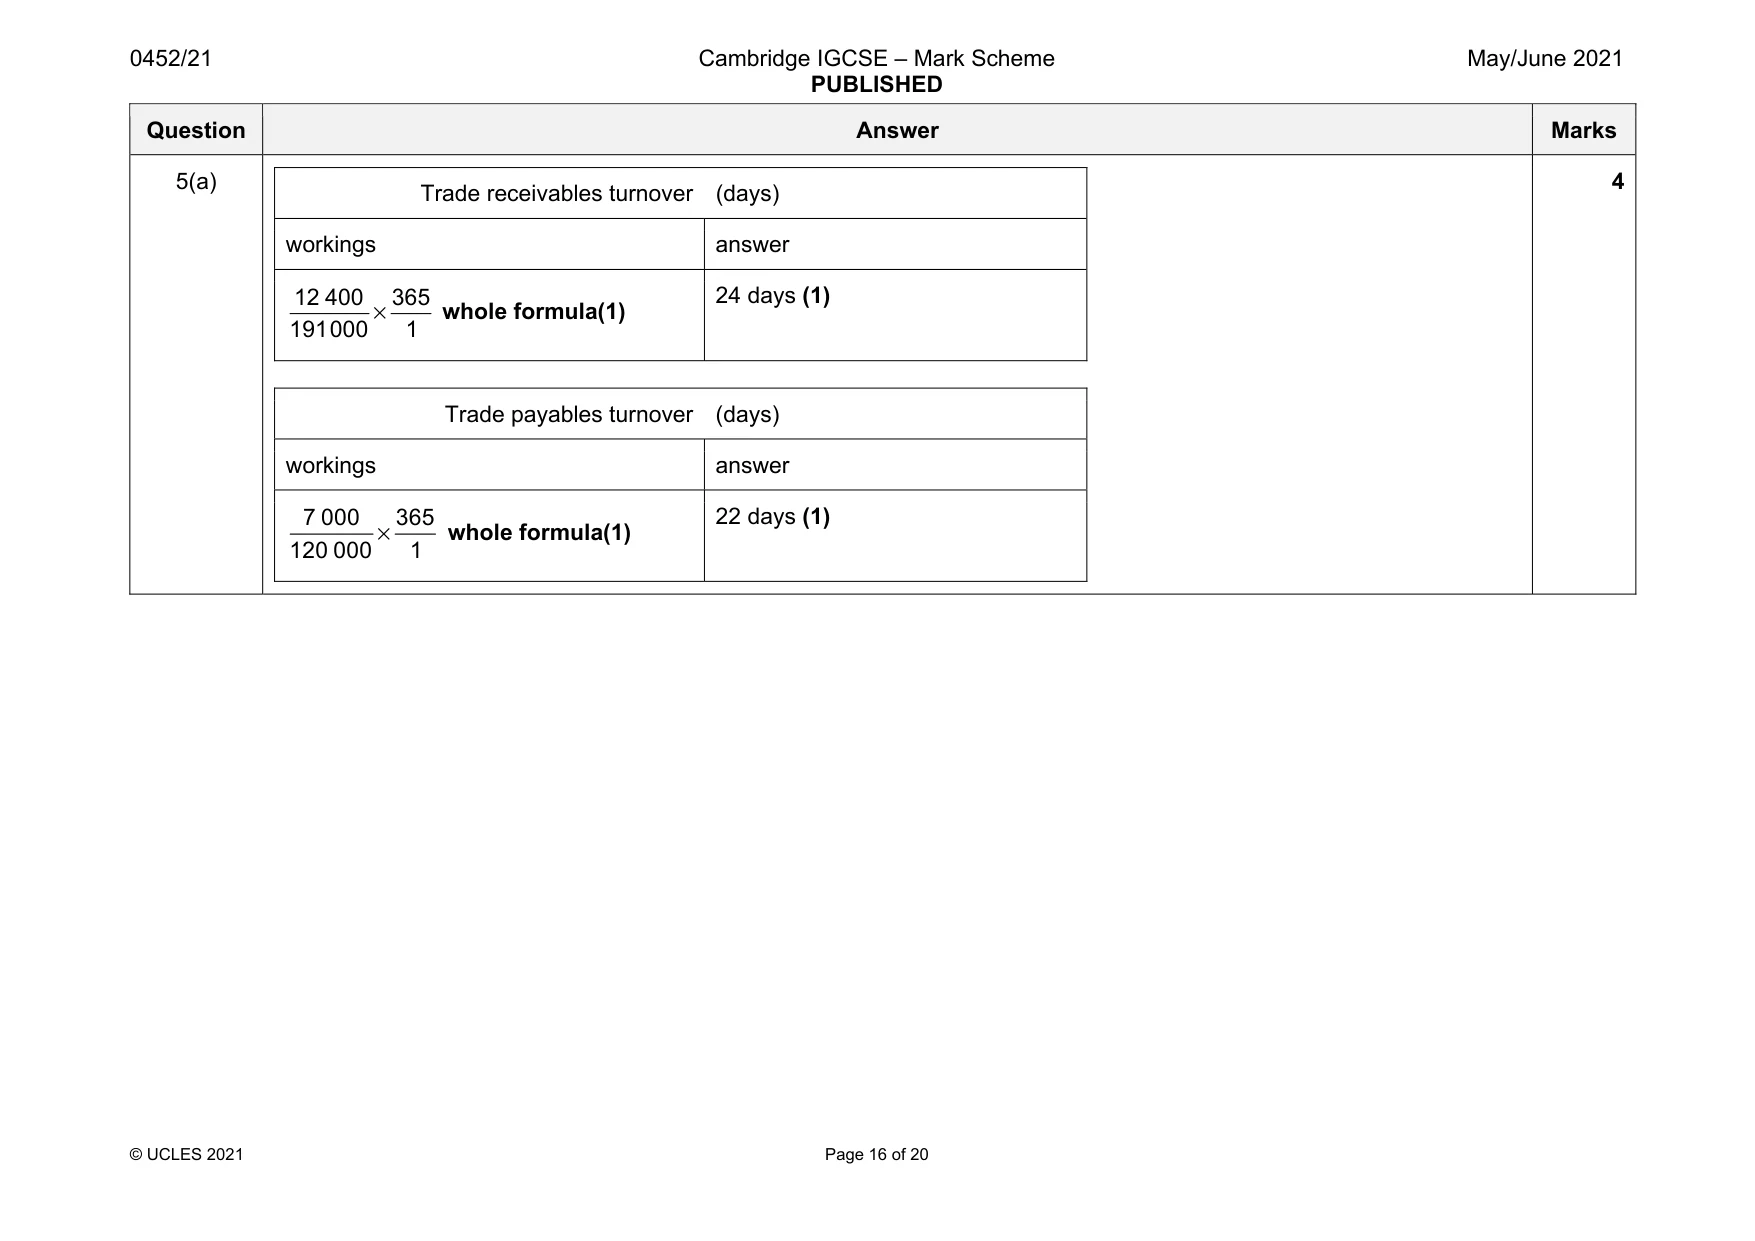
5 An invoice for office cleaning, $235, had been debited to the fixtures and equipment account. REQUIRED (b) Prepare the journal entry to correct each of the above errors. Narratives are not required. Neith Journal Error Details Debit Credit number $ $ ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... ............. .................................................................... ....................... ....................... [10] (c) Complete the table by placing a tick (3) to indicate the effect of correcting each error 2 to 5. Ignore depreciation of non-current assets. The effect of correcting error 1 has been shown as an example. Error number Increases Decreases No effect capital capital on capital 1 3 2 3 4 5 [4] [Total: 20] 5 Omer is a trader. He provided the following information. $ For the year ended 30 April 2021 Credit sales 191 000 Credit purchases 120 000 Gross profit 80 220 Commission receivable 20 280 Expenses 29 830 At 30 April 2021 Trade receivables 12 400 Trade payables 7 000 REQUIRED (a) Calculate the following ratios. Trade receivables turnover (days) workings answer (round up to next whole day) Trade payables turnover (days) workings answer (round up to next whole day) [4]
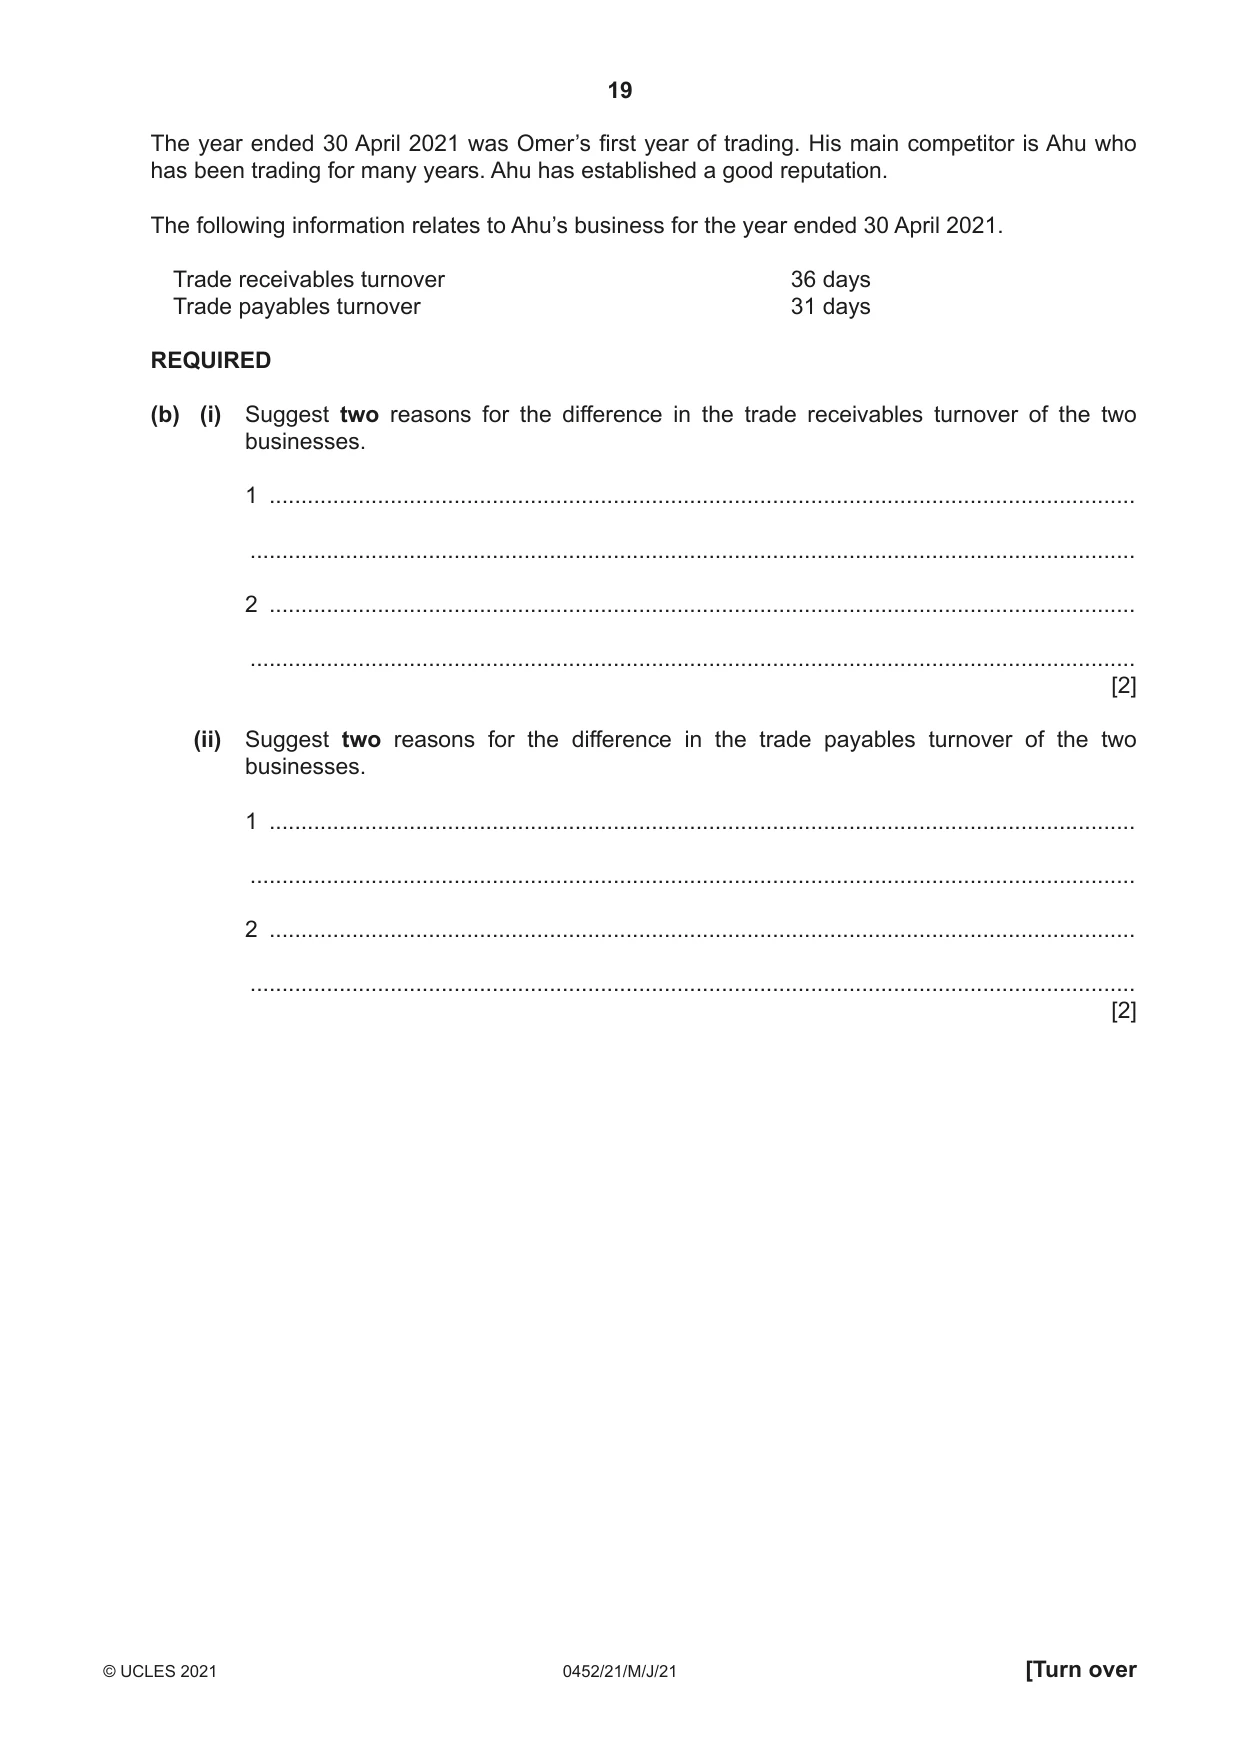
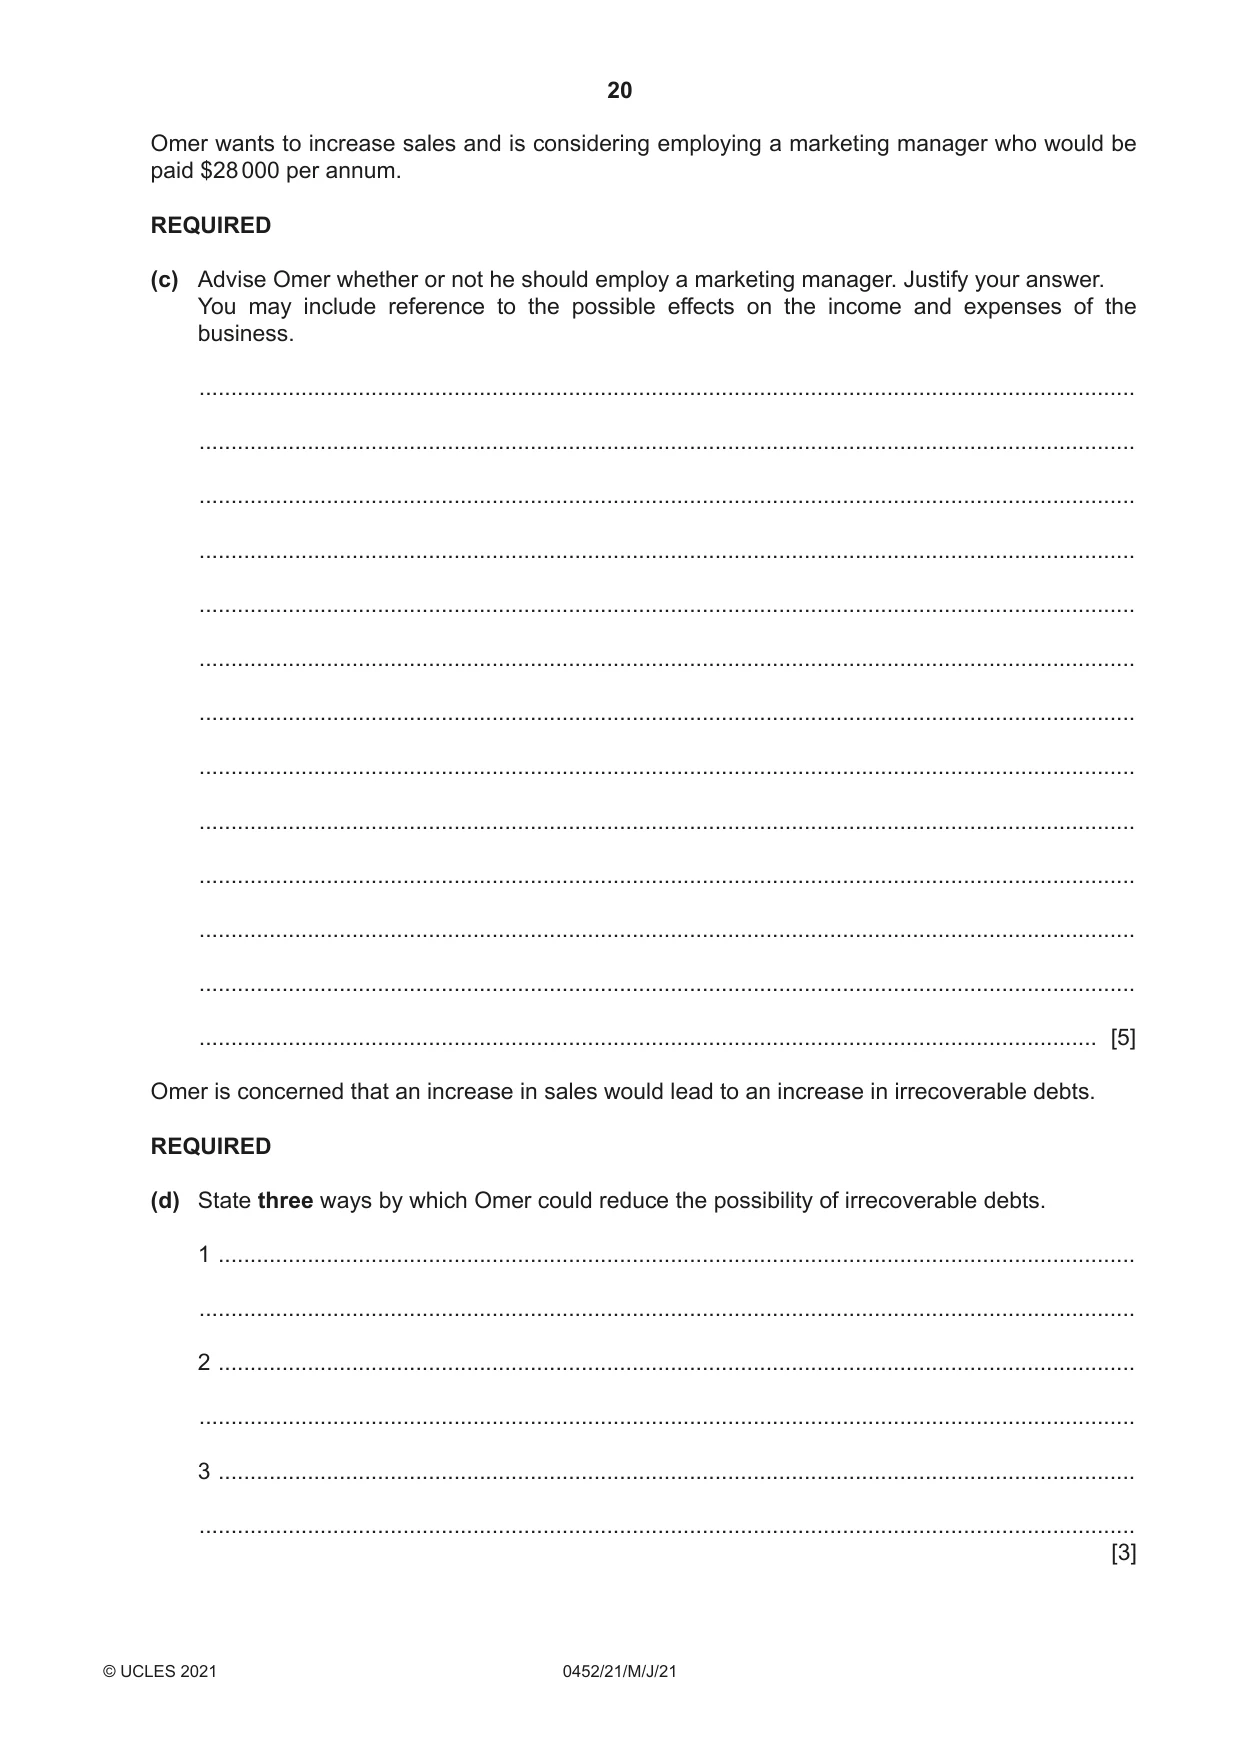
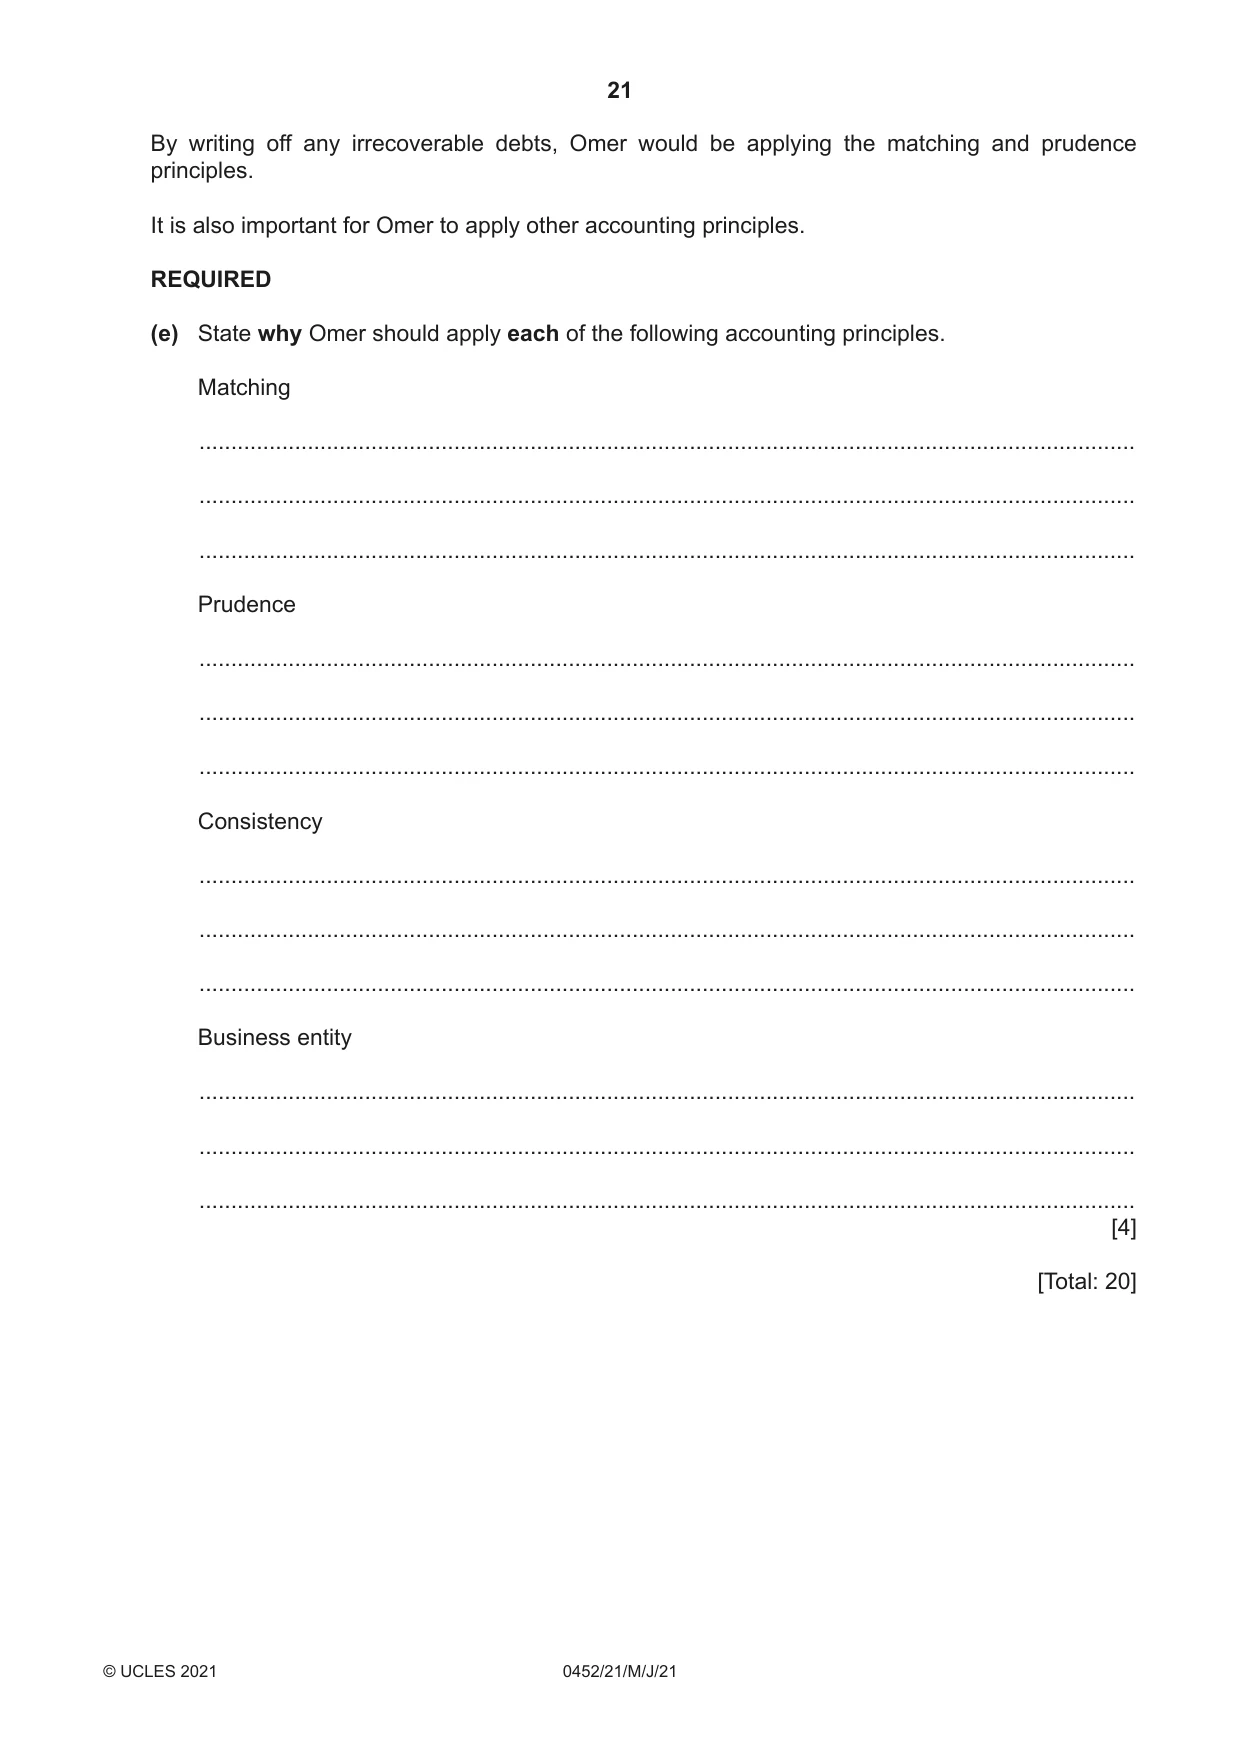
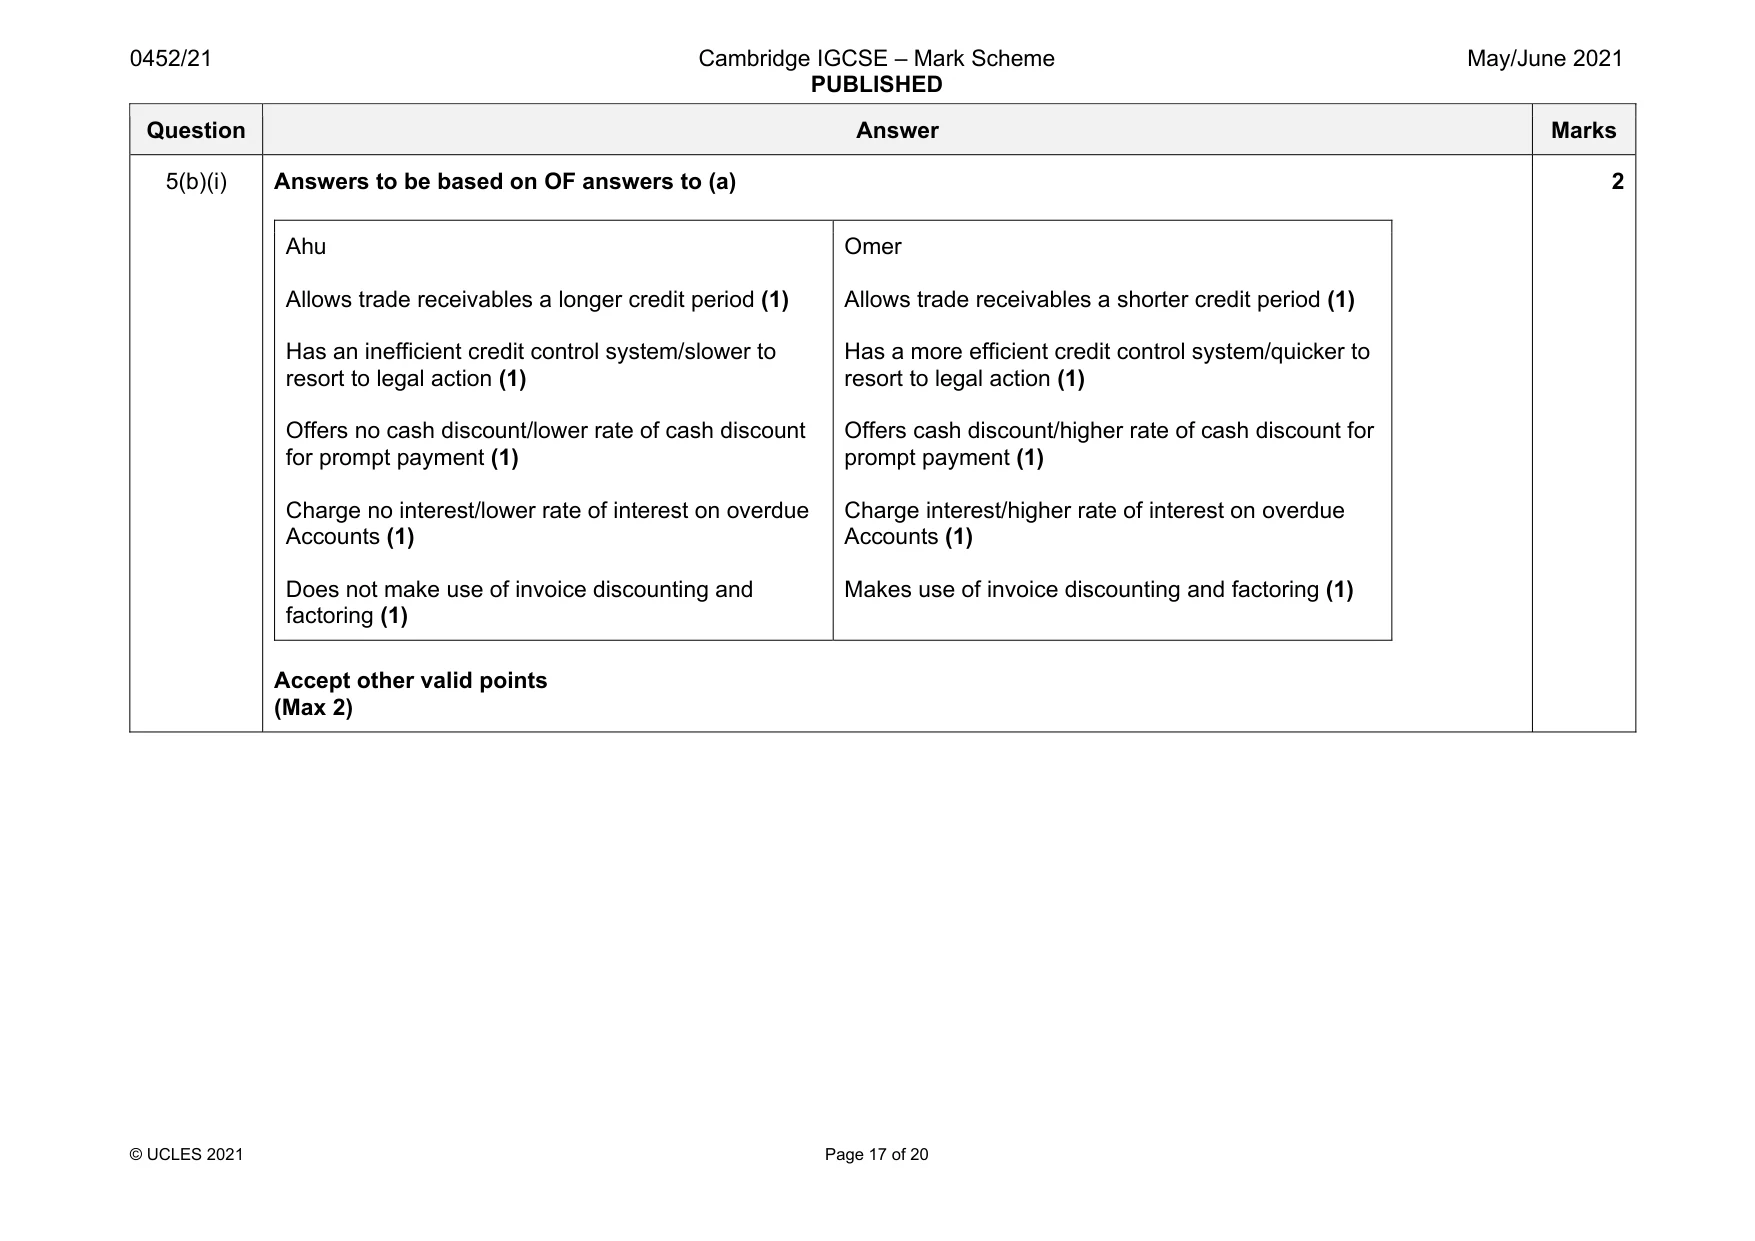
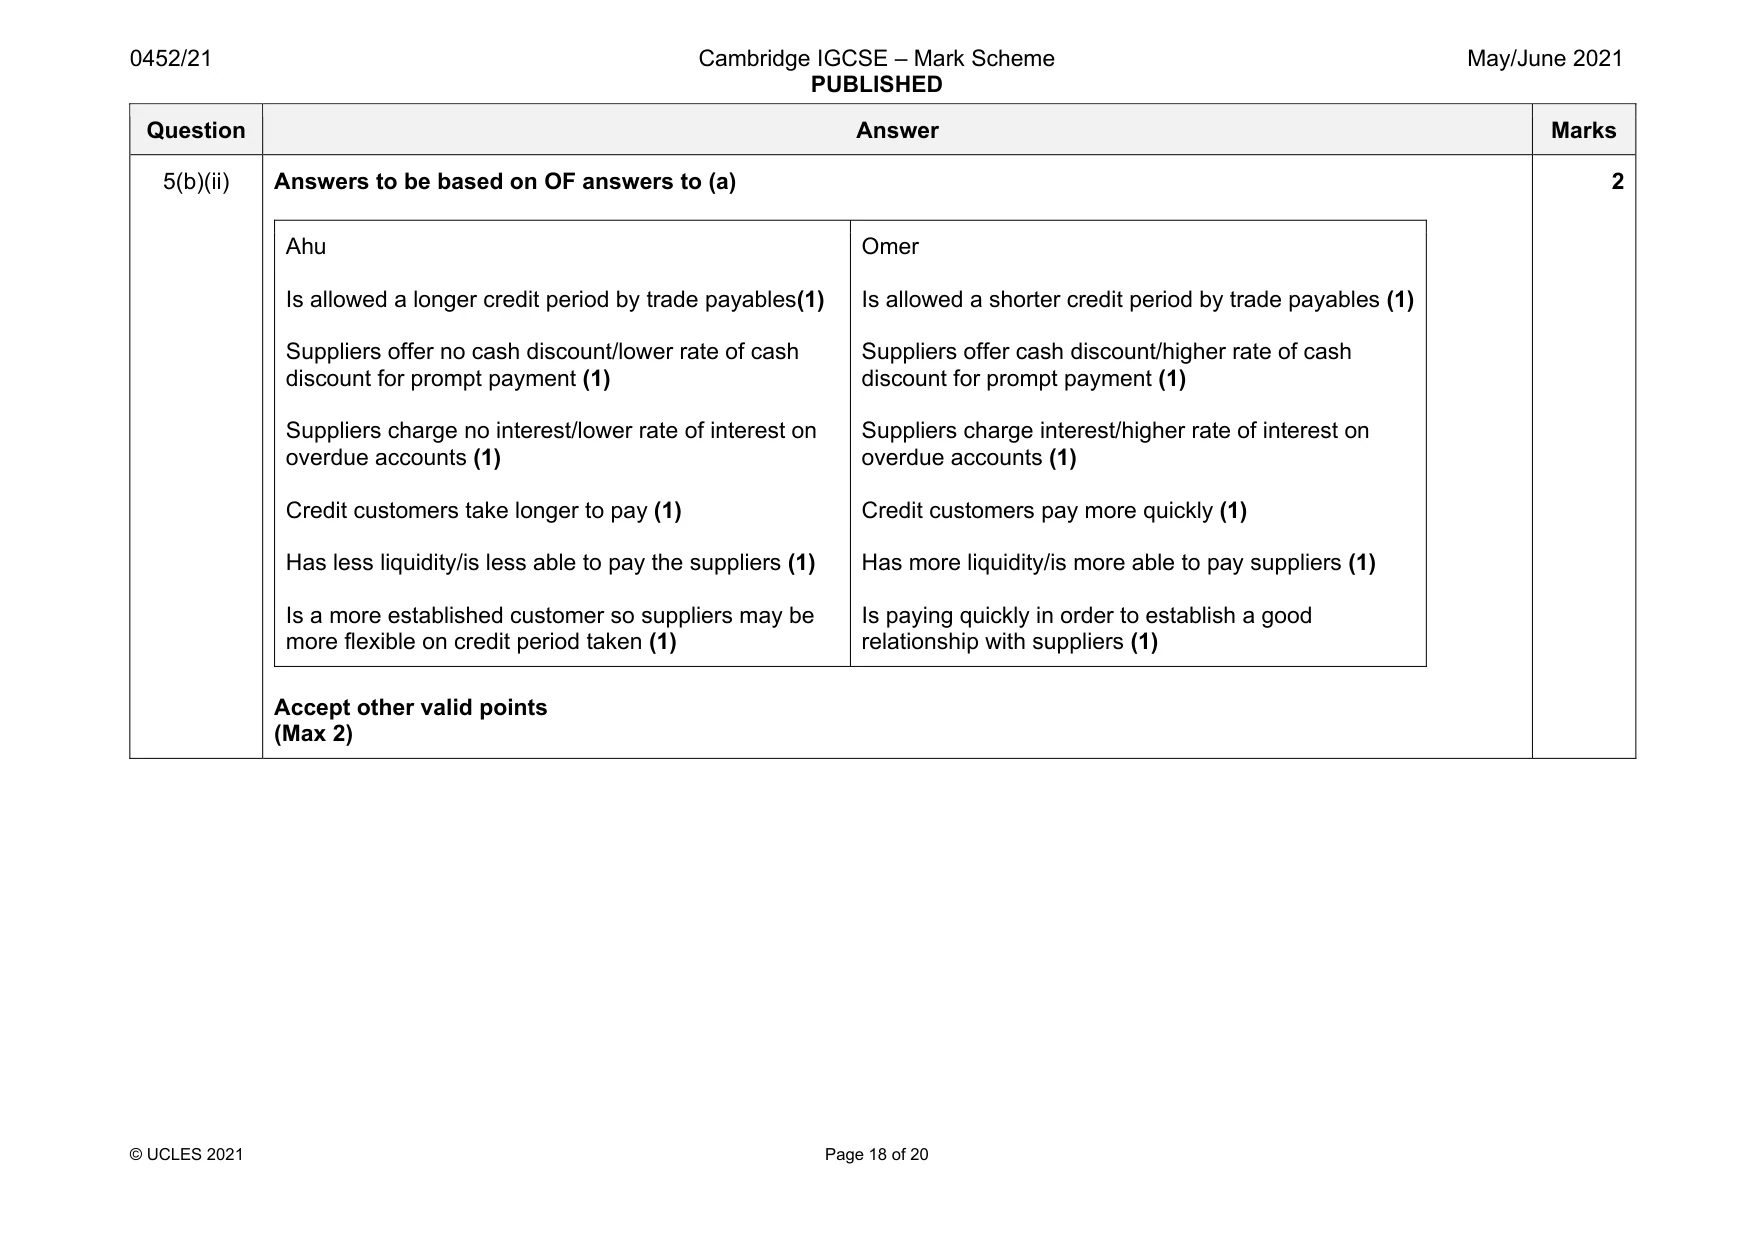
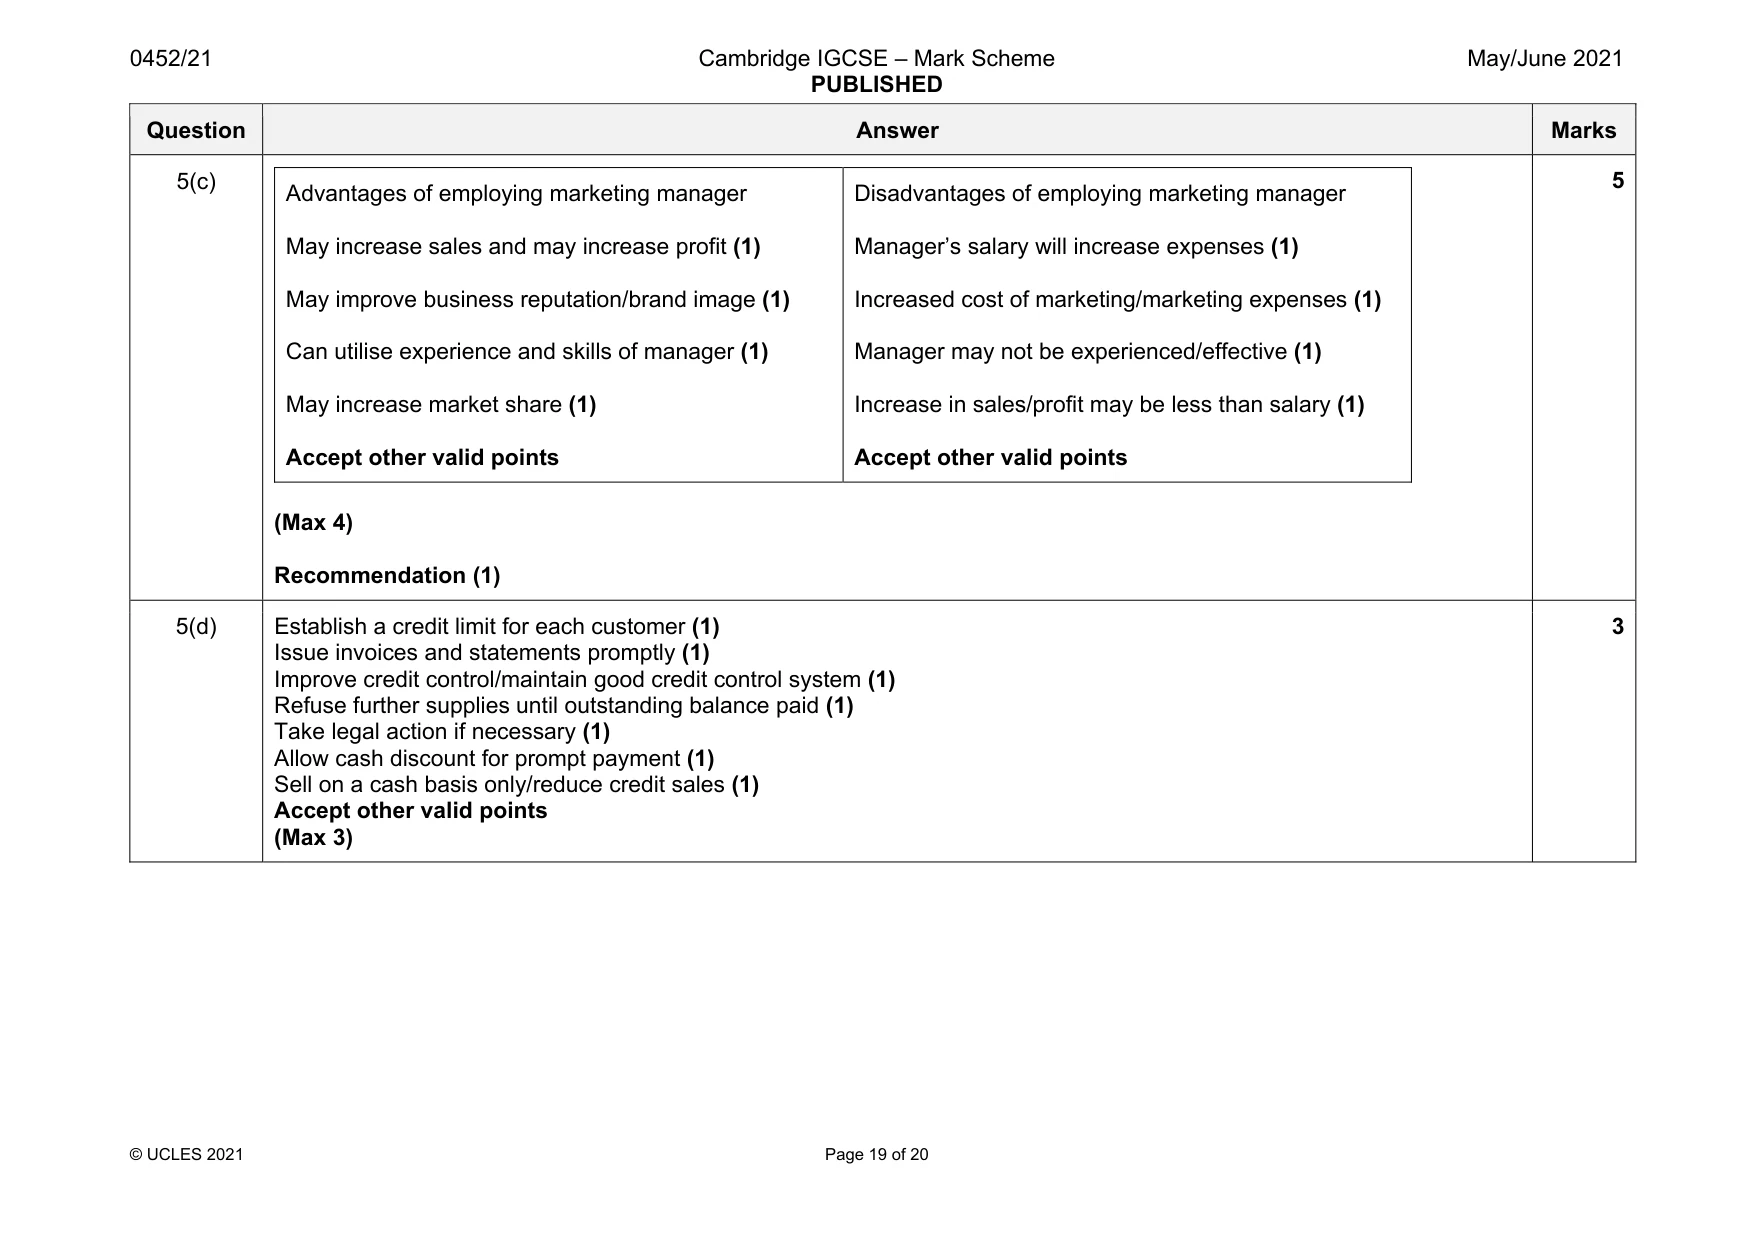
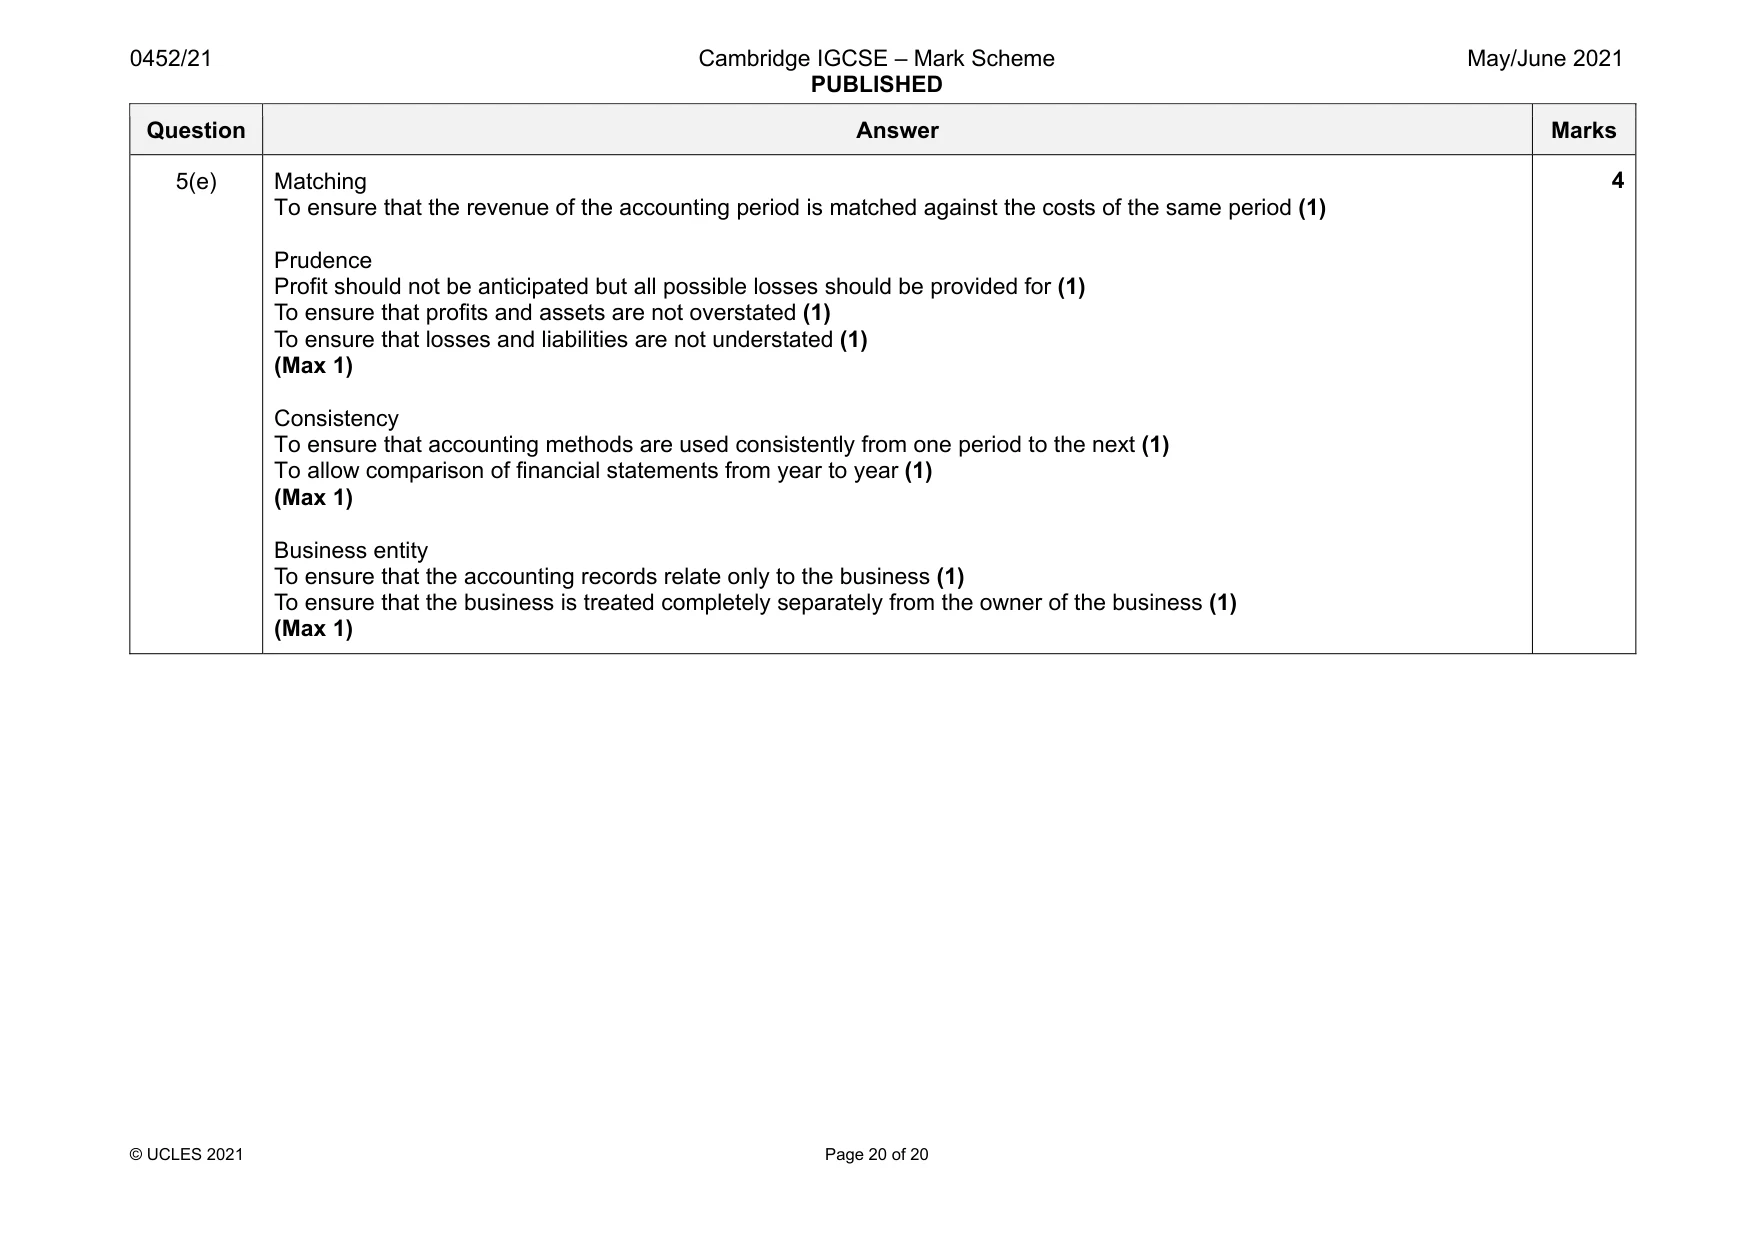
Mark scheme: 5(a) Trade receivables turnover (days) workings answer 12 400 365 191000 1 × whole formula(1) 24 days (1) Trade payables turnover (days) workings answer 7 000 365 120 000 1 × whole formula(1) 22 days (1) 4 Question Answer Marks 5(b)(i) Answers to be based on OF answers to (a) Ahu Allows trade receivables a longer credit period (1) Has an inefficient credit control system/slower to resort to legal action (1) Offers no cash discount/lower rate of cash discount for prompt payment (1) Charge no interest/lower rate of interest on overdue Accounts (1) Does not make use of invoice discounting and factoring (1) Omer Allows trade receivables a shorter credit period (1) Has a more efficient credit control system/quicker to resort to legal action (1) Offers cash discount/higher rate of cash discount for prompt payment (1) Charge interest/higher rate of interest on overdue Accounts (1) Makes use of invoice discounting and factoring (1) Accept other valid points (Max 2) 2 Question Answer Marks 5(b)(ii) Answers to be based on OF answers to (a) Ahu Is allowed a longer credit period by trade payables(1) Suppliers offer no cash discount/lower rate of cash discount for prompt payment (1) Suppliers charge no interest/lower rate of interest on overdue accounts (1) Credit customers take longer to pay (1) Has less liquidity/is less able to pay the suppliers (1) Is a more established customer so suppliers may be more flexible on credit period taken (1) Omer Is allowed a shorter credit period by trade payables (1) Suppliers offer cash discount/higher rate of cash discount for prompt payment (1) Suppliers charge interest/higher rate of interest on overdue accounts (1) Credit customers pay more quickly (1) Has more liquidity/is more able to pay suppliers (1) Is paying quickly in order to establish a good relationship with suppliers (1) Accept other valid points (Max 2) 2 Question Answer Marks 5(c) Advantages of employing marketing manager May increase sales and may increase profit (1) May improve business reputation/brand image (1) Can utilise experience and skills of manager (1) May increase market share (1) Accept other valid points Disadvantages of employing marketing manager Manager’s salary will increase expenses (1) Increased cost of marketing/marketing expenses (1) Manager may not be experienced/effective (1) Increase in sales/profit may be less than salary (1) Accept other valid points (Max 4) Recommendation (1) 5 5(d) Establish a credit limit for each customer (1) Issue invoices and statements promptly (1) Improve credit control/maintain good credit control system (1) Refuse further supplies until outstanding balance paid (1) Take legal action if necessary (1) Allow cash discount for prompt payment (1) Sell on a cash basis only/reduce credit sales (1) Accept other valid points (Max 3) 3 Question Answer Marks 5(e) Matching To ensure that the revenue of the accounting period is matched against the costs of the same period (1) Prudence Profit should not be anticipated but all possible losses should be provided for (1) To ensure that profits and assets are not overstated (1) To ensure that losses and liabilities are not understated (1) (Max 1) Consistency To ensure that accounting methods are used consistently from one period to the next (1) To allow comparison of financial statements from year to year (1) (Max 1) Business entity To ensure that the accounting records relate only to the business (1) To ensure that the business is treated completely separately from the owner of the business (1) (Max 1) 4
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.