Cambridge IGCSE Accounting 0452 — 2021 Feb/March Paper 2 · Variant 2
0452/22/F/M/21 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme23 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Shilpa is a trader
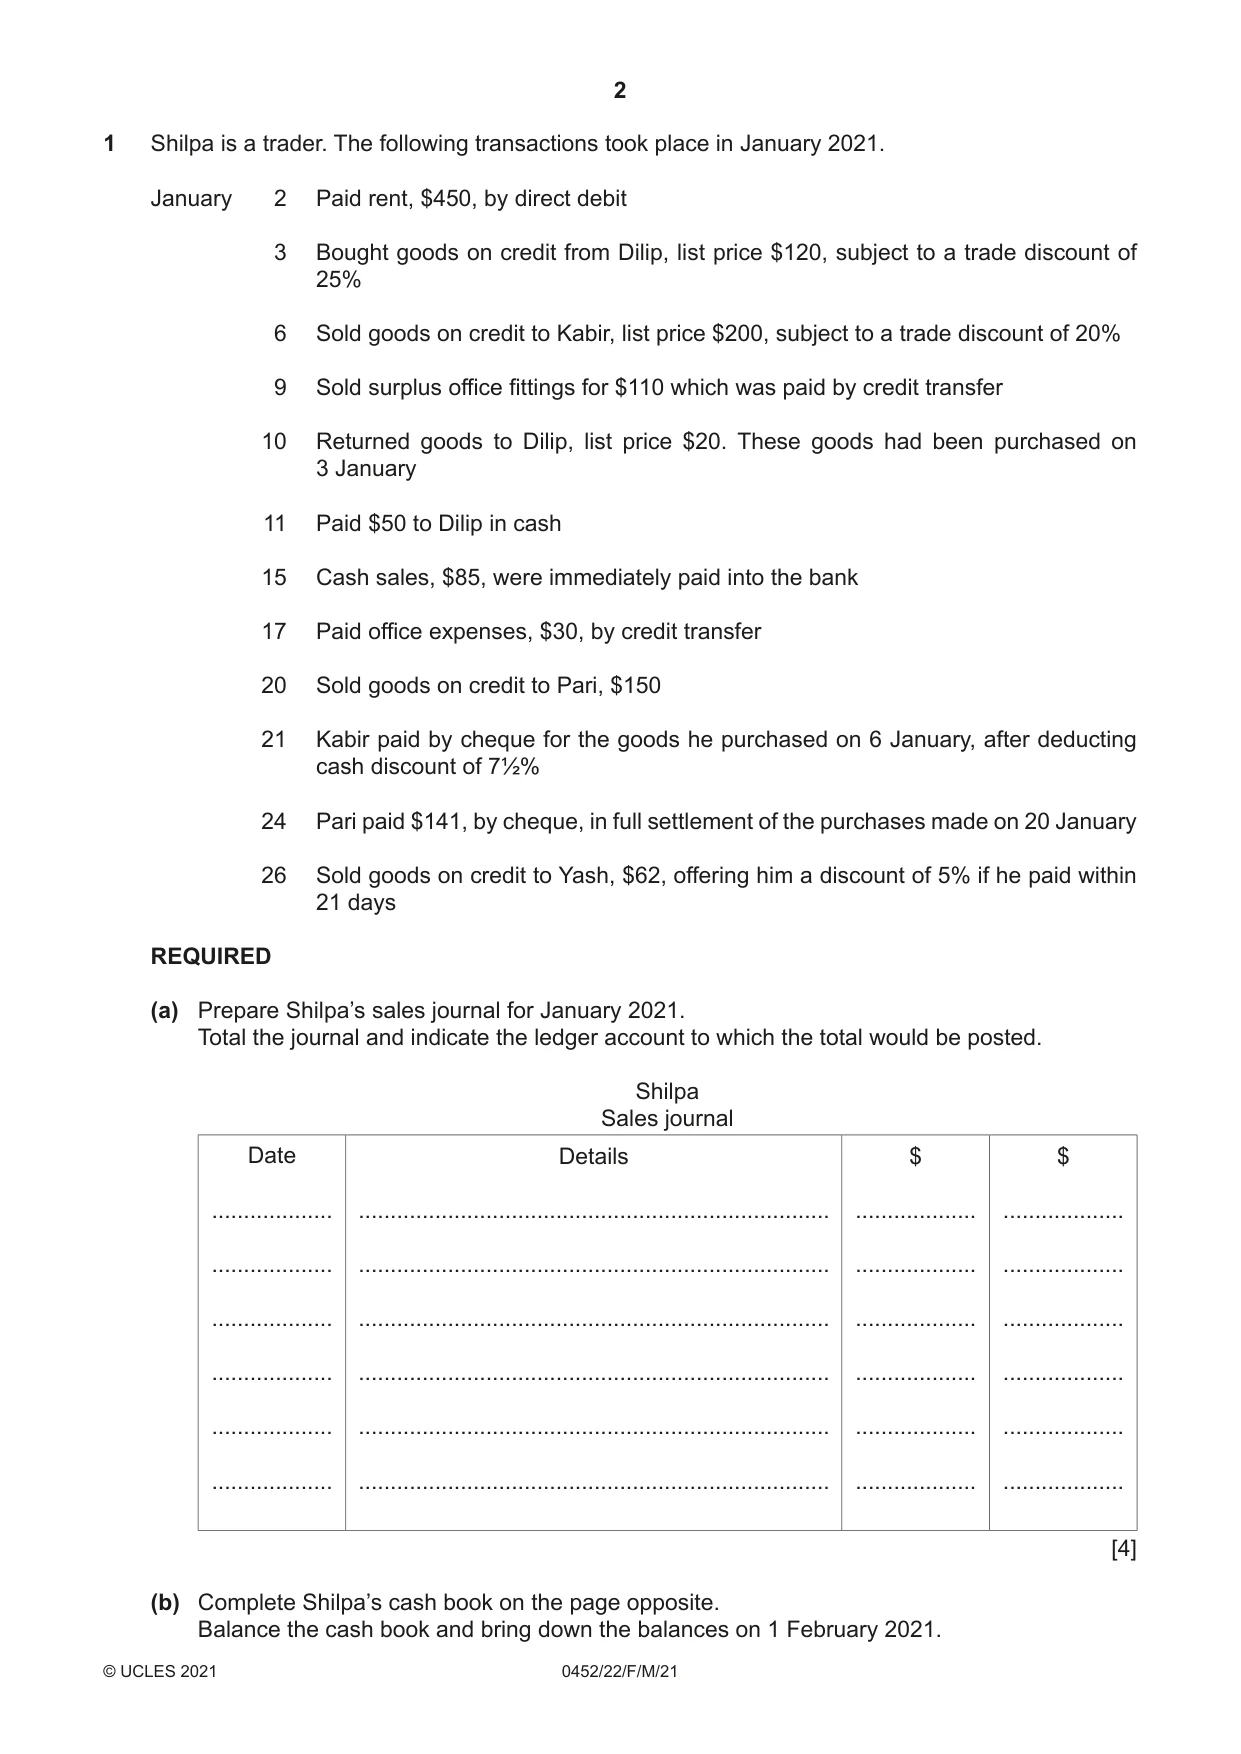
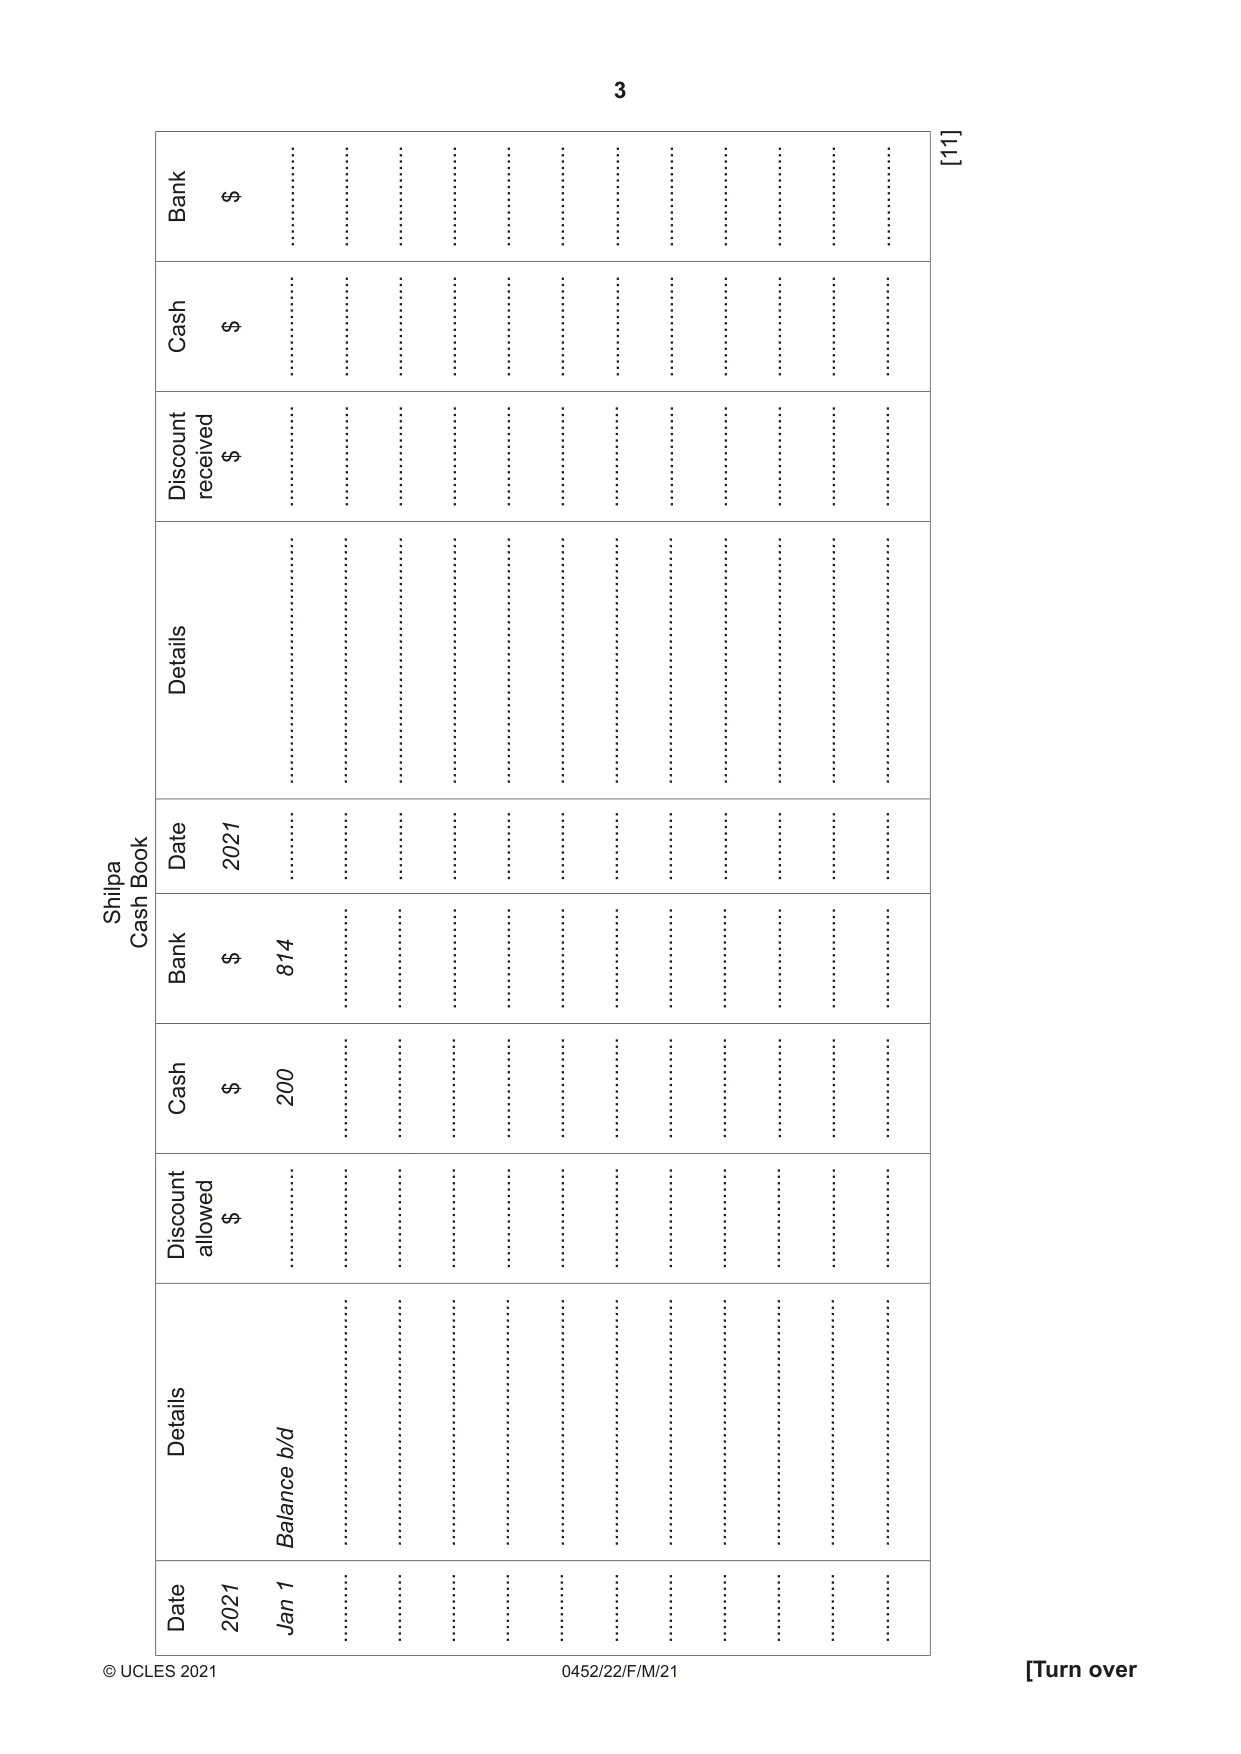
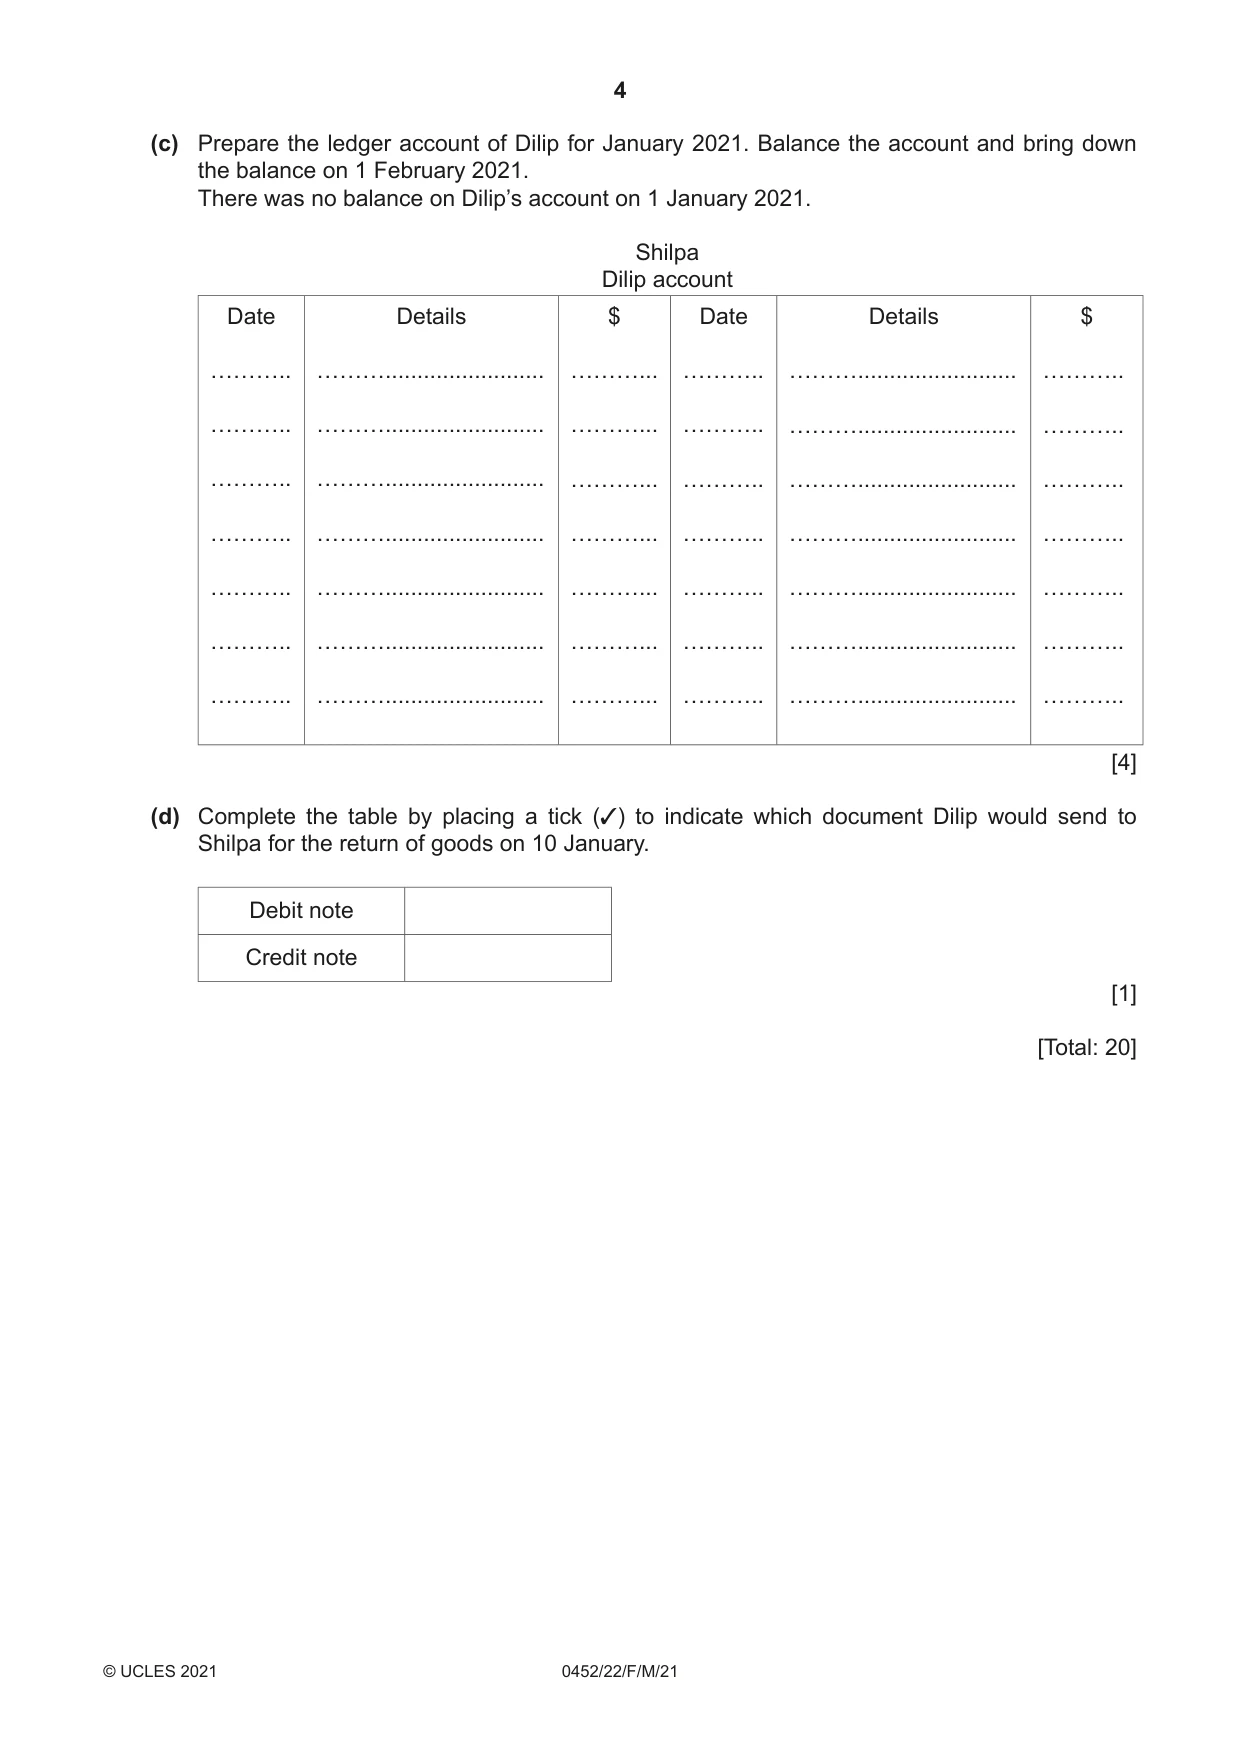
1 Shilpa is a trader. The following transactions took place in January 2021. January 2 Paid rent, $450, by direct debit 3 Bought goods on credit from Dilip, list price $120, subject to a trade discount of 25% 6 Sold goods on credit to Kabir, list price $200, subject to a trade discount of 20% 9 Sold surplus office fittings for $110 which was paid by credit transfer 10 Returned goods to Dilip, list price $20. These goods had been purchased on 3 January 11 Paid $50 to Dilip in cash 15 Cash sales, $85, were immediately paid into the bank 17 Paid office expenses, $30, by credit transfer 20 Sold goods on credit to Pari, $150 21 Kabir paid by cheque for the goods he purchased on 6 January, after deducting cash discount of 7½% 24 Pari paid $141, by cheque, in full settlement of the purchases made on 20 January 26 Sold goods on credit to Yash, $62, offering him a discount of 5% if he paid within 21 days REQUIRED (a) Prepare Shilpa’s sales journal for January 2021. Total the journal and indicate the ledger account to which the total would be posted. Shilpa Sales journal Date Details $ $ ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... [4] (b) Complete Shilpa’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 February 2021. [11] $ Bank ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Cash ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Discountreceived ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ Details ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... Date 2021 ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... Book Shilpa Cash $ 814 Bank ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ 200 Cash ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Discountallowed ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ Details b/d Balance ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... ....................................... (c) Prepare the ledger account of Dilip for January 2021. Balance the account and bring down the balance on 1 February 2021. There was no balance on Dilip’s account on 1 January 2021. Shilpa Dilip account Date Details $ Date Details $ ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. ……….. ………......................... ………... ……….. ………......................... ……….. [4] (d) Complete the table by placing a tick (3) to indicate which document Dilip would send to Shilpa for the return of goods on 10 January. Debit note Credit note [1] [Total: 20]
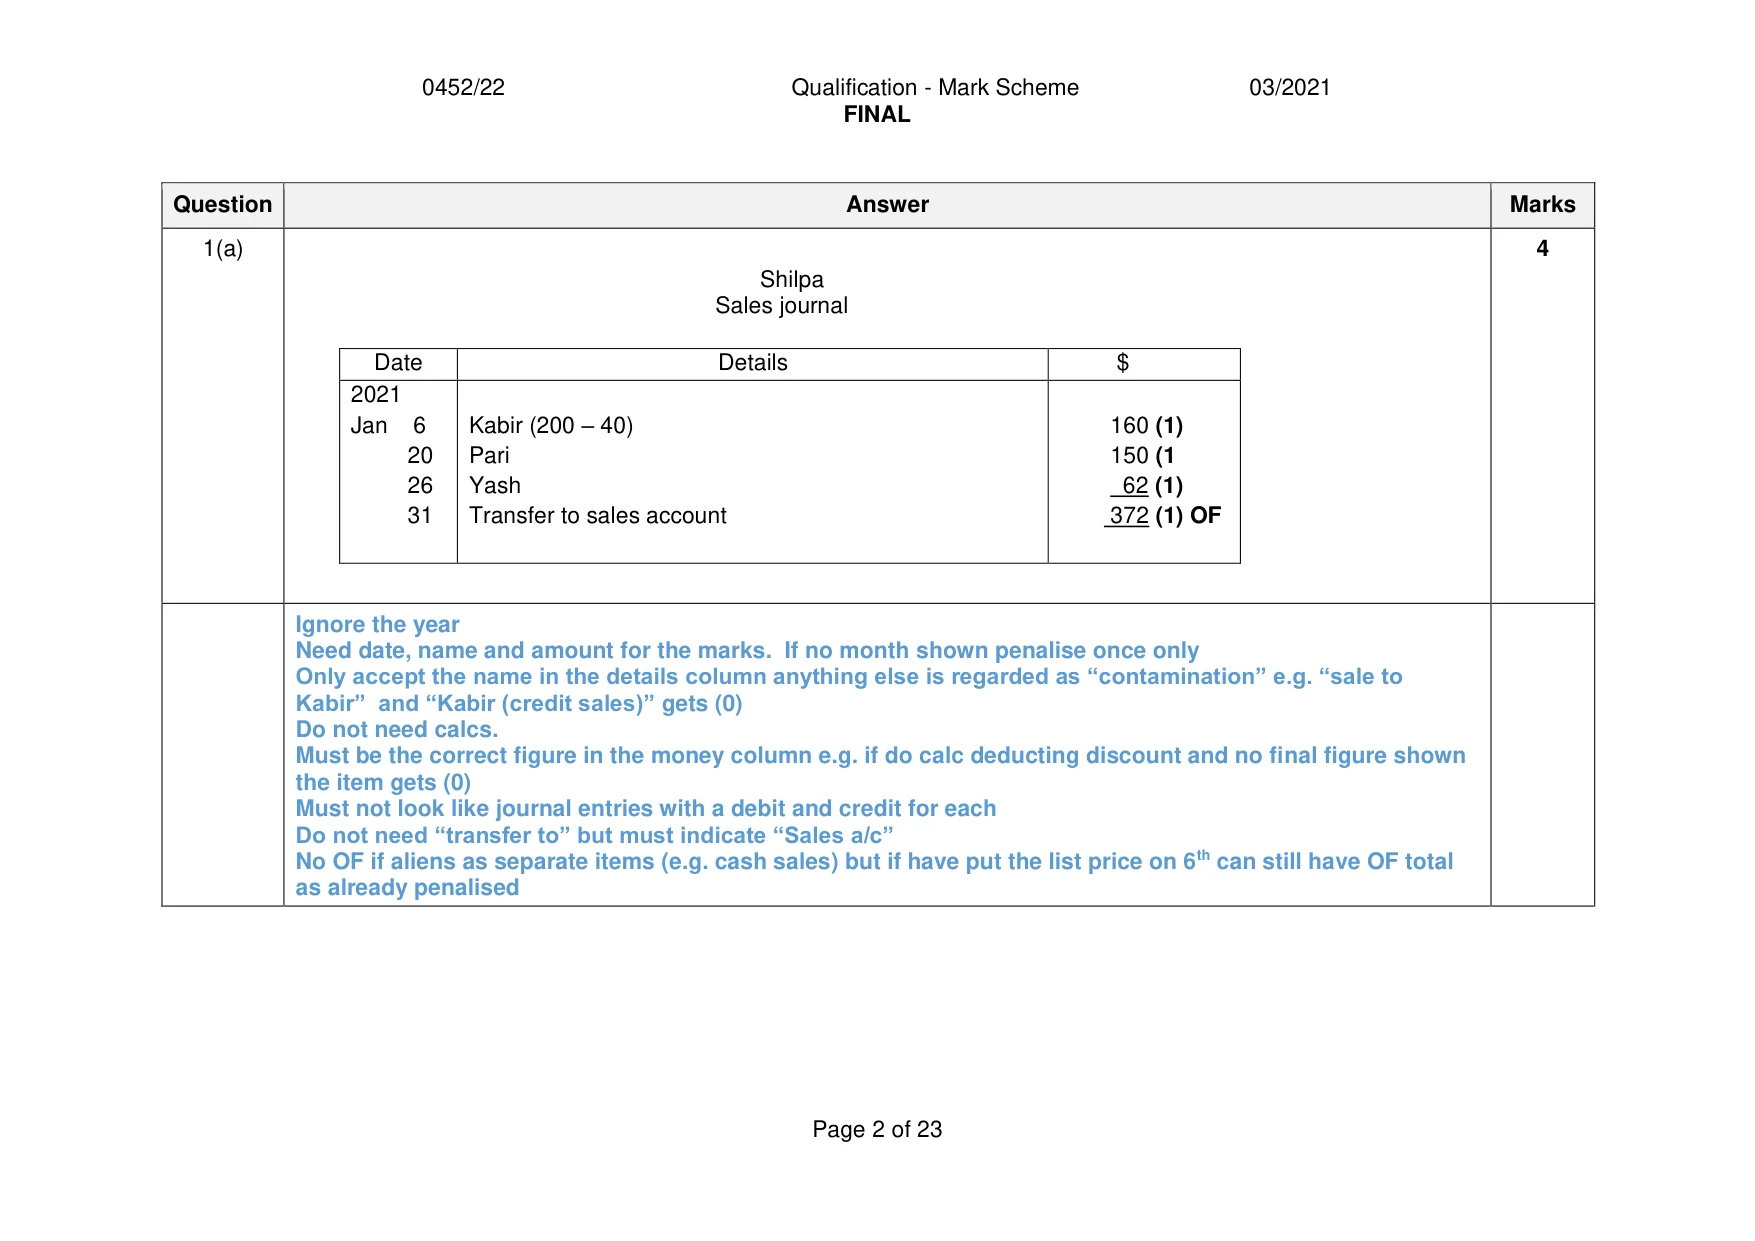
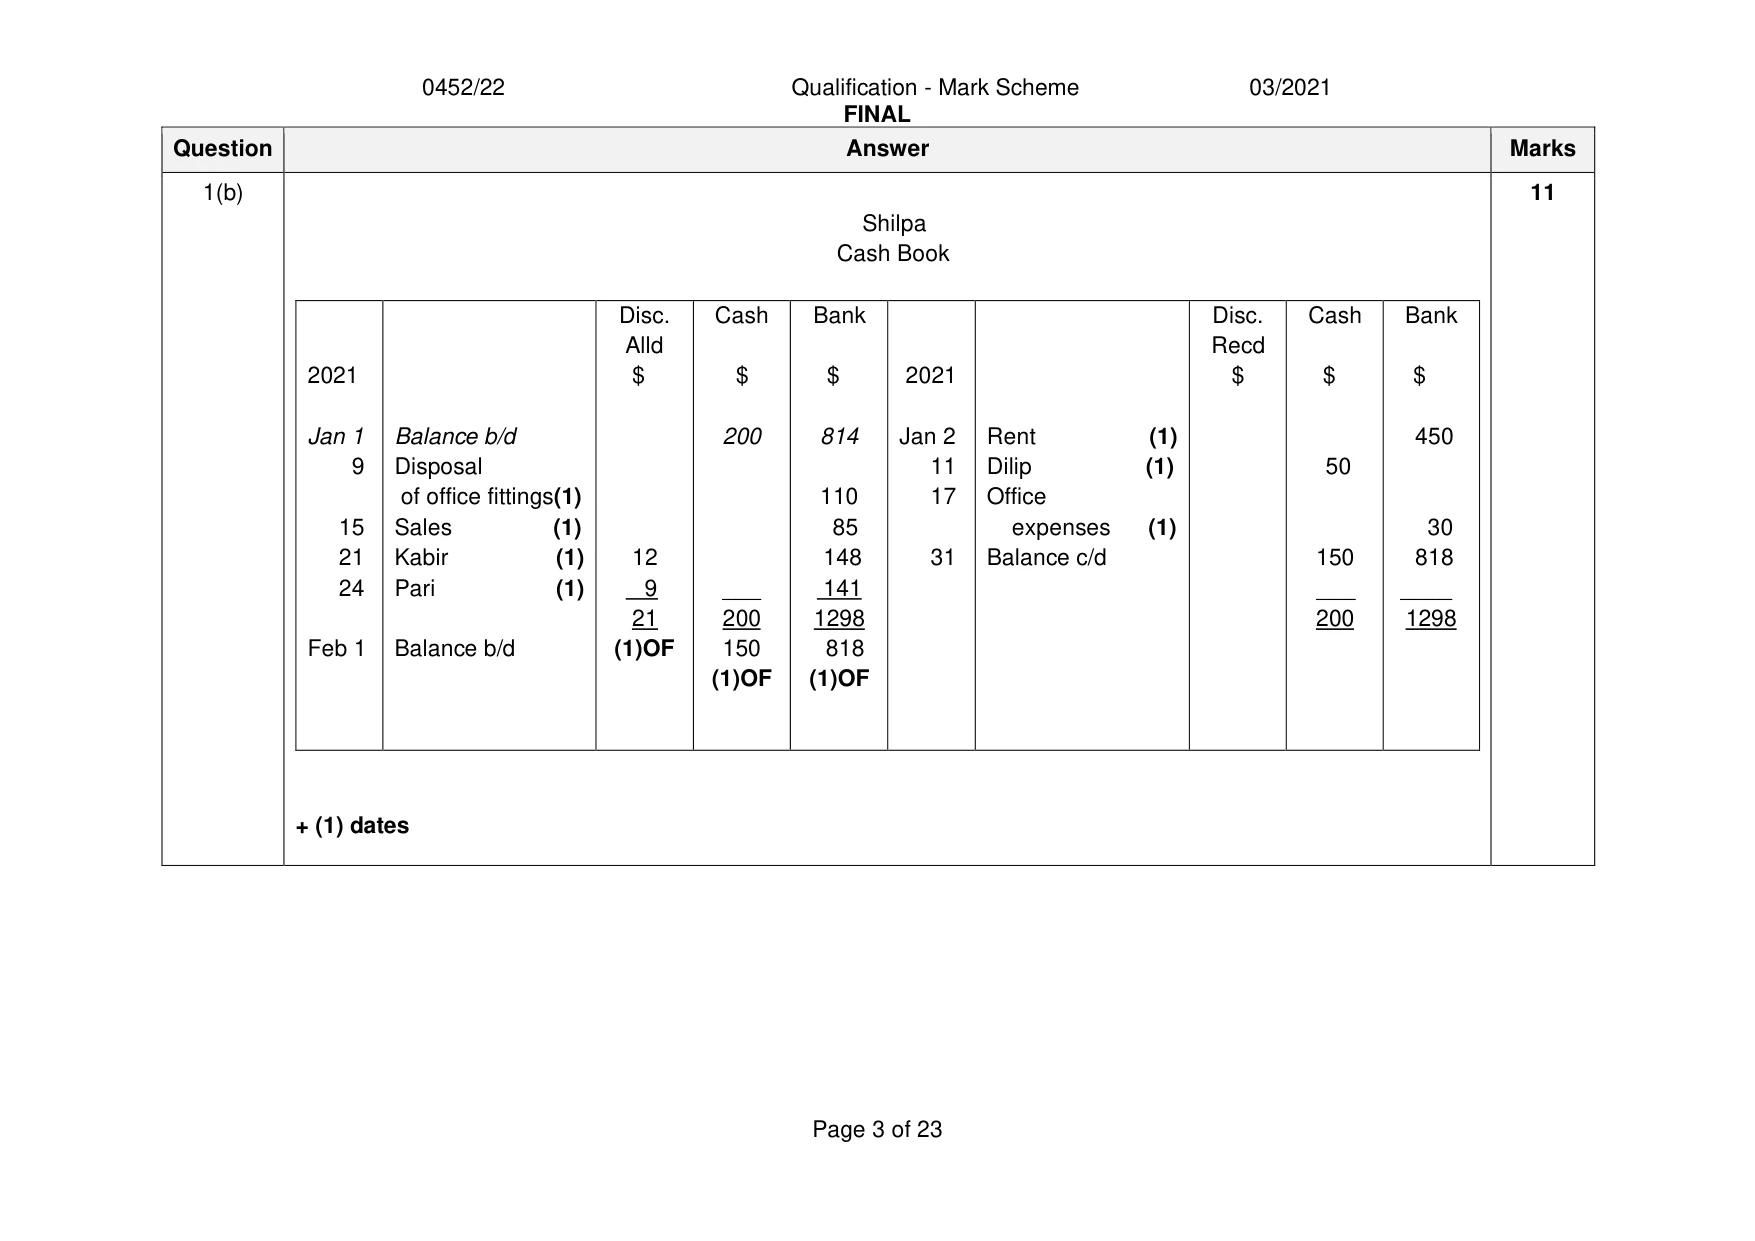
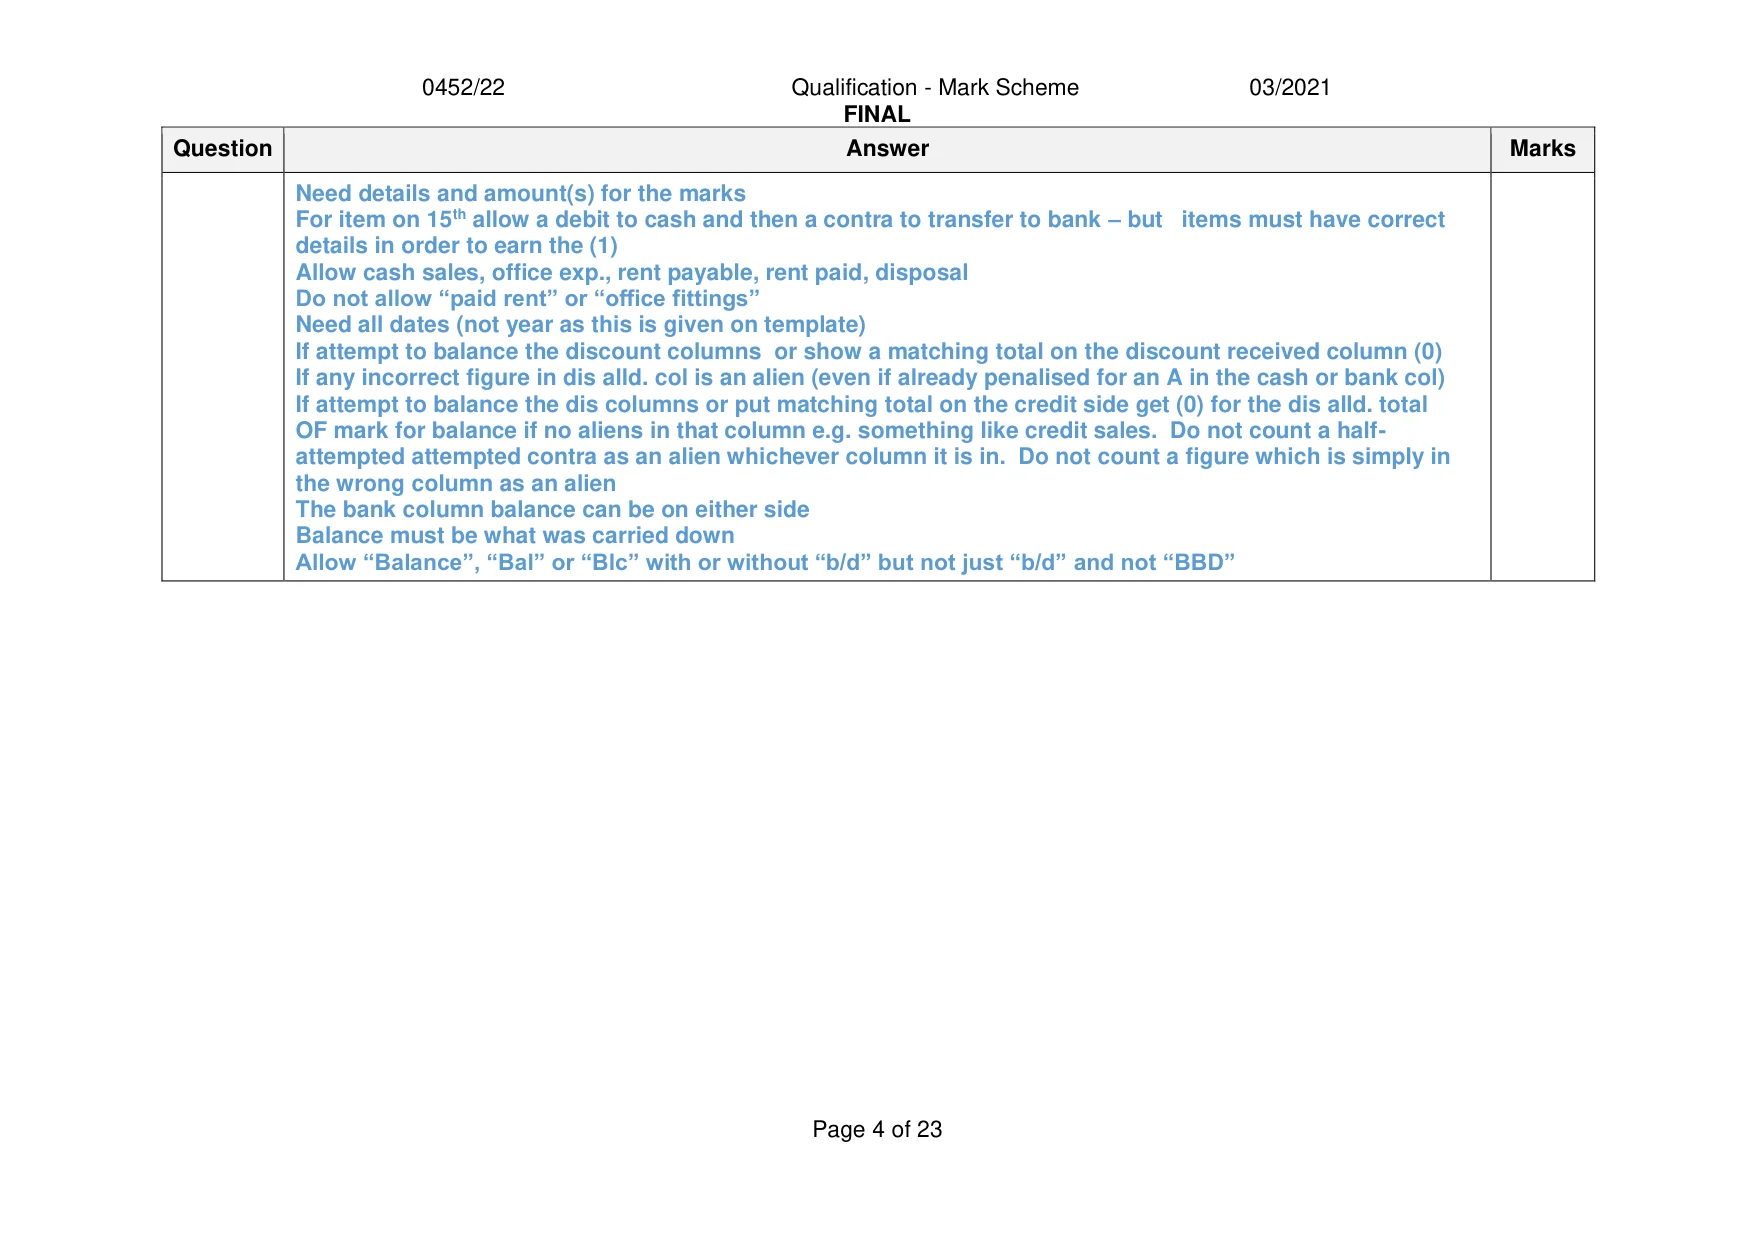
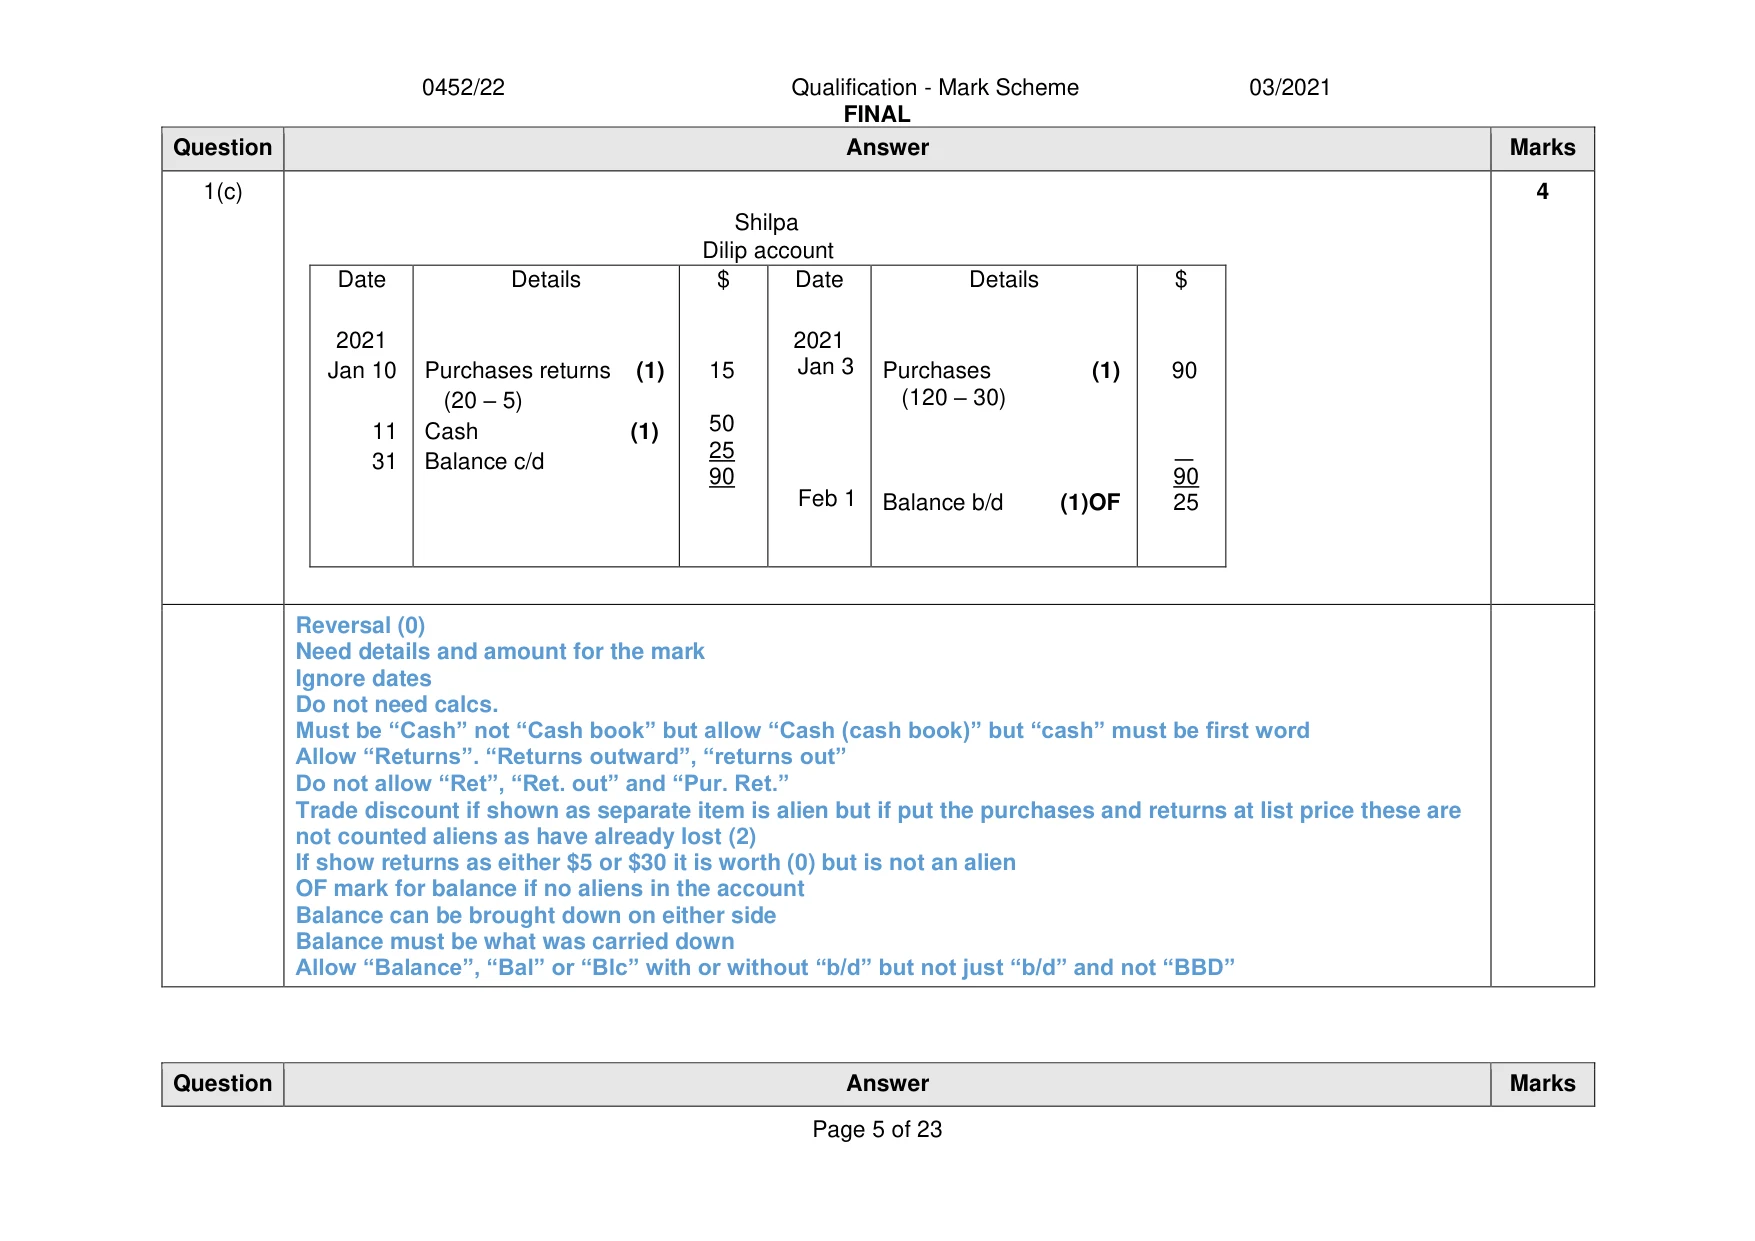
Mark scheme: Question Answer Marks 1(a) 4 Shilpa Sales journal Date Details $ 2021 Jan 6 Kabir (200 – 40) 160 (1) 20 Pari 150 (1 26 Yash 62 (1) 31 Transfer to sales account 372 (1) OF Ignore the year Need date, name and amount for the marks. If no month shown penalise once only Only accept the name in the details column anything else is regarded as “contamination” e.g. “sale to Kabir” and “Kabir (credit sales)” gets (0) Do not need calcs. Must be the correct figure in the money column e.g. if do calc deducting discount and no final figure shown the item gets (0) Must not look like journal entries with a debit and credit for each Do not need “transfer to” but must indicate “Sales a/c” No OF if aliens as separate items (e.g. cash sales) but if have put the list price on 6th can still have OF total as already penalised 1(b) 11 Shilpa Cash Book Disc. Cash Bank Disc. Cash Bank Alld Recd 2021 $ $ $ 2021 $ $ $ Jan 1 Balance b/d 200 814 Jan 2 Rent (1) 450 9 Disposal 11 Dilip (1) 50 of office fittings(1) 110 17 Office 15 Sales (1) 85 expenses (1) 30 21 Kabir (1) 12 148 31 Balance c/d 150 818 24 Pari (1) 9 ___ 141 ___ ____ 21 200 1298 200 1298 Feb 1 Balance b/d (1)OF 150 818 (1)OF (1)OF + (1) dates Need details and amount(s) for the marks For item on 15th allow a debit to cash and then a contra to transfer to bank – but items must have correct details in order to earn the (1) Allow cash sales, office exp., rent payable, rent paid, disposal Do not allow “paid rent” or “office fittings” Need all dates (not year as this is given on template) If attempt to balance the discount columns or show a matching total on the discount received column (0) If any incorrect figure in dis alld. col is an alien (even if already penalised for an A in the cash or bank col) If attempt to balance the dis columns or put matching total on the credit side get (0) for the dis alld. total OF mark for balance if no aliens in that column e.g. something like credit sales. Do not count a half- attempted attempted contra as an alien whichever column it is in. Do not count a figure which is simply in the wrong column as an alien The bank column balance can be on either side Balance must be what was carried down Allow “Balance”, “Bal” or “Blc” with or without “b/d” but not just “b/d” and not “BBD” 1(c) 4 Shilpa Dilip account Date Details $ Date Details $ 2021 2021 Jan 10 Purchases returns (1) 15 Jan 3 Purchases (1) 90 (20 – 5) (120 – 30) 50 11 Cash (1) 25 31 Balance c/d 90 90 Feb 1 Balance b/d (1)OF 25 Reversal (0) Need details and amount for the mark Ignore dates Do not need calcs. Must be “Cash” not “Cash book” but allow “Cash (cash book)” but “cash” must be first word Allow “Returns”. “Returns outward”, “returns out” Do not allow “Ret”, “Ret. out” and “Pur. Ret.” Trade discount if shown as separate item is alien but if put the purchases and returns at list price these are not counted aliens as have already lost (2) If show returns as either $5 or $30 it is worth (0) but is not an alien OF mark for balance if no aliens in the account Balance can be brought down on either side Balance must be what was carried down Allow “Balance”, “Bal” or “Blc” with or without “b/d” but not just “b/d” and not “BBD” Question Answer Marks FINAL 1(d) 1 Debit note Credit note ✓(1)
Q2 · Zamir is in business providing legal services
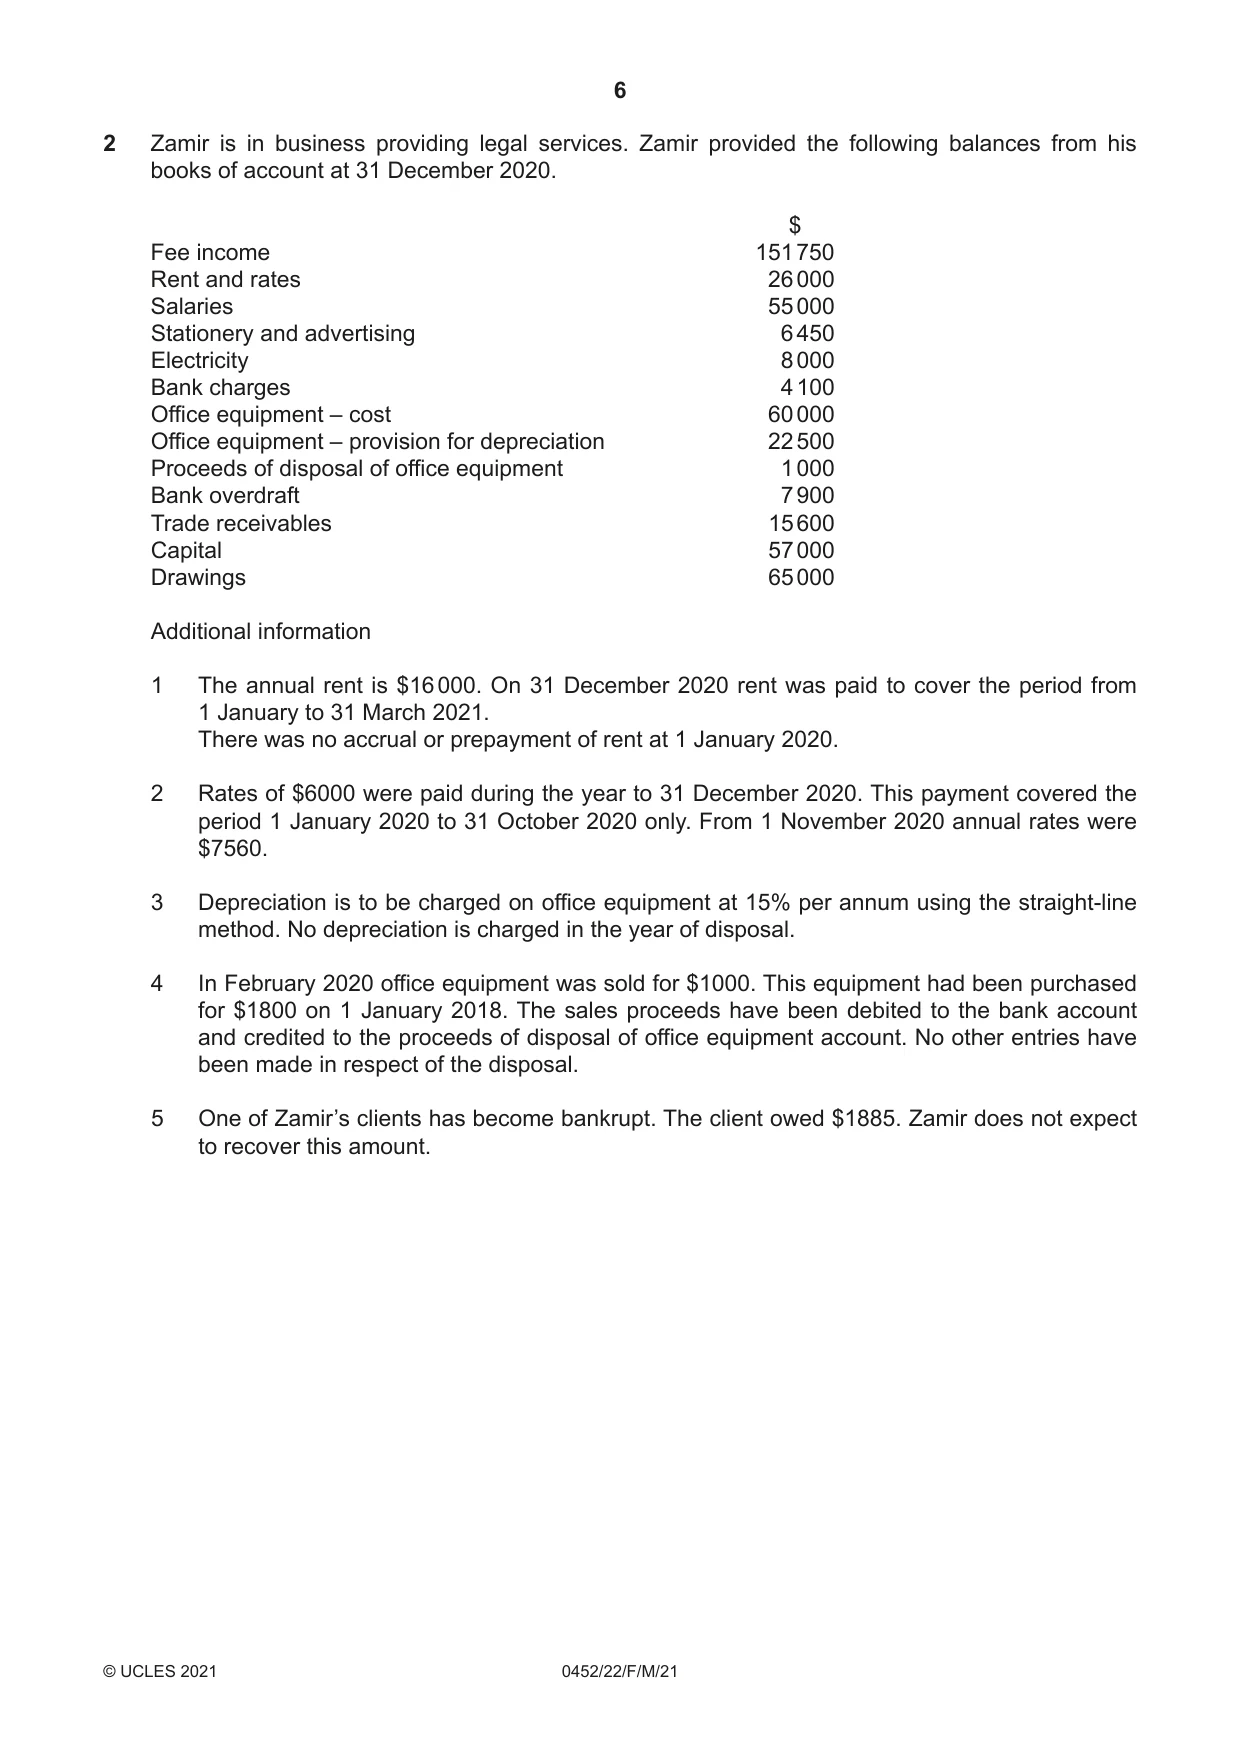
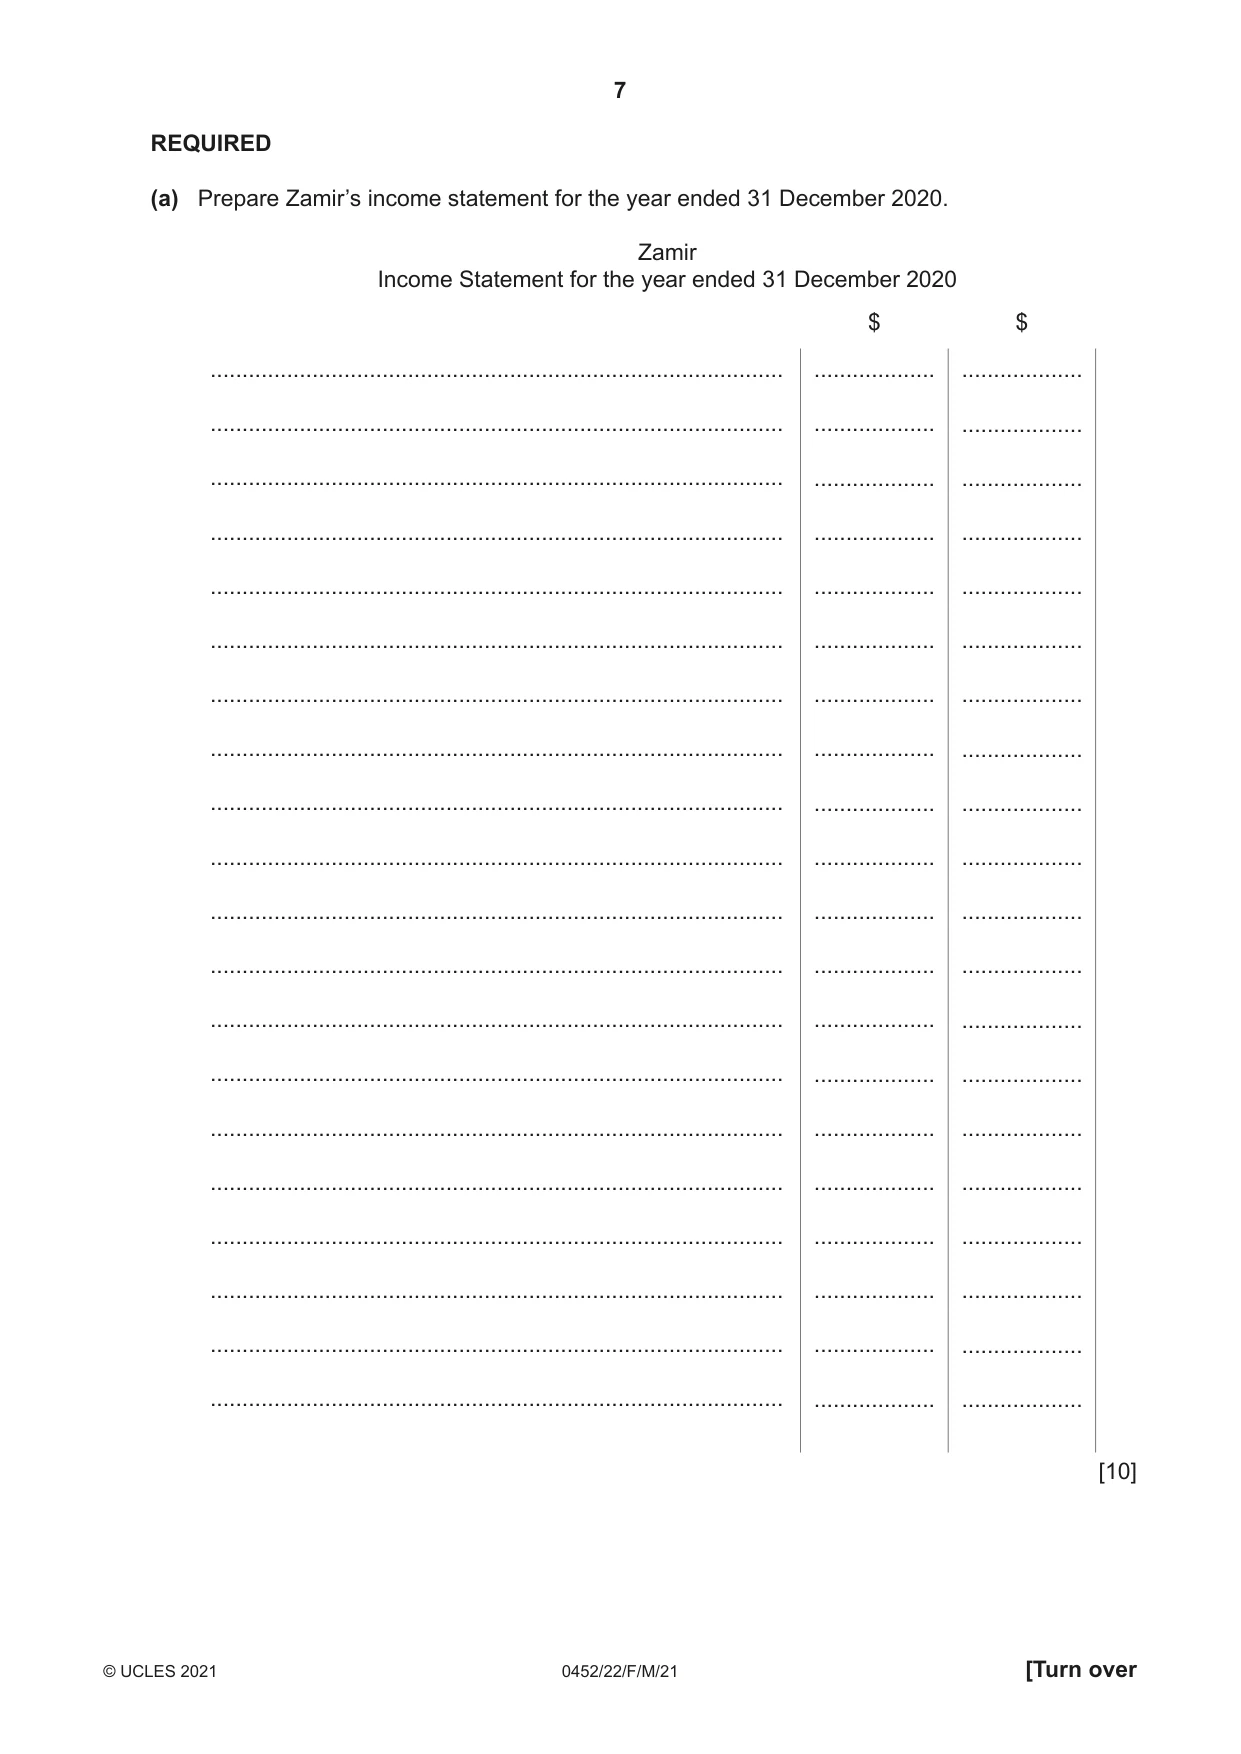
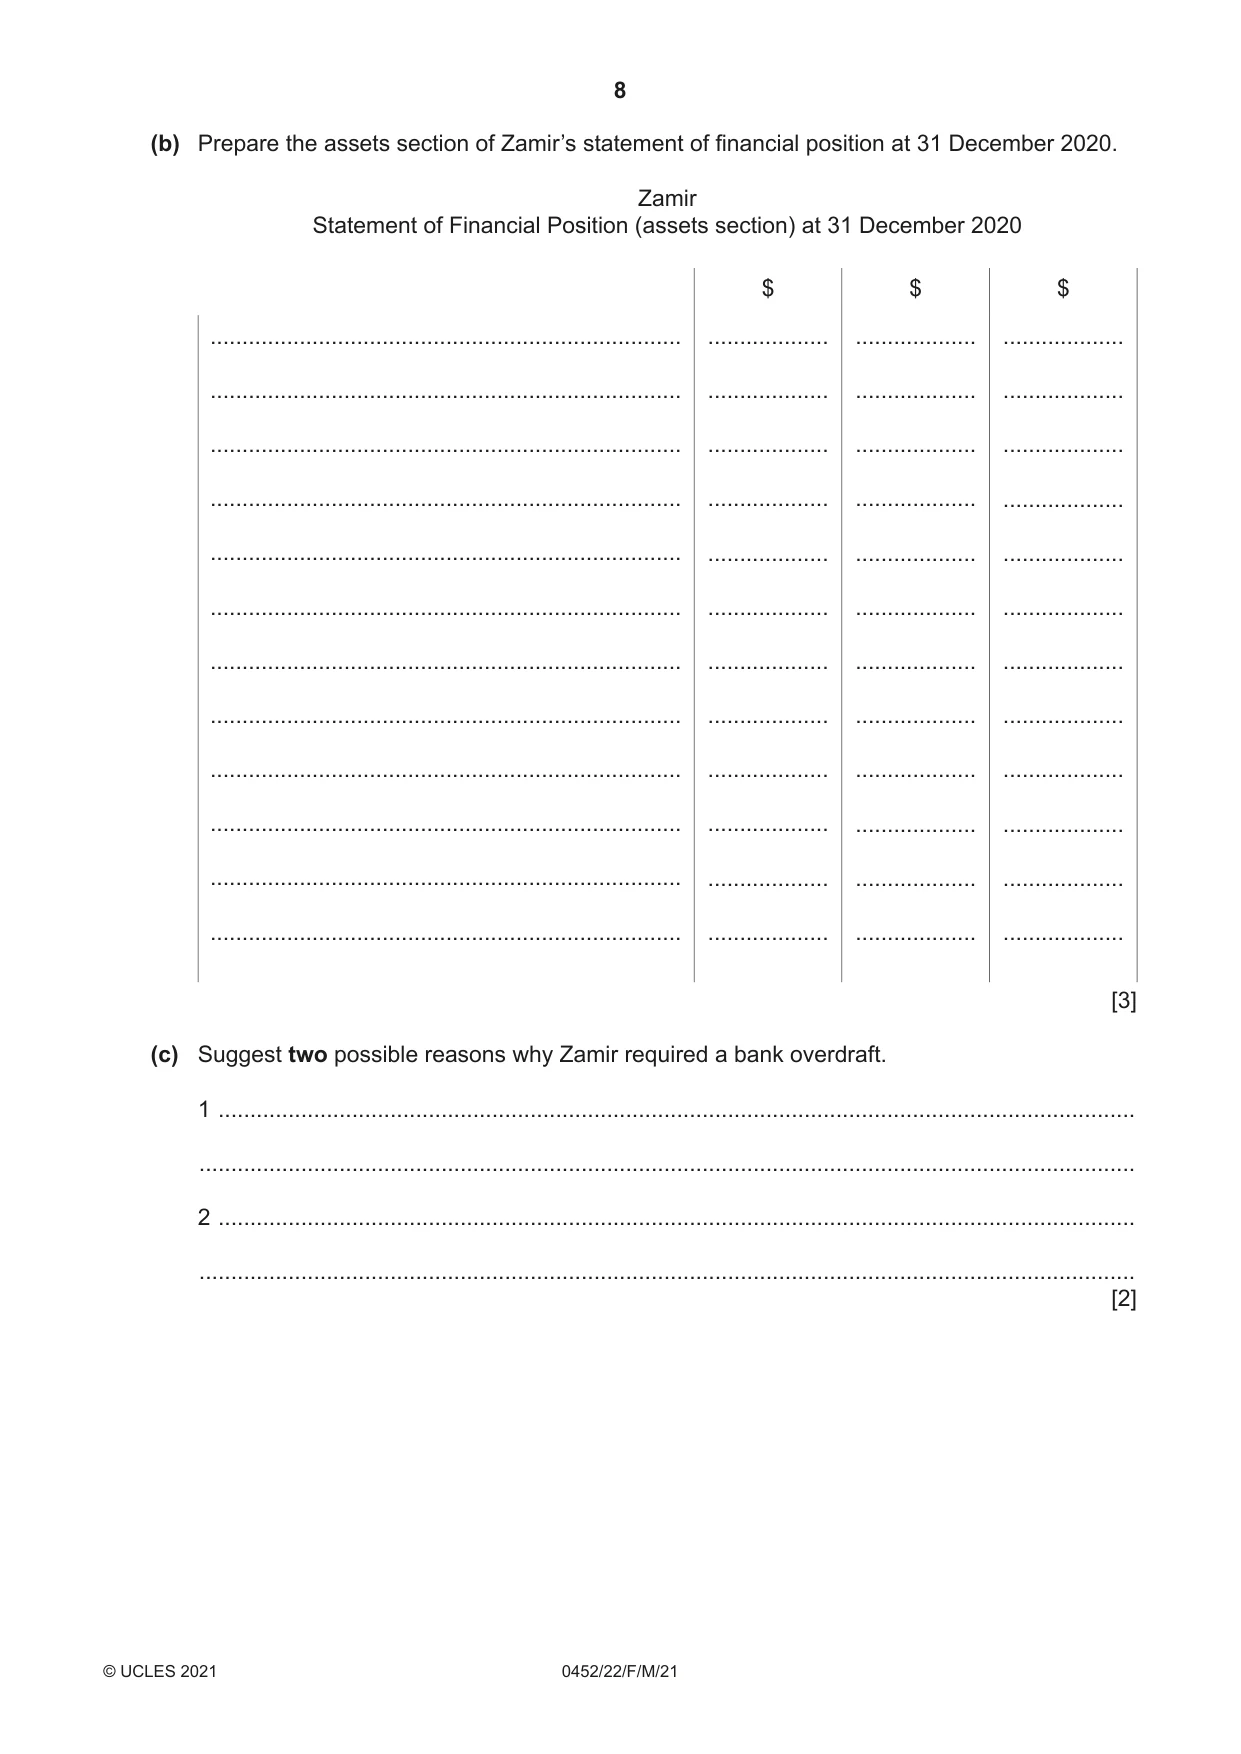
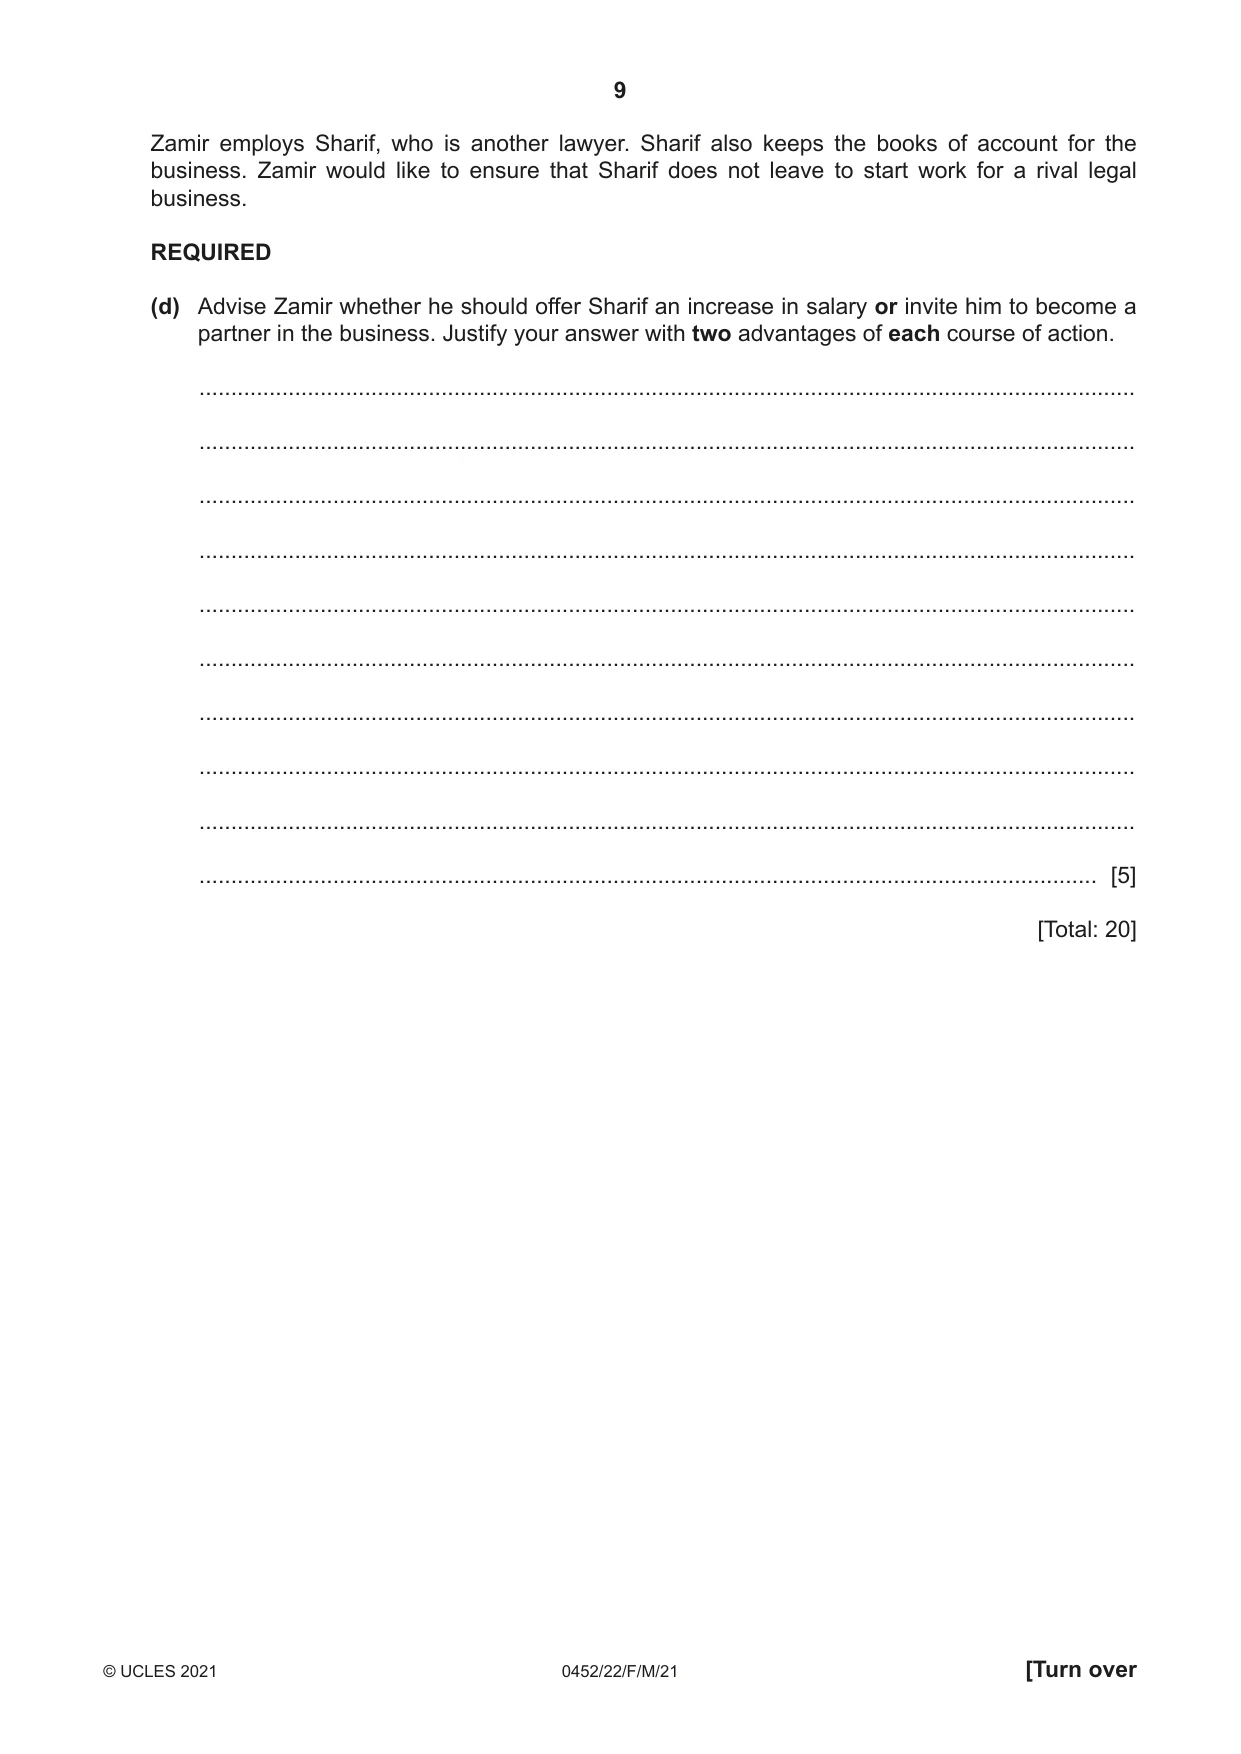
2 Zamir is in business providing legal services. Zamir provided the following balances from his books of account at 31 December 2020. $ Fee income 151 750 Rent and rates 26 000 Salaries 55 000 Stationery and advertising 6 450 Electricity 8 000 Bank charges 4 100 Office equipment – cost 60 000 Office equipment – provision for depreciation 22 500 Proceeds of disposal of office equipment 1 000 Bank overdraft 7 900 Trade receivables 15 600 Capital 57 000 Drawings 65 000 Additional information 1 The annual rent is $16 000. On 31 December 2020 rent was paid to cover the period from 1 January to 31 March 2021. There was no accrual or prepayment of rent at 1 January 2020. 2 Rates of $6000 were paid during the year to 31 December 2020. This payment covered the period 1 January 2020 to 31 October 2020 only. From 1 November 2020 annual rates were $7560. 3 Depreciation is to be charged on office equipment at 15% per annum using the straight-line method. No depreciation is charged in the year of disposal. 4 In February 2020 office equipment was sold for $1000. This equipment had been purchased for $1800 on 1 January 2018. The sales proceeds have been debited to the bank account and credited to the proceeds of disposal of office equipment account. No other entries have been made in respect of the disposal. 5 One of Zamir’s clients has become bankrupt. The client owed $1885. Zamir does not expect to recover this amount. REQUIRED (a) Prepare Zamir’s income statement for the year ended 31 D Zamir Income Statement for the year ended 31 .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... .......................................................................................... (b) Prepare the assets section of Zamir’s statement of financial position at 31 December 2020. Zamir Statement of Financial Position (assets section) at 31 December 2020 $ $ $ .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... .......................................................................... ................... ................... ................... [3] (c) Suggest two possible reasons why Zamir required a bank overdraft. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Zamir employs Sharif, who is another lawyer. Sharif also keeps the books of account for the business. Zamir would like to ensure that Sharif does not leave to start work for a rival legal business. REQUIRED (d) Advise Zamir whether he should offer Sharif an increase in salary or invite him to become a partner in the business. Justify your answer with two advantages of each course of action. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
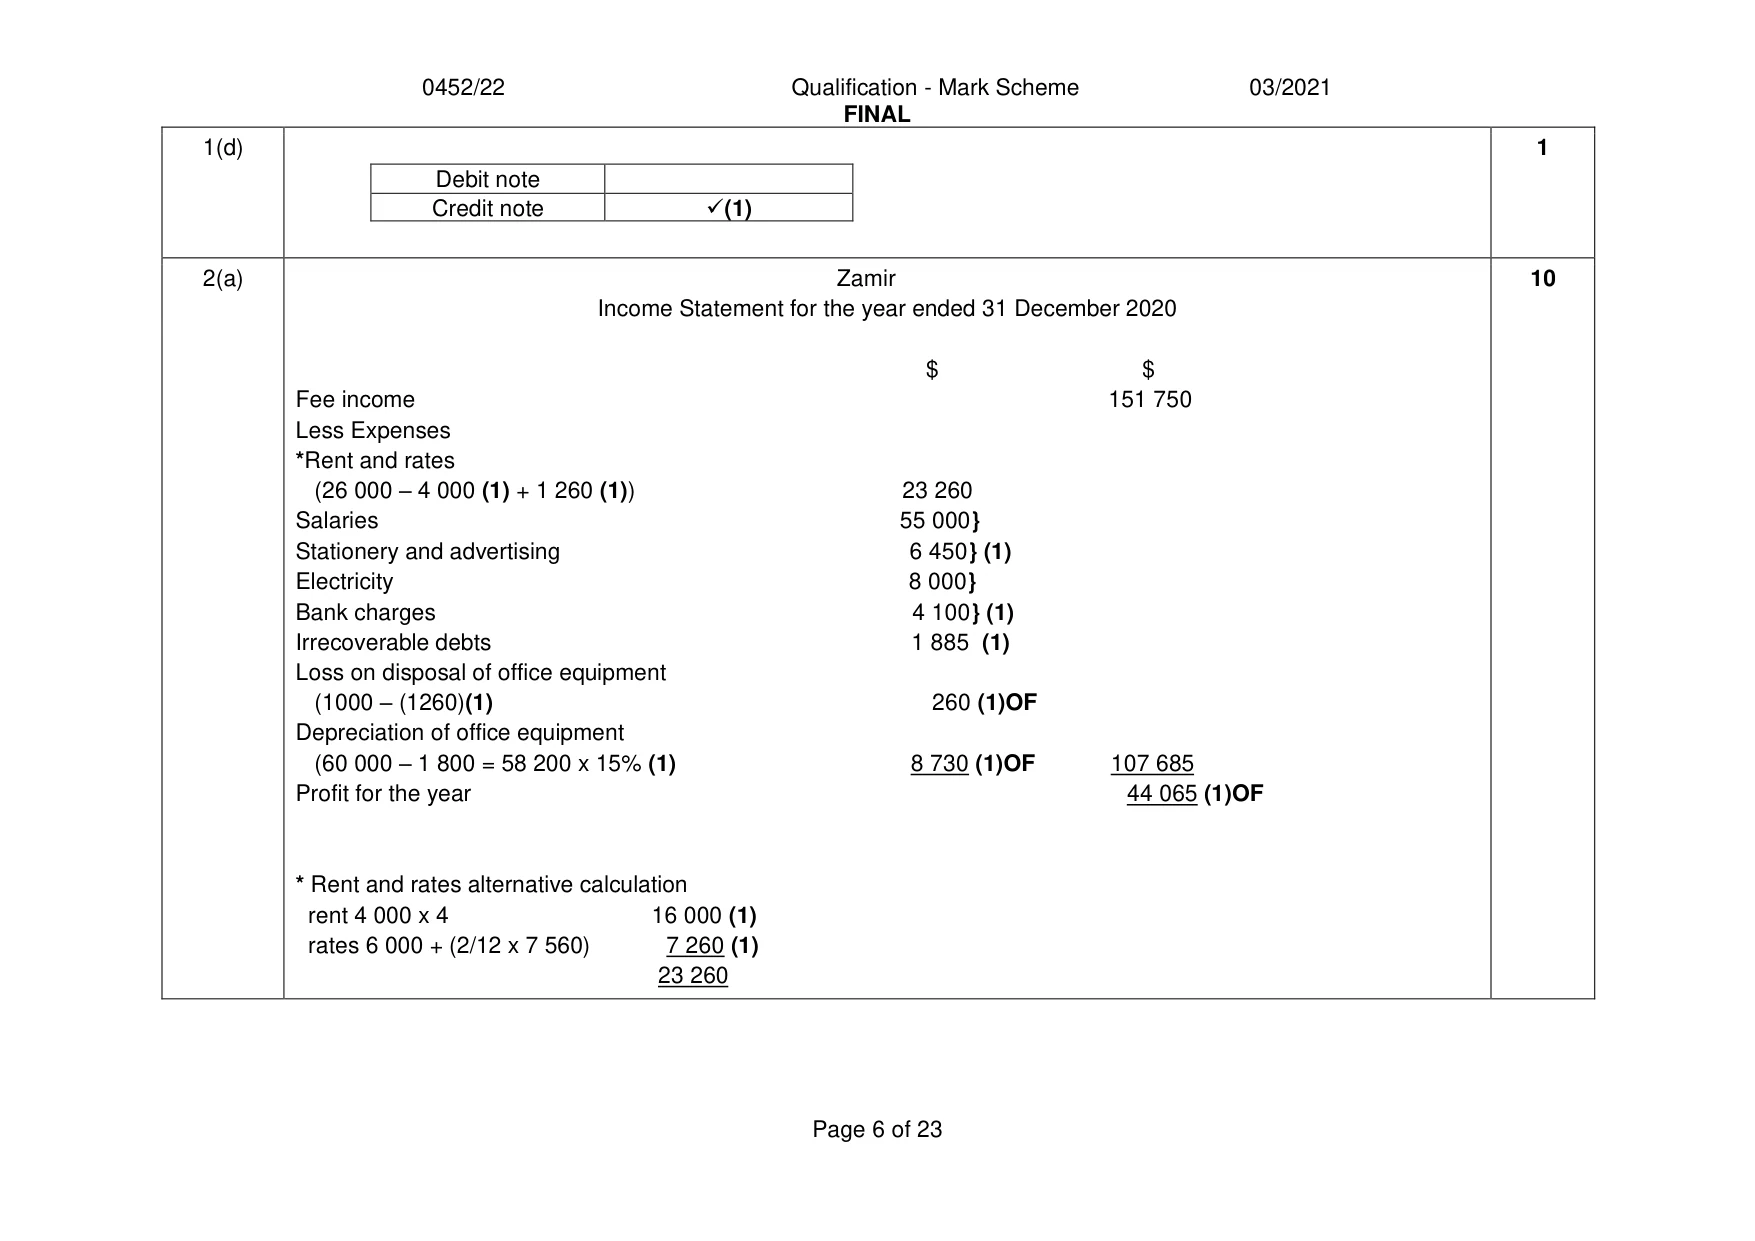
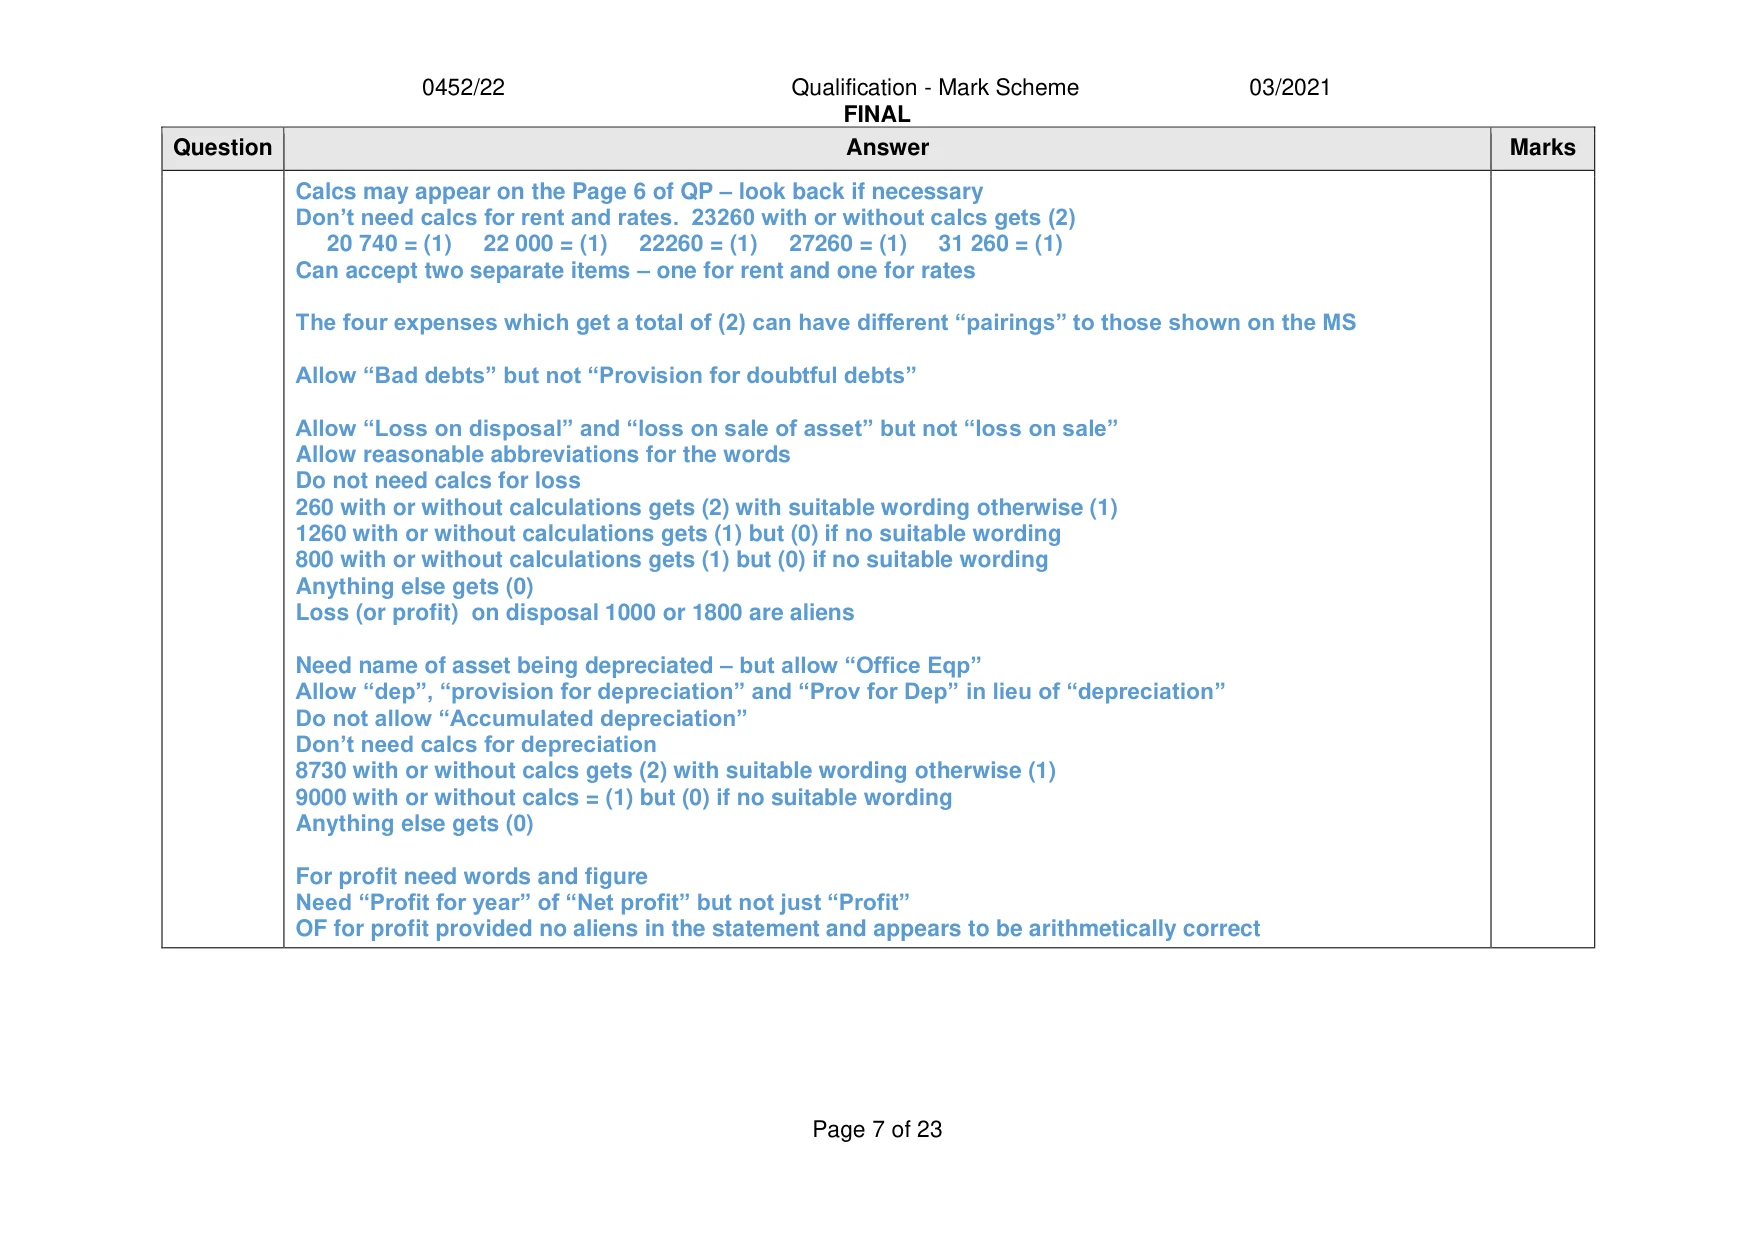
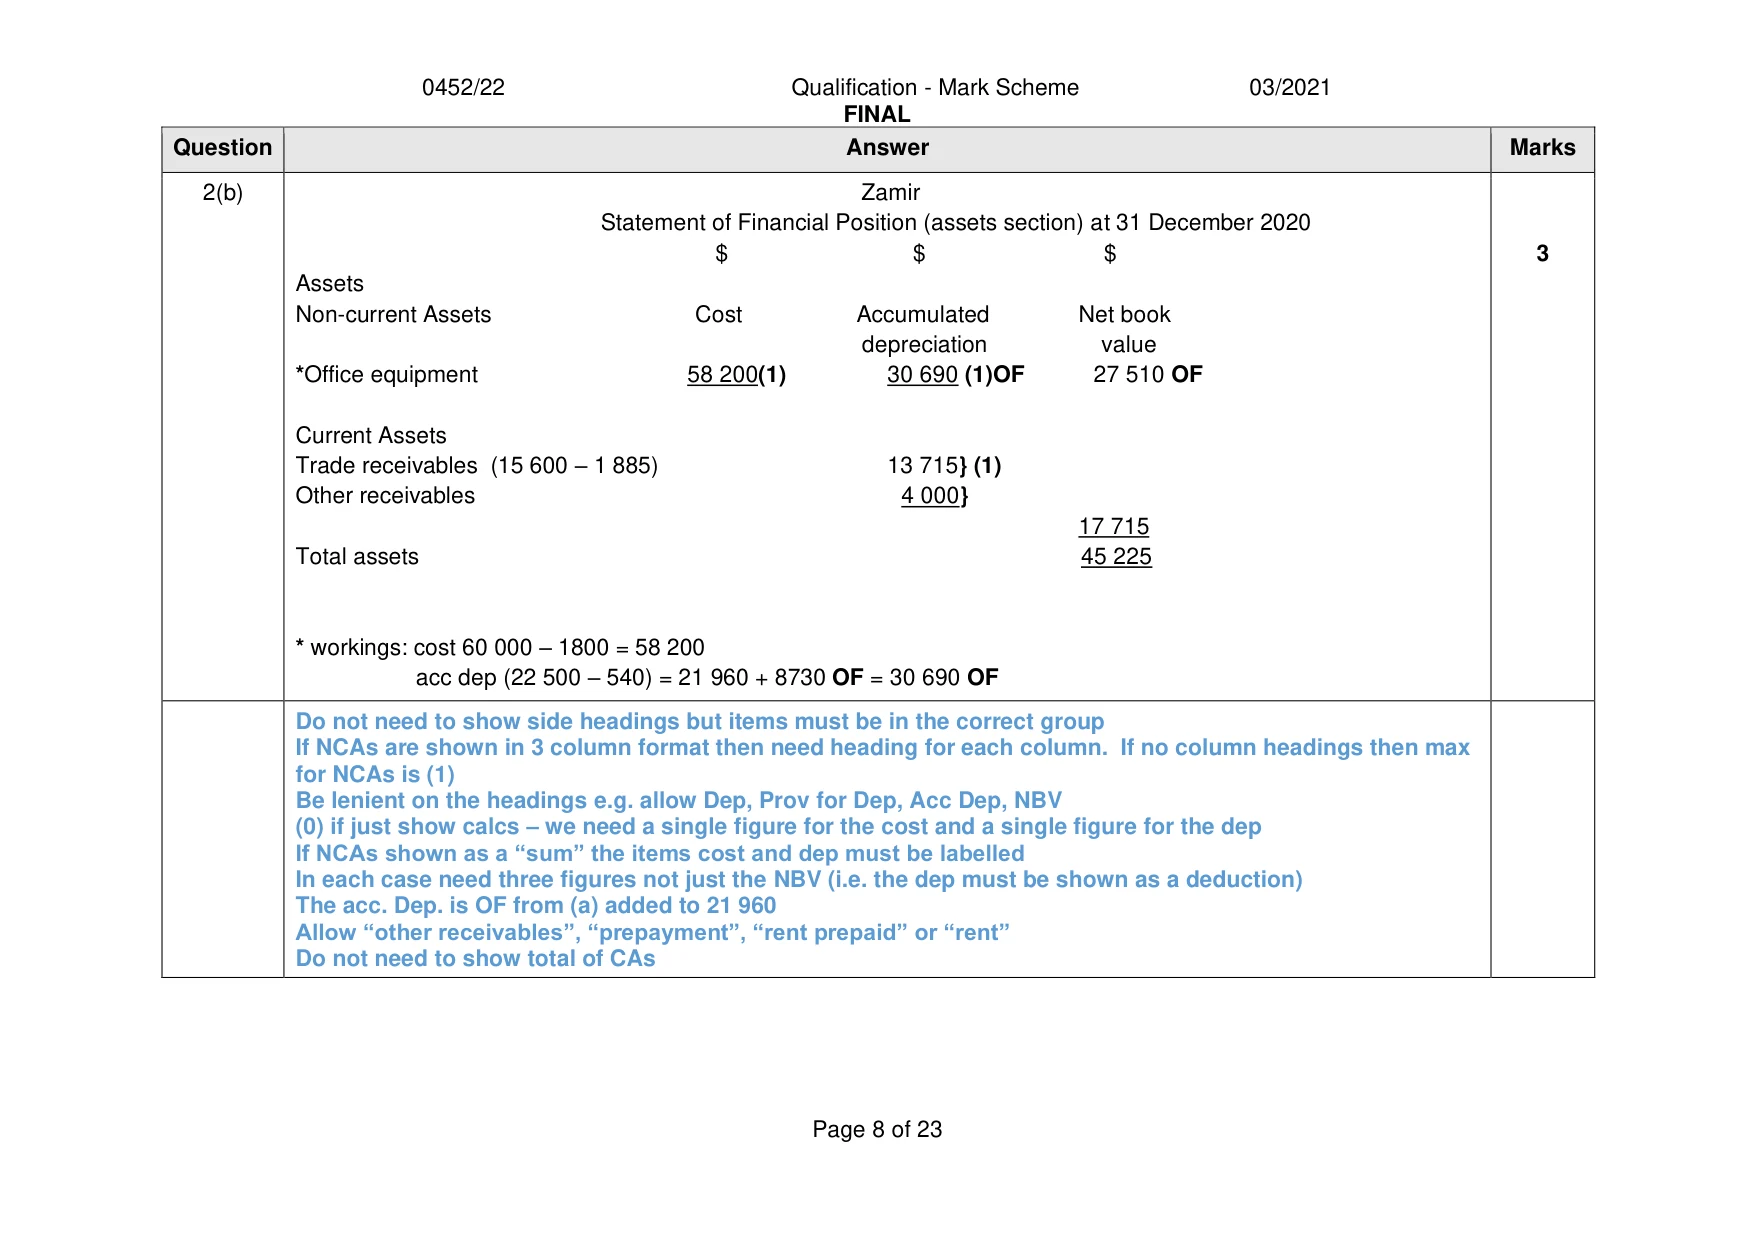
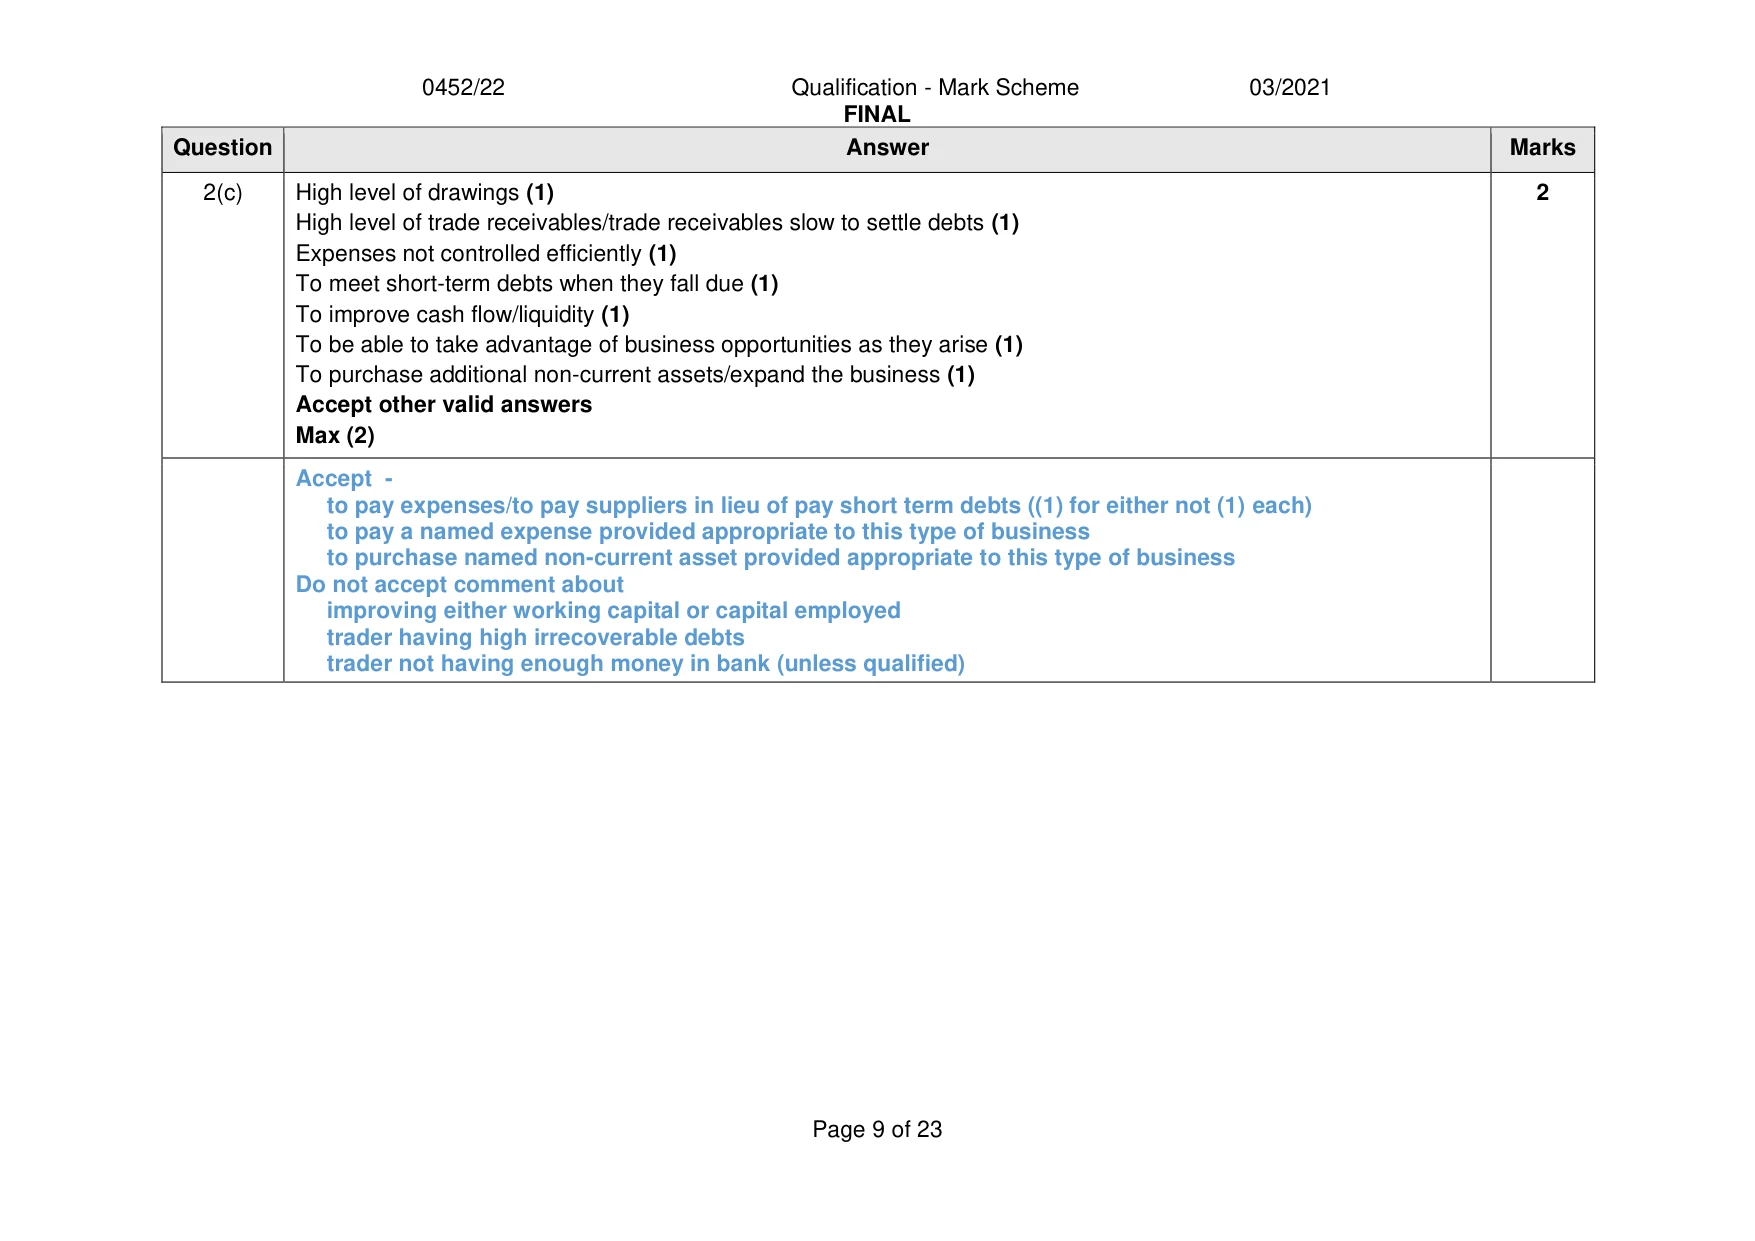
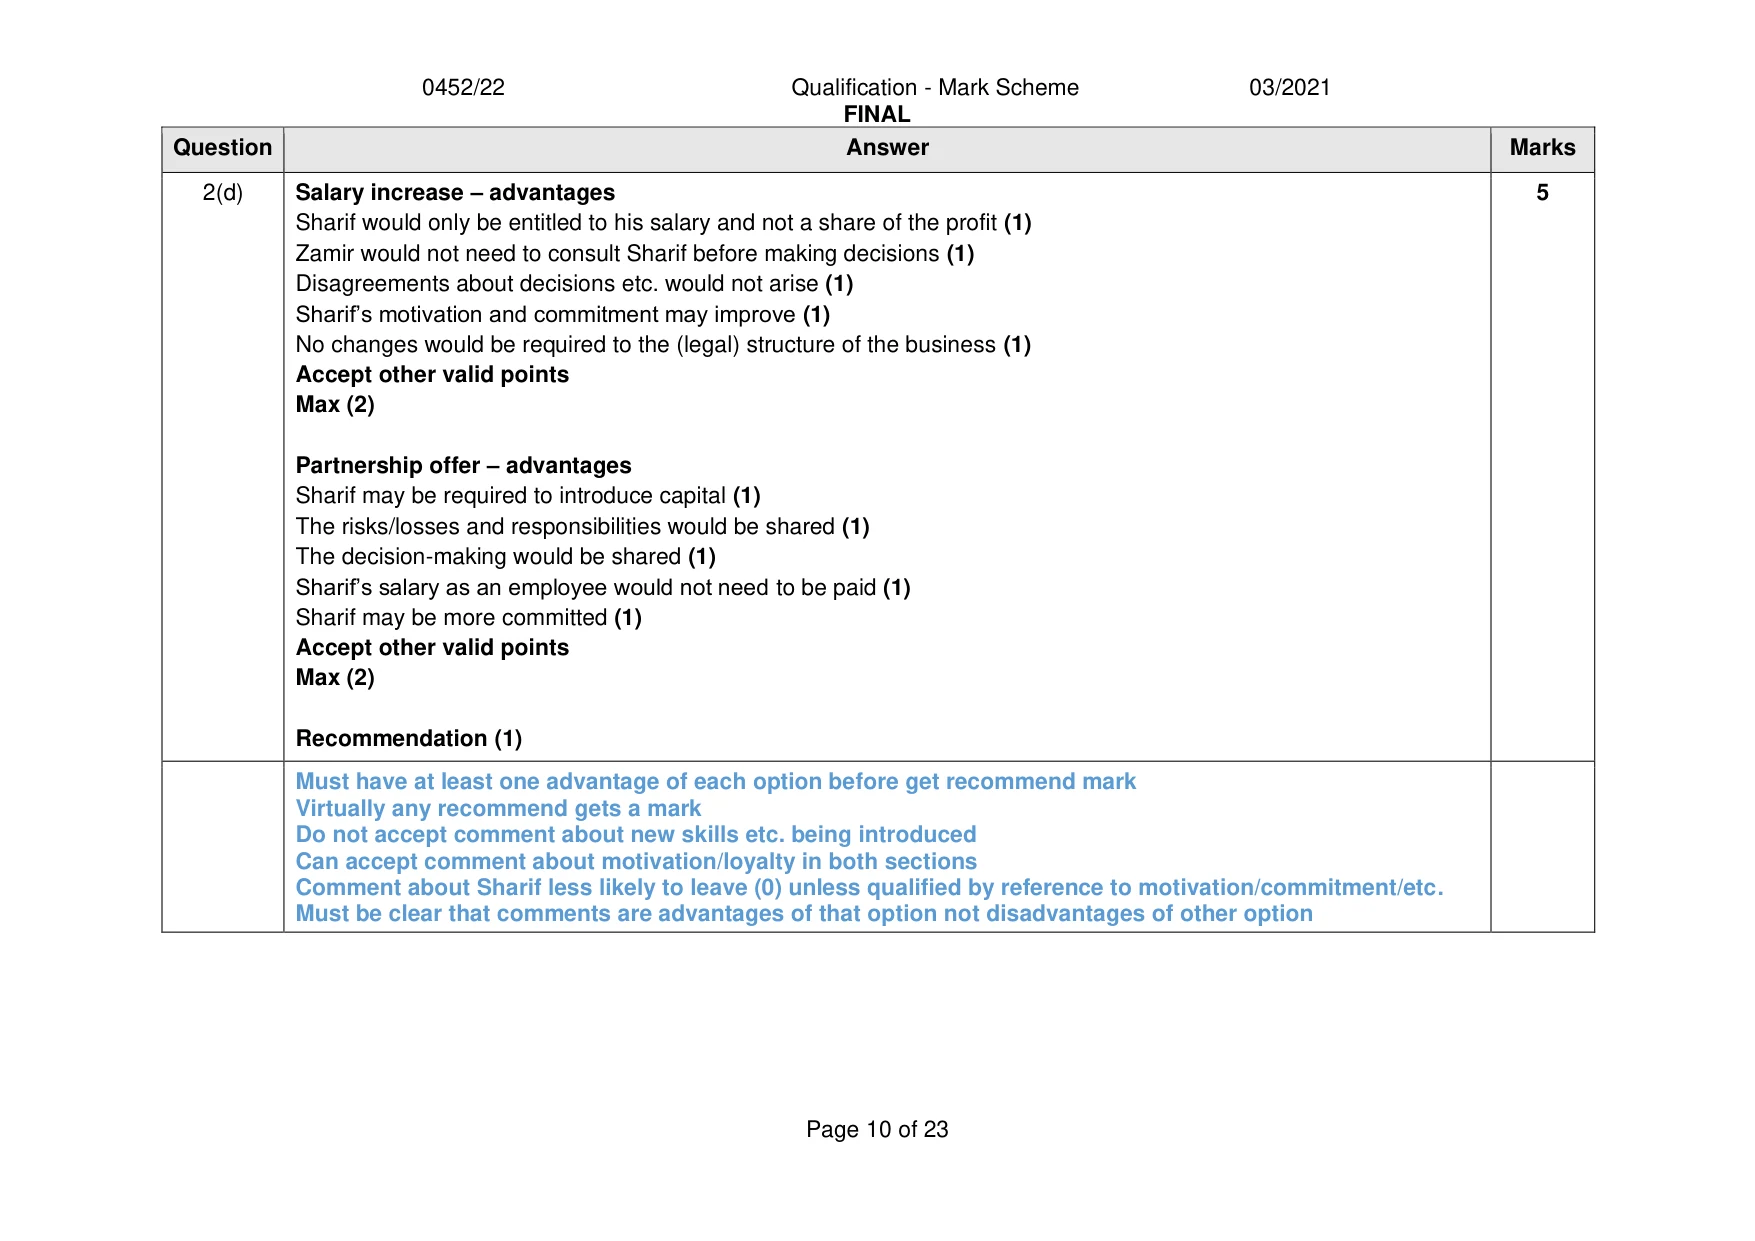
Mark scheme: 2(a) Zamir 10 Income Statement for the year ended 31 December 2020 $ $ Fee income 151 750 Less Expenses *Rent and rates (26 000 – 4 000 (1) + 1 260 (1)) 23 260 Salaries 55 000} Stationery and advertising 6 450} (1) Electricity 8 000} Bank charges 4 100} (1) Irrecoverable debts 1 885 (1) Loss on disposal of office equipment (1000 – (1260)(1) 260 (1)OF Depreciation of office equipment (60 000 – 1 800 = 58 200 x 15% (1) 8 730 (1)OF 107 685 Profit for the year 44 065 (1)OF * Rent and rates alternative calculation rent 4 000 x 4 16 000 (1) rates 6 000 + (2/12 x 7 560) 7 260 (1) 23 260 Calcs may appear on the Page 6 of QP – look back if necessary Don’t need calcs for rent and rates. 23260 with or without calcs gets (2) 20 740 = (1) 22 000 = (1) 22260 = (1) 27260 = (1) 31 260 = (1) Can accept two separate items – one for rent and one for rates The four expenses which get a total of (2) can have different “pairings” to those shown on the MS Allow “Bad debts” but not “Provision for doubtful debts” Allow “Loss on disposal” and “loss on sale of asset” but not “loss on sale” Allow reasonable abbreviations for the words Do not need calcs for loss 260 with or without calculations gets (2) with suitable wording otherwise (1) 1260 with or without calculations gets (1) but (0) if no suitable wording 800 with or without calculations gets (1) but (0) if no suitable wording Anything else gets (0) Loss (or profit) on disposal 1000 or 1800 are aliens Need name of asset being depreciated – but allow “Office Eqp” Allow “dep”, “provision for depreciation” and “Prov for Dep” in lieu of “depreciation” Do not allow “Accumulated depreciation” Don’t need calcs for depreciation 8730 with or without calcs gets (2) with suitable wording otherwise (1) 9000 with or without calcs = (1) but (0) if no suitable wording Anything else gets (0) For profit need words and figure Need “Profit for year” of “Net profit” but not just “Profit” OF for profit provided no aliens in the statement and appears to be arithmetically correct 2(b) Zamir Statement of Financial Position (assets section) at 31 December 2020 $ $ $ 3 Assets Non-current Assets Cost Accumulated Net book depreciation value *Office equipment 58 200(1) 30 690 (1)OF 27 510 OF Current Assets Trade receivables (15 600 – 1 885) 13 715} (1) Other receivables 4 000} 17 715 Total assets 45 225 * workings: cost 60 000 – 1800 = 58 200 acc dep (22 500 – 540) = 21 960 + 8730 OF = 30 690 OF Do not need to show side headings but items must be in the correct group If NCAs are shown in 3 column format then need heading for each column. If no column headings then max for NCAs is (1) Be lenient on the headings e.g. allow Dep, Prov for Dep, Acc Dep, NBV (0) if just show calcs – we need a single figure for the cost and a single figure for the dep If NCAs shown as a “sum” the items cost and dep must be labelled In each case need three figures not just the NBV (i.e. the dep must be shown as a deduction) The acc. Dep. is OF from (a) added to 21 960 Allow “other receivables”, “prepayment”, “rent prepaid” or “rent” Do not need to show total of CAs 2(c) High level of drawings (1) 2 High level of trade receivables/trade receivables slow to settle debts (1) Expenses not controlled efficiently (1) To meet short-term debts when they fall due (1) To improve cash flow/liquidity (1) To be able to take advantage of business opportunities as they arise (1) To purchase additional non-current assets/expand the business (1) Accept other valid answers Max (2) Accept - to pay expenses/to pay suppliers in lieu of pay short term debts ((1) for either not (1) each) to pay a named expense provided appropriate to this type of business to purchase named non-current asset provided appropriate to this type of business Do not accept comment about improving either working capital or capital employed trader having high irrecoverable debts trader not having enough money in bank (unless qualified) 2(d) Salary increase – advantages 5 Sharif would only be entitled to his salary and not a share of the profit (1) Zamir would not need to consult Sharif before making decisions (1) Disagreements about decisions etc. would not arise (1) Sharif’s motivation and commitment may improve (1) No changes would be required to the (legal) structure of the business (1) Accept other valid points Max (2) Partnership offer – advantages Sharif may be required to introduce capital (1) The risks/losses and responsibilities would be shared (1) The decision-making would be shared (1) Sharif’s salary as an employee would not need to be paid (1) Sharif may be more committed (1) Accept other valid points Max (2) Recommendation (1) Must have at least one advantage of each option before get recommend mark Virtually any recommend gets a mark Do not accept comment about new skills etc. being introduced Can accept comment about motivation/loyalty in both sections Comment about Sharif less likely to leave (0) unless qualified by reference to motivation/commitment/etc. Must be clear that comments are advantages of that option not disadvantages of other option
Q3 · Rachel prepared her trial balance at 31 January
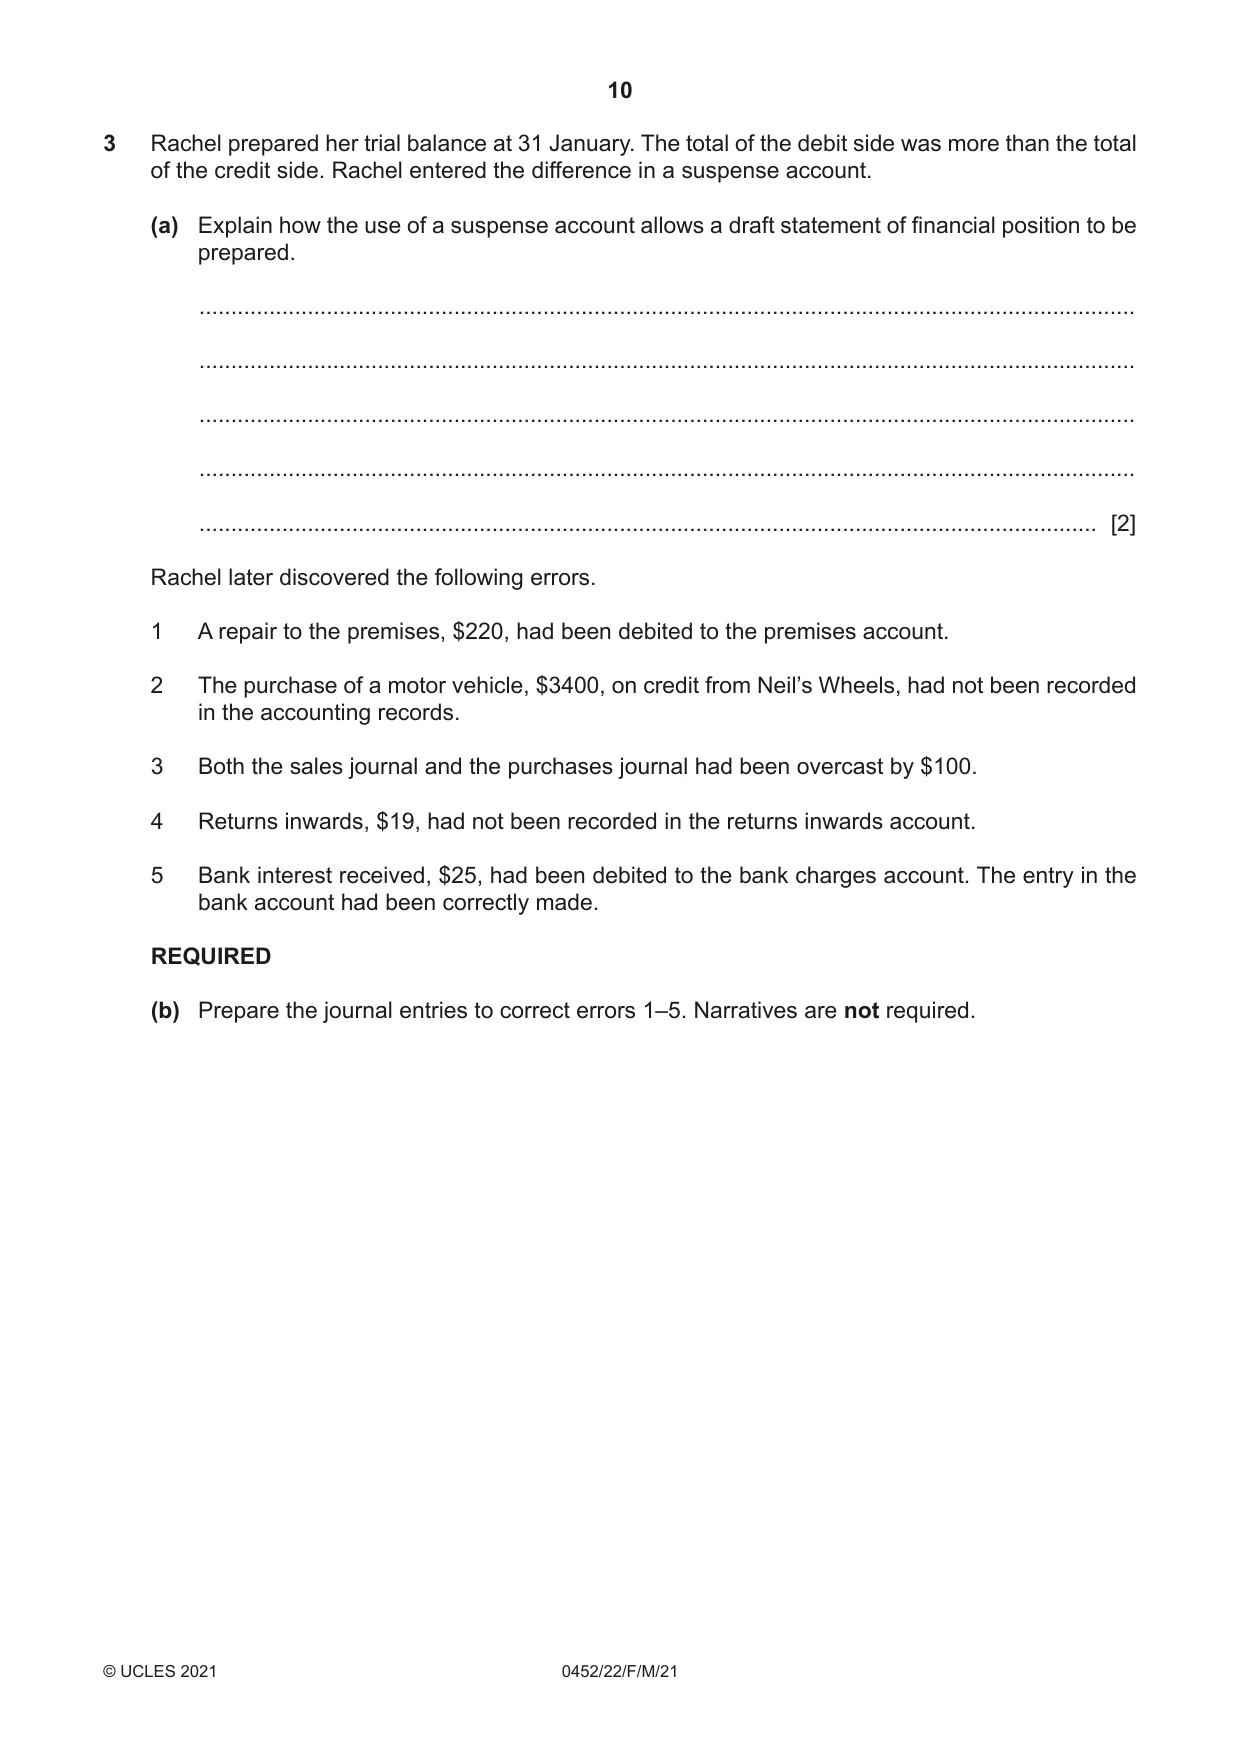
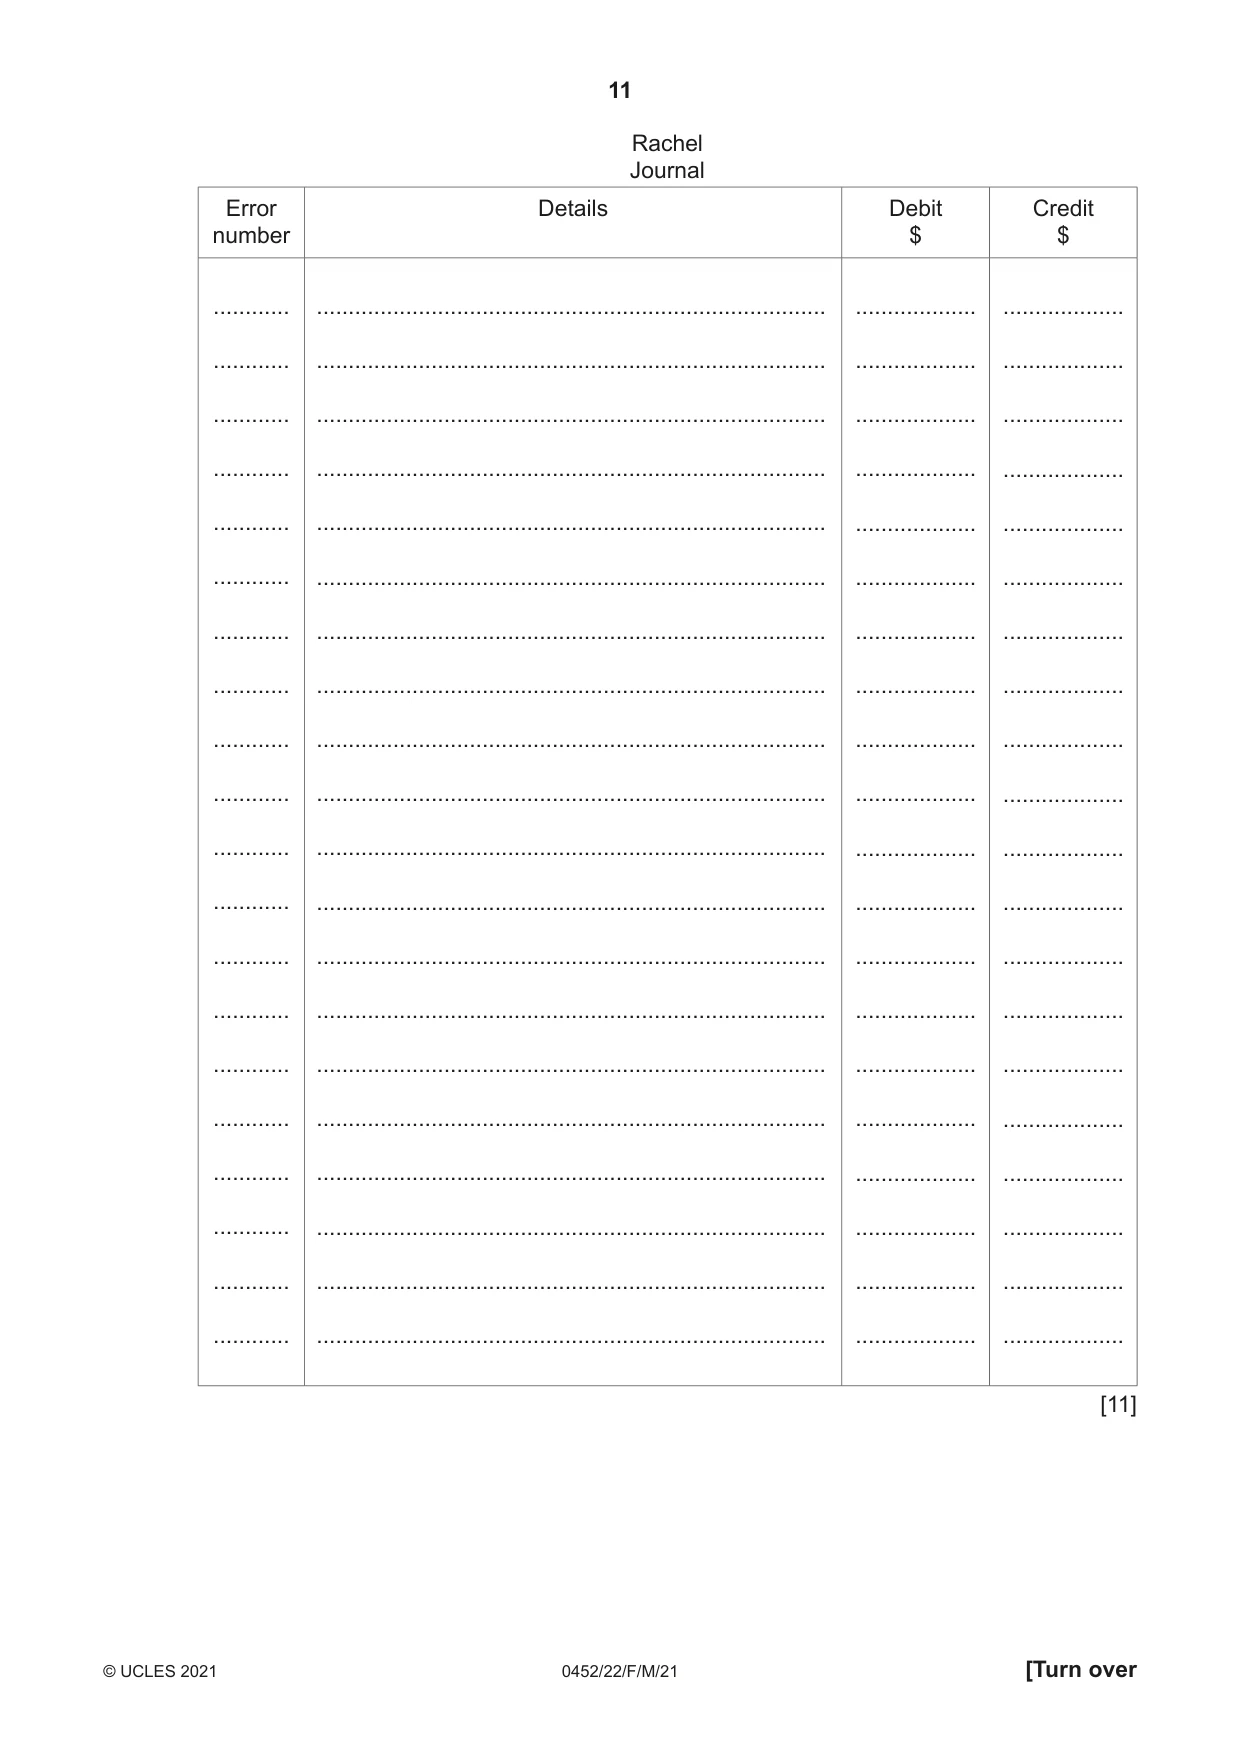
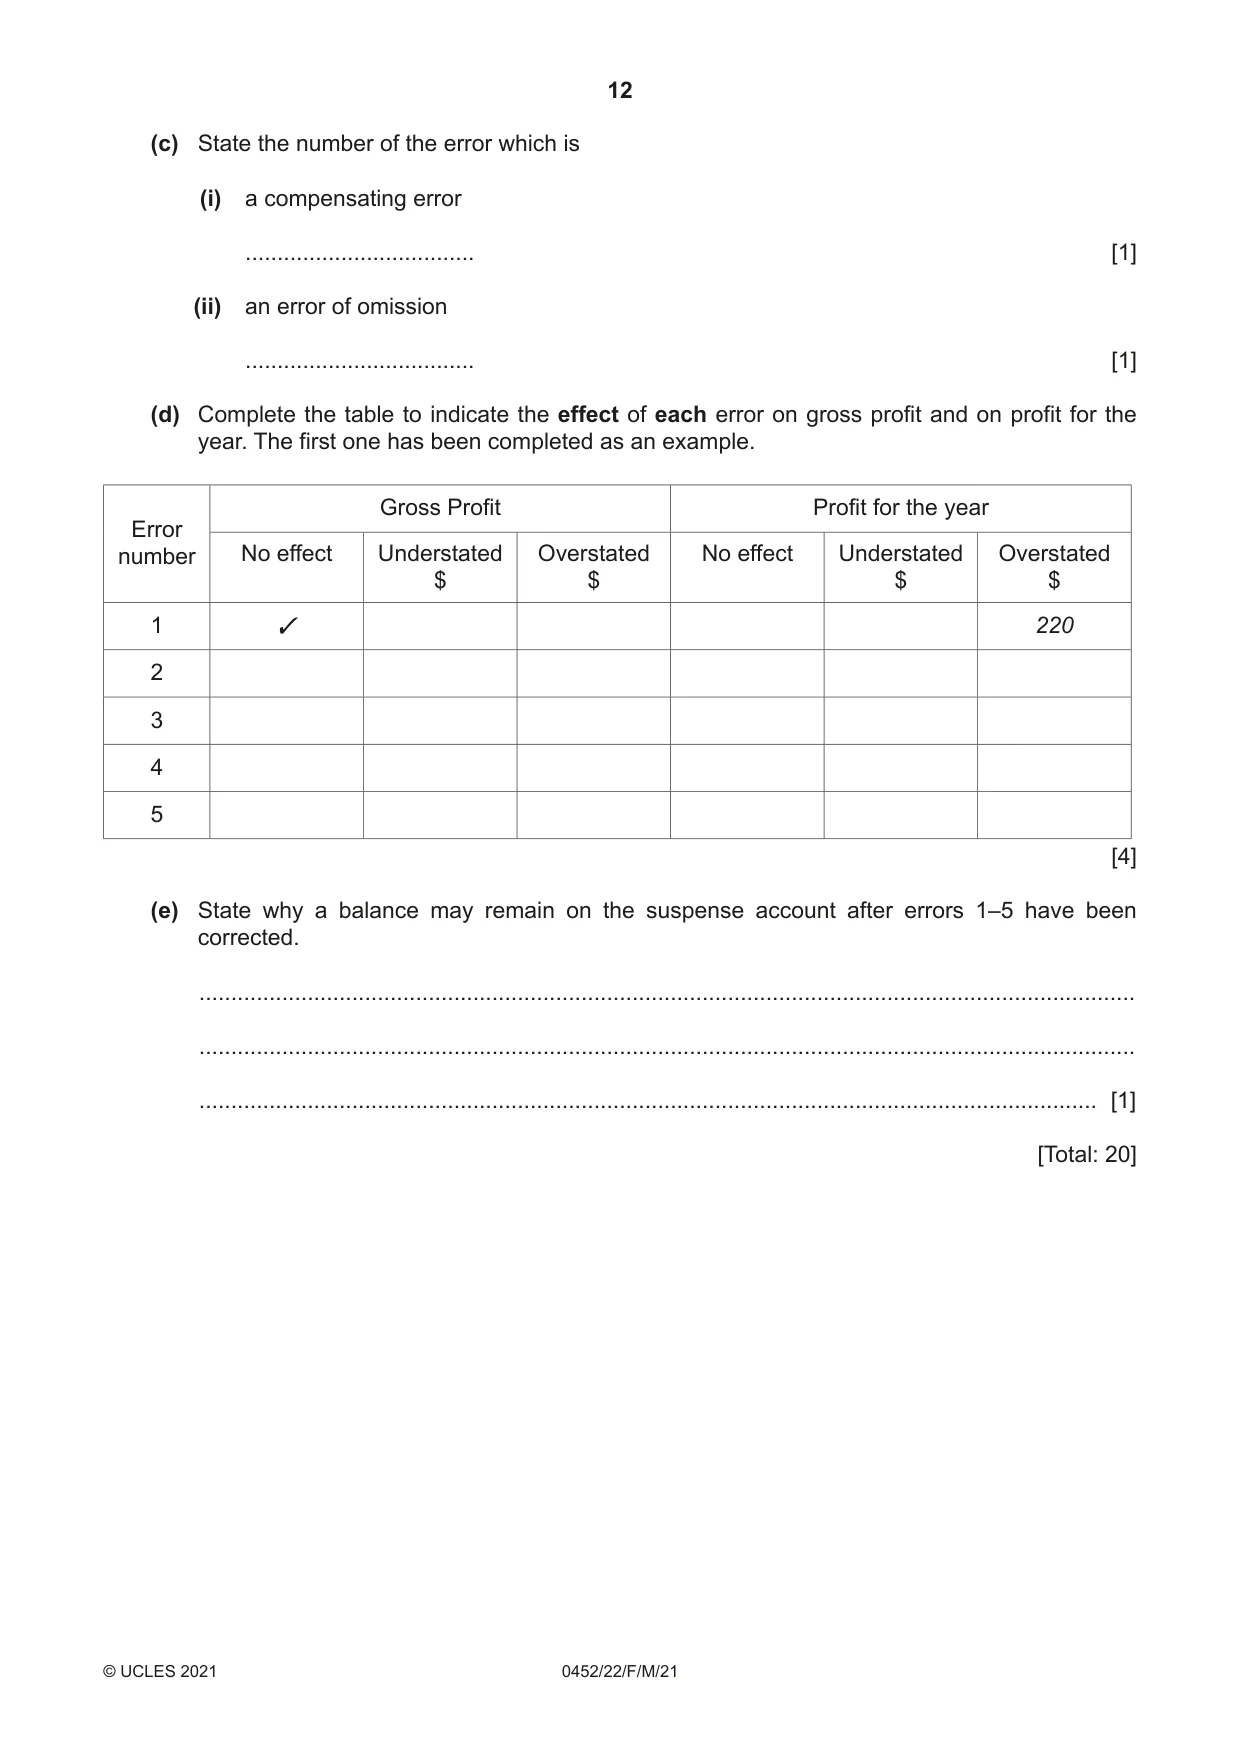
3 Rachel prepared her trial balance at 31 January. The total of the debit side was more than the total of the credit side. Rachel entered the difference in a suspense account. (a) Explain how the use of a suspense account allows a draft statement of financial position to be prepared. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Rachel later discovered the following errors. 1 A repair to the premises, $220, had been debited to the premises account. 2 The purchase of a motor vehicle, $3400, on credit from Neil’s Wheels, had not been recorded in the accounting records. 3 Both the sales journal and the purchases journal had been overcast by $100. 4 Returns inwards, $19, had not been recorded in the returns inwards account. 5 Bank interest received, $25, had been debited to the bank charges account. The entry in the bank account had been correctly made. REQUIRED (b) Prepare the journal entries to correct errors 1–5. Narratives are not required. Rachel Journal Details ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ (c) State the number of the error which is (i) a compensating error .................................... [1] (ii) an error of omission .................................... [1] (d) Complete the table to indicate the effect of each error on gross profit and on profit for the year. The first one has been completed as an example. Gross Profit Profit for the year Error number No effect Understated Overstated No effect Understated Overstated $ $ $ $ 1 3 220 2 3 4 5 [4] (e) State why a balance may remain on the suspense account after errors 1–5 have been corrected. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] [Total: 20]
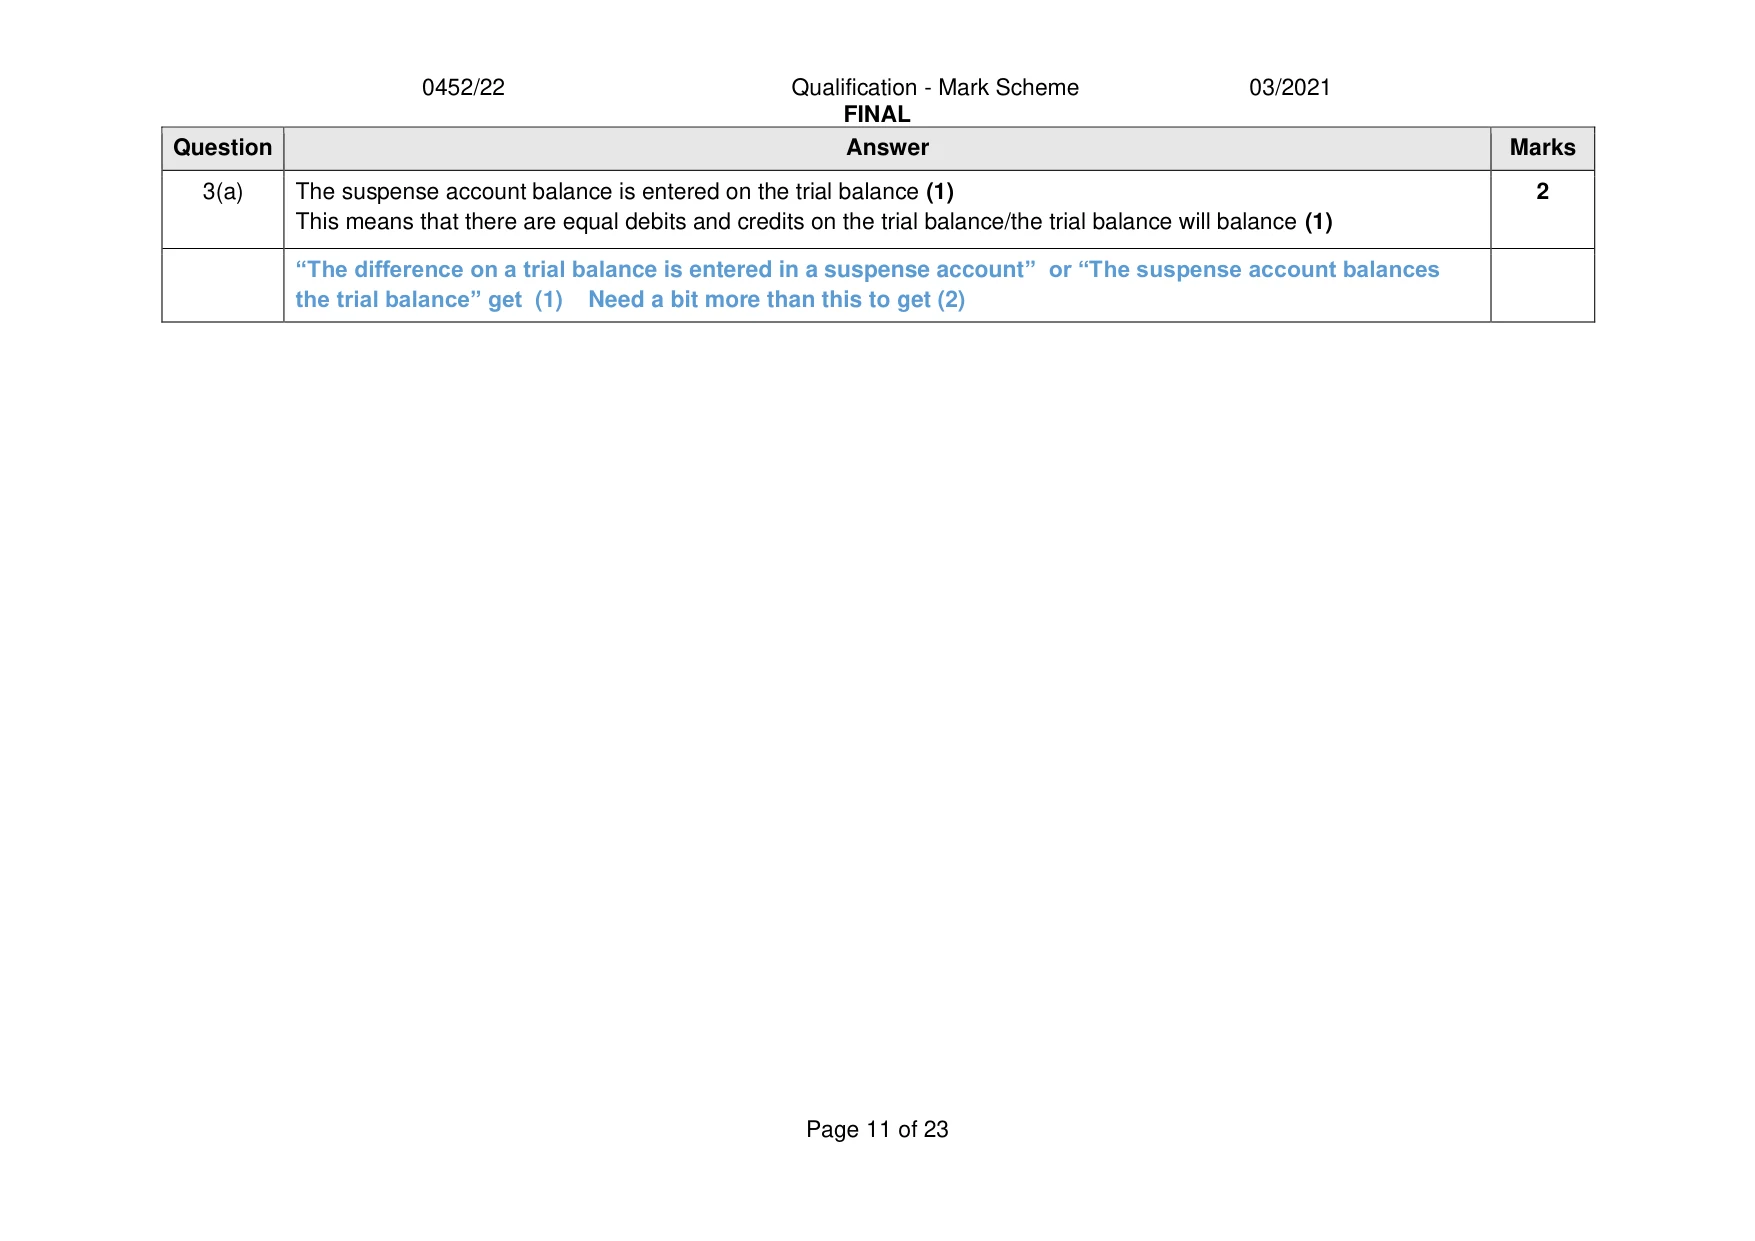
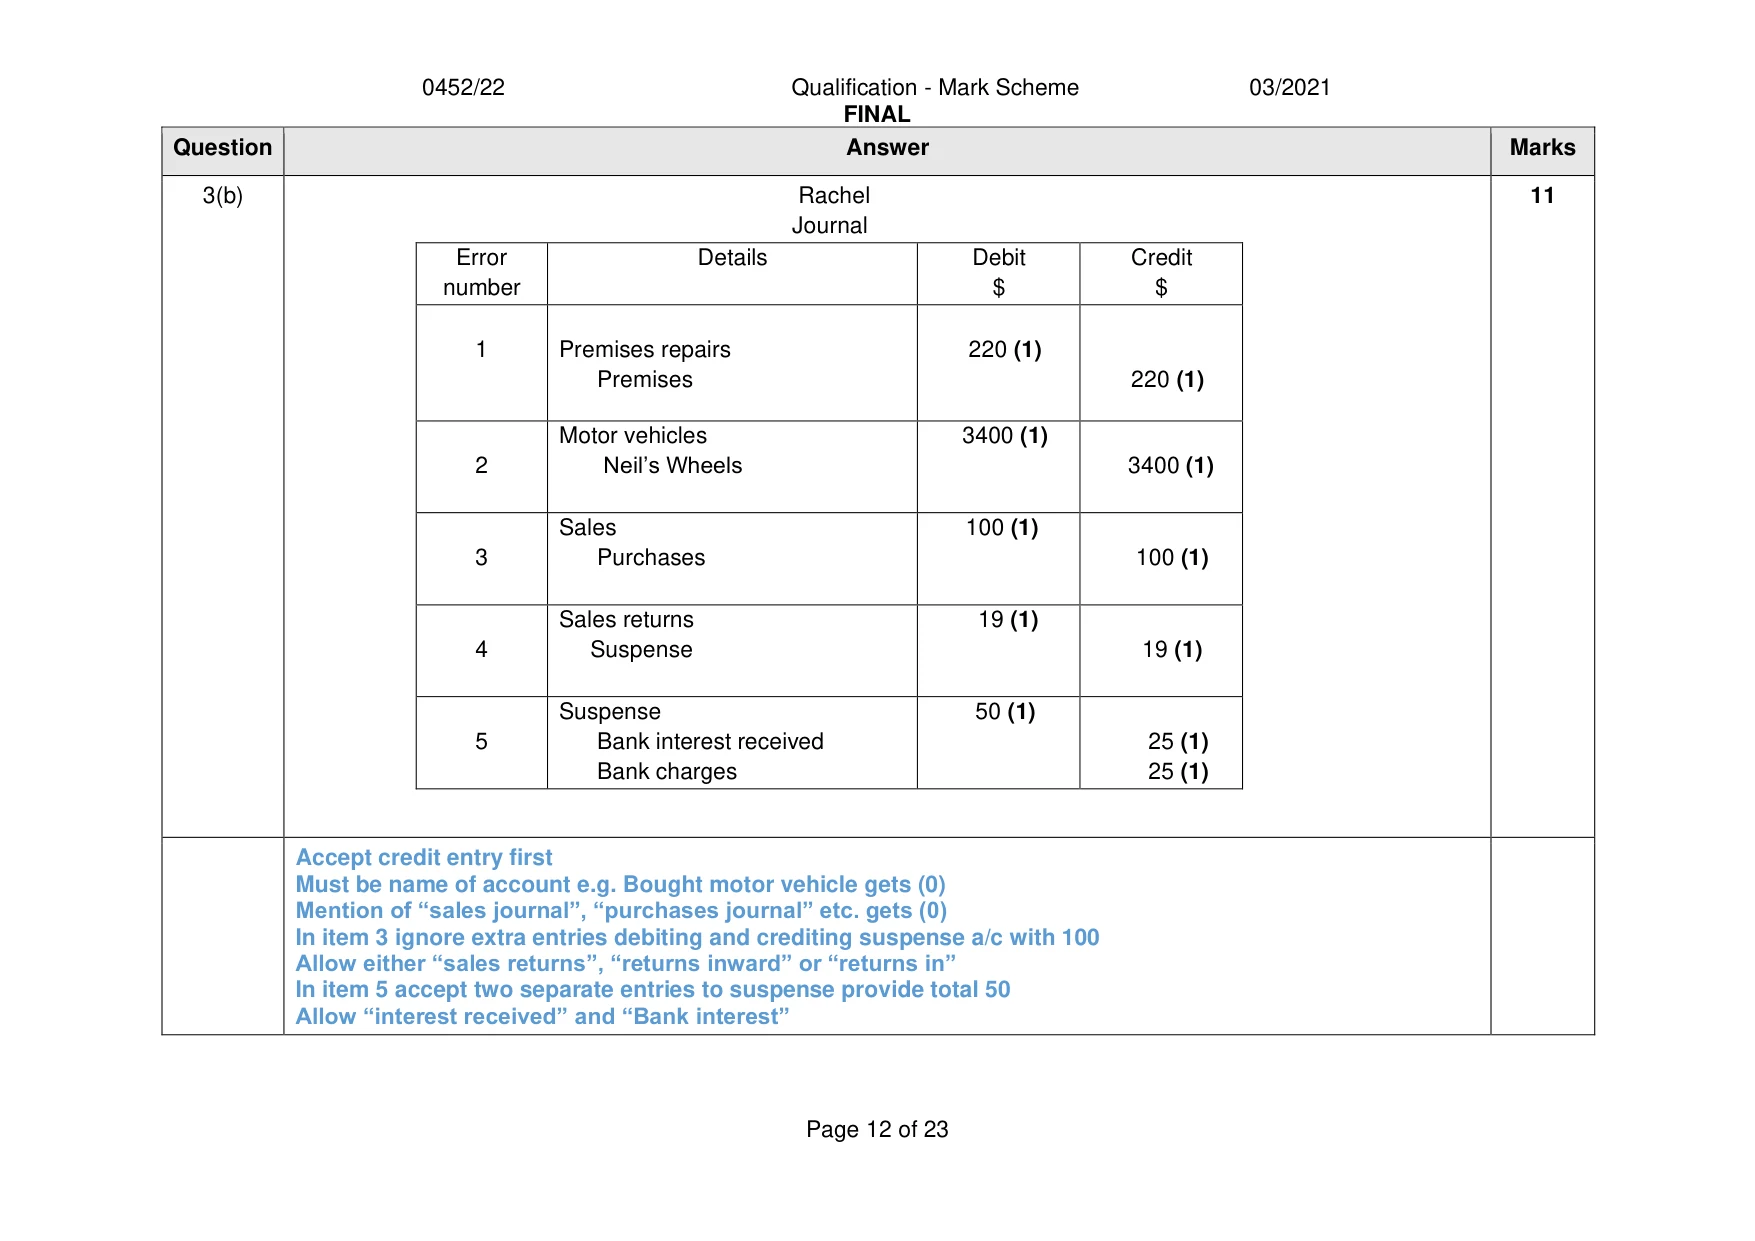
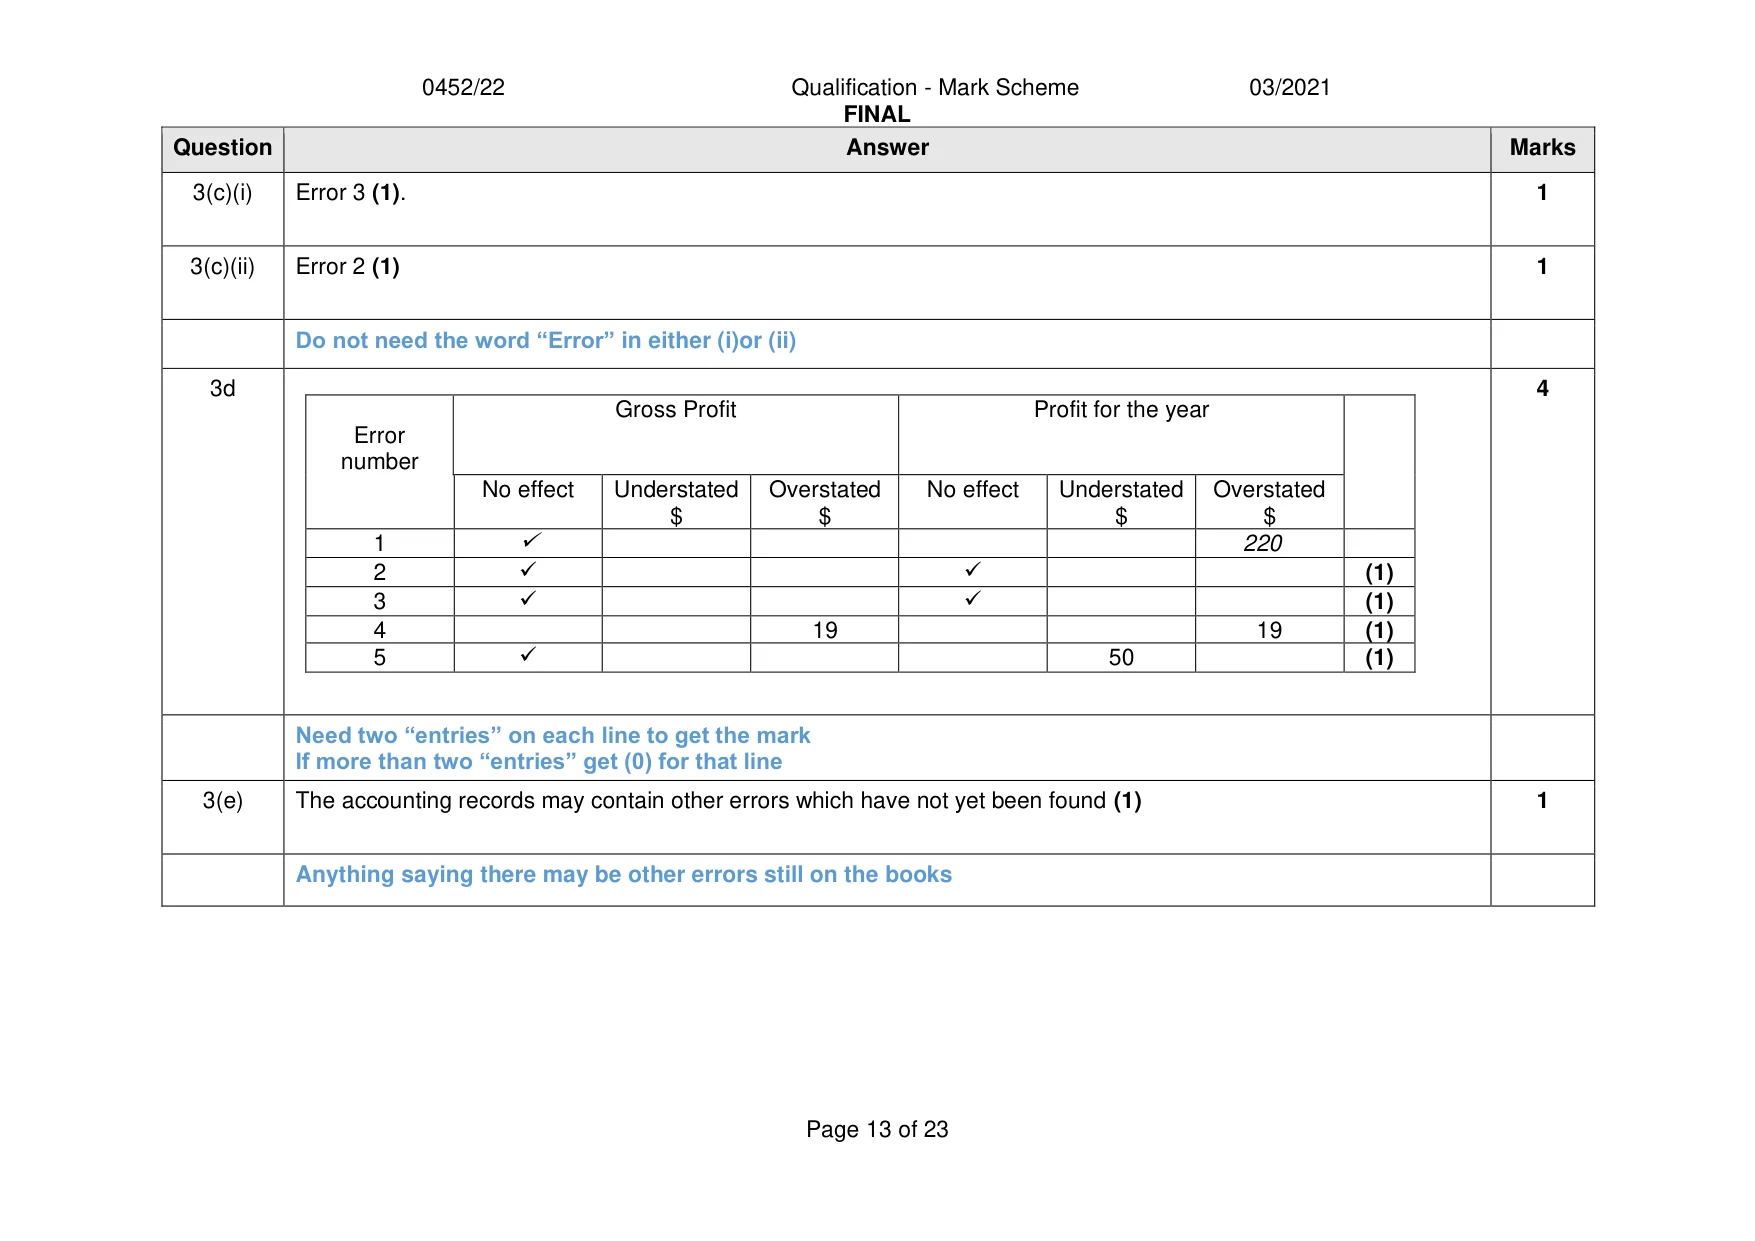
Mark scheme: 3(a) The suspense account balance is entered on the trial balance (1) 2 This means that there are equal debits and credits on the trial balance/the trial balance will balance (1) “The difference on a trial balance is entered in a suspense account” or “The suspense account balances the trial balance” get (1) Need a bit more than this to get (2) 3(b) Rachel 11 Journal Error Details Debit Credit number $ $ 1 Premises repairs 220 (1) Premises 220 (1) Motor vehicles 3400 (1) 2 Neil’s Wheels 3400 (1) Sales 100 (1) 3 Purchases 100 (1) Sales returns 19 (1) 4 Suspense 19 (1) Suspense 50 (1) 5 Bank interest received 25 (1) Bank charges 25 (1) Accept credit entry first Must be name of account e.g. Bought motor vehicle gets (0) Mention of “sales journal”, “purchases journal” etc. gets (0) In item 3 ignore extra entries debiting and crediting suspense a/c with 100 Allow either “sales returns”, “returns inward” or “returns in” In item 5 accept two separate entries to suspense provide total 50 Allow “interest received” and “Bank interest” 3(c)(i) Error 3 (1). 1 3(c)(ii) Error 2 (1) 1 Do not need the word “Error” in either (i)or (ii) 3d 4 Gross Profit Profit for the year Error number No effect Understated Overstated No effect Understated Overstated $ $ $ $ 1 ✓ 220 2 ✓ ✓ (1) 3 ✓ ✓ (1) 4 19 19 (1) 5 ✓ 50 (1) Need two “entries” on each line to get the mark If more than two “entries” get (0) for that line 3(e) The accounting records may contain other errors which have not yet been found (1) 1 Anything saying there may be other errors still on the books
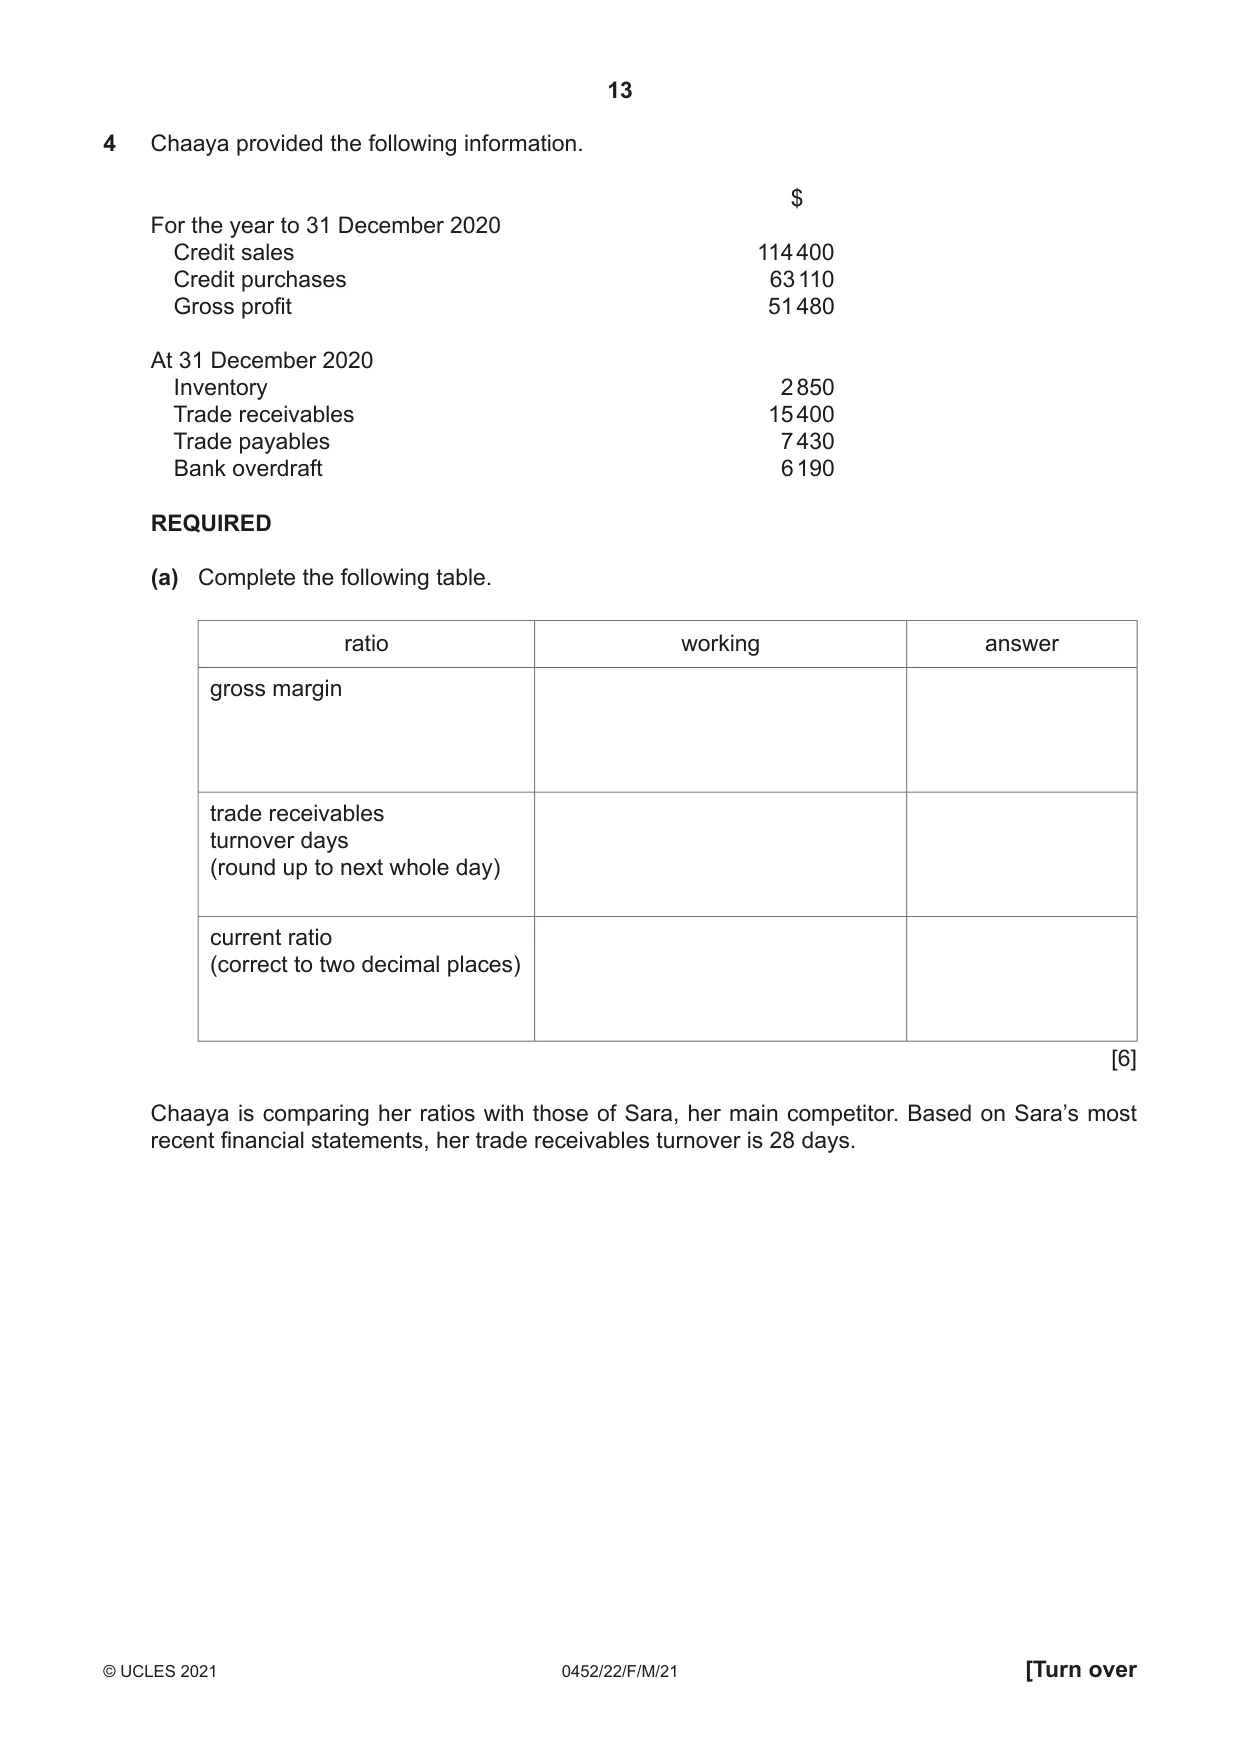
Q4 · Chaaya provided the following information
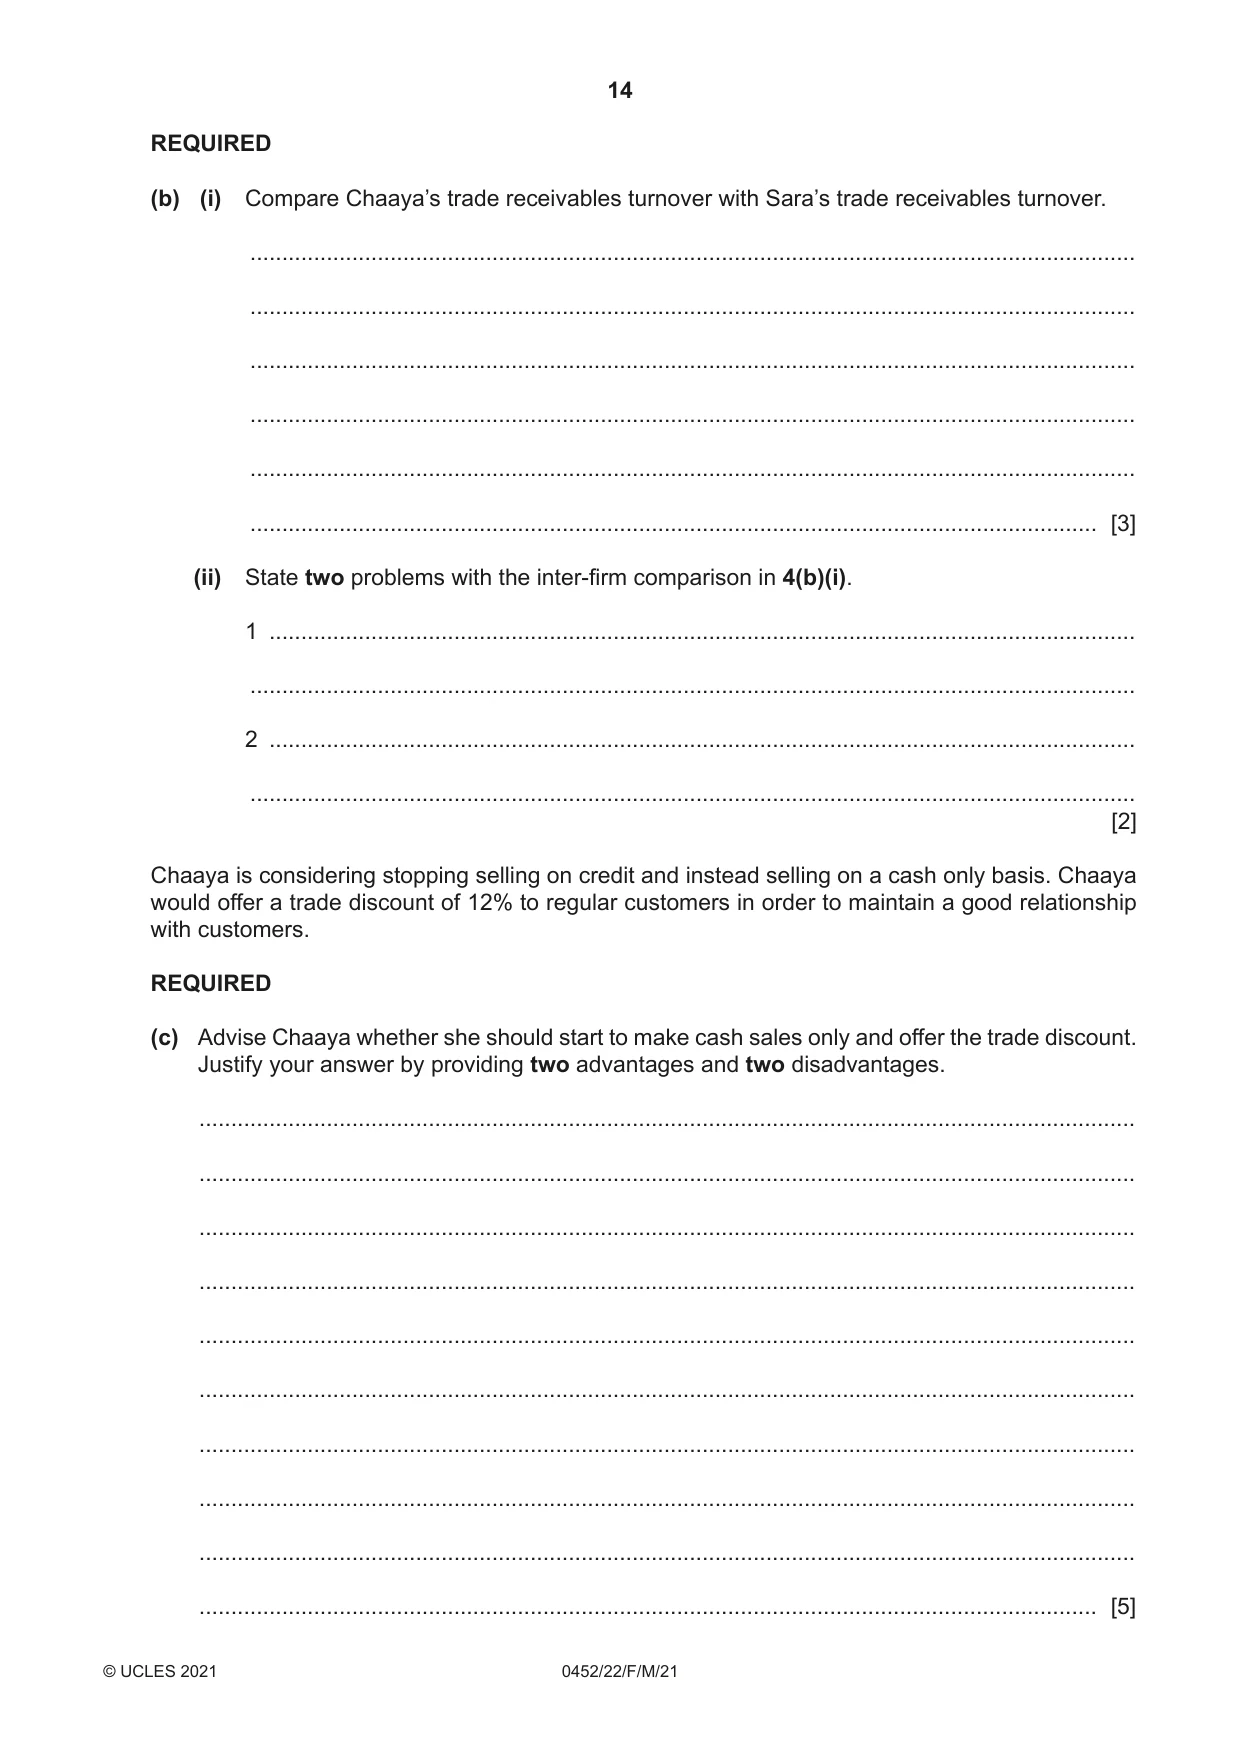
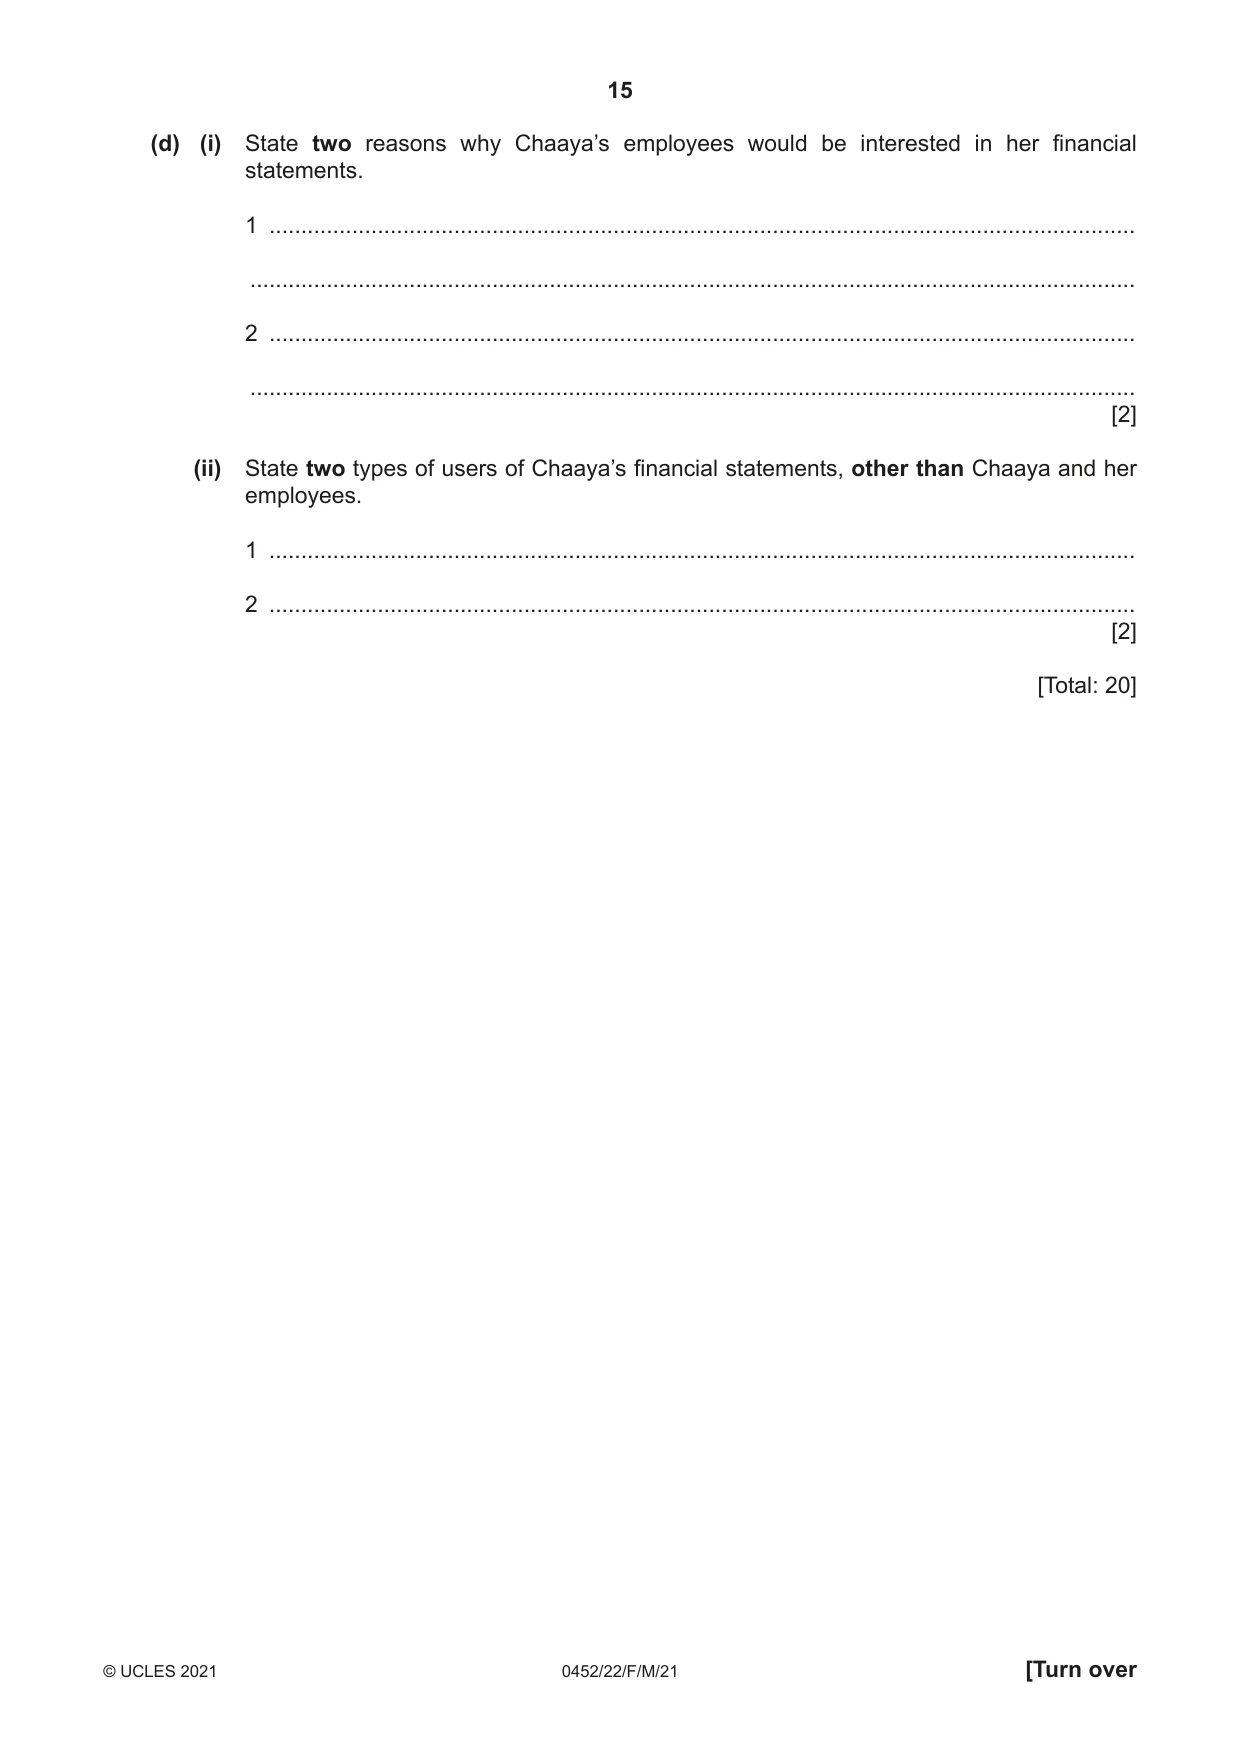
4 Chaaya provided the following information. $ For the year to 31 December 2020 Credit sales 114 400 Credit purchases 63 110 Gross profit 51 480 At 31 December 2020 Inventory 2 850 Trade receivables 15 400 Trade payables 7 430 Bank overdraft 6 190 REQUIRED (a) Complete the following table. ratio working answer gross margin trade receivables turnover days (round up to next whole day) current ratio (correct to two decimal places) [6] Chaaya is comparing her ratios with those of Sara, her main competitor. Based on Sara’s most recent financial statements, her trade receivables turnover is 28 days. REQUIRED (b) (i) Compare Chaaya’s trade receivables turnover with Sara’s trade receivables turnover. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] (ii) State two problems with the inter-firm comparison in 4(b)(i). 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] Chaaya is considering stopping selling on credit and instead selling on a cash only basis. Chaaya would offer a trade discount of 12% to regular customers in order to maintain a good relationship with customers. REQUIRED (c) Advise Chaaya whether she should start to make cash sales only and offer the trade discount. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) (i) State two reasons why Chaaya’s employees would be interested in her financial statements. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (ii) State two types of users of Chaaya’s financial statements, other than Chaaya and her employees. 1 ........................................................................................................................................ 2 ........................................................................................................................................ [2] [Total: 20]
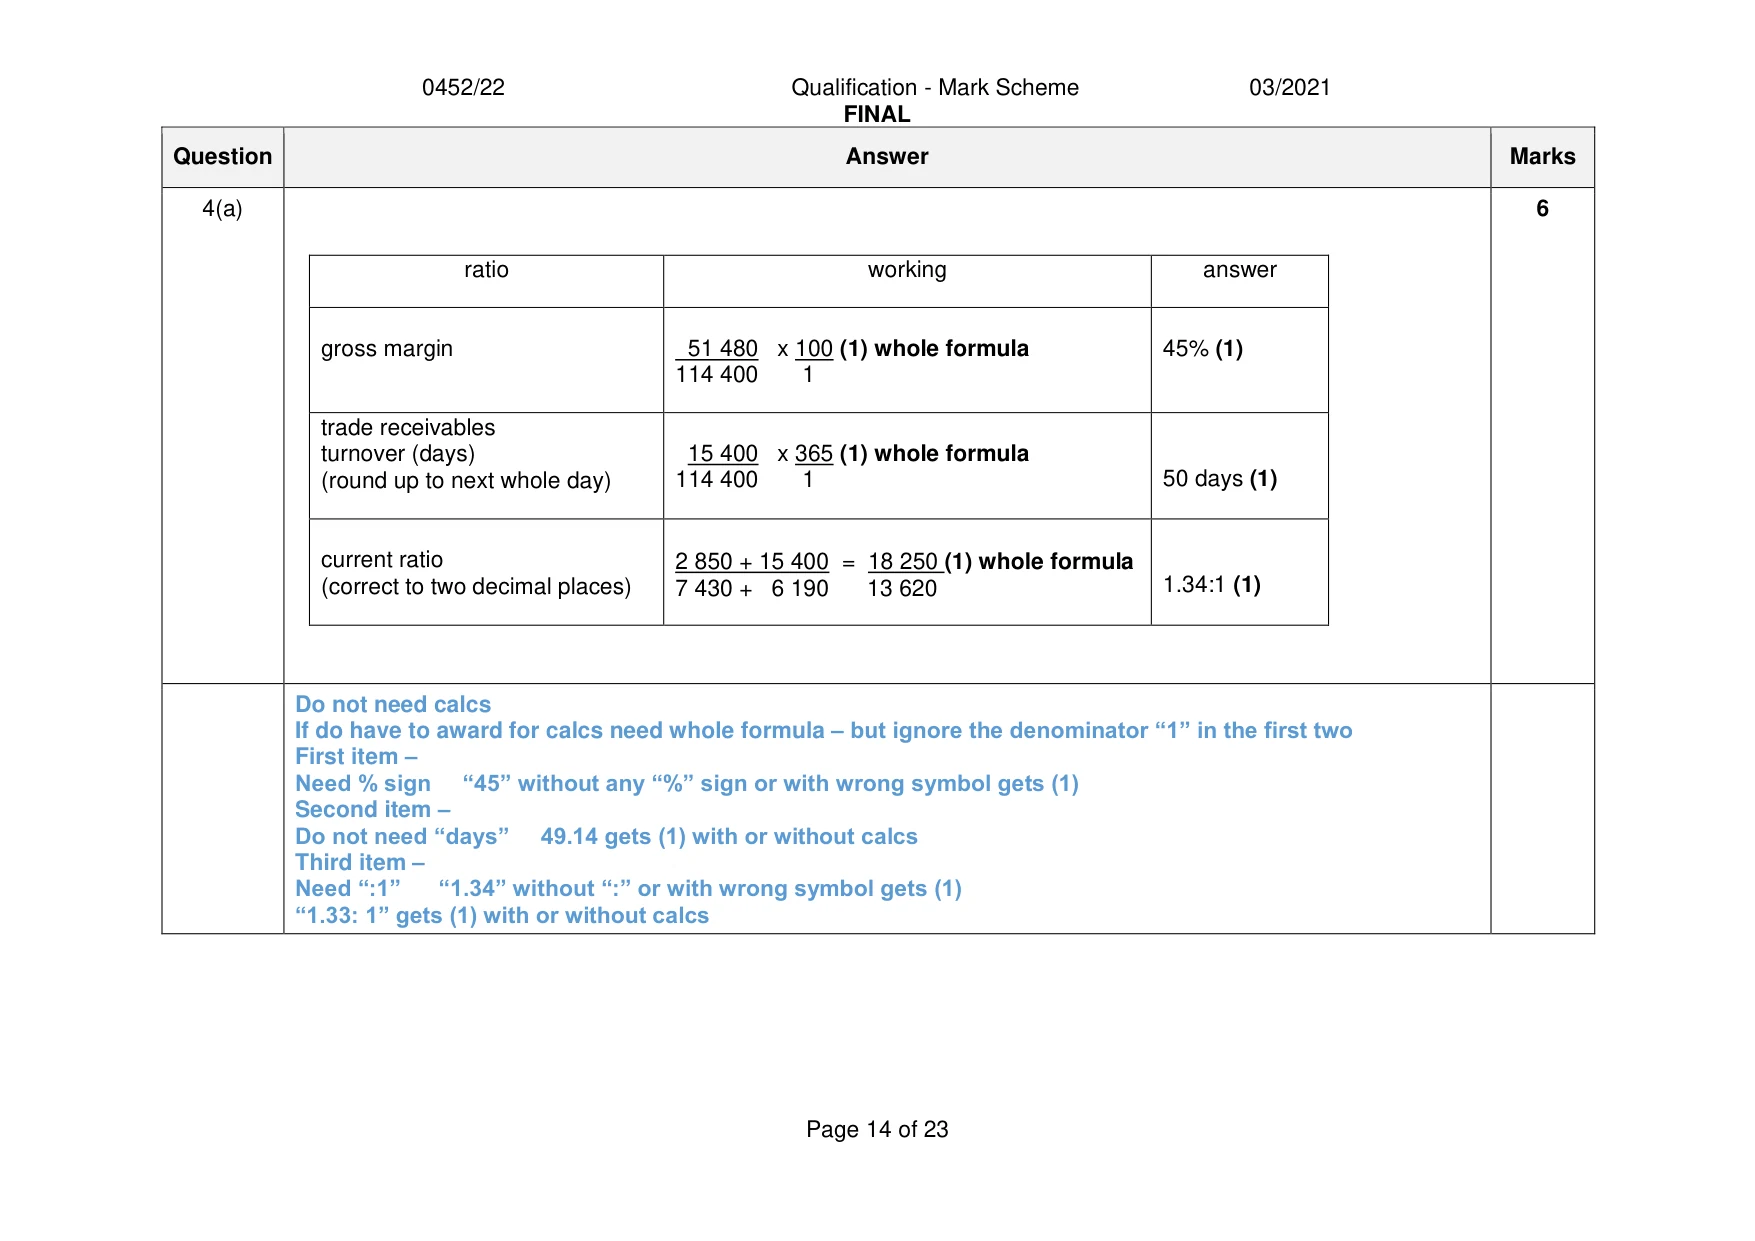
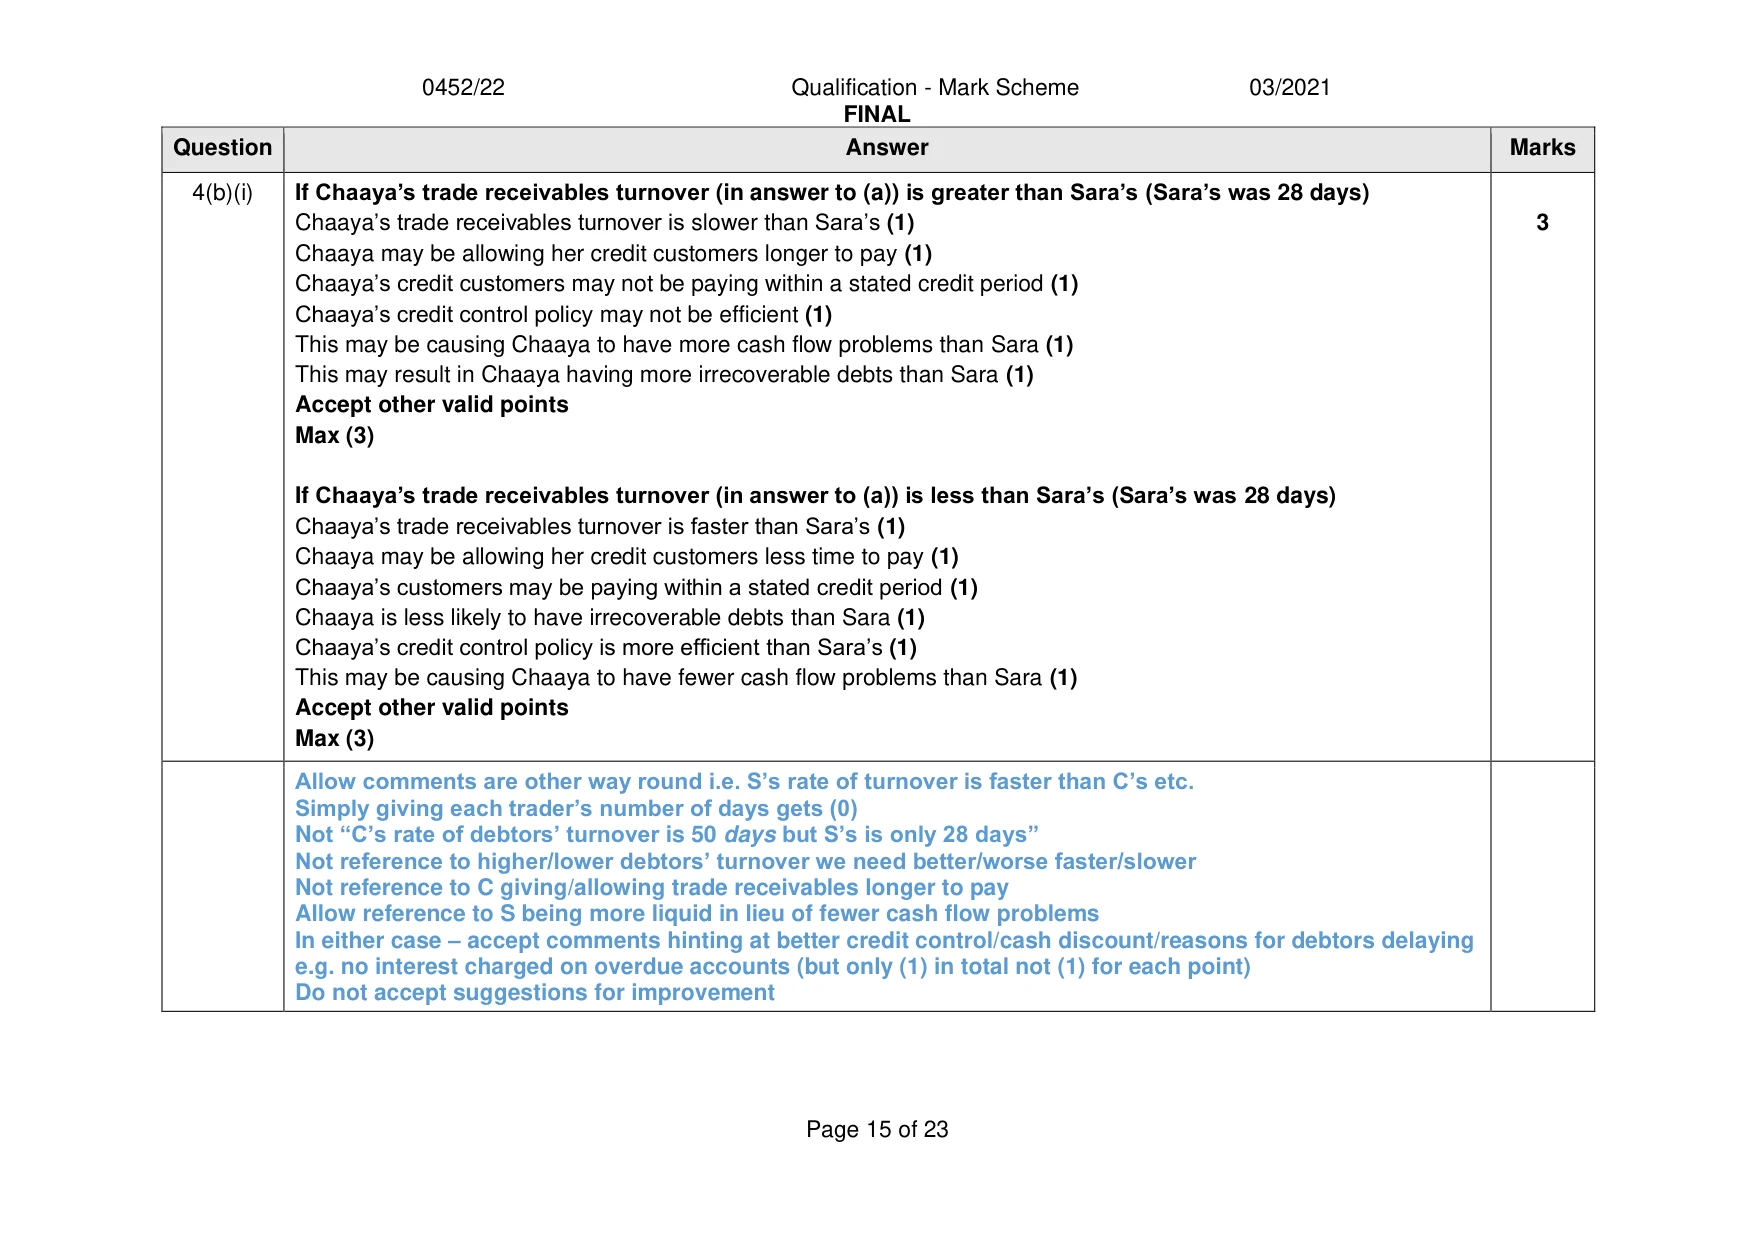
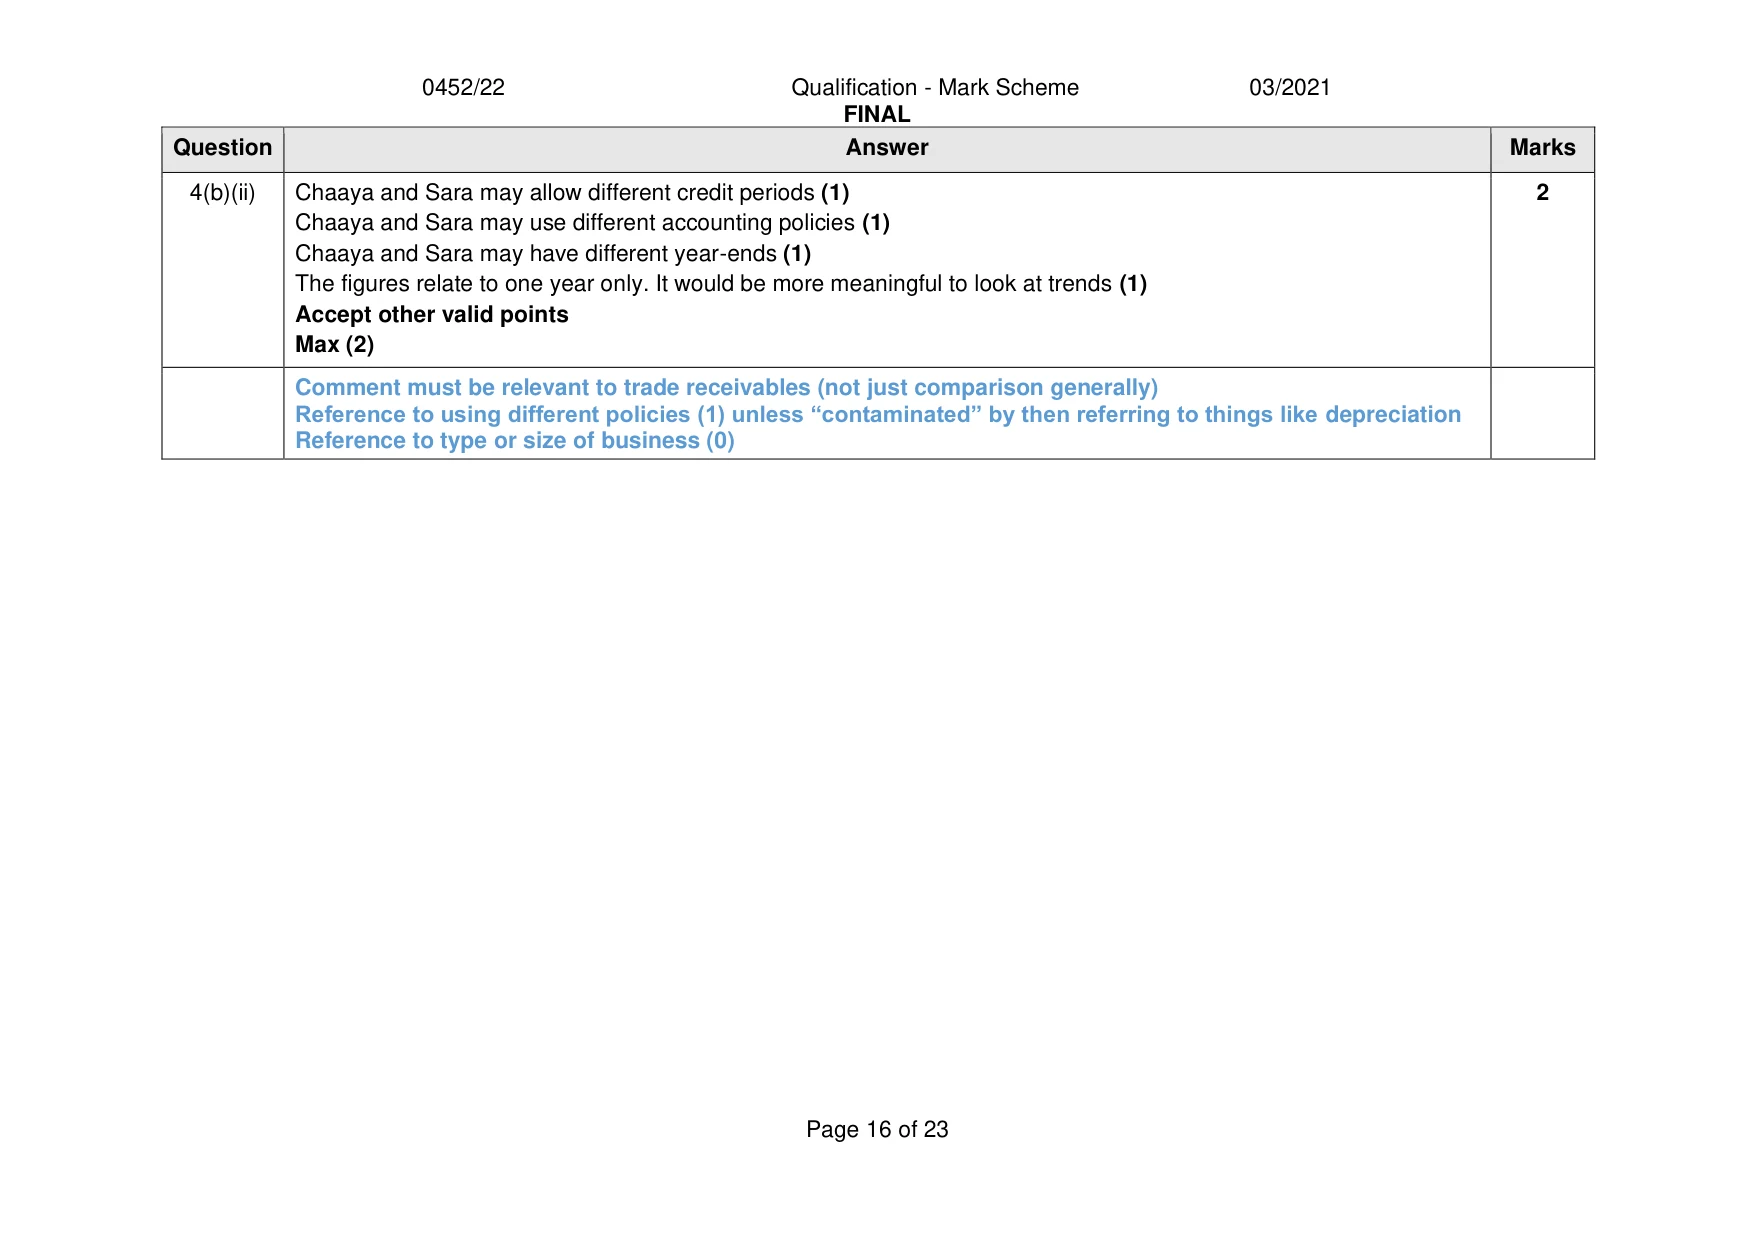
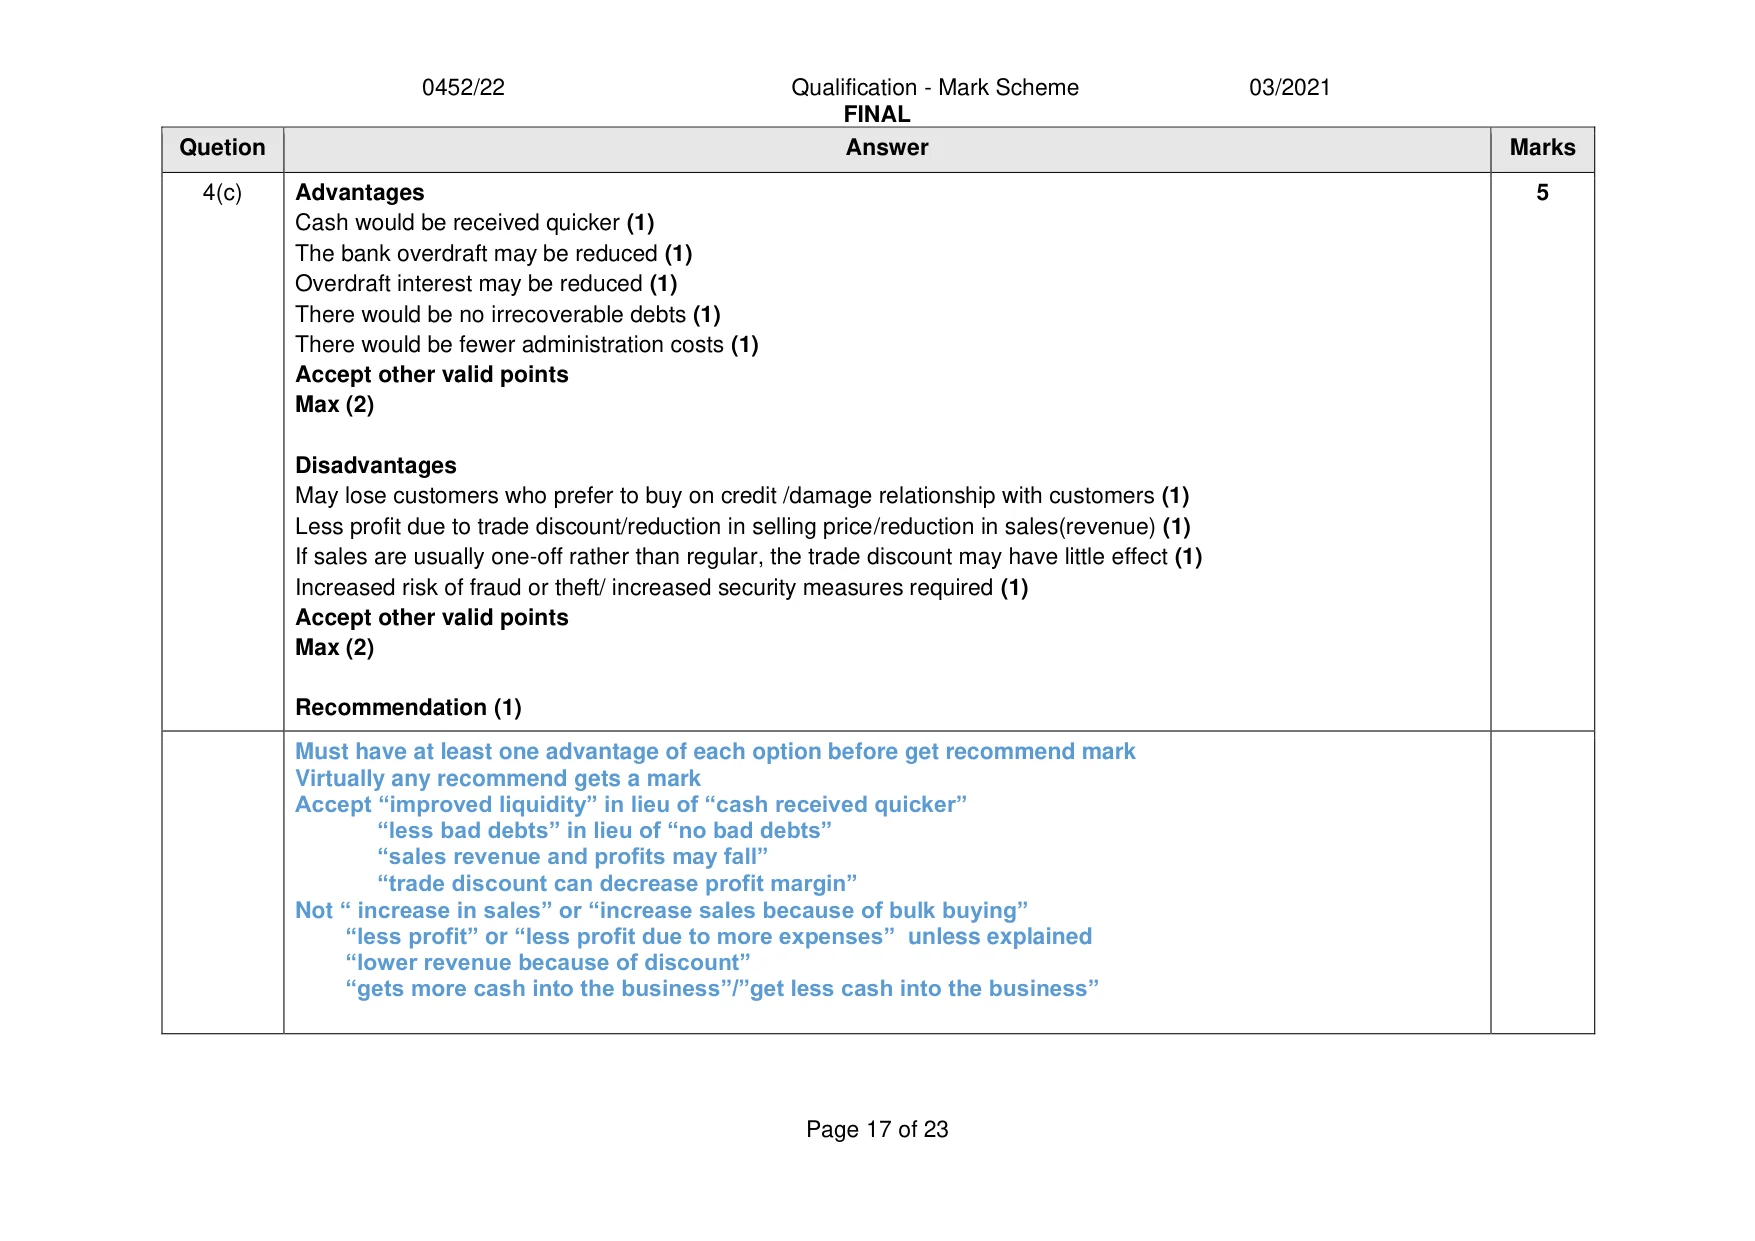
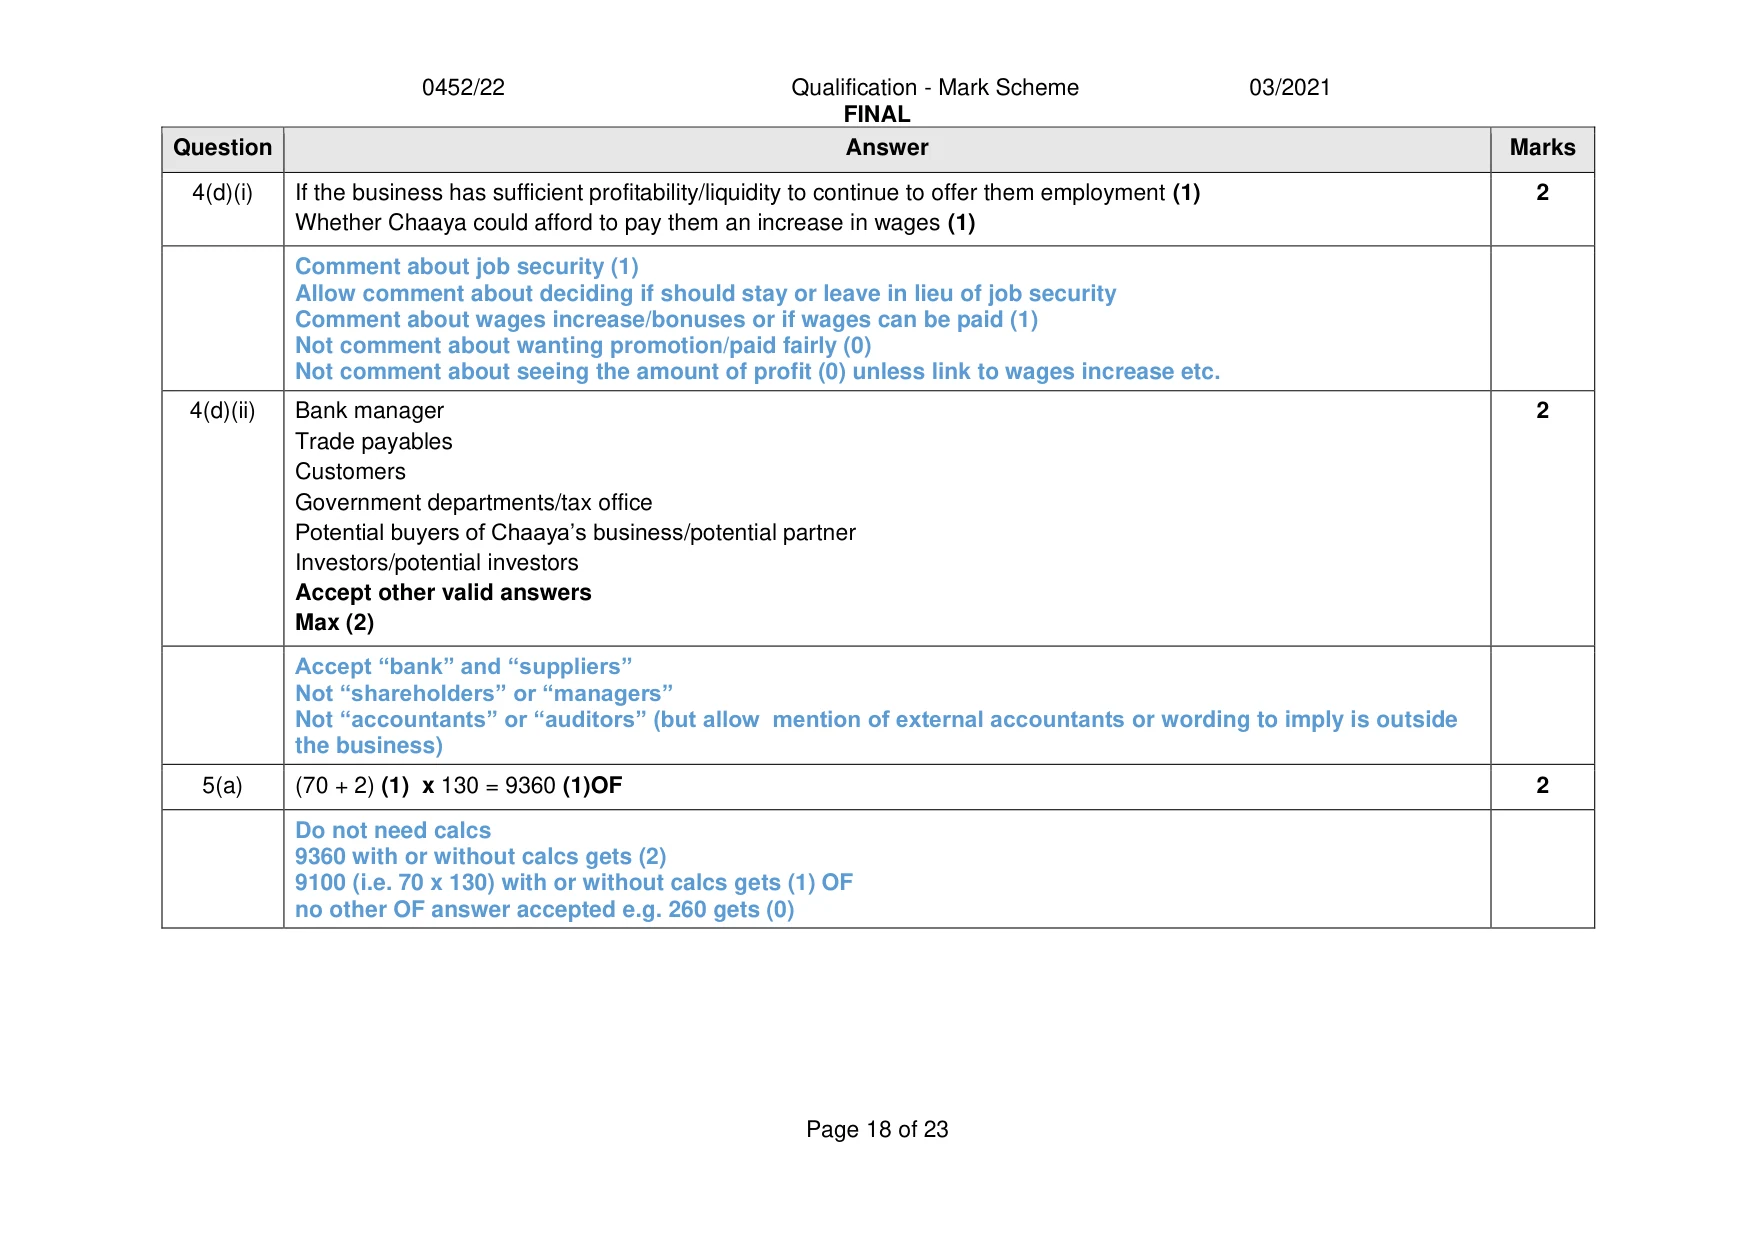
Mark scheme: 4(a) 6 ratio working answer gross margin 51 480 x 100 (1) whole formula 45% (1) 114 400 1 trade receivables turnover (days) 15 400 x 365 (1) whole formula (round up to next whole day) 114 400 1 50 days (1) current ratio 2 850 + 15 400 = 18 250 (1) whole formula (correct to two decimal places) 7 430 + 6 190 13 620 1.34:1 (1) Do not need calcs If do have to award for calcs need whole formula – but ignore the denominator “1” in the first two First item – Need % sign “45” without any “%” sign or with wrong symbol gets (1) Second item – Do not need “days” 49.14 gets (1) with or without calcs Third item – Need “:1” “1.34” without “:” or with wrong symbol gets (1) “1.33: 1” gets (1) with or without calcs 4(b)(i) If Chaaya’s trade receivables turnover (in answer to (a)) is greater than Sara’s (Sara’s was 28 days) Chaaya’s trade receivables turnover is slower than Sara’s (1) 3 Chaaya may be allowing her credit customers longer to pay (1) Chaaya’s credit customers may not be paying within a stated credit period (1) Chaaya’s credit control policy may not be efficient (1) This may be causing Chaaya to have more cash flow problems than Sara (1) This may result in Chaaya having more irrecoverable debts than Sara (1) Accept other valid points Max (3) If Chaaya’s trade receivables turnover (in answer to (a)) is less than Sara’s (Sara’s was 28 days) Chaaya’s trade receivables turnover is faster than Sara’s (1) Chaaya may be allowing her credit customers less time to pay (1) Chaaya’s customers may be paying within a stated credit period (1) Chaaya is less likely to have irrecoverable debts than Sara (1) Chaaya’s credit control policy is more efficient than Sara’s (1) This may be causing Chaaya to have fewer cash flow problems than Sara (1) Accept other valid points Max (3) Allow comments are other way round i.e. S’s rate of turnover is faster than C’s etc. Simply giving each trader’s number of days gets (0) Not “C’s rate of debtors’ turnover is 50 days but S’s is only 28 days” Not reference to higher/lower debtors’ turnover we need better/worse faster/slower Not reference to C giving/allowing trade receivables longer to pay Allow reference to S being more liquid in lieu of fewer cash flow problems In either case – accept comments hinting at better credit control/cash discount/reasons for debtors delaying e.g. no interest charged on overdue accounts (but only (1) in total not (1) for each point) Do not accept suggestions for improvement 4(b)(ii) Chaaya and Sara may allow different credit periods (1) 2 Chaaya and Sara may use different accounting policies (1) Chaaya and Sara may have different year-ends (1) The figures relate to one year only. It would be more meaningful to look at trends (1) Accept other valid points Max (2) Comment must be relevant to trade receivables (not just comparison generally) Reference to using different policies (1) unless “contaminated” by then referring to things like depreciation Reference to type or size of business (0) FINAL Quetion Answer Marks 4(c) Advantages 5 Cash would be received quicker (1) The bank overdraft may be reduced (1) Overdraft interest may be reduced (1) There would be no irrecoverable debts (1) There would be fewer administration costs (1) Accept other valid points Max (2) Disadvantages May lose customers who prefer to buy on credit /damage relationship with customers (1) Less profit due to trade discount/reduction in selling price/reduction in sales(revenue) (1) If sales are usually one-off rather than regular, the trade discount may have little effect (1) Increased risk of fraud or theft/ increased security measures required (1) Accept other valid points Max (2) Recommendation (1) Must have at least one advantage of each option before get recommend mark Virtually any recommend gets a mark Accept “improved liquidity” in lieu of “cash received quicker” “less bad debts” in lieu of “no bad debts” “sales revenue and profits may fall” “trade discount can decrease profit margin” Not “ increase in sales” or “increase sales because of bulk buying” “less profit” or “less profit due to more expenses” unless explained “lower revenue because of discount” “gets more cash into the business”/”get less cash into the business” 4(d)(i) If the business has sufficient profitability/liquidity to continue to offer them employment (1) 2 Whether Chaaya could afford to pay them an increase in wages (1) Comment about job security (1) Allow comment about deciding if should stay or leave in lieu of job security Comment about wages increase/bonuses or if wages can be paid (1) Not comment about wanting promotion/paid fairly (0) Not comment about seeing the amount of profit (0) unless link to wages increase etc. 4(d)(ii) Bank manager 2 Trade payables Customers Government departments/tax office Potential buyers of Chaaya’s business/potential partner Investors/potential investors Accept other valid answers Max (2) Accept “bank” and “suppliers” Not “shareholders” or “managers” Not “accountants” or “auditors” (but allow mention of external accountants or wording to imply is outside the business)
More questions on Calculation and understanding of accounting ratios
Q5 · Maira opened a shop on 1 January 2020
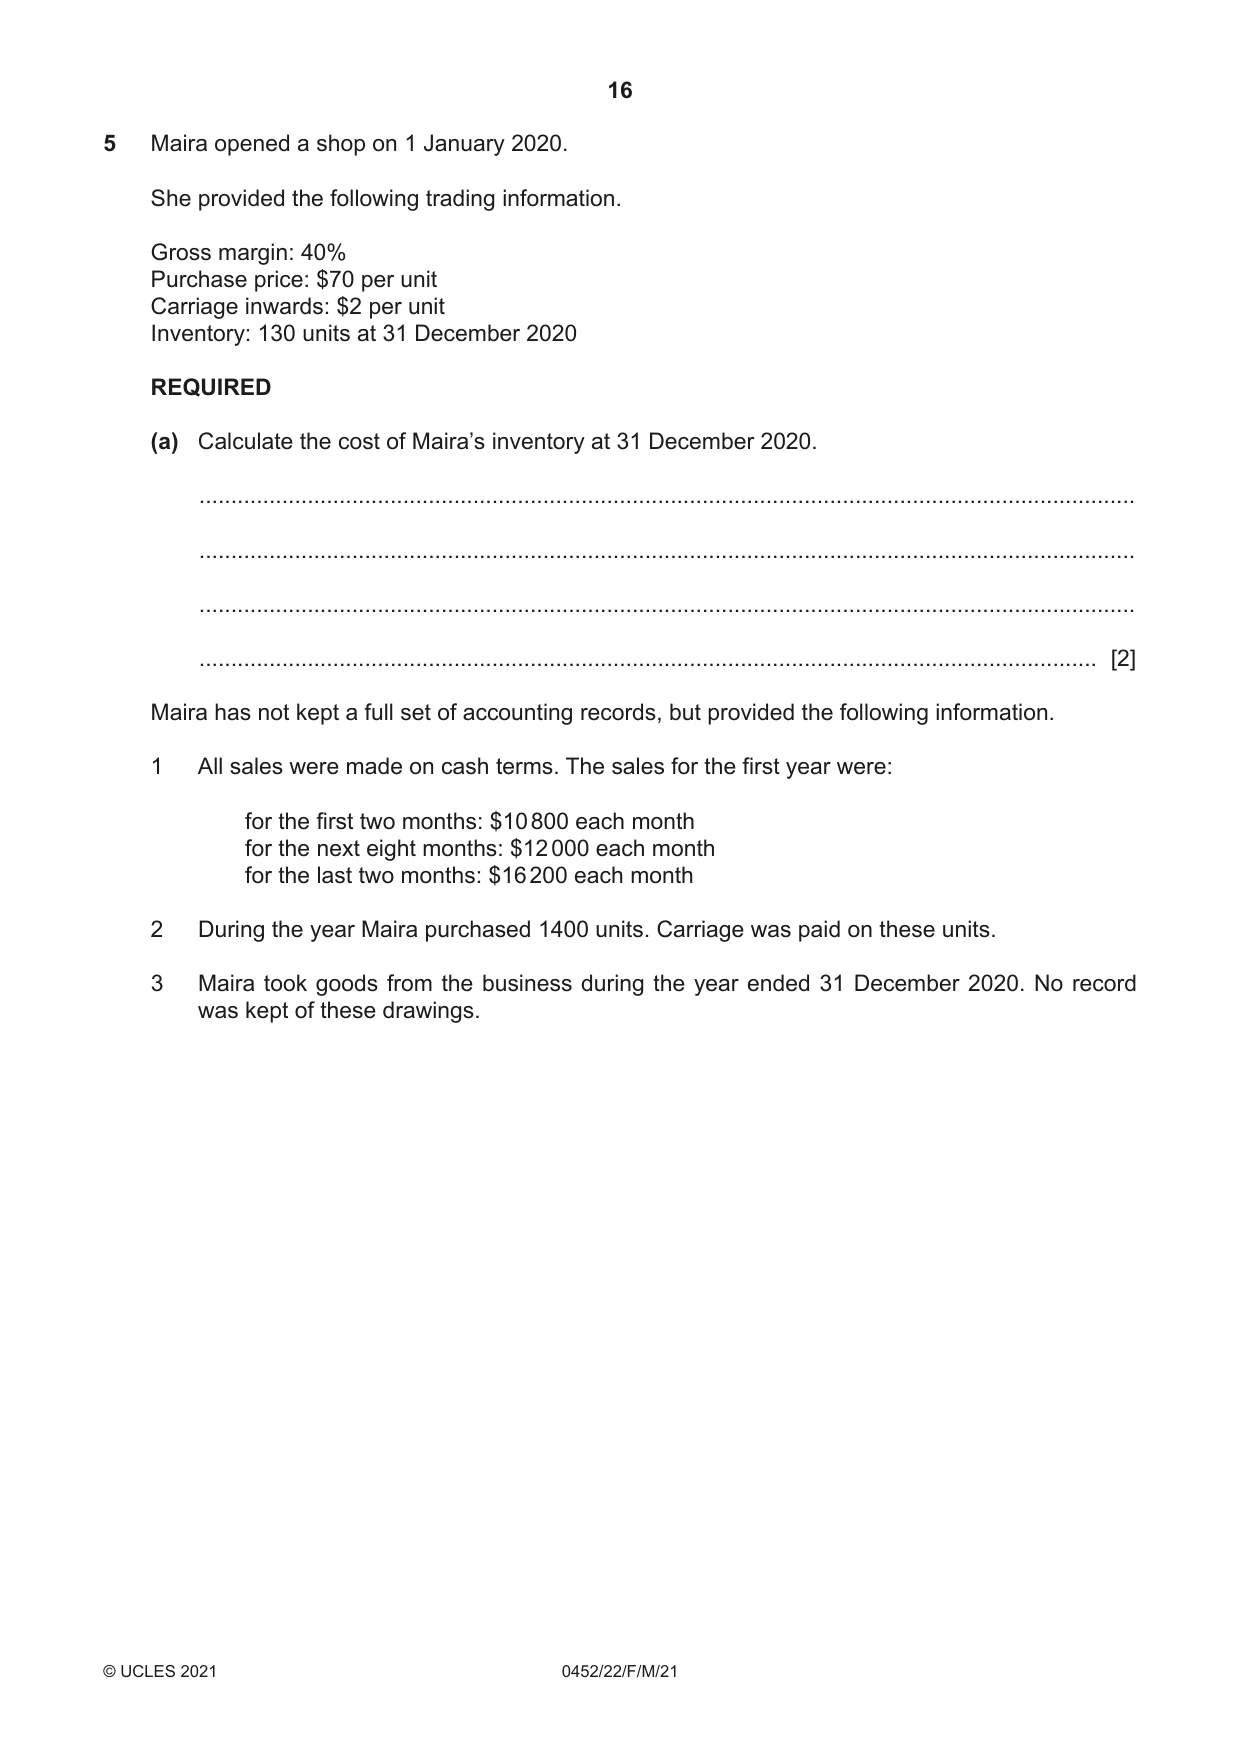
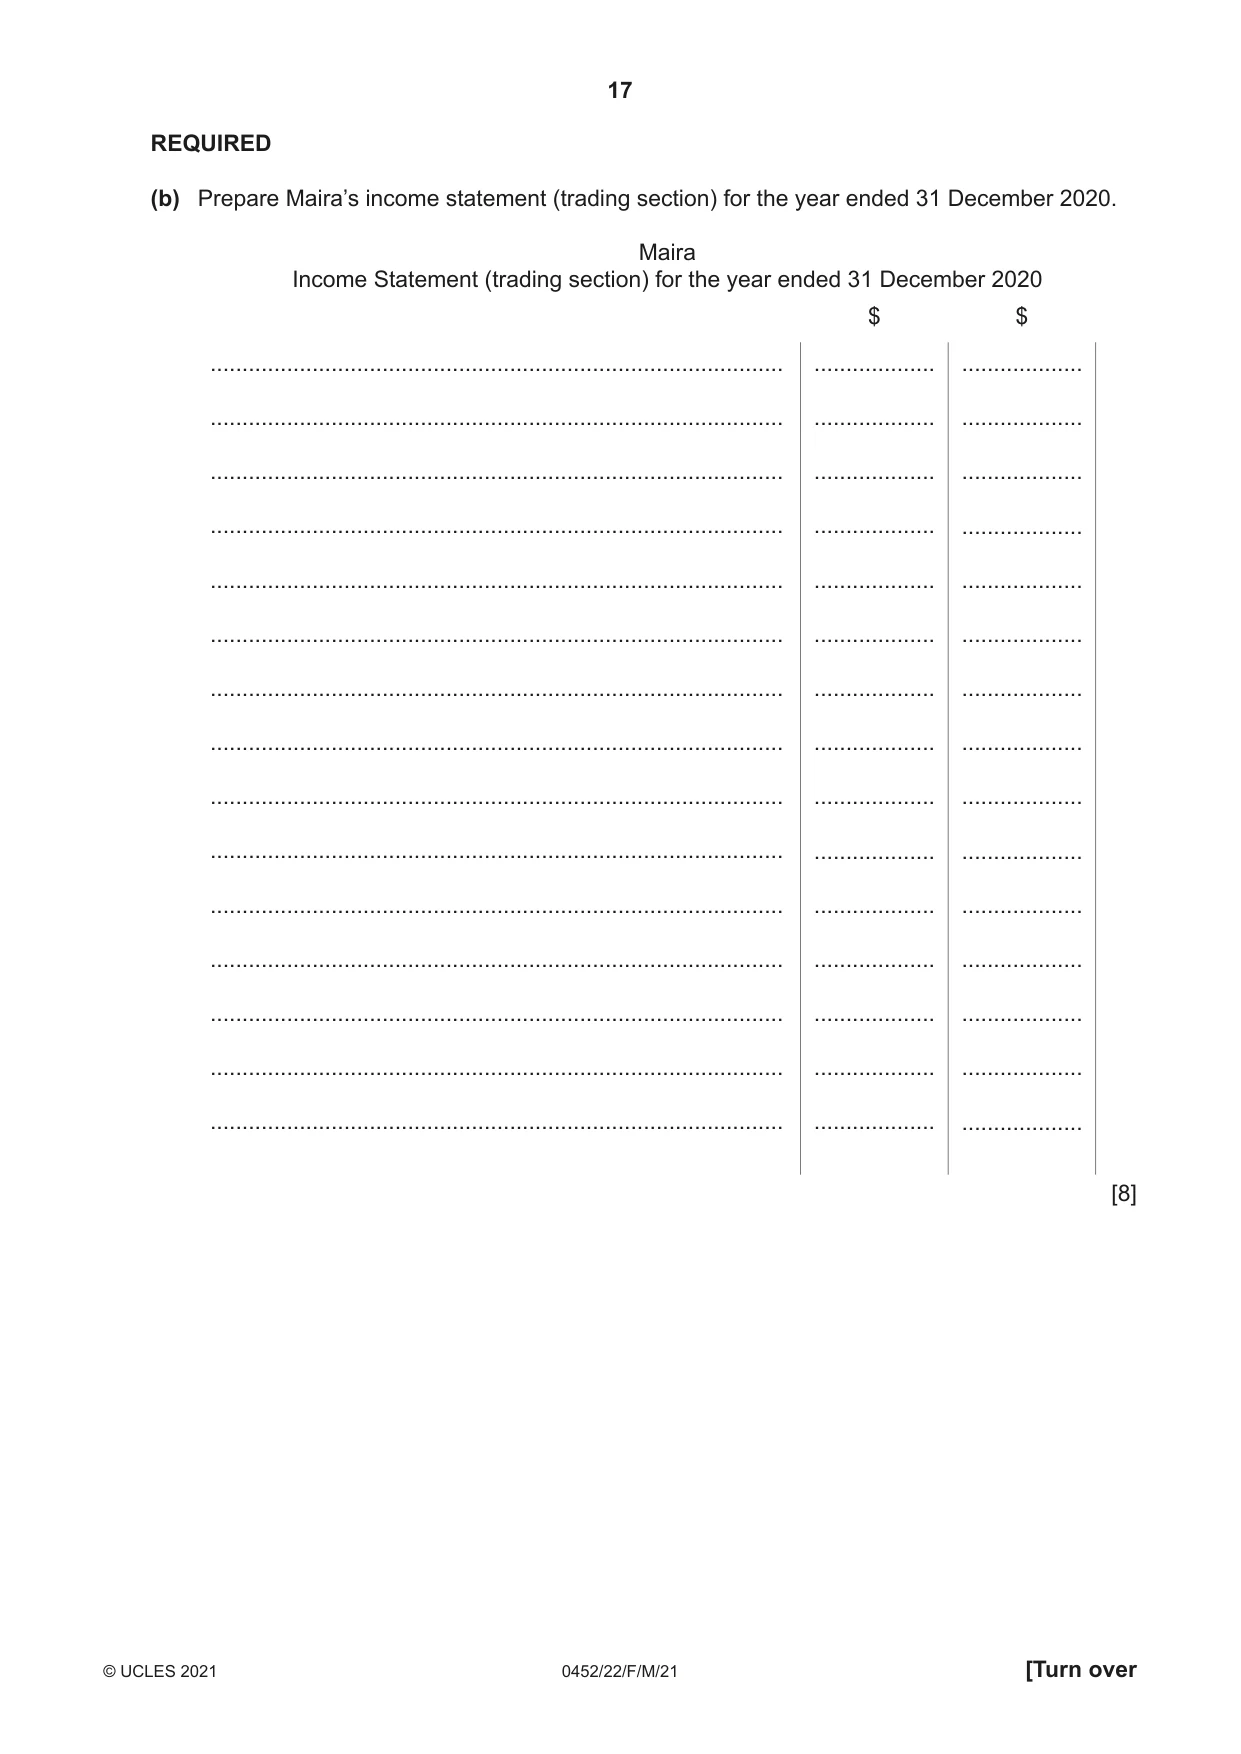
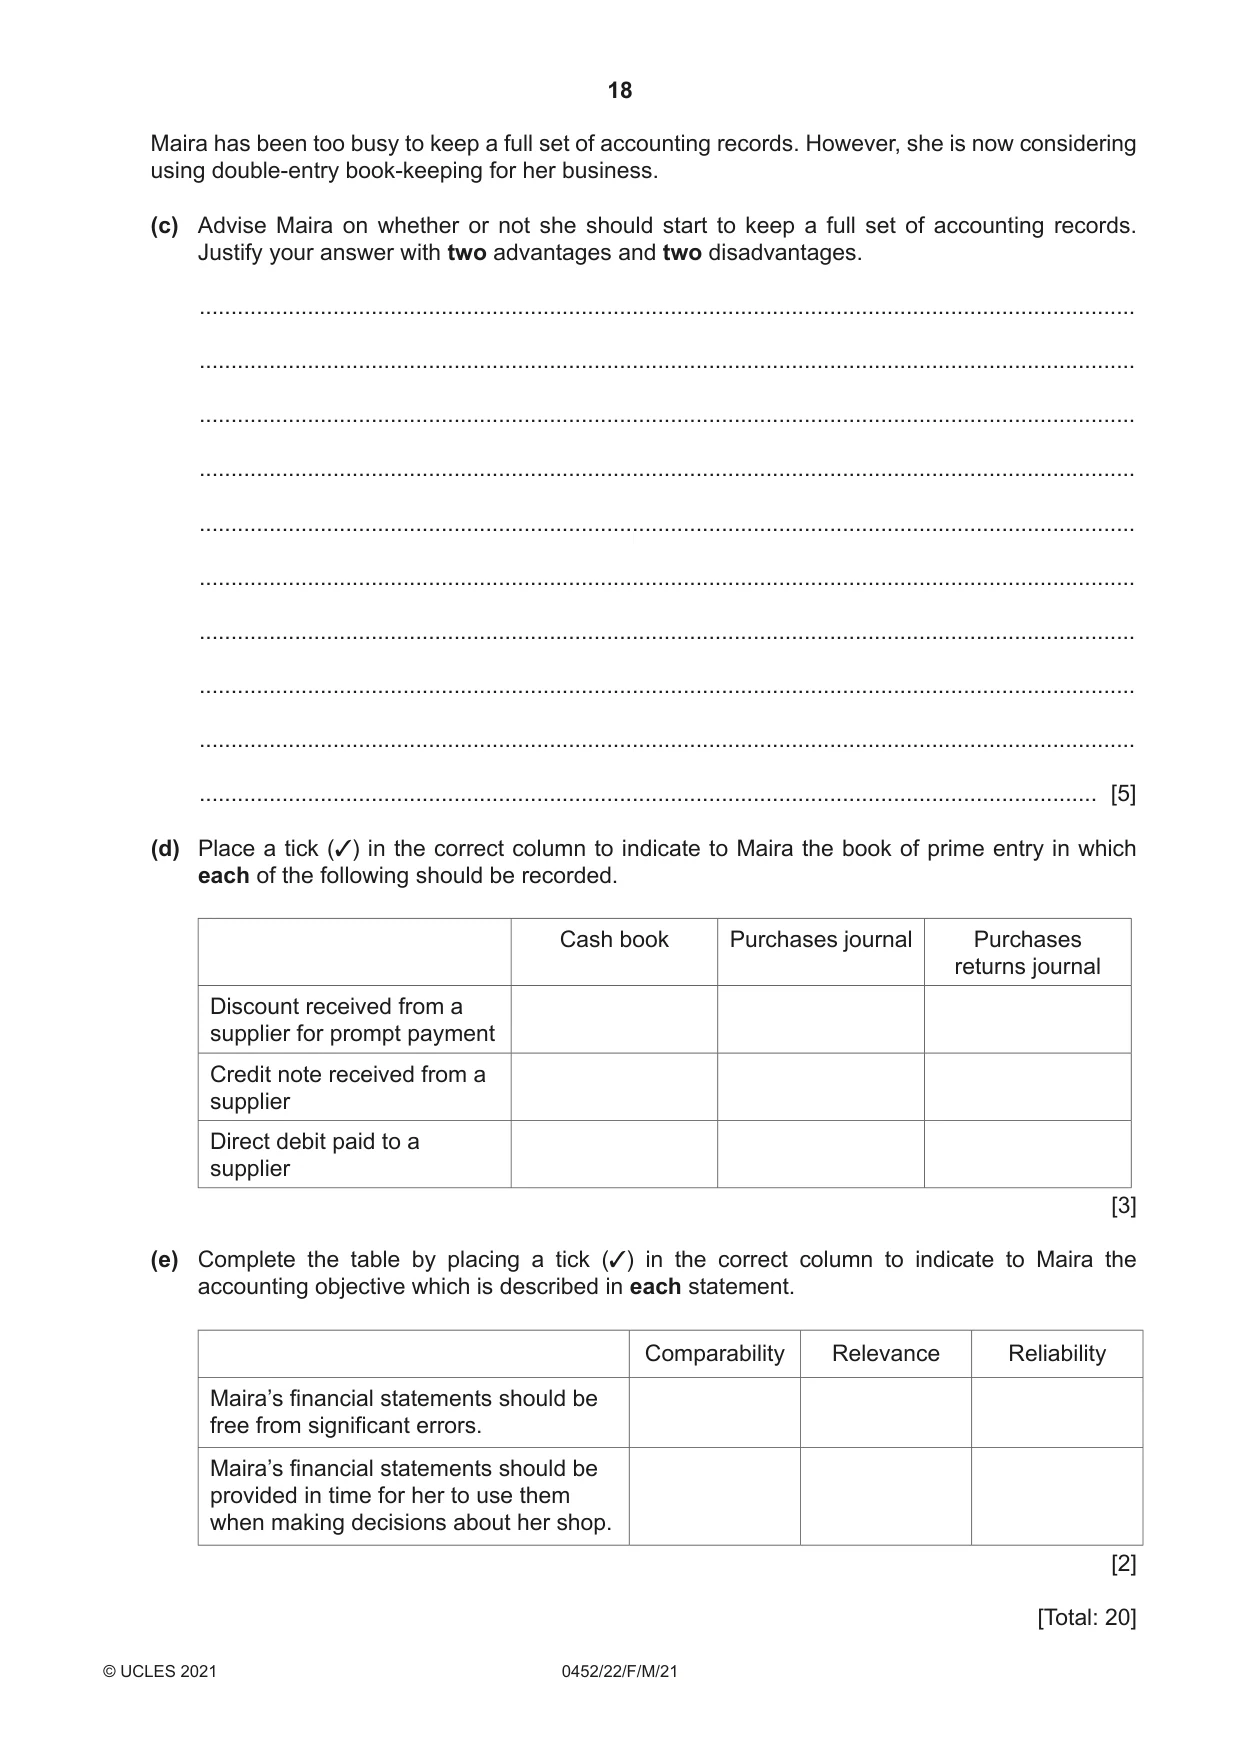
5 Maira opened a shop on 1 January 2020. She provided the following trading information. Gross margin: 40% Purchase price: $70 per unit Carriage inwards: $2 per unit Inventory: 130 units at 31 December 2020 REQUIRED (a) Calculate the cost of Maira’s inventory at 31 December 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Maira has not kept a full set of accounting records, but provided the following information. 1 All sales were made on cash terms. The sales for the first year were: for the first two months: $10 800 each month for the next eight months: $12 000 each month for the last two months: $16 200 each month 2 During the year Maira purchased 1400 units. Carriage was paid on these units. 3 Maira took goods from the business during the year ended 31 December 2020. No record was kept of these drawings. REQUIRED (b) Prepare Maira’s income statement (trading section) for the year ended 31 December 2020. Maira Income Statement (trading section) for the year ended 31 December 2020 $ $ .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... [8] Maira has been too busy to keep a full set of accounting records. However, she is now considering using double-entry book-keeping for her business. (c) Advise Maira on whether or not she should start to keep a full set of accounting records. Justify your answer with two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) Place a tick (3) in the correct column to indicate to Maira the book of prime entry in which each of the following should be recorded. Cash book Purchases journal Purchases returns journal Discount received from a supplier for prompt payment Credit note received from a supplier Direct debit paid to a supplier [3] (e) Complete the table by placing a tick (3) in the correct column to indicate to Maira the accounting objective which is described in each statement. Comparability Relevance Reliability Maira’s financial statements should be free from significant errors. Maira’s financial statements should be provided in time for her to use them when making decisions about her shop. [2] [Total: 20]
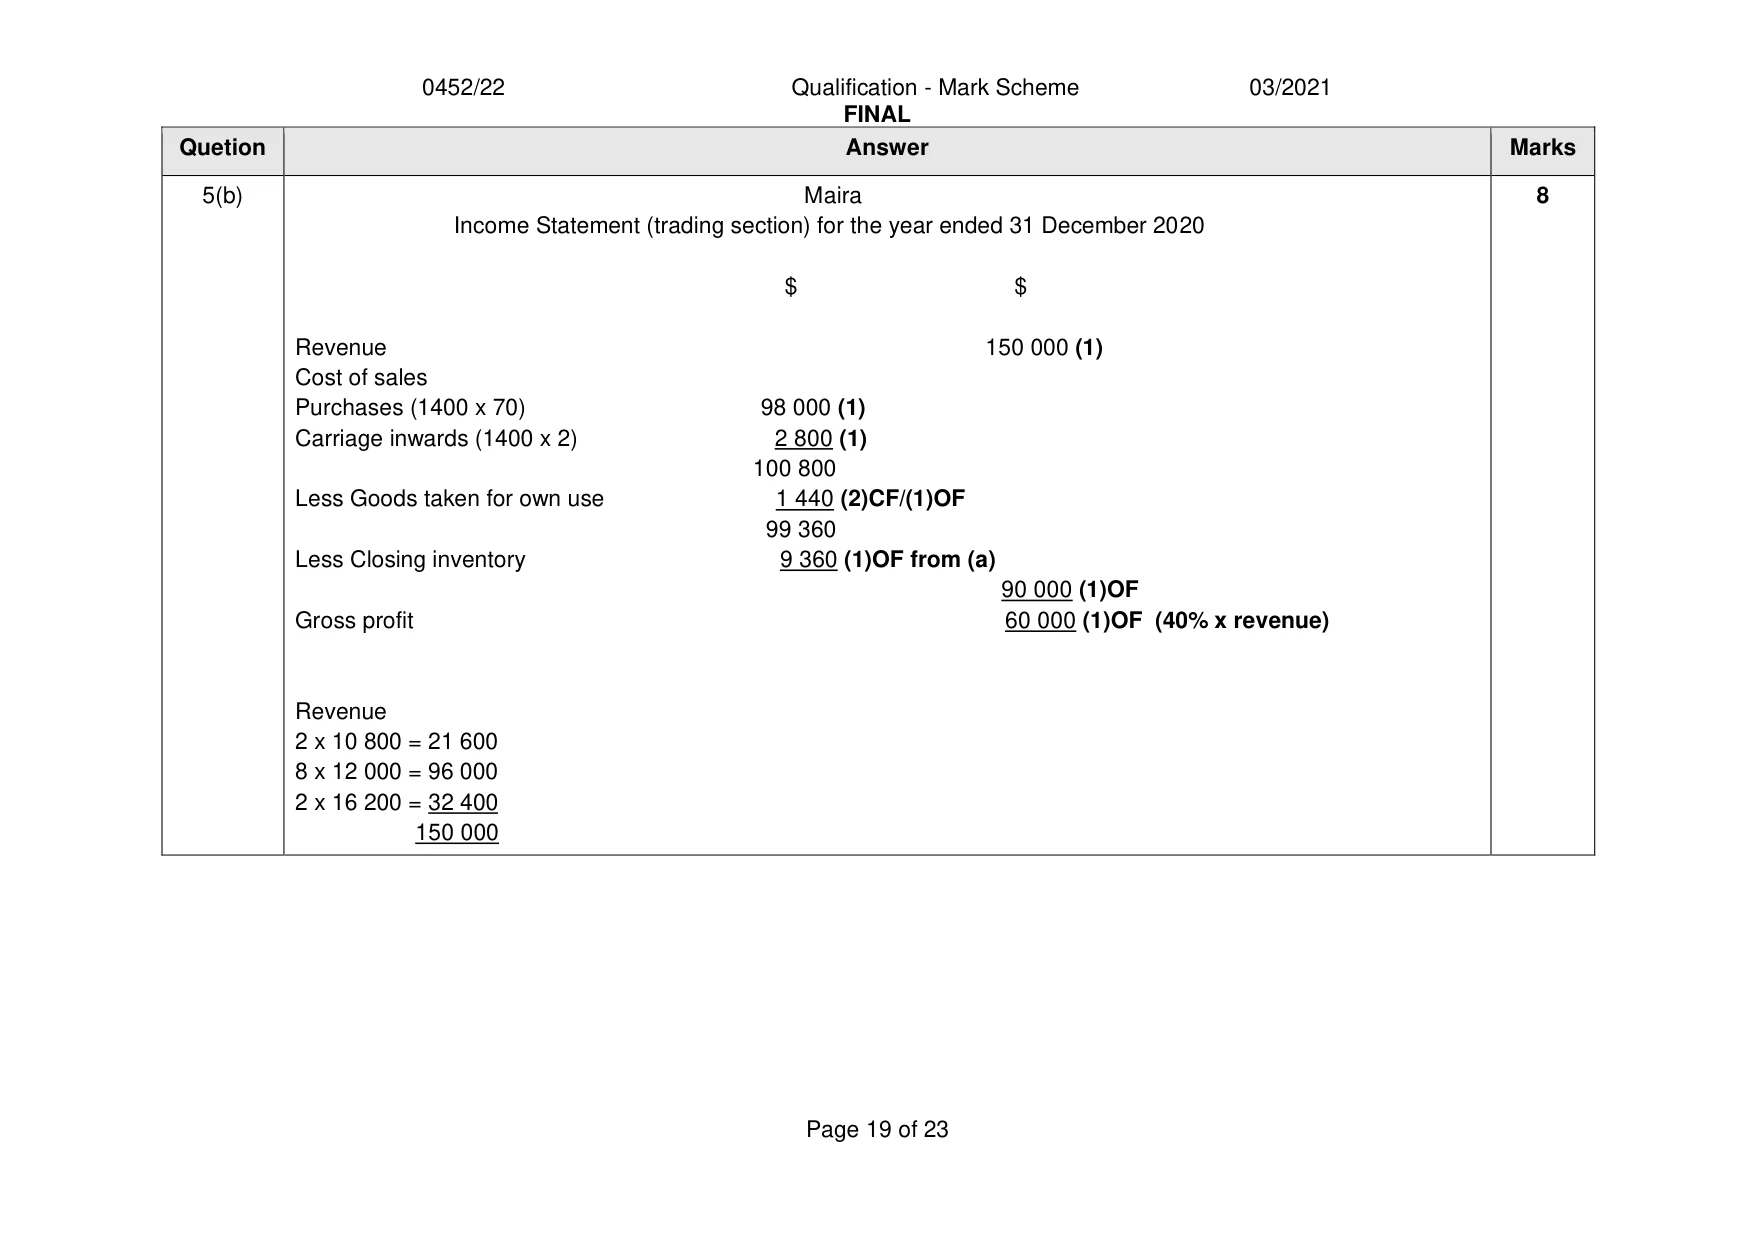
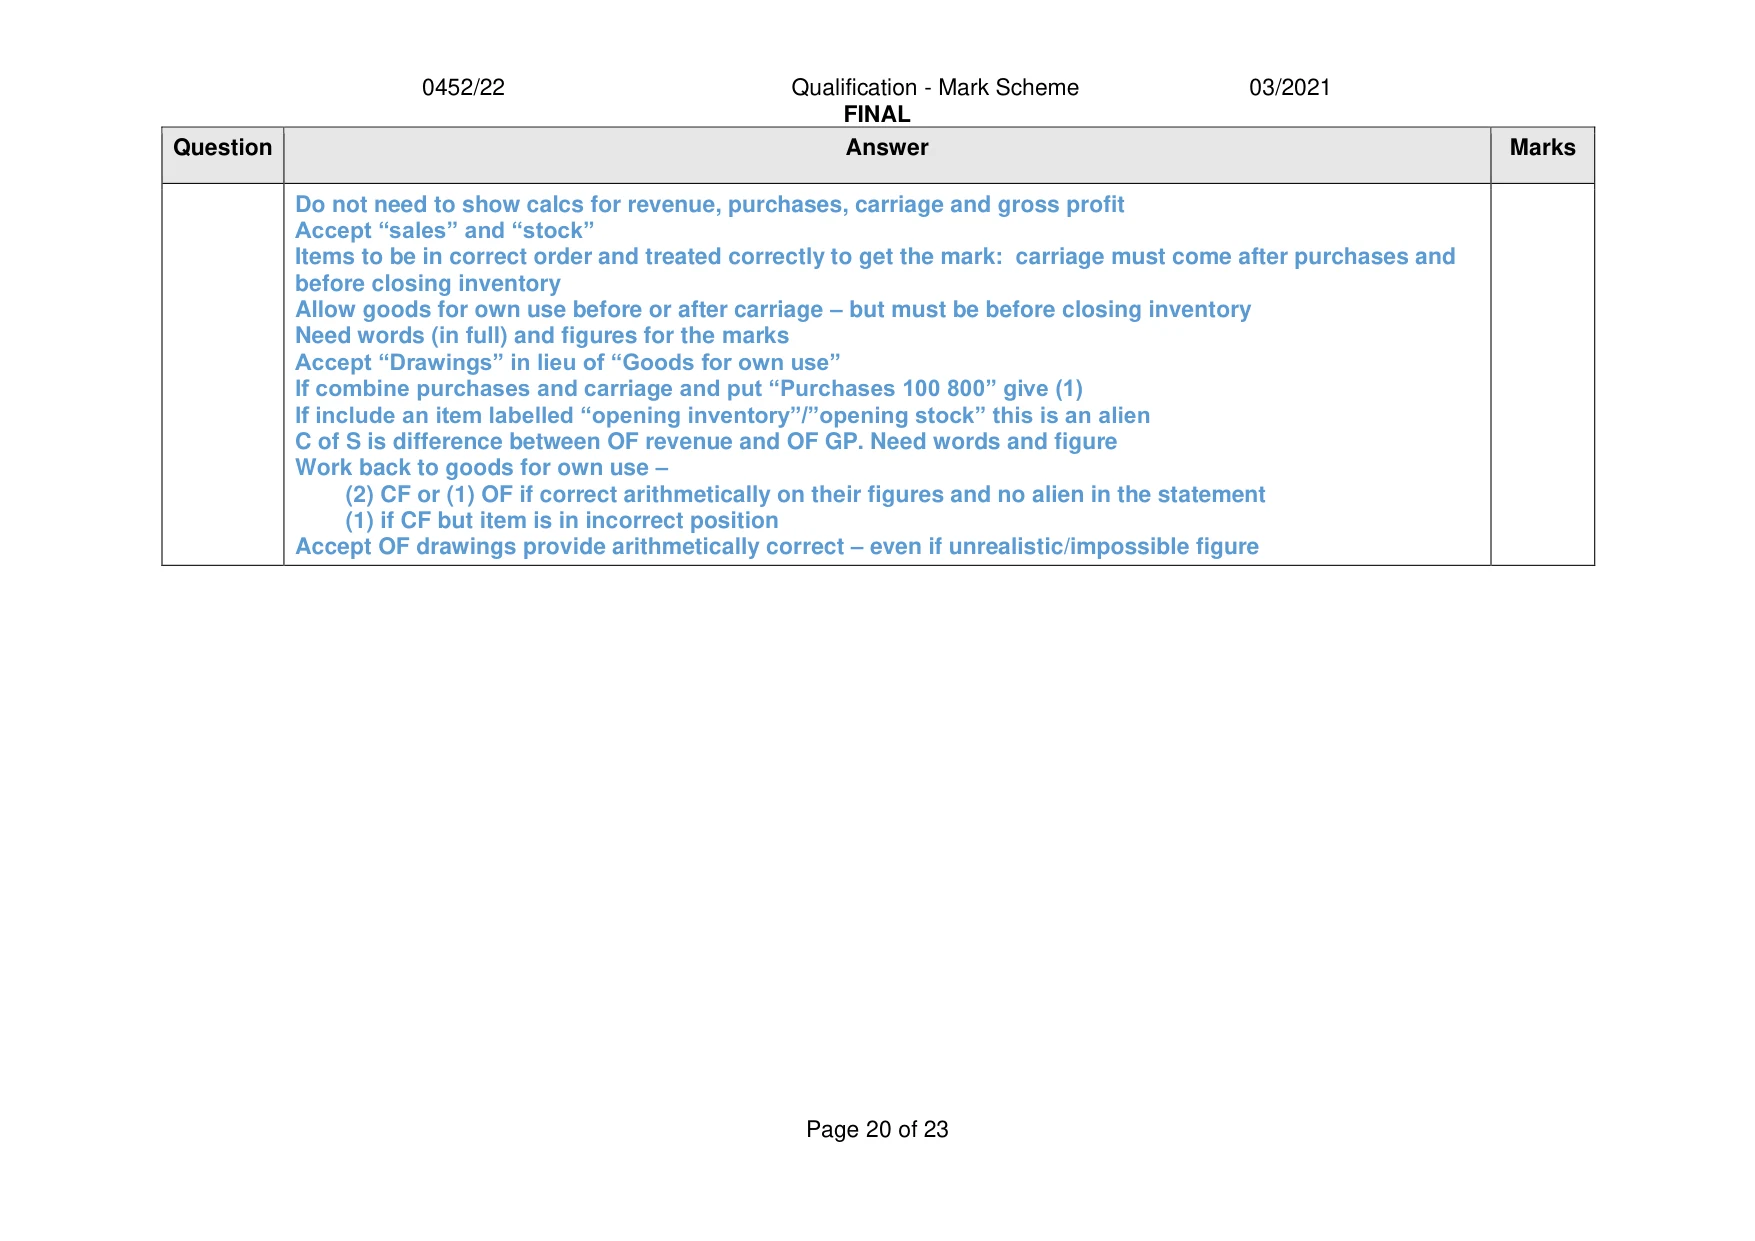
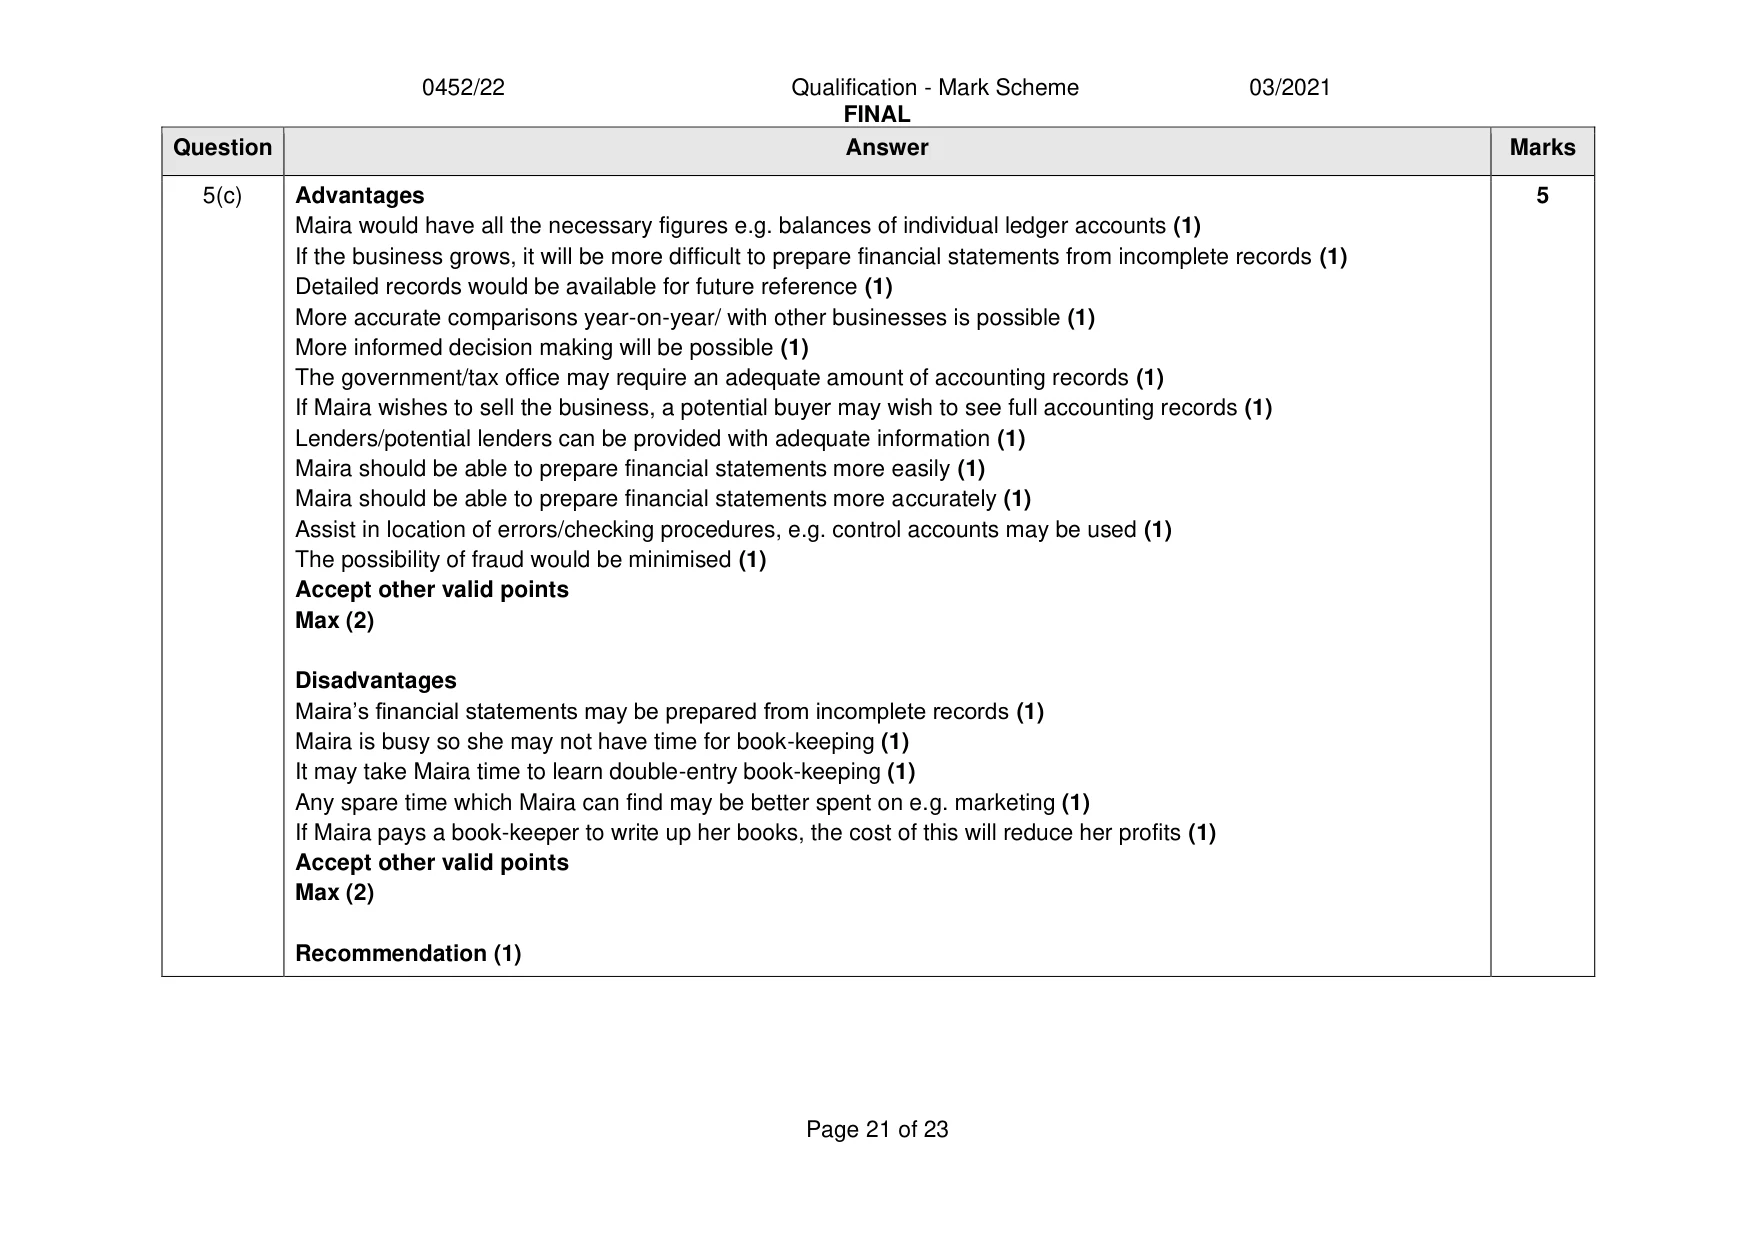
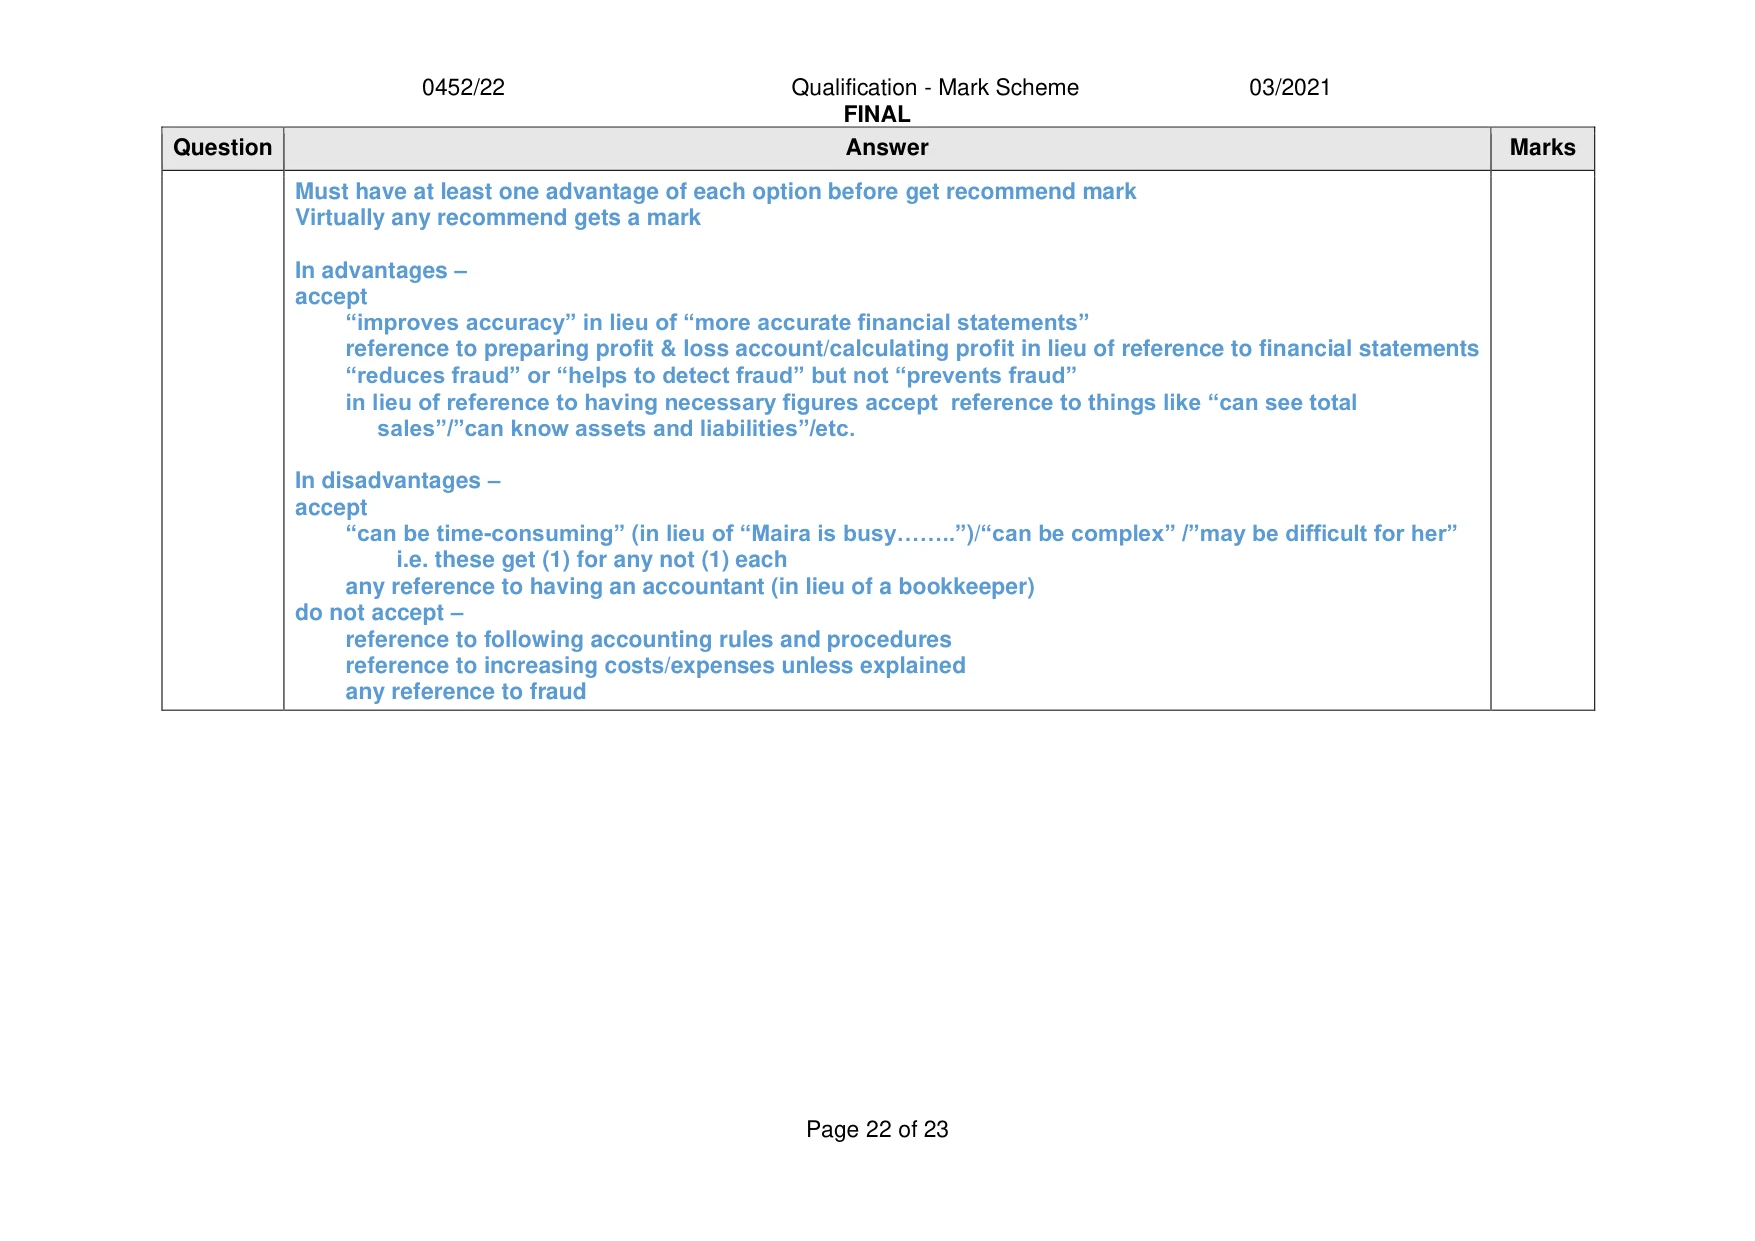
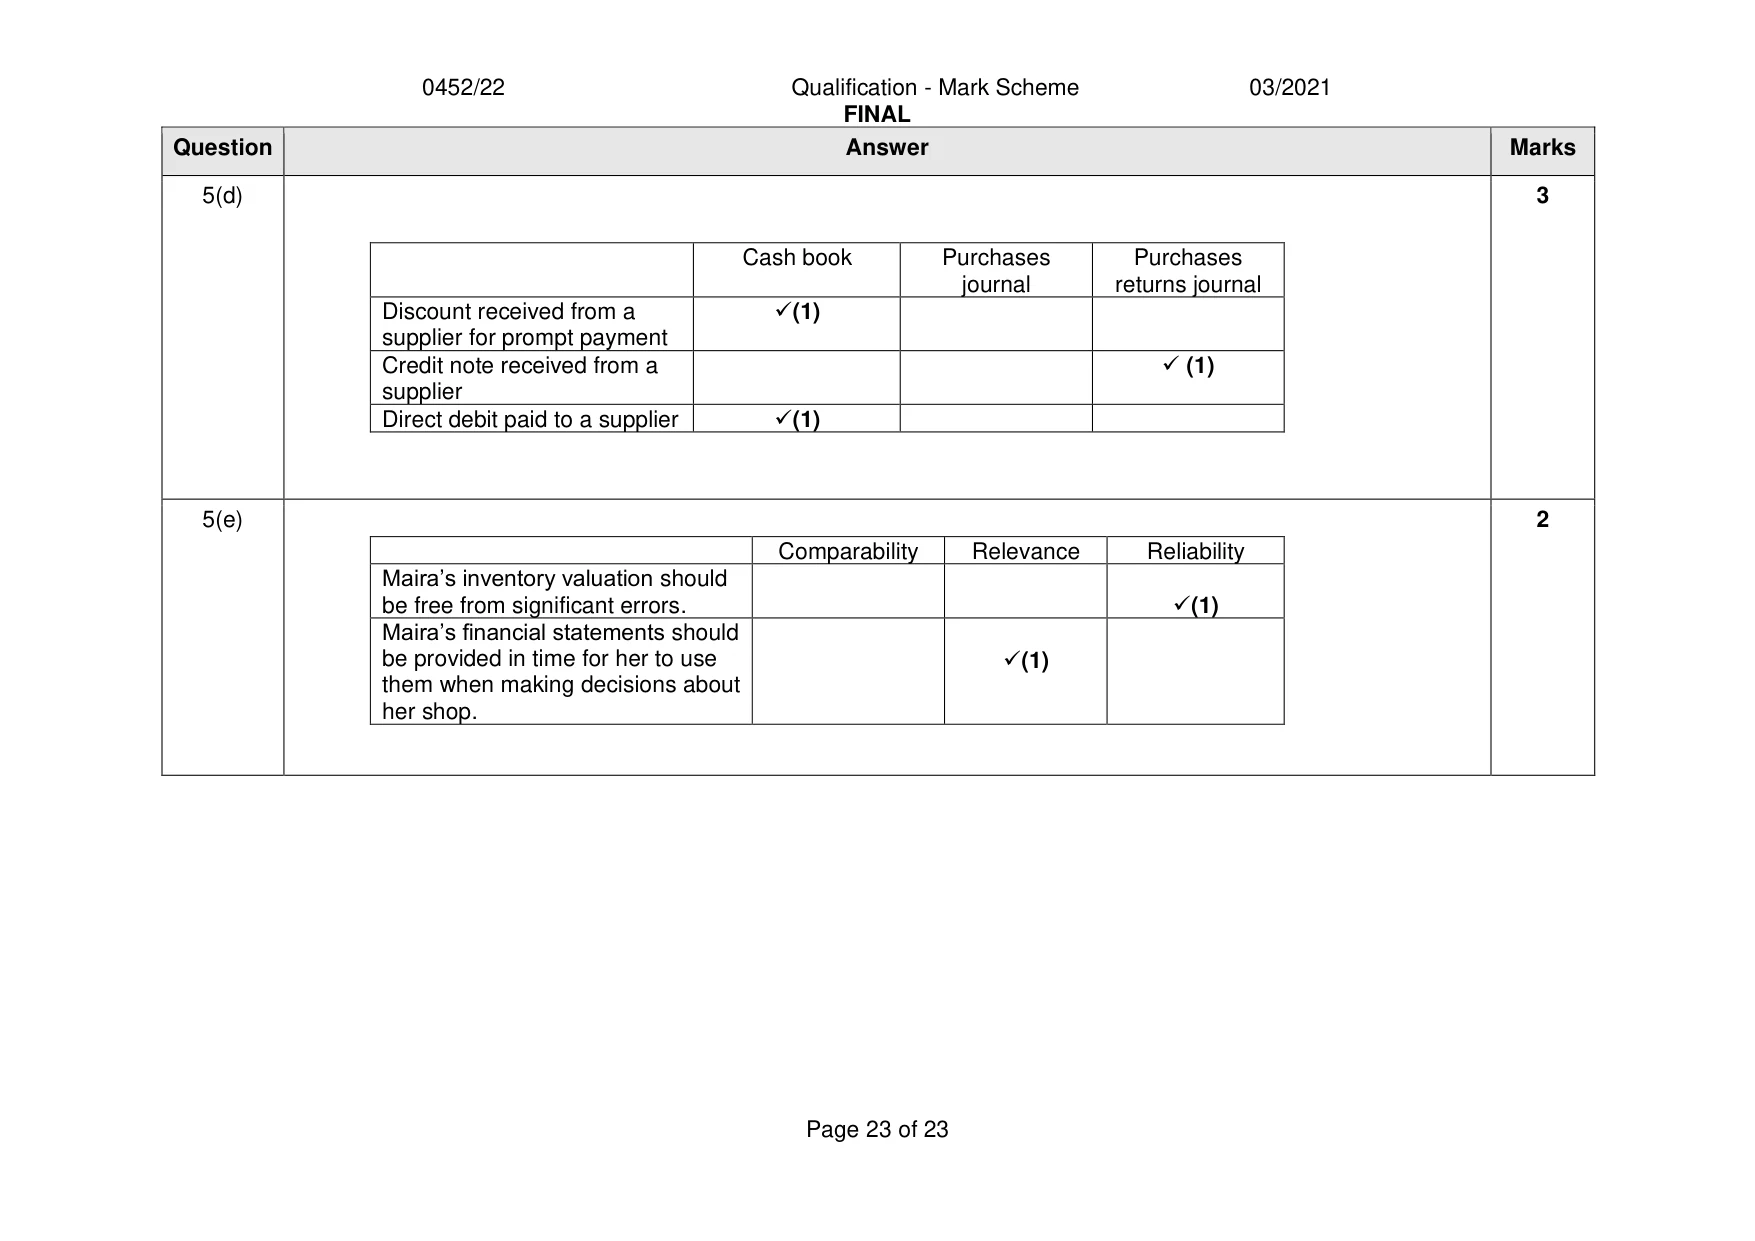
Mark scheme: 5(a) (70 + 2) (1) x 130 = 9360 (1)OF 2 Do not need calcs 9360 with or without calcs gets (2) 9100 (i.e. 70 x 130) with or without calcs gets (1) OF no other OF answer accepted e.g. 260 gets (0) FINAL Quetion Answer Marks 5(b) Maira 8 Income Statement (trading section) for the year ended 31 December 2020 $ $ Revenue 150 000 (1) Cost of sales Purchases (1400 x 70) 98 000 (1) Carriage inwards (1400 x 2) 2 800 (1) 100 800 Less Goods taken for own use 1 440 (2)CF/(1)OF 99 360 Less Closing inventory 9 360 (1)OF from (a) 90 000 (1)OF Gross profit 60 000 (1)OF (40% x revenue) Revenue 2 x 10 800 = 21 600 8 x 12 000 = 96 000 2 x 16 200 = 32 400 150 000 Do not need to show calcs for revenue, purchases, carriage and gross profit Accept “sales” and “stock” Items to be in correct order and treated correctly to get the mark: carriage must come after purchases and before closing inventory Allow goods for own use before or after carriage – but must be before closing inventory Need words (in full) and figures for the marks Accept “Drawings” in lieu of “Goods for own use” If combine purchases and carriage and put “Purchases 100 800” give (1) If include an item labelled “opening inventory”/”opening stock” this is an alien C of S is difference between OF revenue and OF GP. Need words and figure Work back to goods for own use – (2) CF or (1) OF if correct arithmetically on their figures and no alien in the statement (1) if CF but item is in incorrect position Accept OF drawings provide arithmetically correct – even if unrealistic/impossible figure 5(c) Advantages 5 Maira would have all the necessary figures e.g. balances of individual ledger accounts (1) If the business grows, it will be more difficult to prepare financial statements from incomplete records (1) Detailed records would be available for future reference (1) More accurate comparisons year-on-year/ with other businesses is possible (1) More informed decision making will be possible (1) The government/tax office may require an adequate amount of accounting records (1) If Maira wishes to sell the business, a potential buyer may wish to see full accounting records (1) Lenders/potential lenders can be provided with adequate information (1) Maira should be able to prepare financial statements more easily (1) Maira should be able to prepare financial statements more accurately (1) Assist in location of errors/checking procedures, e.g. control accounts may be used (1) The possibility of fraud would be minimised (1) Accept other valid points Max (2) Disadvantages Maira’s financial statements may be prepared from incomplete records (1) Maira is busy so she may not have time for book-keeping (1) It may take Maira time to learn double-entry book-keeping (1) Any spare time which Maira can find may be better spent on e.g. marketing (1) If Maira pays a book-keeper to write up her books, the cost of this will reduce her profits (1) Accept other valid points Max (2) Recommendation (1) Must have at least one advantage of each option before get recommend mark Virtually any recommend gets a mark In advantages – accept “improves accuracy” in lieu of “more accurate financial statements” reference to preparing profit & loss account/calculating profit in lieu of reference to financial statements “reduces fraud” or “helps to detect fraud” but not “prevents fraud” in lieu of reference to having necessary figures accept reference to things like “can see total sales”/”can know assets and liabilities”/etc. In disadvantages – accept “can be time-consuming” (in lieu of “Maira is busy……..”)/“can be complex” /”may be difficult for her” i.e. these get (1) for any not (1) each any reference to having an accountant (in lieu of a bookkeeper) do not accept – reference to following accounting rules and procedures reference to increasing costs/expenses unless explained any reference to fraud 5(d) 3 Cash book Purchases Purchases journal returns journal Discount received from a ✓(1) supplier for prompt payment Credit note received from a ✓ (1) supplier Direct debit paid to a supplier ✓(1) 5(e) 2 Comparability Relevance Reliability Maira’s inventory valuation should be free from significant errors. ✓(1) Maira’s financial statements should be provided in time for her to use ✓(1) them when making decisions about her shop.
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.