Cambridge IGCSE Accounting 0452 — 2020 Feb/March Paper 2 · Variant 2
0452/22/F/M/20 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Amara maintains a petty cash book using the imprest system
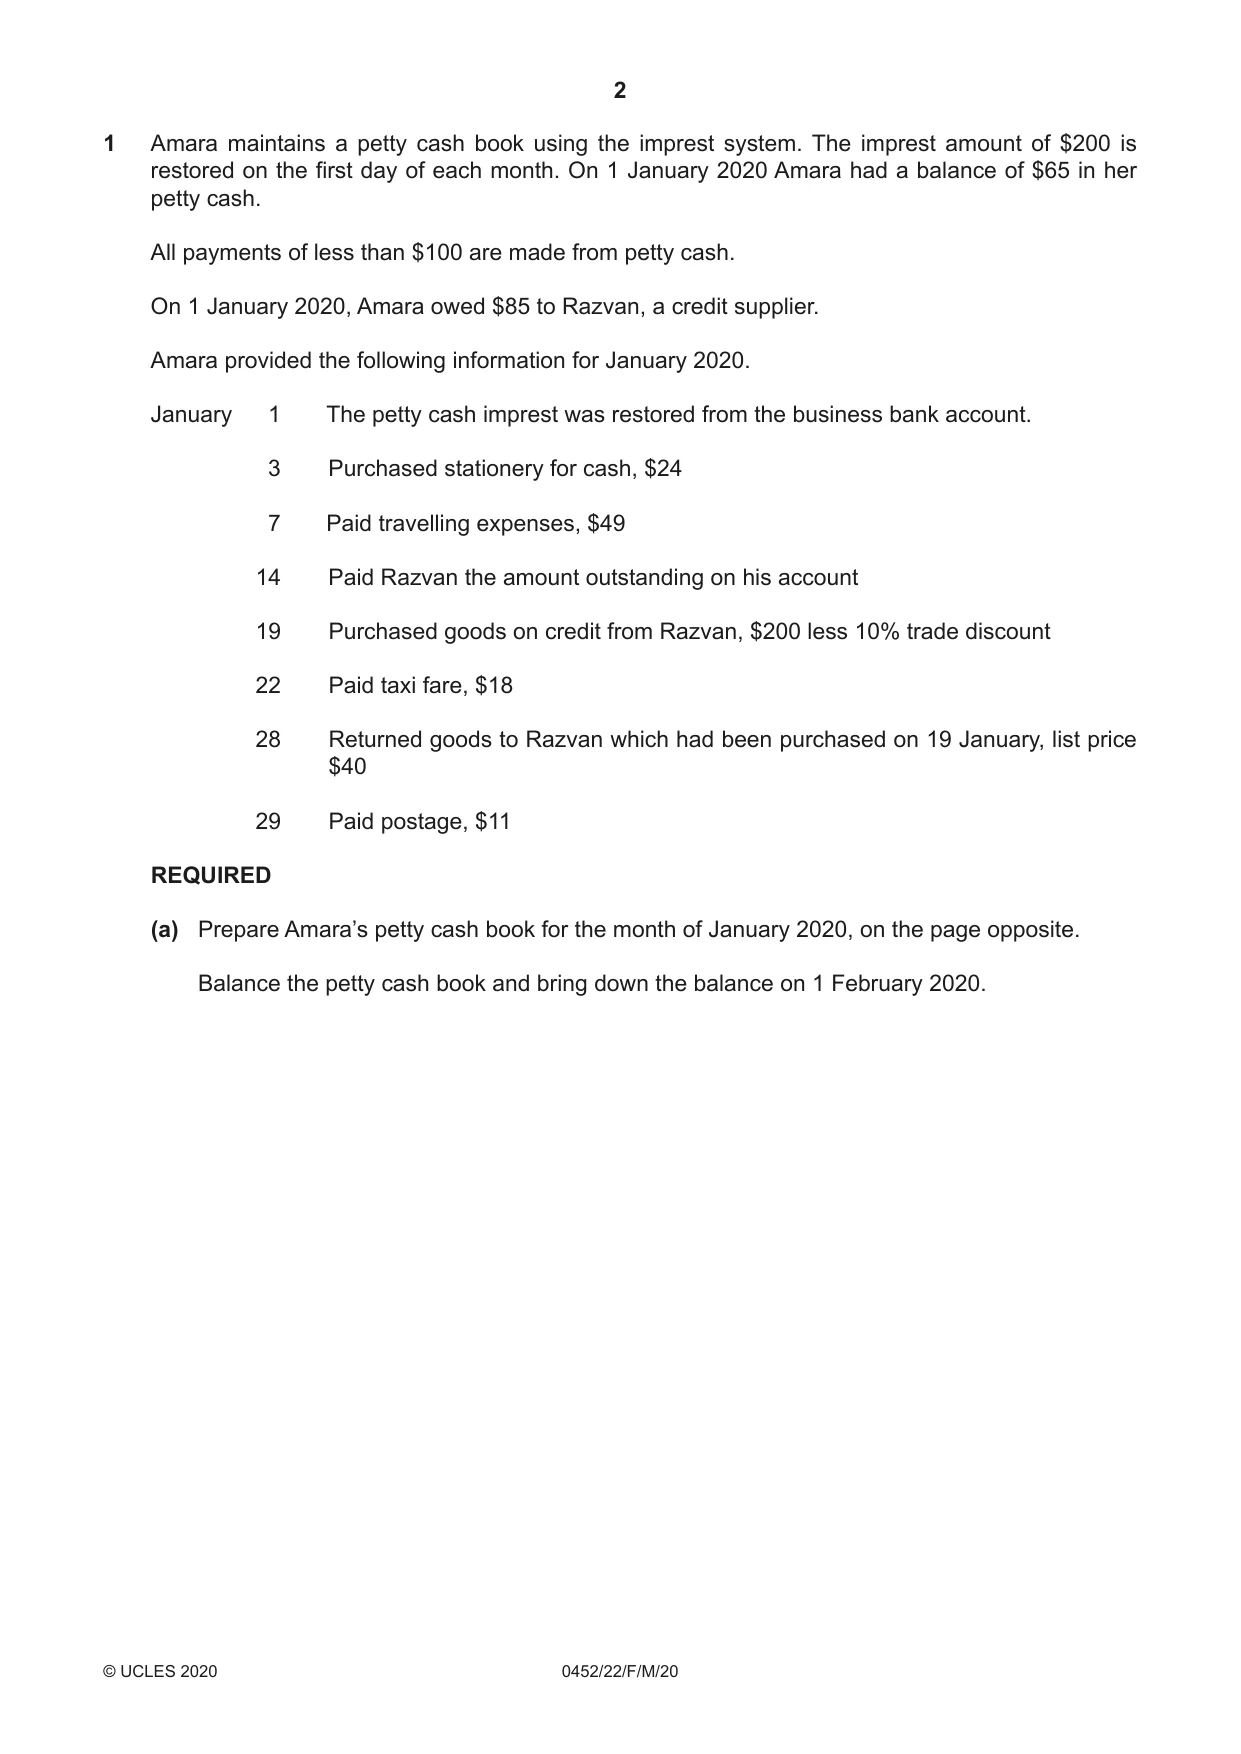
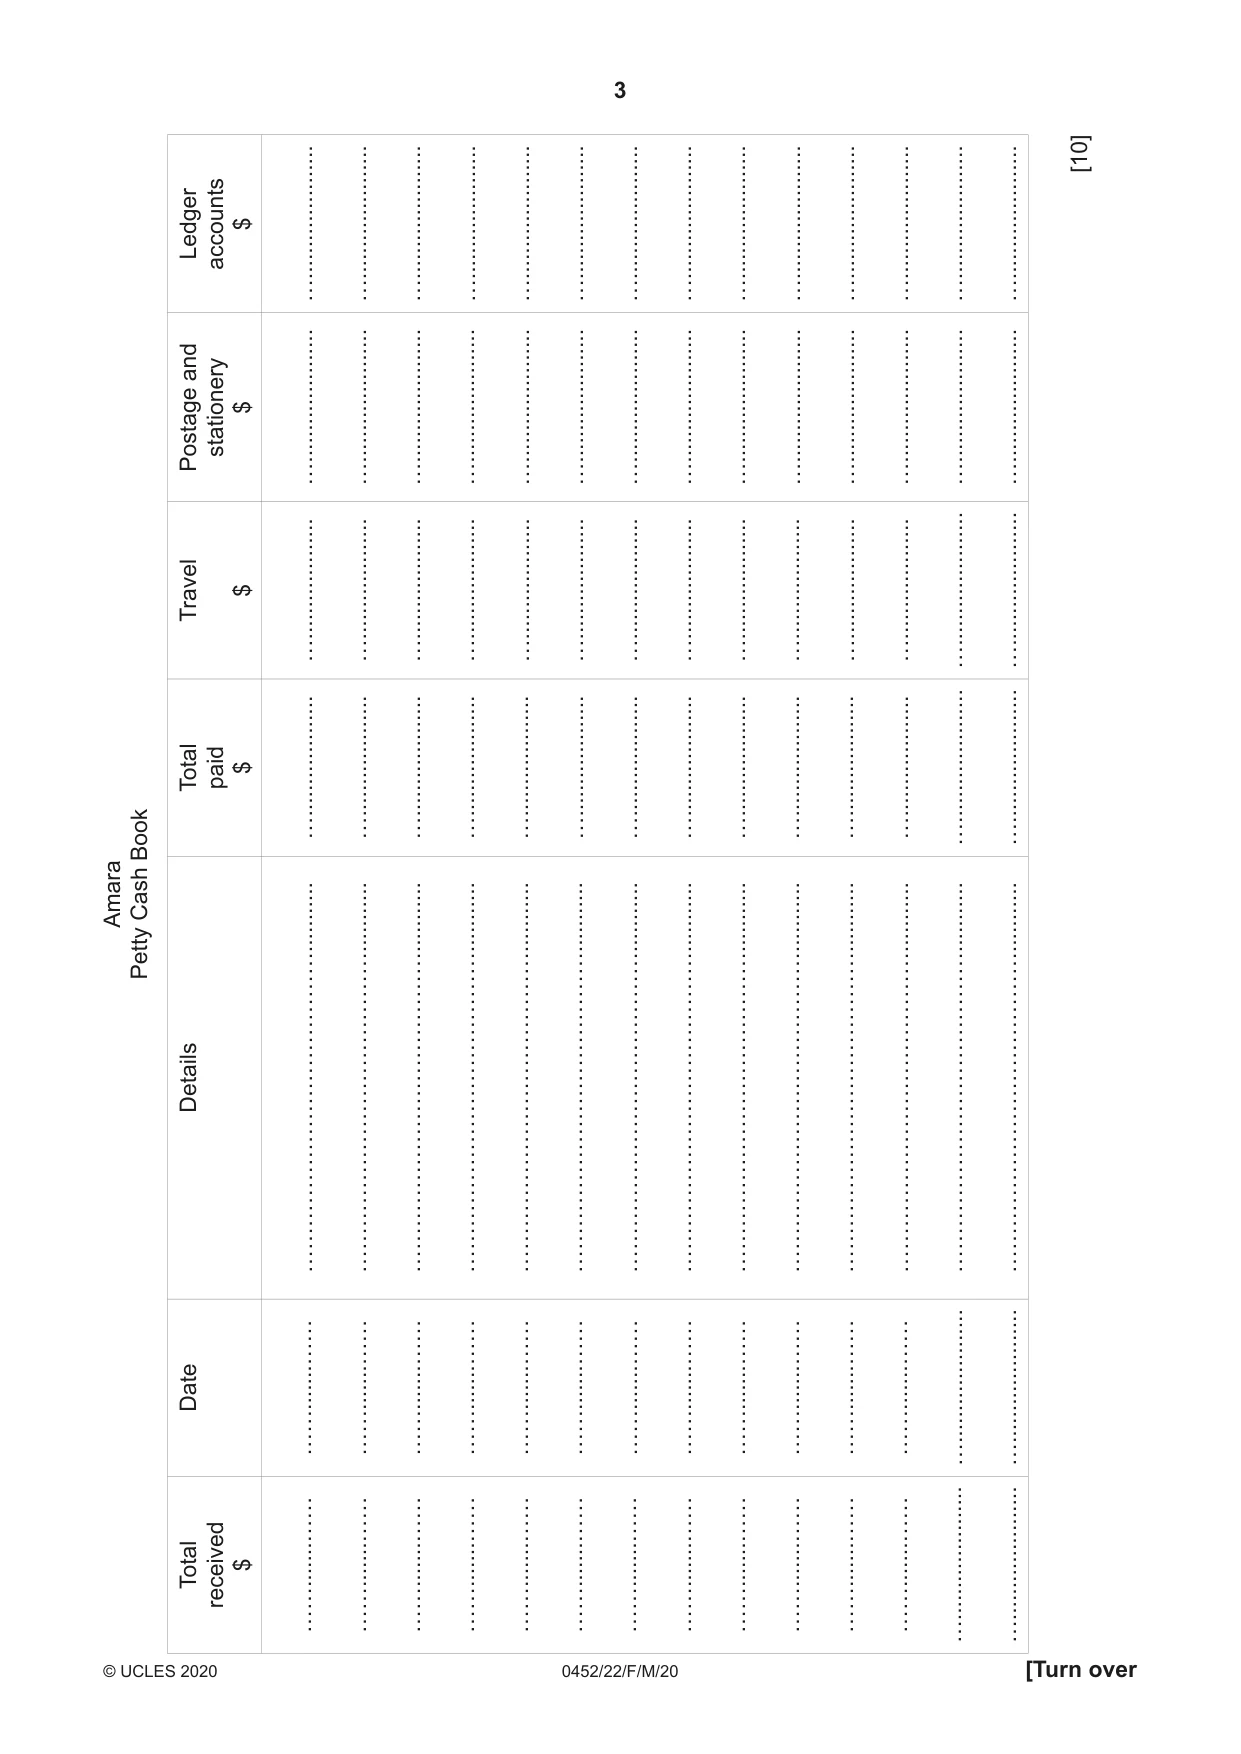
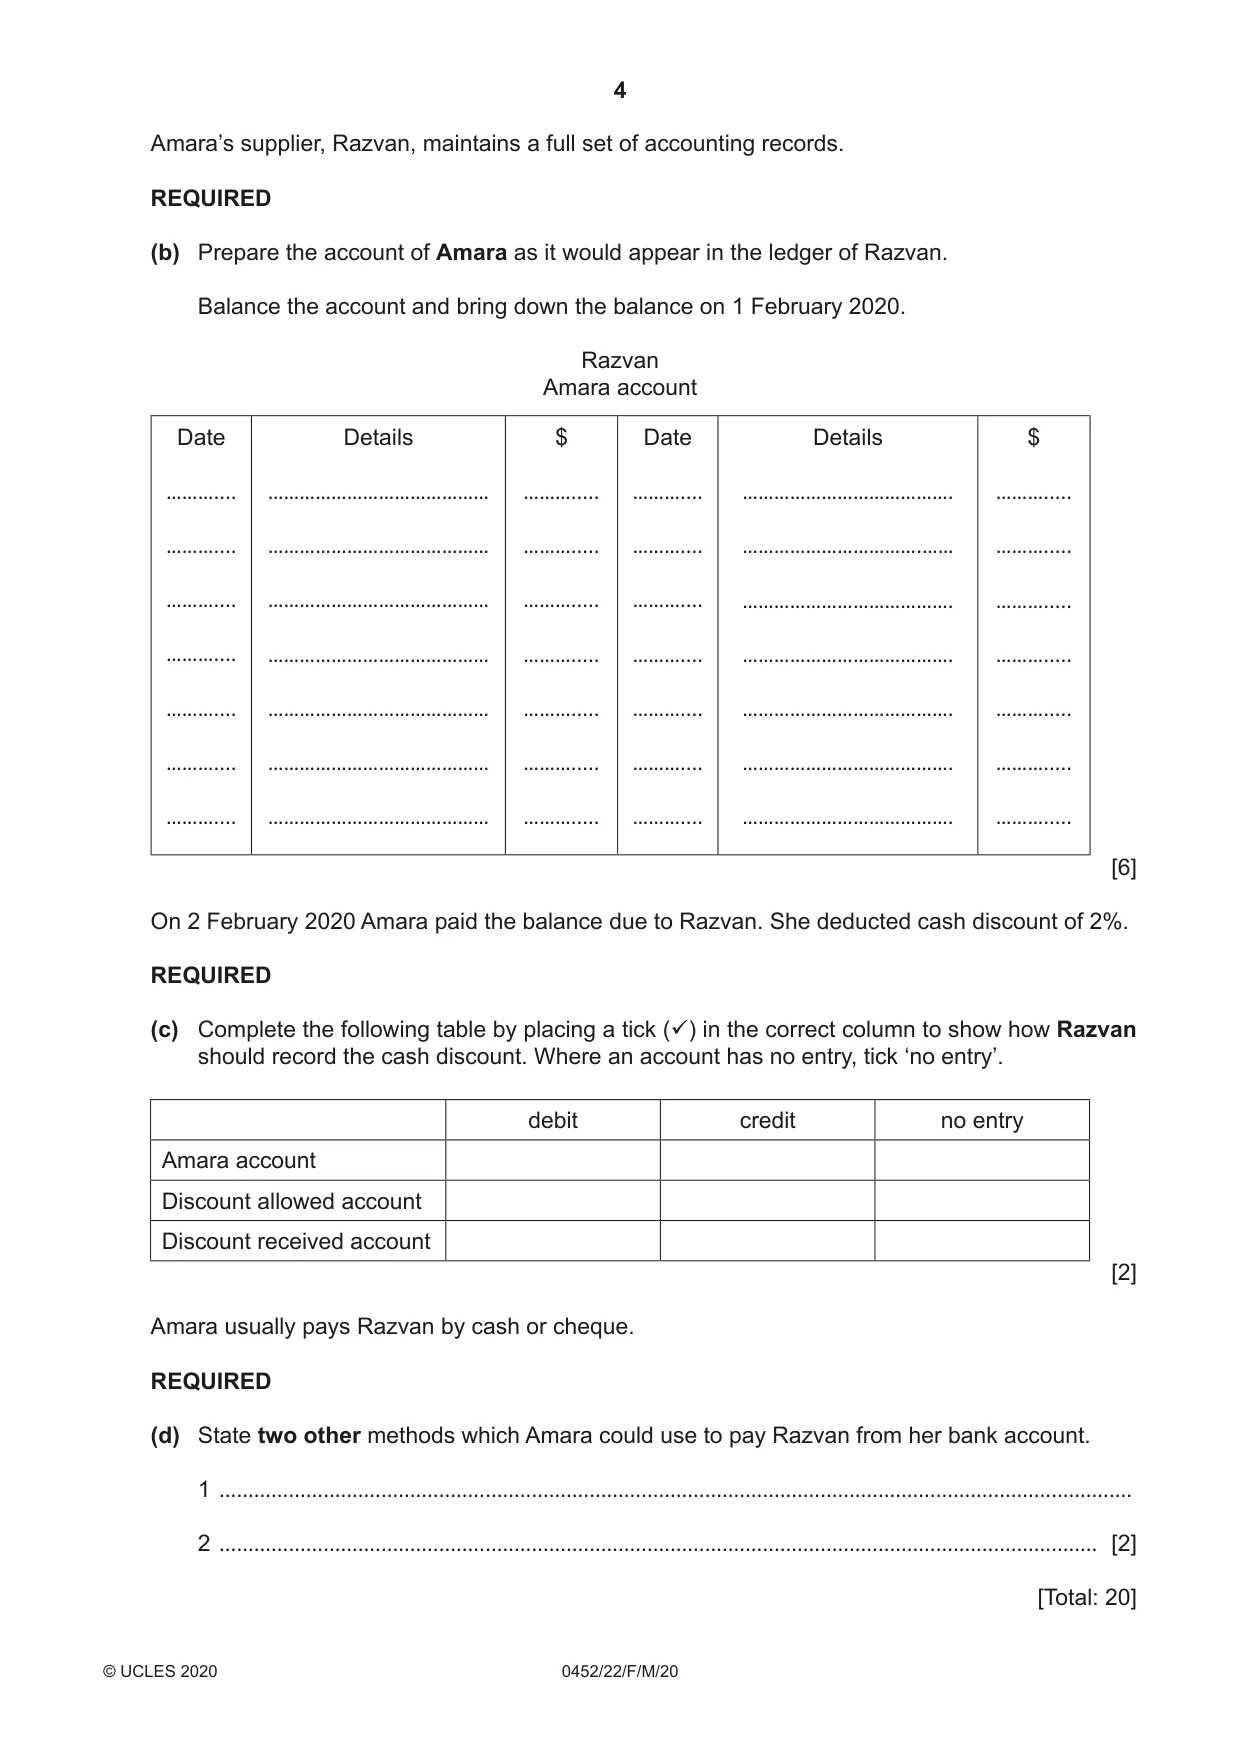
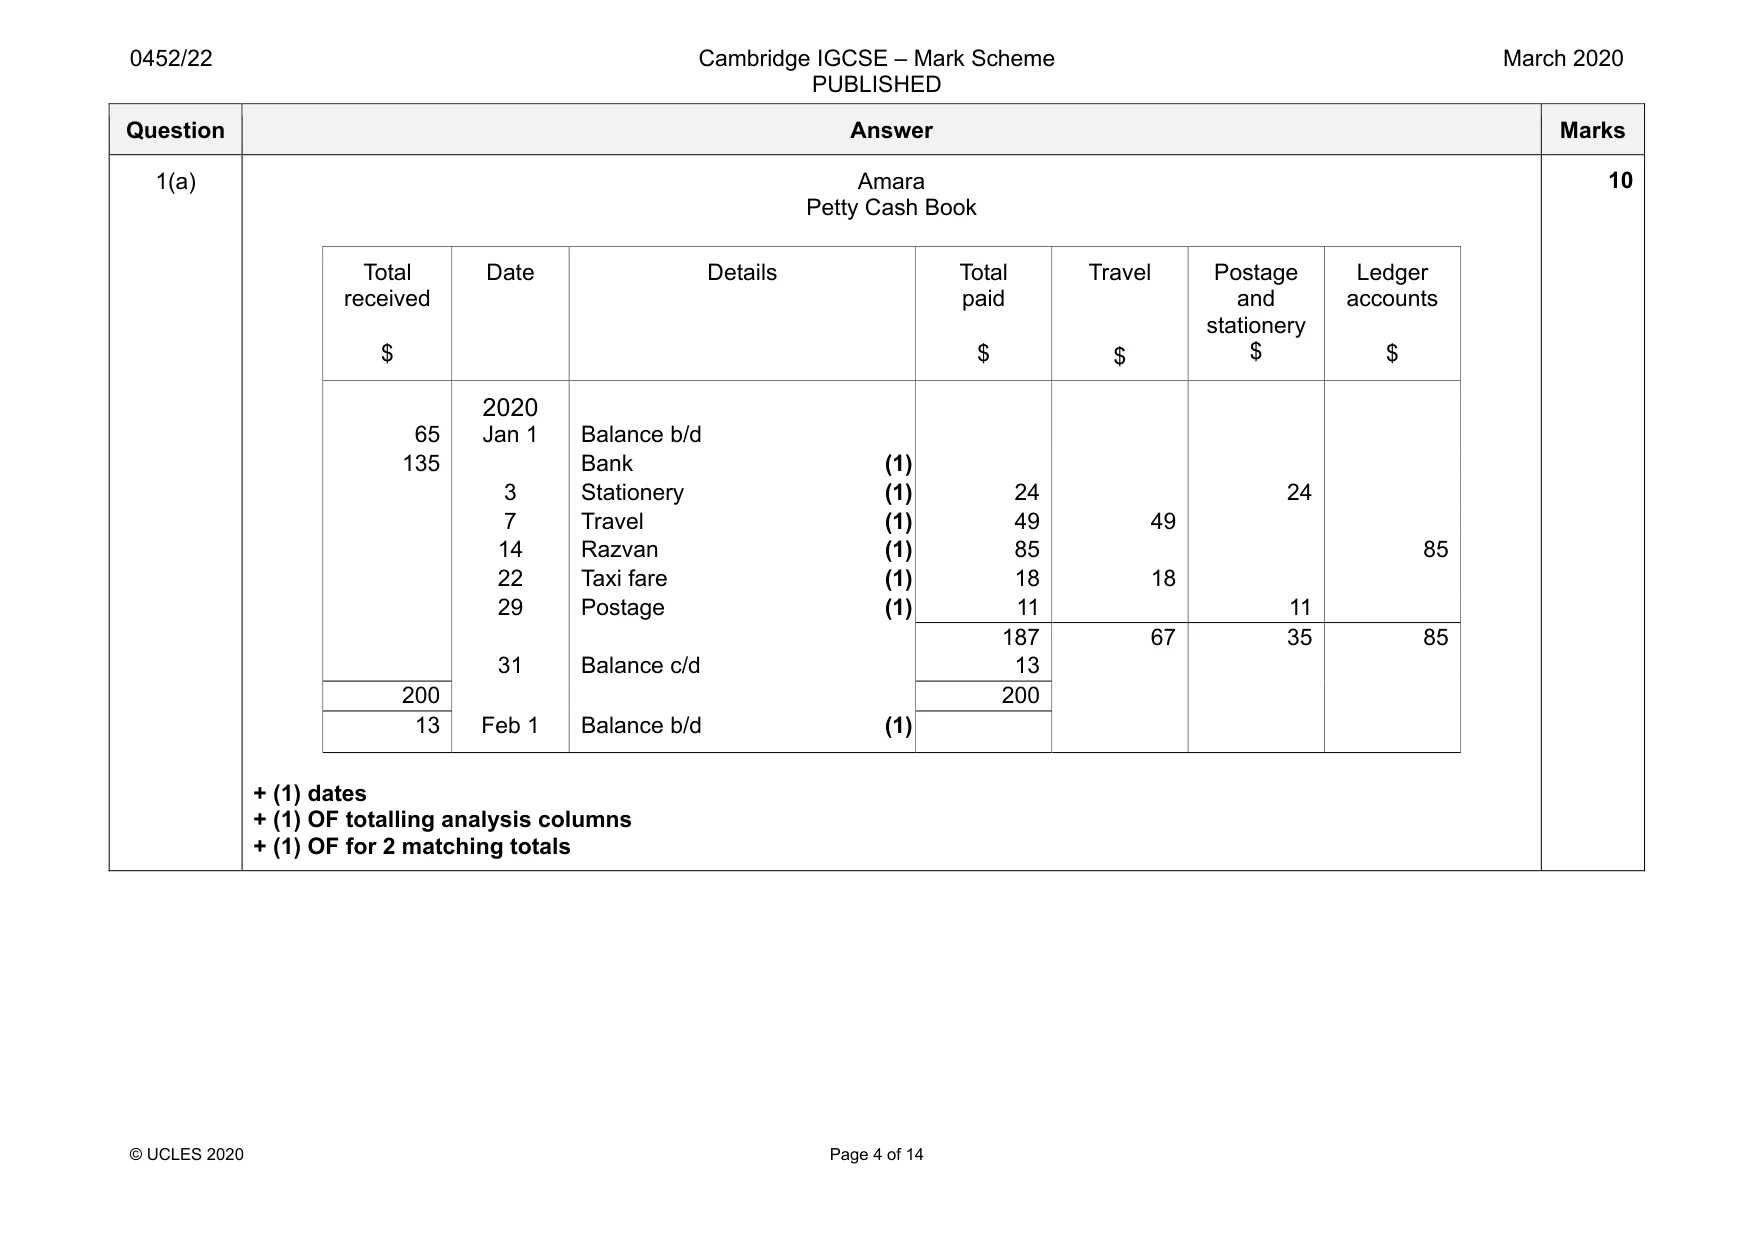
1 Amara maintains a petty cash book using the imprest system. The imprest amount of $200 is restored on the first day of each month. On 1 January 2020 Amara had a balance of $65 in her petty cash. All payments of less than $100 are made from petty cash. On 1 January 2020, Amara owed $85 to Razvan, a credit supplier. Amara provided the following information for January 2020. January 1 The petty cash imprest was restored from the business bank account. 3 Purchased stationery for cash, $24 7 Paid travelling expenses, $49 14 Paid Razvan the amount outstanding on his account 19 Purchased goods on credit from Razvan, $200 less 10% trade discount 22 Paid taxi fare, $18 28 Returned goods to Razvan which had been purchased on 19 January, list price $40 29 Paid postage, $11 REQUIRED (a) Prepare Amara’s petty cash book for the month of January 2020, on the page opposite. Balance the petty cash book and bring down the balance on 1 February 2020. [10] $ Ledger accounts …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... and $ stationery Postage …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... …..................... $ Travel …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …..................... …..................... $ Totalpaid …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …................... …..................... …..................... Book CashAmara Petty Details ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... ……………………………………........... Date …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …….......…… …..................... …..................... Amara’s supplier, Razvan, maintains a full set of accounting records. REQUIRED (b) Prepare the account of Amara as it would appear in the ledger of Razvan. Balance the account and bring down the balance on 1 February 2020. Razvan Amara account Date Details $ Date Details $ ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... [6] On 2 February 2020 Amara paid the balance due to Razvan. She deducted cash discount of 2%. REQUIRED (c) Complete the following table by placing a tick (ü) in the correct column to show how Razvan should record the cash discount. Where an account has no entry, tick ‘no entry’. debit credit no entry Amara account Discount allowed account Discount received account [2] Amara usually pays Razvan by cash or cheque. REQUIRED (d) State two other methods which Amara could use to pay Razvan from her bank account. 1 .............................................................................................................................................................. 2 ........................................................................................................................................................ [2] [Total: 20] PLEASE TURN OVER
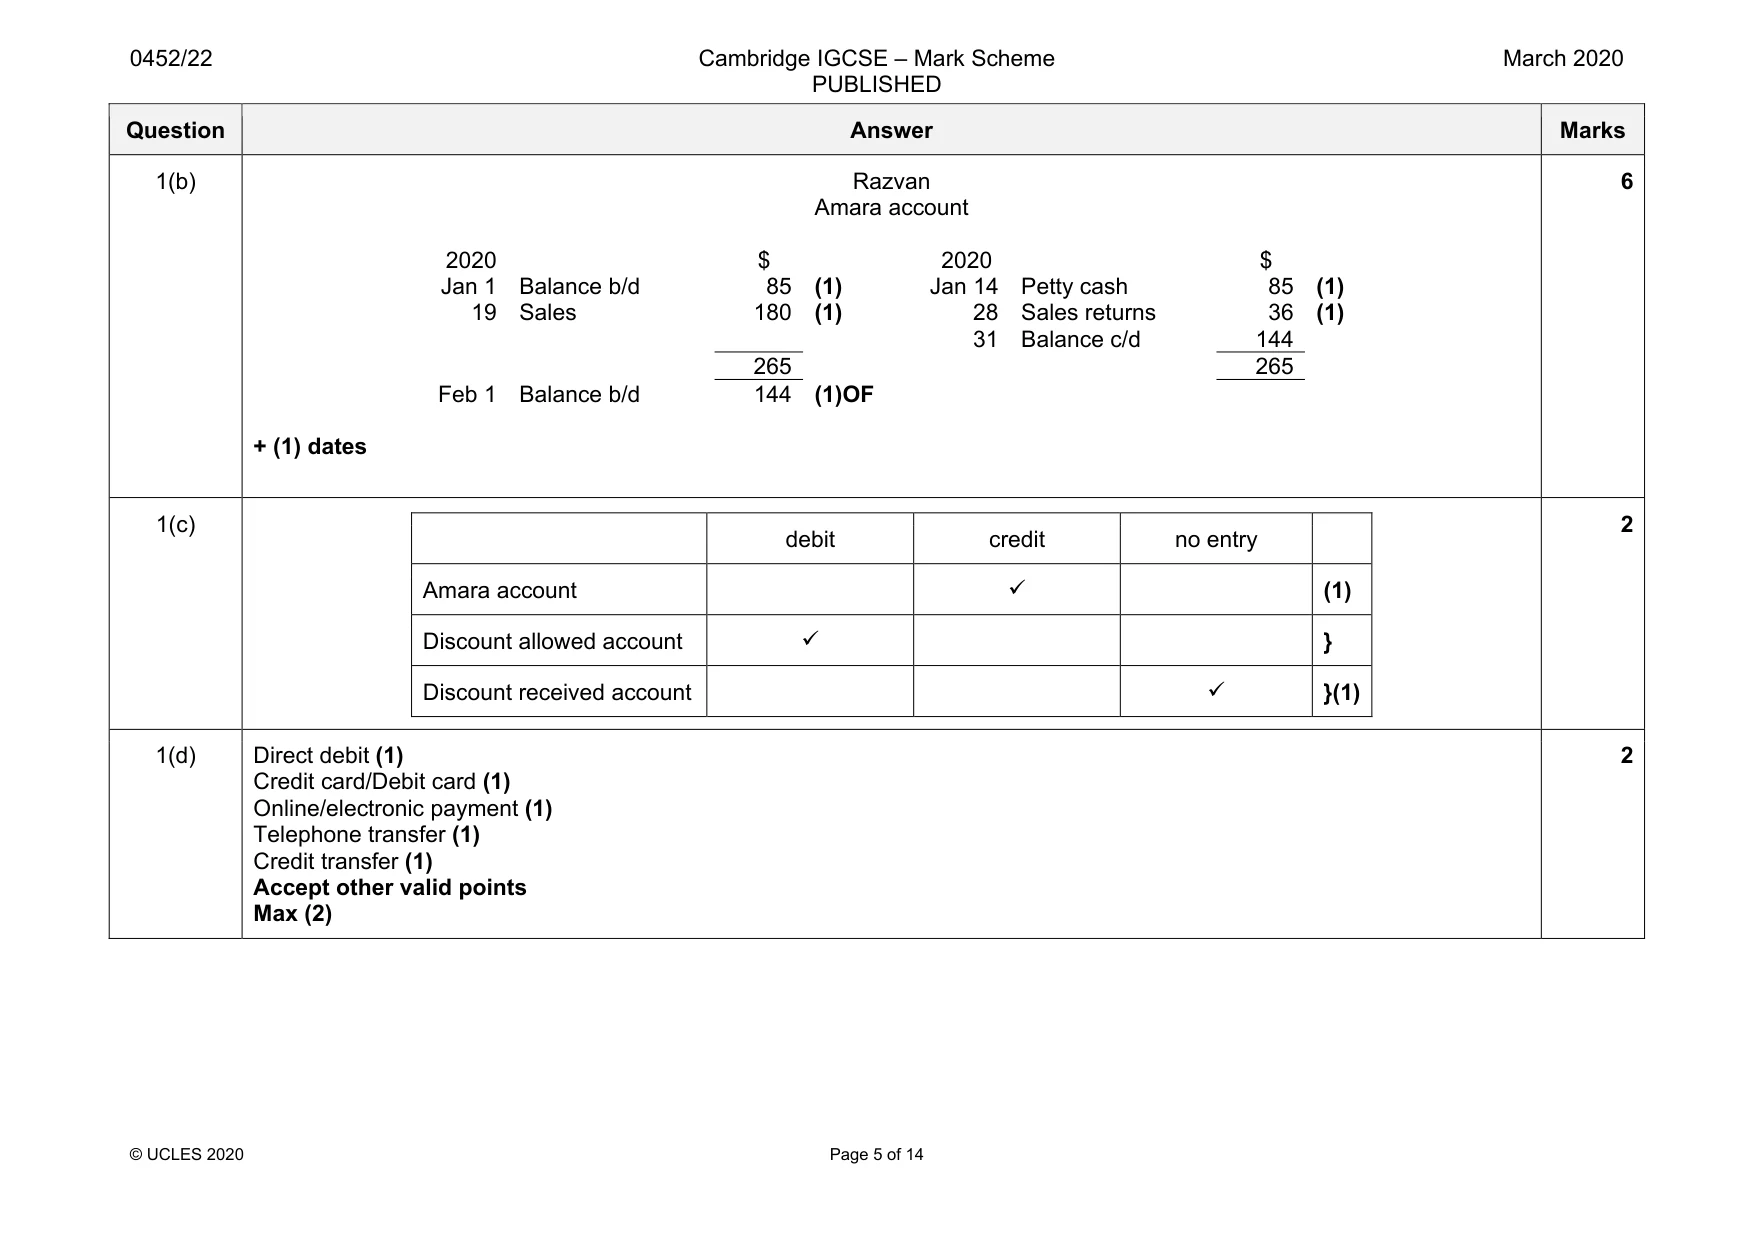
Mark scheme: 1(a) Amara Petty Cash Book Total received $ Date Details Total paid $ Travel $ Postage and stationery $ Ledger accounts $ 2020 65 Jan 1 Balance b/d 135 Bank (1) 3 Stationery (1) 24 24 7 Travel (1) 49 49 14 Razvan (1) 85 85 22 Taxi fare (1) 18 18 29 Postage (1) 11 11 187 67 35 85 31 Balance c/d 13 200 200 13 Feb 1 Balance b/d (1) + (1) dates + (1) OF totalling analysis columns + (1) OF for 2 matching totals Question Answer Marks 1(b) Razvan Amara account 2020 $ 2020 $ Jan 1 Balance b/d 85 (1) Jan 14 Petty cash 85 (1) 19 Sales 180 (1) 28 Sales returns 36 (1) 31 Balance c/d 144 265 265 Feb 1 Balance b/d 144 (1)OF + (1) dates 6 1(c) debit credit no entry Amara account (1) Discount allowed account } Discount received account }(1) 2 1(d) Direct debit (1) Credit card/Debit card (1) Online/electronic payment (1) Telephone transfer (1) Credit transfer (1) Accept other valid points Max (2) 2
Q2 · GHB Limited maintains a full set of accounting records and prepares monthly control…
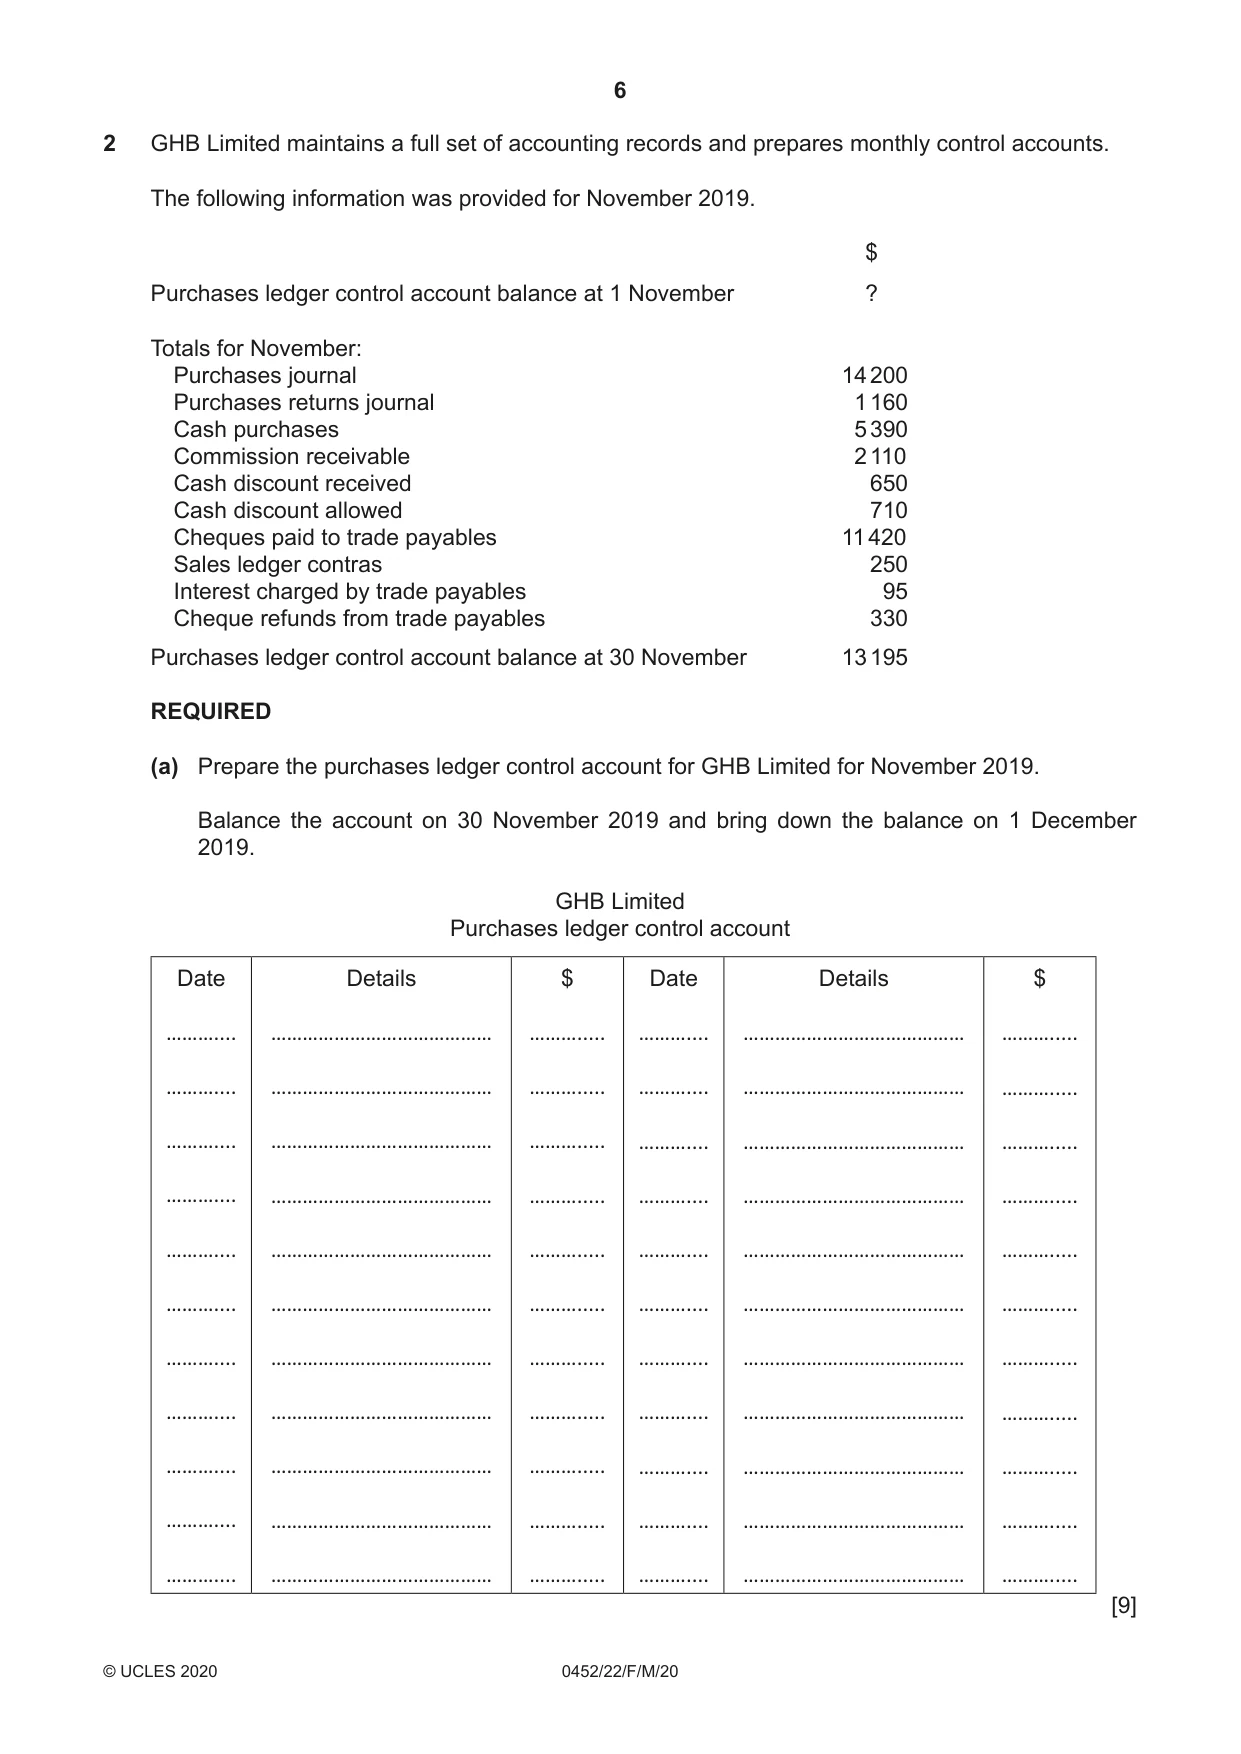
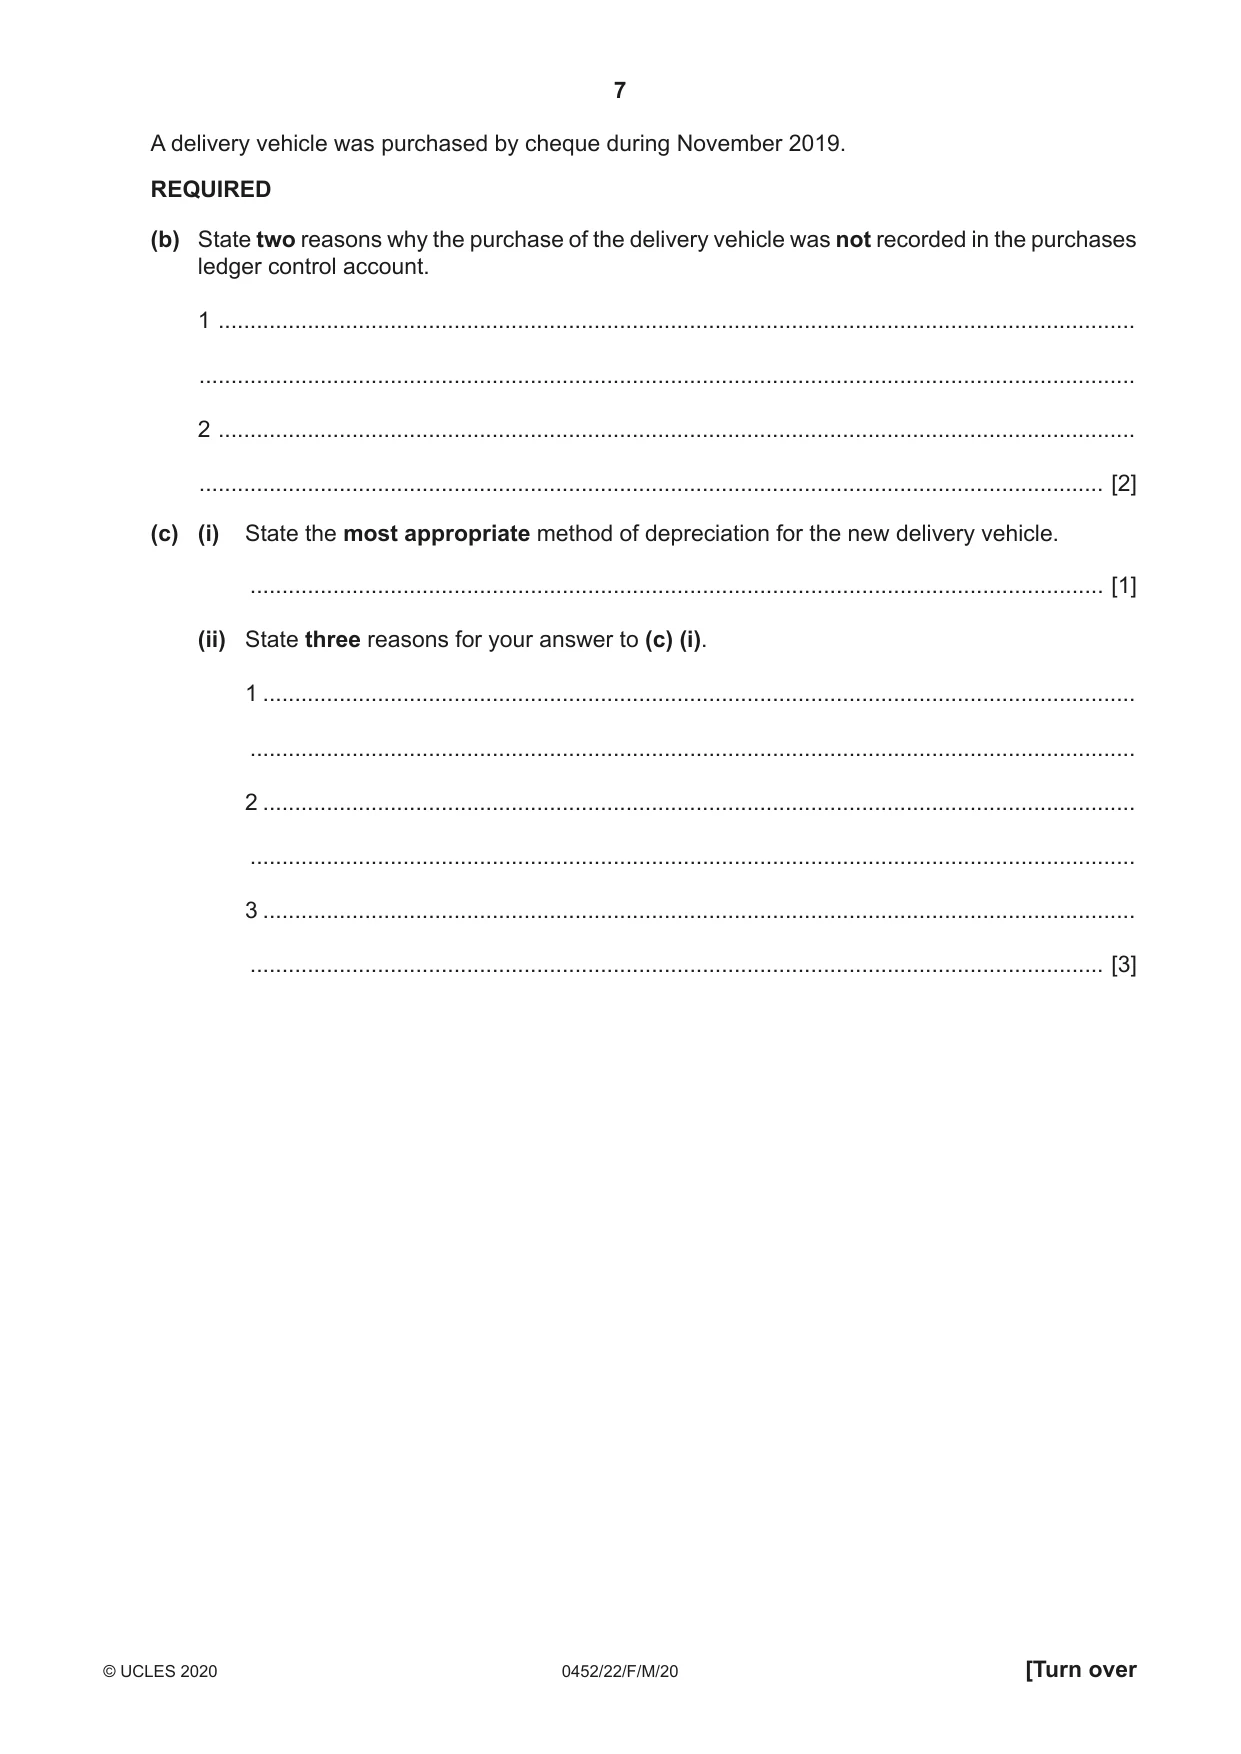
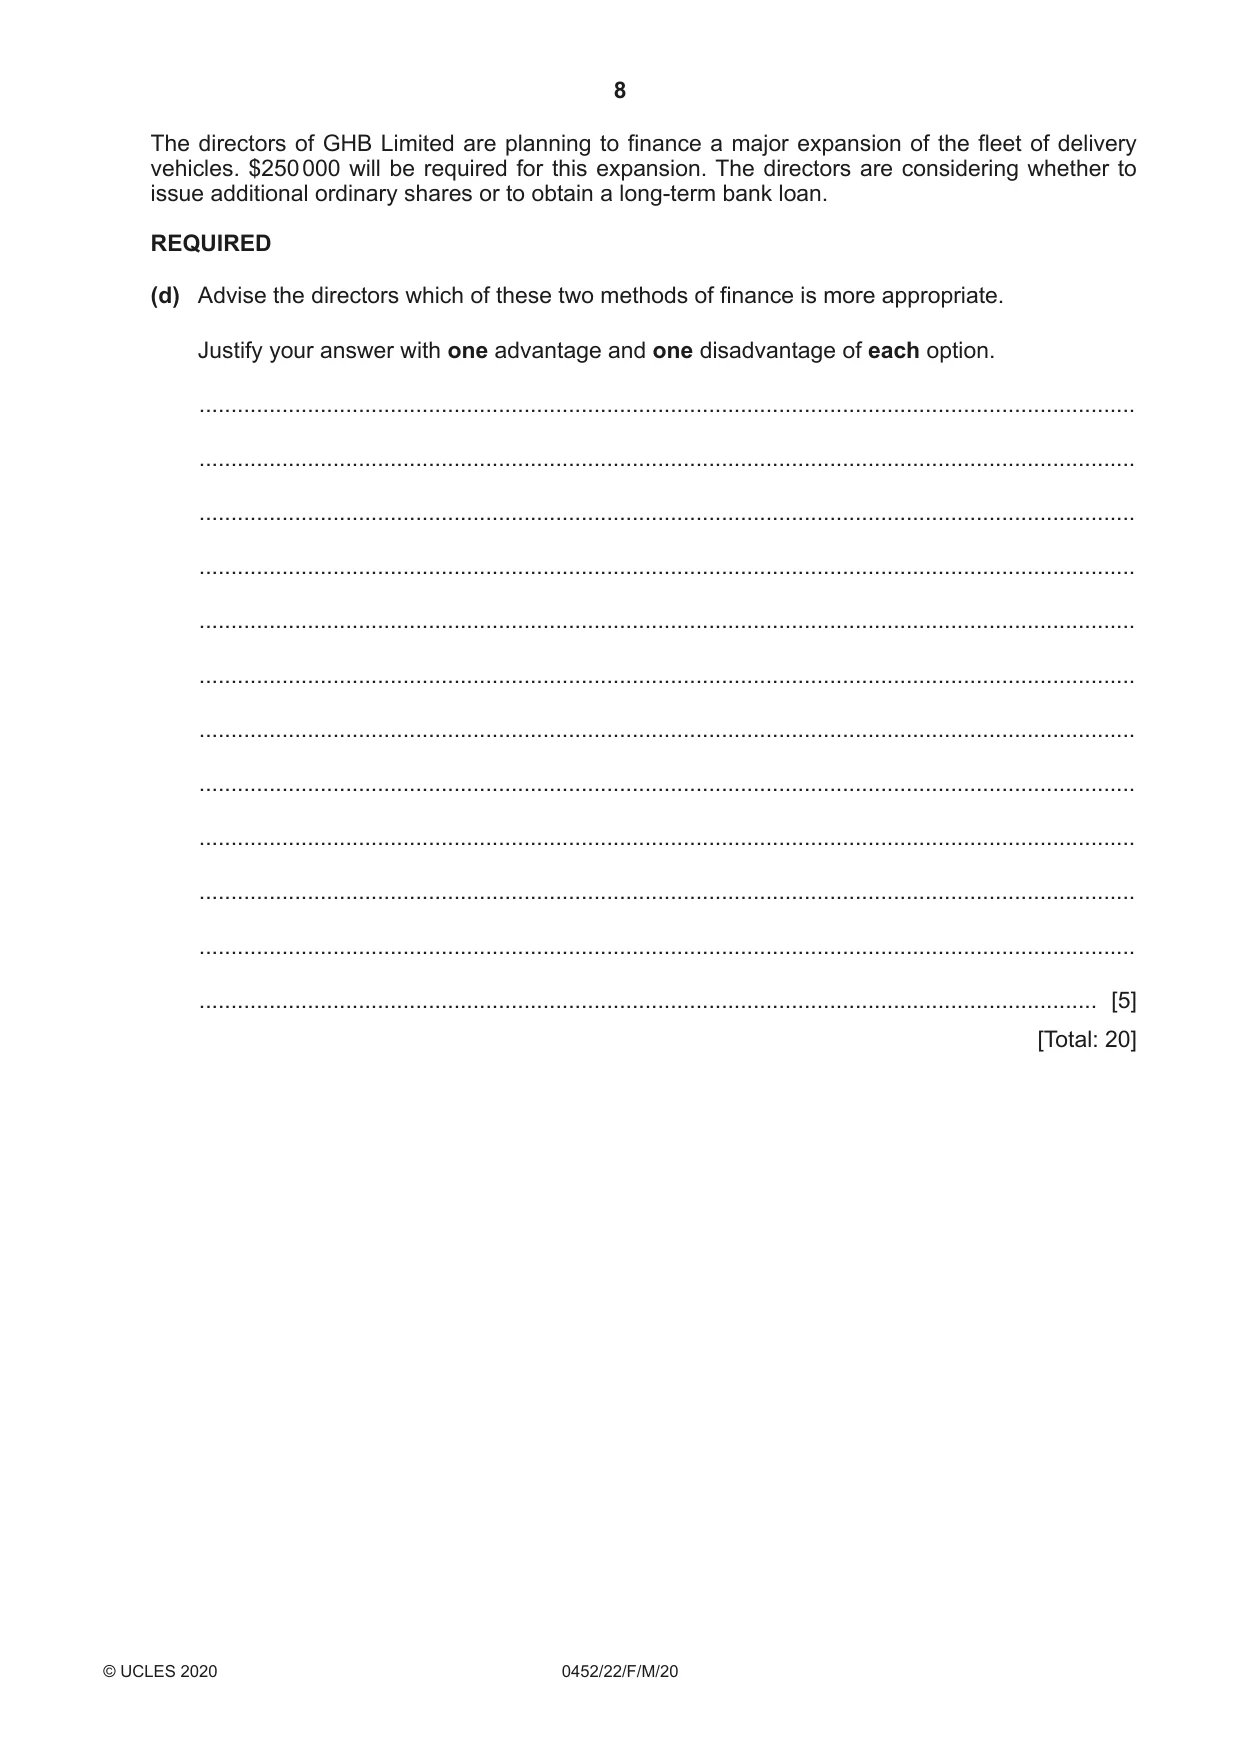
2 GHB Limited maintains a full set of accounting records and prepares monthly control accounts. The following information was provided for November 2019. $ Purchases ledger control account balance at 1 November ? Totals for November: Purchases journal 14 200 Purchases returns journal 1 160 Cash purchases 5 390 Commission receivable 2 110 Cash discount received 650 Cash discount allowed 710 Cheques paid to trade payables 11 420 Sales ledger contras 250 Interest charged by trade payables 95 Cheque refunds from trade payables 330 Purchases ledger control account balance at 30 November 13 195 REQUIRED (a) Prepare the purchases ledger control account for GHB Limited for November 2019. Balance the account on 30 November 2019 and bring down the balance on 1 December 2019. GHB Limited Purchases ledger control account Date Details $ Date Details $ ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... [9] A delivery vehicle was purchased by cheque during November 2019. REQUIRED (b) State two reasons why the purchase of the delivery vehicle was not recorded in the purchases ledger control account. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (c) (i) State the most appropriate method of depreciation for the new delivery vehicle. ...................................................................................................................................... [1] (ii) State three reasons for your answer to (c) (i). 1 ......................................................................................................................................... ........................................................................................................................................... 2 ......................................................................................................................................... ........................................................................................................................................... 3 ......................................................................................................................................... ...................................................................................................................................... [3] The directors of GHB Limited are planning to finance a major expansion of the fleet of delivery vehicles. $250 000 will be required for this expansion. The directors are considering whether to issue additional ordinary shares or to obtain a long-term bank loan. REQUIRED (d) Advise the directors which of these two methods of finance is more appropriate. Justify your answer with one advantage and one disadvantage of each option. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
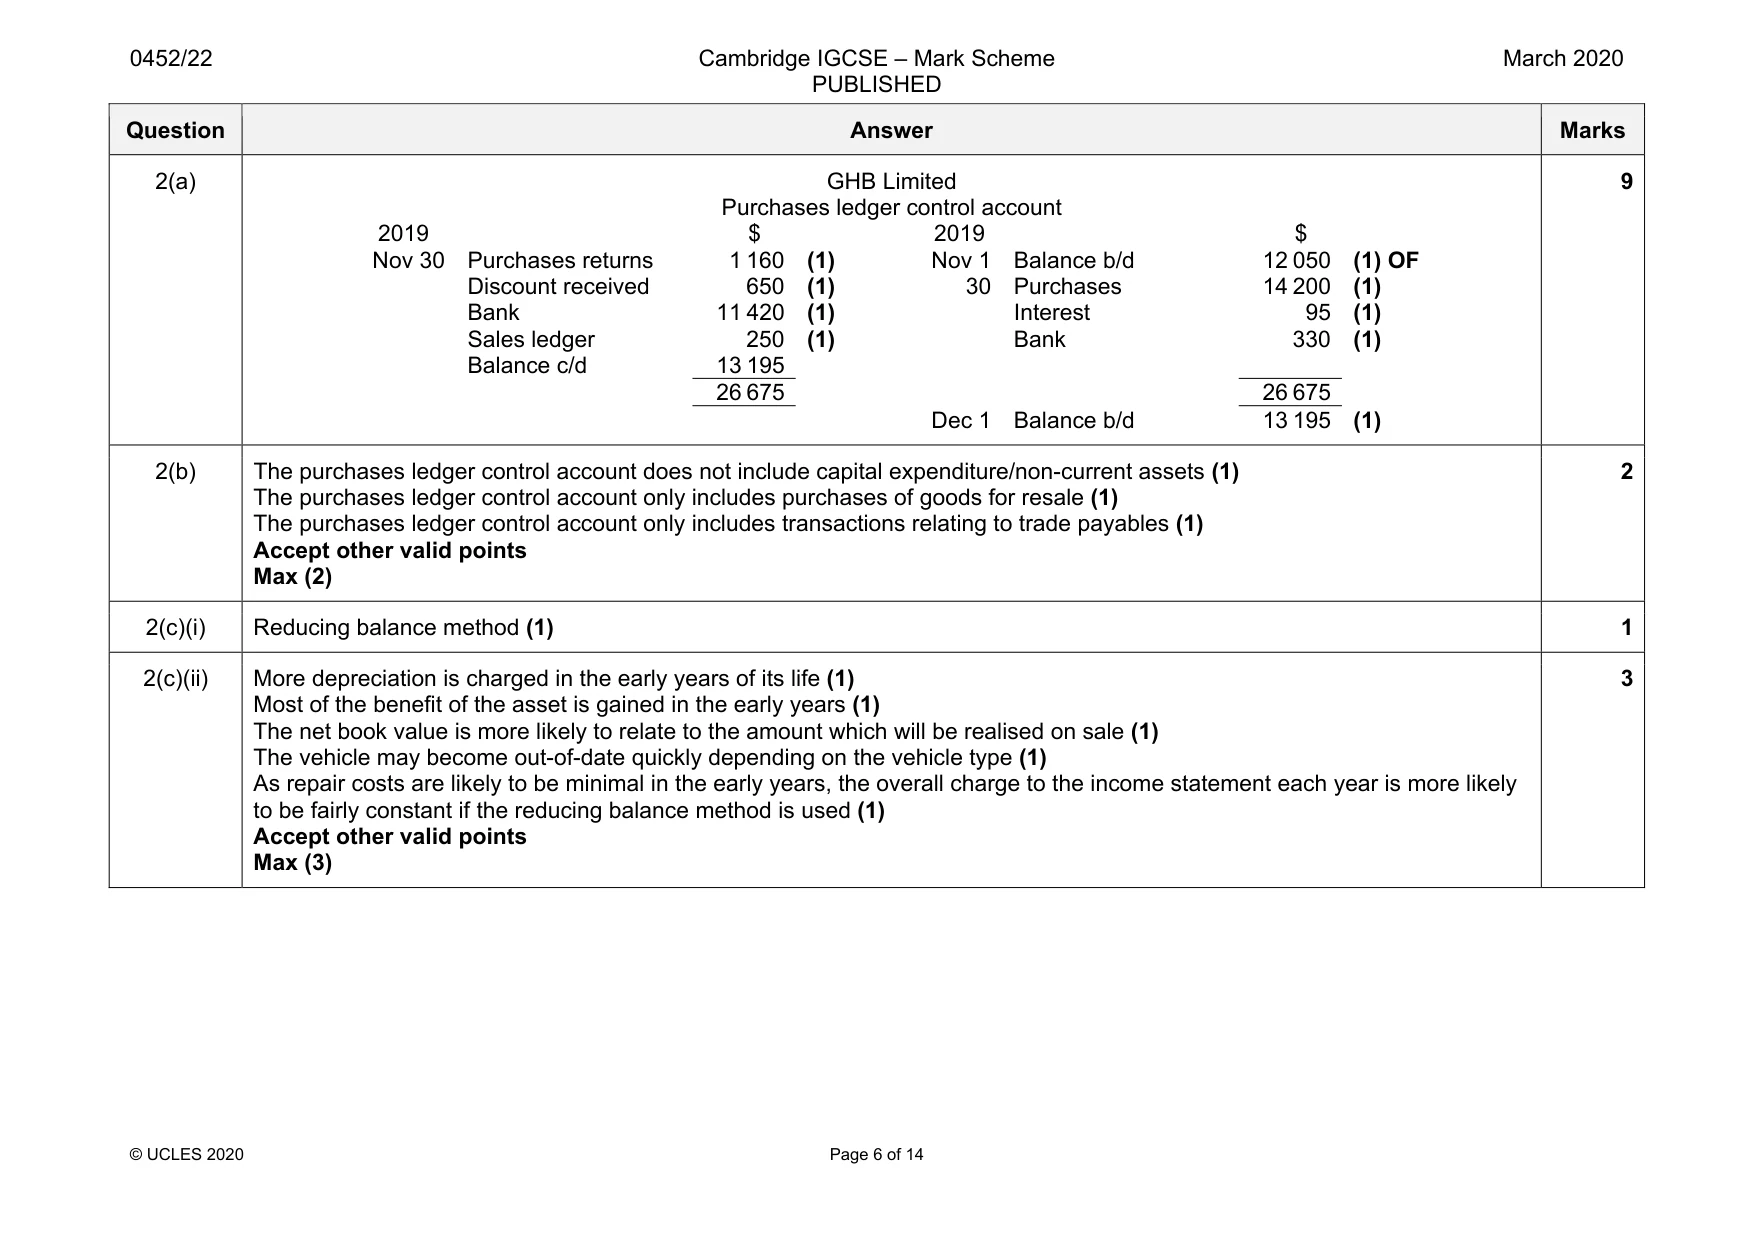
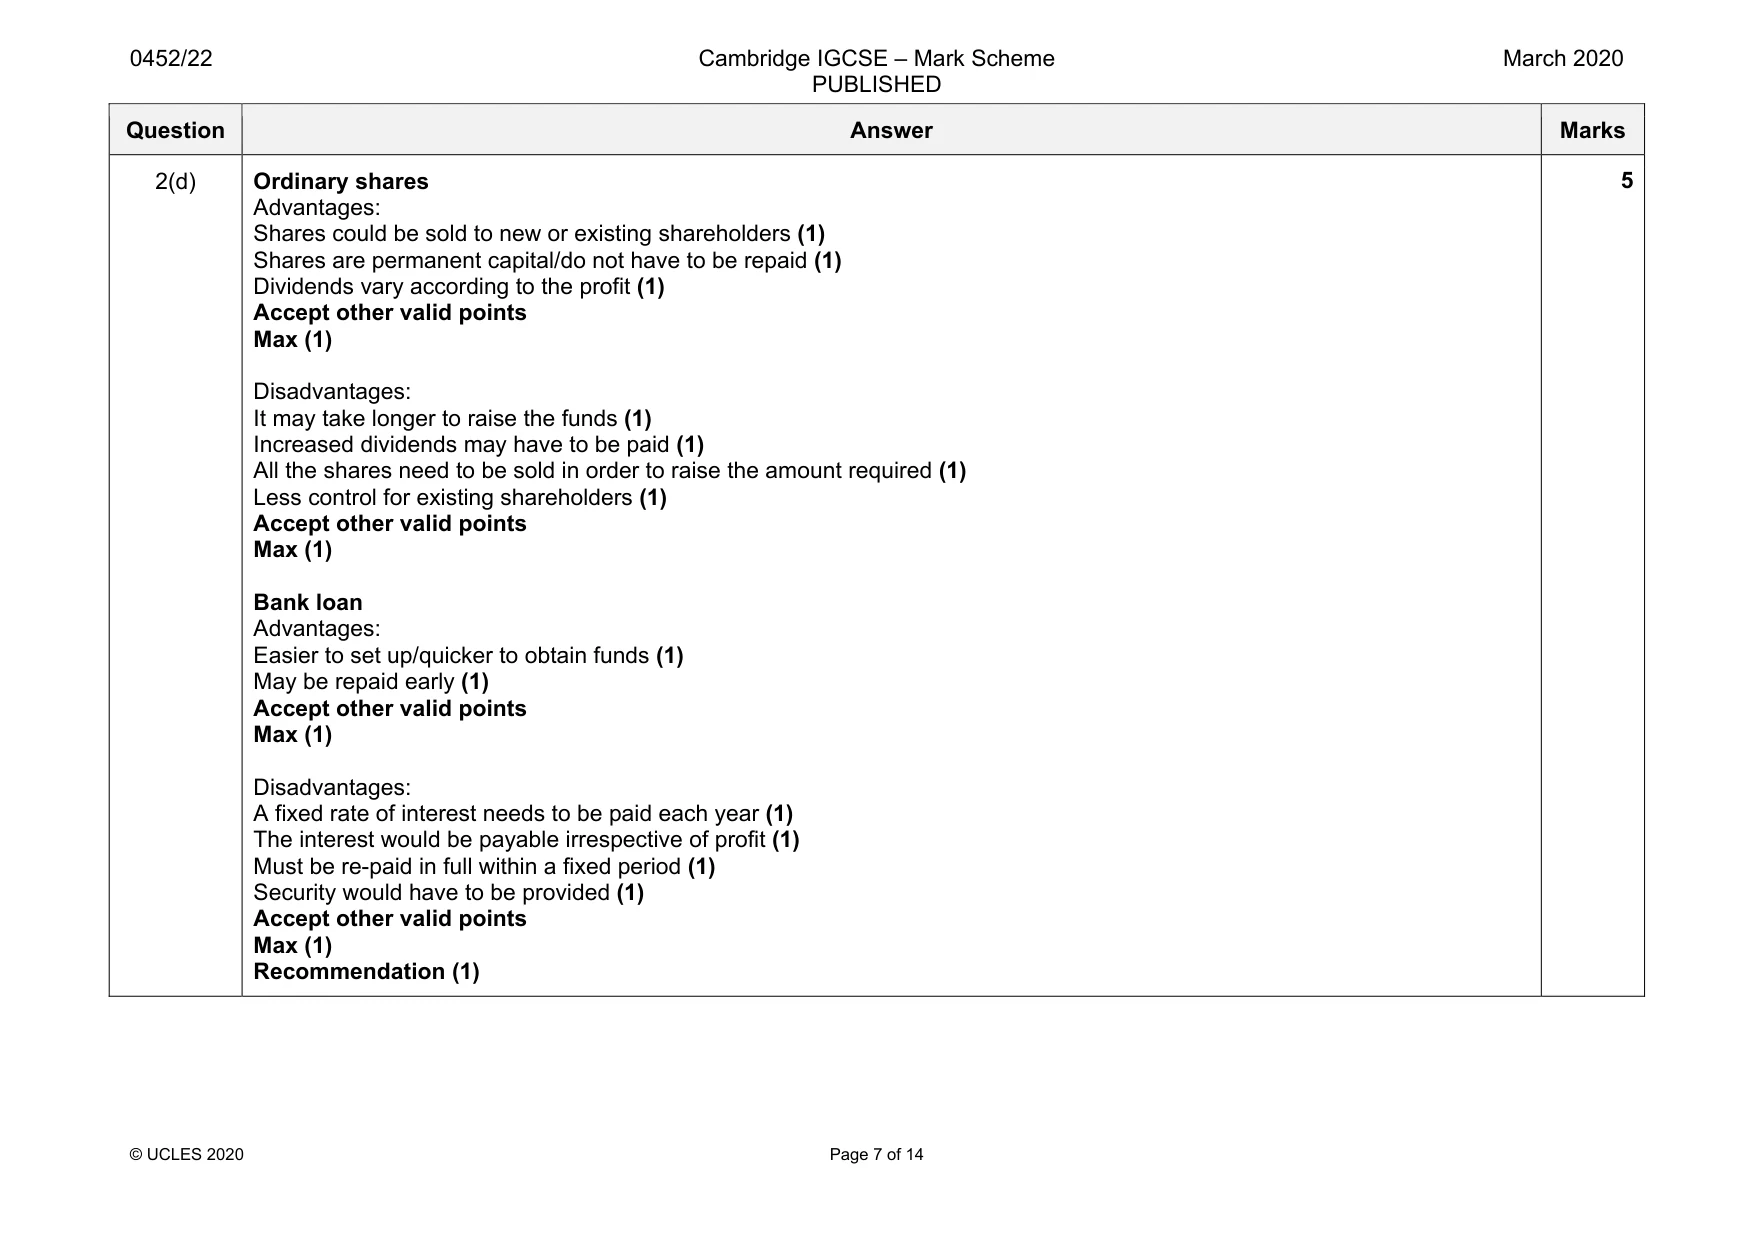
Mark scheme: 2(a) GHB Limited Purchases ledger control account 2019 $ 2019 $ Nov 30 Purchases returns 1 160 (1) Nov 1 Balance b/d 12 050 (1) OF Discount received 650 (1) 30 Purchases 14 200 (1) Bank 11 420 (1) Interest 95 (1) Sales ledger 250 (1) Bank 330 (1) Balance c/d 13 195 26 675 26 675 Dec 1 Balance b/d 13 195 (1) 9 2(b) The purchases ledger control account does not include capital expenditure/non-current assets (1) The purchases ledger control account only includes purchases of goods for resale (1) The purchases ledger control account only includes transactions relating to trade payables (1) Accept other valid points Max (2) 2 2(c)(i) Reducing balance method (1) 1 2(c)(ii) More depreciation is charged in the early years of its life (1) Most of the benefit of the asset is gained in the early years (1) The net book value is more likely to relate to the amount which will be realised on sale (1) The vehicle may become out-of-date quickly depending on the vehicle type (1) As repair costs are likely to be minimal in the early years, the overall charge to the income statement each year is more likely to be fairly constant if the reducing balance method is used (1) Accept other valid points Max (3) 3 Question Answer Marks 2(d) Ordinary shares Advantages: Shares could be sold to new or existing shareholders (1) Shares are permanent capital/do not have to be repaid (1) Dividends vary according to the profit (1) Accept other valid points Max (1) Disadvantages: It may take longer to raise the funds (1) Increased dividends may have to be paid (1) All the shares need to be sold in order to raise the amount required (1) Less control for existing shareholders (1) Accept other valid points Max (1) Bank loan Advantages: Easier to set up/quicker to obtain funds (1) May be repaid early (1) Accept other valid points Max (1) Disadvantages: A fixed rate of interest needs to be paid each year (1) The interest would be payable irrespective of profit (1) Must be re-paid in full within a fixed period (1) Security would have to be provided (1) Accept other valid points Max (1) Recommendation (1) 5
Q3 · Tia and Sarna are partners in a trading business
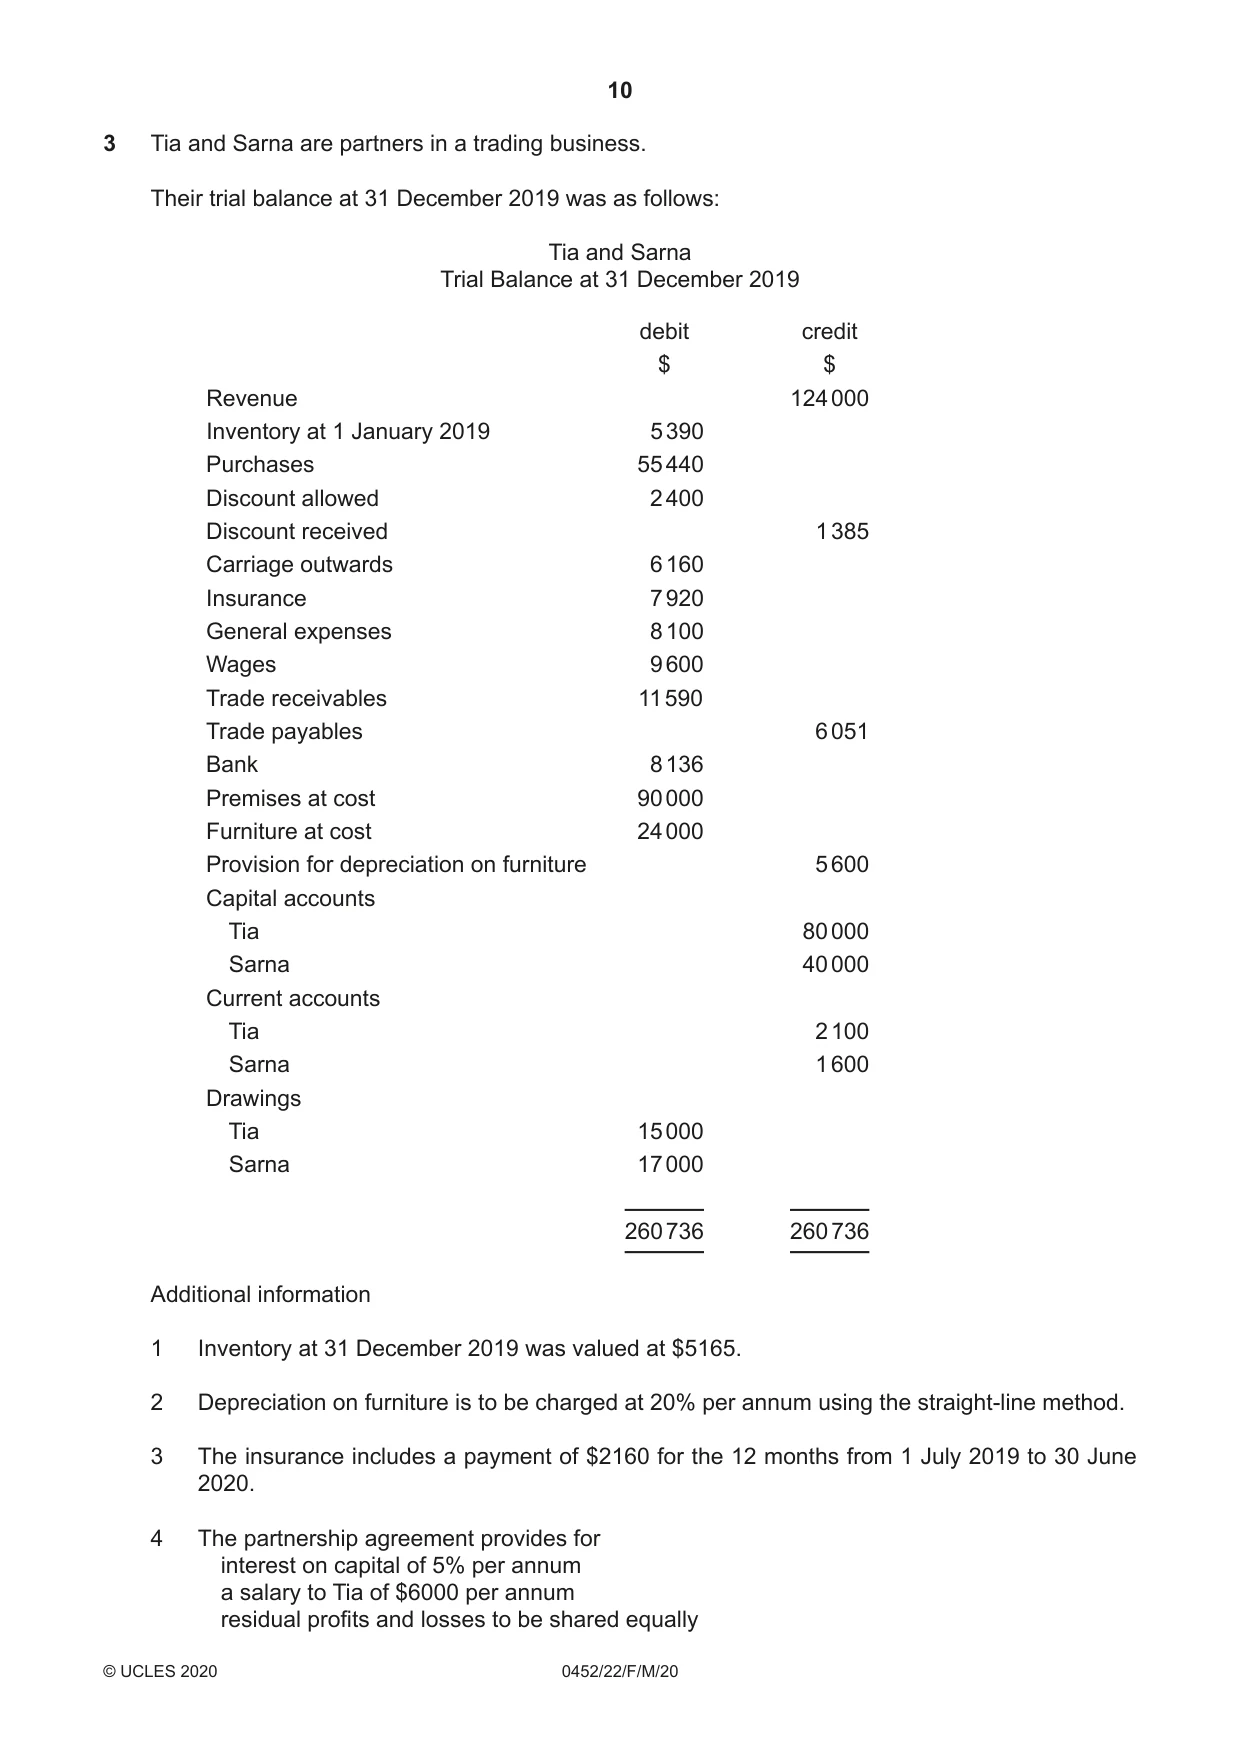
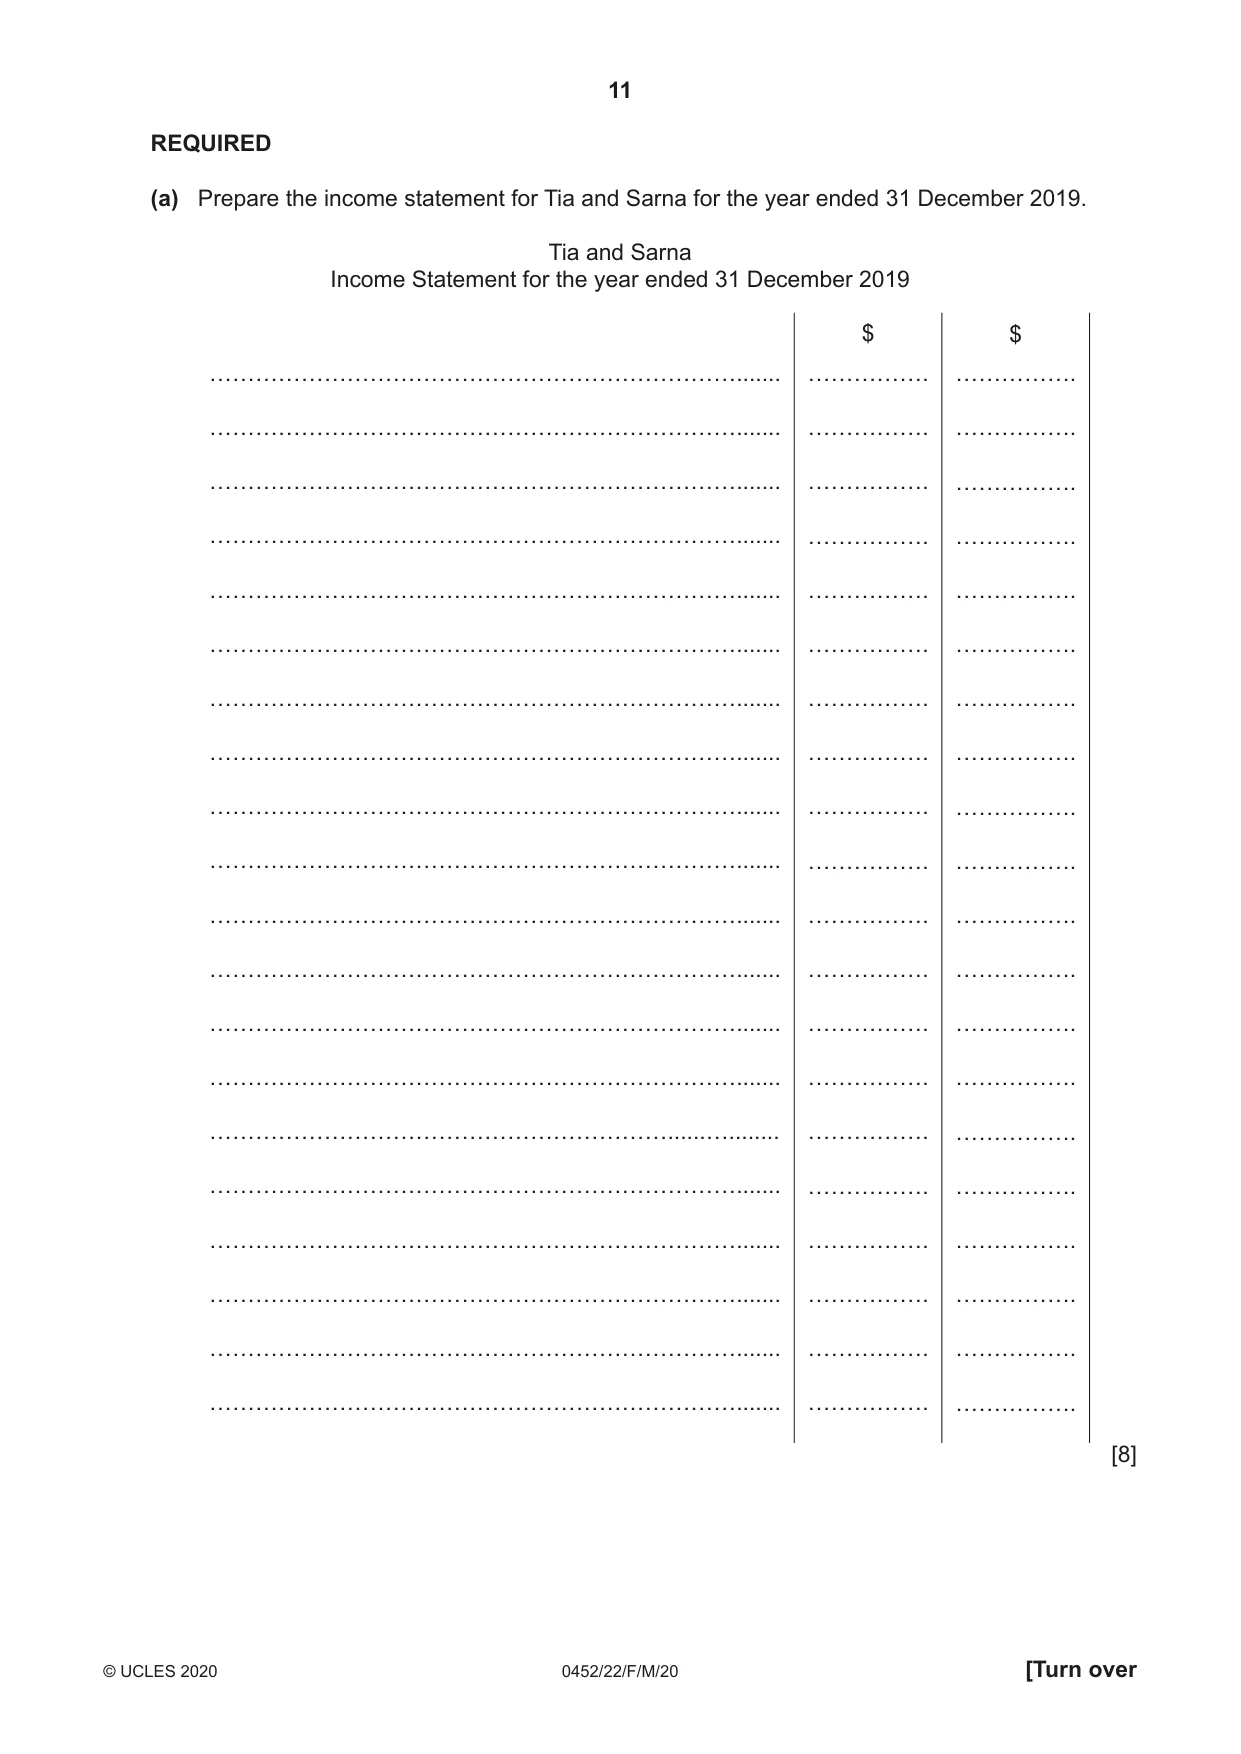
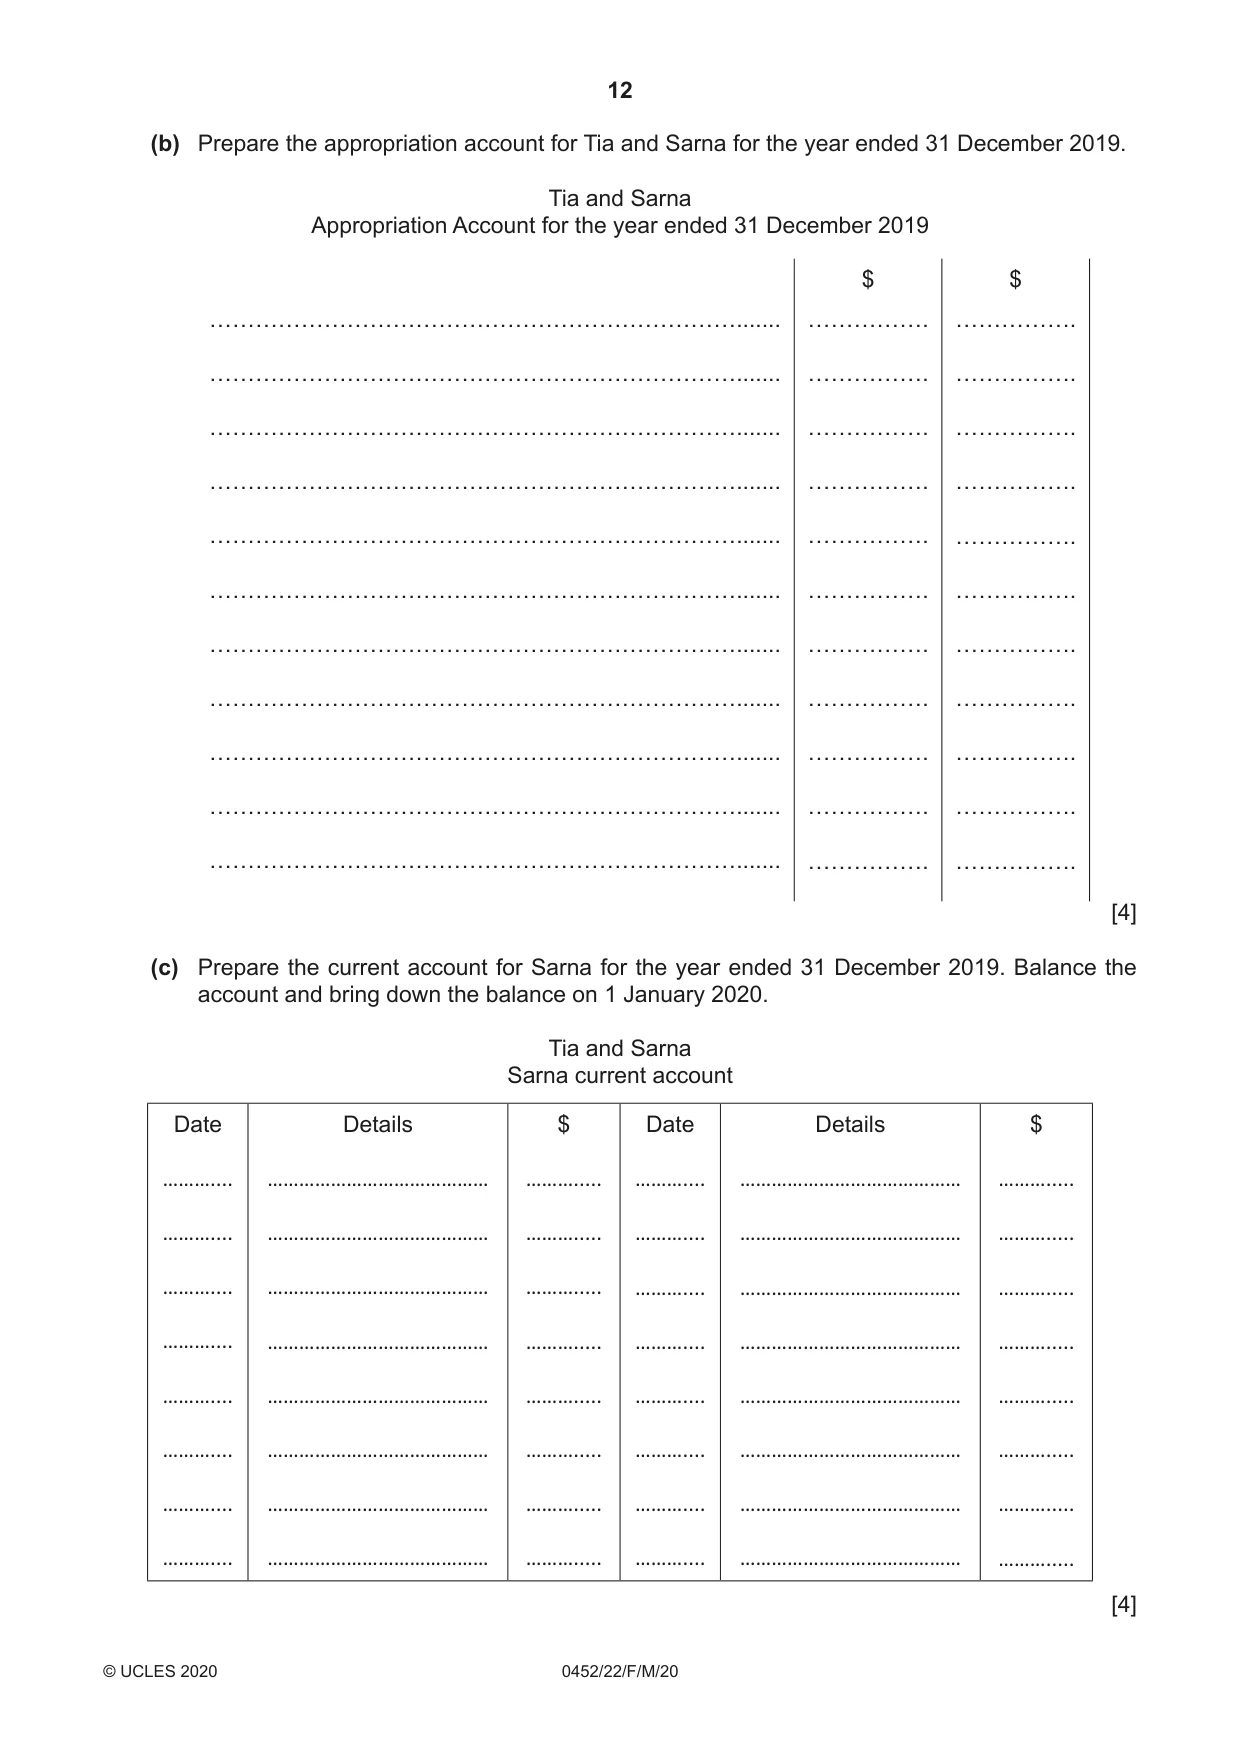
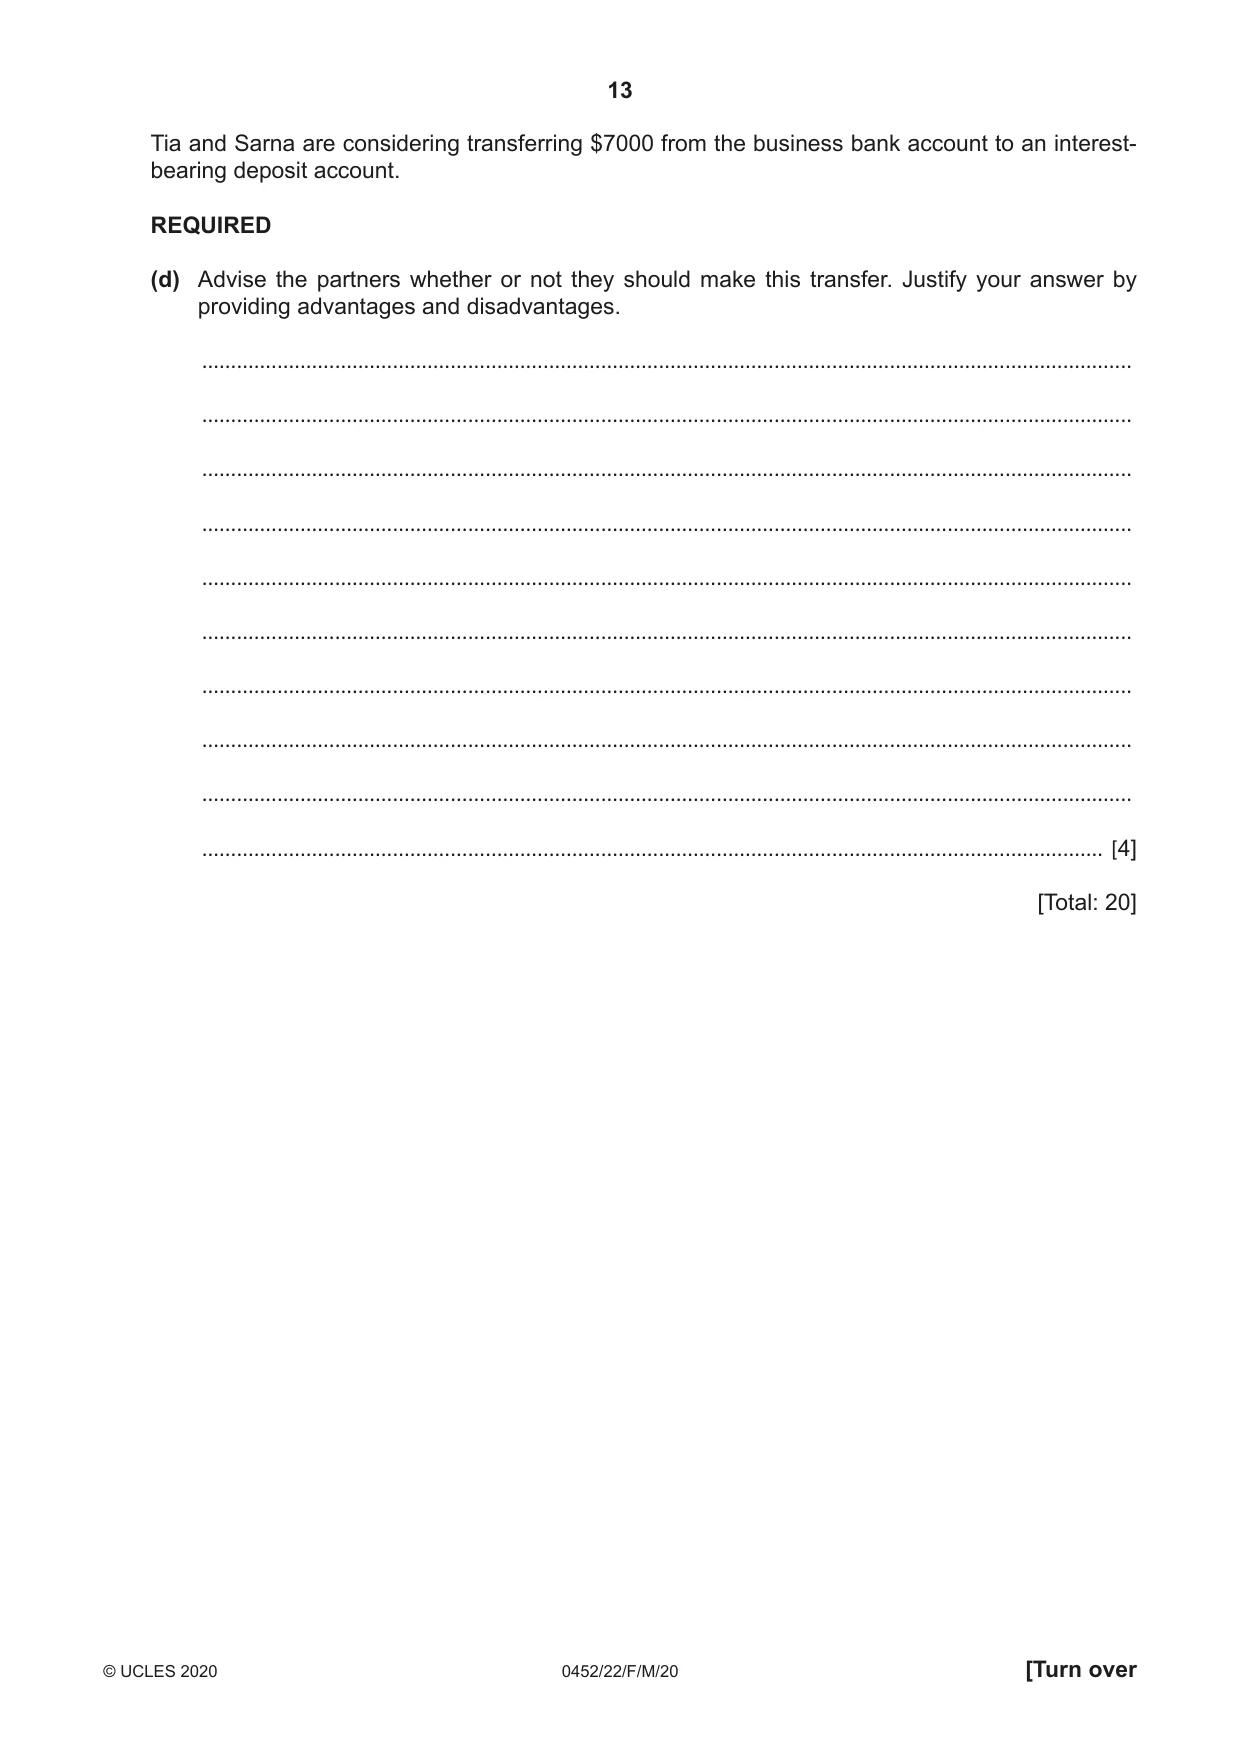
3 Tia and Sarna are partners in a trading business. Their trial balance at 31 December 2019 was as follows: Tia and Sarna Trial Balance at 31 December 2019 debit credit $ $ Revenue 124 000 Inventory at 1 January 2019 5 390 Purchases 55 440 Discount allowed 2 400 Discount received 1 385 Carriage outwards 6 160 Insurance 7 920 General expenses 8 100 Wages 9 600 Trade receivables 11 590 Trade payables 6 051 Bank 8 136 Premises at cost 90 000 Furniture at cost 24 000 Provision for depreciation on furniture 5 600 Capital accounts Tia 80 000 Sarna 40 000 Current accounts Tia 2 100 Sarna 1 600 Drawings Tia 15 000 Sarna 17 000 260 736 260 736 Additional information 1 Inventory at 31 December 2019 was valued at $5165. 2 Depreciation on furniture is to be charged at 20% per annum using the straight-line method. 3 The insurance includes a payment of $2160 for the 12 months from 1 July 2019 to 30 June 2020. 4 The partnership agreement provides for interest on capital of 5% per annum a salary to Tia of $6000 per annum residual profits and losses to be shared equally REQUIRED (a) Prepare the income statement for Tia and Sarna for the ye Tia and Sarna Income Statement for the year ended 31 Dec ……………………………………………………......…........ (b) Prepare the appropriation account for Tia and Sarna for the year ended 31 December 2019. Tia and Sarna Appropriation Account for the year ended 31 December 2019 $ $ ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. [4] (c) Prepare the current account for Sarna for the year ended 31 December 2019. Balance the account and bring down the balance on 1 January 2020. Tia and Sarna Sarna current account Date Details $ Date Details $ ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... ……….... ………..... [4] Tia and Sarna are considering transferring $7000 from the business bank account to an interest- bearing deposit account. REQUIRED (d) Advise the partners whether or not they should make this transfer. Justify your answer by providing advantages and disadvantages. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ................................................................................................................................................................. ............................................................................................................................................................ [4] [Total: 20]
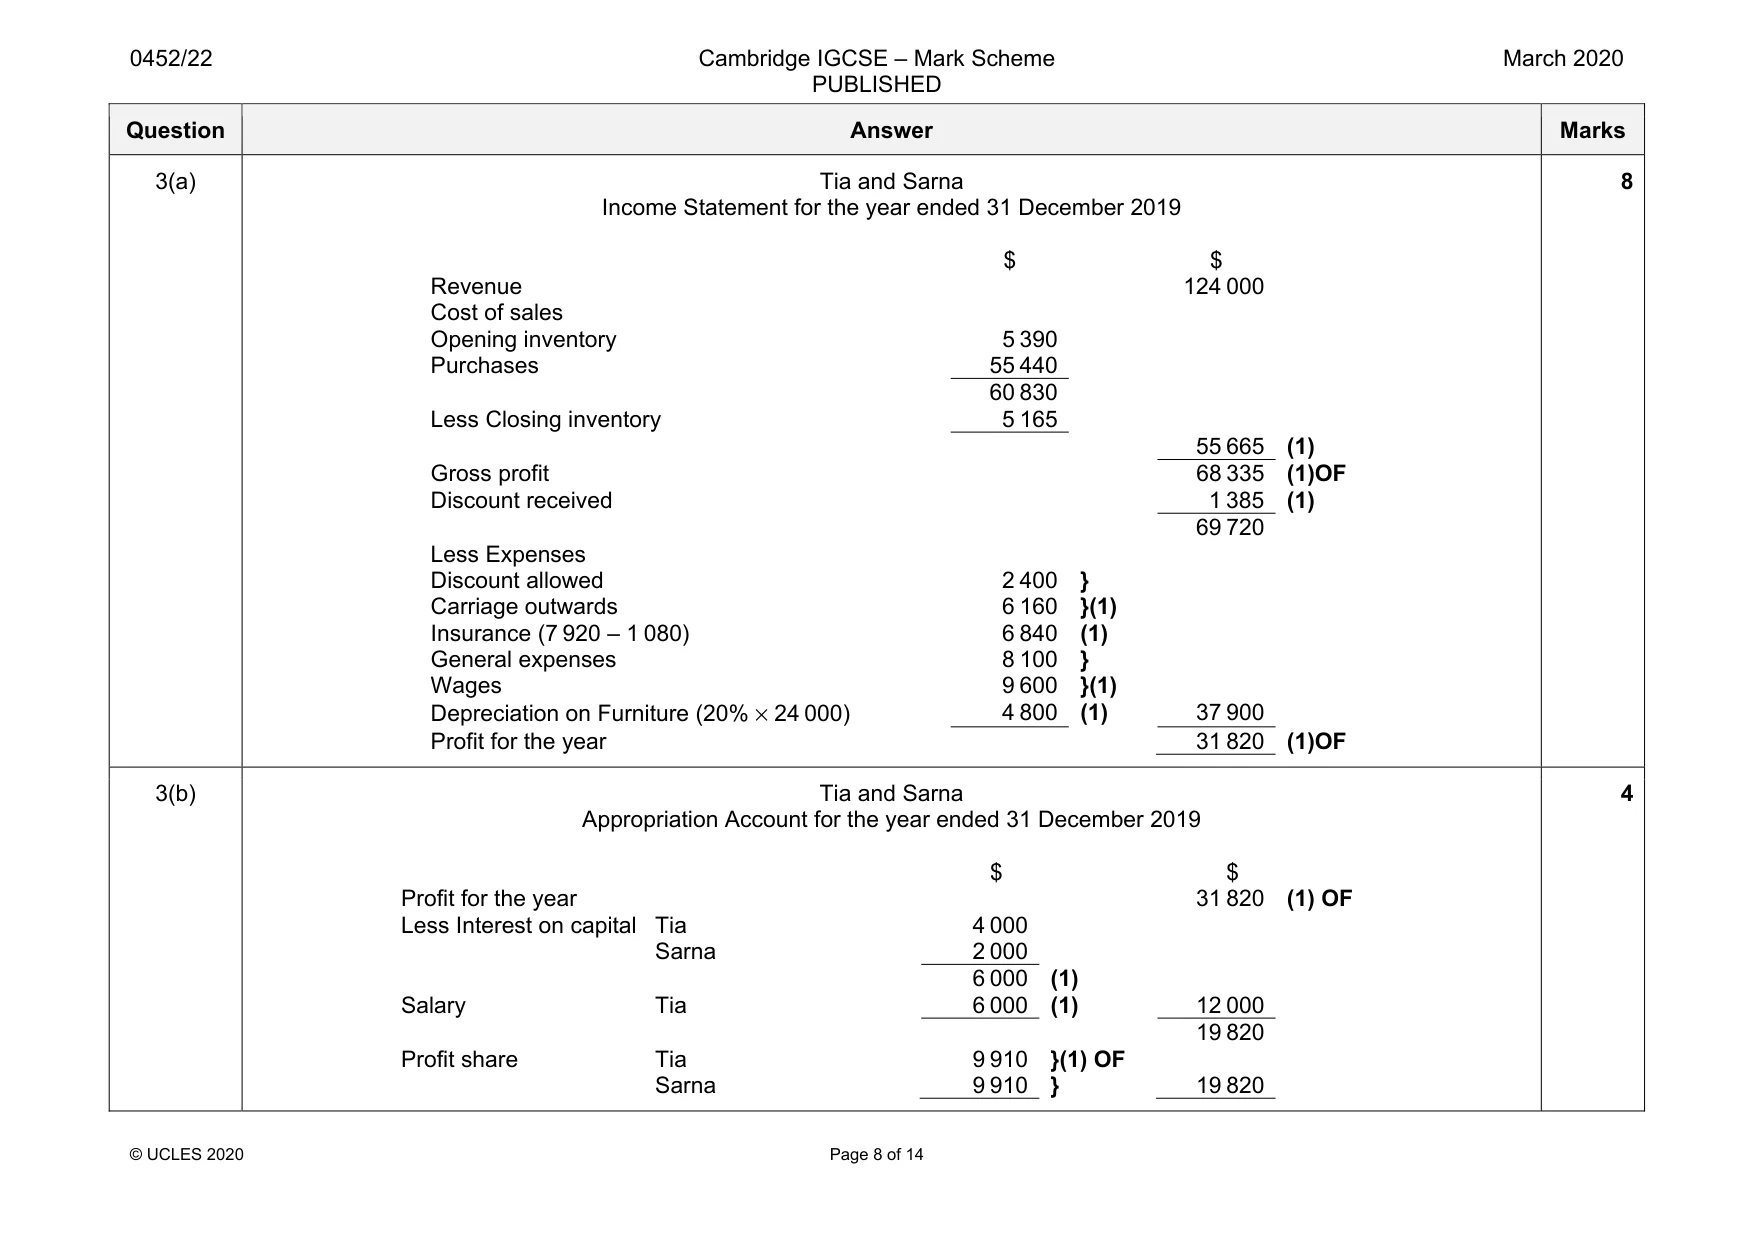
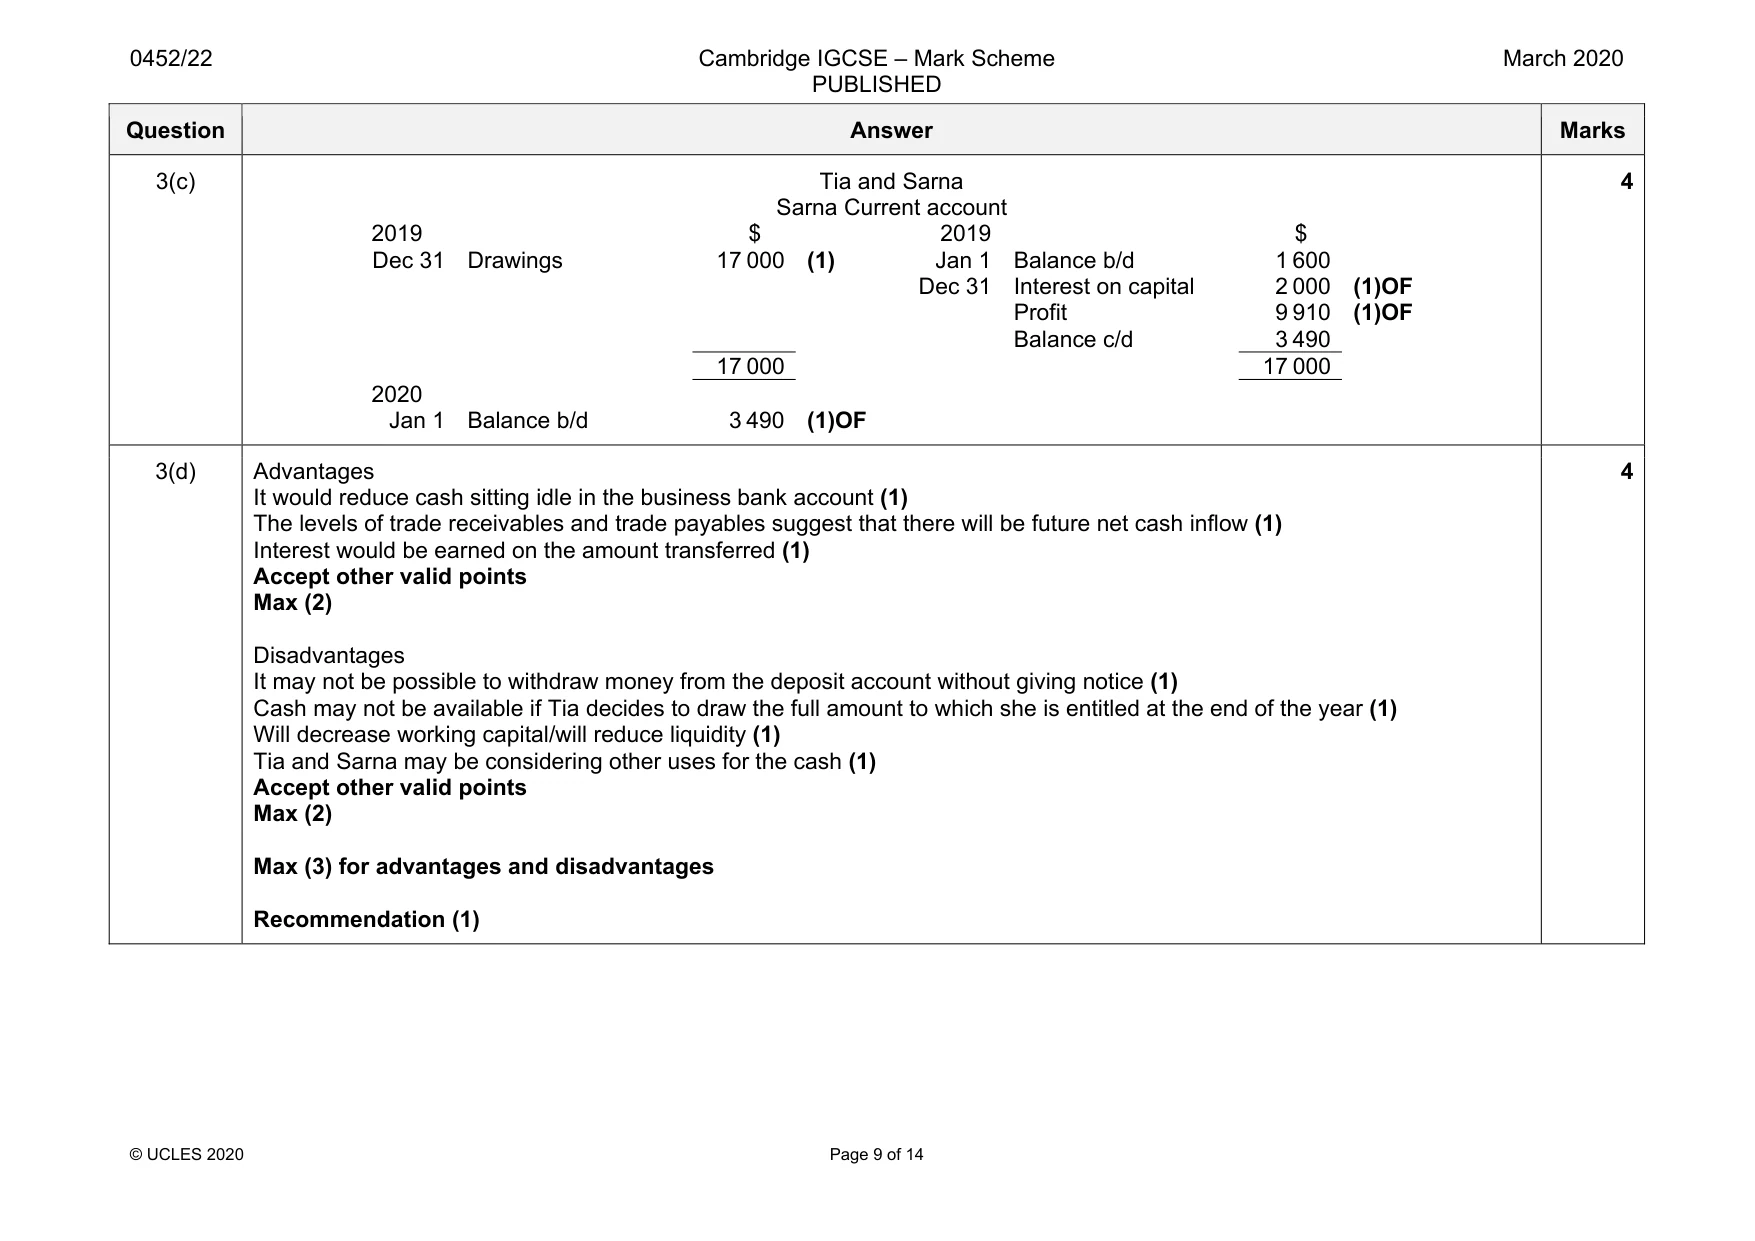
Mark scheme: 3(a) Tia and Sarna Income Statement for the year ended 31 December 2019 $ $ Revenue 124 000 Cost of sales Opening inventory 5 390 Purchases 55 440 60 830 Less Closing inventory 5 165 55 665 (1) Gross profit 68 335 (1)OF Discount received 1 385 (1) 69 720 Less Expenses Discount allowed 2 400 } Carriage outwards 6 160 }(1) Insurance (7 920 – 1 080) 6 840 (1) General expenses 8 100 } Wages 9 600 }(1) Depreciation on Furniture (20% × 24 000) 4 800 (1) 37 900 Profit for the year 31 820 (1)OF 8 3(b) Tia and Sarna Appropriation Account for the year ended 31 December 2019 $ $ Profit for the year 31 820 (1) OF Less Interest on capital Tia 4 000 Sarna 2 000 6 000 (1) Salary Tia 6 000 (1) 12 000 19 820 Profit share Tia 9 910 }(1) OF Sarna 9 910 } 19 820 4 Question Answer Marks 3(c) Tia and Sarna Sarna Current account 2019 $ 2019 $ Dec 31 Drawings 17 000 (1) Jan 1 Balance b/d 1 600 Dec 31 Interest on capital 2 000 (1)OF Profit 9 910 (1)OF Balance c/d 3 490 17 000 17 000 2020 Jan 1 Balance b/d 3 490 (1)OF 4 3(d) Advantages It would reduce cash sitting idle in the business bank account (1) The levels of trade receivables and trade payables suggest that there will be future net cash inflow (1) Interest would be earned on the amount transferred (1) Accept other valid points Max (2) Disadvantages It may not be possible to withdraw money from the deposit account without giving notice (1) Cash may not be available if Tia decides to draw the full amount to which she is entitled at the end of the year (1) Will decrease working capital/will reduce liquidity (1) Tia and Sarna may be considering other uses for the cash (1) Accept other valid points Max (2) Max (3) for advantages and disadvantages Recommendation (1) 4
Q4 · Arjun is a sole trader
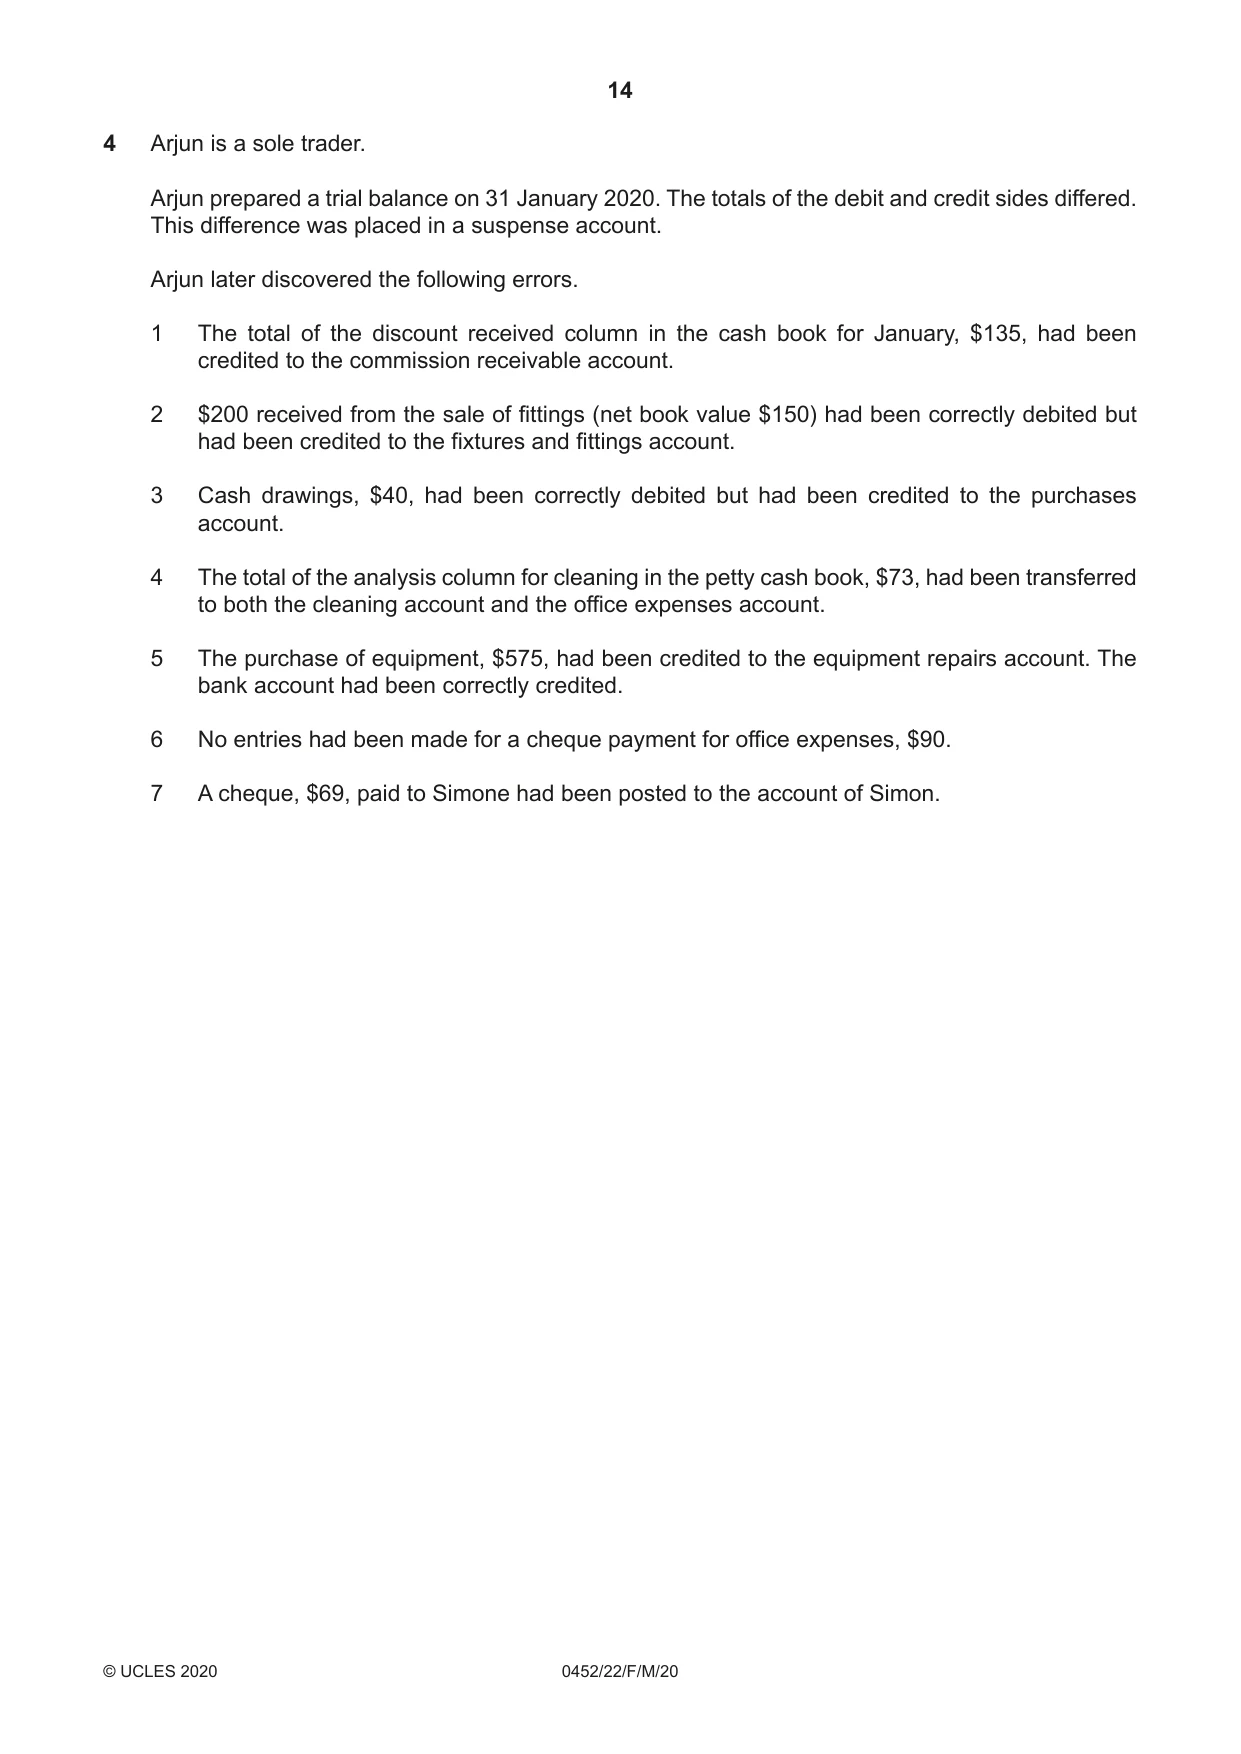
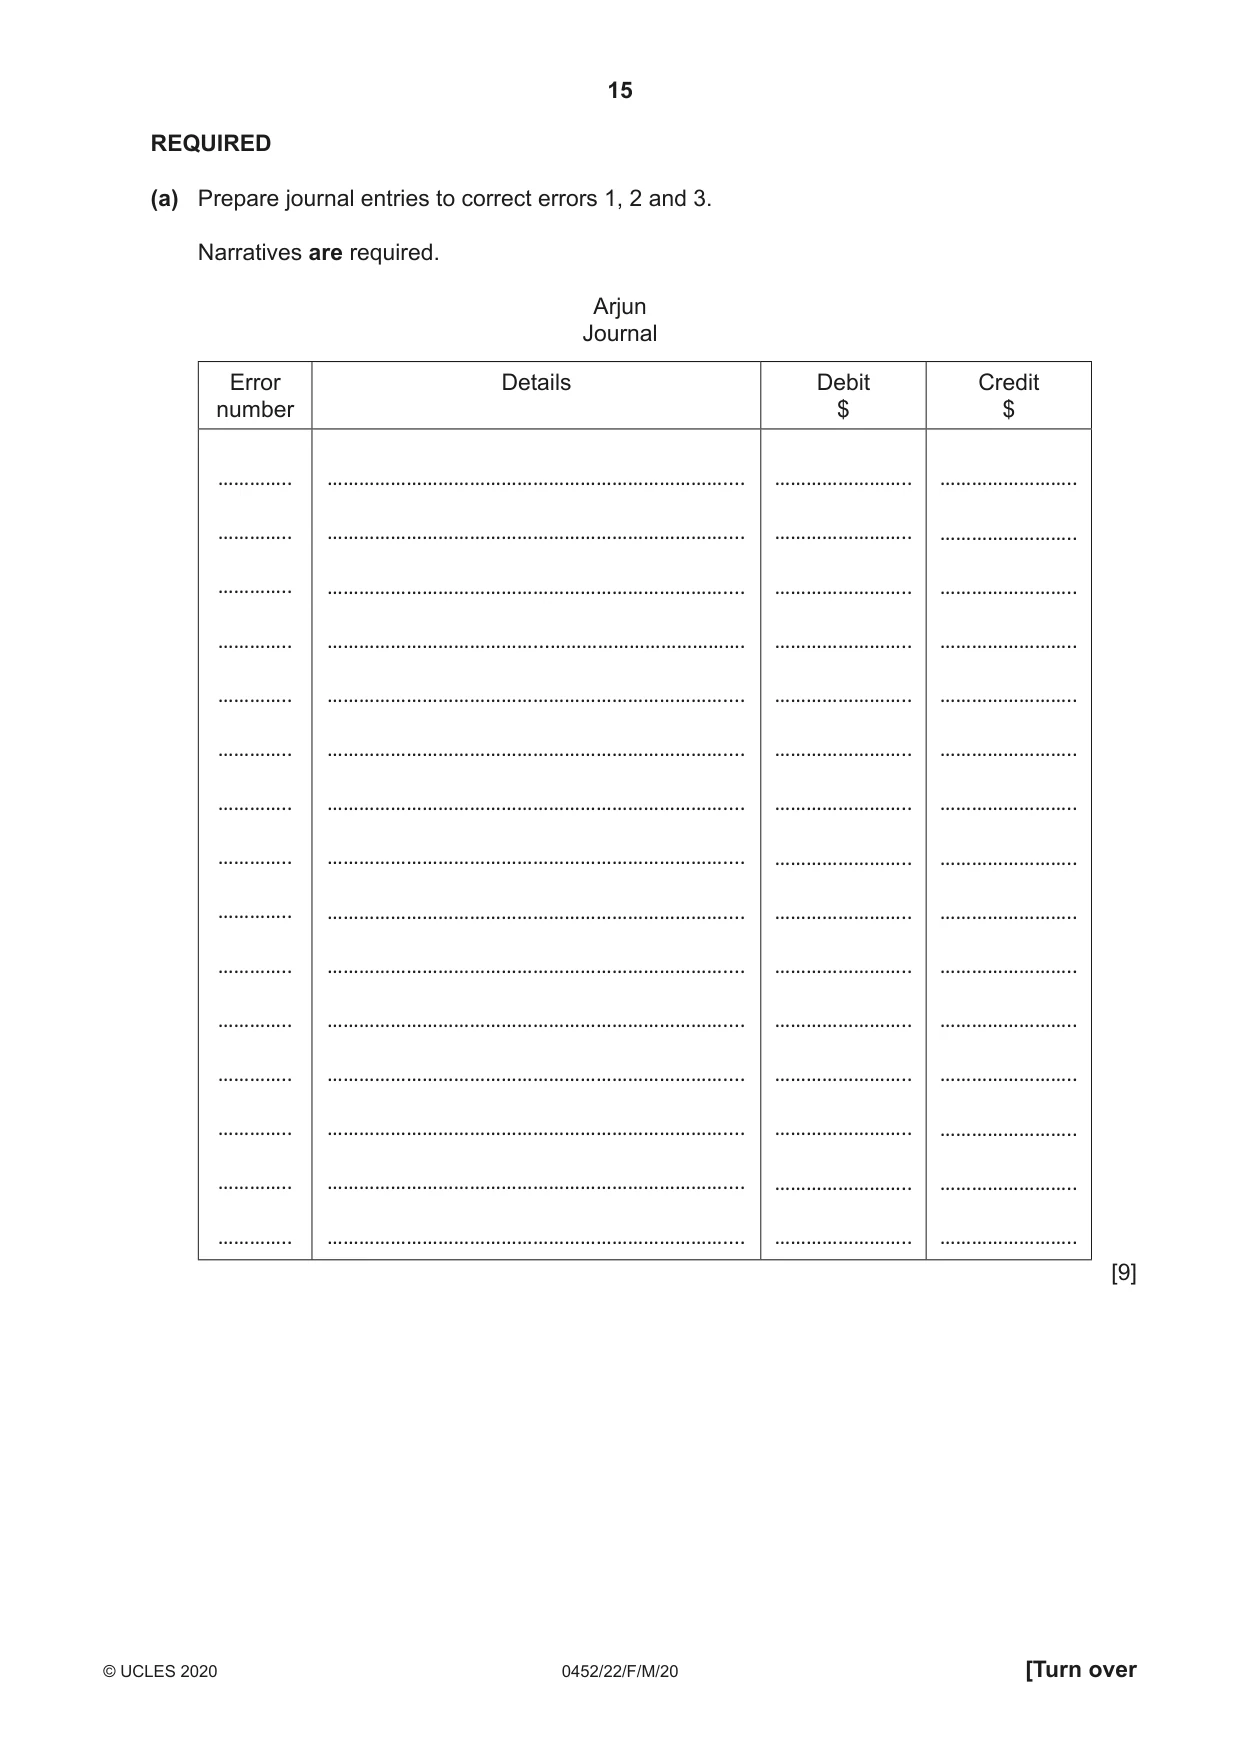
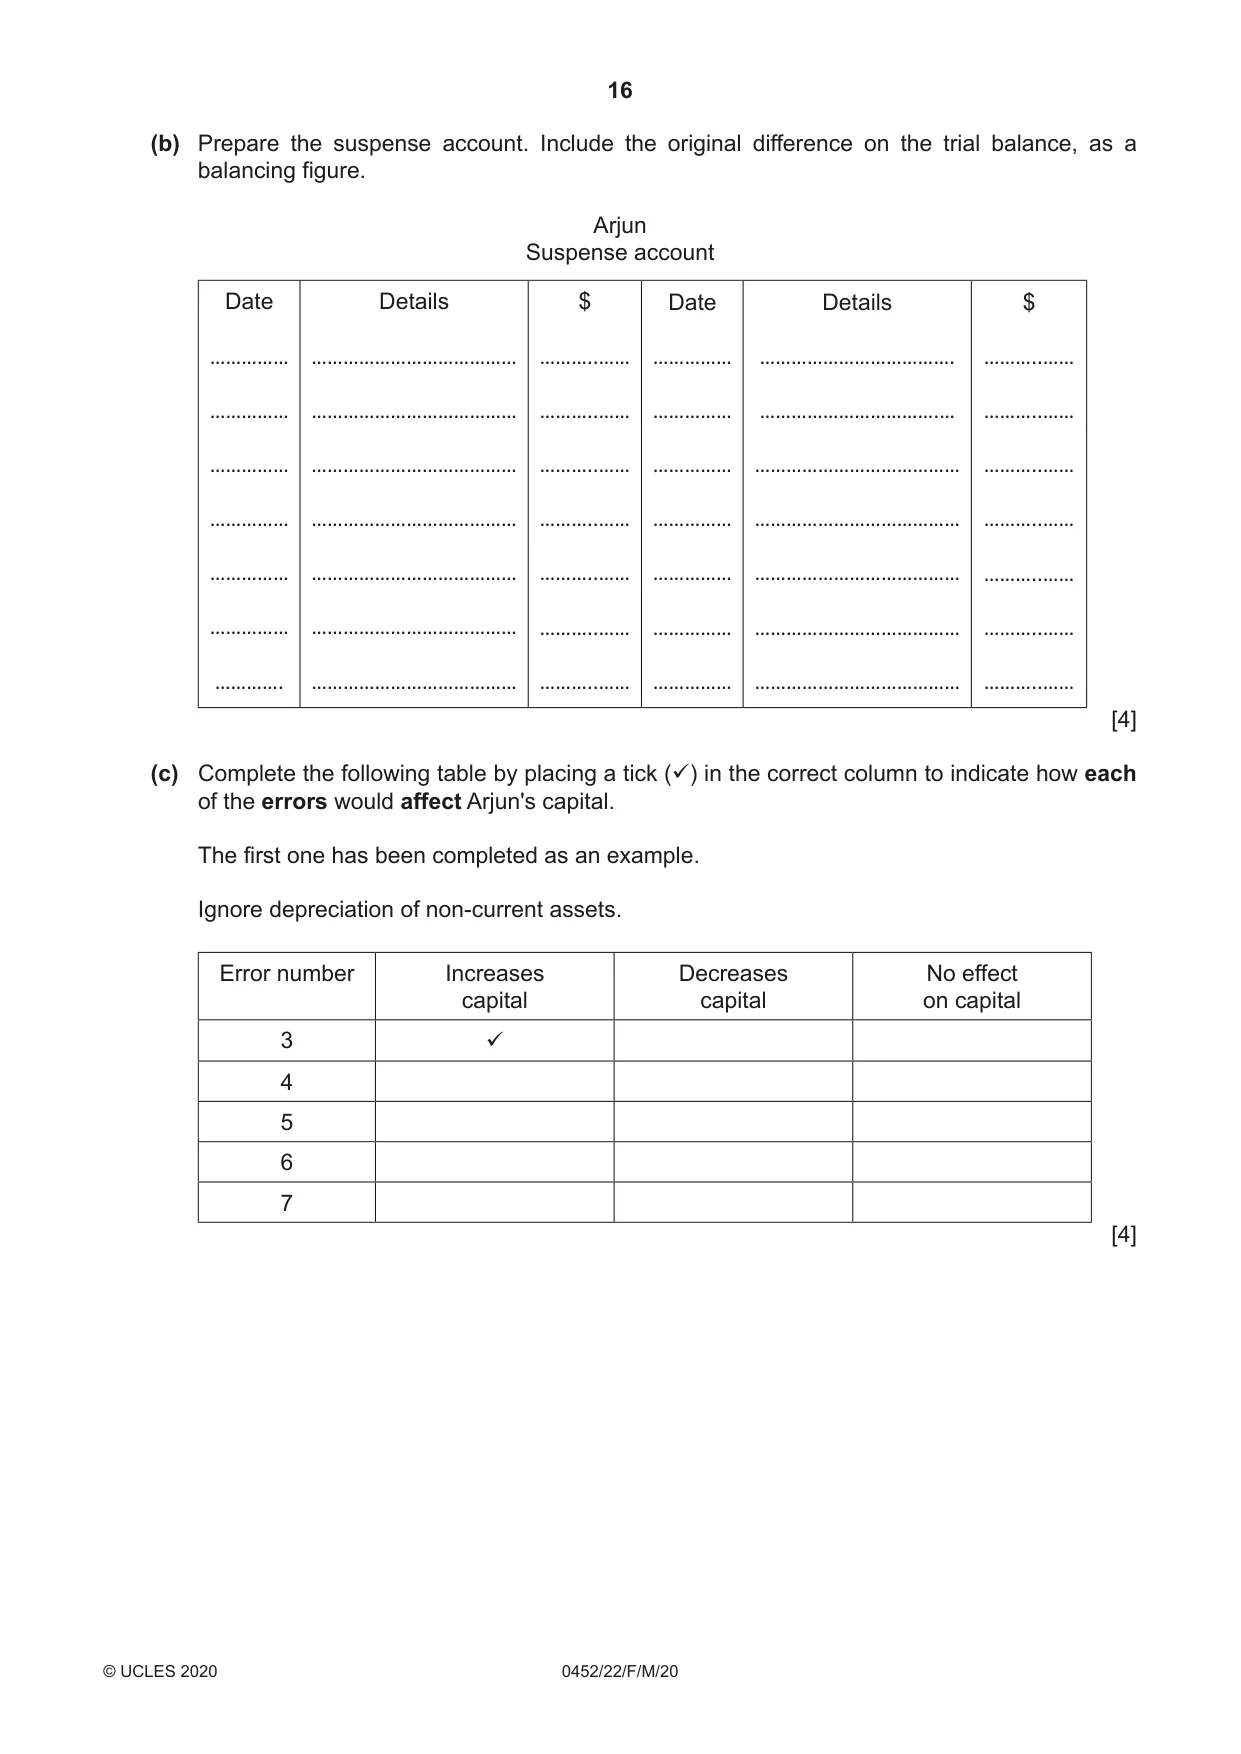
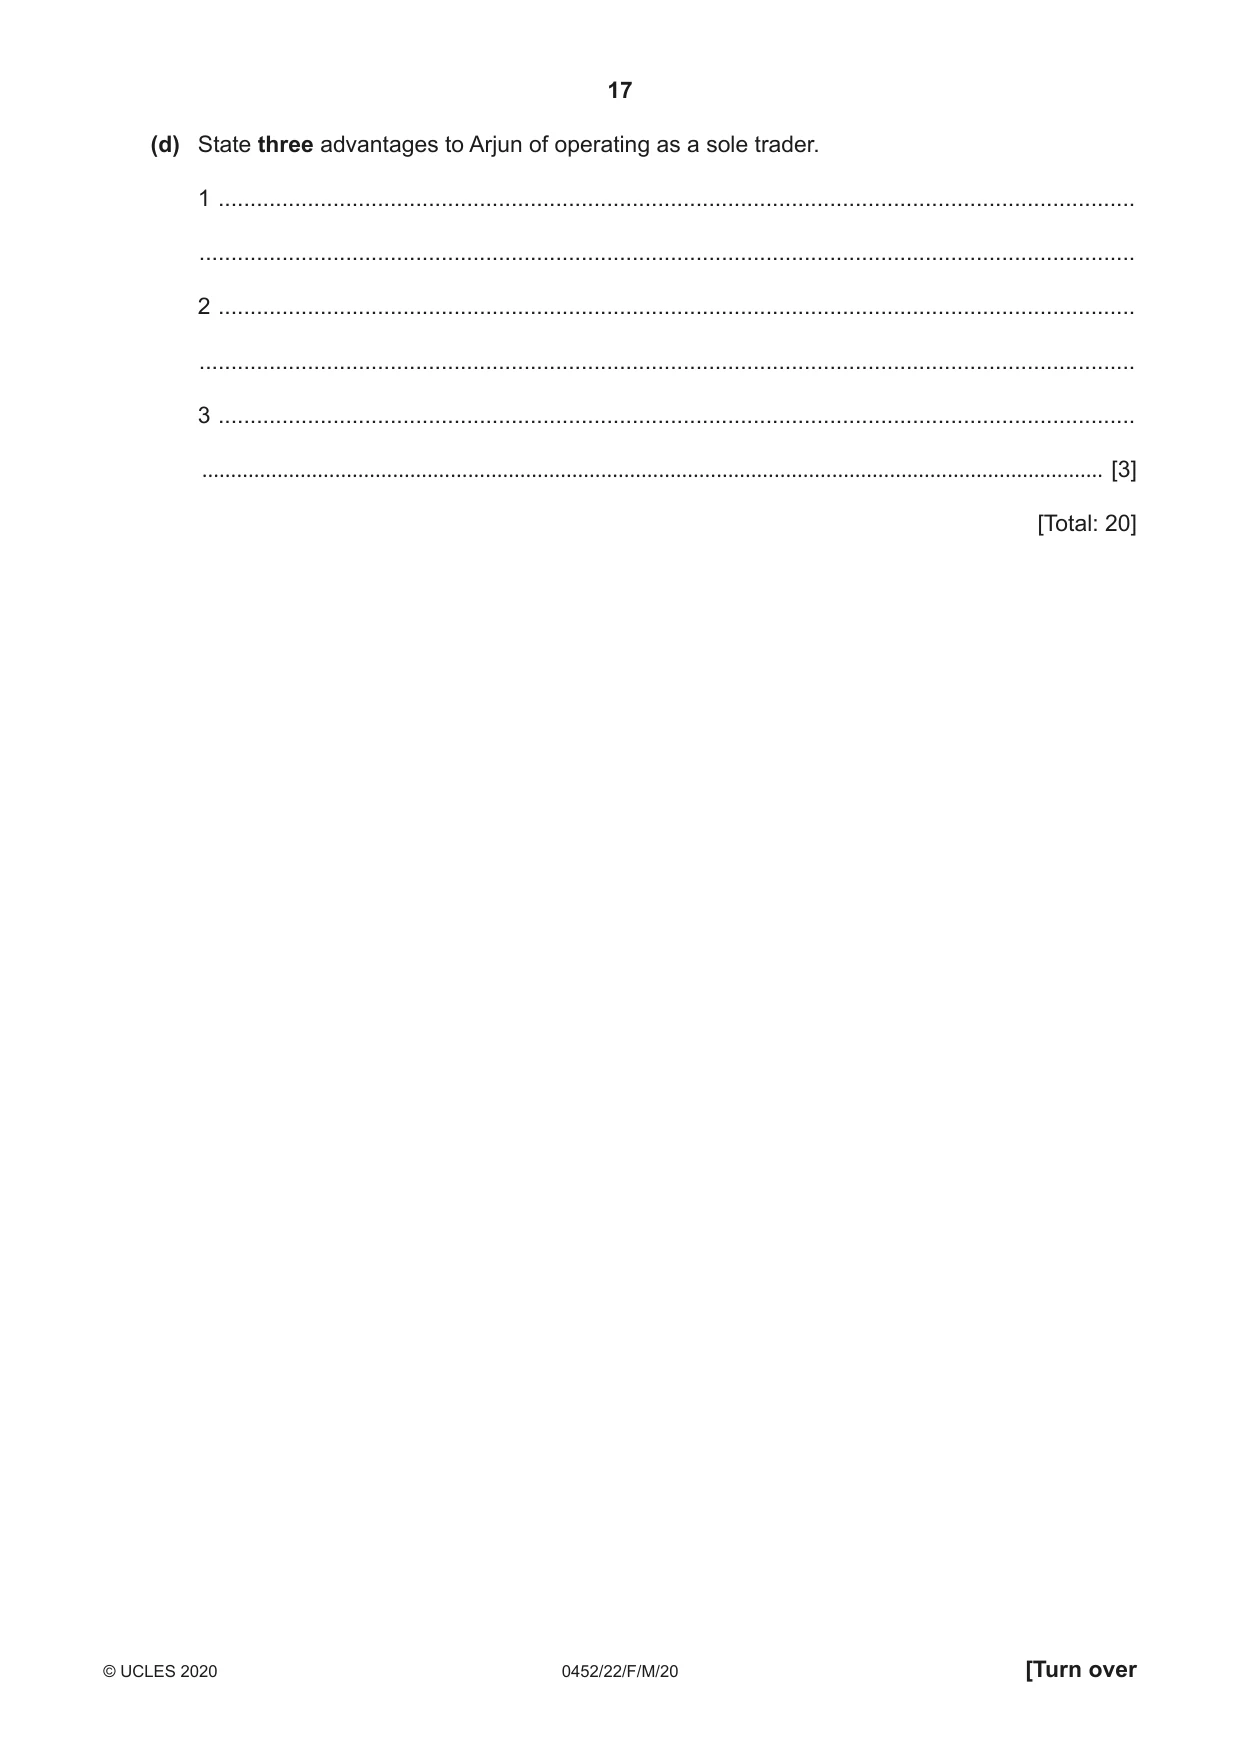
4 Arjun is a sole trader. Arjun prepared a trial balance on 31 January 2020. The totals of the debit and credit sides differed. This difference was placed in a suspense account. Arjun later discovered the following errors. 1 The total of the discount received column in the cash book for January, $135, had been credited to the commission receivable account. 2 $200 received from the sale of fittings (net book value $150) had been correctly debited but had been credited to the fixtures and fittings account. 3 Cash drawings, $40, had been correctly debited but had been credited to the purchases account. 4 The total of the analysis column for cleaning in the petty cash book, $73, had been transferred to both the cleaning account and the office expenses account. 5 The purchase of equipment, $575, had been credited to the equipment repairs account. The bank account had been correctly credited. 6 No entries had been made for a cheque payment for office expenses, $90. 7 A cheque, $69, paid to Simone had been posted to the account of Simon. REQUIRED (a) Prepare journal entries to correct errors 1, 2 and 3. Narratives are required. Arjun Journal Error Details Debit Credit number $ $ ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. ………….. [9] (b) Prepare the suspense account. Include the original difference on the trial balance, as a balancing figure. Arjun Suspense account Date Details $ Date Details $ …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………… ………..…… …………. ………..…… …………… ………..…… [4] (c) Complete the following table by placing a tick (ü) in the correct column to indicate how each of the errors would affect Arjun's capital. The first one has been completed as an example. Ignore depreciation of non-current assets. Error number Increases Decreases No effect capital capital on capital 3 ü 4 5 6 7 [4] (d) State three advantages to Arjun of operating as a sole trader. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ............................................................................................................................................................ [3] [Total: 20]
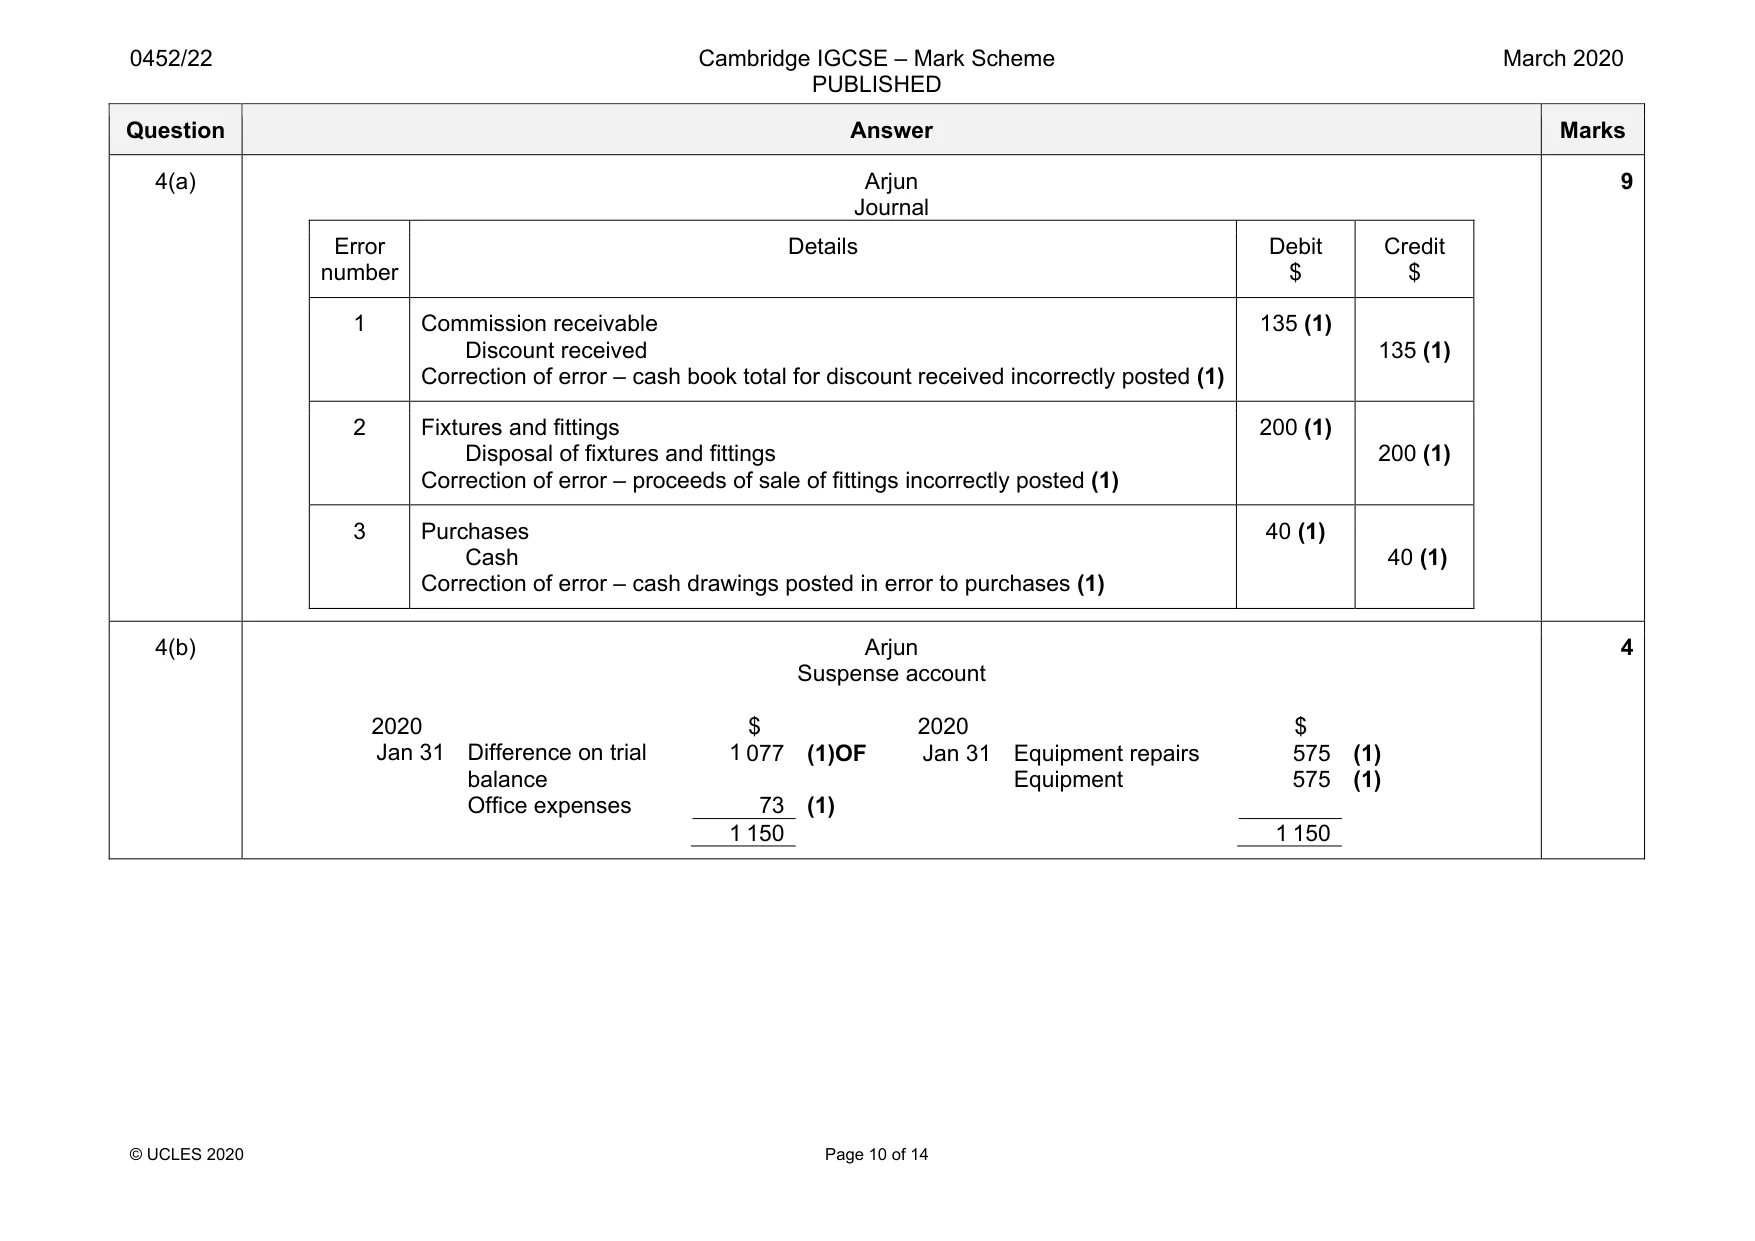
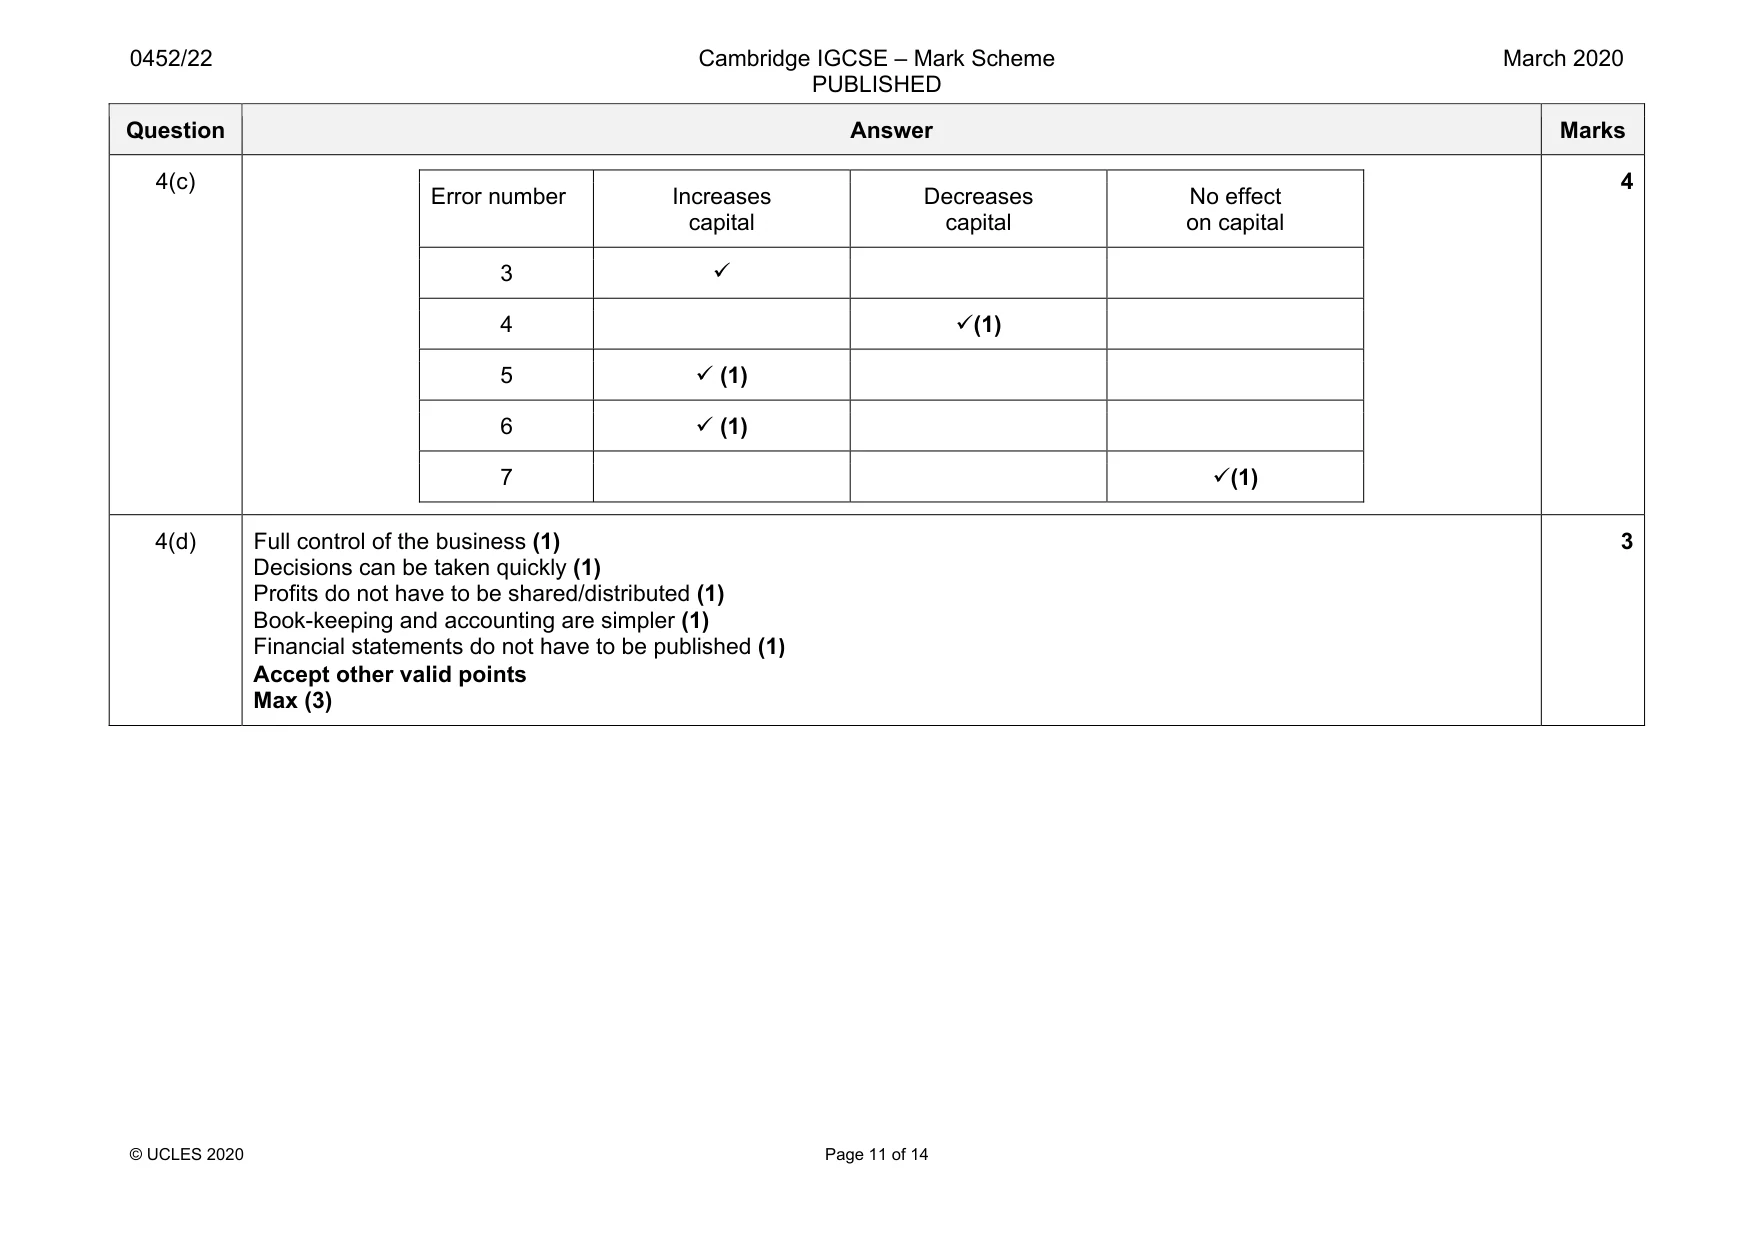
Mark scheme: 4(a) Arjun Journal Error number Details Debit $ Credit $ 1 Commission receivable Discount received Correction of error – cash book total for discount received incorrectly posted (1) 135 (1) 135 (1) 2 Fixtures and fittings Disposal of fixtures and fittings Correction of error – proceeds of sale of fittings incorrectly posted (1) 200 (1) 200 (1) 3 Purchases Cash Correction of error – cash drawings posted in error to purchases (1) 40 (1) 40 (1) 9 4(b) Arjun Suspense account 2020 $ 2020 $ Jan 31 Difference on trial 1 077 (1)OF Jan 31 Equipment repairs 575 (1) balance Equipment 575 (1) Office expenses 73 (1) 1 150 1 150 4 Question Answer Marks 4(c) Error number Increases capital Decreases capital No effect on capital 3 4 (1) 5 (1) 6 (1) 7 (1) 4 4(d) Full control of the business (1) Decisions can be taken quickly (1) Profits do not have to be shared/distributed (1) Book-keeping and accounting are simpler (1) Financial statements do not have to be published (1) Accept other valid points Max (3) 3
Q5 · Adit provided the following information
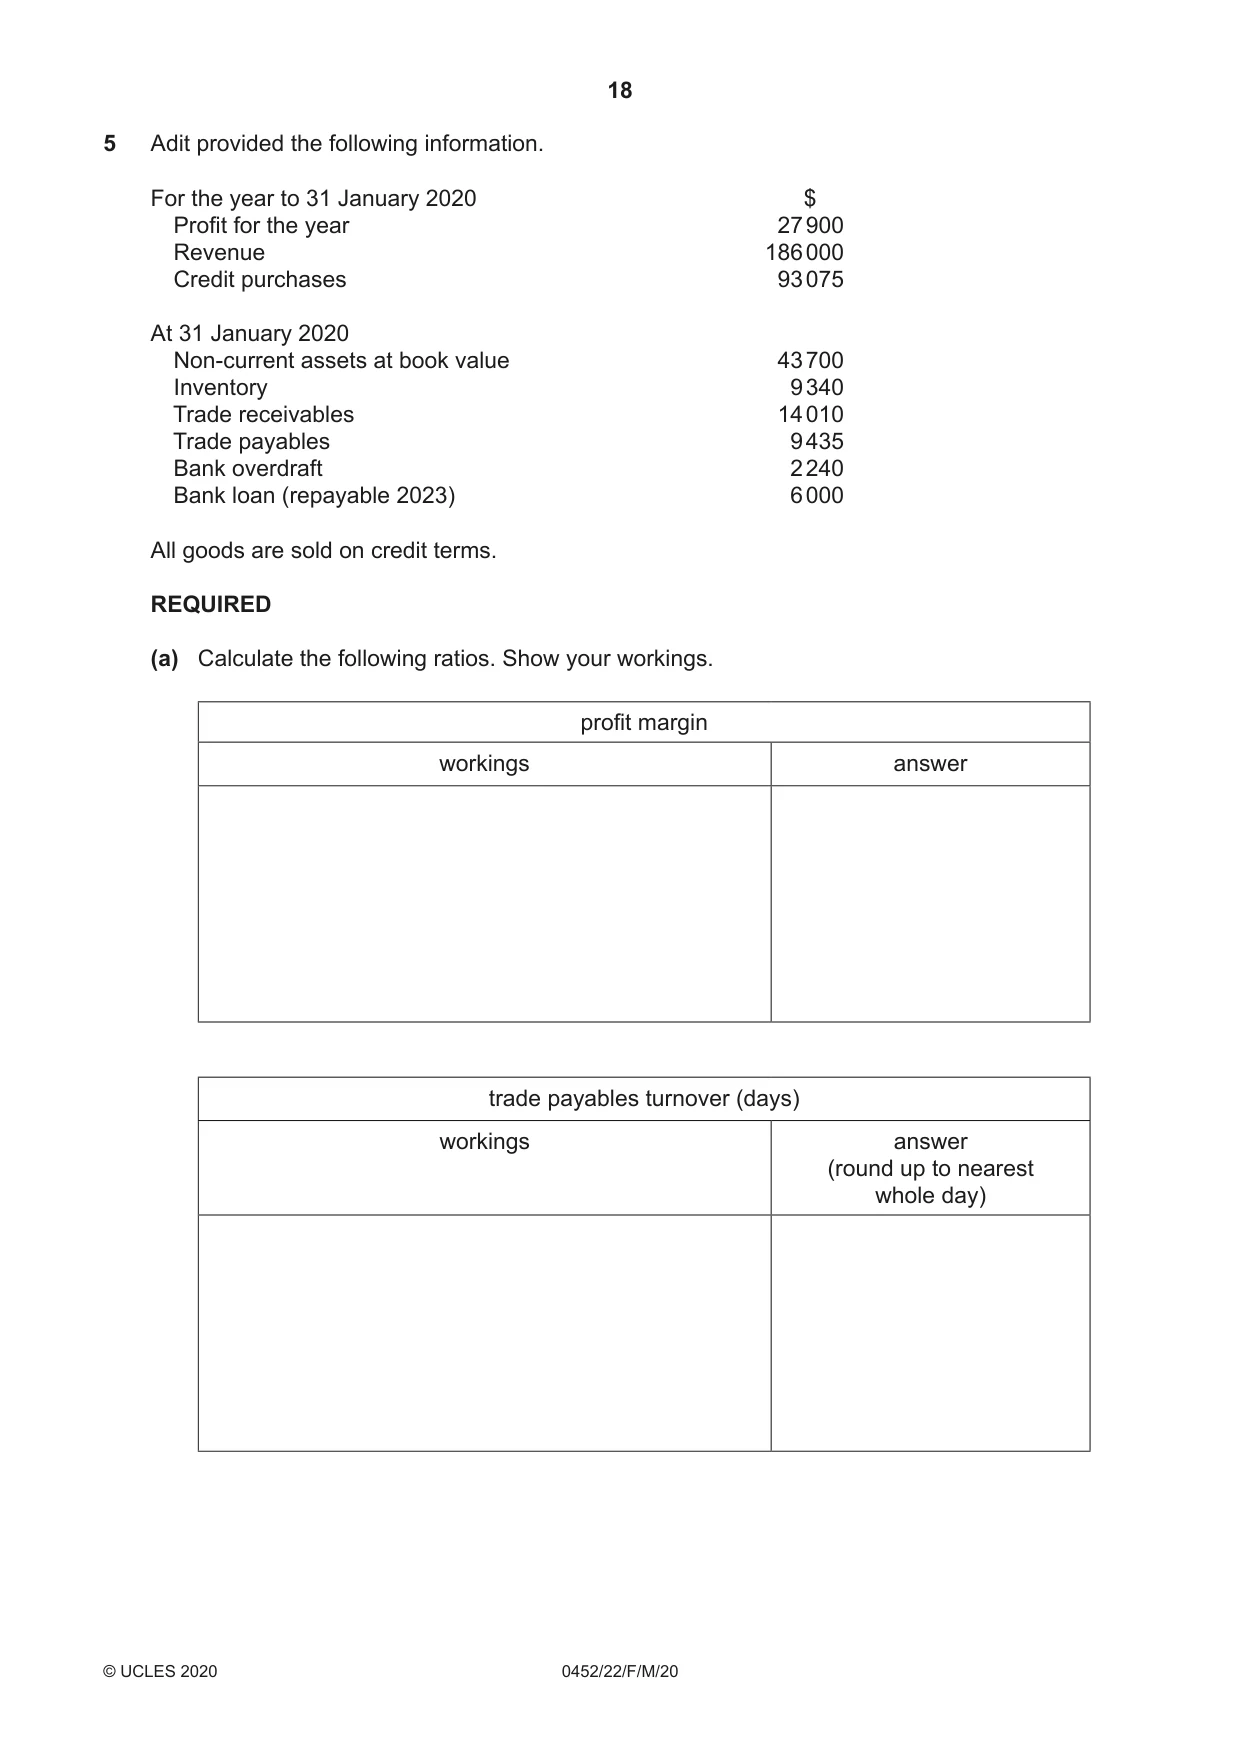
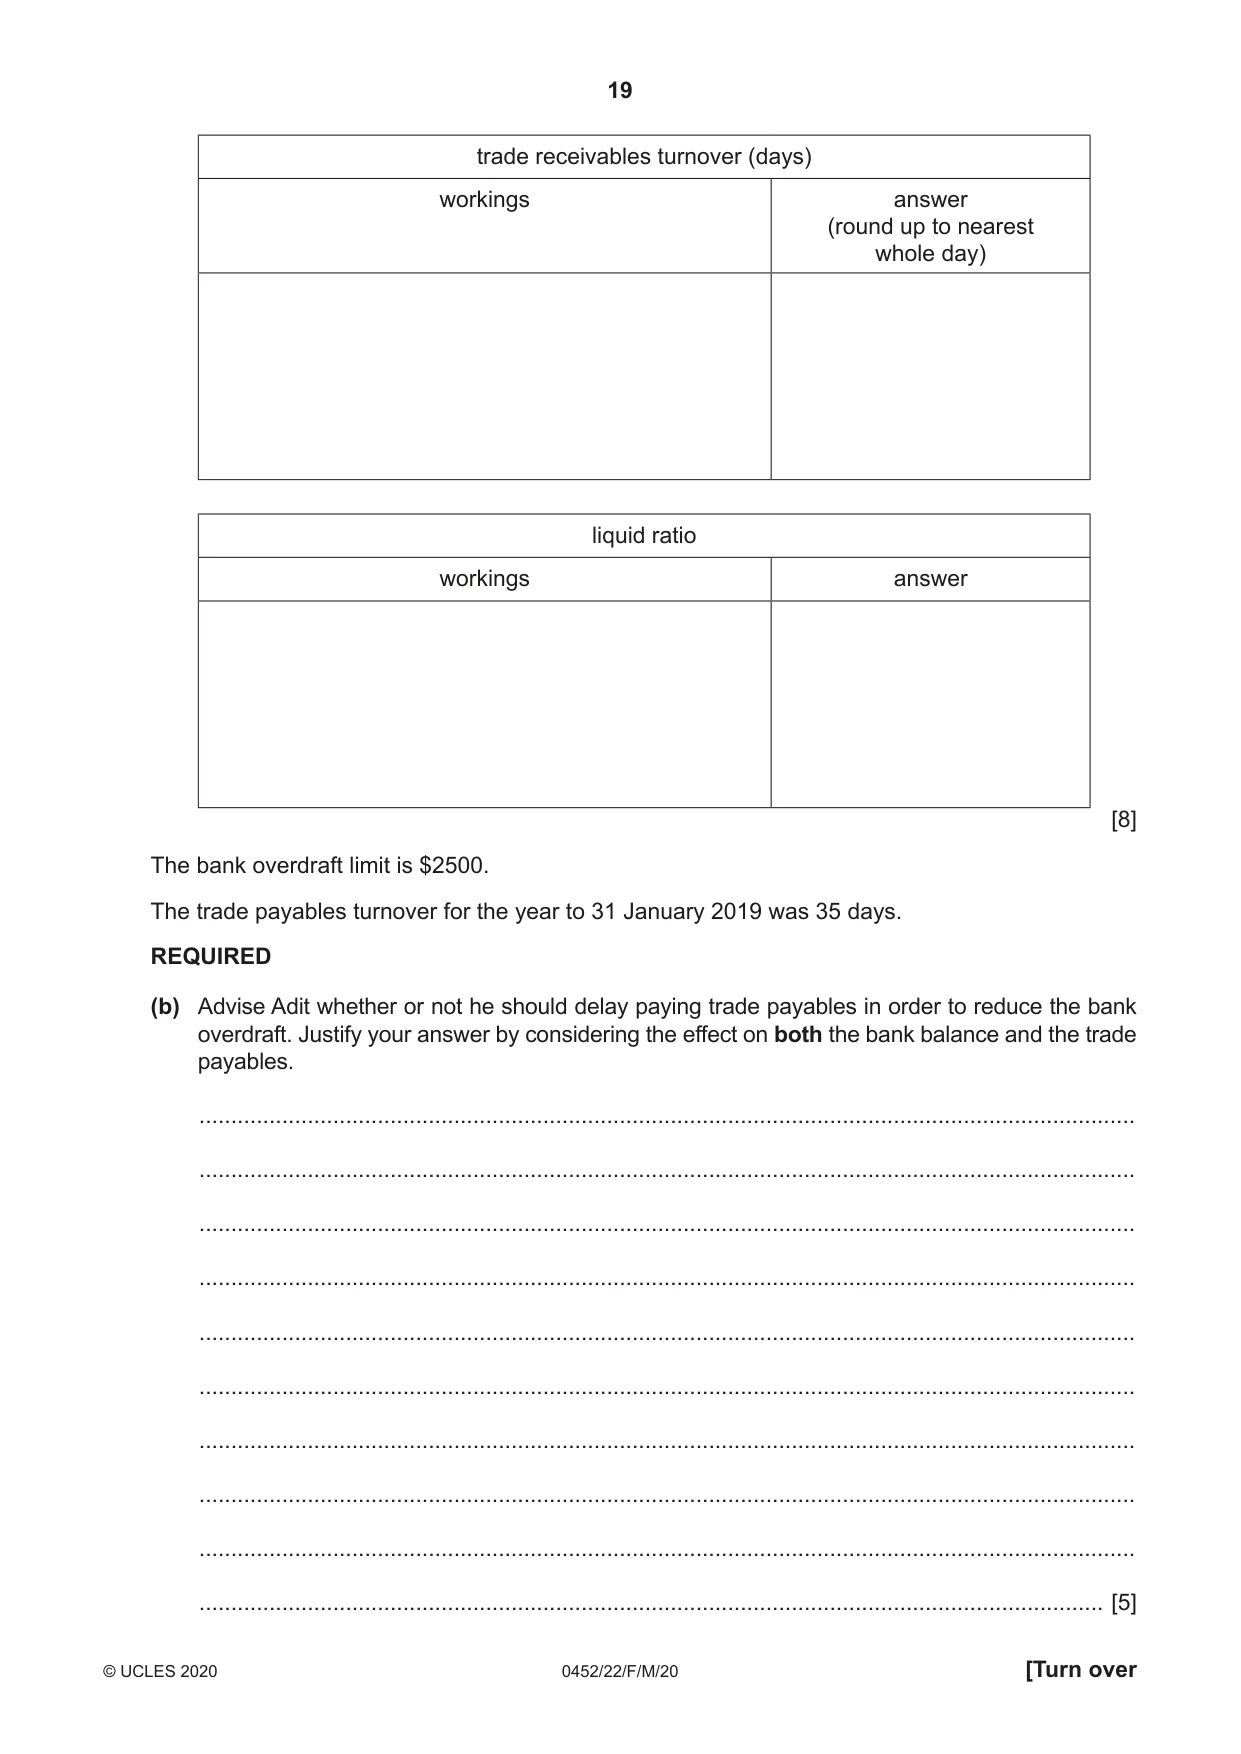
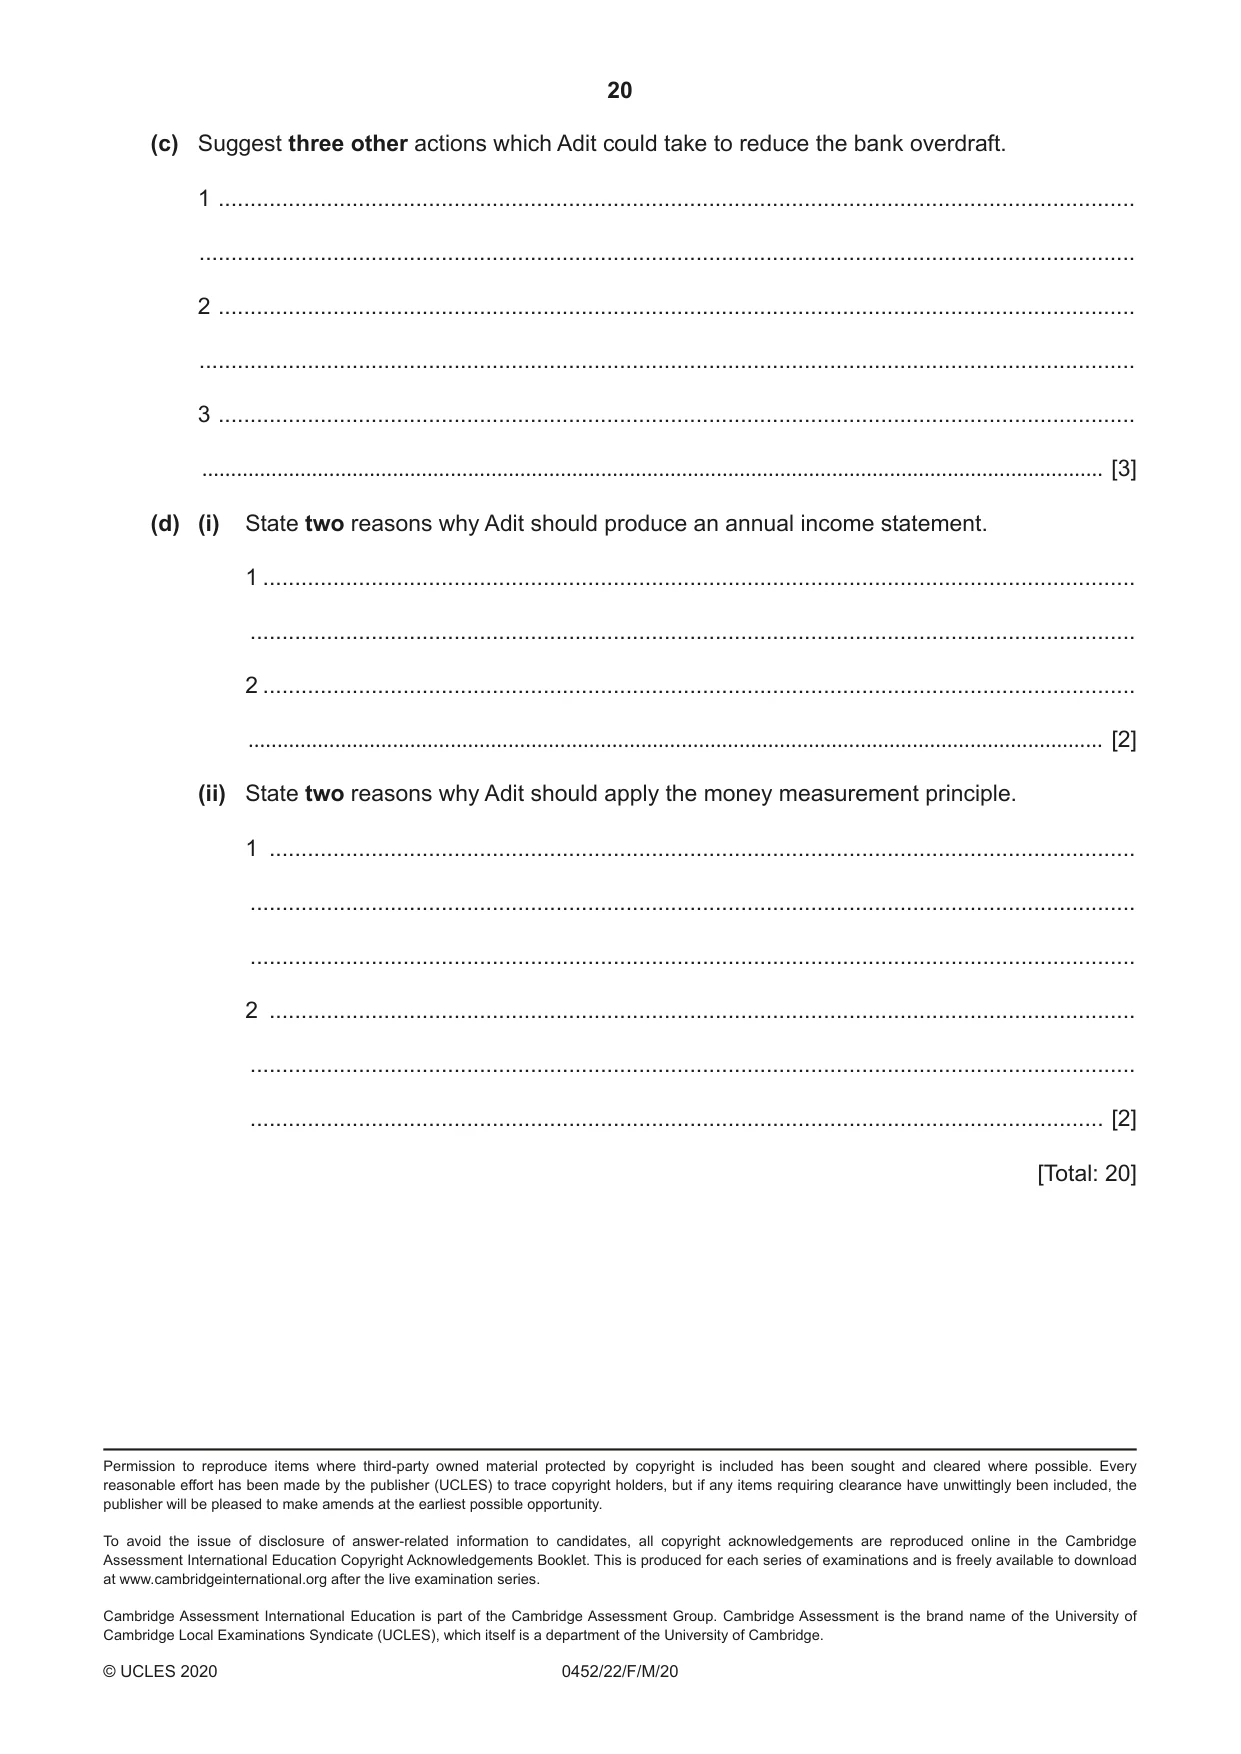
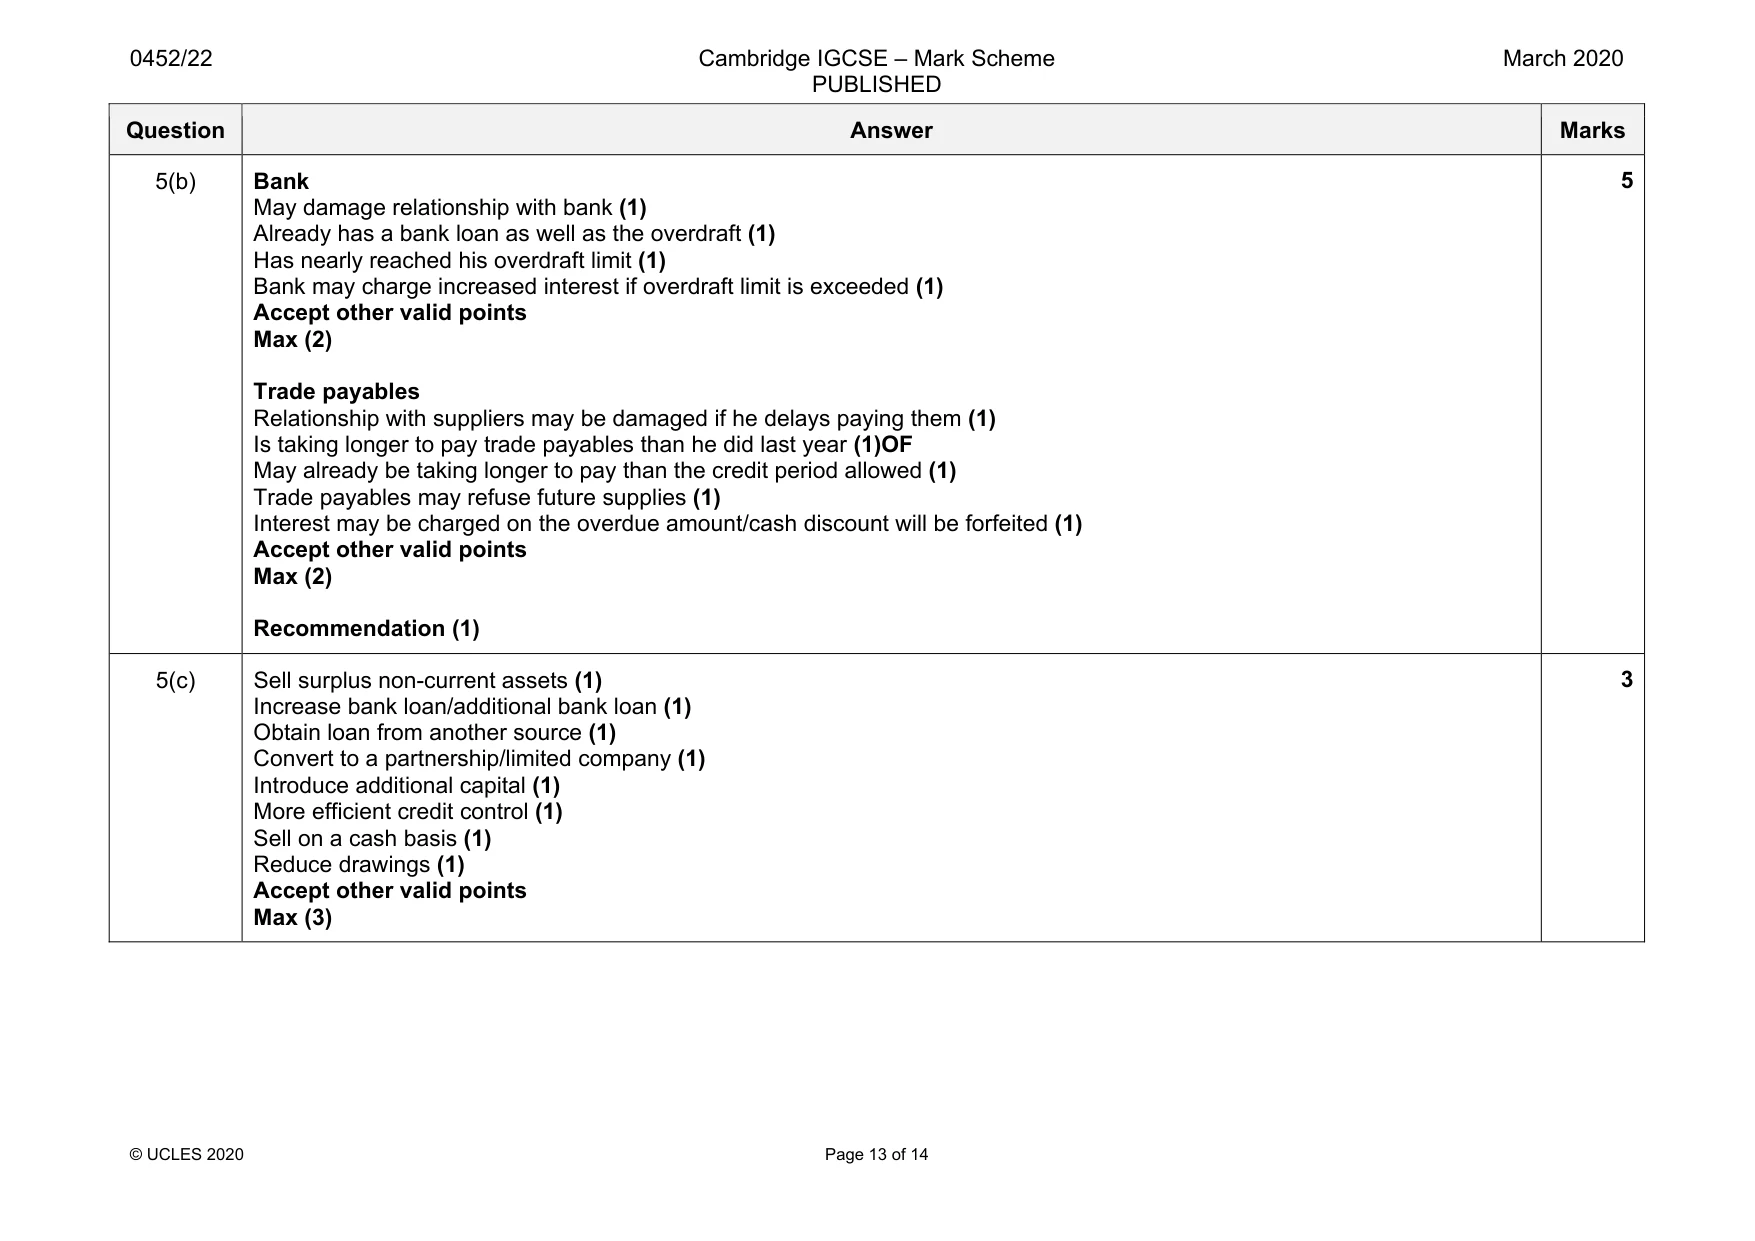
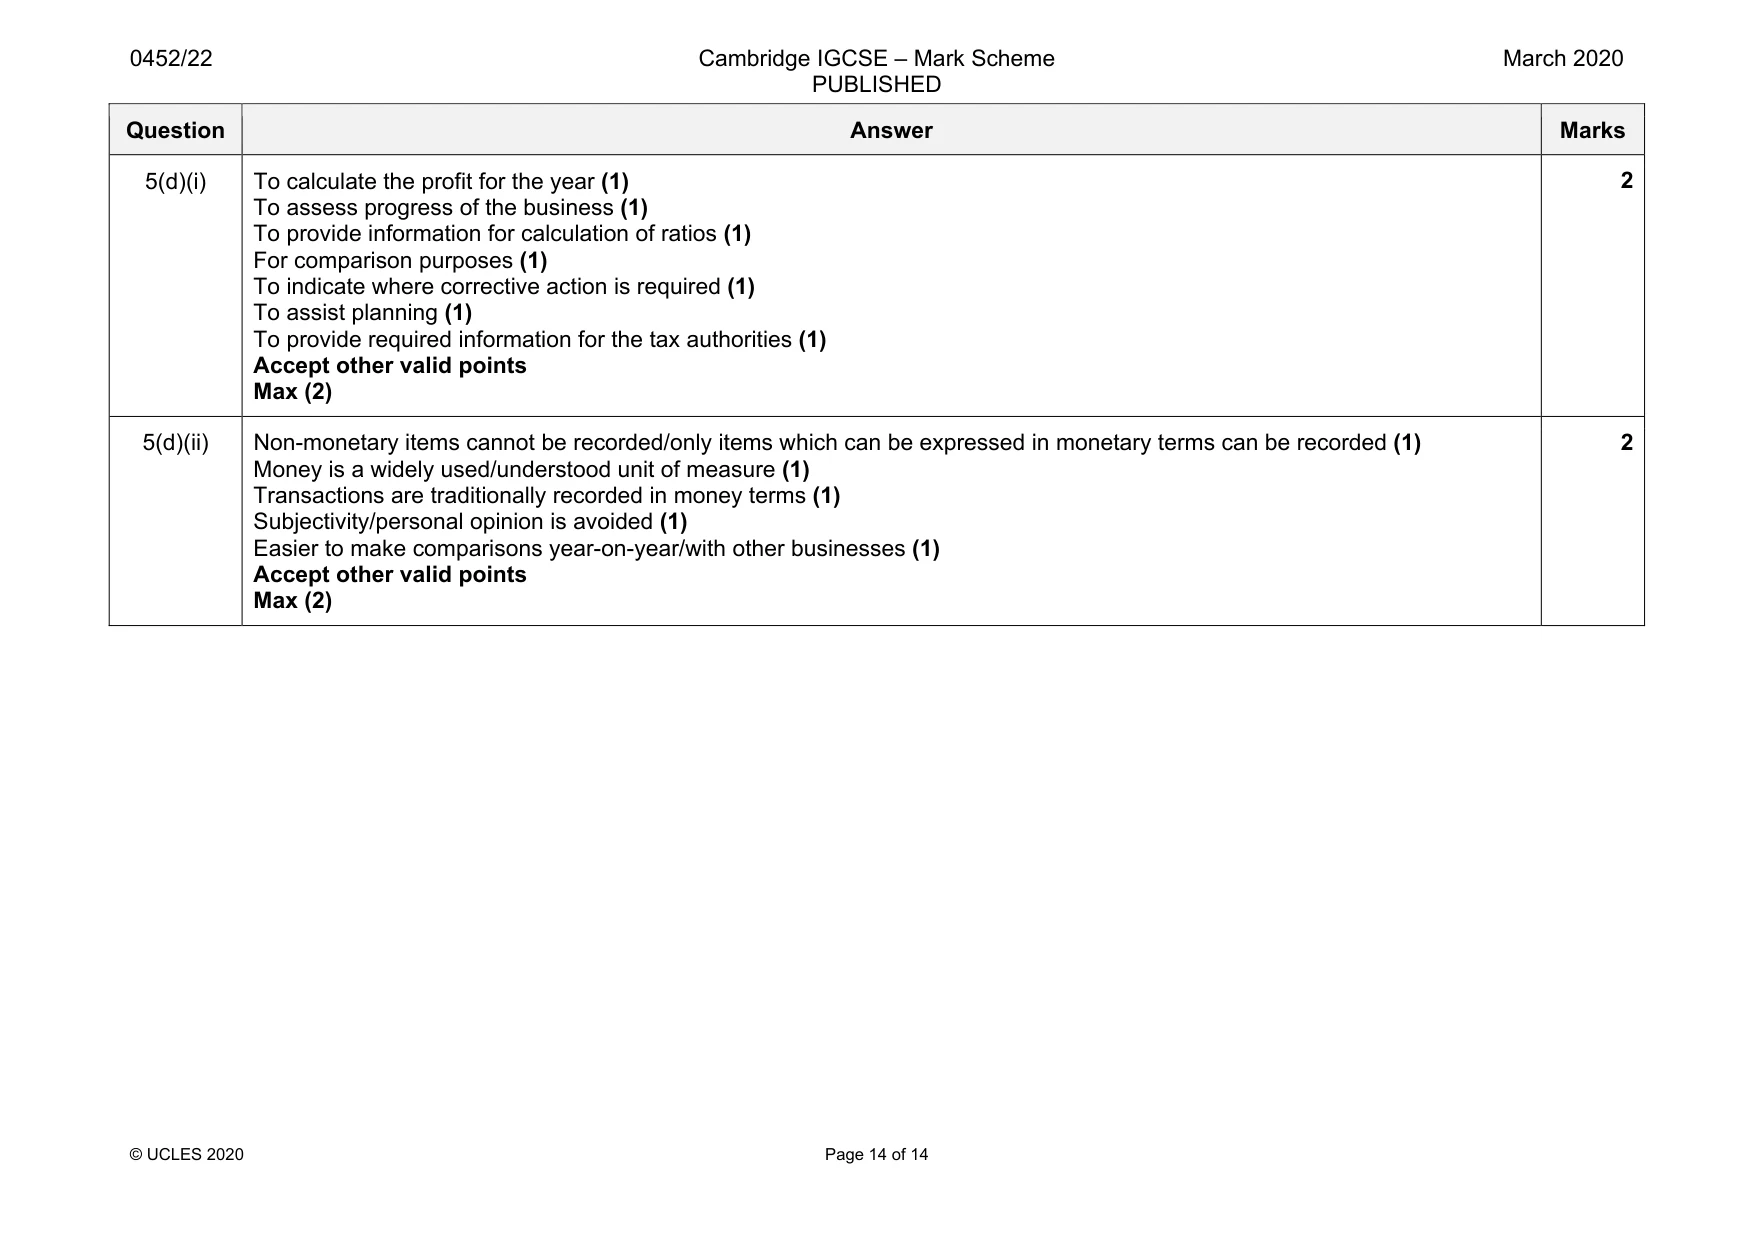
5 Adit provided the following information. For the year to 31 January 2020 $ Profit for the year 27 900 Revenue 186 000 Credit purchases 93 075 At 31 January 2020 Non-current assets at book value 43 700 Inventory 9 340 Trade receivables 14 010 Trade payables 9 435 Bank overdraft 2 240 Bank loan (repayable 2023) 6 000 All goods are sold on credit terms. REQUIRED (a) Calculate the following ratios. Show your workings. profit margin workings answer trade payables turnover (days) workings answer (round up to nearest whole day) trade receivables turnover (days) workings answer (round up to nearest whole day) liquid ratio workings answer [8] The bank overdraft limit is $2500. The trade payables turnover for the year to 31 January 2019 was 35 days. REQUIRED (b) Advise Adit whether or not he should delay paying trade payables in order to reduce the bank overdraft. Justify your answer by considering the effect on both the bank balance and the trade payables. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] (c) Suggest three other actions which Adit could take to reduce the bank overdraft. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ............................................................................................................................................................ [3] (d) (i) State two reasons why Adit should produce an annual income statement. 1 ......................................................................................................................................... ........................................................................................................................................... 2 ......................................................................................................................................... .................................................................................................................................................... [2] (ii) State two reasons why Adit should apply the money measurement principle. 1 ........................................................................................................................................ ........................................................................................................................................... ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... ...................................................................................................................................... [2] [Total: 20]
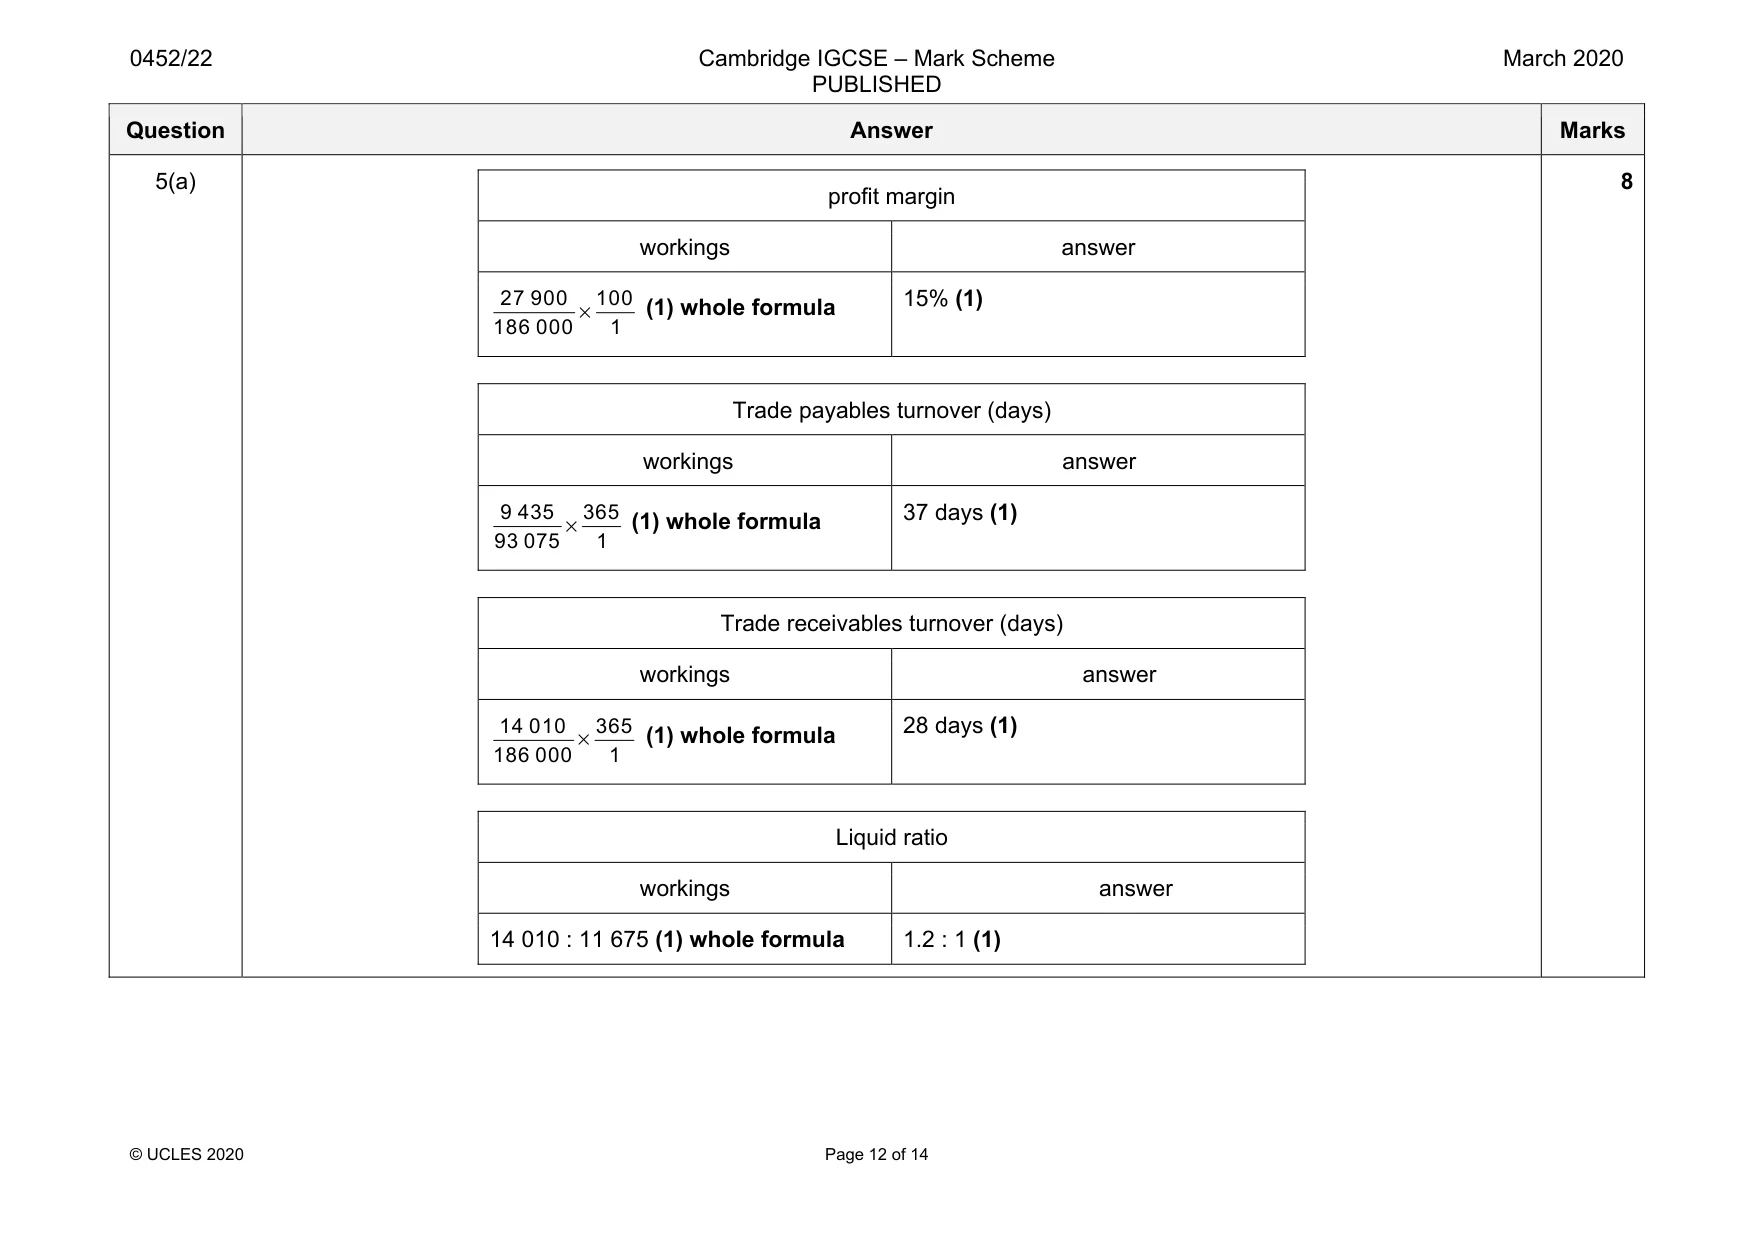
Mark scheme: 5(a) profit margin workings answer 27 900 100 186 000 1 × (1) whole formula 15% (1) Trade payables turnover (days) workings answer 9 435 365 93 075 1 × (1) whole formula 37 days (1) Trade receivables turnover (days) workings answer 14 010 365 186 000 1 × (1) whole formula 28 days (1) Liquid ratio workings answer 14 010 : 11 675 (1) whole formula 1.2 : 1 (1) 8 Question Answer Marks 5(b) Bank May damage relationship with bank (1) Already has a bank loan as well as the overdraft (1) Has nearly reached his overdraft limit (1) Bank may charge increased interest if overdraft limit is exceeded (1) Accept other valid points Max (2) Trade payables Relationship with suppliers may be damaged if he delays paying them (1) Is taking longer to pay trade payables than he did last year (1)OF May already be taking longer to pay than the credit period allowed (1) Trade payables may refuse future supplies (1) Interest may be charged on the overdue amount/cash discount will be forfeited (1) Accept other valid points Max (2) Recommendation (1) 5 5(c) Sell surplus non-current assets (1) Increase bank loan/additional bank loan (1) Obtain loan from another source (1) Convert to a partnership/limited company (1) Introduce additional capital (1) More efficient credit control (1) Sell on a cash basis (1) Reduce drawings (1) Accept other valid points Max (3) 3 Question Answer Marks 5(d)(i) To calculate the profit for the year (1) To assess progress of the business (1) To provide information for calculation of ratios (1) For comparison purposes (1) To indicate where corrective action is required (1) To assist planning (1) To provide required information for the tax authorities (1) Accept other valid points Max (2) 2 5(d)(ii) Non-monetary items cannot be recorded/only items which can be expressed in monetary terms can be recorded (1) Money is a widely used/understood unit of measure (1) Transactions are traditionally recorded in money terms (1) Subjectivity/personal opinion is avoided (1) Easier to make comparisons year-on-year/with other businesses (1) Accept other valid points Max (2) 2
More questions on Calculation and understanding of accounting ratios
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2020 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.