Cambridge IGCSE Accounting 0452 — 2019 Oct/Nov Paper 1 · Variant 2
0452/12/O/N/19 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
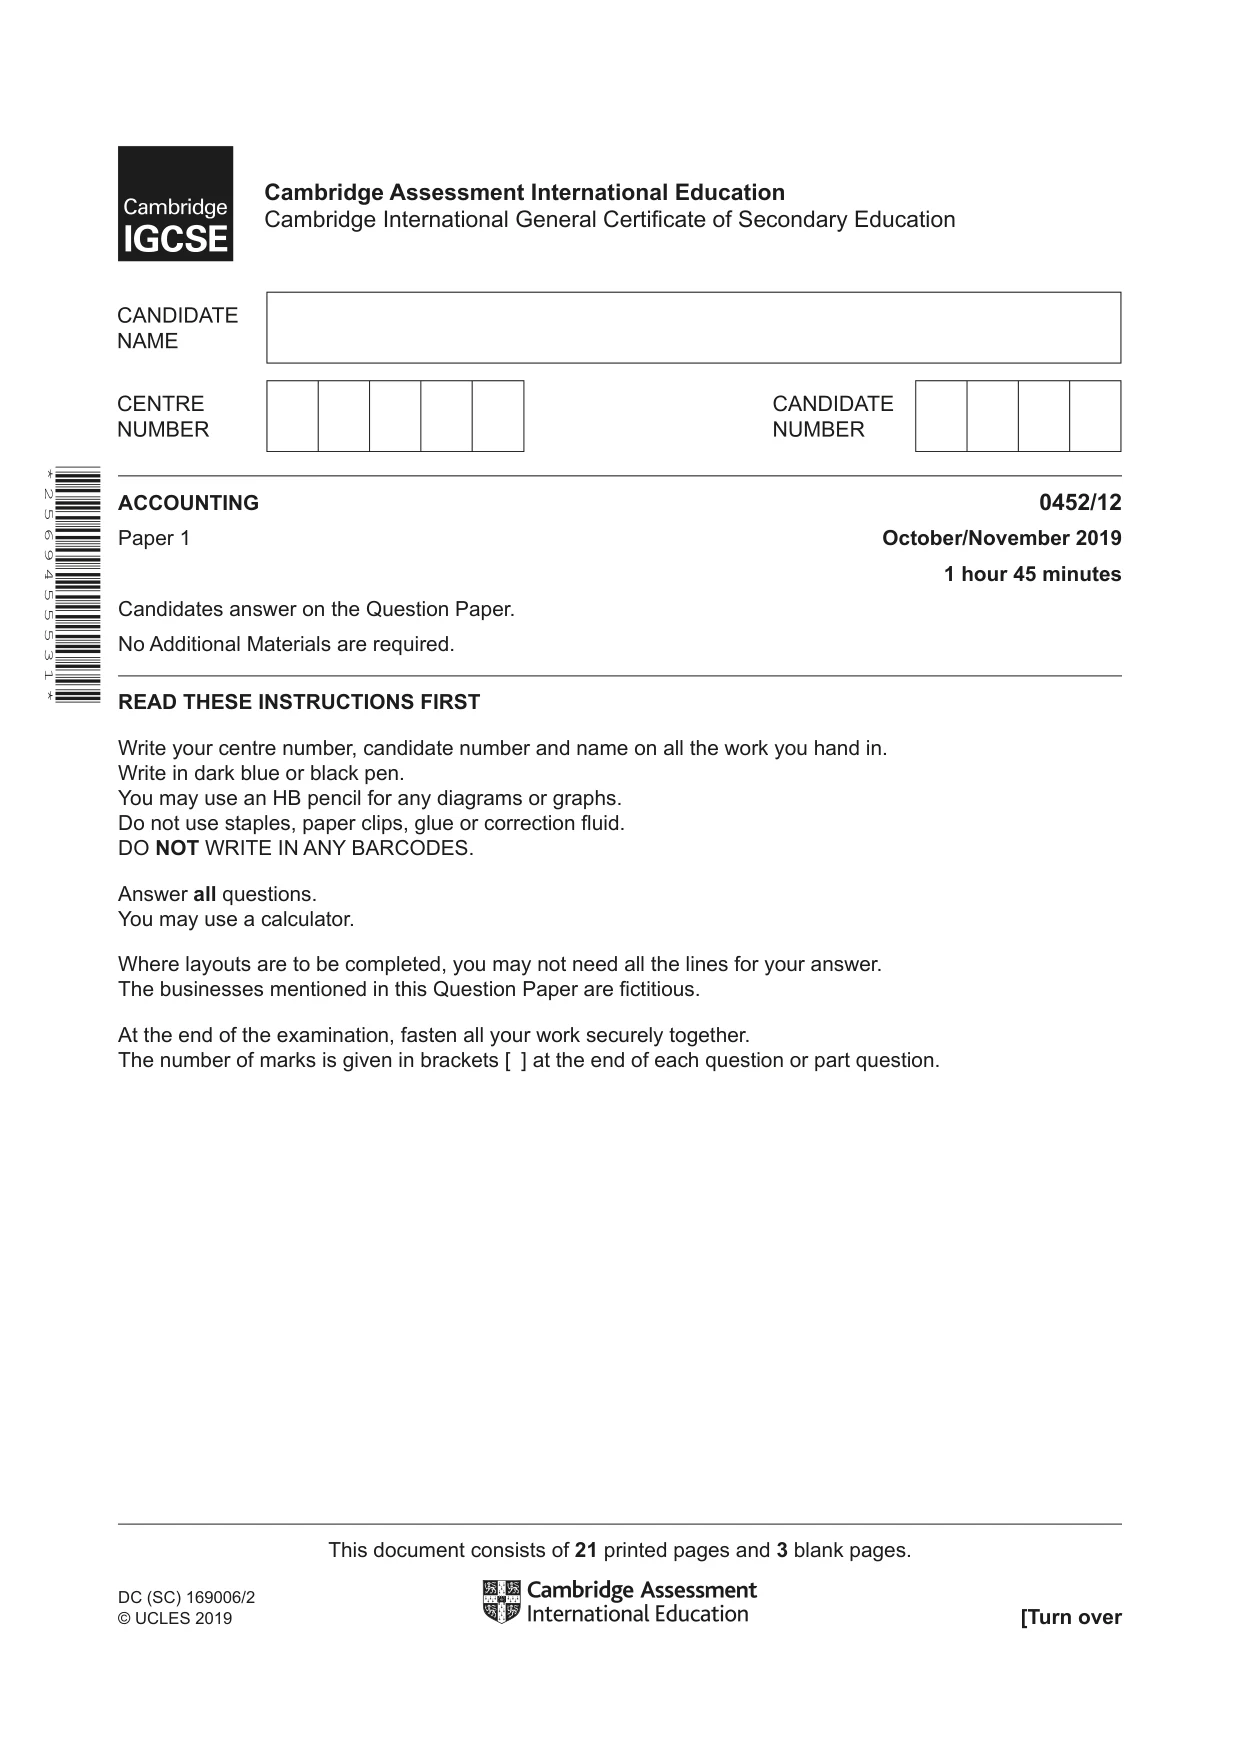
This document consists of 21 printed pages and 3 blank pages. DC (SC) 169006/2 © UCLES 2019 [Turn over * 2 5 6 9 4 5 5 5 3 1 * ACCOUNTING 0452/12 Paper 1 October/November 2019 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use an HB pencil for any diagrams or graphs. Do not use staples, paper clips, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. Cambridge Assessment International Education Cambridge International General Certificate of Secondary Education
Question paper, page 2
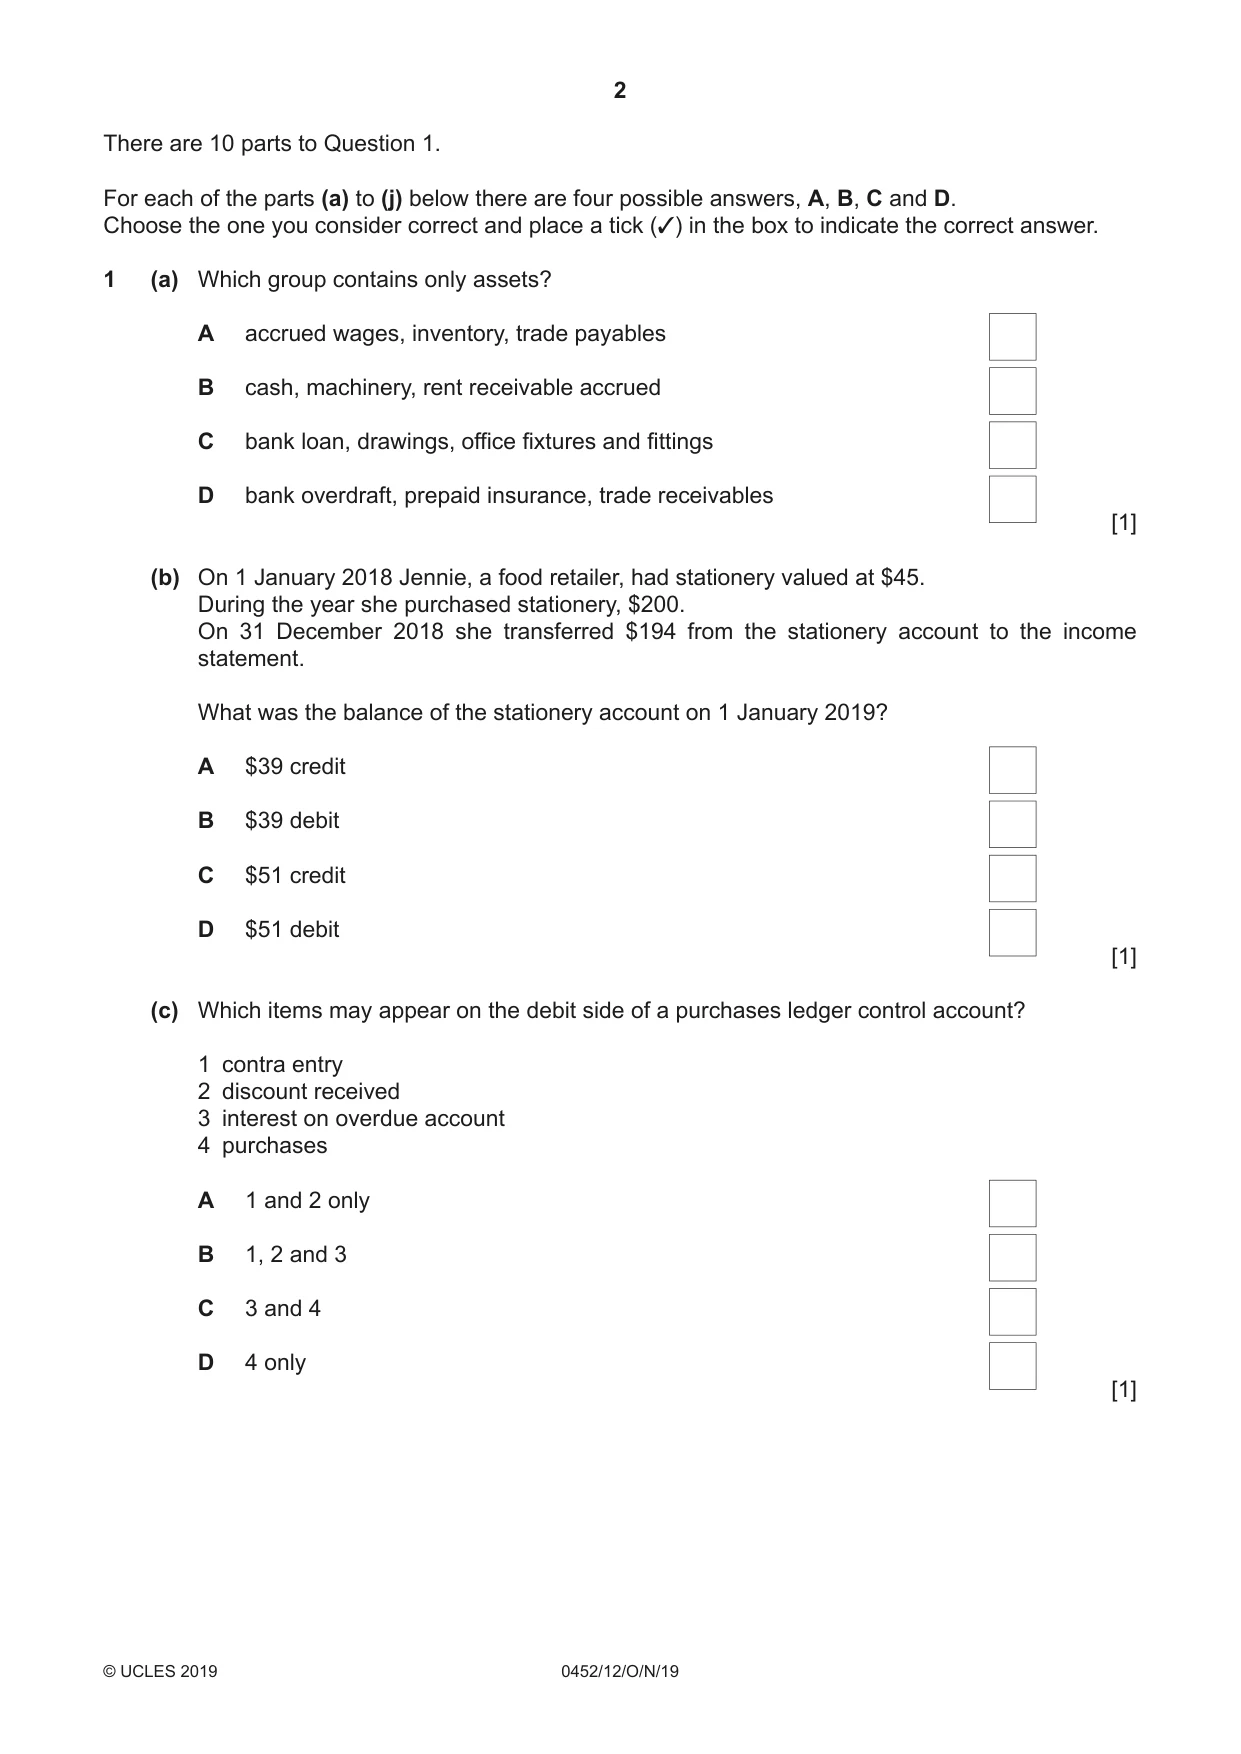
2 0452/12/O/N/19 © UCLES 2019 There are 10 parts to Question 1. For each of the parts (a) to (j) below there are four possible answers, A, B, C and D. Choose the one you consider correct and place a tick (✓) in the box to indicate the correct answer. 1 (a) Which group contains only assets? A accrued wages, inventory, trade payables B cash, machinery, rent receivable accrued C bank loan, drawings, office fixtures and fittings D bank overdraft, prepaid insurance, trade receivables [1] (b) On 1 January 2018 Jennie, a food retailer, had stationery valued at $45. During the year she purchased stationery, $200. On 31 December 2018 she transferred $194 from the stationery account to the income statement. What was the balance of the stationery account on 1 January 2019? A $39 credit B $39 debit C $51 credit D $51 debit [1] (c) Which items may appear on the debit side of a purchases ledger control account? 1 contra entry 2 discount received 3 interest on overdue account 4 purchases A 1 and 2 only B 1, 2 and 3 C 3 and 4 D 4 only [1]
Question paper, page 3
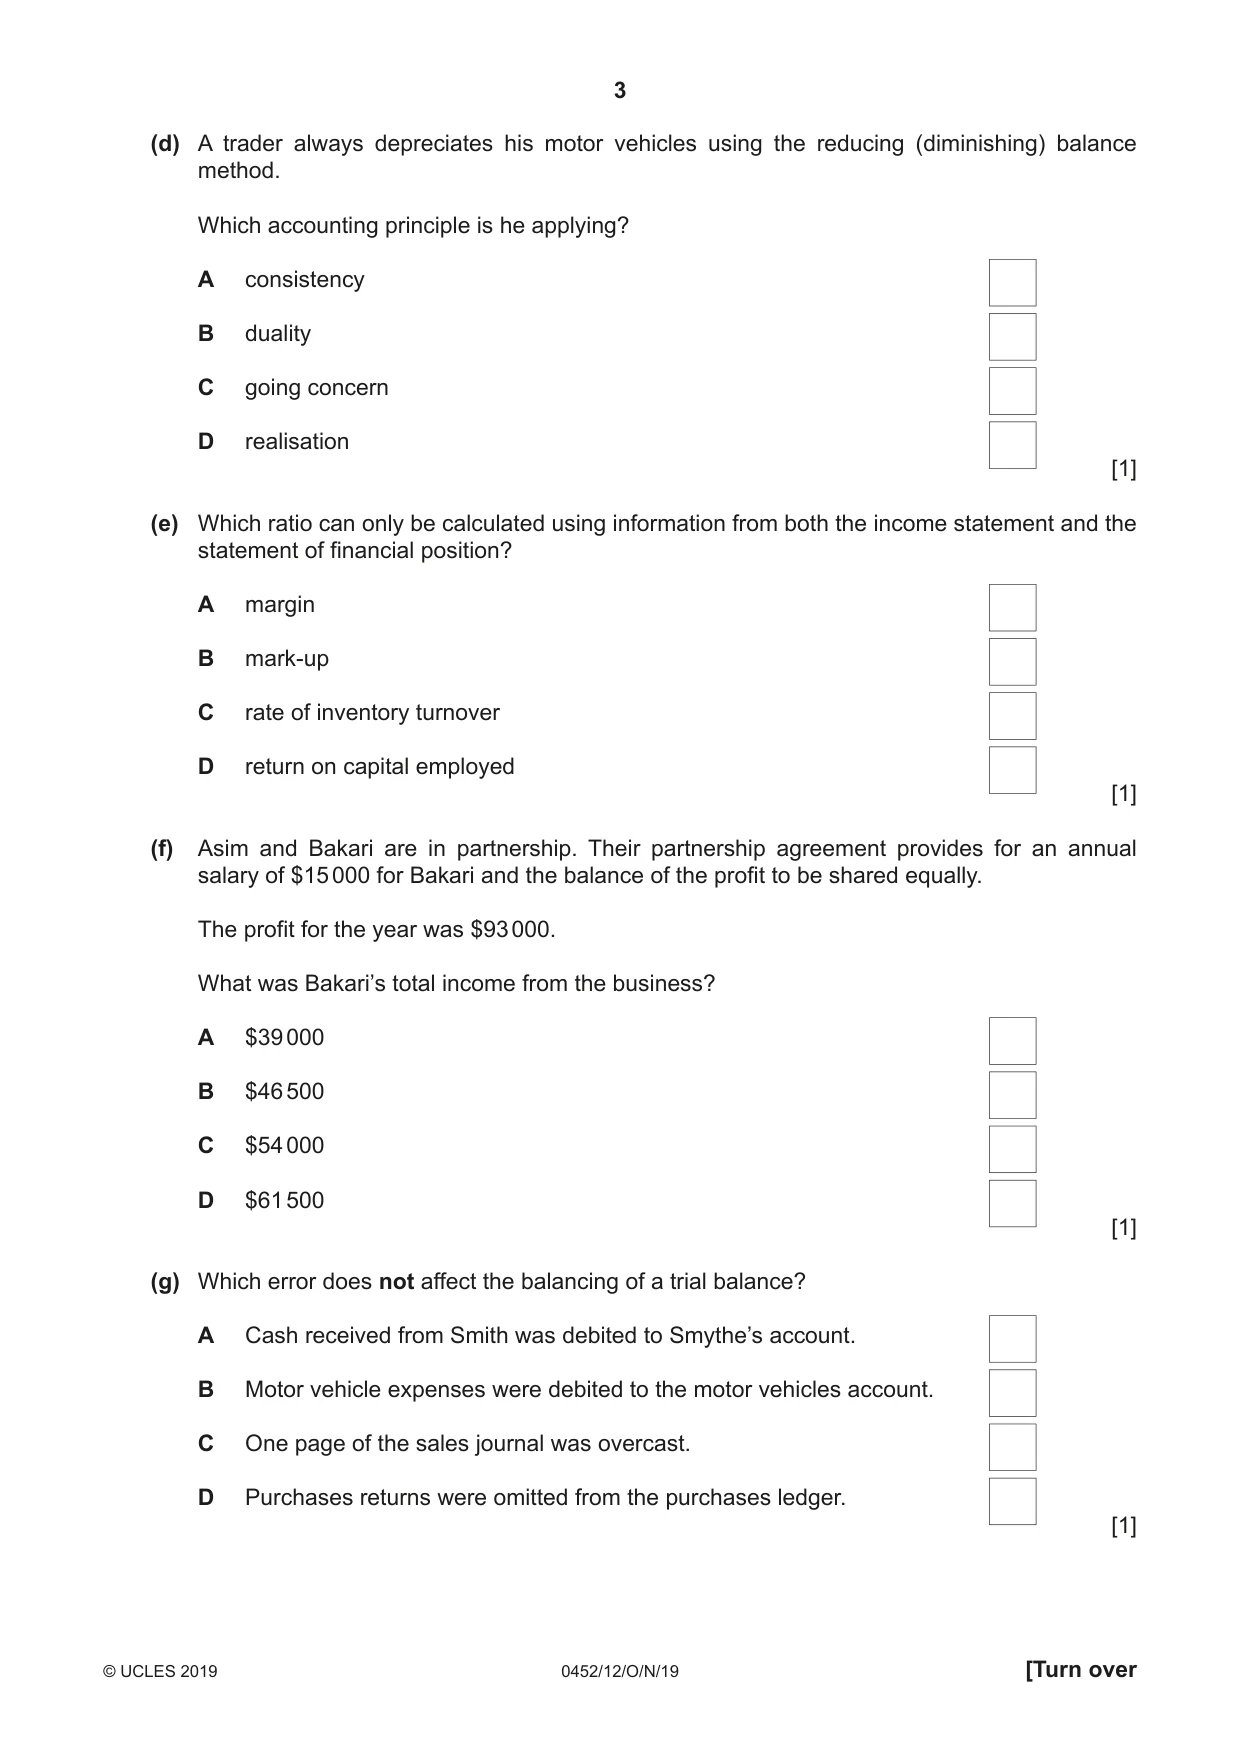
3 0452/12/O/N/19 © UCLES 2019 [Turn over (d) A trader always depreciates his motor vehicles using the reducing (diminishing) balance method. Which accounting principle is he applying? A consistency B duality C going concern D realisation [1] (e) Which ratio can only be calculated using information from both the income statement and the statement of financial position? A margin B mark-up C rate of inventory turnover D return on capital employed [1] (f) Asim and Bakari are in partnership. Their partnership agreement provides for an annual salary of $15 000 for Bakari and the balance of the profit to be shared equally. The profit for the year was $93 000. What was Bakari’s total income from the business? A $39 000 B $46 500 C $54 000 D $61 500 [1] (g) Which error does not affect the balancing of a trial balance? A Cash received from Smith was debited to Smythe’s account. B Motor vehicle expenses were debited to the motor vehicles account. C One page of the sales journal was overcast. D Purchases returns were omitted from the purchases ledger. [1]
Question paper, page 4
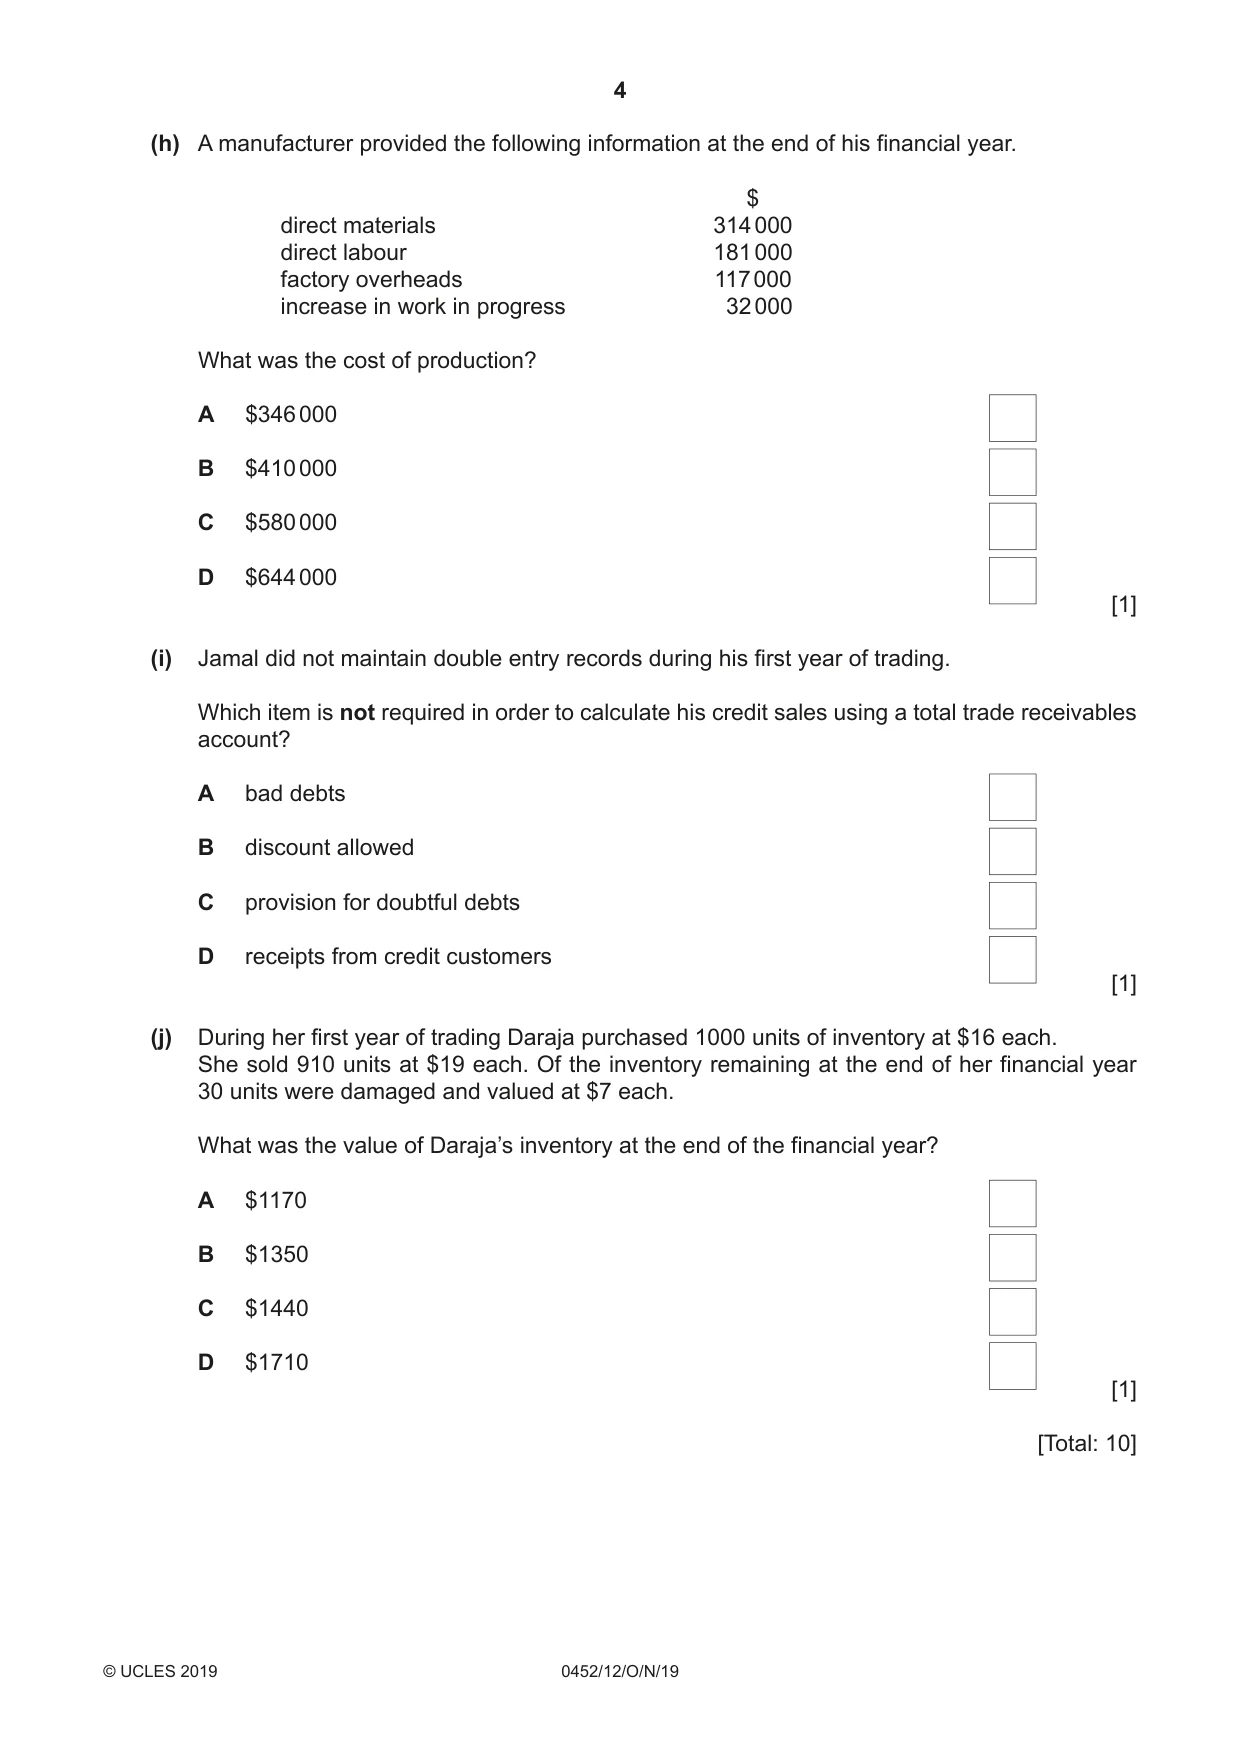
4 0452/12/O/N/19 © UCLES 2019 (h) A manufacturer provided the following information at the end of his financial year. $ direct materials 314 000 direct labour 181 000 factory overheads 117 000 increase in work in progress 32 000 What was the cost of production? A $346 000 B $410 000 C $580 000 D $644 000 [1] (i) Jamal did not maintain double entry records during his first year of trading. Which item is not required in order to calculate his credit sales using a total trade receivables account? A bad debts B discount allowed C provision for doubtful debts D receipts from credit customers [1] (j) During her first year of trading Daraja purchased 1000 units of inventory at $16 each. She sold 910 units at $19 each. Of the inventory remaining at the end of her financial year 30 units were damaged and valued at $7 each. What was the value of Daraja’s inventory at the end of the financial year? A $1170 B $1350 C $1440 D $1710 [1] [Total: 10]
Question paper, page 5
5 0452/12/O/N/19 © UCLES 2019 [Turn over PLEASE TURN OVER
Question paper, page 6
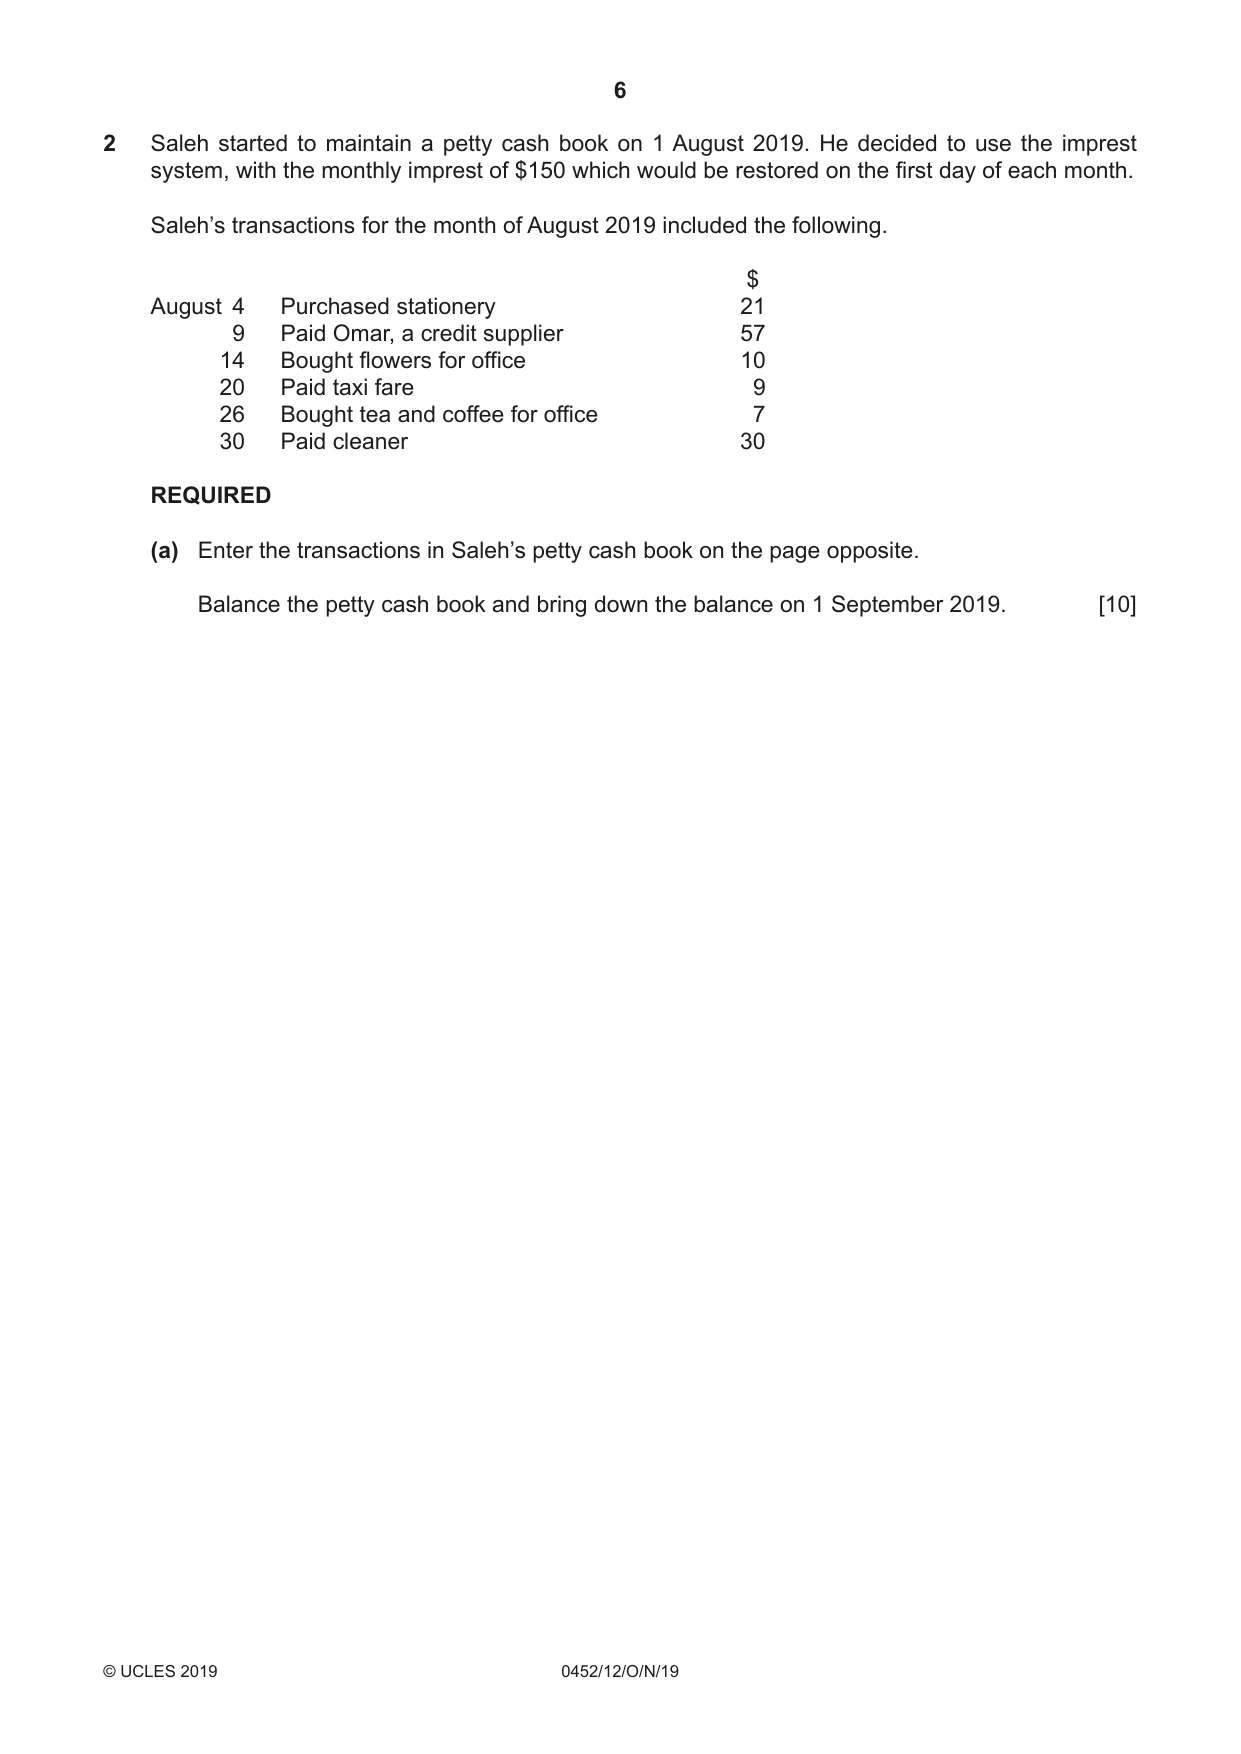
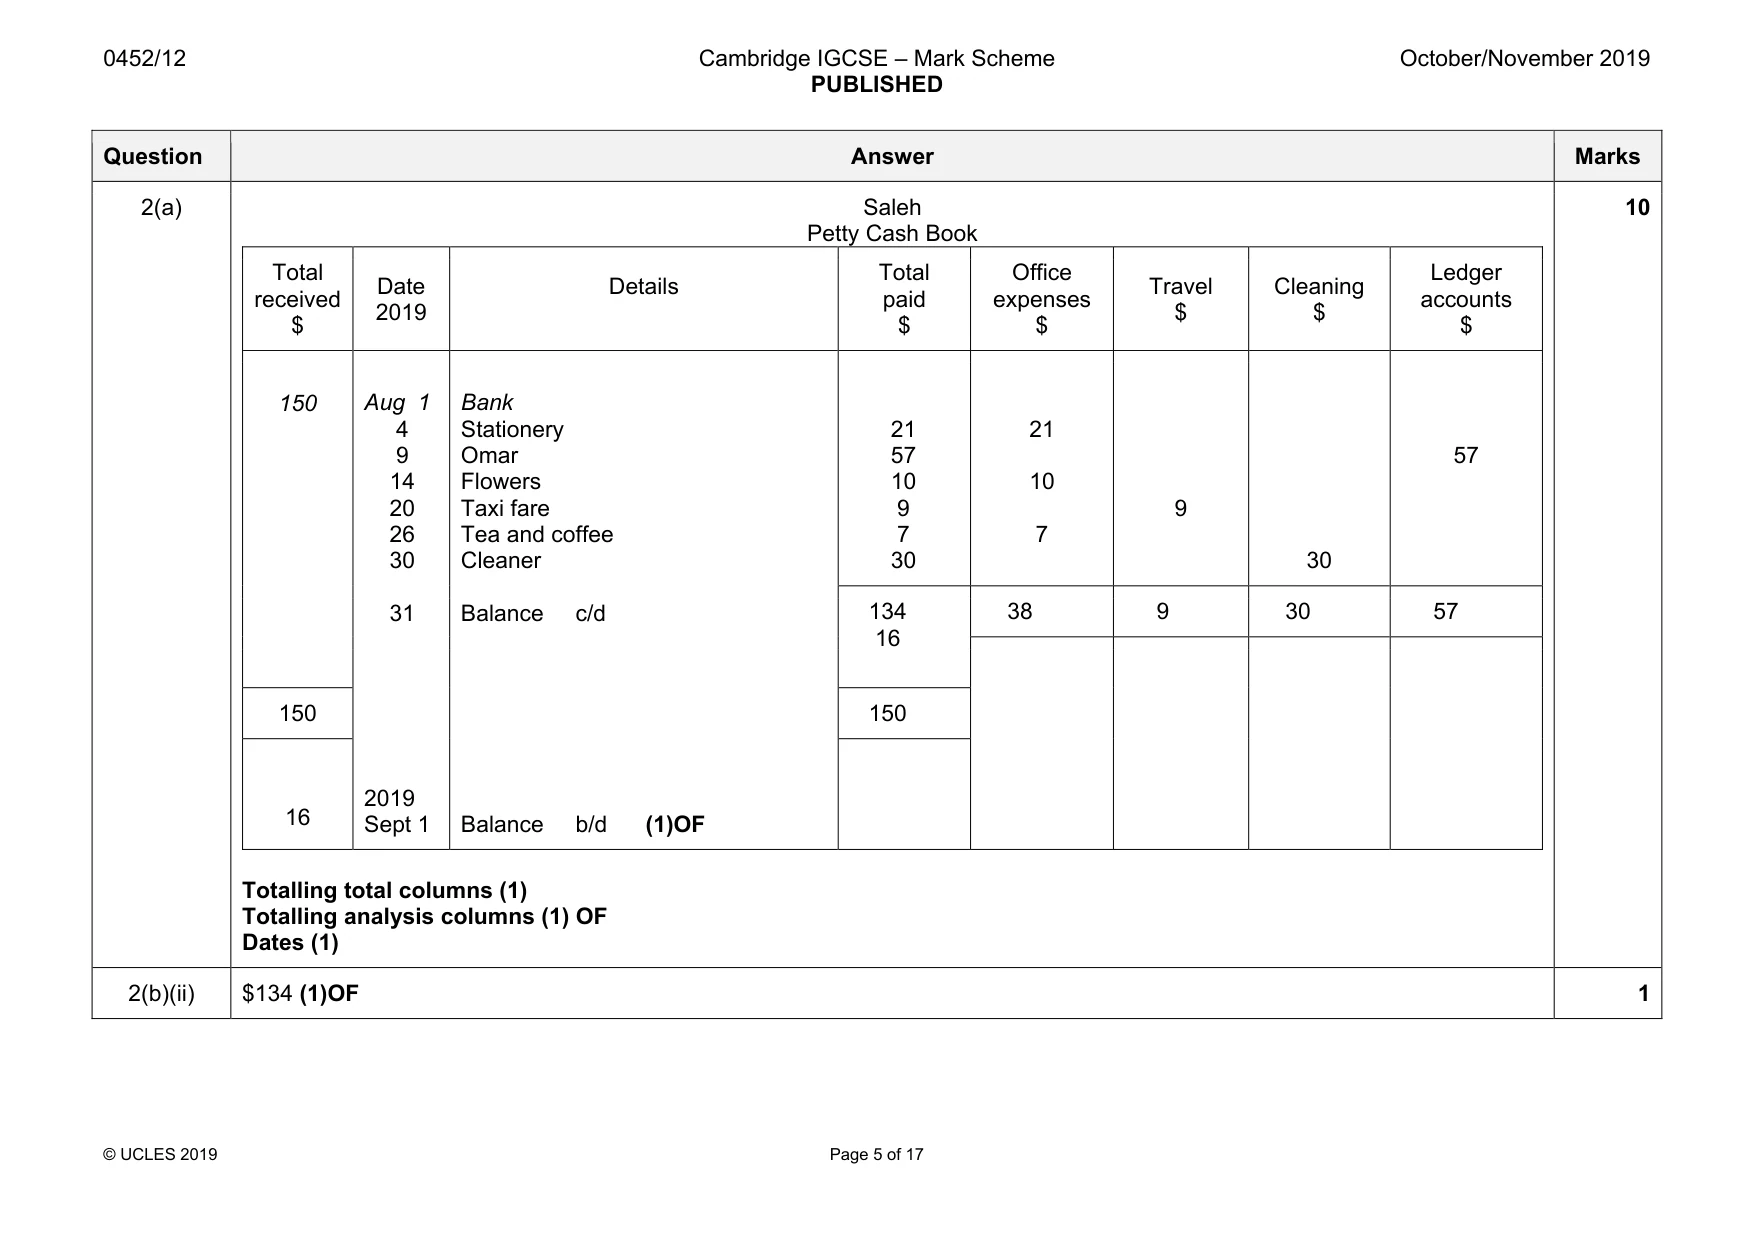
6 0452/12/O/N/19 © UCLES 2019 2 Saleh started to maintain a petty cash book on 1 August 2019. He decided to use the imprest system, with the monthly imprest of $150 which would be restored on the first day of each month. Saleh’s transactions for the month of August 2019 included the following. $ August 4 Purchased stationery 21 9 Paid Omar, a credit supplier 57 14 Bought flowers for office 10 20 Paid taxi fare 9 26 Bought tea and coffee for office 7 30 Paid cleaner 30 REQUIRED (a) Enter the transactions in Saleh’s petty cash book on the page opposite. Balance the petty cash book and bring down the balance on 1 September 2019. [10]
Question paper, page 7
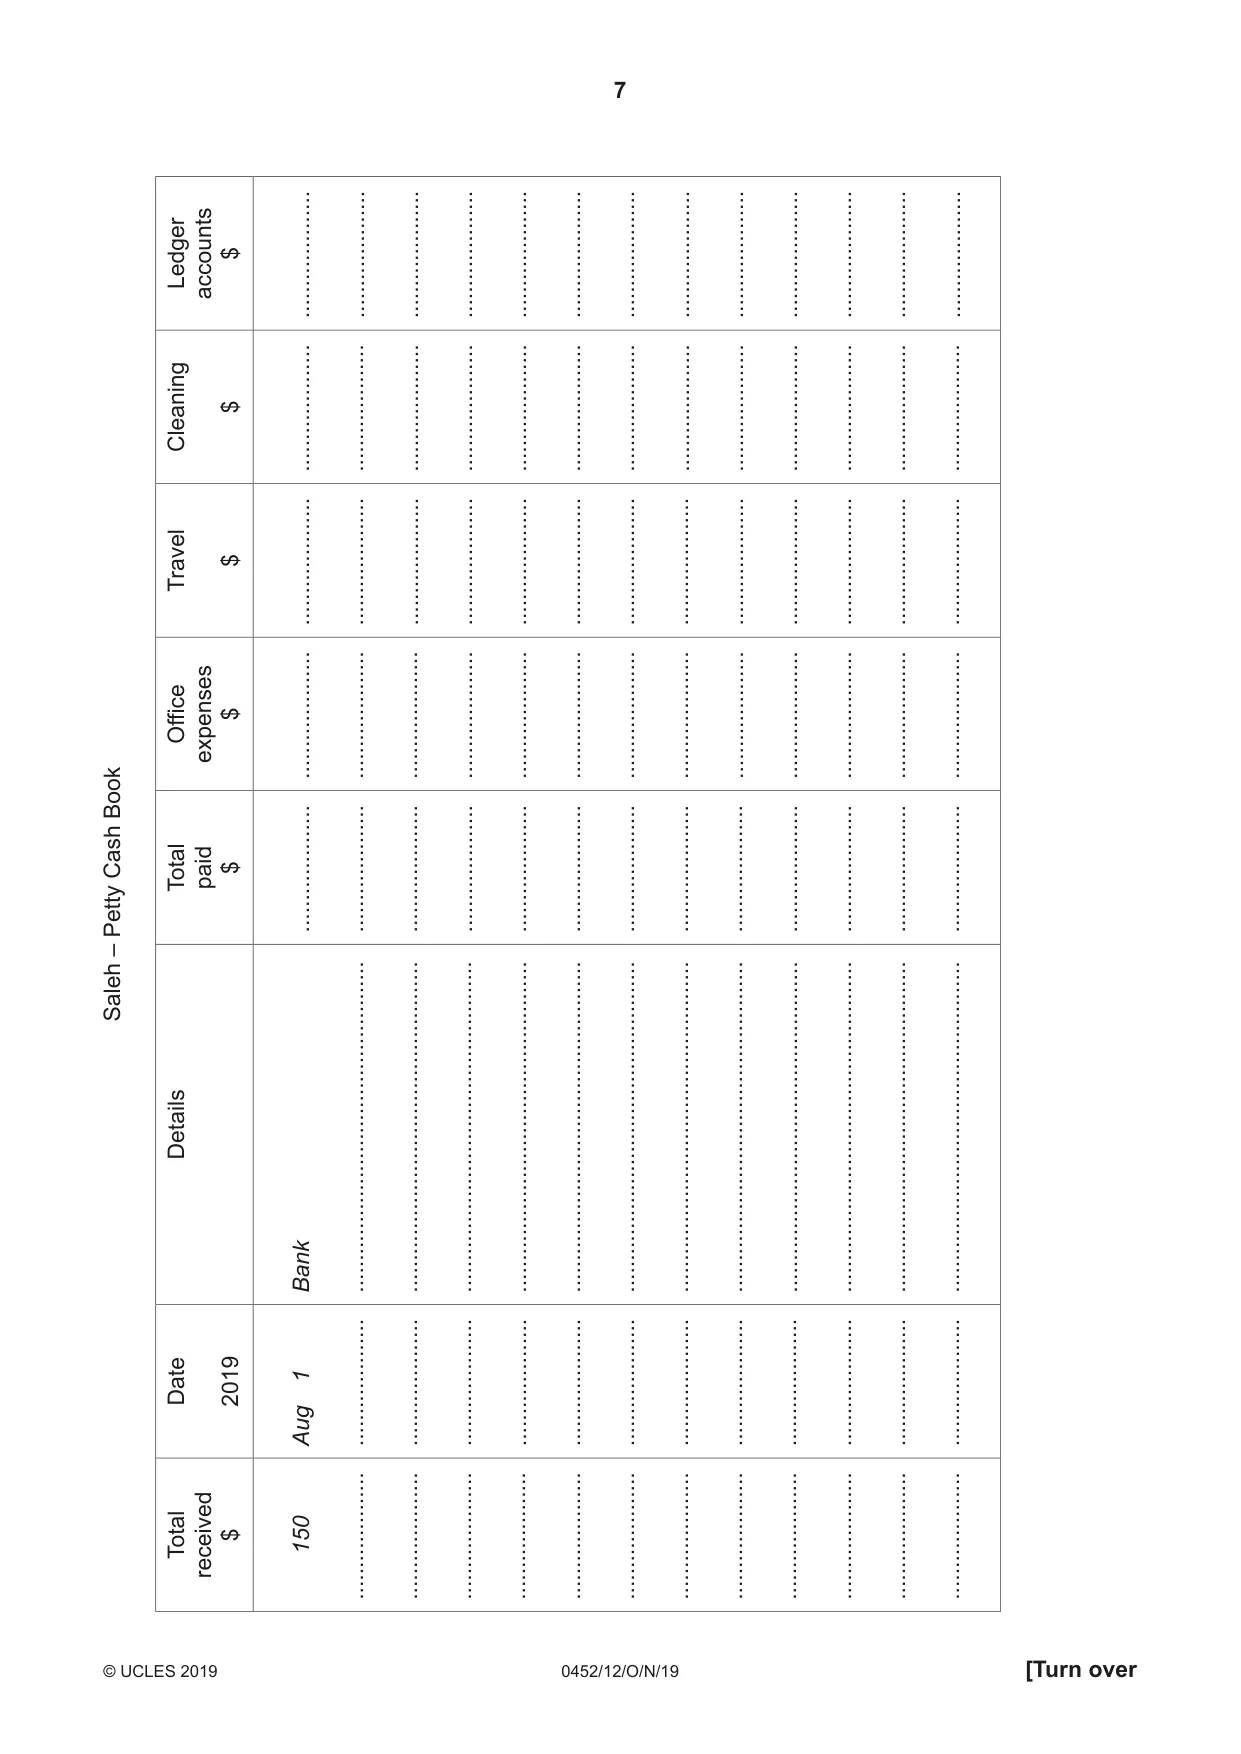
7 0452/12/O/N/19 © UCLES 2019 [Turn over Saleh – Petty Cash Book Total received $ Date 2019 Details Total paid $ Office expenses $ Travel $ Cleaning $ Ledger accounts $ 150 … … … … … … … … … … … … Aug 1 … … … … … … … … … … … … Bank … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 8
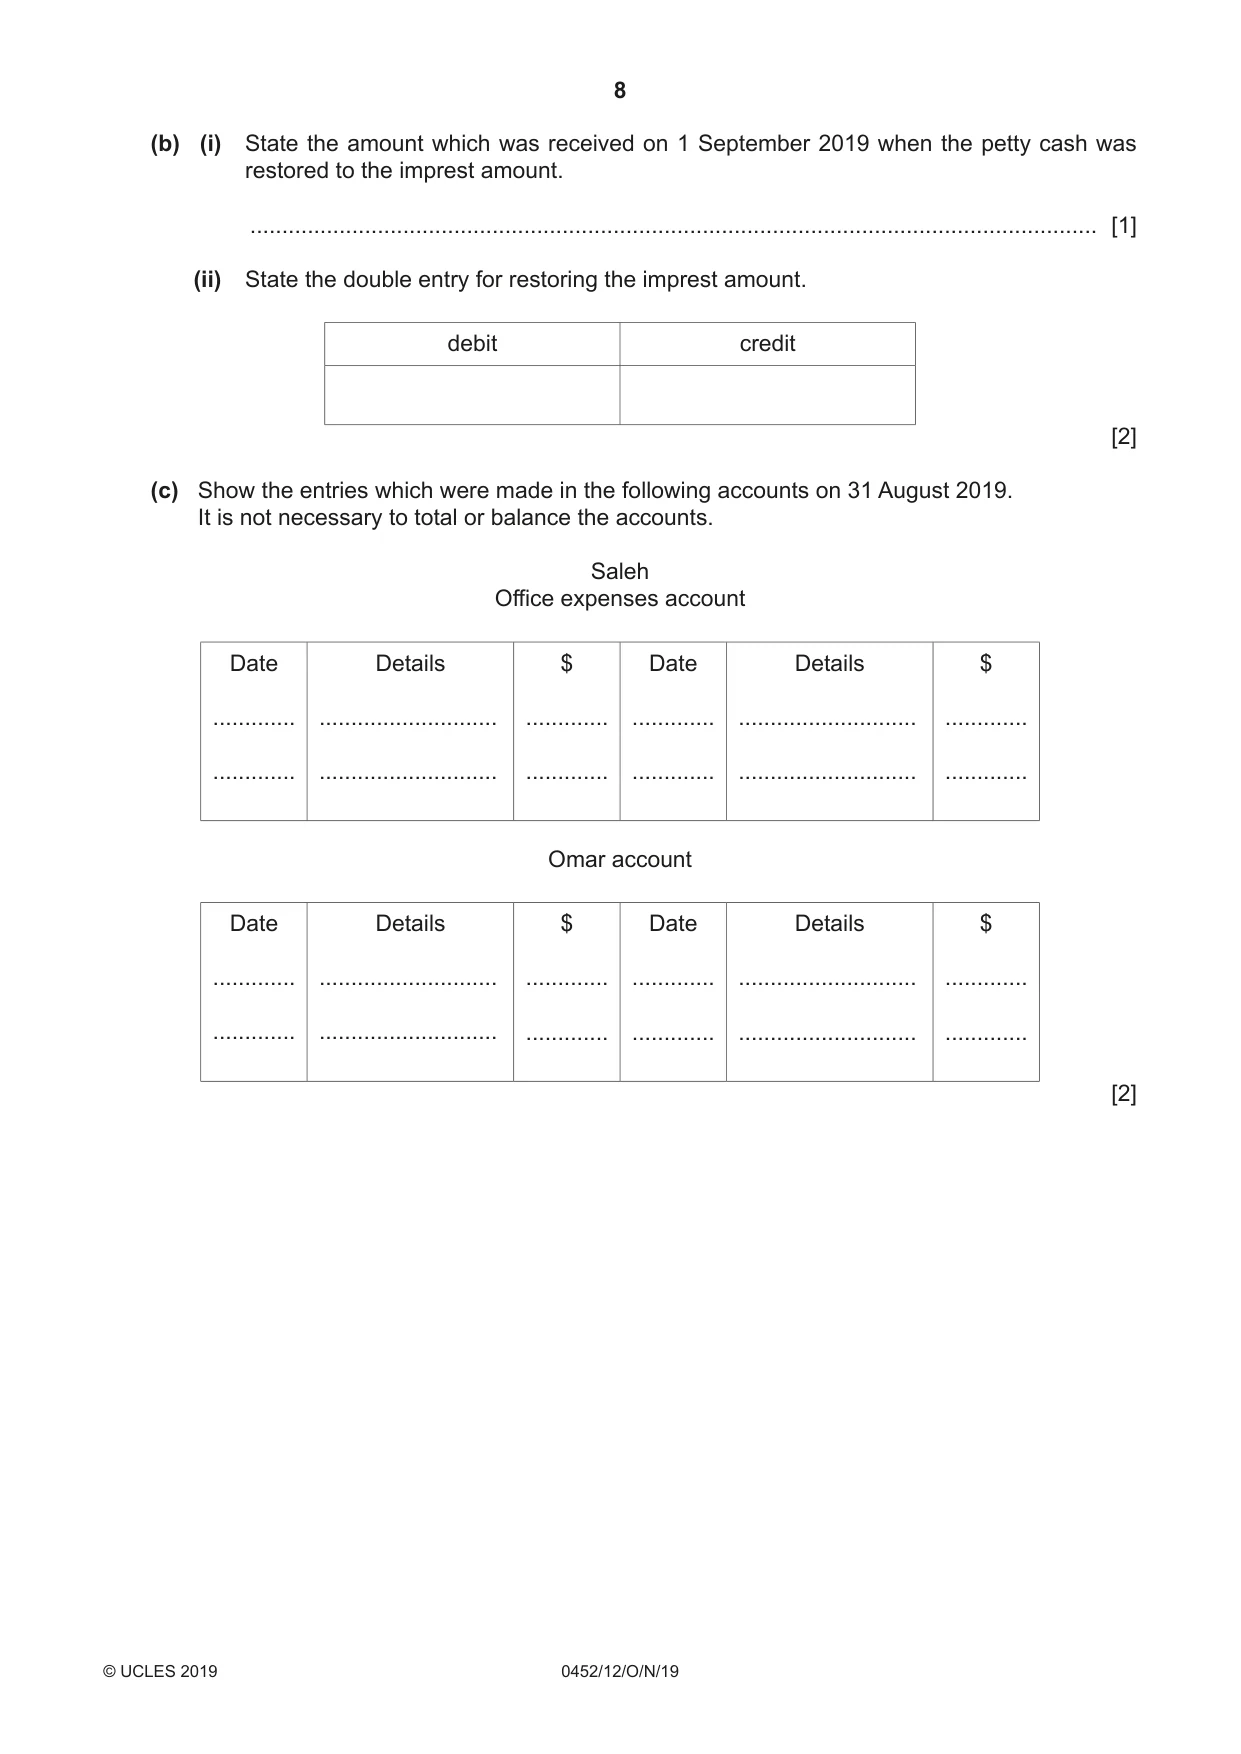
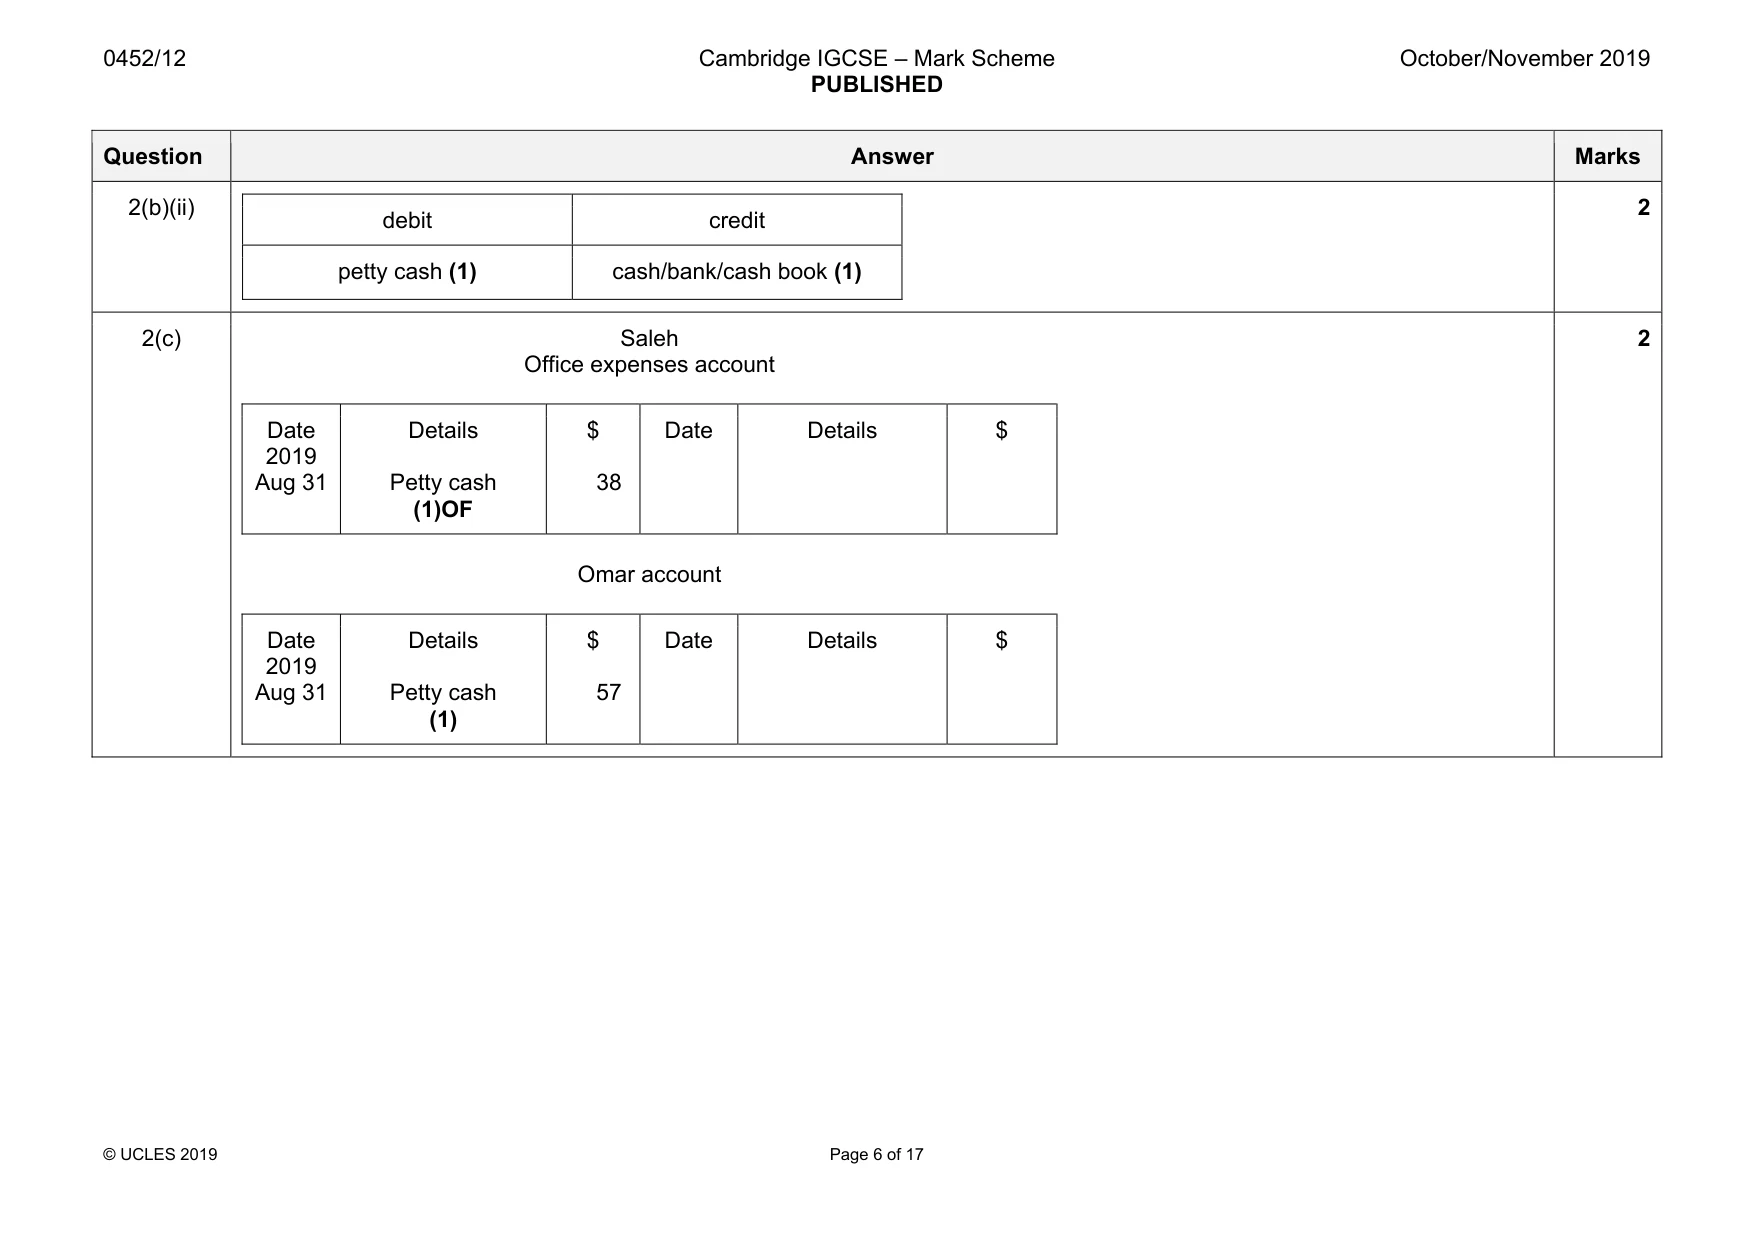
8 0452/12/O/N/19 © UCLES 2019 (b) (i) State the amount which was received on 1 September 2019 when the petty cash was restored to the imprest amount. … [1] (ii) State the double entry for restoring the imprest amount. debit credit [2] (c) Show the entries which were made in the following accounts on 31 August 2019. It is not necessary to total or balance the accounts. Saleh Office expenses account Date … … Details … … $ … … Date … … Details … … $ … … Omar account Date … … Details … … $ … … Date … … Details … … $ … … [2]
Question paper, page 9
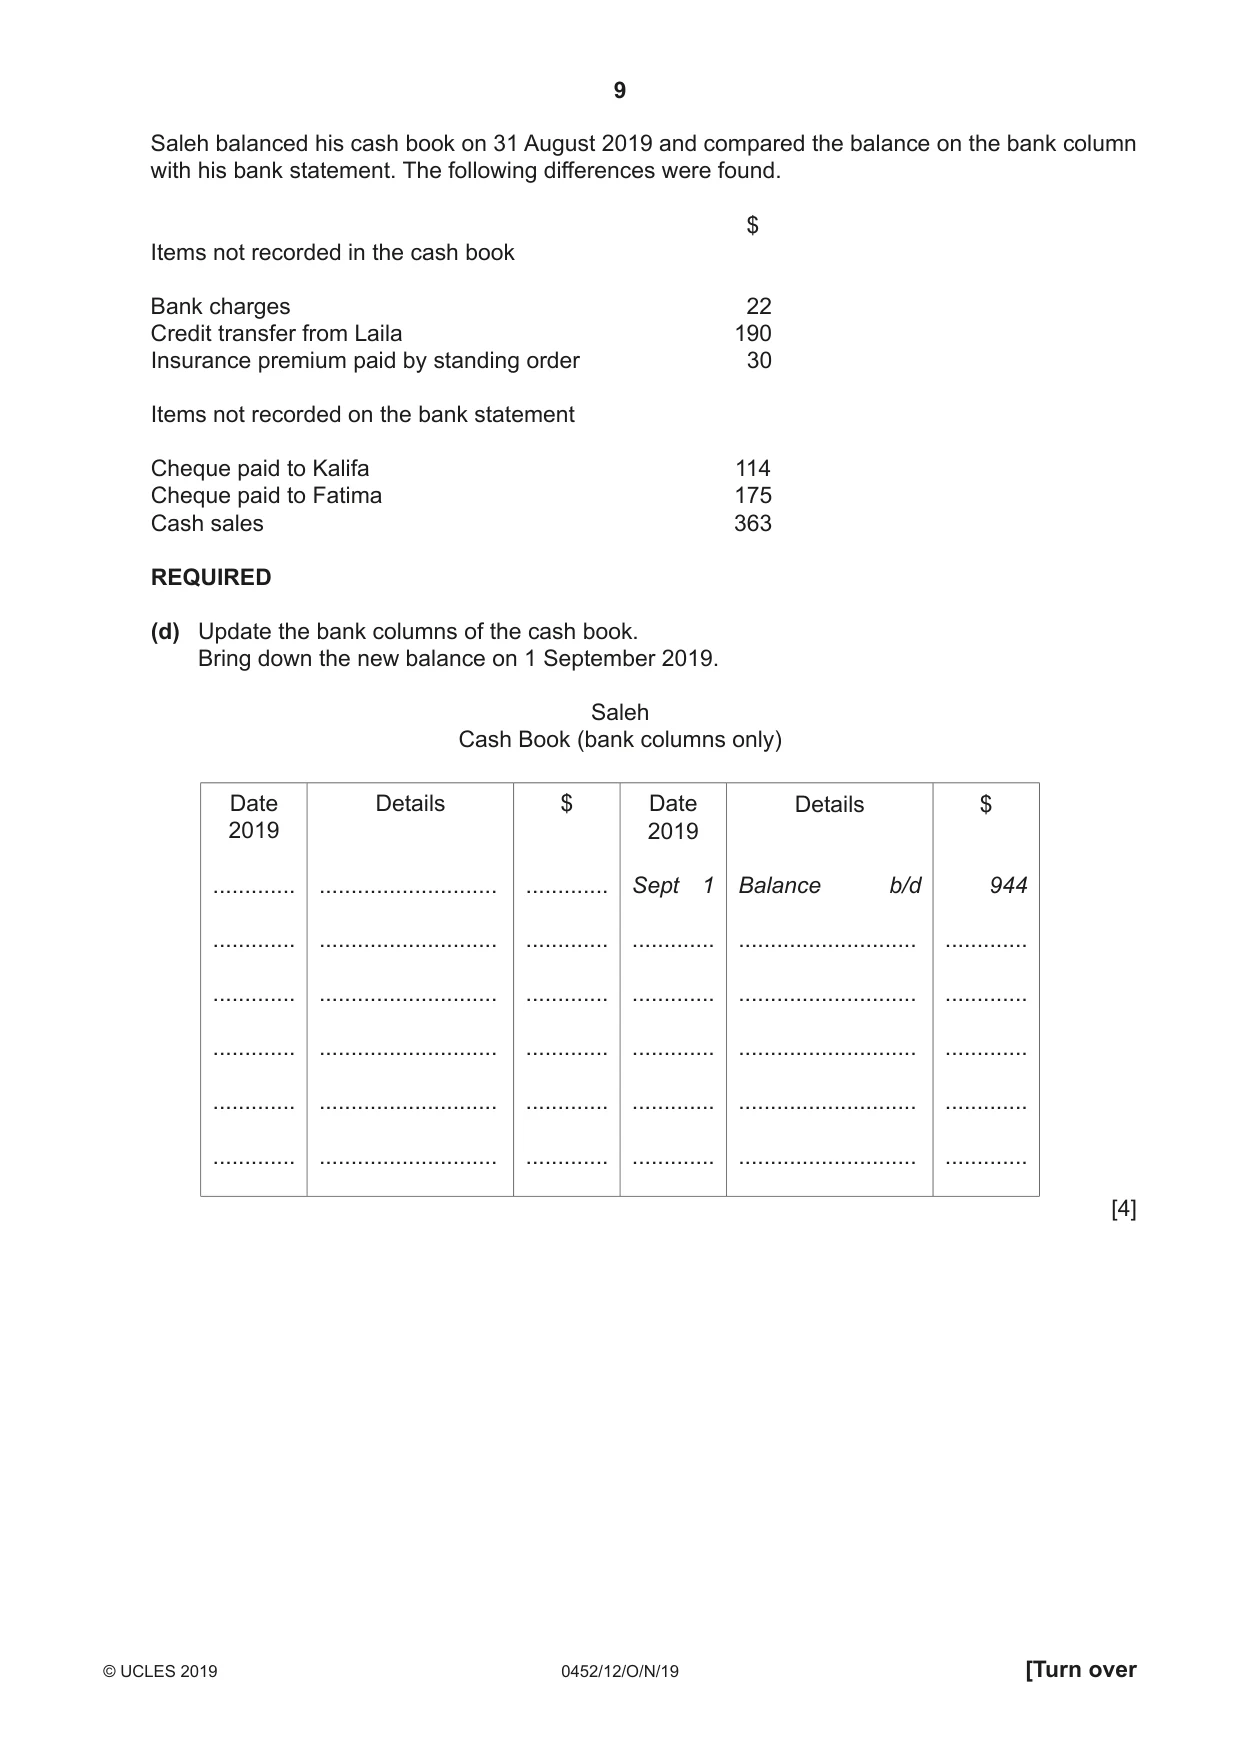
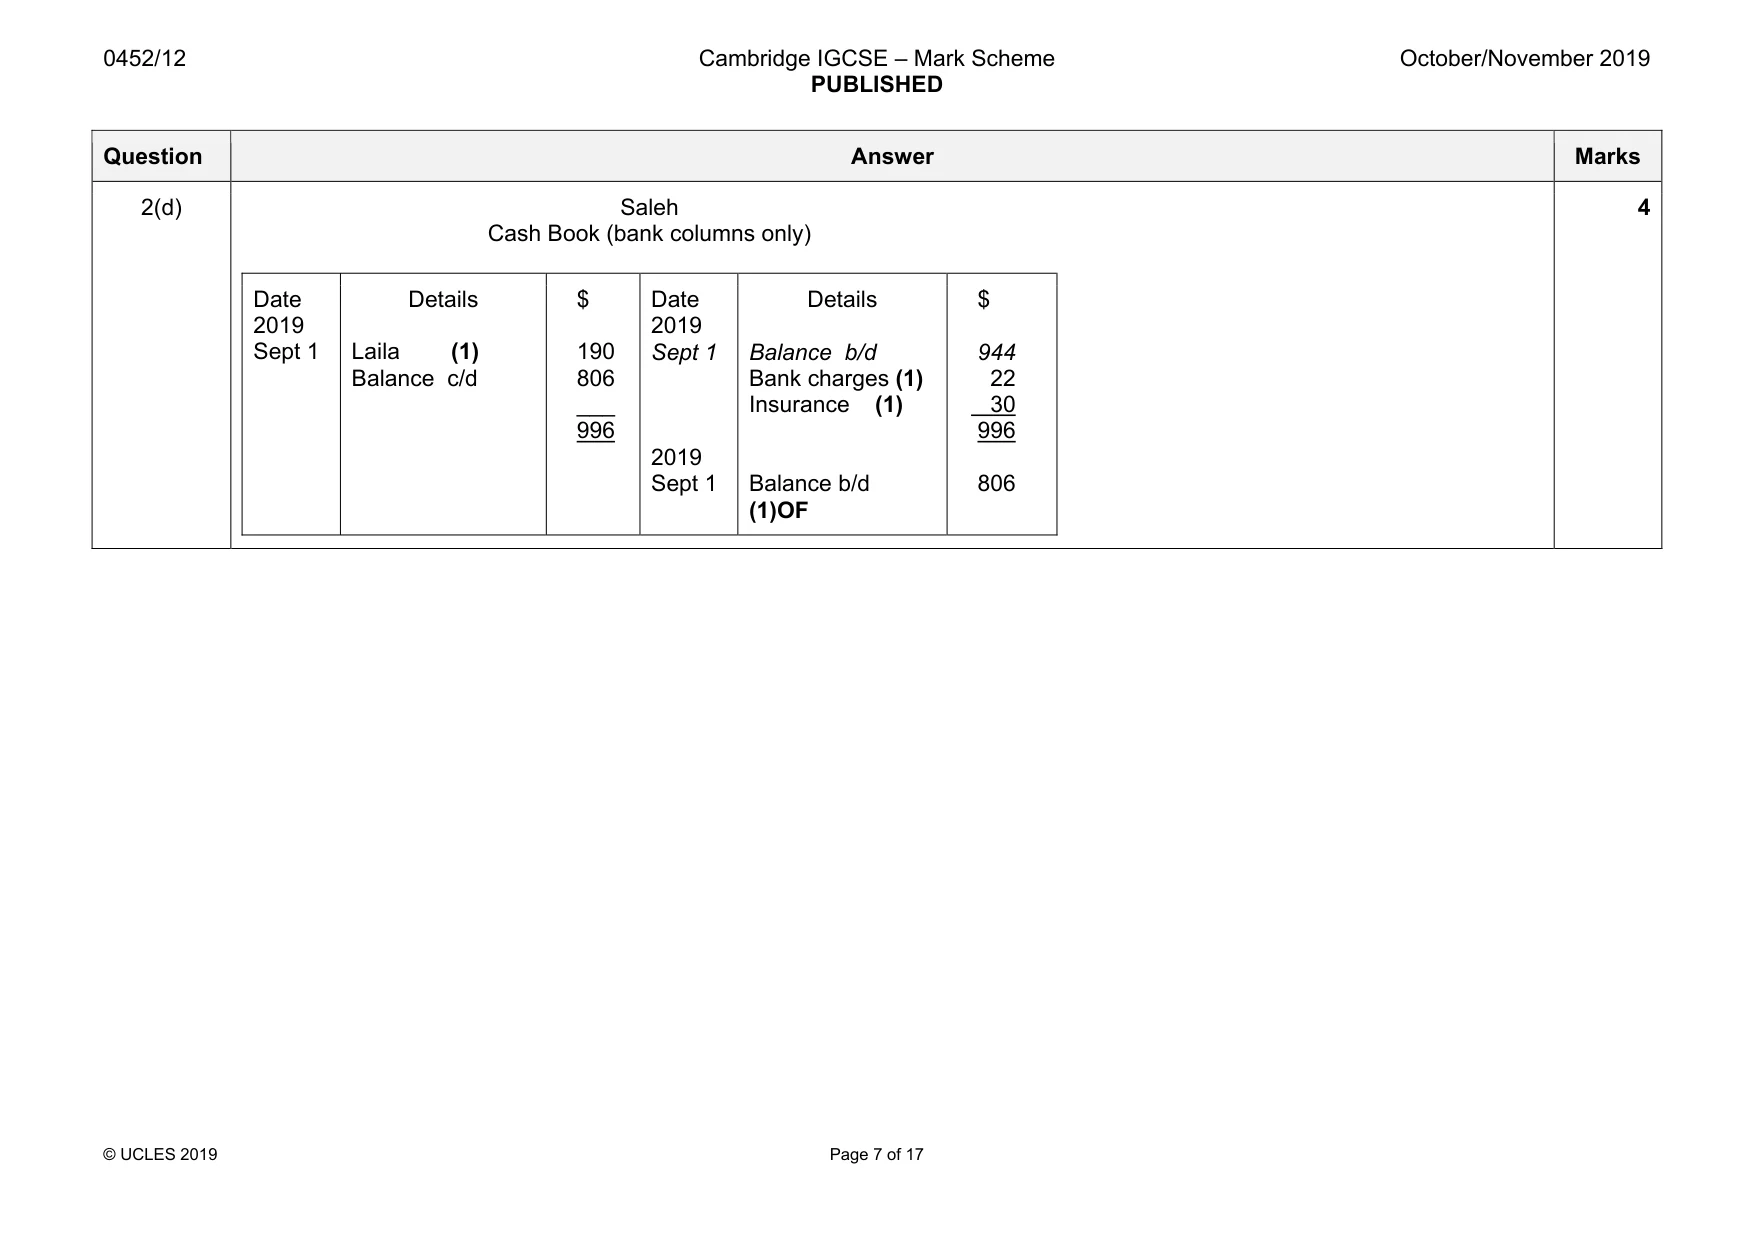
9 0452/12/O/N/19 © UCLES 2019 [Turn over Saleh balanced his cash book on 31 August 2019 and compared the balance on the bank column with his bank statement. The following differences were found. $ Items not recorded in the cash book Bank charges 22 Credit transfer from Laila 190 Insurance premium paid by standing order 30 Items not recorded on the bank statement Cheque paid to Kalifa 114 Cheque paid to Fatima 175 Cash sales 363 REQUIRED (d) Update the bank columns of the cash book. Bring down the new balance on 1 September 2019. Saleh Cash Book (bank columns only) Date 2019 … … … … … … Details … … … … … … $ … … … … … … Date 2019 Sept 1 … … … … … Details Balance b/d … … … … … $ 944 … … … … … [4]
Question paper, page 10
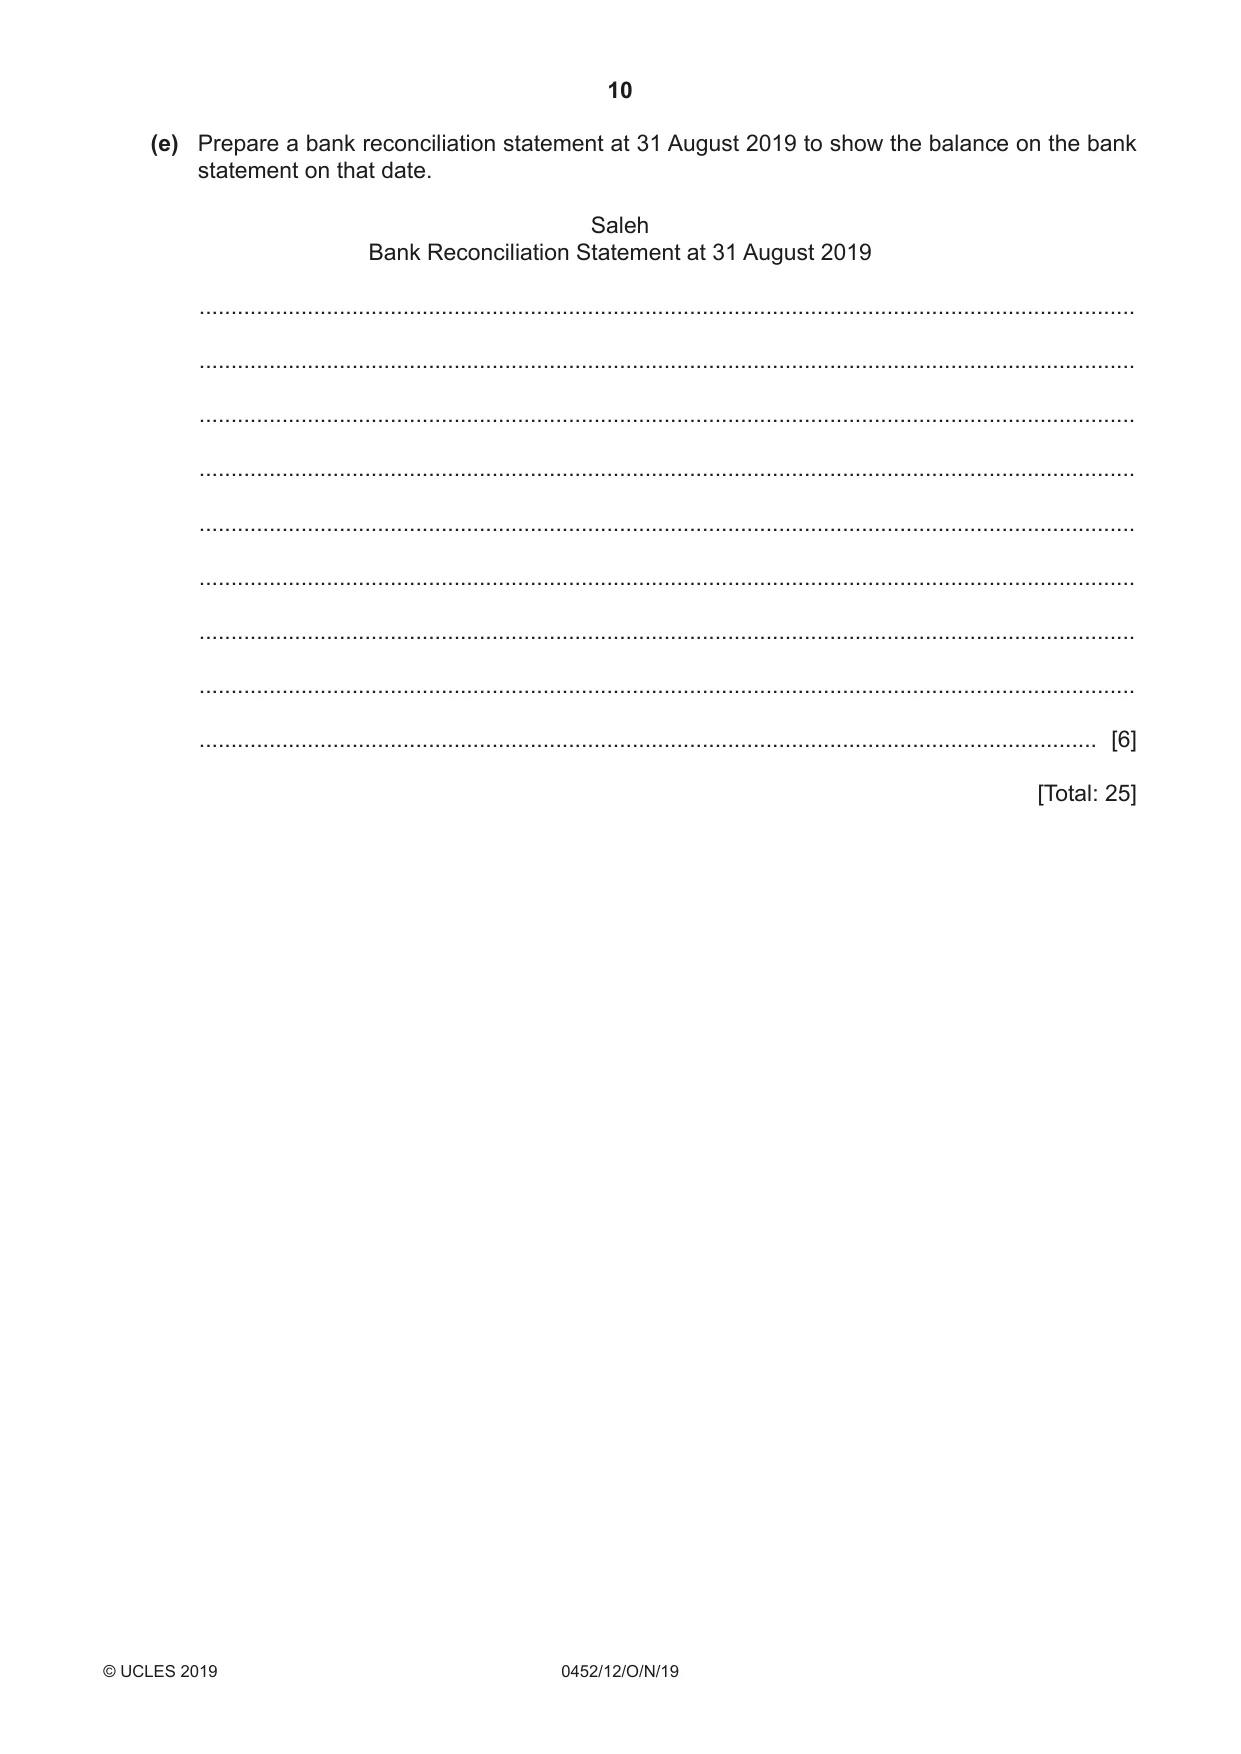
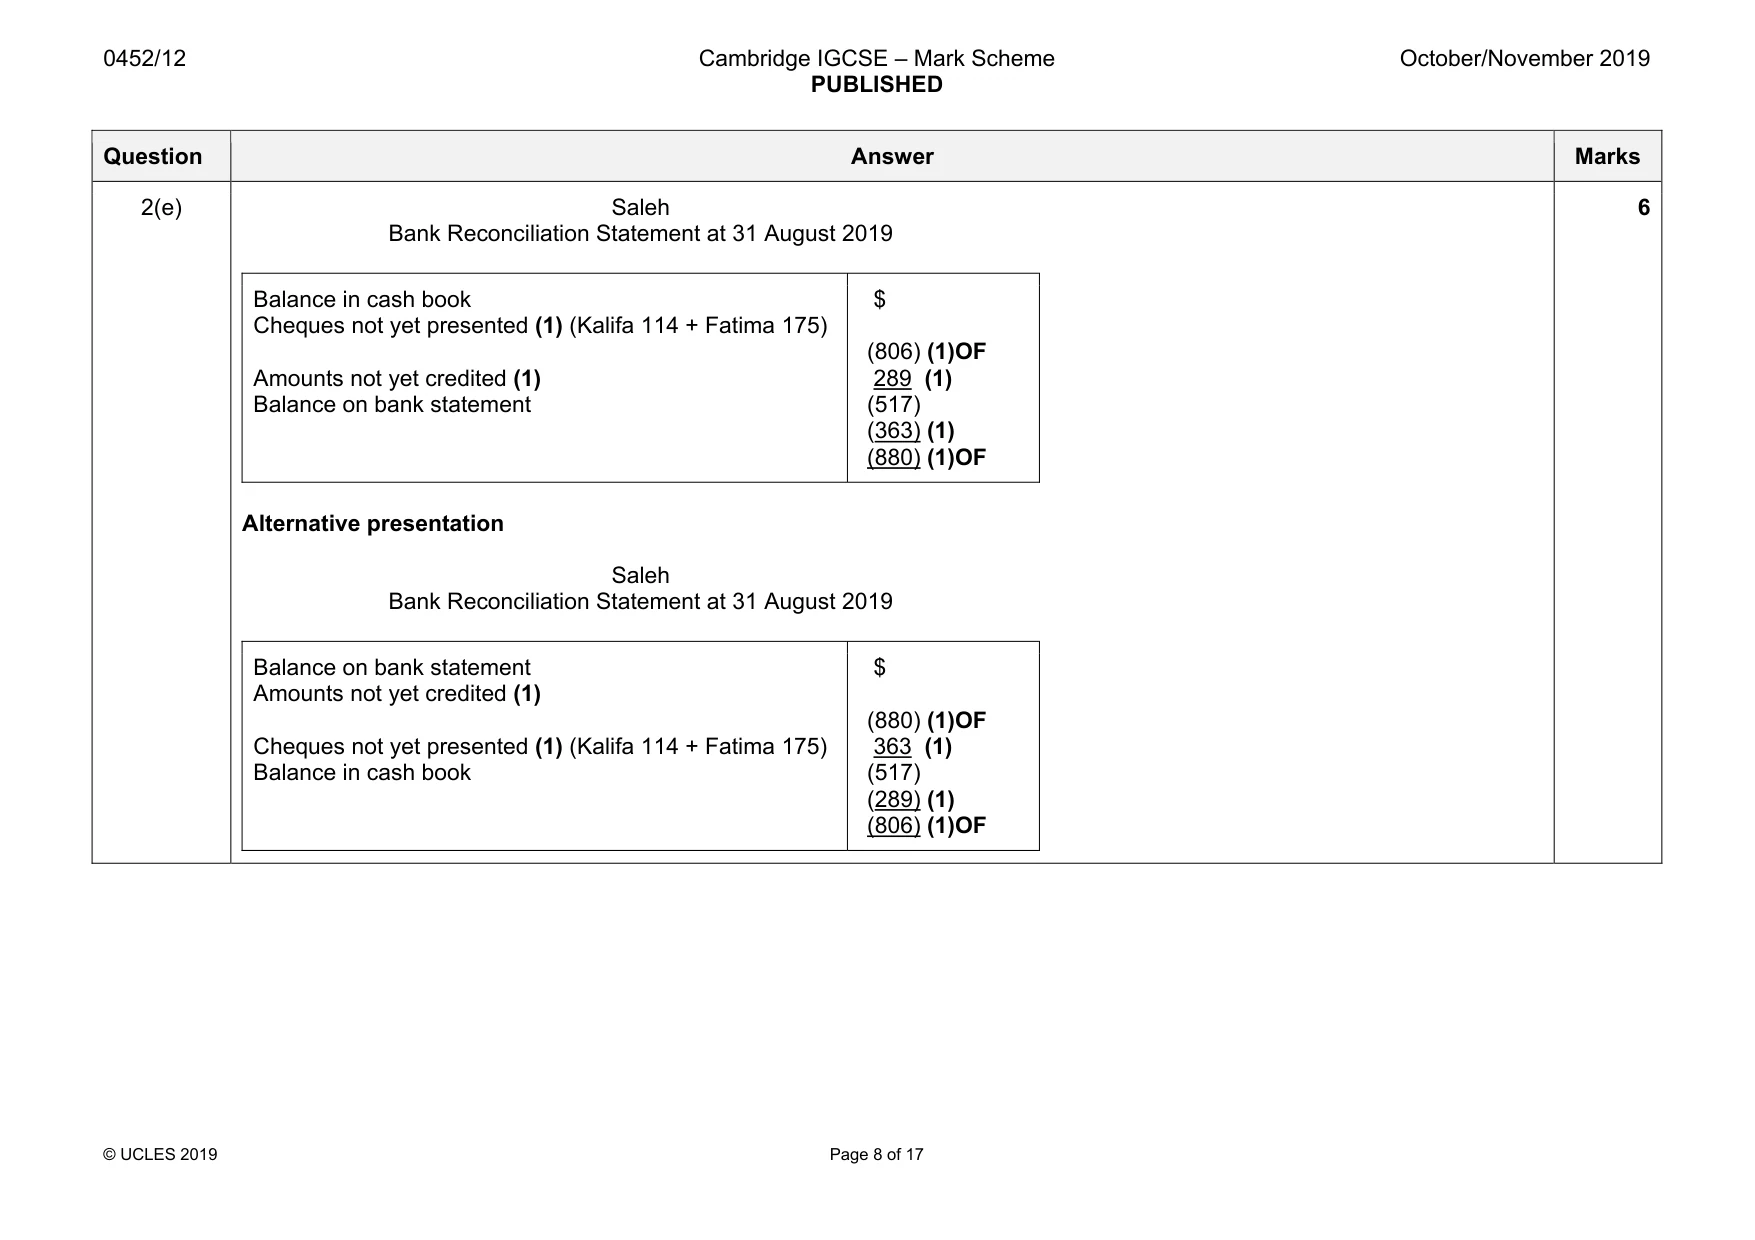
10 0452/12/O/N/19 © UCLES 2019 (e) Prepare a bank reconciliation statement at 31 August 2019 to show the balance on the bank statement on that date. Saleh Bank Reconciliation Statement at 31 August 2019 … … … … … … … … … [6] [Total: 25]
Question paper, page 11
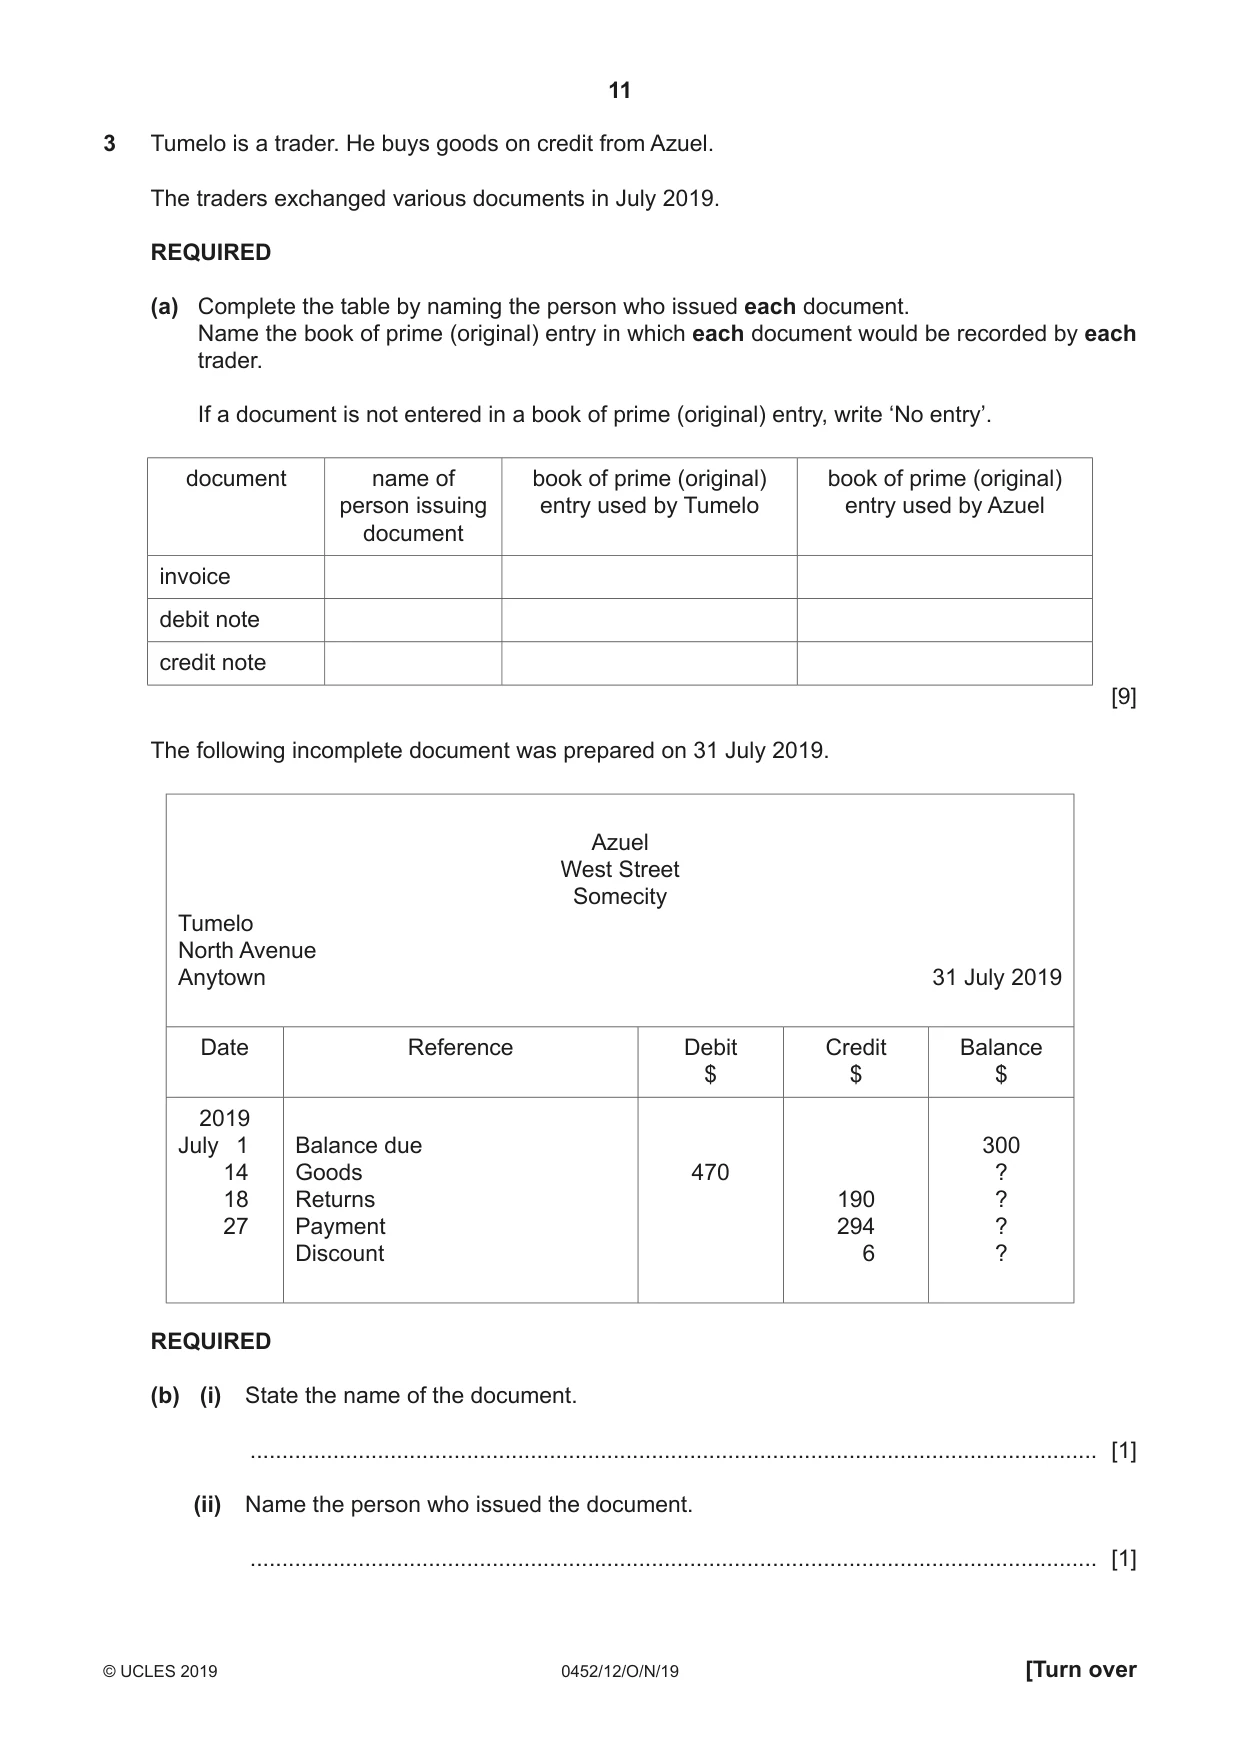
11 0452/12/O/N/19 © UCLES 2019 [Turn over 3 Tumelo is a trader. He buys goods on credit from Azuel. The traders exchanged various documents in July 2019. REQUIRED (a) Complete the table by naming the person who issued each document. Name the book of prime (original) entry in which each document would be recorded by each trader. If a document is not entered in a book of prime (original) entry, write ‘No entry’. document name of person issuing document book of prime (original) entry used by Tumelo book of prime (original) entry used by Azuel invoice debit note credit note [9] The following incomplete document was prepared on 31 July 2019. Azuel West Street Somecity Tumelo North Avenue Anytown 31 July 2019 Date Reference Debit $ Credit $ Balance $ 2019 July 1 14 18 27 Balance due Goods Returns Payment Discount 470 190 294 6 300 ? ? ? ? REQUIRED (b) (i) State the name of the document. … [1] (ii) Name the person who issued the document. … [1]
Question paper, page 12
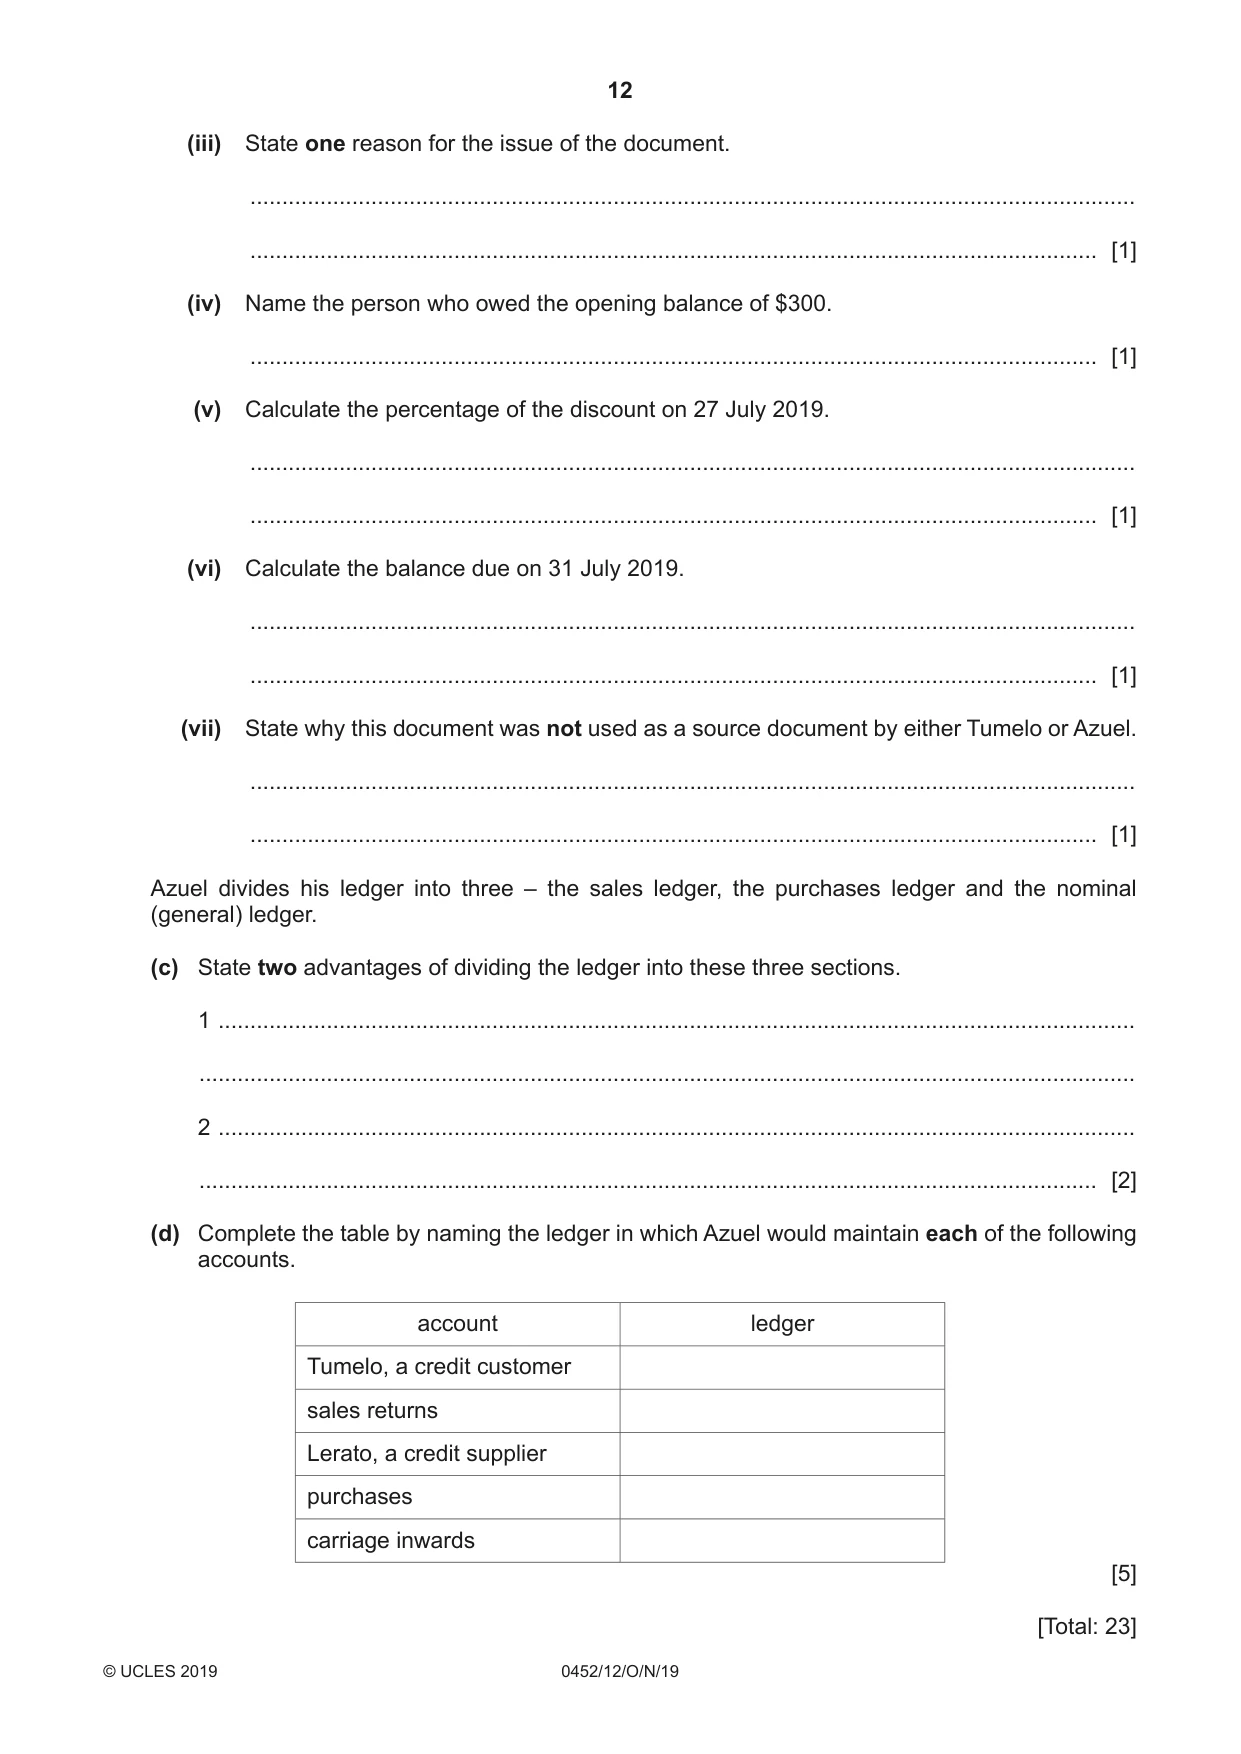
12 0452/12/O/N/19 © UCLES 2019 (iii) State one reason for the issue of the document. … … [1] (iv) Name the person who owed the opening balance of $300. … [1] (v) Calculate the percentage of the discount on 27 July 2019. … … [1] (vi) Calculate the balance due on 31 July 2019. … … [1] (vii) State why this document was not used as a source document by either Tumelo or Azuel. … … [1] Azuel divides his ledger into three – the sales ledger, the purchases ledger and the nominal (general) ledger. (c) State two advantages of dividing the ledger into these three sections. 1 … … 2 … … [2] (d) Complete the table by naming the ledger in which Azuel would maintain each of the following accounts. account ledger Tumelo, a credit customer sales returns Lerato, a credit supplier purchases carriage inwards [5] [Total: 23]
Question paper, page 13
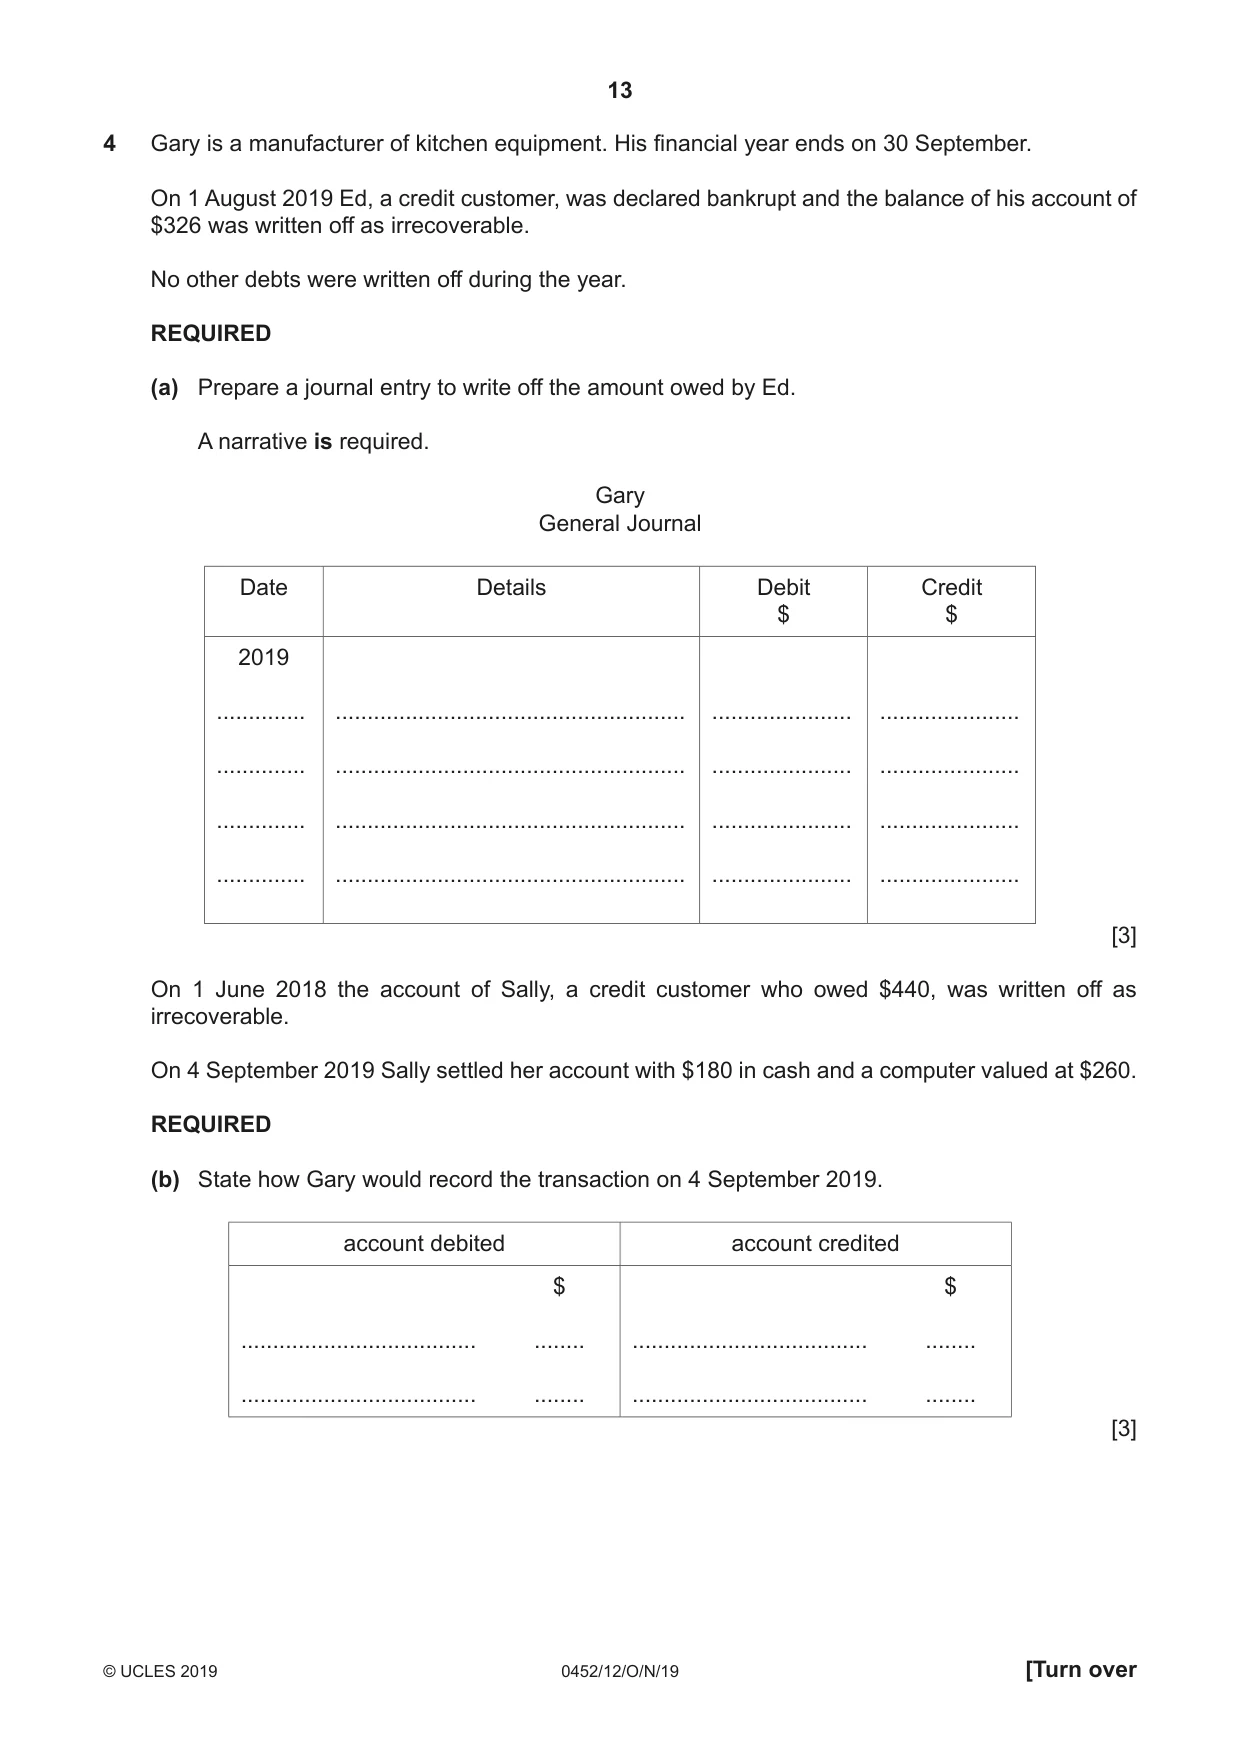
13 0452/12/O/N/19 © UCLES 2019 [Turn over 4 Gary is a manufacturer of kitchen equipment. His financial year ends on 30 September. On 1 August 2019 Ed, a credit customer, was declared bankrupt and the balance of his account of $326 was written off as irrecoverable. No other debts were written off during the year. REQUIRED (a) Prepare a journal entry to write off the amount owed by Ed. A narrative is required. Gary General Journal Date Details Debit $ Credit $ 2019 … … … … … … … … … … … … … … … … [3] On 1 June 2018 the account of Sally, a credit customer who owed $440, was written off as irrecoverable. On 4 September 2019 Sally settled her account with $180 in cash and a computer valued at $260. REQUIRED (b) State how Gary would record the transaction on 4 September 2019. account debited account credited $ … … … … $ … … … … [3]
Question paper, page 14
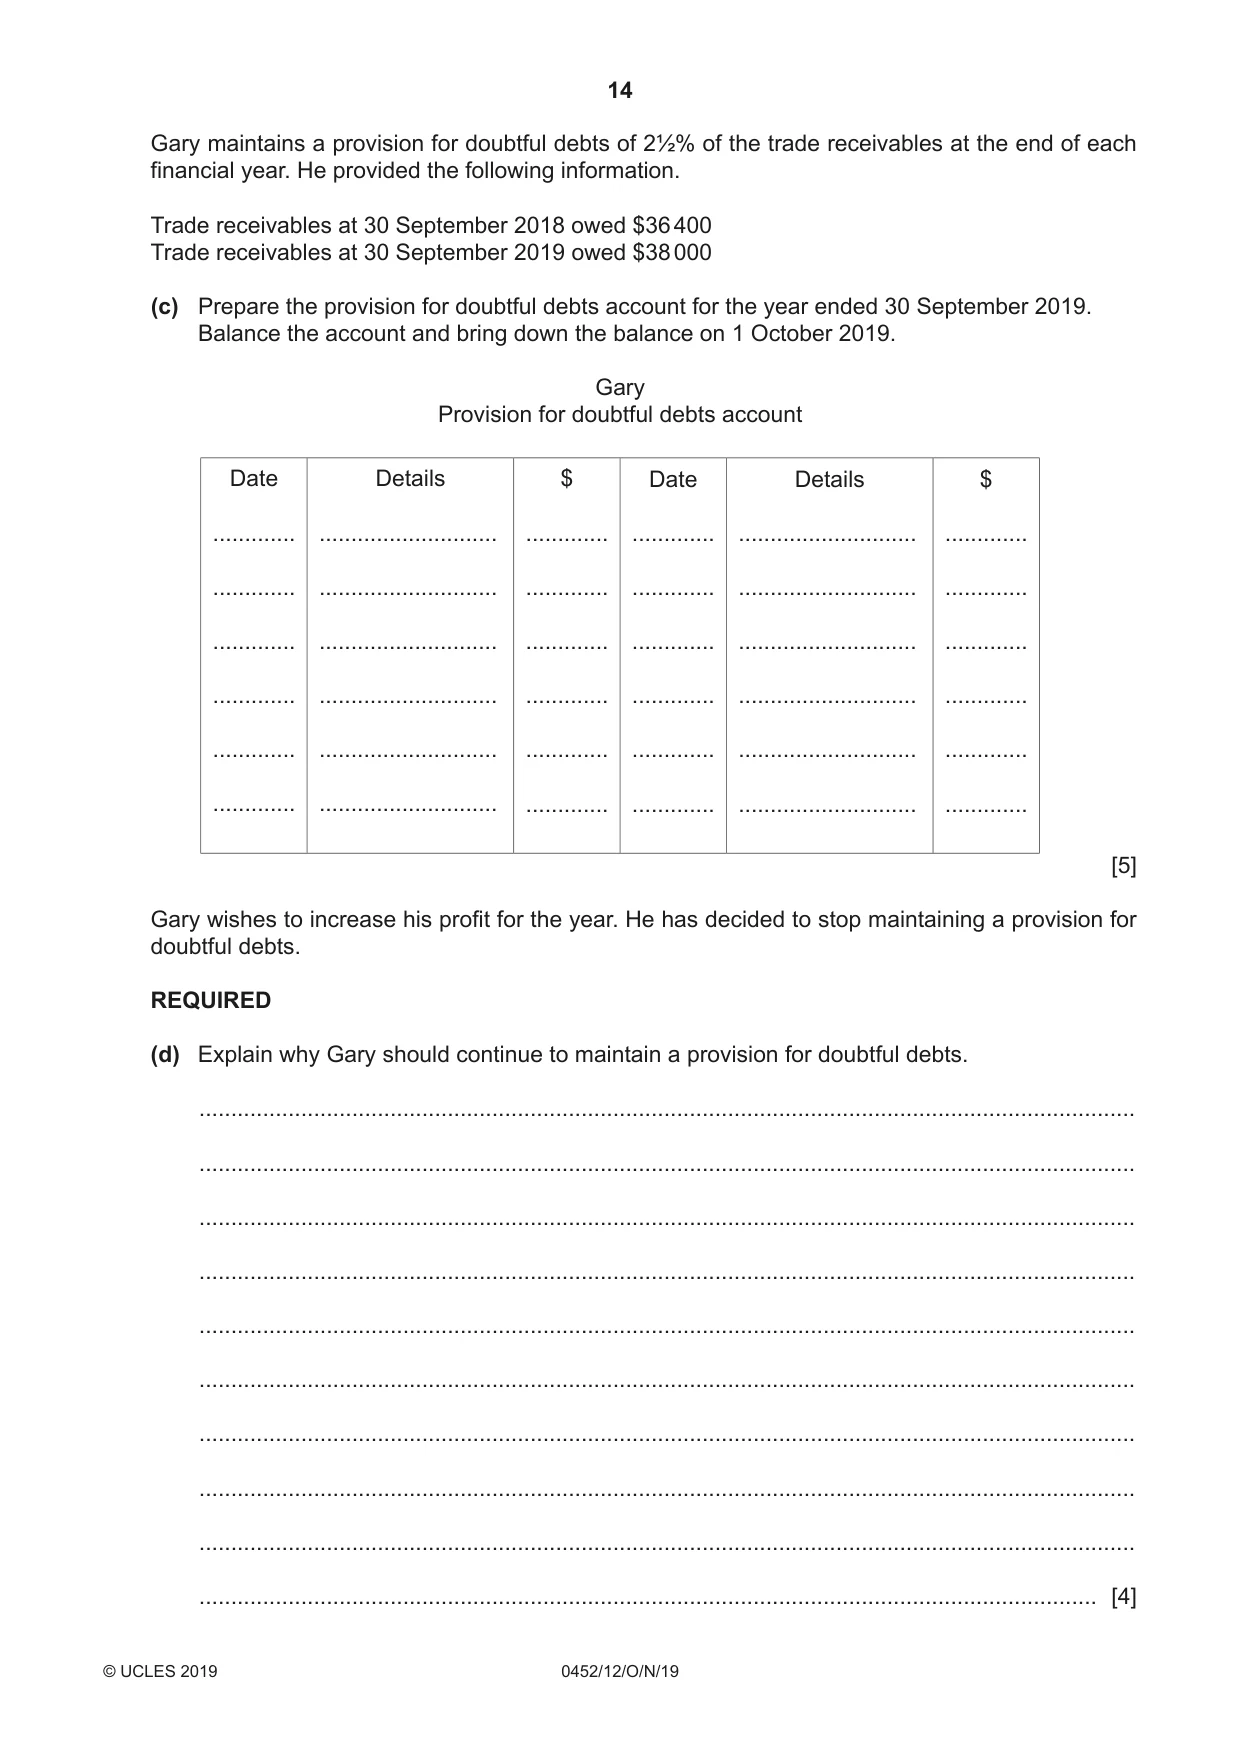
14 0452/12/O/N/19 © UCLES 2019 Gary maintains a provision for doubtful debts of 2½% of the trade receivables at the end of each financial year. He provided the following information. Trade receivables at 30 September 2018 owed $36 400 Trade receivables at 30 September 2019 owed $38 000 (c) Prepare the provision for doubtful debts account for the year ended 30 September 2019. Balance the account and bring down the balance on 1 October 2019. Gary Provision for doubtful debts account Date … … … … … … Details … … … … … … $ … … … … … … Date … … … … … … Details … … … … … … $ … … … … … … [5] Gary wishes to increase his profit for the year. He has decided to stop maintaining a provision for doubtful debts. REQUIRED (d) Explain why Gary should continue to maintain a provision for doubtful debts. … … … … … … … … … … [4]
Question paper, page 15
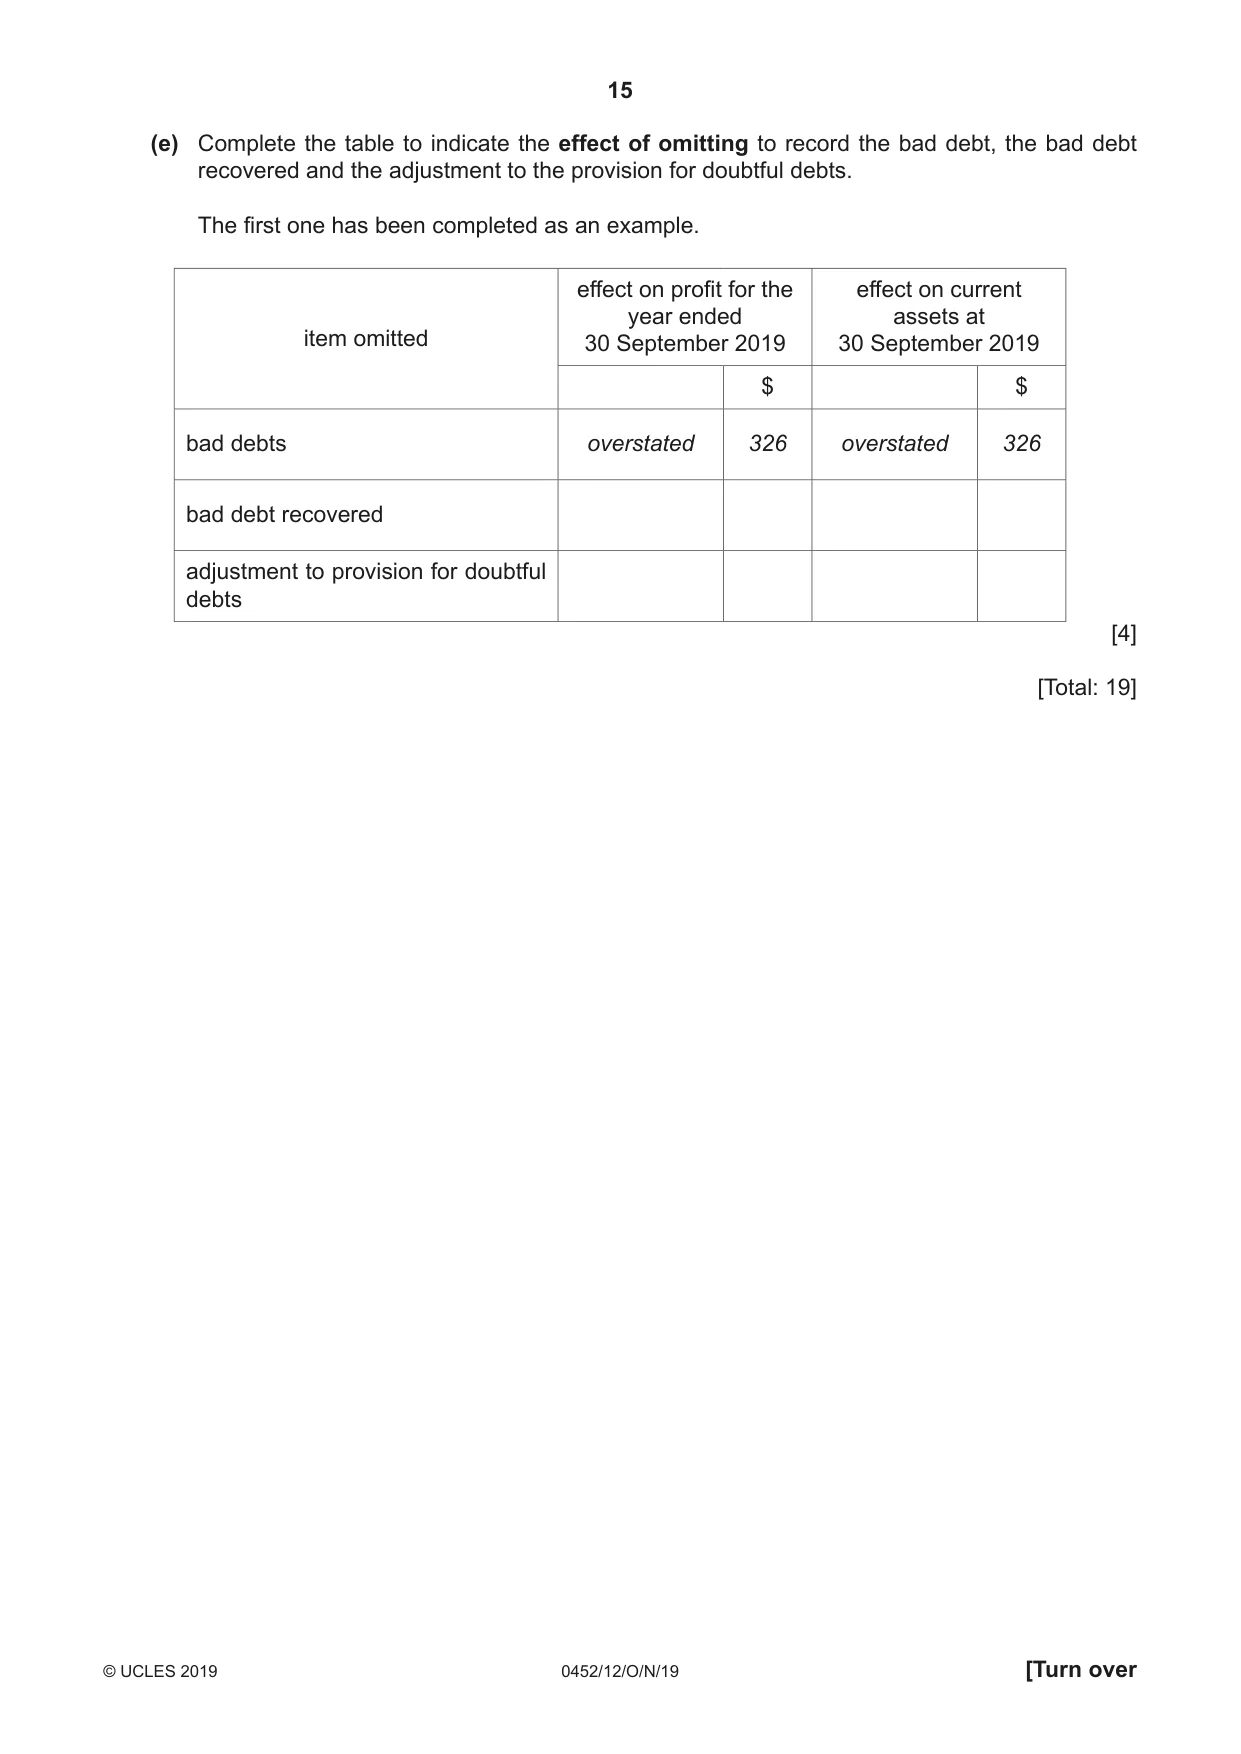
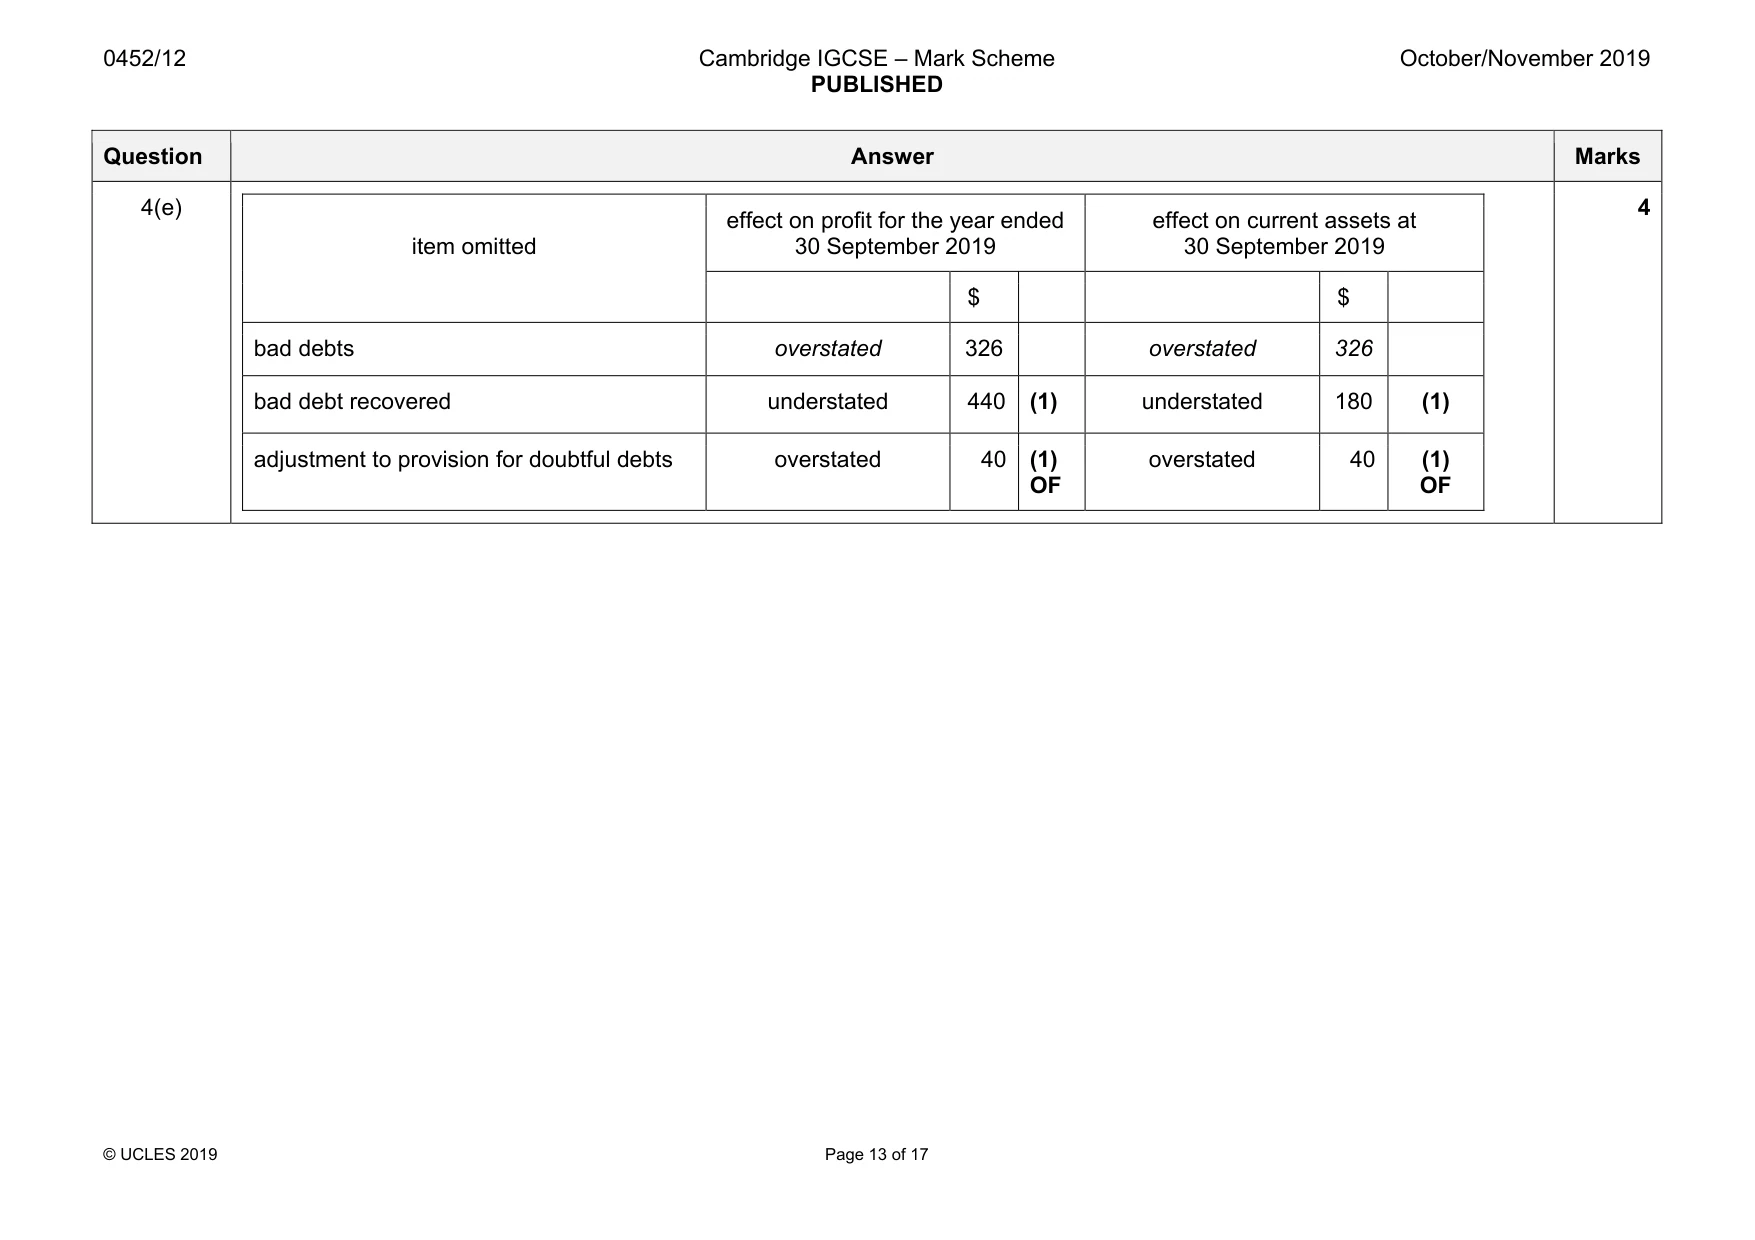
15 0452/12/O/N/19 © UCLES 2019 [Turn over (e) Complete the table to indicate the effect of omitting to record the bad debt, the bad debt recovered and the adjustment to the provision for doubtful debts. The first one has been completed as an example. item omitted effect on profit for the year ended 30 September 2019 effect on current assets at 30 September 2019 $ $ bad debts overstated 326 overstated 326 bad debt recovered adjustment to provision for doubtful debts [4] [Total: 19]
Question paper, page 16
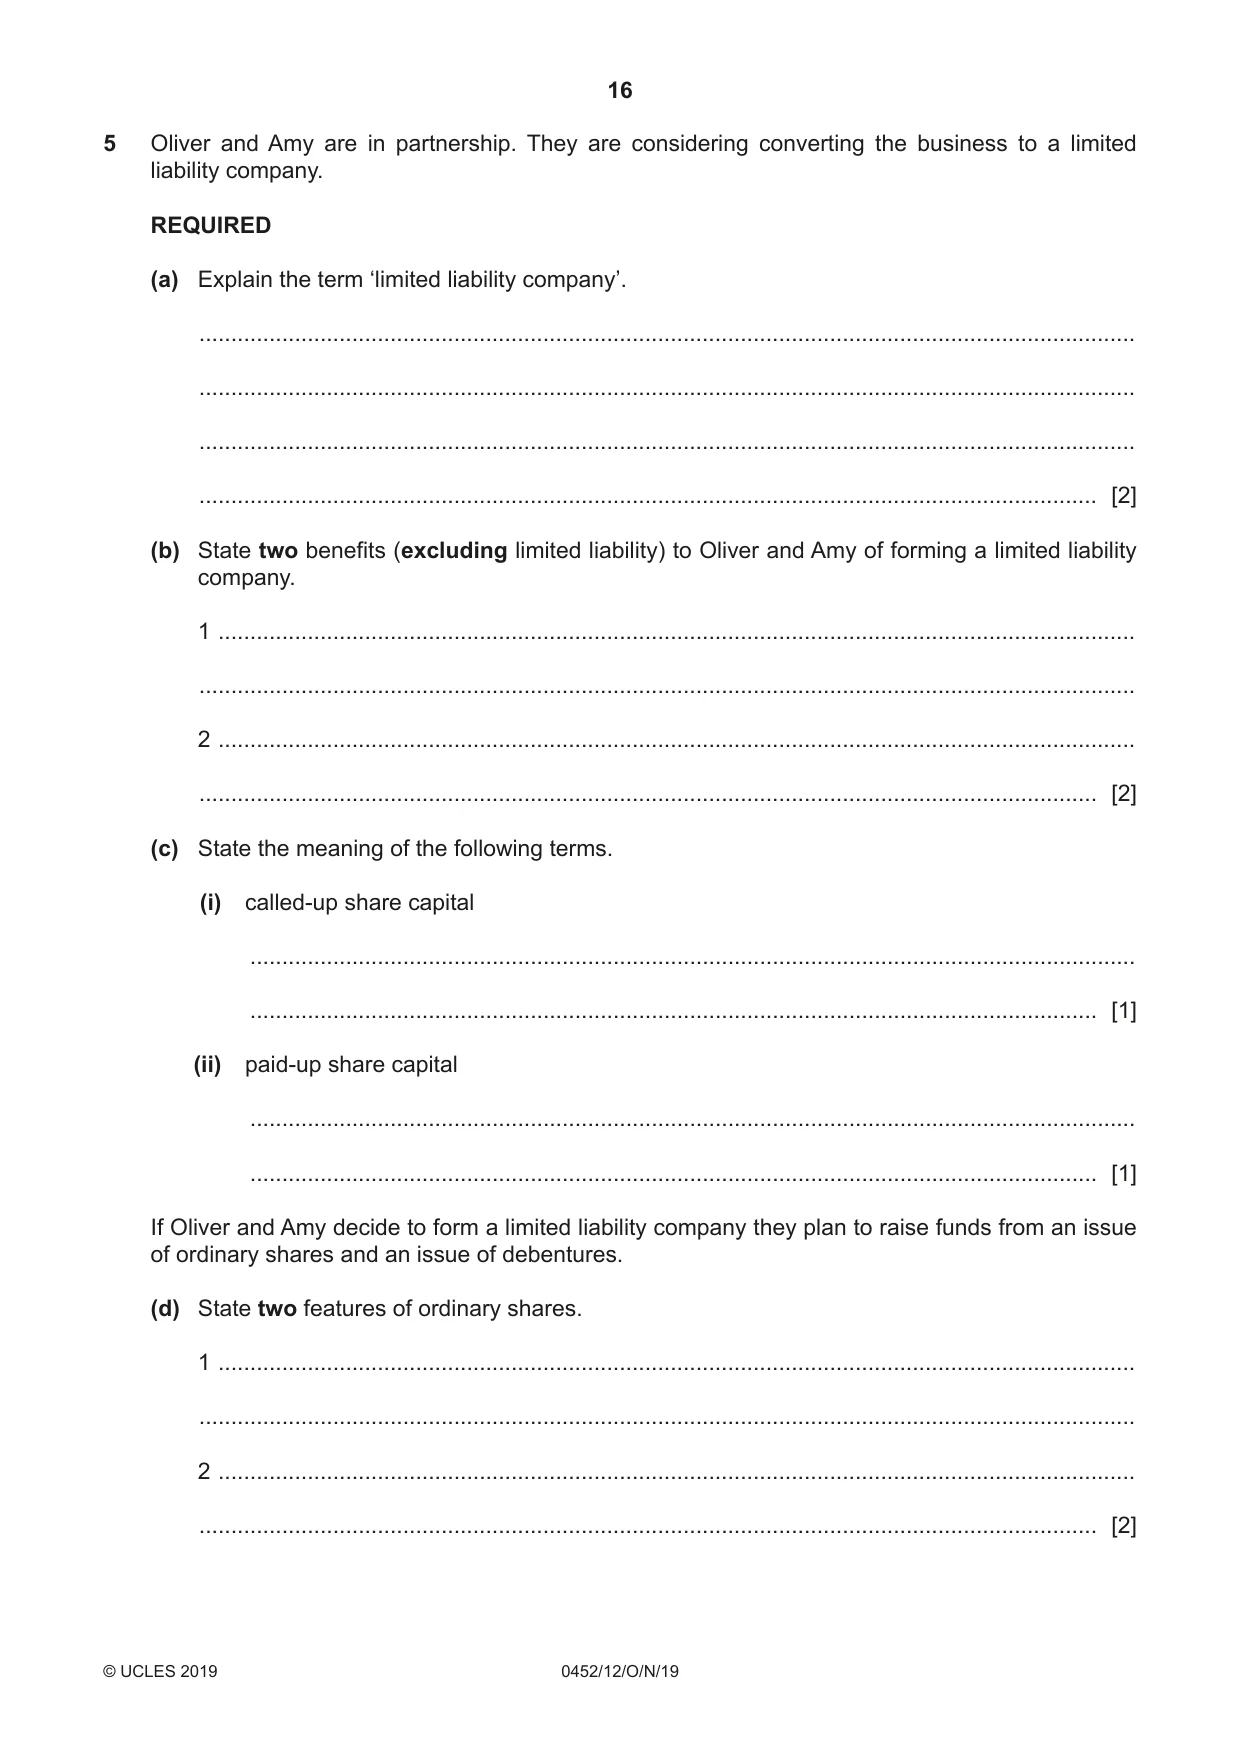
16 0452/12/O/N/19 © UCLES 2019 5 Oliver and Amy are in partnership. They are considering converting the business to a limited liability company. REQUIRED (a) Explain the term ‘limited liability company’. … … … … [2] (b) State two benefits (excluding limited liability) to Oliver and Amy of forming a limited liability company. 1 … … 2 … … [2] (c) State the meaning of the following terms. (i) called-up share capital … … [1] (ii) paid-up share capital … … [1] If Oliver and Amy decide to form a limited liability company they plan to raise funds from an issue of ordinary shares and an issue of debentures. (d) State two features of ordinary shares. 1 … … 2 … … [2]
Question paper, page 17
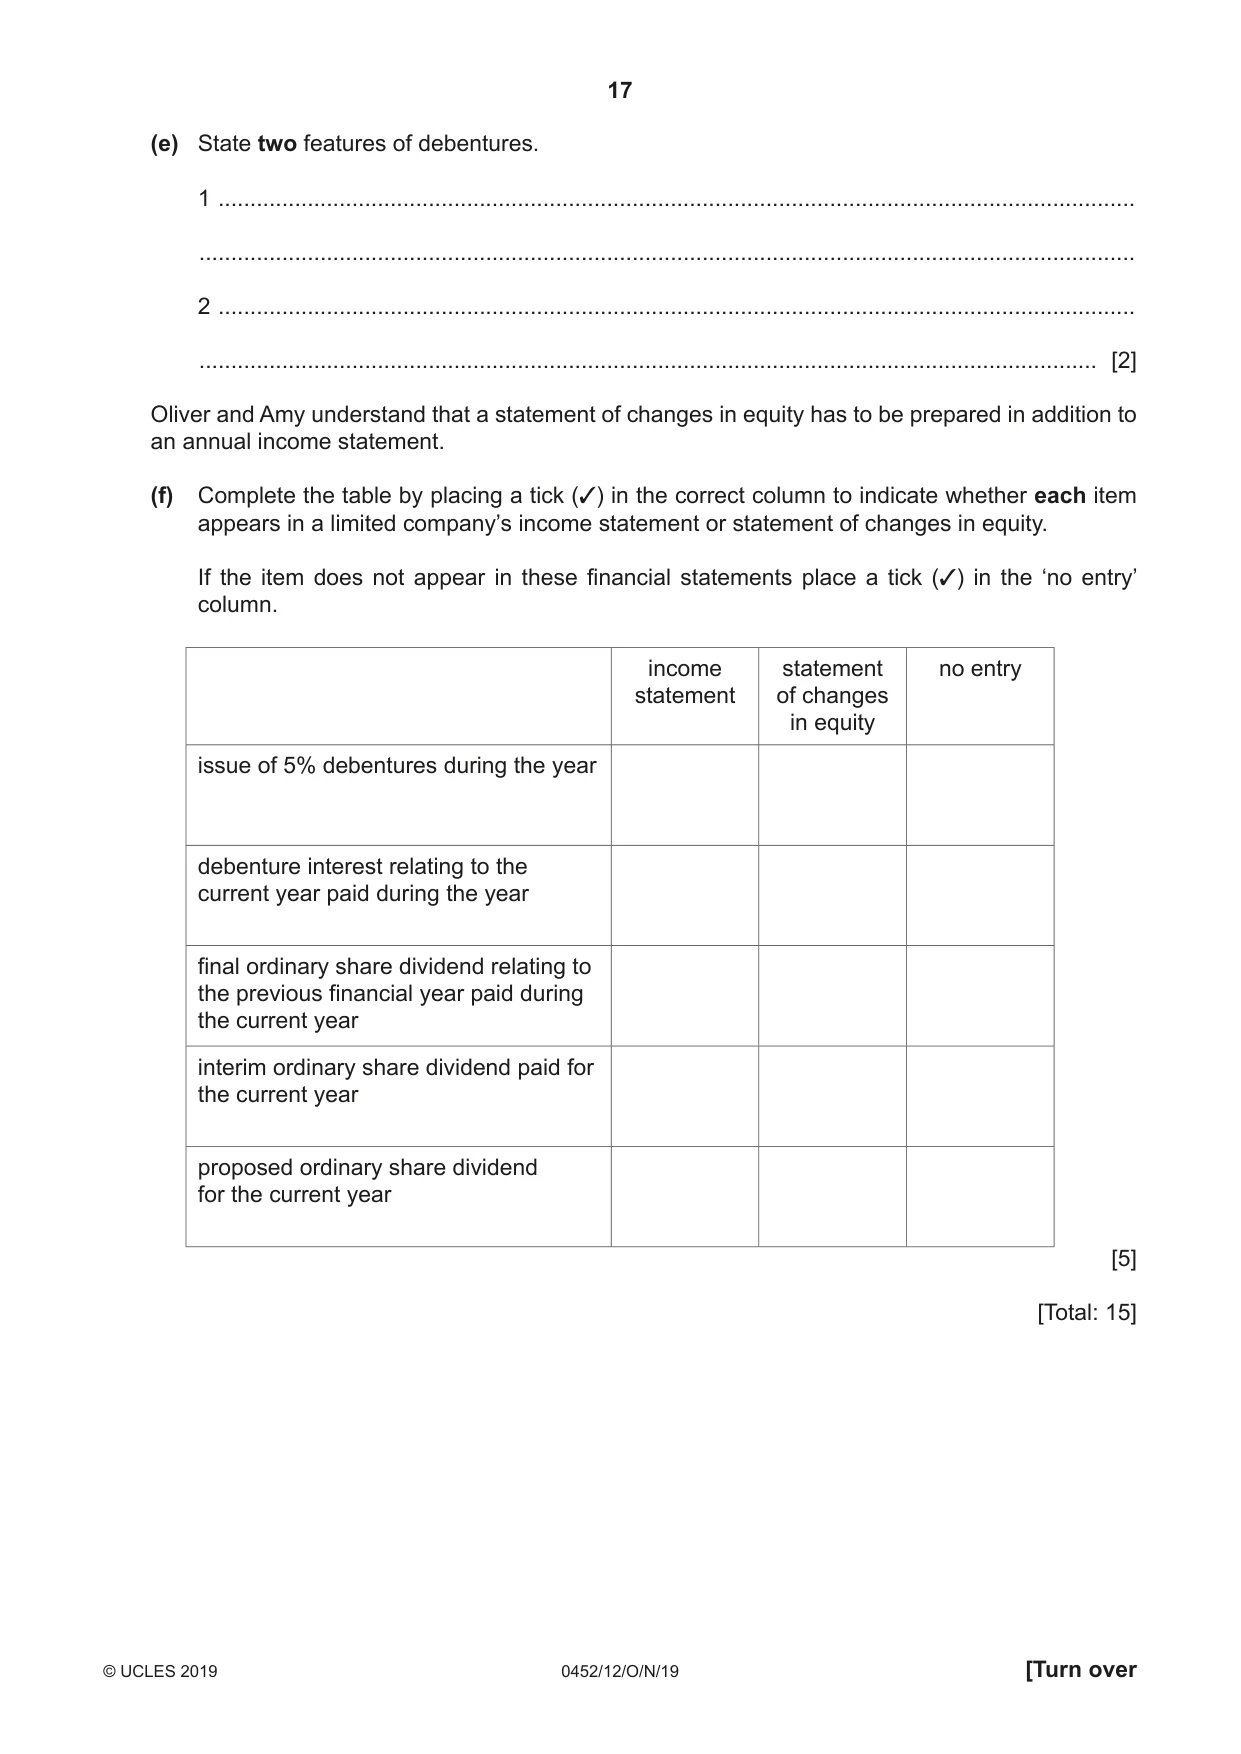
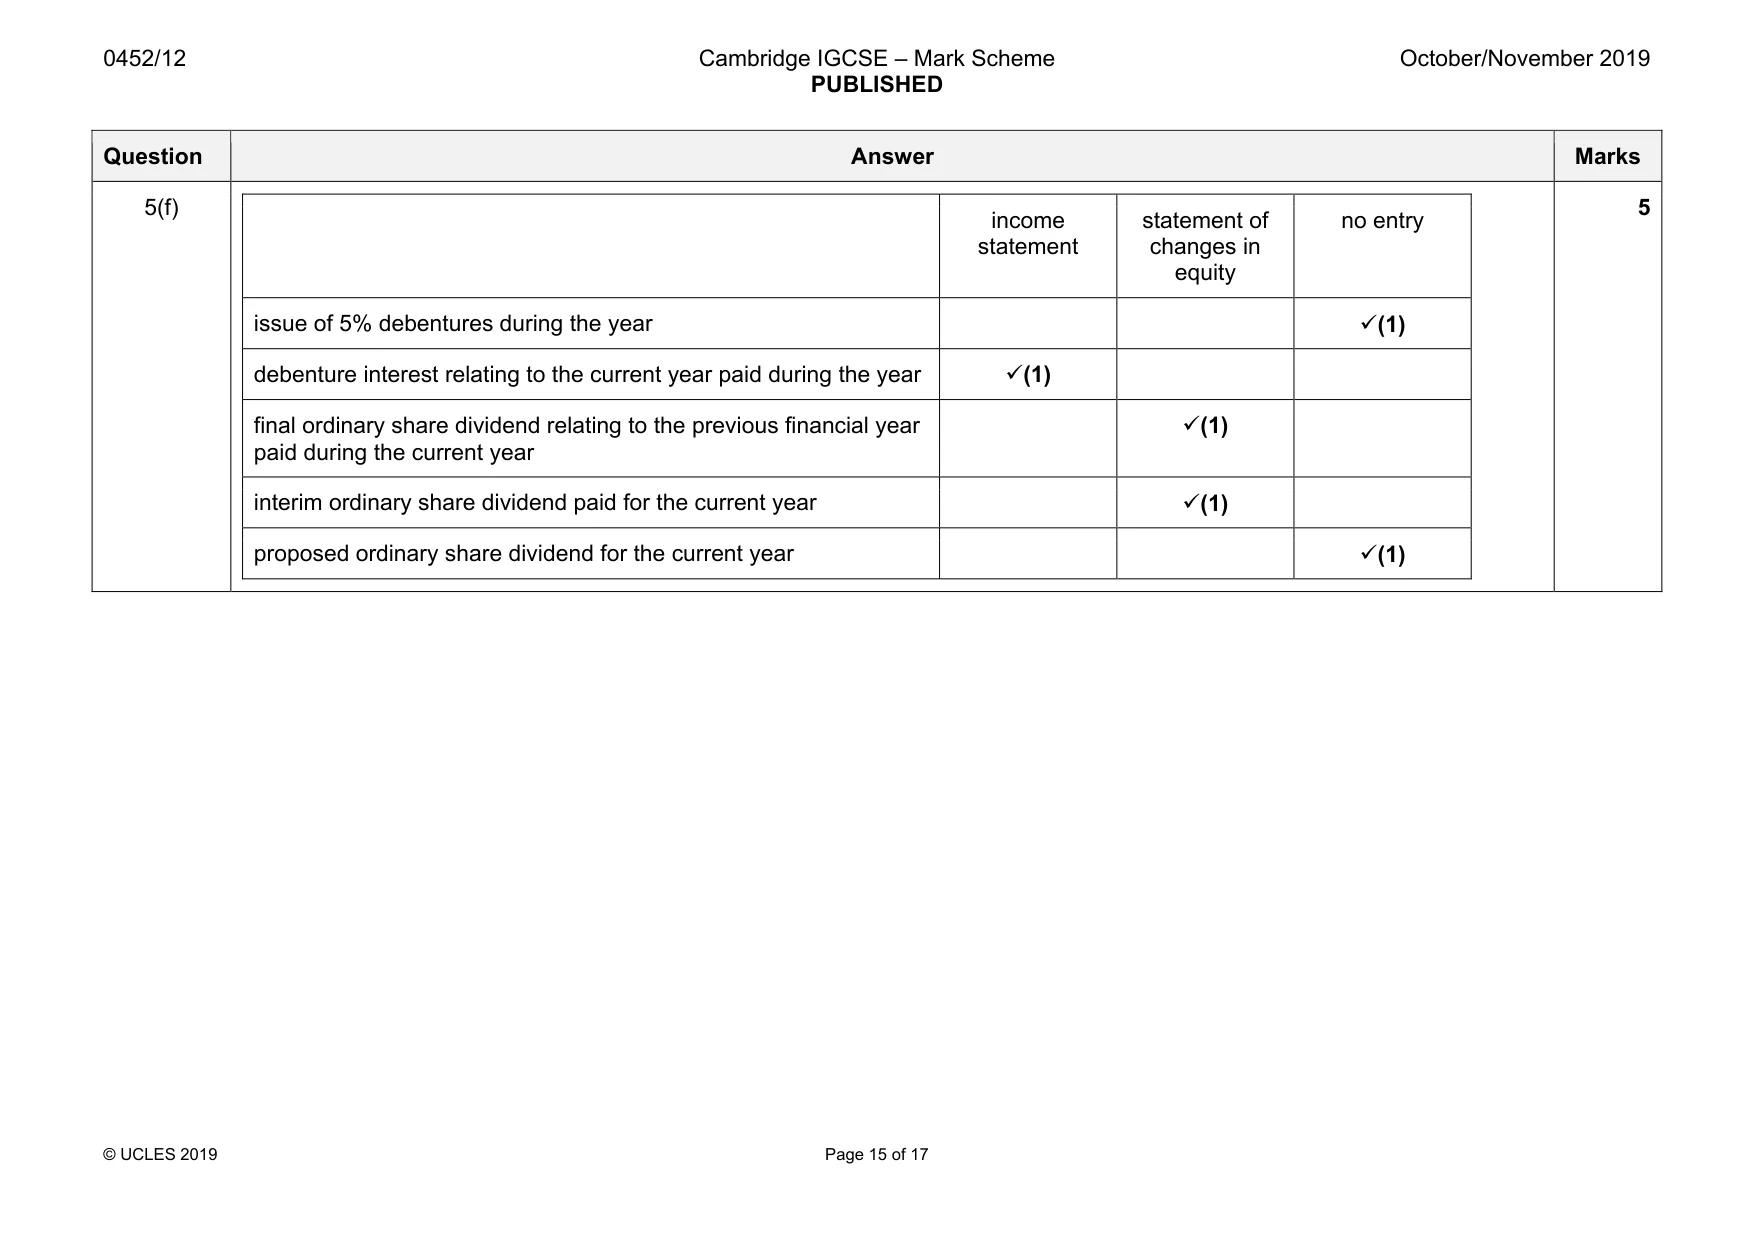
17 0452/12/O/N/19 © UCLES 2019 [Turn over (e) State two features of debentures. 1 … … 2 … … [2] Oliver and Amy understand that a statement of changes in equity has to be prepared in addition to an annual income statement. (f) Complete the table by placing a tick (✓) in the correct column to indicate whether each item appears in a limited company’s income statement or statement of changes in equity. If the item does not appear in these financial statements place a tick (✓) in the ‘no entry’ column. income statement statement of changes in equity no entry issue of 5% debentures during the year debenture interest relating to the current year paid during the year final ordinary share dividend relating to the previous financial year paid during the current year interim ordinary share dividend paid for the current year proposed ordinary share dividend for the current year [5] [Total: 15]
Question paper, page 18
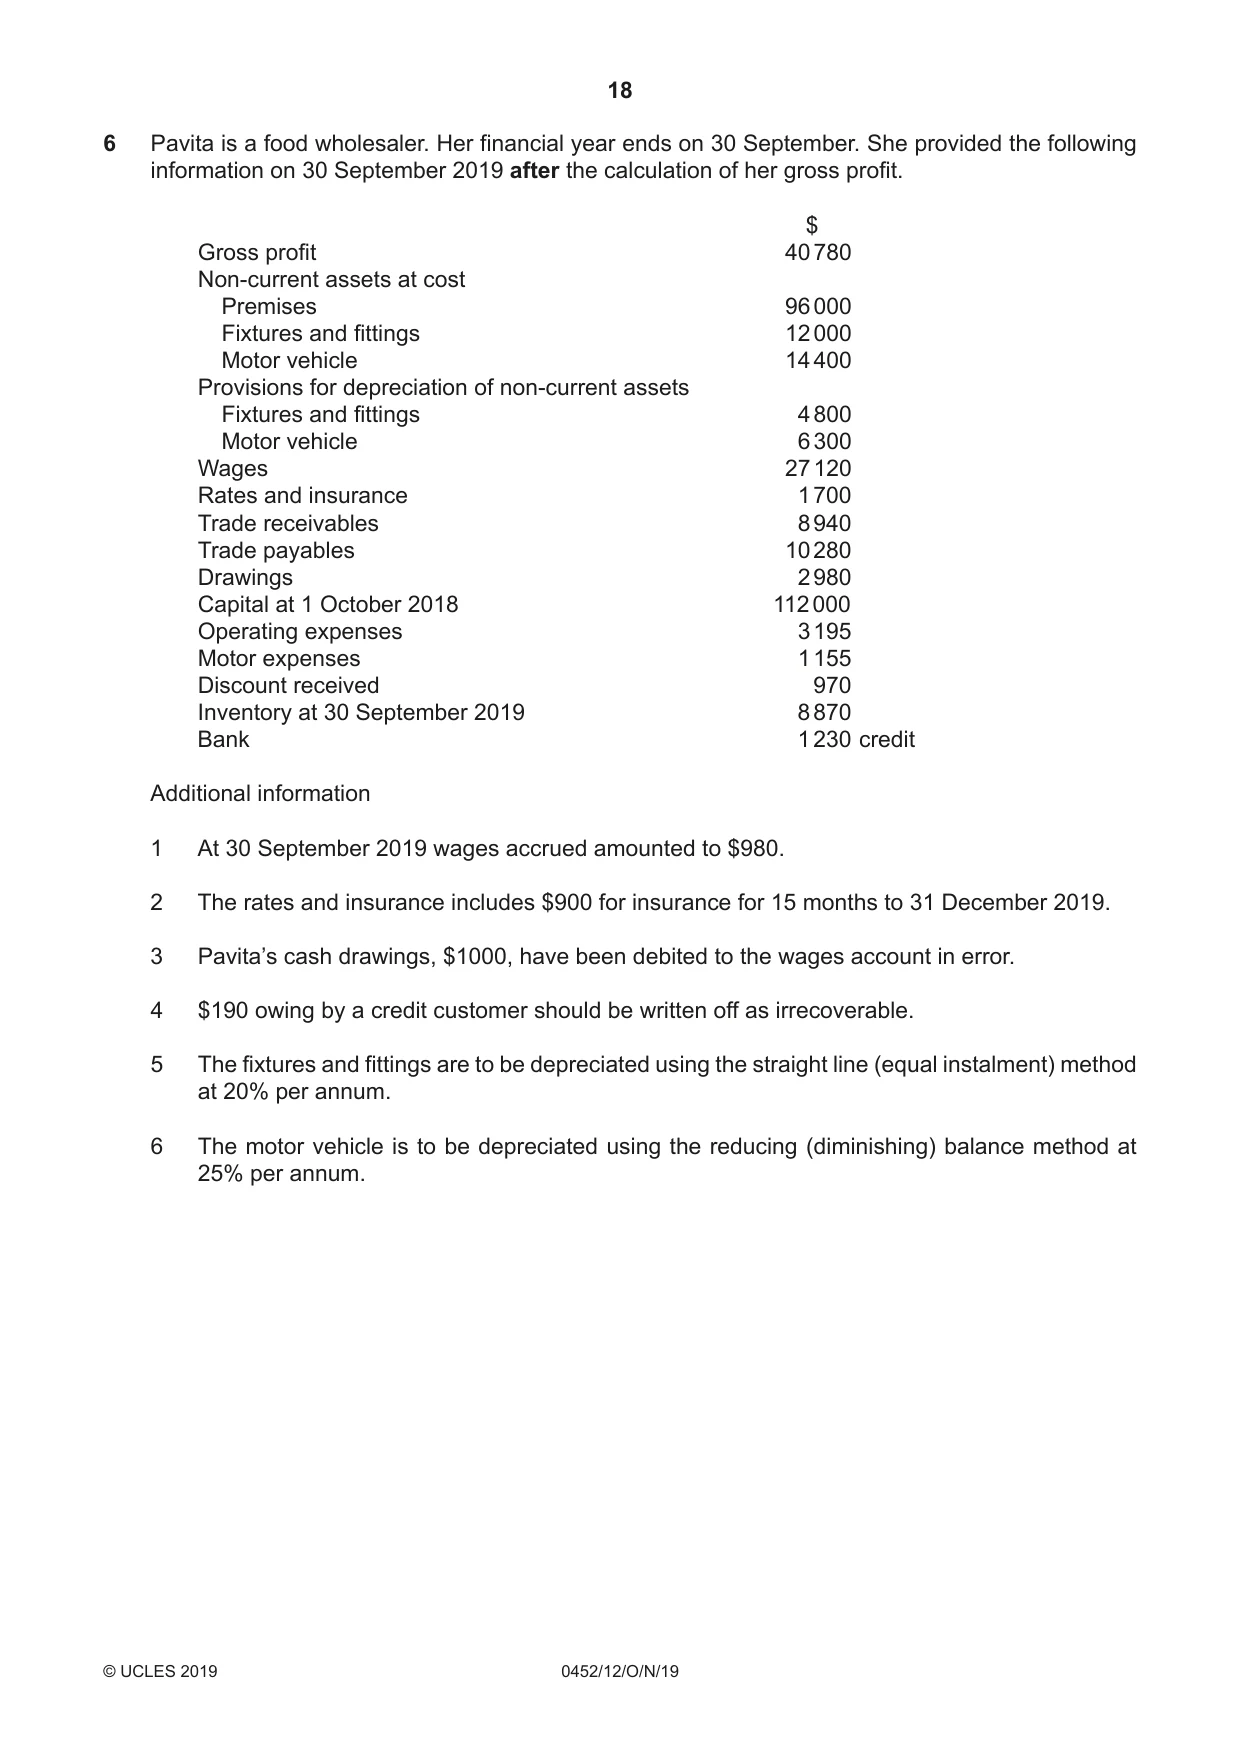
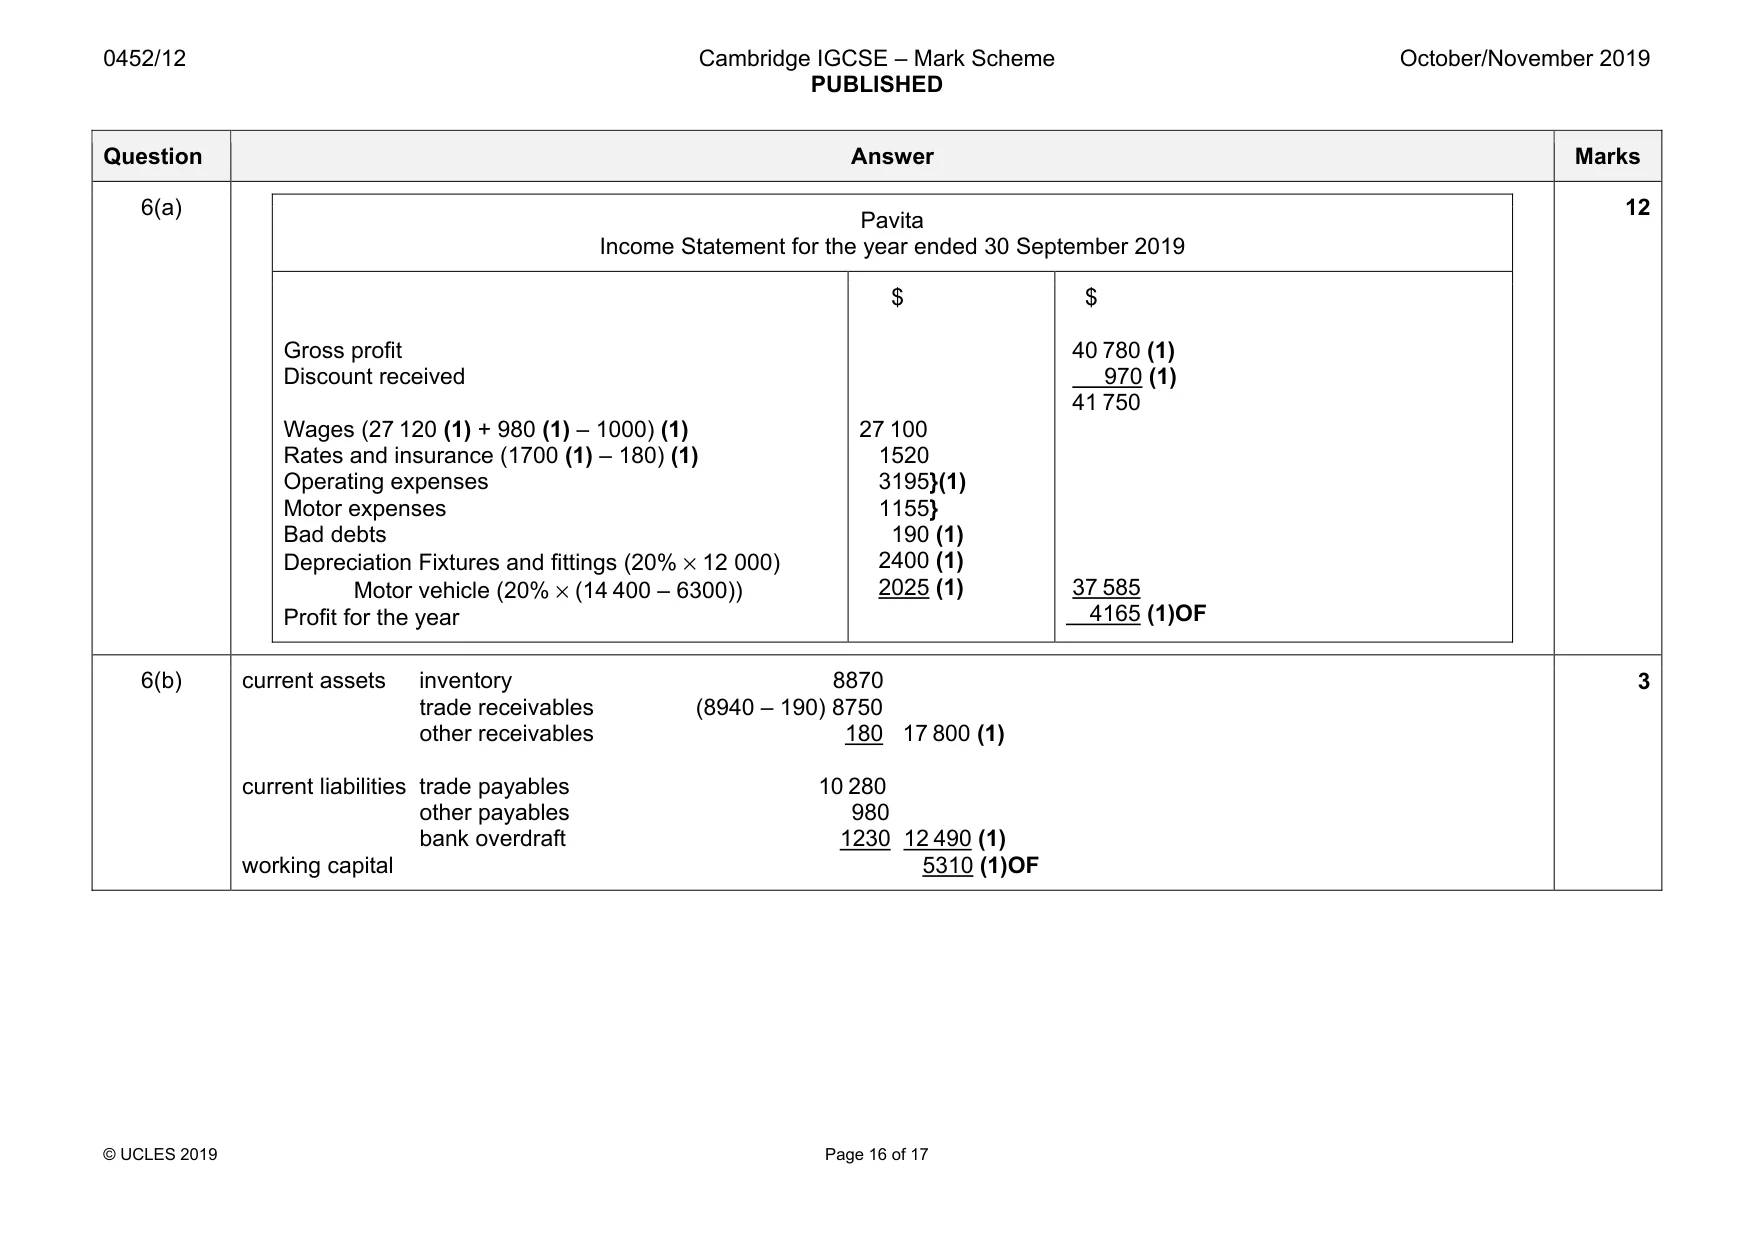
18 0452/12/O/N/19 © UCLES 2019 6 Pavita is a food wholesaler. Her financial year ends on 30 September. She provided the following information on 30 September 2019 after the calculation of her gross profit. $ Gross profit 40 780 Non-current assets at cost Premises 96 000 Fixtures and fittings 12 000 Motor vehicle 14 400 Provisions for depreciation of non-current assets Fixtures and fittings 4 800 Motor vehicle 6 300 Wages 27 120 Rates and insurance 1 700 Trade receivables 8 940 Trade payables 10 280 Drawings 2 980 Capital at 1 October 2018 112 000 Operating expenses 3 195 Motor expenses 1 155 Discount received 970 Inventory at 30 September 2019 8 870 Bank 1 230 credit Additional information 1 At 30 September 2019 wages accrued amounted to $980. 2 The rates and insurance includes $900 for insurance for 15 months to 31 December 2019. 3 Pavita’s cash drawings, $1000, have been debited to the wages account in error. 4 $190 owing by a credit customer should be written off as irrecoverable. 5 The fixtures and fittings are to be depreciated using the straight line (equal instalment) method at 20% per annum. 6 The motor vehicle is to be depreciated using the reducing (diminishing) balance method at 25% per annum.
Question paper, page 19
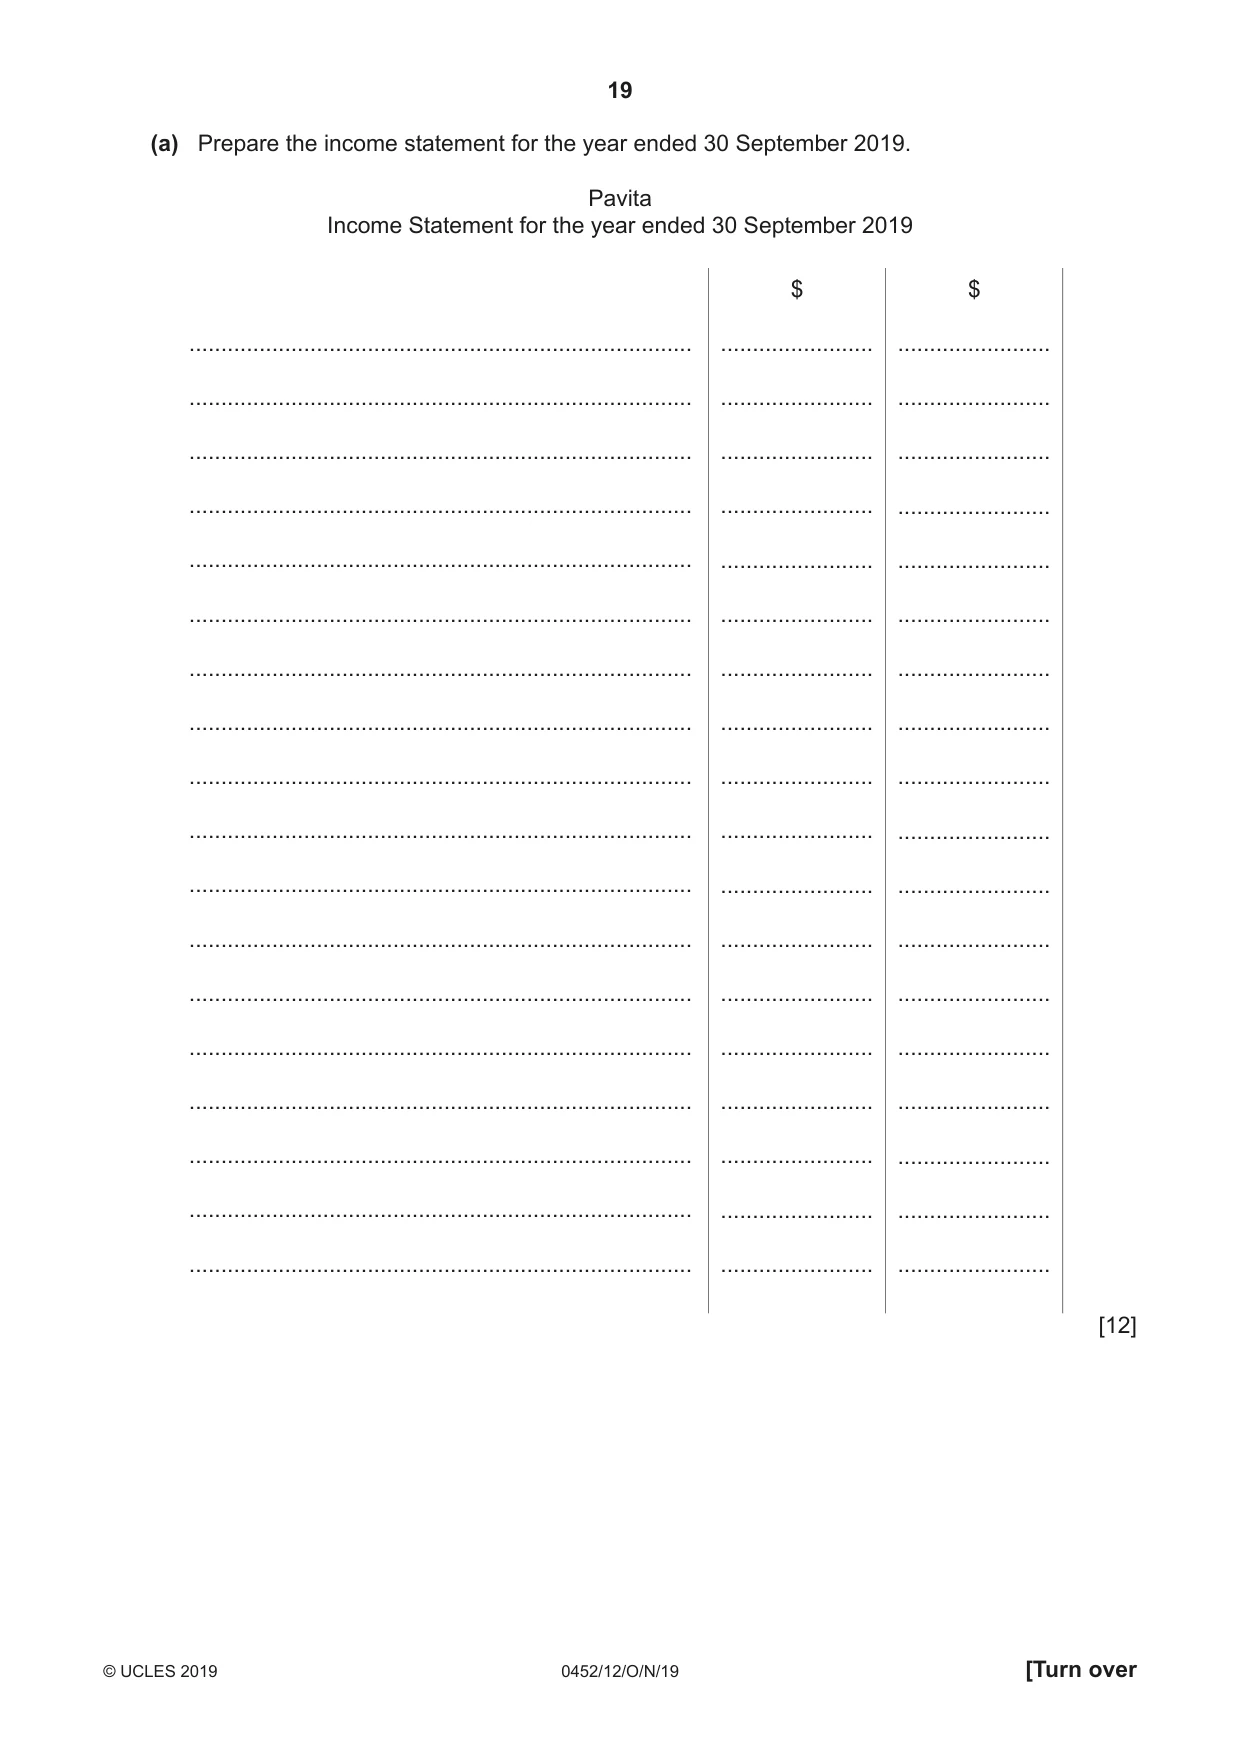
19 0452/12/O/N/19 © UCLES 2019 [Turn over (a) Prepare the income statement for the year ended 30 September 2019. Pavita Income Statement for the year ended 30 September 2019 … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … … … … … [12]
Question paper, page 20
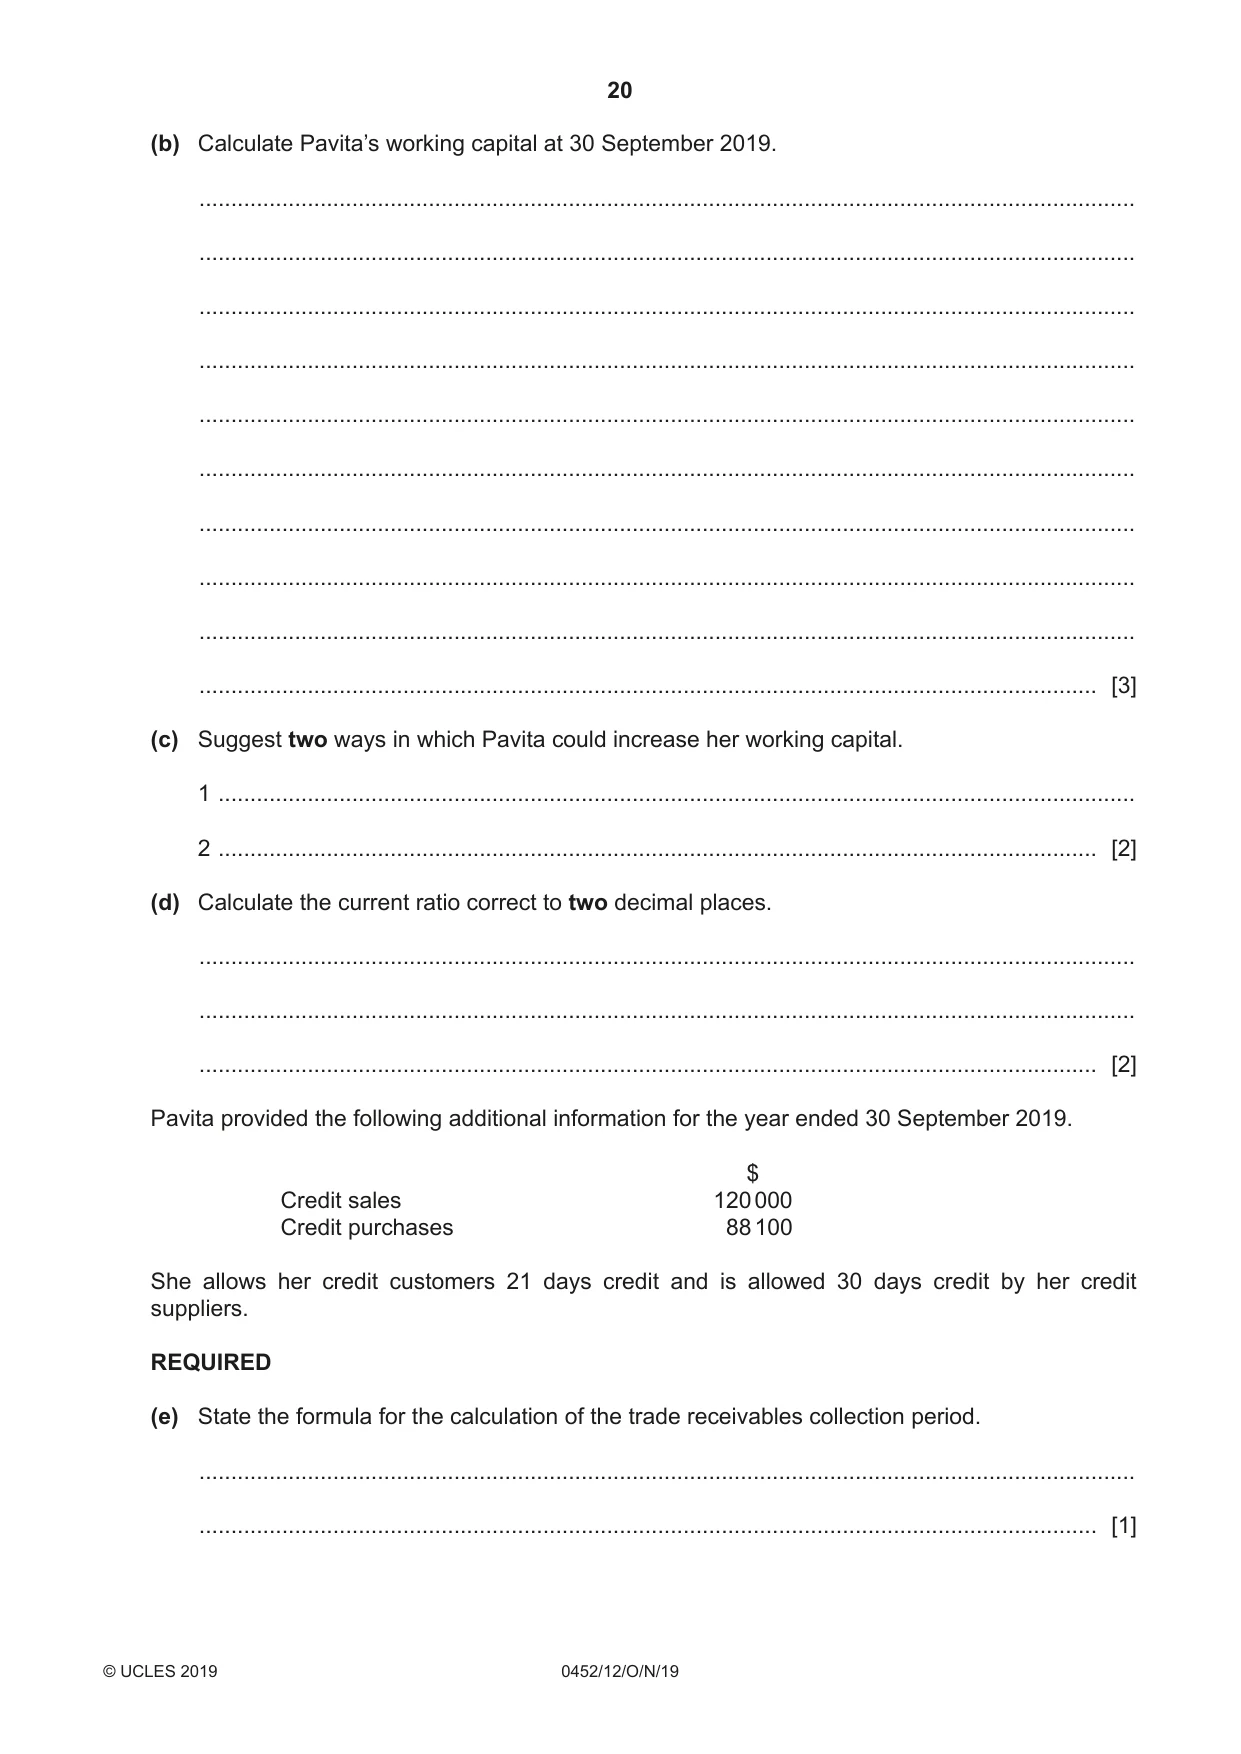
20 0452/12/O/N/19 © UCLES 2019 (b) Calculate Pavita’s working capital at 30 September 2019. … … … … … … … … … … [3] (c) Suggest two ways in which Pavita could increase her working capital. 1 … 2 … [2] (d) Calculate the current ratio correct to two decimal places. … … … [2] Pavita provided the following additional information for the year ended 30 September 2019. $ Credit sales 120 000 Credit purchases 88 100 She allows her credit customers 21 days credit and is allowed 30 days credit by her credit suppliers. REQUIRED (e) State the formula for the calculation of the trade receivables collection period. … … [1]
Question paper, page 21
21 0452/12/O/N/19 © UCLES 2019 (f) Calculate the trade receivables collection period for the year ended 30 September 2019. Round up your answer to the next whole day. … … … … [2] (g) Suggest one way in which Pavita could improve the trade receivables collection period. … … [1] (h) State the formula for the calculation of the trade payables payment period. … … [1] (i) Calculate the trade payables payment period for the year ended 30 September 2019. Round up your answer to the next whole day. … … … … [2] (j) State whether the trade payables would be satisfied with the payment period. Give a reason for your answer. Satisfied? … Reason … … … [2] [Total: 28]
Question paper, page 22
22 0452/12/O/N/19 © UCLES 2019 BLANK PAGE
Question paper, page 23
23 0452/12/O/N/19 © UCLES 2019 BLANK PAGE
Question paper, page 24
24 0452/12/O/N/19 © UCLES 2019 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which itself is a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
This document consists of 17 printed pages. © UCLES 2019 [Turn over Cambridge Assessment International Education Cambridge International General Certificate of Secondary Education ACCOUNTING 0452/12 Paper 1 October/November 2019 MARK SCHEME Maximum Mark: 120 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the October/November 2019 series for most Cambridge IGCSE™, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 2 of 17 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors.
Mark scheme, page 3
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 3 of 17 GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 4
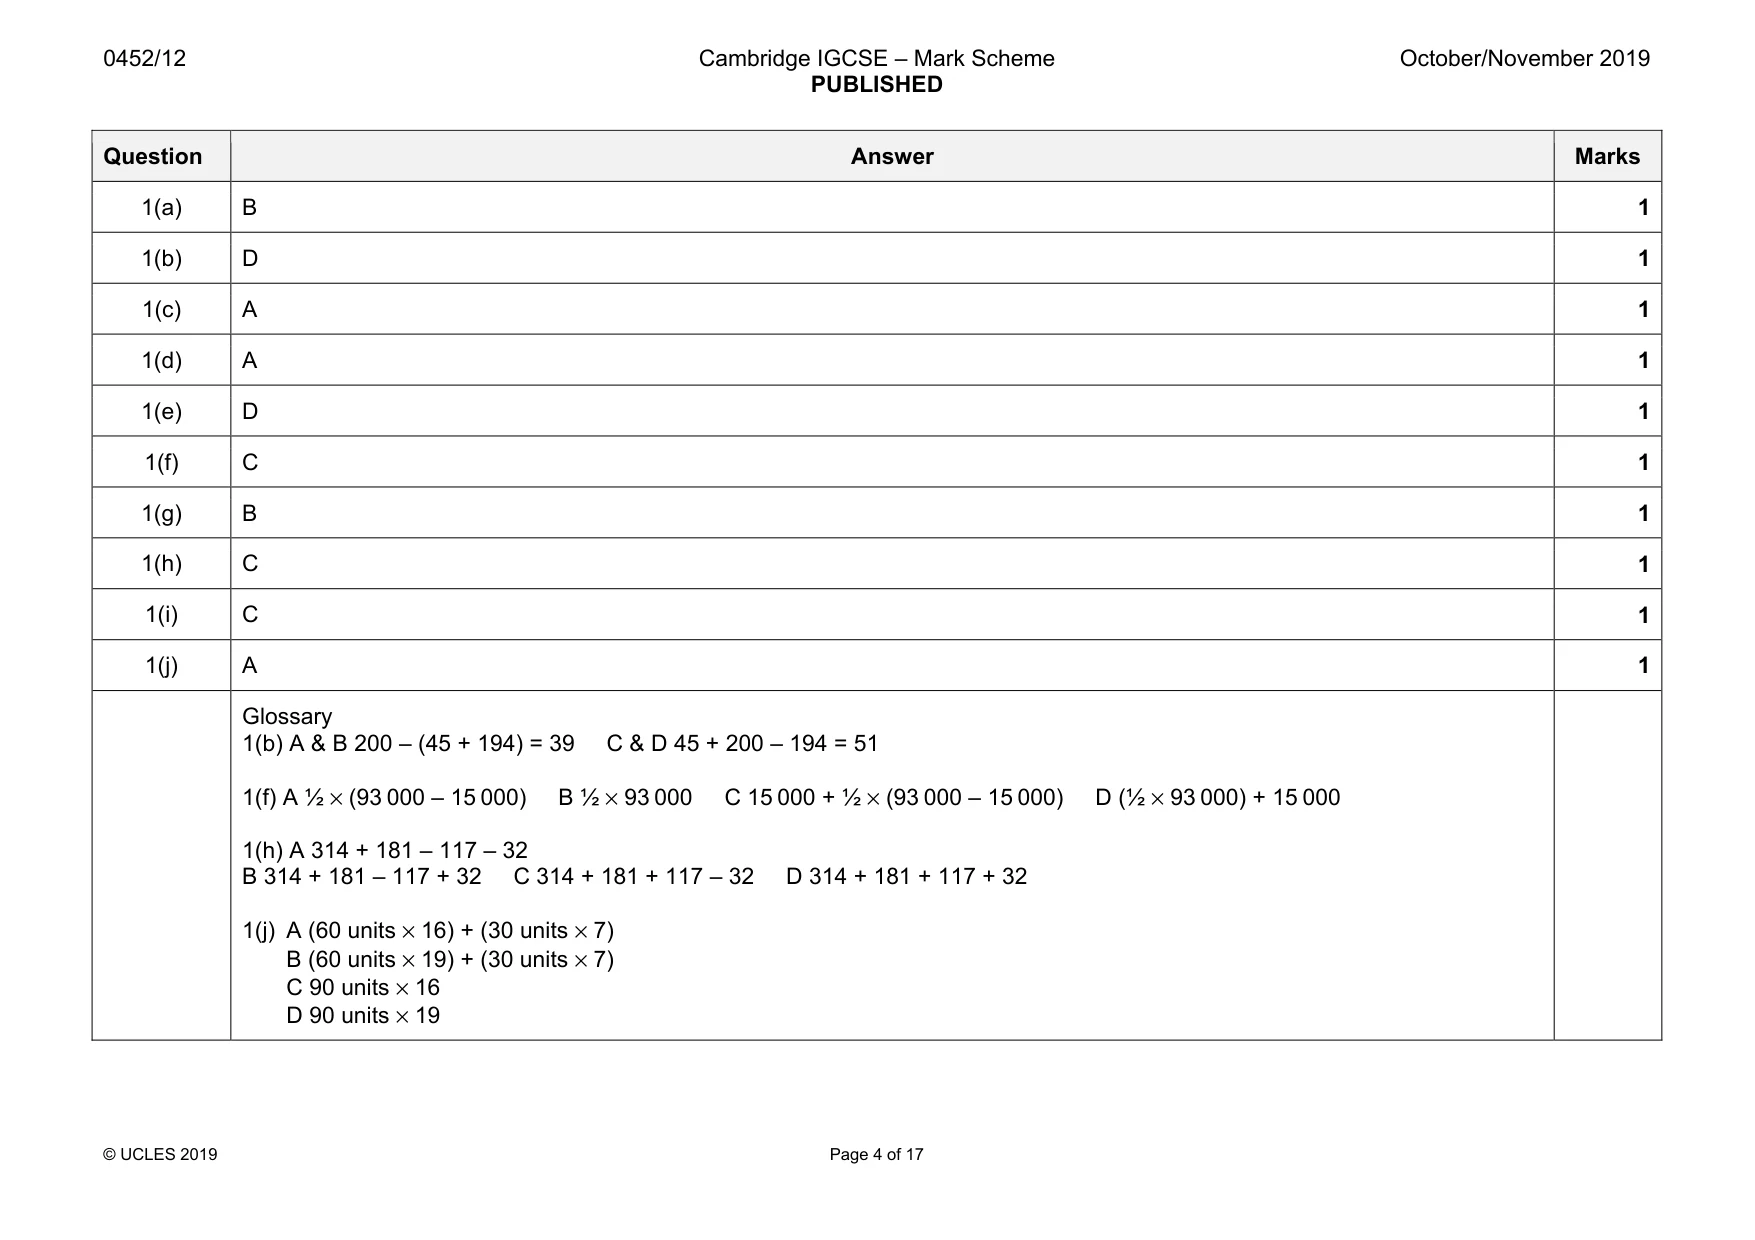
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 4 of 17 Question Answer Marks 1(a) B 1 1(b) D 1 1(c) A 1 1(d) A 1 1(e) D 1 1(f) C 1 1(g) B 1 1(h) C 1 1(i) C 1 1(j) A 1 Glossary 1(b) A & B 200 – (45 + 194) = 39 C & D 45 + 200 – 194 = 51 1(f) A ½ × (93 000 – 15 000) B ½ × 93 000 C 15 000 + ½ × (93 000 – 15 000) D (½ × 93 000) + 15 000 1(h) A 314 + 181 – 117 – 32 B 314 + 181 – 117 + 32 C 314 + 181 + 117 – 32 D 314 + 181 + 117 + 32 1(j) A (60 units × 16) + (30 units × 7) B (60 units × 19) + (30 units × 7) C 90 units × 16 D 90 units × 19
Mark scheme, page 5
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 5 of 17 Question Answer Marks 2(a) Saleh Petty Cash Book Total received $ Date 2019 Details Total paid $ Office expenses $ Travel $ Cleaning $ Ledger accounts $ 150 Aug 1 4 9 14 20 26 30 31 2019 Sept 1 Bank Stationery Omar Flowers Taxi fare Tea and coffee Cleaner Balance c/d Balance b/d (1)OF 21 57 10 9 7 30 21 10 7 9 30 57 134 16 38 9 30 57 150 150 16 Totalling total columns (1) Totalling analysis columns (1) OF Dates (1) 10 2(b)(ii) $134 (1)OF 1
Mark scheme, page 6
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 6 of 17 Question Answer Marks 2(b)(ii) debit credit petty cash (1) cash/bank/cash book (1) 2 2(c) Saleh Office expenses account Date 2019 Aug 31 Details Petty cash (1)OF $ 38 Date Details $ Omar account Date 2019 Aug 31 Details Petty cash (1) $ 57 Date Details $ 2
Mark scheme, page 7
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 7 of 17 Question Answer Marks 2(d) Saleh Cash Book (bank columns only) Date 2019 Sept 1 Details Laila (1) Balance c/d $ 190 806 ___ 996 Date 2019 Sept 1 2019 Sept 1 Details Balance b/d Bank charges (1) Insurance (1) Balance b/d (1)OF $ 944 22 30 996 806 4
Mark scheme, page 8
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 8 of 17 Question Answer Marks 2(e) Saleh Bank Reconciliation Statement at 31 August 2019 Balance in cash book Cheques not yet presented (1) (Kalifa 114 + Fatima 175) Amounts not yet credited (1) Balance on bank statement $ (806) (1)OF 289 (1) (517) (363) (1) (880) (1)OF Alternative presentation Saleh Bank Reconciliation Statement at 31 August 2019 Balance on bank statement Amounts not yet credited (1) Cheques not yet presented (1) (Kalifa 114 + Fatima 175) Balance in cash book $ (880) (1)OF 363 (1) (517) (289) (1) (806) (1)OF 6
Mark scheme, page 9
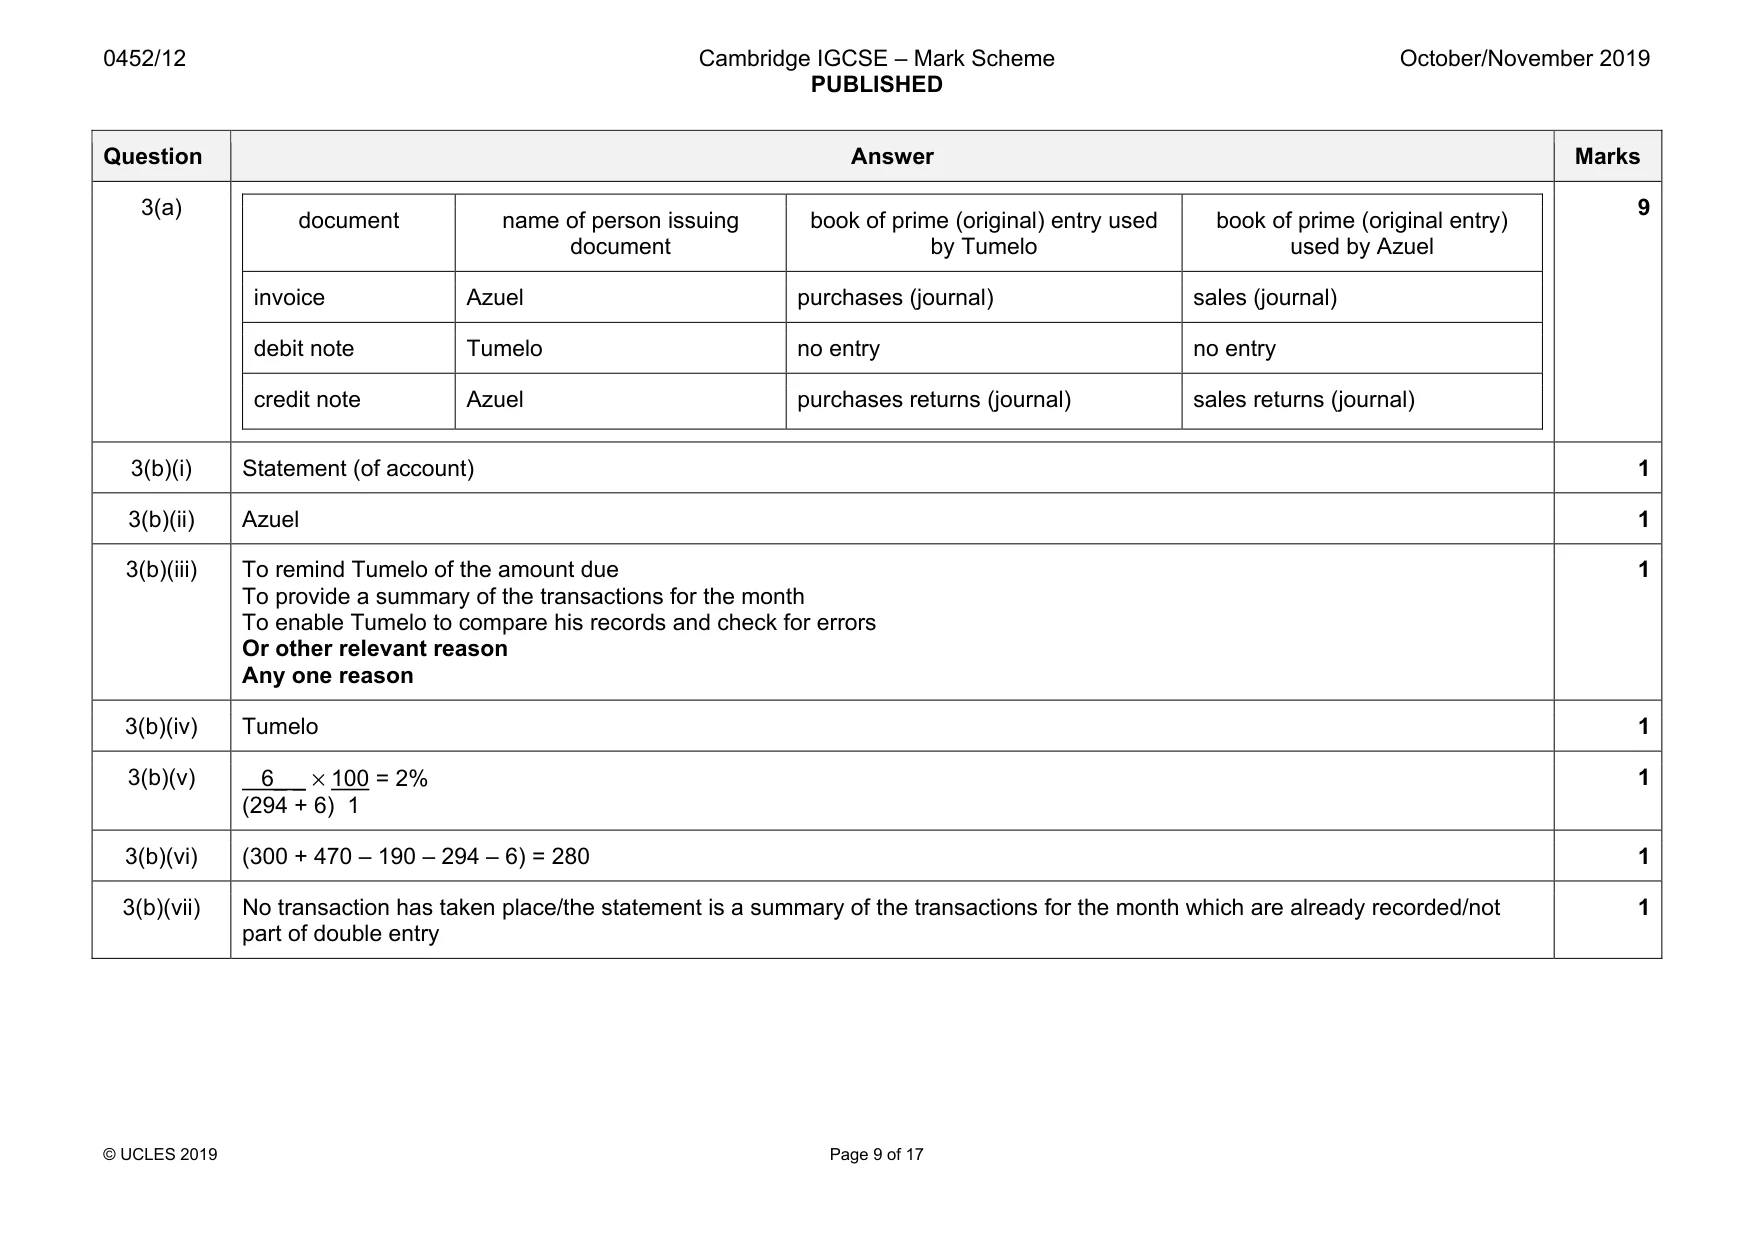
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 9 of 17 Question Answer Marks 3(a) document name of person issuing document book of prime (original) entry used by Tumelo book of prime (original entry) used by Azuel invoice Azuel purchases (journal) sales (journal) debit note Tumelo no entry no entry credit note Azuel purchases returns (journal) sales returns (journal) 9 3(b)(i) Statement (of account) 1 3(b)(ii) Azuel 1 3(b)(iii) To remind Tumelo of the amount due To provide a summary of the transactions for the month To enable Tumelo to compare his records and check for errors Or other relevant reason Any one reason 1 3(b)(iv) Tumelo 1 3(b)(v) 6_ _ × 100 = 2% (294 + 6) 1 1 3(b)(vi) (300 + 470 – 190 – 294 – 6) = 280 1 3(b)(vii) No transaction has taken place/the statement is a summary of the transactions for the month which are already recorded/not part of double entry 1
Mark scheme, page 10
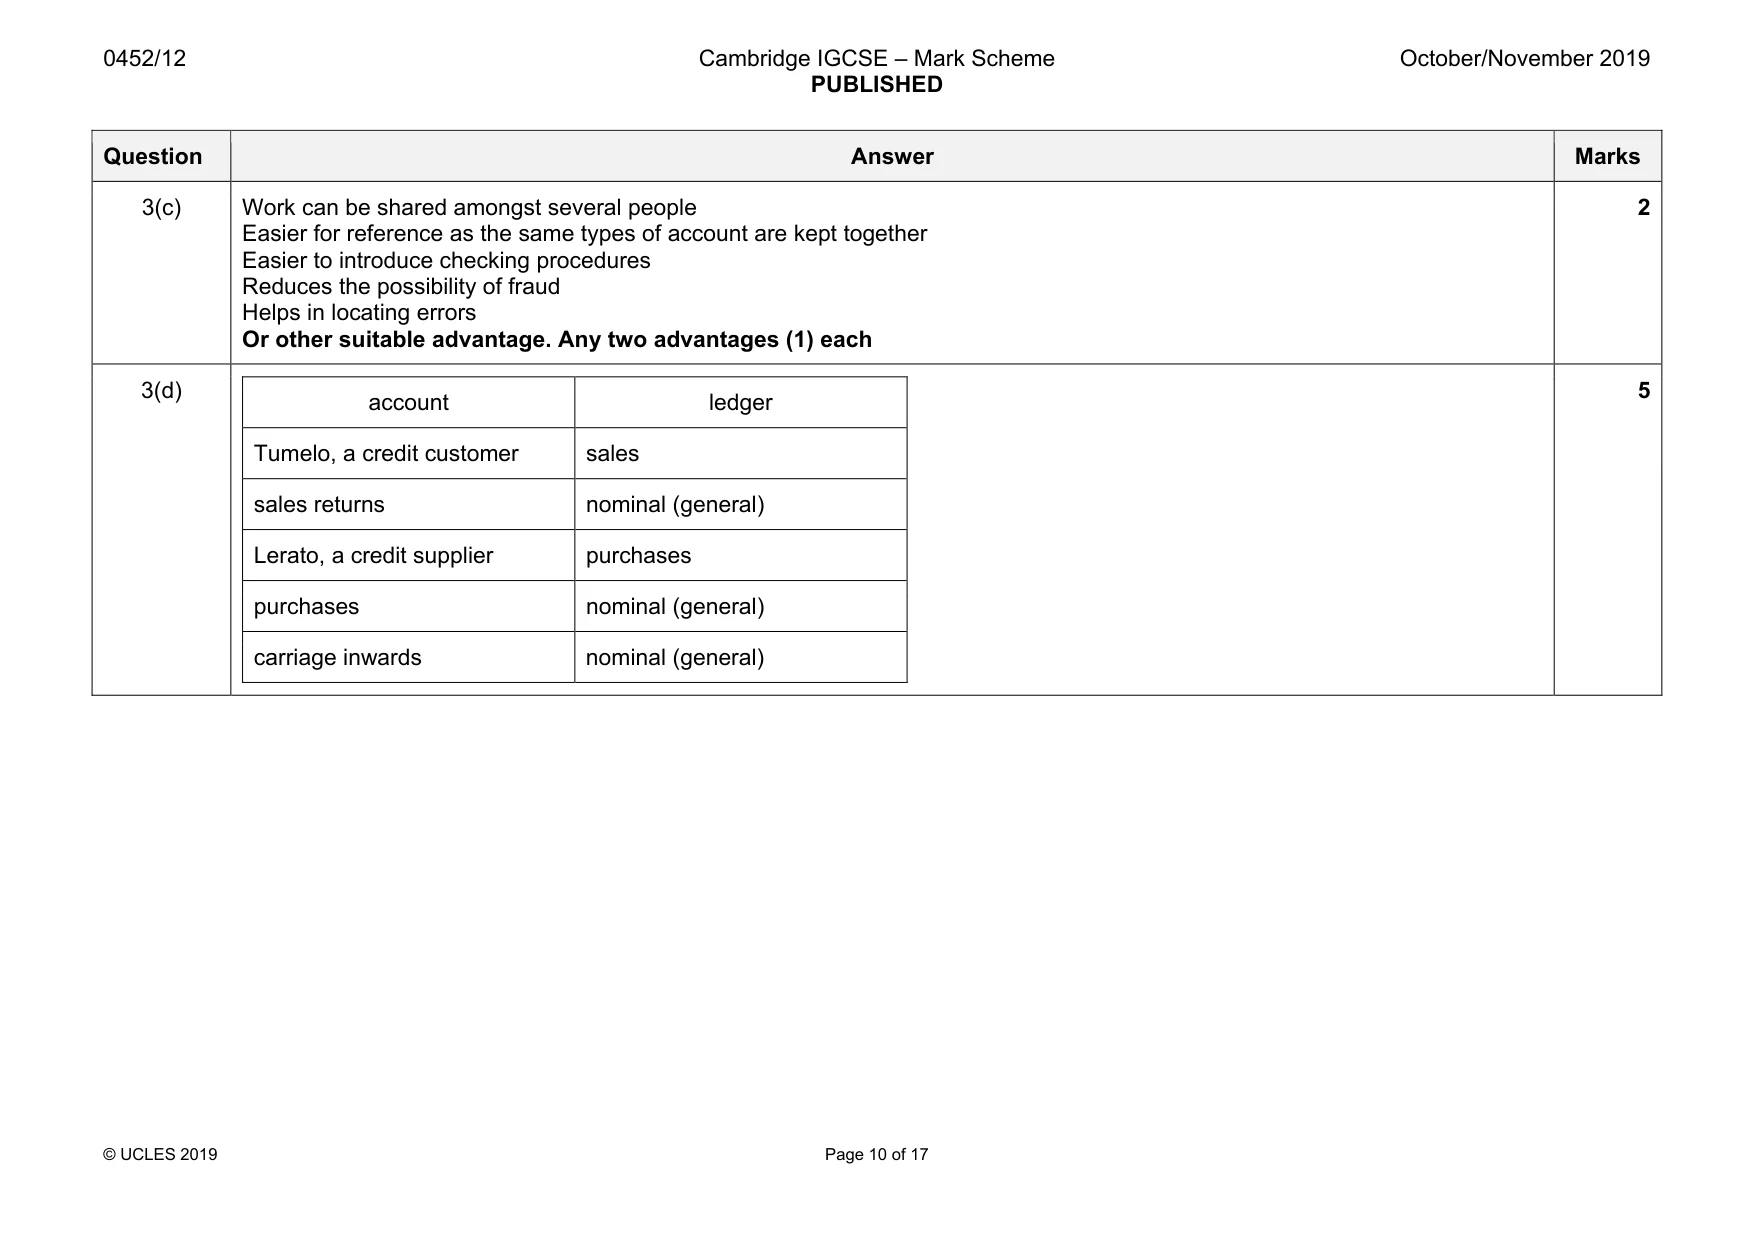
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 10 of 17 Question Answer Marks 3(c) Work can be shared amongst several people Easier for reference as the same types of account are kept together Easier to introduce checking procedures Reduces the possibility of fraud Helps in locating errors Or other suitable advantage. Any two advantages (1) each 2 3(d) account ledger Tumelo, a credit customer sales sales returns nominal (general) Lerato, a credit supplier purchases purchases nominal (general) carriage inwards nominal (general) 5
Mark scheme, page 11
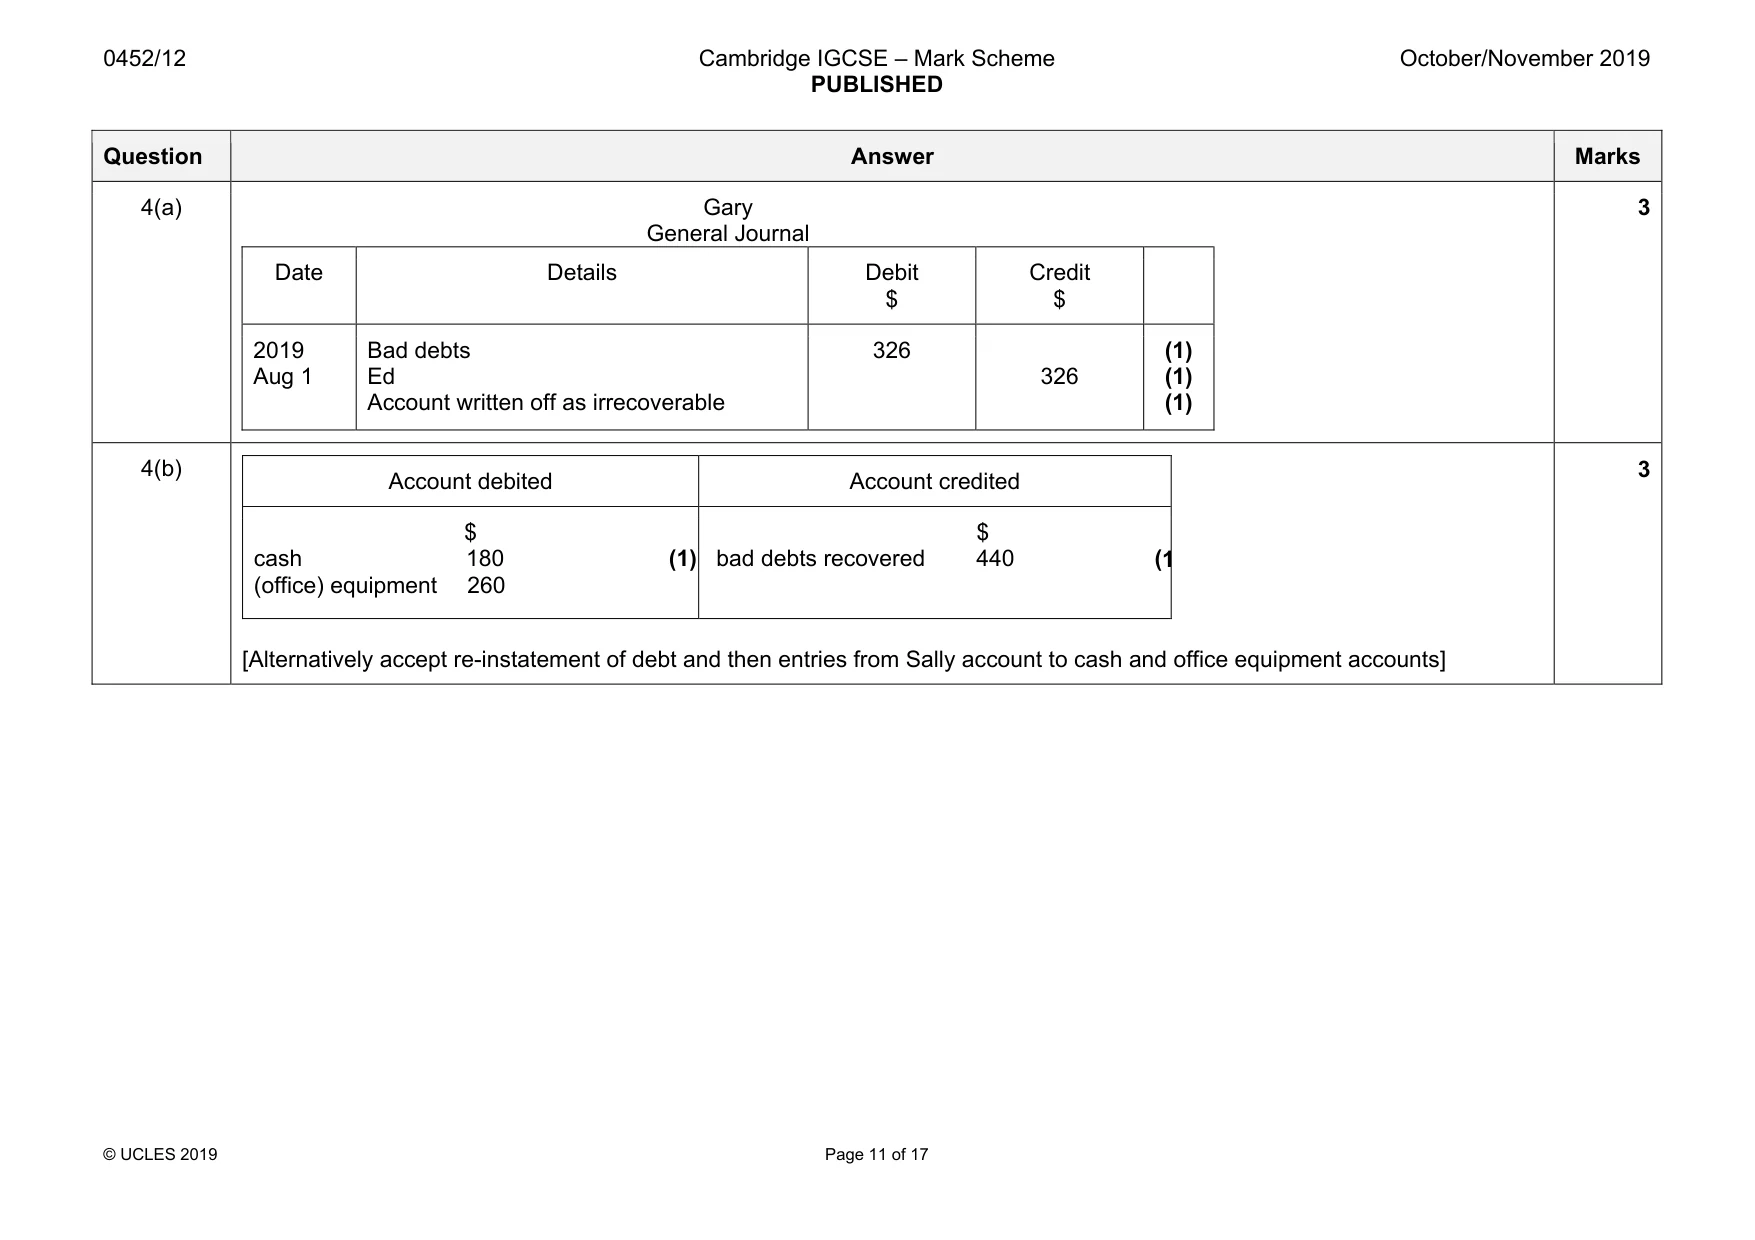
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 11 of 17 Question Answer Marks 4(a) Gary General Journal Date Details Debit $ Credit $ 2019 Aug 1 Bad debts Ed Account written off as irrecoverable 326 326 (1) (1) (1) 3 4(b) Account debited Account credited $ cash 180 (1) (office) equipment 260 $ bad debts recovered 440 (1 [Alternatively accept re-instatement of debt and then entries from Sally account to cash and office equipment accounts] 3
Mark scheme, page 12
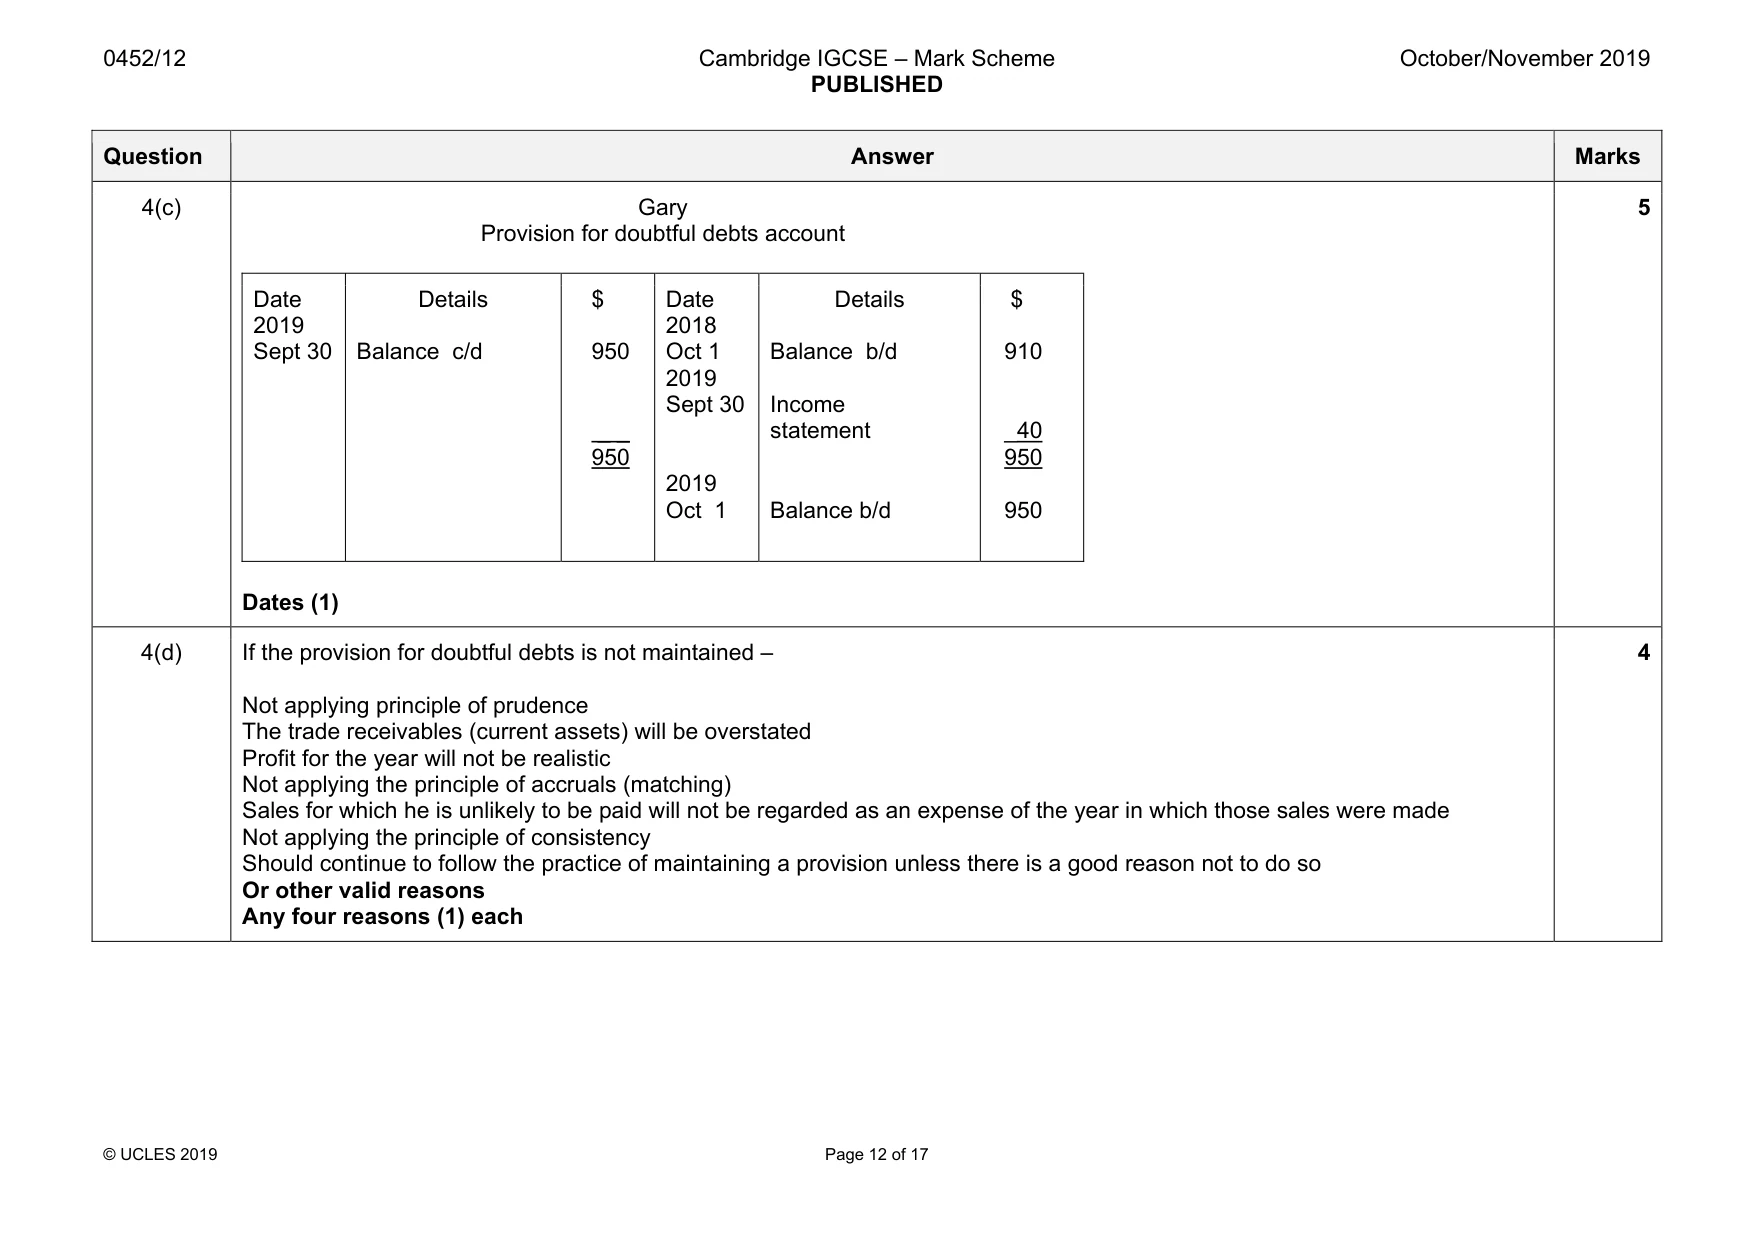
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 12 of 17 Question Answer Marks 4(c) Gary Provision for doubtful debts account Date 2019 Sept 30 Details Balance c/d $ 950 _ _ 950 Date 2018 Oct 1 2019 Sept 30 2019 Oct 1 Details Balance b/d Income statement Balance b/d $ 910 _40 950 950 Dates (1) 5 4(d) If the provision for doubtful debts is not maintained – Not applying principle of prudence The trade receivables (current assets) will be overstated Profit for the year will not be realistic Not applying the principle of accruals (matching) Sales for which he is unlikely to be paid will not be regarded as an expense of the year in which those sales were made Not applying the principle of consistency Should continue to follow the practice of maintaining a provision unless there is a good reason not to do so Or other valid reasons Any four reasons (1) each 4
Mark scheme, page 13
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 13 of 17 Question Answer Marks 4(e) item omitted effect on profit for the year ended 30 September 2019 effect on current assets at 30 September 2019 $ $ bad debts overstated 326 overstated 326 bad debt recovered understated 440 (1) understated 180 (1) adjustment to provision for doubtful debts overstated 40 (1) OF overstated 40 (1) OF 4
Mark scheme, page 14
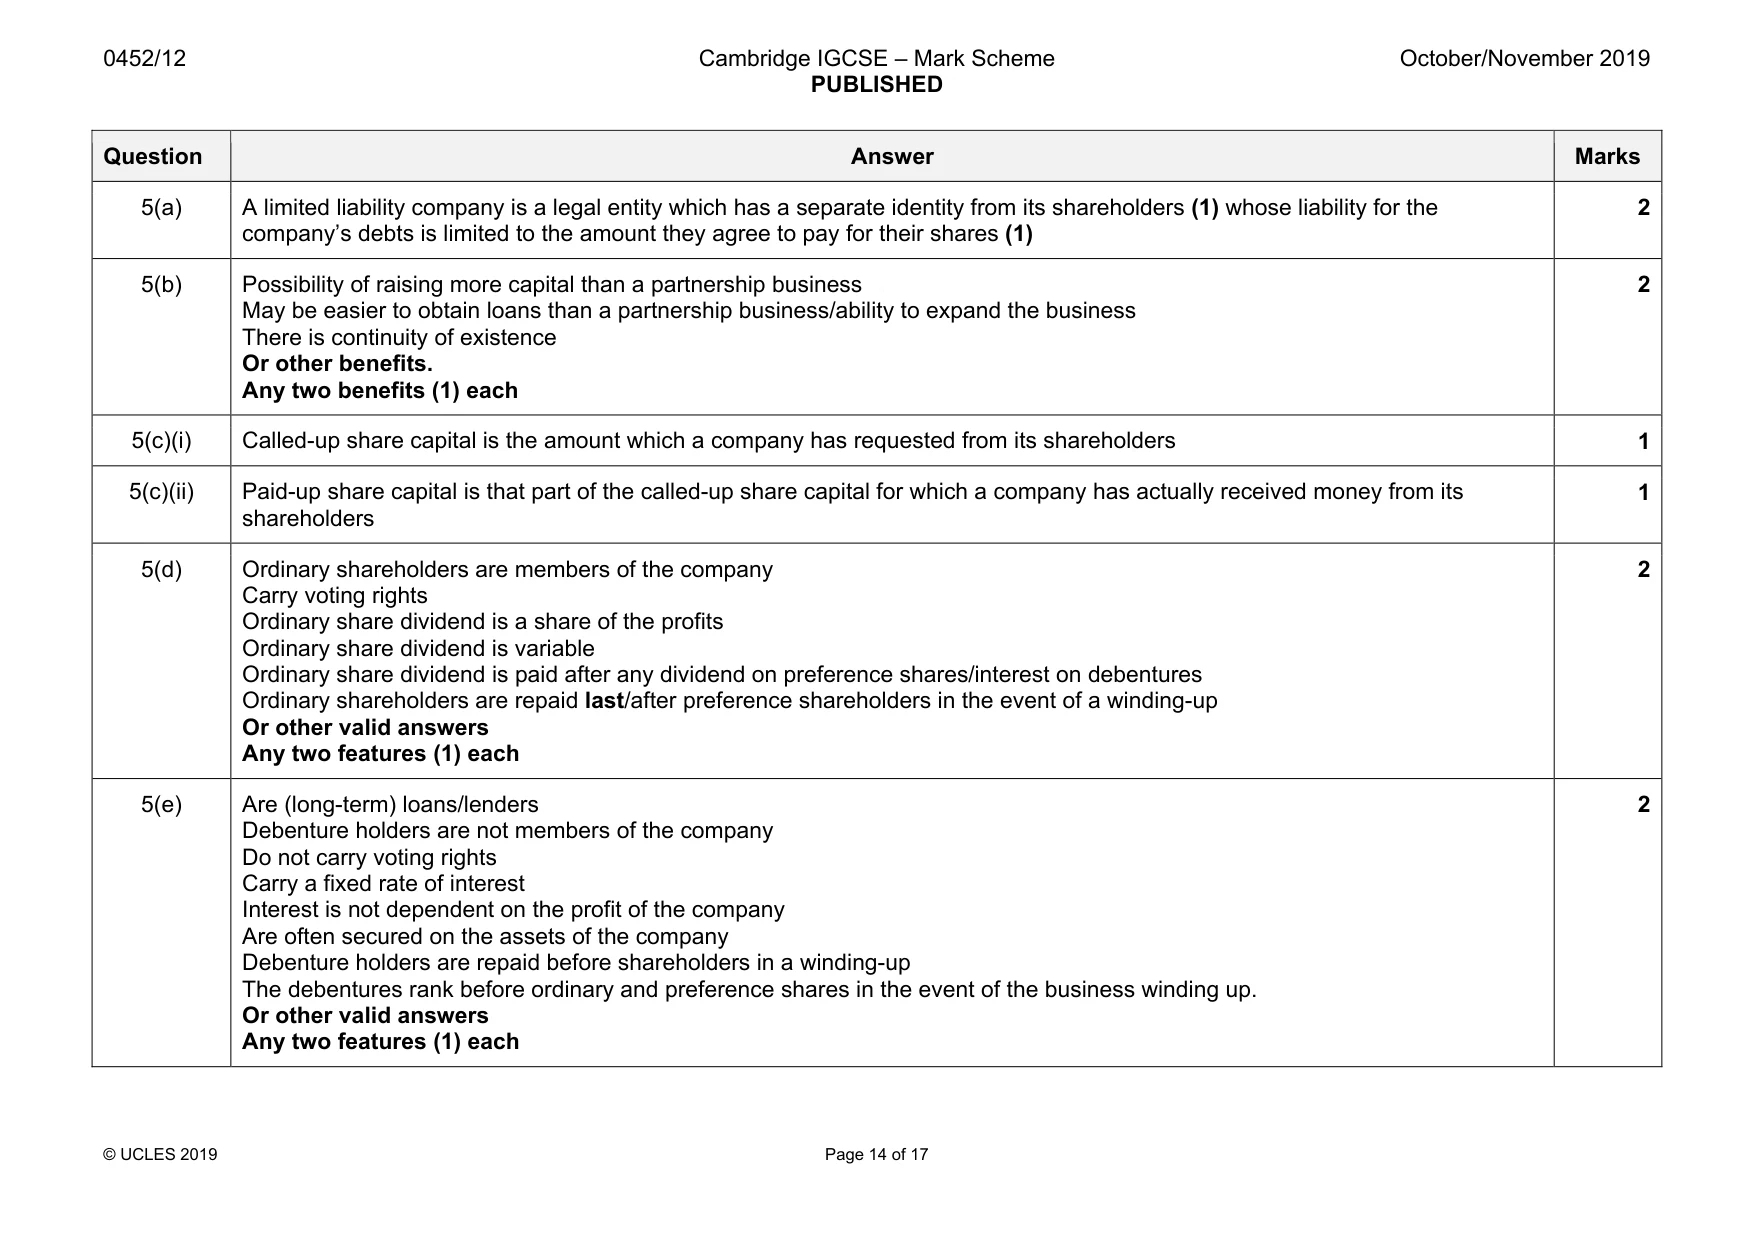
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 14 of 17 Question Answer Marks 5(a) A limited liability company is a legal entity which has a separate identity from its shareholders (1) whose liability for the company’s debts is limited to the amount they agree to pay for their shares (1) 2 5(b) Possibility of raising more capital than a partnership business May be easier to obtain loans than a partnership business/ability to expand the business There is continuity of existence Or other benefits. Any two benefits (1) each 2 5(c)(i) Called-up share capital is the amount which a company has requested from its shareholders 1 5(c)(ii) Paid-up share capital is that part of the called-up share capital for which a company has actually received money from its shareholders 1 5(d) Ordinary shareholders are members of the company Carry voting rights Ordinary share dividend is a share of the profits Ordinary share dividend is variable Ordinary share dividend is paid after any dividend on preference shares/interest on debentures Ordinary shareholders are repaid last/after preference shareholders in the event of a winding-up Or other valid answers Any two features (1) each 2 5(e) Are (long-term) loans/lenders Debenture holders are not members of the company Do not carry voting rights Carry a fixed rate of interest Interest is not dependent on the profit of the company Are often secured on the assets of the company Debenture holders are repaid before shareholders in a winding-up The debentures rank before ordinary and preference shares in the event of the business winding up. Or other valid answers Any two features (1) each 2
Mark scheme, page 15
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 15 of 17 Question Answer Marks 5(f) income statement statement of changes in equity no entry issue of 5% debentures during the year 9(1) debenture interest relating to the current year paid during the year 9(1) final ordinary share dividend relating to the previous financial year paid during the current year 9(1) interim ordinary share dividend paid for the current year 9(1) proposed ordinary share dividend for the current year 9(1) 5
Mark scheme, page 16
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 16 of 17 Question Answer Marks 6(a) Pavita Income Statement for the year ended 30 September 2019 Gross profit Discount received Wages (27 120 (1) + 980 (1) – 1000) (1) Rates and insurance (1700 (1) – 180) (1) Operating expenses Motor expenses Bad debts Depreciation Fixtures and fittings (20% × 12 000) Motor vehicle (20% × (14 400 – 6300)) Profit for the year $ 27 100 1520 3195}(1) 1155} 190 (1) 2400 (1) 2025 (1) $ 40 780 (1) 970 (1) 41 750 37 585 4165 (1)OF 12 6(b) current assets inventory 8870 trade receivables (8940 – 190) 8750 other receivables 180 17 800 (1) current liabilities trade payables 10 280 other payables 980 bank overdraft 1230 12 490 (1) working capital 5310 (1)OF 3
Mark scheme, page 17
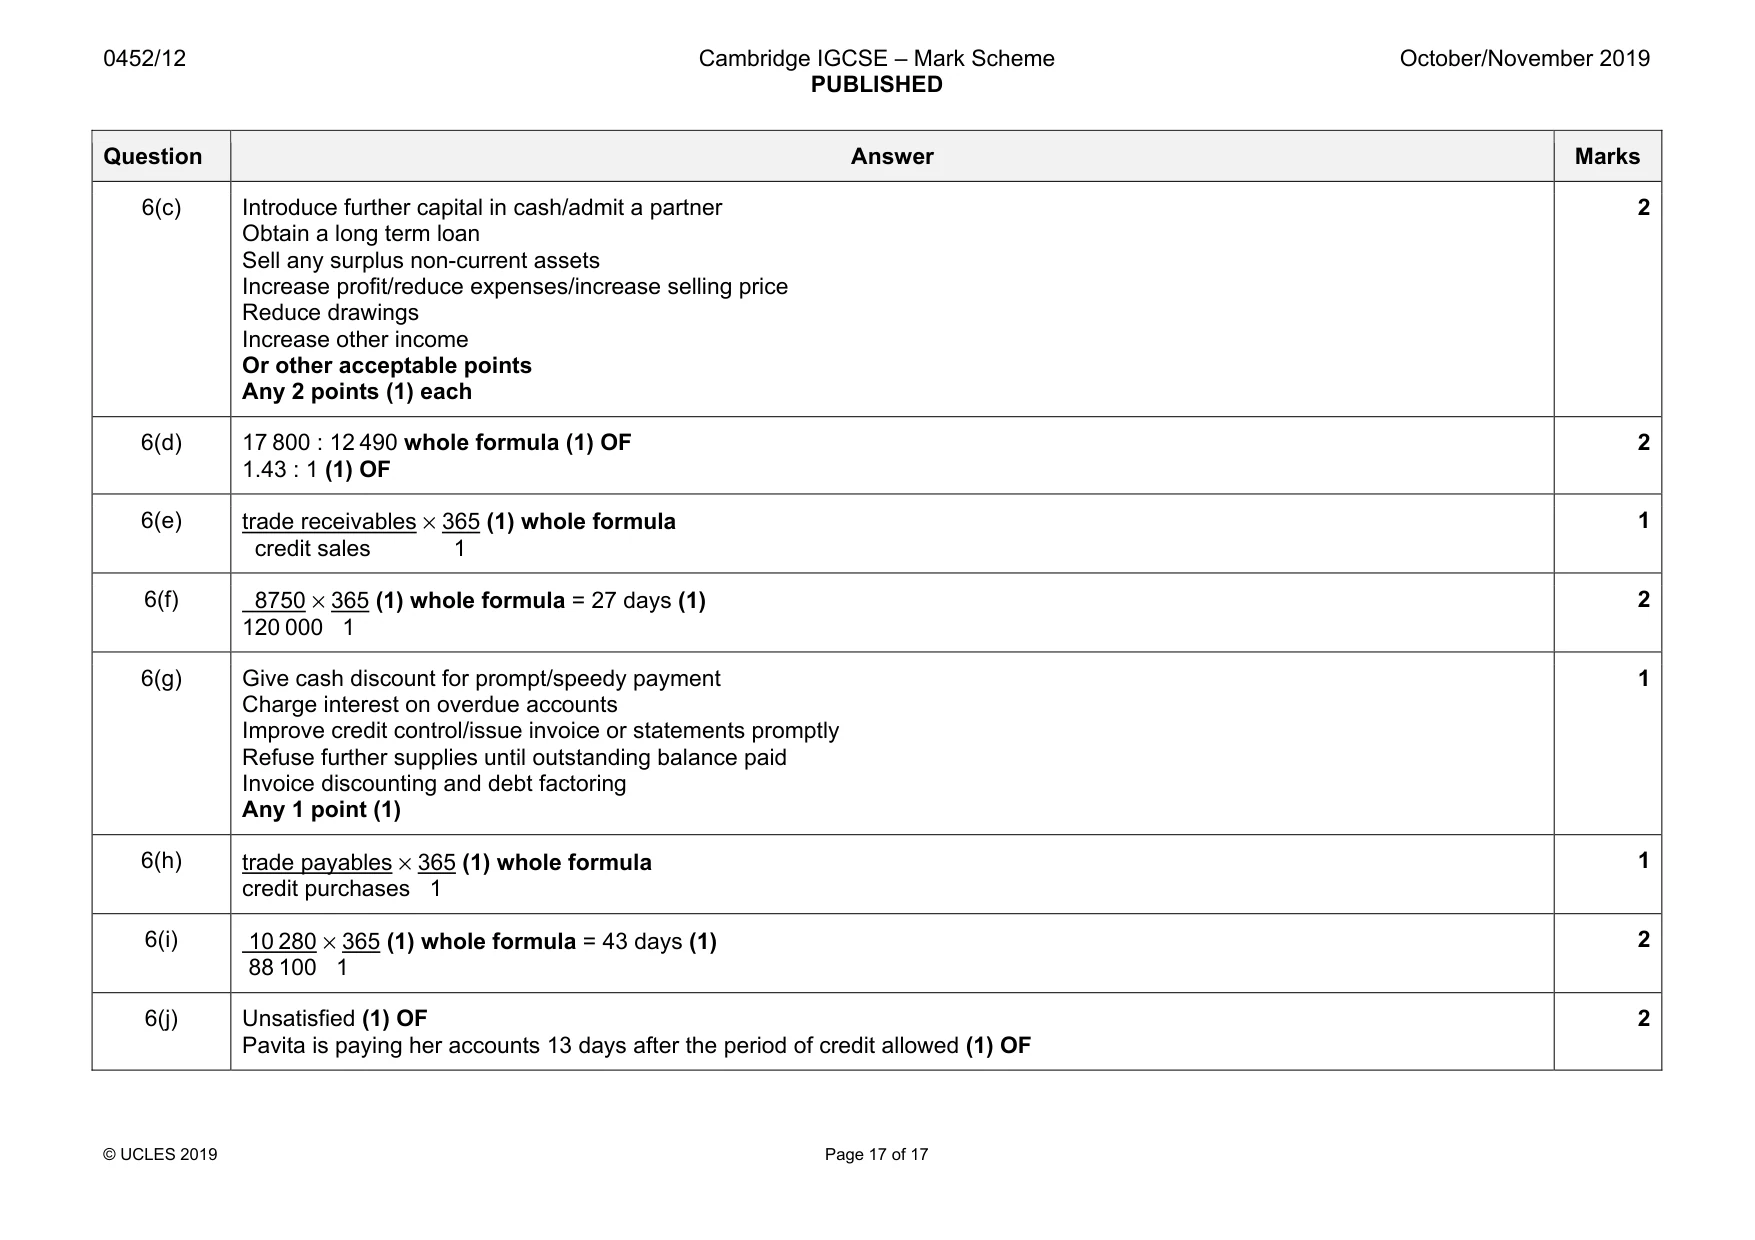
0452/12 Cambridge IGCSE – Mark Scheme PUBLISHED October/November 2019 © UCLES 2019 Page 17 of 17 Question Answer Marks 6(c) Introduce further capital in cash/admit a partner Obtain a long term loan Sell any surplus non-current assets Increase profit/reduce expenses/increase selling price Reduce drawings Increase other income Or other acceptable points Any 2 points (1) each 2 6(d) 17 800 : 12 490 whole formula (1) OF 1.43 : 1 (1) OF 2 6(e) trade receivables × 365 (1) whole formula credit sales 1 1 6(f) 8750 × 365 (1) whole formula = 27 days (1) 120 000 1 2 6(g) Give cash discount for prompt/speedy payment Charge interest on overdue accounts Improve credit control/issue invoice or statements promptly Refuse further supplies until outstanding balance paid Invoice discounting and debt factoring Any 1 point (1) 1 6(h) trade payables × 365 (1) whole formula credit purchases 1 1 6(i) 10 280 × 365 (1) whole formula = 43 days (1) 88 100 1 2 6(j) Unsatisfied (1) OF Pavita is paying her accounts 13 days after the period of credit allowed (1) OF 2
What you needed in this session
Cambridge’s own grade thresholds for 2019 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.