Cambridge IGCSE Accounting 0452 — 2019 May/June Paper 1 · Variant 3
0452/13/M/J/19 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 22 printed pages and 2 blank pages. DC (MM) 181611 © UCLES 2019 [Turn over * 6 6 9 7 8 8 3 5 6 9 * ACCOUNTING 0452/13 Paper 1 May/June 2019 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use an HB pencil for any diagrams or graphs. Do not use staples, paper clips, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. Cambridge Assessment International Education Cambridge International General Certificate of Secondary Education
Question paper, page 2
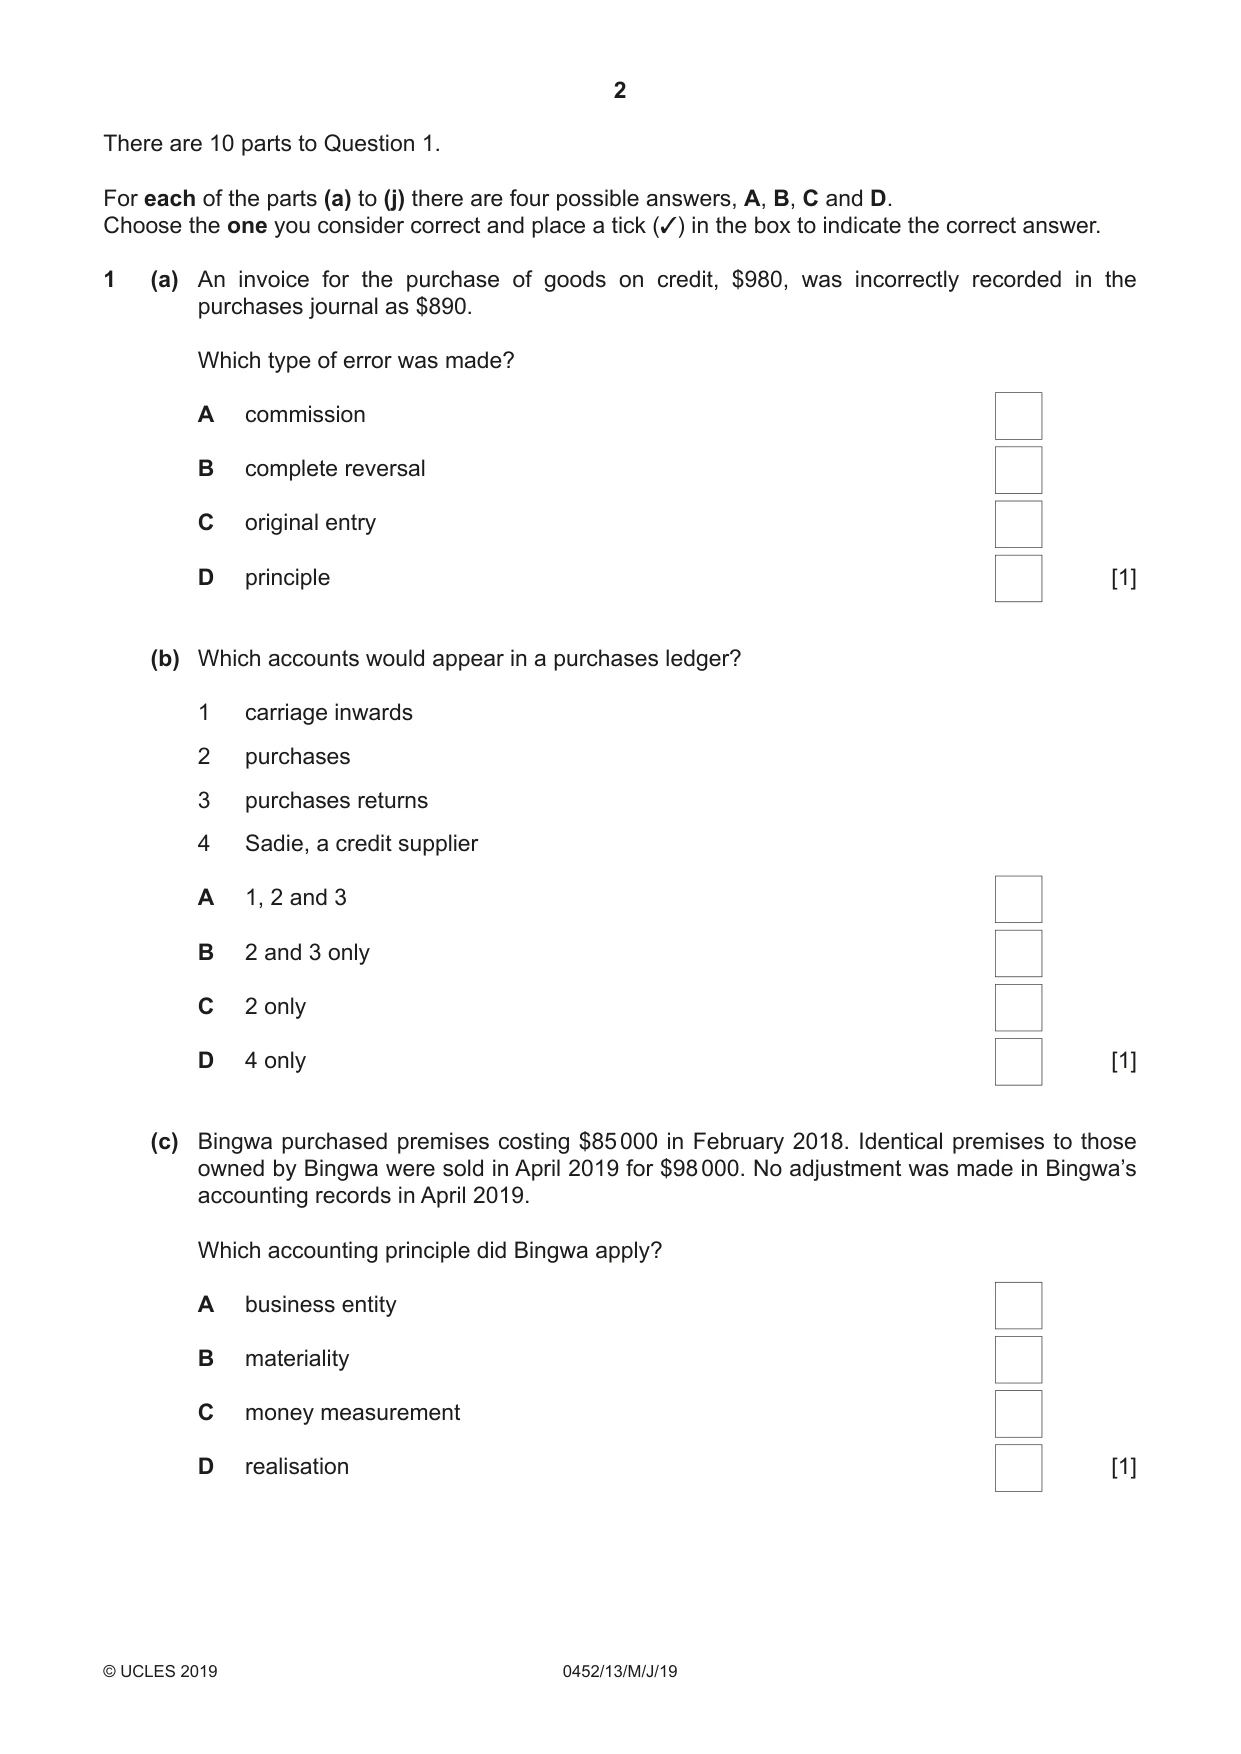
2 0452/13/M/J/19 © UCLES 2019 There are 10 parts to Question 1. For each of the parts (a) to (j) there are four possible answers, A, B, C and D. Choose the one you consider correct and place a tick (3) in the box to indicate the correct answer. 1 (a) An invoice for the purchase of goods on credit, $980, was incorrectly recorded in the purchases journal as $890. Which type of error was made? A commission B complete reversal C original entry D principle [1] (b) Which accounts would appear in a purchases ledger? 1 carriage inwards 2 purchases 3 purchases returns 4 Sadie, a credit supplier A 1, 2 and 3 B 2 and 3 only C 2 only D 4 only [1] (c) Bingwa purchased premises costing $85 000 in February 2018. Identical premises to those owned by Bingwa were sold in April 2019 for $98 000. No adjustment was made in Bingwa’s accounting records in April 2019. Which accounting principle did Bingwa apply? A business entity B materiality C money measurement D realisation [1]
Question paper, page 3
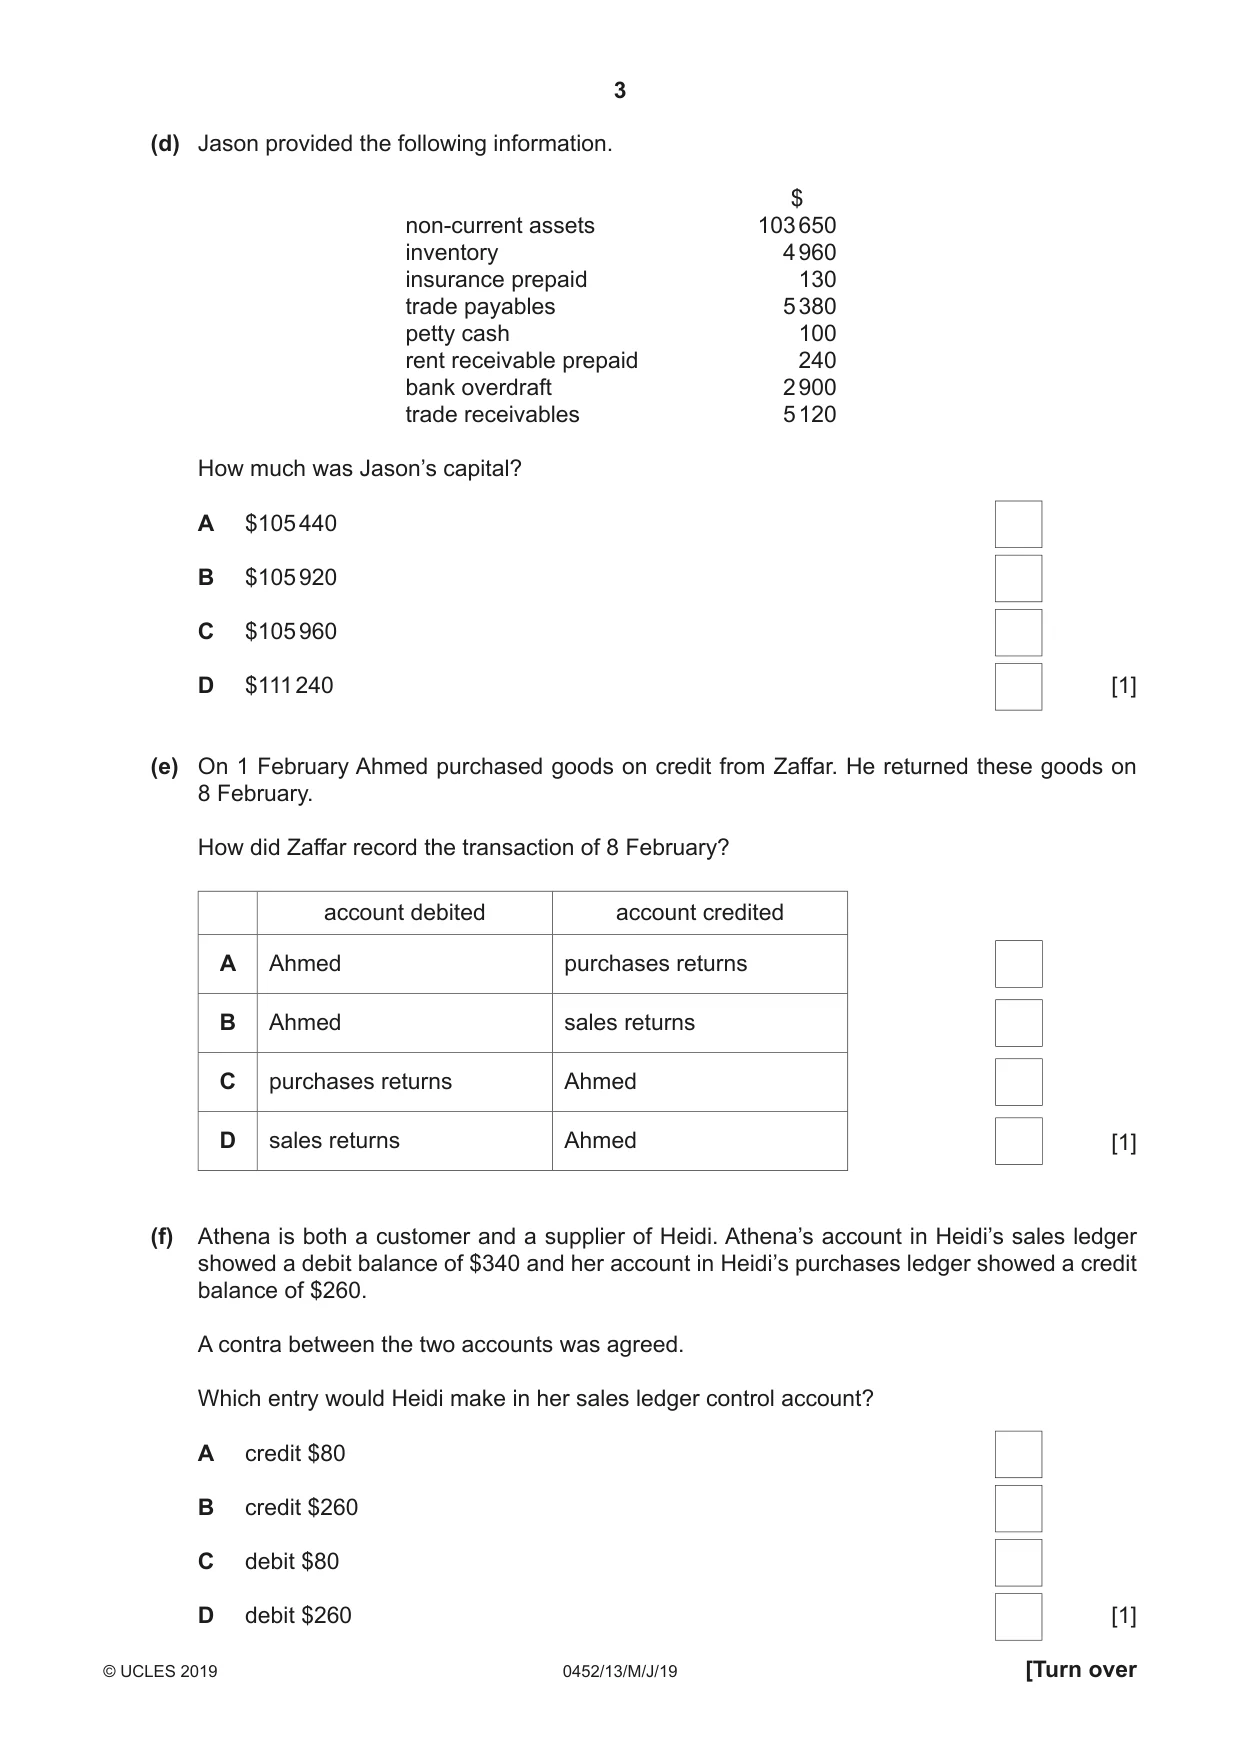
3 0452/13/M/J/19 © UCLES 2019 [Turn over (d) Jason provided the following information. $ non-current assets 103 650 inventory 4 960 insurance prepaid 130 trade payables 5 380 petty cash 100 rent receivable prepaid 240 bank overdraft 2 900 trade receivables 5 120 How much was Jason’s capital? A $105 440 B $105 920 C $105 960 D $111 240 [1] (e) On 1 February Ahmed purchased goods on credit from Zaffar. He returned these goods on 8 February. How did Zaffar record the transaction of 8 February? account debited account credited A Ahmed purchases returns B Ahmed sales returns C purchases returns Ahmed D sales returns Ahmed [1] (f) Athena is both a customer and a supplier of Heidi. Athena’s account in Heidi’s sales ledger showed a debit balance of $340 and her account in Heidi’s purchases ledger showed a credit balance of $260. A contra between the two accounts was agreed. Which entry would Heidi make in her sales ledger control account? A credit $80 B credit $260 C debit $80 D debit $260 [1]
Question paper, page 4
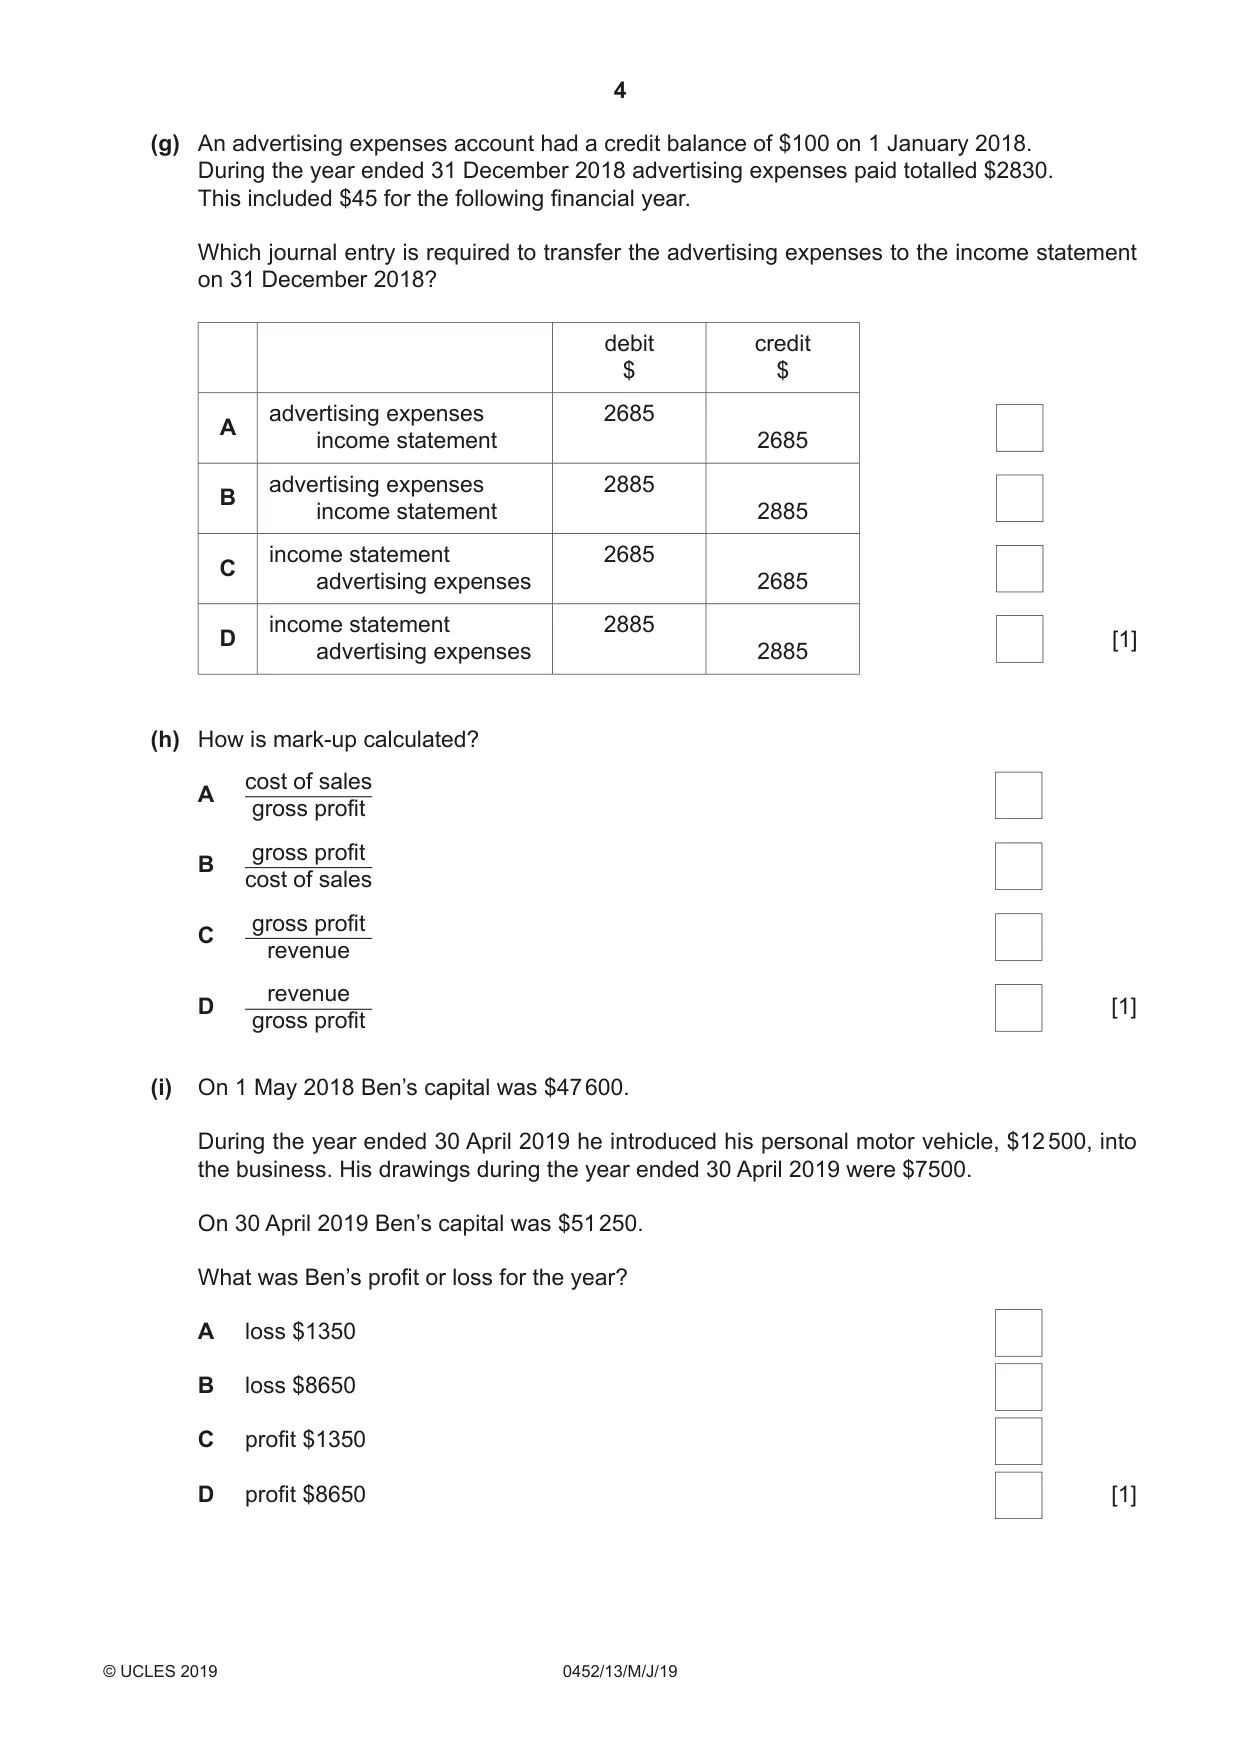
4 0452/13/M/J/19 © UCLES 2019 (g) An advertising expenses account had a credit balance of $100 on 1 January 2018. During the year ended 31 December 2018 advertising expenses paid totalled $2830. This included $45 for the following financial year. Which journal entry is required to transfer the advertising expenses to the income statement on 31 December 2018? debit $ credit $ A advertising expenses income statement 2685 2685 B advertising expenses income statement 2885 2885 C income statement advertising expenses 2685 2685 D income statement advertising expenses 2885 2885 [1] (h) How is mark-up calculated? A cost of sales gross profit B gross profit cost of sales C gross profit revenue D revenue gross profit [1] (i) On 1 May 2018 Ben’s capital was $47 600. During the year ended 30 April 2019 he introduced his personal motor vehicle, $12 500, into the business. His drawings during the year ended 30 April 2019 were $7500. On 30 April 2019 Ben’s capital was $51 250. What was Ben’s profit or loss for the year? A loss $1350 B loss $8650 C profit $1350 D profit $8650 [1]
Question paper, page 5
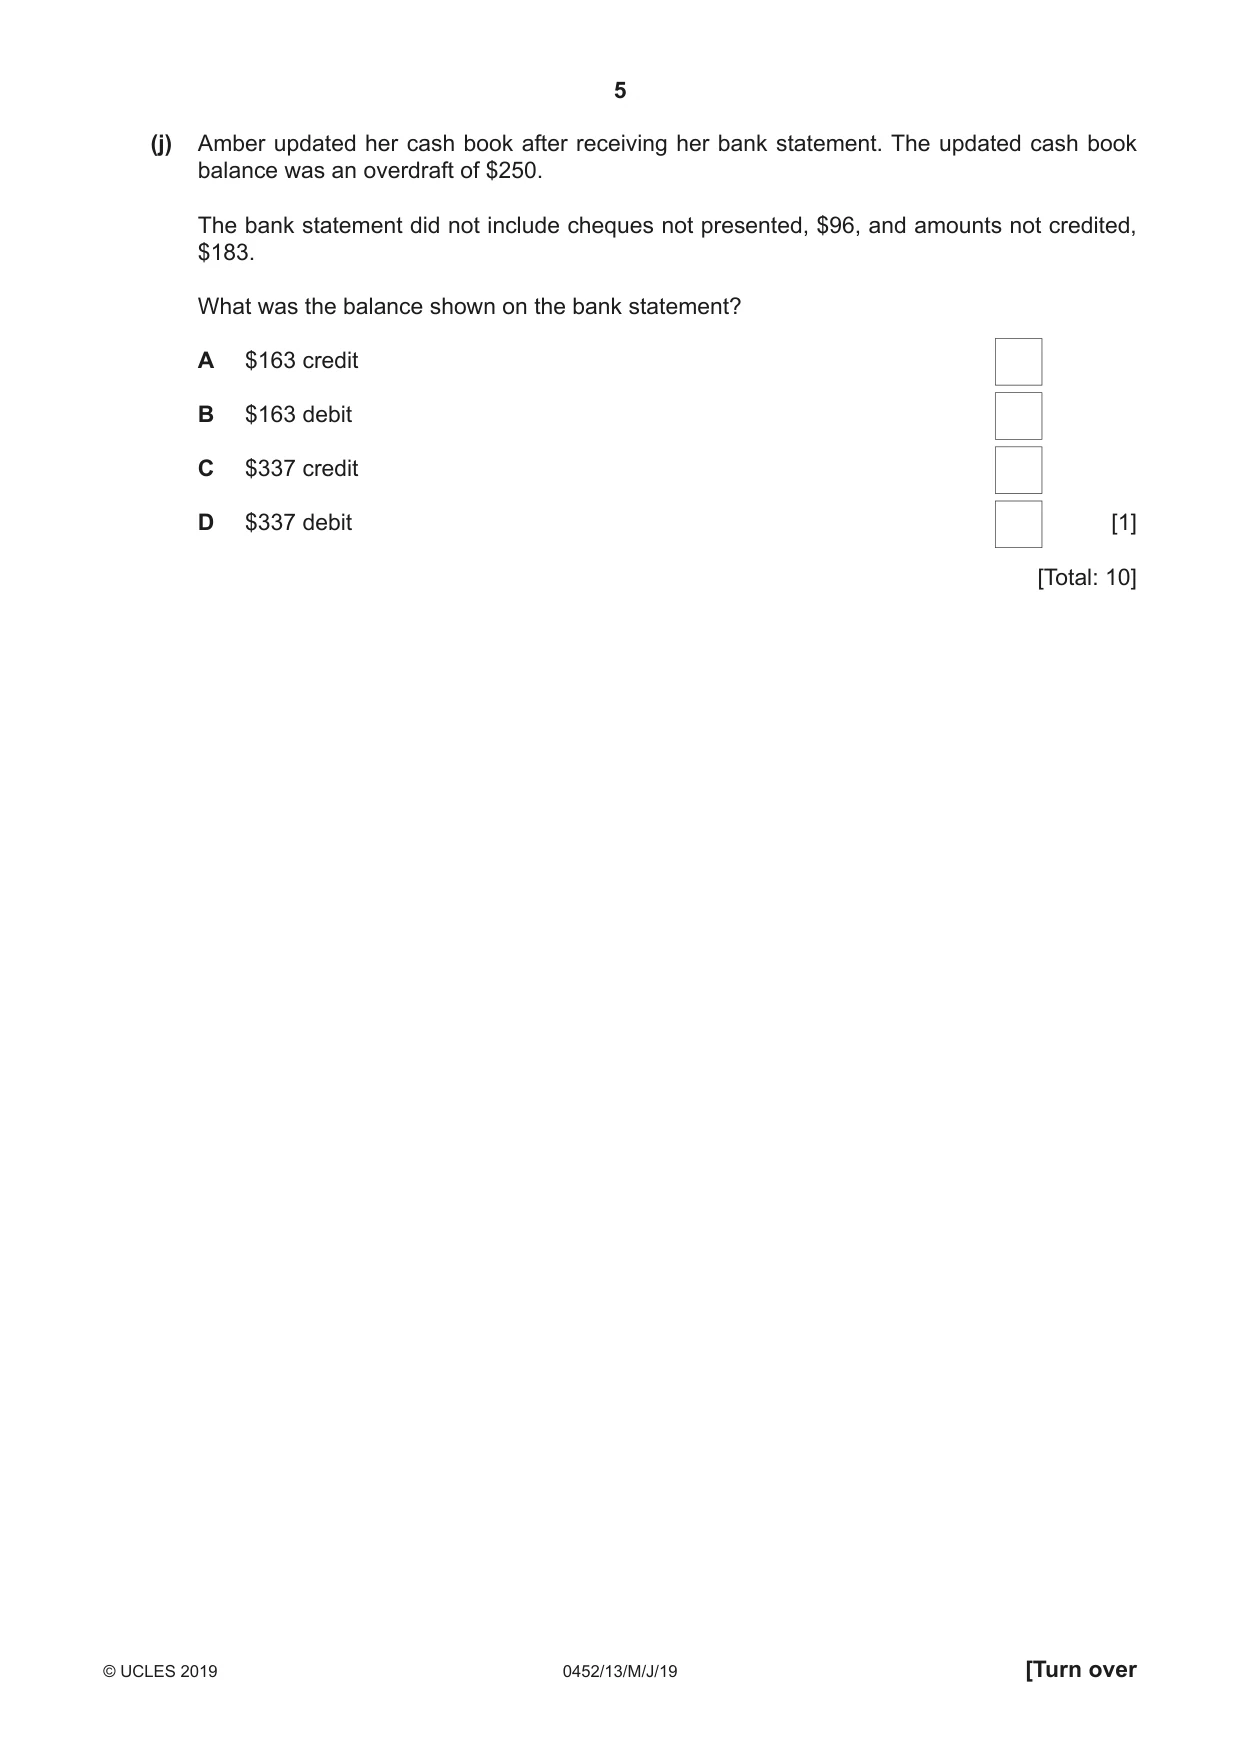
5 0452/13/M/J/19 © UCLES 2019 [Turn over (j) Amber updated her cash book after receiving her bank statement. The updated cash book balance was an overdraft of $250. The bank statement did not include cheques not presented, $96, and amounts not credited, $183. What was the balance shown on the bank statement? A $163 credit B $163 debit C $337 credit D $337 debit [1] [Total: 10]
Question paper, page 6
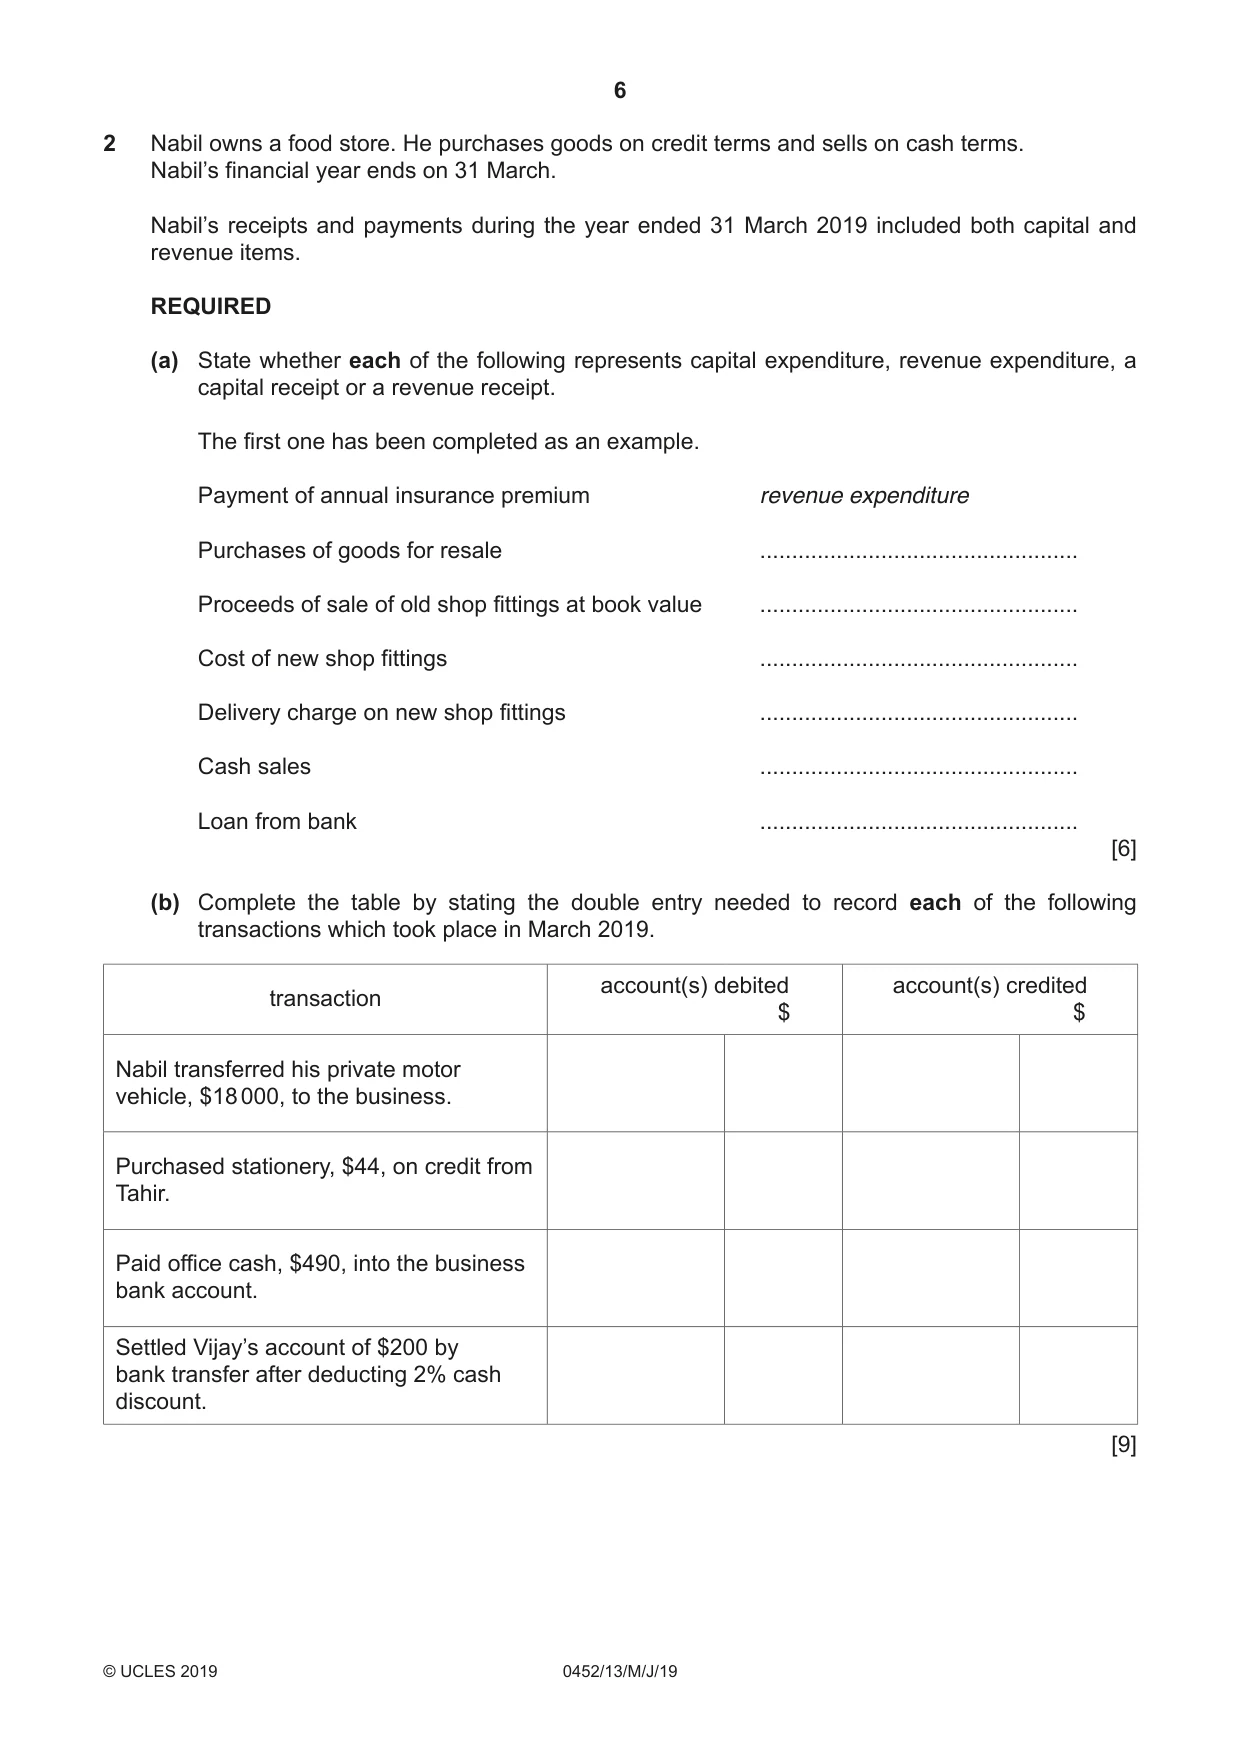
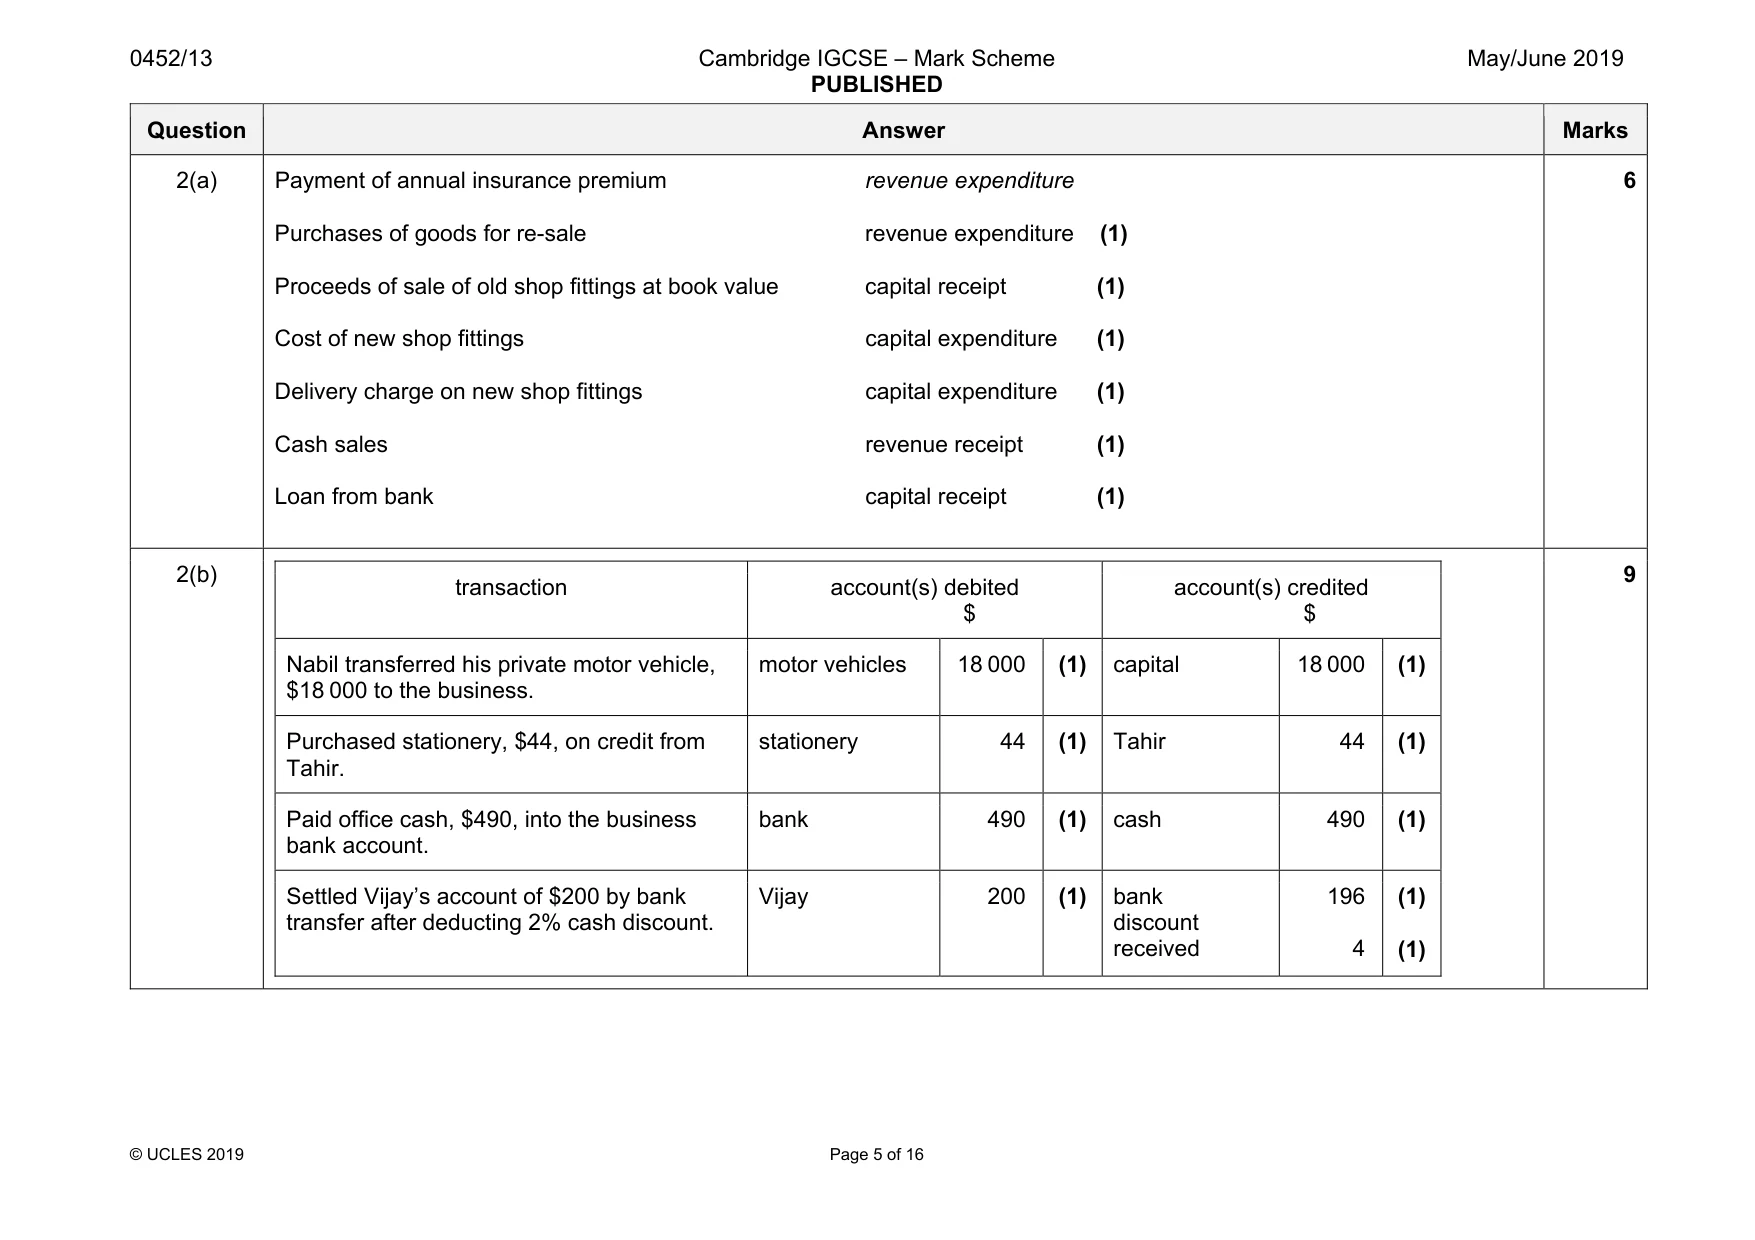
6 0452/13/M/J/19 © UCLES 2019 2 Nabil owns a food store. He purchases goods on credit terms and sells on cash terms. Nabil’s financial year ends on 31 March. Nabil’s receipts and payments during the year ended 31 March 2019 included both capital and revenue items. REQUIRED (a) State whether each of the following represents capital expenditure, revenue expenditure, a capital receipt or a revenue receipt. The first one has been completed as an example. Payment of annual insurance premium revenue expenditure Purchases of goods for resale … Proceeds of sale of old shop fittings at book value … Cost of new shop fittings … Delivery charge on new shop fittings … Cash sales … Loan from bank … [6] (b) Complete the table by stating the double entry needed to record each of the following transactions which took place in March 2019. transaction account(s) debited $ account(s) credited $ Nabil transferred his private motor vehicle, $18 000, to the business. Purchased stationery, $44, on credit from Tahir. Paid office cash, $490, into the business bank account. Settled Vijay’s account of $200 by bank transfer after deducting 2% cash discount. [9]
Question paper, page 7
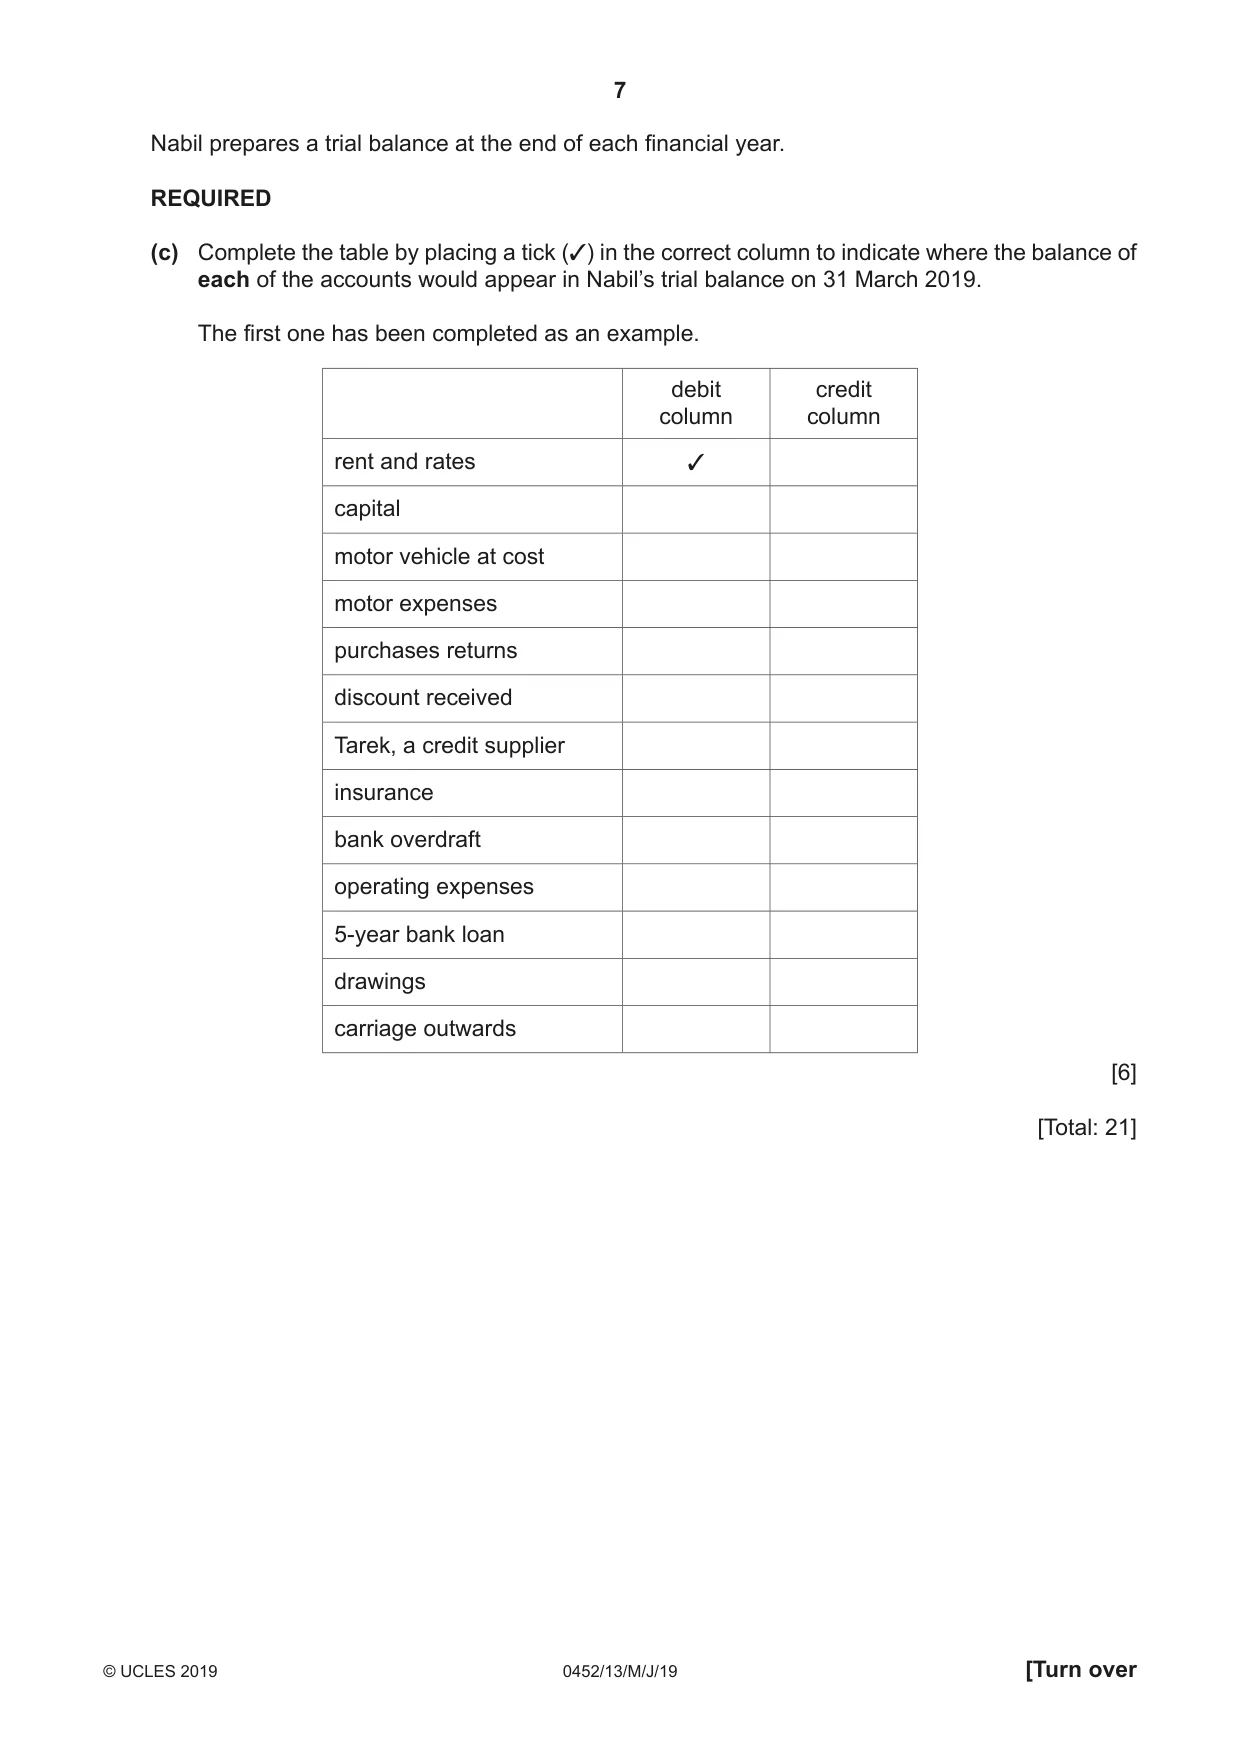
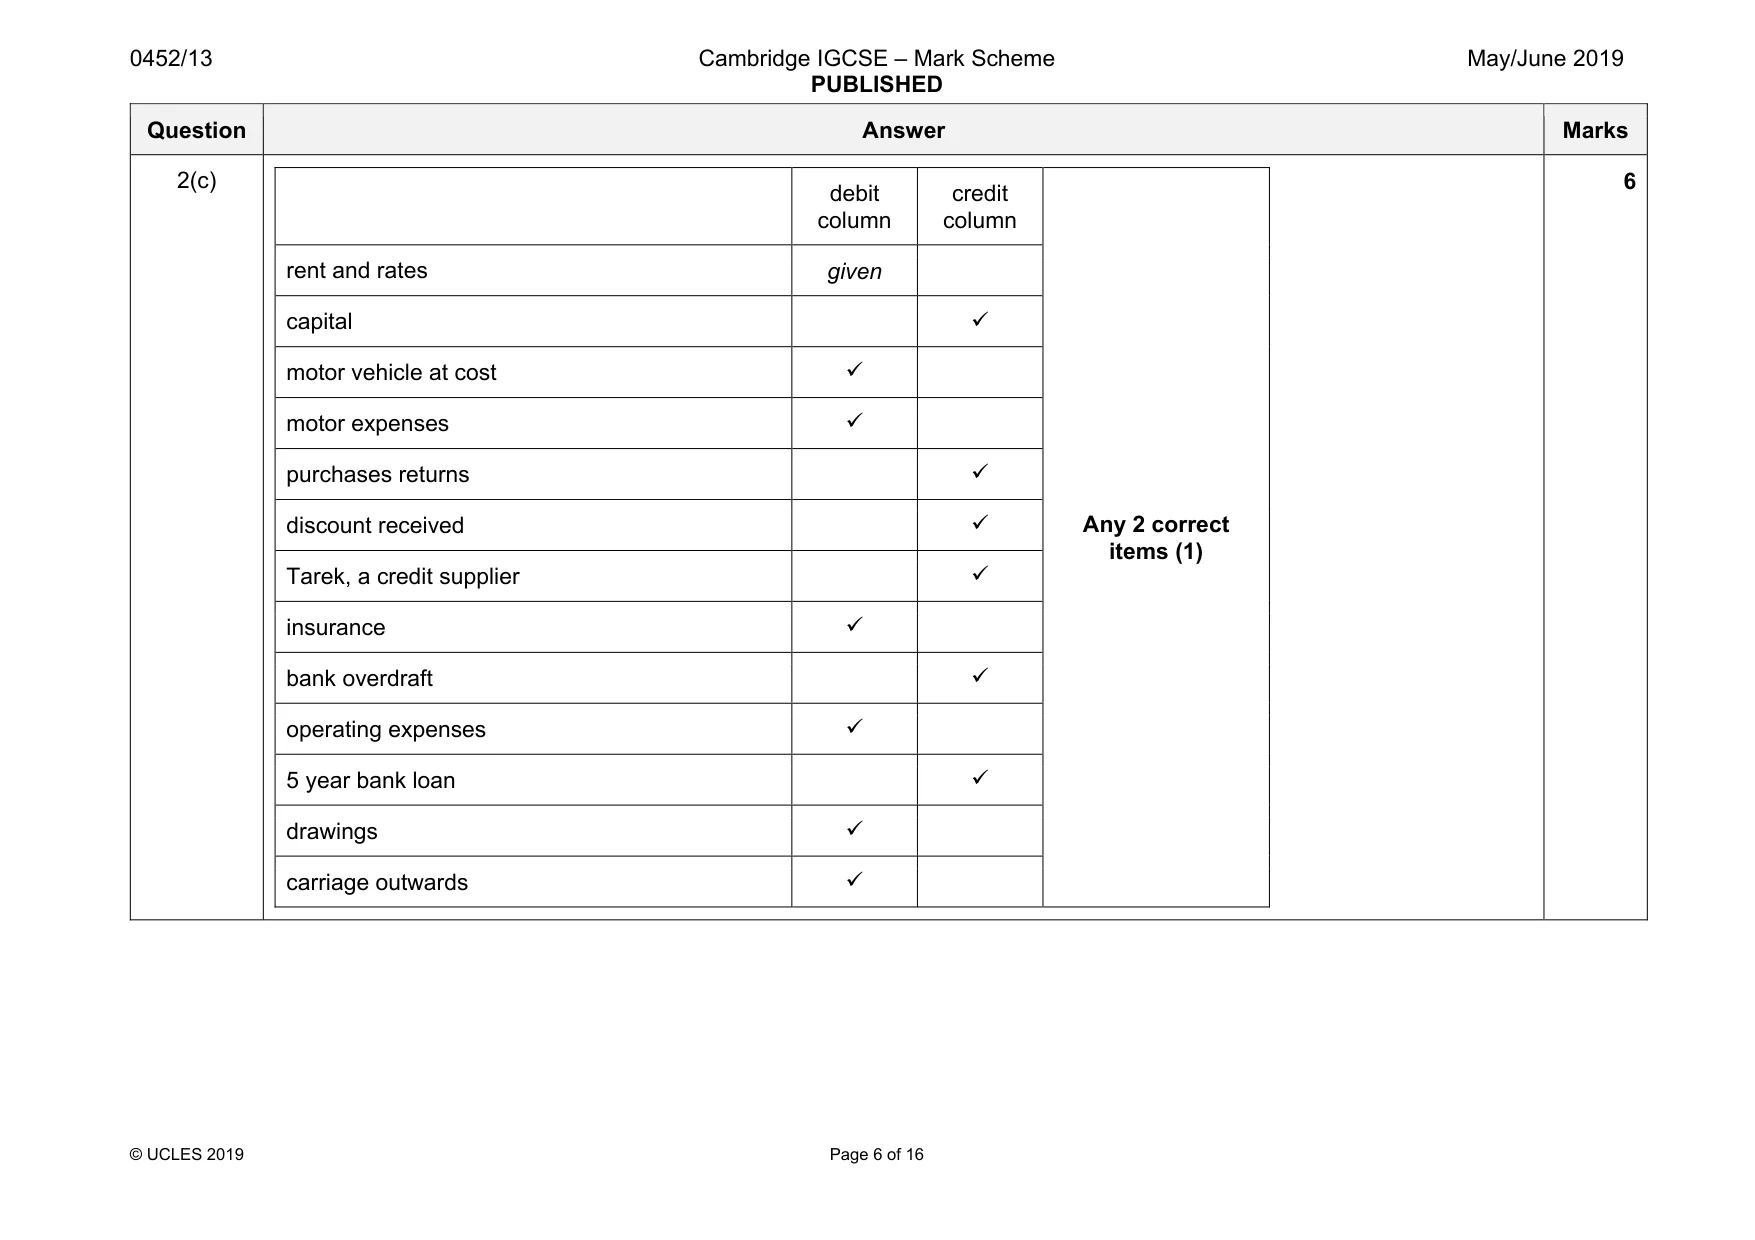
7 0452/13/M/J/19 © UCLES 2019 [Turn over Nabil prepares a trial balance at the end of each financial year. REQUIRED (c) Complete the table by placing a tick (3) in the correct column to indicate where the balance of each of the accounts would appear in Nabil’s trial balance on 31 March 2019. The first one has been completed as an example. debit column credit column rent and rates 3 capital motor vehicle at cost motor expenses purchases returns discount received Tarek, a credit supplier insurance bank overdraft operating expenses 5-year bank loan drawings carriage outwards [6] [Total: 21]
Question paper, page 8
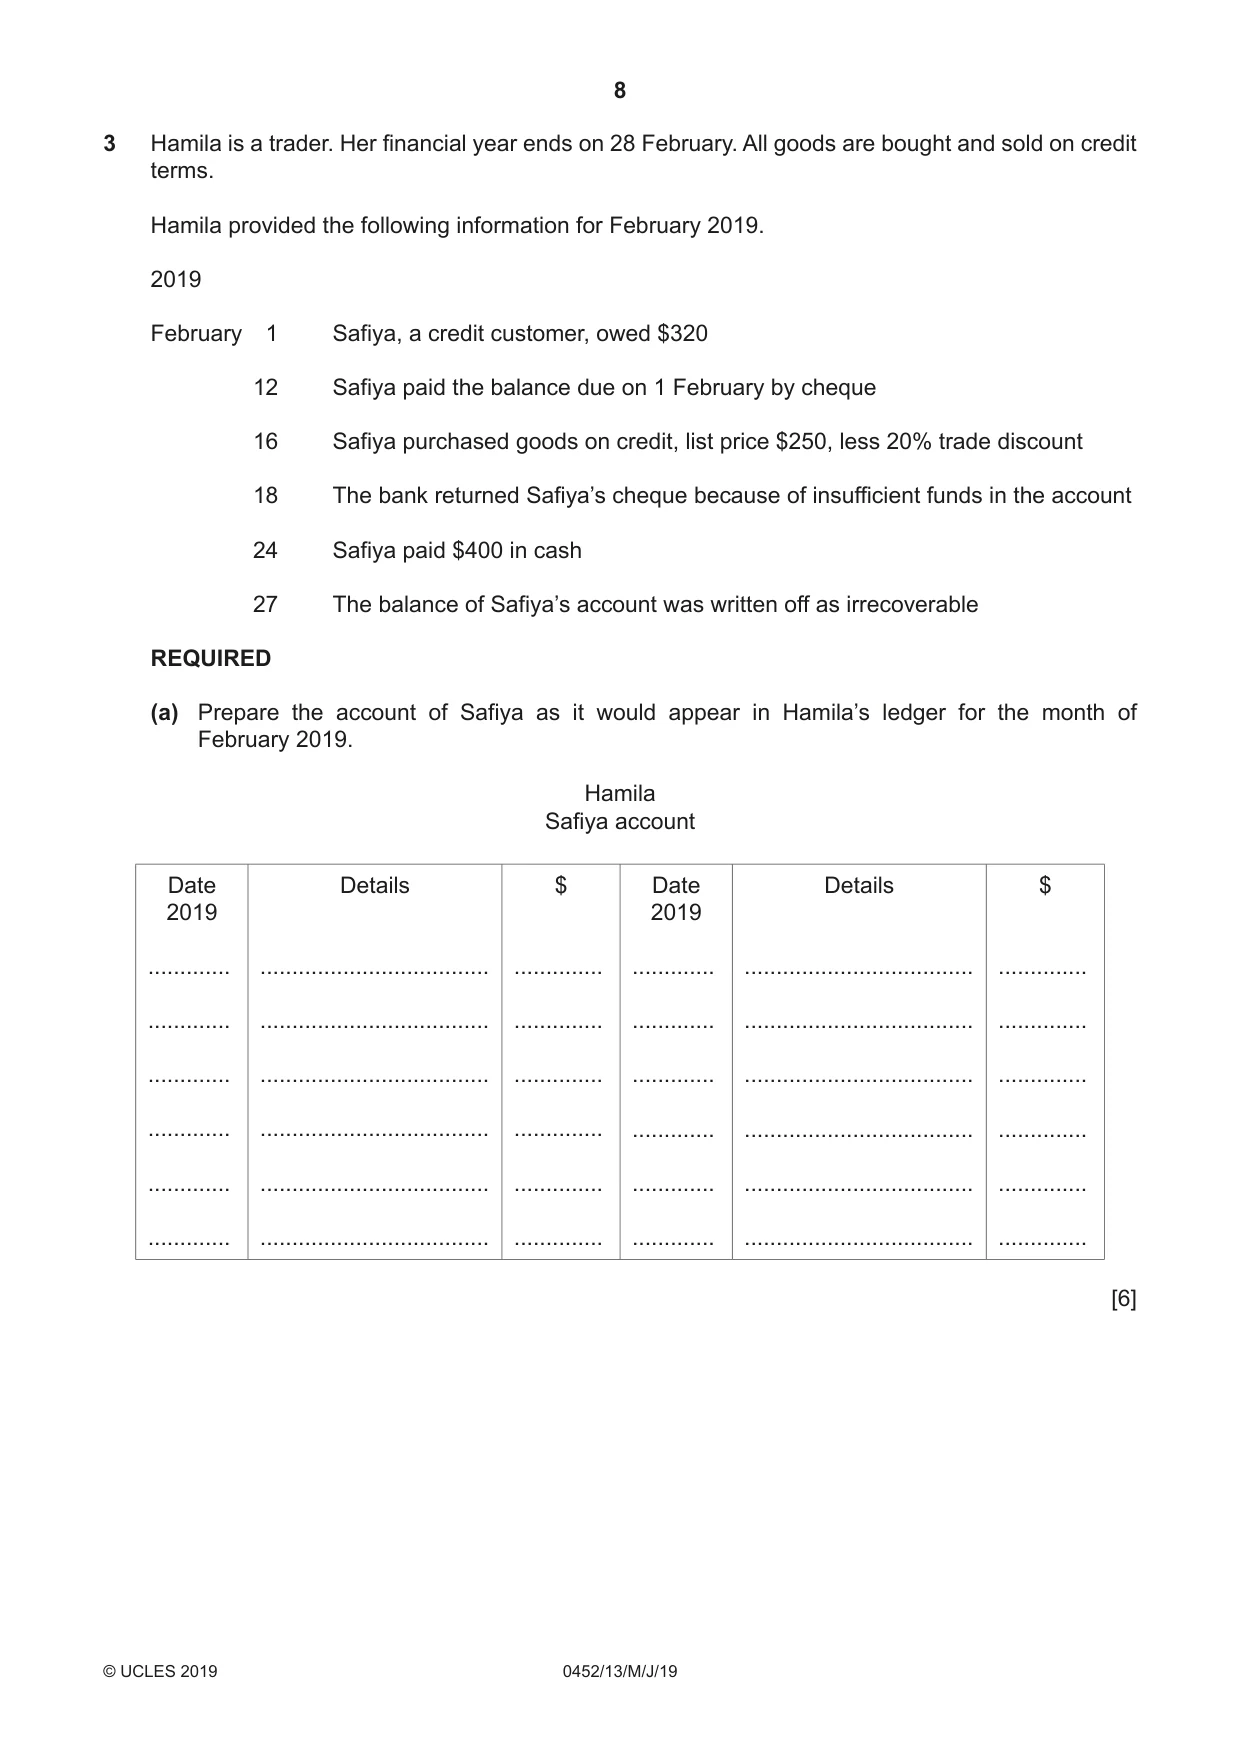
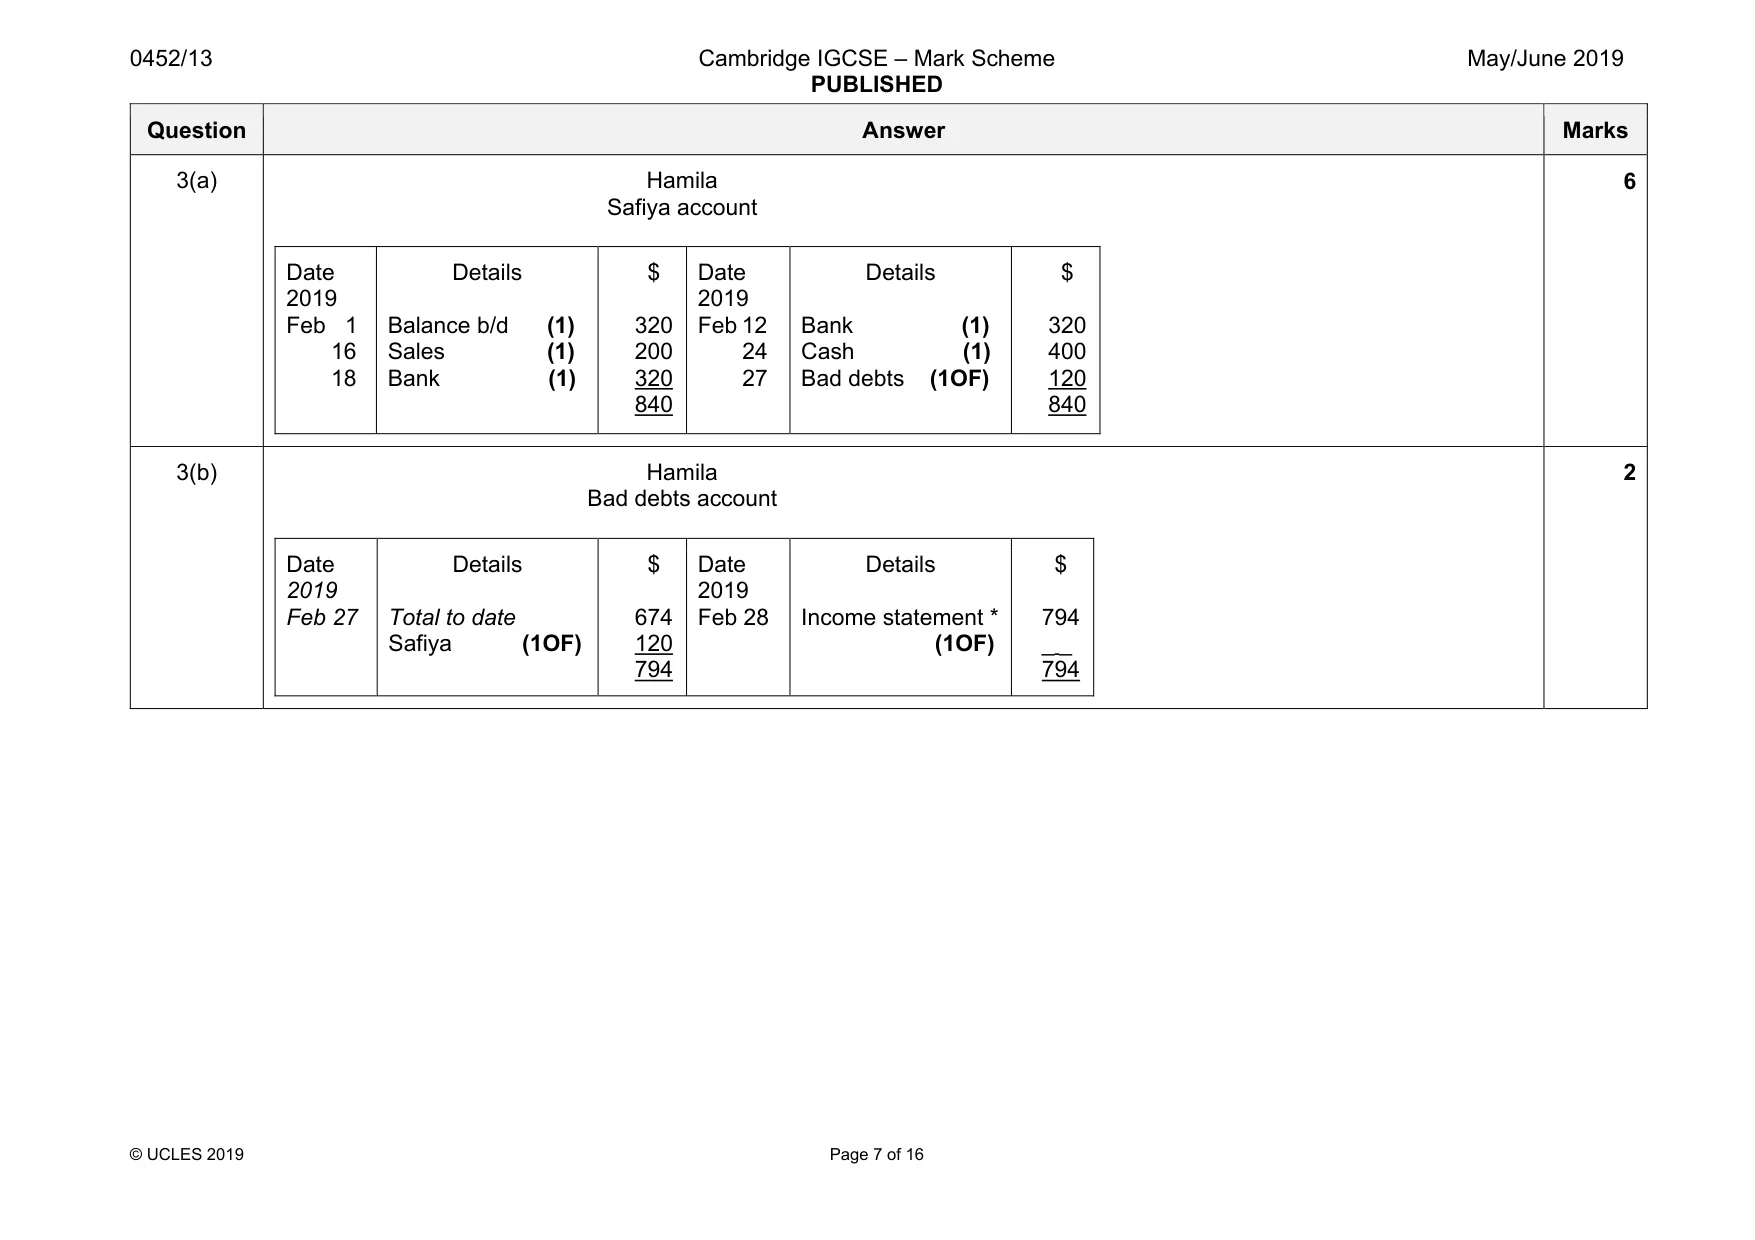
8 0452/13/M/J/19 © UCLES 2019 3 Hamila is a trader. Her financial year ends on 28 February. All goods are bought and sold on credit terms. Hamila provided the following information for February 2019. 2019 February 1 Safiya, a credit customer, owed $320 12 Safiya paid the balance due on 1 February by cheque 16 Safiya purchased goods on credit, list price $250, less 20% trade discount 18 The bank returned Safiya’s cheque because of insufficient funds in the account 24 Safiya paid $400 in cash 27 The balance of Safiya’s account was written off as irrecoverable REQUIRED (a) Prepare the account of Safiya as it would appear in Hamila’s ledger for the month of February 2019. Hamila Safiya account Date 2019 … … … … … … Details … … … … … … $ … … … … … … Date 2019 … … … … … … Details … … … … … … $ … … … … … … [6]
Question paper, page 9
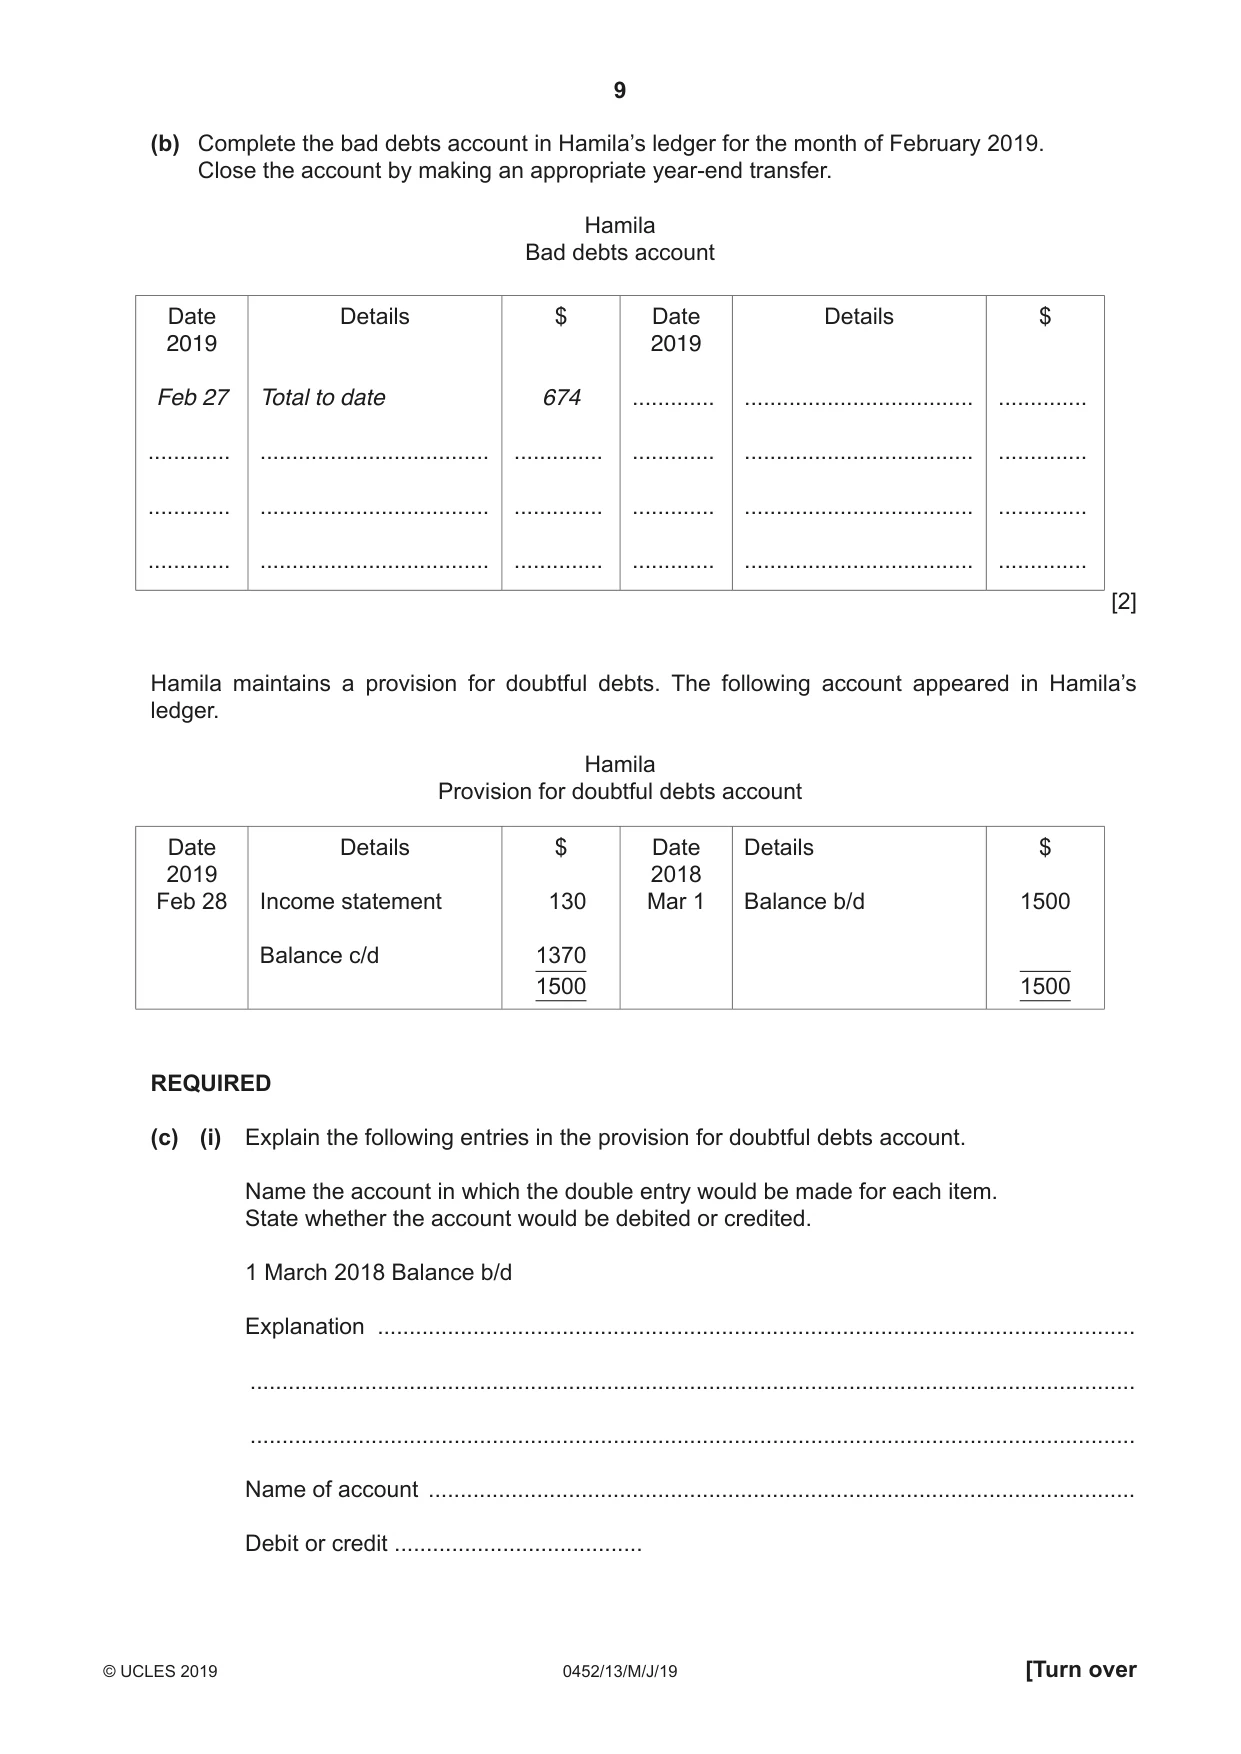
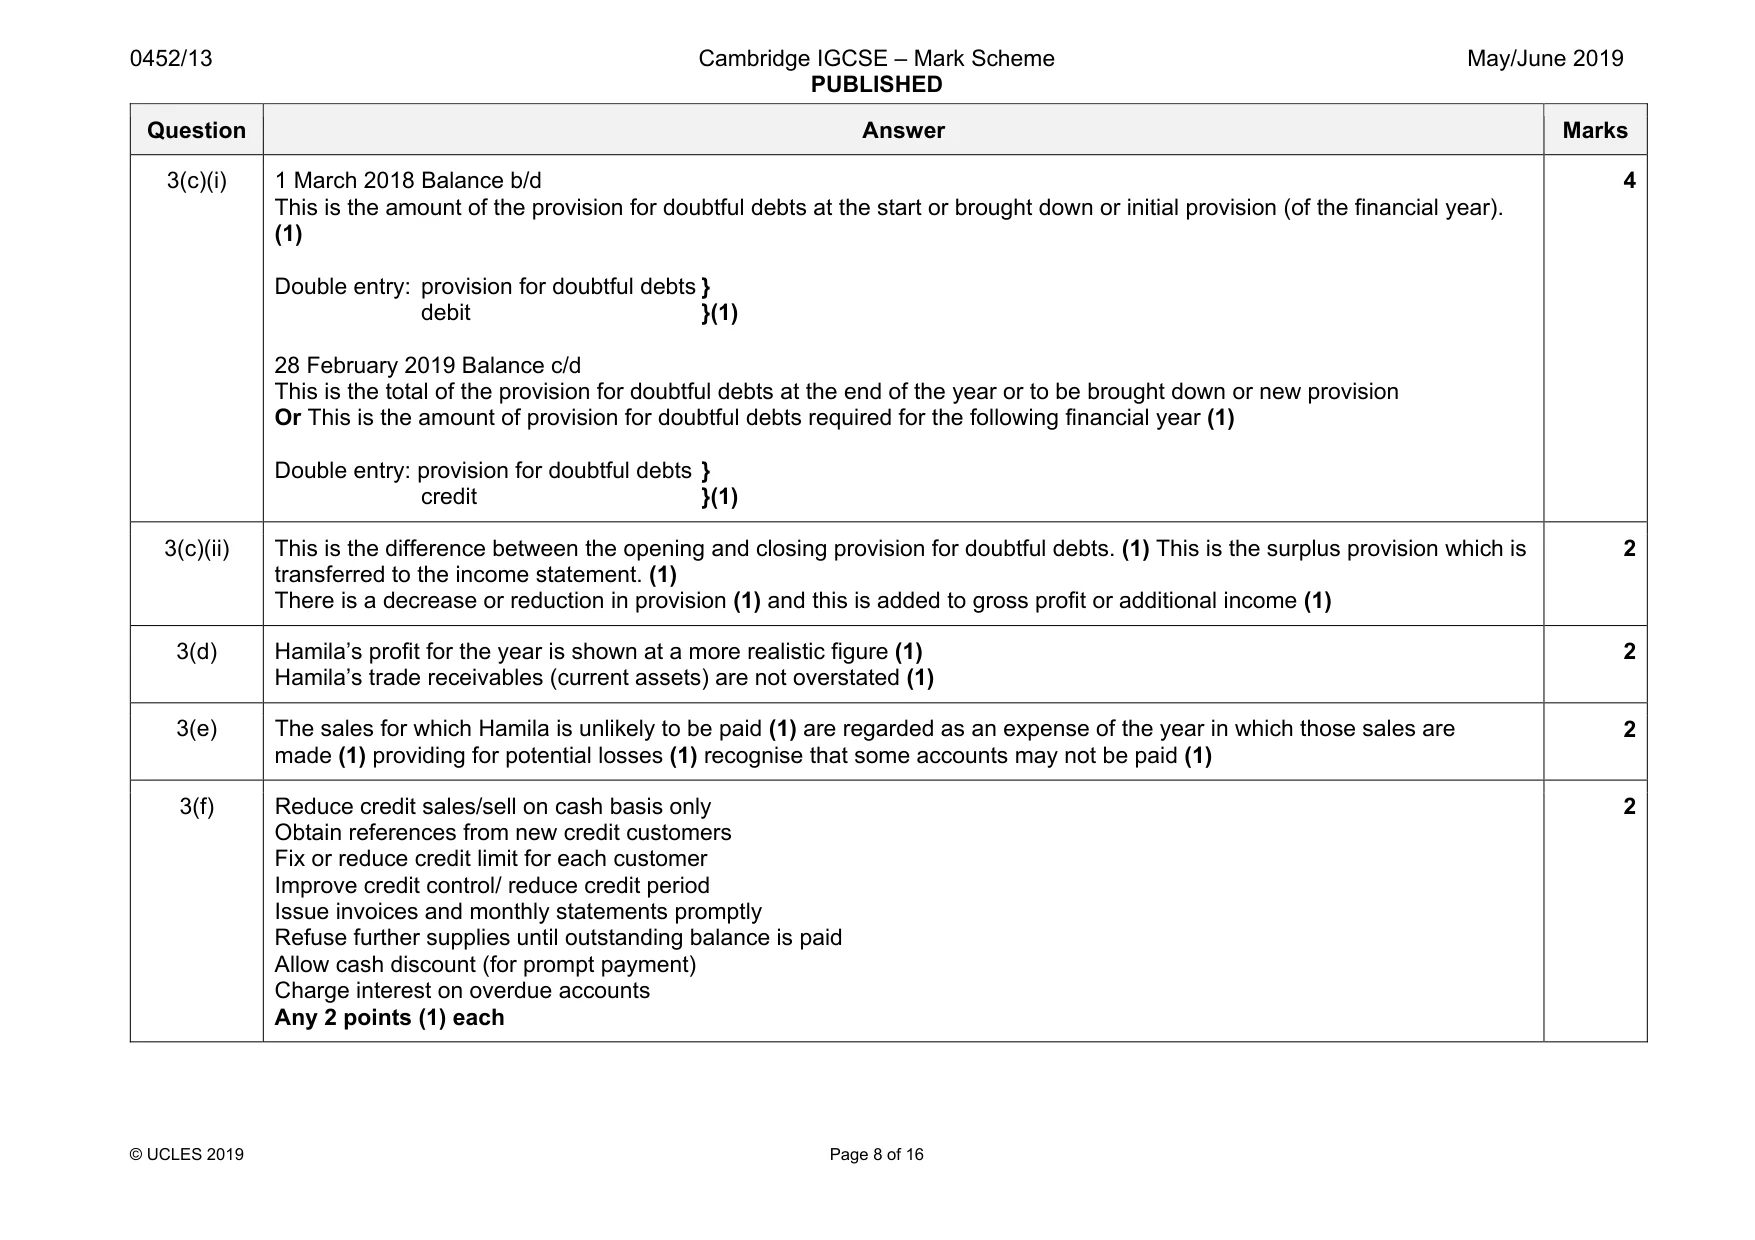
9 0452/13/M/J/19 © UCLES 2019 [Turn over (b) Complete the bad debts account in Hamila’s ledger for the month of February 2019. Close the account by making an appropriate year-end transfer. Hamila Bad debts account Date 2019 Feb 27 … … … Details Total to date … … … $ 674 … … … Date 2019 … … … … Details … … … … $ … … … … [2] Hamila maintains a provision for doubtful debts. The following account appeared in Hamila’s ledger. Hamila Provision for doubtful debts account Date 2019 Feb 28 Details Income statement Balance c/d $ 130 1370 1500 Date 2018 Mar 1 Details Balance b/d $ 1500 1500 REQUIRED (c) (i) Explain the following entries in the provision for doubtful debts account. Name the account in which the double entry would be made for each item. State whether the account would be debited or credited. 1 March 2018 Balance b/d Explanation … … … Name of account … Debit or credit …
Question paper, page 10
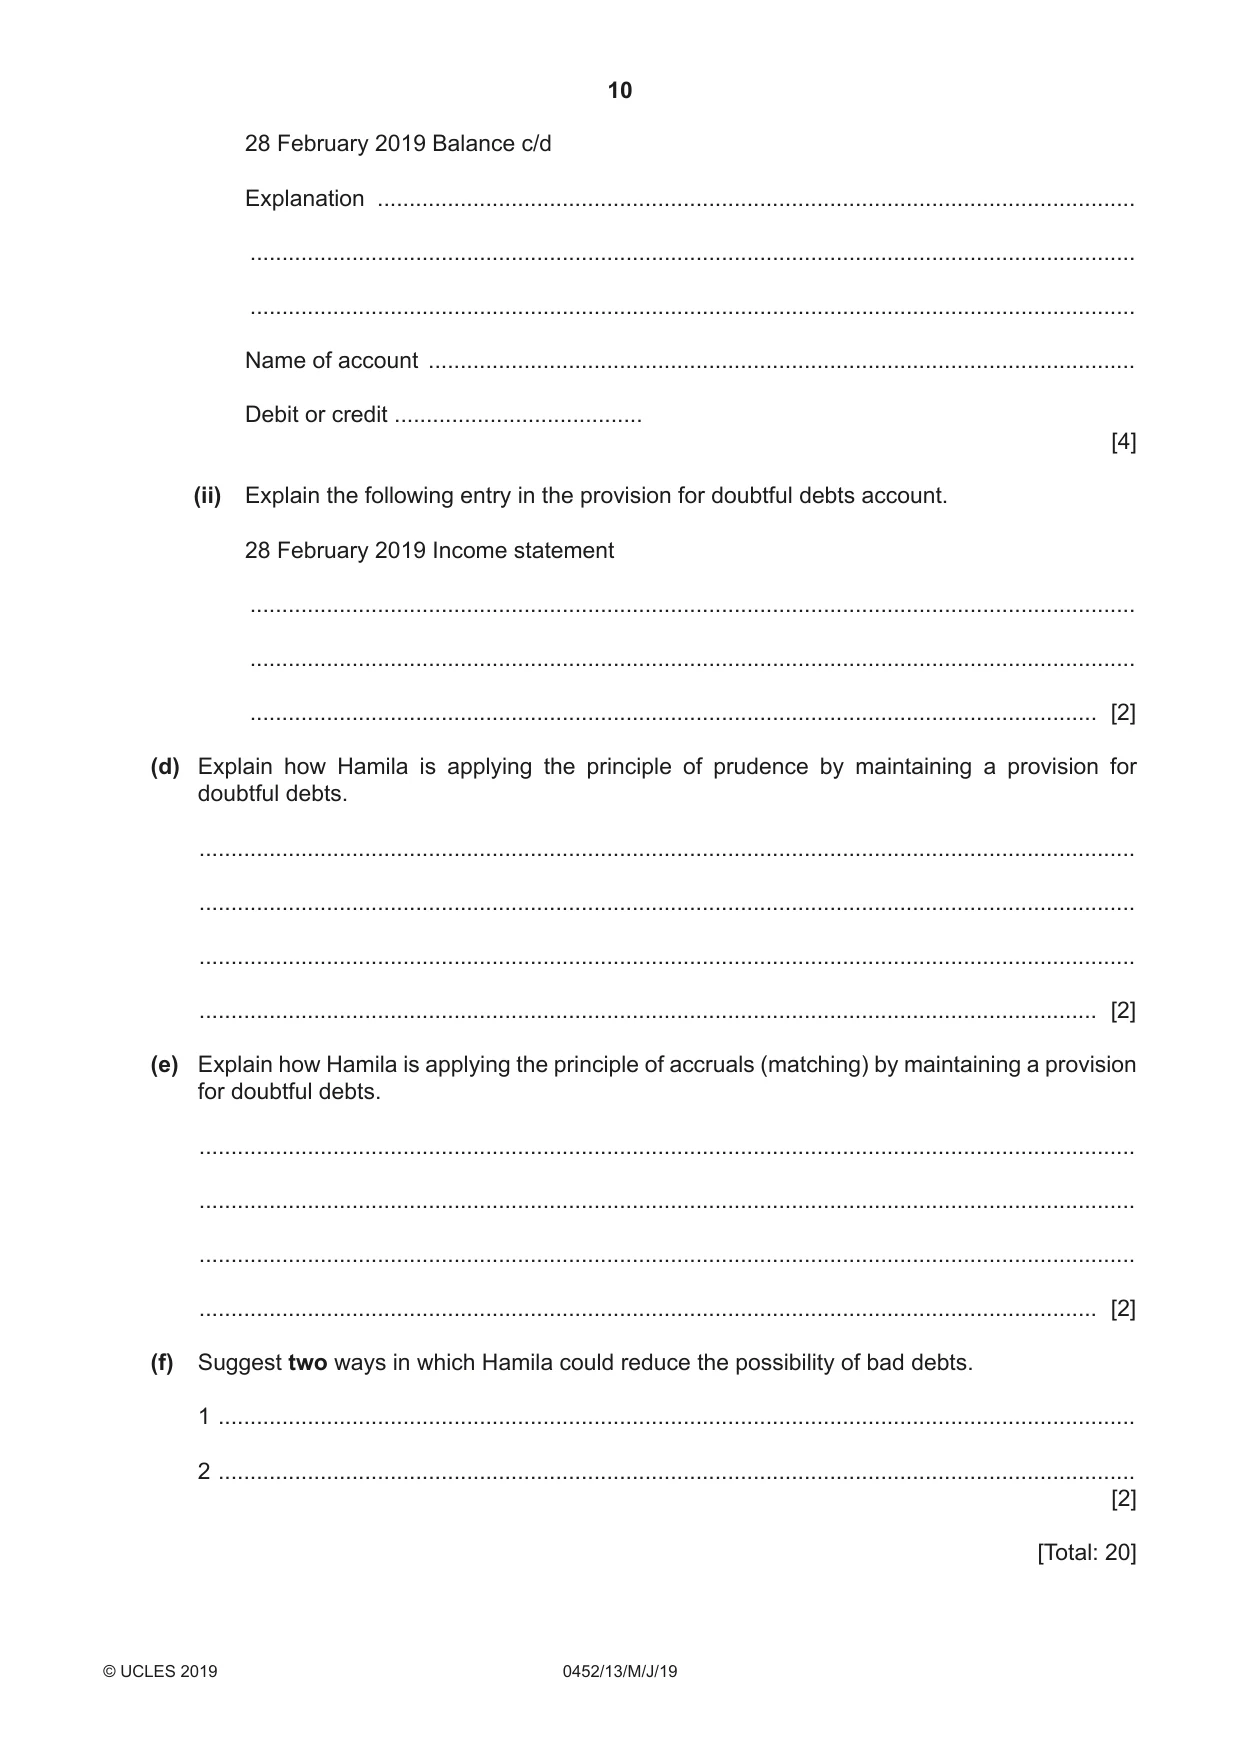
10 0452/13/M/J/19 © UCLES 2019 28 February 2019 Balance c/d Explanation … … … Name of account … Debit or credit … [4] (ii) Explain the following entry in the provision for doubtful debts account. 28 February 2019 Income statement … … … [2] (d) Explain how Hamila is applying the principle of prudence by maintaining a provision for doubtful debts. … … … … [2] (e) Explain how Hamila is applying the principle of accruals (matching) by maintaining a provision for doubtful debts. … … … … [2] (f) Suggest two ways in which Hamila could reduce the possibility of bad debts. 1 … 2 … [2] [Total: 20]
Question paper, page 11
11 0452/13/M/J/19 © UCLES 2019 [Turn over PLEASE TURN OVER
Question paper, page 12
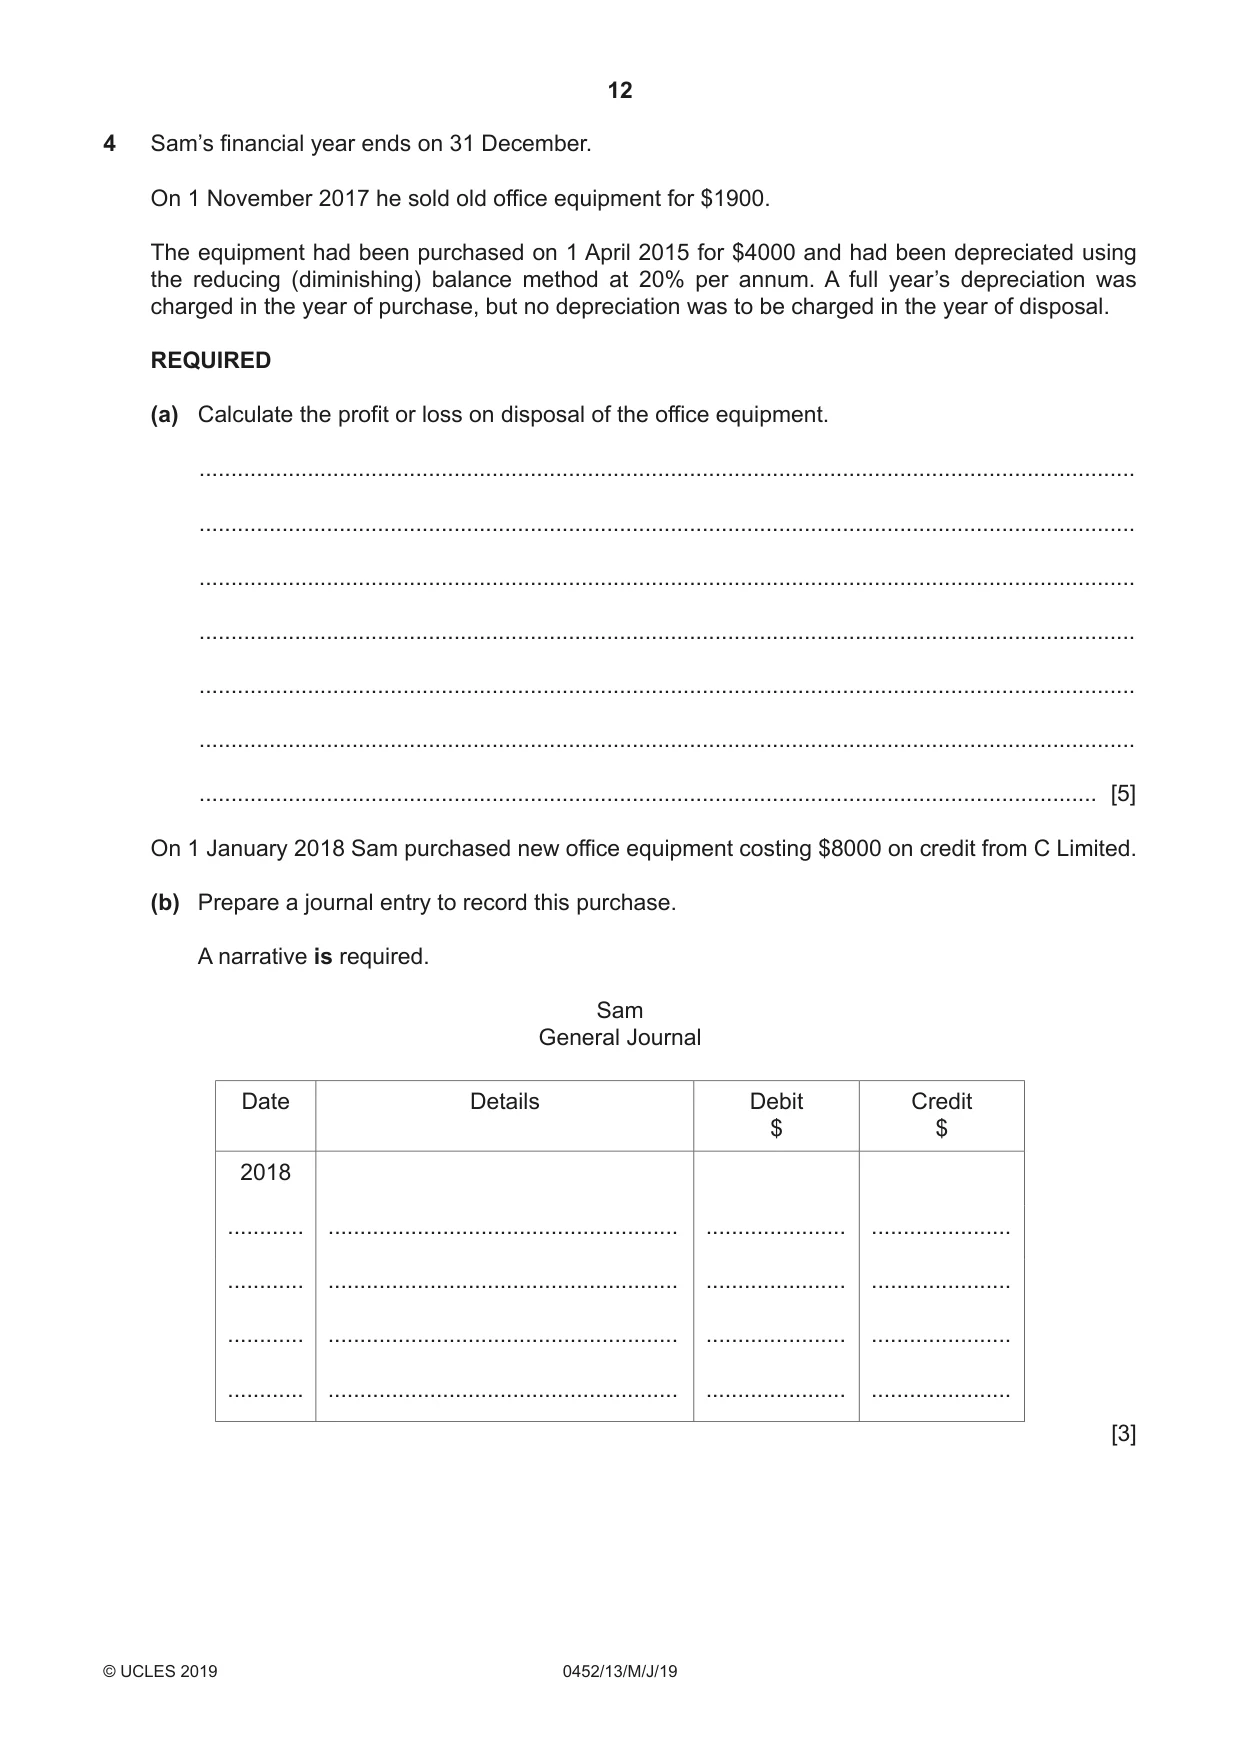
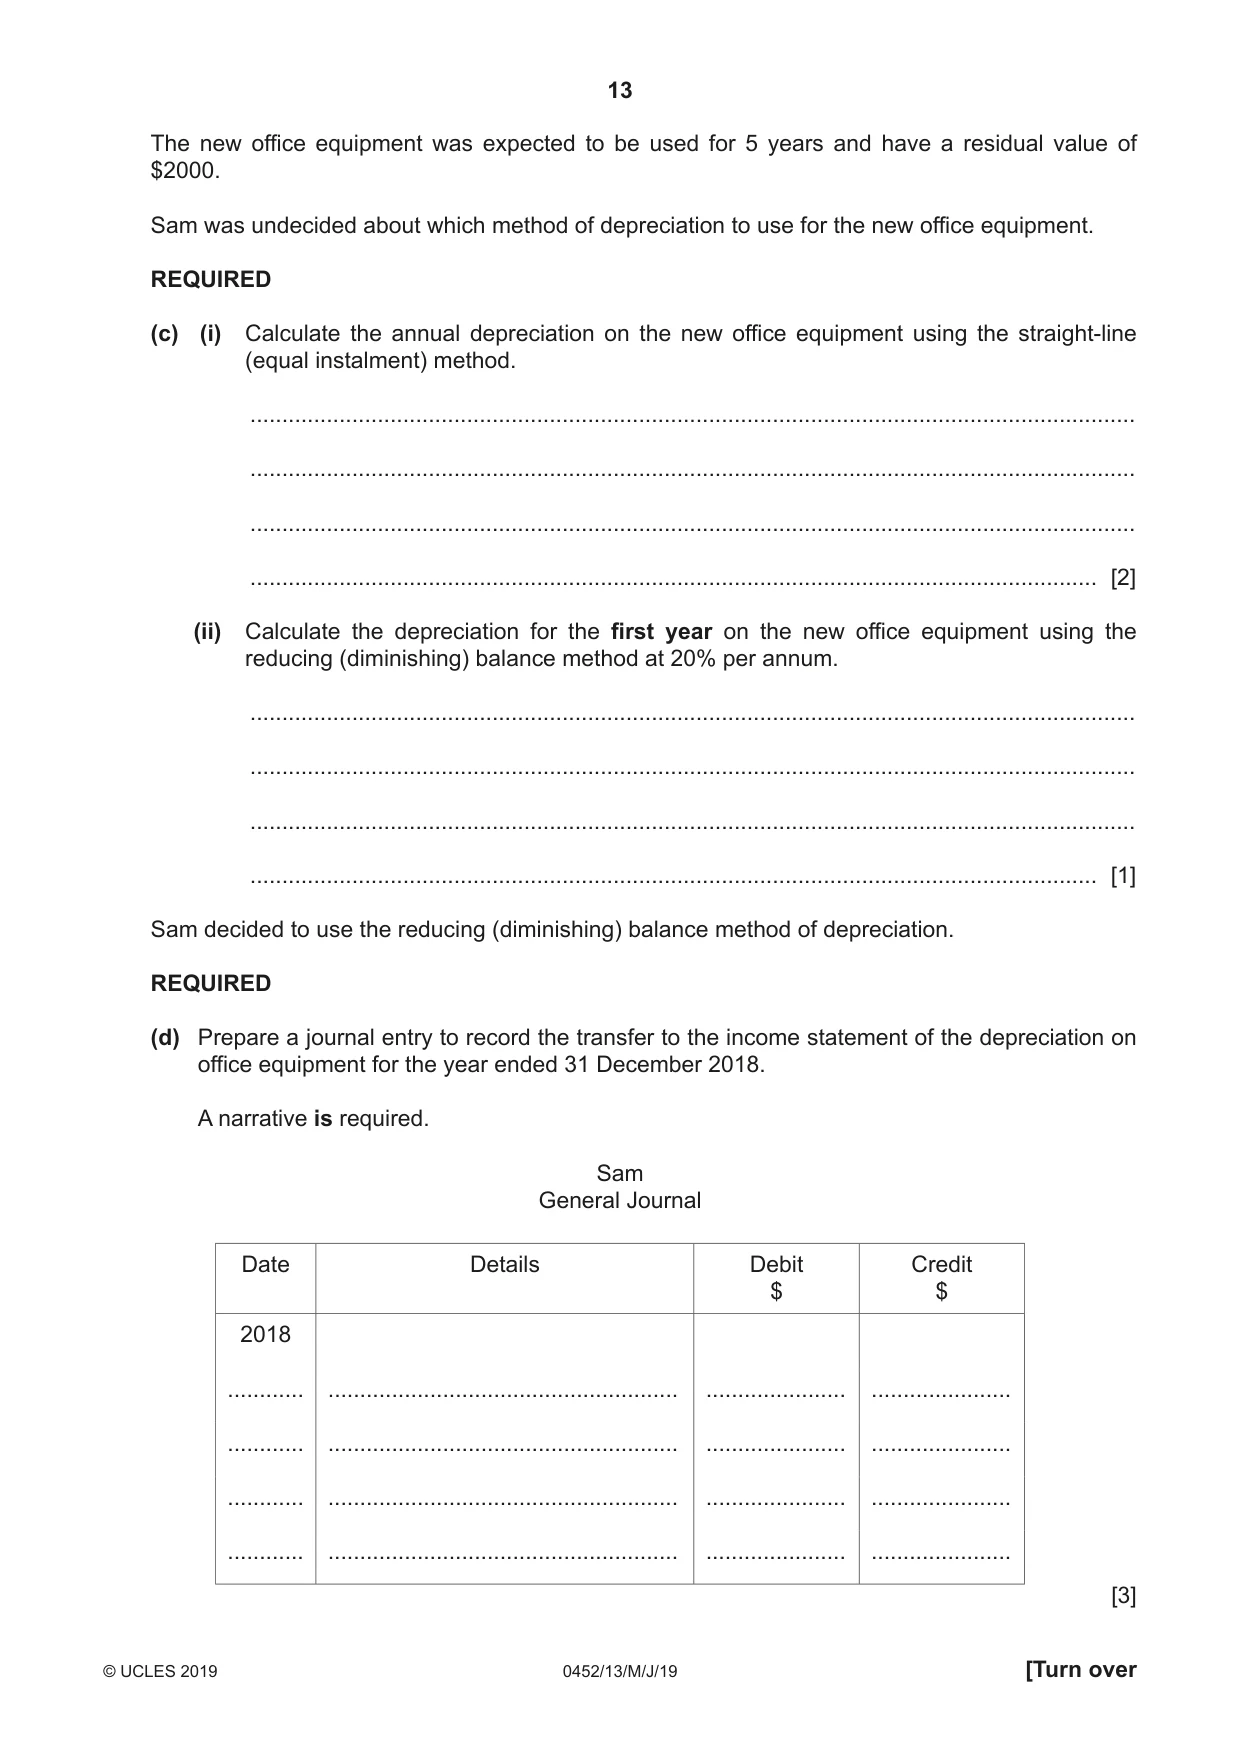
12 0452/13/M/J/19 © UCLES 2019 4 Sam’s financial year ends on 31 December. On 1 November 2017 he sold old office equipment for $1900. The equipment had been purchased on 1 April 2015 for $4000 and had been depreciated using the reducing (diminishing) balance method at 20% per annum. A full year’s depreciation was charged in the year of purchase, but no depreciation was to be charged in the year of disposal. REQUIRED (a) Calculate the profit or loss on disposal of the office equipment. … … … … … … … [5] On 1 January 2018 Sam purchased new office equipment costing $8000 on credit from C Limited. (b) Prepare a journal entry to record this purchase. A narrative is required. Sam General Journal Date Details Debit $ Credit $ 2018 … … … … … … … … … … … … … … … … [3]
Question paper, page 13
13 0452/13/M/J/19 © UCLES 2019 [Turn over The new office equipment was expected to be used for 5 years and have a residual value of $2000. Sam was undecided about which method of depreciation to use for the new office equipment. REQUIRED (c) (i) Calculate the annual depreciation on the new office equipment using the straight-line (equal instalment) method. … … … … [2] (ii) Calculate the depreciation for the first year on the new office equipment using the reducing (diminishing) balance method at 20% per annum. … … … … [1] Sam decided to use the reducing (diminishing) balance method of depreciation. REQUIRED (d) Prepare a journal entry to record the transfer to the income statement of the depreciation on office equipment for the year ended 31 December 2018. A narrative is required. Sam General Journal Date Details Debit $ Credit $ 2018 … … … … … … … … … … … … … … … … [3]
Question paper, page 14
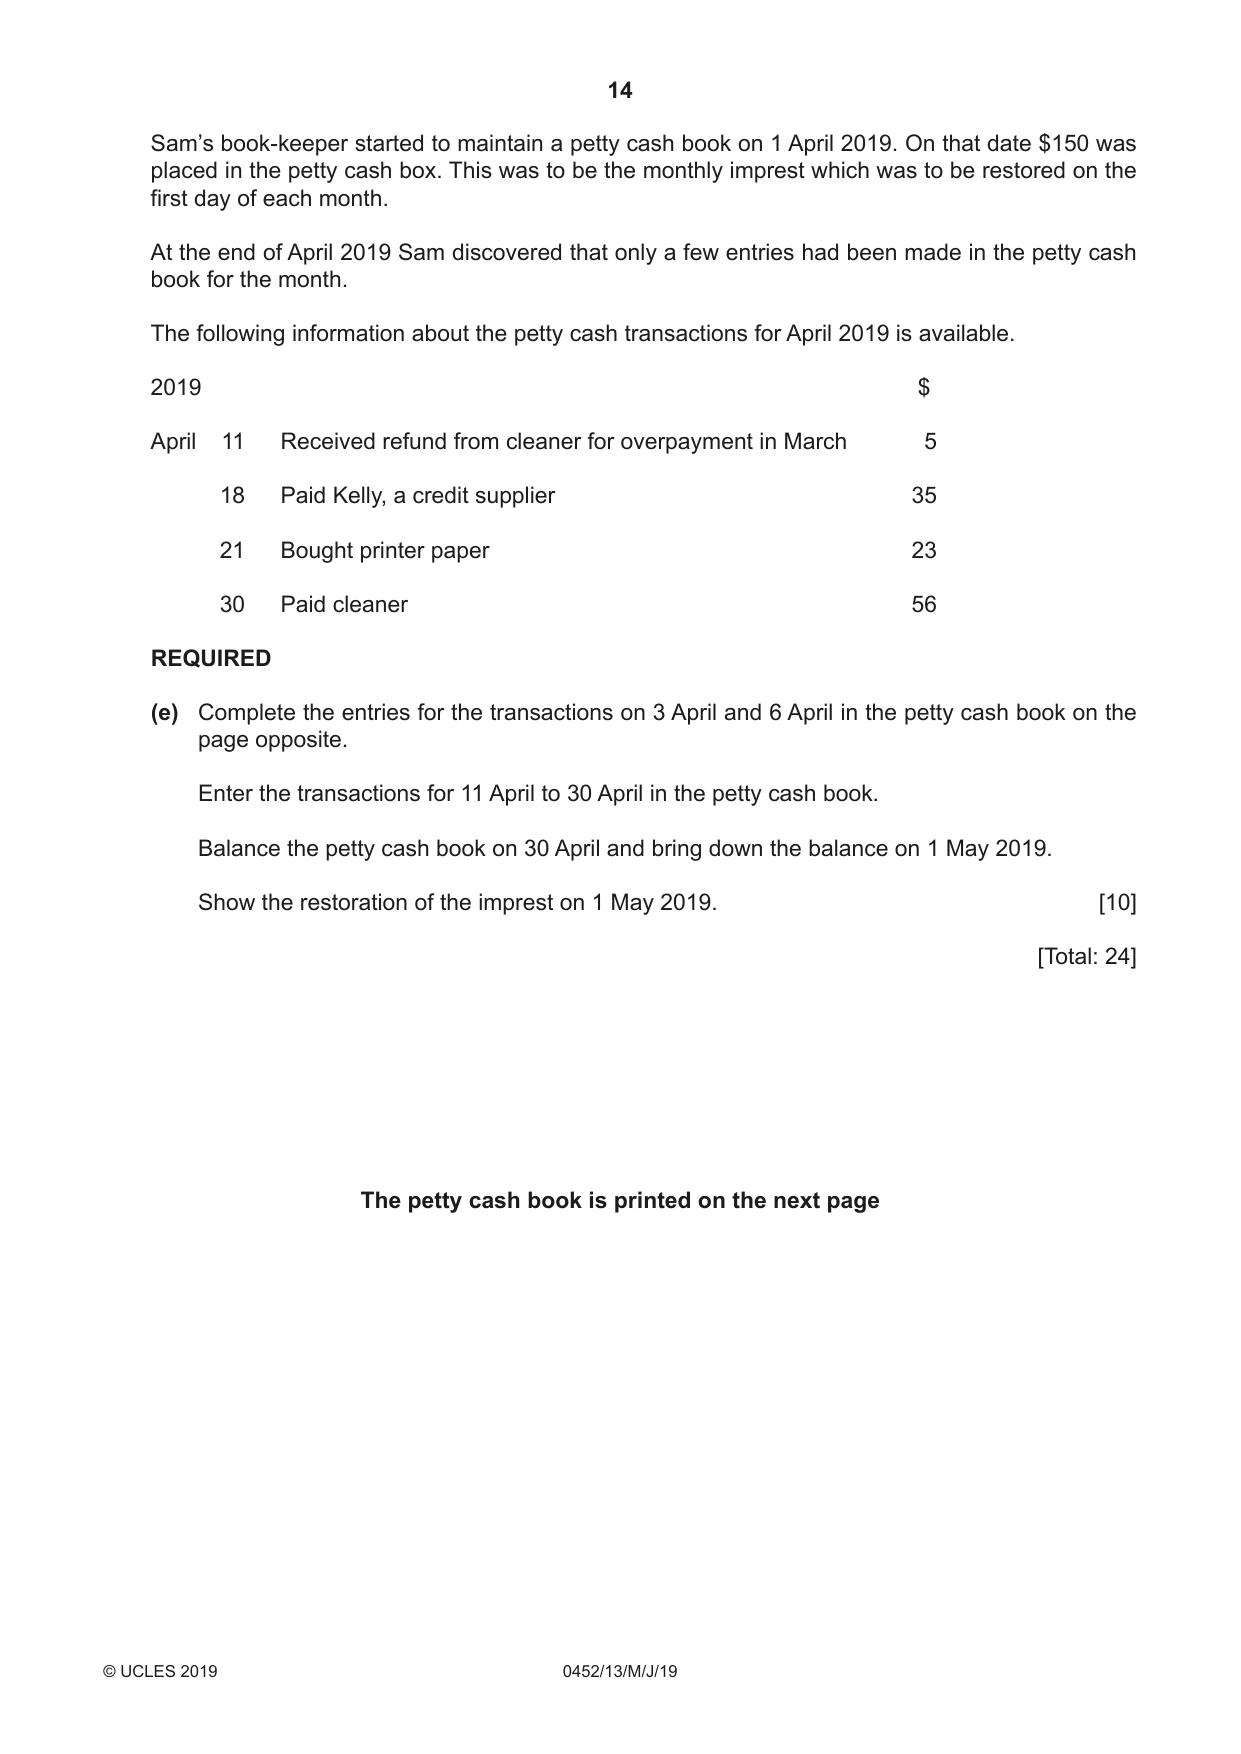
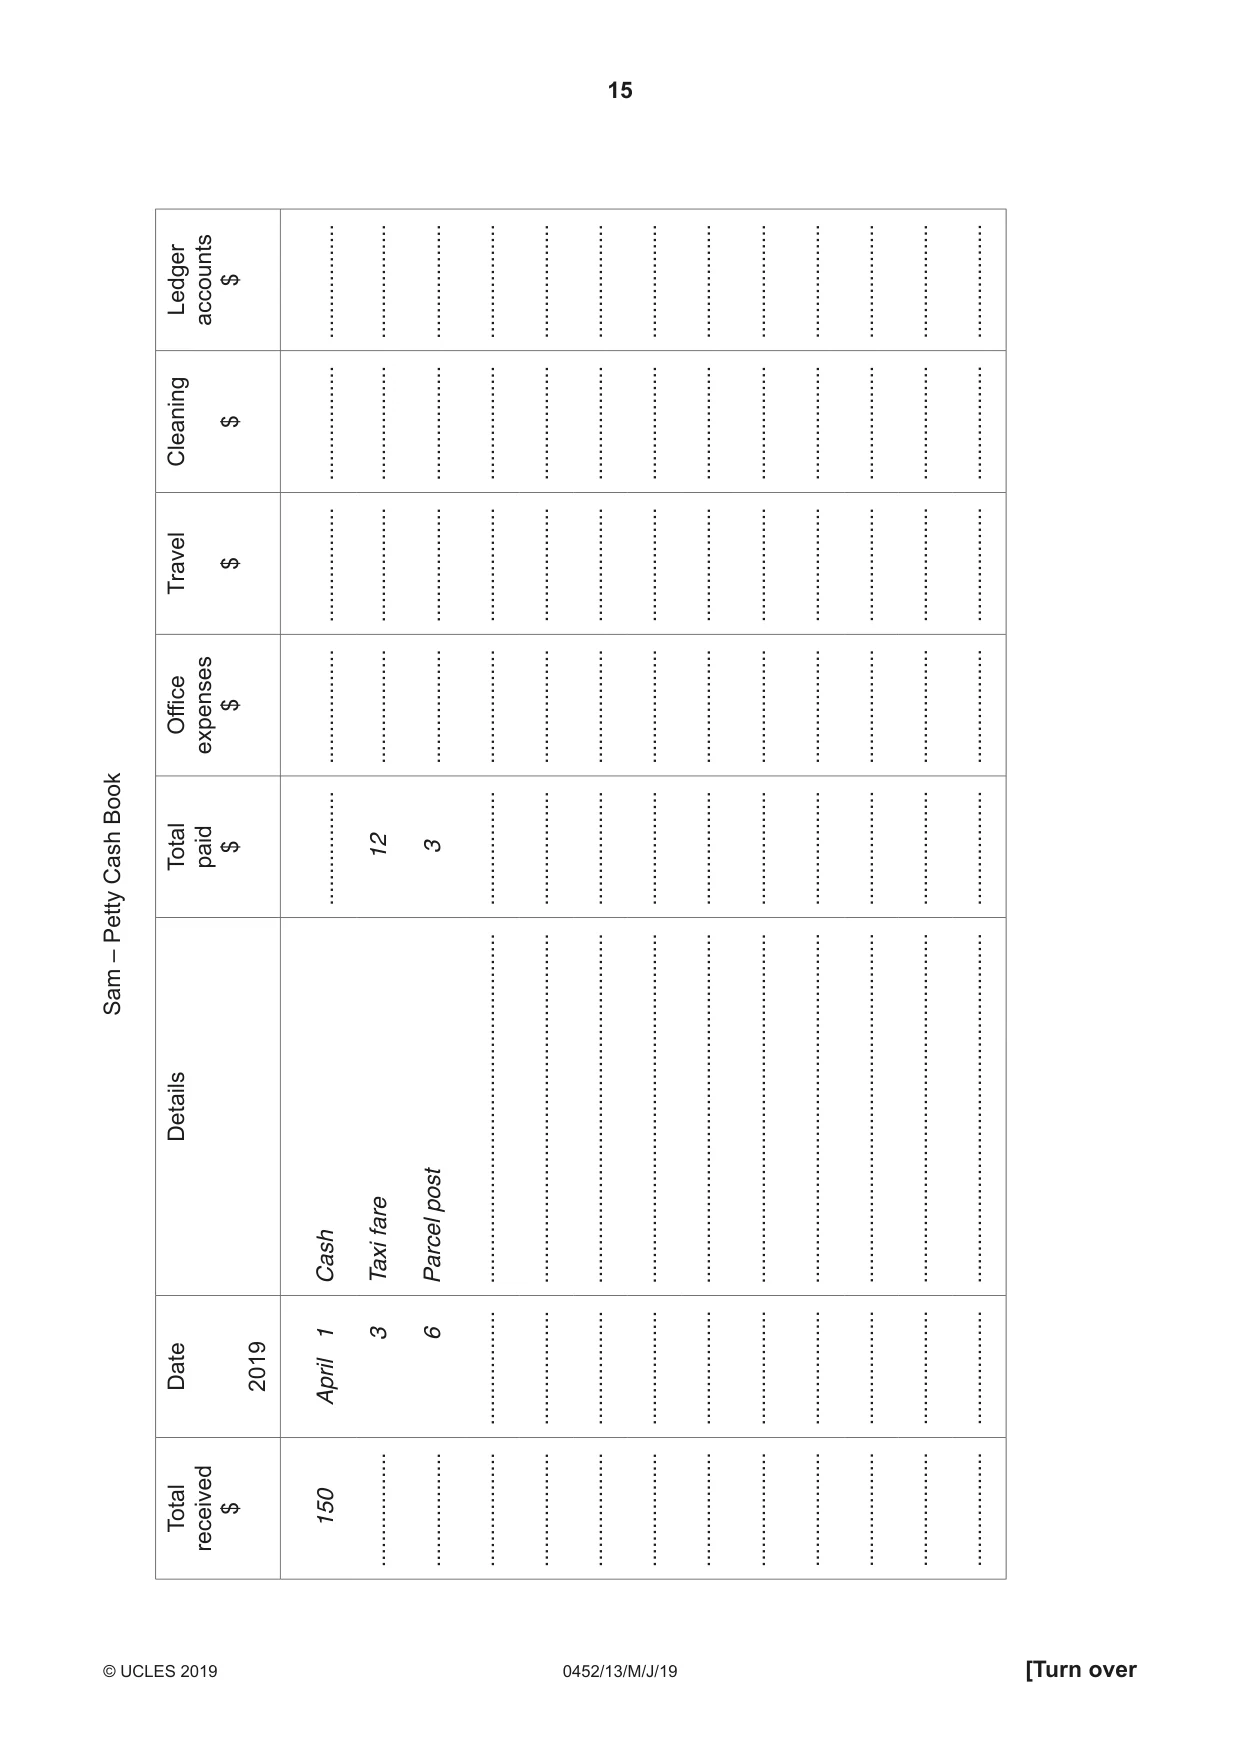
14 0452/13/M/J/19 © UCLES 2019 Sam’s book-keeper started to maintain a petty cash book on 1 April 2019. On that date $150 was placed in the petty cash box. This was to be the monthly imprest which was to be restored on the first day of each month. At the end of April 2019 Sam discovered that only a few entries had been made in the petty cash book for the month. The following information about the petty cash transactions for April 2019 is available. 2019 $ April 11 Received refund from cleaner for overpayment in March 5 18 Paid Kelly, a credit supplier 35 21 Bought printer paper 23 30 Paid cleaner 56 REQUIRED (e) Complete the entries for the transactions on 3 April and 6 April in the petty cash book on the page opposite. Enter the transactions for 11 April to 30 April in the petty cash book. Balance the petty cash book on 30 April and bring down the balance on 1 May 2019. Show the restoration of the imprest on 1 May 2019. [10] [Total: 24] The petty cash book is printed on the next page
Question paper, page 15
15 0452/13/M/J/19 © UCLES 2019 [Turn over Sam – Petty Cash Book Total received $ Date 2019 Details Total paid $ Office expenses $ Travel $ Cleaning $ Ledger accounts $ 150 April 1 Cash … … … … … … 3 Taxi fare 12 … … … … … 6 Parcel post 3 … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 16
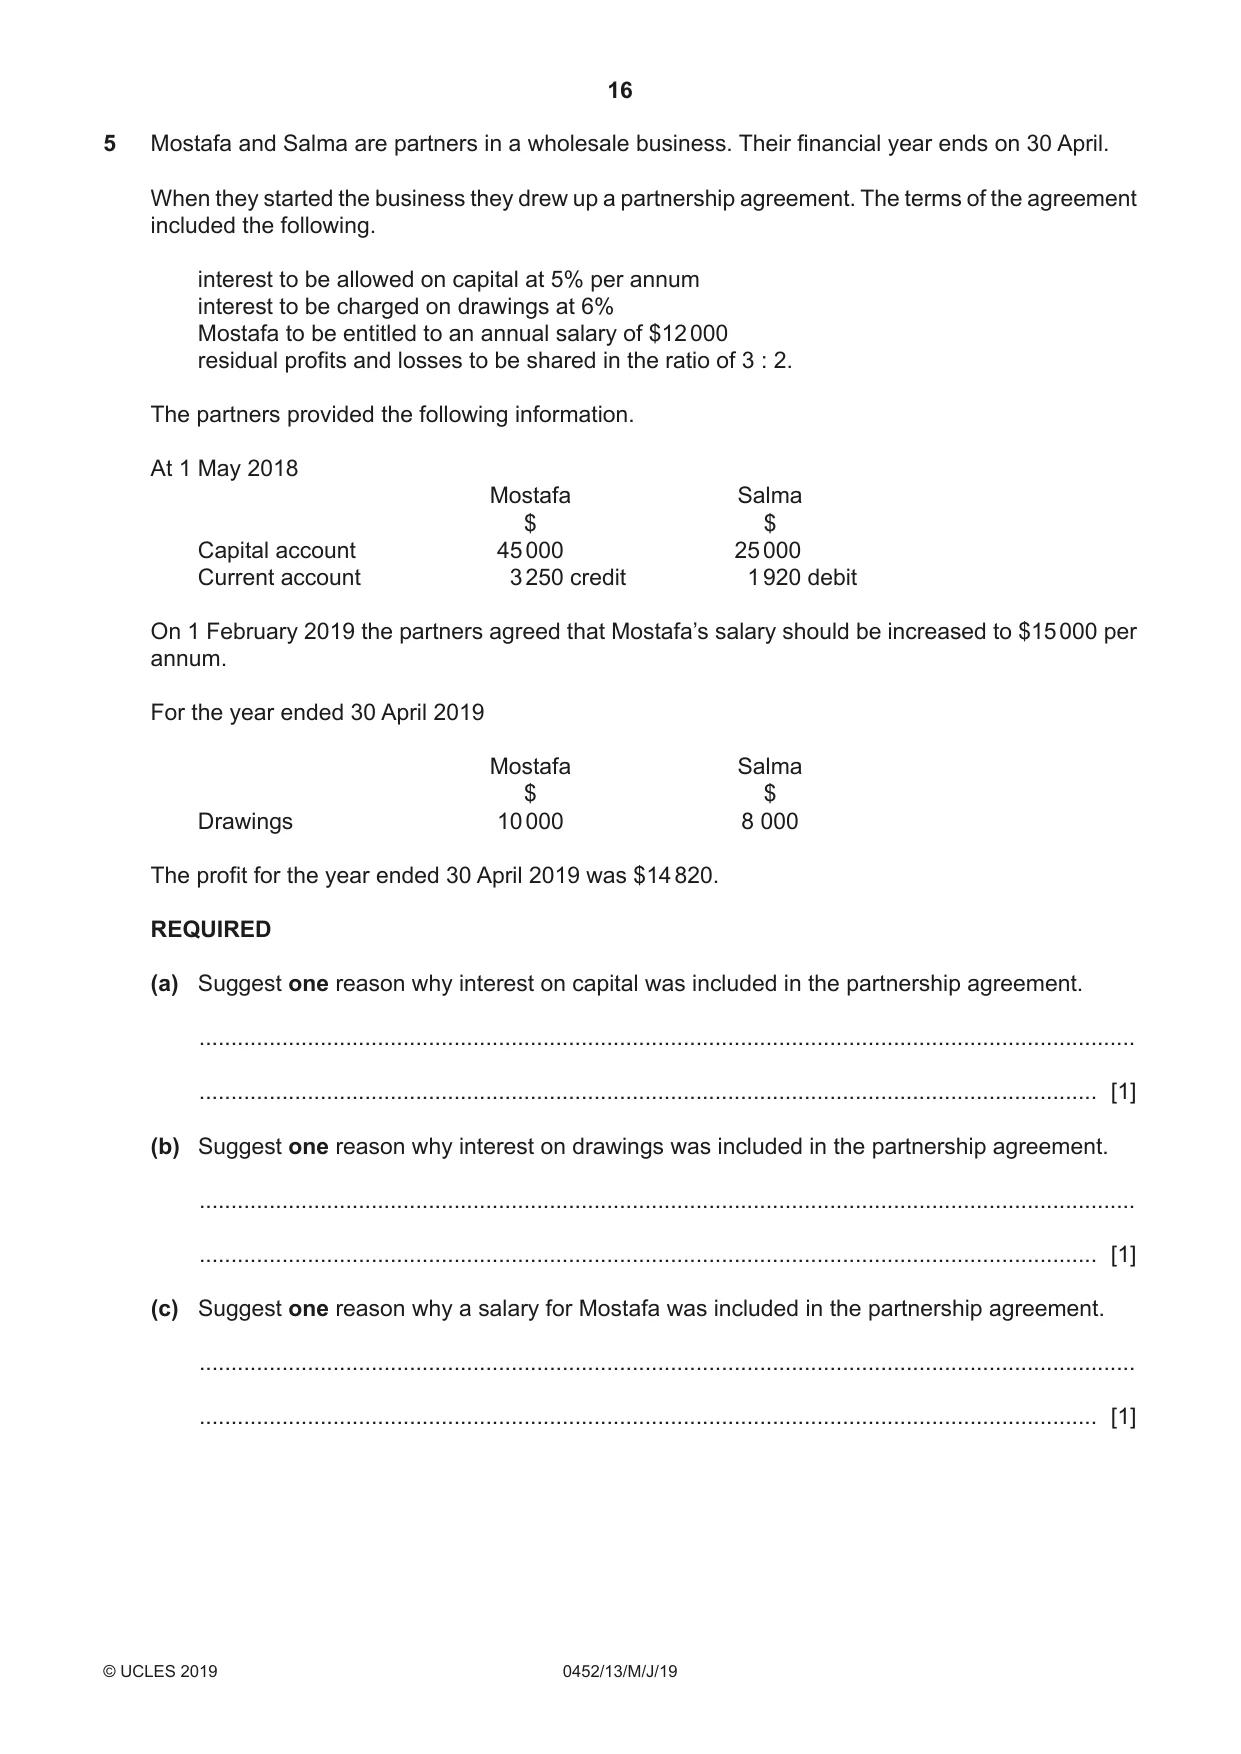
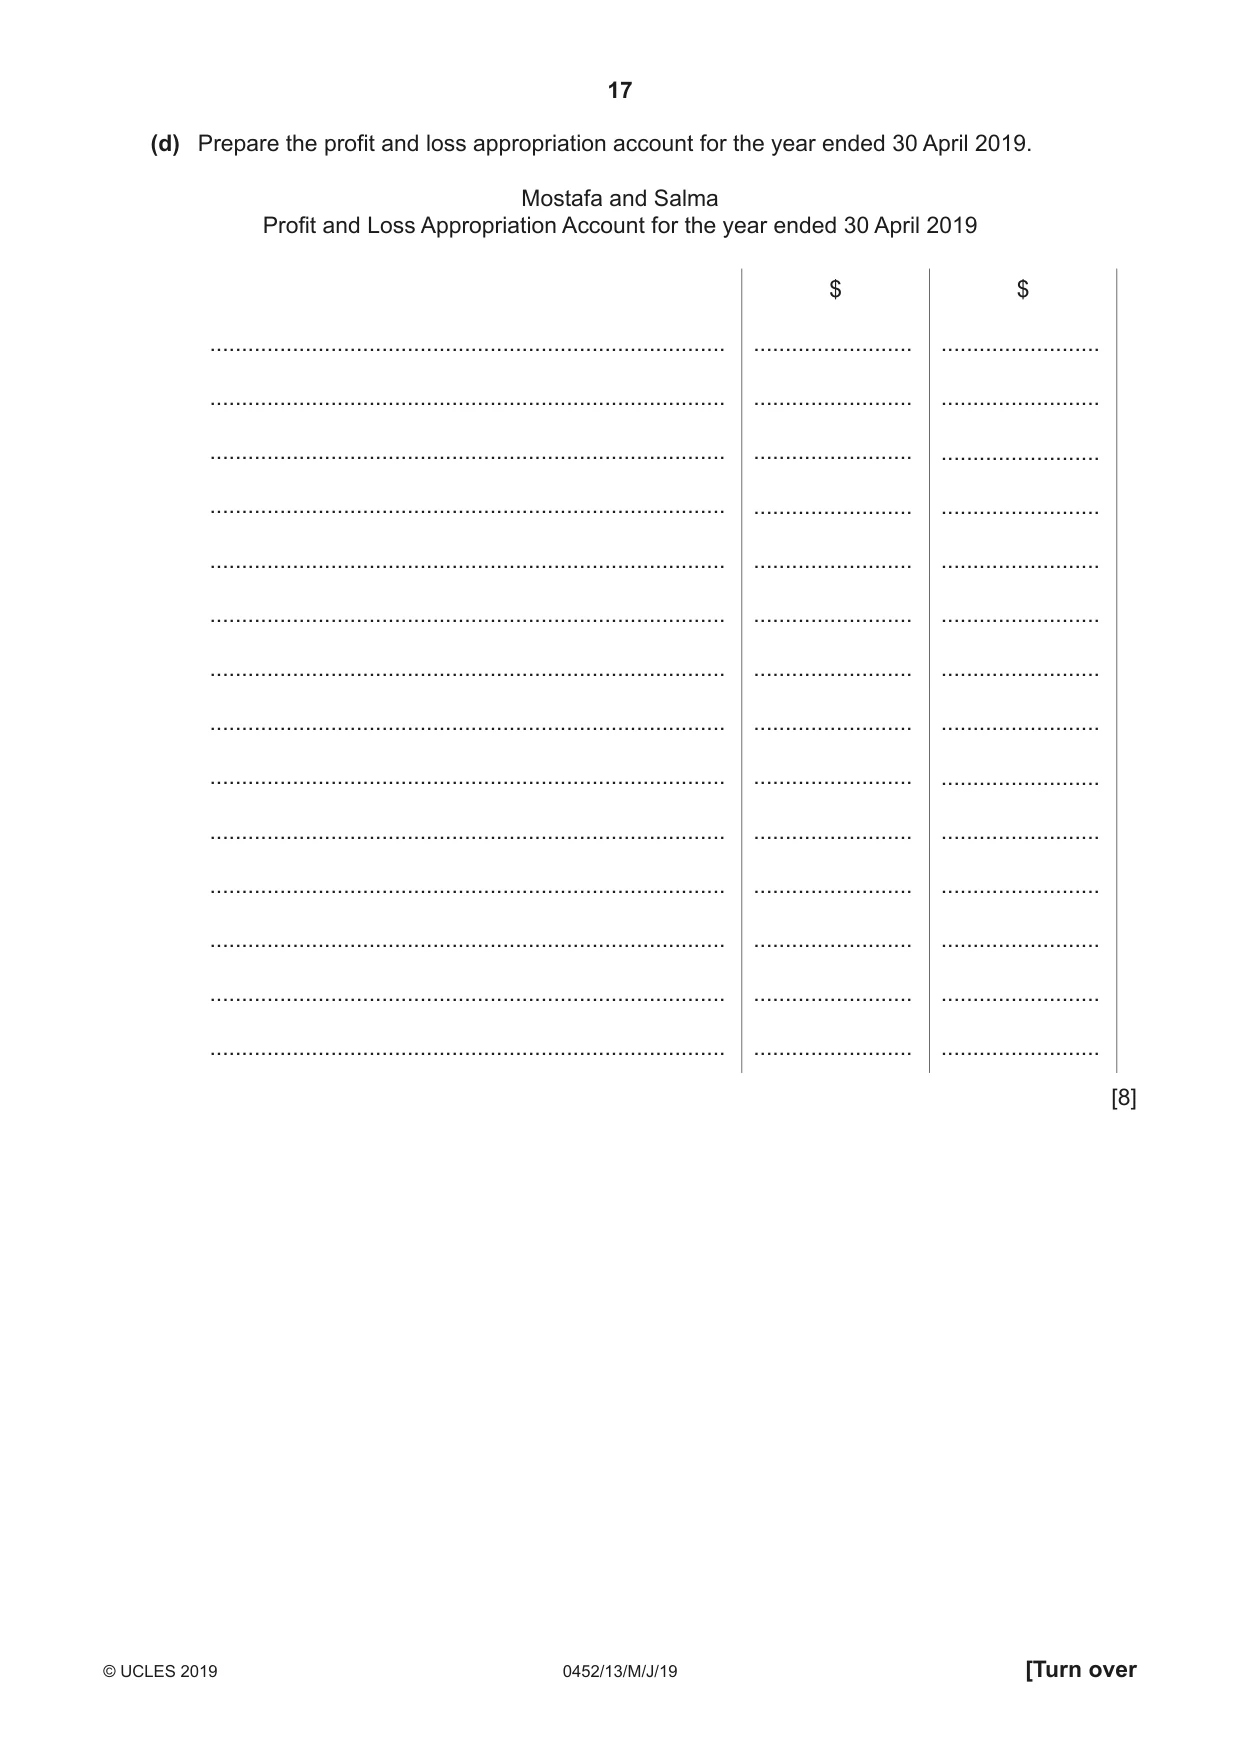
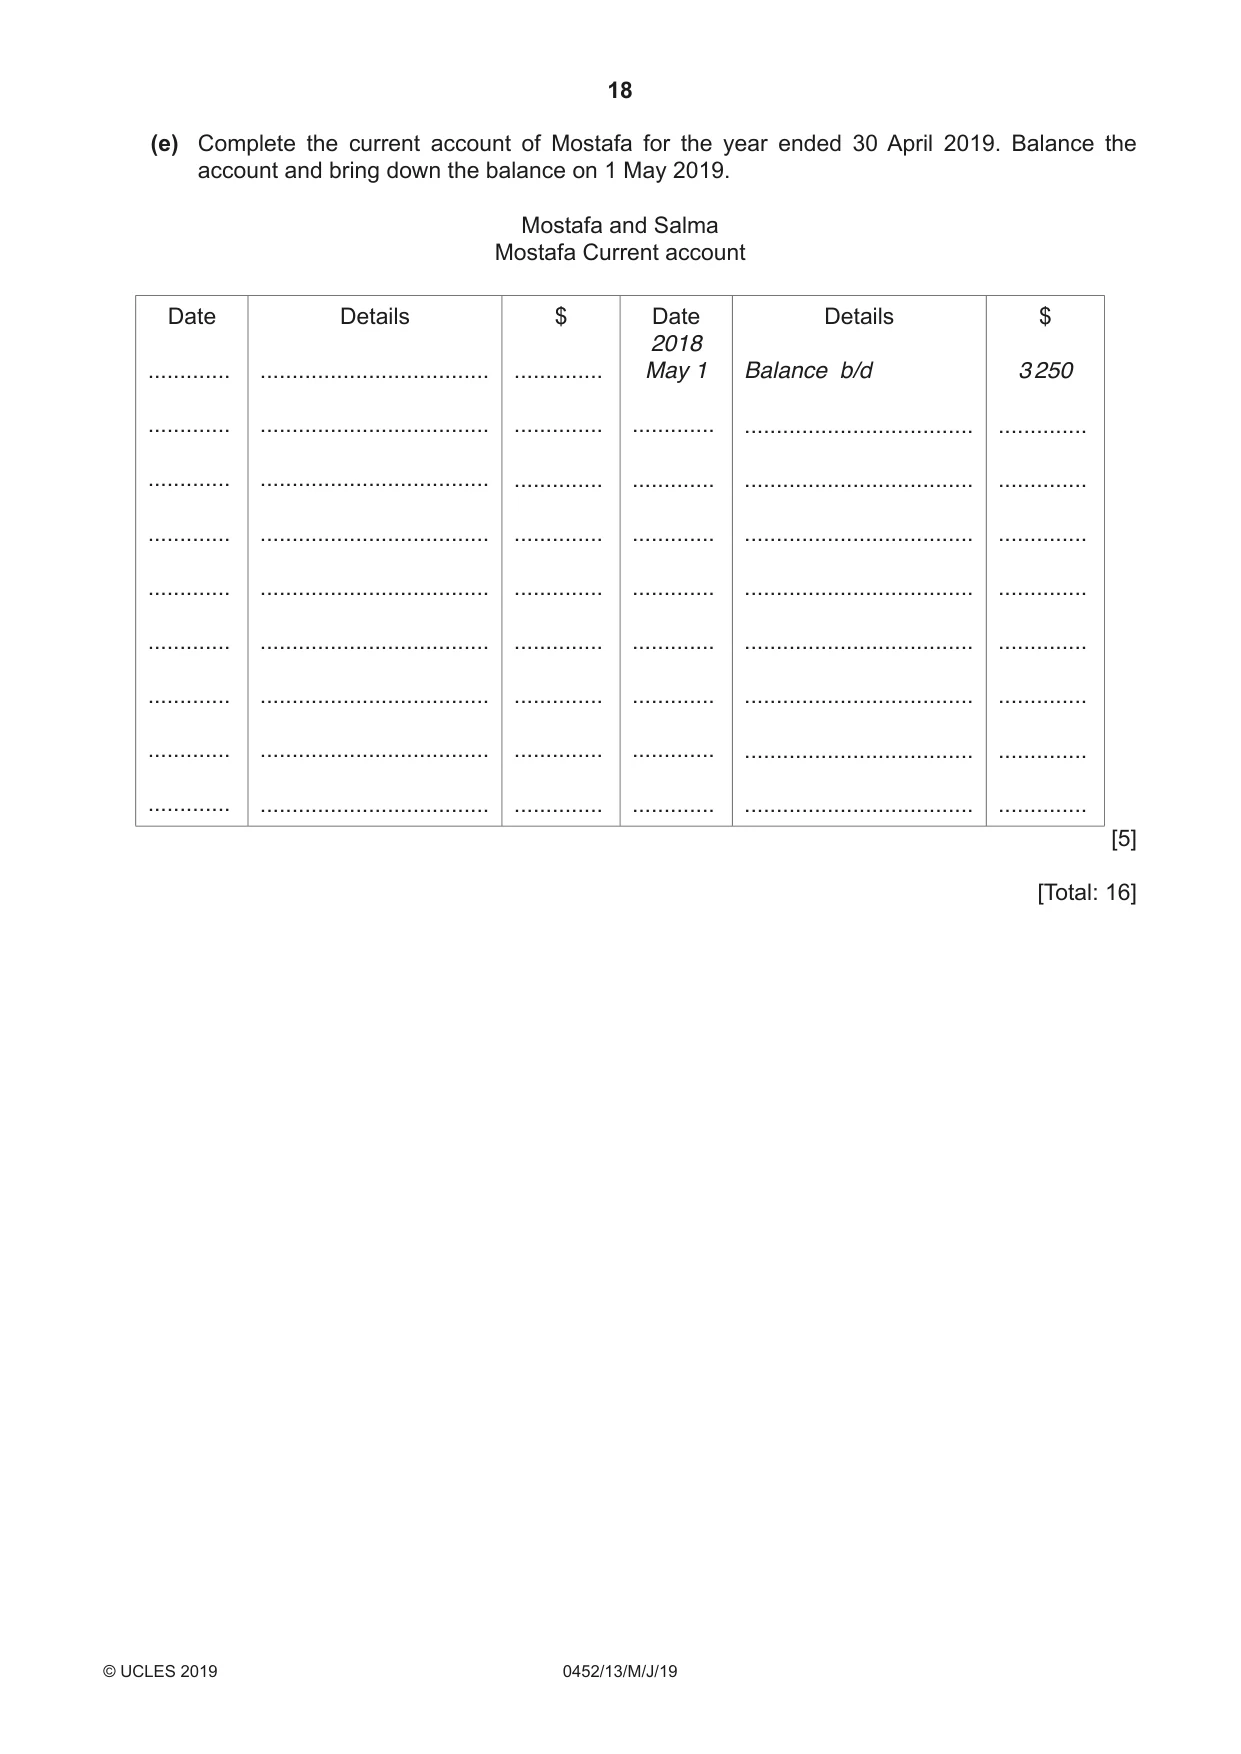
16 0452/13/M/J/19 © UCLES 2019 5 Mostafa and Salma are partners in a wholesale business. Their financial year ends on 30 April. When they started the business they drew up a partnership agreement. The terms of the agreement included the following. interest to be allowed on capital at 5% per annum interest to be charged on drawings at 6% Mostafa to be entitled to an annual salary of $12 000 residual profits and losses to be shared in the ratio of 3 : 2. The partners provided the following information. At 1 May 2018 Mostafa Salma $ $ Capital account 45 000 25 000 Current account 3 250 credit 1 920 debit On 1 February 2019 the partners agreed that Mostafa’s salary should be increased to $15 000 per annum. For the year ended 30 April 2019 Mostafa Salma $ $ Drawings 10 000 8 000 The profit for the year ended 30 April 2019 was $14 820. REQUIRED (a) Suggest one reason why interest on capital was included in the partnership agreement. … … [1] (b) Suggest one reason why interest on drawings was included in the partnership agreement. … … [1] (c) Suggest one reason why a salary for Mostafa was included in the partnership agreement. … … [1]
Question paper, page 17
17 0452/13/M/J/19 © UCLES 2019 [Turn over (d) Prepare the profit and loss appropriation account for the year ended 30 April 2019. Mostafa and Salma Profit and Loss Appropriation Account for the year ended 30 April 2019 … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … [8]
Question paper, page 18
18 0452/13/M/J/19 © UCLES 2019 (e) Complete the current account of Mostafa for the year ended 30 April 2019. Balance the account and bring down the balance on 1 May 2019. Mostafa and Salma Mostafa Current account Date … … … … … … … … … Details … … … … … … … … … $ … … … … … … … … … Date 2018 May 1 … … … … … … … … Details Balance b/d … … … … … … … … $ 3 250 … … … … … … … … [5] [Total: 16]
Question paper, page 19
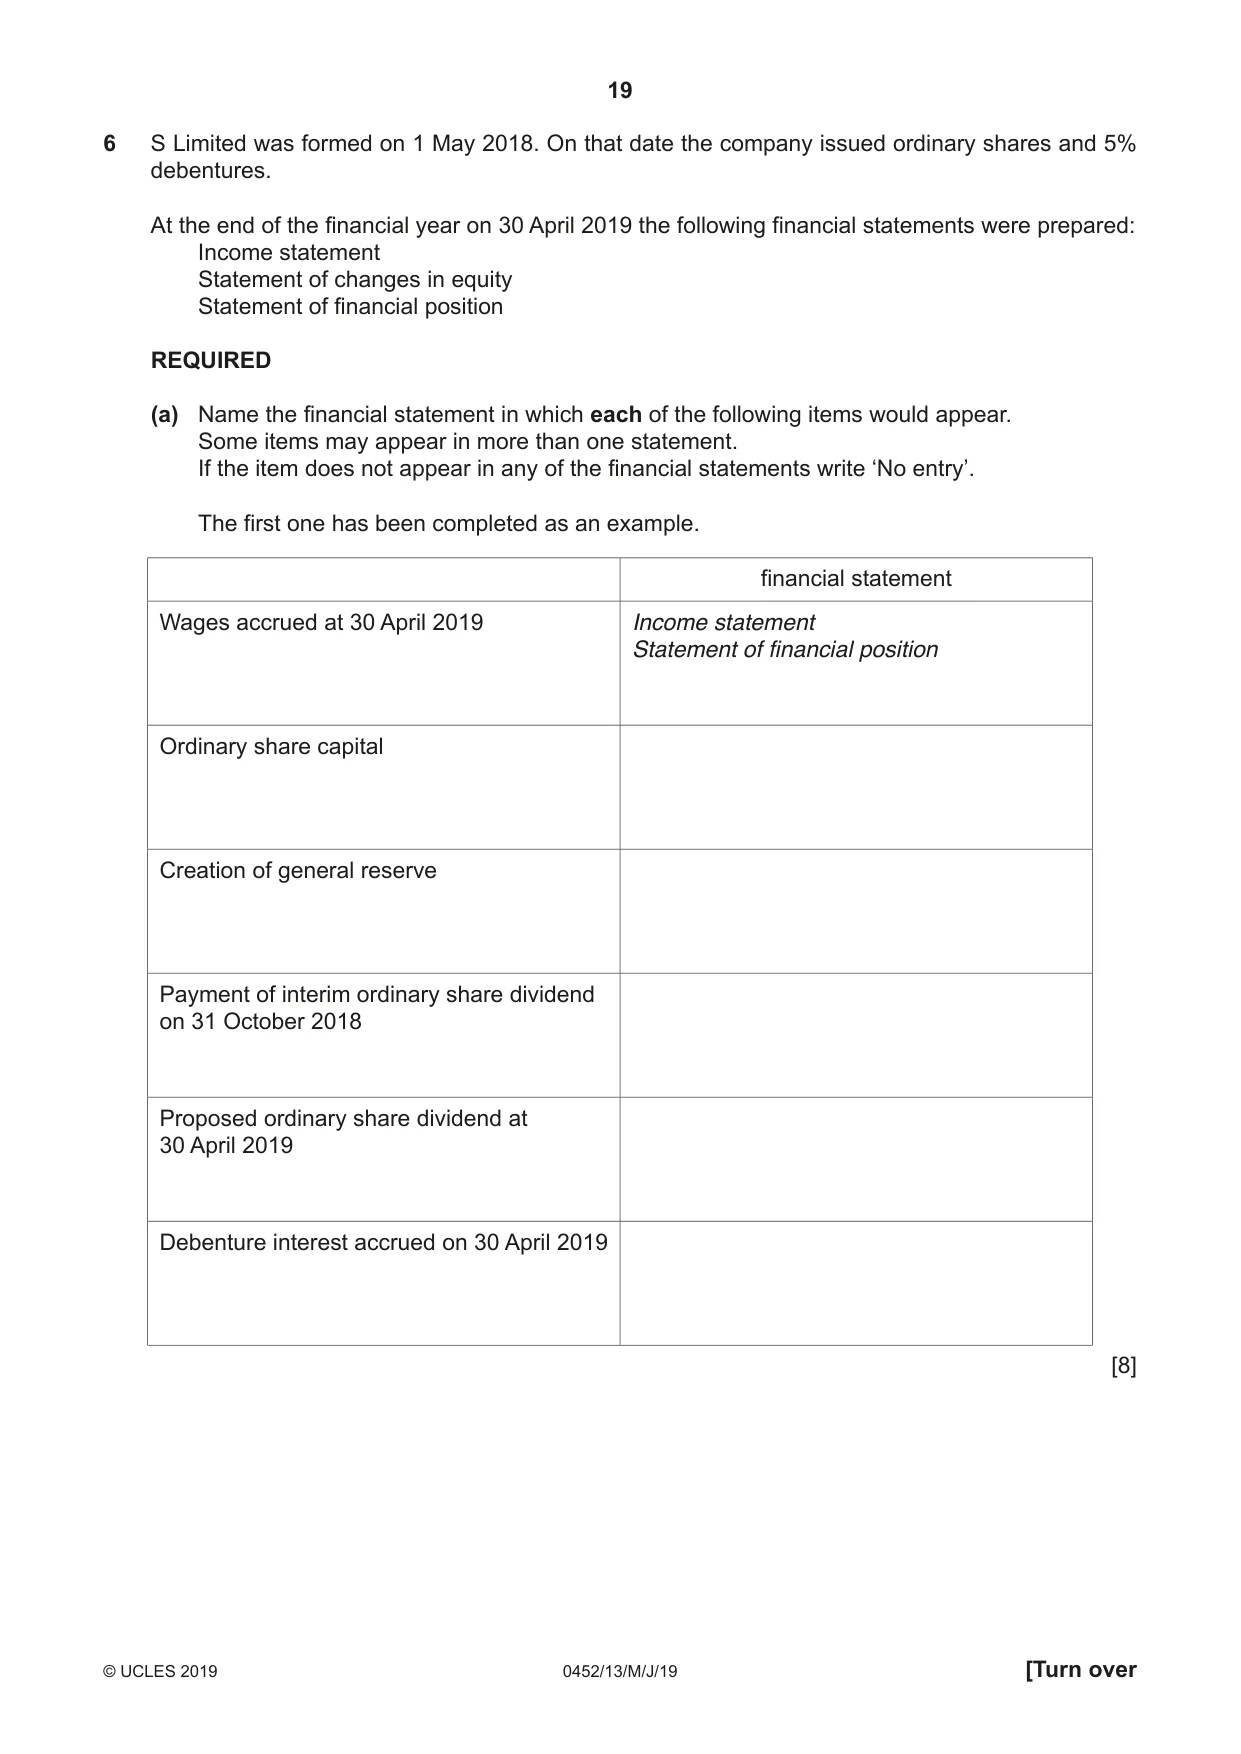
19 0452/13/M/J/19 © UCLES 2019 [Turn over 6 S Limited was formed on 1 May 2018. On that date the company issued ordinary shares and 5% debentures. At the end of the financial year on 30 April 2019 the following financial statements were prepared: Income statement Statement of changes in equity Statement of financial position REQUIRED (a) Name the financial statement in which each of the following items would appear. Some items may appear in more than one statement. If the item does not appear in any of the financial statements write ‘No entry’. The first one has been completed as an example. financial statement Wages accrued at 30 April 2019 Income statement Statement of financial position Ordinary share capital Creation of general reserve Payment of interim ordinary share dividend on 31 October 2018 Proposed ordinary share dividend at 30 April 2019 Debenture interest accrued on 30 April 2019 [8]
Question paper, page 20
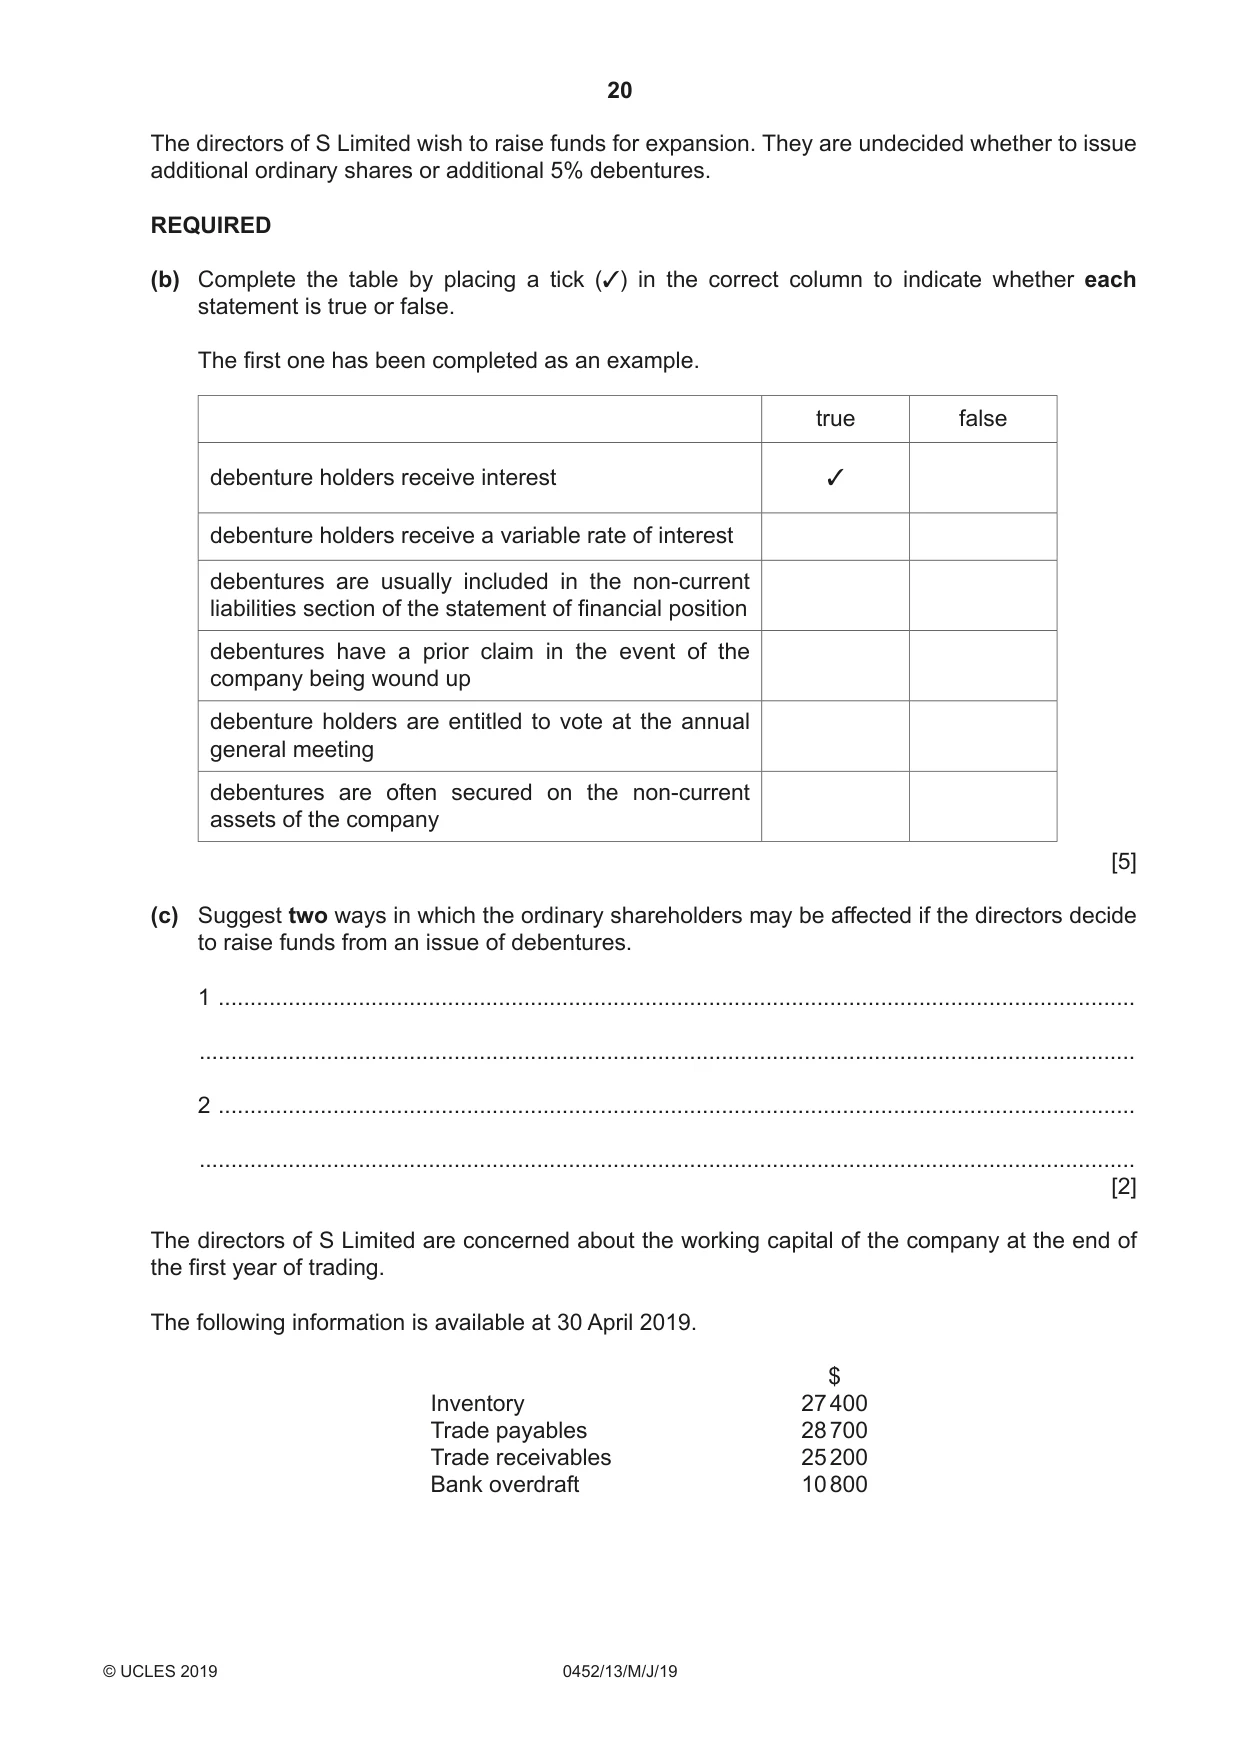
20 0452/13/M/J/19 © UCLES 2019 The directors of S Limited wish to raise funds for expansion. They are undecided whether to issue additional ordinary shares or additional 5% debentures. REQUIRED (b) Complete the table by placing a tick (3) in the correct column to indicate whether each statement is true or false. The first one has been completed as an example. true false debenture holders receive interest 3 debenture holders receive a variable rate of interest debentures are usually included in the non-current liabilities section of the statement of financial position debentures have a prior claim in the event of the company being wound up debenture holders are entitled to vote at the annual general meeting debentures are often secured on the non-current assets of the company [5] (c) Suggest two ways in which the ordinary shareholders may be affected if the directors decide to raise funds from an issue of debentures. 1 … … 2 … … [2] The directors of S Limited are concerned about the working capital of the company at the end of the first year of trading. The following information is available at 30 April 2019. $ Inventory 27 400 Trade payables 28 700 Trade receivables 25 200 Bank overdraft 10 800
Question paper, page 21
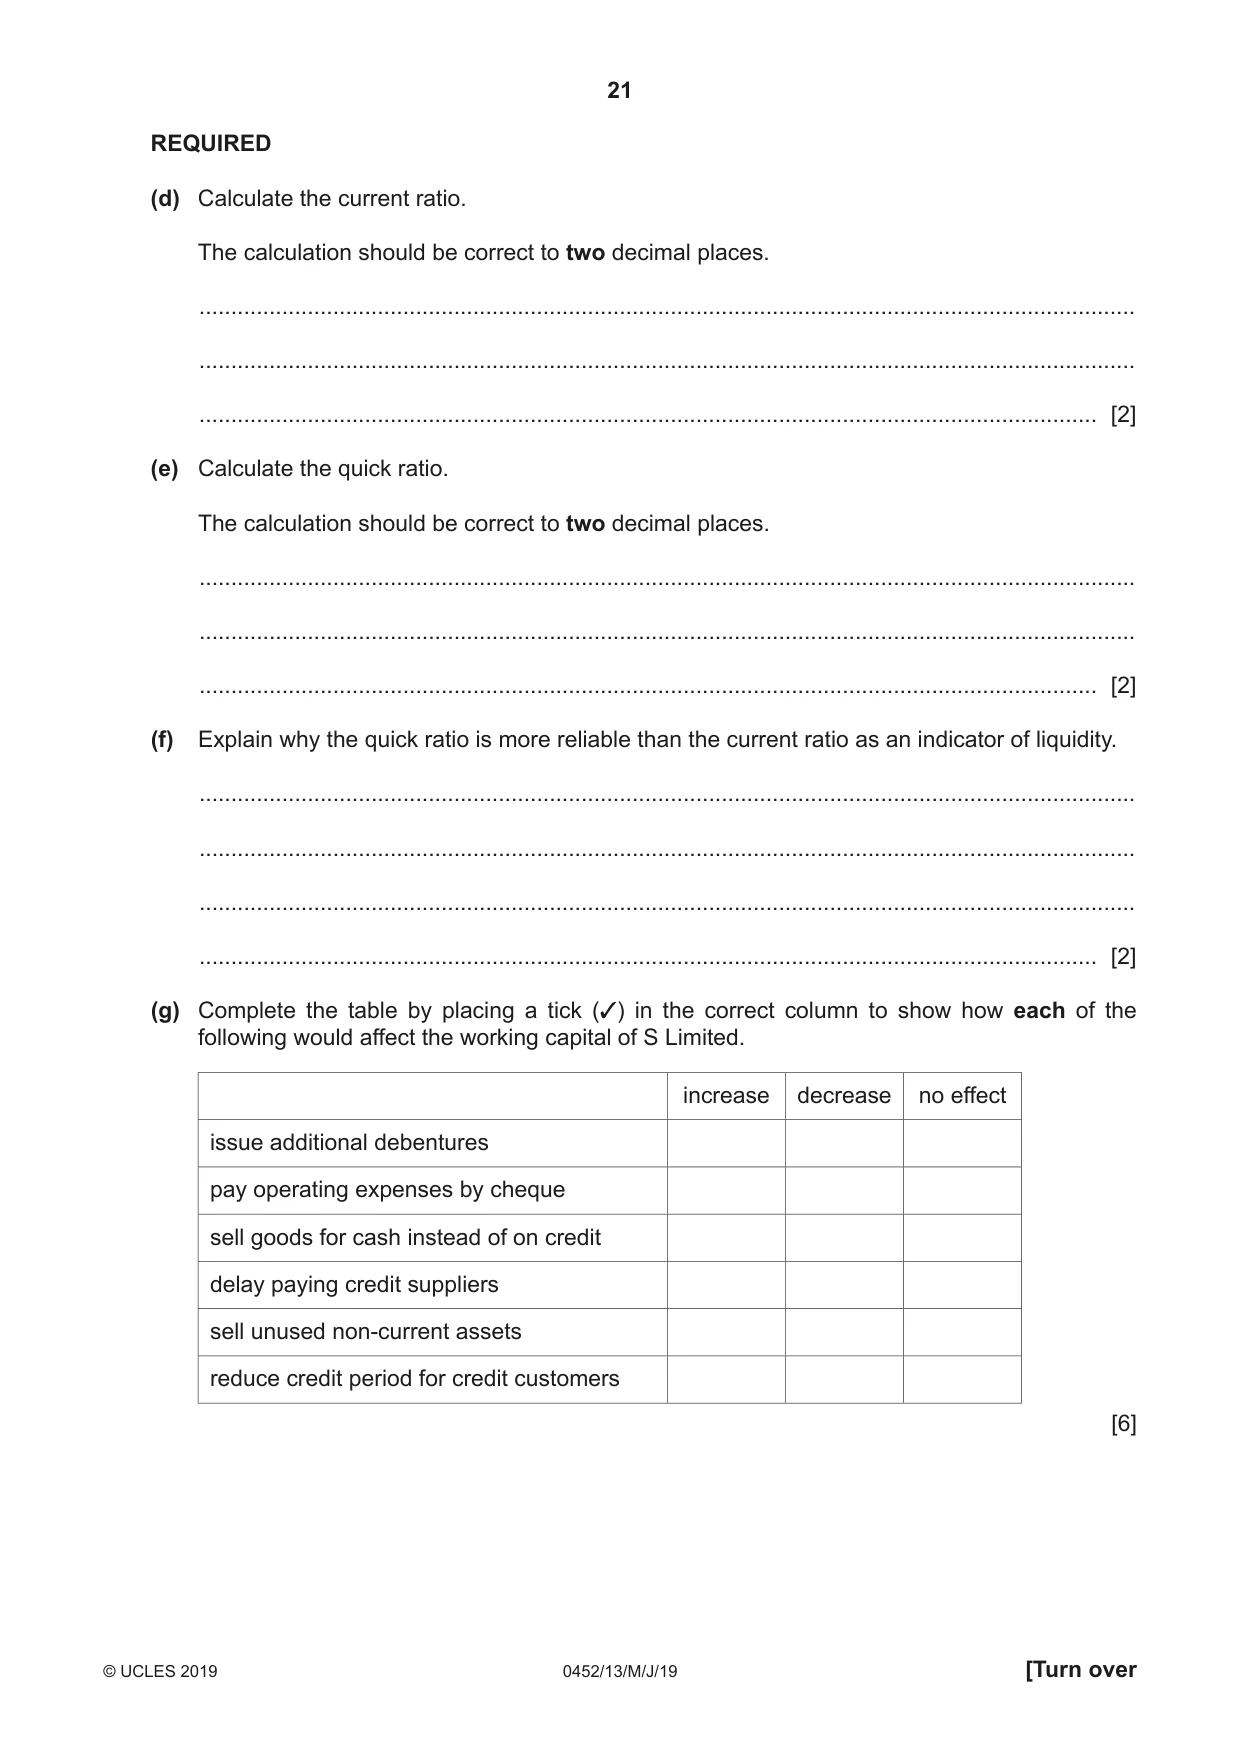
21 0452/13/M/J/19 © UCLES 2019 [Turn over REQUIRED (d) Calculate the current ratio. The calculation should be correct to two decimal places. … … … [2] (e) Calculate the quick ratio. The calculation should be correct to two decimal places. … … … [2] (f) Explain why the quick ratio is more reliable than the current ratio as an indicator of liquidity. … … … … [2] (g) Complete the table by placing a tick (3) in the correct column to show how each of the following would affect the working capital of S Limited. increase decrease no effect issue additional debentures pay operating expenses by cheque sell goods for cash instead of on credit delay paying credit suppliers sell unused non-current assets reduce credit period for credit customers [6]
Question paper, page 22
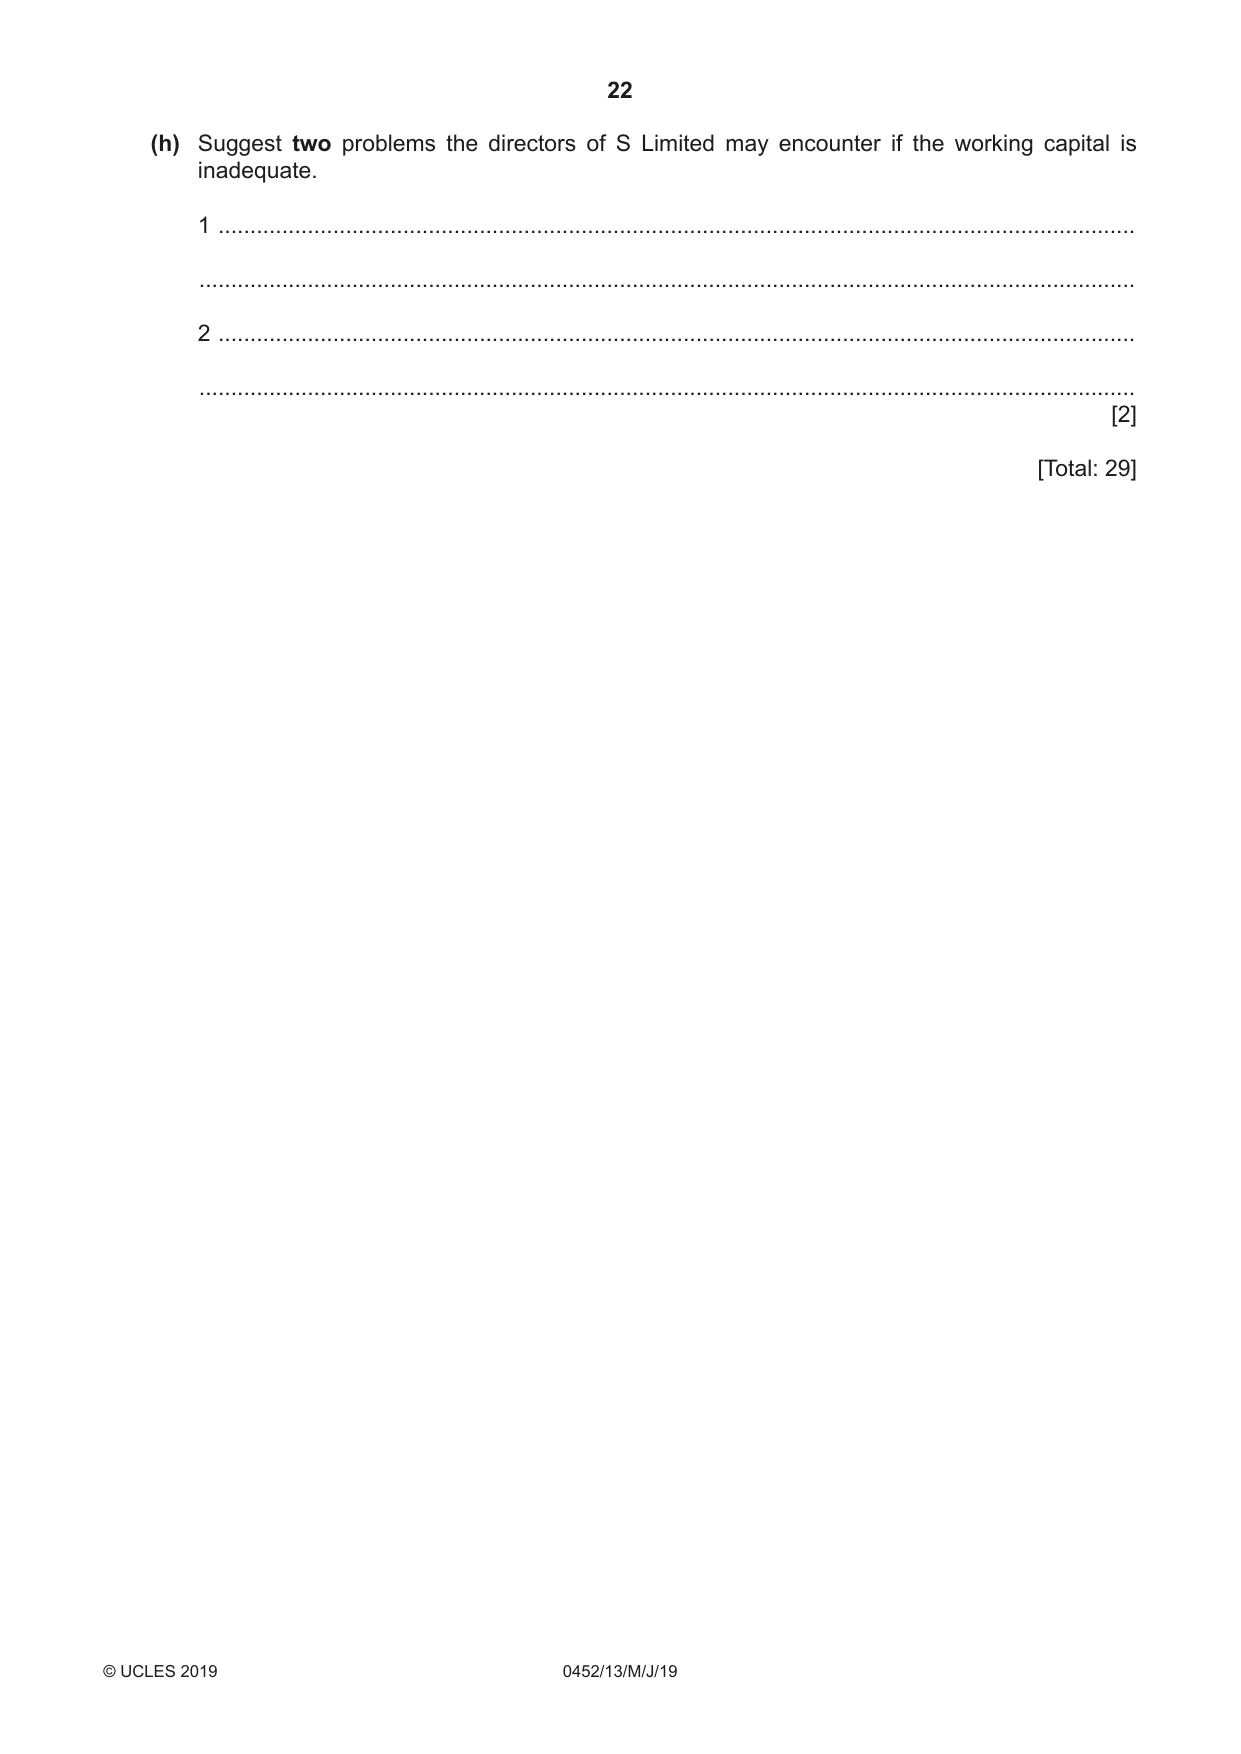
22 0452/13/M/J/19 © UCLES 2019 (h) Suggest two problems the directors of S Limited may encounter if the working capital is inadequate. 1 … … 2 … … [2] [Total: 29]
Question paper, page 23
23 0452/13/M/J/19 © UCLES 2019 BLANK PAGE
Question paper, page 24
24 0452/13/M/J/19 © UCLES 2019 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which itself is a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
This document consists of 16 printed pages. © UCLES 2019 [Turn over Cambridge Assessment International Education Cambridge International General Certificate of Secondary Education ACCOUNTING 0452/13 Paper 1 May/June 2019 MARK SCHEME Maximum Mark: 120 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the May/June 2019 series for most Cambridge IGCSE™, Cambridge International A and AS Level and Cambridge Pre-U components, and some Cambridge O Level components.
Mark scheme, page 2
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 2 of 16 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors.
Mark scheme, page 3
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 3 of 16 GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 4
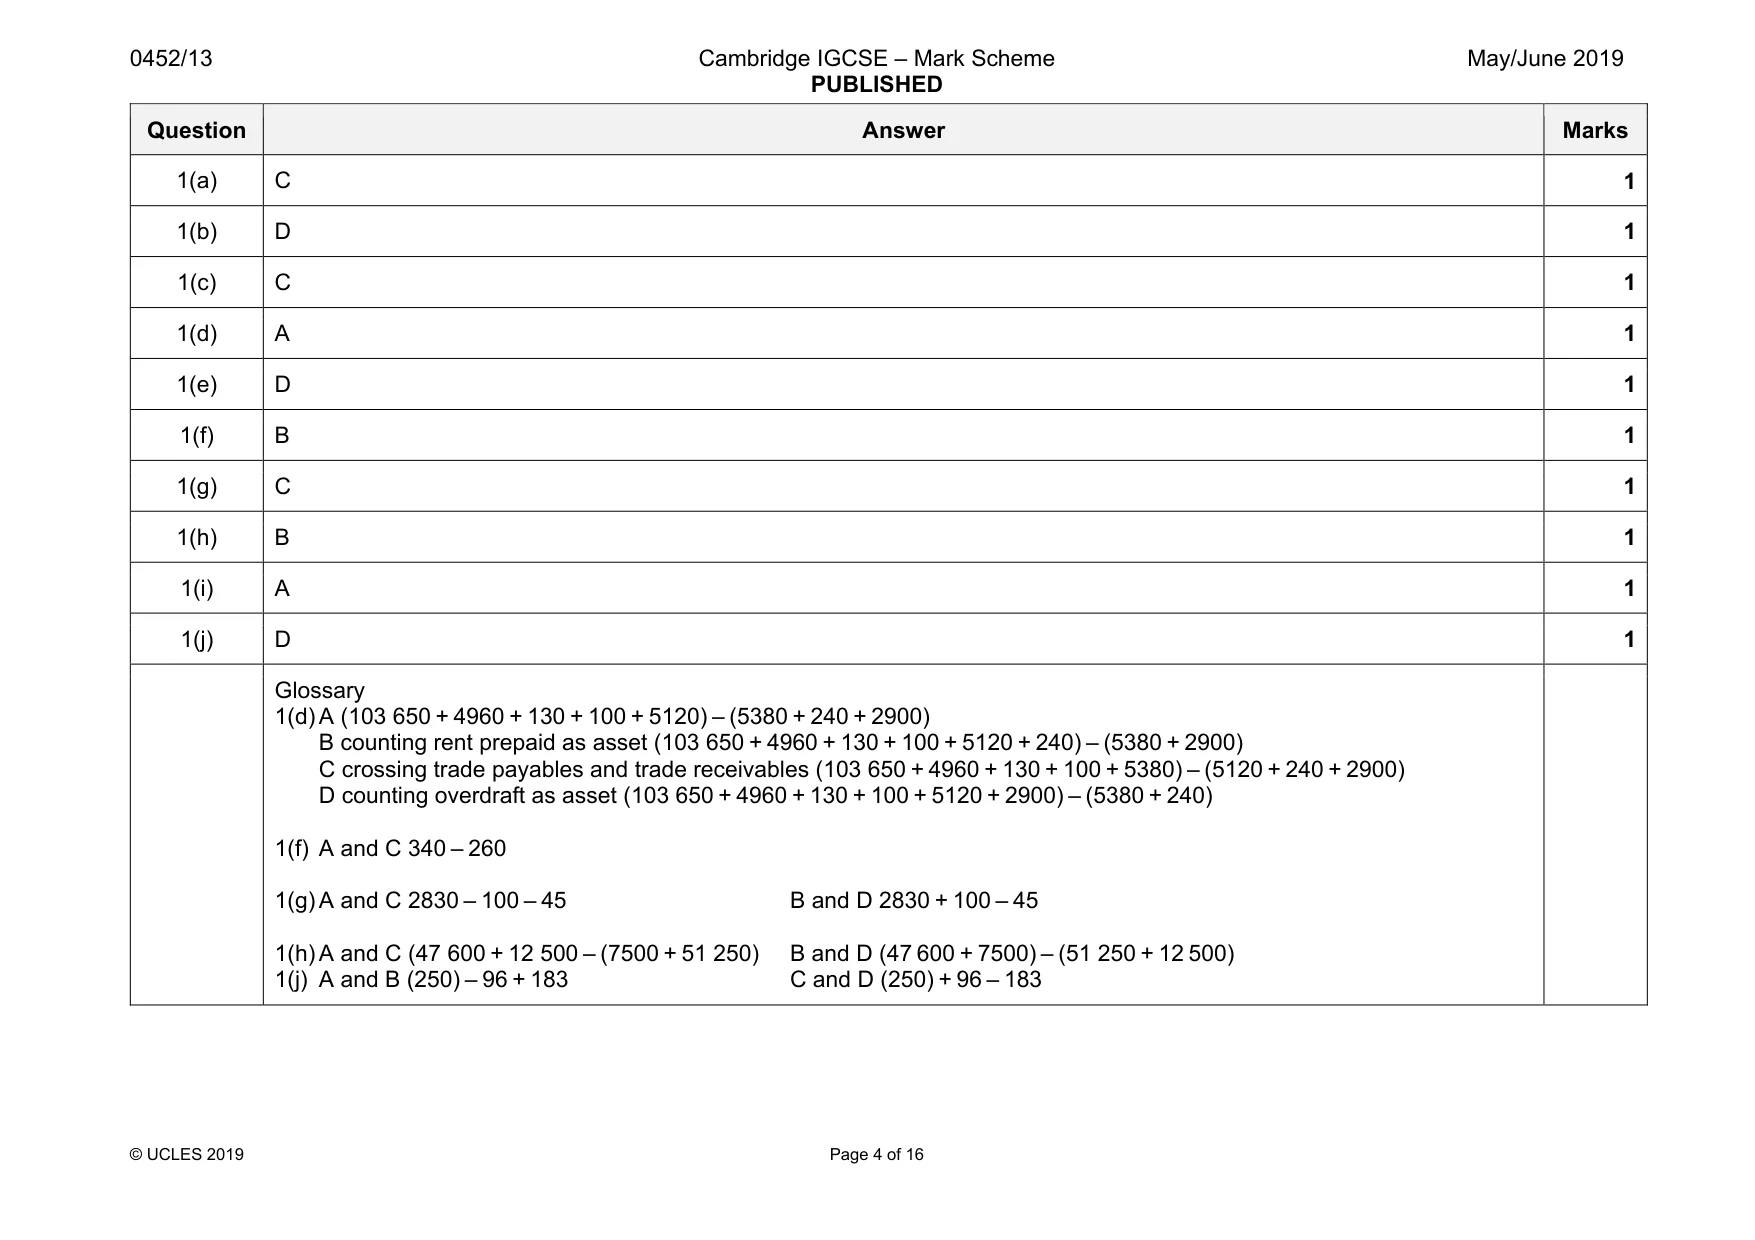
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 4 of 16 Question Answer Marks 1(a) C 1 1(b) D 1 1(c) C 1 1(d) A 1 1(e) D 1 1(f) B 1 1(g) C 1 1(h) B 1 1(i) A 1 1(j) D 1 Glossary 1(d) A (103 650 + 4960 + 130 + 100 + 5120) – (5380 + 240 + 2900) B counting rent prepaid as asset (103 650 + 4960 + 130 + 100 + 5120 + 240) – (5380 + 2900) C crossing trade payables and trade receivables (103 650 + 4960 + 130 + 100 + 5380) – (5120 + 240 + 2900) D counting overdraft as asset (103 650 + 4960 + 130 + 100 + 5120 + 2900) – (5380 + 240) 1(f) A and C 340 – 260 1(g) A and C 2830 – 100 – 45 B and D 2830 + 100 – 45 1(h) A and C (47 600 + 12 500 – (7500 + 51 250) B and D (47 600 + 7500) – (51 250 + 12 500) 1(j) A and B (250) – 96 + 183 C and D (250) + 96 – 183
Mark scheme, page 5
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 5 of 16 Question Answer Marks 2(a) Payment of annual insurance premium revenue expenditure Purchases of goods for re-sale revenue expenditure (1) Proceeds of sale of old shop fittings at book value capital receipt (1) Cost of new shop fittings capital expenditure (1) Delivery charge on new shop fittings capital expenditure (1) Cash sales revenue receipt (1) Loan from bank capital receipt (1) 6 2(b) transaction account(s) debited $ account(s) credited $ Nabil transferred his private motor vehicle, $18 000 to the business. motor vehicles 18 000 (1) capital 18 000 (1) Purchased stationery, $44, on credit from Tahir. stationery 44 (1) Tahir 44 (1) Paid office cash, $490, into the business bank account. bank 490 (1) cash 490 (1) Settled Vijay’s account of $200 by bank transfer after deducting 2% cash discount. Vijay 200 (1) bank discount received 196 4 (1) (1) 9
Mark scheme, page 6
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 6 of 16 Question Answer Marks 2(c) debit column credit column Any 2 correct items (1) rent and rates given capital 9 motor vehicle at cost 9 motor expenses 9 purchases returns 9 discount received 9 Tarek, a credit supplier 9 insurance 9 bank overdraft 9 operating expenses 9 5 year bank loan 9 drawings 9 carriage outwards 9 6
Mark scheme, page 7
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 7 of 16 Question Answer Marks 3(a) Hamila Safiya account Date 2019 Feb 1 16 18 Details Balance b/d (1) Sales (1) Bank (1) $ 320 200 320 840 Date 2019 Feb 12 24 27 Details Bank (1) Cash (1) Bad debts (1OF) $ 320 400 120 840 6 3(b) Hamila Bad debts account Date 2019 Feb 27 Details Total to date Safiya (1OF) $ 674 120 794 Date 2019 Feb 28 Details Income statement * (1OF) $ 794 _ _ 794 2
Mark scheme, page 8
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 8 of 16 Question Answer Marks 3(c)(i) 1 March 2018 Balance b/d This is the amount of the provision for doubtful debts at the start or brought down or initial provision (of the financial year). (1) Double entry: provision for doubtful debts } debit }(1) 28 February 2019 Balance c/d This is the total of the provision for doubtful debts at the end of the year or to be brought down or new provision Or This is the amount of provision for doubtful debts required for the following financial year (1) Double entry: provision for doubtful debts } credit }(1) 4 3(c)(ii) This is the difference between the opening and closing provision for doubtful debts. (1) This is the surplus provision which is transferred to the income statement. (1) There is a decrease or reduction in provision (1) and this is added to gross profit or additional income (1) 2 3(d) Hamila’s profit for the year is shown at a more realistic figure (1) Hamila’s trade receivables (current assets) are not overstated (1) 2 3(e) The sales for which Hamila is unlikely to be paid (1) are regarded as an expense of the year in which those sales are made (1) providing for potential losses (1) recognise that some accounts may not be paid (1) 2 3(f) Reduce credit sales/sell on cash basis only Obtain references from new credit customers Fix or reduce credit limit for each customer Improve credit control/ reduce credit period Issue invoices and monthly statements promptly Refuse further supplies until outstanding balance is paid Allow cash discount (for prompt payment) Charge interest on overdue accounts Any 2 points (1) each 2
Mark scheme, page 9
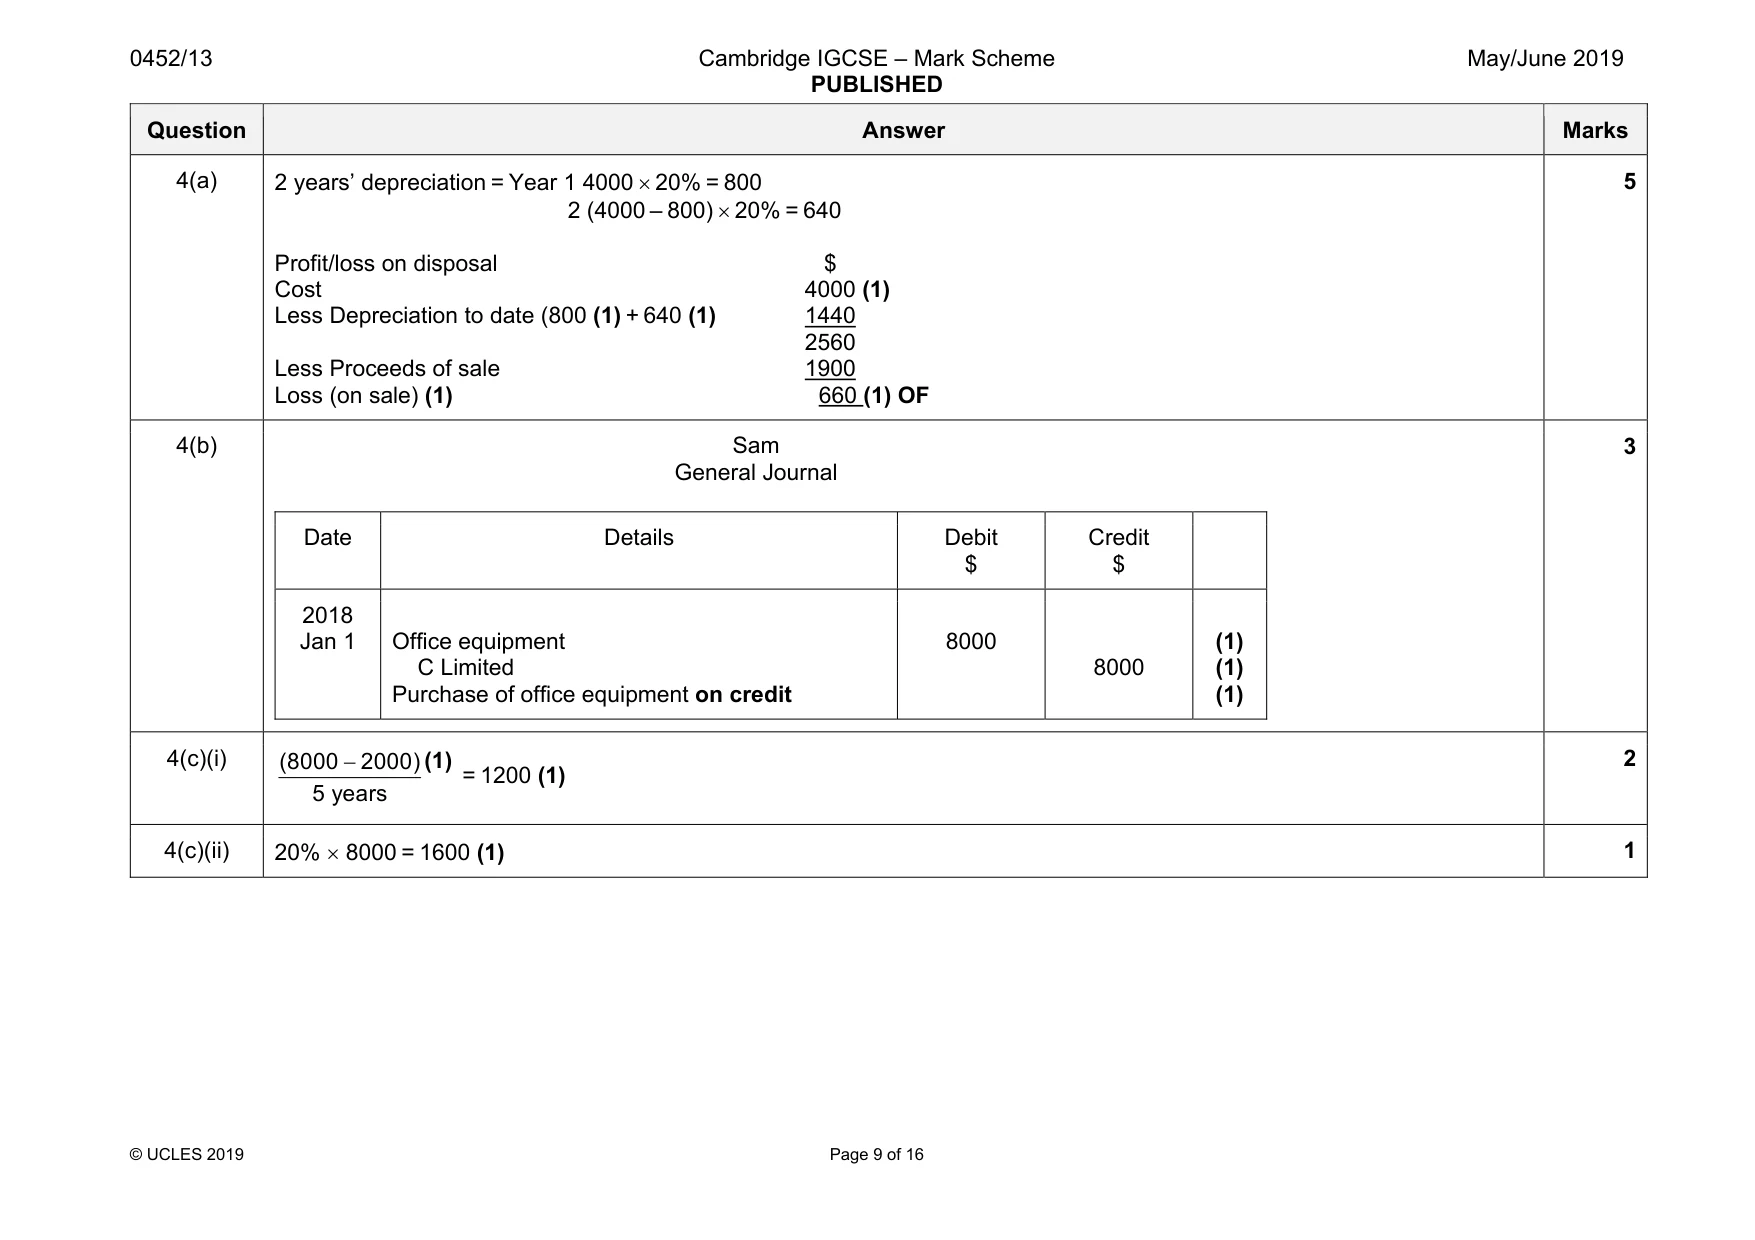
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 9 of 16 Question Answer Marks 4(a) 2 years’ depreciation = Year 1 4000 × 20% = 800 2 (4000 – 800) × 20% = 640 Profit/loss on disposal $ Cost 4000 (1) Less Depreciation to date (800 (1) + 640 (1) 1440 2560 Less Proceeds of sale 1900 Loss (on sale) (1) 660 (1) OF 5 4(b) Sam General Journal Date Details Debit $ Credit $ 2018 Jan 1 Office equipment C Limited Purchase of office equipment on credit 8000 8000 (1) (1) (1) 3 4(c)(i) (8000 2000) 5 years − (1) = 1200 (1) 2 4(c)(ii) 20% × 8000 = 1600 (1) 1
Mark scheme, page 10
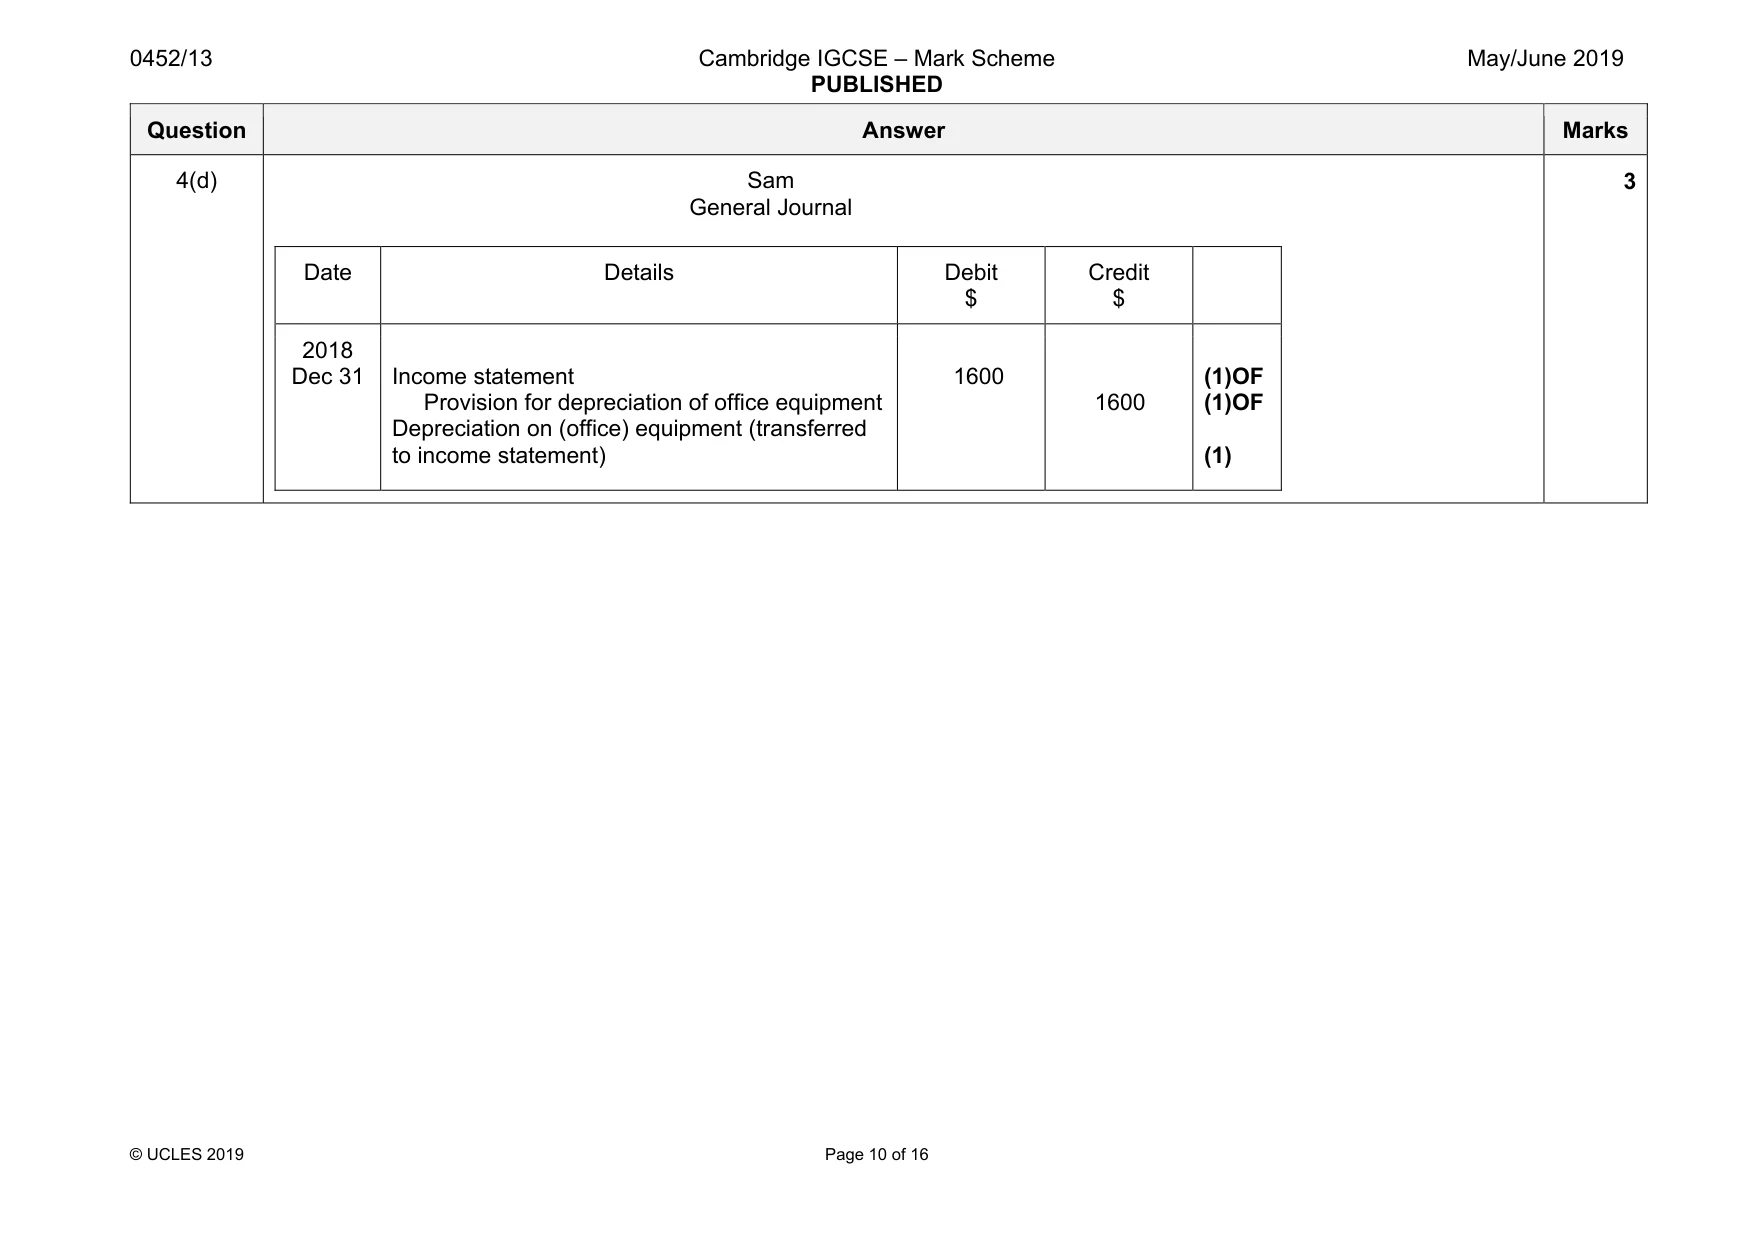
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 10 of 16 Question Answer Marks 4(d) Sam General Journal Date Details Debit $ Credit $ 2018 Dec 31 Income statement Provision for depreciation of office equipment Depreciation on (office) equipment (transferred to income statement) 1600 1600 (1)OF (1)OF (1) 3
Mark scheme, page 11
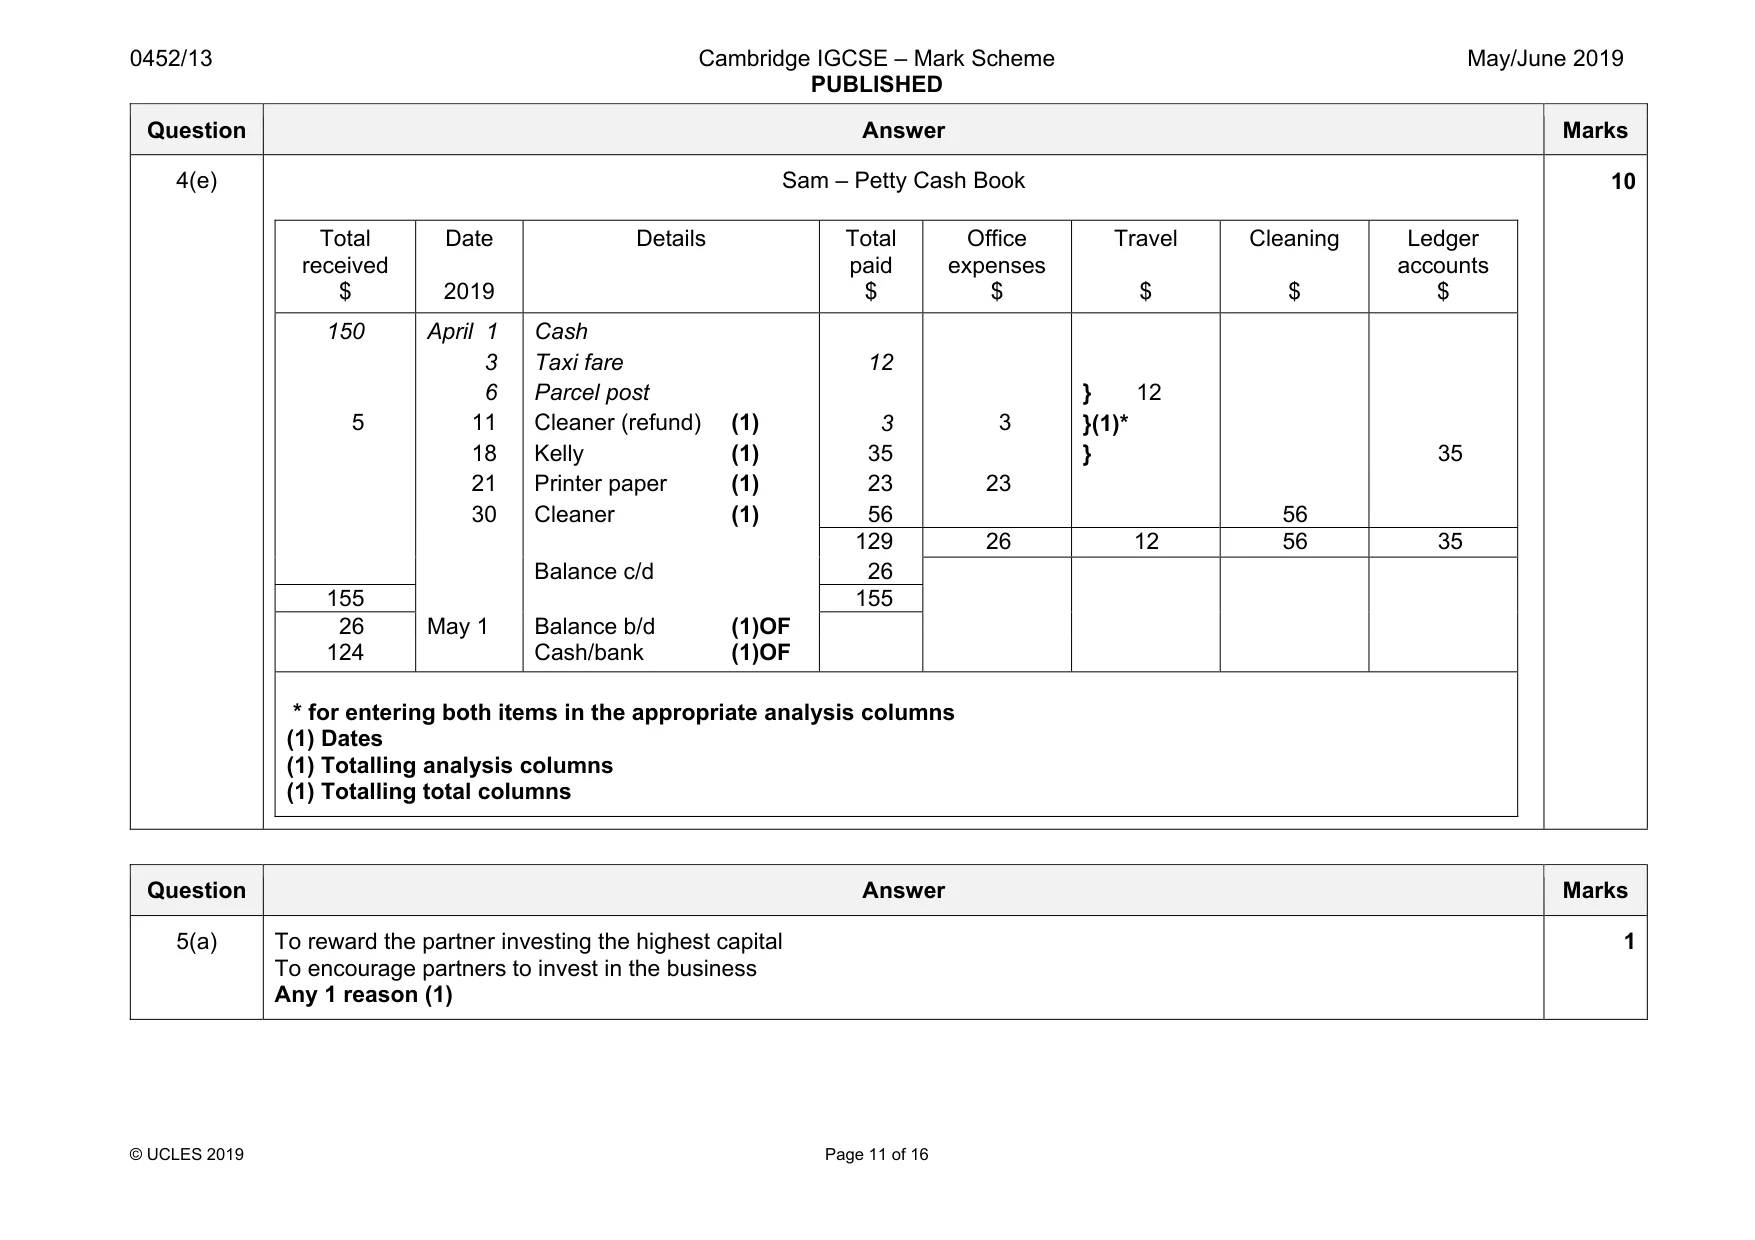
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 11 of 16 Question Answer Marks 4(e) Sam – Petty Cash Book Total received $ Date 2019 Details Total paid $ Office expenses $ Travel $ Cleaning $ Ledger accounts $ 150 5 April 1 3 6 11 18 21 30 Cash Taxi fare Parcel post Cleaner (refund) (1) Kelly (1) Printer paper (1) Cleaner (1) 12 3 35 23 56 3 23 } 12 }(1)* } 56 35 129 26 12 56 35 Balance c/d 26 155 155 26 May 1 Balance b/d (1)OF 124 Cash/bank (1)OF * for entering both items in the appropriate analysis columns (1) Dates (1) Totalling analysis columns (1) Totalling total columns 10 Question Answer Marks 5(a) To reward the partner investing the highest capital To encourage partners to invest in the business Any 1 reason (1) 1
Mark scheme, page 12
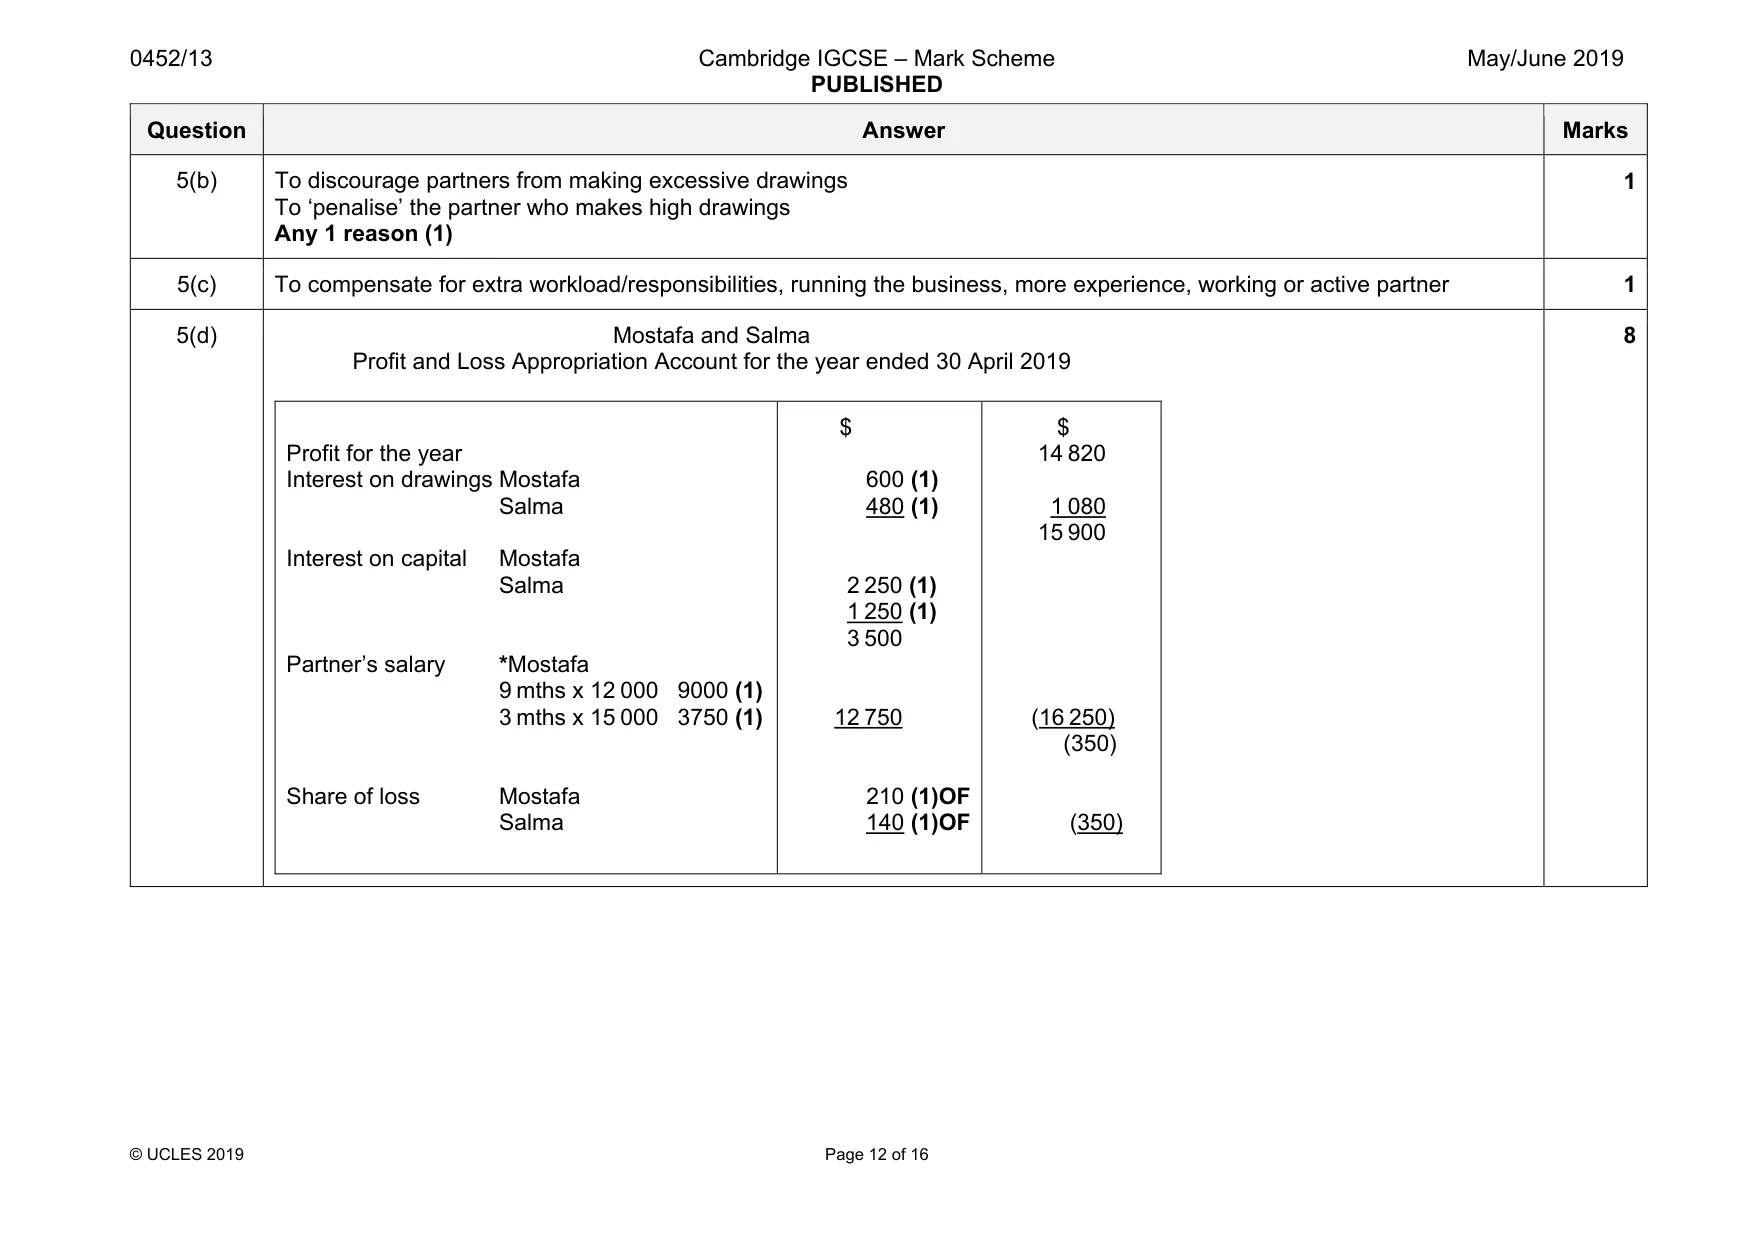
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 12 of 16 Question Answer Marks 5(b) To discourage partners from making excessive drawings To ‘penalise’ the partner who makes high drawings Any 1 reason (1) 1 5(c) To compensate for extra workload/responsibilities, running the business, more experience, working or active partner 1 5(d) Mostafa and Salma Profit and Loss Appropriation Account for the year ended 30 April 2019 Profit for the year Interest on drawings Mostafa Salma Interest on capital Mostafa Salma Partner’s salary *Mostafa 9 mths x 12 000 9000 (1) 3 mths x 15 000 3750 (1) Share of loss Mostafa Salma $ 600 (1) 480 (1) 2 250 (1) 1 250 (1) 3 500 12 750 210 (1)OF 140 (1)OF $ 14 820 1 080 15 900 (16 250) (350) (350) 8
Mark scheme, page 13
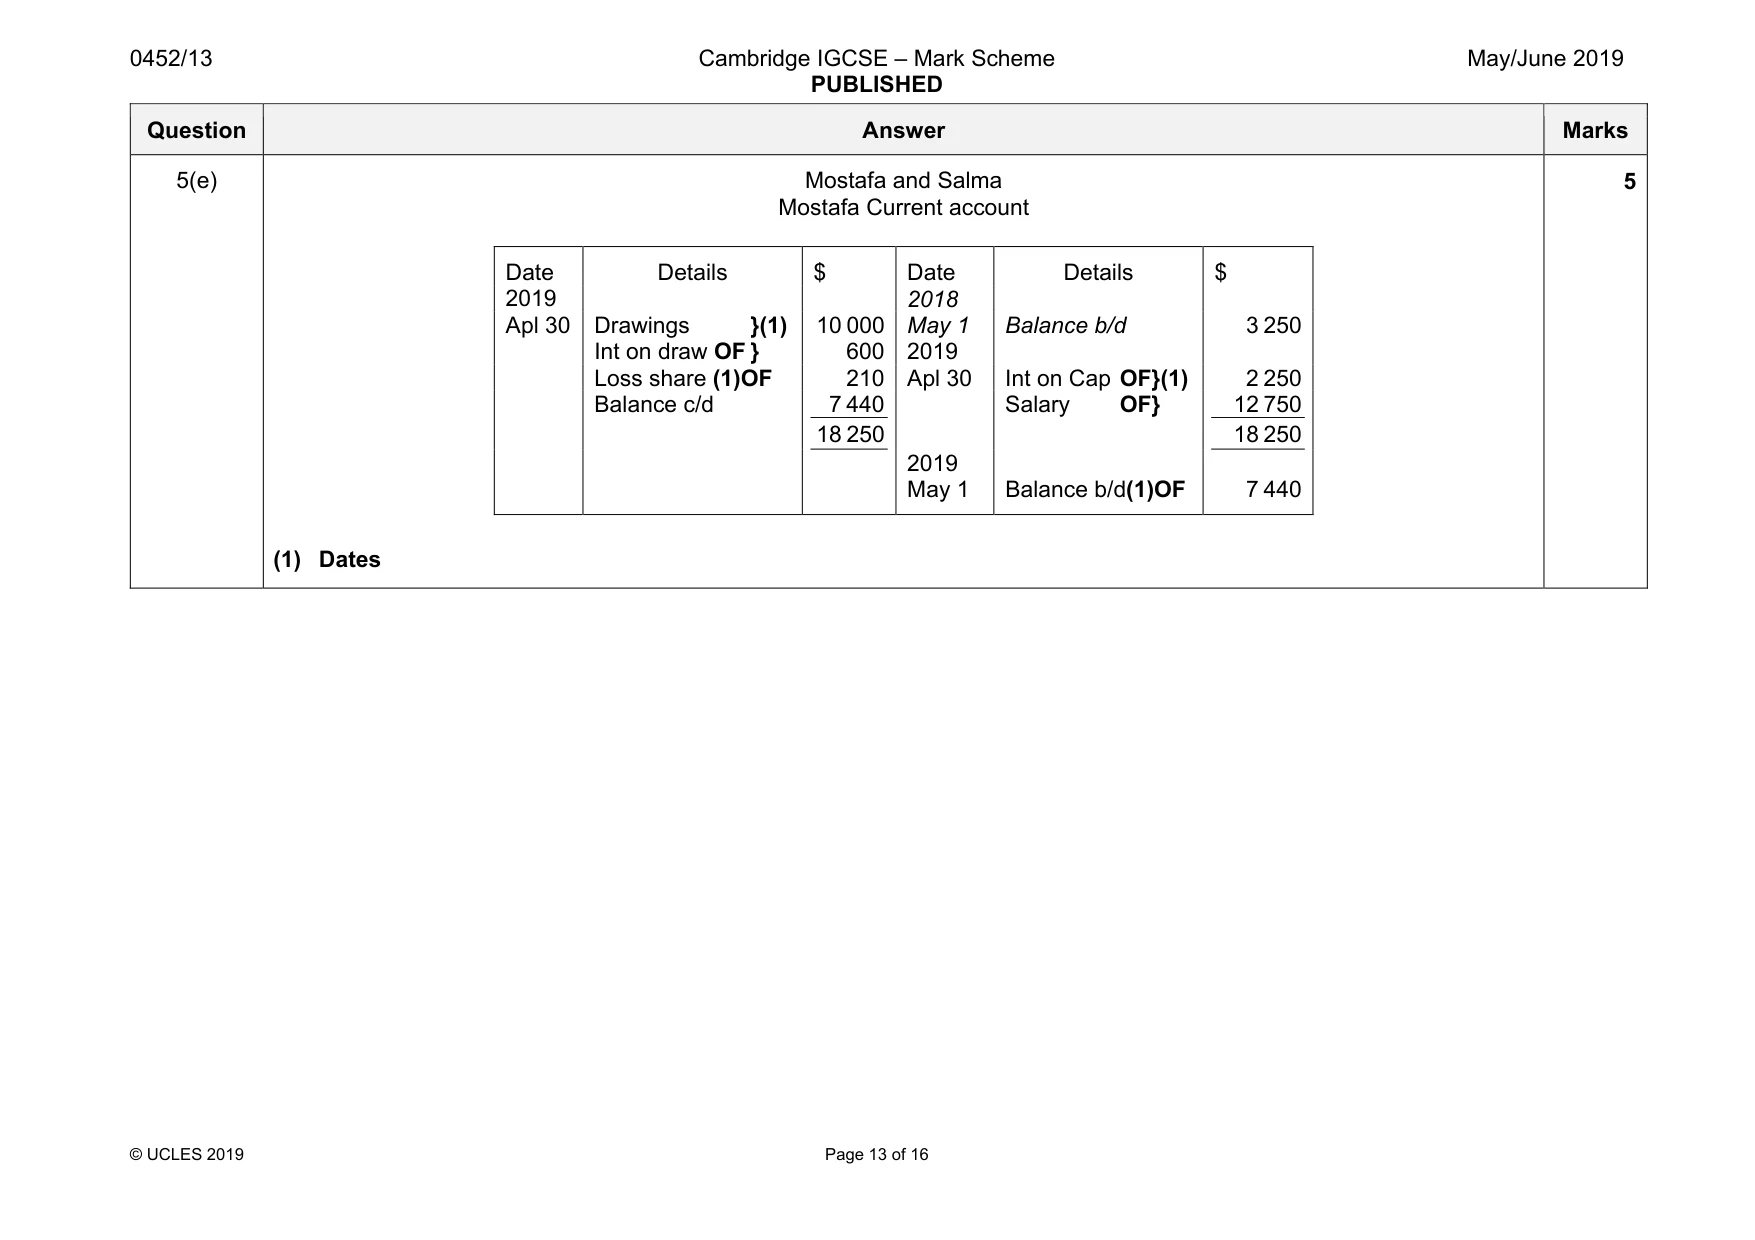
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 13 of 16 Question Answer Marks 5(e) Mostafa and Salma Mostafa Current account Date Details $ Date Details $ 2019 2018 Apl 30 Drawings }(1) 10 000 May 1 Balance b/d 3 250 Int on draw OF } 600 2019 Loss share (1)OF 210 Apl 30 Int on Cap OF}(1) 2 250 Balance c/d 7 440 Salary OF} 12 750 18 250 18 250 2019 May 1 Balance b/d(1)OF 7 440 (1) Dates 5
Mark scheme, page 14
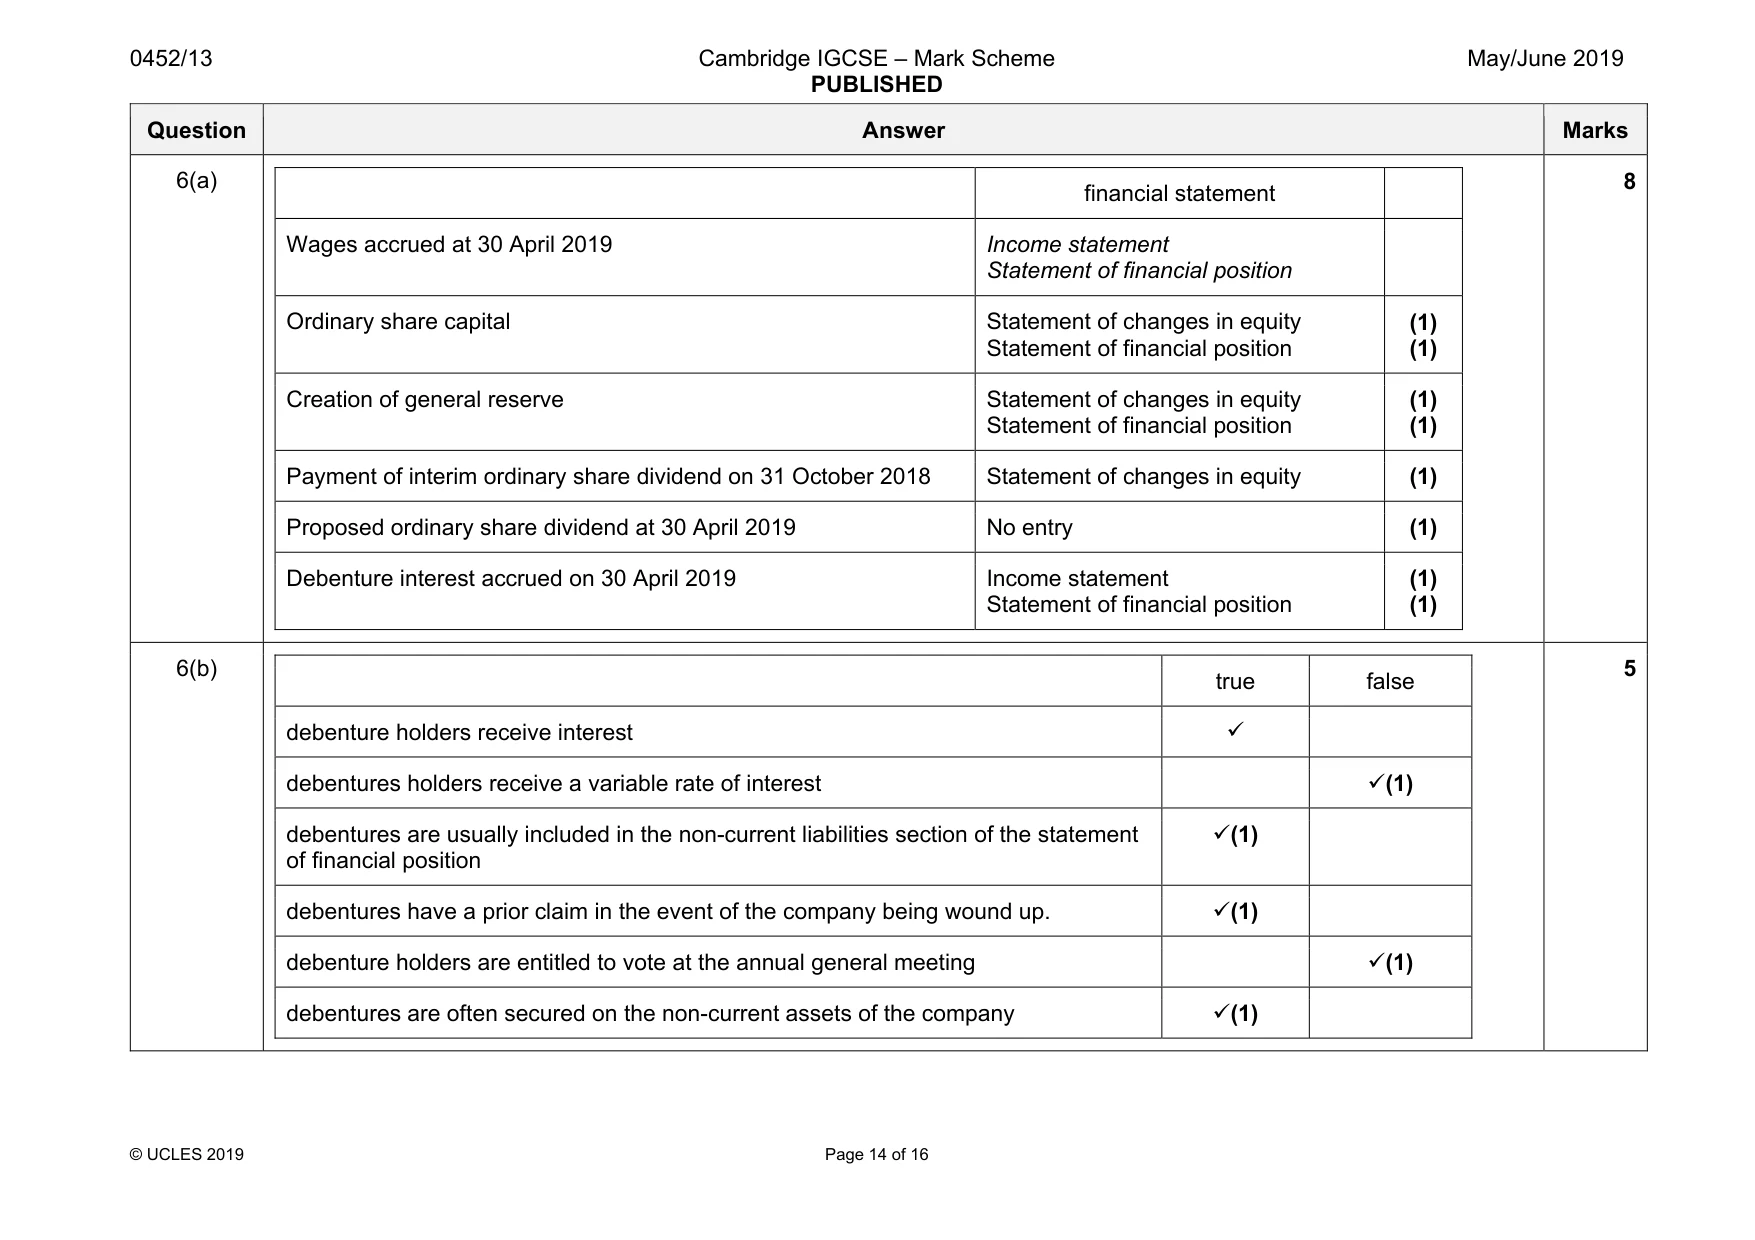
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 14 of 16 Question Answer Marks 6(a) financial statement Wages accrued at 30 April 2019 Income statement Statement of financial position Ordinary share capital Statement of changes in equity Statement of financial position (1) (1) Creation of general reserve Statement of changes in equity Statement of financial position (1) (1) Payment of interim ordinary share dividend on 31 October 2018 Statement of changes in equity (1) Proposed ordinary share dividend at 30 April 2019 No entry (1) Debenture interest accrued on 30 April 2019 Income statement Statement of financial position (1) (1) 8 6(b) true false debenture holders receive interest 9 debentures holders receive a variable rate of interest 9(1) debentures are usually included in the non-current liabilities section of the statement of financial position 9(1) debentures have a prior claim in the event of the company being wound up. 9(1) debenture holders are entitled to vote at the annual general meeting 9(1) debentures are often secured on the non-current assets of the company 9(1) 5
Mark scheme, page 15
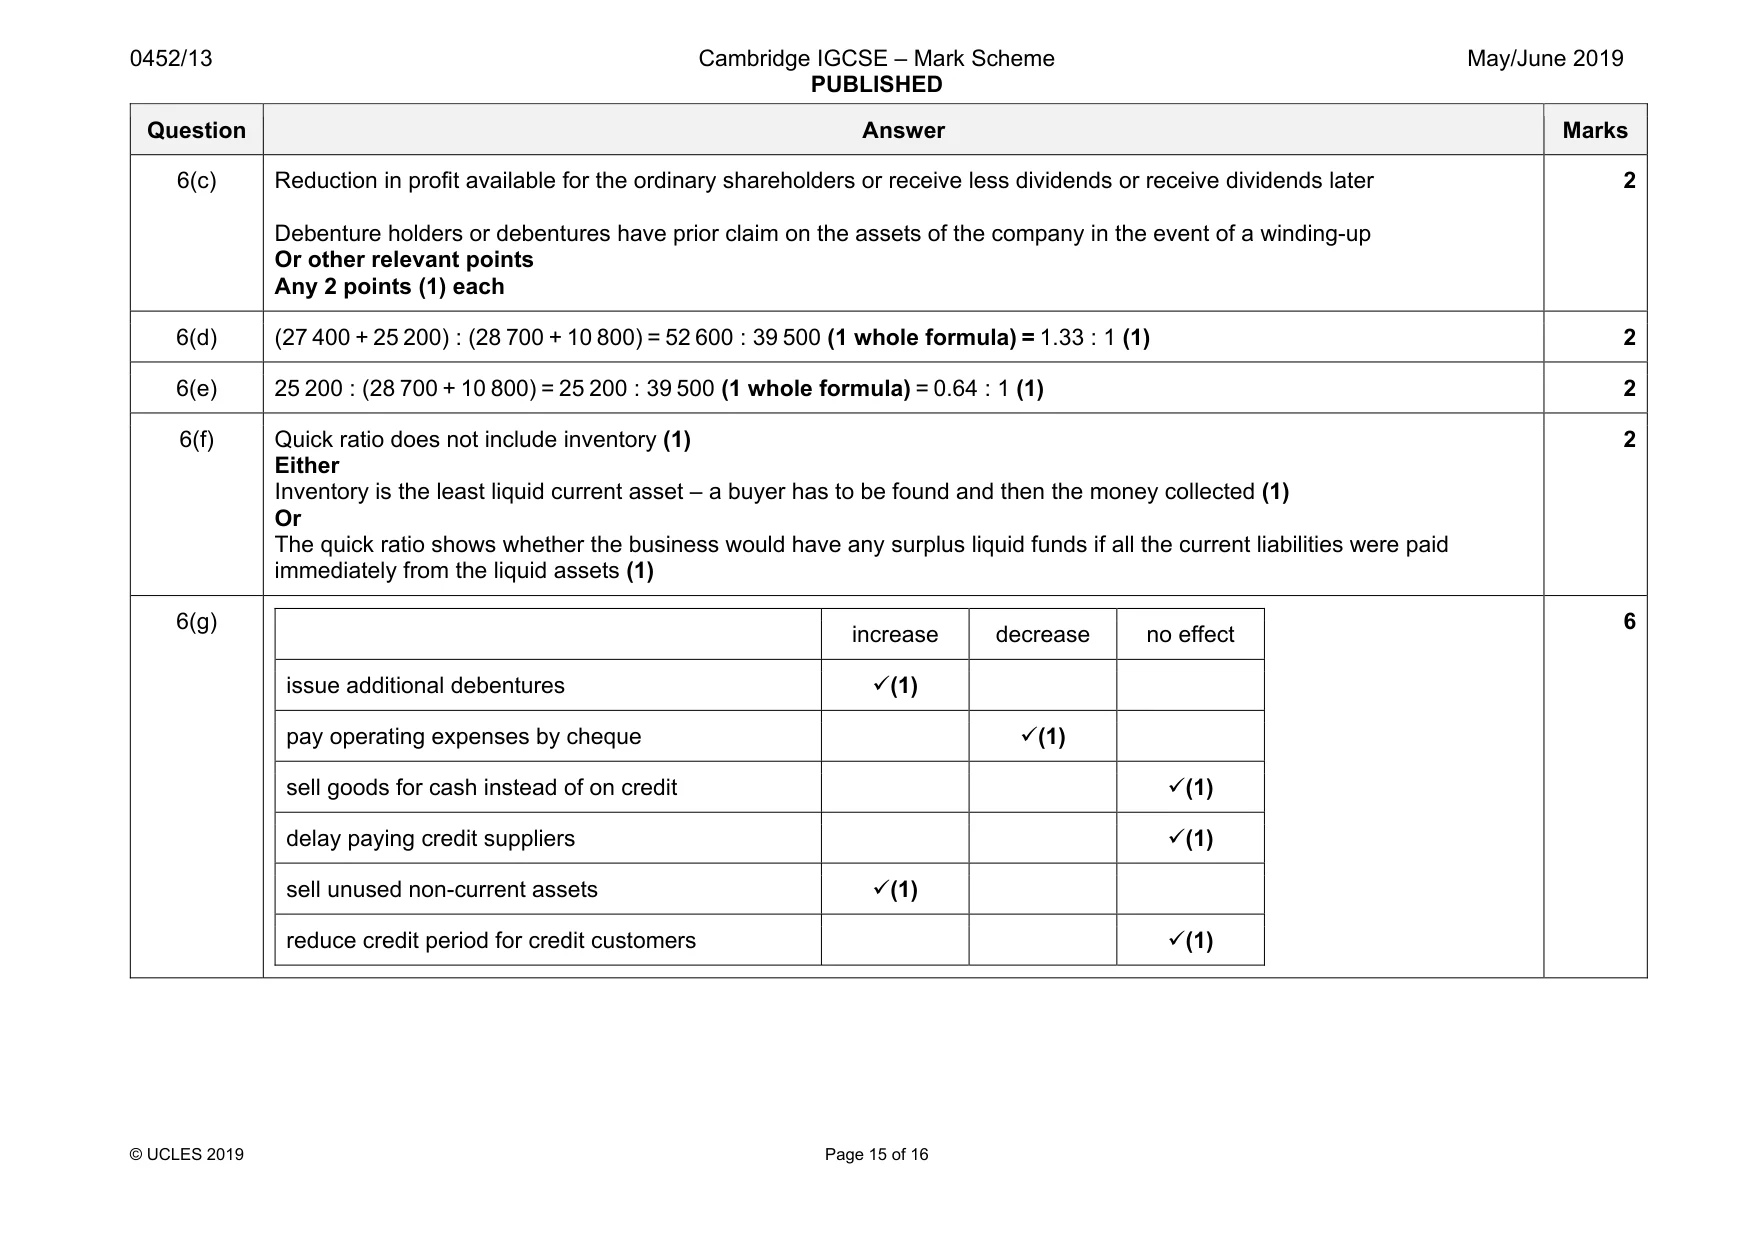
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 15 of 16 Question Answer Marks 6(c) Reduction in profit available for the ordinary shareholders or receive less dividends or receive dividends later Debenture holders or debentures have prior claim on the assets of the company in the event of a winding-up Or other relevant points Any 2 points (1) each 2 6(d) (27 400 + 25 200) : (28 700 + 10 800) = 52 600 : 39 500 (1 whole formula) = 1.33 : 1 (1) 2 6(e) 25 200 : (28 700 + 10 800) = 25 200 : 39 500 (1 whole formula) = 0.64 : 1 (1) 2 6(f) Quick ratio does not include inventory (1) Either Inventory is the least liquid current asset – a buyer has to be found and then the money collected (1) Or The quick ratio shows whether the business would have any surplus liquid funds if all the current liabilities were paid immediately from the liquid assets (1) 2 6(g) increase decrease no effect issue additional debentures 9(1) pay operating expenses by cheque 9(1) sell goods for cash instead of on credit 9(1) delay paying credit suppliers 9(1) sell unused non-current assets 9(1) reduce credit period for credit customers 9(1) 6
Mark scheme, page 16
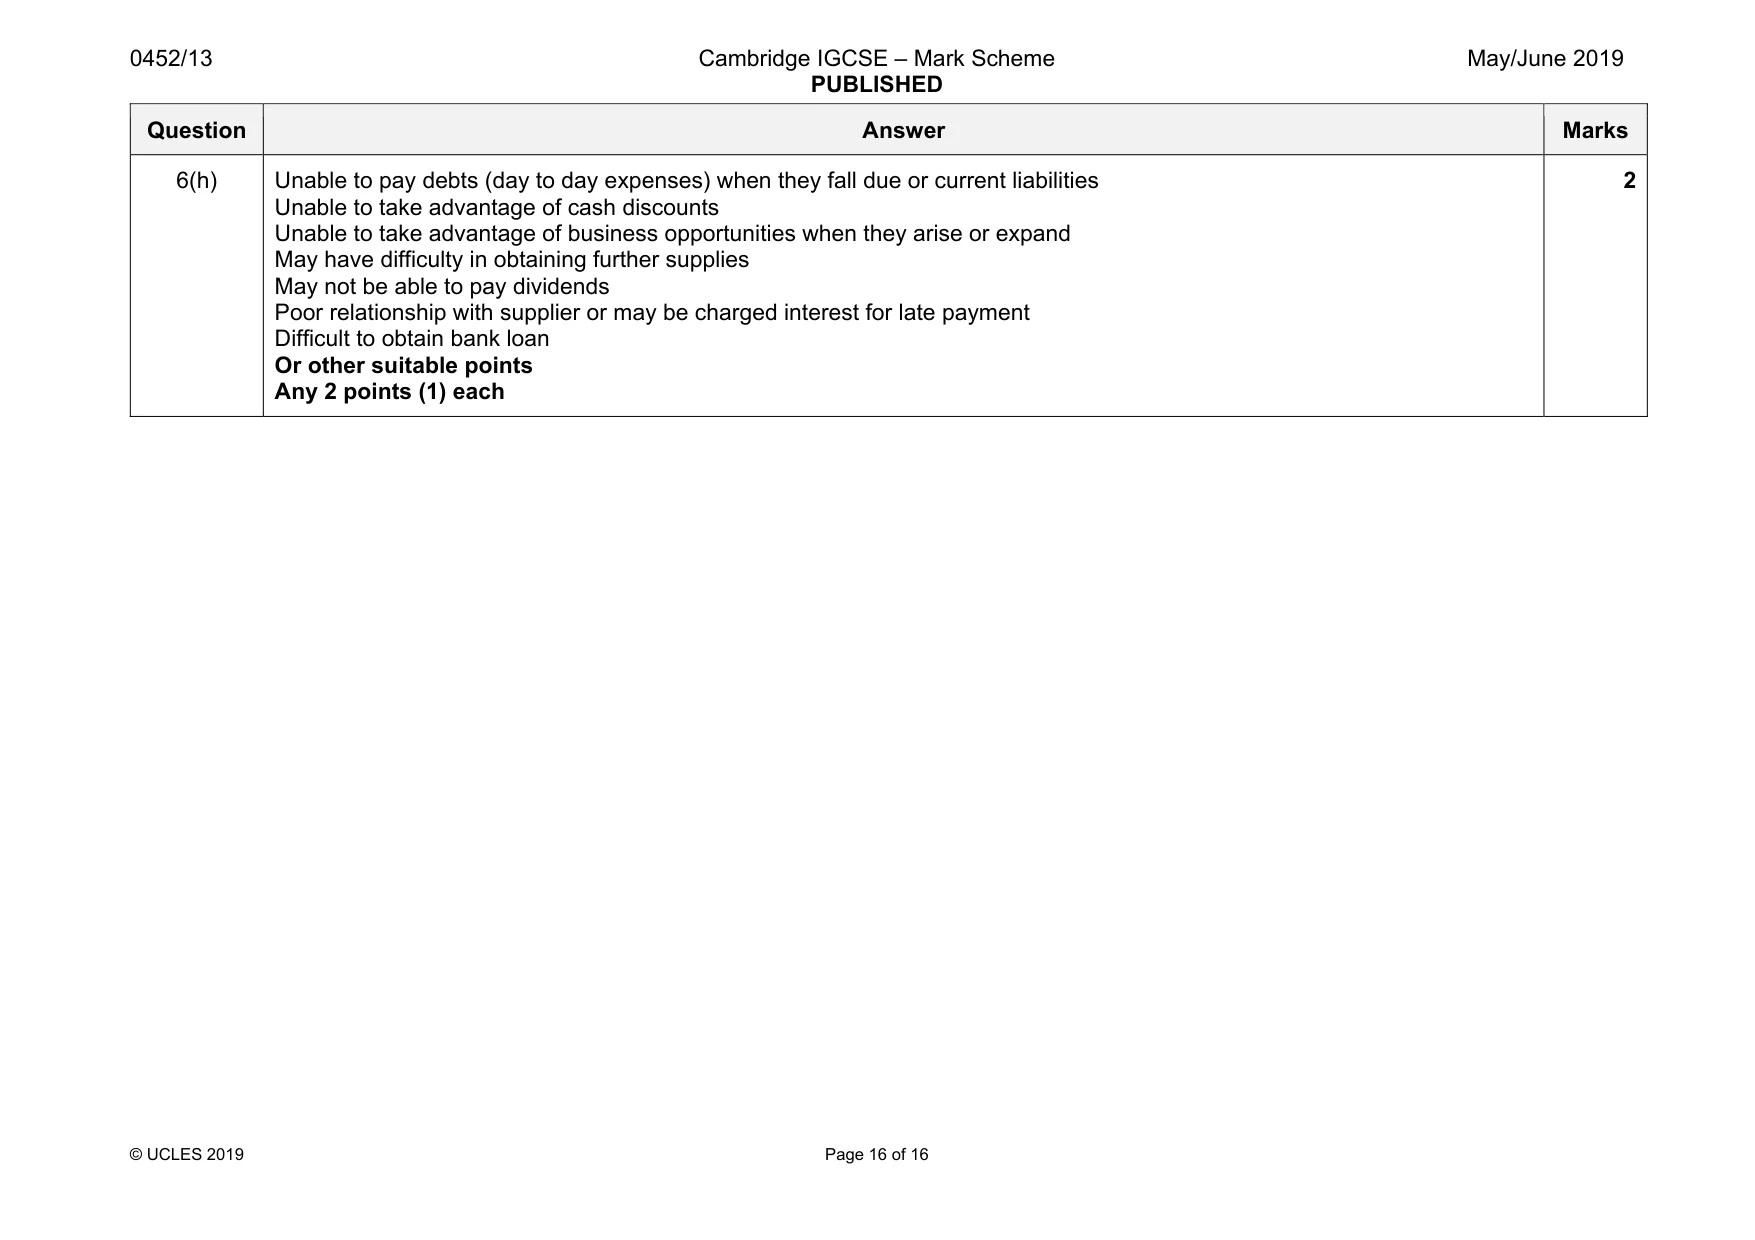
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2019 © UCLES 2019 Page 16 of 16 Question Answer Marks 6(h) Unable to pay debts (day to day expenses) when they fall due or current liabilities Unable to take advantage of cash discounts Unable to take advantage of business opportunities when they arise or expand May have difficulty in obtaining further supplies May not be able to pay dividends Poor relationship with supplier or may be charged interest for late payment Difficult to obtain bank loan Or other suitable points Any 2 points (1) each 2
What you needed in this session
Cambridge’s own grade thresholds for 2019 May/June, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.