Cambridge IGCSE Accounting 0452 — 2019 Feb/March Paper 2 · Variant 2
0452/22/F/M/19 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme11 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Narinder is a wholesaler who trades in handicrafts
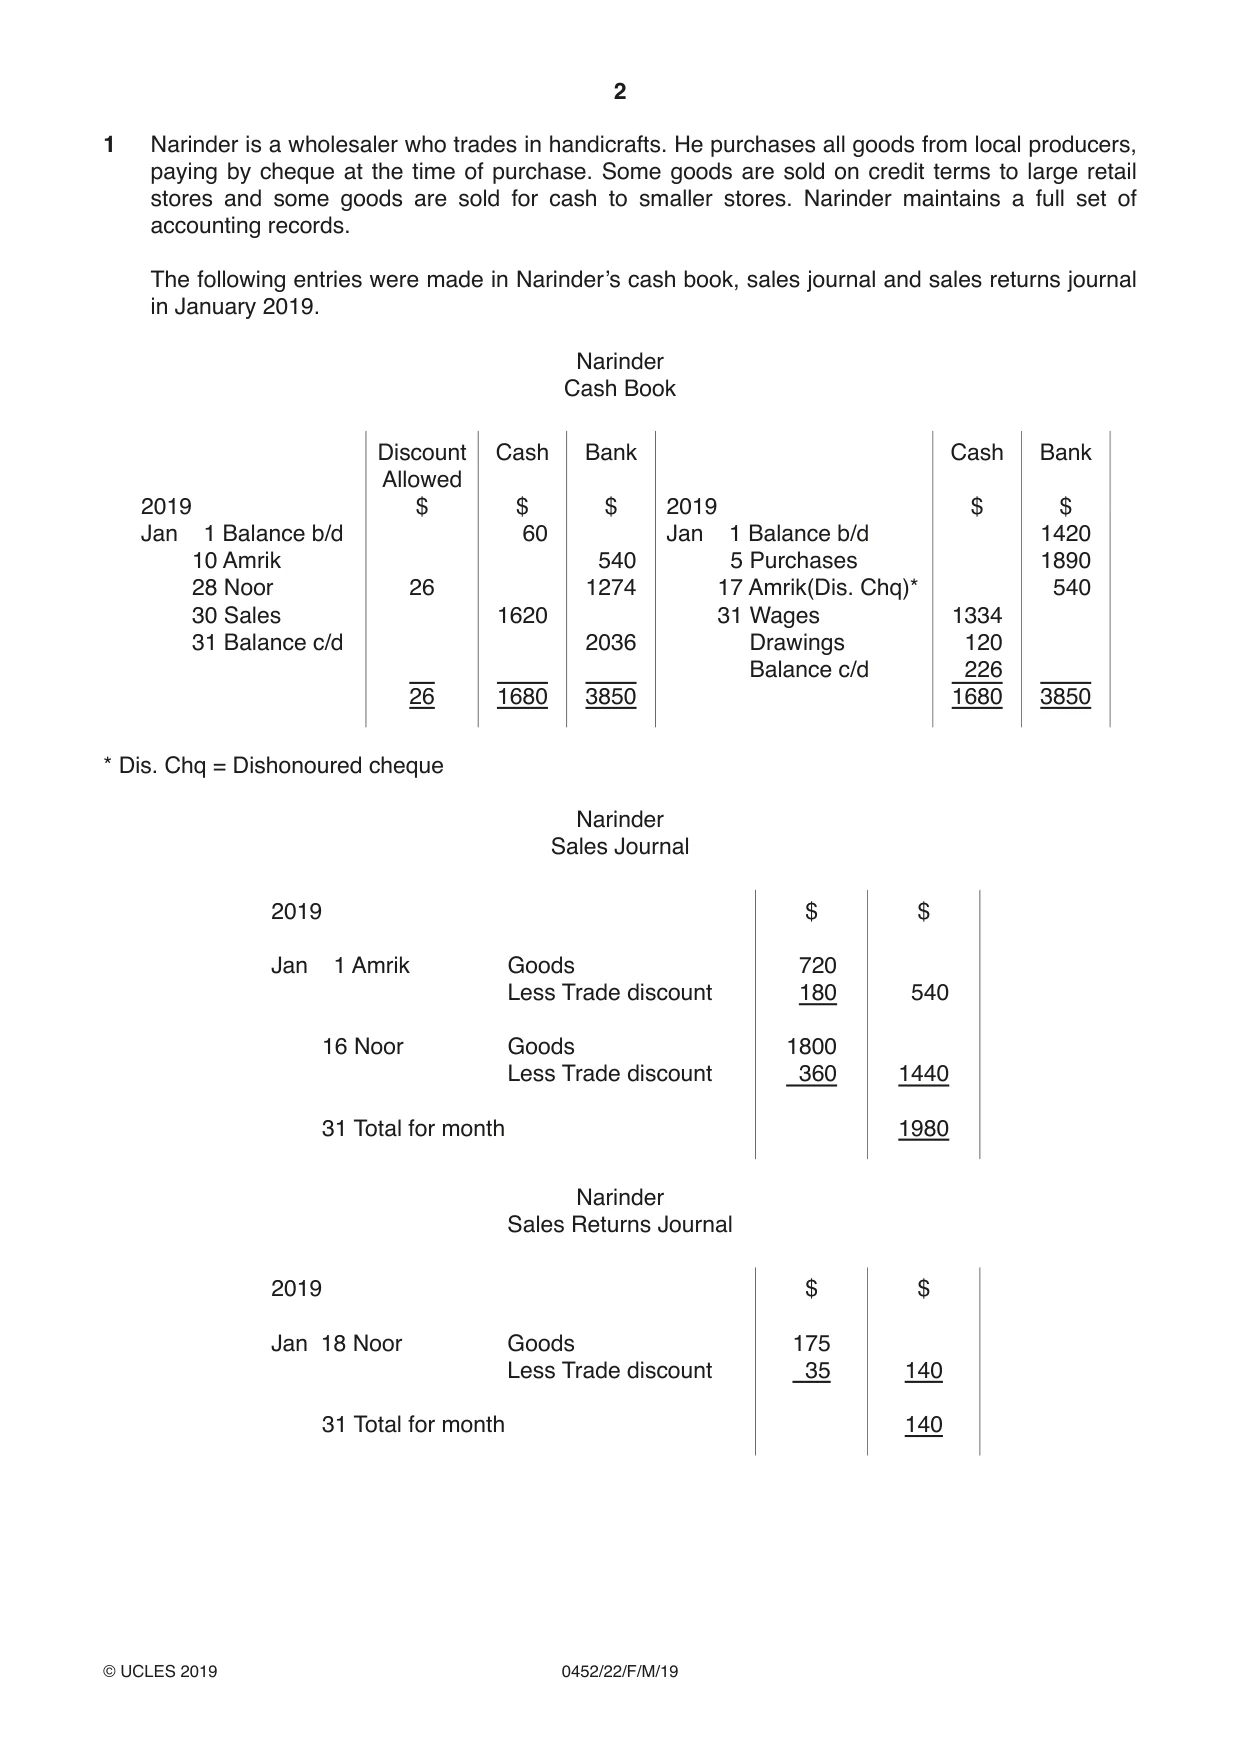
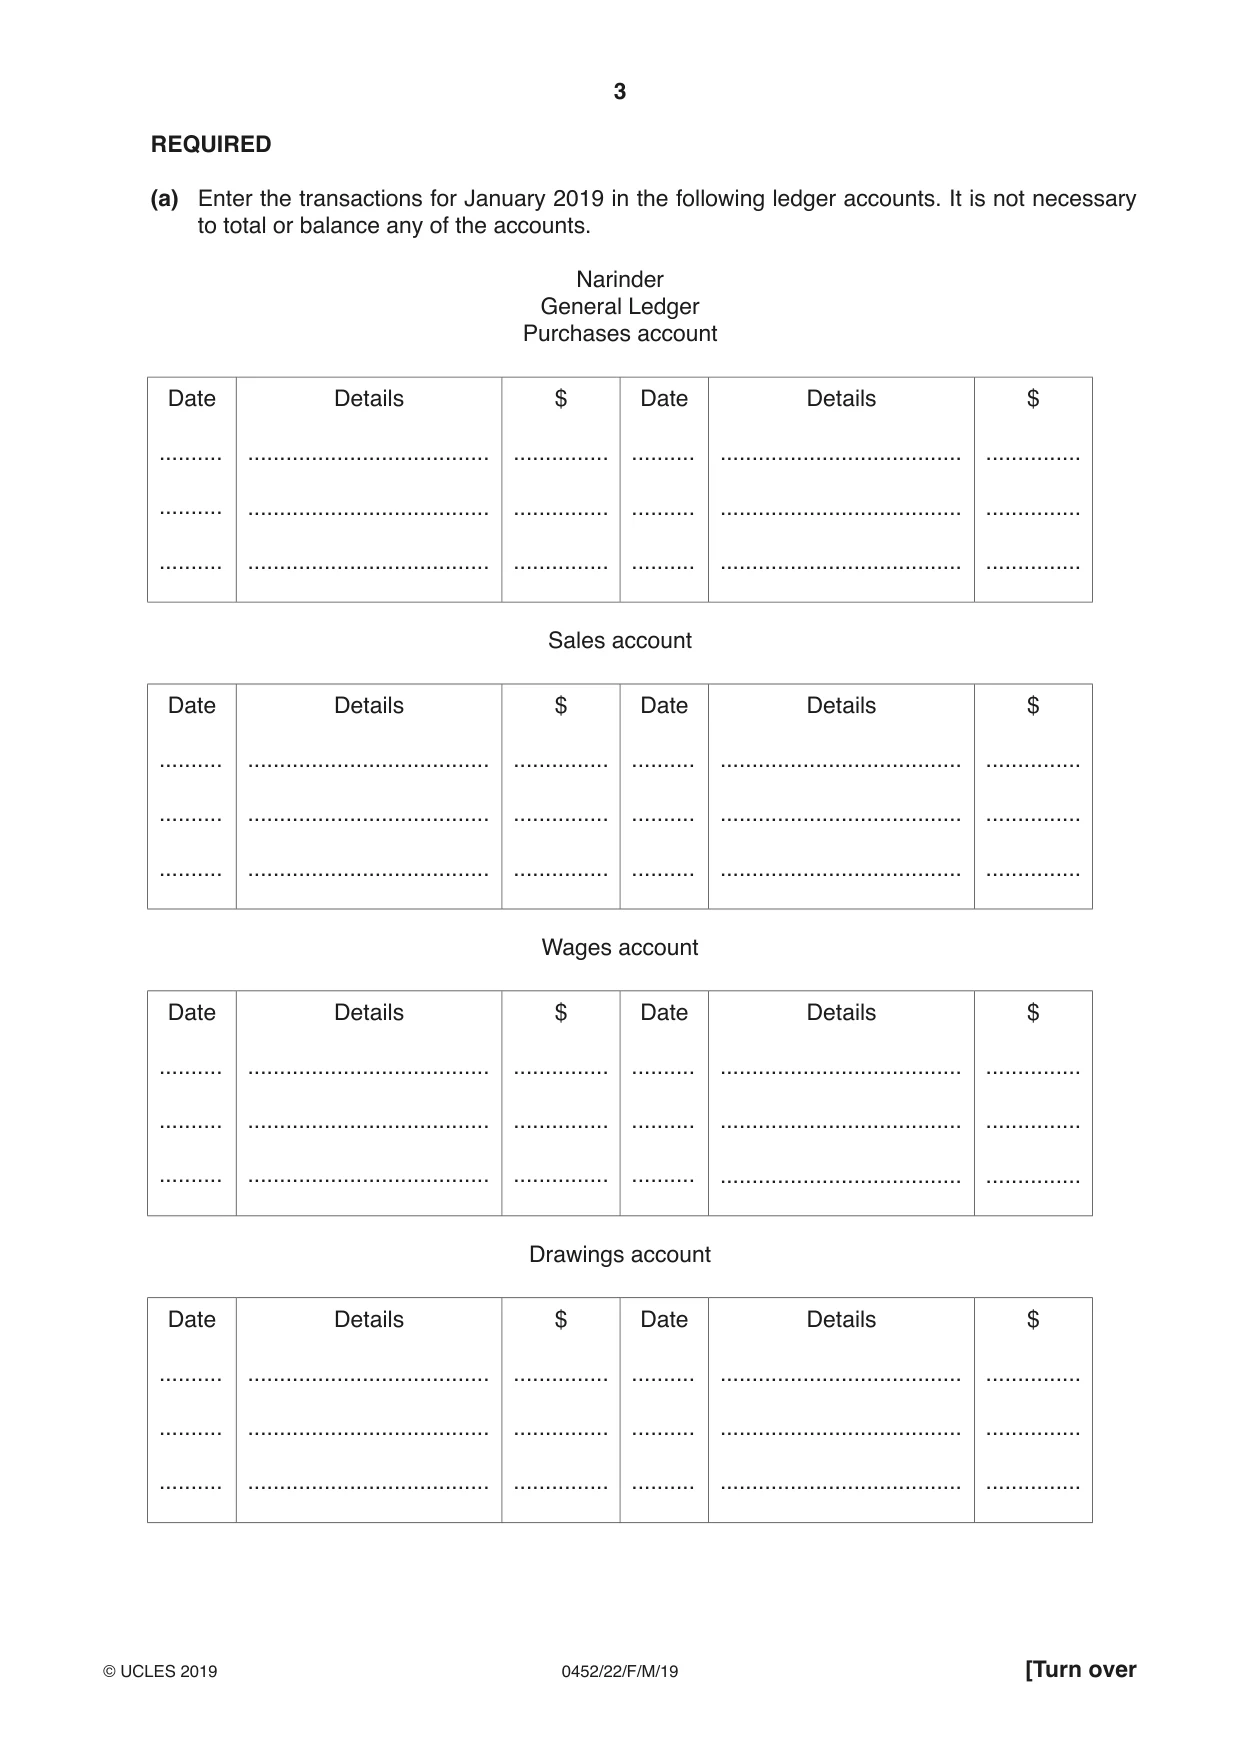
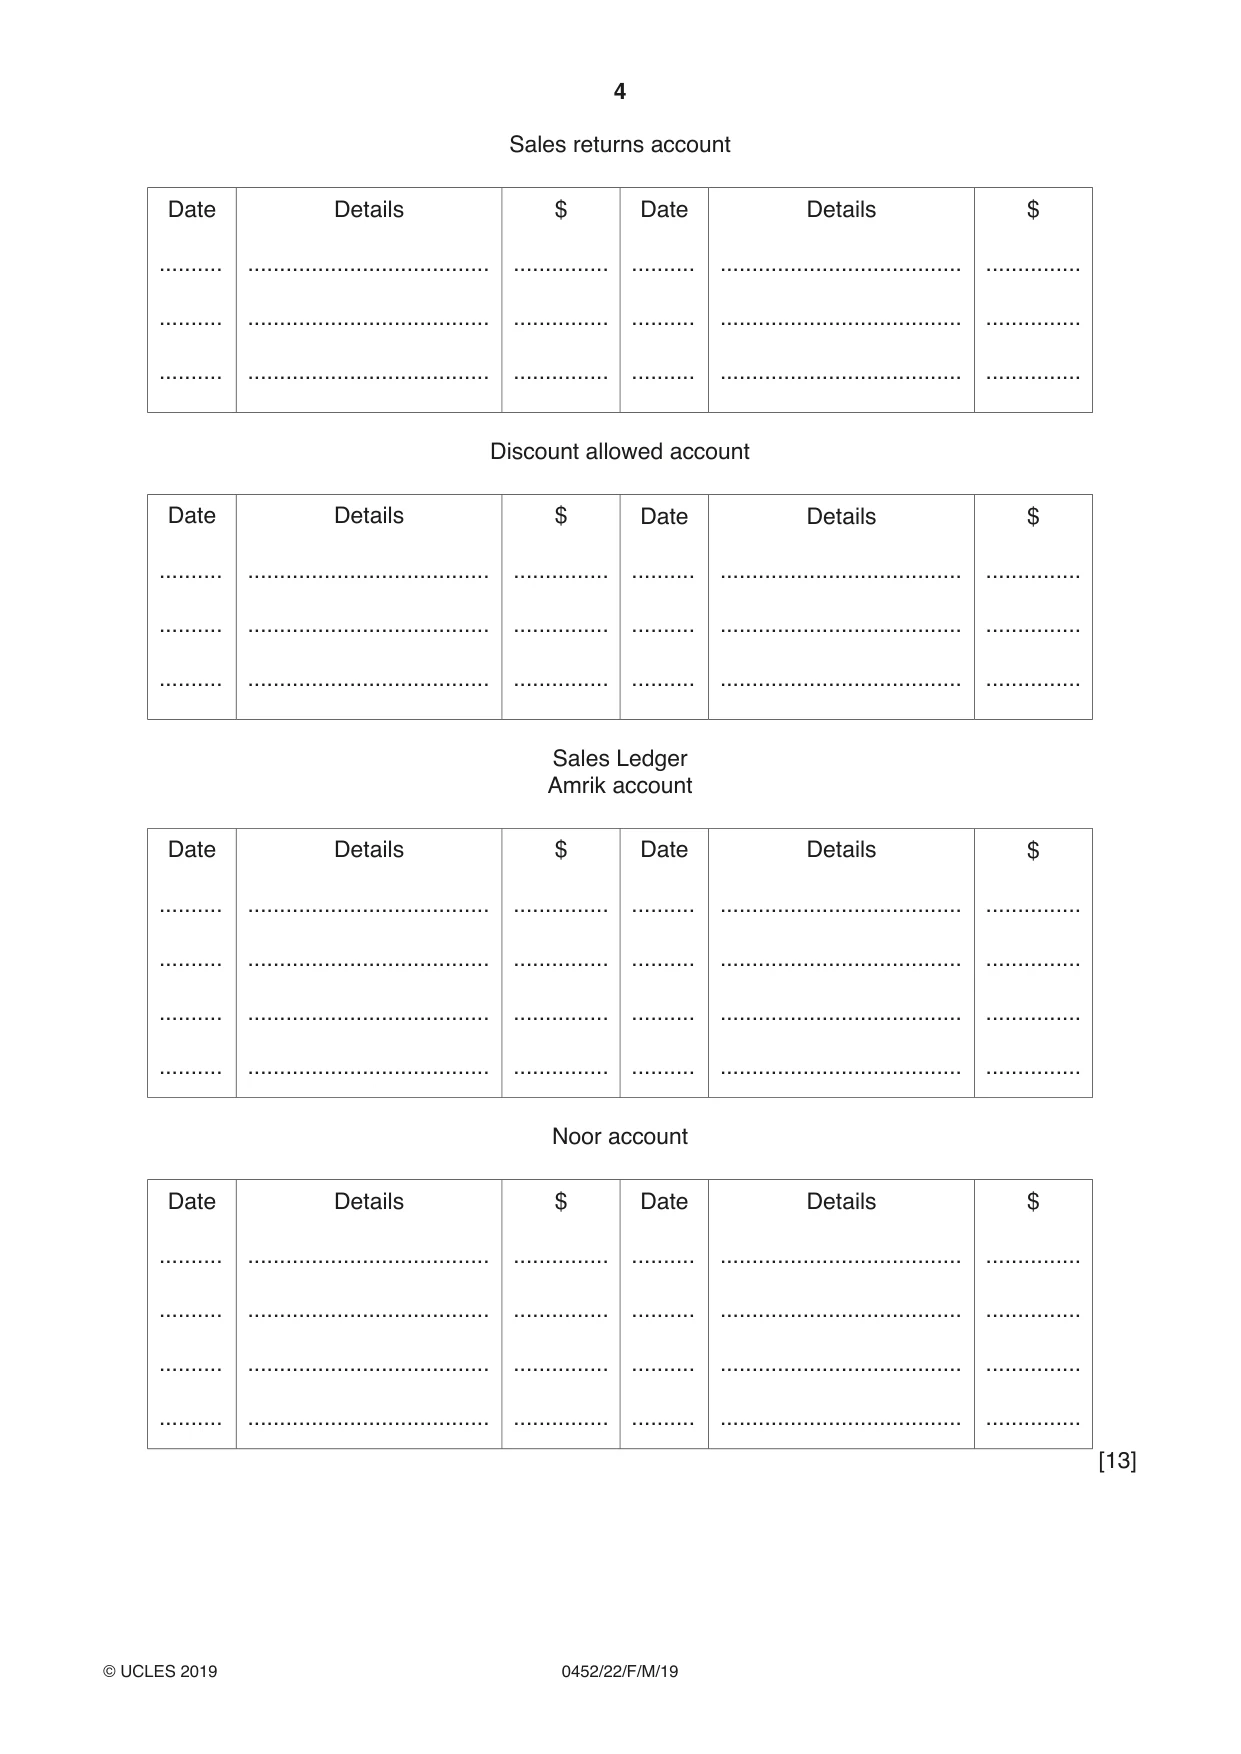
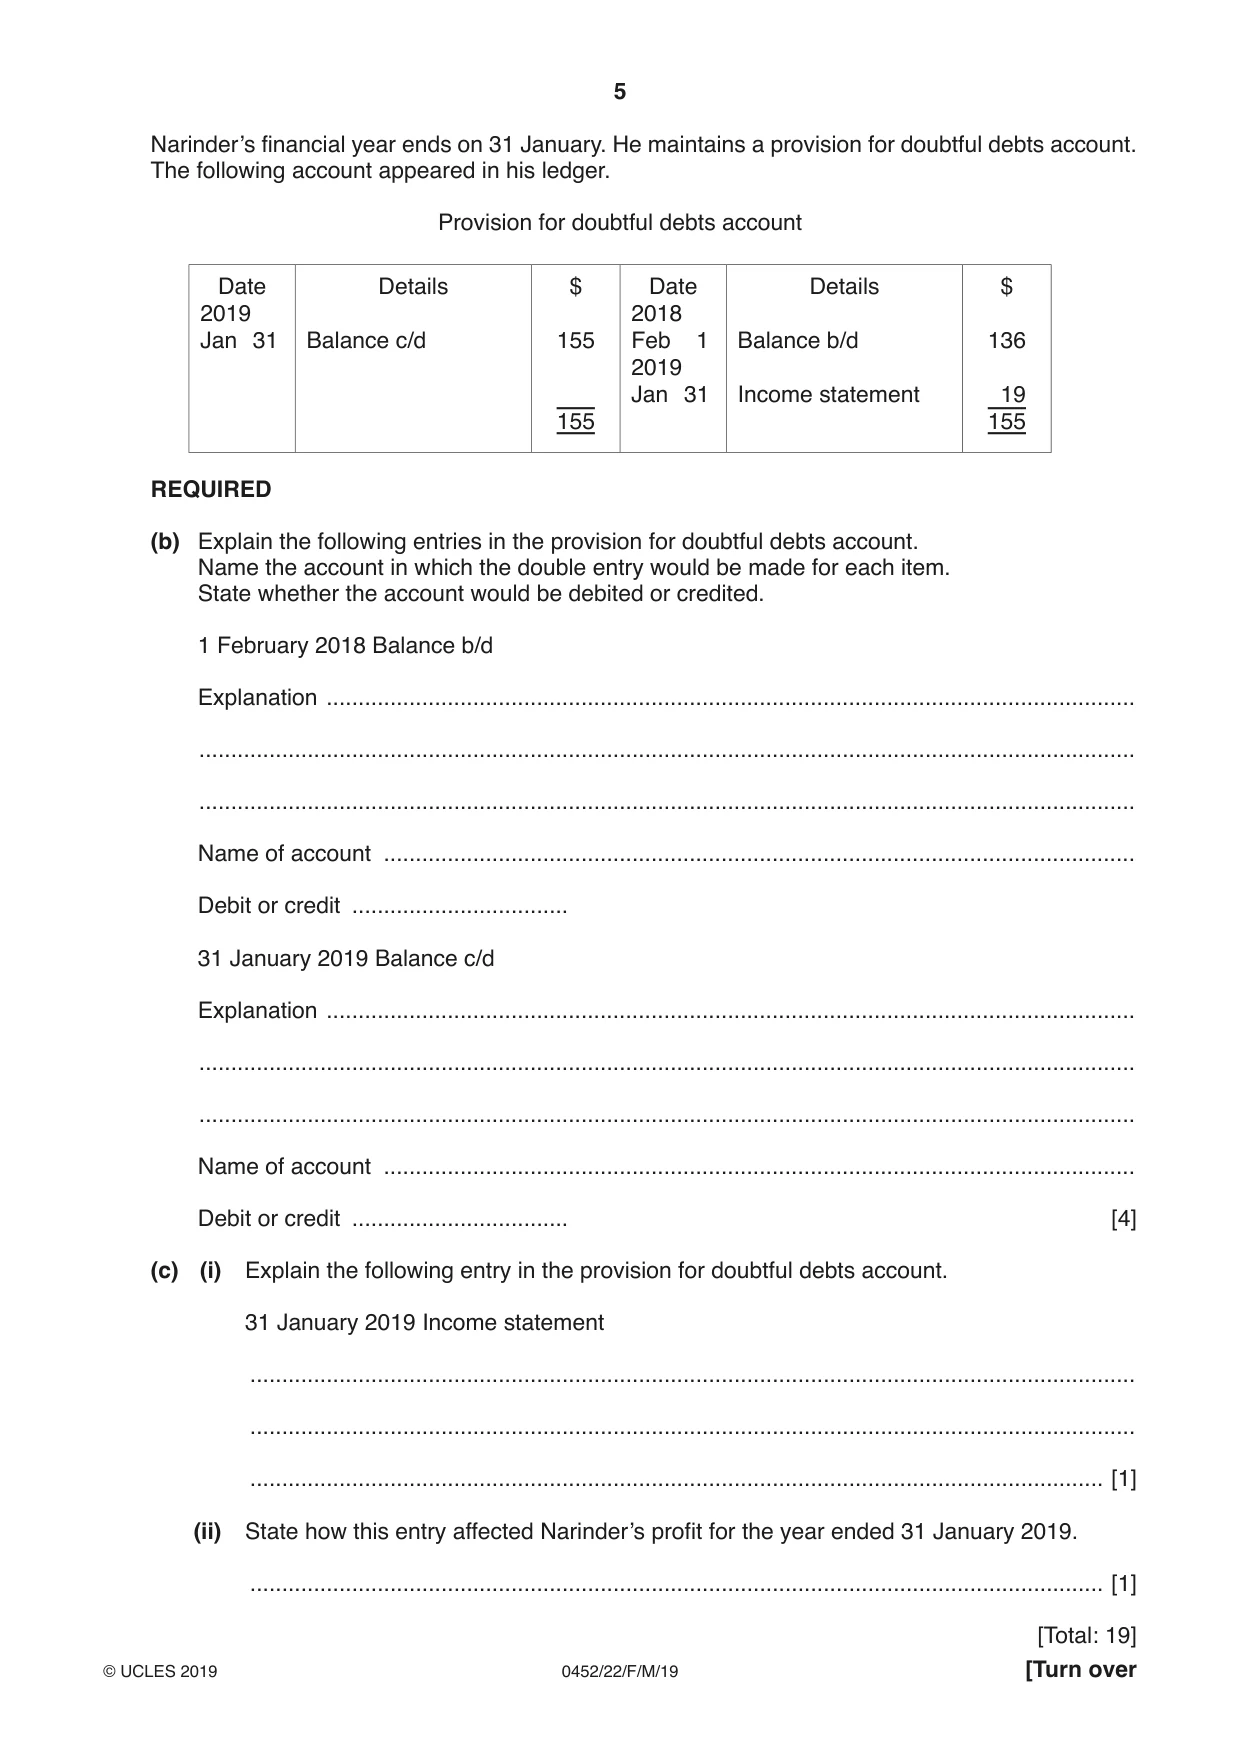
1 Narinder is a wholesaler who trades in handicrafts. He purchases all goods from local producers, paying by cheque at the time of purchase. Some goods are sold on credit terms to large retail stores and some goods are sold for cash to smaller stores. Narinder maintains a full set of accounting records. The following entries were made in Narinder’s cash book, sales journal and sales returns journal in January 2019. Narinder Cash Book Discount Cash Bank Cash Bank Allowed 2019 $ $ $ 2019 $ $ Jan 1 Balance b/d 60 Jan 1 Balance b/d 1420 10 Amrik 540 5 Purchases 1890 28 Noor 26 1274 17 Amrik(Dis. Chq)* 540 30 Sales 1620 31 Wages 1334 31 Balance c/d 2036 Drawings 120 Balance c/d 226 26 1680 3850 1680 3850 * Dis. Chq = Dishonoured cheque Narinder Sales Journal 2019 $ $ Jan 1 Amrik Goods 720 Less Trade discount 180 540 16 Noor Goods 1800 Less Trade discount 360 1440 31 Total for month 1980 Narinder Sales Returns Journal 2019 $ $ Jan 18 Noor Goods 175 Less Trade discount 35 140 31 Total for month 140 REQUIRED (a) Enter the transactions for January 2019 in the following ledger accounts. It is not necessary to total or balance any of the accounts. Narinder General Ledger Purchases account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Sales account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Wages account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Drawings account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Sales returns account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Discount allowed account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Sales Ledger Amrik account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Noor account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... [13] Narinder’s financial year ends on 31 January. He maintains a provision for doubtful debts account. The following account appeared in his ledger. Provision for doubtful debts account Date Details $ Date Details $ 2019 2018 Jan 31 Balance c/d 155 Feb 1 Balance b/d 136 2019 Jan 31 Income statement 19 155 155 REQUIRED (b) Explain the following entries in the provision for doubtful debts account. Name the account in which the double entry would be made for each item. State whether the account would be debited or credited. 1 February 2018 Balance b/d Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Name of account ...................................................................................................................... Debit or credit .................................. 31 January 2019 Balance c/d Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Name of account ...................................................................................................................... Debit or credit .................................. [4] (c) (i) Explain the following entry in the provision for doubtful debts account. 31 January 2019 Income statement ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [1] (ii) State how this entry affected Narinder’s profit for the year ended 31 January 2019. ...................................................................................................................................... [1] [Total: 19]
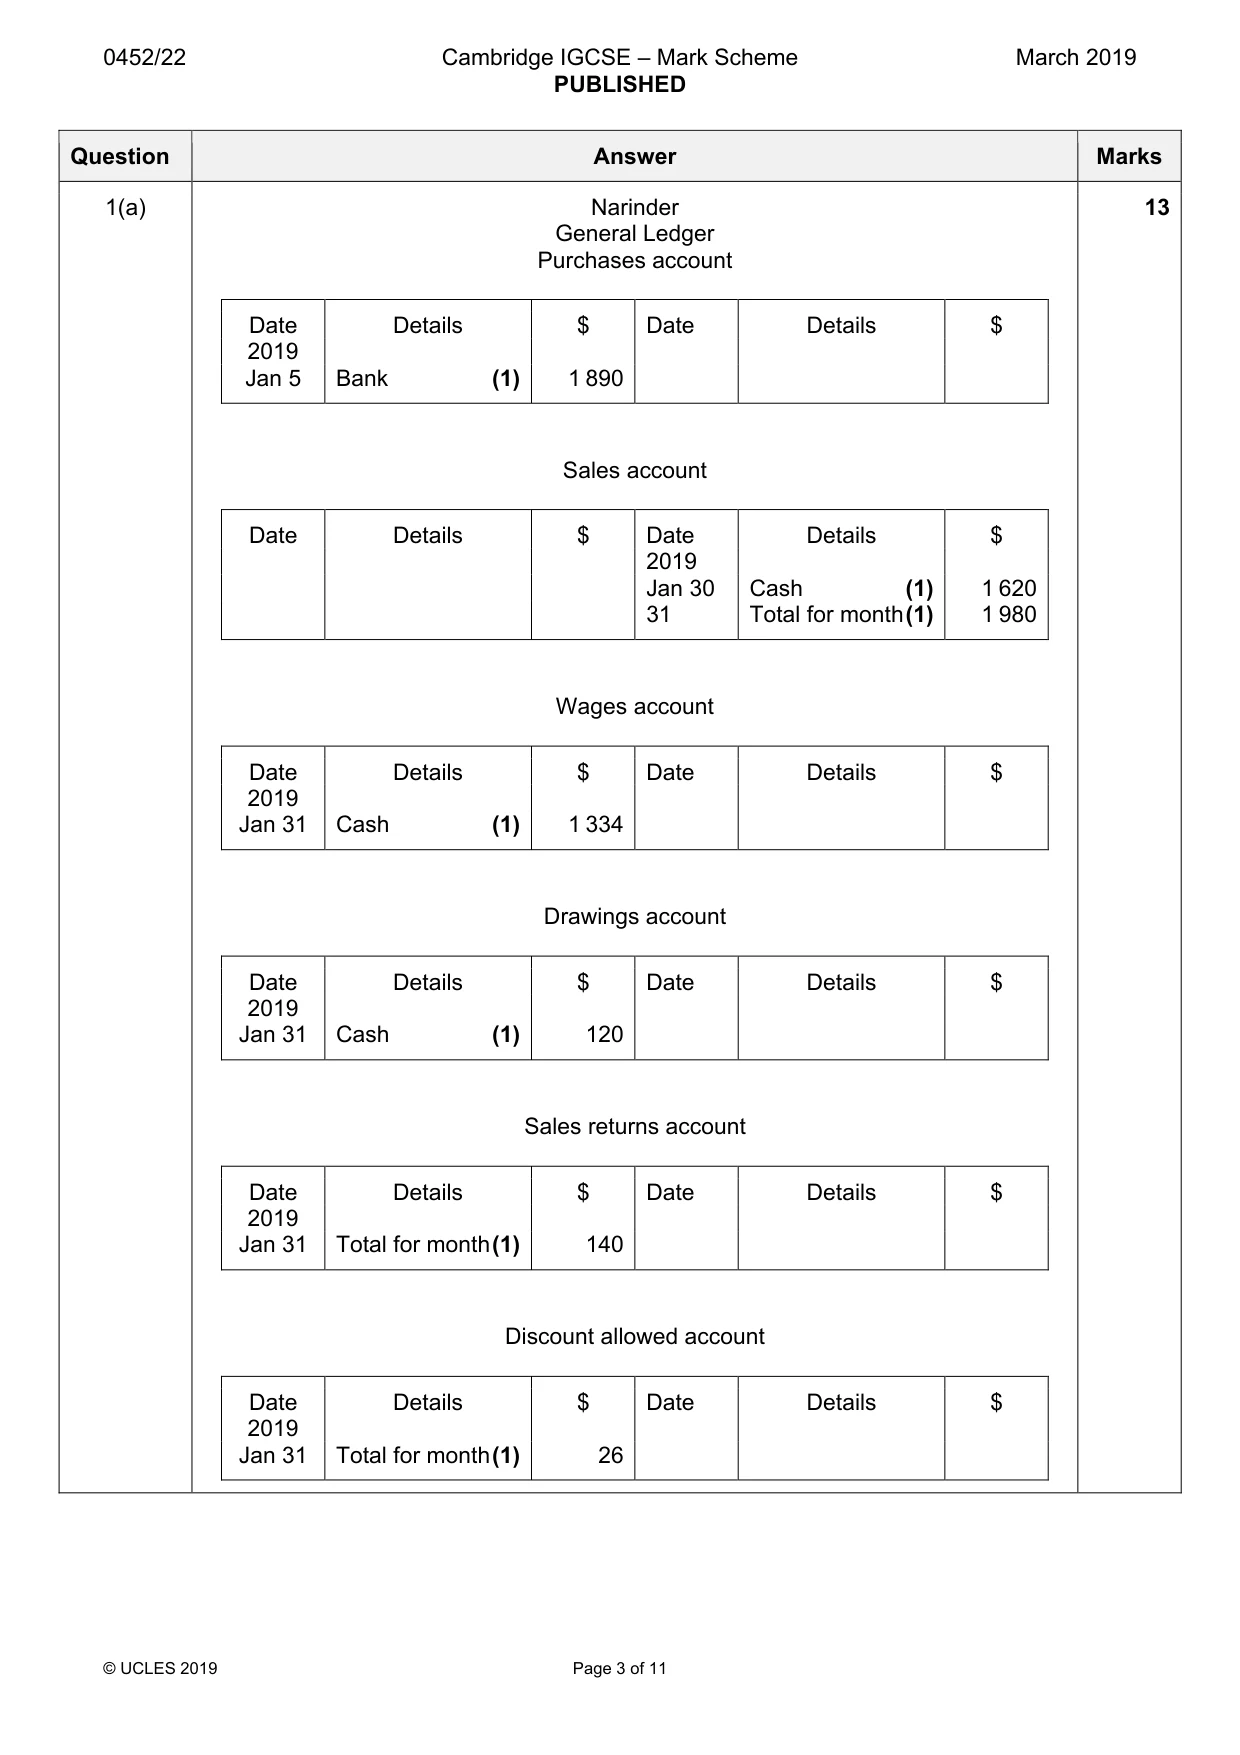
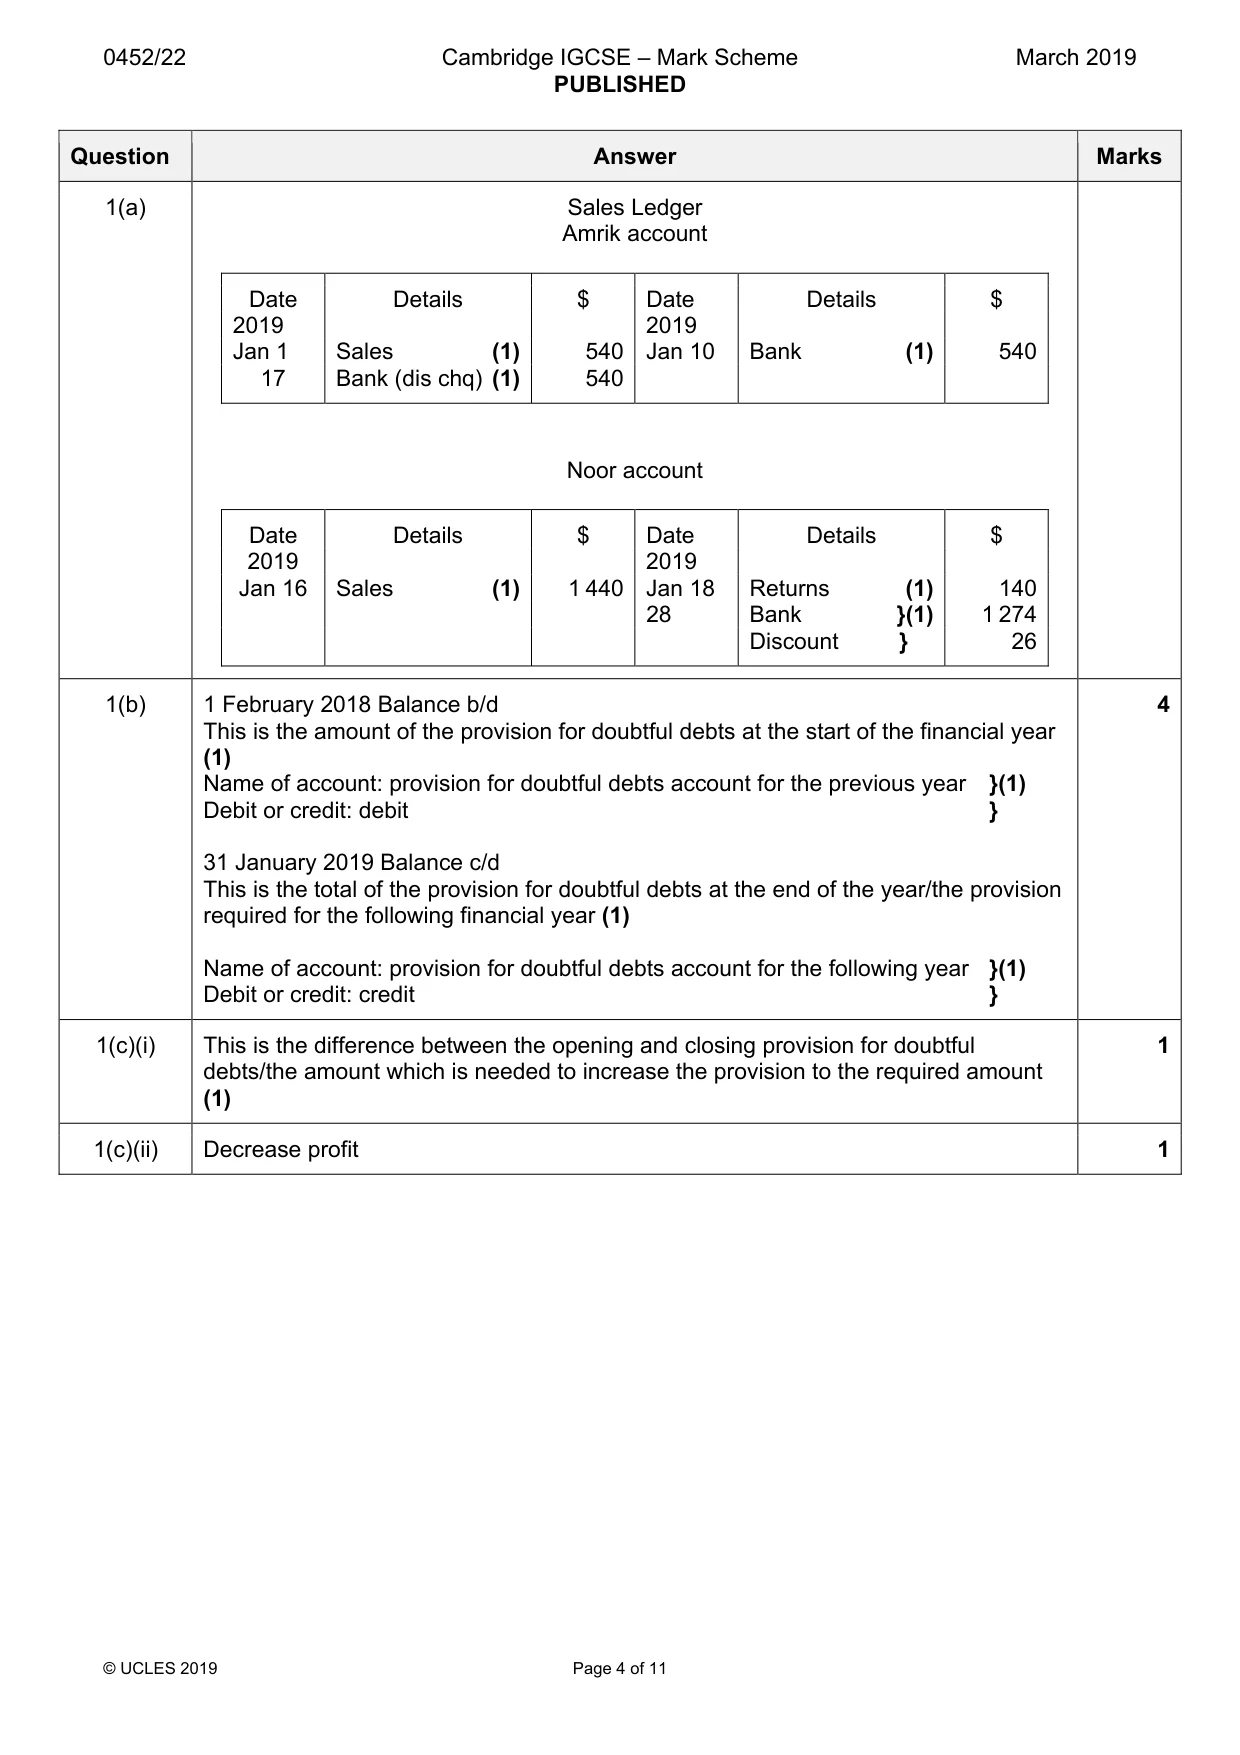
Mark scheme: Question Answer Marks 1(a) Narinder 13 General Ledger Purchases account Date Details $ Date Details $ 2019 Jan 5 Bank (1) 1 890 Sales account Date Details $ Date Details $ 2019 Jan 30 Cash (1) 1 620 31 Total for month (1) 1 980 Wages account Date Details $ Date Details $ 2019 Jan 31 Cash (1) 1 334 Drawings account Date Details $ Date Details $ 2019 Jan 31 Cash (1) 120 Sales returns account Date Details $ Date Details $ 2019 Jan 31 Total for month (1) 140 Discount allowed account Date Details $ Date Details $ 2019 Jan 31 Total for month (1) 26 1(a) Sales Ledger Amrik account Date Details $ Date Details $ 2019 2019 Jan 1 Sales (1) 540 Jan 10 Bank (1) 540 17 Bank (dis chq) (1) 540 Noor account Date Details $ Date Details $ 2019 2019 Jan 16 Sales (1) 1 440 Jan 18 Returns (1) 140 28 Bank }(1) 1 274 Discount } 26 1(b) 1 February 2018 Balance b/d 4 This is the amount of the provision for doubtful debts at the start of the financial year (1) Name of account: provision for doubtful debts account for the previous year }(1) Debit or credit: debit } 31 January 2019 Balance c/d This is the total of the provision for doubtful debts at the end of the year/the provision required for the following financial year (1) Name of account: provision for doubtful debts account for the following year }(1) Debit or credit: credit } 1(c)(i) This is the difference between the opening and closing provision for doubtful 1 debts/the amount which is needed to increase the provision to the required amount (1) 1(c)(ii) Decrease profit 1
Q2 · Aysha trades in children’s shoes
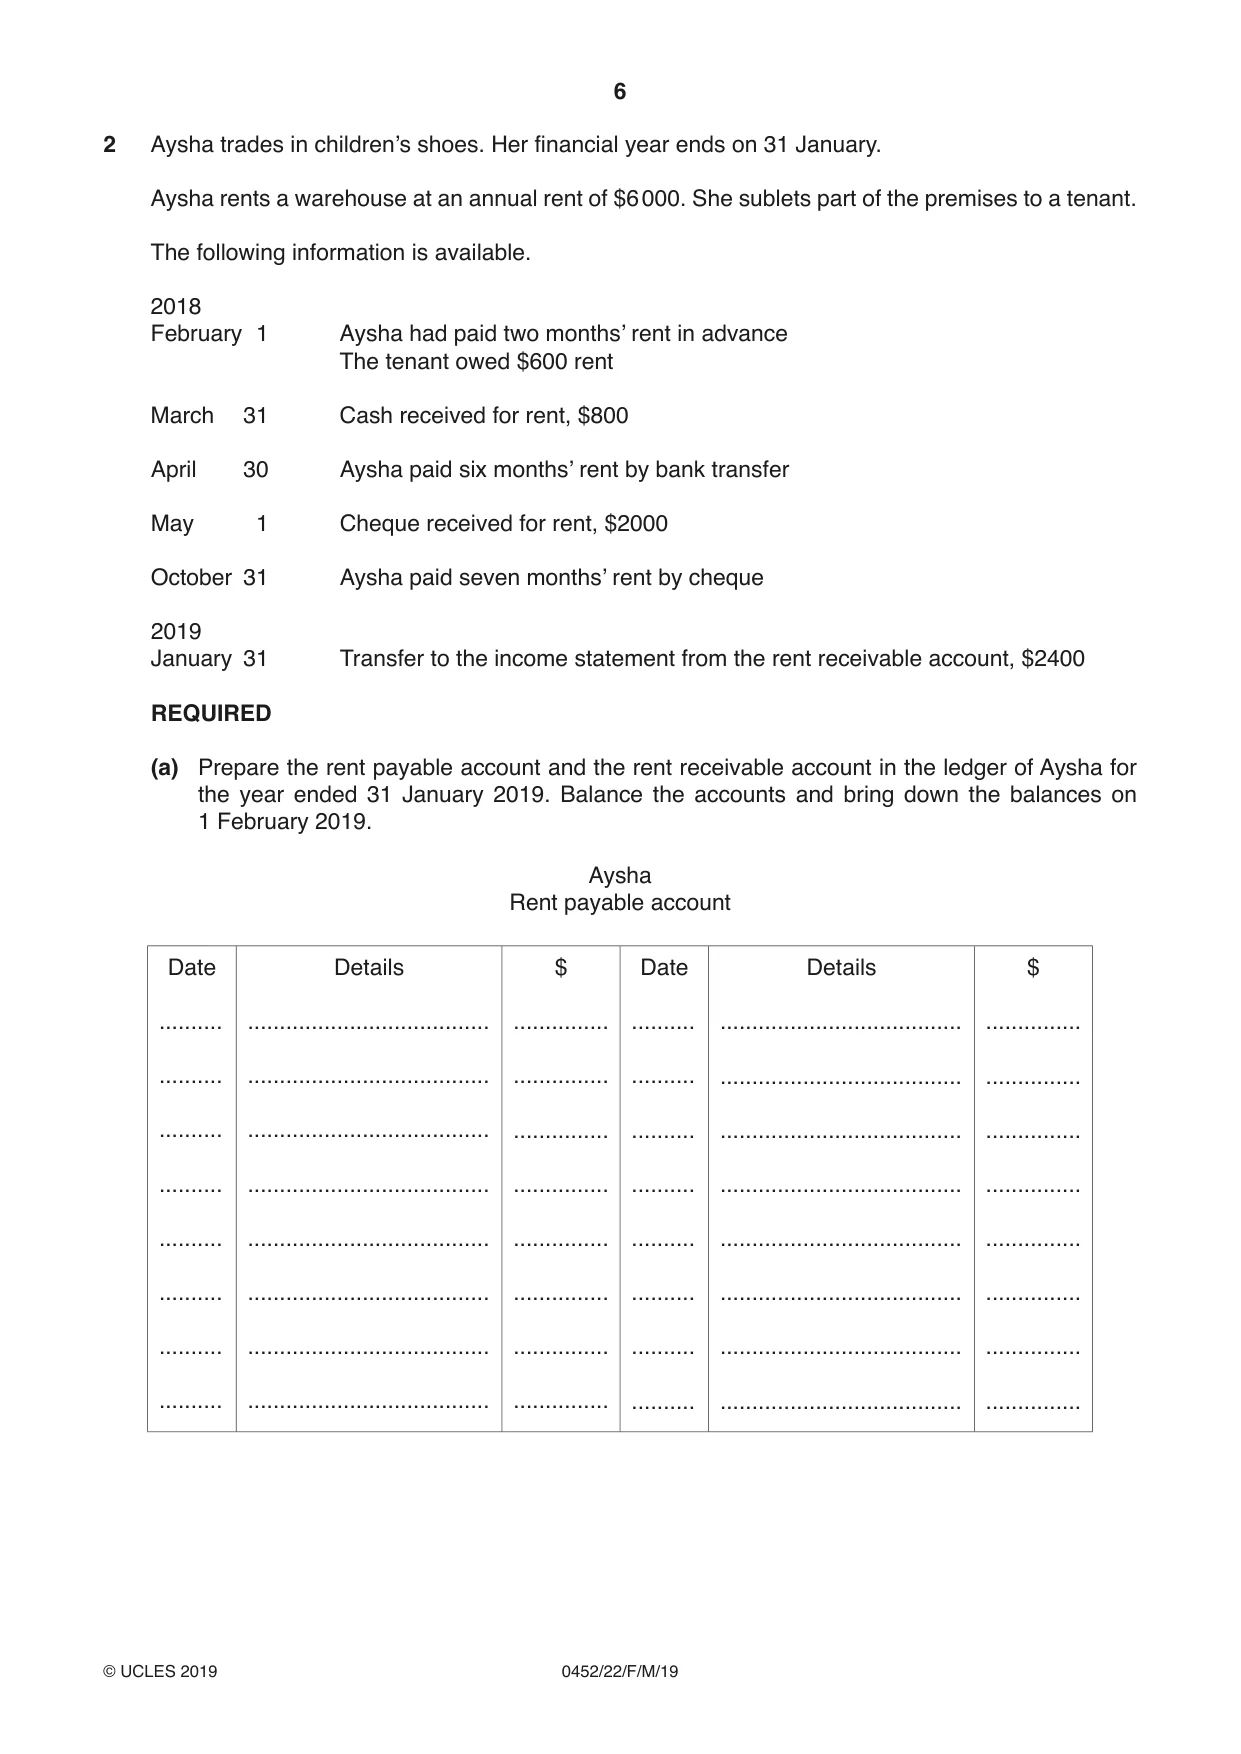
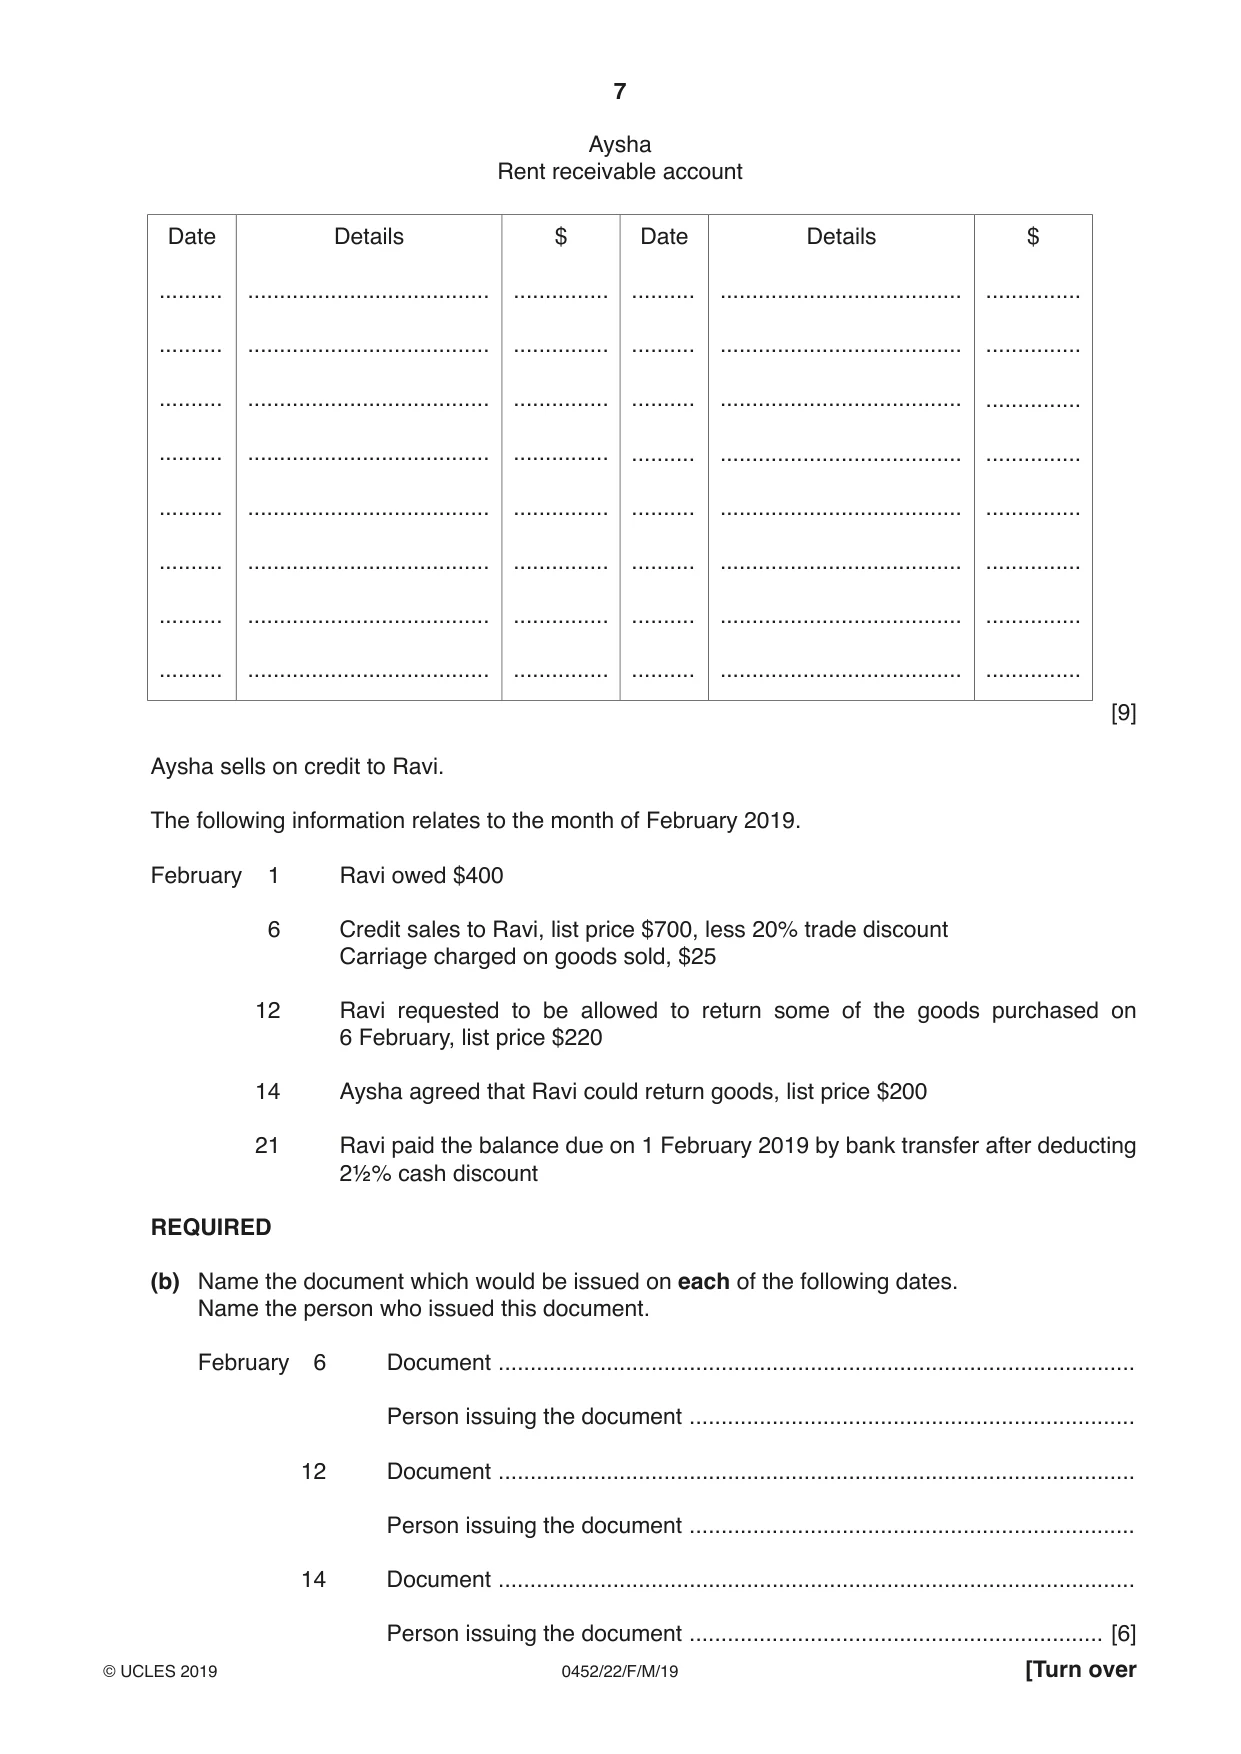
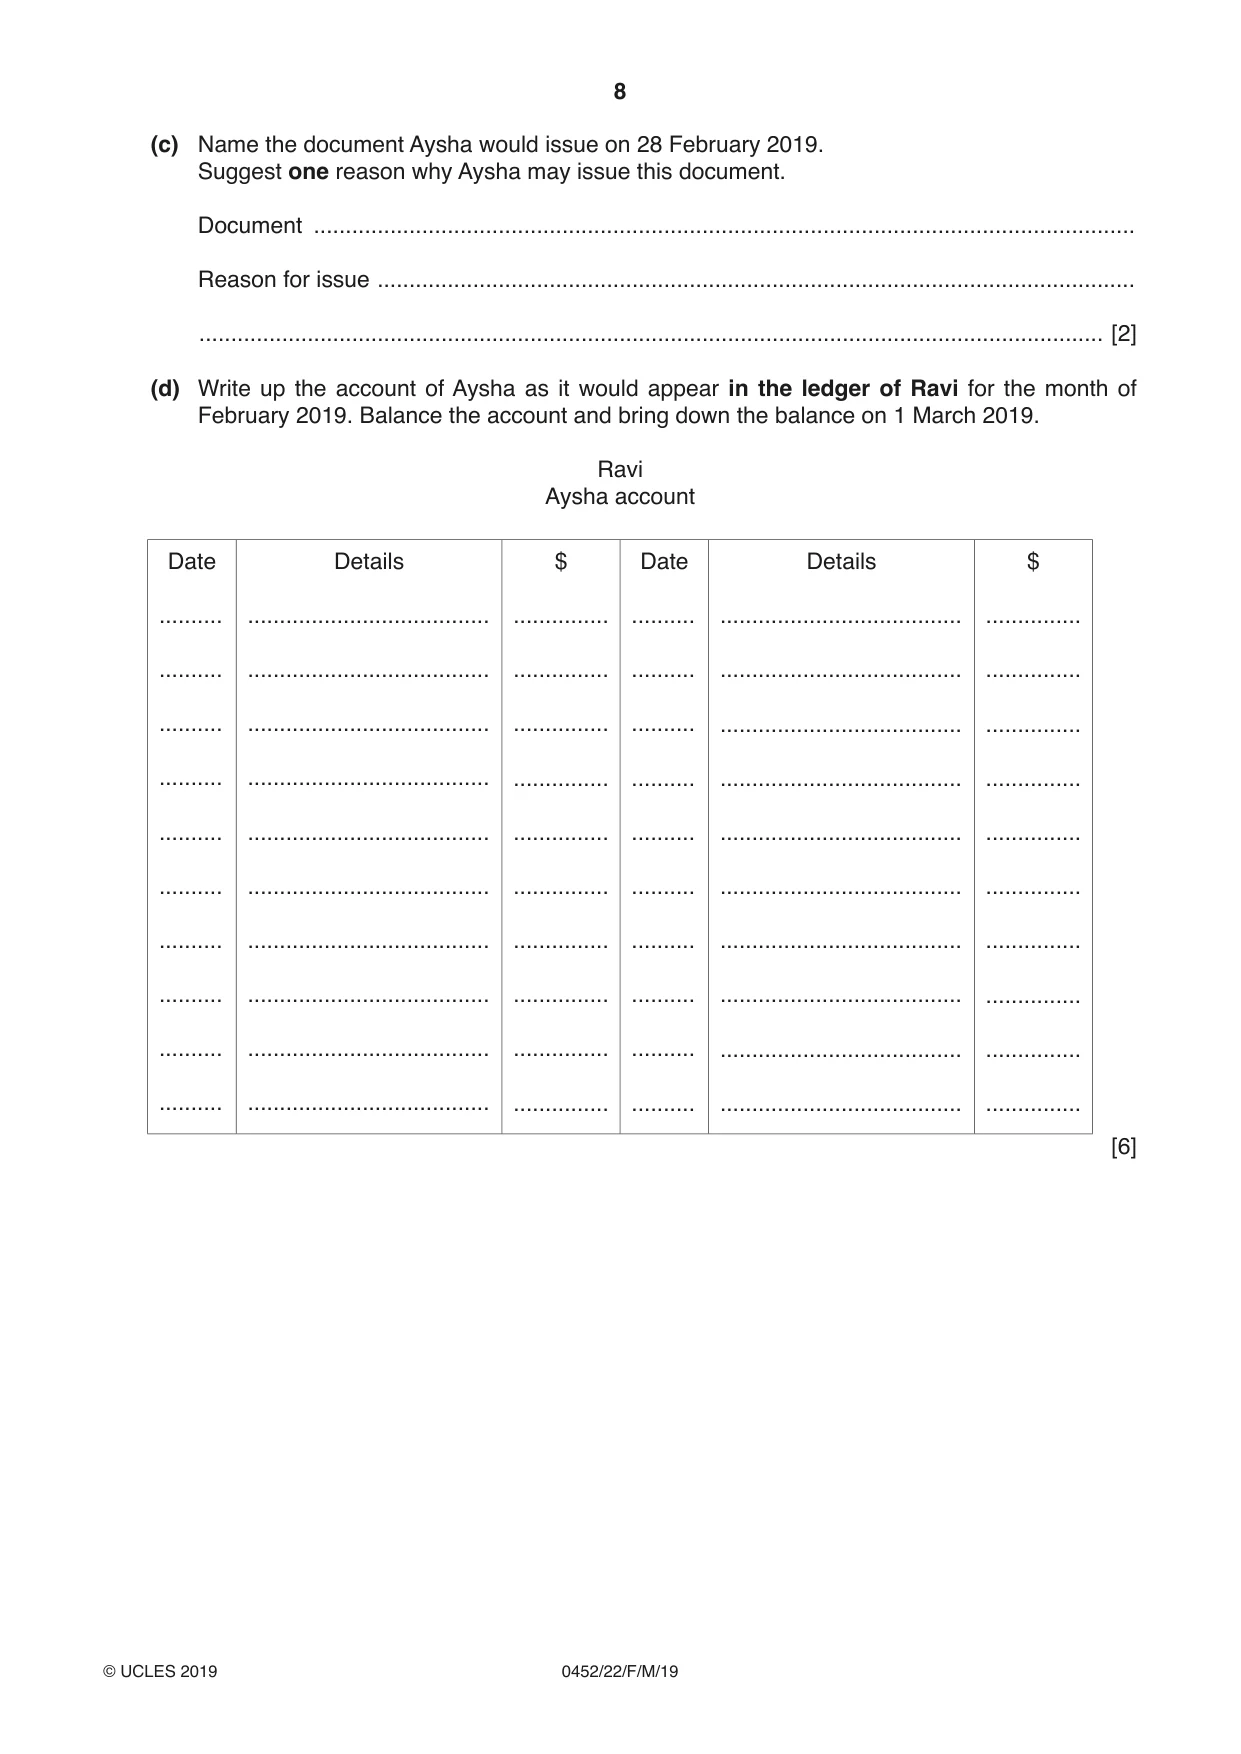
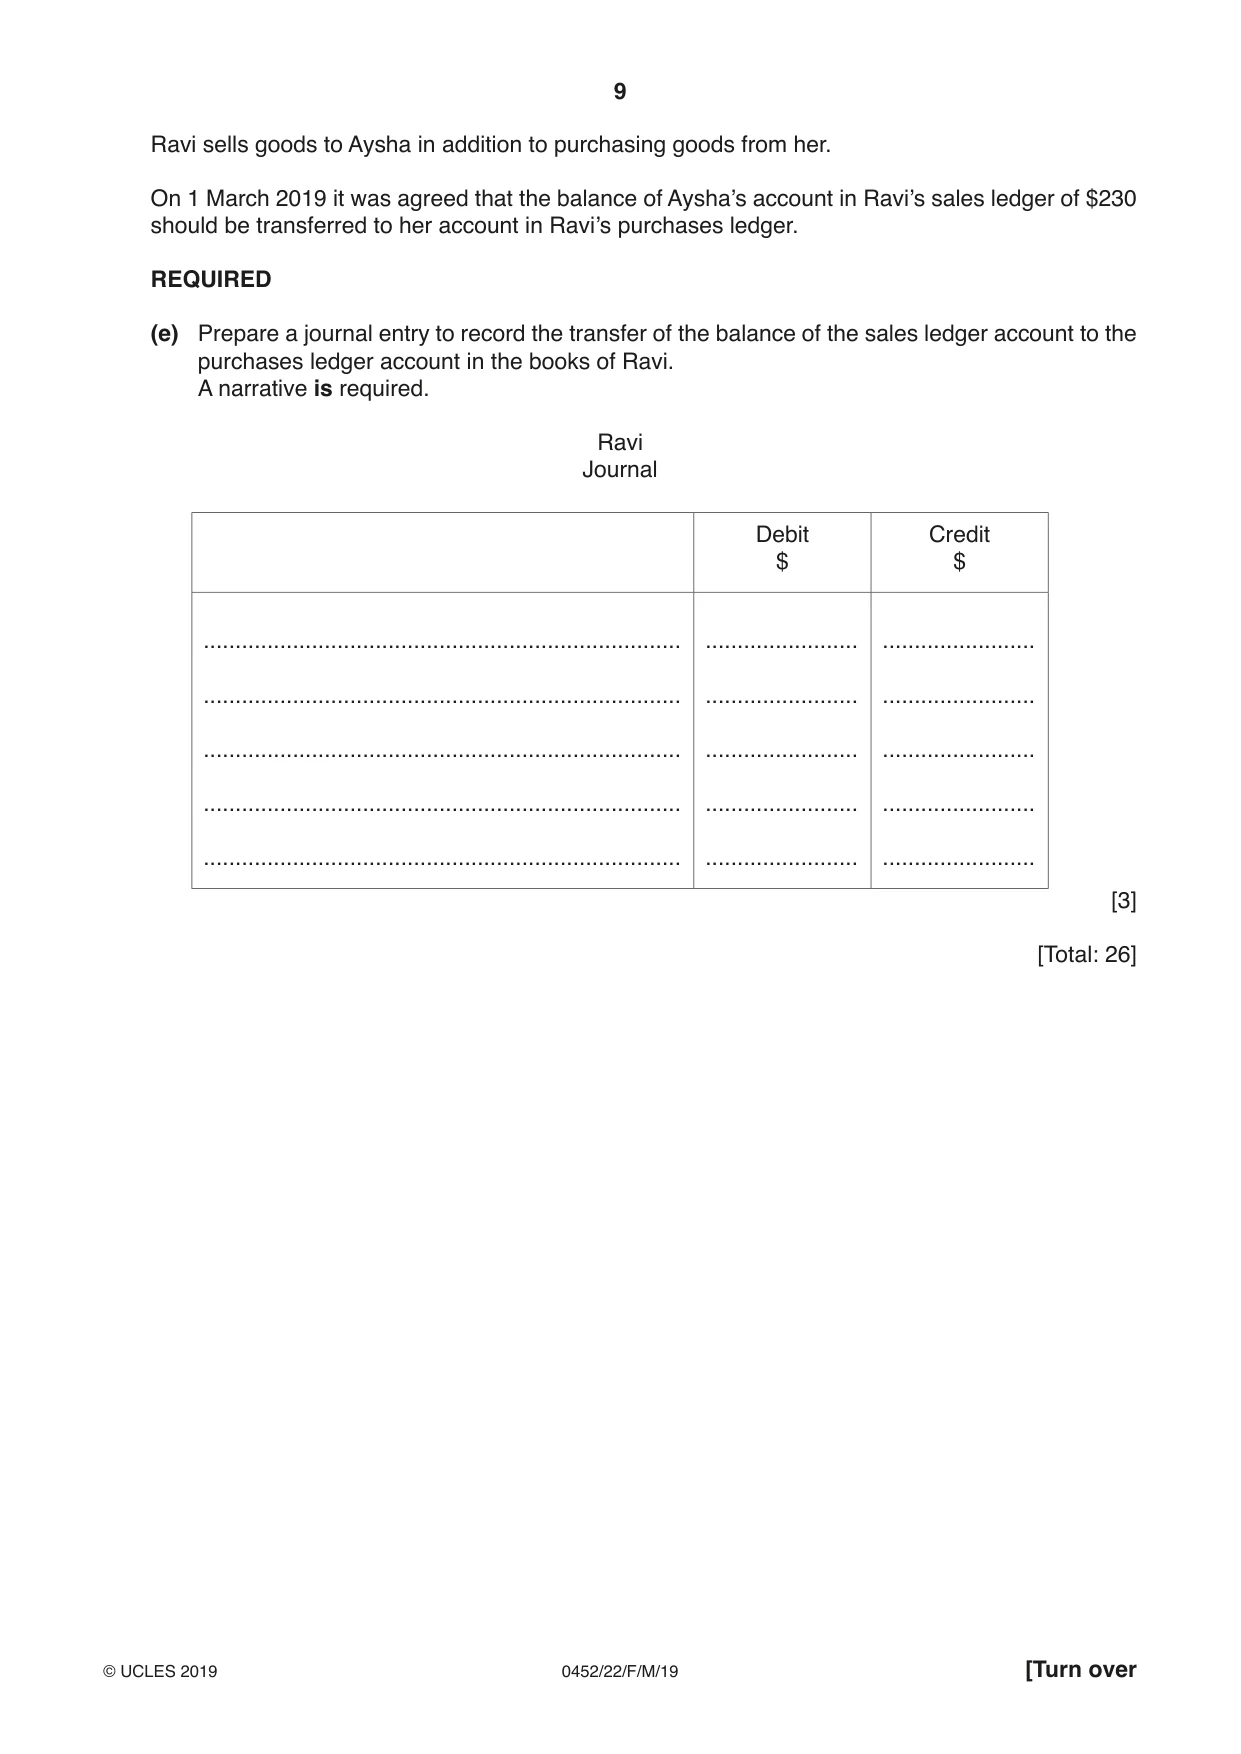
2 Aysha trades in children’s shoes. Her financial year ends on 31 January. Aysha rents a warehouse at an annual rent of $6 000. She sublets part of the premises to a tenant. The following information is available. 2018 February 1 Aysha had paid two months’ rent in advance The tenant owed $600 rent March 31 Cash received for rent, $800 April 30 Aysha paid six months’ rent by bank transfer May 1 Cheque received for rent, $2000 October 31 Aysha paid seven months’ rent by cheque 2019 January 31 Transfer to the income statement from the rent receivable account, $2400 REQUIRED (a) Prepare the rent payable account and the rent receivable account in the ledger of Aysha for the year ended 31 January 2019. Balance the accounts and bring down the balances on 1 February 2019. Aysha Rent payable account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... Aysha Rent receivable account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... [9] Aysha sells on credit to Ravi. The following information relates to the month of February 2019. February 1 Ravi owed $400 6 Credit sales to Ravi, list price $700, less 20% trade discount Carriage charged on goods sold, $25 12 Ravi requested to be allowed to return some of the goods purchased on 6 February, list price $220 14 Aysha agreed that Ravi could return goods, list price $200 21 Ravi paid the balance due on 1 February 2019 by bank transfer after deducting 2½% cash discount REQUIRED (b) Name the document which would be issued on each of the following dates. Name the person who issued this document. February 6 Document .................................................................................................... Person issuing the document ...................................................................... 12 Document .................................................................................................... Person issuing the document ...................................................................... 14 Document .................................................................................................... Person issuing the document ................................................................. [6] (c) Name the document Aysha would issue on 28 February 2019. Suggest one reason why Aysha may issue this document. Document ................................................................................................................................. Reason for issue ....................................................................................................................... .............................................................................................................................................. [2] (d) Write up the account of Aysha as it would appear in the ledger of Ravi for the month of February 2019. Balance the account and bring down the balance on 1 March 2019. Ravi Aysha account Date Details $ Date Details $ .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... .......... ...................................... ............... [6] Ravi sells goods to Aysha in addition to purchasing goods from her. On 1 March 2019 it was agreed that the balance of Aysha’s account in Ravi’s sales ledger of $230 should be transferred to her account in Ravi’s purchases ledger. REQUIRED (e) Prepare a journal entry to record the transfer of the balance of the sales ledger account to the purchases ledger account in the books of Ravi. A narrative is required. Ravi Journal Debit Credit $ $ ........................................................................... ........................ ........................ ........................................................................... ........................ ........................ ........................................................................... ........................ ........................ ........................................................................... ........................ ........................ ........................................................................... ........................ ........................ [3] [Total: 26]
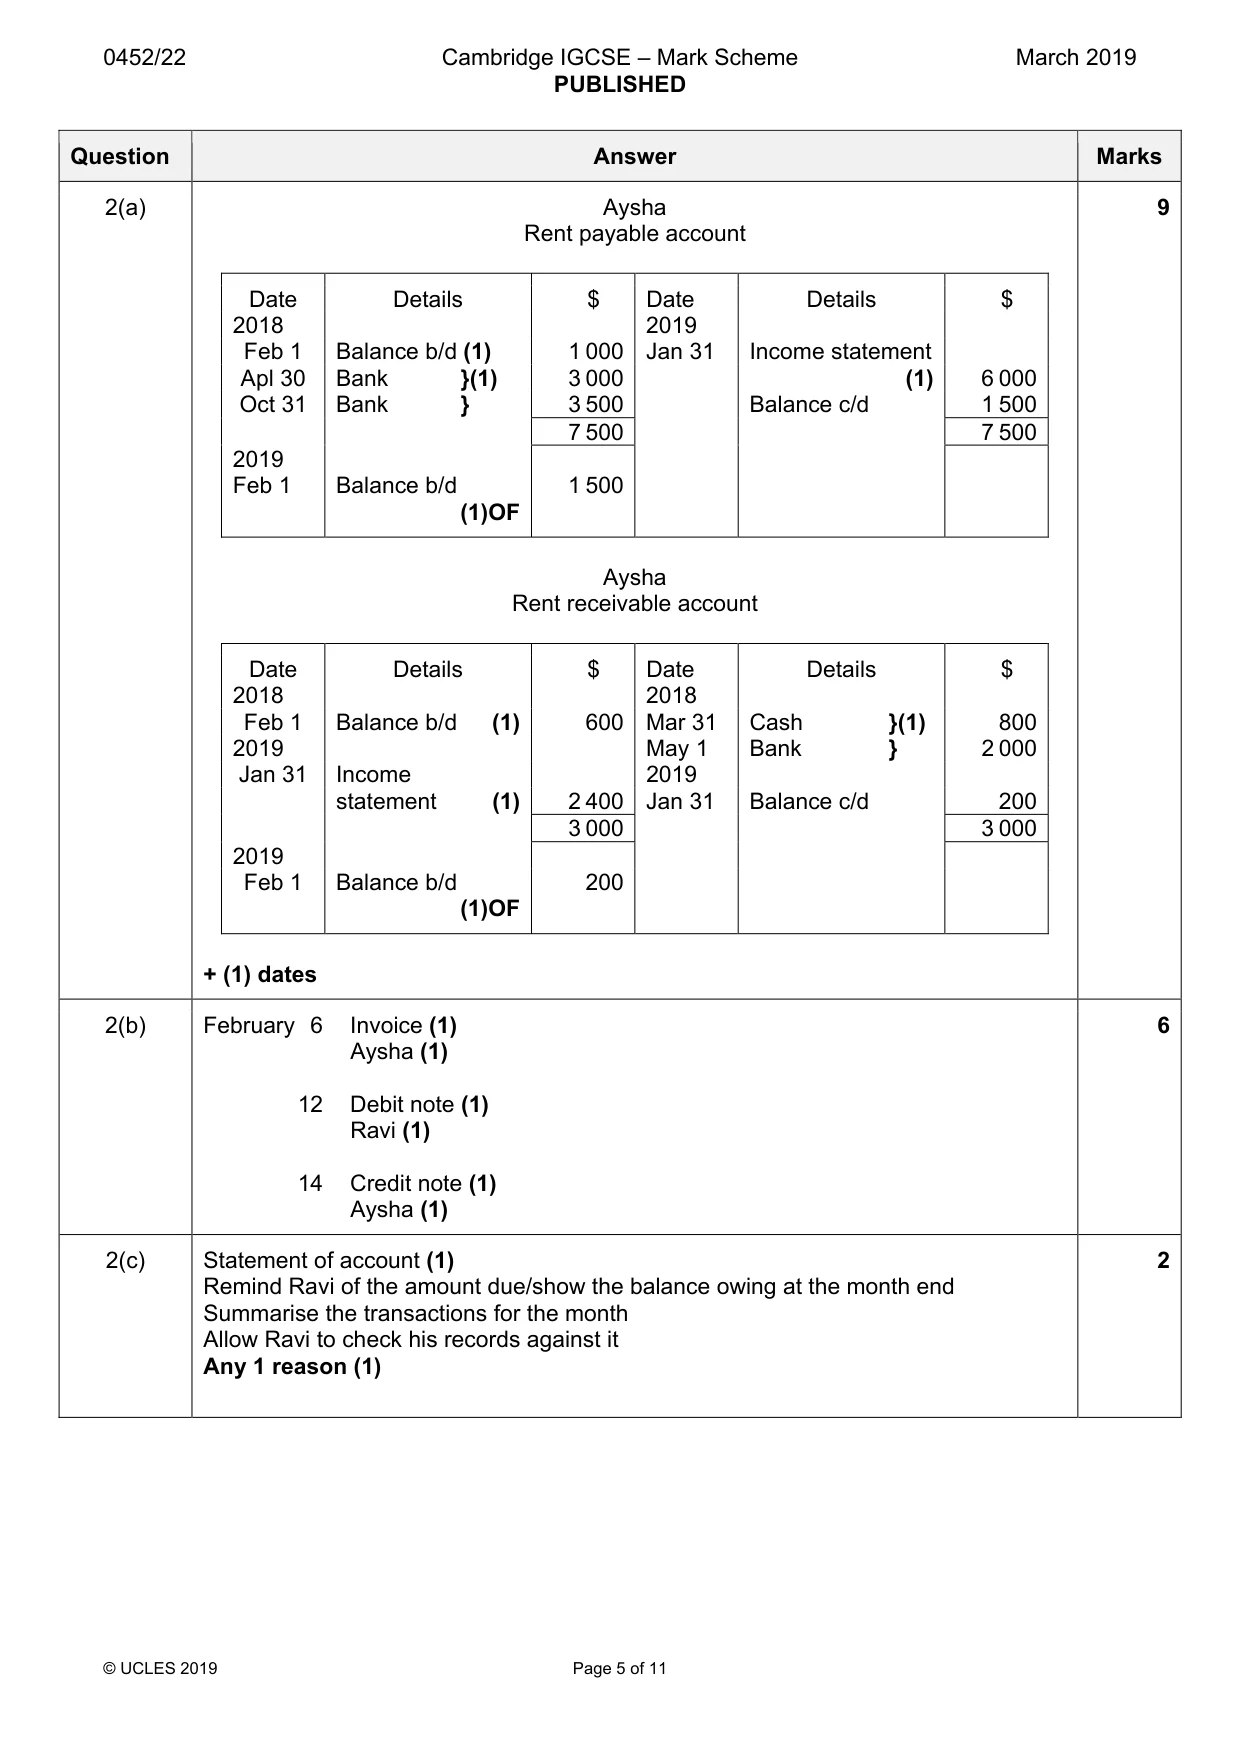
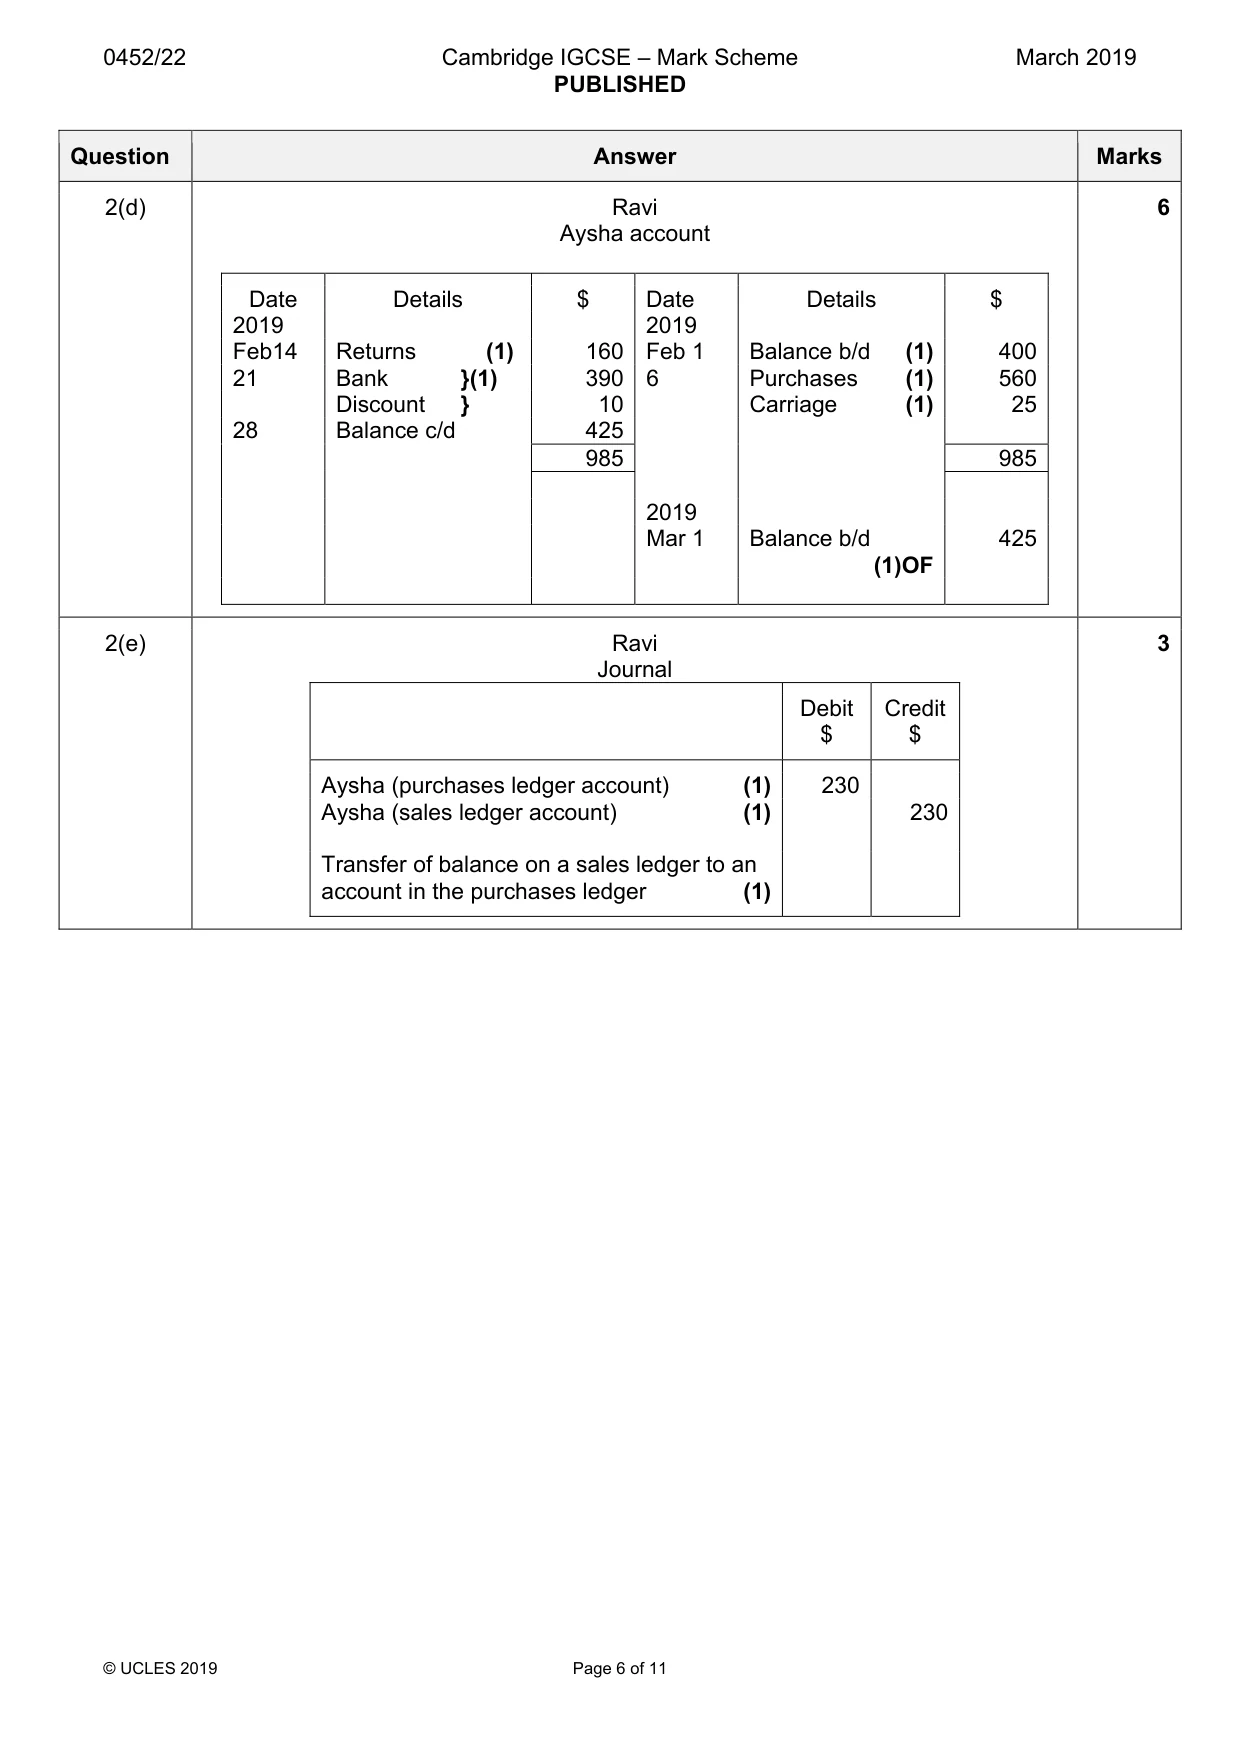
Mark scheme: 2(a) Aysha 9 Rent payable account Date Details $ Date Details $ 2018 2019 Feb 1 Balance b/d (1) 1 000 Jan 31 Income statement Apl 30 Bank }(1) 3 000 (1) 6 000 Oct 31 Bank } 3 500 Balance c/d 1 500 7 500 7 500 2019 Feb 1 Balance b/d 1 500 (1)OF Aysha Rent receivable account Date Details $ Date Details $ 2018 2018 Feb 1 Balance b/d (1) 600 Mar 31 Cash }(1) 800 2019 May 1 Bank } 2 000 Jan 31 Income 2019 statement (1) 2 400 Jan 31 Balance c/d 200 3 000 3 000 2019 Feb 1 Balance b/d 200 (1)OF + (1) dates 2(b) February 6 Invoice (1) 6 Aysha (1) 12 Debit note (1) Ravi (1) 14 Credit note (1) Aysha (1) 2(c) Statement of account (1) 2 Remind Ravi of the amount due/show the balance owing at the month end Summarise the transactions for the month Allow Ravi to check his records against it Any 1 reason (1) 2(d) Ravi 6 Aysha account Date Details $ Date Details $ 2019 2019 Feb14 Returns (1) 160 Feb 1 Balance b/d (1) 400 21 Bank }(1) 390 6 Purchases (1) 560 Discount } 10 Carriage (1) 25 28 Balance c/d 425 985 985 2019 Mar 1 Balance b/d 425 (1)OF 2(e) Ravi 3 Journal Debit Credit $ $ Aysha (purchases ledger account) (1) 230 Aysha (sales ledger account) (1) 230 Transfer of balance on a sales ledger to an account in the purchases ledger (1)
Q3 · Bari and Nada are in partnership
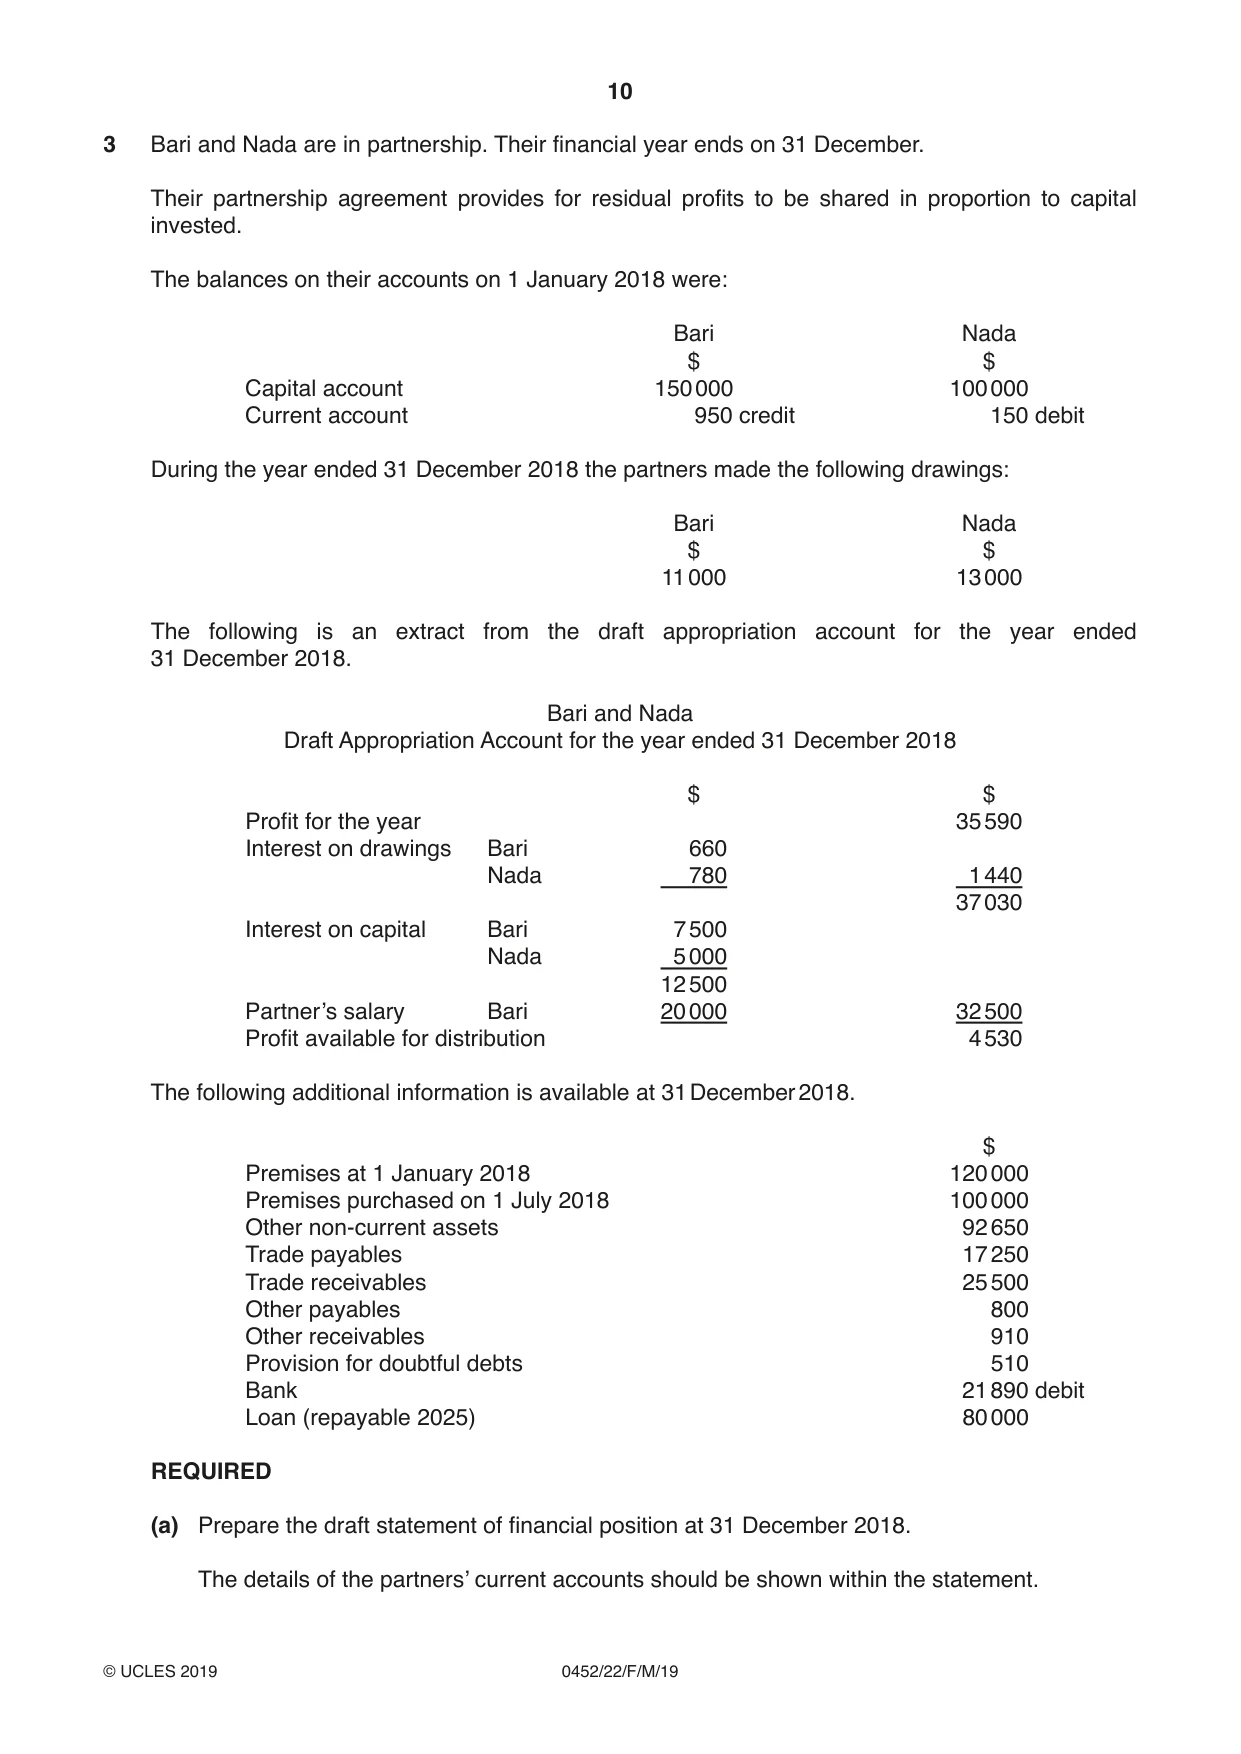
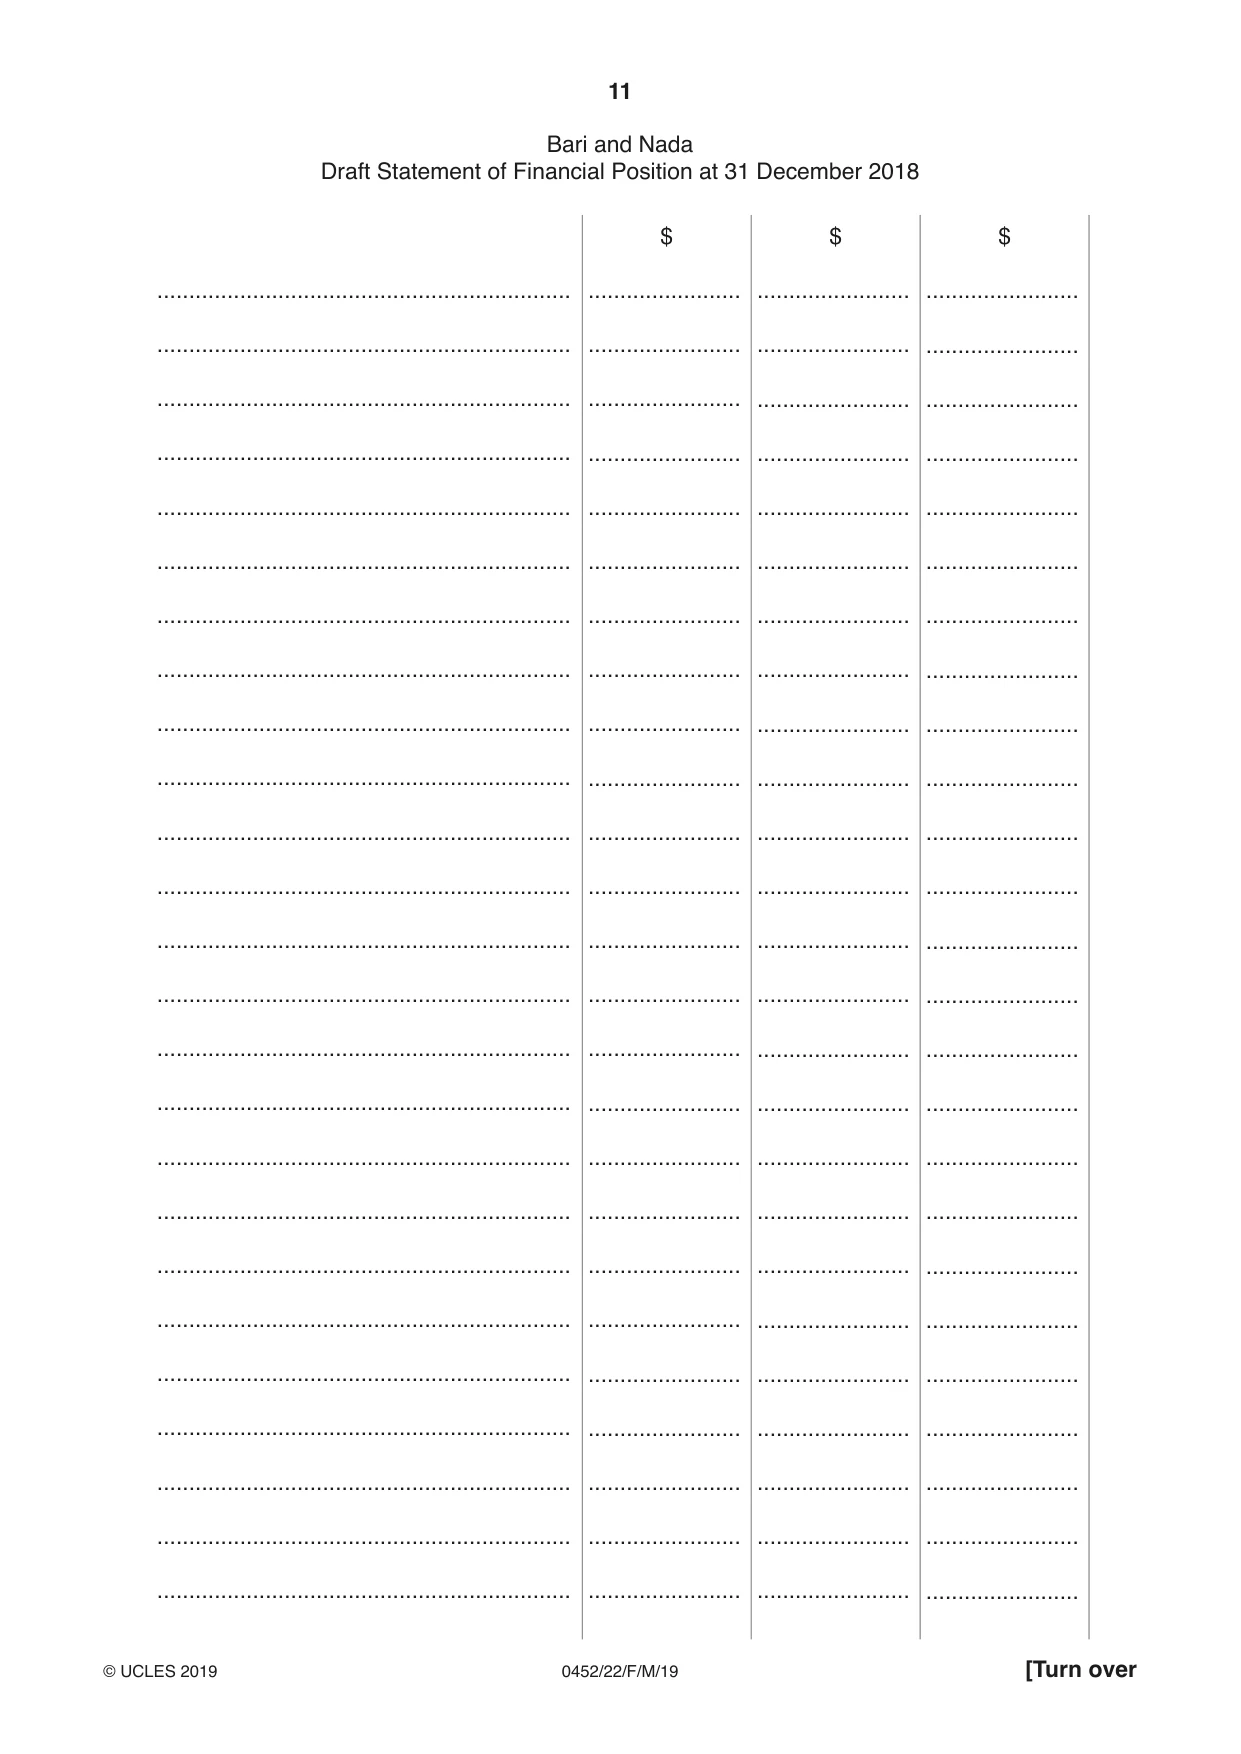
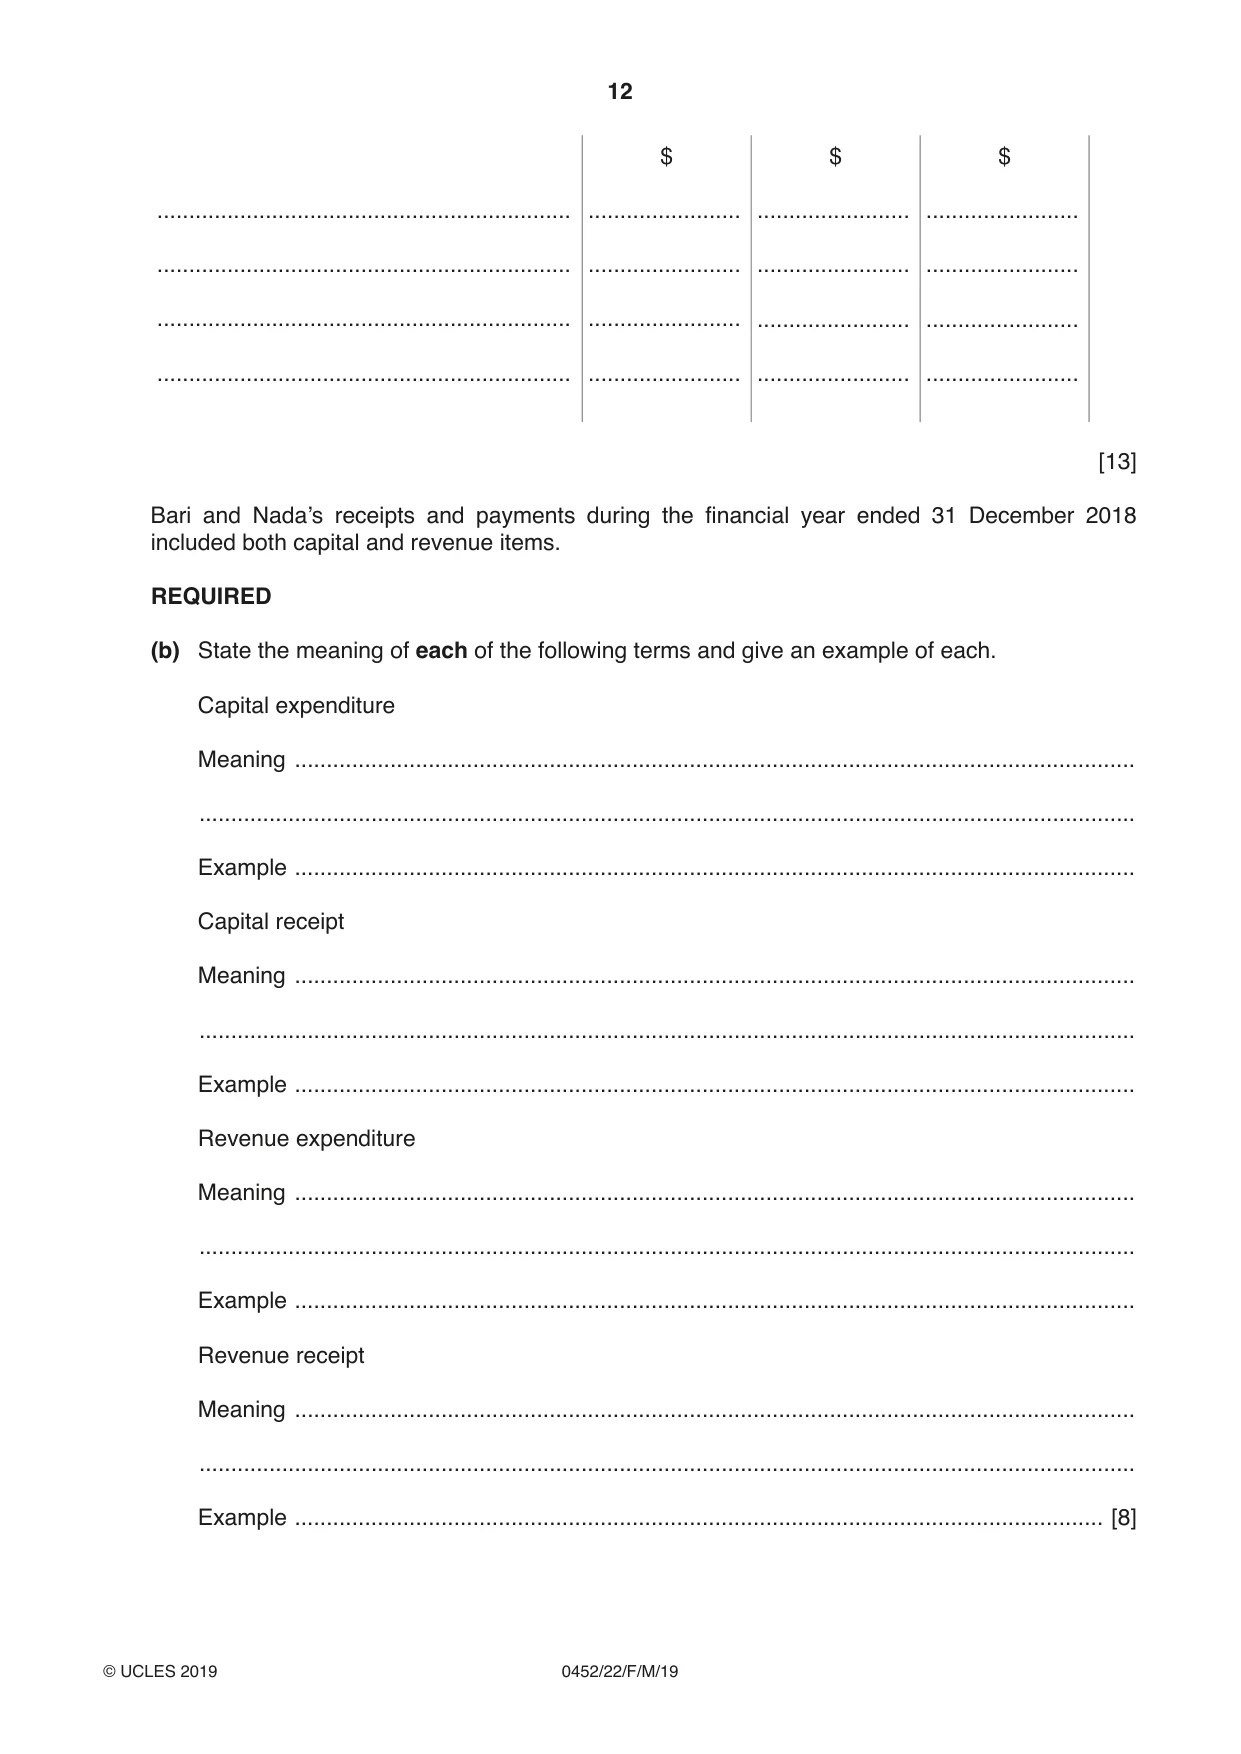
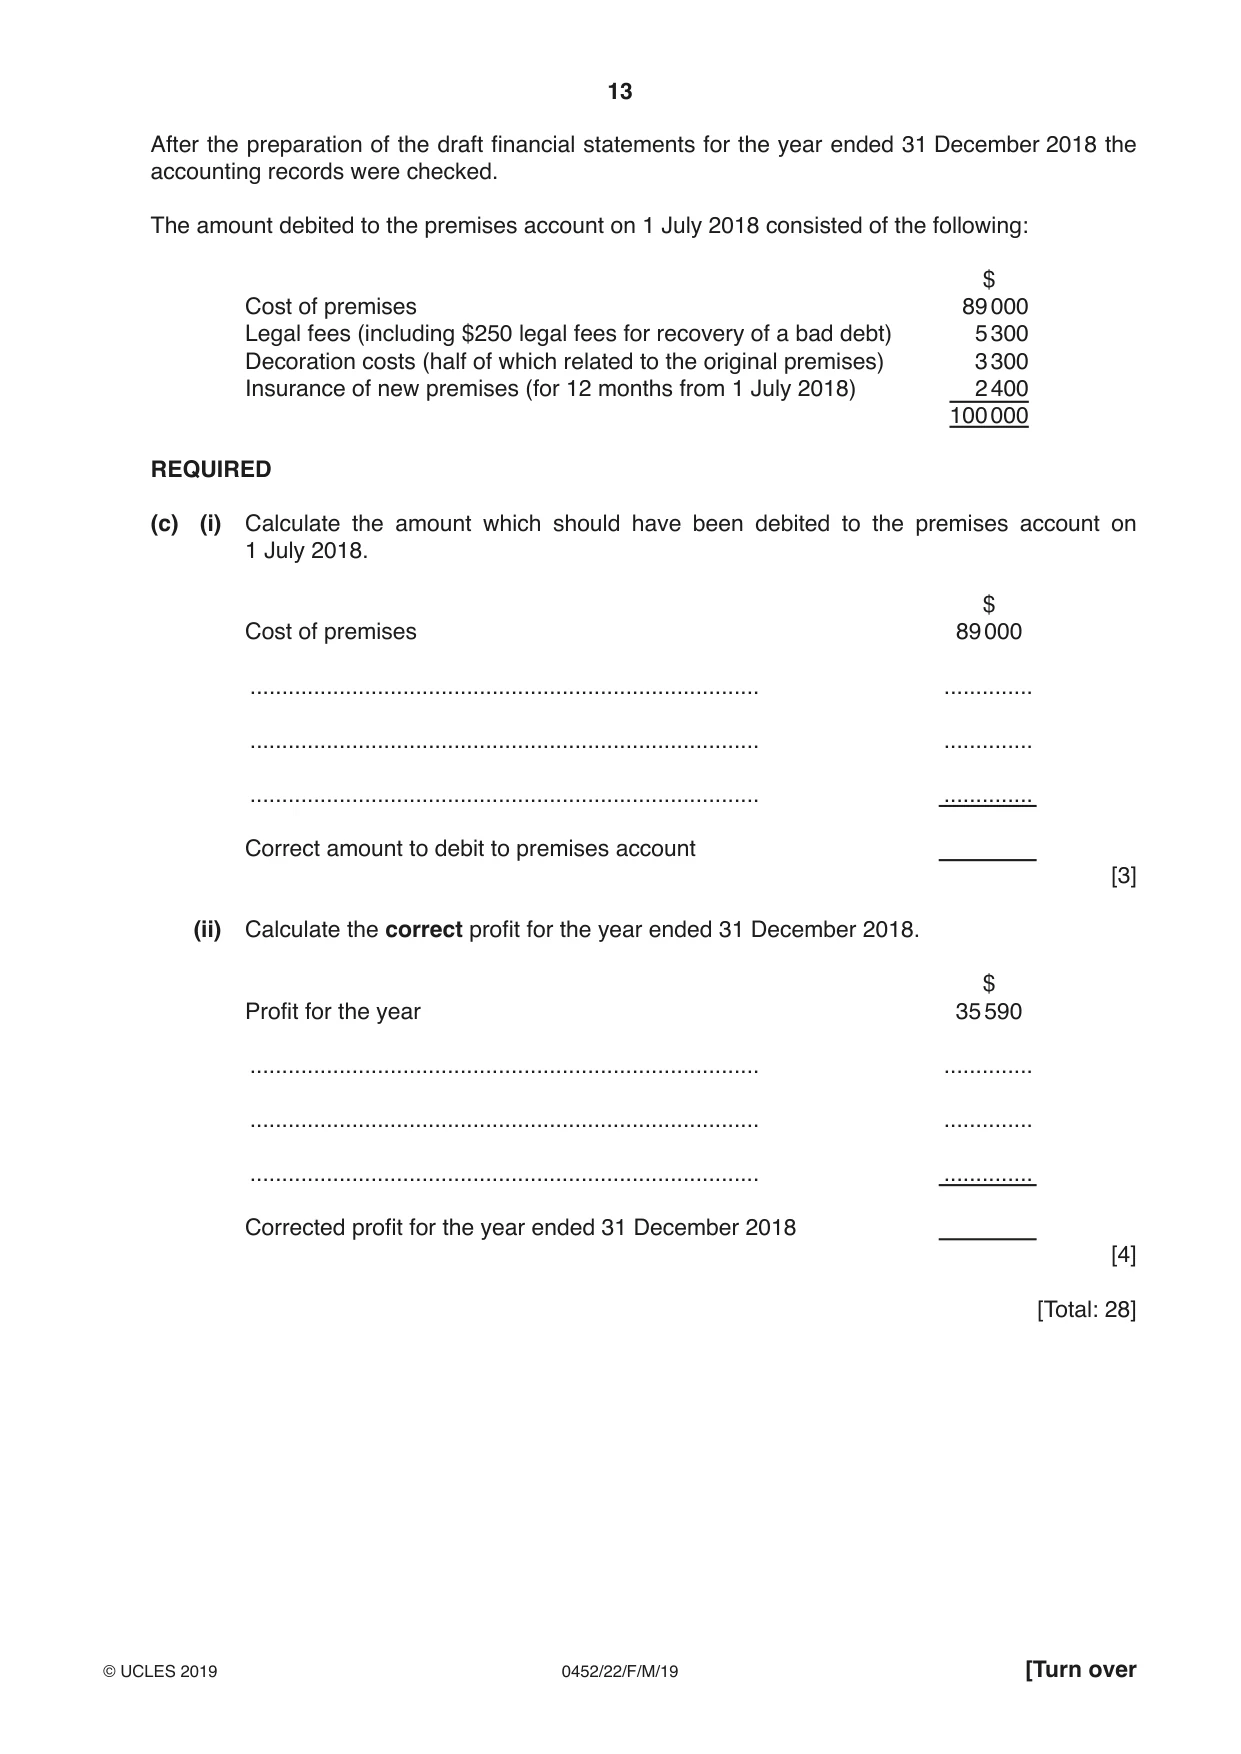
3 Bari and Nada are in partnership. Their financial year ends on 31 December. Their partnership agreement provides for residual profits to be shared in proportion to capital invested. The balances on their accounts on 1 January 2018 were: Bari Nada $ $ Capital account 150 000 100 000 Current account 950 credit 150 debit During the year ended 31 December 2018 the partners made the following drawings: Bari Nada $ $ 11 000 13 000 The following is an extract from the draft appropriation account for the year ended 31 December 2018. Bari and Nada Draft Appropriation Account for the year ended 31 December 2018 $ $ Profit for the year 35 590 Interest on drawings Bari 660 Nada 780 1 440 37 030 Interest on capital Bari 7 500 Nada 5 000 12 500 Partner’s salary Bari 20 000 32 500 Profit available for distribution 4 530 The following additional information is available at 31 December 2018. $ Premises at 1 January 2018 120 000 Premises purchased on 1 July 2018 100 000 Other non-current assets 92 650 Trade payables 17 250 Trade receivables 25 500 Other payables 800 Other receivables 910 Provision for doubtful debts 510 Bank 21 890 debit Loan (repayable 2025) 80 000 REQUIRED (a) Prepare the draft statement of financial position at 31 December 2018. The details of the partners’ current accounts should be shown within the statement. and Nada al Position at 3 $ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ ........................ $ $ $ ................................................................. ........................ ........................ ........................ ................................................................. ........................ ........................ ........................ ................................................................. ........................ ........................ ........................ ................................................................. ........................ ........................ ........................ [13] Bari and Nada’s receipts and payments during the financial year ended 31 December 2018 included both capital and revenue items. REQUIRED (b) State the meaning of each of the following terms and give an example of each. Capital expenditure Meaning .................................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... Capital receipt Meaning .................................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... Revenue expenditure Meaning .................................................................................................................................... ................................................................................................................................................... Example .................................................................................................................................... Revenue receipt Meaning .................................................................................................................................... ................................................................................................................................................... Example ............................................................................................................................... [8] After the preparation of the draft financial statements for the year ended 31 December 2018 the accounting records were checked. The amount debited to the premises account on 1 July 2018 consisted of the following: $ Cost of premises 89 000 Legal fees (including $250 legal fees for recovery of a bad debt) 5 300 Decoration costs (half of which related to the original premises) 3 300 Insurance of new premises (for 12 months from 1 July 2018) 2 400 100 000 REQUIRED (c) (i) Calculate the amount which should have been debited to the premises account on 1 July 2018. $ Cost of premises 89 000 ................................................................................ .............. ................................................................................ .............. ................................................................................ .............. Correct amount to debit to premises account [3] (ii) Calculate the correct profit for the year ended 31 December 2018. $ Profit for the year 35 590 ................................................................................ .............. ................................................................................ .............. ................................................................................ .............. Corrected profit for the year ended 31 December 2018 [4] [Total: 28]
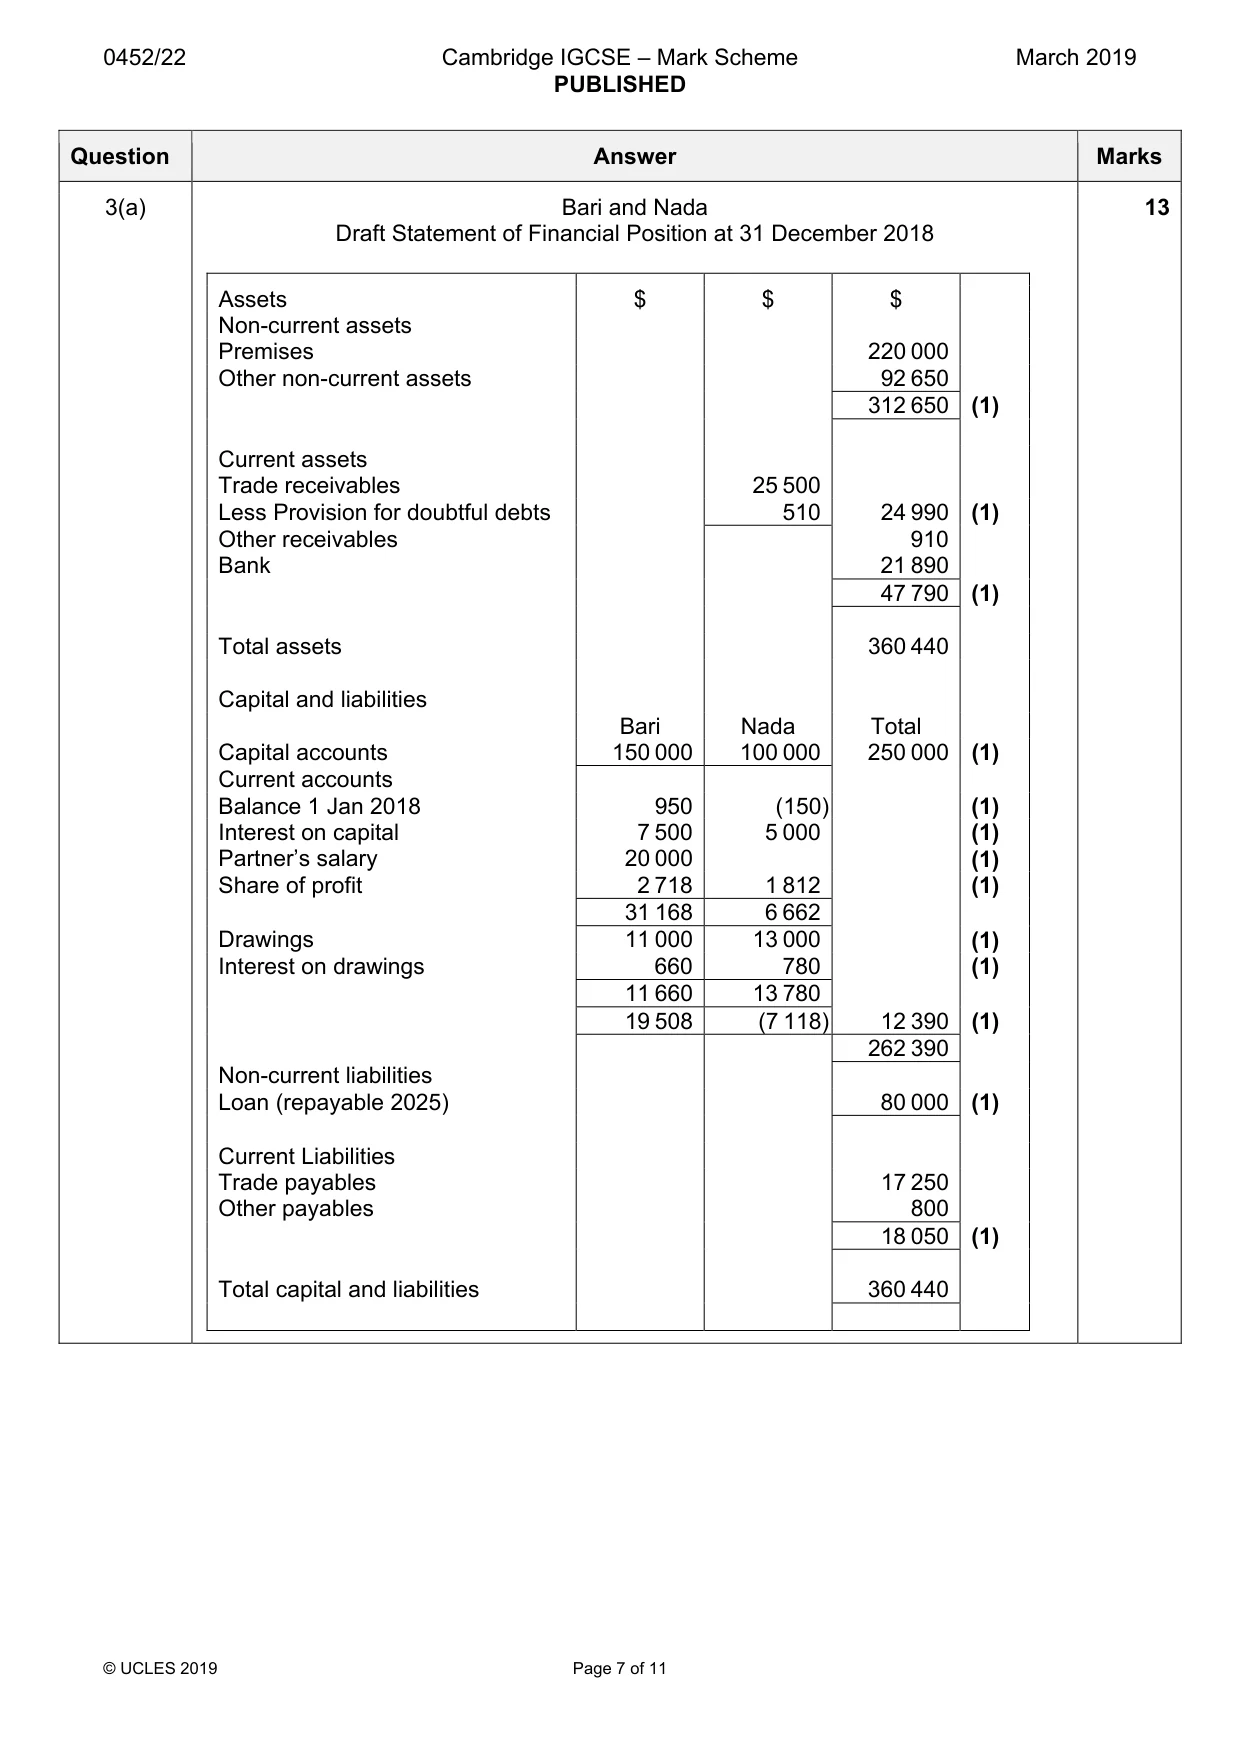
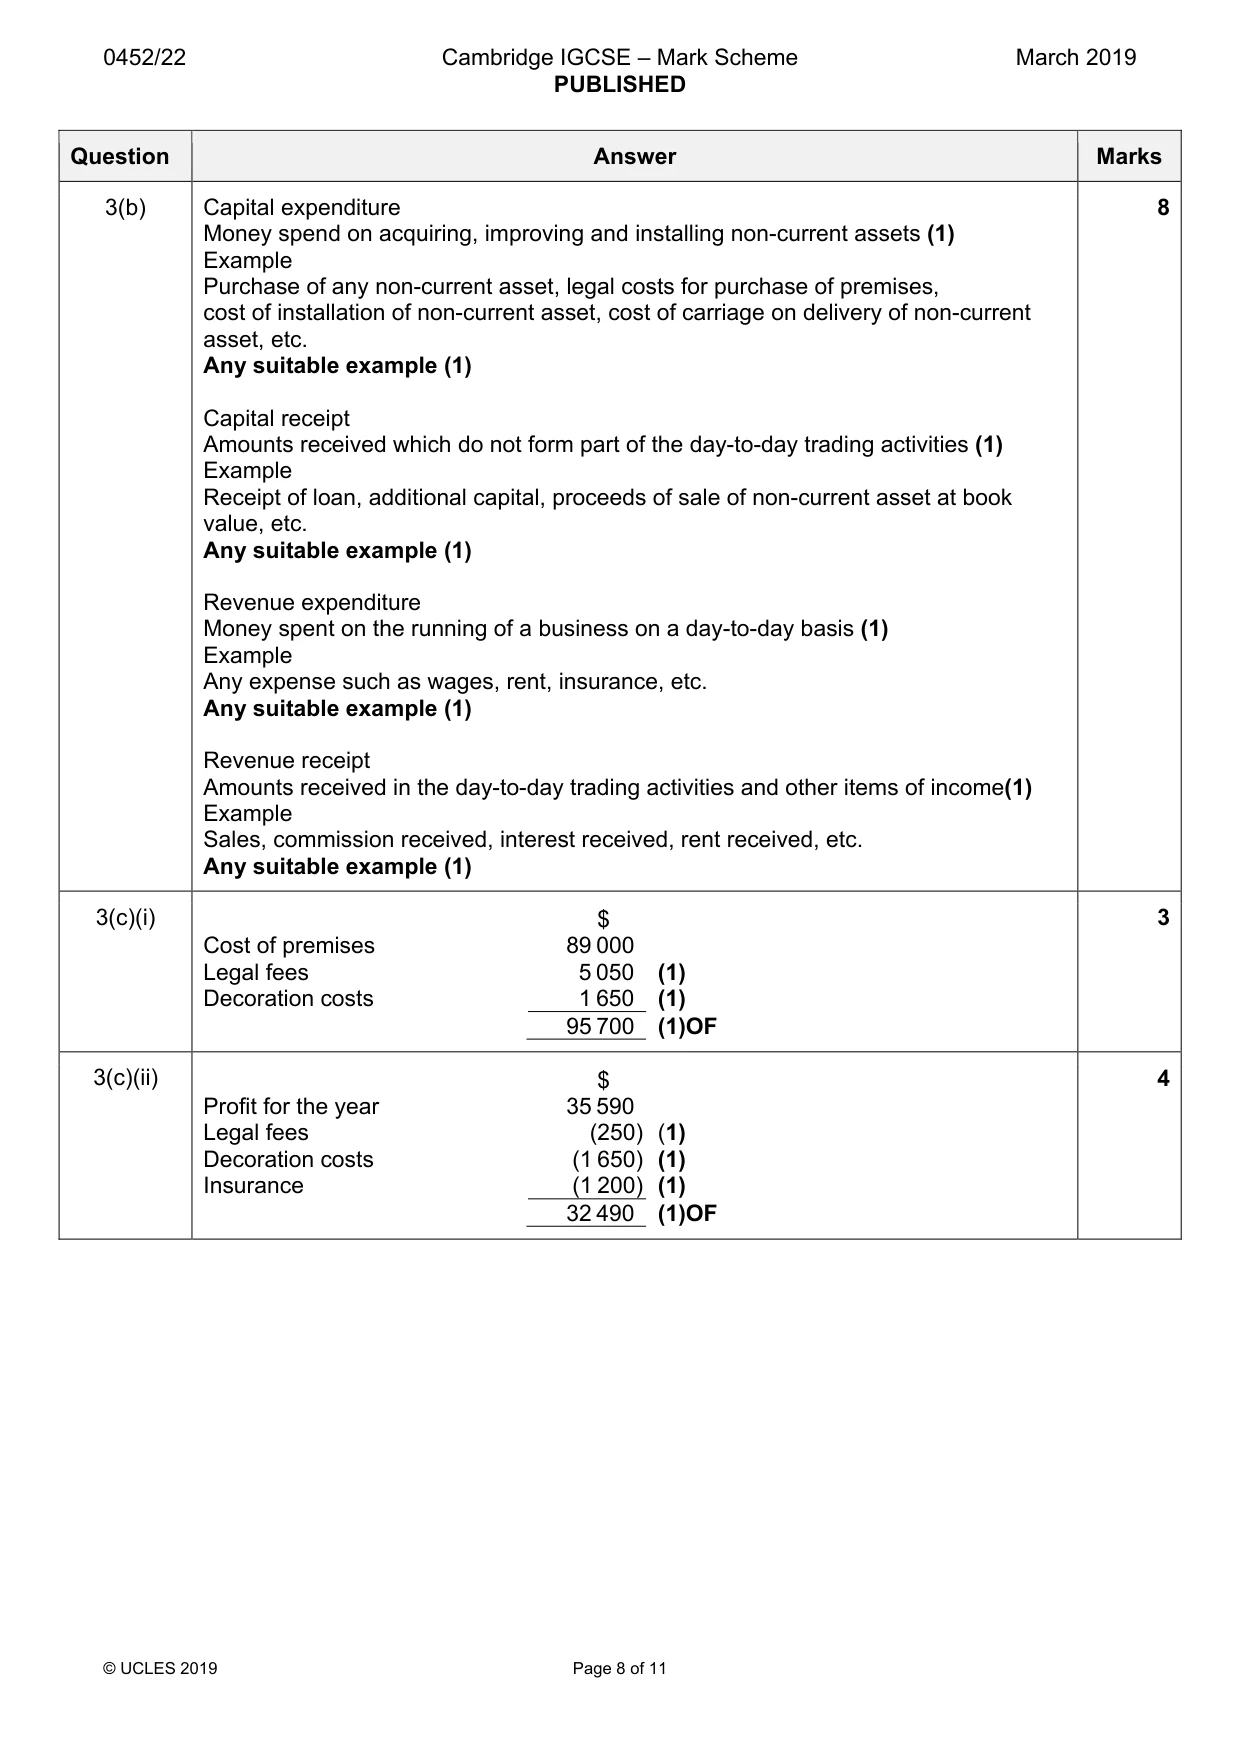
Mark scheme: 3(a) Bari and Nada 13 Draft Statement of Financial Position at 31 December 2018 Assets $ $ $ Non-current assets Premises 220 000 Other non-current assets 92 650 312 650 (1) Current assets Trade receivables 25 500 Less Provision for doubtful debts 510 24 990 (1) Other receivables 910 Bank 21 890 47 790 (1) Total assets 360 440 Capital and liabilities Bari Nada Total Capital accounts 150 000 100 000 250 000 (1) Current accounts Balance 1 Jan 2018 950 (150) (1) Interest on capital 7 500 5 000 (1) Partner’s salary 20 000 (1) Share of profit 2 718 1 812 (1) 31 168 6 662 Drawings 11 000 13 000 (1) Interest on drawings 660 780 (1) 11 660 13 780 19 508 (7 118) 12 390 (1) 262 390 Non-current liabilities Loan (repayable 2025) 80 000 (1) Current Liabilities Trade payables 17 250 Other payables 800 18 050 (1) Total capital and liabilities 360 440 3(b) Capital expenditure 8 Money spend on acquiring, improving and installing non-current assets (1) Example Purchase of any non-current asset, legal costs for purchase of premises, cost of installation of non-current asset, cost of carriage on delivery of non-current asset, etc. Any suitable example (1) Capital receipt Amounts received which do not form part of the day-to-day trading activities (1) Example Receipt of loan, additional capital, proceeds of sale of non-current asset at book value, etc. Any suitable example (1) Revenue expenditure Money spent on the running of a business on a day-to-day basis (1) Example Any expense such as wages, rent, insurance, etc. Any suitable example (1) Revenue receipt Amounts received in the day-to-day trading activities and other items of income(1) Example Sales, commission received, interest received, rent received, etc. Any suitable example (1) 3(c)(i) $ 3 Cost of premises 89 000 Legal fees 5 050 (1) Decoration costs 1 650 (1) 95 700 (1)OF 3(c)(ii) $ 4 Profit for the year 35 590 Legal fees (250) (1) Decoration costs (1 650) (1) Insurance (1 200) (1) 32 490 (1)OF
Q4 · Jai’s financial year ends on 31 December
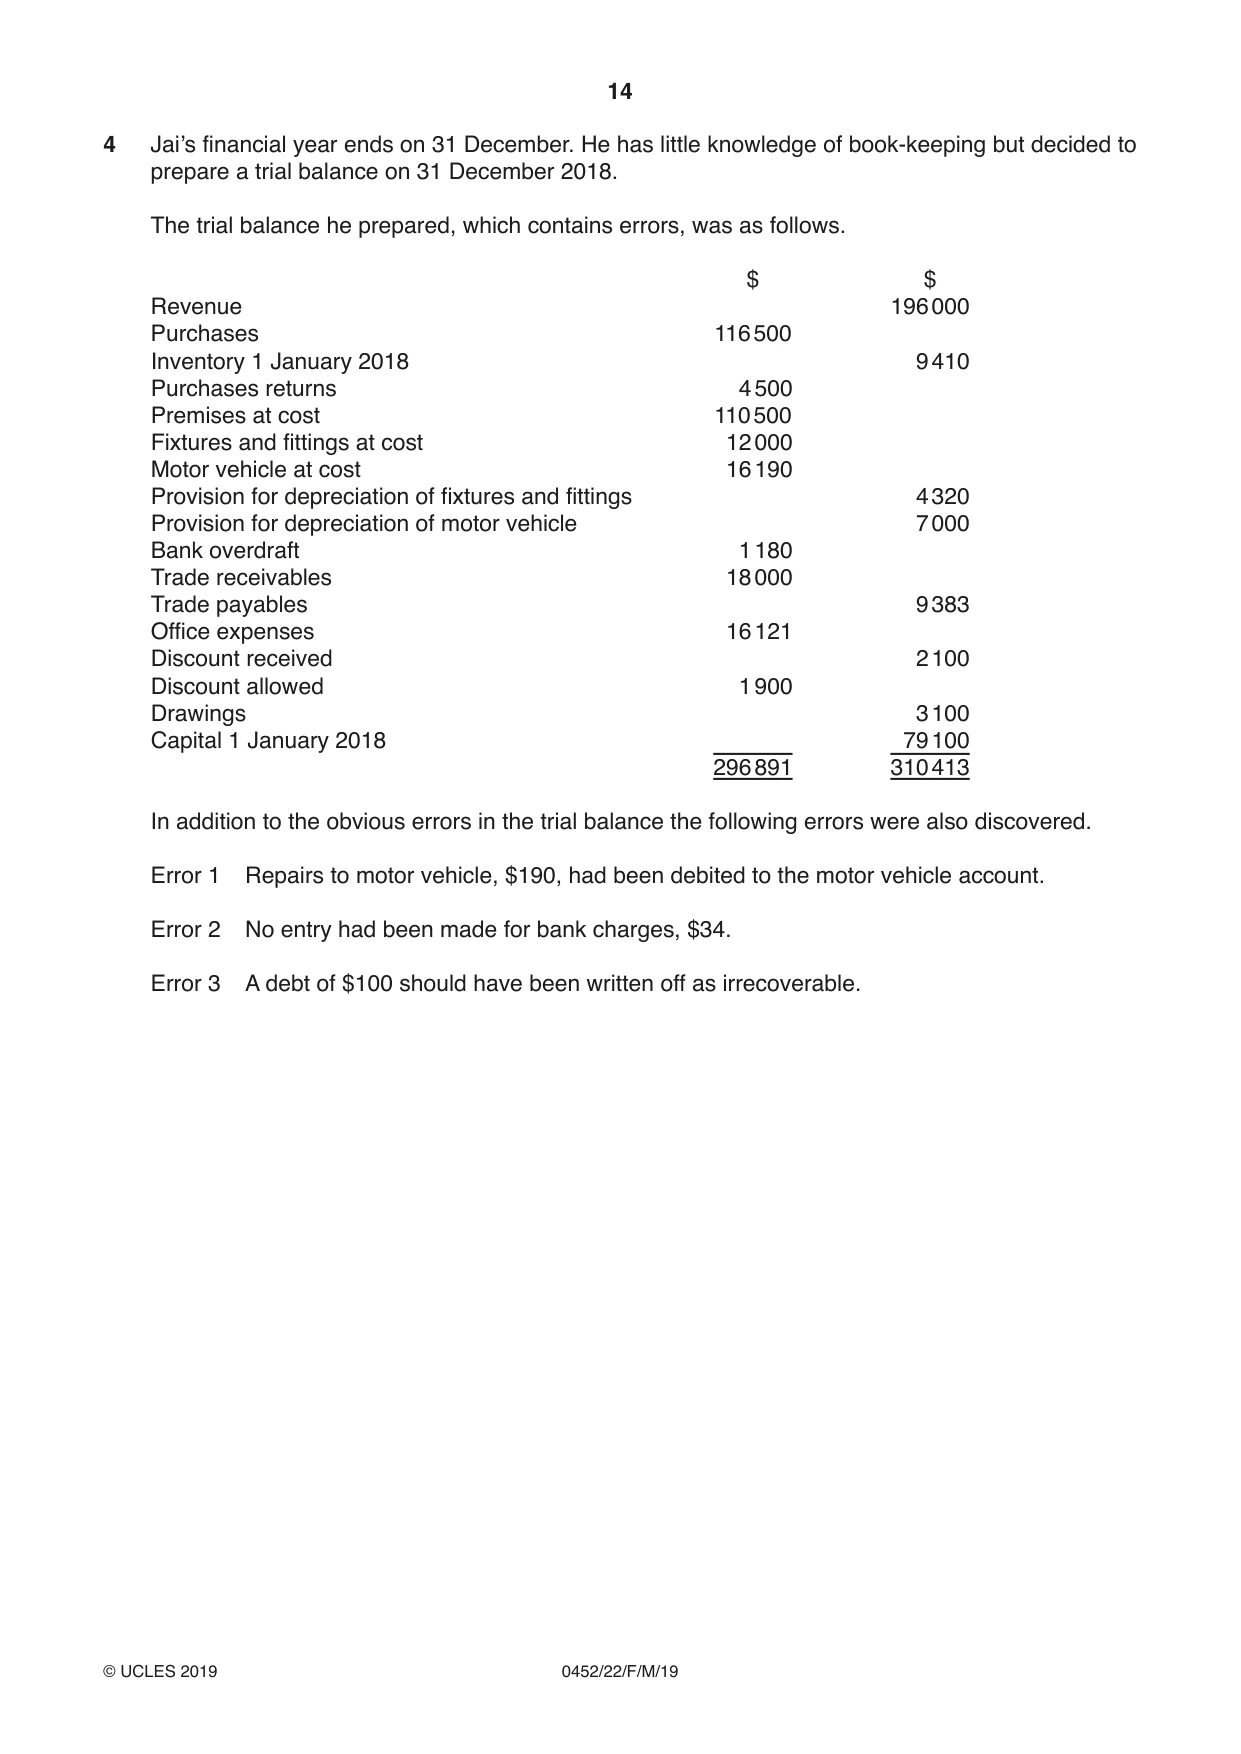
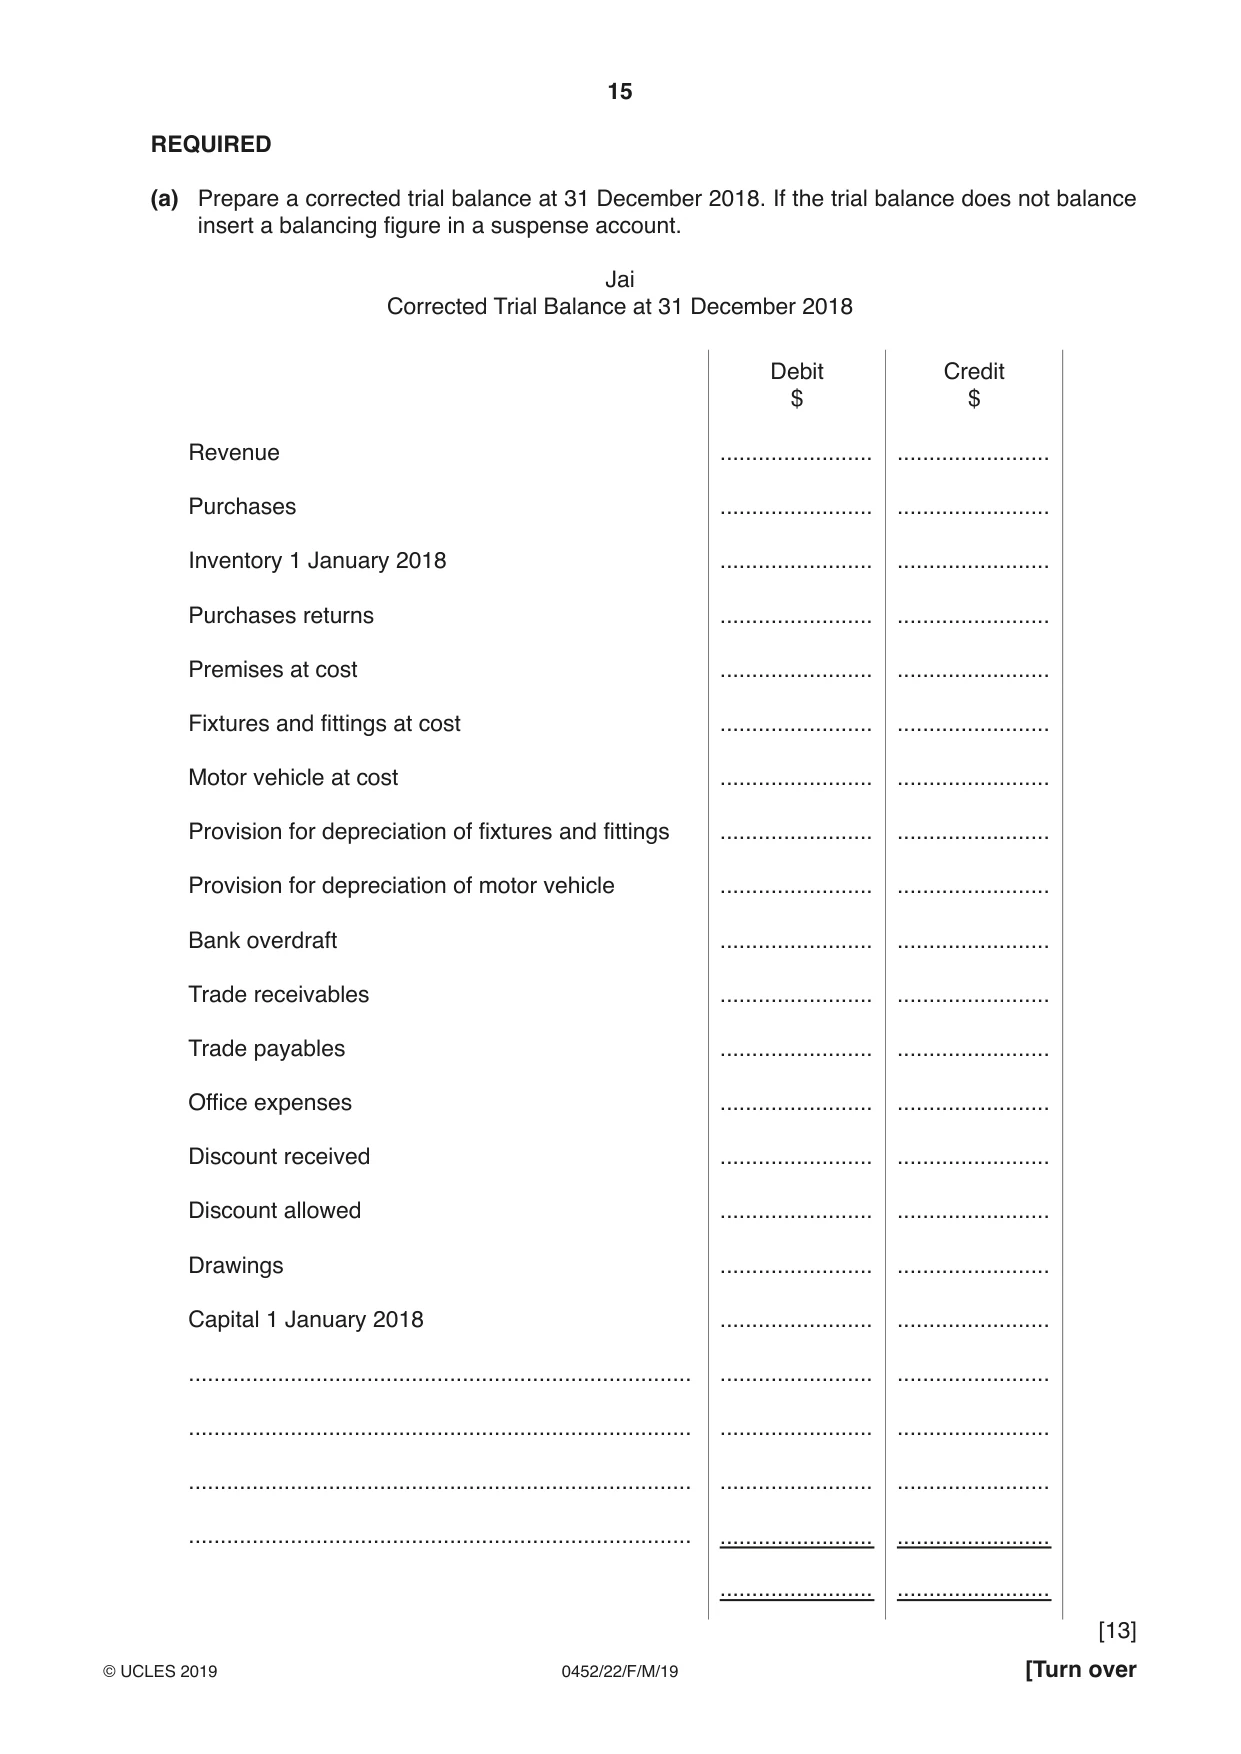
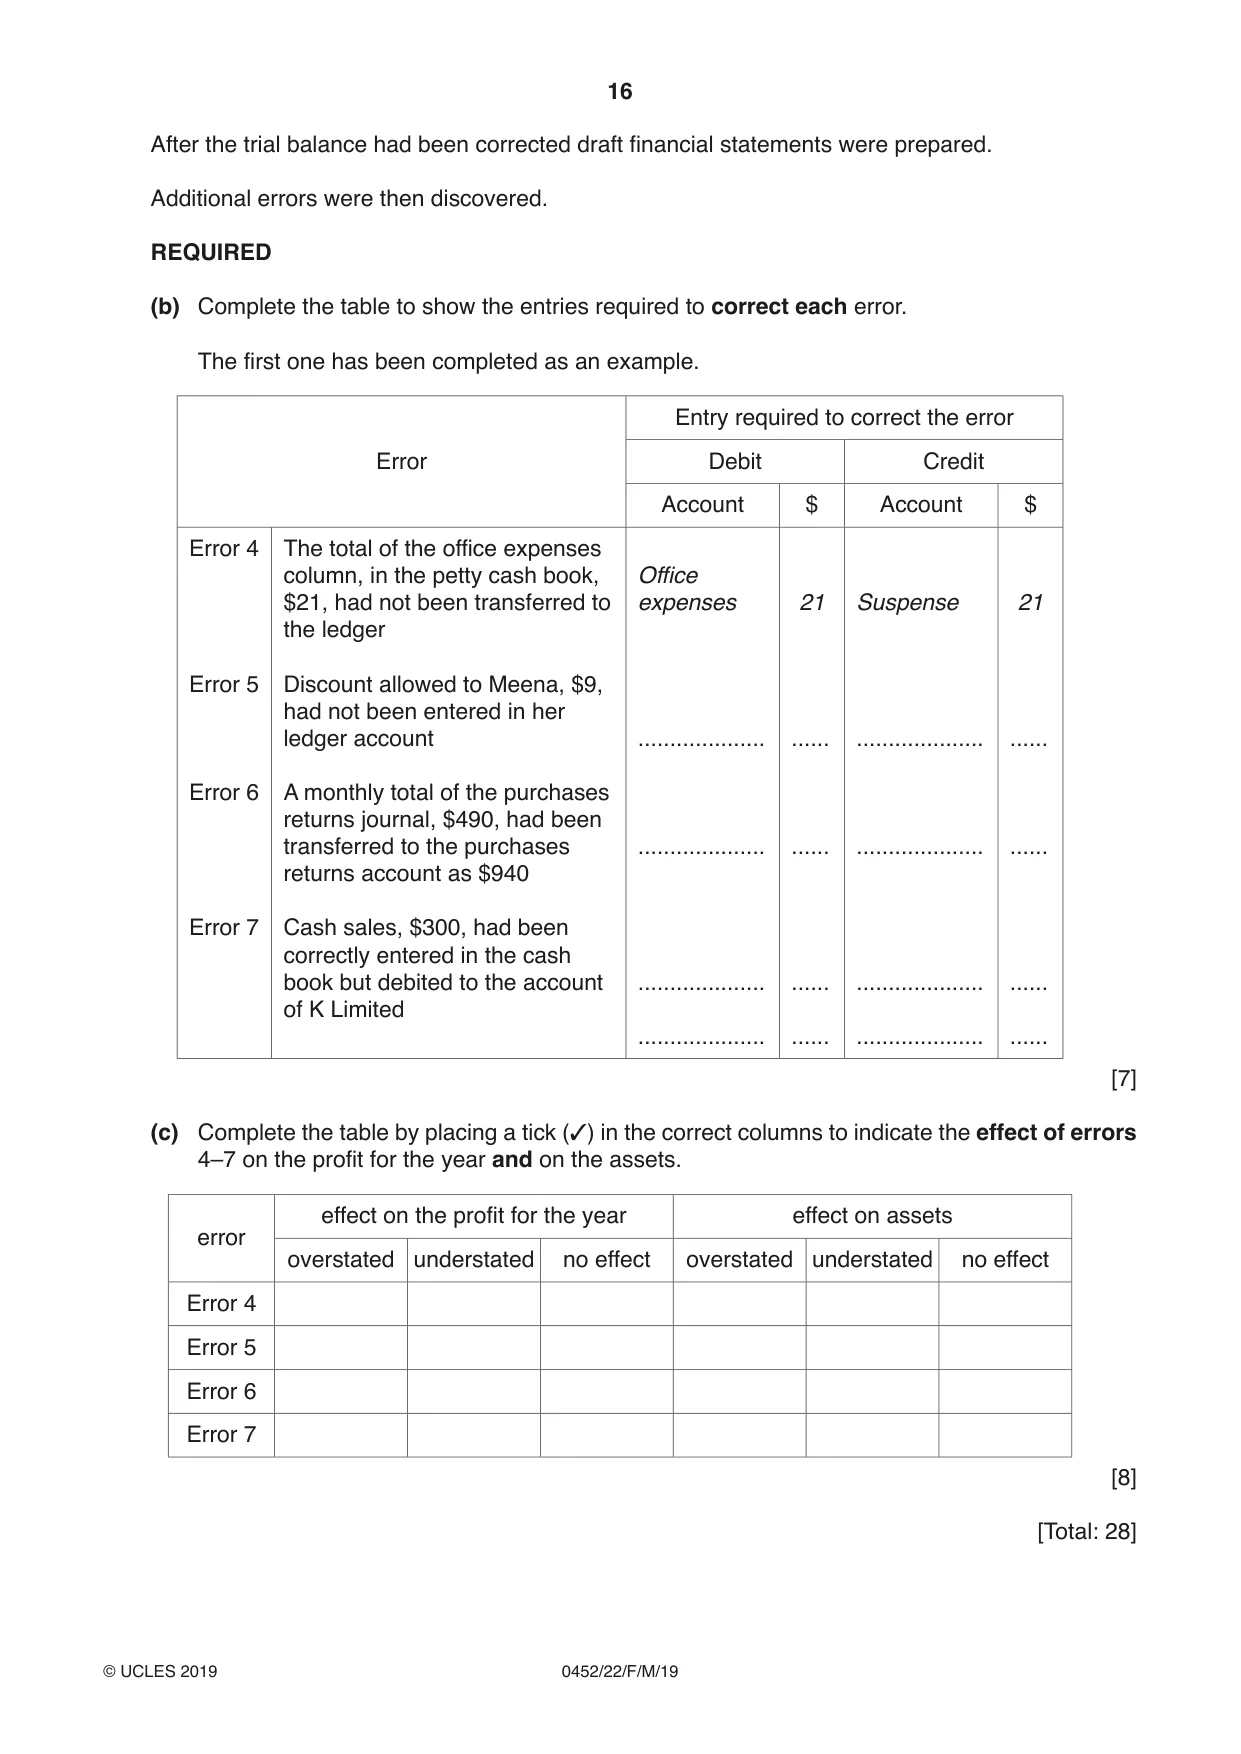
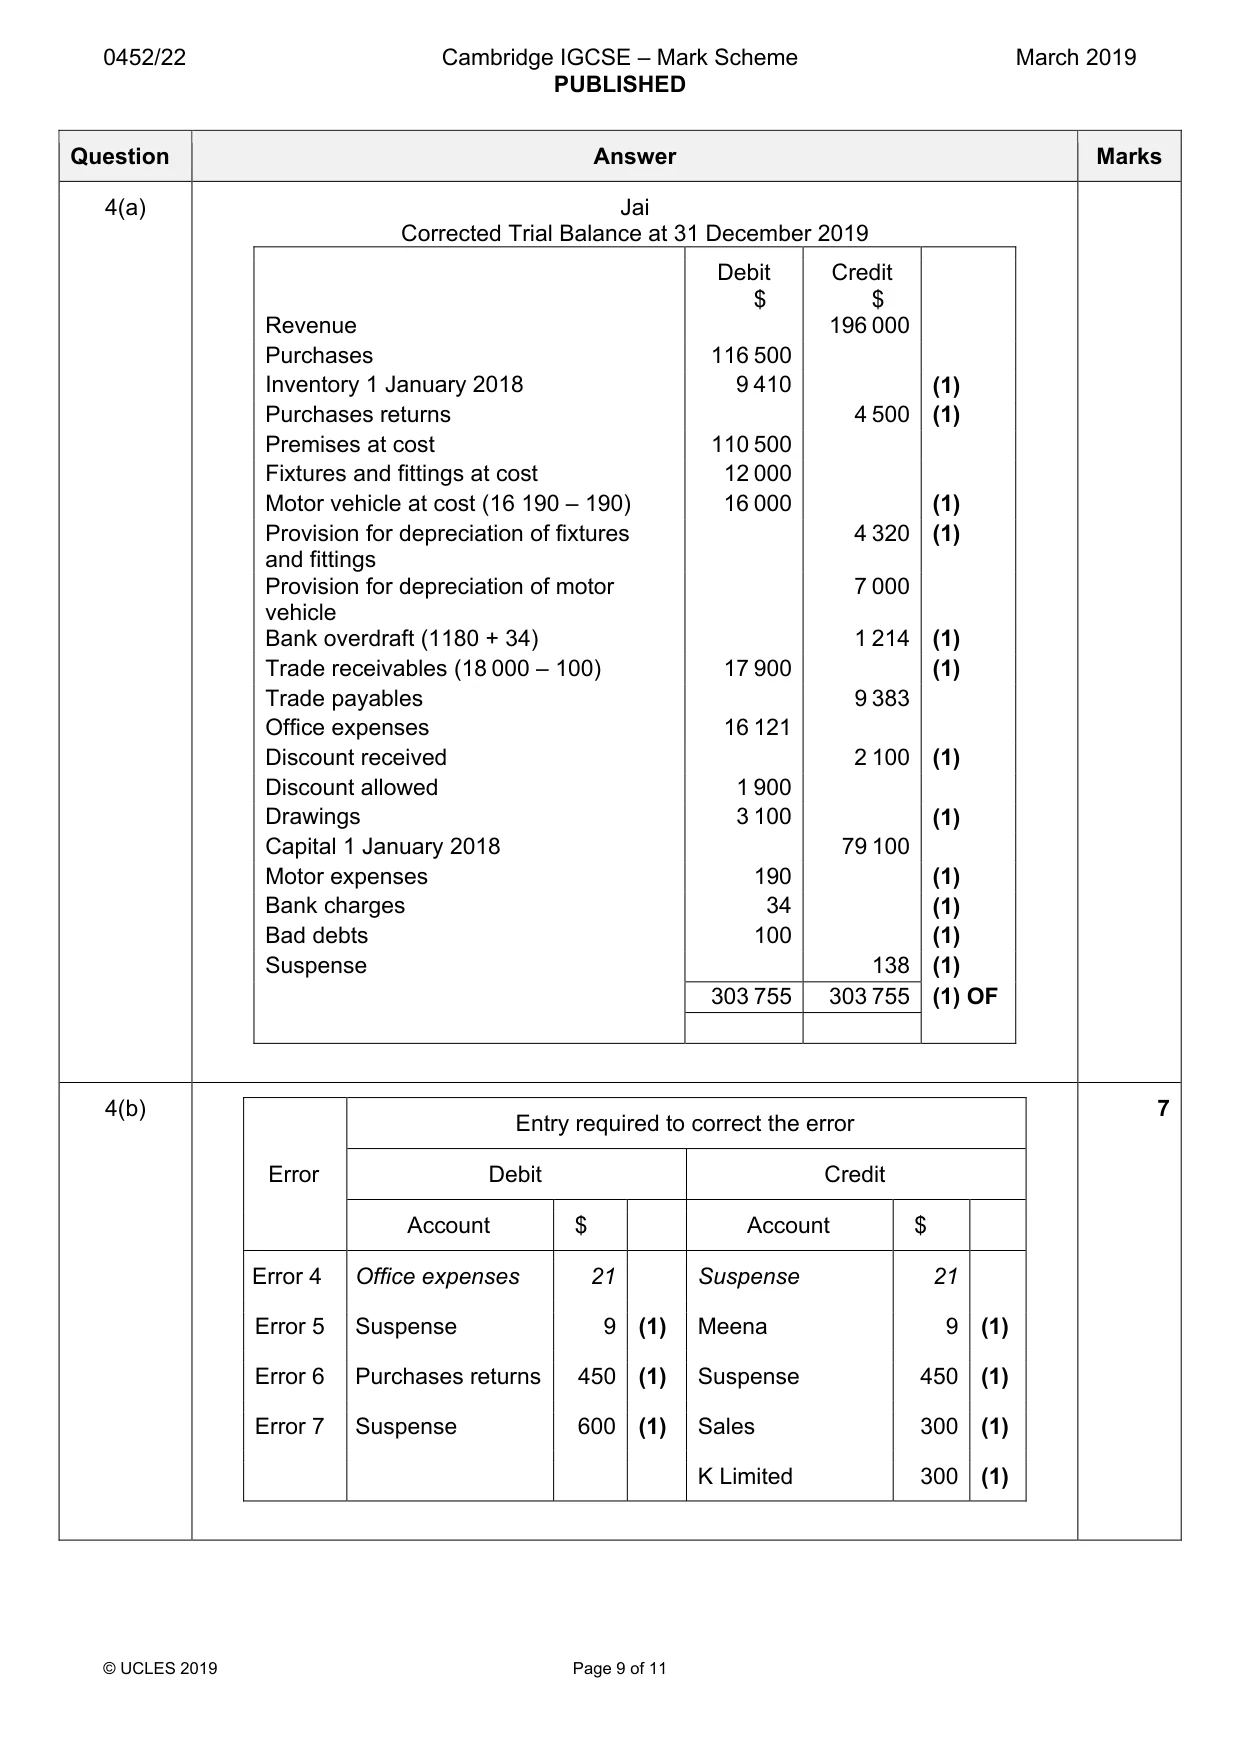
4 Jai’s financial year ends on 31 December. He has little knowledge of book-keeping but decided to prepare a trial balance on 31 December 2018. The trial balance he prepared, which contains errors, was as follows. $ $ Revenue 196 000 Purchases 116 500 Inventory 1 January 2018 9 410 Purchases returns 4 500 Premises at cost 110 500 Fixtures and fittings at cost 12 000 Motor vehicle at cost 16 190 Provision for depreciation of fixtures and fittings 4 320 Provision for depreciation of motor vehicle 7 000 Bank overdraft 1 180 Trade receivables 18 000 Trade payables 9 383 Office expenses 16 121 Discount received 2 100 Discount allowed 1 900 Drawings 3 100 Capital 1 January 2018 79 100 296 891 310 413 In addition to the obvious errors in the trial balance the following errors were also discovered. Error 1 Repairs to motor vehicle, $190, had been debited to the motor vehicle account. Error 2 No entry had been made for bank charges, $34. Error 3 A debt of $100 should have been written off as irrecoverable. REQUIRED (a) Prepare a corrected trial balance at 31 December insert a balancing figure in a suspense account. Jai Corrected Trial Balance at 31 Revenue Purchases Inventory 1 January 2018 Purchases returns Premises at cost Fixtures and fittings at cost Motor vehicle at cost Provision for depreciation of fixtures and fittings Provision for depreciation of motor vehicle Bank overdraft Trade receivables Trade payables Office expenses Discount received Discount allowed Drawings Capital 1 January 2018 ............................................................................... ............................................................................... ............................................................................... ............................................................................... After the trial balance had been corrected draft financial statements were prepared. Additional errors were then discovered. REQUIRED (b) Complete the table to show the entries required to correct each error. The first one has been completed as an example. Entry required to correct the error Error Debit Credit Account $ Account $ Error 4 The total of the office expenses column, in the petty cash book, Office $21, had not been transferred to expenses 21 Suspense 21 the ledger Error 5 Discount allowed to Meena, $9, had not been entered in her ledger account .................... ...... .................... ...... Error 6 A monthly total of the purchases returns journal, $490, had been transferred to the purchases .................... ...... .................... ...... returns account as $940 Error 7 Cash sales, $300, had been correctly entered in the cash book but debited to the account .................... ...... .................... ...... of K Limited .................... ...... .................... ...... [7] (c) Complete the table by placing a tick (✓) in the correct columns to indicate the effect of errors 4–7 on the profit for the year and on the assets. effect on the profit for the year effect on assets error overstated understated no effect overstated understated no effect Error 4 Error 5 Error 6 Error 7 [8] [Total: 28] PLEASE TURN OVER
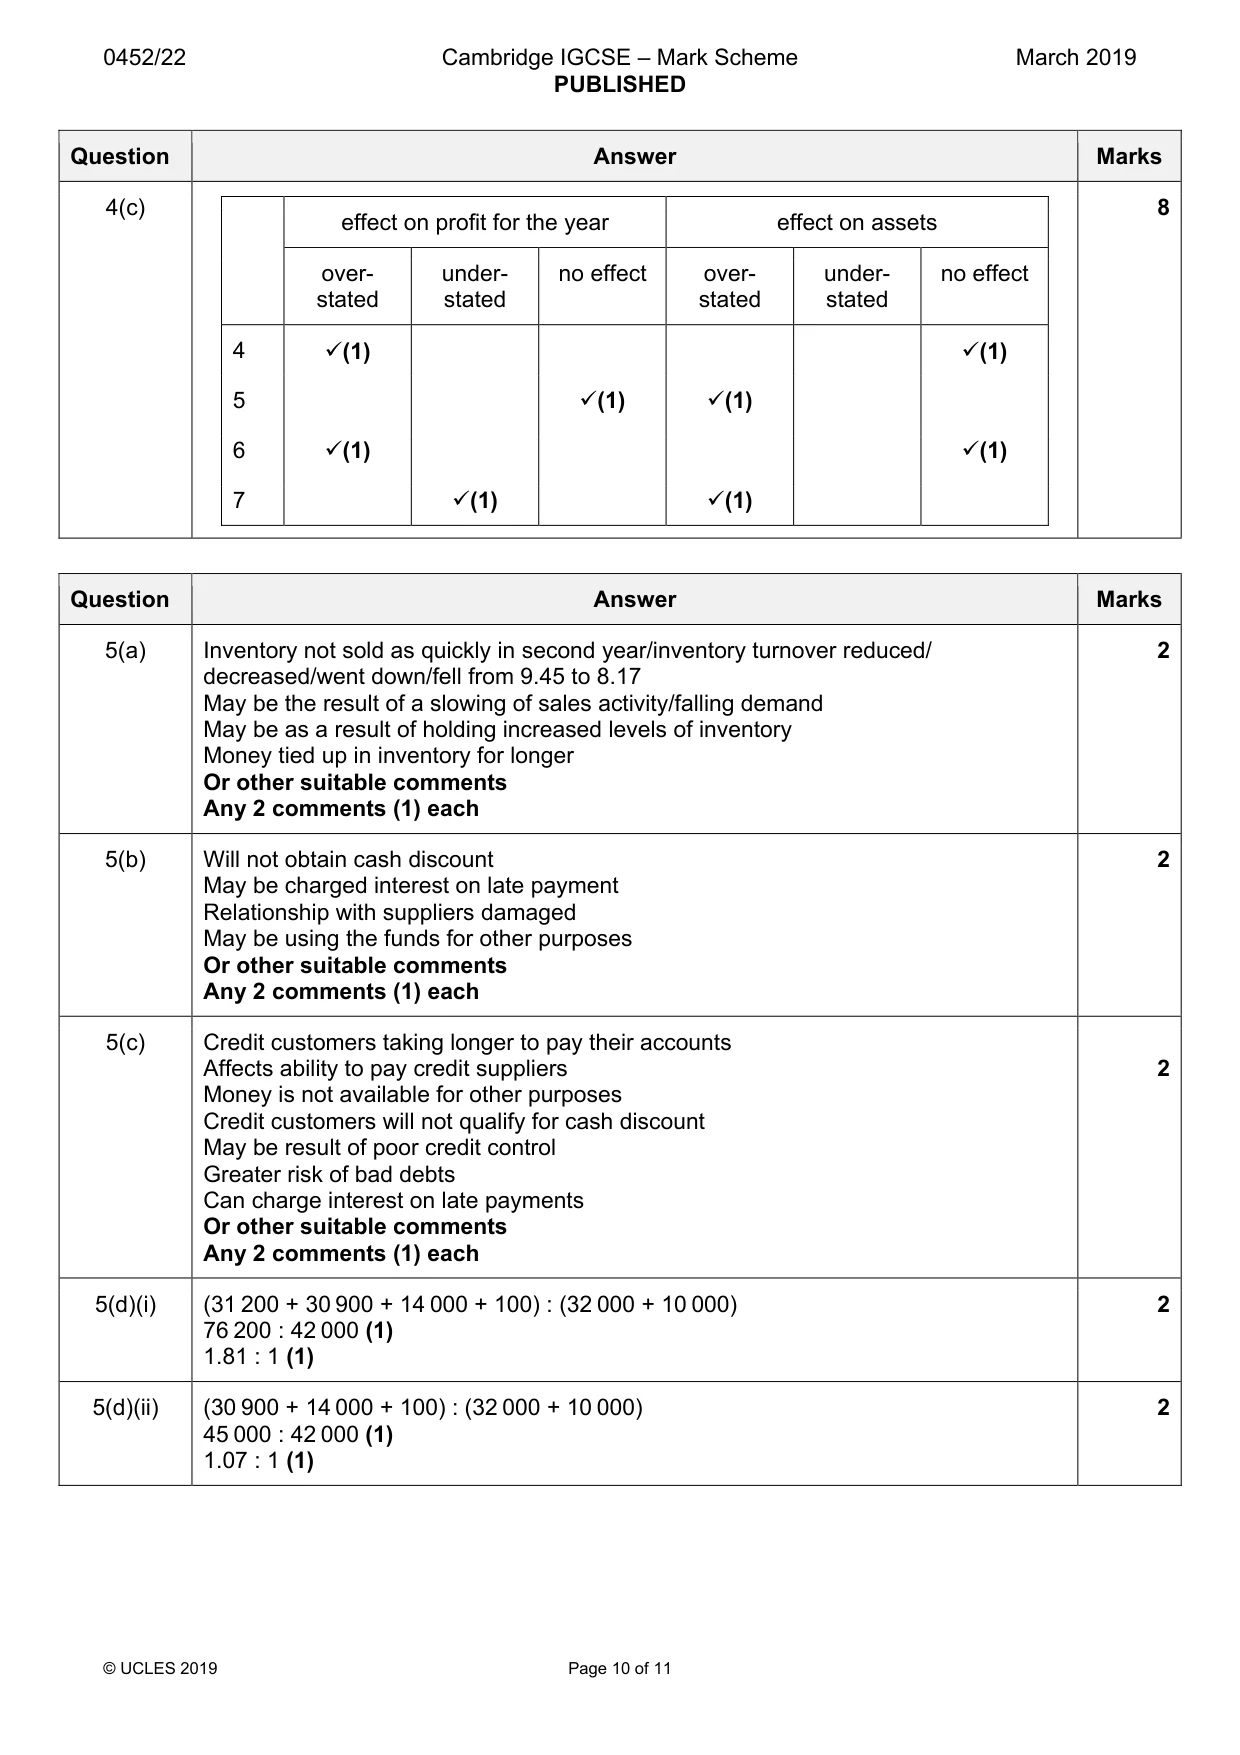
Mark scheme: 4(b) 7 Entry required to correct the error Error Debit Credit Account $ Account $ Error 4 Office expenses 21 Suspense 21 Error 5 Suspense 9 (1) Meena 9 (1) Error 6 Purchases returns 450 (1) Suspense 450 (1) Error 7 Suspense 600 (1) Sales 300 (1) K Limited 300 (1) 4(c) 8 effect on profit for the year effect on assets over- under- no effect over- under- no effect stated stated stated stated 4 9(1) 9(1) 5 9(1) 9(1) 6 9(1) 9(1) 7 9(1) 9(1)
Q5 · The financial year of LW Limited ends on 31 January
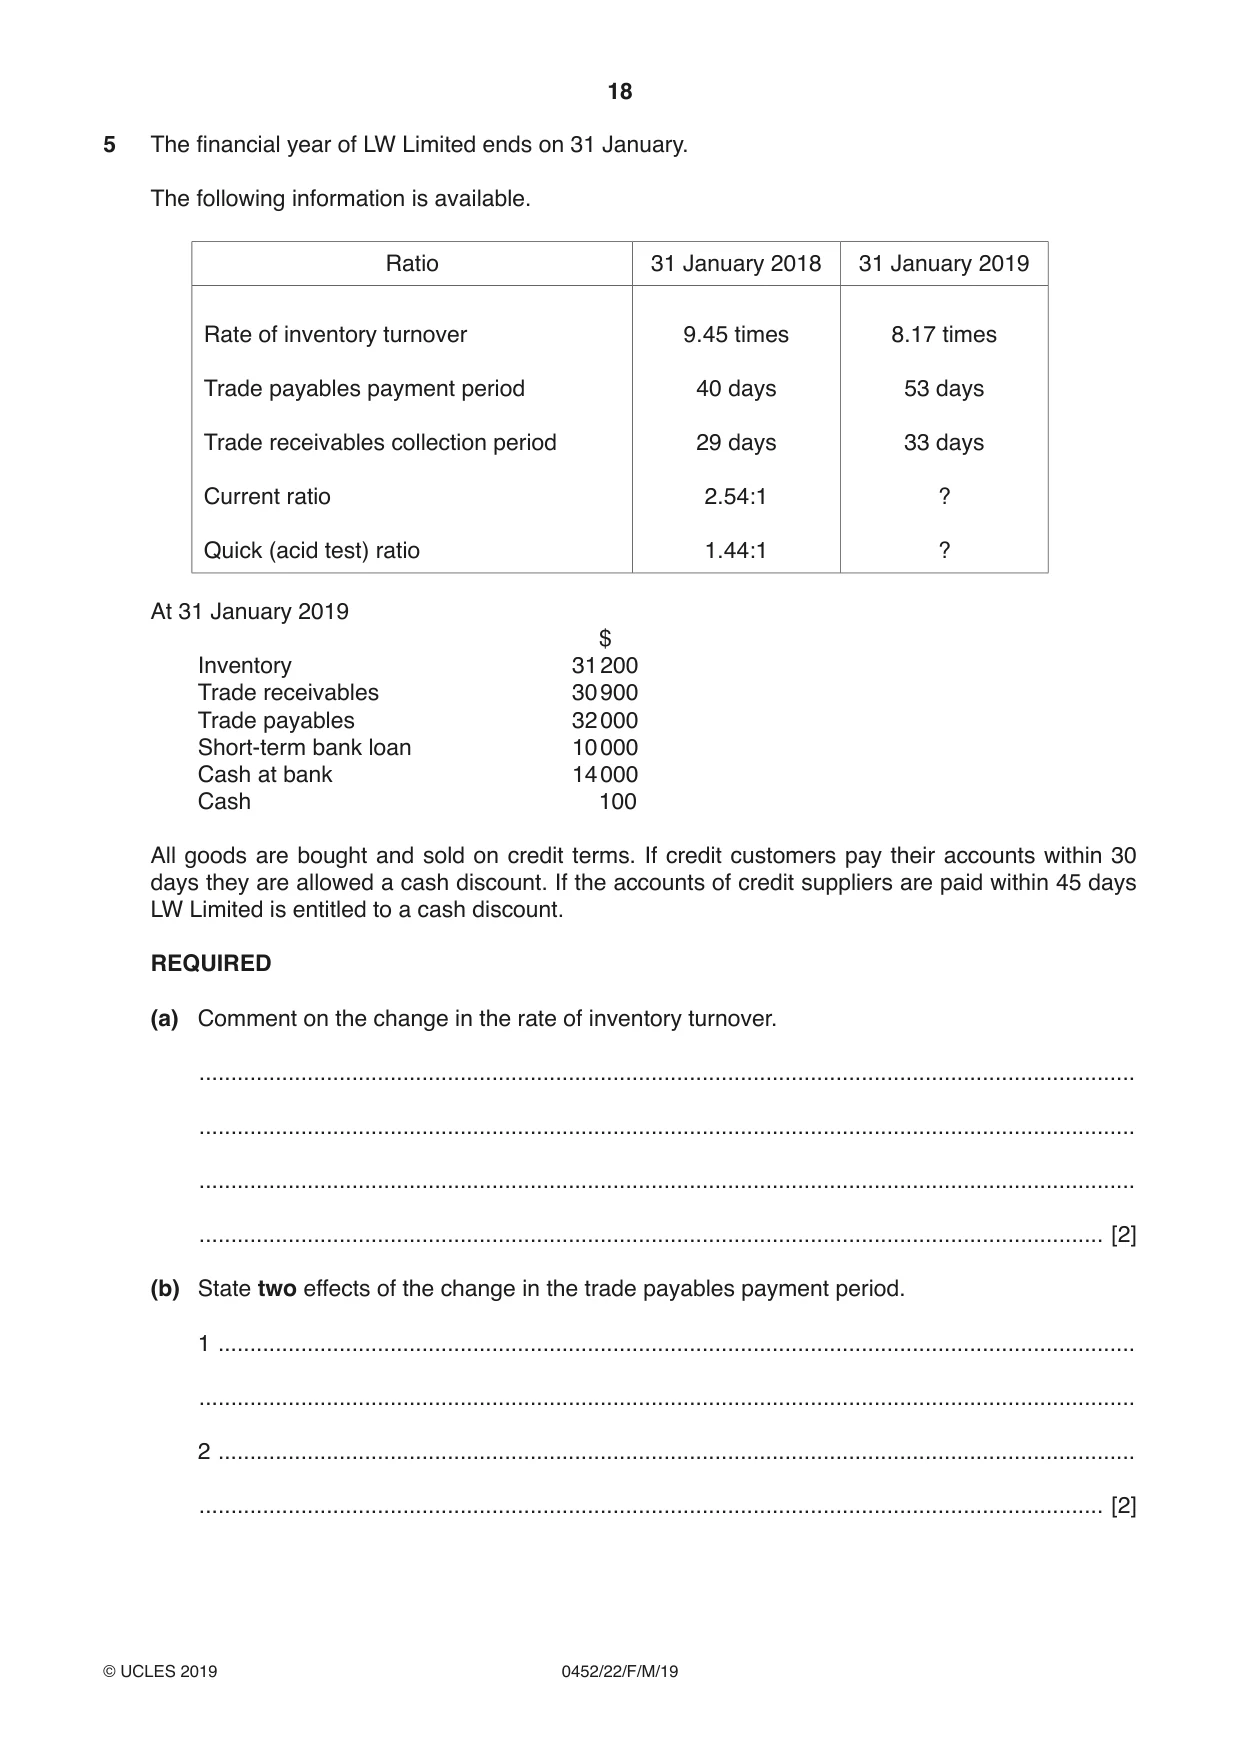
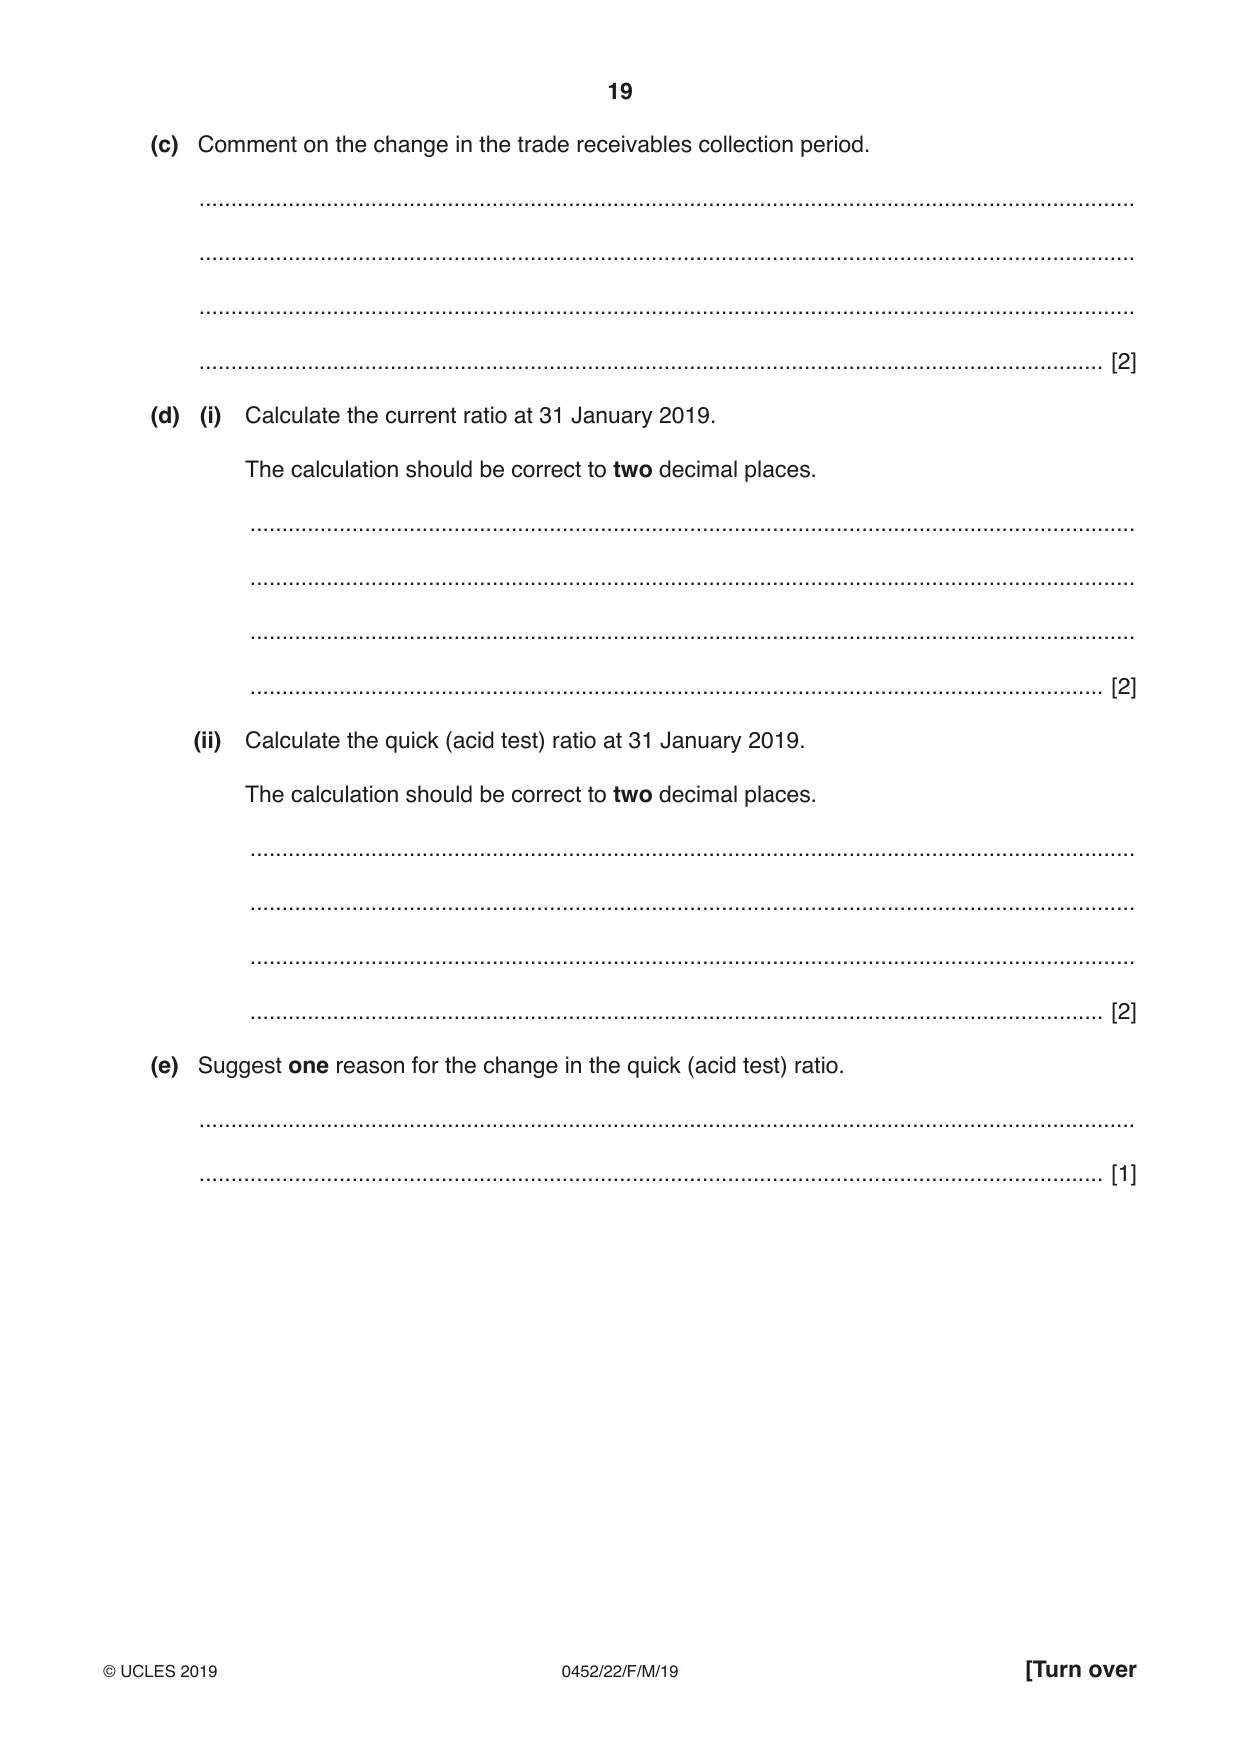
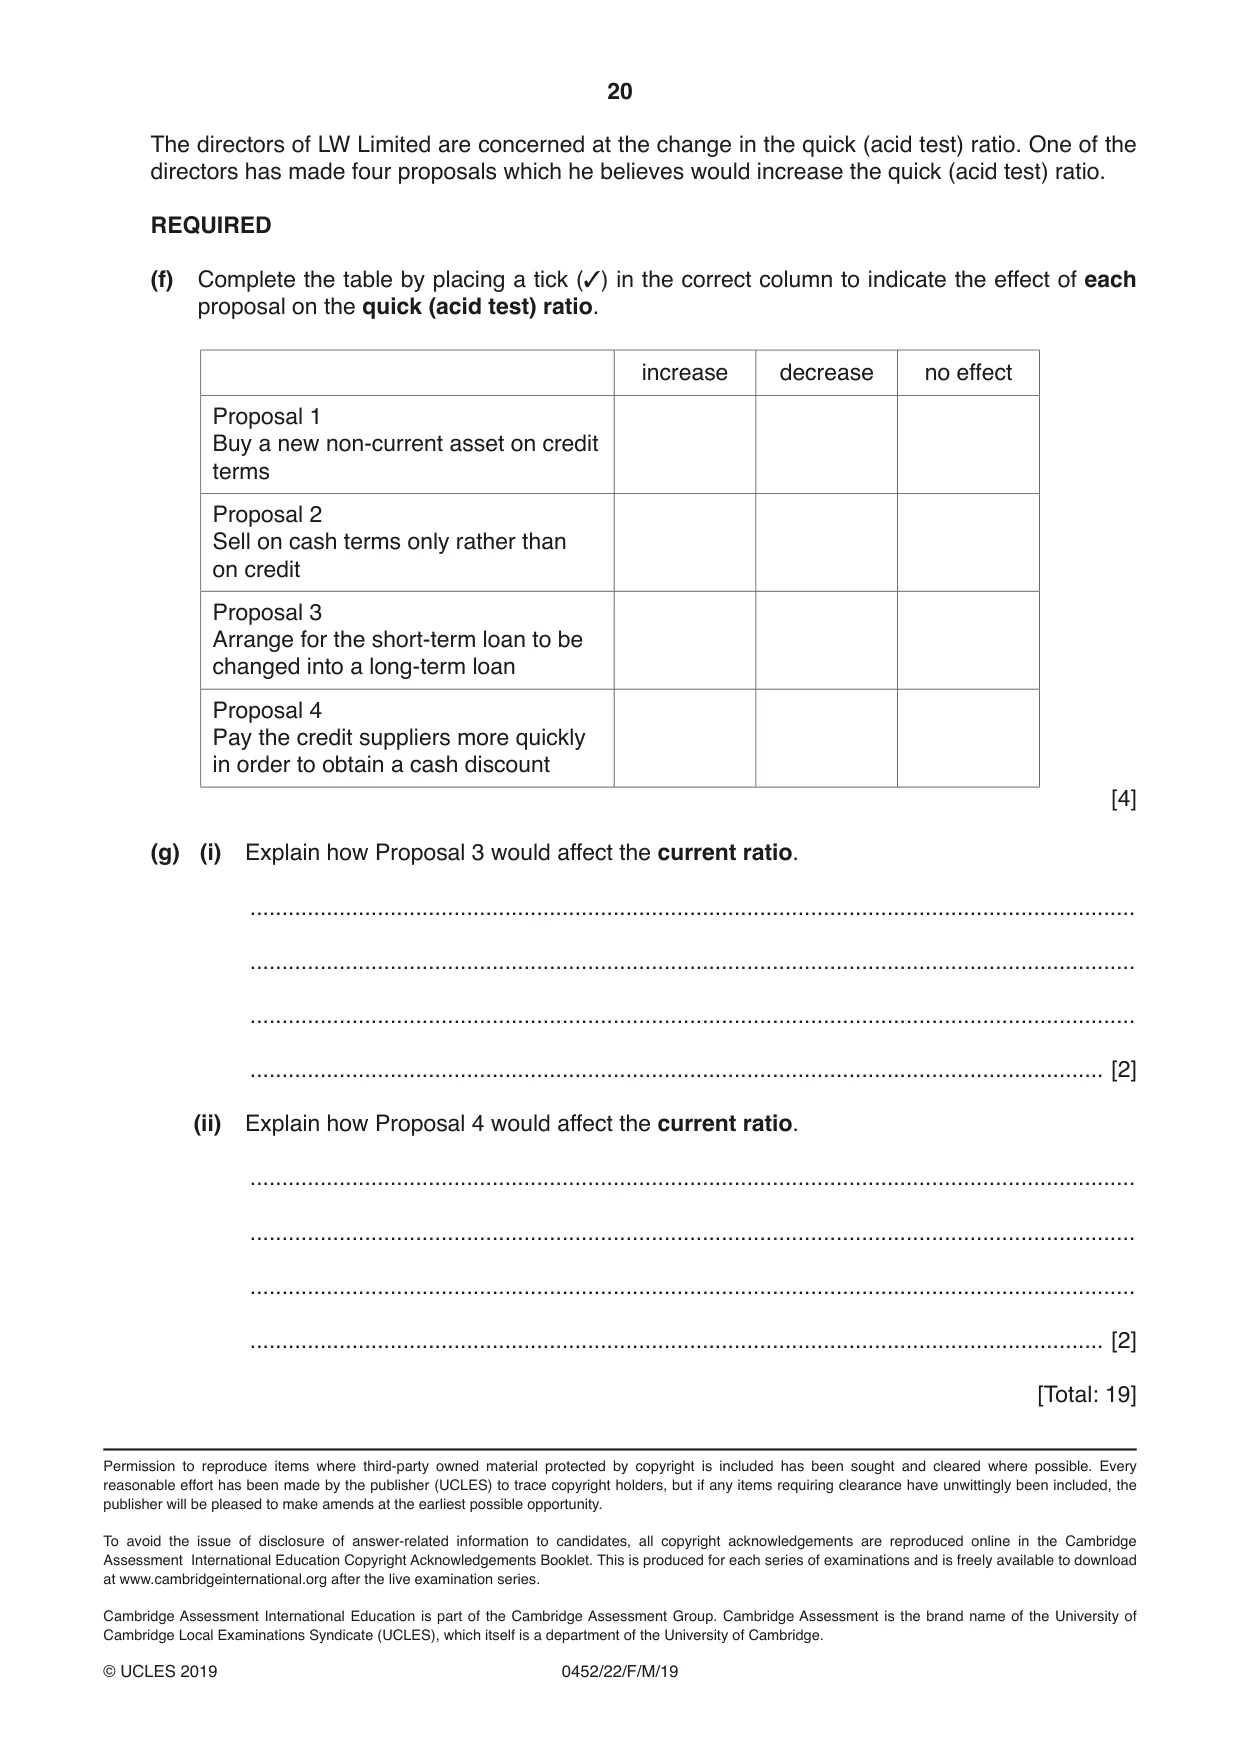
5 The financial year of LW Limited ends on 31 January. The following information is available. Ratio 31 January 2018 31 January 2019 Rate of inventory turnover 9.45 times 8.17 times Trade payables payment period 40 days 53 days Trade receivables collection period 29 days 33 days Current ratio 2.54:1 ? Quick (acid test) ratio 1.44:1 ? At 31 January 2019 $ Inventory 31 200 Trade receivables 30 900 Trade payables 32 000 Short-term bank loan 10 000 Cash at bank 14 000 Cash 100 All goods are bought and sold on credit terms. If credit customers pay their accounts within 30 days they are allowed a cash discount. If the accounts of credit suppliers are paid within 45 days LW Limited is entitled to a cash discount. REQUIRED (a) Comment on the change in the rate of inventory turnover. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (b) State two effects of the change in the trade payables payment period. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ .............................................................................................................................................. [2] (c) Comment on the change in the trade receivables collection period. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (d) (i) Calculate the current ratio at 31 January 2019. The calculation should be correct to two decimal places. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] (ii) Calculate the quick (acid test) ratio at 31 January 2019. The calculation should be correct to two decimal places. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] (e) Suggest one reason for the change in the quick (acid test) ratio. ................................................................................................................................................... .............................................................................................................................................. [1] The directors of LW Limited are concerned at the change in the quick (acid test) ratio. One of the directors has made four proposals which he believes would increase the quick (acid test) ratio. REQUIRED (f) Complete the table by placing a tick (✓) in the correct column to indicate the effect of each proposal on the quick (acid test) ratio. increase decrease no effect Proposal 1 Buy a new non-current asset on credit terms Proposal 2 Sell on cash terms only rather than on credit Proposal 3 Arrange for the short-term loan to be changed into a long-term loan Proposal 4 Pay the credit suppliers more quickly in order to obtain a cash discount [4] (g) (i) Explain how Proposal 3 would affect the current ratio. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] (ii) Explain how Proposal 4 would affect the current ratio. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [2] [Total: 19]
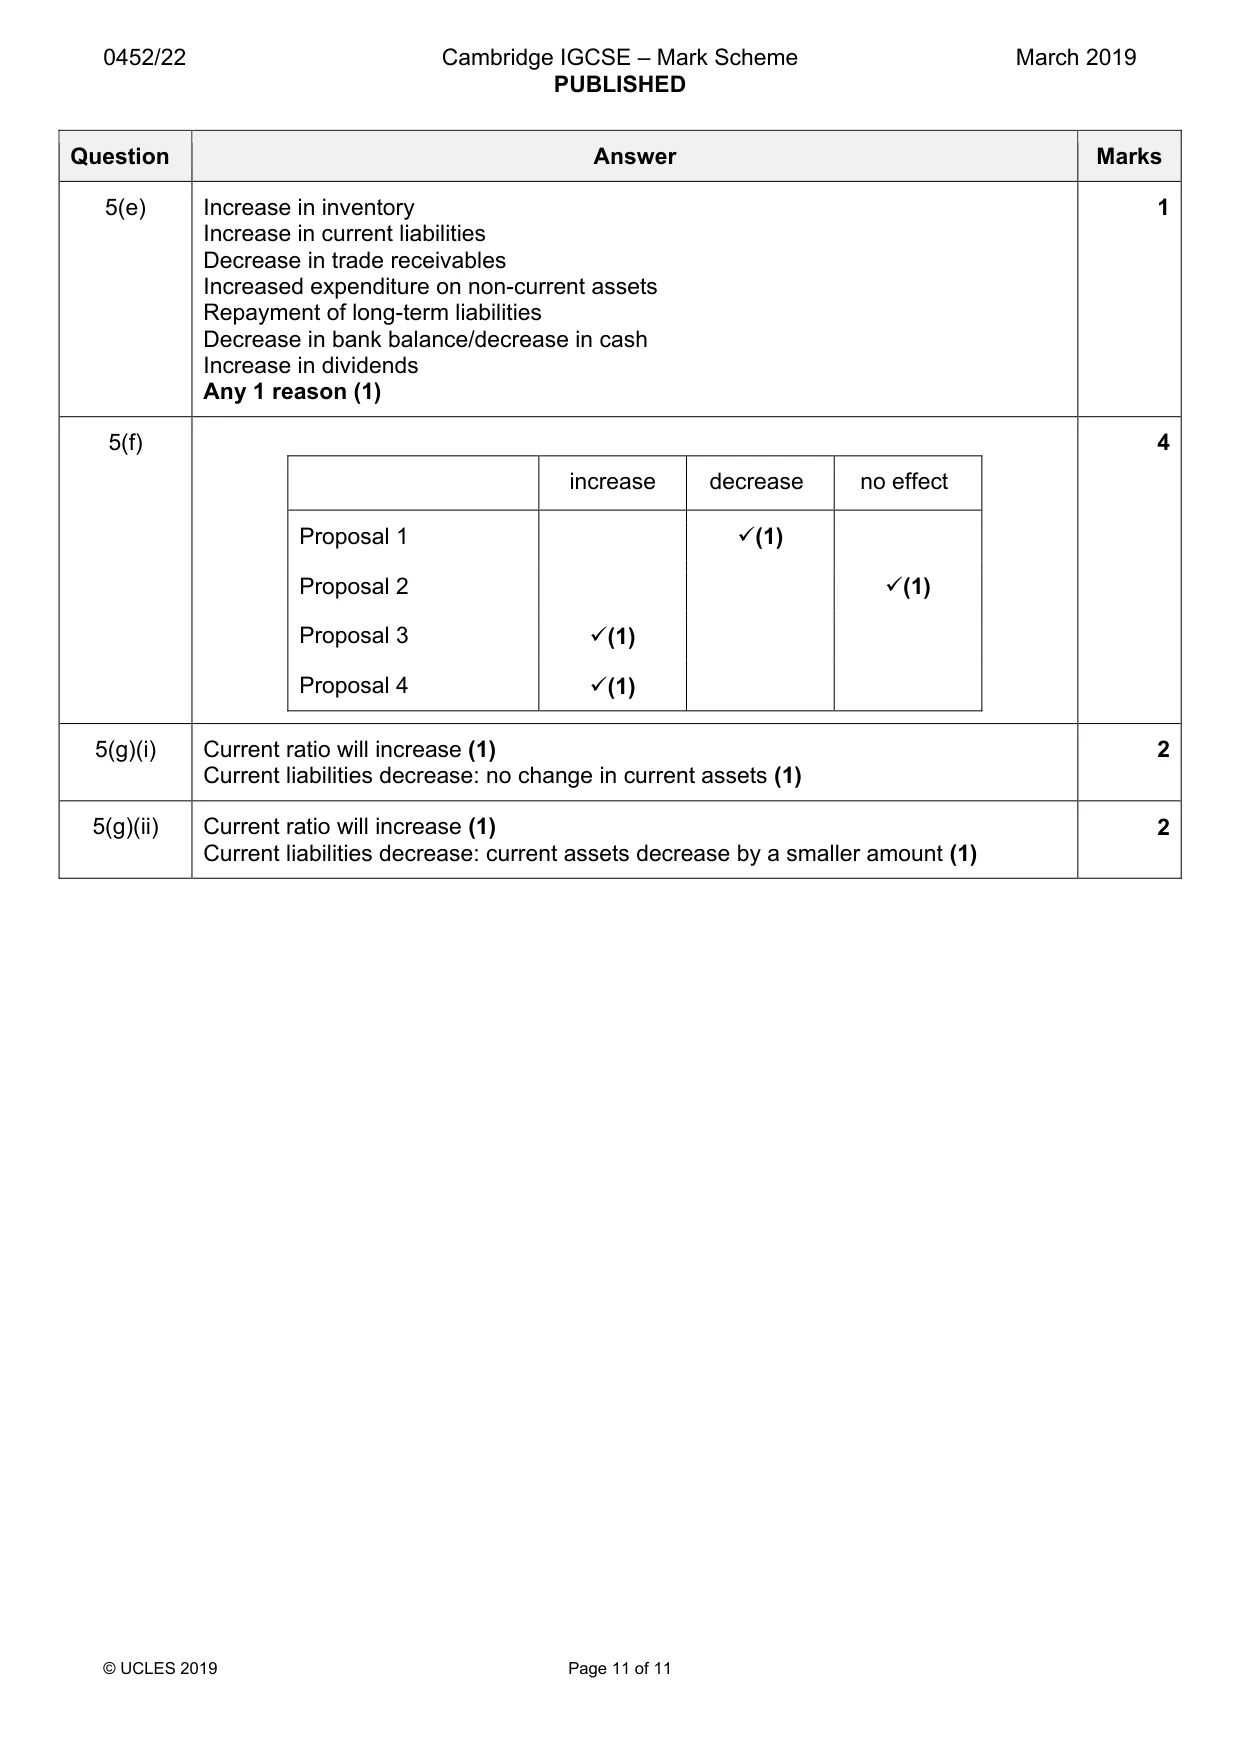
Mark scheme: 5(a) Inventory not sold as quickly in second year/inventory turnover reduced/ 2 decreased/went down/fell from 9.45 to 8.17 May be the result of a slowing of sales activity/falling demand May be as a result of holding increased levels of inventory Money tied up in inventory for longer Or other suitable comments Any 2 comments (1) each 5(b) Will not obtain cash discount 2 May be charged interest on late payment Relationship with suppliers damaged May be using the funds for other purposes Or other suitable comments Any 2 comments (1) each 5(c) Credit customers taking longer to pay their accounts Affects ability to pay credit suppliers 2 Money is not available for other purposes Credit customers will not qualify for cash discount May be result of poor credit control Greater risk of bad debts Can charge interest on late payments Or other suitable comments Any 2 comments (1) each 5(d)(i) (31 200 + 30 900 + 14 000 + 100) : (32 000 + 10 000) 2 76 200 : 42 000 (1) 1.81 : 1 (1) 5(d)(ii) (30 900 + 14 000 + 100) : (32 000 + 10 000) 2 45 000 : 42 000 (1) 1.07 : 1 (1) 5(e) Increase in inventory 1 Increase in current liabilities Decrease in trade receivables Increased expenditure on non-current assets Repayment of long-term liabilities Decrease in bank balance/decrease in cash Increase in dividends Any 1 reason (1) 5(f) 4 increase decrease no effect Proposal 1 9(1) Proposal 2 9(1) Proposal 3 9(1) Proposal 4 9(1) 5(g)(i) Current ratio will increase (1) 2 Current liabilities decrease: no change in current assets (1) 5(g)(ii) Current ratio will increase (1) 2 Current liabilities decrease: current assets decrease by a smaller amount (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2019 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.