Cambridge IGCSE Accounting 0452 — 2018 May/June Paper 2 · Variant 1
0452/21/M/J/18 · 6 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme18 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Lydia is a trader
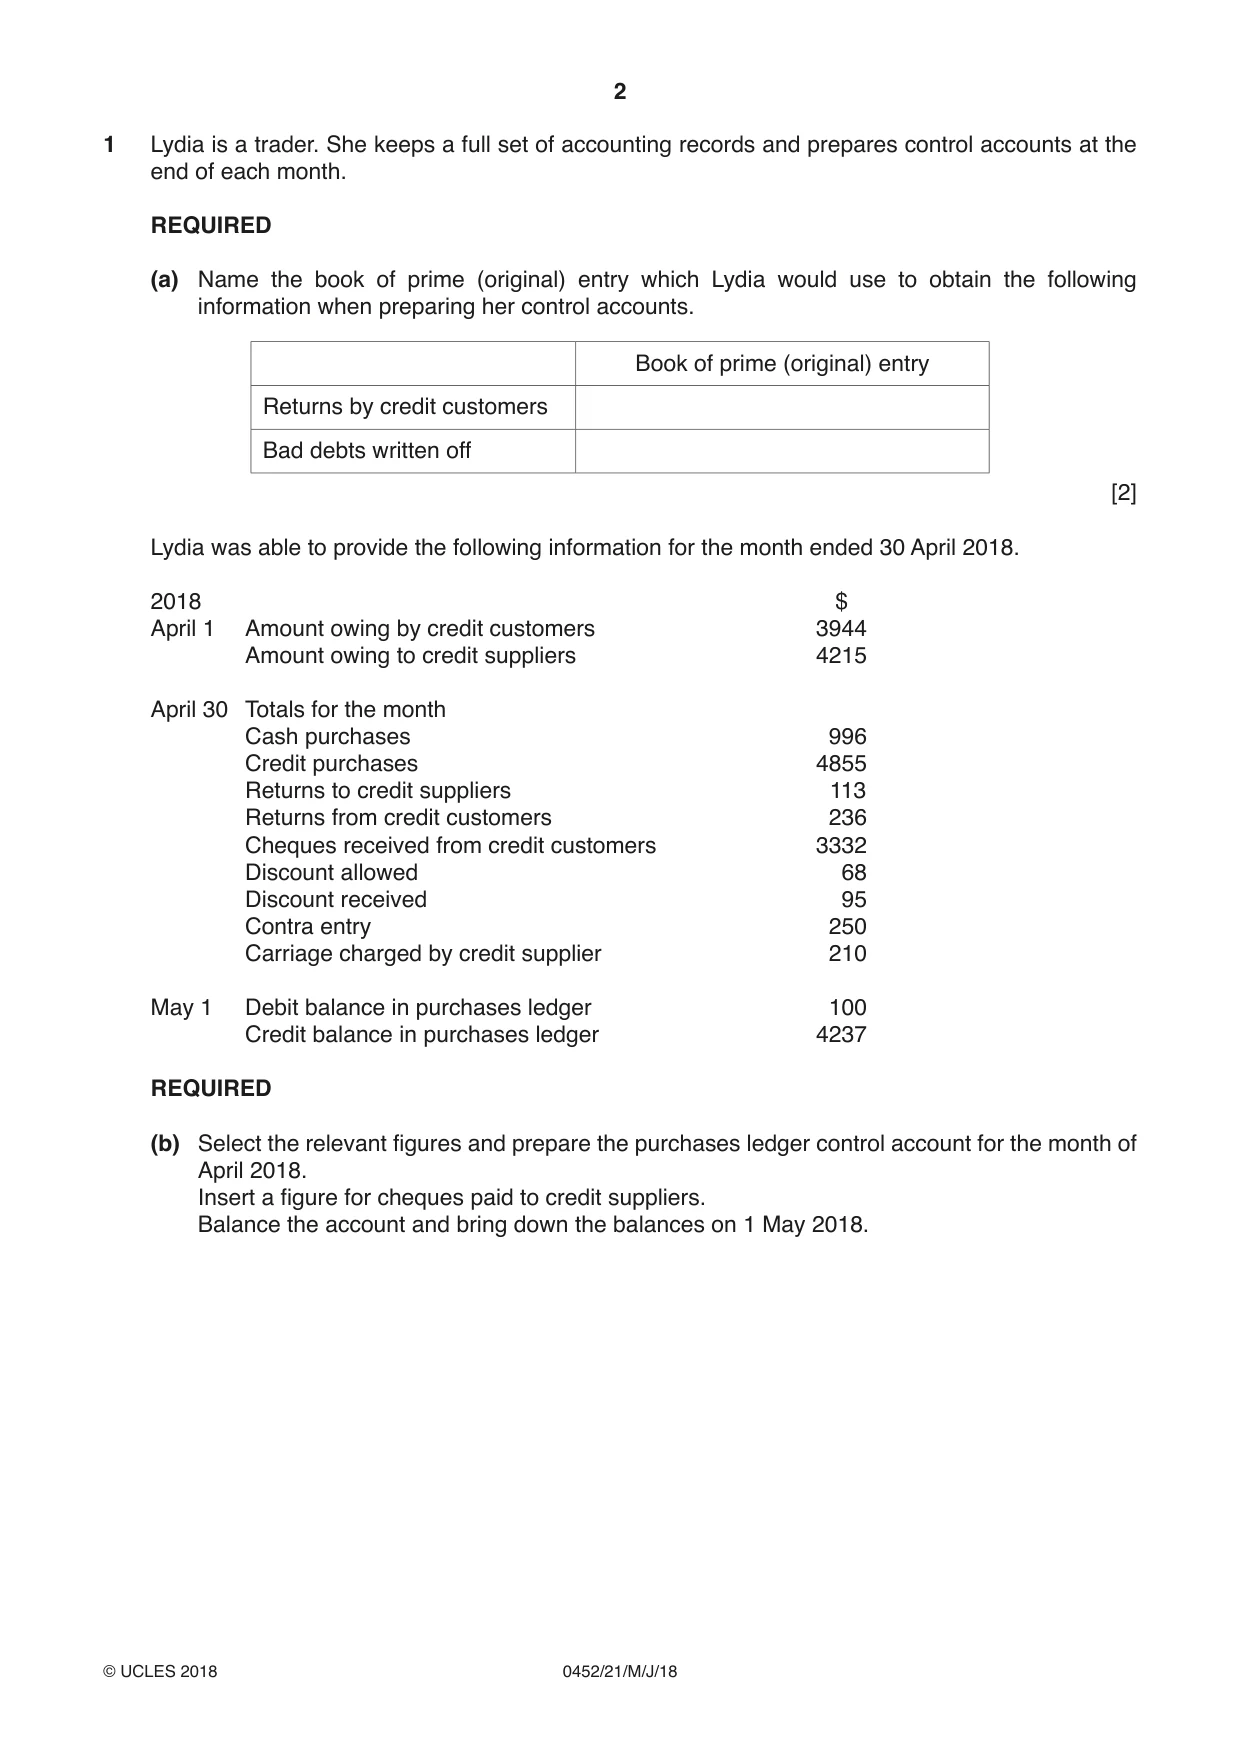
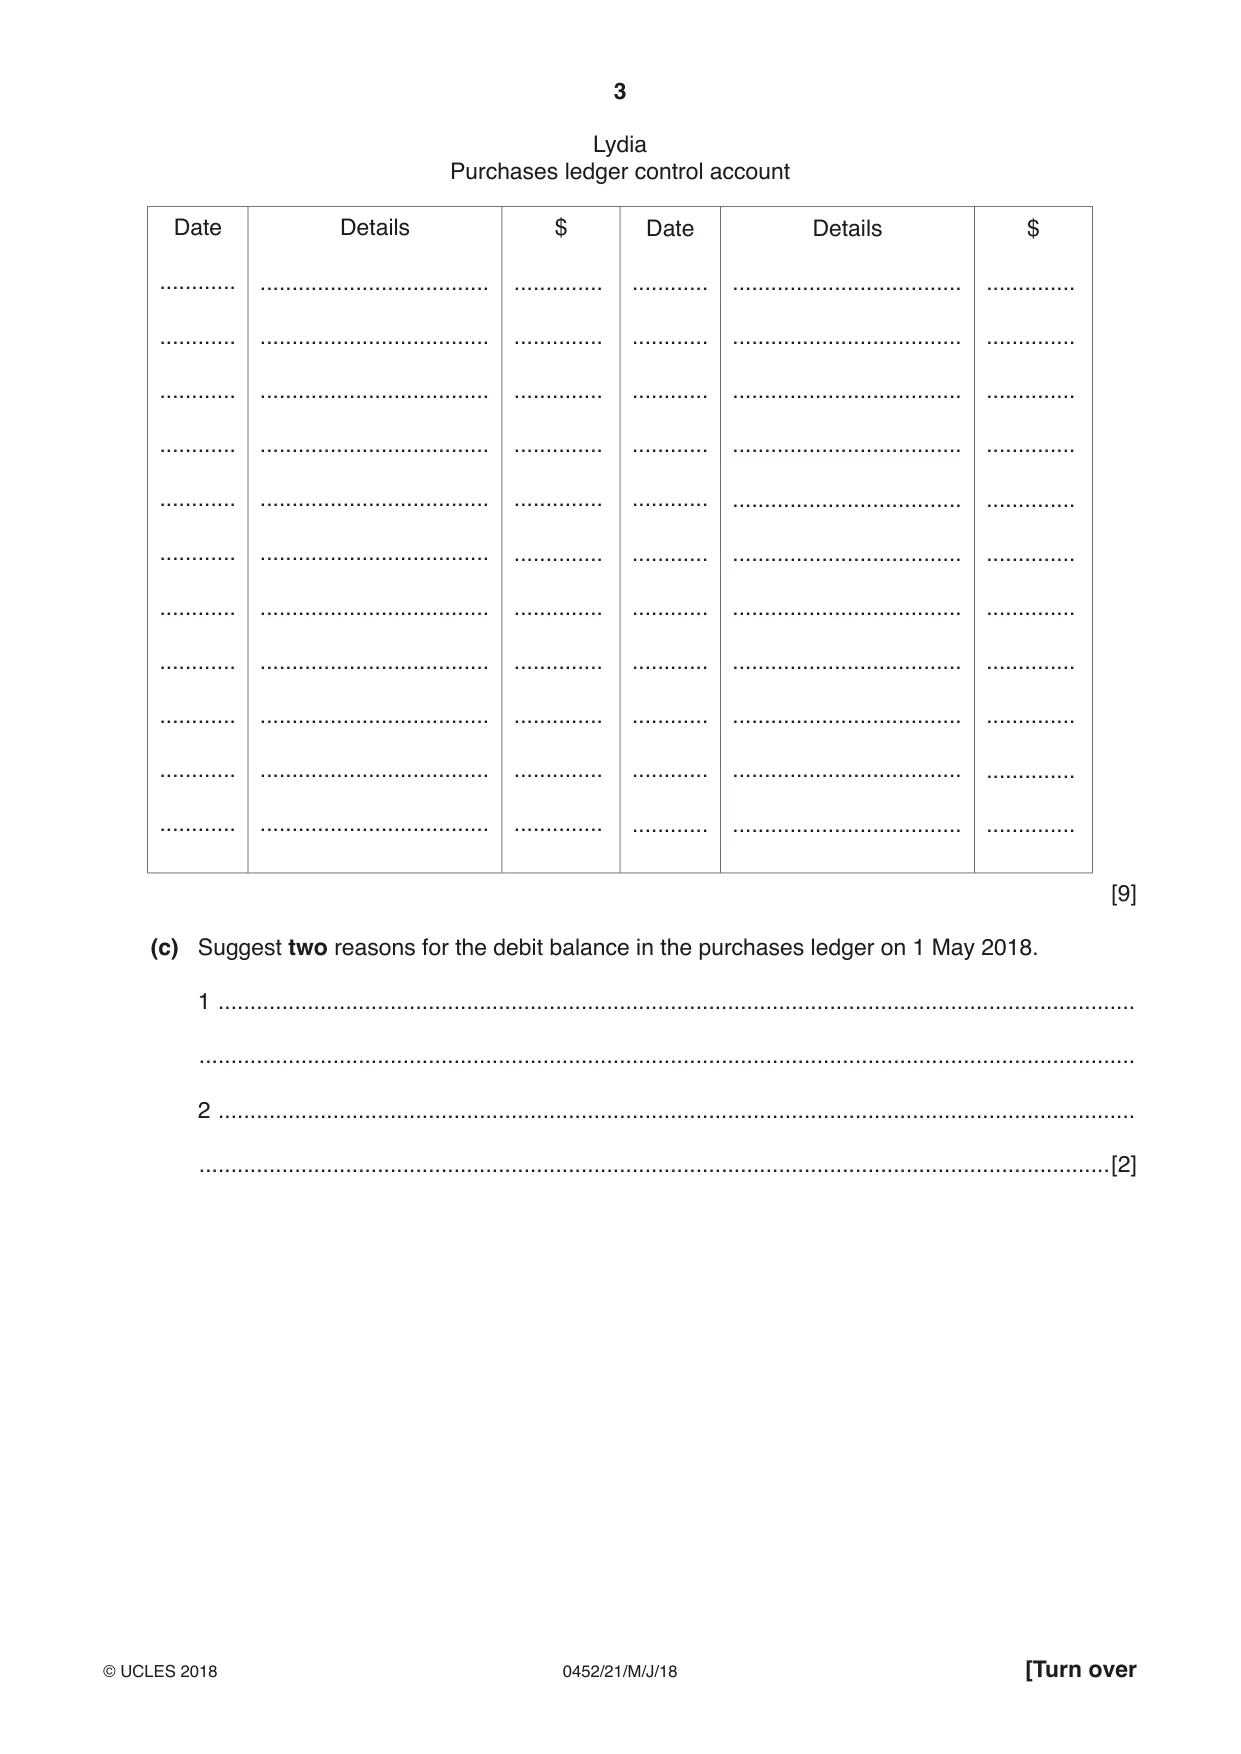
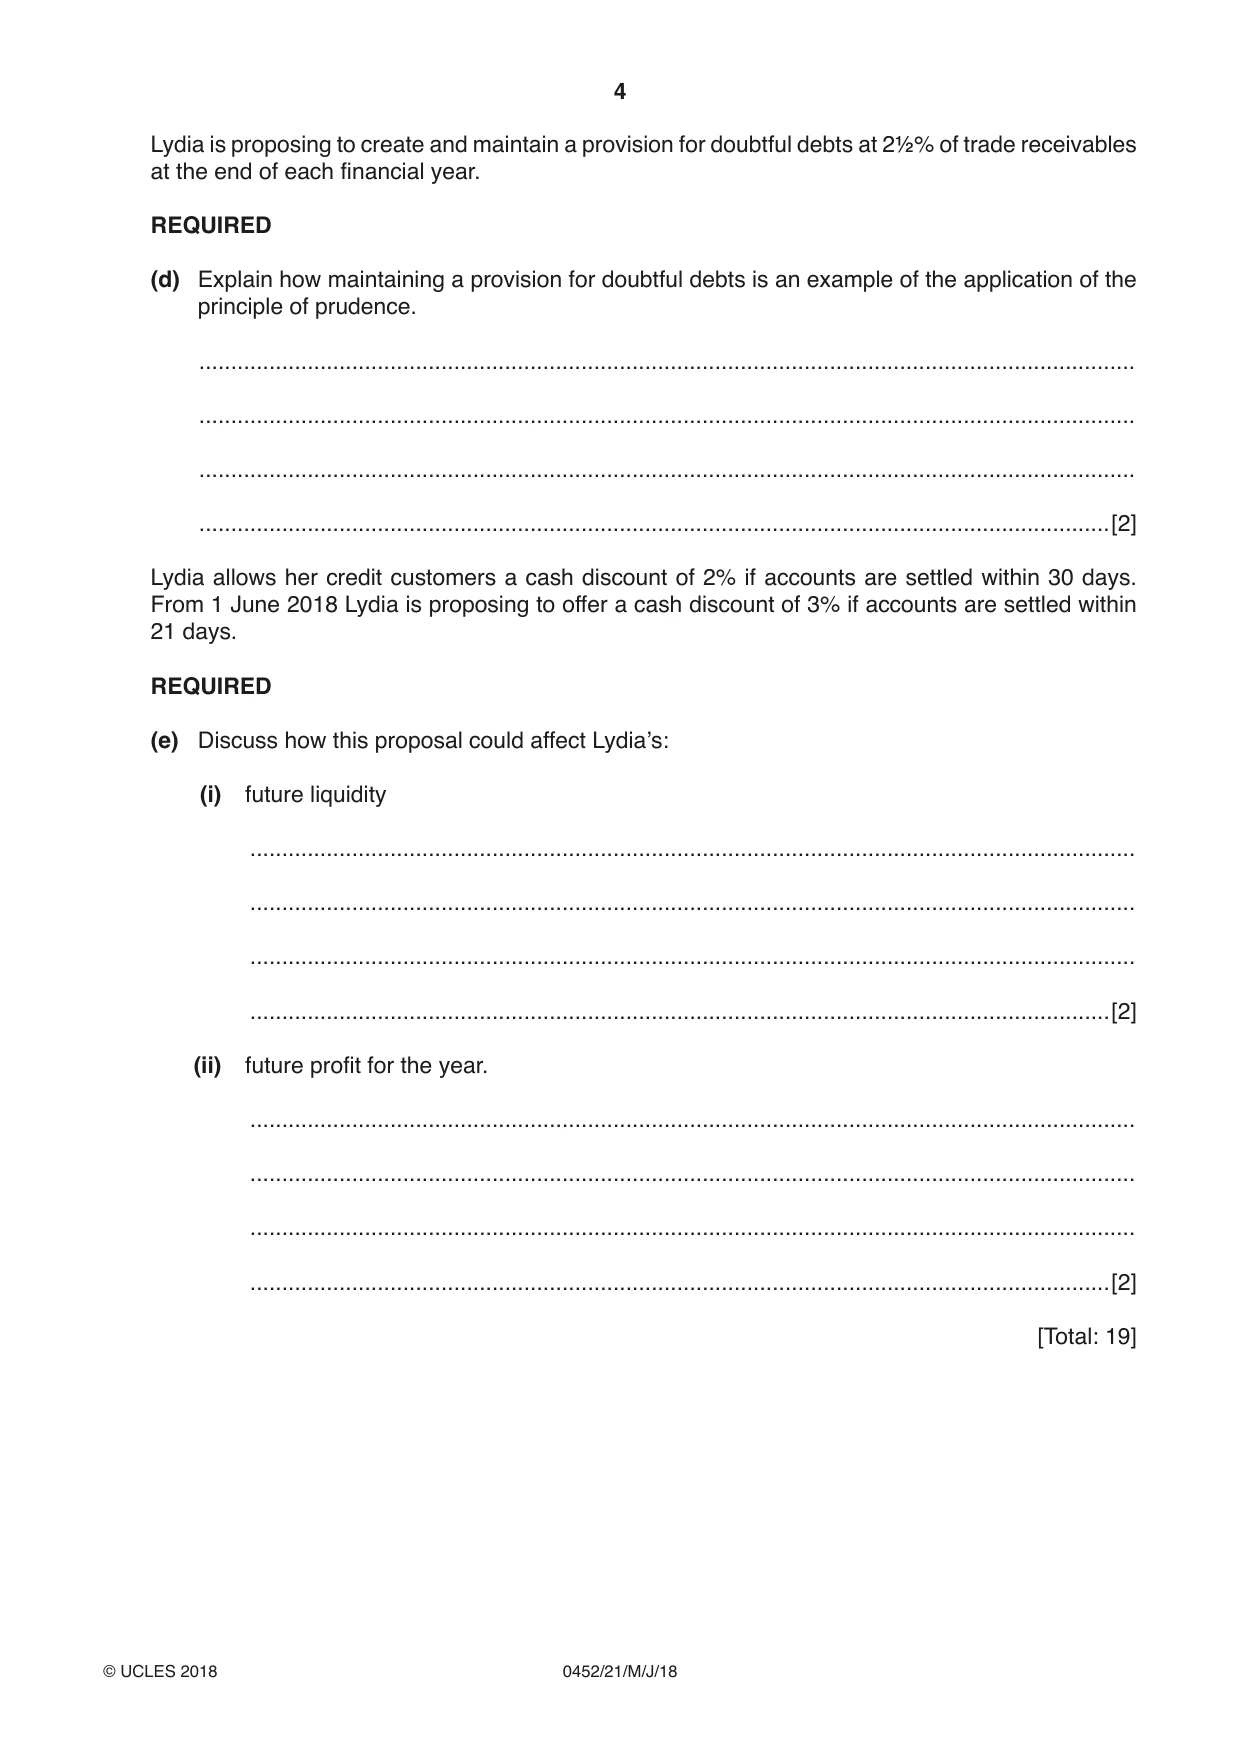
1 Lydia is a trader. She keeps a full set of accounting records and prepares control accounts at the end of each month. REQUIRED (a) Name the book of prime (original) entry which Lydia would use to obtain the following information when preparing her control accounts. Book of prime (original) entry Returns by credit customers Bad debts written off [2] Lydia was able to provide the following information for the month ended 30 April 2018. 2018 $ April 1 Amount owing by credit customers 3944 Amount owing to credit suppliers 4215 April 30 Totals for the month Cash purchases 996 Credit purchases 4855 Returns to credit suppliers 113 Returns from credit customers 236 Cheques received from credit customers 3332 Discount allowed 68 Discount received 95 Contra entry 250 Carriage charged by credit supplier 210 May 1 Debit balance in purchases ledger 100 Credit balance in purchases ledger 4237 REQUIRED (b) Select the relevant figures and prepare the purchases ledger control account for the month of April 2018. Insert a figure for cheques paid to credit suppliers. Balance the account and bring down the balances on 1 May 2018. Lydia Purchases ledger control account Date Details $ Date Details $ ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. [9] (c) Suggest two reasons for the debit balance in the purchases ledger on 1 May 2018. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] Lydia is proposing to create and maintain a provision for doubtful debts at 2½% of trade receivables at the end of each financial year. REQUIRED (d) Explain how maintaining a provision for doubtful debts is an example of the application of the principle of prudence. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] Lydia allows her credit customers a cash discount of 2% if accounts are settled within 30 days. From 1 June 2018 Lydia is proposing to offer a cash discount of 3% if accounts are settled within 21 days. REQUIRED (e) Discuss how this proposal could affect Lydia’s: (i) future liquidity ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] (ii) future profit for the year. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... .......................................................................................................................................[2] [Total: 19]
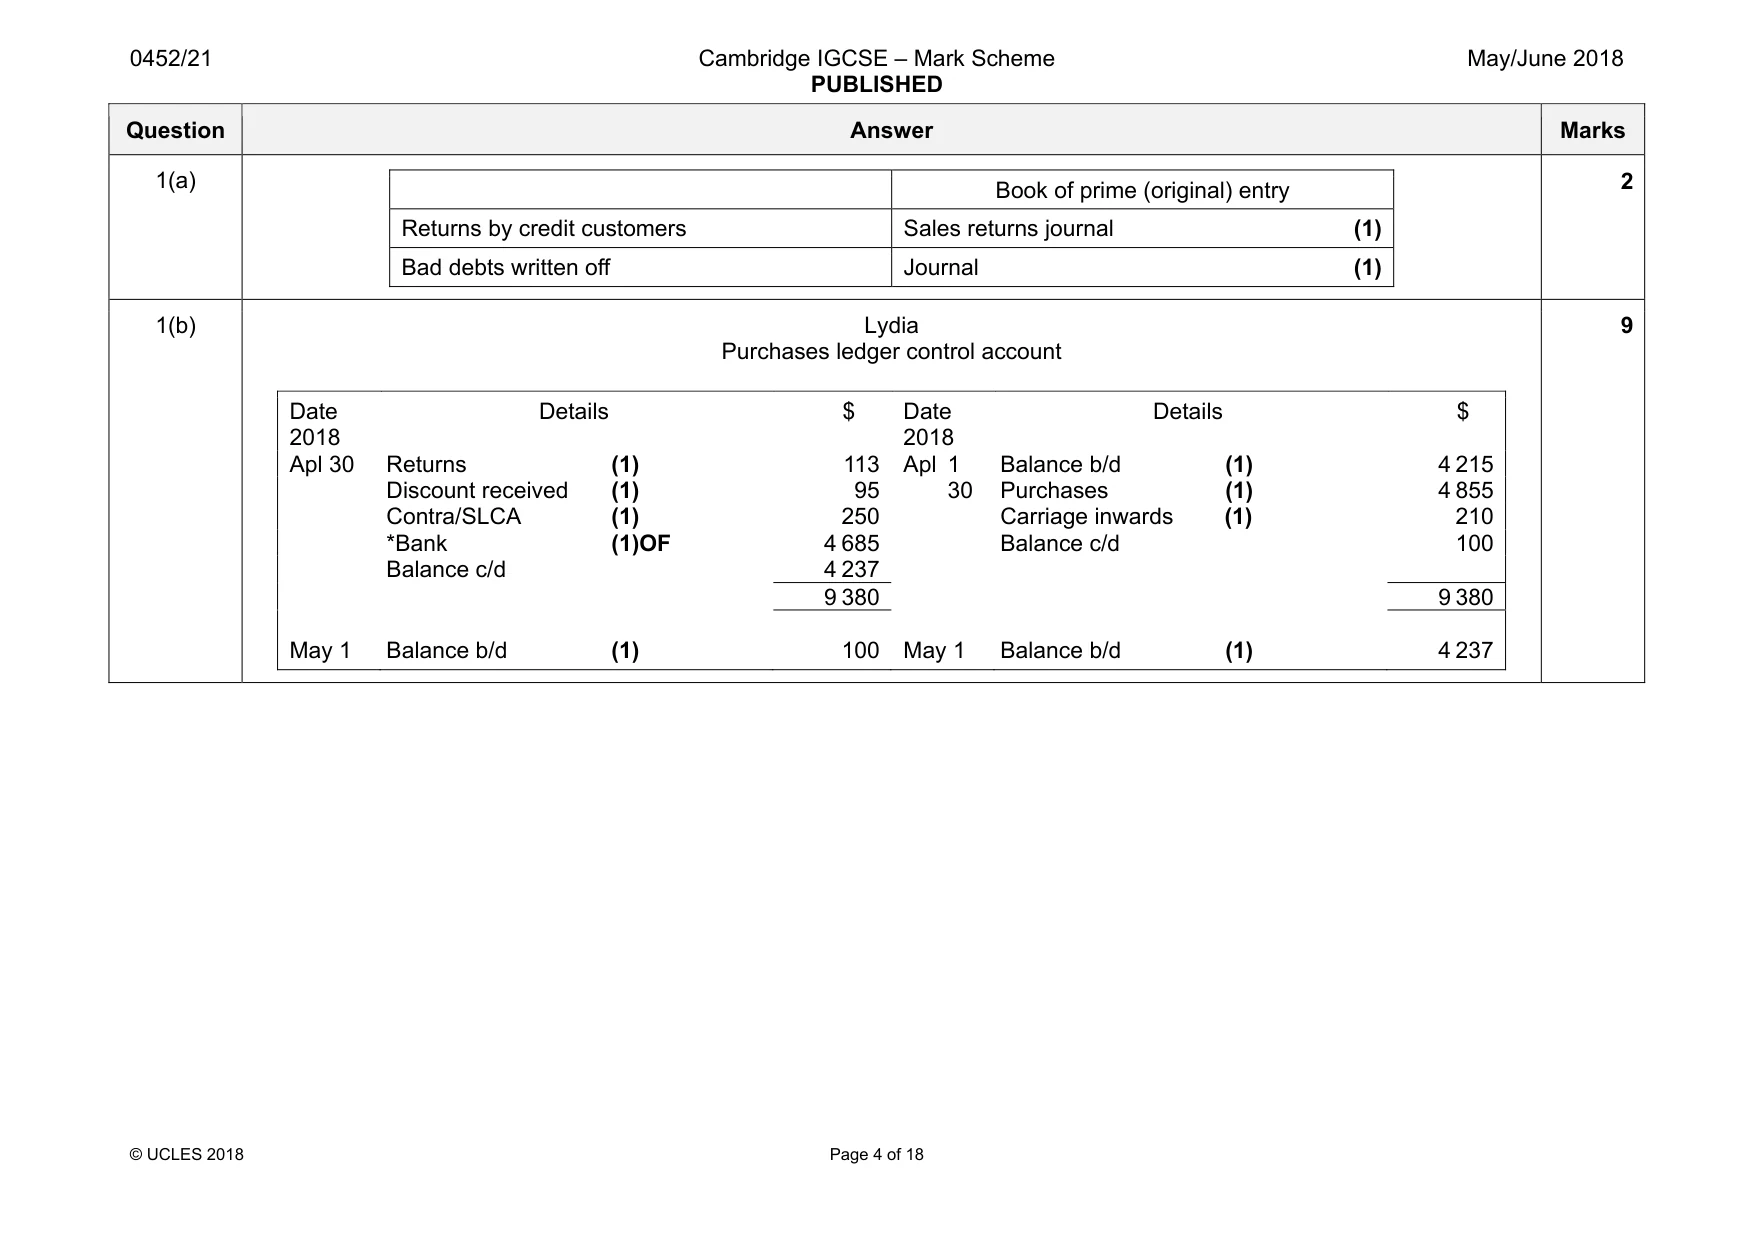
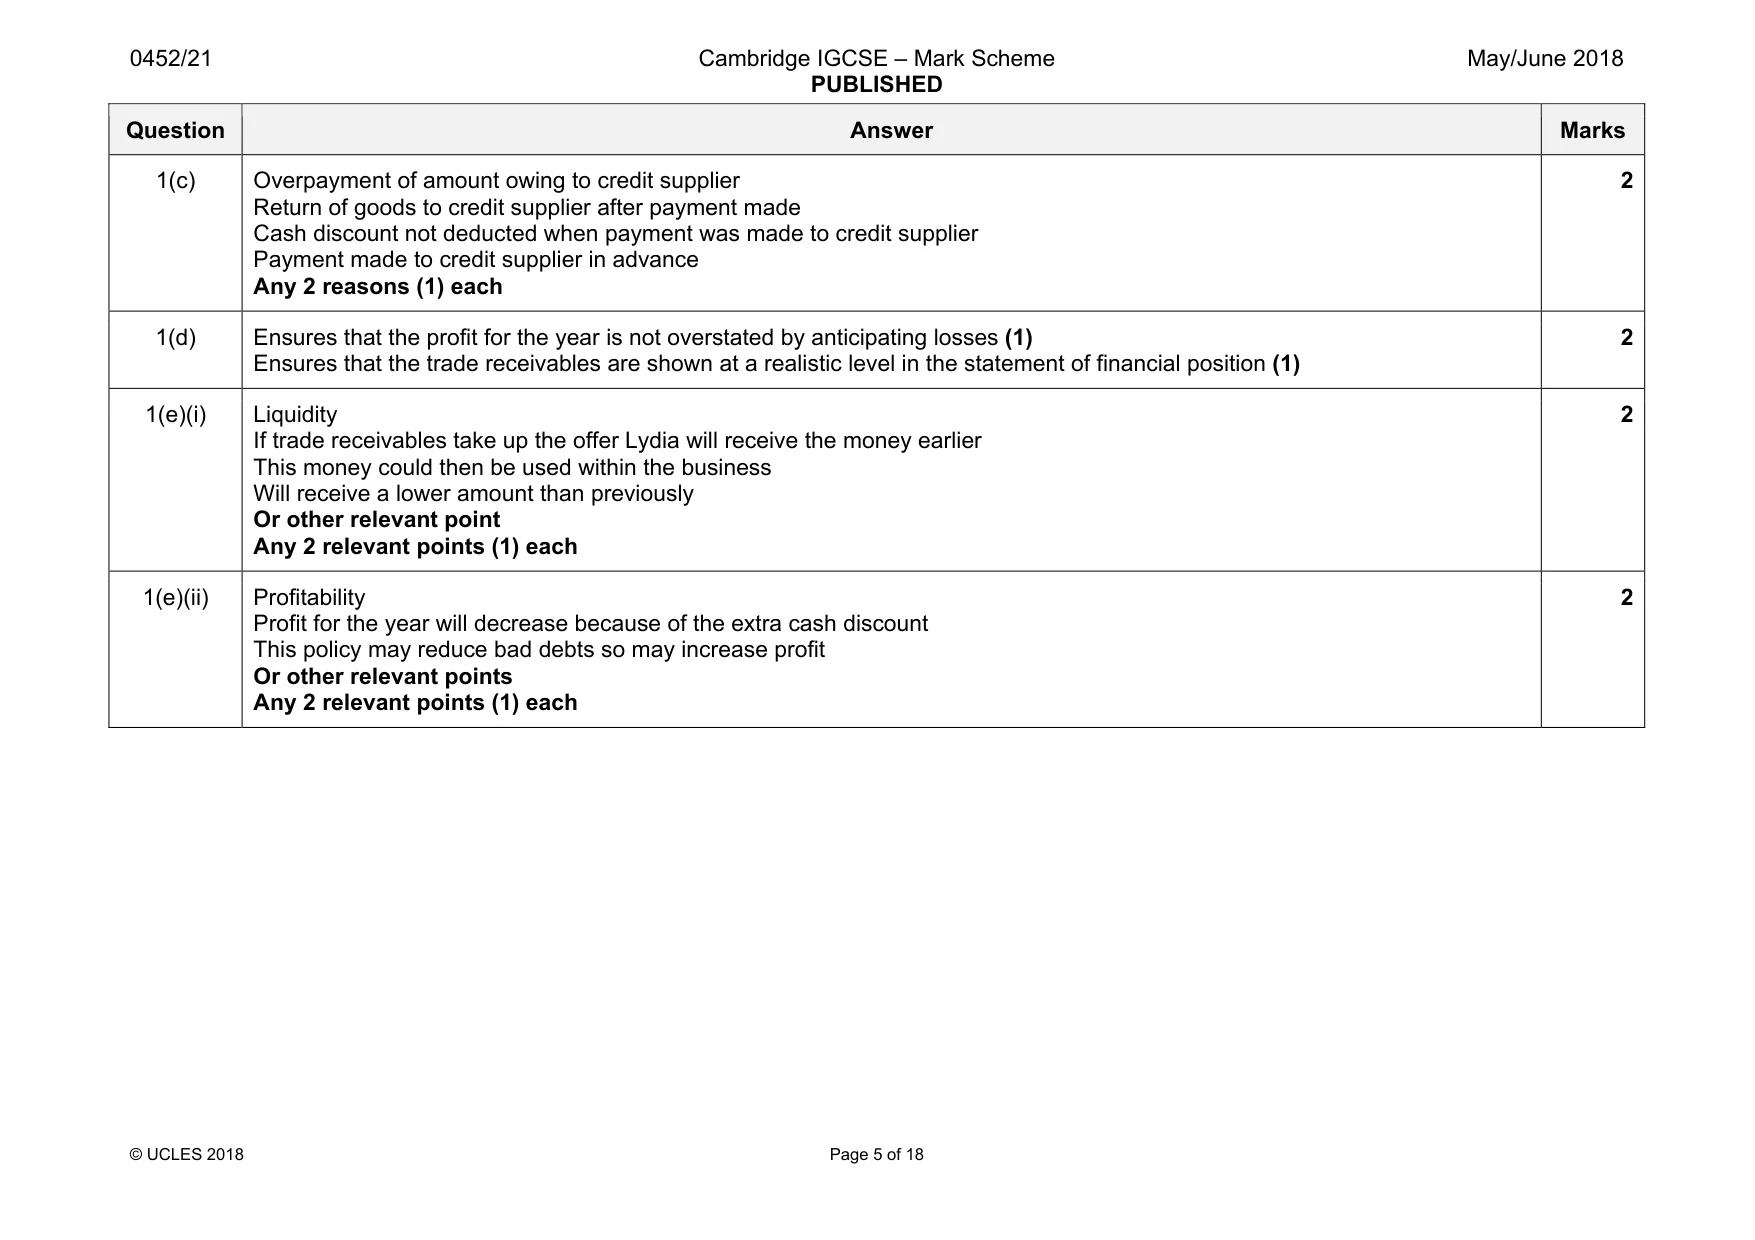
Mark scheme: 1(a) Book of prime (original) entry Returns by credit customers Sales returns journal (1) Bad debts written off Journal (1) 2 1(b) Lydia Purchases ledger control account Date 2018 Details $ Date 2018 Details $ Apl 30 Returns (1) 113 Apl 1 Balance b/d (1) 4 215 Discount received (1) 95 30 Purchases (1) 4 855 Contra/SLCA (1) 250 Carriage inwards (1) 210 *Bank (1)OF 4 685 Balance c/d 100 Balance c/d 4 237 9 380 9 380 May 1 Balance b/d (1) 100 May 1 Balance b/d (1) 4 237 9 Question Answer Marks 1(c) Overpayment of amount owing to credit supplier Return of goods to credit supplier after payment made Cash discount not deducted when payment was made to credit supplier Payment made to credit supplier in advance Any 2 reasons (1) each 2 1(d) Ensures that the profit for the year is not overstated by anticipating losses (1) Ensures that the trade receivables are shown at a realistic level in the statement of financial position (1) 2 1(e)(i) Liquidity If trade receivables take up the offer Lydia will receive the money earlier This money could then be used within the business Will receive a lower amount than previously Or other relevant point Any 2 relevant points (1) each 2 1(e)(ii) Profitability Profit for the year will decrease because of the extra cash discount This policy may reduce bad debts so may increase profit Or other relevant points Any 2 relevant points (1) each 2
Q2 · On 1 March 2017 Nabil started a business buying and selling office supplies on credit
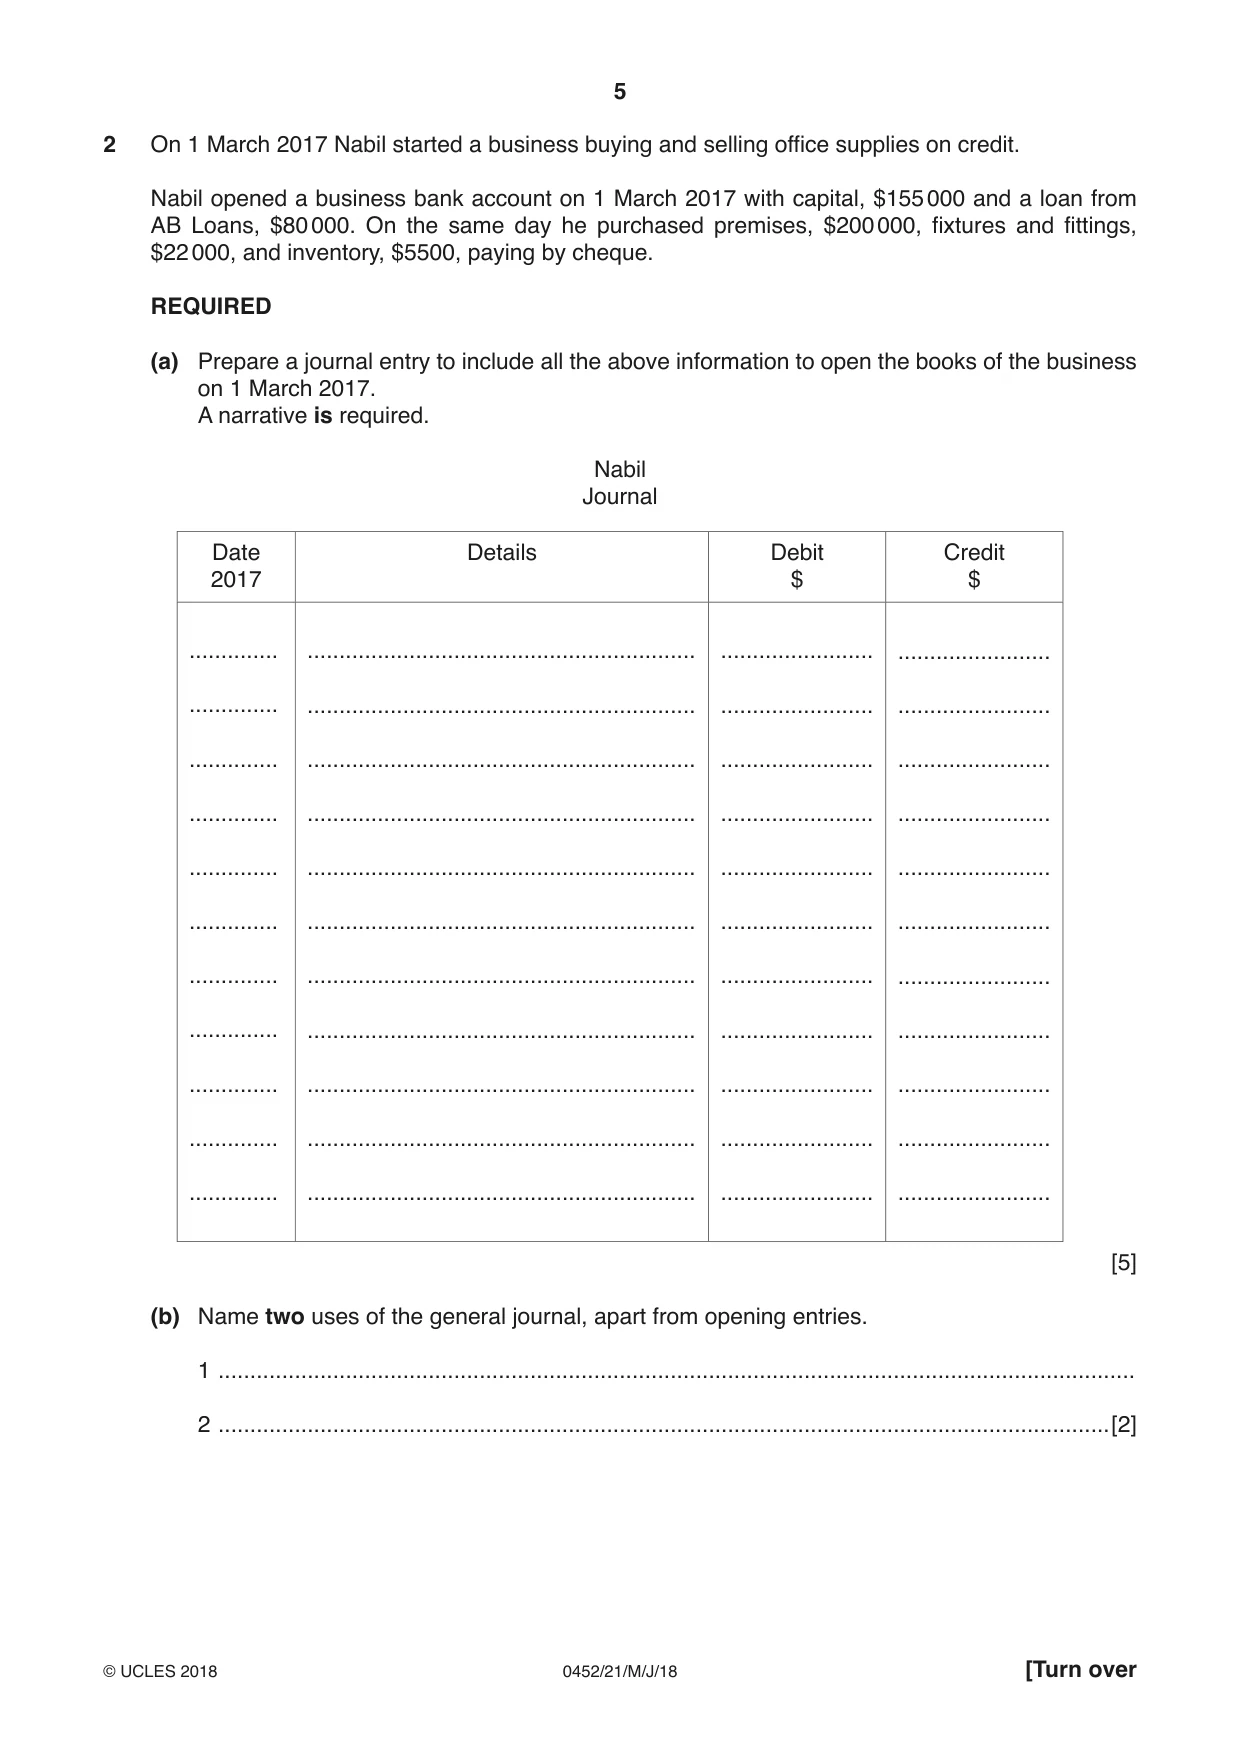
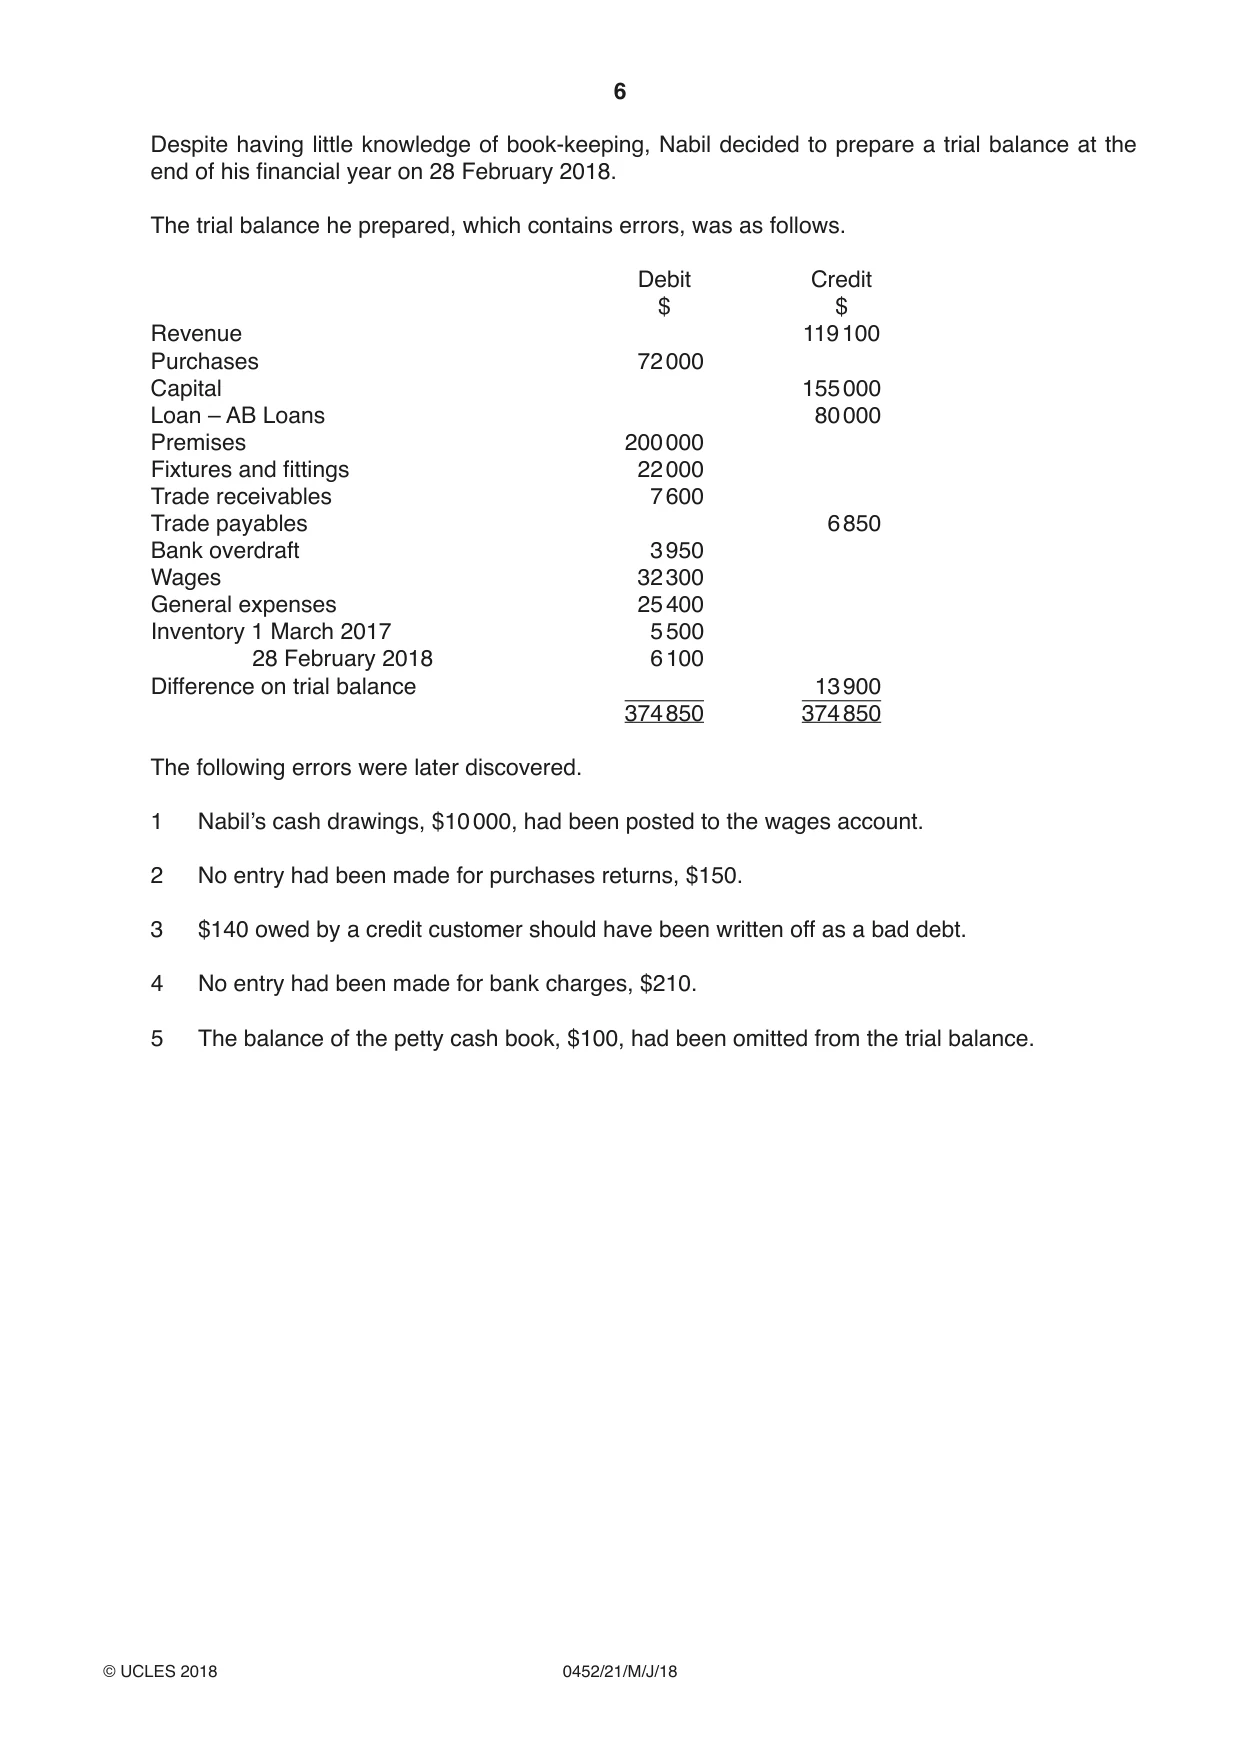
2 On 1 March 2017 Nabil started a business buying and selling office supplies on credit. Nabil opened a business bank account on 1 March 2017 with capital, $155 000 and a loan from AB Loans, $80 000. On the same day he purchased premises, $200 000, fixtures and fittings, $22 000, and inventory, $5500, paying by cheque. REQUIRED (a) Prepare a journal entry to include all the above information to open the books of the business on 1 March 2017. A narrative is required. Nabil Journal Date Details Debit Credit 2017 $ $ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ .............. ............................................................. ........................ ........................ [5] (b) Name two uses of the general journal, apart from opening entries. 1 ................................................................................................................................................ 2 ............................................................................................................................................[2] Despite having little knowledge of book-keeping, Nabil decided to prepare a trial balance at the end of his financial year on 28 February 2018. The trial balance he prepared, which contains errors, was as follows. Debit Credit $ $ Revenue 119 100 Purchases 72 000 Capital 155 000 Loan – AB Loans 80 000 Premises 200 000 Fixtures and fittings 22 000 Trade receivables 7 600 Trade payables 6 850 Bank overdraft 3 950 Wages 32 300 General expenses 25 400 Inventory 1 March 2017 5 500 28 February 2018 6 100 Difference on trial balance 13 900 374 850 374 850 The following errors were later discovered. 1 Nabil’s cash drawings, $10 000, had been posted to the wages account. 2 No entry had been made for purchases returns, $150.
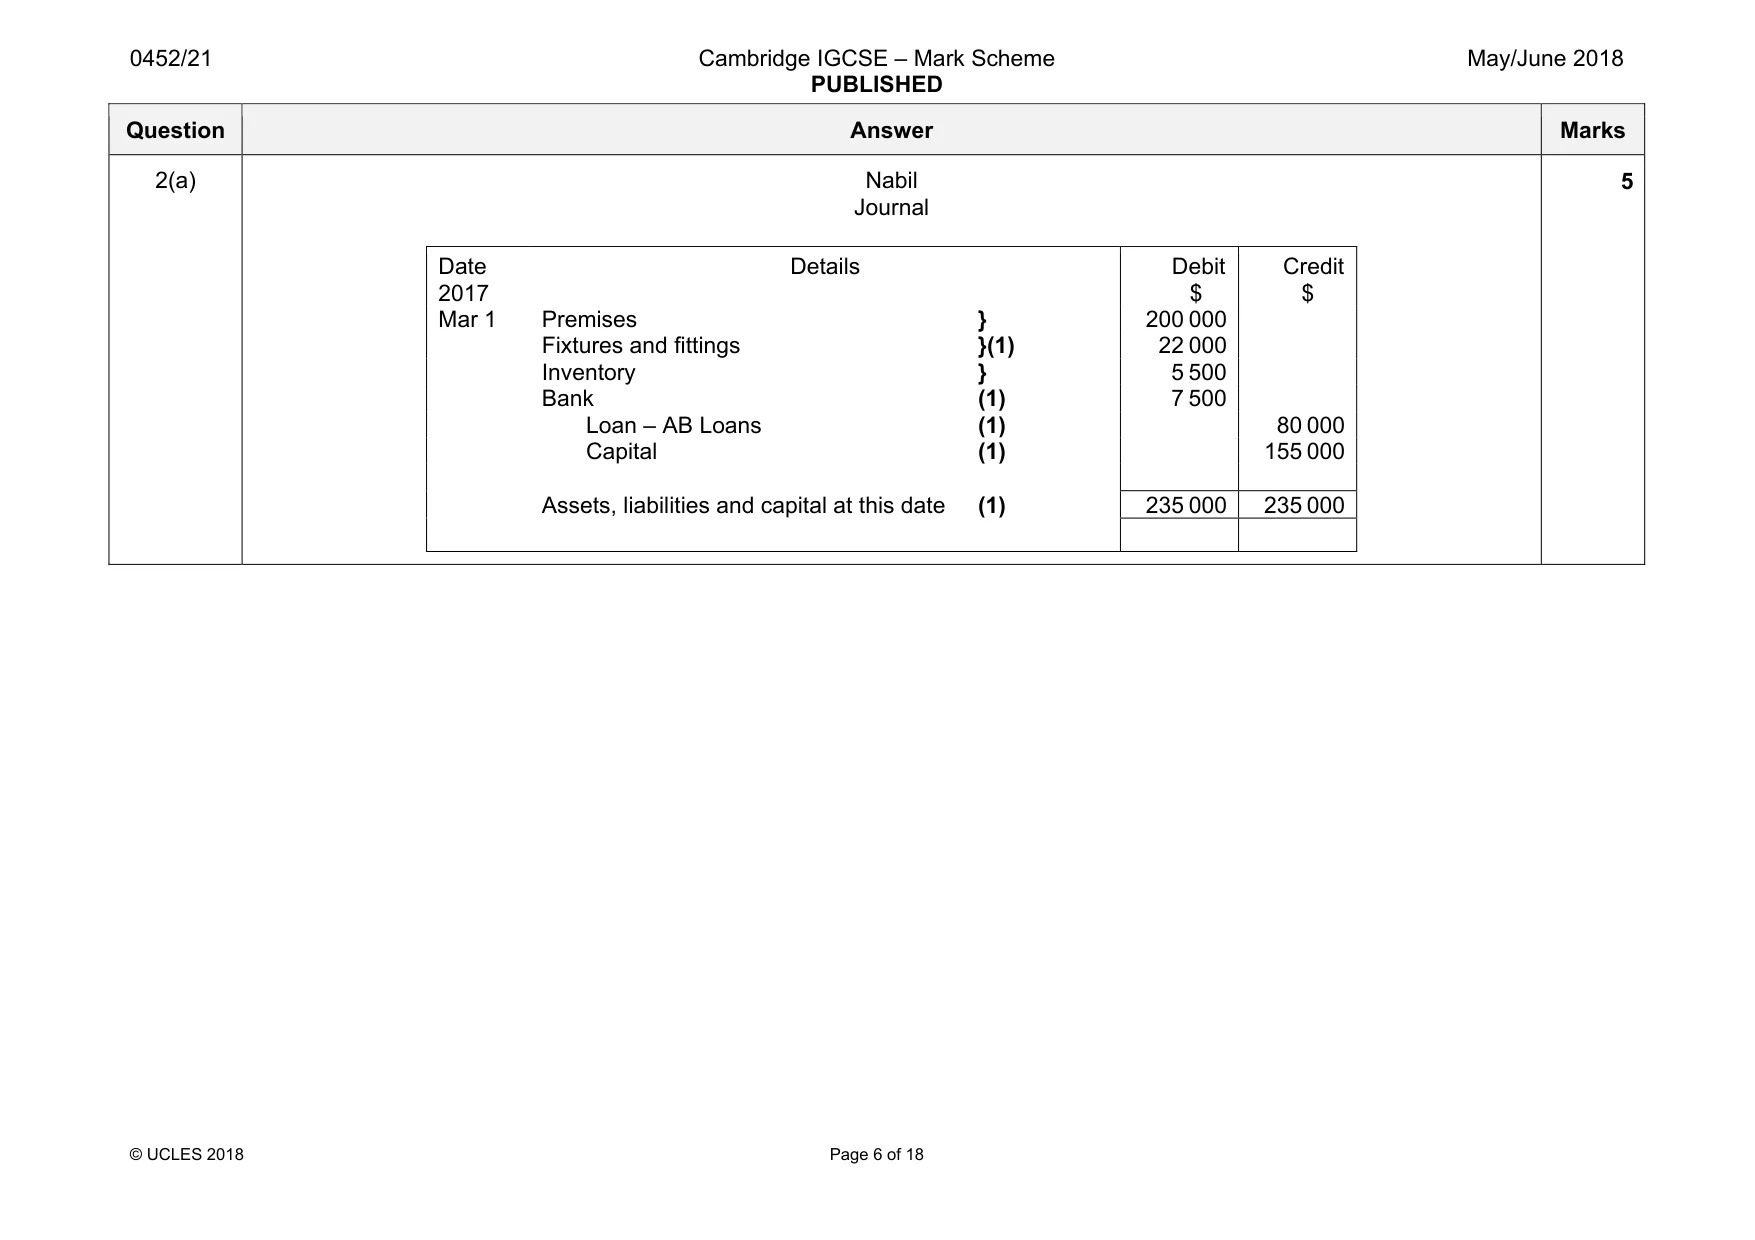
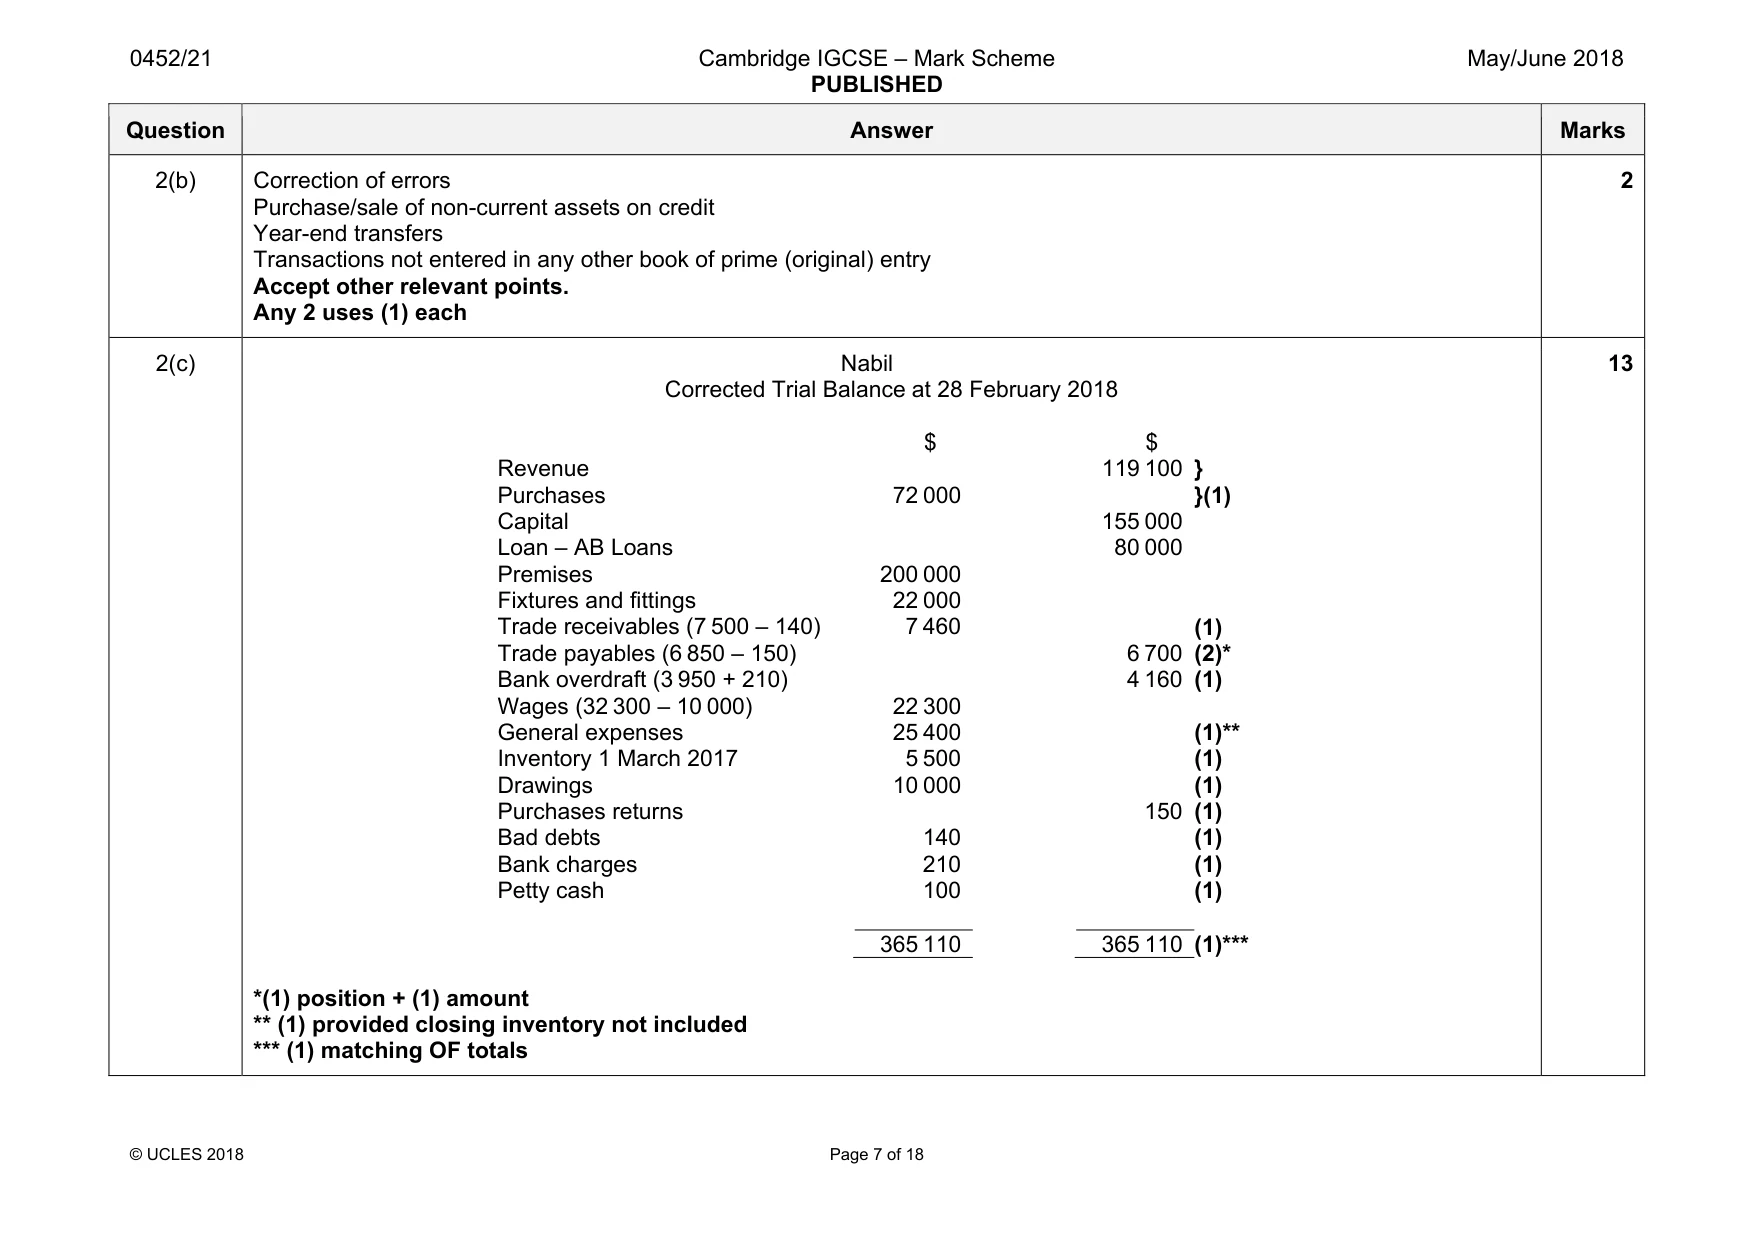
Mark scheme: 2(a) Nabil Journal Date 2017 Details Debit $ Credit $ Mar 1 Premises } 200 000 Fixtures and fittings }(1) 22 000 Inventory } 5 500 Bank (1) 7 500 Loan – AB Loans (1) 80 000 Capital (1) 155 000 Assets, liabilities and capital at this date (1) 235 000 235 000 5 Question Answer Marks 2(b) Correction of errors Purchase/sale of non-current assets on credit Year-end transfers Transactions not entered in any other book of prime (original) entry Accept other relevant points. Any 2 uses (1) each 2 2(c) Nabil Corrected Trial Balance at 28 February 2018 $ $ Revenue 119 100 } Purchases 72 000 }(1) Capital 155 000 Loan – AB Loans 80 000 Premises 200 000 Fixtures and fittings 22 000 Trade receivables (7 500 – 140) 7 460 (1) Trade payables (6 850 – 150) 6 700 (2)* Bank overdraft (3 950 + 210) 4 160 (1) Wages (32 300 – 10 000) 22 300 General expenses 25 400 (1)** Inventory 1 March 2017 5 500 (1) Drawings 10 000 (1) Purchases returns 150 (1) Bad debts 140 (1) Bank charges 210 (1) Petty cash 100 (1) 365 110 365 110 (1)*** *(1) position + (1) amount ** (1) provided closing inventory not included *** (1) matching OF totals 13
Q3 · Masuma owns a furniture store
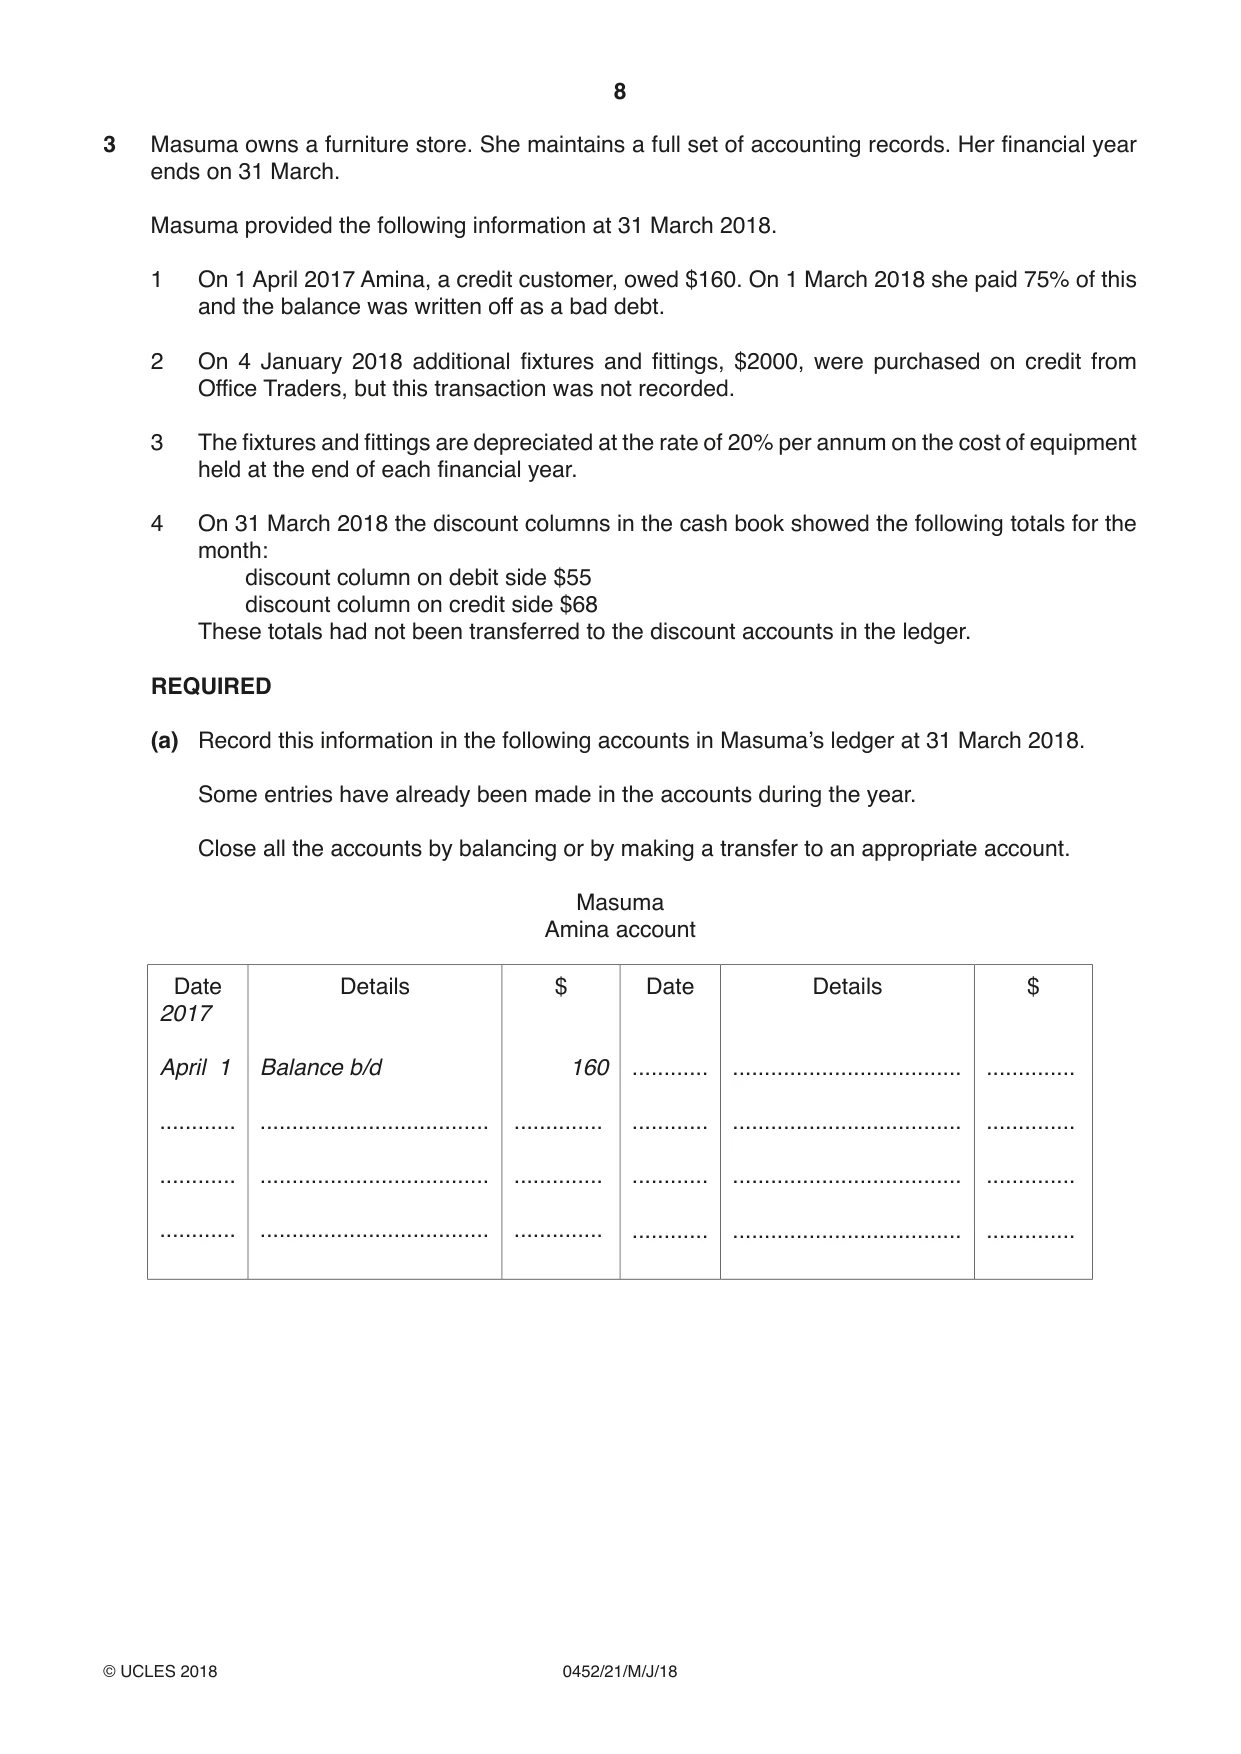
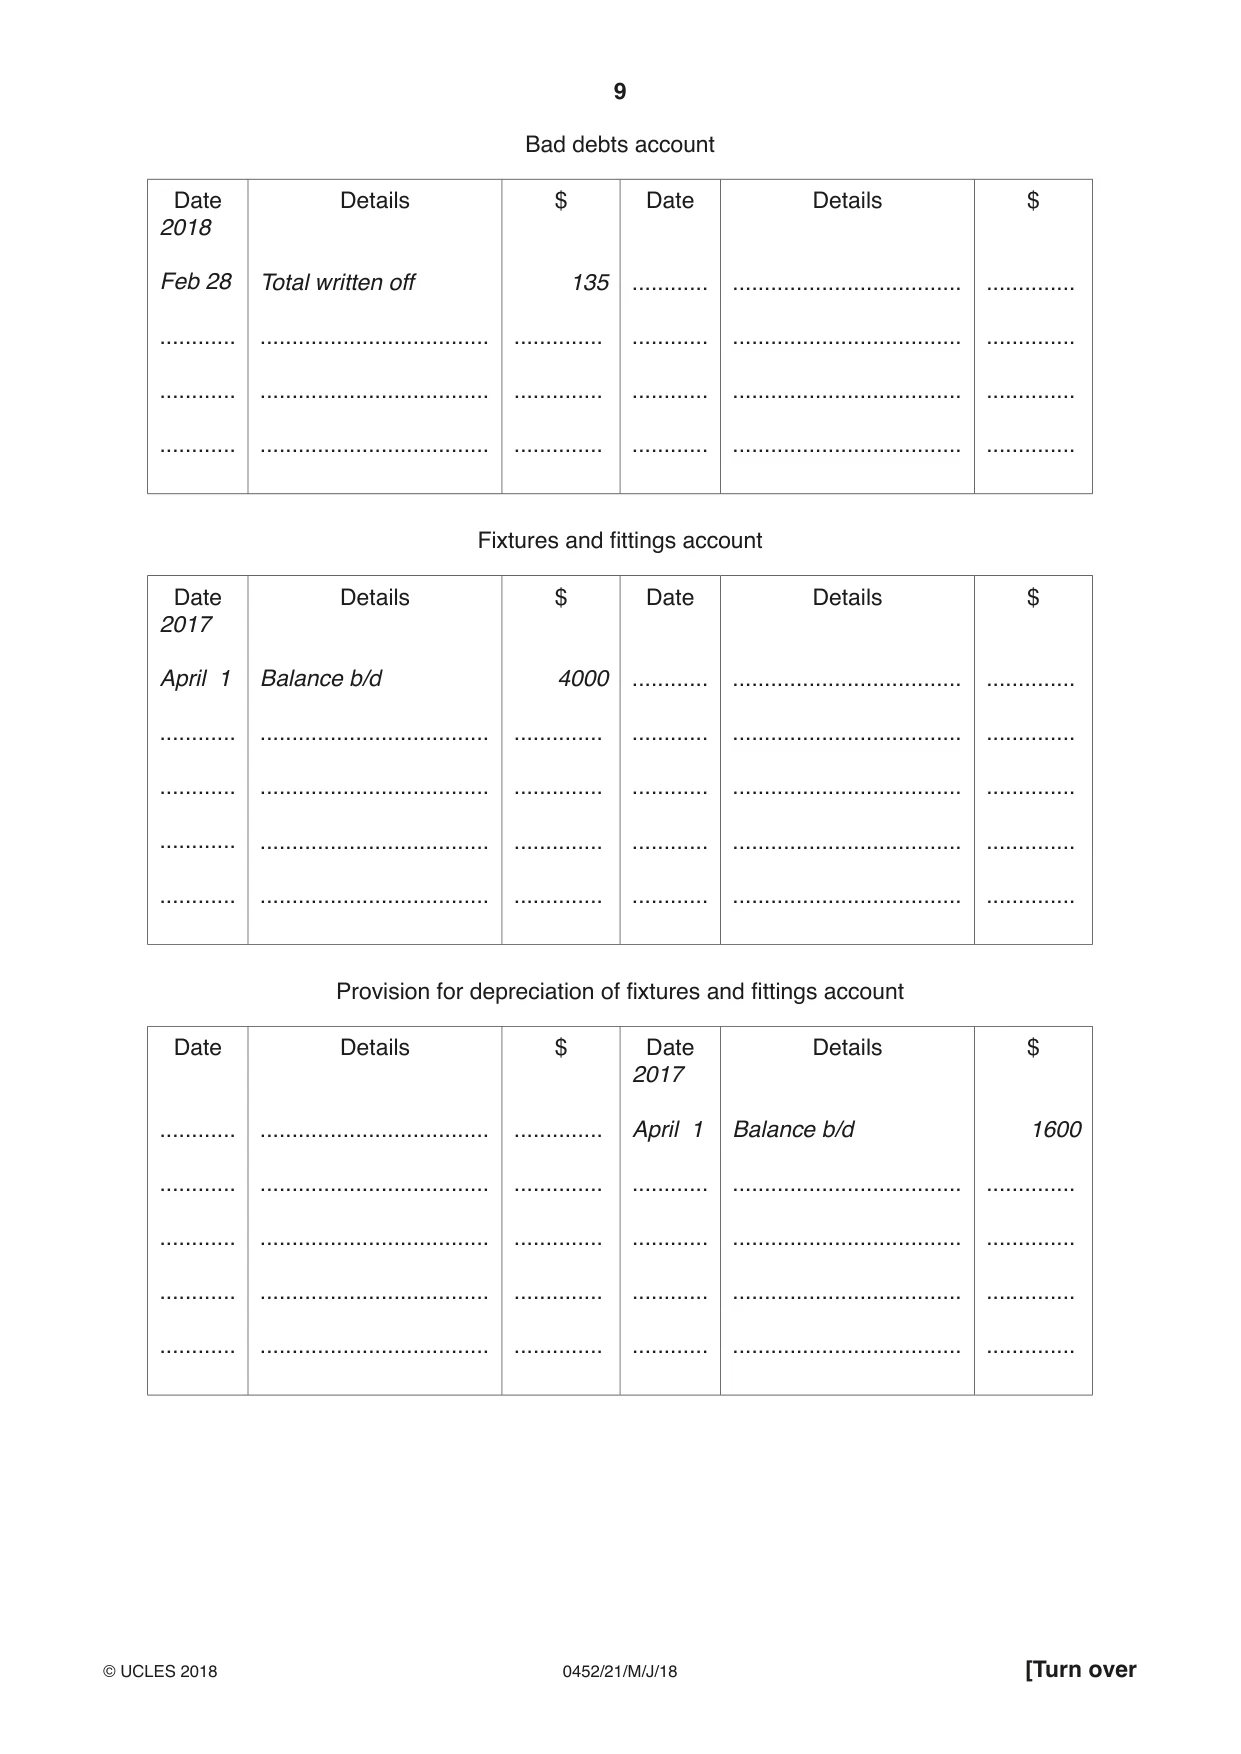
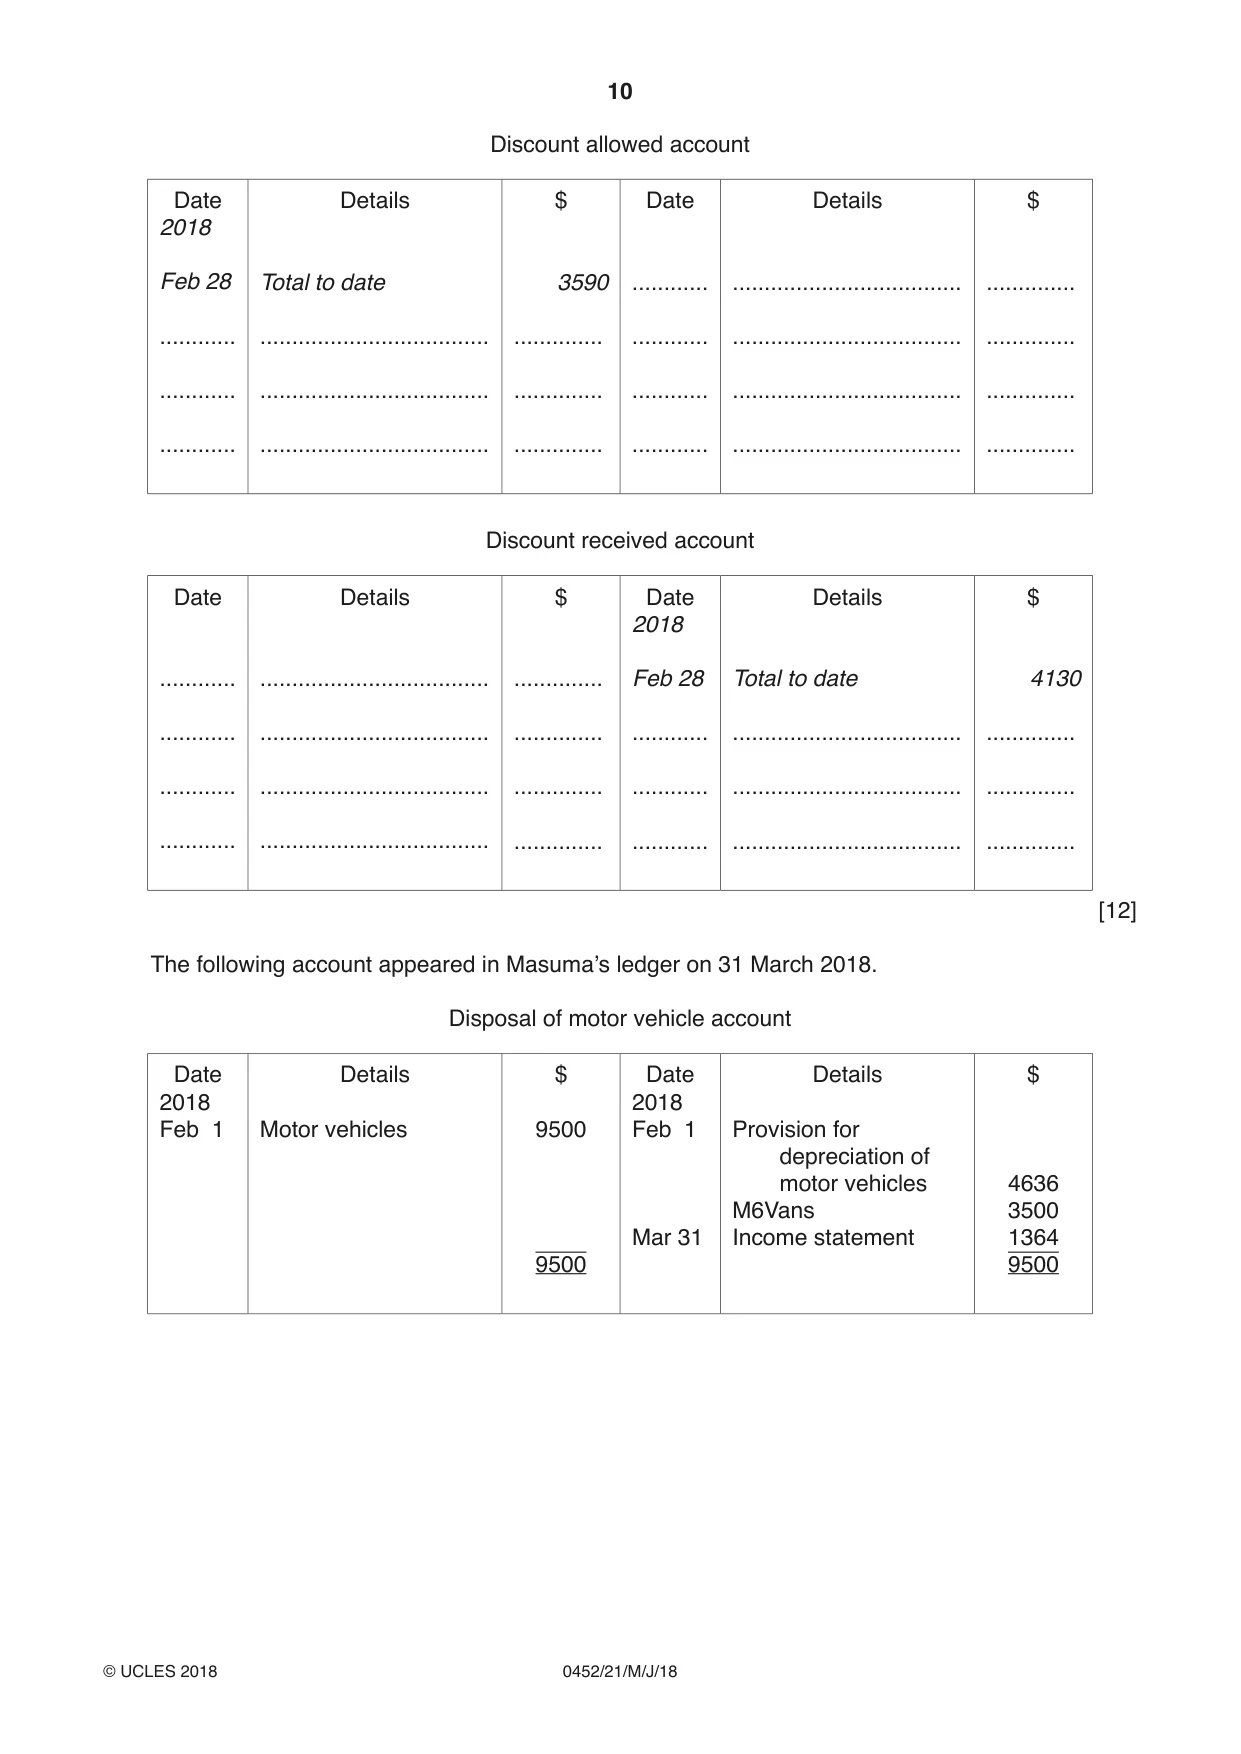
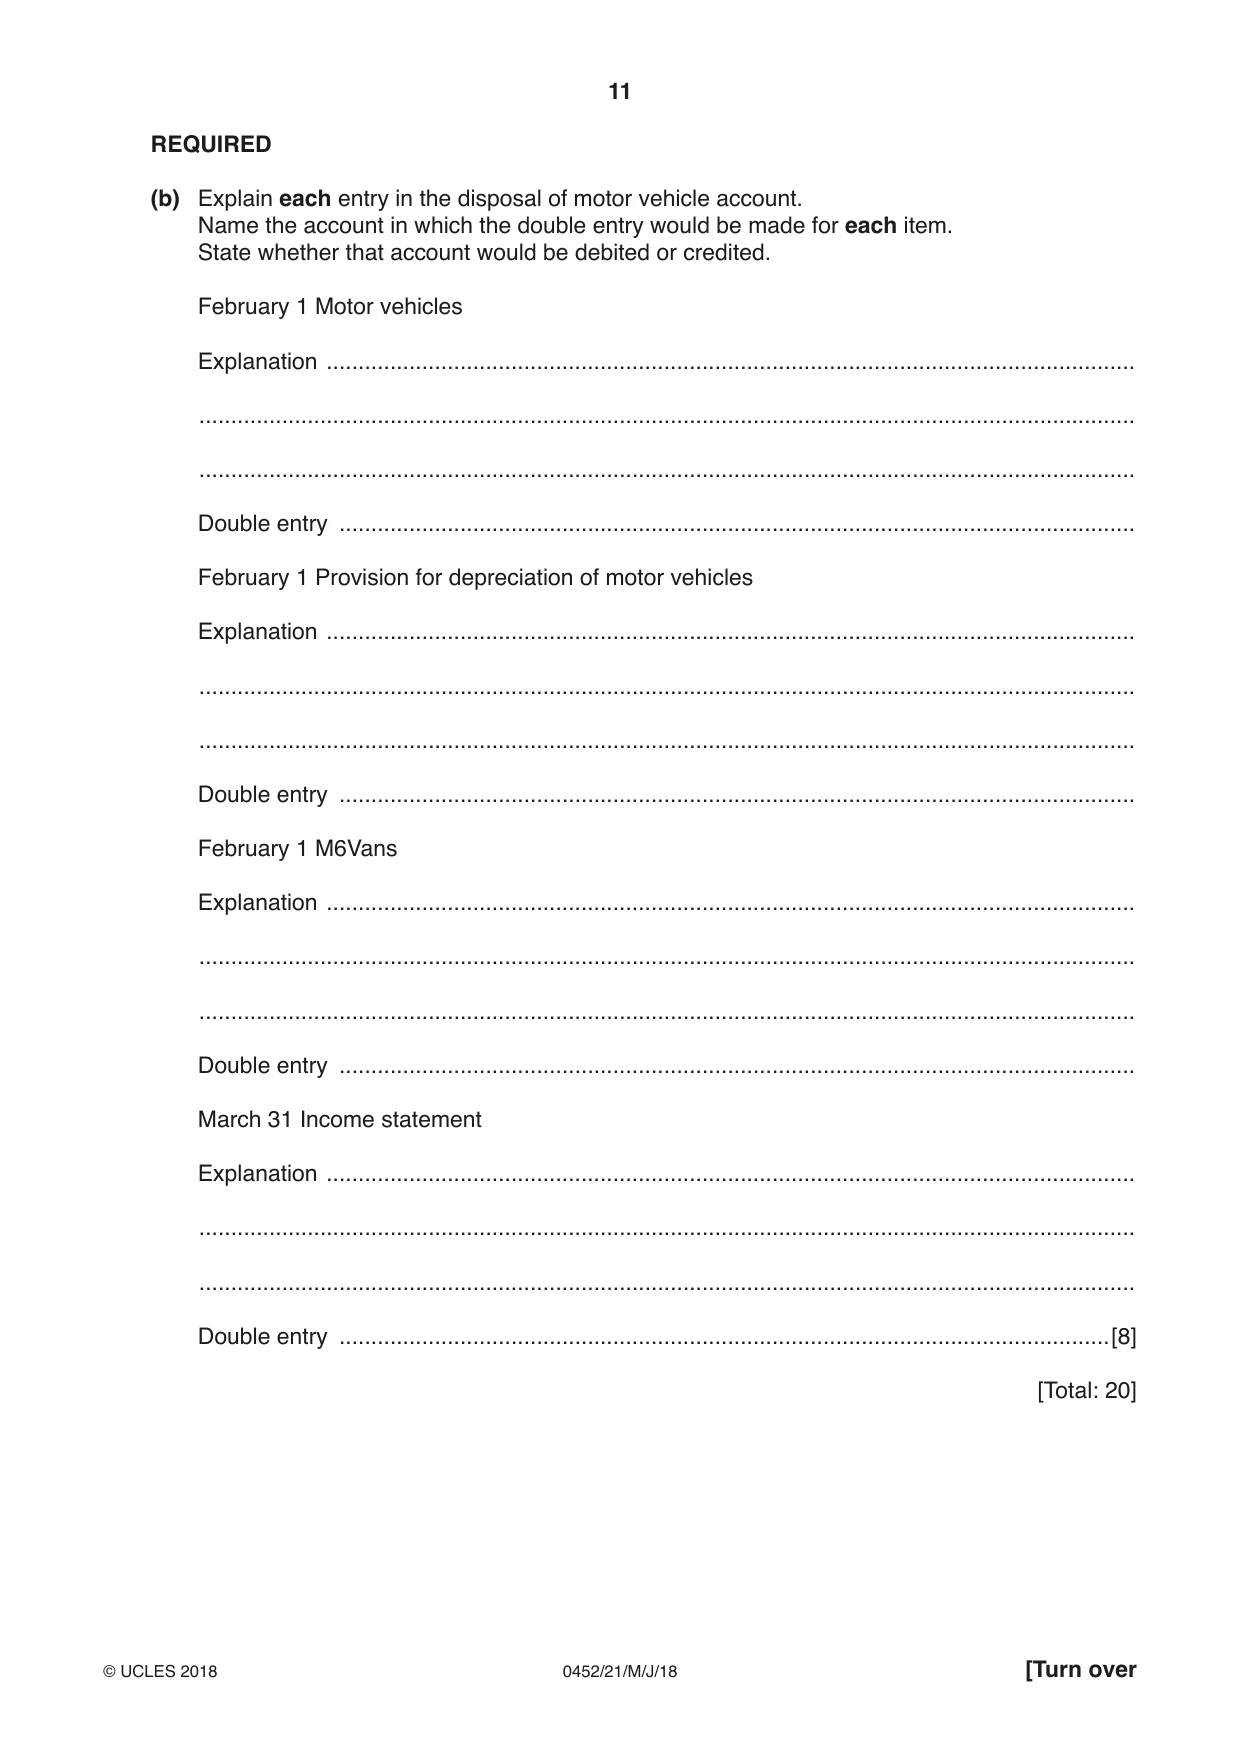
3 Masuma owns a furniture store. She maintains a full set of accounting records. Her financial year ends on 31 March. Masuma provided the following information at 31 March 2018. 1 On 1 April 2017 Amina, a credit customer, owed $160. On 1 March 2018 she paid 75% of this and the balance was written off as a bad debt. 2 On 4 January 2018 additional fixtures and fittings, $2000, were purchased on credit from Office Traders, but this transaction was not recorded. 3 The fixtures and fittings are depreciated at the rate of 20% per annum on the cost of equipment held at the end of each financial year. 4 On 31 March 2018 the discount columns in the cash book showed the following totals for the month: discount column on debit side $55 discount column on credit side $68 These totals had not been transferred to the discount accounts in the ledger. REQUIRED (a) Record this information in the following accounts in Masuma’s ledger at 31 March 2018. Some entries have already been made in the accounts during the year. Close all the accounts by balancing or by making a transfer to an appropriate account. Masuma Amina account Date Details $ Date Details $ 2017 April 1 Balance b/d 160 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Bad debts account Date Details $ Date Details $ 2018 Feb 28 Total written off 135 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Fixtures and fittings account Date Details $ Date Details $ 2017 April 1 Balance b/d 4000 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Provision for depreciation of fixtures and fittings account Date Details $ Date Details $ 2017 ............ .................................... .............. April 1 Balance b/d 1600 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Discount allowed account Date Details $ Date Details $ 2018 Feb 28 Total to date 3590 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Discount received account Date Details $ Date Details $ 2018 ............ .................................... .............. Feb 28 Total to date 4130 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. [12] The following account appeared in Masuma’s ledger on 31 March 2018. Disposal of motor vehicle account Date Details $ Date Details $ 2018 2018 Feb 1 Motor vehicles 9500 Feb 1 Provision for depreciation of motor vehicles 4636 M6Vans 3500 Mar 31 Income statement 1364 9500 9500 REQUIRED (b) Explain each entry in the disposal of motor vehicle account. Name the account in which the double entry would be made for each item. State whether that account would be debited or credited. February 1 Motor vehicles Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. February 1 Provision for depreciation of motor vehicles Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. February 1 M6Vans Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. March 31 Income statement Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry .........................................................................................................................[8] [Total: 20]
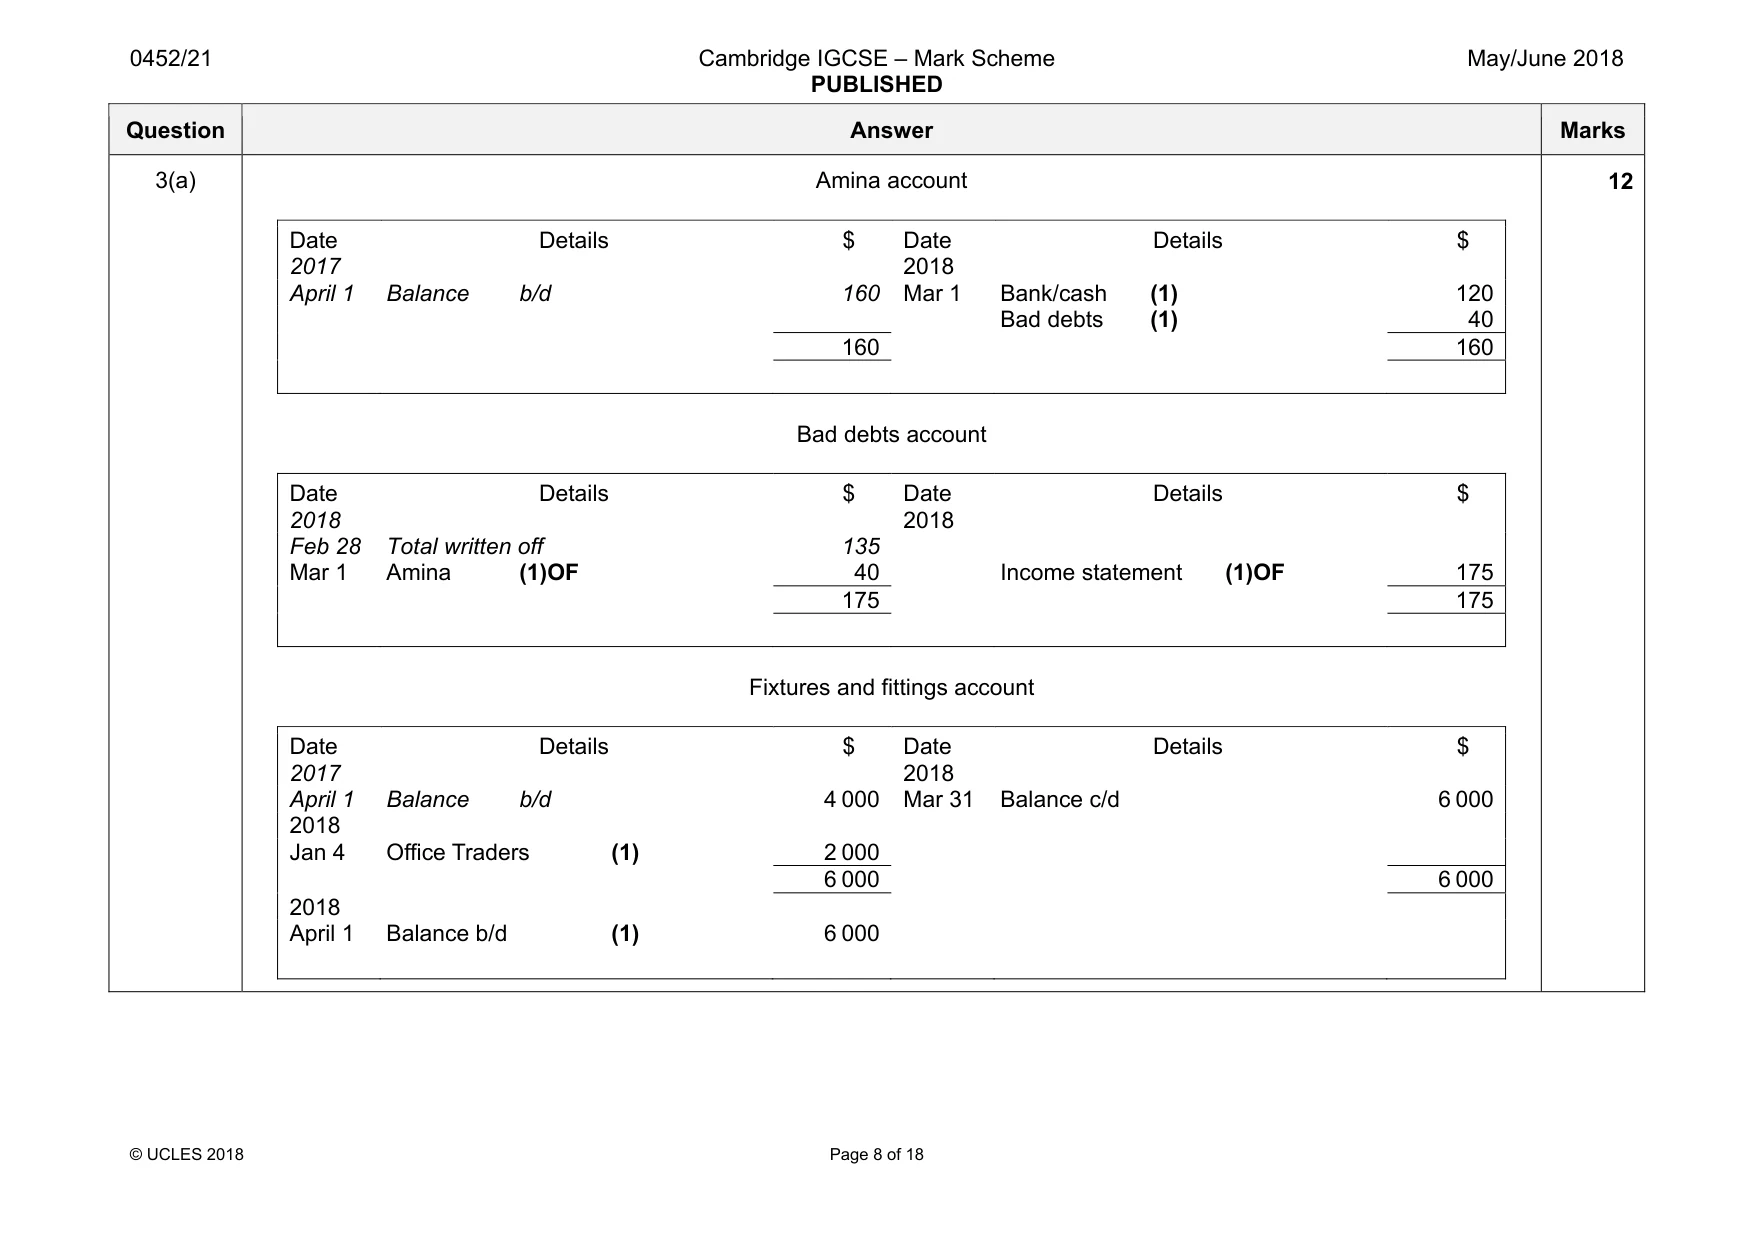
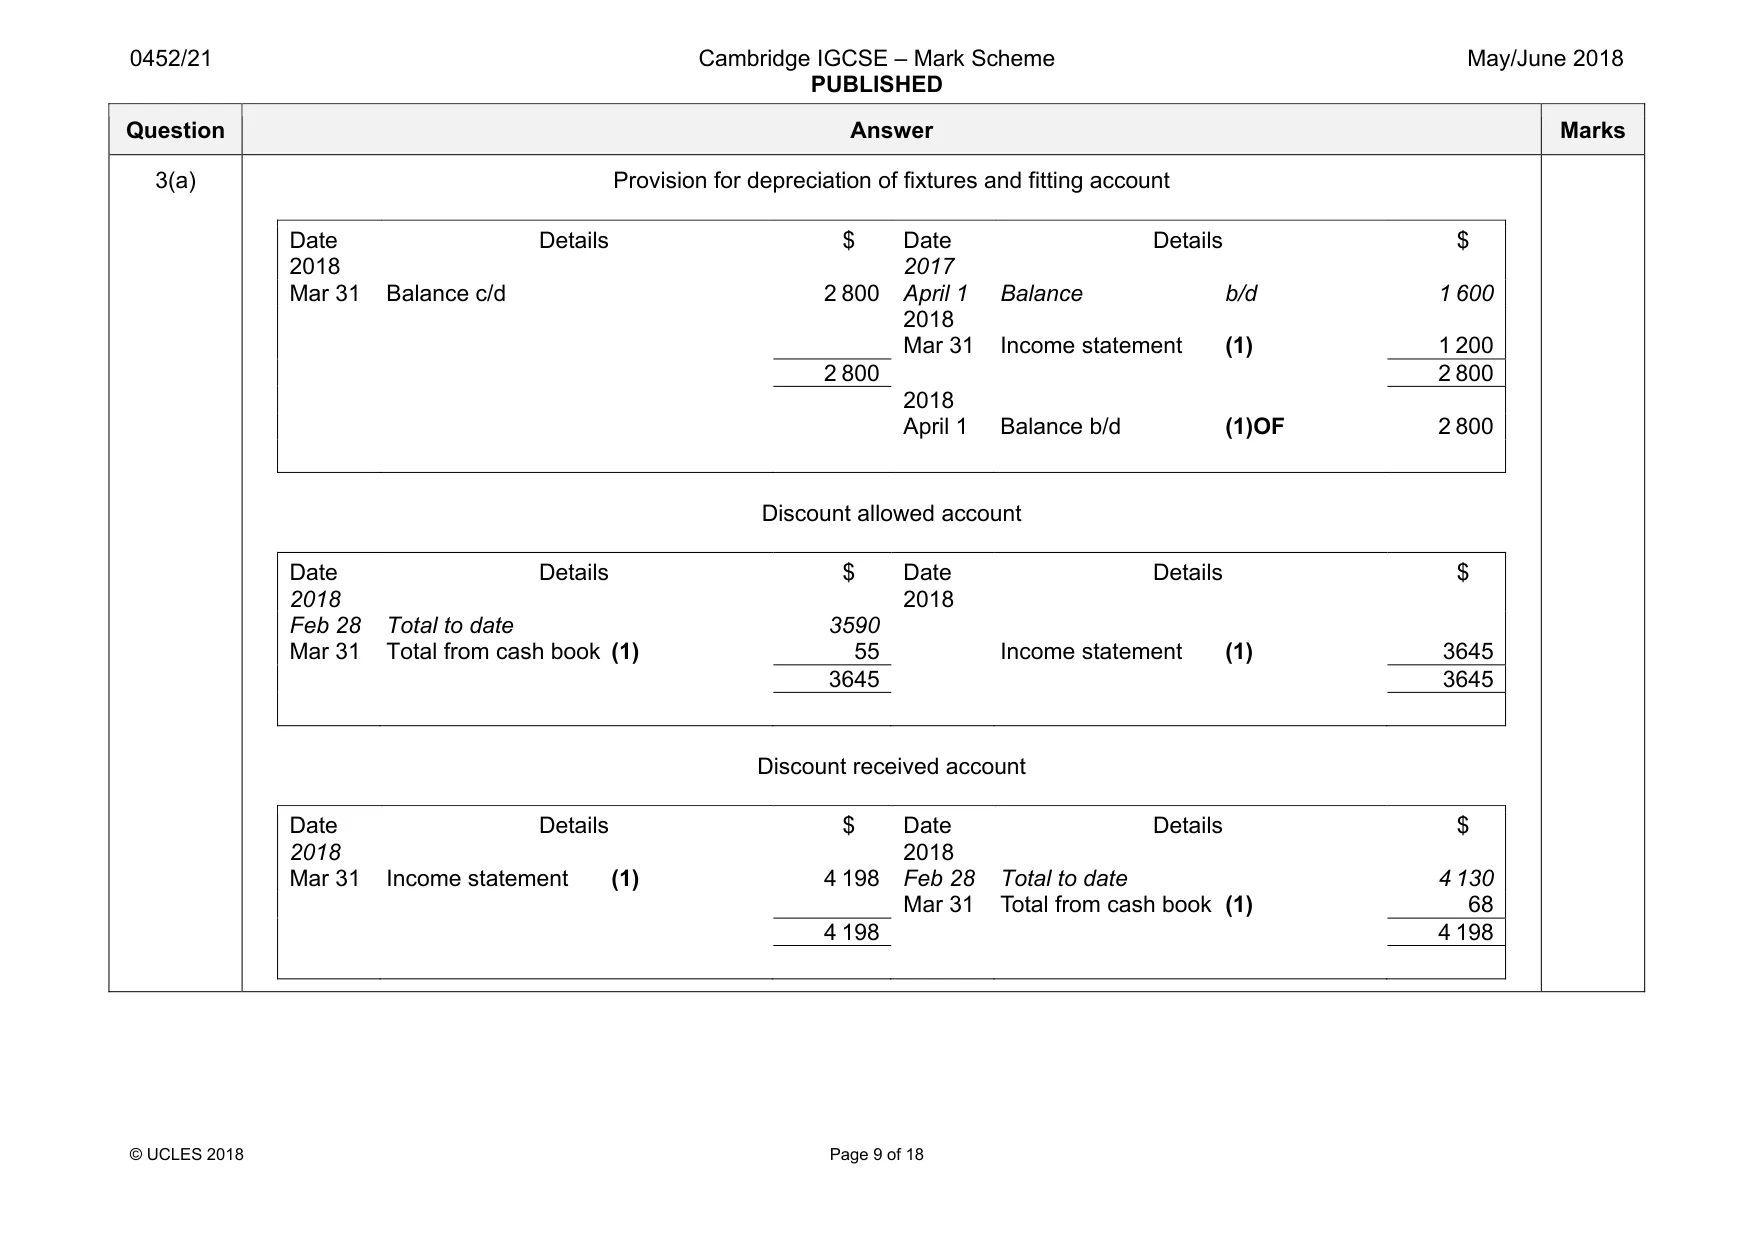
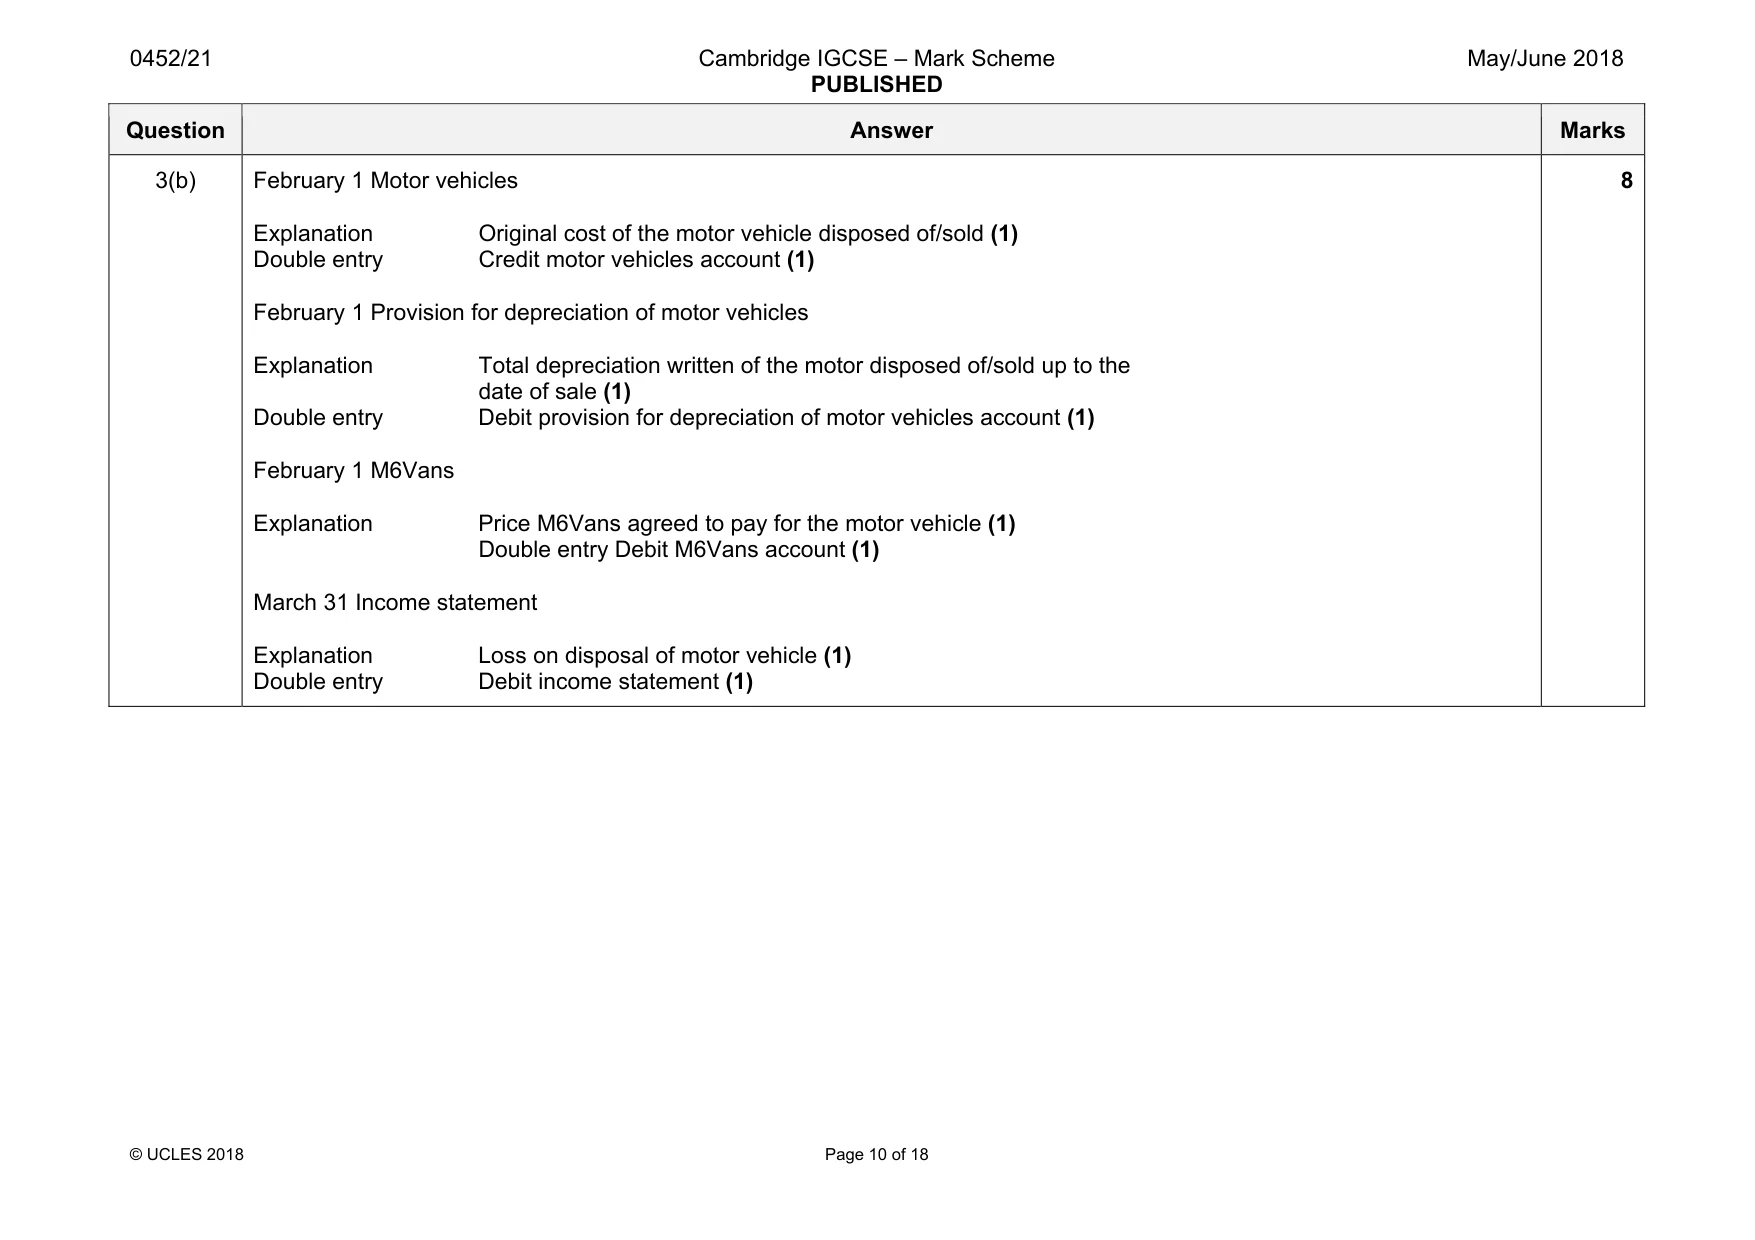
Mark scheme: 3(a) Amina account Date 2017 Details $ Date 2018 Details $ April 1 Balance b/d 160 Mar 1 Bank/cash (1) 120 Bad debts (1) 40 160 160 Bad debts account Date 2018 Details $ Date 2018 Details $ Feb 28 Total written off 135 Mar 1 Amina (1)OF 40 Income statement (1)OF 175 175 175 Fixtures and fittings account Date 2017 Details $ Date 2018 Details $ April 1 Balance b/d 4 000 Mar 31 Balance c/d 6 000 2018 Jan 4 Office Traders (1) 2 000 6 000 6 000 2018 April 1 Balance b/d (1) 6 000 12 Question Answer Marks 3(a) Provision for depreciation of fixtures and fitting account Date 2018 Details $ Date 2017 Details $ Mar 31 Balance c/d 2 800 April 1 Balance b/d 1 600 2018 Mar 31 Income statement (1) 1 200 2 800 2 800 2018 April 1 Balance b/d (1)OF 2 800 Discount allowed account Date 2018 Details $ Date 2018 Details $ Feb 28 Total to date 3590 Mar 31 Total from cash book (1) 55 Income statement (1) 3645 3645 3645 Discount received account Date 2018 Details $ Date 2018 Details $ Mar 31 Income statement (1) 4 198 Feb 28 Total to date 4 130 Mar 31 Total from cash book (1) 68 4 198 4 198 Question Answer Marks 3(b) February 1 Motor vehicles Explanation Original cost of the motor vehicle disposed of/sold (1) Double entry Credit motor vehicles account (1) February 1 Provision for depreciation of motor vehicles Explanation Total depreciation written of the motor disposed of/sold up to the date of sale (1) Double entry Debit provision for depreciation of motor vehicles account (1) February 1 M6Vans Explanation Price M6Vans agreed to pay for the motor vehicle (1) Double entry Debit M6Vans account (1) March 31 Income statement Explanation Loss on disposal of motor vehicle (1) Double entry Debit income statement (1) 8
Q4 · Asim has an advertising agency
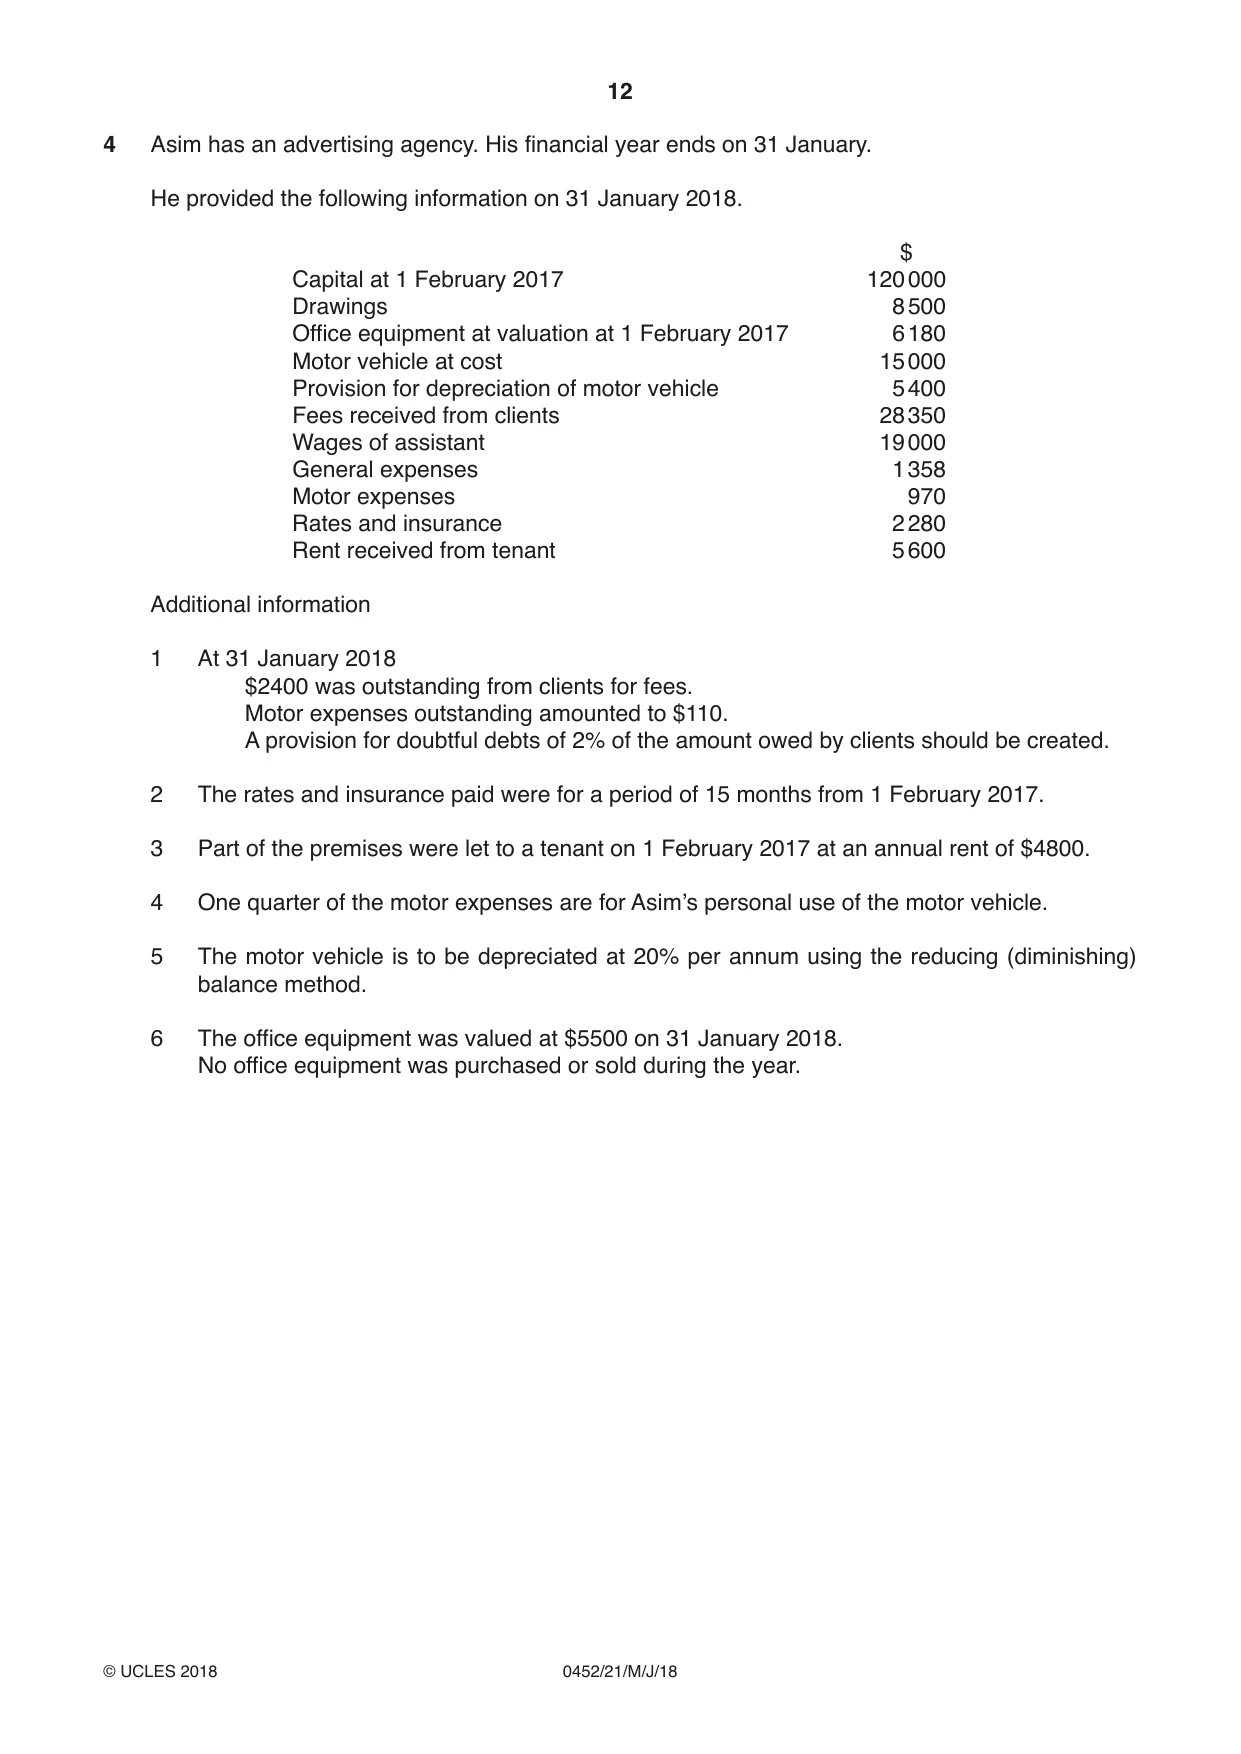
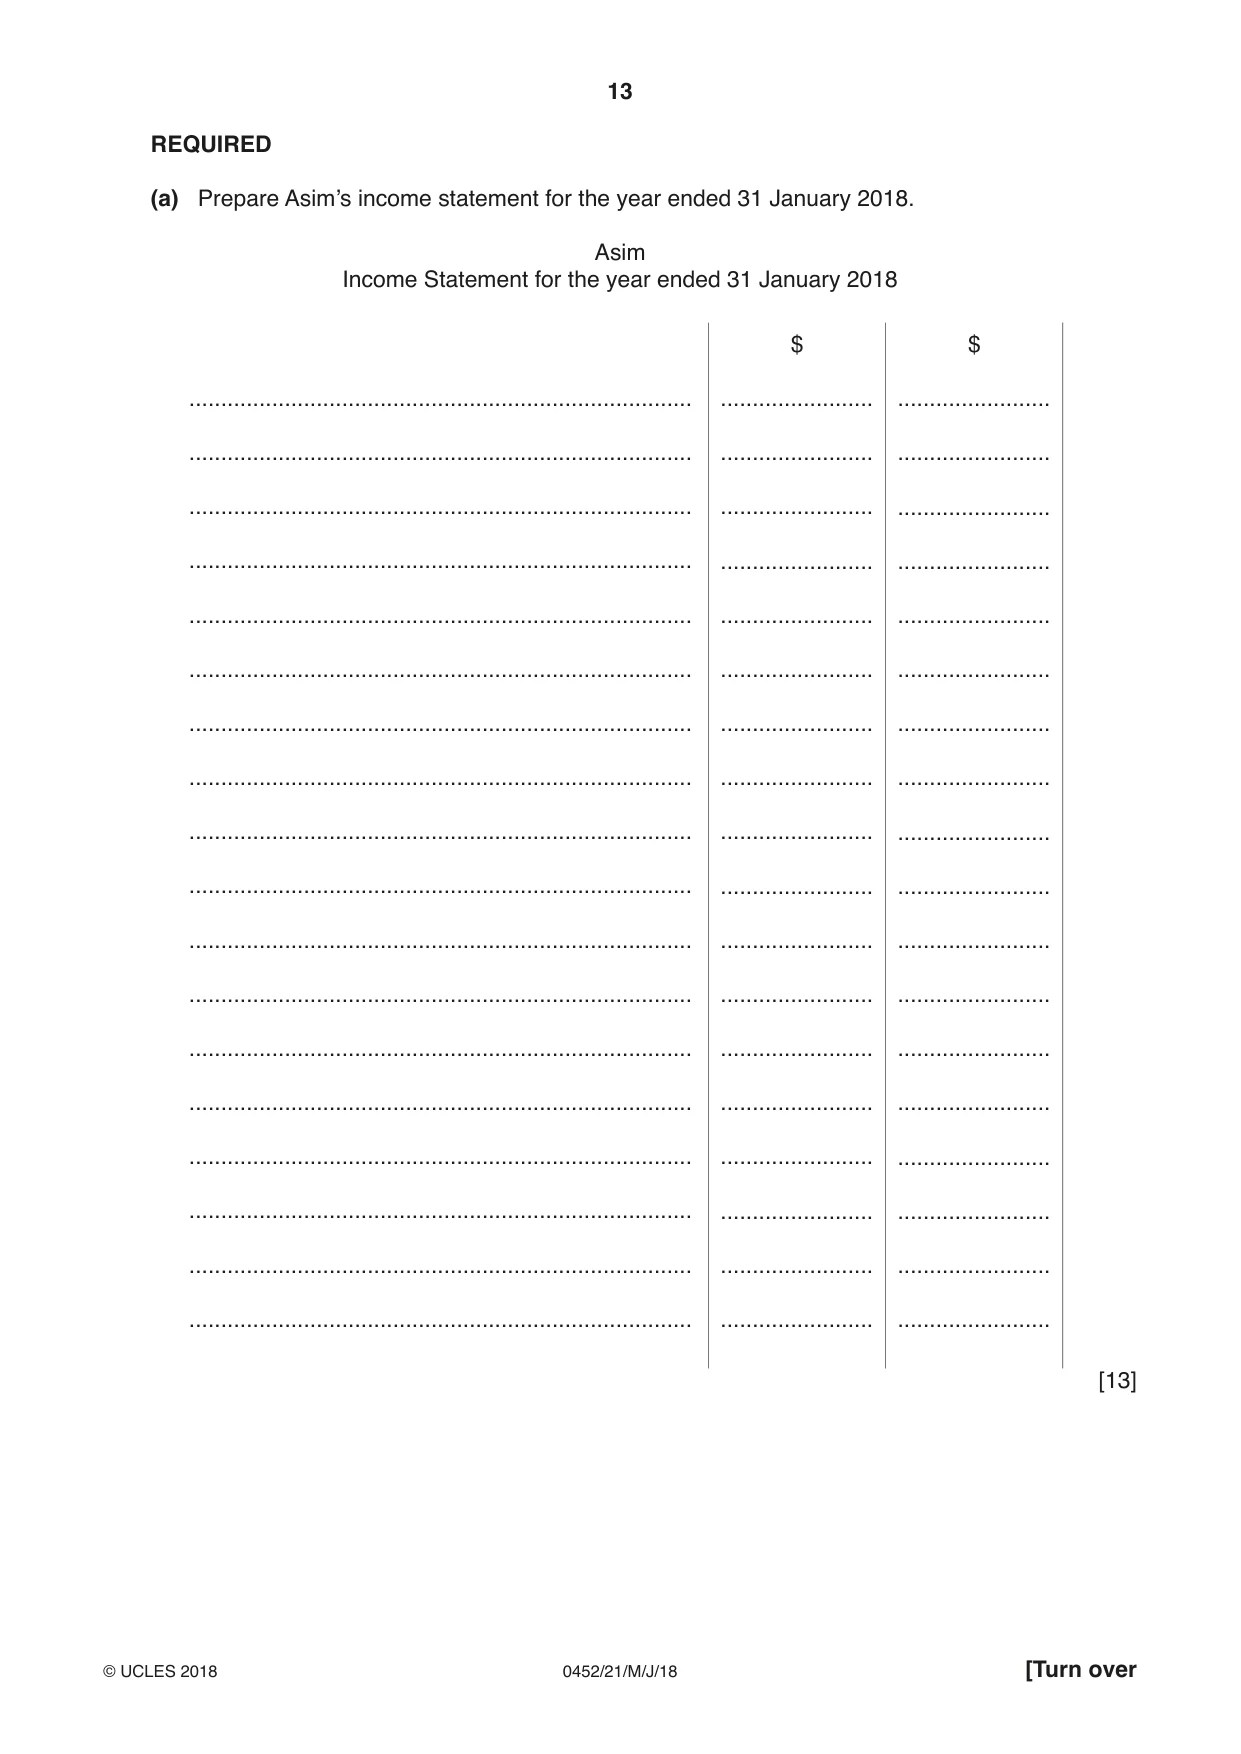
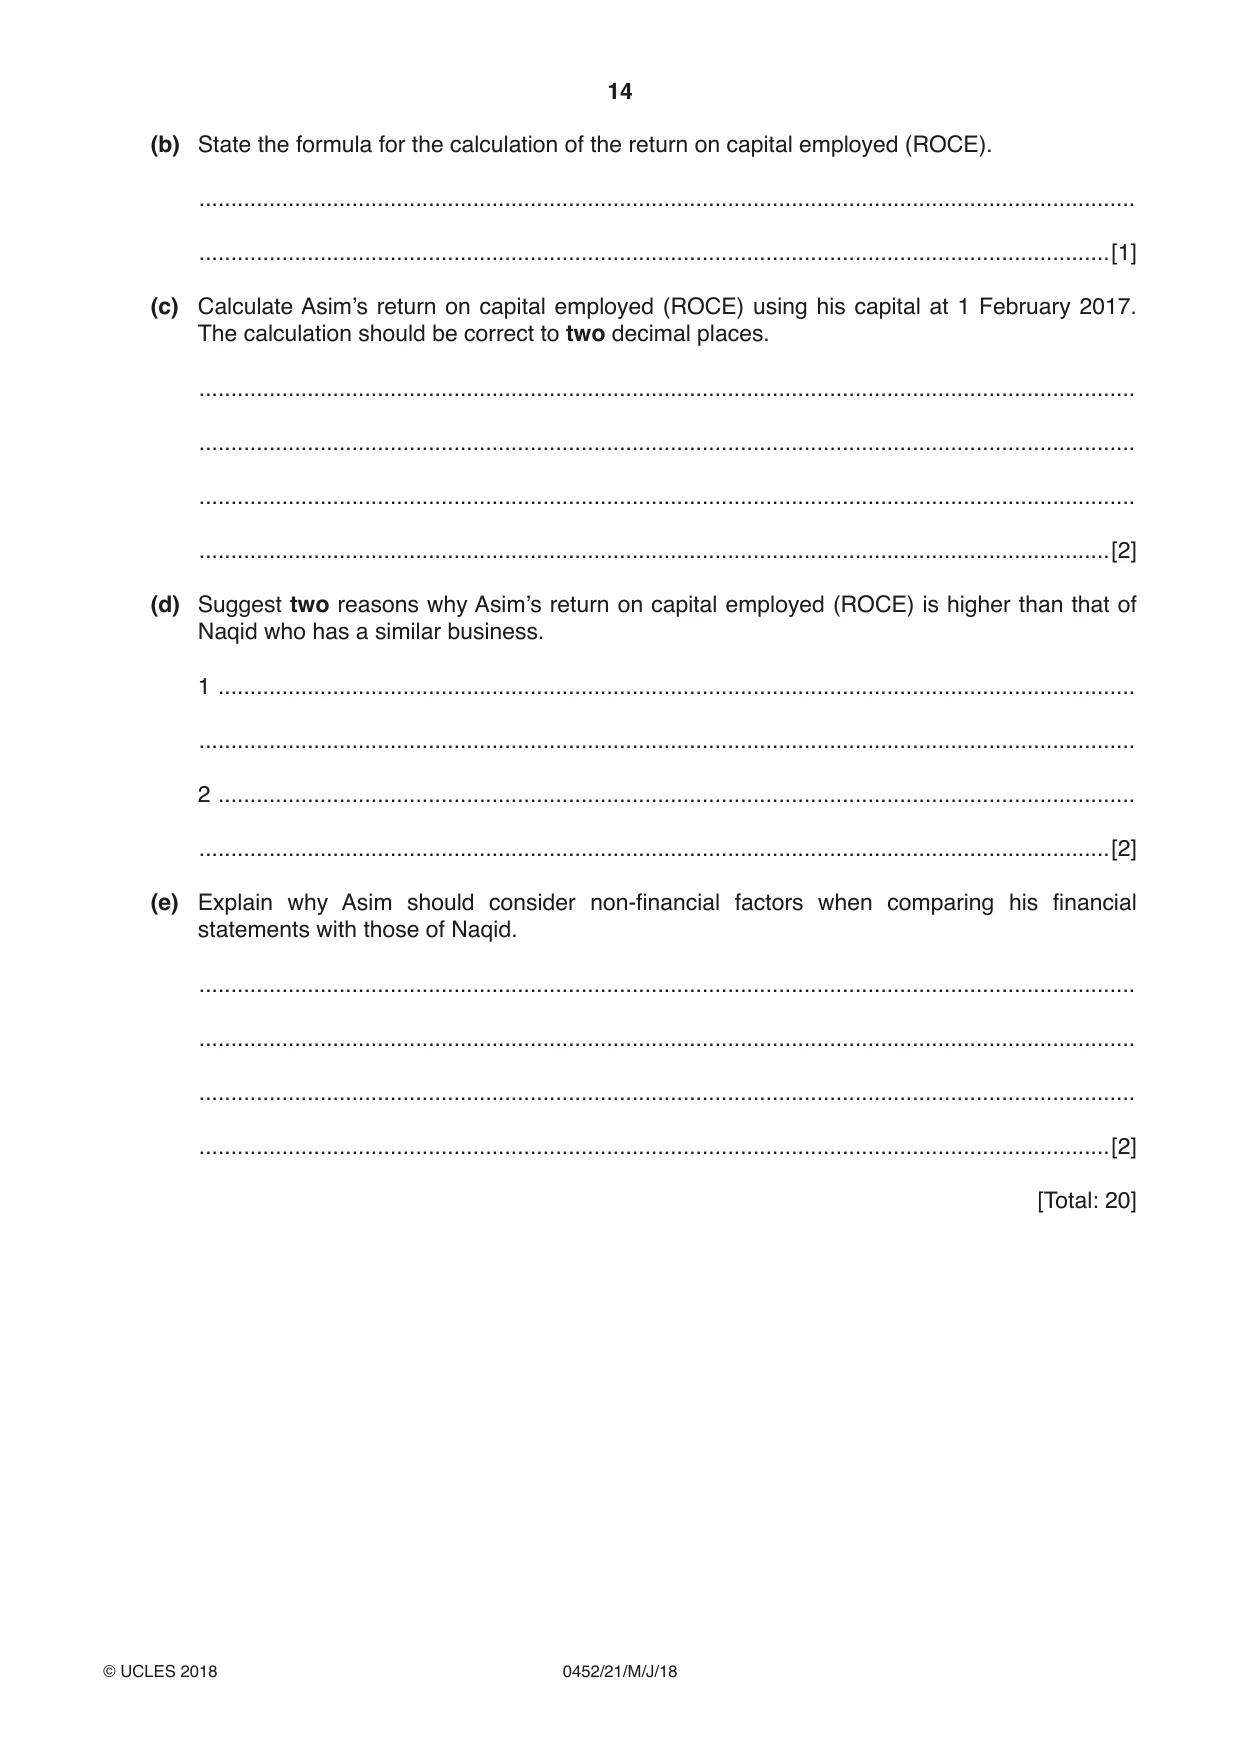
4 Asim has an advertising agency. His financial year ends on 31 January. He provided the following information on 31 January 2018. $ Capital at 1 February 2017 120 000 Drawings 8 500 Office equipment at valuation at 1 February 2017 6 180 Motor vehicle at cost 15 000 Provision for depreciation of motor vehicle 5 400 Fees received from clients 28 350 Wages of assistant 19 000 General expenses 1 358 Motor expenses 970 Rates and insurance 2 280 Rent received from tenant 5 600 Additional information 1 At 31 January 2018 $2400 was outstanding from clients for fees. Motor expenses outstanding amounted to $110. A provision for doubtful debts of 2% of the amount owed by clients should be created. 2 The rates and insurance paid were for a period of 15 months from 1 February 2017. 3 Part of the premises were let to a tenant on 1 February 2017 at an annual rent of $4800. 4 One quarter of the motor expenses are for Asim’s personal use of the motor vehicle. 5 The motor vehicle is to be depreciated at 20% per annum using the reducing (diminishing) balance method. 6 The office equipment was valued at $5500 on 31 January 2018. No office equipment was purchased or sold during the year. REQUIRED (a) Prepare Asim’s income statement for the year ended 31 January 2018. Asim Income Statement for the year ended 31 January 2018 $ $ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ [13] (b) State the formula for the calculation of the return on capital employed (ROCE). ................................................................................................................................................... ...............................................................................................................................................[1] (c) Calculate Asim’s return on capital employed (ROCE) using his capital at 1 February 2017. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (d) Suggest two reasons why Asim’s return on capital employed (ROCE) is higher than that of Naqid who has a similar business. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] (e) Explain why Asim should consider non-financial factors when comparing his financial statements with those of Naqid. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] [Total: 20]
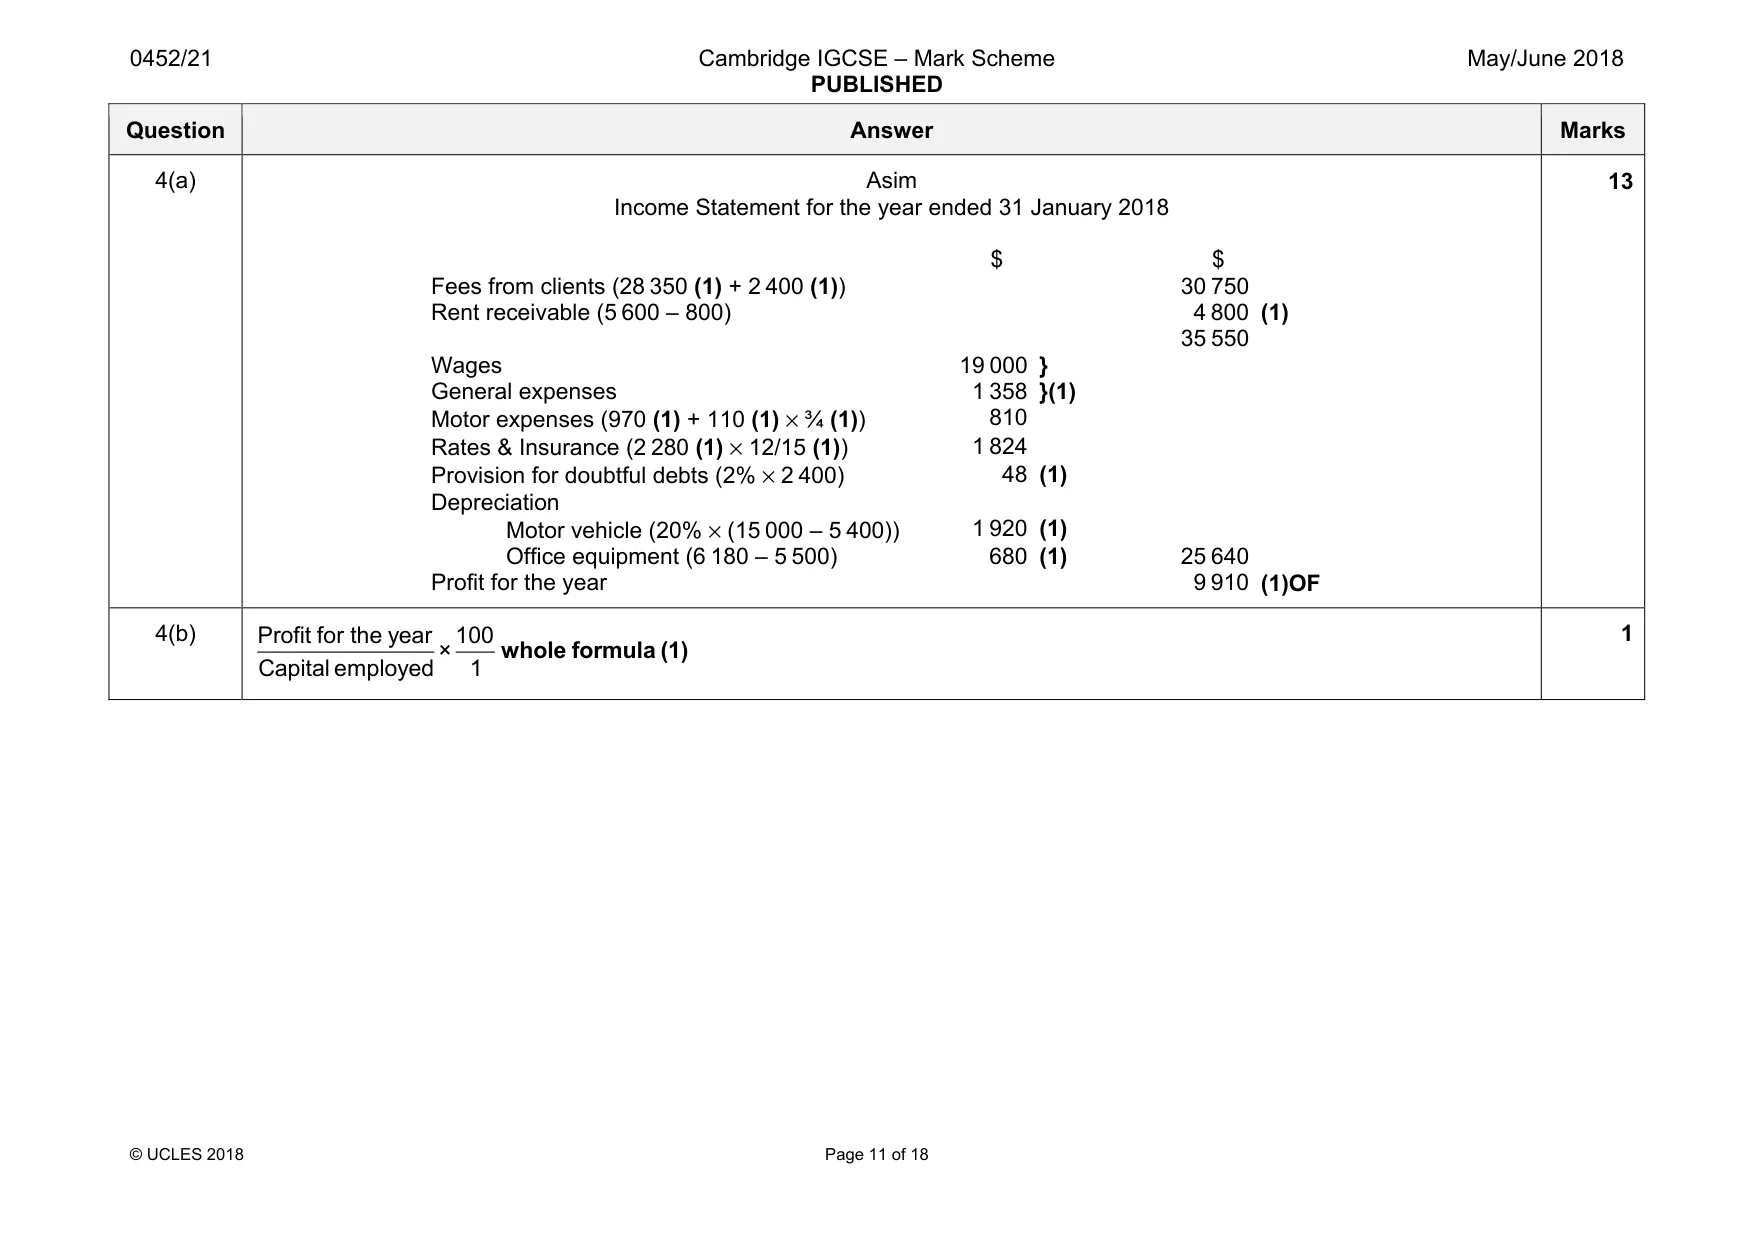
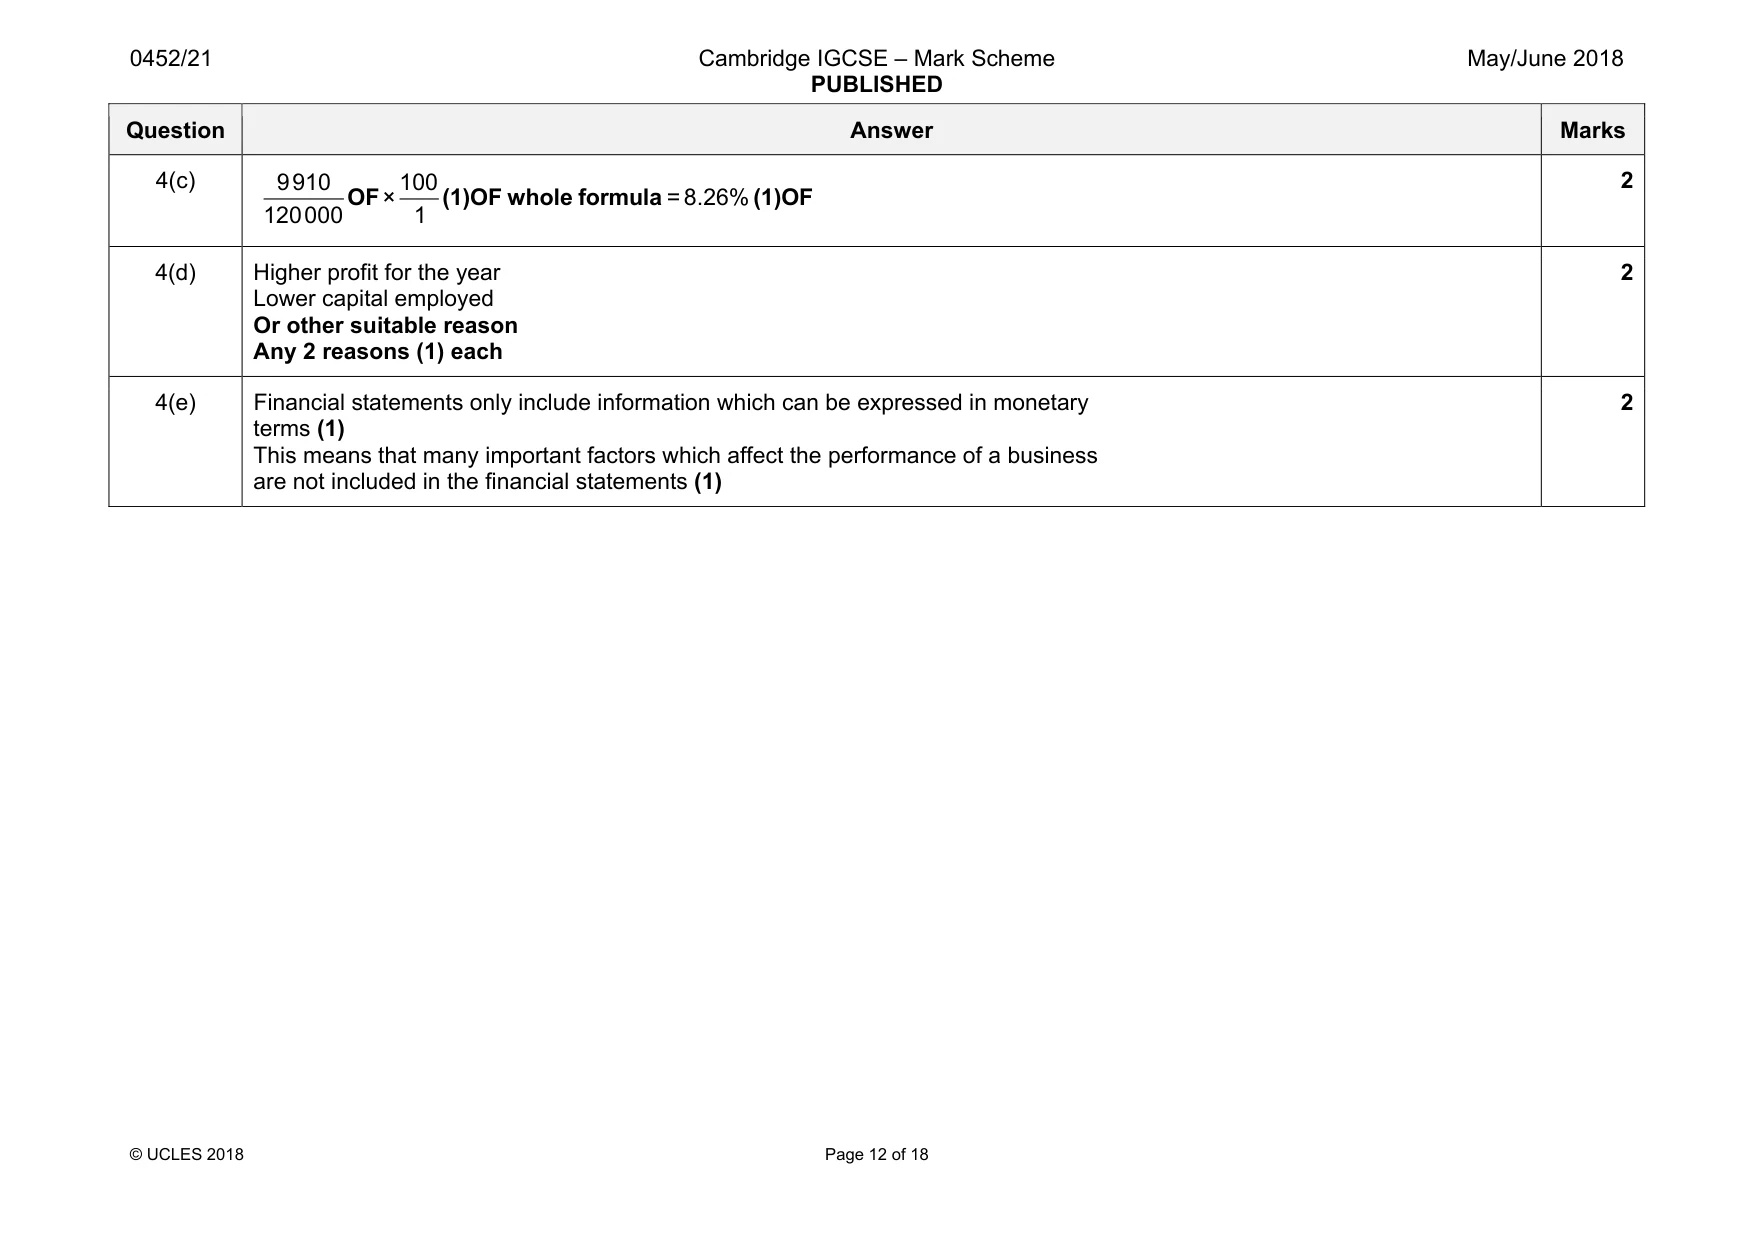
Mark scheme: 4(a) Asim Income Statement for the year ended 31 January 2018 $ $ Fees from clients (28 350 (1) + 2 400 (1)) 30 750 Rent receivable (5 600 – 800) 4 800 (1) 35 550 Wages 19 000 } General expenses 1 358 }(1) Motor expenses (970 (1) + 110 (1) × ¾ (1)) 810 Rates & Insurance (2 280 (1) × 12/15 (1)) 1 824 Provision for doubtful debts (2% × 2 400) 48 (1) Depreciation Motor vehicle (20% × (15 000 – 5 400)) 1 920 (1) Office equipment (6 180 – 5 500) 680 (1) 25 640 Profit for the year 9 910 (1)OF 13 4(b) Profit for the year 100 × Capital employed 1 whole formula (1) 1 Question Answer Marks 4(c) 9910 100 × = 8.26% 120000 1 OF (1)OF whole formula (1)OF 2 4(d) Higher profit for the year Lower capital employed Or other suitable reason Any 2 reasons (1) each 2 4(e) Financial statements only include information which can be expressed in monetary terms (1) This means that many important factors which affect the performance of a business are not included in the financial statements (1) 2
Q5 · UIRED Prepare a corrected trial balance at 28 Februar Nabil Corrected Trial Balance at 28…
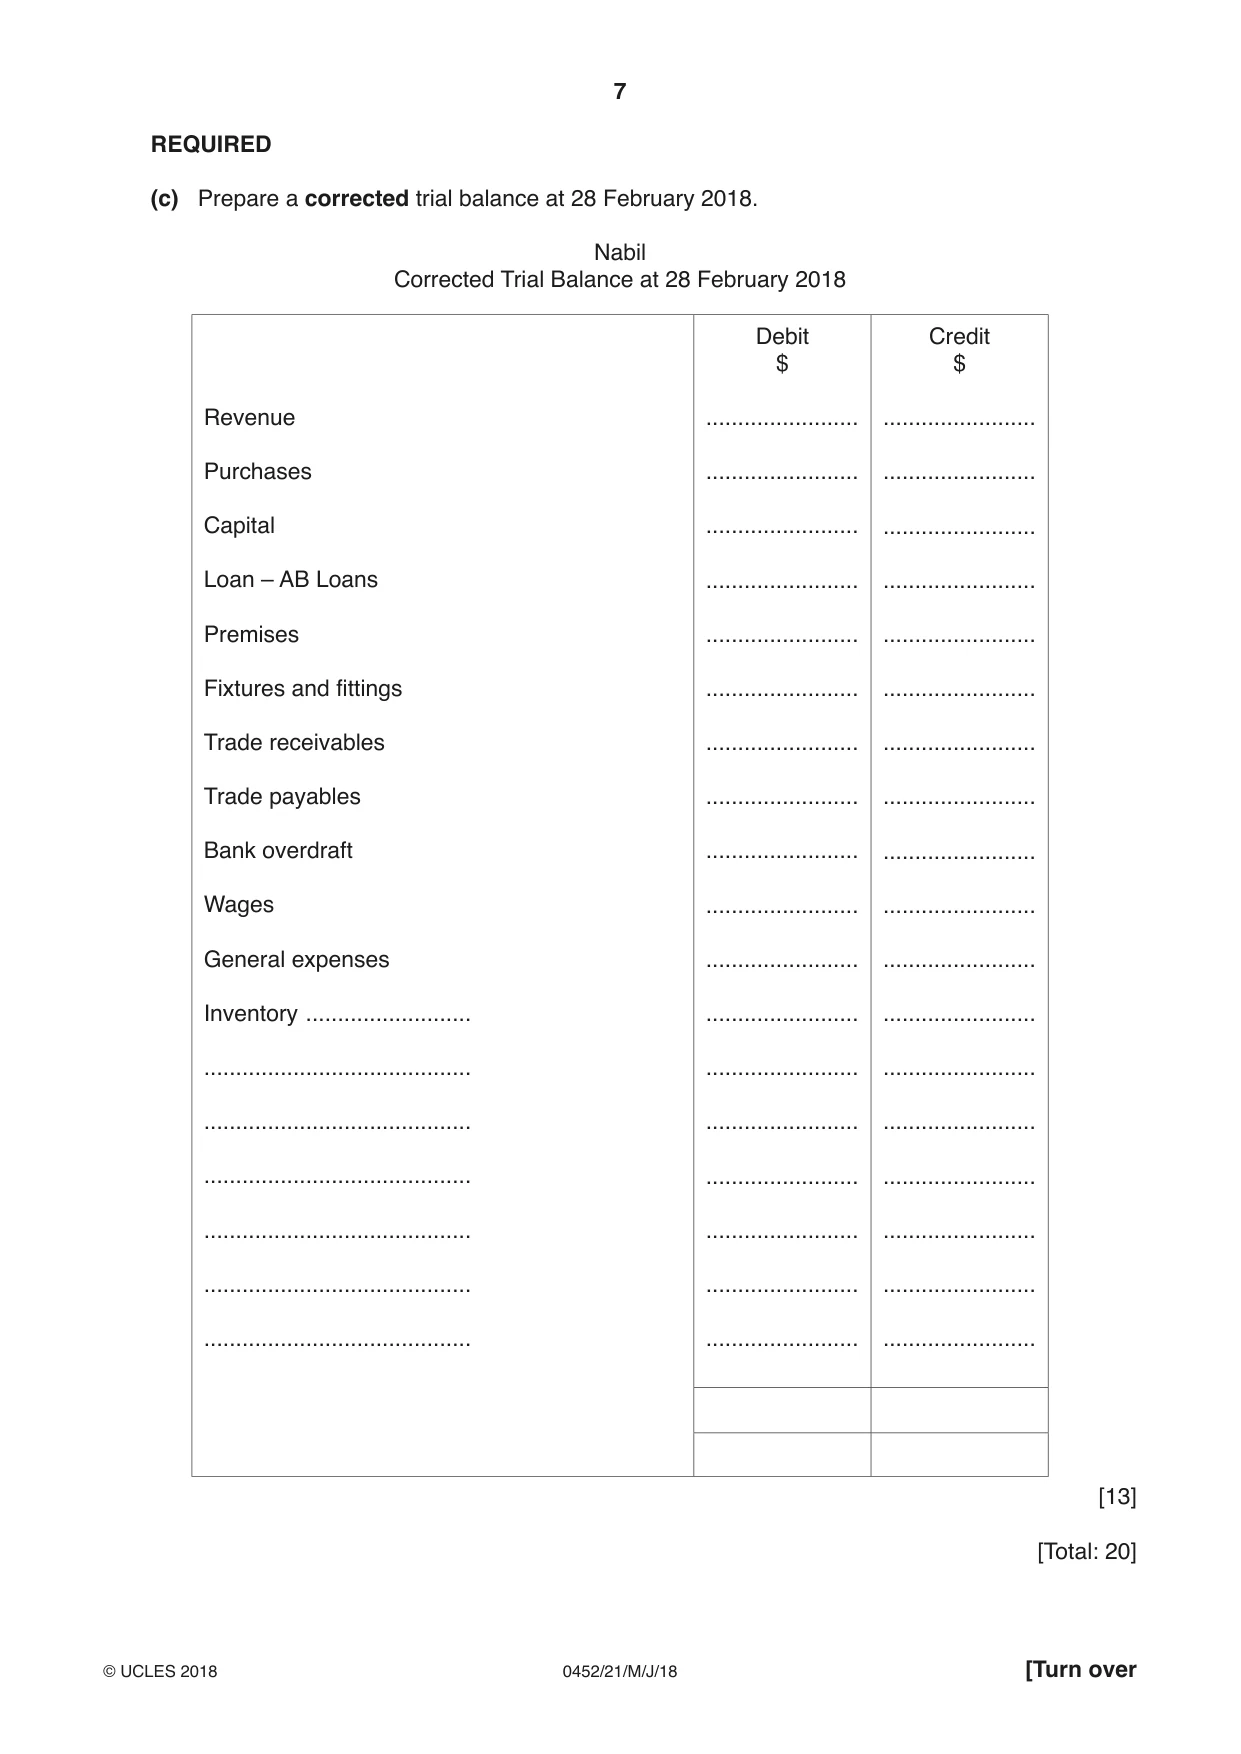
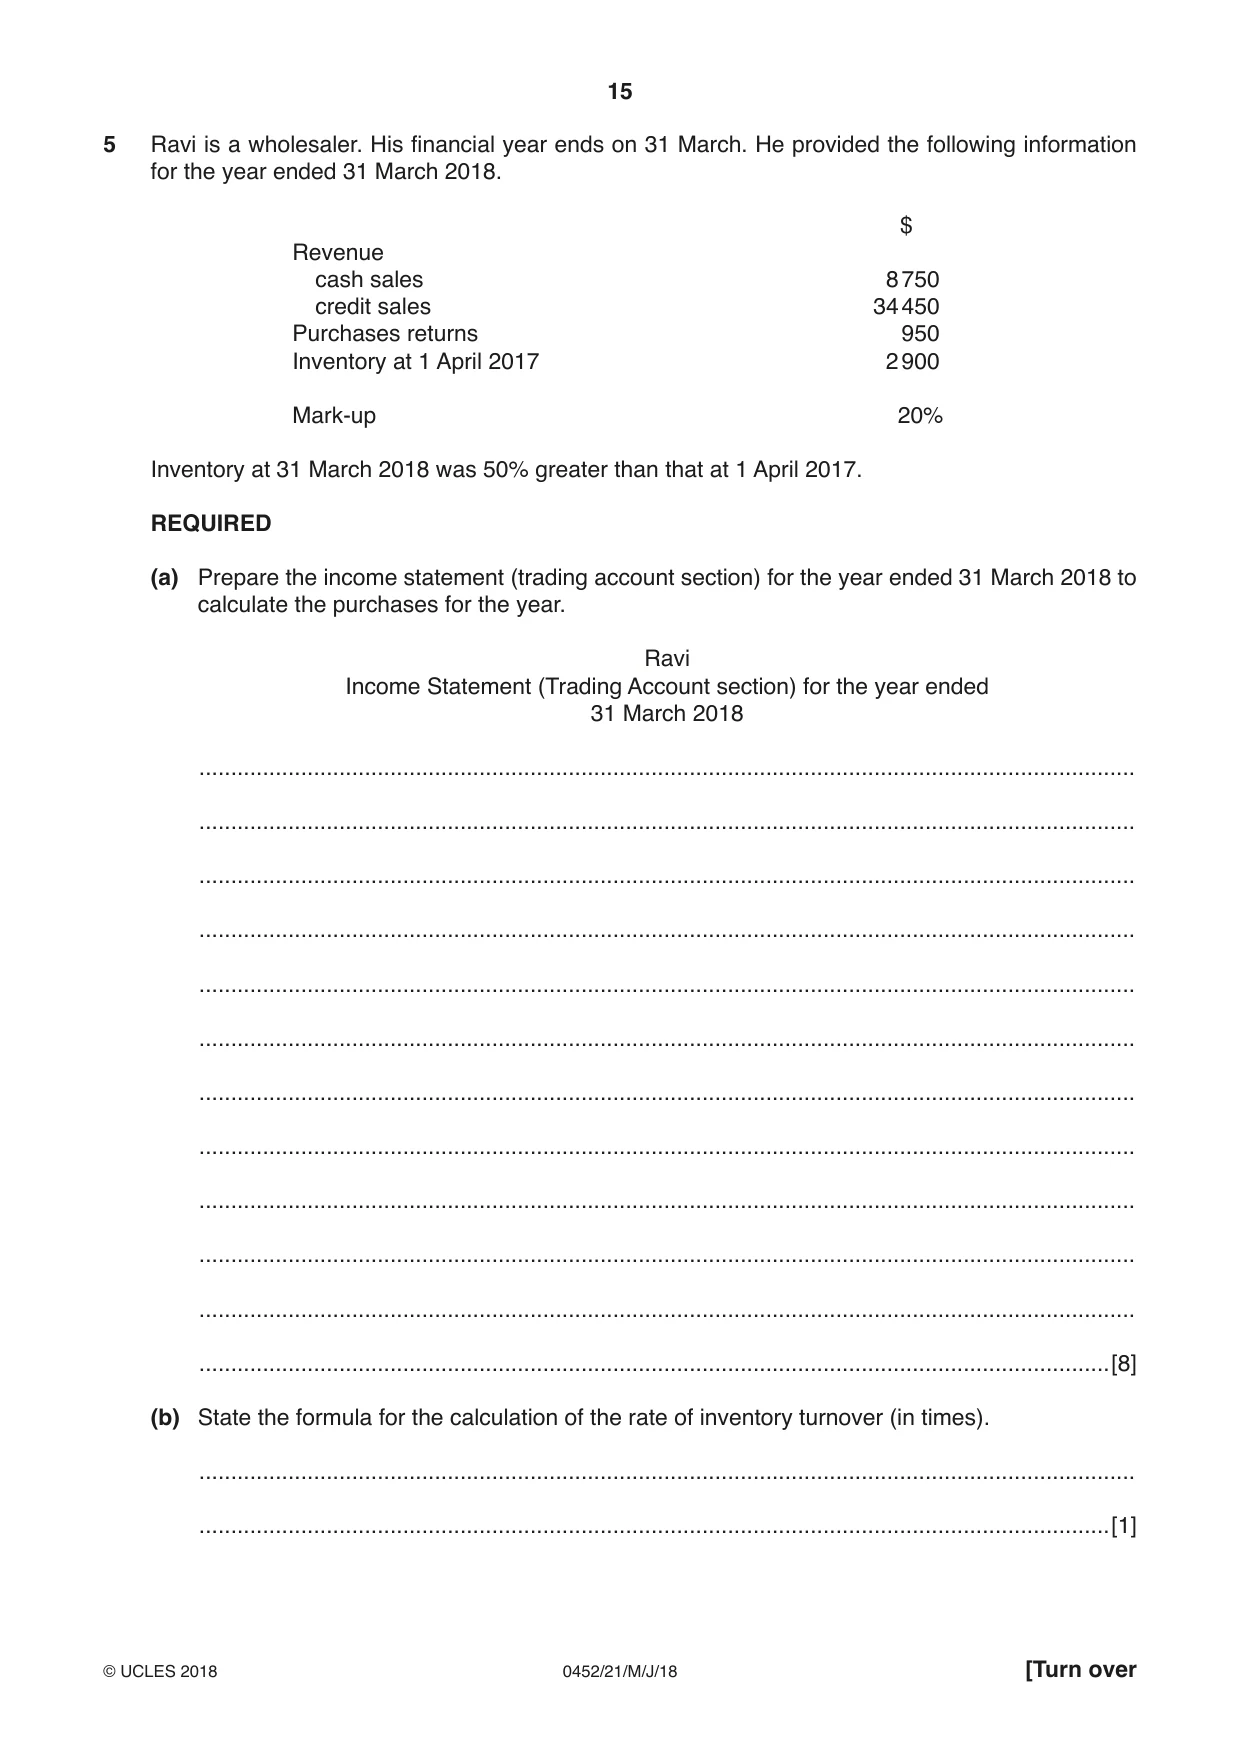
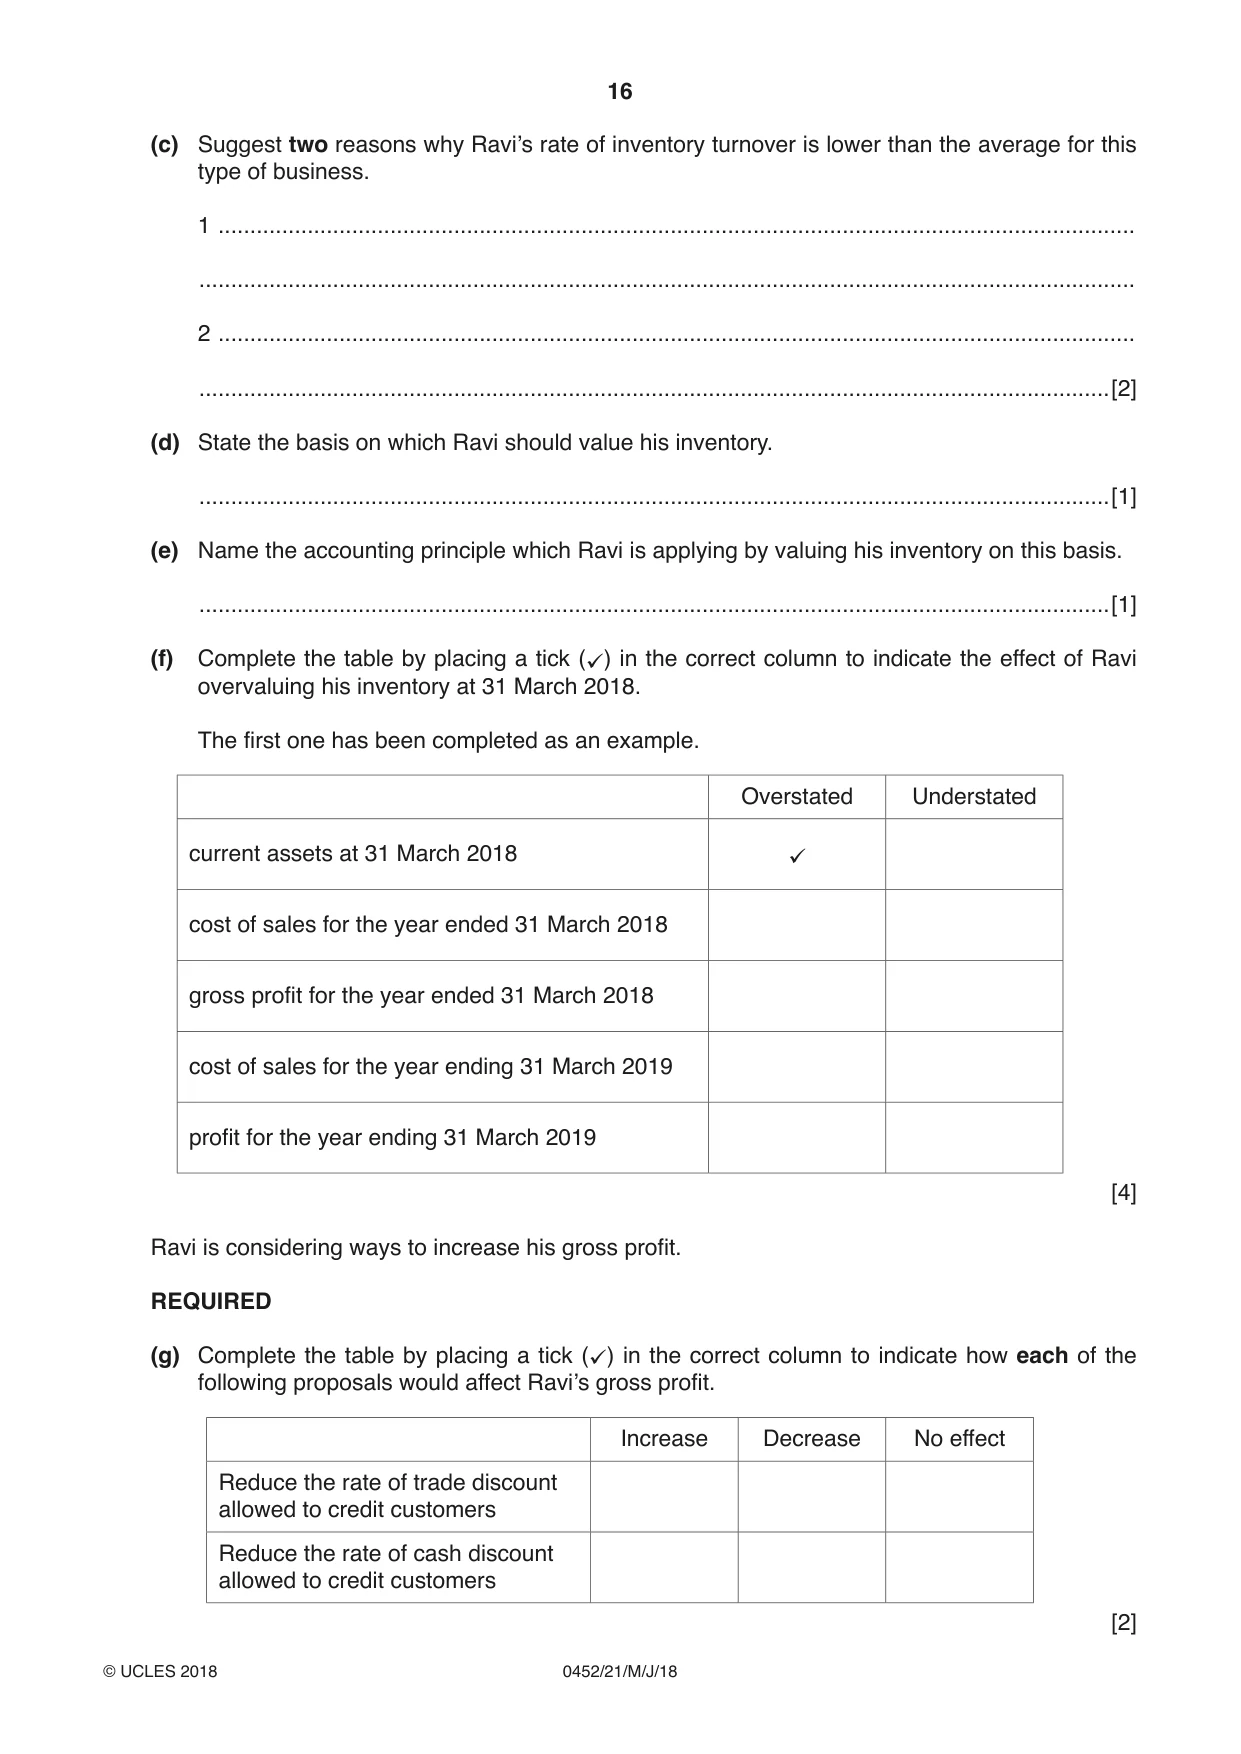
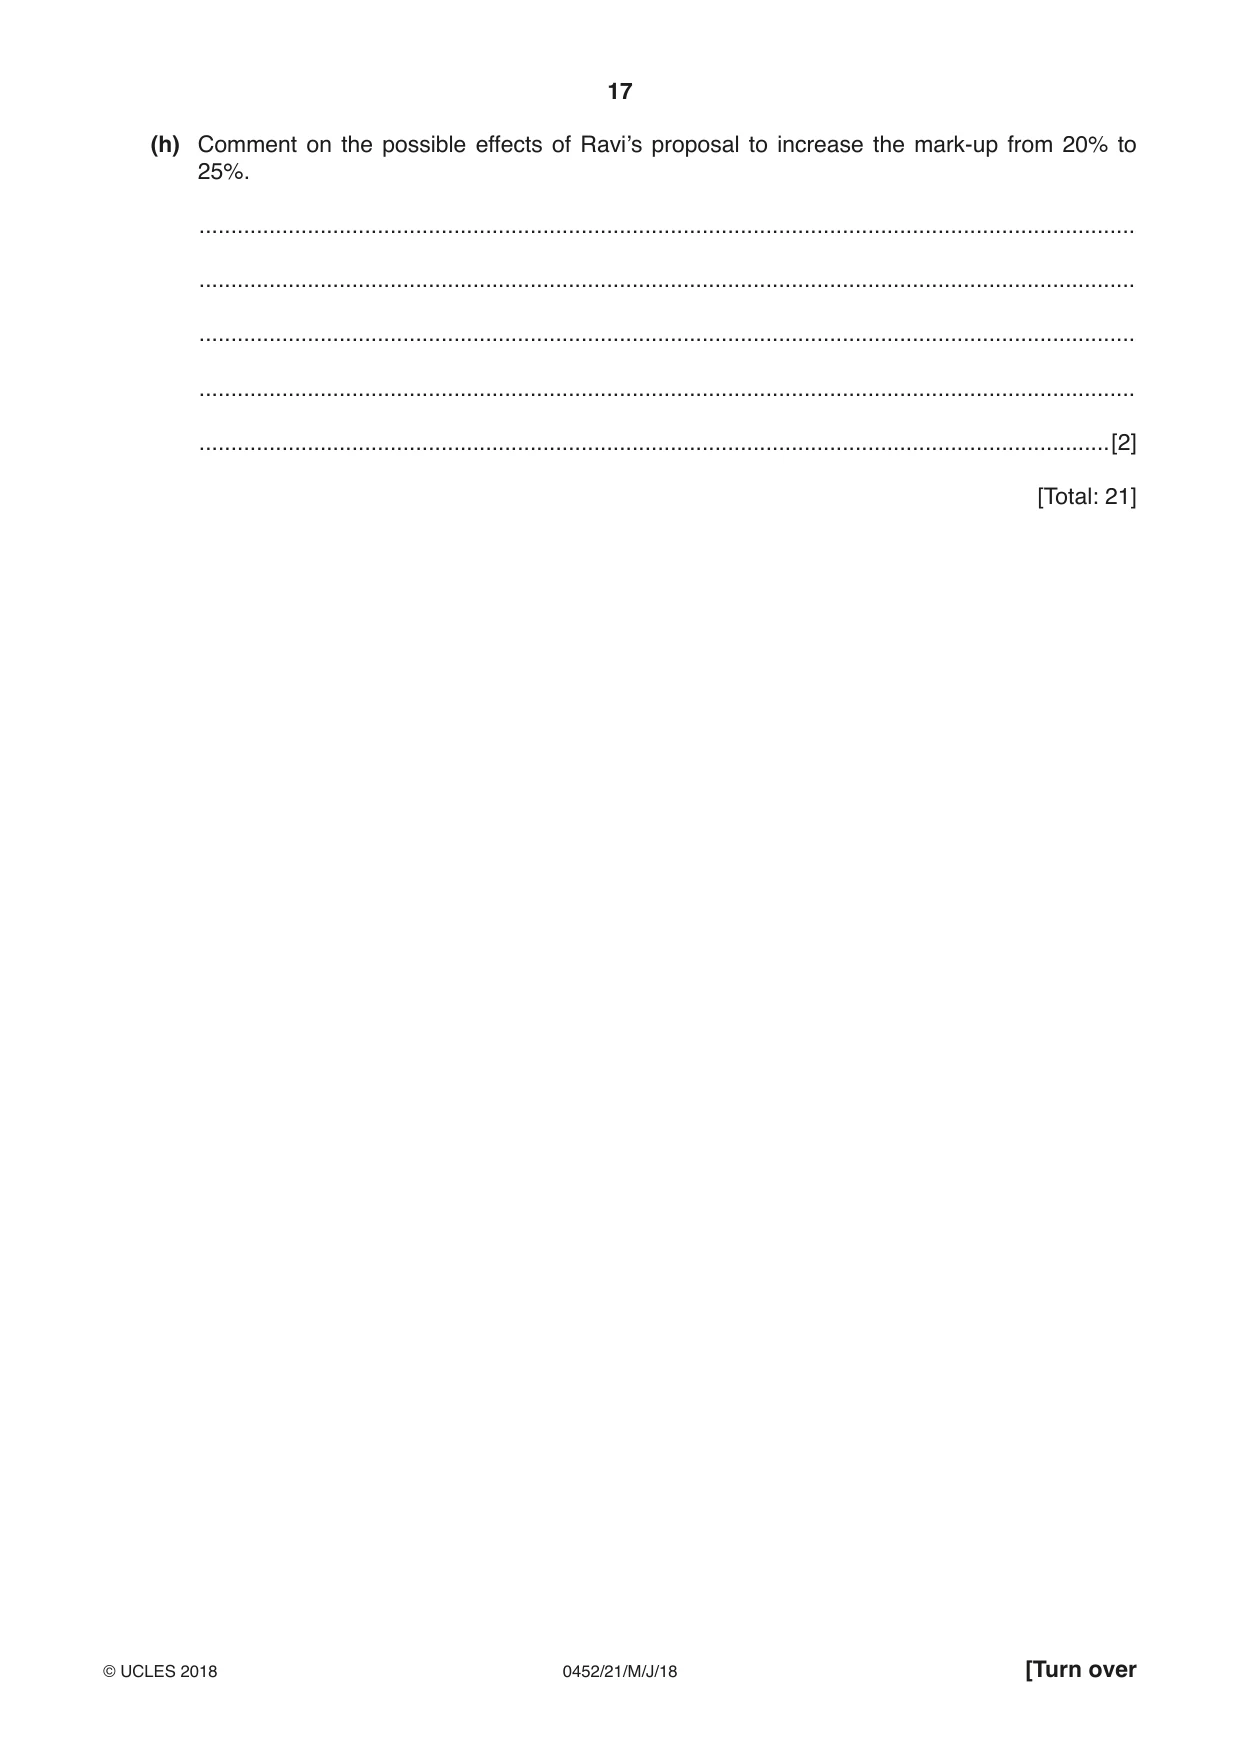
UIRED Prepare a corrected trial balance at 28 Februar Nabil Corrected Trial Balance at 28 Revenue Purchases Capital Loan – AB Loans Premises Fixtures and fittings Trade receivables Trade payables Bank overdraft Wages General expenses Inventory .......................... .......................................... .......................................... .......................................... .......................................... .......................................... .......................................... 3 Masuma owns a furniture store. She maintains a full set of accounting records. Her financial year ends on 31 March. Masuma provided the following information at 31 March 2018. 1 On 1 April 2017 Amina, a credit customer, owed $160. On 1 March 2018 she paid 75% of this and the balance was written off as a bad debt. 2 On 4 January 2018 additional fixtures and fittings, $2000, were purchased on credit from Office Traders, but this transaction was not recorded. 3 The fixtures and fittings are depreciated at the rate of 20% per annum on the cost of equipment held at the end of each financial year. 4 On 31 March 2018 the discount columns in the cash book showed the following totals for the month: discount column on debit side $55 discount column on credit side $68 These totals had not been transferred to the discount accounts in the ledger. REQUIRED (a) Record this information in the following accounts in Masuma’s ledger at 31 March 2018. Some entries have already been made in the accounts during the year. Close all the accounts by balancing or by making a transfer to an appropriate account. Masuma Amina account Date Details $ Date Details $ 2017 April 1 Balance b/d 160 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Bad debts account Date Details $ Date Details $ 2018 Feb 28 Total written off 135 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Fixtures and fittings account Date Details $ Date Details $ 2017 April 1 Balance b/d 4000 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Provision for depreciation of fixtures and fittings account Date Details $ Date Details $ 2017 ............ .................................... .............. April 1 Balance b/d 1600 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Discount allowed account Date Details $ Date Details $ 2018 Feb 28 Total to date 3590 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. Discount received account Date Details $ Date Details $ 2018 ............ .................................... .............. Feb 28 Total to date 4130 ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. ............ .................................... .............. [12] The following account appeared in Masuma’s ledger on 31 March 2018. Disposal of motor vehicle account Date Details $ Date Details $ 2018 2018 Feb 1 Motor vehicles 9500 Feb 1 Provision for depreciation of motor vehicles 4636 M6Vans 3500 Mar 31 Income statement 1364 9500 9500 REQUIRED (b) Explain each entry in the disposal of motor vehicle account. Name the account in which the double entry would be made for each item. State whether that account would be debited or credited. February 1 Motor vehicles Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. February 1 Provision for depreciation of motor vehicles Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. February 1 M6Vans Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry ............................................................................................................................. March 31 Income statement Explanation ............................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Double entry .........................................................................................................................[8] [Total: 20] 4 Asim has an advertising agency. His financial year ends on 31 January. He provided the following information on 31 January 2018. $ Capital at 1 February 2017 120 000 Drawings 8 500 Office equipment at valuation at 1 February 2017 6 180 Motor vehicle at cost 15 000 Provision for depreciation of motor vehicle 5 400 Fees received from clients 28 350 Wages of assistant 19 000 General expenses 1 358 Motor expenses 970 Rates and insurance 2 280 Rent received from tenant 5 600 Additional information 1 At 31 January 2018 $2400 was outstanding from clients for fees. Motor expenses outstanding amounted to $110. A provision for doubtful debts of 2% of the amount owed by clients should be created. 2 The rates and insurance paid were for a period of 15 months from 1 February 2017. 3 Part of the premises were let to a tenant on 1 February 2017 at an annual rent of $4800. 4 One quarter of the motor expenses are for Asim’s personal use of the motor vehicle. 5 The motor vehicle is to be depreciated at 20% per annum using the reducing (diminishing) balance method. 6 The office equipment was valued at $5500 on 31 January 2018. No office equipment was purchased or sold during the year. REQUIRED (a) Prepare Asim’s income statement for the year ended 31 January 2018. Asim Income Statement for the year ended 31 January 2018 $ $ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ ............................................................................... ........................ ........................ [13] (b) State the formula for the calculation of the return on capital employed (ROCE). ................................................................................................................................................... ...............................................................................................................................................[1] (c) Calculate Asim’s return on capital employed (ROCE) using his capital at 1 February 2017. The calculation should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] (d) Suggest two reasons why Asim’s return on capital employed (ROCE) is higher than that of Naqid who has a similar business. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] (e) Explain why Asim should consider non-financial factors when comparing his financial statements with those of Naqid. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] [Total: 20] 5 Ravi is a wholesaler. His financial year ends on 31 March. He provided the following information for the year ended 31 March 2018. $ Revenue cash sales 8 750 credit sales 34 450 Purchases returns 950 Inventory at 1 April 2017 2 900 Mark-up 20% Inventory at 31 March 2018 was 50% greater than that at 1 April 2017. REQUIRED (a) Prepare the income statement (trading account section) for the year ended 31 March 2018 to calculate the purchases for the year. Ravi Income Statement (Trading Account section) for the year ended 31 March 2018 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[8] (b) State the formula for the calculation of the rate of inventory turnover (in times). ................................................................................................................................................... ...............................................................................................................................................[1] (c) Suggest two reasons why Ravi’s rate of inventory turnover is lower than the average for this type of business. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] (d) State the basis on which Ravi should value his inventory. ...............................................................................................................................................[1] (e) Name the accounting principle which Ravi is applying by valuing his inventory on this basis. ...............................................................................................................................................[1] (f) Complete the table by placing a tick () in the correct column to indicate the effect of Ravi overvaluing his inventory at 31 March 2018. The first one has been completed as an example. Overstated Understated current assets at 31 March 2018 cost of sales for the year ended 31 March 2018 gross profit for the year ended 31 March 2018 cost of sales for the year ending 31 March 2019 profit for the year ending 31 March 2019 [4] Ravi is considering ways to increase his gross profit. REQUIRED (g) Complete the table by placing a tick () in the correct column to indicate how each of the following proposals would affect Ravi’s gross profit. Increase Decrease No effect Reduce the rate of trade discount allowed to credit customers Reduce the rate of cash discount allowed to credit customers [2] (h) Comment on the possible effects of Ravi’s proposal to increase the mark-up from 20% to 25%. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[2] [Total: 21]
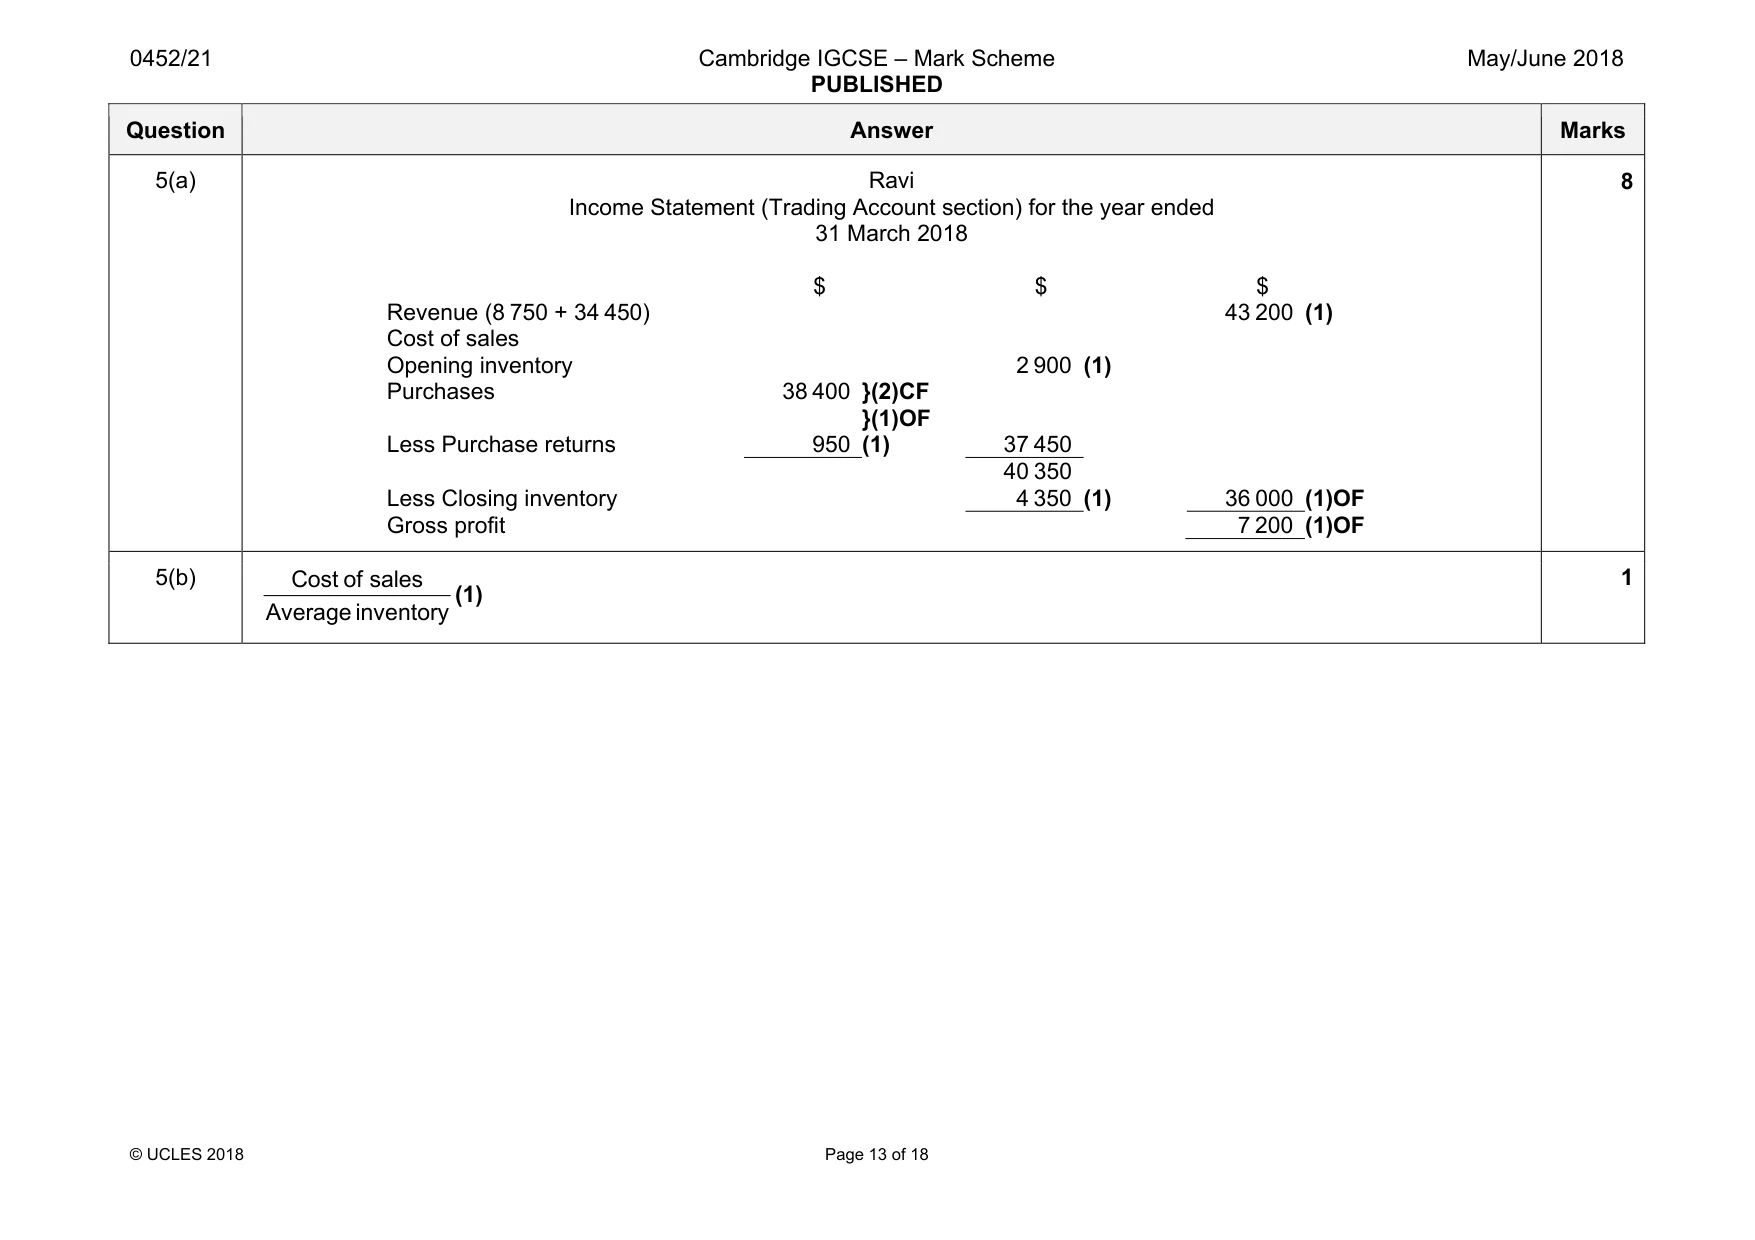
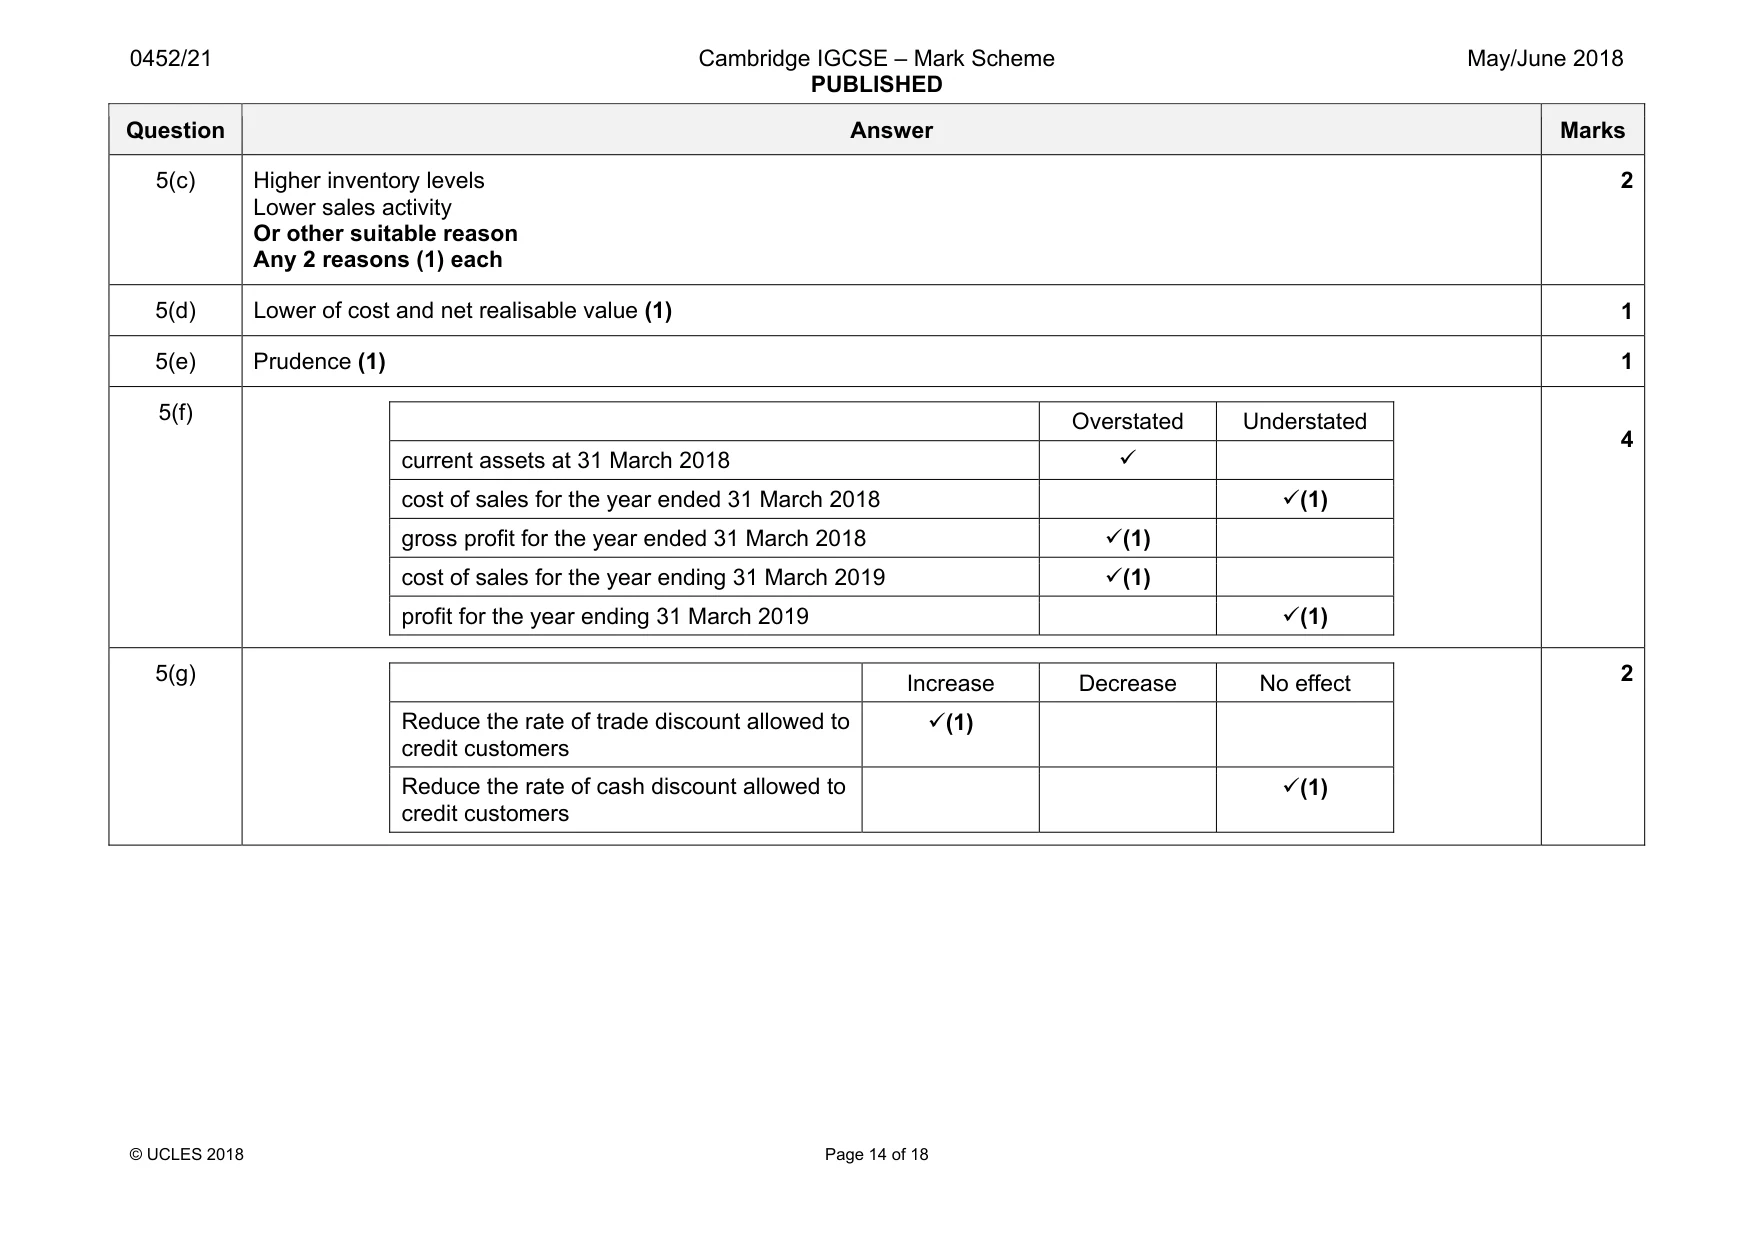
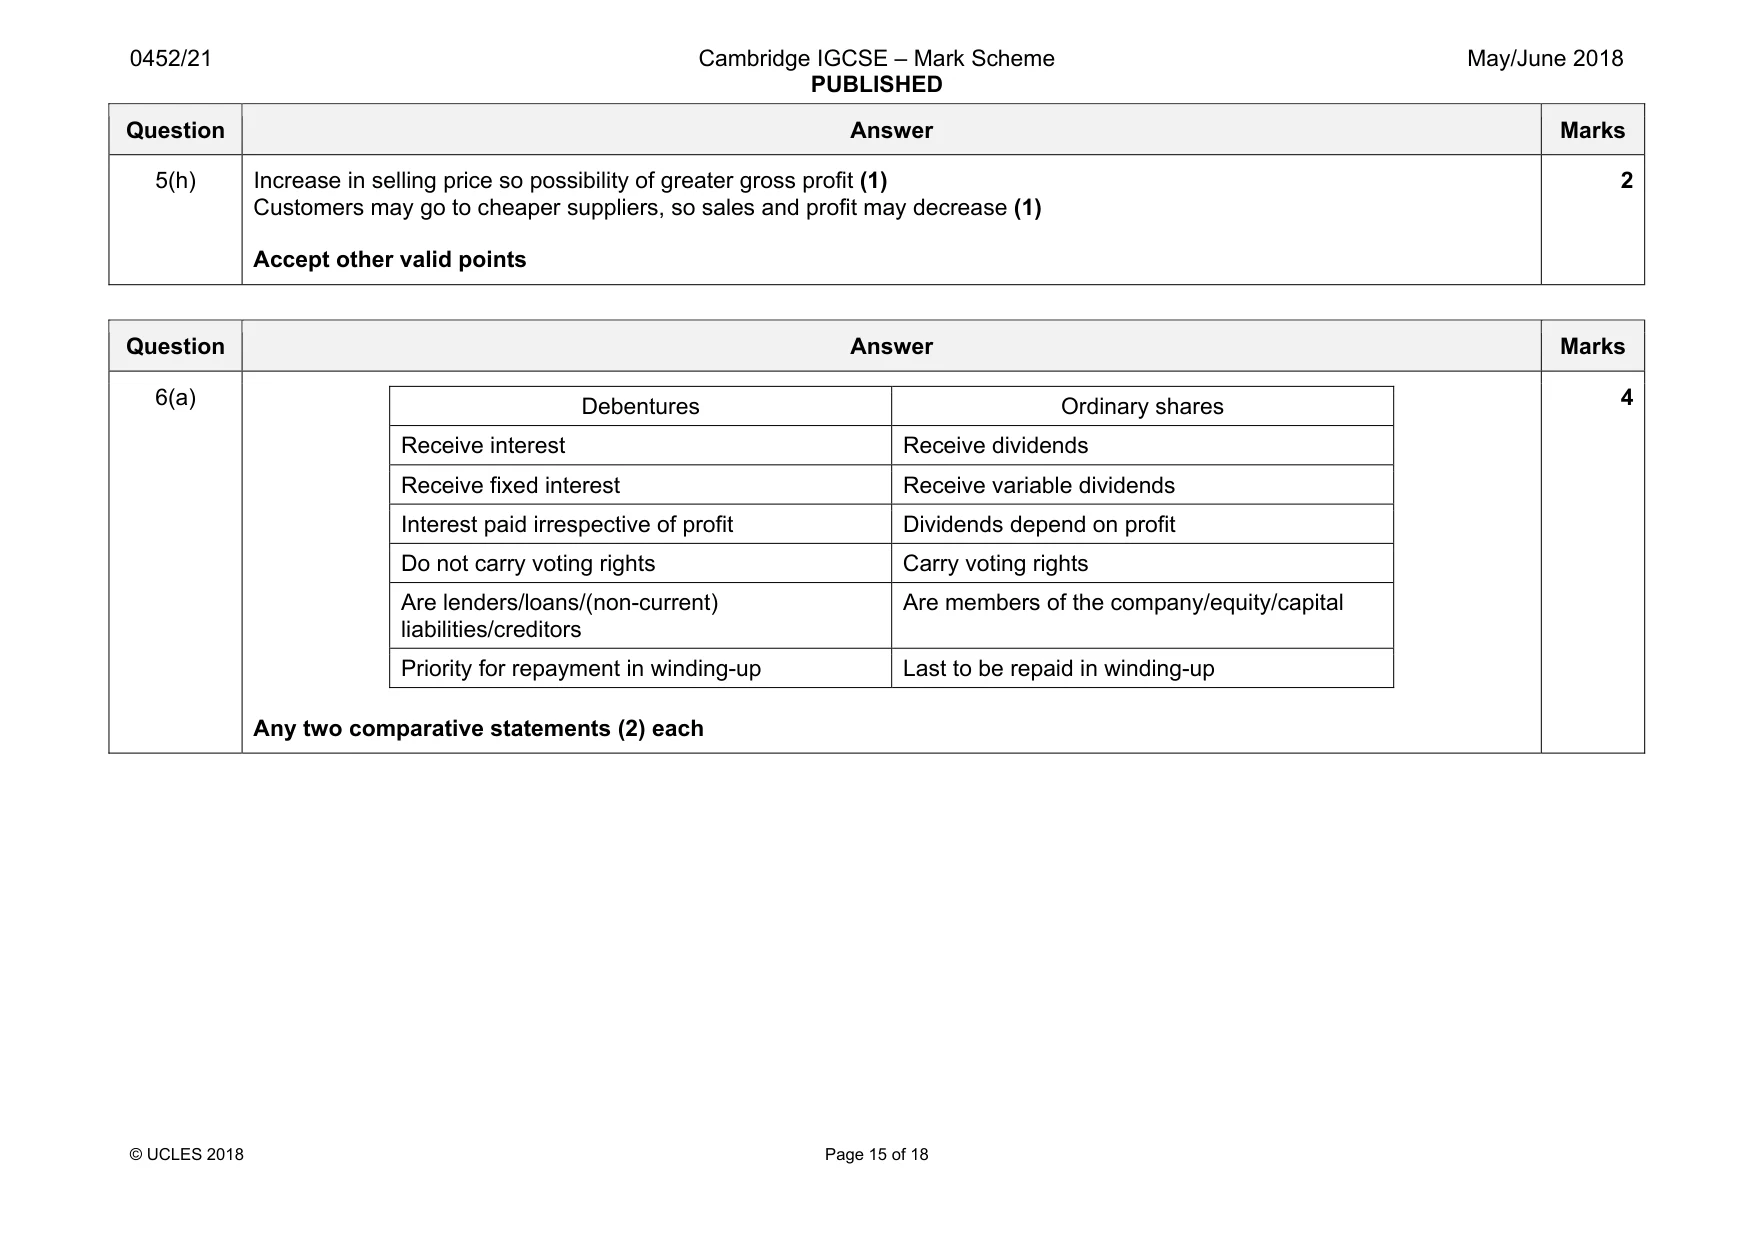
Mark scheme: 5(a) Ravi Income Statement (Trading Account section) for the year ended 31 March 2018 $ $ $ Revenue (8 750 + 34 450) 43 200 (1) Cost of sales Opening inventory 2 900 (1) Purchases 38 400 }(2)CF }(1)OF Less Purchase returns 950 (1) 37 450 40 350 Less Closing inventory 4 350 (1) 36 000 (1)OF Gross profit 7 200 (1)OF 8 5(b) Cost of sales Average inventory (1) 1 Question Answer Marks 5(c) Higher inventory levels Lower sales activity Or other suitable reason Any 2 reasons (1) each 2 5(d) Lower of cost and net realisable value (1) 1 5(e) Prudence (1) 1 5(f) Overstated Understated current assets at 31 March 2018 9 cost of sales for the year ended 31 March 2018 9(1) gross profit for the year ended 31 March 2018 9(1) cost of sales for the year ending 31 March 2019 9(1) profit for the year ending 31 March 2019 9(1) 4 5(g) Increase Decrease No effect Reduce the rate of trade discount allowed to credit customers 9(1) Reduce the rate of cash discount allowed to credit customers 9(1) 2 Question Answer Marks 5(h) Increase in selling price so possibility of greater gross profit (1) Customers may go to cheaper suppliers, so sales and profit may decrease (1) Accept other valid points 2
Q6 · The financial year of CD Limited ends on 30 April
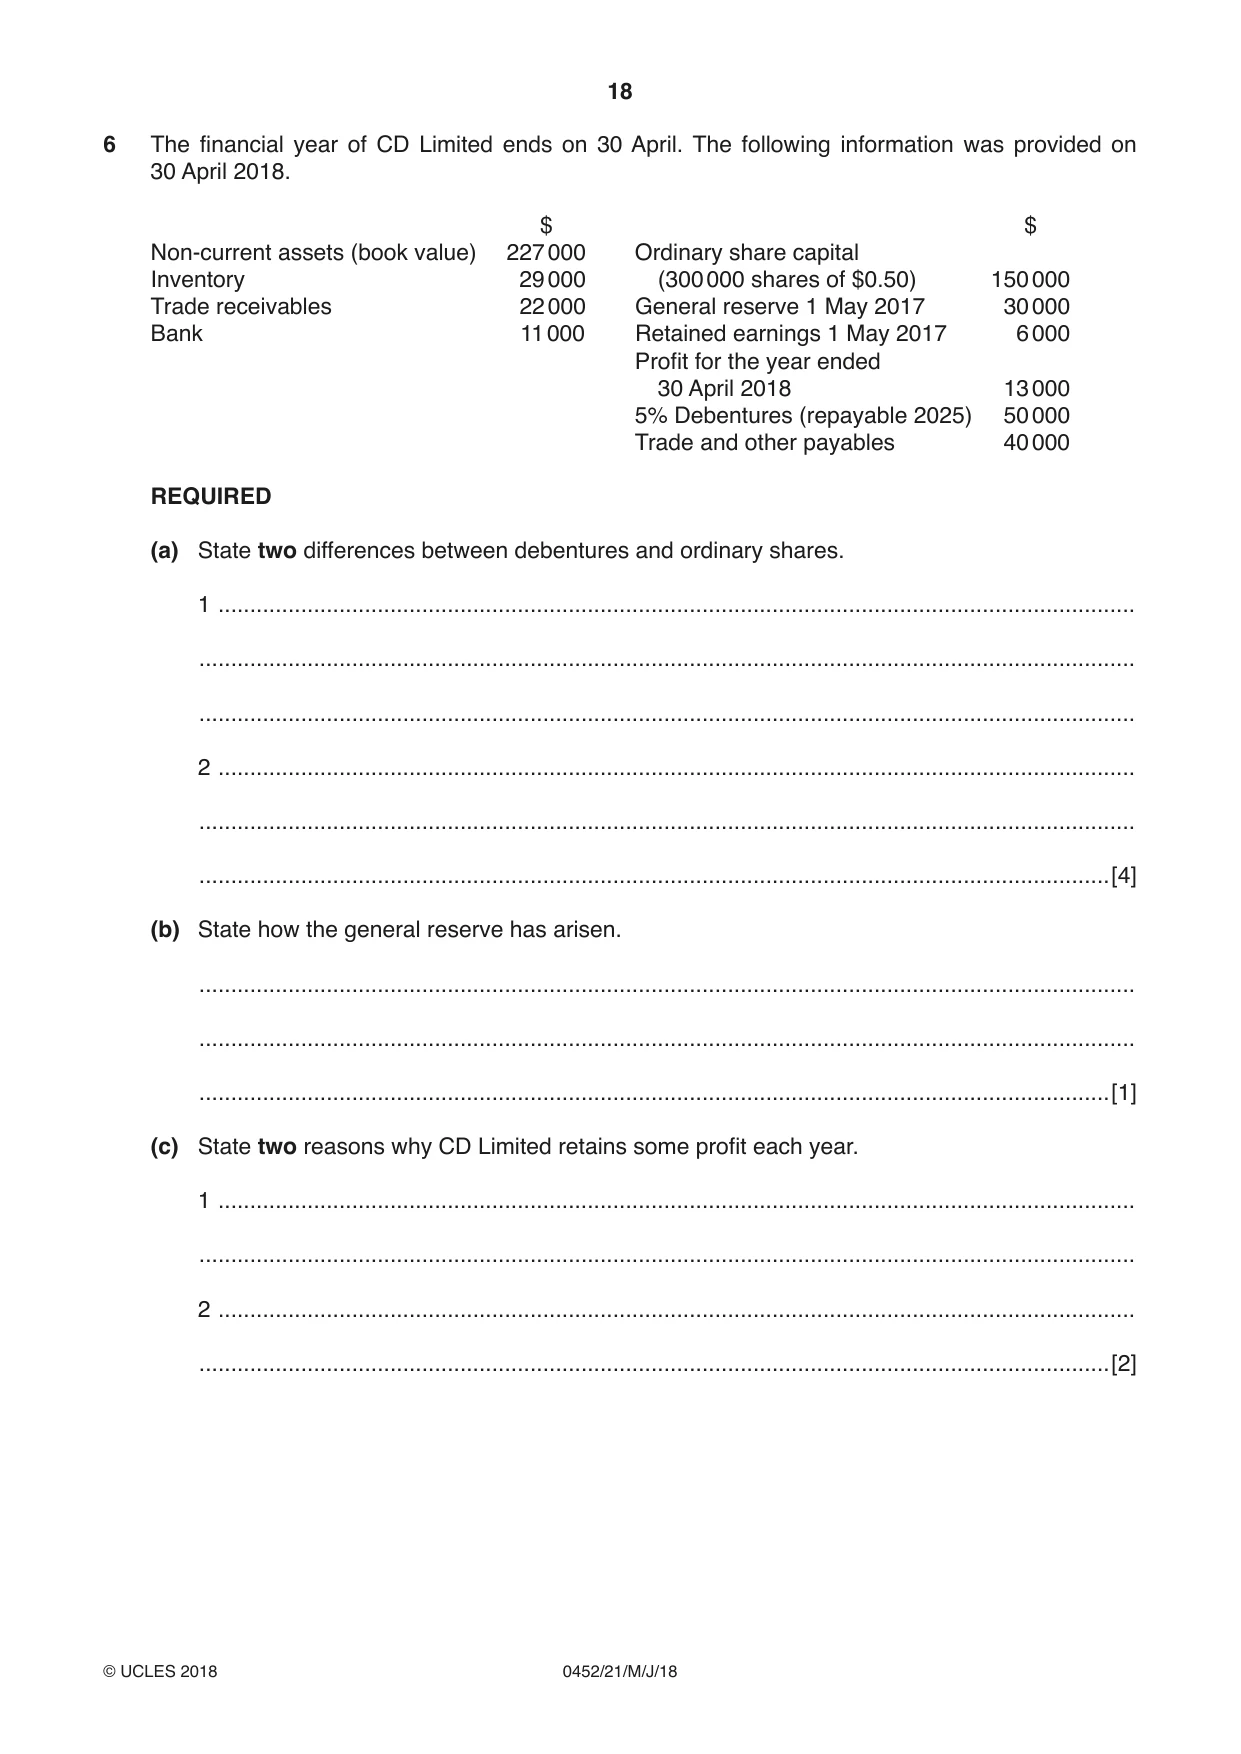
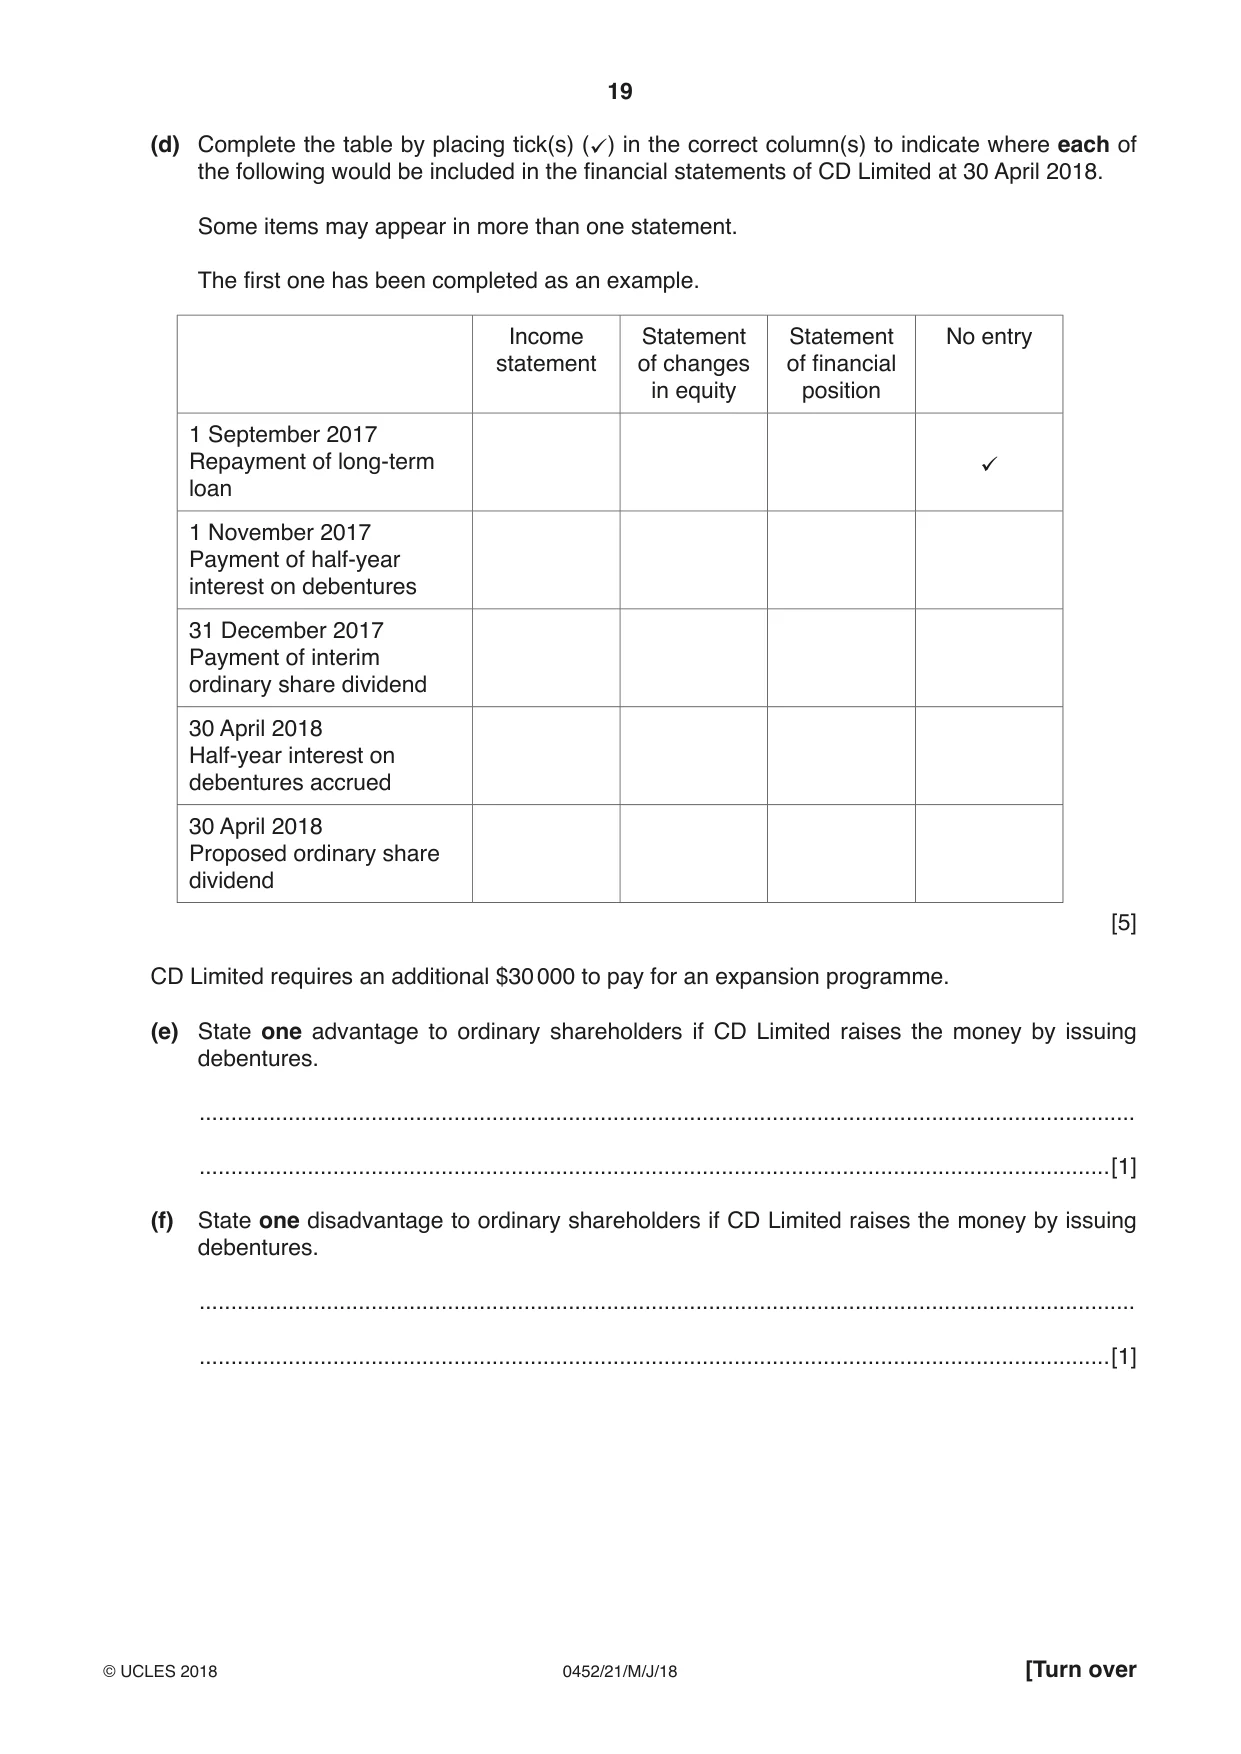
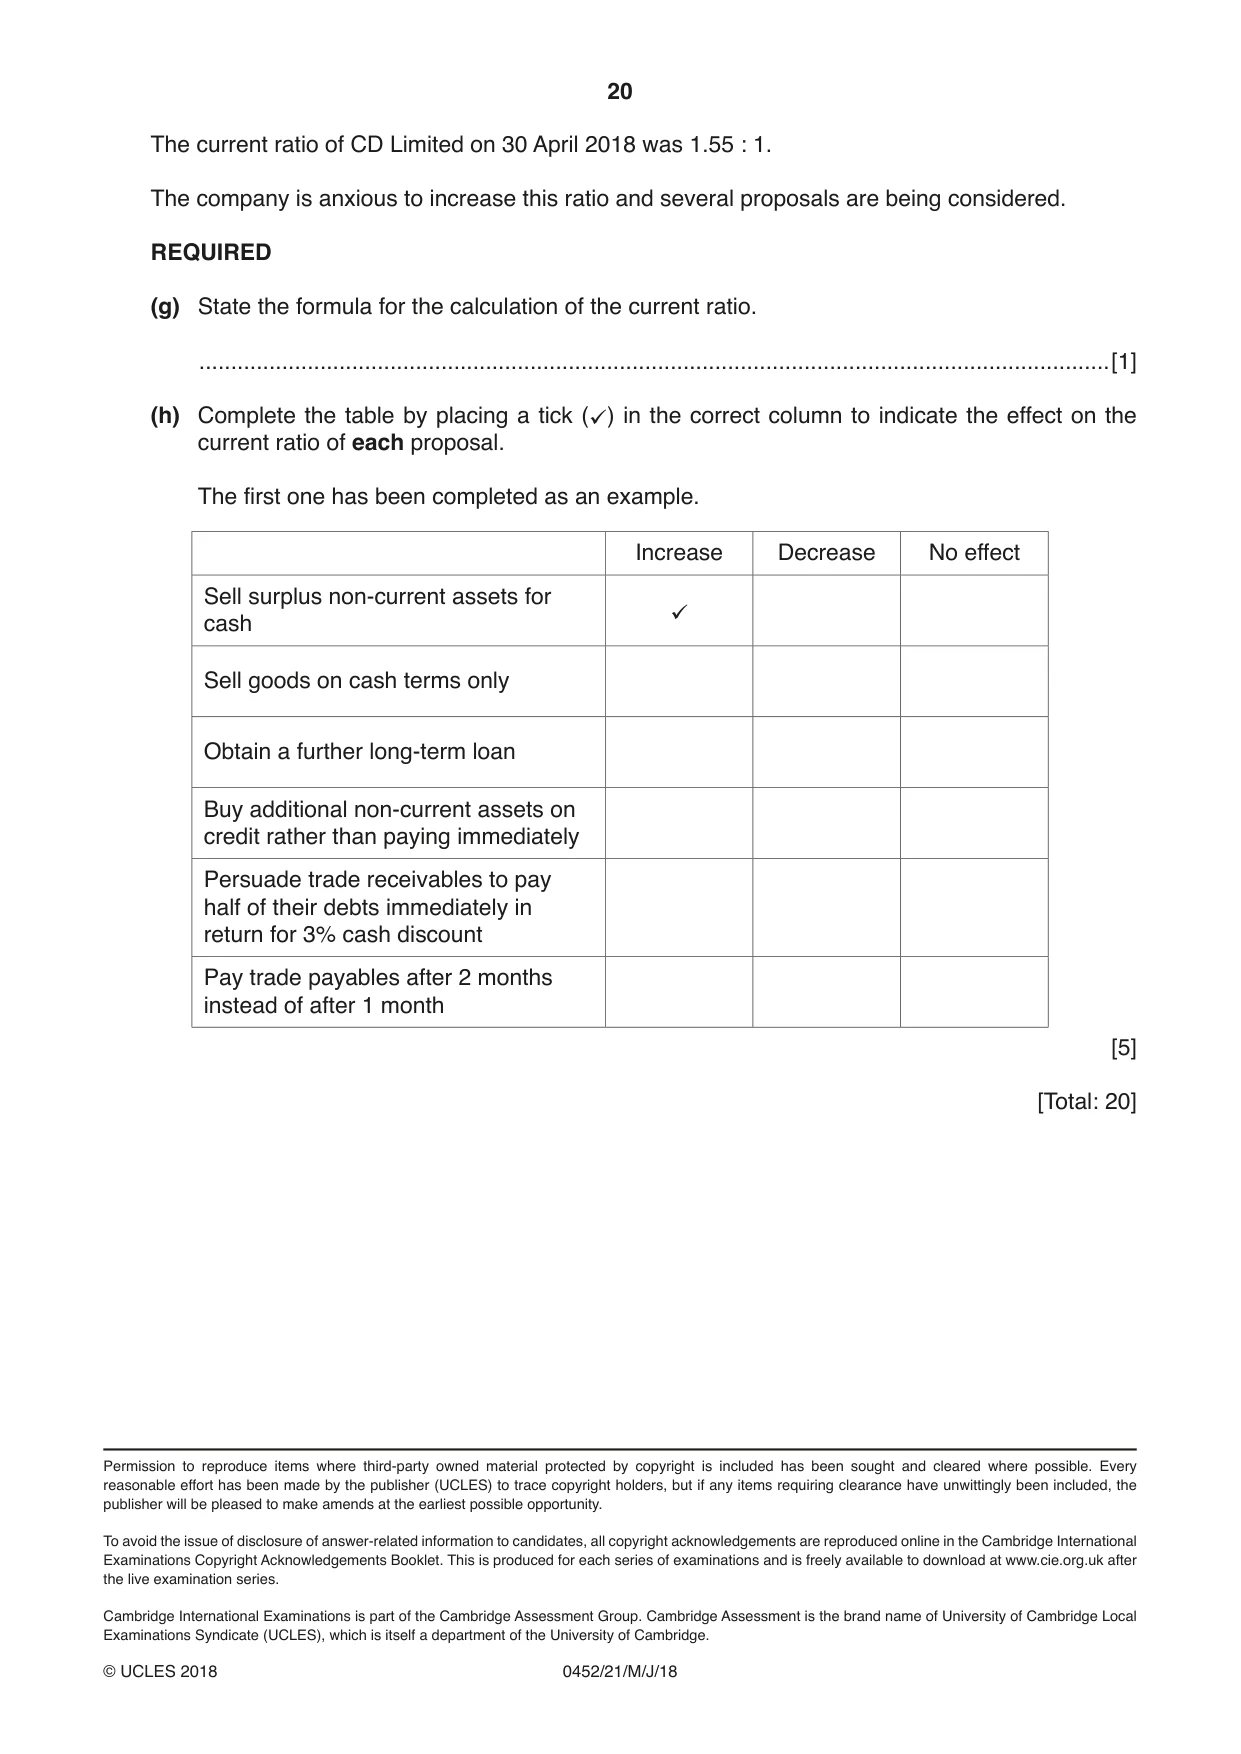
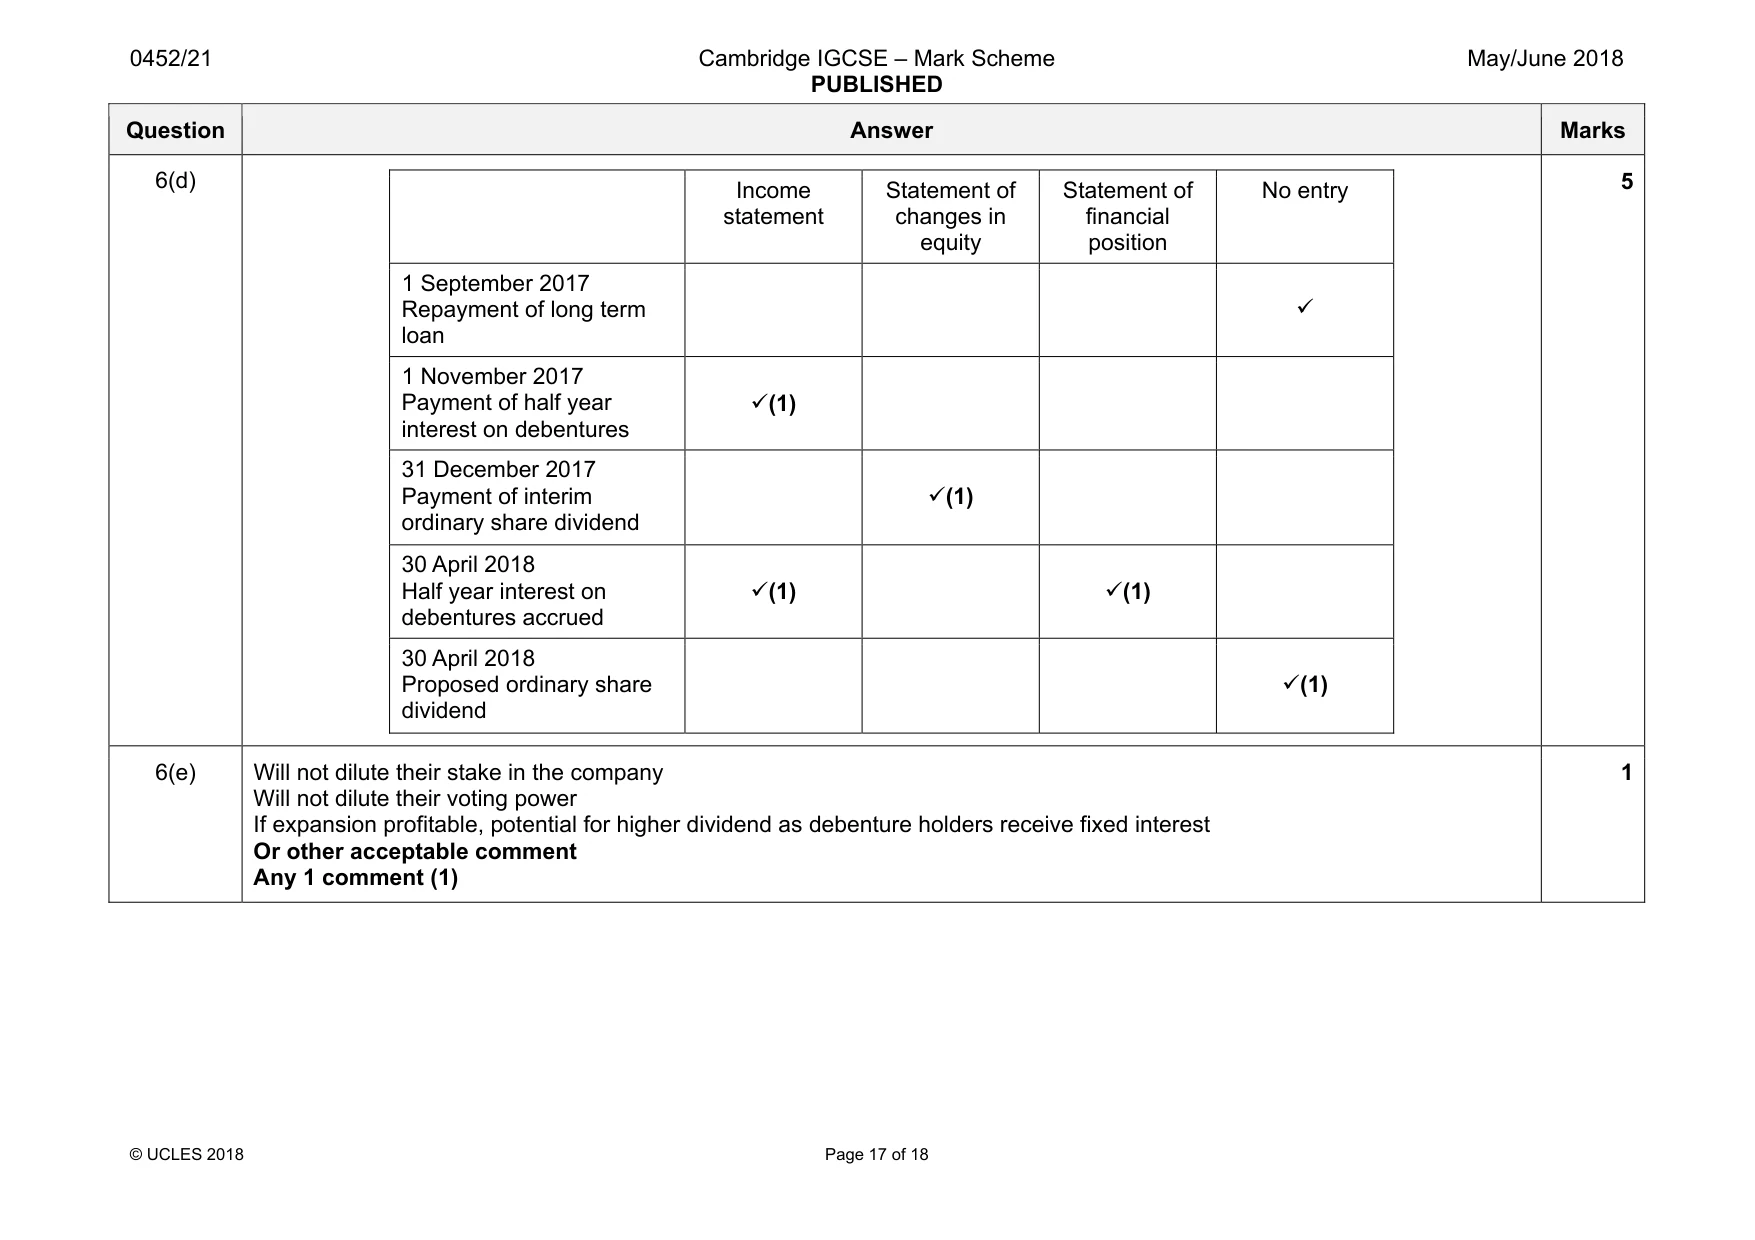
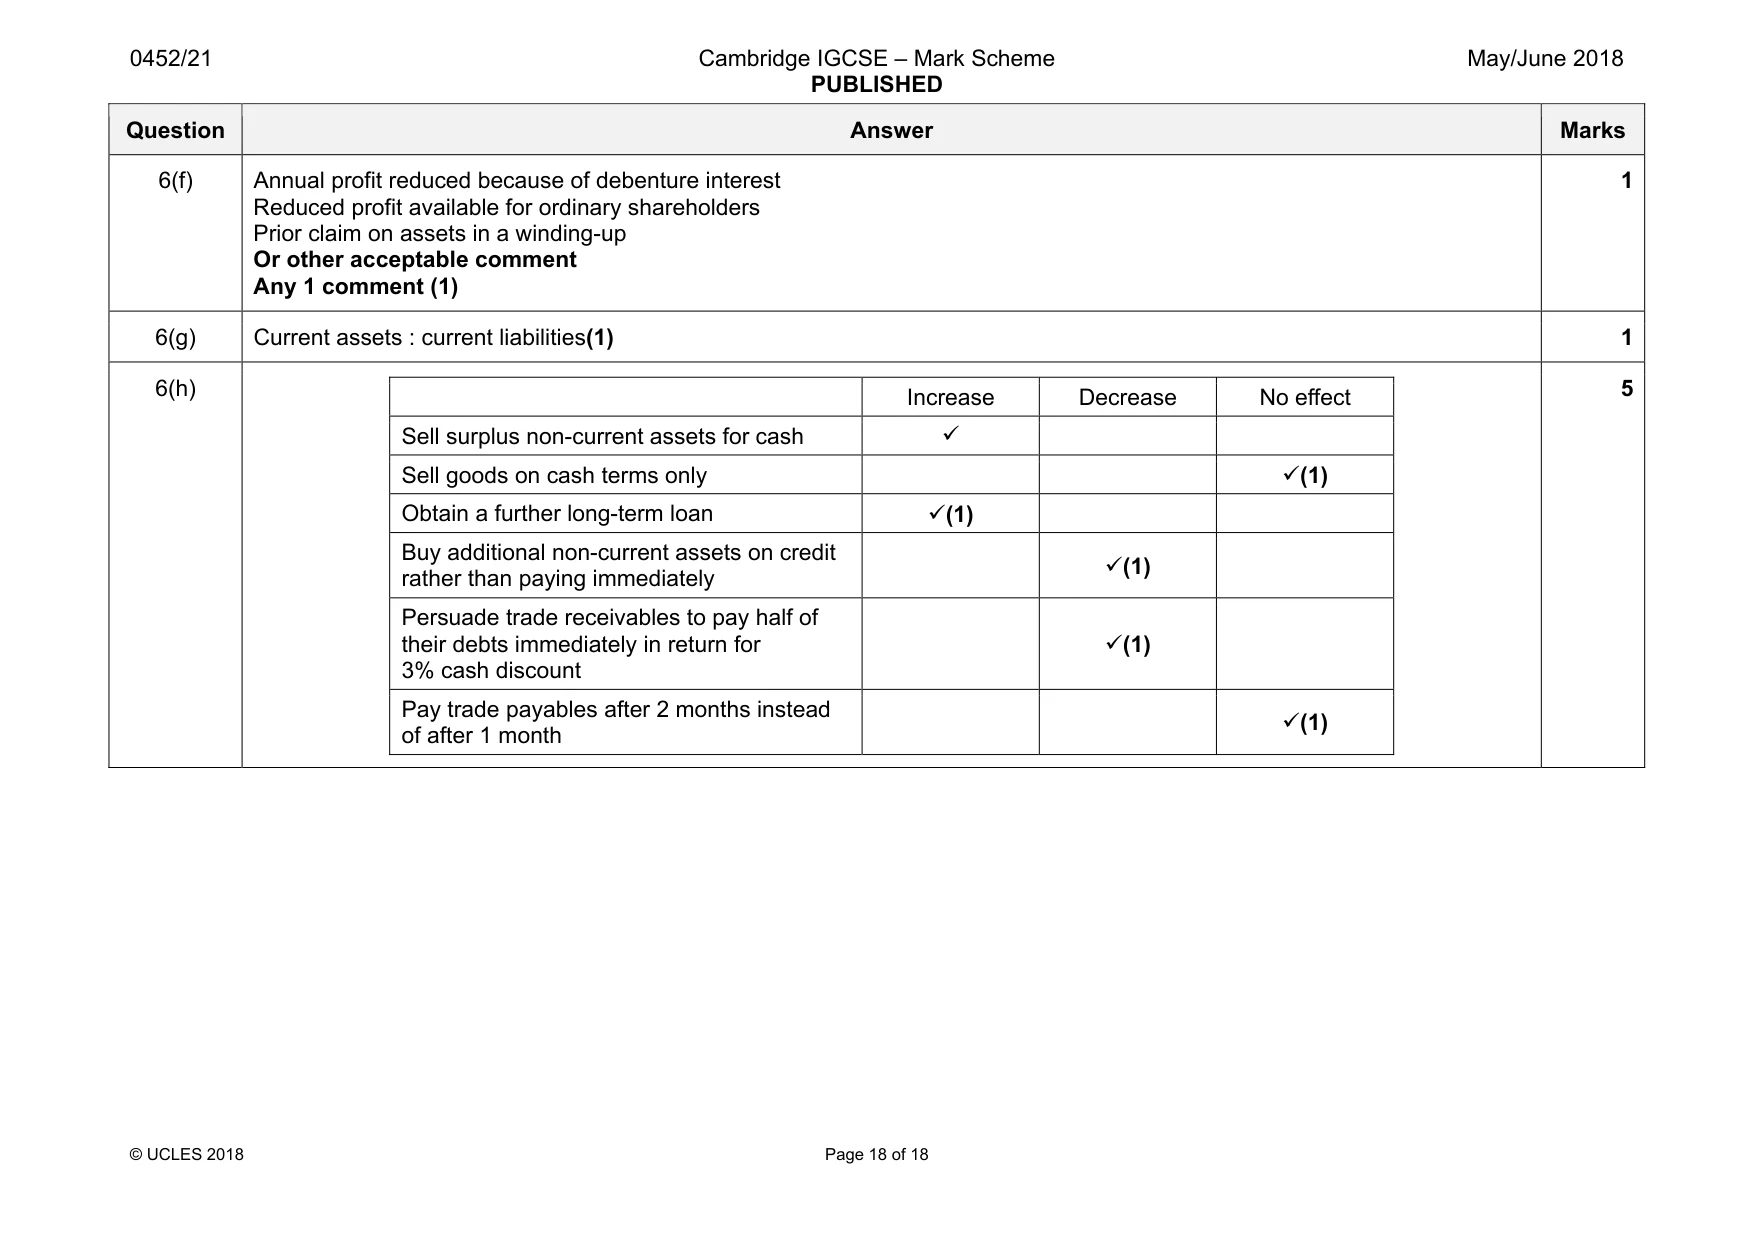
6 The financial year of CD Limited ends on 30 April. The following information was provided on 30 April 2018. $ $ Non-current assets (book value) 227 000 Ordinary share capital Inventory 29 000 (300 000 shares of $0.50) 150 000 Trade receivables 22 000 General reserve 1 May 2017 30 000 Bank 11 000 Retained earnings 1 May 2017 6 000 Profit for the year ended 30 April 2018 13 000 5% Debentures (repayable 2025) 50 000 Trade and other payables 40 000 REQUIRED (a) State two differences between debentures and ordinary shares. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ...............................................................................................................................................[4] (b) State how the general reserve has arisen. ................................................................................................................................................... ................................................................................................................................................... ...............................................................................................................................................[1] (c) State two reasons why CD Limited retains some profit each year. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ...............................................................................................................................................[2] (d) Complete the table by placing tick(s) () in the correct column(s) to indicate where each of the following would be included in the financial statements of CD Limited at 30 April 2018. Some items may appear in more than one statement. The first one has been completed as an example. Income Statement Statement No entry statement of changes of financial in equity position 1 September 2017 Repayment of long-term loan 1 November 2017 Payment of half-year interest on debentures 31 December 2017 Payment of interim ordinary share dividend 30 April 2018 Half-year interest on debentures accrued 30 April 2018 Proposed ordinary share dividend [5] CD Limited requires an additional $30 000 to pay for an expansion programme. (e) State one advantage to ordinary shareholders if CD Limited raises the money by issuing debentures. ................................................................................................................................................... ...............................................................................................................................................[1] (f) State one disadvantage to ordinary shareholders if CD Limited raises the money by issuing debentures. ................................................................................................................................................... ...............................................................................................................................................[1] The current ratio of CD Limited on 30 April 2018 was 1.55 : 1. The company is anxious to increase this ratio and several proposals are being considered. REQUIRED (g) State the formula for the calculation of the current ratio. ...............................................................................................................................................[1] (h) Complete the table by placing a tick () in the correct column to indicate the effect on the current ratio of each proposal. The first one has been completed as an example. Increase Decrease No effect Sell surplus non-current assets for cash Sell goods on cash terms only Obtain a further long-term loan Buy additional non-current assets on credit rather than paying immediately Persuade trade receivables to pay half of their debts immediately in return for 3% cash discount Pay trade payables after 2 months instead of after 1 month [5] [Total: 20]
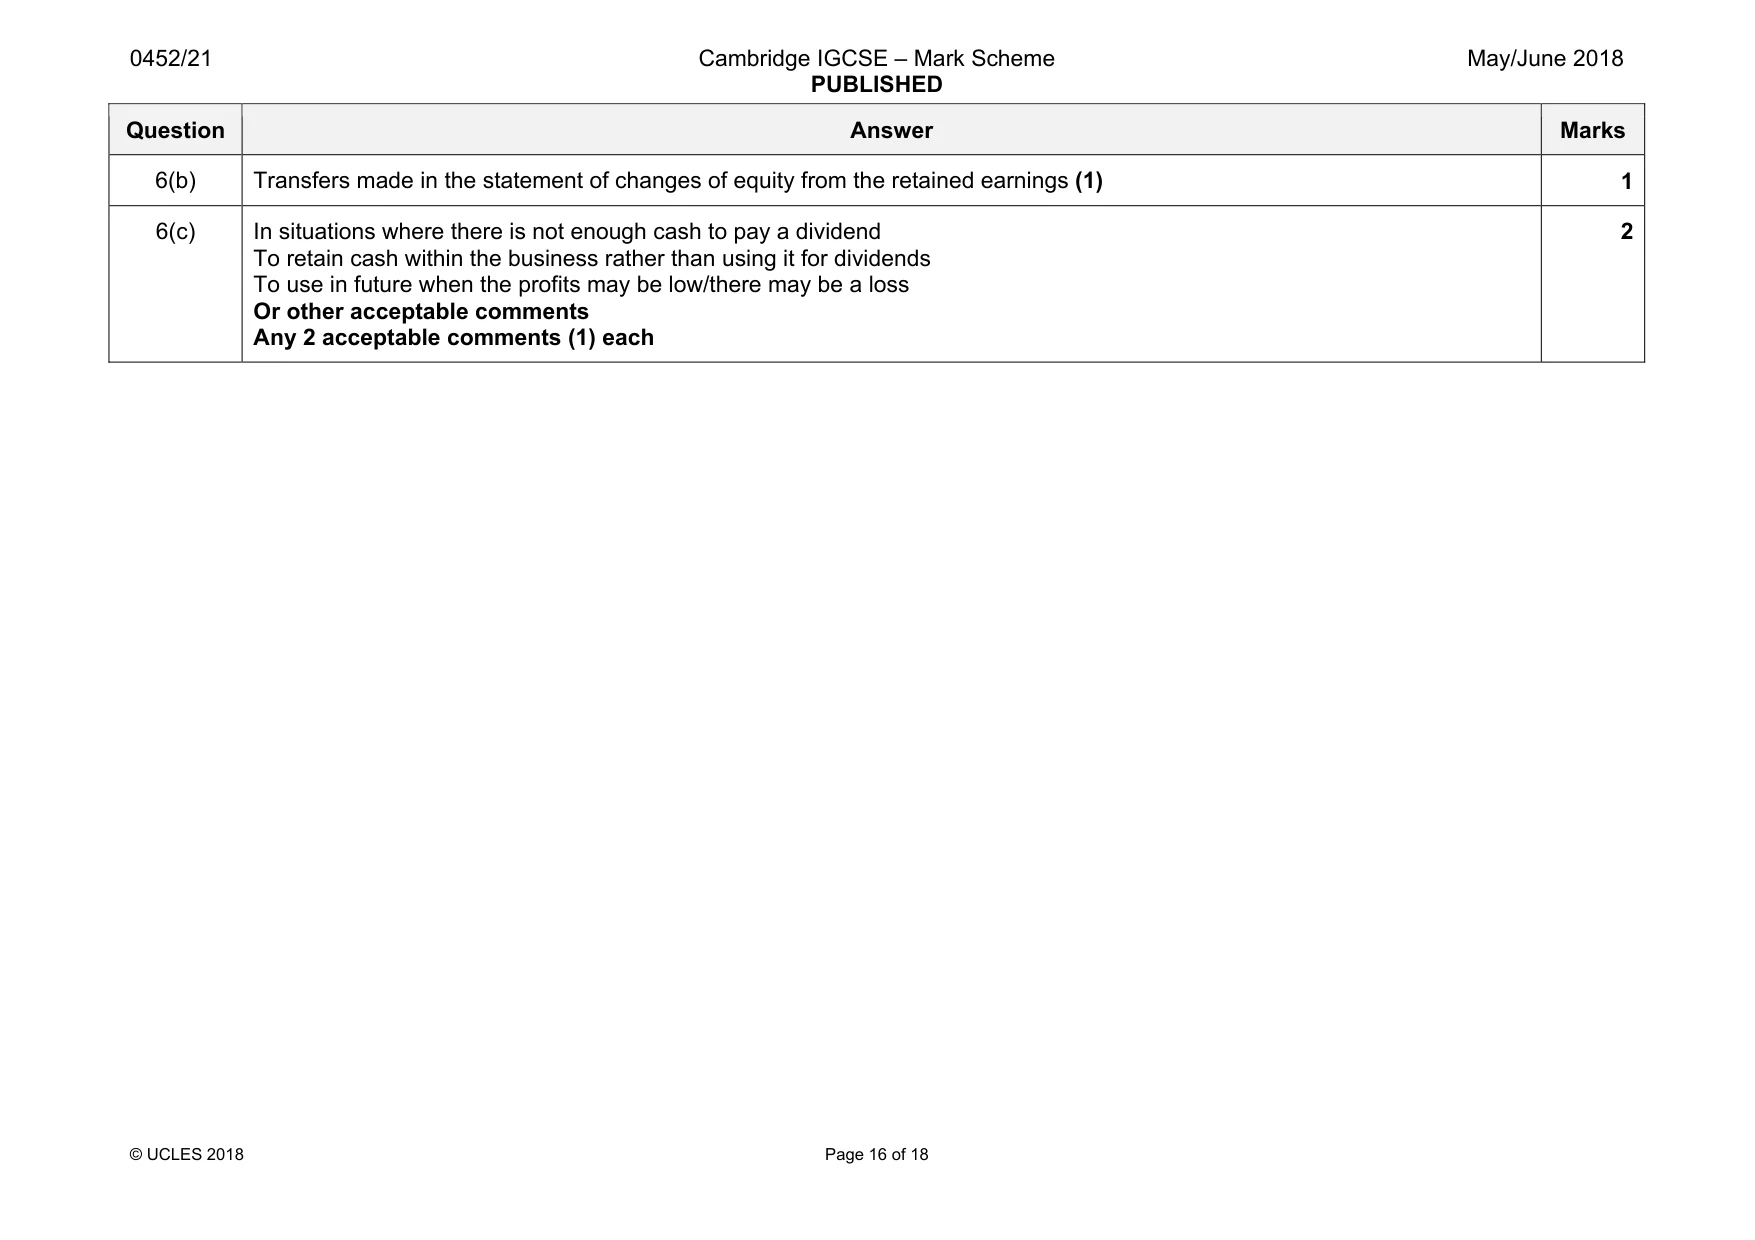
Mark scheme: 6(a) Debentures Ordinary shares Receive interest Receive dividends Receive fixed interest Receive variable dividends Interest paid irrespective of profit Dividends depend on profit Do not carry voting rights Carry voting rights Are lenders/loans/(non-current) liabilities/creditors Are members of the company/equity/capital Priority for repayment in winding-up Last to be repaid in winding-up Any two comparative statements (2) each 4 Question Answer Marks 6(b) Transfers made in the statement of changes of equity from the retained earnings (1) 1 6(c) In situations where there is not enough cash to pay a dividend To retain cash within the business rather than using it for dividends To use in future when the profits may be low/there may be a loss Or other acceptable comments Any 2 acceptable comments (1) each 2 Question Answer Marks 6(d) Income statement Statement of changes in equity Statement of financial position No entry 1 September 2017 Repayment of long term loan 9 1 November 2017 Payment of half year interest on debentures 9(1) 31 December 2017 Payment of interim ordinary share dividend 9(1) 30 April 2018 Half year interest on debentures accrued 9(1) 9(1) 30 April 2018 Proposed ordinary share dividend 9(1) 5 6(e) Will not dilute their stake in the company Will not dilute their voting power If expansion profitable, potential for higher dividend as debenture holders receive fixed interest Or other acceptable comment Any 1 comment (1) 1 Question Answer Marks 6(f) Annual profit reduced because of debenture interest Reduced profit available for ordinary shareholders Prior claim on assets in a winding-up Or other acceptable comment Any 1 comment (1) 1 6(g) Current assets : current liabilities(1) 1 6(h) Increase Decrease No effect Sell surplus non-current assets for cash 9 Sell goods on cash terms only 9(1) Obtain a further long-term loan 9(1) Buy additional non-current assets on credit rather than paying immediately 9(1) Persuade trade receivables to pay half of their debts immediately in return for 3% cash discount 9(1) Pay trade payables after 2 months instead of after 1 month 9(1) 5
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2018 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.