Cambridge IGCSE Accounting 0452 — 2017 May/June Paper 1 · Variant 3
0452/13/M/J/17 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme11 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 20 printed pages. DC (ST) 143276 © UCLES 2017 [Turn over Cambridge International Examinations Cambridge International General Certificate of Secondary Education * 9 1 8 3 7 2 9 6 3 2 * ACCOUNTING 0452/13 Paper 1 May/June 2017 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use an HB pencil for any diagrams or graphs. Do not use staples, paper clips, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
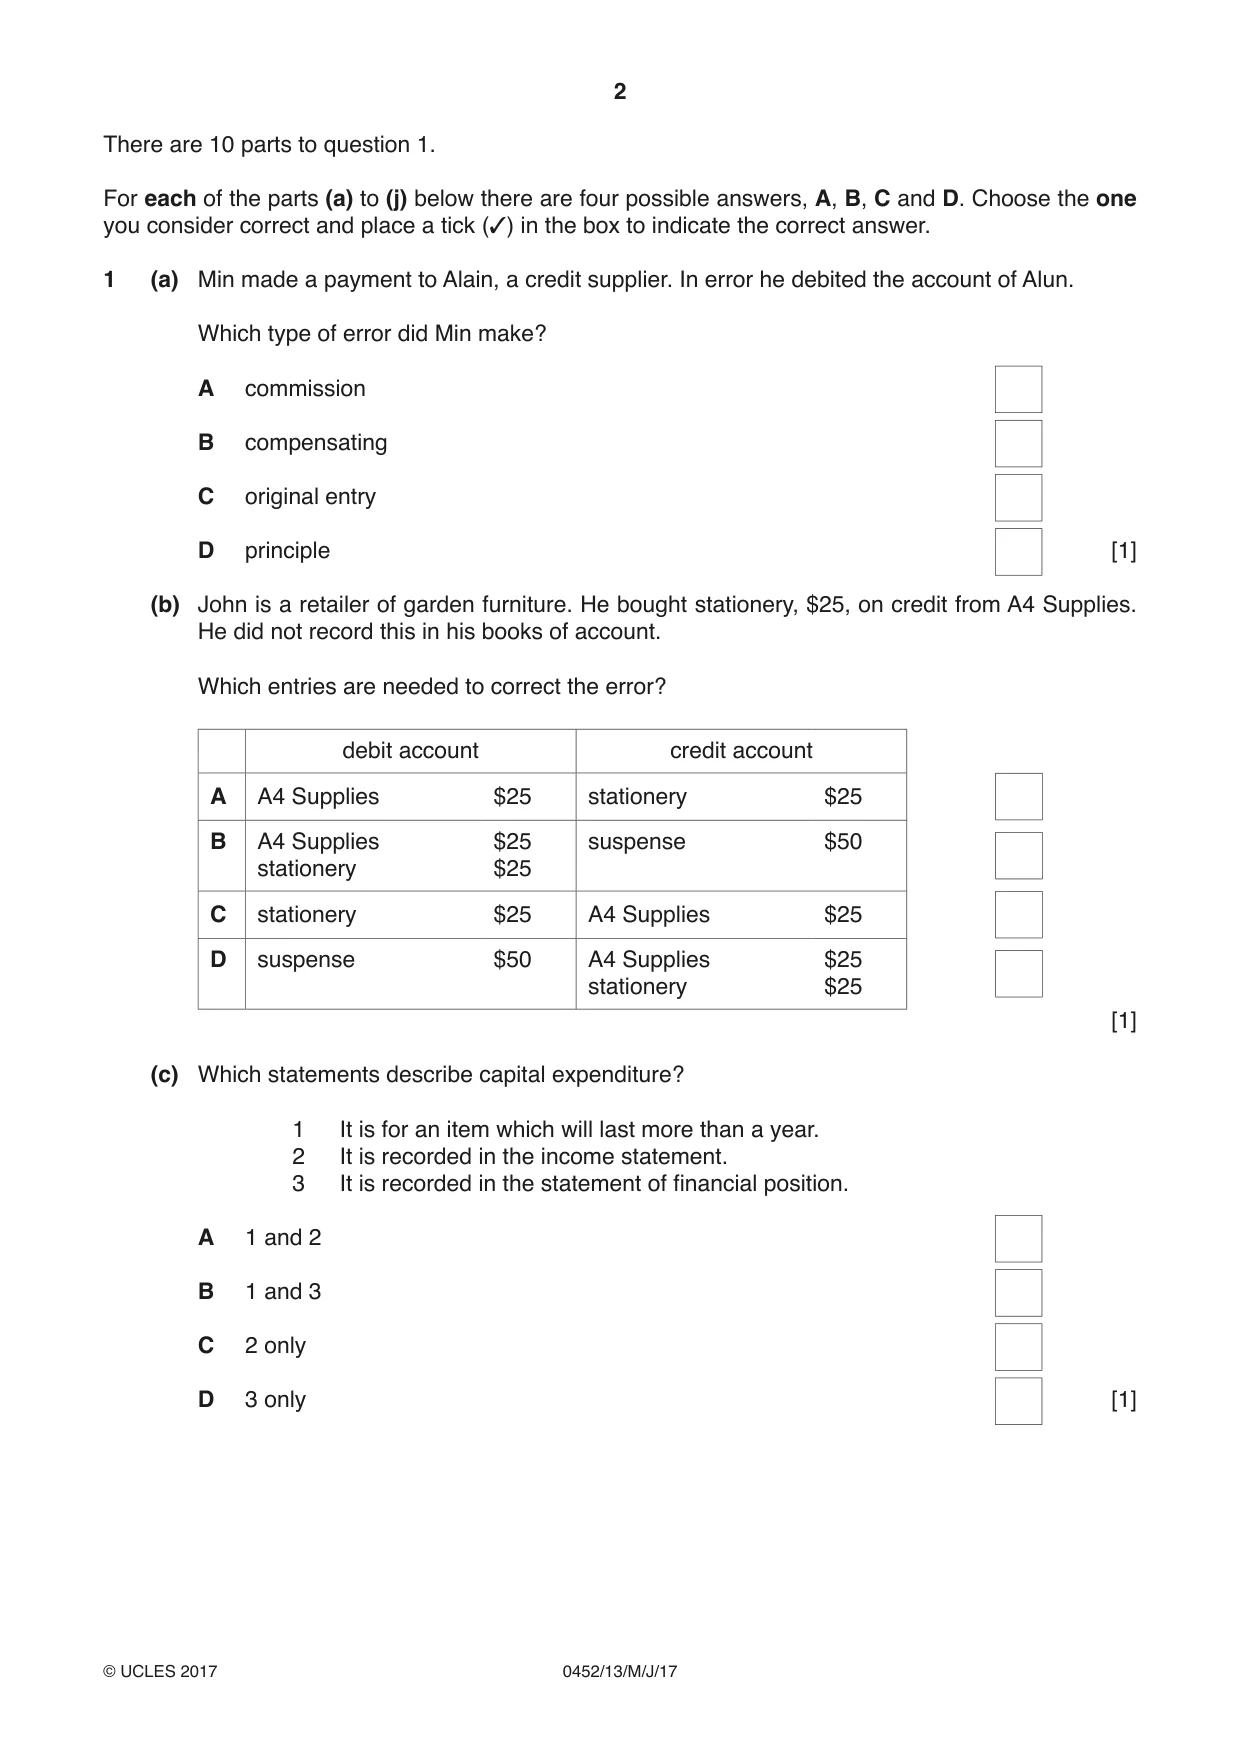
2 0452/13/M/J/17 © UCLES 2017 There are 10 parts to question 1. For each of the parts (a) to (j) below there are four possible answers, A, B, C and D. Choose the one you consider correct and place a tick (✓) in the box to indicate the correct answer. 1 (a) Min made a payment to Alain, a credit supplier. In error he debited the account of Alun. Which type of error did Min make? A commission B compensating C original entry D principle [1] (b) John is a retailer of garden furniture. He bought stationery, $25, on credit from A4 Supplies. He did not record this in his books of account. Which entries are needed to correct the error? debit account credit account A A4 Supplies $25 stationery $25 B A4 Supplies stationery $25 $25 suspense $50 C stationery $25 A4 Supplies $25 D suspense $50 A4 Supplies stationery $25 $25 [1] (c) Which statements describe capital expenditure? 1 It is for an item which will last more than a year. 2 It is recorded in the income statement. 3 It is recorded in the statement of financial position. A 1 and 2 B 1 and 3 C 2 only D 3 only [1]
Question paper, page 3
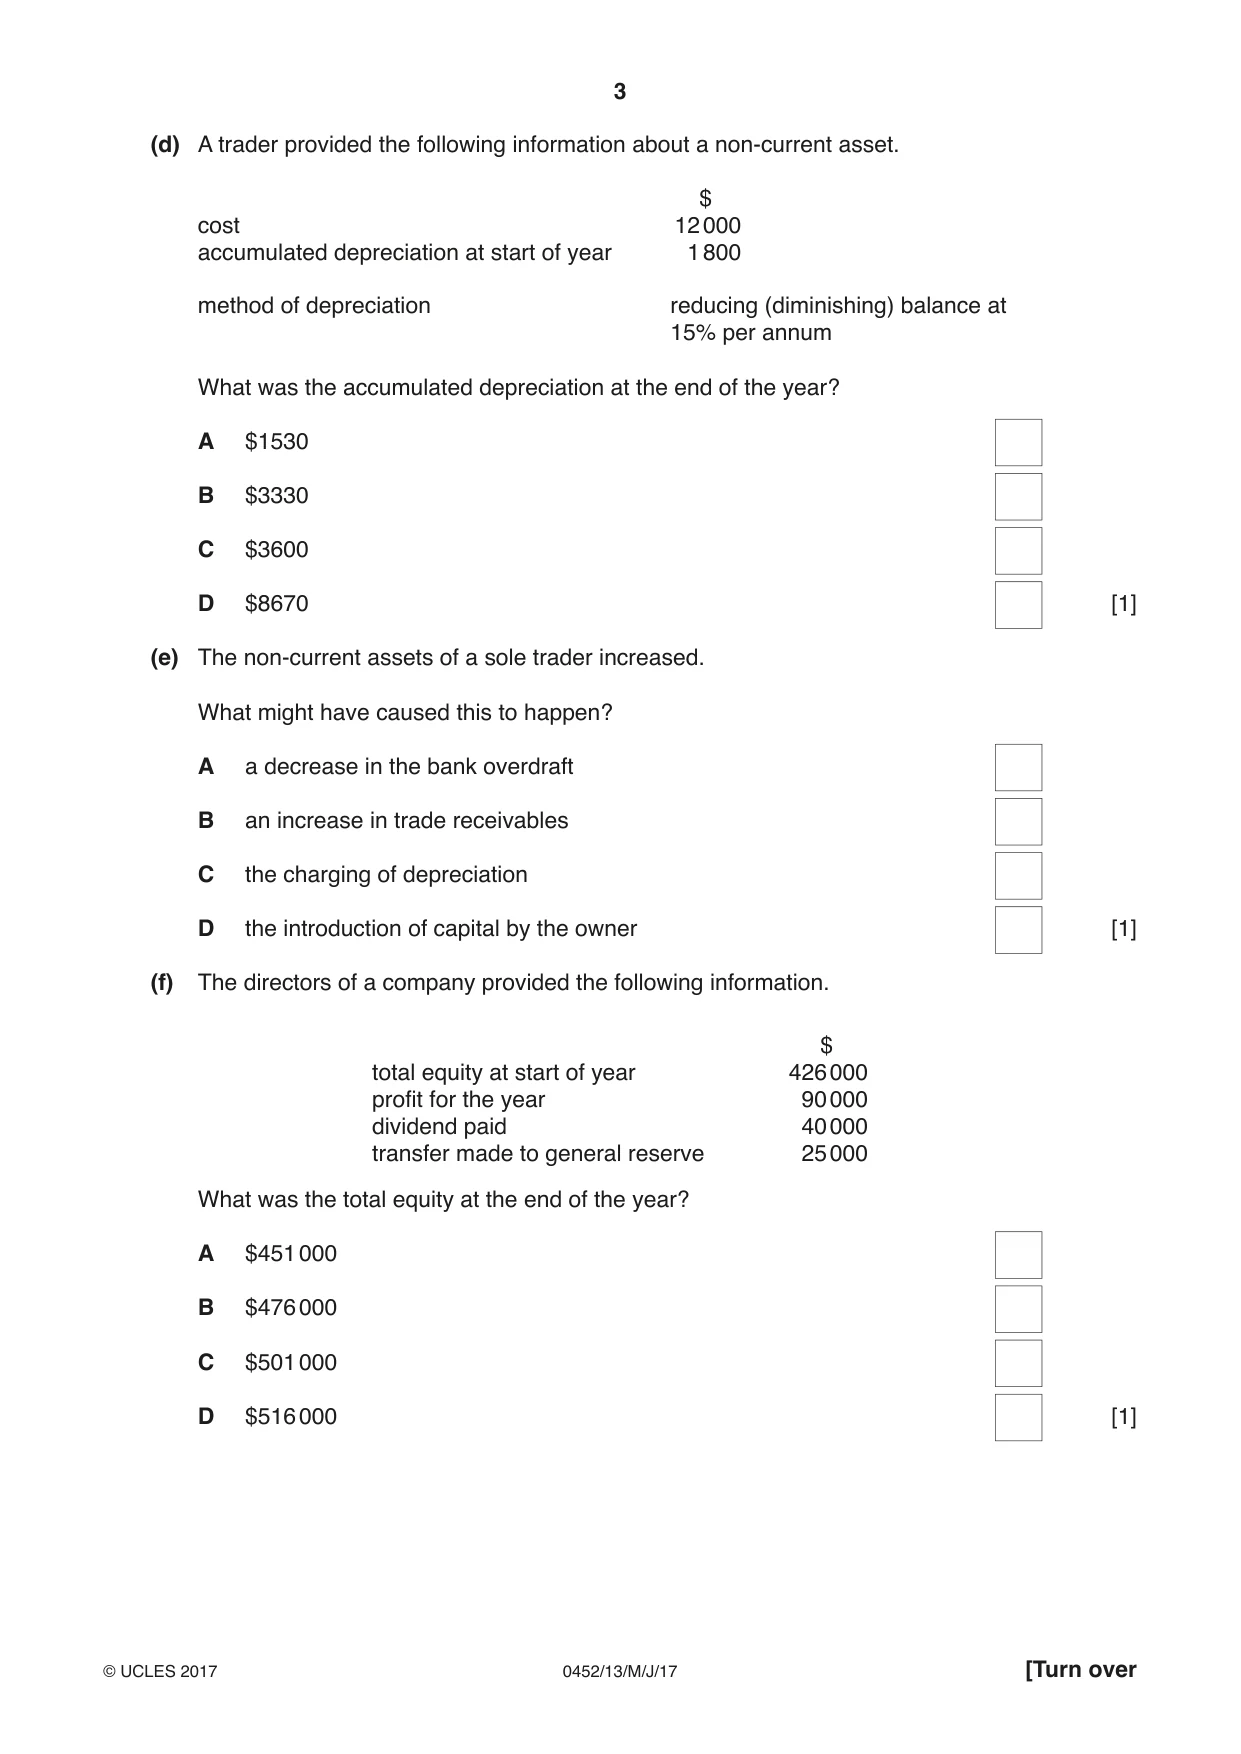
3 0452/13/M/J/17 © UCLES 2017 [Turn over (d) A trader provided the following information about a non-current asset. $ cost 12 000 accumulated depreciation at start of year 1 800 method of depreciation reducing (diminishing) balance at 15% per annum What was the accumulated depreciation at the end of the year? A $1530 B $3330 C $3600 D $8670 [1] (e) The non-current assets of a sole trader increased. What might have caused this to happen? A a decrease in the bank overdraft B an increase in trade receivables C the charging of depreciation D the introduction of capital by the owner [1] (f) The directors of a company provided the following information. $ total equity at start of year 426 000 profit for the year 90 000 dividend paid 40 000 transfer made to general reserve 25 000 What was the total equity at the end of the year? A $451 000 B $476 000 C $501 000 D $516 000 [1]
Question paper, page 4
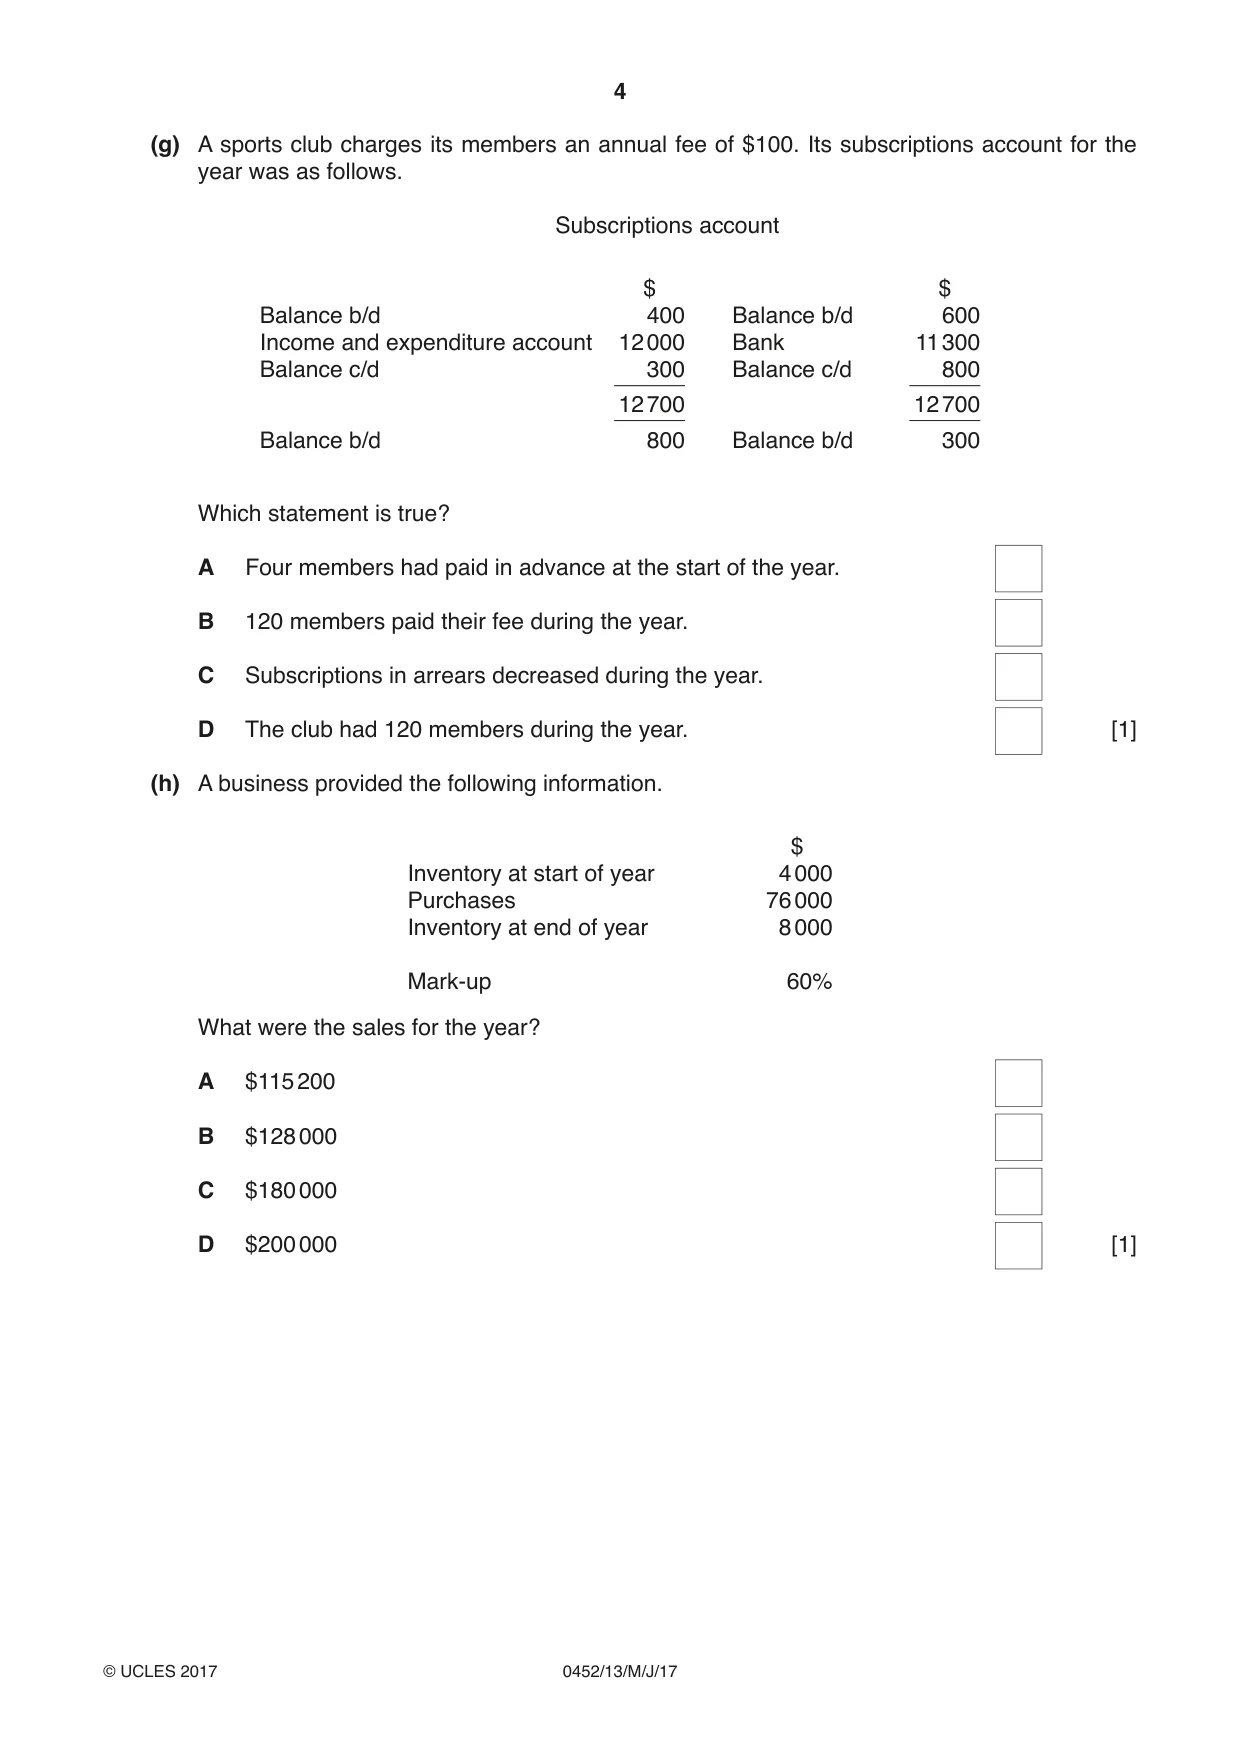
4 0452/13/M/J/17 © UCLES 2017 (g) A sports club charges its members an annual fee of $100. Its subscriptions account for the year was as follows. Subscriptions account $ $ Balance b/d 400 Balance b/d 600 Income and expenditure account 12 000 Bank 11 300 Balance c/d 300 Balance c/d 800 12 700 12 700 Balance b/d 800 Balance b/d 300 Which statement is true? A Four members had paid in advance at the start of the year. B 120 members paid their fee during the year. C Subscriptions in arrears decreased during the year. D The club had 120 members during the year. [1] (h) A business provided the following information. $ Inventory at start of year 4 000 Purchases 76 000 Inventory at end of year 8 000 Mark-up 60% What were the sales for the year? A $115 200 B $128 000 C $180 000 D $200 000 [1]
Question paper, page 5
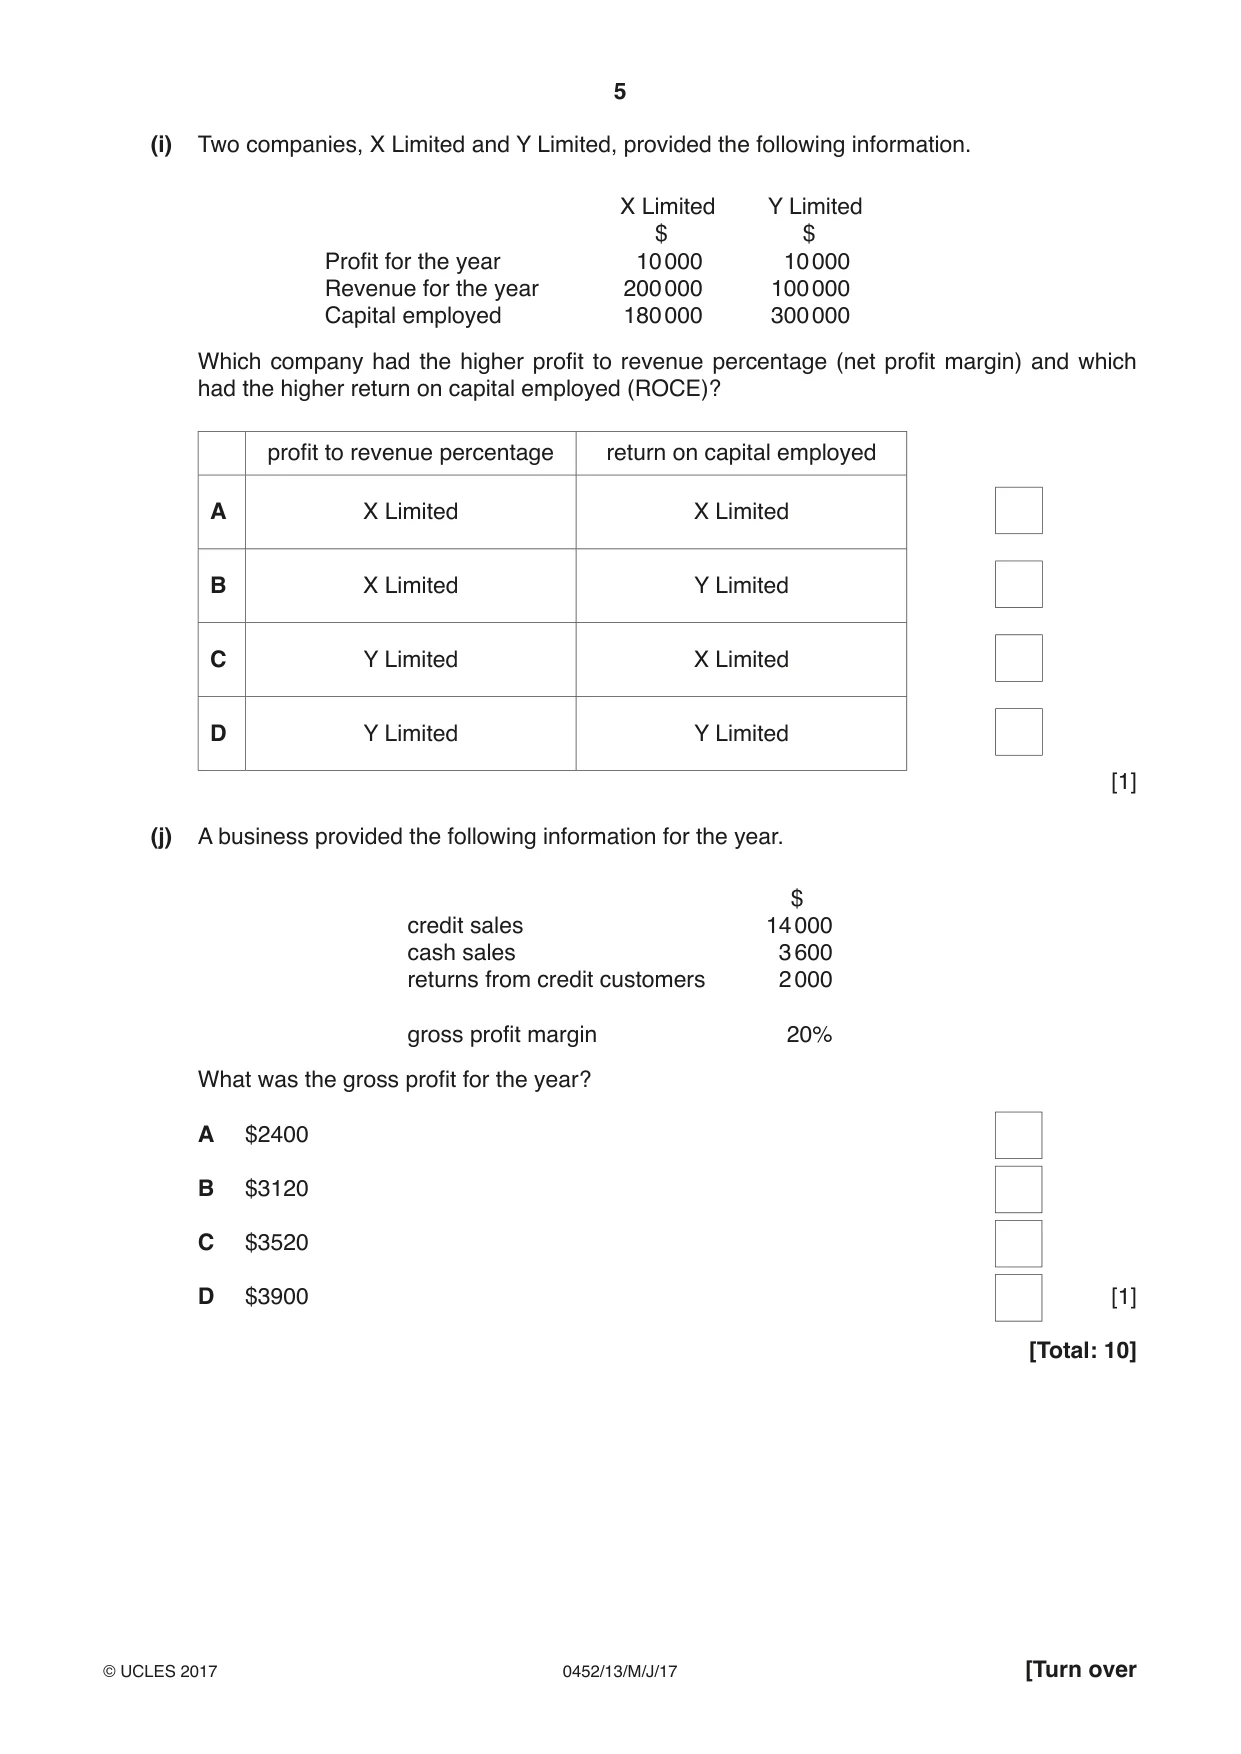
5 0452/13/M/J/17 © UCLES 2017 [Turn over (i) Two companies, X Limited and Y Limited, provided the following information. X Limited Y Limited $ $ Profit for the year 10 000 10 000 Revenue for the year 200 000 100 000 Capital employed 180 000 300 000 Which company had the higher profit to revenue percentage (net profit margin) and which had the higher return on capital employed (ROCE)? profit to revenue percentage return on capital employed A X Limited X Limited B X Limited Y Limited C Y Limited X Limited D Y Limited Y Limited [1] (j) A business provided the following information for the year. $ credit sales 14 000 cash sales 3 600 returns from credit customers 2 000 gross profit margin 20% What was the gross profit for the year? A $2400 B $3120 C $3520 D $3900 [1] [Total: 10]
Question paper, page 6
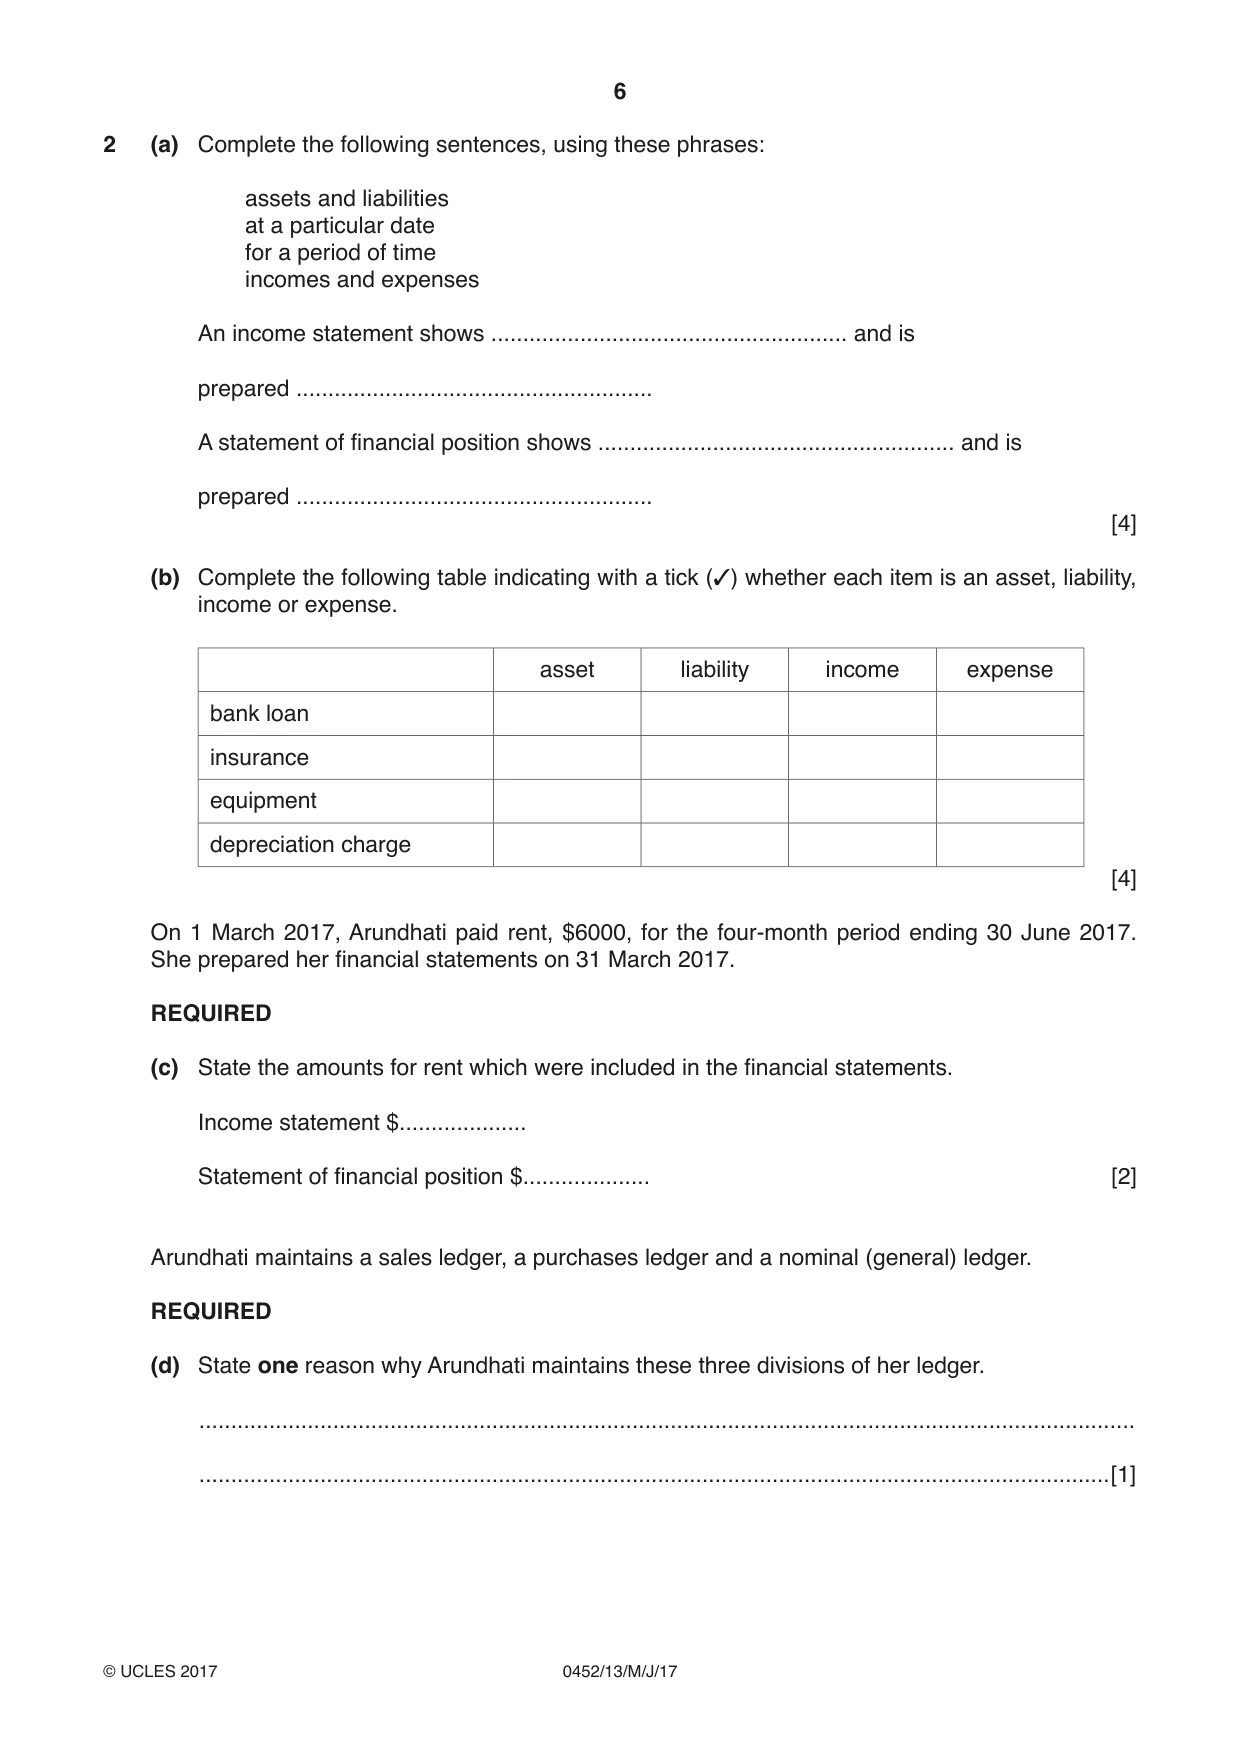
6 0452/13/M/J/17 © UCLES 2017 2 (a) Complete the following sentences, using these phrases: assets and liabilities at a particular date for a period of time incomes and expenses An income statement shows … and is prepared … A statement of financial position shows … and is prepared … [4] (b) Complete the following table indicating with a tick (✓) whether each item is an asset, liability, income or expense. asset liability income expense bank loan insurance equipment depreciation charge [4] On 1 March 2017, Arundhati paid rent, $6000, for the four-month period ending 30 June 2017. She prepared her financial statements on 31 March 2017. REQUIRED (c) State the amounts for rent which were included in the financial statements. Income statement $… Statement of financial position $… [2] Arundhati maintains a sales ledger, a purchases ledger and a nominal (general) ledger. REQUIRED (d) State one reason why Arundhati maintains these three divisions of her ledger. … …[1]
Question paper, page 7
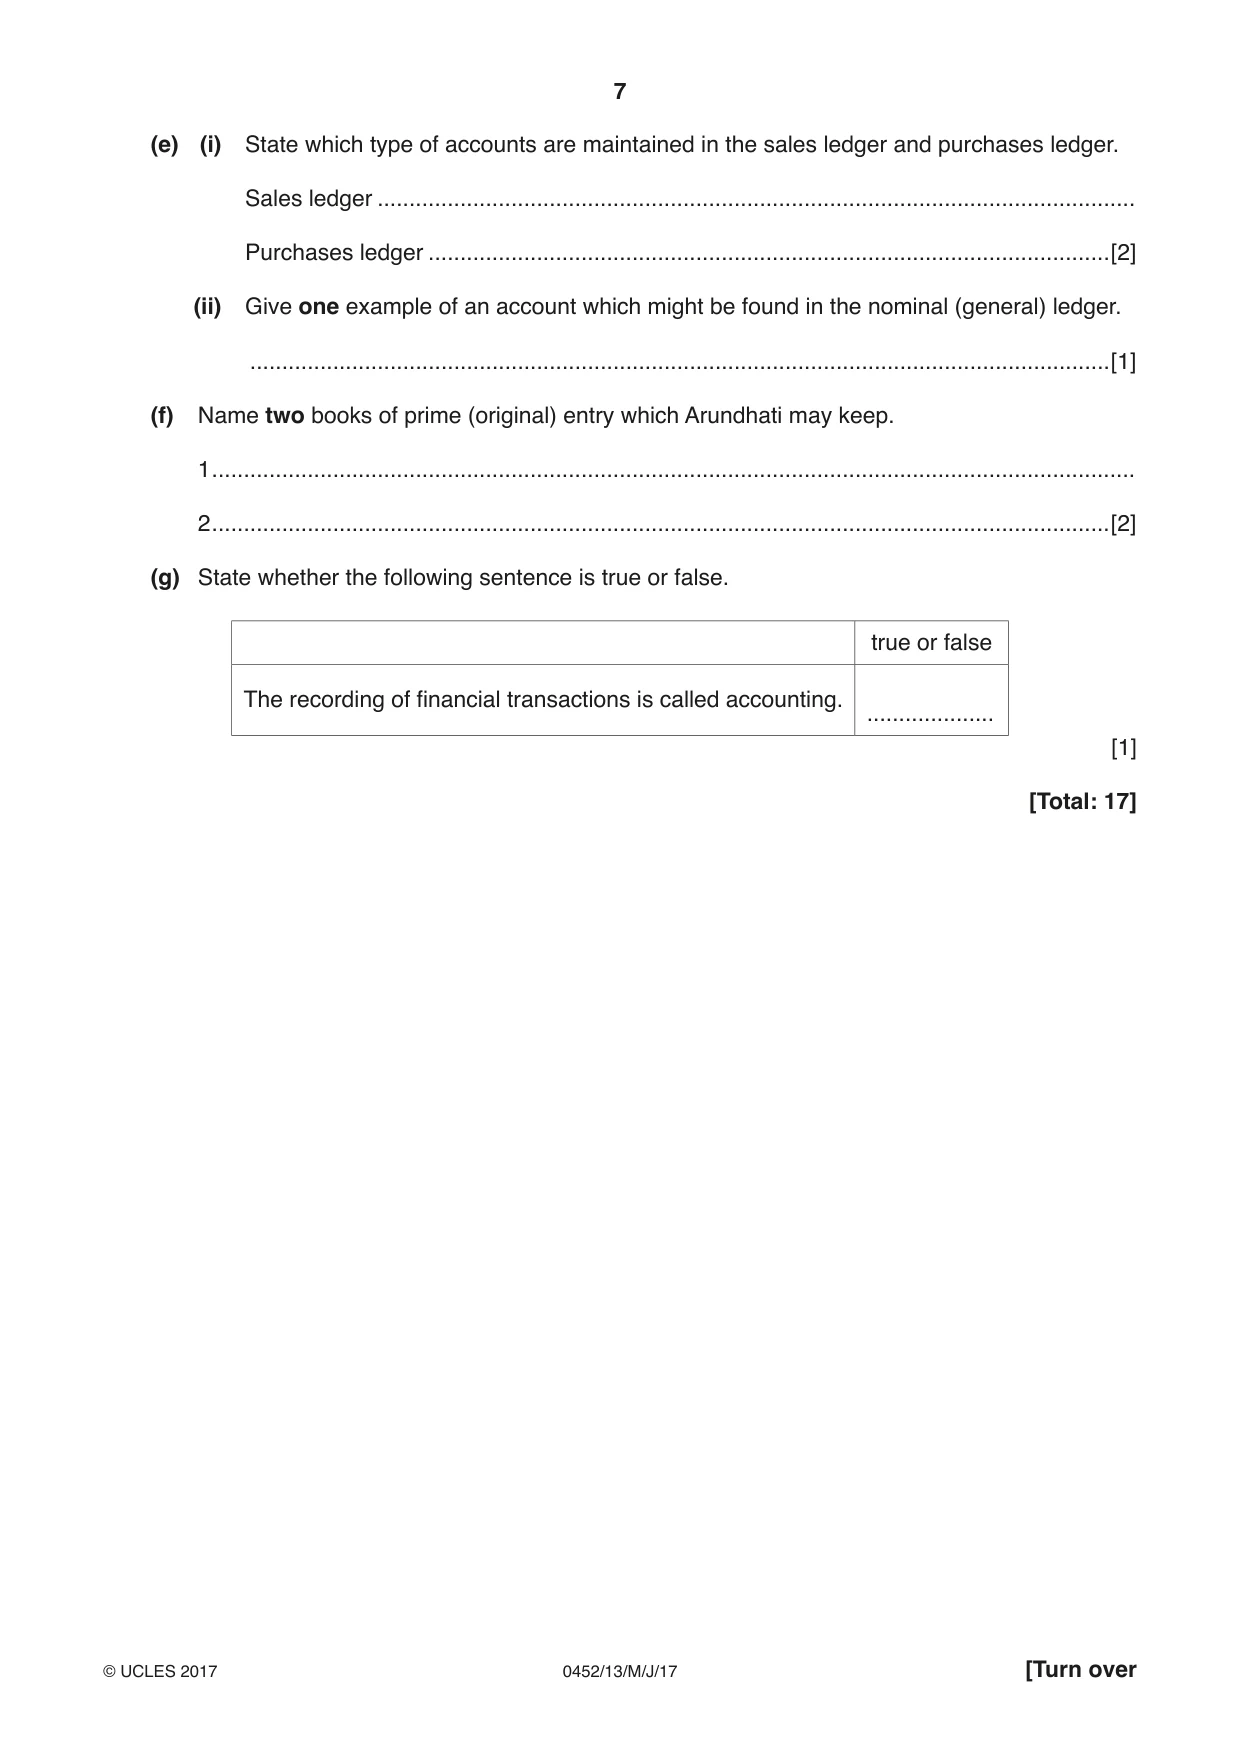
7 0452/13/M/J/17 © UCLES 2017 [Turn over (e) (i) State which type of accounts are maintained in the sales ledger and purchases ledger. Sales ledger … Purchases ledger …[2] (ii) Give one example of an account which might be found in the nominal (general) ledger. …[1] (f) Name two books of prime (original) entry which Arundhati may keep. 1 … 2 …[2] (g) State whether the following sentence is true or false. true or false The recording of financial transactions is called accounting. … [1] [Total: 17]
Question paper, page 8
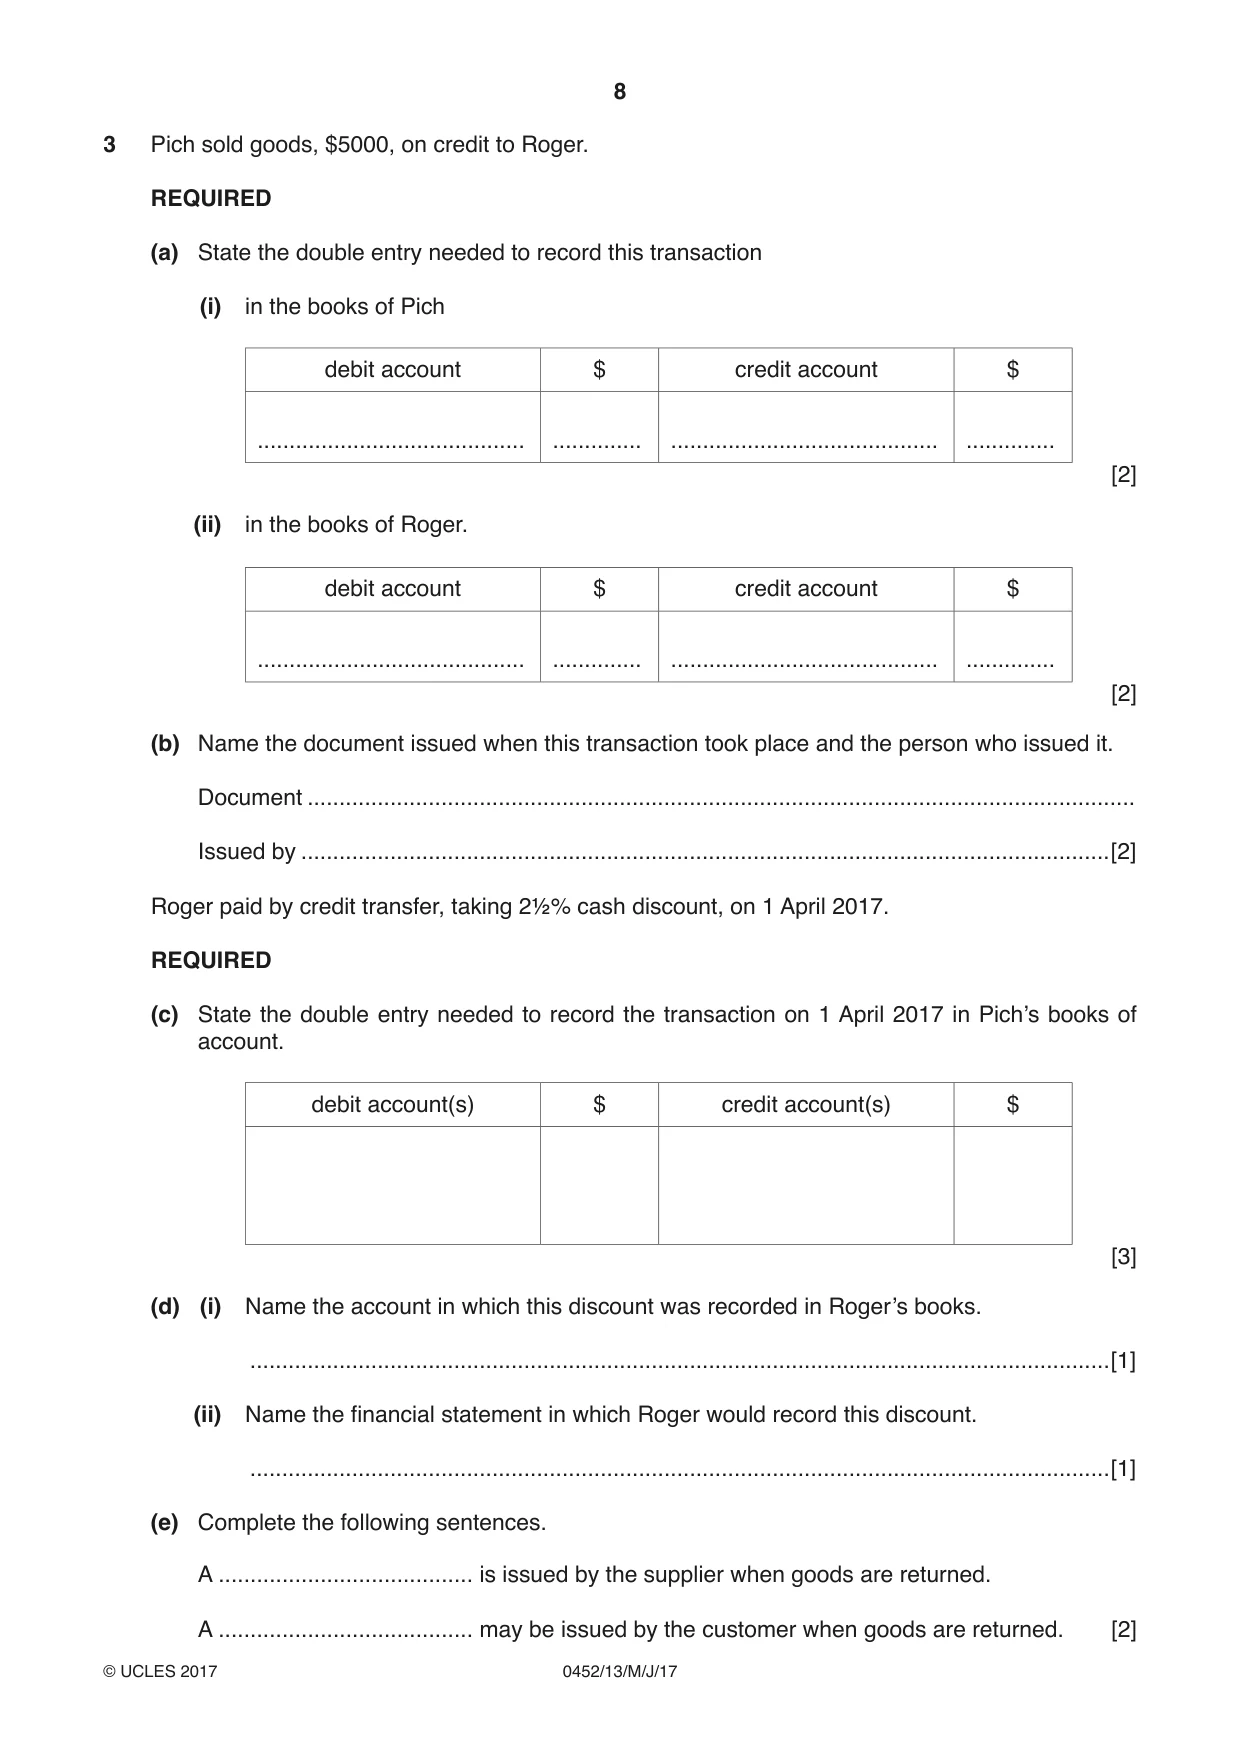
8 0452/13/M/J/17 © UCLES 2017 3 Pich sold goods, $5000, on credit to Roger. REQUIRED (a) State the double entry needed to record this transaction (i) in the books of Pich debit account $ credit account $ … … … … [2] (ii) in the books of Roger. debit account $ credit account $ … … … … [2] (b) Name the document issued when this transaction took place and the person who issued it. Document … Issued by …[2] Roger paid by credit transfer, taking 2½% cash discount, on 1 April 2017. REQUIRED (c) State the double entry needed to record the transaction on 1 April 2017 in Pich’s books of account. debit account(s) $ credit account(s) $ [3] (d) (i) Name the account in which this discount was recorded in Roger’s books. …[1] (ii) Name the financial statement in which Roger would record this discount. …[1] (e) Complete the following sentences. A … is issued by the supplier when goods are returned. A … may be issued by the customer when goods are returned. [2]
Question paper, page 9
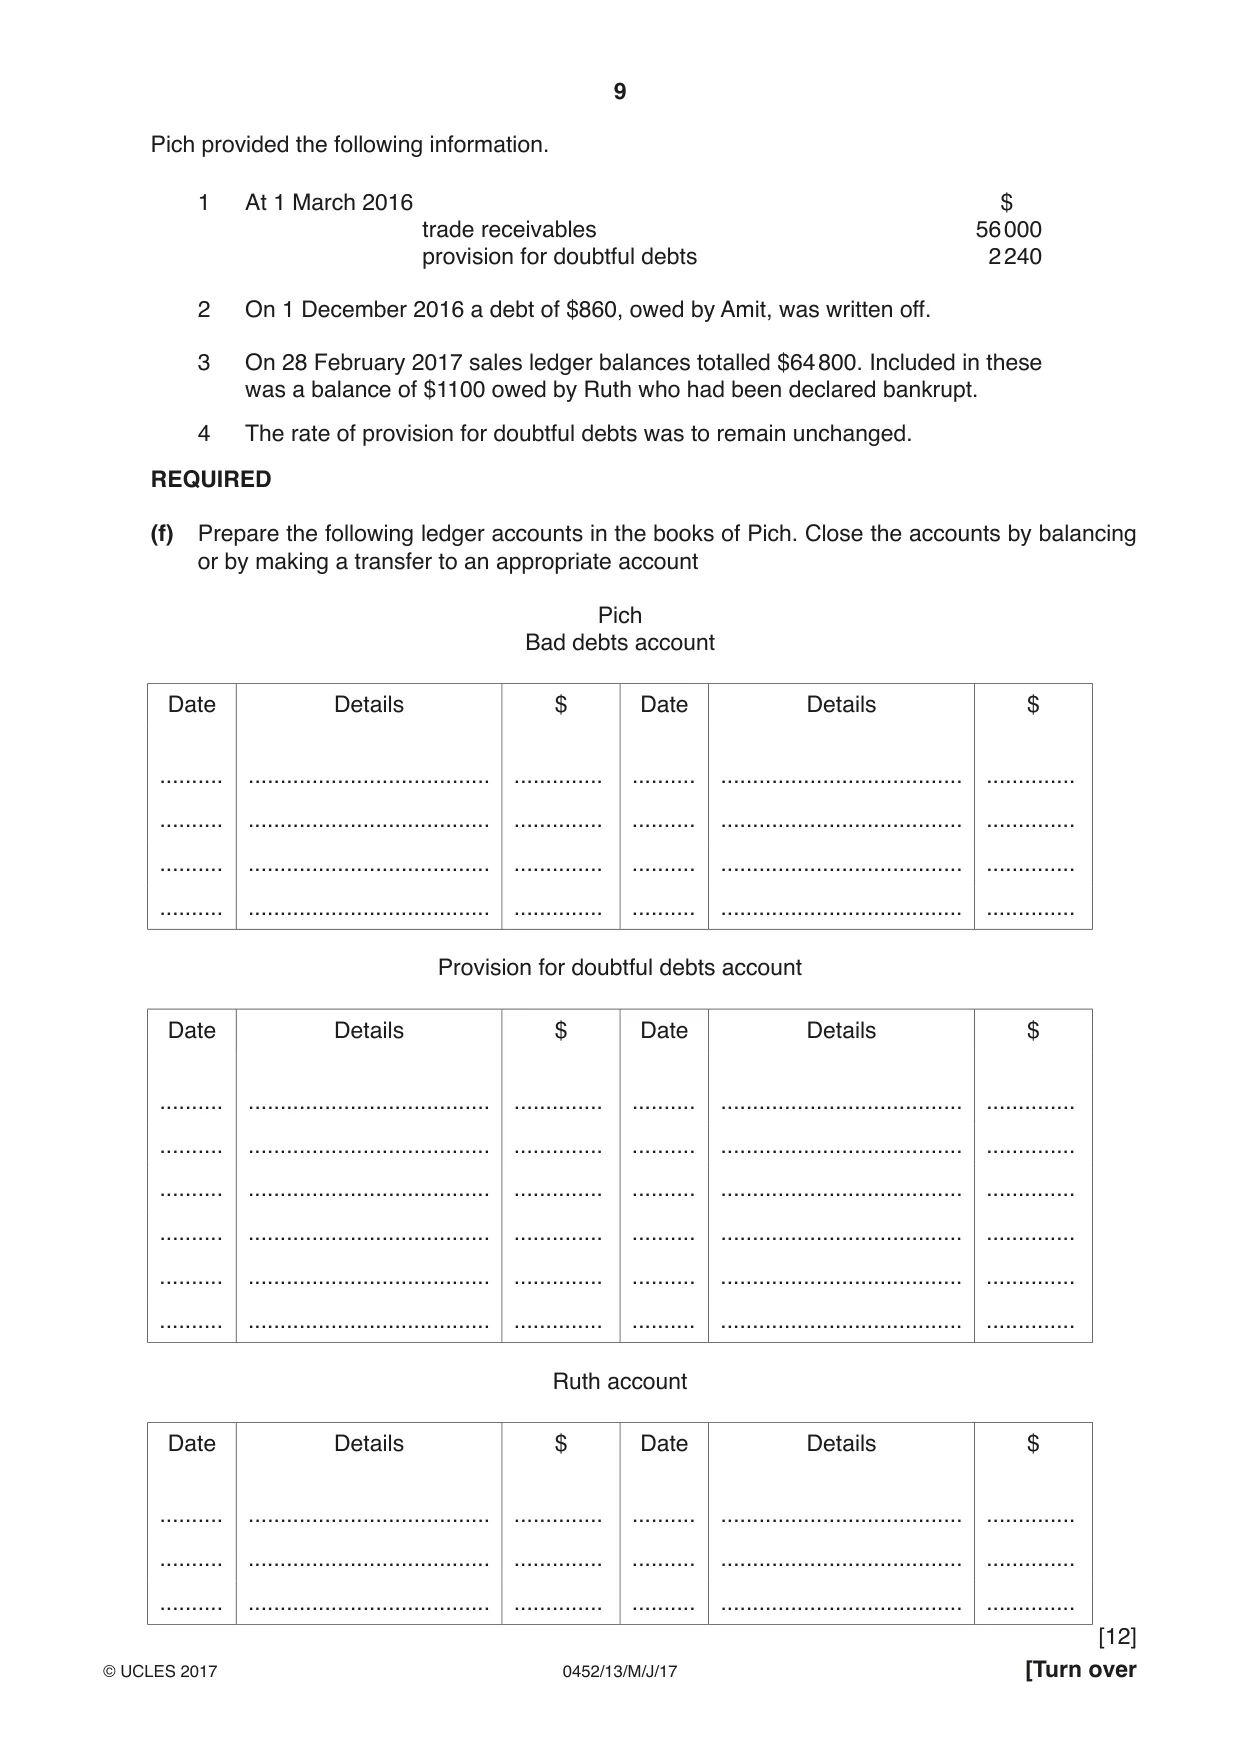
9 0452/13/M/J/17 © UCLES 2017 [Turn over Pich provided the following information. 1 At 1 March 2016 $ trade receivables 56 000 provision for doubtful debts 2 240 2 On 1 December 2016 a debt of $860, owed by Amit, was written off. 3 On 28 February 2017 sales ledger balances totalled $64 800. Included in these was a balance of $1100 owed by Ruth who had been declared bankrupt. 4 The rate of provision for doubtful debts was to remain unchanged. REQUIRED (f) Prepare the following ledger accounts in the books of Pich. Close the accounts by balancing or by making a transfer to an appropriate account Pich Bad debts account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … Provision for doubtful debts account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … Ruth account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … [12]
Question paper, page 10
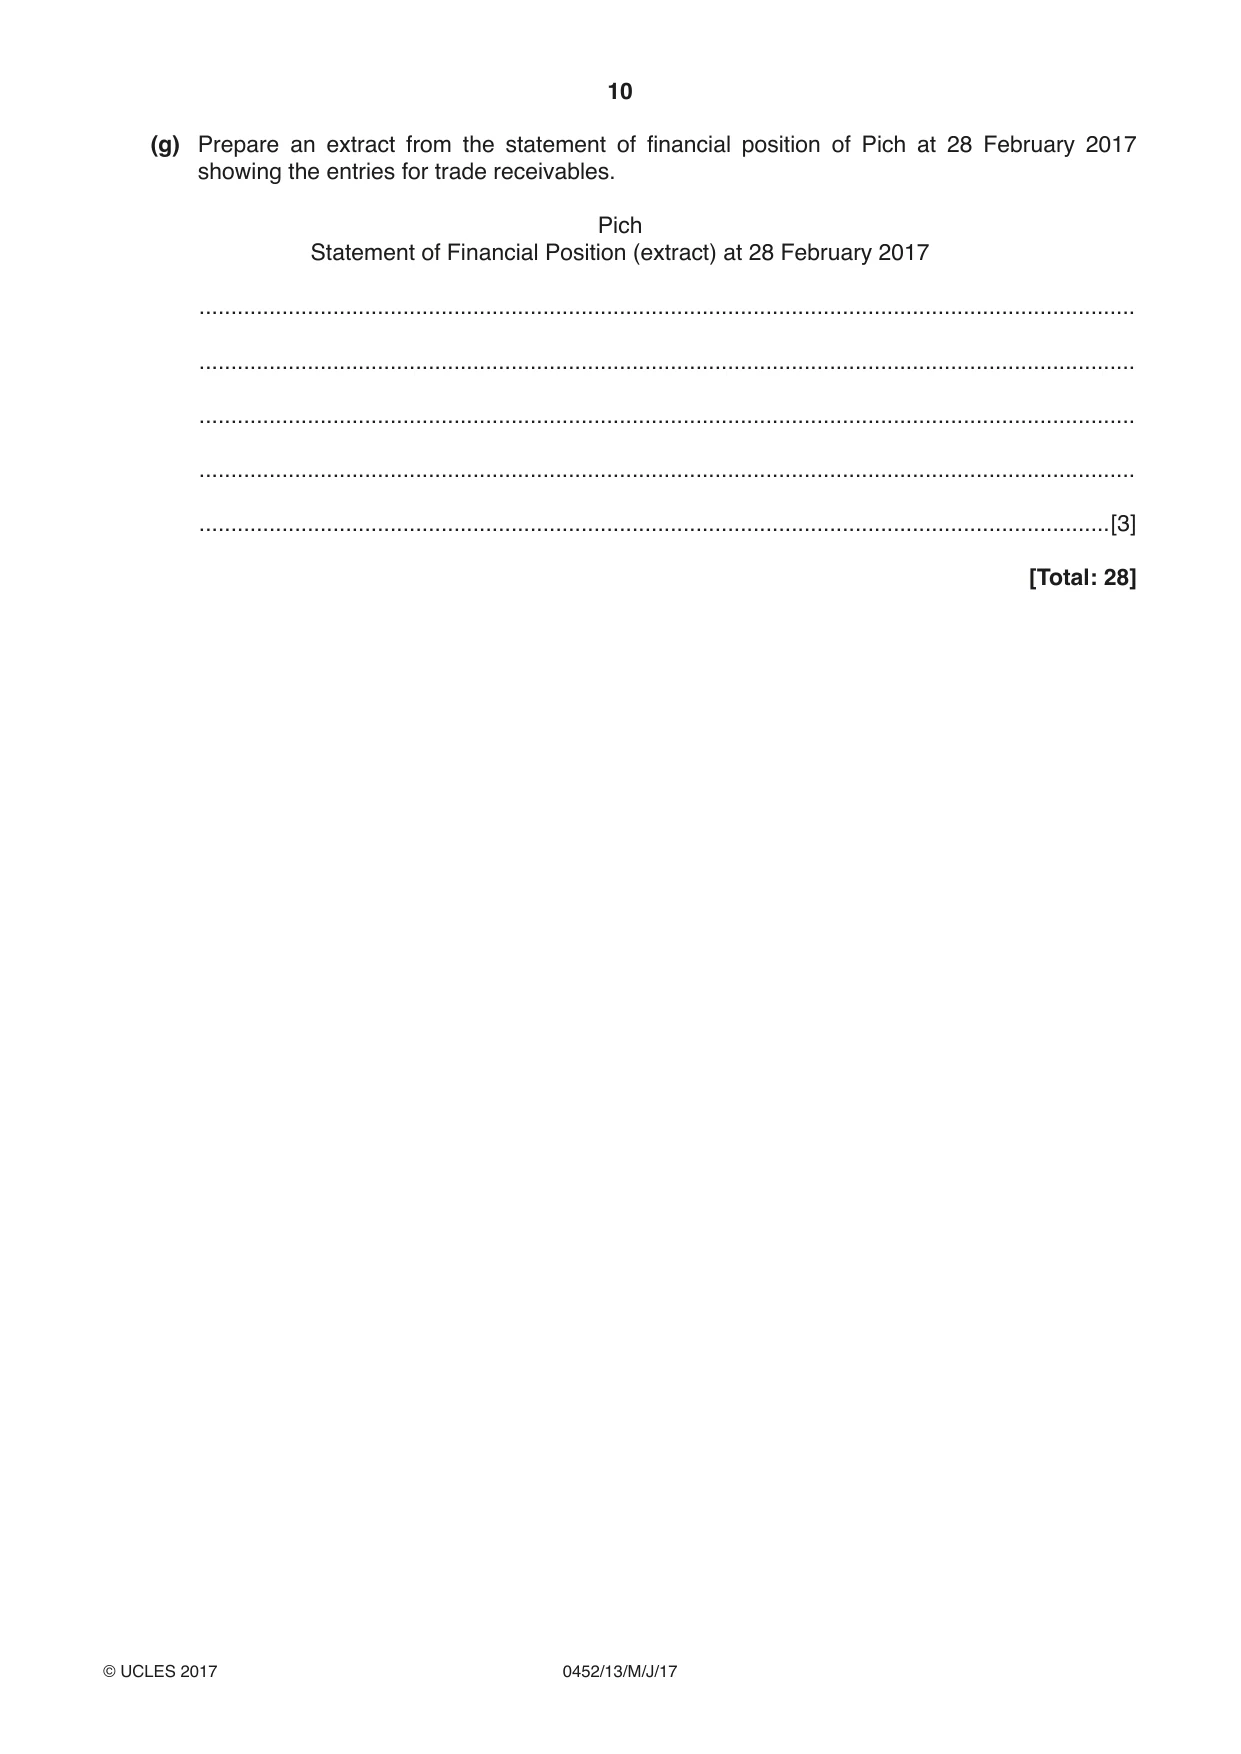
10 0452/13/M/J/17 © UCLES 2017 (g) Prepare an extract from the statement of financial position of Pich at 28 February 2017 showing the entries for trade receivables. Pich Statement of Financial Position (extract) at 28 February 2017 … … … … …[3] [Total: 28]
Question paper, page 11
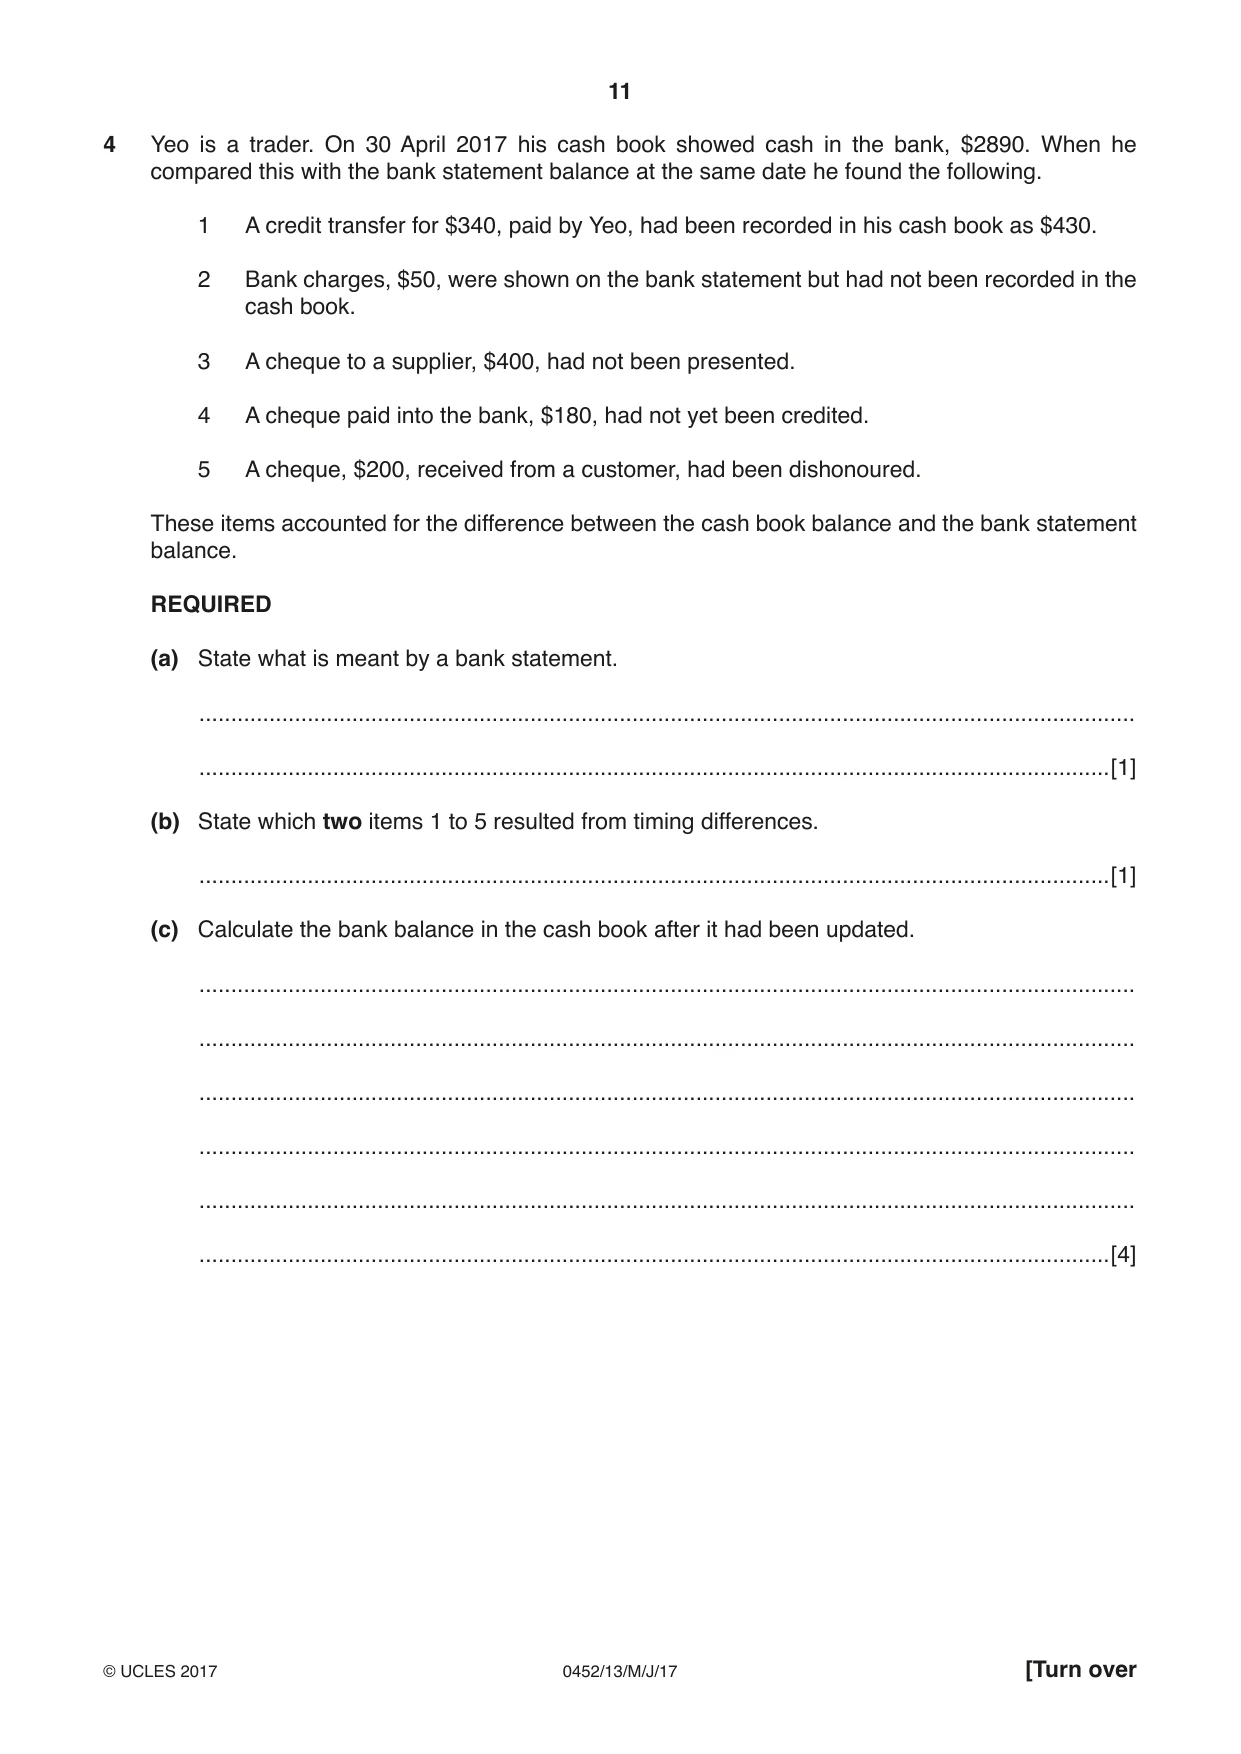
11 0452/13/M/J/17 © UCLES 2017 [Turn over 4 Yeo is a trader. On 30 April 2017 his cash book showed cash in the bank, $2890. When he compared this with the bank statement balance at the same date he found the following. 1 A credit transfer for $340, paid by Yeo, had been recorded in his cash book as $430. 2 Bank charges, $50, were shown on the bank statement but had not been recorded in the cash book. 3 A cheque to a supplier, $400, had not been presented. 4 A cheque paid into the bank, $180, had not yet been credited. 5 A cheque, $200, received from a customer, had been dishonoured. These items accounted for the difference between the cash book balance and the bank statement balance. REQUIRED (a) State what is meant by a bank statement. … …[1] (b) State which two items 1 to 5 resulted from timing differences. …[1] (c) Calculate the bank balance in the cash book after it had been updated. … … … … … …[4]
Question paper, page 12
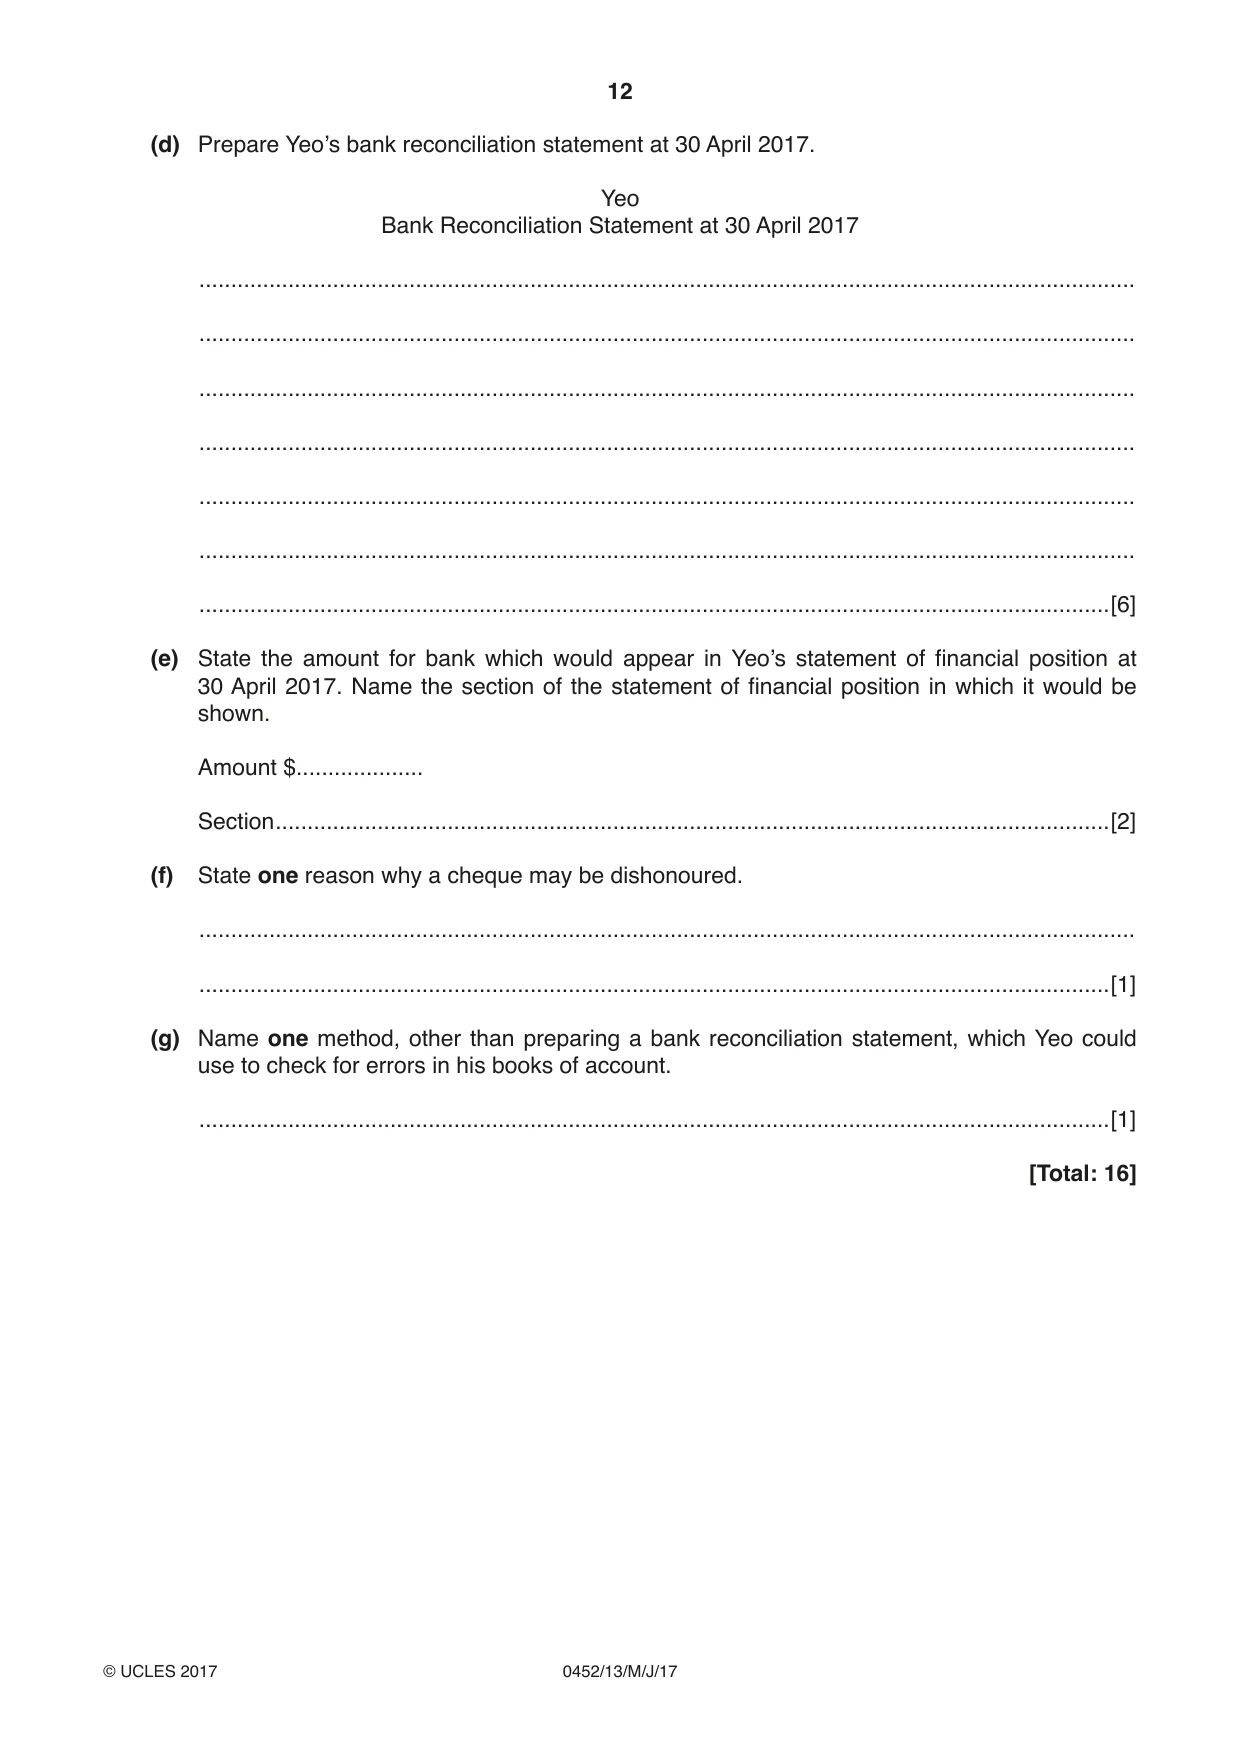
12 0452/13/M/J/17 © UCLES 2017 (d) Prepare Yeo’s bank reconciliation statement at 30 April 2017. Yeo Bank Reconciliation Statement at 30 April 2017 … … … … … … …[6] (e) State the amount for bank which would appear in Yeo’s statement of financial position at 30 April 2017. Name the section of the statement of financial position in which it would be shown. Amount $… Section …[2] (f) State one reason why a cheque may be dishonoured. … …[1] (g) Name one method, other than preparing a bank reconciliation statement, which Yeo could use to check for errors in his books of account. …[1] [Total: 16]
Question paper, page 13
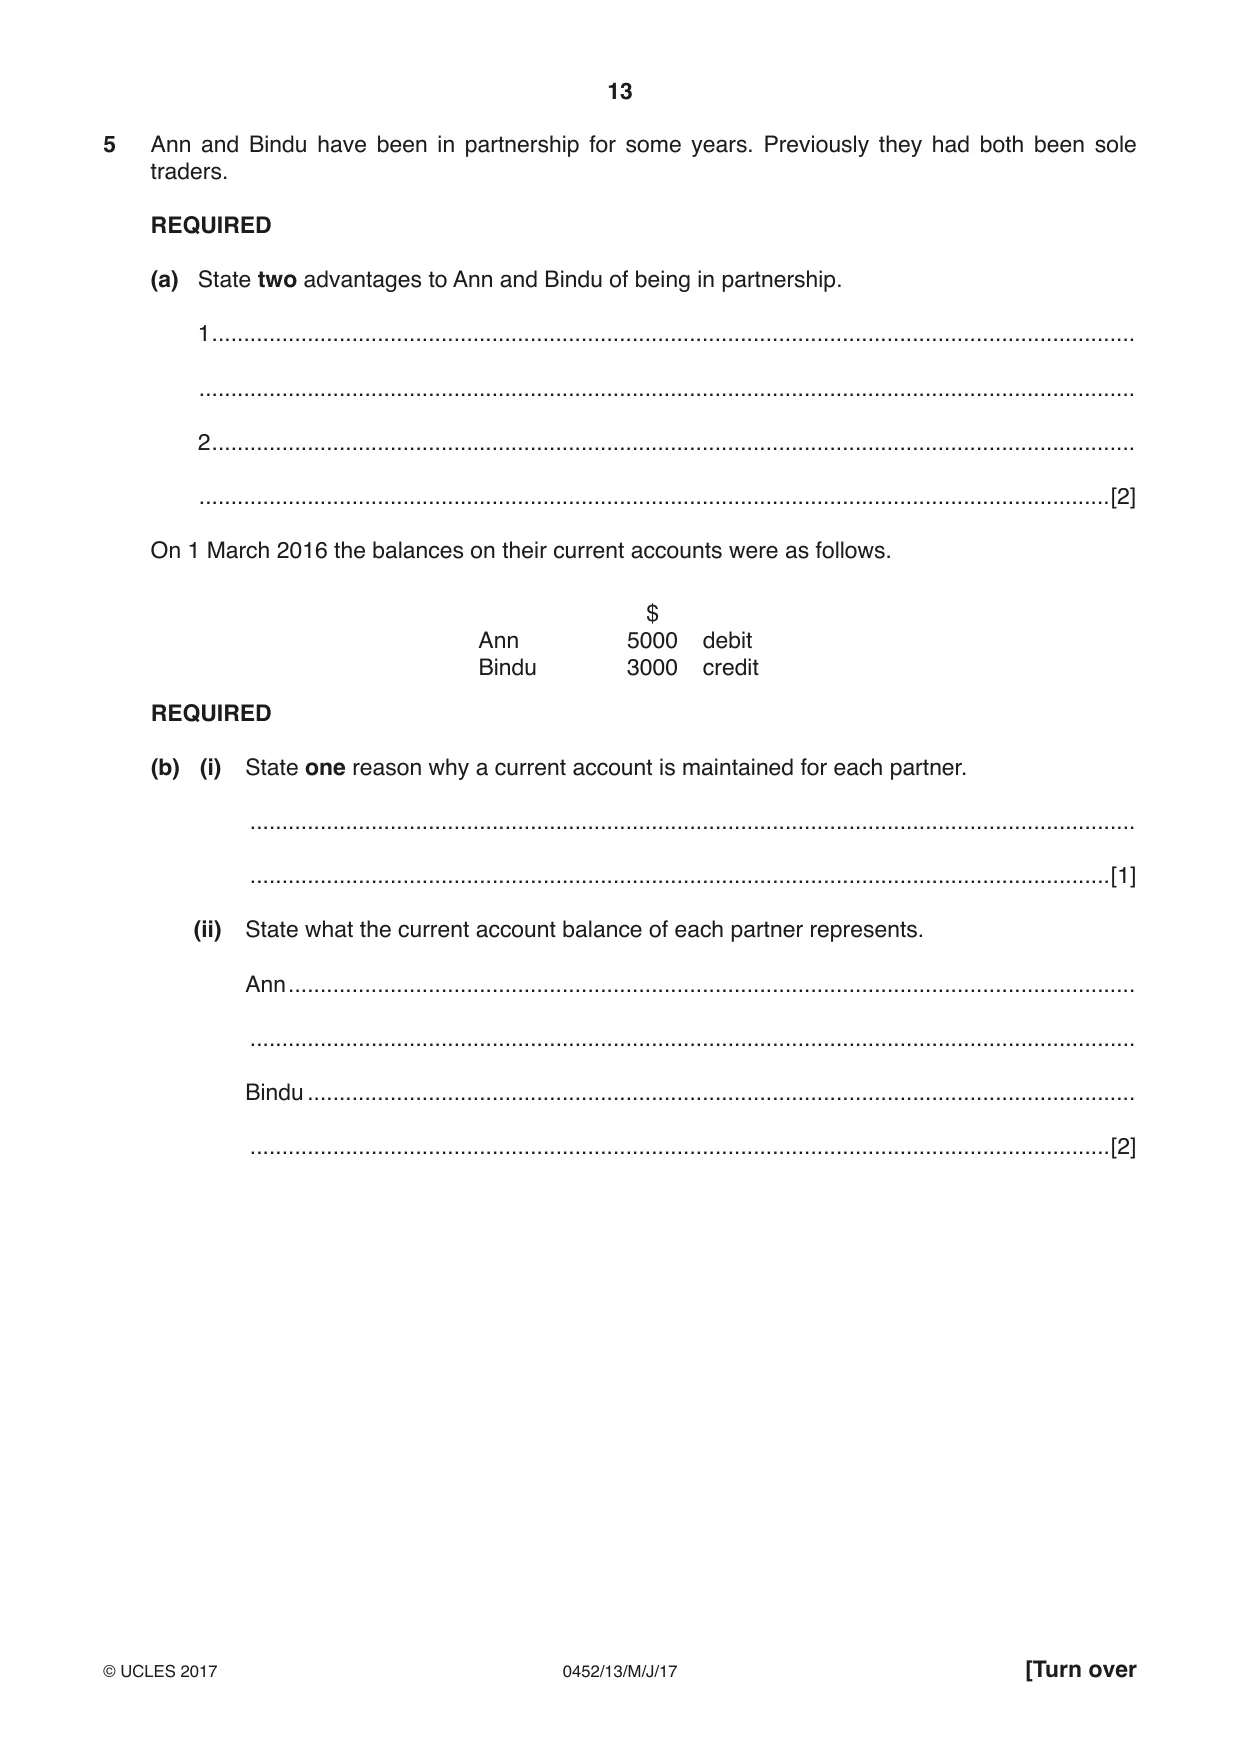
13 0452/13/M/J/17 © UCLES 2017 [Turn over 5 Ann and Bindu have been in partnership for some years. Previously they had both been sole traders. REQUIRED (a) State two advantages to Ann and Bindu of being in partnership. 1 … … 2 … …[2] On 1 March 2016 the balances on their current accounts were as follows. $ Ann 5000 debit Bindu 3000 credit REQUIRED (b) (i) State one reason why a current account is maintained for each partner. … …[1] (ii) State what the current account balance of each partner represents. Ann … … Bindu … …[2]
Question paper, page 14
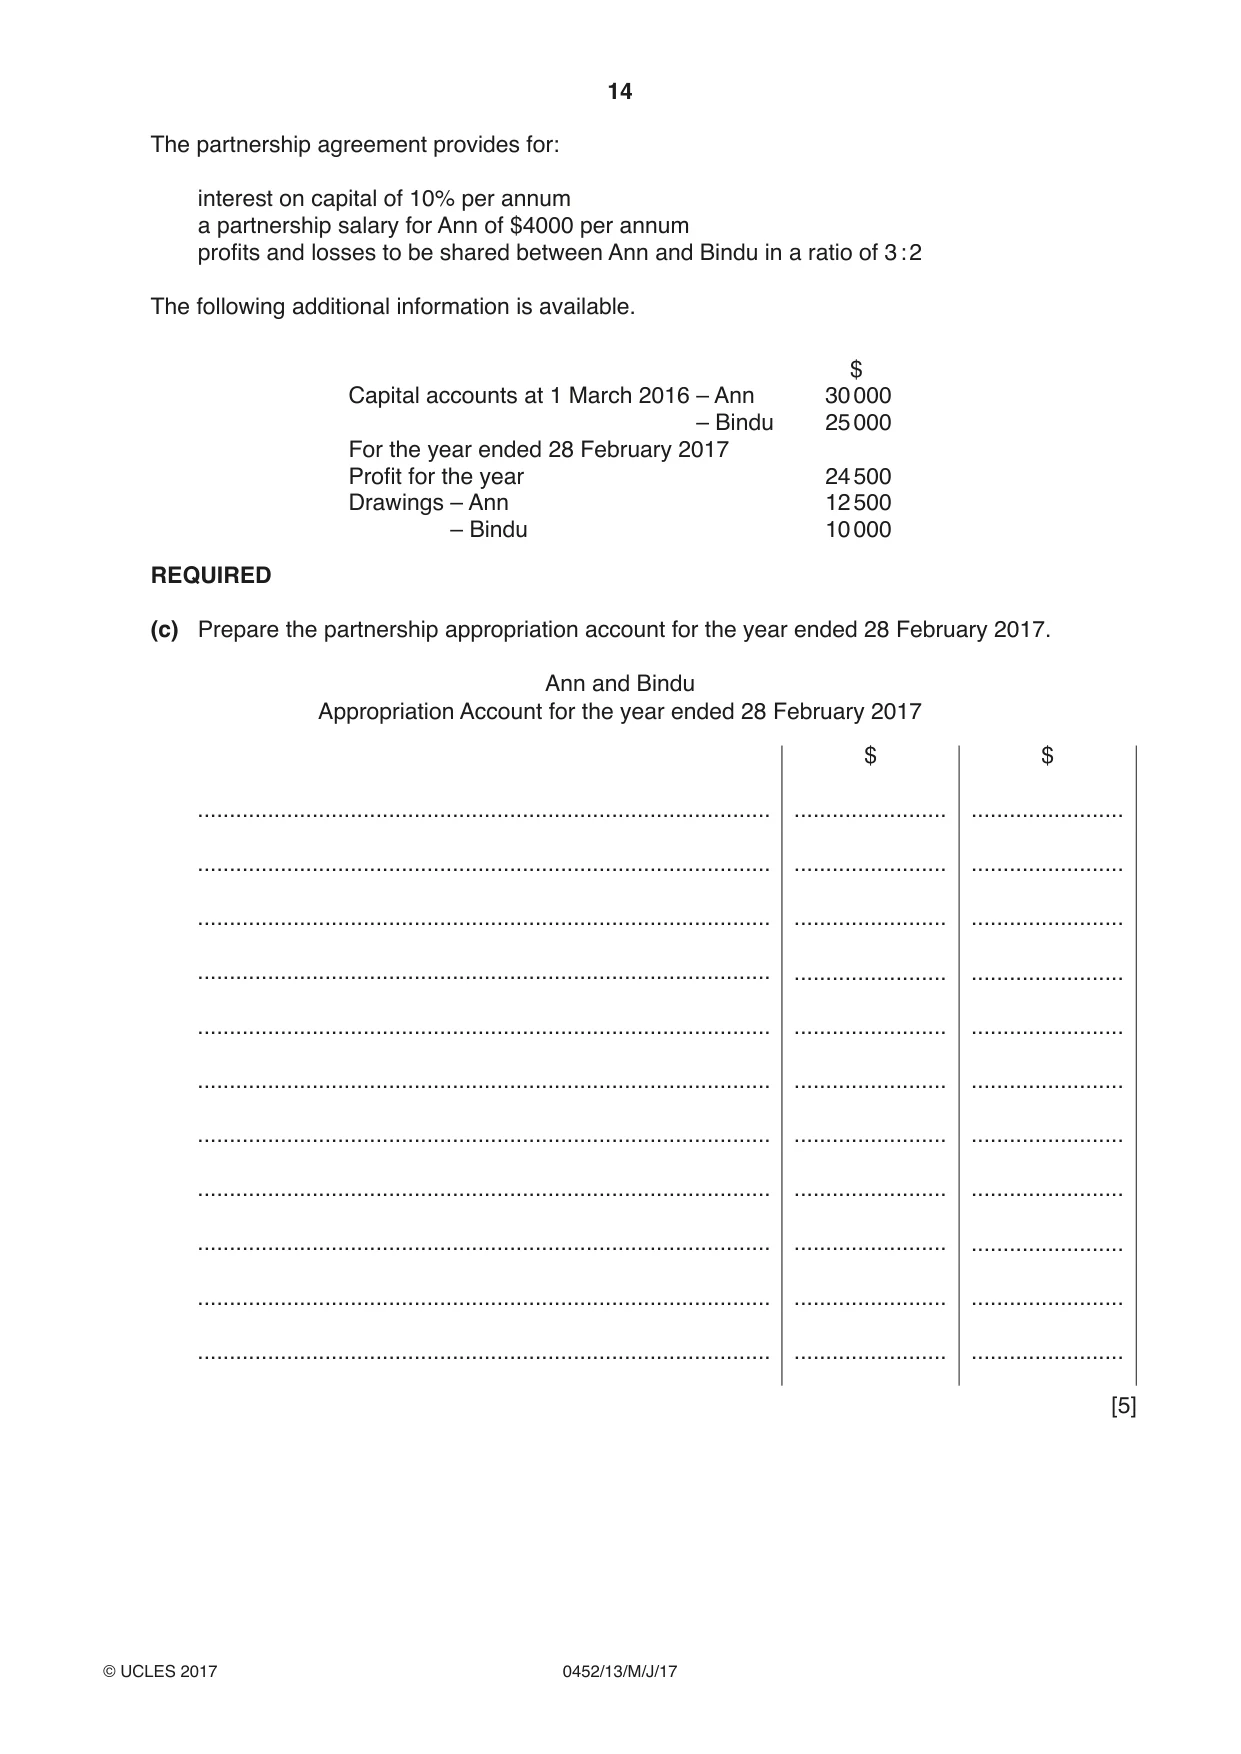
14 0452/13/M/J/17 © UCLES 2017 The partnership agreement provides for: interest on capital of 10% per annum a partnership salary for Ann of $4000 per annum profits and losses to be shared between Ann and Bindu in a ratio of 3 : 2 The following additional information is available. $ Capital accounts at 1 March 2016 – Ann – Bindu 30 000 25 000 For the year ended 28 February 2017 Profit for the year 24 500 Drawings – Ann – Bindu 12 500 10 000 REQUIRED (c) Prepare the partnership appropriation account for the year ended 28 February 2017. Ann and Bindu Appropriation Account for the year ended 28 February 2017 … … … … … … … … … … … $ … … … … … … … … … … … $ … … … … … … … … … … … [5]
Question paper, page 15
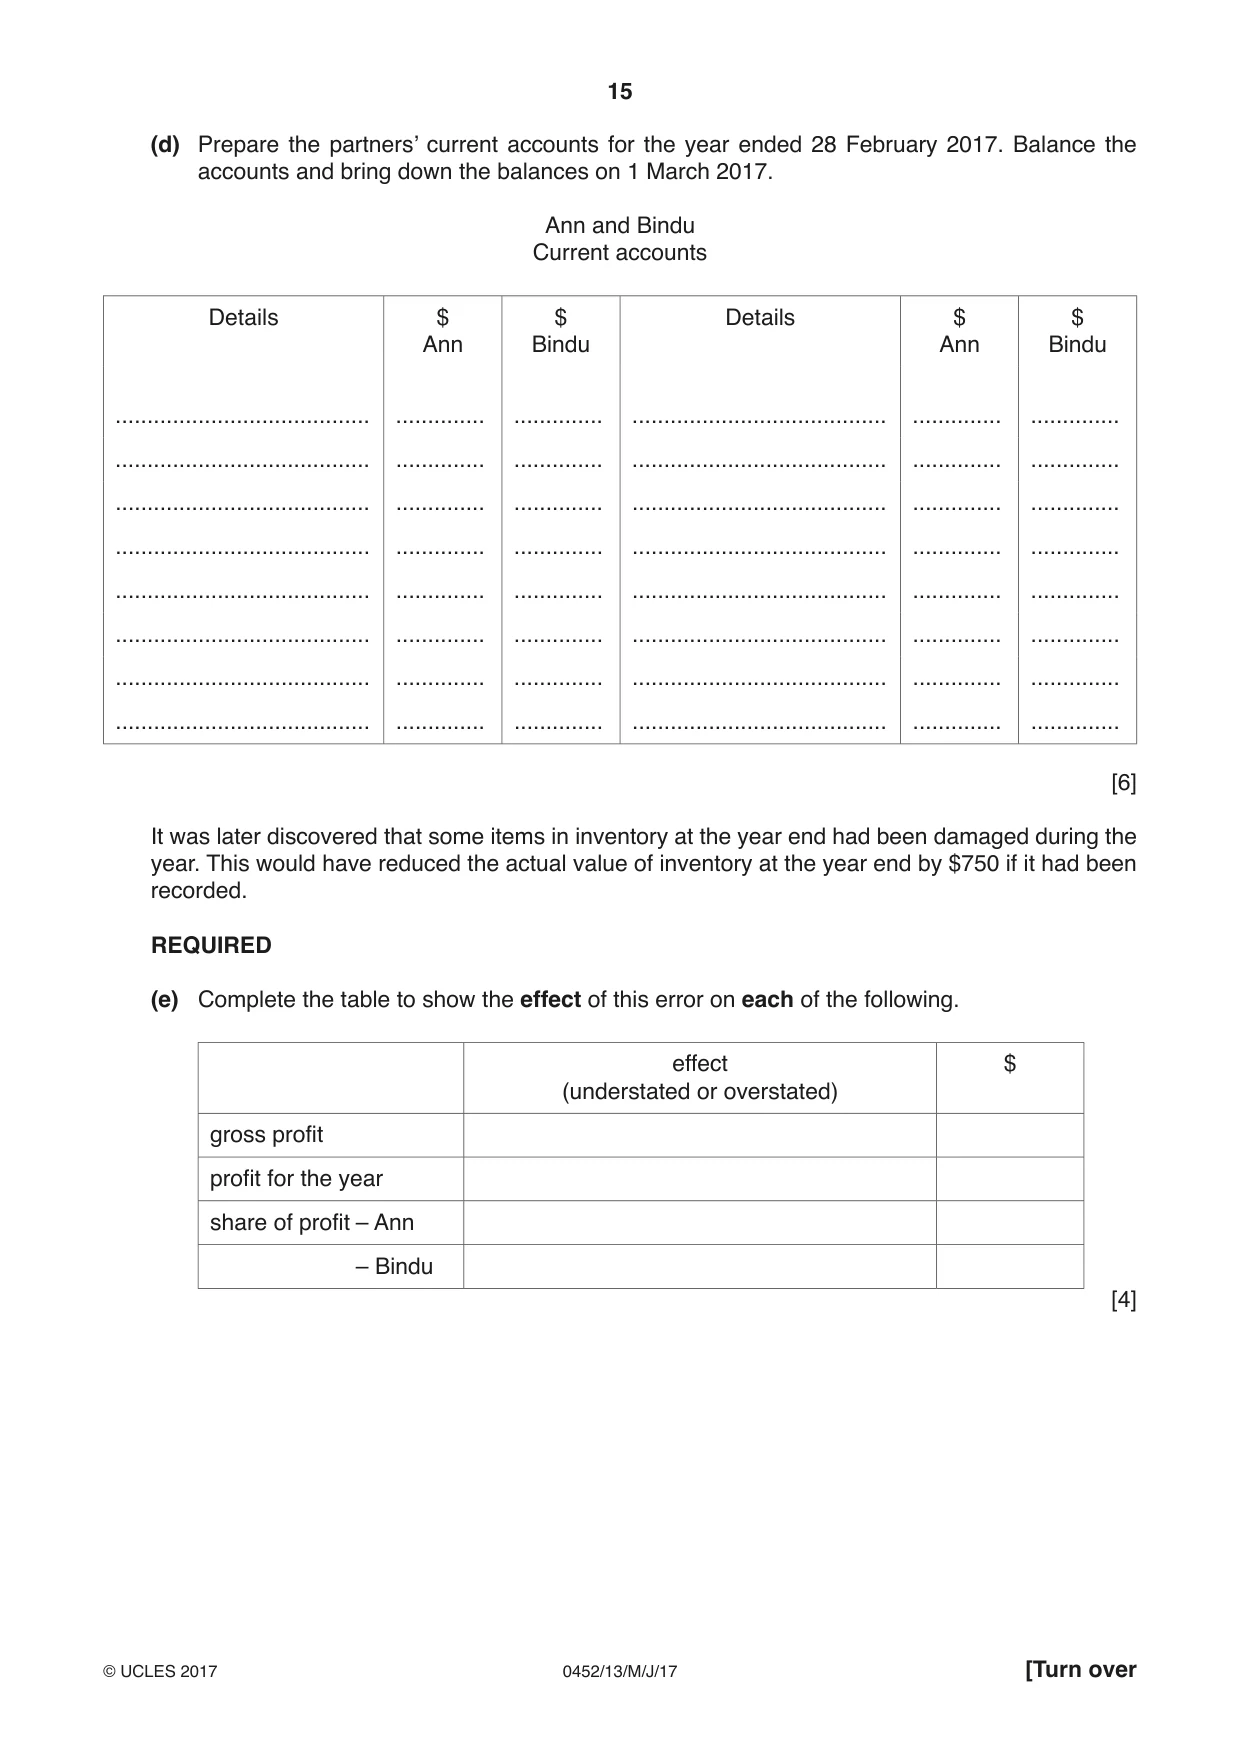
15 0452/13/M/J/17 © UCLES 2017 [Turn over (d) Prepare the partners’ current accounts for the year ended 28 February 2017. Balance the accounts and bring down the balances on 1 March 2017. Ann and Bindu Current accounts Details $ Ann $ Bindu Details $ Ann $ Bindu … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] It was later discovered that some items in inventory at the year end had been damaged during the year. This would have reduced the actual value of inventory at the year end by $750 if it had been recorded. REQUIRED (e) Complete the table to show the effect of this error on each of the following. effect (understated or overstated) $ gross profit profit for the year share of profit – Ann – Bindu [4]
Question paper, page 16
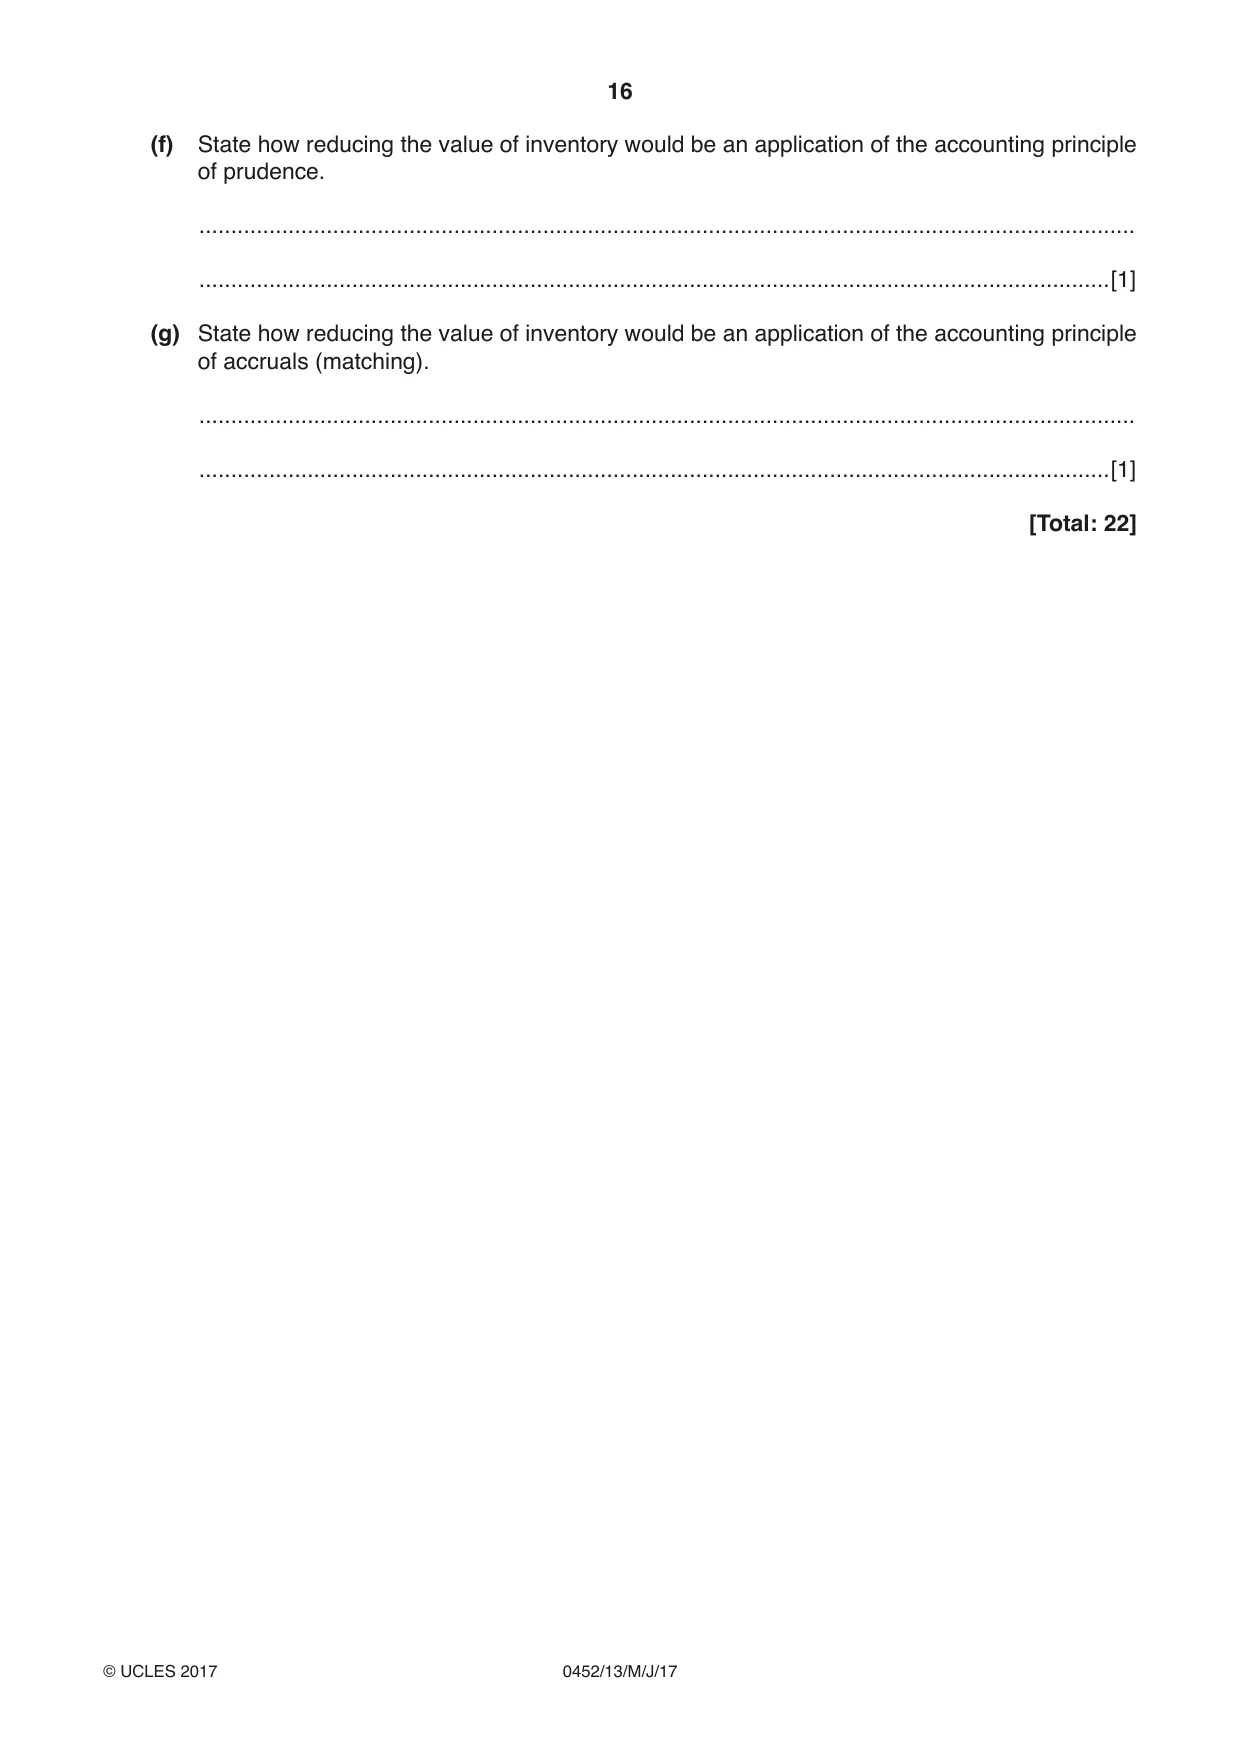
16 0452/13/M/J/17 © UCLES 2017 (f) State how reducing the value of inventory would be an application of the accounting principle of prudence. … …[1] (g) State how reducing the value of inventory would be an application of the accounting principle of accruals (matching). … …[1] [Total: 22]
Question paper, page 17
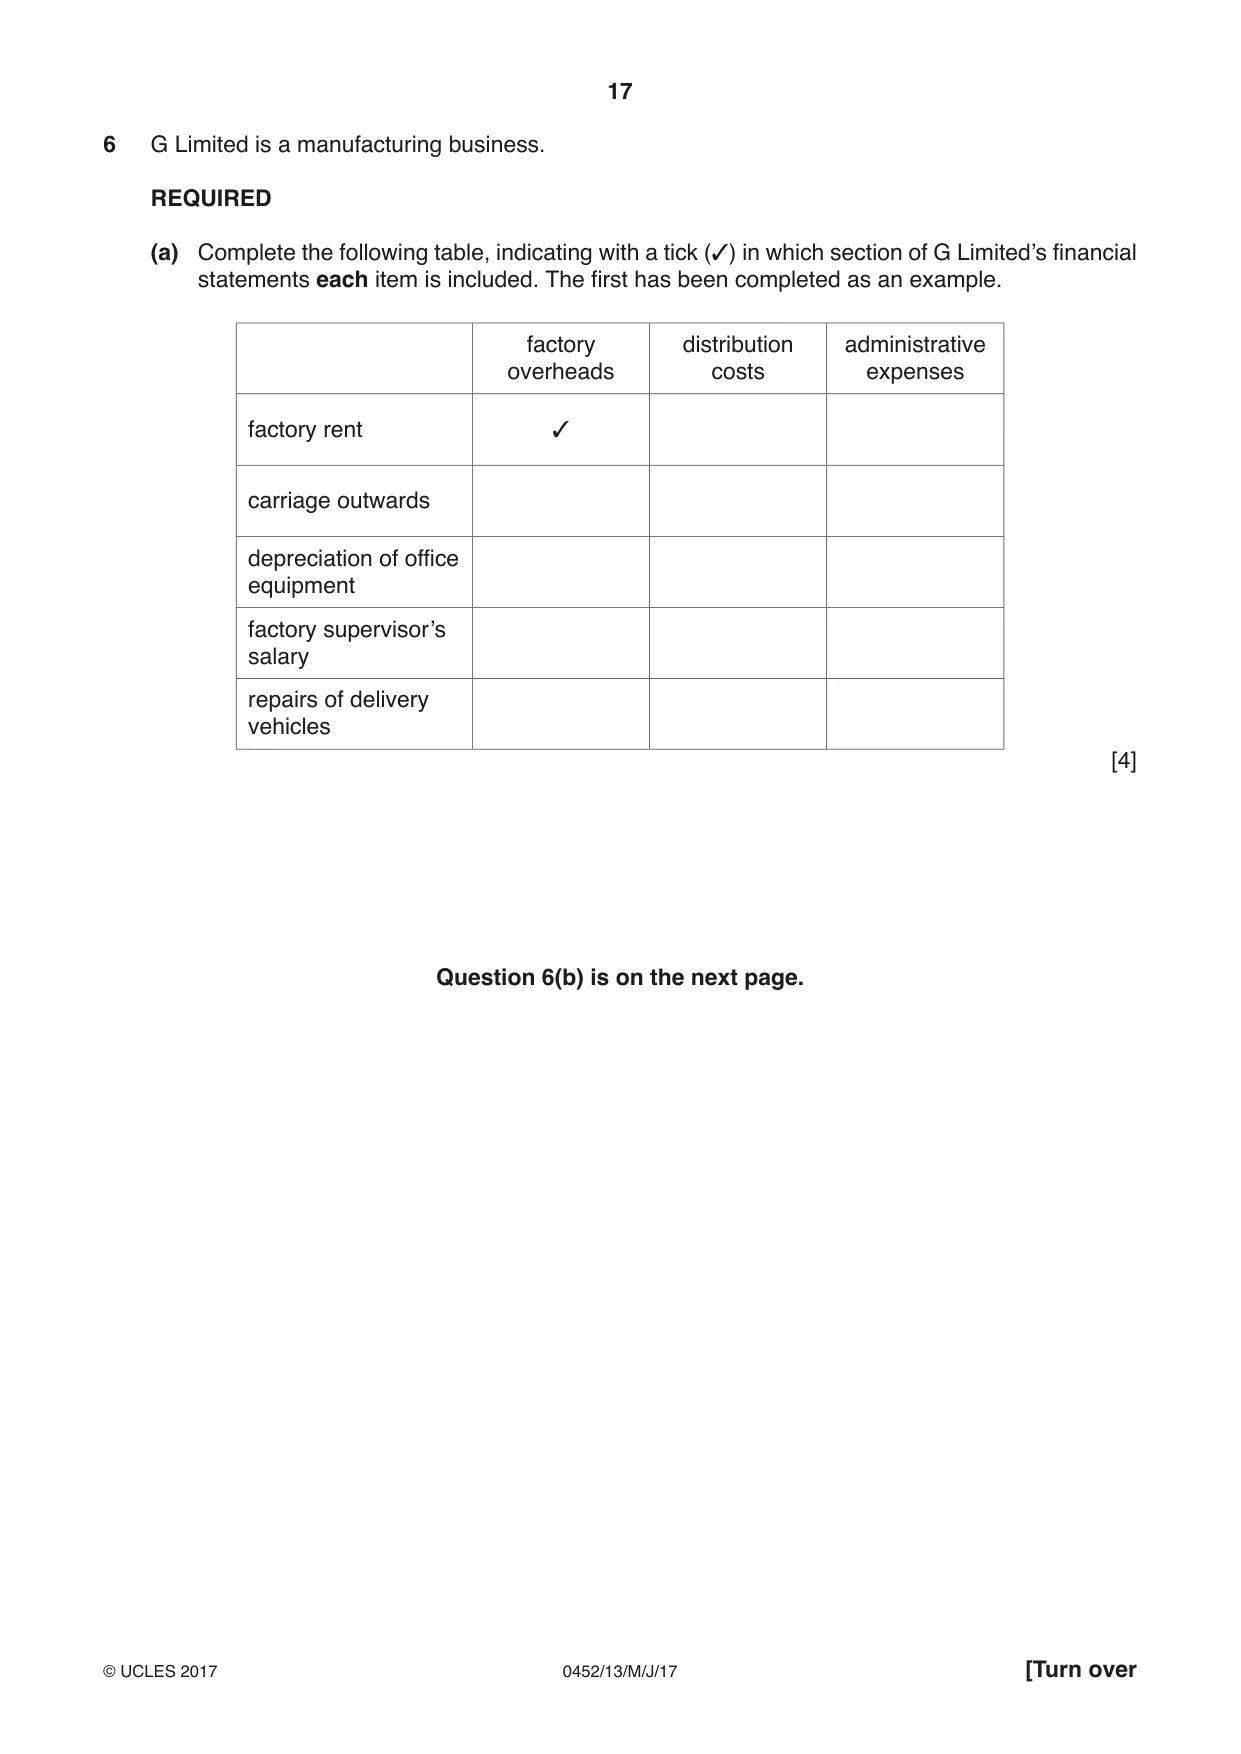
17 0452/13/M/J/17 © UCLES 2017 [Turn over 6 G Limited is a manufacturing business. REQUIRED (a) Complete the following table, indicating with a tick (✓) in which section of G Limited’s financial statements each item is included. The first has been completed as an example. factory overheads distribution costs administrative expenses factory rent ✓ carriage outwards depreciation of office equipment factory supervisor’s salary repairs of delivery vehicles [4] Question 6(b) is on the next page.
Question paper, page 18
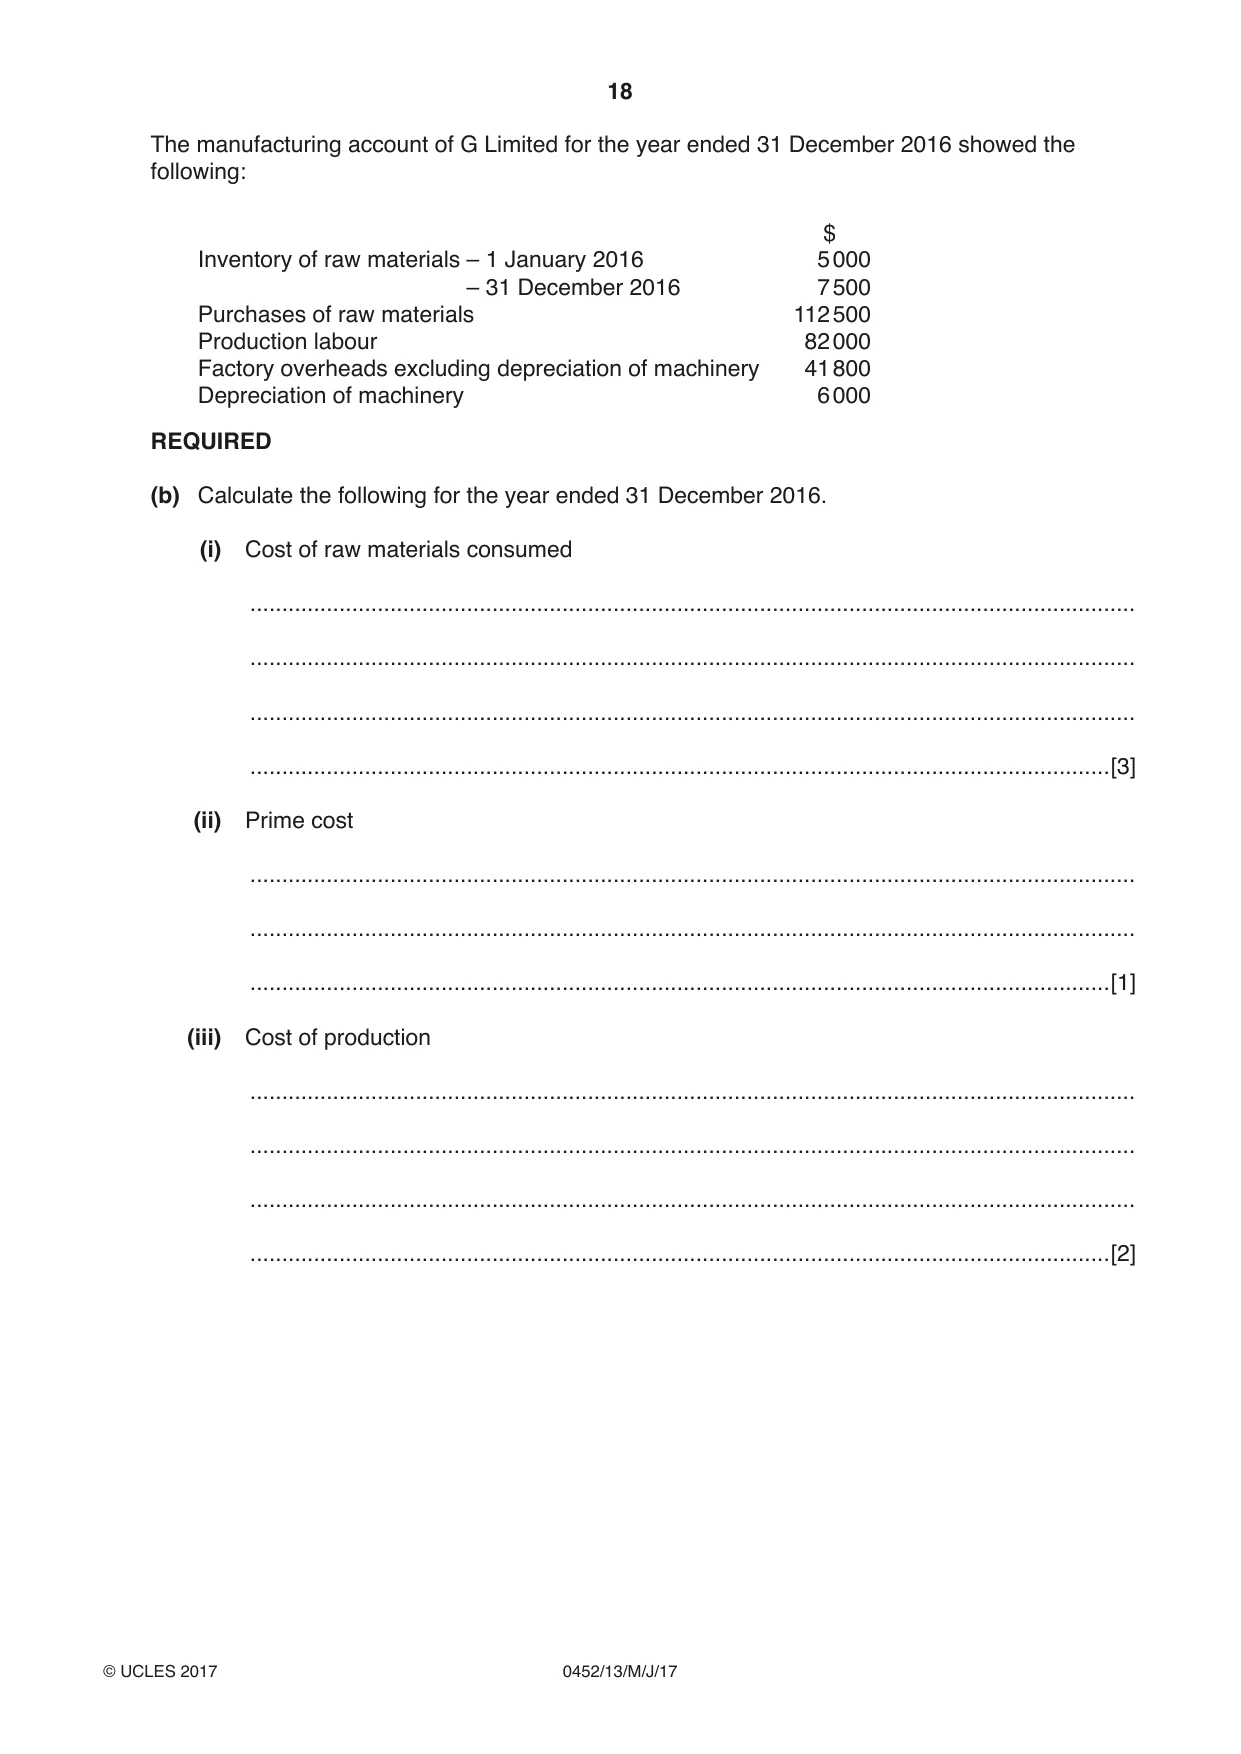
18 0452/13/M/J/17 © UCLES 2017 The manufacturing account of G Limited for the year ended 31 December 2016 showed the following: $ Inventory of raw materials – 1 January 2016 – 31 December 2016 5 000 7 500 Purchases of raw materials 112 500 Production labour 82 000 Factory overheads excluding depreciation of machinery 41 800 Depreciation of machinery 6 000 REQUIRED (b) Calculate the following for the year ended 31 December 2016. (i) Cost of raw materials consumed … … … …[3] (ii) Prime cost … … …[1] (iii) Cost of production … … … …[2]
Question paper, page 19
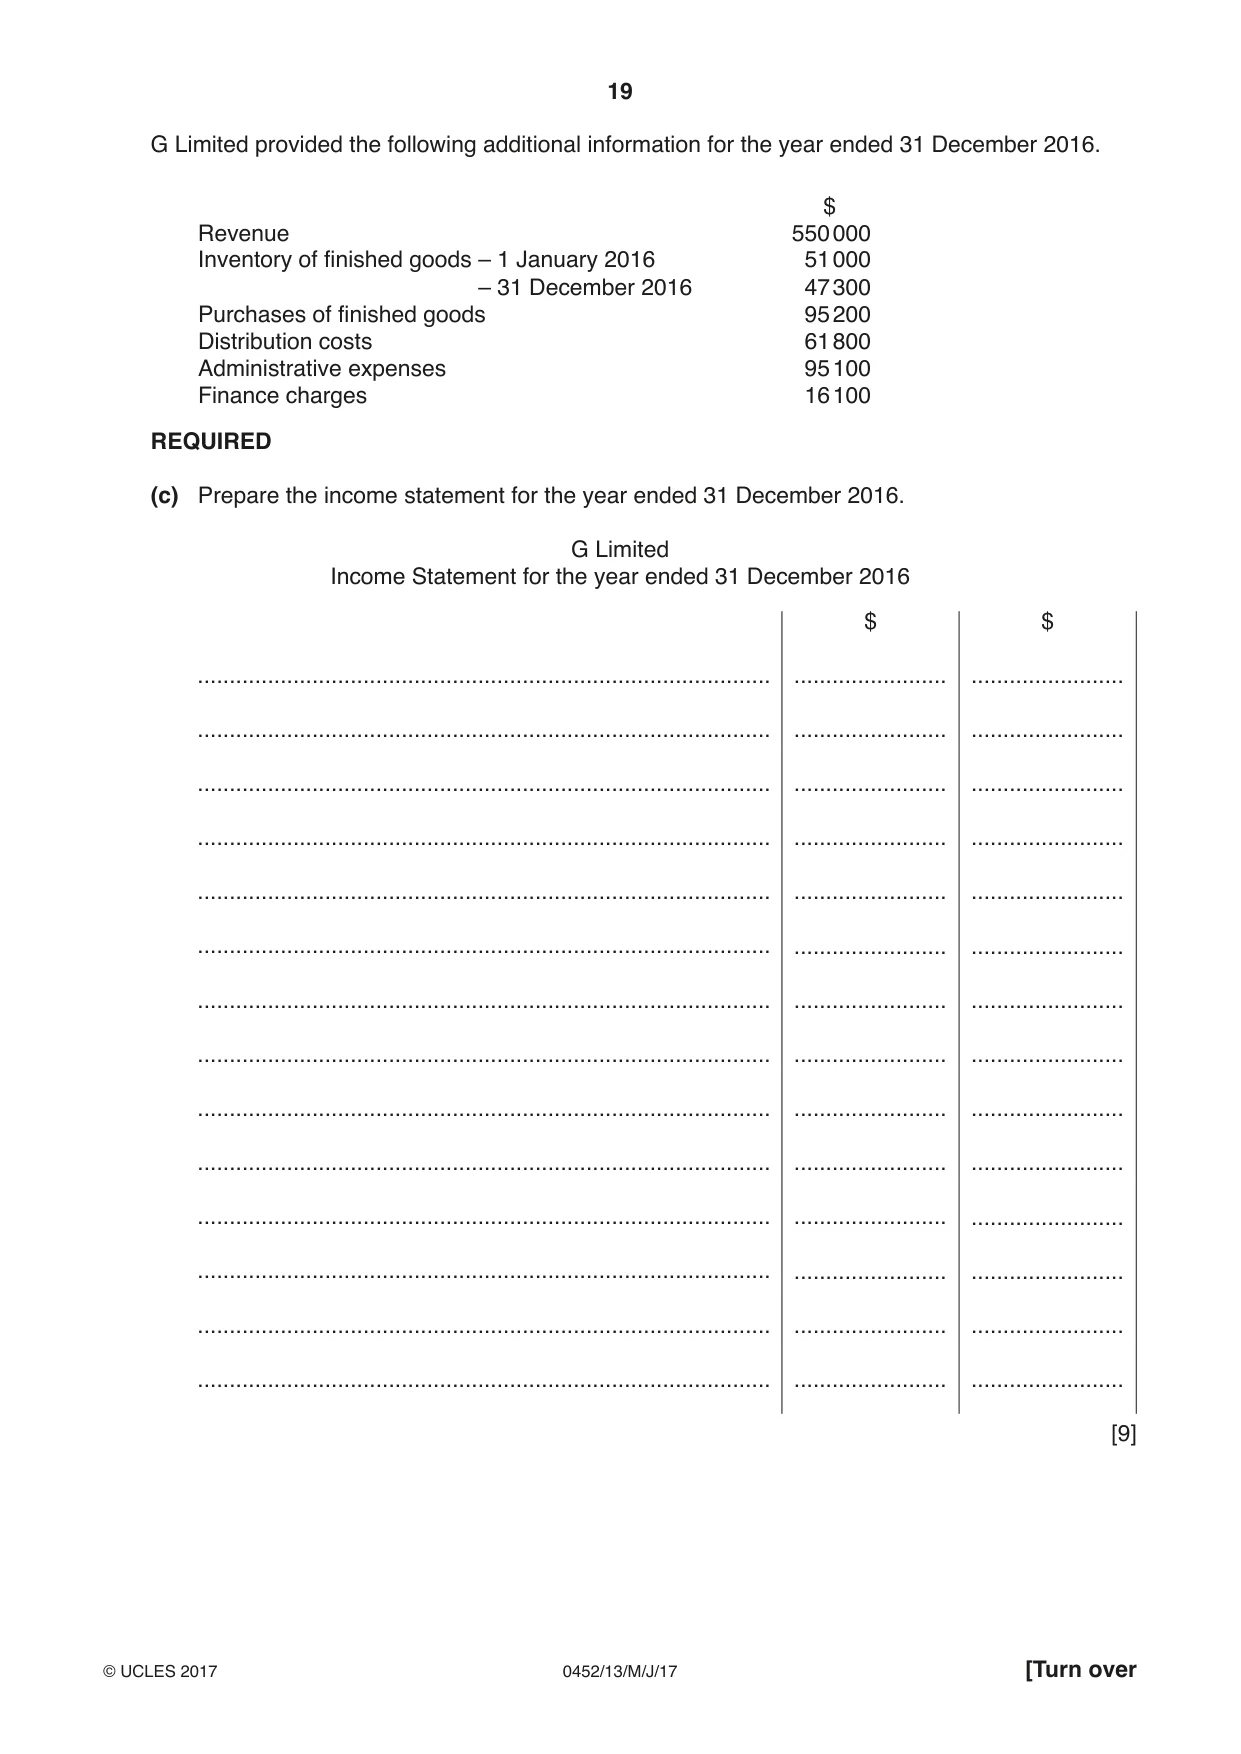
19 0452/13/M/J/17 © UCLES 2017 [Turn over G Limited provided the following additional information for the year ended 31 December 2016. $ Revenue 550 000 Inventory of finished goods – 1 January 2016 – 31 December 2016 51 000 47 300 Purchases of finished goods 95 200 Distribution costs 61 800 Administrative expenses 95 100 Finance charges 16 100 REQUIRED (c) Prepare the income statement for the year ended 31 December 2016. G Limited Income Statement for the year ended 31 December 2016 … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … $ … … … … … … … … … … … … … … [9]
Question paper, page 20
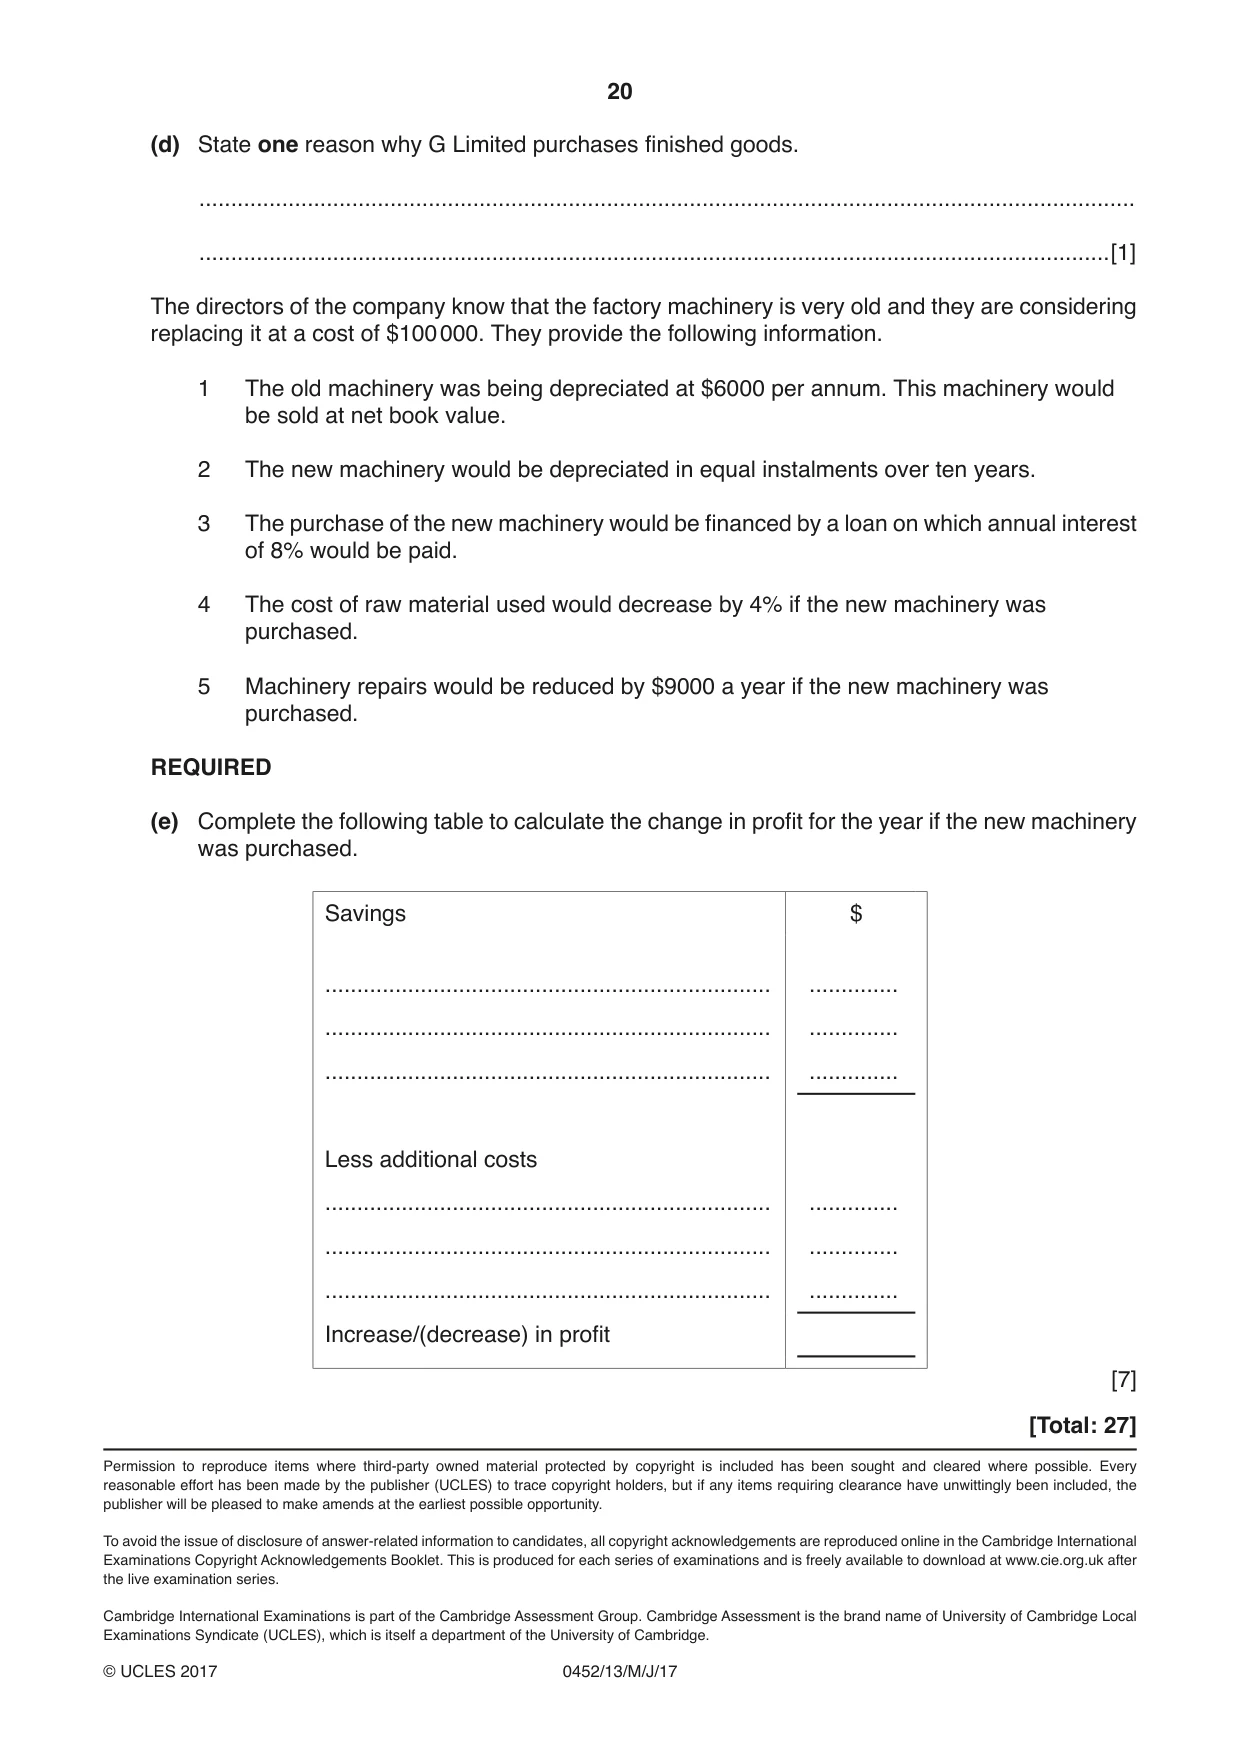
20 0452/13/M/J/17 © UCLES 2017 (d) State one reason why G Limited purchases finished goods. … …[1] The directors of the company know that the factory machinery is very old and they are considering replacing it at a cost of $100 000. They provide the following information. 1 The old machinery was being depreciated at $6000 per annum. This machinery would be sold at net book value. 2 The new machinery would be depreciated in equal instalments over ten years. 3 The purchase of the new machinery would be financed by a loan on which annual interest of 8% would be paid. 4 The cost of raw material used would decrease by 4% if the new machinery was purchased. 5 Machinery repairs would be reduced by $9000 a year if the new machinery was purchased. REQUIRED (e) Complete the following table to calculate the change in profit for the year if the new machinery was purchased. Savings $ … … … … … … Less additional costs … … … … … … Increase/(decrease) in profit [7] [Total: 27] Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge International Examinations Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cie.org.uk after the live examination series. Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge.
Mark scheme, page 1
® IGCSE is a registered trademark. This document consists of 11 printed pages. © UCLES 2017 [Turn over Cambridge International Examinations Cambridge International General Certificate of Secondary Education ACCOUNTING 0452/13 Paper 1 May/June 2017 MARK SCHEME Maximum Mark: 120 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the May/June 2017 series for most Cambridge IGCSE®, Cambridge International A and AS Level and Cambridge Pre-U components, and some Cambridge O Level components.
Mark scheme, page 2
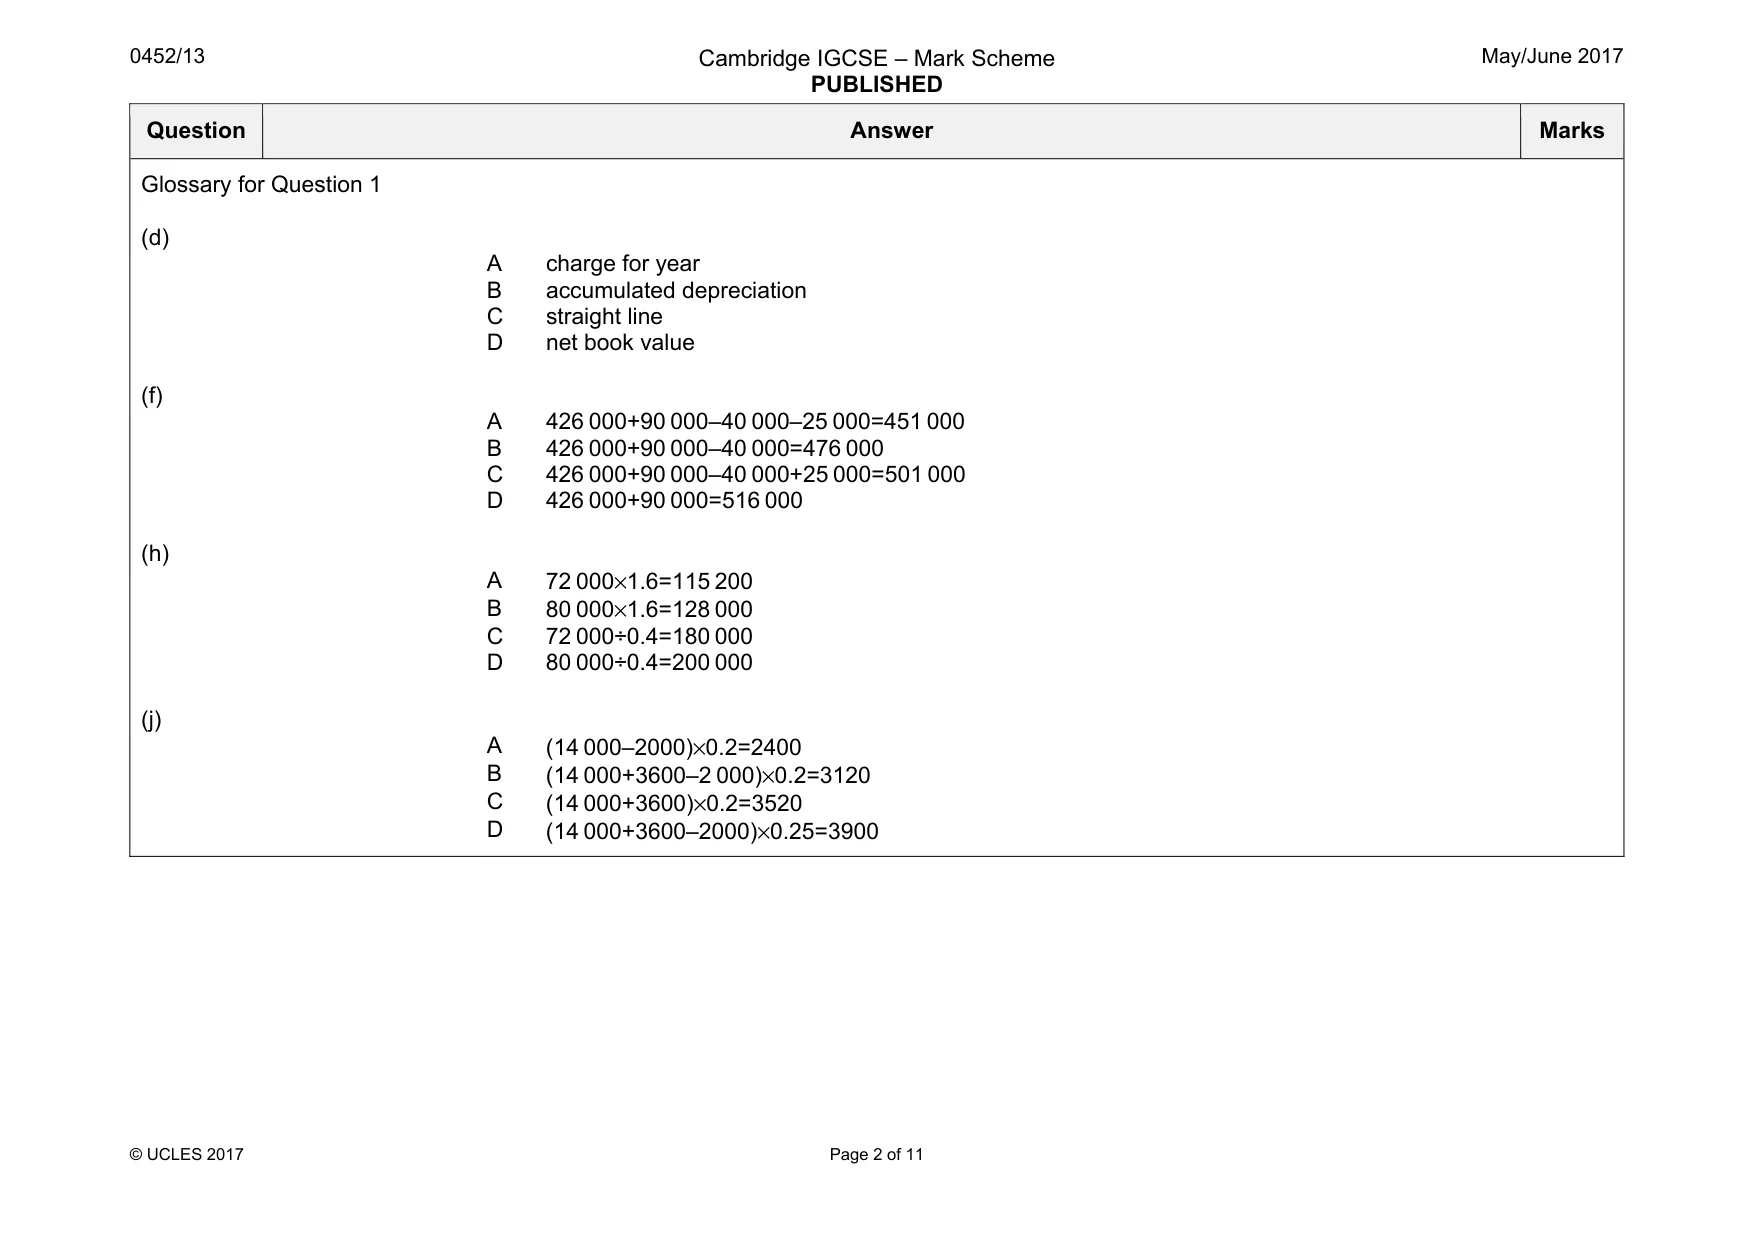
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 2 of 11 Question Answer Marks Glossary for Question 1 (d) A charge for year B accumulated depreciation C straight line D net book value (f) A 426 000+90 000–40 000–25 000=451 000 B 426 000+90 000–40 000=476 000 C 426 000+90 000–40 000+25 000=501 000 D 426 000+90 000=516 000 (h) A 72 000×1.6=115 200 B 80 000×1.6=128 000 C 72 000÷0.4=180 000 D 80 000÷0.4=200 000 (j) A (14 000–2000)×0.2=2400 B (14 000+3600–2 000)×0.2=3120 C (14 000+3600)×0.2=3520 D (14 000+3600–2000)×0.25=3900
Mark scheme, page 3
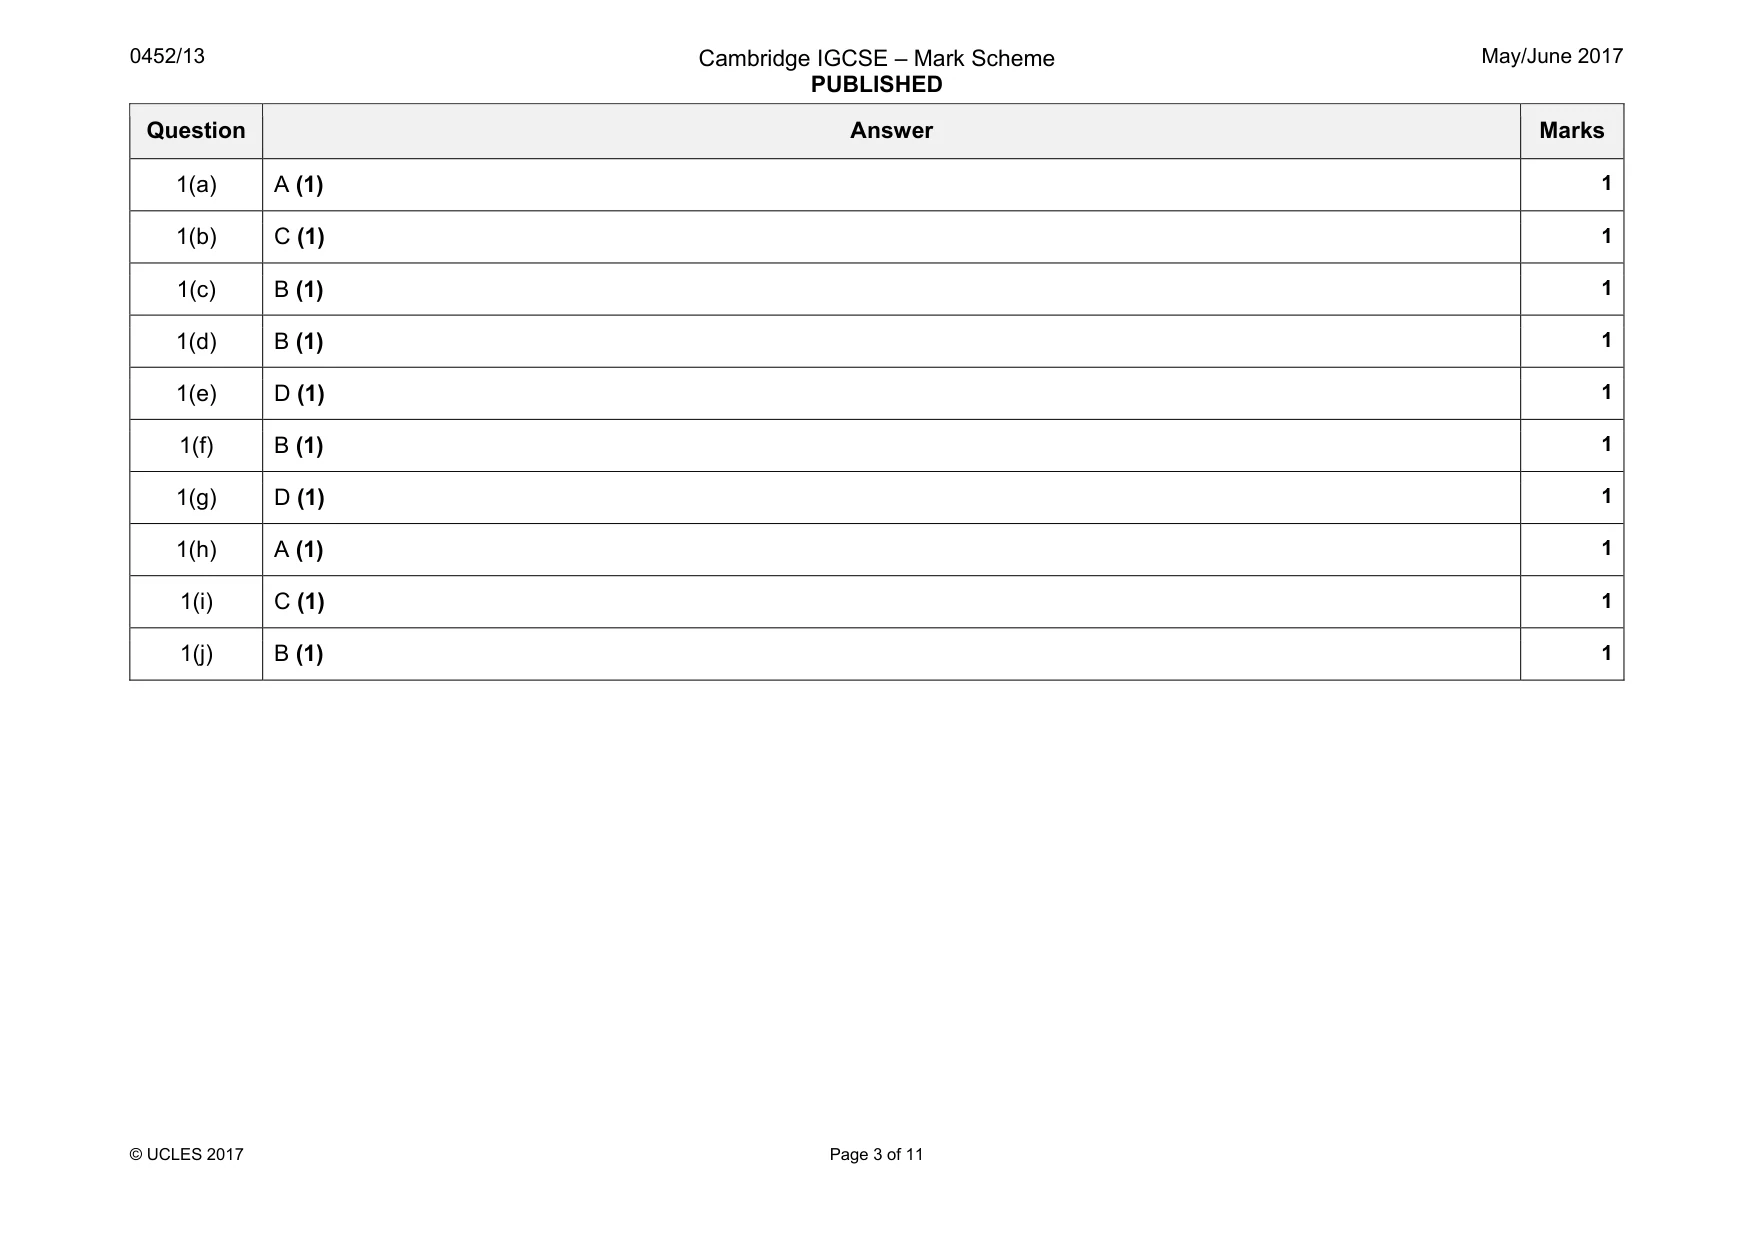
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 3 of 11 Question Answer Marks 1(a) A (1) 1 1(b) C (1) 1 1(c) B (1) 1 1(d) B (1) 1 1(e) D (1) 1 1(f) B (1) 1 1(g) D (1) 1 1(h) A (1) 1 1(i) C (1) 1 1(j) B (1) 1
Mark scheme, page 4
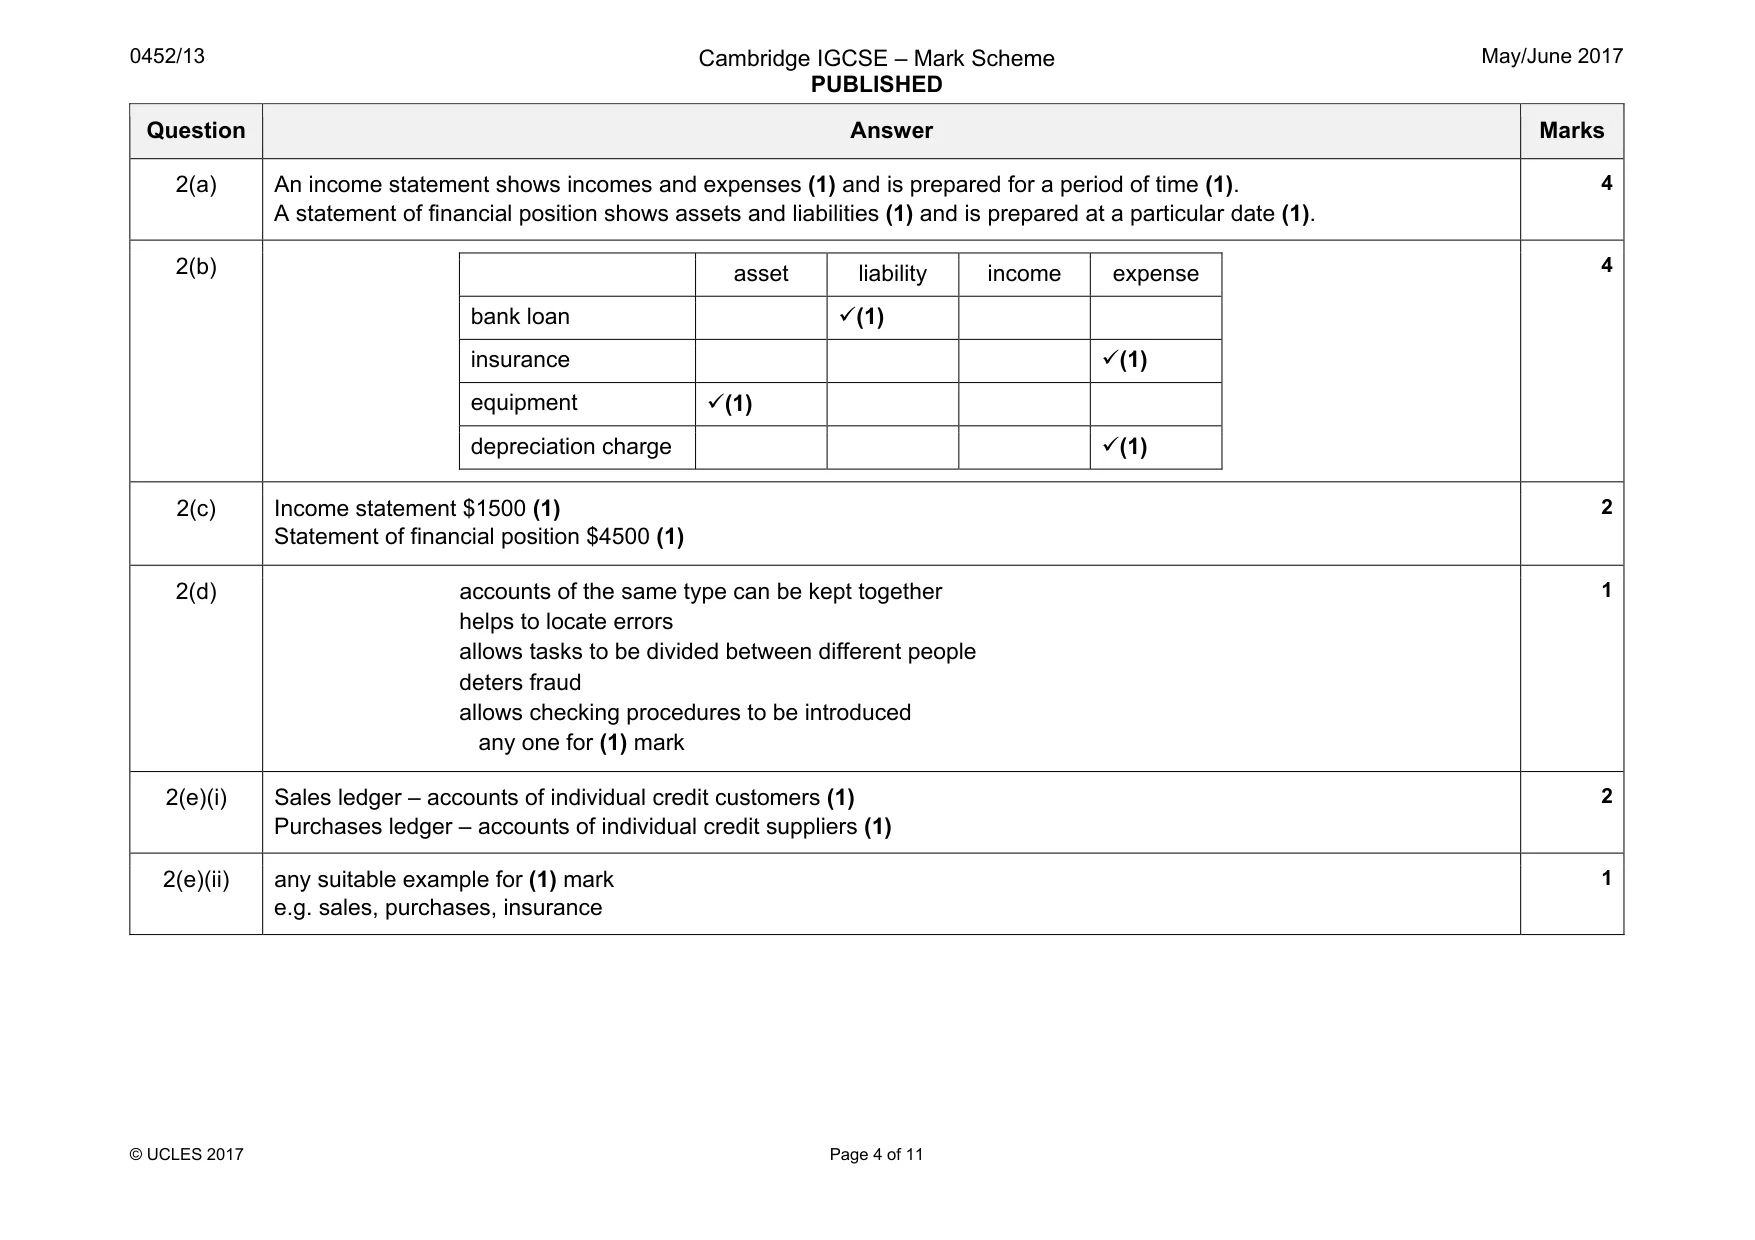
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 4 of 11 Question Answer Marks 2(a) An income statement shows incomes and expenses (1) and is prepared for a period of time (1). A statement of financial position shows assets and liabilities (1) and is prepared at a particular date (1). 4 2(b) asset liability income expense bank loan 9(1) insurance 9(1) equipment 9(1) depreciation charge 9(1) 4 2(c) Income statement $1500 (1) Statement of financial position $4500 (1) 2 2(d) accounts of the same type can be kept together helps to locate errors allows tasks to be divided between different people deters fraud allows checking procedures to be introduced any one for (1) mark 1 2(e)(i) Sales ledger – accounts of individual credit customers (1) Purchases ledger – accounts of individual credit suppliers (1) 2 2(e)(ii) any suitable example for (1) mark e.g. sales, purchases, insurance 1
Mark scheme, page 5
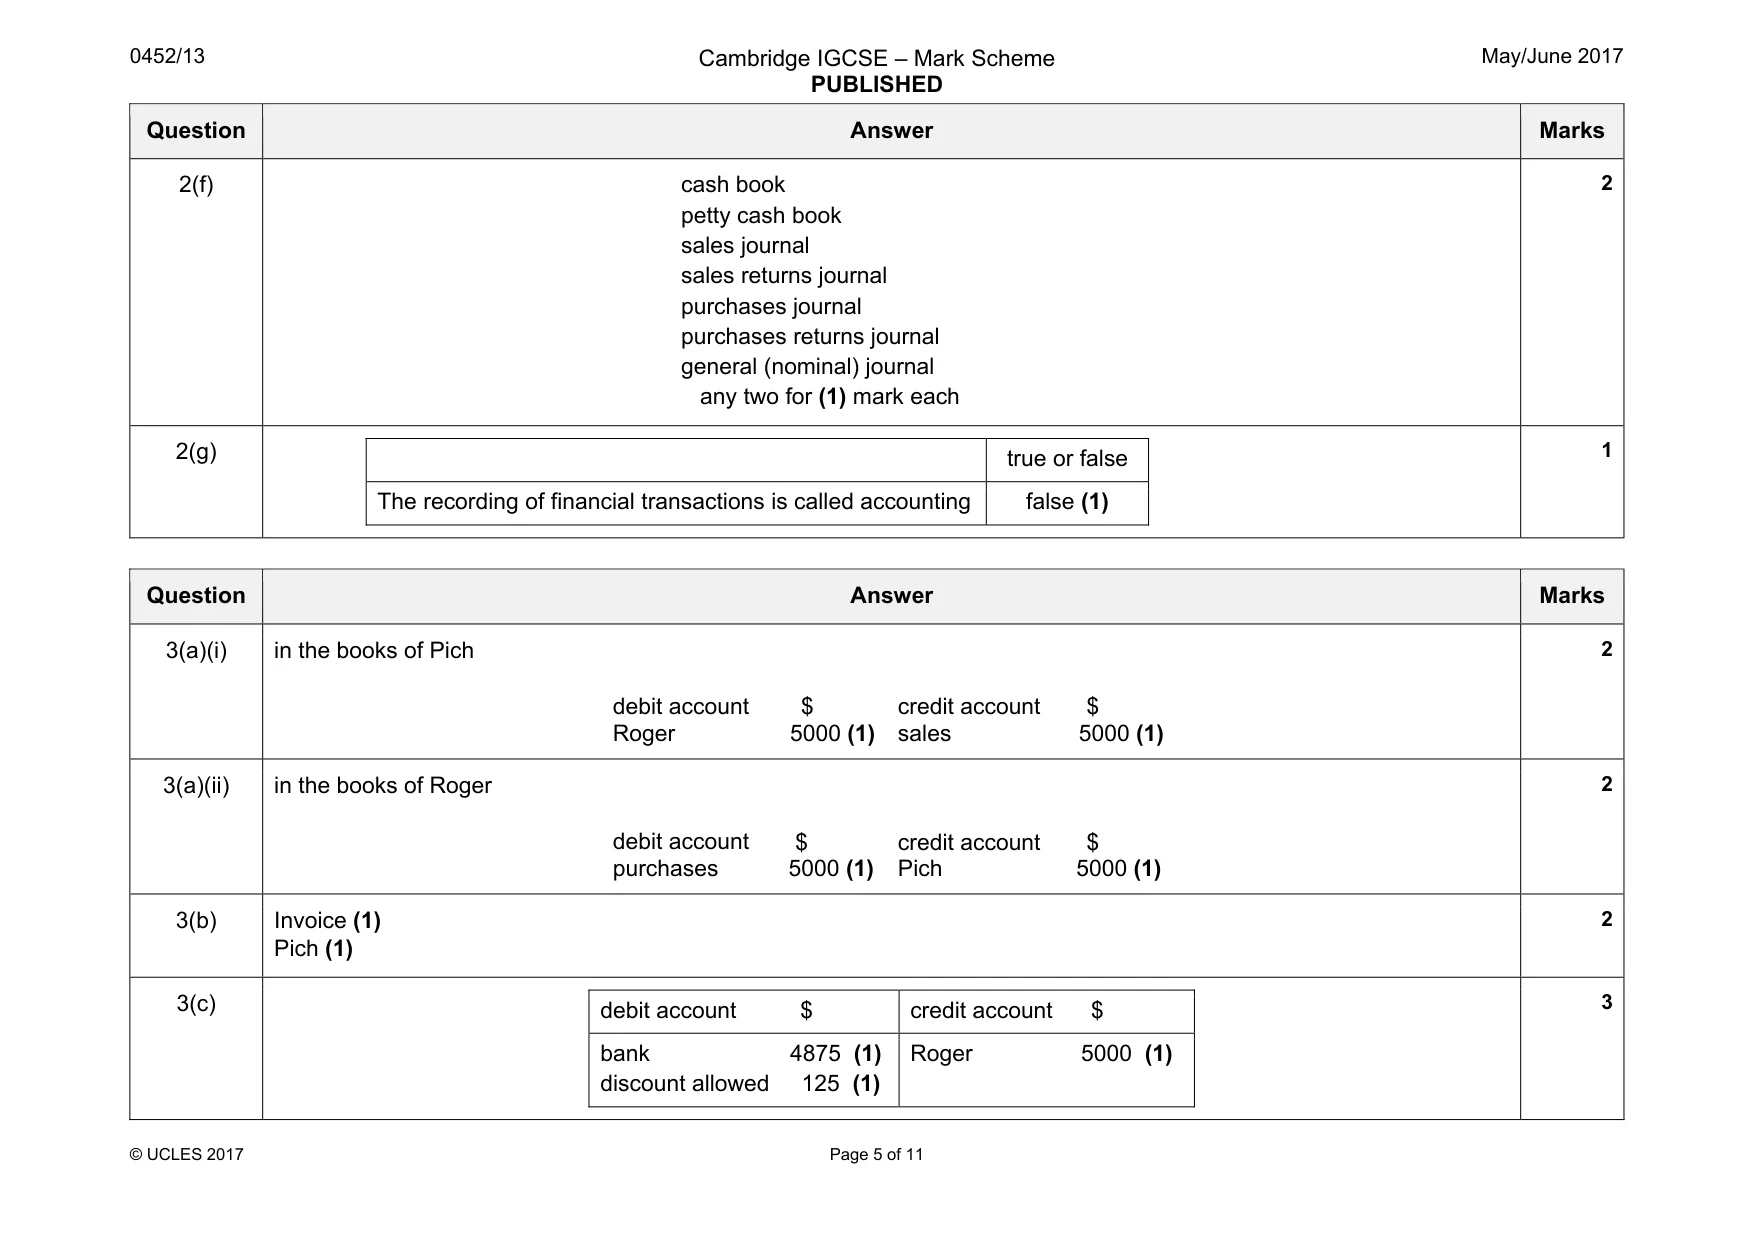
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 5 of 11 Question Answer Marks 2(f) cash book petty cash book sales journal sales returns journal purchases journal purchases returns journal general (nominal) journal any two for (1) mark each 2 2(g) true or false The recording of financial transactions is called accounting false (1) 1 Question Answer Marks 3(a)(i) in the books of Pich debit account $ credit account $ Roger 5000 (1) sales 5000 (1) 2 3(a)(ii) in the books of Roger debit account $ credit account $ purchases 5000 (1) Pich 5000 (1) 2 3(b) Invoice (1) Pich (1) 2 3(c) debit account $ credit account $ bank 4875 (1) discount allowed 125 (1) Roger 5000 (1) 3
Mark scheme, page 6
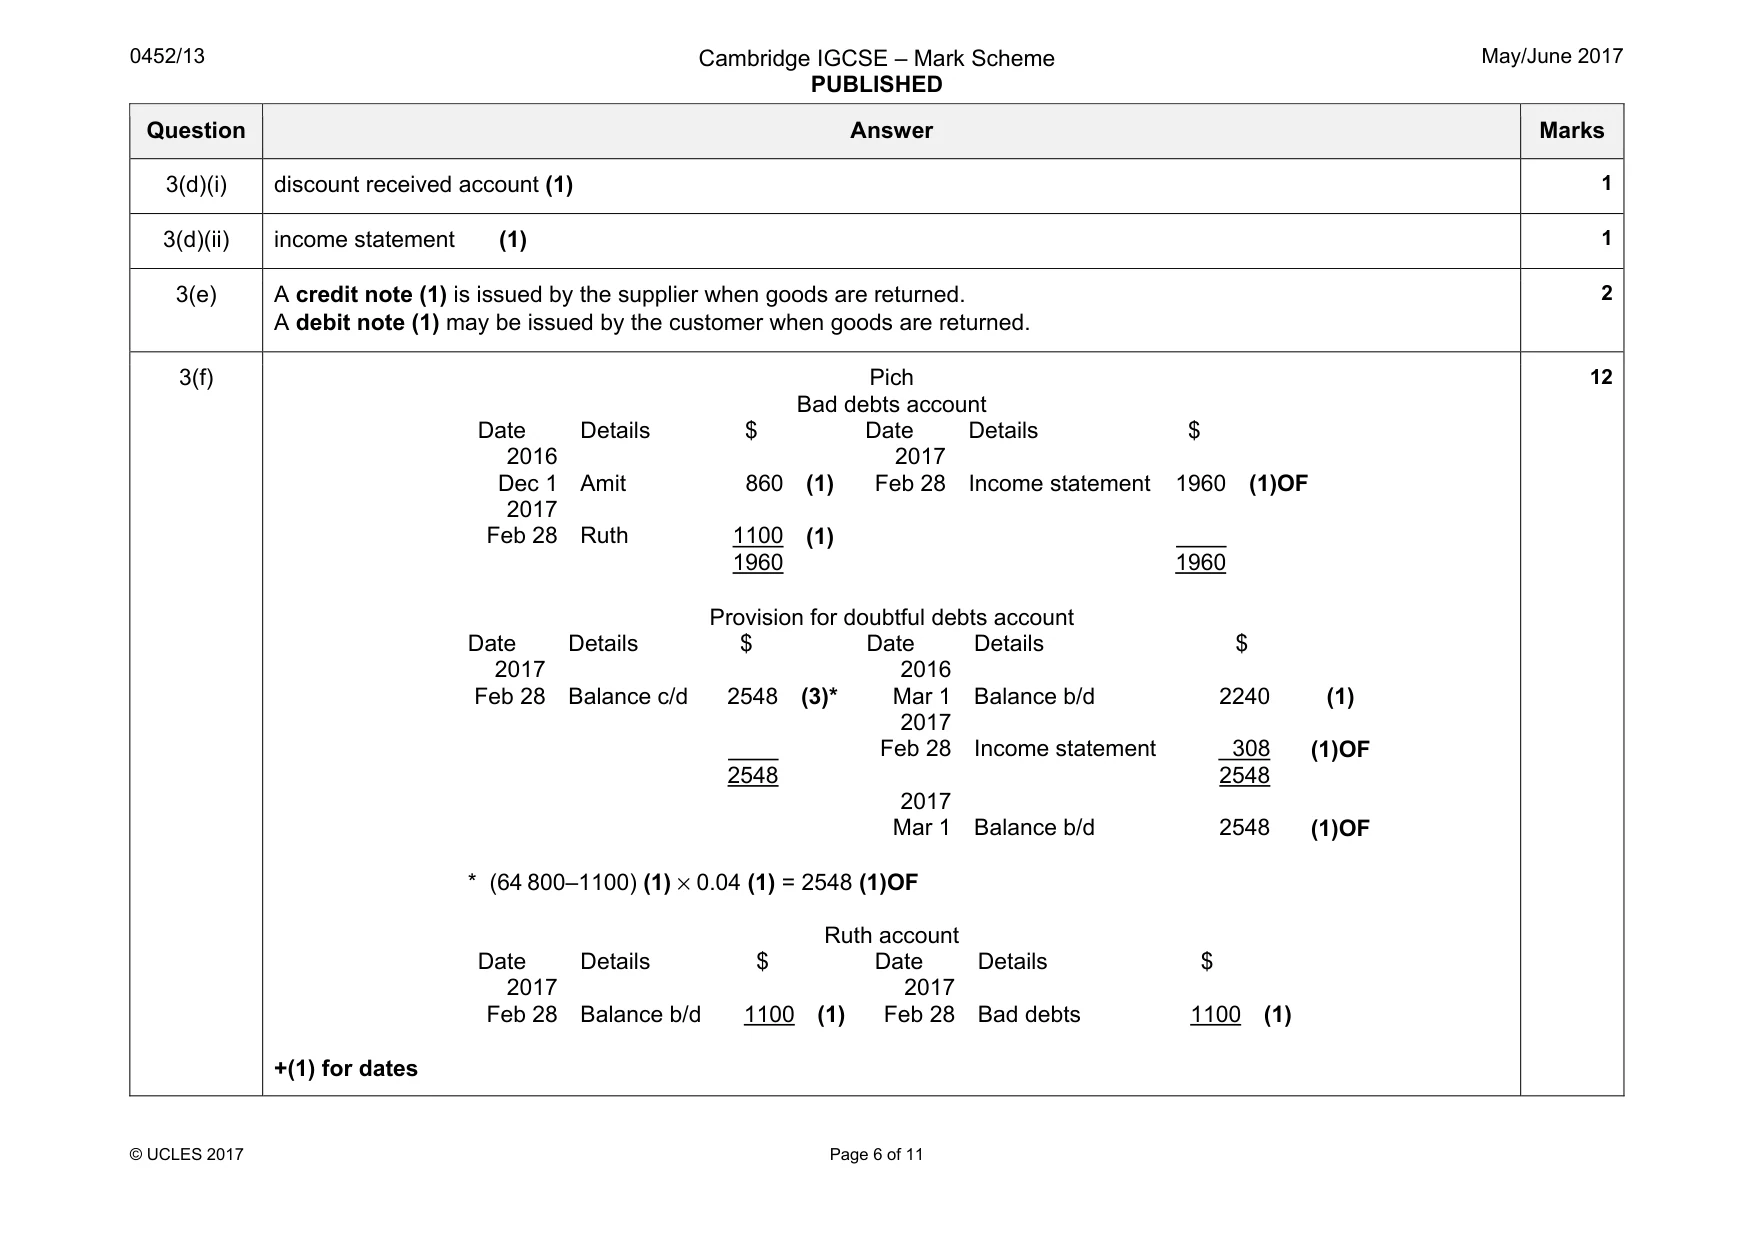
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 6 of 11 Question Answer Marks 3(d)(i) discount received account (1) 1 3(d)(ii) income statement (1) 1 3(e) A credit note (1) is issued by the supplier when goods are returned. A debit note (1) may be issued by the customer when goods are returned. 2 3(f) Pich Bad debts account Date Details $ Date Details $ 2016 Dec 1 Amit 860 (1) 2017 Feb 28 Income statement 1960 (1)OF 2017 Feb 28 Ruth 1100 (1) 1960 1960 Provision for doubtful debts account Date Details $ Date Details $ 2017 Feb 28 Balance c/d 2548 (3)* 2016 Mar 1 Balance b/d 2240 (1) 2017 Feb 28 Income statement 308 (1)OF 2548 2548 2017 Mar 1 Balance b/d 2548 (1)OF * (64 800–1100) (1) × 0.04 (1) = 2548 (1)OF Ruth account Date Details $ Date Details $ 2017 2017 Feb 28 Balance b/d 1100 (1) Feb 28 Bad debts 1100 (1) +(1) for dates 12
Mark scheme, page 7
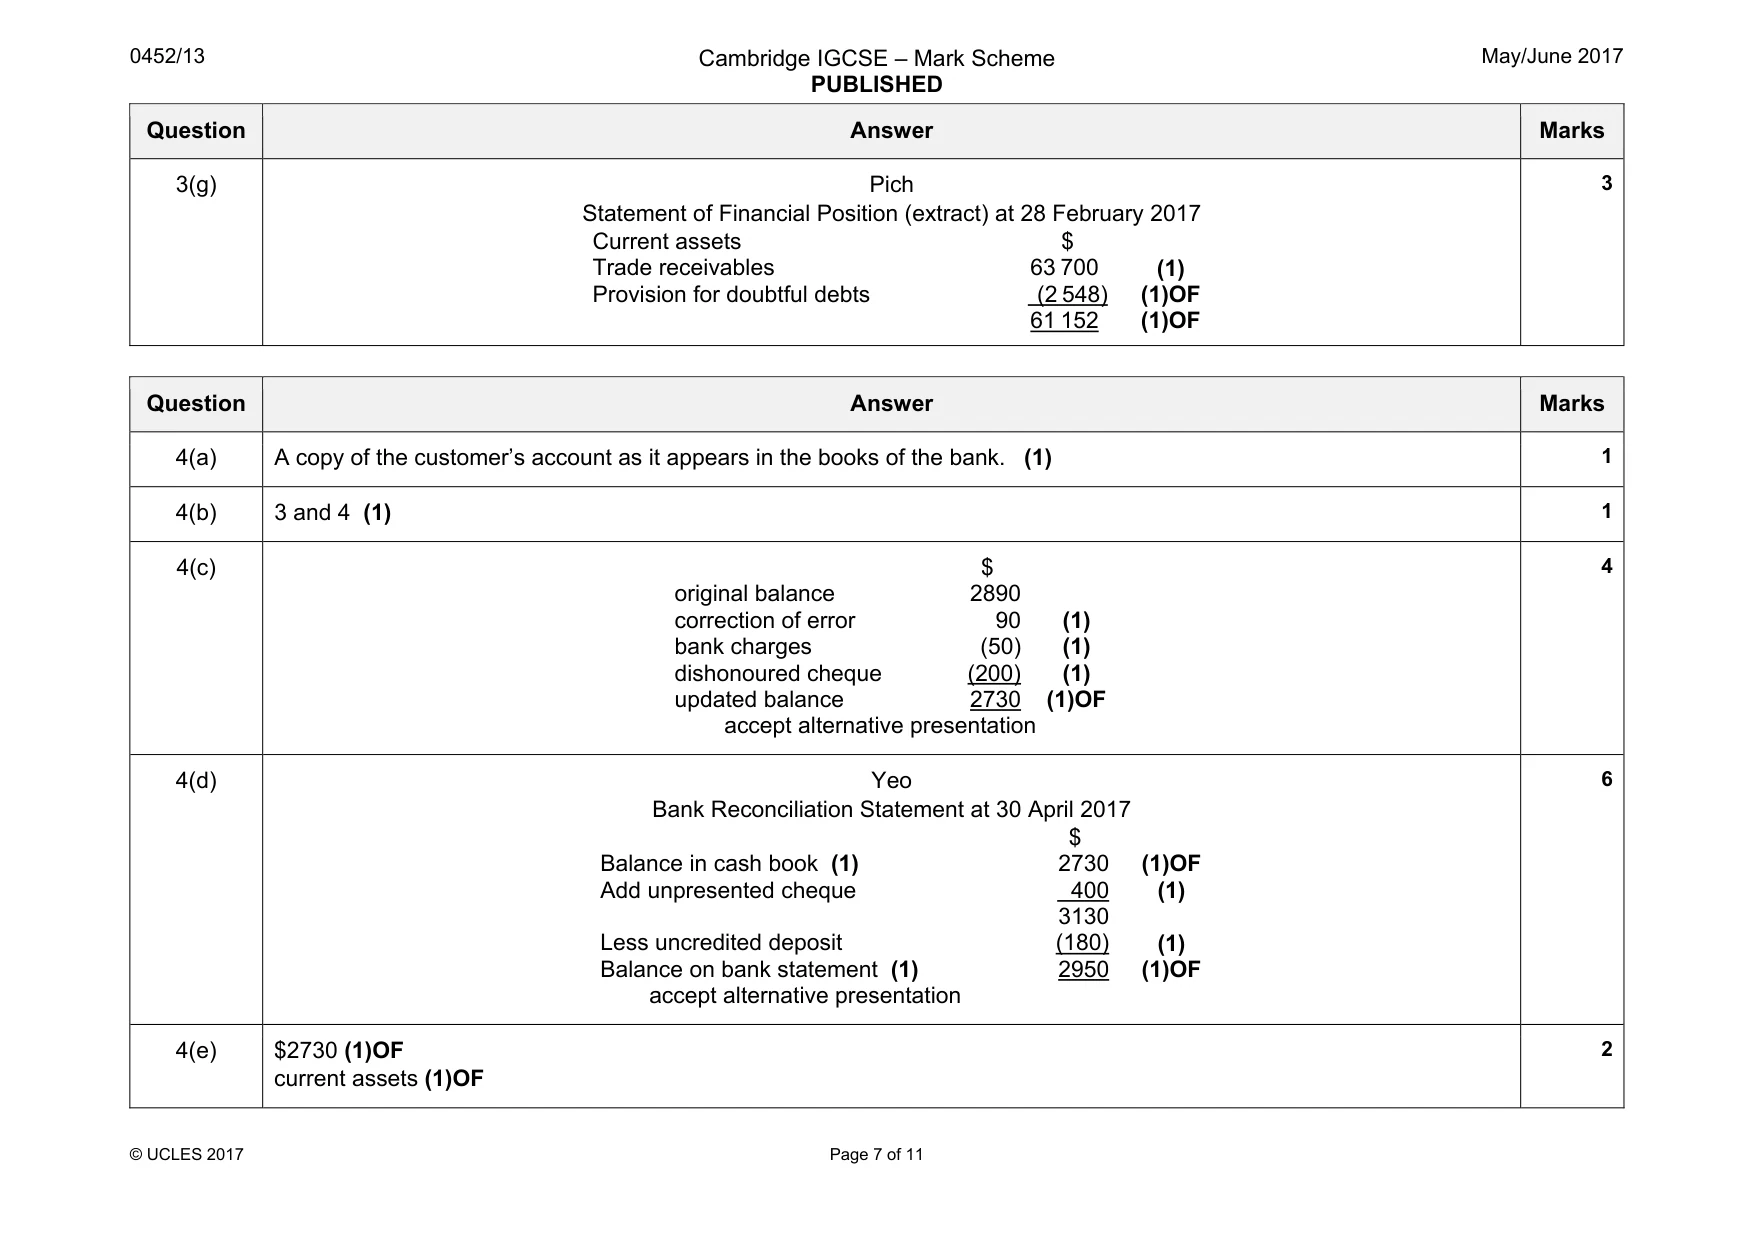
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 7 of 11 Question Answer Marks 3(g) Pich Statement of Financial Position (extract) at 28 February 2017 Current assets $ Trade receivables 63 700 (1) Provision for doubtful debts (2 548) (1)OF 61 152 (1)OF 3 Question Answer Marks 4(a) A copy of the customer’s account as it appears in the books of the bank. (1) 1 4(b) 3 and 4 (1) 1 4(c) $ original balance 2890 correction of error 90 (1) bank charges (50) (1) dishonoured cheque (200) (1) updated balance 2730 (1)OF accept alternative presentation 4 4(d) Yeo Bank Reconciliation Statement at 30 April 2017 $ Balance in cash book (1) 2730 (1)OF Add unpresented cheque 400 (1) 3130 Less uncredited deposit (180) (1) Balance on bank statement (1) 2950 (1)OF accept alternative presentation 6 4(e) $2730 (1)OF current assets (1)OF 2
Mark scheme, page 8
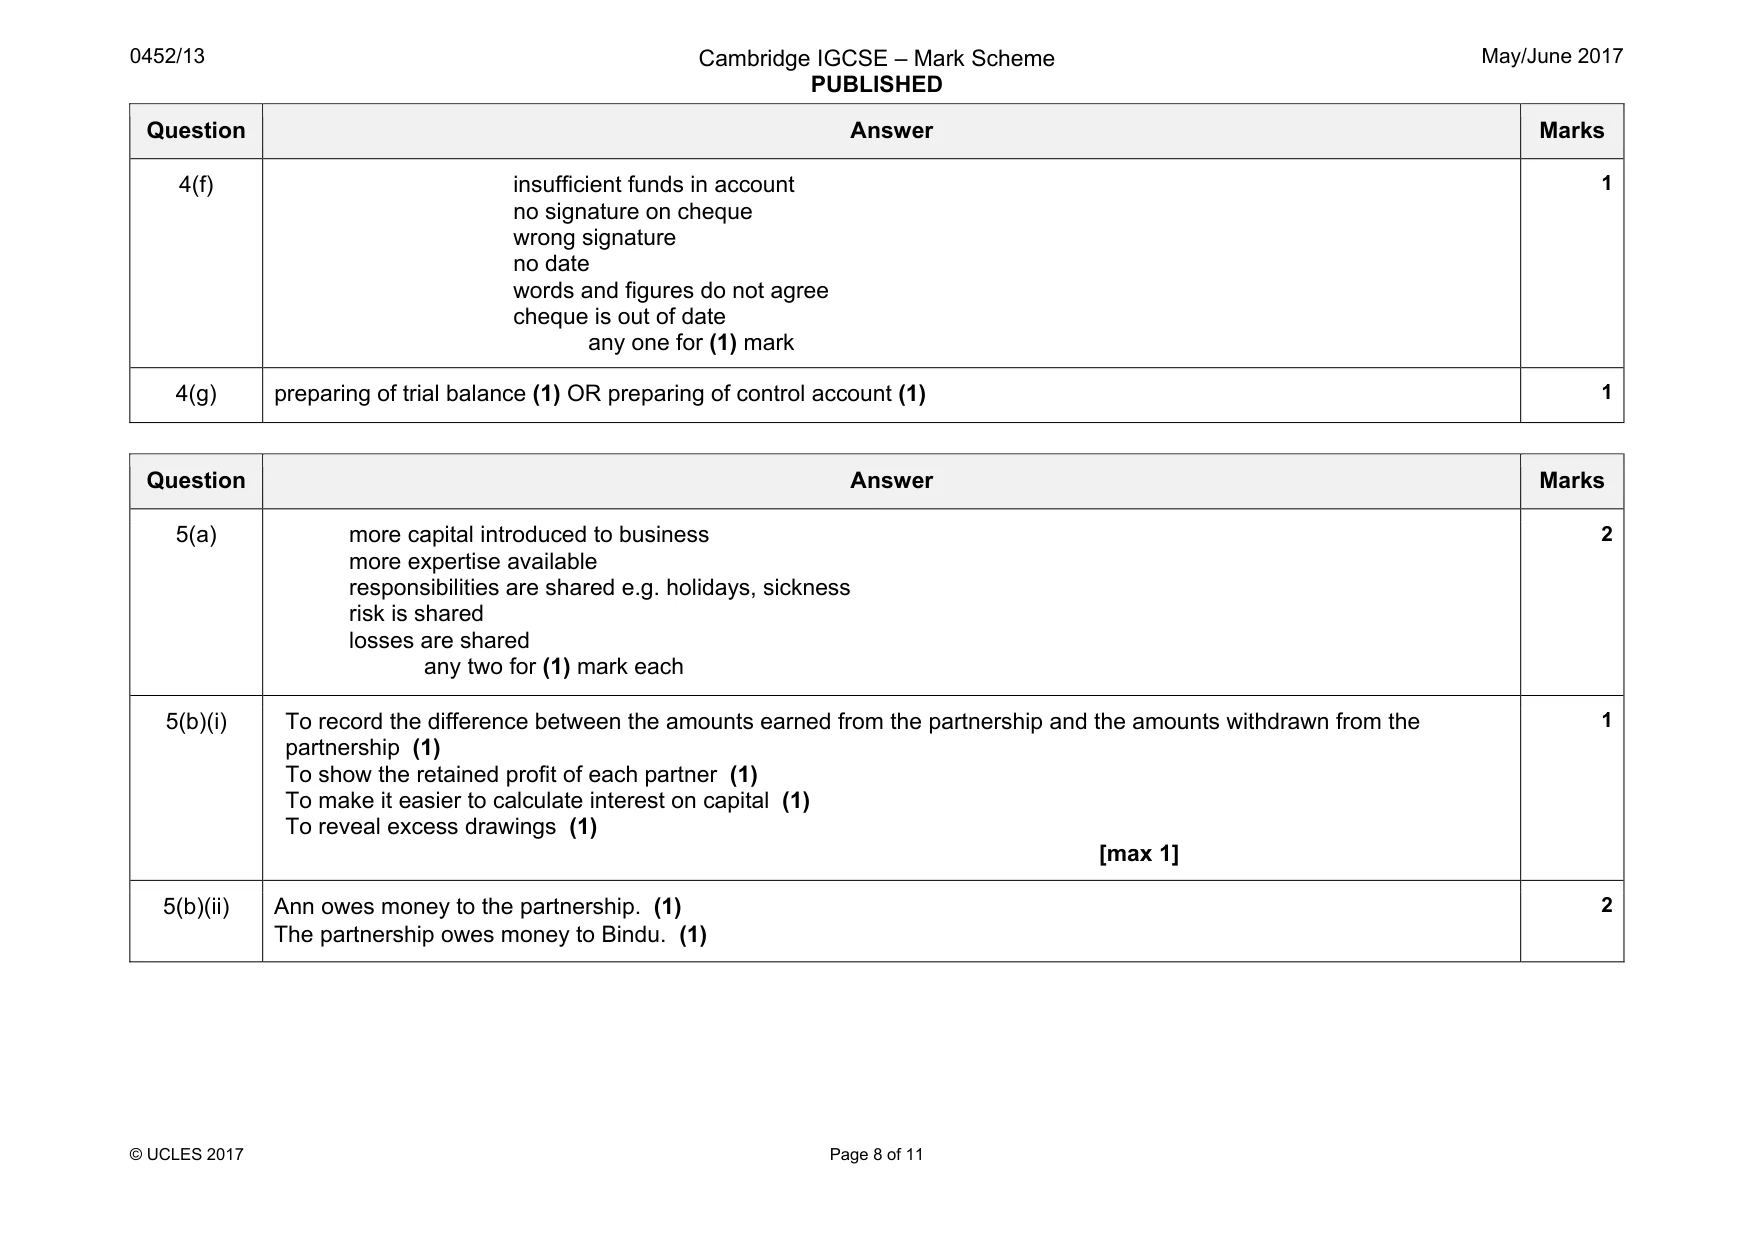
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 8 of 11 Question Answer Marks 4(f) insufficient funds in account no signature on cheque wrong signature no date words and figures do not agree cheque is out of date any one for (1) mark 1 4(g) preparing of trial balance (1) OR preparing of control account (1) 1 Question Answer Marks 5(a) more capital introduced to business more expertise available responsibilities are shared e.g. holidays, sickness risk is shared losses are shared any two for (1) mark each 2 5(b)(i) To record the difference between the amounts earned from the partnership and the amounts withdrawn from the partnership (1) To show the retained profit of each partner (1) To make it easier to calculate interest on capital (1) To reveal excess drawings (1) [max 1] 1 5(b)(ii) Ann owes money to the partnership. (1) The partnership owes money to Bindu. (1) 2
Mark scheme, page 9
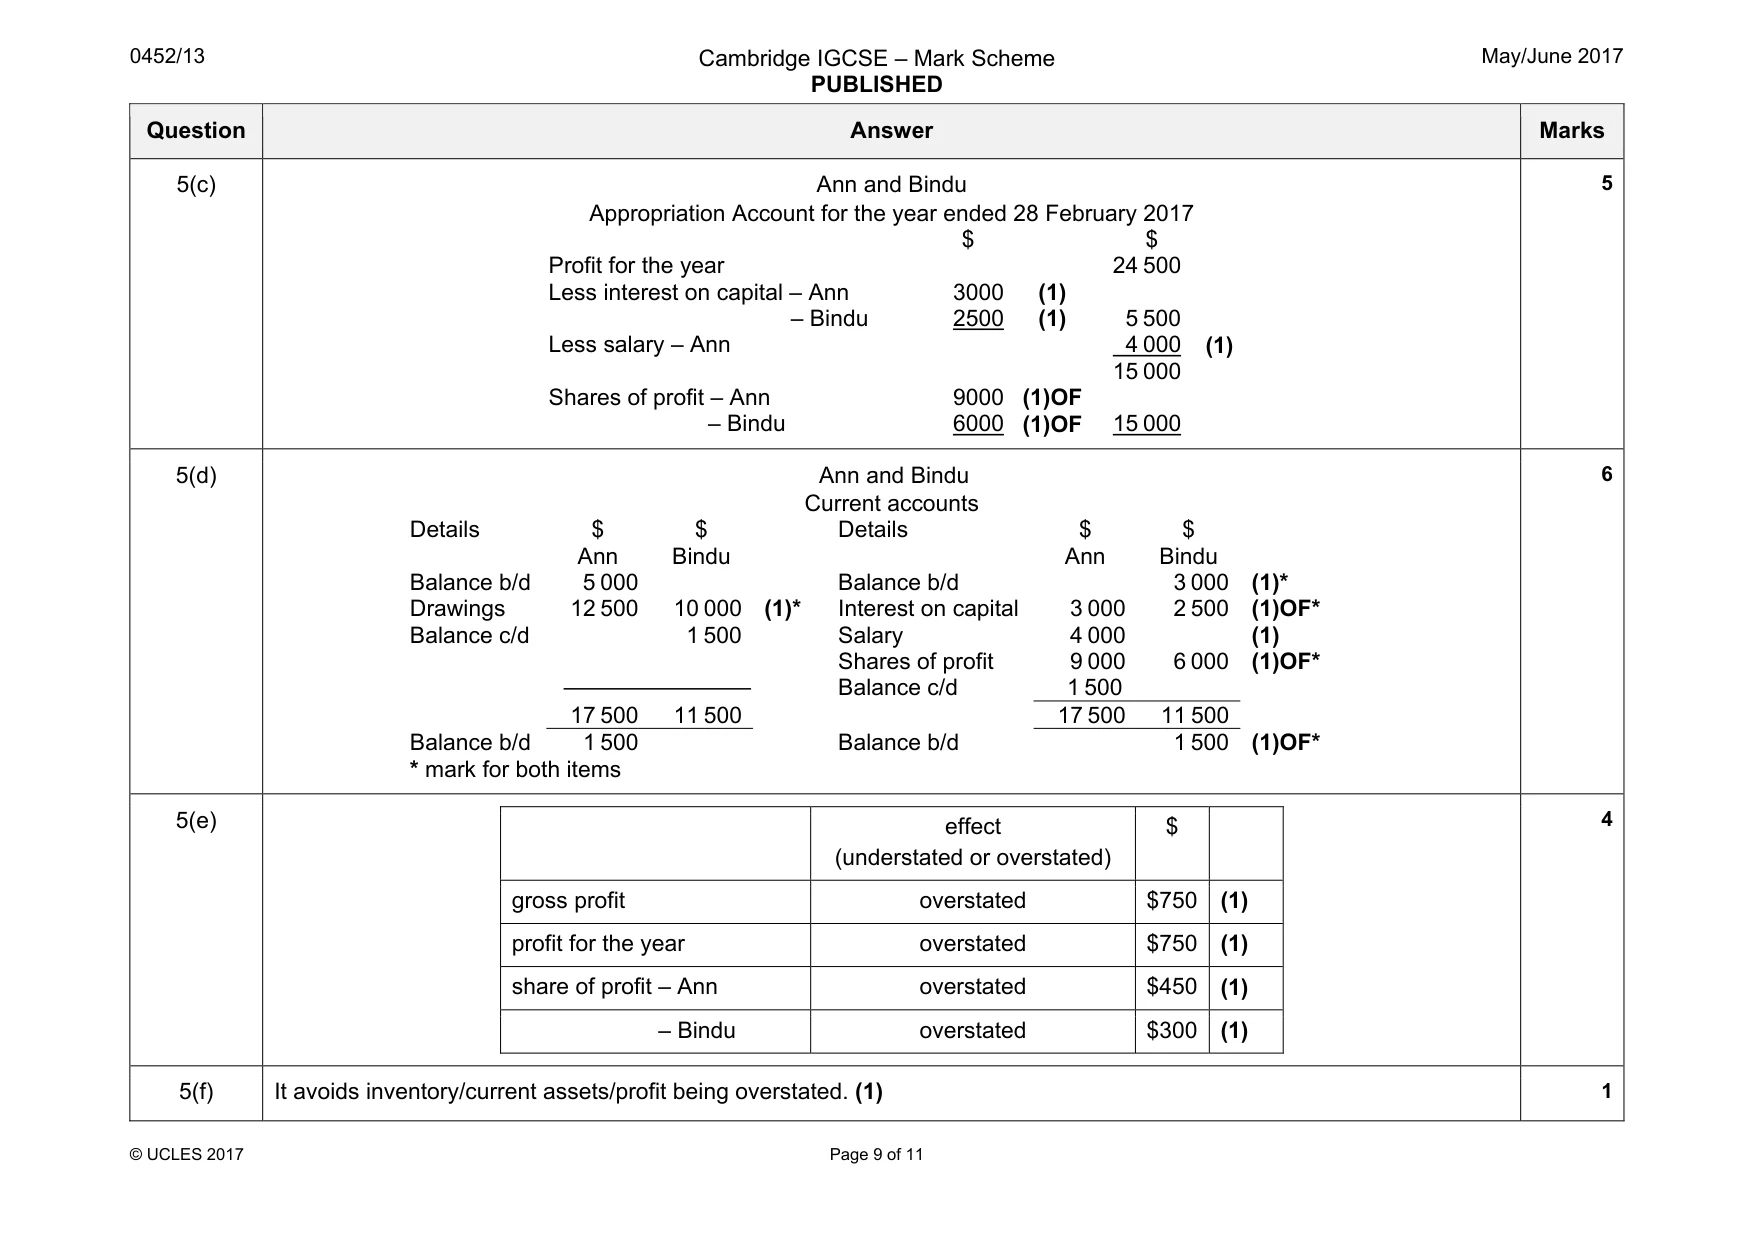
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 9 of 11 Question Answer Marks 5(c) Ann and Bindu Appropriation Account for the year ended 28 February 2017 $ $ Profit for the year 24 500 Less interest on capital – Ann 3000 (1) – Bindu 2500 (1) 5 500 Less salary – Ann 4 000 (1) 15 000 Shares of profit – Ann 9000 (1)OF – Bindu 6000 (1)OF 15 000 5 5(d) Ann and Bindu Current accounts Details $ Ann $ Bindu Details $ Ann $ Bindu Balance b/d 5 000 Balance b/d 3 000 (1)* Drawings 12 500 10 000 (1)* Interest on capital 3 000 2 500 (1)OF* Balance c/d 1 500 Salary 4 000 (1) Shares of profit 9 000 6 000 (1)OF* Balance c/d 1 500 17 500 11 500 17 500 11 500 Balance b/d 1 500 Balance b/d 1 500 (1)OF* * mark for both items 6 5(e) effect (understated or overstated) $ gross profit overstated $750 (1) profit for the year overstated $750 (1) share of profit – Ann overstated $450 (1) – Bindu overstated $300 (1) 4 5(f) It avoids inventory/current assets/profit being overstated. (1) 1
Mark scheme, page 10
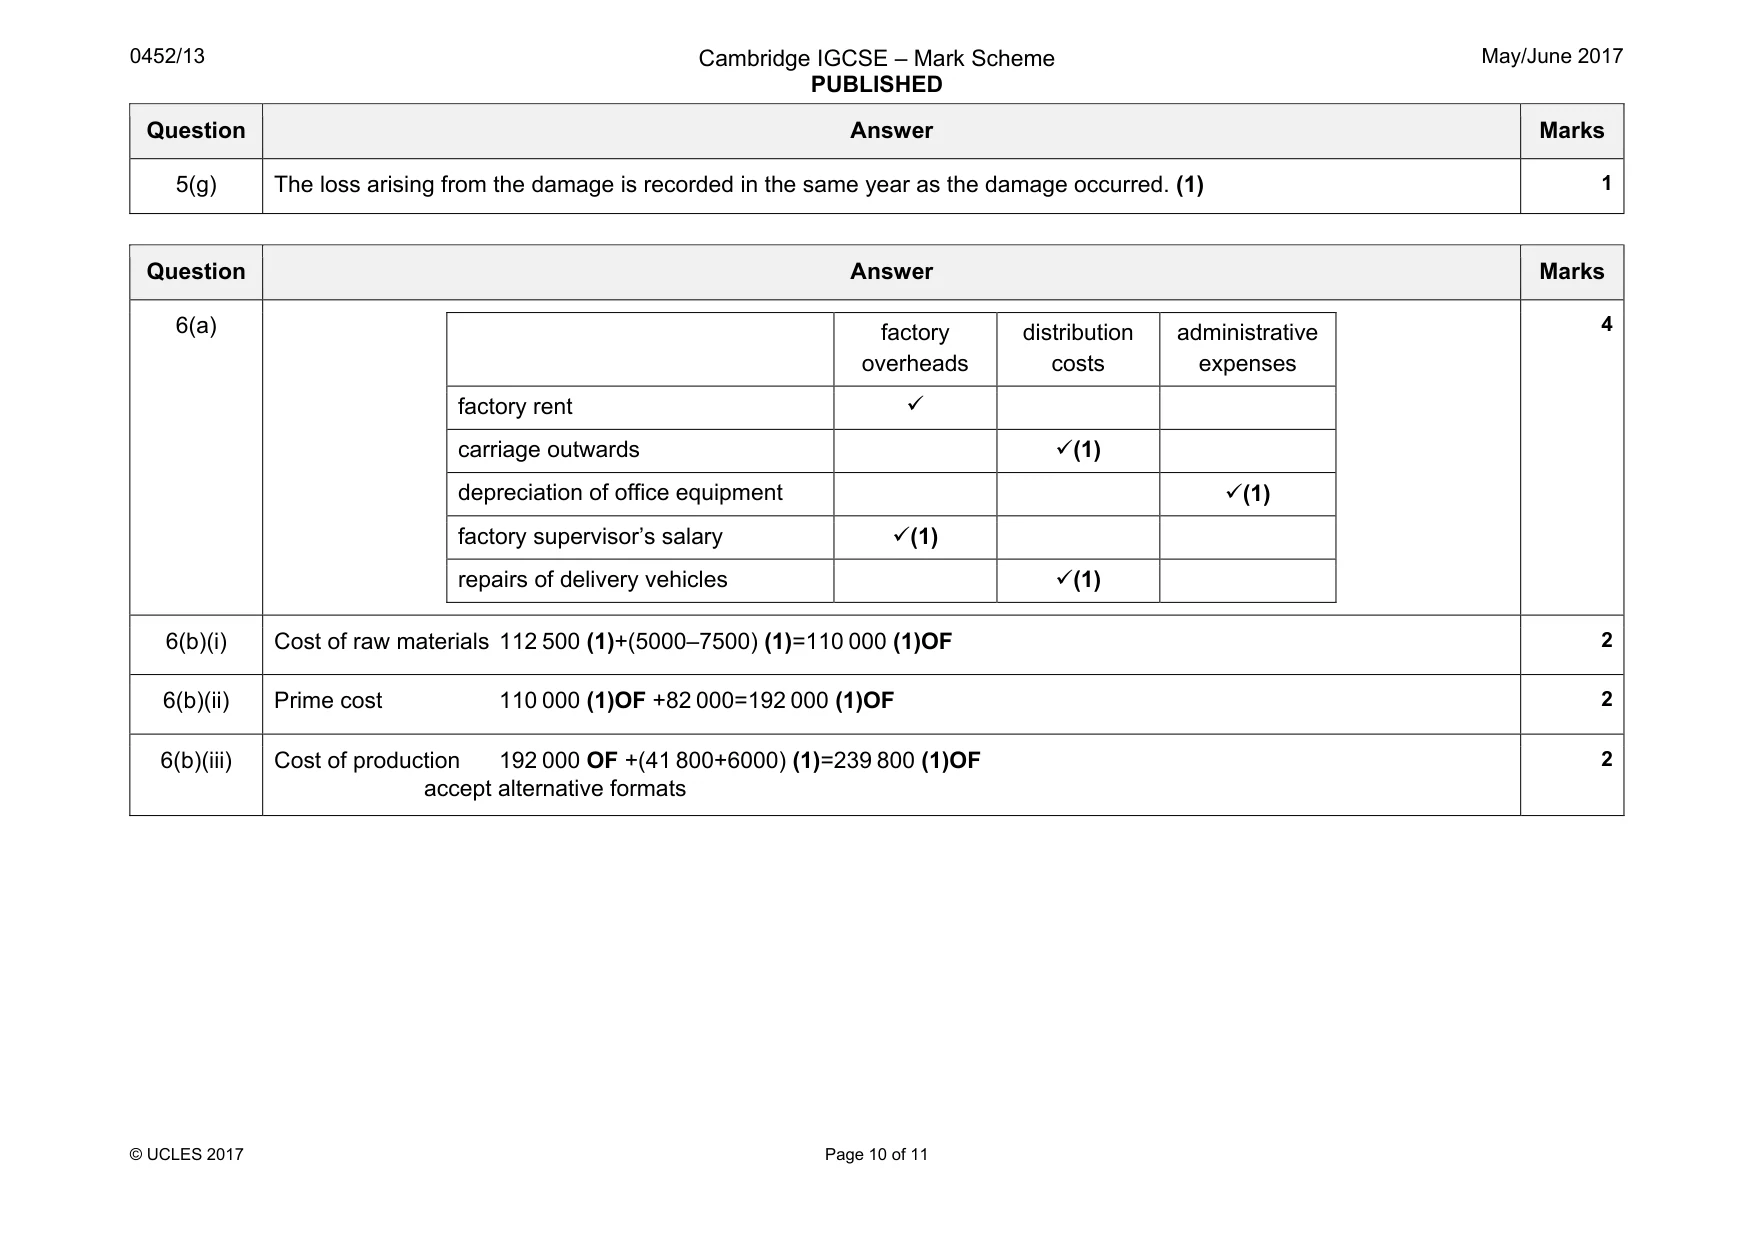
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 10 of 11 Question Answer Marks 5(g) The loss arising from the damage is recorded in the same year as the damage occurred. (1) 1 Question Answer Marks 6(a) factory overheads distribution costs administrative expenses factory rent 9 carriage outwards 9(1) depreciation of office equipment 9(1) factory supervisor’s salary 9(1) repairs of delivery vehicles 9(1) 4 6(b)(i) Cost of raw materials 112 500 (1)+(5000–7500) (1)=110 000 (1)OF 2 6(b)(ii) Prime cost 110 000 (1)OF +82 000=192 000 (1)OF 2 6(b)(iii) Cost of production 192 000 OF +(41 800+6000) (1)=239 800 (1)OF accept alternative formats 2
Mark scheme, page 11
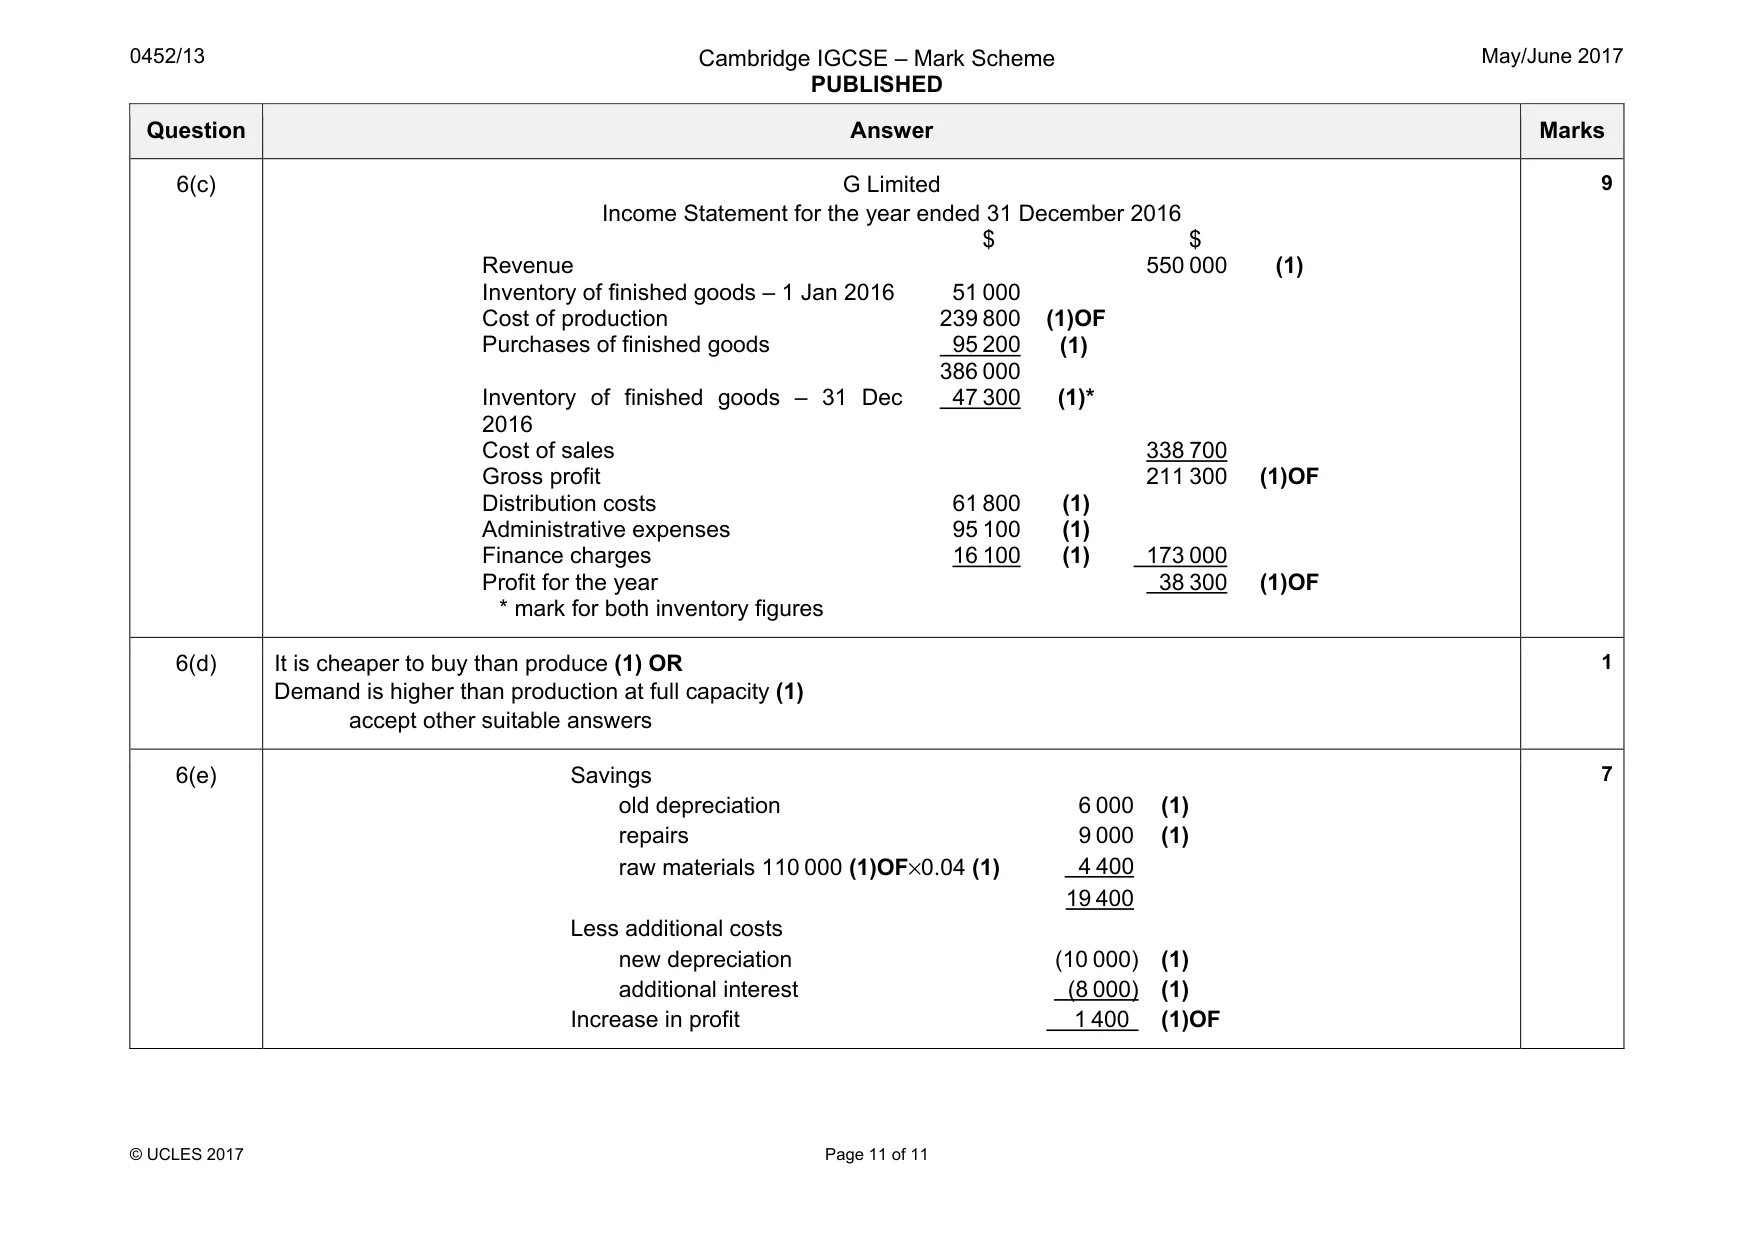
0452/13 Cambridge IGCSE – Mark Scheme PUBLISHED May/June 2017 © UCLES 2017 Page 11 of 11 Question Answer Marks 6(c) G Limited Income Statement for the year ended 31 December 2016 $ $ Revenue 550 000 (1) Inventory of finished goods – 1 Jan 2016 51 000 Cost of production 239 800 (1)OF Purchases of finished goods 95 200 (1) 386 000 Inventory of finished goods – 31 Dec 2016 47 300 (1)* Cost of sales 338 700 Gross profit 211 300 (1)OF Distribution costs 61 800 (1) Administrative expenses 95 100 (1) Finance charges 16 100 (1) 173 000 Profit for the year 38 300 (1)OF * mark for both inventory figures 9 6(d) It is cheaper to buy than produce (1) OR Demand is higher than production at full capacity (1) accept other suitable answers 1 6(e) Savings old depreciation 6 000 (1) repairs 9 000 (1) raw materials 110 000 (1)OF×0.04 (1) 4 400 19 400 Less additional costs new depreciation (10 000) (1) additional interest (8 000) (1) Increase in profit 1 400 (1)OF 7
What you needed in this session
Cambridge’s own grade thresholds for 2017 May/June, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.