Cambridge IGCSE Accounting 0452 — 2007 May/June Paper 2 · Variant 1
0452/21/M/J/07 · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme6 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 15 printed pages and 1 blank page. IB07 06_0452_02/3RP © UCLES 2007 [Turn over *9092285632* For Examiner's Use 1 2 3 4 5 Total UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/02 Paper 2 May/June 2007 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for any diagrams or graphs. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. www.theallpapers.com
Question paper, page 2
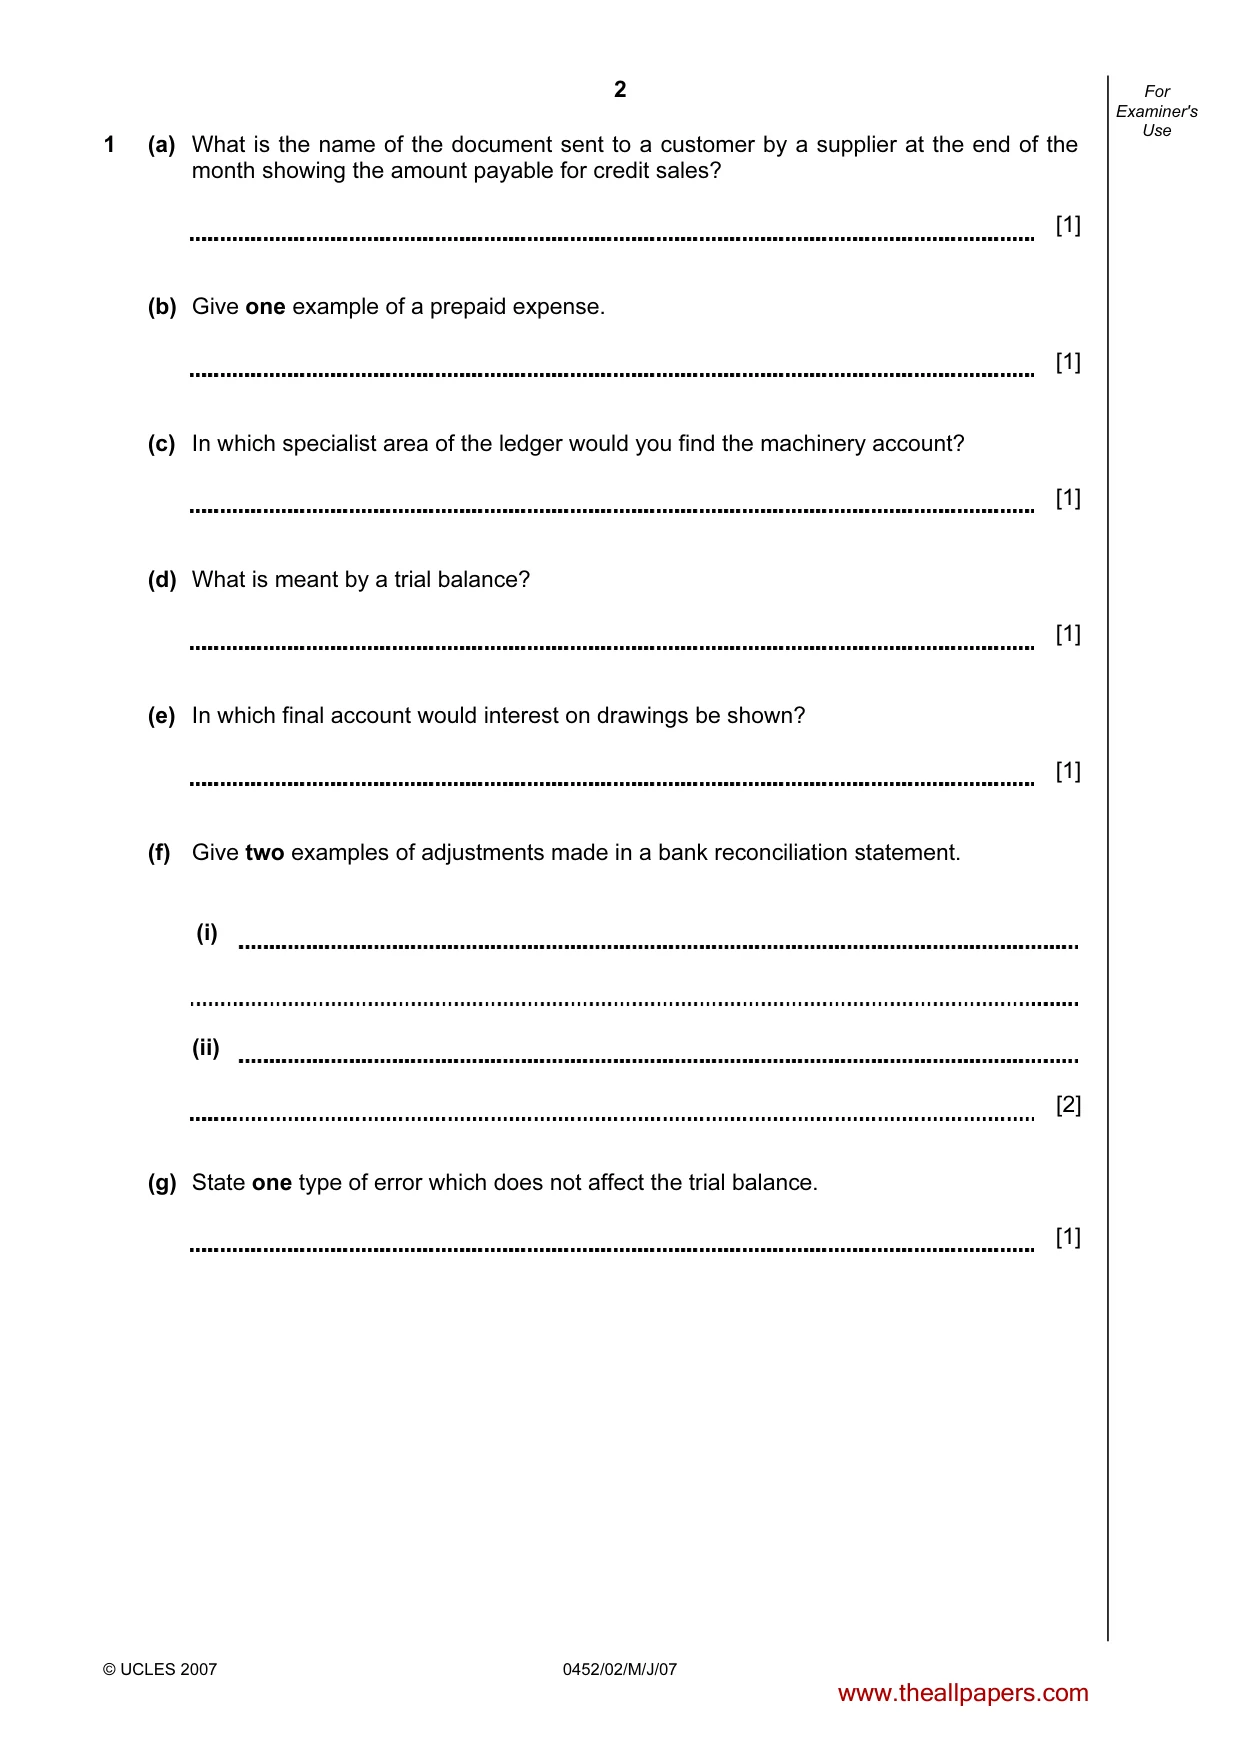
2 © UCLES 2007 0452/02/M/J/07 For Examiner's Use 1 (a) What is the name of the document sent to a customer by a supplier at the end of the month showing the amount payable for credit sales? [1] (b) Give one example of a prepaid expense. [1] (c) In which specialist area of the ledger would you find the machinery account? [1] (d) What is meant by a trial balance? [1] (e) In which final account would interest on drawings be shown? [1] (f) Give two examples of adjustments made in a bank reconciliation statement. (i) (ii) [2] (g) State one type of error which does not affect the trial balance. [1] www.theallpapers.com
Question paper, page 3
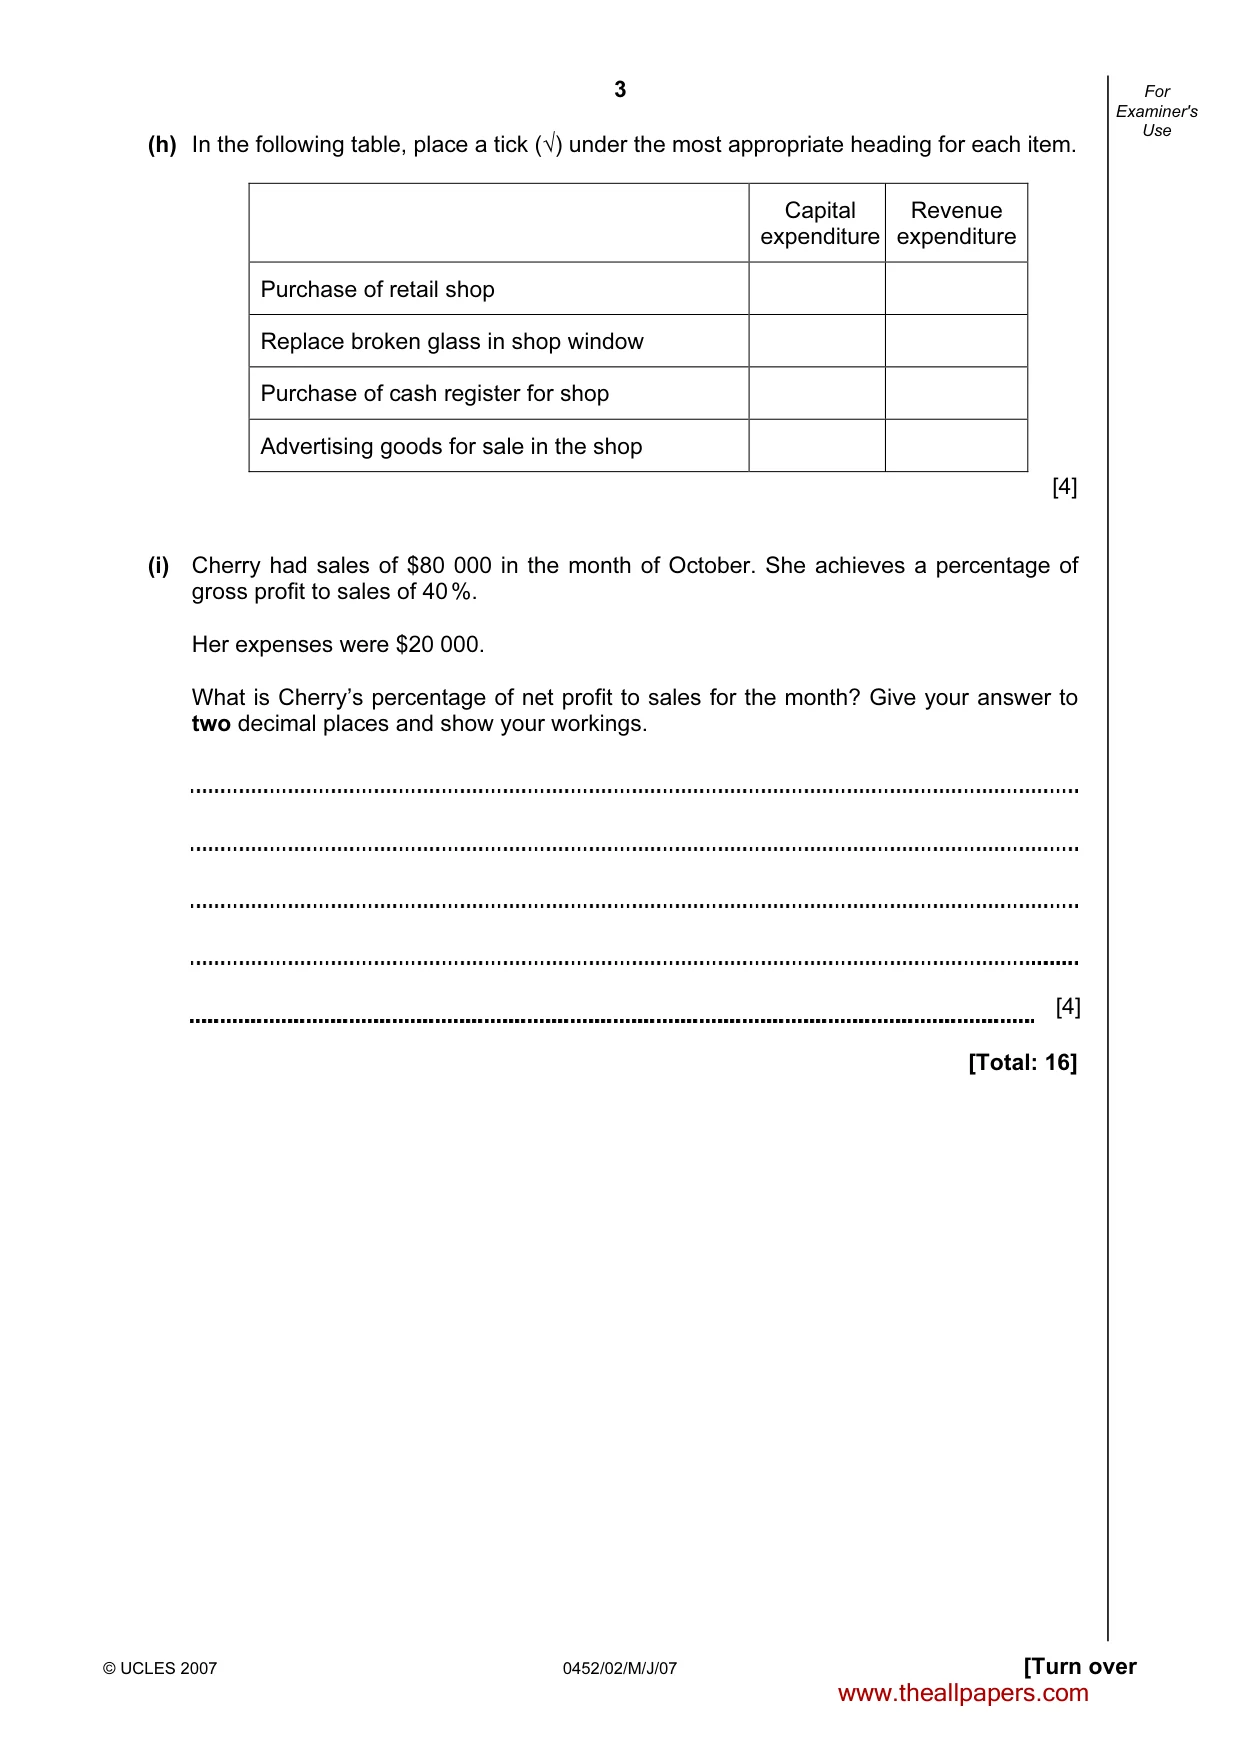
3 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use (h) In the following table, place a tick (√) under the most appropriate heading for each item. Capital expenditure Revenue expenditure Purchase of retail shop Replace broken glass in shop window Purchase of cash register for shop Advertising goods for sale in the shop [4] (i) Cherry had sales of $80 000 in the month of October. She achieves a percentage of gross profit to sales of 40 %. Her expenses were $20 000. What is Cherry’s percentage of net profit to sales for the month? Give your answer to two decimal places and show your workings. [4] [Total: 16] www.theallpapers.com
Question paper, page 4
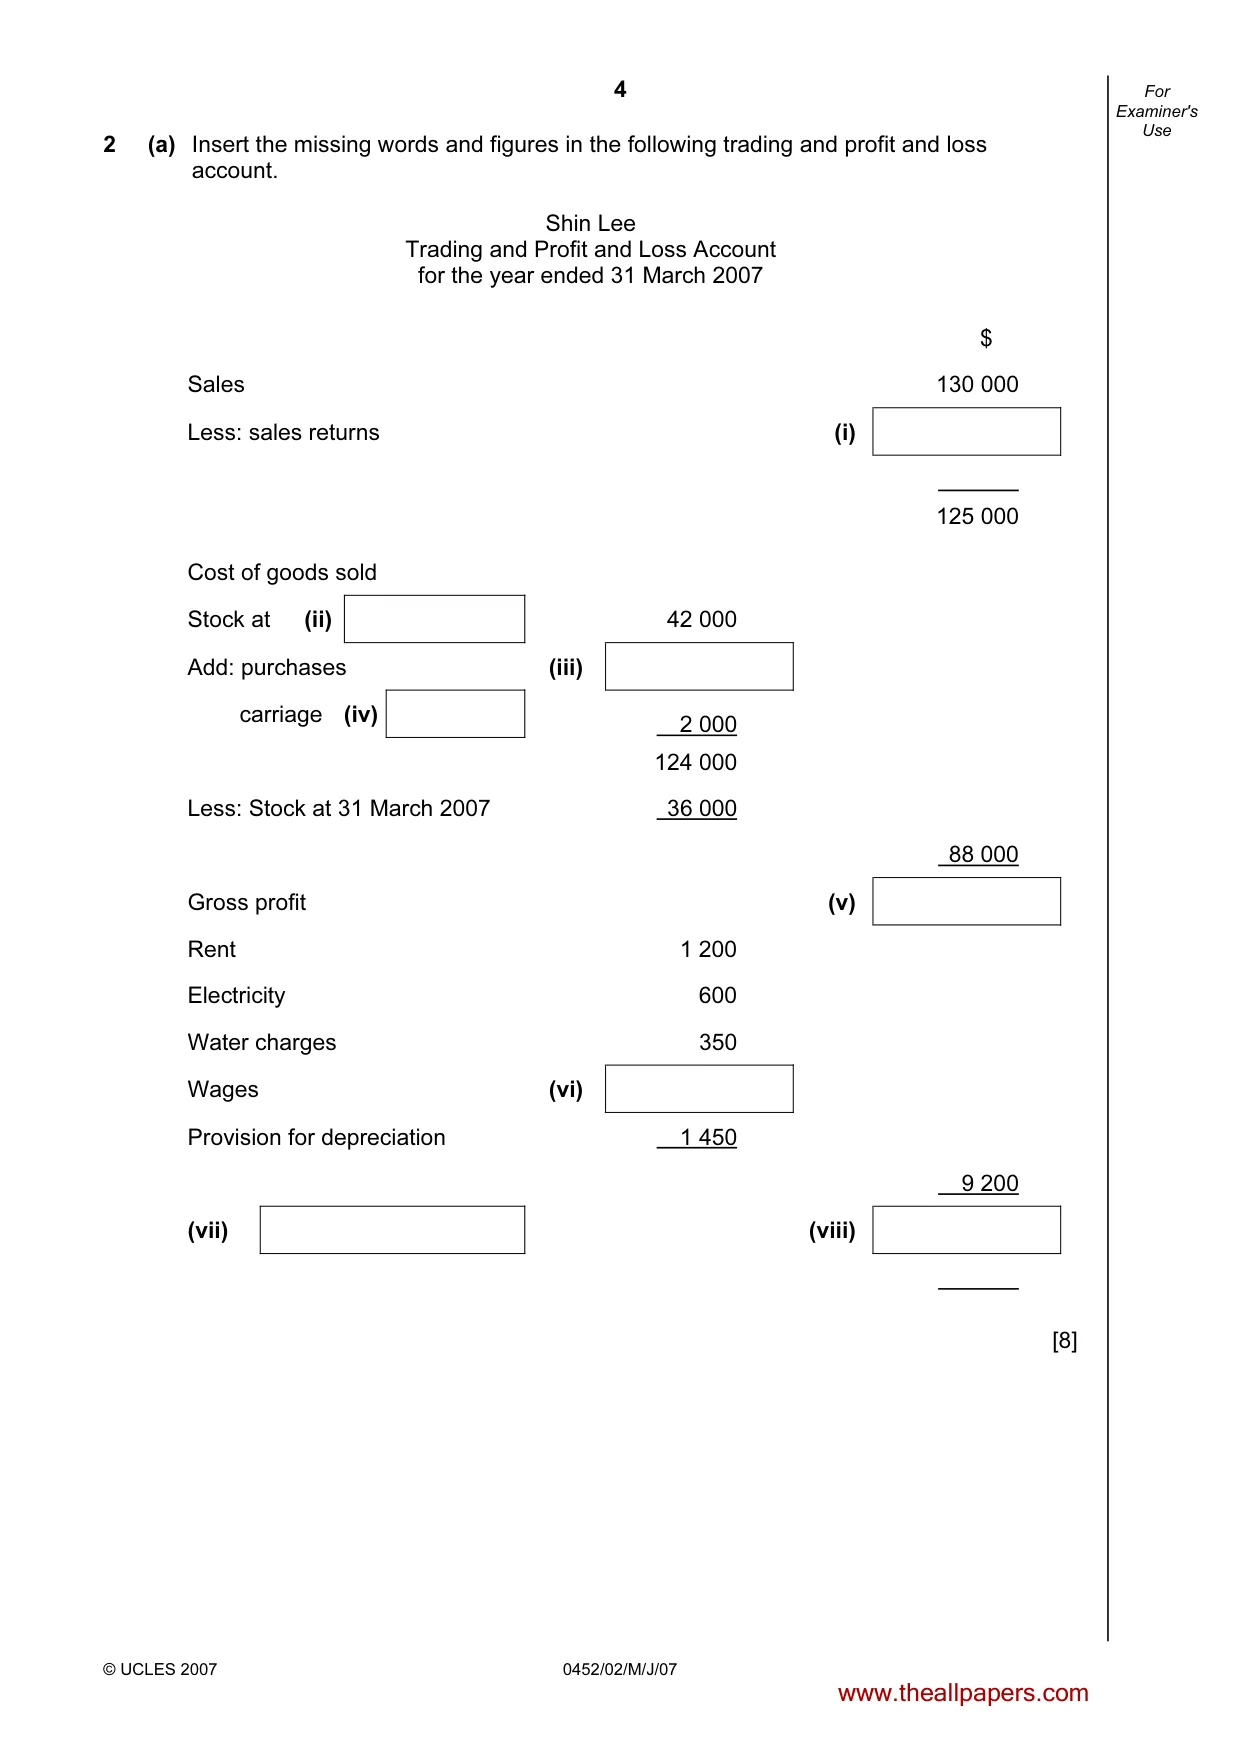
4 © UCLES 2007 0452/02/M/J/07 For Examiner's Use 2 (a) Insert the missing words and figures in the following trading and profit and loss account. Shin Lee Trading and Profit and Loss Account for the year ended 31 March 2007 $ Sales 130 000 Less: sales returns (i) 125 000 Cost of goods sold Stock at (ii) 42 000 Add: purchases (iii) carriage (iv) 2 000 124 000 Less: Stock at 31 March 2007 36 000 88 000 Gross profit (v) Rent 1 200 Electricity 600 Water charges 350 Wages (vi) Provision for depreciation 1 450 9 200 (vii) (viii) [8] www.theallpapers.com
Question paper, page 5
5 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use (b) From the information in part (a) calculate to two decimal places Shin Lee’s rate of stock turnover for the year ended 31 March 2007. Show your workings. [4] (c) Give one example of a business with: (i) A high rate of stock turnover; (ii) A low rate of stock turnover. [4] [Total: 16] www.theallpapers.com
Question paper, page 6
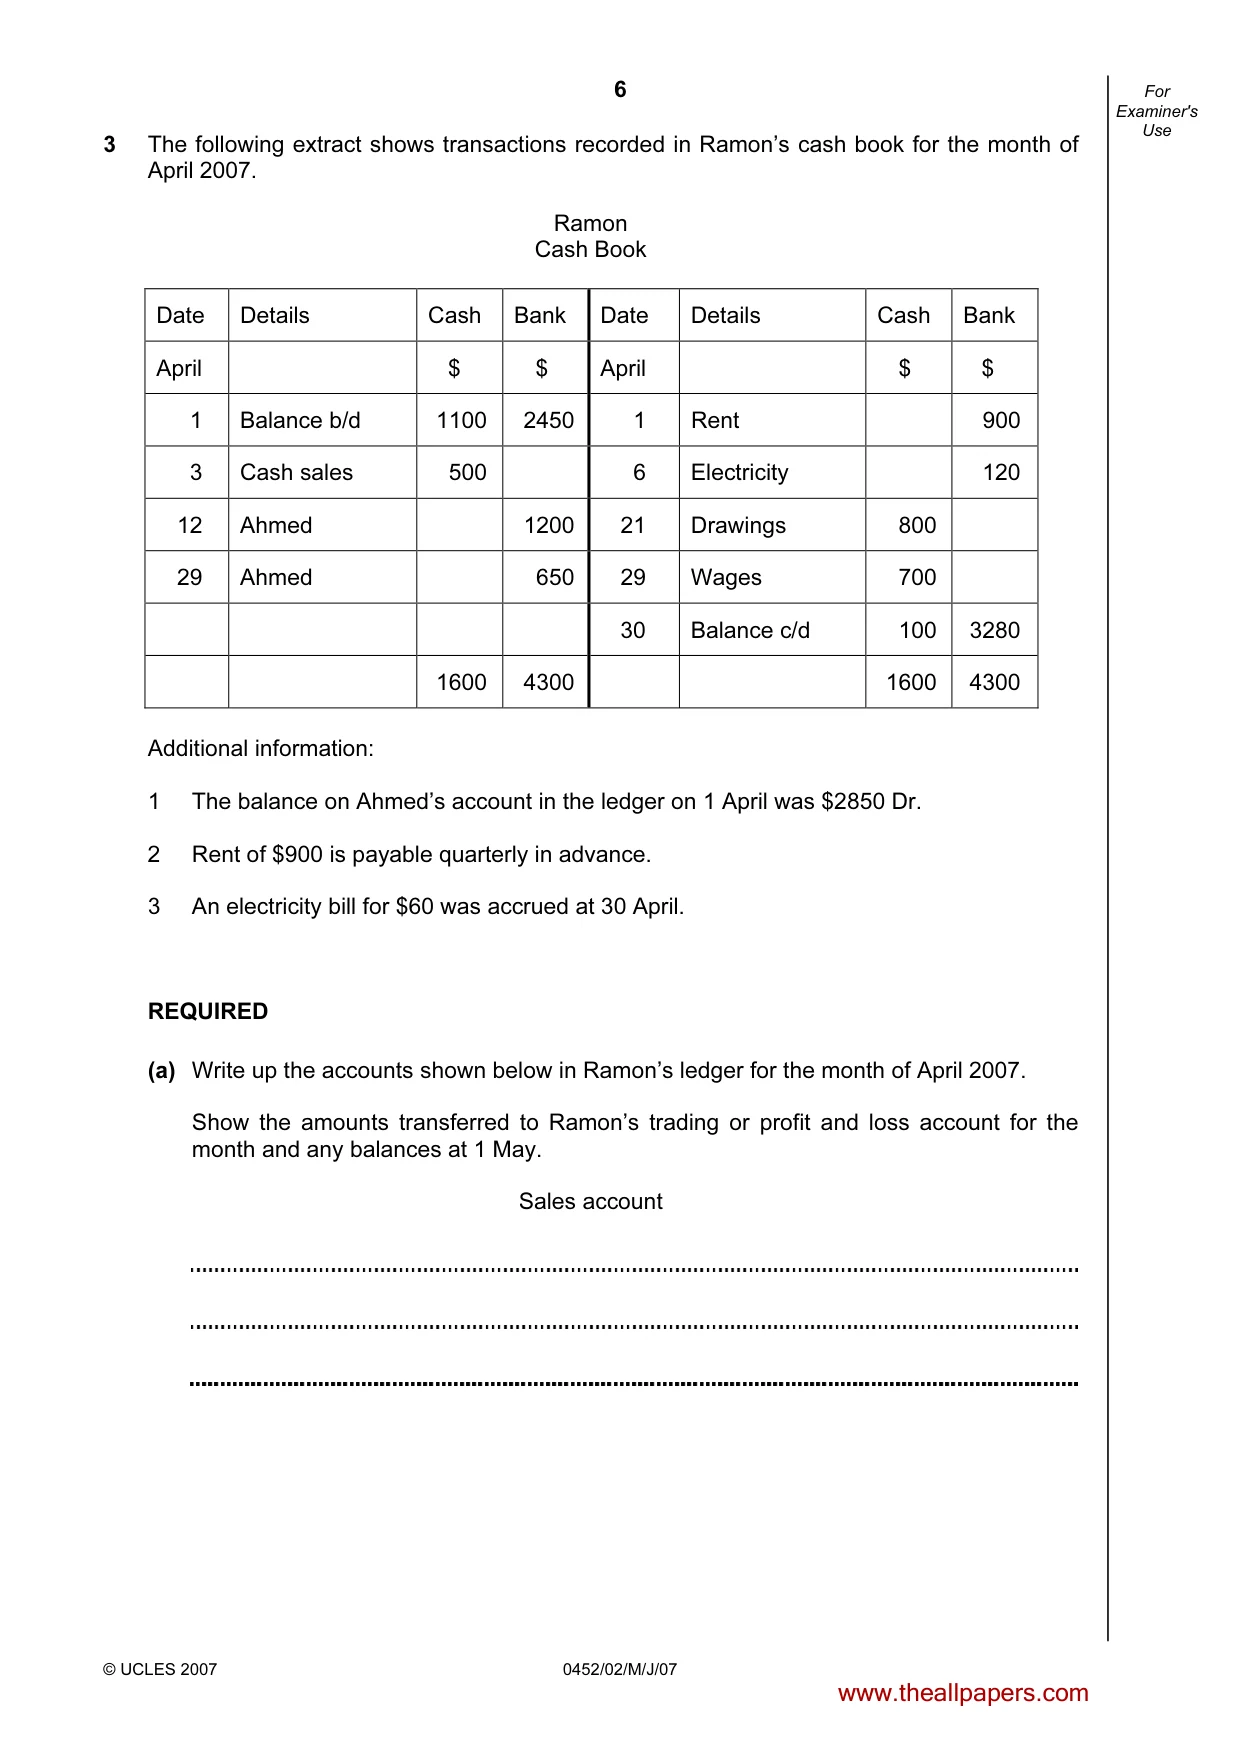
6 © UCLES 2007 0452/02/M/J/07 For Examiner's Use 3 The following extract shows transactions recorded in Ramon’s cash book for the month of April 2007. Ramon Cash Book Date Details Cash Bank Date Details Cash Bank April $ $ April $ $ 1 Balance b/d 1100 2450 1 Rent 900 3 Cash sales 500 6 Electricity 120 12 Ahmed 1200 21 Drawings 800 29 Ahmed 650 29 Wages 700 30 Balance c/d 100 3280 1600 4300 1600 4300 Additional information: 1 The balance on Ahmed’s account in the ledger on 1 April was $2850 Dr. 2 Rent of $900 is payable quarterly in advance. 3 An electricity bill for $60 was accrued at 30 April. REQUIRED (a) Write up the accounts shown below in Ramon’s ledger for the month of April 2007. Show the amounts transferred to Ramon’s trading or profit and loss account for the month and any balances at 1 May. Sales account www.theallpapers.com
Question paper, page 7
7 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use Ahmed account Rent account Electricity account Drawings account Wages account [16] www.theallpapers.com
Question paper, page 8
8 © UCLES 2007 0452/02/M/J/07 For Examiner's Use (b) Suggest two ways in which Ramon may encourage Ahmed to pay his outstanding account more quickly. (i) (ii) [4] [Total: 20] www.theallpapers.com
Question paper, page 9
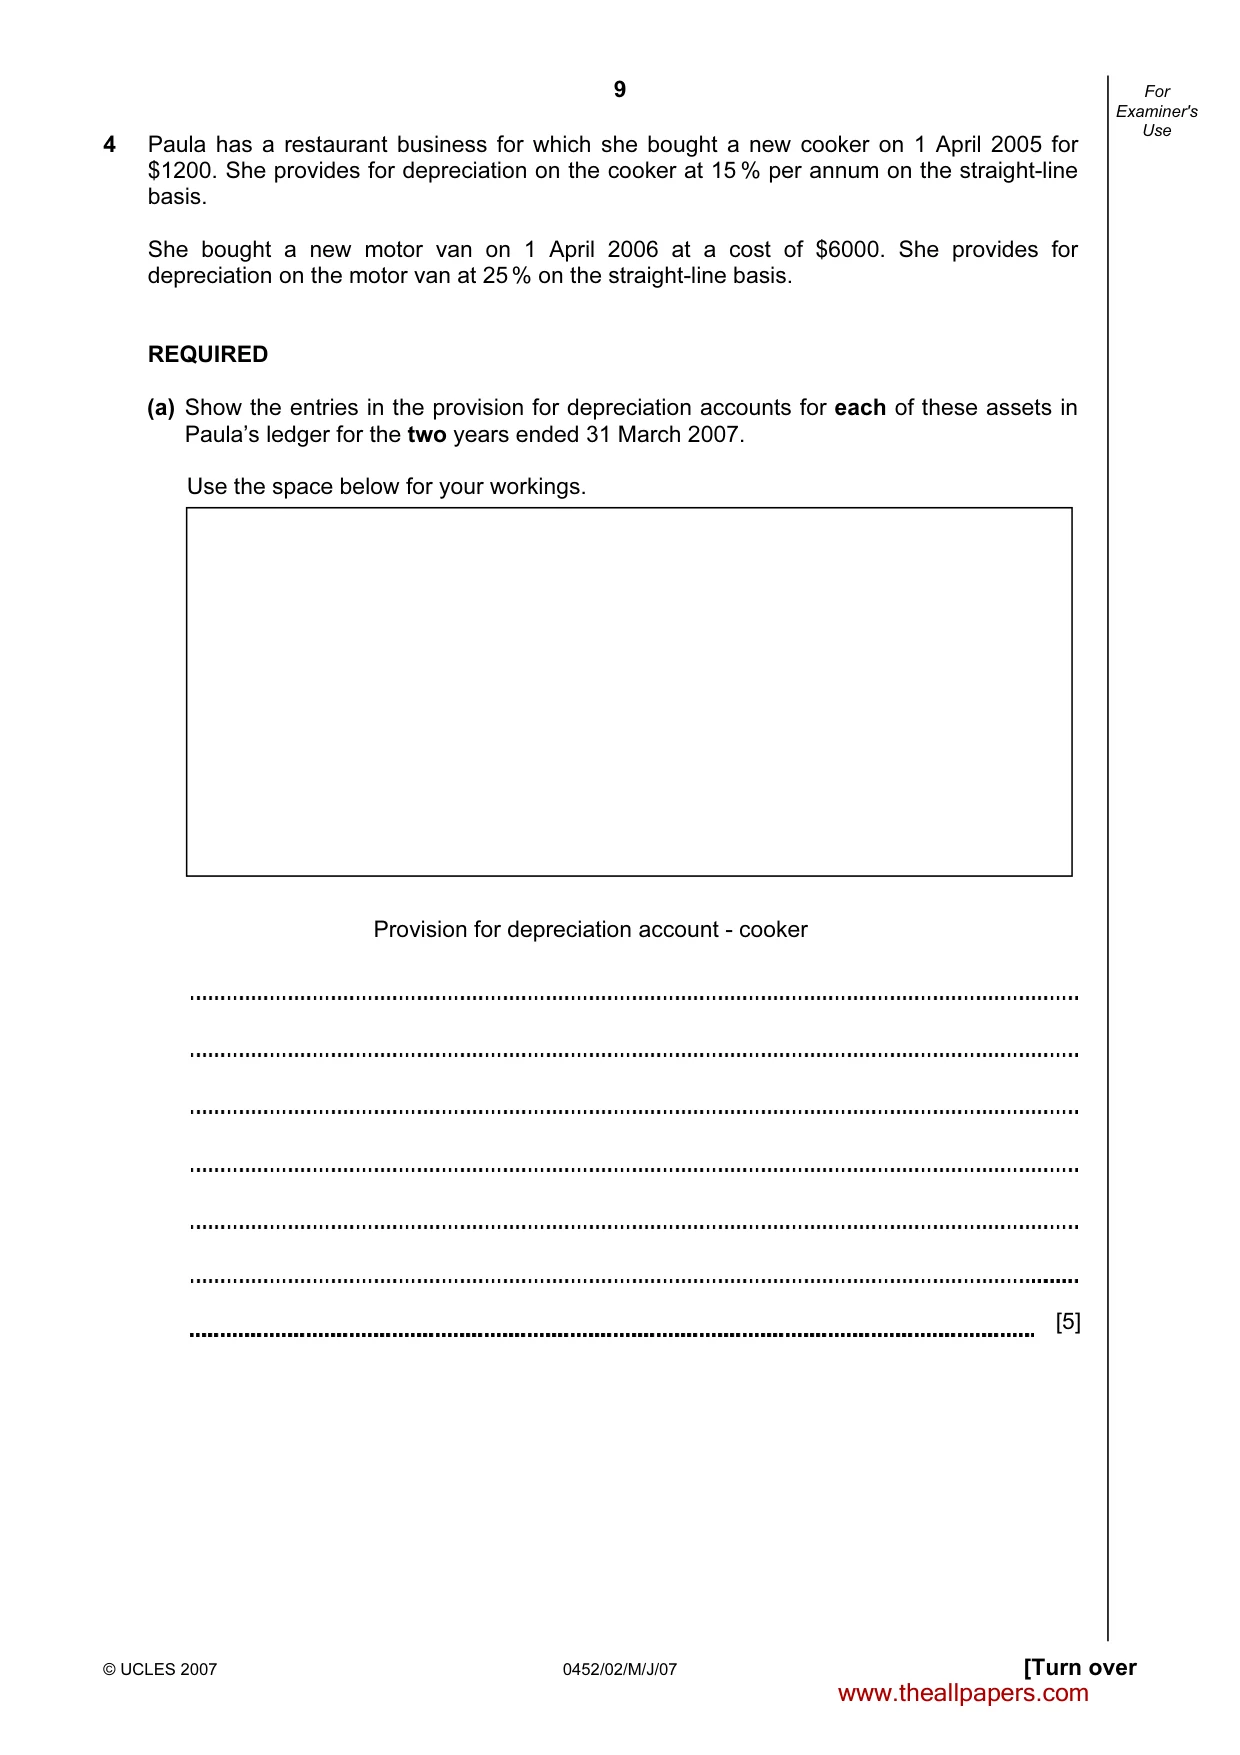
9 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use 4 Paula has a restaurant business for which she bought a new cooker on 1 April 2005 for $1200. She provides for depreciation on the cooker at 15 % per annum on the straight-line basis. She bought a new motor van on 1 April 2006 at a cost of $6000. She provides for depreciation on the motor van at 25 % on the straight-line basis. REQUIRED (a) Show the entries in the provision for depreciation accounts for each of these assets in Paula’s ledger for the two years ended 31 March 2007. Use the space below for your workings. Provision for depreciation account - cooker [5] www.theallpapers.com
Question paper, page 10
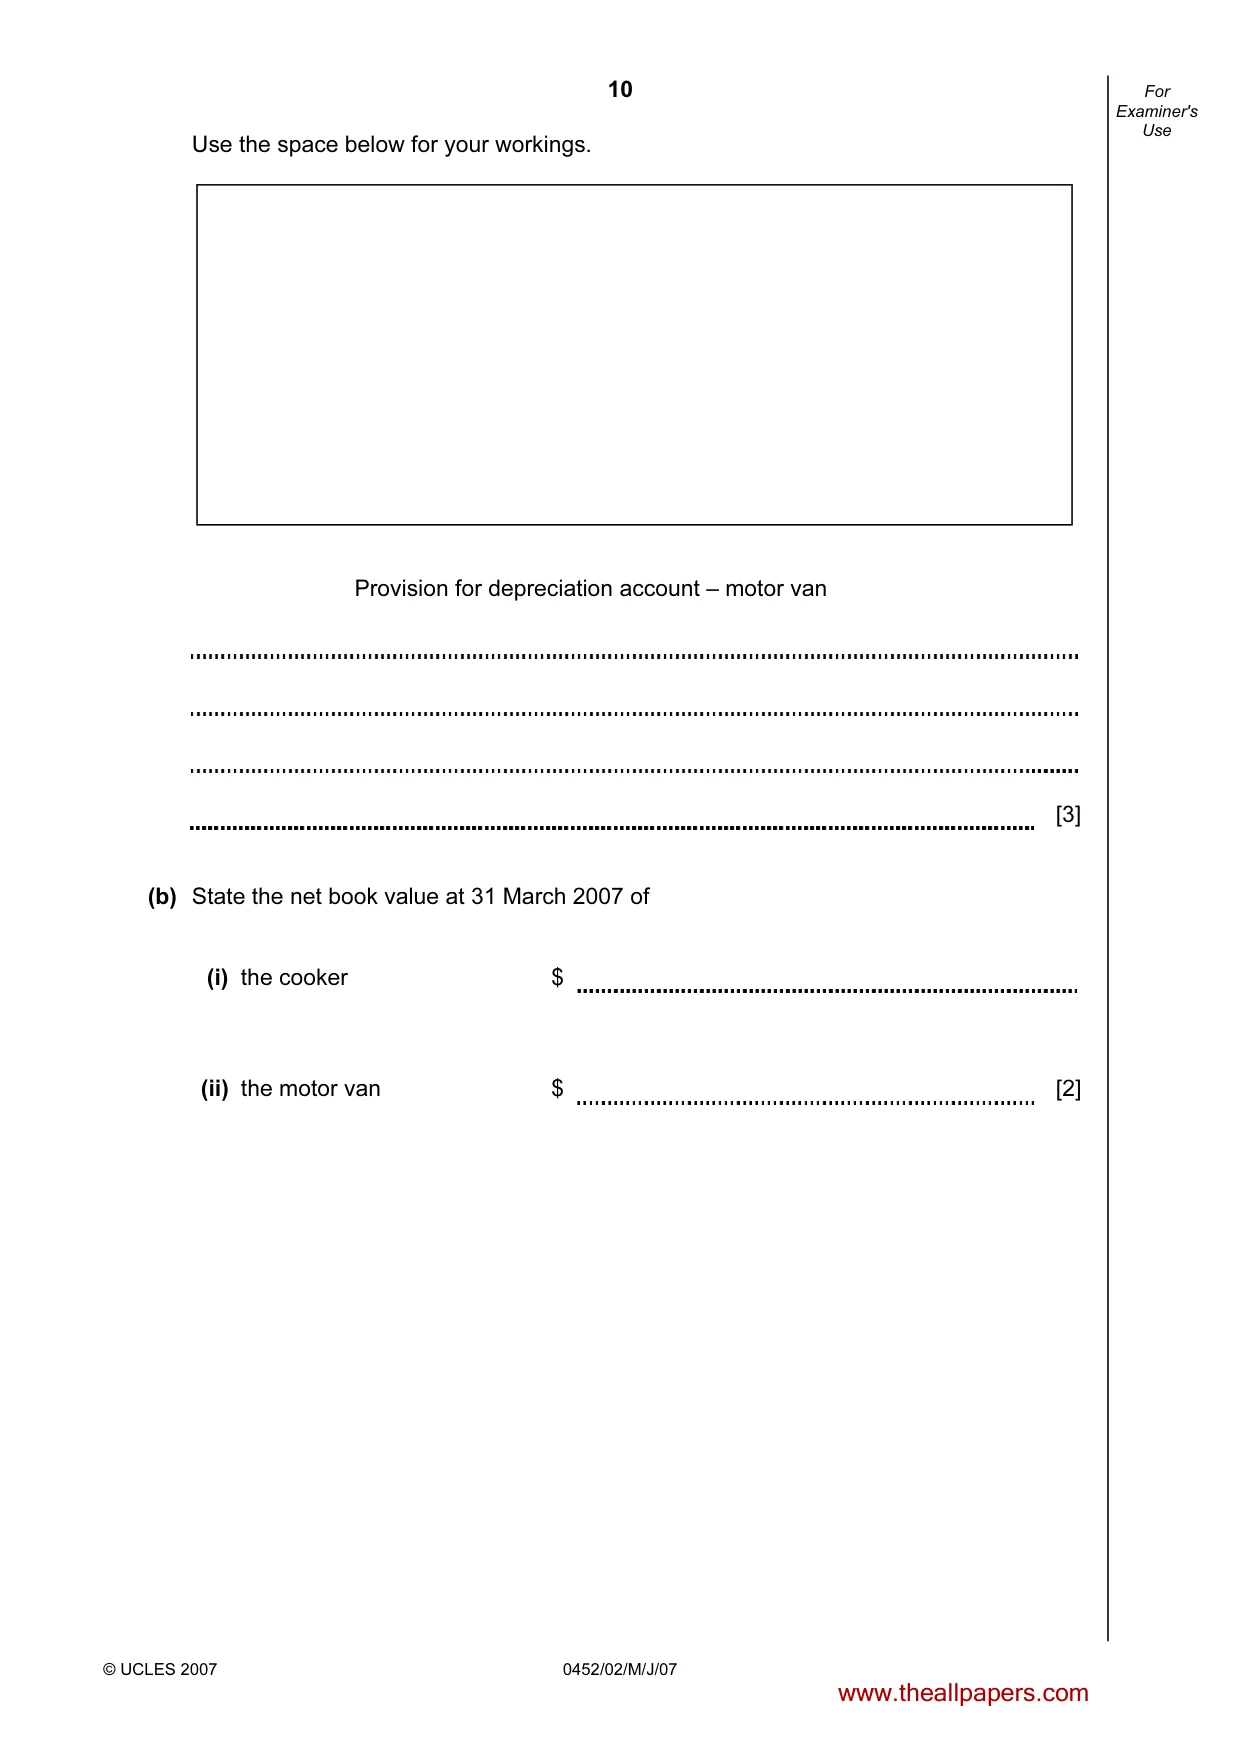
10 © UCLES 2007 0452/02/M/J/07 For Examiner's Use Use the space below for your workings. Provision for depreciation account – motor van [3] (b) State the net book value at 31 March 2007 of (i) the cooker $ (ii) the motor van $ [2] www.theallpapers.com
Question paper, page 11
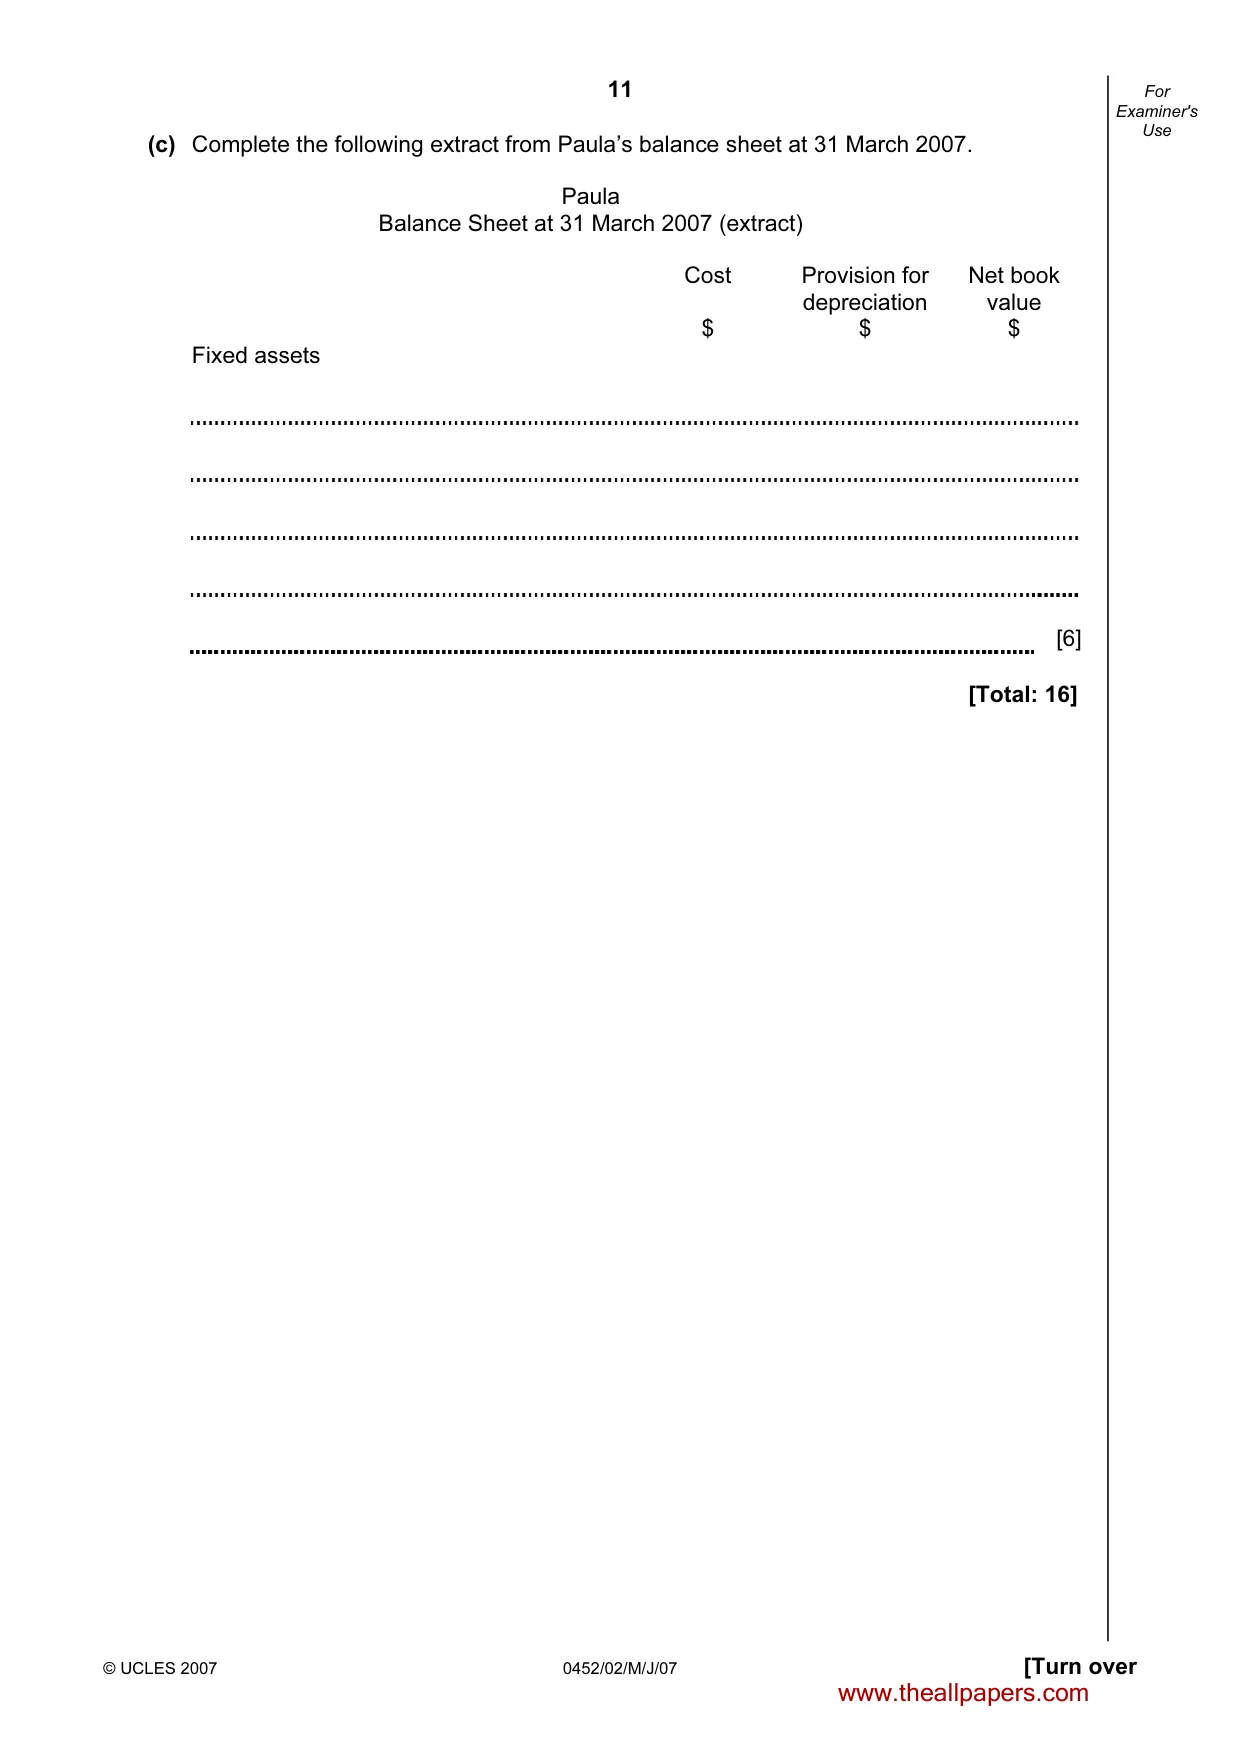
11 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use (c) Complete the following extract from Paula’s balance sheet at 31 March 2007. Paula Balance Sheet at 31 March 2007 (extract) Cost Provision for depreciation Net book value $ $ $ Fixed assets [6] [Total: 16] www.theallpapers.com
Question paper, page 12
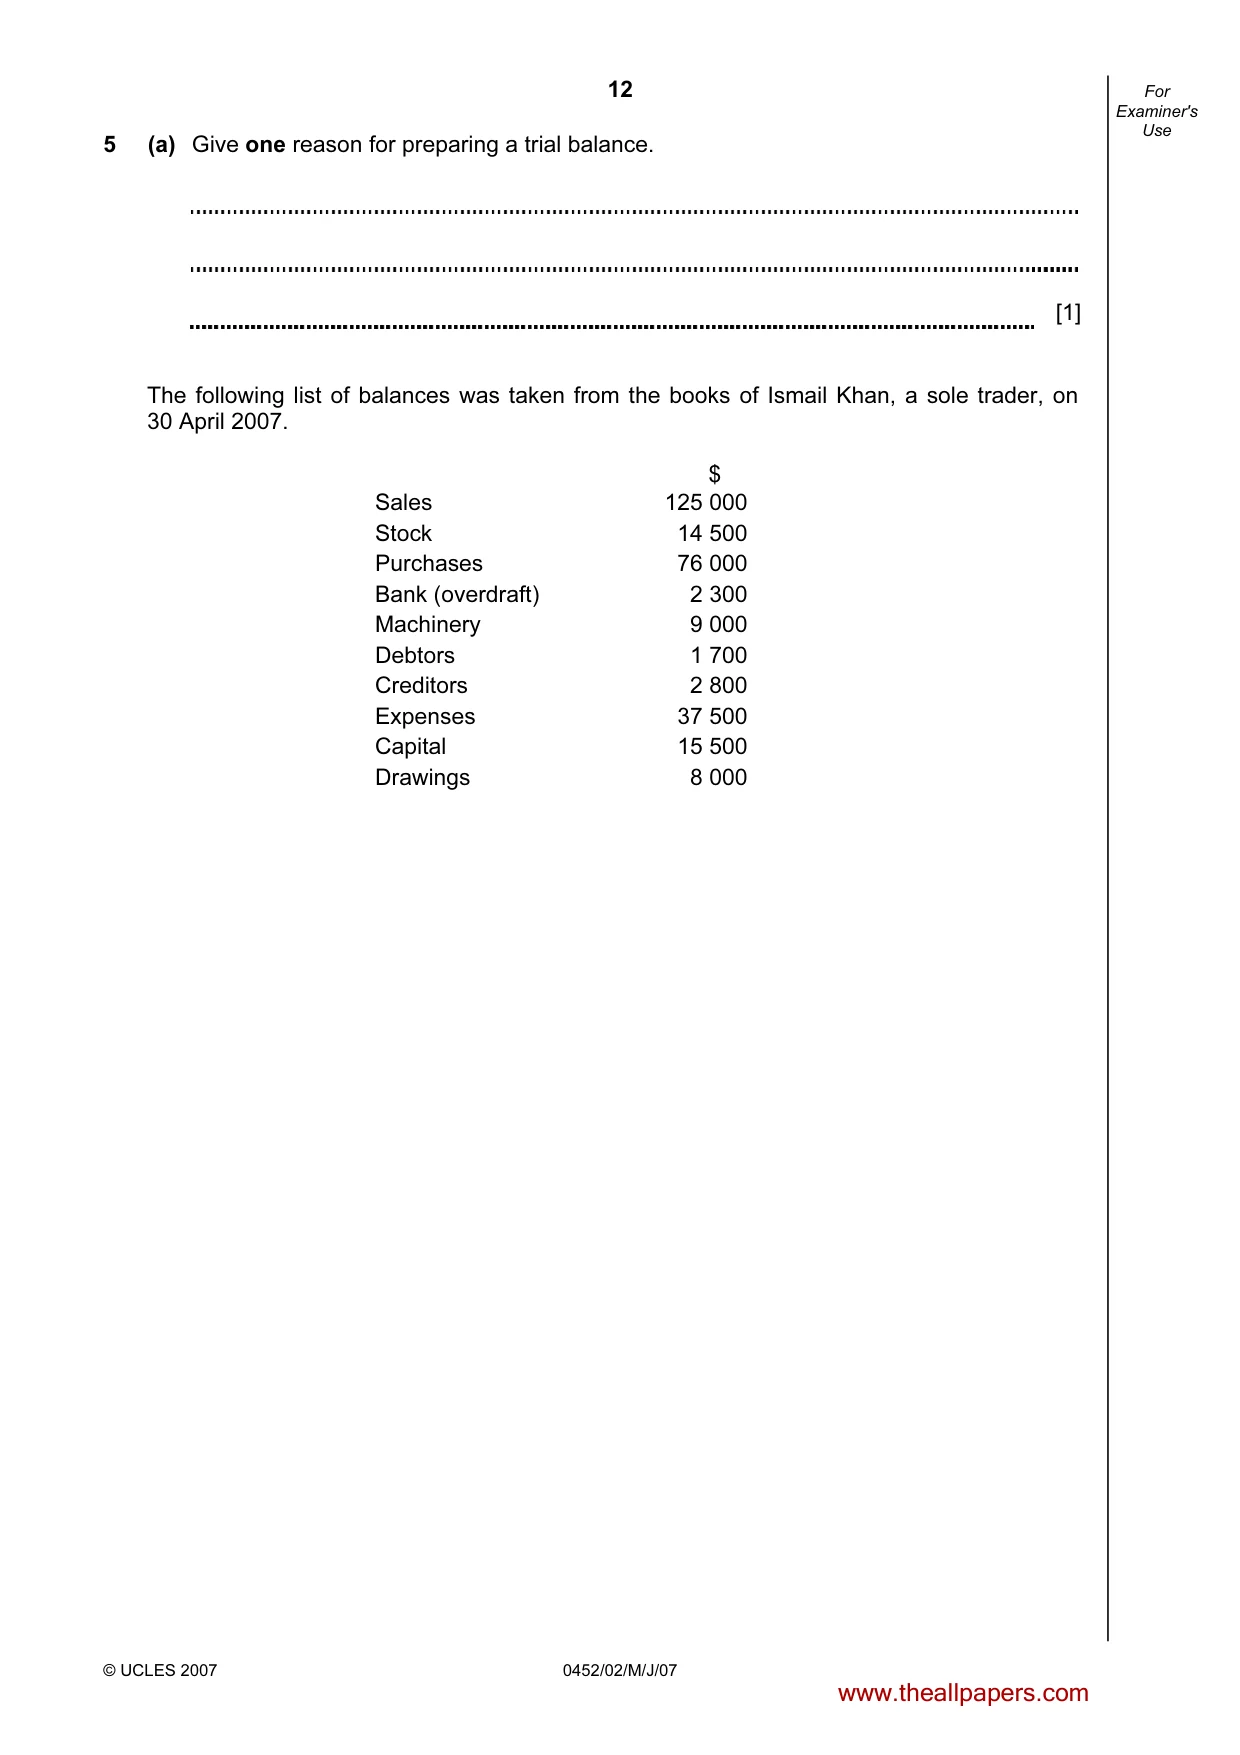
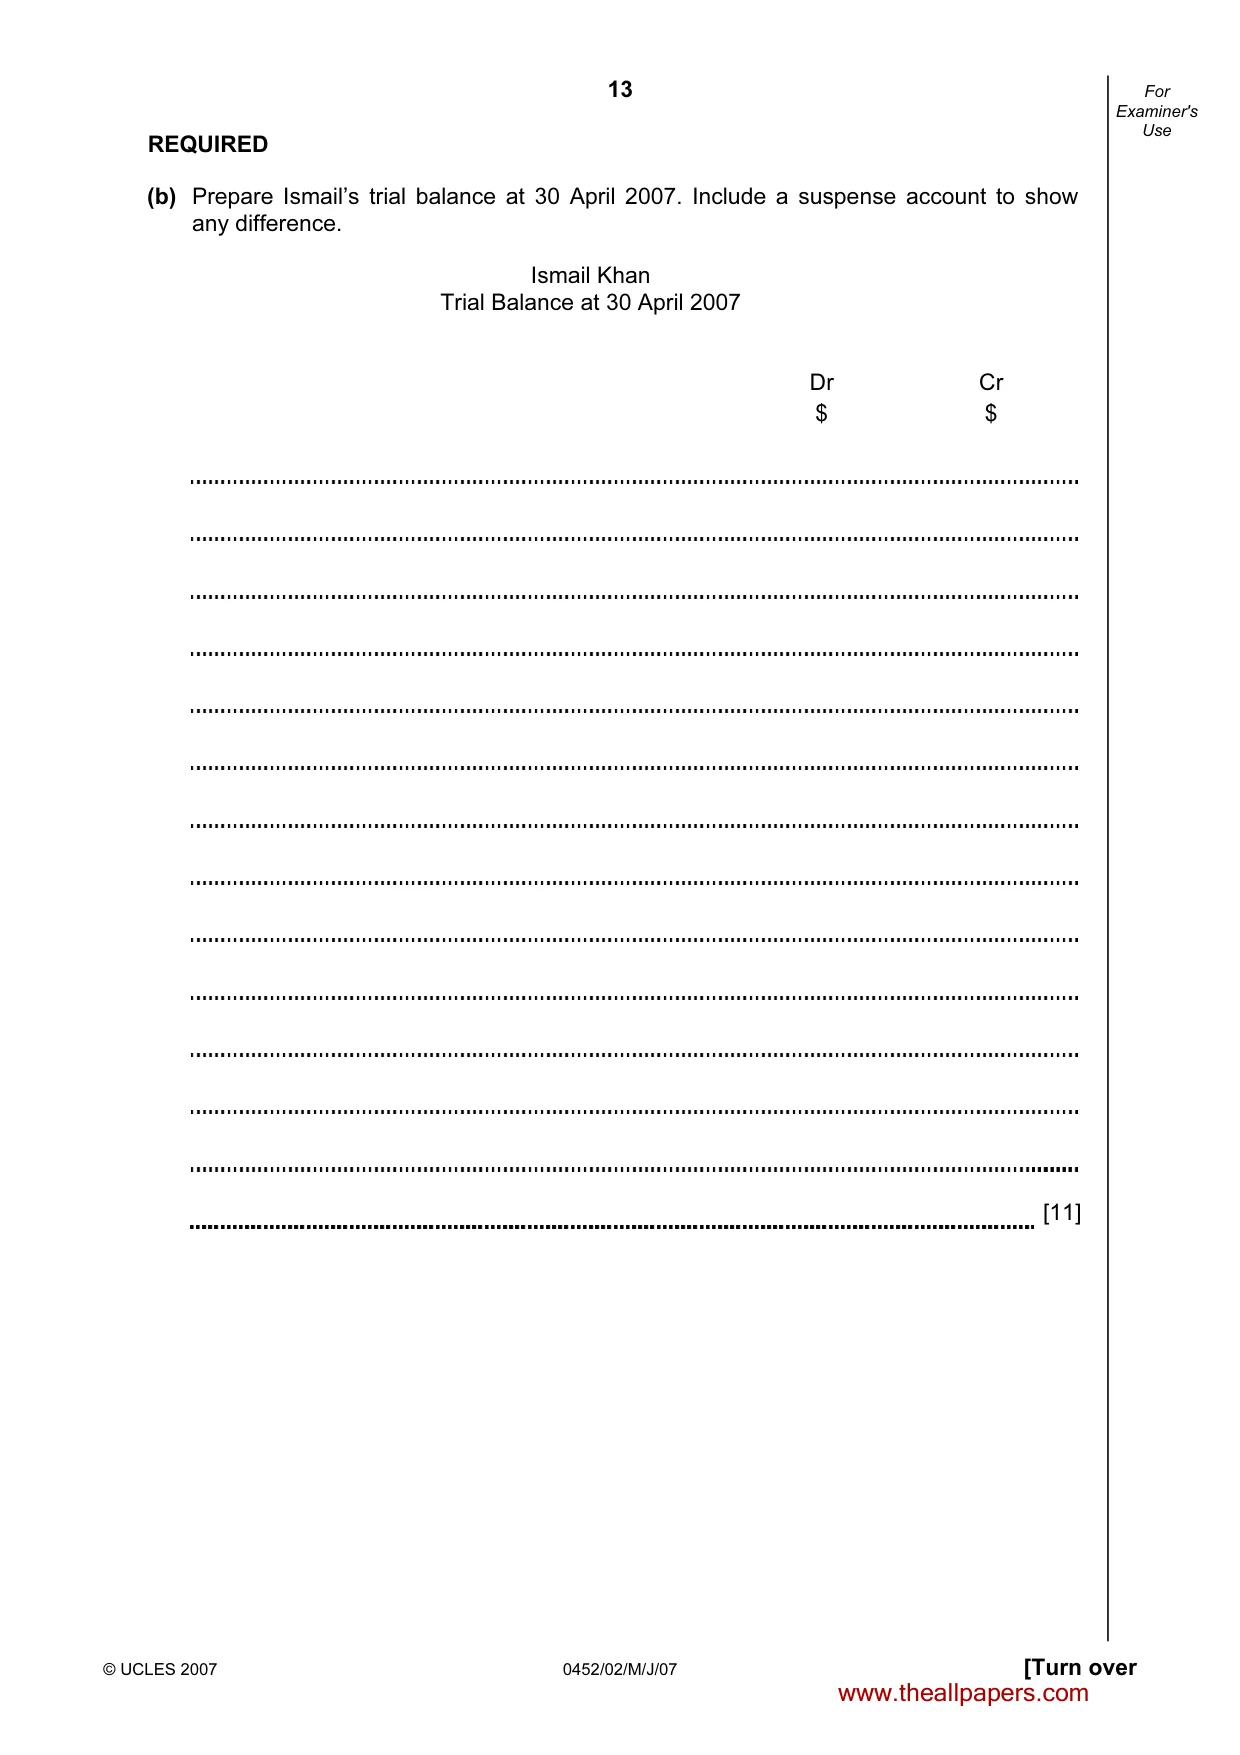
12 © UCLES 2007 0452/02/M/J/07 For Examiner's Use 5 (a) Give one reason for preparing a trial balance. [1] The following list of balances was taken from the books of Ismail Khan, a sole trader, on 30 April 2007. $ Sales 125 000 Stock 14 500 Purchases 76 000 Bank (overdraft) 2 300 Machinery 9 000 Debtors 1 700 Creditors 2 800 Expenses 37 500 Capital 15 500 Drawings 8 000 www.theallpapers.com
Question paper, page 13
13 © UCLES 2007 0452/02/M/J/07 [Turn over For Examiner's Use REQUIRED (b) Prepare Ismail’s trial balance at 30 April 2007. Include a suspense account to show any difference. Ismail Khan Trial Balance at 30 April 2007 Dr Cr $ $ [11] www.theallpapers.com
Question paper, page 14
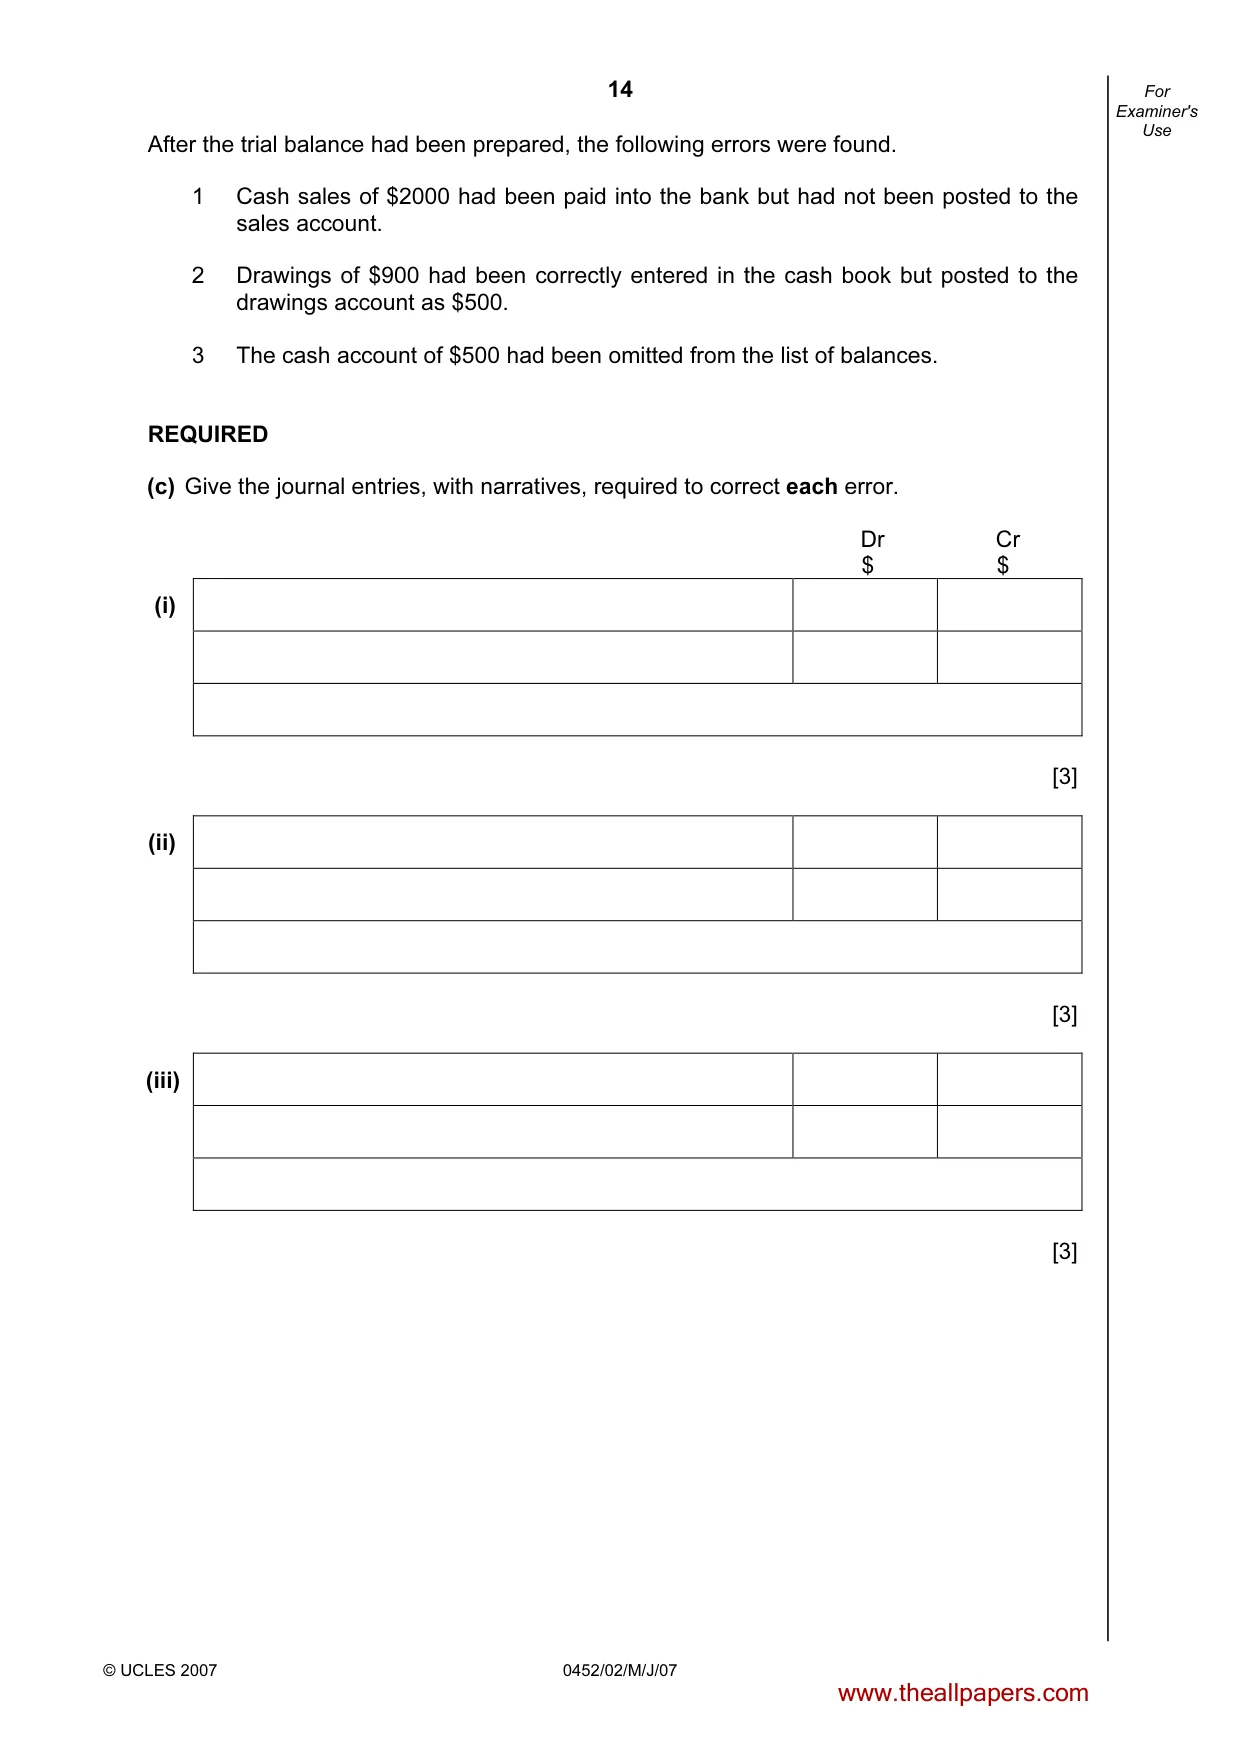
14 © UCLES 2007 0452/02/M/J/07 For Examiner's Use After the trial balance had been prepared, the following errors were found. 1 Cash sales of $2000 had been paid into the bank but had not been posted to the sales account. 2 Drawings of $900 had been correctly entered in the cash book but posted to the drawings account as $500. 3 The cash account of $500 had been omitted from the list of balances. REQUIRED (c) Give the journal entries, with narratives, required to correct each error. Dr Cr $ $ (i) [3] (ii) [3] (iii) [3] www.theallpapers.com
Question paper, page 15
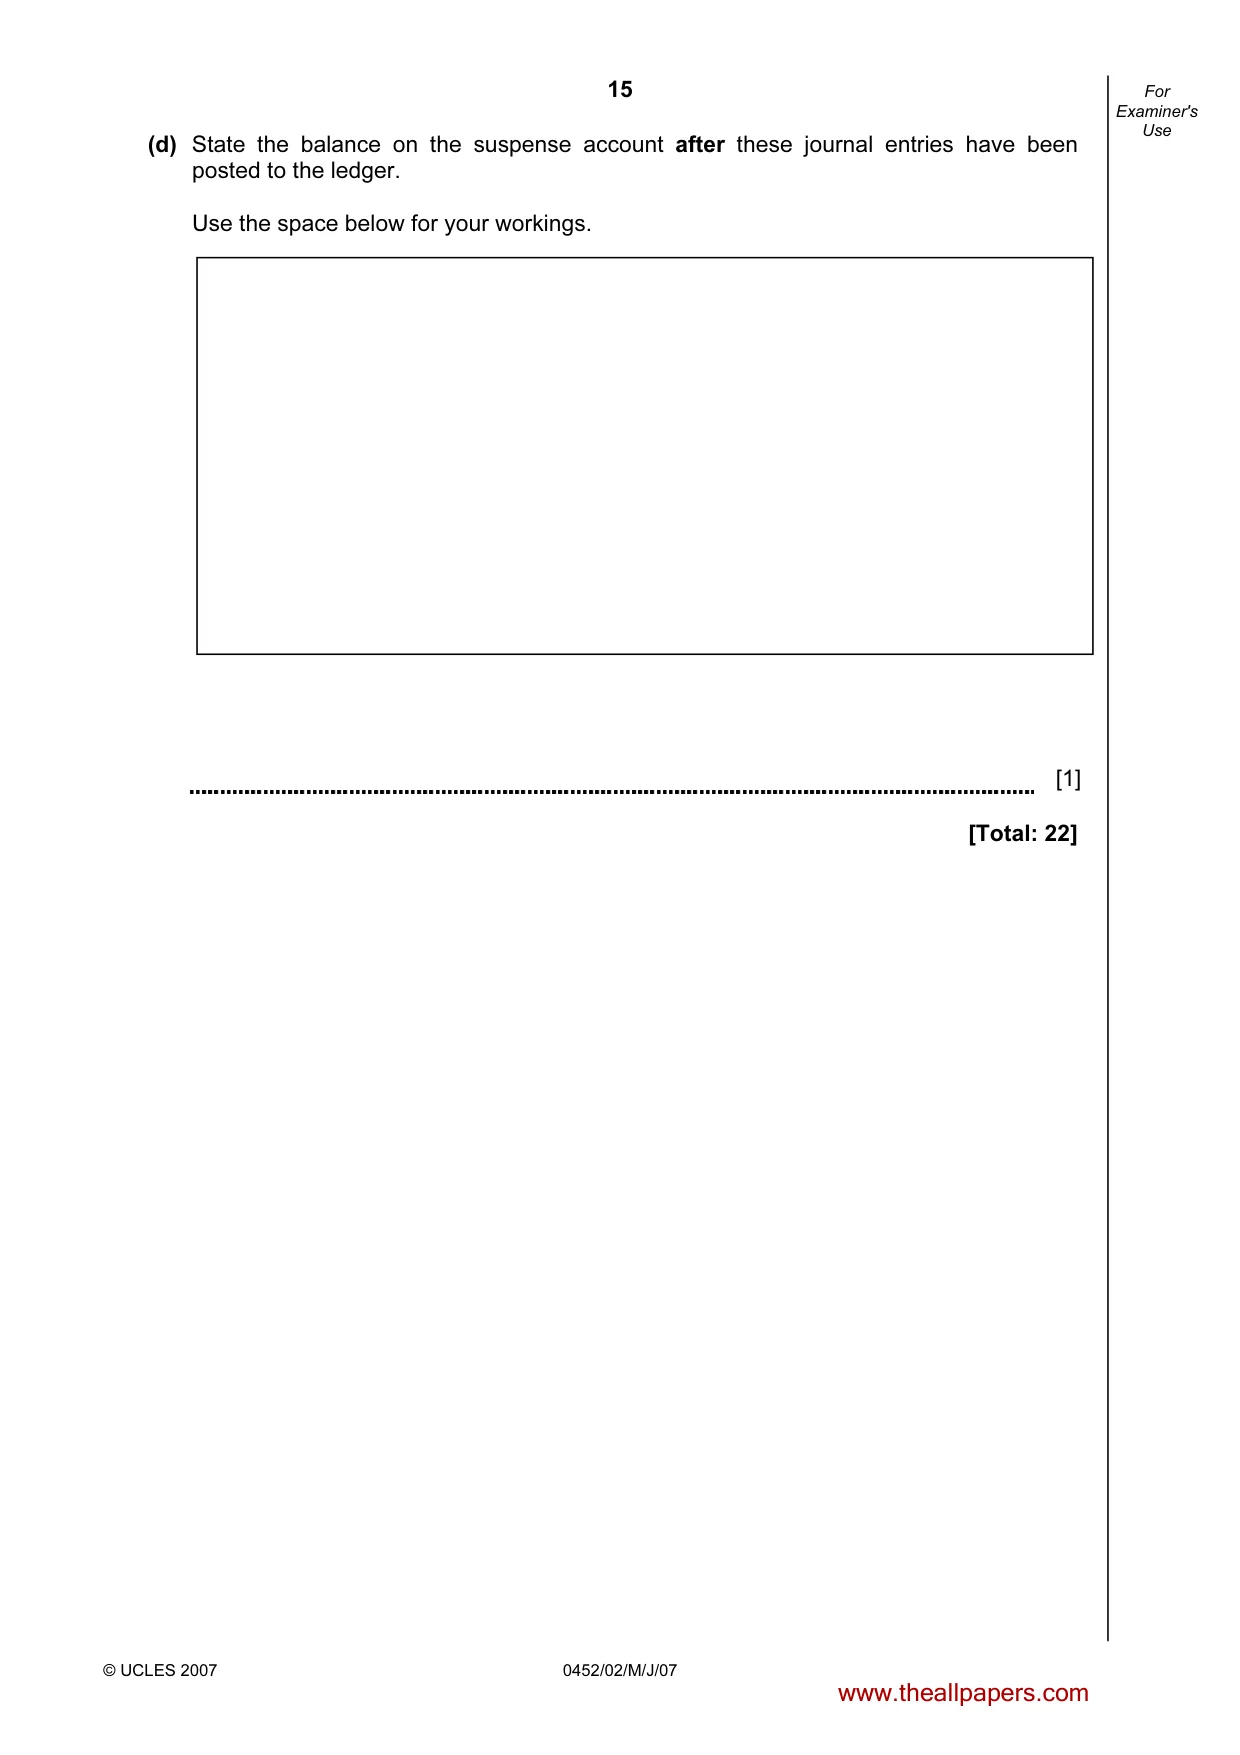
15 © UCLES 2007 0452/02/M/J/07 For Examiner's Use (d) State the balance on the suspense account after these journal entries have been posted to the ledger. Use the space below for your workings. [1] [Total: 22] www.theallpapers.com
Question paper, page 16
16 BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. 0452/02/M/J/07 www.theallpapers.com
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the May/June 2007 question paper 0452 ACCOUNTING 0452/02 Paper 2, maximum raw mark 90 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the report on the examination. • CIE will not enter into discussions or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the May/June 2007 question papers for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses. www.theallpapers.com
Mark scheme, page 2
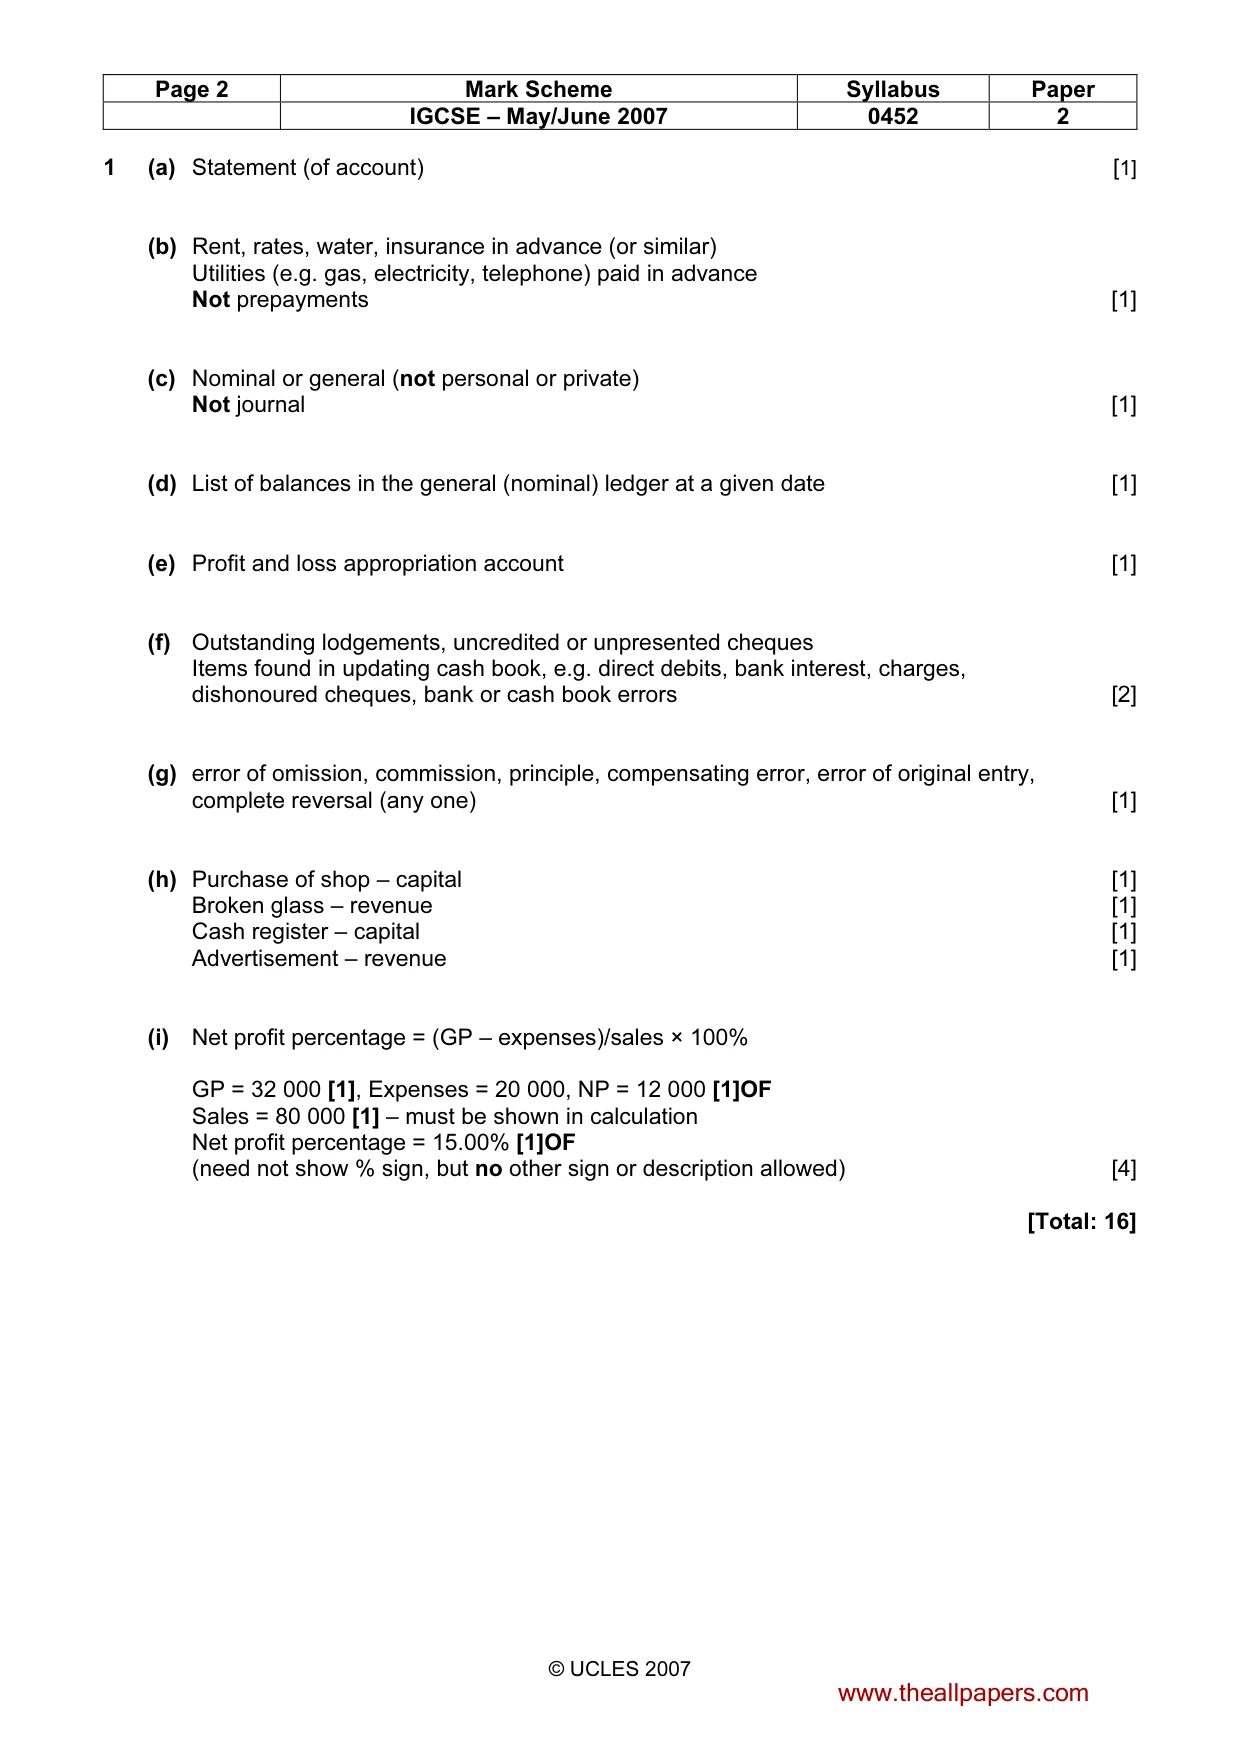
Page 2 Mark Scheme Syllabus Paper IGCSE – May/June 2007 0452 2 © UCLES 2007 1 (a) Statement (of account) [1] (b) Rent, rates, water, insurance in advance (or similar) Utilities (e.g. gas, electricity, telephone) paid in advance Not prepayments [1] (c) Nominal or general (not personal or private) Not journal [1] (d) List of balances in the general (nominal) ledger at a given date [1] (e) Profit and loss appropriation account [1] (f) Outstanding lodgements, uncredited or unpresented cheques Items found in updating cash book, e.g. direct debits, bank interest, charges, dishonoured cheques, bank or cash book errors [2] (g) error of omission, commission, principle, compensating error, error of original entry, complete reversal (any one) [1] (h) Purchase of shop – capital [1] Broken glass – revenue [1] Cash register – capital [1] Advertisement – revenue [1] (i) Net profit percentage = (GP – expenses)/sales × 100% GP = 32 000 [1], Expenses = 20 000, NP = 12 000 [1]OF Sales = 80 000 [1] – must be shown in calculation Net profit percentage = 15.00% [1]OF (need not show % sign, but no other sign or description allowed) [4] [Total: 16] www.theallpapers.com
Mark scheme, page 3
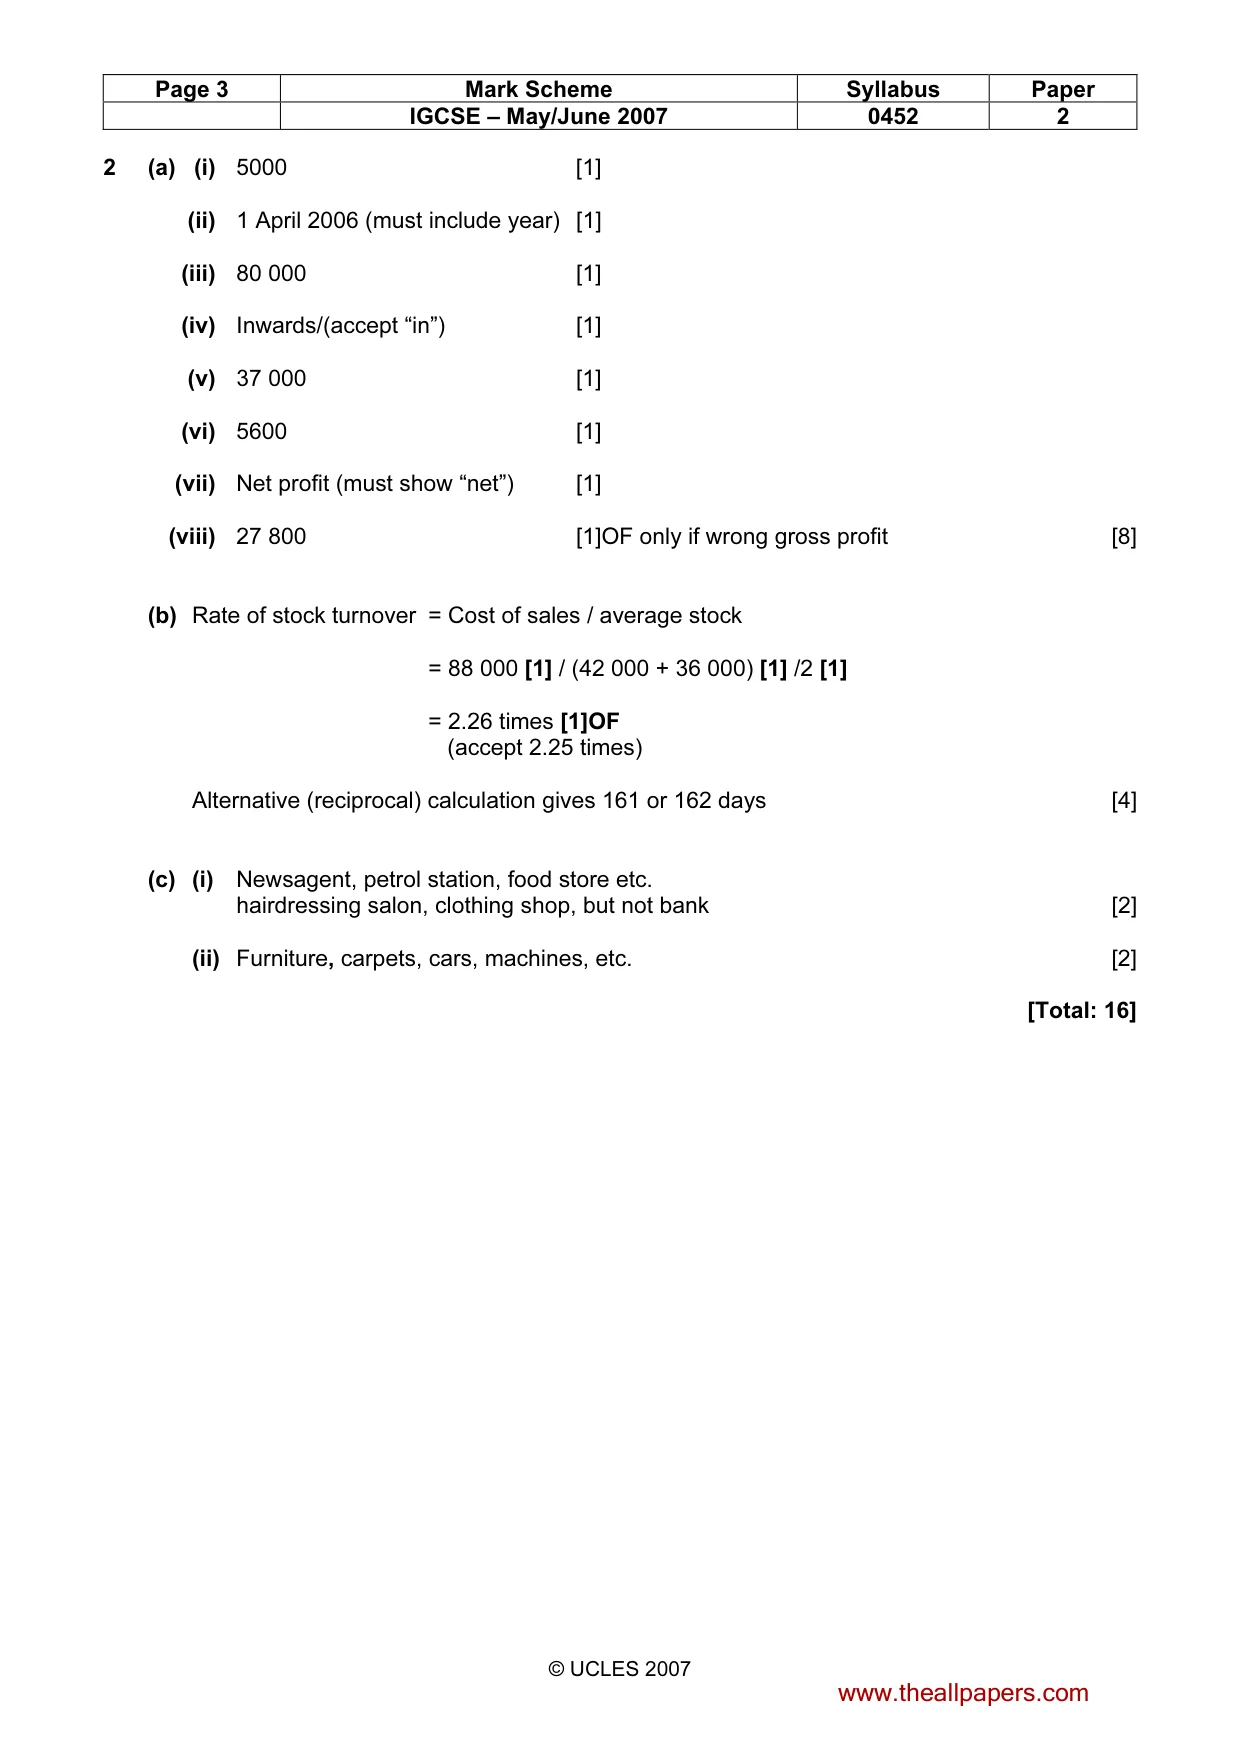
Page 3 Mark Scheme Syllabus Paper IGCSE – May/June 2007 0452 2 © UCLES 2007 2 (a) (i) 5000 [1] (ii) 1 April 2006 (must include year) [1] (iii) 80 000 [1] (iv) Inwards/(accept “in”) [1] (v) 37 000 [1] (vi) 5600 [1] (vii) Net profit (must show “net”) [1] (viii) 27 800 [1]OF only if wrong gross profit [8] (b) Rate of stock turnover = Cost of sales / average stock = 88 000 [1] / (42 000 + 36 000) [1] /2 [1] = 2.26 times [1]OF (accept 2.25 times) Alternative (reciprocal) calculation gives 161 or 162 days [4] (c) (i) Newsagent, petrol station, food store etc. hairdressing salon, clothing shop, but not bank [2] (ii) Furniture, carpets, cars, machines, etc. [2] [Total: 16] www.theallpapers.com
Mark scheme, page 4
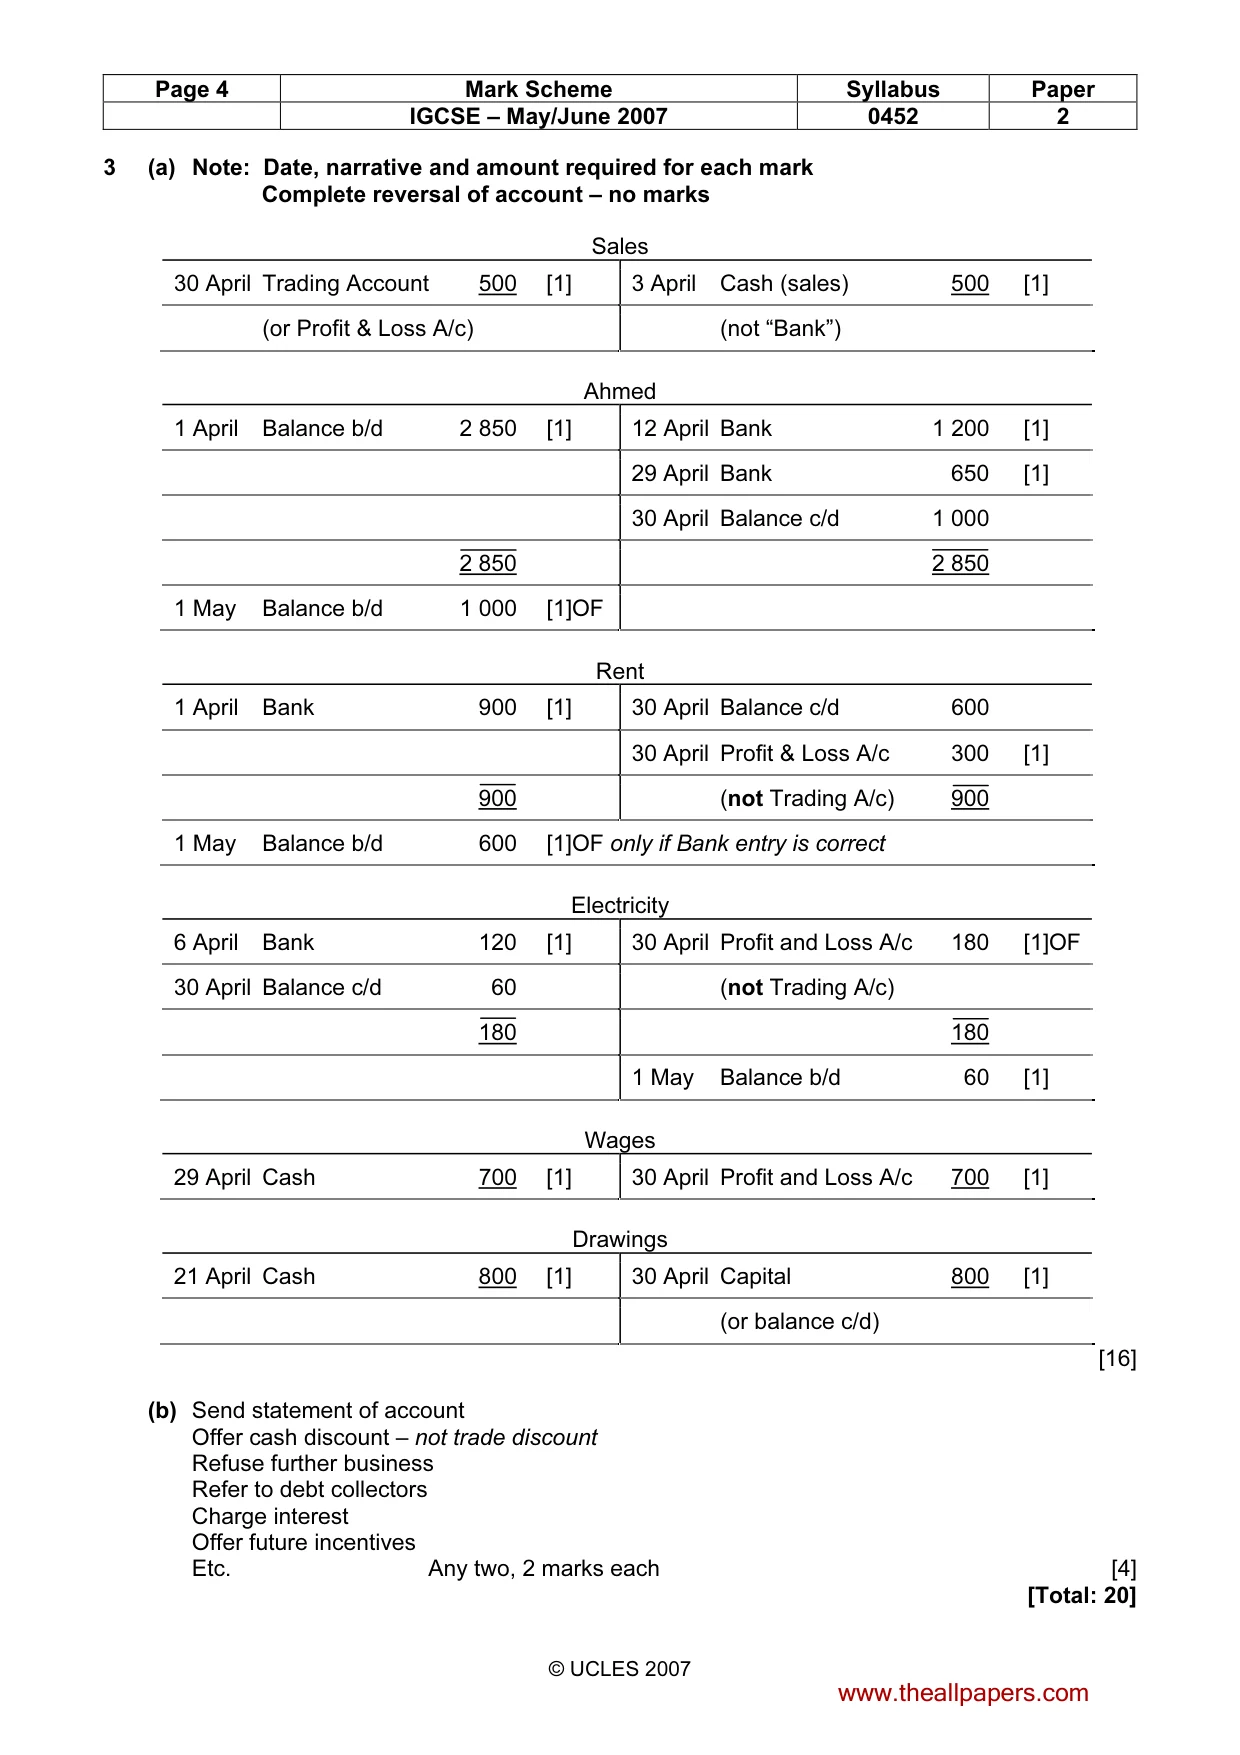
Page 4 Mark Scheme Syllabus Paper IGCSE – May/June 2007 0452 2 © UCLES 2007 3 (a) Note: Date, narrative and amount required for each mark Complete reversal of account – no marks Sales 30 April Trading Account 500 [1] 3 April Cash (sales) 500 [1] (or Profit & Loss A/c) (not “Bank”) Ahmed 1 April Balance b/d 2 850 [1] 12 April Bank 1 200 [1] 29 April Bank 650 [1] 30 April Balance c/d 1 000 2 850 2 850 1 May Balance b/d 1 000 [1]OF Rent 1 April Bank 900 [1] 30 April Balance c/d 600 30 April Profit & Loss A/c 300 [1] 900 (not Trading A/c) 900 1 May Balance b/d 600 [1]OF only if Bank entry is correct Electricity 6 April Bank 120 [1] 30 April Profit and Loss A/c 180 [1]OF 30 April Balance c/d 60 (not Trading A/c) 180 180 1 May Balance b/d 60 [1] Wages 29 April Cash 700 [1] 30 April Profit and Loss A/c 700 [1] Drawings 21 April Cash 800 [1] 30 April Capital 800 [1] (or balance c/d) [16] (b) Send statement of account Offer cash discount – not trade discount Refuse further business Refer to debt collectors Charge interest Offer future incentives Etc. Any two, 2 marks each [4] [Total: 20] www.theallpapers.com
Mark scheme, page 5
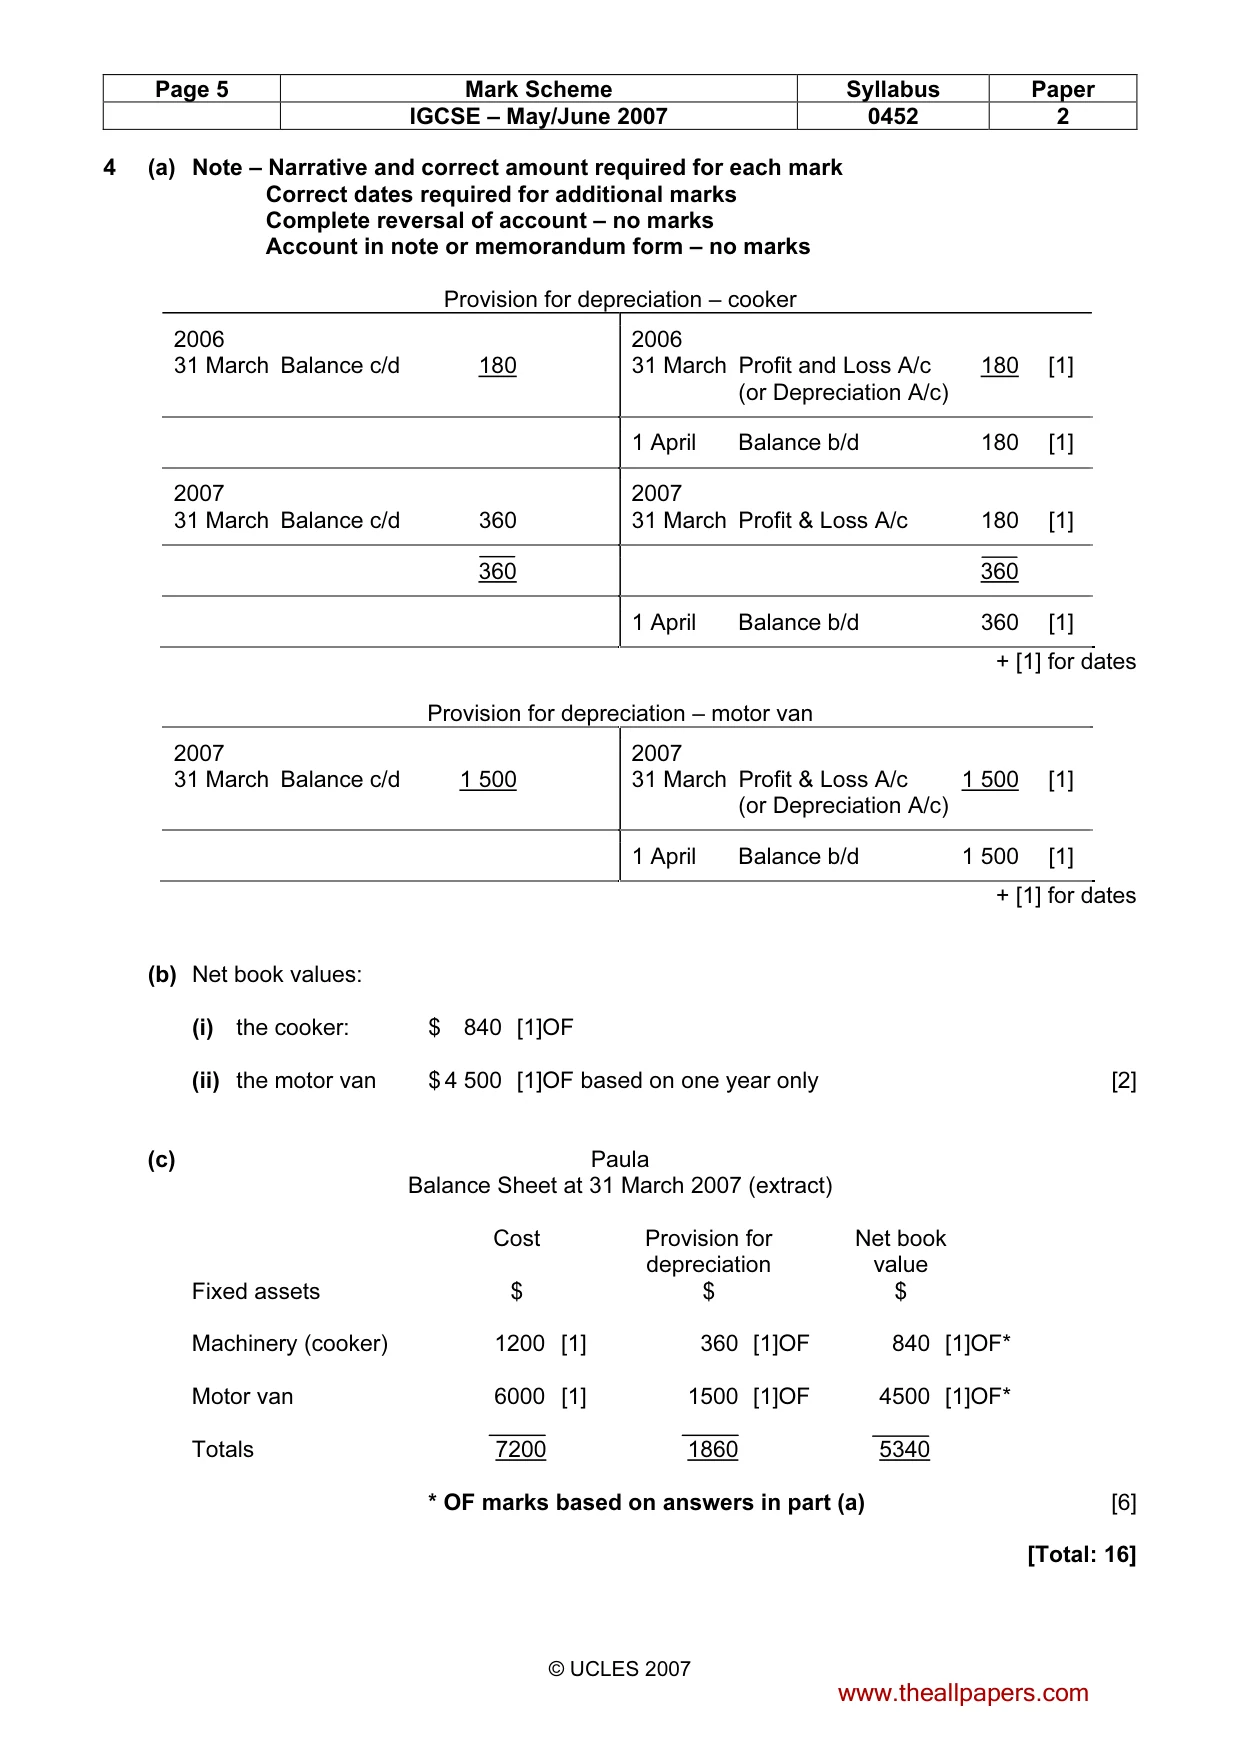
Page 5 Mark Scheme Syllabus Paper IGCSE – May/June 2007 0452 2 © UCLES 2007 4 (a) Note – Narrative and correct amount required for each mark Correct dates required for additional marks Complete reversal of account – no marks Account in note or memorandum form – no marks Provision for depreciation – cooker 2006 31 March Balance c/d 180 2006 31 March Profit and Loss A/c 180 [1] (or Depreciation A/c) 1 April Balance b/d 180 [1] 2007 31 March Balance c/d 360 2007 31 March Profit & Loss A/c 180 [1] 360 360 1 April Balance b/d 360 [1] + [1] for dates Provision for depreciation – motor van 2007 31 March Balance c/d 1 500 2007 31 March Profit & Loss A/c 1 500 [1] (or Depreciation A/c) 1 April Balance b/d 1 500 [1] + [1] for dates (b) Net book values: (i) the cooker: $ 840 [1]OF (ii) the motor van $ 4 500 [1]OF based on one year only [2] (c) Paula Balance Sheet at 31 March 2007 (extract) Cost Provision for Net book depreciation value Fixed assets $ $ $ Machinery (cooker) 1200 [1] 360 [1]OF 840 [1]OF* Motor van 6000 [1] 1500 [1]OF 4500 [1]OF* Totals 7200 1860 5340 * OF marks based on answers in part (a) [6] [Total: 16] www.theallpapers.com
Mark scheme, page 6
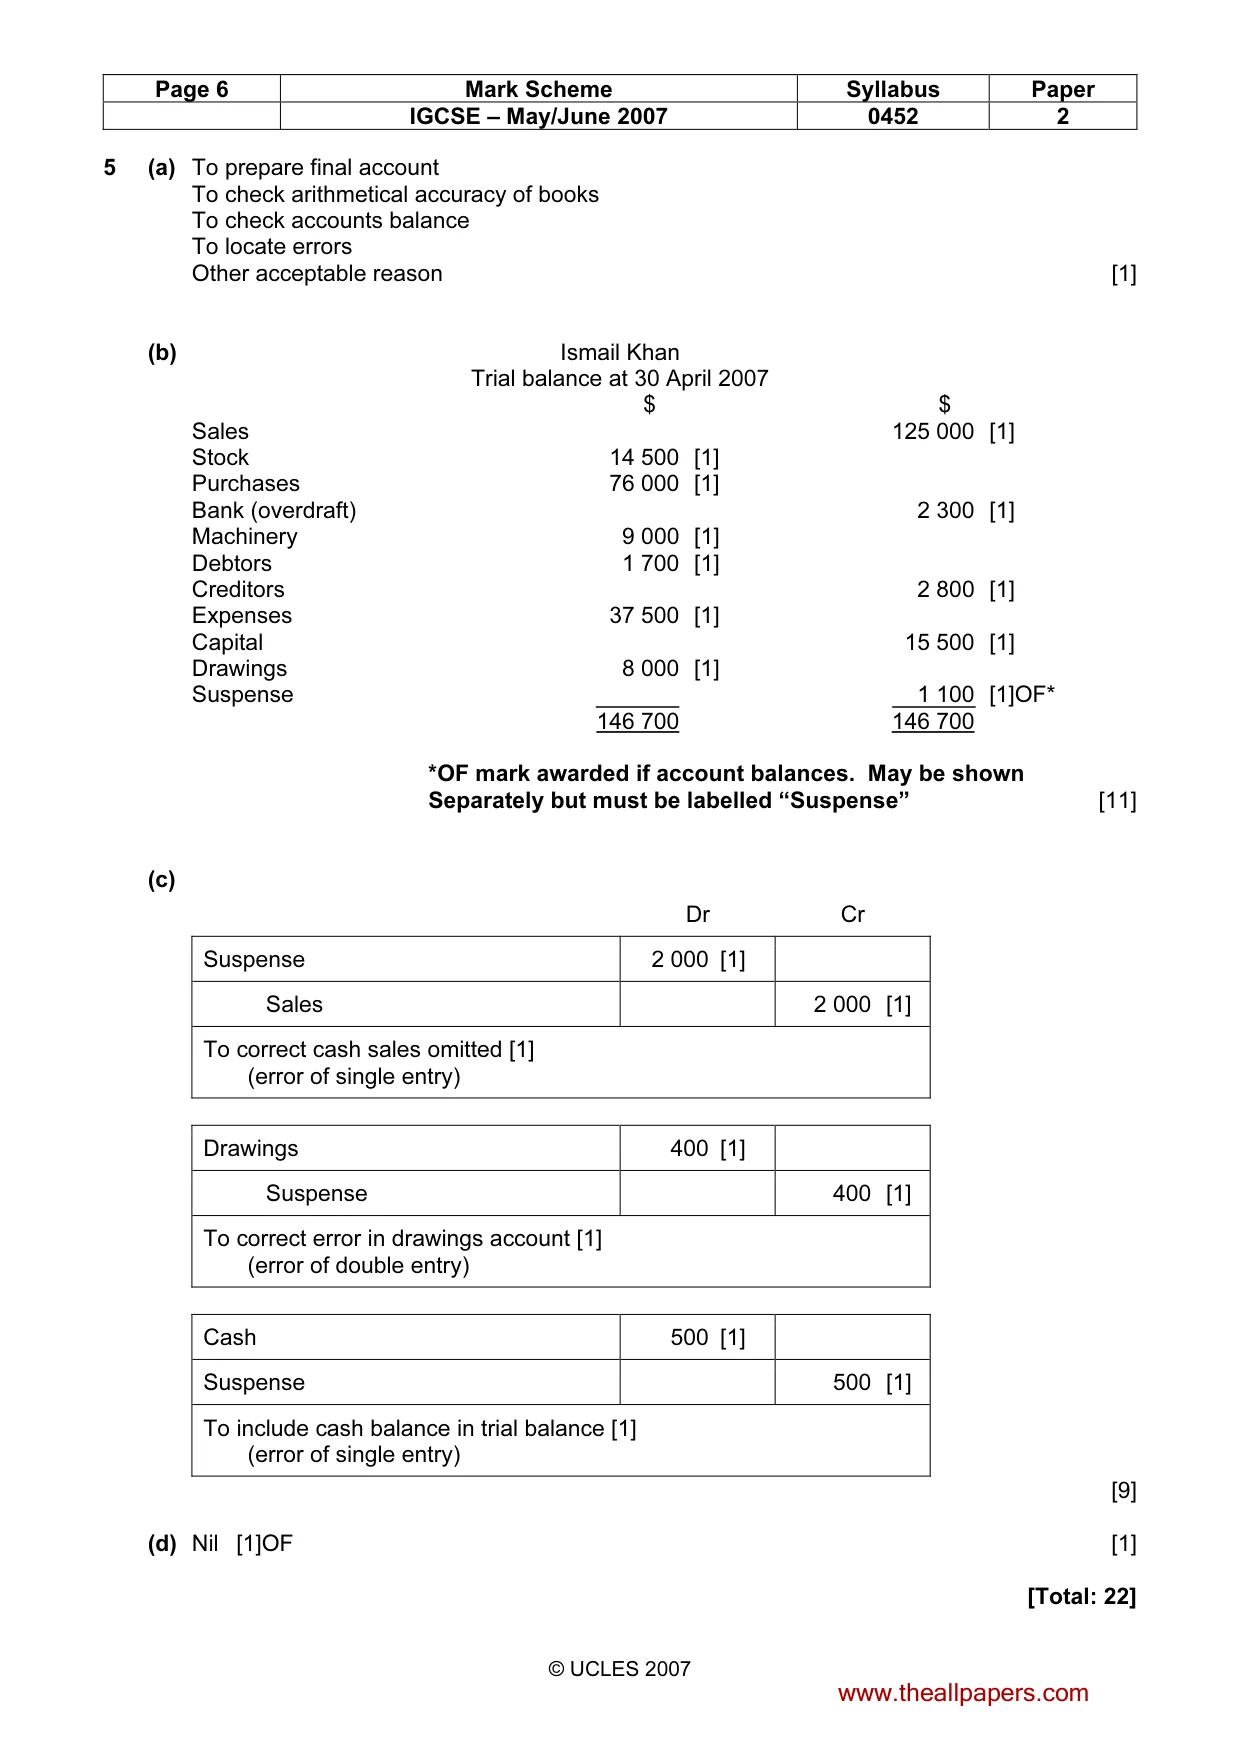
Page 6 Mark Scheme Syllabus Paper IGCSE – May/June 2007 0452 2 © UCLES 2007 5 (a) To prepare final account To check arithmetical accuracy of books To check accounts balance To locate errors Other acceptable reason [1] (b) Ismail Khan Trial balance at 30 April 2007 $ $ Sales 125 000 [1] Stock 14 500 [1] Purchases 76 000 [1] Bank (overdraft) 2 300 [1] Machinery 9 000 [1] Debtors 1 700 [1] Creditors 2 800 [1] Expenses 37 500 [1] Capital 15 500 [1] Drawings 8 000 [1] Suspense 1 100 [1]OF* 146 700 146 700 *OF mark awarded if account balances. May be shown Separately but must be labelled “Suspense” [11] (c) Dr Cr Suspense 2 000 [1] Sales 2 000 [1] To correct cash sales omitted [1] (error of single entry) Drawings 400 [1] Suspense 400 [1] To correct error in drawings account [1] (error of double entry) Cash 500 [1] Suspense 500 [1] To include cash balance in trial balance [1] (error of single entry) [9] (d) Nil [1]OF [1] [Total: 22] www.theallpapers.com
What you needed in this session
Cambridge’s own grade thresholds for 2007 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.