Cambridge IGCSE Accounting 0452 — 2005 Oct/Nov Paper 2 · Variant 1
0452/21/O/N/05
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme8 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 12 printed pages and 4 blank pages. SP (NH) S83637/1 © UCLES 2005 [Turn over UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/02 Paper 2 October/November 2005 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. For Examiner’s Use 1 2 3 4 5 Total Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. www.theallpapers.com
Question paper, page 2
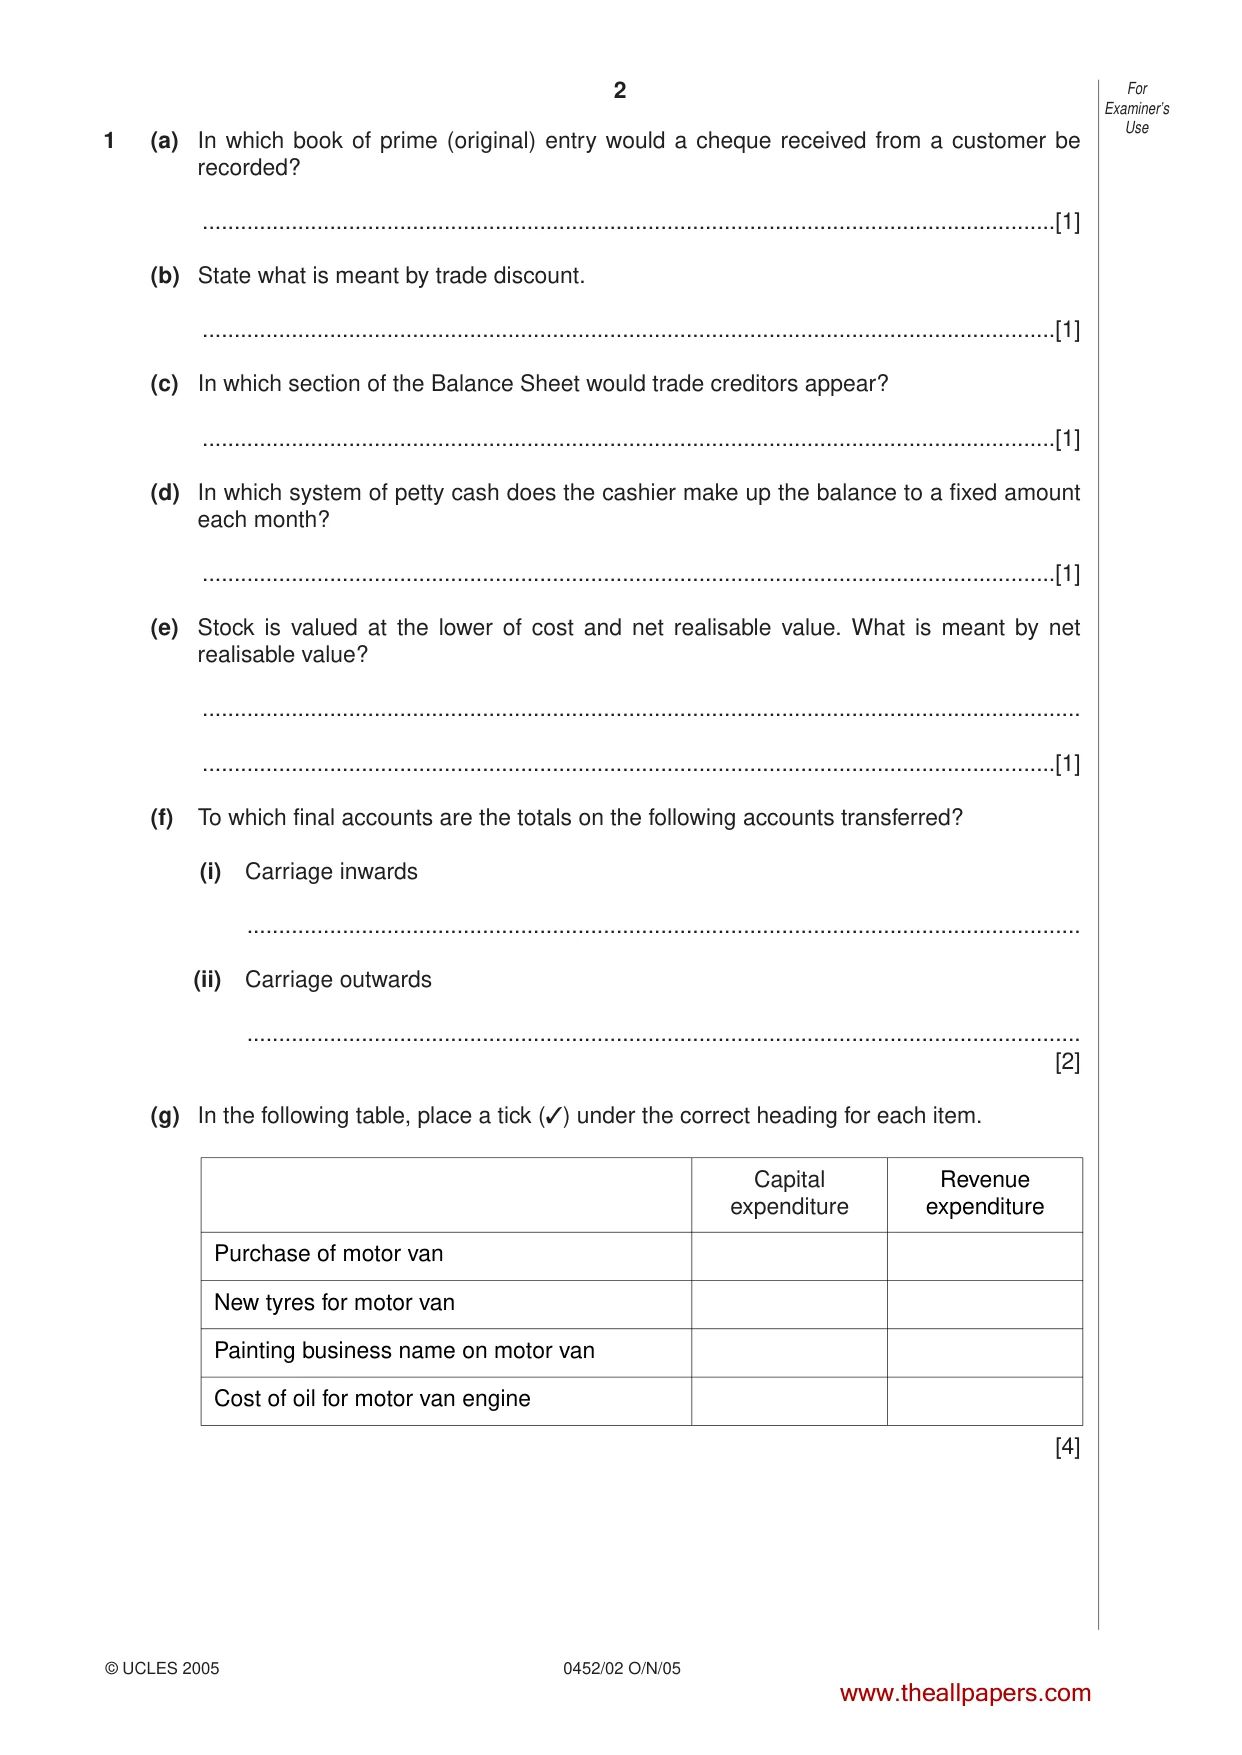
2 © UCLES 2005 0452/02 O/N/05 1 (a) In which book of prime (original) entry would a cheque received from a customer be recorded? …[1] (b) State what is meant by trade discount. …[1] (c) In which section of the Balance Sheet would trade creditors appear? …[1] (d) In which system of petty cash does the cashier make up the balance to a fixed amount each month? …[1] (e) Stock is valued at the lower of cost and net realisable value. What is meant by net realisable value? … …[1] (f) To which final accounts are the totals on the following accounts transferred? (i) Carriage inwards … (ii) Carriage outwards … [2] (g) In the following table, place a tick (✓) under the correct heading for each item. [4] For Examiner’s Use Capital expenditure Revenue expenditure Purchase of motor van New tyres for motor van Painting business name on motor van Cost of oil for motor van engine www.theallpapers.com
Question paper, page 3
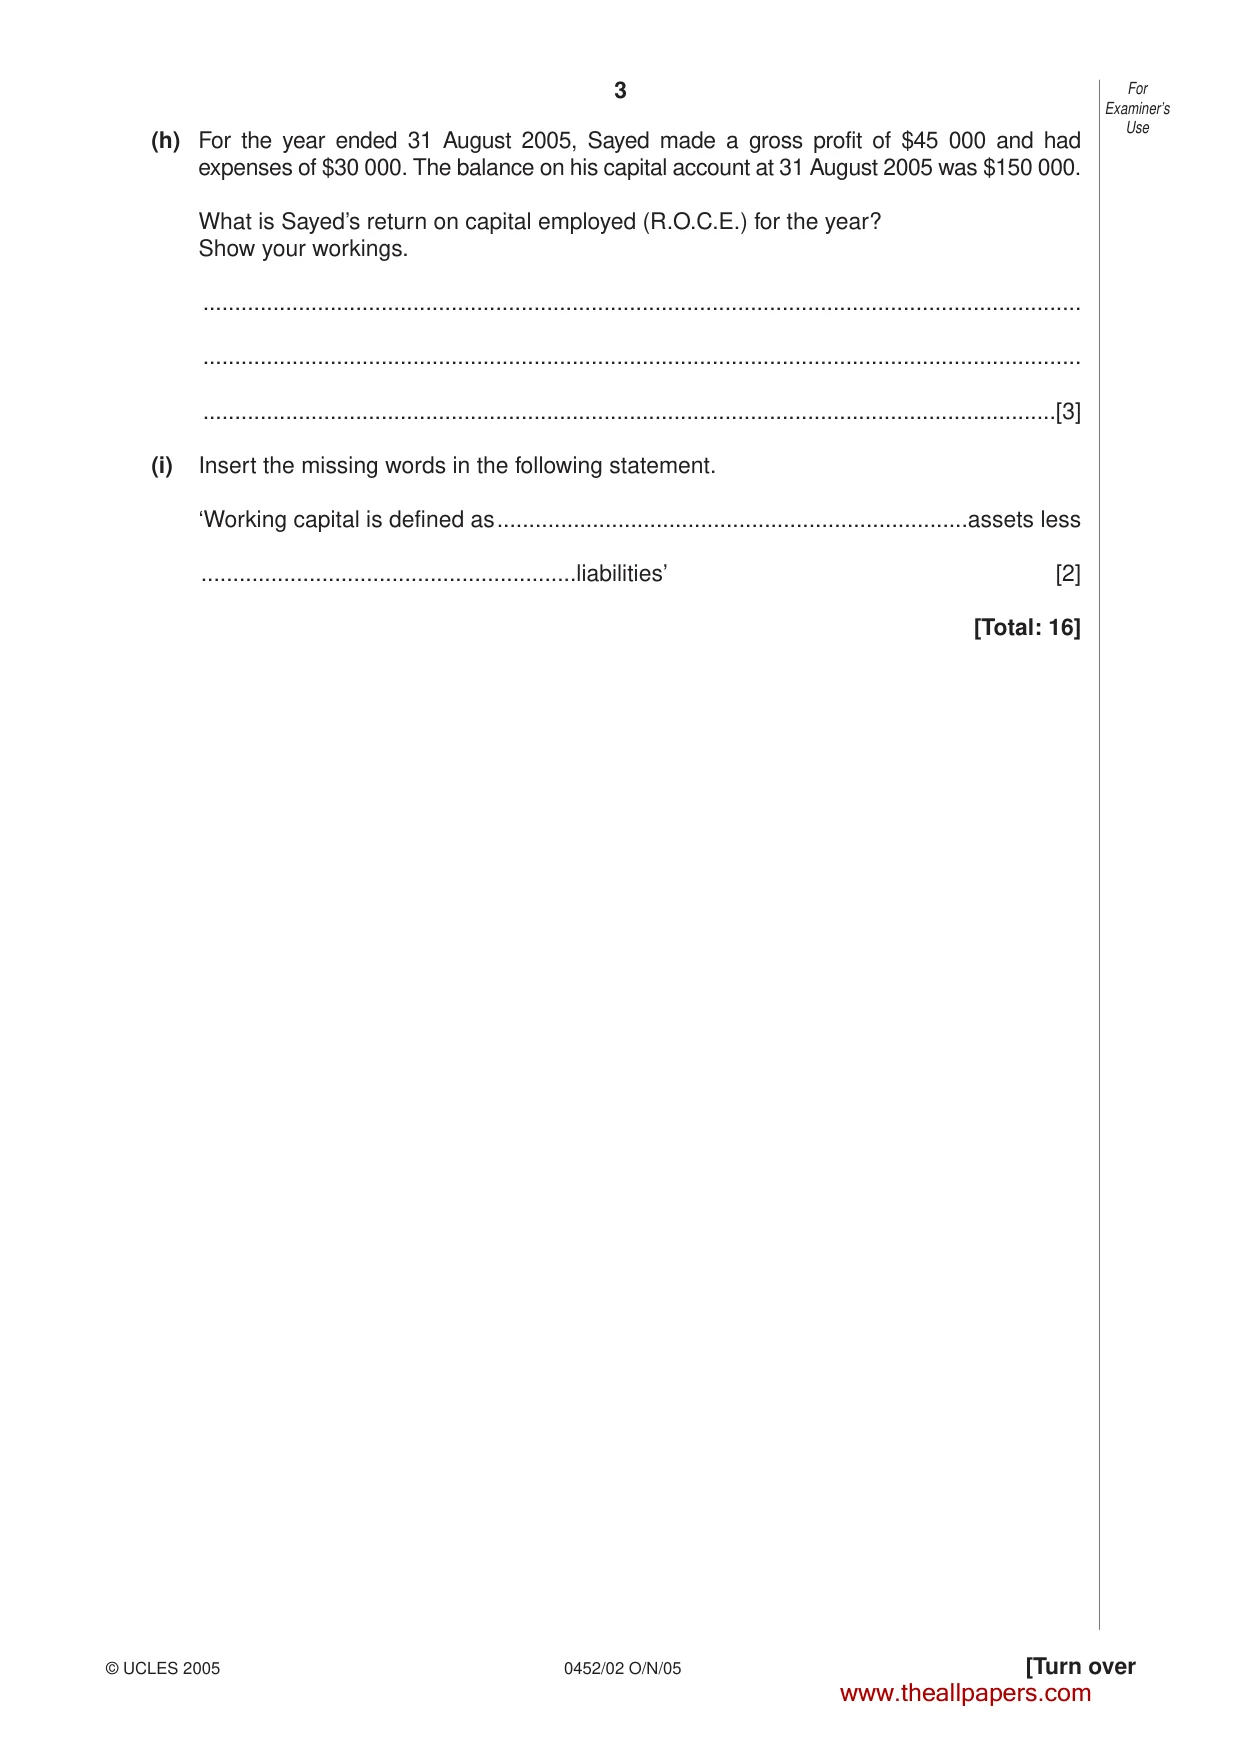
3 © UCLES 2005 0452/02 O/N/05 [Turn over (h) For the year ended 31 August 2005, Sayed made a gross profit of $45 000 and had expenses of $30 000. The balance on his capital account at 31 August 2005 was $150 000. What is Sayed’s return on capital employed (R.O.C.E.) for the year? Show your workings. … … …[3] (i) Insert the missing words in the following statement. ‘Working capital is defined as…assets less …liabilities’ [2] [Total: 16] For Examiner’s Use www.theallpapers.com
Question paper, page 4
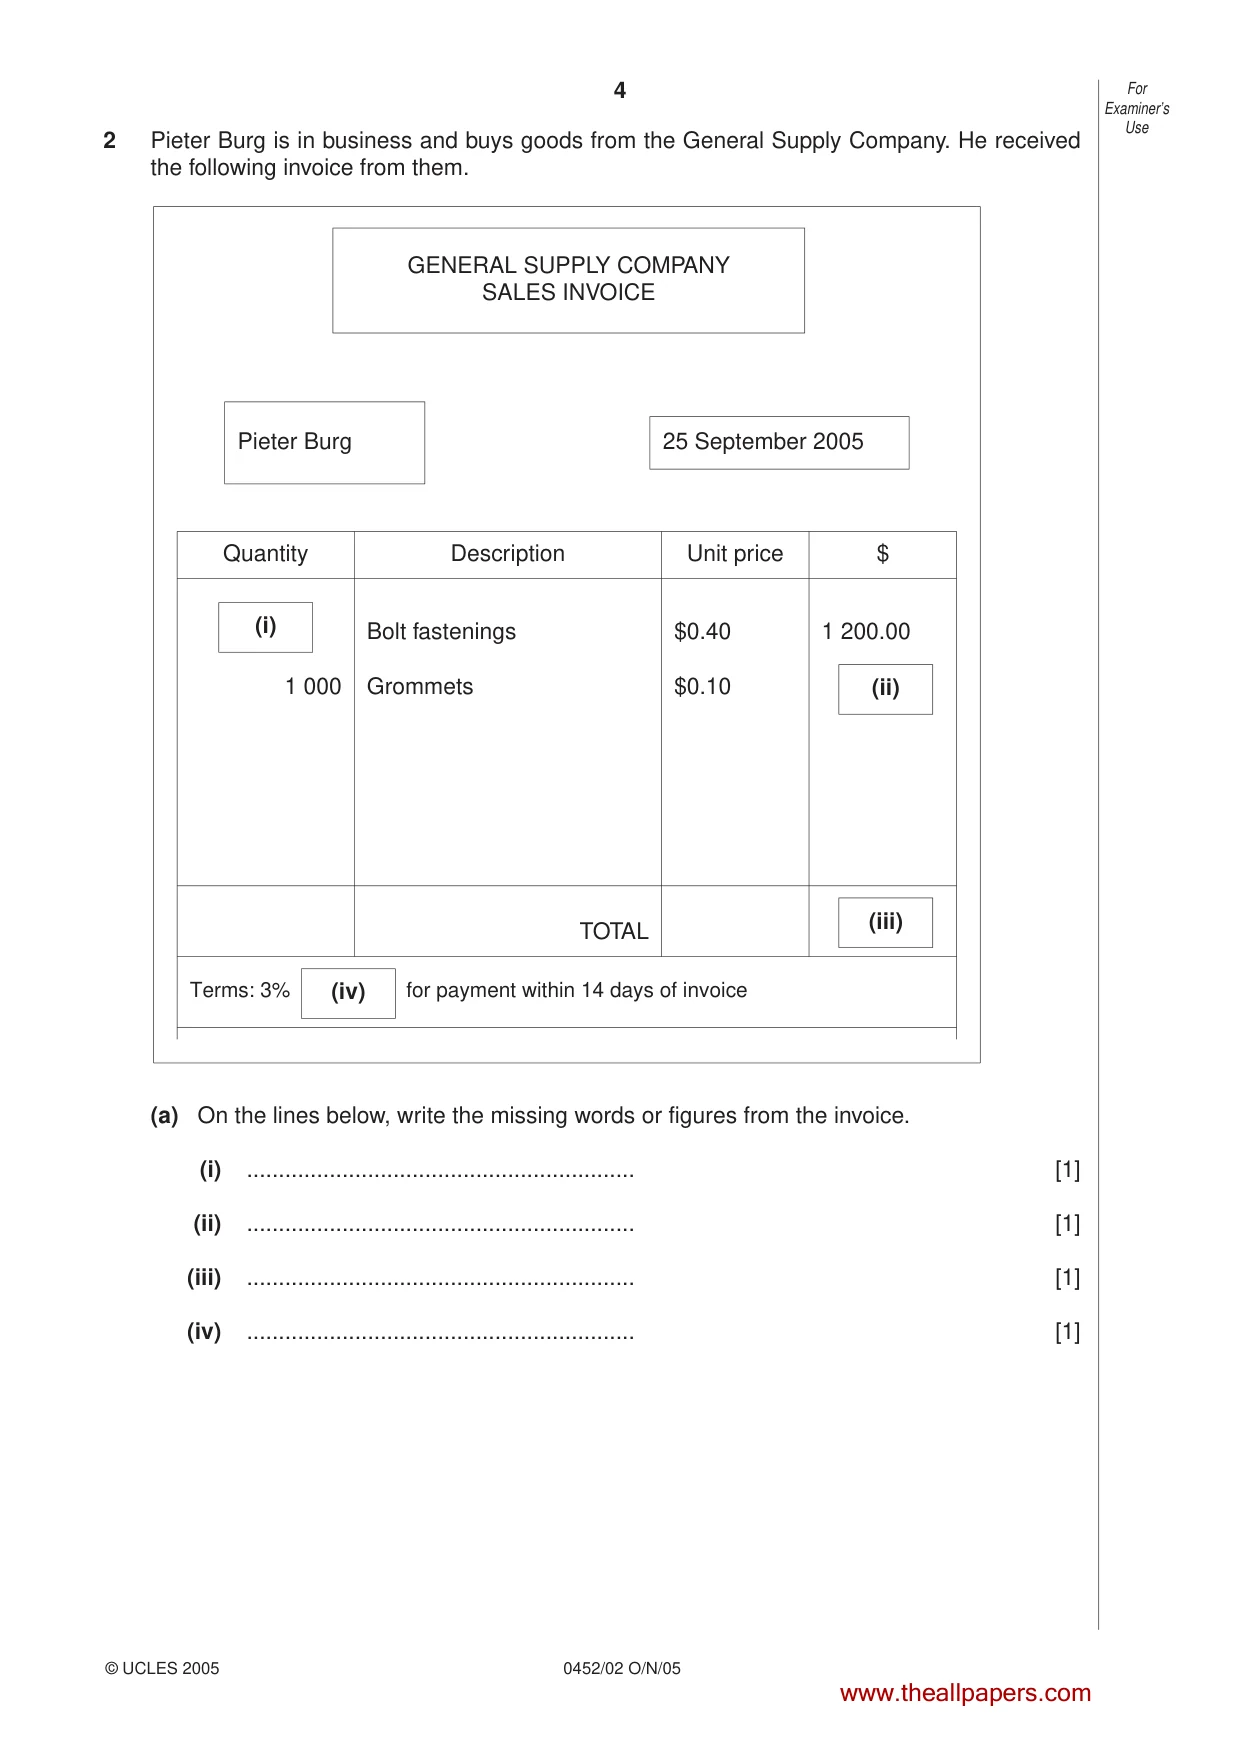
4 © UCLES 2005 0452/02 O/N/05 2 Pieter Burg is in business and buys goods from the General Supply Company. He received the following invoice from them. (a) On the lines below, write the missing words or figures from the invoice. (i) … [1] (ii) … [1] (iii) … [1] (iv) … [1] For Examiner’s Use GENERAL SUPPLY COMPANY SALES INVOICE Pieter Burg 25 September 2005 Quantity Bolt fastenings Grommets $0.40 $0.10 1 200.00 1 000 Description TOTAL Terms: 3% for payment within 14 days of invoice Unit price $ (i) (ii) (iii) (iv) www.theallpapers.com
Question paper, page 5
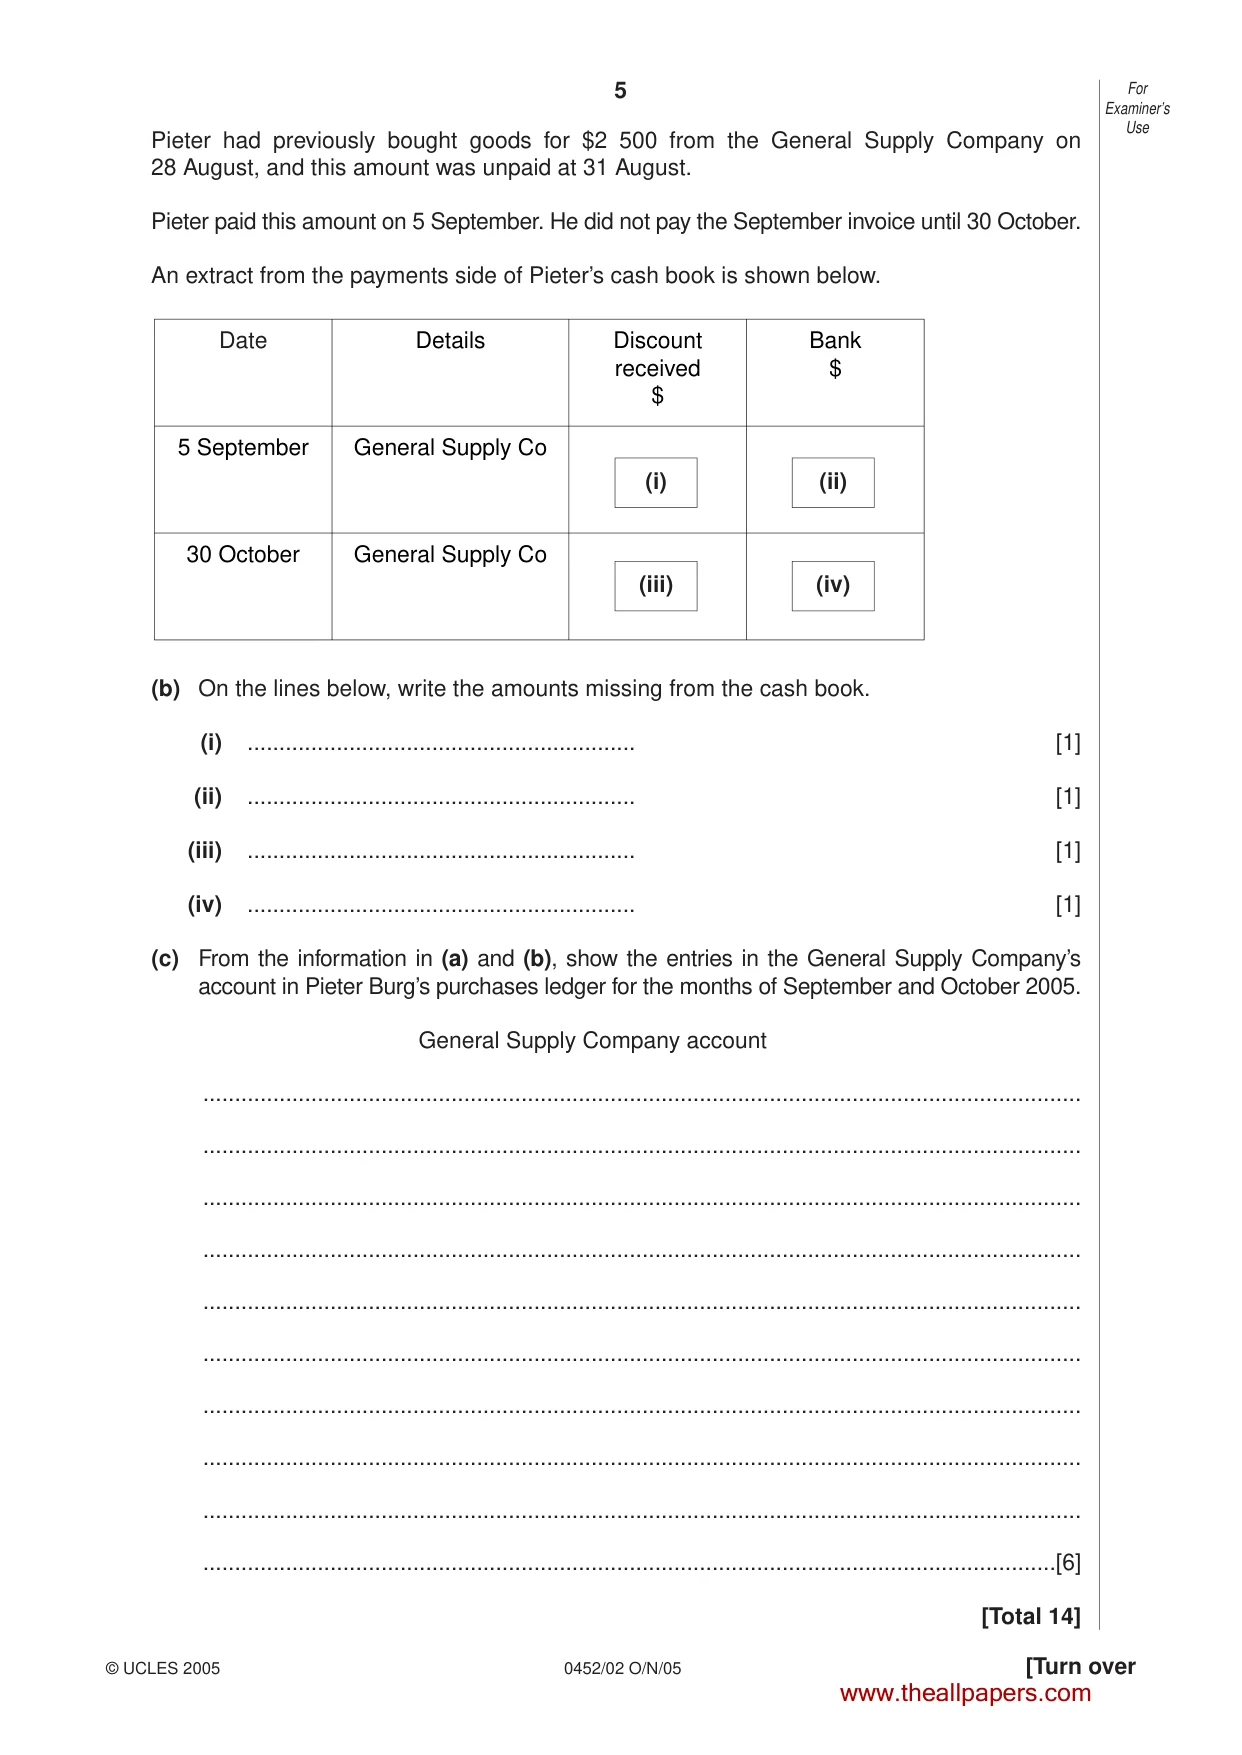
5 © UCLES 2005 0452/02 O/N/05 [Turn over Pieter had previously bought goods for $2 500 from the General Supply Company on 28 August, and this amount was unpaid at 31 August. Pieter paid this amount on 5 September. He did not pay the September invoice until 30 October. An extract from the payments side of Pieter’s cash book is shown below. (b) On the lines below, write the amounts missing from the cash book. (i) … [1] (ii) … [1] (iii) … [1] (iv) … [1] (c) From the information in (a) and (b), show the entries in the General Supply Company’s account in Pieter Burg’s purchases ledger for the months of September and October 2005. General Supply Company account … … … … … … … … … …[6] [Total 14] For Examiner’s Use Date Details Discount received $ Bank $ 5 September General Supply Co 30 October General Supply Co (i) (iii) (iv) (ii) www.theallpapers.com
Question paper, page 6
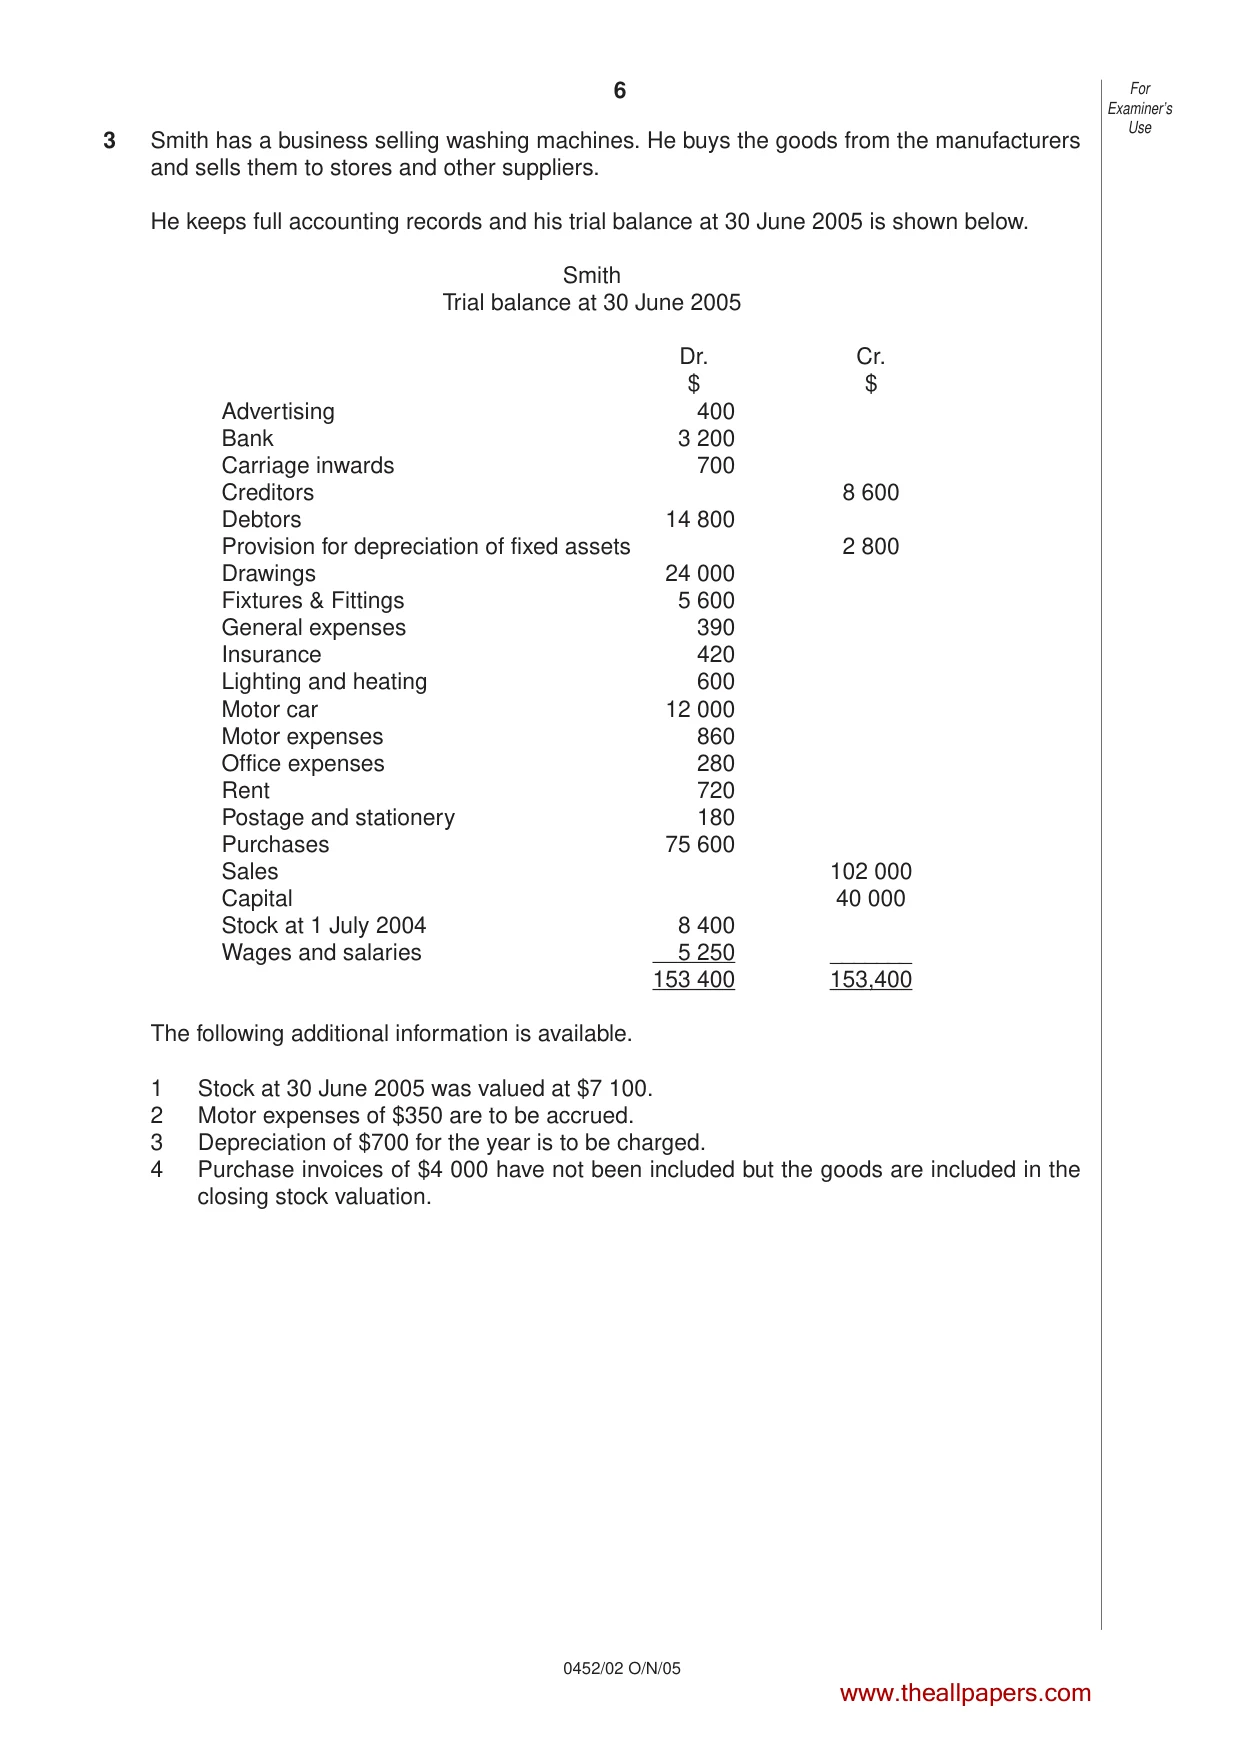
6 0452/02 O/N/05 3 Smith has a business selling washing machines. He buys the goods from the manufacturers and sells them to stores and other suppliers. He keeps full accounting records and his trial balance at 30 June 2005 is shown below. Smith Trial balance at 30 June 2005 Dr. Cr. $ $ Advertising 400 Bank 3 200 Carriage inwards 700 Creditors 8 600 Debtors 14 800 Provision for depreciation of fixed assets 2 800 Drawings 24 000 Fixtures & Fittings 5 600 General expenses 390 Insurance 420 Lighting and heating 600 Motor car 12 000 Motor expenses 860 Office expenses 280 Rent 720 Postage and stationery 180 Purchases 75 600 Sales 102 000 Capital 40 000 Stock at 1 July 2004 8 400 Wages and salaries 5 250 _______ 153 400 153,400 The following additional information is available. 1 Stock at 30 June 2005 was valued at $7 100. 2 Motor expenses of $350 are to be accrued. 3 Depreciation of $700 for the year is to be charged. 4 Purchase invoices of $4 000 have not been included but the goods are included in the closing stock valuation. For Examiner’s Use www.theallpapers.com
Question paper, page 7
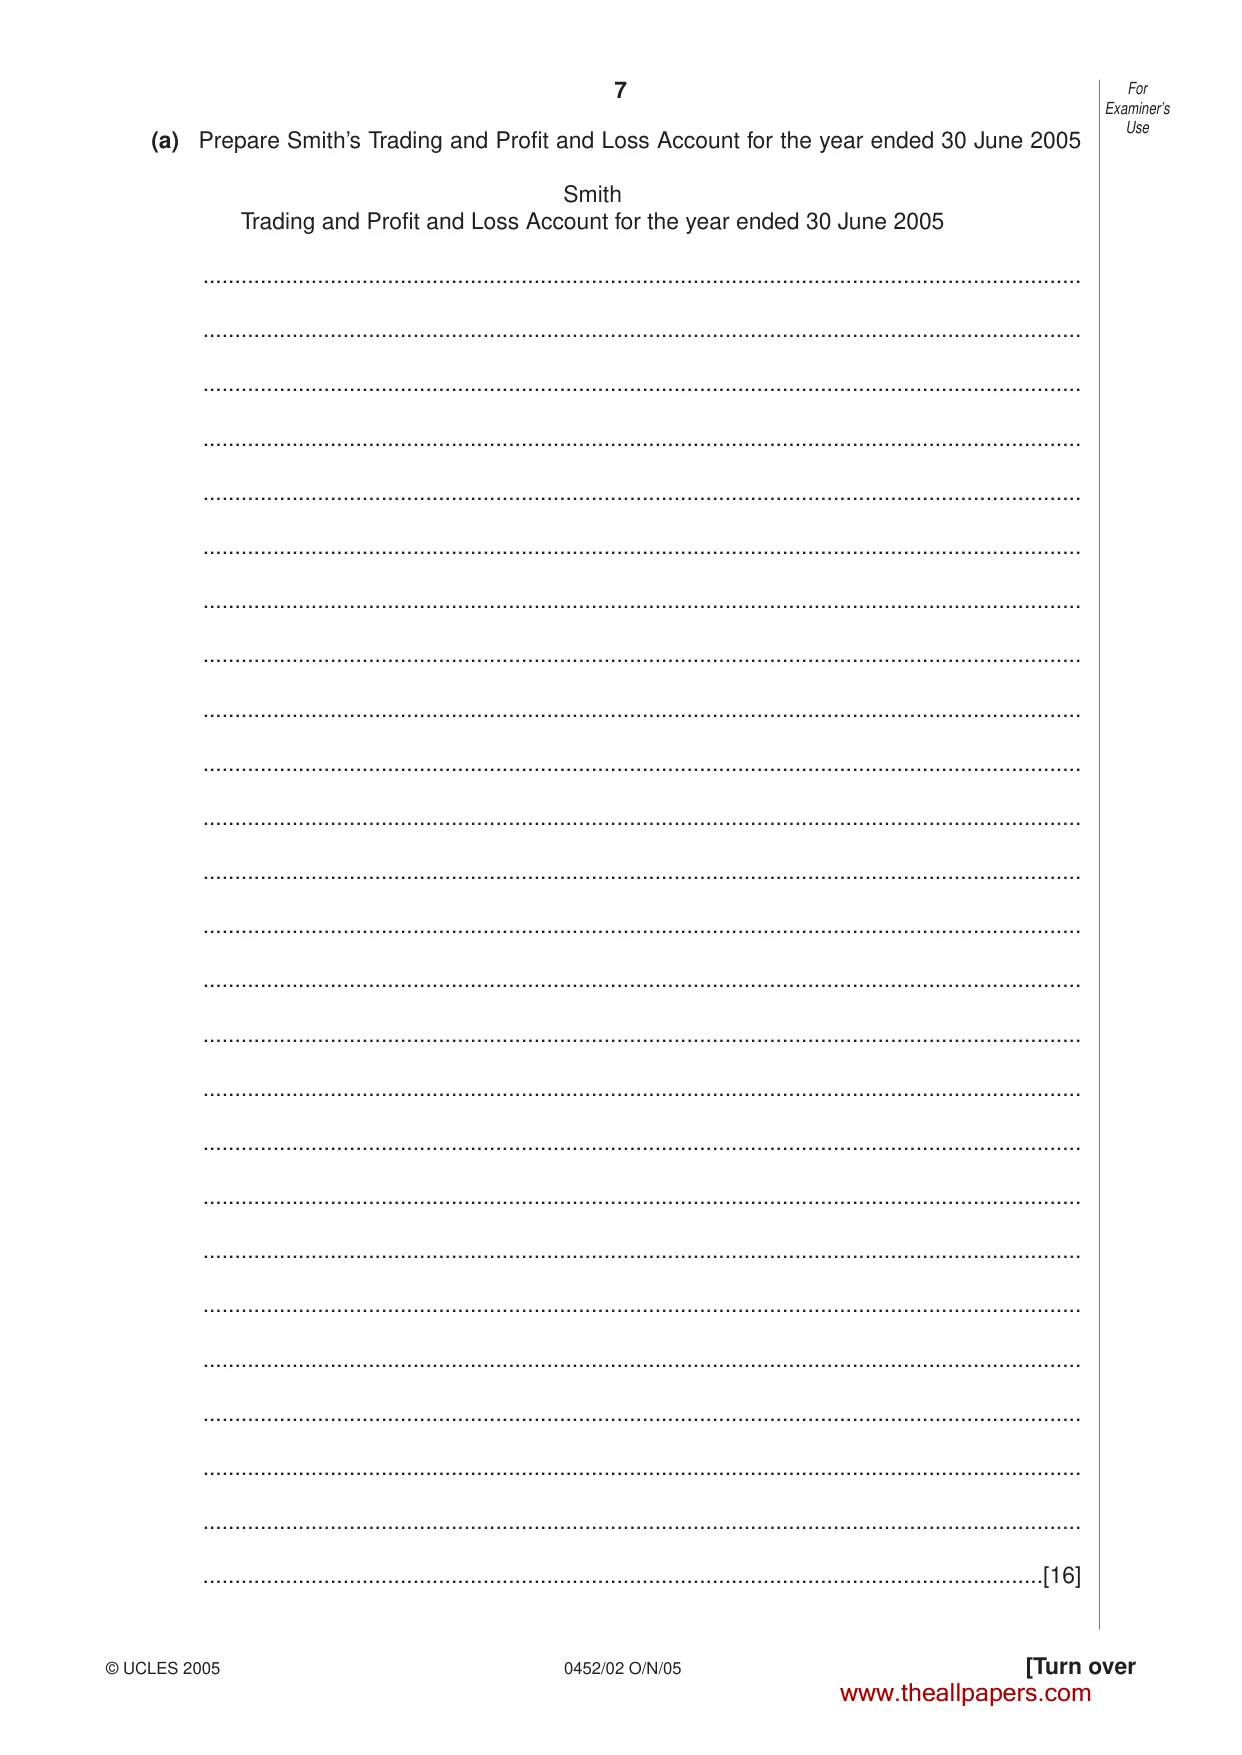
7 © UCLES 2005 0452/02 O/N/05 [Turn over (a) Prepare Smith’s Trading and Profit and Loss Account for the year ended 30 June 2005 Smith Trading and Profit and Loss Account for the year ended 30 June 2005 … … … … … … … … … … … … … … … … … … … … … … … … …[16] For Examiner’s Use www.theallpapers.com
Question paper, page 8
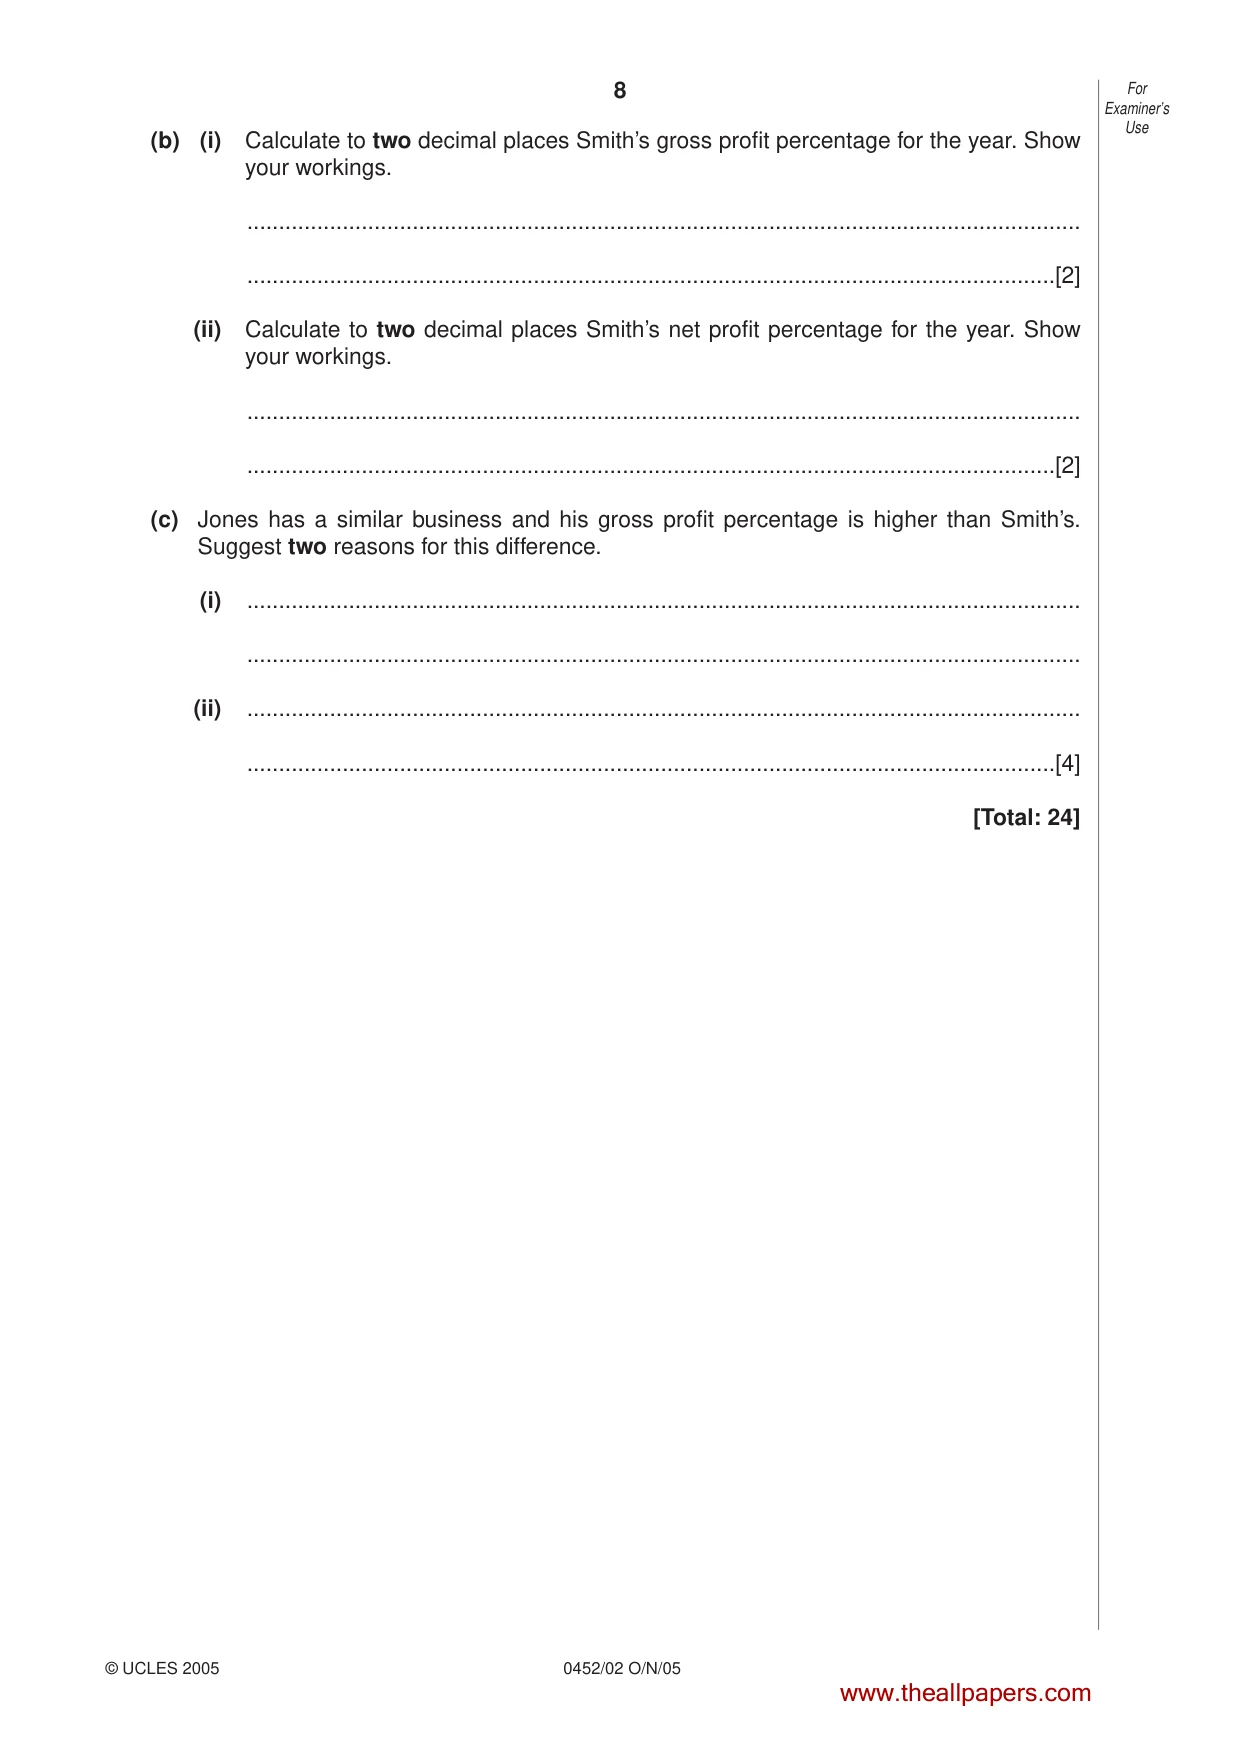
8 © UCLES 2005 0452/02 O/N/05 (b) (i) Calculate to two decimal places Smith’s gross profit percentage for the year. Show your workings. … …[2] (ii) Calculate to two decimal places Smith’s net profit percentage for the year. Show your workings. … …[2] (c) Jones has a similar business and his gross profit percentage is higher than Smith’s. Suggest two reasons for this difference. (i) … … (ii) … …[4] [Total: 24] For Examiner’s Use www.theallpapers.com
Question paper, page 9
9 © UCLES 2005 0452/02 O/N/05 [Turn over BLANK PAGE Question 4 is on the following page www.theallpapers.com
Question paper, page 10
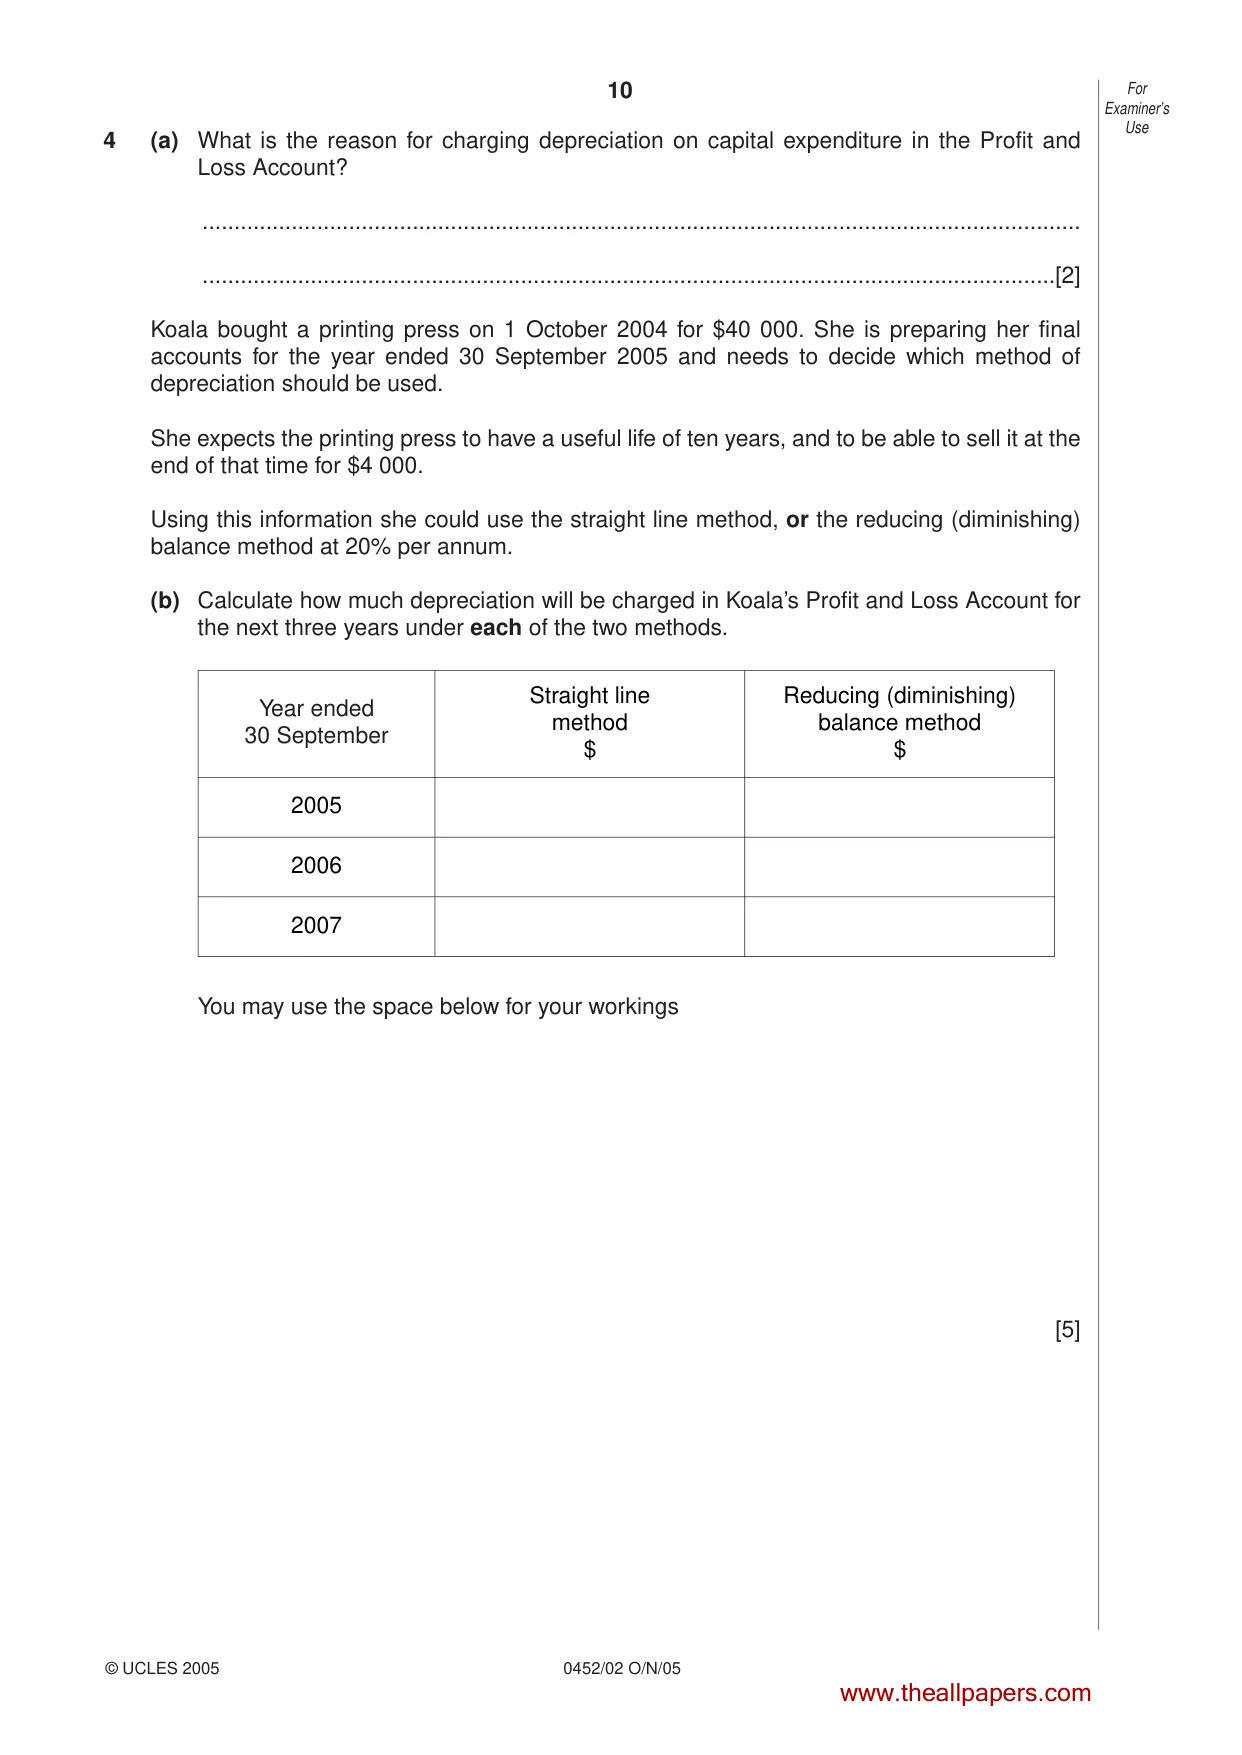
10 © UCLES 2005 0452/02 O/N/05 4 (a) What is the reason for charging depreciation on capital expenditure in the Profit and Loss Account? … …[2] Koala bought a printing press on 1 October 2004 for $40 000. She is preparing her final accounts for the year ended 30 September 2005 and needs to decide which method of depreciation should be used. She expects the printing press to have a useful life of ten years, and to be able to sell it at the end of that time for $4 000. Using this information she could use the straight line method, or the reducing (diminishing) balance method at 20% per annum. (b) Calculate how much depreciation will be charged in Koala’s Profit and Loss Account for the next three years under each of the two methods. You may use the space below for your workings [5] For Examiner’s Use Year ended 30 September Straight line method $ Reducing (diminishing) balance method $ 2005 2006 2007 www.theallpapers.com
Question paper, page 11
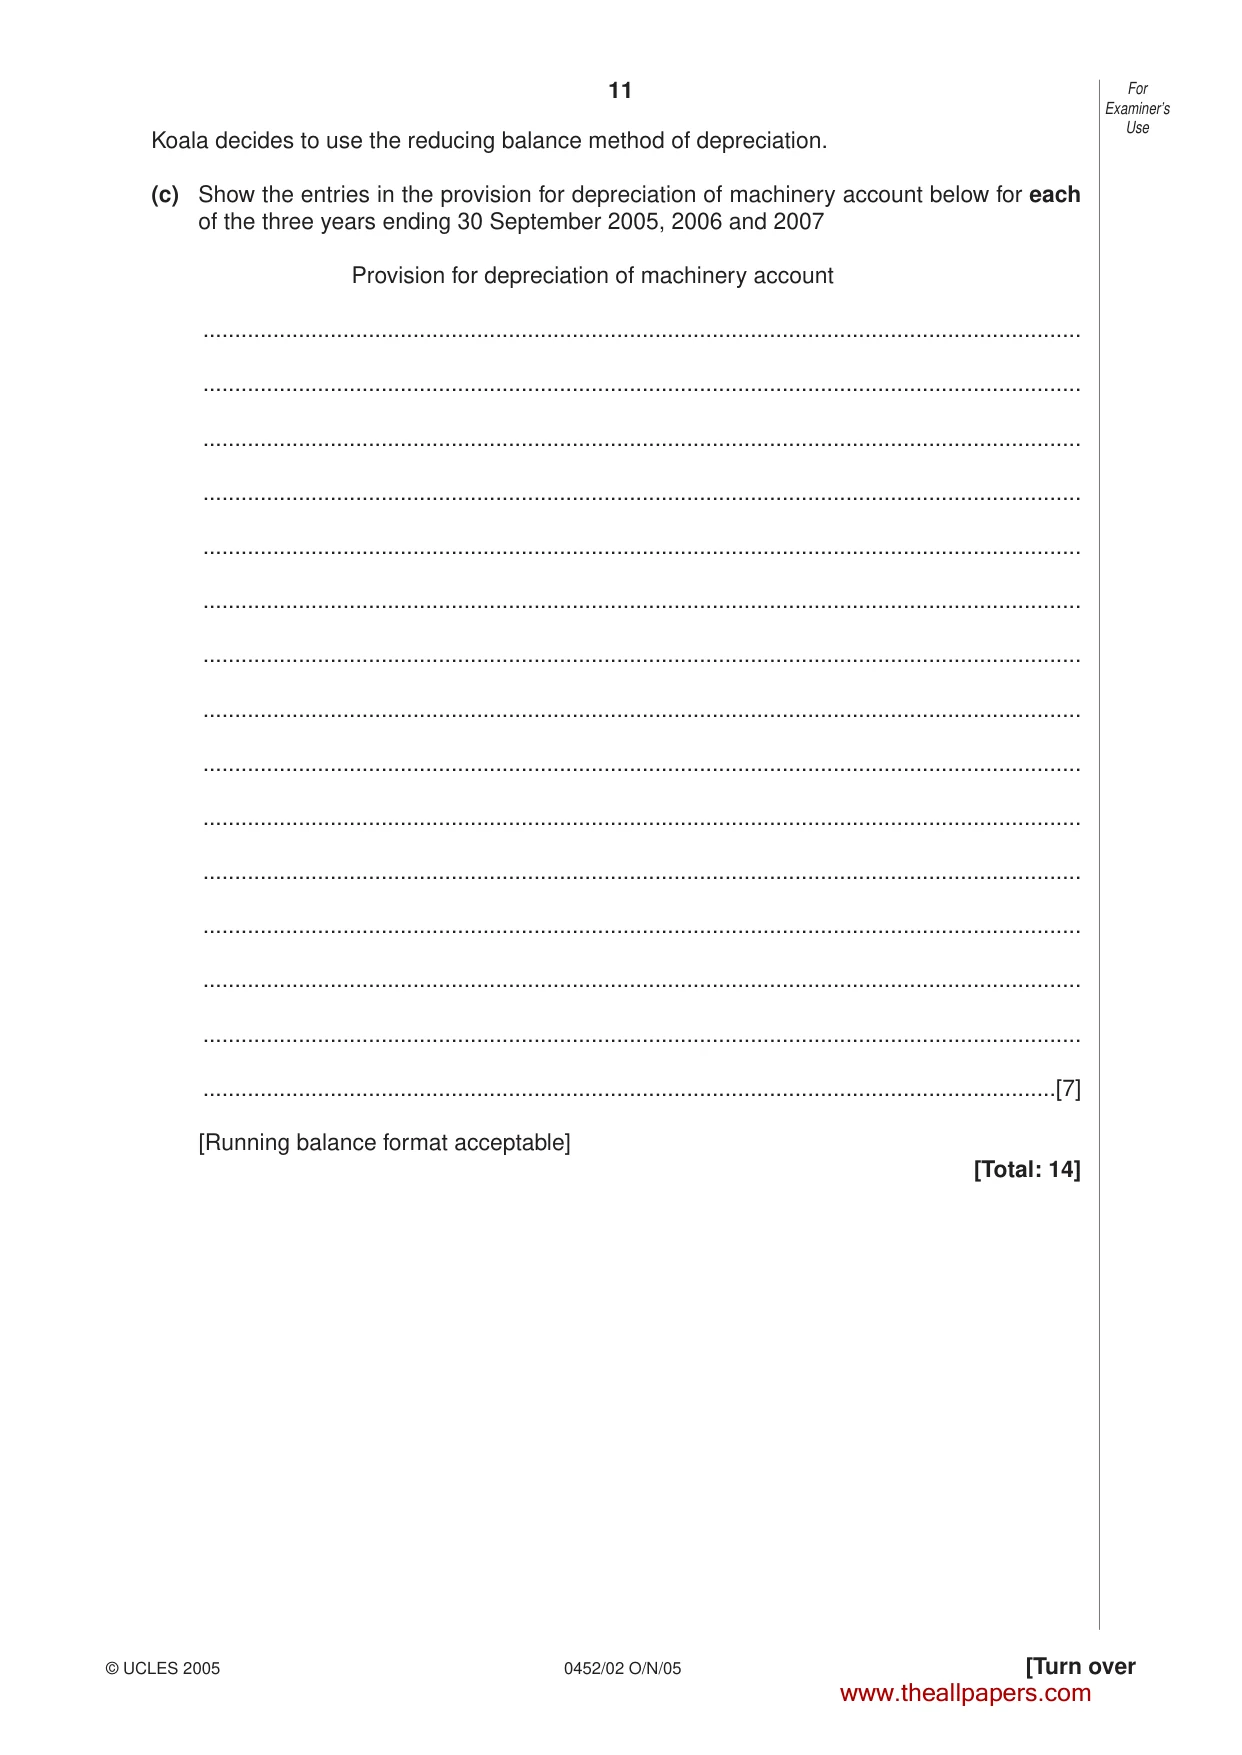
11 © UCLES 2005 0452/02 O/N/05 [Turn over Koala decides to use the reducing balance method of depreciation. (c) Show the entries in the provision for depreciation of machinery account below for each of the three years ending 30 September 2005, 2006 and 2007 Provision for depreciation of machinery account … … … … … … … … … … … … … … …[7] [Running balance format acceptable] [Total: 14] For Examiner’s Use www.theallpapers.com
Question paper, page 12
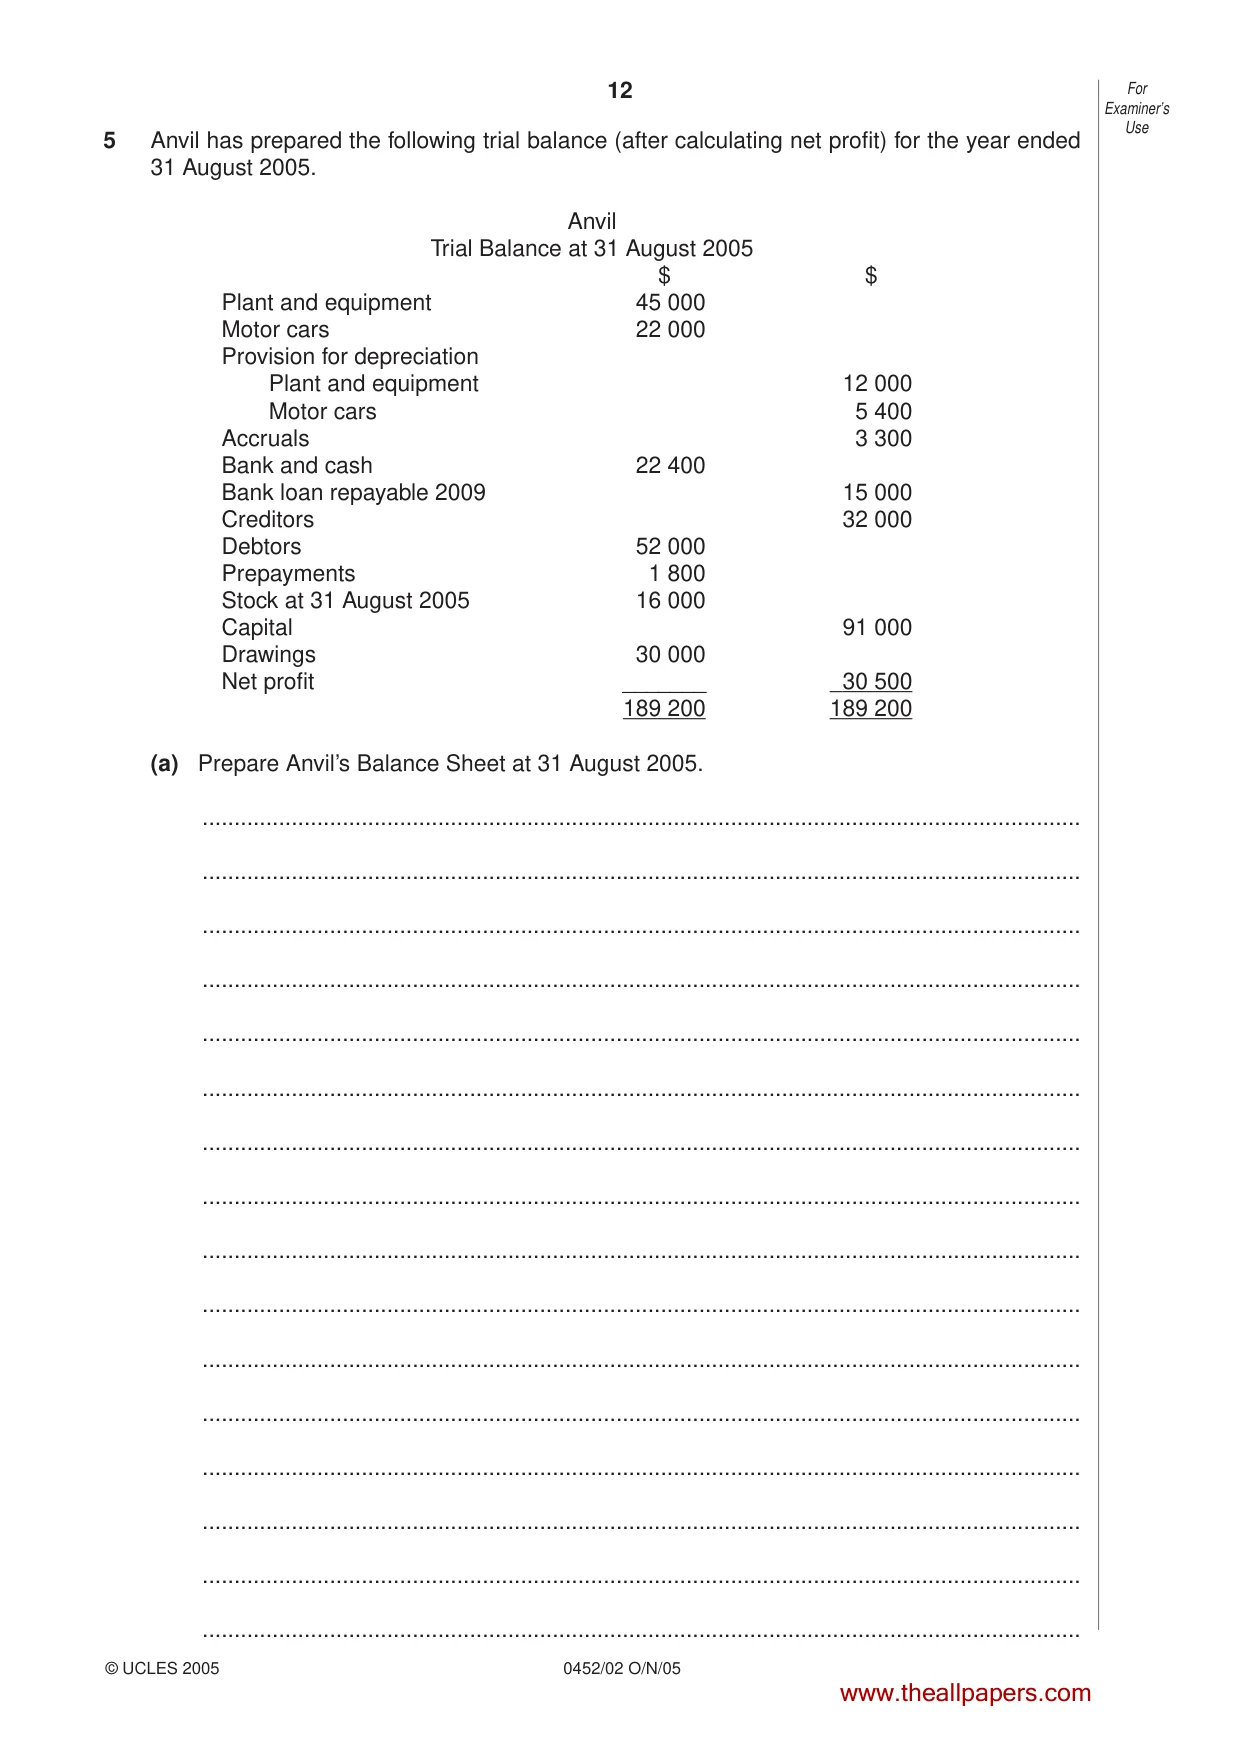
12 © UCLES 2005 0452/02 O/N/05 5 Anvil has prepared the following trial balance (after calculating net profit) for the year ended 31 August 2005. Anvil Trial Balance at 31 August 2005 $ $ Plant and equipment 45 000 Motor cars 22 000 Provision for depreciation Plant and equipment 12 000 Motor cars 5 400 Accruals 3 300 Bank and cash 22 400 Bank loan repayable 2009 15 000 Creditors 32 000 Debtors 52 000 Prepayments 1 800 Stock at 31 August 2005 16 000 Capital 91 000 Drawings 30 000 Net profit _______ 30 500 189 200 189 200 (a) Prepare Anvil’s Balance Sheet at 31 August 2005. … … … … … … … … … … … … … … … … For Examiner’s Use www.theallpapers.com
Question paper, page 13
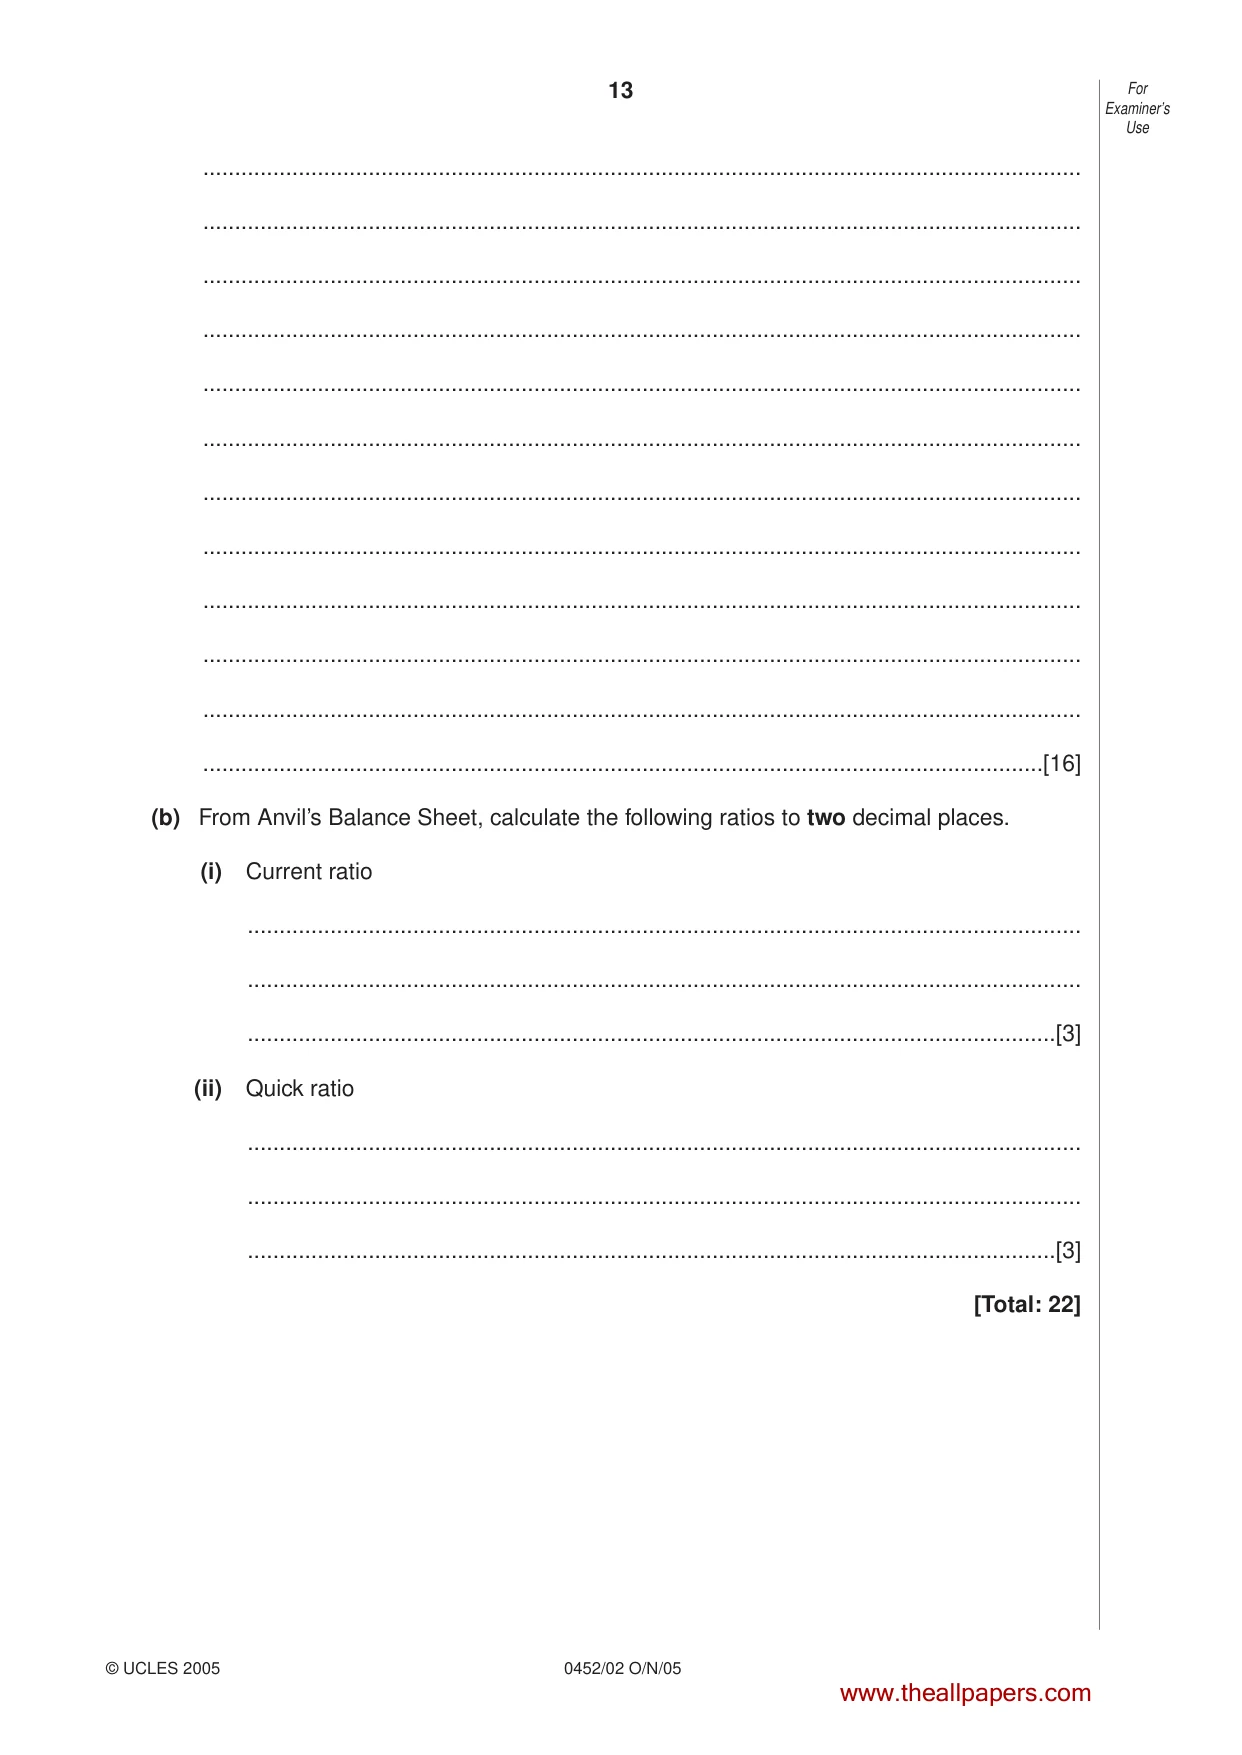
13 © UCLES 2005 0452/02 O/N/05 … … … … … … … … … … … …[16] (b) From Anvil’s Balance Sheet, calculate the following ratios to two decimal places. (i) Current ratio … … …[3] (ii) Quick ratio … … …[3] [Total: 22] For Examiner’s Use www.theallpapers.com
Question paper, page 14
14 0452/02 O/N/05 BLANK PAGE www.theallpapers.com
Question paper, page 15
15 0452/02 O/N/05 BLANK PAGE www.theallpapers.com
Question paper, page 16
16 0452/02 O/N/05 BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. www.theallpapers.com
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the November 2005 question paper ACCOUNTING 0452/02 Paper 2 maximum raw mark 90 This mark scheme is published as an aid to teachers and students, to indicate the requirements of the examination. It shows the basis on which Examiners were initially instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. Any substantial changes to the mark scheme that arose from these discussions will be recorded in the published Report on the Examination. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the Report on the Examination. The minimum marks in these components needed for various grades were previously published with these mark schemes, but are now instead included in the Report on the Examination for this session. • CIE will not enter into discussion or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the November 2005 question papers for most IGCSE and GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses. www.theallpapers.com
Mark scheme, page 2
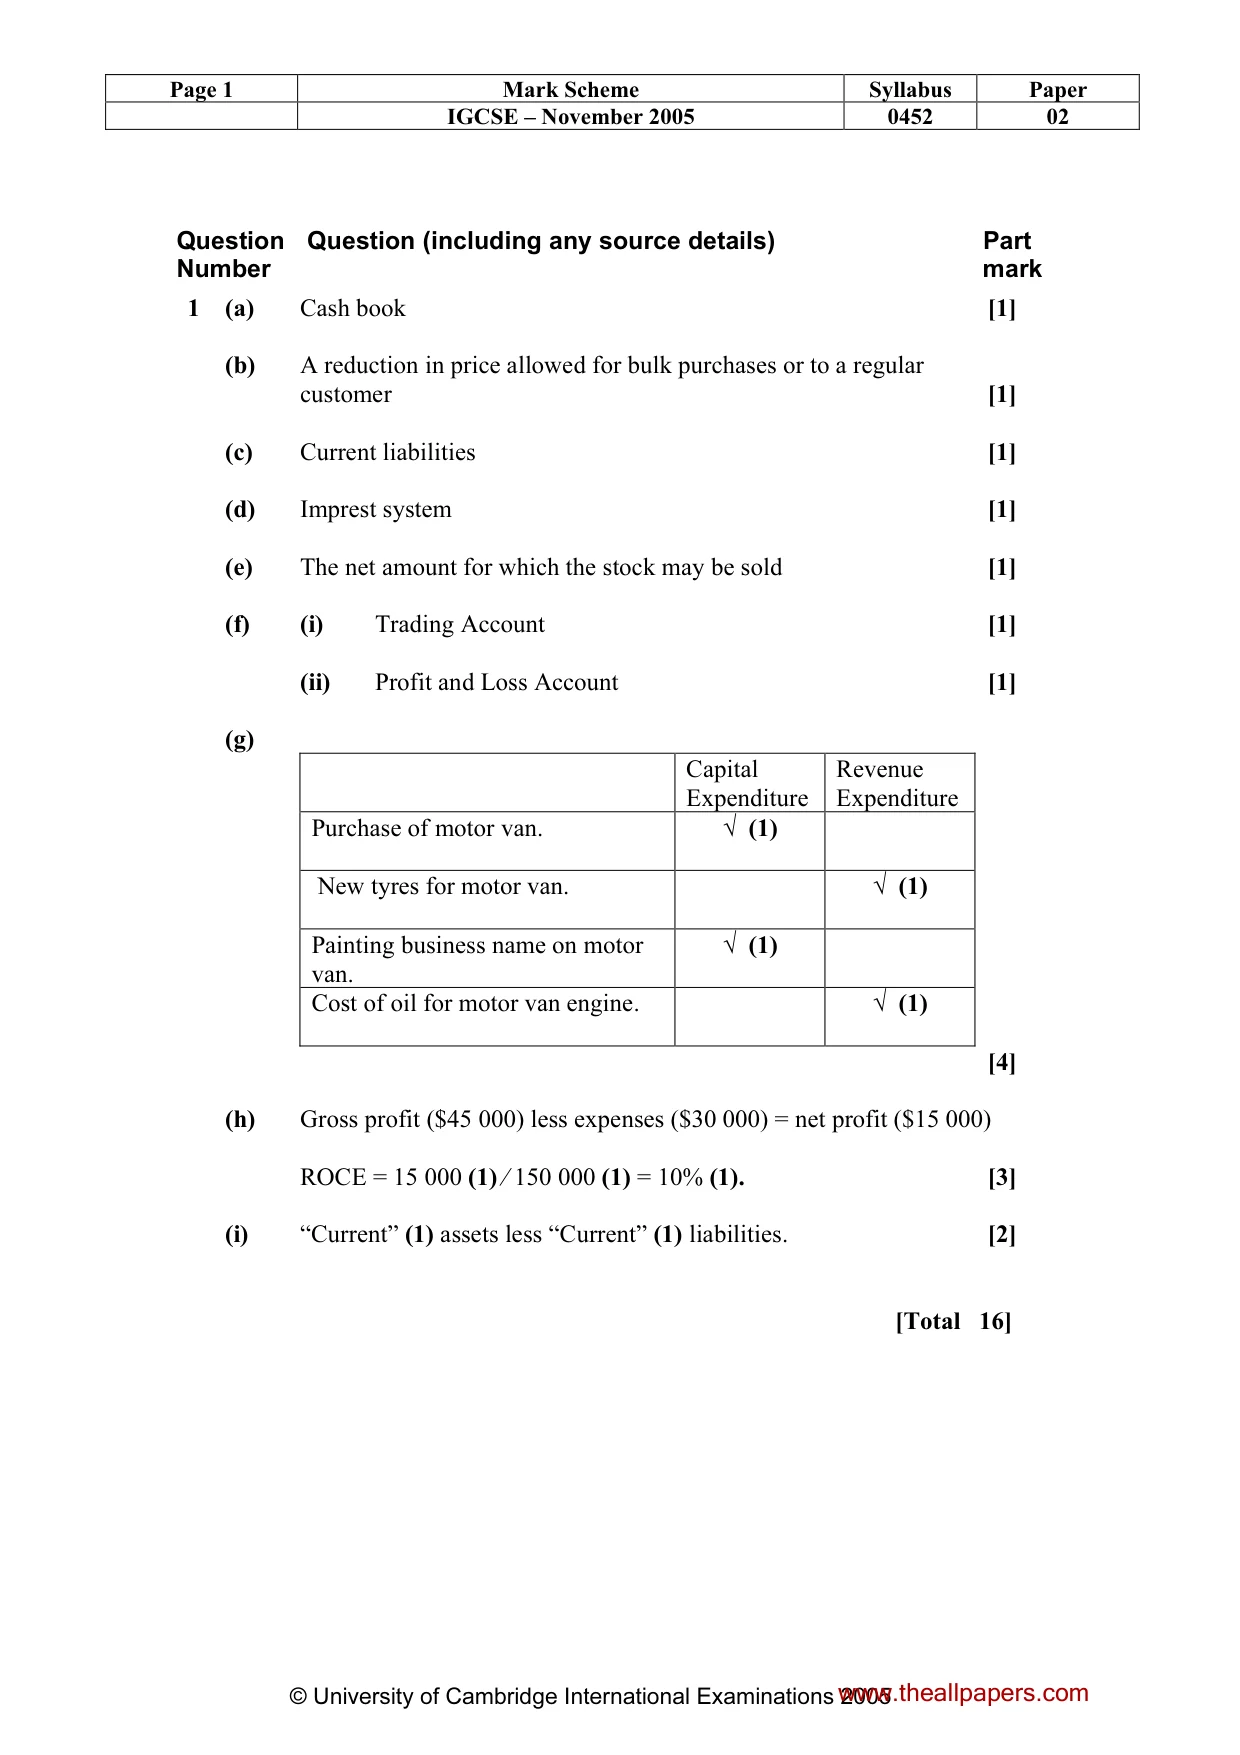
Page 1 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark 1 (a) Cash book [1] (b) A reduction in price allowed for bulk purchases or to a regular customer [1] (c) Current liabilities [1] (d) Imprest system [1] (e) The net amount for which the stock may be sold [1] (f) (i) Trading Account [1] (ii) Profit and Loss Account [1] (g) Capital Expenditure Revenue Expenditure Purchase of motor van. √ (1) New tyres for motor van. √ (1) Painting business name on motor van. √ (1) Cost of oil for motor van engine. √ (1) [4] (h) Gross profit ($45 000) less expenses ($30 000) = net profit ($15 000) ROCE = 15 000 (1) ⁄ 150 000 (1) = 10% (1). [3] (i) “Current” (1) assets less “Current” (1) liabilities. [2] [Total 16] www.theallpapers.com
Mark scheme, page 3
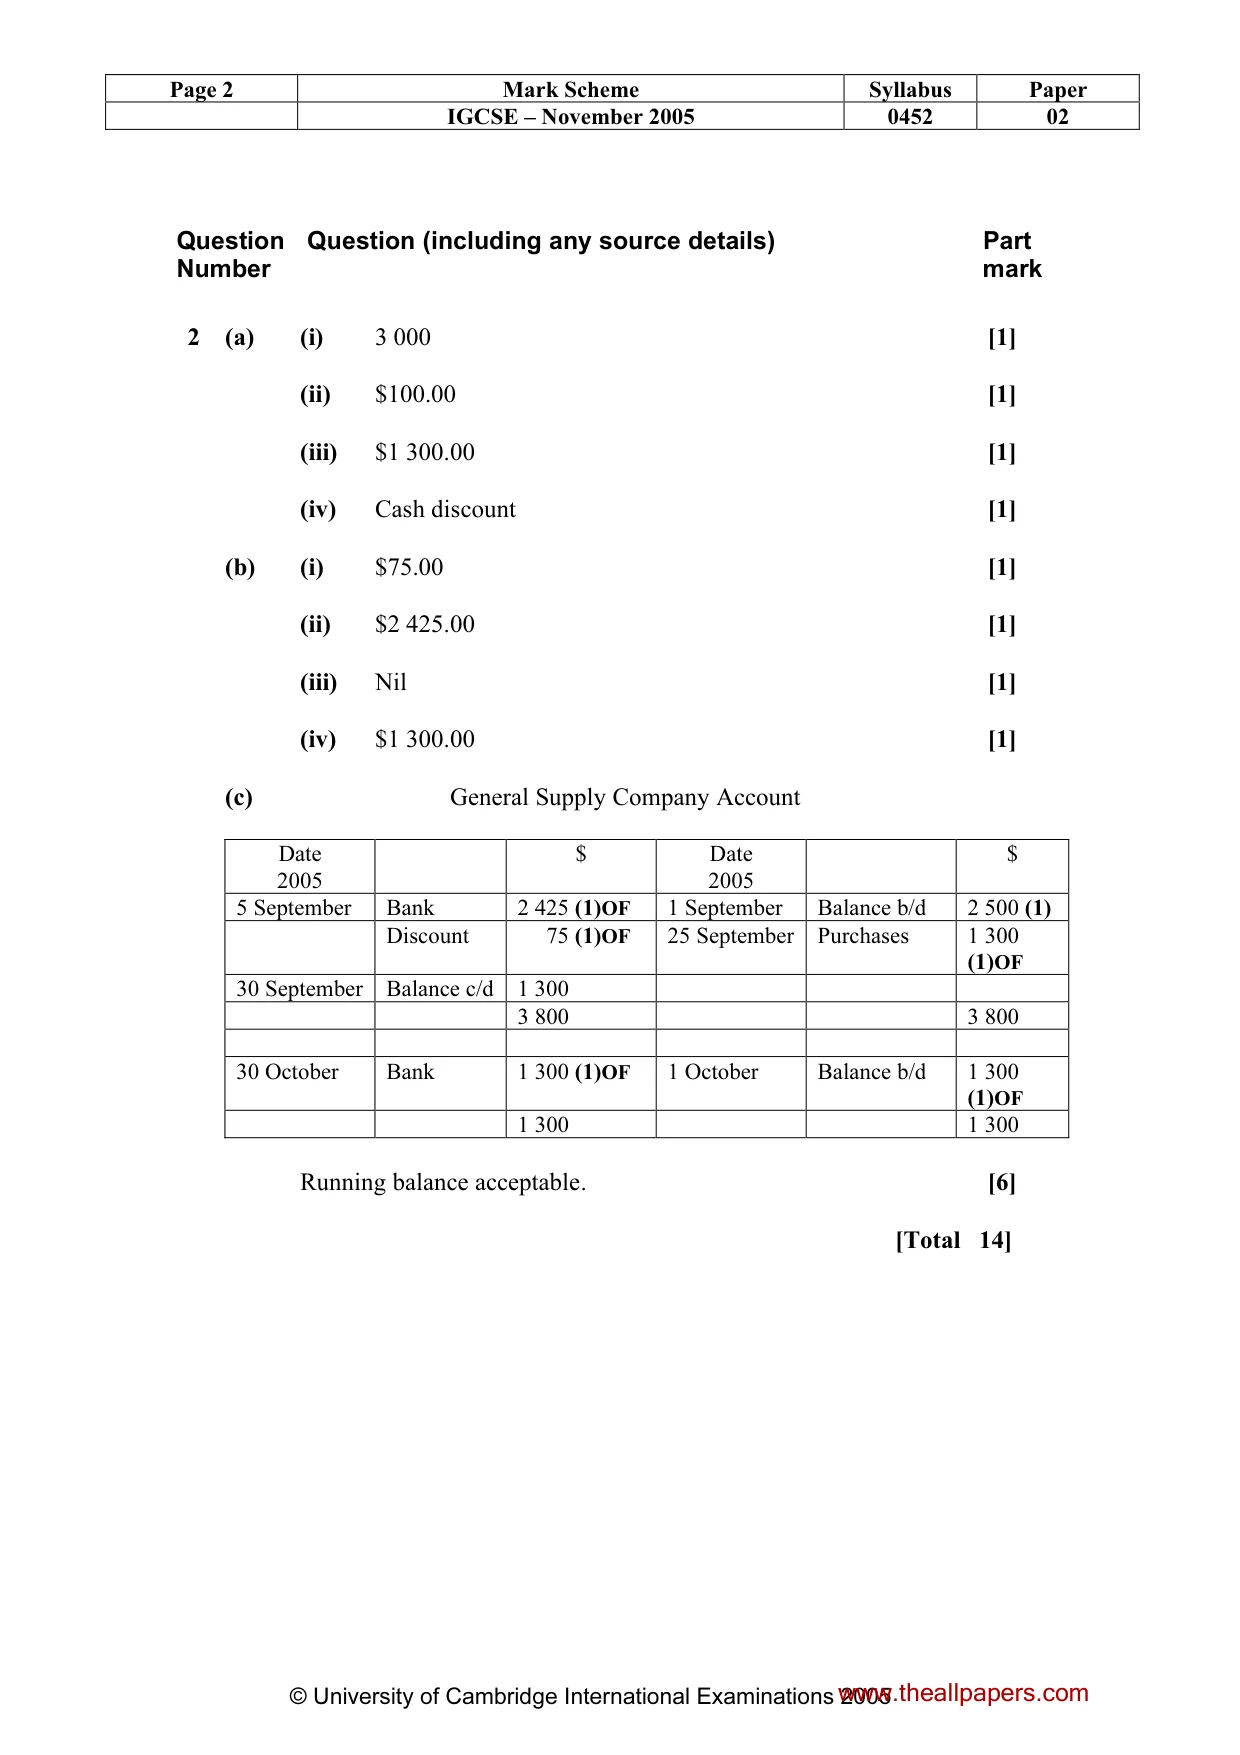
Page 2 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark 2 (a) (i) 3 000 [1] (ii) $100.00 [1] (iii) $1 300.00 [1] (iv) Cash discount [1] (b) (i) $75.00 [1] (ii) $2 425.00 [1] (iii) Nil [1] (iv) $1 300.00 [1] (c) General Supply Company Account Date 2005 $ Date 2005 $ 5 September Bank 2 425 (1)OF 1 September Balance b/d 2 500 (1) Discount 75 (1)OF 25 September Purchases 1 300 (1)OF 30 September Balance c/d 1 300 3 800 3 800 30 October Bank 1 300 (1)OF 1 October Balance b/d 1 300 (1)OF 1 300 1 300 Running balance acceptable. [6] [Total 14] www.theallpapers.com
Mark scheme, page 4
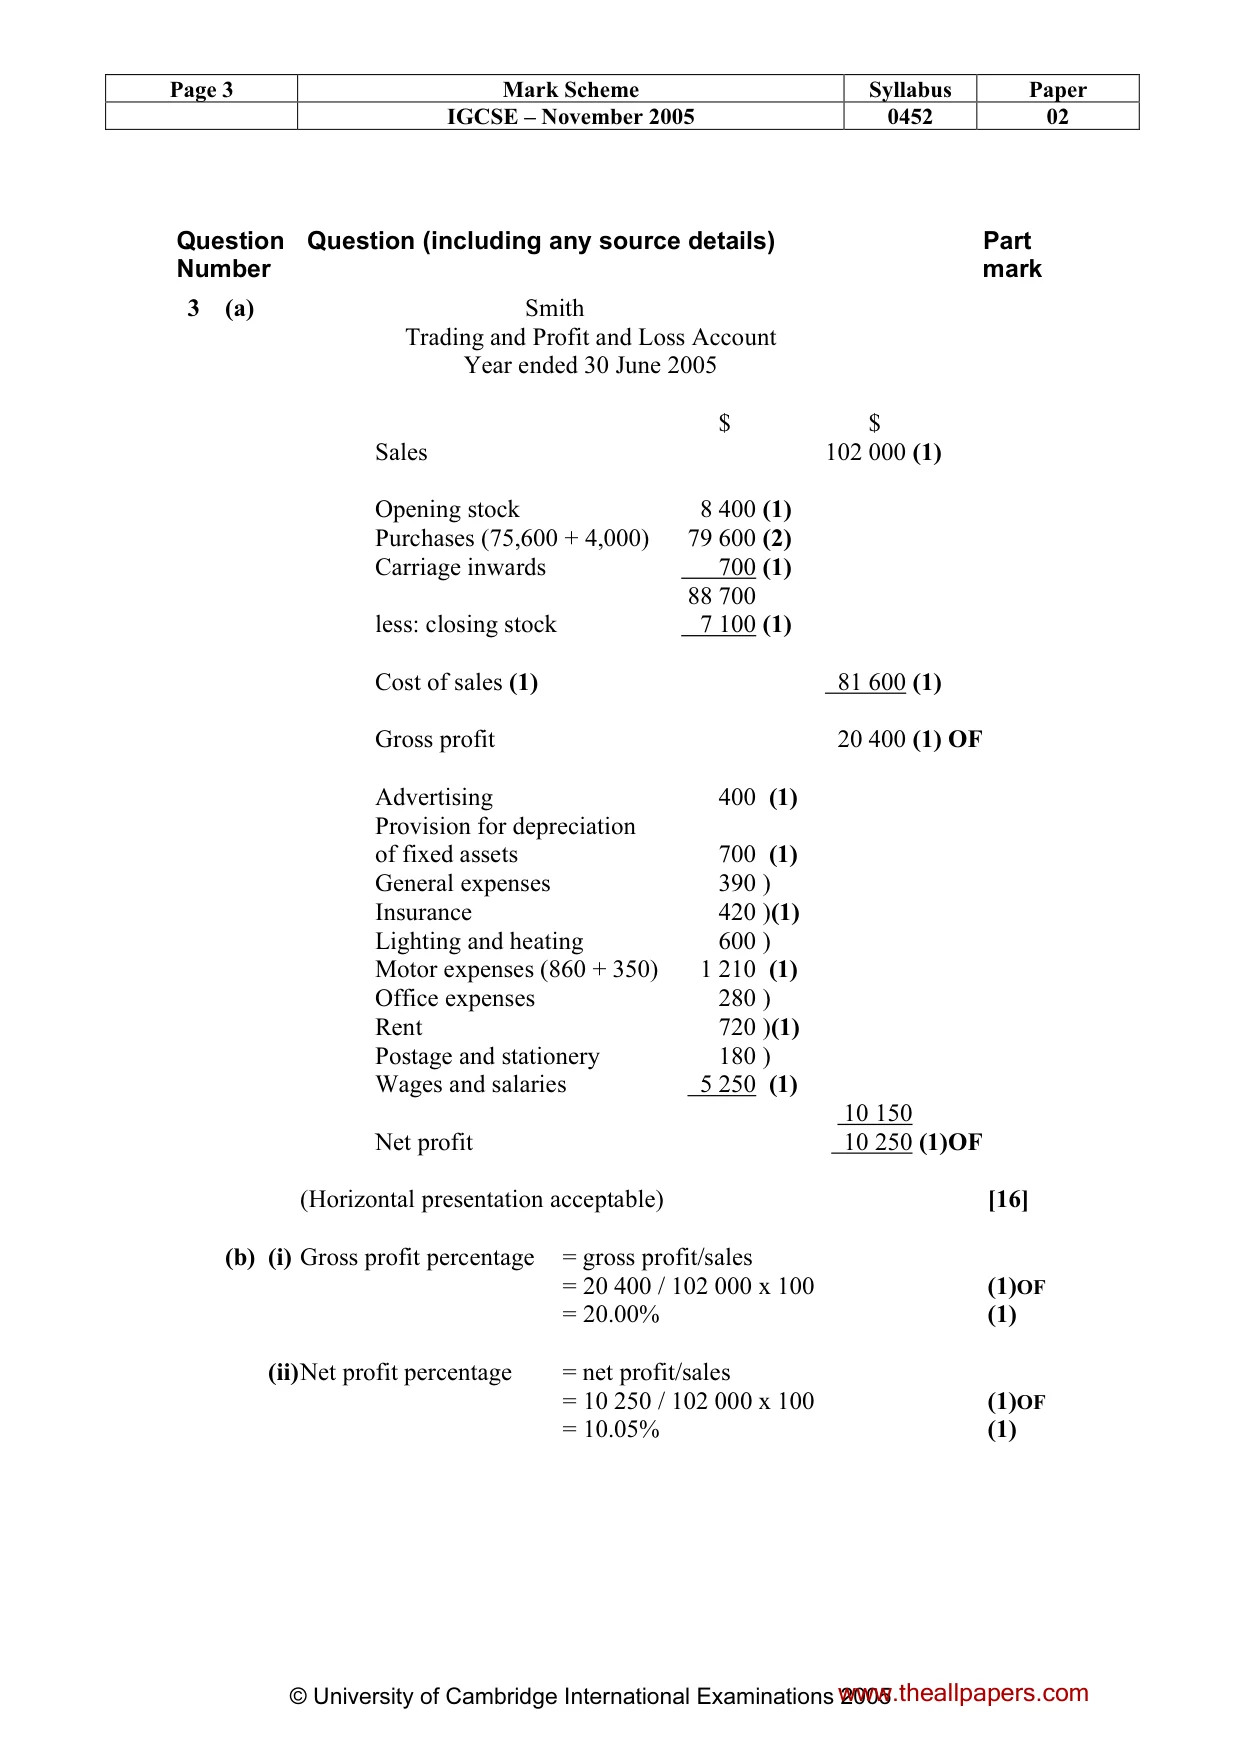
Page 3 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark 3 (a) Smith Trading and Profit and Loss Account Year ended 30 June 2005 $ $ Sales 102 000 (1) Opening stock 8 400 (1) Purchases (75,600 + 4,000) 79 600 (2) Carriage inwards 700 (1) 88 700 less: closing stock 7 100 (1) Cost of sales (1) 81 600 (1) Gross profit 20 400 (1) OF Advertising 400 (1) Provision for depreciation of fixed assets 700 (1) General expenses 390 ) Insurance 420 )(1) Lighting and heating 600 ) Motor expenses (860 + 350) 1 210 (1) Office expenses 280 ) Rent 720 )(1) Postage and stationery 180 ) Wages and salaries 5 250 (1) 10 150 Net profit 10 250 (1)OF (Horizontal presentation acceptable) [16] (b) (i) Gross profit percentage = gross profit/sales = 20 400 / 102 000 x 100 (1)OF = 20.00% (1) (ii) Net profit percentage = net profit/sales = 10 250 / 102 000 x 100 (1)OF = 10.05% (1) www.theallpapers.com
Mark scheme, page 5
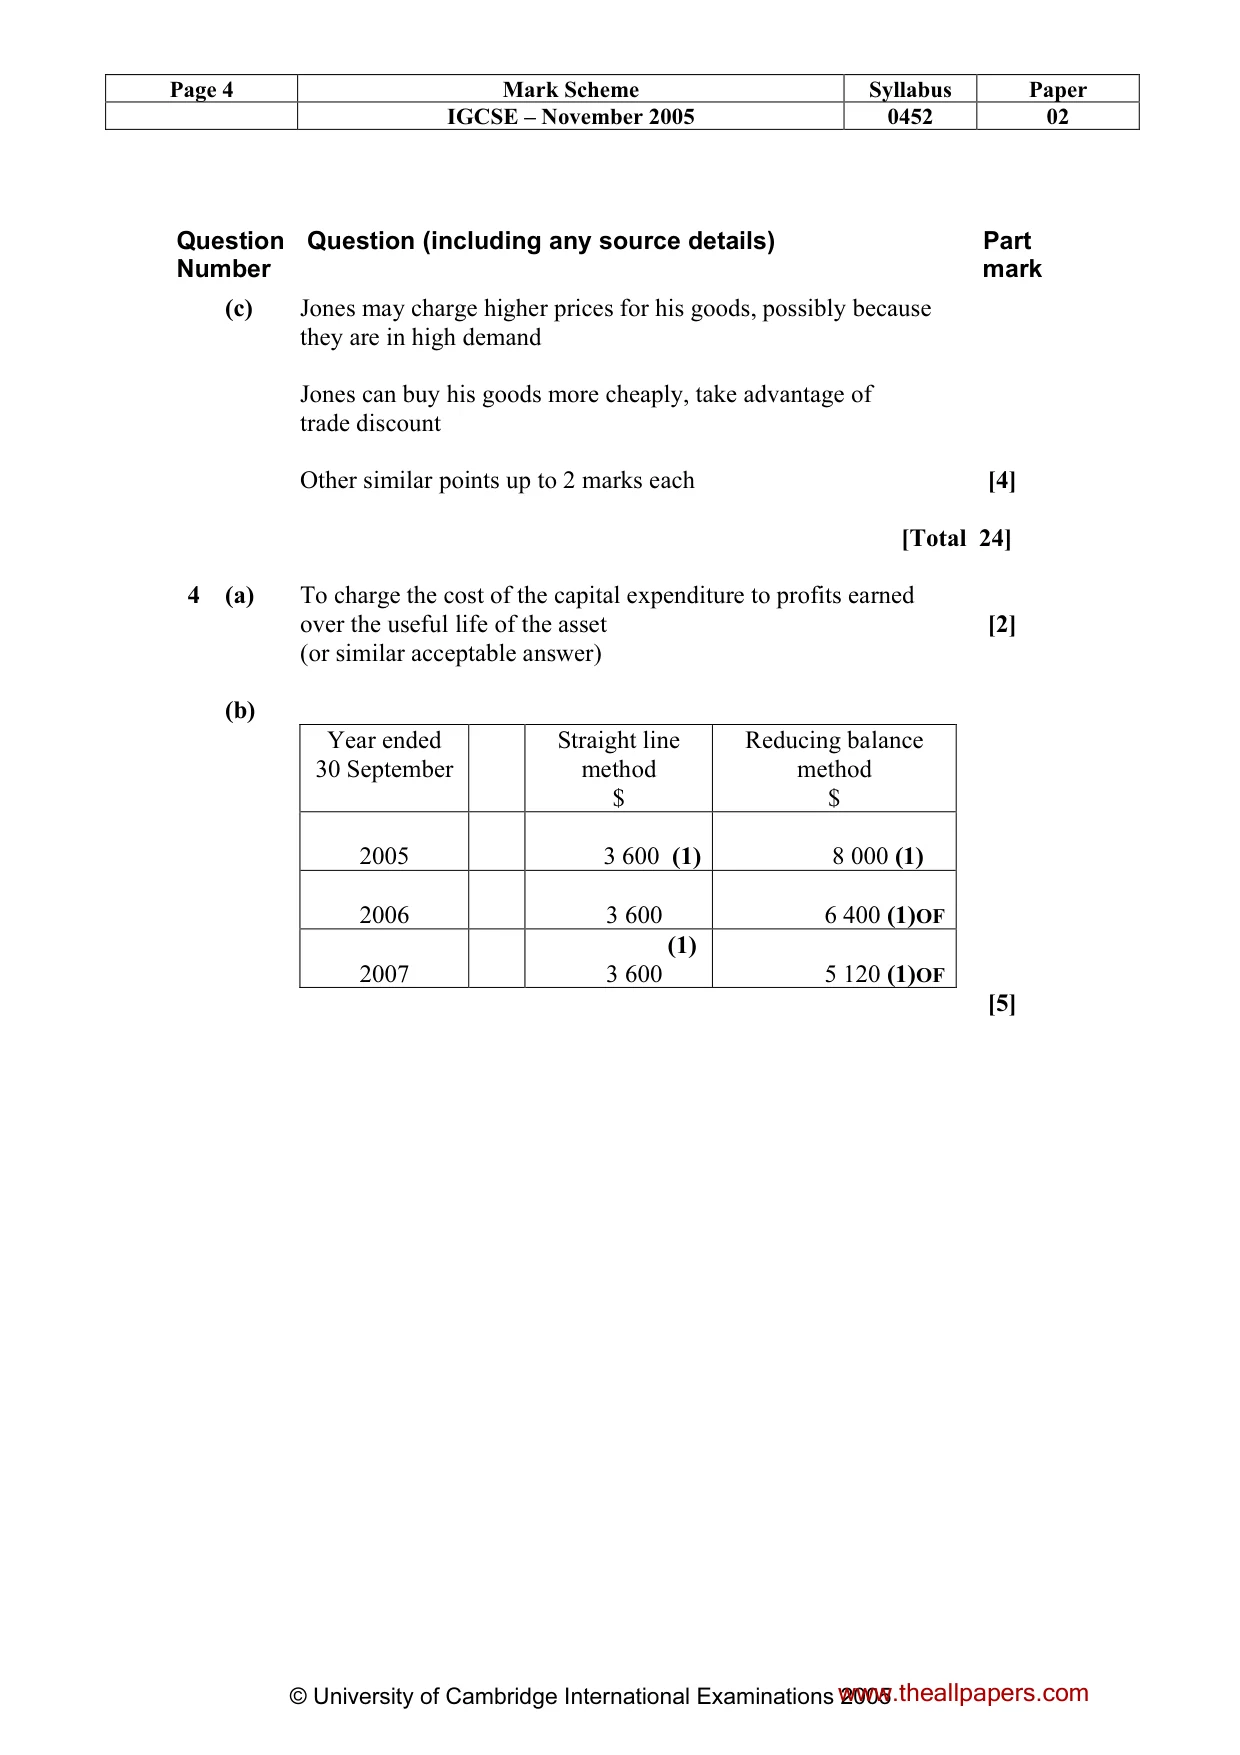
Page 4 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark (c) Jones may charge higher prices for his goods, possibly because they are in high demand Jones can buy his goods more cheaply, take advantage of trade discount Other similar points up to 2 marks each [4] [Total 24] 4 (a) To charge the cost of the capital expenditure to profits earned over the useful life of the asset [2] (or similar acceptable answer) (b) Year ended 30 September Straight line method $ Reducing balance method $ 2005 3 600 (1) 8 000 (1) 2006 3 600 6 400 (1)OF 2007 (1) 3 600 5 120 (1)OF [5] www.theallpapers.com
Mark scheme, page 6
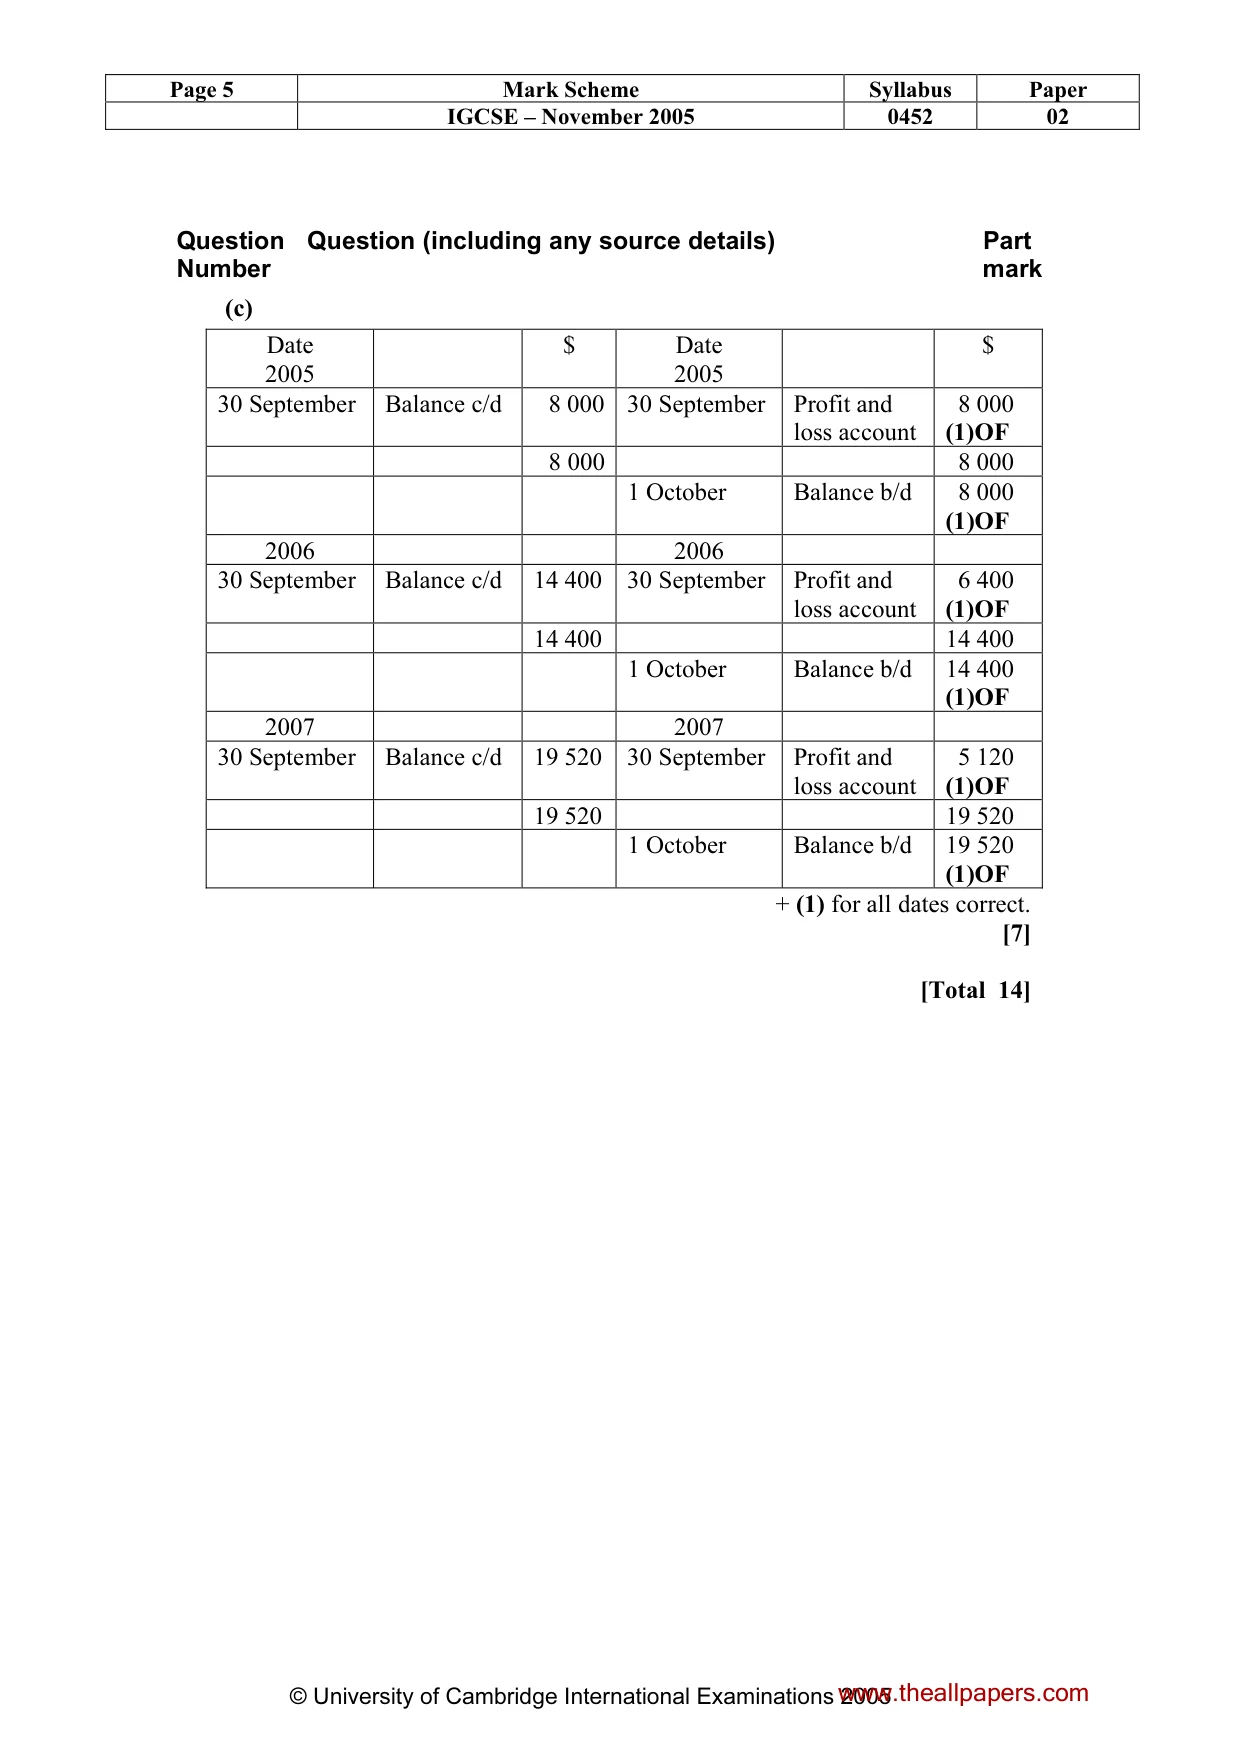
Page 5 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark (c) Date 2005 $ Date 2005 $ 30 September Balance c/d 8 000 30 September Profit and loss account 8 000 (1)OF 8 000 8 000 1 October Balance b/d 8 000 (1)OF 2006 2006 30 September Balance c/d 14 400 30 September Profit and loss account 6 400 (1)OF 14 400 14 400 1 October Balance b/d 14 400 (1)OF 2007 2007 30 September Balance c/d 19 520 30 September Profit and loss account 5 120 (1)OF 19 520 19 520 1 October Balance b/d 19 520 (1)OF + (1) for all dates correct. [7] [Total 14] www.theallpapers.com
Mark scheme, page 7
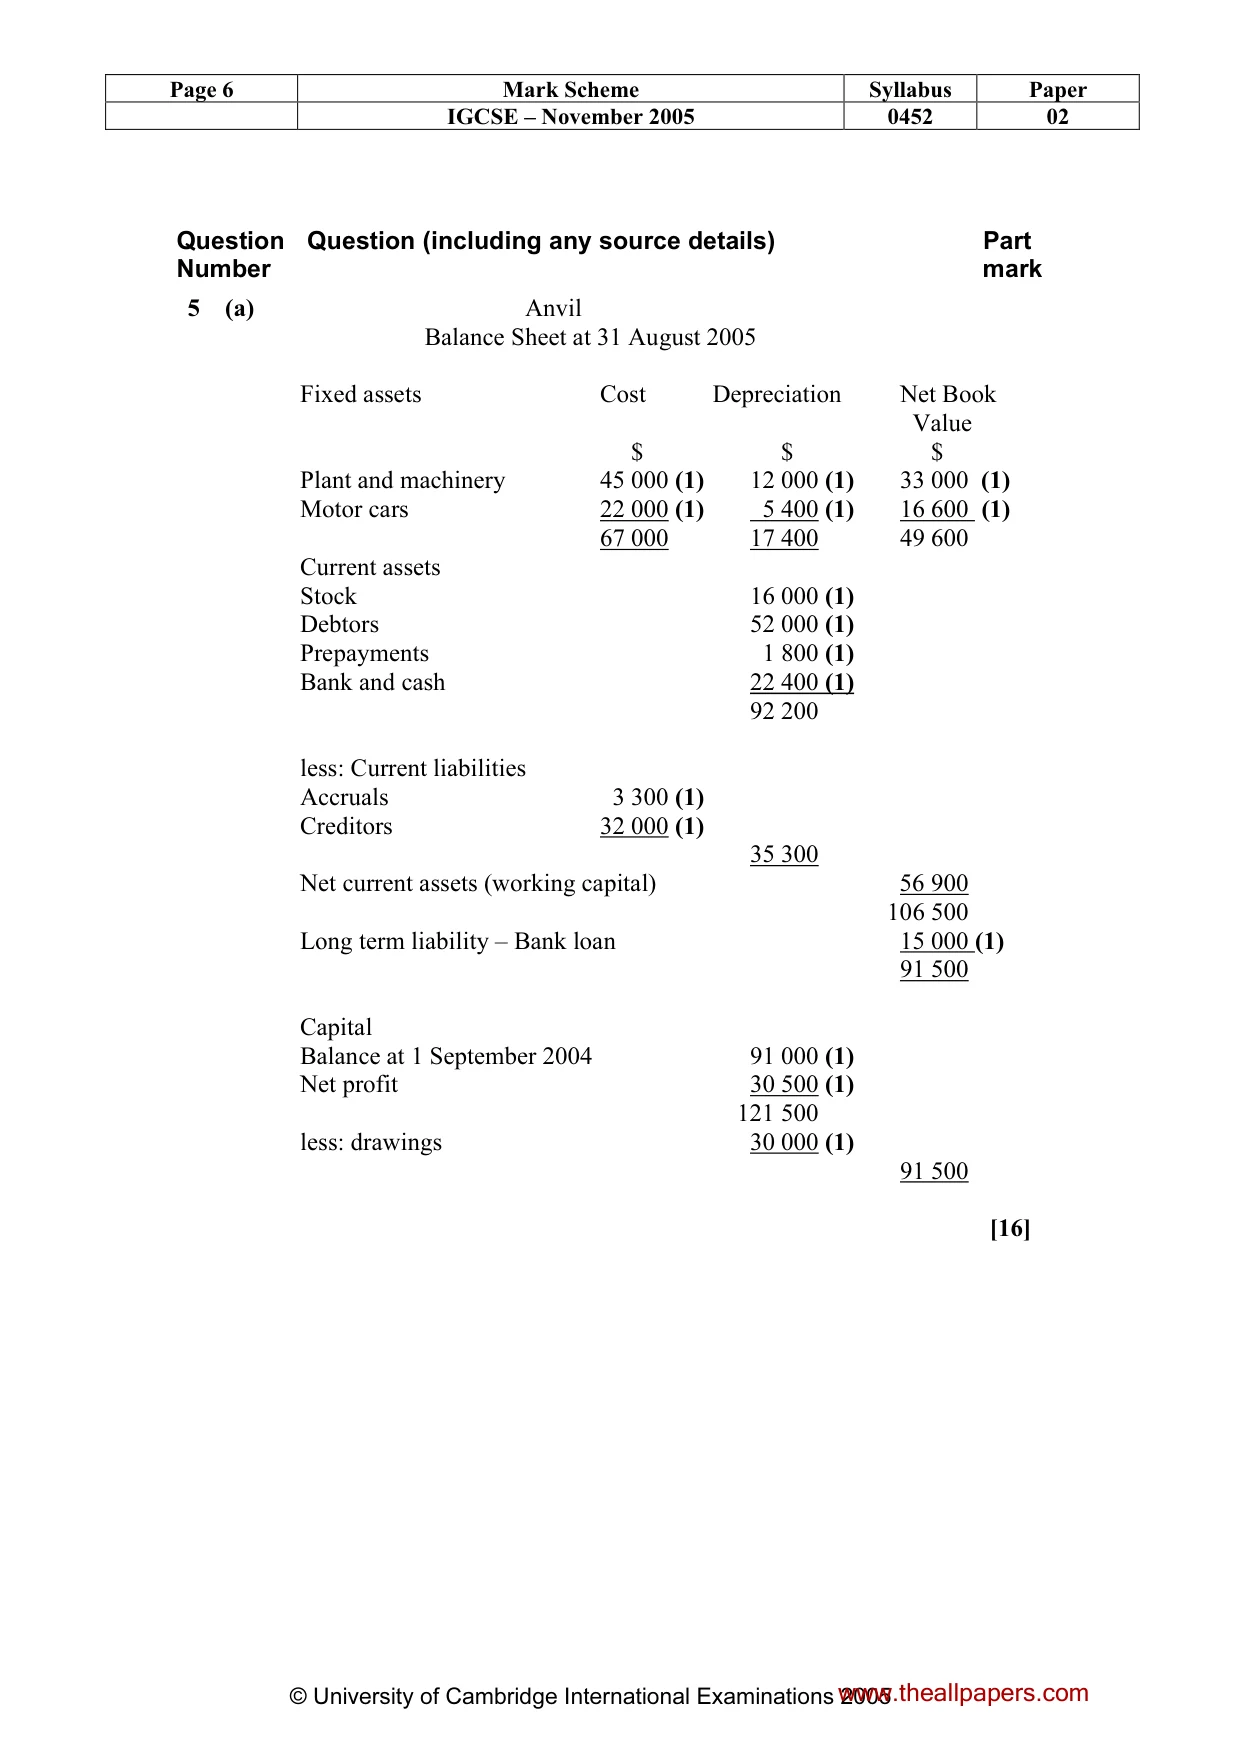
Page 6 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark 5 (a) Anvil Balance Sheet at 31 August 2005 Fixed assets Cost Depreciation Net Book Value $ $ $ Plant and machinery 45 000 (1) 12 000 (1) 33 000 (1) Motor cars 22 000 (1) 5 400 (1) 16 600 (1) 67 000 17 400 49 600 Current assets Stock 16 000 (1) Debtors 52 000 (1) Prepayments 1 800 (1) Bank and cash 22 400 (1) 92 200 less: Current liabilities Accruals 3 300 (1) Creditors 32 000 (1) 35 300 Net current assets (working capital) 56 900 106 500 Long term liability – Bank loan 15 000 (1) 91 500 Capital Balance at 1 September 2004 91 000 (1) Net profit 30 500 (1) 121 500 less: drawings 30 000 (1) 91 500 [16] www.theallpapers.com
Mark scheme, page 8
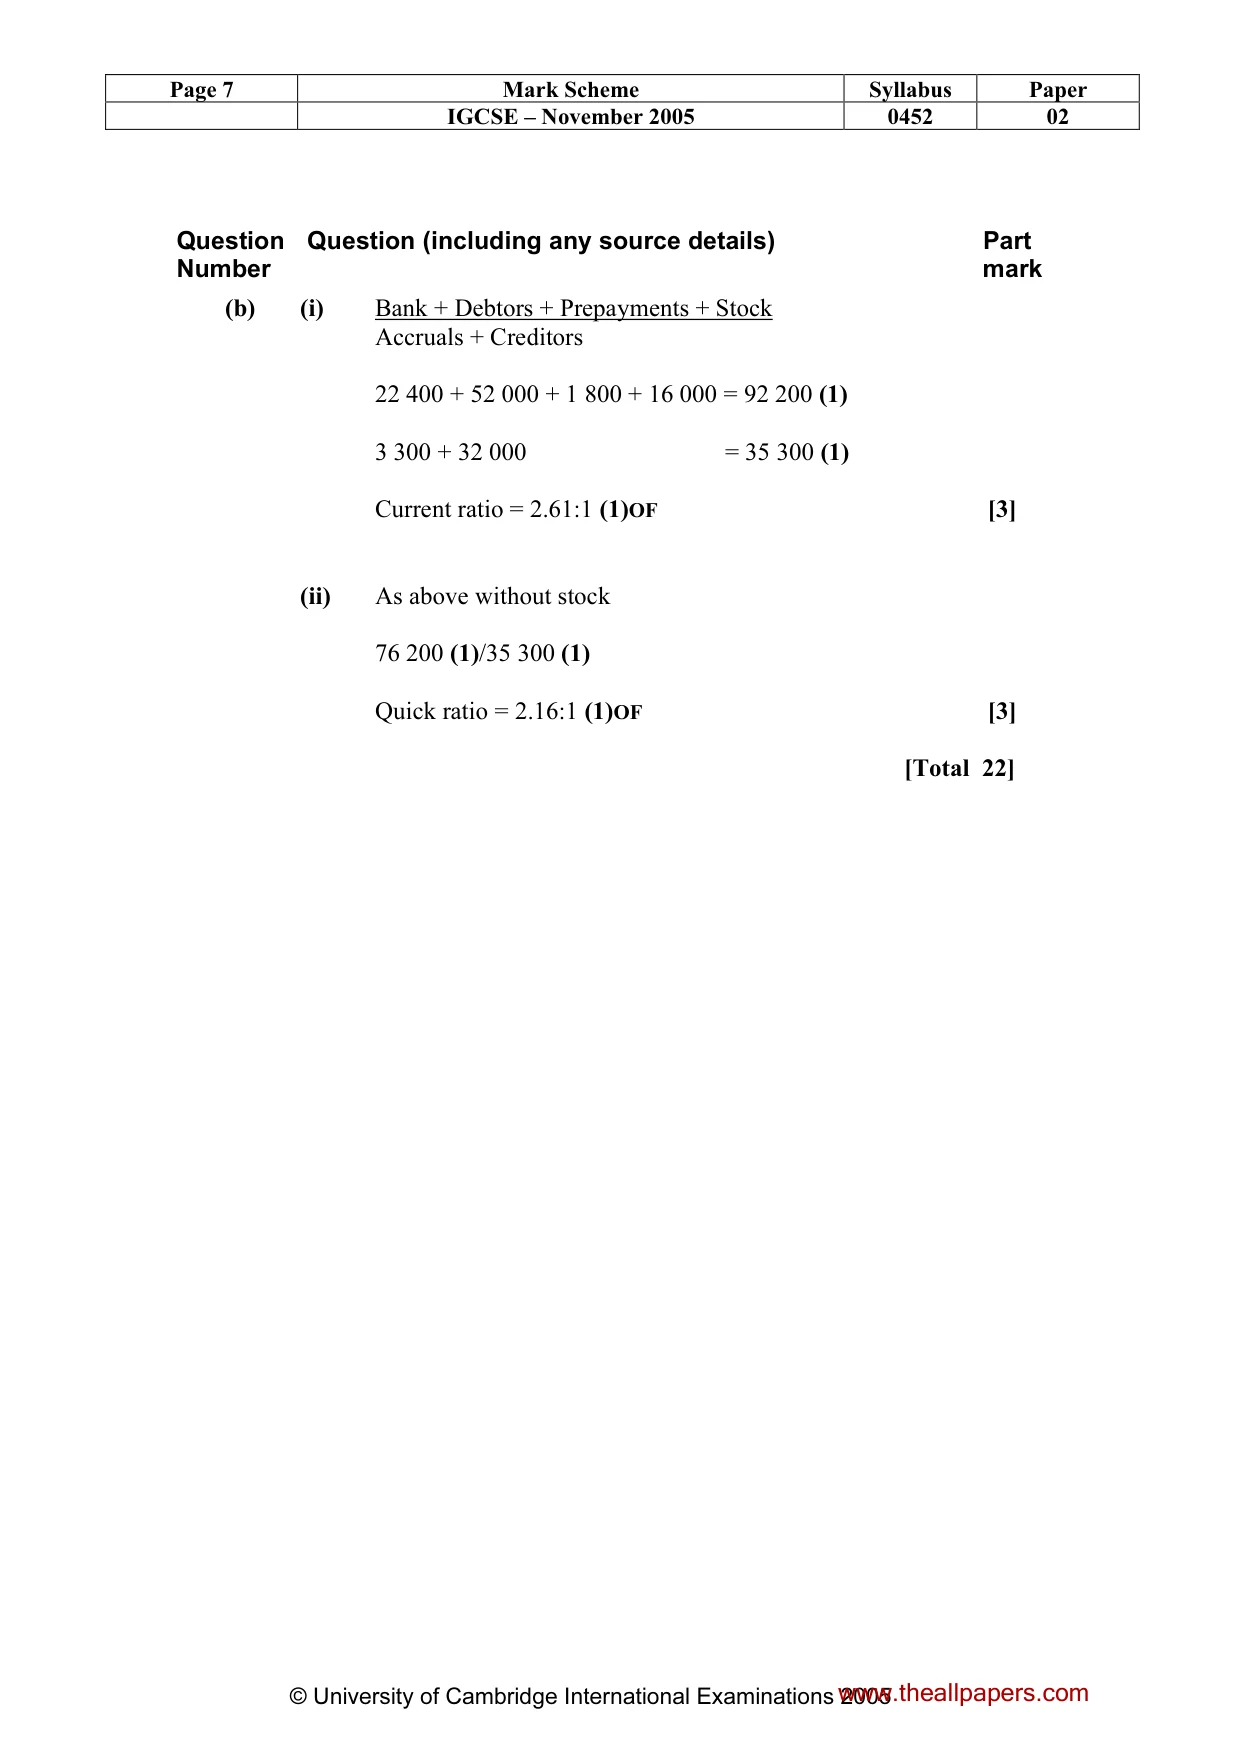
Page 7 Mark Scheme Syllabus Paper IGCSE – November 2005 0452 02 © University of Cambridge International Examinations 2005 Question Number Question (including any source details) Part mark (b) (i) Bank + Debtors + Prepayments + Stock Accruals + Creditors 22 400 + 52 000 + 1 800 + 16 000 = 92 200 (1) 3 300 + 32 000 = 35 300 (1) Current ratio = 2.61:1 (1)OF [3] (ii) As above without stock 76 200 (1)/35 300 (1) Quick ratio = 2.16:1 (1)OF [3] [Total 22] www.theallpapers.com