Cambridge IGCSE Accounting 0452 — 2005 May/June Paper 2 · Variant 1
0452/21/M/J/05
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 13 printed pages and 3 blank pages. SP (NH) S83636/4 © UCLES 2005 [Turn over UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/02 Paper 2 May/June 2005 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. For Examiner’s Use 1 2 3 4 5 Total Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. www.theallpapers.com
Question paper, page 2
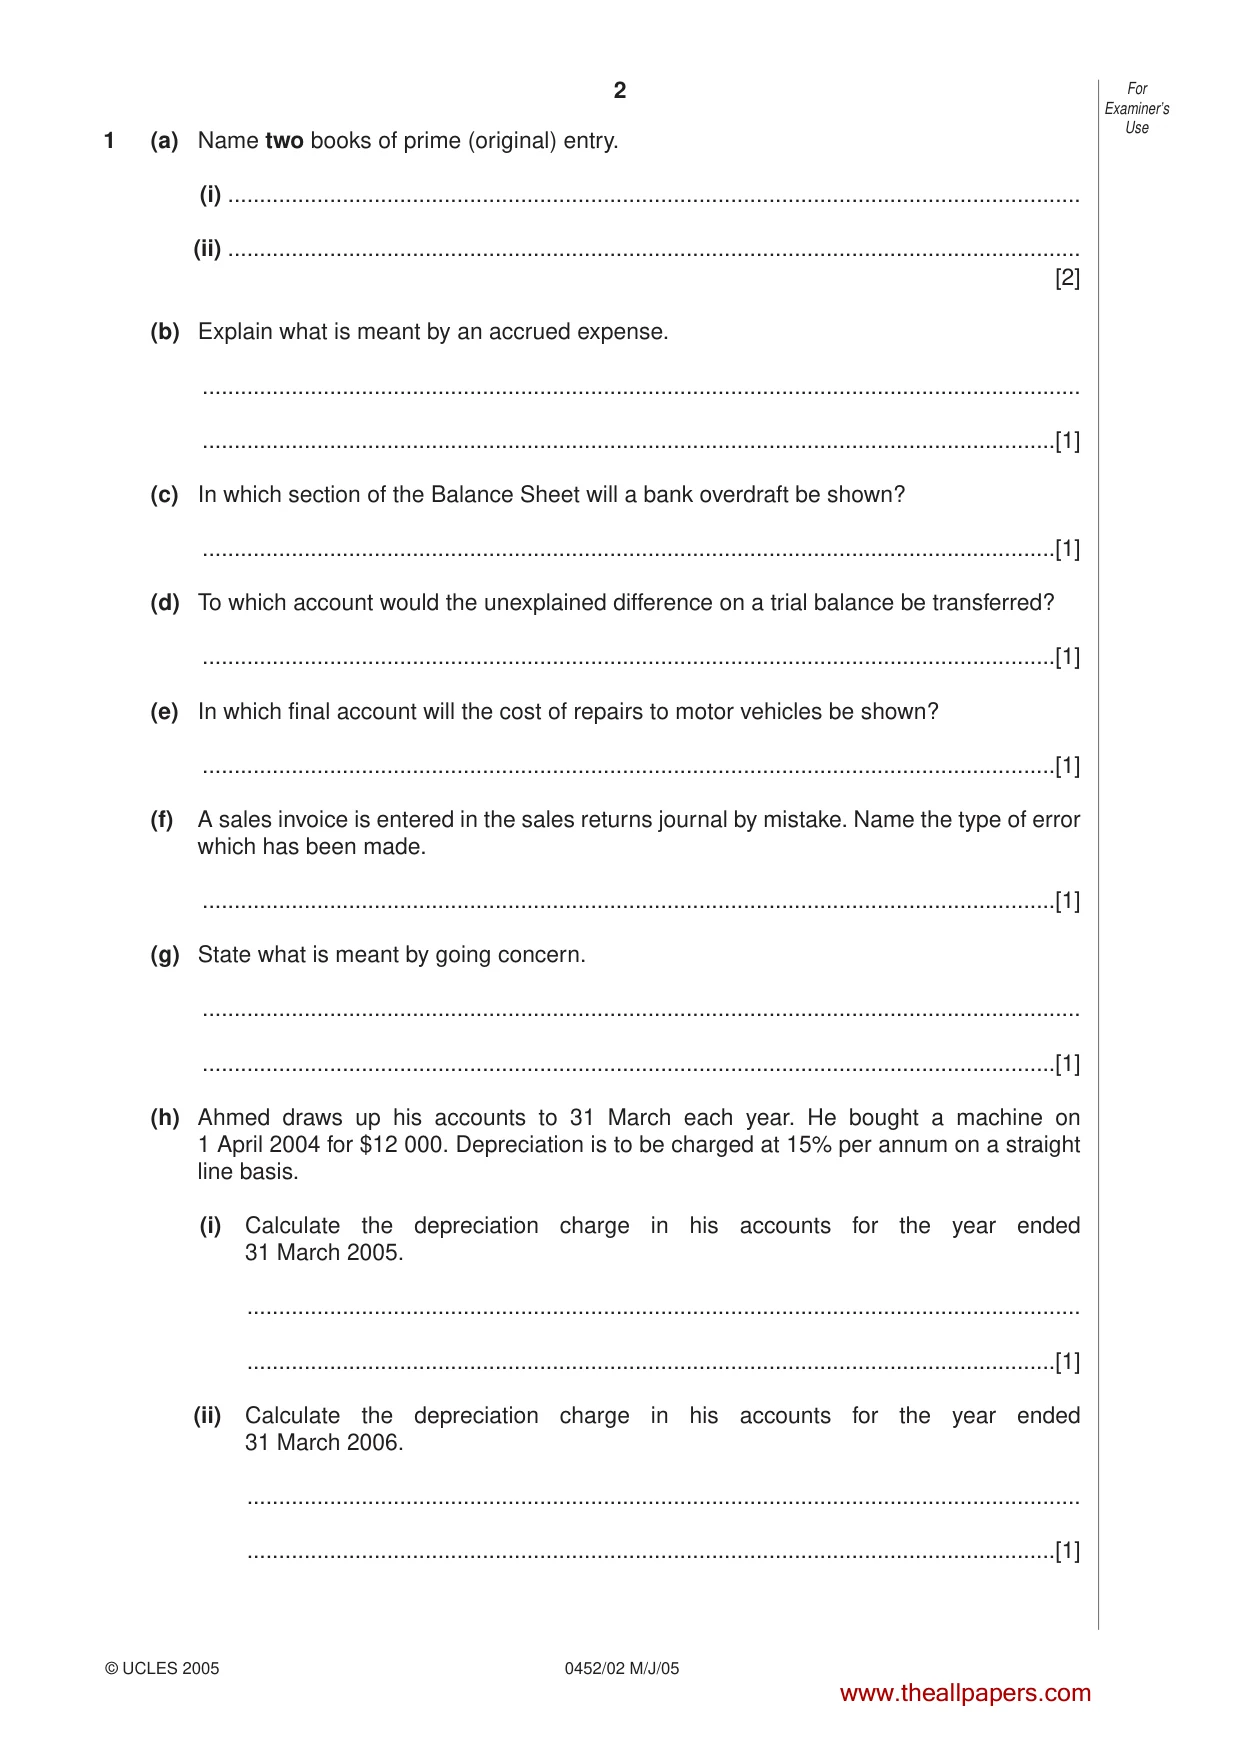
2 © UCLES 2005 0452/02 M/J/05 1 (a) Name two books of prime (original) entry. (i) … (ii) … [2] (b) Explain what is meant by an accrued expense. … …[1] (c) In which section of the Balance Sheet will a bank overdraft be shown? …[1] (d) To which account would the unexplained difference on a trial balance be transferred? …[1] (e) In which final account will the cost of repairs to motor vehicles be shown? …[1] (f) A sales invoice is entered in the sales returns journal by mistake. Name the type of error which has been made. …[1] (g) State what is meant by going concern. … …[1] (h) Ahmed draws up his accounts to 31 March each year. He bought a machine on 1 April 2004 for $12 000. Depreciation is to be charged at 15% per annum on a straight line basis. (i) Calculate the depreciation charge in his accounts for the year ended 31 March 2005. … …[1] (ii) Calculate the depreciation charge in his accounts for the year ended 31 March 2006. … …[1] For Examiner’s Use www.theallpapers.com
Question paper, page 3
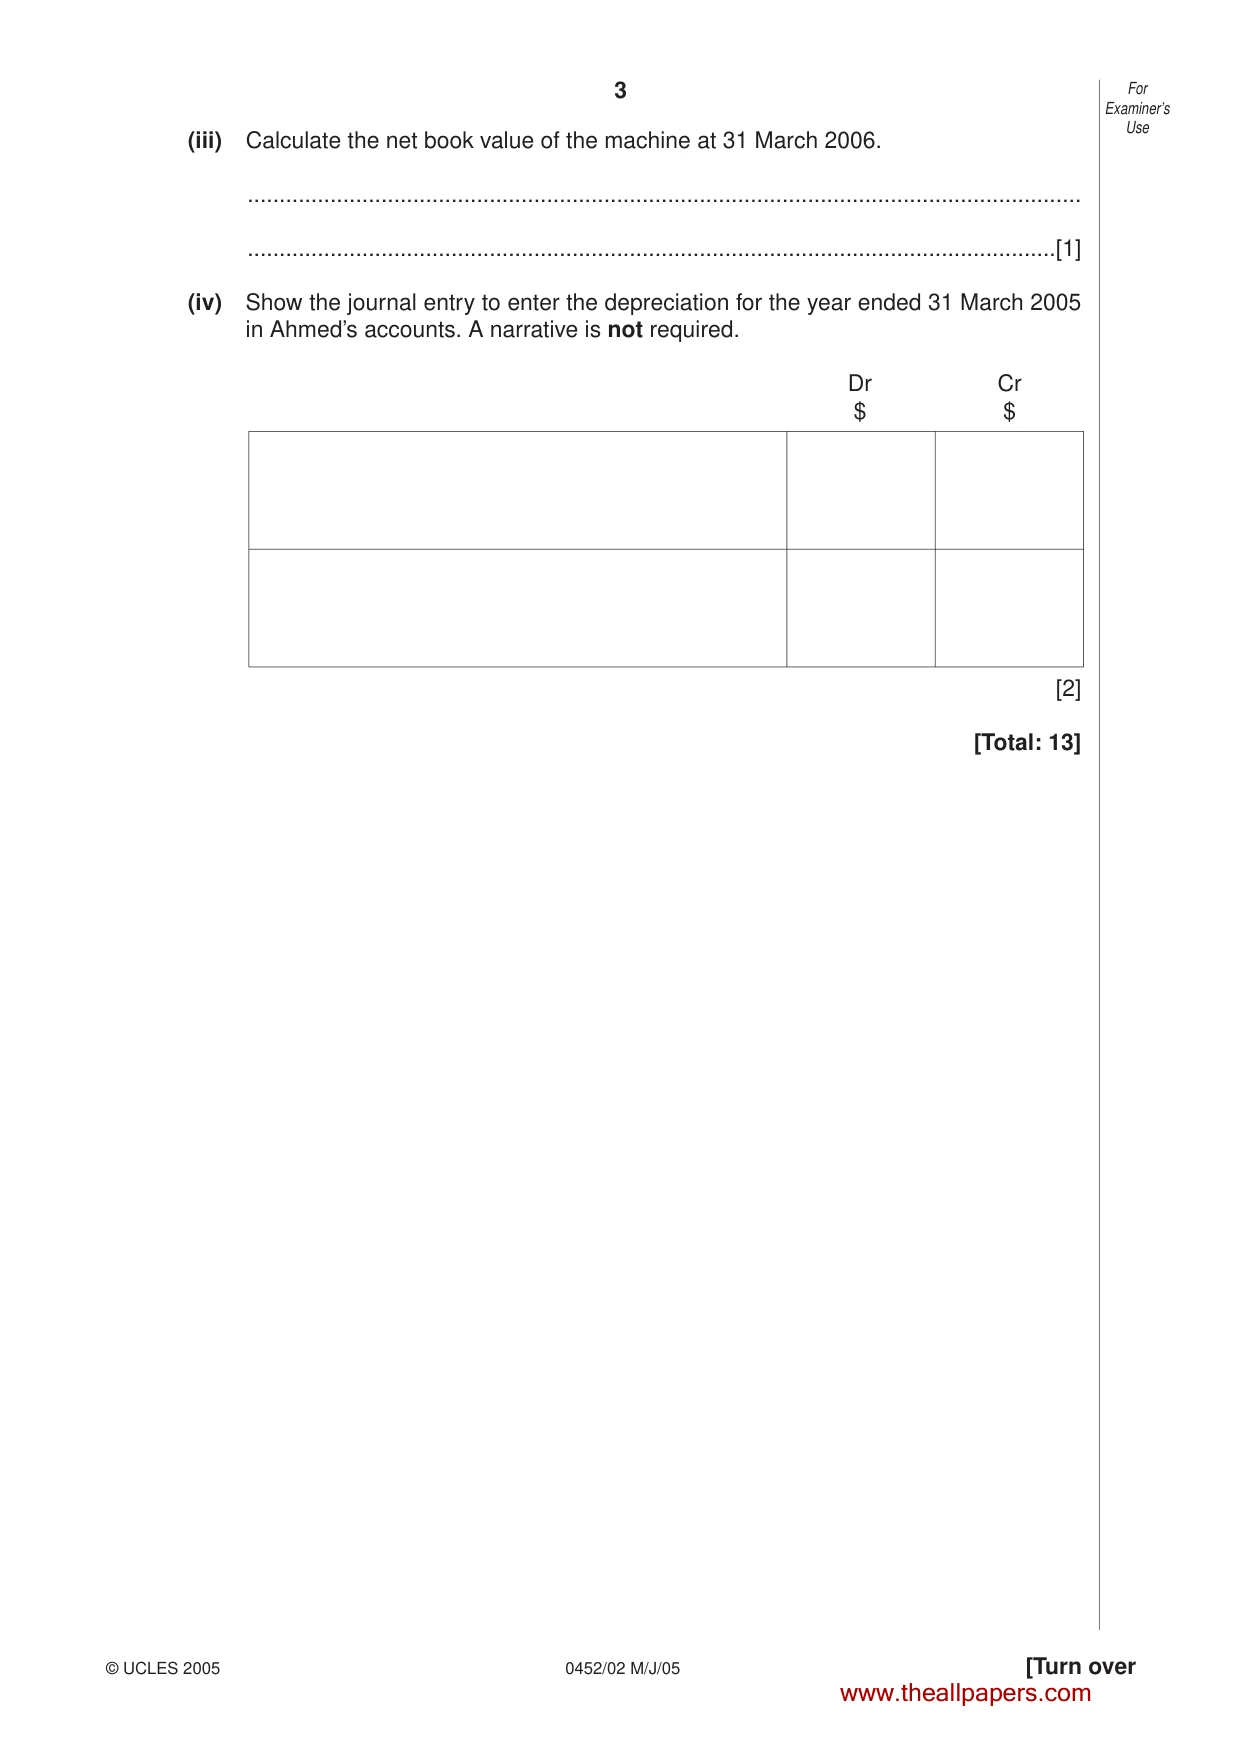
3 © UCLES 2005 0452/02 M/J/05 [Turn over (iii) Calculate the net book value of the machine at 31 March 2006. … …[1] (iv) Show the journal entry to enter the depreciation for the year ended 31 March 2005 in Ahmed’s accounts. A narrative is not required. Dr Cr $ $ [2] [Total: 13] For Examiner’s Use www.theallpapers.com
Question paper, page 4
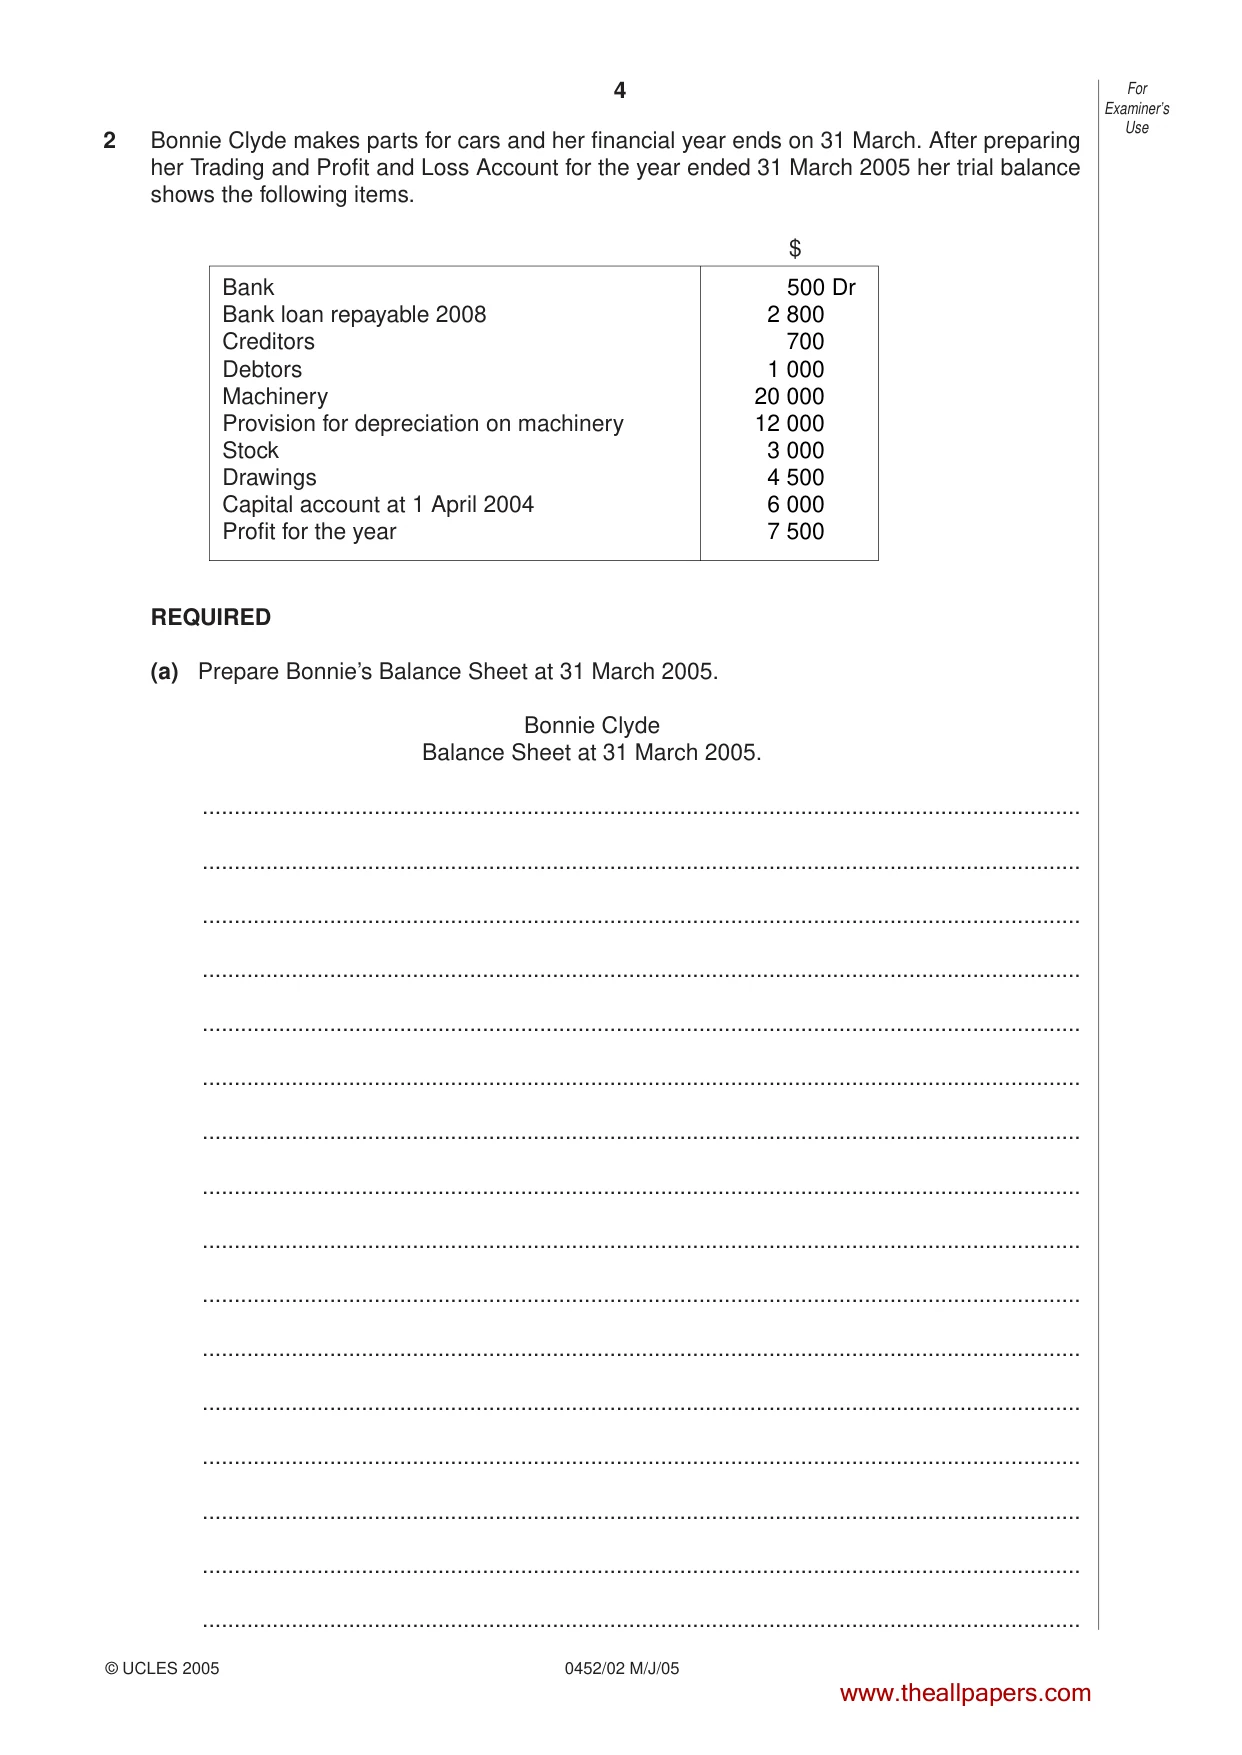
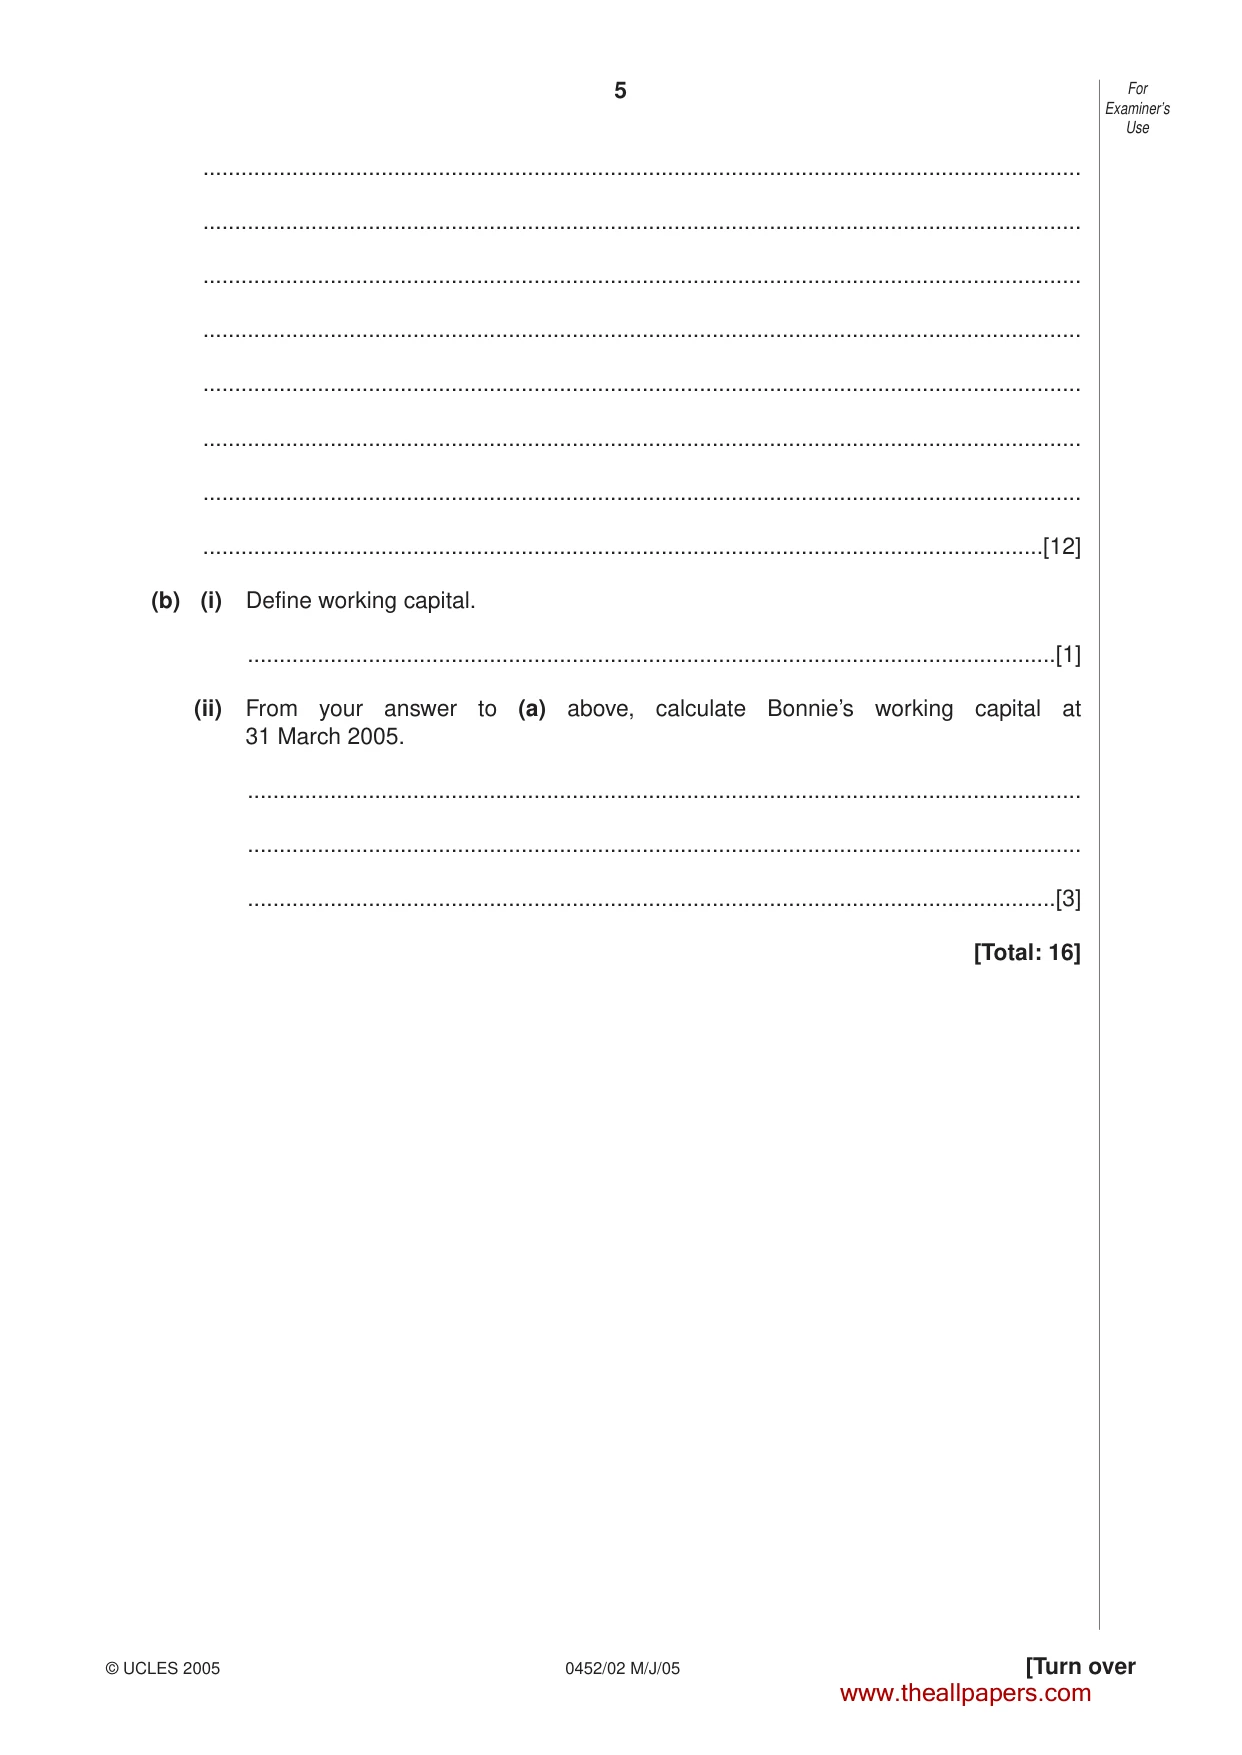
4 © UCLES 2005 0452/02 M/J/05 2 Bonnie Clyde makes parts for cars and her financial year ends on 31 March. After preparing her Trading and Profit and Loss Account for the year ended 31 March 2005 her trial balance shows the following items. $ REQUIRED (a) Prepare Bonnie’s Balance Sheet at 31 March 2005. Bonnie Clyde Balance Sheet at 31 March 2005. … … … … … … … … … … … … … … … … For Examiner’s Use Bank Bank loan repayable 2008 Creditors Debtors Machinery Provision for depreciation on machinery Stock Drawings Capital account at 1 April 2004 Profit for the year 500 Dr 2 800 700 1 000 20 000 12 000 3 000 4 500 6 000 7 500 www.theallpapers.com
Question paper, page 5
5 © UCLES 2005 0452/02 M/J/05 [Turn over … … … … … … … …[12] (b) (i) Define working capital. …[1] (ii) From your answer to (a) above, calculate Bonnie’s working capital at 31 March 2005. … … …[3] [Total: 16] For Examiner’s Use www.theallpapers.com
Question paper, page 6
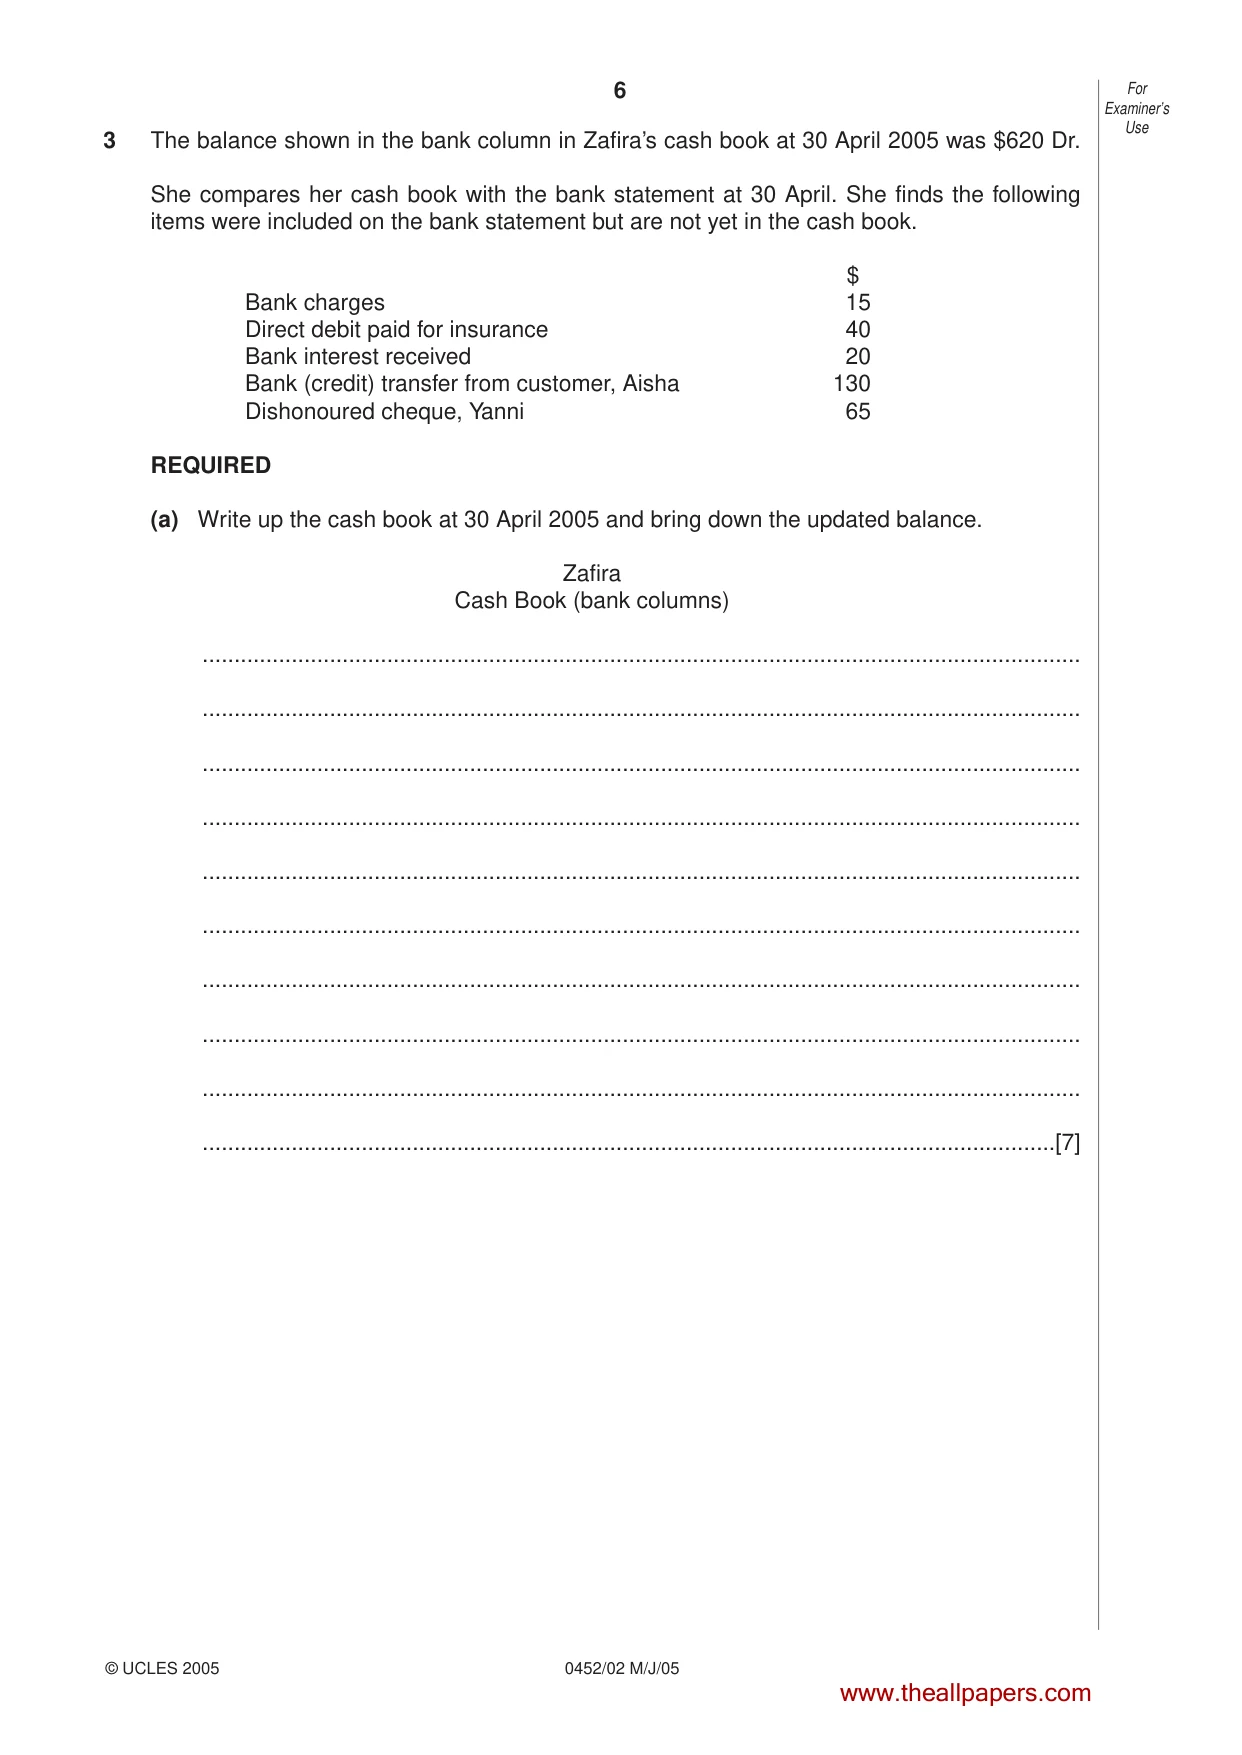
6 © UCLES 2005 0452/02 M/J/05 3 The balance shown in the bank column in Zafira’s cash book at 30 April 2005 was $620 Dr. She compares her cash book with the bank statement at 30 April. She finds the following items were included on the bank statement but are not yet in the cash book. $ Bank charges 15 Direct debit paid for insurance 40 Bank interest received 20 Bank (credit) transfer from customer, Aisha 130 Dishonoured cheque, Yanni 65 REQUIRED (a) Write up the cash book at 30 April 2005 and bring down the updated balance. Zafira Cash Book (bank columns) … … … … … … … … … …[7] For Examiner’s Use www.theallpapers.com
Question paper, page 7
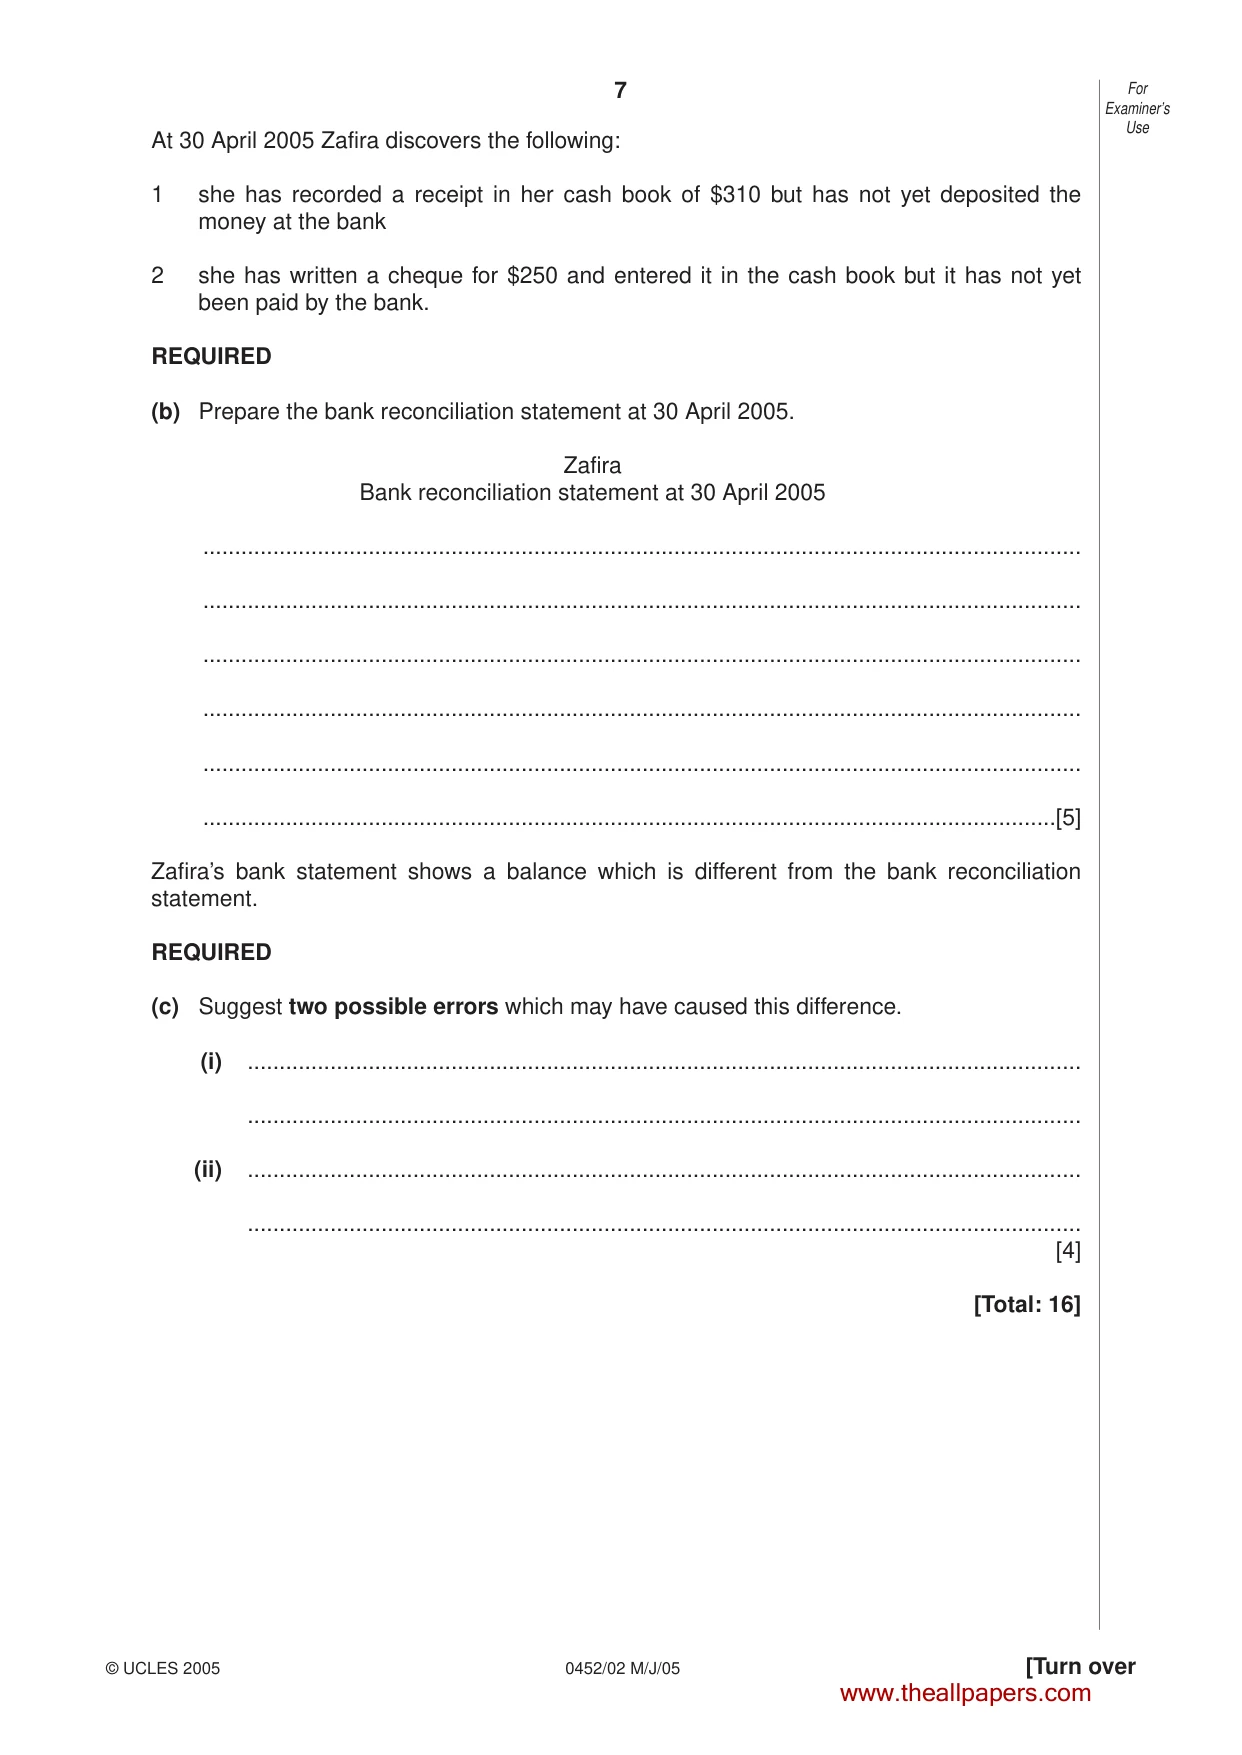
7 © UCLES 2005 0452/02 M/J/05 [Turn over At 30 April 2005 Zafira discovers the following: 1 she has recorded a receipt in her cash book of $310 but has not yet deposited the money at the bank 2 she has written a cheque for $250 and entered it in the cash book but it has not yet been paid by the bank. REQUIRED (b) Prepare the bank reconciliation statement at 30 April 2005. Zafira Bank reconciliation statement at 30 April 2005 … … … … … …[5] Zafira’s bank statement shows a balance which is different from the bank reconciliation statement. REQUIRED (c) Suggest two possible errors which may have caused this difference. (i) … … (ii) … … [4] [Total: 16] For Examiner’s Use www.theallpapers.com
Question paper, page 8
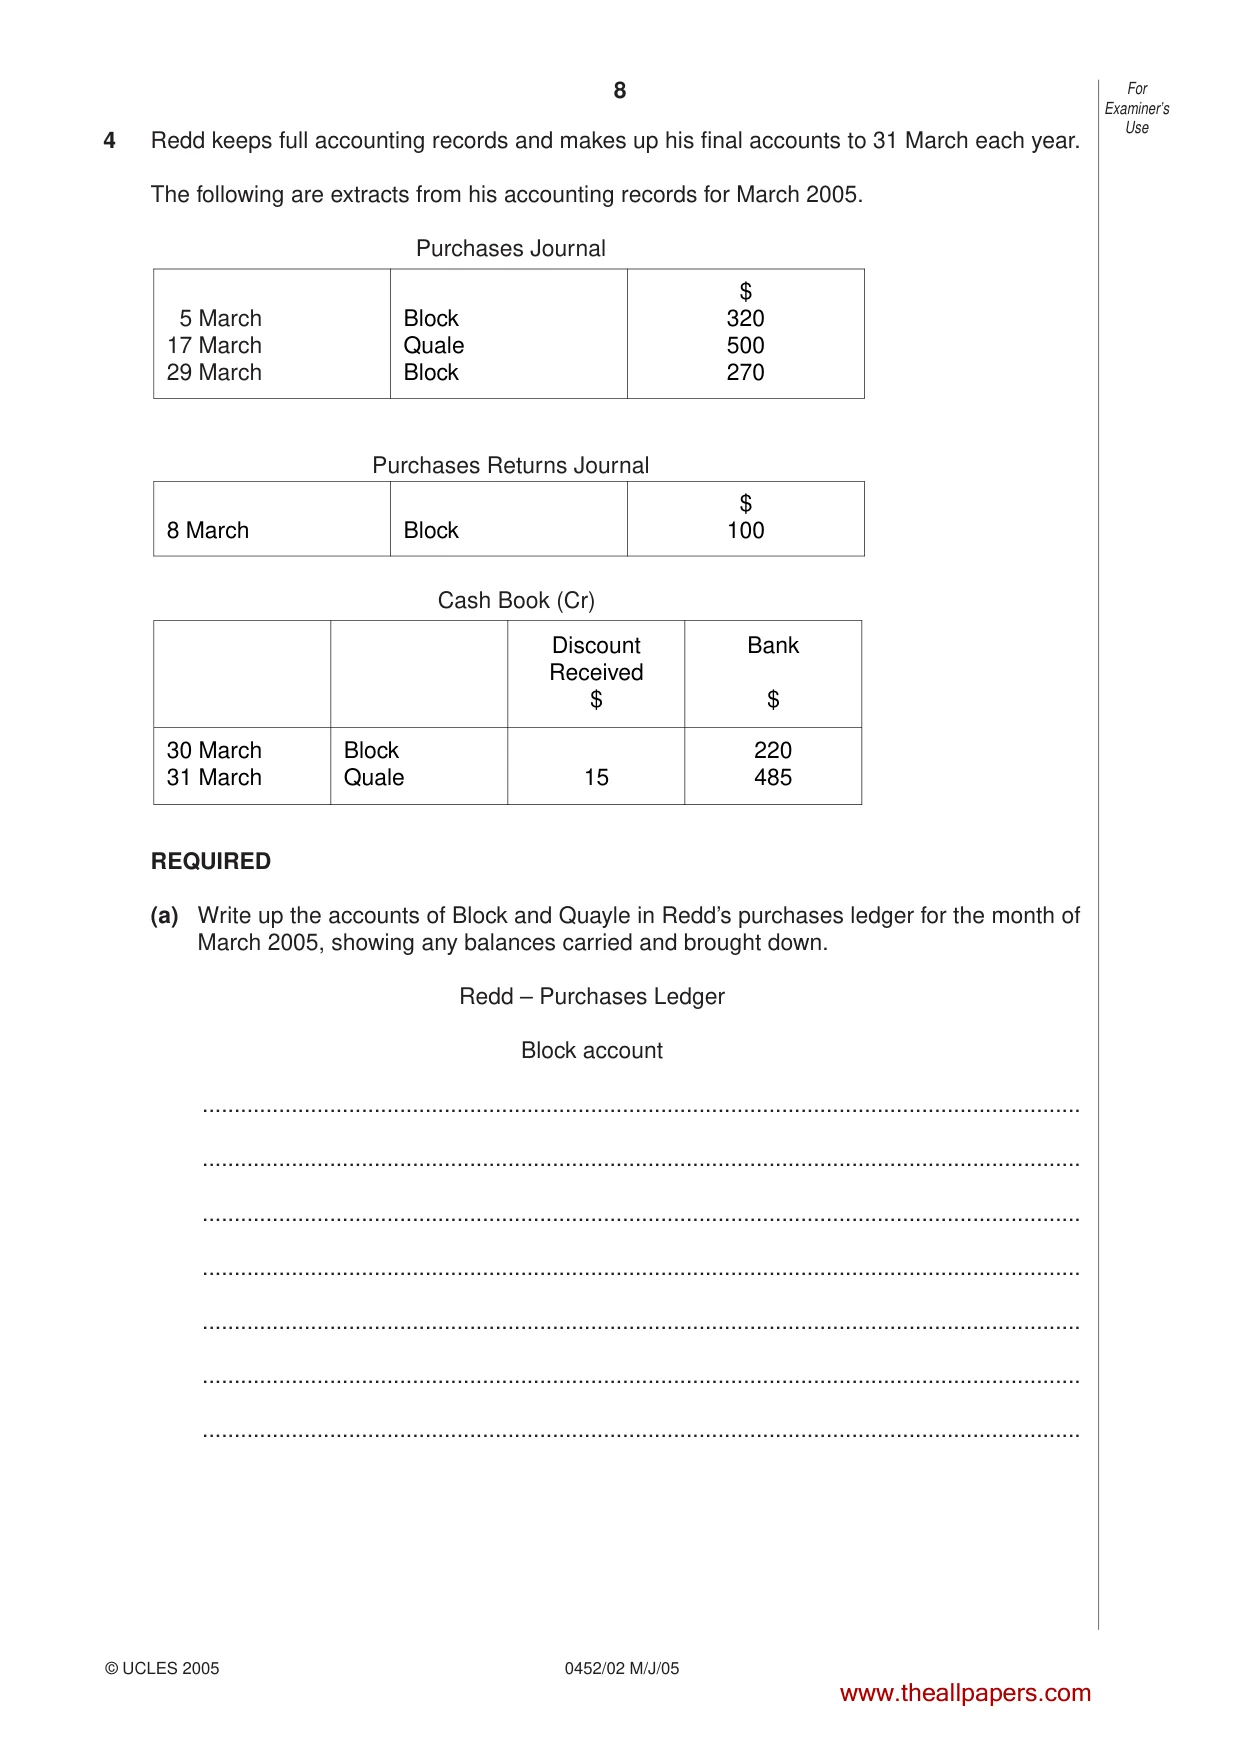
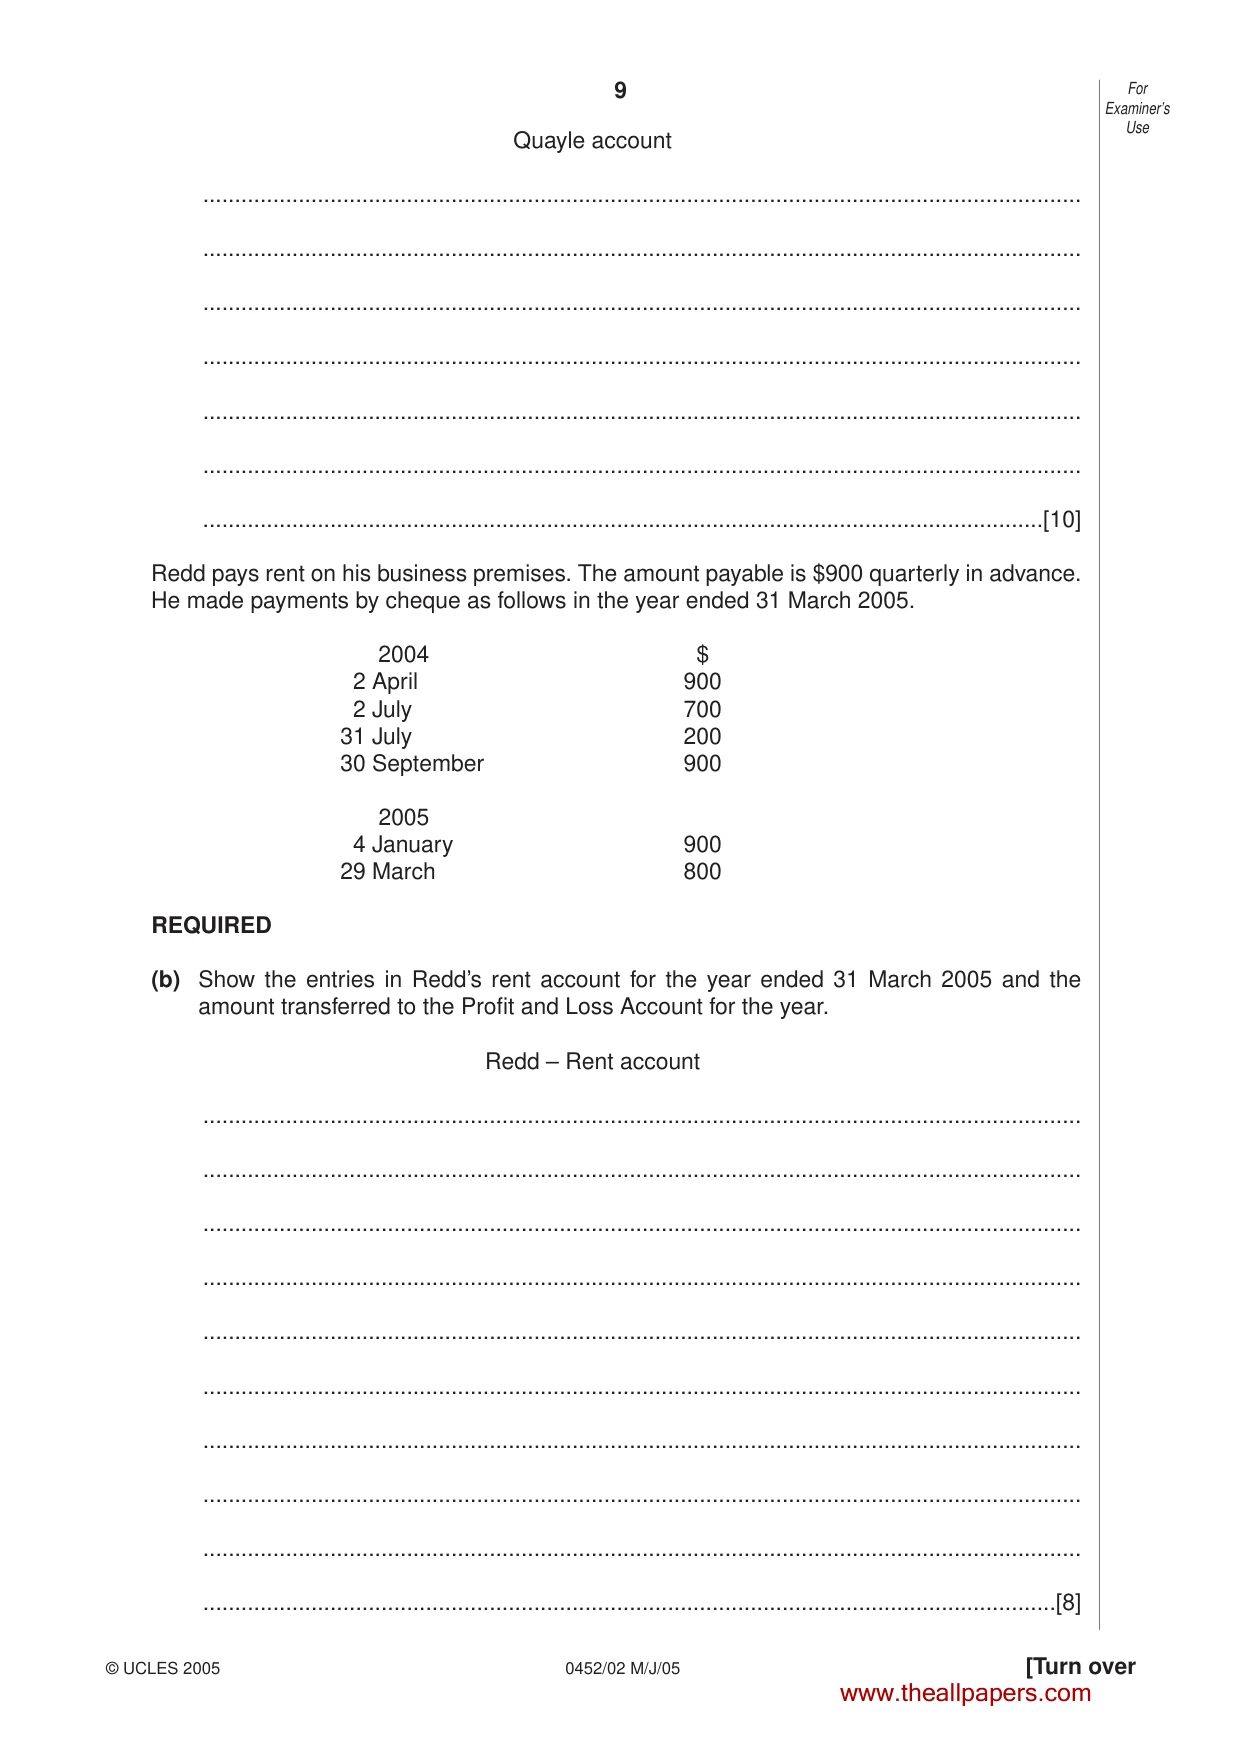
8 © UCLES 2005 0452/02 M/J/05 4 Redd keeps full accounting records and makes up his final accounts to 31 March each year. The following are extracts from his accounting records for March 2005. Purchases Journal Purchases Returns Journal Cash Book (Cr) REQUIRED (a) Write up the accounts of Block and Quayle in Redd’s purchases ledger for the month of March 2005, showing any balances carried and brought down. Redd – Purchases Ledger Block account … … … … … … … For Examiner’s Use 5 March 17 March 29 March Block Quale Block $ 320 500 270 8 March Block $ 100 Discount Received $ Bank $ 30 March 31 March Block Quale 15 220 485 www.theallpapers.com
Question paper, page 9
9 © UCLES 2005 0452/02 M/J/05 [Turn over Quayle account … … … … … … …[10] Redd pays rent on his business premises. The amount payable is $900 quarterly in advance. He made payments by cheque as follows in the year ended 31 March 2005. 2004 $ 2 April 900 2 July 700 31 July 200 30 September 900 2005 4 January 900 29 March 800 REQUIRED (b) Show the entries in Redd’s rent account for the year ended 31 March 2005 and the amount transferred to the Profit and Loss Account for the year. Redd – Rent account … … … … … … … … … …[8] For Examiner’s Use www.theallpapers.com
Question paper, page 10
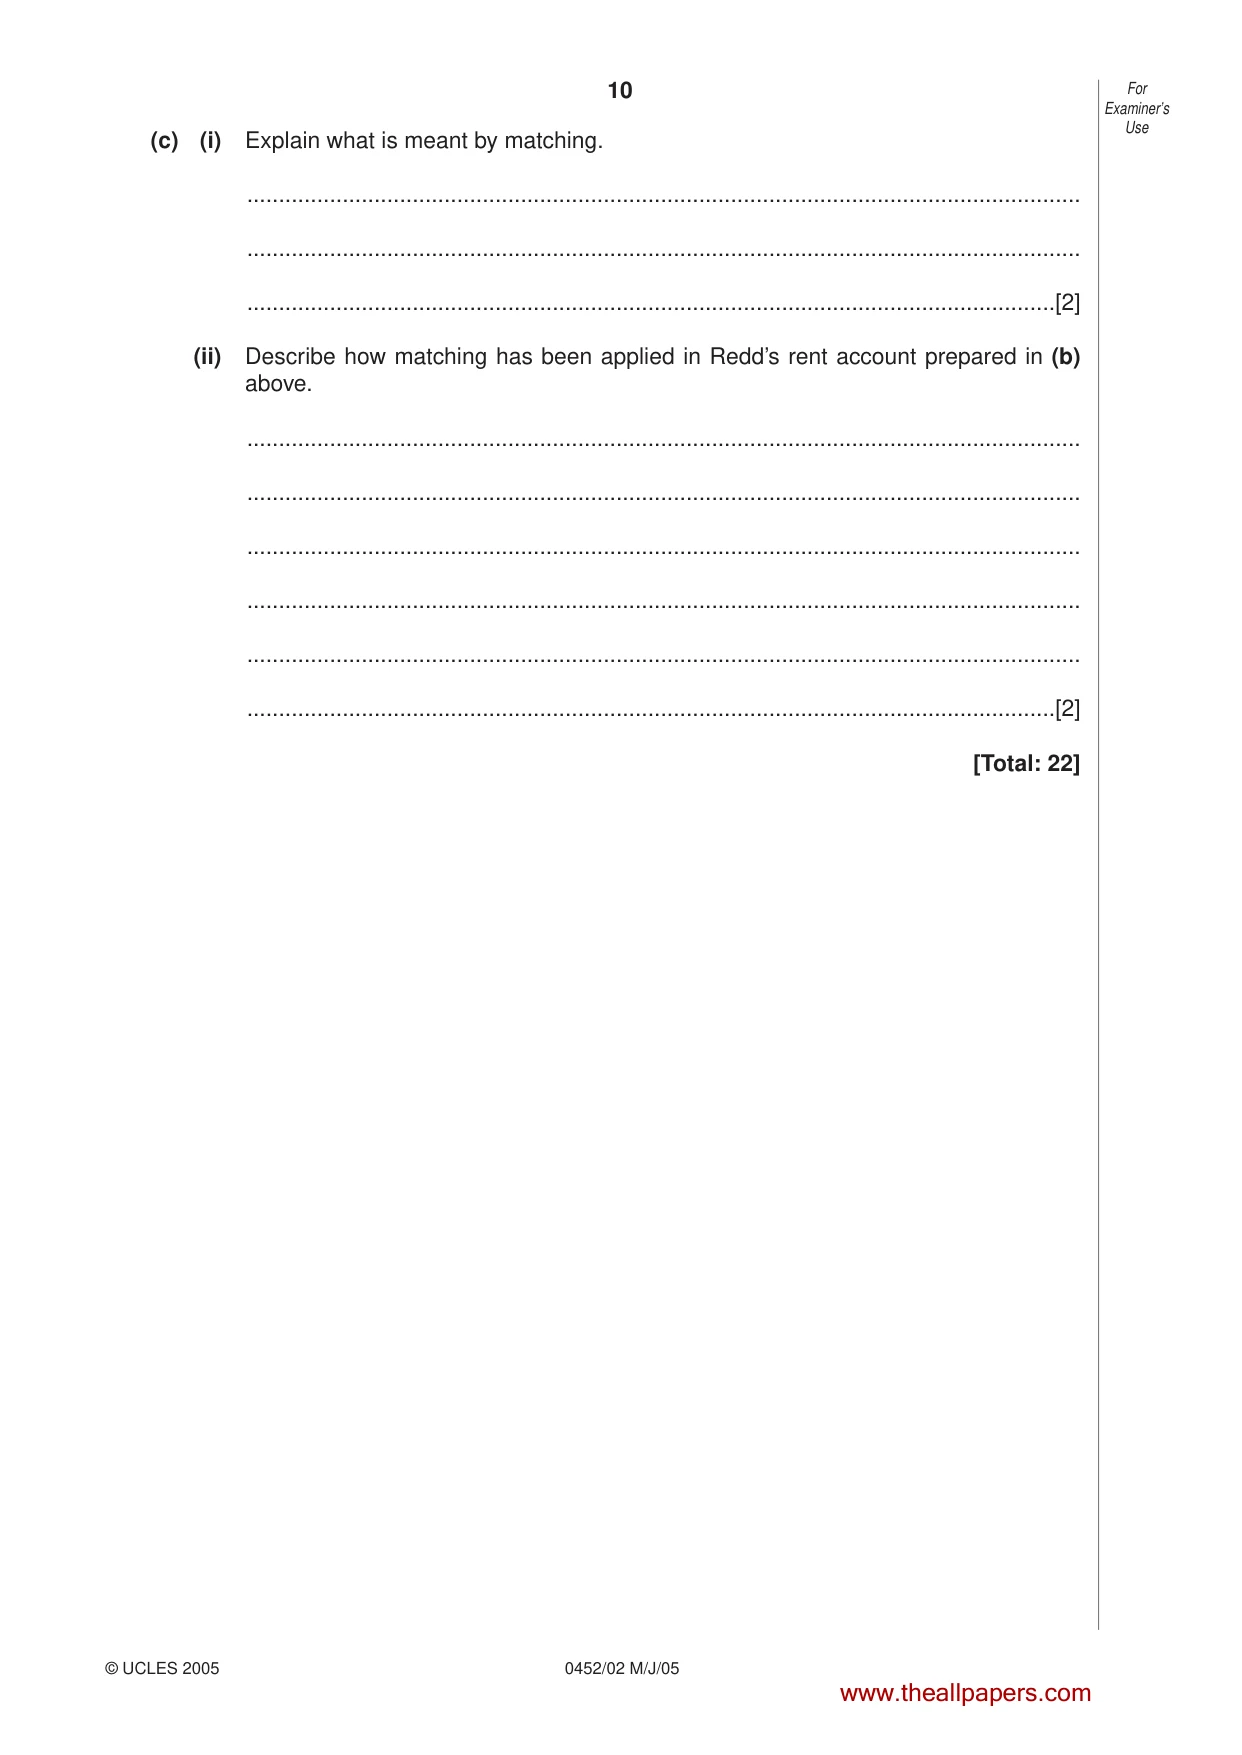
10 © UCLES 2005 0452/02 M/J/05 (c) (i) Explain what is meant by matching. … … …[2] (ii) Describe how matching has been applied in Redd’s rent account prepared in (b) above. … … … … … …[2] [Total: 22] For Examiner’s Use www.theallpapers.com
Question paper, page 11
11 0452/02 M/J/05 BLANK PAGE Question 5 is on the following page. [Turn over www.theallpapers.com
Question paper, page 12
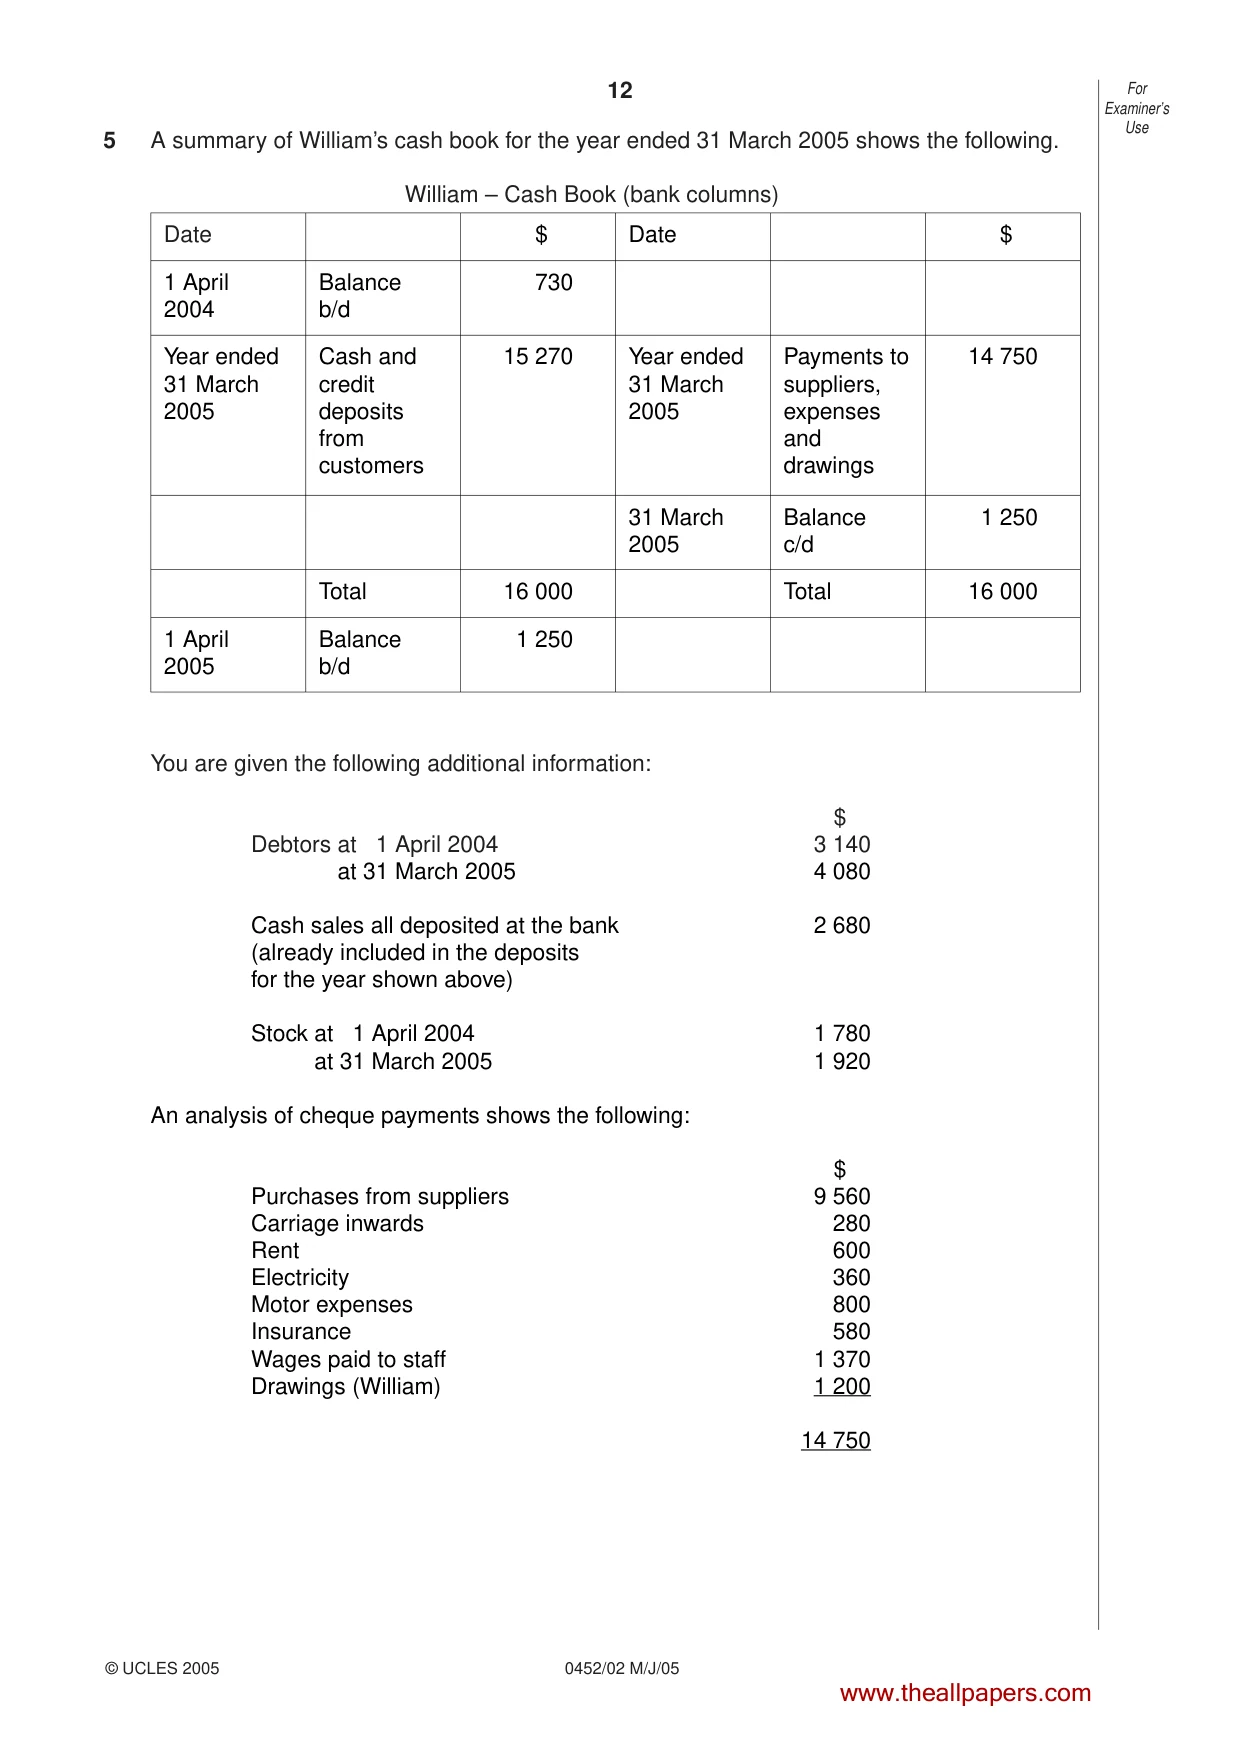
12 © UCLES 2005 0452/02 M/J/05 5 A summary of William’s cash book for the year ended 31 March 2005 shows the following. William – Cash Book (bank columns) You are given the following additional information: $ Debtors at 1 April 2004 3 140 Debtors at 31 March 2005 4 080 Cash sales all deposited at the bank 2 680 (already included in the deposits for the year shown above) Stock at 1 April 2004 1 780 Stock at 31 March 2005 1 920 An analysis of cheque payments shows the following: $ Purchases from suppliers 9 560 Carriage inwards 280 Rent 600 Electricity 360 Motor expenses 800 Insurance 580 Wages paid to staff 1 370 Drawings (William) 1 200 14 750 For Examiner’s Use Date $ Date $ 1 April 2004 Balance b/d 730 Year ended 31 March 2005 Cash and credit deposits from customers 15 270 Year ended 31 March 2005 Payments to suppliers, expenses and drawings 14 750 31 March 2005 Balance c/d 1 250 Total 16 000 Total 16 000 1 April 2005 Balance b/d 1 250 www.theallpapers.com
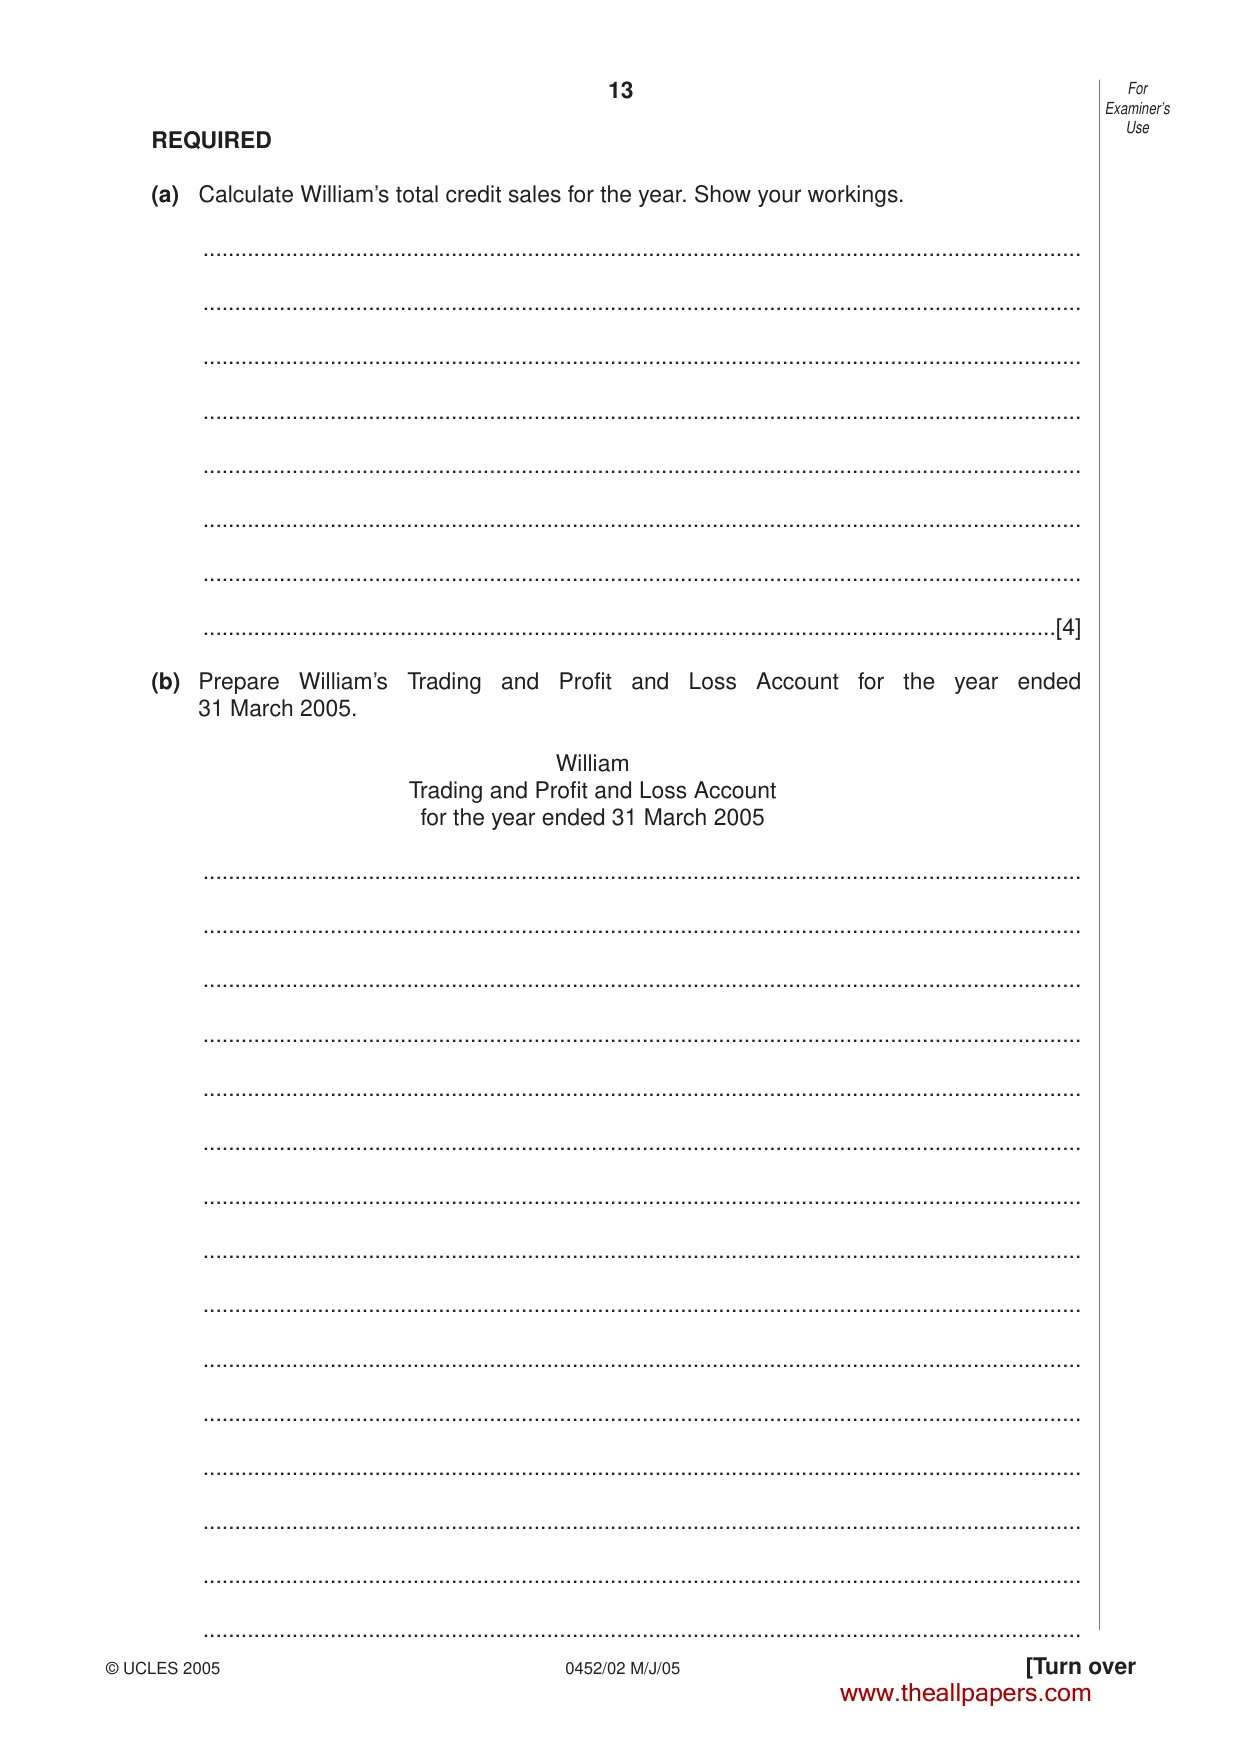
Question paper, page 13
13 © UCLES 2005 0452/02 M/J/05 [Turn over For Examiner’s Use REQUIRED (a) Calculate William’s total credit sales for the year. Show your workings. … … … … … … … …[4] (b) Prepare William’s Trading and Profit and Loss Account for the year ended 31 March 2005. William Trading and Profit and Loss Account for the year ended 31 March 2005 … … … … … … … … … … … … … … … www.theallpapers.com
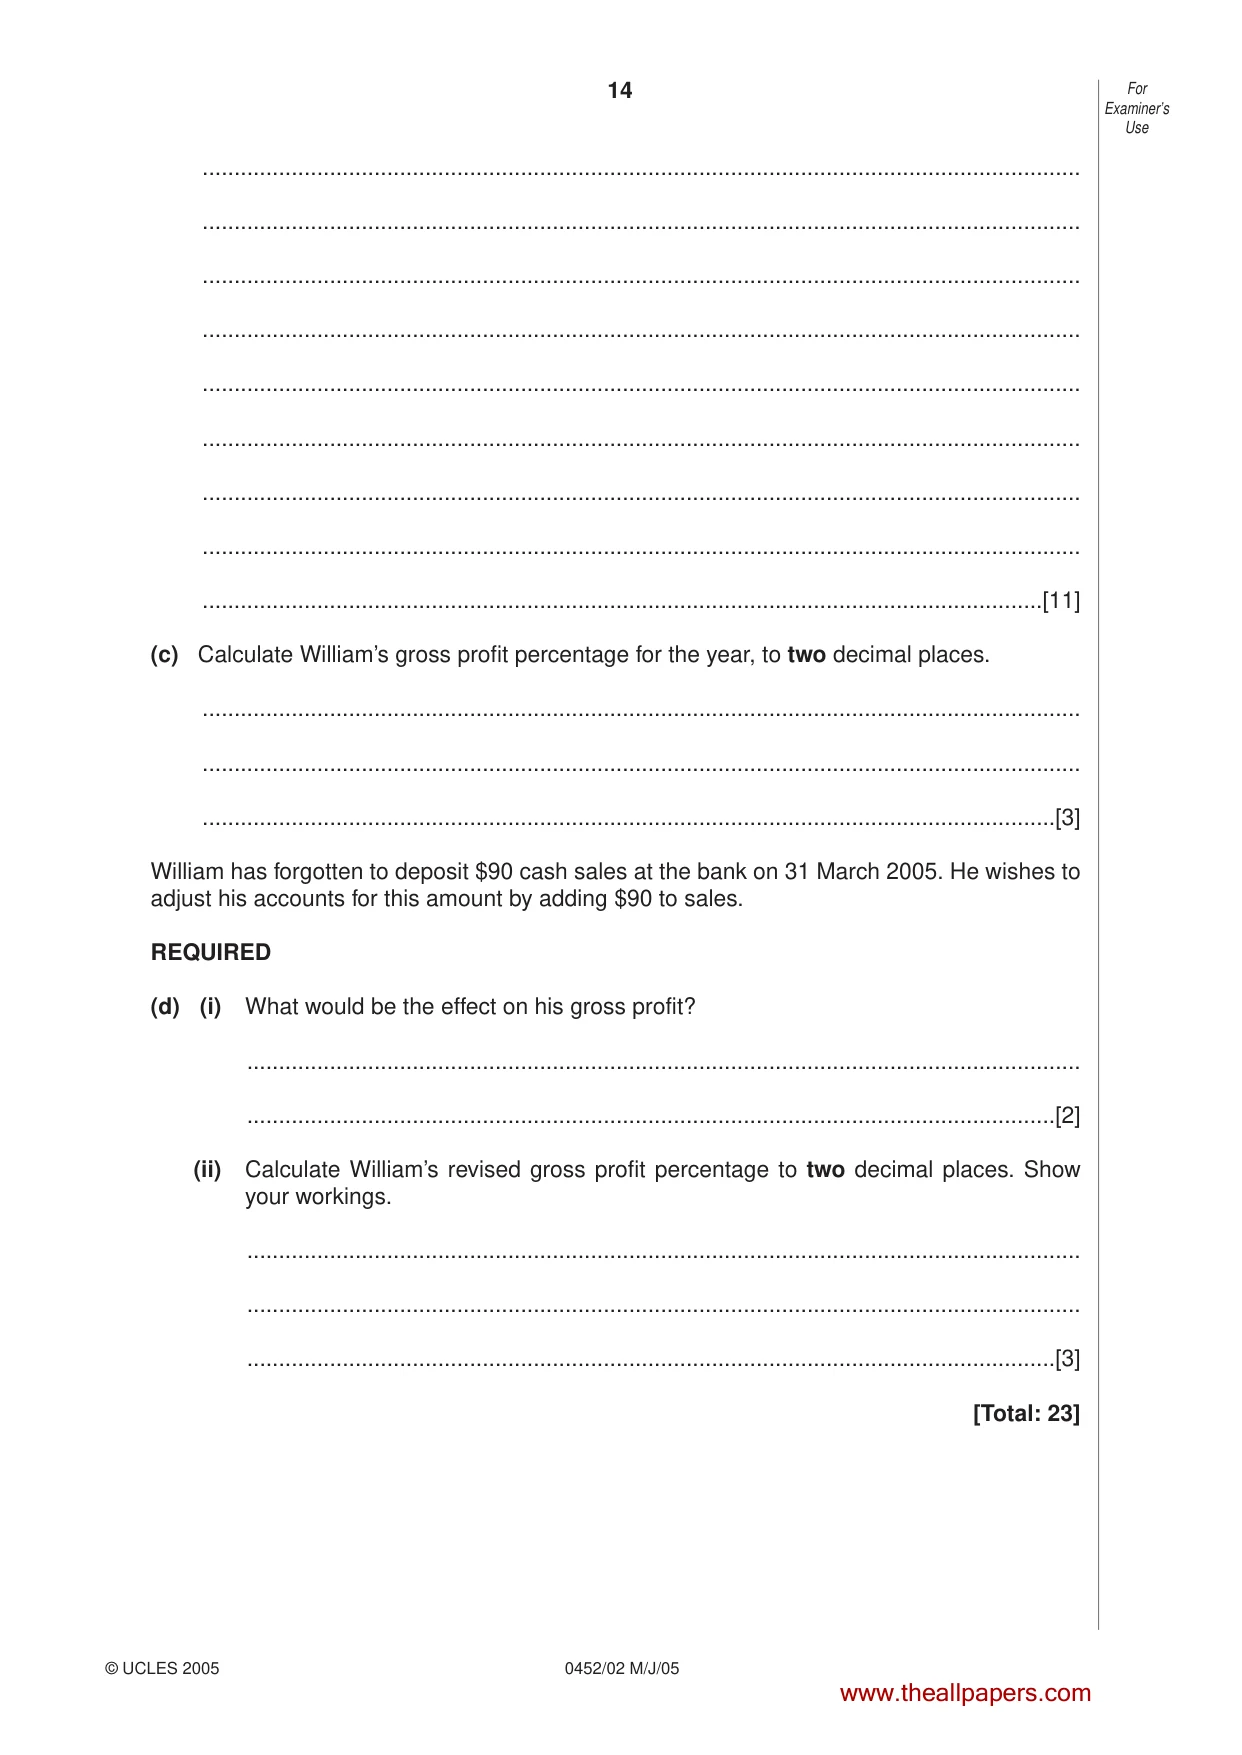
Question paper, page 14
14 © UCLES 2005 0452/02 M/J/05 … … … … … … … … …[11] (c) Calculate William’s gross profit percentage for the year, to two decimal places. … … …[3] William has forgotten to deposit $90 cash sales at the bank on 31 March 2005. He wishes to adjust his accounts for this amount by adding $90 to sales. REQUIRED (d) (i) What would be the effect on his gross profit? … …[2] (ii) Calculate William’s revised gross profit percentage to two decimal places. Show your workings. … … …[3] [Total: 23] For Examiner’s Use www.theallpapers.com
Question paper, page 15
15 0452/02 M/J/05 BLANK PAGE www.theallpapers.com
Question paper, page 16
16 0452/02 M/J/05 BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. www.theallpapers.com
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the June 2005 question paper 0452 ACCOUNTING 0452/02 Paper 2, maximum raw mark 90 This mark scheme is published as an aid to teachers and students, to indicate the requirements of the examination. It shows the basis on which Examiners were initially instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. Any substantial changes to the mark scheme that arose from these discussions will be recorded in the published Report on the Examination. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the Report on the Examination. • CIE will not enter into discussion or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the June 2005 question papers for most IGCSE and GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses. www.theallpapers.com
Mark scheme, page 2
Grade thresholds for Syllabus 0452 (Accounting) in the June 2005 examination. Minimum mark required for grade: Maximum mark available A C E F Component 2 90 73 58 39 30 The threshold (minimum mark) for B is set halfway between those for Grades A and C. The threshold (minimum mark) for D is set halfway between those for Grades C and E. The threshold (minimum mark) for G is set as many marks below F threshold as the E threshold is above it. Grade A* does not exist at the level of an individual component. www.theallpapers.com
Mark scheme, page 3
June 2005 IGCSE MARK SCHEME MAXIMUM MARK: 90 SYLLABUS/COMPONENT: 0452/02 ACCOUNTING Paper 2 www.theallpapers.com
Mark scheme, page 4
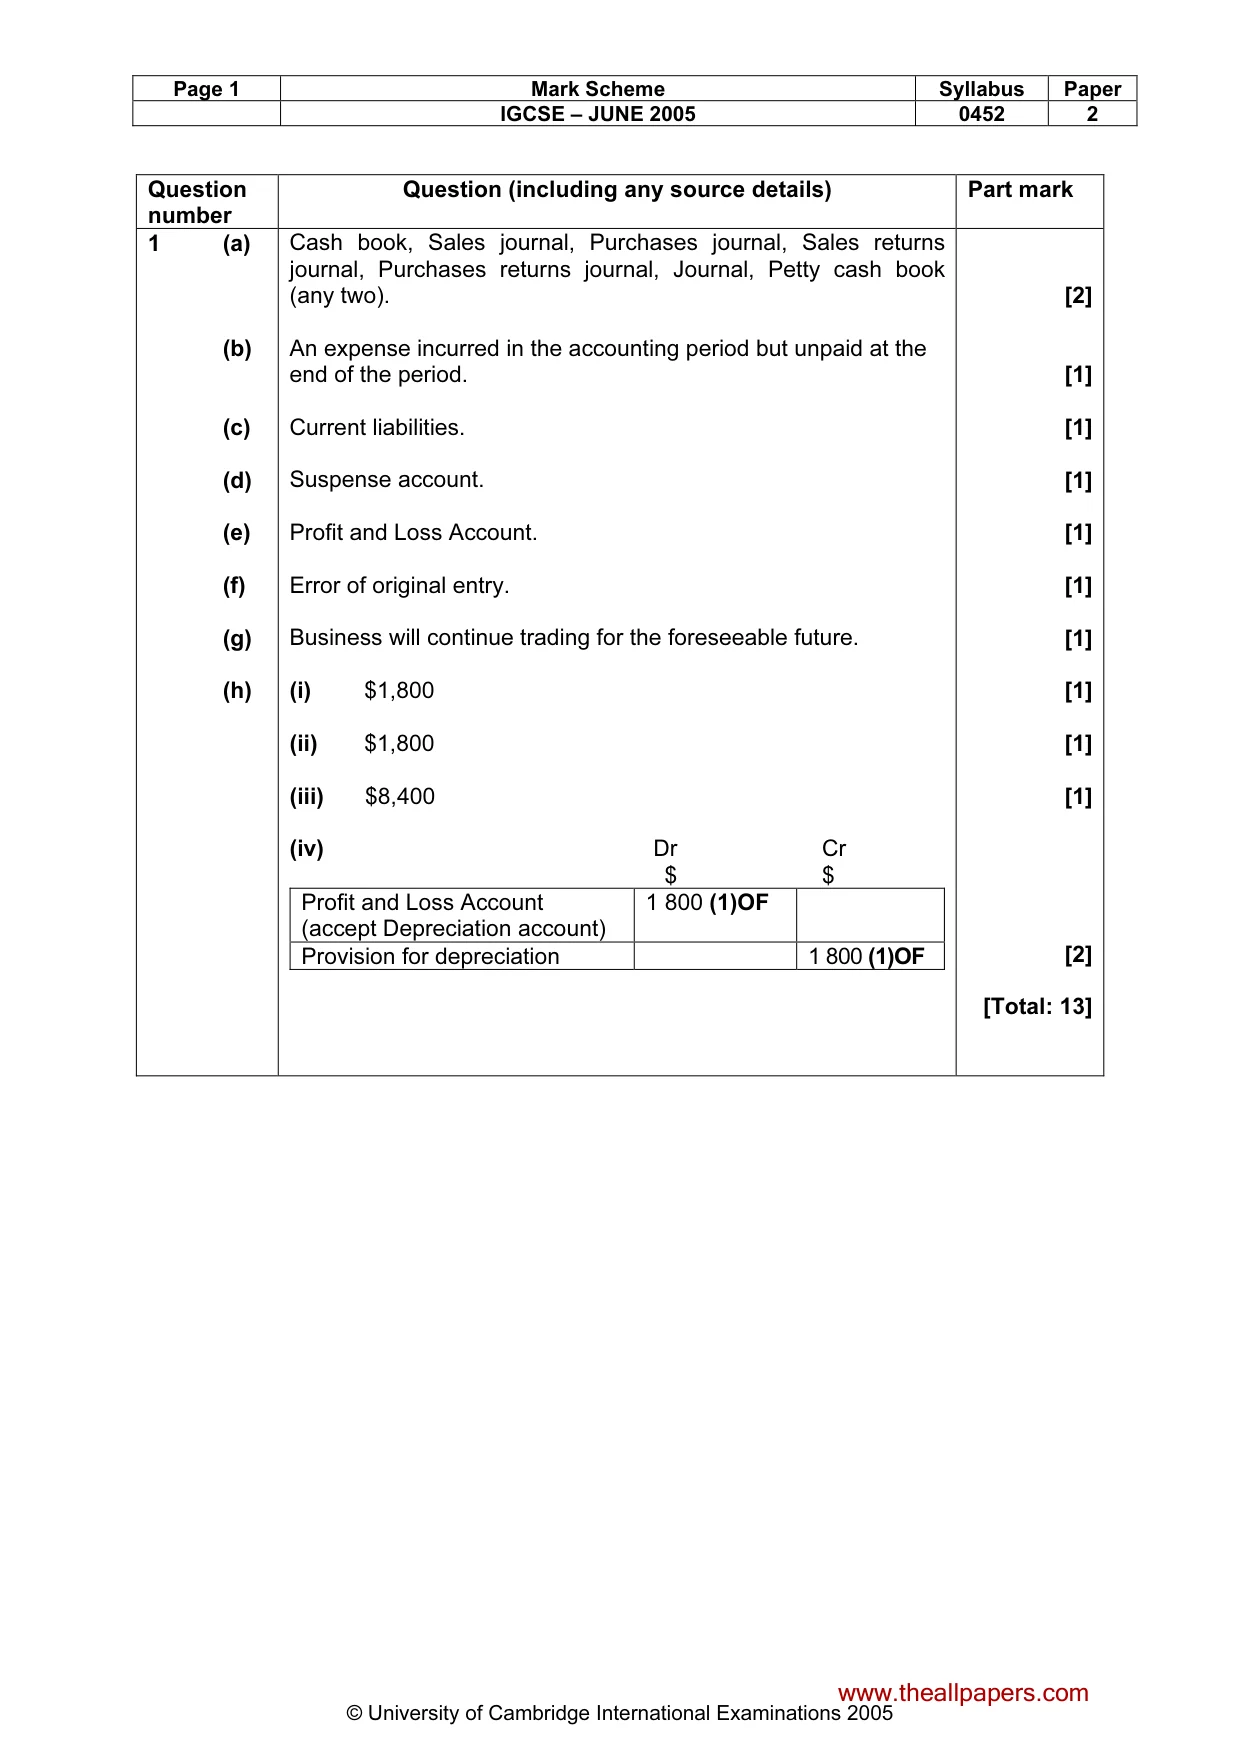
Page 1 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark 1 (a) (b) (c) (d) (e) (f) (g) (h) Cash book, Sales journal, Purchases journal, Sales returns journal, Purchases returns journal, Journal, Petty cash book (any two). An expense incurred in the accounting period but unpaid at the end of the period. Current liabilities. Suspense account. Profit and Loss Account. Error of original entry. Business will continue trading for the foreseeable future. (i) $1,800 (ii) $1,800 (iii) $8,400 (iv) Dr Cr $ $ Profit and Loss Account (accept Depreciation account) 1 800 (1)OF Provision for depreciation 1 800 (1)OF [2] [1] [1] [1] [1] [1] [1] [1] [1] [1] [2] [Total: 13] www.theallpapers.com
Mark scheme, page 5
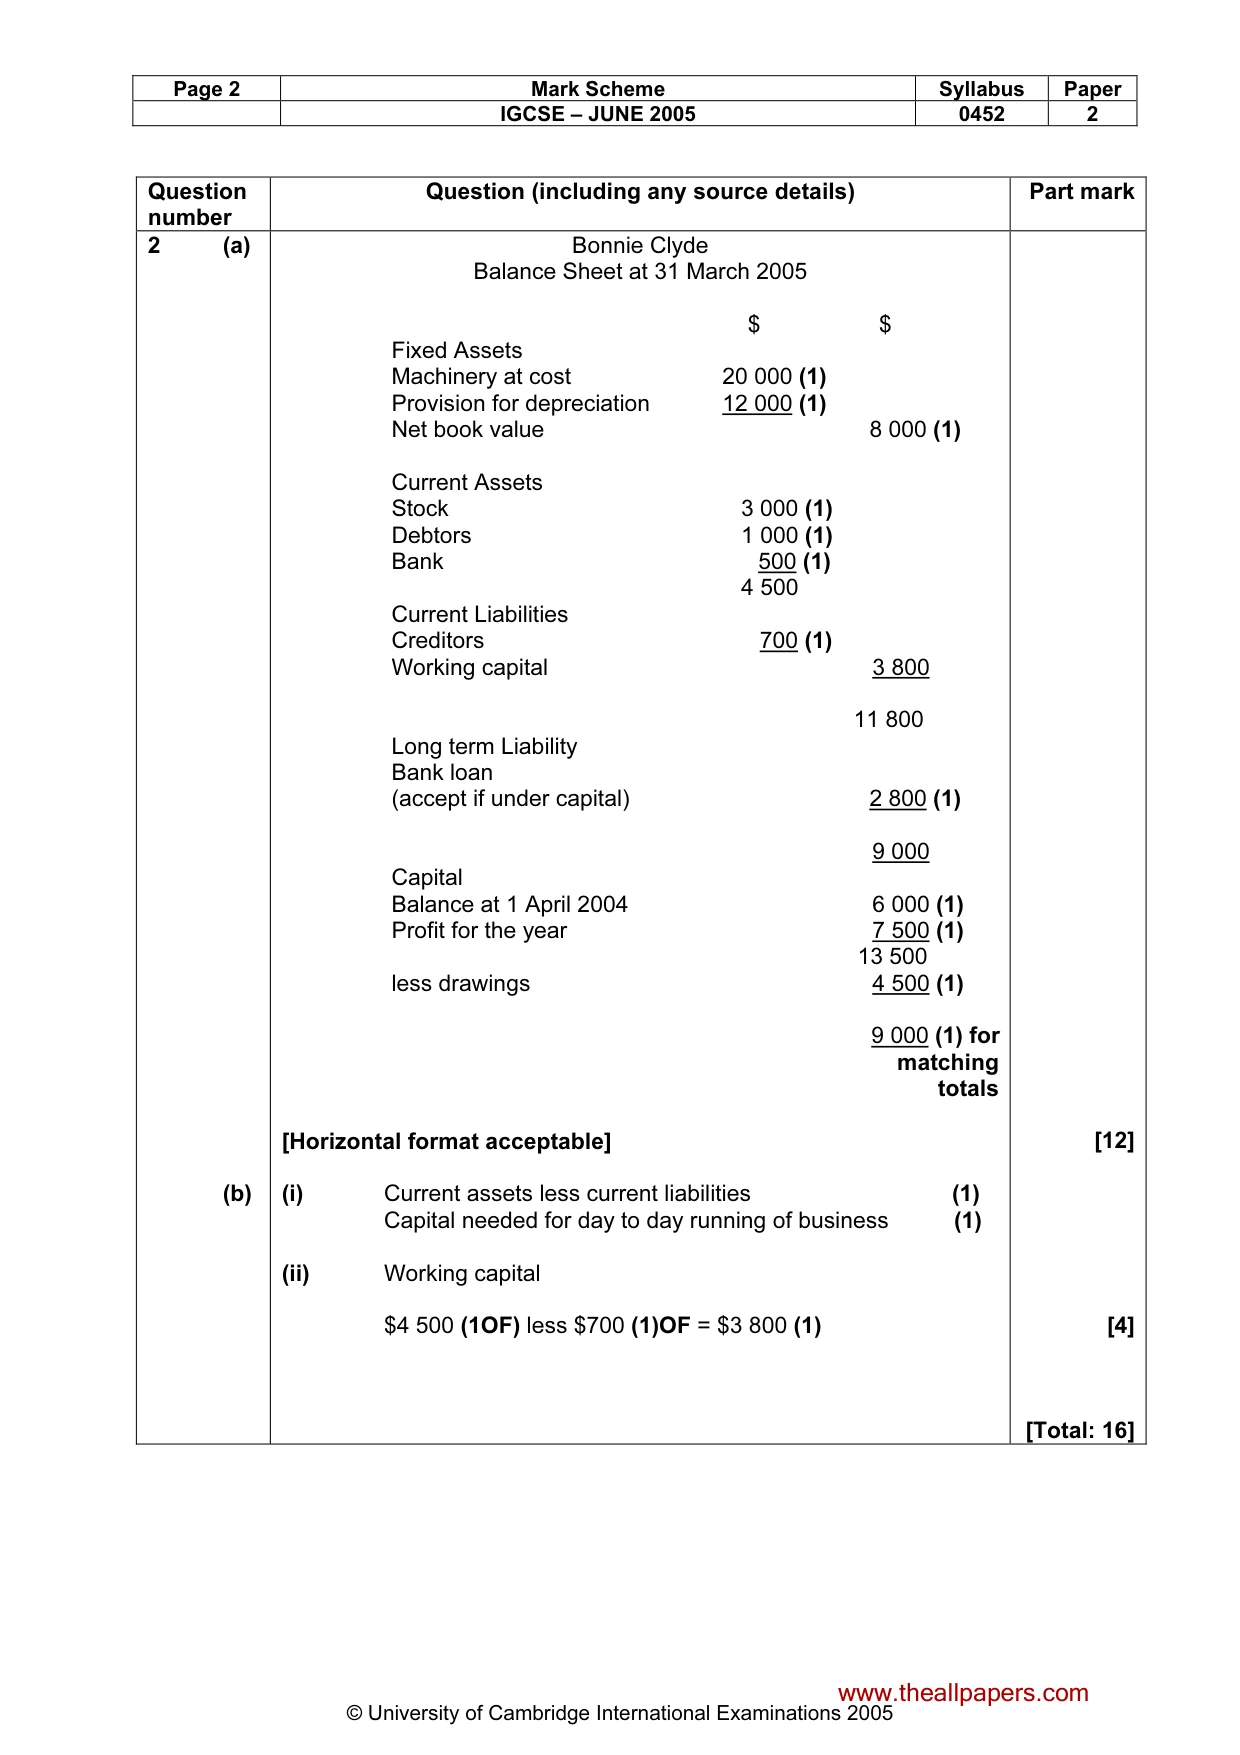
Page 2 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark 2 (a) (b) Bonnie Clyde Balance Sheet at 31 March 2005 $ $ Fixed Assets Machinery at cost 20 000 (1) Provision for depreciation 12 000 (1) Net book value 8 000 (1) Current Assets Stock 3 000 (1) Debtors 1 000 (1) Bank 500 (1) 4 500 Current Liabilities Creditors 700 (1) Working capital 3 800 11 800 Long term Liability Bank loan (accept if under capital) 2 800 (1) 9 000 Capital Balance at 1 April 2004 6 000 (1) Profit for the year 7 500 (1) 13 500 less drawings 4 500 (1) 9 000 (1) for matching totals [Horizontal format acceptable] (i) Current assets less current liabilities (1) Capital needed for day to day running of business (1) (ii) Working capital $4 500 (1OF) less $700 (1)OF = $3 800 (1) [12] [4] [Total: 16] www.theallpapers.com
Mark scheme, page 6
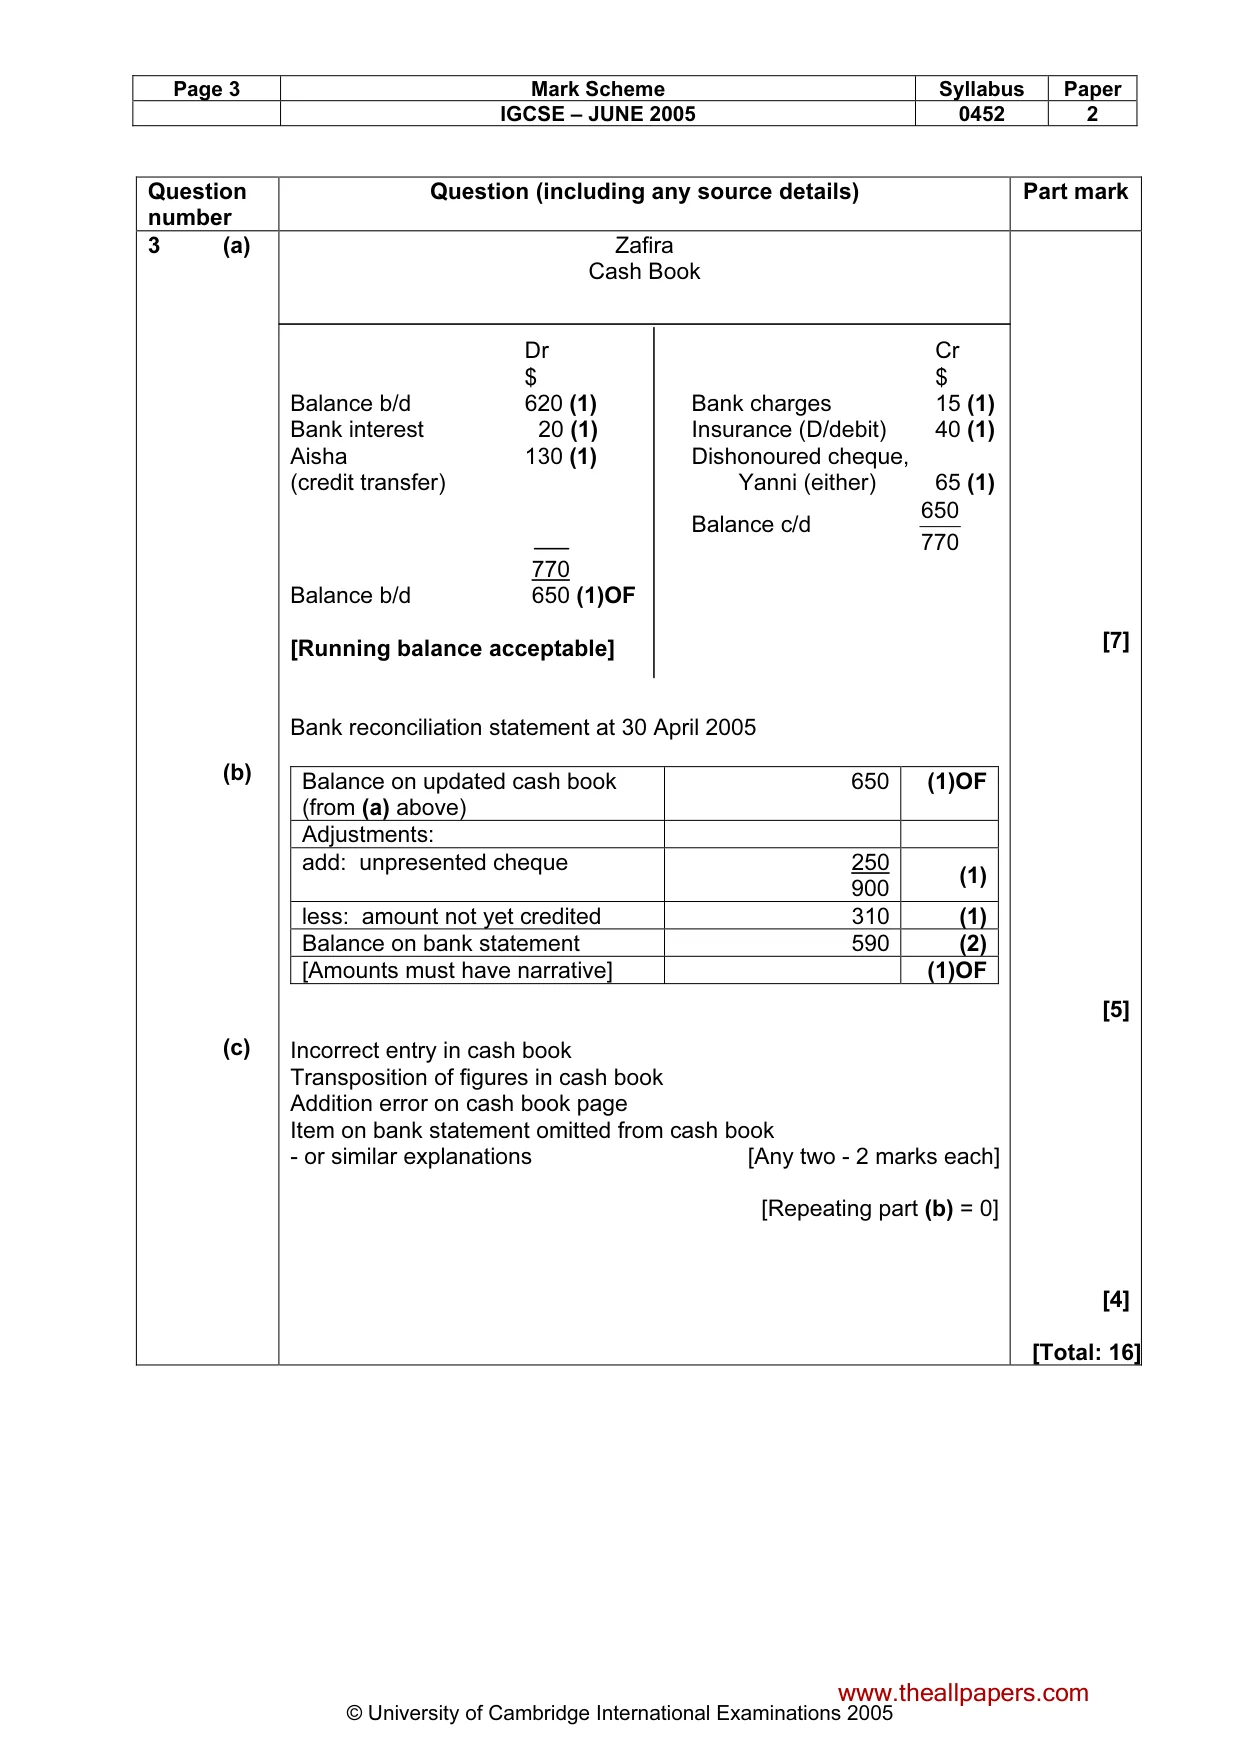
Page 3 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark 3 (a) (b) (c) Zafira Cash Book Dr Cr $ $ Balance b/d 620 (1) Bank charges 15 (1) Bank interest 20 (1) Insurance (D/debit) 40 (1) Aisha 130 (1) Dishonoured cheque, (credit transfer) Yanni (either) 65 (1) Balance c/d 770 650 770 Balance b/d 650 (1)OF [Running balance acceptable] Bank reconciliation statement at 30 April 2005 Balance on updated cash book (from (a) above) 650 (1)OF Adjustments: add: unpresented cheque 250 900 (1) less: amount not yet credited 310 (1) Balance on bank statement 590 (2) [Amounts must have narrative] (1)OF Incorrect entry in cash book Transposition of figures in cash book Addition error on cash book page Item on bank statement omitted from cash book - or similar explanations [Any two - 2 marks each] [Repeating part (b) = 0] [7] [5] [4] [Total: 16] www.theallpapers.com
Mark scheme, page 7
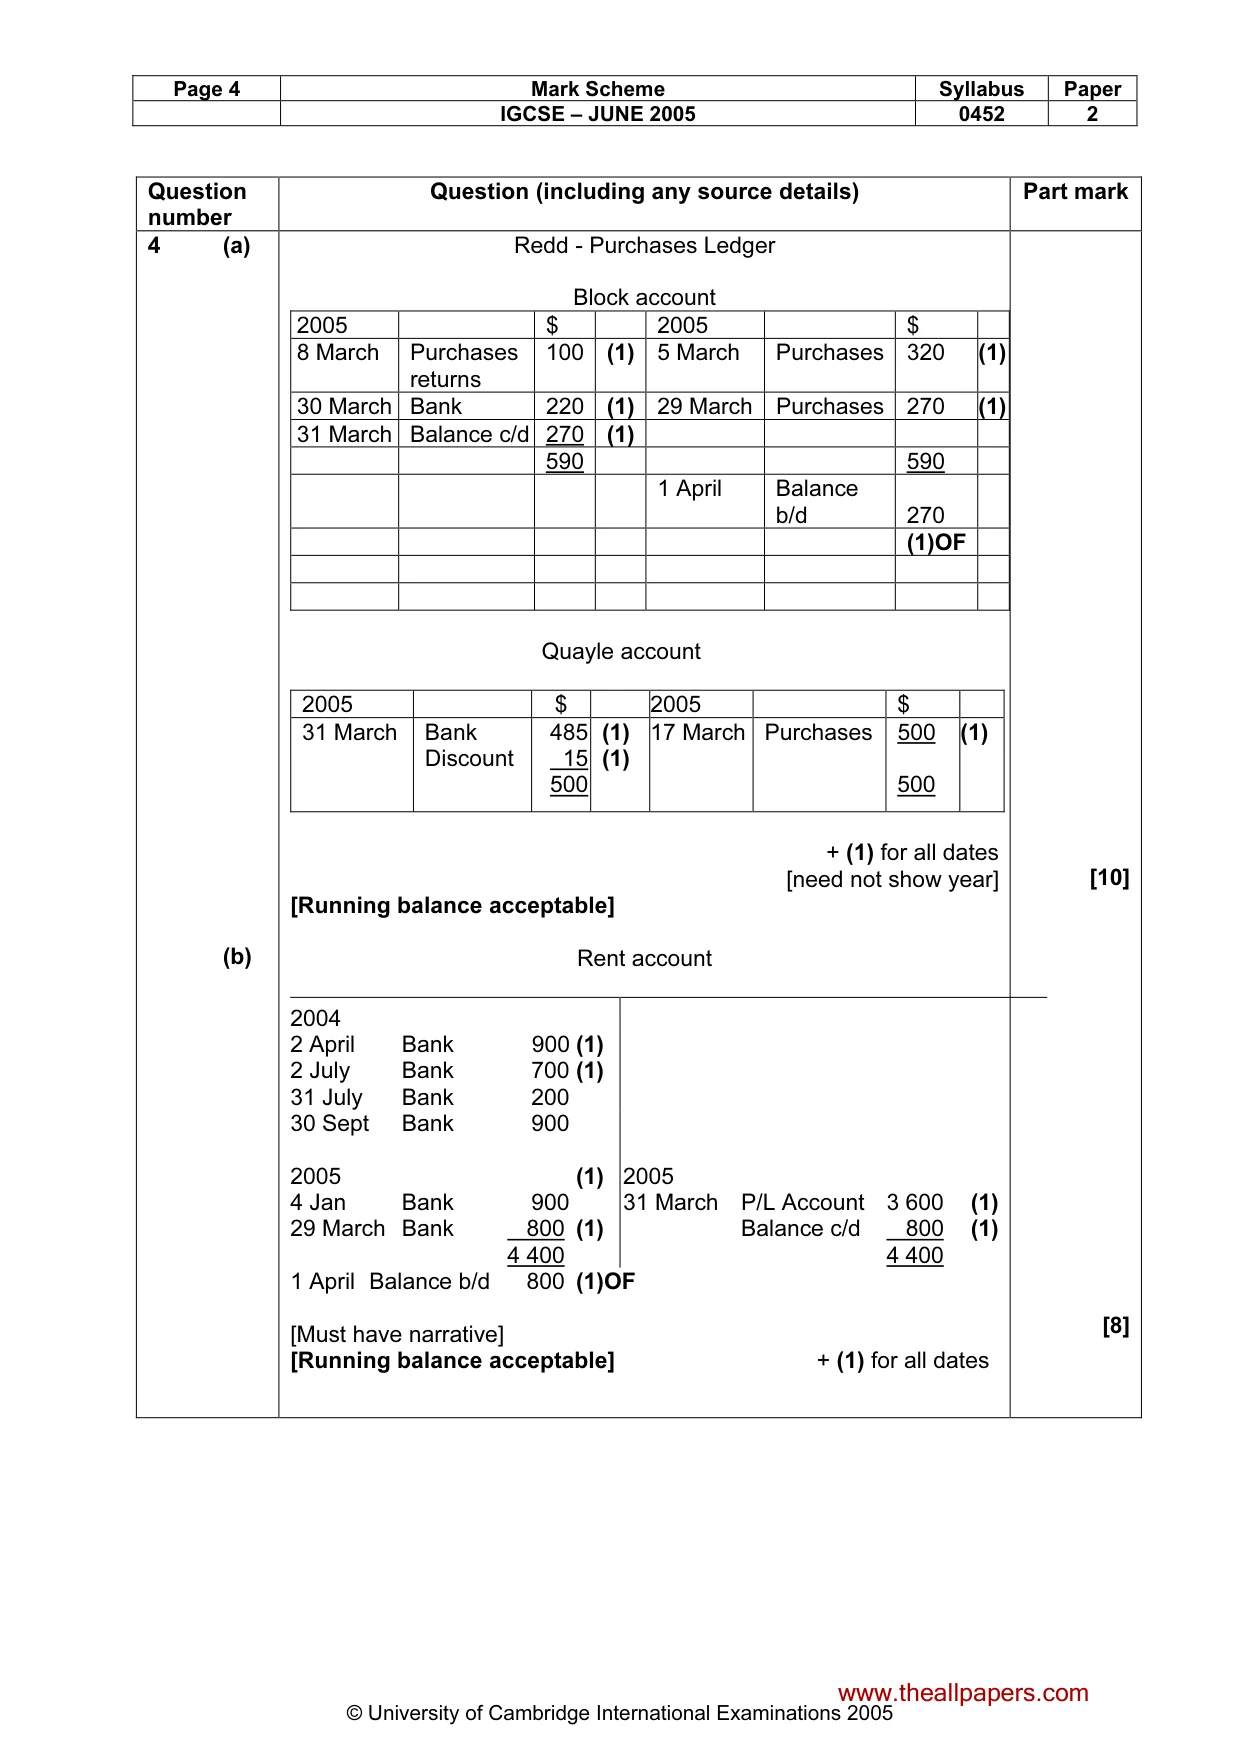
Page 4 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark 4 (a) (b) Redd - Purchases Ledger Block account 2005 $ 2005 $ 8 March Purchases returns 100 (1) 5 March Purchases 320 (1) 30 March Bank 220 (1) 29 March Purchases 270 (1) 31 March Balance c/d 270 (1) 590 590 1 April Balance b/d 270 (1)OF Quayle account 2005 $ 2005 $ 31 March Bank Discount 485 15 500 (1) (1) 17 March Purchases 500 500 (1) + (1) for all dates [need not show year] [Running balance acceptable] Rent account 2004 2 April Bank 900 (1) 2 July Bank 700 (1) 31 July Bank 200 30 Sept Bank 900 2005 (1) 2005 4 Jan Bank 900 31 March P/L Account 3 600 (1) 29 March Bank 800 (1) Balance c/d 800 (1) 4 400 4 400 1 April Balance b/d 800 (1)OF [Must have narrative] [Running balance acceptable] + (1) for all dates [10] [8] www.theallpapers.com
Mark scheme, page 8
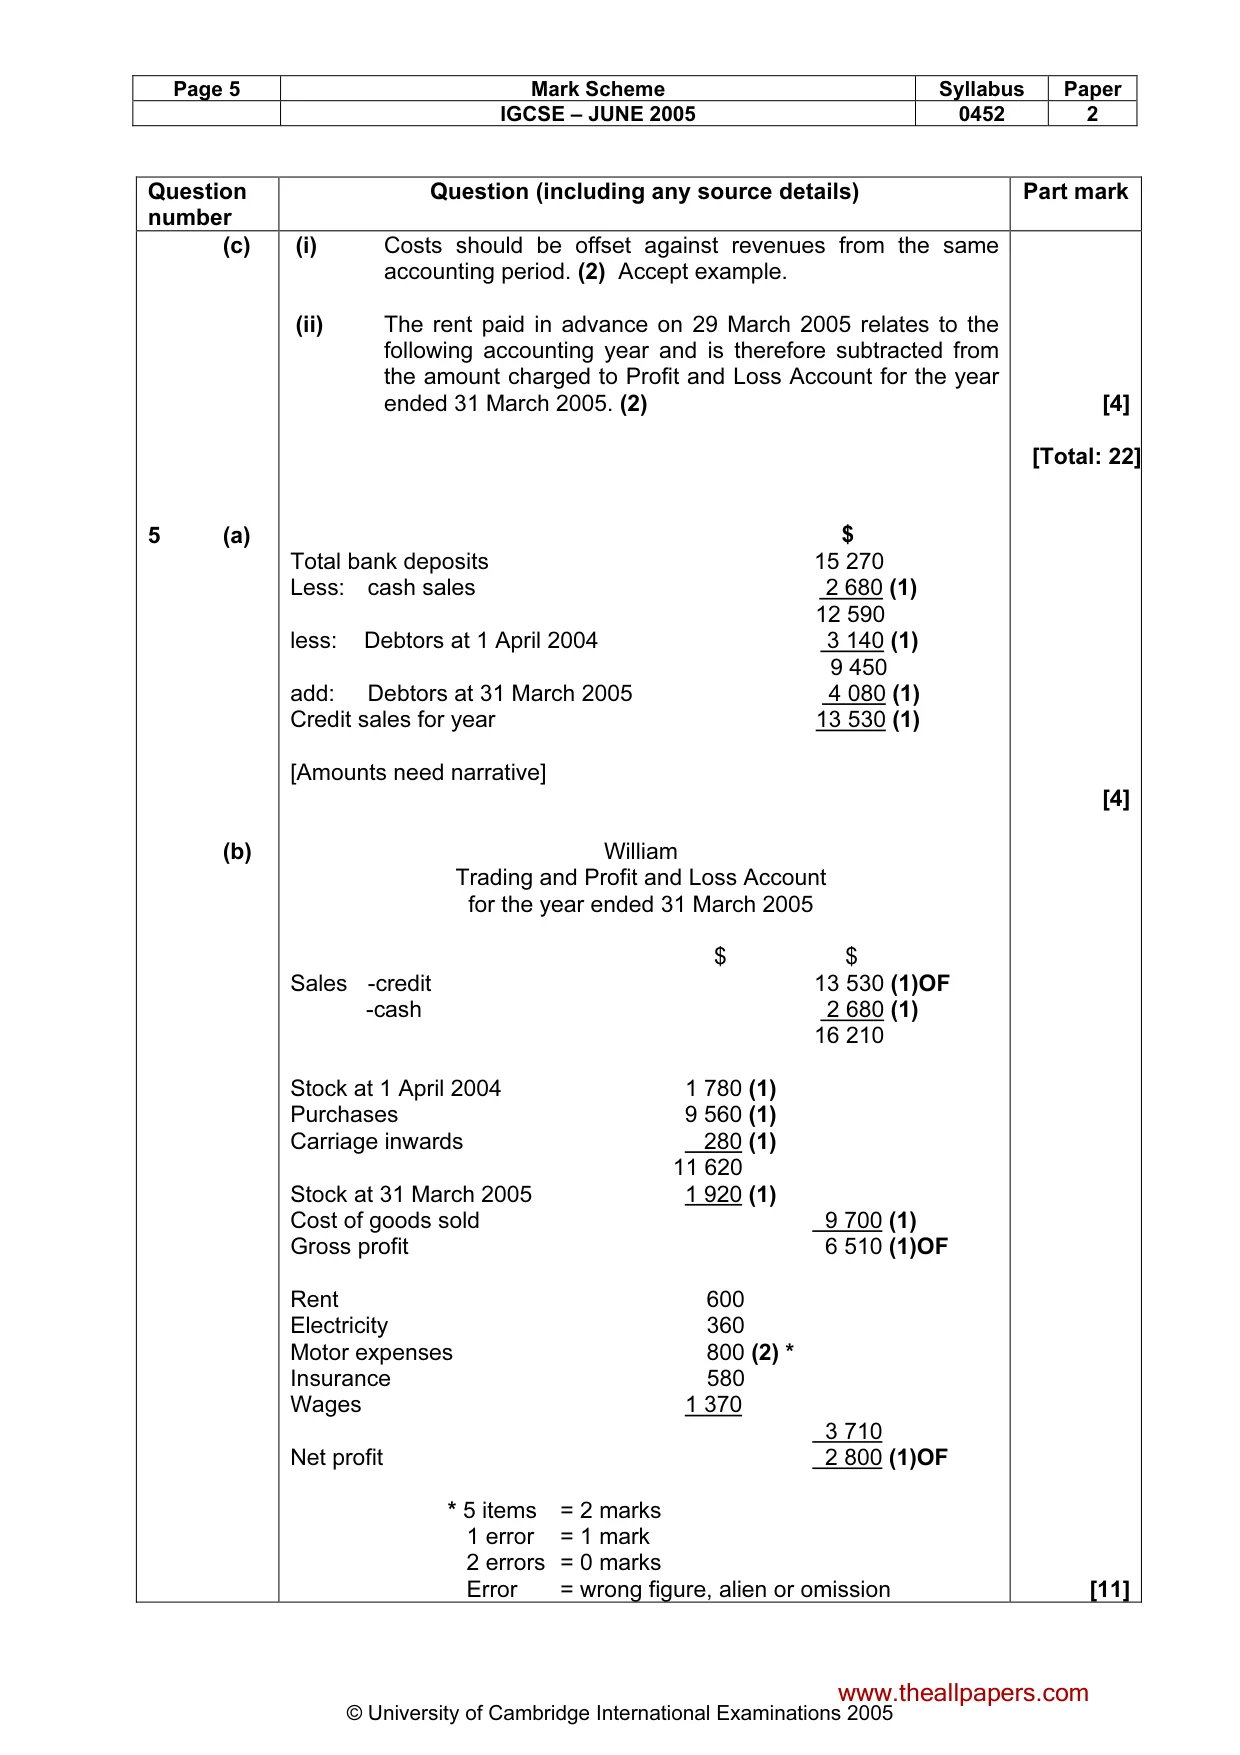
Page 5 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark (c) 5 (a) (b) (i) Costs should be offset against revenues from the same accounting period. (2) Accept example. (ii) The rent paid in advance on 29 March 2005 relates to the following accounting year and is therefore subtracted from the amount charged to Profit and Loss Account for the year ended 31 March 2005. (2) $ Total bank deposits 15 270 Less: cash sales 2 680 (1) 12 590 less: Debtors at 1 April 2004 3 140 (1) 9 450 add: Debtors at 31 March 2005 4 080 (1) Credit sales for year 13 530 (1) [Amounts need narrative] William Trading and Profit and Loss Account for the year ended 31 March 2005 $ $ Sales -credit 13 530 (1)OF -cash 2 680 (1) 16 210 Stock at 1 April 2004 1 780 (1) Purchases 9 560 (1) Carriage inwards 280 (1) 11 620 Stock at 31 March 2005 1 920 (1) Cost of goods sold 9 700 (1) Gross profit 6 510 (1)OF Rent 600 Electricity 360 Motor expenses 800 (2) * Insurance 580 Wages 1 370 3 710 Net profit 2 800 (1)OF * 5 items = 2 marks 1 error = 1 mark 2 errors = 0 marks Error = wrong figure, alien or omission [4] [Total: 22] [4] [11] www.theallpapers.com
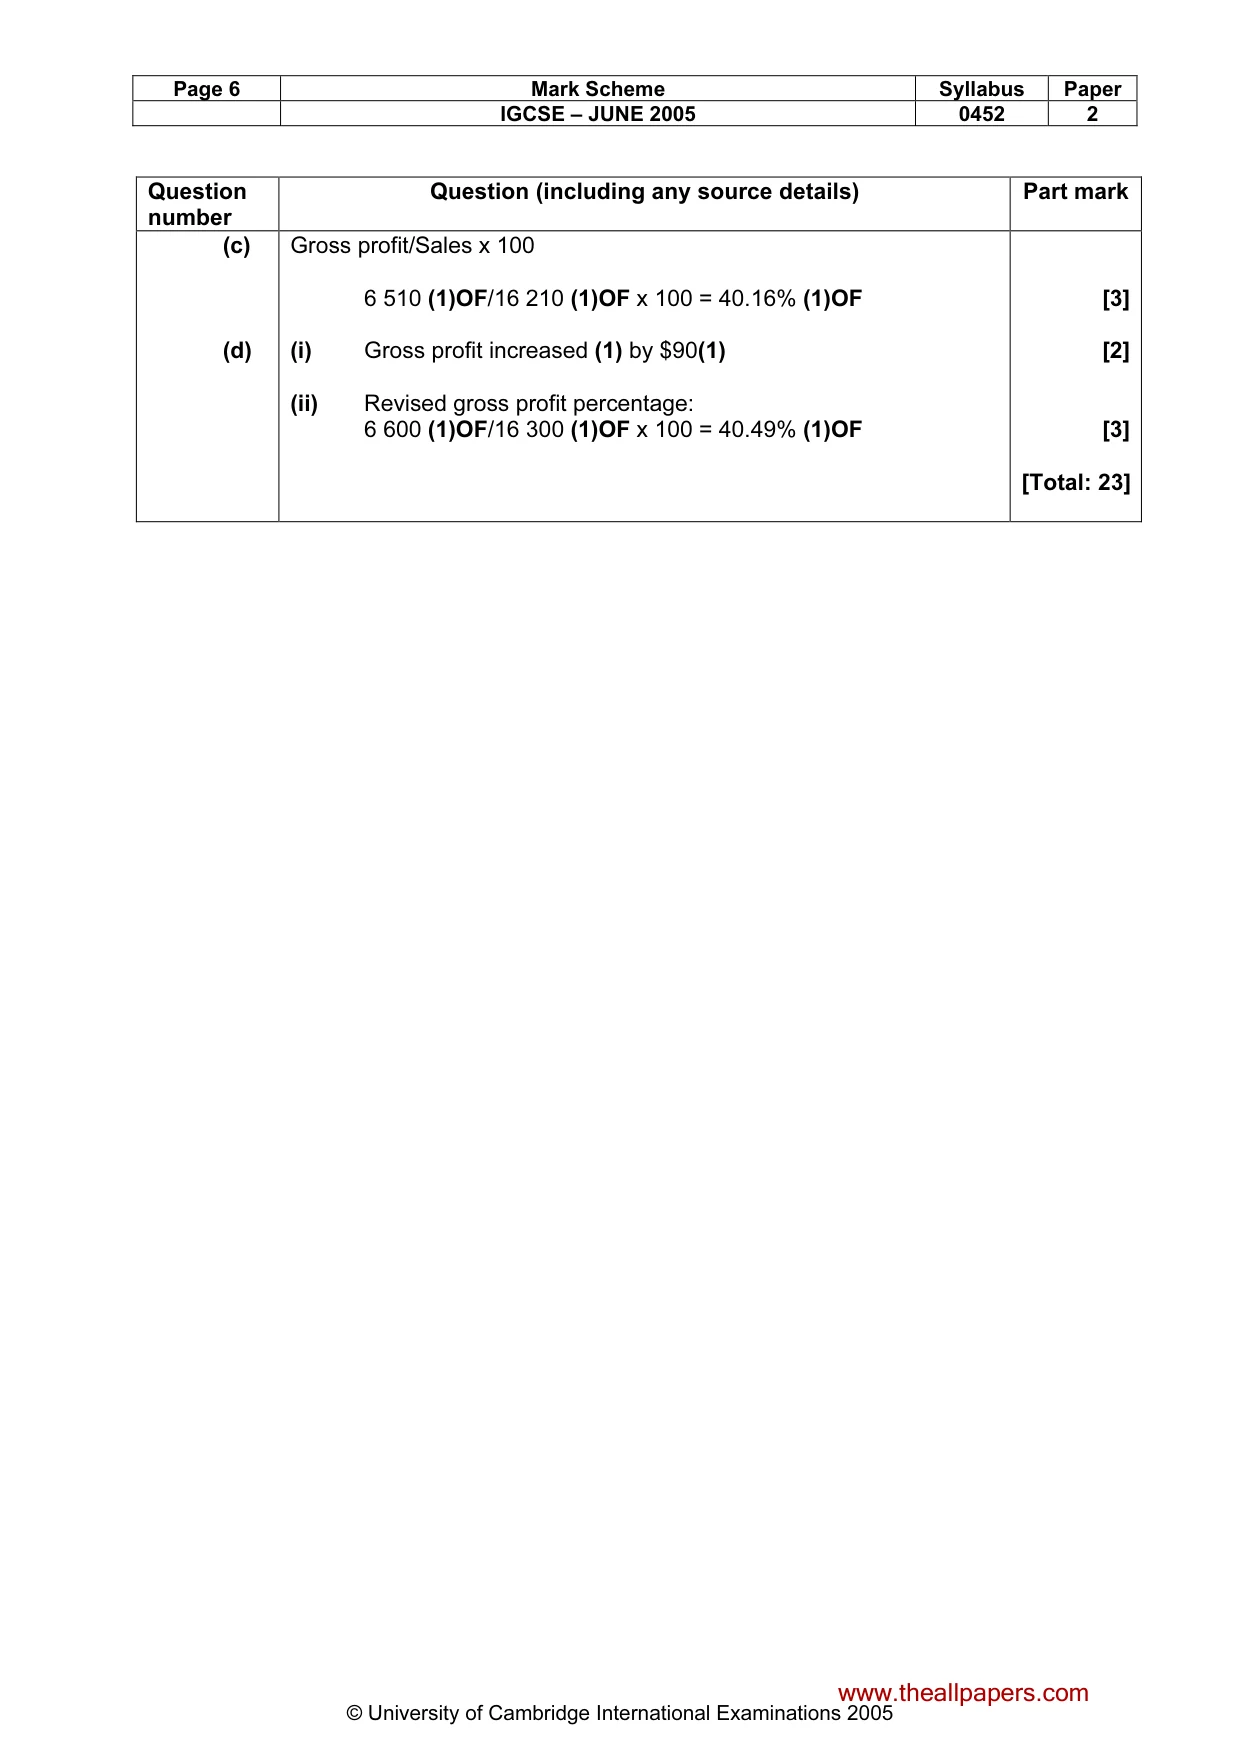
Mark scheme, page 9
Page 6 Mark Scheme Syllabus Paper IGCSE – JUNE 2005 0452 2 © University of Cambridge International Examinations 2005 Question number Question (including any source details) Part mark (c) (d) Gross profit/Sales x 100 6 510 (1)OF/16 210 (1)OF x 100 = 40.16% (1)OF (i) Gross profit increased (1) by $90(1) (ii) Revised gross profit percentage: 6 600 (1)OF/16 300 (1)OF x 100 = 40.49% (1)OF [3] [2] [3] [Total: 23] www.theallpapers.com