Cambridge IGCSE Accounting 0452 — 2002 Oct/Nov Paper 2 · Variant 1
0452/21/O/N/02
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme7 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This question paper consists of 12 printed pages. SP (SJF2289) S15727/4 © CIE 2002 [Turn over International General Certificate of Secondary Education CAMBRIDGE INTERNATIONAL EXAMINATIONS ACCOUNTING 0452/2 PAPER 2 OCTOBER/NOVEMBER SESSION 2002 1 hour 30 minutes Candidates answer on the question paper. No additional materials are required. TIME 1 hour 30 minutes INSTRUCTIONS TO CANDIDATES Write your name, Centre number and candidate number in the spaces provided at the top of this page. Answer all questions. Write your answers in the spaces provided on the question paper. INFORMATION FOR CANDIDATES The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this question paper are fictitious. Candidate Centre Number Number Candidate Name FOR EXAMINER’S USE 1 2 3 4 5 TOTAL www.theallpapers.com
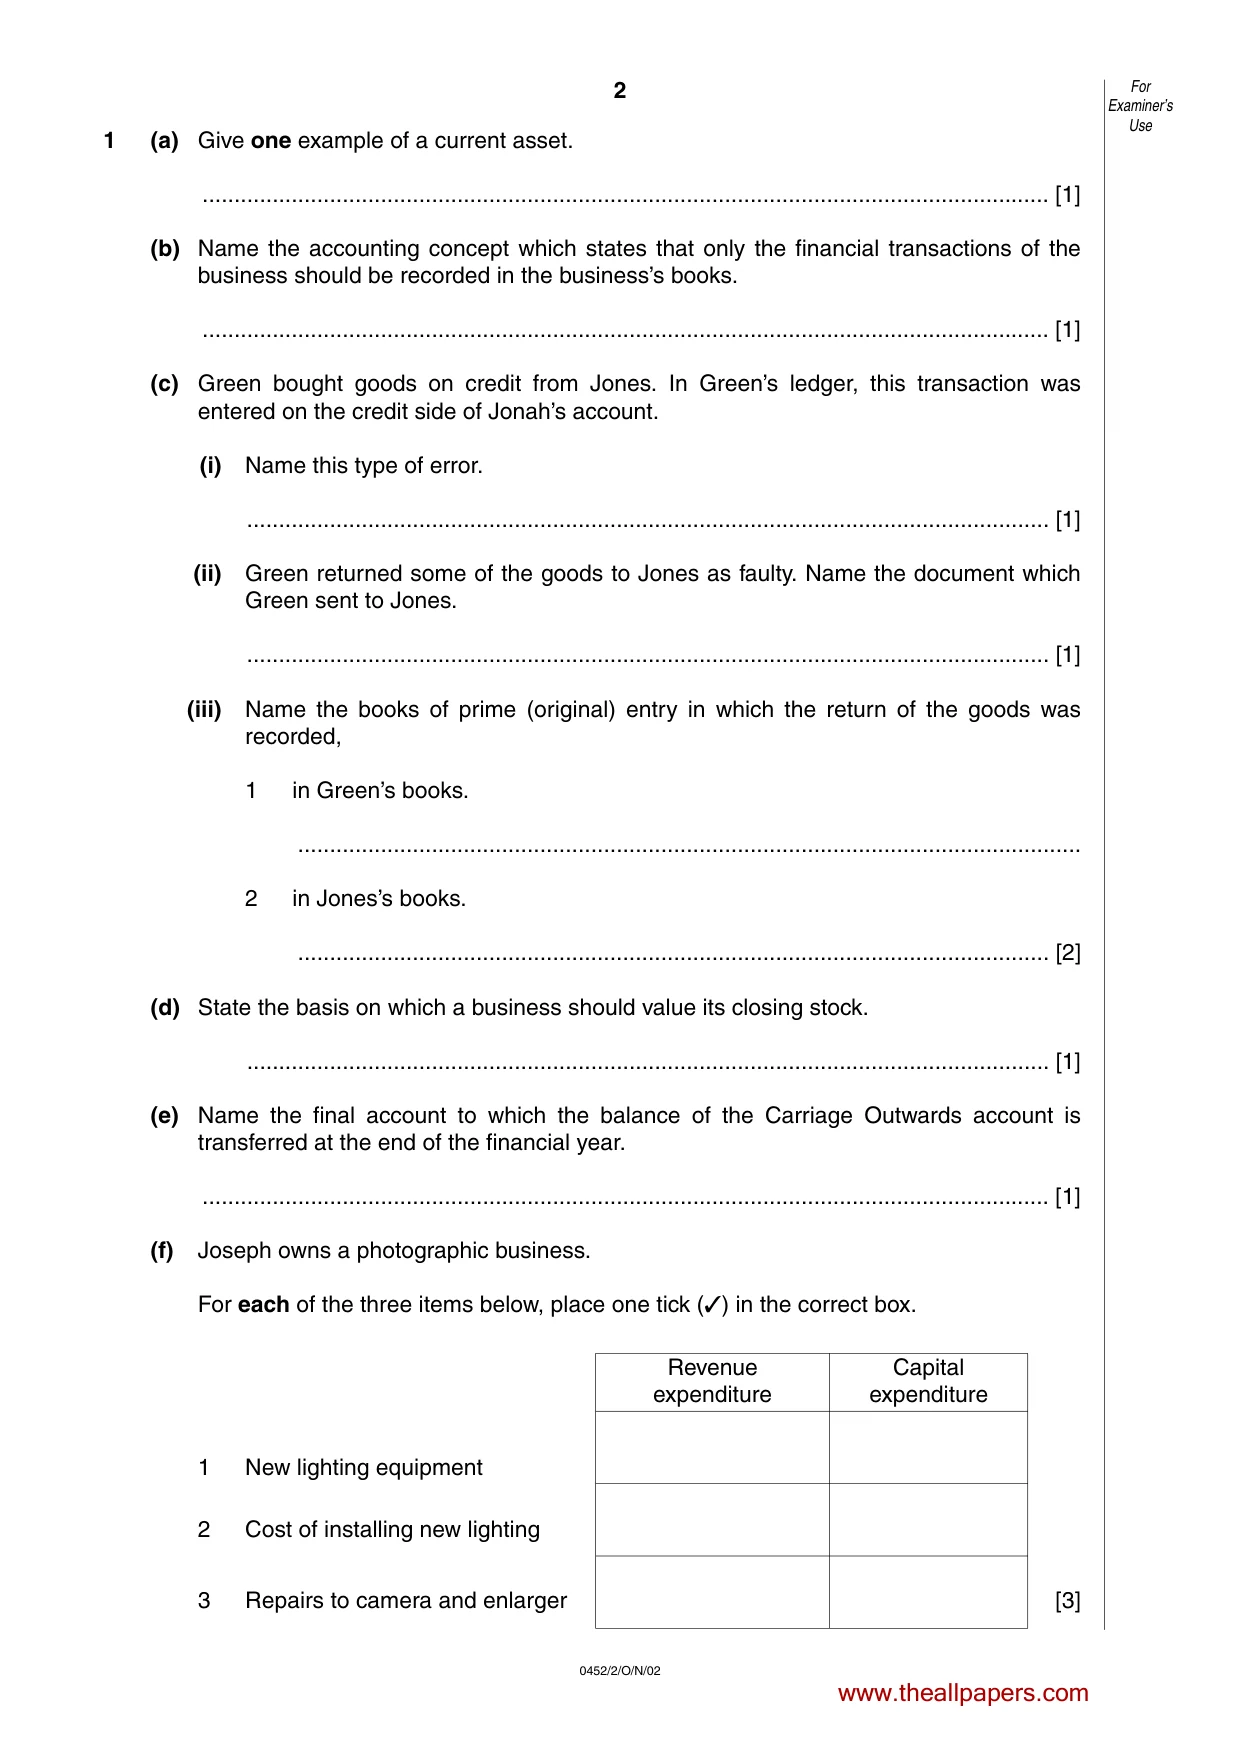
Question paper, page 2
2 0452/2/O/N/02 1 (a) Give one example of a current asset. … [1] (b) Name the accounting concept which states that only the financial transactions of the business should be recorded in the business’s books. … [1] (c) Green bought goods on credit from Jones. In Green’s ledger, this transaction was entered on the credit side of Jonah’s account. (i) Name this type of error. … [1] (ii) Green returned some of the goods to Jones as faulty. Name the document which Green sent to Jones. … [1] (iii) Name the books of prime (original) entry in which the return of the goods was recorded, 1 in Green’s books. … 2 in Jones’s books. … [2] (d) State the basis on which a business should value its closing stock. … [1] (e) Name the final account to which the balance of the Carriage Outwards account is transferred at the end of the financial year. … [1] (f) Joseph owns a photographic business. For each of the three items below, place one tick (✓) in the correct box. 1 New lighting equipment 2 Cost of installing new lighting 3 Repairs to camera and enlarger [3] For Examiner’s Use Revenue expenditure Capital expenditure www.theallpapers.com
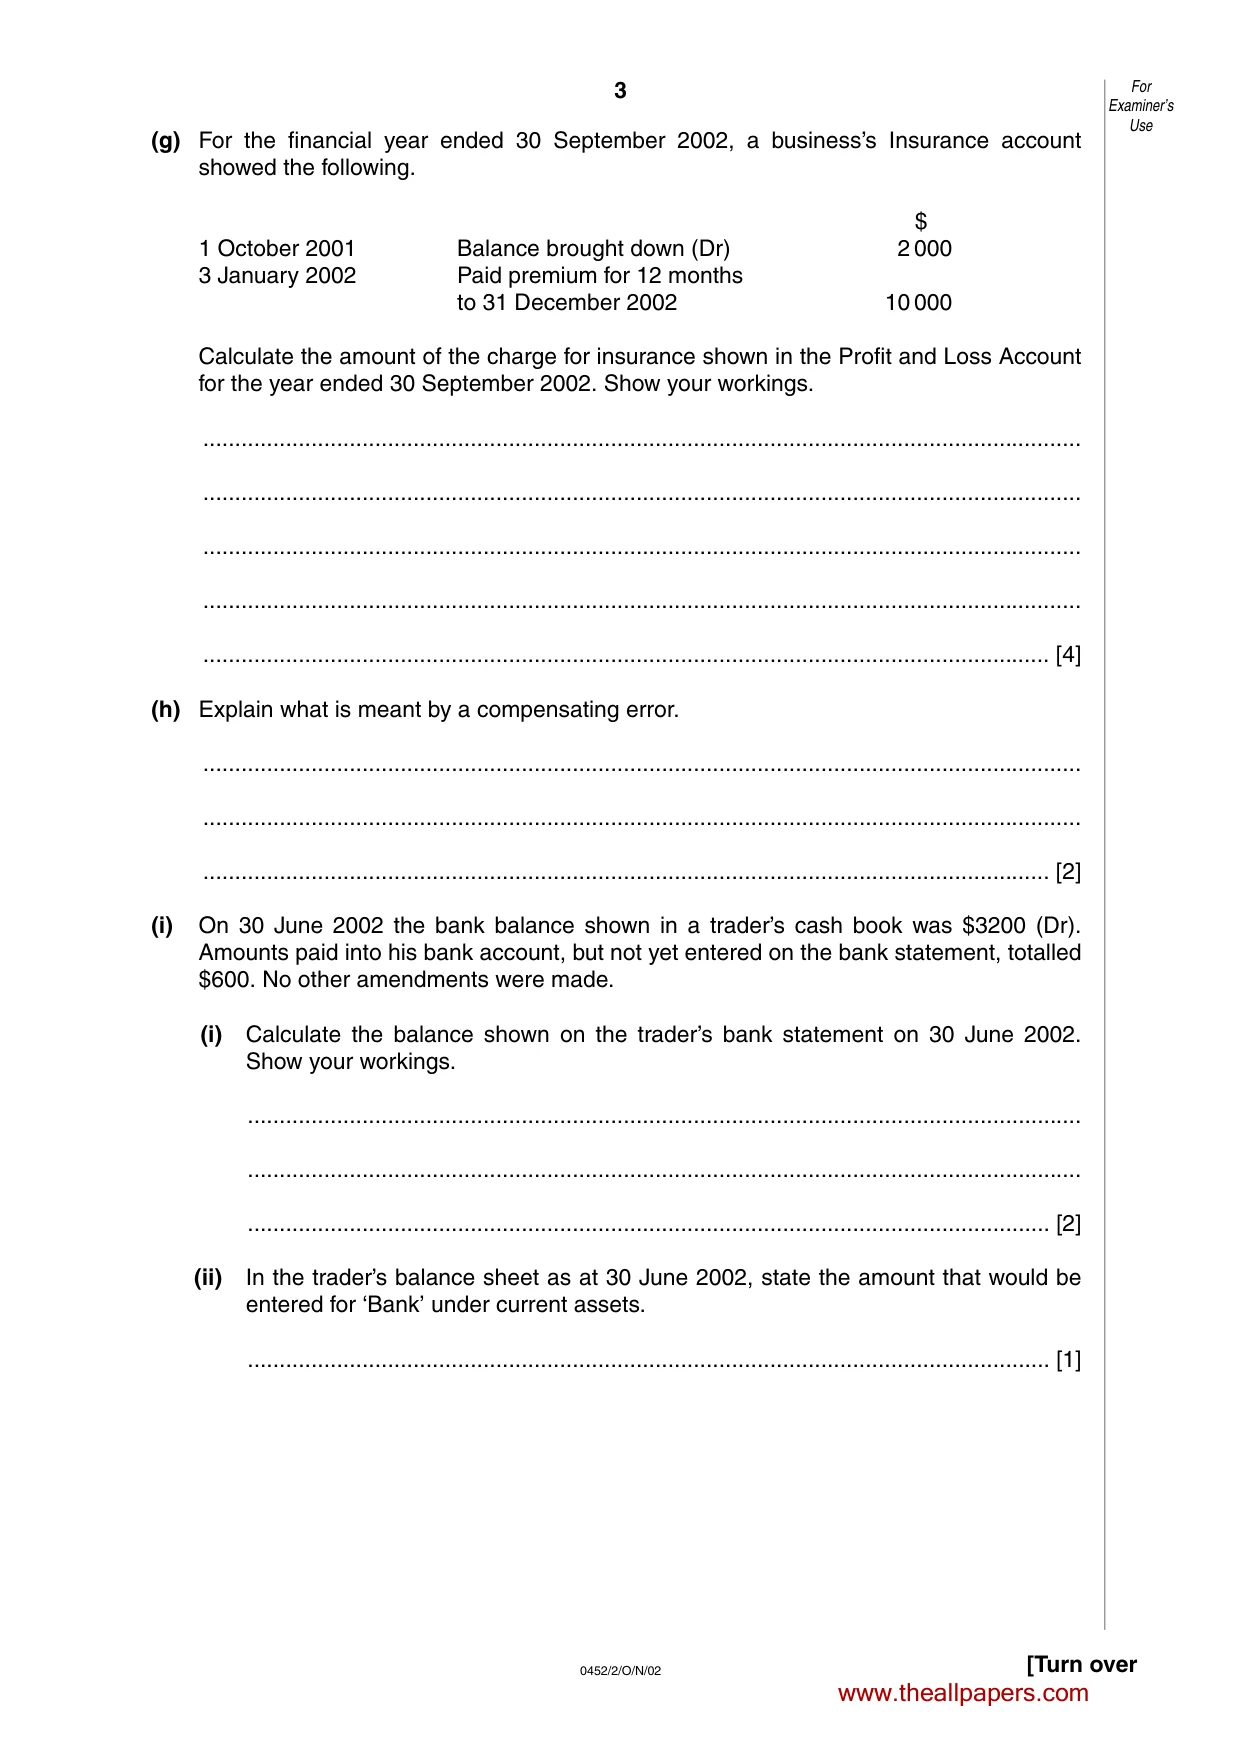
Question paper, page 3
3 0452/2/O/N/02 [Turn over (g) For the financial year ended 30 September 2002, a business’s Insurance account showed the following. $ 1 October 2001 Balance brought down (Dr) 2 000 3 January 2002 Paid premium for 12 months to 31 December 2002 10 000 Calculate the amount of the charge for insurance shown in the Profit and Loss Account for the year ended 30 September 2002. Show your workings. … … … … … [4] (h) Explain what is meant by a compensating error. … … … [2] (i) On 30 June 2002 the bank balance shown in a trader’s cash book was $3200 (Dr). Amounts paid into his bank account, but not yet entered on the bank statement, totalled $600. No other amendments were made. (i) Calculate the balance shown on the trader’s bank statement on 30 June 2002. Show your workings. … … … [2] (ii) In the trader’s balance sheet as at 30 June 2002, state the amount that would be entered for ‘Bank’ under current assets. … [1] For Examiner’s Use www.theallpapers.com
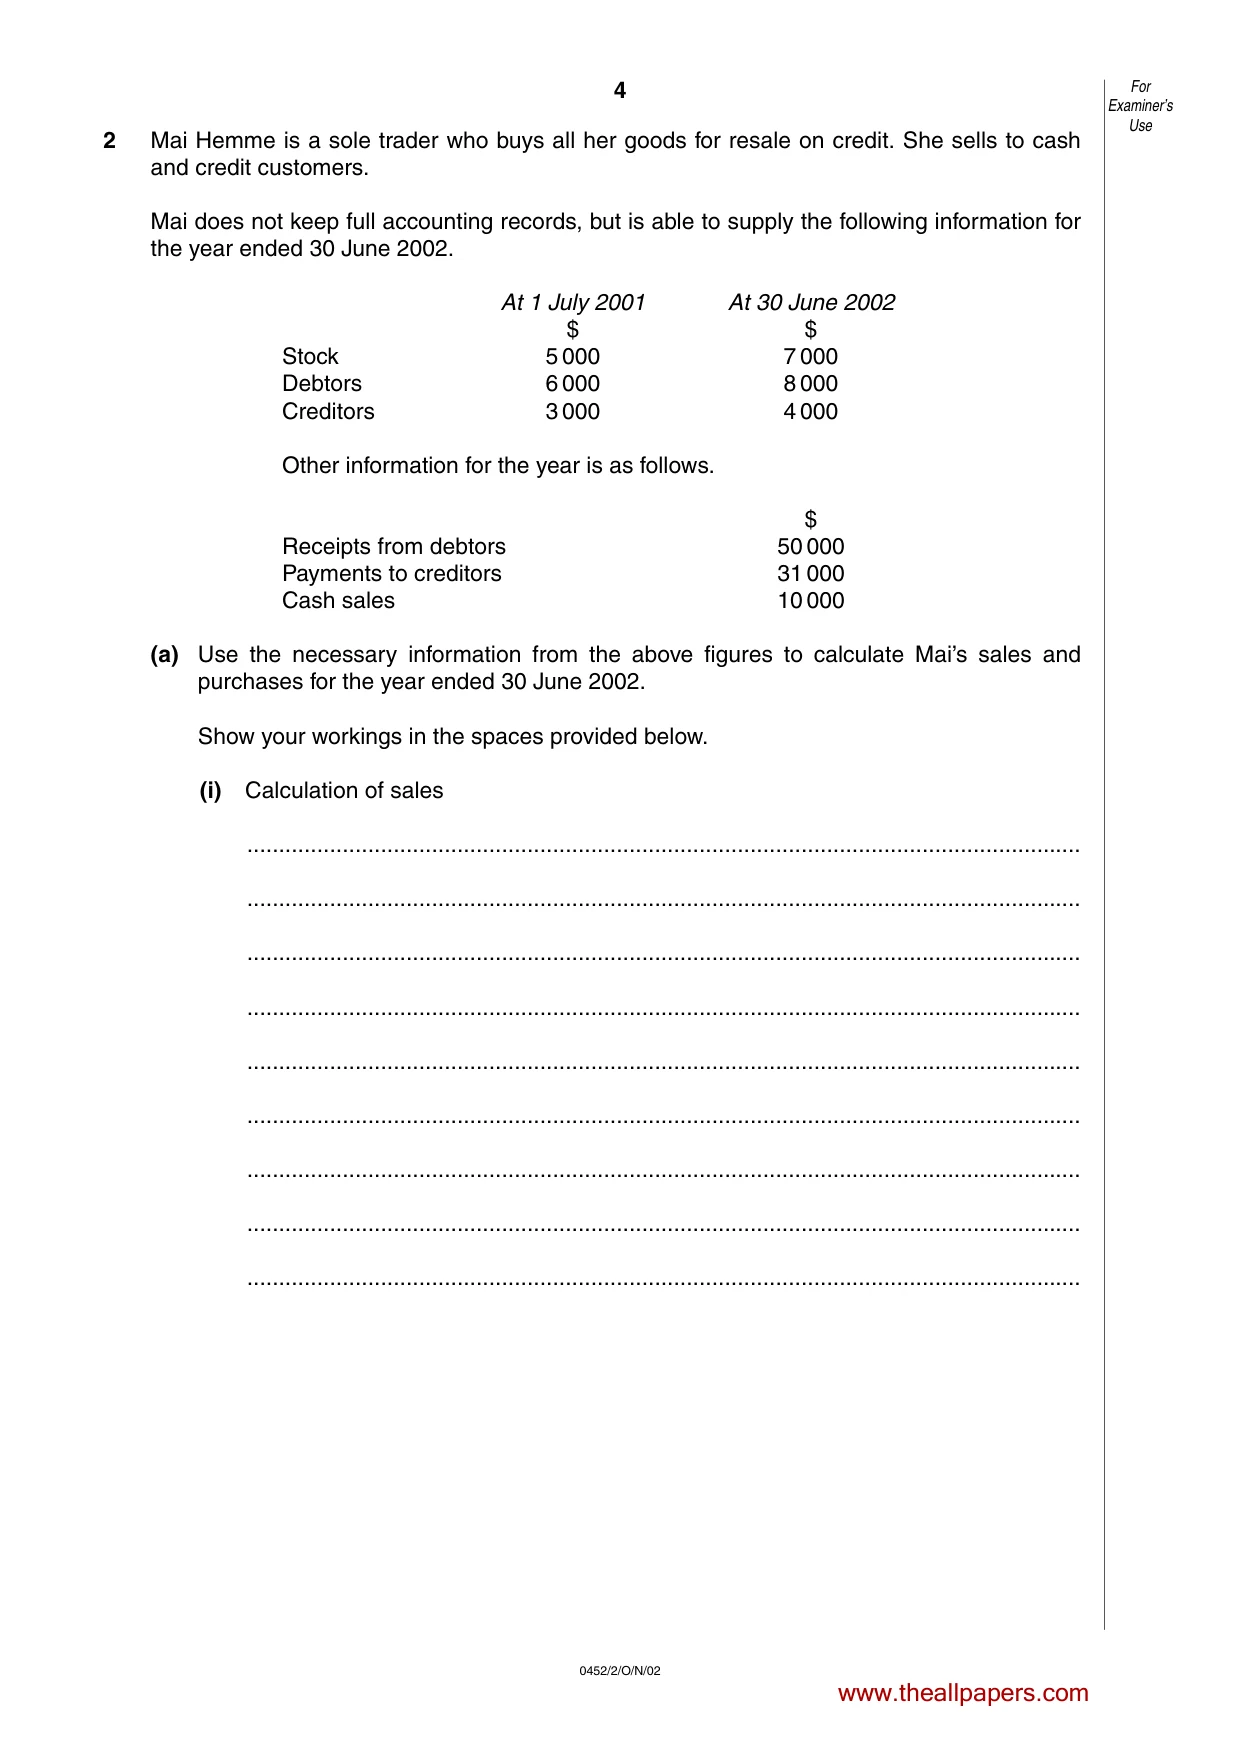
Question paper, page 4
4 0452/2/O/N/02 2 Mai Hemme is a sole trader who buys all her goods for resale on credit. She sells to cash and credit customers. Mai does not keep full accounting records, but is able to supply the following information for the year ended 30 June 2002. At 1 July 2001 At 30 June 2002 $ $ Stock 5 000 7 000 Debtors 6 000 8 000 Creditors 3 000 4 000 Other information for the year is as follows. $ Receipts from debtors 50 000 Payments to creditors 31 000 Cash sales 10 000 (a) Use the necessary information from the above figures to calculate Mai’s sales and purchases for the year ended 30 June 2002. Show your workings in the spaces provided below. (i) Calculation of sales … … … … … … … … … For Examiner’s Use www.theallpapers.com
Question paper, page 5
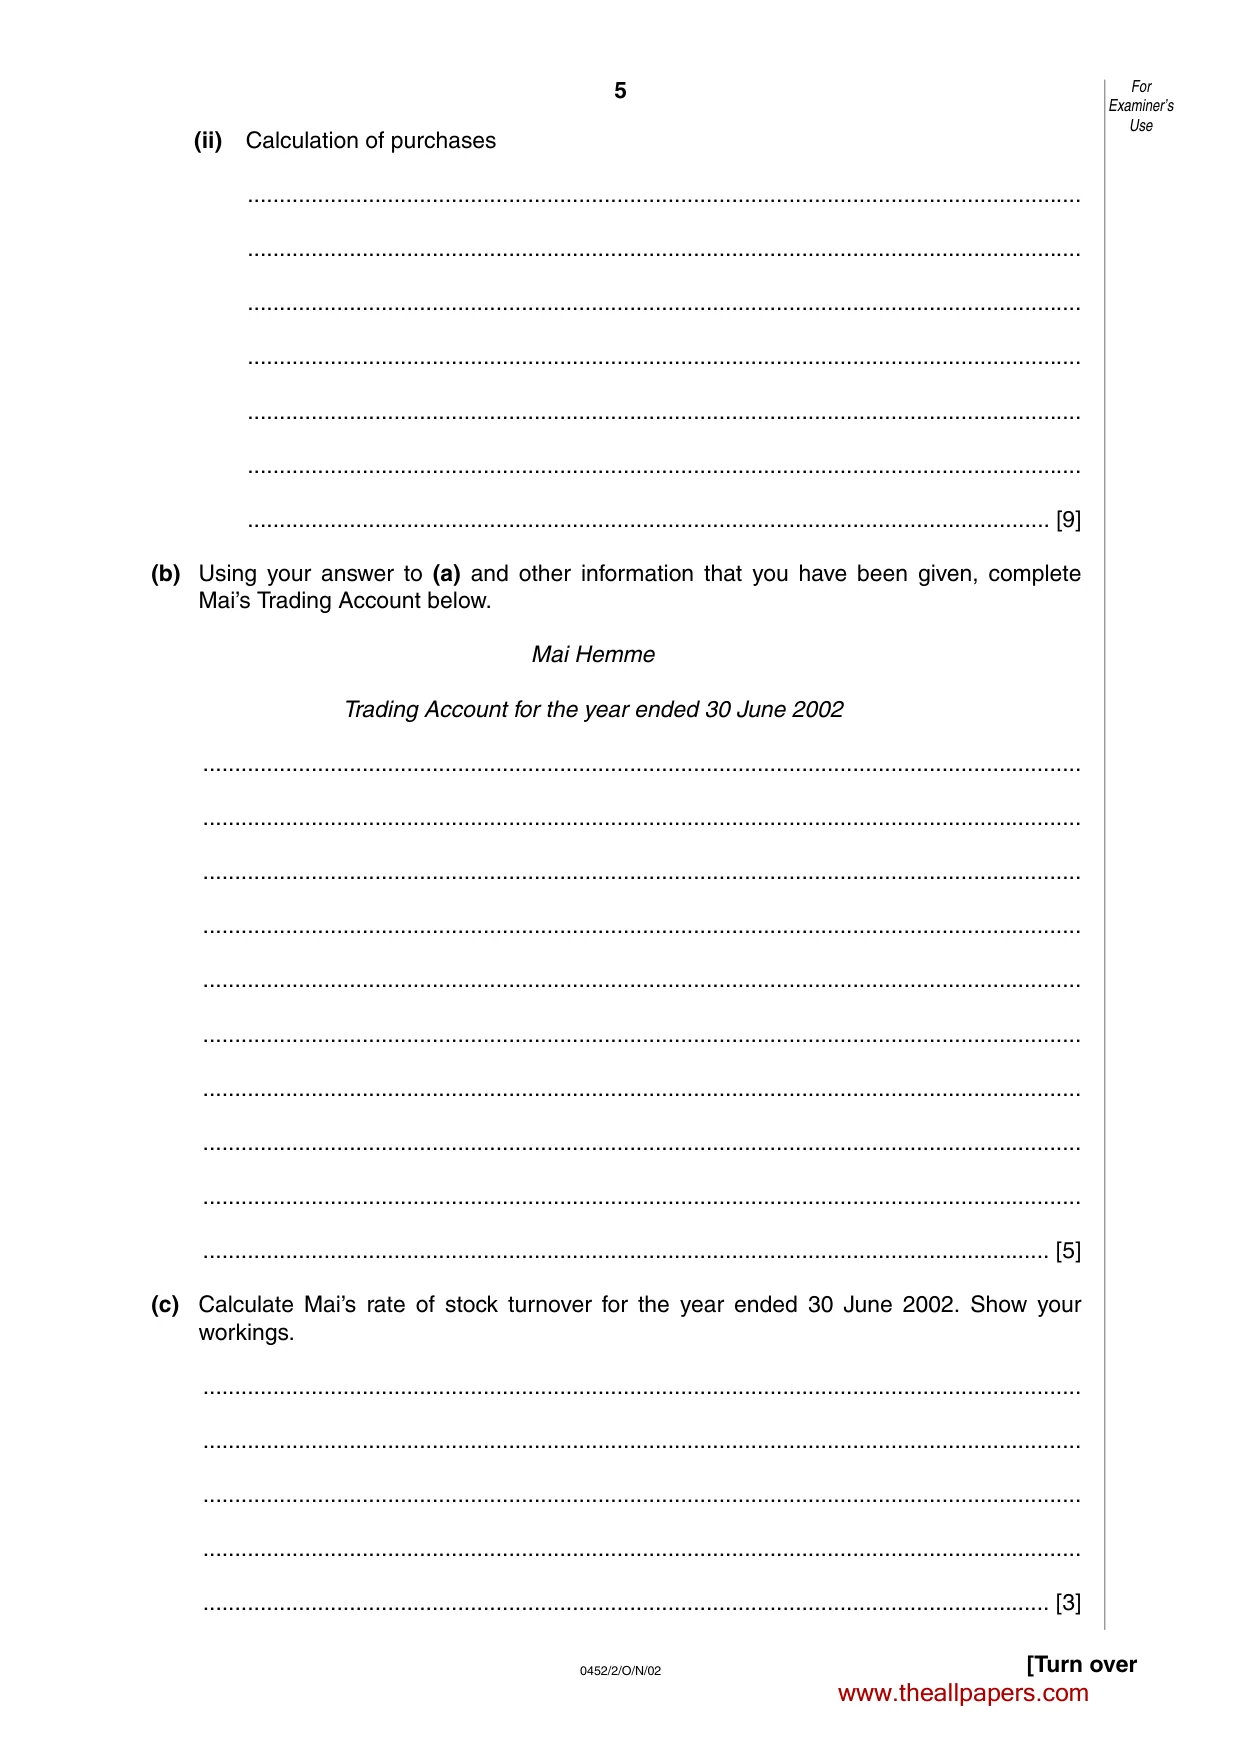
5 0452/2/O/N/02 [Turn over (ii) Calculation of purchases … … … … … … … [9] (b) Using your answer to (a) and other information that you have been given, complete Mai’s Trading Account below. Mai Hemme Trading Account for the year ended 30 June 2002 … … … … … … … … … … [5] (c) Calculate Mai’s rate of stock turnover for the year ended 30 June 2002. Show your workings. … … … … … [3] For Examiner’s Use www.theallpapers.com
Question paper, page 6
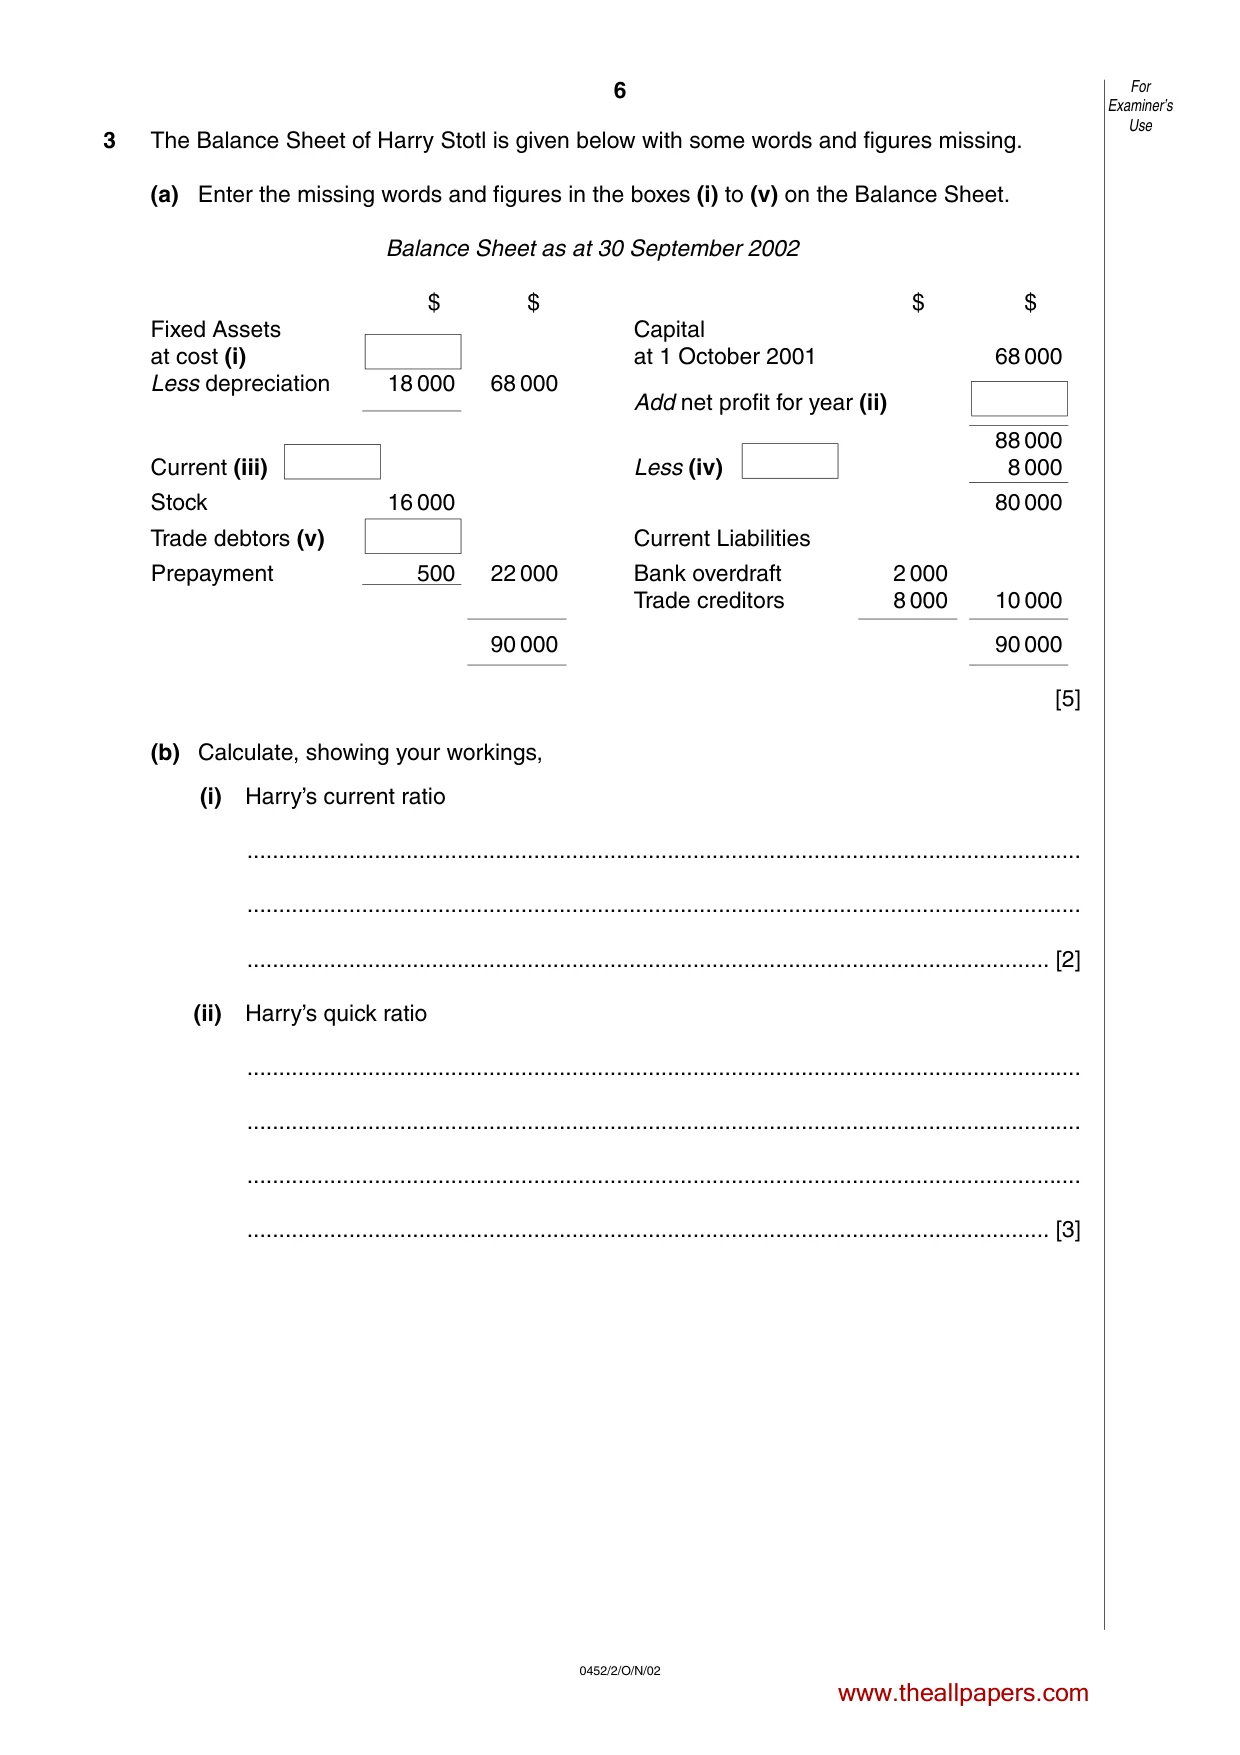
6 0452/2/O/N/02 3 The Balance Sheet of Harry Stotl is given below with some words and figures missing. (a) Enter the missing words and figures in the boxes (i) to (v) on the Balance Sheet. Balance Sheet as at 30 September 2002 $ $ $ $ Fixed Assets Capital at cost (i) at 1 October 2001 68 000 Less depreciation 18 000 68 000 Add net profit for year (ii) 88 000 Current (iii) Less (iv) 8 000 Stock 16 000 80 000 Trade debtors (v) Current Liabilities Prepayment 500 22 000 Bank overdraft 2 000 Trade creditors 8 000 10 000 90 000 90 000 [5] (b) Calculate, showing your workings, (i) Harry’s current ratio … … … [2] (ii) Harry’s quick ratio … … … … [3] For Examiner’s Use www.theallpapers.com
Question paper, page 7
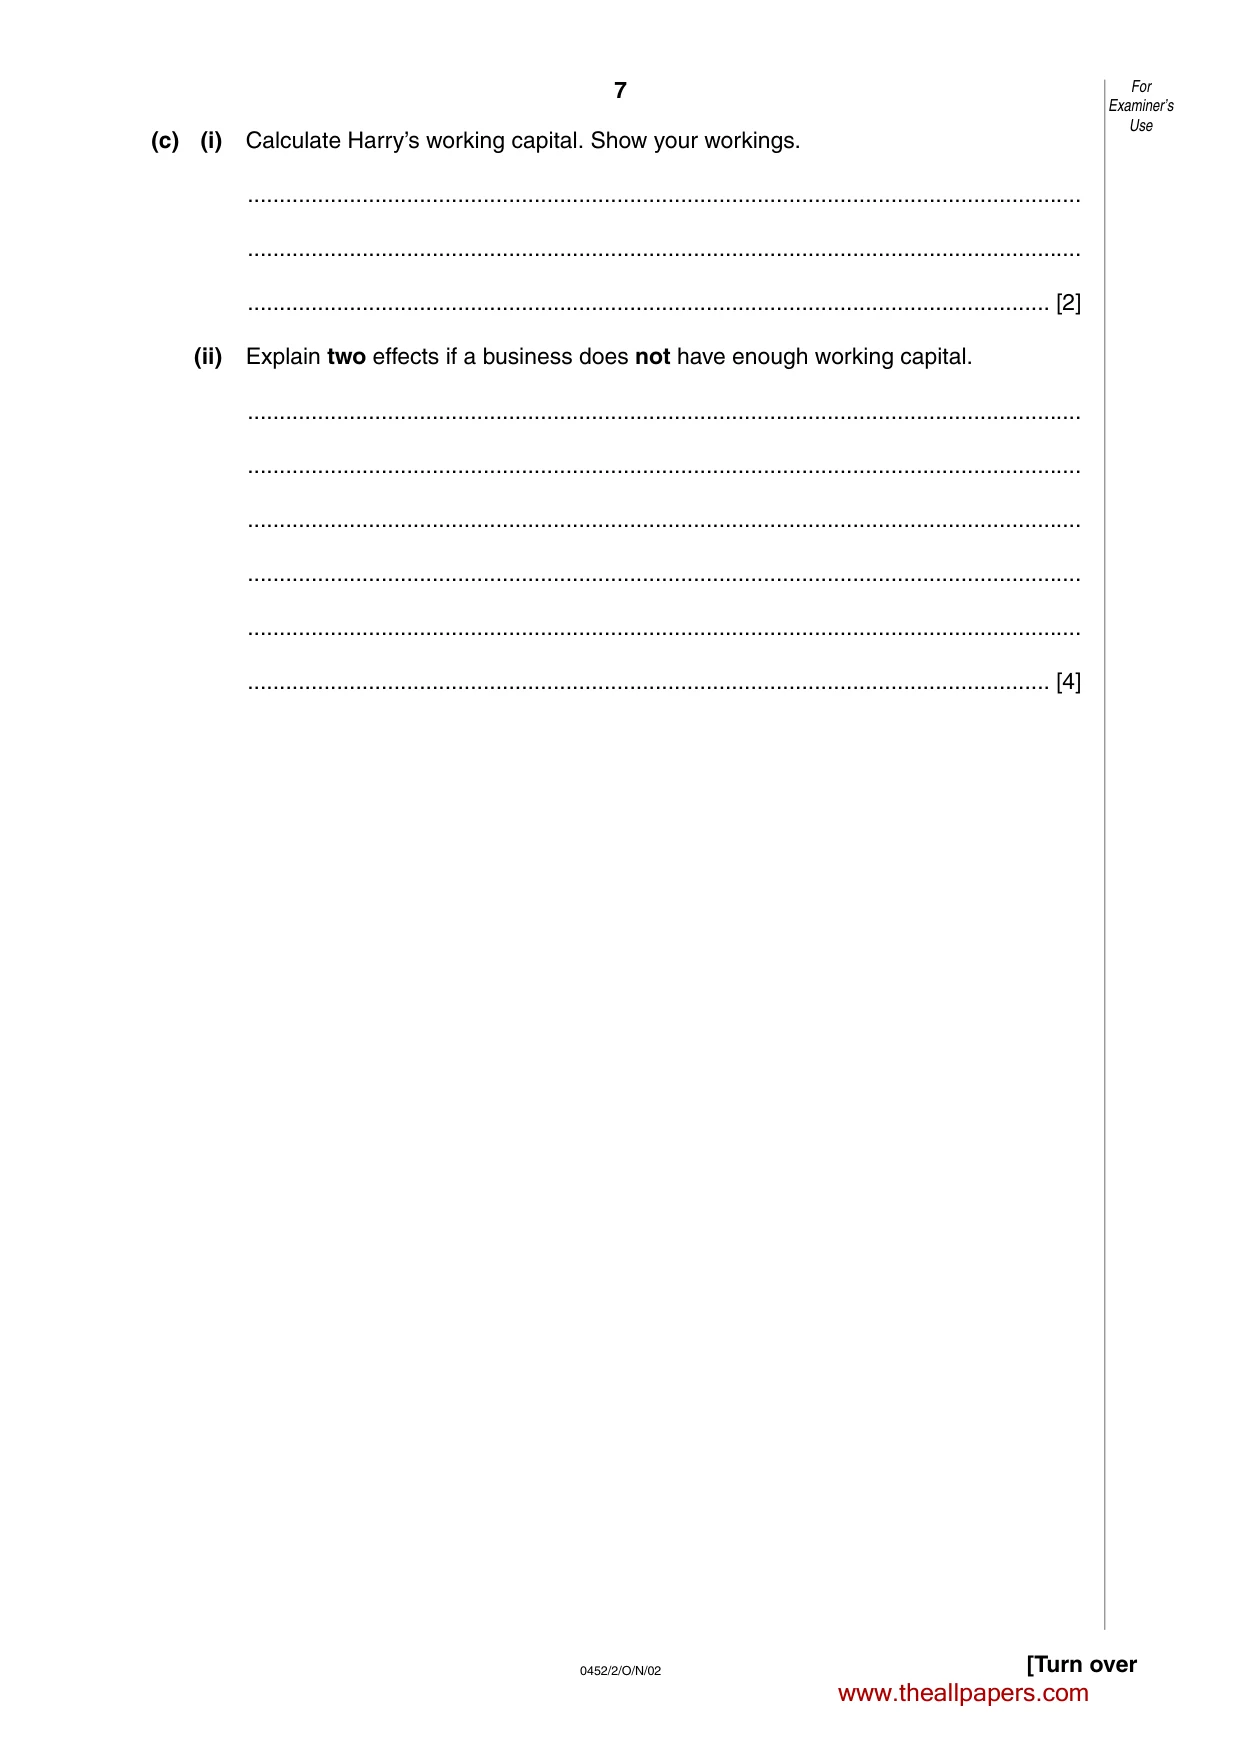
7 0452/2/O/N/02 [Turn over (c) (i) Calculate Harry’s working capital. Show your workings. … … … [2] (ii) Explain two effects if a business does not have enough working capital. … … … … … … [4] For Examiner’s Use www.theallpapers.com
Question paper, page 8
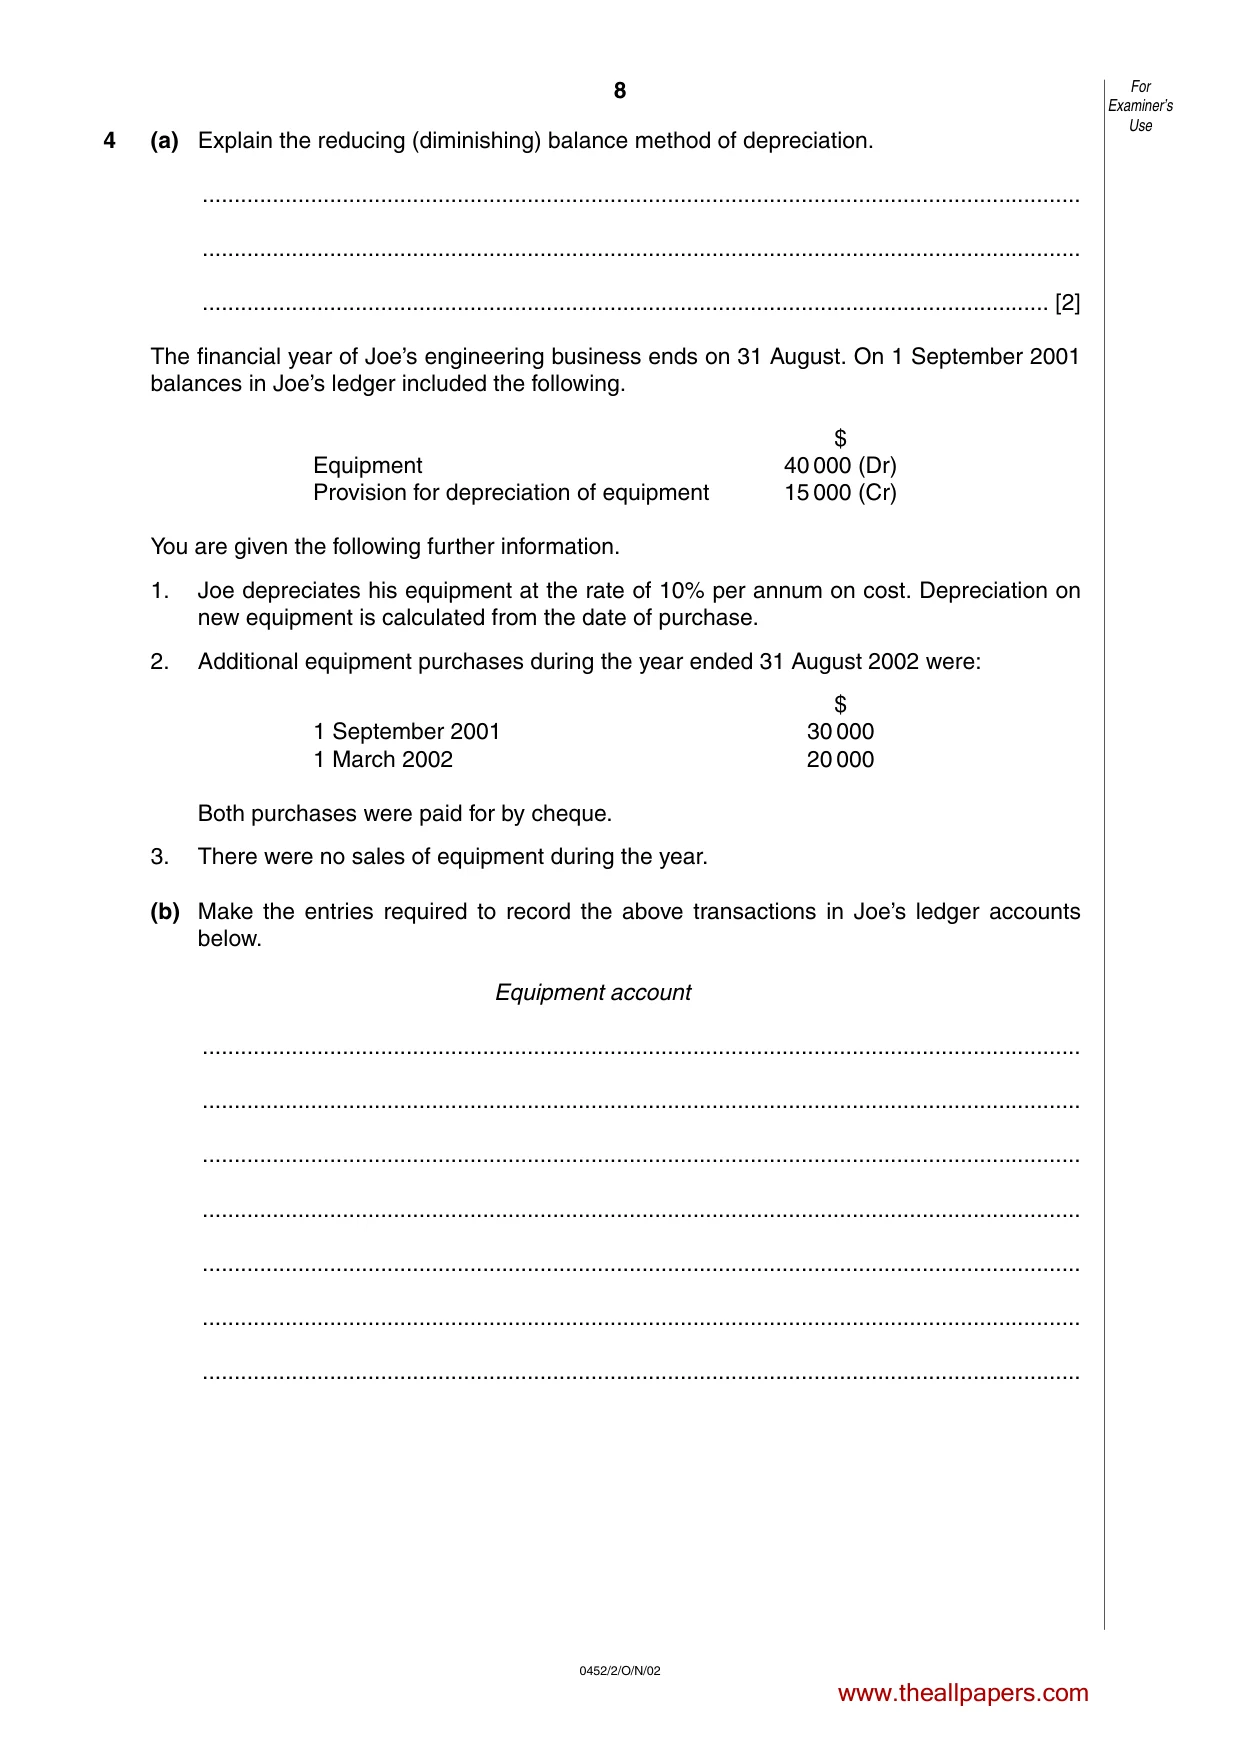
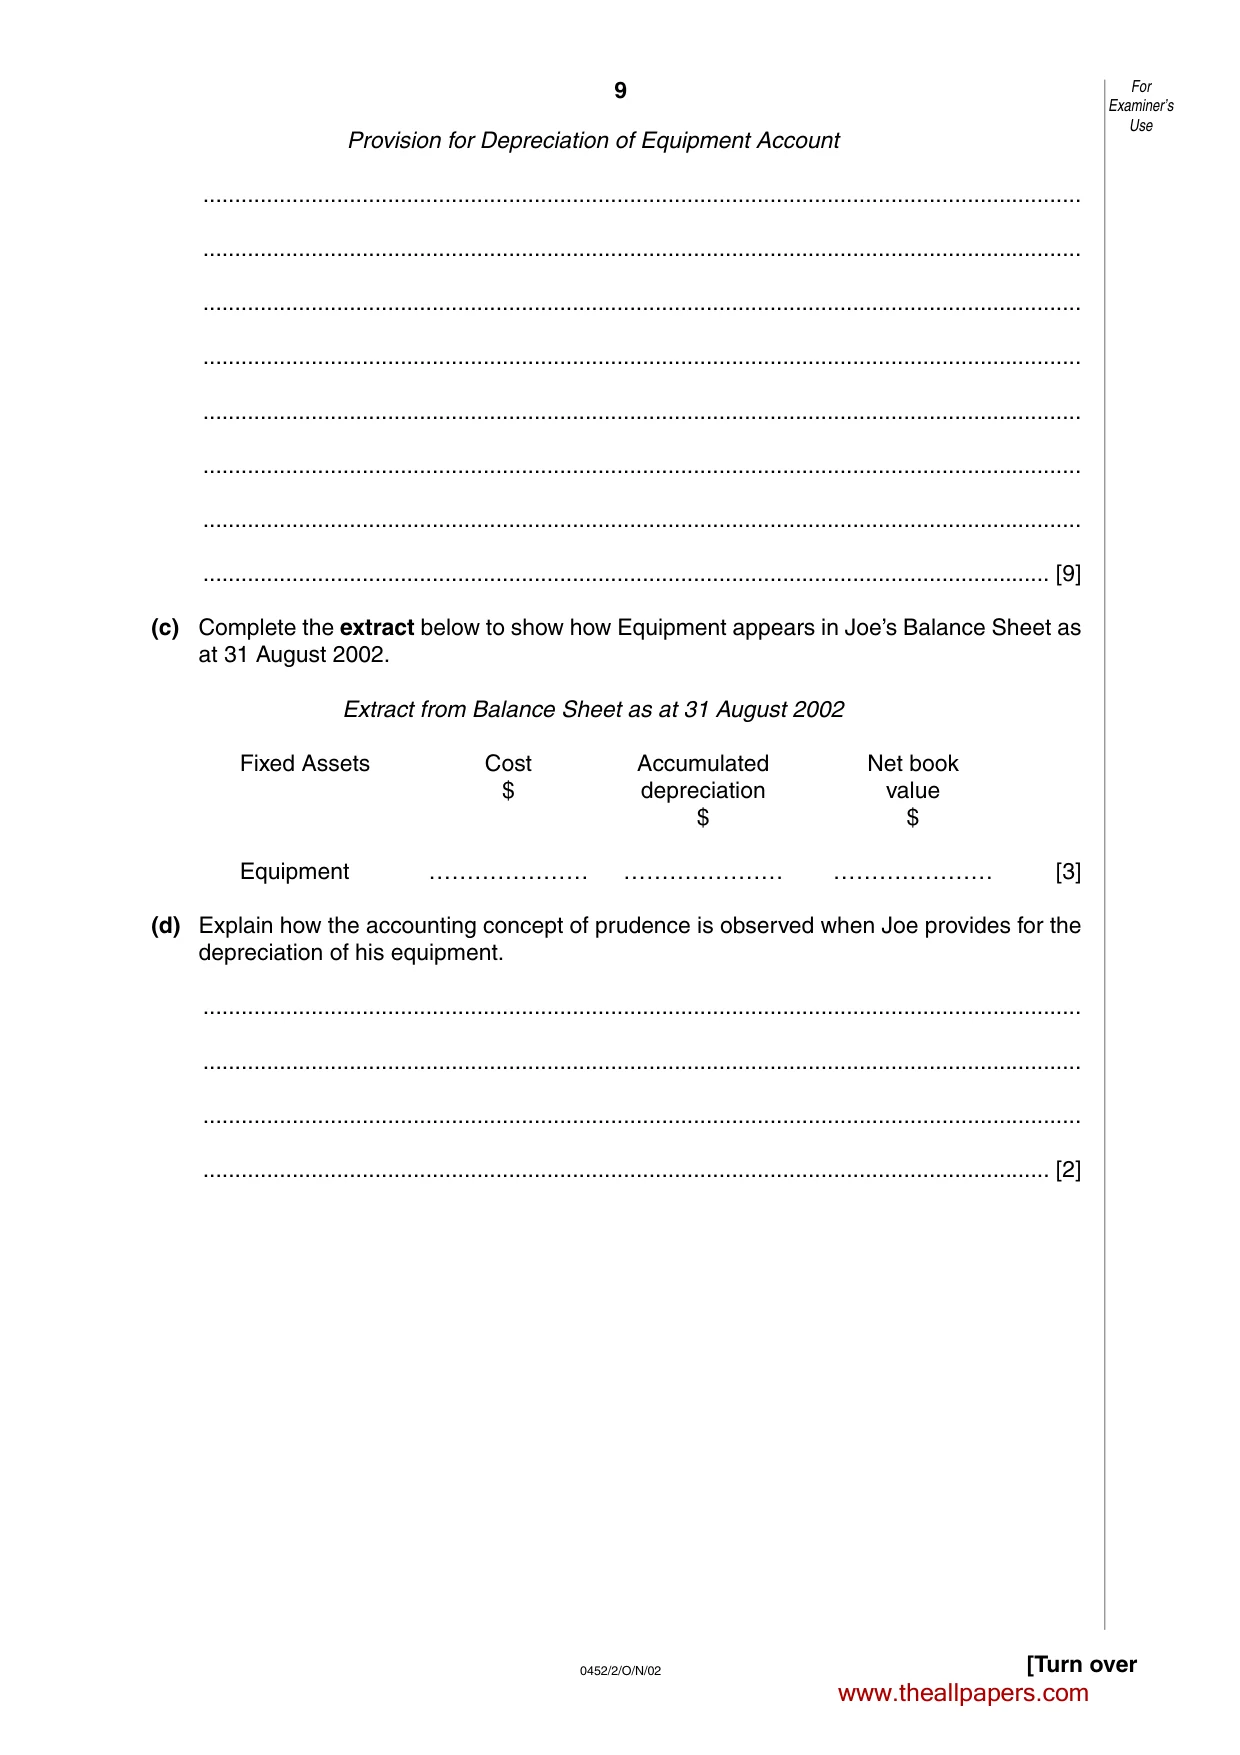
8 0452/2/O/N/02 4 (a) Explain the reducing (diminishing) balance method of depreciation. … … … [2] The financial year of Joe’s engineering business ends on 31 August. On 1 September 2001 balances in Joe’s ledger included the following. $ Equipment 40 000 (Dr) Provision for depreciation of equipment 15 000 (Cr) You are given the following further information. 1. Joe depreciates his equipment at the rate of 10% per annum on cost. Depreciation on new equipment is calculated from the date of purchase. 2. Additional equipment purchases during the year ended 31 August 2002 were: $ 1 September 2001 30 000 1 March 2002 20 000 Both purchases were paid for by cheque. 3. There were no sales of equipment during the year. (b) Make the entries required to record the above transactions in Joe’s ledger accounts below. Equipment account … … … … … … … For Examiner’s Use www.theallpapers.com
Question paper, page 9
9 0452/2/O/N/02 [Turn over Provision for Depreciation of Equipment Account … … … … … … … … [9] (c) Complete the extract below to show how Equipment appears in Joe’s Balance Sheet as at 31 August 2002. Extract from Balance Sheet as at 31 August 2002 Fixed Assets Cost Accumulated Net book $ depreciation value $ $ Equipment ………………… ………………… ………………… [3] (d) Explain how the accounting concept of prudence is observed when Joe provides for the depreciation of his equipment. … … … … [2] For Examiner’s Use www.theallpapers.com
Question paper, page 10
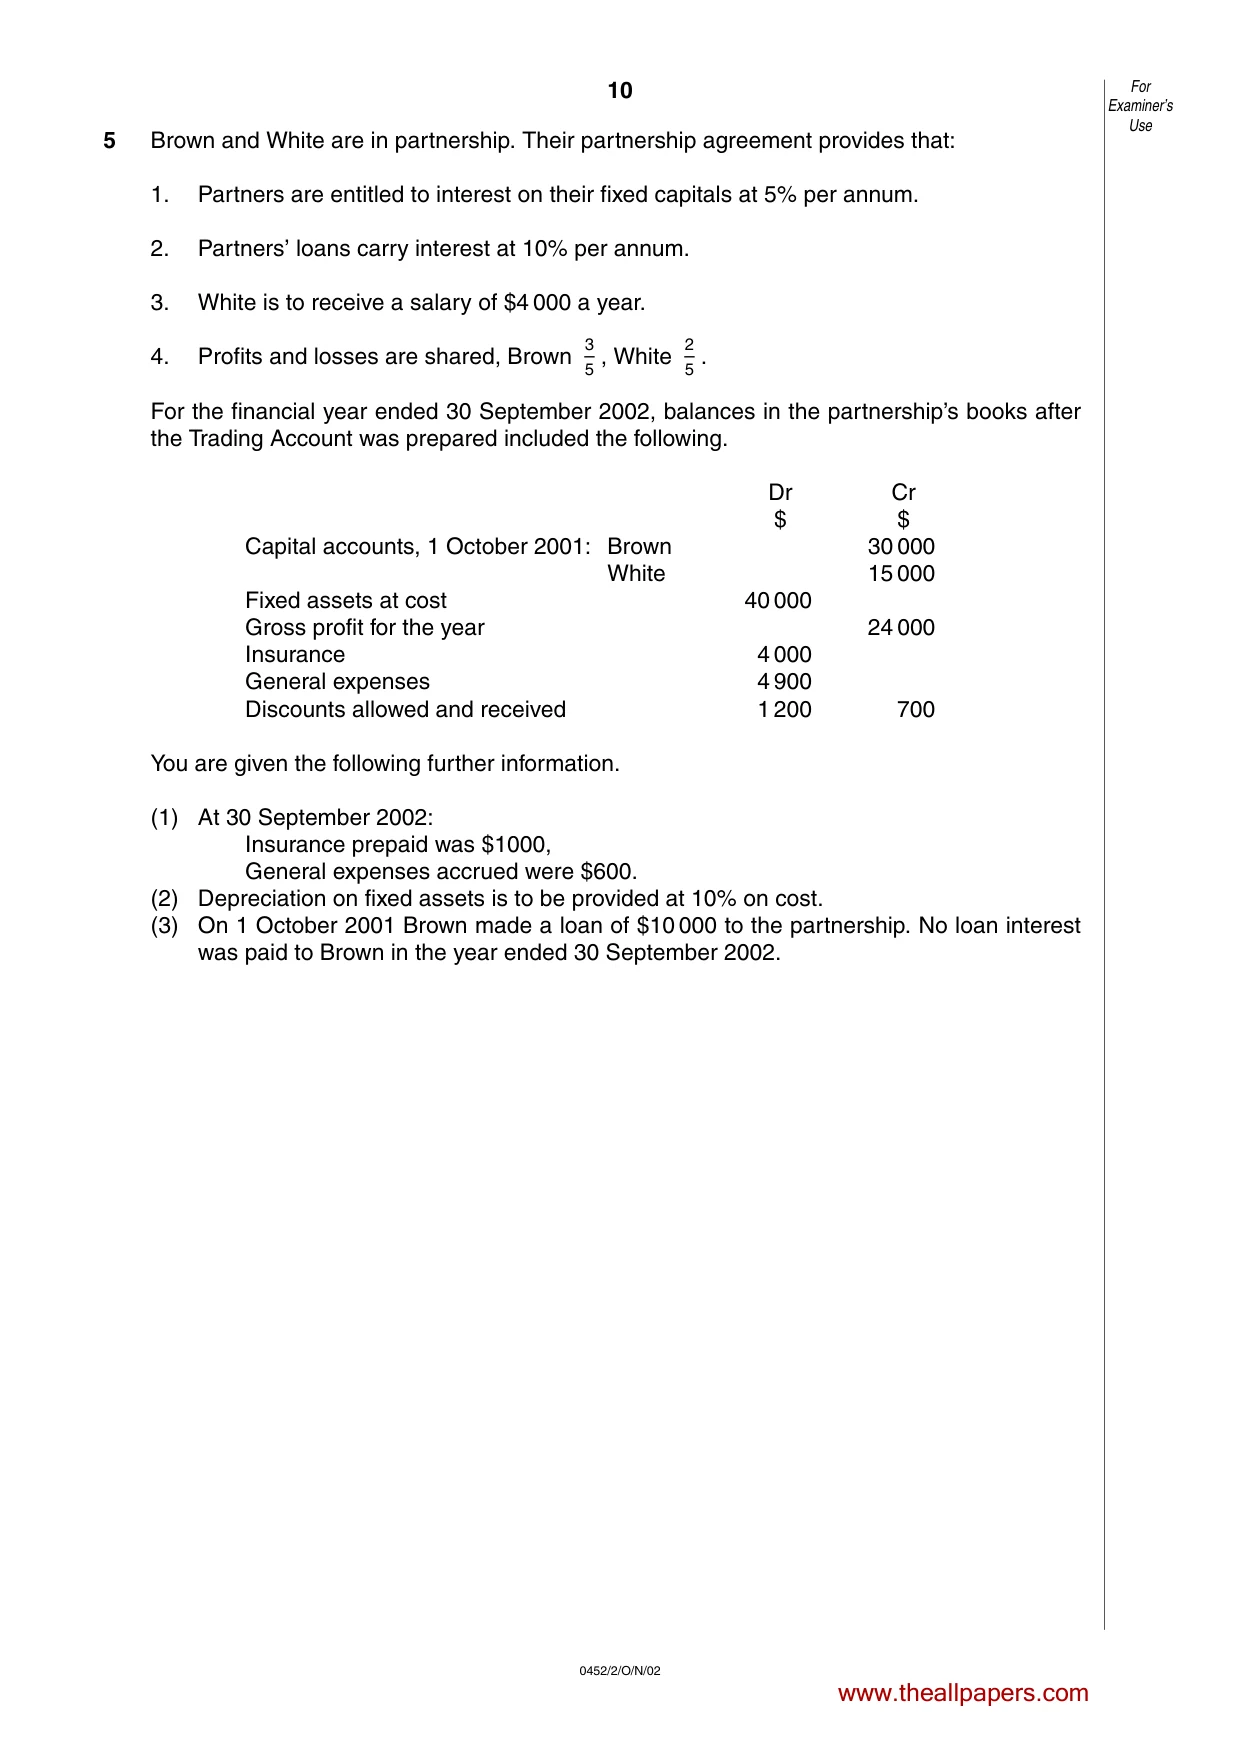
10 0452/2/O/N/02 5 Brown and White are in partnership. Their partnership agreement provides that: 1. Partners are entitled to interest on their fixed capitals at 5% per annum. 2. Partners’ loans carry interest at 10% per annum. 3. White is to receive a salary of $4 000 a year. 4. Profits and losses are shared, Brown , White . For the financial year ended 30 September 2002, balances in the partnership’s books after the Trading Account was prepared included the following. Dr Cr $ $ Capital accounts, 1 October 2001: Brown 30 000 White 15 000 Fixed assets at cost 40 000 Gross profit for the year 24 000 Insurance 4 000 General expenses 4 900 Discounts allowed and received 1 200 700 You are given the following further information. (1) At 30 September 2002: Insurance prepaid was $1000, General expenses accrued were $600. (2) Depreciation on fixed assets is to be provided at 10% on cost. (3) On 1 October 2001 Brown made a loan of $10 000 to the partnership. No loan interest was paid to Brown in the year ended 30 September 2002. 2–5 3–5 For Examiner’s Use www.theallpapers.com
Question paper, page 11
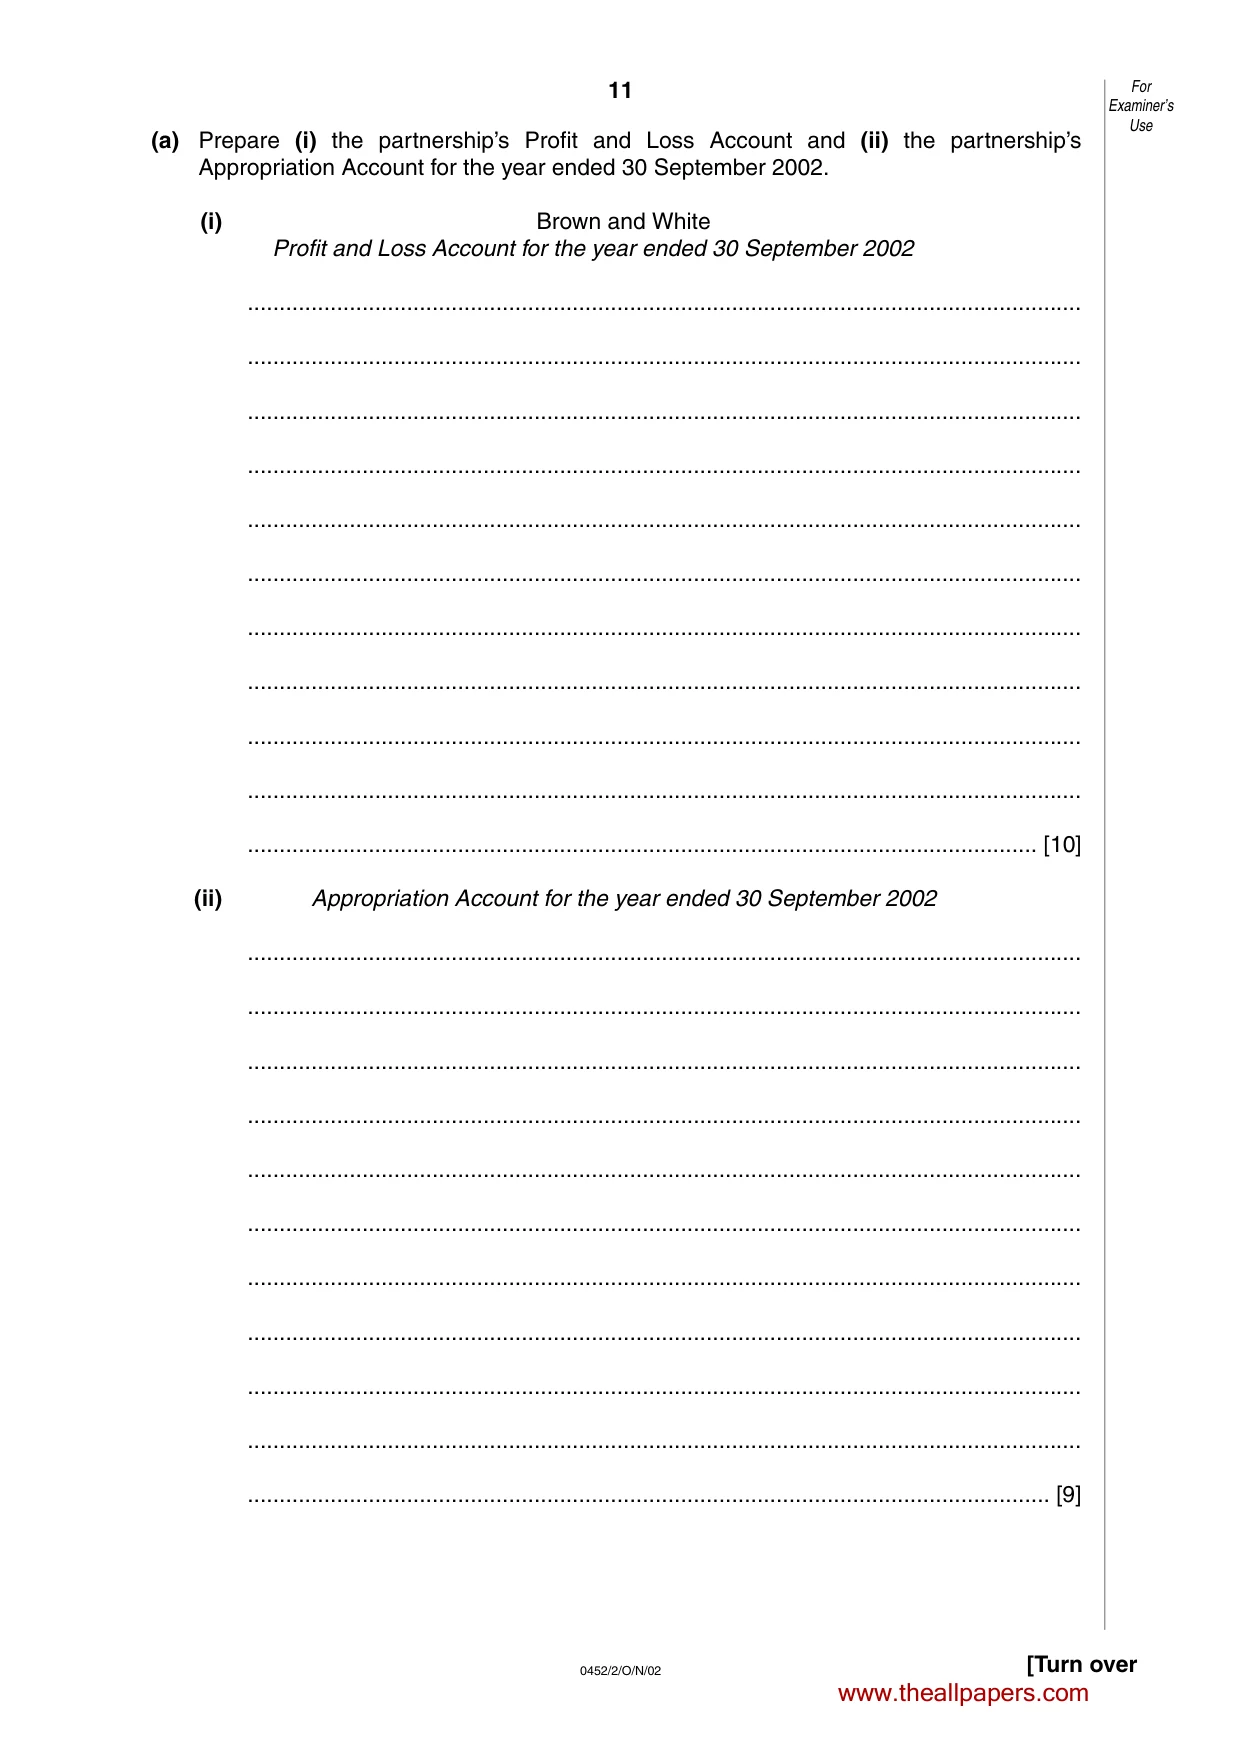
11 0452/2/O/N/02 [Turn over (a) Prepare (i) the partnership’s Profit and Loss Account and (ii) the partnership’s Appropriation Account for the year ended 30 September 2002. (i) Brown and White Profit and Loss Account for the year ended 30 September 2002 … … … … … … … … … … … [10] (ii) Appropriation Account for the year ended 30 September 2002 … … … … … … … … … … … [9] For Examiner’s Use www.theallpapers.com
Question paper, page 12
12 0452/2/O/N/02 (b) State and explain one possible reason why White receives a salary in addition to his share of partnership profits. … … … … [2] For Examiner’s Use www.theallpapers.com
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS CAMBRIDGE INTERNATIONAL EXAMINATIONS international General Certificate of Secondary Education MARK SCHEME FOR the November 2002 question papers 0452 ACCOUNTING 0452/02 Paper 2, maximum raw mark 90 0452/03 Paper 3, maximum raw mark 100 These mark schemes are published as an aid to teachers and students, to indicate the requirements of the examination. They show the basis on which Examiners were initially instructed to award marks. They do not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. Any substantial changes to the mark scheme that arose from these discussions will be recorded in the published Report on the Examination. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the Report on the Examination. . CIE will not enter into discussions or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the October/November 2002 question papers for most IGCSE, GCE Advanced Subsidiary (AS) and GCE Advanced (A) Level syllabuses. UNIVERSITY of CAMBRIDGE Local Examinations Syndicate www.theallpapers.com
Mark scheme, page 2
CAMBRIDGE INTERNATIONAL EXAMINATIONS November 2002 INTERNATIONAL GCSE MARK SCHEME UNIVERSITY of CAMBRIDGE Local Examinations Syndicate www.theallpapers.com
Mark scheme, page 3
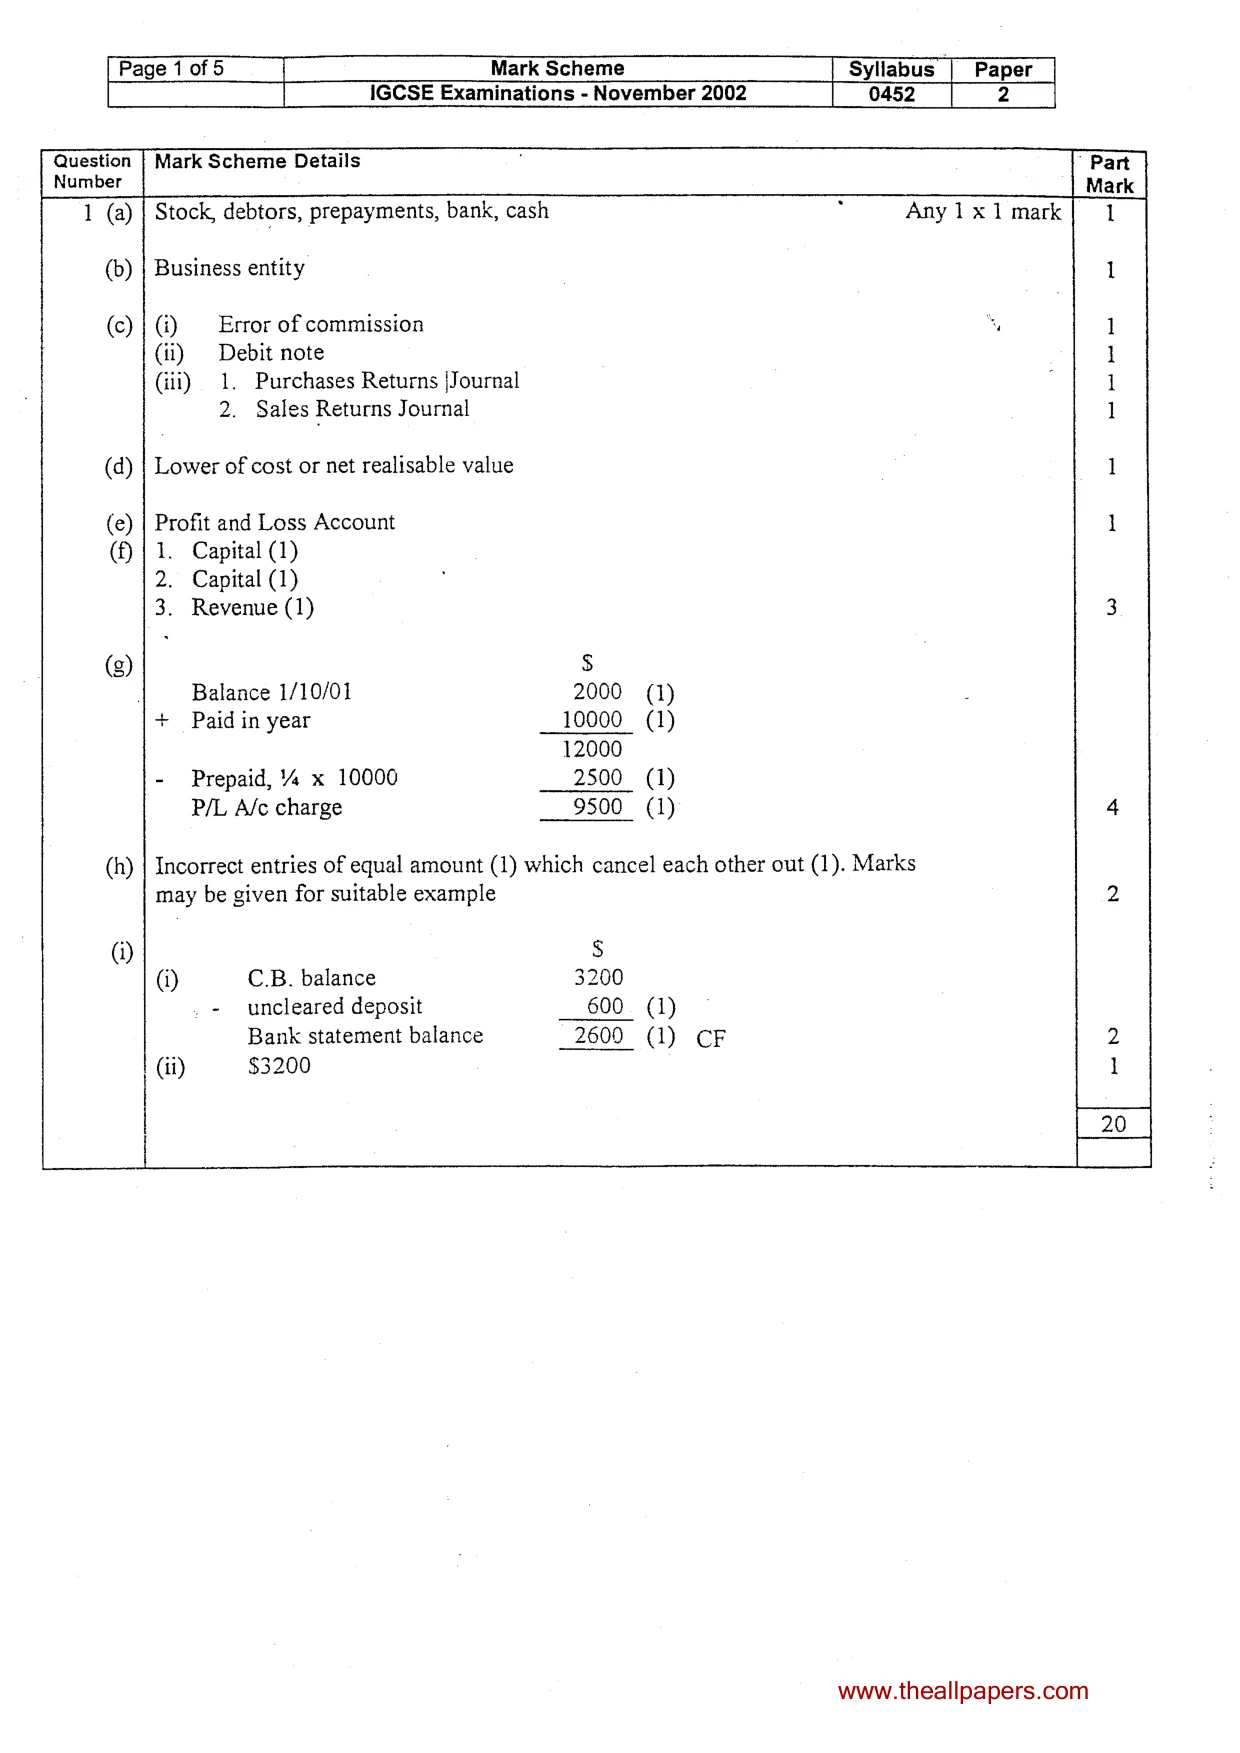
Page 1 of 5 Mark Scheme Syllabus Paper IGCSE Examinations - November 2002 0452 2 Question | Mark Scheme Details Part Number Mark 1 (a) | Stock, debtors, prepayments, bank, cash . Any1x1mark] 1 (b) | Business entity 1 (c)| (i Error of commission “ 1 (ii) Debit note 1 (iii) 1. Purchases Returns jJournal 1 2. Sales Returns Journal 1 (d) | Lower of cost or net realisable value 1 (e) | Profit and Loss Account 1 (| 1. Capital (1) 2. Capital (1) 3. Revenue (1) 3 (g) $s Balance 1/10/01 2000 (1) + Paid in year 10000 (1) 12000 - Prepaid, % x 10000 2500_ (1) P/L A/c charge 9500 (1) 4 (h) | Incorrect entries of equal amount (1) which cancel each other out (1). Marks may be given for suitable example 2 (i) $ (i) C.B. balance 3200 - uncleared deposit 600 (1) Bank statement balance 2600 (1) CF 2 (ii) $3200 1 20 www.theallpapers.com
Mark scheme, page 4
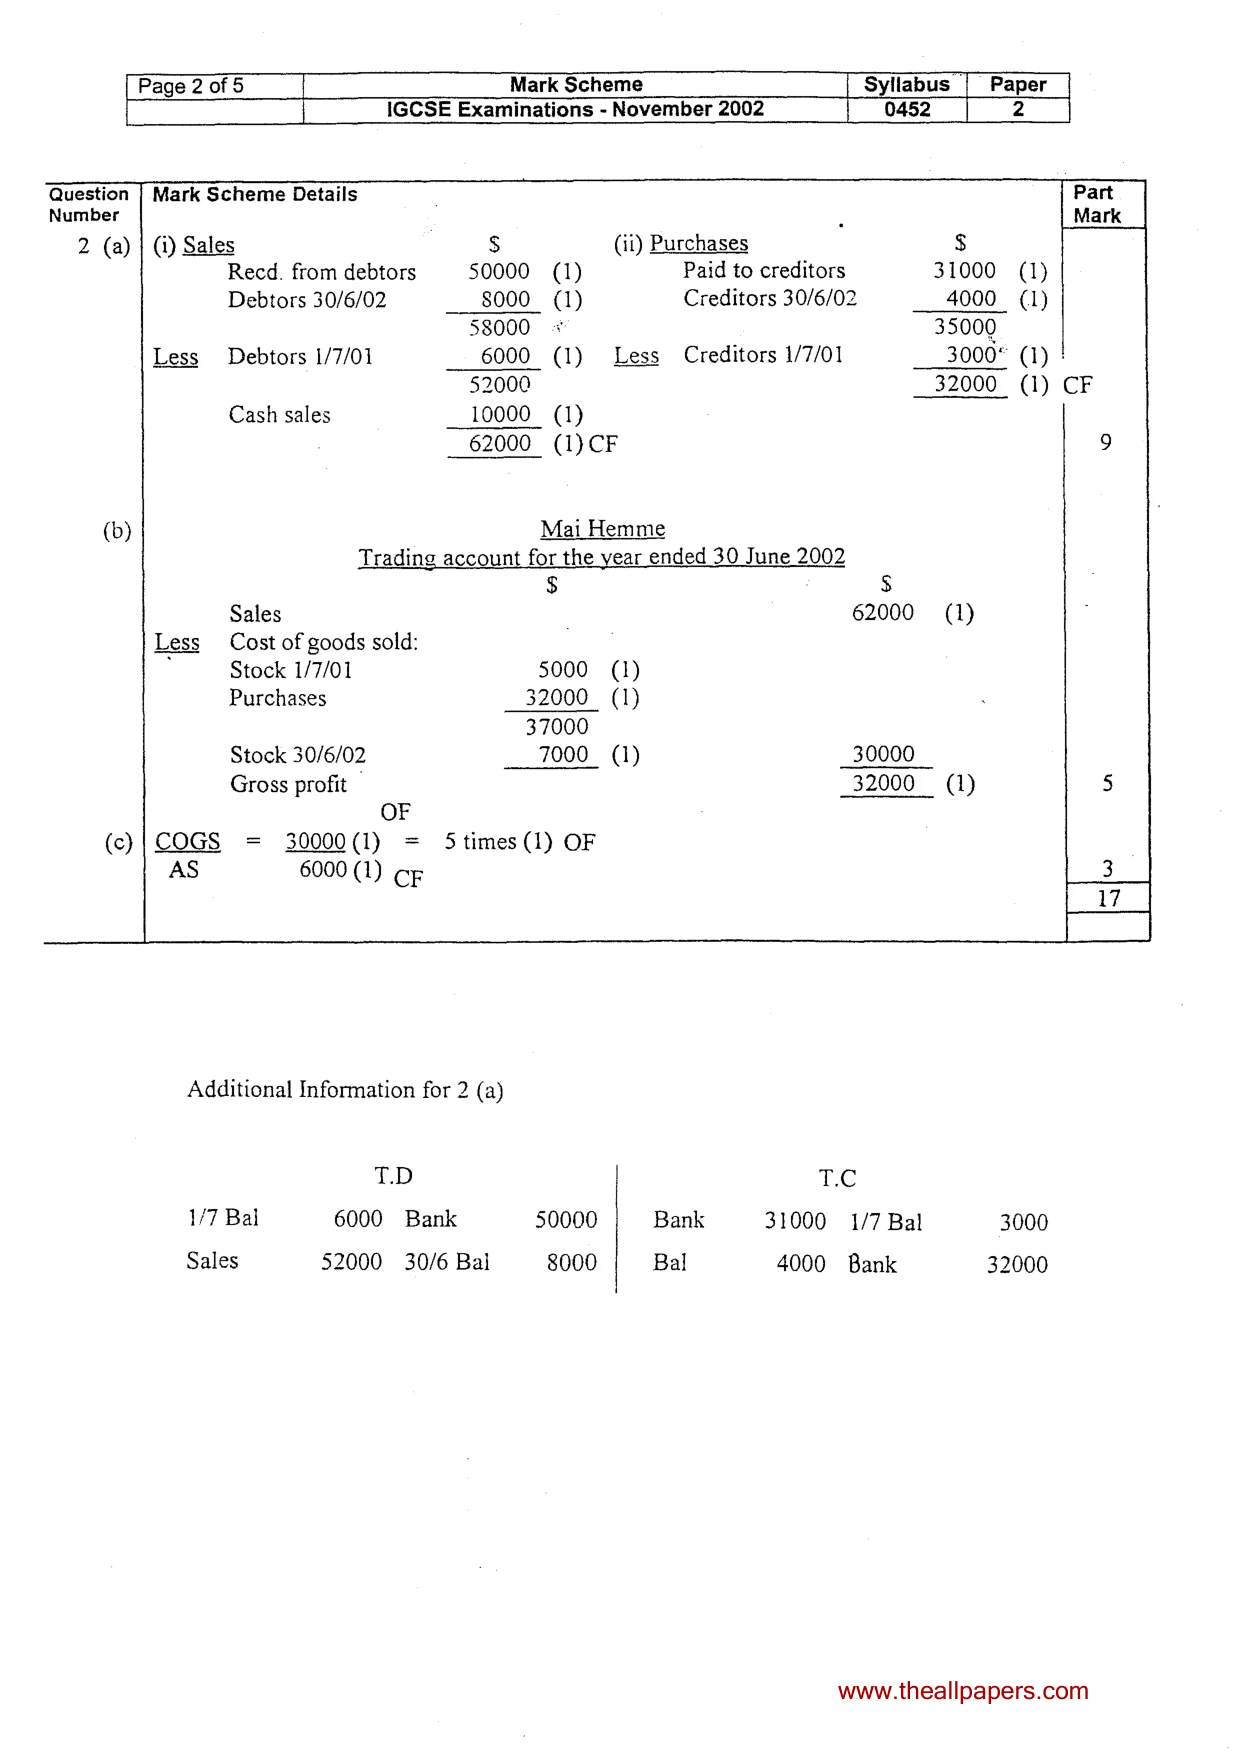
Page 2 of 5 Mark Scheme Syilabus | Paper IGCSE Examinations - November 2002 0452 2 Question | Mark Scheme Details Part Number . Mark 2 (a) | (i) Sales $ (ii) Purchases $ Recd. from debtors 50000 (1) Paid to creditors 31000 (1) Debtors 30/6/02 g000_ (1) Creditors 30/6/02 4000 (1) 58000 < 35000 Less Debtors 1/7/01 6000 (1) Less Creditors 1/7/01 3000° (1)! 52000 32000. (1) CF Cash sales 10000 (1) 62000 (1)CF 9 (b) Mai Hemme Trading account for the year ended 30 June 2002 $ 3 Sales 62000 (1) Less Cost of goods sold: . Stock 1/7/01 5000 (1) Purchases 32000 (1) 37000 Stock 30/6/02 7000 (1) 30000 Gross profit ~ 32000 (1) 5 OF (c)| COGS = 30000(1) = Stimes(1) OF AS 6000 (1) CF 3 | 7 Additional Information for 2 (a) T.D T.C 1/7 Bal 6000 Bank 50000 Bank 31000 1/7 Bal 3000 Sales 52000 30/6 Bal 8000 Bal 4000 Bank 32000 www.theallpapers.com
Mark scheme, page 5
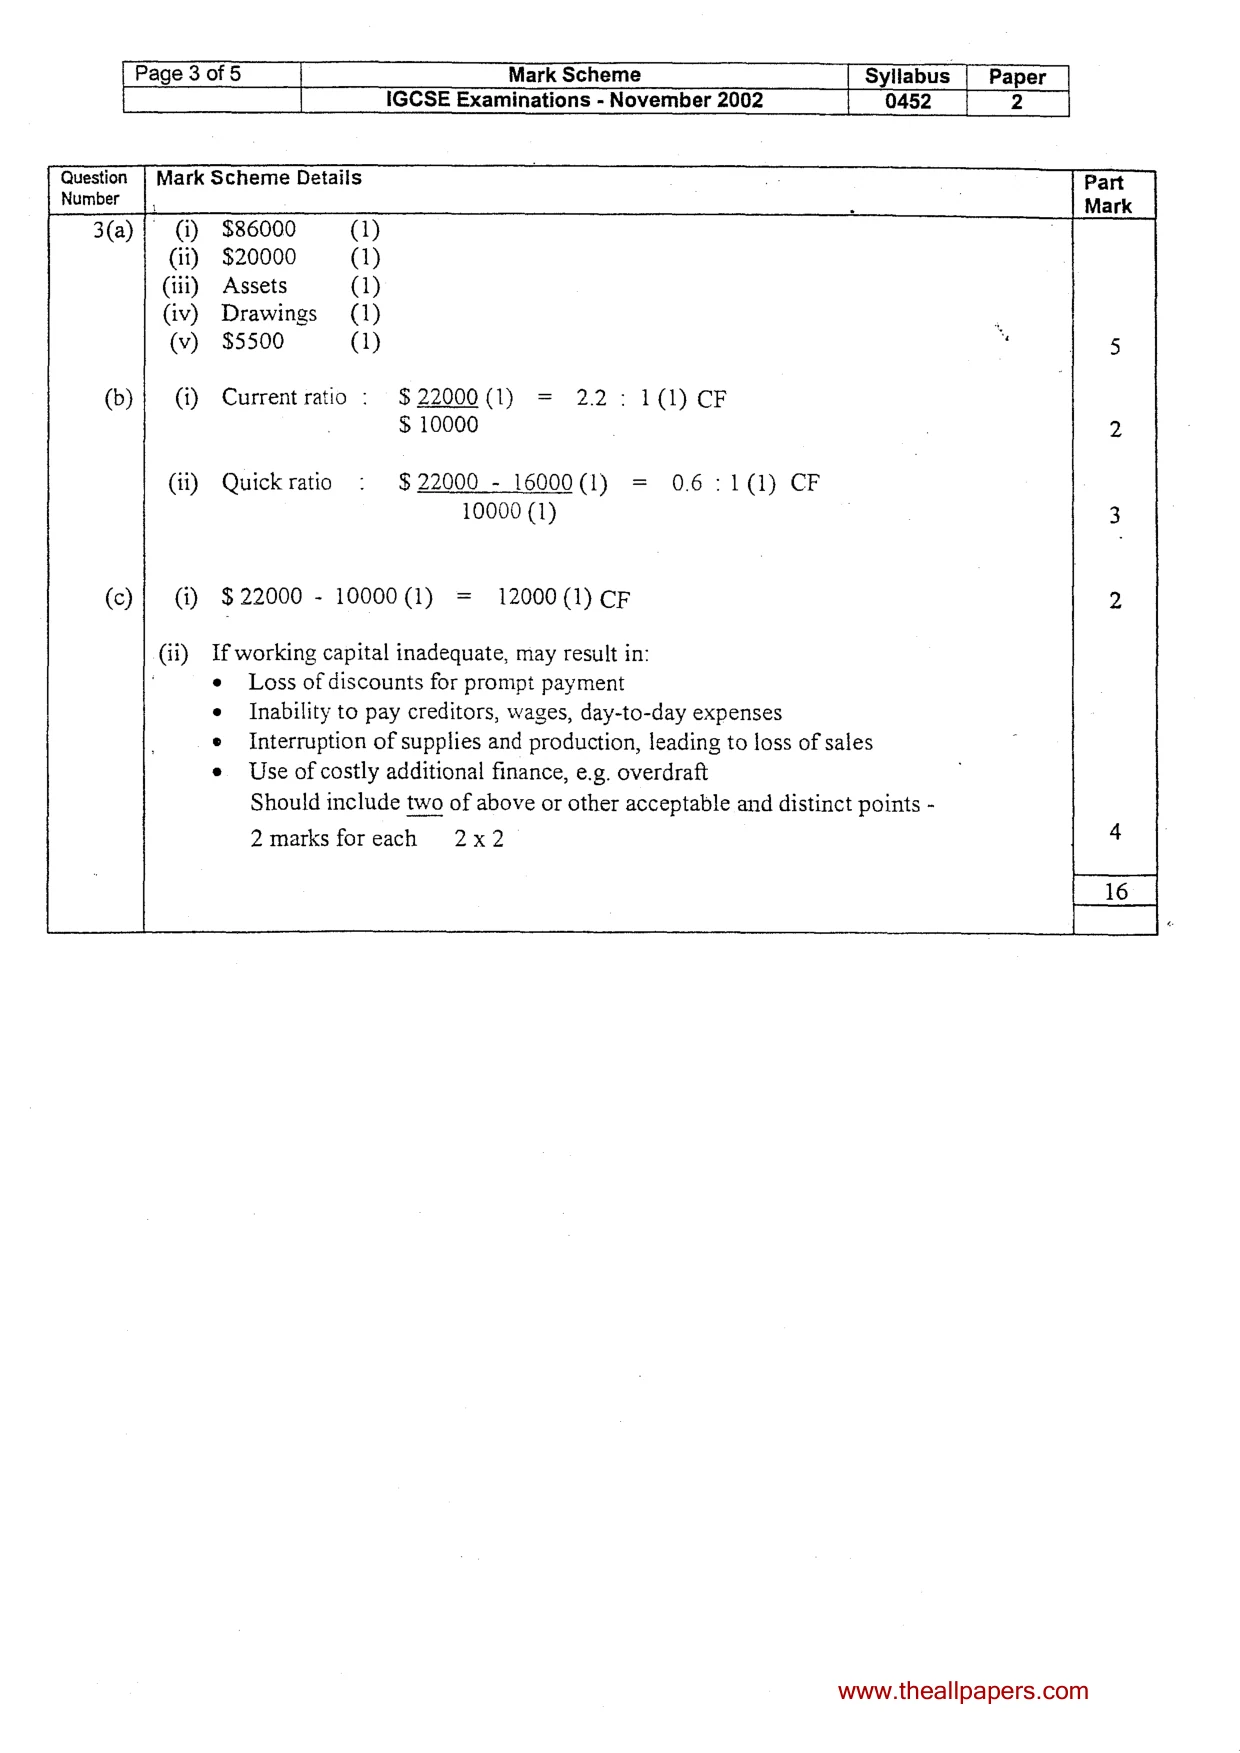
Page 3 of 5 Mark Scheme Syllabus | Paper IGCSE Examinations - November 2002 0452 2 Question Number Mark Scheme Details 3(a) (b) ©) 10} (i) (iii) (iv) ) @ (ii) @ Gi) $86000 6) $20000 (1) Assets Q) Drawings (1) . $5500 qa) “ Current ratio : $22000(1) = 2.2: 1(1) CF $ 10000 Quick ratio : $22000 - 16000(1) = 06:1(1) CF 10000 (1) $22000 - 10000(1) = 12000(1) CF If working capital inadequate, may result in: ¢ Loss of discounts for prompt payment ¢ Inability to pay creditors, wages, day-to-day expenses e Interruption of supplies and production, leading to loss of sales ¢ Use of costly additional finance, e.g. overdraft Should include two of above or other acceptable and distinct points - 2 marks foreach 2x2 Part Mark 16 www.theallpapers.com
Mark scheme, page 6
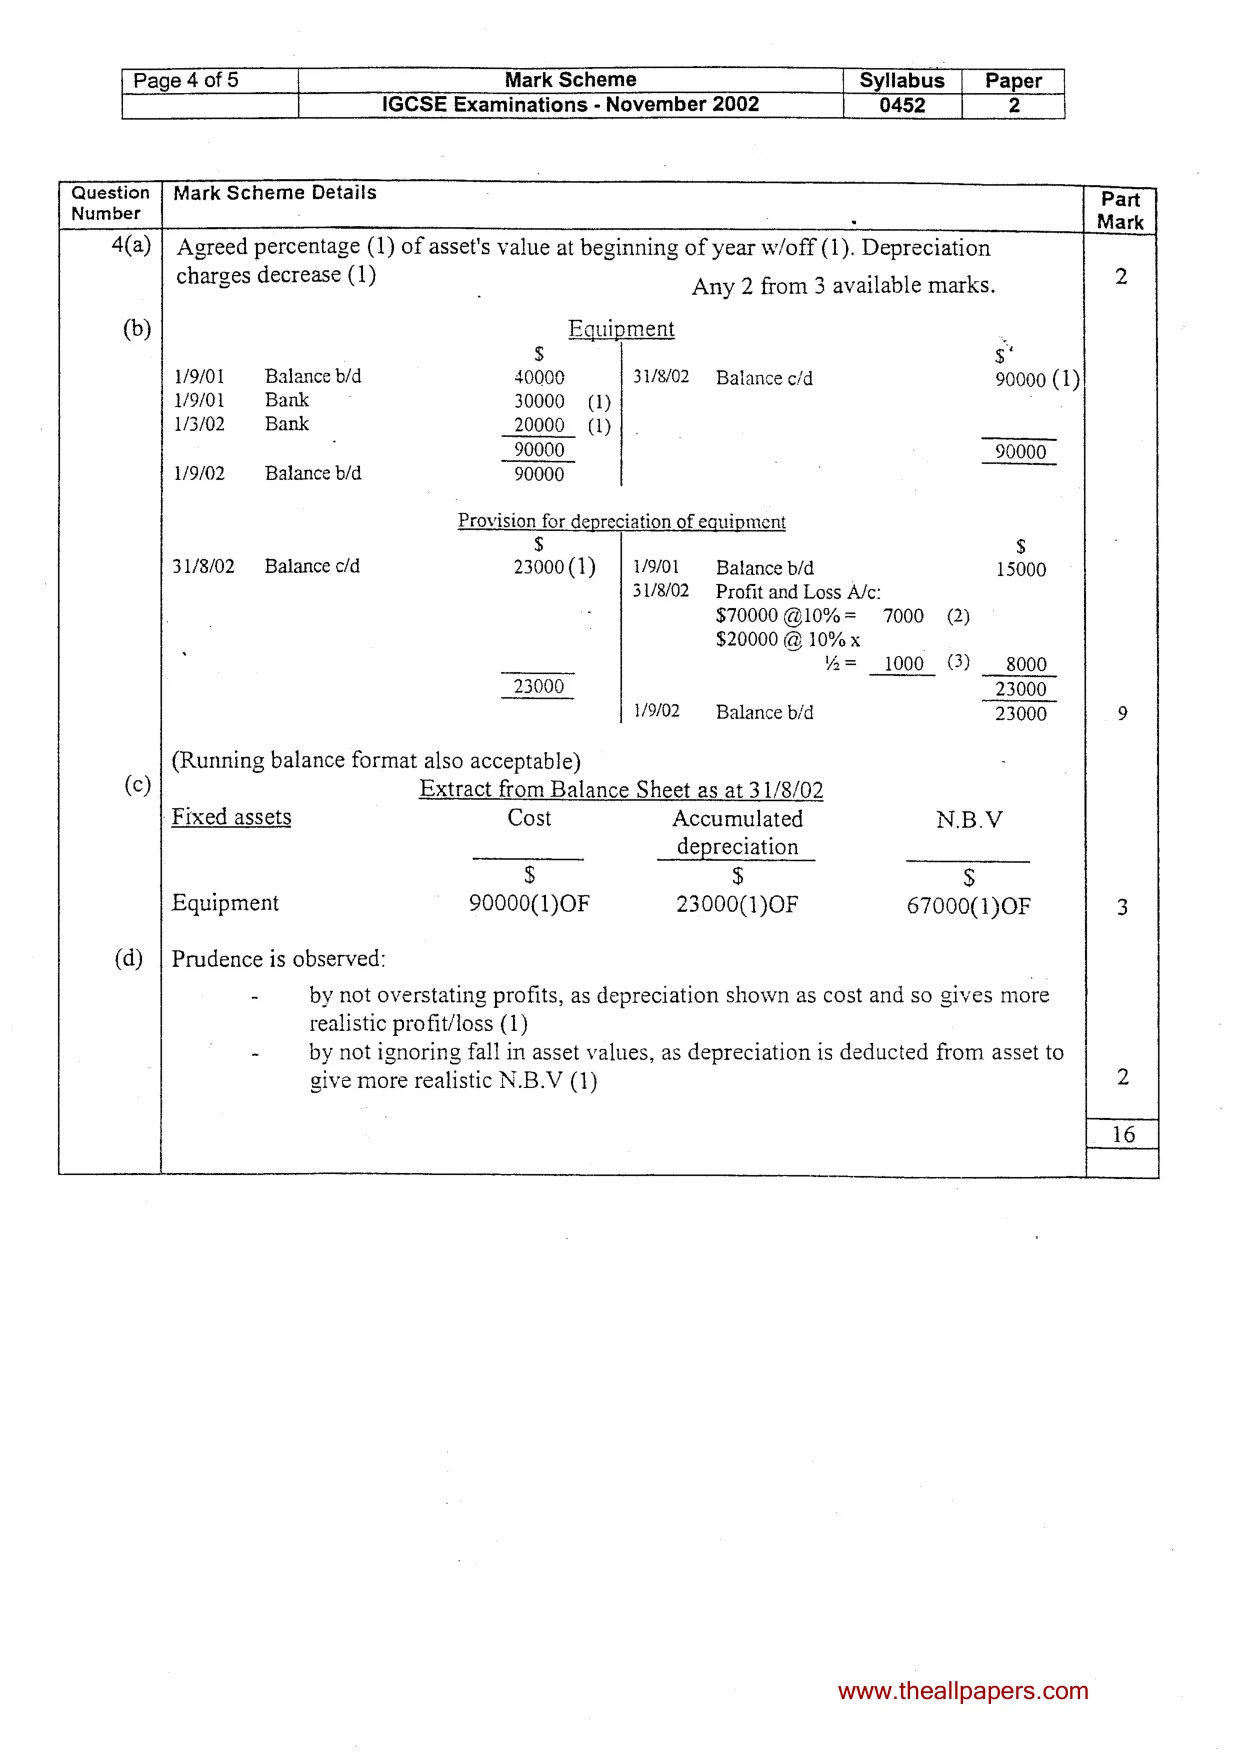
Page 4 of 5 Mark Scheme Syllabus | Paper IGCSE Examinations - November 2002 0452 2 Question | Mark Scheme Details Part Number : Mark | 4(a) | Agreed percentage (1) of asset's value at beginning of year w/off (1). Depreciation charges decrease (1) . Any 2 from 3 available marks. 2 (b) quipment . $ s‘ 1/9/01 Balance b/d 40000 31/8/02 Balance ¢/d 90000 (1) V9/0L Bank 30000 (1) 1/3/02 Bank 20000 (1) ° 90000 90000 1/9/02 Balance b/d 90000 Provision for depreciation of equipment $ $ 31/8/02 Balance c/d 23000 (1) 1/9/01 Balance b/d. 15000 31/8/02 Profit and Loss A/c: $70000 @10%= 7000 (2) $20000 @ 10% x Y= 1000 (3) 8000 23000 23000 1/9/02 Balance b/d 23000 9 (Running balance format also acceptable) (c) Extract from Balance Sheet as at 31/8/02 Fixed assets Cost Accumulated NB.V depreciation $ $ $ Equipment 90000(1)OF 23000(1)OF 67000(1)OF 3 (d) | Prudence is observed: - by not overstating profits, as depreciation shown as cost and so gives more realistic profit/loss (1) - by not ignoring fall in asset values, as depreciation is deducted from asset to give more realistic N.B.V (1) 2 16 www.theallpapers.com
Mark scheme, page 7
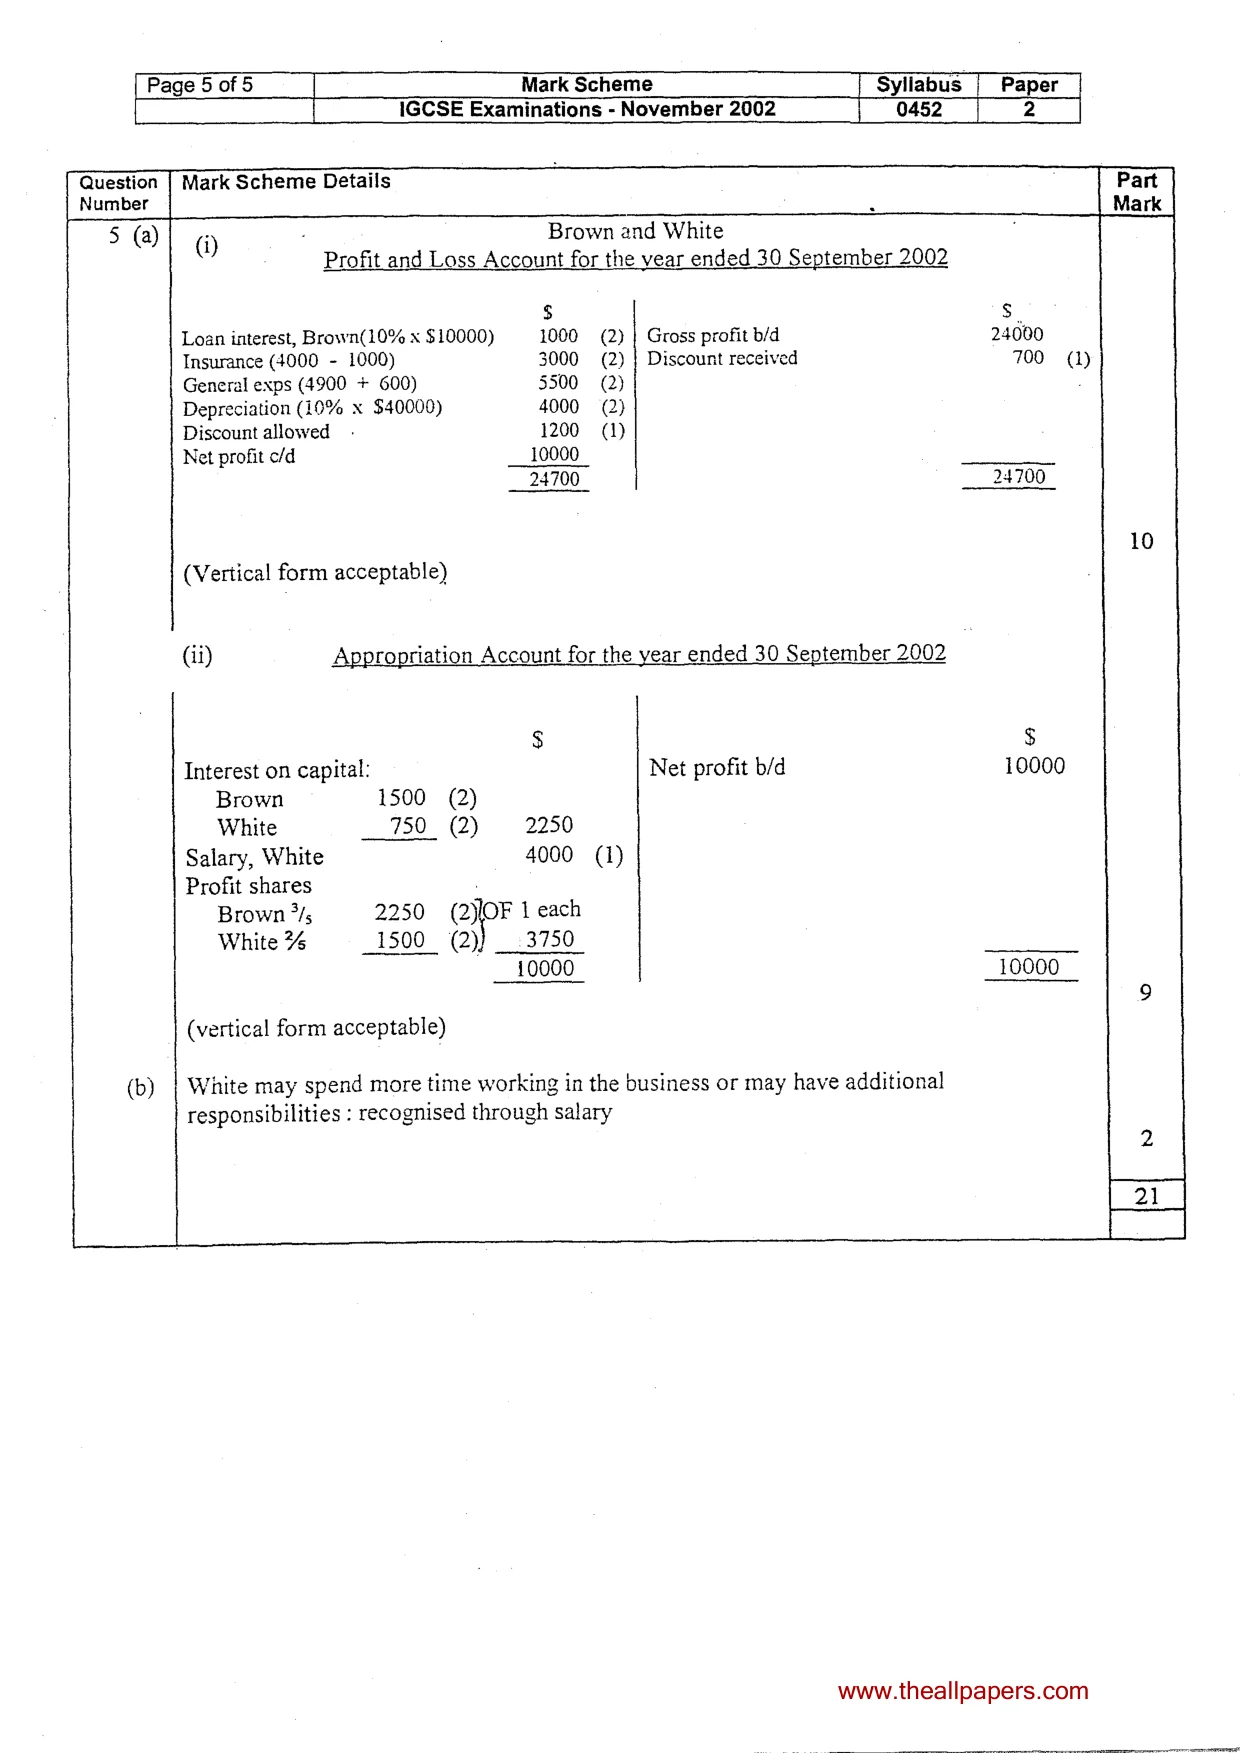
Page 5 of 5 Mark Scheme Syllabus | Paper IGCSE Examinations - November 2002 0452 2 Question | Mark Scheme Details Part Number : Mark 5 (a) (i) : Brown and White Profit and Loss Account for the vear ended 30 September 2002 $ Ss. Loan interest, Brown(10% x $10000) 1000 (2) | Gross profit b/d 24000 Insurance (4000 - 1000) 3000 (2) | Discount received 700 (1) General exps (4900 + 600) 5500 (2) Depreciation (10% x $40000) 4000 (2) Discount allowed 1200 (1) Net profit c/d 10000 24700 24700 10 (Vertical form acceptable) (ii) Appropriation Account for the year ended 30 September 2002 $ $ Interest on capital: Net profit b/d 10000 Brown 1500 (2) White 750. (2) = 2250 Salary, White 4000 (1) Profit shares Brown */s 2250 GPF leach White % 1500_ (2), 3750 10000 10000 9 (vertical form acceptable) (b) | White may spend more time working in the business or may have additional responsibilities : recognised through salary 2 21 www.theallpapers.com