Cambridge A Level Business (for first examination in 2016) 9609 — 2021 May/June Paper 1 · Variant 3
9609/13/M/J/21 · 40 marks · ≈45 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper4 pages
Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document has 4 pages. Any blank pages are indicated. Cambridge International AS & A Level BUSINESS 9609/13 Paper 1 Short Answer and Essay May/June 2021 1 hour 15 minutes You must answer on the enclosed answer booklet. You will need: Answer booklet (enclosed) INSTRUCTIONS ● Section A: answer all questions. ● Section B: answer one question. ● Follow the instructions on the front cover of the answer booklet. If you need additional answer paper, ask the invigilator for a continuation booklet. INFORMATION ● The total mark for this paper is 40. ● The number of marks for each question or part question is shown in brackets [ ]. DC (MB) 206362/1 © UCLES 2021 [Turn over * 0 7 8 1 8 5 7 3 0 1 *
Question paper, page 2
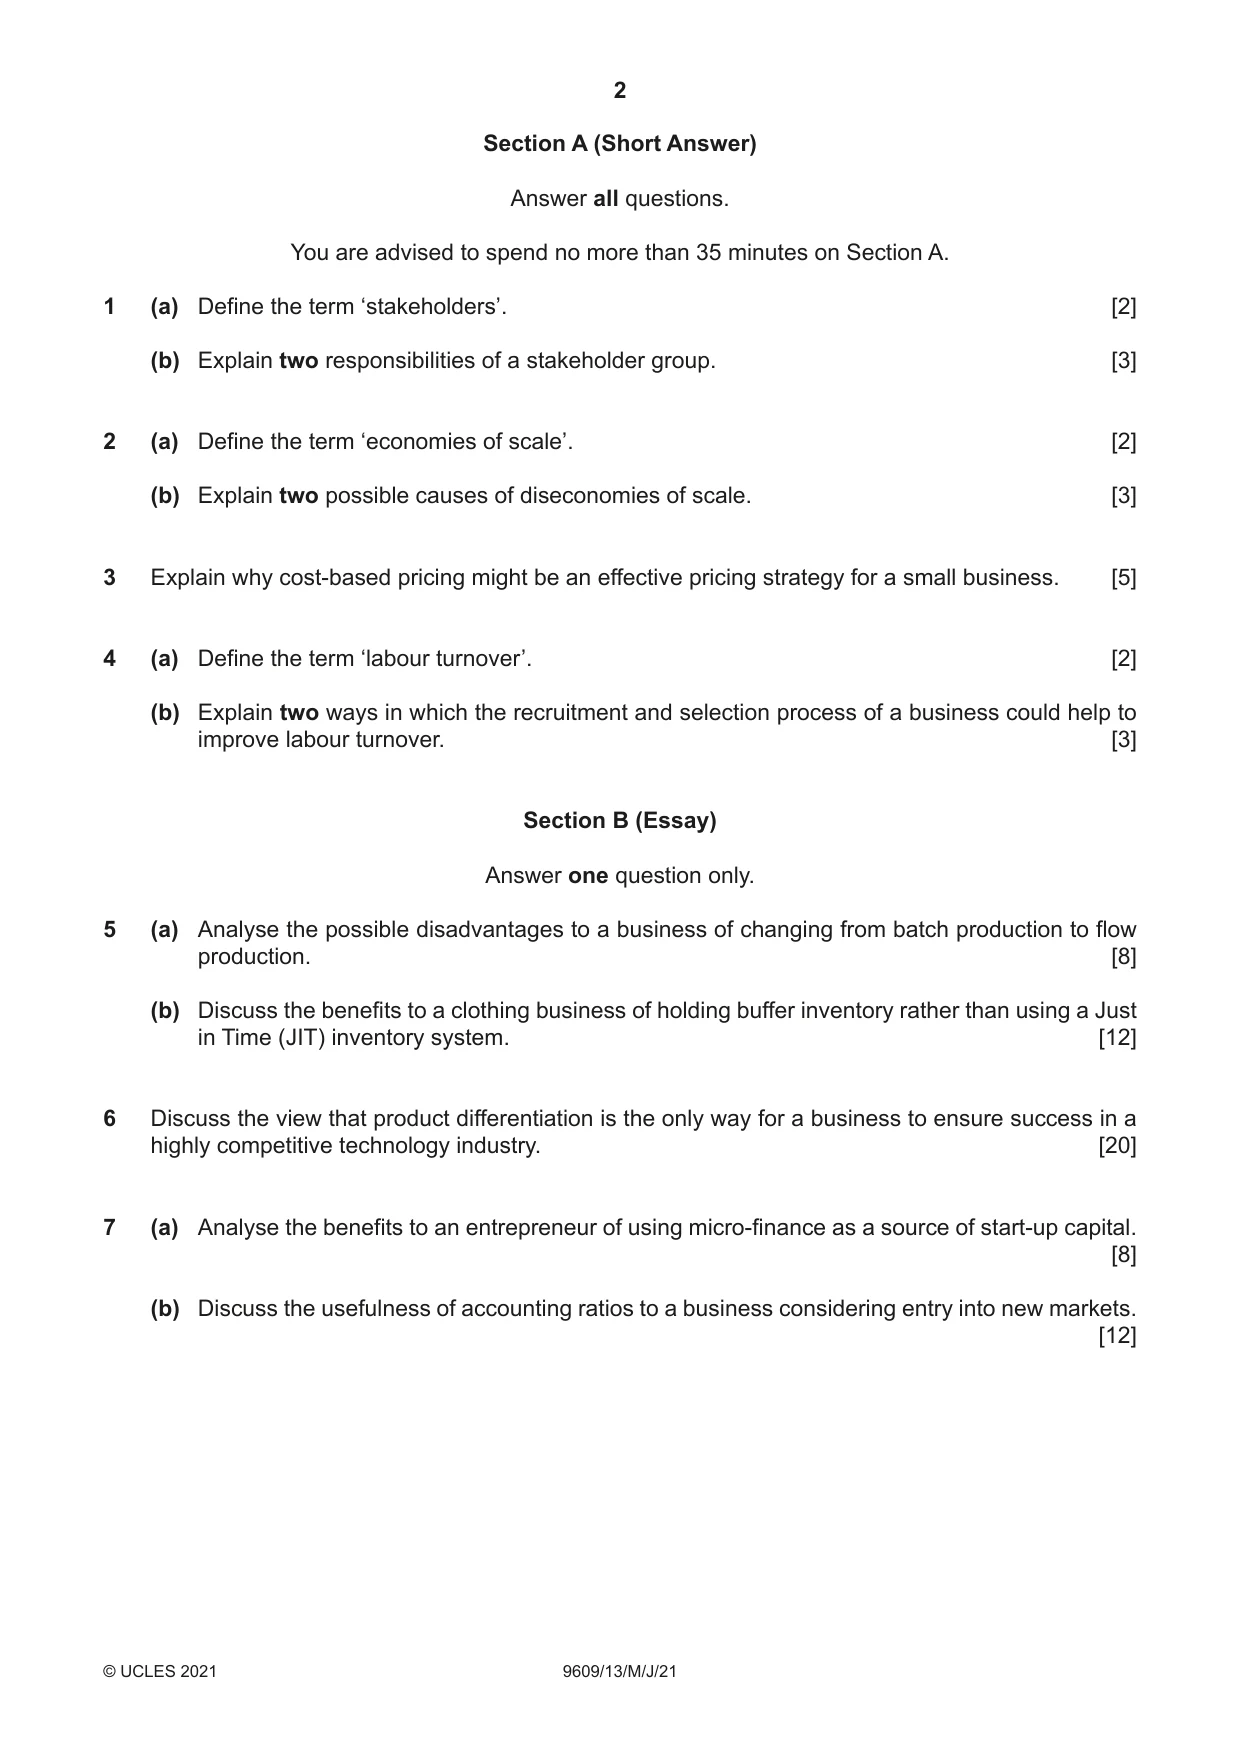
2 9609/13/M/J/21 © UCLES 2021 Section A (Short Answer) Answer all questions. You are advised to spend no more than 35 minutes on Section A. 1 (a) Define the term ‘stakeholders’. [2] (b) Explain two responsibilities of a stakeholder group. [3] 2 (a) Define the term ‘economies of scale’. [2] (b) Explain two possible causes of diseconomies of scale. [3] 3 Explain why cost-based pricing might be an effective pricing strategy for a small business. [5] 4 (a) Define the term ‘labour turnover’. [2] (b) Explain two ways in which the recruitment and selection process of a business could help to improve labour turnover. [3] Section B (Essay) Answer one question only. 5 (a) Analyse the possible disadvantages to a business of changing from batch production to flow production. [8] (b) Discuss the benefits to a clothing business of holding buffer inventory rather than using a Just in Time (JIT) inventory system. [12] 6 Discuss the view that product differentiation is the only way for a business to ensure success in a highly competitive technology industry. [20] 7 (a) Analyse the benefits to an entrepreneur of using micro-finance as a source of start-up capital. [8] (b) Discuss the usefulness of accounting ratios to a business considering entry into new markets. [12]
Question paper, page 3
3 9609/13/M/J/21 © UCLES 2021 BLANK PAGE
Question paper, page 4
4 9609/13/M/J/21 © UCLES 2021 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which itself is a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
This document consists of 19 printed pages. © UCLES 2021 [Turn over Cambridge International AS & A Level BUSINESS 9609/13 Paper 1 Short Answer and Essay May/June 2021 MARK SCHEME Maximum Mark: 40 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the May/June 2021 series for most Cambridge IGCSE™, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 2 of 19 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently, e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors. GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 3
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 3 of 19 Social Science-Specific Marking Principles (for point-based marking) 1 Components using point-based marking: • Point marking is often used to reward knowledge, understanding and application of skills. We give credit where the candidate’s answer shows relevant knowledge, understanding and application of skills in answering the question. We do not give credit where the answer shows confusion. From this it follows that we: a DO credit answers which are worded differently from the mark scheme if they clearly convey the same meaning (unless the mark scheme requires a specific term) b DO credit alternative answers/examples which are not written in the mark scheme if they are correct c DO credit answers where candidates give more than one correct answer in one prompt/numbered/scaffolded space where extended writing is required rather than list-type answers. For example, questions that require n reasons (e.g. State two reasons …). d DO NOT credit answers simply for using a ‘key term’ unless that is all that is required. (Check for evidence it is understood and not used wrongly.) e DO NOT credit answers which are obviously self-contradicting or trying to cover all possibilities f DO NOT give further credit for what is effectively repetition of a correct point already credited unless the language itself is being tested. This applies equally to ‘mirror statements’ (i.e. polluted/not polluted). g DO NOT require spellings to be correct, unless this is part of the test. However spellings of syllabus terms must allow for clear and unambiguous separation from other syllabus terms with which they may be confused (e.g. Corrasion/Corrosion) 2 Presentation of mark scheme: • Slashes (/) or the word ‘or’ separate alternative ways of making the same point. • Semi colons (;) bullet points (•) or figures in brackets (1) separate different points. • Content in the answer column in brackets is for examiner information/context to clarify the marking but is not required to earn the mark (except Accounting syllabuses where they indicate negative numbers). 3 Calculation questions: • The mark scheme will show the steps in the most likely correct method(s), the mark for each step, the correct answer(s) and the mark for each answer • If working/explanation is considered essential for full credit, this will be indicated in the question paper and in the mark scheme. In all other instances, the correct answer to a calculation should be given full credit, even if no supporting working is shown. • Where the candidate uses a valid method which is not covered by the mark scheme, award equivalent marks for reaching equivalent stages. • Where an answer makes use of a candidate’s own incorrect figure from previous working, the ‘own figure rule’ applies: full marks will be given if a correct and complete method is used. Further guidance will be included in the mark scheme where necessary and any exceptions to this general principle will be noted.
Mark scheme, page 4
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 4 of 19 4 Annotation: • For point marking, ticks can be used to indicate correct answers and crosses can be used to indicate wrong answers. There is no direct relationship between ticks and marks. Ticks have no defined meaning for levels of response marking. • For levels of response marking, the level awarded should be annotated on the script. • Other annotations will be used by examiners as agreed during standardisation, and the meaning will be understood by all examiners who marked that paper.
Mark scheme, page 5
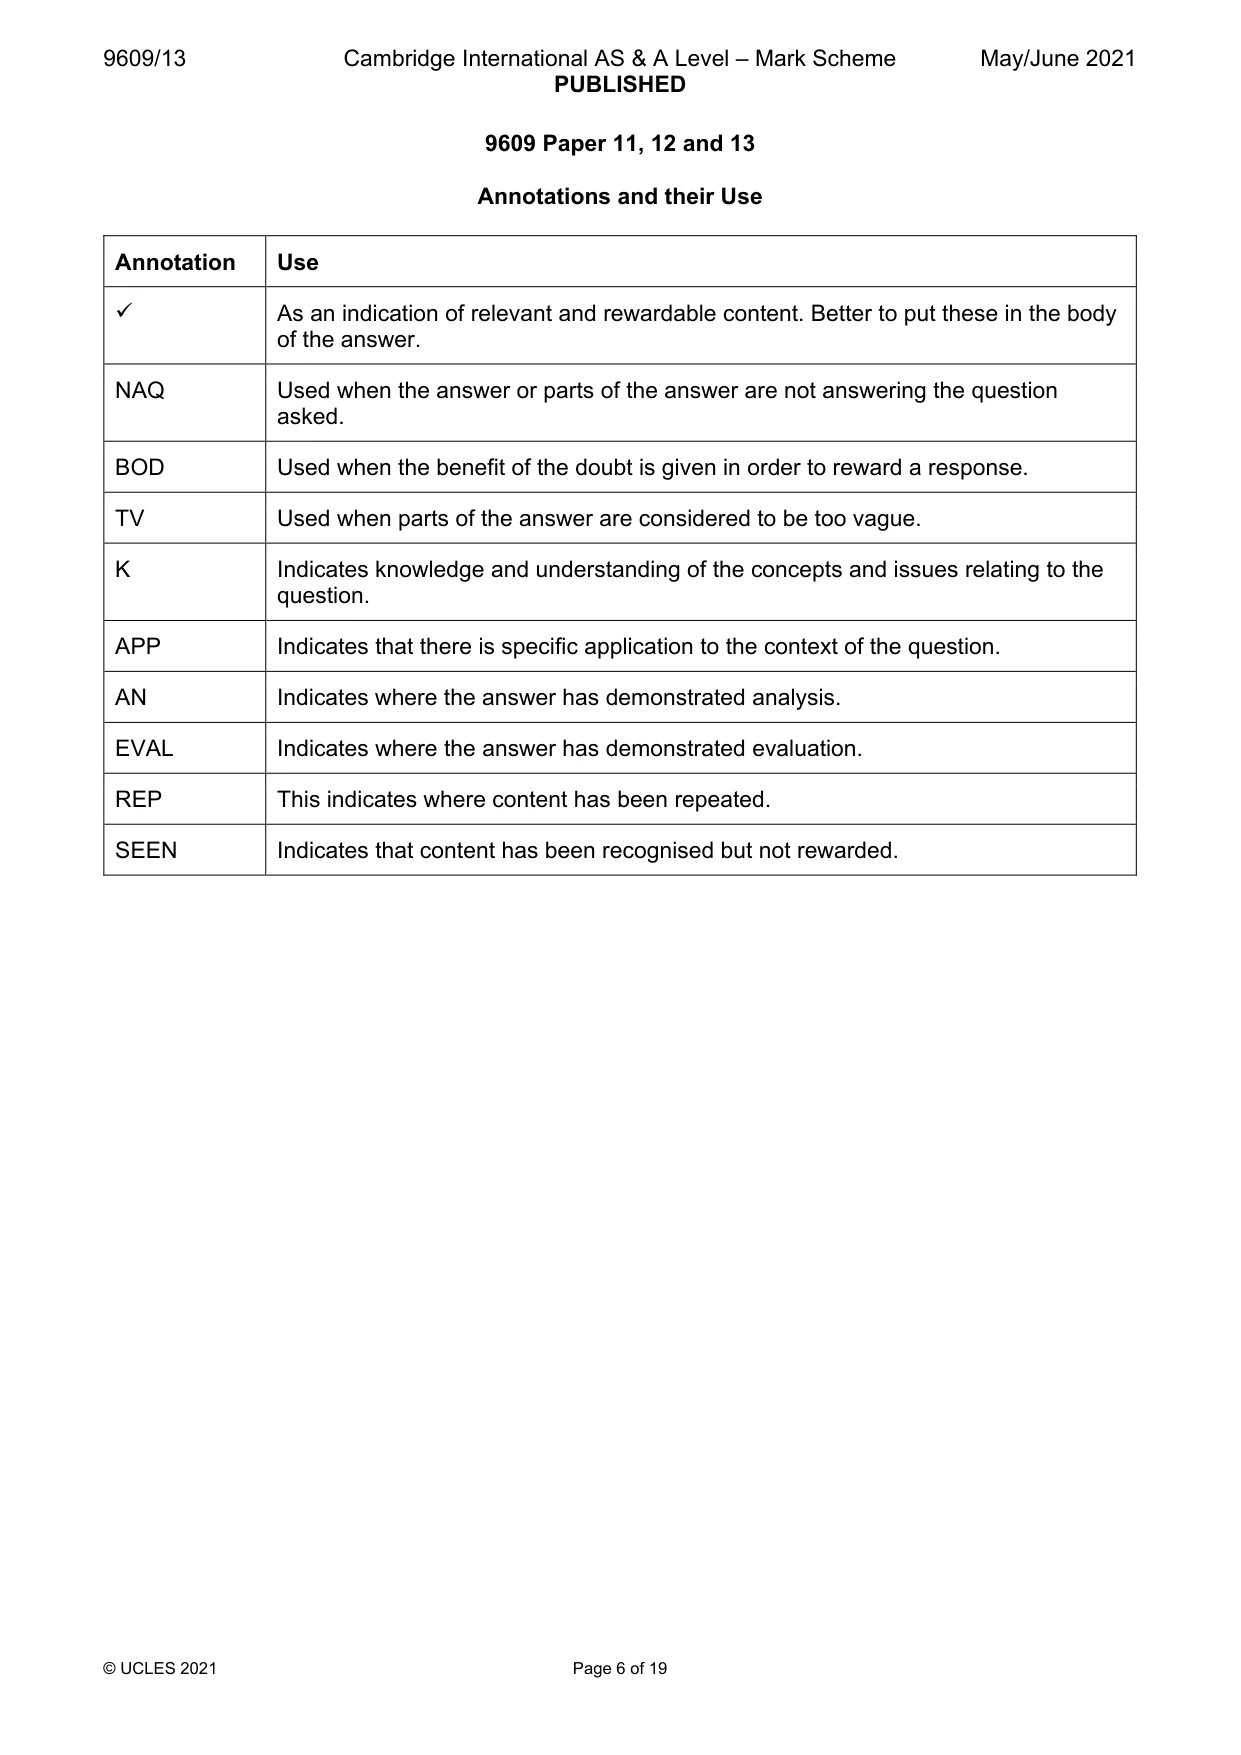
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 5 of 19 9609 Paper 1 Specific Marking Principles Marks are awarded for each answer when the following Assessment Objectives (AO) are met. The mark scheme for each answer indicates when and how each AO can be met. AO1 – Demonstrate knowledge and understanding of business concepts. The focus in Section A of the Examination Paper is on this first AO. (a) Questions 1, 2, and 4 will meet this AO using definitions and explanations of business concepts. (b) Question 3 provides an opportunity for the application and a more developed explanation of a business concept. The 4–5 mark level specifically provides for this more developed explanation. In Section B of the Examination Paper. (a) Questions 5, 6, and 7 still require supporting Knowledge and Understanding (AO1), but there is now a focus on Application (AO2), Analysis (AO3), and Evaluation (AO4). These skills are set out below: AO2 – Apply knowledge and understanding of business concepts to general and specific situations and contexts. (a) Where a specific business or context is named in the question then the candidate is required to relate answers specifically to this business or context. (b) It is not sufficient to merely repeat the name of the business or the context. AO3 – Analyse business problems, issues, situations and contexts, through a discussion and interpretation of evidence, debate, theory, impact and consequence, to produce reasoned and coherent arguments. (a) Level 3 answers will likely use terms such as – because, leads to, therefore, so that, as a result, consequently – thereby showing analytical development for AO3. AO4 – Limited Evaluation is given (a) When an attempt is made, (probably in a concluding section of an answer), to address and comment on the value and validity of the previous analysis. (b) These comments may be quite brief and be more opinionated than reasoned. (c) A mere concluding summary of preceding analysis is, however, not evaluation. AO4 – Evaluation occurs (a) When an answer comments on the validity/significance of previous analysis in an evidence based and reasoned way. (b) This often leads to the presentation of appropriate substantiated judgements, decisions, or recommendations.
Mark scheme, page 6
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 6 of 19 9609 Paper 11, 12 and 13 Annotations and their Use Annotation Use As an indication of relevant and rewardable content. Better to put these in the body of the answer. NAQ Used when the answer or parts of the answer are not answering the question asked. BOD Used when the benefit of the doubt is given in order to reward a response. TV Used when parts of the answer are considered to be too vague. K Indicates knowledge and understanding of the concepts and issues relating to the question. APP Indicates that there is specific application to the context of the question. AN Indicates where the answer has demonstrated analysis. EVAL Indicates where the answer has demonstrated evaluation. REP This indicates where content has been repeated. SEEN Indicates that content has been recognised but not rewarded.
Mark scheme, page 7
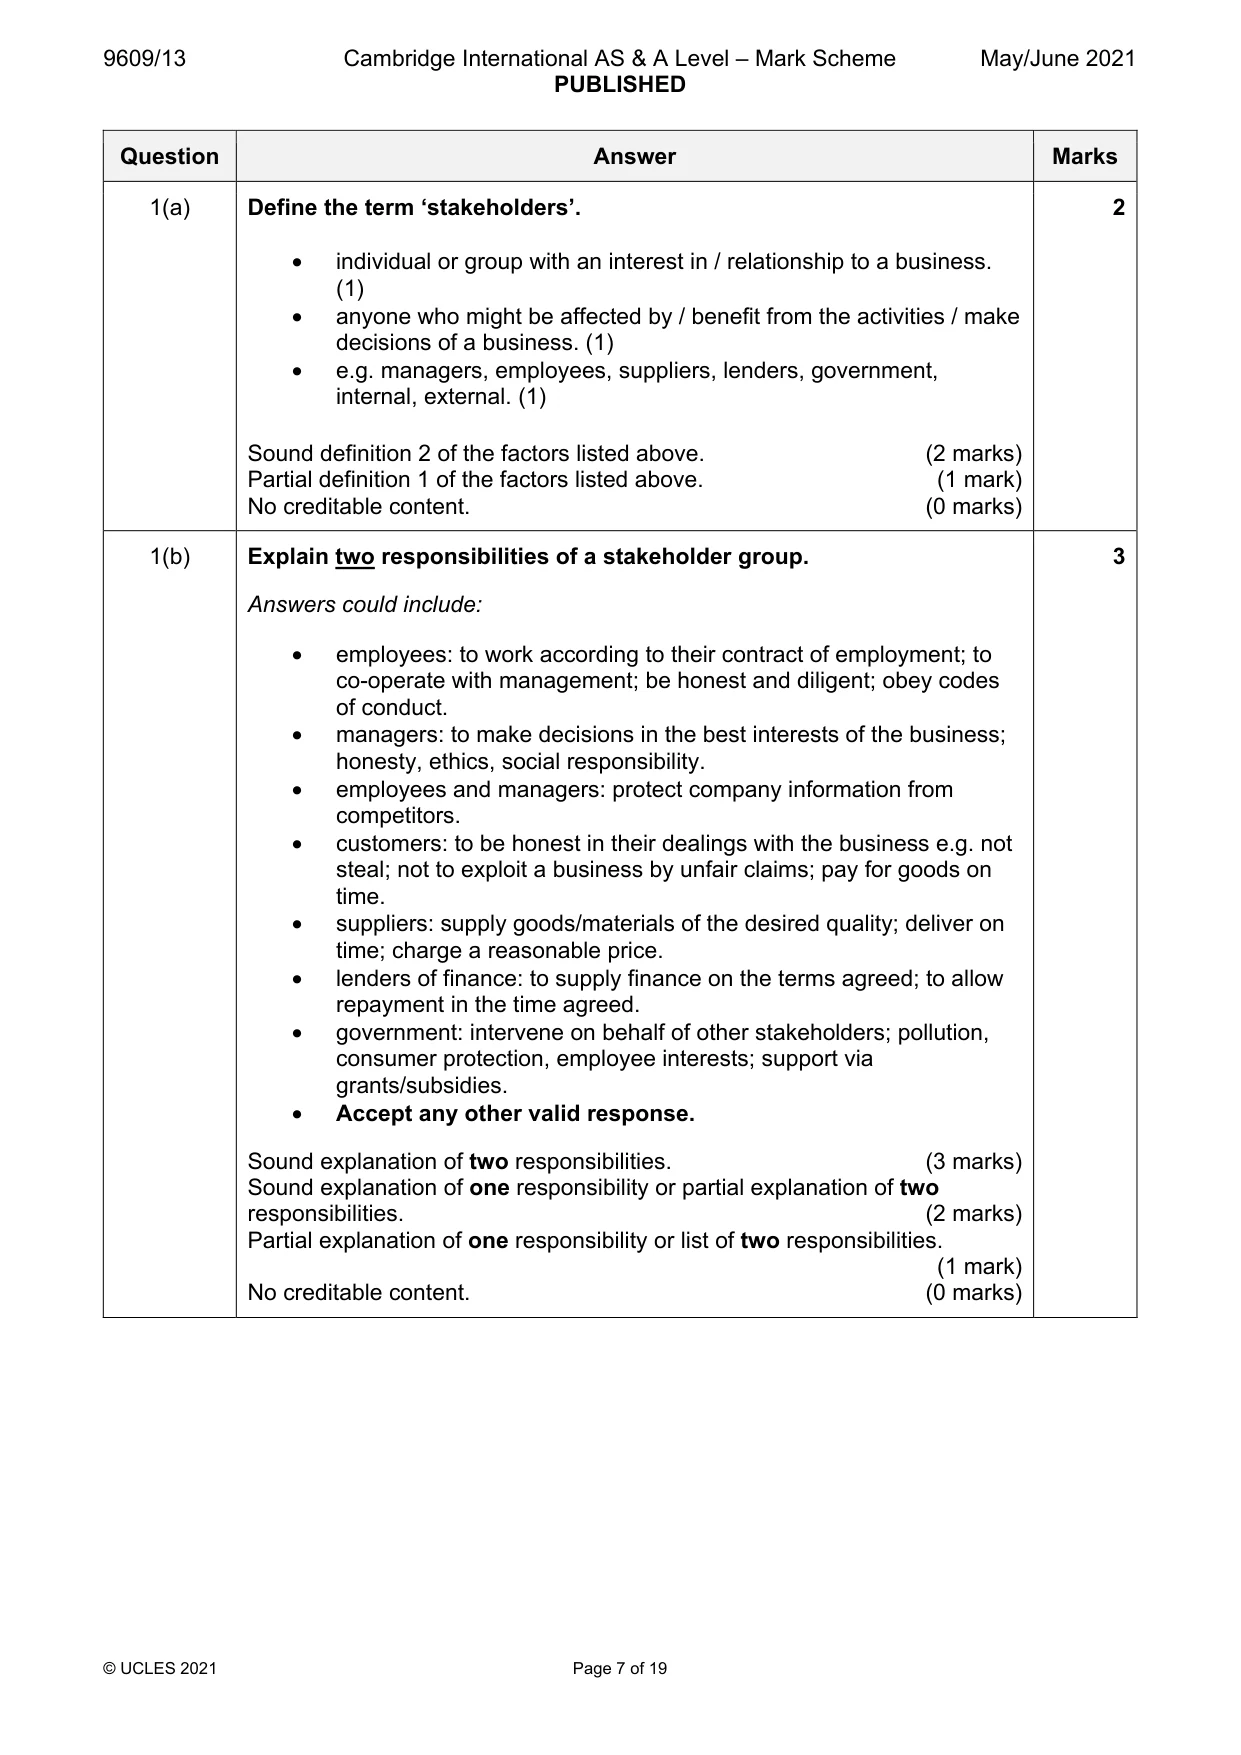
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 7 of 19 Question Answer Marks 1(a) Define the term ‘stakeholders’. • individual or group with an interest in / relationship to a business. (1) • anyone who might be affected by / benefit from the activities / make decisions of a business. (1) • e.g. managers, employees, suppliers, lenders, government, internal, external. (1) Sound definition 2 of the factors listed above. (2 marks) Partial definition 1 of the factors listed above. (1 mark) No creditable content. (0 marks) 2 1(b) Explain two responsibilities of a stakeholder group. Answers could include: • employees: to work according to their contract of employment; to co-operate with management; be honest and diligent; obey codes of conduct. • managers: to make decisions in the best interests of the business; honesty, ethics, social responsibility. • employees and managers: protect company information from competitors. • customers: to be honest in their dealings with the business e.g. not steal; not to exploit a business by unfair claims; pay for goods on time. • suppliers: supply goods/materials of the desired quality; deliver on time; charge a reasonable price. • lenders of finance: to supply finance on the terms agreed; to allow repayment in the time agreed. • government: intervene on behalf of other stakeholders; pollution, consumer protection, employee interests; support via grants/subsidies. • Accept any other valid response. Sound explanation of two responsibilities. (3 marks) Sound explanation of one responsibility or partial explanation of two responsibilities. (2 marks) Partial explanation of one responsibility or list of two responsibilities. (1 mark) No creditable content. (0 marks) 3
Mark scheme, page 8
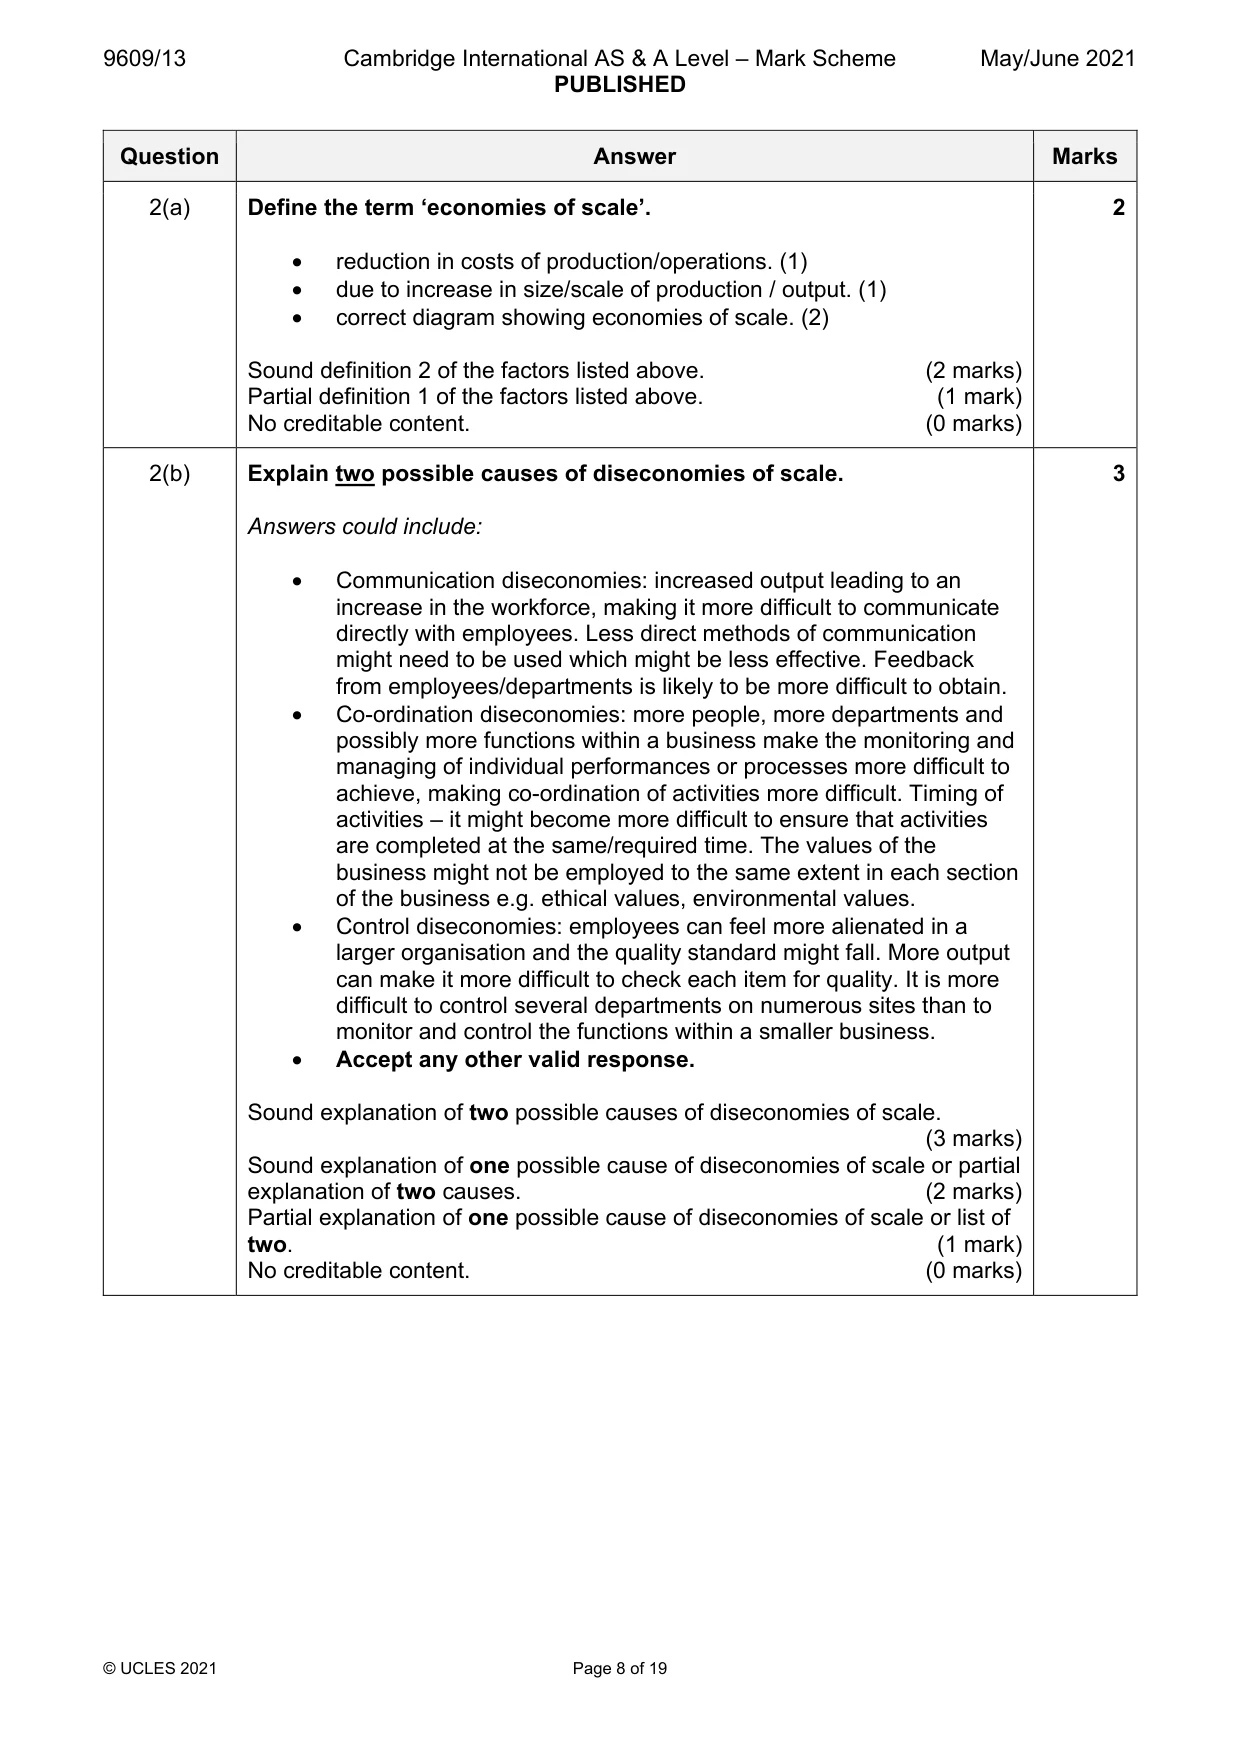
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 8 of 19 Question Answer Marks 2(a) Define the term ‘economies of scale’. • reduction in costs of production/operations. (1) • due to increase in size/scale of production / output. (1) • correct diagram showing economies of scale. (2) Sound definition 2 of the factors listed above. (2 marks) Partial definition 1 of the factors listed above. (1 mark) No creditable content. (0 marks) 2 2(b) Explain two possible causes of diseconomies of scale. Answers could include: • Communication diseconomies: increased output leading to an increase in the workforce, making it more difficult to communicate directly with employees. Less direct methods of communication might need to be used which might be less effective. Feedback from employees/departments is likely to be more difficult to obtain. • Co-ordination diseconomies: more people, more departments and possibly more functions within a business make the monitoring and managing of individual performances or processes more difficult to achieve, making co-ordination of activities more difficult. Timing of activities – it might become more difficult to ensure that activities are completed at the same/required time. The values of the business might not be employed to the same extent in each section of the business e.g. ethical values, environmental values. • Control diseconomies: employees can feel more alienated in a larger organisation and the quality standard might fall. More output can make it more difficult to check each item for quality. It is more difficult to control several departments on numerous sites than to monitor and control the functions within a smaller business. • Accept any other valid response. Sound explanation of two possible causes of diseconomies of scale. (3 marks) Sound explanation of one possible cause of diseconomies of scale or partial explanation of two causes. (2 marks) Partial explanation of one possible cause of diseconomies of scale or list of two. (1 mark) No creditable content. (0 marks) 3
Mark scheme, page 9
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 9 of 19 Question Answer Marks 3(a) Explain why cost-based pricing might be an effective pricing strategy for a small business. Answers could include: • Cost-based pricing is determined by the costs of production of a product/service. • Cost plus pricing - the full costs of a product are calculated and a margin is added to achieve the desired profit level. • Contribution cost pricing – in a small business, it is likely that the fixed costs per product are known due to the small scale of the business, making it easier to include a proportion of them in the price of each item produced. • A small business needs to ensure that all the costs of production are covered by the price charged to its customers. • The fixed costs together with all variable costs will be included and a percentage added to give a profit. • This can ensure that the business recovers all costs when goods are sold. • The amount of profit added on to the costs of the business can be adjusted to make sure that the business is able to compete on price with its competitors. • Accept any other valid response. Effective explanation of why cost-based pricing might be an effective pricing strategy for a small business. (4–5 marks) Limited explanation of why cost-based pricing might be an effective pricing strategy for a business. (2–3 marks) Explanation of cost-based pricing. (1 mark) No creditable content. (0 marks) 5
Mark scheme, page 10
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 10 of 19 Question Answer Marks 4(a) Define the term ‘labour turnover’. • The rate at which employees leave a business (2) • Correct formula Number of employees leaving (in a year) 100 Number of employees in the business (in a year) × (2) • Employees leaving the business. (1) • In a given time period. (1) • Through dismissal, resignation, redundancy, new employment. (1) Sound definition will be either the first bullet point or the formula or 2 of the other 3 bullet points. (2 marks) Partial definition 1 of bullet points 3, 4 or 5. (1 mark) No creditable content. (0 marks) 2 4(b) Explain two ways in which the recruitment and selection process of a business could help to improve labour turnover. Answers could include: • be sure that the job description accurately describes the tasks and responsibilities of the job to recruit the most suitable people. • be sure that the person specification is focused on the qualities and qualifications required when recruiting staff. • Investigate/analyse previous employees’ reasons for leaving. • use an appropriate medium for advertising any posts e.g. social media, recruitment sites or agencies, local newspapers, depending on the role. • check that applicants have the relevant essential and desirable qualities. If not, then reject the application. • use an appropriate selection technique or a combination of methods e.g. an aptitude test followed by an interview. It is possible that using only one technique might not give the most reliable results. For example, some people are able to interview well but might not perform as well in an aptitude test. • the more thorough/appropriate the recruitment and selection process is, the more likely it is that the best candidate is selected. If the person is right for the job, it is less likely that they will leave, therefore labour turnover will improve. • Accept any other valid response. Sound explanation of two ways. (3 marks) Sound explanation of one way or partial explanation of two ways. (2 marks) Partial explanation of one way or list of two ways. (1 mark) No creditable content. (0 marks) 3
Mark scheme, page 11
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 11 of 19 Question Answer Marks 5(a) Analyse the possible disadvantages to a business of changing from batch production to flow production. Level Description Marks 4 Good analysis of the possible disadvantages to a business of changing from batch to flow production. 7–8 3 Limited analysis of the possible disadvantages to a business of changing from batch to flow production. 5–6 2 Application of the possible disadvantages to a business of changing from batch to flow production. 3–4 1 Knowledge and understanding of batch/ flow production. 1–2 0 No creditable content. 0 Answers could include: Knowledge and Understanding 2 marks • Clear understanding of batch production. • Clear understanding of flow production. Application 2 marks • Reference to change from batch to flow production. Analysis 4 marks • Batch: the production of a limited number of identical products. Each stage of production is completed before the next stage commences. • Flow: the production of identical products in a continuous flow. Disadvantages can include: • The high cost of setting up a flow production method. More equipment might be involved that adds to the costs of production in the short-term. • Fewer employees might be needed, causing some redundancies, leading to demotivated workforce. • High levels of output usually required to make flow production a profitable option. Is demand of the business high enough to justify the change? • If there is a fall in demand it is more difficult to switch to the production of different products because flow production usually has dedicated equipment for the production on one product. • If the business produces a wide variety of products, batch production might be more efficient. Non-productive time would occur while the flow production equipment was being switched to the production of a different product. • Accept any other valid response. 8
Mark scheme, page 12
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 12 of 19 Question Answer Marks 5(b) Discuss the benefits to a clothing business of holding buffer inventory rather than using a Just in Time (JIT) inventory system. Level The Description Marks 4 Effective evaluation of the benefits to a clothing business of holding buffer inventory rather than using a Just in Time (JIT) inventory system. 9–12 3 Limited evaluation of the benefits to a business of holding buffer inventory and/or using a Just in Time (JIT) inventory system. 7–8 2 Analysis and application of the benefits of holding buffer inventory and/or using a Just in Time (JIT) inventory system. 3–6 1 Knowledge and understanding of buffer inventory/JIT inventory system. 1–2 0 No creditable content 0 Answers could include: Knowledge and Understanding 2 marks • Clear understanding of buffer inventory. • Clear understanding of JIT inventory system. Application 2 marks • Reference to the use of inventory systems such as buffer and JIT. Analysis 2 mark • Buffer – the minimum amount of inventory held to ensure that production can continue uninterrupted if delivery of inventory is delayed or to ensure that a variation in demand can be met. • JIT – the management of inventory that ensures that new inventory arrives just at the time when it is required and not before. It removes the need for inventory to be held in storage until it is required. • When holding buffer inventory, the business is able to continue to operate even if there is a delay in delivery from suppliers. • The cost of holding the additional inventory might be worthwhile in order to ensure that customer demand can be satisfied. • With JIT, equipment and employees would be idle if inventory failed to arrive on time. Holding buffer inventory avoids that problem. • Using buffer inventory also means that larger orders can be placed to gain bulk buying benefits. 12
Mark scheme, page 13
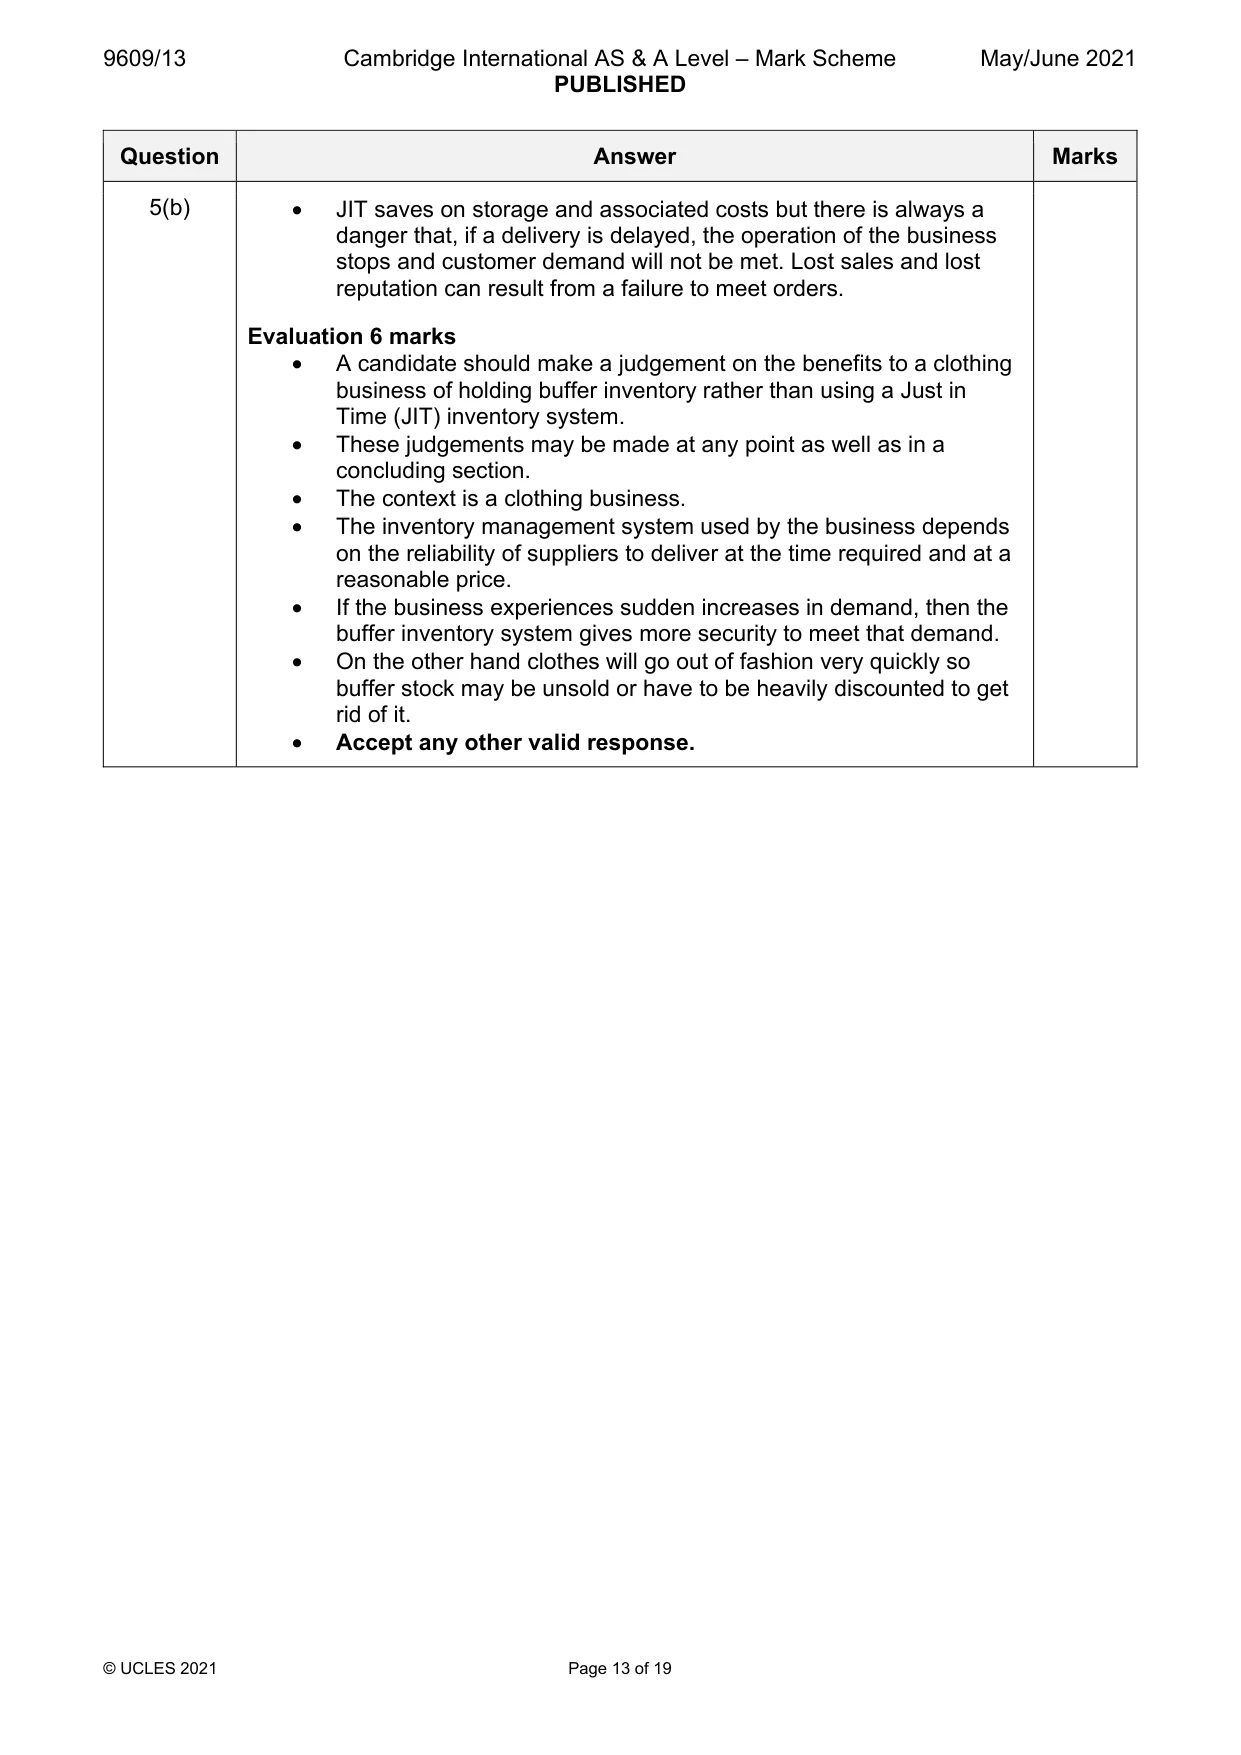
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 13 of 19 Question Answer Marks 5(b) • JIT saves on storage and associated costs but there is always a danger that, if a delivery is delayed, the operation of the business stops and customer demand will not be met. Lost sales and lost reputation can result from a failure to meet orders. Evaluation 6 marks • A candidate should make a judgement on the benefits to a clothing business of holding buffer inventory rather than using a Just in Time (JIT) inventory system. • These judgements may be made at any point as well as in a concluding section. • The context is a clothing business. • The inventory management system used by the business depends on the reliability of suppliers to deliver at the time required and at a reasonable price. • If the business experiences sudden increases in demand, then the buffer inventory system gives more security to meet that demand. • On the other hand clothes will go out of fashion very quickly so buffer stock may be unsold or have to be heavily discounted to get rid of it. • Accept any other valid response.
Mark scheme, page 14
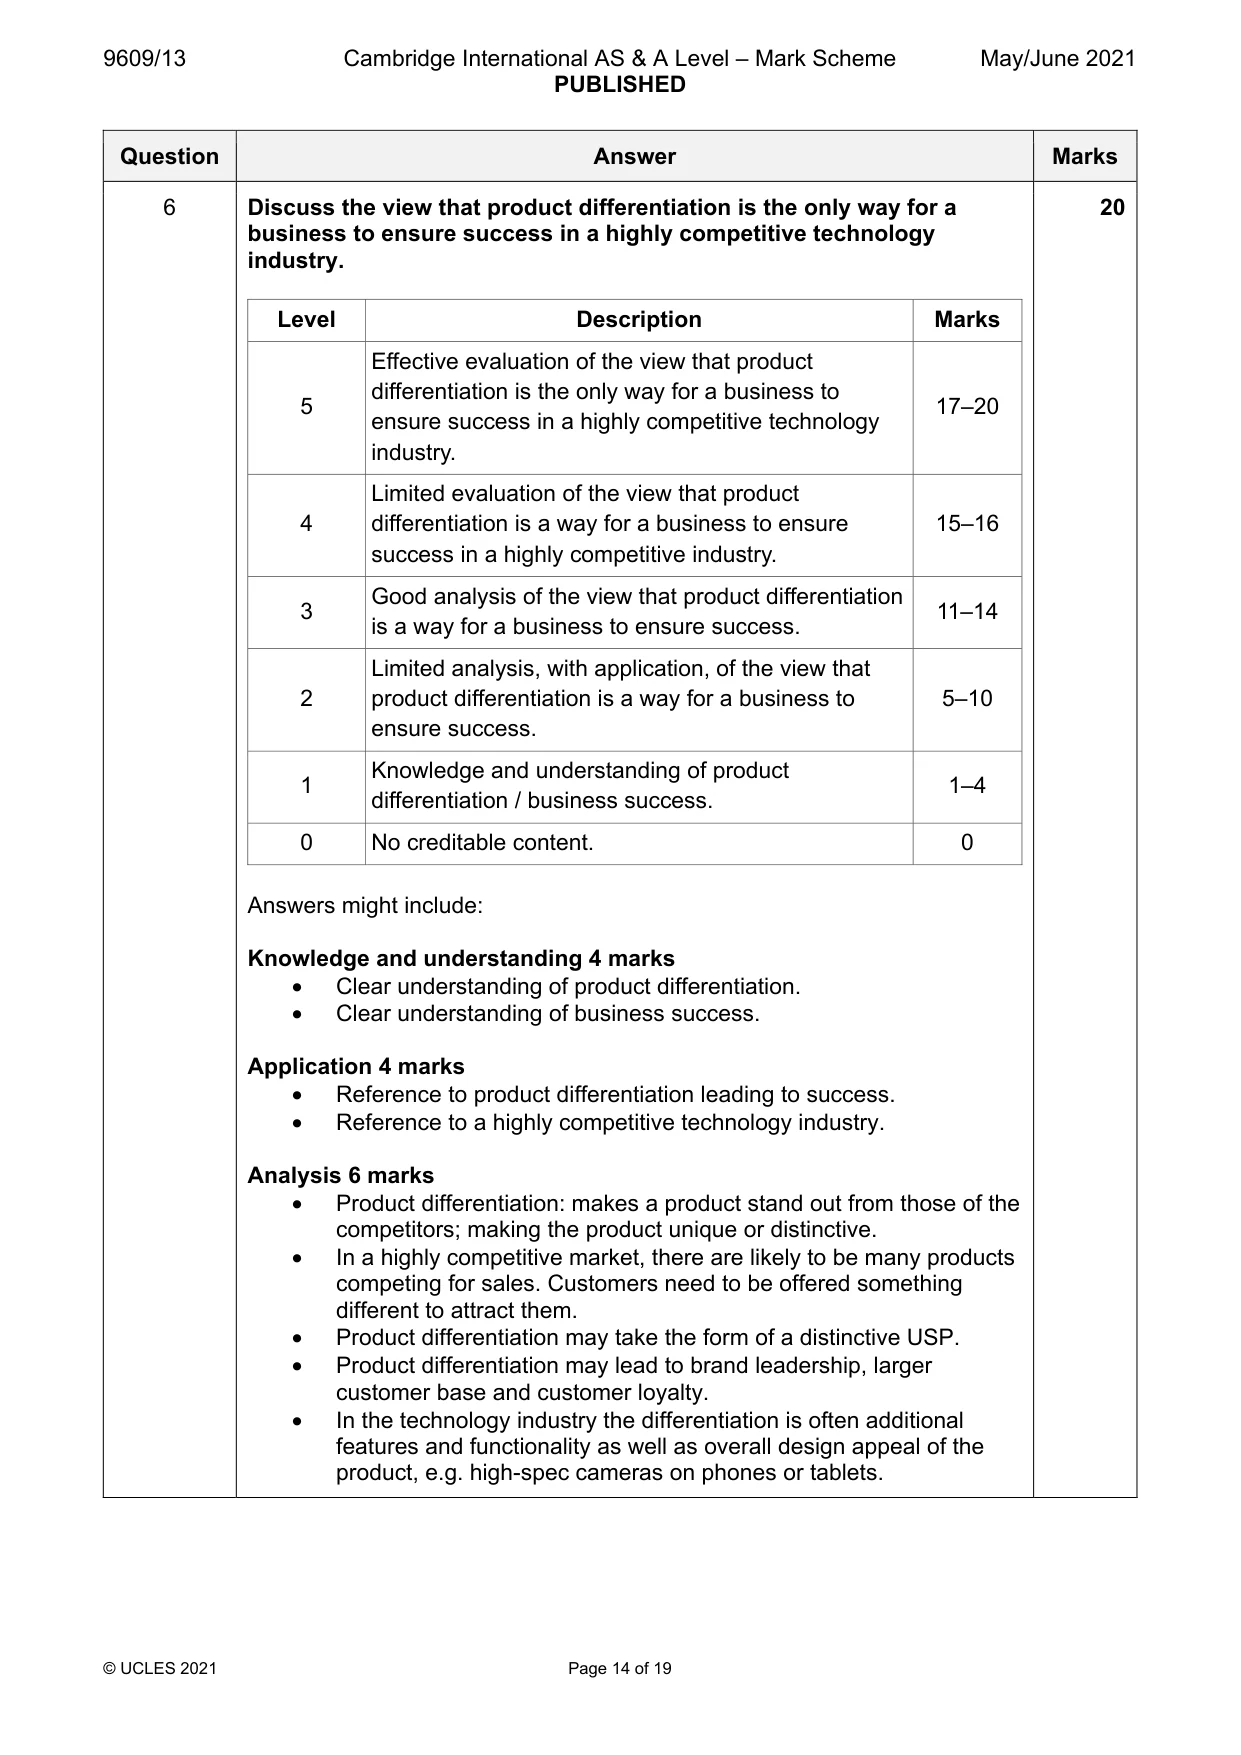
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 14 of 19 Question Answer Marks 6 Discuss the view that product differentiation is the only way for a business to ensure success in a highly competitive technology industry. Level Description Marks 5 Effective evaluation of the view that product differentiation is the only way for a business to ensure success in a highly competitive technology industry. 17–20 4 Limited evaluation of the view that product differentiation is a way for a business to ensure success in a highly competitive industry. 15–16 3 Good analysis of the view that product differentiation is a way for a business to ensure success. 11–14 2 Limited analysis, with application, of the view that product differentiation is a way for a business to ensure success. 5–10 1 Knowledge and understanding of product differentiation / business success. 1–4 0 No creditable content. 0 Answers might include: Knowledge and understanding 4 marks • Clear understanding of product differentiation. • Clear understanding of business success. Application 4 marks • Reference to product differentiation leading to success. • Reference to a highly competitive technology industry. Analysis 6 marks • Product differentiation: makes a product stand out from those of the competitors; making the product unique or distinctive. • In a highly competitive market, there are likely to be many products competing for sales. Customers need to be offered something different to attract them. • Product differentiation may take the form of a distinctive USP. • Product differentiation may lead to brand leadership, larger customer base and customer loyalty. • In the technology industry the differentiation is often additional features and functionality as well as overall design appeal of the product, e.g. high-spec cameras on phones or tablets. 20
Mark scheme, page 15
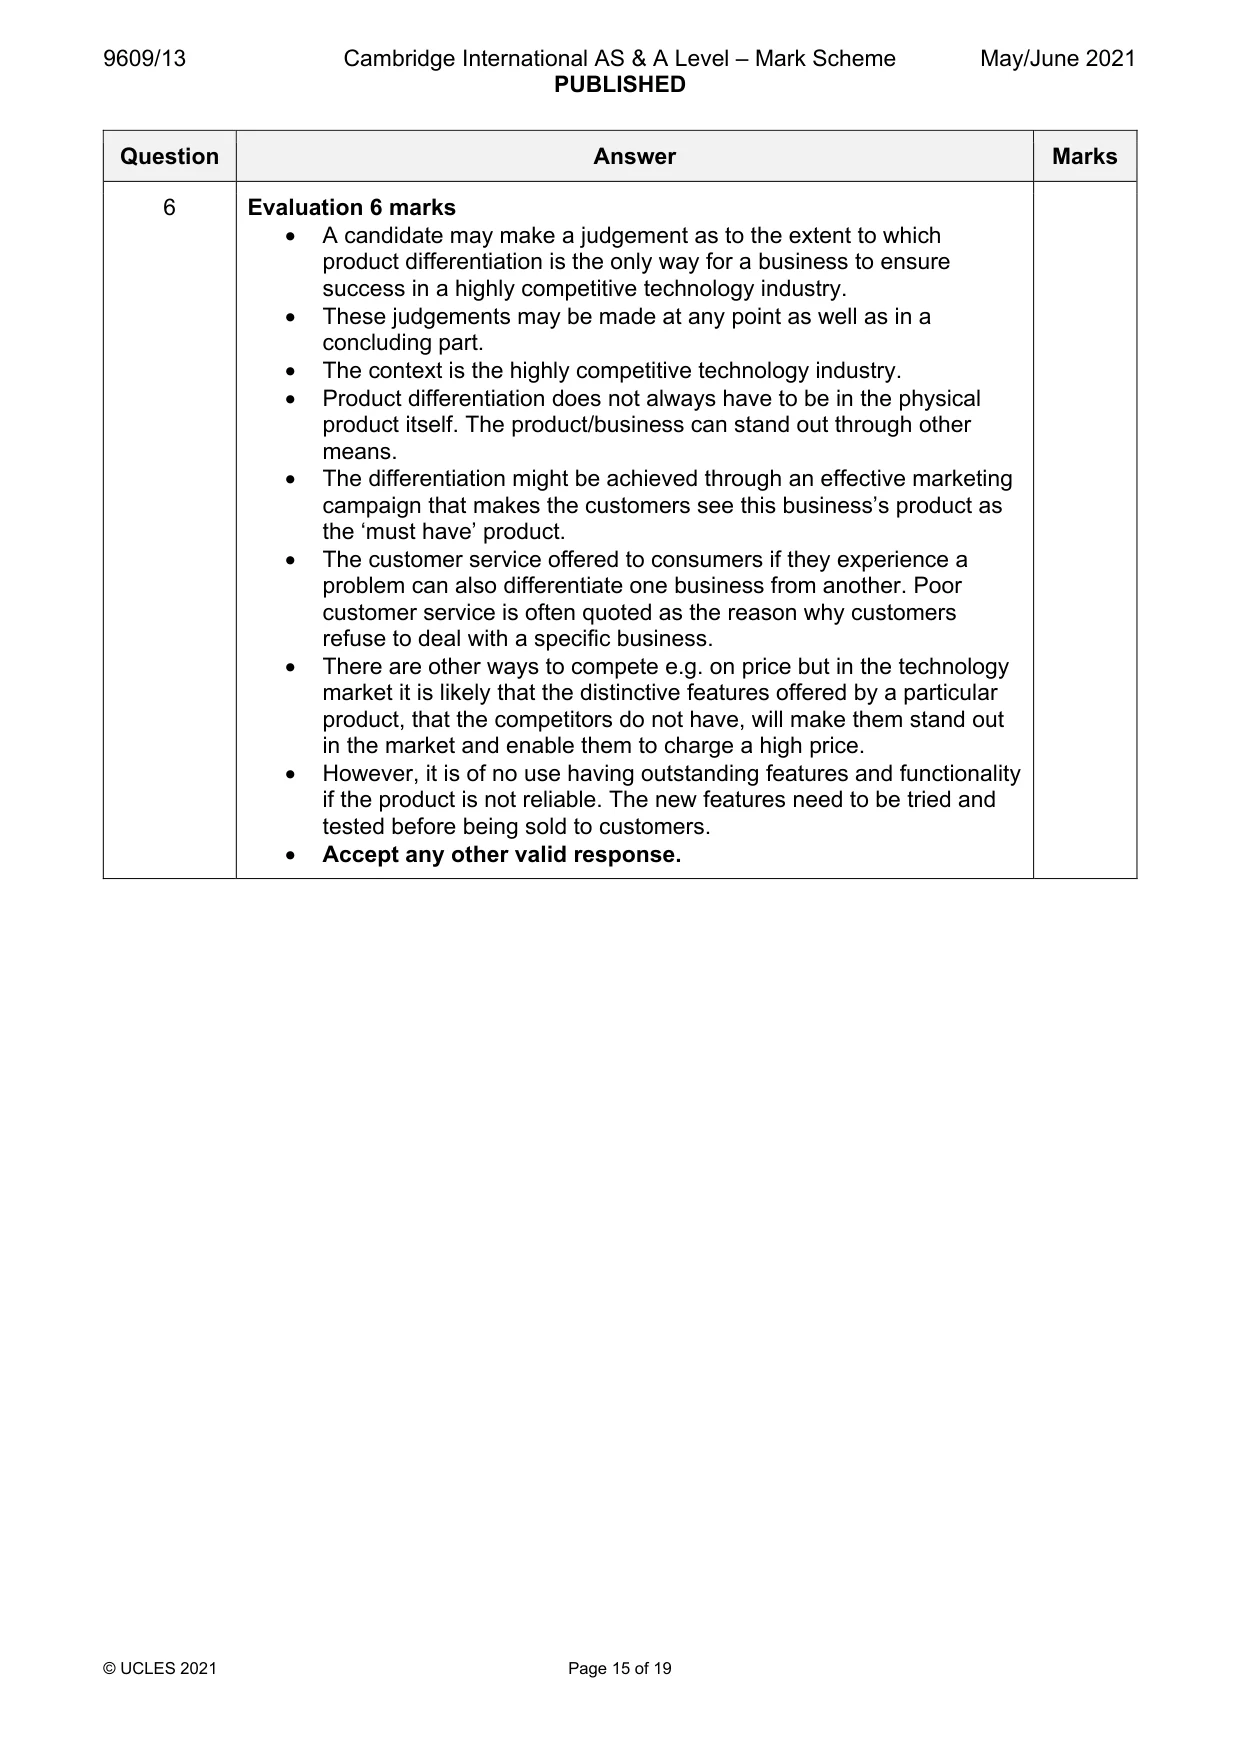
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 15 of 19 Question Answer Marks 6 Evaluation 6 marks • A candidate may make a judgement as to the extent to which product differentiation is the only way for a business to ensure success in a highly competitive technology industry. • These judgements may be made at any point as well as in a concluding part. • The context is the highly competitive technology industry. • Product differentiation does not always have to be in the physical product itself. The product/business can stand out through other means. • The differentiation might be achieved through an effective marketing campaign that makes the customers see this business’s product as the ‘must have’ product. • The customer service offered to consumers if they experience a problem can also differentiate one business from another. Poor customer service is often quoted as the reason why customers refuse to deal with a specific business. • There are other ways to compete e.g. on price but in the technology market it is likely that the distinctive features offered by a particular product, that the competitors do not have, will make them stand out in the market and enable them to charge a high price. • However, it is of no use having outstanding features and functionality if the product is not reliable. The new features need to be tried and tested before being sold to customers. • Accept any other valid response.
Mark scheme, page 16
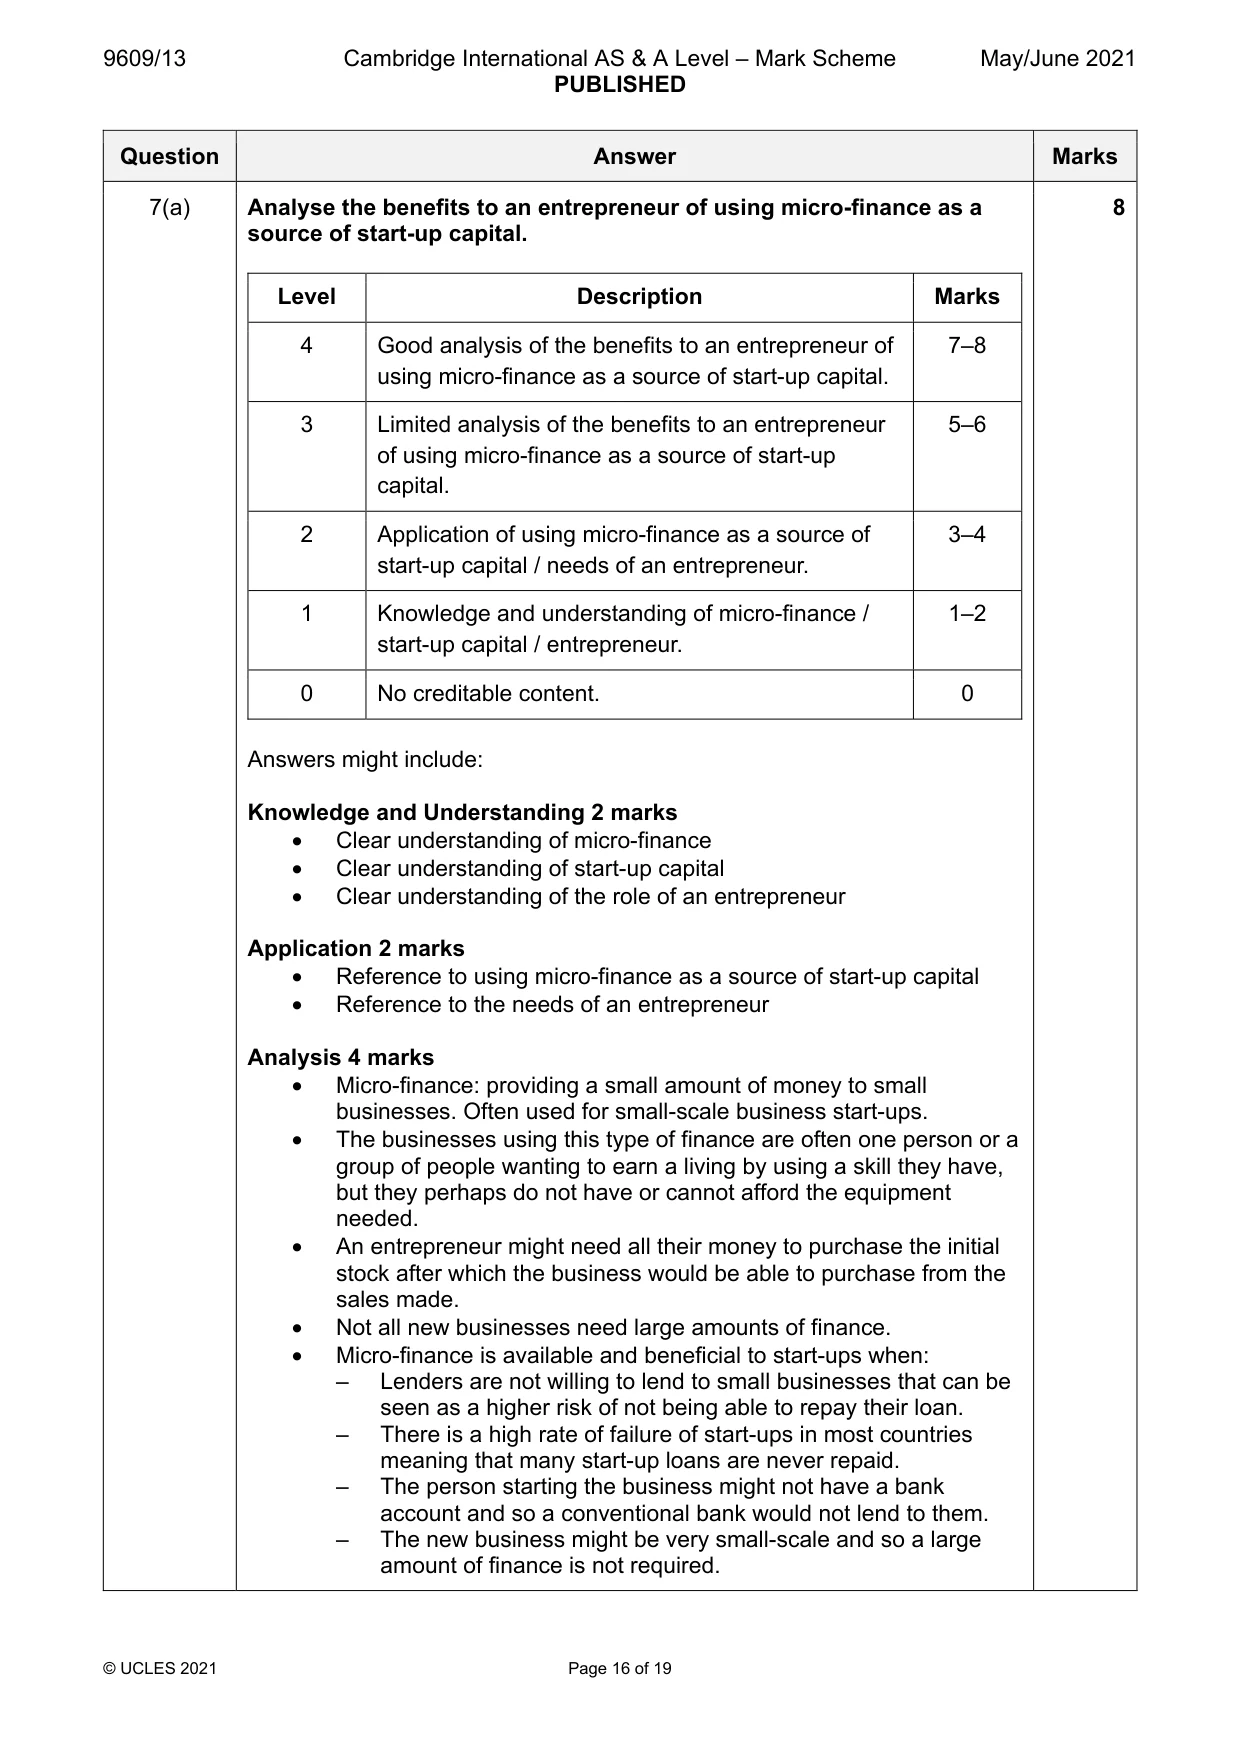
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 16 of 19 Question Answer Marks 7(a) Analyse the benefits to an entrepreneur of using micro-finance as a source of start-up capital. Level Description Marks 4 Good analysis of the benefits to an entrepreneur of using micro-finance as a source of start-up capital. 7–8 3 Limited analysis of the benefits to an entrepreneur of using micro-finance as a source of start-up capital. 5–6 2 Application of using micro-finance as a source of start-up capital / needs of an entrepreneur. 3–4 1 Knowledge and understanding of micro-finance / start-up capital / entrepreneur. 1–2 0 No creditable content. 0 Answers might include: Knowledge and Understanding 2 marks • Clear understanding of micro-finance • Clear understanding of start-up capital • Clear understanding of the role of an entrepreneur Application 2 marks • Reference to using micro-finance as a source of start-up capital • Reference to the needs of an entrepreneur Analysis 4 marks • Micro-finance: providing a small amount of money to small businesses. Often used for small-scale business start-ups. • The businesses using this type of finance are often one person or a group of people wanting to earn a living by using a skill they have, but they perhaps do not have or cannot afford the equipment needed. • An entrepreneur might need all their money to purchase the initial stock after which the business would be able to purchase from the sales made. • Not all new businesses need large amounts of finance. • Micro-finance is available and beneficial to start-ups when: – Lenders are not willing to lend to small businesses that can be seen as a higher risk of not being able to repay their loan. – There is a high rate of failure of start-ups in most countries meaning that many start-up loans are never repaid. – The person starting the business might not have a bank account and so a conventional bank would not lend to them. – The new business might be very small-scale and so a large amount of finance is not required. 8
Mark scheme, page 17
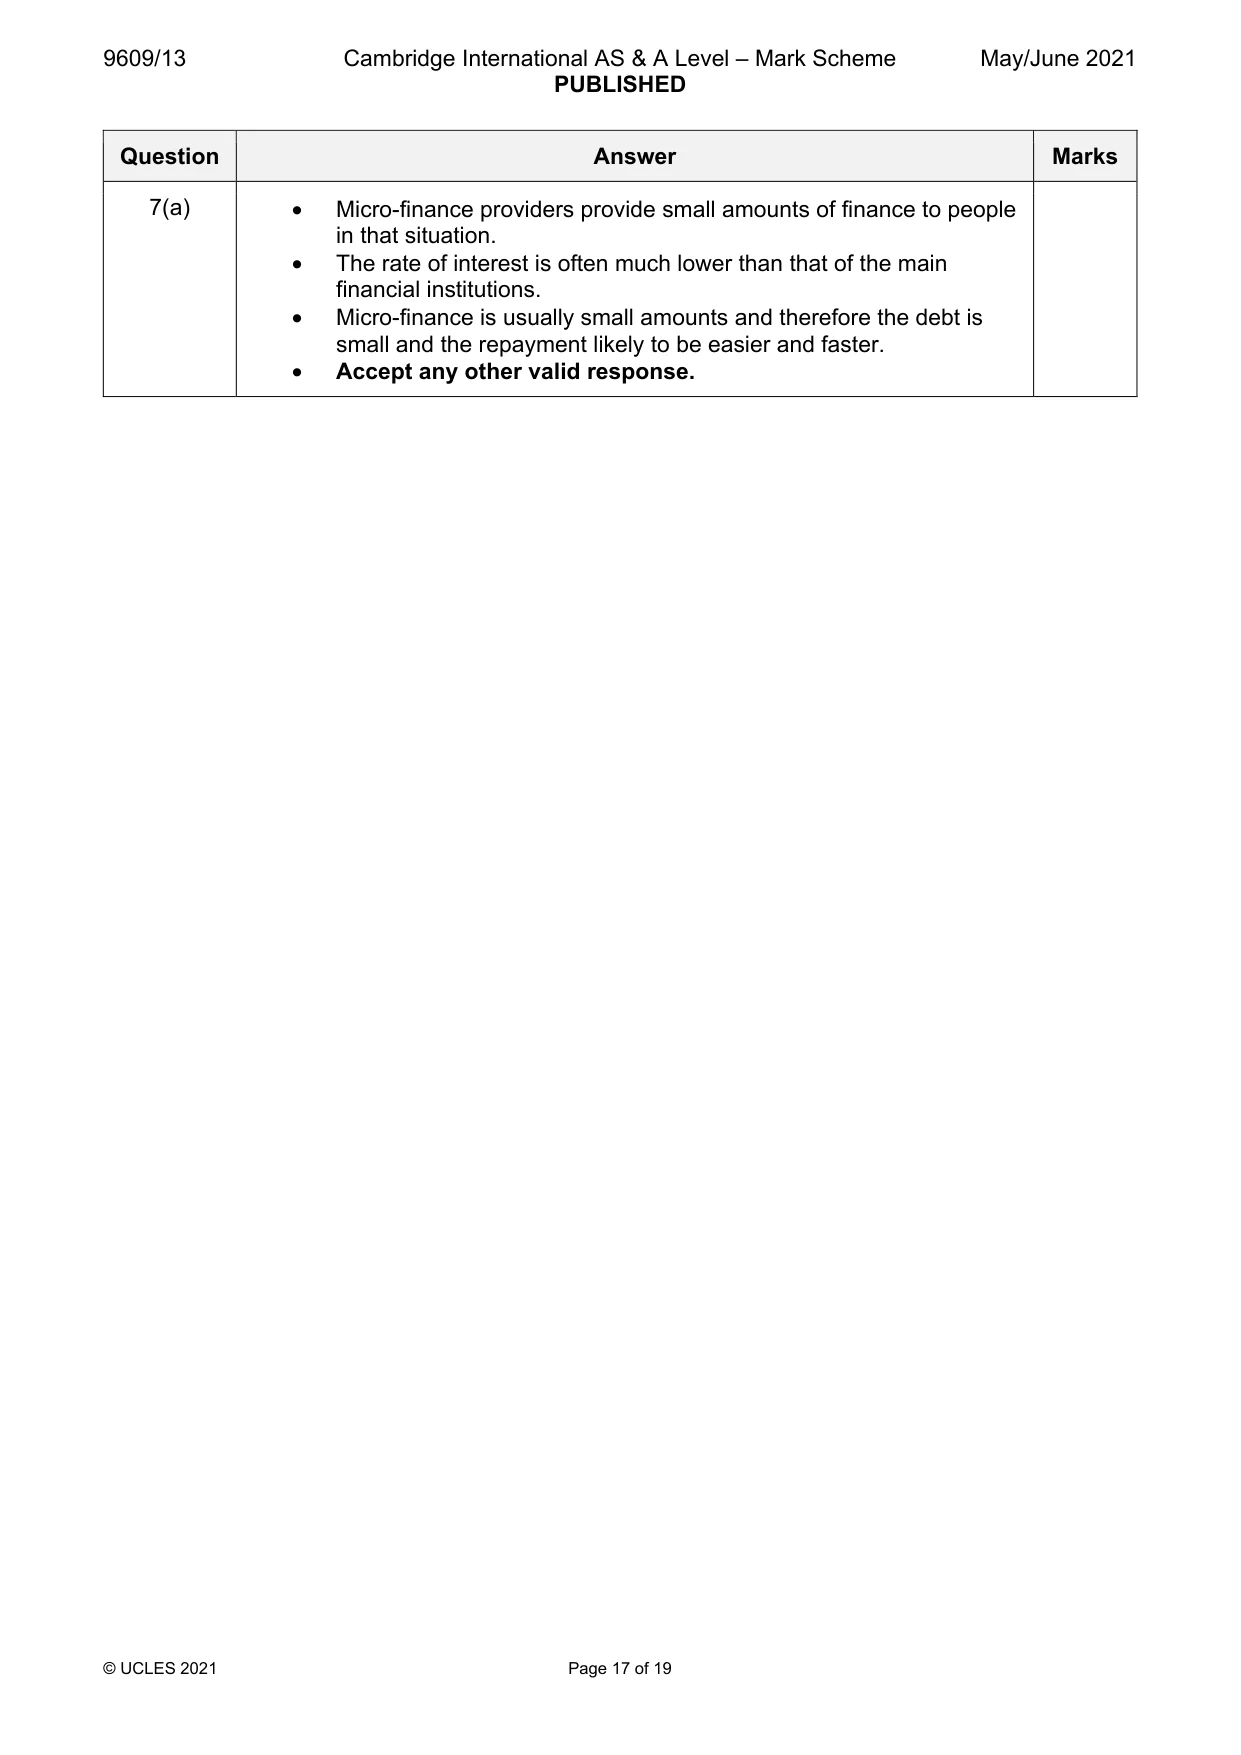
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 17 of 19 Question Answer Marks 7(a) • Micro-finance providers provide small amounts of finance to people in that situation. • The rate of interest is often much lower than that of the main financial institutions. • Micro-finance is usually small amounts and therefore the debt is small and the repayment likely to be easier and faster. • Accept any other valid response.
Mark scheme, page 18
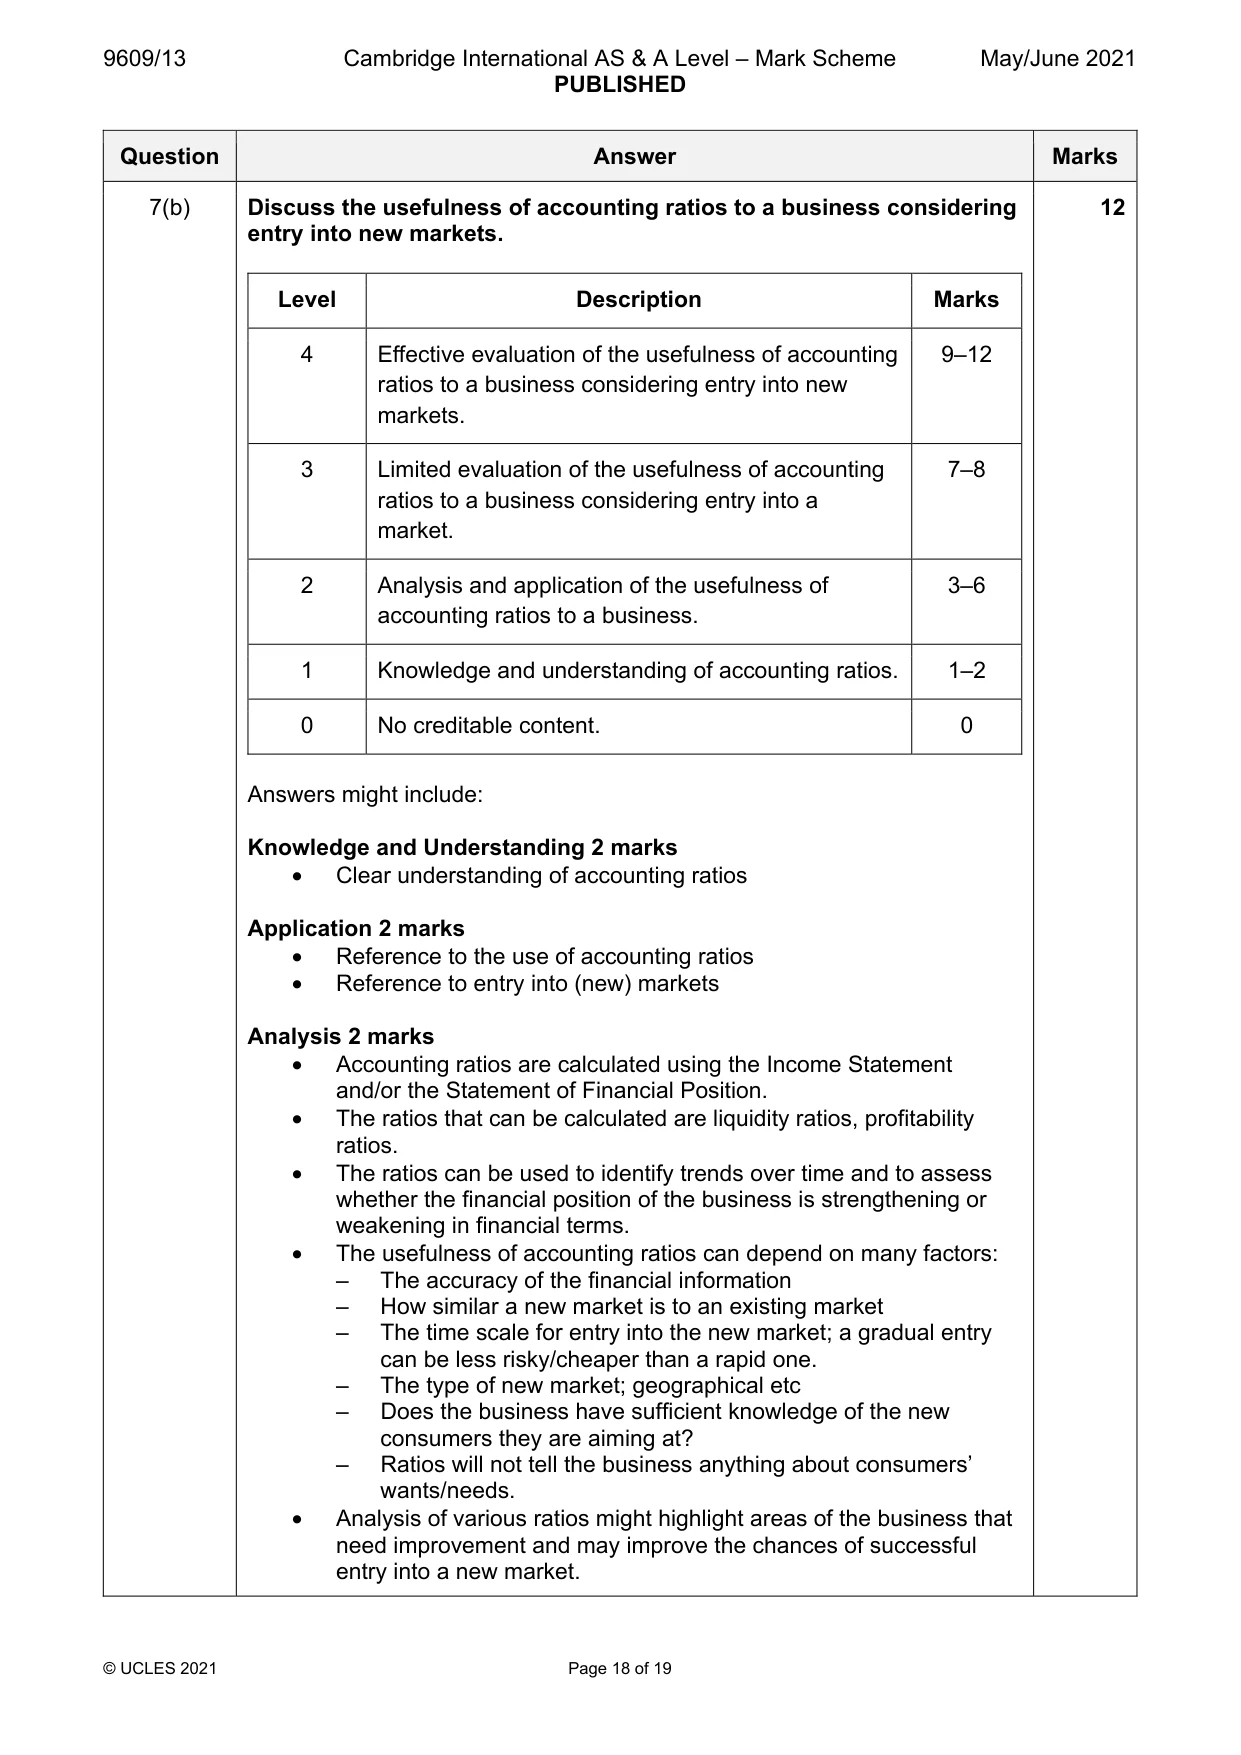
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 18 of 19 Question Answer Marks 7(b) Discuss the usefulness of accounting ratios to a business considering entry into new markets. Level Description Marks 4 Effective evaluation of the usefulness of accounting ratios to a business considering entry into new markets. 9–12 3 Limited evaluation of the usefulness of accounting ratios to a business considering entry into a market. 7–8 2 Analysis and application of the usefulness of accounting ratios to a business. 3–6 1 Knowledge and understanding of accounting ratios. 1–2 0 No creditable content. 0 Answers might include: Knowledge and Understanding 2 marks • Clear understanding of accounting ratios Application 2 marks • Reference to the use of accounting ratios • Reference to entry into (new) markets Analysis 2 marks • Accounting ratios are calculated using the Income Statement and/or the Statement of Financial Position. • The ratios that can be calculated are liquidity ratios, profitability ratios. • The ratios can be used to identify trends over time and to assess whether the financial position of the business is strengthening or weakening in financial terms. • The usefulness of accounting ratios can depend on many factors: – The accuracy of the financial information – How similar a new market is to an existing market – The time scale for entry into the new market; a gradual entry can be less risky/cheaper than a rapid one. – The type of new market; geographical etc – Does the business have sufficient knowledge of the new consumers they are aiming at? – Ratios will not tell the business anything about consumers’ wants/needs. • Analysis of various ratios might highlight areas of the business that need improvement and may improve the chances of successful entry into a new market. 12
Mark scheme, page 19
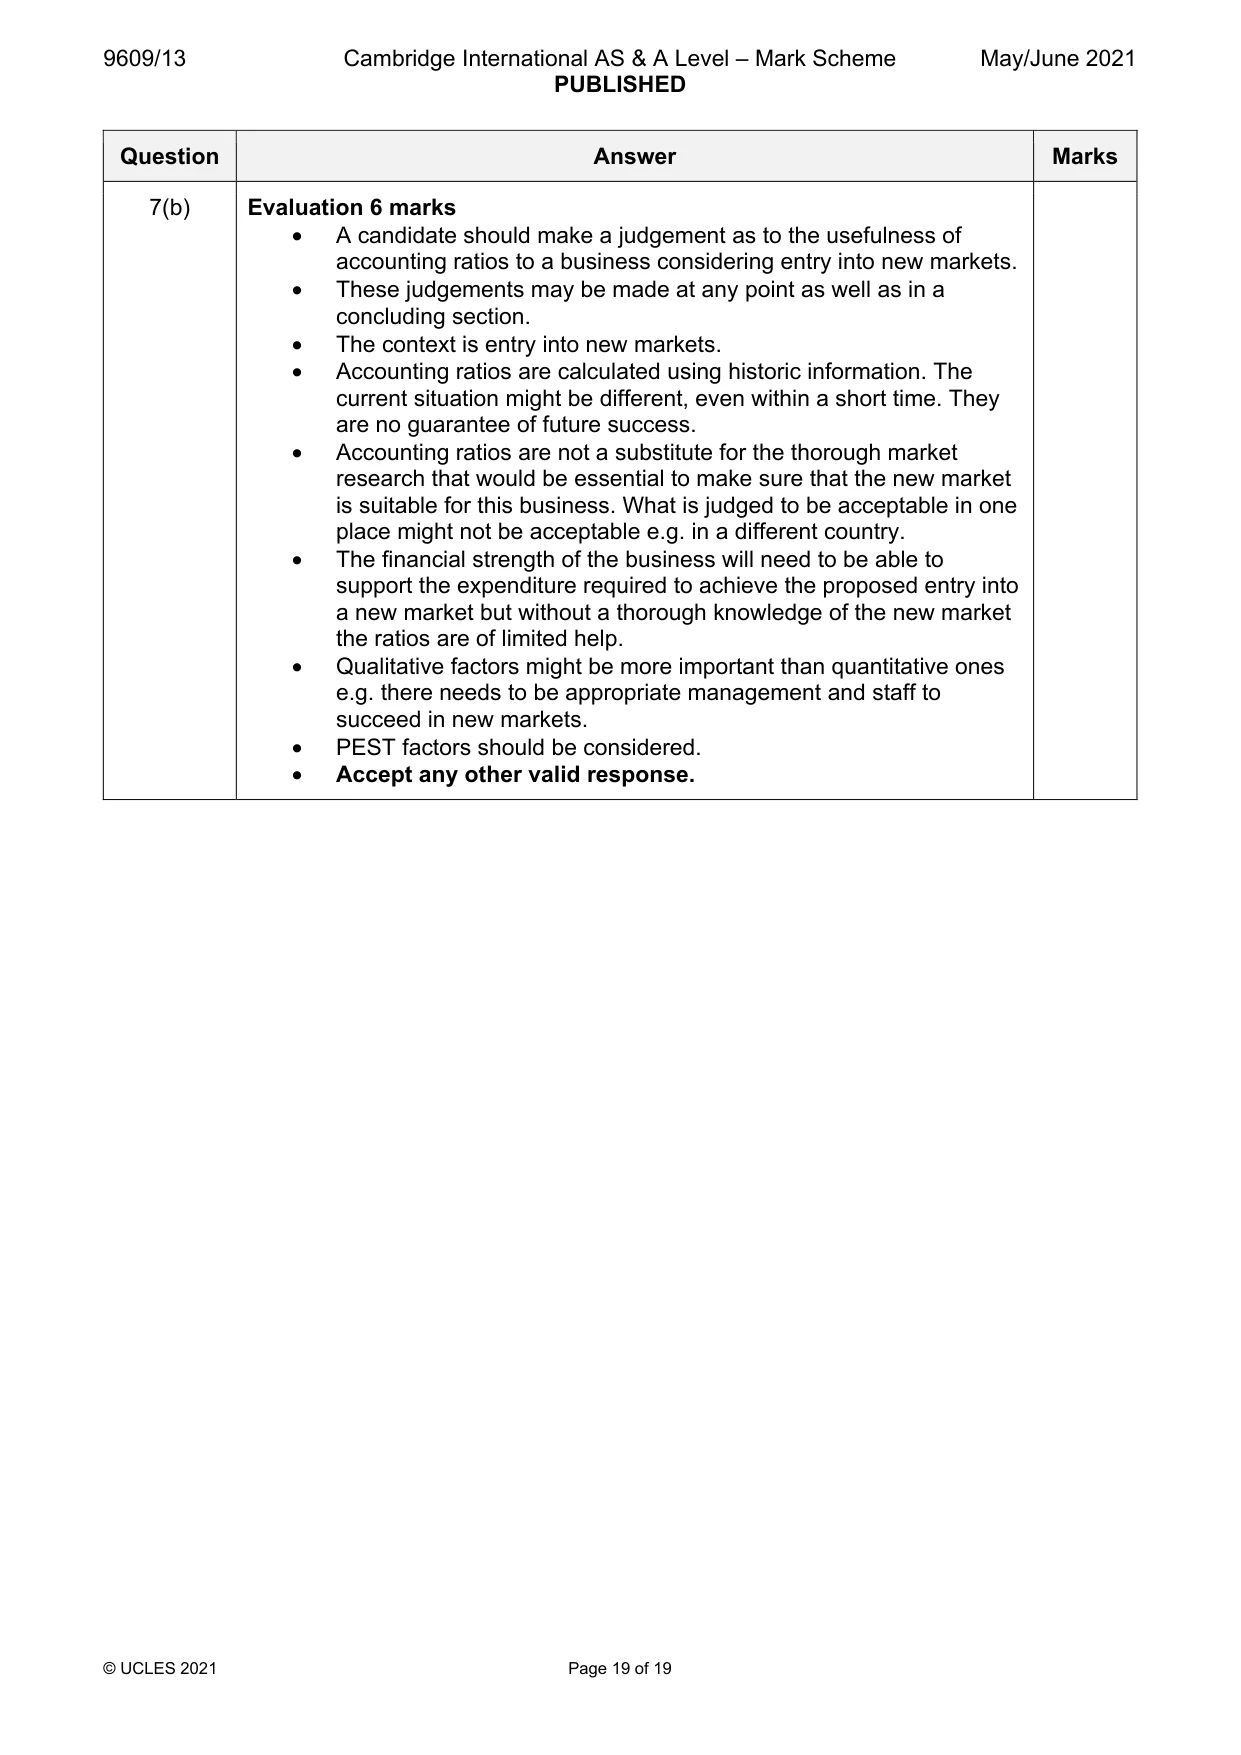
9609/13 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 19 of 19 Question Answer Marks 7(b) Evaluation 6 marks • A candidate should make a judgement as to the usefulness of accounting ratios to a business considering entry into new markets. • These judgements may be made at any point as well as in a concluding section. • The context is entry into new markets. • Accounting ratios are calculated using historic information. The current situation might be different, even within a short time. They are no guarantee of future success. • Accounting ratios are not a substitute for the thorough market research that would be essential to make sure that the new market is suitable for this business. What is judged to be acceptable in one place might not be acceptable e.g. in a different country. • The financial strength of the business will need to be able to support the expenditure required to achieve the proposed entry into a new market but without a thorough knowledge of the new market the ratios are of limited help. • Qualitative factors might be more important than quantitative ones e.g. there needs to be appropriate management and staff to succeed in new markets. • PEST factors should be considered. • Accept any other valid response.
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 1 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.