Cambridge IGCSE Accounting (9-1) 0985 — 2025 Oct/Nov Paper 1 · Variant 2
0985/12/O/N/25 · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Paper as text
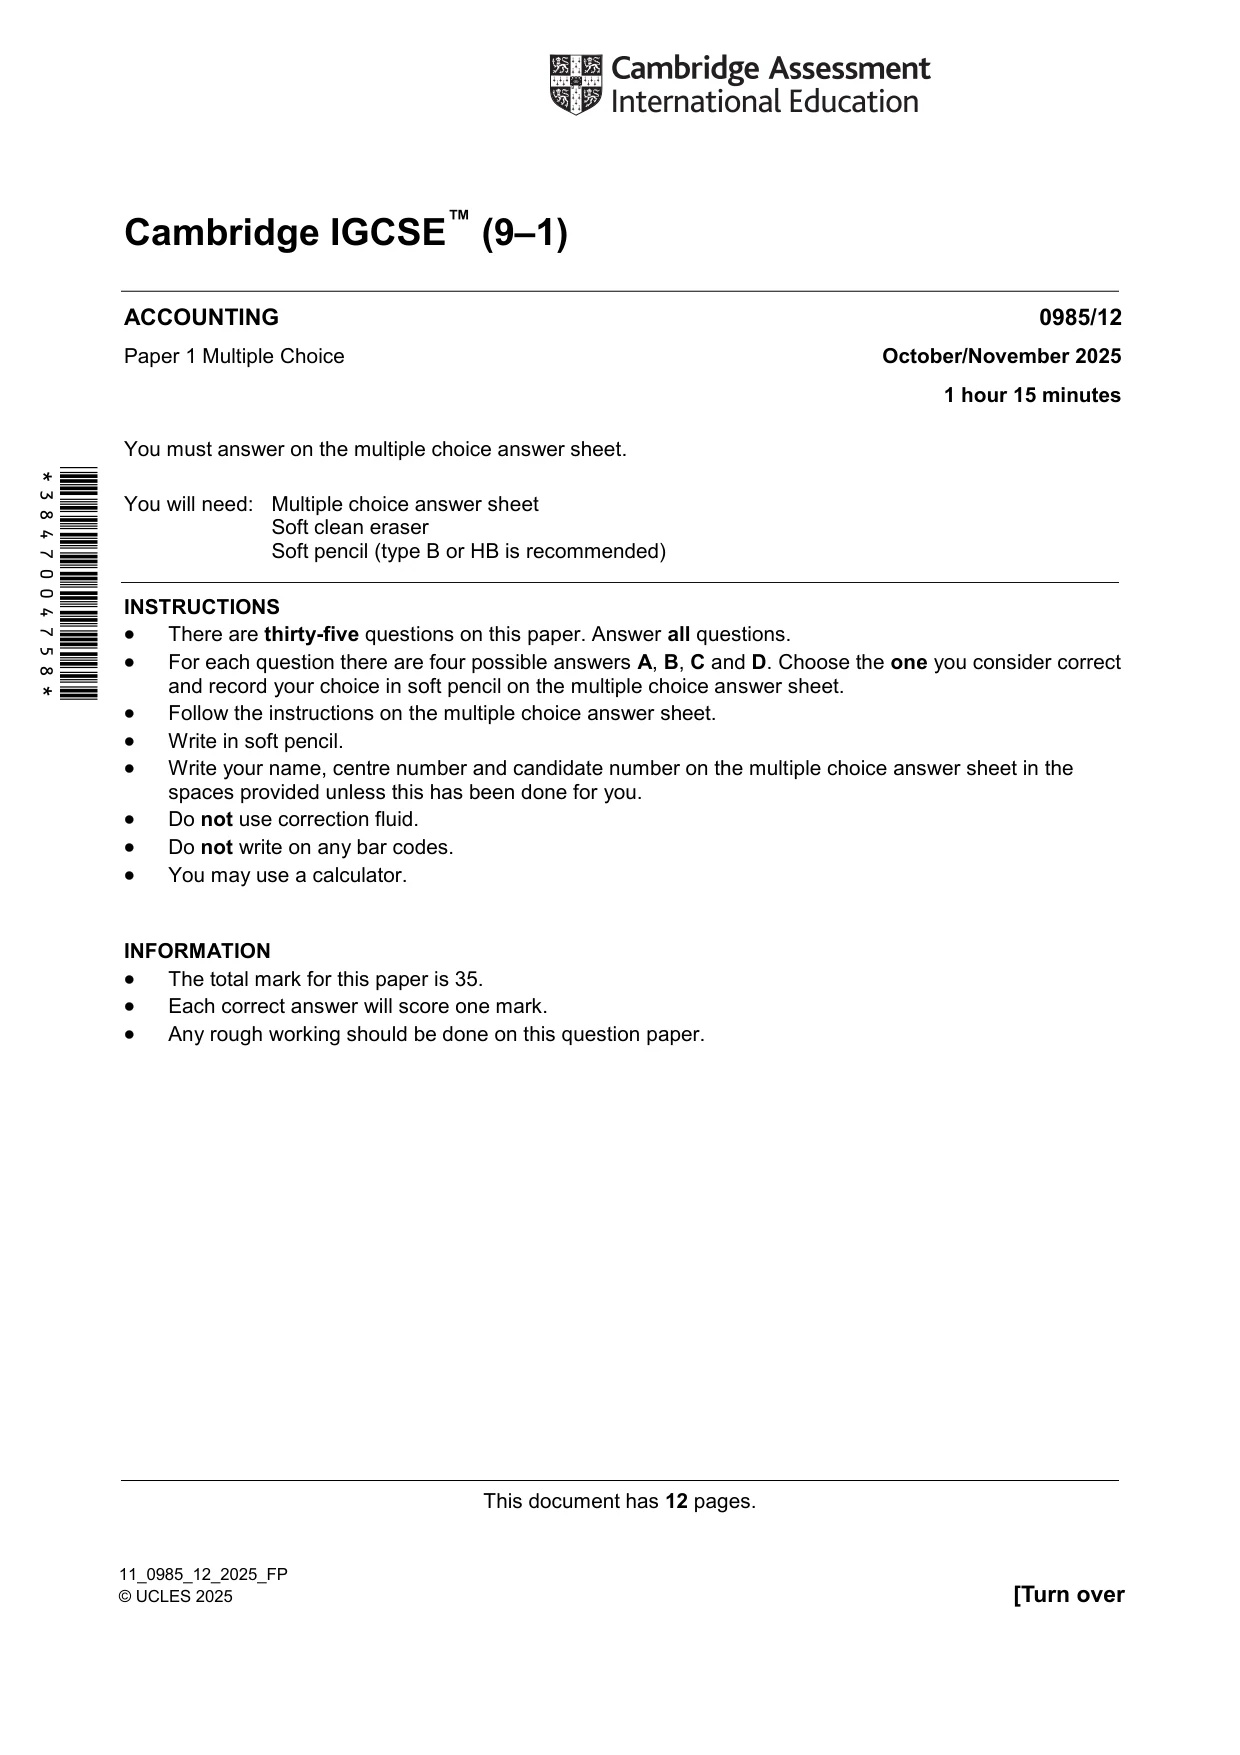
Question paper, page 1
This document has 12 pages. 11_0985_12_2025_FP © UCLES 2025 *3847004758* Cambridge IGCSE™ (9–1) ACCOUNTING 0985/12 Paper 1 Multiple Choice October/November 2025 1 hour 15 minutes You must answer on the multiple choice answer sheet. You will need: Multiple choice answer sheet Soft clean eraser Soft pencil (type B or HB is recommended) INSTRUCTIONS There are thirty-five questions on this paper. Answer all questions. For each question there are four possible answers A, B, C and D. Choose the one you consider correct and record your choice in soft pencil on the multiple choice answer sheet. Follow the instructions on the multiple choice answer sheet. Write in soft pencil. Write your name, centre number and candidate number on the multiple choice answer sheet in the spaces provided unless this has been done for you. Do not use correction fluid. Do not write on any bar codes. You may use a calculator. INFORMATION The total mark for this paper is 35. Each correct answer will score one mark. Any rough working should be done on this question paper. [Turn over
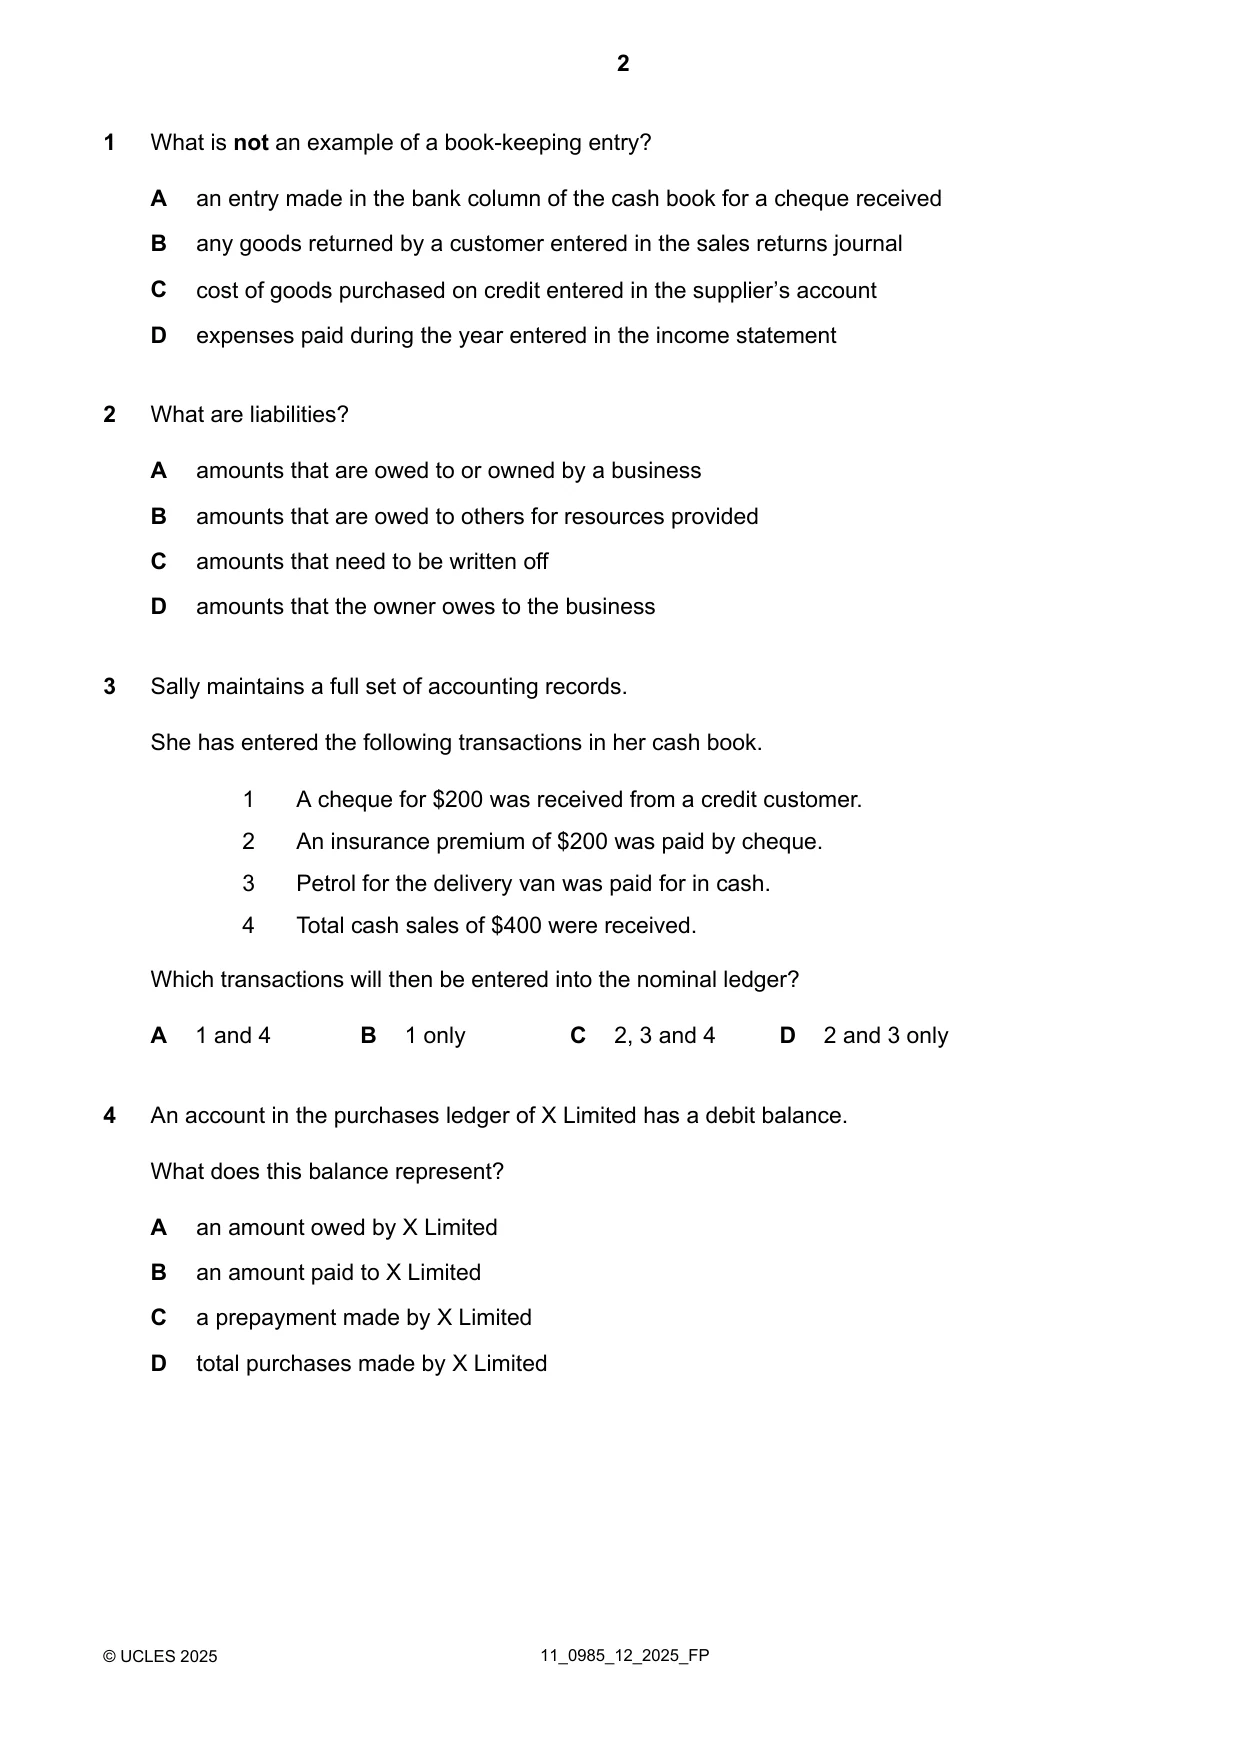
Question paper, page 2
What is not an example of a book-keeping entry? 1 an entry made in the bank column of the cash book for a cheque received A any goods returned by a customer entered in the sales returns journal B cost of goods purchased on credit entered in the supplier’s account C expenses paid during the year entered in the income statement D What are liabilities? 2 amounts that are owed to or owned by a business A amounts that are owed to others for resources provided B amounts that need to be written off C amounts that the owner owes to the business D Sally maintains a full set of accounting records. She has entered the following transactions in her cash book. 3 1 A cheque for $200 was received from a credit customer. 2 An insurance premium of $200 was paid by cheque. 3 Petrol for the delivery van was paid for in cash. 4 Total cash sales of $400 were received. Which transactions will then be entered into the nominal ledger? 2 and 3 only D 2, 3 and 4 C 1 only B 1 and 4 A An account in the purchases ledger of X Limited has a debit balance. What does this balance represent? 4 an amount owed by X Limited A an amount paid to X Limited B a prepayment made by X Limited C total purchases made by X Limited D 11_0985_12_2025_FP © UCLES 2025 2
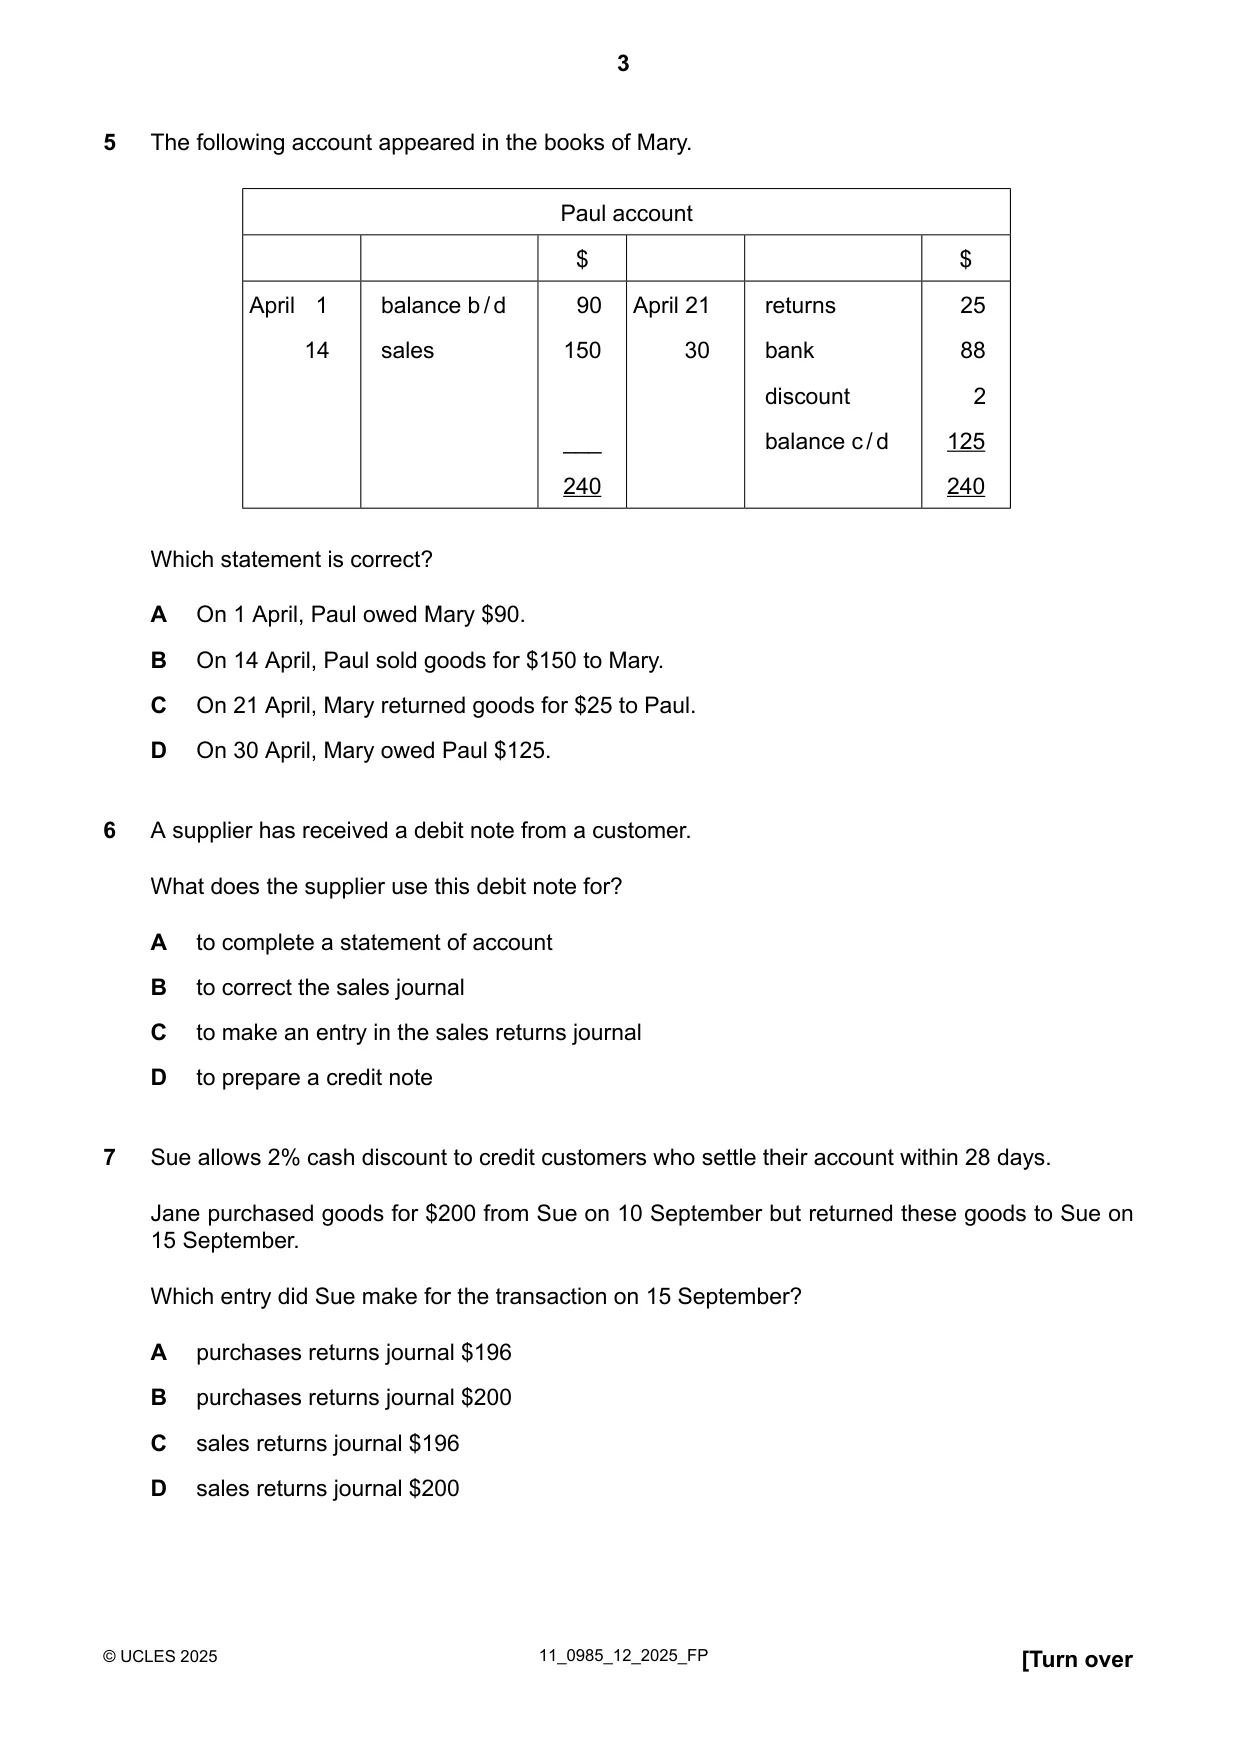
Question paper, page 3
The following account appeared in the books of Mary. 5 Paul account $ $ 25 returns April 21 90 balance b/d April 1 88 bank 30 150 sales 14 2 discount 125 balance c/d ___ 240 240 Which statement is correct? On 1 April, Paul owed Mary $90. A On 14 April, Paul sold goods for $150 to Mary. B On 21 April, Mary returned goods for $25 to Paul. C On 30 April, Mary owed Paul $125. D A supplier has received a debit note from a customer. What does the supplier use this debit note for? 6 to complete a statement of account A to correct the sales journal B to make an entry in the sales returns journal C to prepare a credit note D Sue allows 2% cash discount to credit customers who settle their account within 28 days. Jane purchased goods for $200 from Sue on 10 September but returned these goods to Sue on 15 September. Which entry did Sue make for the transaction on 15 September? 7 purchases returns journal $196 A purchases returns journal $200 B sales returns journal $196 C sales returns journal $200 D [Turn over 11_0985_12_2025_FP © UCLES 2025 3
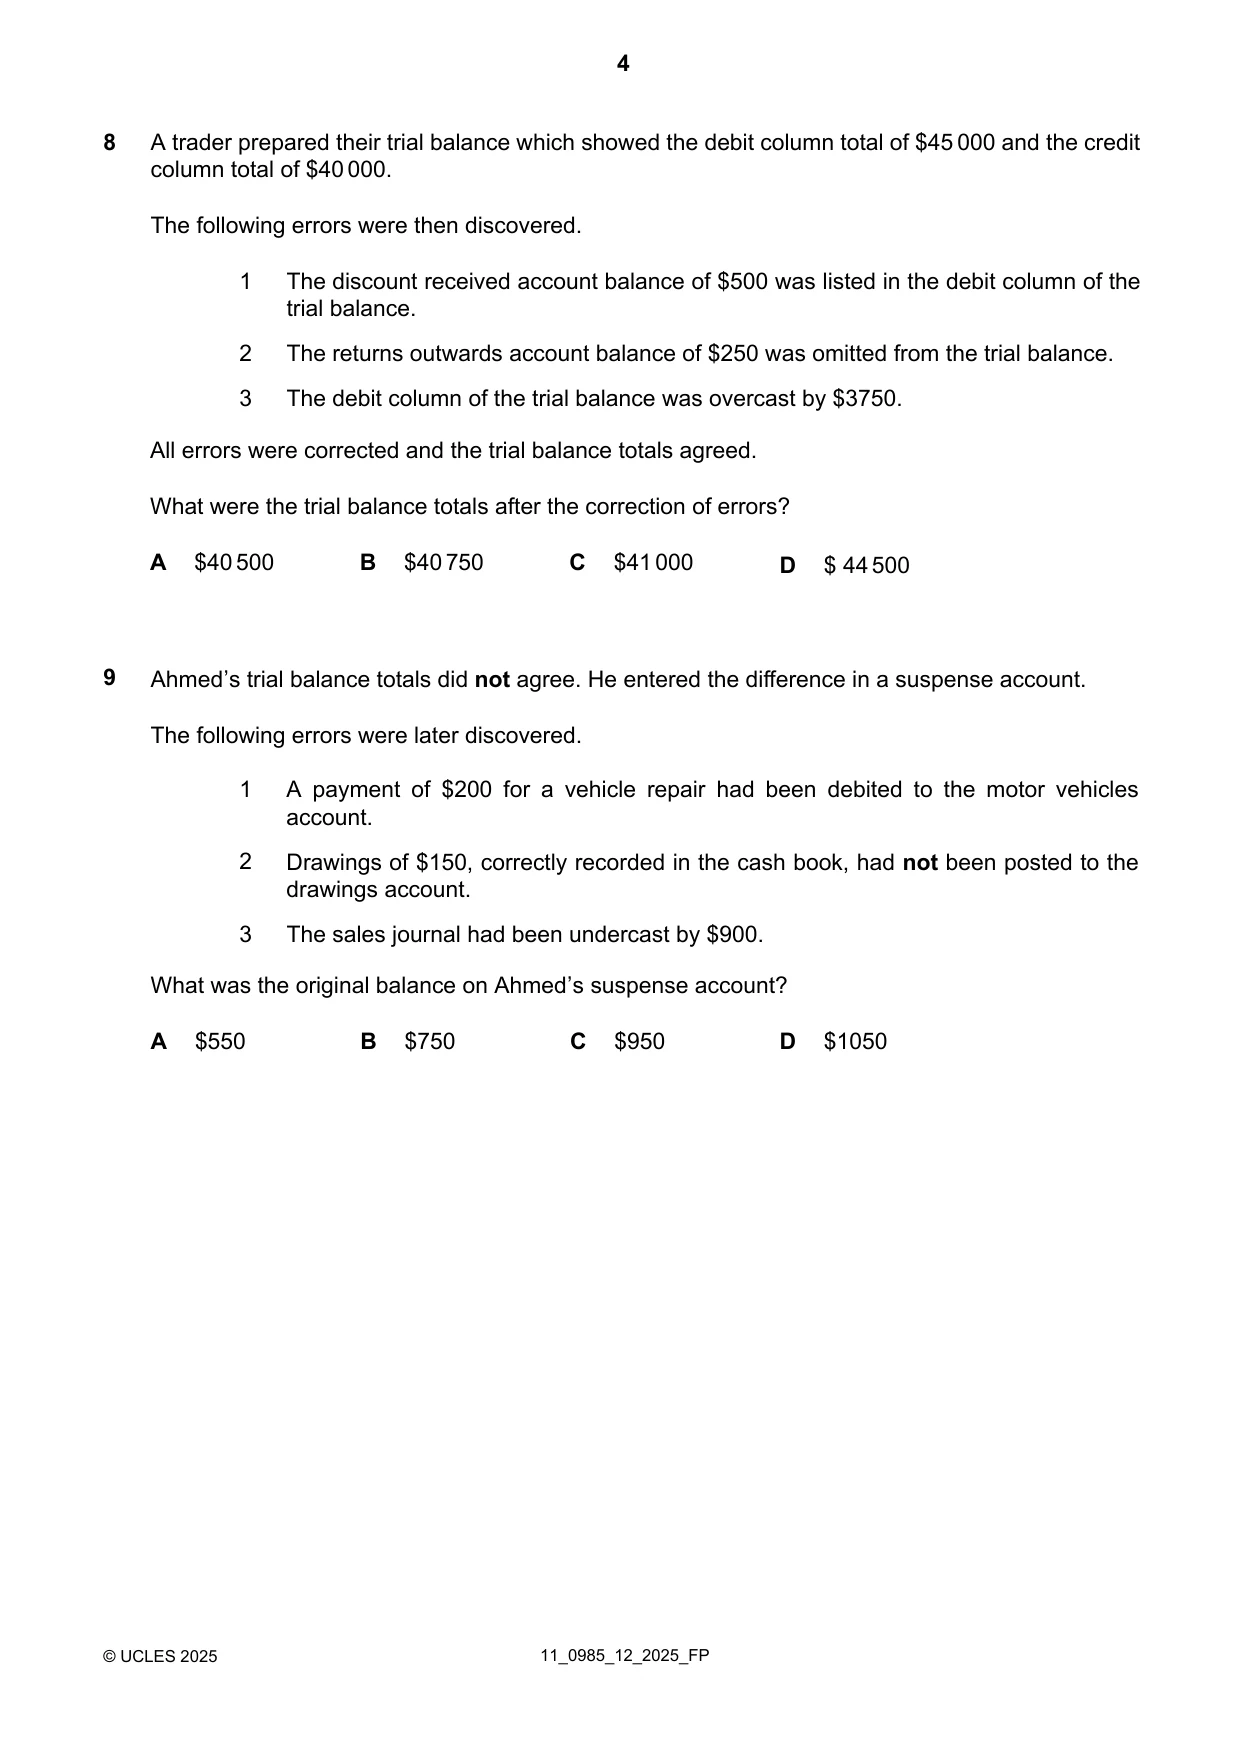
Question paper, page 4
A trader prepared their trial balance which showed the debit column total of $45 000 and the credit column total of $40 000. The following errors were then discovered. 8 The discount received account balance of $500 was listed in the debit column of the trial balance. 1 The returns outwards account balance of $250 was omitted from the trial balance. 2 The debit column of the trial balance was overcast by $3750. 3 $ 44500 D All errors were corrected and the trial balance totals agreed. What were the trial balance totals after the correction of errors? A $40 500 B $40 750 C $41 000 Ahmed’s trial balance totals did not agree. He entered the difference in a suspense account. The following errors were later discovered. 9 A payment of $200 for a vehicle repair had been debited to the motor vehicles account. 1 Drawings of $150, correctly recorded in the cash book, had not been posted to the drawings account. 2 The sales journal had been undercast by $900. 3 What was the original balance on Ahmed’s suspense account? $1050 D $950 C $750 B $550 A 11_0985_12_2025_FP © UCLES 2025 4
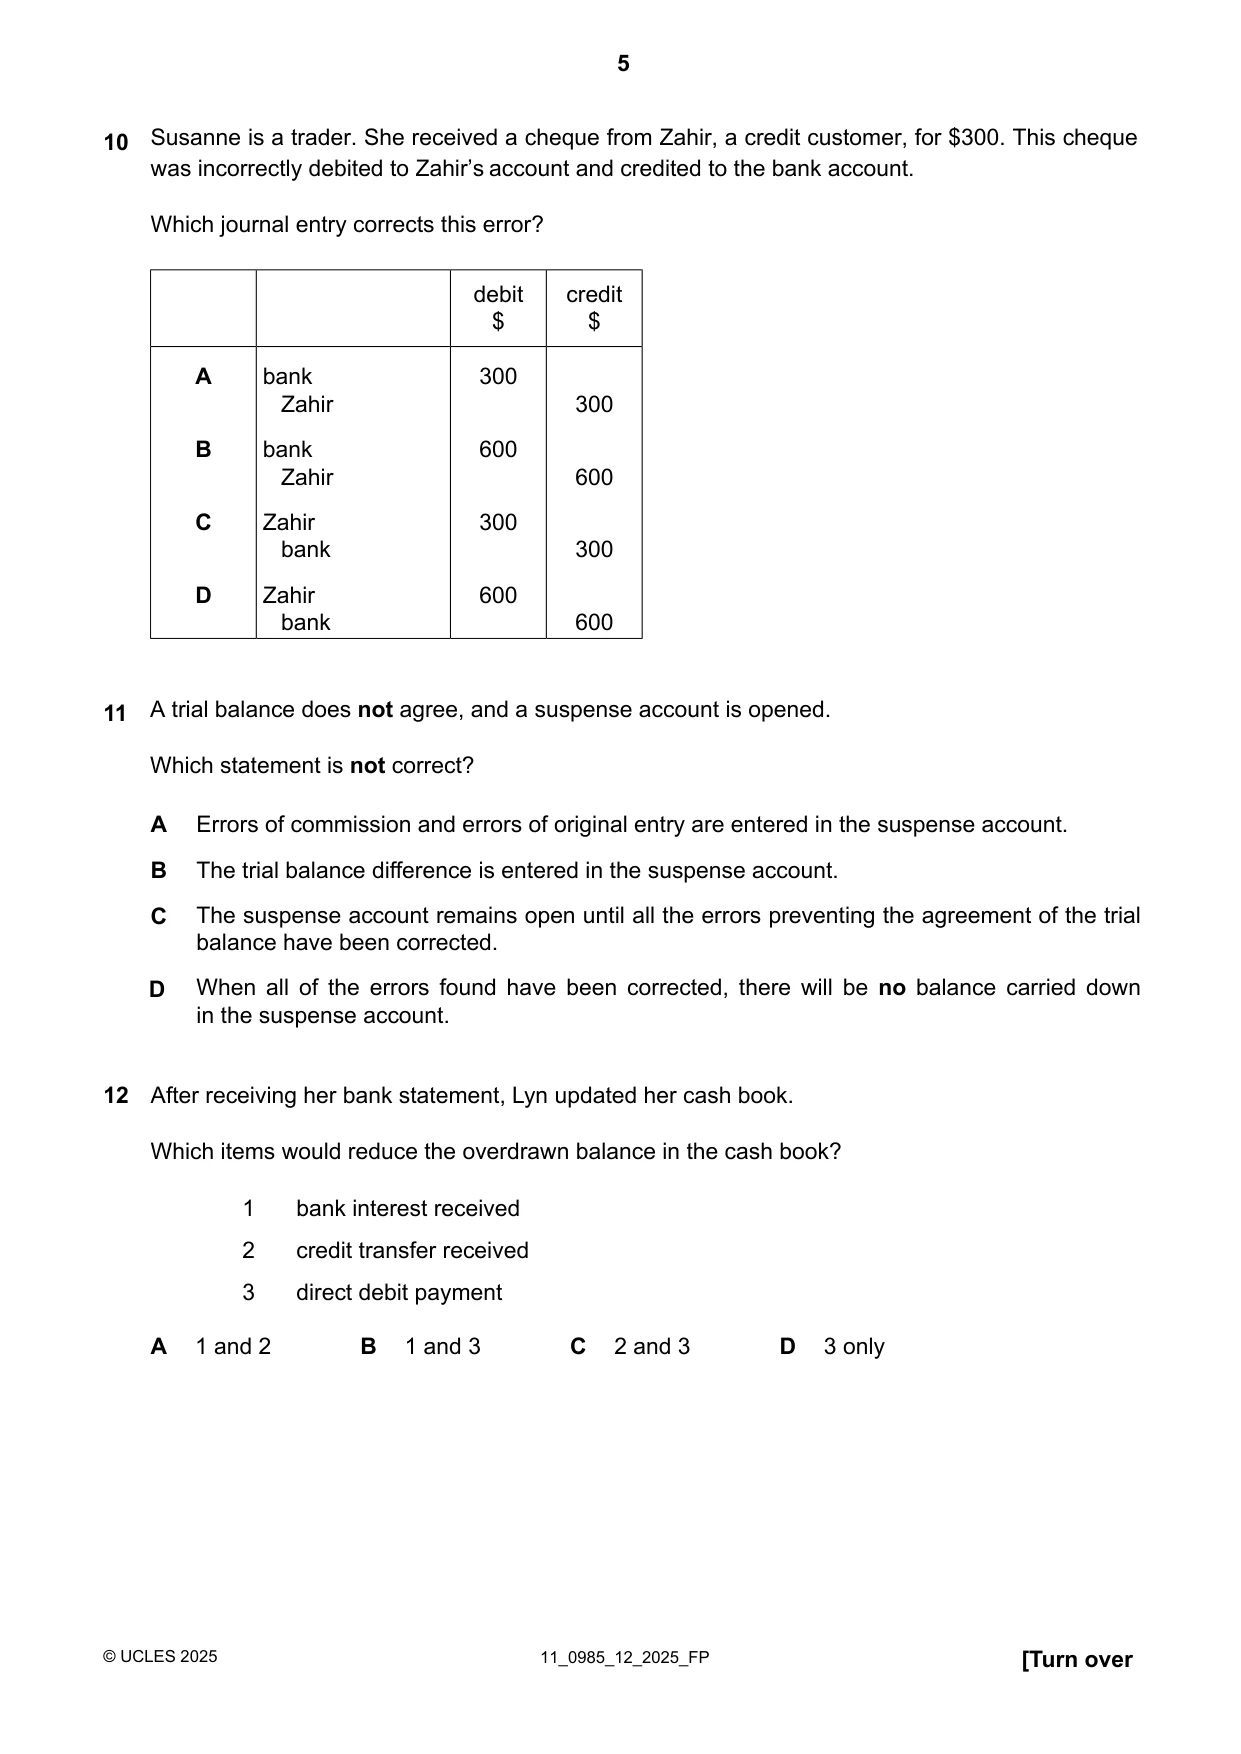
Question paper, page 5
Susanne is a trader. She received a cheque from Zahir, a credit customer, for $300. This cheque was incorrectly debited to Zahir’s account and credited to the bank account. Which journal entry corrects this error? 10 credit $ debit $ 300 300 bank Zahir A 600 600 bank Zahir B 300 300 Zahir bank C 600 600 Zahir bank D A trial balance does not agree, and a suspense account is opened. Which statement is not correct? 11 Errors of commission and errors of original entry are entered in the suspense account. A The trial balance difference is entered in the suspense account. B C The suspense account remains open until all the errors preventing the agreement of the trial balance have been corrected. When all of the errors found have been corrected, there will be no balance carried down in the suspense account. D After receiving her bank statement, Lyn updated her cash book. Which items would reduce the overdrawn balance in the cash book? 12 1 bank interest received 2 credit transfer received 3 direct debit payment 3 only D 2 and 3 C 1 and 3 B 1 and 2 A [Turn over 11_0985_12_2025_FP © UCLES 2025 5
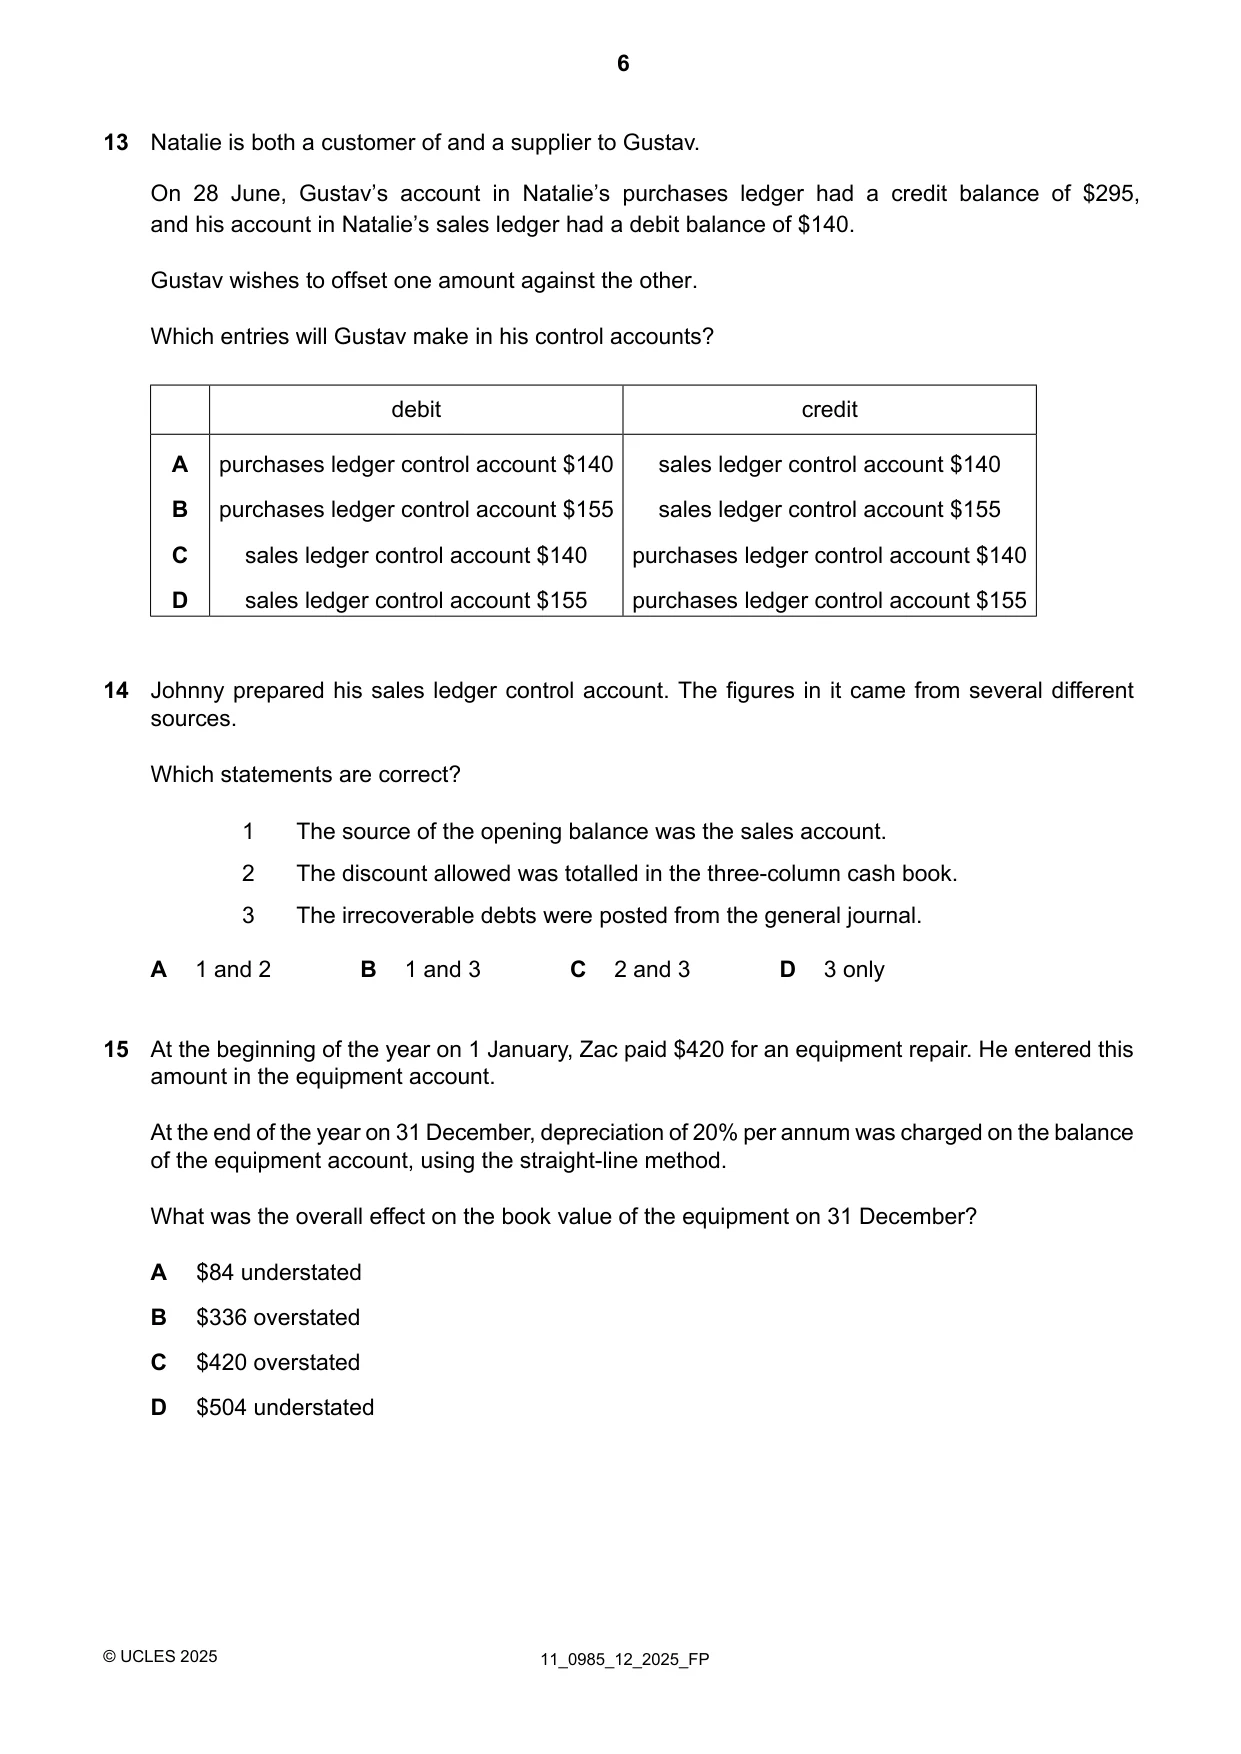
Question paper, page 6
Natalie is both a customer of and a supplier to Gustav. On 28 June, Gustav’s account in Natalie’s purchases ledger had a credit balance of $295, and his account in Natalie’s sales ledger had a debit balance of $140. Gustav wishes to offset one amount against the other. Which entries will Gustav make in his control accounts? 13 credit debit sales ledger control account $140 purchases ledger control account $140 A sales ledger control account $155 purchases ledger control account $155 B purchases ledger control account $140 sales ledger control account $140 C purchases ledger control account $155 sales ledger control account $155 D Johnny prepared his sales ledger control account. The figures in it came from several different sources. Which statements are correct? 14 1 The source of the opening balance was the sales account. 2 The discount allowed was totalled in the three-column cash book. 3 The irrecoverable debts were posted from the general journal. 3 only D 2 and 3 C 1 and 3 B 1 and 2 A At the beginning of the year on 1 January, Zac paid $420 for an equipment repair. He entered this amount in the equipment account. At the end of the year on 31 December, depreciation of 20% per annum was charged on the balance of the equipment account, using the straight-line method. What was the overall effect on the book value of the equipment on 31 December? 15 $84 understated A $336 overstated B $420 overstated C $504 understated D 11_0985_12_2025_FP © UCLES 2025 6
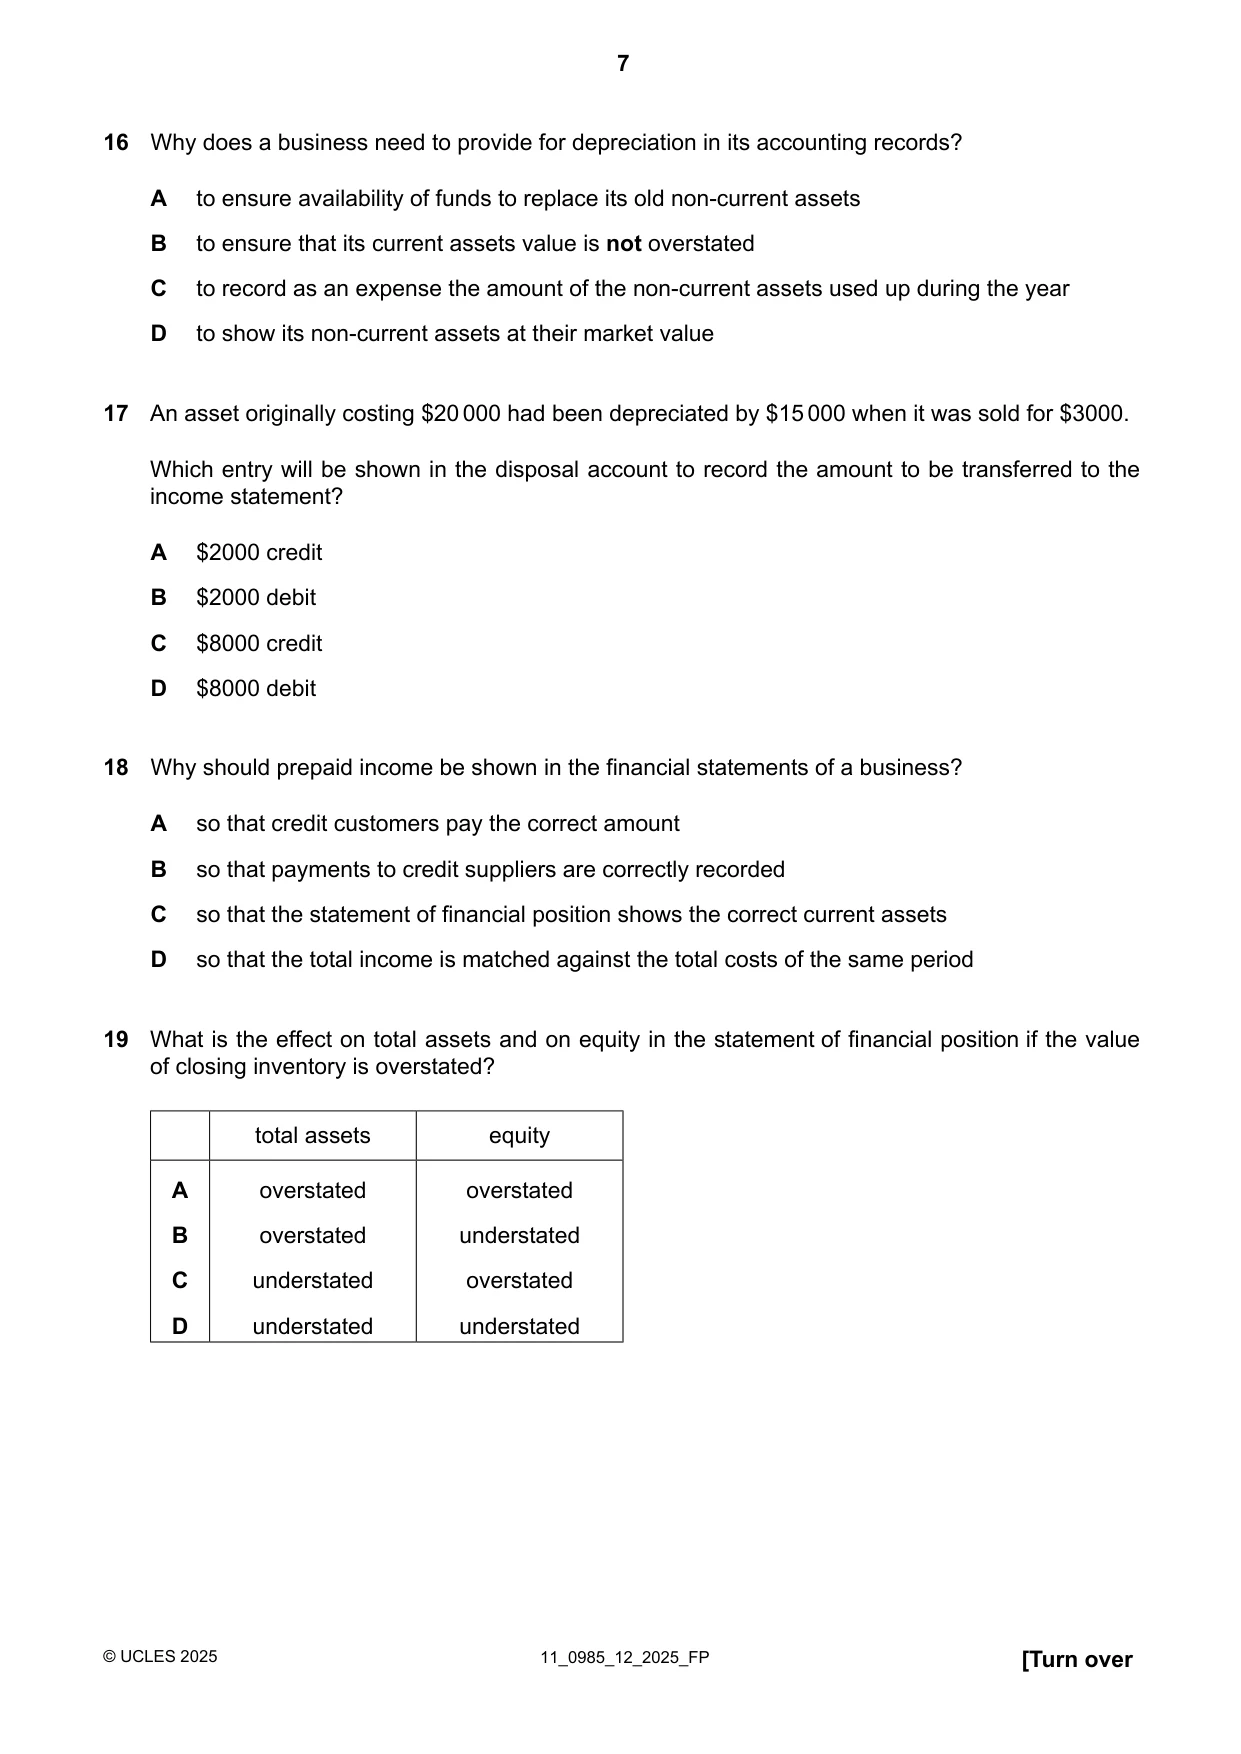
Question paper, page 7
Why does a business need to provide for depreciation in its accounting records? 16 to ensure availability of funds to replace its old non-current assets A to ensure that its current assets value is not overstated B to record as an expense the amount of the non-current assets used up during the year C to show its non-current assets at their market value D An asset originally costing $20 000 had been depreciated by $15 000 when it was sold for $3000. Which entry will be shown in the disposal account to record the amount to be transferred to the income statement? 17 $2000 credit A $2000 debit B $8000 credit C $8000 debit D Why should prepaid income be shown in the financial statements of a business? 18 so that credit customers pay the correct amount A so that payments to credit suppliers are correctly recorded B so that the statement of financial position shows the correct current assets C so that the total income is matched against the total costs of the same period D What is the effect on total assets and on equity in the statement of financial position if the value of closing inventory is overstated? 19 equity total assets overstated overstated A understated overstated B overstated understated C understated understated D [Turn over 11_0985_12_2025_FP © UCLES 2025 7
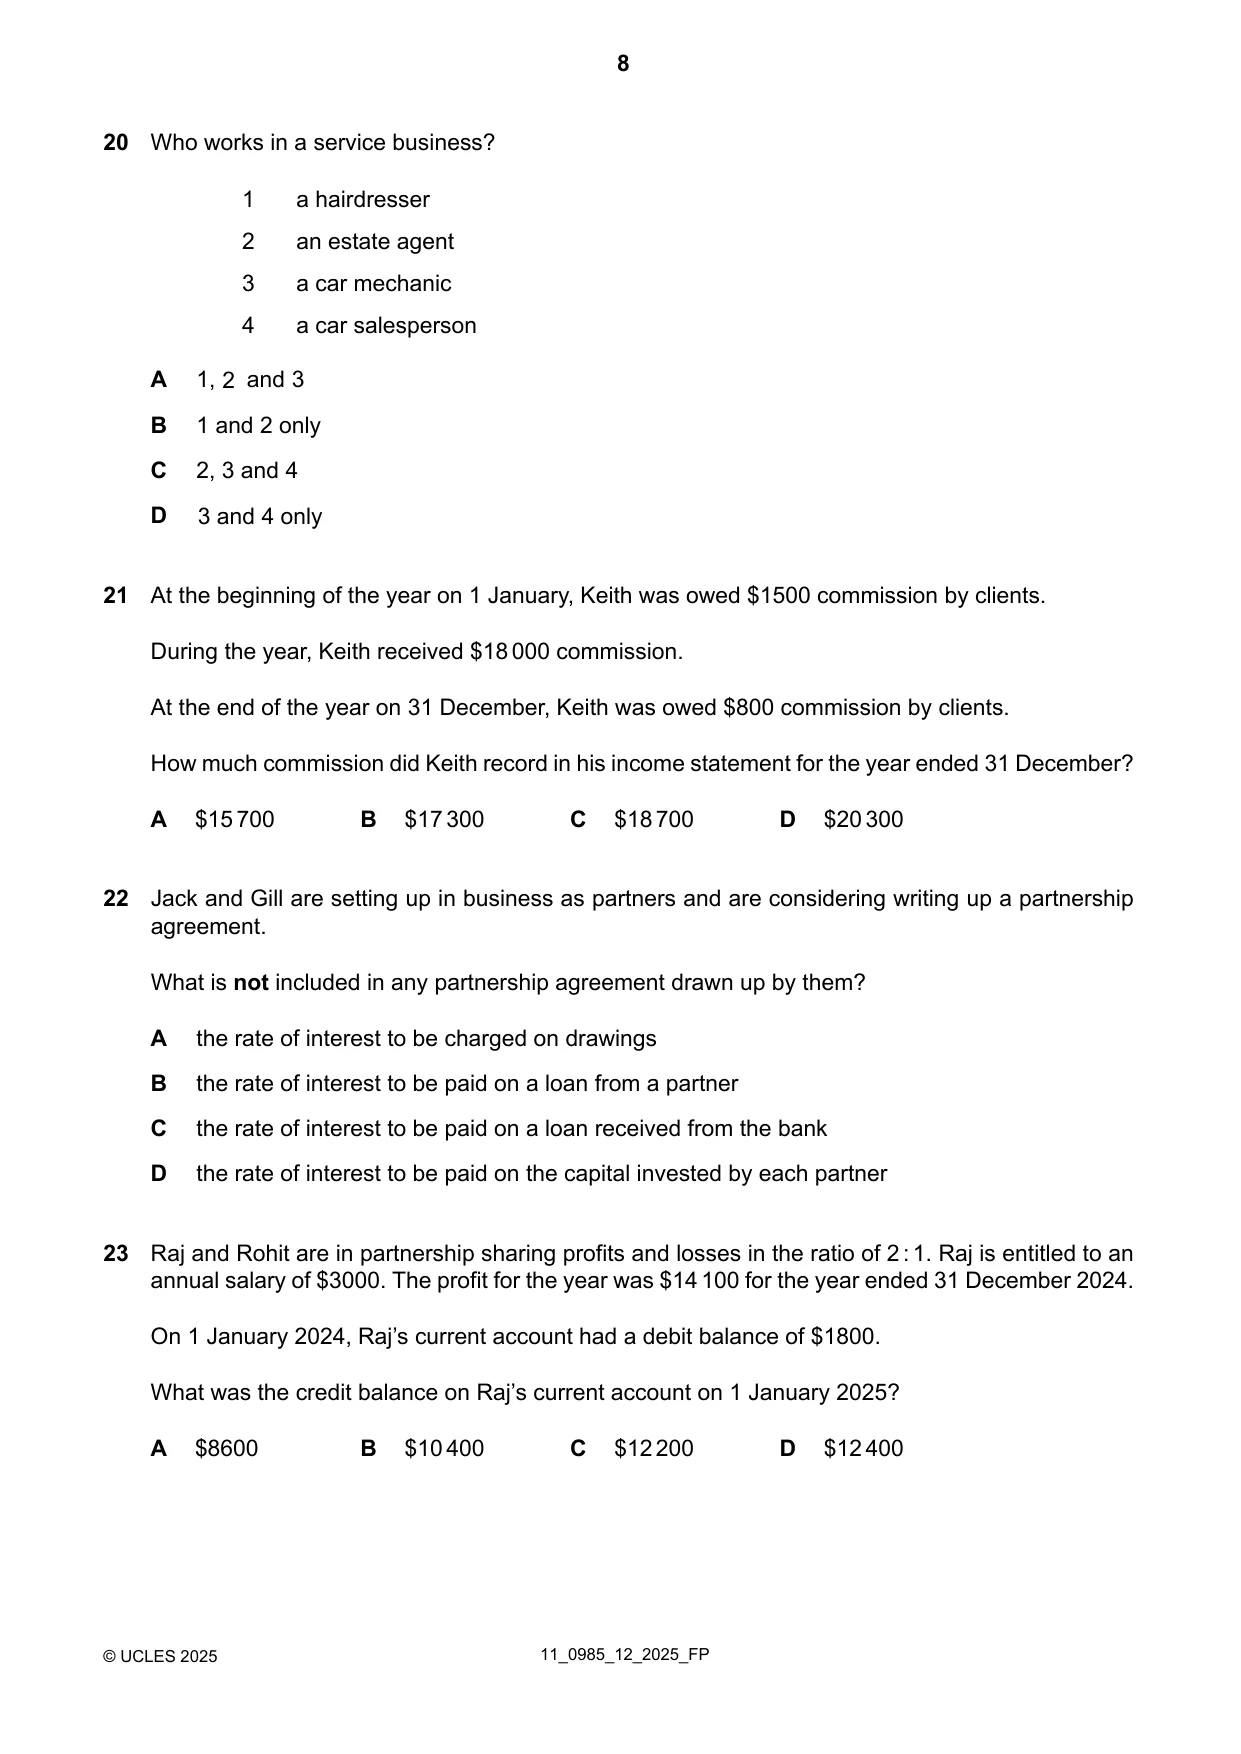
Question paper, page 8
Who works in a service business? 20 1 a hairdresser 2 an estate agent 3 a car mechanic 4 a car salesperson 1, 2 and 3 A 1 and 2 only B 2, 3 and 4 C 3 and 4 only D At the beginning of the year on 1 January, Keith was owed $1500 commission by clients. During the year, Keith received $18000 commission. At the end of the year on 31 December, Keith was owed $800 commission by clients. How much commission did Keith record in his income statement for the year ended 31 December? 21 $20300 D $18700 C $17300 B $15700 A Jack and Gill are setting up in business as partners and are considering writing up a partnership agreement. What is not included in any partnership agreement drawn up by them? 22 the rate of interest to be charged on drawings A the rate of interest to be paid on a loan from a partner B the rate of interest to be paid on a loan received from the bank C the rate of interest to be paid on the capital invested by each partner D Raj and Rohit are in partnership sharing profits and losses in the ratio of 2:1. Raj is entitled to an annual salary of $3000. The profit for the year was $14100 for the year ended 31 December 2024. On 1 January 2024, Raj’s current account had a debit balance of $1800. What was the credit balance on Raj’s current account on 1 January 2025? 23 $12400 D $12200 C $10400 B $8600 A 11_0985_12_2025_FP © UCLES 2025 8
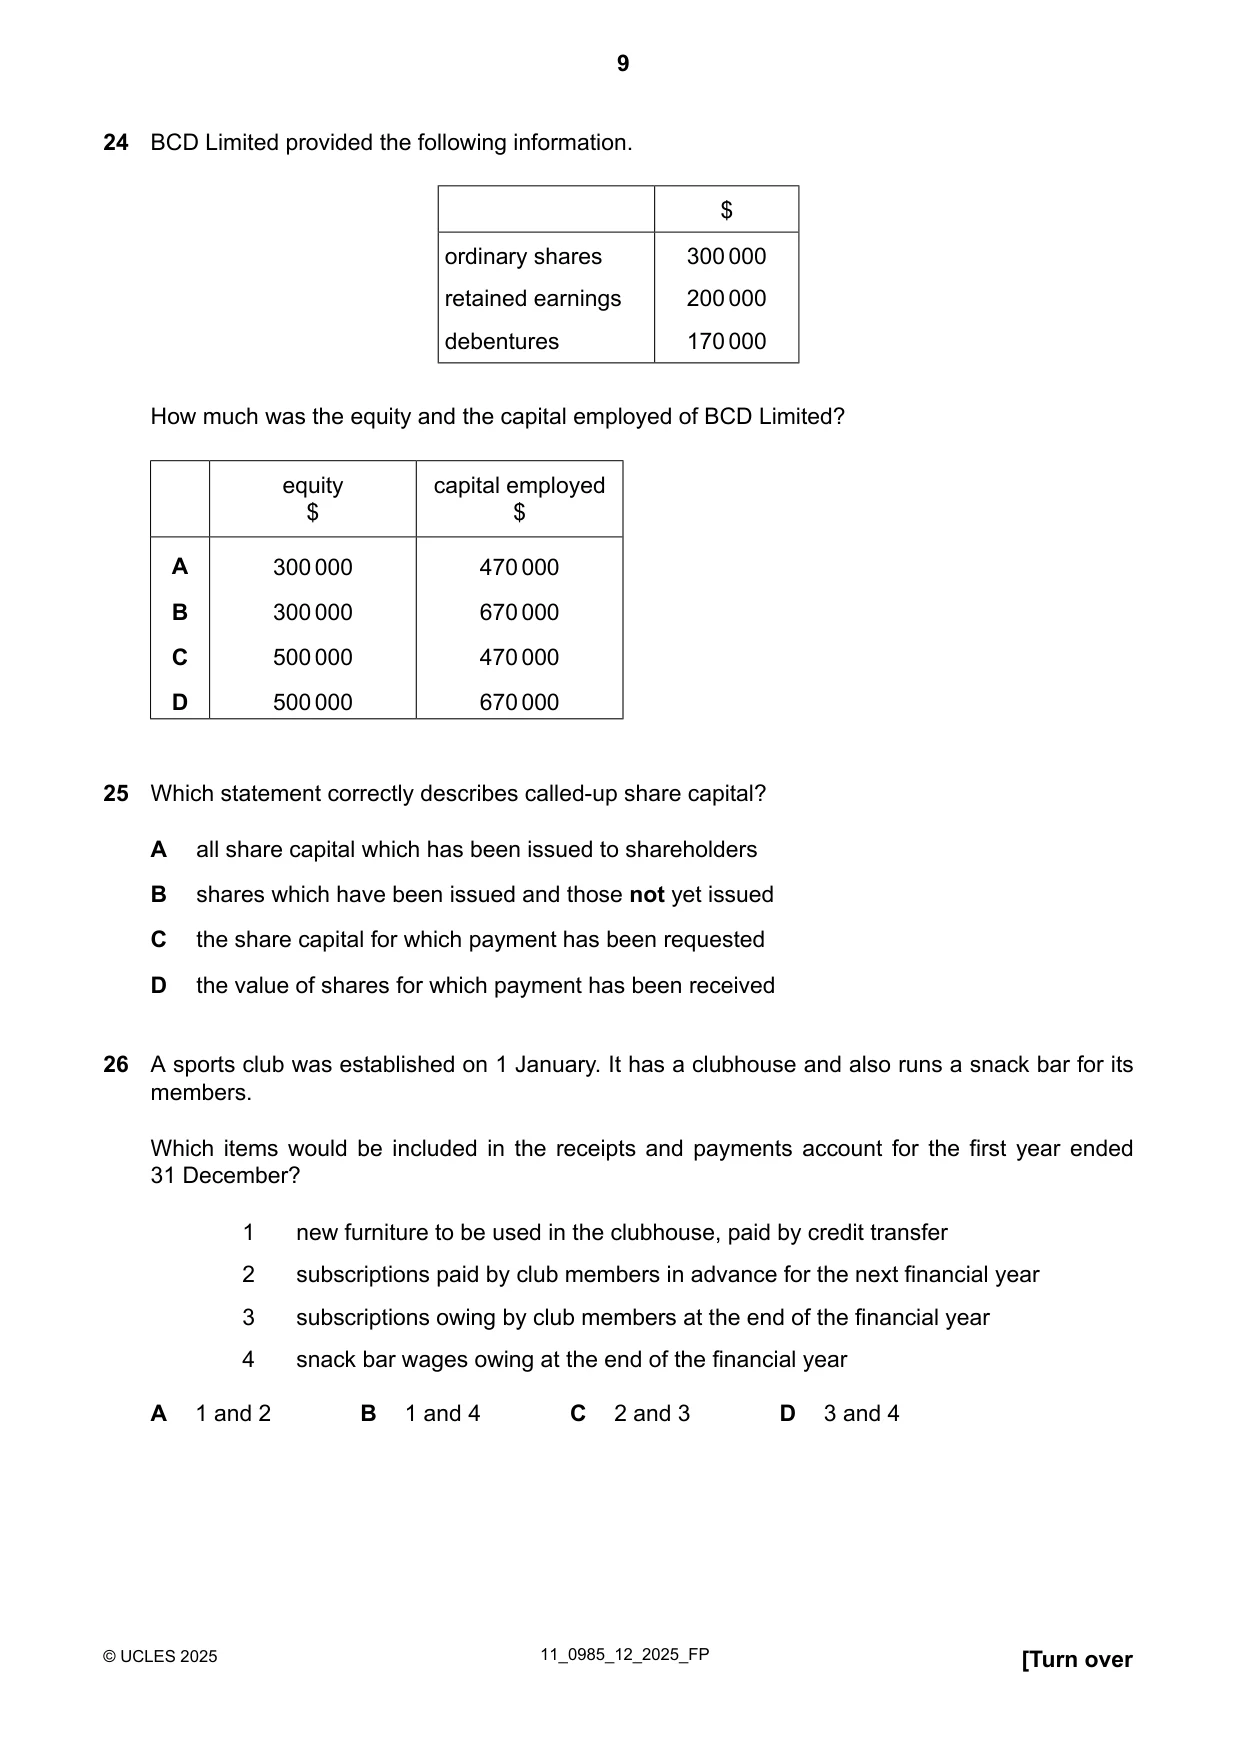
Question paper, page 9
BCD Limited provided the following information. 24 $ 300000 200000 170000 ordinary shares retained earnings debentures How much was the equity and the capital employed of BCD Limited? capital employed $ equity $ 470000 300000 A 670000 300000 B 470000 500000 C 670000 500000 D Which statement correctly describes called-up share capital? 25 all share capital which has been issued to shareholders A shares which have been issued and those not yet issued B the share capital for which payment has been requested C the value of shares for which payment has been received D A sports club was established on 1 January. It has a clubhouse and also runs a snack bar for its members. Which items would be included in the receipts and payments account for the first year ended 31 December? 26 1 new furniture to be used in the clubhouse, paid by credit transfer 2 subscriptions paid by club members in advance for the next financial year 3 subscriptions owing by club members at the end of the financial year 4 snack bar wages owing at the end of the financial year 3 and 4 D 2 and 3 C 1 and 4 B 1 and 2 A [Turn over 11_0985_12_2025_FP © UCLES 2025 9
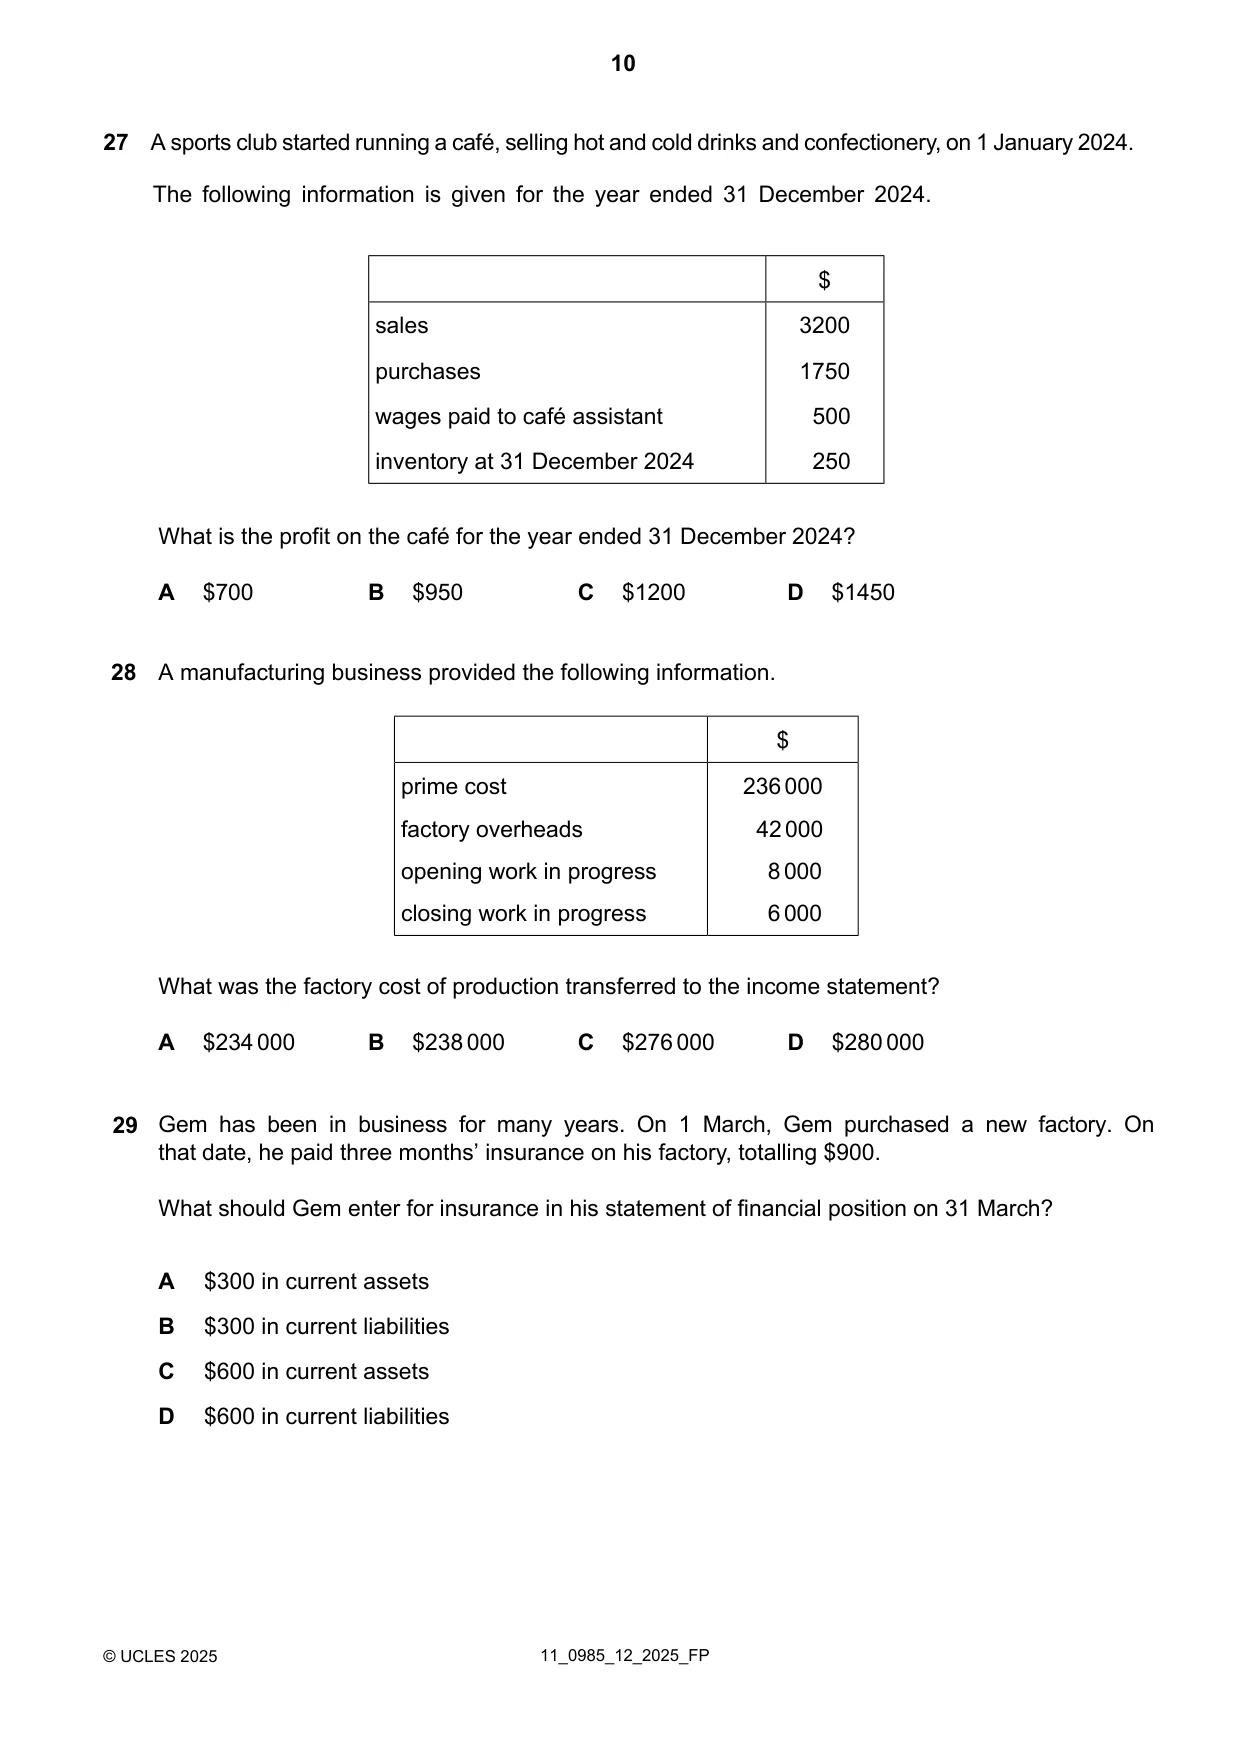
Question paper, page 10
A sports club started running a café, selling hot and cold drinks and confectionery, on 1 January 2024. 27 $ 3200 sales 1750 purchases 500 wages paid to café assistant 250 inventory at 31 December 2024 What is the profit on the café for the year ended 31 December 2024? $1450 D $1200 C $950 B $700 A A manufacturing business provided the following information. 28 $ 236000 42000 8000 6000 prime cost factory overheads opening work in progress closing work in progress What was the factory cost of production transferred to the income statement? A $234 000 B $238 000 C $276 000 D $280 000 Gem has been in business for many years. On 1 March, Gem purchased a new factory. On that date, he paid three months’ insurance on his factory, totalling $900. What should Gem enter for insurance in his statement of financial position on 31 March? 29 $300 in current assets A $300 in current liabilities B $600 in current assets C $600 in current liabilities D 11_0985_12_2025_FP © UCLES 2025 10 The following information is given for the year ended 31 December 2024.
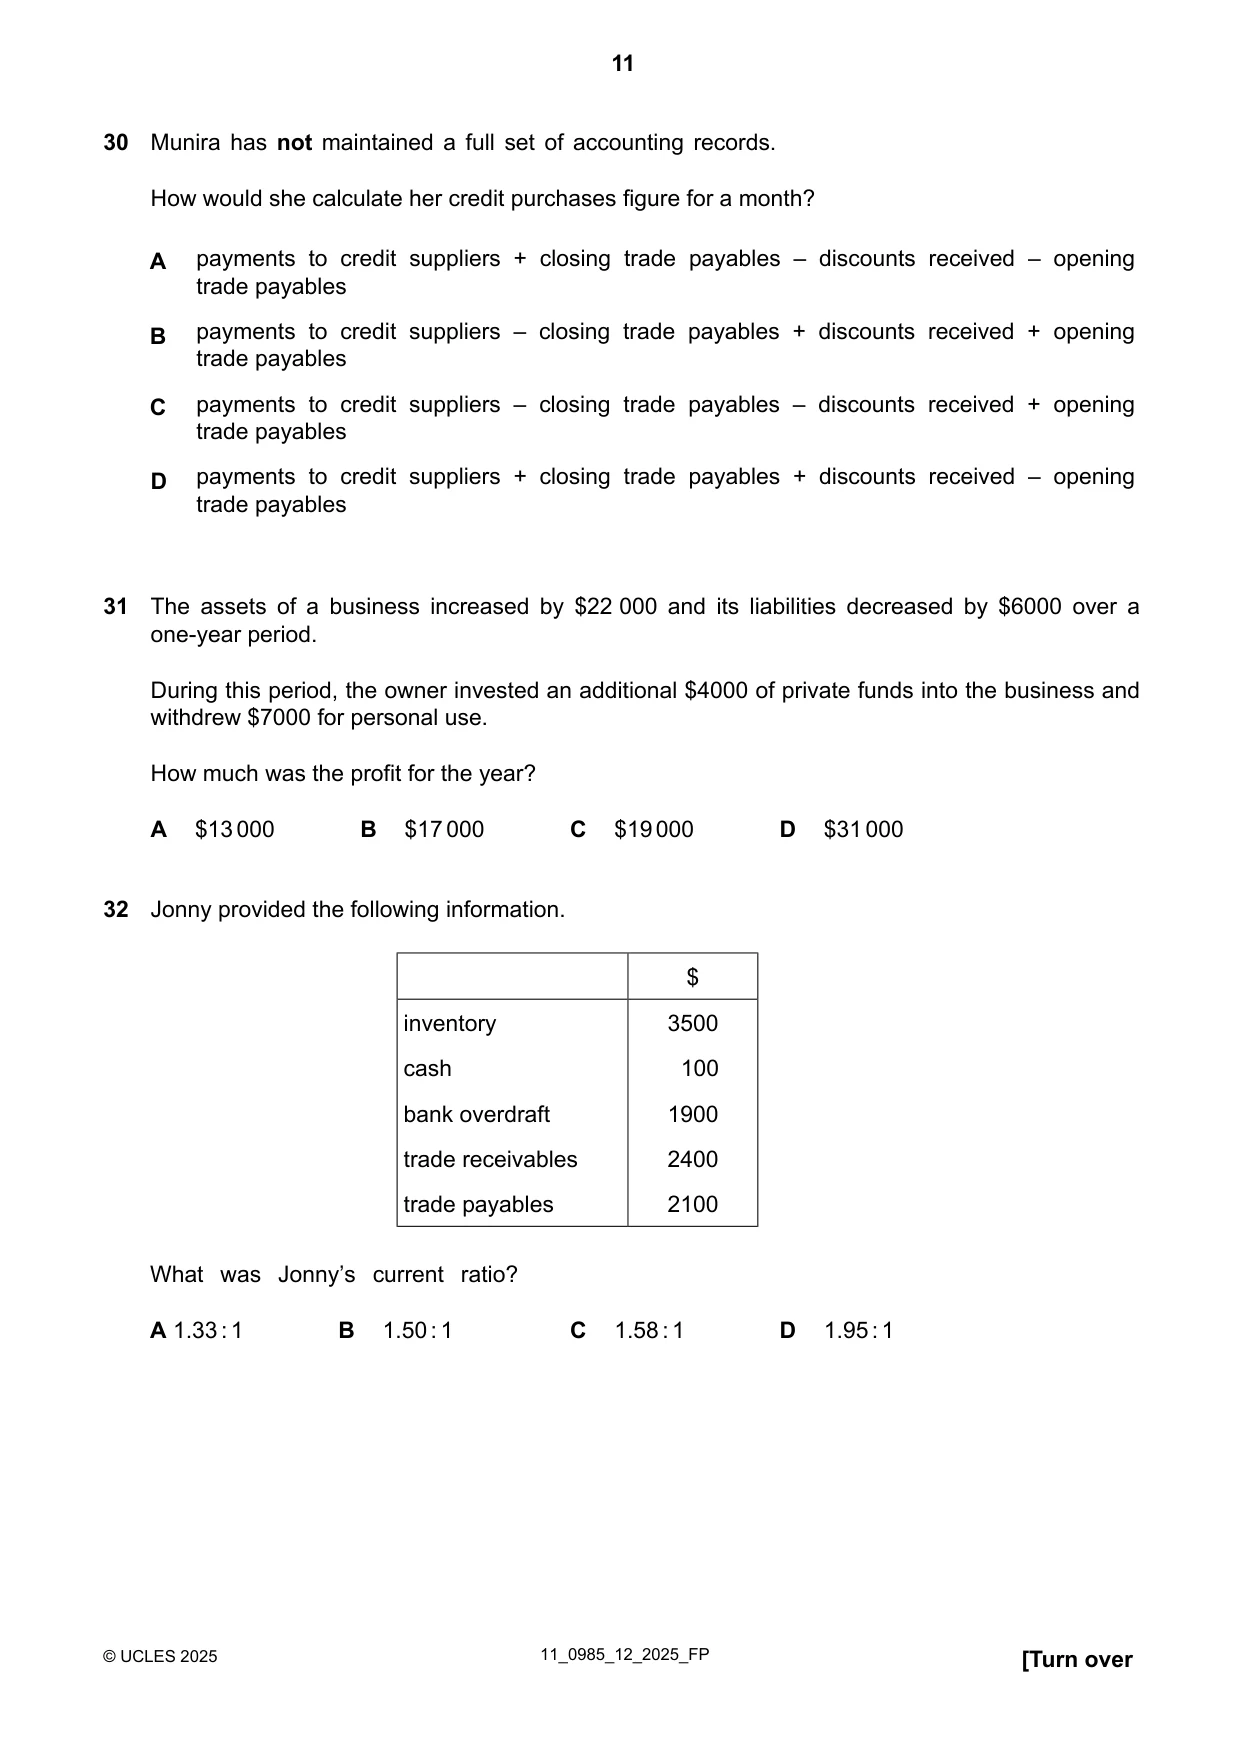
Question paper, page 11
Munira has not maintained a full set of accounting records. How would she calculate her credit purchases figure for a month? 30 A B C payments to credit suppliers + closing trade payables – discounts received – opening trade payables payments to credit suppliers – closing trade payables + discounts received + opening trade payables payments to credit suppliers – closing trade payables – discounts received + opening trade payables payments to credit suppliers + closing trade payables + discounts received – opening trade payables D The assets of a business increased by $22 000 and its liabilities decreased by $6000 over a one-year period. During this period, the owner invested an additional $4000 of private funds into the business and withdrew $7000 for personal use. How much was the profit for the year? 31 $31000 D $19000 C $17000 B $13000 A Jonny provided the following information. 32 $ 3500 inventory 100 cash 1900 bank overdraft 2400 trade receivables 2100 trade payables 1.95:1 D 1.58:1 C What was Jonny’s current ratio? A 1.33 : 1 B 1.50 : 1 [Turn over 11_0985_12_2025_FP © UCLES 2025 11
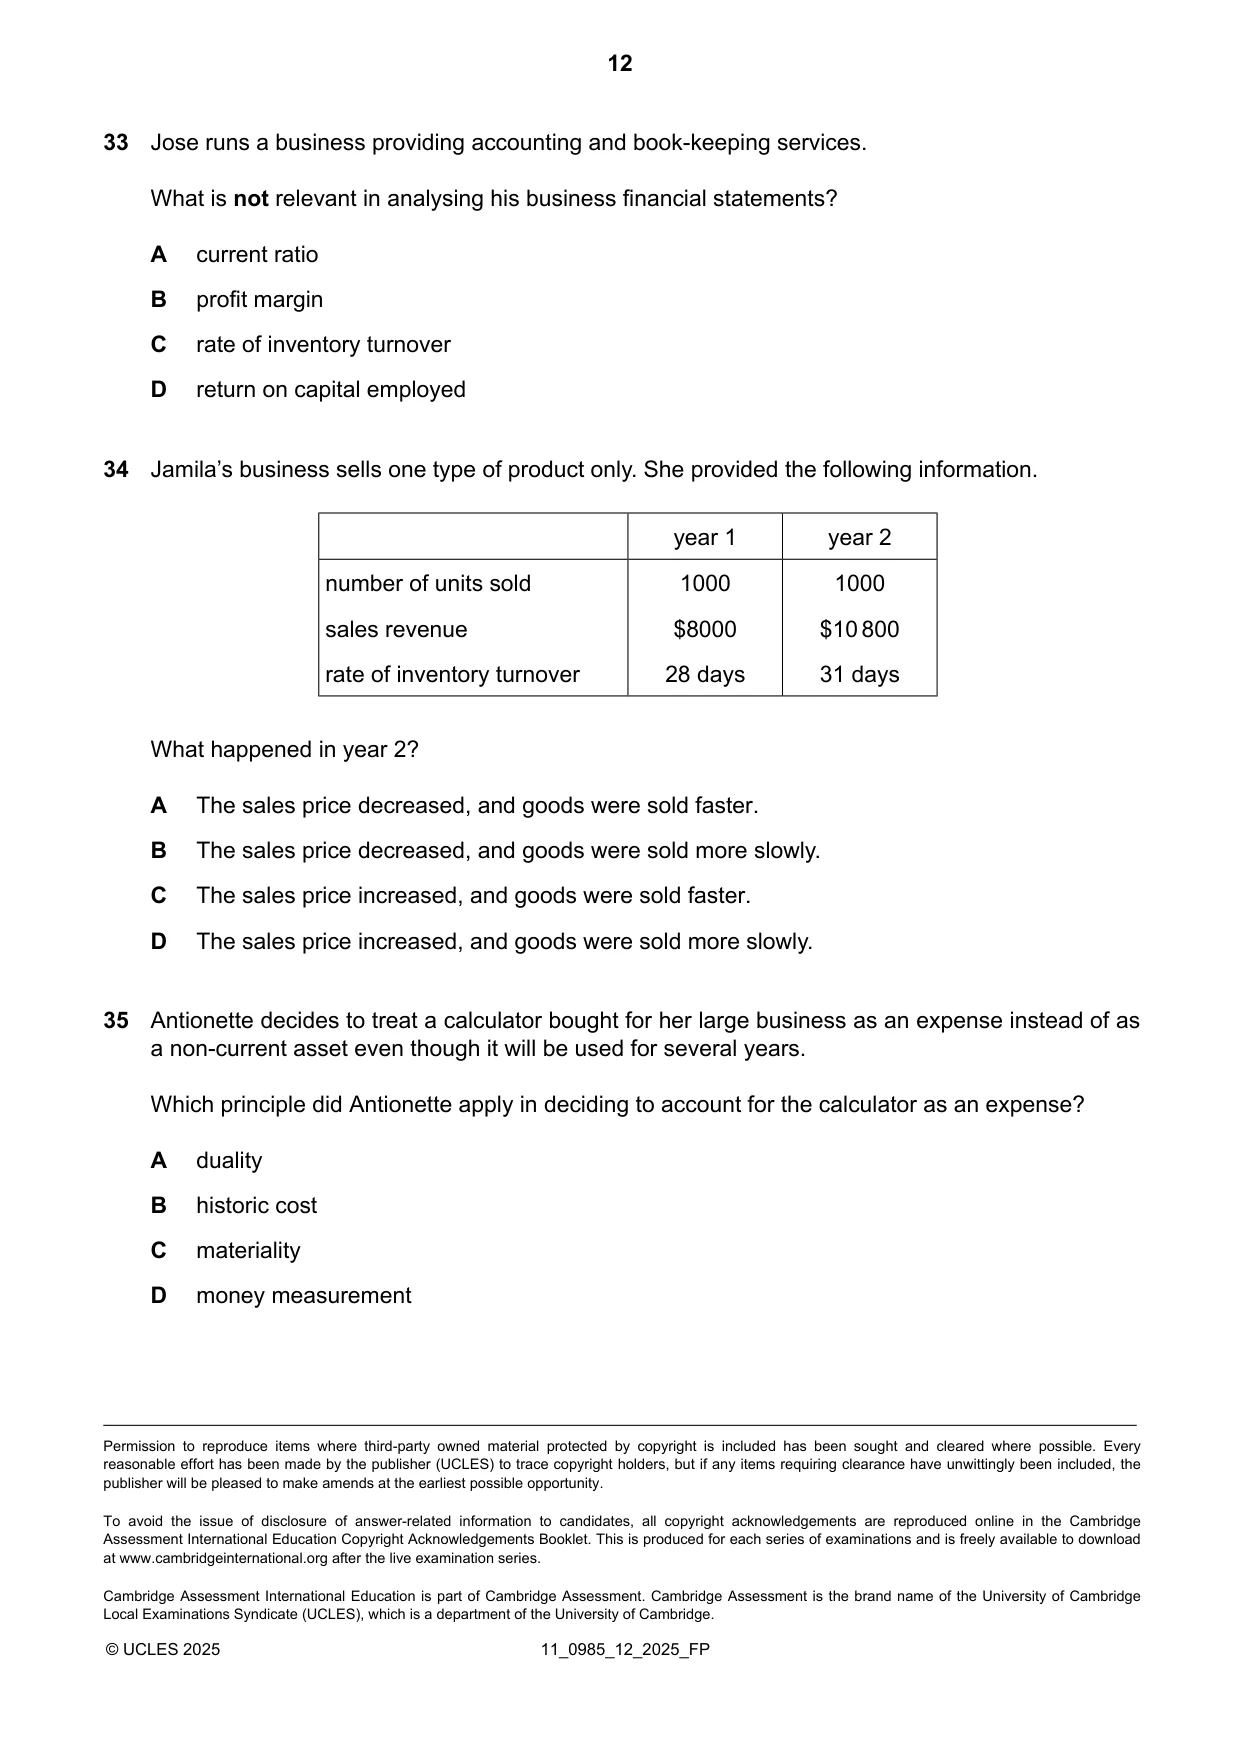
Question paper, page 12
Jose runs a business providing accounting and book-keeping services. What is not relevant in analysing his business financial statements? 33 current ratio A profit margin B rate of inventory turnover C return on capital employed D Jamila’s business sells one type of product only. She provided the following information. 34 year 2 year 1 1000 1000 number of units sold $10800 $8000 sales revenue 31 days 28 days rate of inventory turnover What happened in year 2? The sales price decreased, and goods were sold faster. A The sales price decreased, and goods were sold more slowly. B The sales price increased, and goods were sold faster. C The sales price increased, and goods were sold more slowly. D Antionette decides to treat a calculator bought for her large business as an expense instead of as a non-current asset even though it will be used for several years. Which principle did Antionette apply in deciding to account for the calculator as an expense? 35 duality A historic cost B materiality C money measurement D Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of Cambridge Assessment. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which is a department of the University of Cambridge. 11_0985_12_2025_FP © UCLES 2025 12
Mark scheme, page 1
This document consists of 3 printed pages. © Cambridge University Press & Assessment 2025 [Turn over Cambridge IGCSE™ (9–1) ACCOUNTING 0985/12 Paper 1 Multiple Choice October/November 2025 MARK SCHEME Maximum Mark: 35 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the October/November 2025 series for most Cambridge IGCSE, Cambridge International A and AS Level components, and some Cambridge O Level components.
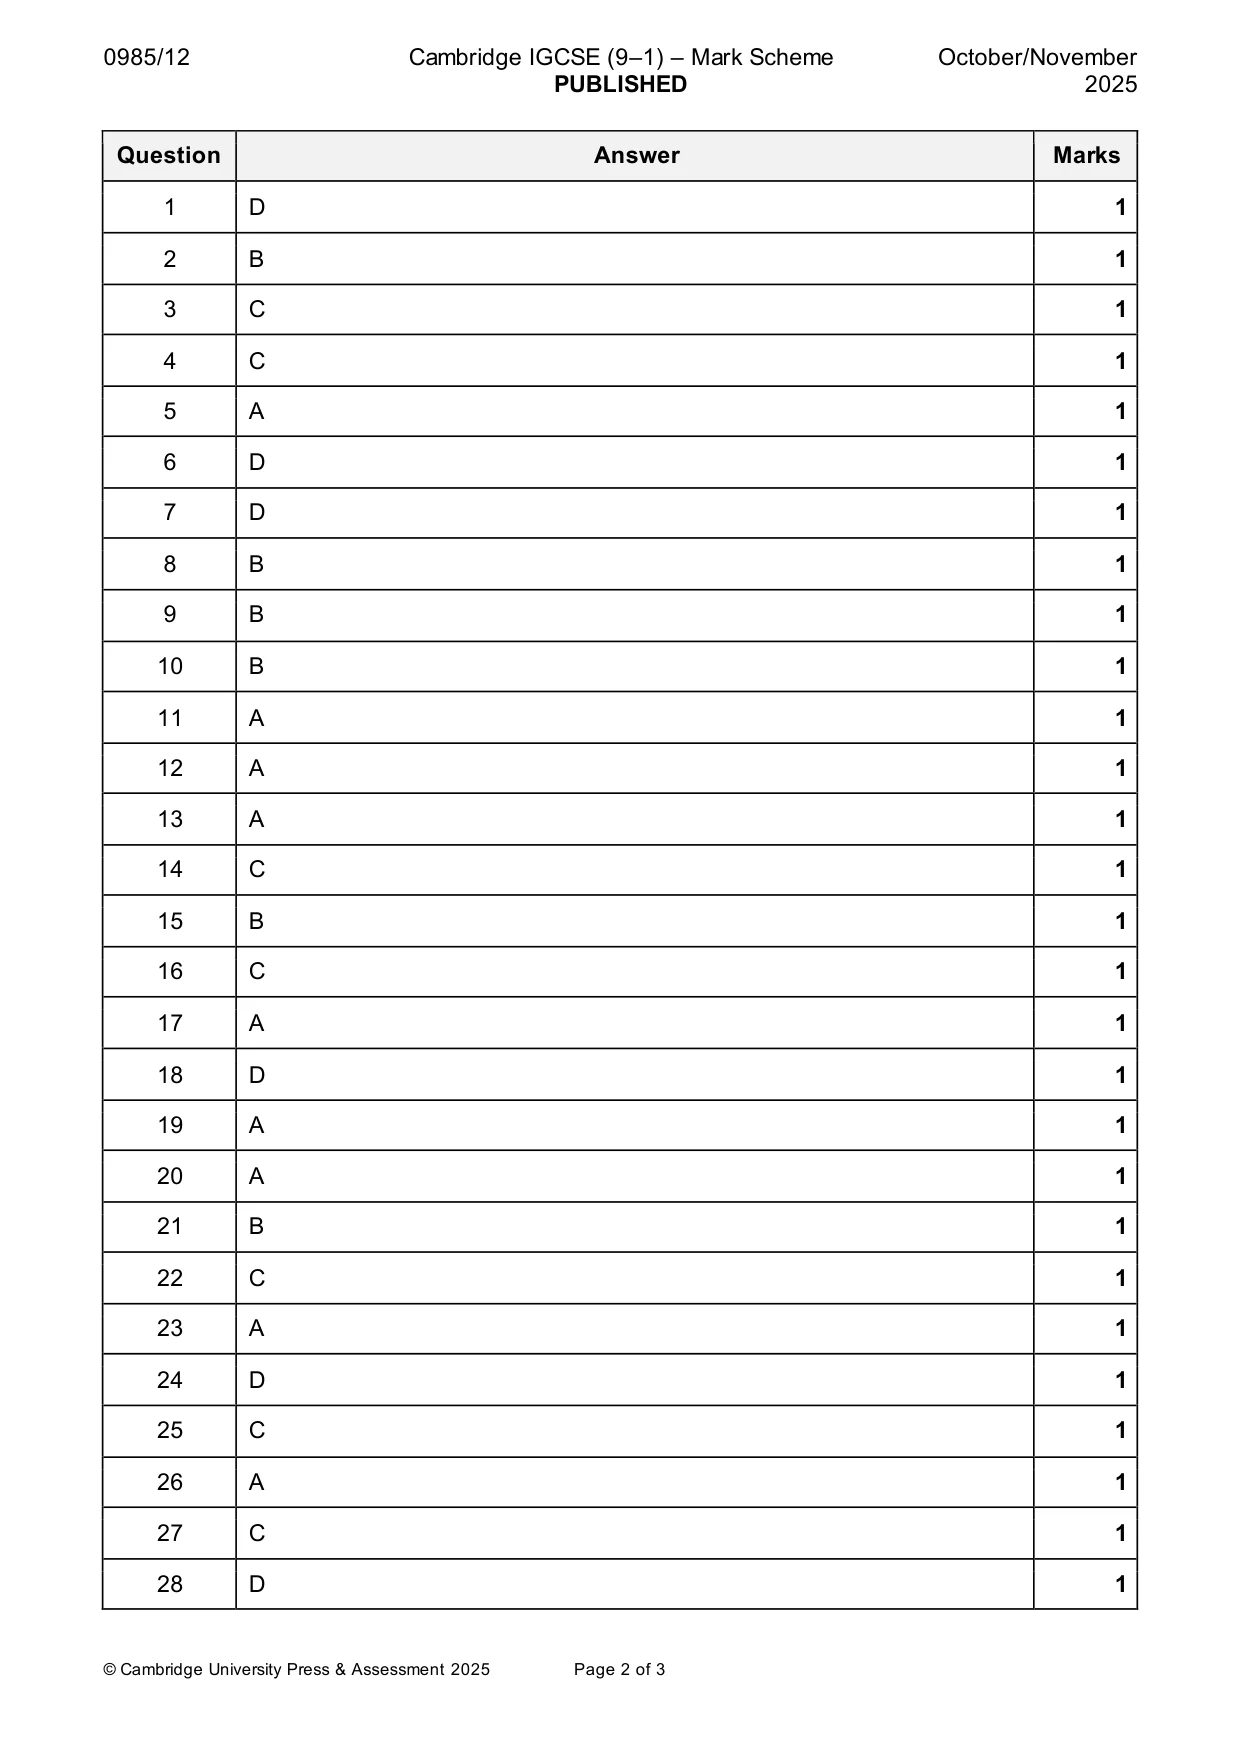
Mark scheme, page 2
0985/12 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED October/November 2025 © Cambridge University Press & Assessment 2025 Page 2 of 3 Question Answer Marks 1 D 1 2 B 1 3 C 1 4 C 1 5 A 1 6 D 1 7 D 1 8 B 1 9 B 1 10 B 1 11 A 1 12 A 1 13 A 1 14 C 1 15 B 1 16 C 1 17 A 1 18 D 1 19 A 1 20 A 1 21 B 1 22 C 1 23 A 1 24 D 1 25 C 1 26 A 1 27 C 1 28 D 1
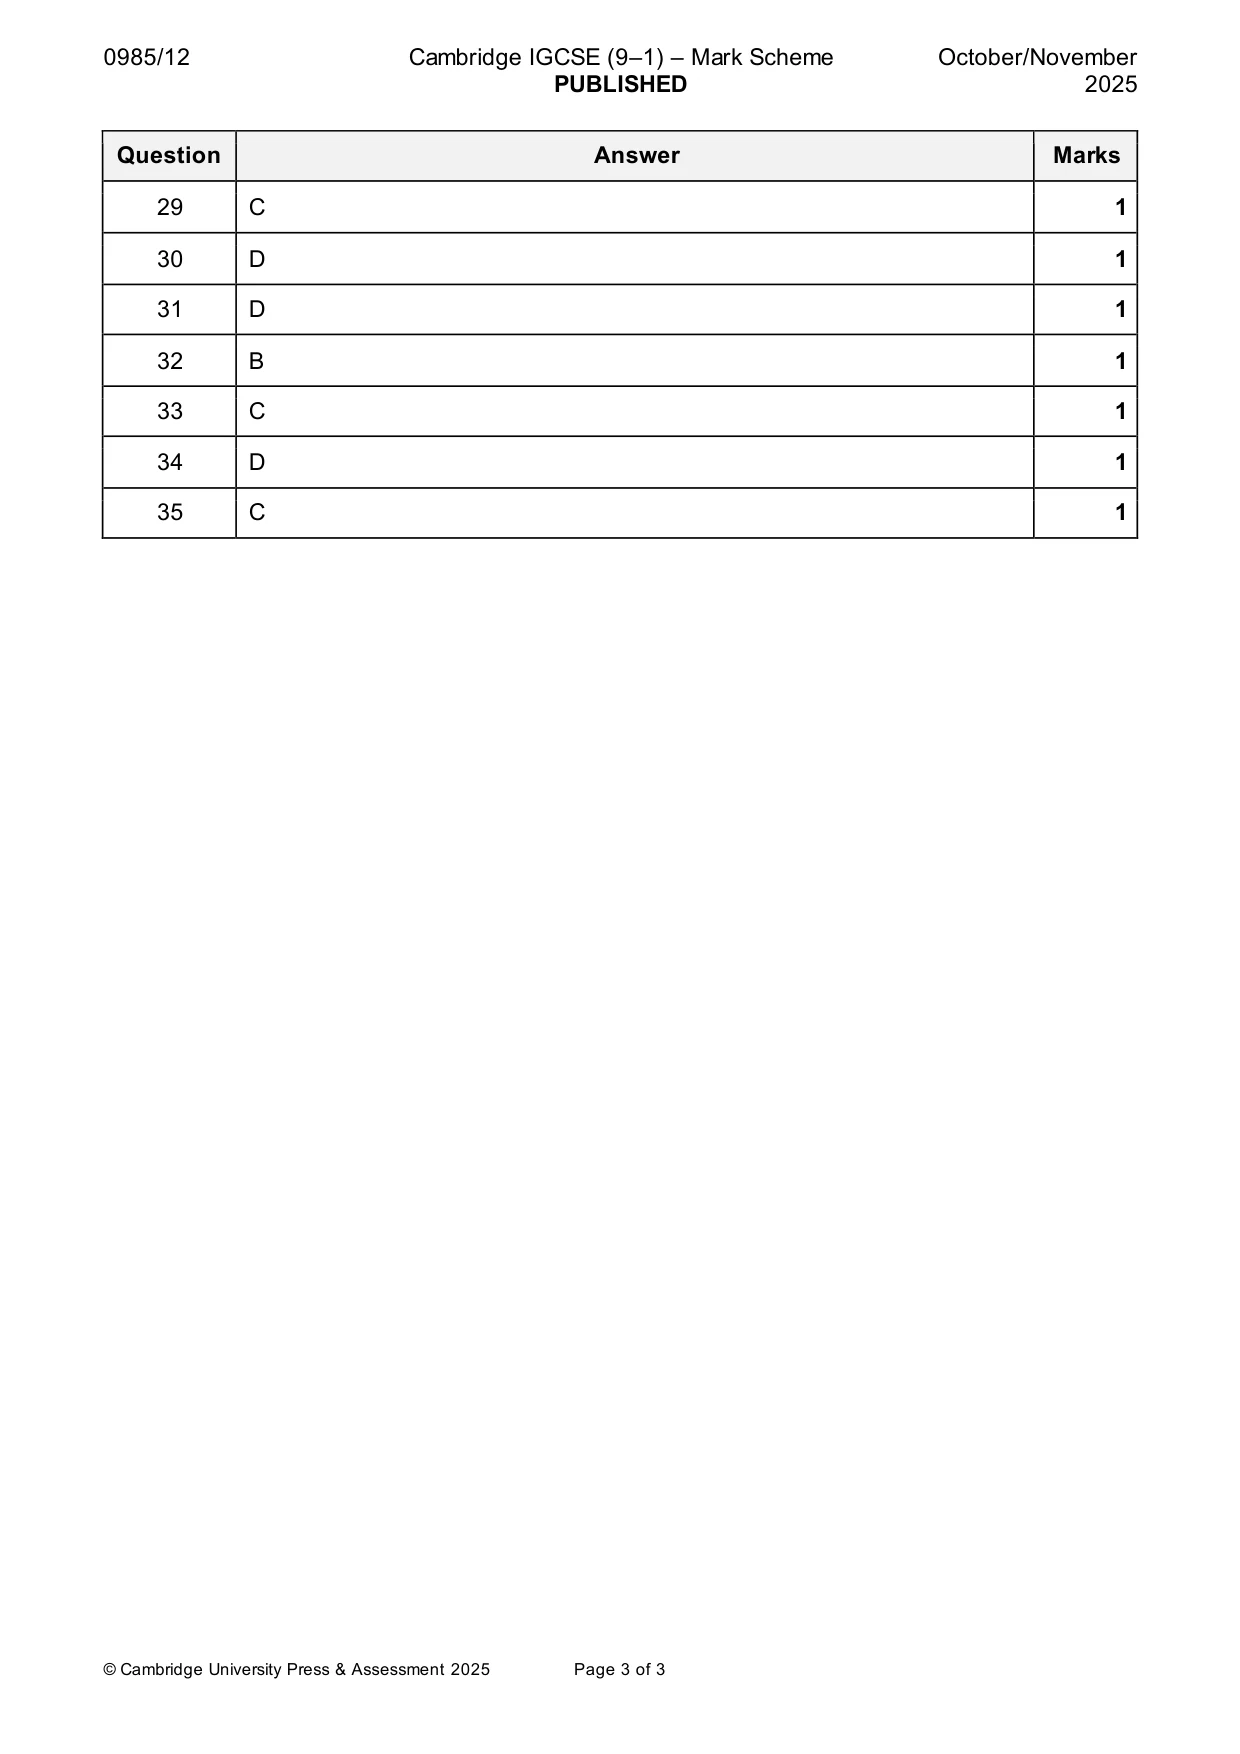
Mark scheme, page 3
0985/12 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED October/November 2025 © Cambridge University Press & Assessment 2025 Page 3 of 3 Question Answer Marks 29 C 1 30 D 1 31 D 1 32 B 1 33 C 1 34 D 1 35 C 1
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.