Cambridge A Level Business (for first examination in 2016) 9609 — 2023 Feb/March Paper 3 · Variant 2
9609/32/F/M/23 · 60 marks · ≈68 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages

Mark scheme24 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document has 12 pages. Any blank pages are indicated. [Turn over Cambridge International AS & A Level DC (CE) 315428/1 © UCLES 2023 BUSINESS 9609/32 Paper 3 Business Decision-Making February/March 2023 1 hour 45 minutes You must answer on the question paper. You will need: Insert (enclosed) INSTRUCTIONS ● Answer all questions. ● Use a black or dark blue pen. ● Write your name, centre number and candidate number in the boxes at the top of the page. ● Write your answer to each question in the space provided. ● Do not use an erasable pen or correction fluid. ● Do not write on any bar codes. ● You may use an HB pencil for any diagrams, graphs or rough working. INFORMATION ● The total mark for this paper is 60. ● The number of marks for each question or part question is shown in brackets [ ]. ● The insert contains the case study. * 2 4 4 5 7 6 5 8 0 1 *
Question paper, page 2
2 9609/32/F/M/23 © UCLES 2023 Answer all questions. 1 Analyse how two legal changes planned by the new government will impact FWB. … … … … … … … … … … … … … … … … … … … … … … … … [8]
Question paper, page 3
3 9609/32/F/M/23 © UCLES 2023 [Turn over 2 Analyse two benefits to FWB of delegating more decision-making to van managers. … … … … … … … … … … … … … … … … … … … … … … … … [8]
Question paper, page 4
4 9609/32/F/M/23 © UCLES 2023 3 (a) Assume FWB increases spending on promotion by 20% and the promotional elasticity of demand is 0.8. Calculate the percentage change in FWB’s revenue. … … … [1] (b) Refer to lines 30–32. Calculate the estimated price elasticity of demand if FWB increases the price of coffee from $2.00 to $2.30. … … … … … … … … … [3] (c) Evaluate the usefulness of the concept of elasticity of demand to FWB when deciding on a new marketing mix. … … … … … … … … … … … …
Question paper, page 5
5 9609/32/F/M/23 © UCLES 2023 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … [12]
Question paper, page 6
6 9609/32/F/M/23 © UCLES 2023 4 (a) Refer to lines 47–49 and Table 1.1. Calculate the accounting rate of return (ARR). … … … … … … … … … … … … [4] (b) Evaluate whether FWB should invest in enterprise resource planning (ERP). … … … … … … … … … … … … … …
Question paper, page 7
7 9609/32/F/M/23 © UCLES 2023 [Turn over … … … … … … … … … … … … … … … … … … … … … … [12]
Question paper, page 8
8 9609/32/F/M/23 © UCLES 2023 5 Evaluate the usefulness of FWB’s accounting ratio analysis to its directors when making business decisions. … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 9
9 9609/32/F/M/23 © UCLES 2023 … … … … … … … … … [12]
Question paper, page 10
10 9609/32/F/M/23 © UCLES 2023 BLANK PAGE
Question paper, page 11
11 9609/32/F/M/23 © UCLES 2023 BLANK PAGE
Question paper, page 12
12 9609/32/F/M/23 © UCLES 2023 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of Cambridge Assessment. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which is a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
This document consists of 24 printed pages. © UCLES 2023 [Turn over Cambridge International AS & A Level BUSINESS 9609/32 Paper 3 Business Decision-Making February/March 2023 MARK SCHEME Maximum Mark: 60 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the February/March 2023 series for most Cambridge IGCSE™, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 2 of 24 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently, e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors.
Mark scheme, page 3
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 3 of 24 GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 4
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 4 of 24 Social Science-Specific Marking Principles (for point-based marking) 1 Components using point-based marking: • Point marking is often used to reward knowledge, understanding and application of skills. We give credit where the candidate’s answer shows relevant knowledge, understanding and application of skills in answering the question. We do not give credit where the answer shows confusion. From this it follows that we: a DO credit answers which are worded differently from the mark scheme if they clearly convey the same meaning (unless the mark scheme requires a specific term) b DO credit alternative answers/examples which are not written in the mark scheme if they are correct c DO credit answers where candidates give more than one correct answer in one prompt/numbered/scaffolded space where extended writing is required rather than list-type answers. For example, questions that require n reasons (e.g. State two reasons …). d DO NOT credit answers simply for using a ‘key term’ unless that is all that is required. (Check for evidence it is understood and not used wrongly.) e DO NOT credit answers which are obviously self-contradicting or trying to cover all possibilities f DO NOT give further credit for what is effectively repetition of a correct point already credited unless the language itself is being tested. This applies equally to ‘mirror statements’ (i.e. polluted/not polluted). g DO NOT require spellings to be correct, unless this is part of the test. However spellings of syllabus terms must allow for clear and unambiguous separation from other syllabus terms with which they may be confused (e.g. Corrasion/Corrosion) 2 Presentation of mark scheme: • Slashes (/) or the word ‘or’ separate alternative ways of making the same point. • Semi colons (;) bullet points (•) or figures in brackets (1) separate different points. • Content in the answer column in brackets is for examiner information/context to clarify the marking but is not required to earn the mark (except Accounting syllabuses where they indicate negative numbers).
Mark scheme, page 5
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 5 of 24 3 Calculation questions: • The mark scheme will show the steps in the most likely correct method(s), the mark for each step, the correct answer(s) and the mark for each answer • If working/explanation is considered essential for full credit, this will be indicated in the question paper and in the mark scheme. In all other instances, the correct answer to a calculation should be given full credit, even if no supporting working is shown. • Where the candidate uses a valid method which is not covered by the mark scheme, award equivalent marks for reaching equivalent stages. • Where an answer makes use of a candidate’s own incorrect figure from previous working, the ‘own figure rule’ applies: full marks will be given if a correct and complete method is used. Further guidance will be included in the mark scheme where necessary and any exceptions to this general principle will be noted. 4 Annotation: • For point marking, ticks can be used to indicate correct answers and crosses can be used to indicate wrong answers. There is no direct relationship between ticks and marks. Ticks have no defined meaning for levels of response marking. • For levels of response marking, the level awarded should be annotated on the script. • Other annotations will be used by examiners as agreed during standardisation, and the meaning will be understood by all examiners who marked that paper.
Mark scheme, page 6
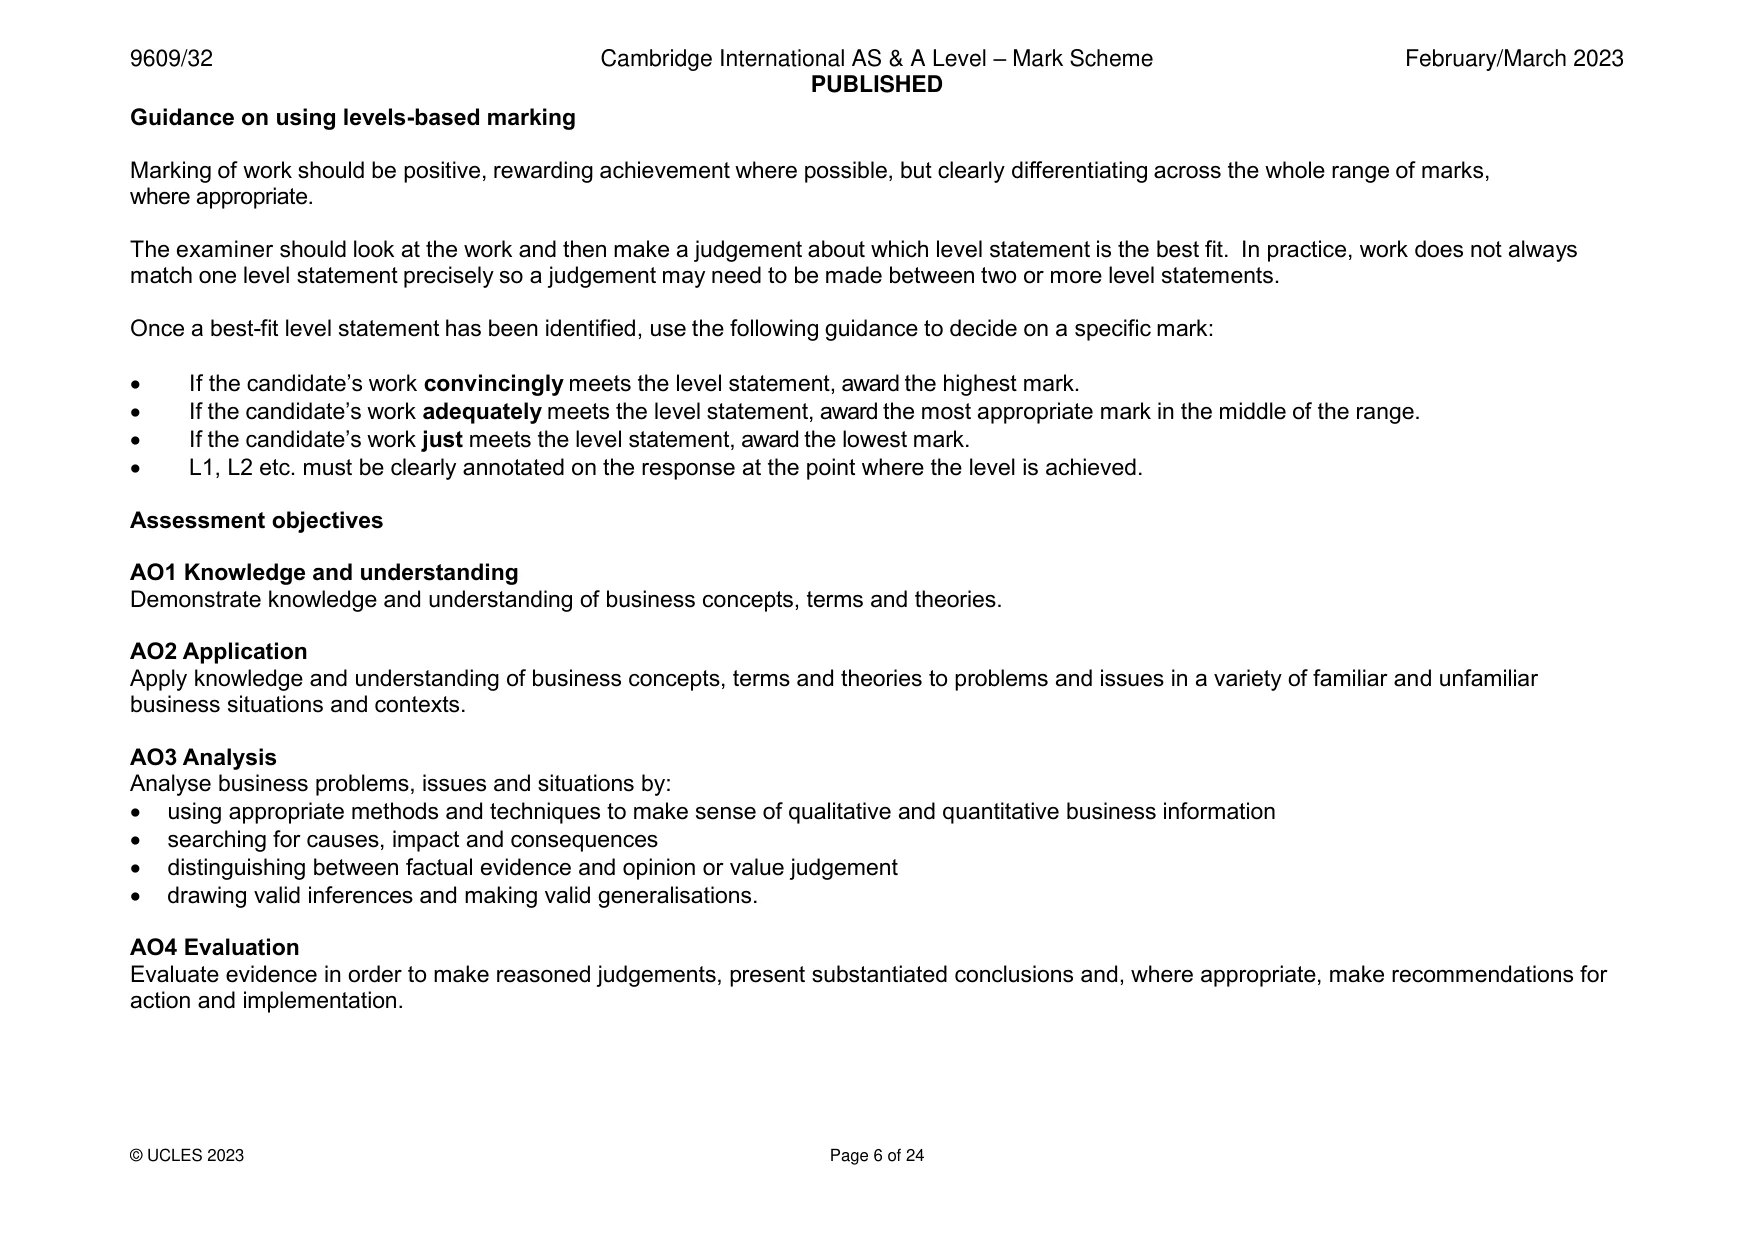
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 6 of 24 Guidance on using levels-based marking Marking of work should be positive, rewarding achievement where possible, but clearly differentiating across the whole range of marks, where appropriate. The examiner should look at the work and then make a judgement about which level statement is the best fit. In practice, work does not always match one level statement precisely so a judgement may need to be made between two or more level statements. Once a best-fit level statement has been identified, use the following guidance to decide on a specific mark: • If the candidate’s work convincingly meets the level statement, award the highest mark. • If the candidate’s work adequately meets the level statement, award the most appropriate mark in the middle of the range. • If the candidate’s work just meets the level statement, award the lowest mark. • L1, L2 etc. must be clearly annotated on the response at the point where the level is achieved. Assessment objectives AO1 Knowledge and understanding Demonstrate knowledge and understanding of business concepts, terms and theories. AO2 Application Apply knowledge and understanding of business concepts, terms and theories to problems and issues in a variety of familiar and unfamiliar business situations and contexts. AO3 Analysis Analyse business problems, issues and situations by: • using appropriate methods and techniques to make sense of qualitative and quantitative business information • searching for causes, impact and consequences • distinguishing between factual evidence and opinion or value judgement • drawing valid inferences and making valid generalisations. AO4 Evaluation Evaluate evidence in order to make reasoned judgements, present substantiated conclusions and, where appropriate, make recommendations for action and implementation.
Mark scheme, page 7
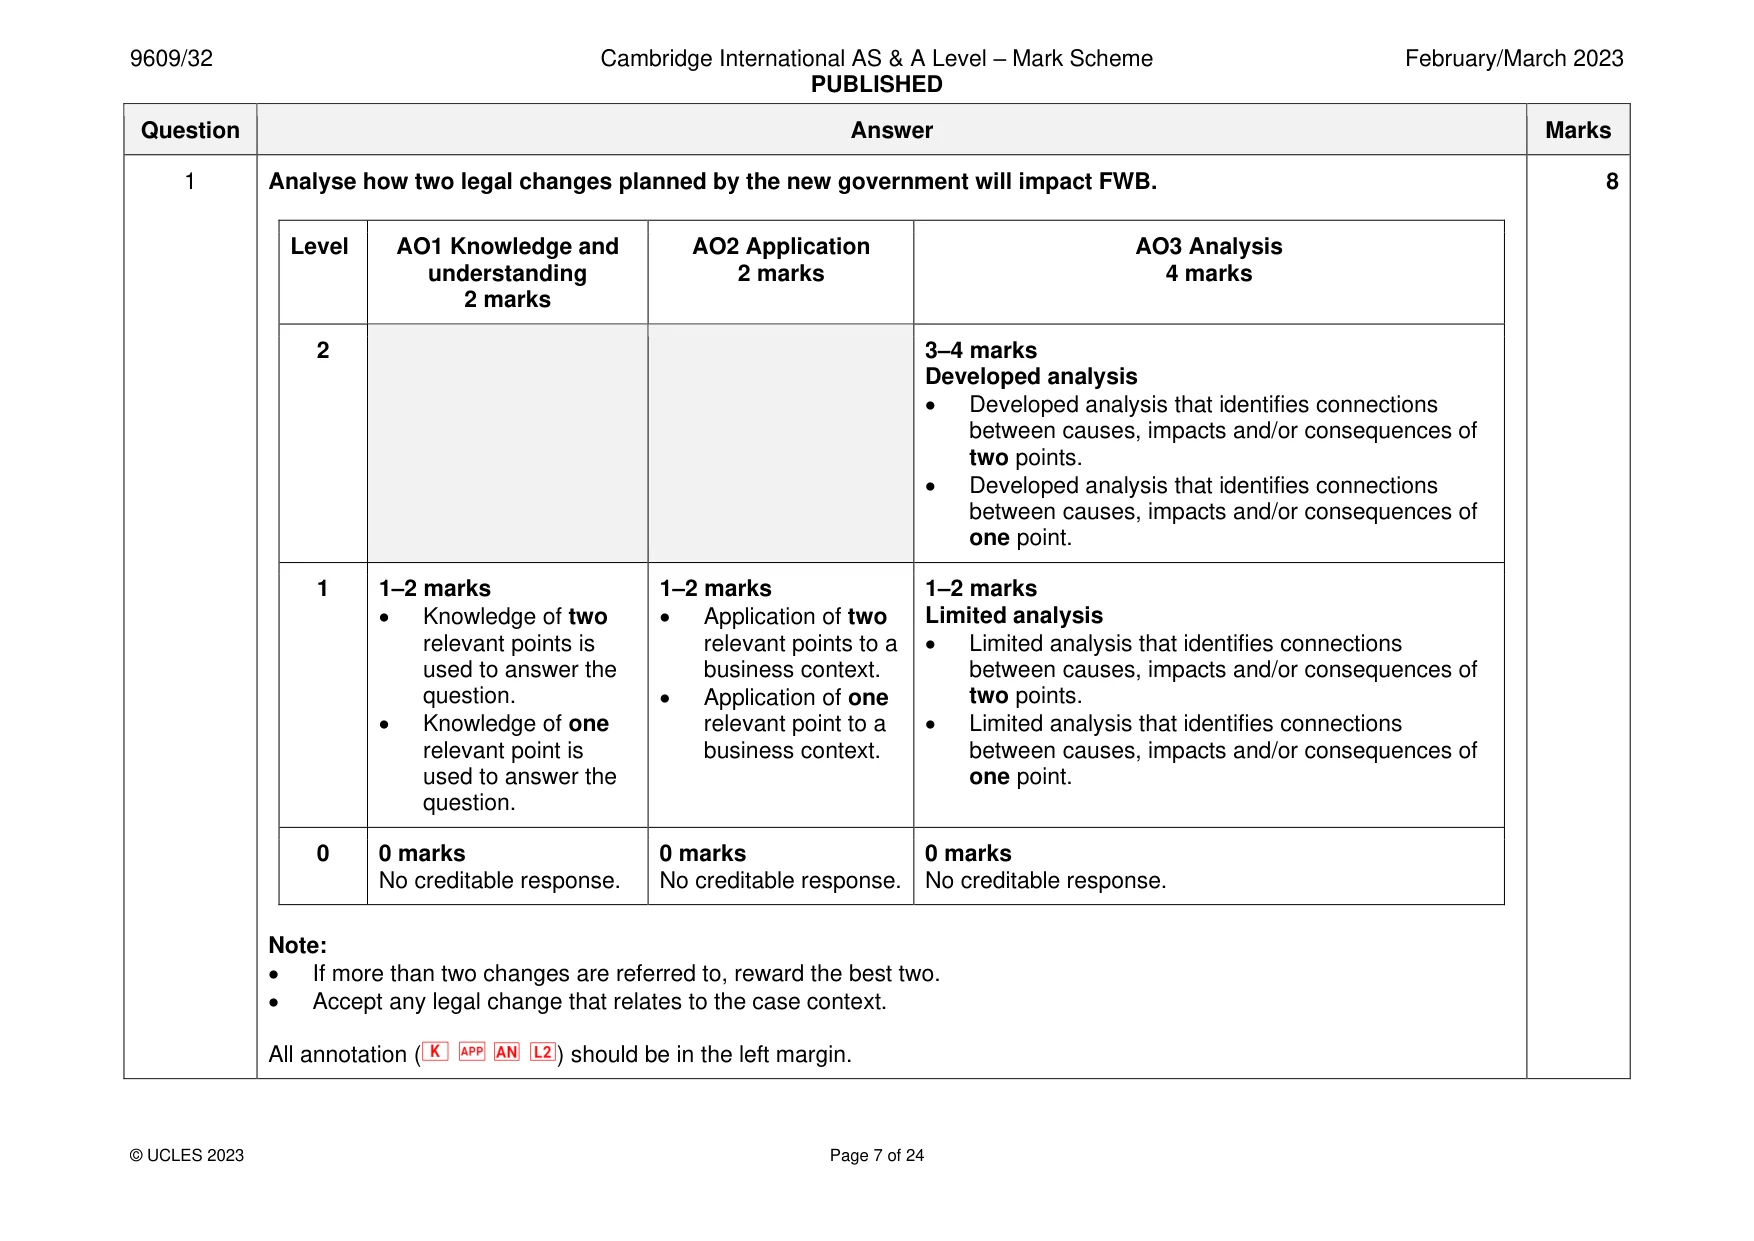
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 7 of 24 Question Answer Marks 1 Analyse how two legal changes planned by the new government will impact FWB. Level AO1 Knowledge and understanding 2 marks AO2 Application 2 marks AO3 Analysis 4 marks 2 3–4 marks Developed analysis • Developed analysis that identifies connections between causes, impacts and/or consequences of two points. • Developed analysis that identifies connections between causes, impacts and/or consequences of one point. 1 1–2 marks • Knowledge of two relevant points is used to answer the question. • Knowledge of one relevant point is used to answer the question. 1–2 marks • Application of two relevant points to a business context. • Application of one relevant point to a business context. 1–2 marks Limited analysis • Limited analysis that identifies connections between causes, impacts and/or consequences of two points. • Limited analysis that identifies connections between causes, impacts and/or consequences of one point. 0 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. Note: • If more than two changes are referred to, reward the best two. • Accept any legal change that relates to the case context. All annotation ( ) should be in the left margin. 8
Mark scheme, page 8
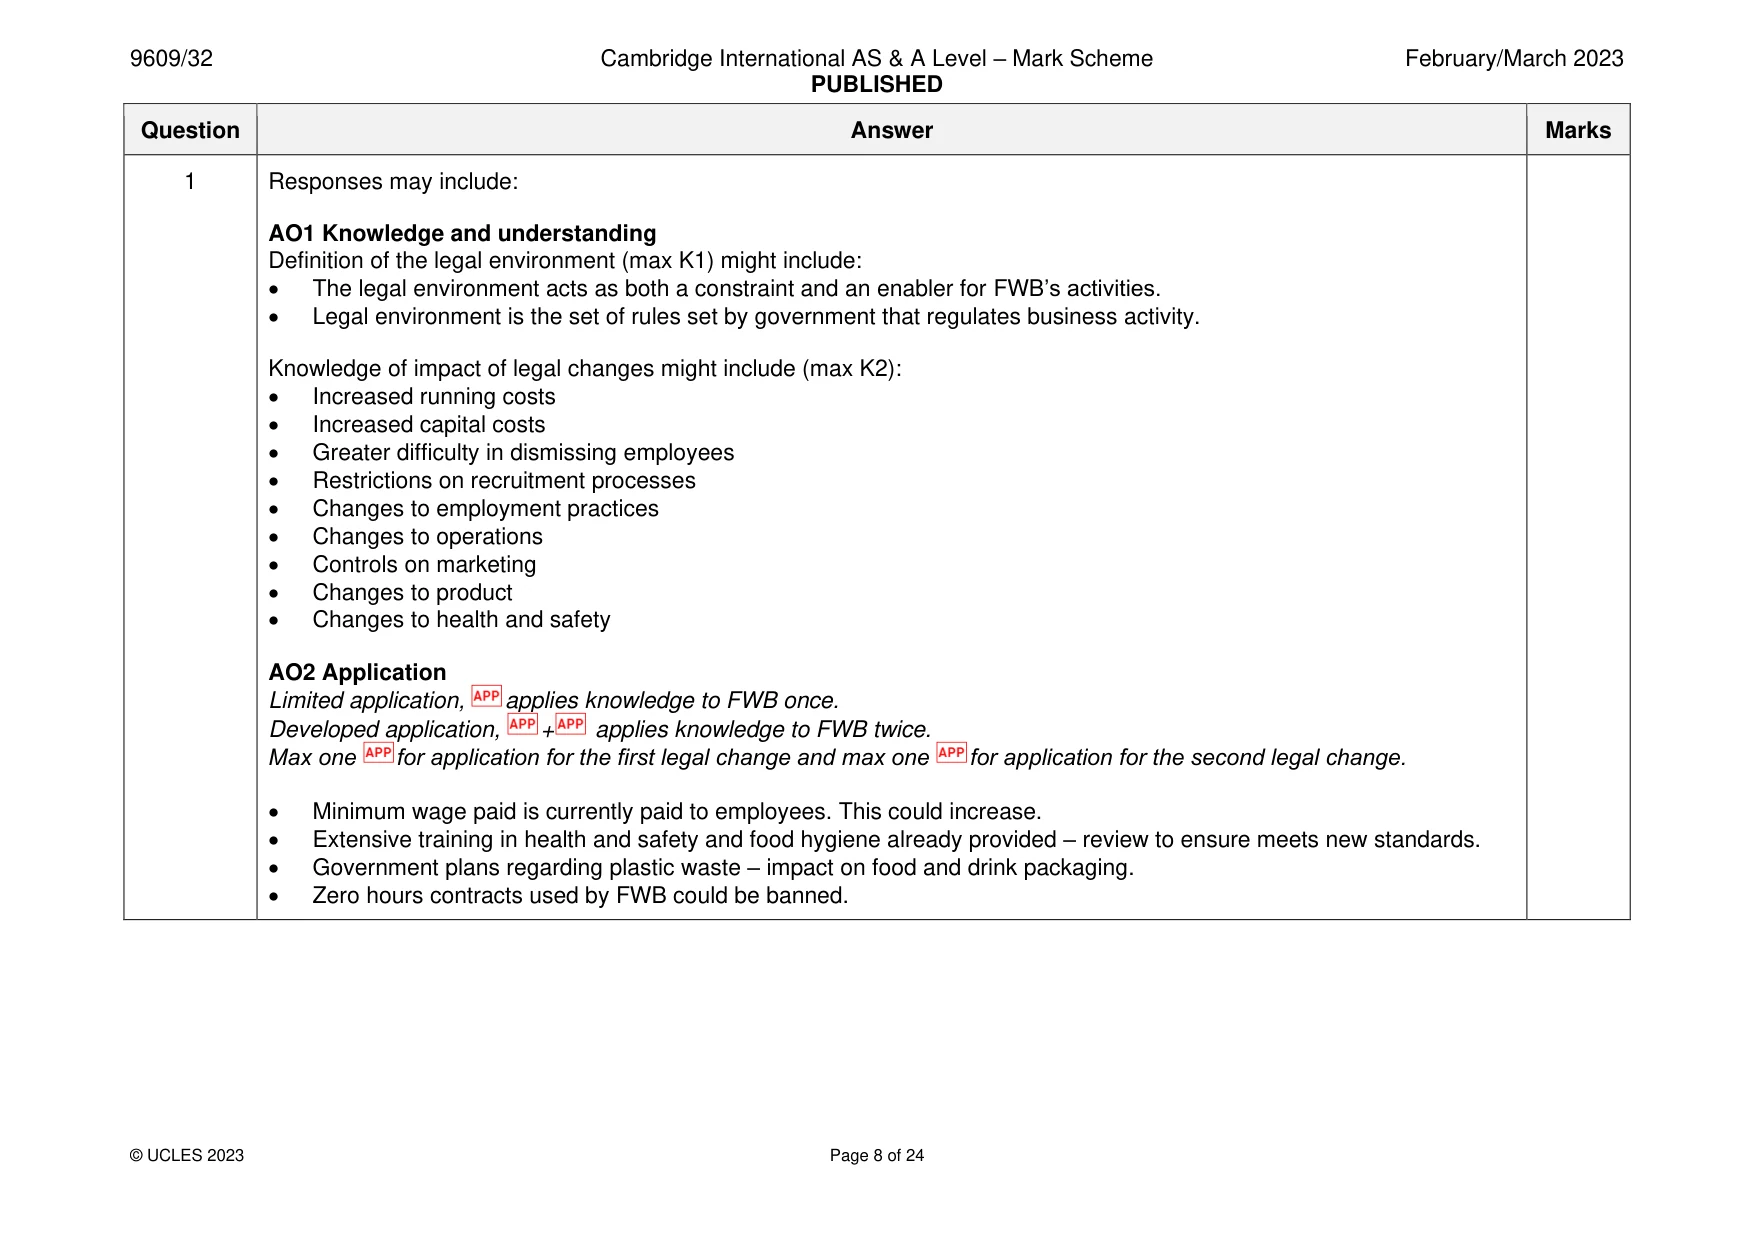
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 8 of 24 Question Answer Marks 1 Responses may include: AO1 Knowledge and understanding Definition of the legal environment (max K1) might include: • The legal environment acts as both a constraint and an enabler for FWB’s activities. • Legal environment is the set of rules set by government that regulates business activity. Knowledge of impact of legal changes might include (max K2): • Increased running costs • Increased capital costs • Greater difficulty in dismissing employees • Restrictions on recruitment processes • Changes to employment practices • Changes to operations • Controls on marketing • Changes to product • Changes to health and safety AO2 Application Limited application, applies knowledge to FWB once. Developed application, + applies knowledge to FWB twice. Max one for application for the first legal change and max one for application for the second legal change. • Minimum wage paid is currently paid to employees. This could increase. • Extensive training in health and safety and food hygiene already provided – review to ensure meets new standards. • Government plans regarding plastic waste – impact on food and drink packaging. • Zero hours contracts used by FWB could be banned.
Mark scheme, page 9
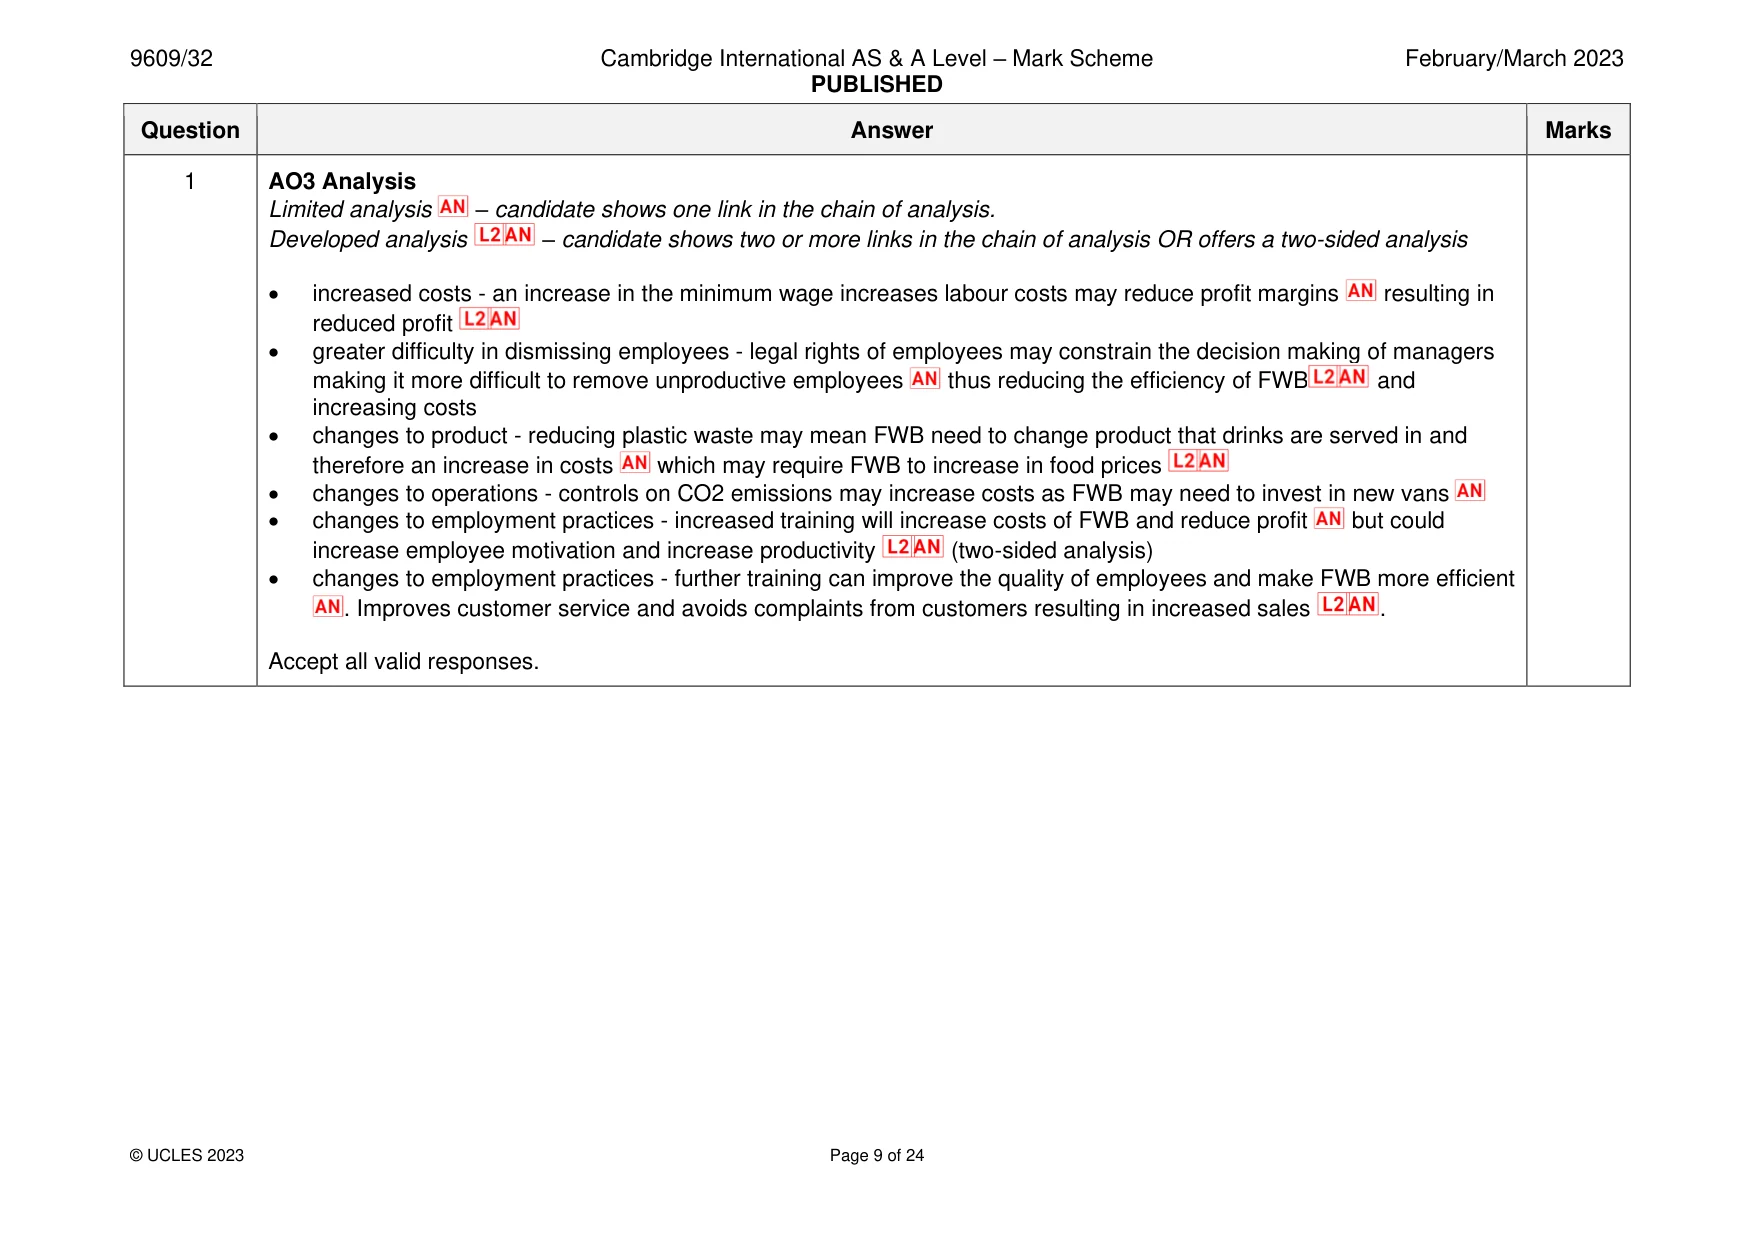
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 9 of 24 Question Answer Marks 1 AO3 Analysis Limited analysis – candidate shows one link in the chain of analysis. Developed analysis – candidate shows two or more links in the chain of analysis OR offers a two-sided analysis • increased costs - an increase in the minimum wage increases labour costs may reduce profit margins resulting in reduced profit • greater difficulty in dismissing employees - legal rights of employees may constrain the decision making of managers making it more difficult to remove unproductive employees thus reducing the efficiency of FWB and increasing costs • changes to product - reducing plastic waste may mean FWB need to change product that drinks are served in and therefore an increase in costs which may require FWB to increase in food prices • changes to operations - controls on CO2 emissions may increase costs as FWB may need to invest in new vans • changes to employment practices - increased training will increase costs of FWB and reduce profit but could increase employee motivation and increase productivity (two-sided analysis) • changes to employment practices - further training can improve the quality of employees and make FWB more efficient . Improves customer service and avoids complaints from customers resulting in increased sales . Accept all valid responses.
Mark scheme, page 10
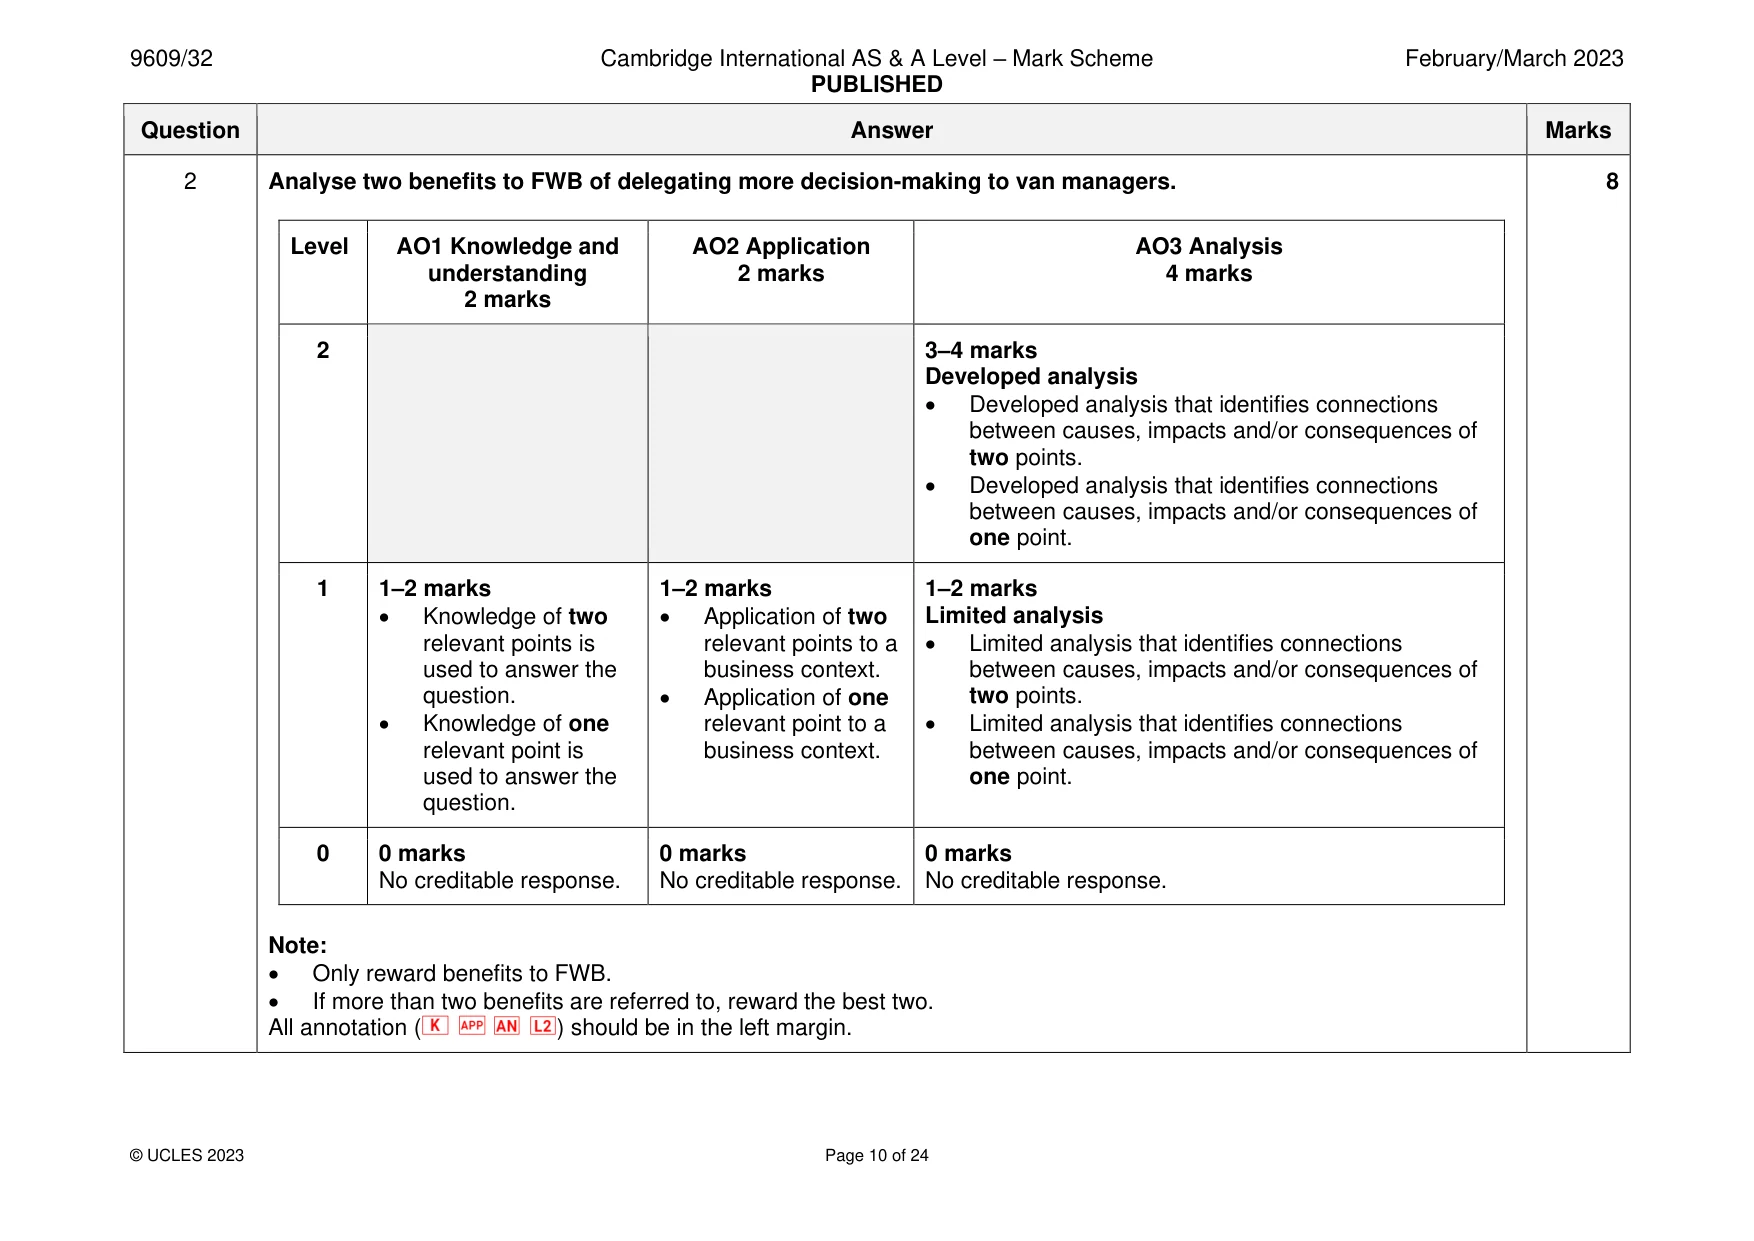
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 10 of 24 Question Answer Marks 2 Analyse two benefits to FWB of delegating more decision-making to van managers. Level AO1 Knowledge and understanding 2 marks AO2 Application 2 marks AO3 Analysis 4 marks 2 3–4 marks Developed analysis • Developed analysis that identifies connections between causes, impacts and/or consequences of two points. • Developed analysis that identifies connections between causes, impacts and/or consequences of one point. 1 1–2 marks • Knowledge of two relevant points is used to answer the question. • Knowledge of one relevant point is used to answer the question. 1–2 marks • Application of two relevant points to a business context. • Application of one relevant point to a business context. 1–2 marks Limited analysis • Limited analysis that identifies connections between causes, impacts and/or consequences of two points. • Limited analysis that identifies connections between causes, impacts and/or consequences of one point. 0 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. Note: • Only reward benefits to FWB. • If more than two benefits are referred to, reward the best two. All annotation ( ) should be in the left margin. 8
Mark scheme, page 11
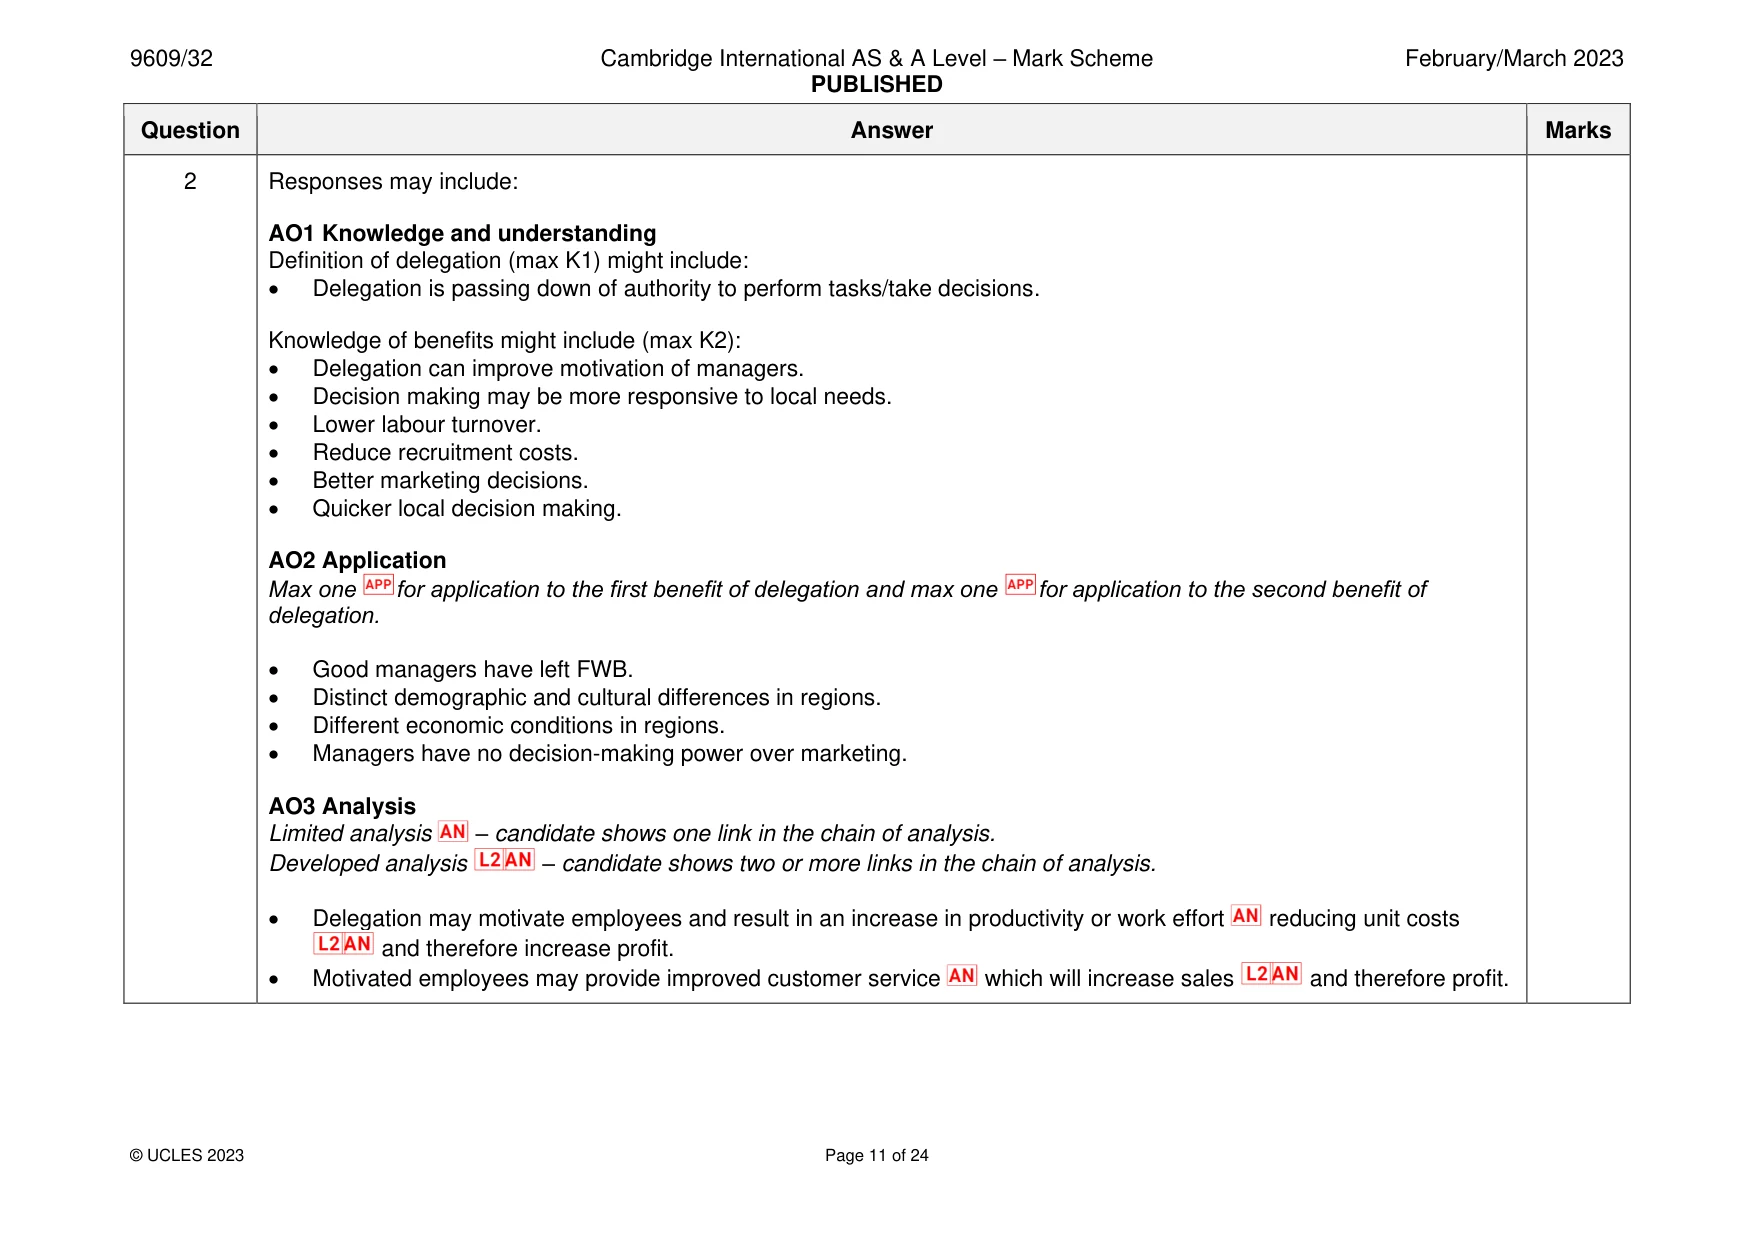
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 11 of 24 Question Answer Marks 2 Responses may include: AO1 Knowledge and understanding Definition of delegation (max K1) might include: • Delegation is passing down of authority to perform tasks/take decisions. Knowledge of benefits might include (max K2): • Delegation can improve motivation of managers. • Decision making may be more responsive to local needs. • Lower labour turnover. • Reduce recruitment costs. • Better marketing decisions. • Quicker local decision making. AO2 Application Max one for application to the first benefit of delegation and max one for application to the second benefit of delegation. • Good managers have left FWB. • Distinct demographic and cultural differences in regions. • Different economic conditions in regions. • Managers have no decision-making power over marketing. AO3 Analysis Limited analysis – candidate shows one link in the chain of analysis. Developed analysis – candidate shows two or more links in the chain of analysis. • Delegation may motivate employees and result in an increase in productivity or work effort reducing unit costs and therefore increase profit. • Motivated employees may provide improved customer service which will increase sales and therefore profit.
Mark scheme, page 12
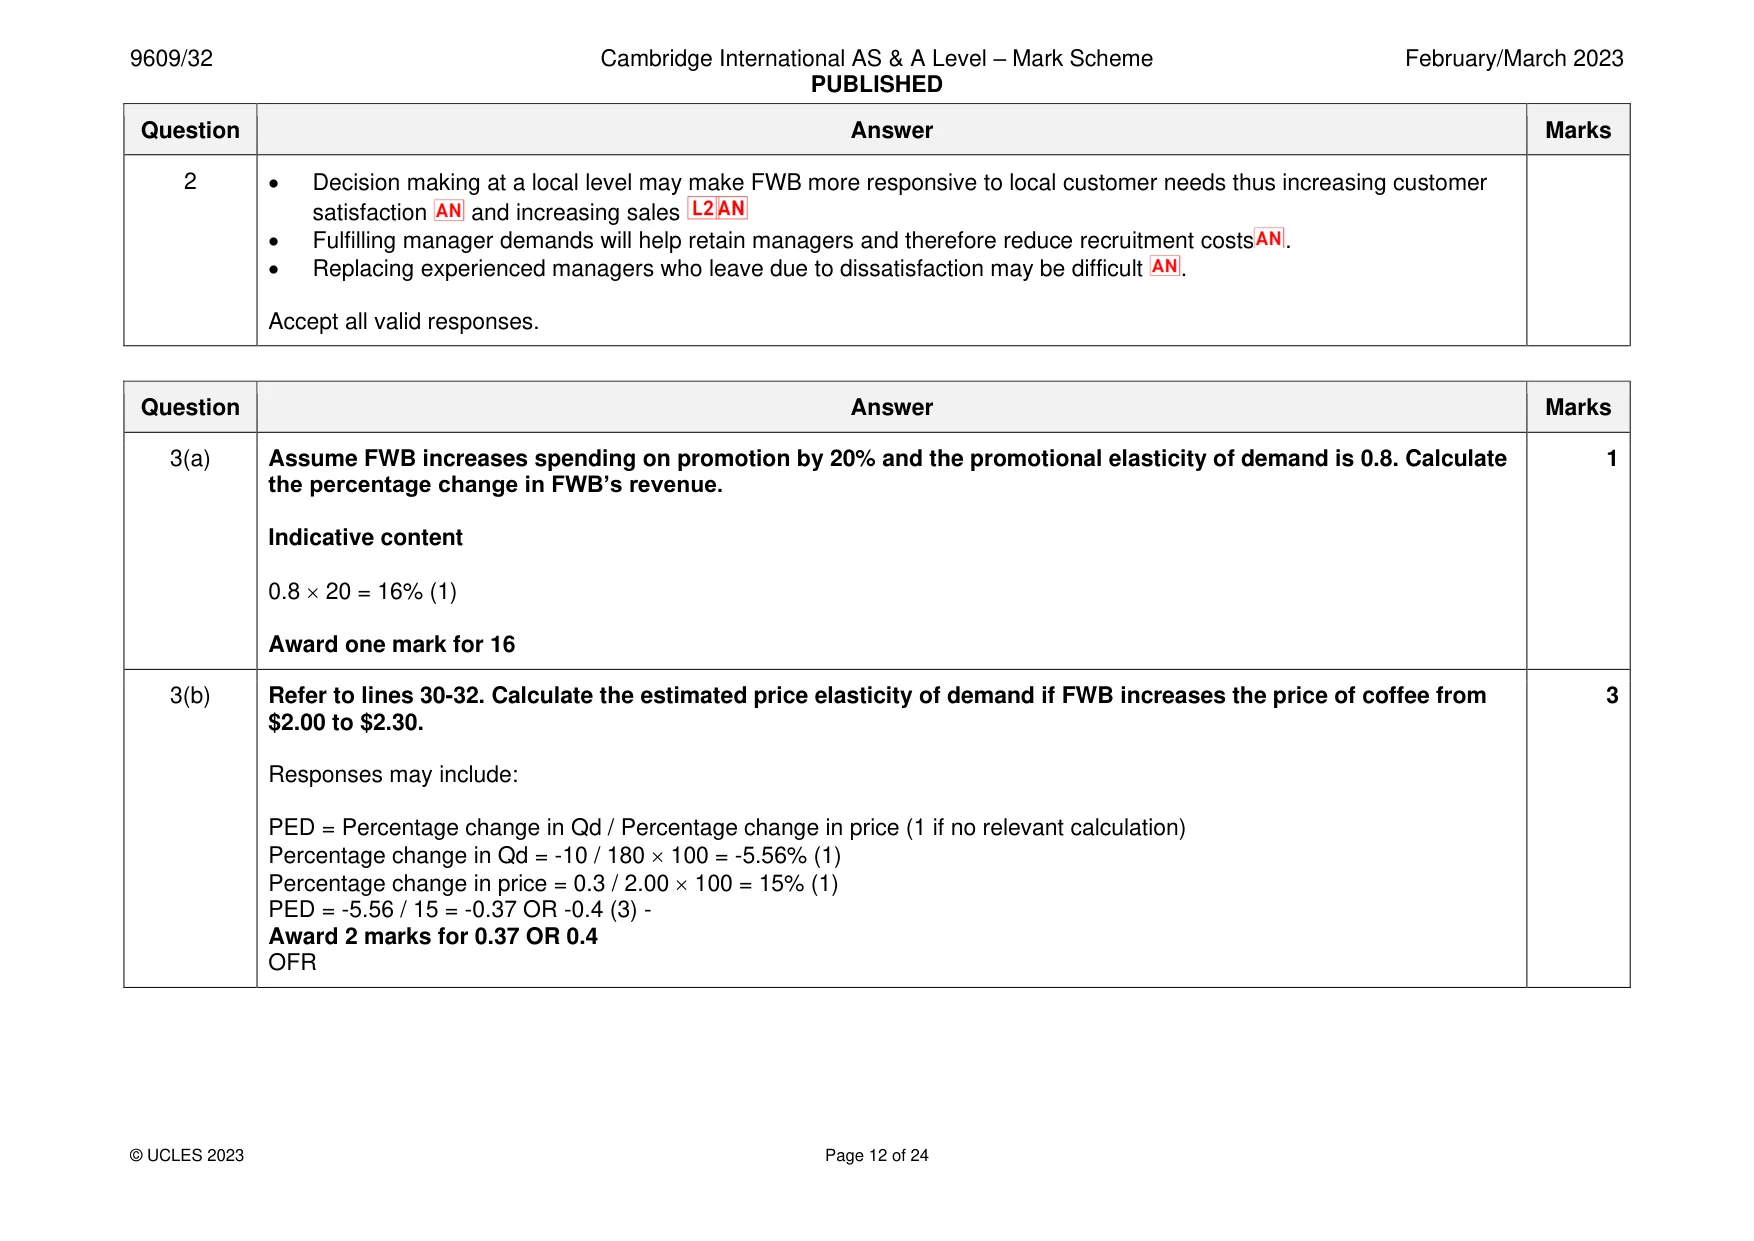
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 12 of 24 Question Answer Marks 2 • Decision making at a local level may make FWB more responsive to local customer needs thus increasing customer satisfaction and increasing sales • Fulfilling manager demands will help retain managers and therefore reduce recruitment costs . • Replacing experienced managers who leave due to dissatisfaction may be difficult . Accept all valid responses. Question Answer Marks 3(a) Assume FWB increases spending on promotion by 20% and the promotional elasticity of demand is 0.8. Calculate the percentage change in FWB’s revenue. Indicative content 0.8 20 = 16% (1) Award one mark for 16 1 3(b) Refer to lines 30-32. Calculate the estimated price elasticity of demand if FWB increases the price of coffee from $2.00 to $2.30. Responses may include: PED = Percentage change in Qd / Percentage change in price (1 if no relevant calculation) Percentage change in Qd = -10 / 180 100 = -5.56% (1) Percentage change in price = 0.3 / 2.00 100 = 15% (1) PED = -5.56 / 15 = -0.37 OR -0.4 (3) - Award 2 marks for 0.37 OR 0.4 OFR 3
Mark scheme, page 13
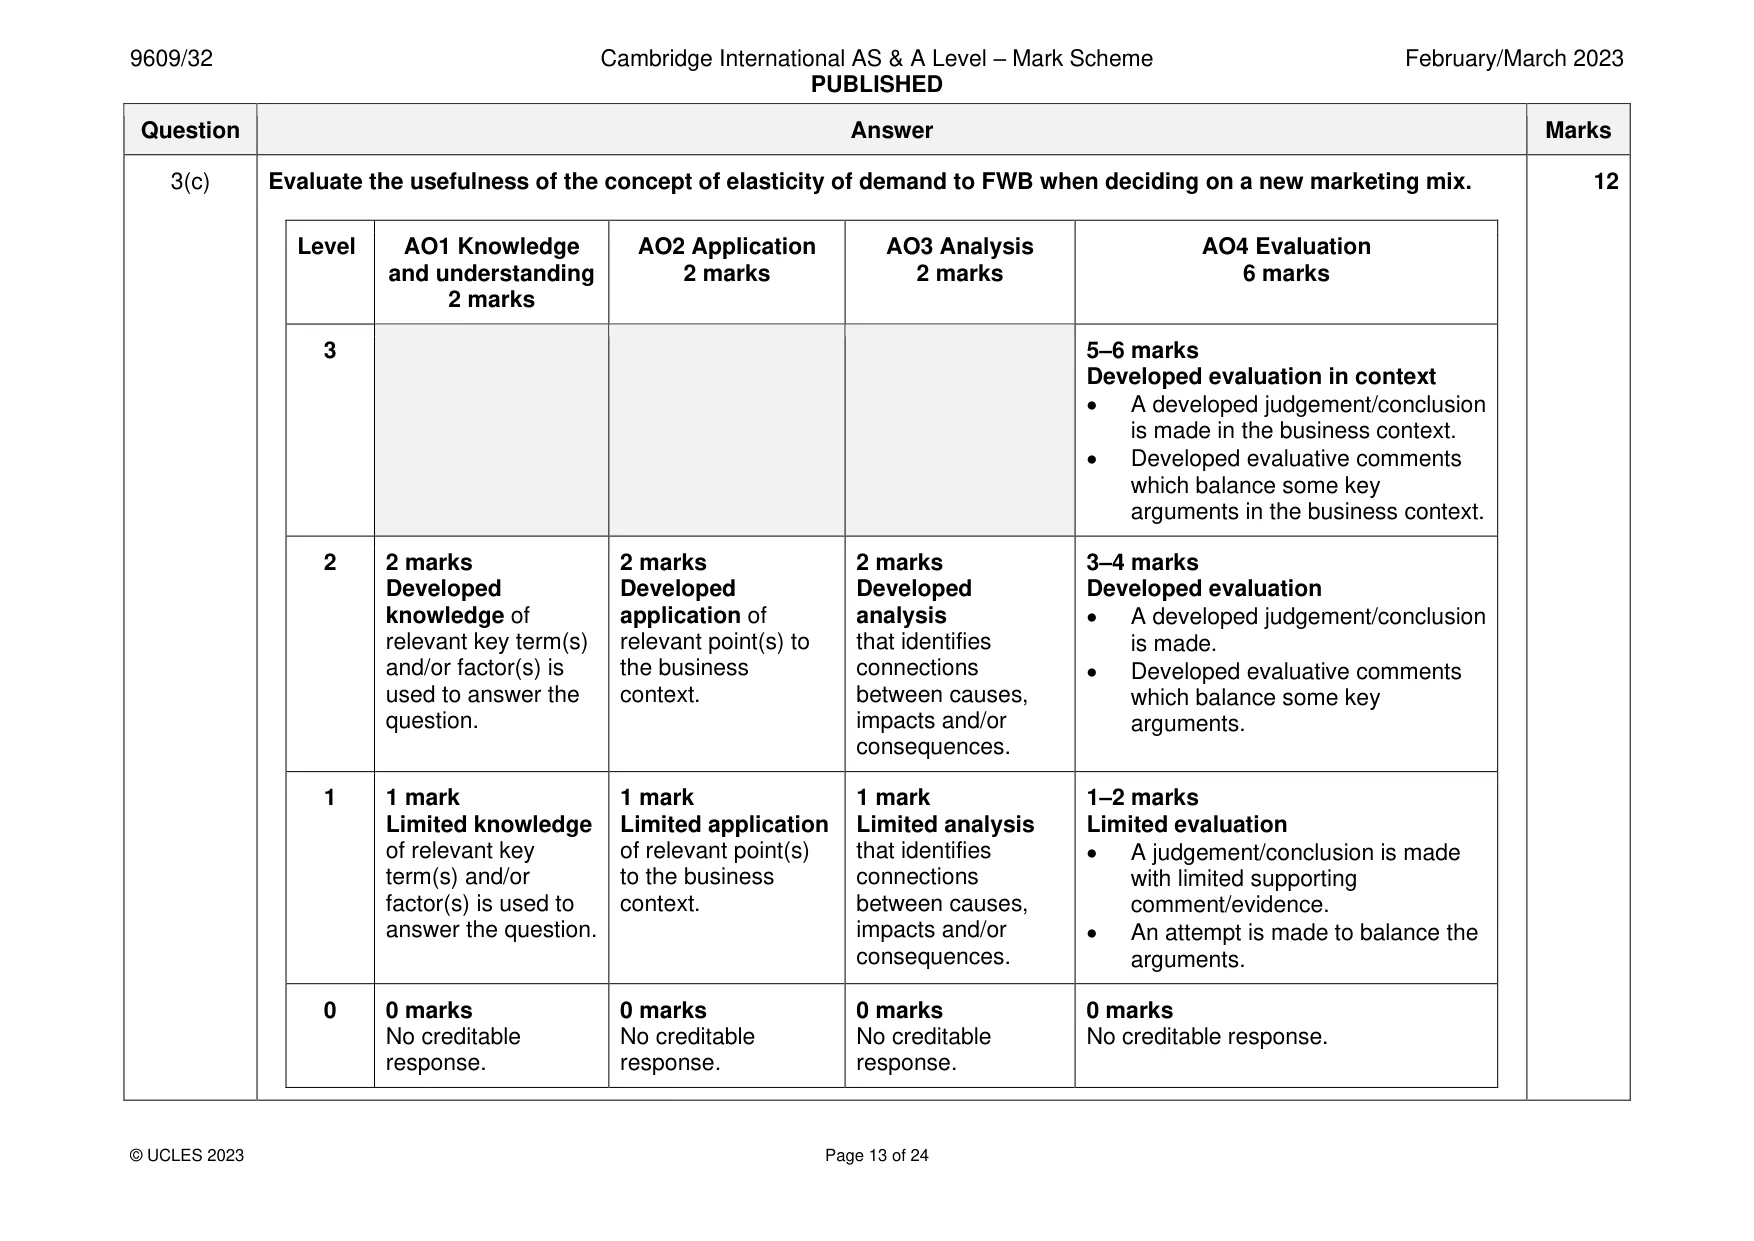
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 13 of 24 Question Answer Marks 3(c) Evaluate the usefulness of the concept of elasticity of demand to FWB when deciding on a new marketing mix. Level AO1 Knowledge and understanding 2 marks AO2 Application 2 marks AO3 Analysis 2 marks AO4 Evaluation 6 marks 3 5–6 marks Developed evaluation in context • A developed judgement/conclusion is made in the business context. • Developed evaluative comments which balance some key arguments in the business context. 2 2 marks Developed knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 2 marks Developed application of relevant point(s) to the business context. 2 marks Developed analysis that identifies connections between causes, impacts and/or consequences. 3–4 marks Developed evaluation • A developed judgement/conclusion is made. • Developed evaluative comments which balance some key arguments. 1 1 mark Limited knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 1 mark Limited application of relevant point(s) to the business context. 1 mark Limited analysis that identifies connections between causes, impacts and/or consequences. 1–2 marks Limited evaluation • A judgement/conclusion is made with limited supporting comment/evidence. • An attempt is made to balance the arguments. 0 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 12
Mark scheme, page 14
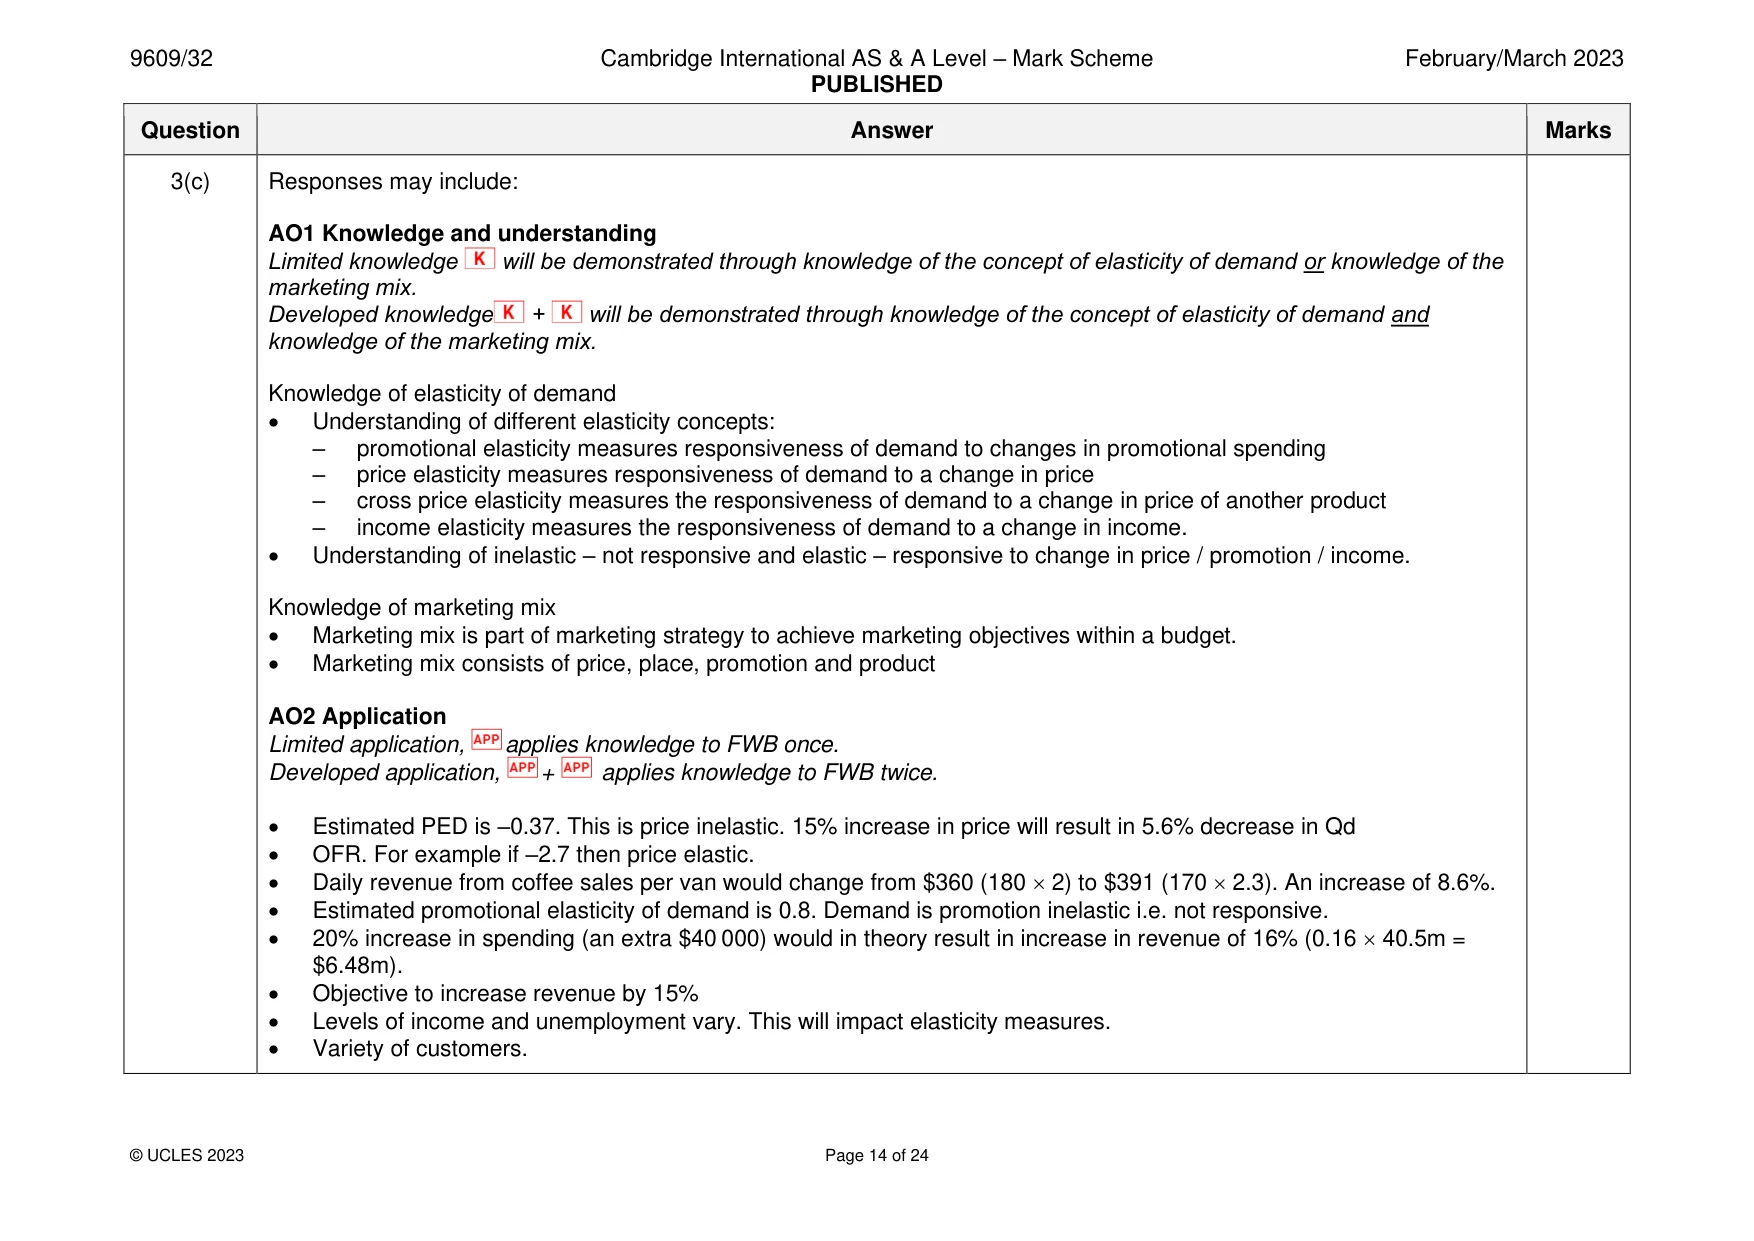
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 14 of 24 Question Answer Marks 3(c) Responses may include: AO1 Knowledge and understanding Limited knowledge will be demonstrated through knowledge of the concept of elasticity of demand or knowledge of the marketing mix. Developed knowledge + will be demonstrated through knowledge of the concept of elasticity of demand and knowledge of the marketing mix. Knowledge of elasticity of demand • Understanding of different elasticity concepts: – promotional elasticity measures responsiveness of demand to changes in promotional spending – price elasticity measures responsiveness of demand to a change in price – cross price elasticity measures the responsiveness of demand to a change in price of another product – income elasticity measures the responsiveness of demand to a change in income. • Understanding of inelastic – not responsive and elastic – responsive to change in price / promotion / income. Knowledge of marketing mix • Marketing mix is part of marketing strategy to achieve marketing objectives within a budget. • Marketing mix consists of price, place, promotion and product AO2 Application Limited application, applies knowledge to FWB once. Developed application, + applies knowledge to FWB twice. • Estimated PED is –0.37. This is price inelastic. 15% increase in price will result in 5.6% decrease in Qd • OFR. For example if –2.7 then price elastic. • Daily revenue from coffee sales per van would change from $360 (180 2) to $391 (170 2.3). An increase of 8.6%. • Estimated promotional elasticity of demand is 0.8. Demand is promotion inelastic i.e. not responsive. • 20% increase in spending (an extra $40 000) would in theory result in increase in revenue of 16% (0.16 40.5m = $6.48m). • Objective to increase revenue by 15% • Levels of income and unemployment vary. This will impact elasticity measures. • Variety of customers.
Mark scheme, page 15
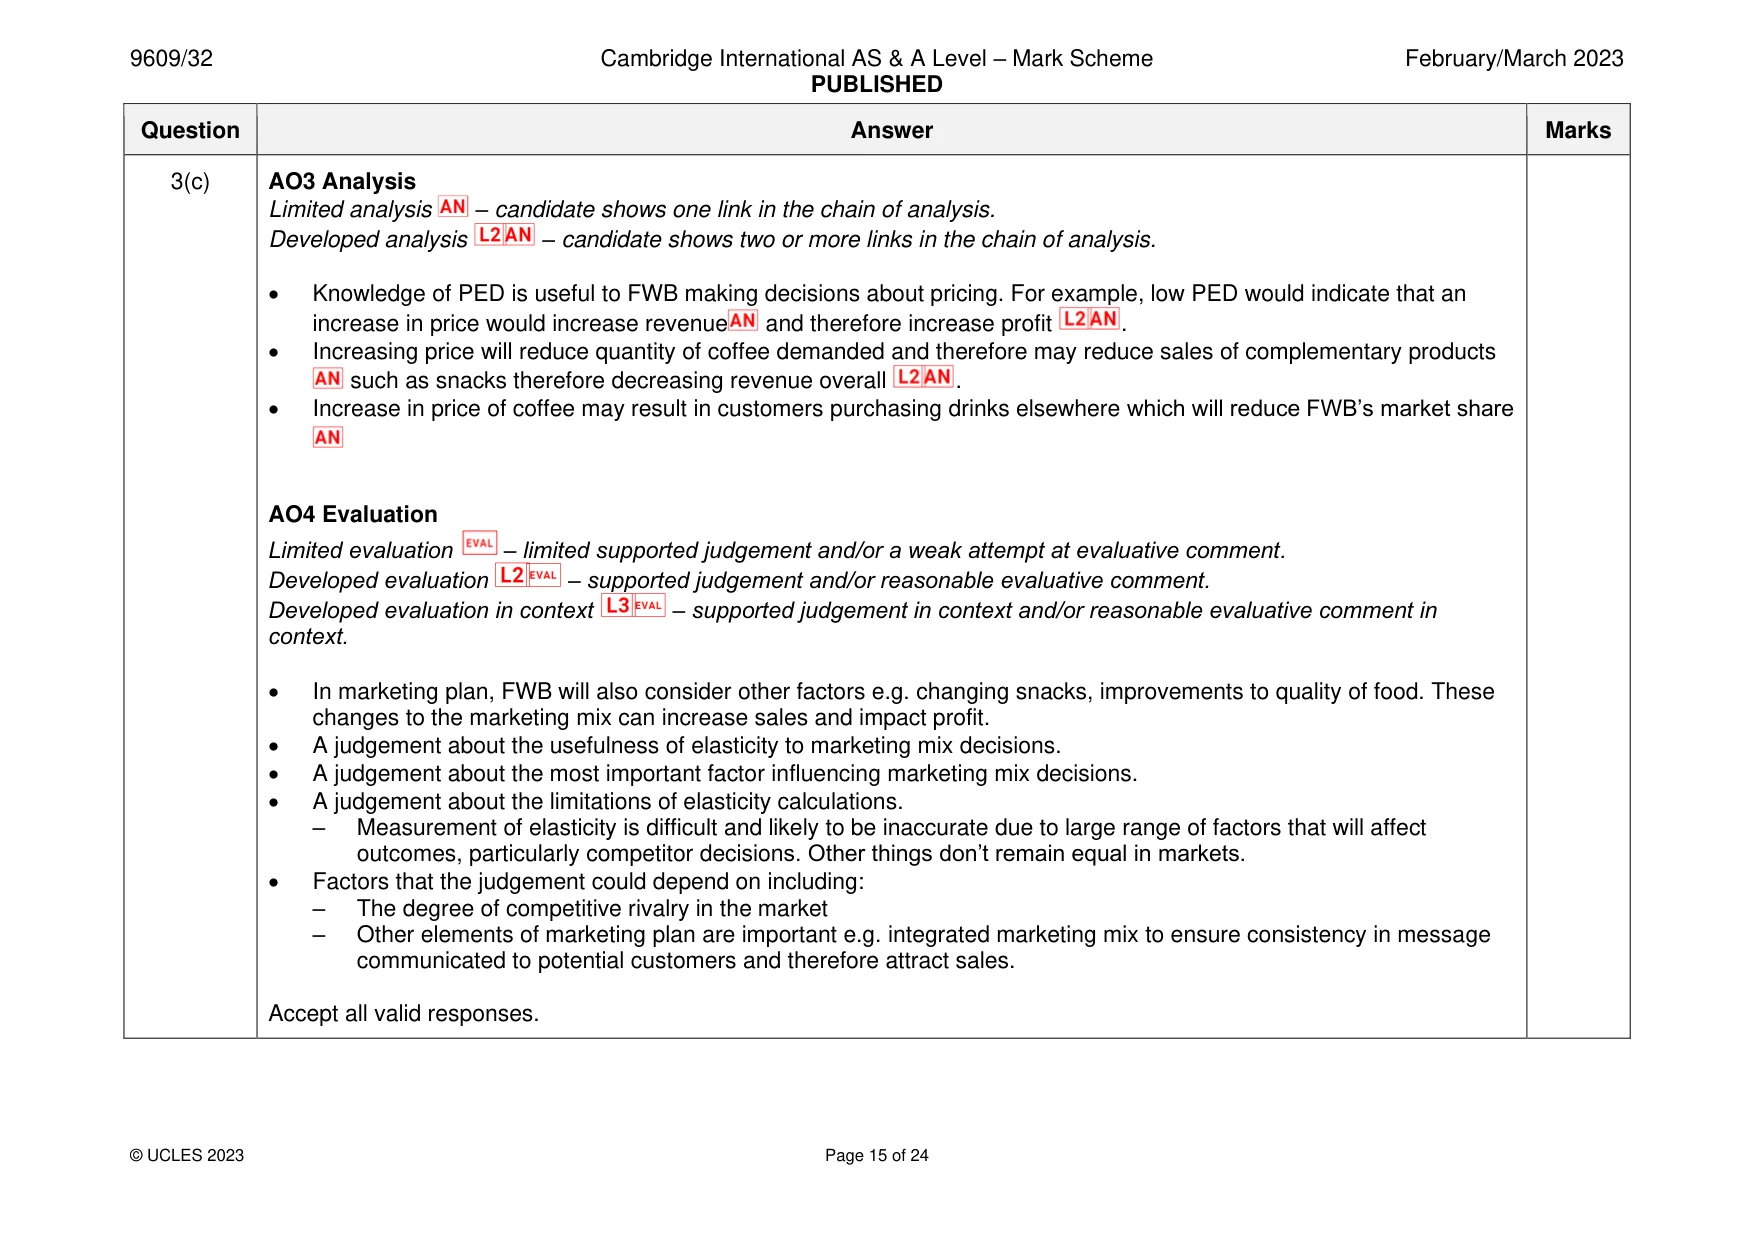
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 15 of 24 Question Answer Marks 3(c) AO3 Analysis Limited analysis – candidate shows one link in the chain of analysis. Developed analysis – candidate shows two or more links in the chain of analysis. • Knowledge of PED is useful to FWB making decisions about pricing. For example, low PED would indicate that an increase in price would increase revenue and therefore increase profit . • Increasing price will reduce quantity of coffee demanded and therefore may reduce sales of complementary products such as snacks therefore decreasing revenue overall . • Increase in price of coffee may result in customers purchasing drinks elsewhere which will reduce FWB’s market share AO4 Evaluation Limited evaluation – limited supported judgement and/or a weak attempt at evaluative comment. Developed evaluation – supported judgement and/or reasonable evaluative comment. Developed evaluation in context – supported judgement in context and/or reasonable evaluative comment in context. • In marketing plan, FWB will also consider other factors e.g. changing snacks, improvements to quality of food. These changes to the marketing mix can increase sales and impact profit. • A judgement about the usefulness of elasticity to marketing mix decisions. • A judgement about the most important factor influencing marketing mix decisions. • A judgement about the limitations of elasticity calculations. – Measurement of elasticity is difficult and likely to be inaccurate due to large range of factors that will affect outcomes, particularly competitor decisions. Other things don’t remain equal in markets. • Factors that the judgement could depend on including: – The degree of competitive rivalry in the market – Other elements of marketing plan are important e.g. integrated marketing mix to ensure consistency in message communicated to potential customers and therefore attract sales. Accept all valid responses.
Mark scheme, page 16
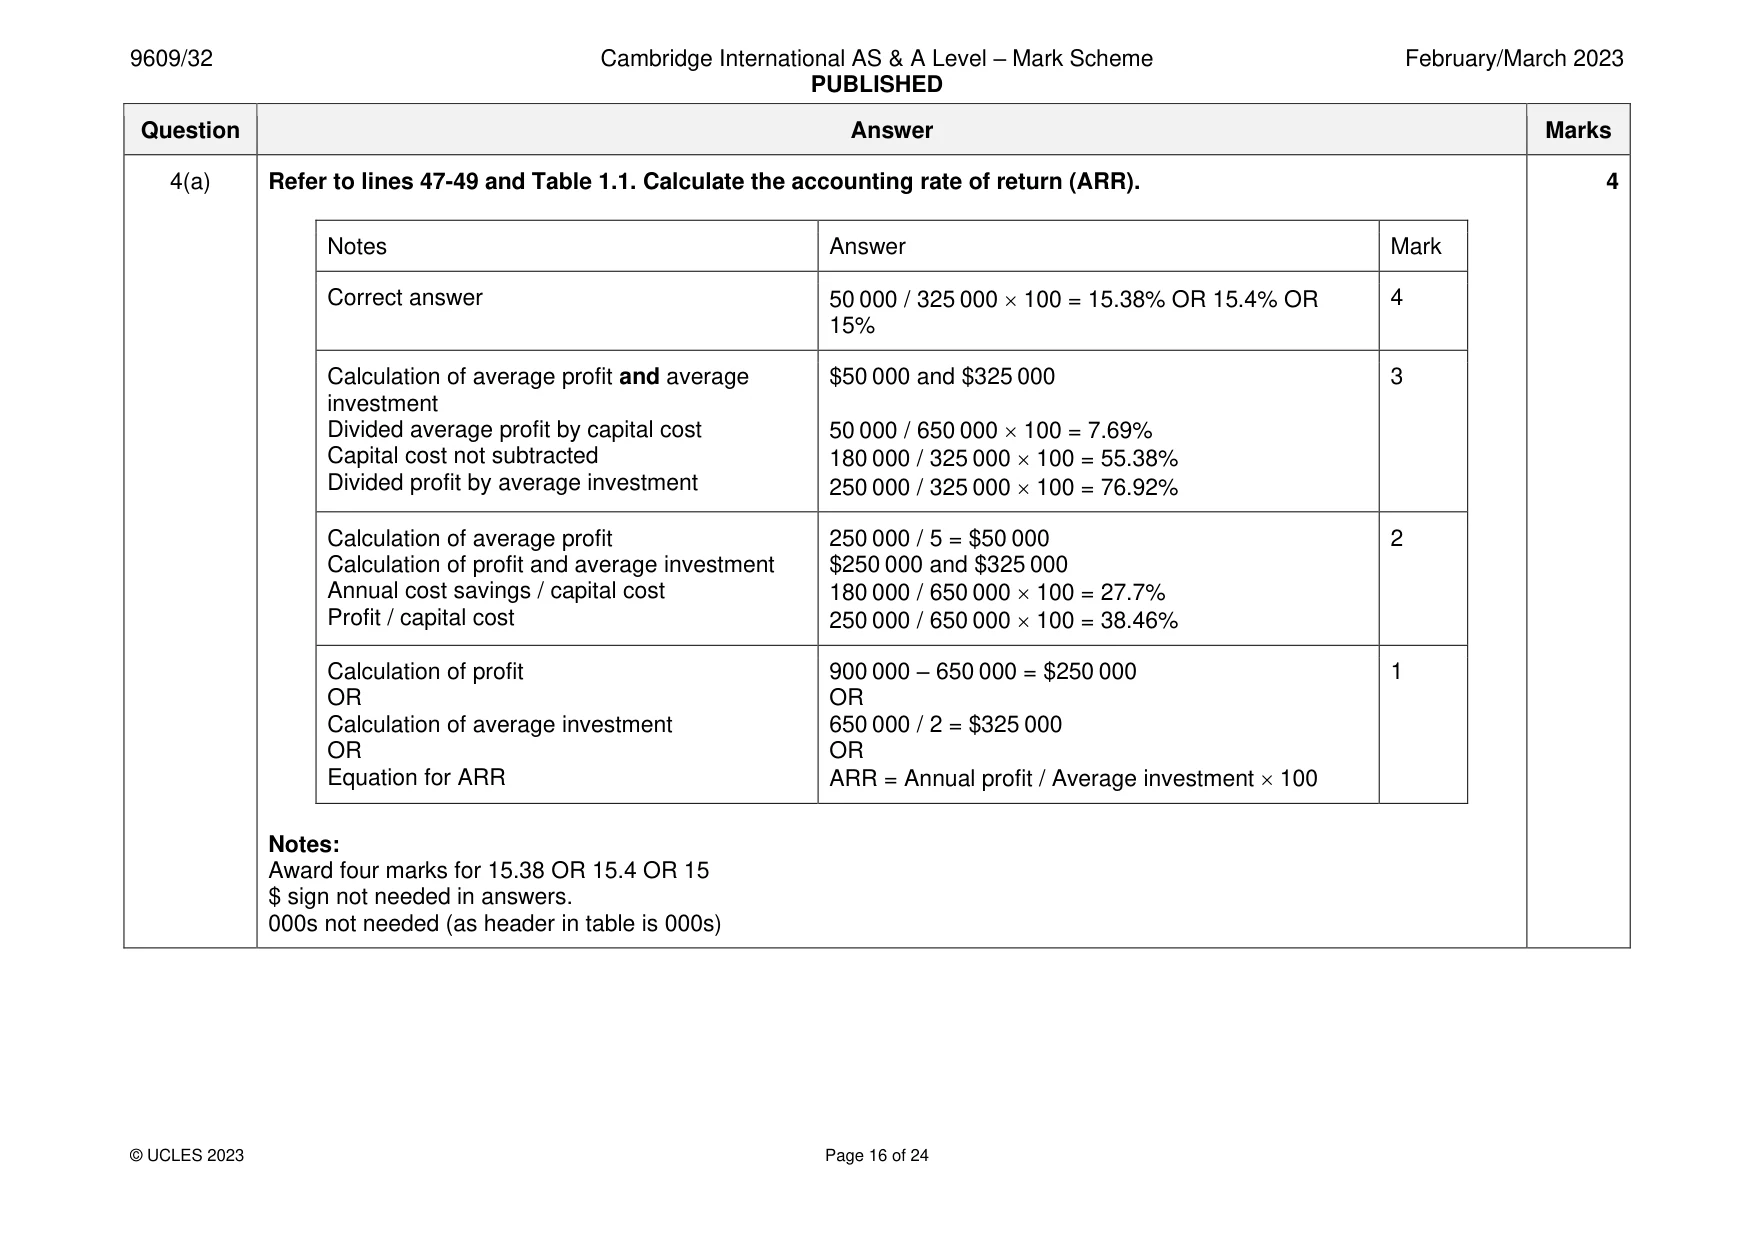
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 16 of 24 Question Answer Marks 4(a) Refer to lines 47-49 and Table 1.1. Calculate the accounting rate of return (ARR). Notes Answer Mark Correct answer 50 000 / 325 000 100 = 15.38% OR 15.4% OR 15% 4 Calculation of average profit and average investment Divided average profit by capital cost Capital cost not subtracted Divided profit by average investment $50 000 and $325 000 50 000 / 650 000 100 = 7.69% 180 000 / 325 000 100 = 55.38% 250 000 / 325 000 100 = 76.92% 3 Calculation of average profit Calculation of profit and average investment Annual cost savings / capital cost Profit / capital cost 250 000 / 5 = $50 000 $250 000 and $325 000 180 000 / 650 000 100 = 27.7% 250 000 / 650 000 100 = 38.46% 2 Calculation of profit OR Calculation of average investment OR Equation for ARR 900 000 – 650 000 = $250 000 OR 650 000 / 2 = $325 000 OR ARR = Annual profit / Average investment 100 1 Notes: Award four marks for 15.38 OR 15.4 OR 15 $ sign not needed in answers. 000s not needed (as header in table is 000s) 4
Mark scheme, page 17
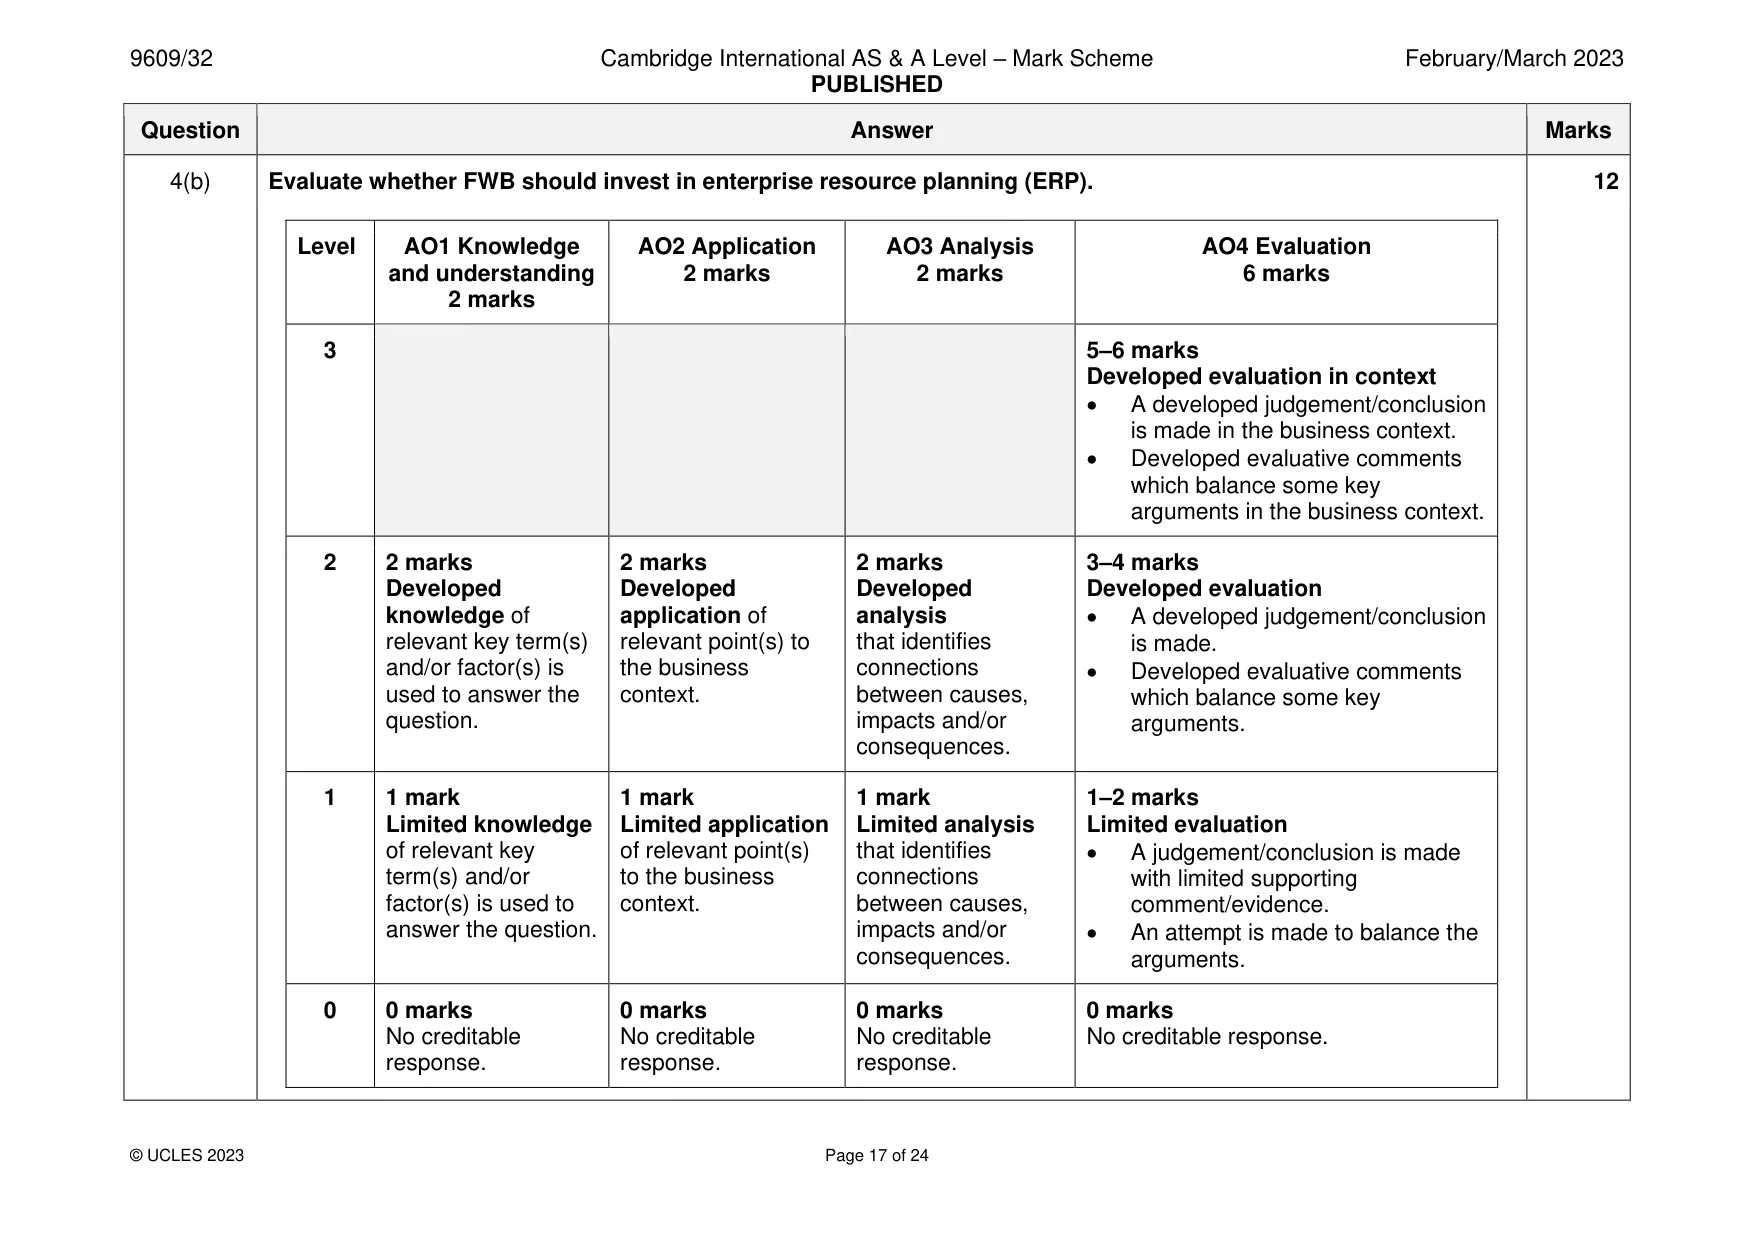
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 17 of 24 Question Answer Marks 4(b) Evaluate whether FWB should invest in enterprise resource planning (ERP). Level AO1 Knowledge and understanding 2 marks AO2 Application 2 marks AO3 Analysis 2 marks AO4 Evaluation 6 marks 3 5–6 marks Developed evaluation in context • A developed judgement/conclusion is made in the business context. • Developed evaluative comments which balance some key arguments in the business context. 2 2 marks Developed knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 2 marks Developed application of relevant point(s) to the business context. 2 marks Developed analysis that identifies connections between causes, impacts and/or consequences. 3–4 marks Developed evaluation • A developed judgement/conclusion is made. • Developed evaluative comments which balance some key arguments. 1 1 mark Limited knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 1 mark Limited application of relevant point(s) to the business context. 1 mark Limited analysis that identifies connections between causes, impacts and/or consequences. 1–2 marks Limited evaluation • A judgement/conclusion is made with limited supporting comment/evidence. • An attempt is made to balance the arguments. 0 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 12
Mark scheme, page 18
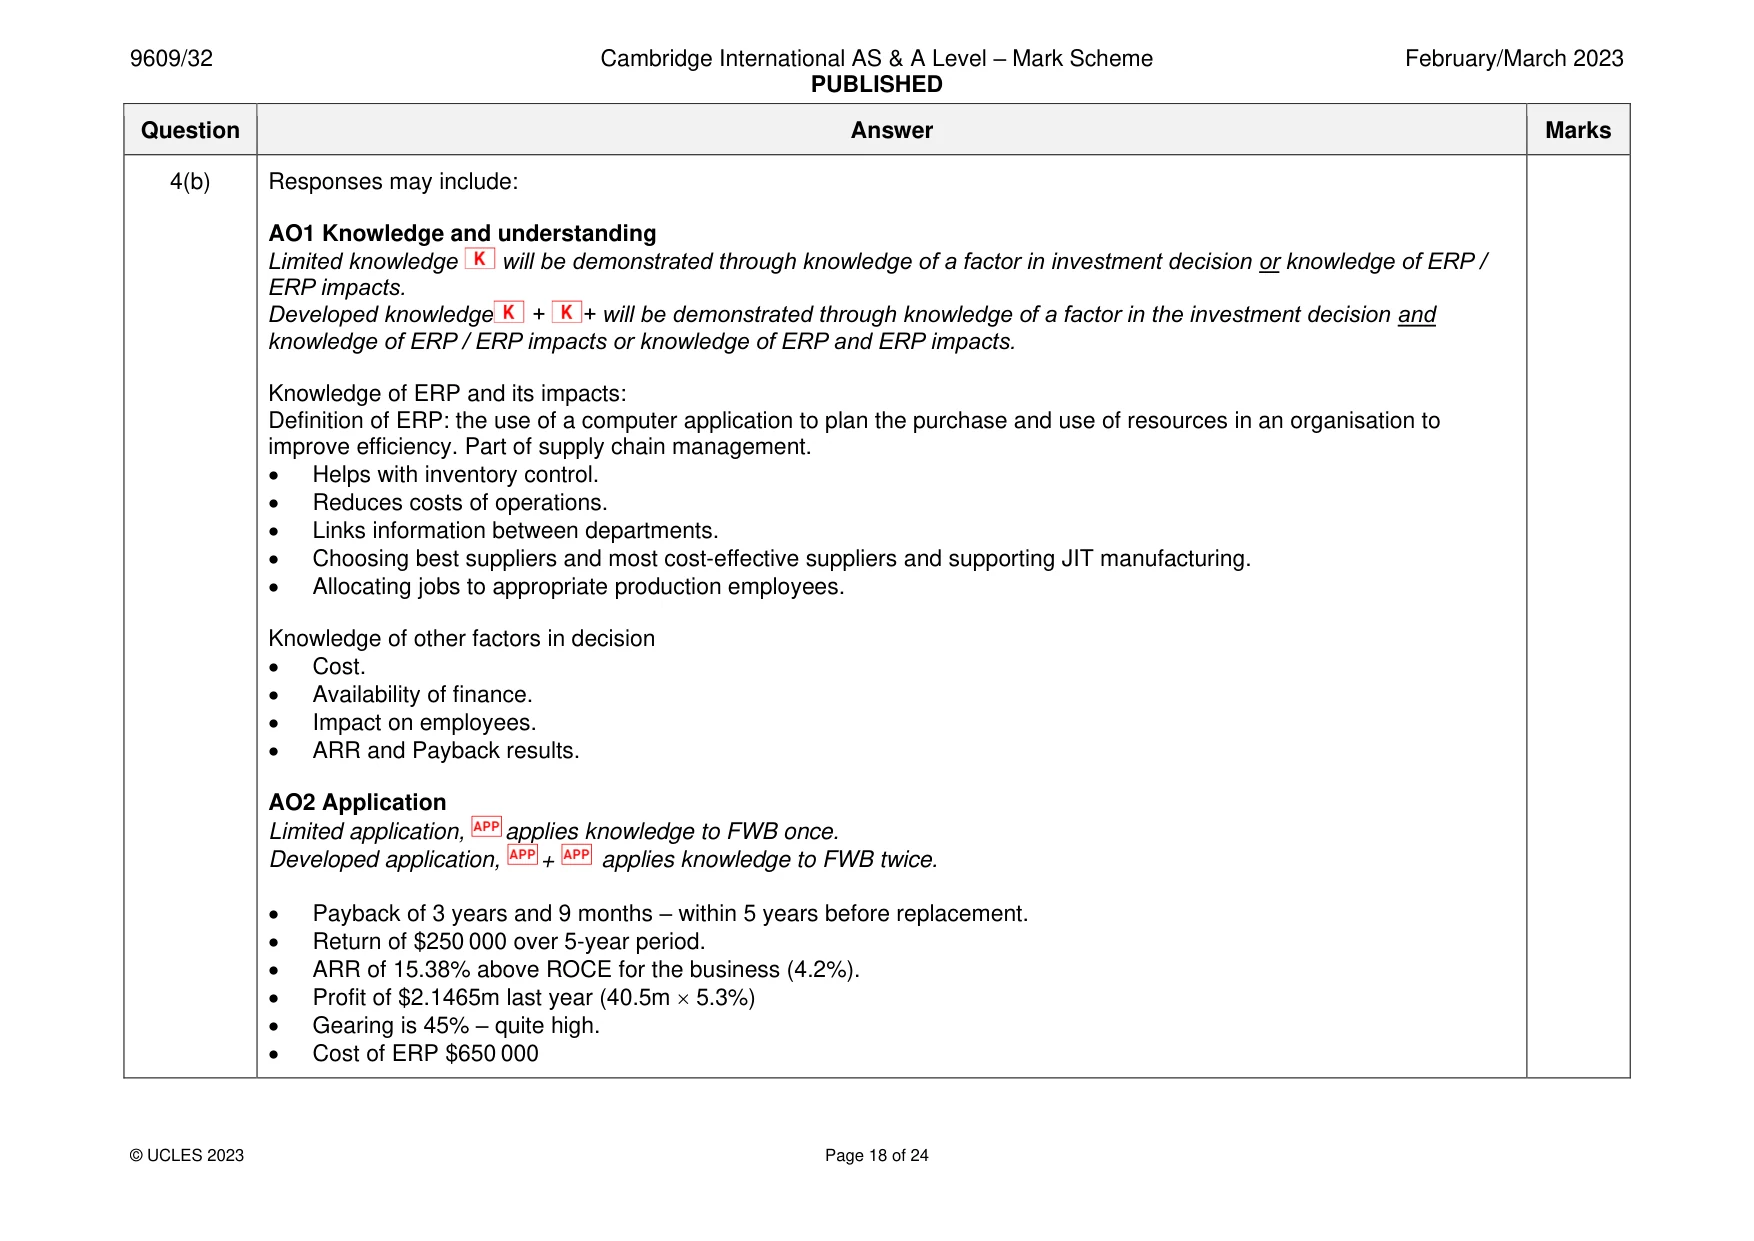
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 18 of 24 Question Answer Marks 4(b) Responses may include: AO1 Knowledge and understanding Limited knowledge will be demonstrated through knowledge of a factor in investment decision or knowledge of ERP / ERP impacts. Developed knowledge + + will be demonstrated through knowledge of a factor in the investment decision and knowledge of ERP / ERP impacts or knowledge of ERP and ERP impacts. Knowledge of ERP and its impacts: Definition of ERP: the use of a computer application to plan the purchase and use of resources in an organisation to improve efficiency. Part of supply chain management. • Helps with inventory control. • Reduces costs of operations. • Links information between departments. • Choosing best suppliers and most cost-effective suppliers and supporting JIT manufacturing. • Allocating jobs to appropriate production employees. Knowledge of other factors in decision • Cost. • Availability of finance. • Impact on employees. • ARR and Payback results. AO2 Application Limited application, applies knowledge to FWB once. Developed application, + applies knowledge to FWB twice. • Payback of 3 years and 9 months – within 5 years before replacement. • Return of $250 000 over 5-year period. • ARR of 15.38% above ROCE for the business (4.2%). • Profit of $2.1465m last year (40.5m 5.3%) • Gearing is 45% – quite high. • Cost of ERP $650 000
Mark scheme, page 19
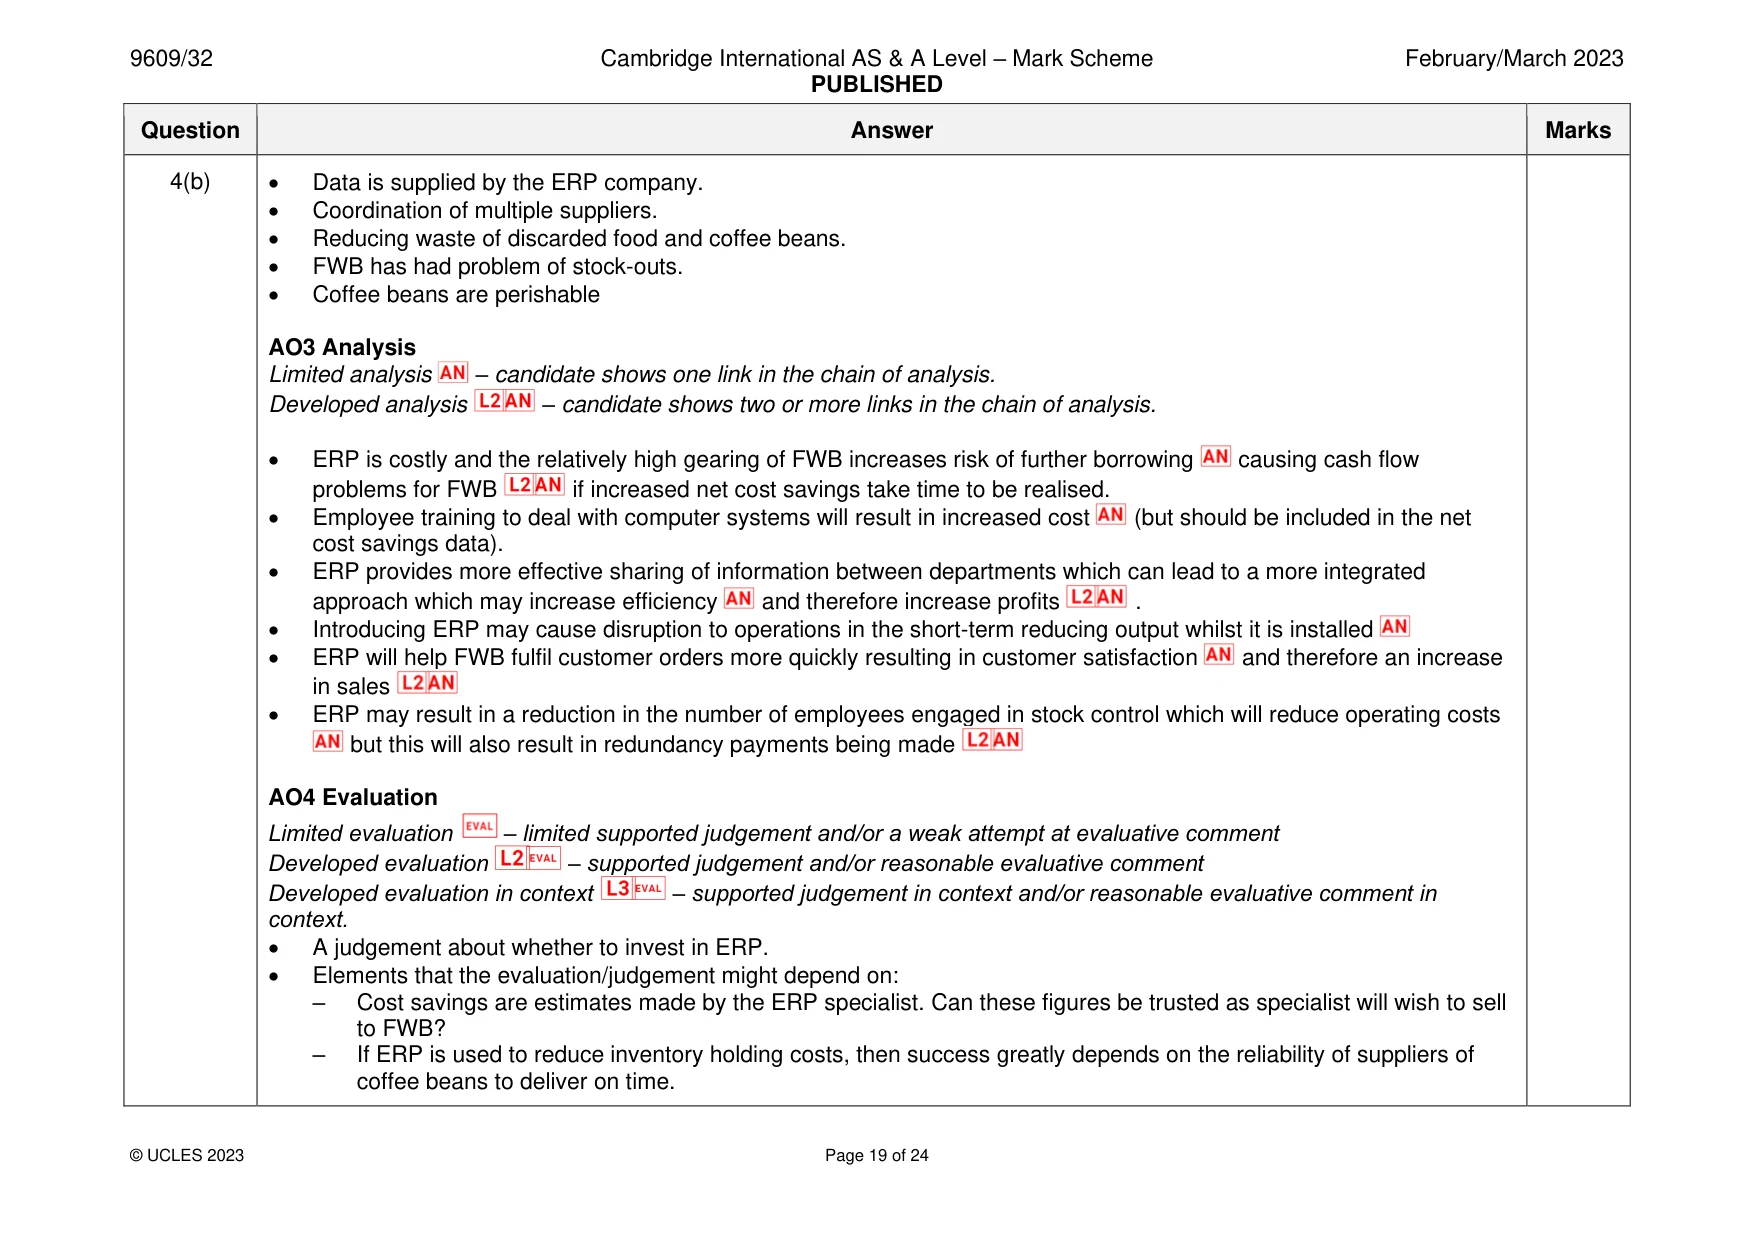
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 19 of 24 Question Answer Marks 4(b) • Data is supplied by the ERP company. • Coordination of multiple suppliers. • Reducing waste of discarded food and coffee beans. • FWB has had problem of stock-outs. • Coffee beans are perishable AO3 Analysis Limited analysis – candidate shows one link in the chain of analysis. Developed analysis – candidate shows two or more links in the chain of analysis. • ERP is costly and the relatively high gearing of FWB increases risk of further borrowing causing cash flow problems for FWB if increased net cost savings take time to be realised. • Employee training to deal with computer systems will result in increased cost (but should be included in the net cost savings data). • ERP provides more effective sharing of information between departments which can lead to a more integrated approach which may increase efficiency and therefore increase profits . • Introducing ERP may cause disruption to operations in the short-term reducing output whilst it is installed • ERP will help FWB fulfil customer orders more quickly resulting in customer satisfaction and therefore an increase in sales • ERP may result in a reduction in the number of employees engaged in stock control which will reduce operating costs but this will also result in redundancy payments being made AO4 Evaluation Limited evaluation – limited supported judgement and/or a weak attempt at evaluative comment Developed evaluation – supported judgement and/or reasonable evaluative comment Developed evaluation in context – supported judgement in context and/or reasonable evaluative comment in context. • A judgement about whether to invest in ERP. • Elements that the evaluation/judgement might depend on: – Cost savings are estimates made by the ERP specialist. Can these figures be trusted as specialist will wish to sell to FWB? – If ERP is used to reduce inventory holding costs, then success greatly depends on the reliability of suppliers of coffee beans to deliver on time.
Mark scheme, page 20
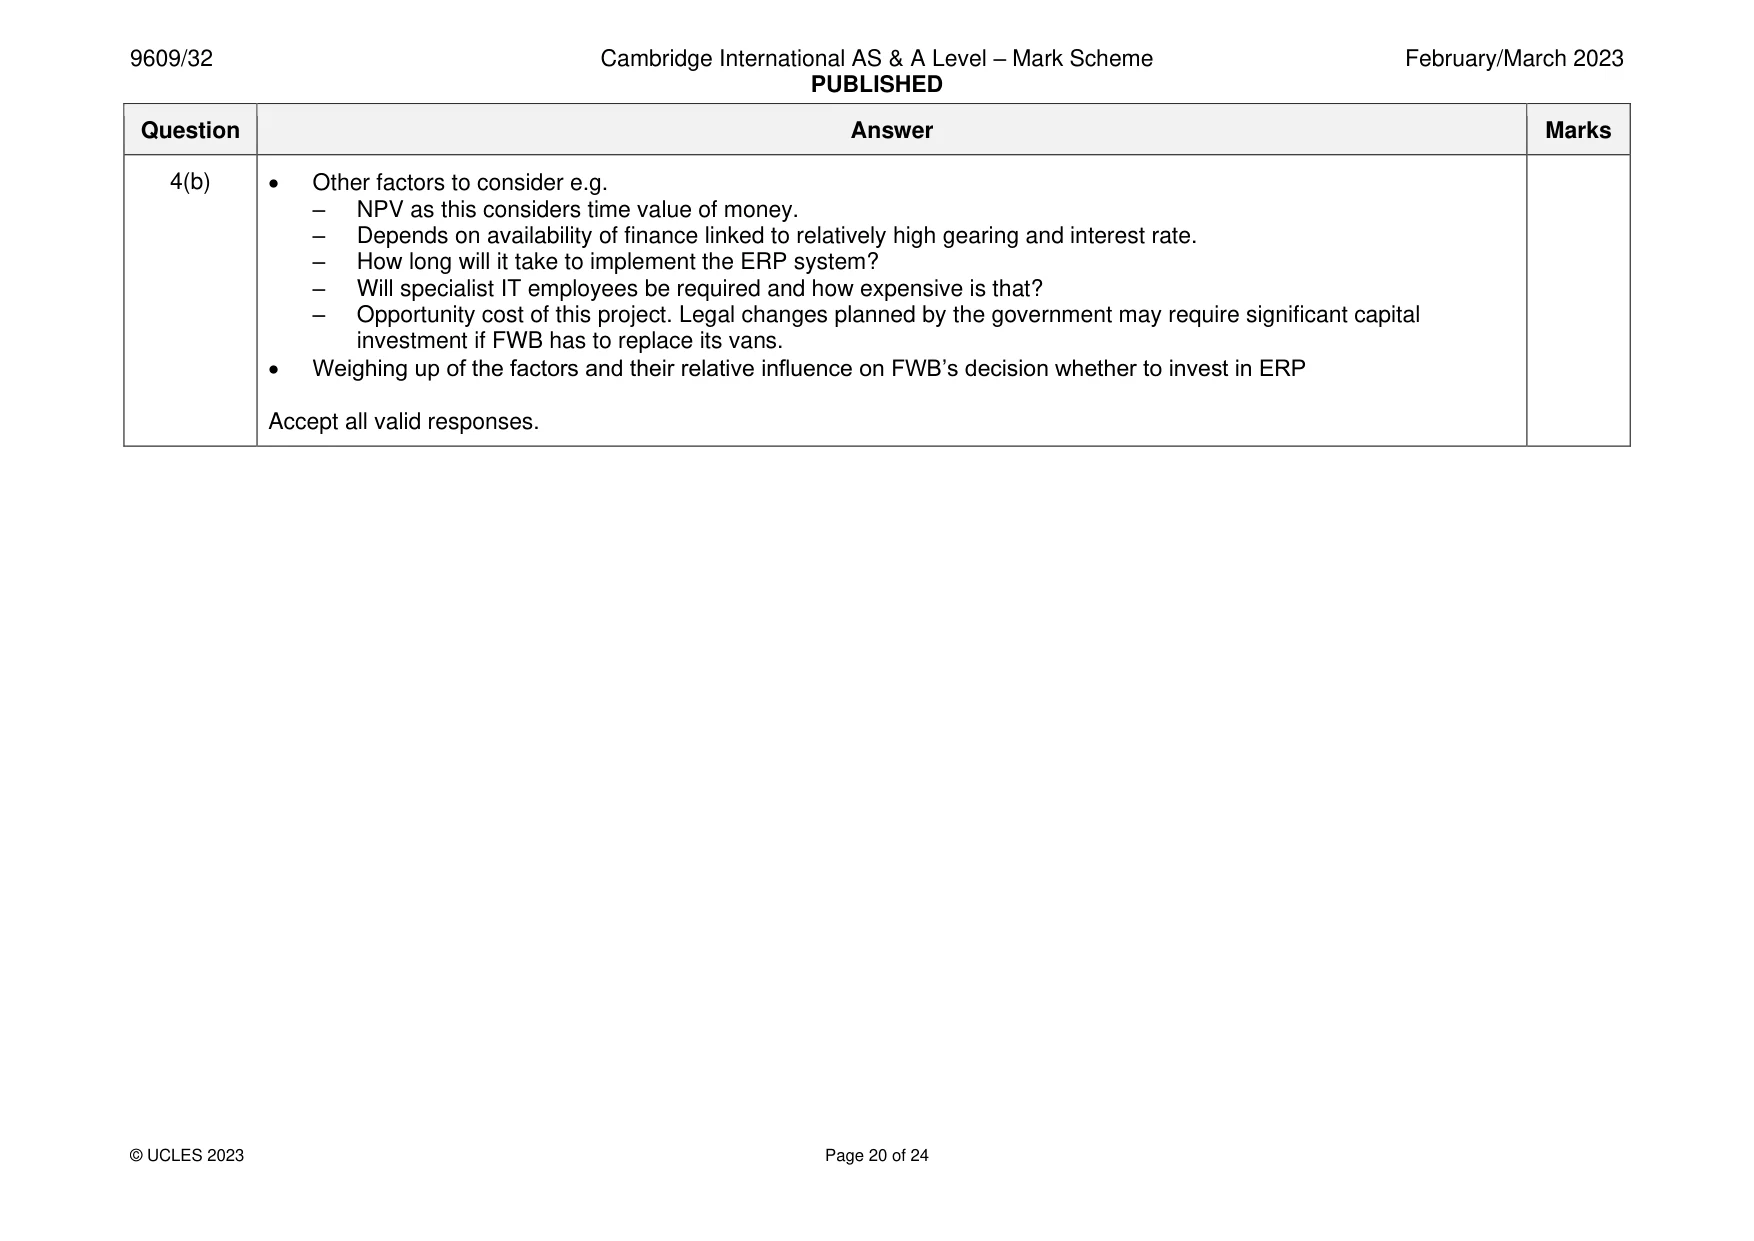
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 20 of 24 Question Answer Marks 4(b) • Other factors to consider e.g. – NPV as this considers time value of money. – Depends on availability of finance linked to relatively high gearing and interest rate. – How long will it take to implement the ERP system? – Will specialist IT employees be required and how expensive is that? – Opportunity cost of this project. Legal changes planned by the government may require significant capital investment if FWB has to replace its vans. • Weighing up of the factors and their relative influence on FWB’s decision whether to invest in ERP Accept all valid responses.
Mark scheme, page 21
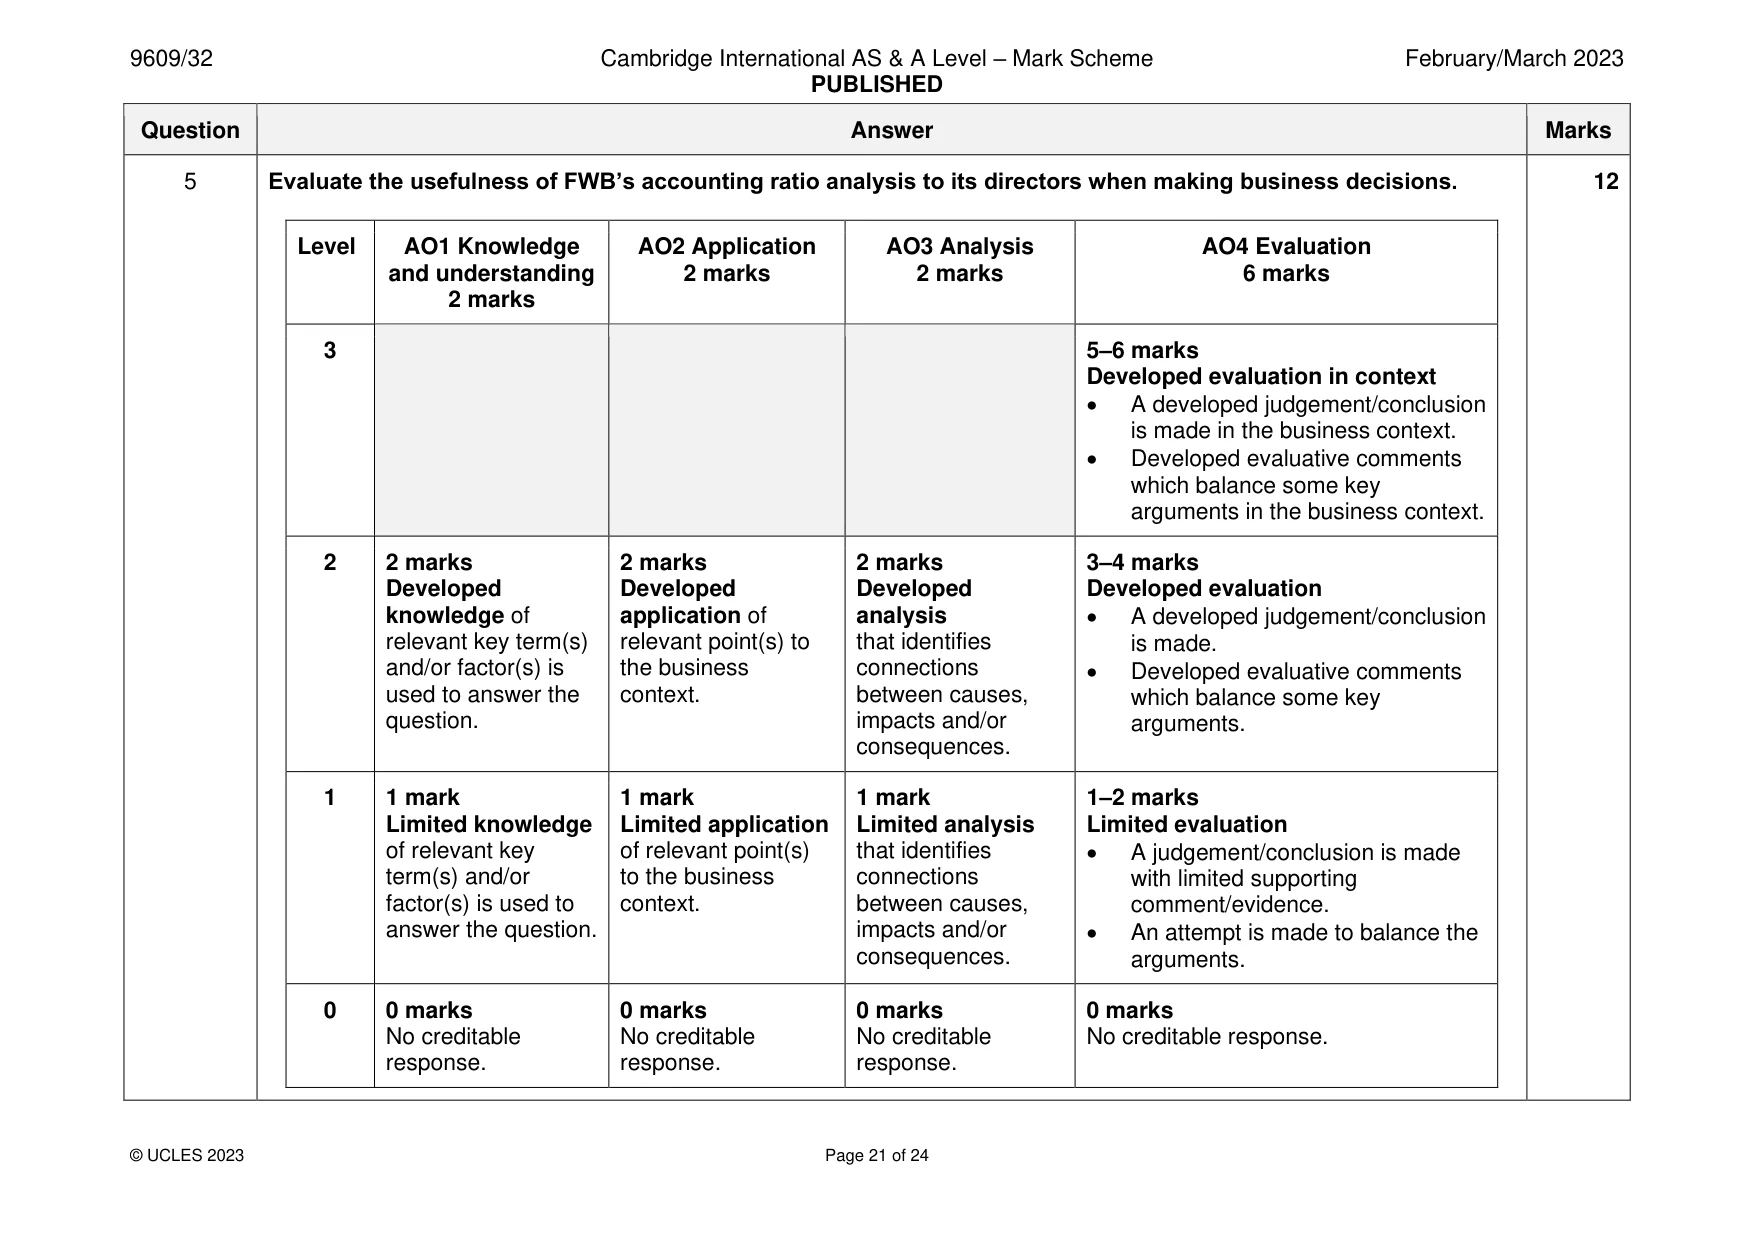
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 21 of 24 Question Answer Marks 5 Evaluate the usefulness of FWB’s accounting ratio analysis to its directors when making business decisions. Level AO1 Knowledge and understanding 2 marks AO2 Application 2 marks AO3 Analysis 2 marks AO4 Evaluation 6 marks 3 5–6 marks Developed evaluation in context • A developed judgement/conclusion is made in the business context. • Developed evaluative comments which balance some key arguments in the business context. 2 2 marks Developed knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 2 marks Developed application of relevant point(s) to the business context. 2 marks Developed analysis that identifies connections between causes, impacts and/or consequences. 3–4 marks Developed evaluation • A developed judgement/conclusion is made. • Developed evaluative comments which balance some key arguments. 1 1 mark Limited knowledge of relevant key term(s) and/or factor(s) is used to answer the question. 1 mark Limited application of relevant point(s) to the business context. 1 mark Limited analysis that identifies connections between causes, impacts and/or consequences. 1–2 marks Limited evaluation • A judgement/conclusion is made with limited supporting comment/evidence. • An attempt is made to balance the arguments. 0 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 0 marks No creditable response. 12
Mark scheme, page 22
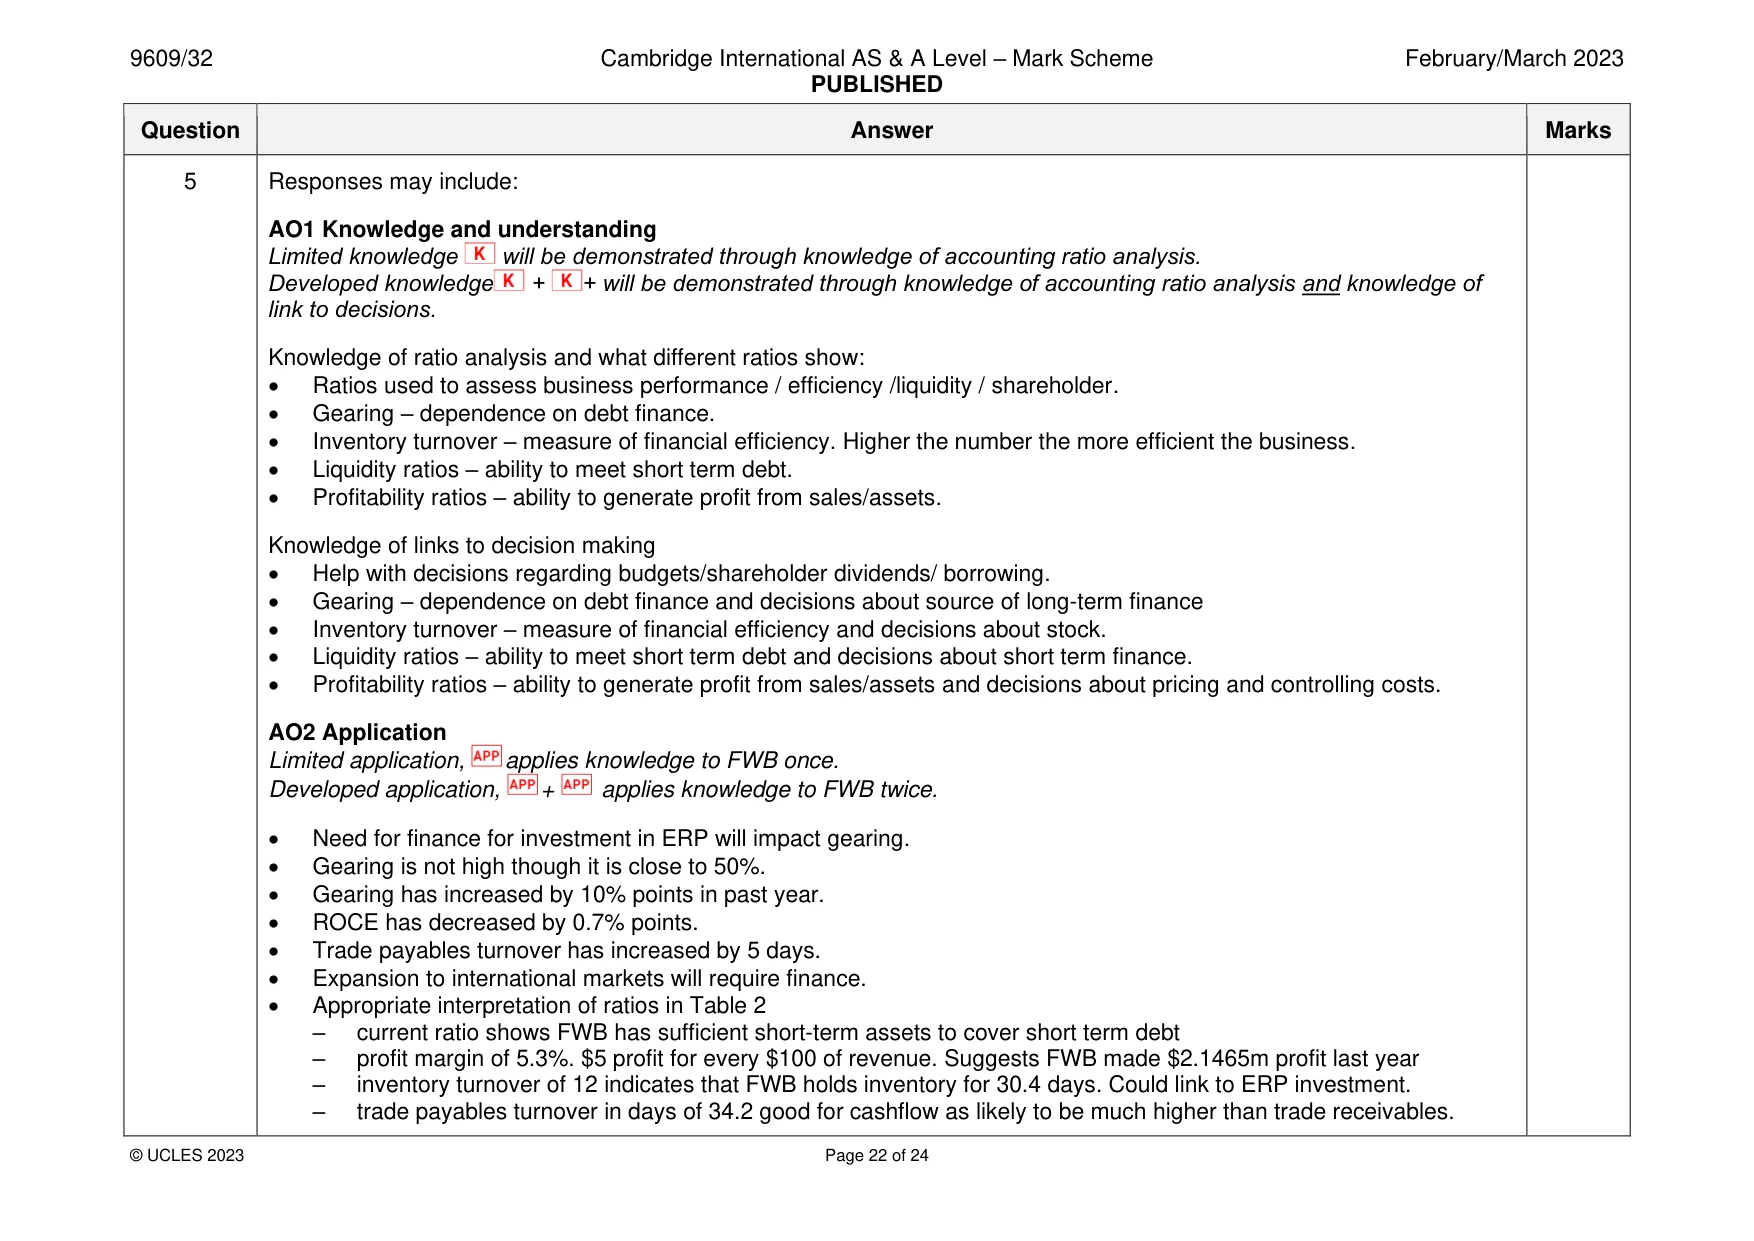
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 22 of 24 Question Answer Marks 5 Responses may include: AO1 Knowledge and understanding Limited knowledge will be demonstrated through knowledge of accounting ratio analysis. Developed knowledge + + will be demonstrated through knowledge of accounting ratio analysis and knowledge of link to decisions. Knowledge of ratio analysis and what different ratios show: • Ratios used to assess business performance / efficiency /liquidity / shareholder. • Gearing – dependence on debt finance. • Inventory turnover – measure of financial efficiency. Higher the number the more efficient the business. • Liquidity ratios – ability to meet short term debt. • Profitability ratios – ability to generate profit from sales/assets. Knowledge of links to decision making • Help with decisions regarding budgets/shareholder dividends/ borrowing. • Gearing – dependence on debt finance and decisions about source of long-term finance • Inventory turnover – measure of financial efficiency and decisions about stock. • Liquidity ratios – ability to meet short term debt and decisions about short term finance. • Profitability ratios – ability to generate profit from sales/assets and decisions about pricing and controlling costs. AO2 Application Limited application, applies knowledge to FWB once. Developed application, + applies knowledge to FWB twice. • Need for finance for investment in ERP will impact gearing. • Gearing is not high though it is close to 50%. • Gearing has increased by 10% points in past year. • ROCE has decreased by 0.7% points. • Trade payables turnover has increased by 5 days. • Expansion to international markets will require finance. • Appropriate interpretation of ratios in Table 2 – current ratio shows FWB has sufficient short-term assets to cover short term debt – profit margin of 5.3%. $5 profit for every $100 of revenue. Suggests FWB made $2.1465m profit last year – inventory turnover of 12 indicates that FWB holds inventory for 30.4 days. Could link to ERP investment. – trade payables turnover in days of 34.2 good for cashflow as likely to be much higher than trade receivables.
Mark scheme, page 23
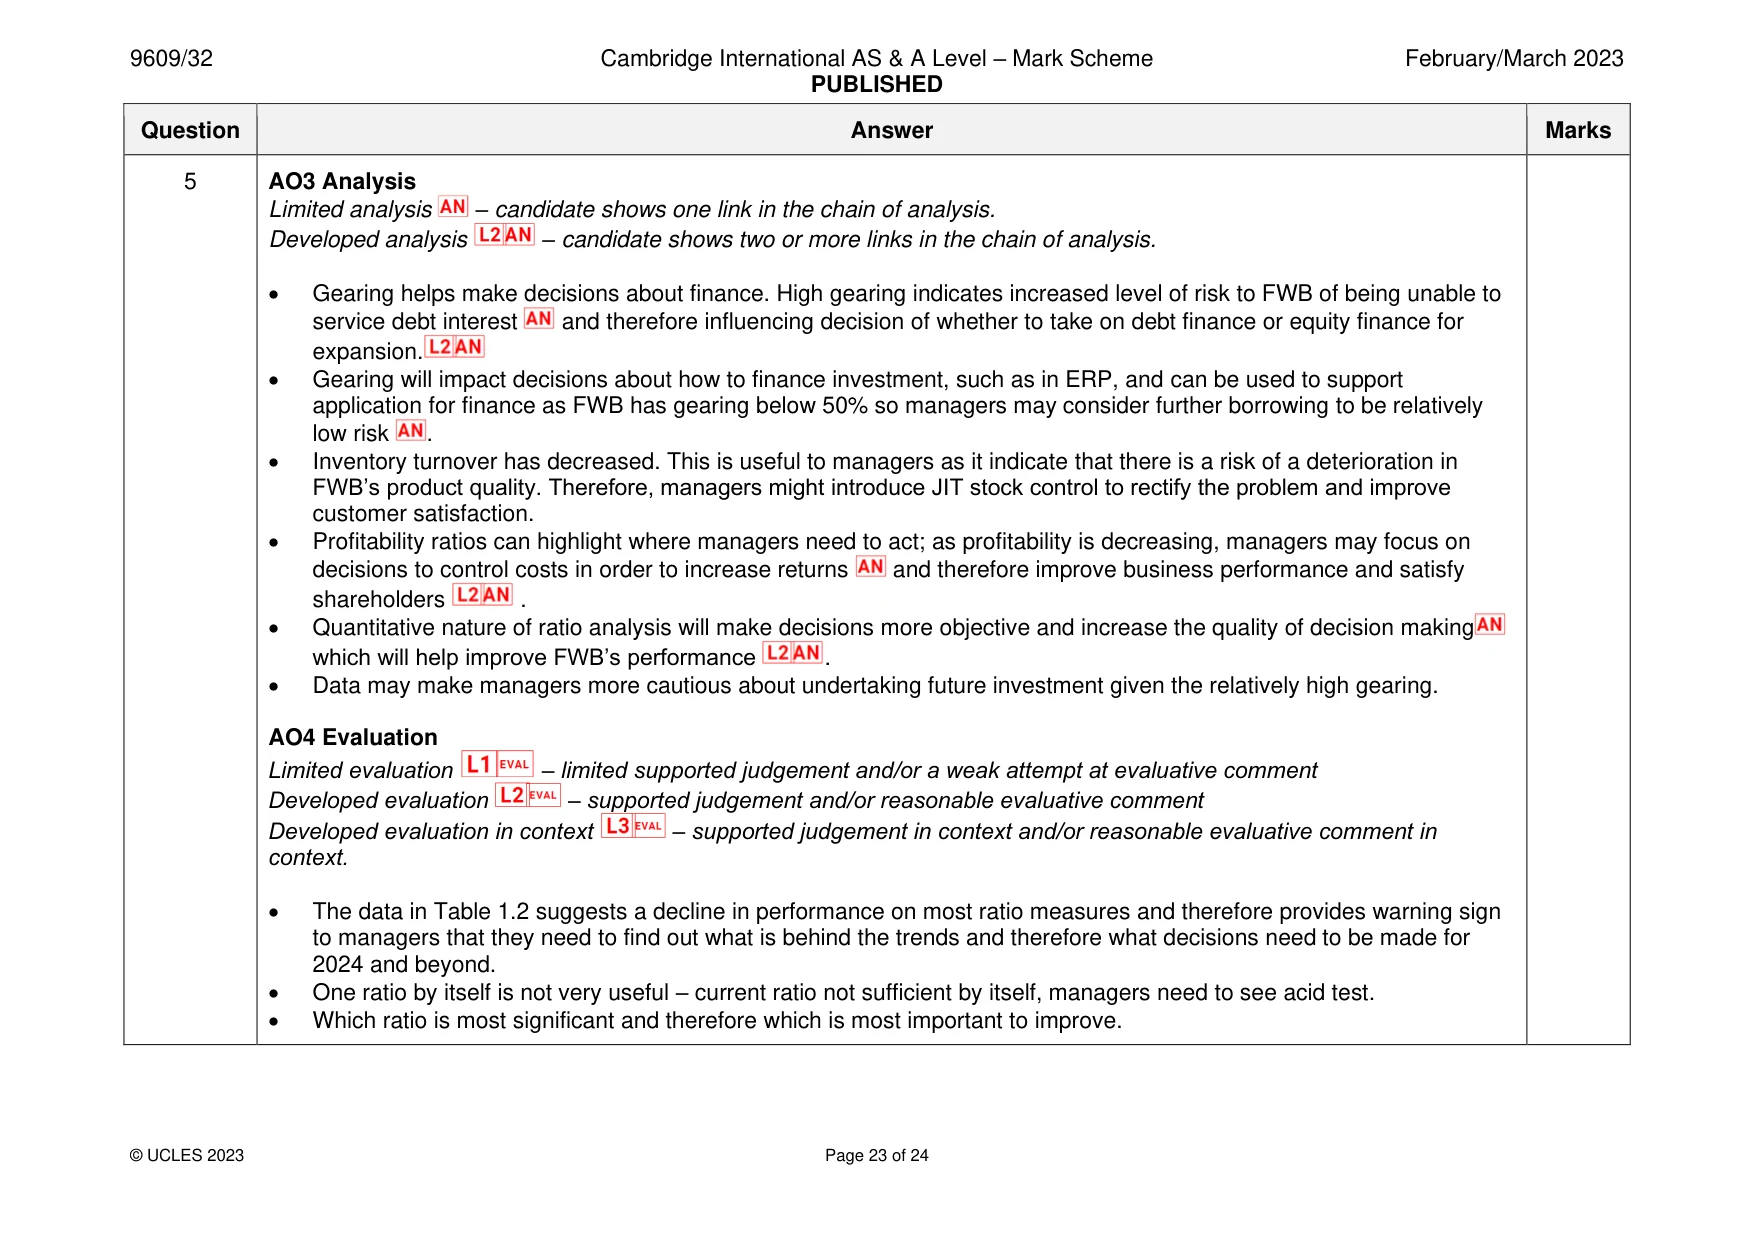
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 23 of 24 Question Answer Marks 5 AO3 Analysis Limited analysis – candidate shows one link in the chain of analysis. Developed analysis – candidate shows two or more links in the chain of analysis. • Gearing helps make decisions about finance. High gearing indicates increased level of risk to FWB of being unable to service debt interest and therefore influencing decision of whether to take on debt finance or equity finance for expansion. • Gearing will impact decisions about how to finance investment, such as in ERP, and can be used to support application for finance as FWB has gearing below 50% so managers may consider further borrowing to be relatively low risk . • Inventory turnover has decreased. This is useful to managers as it indicate that there is a risk of a deterioration in FWB’s product quality. Therefore, managers might introduce JIT stock control to rectify the problem and improve customer satisfaction. • Profitability ratios can highlight where managers need to act; as profitability is decreasing, managers may focus on decisions to control costs in order to increase returns and therefore improve business performance and satisfy shareholders . • Quantitative nature of ratio analysis will make decisions more objective and increase the quality of decision making which will help improve FWB’s performance . • Data may make managers more cautious about undertaking future investment given the relatively high gearing. AO4 Evaluation Limited evaluation – limited supported judgement and/or a weak attempt at evaluative comment Developed evaluation – supported judgement and/or reasonable evaluative comment Developed evaluation in context – supported judgement in context and/or reasonable evaluative comment in context. • The data in Table 1.2 suggests a decline in performance on most ratio measures and therefore provides warning sign to managers that they need to find out what is behind the trends and therefore what decisions need to be made for 2024 and beyond. • One ratio by itself is not very useful – current ratio not sufficient by itself, managers need to see acid test. • Which ratio is most significant and therefore which is most important to improve.
Mark scheme, page 24
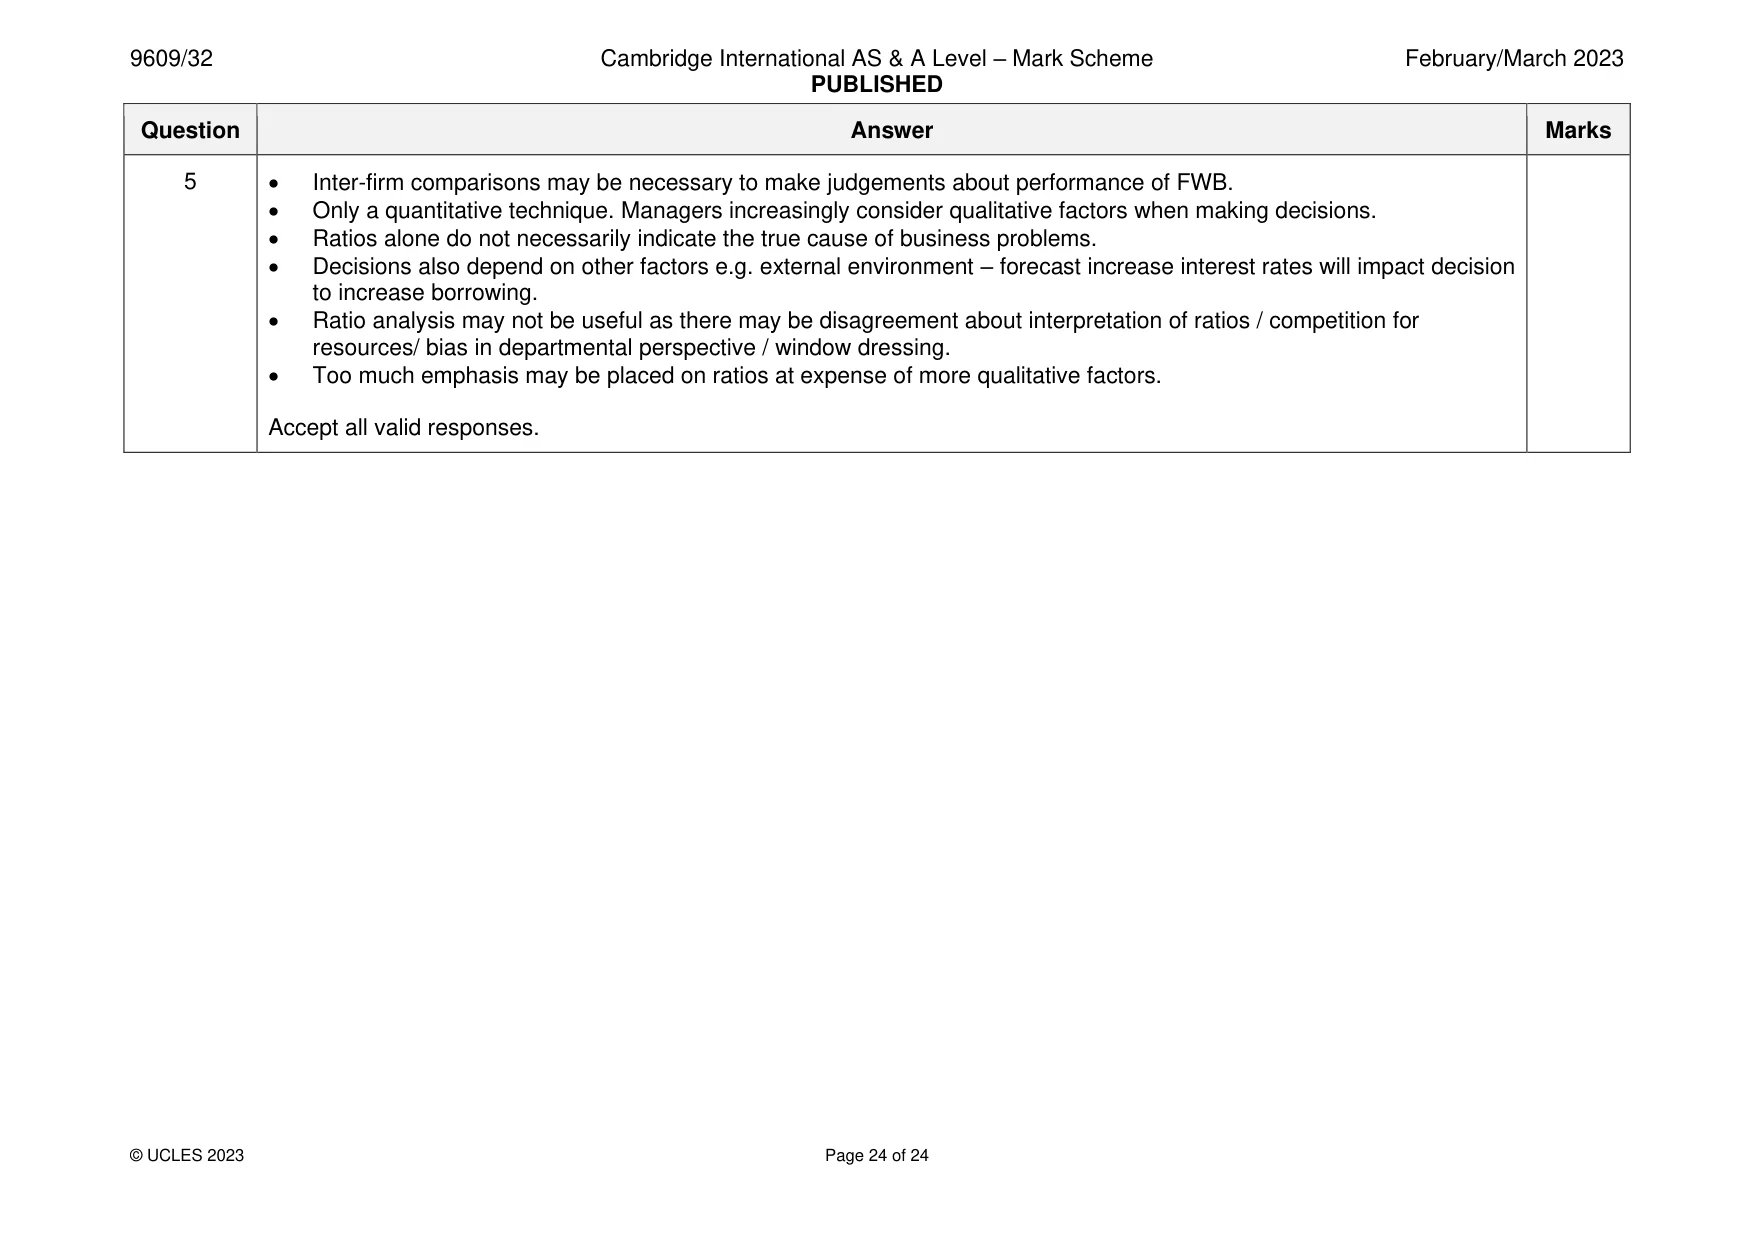
9609/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED February/March 2023 © UCLES 2023 Page 24 of 24 Question Answer Marks 5 • Inter-firm comparisons may be necessary to make judgements about performance of FWB. • Only a quantitative technique. Managers increasingly consider qualitative factors when making decisions. • Ratios alone do not necessarily indicate the true cause of business problems. • Decisions also depend on other factors e.g. external environment – forecast increase interest rates will impact decision to increase borrowing. • Ratio analysis may not be useful as there may be disagreement about interpretation of ratios / competition for resources/ bias in departmental perspective / window dressing. • Too much emphasis may be placed on ratios at expense of more qualitative factors. Accept all valid responses.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Feb/March, Paper 3 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.