Cambridge A Level Business (for first examination in 2016) 9609 — 2021 May/June Paper 3 · Variant 4
9609/34/M/J/21 · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages









Mark scheme23 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document has 20 pages. Any blank pages are indicated. Cambridge International AS & A Level DC (MB) 213382 © UCLES 2021 [Turn over * 0 5 2 6 2 8 3 3 1 2 * BUSINESS 9609/34 Paper 3 Case Study May/June 2021 3 hours You must answer on the question paper. You will need: Insert (enclosed) INSTRUCTIONS ● Section A: answer all questions. ● Section B: answer one question. ● Use a black or dark blue pen. ● Write your name, centre number and candidate number in the boxes at the top of the page. ● Write your answer to each question in the space provided. ● Do not use an erasable pen or correction fluid. ● Do not write on any bar codes. ● You may use an HB pencil for any diagrams, graphs or rough working. INFORMATION ● The total mark for this paper is 100. ● The number of marks for each question or part question is shown in brackets [ ]. ● The insert contains the case study.
Question paper, page 2
2 9609/34/M/J/21 © UCLES 2021 Section A Answer all questions in this section. 1 Analyse how TT might be affected by an increase in interest rates in the Eurozone. … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 3
3 9609/34/M/J/21 © UCLES 2021 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … … … … … [10]
Question paper, page 4
4 9609/34/M/J/21 © UCLES 2021 2 (a) Refer to Appendix 1 and lines 35–37. Calculate the impact on TT’s profit if the special order from the US toy retailer is accepted. … … … … … … … … … … … … [6]
Question paper, page 5
5 9609/34/M/J/21 © UCLES 2021 [Turn over (b) Refer to your answer to part (a) and other information from the case. Advise TT whether to accept the special order from the US toy retailer. … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 6
6 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … … [12]
Question paper, page 7
7 9609/34/M/J/21 © UCLES 2021 [Turn over 3 Refer to Appendix 3 and other information from the case. Discuss whether TT’s directors made the right decision in choosing candidate Y as the new Marketing manager. … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 8
8 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 9
9 9609/34/M/J/21 © UCLES 2021 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … … … … … [16]
Question paper, page 10
10 9609/34/M/J/21 © UCLES 2021 4 (a) Refer to Appendix 2. Calculate, for the purchase of the CAM equipment: (i) the payback period … … … … [2] (ii) the accounting rate of return (ARR) … … … … … … … … [4]
Question paper, page 11
11 9609/34/M/J/21 © UCLES 2021 [Turn over (b) Refer to your answers to part (a) and other information from the case. Recommend whether TT should purchase the CAM equipment or outsource toy train production. Justify your recommendation. … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 12
12 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … … [14]
Question paper, page 13
13 9609/34/M/J/21 © UCLES 2021 [Turn over 5 Discuss whether TT should introduce Total Quality Management (TQM). … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 14
14 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 15
15 9609/34/M/J/21 © UCLES 2021 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … … … … … [16]
Question paper, page 16
16 9609/34/M/J/21 © UCLES 2021 Section B Answer one question from this section. 6 Discuss the usefulness of strategic choice techniques to TT’s directors when choosing between the joint venture with company A or the merger with company B. 7 Assume TT merges with company B. Evaluate strategies senior management could use to manage the necessary changes. Write the question number here: … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 17
17 9609/34/M/J/21 © UCLES 2021 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 18
18 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 19
19 9609/34/M/J/21 © UCLES 2021 … … … … … … … … … … … … … … … … … … … … … … … … … … … … [20]
Question paper, page 20
20 9609/34/M/J/21 © UCLES 2021 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which itself is a department of the University of Cambridge. BLANK PAGE
Mark scheme, page 1
This document consists of 23 printed pages. © UCLES 2021 [Turn over Cambridge International AS & A Level BUSINESS 9609/34 Paper 3 Case Study May/June 2021 MARK SCHEME Maximum Mark: 100 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the May/June 2021 series for most Cambridge IGCSE™, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 2 of 23 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently, e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors. GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 3
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 3 of 23 Social Science-Specific Marking Principles (for point-based marking) 1 Components using point-based marking: • Point marking is often used to reward knowledge, understanding and application of skills. We give credit where the candidate’s answer shows relevant knowledge, understanding and application of skills in answering the question. We do not give credit where the answer shows confusion. From this it follows that we: a DO credit answers which are worded differently from the mark scheme if they clearly convey the same meaning (unless the mark scheme requires a specific term) b DO credit alternative answers/examples which are not written in the mark scheme if they are correct c DO credit answers where candidates give more than one correct answer in one prompt/numbered/scaffolded space where extended writing is required rather than list-type answers. For example, questions that require n reasons (e.g. State two reasons …). d DO NOT credit answers simply for using a ‘key term’ unless that is all that is required. (Check for evidence it is understood and not used wrongly.) e DO NOT credit answers which are obviously self-contradicting or trying to cover all possibilities f DO NOT give further credit for what is effectively repetition of a correct point already credited unless the language itself is being tested. This applies equally to ‘mirror statements’ (i.e. polluted/not polluted). g DO NOT require spellings to be correct, unless this is part of the test. However spellings of syllabus terms must allow for clear and unambiguous separation from other syllabus terms with which they may be confused (e.g. Corrasion/Corrosion) 2 Presentation of mark scheme: • Slashes (/) or the word ‘or’ separate alternative ways of making the same point. • Semi colons (;) bullet points (•) or figures in brackets (1) separate different points. • Content in the answer column in brackets is for examiner information/context to clarify the marking but is not required to earn the mark (except Accounting syllabuses where they indicate negative numbers). 3 Calculation questions: • The mark scheme will show the steps in the most likely correct method(s), the mark for each step, the correct answer(s) and the mark for each answer • If working/explanation is considered essential for full credit, this will be indicated in the question paper and in the mark scheme. In all other instances, the correct answer to a calculation should be given full credit, even if no supporting working is shown. • Where the candidate uses a valid method which is not covered by the mark scheme, award equivalent marks for reaching equivalent stages. • Where an answer makes use of a candidate’s own incorrect figure from previous working, the ‘own figure rule’ applies: full marks will be given if a correct and complete method is used. Further guidance will be included in the mark scheme where necessary and any exceptions to this general principle will be noted.
Mark scheme, page 4
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 4 of 23 4 Annotation: • For point marking, ticks can be used to indicate correct answers and crosses can be used to indicate wrong answers. There is no direct relationship between ticks and marks. Ticks have no defined meaning for levels of response marking. • For levels of response marking, the level awarded should be annotated on the script. • Other annotations will be used by examiners as agreed during standardisation, and the meaning will be understood by all examiners who marked that paper. PREPARATION FOR MARKING 1 Make sure that you have completed the relevant training and have access to the RM Assessor Guide. 2 Make sure that you have read and understand the question paper, which you can download from https://support.rm.com/ca 3 Log in to RM Assessor then mark and submit the required number of practice and standardisation scripts. You will need to mark the standardisation scripts to the required accuracy in order to be approved for marking live scripts. You may be asked to re-mark them, or to mark a second sample, if you do not meet the required accuracy on your first attempt. MARKING PROCESS 1 Mark strictly to the FINAL mark scheme, applying the criteria consistently and the general marking principles outlined on the previous page. 2 If you are in doubt about applying the mark scheme, consult your Team Leader. 3 Mark at a steady rate through the marking period. Do not rush, and do not leave too much until the end. If you anticipate a problem in meeting the deadline, contact your Team Leader immediately and the Examiners’ Helpdesk. 4 Examiners will prepare a brief report on the performance of candidates to send to their Team Leader via email by the end of the marking period. The Examiner should note strengths seen in answers and common errors or weaknesses. Constructive comments on the question paper, mark scheme or procedures are also appreciated. MARKING SPECIFICS Crossed out work 1 All of a candidate’s answers, crossed out or not, optional or not, must be marked. 2 The only response not to be marked is one that has been crossed out and replaced by another response for that exact same question. 3 Consequently, if a candidate has crossed out their response to an optional question and gone on to answer a different optional question then both attempts must be marked. The higher mark will be awarded by the system according to the rubric. 0 (zero) marks or NR (no response) 1 Award NR if there is nothing at all written in answer to that question (often the case for optional questions). 2 Award NR if there is a comment which is not an attempt at the question (e.g. ‘can’t do it’ or ‘don’t know’ etc.) 3 Award NR if there is a symbol which is not an attempt at the question, such as a dash or question mark. 4 Award 0 (zero) if there is any attempt at the question which does not score marks. This includes copying the question onto an Answer Booklet. Annotation 1 Every question must have at least one annotation e.g. <NAQ> if it is an NR and <X> or <seen> if 0 marks are awarded. 2 Every page of a script must have at least one annotation e.g. <BP> for a blank page.
Mark scheme, page 5
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 5 of 23 Paper 3 Specific Marking Guidance • When examiners are in doubt regarding the application of the mark scheme to a candidate’s response, the team leader must be consulted. • Handwriting and use of English language are not to be assessed. • A response consisting of a list should be assessed. It is unlikely that such a response will score highly in the levels in each Assessment Objective. • If a response does not fit in the space provided it should be assessed as if it did whether it is shorted, or longer and a continuation sheet is used. • The main RM Assessor annotations to be used are K (Knowledge), APP (Application), AN (Analysis), EVAL (Evaluation). • For each of these four annotations, the number of marks awarded must match the number of times that annotation is on the response. • Only award EVAL if the candidate has also demonstrated APP. • Application marks are not awarded for repeating material from the case study. Application is achieved by answering in the context of the case or by using the information in the case to help answer the question. • In Section B, candidates answer either Question 6 or Question 7. The Section B question that the candidate does not answer must be entered as ‘no response’. This mark scheme includes a summary of appropriate content for answering each question. It should be emphasised, however, that this material is for illustrative purposes and is not intended to provide a definitive guide to acceptable answers. It is quite possible that among the scripts there will be some candidate answers that are not covered directly by the content of this mark scheme. In such cases, professional judgement should be exercised in assessing the merits of the answer and the senior examiners should be consulted if further guidance is required.
Mark scheme, page 6
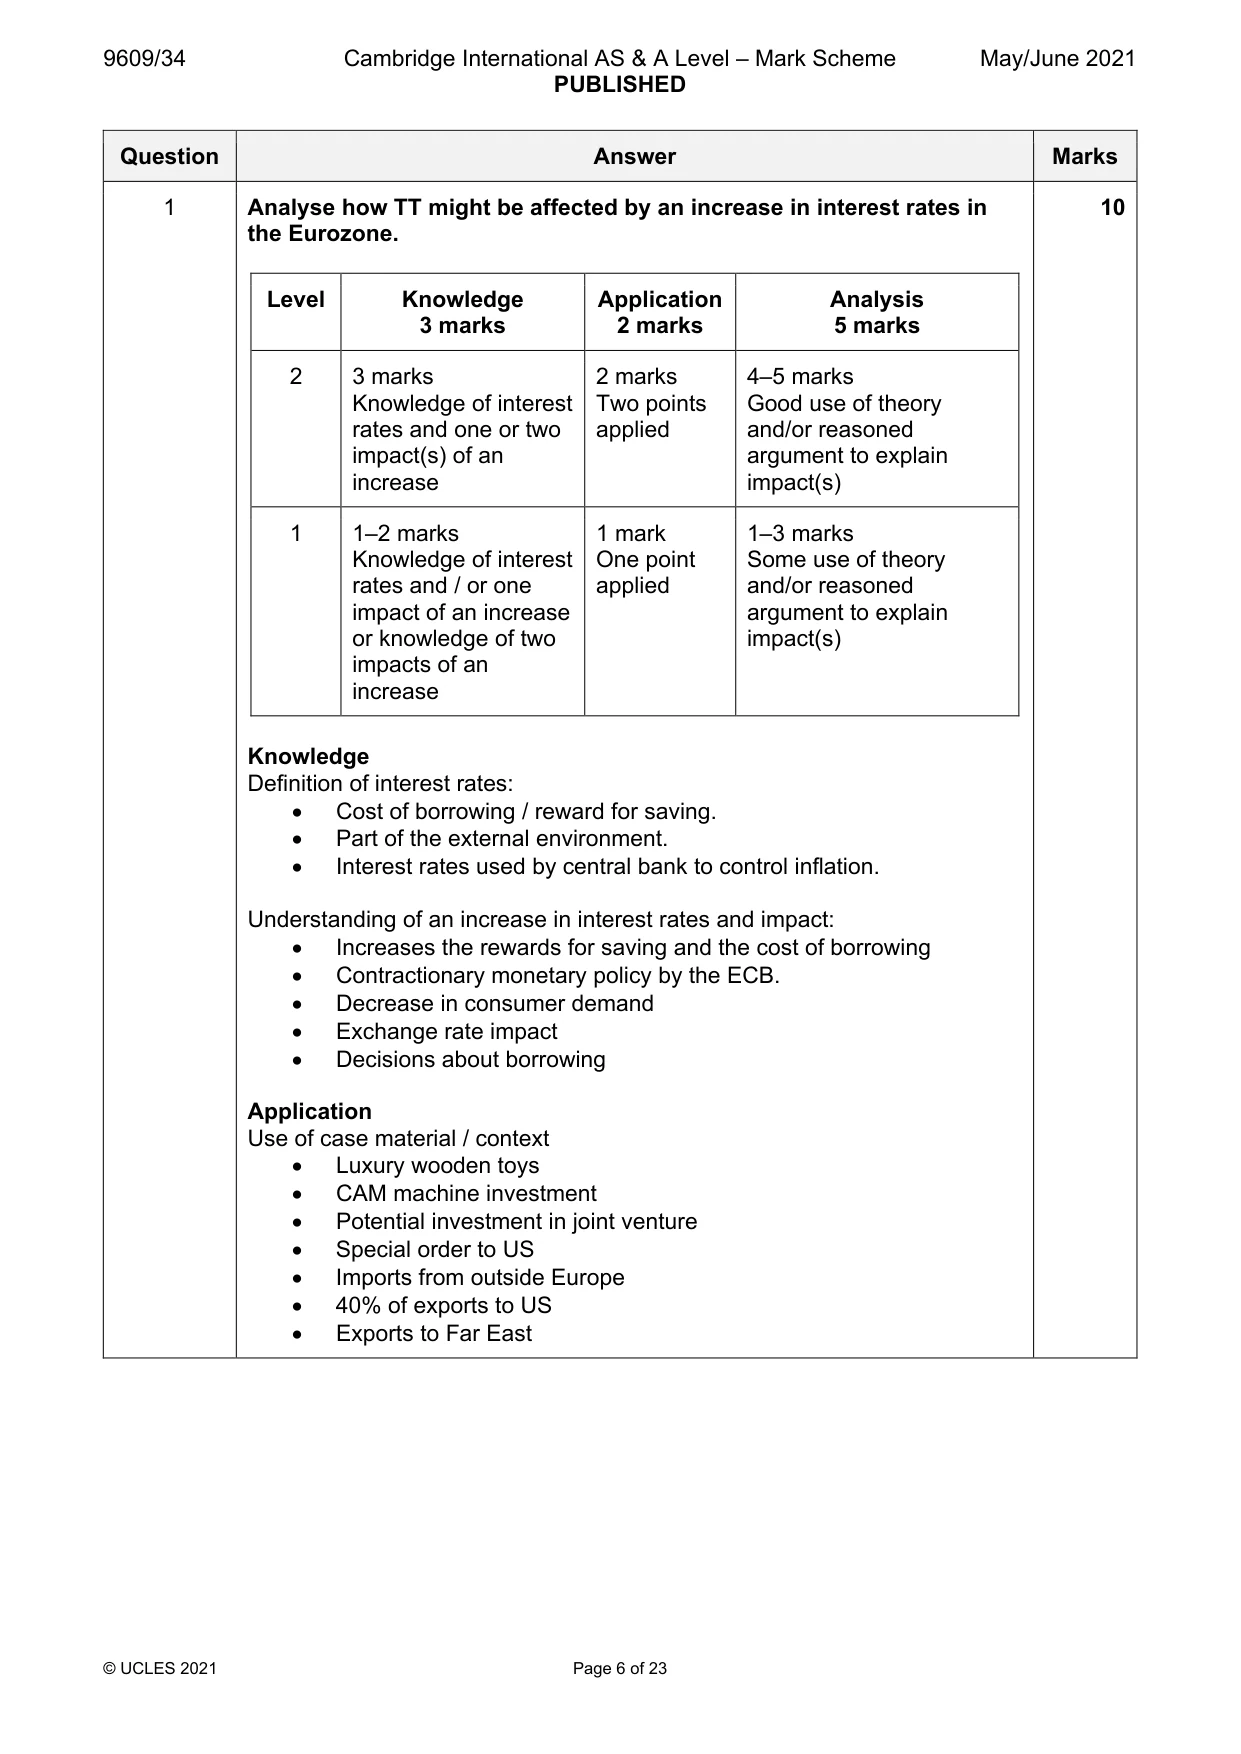
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 6 of 23 Question Answer Marks 1 Analyse how TT might be affected by an increase in interest rates in the Eurozone. Level Knowledge 3 marks Application 2 marks Analysis 5 marks 2 3 marks Knowledge of interest rates and one or two impact(s) of an increase 2 marks Two points applied 4–5 marks Good use of theory and/or reasoned argument to explain impact(s) 1 1–2 marks Knowledge of interest rates and / or one impact of an increase or knowledge of two impacts of an increase 1 mark One point applied 1–3 marks Some use of theory and/or reasoned argument to explain impact(s) Knowledge Definition of interest rates: • Cost of borrowing / reward for saving. • Part of the external environment. • Interest rates used by central bank to control inflation. Understanding of an increase in interest rates and impact: • Increases the rewards for saving and the cost of borrowing • Contractionary monetary policy by the ECB. • Decrease in consumer demand • Exchange rate impact • Decisions about borrowing Application Use of case material / context • Luxury wooden toys • CAM machine investment • Potential investment in joint venture • Special order to US • Imports from outside Europe • 40% of exports to US • Exports to Far East 10
Mark scheme, page 7
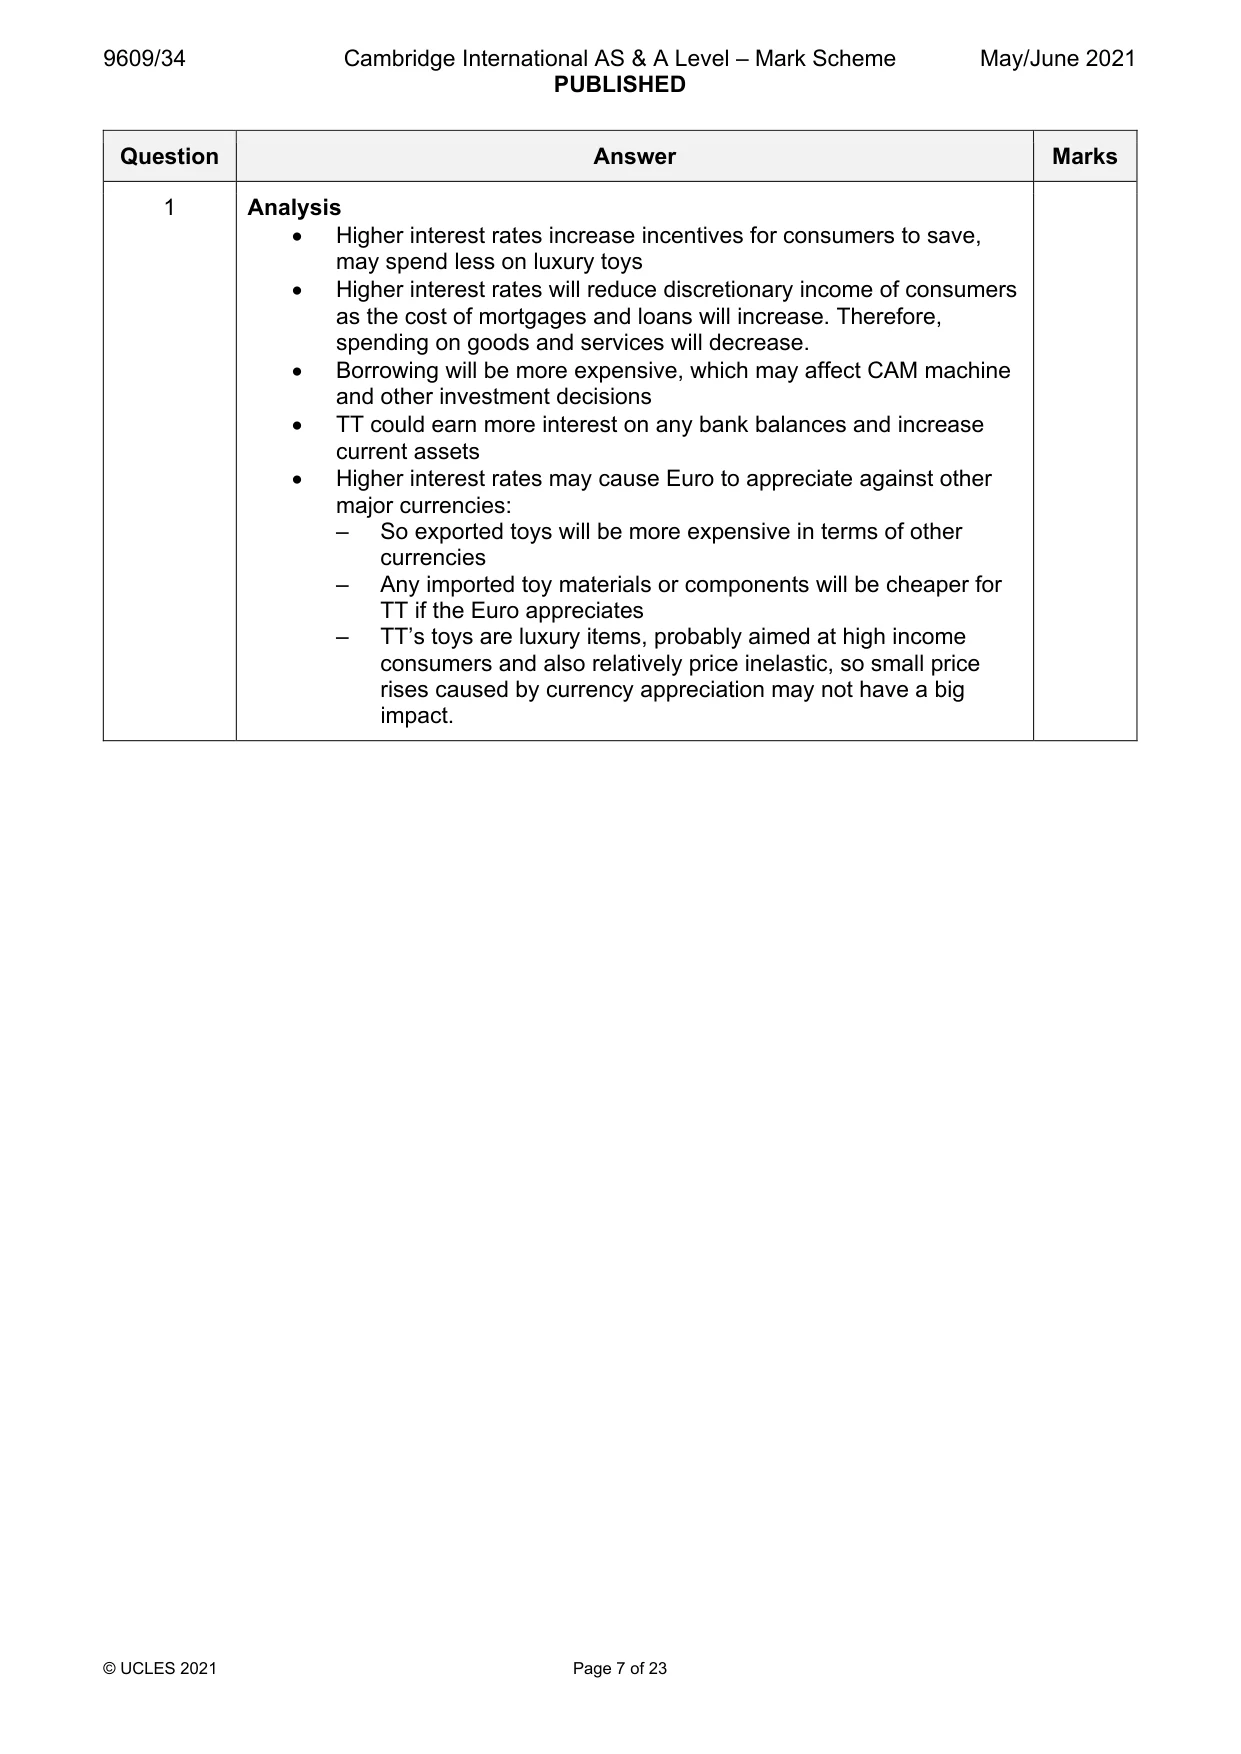
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 7 of 23 Question Answer Marks 1 Analysis • Higher interest rates increase incentives for consumers to save, may spend less on luxury toys • Higher interest rates will reduce discretionary income of consumers as the cost of mortgages and loans will increase. Therefore, spending on goods and services will decrease. • Borrowing will be more expensive, which may affect CAM machine and other investment decisions • TT could earn more interest on any bank balances and increase current assets • Higher interest rates may cause Euro to appreciate against other major currencies: – So exported toys will be more expensive in terms of other currencies – Any imported toy materials or components will be cheaper for TT if the Euro appreciates – TT’s toys are luxury items, probably aimed at high income consumers and also relatively price inelastic, so small price rises caused by currency appreciation may not have a big impact.
Mark scheme, page 8
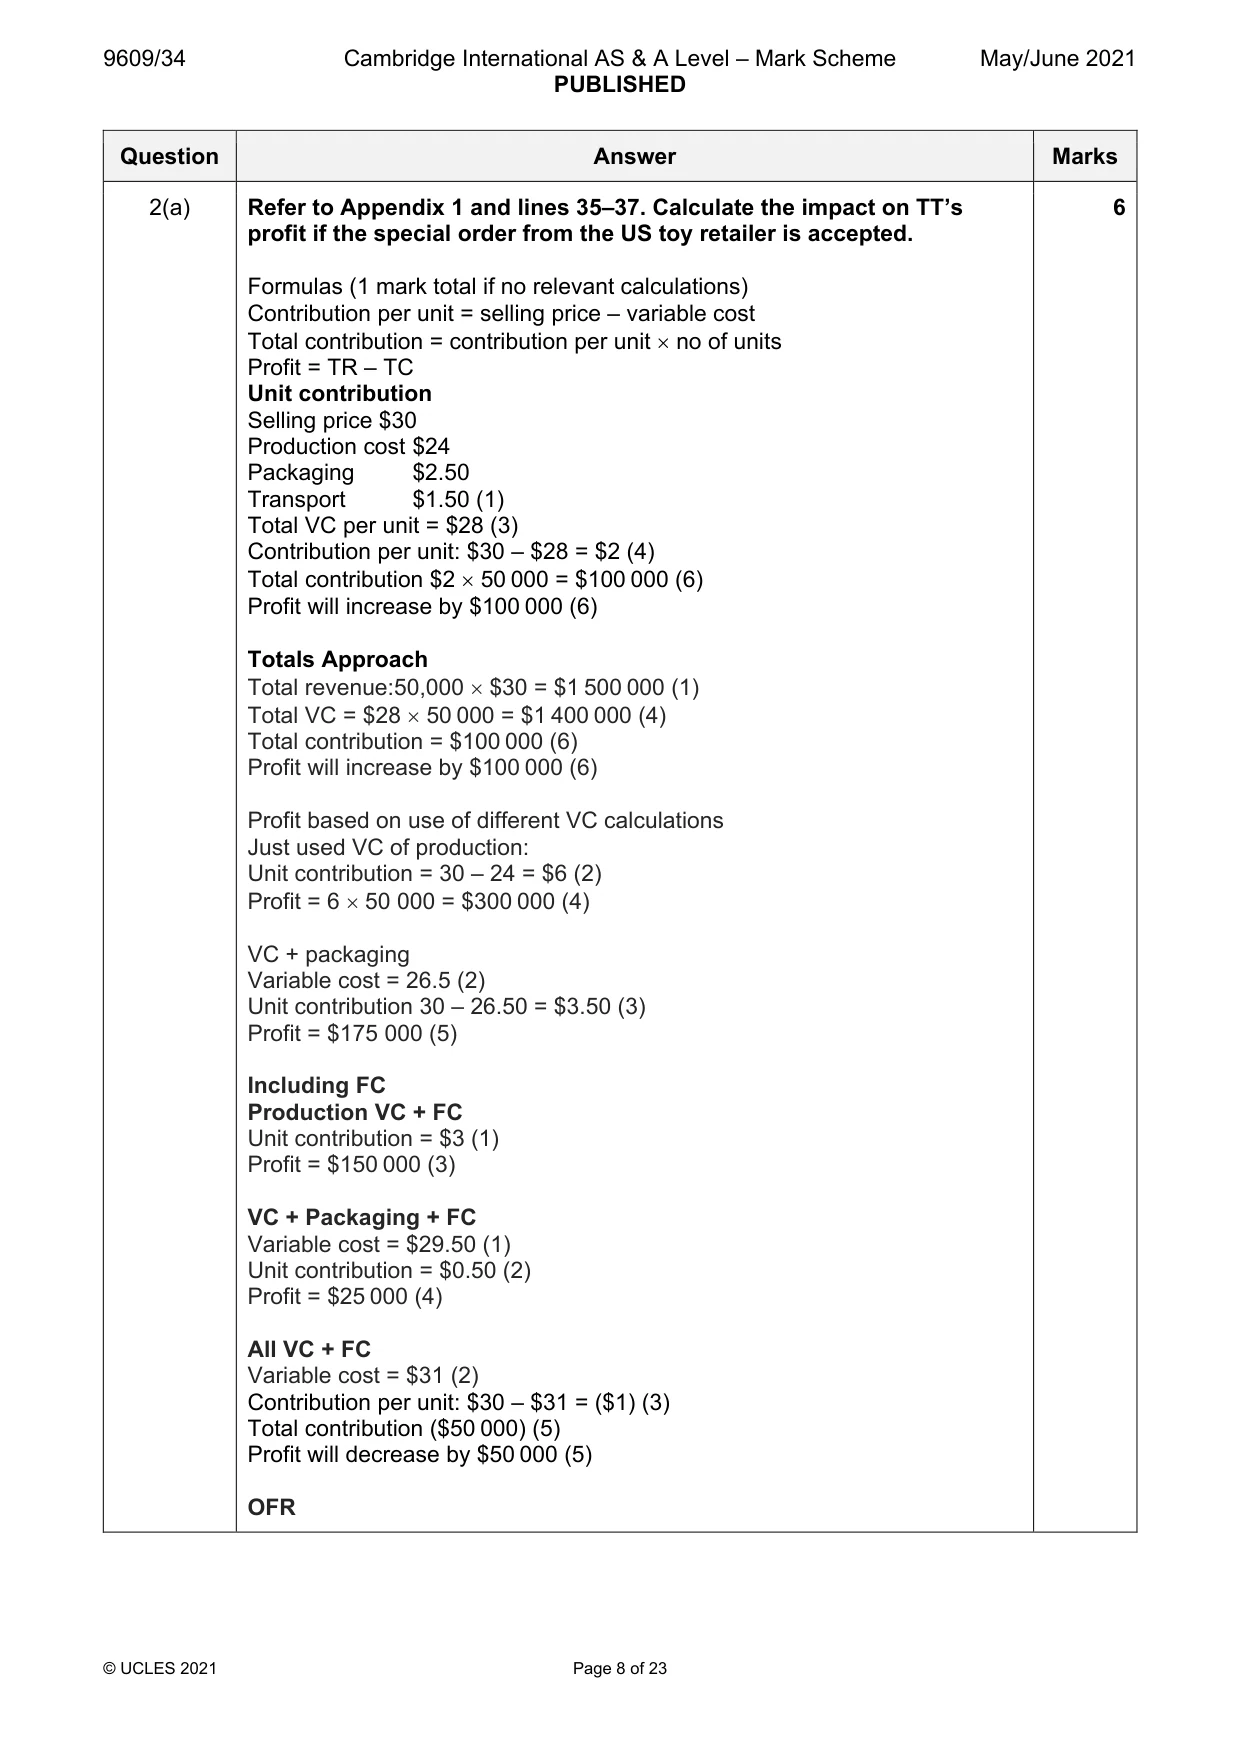
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 8 of 23 Question Answer Marks 2(a) Refer to Appendix 1 and lines 35–37. Calculate the impact on TT’s profit if the special order from the US toy retailer is accepted. Formulas (1 mark total if no relevant calculations) Contribution per unit = selling price – variable cost Total contribution = contribution per unit × no of units Profit = TR – TC Unit contribution Selling price $30 Production cost $24 Packaging $2.50 Transport $1.50 (1) Total VC per unit = $28 (3) Contribution per unit: $30 – $28 = $2 (4) Total contribution $2 × 50 000 = $100 000 (6) Profit will increase by $100 000 (6) Totals Approach Total revenue:50,000 × $30 = $1 500 000 (1) Total VC = $28 × 50 000 = $1 400 000 (4) Total contribution = $100 000 (6) Profit will increase by $100 000 (6) Profit based on use of different VC calculations Just used VC of production: Unit contribution = 30 – 24 = $6 (2) Profit = 6 × 50 000 = $300 000 (4) VC + packaging Variable cost = 26.5 (2) Unit contribution 30 – 26.50 = $3.50 (3) Profit = $175 000 (5) Including FC Production VC + FC Unit contribution = $3 (1) Profit = $150 000 (3) VC + Packaging + FC Variable cost = $29.50 (1) Unit contribution = $0.50 (2) Profit = $25 000 (4) All VC + FC Variable cost = $31 (2) Contribution per unit: $30 – $31 = ($1) (3) Total contribution ($50 000) (5) Profit will decrease by $50 000 (5) OFR 6
Mark scheme, page 9
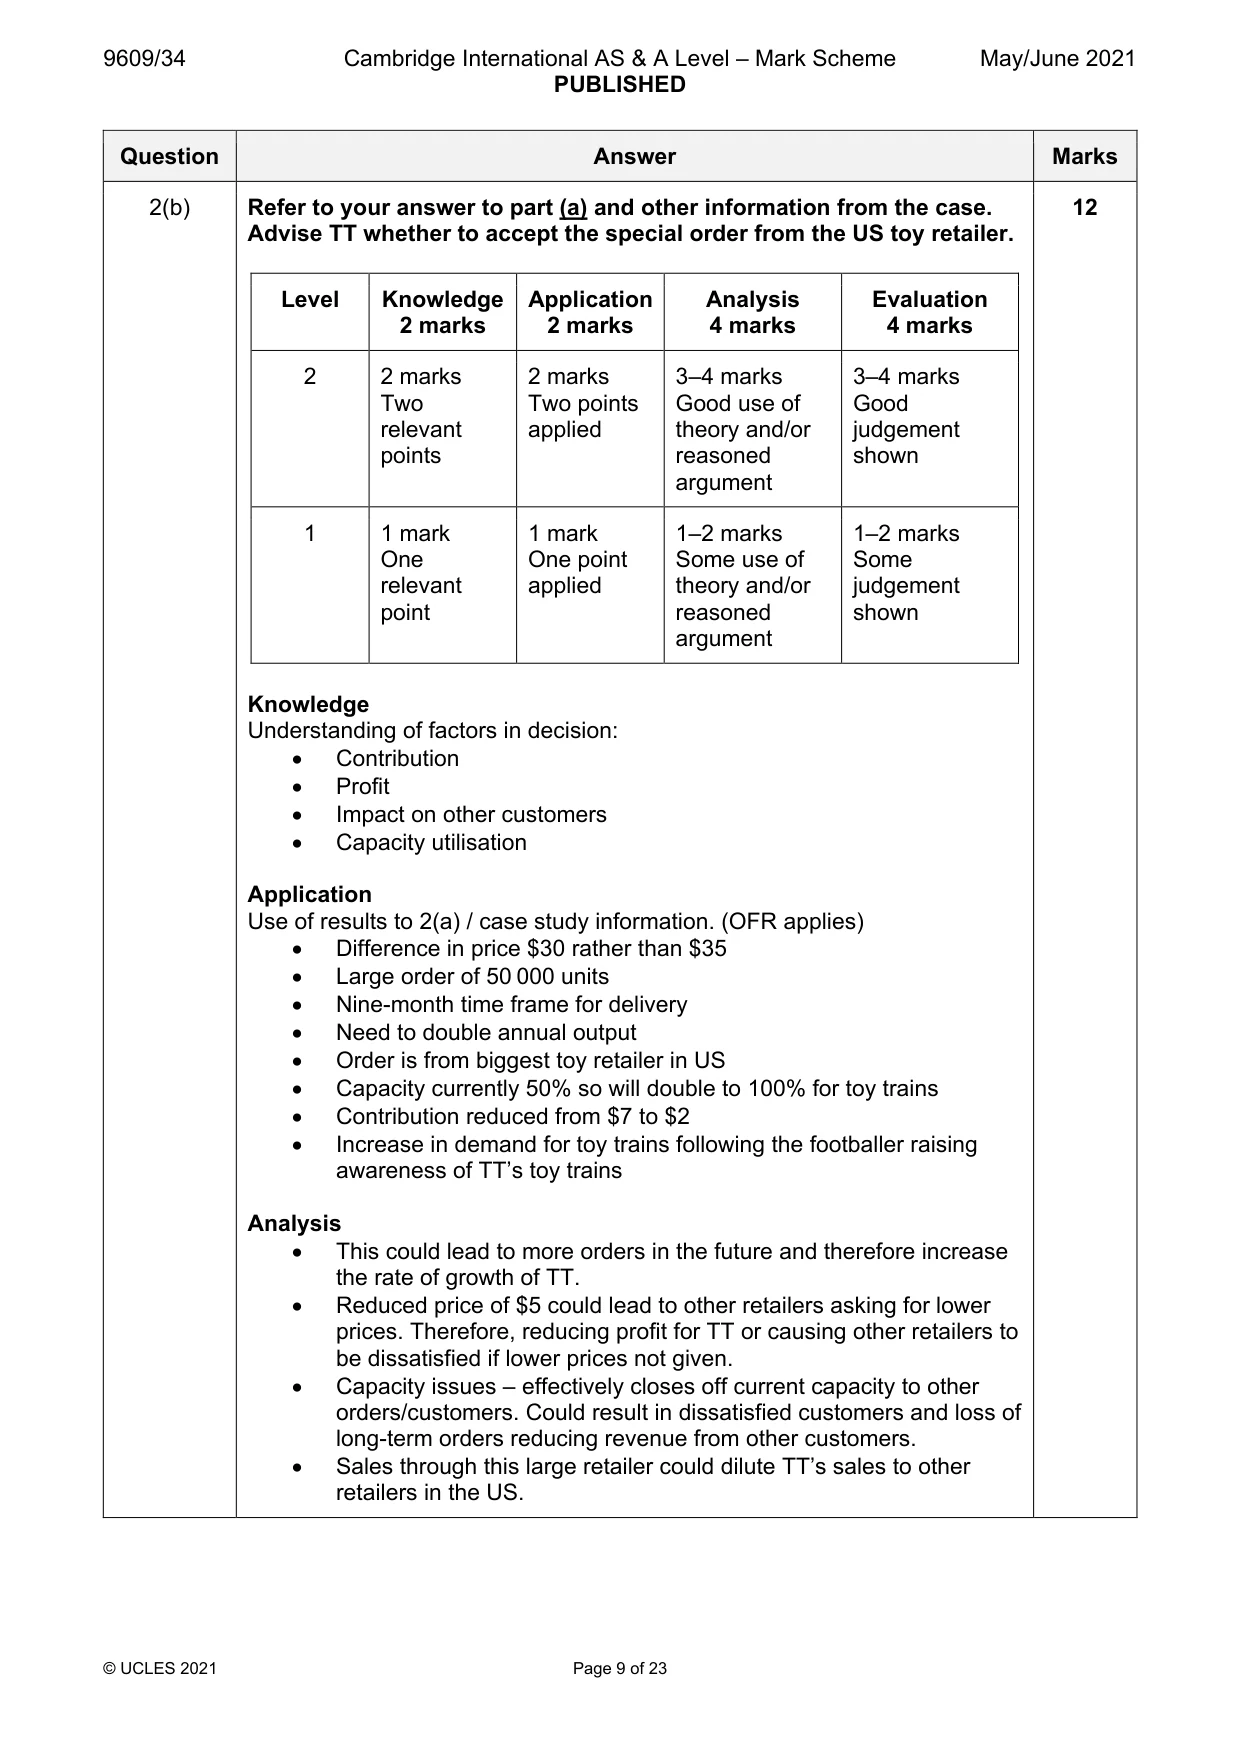
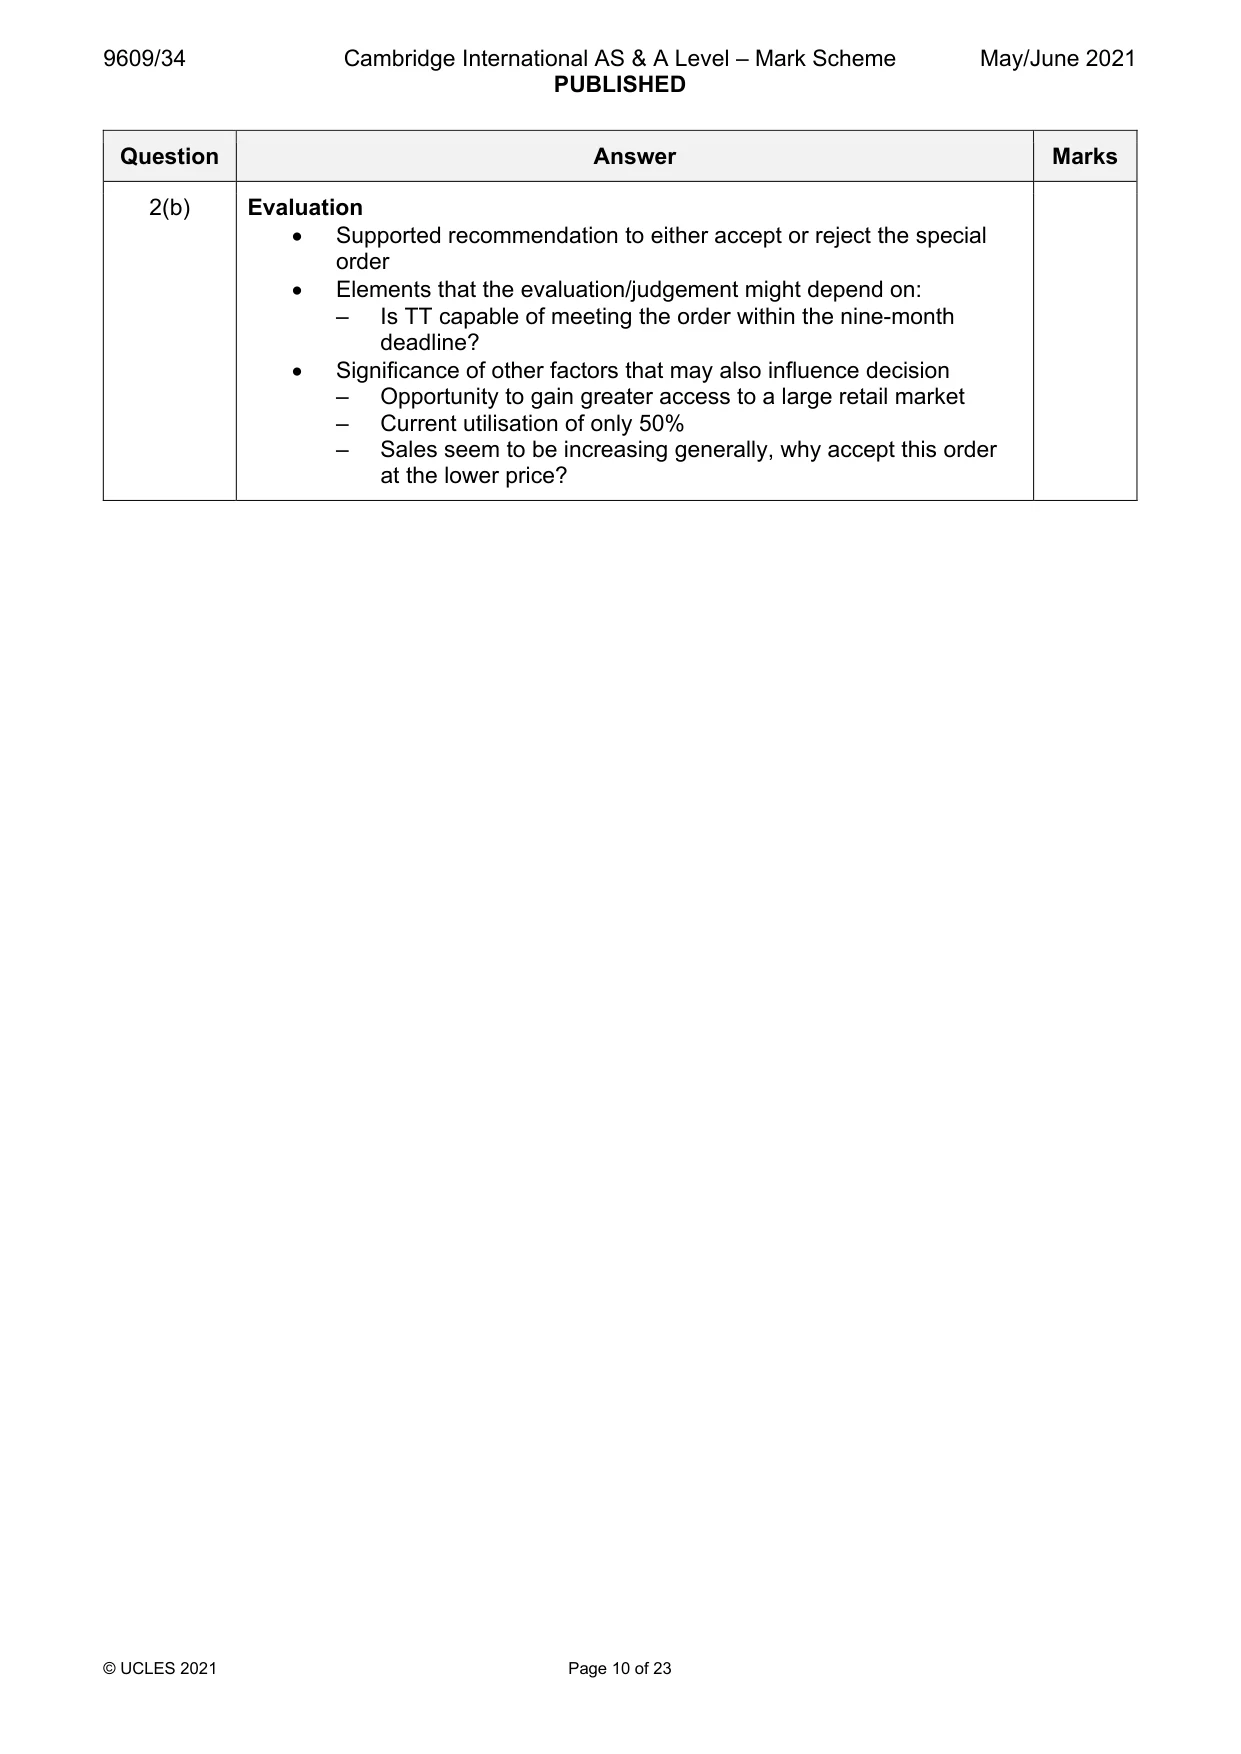
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 9 of 23 Question Answer Marks 2(b) Refer to your answer to part (a) and other information from the case. Advise TT whether to accept the special order from the US toy retailer. Level Knowledge 2 marks Application 2 marks Analysis 4 marks Evaluation 4 marks 2 2 marks Two relevant points 2 marks Two points applied 3–4 marks Good use of theory and/or reasoned argument 3–4 marks Good judgement shown 1 1 mark One relevant point 1 mark One point applied 1–2 marks Some use of theory and/or reasoned argument 1–2 marks Some judgement shown Knowledge Understanding of factors in decision: • Contribution • Profit • Impact on other customers • Capacity utilisation Application Use of results to 2(a) / case study information. (OFR applies) • Difference in price $30 rather than $35 • Large order of 50 000 units • Nine-month time frame for delivery • Need to double annual output • Order is from biggest toy retailer in US • Capacity currently 50% so will double to 100% for toy trains • Contribution reduced from $7 to $2 • Increase in demand for toy trains following the footballer raising awareness of TT’s toy trains Analysis • This could lead to more orders in the future and therefore increase the rate of growth of TT. • Reduced price of $5 could lead to other retailers asking for lower prices. Therefore, reducing profit for TT or causing other retailers to be dissatisfied if lower prices not given. • Capacity issues – effectively closes off current capacity to other orders/customers. Could result in dissatisfied customers and loss of long-term orders reducing revenue from other customers. • Sales through this large retailer could dilute TT’s sales to other retailers in the US. 12
Mark scheme, page 10
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 10 of 23 Question Answer Marks 2(b) Evaluation • Supported recommendation to either accept or reject the special order • Elements that the evaluation/judgement might depend on: – Is TT capable of meeting the order within the nine-month deadline? • Significance of other factors that may also influence decision – Opportunity to gain greater access to a large retail market – Current utilisation of only 50% – Sales seem to be increasing generally, why accept this order at the lower price?
Mark scheme, page 11
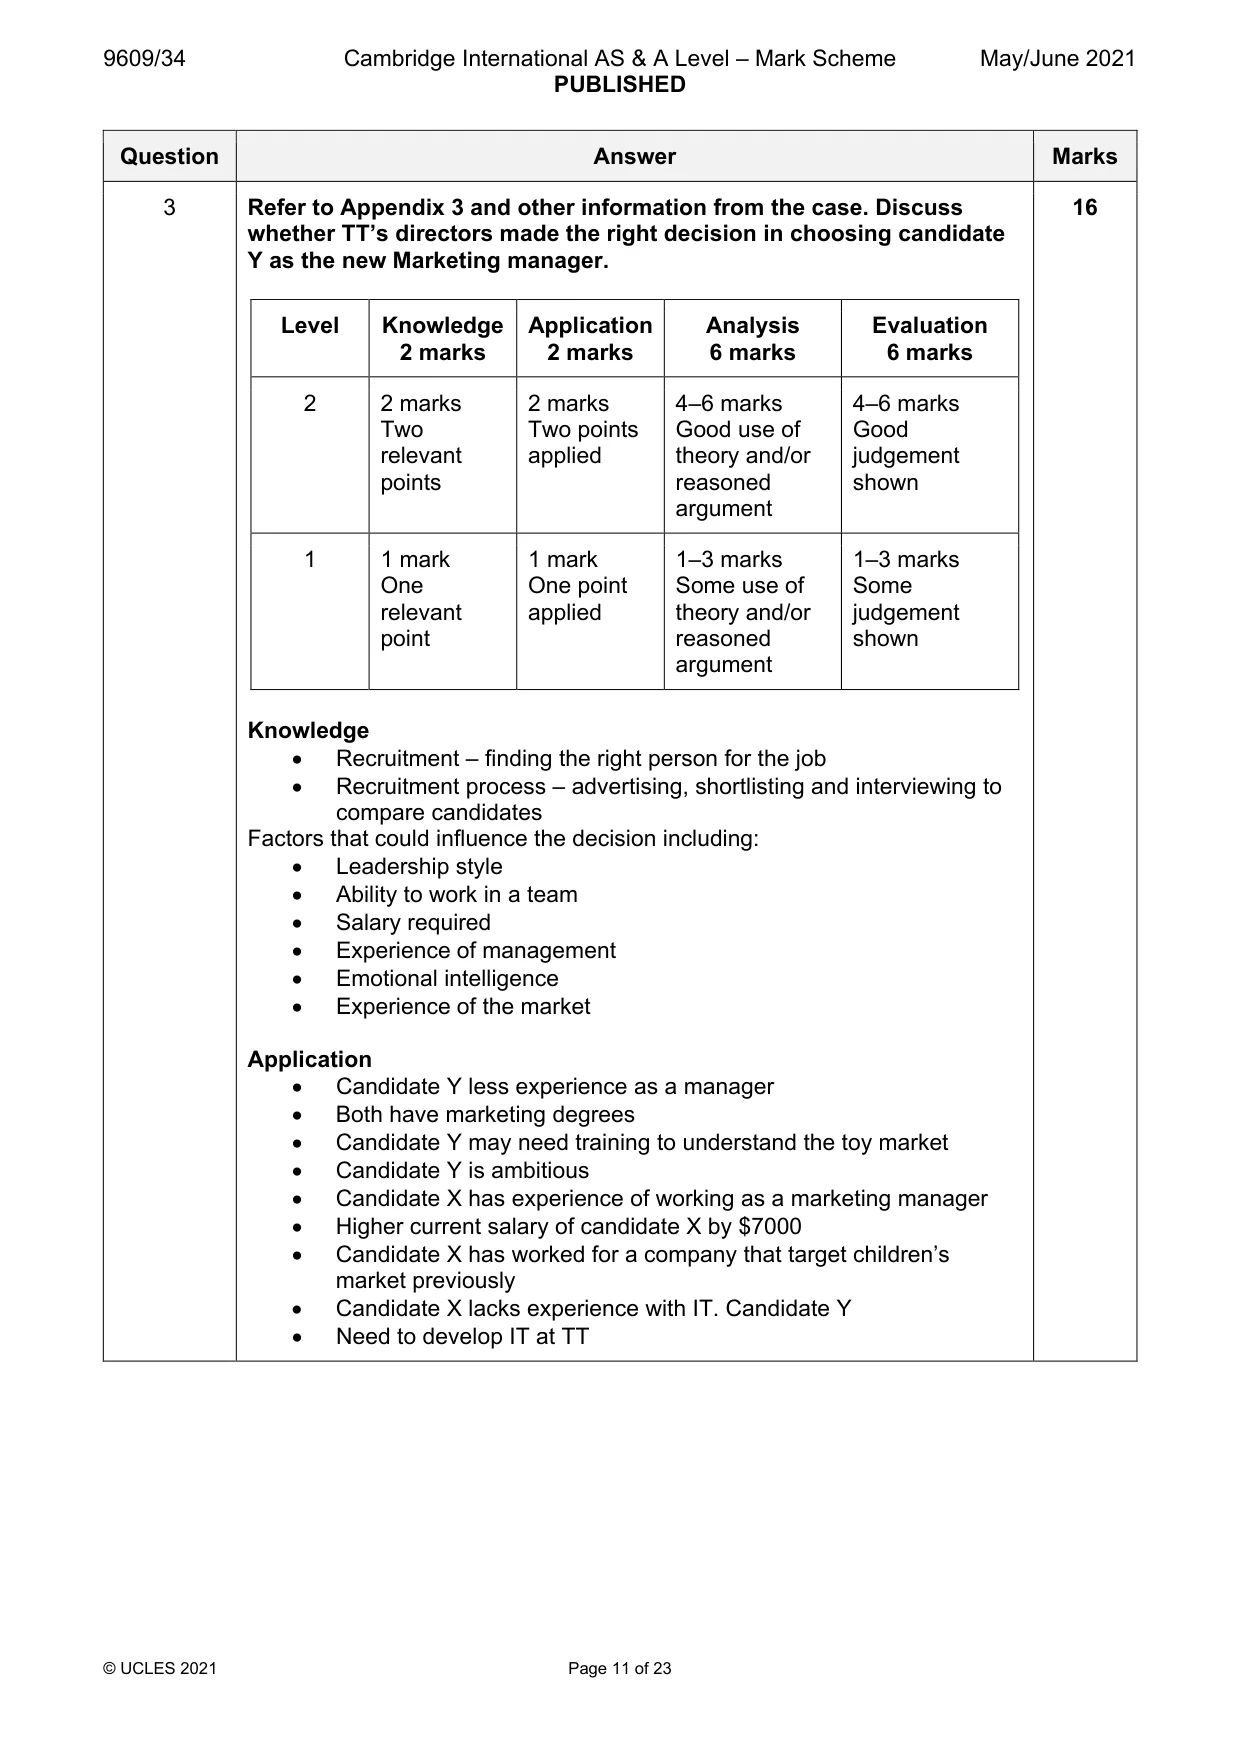
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 11 of 23 Question Answer Marks 3 Refer to Appendix 3 and other information from the case. Discuss whether TT’s directors made the right decision in choosing candidate Y as the new Marketing manager. Level Knowledge 2 marks Application 2 marks Analysis 6 marks Evaluation 6 marks 2 2 marks Two relevant points 2 marks Two points applied 4–6 marks Good use of theory and/or reasoned argument 4–6 marks Good judgement shown 1 1 mark One relevant point 1 mark One point applied 1–3 marks Some use of theory and/or reasoned argument 1–3 marks Some judgement shown Knowledge • Recruitment – finding the right person for the job • Recruitment process – advertising, shortlisting and interviewing to compare candidates Factors that could influence the decision including: • Leadership style • Ability to work in a team • Salary required • Experience of management • Emotional intelligence • Experience of the market Application • Candidate Y less experience as a manager • Both have marketing degrees • Candidate Y may need training to understand the toy market • Candidate Y is ambitious • Candidate X has experience of working as a marketing manager • Higher current salary of candidate X by $7000 • Candidate X has worked for a company that target children’s market previously • Candidate X lacks experience with IT. Candidate Y • Need to develop IT at TT 16
Mark scheme, page 12
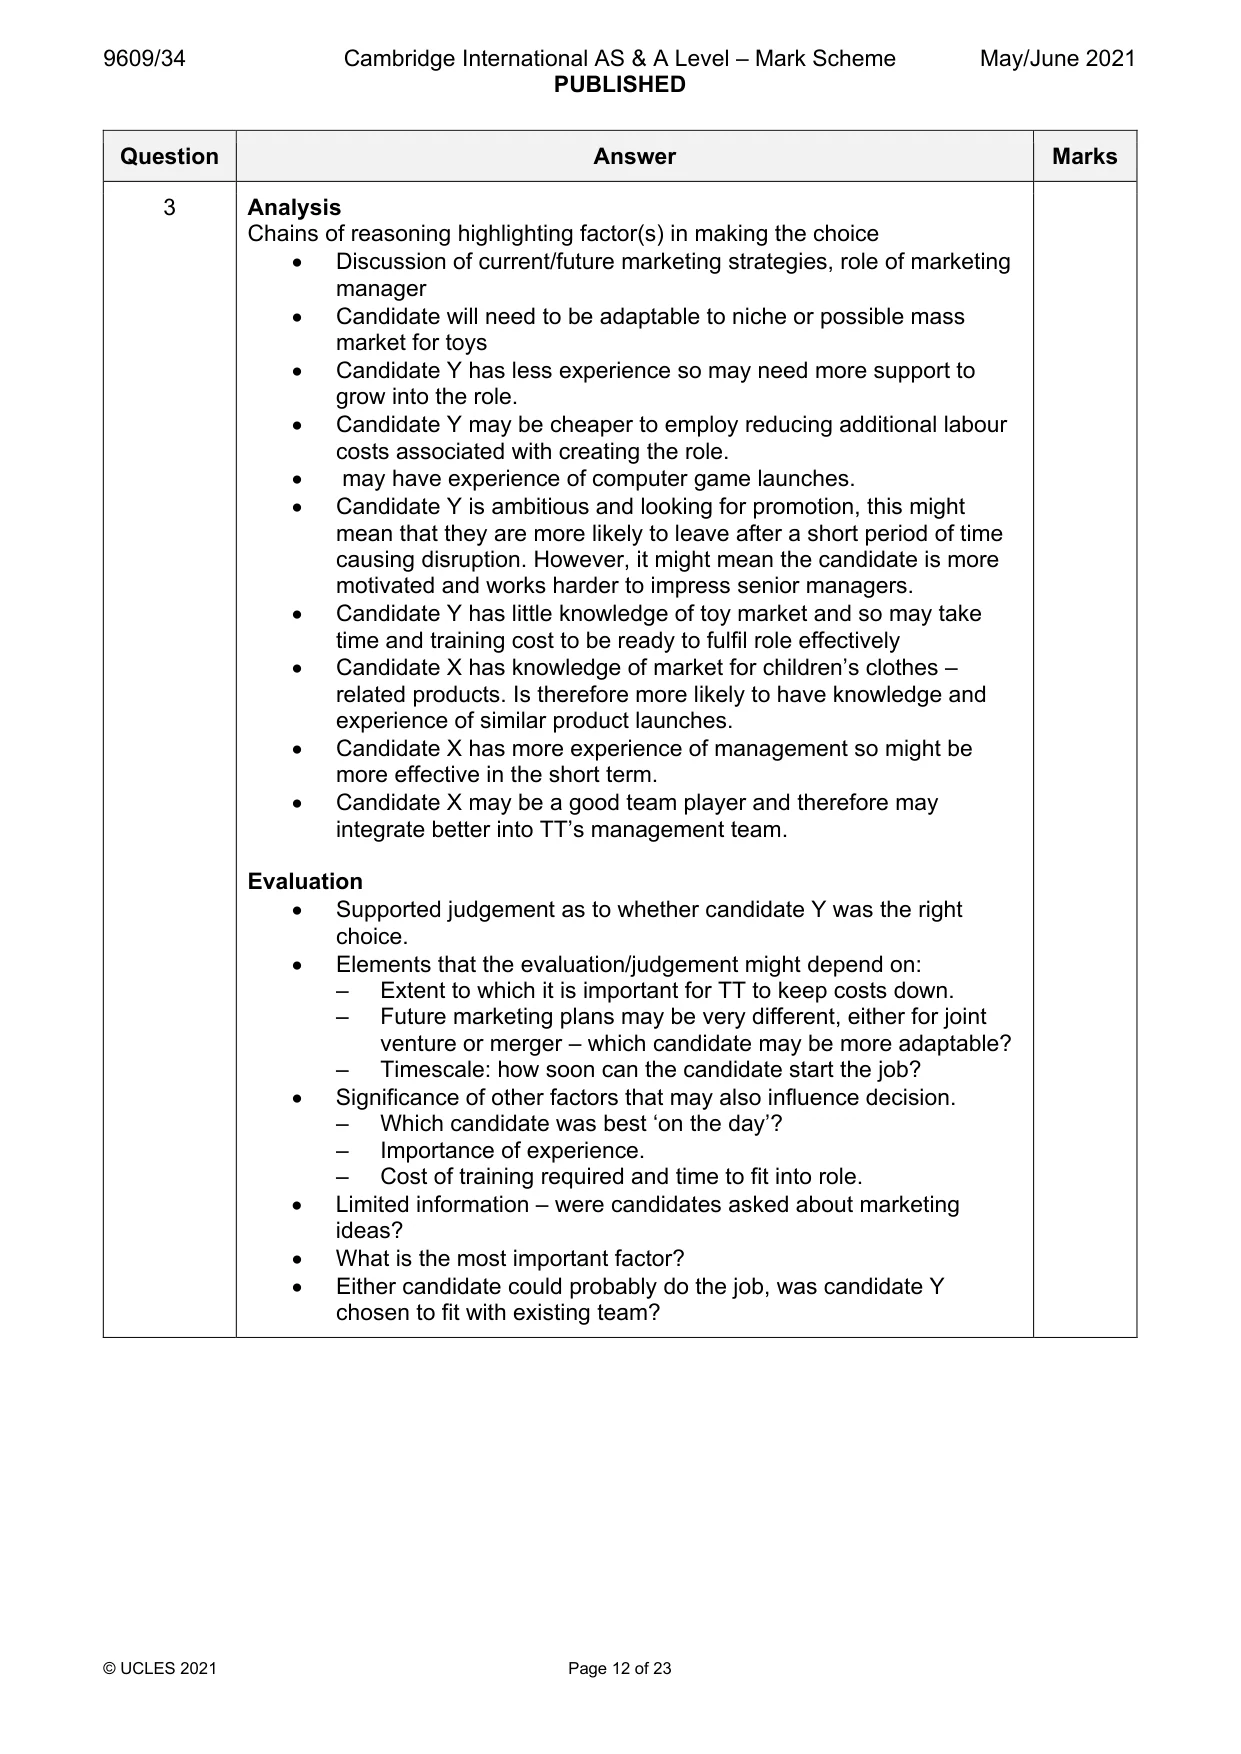
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 12 of 23 Question Answer Marks 3 Analysis Chains of reasoning highlighting factor(s) in making the choice • Discussion of current/future marketing strategies, role of marketing manager • Candidate will need to be adaptable to niche or possible mass market for toys • Candidate Y has less experience so may need more support to grow into the role. • Candidate Y may be cheaper to employ reducing additional labour costs associated with creating the role. • may have experience of computer game launches. • Candidate Y is ambitious and looking for promotion, this might mean that they are more likely to leave after a short period of time causing disruption. However, it might mean the candidate is more motivated and works harder to impress senior managers. • Candidate Y has little knowledge of toy market and so may take time and training cost to be ready to fulfil role effectively • Candidate X has knowledge of market for children’s clothes – related products. Is therefore more likely to have knowledge and experience of similar product launches. • Candidate X has more experience of management so might be more effective in the short term. • Candidate X may be a good team player and therefore may integrate better into TT’s management team. Evaluation • Supported judgement as to whether candidate Y was the right choice. • Elements that the evaluation/judgement might depend on: – Extent to which it is important for TT to keep costs down. – Future marketing plans may be very different, either for joint venture or merger – which candidate may be more adaptable? – Timescale: how soon can the candidate start the job? • Significance of other factors that may also influence decision. – Which candidate was best ‘on the day’? – Importance of experience. – Cost of training required and time to fit into role. • Limited information – were candidates asked about marketing ideas? • What is the most important factor? • Either candidate could probably do the job, was candidate Y chosen to fit with existing team?
Mark scheme, page 13
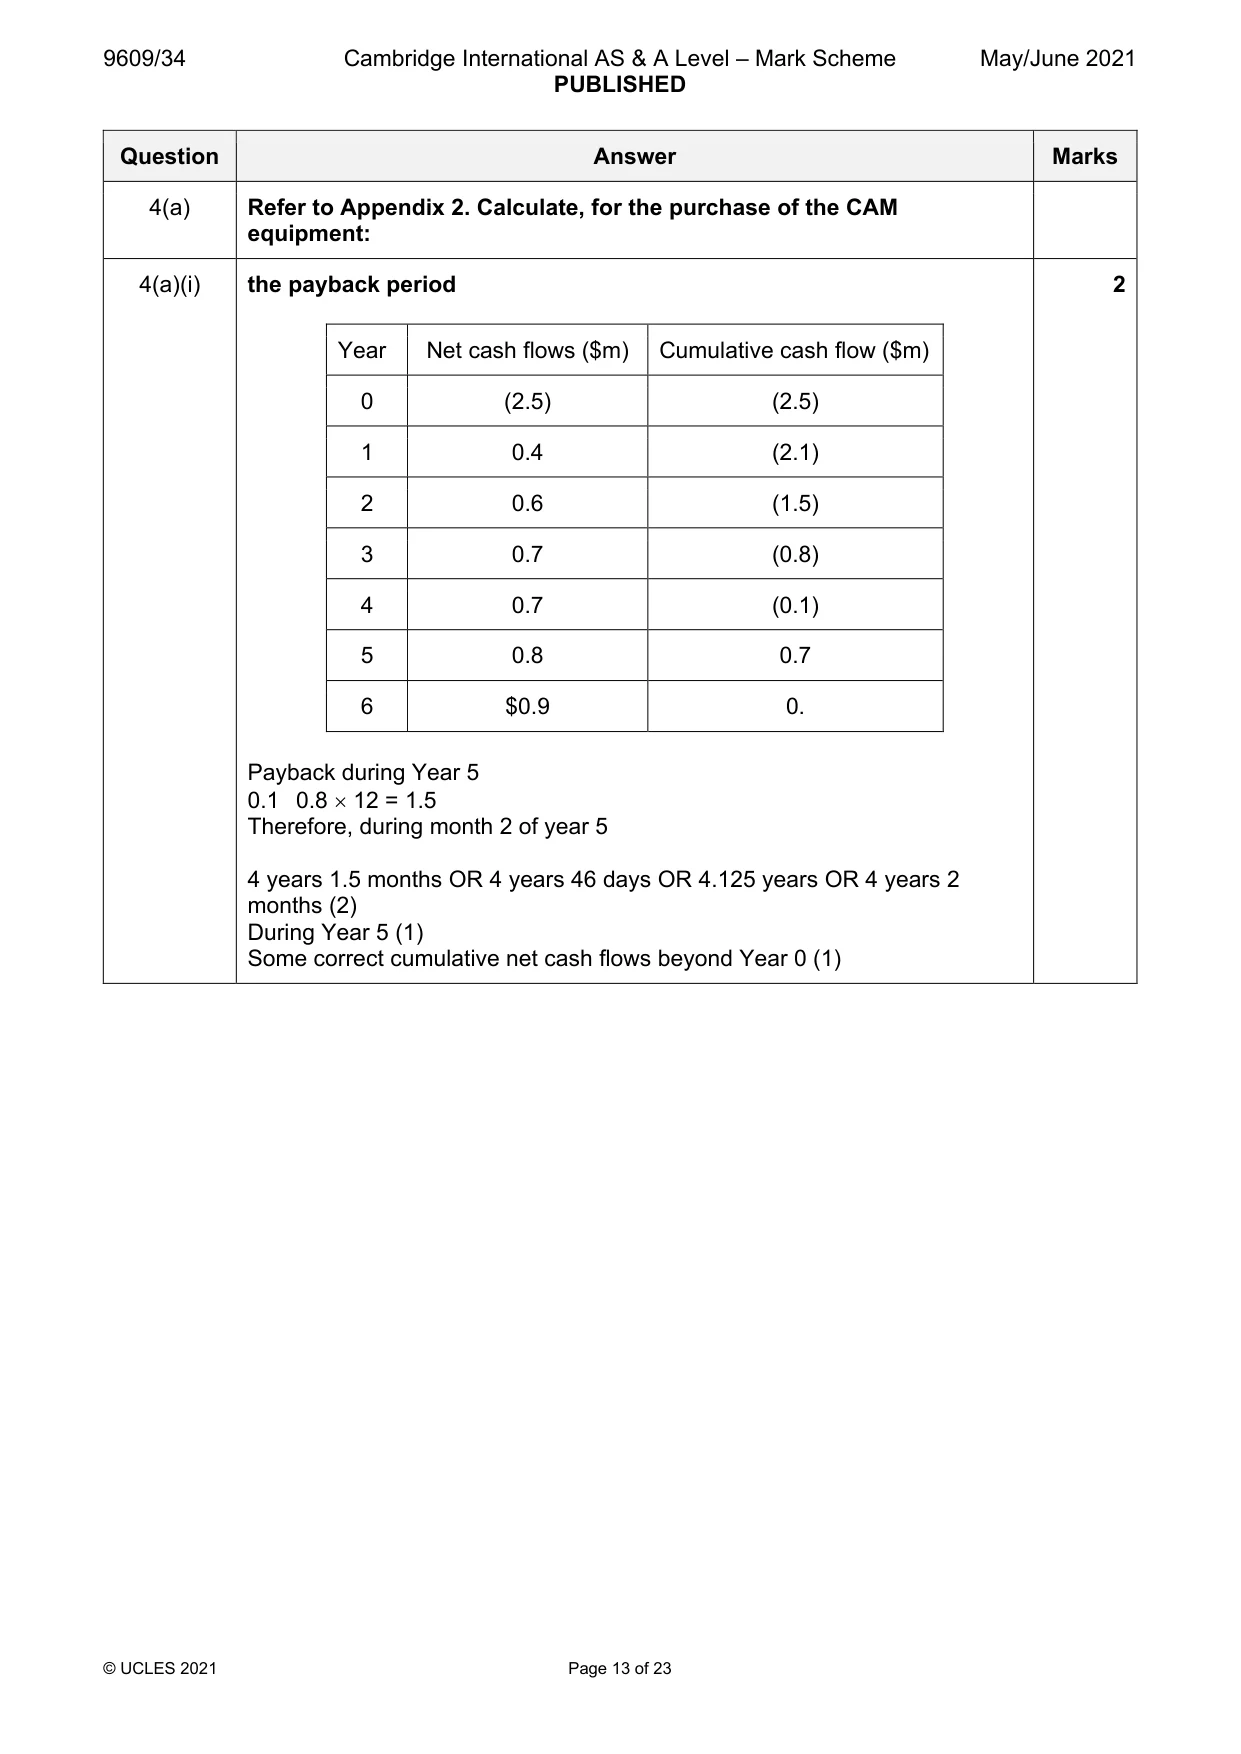
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 13 of 23 Question Answer Marks 4(a) Refer to Appendix 2. Calculate, for the purchase of the CAM equipment: 4(a)(i) the payback period Year Net cash flows ($m) Cumulative cash flow ($m) 0 (2.5) (2.5) 1 0.4 (2.1) 2 0.6 (1.5) 3 0.7 (0.8) 4 0.7 (0.1) 5 0.8 0.7 6 $0.9 0. Payback during Year 5 0.1 0.8 × 12 = 1.5 Therefore, during month 2 of year 5 4 years 1.5 months OR 4 years 46 days OR 4.125 years OR 4 years 2 months (2) During Year 5 (1) Some correct cumulative net cash flows beyond Year 0 (1) 2
Mark scheme, page 14
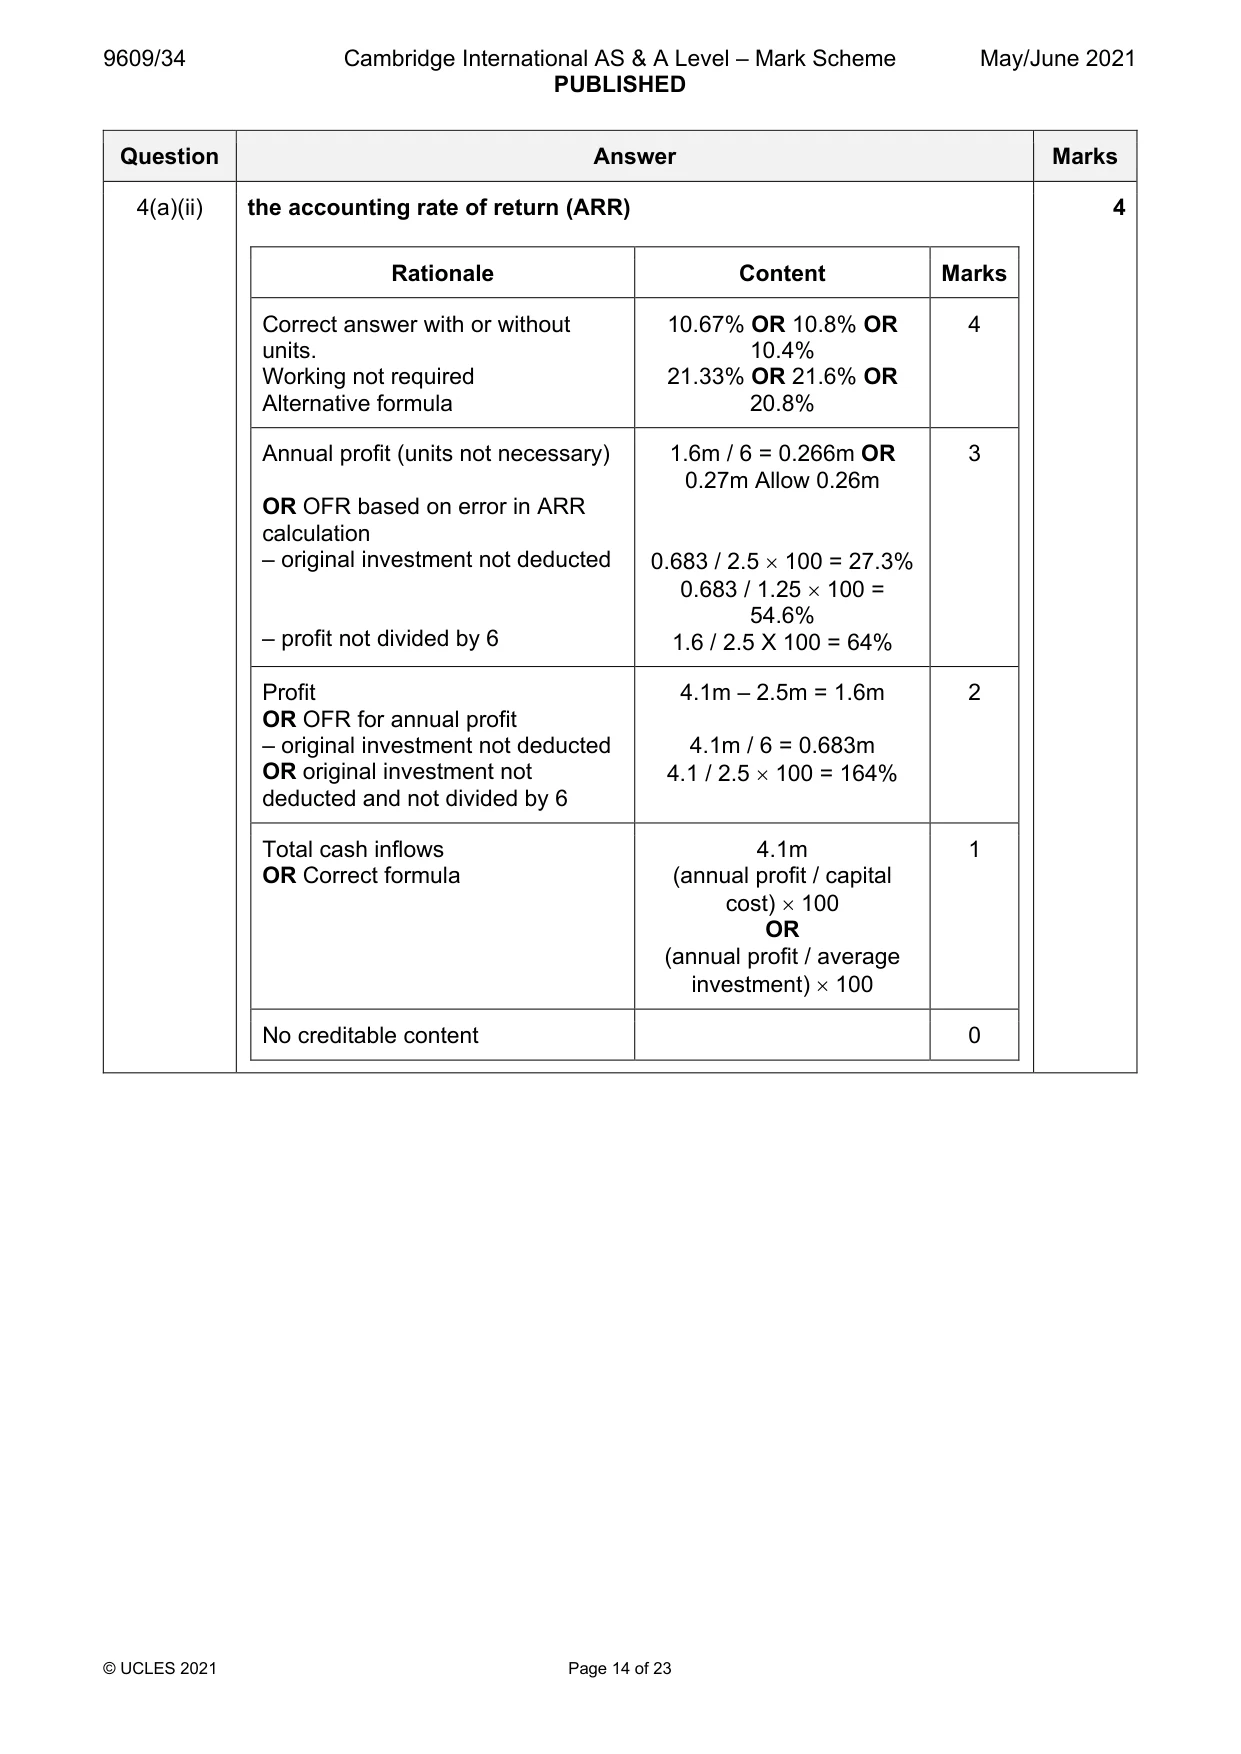
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 14 of 23 Question Answer Marks 4(a)(ii) the accounting rate of return (ARR) Rationale Content Marks Correct answer with or without units. Working not required Alternative formula 10.67% OR 10.8% OR 10.4% 21.33% OR 21.6% OR 20.8% 4 Annual profit (units not necessary) OR OFR based on error in ARR calculation – original investment not deducted – profit not divided by 6 1.6m / 6 = 0.266m OR 0.27m Allow 0.26m 0.683 / 2.5 × 100 = 27.3% 0.683 / 1.25 × 100 = 54.6% 1.6 / 2.5 X 100 = 64% 3 Profit OR OFR for annual profit – original investment not deducted OR original investment not deducted and not divided by 6 4.1m – 2.5m = 1.6m 4.1m / 6 = 0.683m 4.1 / 2.5 × 100 = 164% 2 Total cash inflows OR Correct formula 4.1m (annual profit / capital cost) × 100 OR (annual profit / average investment) × 100 1 No creditable content 0 4
Mark scheme, page 15
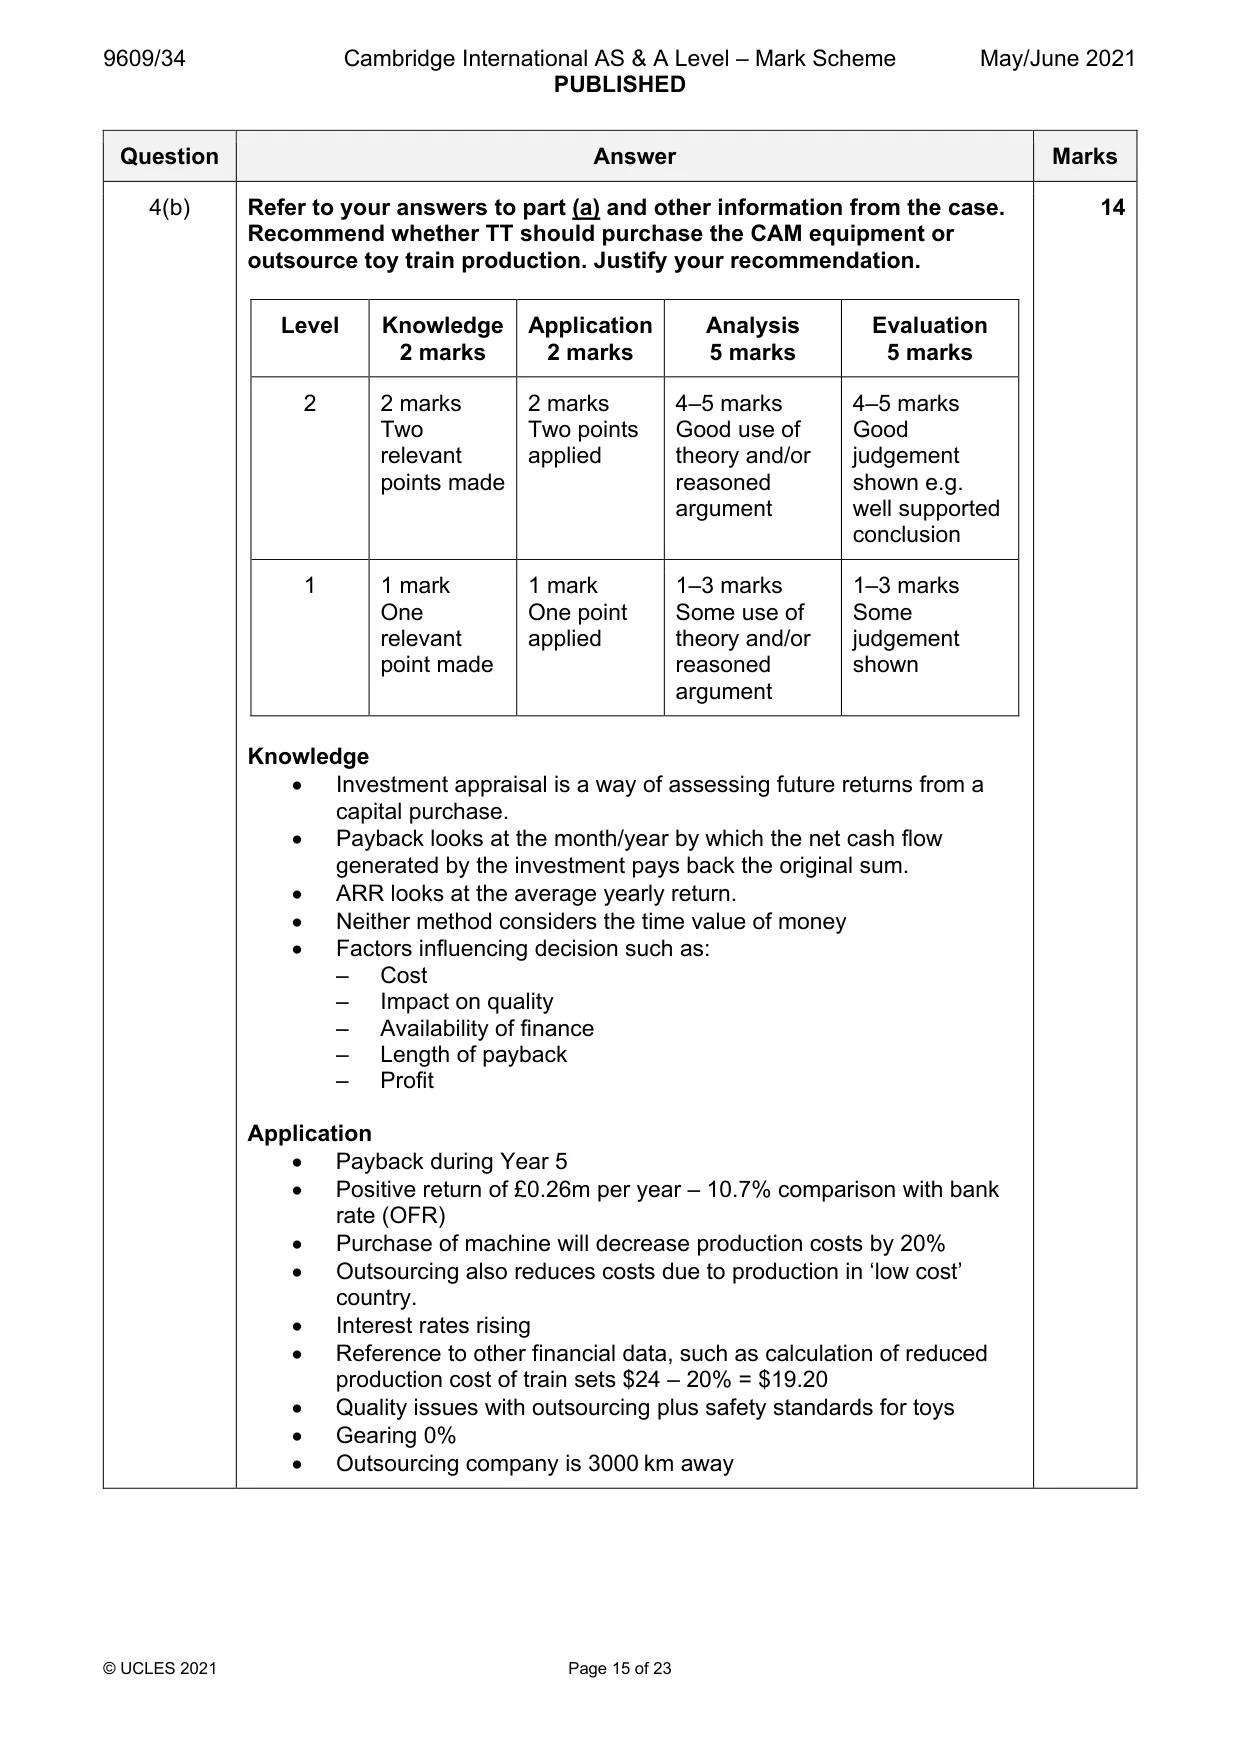
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 15 of 23 Question Answer Marks 4(b) Refer to your answers to part (a) and other information from the case. Recommend whether TT should purchase the CAM equipment or outsource toy train production. Justify your recommendation. Level Knowledge 2 marks Application 2 marks Analysis 5 marks Evaluation 5 marks 2 2 marks Two relevant points made 2 marks Two points applied 4–5 marks Good use of theory and/or reasoned argument 4–5 marks Good judgement shown e.g. well supported conclusion 1 1 mark One relevant point made 1 mark One point applied 1–3 marks Some use of theory and/or reasoned argument 1–3 marks Some judgement shown Knowledge • Investment appraisal is a way of assessing future returns from a capital purchase. • Payback looks at the month/year by which the net cash flow generated by the investment pays back the original sum. • ARR looks at the average yearly return. • Neither method considers the time value of money • Factors influencing decision such as: – Cost – Impact on quality – Availability of finance – Length of payback – Profit Application • Payback during Year 5 • Positive return of £0.26m per year – 10.7% comparison with bank rate (OFR) • Purchase of machine will decrease production costs by 20% • Outsourcing also reduces costs due to production in ‘low cost’ country. • Interest rates rising • Reference to other financial data, such as calculation of reduced production cost of train sets $24 – 20% = $19.20 • Quality issues with outsourcing plus safety standards for toys • Gearing 0% • Outsourcing company is 3000 km away 14
Mark scheme, page 16
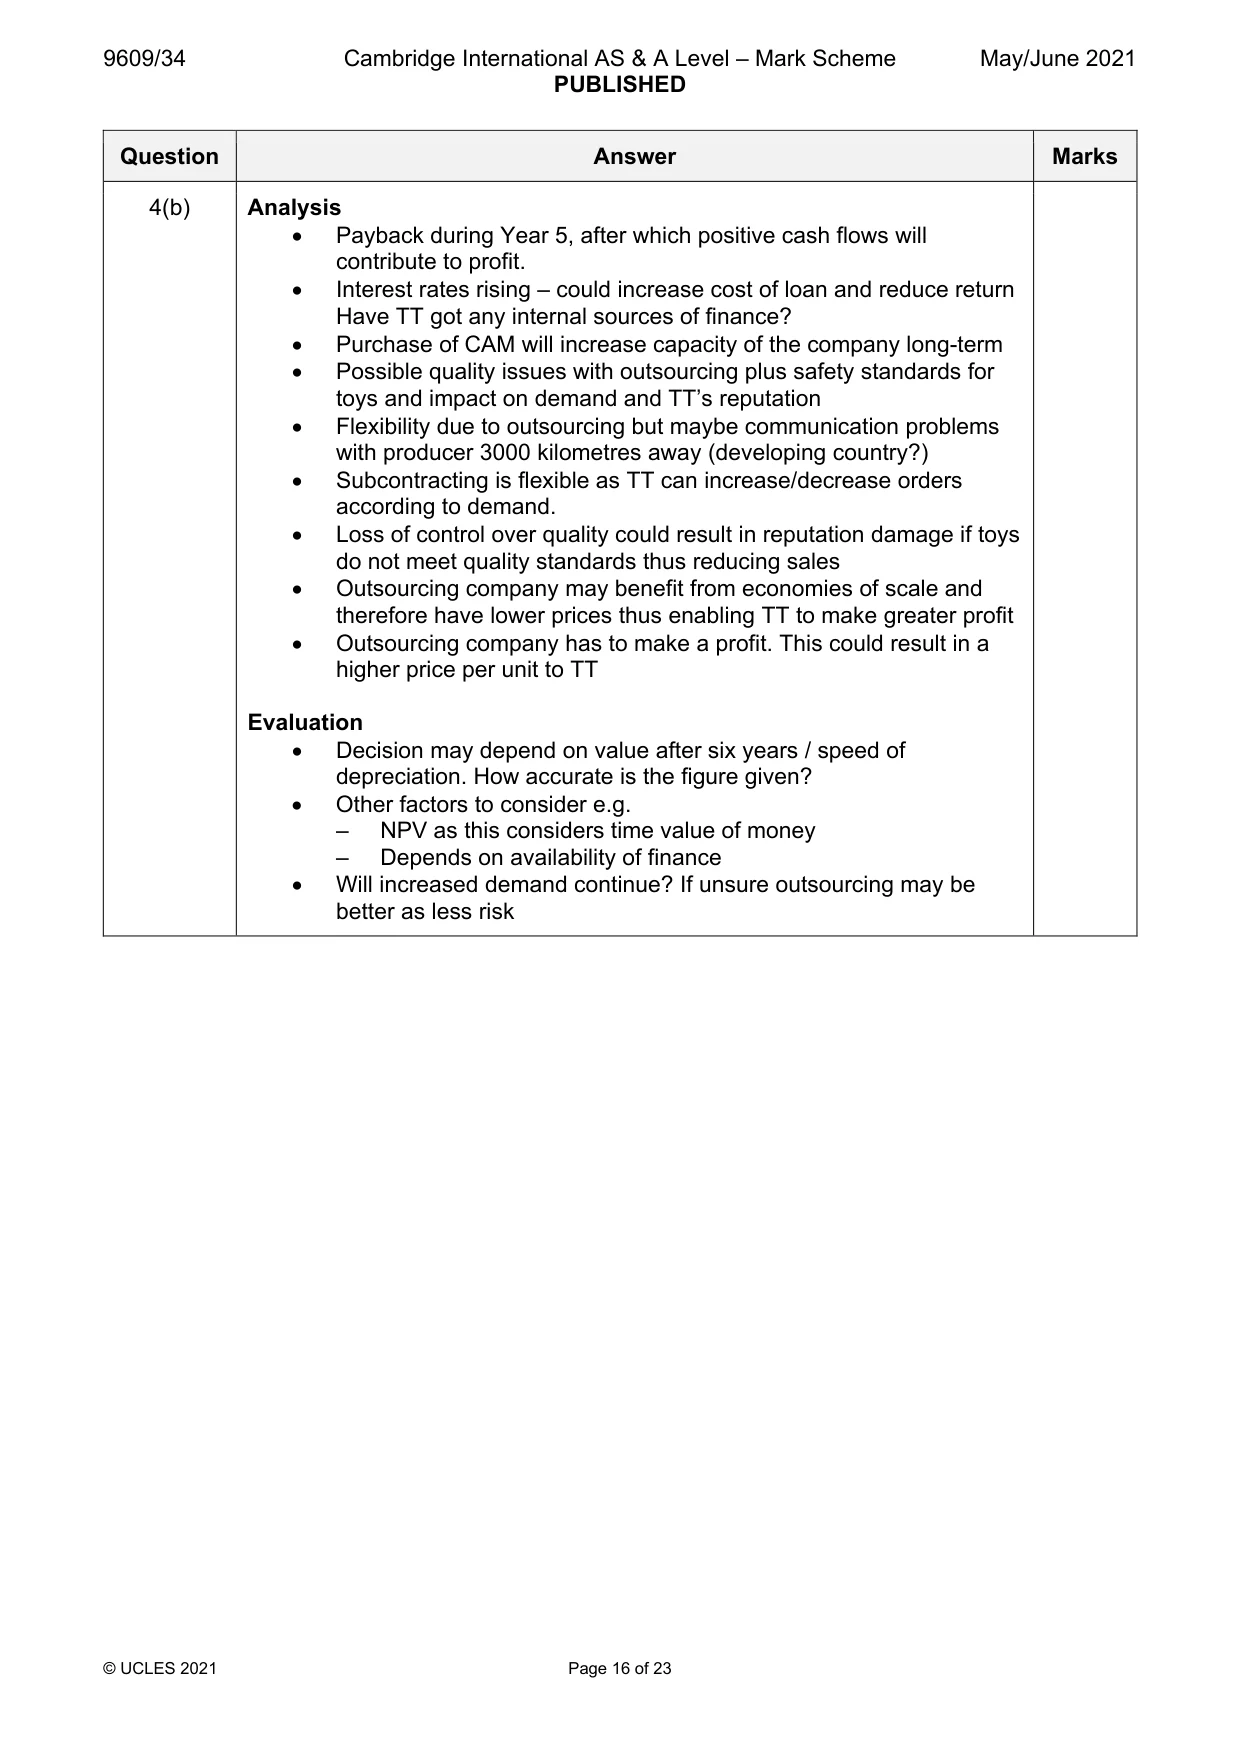
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 16 of 23 Question Answer Marks 4(b) Analysis • Payback during Year 5, after which positive cash flows will contribute to profit. • Interest rates rising – could increase cost of loan and reduce return Have TT got any internal sources of finance? • Purchase of CAM will increase capacity of the company long-term • Possible quality issues with outsourcing plus safety standards for toys and impact on demand and TT’s reputation • Flexibility due to outsourcing but maybe communication problems with producer 3000 kilometres away (developing country?) • Subcontracting is flexible as TT can increase/decrease orders according to demand. • Loss of control over quality could result in reputation damage if toys do not meet quality standards thus reducing sales • Outsourcing company may benefit from economies of scale and therefore have lower prices thus enabling TT to make greater profit • Outsourcing company has to make a profit. This could result in a higher price per unit to TT Evaluation • Decision may depend on value after six years / speed of depreciation. How accurate is the figure given? • Other factors to consider e.g. – NPV as this considers time value of money – Depends on availability of finance • Will increased demand continue? If unsure outsourcing may be better as less risk
Mark scheme, page 17
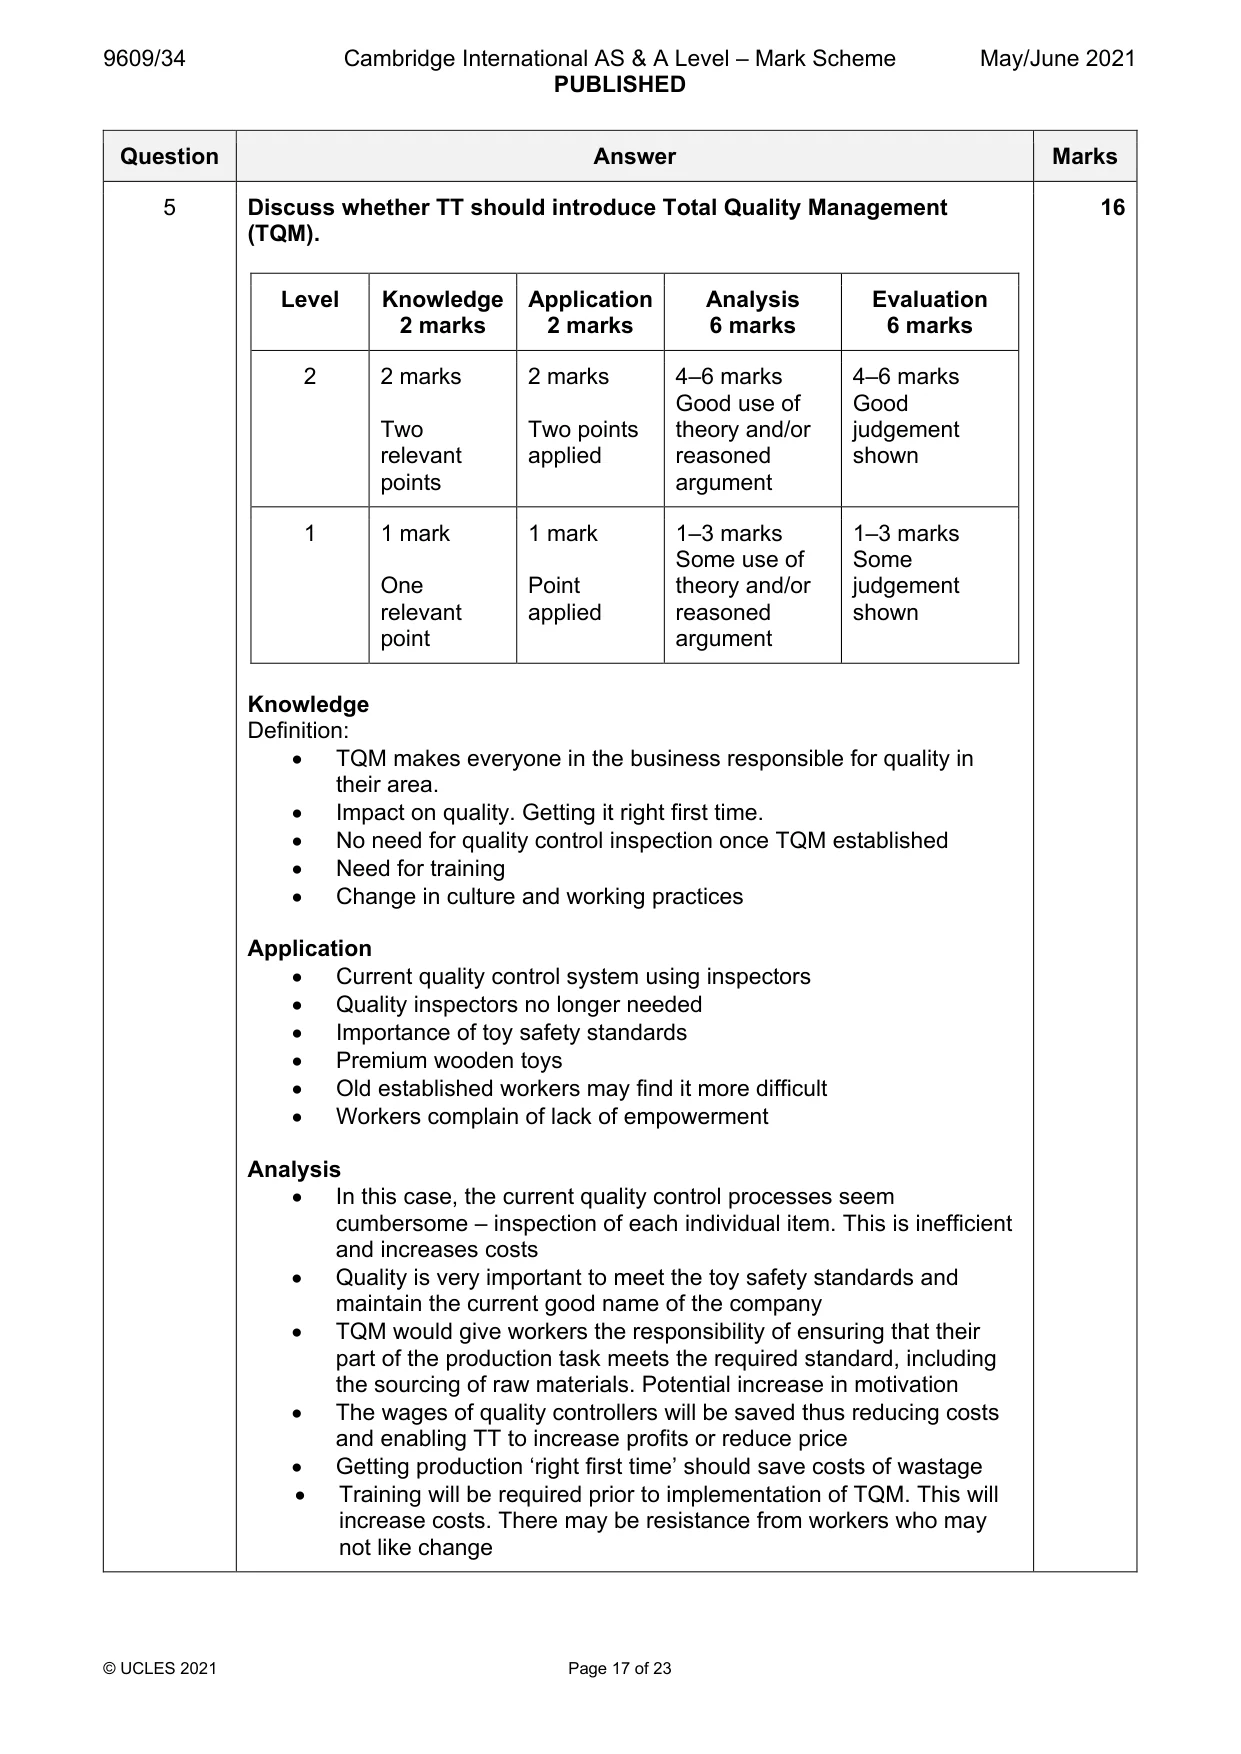
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 17 of 23 Question Answer Marks 5 Discuss whether TT should introduce Total Quality Management (TQM). Level Knowledge 2 marks Application 2 marks Analysis 6 marks Evaluation 6 marks 2 2 marks Two relevant points 2 marks Two points applied 4–6 marks Good use of theory and/or reasoned argument 4–6 marks Good judgement shown 1 1 mark One relevant point 1 mark Point applied 1–3 marks Some use of theory and/or reasoned argument 1–3 marks Some judgement shown Knowledge Definition: • TQM makes everyone in the business responsible for quality in their area. • Impact on quality. Getting it right first time. • No need for quality control inspection once TQM established • Need for training • Change in culture and working practices Application • Current quality control system using inspectors • Quality inspectors no longer needed • Importance of toy safety standards • Premium wooden toys • Old established workers may find it more difficult • Workers complain of lack of empowerment Analysis • In this case, the current quality control processes seem cumbersome – inspection of each individual item. This is inefficient and increases costs • Quality is very important to meet the toy safety standards and maintain the current good name of the company • TQM would give workers the responsibility of ensuring that their part of the production task meets the required standard, including the sourcing of raw materials. Potential increase in motivation • The wages of quality controllers will be saved thus reducing costs and enabling TT to increase profits or reduce price • Getting production ‘right first time’ should save costs of wastage • Training will be required prior to implementation of TQM. This will increase costs. There may be resistance from workers who may not like change 16
Mark scheme, page 18
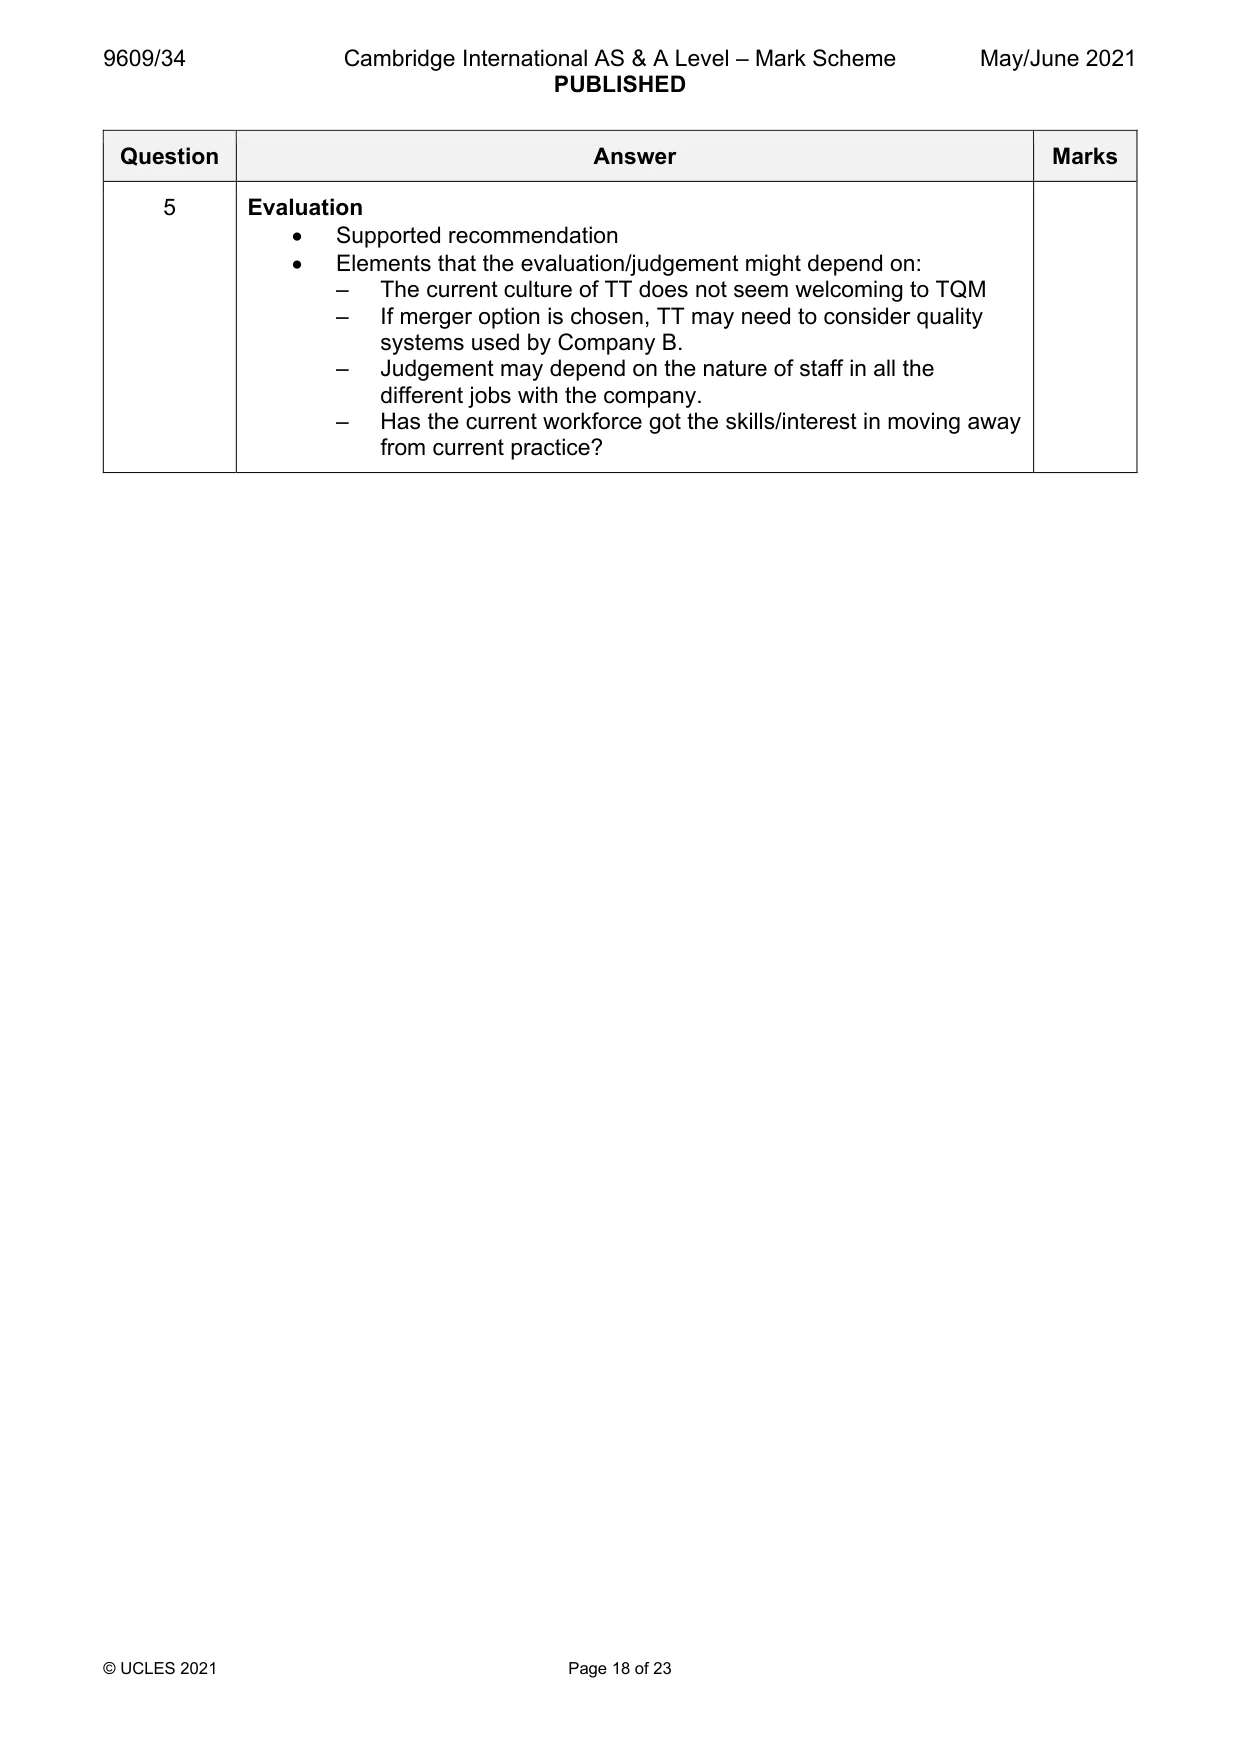
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 18 of 23 Question Answer Marks 5 Evaluation • Supported recommendation • Elements that the evaluation/judgement might depend on: – The current culture of TT does not seem welcoming to TQM – If merger option is chosen, TT may need to consider quality systems used by Company B. – Judgement may depend on the nature of staff in all the different jobs with the company. – Has the current workforce got the skills/interest in moving away from current practice?
Mark scheme, page 19
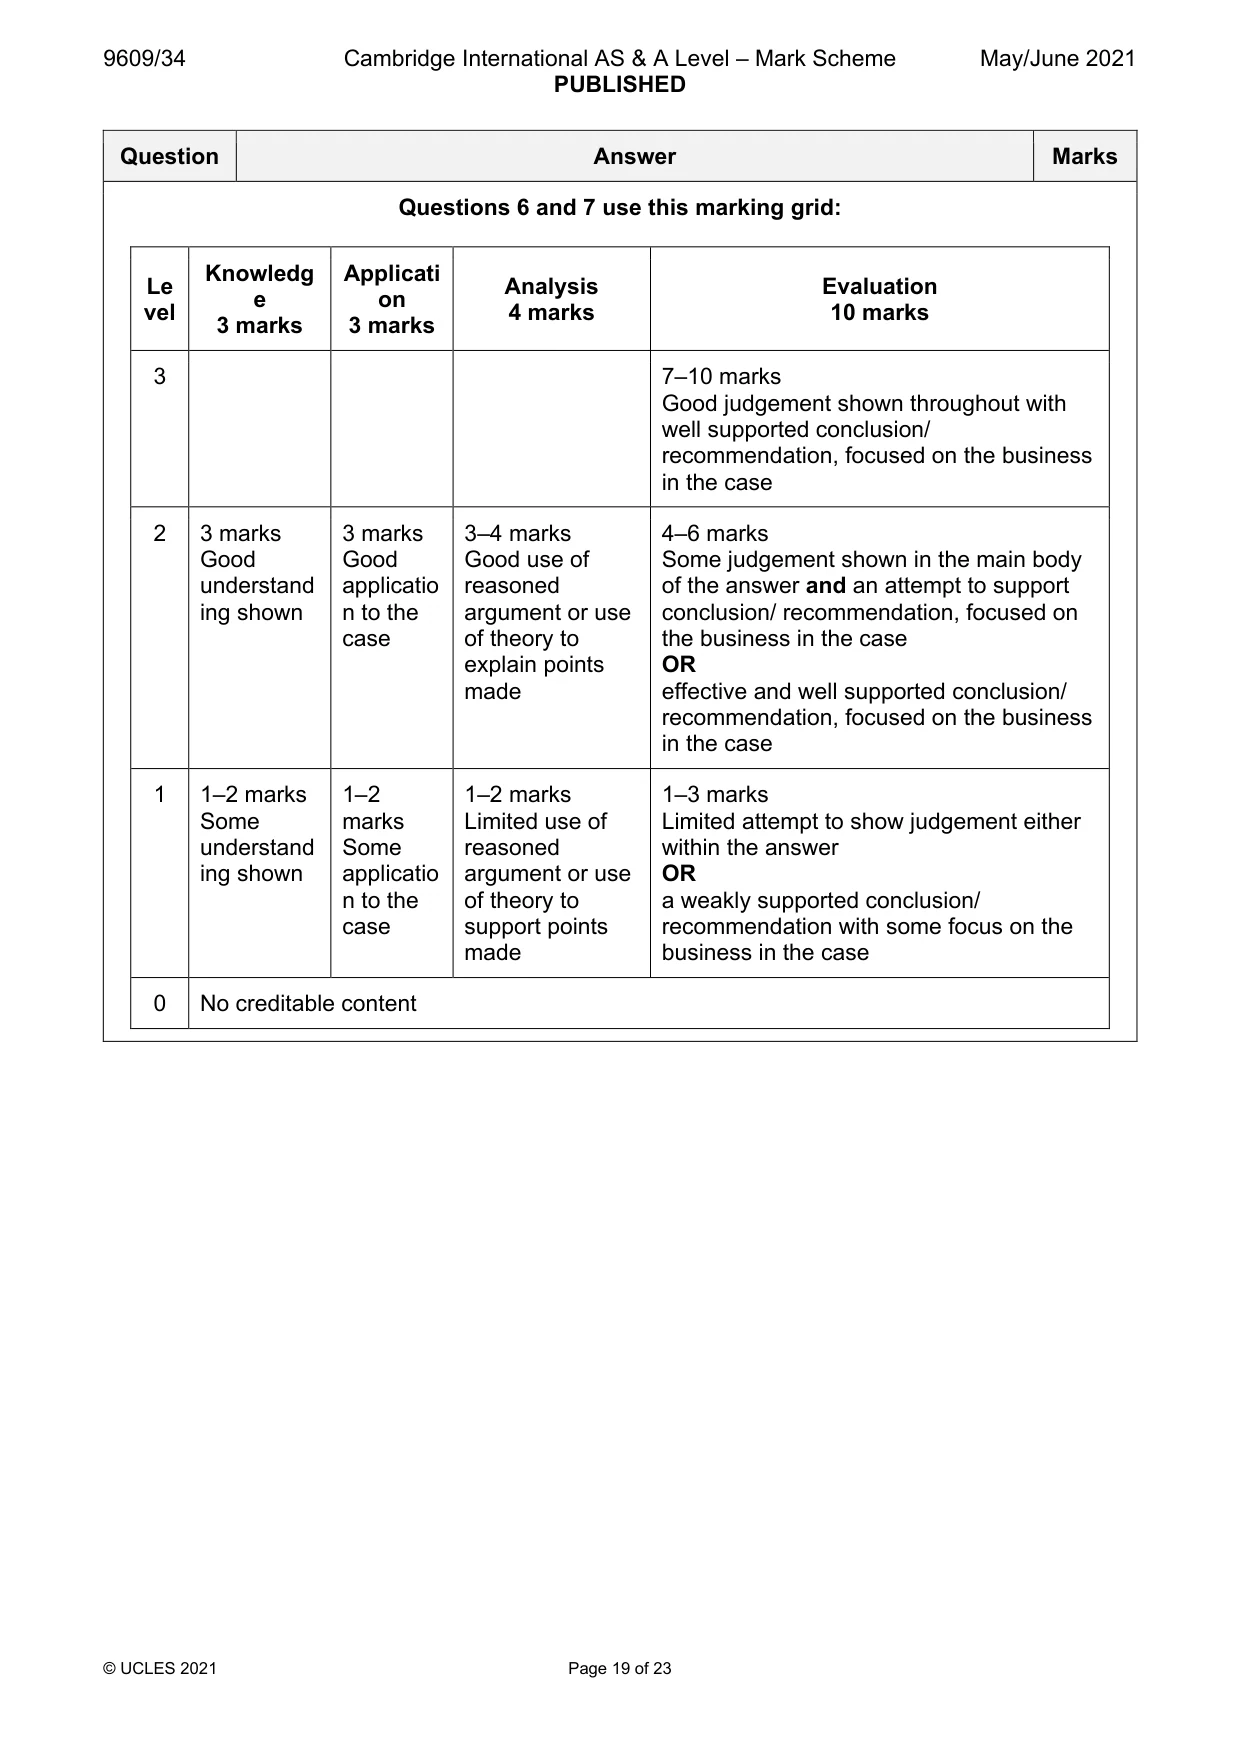
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 19 of 23 Question Answer Marks Questions 6 and 7 use this marking grid: Le vel Knowledg e 3 marks Applicati on 3 marks Analysis 4 marks Evaluation 10 marks 3 7–10 marks Good judgement shown throughout with well supported conclusion/ recommendation, focused on the business in the case 2 3 marks Good understand ing shown 3 marks Good applicatio n to the case 3–4 marks Good use of reasoned argument or use of theory to explain points made 4–6 marks Some judgement shown in the main body of the answer and an attempt to support conclusion/ recommendation, focused on the business in the case OR effective and well supported conclusion/ recommendation, focused on the business in the case 1 1–2 marks Some understand ing shown 1–2 marks Some applicatio n to the case 1–2 marks Limited use of reasoned argument or use of theory to support points made 1–3 marks Limited attempt to show judgement either within the answer OR a weakly supported conclusion/ recommendation with some focus on the business in the case 0 No creditable content
Mark scheme, page 20
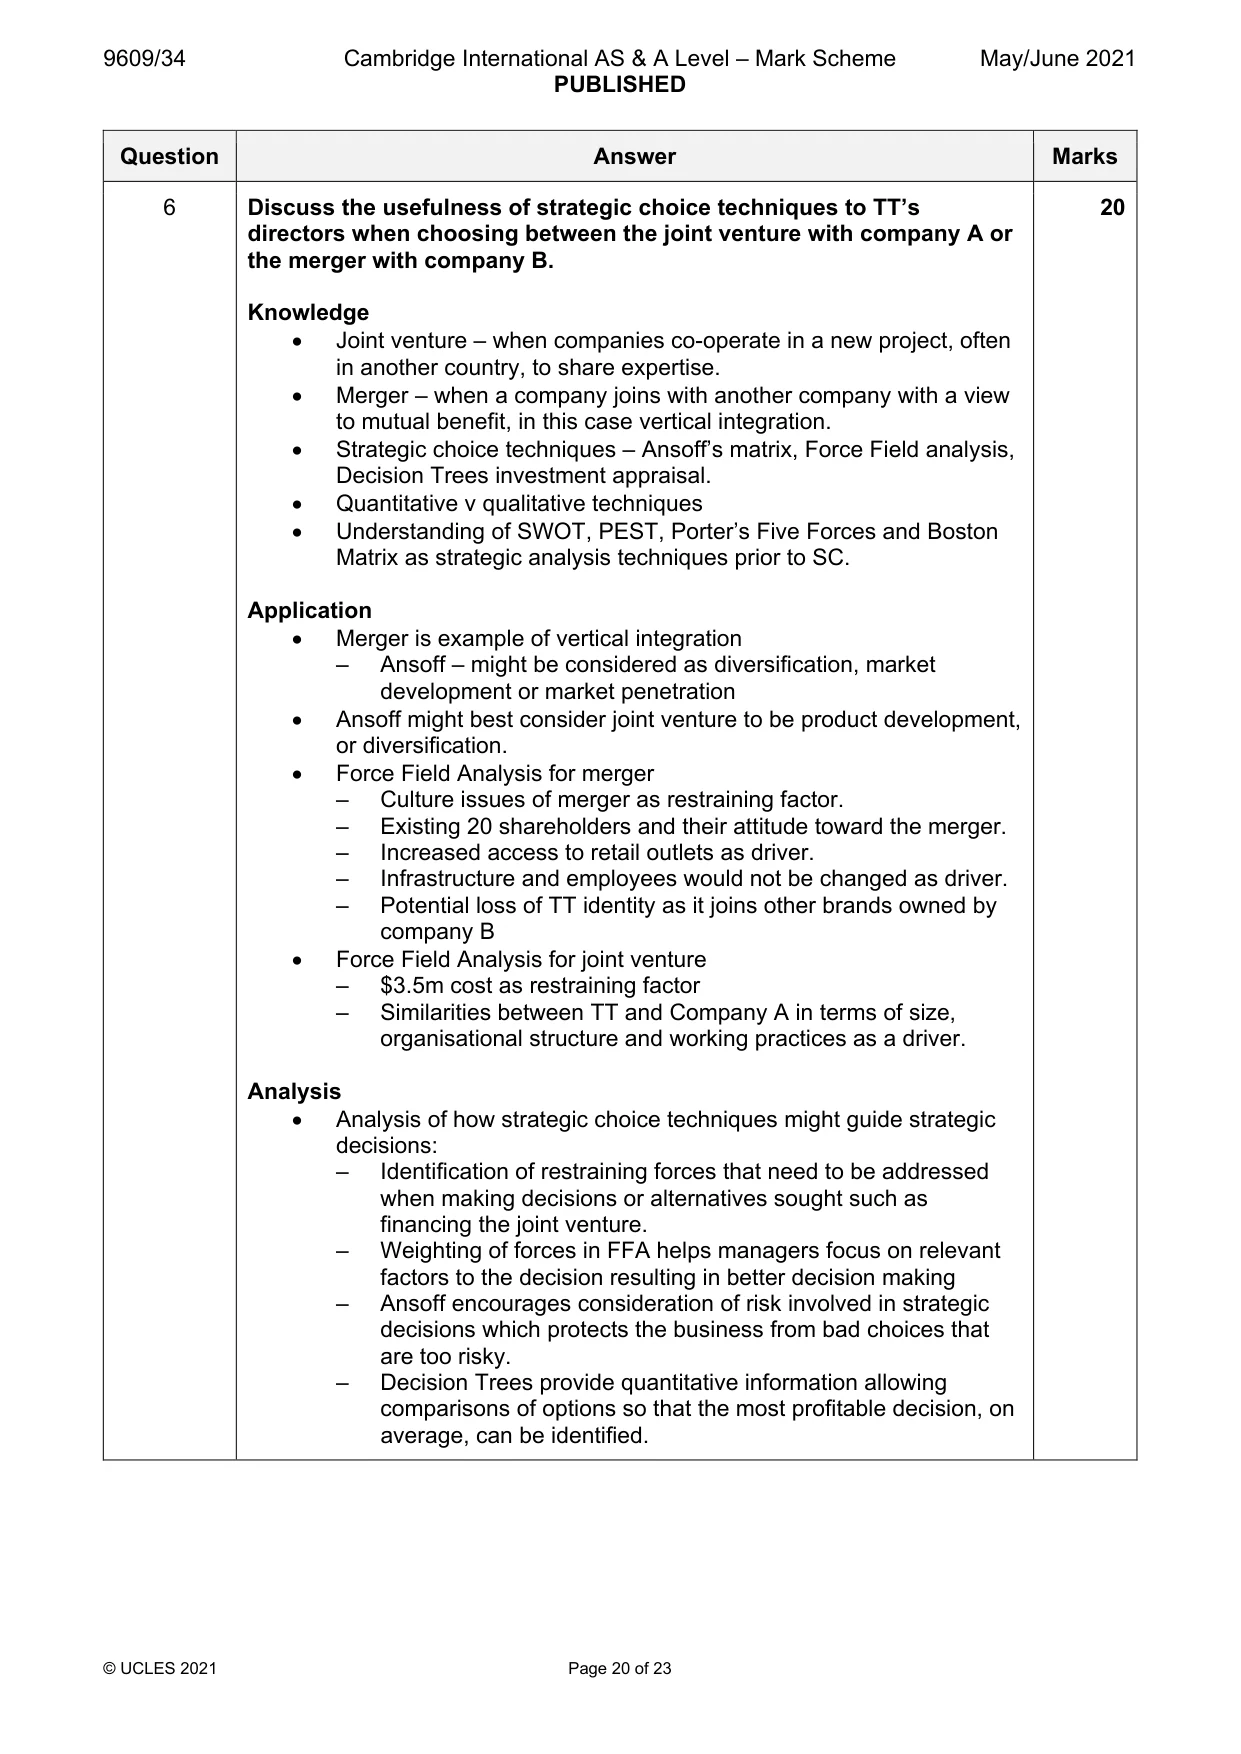
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 20 of 23 Question Answer Marks 6 Discuss the usefulness of strategic choice techniques to TT’s directors when choosing between the joint venture with company A or the merger with company B. Knowledge • Joint venture – when companies co-operate in a new project, often in another country, to share expertise. • Merger – when a company joins with another company with a view to mutual benefit, in this case vertical integration. • Strategic choice techniques – Ansoff’s matrix, Force Field analysis, Decision Trees investment appraisal. • Quantitative v qualitative techniques • Understanding of SWOT, PEST, Porter’s Five Forces and Boston Matrix as strategic analysis techniques prior to SC. Application • Merger is example of vertical integration – Ansoff – might be considered as diversification, market development or market penetration • Ansoff might best consider joint venture to be product development, or diversification. • Force Field Analysis for merger – Culture issues of merger as restraining factor. – Existing 20 shareholders and their attitude toward the merger. – Increased access to retail outlets as driver. – Infrastructure and employees would not be changed as driver. – Potential loss of TT identity as it joins other brands owned by company B • Force Field Analysis for joint venture – $3.5m cost as restraining factor – Similarities between TT and Company A in terms of size, organisational structure and working practices as a driver. Analysis • Analysis of how strategic choice techniques might guide strategic decisions: – Identification of restraining forces that need to be addressed when making decisions or alternatives sought such as financing the joint venture. – Weighting of forces in FFA helps managers focus on relevant factors to the decision resulting in better decision making – Ansoff encourages consideration of risk involved in strategic decisions which protects the business from bad choices that are too risky. – Decision Trees provide quantitative information allowing comparisons of options so that the most profitable decision, on average, can be identified. 20
Mark scheme, page 21
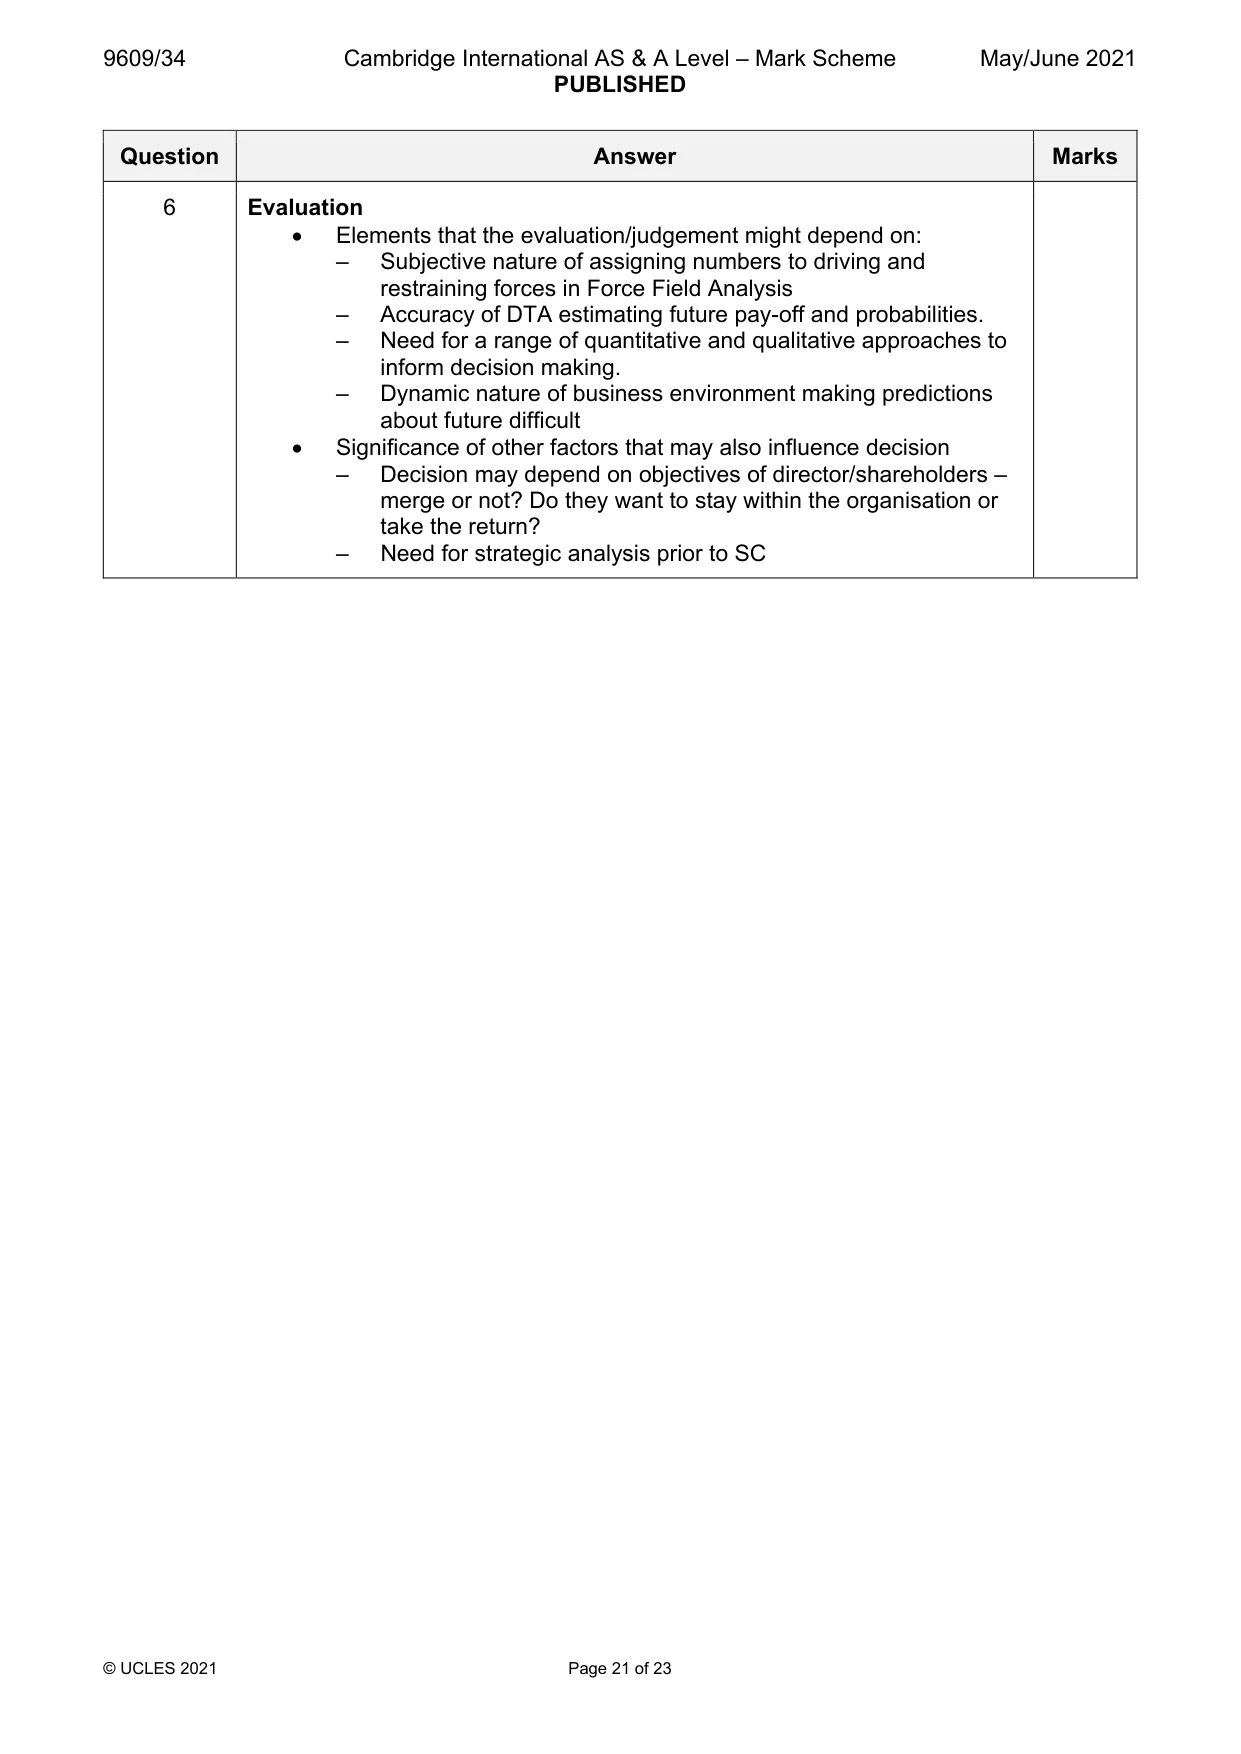
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 21 of 23 Question Answer Marks 6 Evaluation • Elements that the evaluation/judgement might depend on: – Subjective nature of assigning numbers to driving and restraining forces in Force Field Analysis – Accuracy of DTA estimating future pay-off and probabilities. – Need for a range of quantitative and qualitative approaches to inform decision making. – Dynamic nature of business environment making predictions about future difficult • Significance of other factors that may also influence decision – Decision may depend on objectives of director/shareholders – merge or not? Do they want to stay within the organisation or take the return? – Need for strategic analysis prior to SC
Mark scheme, page 22
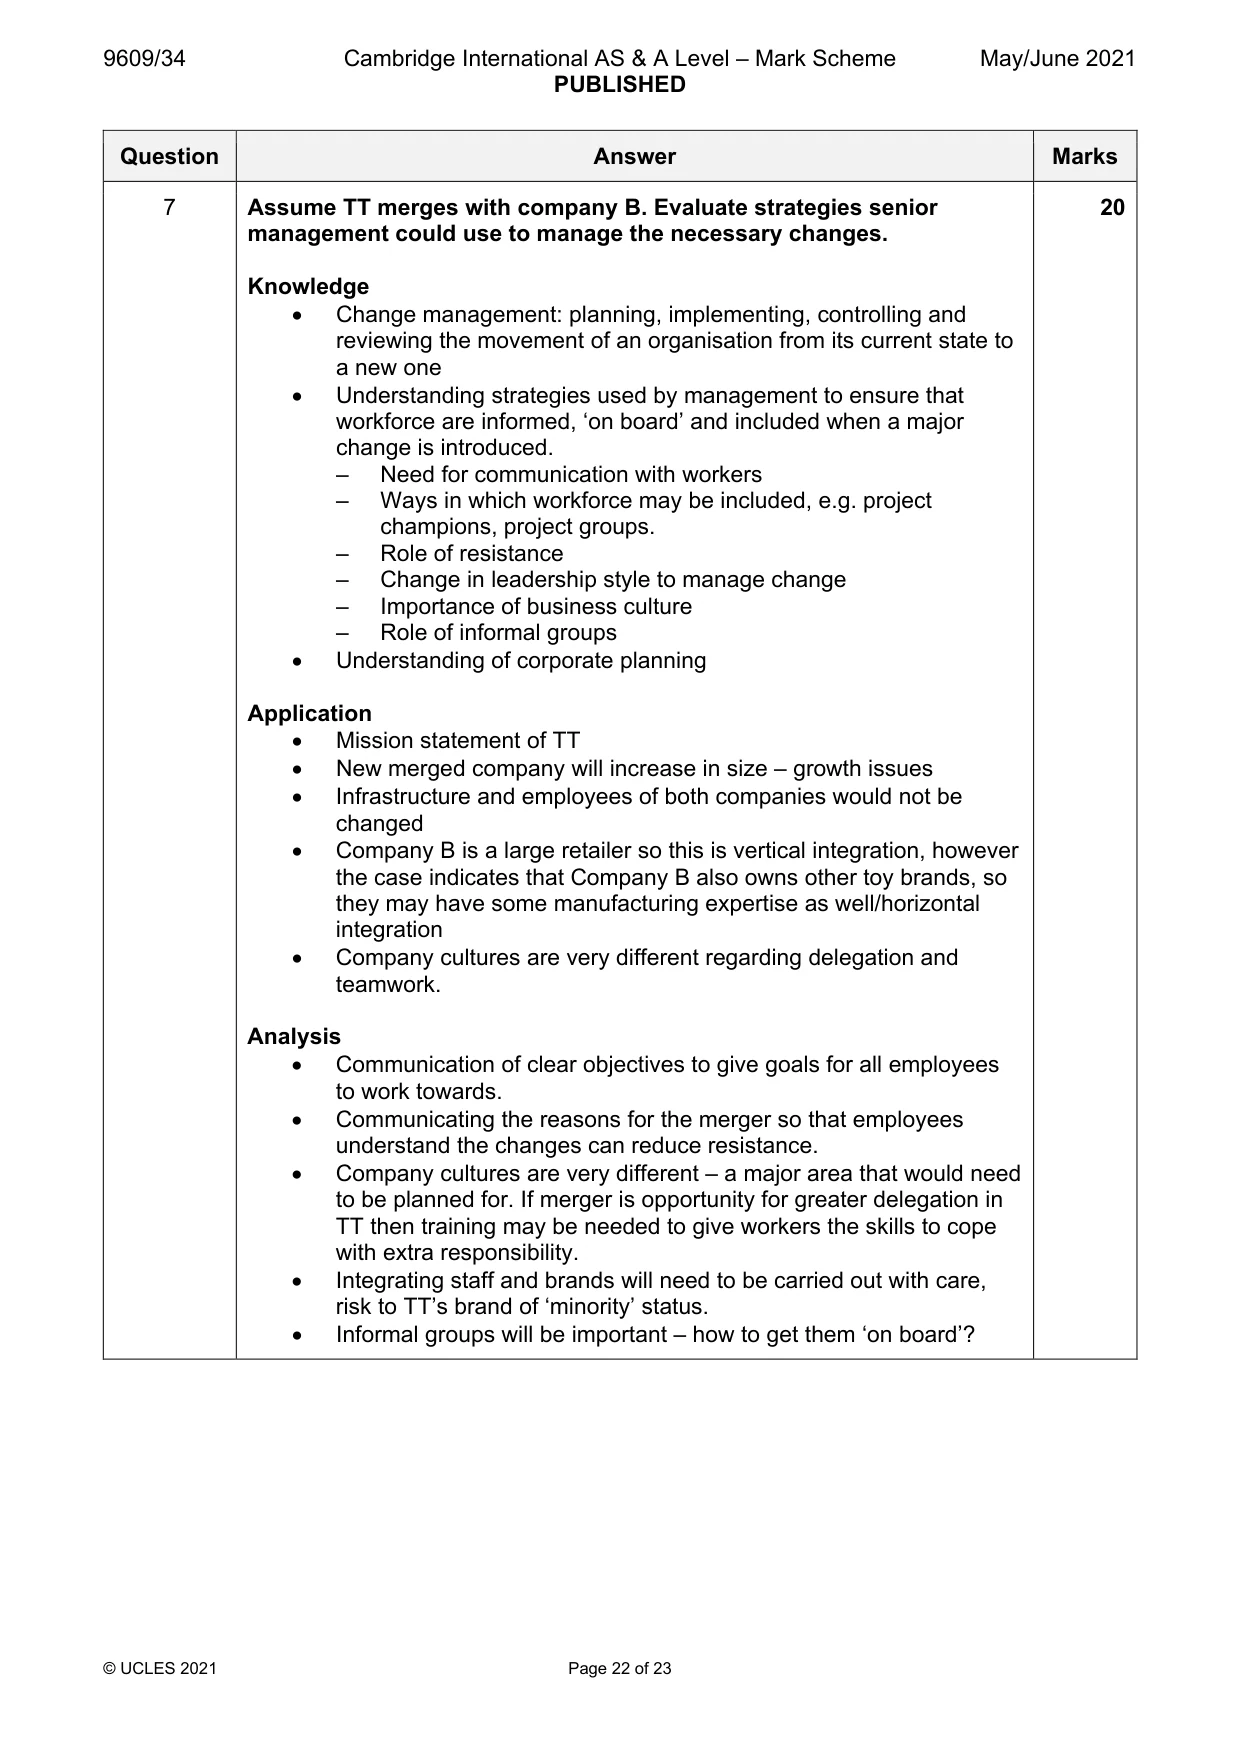
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 22 of 23 Question Answer Marks 7 Assume TT merges with company B. Evaluate strategies senior management could use to manage the necessary changes. Knowledge • Change management: planning, implementing, controlling and reviewing the movement of an organisation from its current state to a new one • Understanding strategies used by management to ensure that workforce are informed, ‘on board’ and included when a major change is introduced. – Need for communication with workers – Ways in which workforce may be included, e.g. project champions, project groups. – Role of resistance – Change in leadership style to manage change – Importance of business culture – Role of informal groups • Understanding of corporate planning Application • Mission statement of TT • New merged company will increase in size – growth issues • Infrastructure and employees of both companies would not be changed • Company B is a large retailer so this is vertical integration, however the case indicates that Company B also owns other toy brands, so they may have some manufacturing expertise as well/horizontal integration • Company cultures are very different regarding delegation and teamwork. Analysis • Communication of clear objectives to give goals for all employees to work towards. • Communicating the reasons for the merger so that employees understand the changes can reduce resistance. • Company cultures are very different – a major area that would need to be planned for. If merger is opportunity for greater delegation in TT then training may be needed to give workers the skills to cope with extra responsibility. • Integrating staff and brands will need to be carried out with care, risk to TT’s brand of ‘minority’ status. • Informal groups will be important – how to get them ‘on board’? 20
Mark scheme, page 23
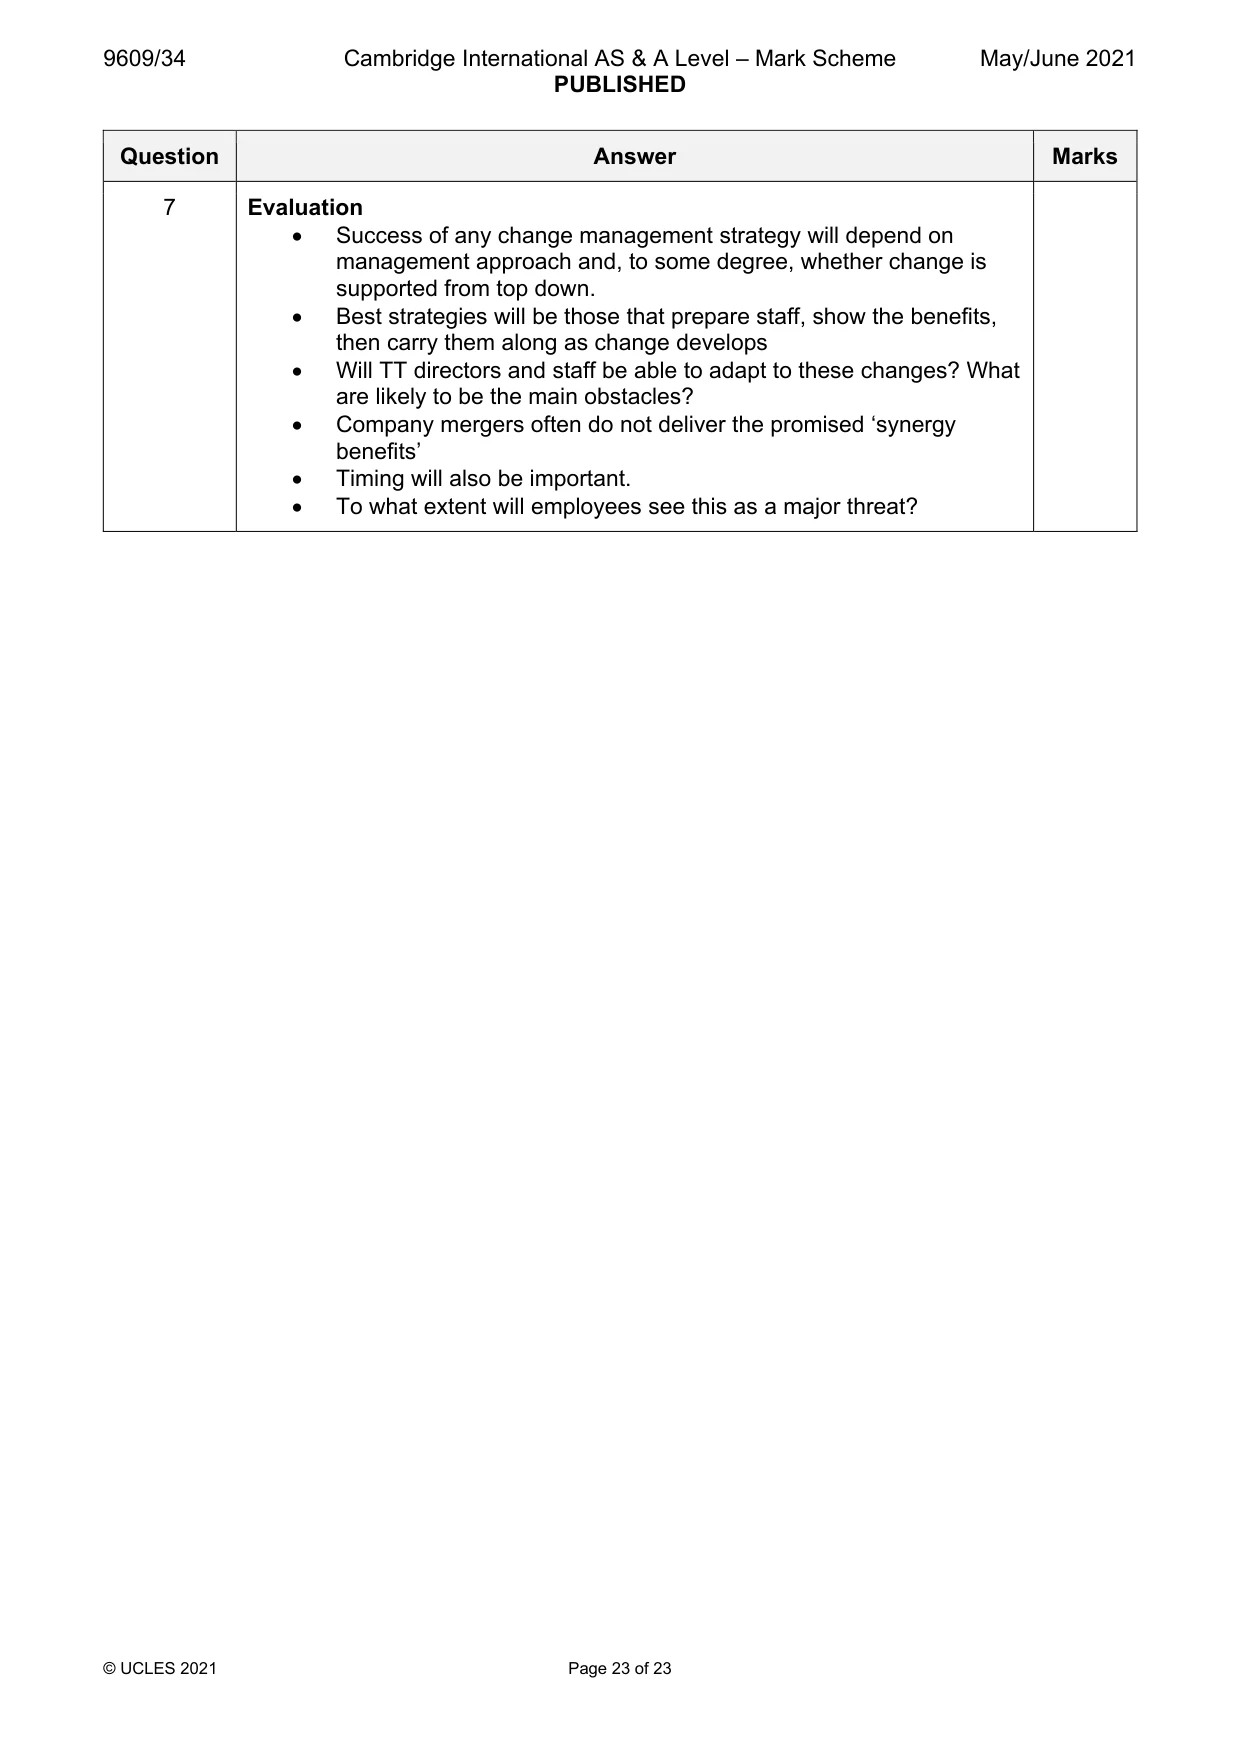
9609/34 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2021 © UCLES 2021 Page 23 of 23 Question Answer Marks 7 Evaluation • Success of any change management strategy will depend on management approach and, to some degree, whether change is supported from top down. • Best strategies will be those that prepare staff, show the benefits, then carry them along as change develops • Will TT directors and staff be able to adapt to these changes? What are likely to be the main obstacles? • Company mergers often do not deliver the promised ‘synergy benefits’ • Timing will also be important. • To what extent will employees see this as a major threat?
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 3 · Variant 4. A higher threshold means an easier paper — the bar moves with how the cohort did.