Cambridge IGCSE Business Studies (9-1) 0986 — 2024 May/June Paper 1 · Variant 1
0986/11/M/J/24 · 80 marks · ≈90 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme26 pages
Answers below. Sit the paper first if you are practising.
Paper as text
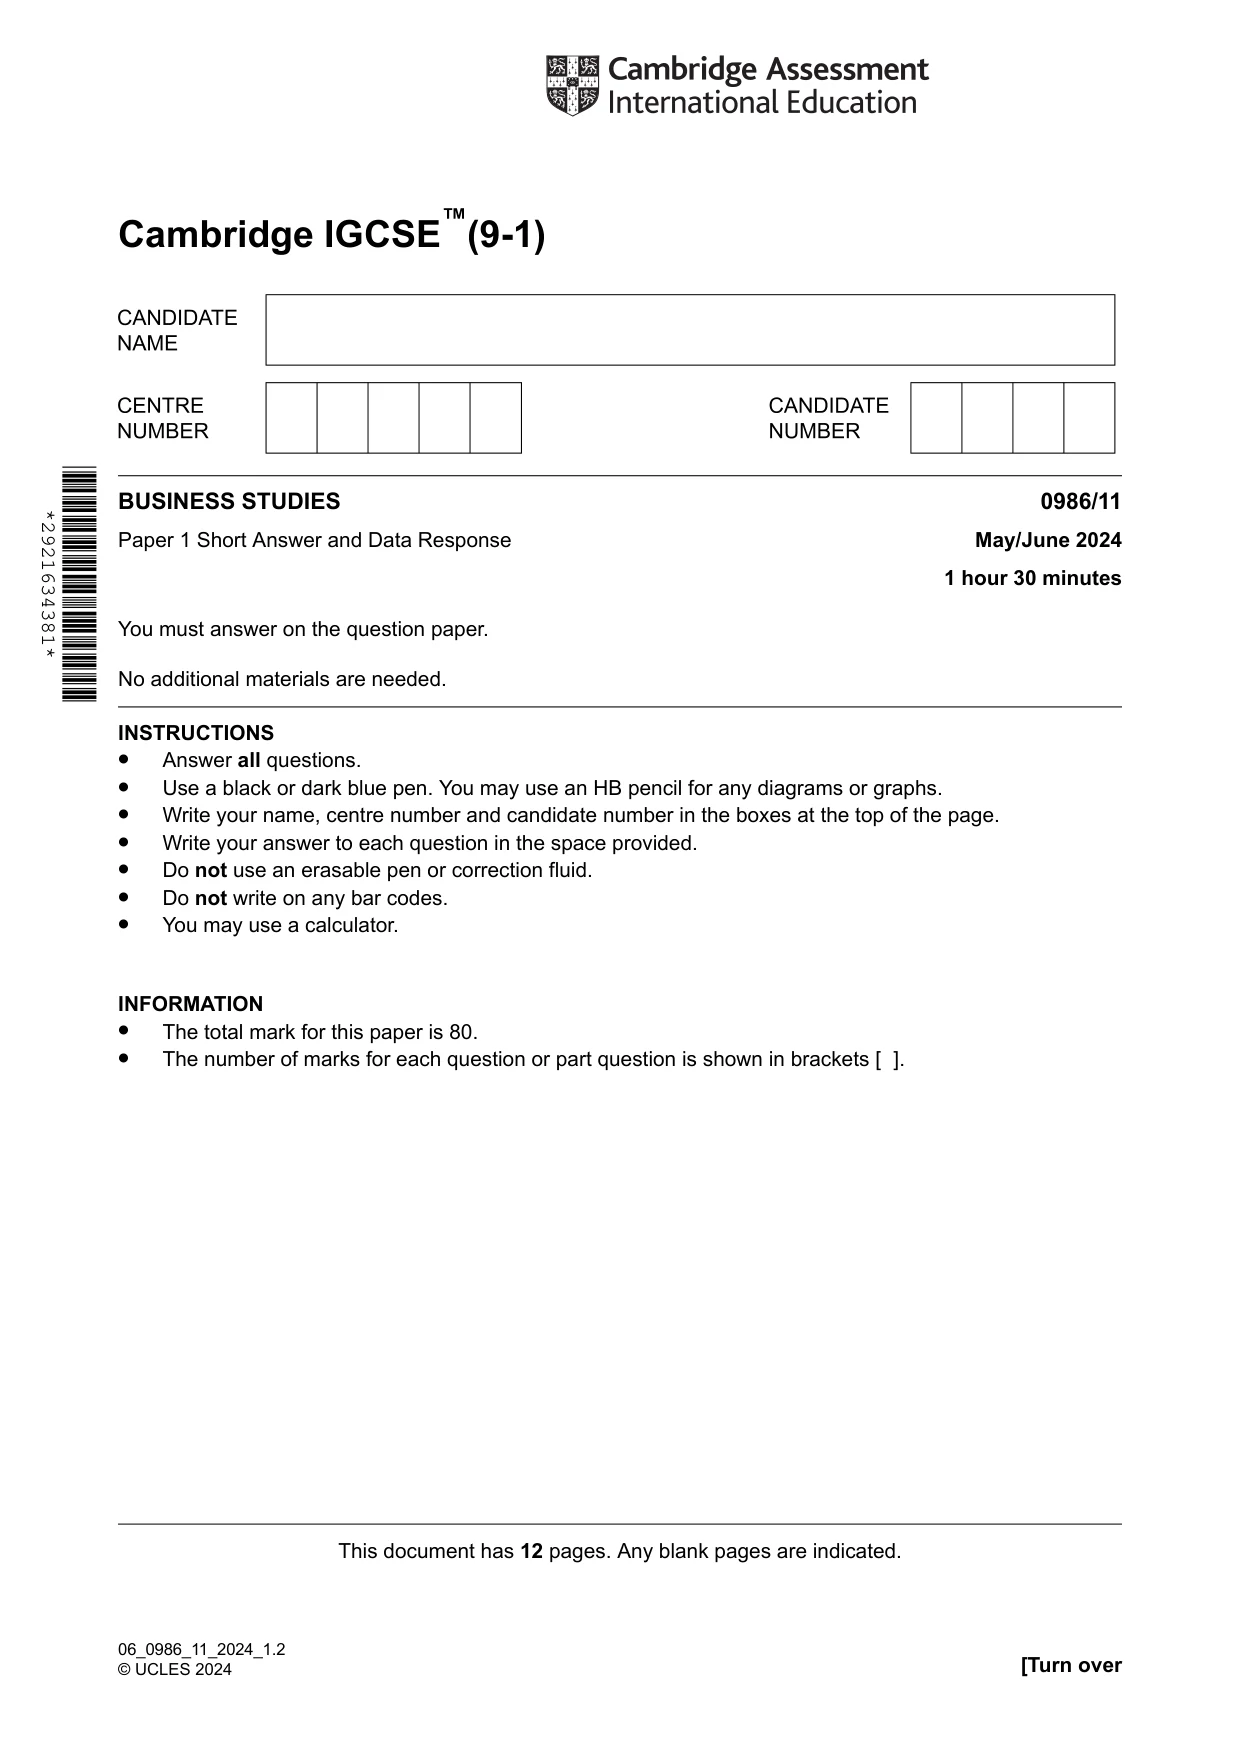
Question paper, page 1
Cambridge IGCSE™(9-1) 0986/11 May/June 2024 1 hour 30 minutes BUSINESS STUDIES Paper 1 Short Answer and Data Response You must answer on the question paper. No additional materials are needed. INSTRUCTIONS • Answer all questions. • Use a black or dark blue pen. You may use an HB pencil for any diagrams or graphs. • Write your name, centre number and candidate number in the boxes at the top of the page. • Write your answer to each question in the space provided. • Do not use an erasable pen or correction fluid. • Do not write on any bar codes. • You may use a calculator. INFORMATION • The total mark for this paper is 80. • The number of marks for each question or part question is shown in brackets [ ]. This document has 12 pages. Any blank pages are indicated. [Turn over 06_0986_11_2024_1.2 © UCLES 2024 *2921634381*
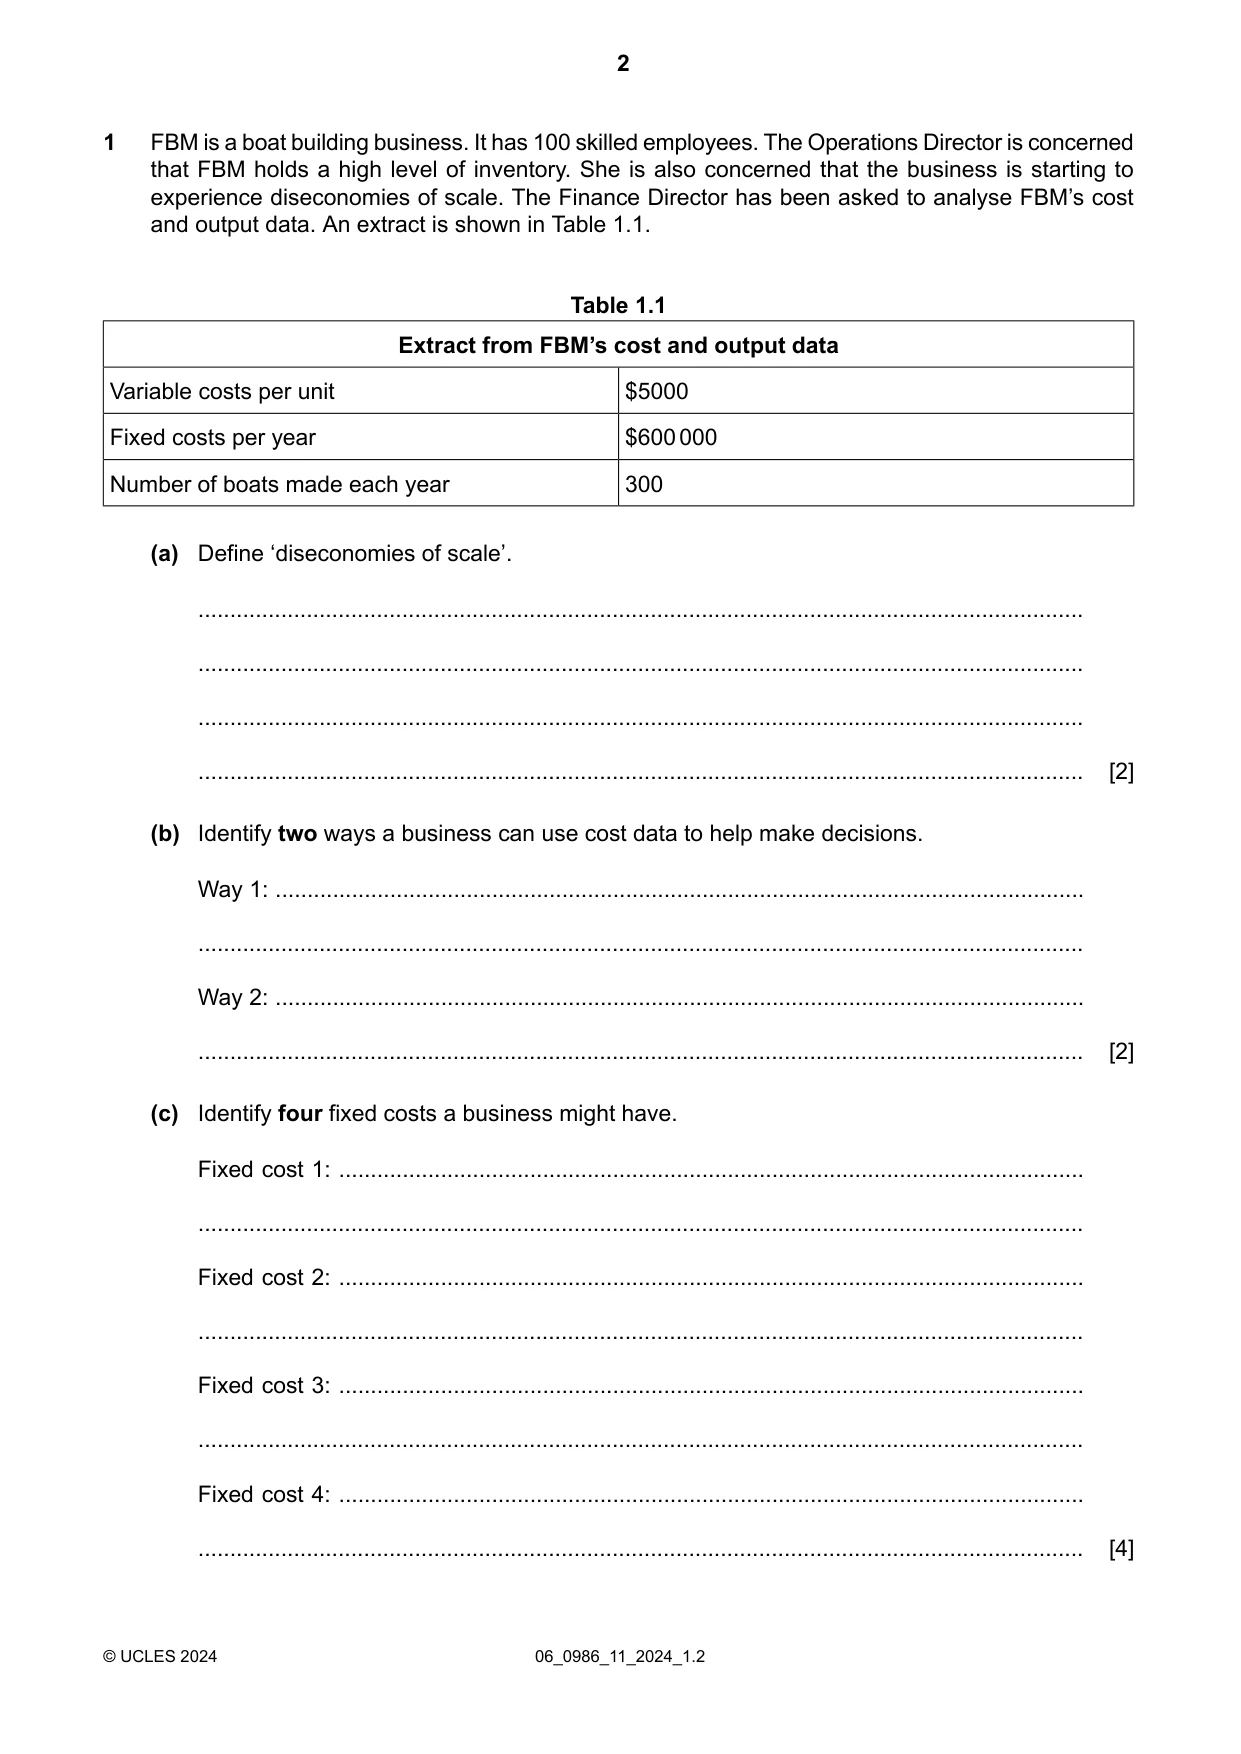
Question paper, page 2
FBM is a boat building business. It has 100 skilled employees. The Operations Director is concerned that FBM holds a high level of inventory. She is also concerned that the business is starting to 1 experience diseconomies of scale. The Finance Director has been asked to analyse FBM’s cost and output data. An extract is shown in Table 1.1. Table 1.1 Extract from FBM’s cost and output data $5000 Variable costs per unit $600000 Fixed costs per year 300 Number of boats made each year Define ‘diseconomies of scale’. (a) … … … … [2] Identify two ways a business can use cost data to help make decisions. (b) Way 1: … … Way 2: … … [2] Identify four fixed costs a business might have. (c) Fixed cost 1: … … Fixed cost 2: … … Fixed cost 3: … … Fixed cost 4: … … [4] 06_0986_11_2024_1.2 © UCLES 2024 2
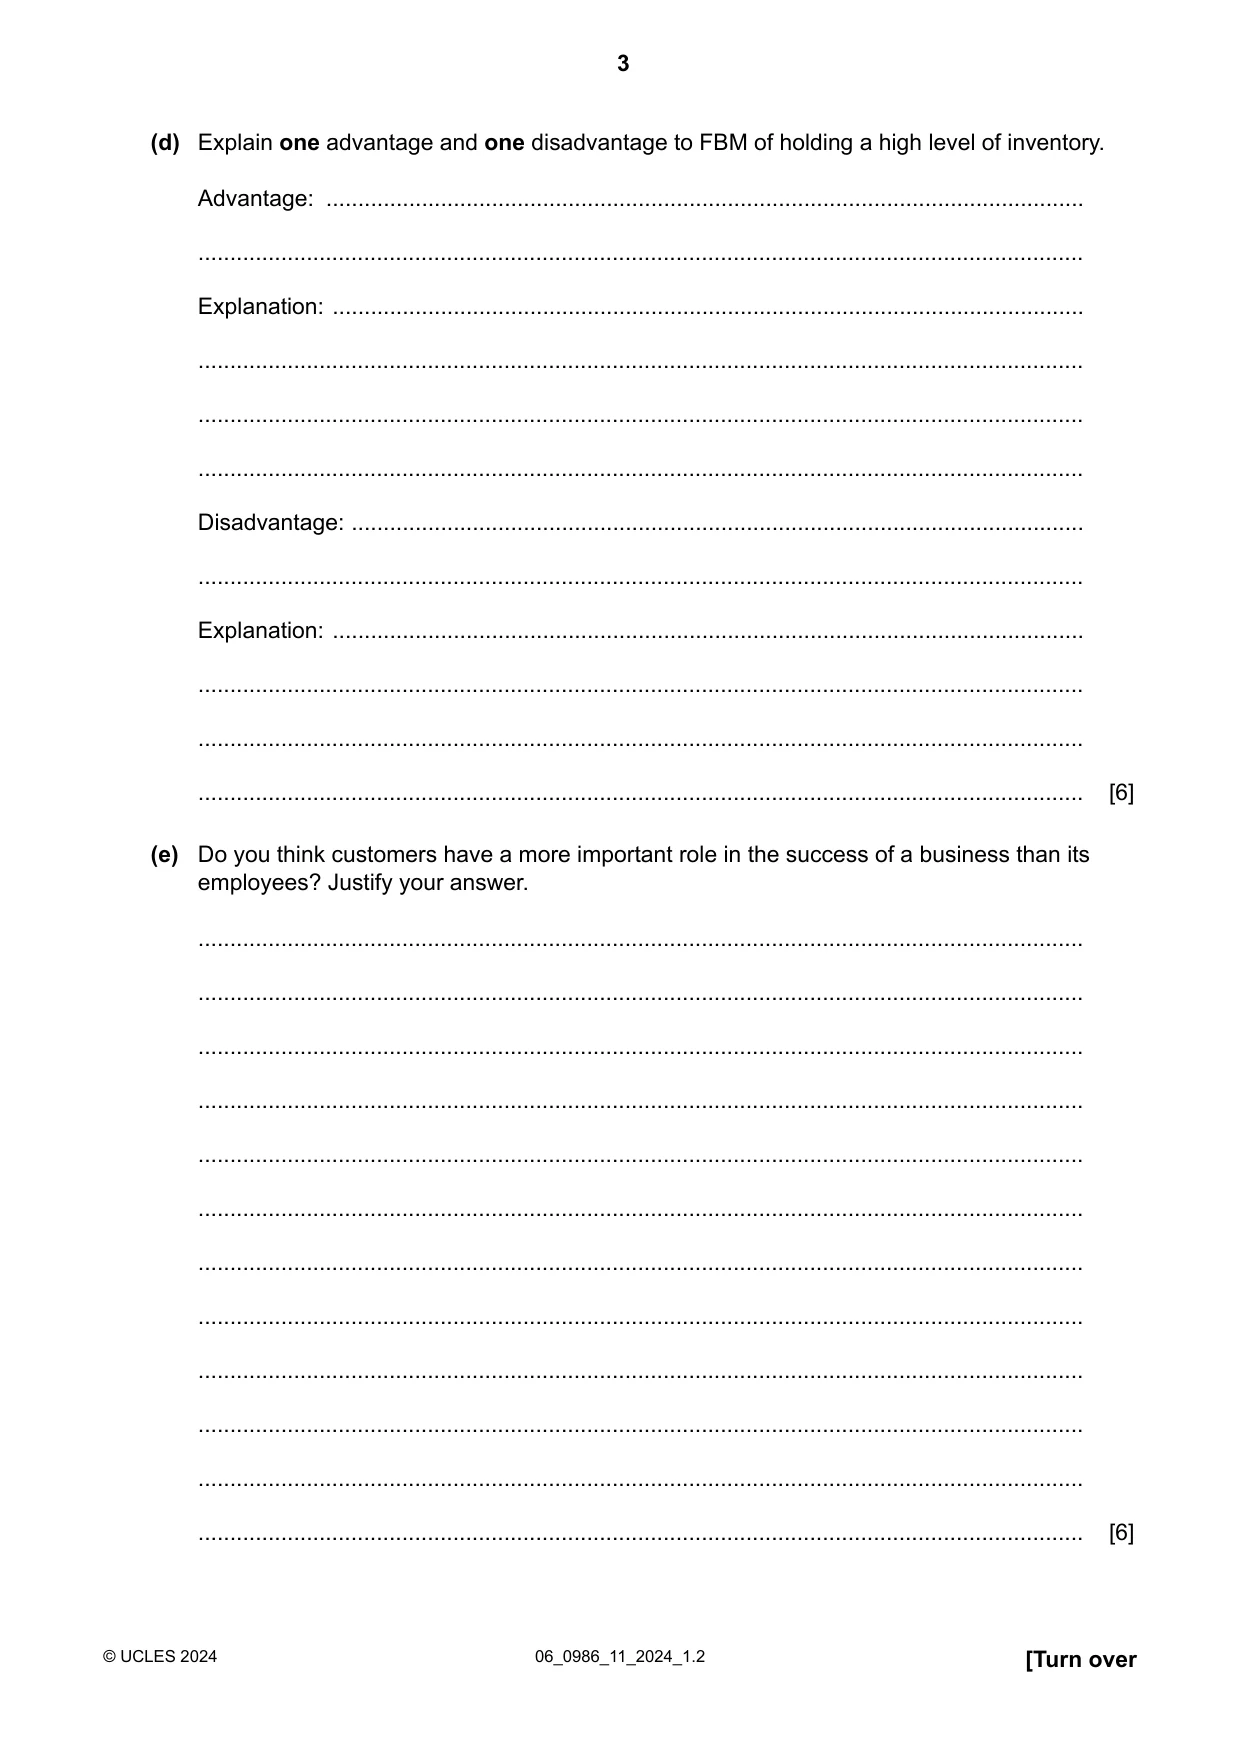
Question paper, page 3
Explain one advantage and one disadvantage to FBM of holding a high level of inventory. (d) Advantage: … … Explanation: … … … … Disadvantage: … … Explanation: … … … … [6] Do you think customers have a more important role in the success of a business than its employees? Justify your answer. (e) … … … … … … … … … … … … [6] [Turn over 06_0986_11_2024_1.2 © UCLES 2024 3
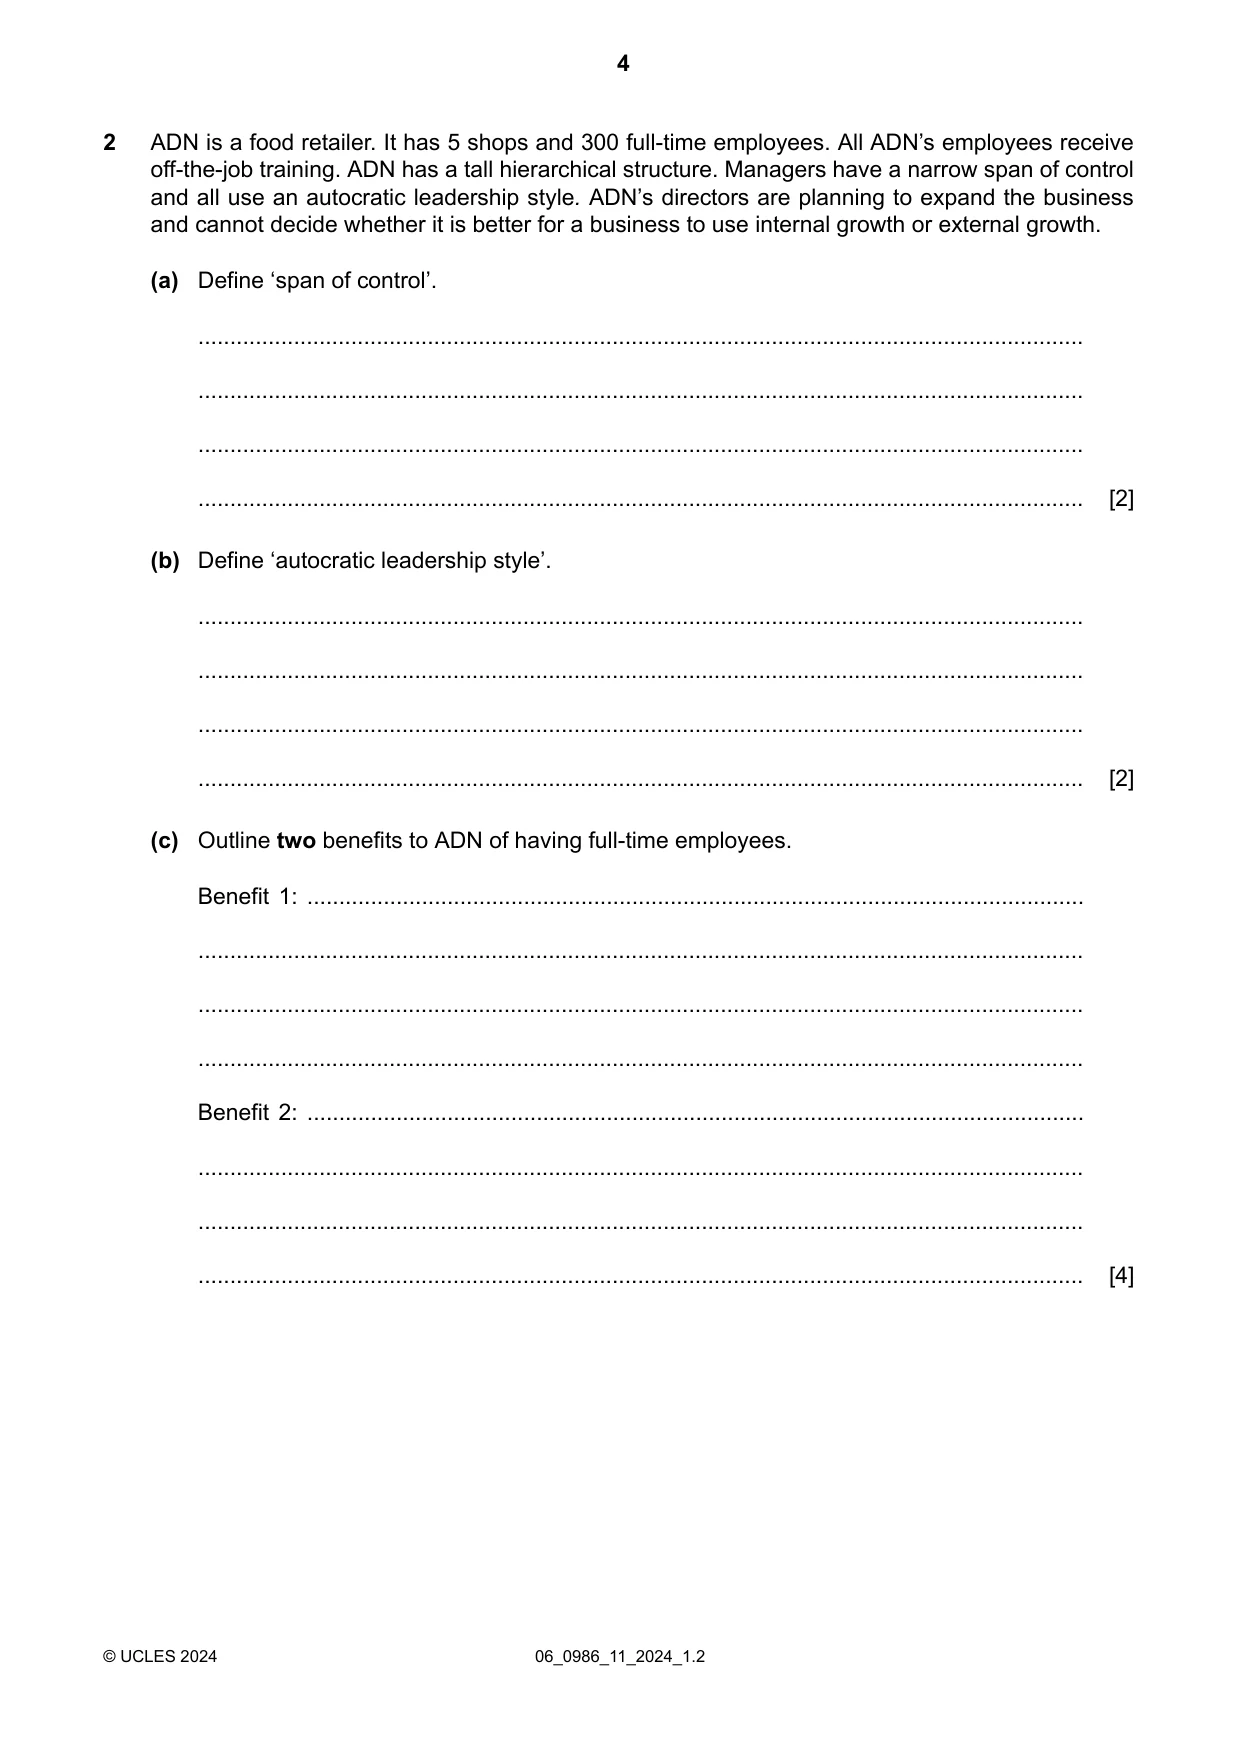
Question paper, page 4
ADN is a food retailer. It has 5 shops and 300 full-time employees. All ADN’s employees receive off-the-job training. ADN has a tall hierarchical structure. Managers have a narrow span of control 2 and all use an autocratic leadership style. ADN’s directors are planning to expand the business and cannot decide whether it is better for a business to use internal growth or external growth. Define ‘span of control’. (a) … … … … [2] Define ‘autocratic leadership style’. (b) … … … … [2] Outline two benefits to ADN of having full-time employees. (c) Benefit 1: … … … … Benefit 2: … … … … [4] 06_0986_11_2024_1.2 © UCLES 2024 4
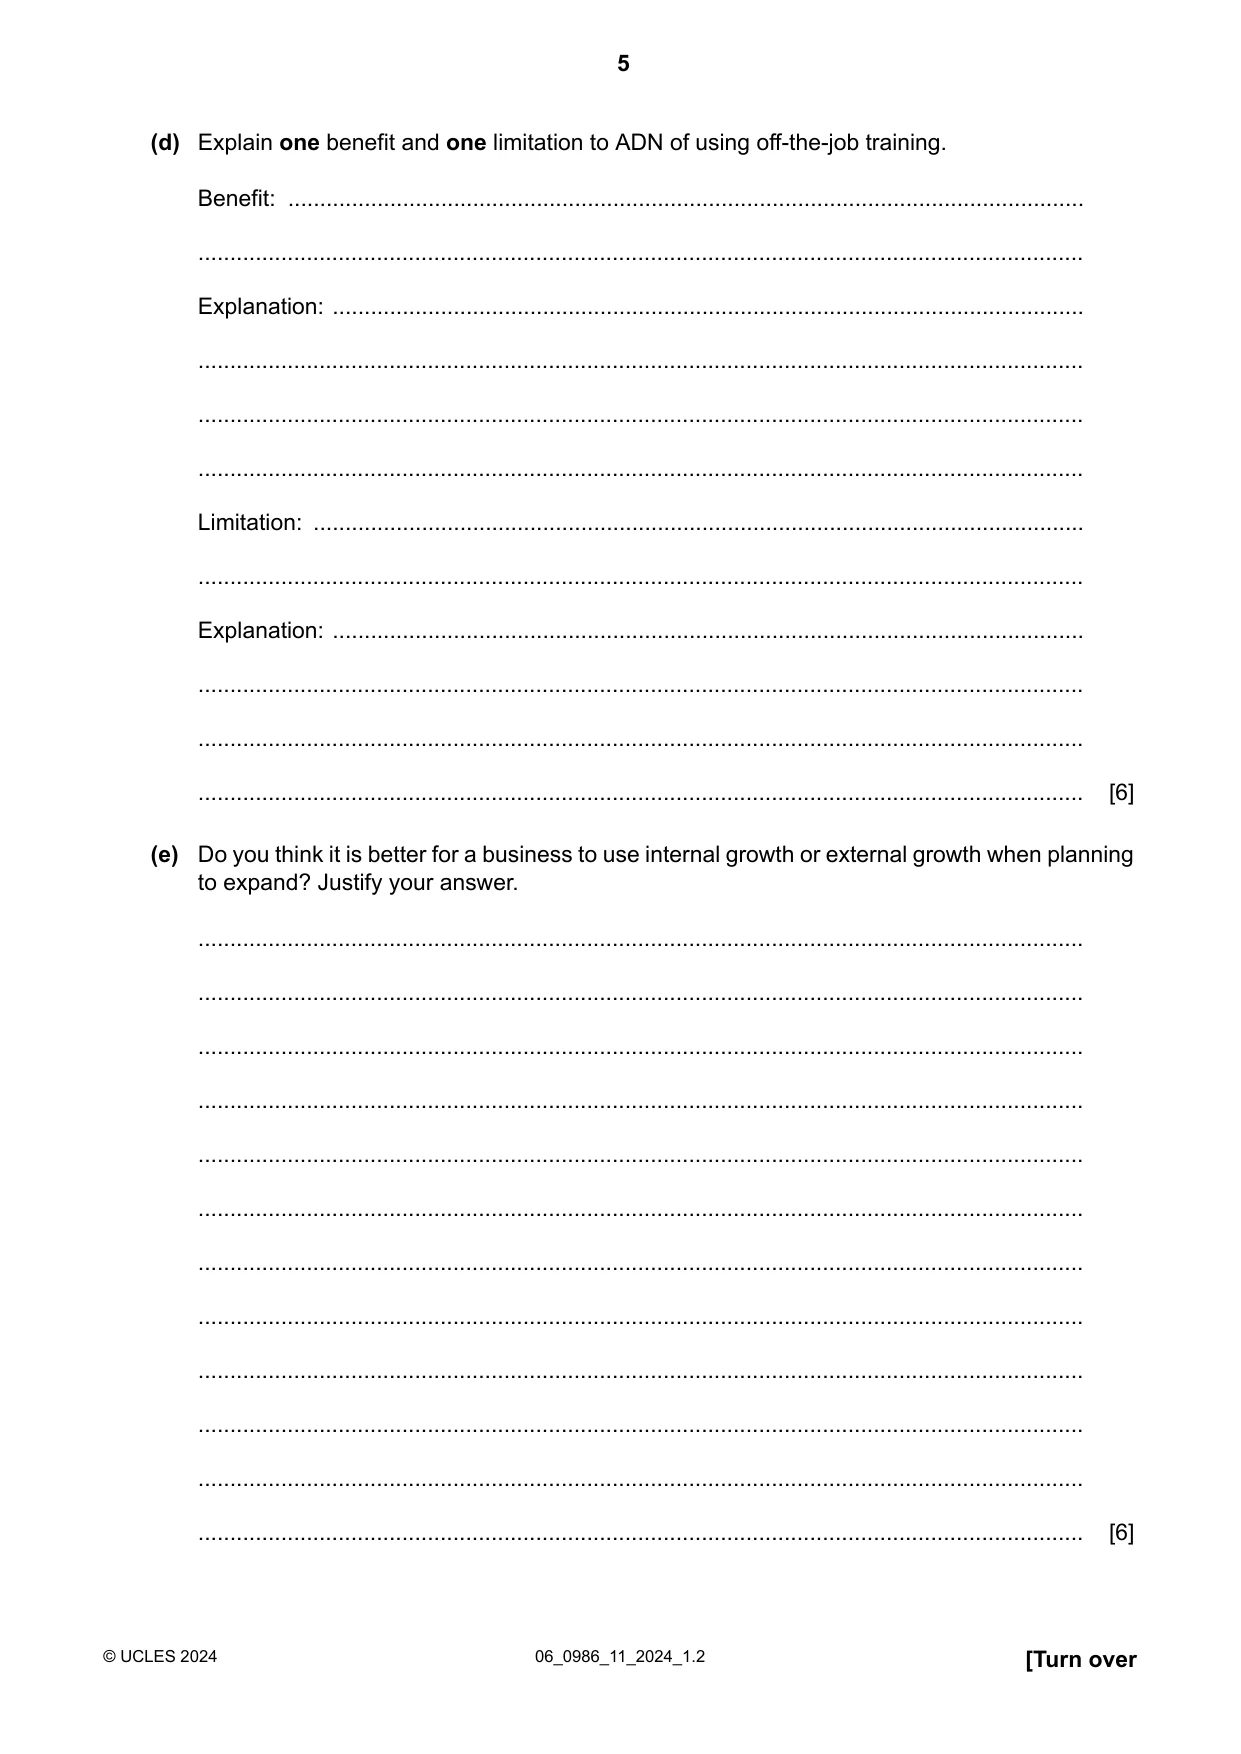
Question paper, page 5
Explain one benefit and one limitation to ADN of using off-the-job training. (d) Benefit: … … Explanation: … … … … Limitation: … … Explanation: … … … … [6] Do you think it is better for a business to use internal growth or external growth when planning to expand? Justify your answer. (e) … … … … … … … … … … … … [6] [Turn over 06_0986_11_2024_1.2 © UCLES 2024 5
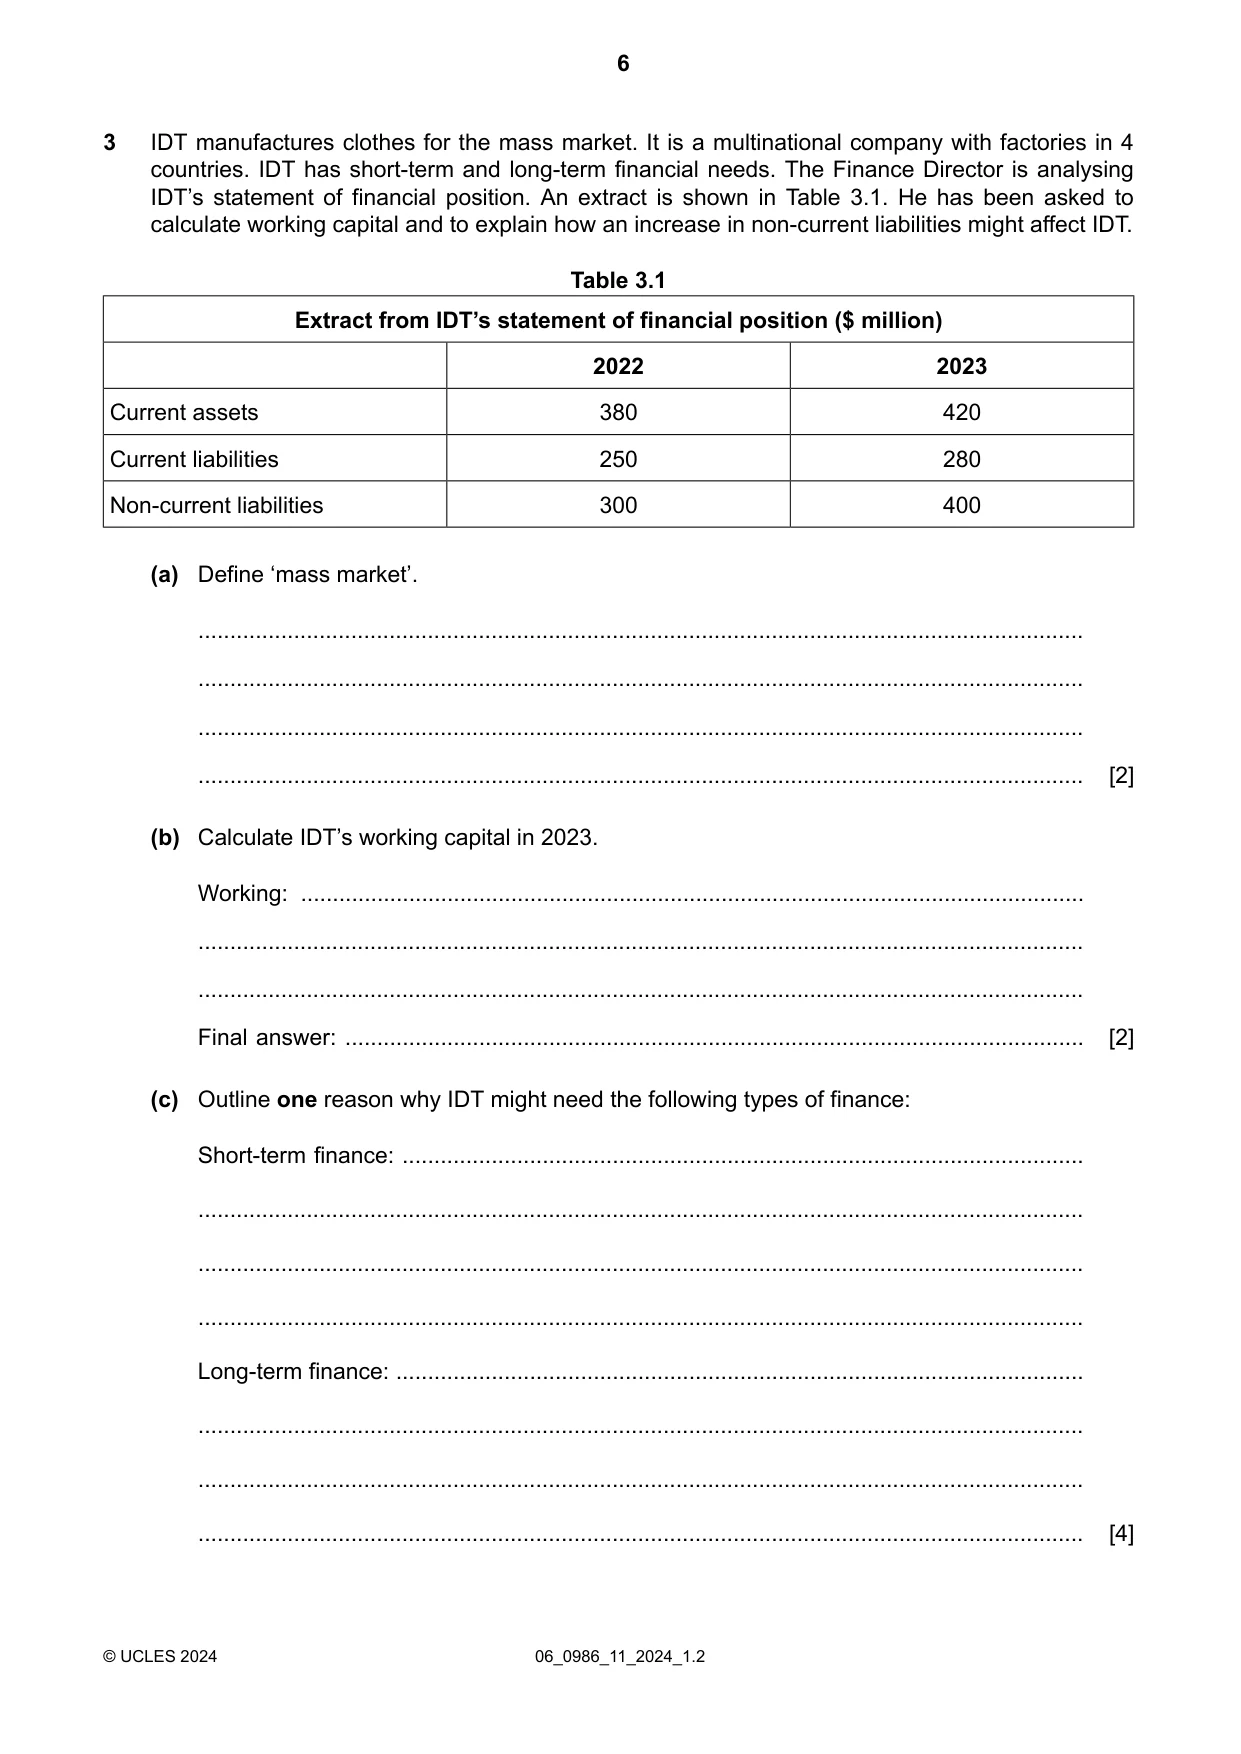
Question paper, page 6
IDT manufactures clothes for the mass market. It is a multinational company with factories in 4 countries. IDT has short-term and long-term financial needs. The Finance Director is analysing 3 IDT’s statement of financial position. An extract is shown in Table 3.1. He has been asked to calculate working capital and to explain how an increase in non-current liabilities might affect IDT. Table 3.1 Extract from IDT’s statement of financial position ($ million) 2023 2022 420 380 Current assets 280 250 Current liabilities 400 300 Non-current liabilities Define ‘mass market’. (a) … … … … [2] Calculate IDT’s working capital in 2023. (b) Working: … … … Final answer: … [2] Outline one reason why IDT might need the following types of finance: (c) Short-term finance: … … … … Long-term finance: … … … … [4] 06_0986_11_2024_1.2 © UCLES 2024 6
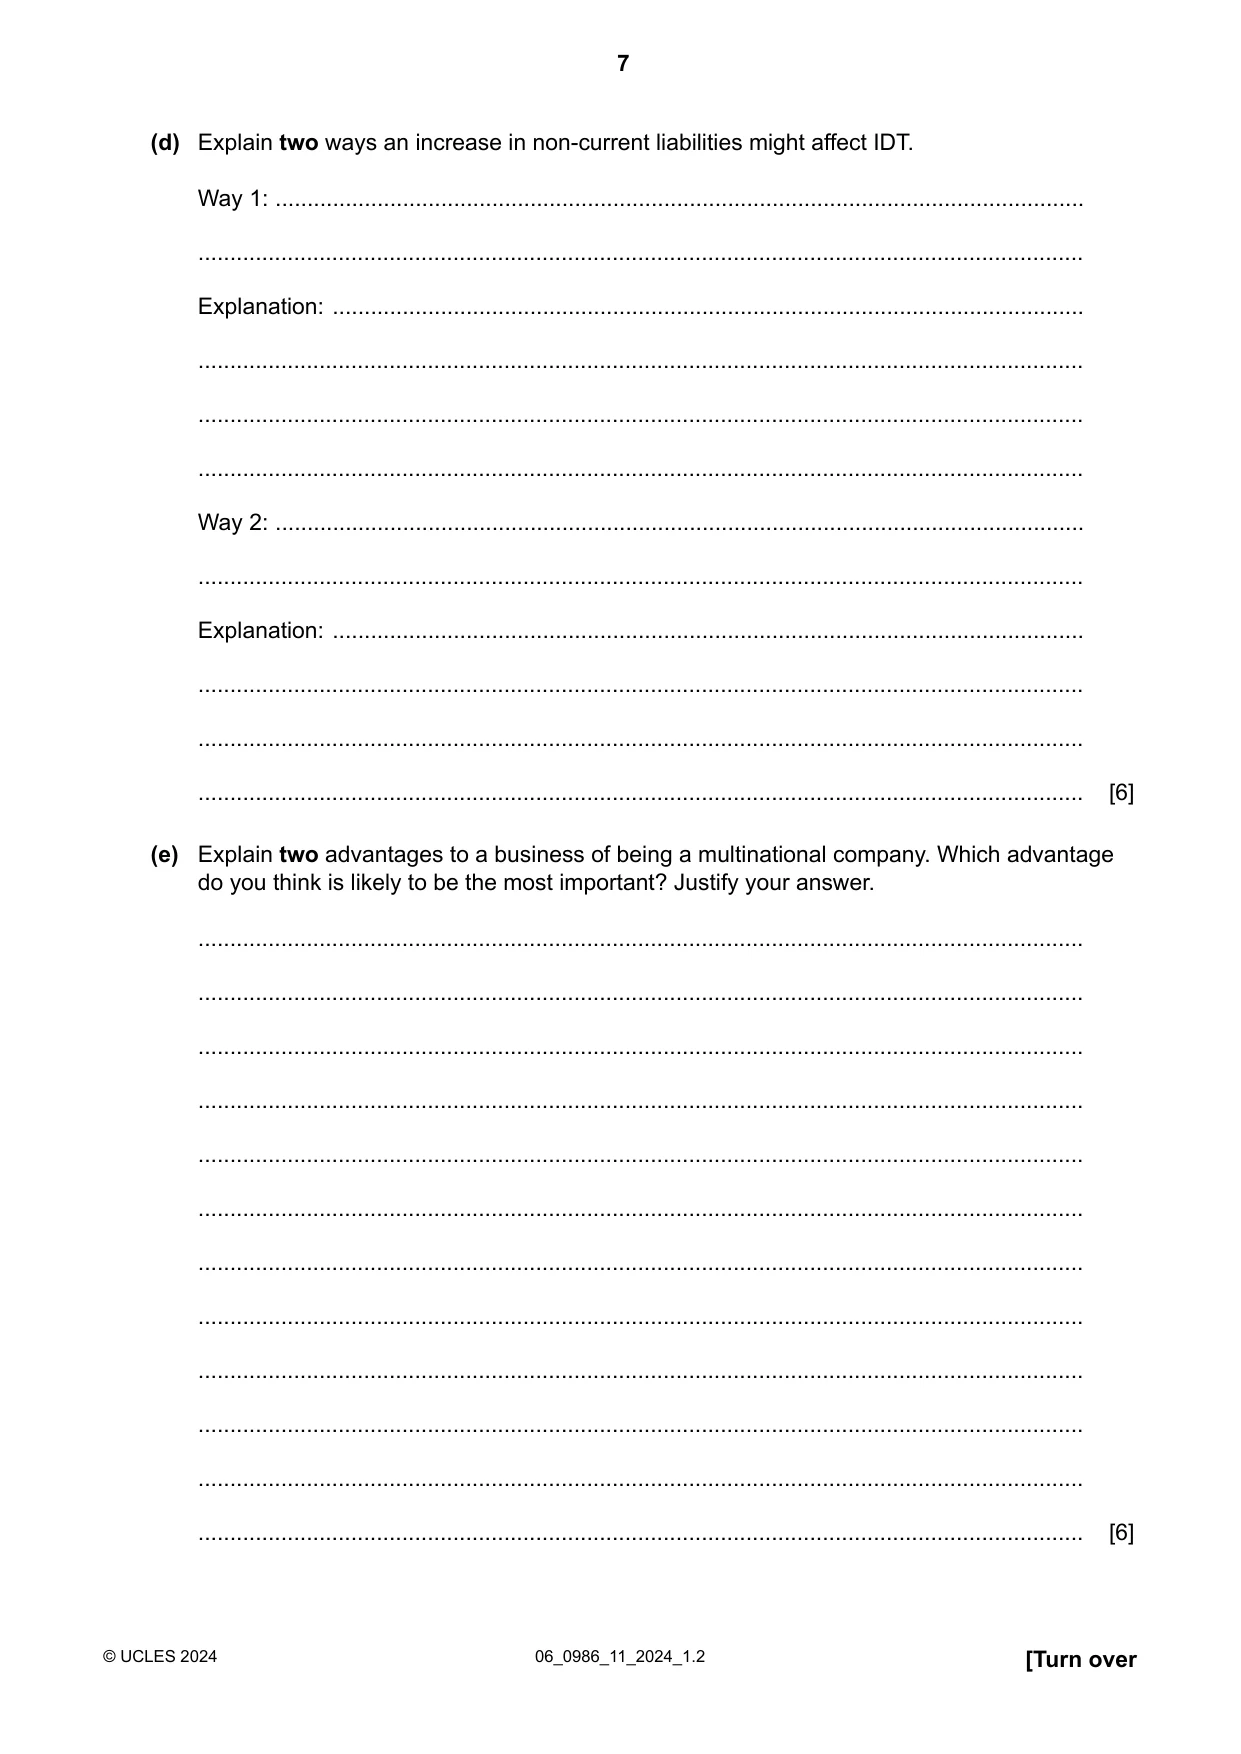
Question paper, page 7
Explain two ways an increase in non-current liabilities might affect IDT. (d) Way 1: … … Explanation: … … … … Way 2: … … Explanation: … … … … [6] Explain two advantages to a business of being a multinational company. Which advantage do you think is likely to be the most important? Justify your answer. (e) … … … … … … … … … … … … [6] [Turn over 06_0986_11_2024_1.2 © UCLES 2024 7
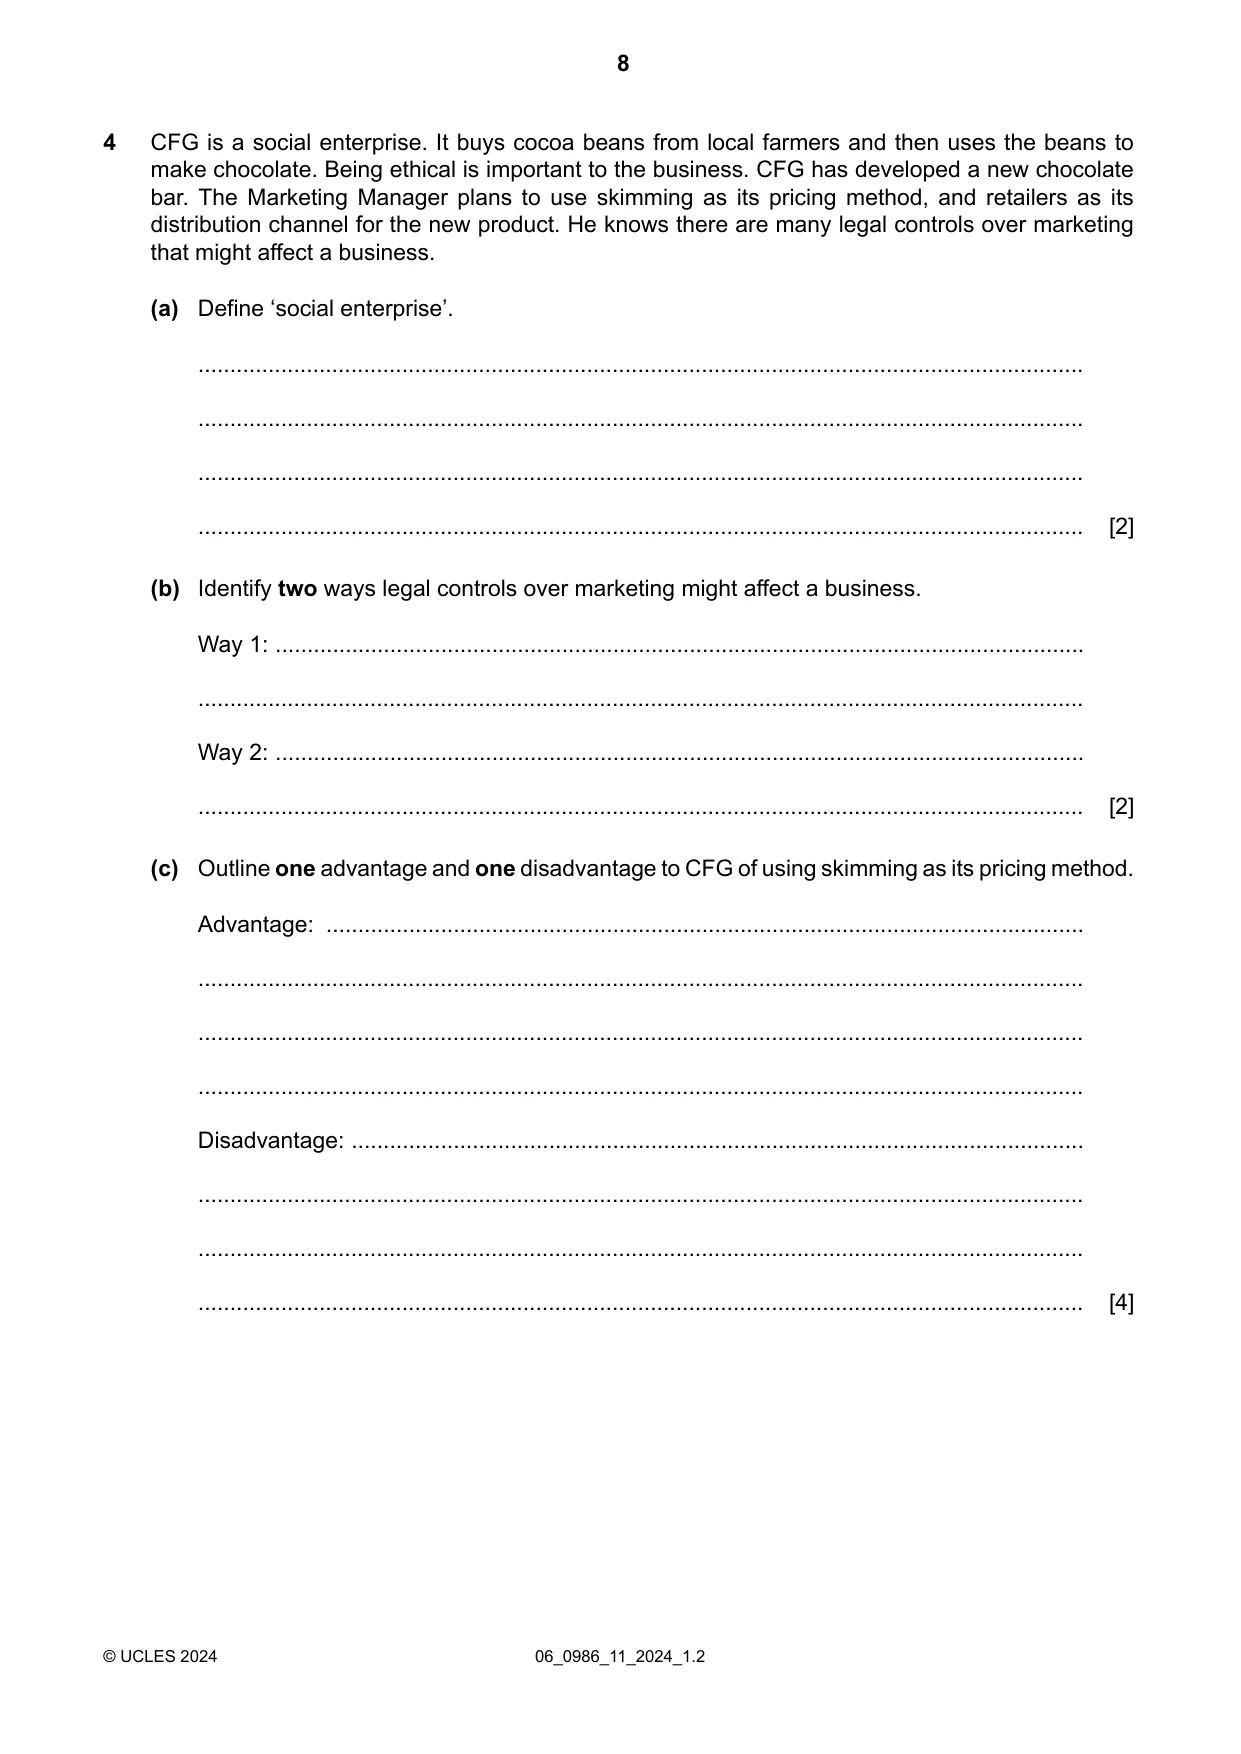
Question paper, page 8
CFG is a social enterprise. It buys cocoa beans from local farmers and then uses the beans to make chocolate. Being ethical is important to the business. CFG has developed a new chocolate 4 bar. The Marketing Manager plans to use skimming as its pricing method, and retailers as its distribution channel for the new product. He knows there are many legal controls over marketing that might affect a business. Define ‘social enterprise’. (a) … … … … [2] Identify two ways legal controls over marketing might affect a business. (b) Way 1: … … Way 2: … … [2] Outline one advantage and one disadvantage to CFG of using skimming as its pricing method. (c) Advantage: … … … … Disadvantage: … … … … [4] 06_0986_11_2024_1.2 © UCLES 2024 8
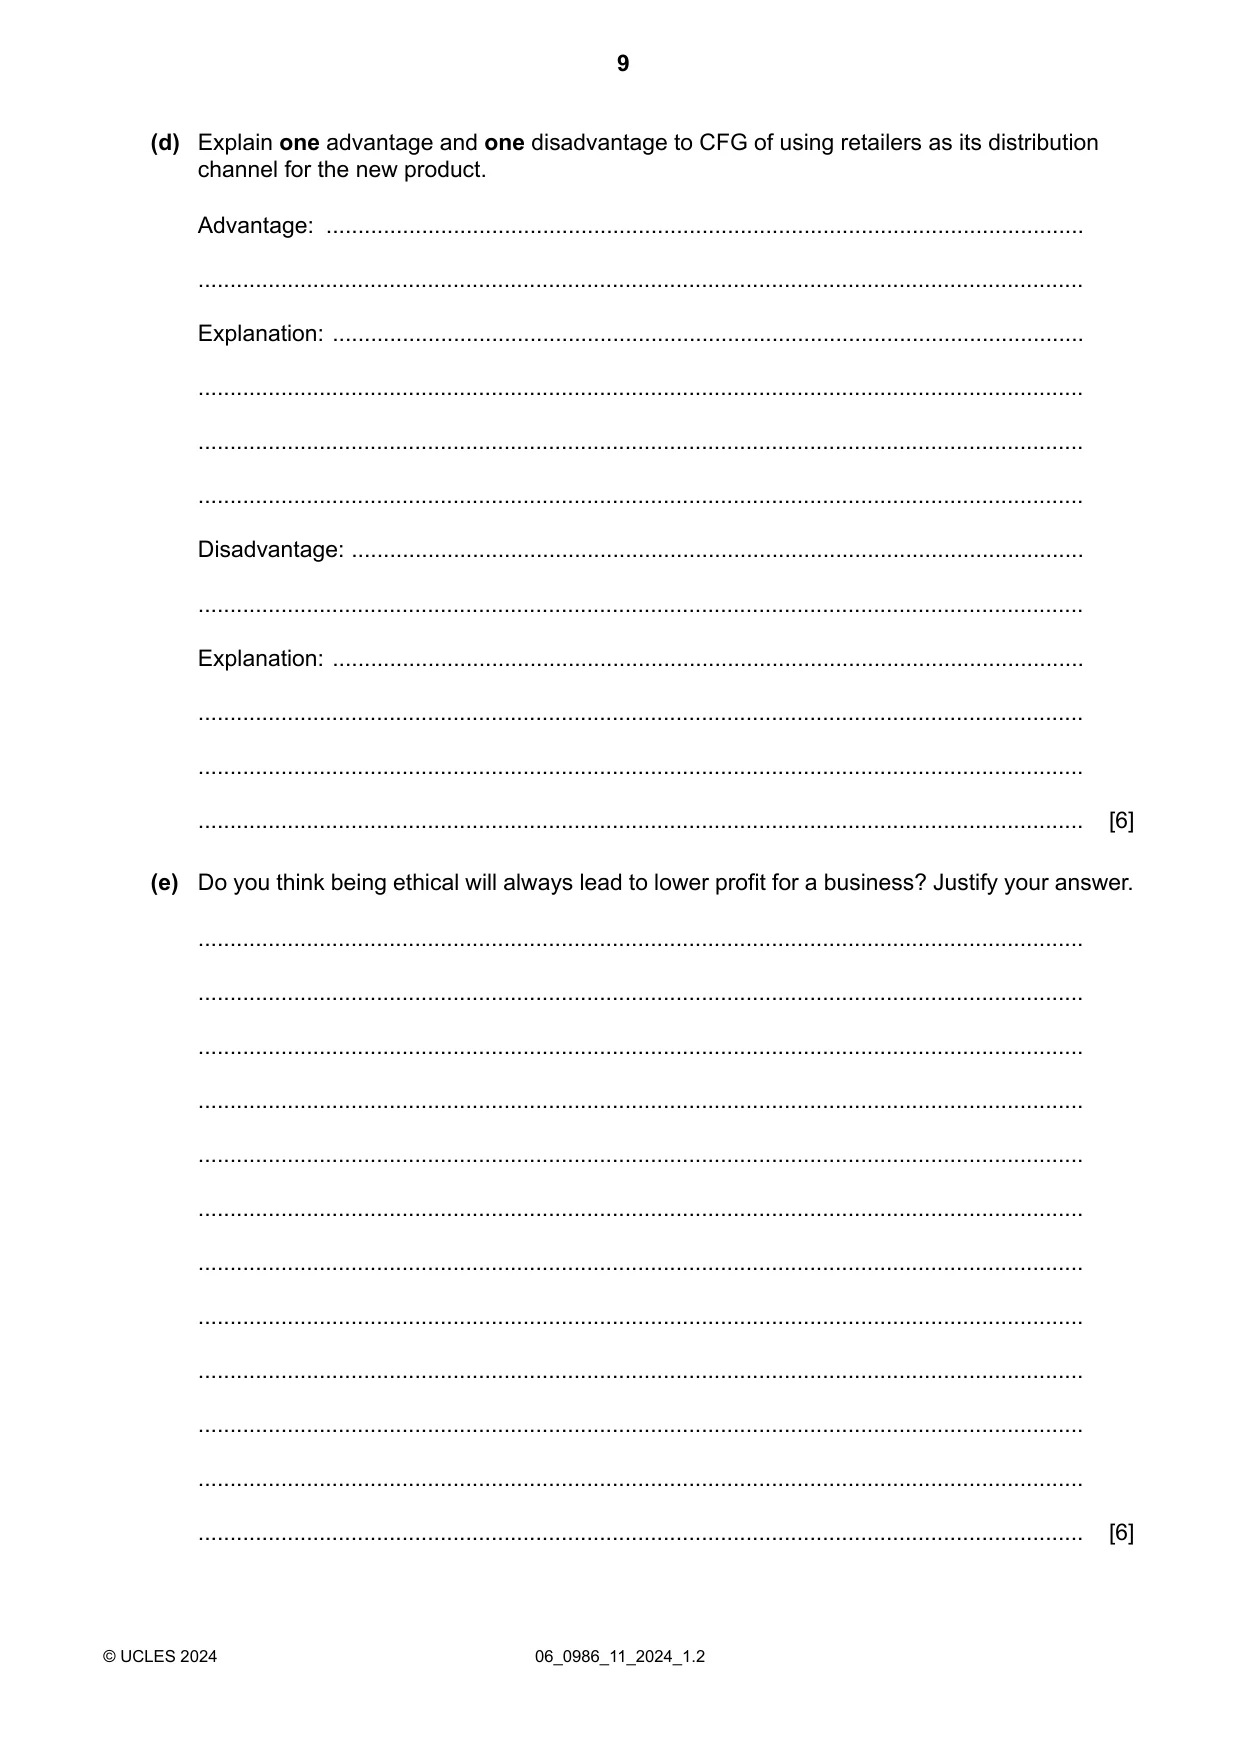
Question paper, page 9
Explain one advantage and one disadvantage to CFG of using retailers as its distribution channel for the new product. (d) Advantage: … … Explanation: … … … … Disadvantage: … … Explanation: … … … … [6] Do you think being ethical will always lead to lower profit for a business? Justify your answer. (e) … … … … … … … … … … … … [6] 06_0986_11_2024_1.2 © UCLES 2024 9
Question paper, page 10
BLANK PAGE 06_0986_11_2024_1.2 © UCLES 2024 10
Question paper, page 11
BLANK PAGE 06_0986_11_2024_1.2 © UCLES 2024 11
Question paper, page 12
BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of Cambridge Assessment. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which is a department of the University of Cambridge. 06_0986_11_2024_1.2 © UCLES 2024 12
Mark scheme, page 1
This document consists of 26 printed pages. © Cambridge University Press & Assessment 2024 [Turn over Cambridge IGCSE™ (9–1) BUSINESS STUDIES 0986/11 Paper 1 Short Answer/Data Response May/June 2024 MARK SCHEME Maximum Mark: 80 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the May/June 2024 series for most Cambridge IGCSE, Cambridge International A and AS Level and Cambridge Pre-U components, and some Cambridge O Level components.
Mark scheme, page 2
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 2 of 26 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptions for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: the specific content of the mark scheme or the generic level descriptors for the question the specific skills defined in the mark scheme or in the generic level descriptors for the question the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate marks are awarded when candidates clearly demonstrate what they know and can do marks are not deducted for errors marks are not deducted for omissions answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently, e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors.
Mark scheme, page 3
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 3 of 26 GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 4
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 4 of 26 Social Science-Specific Marking Principles (for point-based marking) 1 Components using point-based marking: Point marking is often used to reward knowledge, understanding and application of skills. We give credit where the candidate’s answer shows relevant knowledge, understanding and application of skills in answering the question. We do not give credit where the answer shows confusion. From this it follows that we: a DO credit answers which are worded differently from the mark scheme if they clearly convey the same meaning (unless the mark scheme requires a specific term) b DO credit alternative answers/examples which are not written in the mark scheme if they are correct c DO credit answers where candidates give more than one correct answer in one prompt/numbered/scaffolded space where extended writing is required rather than list-type answers. For example, questions that require n reasons (e.g. State two reasons …). d DO NOT credit answers simply for using a ‘key term’ unless that is all that is required. (Check for evidence it is understood and not used wrongly.) e DO NOT credit answers which are obviously self-contradicting or trying to cover all possibilities f DO NOT give further credit for what is effectively repetition of a correct point already credited unless the language itself is being tested. This applies equally to ‘mirror statements’ (i.e. polluted/not polluted). g DO NOT require spellings to be correct, unless this is part of the test. However spellings of syllabus terms must allow for clear and unambiguous separation from other syllabus terms with which they may be confused (e.g. Corrasion/Corrosion) 2 Presentation of mark scheme: Slashes (/) or the word ‘or’ separate alternative ways of making the same point. Semi colons (;) bullet points (•) or figures in brackets (1) separate different points. Content in the answer column in brackets is for examiner information/context to clarify the marking but is not required to earn the mark (except Accounting syllabuses where they indicate negative numbers).
Mark scheme, page 5
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 5 of 26 3 Calculation questions: The mark scheme will show the steps in the most likely correct method(s), the mark for each step, the correct answer(s) and the mark for each answer If working/explanation is considered essential for full credit, this will be indicated in the question paper and in the mark scheme. In all other instances, the correct answer to a calculation should be given full credit, even if no supporting working is shown. Where the candidate uses a valid method which is not covered by the mark scheme, award equivalent marks for reaching equivalent stages. Where an answer makes use of a candidate’s own incorrect figure from previous working, the ‘own figure rule’ applies: full marks will be given if a correct and complete method is used. Further guidance will be included in the mark scheme where necessary and any exceptions to this general principle will be noted. 4 Annotation: For point marking, ticks can be used to indicate correct answers and crosses can be used to indicate wrong answers. There is no direct relationship between ticks and marks. Ticks have no defined meaning for levels of response marking. For levels of response marking, the level awarded should be annotated on the script. Other annotations will be used by examiners as agreed during standardisation, and the meaning will be understood by all examiners who marked that paper.
Mark scheme, page 6
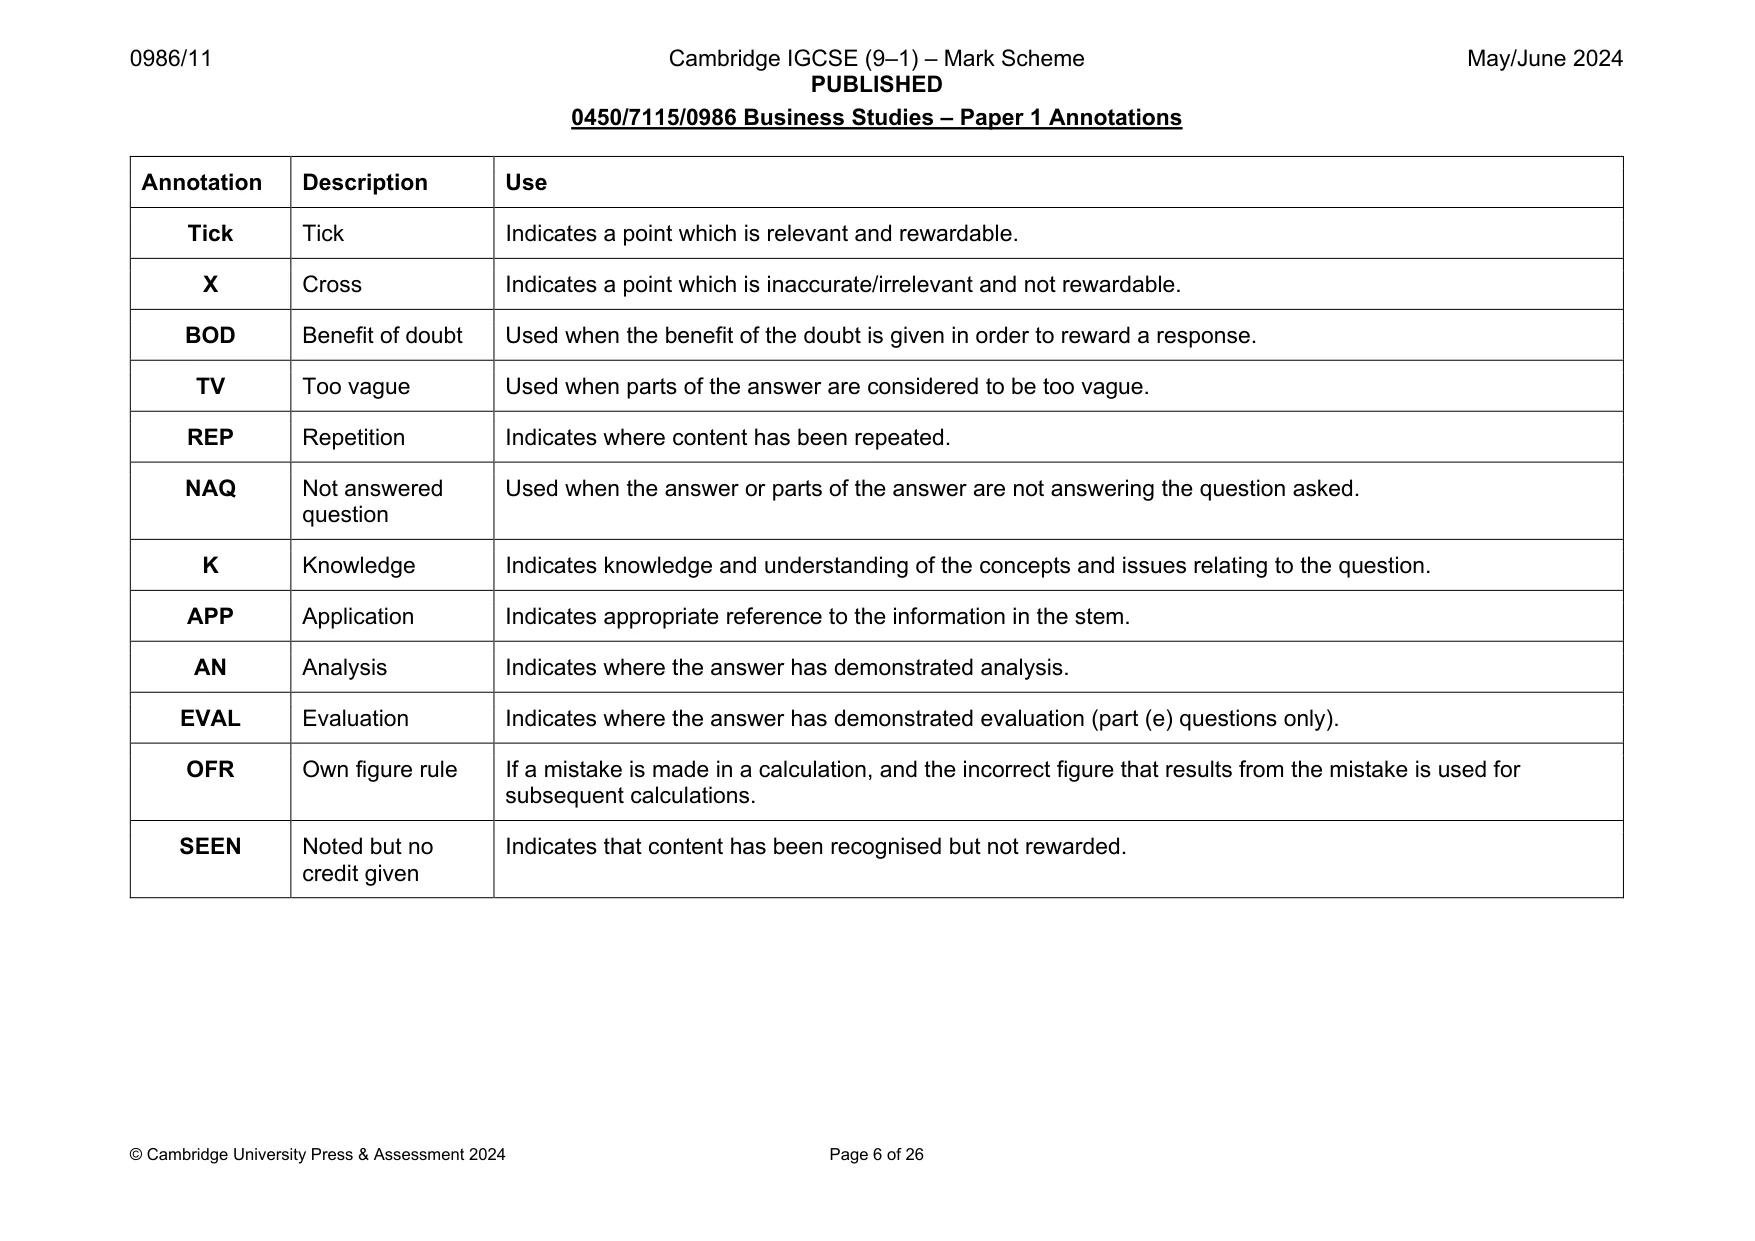
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 6 of 26 0450/7115/0986 Business Studies – Paper 1 Annotations Annotation Description Use Tick Tick Indicates a point which is relevant and rewardable. X Cross Indicates a point which is inaccurate/irrelevant and not rewardable. BOD Benefit of doubt Used when the benefit of the doubt is given in order to reward a response. TV Too vague Used when parts of the answer are considered to be too vague. REP Repetition Indicates where content has been repeated. NAQ Not answered question Used when the answer or parts of the answer are not answering the question asked. K Knowledge Indicates knowledge and understanding of the concepts and issues relating to the question. APP Application Indicates appropriate reference to the information in the stem. AN Analysis Indicates where the answer has demonstrated analysis. EVAL Evaluation Indicates where the answer has demonstrated evaluation (part (e) questions only). OFR Own figure rule If a mistake is made in a calculation, and the incorrect figure that results from the mistake is used for subsequent calculations. SEEN Noted but no credit given Indicates that content has been recognised but not rewarded.
Mark scheme, page 7
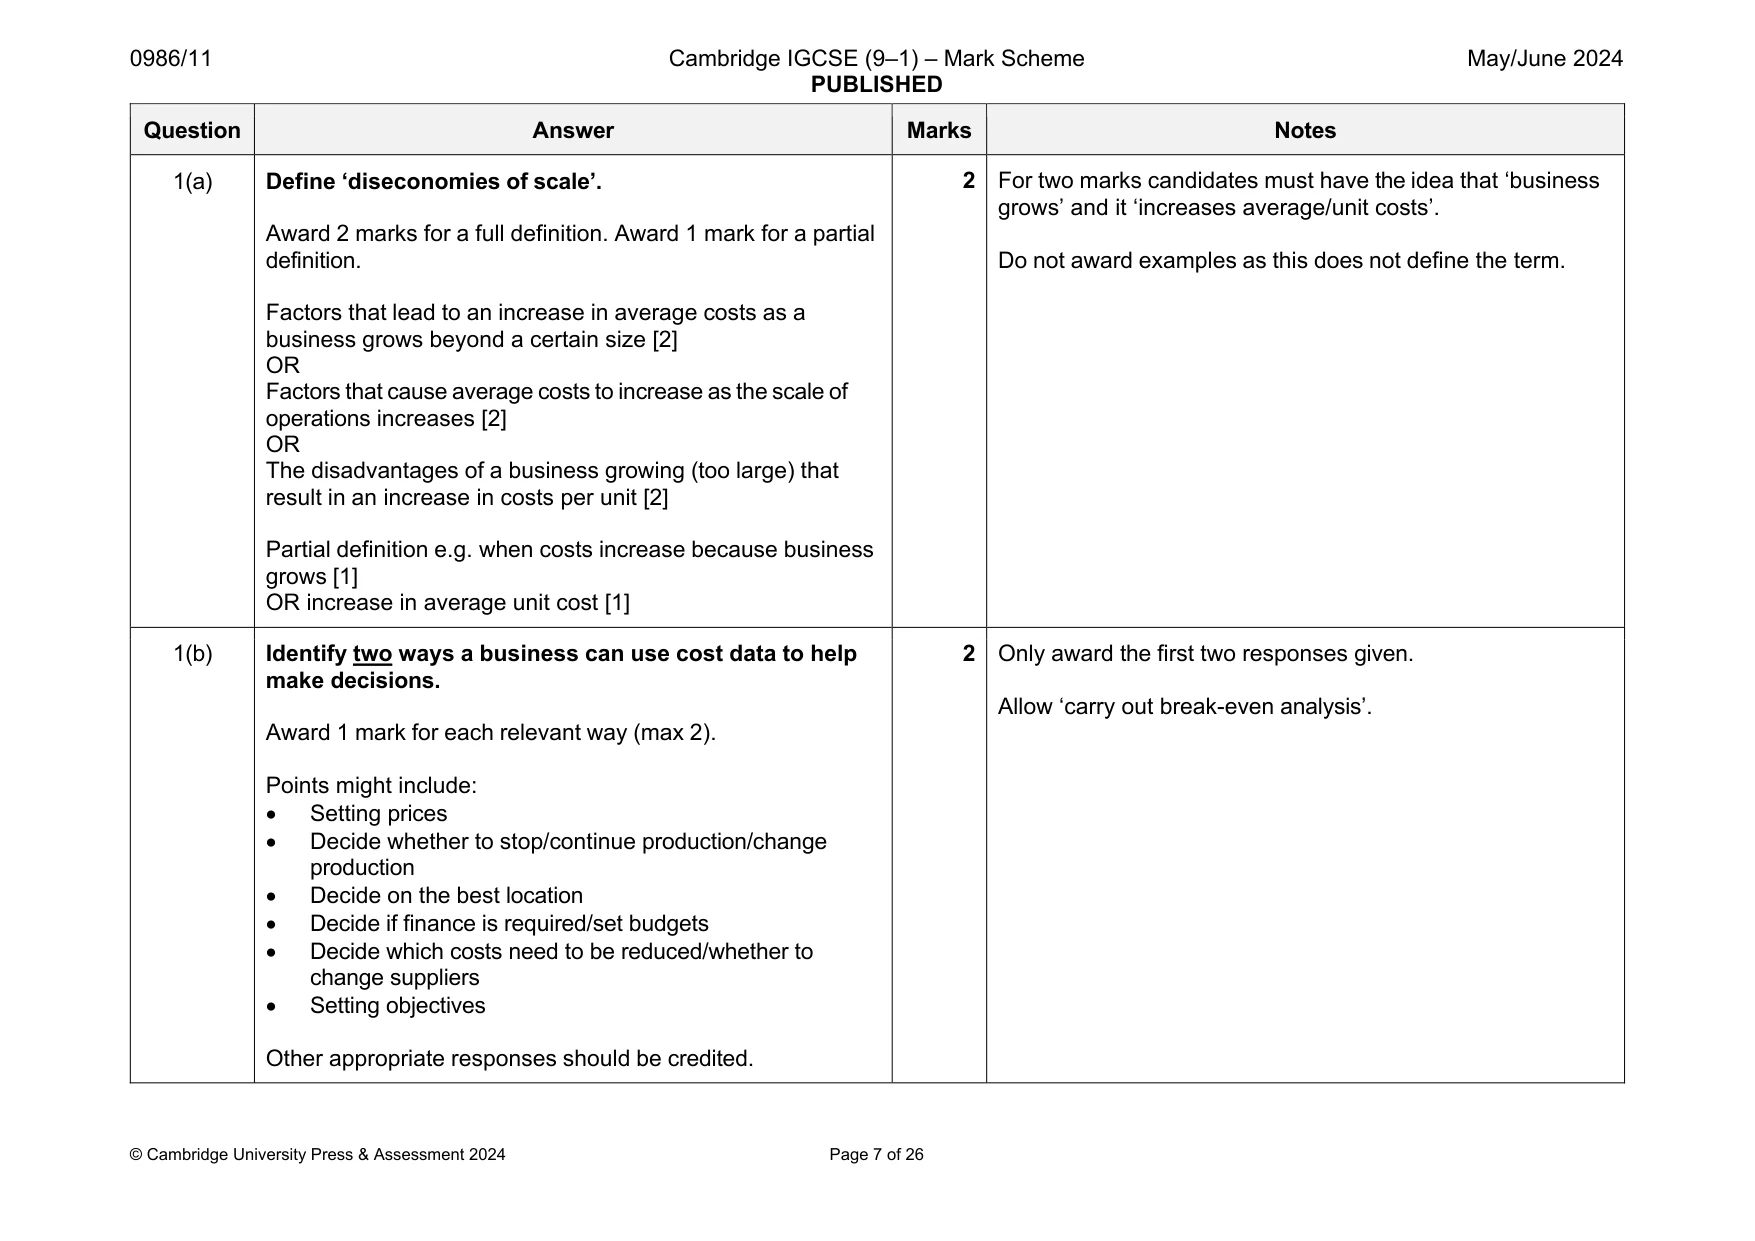
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 7 of 26 Question Answer Marks Notes 1(a) Define ‘diseconomies of scale’. Award 2 marks for a full definition. Award 1 mark for a partial definition. Factors that lead to an increase in average costs as a business grows beyond a certain size [2] OR Factors that cause average costs to increase as the scale of operations increases [2] OR The disadvantages of a business growing (too large) that result in an increase in costs per unit [2] Partial definition e.g. when costs increase because business grows [1] OR increase in average unit cost [1] 2 For two marks candidates must have the idea that ‘business grows’ and it ‘increases average/unit costs’. Do not award examples as this does not define the term. 1(b) Identify two ways a business can use cost data to help make decisions. Award 1 mark for each relevant way (max 2). Points might include: Setting prices Decide whether to stop/continue production/change production Decide on the best location Decide if finance is required/set budgets Decide which costs need to be reduced/whether to change suppliers Setting objectives Other appropriate responses should be credited. 2 Only award the first two responses given. Allow ‘carry out break-even analysis’.
Mark scheme, page 8
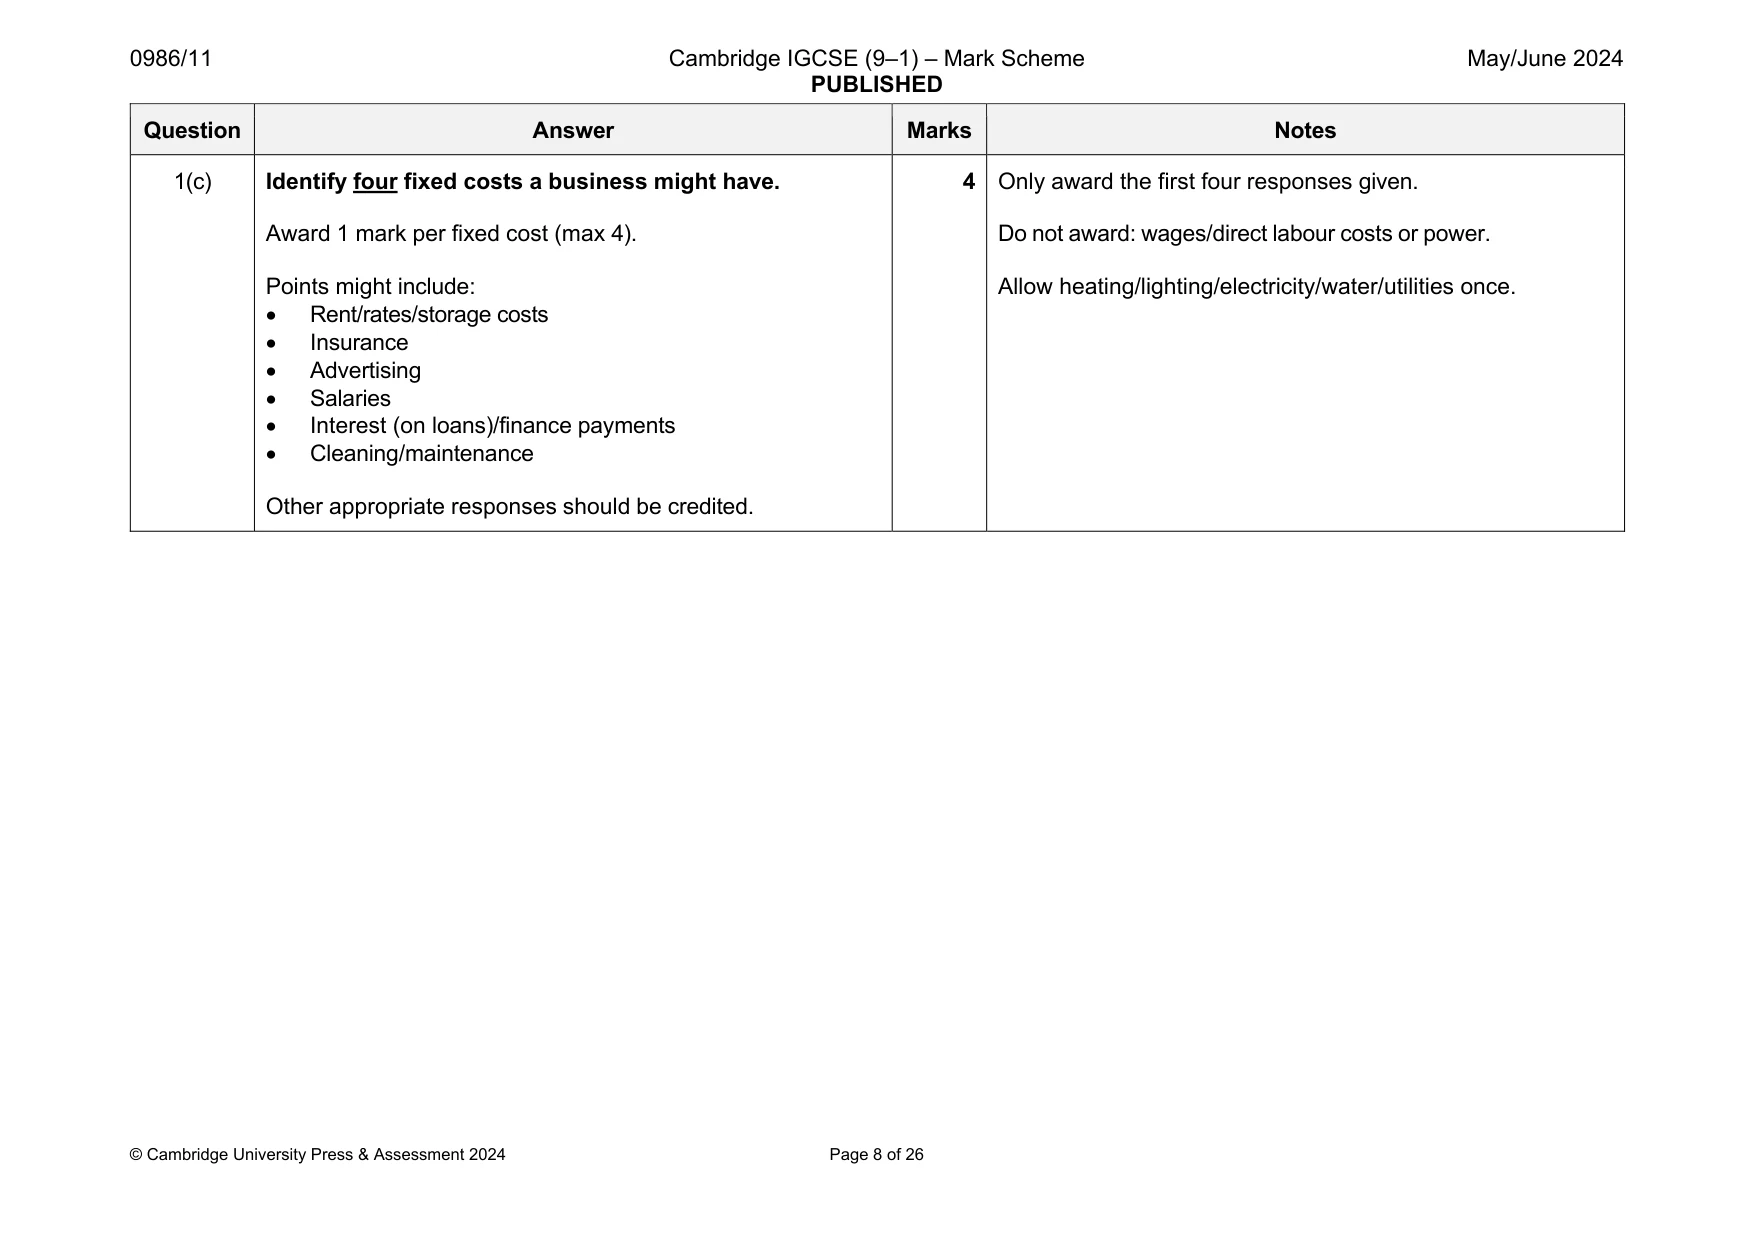
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 8 of 26 Question Answer Marks Notes 1(c) Identify four fixed costs a business might have. Award 1 mark per fixed cost (max 4). Points might include: Rent/rates/storage costs Insurance Advertising Salaries Interest (on loans)/finance payments Cleaning/maintenance Other appropriate responses should be credited. 4 Only award the first four responses given. Do not award: wages/direct labour costs or power. Allow heating/lighting/electricity/water/utilities once.
Mark scheme, page 9
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 9 of 26 Question Answer Marks Notes 1(d) Explain one advantage and one disadvantage to FBM of holding a high level of inventory. Award 1 mark for identification of each relevant reason (max 2). Award 1 mark for each relevant reference to this business (max 2). Award 1 mark for each relevant explanation (max 2). Points might include: Advantages: Maintain production [k] so able to meet orders on time [an] of boats [app] Benefit from (purchasing) economies of scale [k] leading to lower average/unit cost [an] Able to respond quickly to unexpected order [k] increasing customer loyalty [an] Disadvantages: Space needed to store products [k] increasing (storage) costs [an] so costs increase above $600 000 [app] Cash/money tied up in inventory [k] leading to cash flow/liquidity problems [an] Risk of damage/waste[k] Opportunity cost [k] Insurance [k] Other appropriate responses should be credited. 6 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Boat (building) or related words 100 employees Skilled (workers) Diseconomies of scale $5000 (variable cost) $600 000 (fixed costs) 300 (boats) Total cost 2 100 000 Other appropriate examples can be credited. The same analysis can be used for different points but only award once.
Mark scheme, page 10
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 10 of 26 Question Answer Marks Notes 1(e) Do you think customers have a more important role in the success of a business than its employees? Justify your answer. Award up to 2 marks for identification of relevant points. Award up to 2 marks for relevant development of points. Award up to 2 marks for a justified decision as to whether customers have a more important role in the success of a business than its employees. Points might include: Customers: Buy the products [k] and if ignores their needs the business will lose revenue/won’t survive [an] Can share opinions to help improve products [k] which can help increase market share [an] Provide recommendations/word of mouth advertising [k] Employees: Make the products [k] otherwise there is nothing to sell [an] Employees can affect quality [k] which could damage/improve its reputation [an] Employees provide customer service [k] which is important for brand image [an] Without sufficient employees the business may not be able to meet demand [k] Workers can be replaced by machines [k] Other appropriate responses should be credited. 6 This is a general question so there are no marks for application. For evaluation to be awarded justification will usually follow on from relevant analysis of points.
Mark scheme, page 11
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 11 of 26 Question Answer Marks Notes 1(e) Justification might include: Customers are important, they buy the products [k] which generates revenue [an]. Employees make the goods [k] without them, there is nothing to sell [an]. However, customers are more important as without revenue, the business cannot cover its costs and survive in long term [eval]. A business can use automation reducing the importance of employees [eval]. Question Answer Marks Notes 2(a) Define ‘span of control’. Award 2 marks for a full definition. Award 1 mark for a partial definition. (Number of) subordinates working directly under a manager [2] OR (Number of) subordinates reporting to each supervisor/manager [2] OR (Number of) subordinates someone has within their authority/under their control [2] Partial definition e.g. (number of) staff that a manager is responsible for [1] OR subordinates who work under a manager [1] 2
Mark scheme, page 12
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 12 of 26 Question Answer Marks Notes 2(b) Define ‘autocratic leadership style’. Award 2 marks for a full definition. Award 1 mark for a partial definition. Leader/manager makes all the decisions [2] OR Where the manager expects to be in charge of the business and to have their orders followed [2] Partial definitions e.g. employees are simply told what to do [1] OR employees have no say in decisions [1] 2 For two marks the candidates need to show awareness that the decision making is by a leader or manager not a director or person in the company. 2(c) Outline two benefits to ADN of having full-time employees. Award 1 mark for each relevant benefit (max 2). Award 1 mark for each relevant reference to this business (max 2). Points might include: Consistent service [k] at the 5 shops [app] Workers likely to be loyal/less likely to leave [k] the food retailer [app] Easy to communicate with/update [k] the 300 employees [app] Need to recruit/train fewer employees [k] Other appropriate responses should be credited. 4 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Food or related words 5 (locations) Shops/retailer 300 employees Tall hierarchical organisational structure Narrow span of control Autocratic leadership style Planning to expand/internal growth/external growth Other appropriate examples can be credited.
Mark scheme, page 13
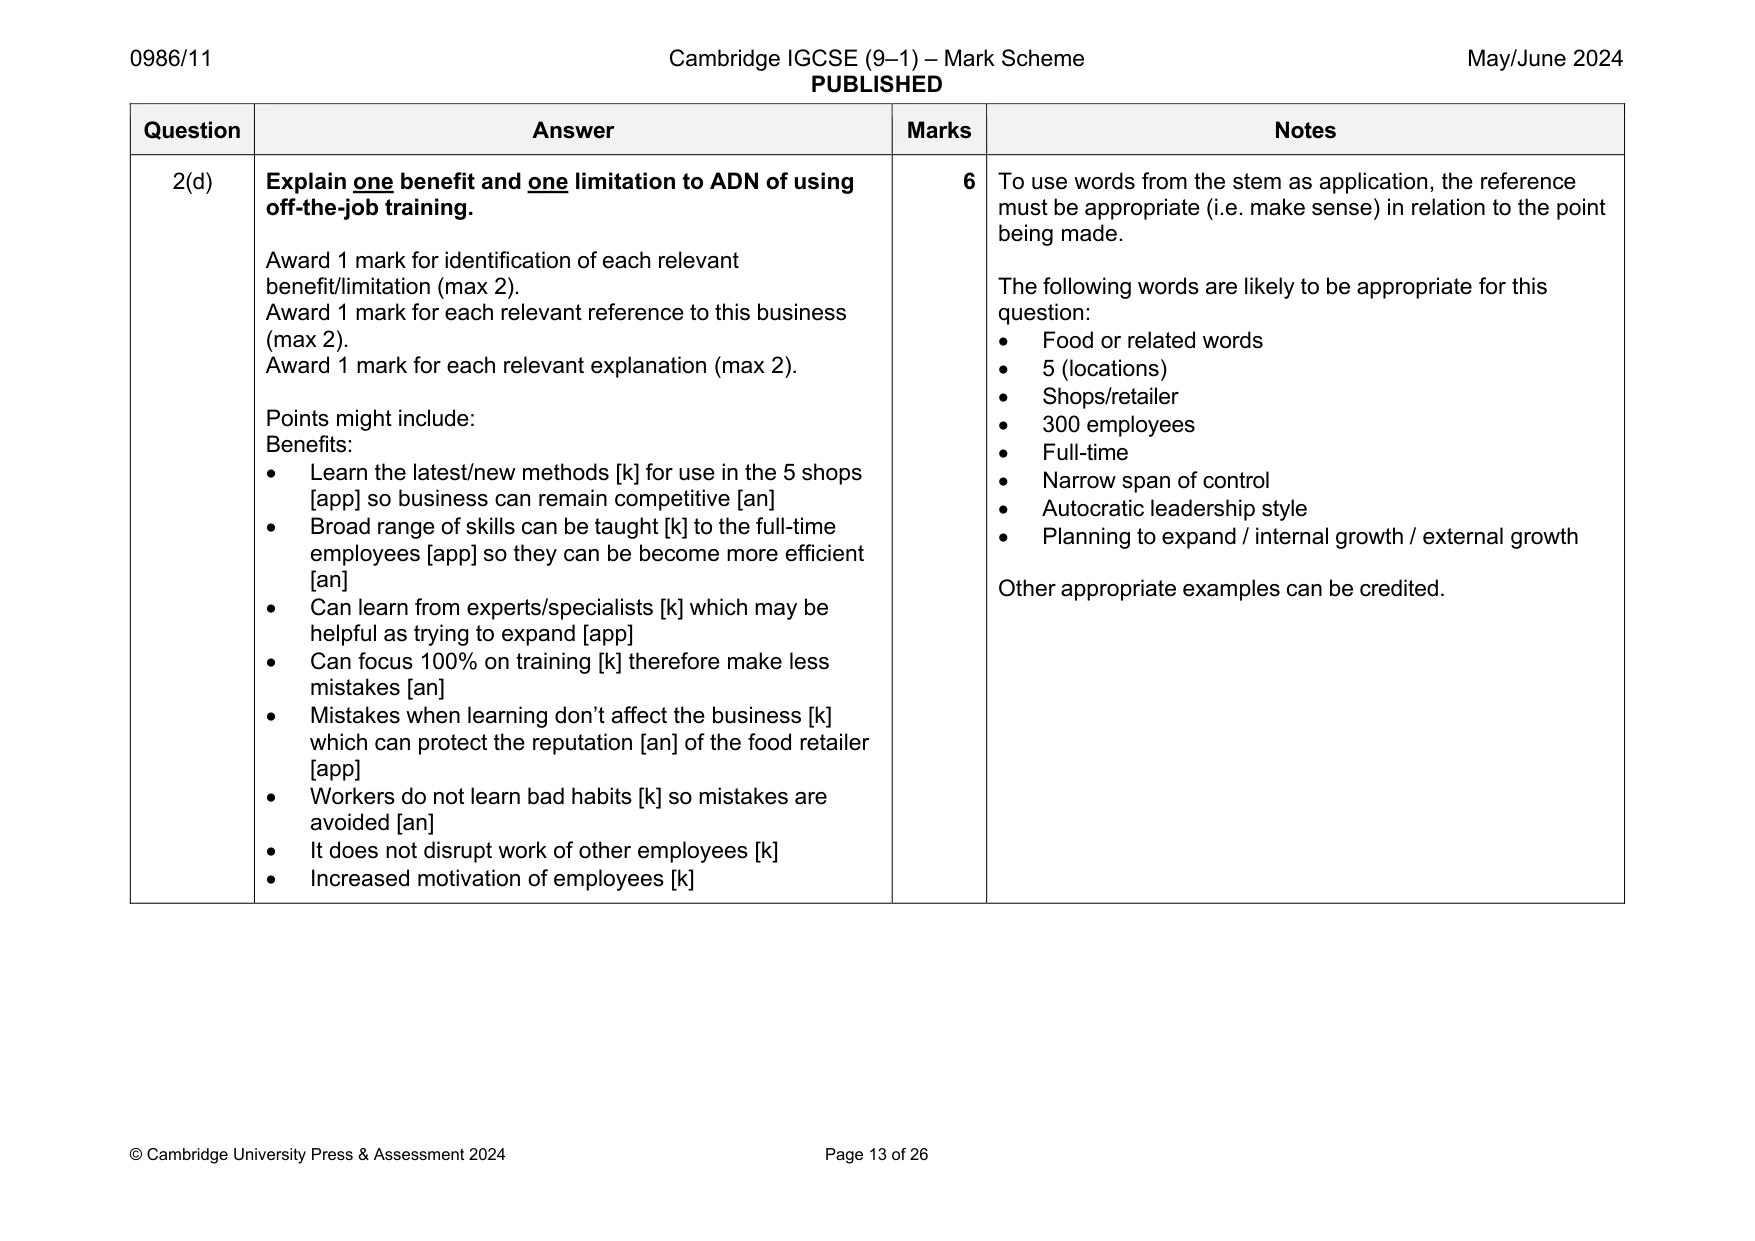
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 13 of 26 Question Answer Marks Notes 2(d) Explain one benefit and one limitation to ADN of using off-the-job training. Award 1 mark for identification of each relevant benefit/limitation (max 2). Award 1 mark for each relevant reference to this business (max 2). Award 1 mark for each relevant explanation (max 2). Points might include: Benefits: Learn the latest/new methods [k] for use in the 5 shops [app] so business can remain competitive [an] Broad range of skills can be taught [k] to the full-time employees [app] so they can be become more efficient [an] Can learn from experts/specialists [k] which may be helpful as trying to expand [app] Can focus 100% on training [k] therefore make less mistakes [an] Mistakes when learning don’t affect the business [k] which can protect the reputation [an] of the food retailer [app] Workers do not learn bad habits [k] so mistakes are avoided [an] It does not disrupt work of other employees [k] Increased motivation of employees [k] 6 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Food or related words 5 (locations) Shops/retailer 300 employees Full-time Narrow span of control Autocratic leadership style Planning to expand / internal growth / external growth Other appropriate examples can be credited.
Mark scheme, page 14
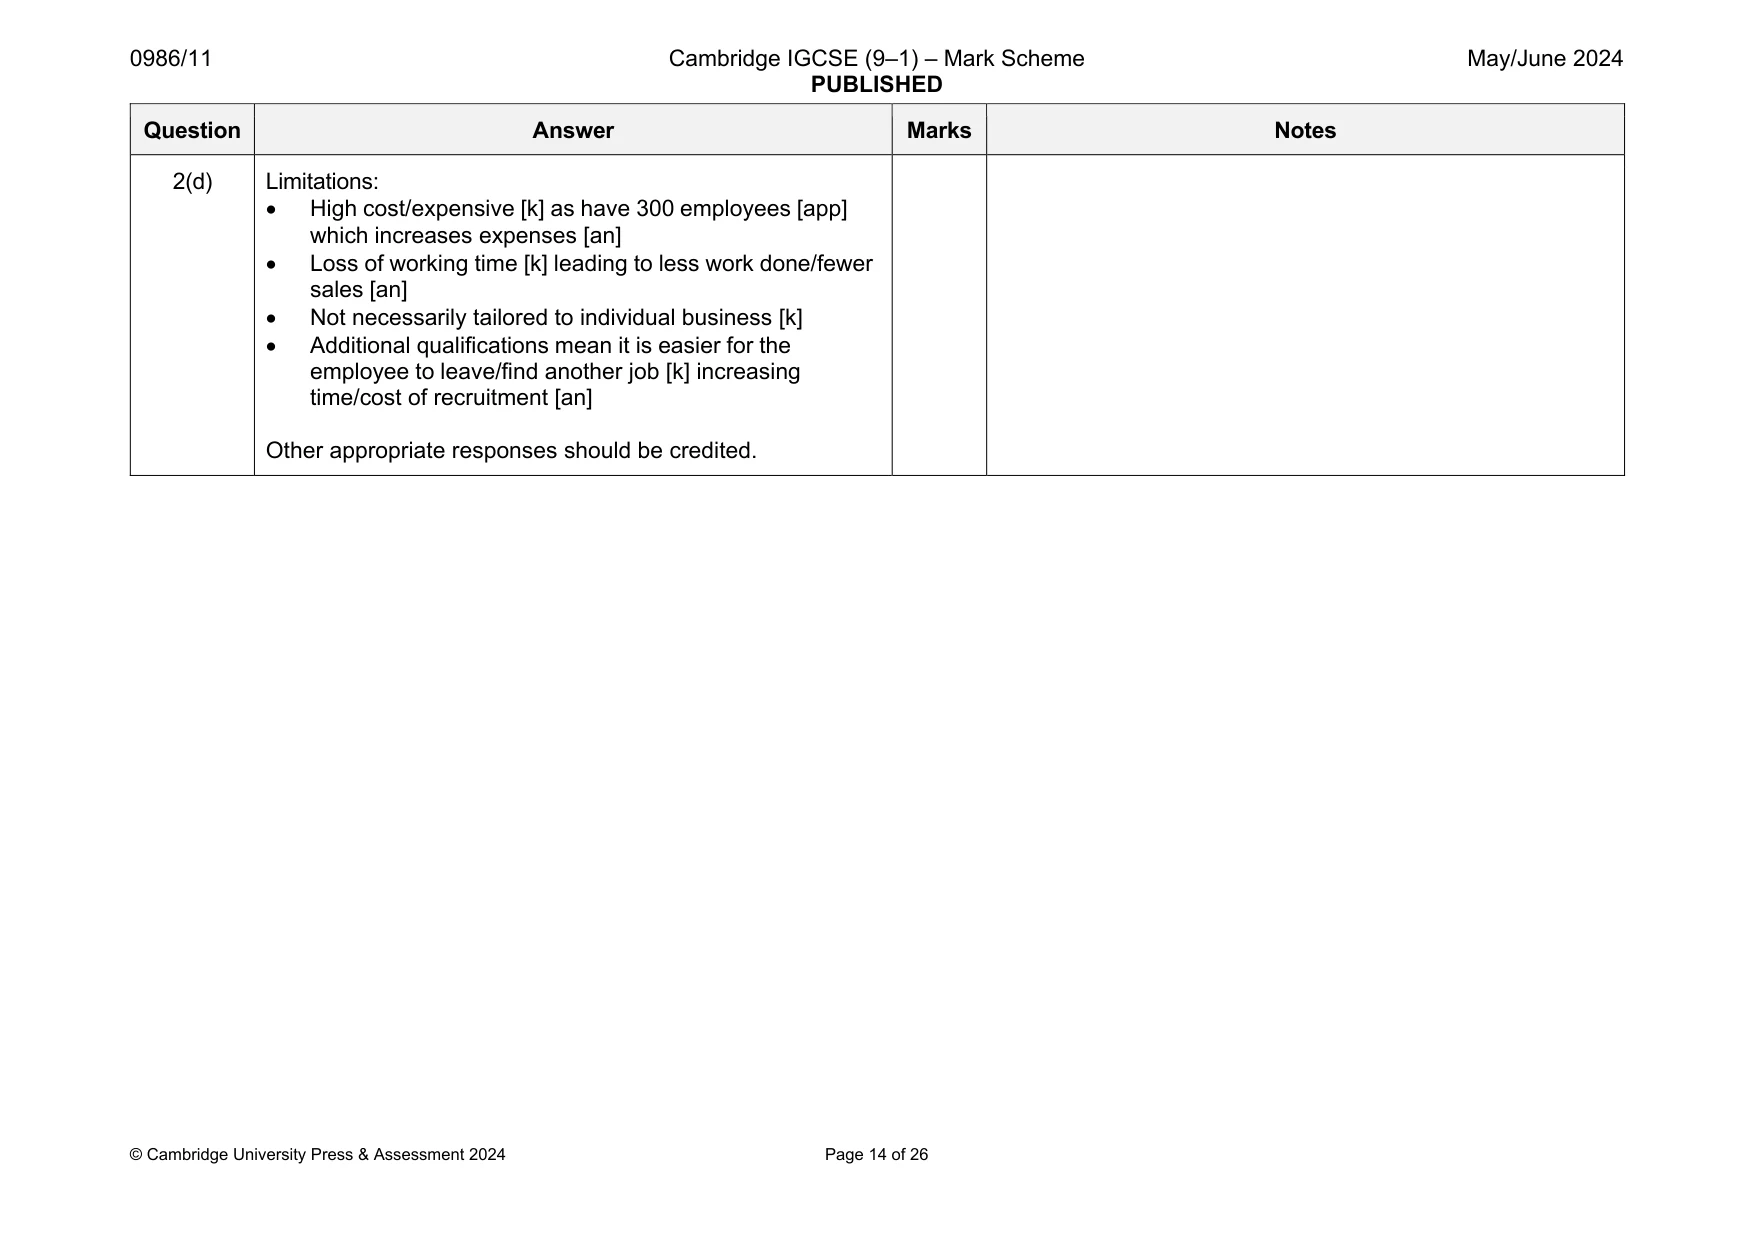
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 14 of 26 Question Answer Marks Notes 2(d) Limitations: High cost/expensive [k] as have 300 employees [app] which increases expenses [an] Loss of working time [k] leading to less work done/fewer sales [an] Not necessarily tailored to individual business [k] Additional qualifications mean it is easier for the employee to leave/find another job [k] increasing time/cost of recruitment [an] Other appropriate responses should be credited.
Mark scheme, page 15
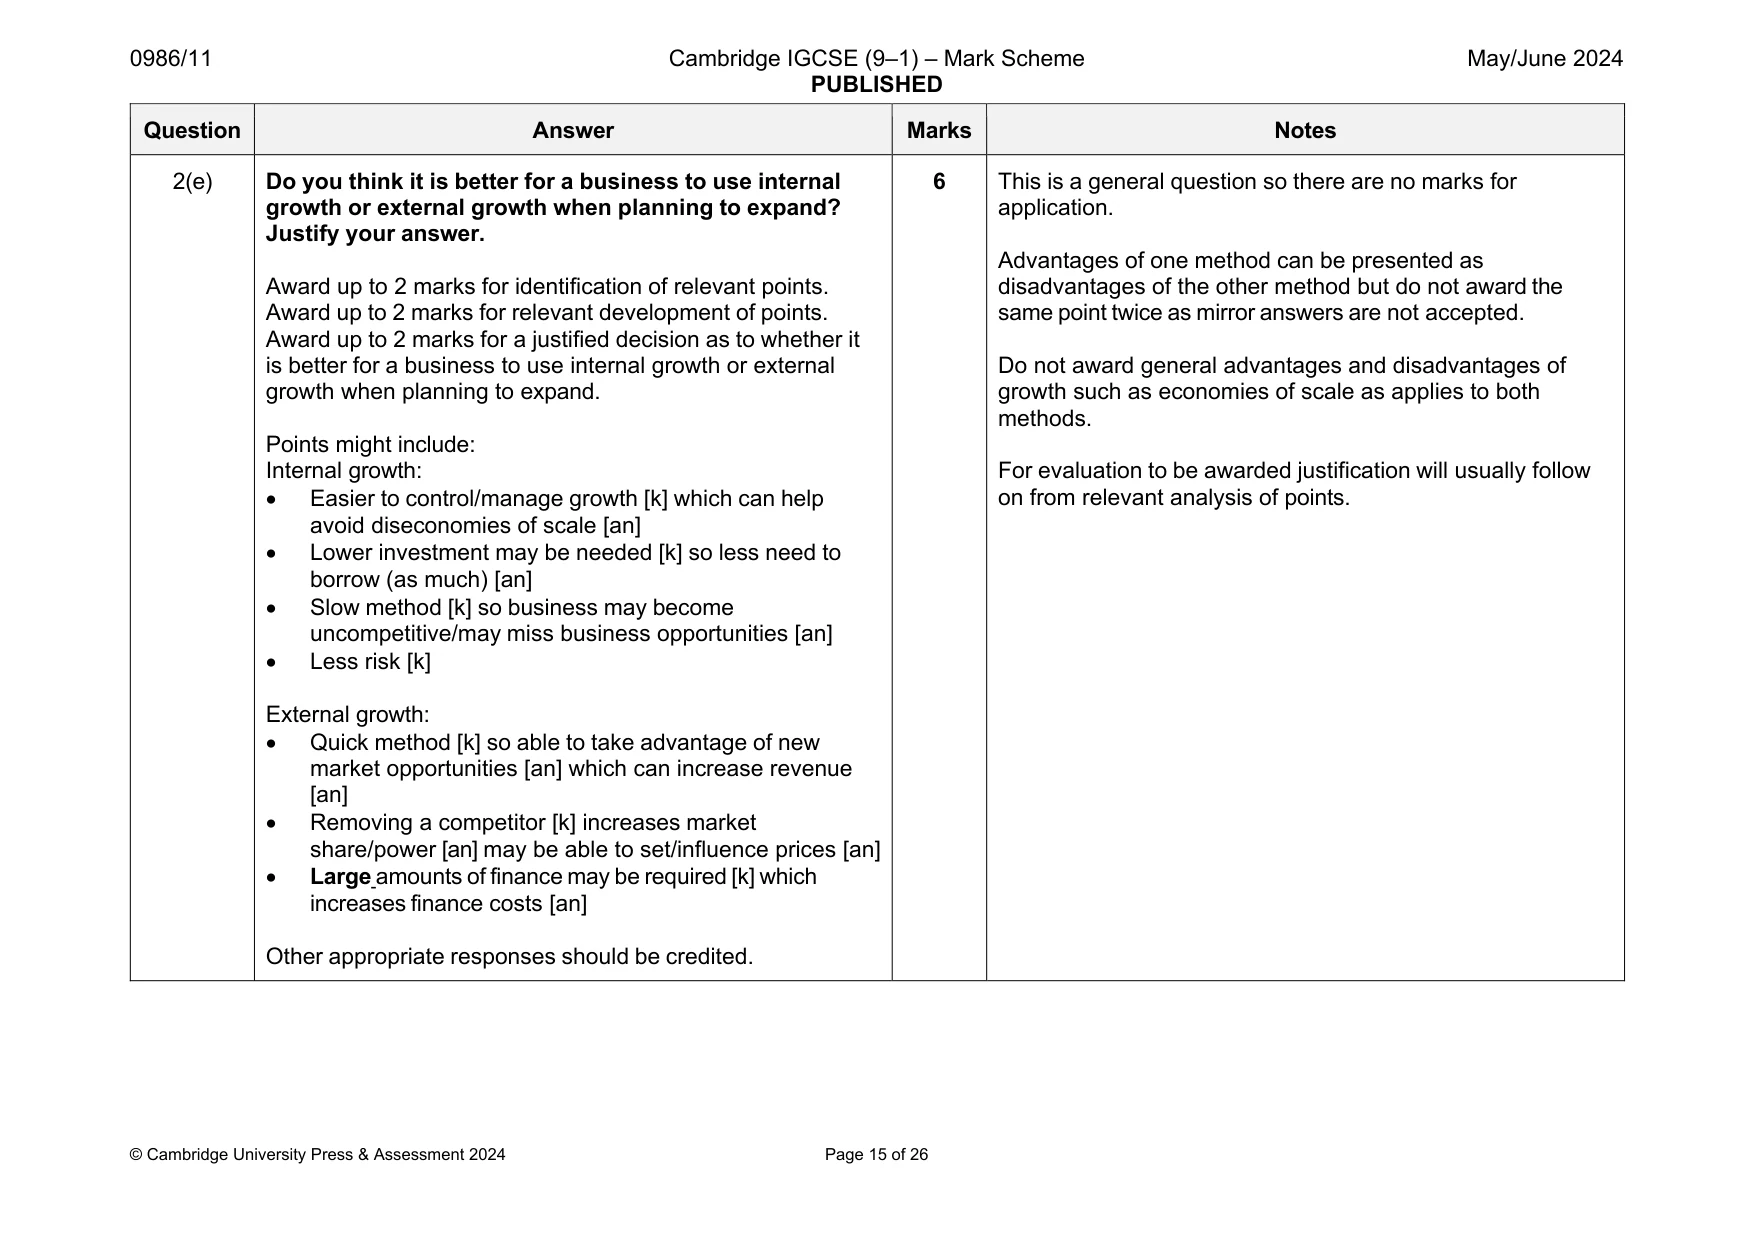
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 15 of 26 Question Answer Marks Notes 2(e) Do you think it is better for a business to use internal growth or external growth when planning to expand? Justify your answer. Award up to 2 marks for identification of relevant points. Award up to 2 marks for relevant development of points. Award up to 2 marks for a justified decision as to whether it is better for a business to use internal growth or external growth when planning to expand. Points might include: Internal growth: Easier to control/manage growth [k] which can help avoid diseconomies of scale [an] Lower investment may be needed [k] so less need to borrow (as much) [an] Slow method [k] so business may become uncompetitive/may miss business opportunities [an] Less risk [k] External growth: Quick method [k] so able to take advantage of new market opportunities [an] which can increase revenue [an] Removing a competitor [k] increases market share/power [an] may be able to set/influence prices [an] Large amounts of finance may be required [k] which increases finance costs [an] Other appropriate responses should be credited. 6 This is a general question so there are no marks for application. Advantages of one method can be presented as disadvantages of the other method but do not award the same point twice as mirror answers are not accepted. Do not award general advantages and disadvantages of growth such as economies of scale as applies to both methods. For evaluation to be awarded justification will usually follow on from relevant analysis of points.
Mark scheme, page 16
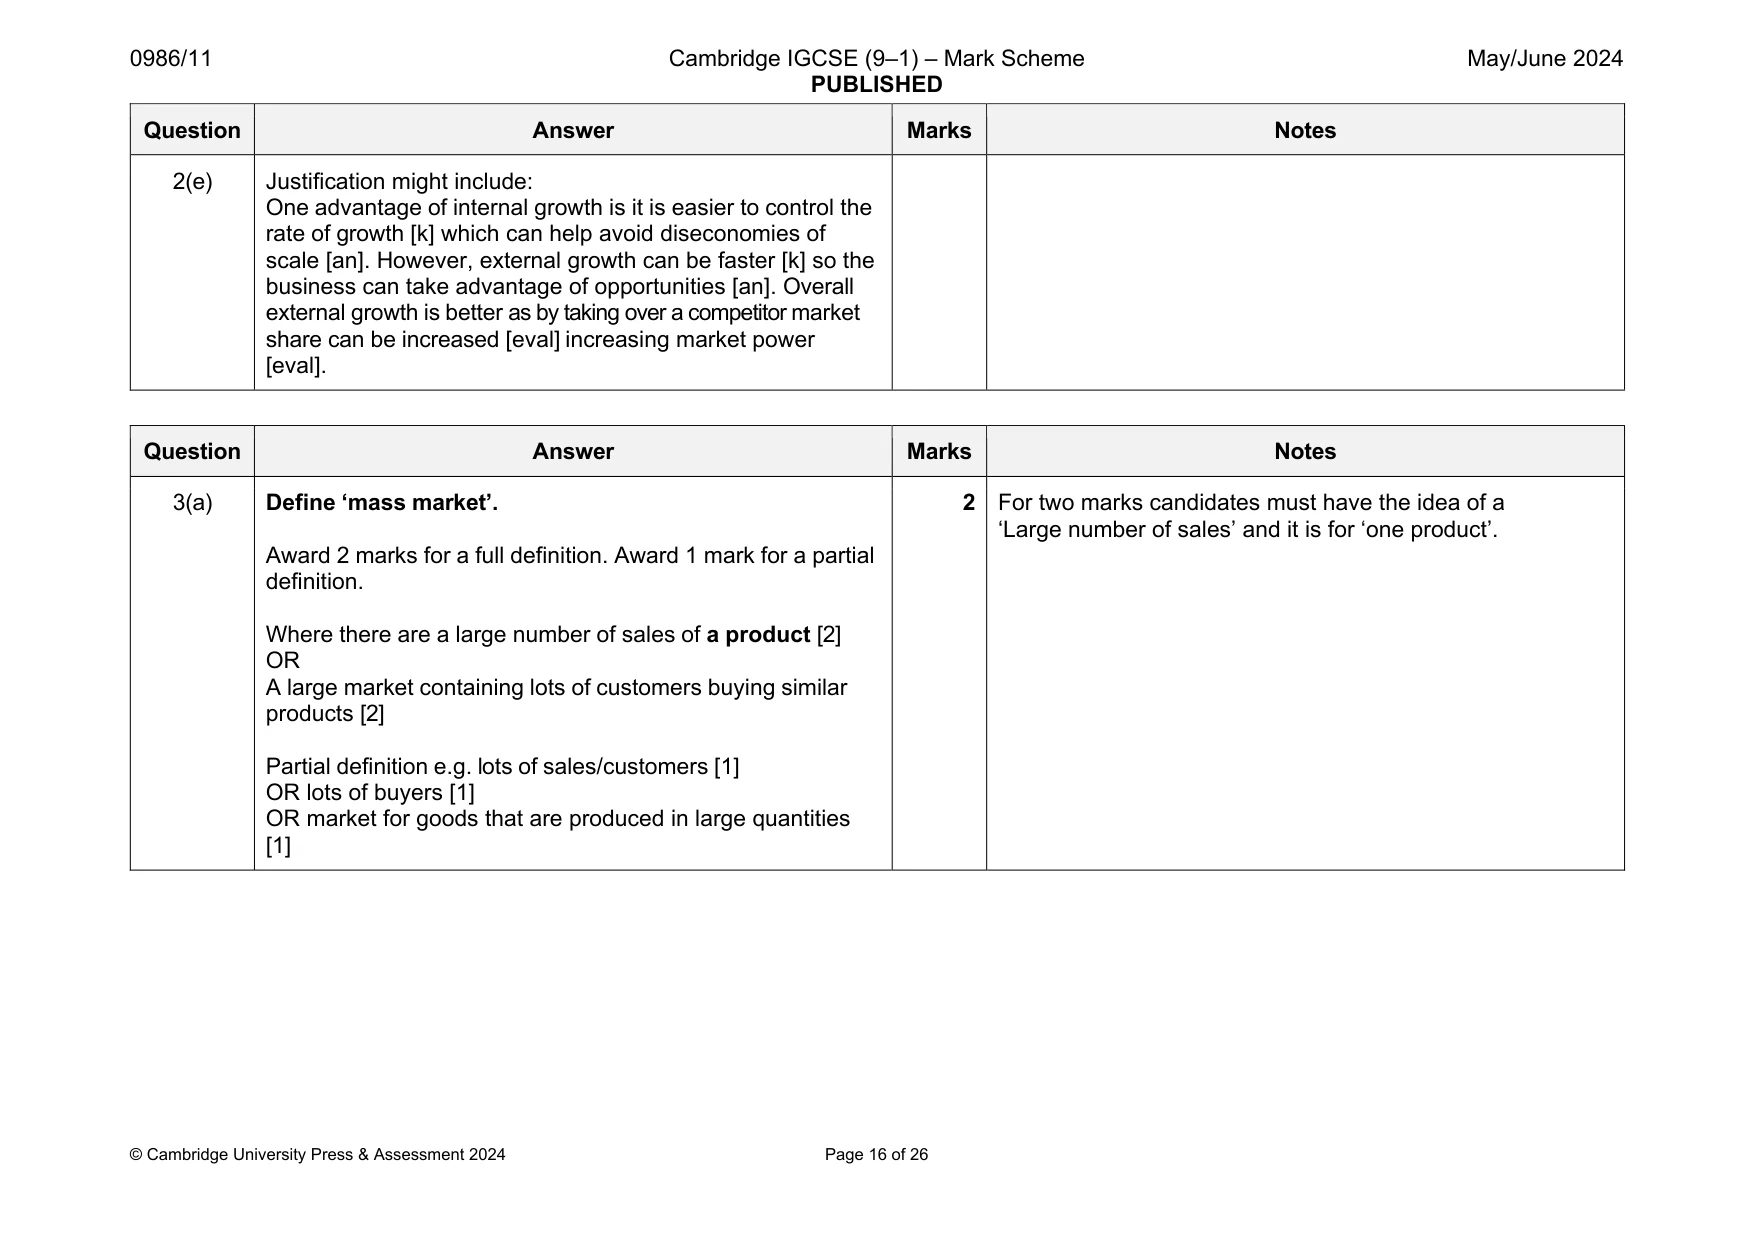
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 16 of 26 Question Answer Marks Notes 2(e) Justification might include: One advantage of internal growth is it is easier to control the rate of growth [k] which can help avoid diseconomies of scale [an]. However, external growth can be faster [k] so the business can take advantage of opportunities [an]. Overall external growth is better as by taking over a competitor market share can be increased [eval] increasing market power [eval]. Question Answer Marks Notes 3(a) Define ‘mass market’. Award 2 marks for a full definition. Award 1 mark for a partial definition. Where there are a large number of sales of a product [2] OR A large market containing lots of customers buying similar products [2] Partial definition e.g. lots of sales/customers [1] OR lots of buyers [1] OR market for goods that are produced in large quantities [1] 2 For two marks candidates must have the idea of a ‘Large number of sales’ and it is for ‘one product’.
Mark scheme, page 17
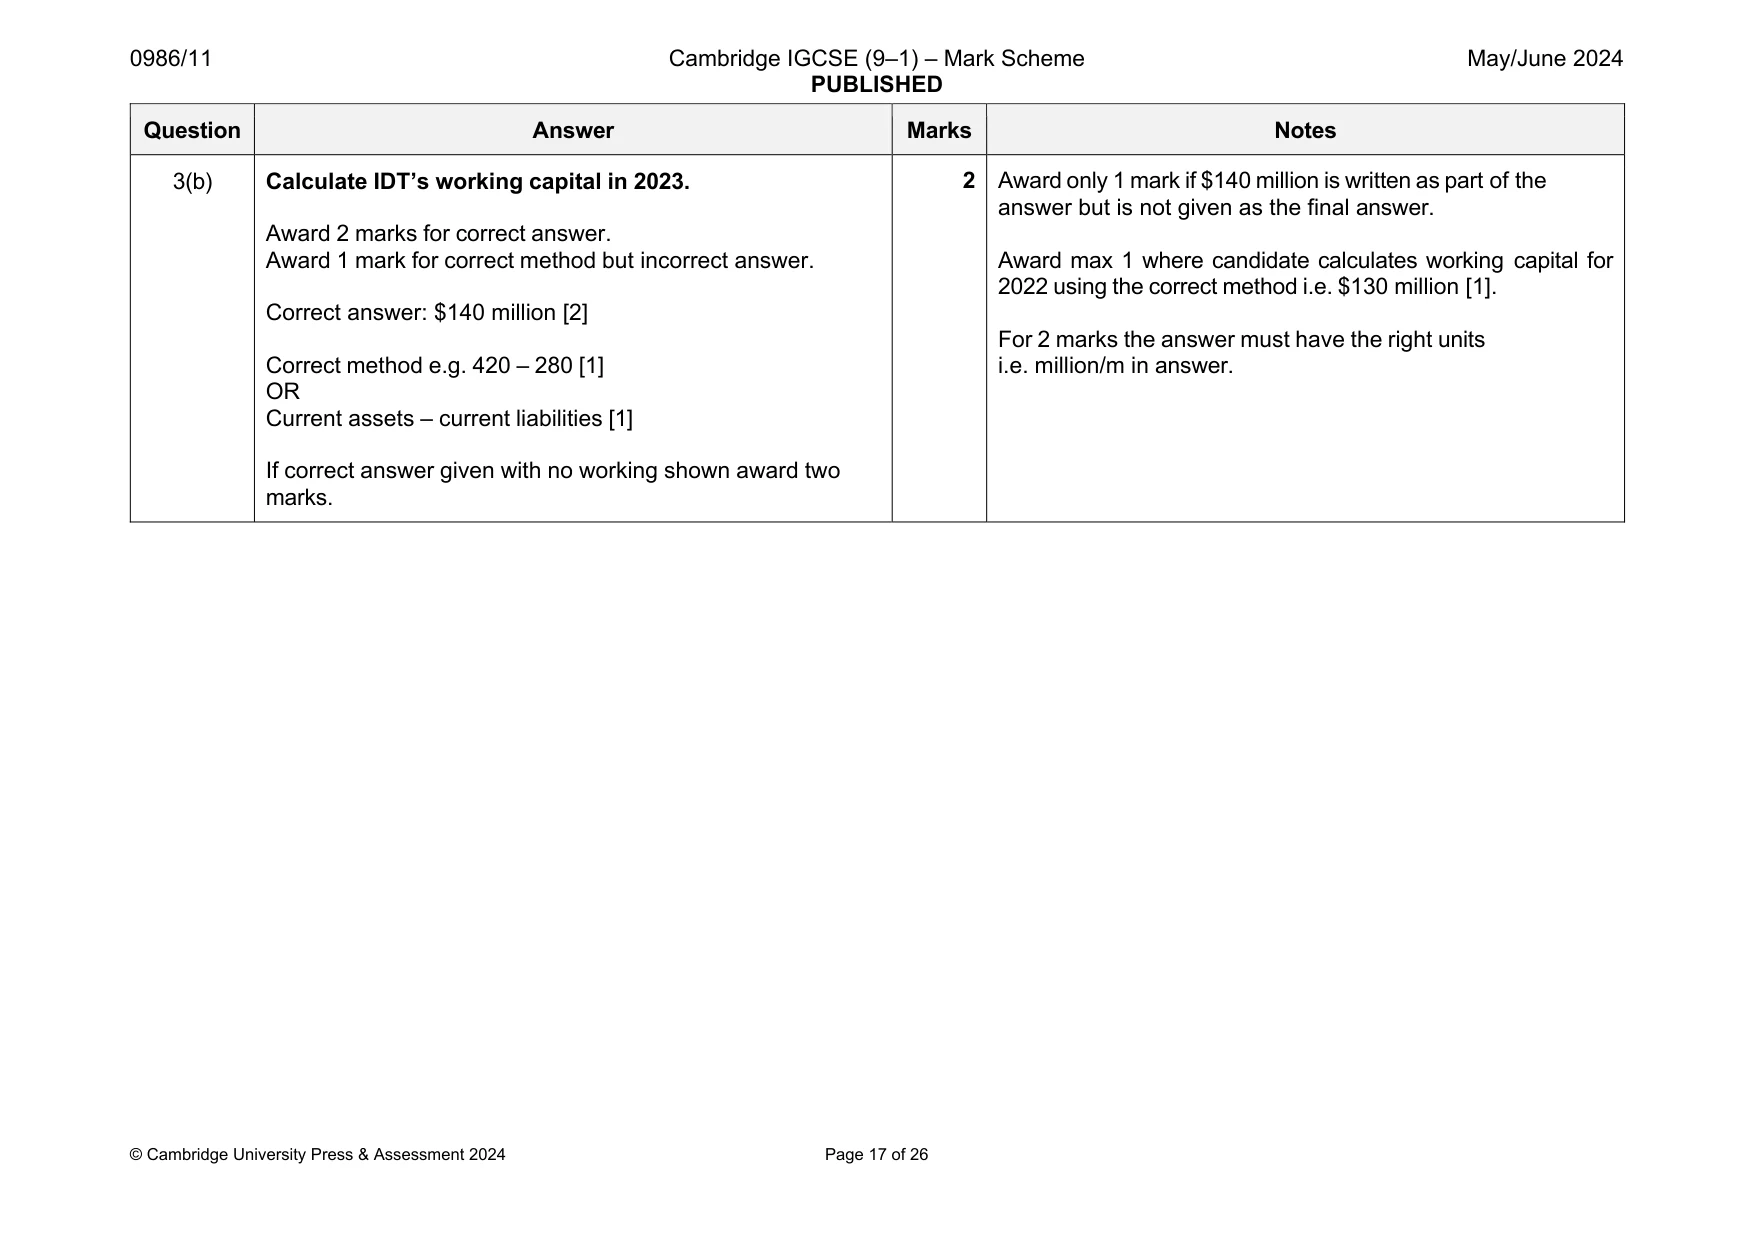
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 17 of 26 Question Answer Marks Notes 3(b) Calculate IDT’s working capital in 2023. Award 2 marks for correct answer. Award 1 mark for correct method but incorrect answer. Correct answer: $140 million [2] Correct method e.g. 420 – 280 [1] OR Current assets – current liabilities [1] If correct answer given with no working shown award two marks. 2 Award only 1 mark if $140 million is written as part of the answer but is not given as the final answer. Award max 1 where candidate calculates working capital for 2022 using the correct method i.e. $130 million [1]. For 2 marks the answer must have the right units i.e. million/m in answer.
Mark scheme, page 18
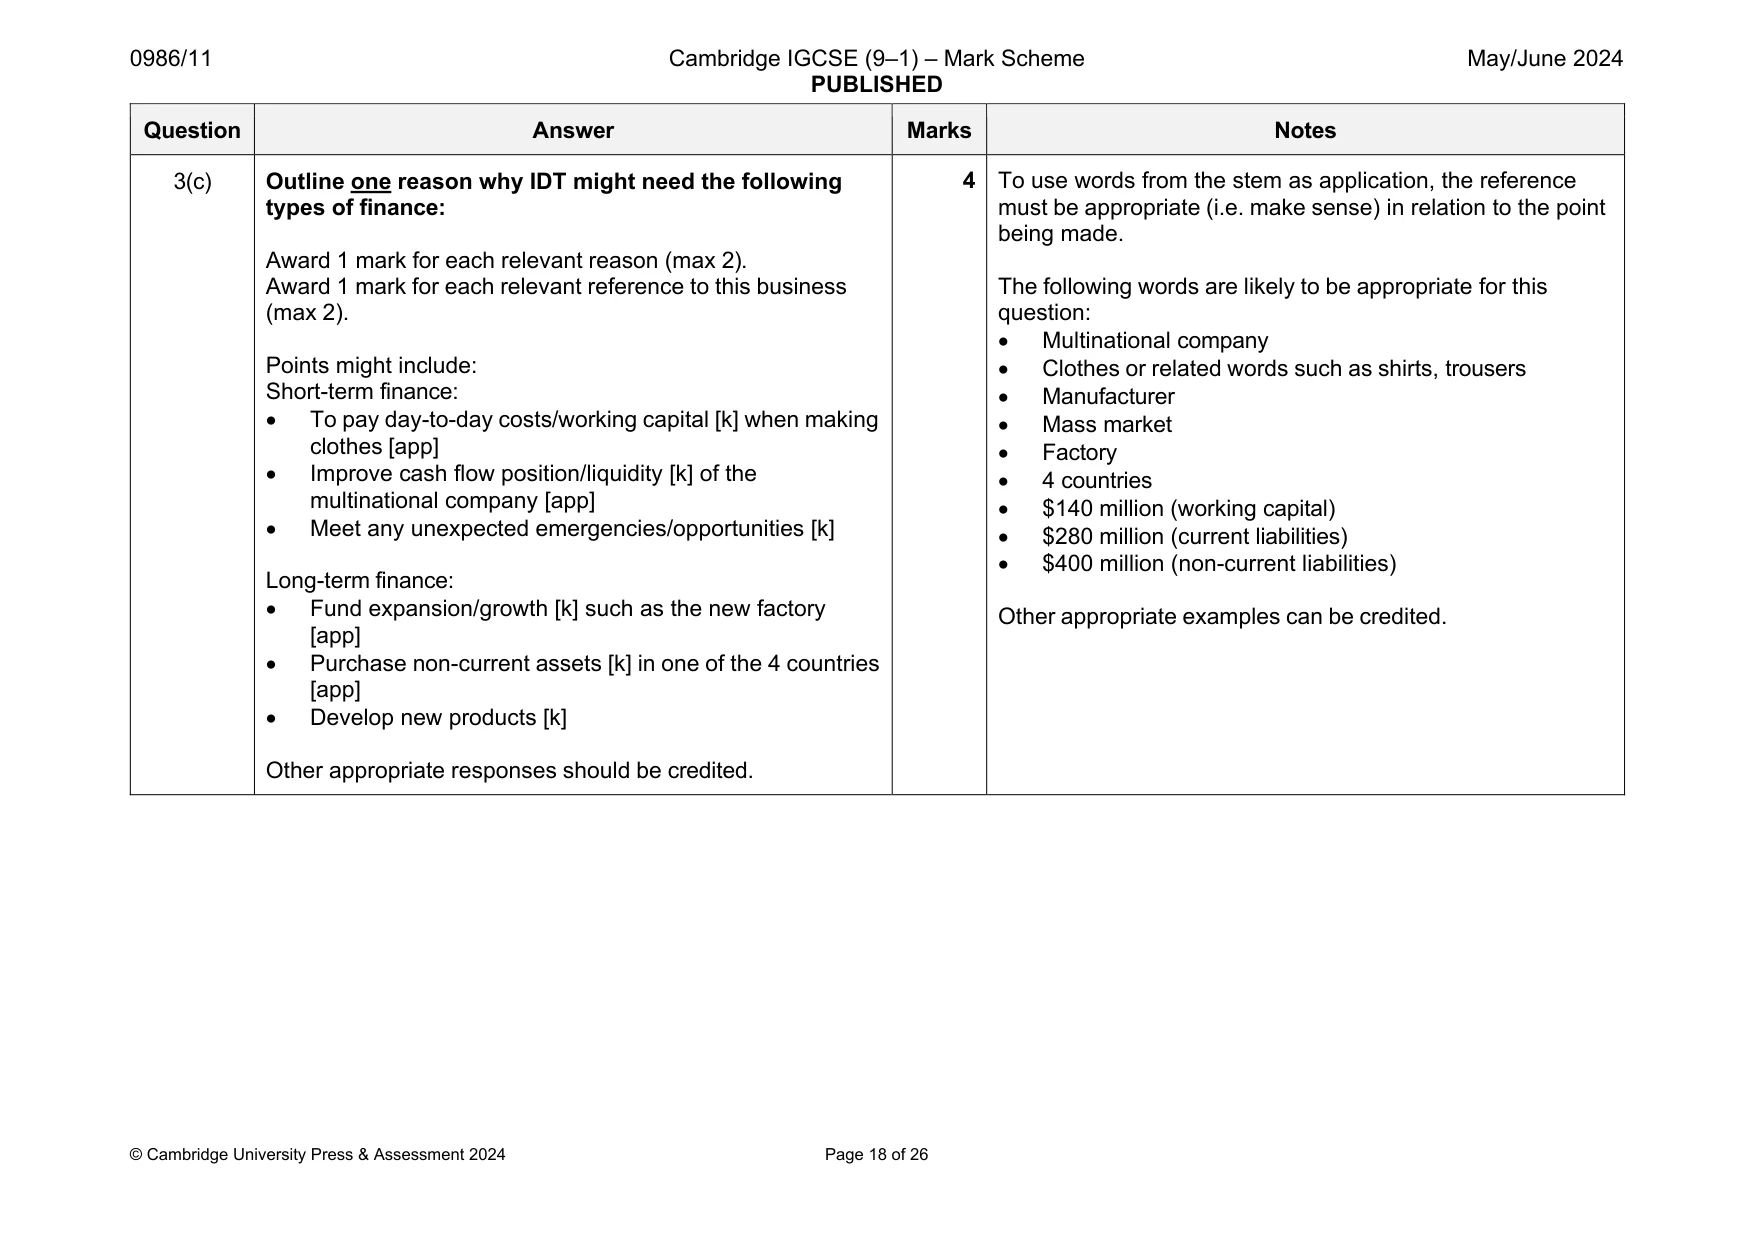
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 18 of 26 Question Answer Marks Notes 3(c) Outline one reason why IDT might need the following types of finance: Award 1 mark for each relevant reason (max 2). Award 1 mark for each relevant reference to this business (max 2). Points might include: Short-term finance: To pay day-to-day costs/working capital [k] when making clothes [app] Improve cash flow position/liquidity [k] of the multinational company [app] Meet any unexpected emergencies/opportunities [k] Long-term finance: Fund expansion/growth [k] such as the new factory [app] Purchase non-current assets [k] in one of the 4 countries [app] Develop new products [k] Other appropriate responses should be credited. 4 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Multinational company Clothes or related words such as shirts, trousers Manufacturer Mass market Factory 4 countries $140 million (working capital) $280 million (current liabilities) $400 million (non-current liabilities) Other appropriate examples can be credited.
Mark scheme, page 19
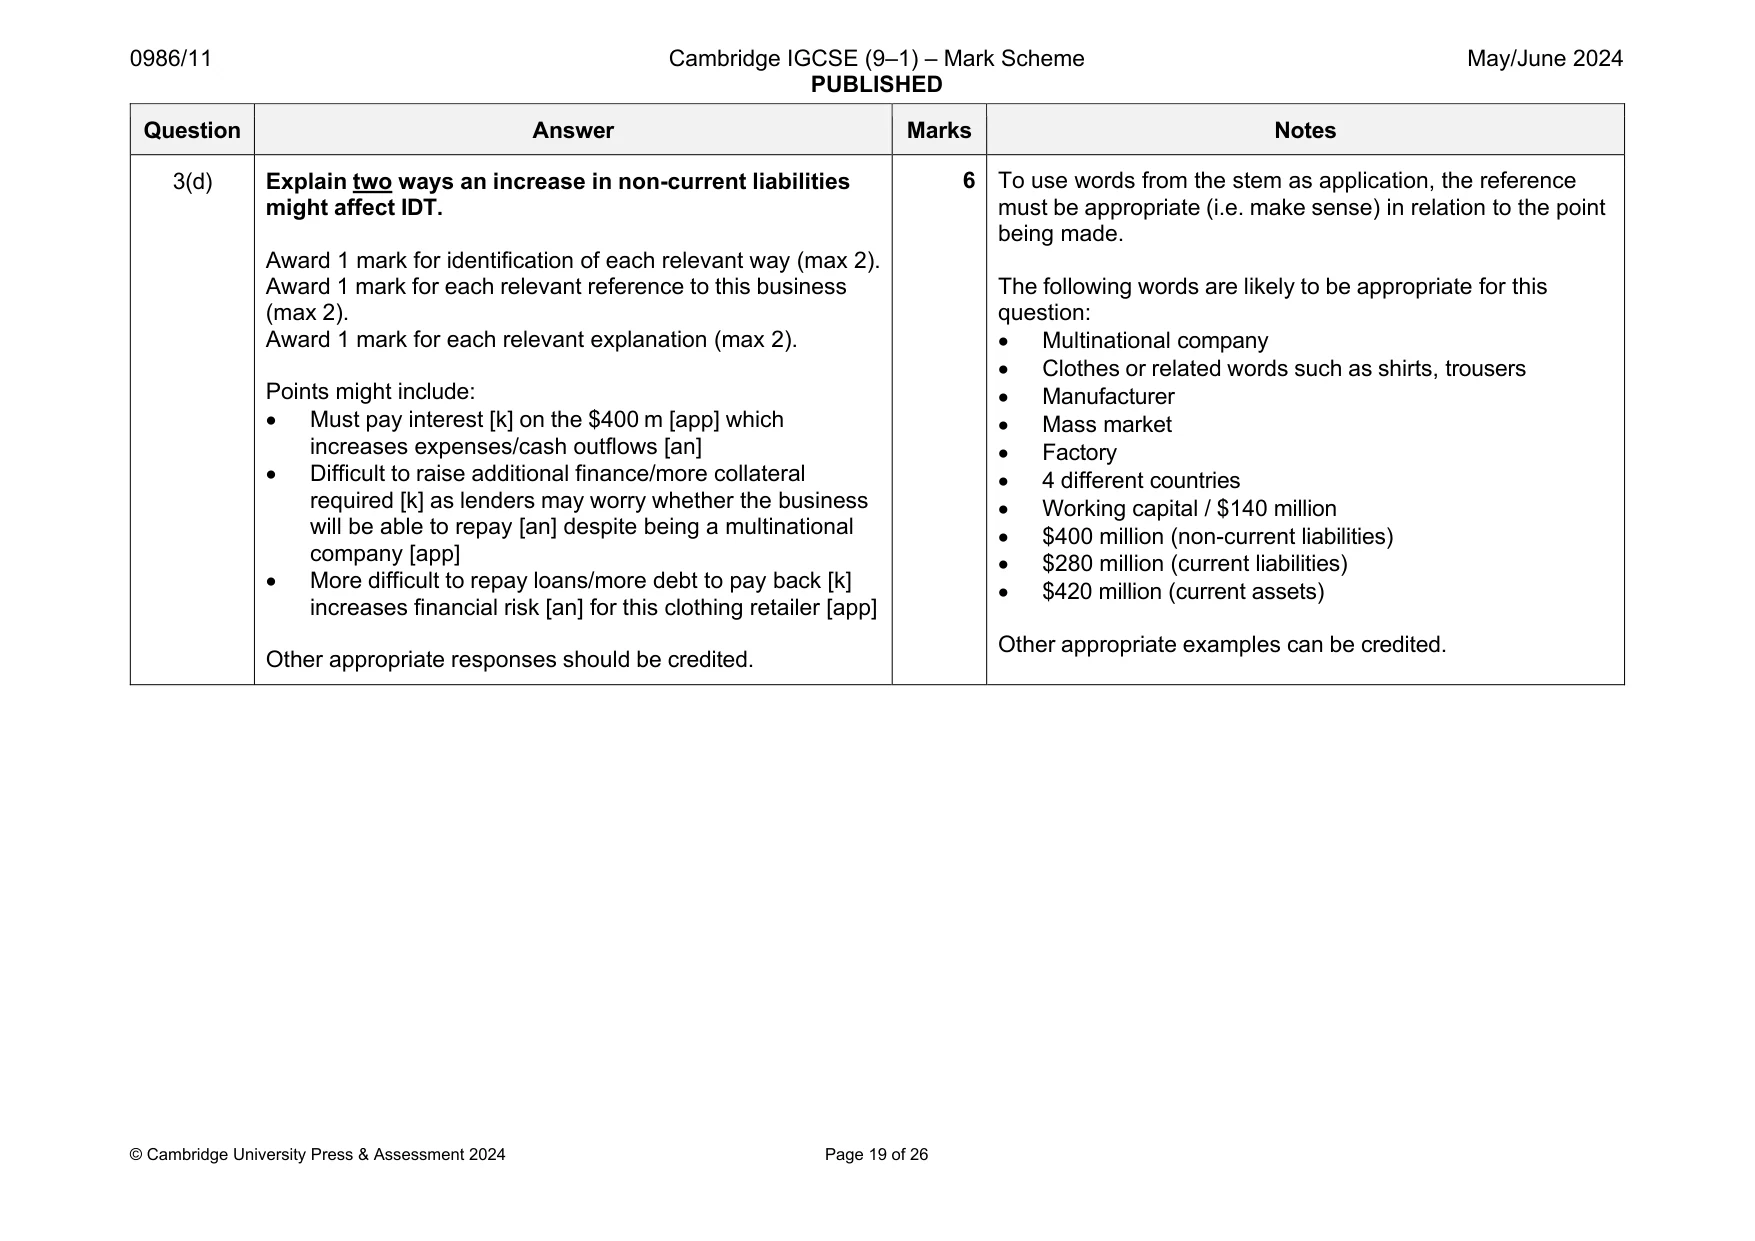
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 19 of 26 Question Answer Marks Notes 3(d) Explain two ways an increase in non-current liabilities might affect IDT. Award 1 mark for identification of each relevant way (max 2). Award 1 mark for each relevant reference to this business (max 2). Award 1 mark for each relevant explanation (max 2). Points might include: Must pay interest [k] on the $400 m [app] which increases expenses/cash outflows [an] Difficult to raise additional finance/more collateral required [k] as lenders may worry whether the business will be able to repay [an] despite being a multinational company [app] More difficult to repay loans/more debt to pay back [k] increases financial risk [an] for this clothing retailer [app] Other appropriate responses should be credited. 6 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Multinational company Clothes or related words such as shirts, trousers Manufacturer Mass market Factory 4 different countries Working capital / $140 million $400 million (non-current liabilities) $280 million (current liabilities) $420 million (current assets) Other appropriate examples can be credited.
Mark scheme, page 20
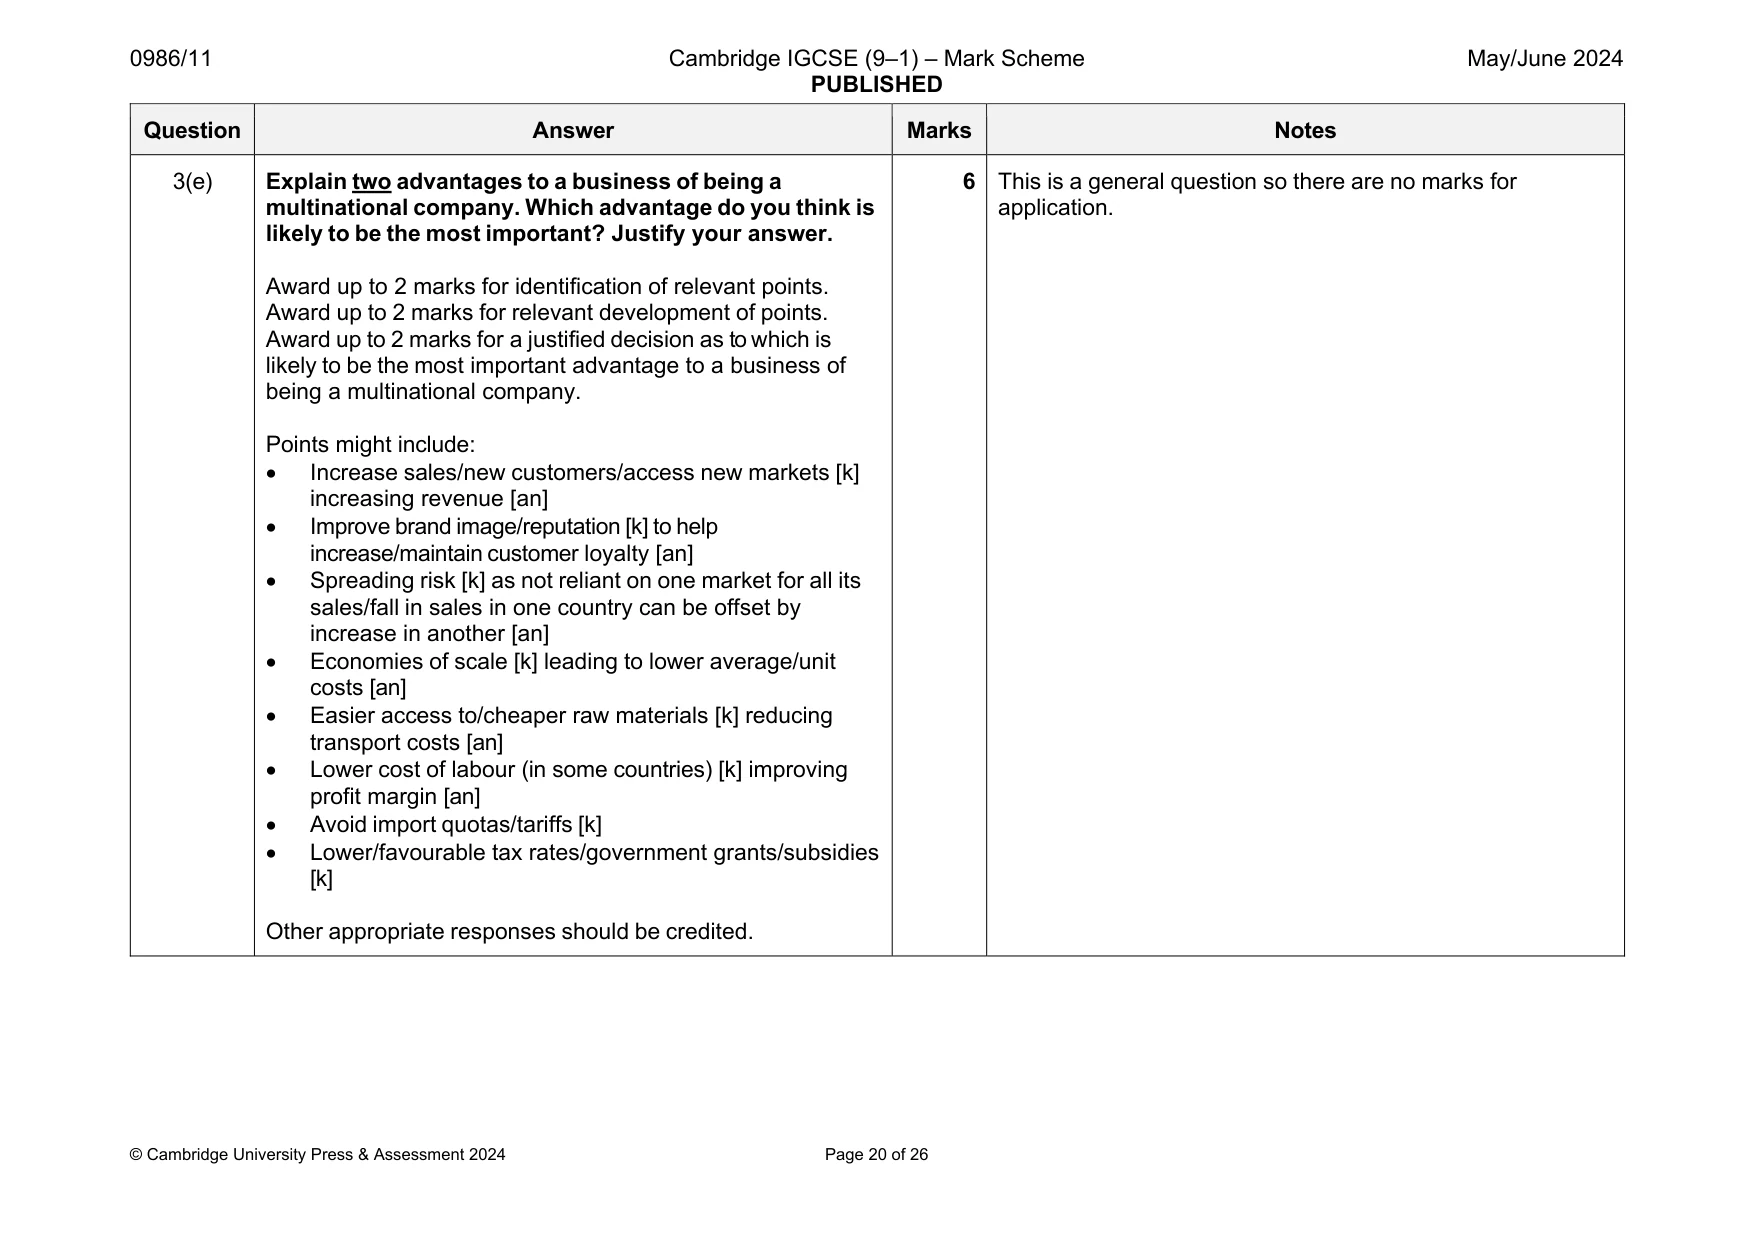
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 20 of 26 Question Answer Marks Notes 3(e) Explain two advantages to a business of being a multinational company. Which advantage do you think is likely to be the most important? Justify your answer. Award up to 2 marks for identification of relevant points. Award up to 2 marks for relevant development of points. Award up to 2 marks for a justified decision as to which is likely to be the most important advantage to a business of being a multinational company. Points might include: Increase sales/new customers/access new markets [k] increasing revenue [an] Improve brand image/reputation [k] to help increase/maintain customer loyalty [an] Spreading risk [k] as not reliant on one market for all its sales/fall in sales in one country can be offset by increase in another [an] Economies of scale [k] leading to lower average/unit costs [an] Easier access to/cheaper raw materials [k] reducing transport costs [an] Lower cost of labour (in some countries) [k] improving profit margin [an] Avoid import quotas/tariffs [k] Lower/favourable tax rates/government grants/subsidies [k] Other appropriate responses should be credited. 6 This is a general question so there are no marks for application.
Mark scheme, page 21
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 21 of 26 Question Answer Marks Notes 3(e) Justification might include: An advantage is access to new markets [k] increasing revenue [an]. Also easier access to raw materials [k] may reduce transport costs [an]. Access to raw materials is more important because lower costs may lead to lower prices helping the business be more competitive [eval] and improve their market share [eval]. Question Answer Marks Notes 4(a) Define ‘social enterprise’. Award 2 marks for a full definition. Award 1 mark for a partial definition. An organisation that has social objectives as well as an aim to make a profit to reinvest back into the business [2] OR A business with social objectives that reinvests most of its profits back into the business/into benefiting society at large [2] OR A business that seeks to raise income, which it invests in a specific social or environmental issue [2] OR A business set up to help society/a community rather than make a profit [2] Partial definition e.g. a business that aims to help/benefit society [1] 2
Mark scheme, page 22
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 22 of 26 Question Answer Marks Notes 4(b) Identify two ways legal controls over marketing might affect a business. Award 1 mark per way (max 2). Points might include: No misleading promotion/advertising No price fixing/charging very high prices where there is little or no competition No selling faulty/dangerous goods/certain ingredients Ensure products are fit for purpose Price reductions must be genuine Increased costs to meet the legal controls/pay fines Spend longer time ensuring they meet the legal controls May need to alter packaging Restrictions on advertising certain products to some age groups/places. Other appropriate responses should also be credited. 2 Only award the first two responses given.
Mark scheme, page 23
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 23 of 26 Question Answer Marks Notes 4(c) Outline one advantage and one disadvantage to CFG of using skimming as its pricing method. Award 1 mark for each relevant advantage/disadvantage (max 2). Award 1 mark for each relevant reference to this business (max 2). Points might include: Advantages: Helps establish a high-quality image/customers may think it is a good quality [k] which may also help as want to be ethical [app] Can quickly recover research/development costs [k] which is important as developed a new product [app] Higher revenue per item [k] for its chocolate [app] May have a lower break-even output [k] Disadvantages: High price might discourage (potential) customers [k] for this social enterprise [app] High prices/profitability could encourage competitors to enter market [k] so may not be able to support local farmers [app] Other appropriate responses should be credited. 4 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Social enterprise Cocoa beans Local farmers Chocolate (bar) Retailers Ethical (Developed) a new product Legal controls over marketing Other appropriate responses can be credited.
Mark scheme, page 24
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 24 of 26 Question Answer Marks Notes 4(d) Explain one advantage and one disadvantage to CFG of using retailers as its distribution channel for the new product. Award 1 mark for identification of each relevant advantage/disadvantage (max 2). Award 1 mark for each relevant reference to this business (max 2). Award 1 mark for each relevant explanation (max 2). Points might include: Advantages: Producers can sell in large quantities to retailers [k] increasing revenue [an] from its new product [app] Reduced costs (compared to selling direct to consumers) [k] increasing profit margin [an] in this social enterprise [app] Retailer shares the cost of holding inventory [k] lowering expenses [an] Retailers will promote the product [k] reducing the cost of promotion/increasing sales [an] Access wider range of customers [k] Disadvantages: No direct contact with consumer [k] about its chocolate bar [app] so may not adapt to changing needs [an] Final price (paid by consumer) is often high [k] so may be uncompetitive [an] Retailer takes some of profit away from the producer [k] Producer loses some control of marketing mix [k] Retailers usually sell competitors’ products as well [k] Other appropriate responses should also be credited. 6 To use words from the stem as application, the reference must be appropriate (i.e. make sense) in relation to the point being made. The following words are likely to be appropriate for this question: Social enterprise Cocoa beans (Make) bars of chocolate Ethical (Local) farmers Legal controls over marketing Other appropriate responses can be credited.
Mark scheme, page 25
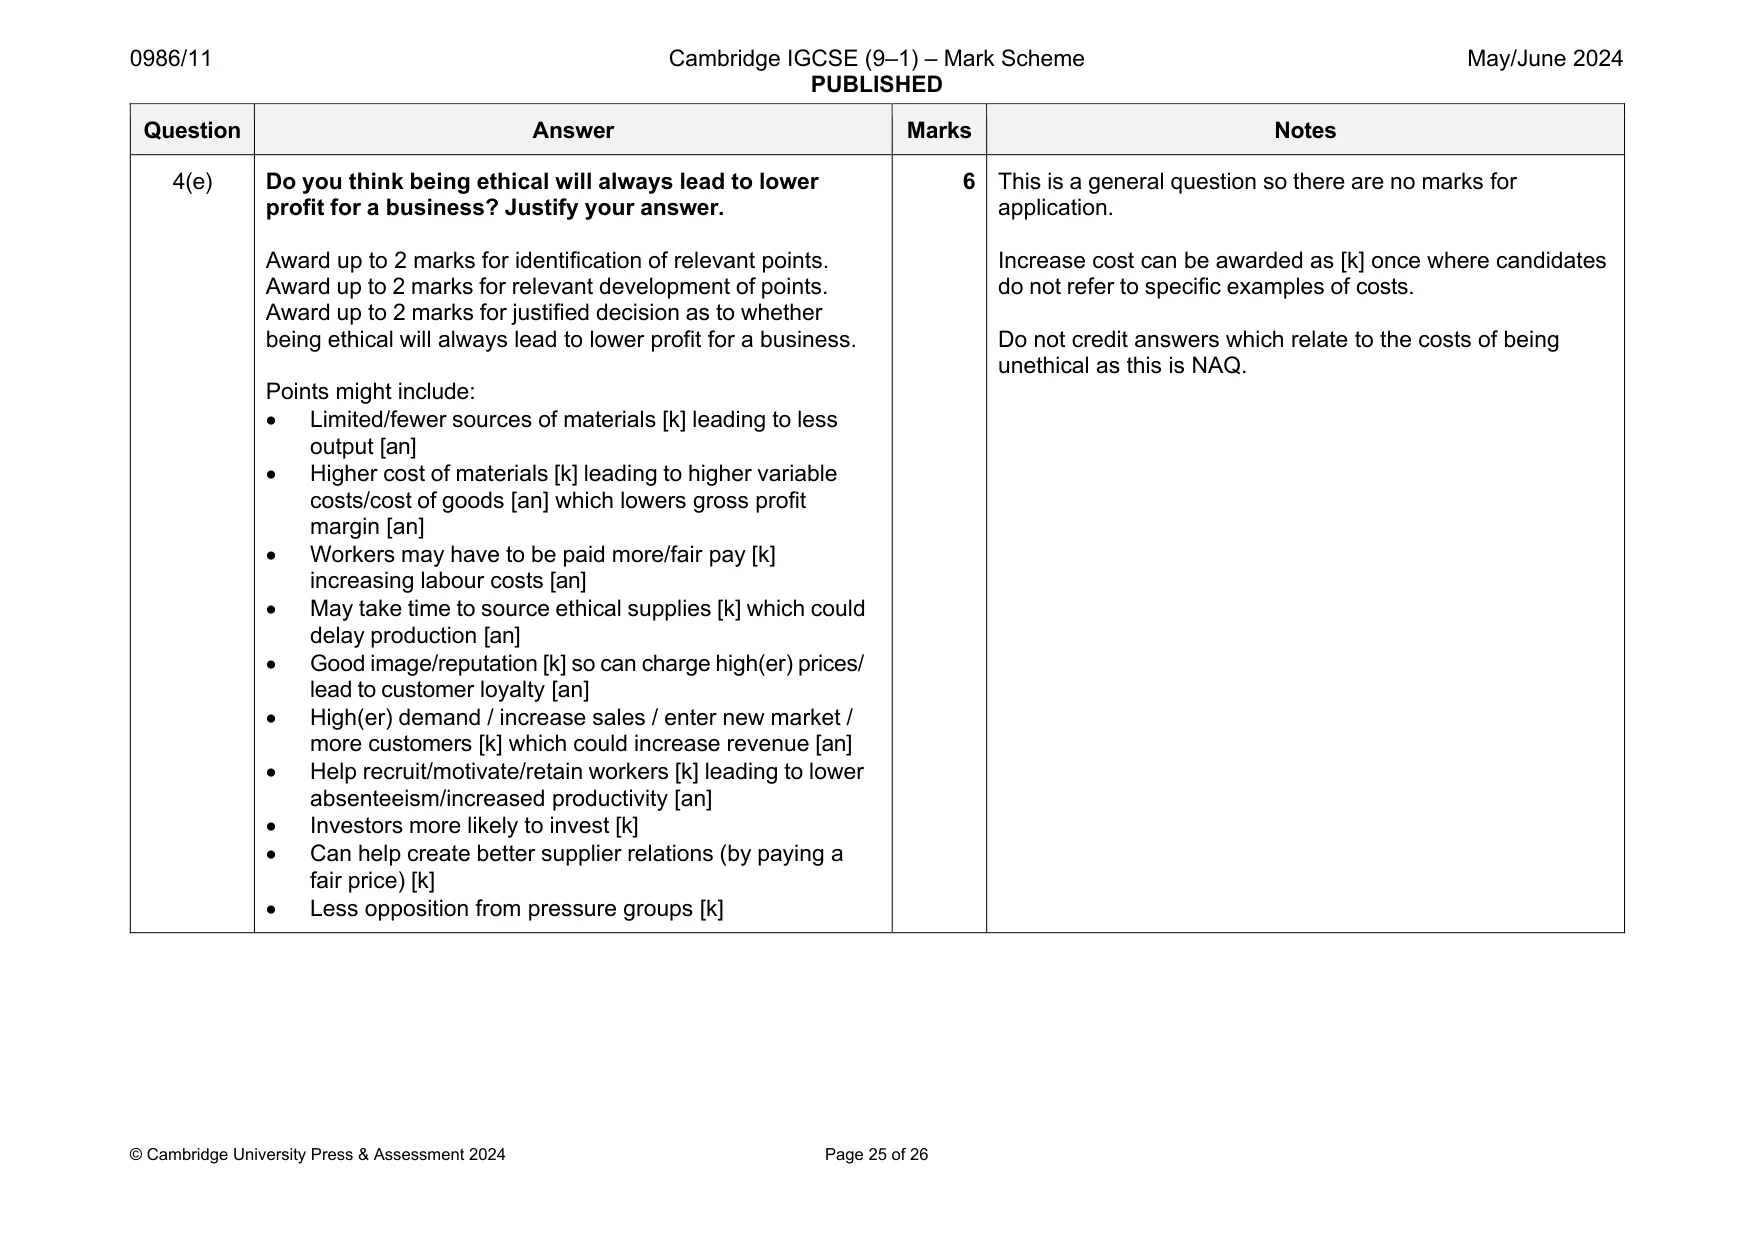
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 25 of 26 Question Answer Marks Notes 4(e) Do you think being ethical will always lead to lower profit for a business? Justify your answer. Award up to 2 marks for identification of relevant points. Award up to 2 marks for relevant development of points. Award up to 2 marks for justified decision as to whether being ethical will always lead to lower profit for a business. Points might include: Limited/fewer sources of materials [k] leading to less output [an] Higher cost of materials [k] leading to higher variable costs/cost of goods [an] which lowers gross profit margin [an] Workers may have to be paid more/fair pay [k] increasing labour costs [an] May take time to source ethical supplies [k] which could delay production [an] Good image/reputation [k] so can charge high(er) prices/ lead to customer loyalty [an] High(er) demand / increase sales / enter new market / more customers [k] which could increase revenue [an] Help recruit/motivate/retain workers [k] leading to lower absenteeism/increased productivity [an] Investors more likely to invest [k] Can help create better supplier relations (by paying a fair price) [k] Less opposition from pressure groups [k] 6 This is a general question so there are no marks for application. Increase cost can be awarded as [k] once where candidates do not refer to specific examples of costs. Do not credit answers which relate to the costs of being unethical as this is NAQ.
Mark scheme, page 26
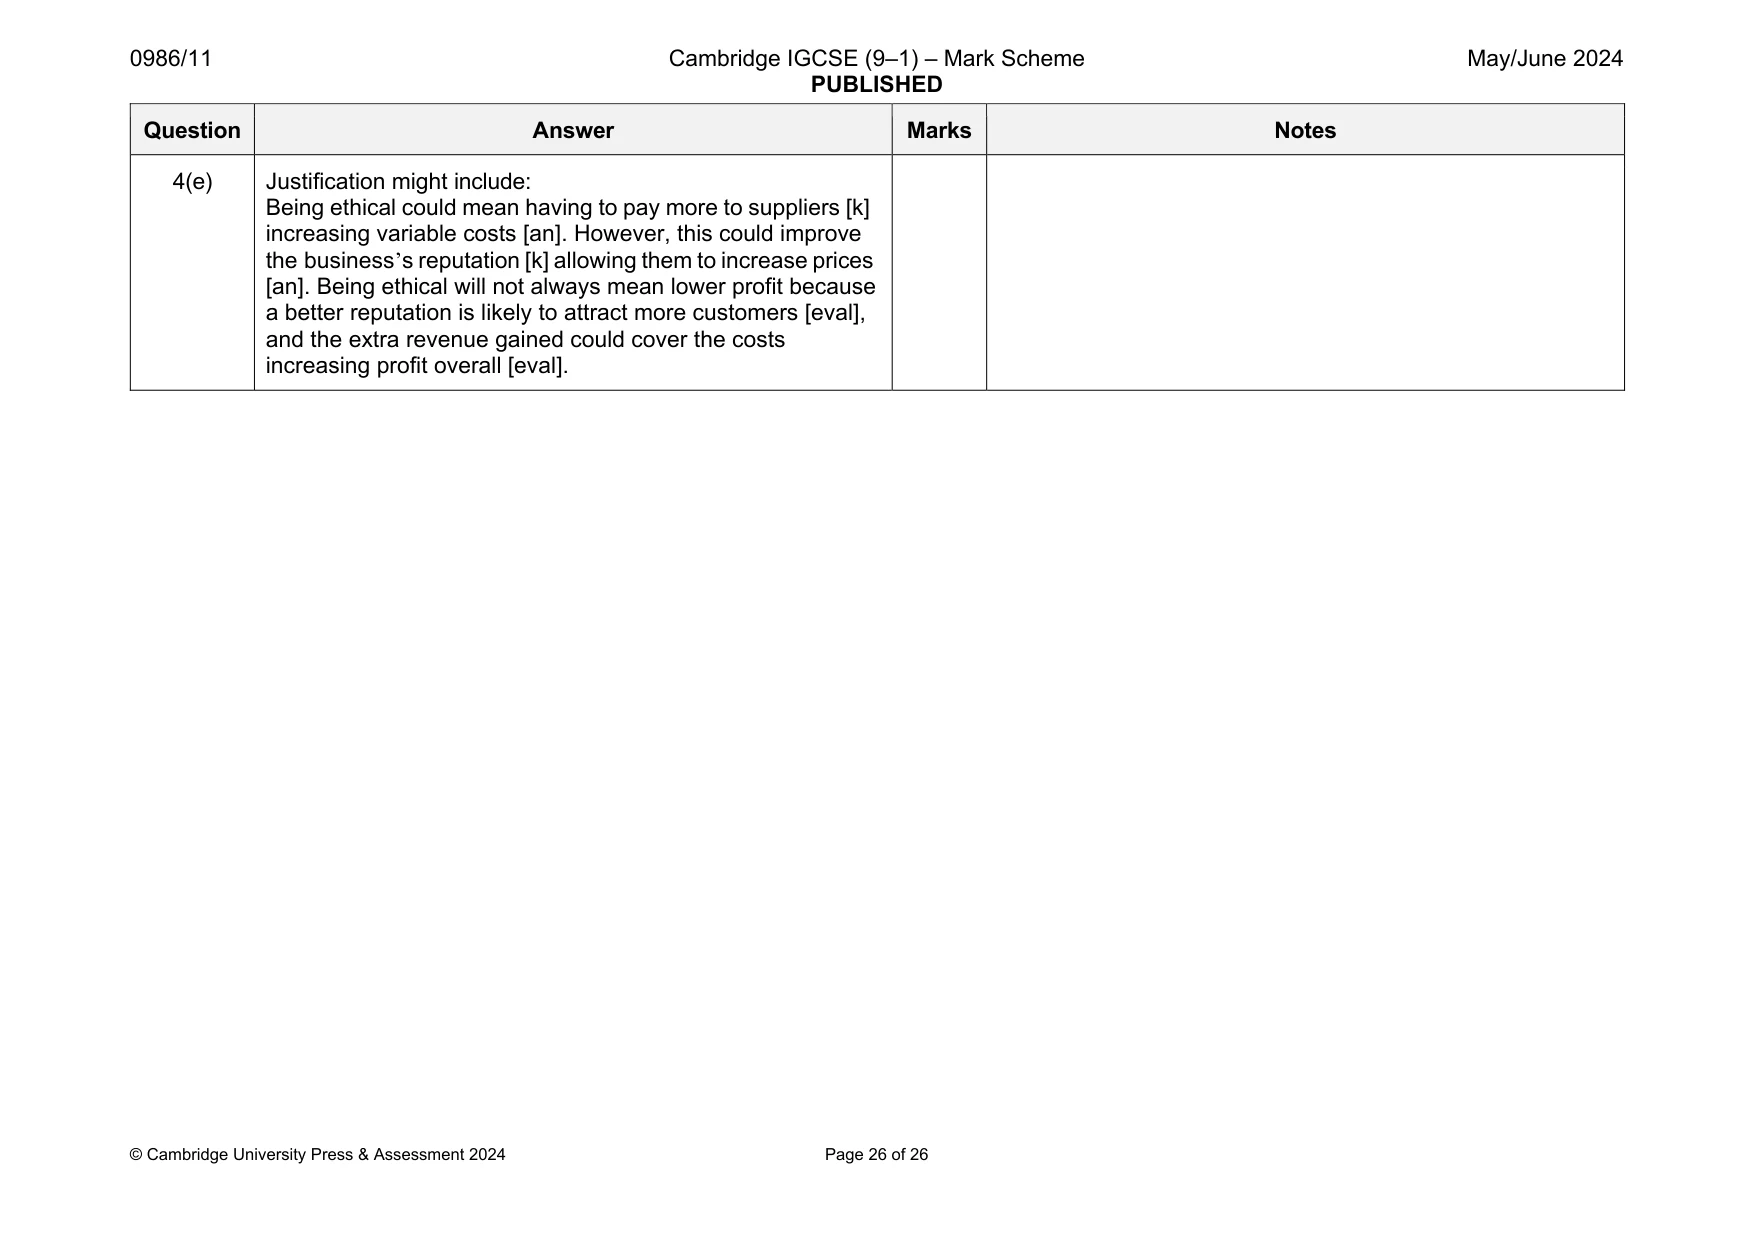
0986/11 Cambridge IGCSE (9–1) – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 26 of 26 Question Answer Marks Notes 4(e) Justification might include: Being ethical could mean having to pay more to suppliers [k] increasing variable costs [an]. However, this could improve the business’s reputation [k] allowing them to increase prices [an]. Being ethical will not always mean lower profit because a better reputation is likely to attract more customers [eval], and the extra revenue gained could cover the costs increasing profit overall [eval].
What you needed in this session
Cambridge’s own grade thresholds for 2024 May/June, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.