Cambridge A Level Accounting 9706 — 2021 Feb/March Paper 3 · Variant 2
9706/32/F/M/21 · 150 marks · ≈169 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper28 pages
Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
Cambridge International AS & A Level This document has 28 pages. Any blank pages are indicated. * 6 5 0 5 3 7 5 8 5 8 * DC (LEG) 201968/5 © UCLES 2021 [Turn over ACCOUNTING 9706/32 Paper 3 Structured Questions February/March 2021 3 hours You must answer on the question paper. You will need: Insert (enclosed) INSTRUCTIONS ● Answer all questions. ● Use a black or dark blue pen. ● Write your name, centre number and candidate number in the boxes at the top of the page. ● Write your answer to each question in the space provided. ● Do not use an erasable pen or correction fluid. ● Do not write on any bar codes. ● You may use an HB pencil for any diagrams, graphs or rough working. ● You may use a calculator. ● International accounting terms and formats should be used as appropriate. ● You should show your workings. INFORMATION ● The total mark for this paper is 150. ● The number of marks for each question or part question is shown in brackets [ ]. ● The insert contains all of the required information and questions.
Question paper, page 2
2 9706/32/F/M/21 © UCLES 2021 Section A: Financial Accounting Answer all questions. 1 Read Source A1 in the insert. (a) Explain how purchased goodwill may arise. … … … … … … … … [4] (b) Calculate the amount of consideration payable by P Limited to Euan. … … … … … … [2]
Question paper, page 3
3 9706/32/F/M/21 © UCLES 2021 [Turn over (c) Prepare the statement of financial position of P Limited immediately after acquiring Euan’s business. Use the space provided on the next page to show your workings. … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 4
4 9706/32/F/M/21 © UCLES 2021 Workings: [13]
Question paper, page 5
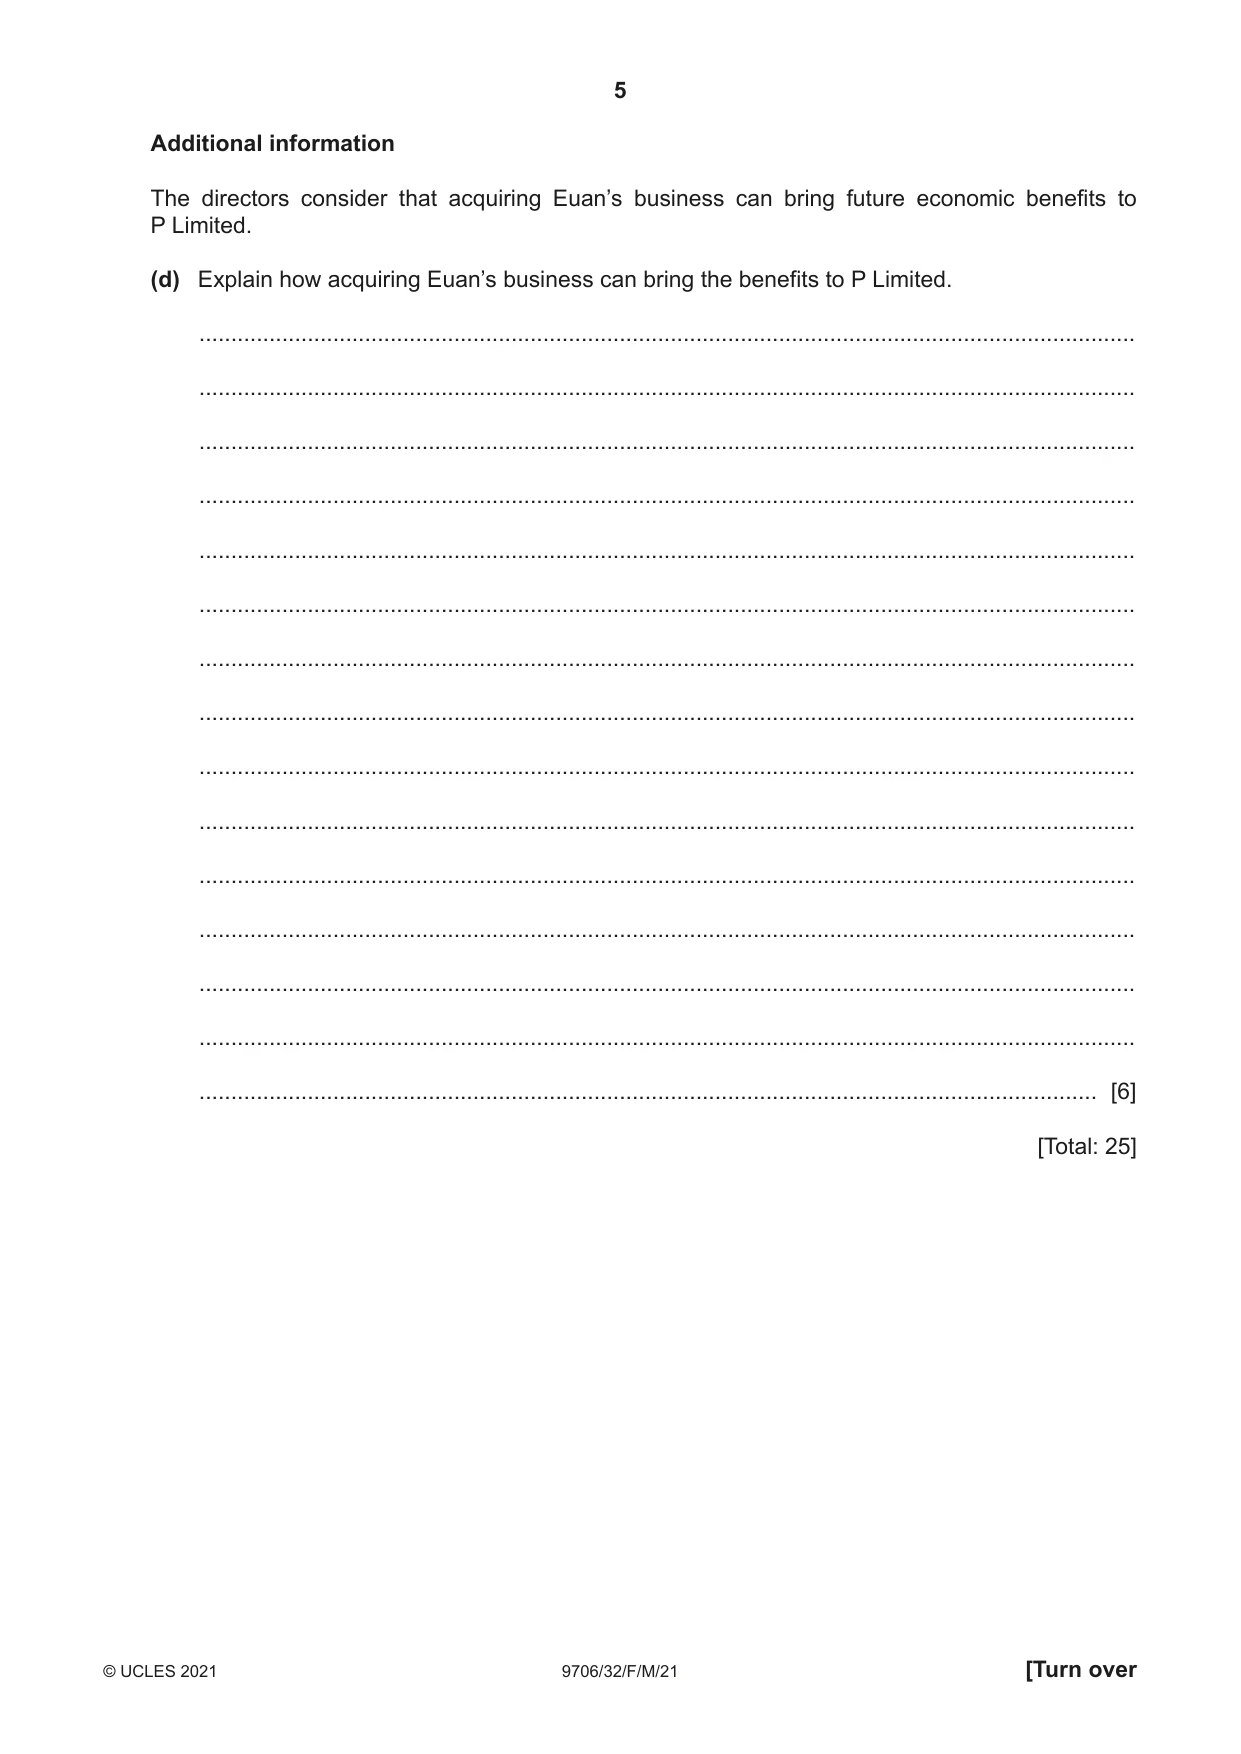
5 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information The directors consider that acquiring Euan’s business can bring future economic benefits to P Limited. (d) Explain how acquiring Euan’s business can bring the benefits to P Limited. … … … … … … … … … … … … … … … [6] [Total: 25]
Question paper, page 6
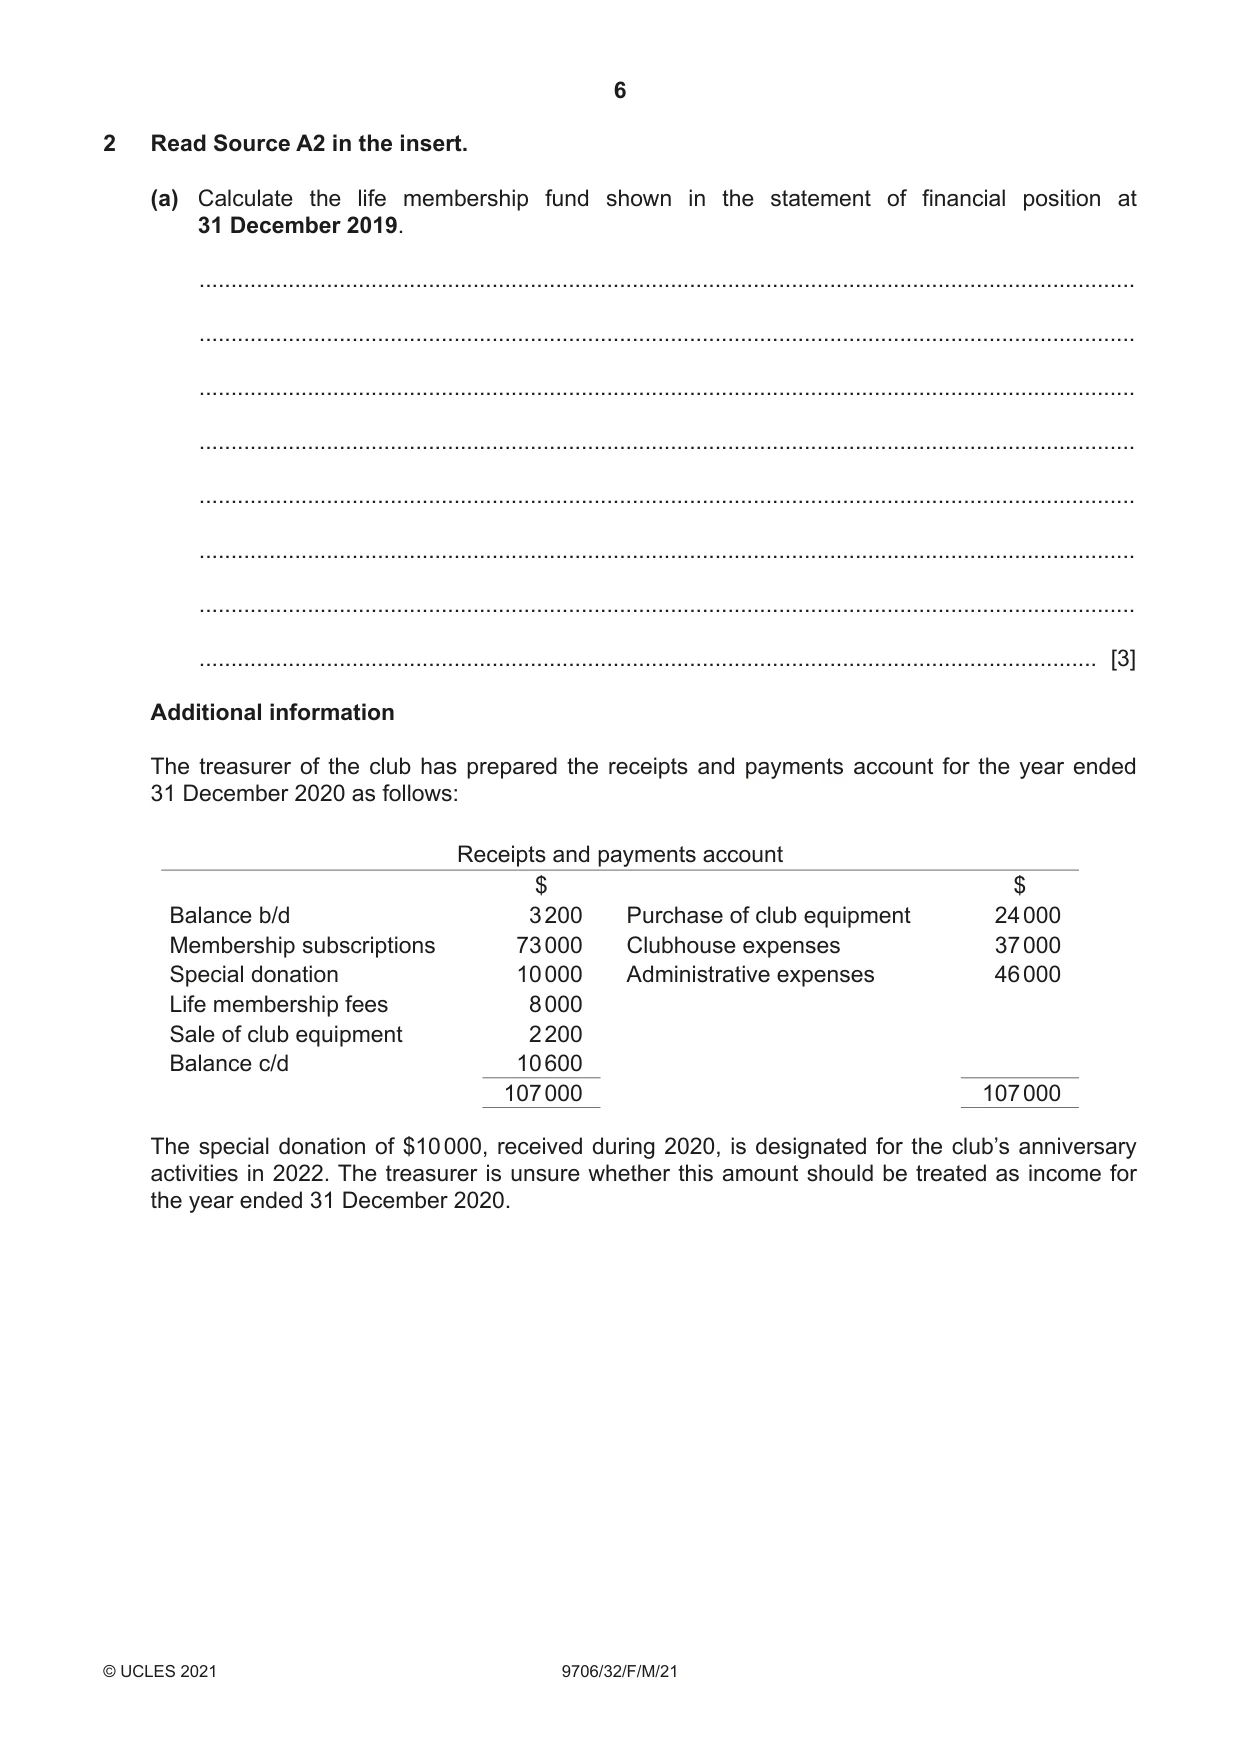
6 9706/32/F/M/21 © UCLES 2021 2 Read Source A2 in the insert. (a) Calculate the life membership fund shown in the statement of financial position at 31 December 2019. … … … … … … … … [3] Additional information The treasurer of the club has prepared the receipts and payments account for the year ended 31 December 2020 as follows: Receipts and payments account $ $ Balance b/d 3 200 Purchase of club equipment 24 000 Membership subscriptions 73 000 Clubhouse expenses 37 000 Special donation 10 000 Administrative expenses 46 000 Life membership fees 8 000 Sale of club equipment 2 200 Balance c/d 10 600 107 000 107 000 The special donation of $10 000, received during 2020, is designated for the club’s anniversary activities in 2022. The treasurer is unsure whether this amount should be treated as income for the year ended 31 December 2020.
Question paper, page 7
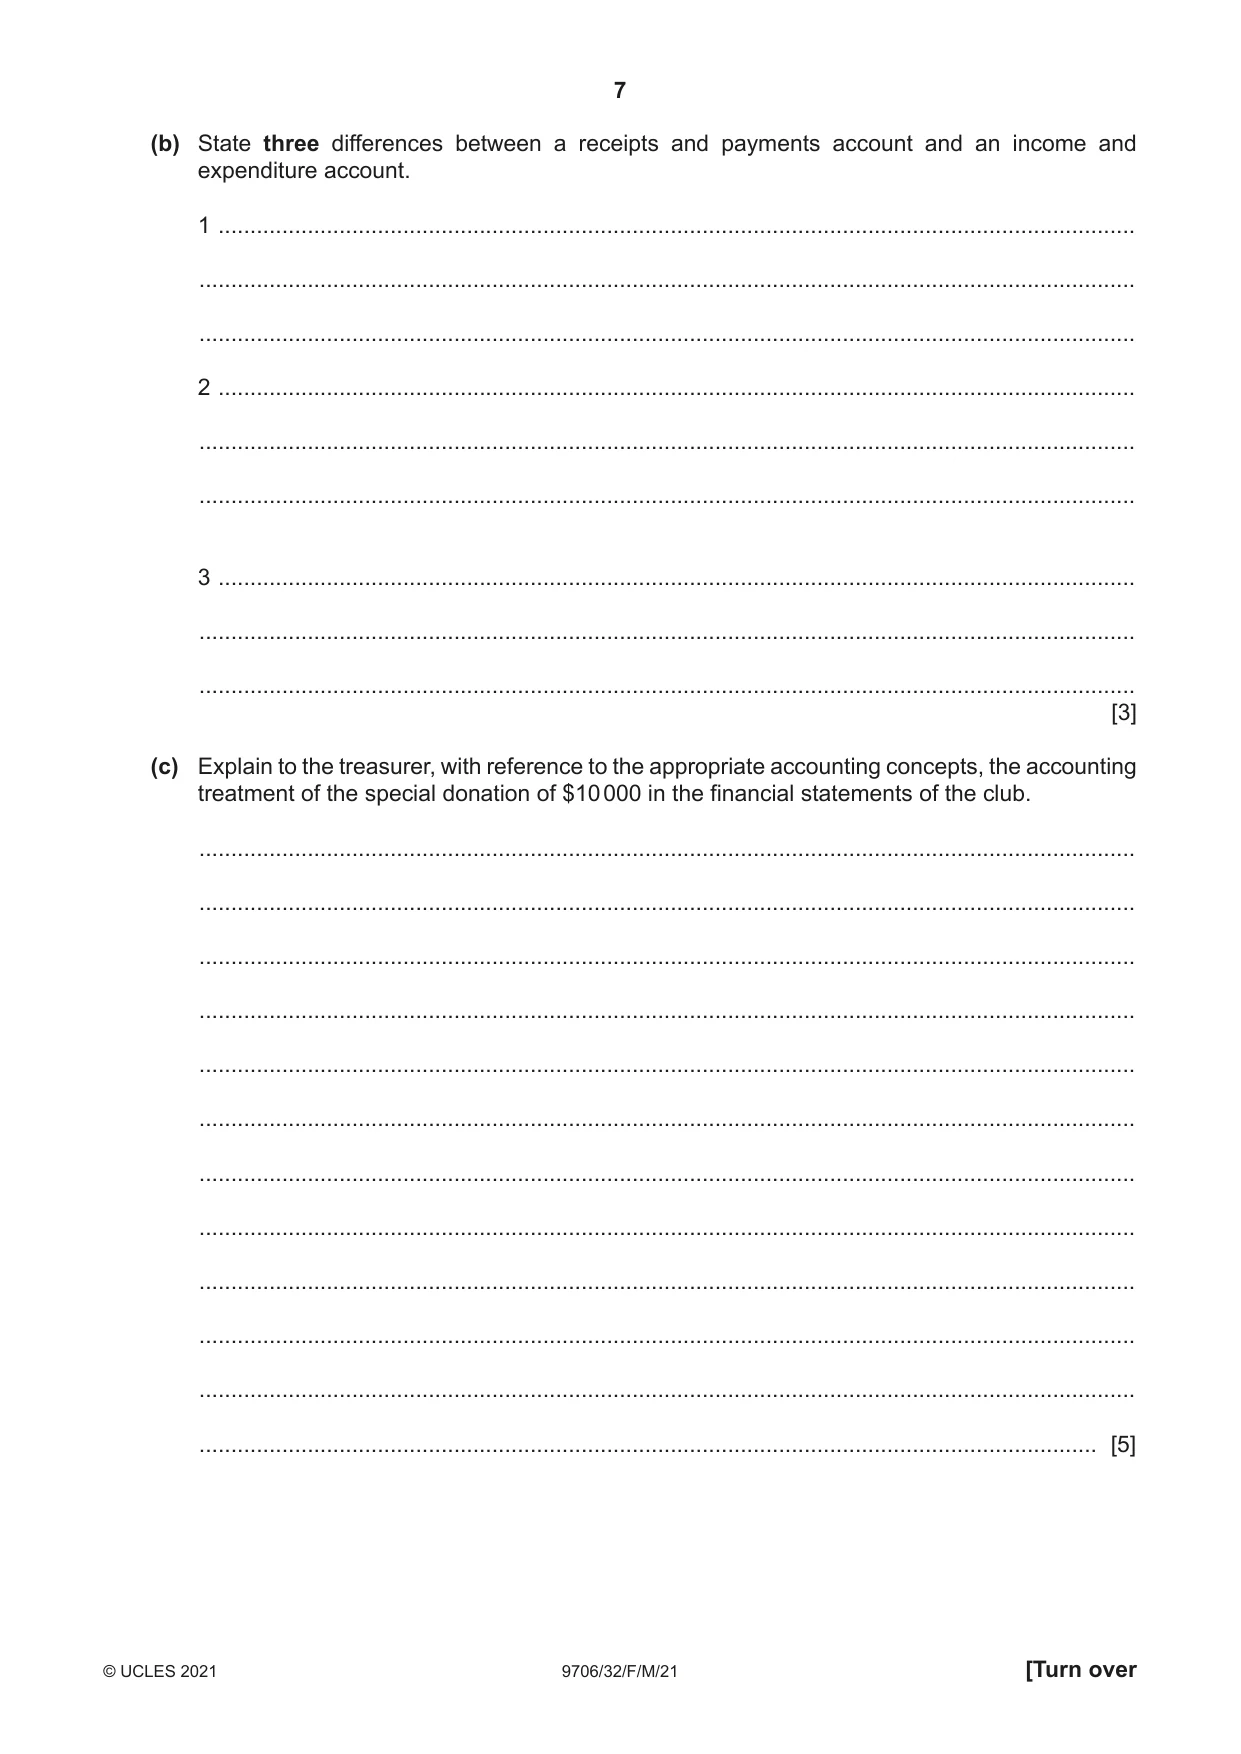
7 9706/32/F/M/21 © UCLES 2021 [Turn over (b) State three differences between a receipts and payments account and an income and expenditure account. 1 … … … 2 … … … 3 … … … [3] (c) Explain to the treasurer, with reference to the appropriate accounting concepts, the accounting treatment of the special donation of $10 000 in the financial statements of the club. … … … … … … … … … … … … [5]
Question paper, page 8
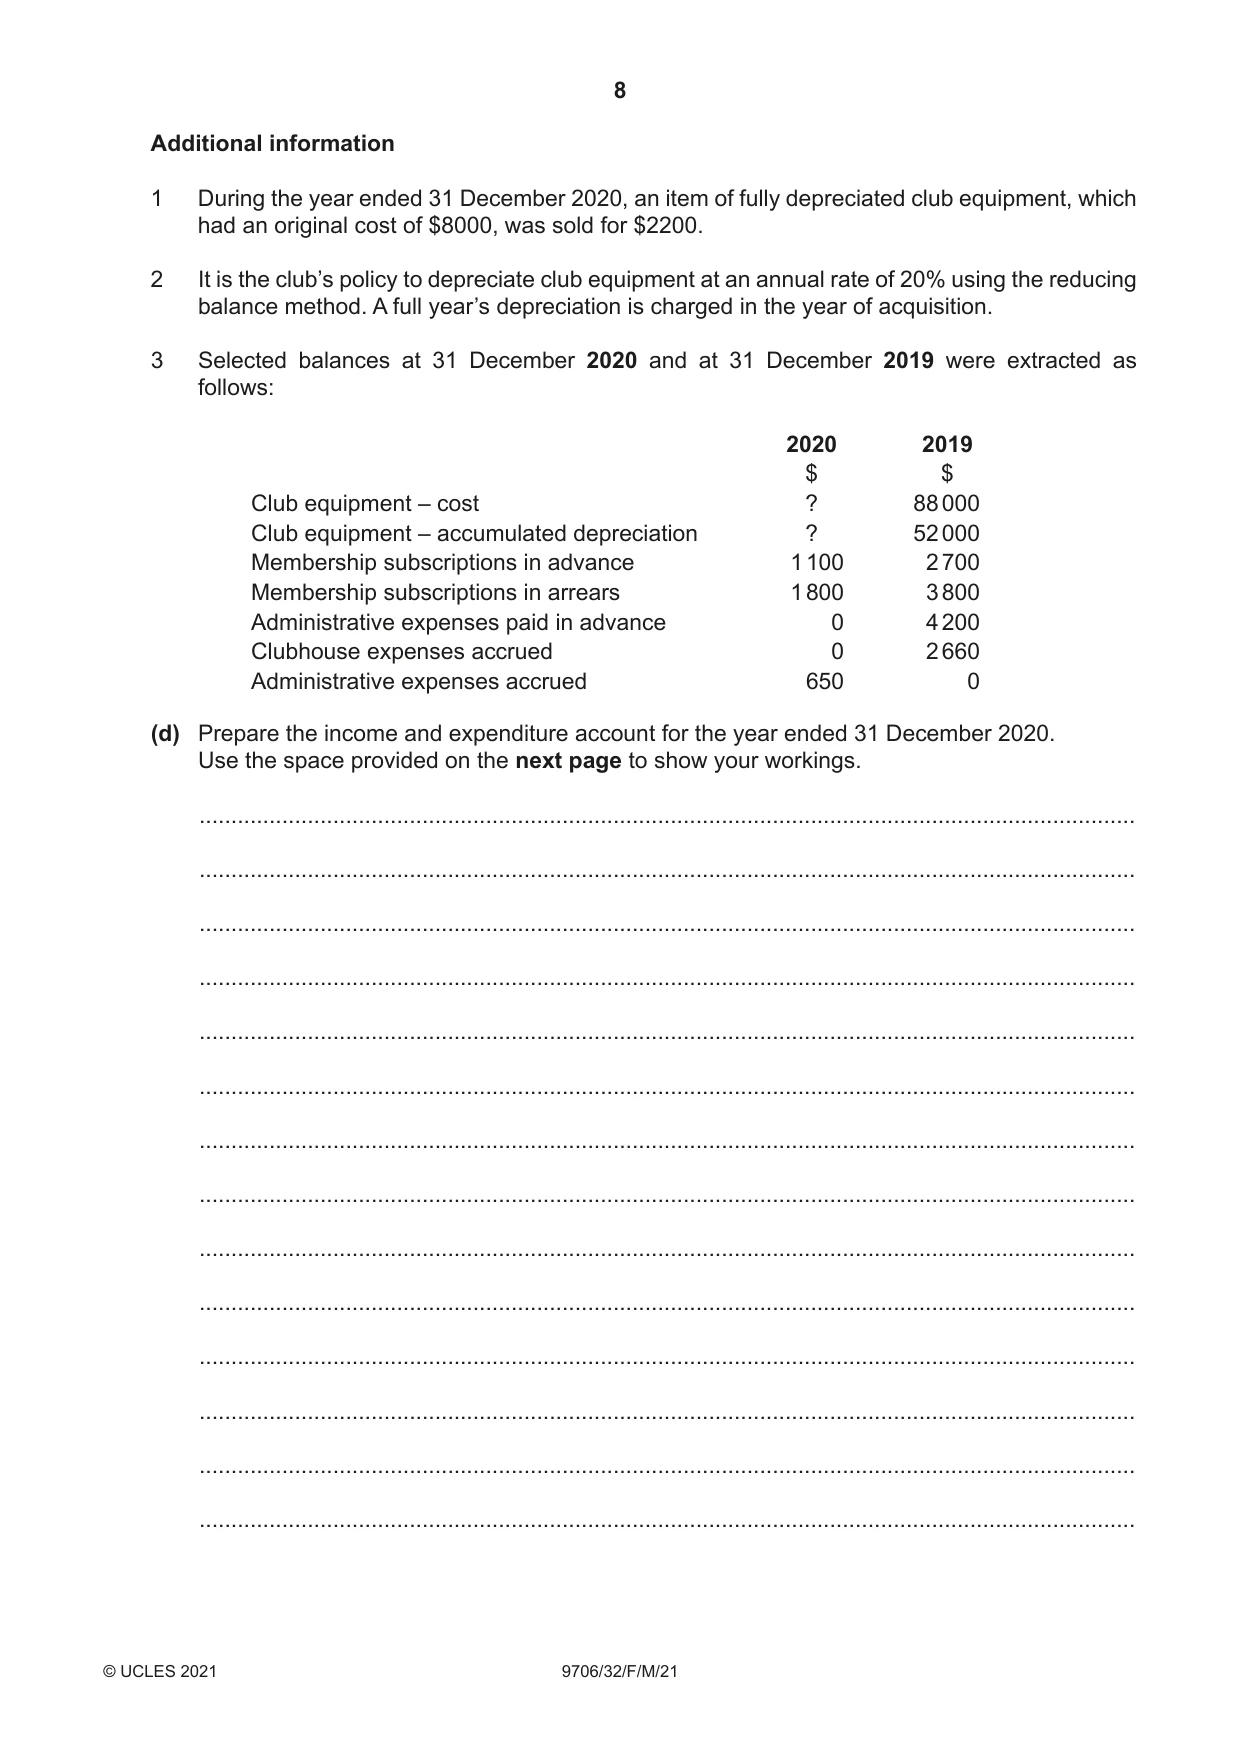
8 9706/32/F/M/21 © UCLES 2021 Additional information 1 During the year ended 31 December 2020, an item of fully depreciated club equipment, which had an original cost of $8000, was sold for $2200. 2 It is the club’s policy to depreciate club equipment at an annual rate of 20% using the reducing balance method. A full year’s depreciation is charged in the year of acquisition. 3 Selected balances at 31 December 2020 and at 31 December 2019 were extracted as follows: 2020 2019 $ $ Club equipment – cost ? 88 000 Club equipment – accumulated depreciation ? 52 000 Membership subscriptions in advance 1 100 2 700 Membership subscriptions in arrears 1 800 3 800 Administrative expenses paid in advance 0 4 200 Clubhouse expenses accrued 0 2 660 Administrative expenses accrued 650 0 (d) Prepare the income and expenditure account for the year ended 31 December 2020. Use the space provided on the next page to show your workings. … … … … … … … … … … … … … …
Question paper, page 9
9 9706/32/F/M/21 © UCLES 2021 [Turn over Workings: [8] Additional information The chairman of the club decided to transfer $6000 from the accumulated fund to a fund designated for the anniversary activities on 31 December 2020. (e) (i) Calculate the accumulated fund at 31 December 2019. … … … … … … … … … … … … [3]
Question paper, page 10
10 9706/32/F/M/21 © UCLES 2021 (ii) Prepare a statement showing the movement on the accumulated fund for the year ended 31 December 2020. … … … … … … [3] [Total: 25]
Question paper, page 11
11 9706/32/F/M/21 © UCLES 2021 [Turn over 3 Read Source A3 in the insert. (a) Prepare the statement of changes in equity for the year ended 31 December 2020, showing the profit for the year as the balancing figure. A total column is required. … … … … … … … … … … … … … … … … … [7] Additional information The following transactions took place during the year ended 31 December 2020. 1 Additional machinery was purchased at the cost of $93 000. 2 A motor vehicle was sold for $26 000. It had a net book value of $29 000 at the date of disposal. 3 Interest paid and charged to the income statement amounted to $19 500.
Question paper, page 12
12 9706/32/F/M/21 © UCLES 2021 (b) Prepare a statement of cash flows for the year ended 31 December 2020 in accordance with IAS 7. Use the space provided on the next page to show your workings. … … … … … … … … … … … … … … … … … … … … … … … … … … …
Question paper, page 13
13 9706/32/F/M/21 © UCLES 2021 [Turn over … … … … … … … … … … … … … Workings: [13]
Question paper, page 14
14 9706/32/F/M/21 © UCLES 2021 (c) Assess the impact of the payment of the dividend and the partial repayment of the debenture on the cash and cash equivalents at 31 December 2020 of T Limited. … … … … … … … … … … … … … … … … … [5] [Total: 25]
Question paper, page 15
15 9706/32/F/M/21 © UCLES 2021 [Turn over PLEASE TURN OVER
Question paper, page 16
16 9706/32/F/M/21 © UCLES 2021 4 Read Source A4 in the insert. (a) State two benefits to each of the following groups when a company issues preference shares. (i) the directors 1 … … 2 … … [2] (ii) the preference shareholders 1 … … 2 … … [2] Additional information Retained earnings at 1 January 2020 amounted to $195 000. During the year 2020, the preference shares dividend, $28 000, and the ordinary shares dividend, $90 000, were paid. A dividend of $0.05 on each of the ordinary shares was proposed at the end of the year. (b) Calculate the profit from operations for the year ended 31 December 2020. … … … … … … … … … [3]
Question paper, page 17
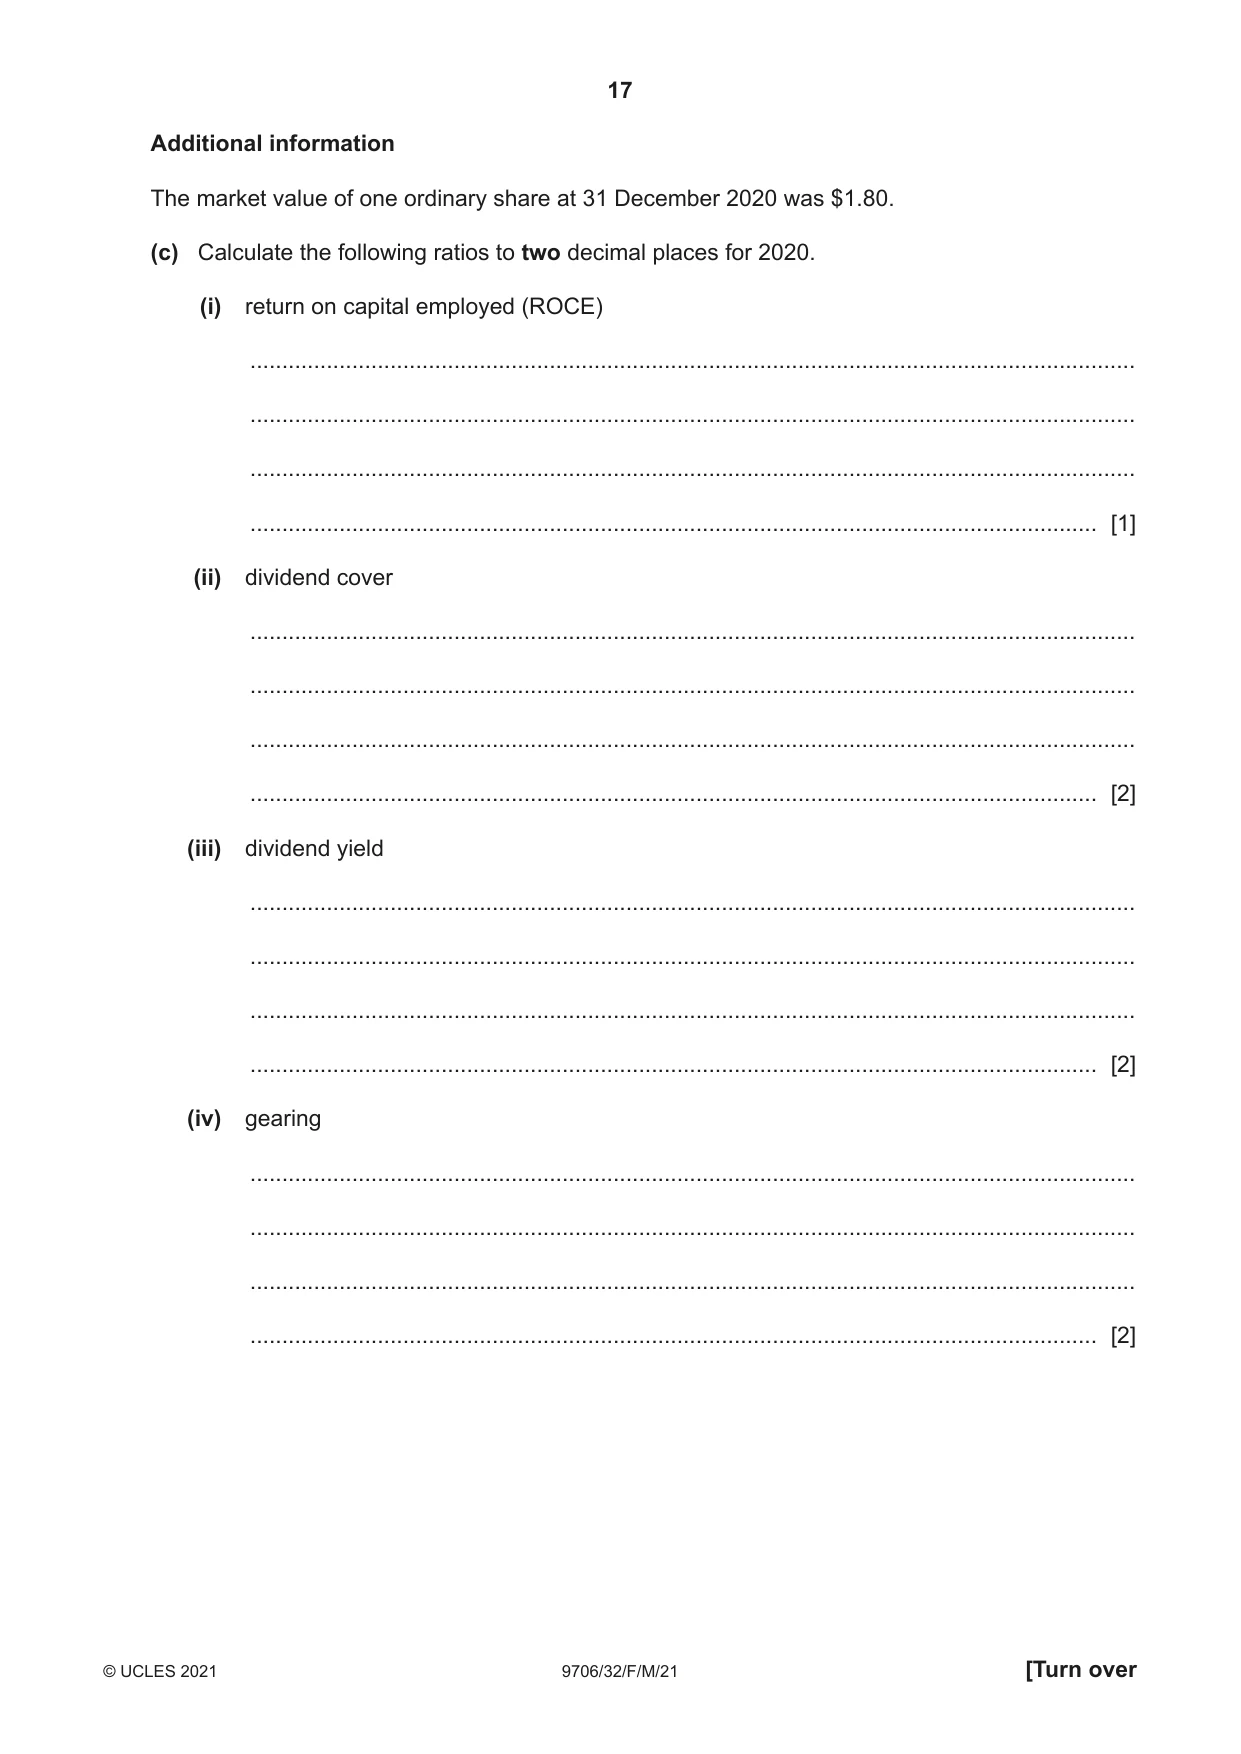
17 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information The market value of one ordinary share at 31 December 2020 was $1.80. (c) Calculate the following ratios to two decimal places for 2020. (i) return on capital employed (ROCE) … … … … [1] (ii) dividend cover … … … … [2] (iii) dividend yield … … … … [2] (iv) gearing … … … … [2]
Question paper, page 18
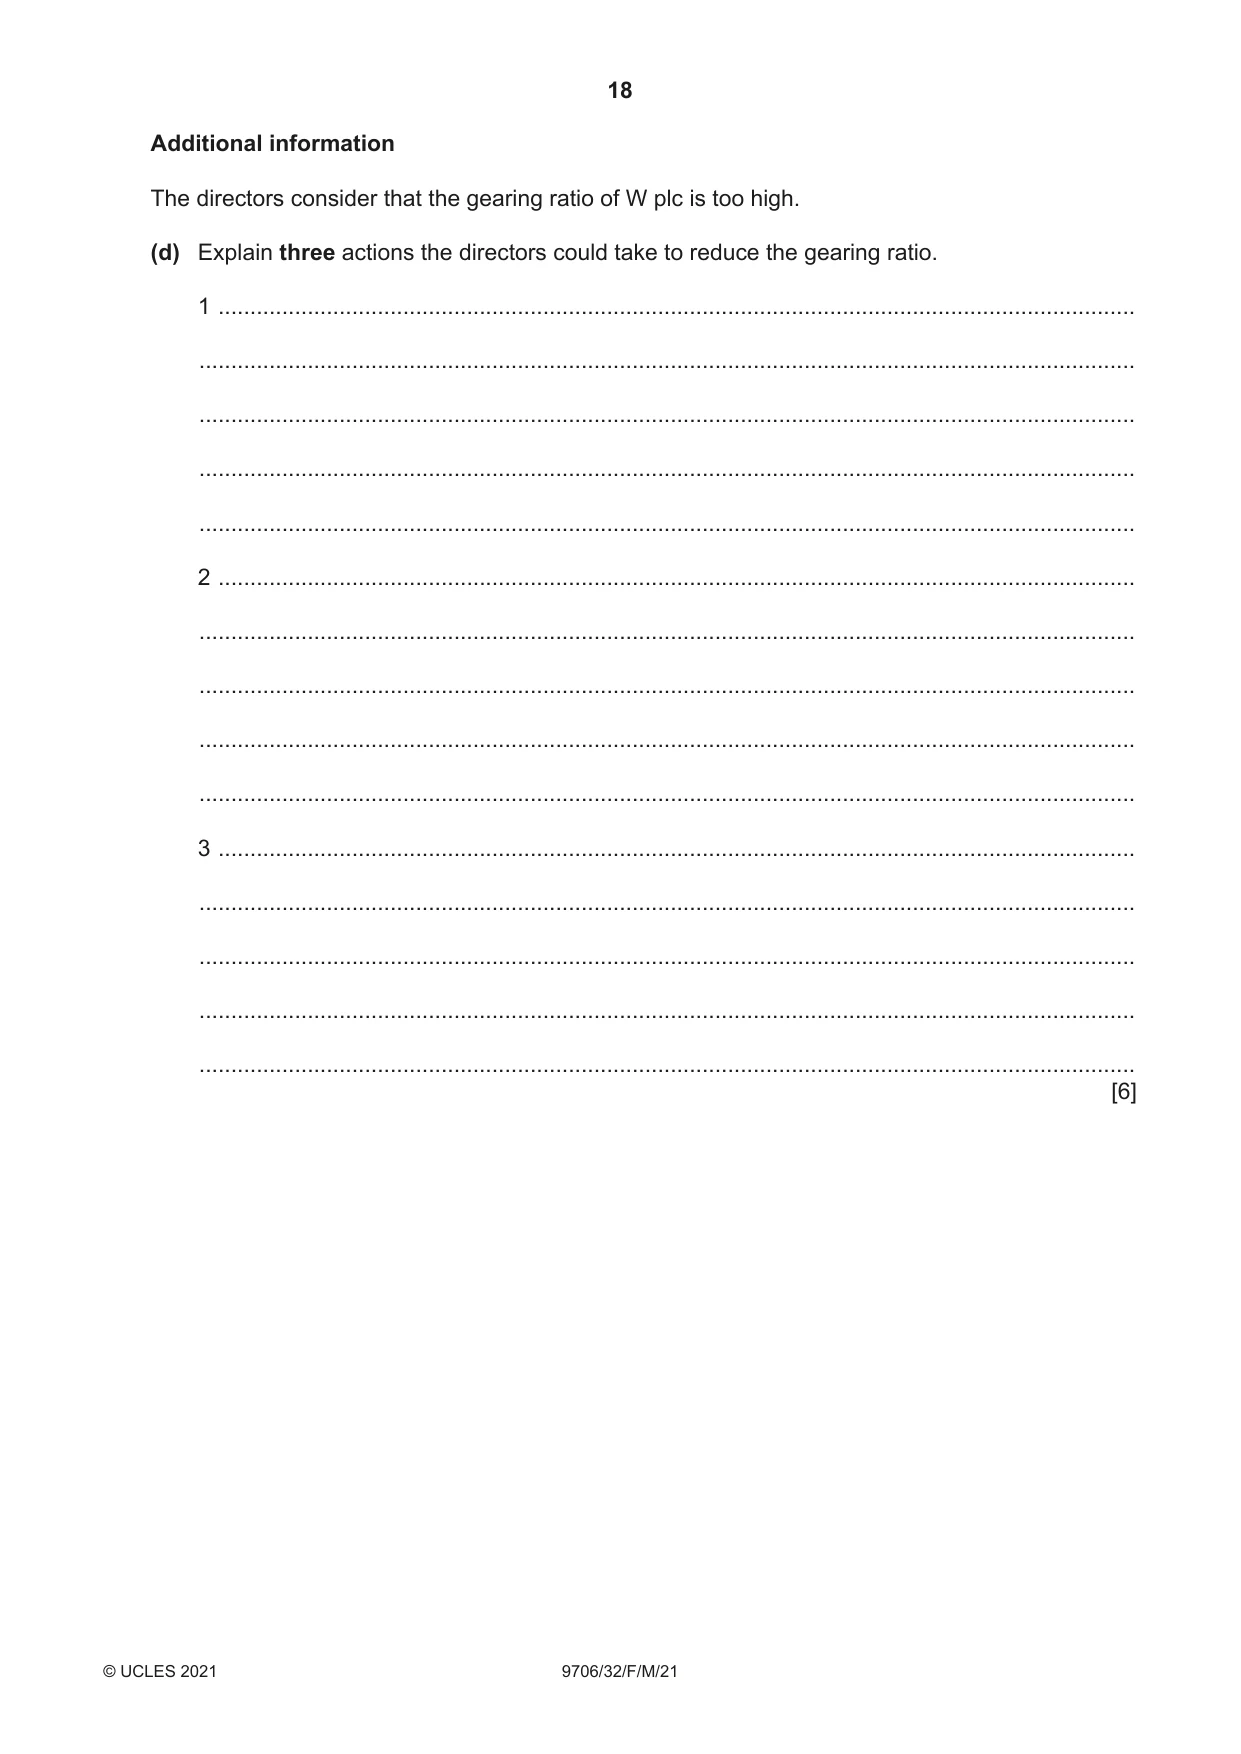
18 9706/32/F/M/21 © UCLES 2021 Additional information The directors consider that the gearing ratio of W plc is too high. (d) Explain three actions the directors could take to reduce the gearing ratio. 1 … … … … … 2 … … … … … 3 … … … … … [6]
Question paper, page 19
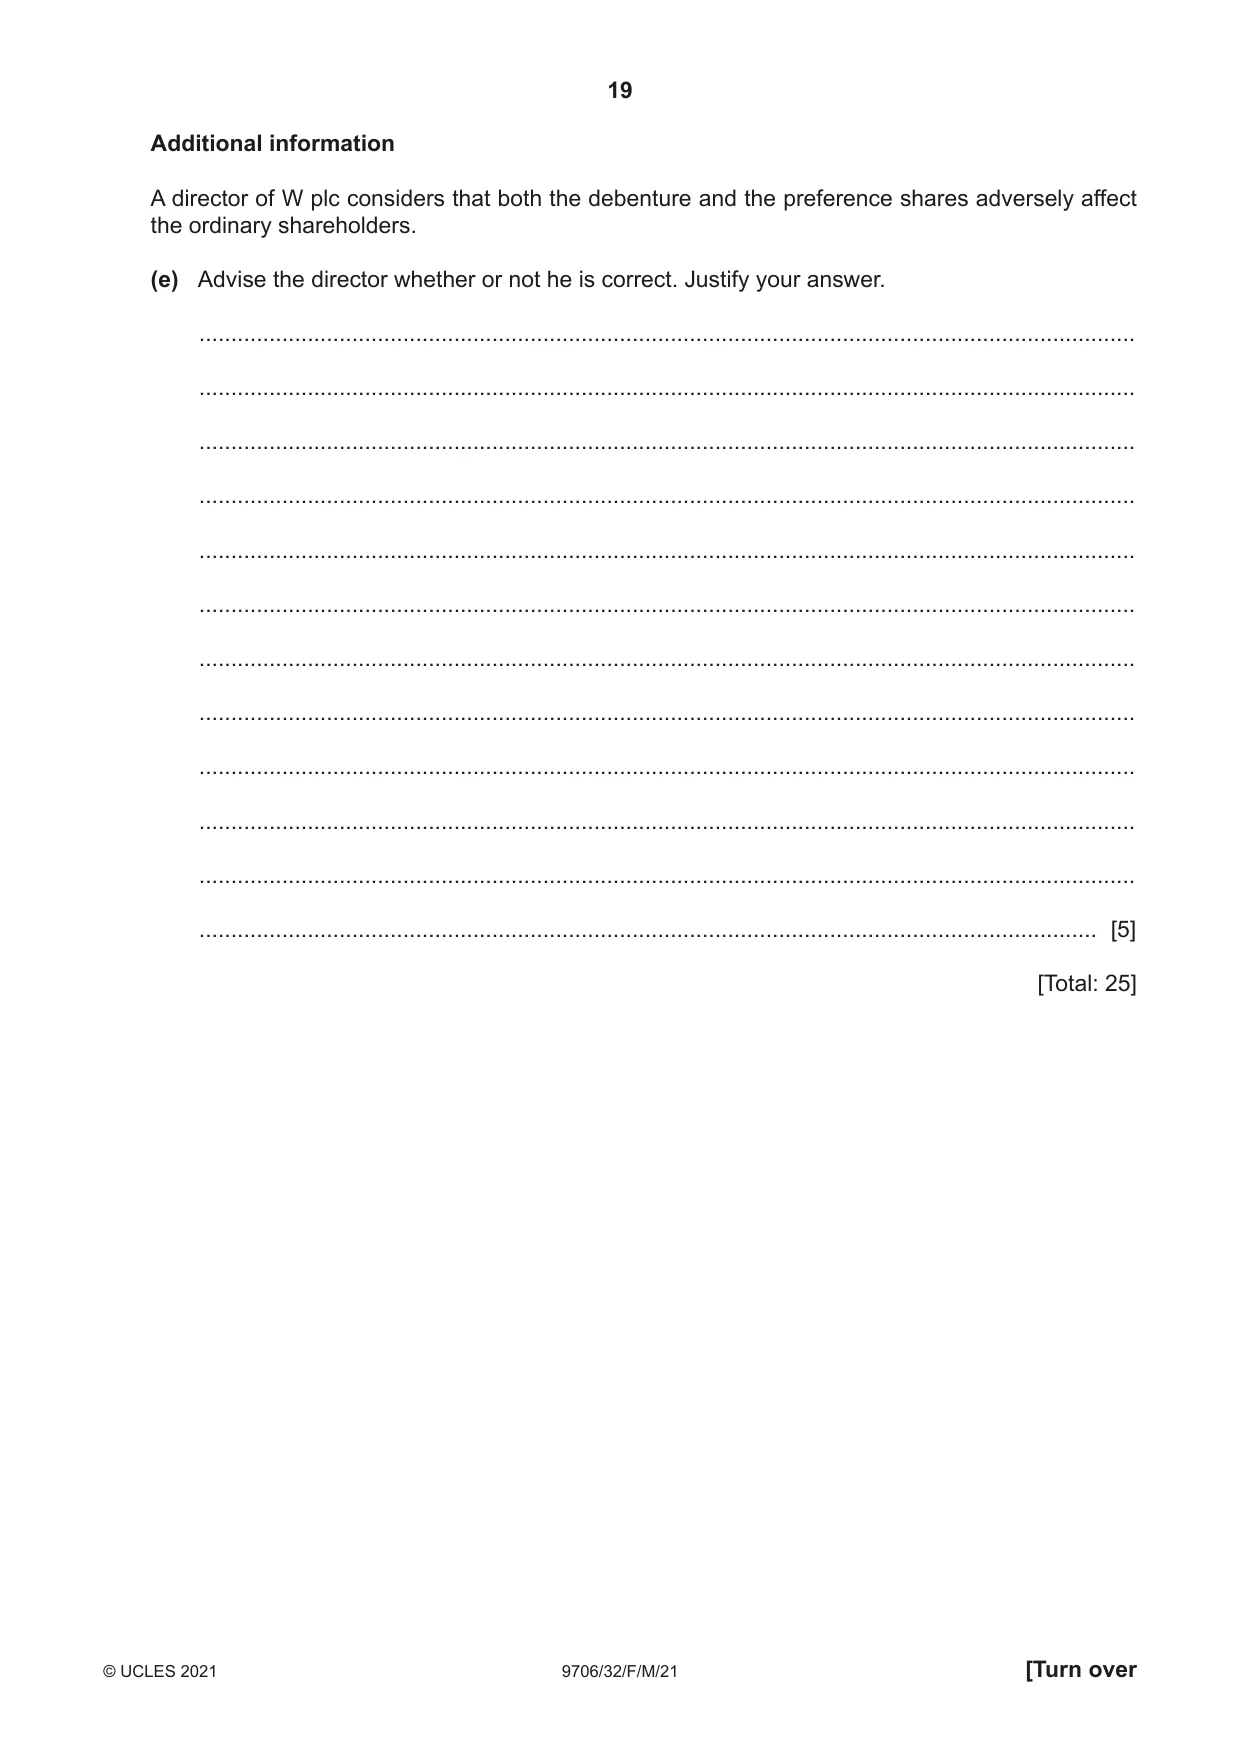
19 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information A director of W plc considers that both the debenture and the preference shares adversely affect the ordinary shareholders. (e) Advise the director whether or not he is correct. Justify your answer. … … … … … … … … … … … … [5] [Total: 25]
Question paper, page 20
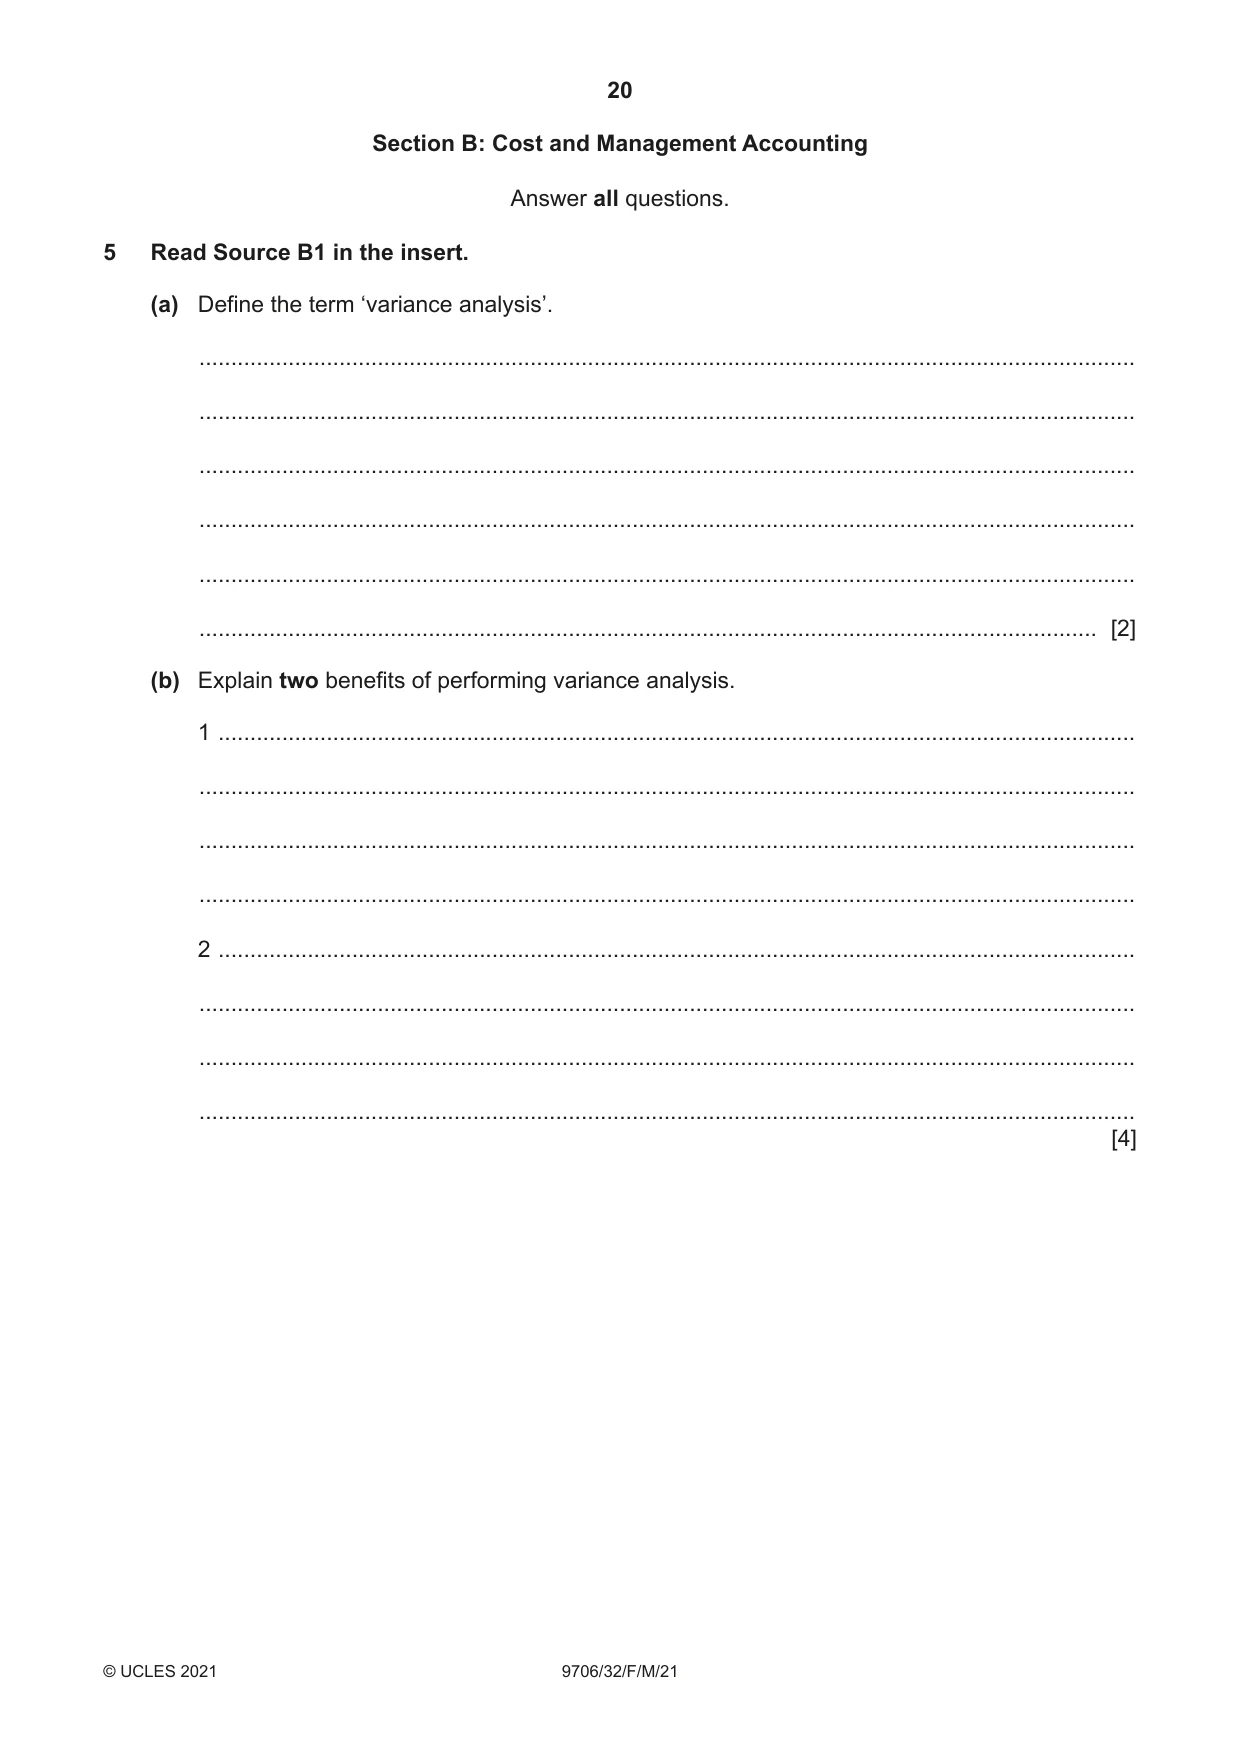
20 9706/32/F/M/21 © UCLES 2021 Section B: Cost and Management Accounting Answer all questions. 5 Read Source B1 in the insert. (a) Define the term ‘variance analysis’. … … … … … … [2] (b) Explain two benefits of performing variance analysis. 1 … … … … 2 … … … … [4]
Question paper, page 21
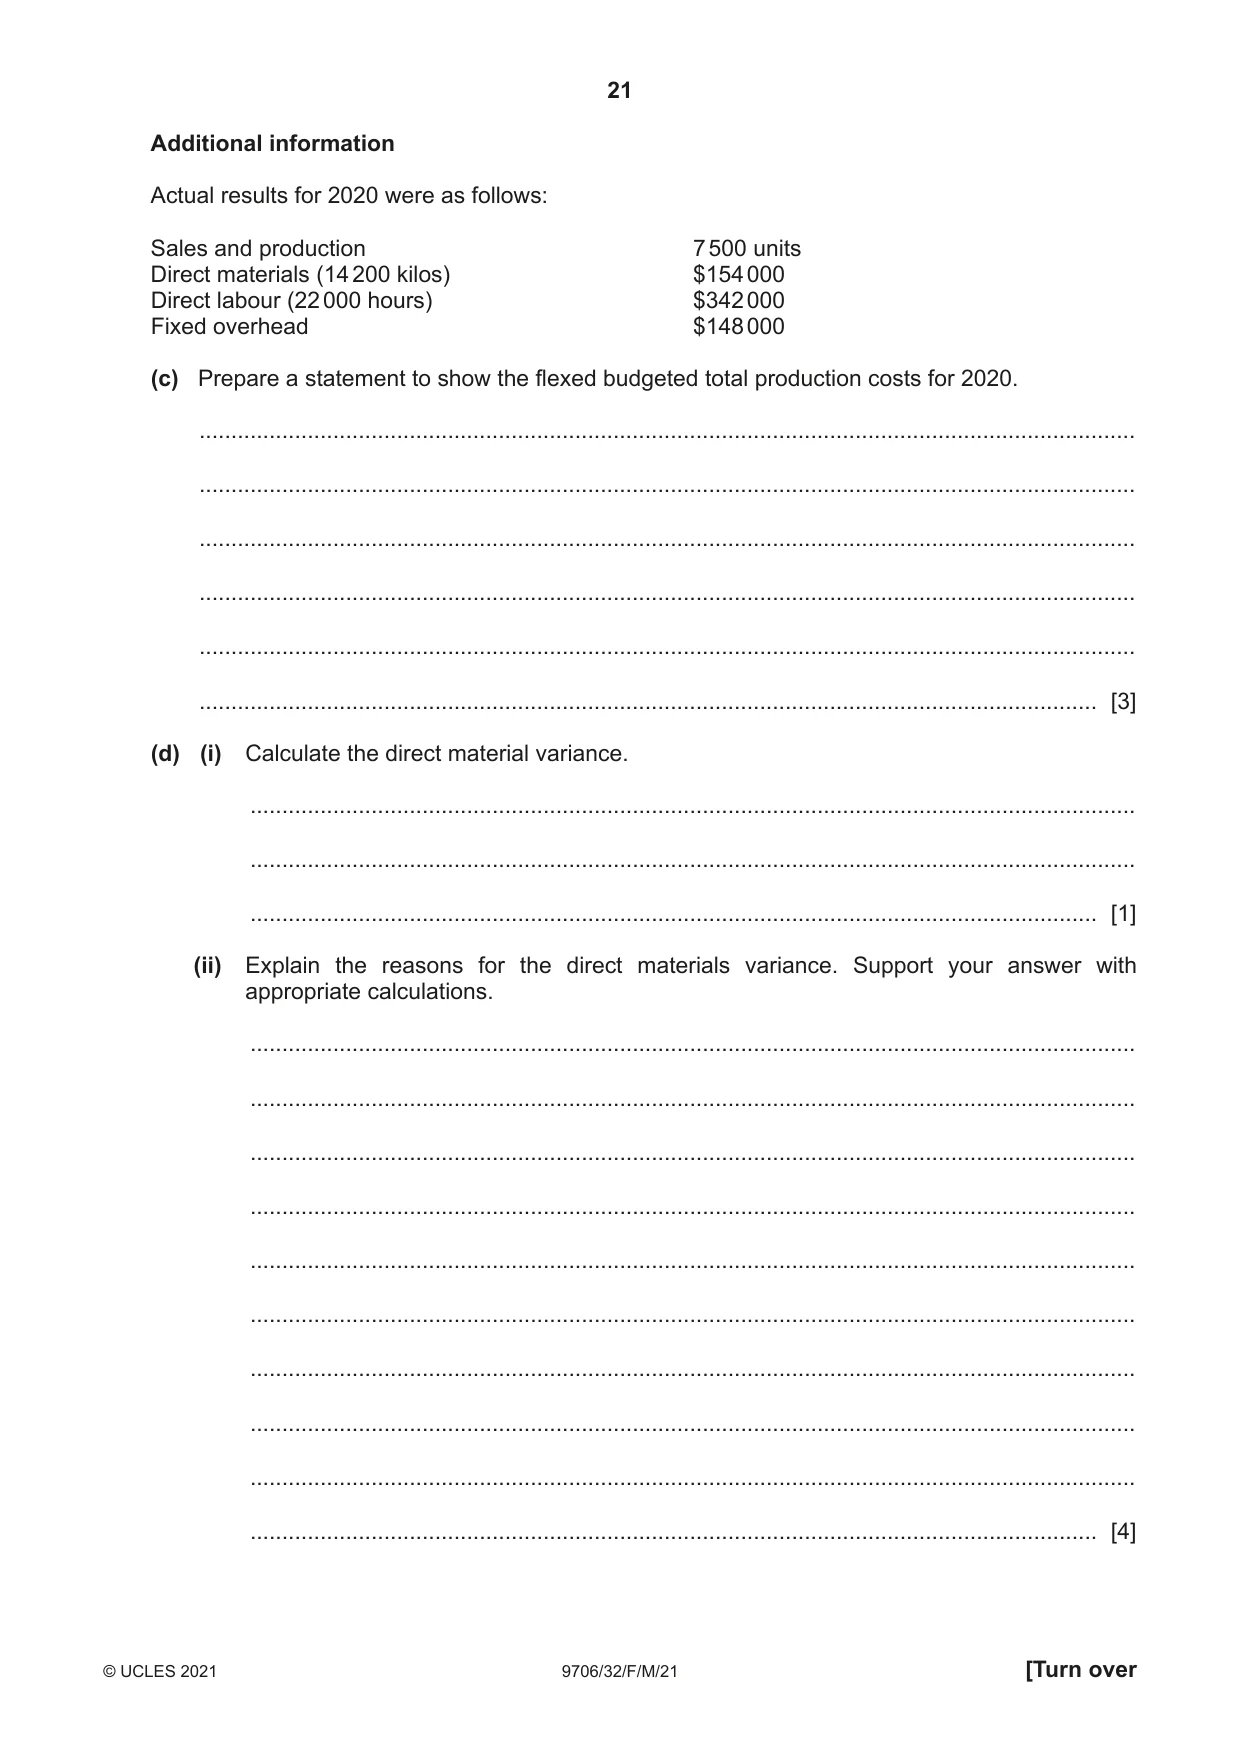
21 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information Actual results for 2020 were as follows: Sales and production 7 500 units Direct materials (14 200 kilos) $154 000 Direct labour (22 000 hours) $342 000 Fixed overhead $148 000 (c) Prepare a statement to show the flexed budgeted total production costs for 2020. … … … … … … [3] (d) (i) Calculate the direct material variance. … … … [1] (ii) Explain the reasons for the direct materials variance. Support your answer with appropriate calculations. … … … … … … … … … … [4]
Question paper, page 22
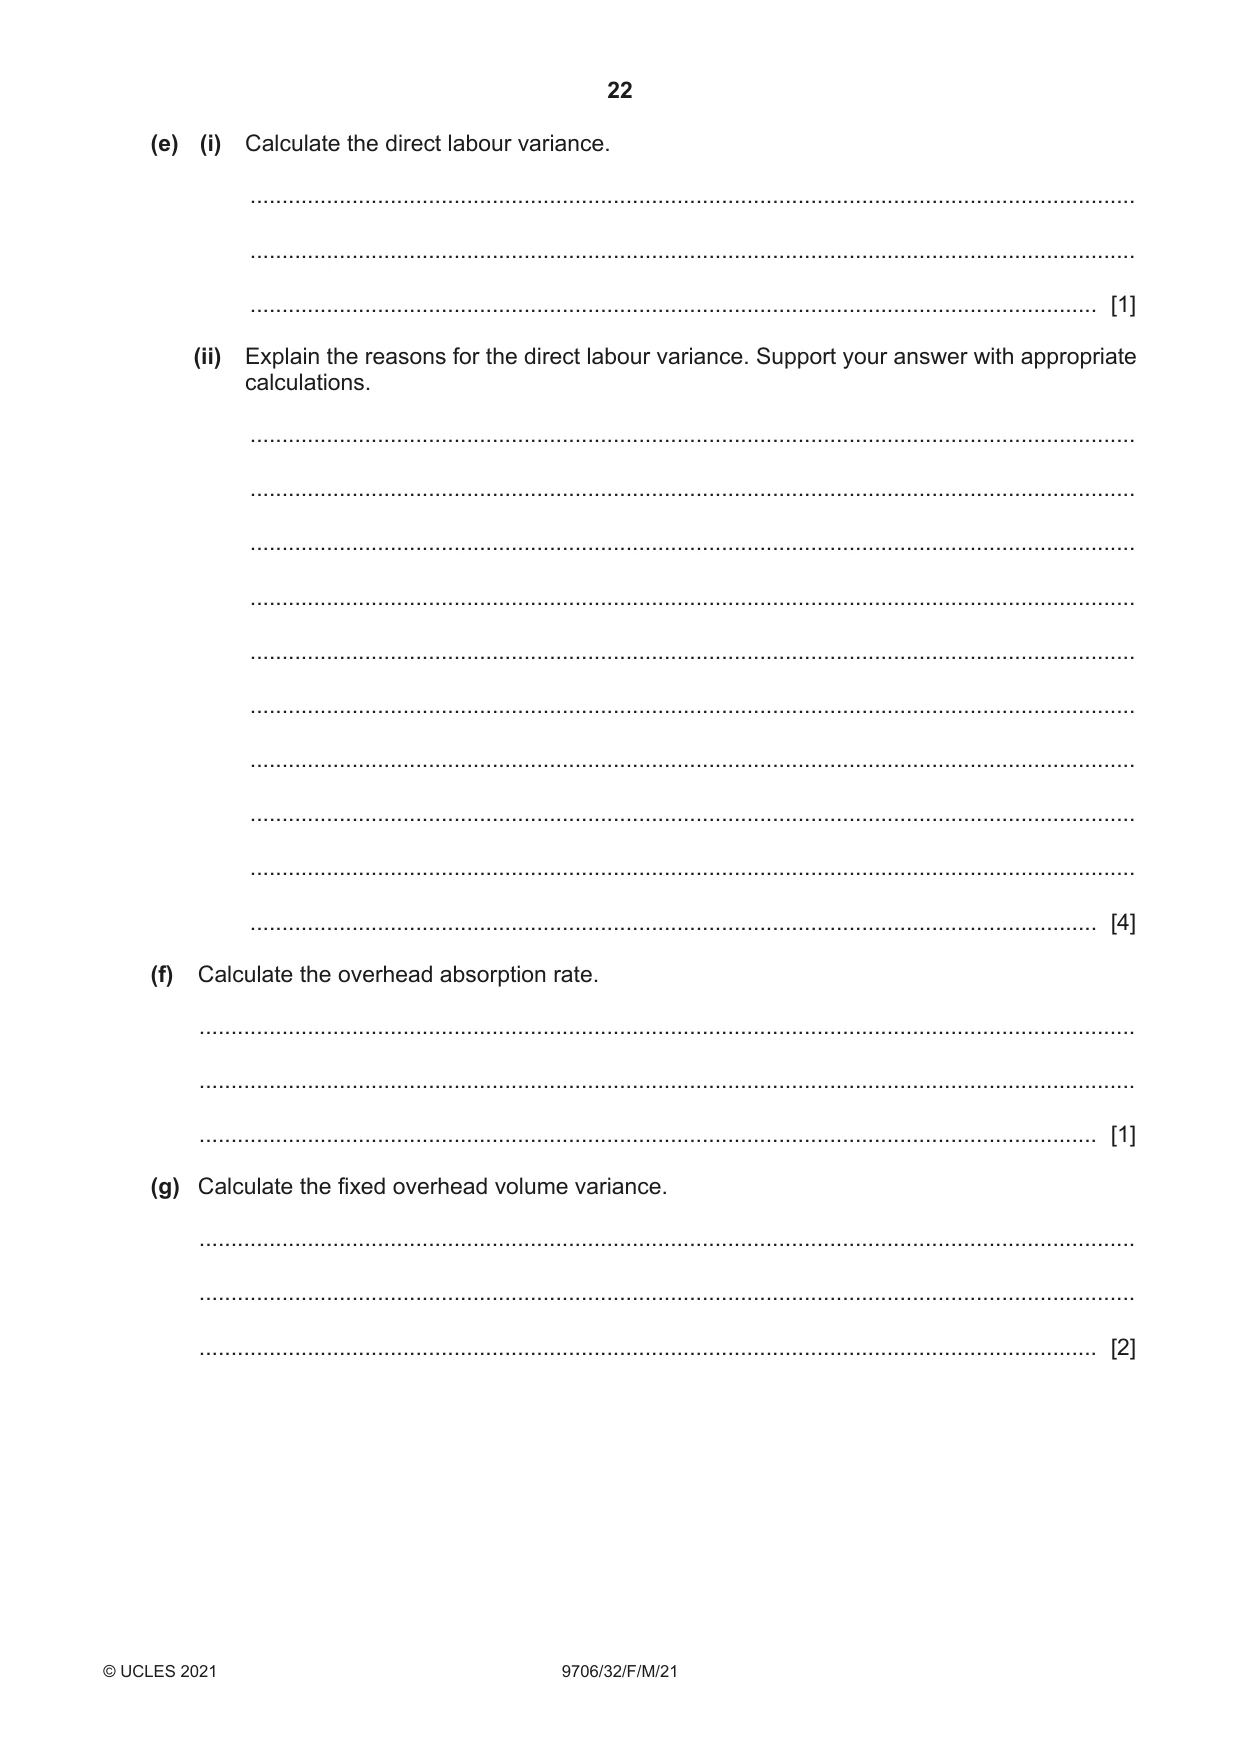
22 9706/32/F/M/21 © UCLES 2021 (e) (i) Calculate the direct labour variance. … … … [1] (ii) Explain the reasons for the direct labour variance. Support your answer with appropriate calculations. … … … … … … … … … … [4] (f) Calculate the overhead absorption rate. … … … [1] (g) Calculate the fixed overhead volume variance. … … … [2]
Question paper, page 23
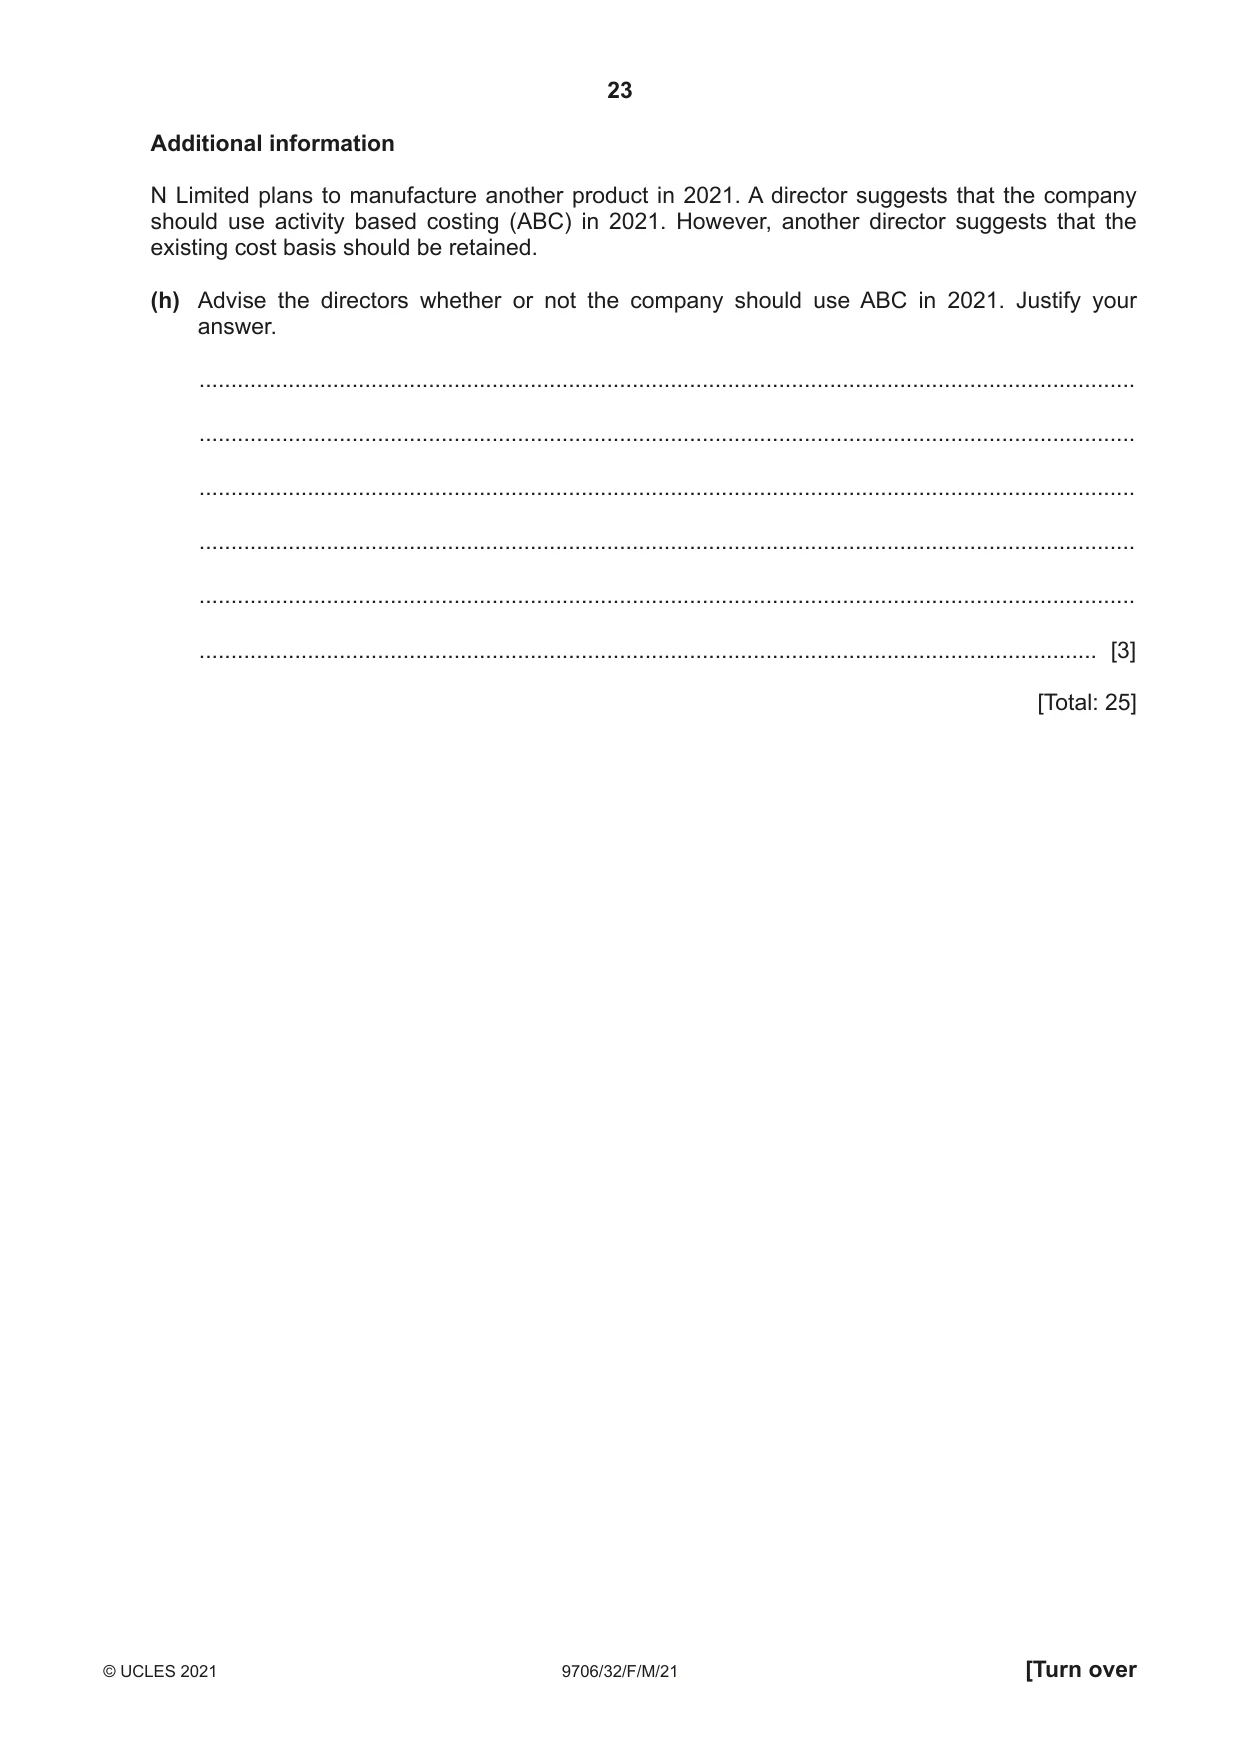
23 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information N Limited plans to manufacture another product in 2021. A director suggests that the company should use activity based costing (ABC) in 2021. However, another director suggests that the existing cost basis should be retained. (h) Advise the directors whether or not the company should use ABC in 2021. Justify your answer. … … … … … … [3] [Total: 25]
Question paper, page 24
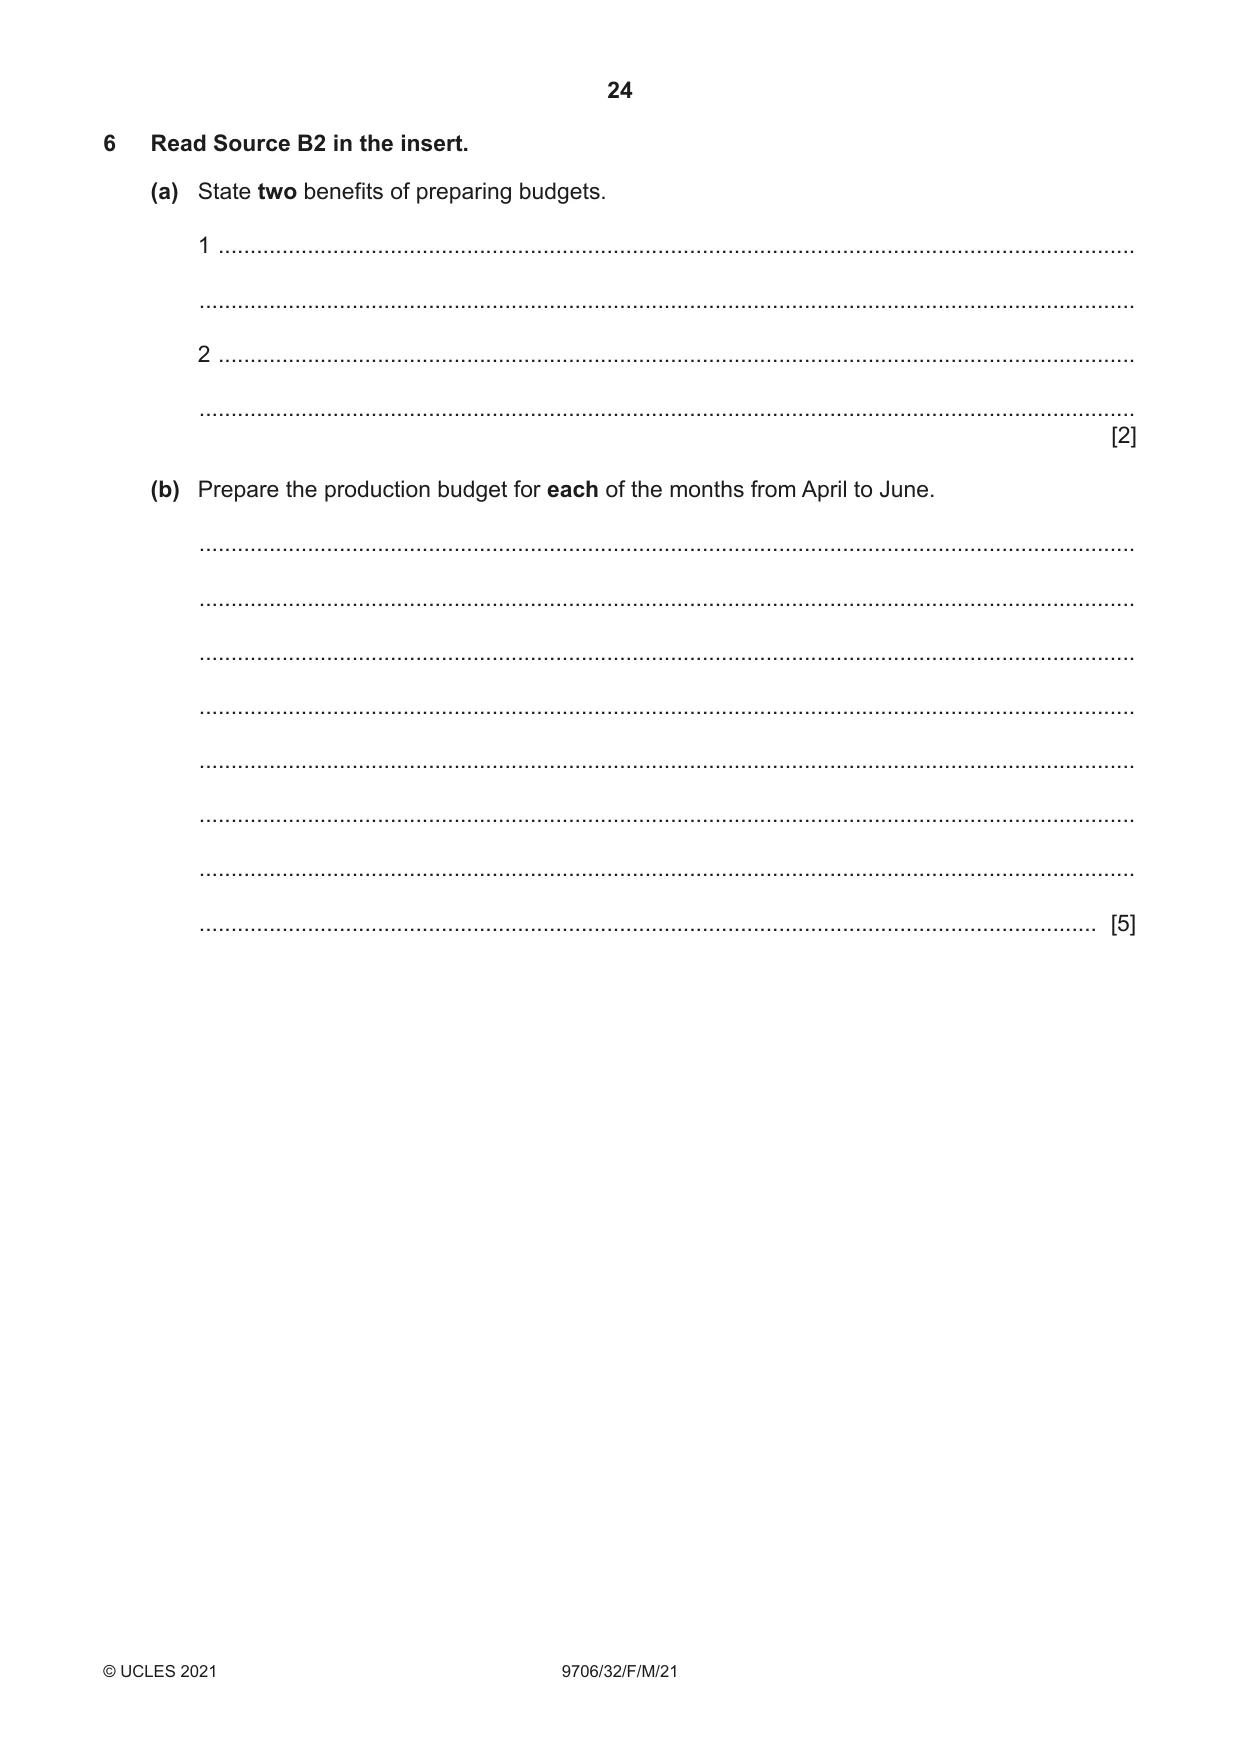
24 9706/32/F/M/21 © UCLES 2021 6 Read Source B2 in the insert. (a) State two benefits of preparing budgets. 1 … … 2 … … [2] (b) Prepare the production budget for each of the months from April to June. … … … … … … … … [5]
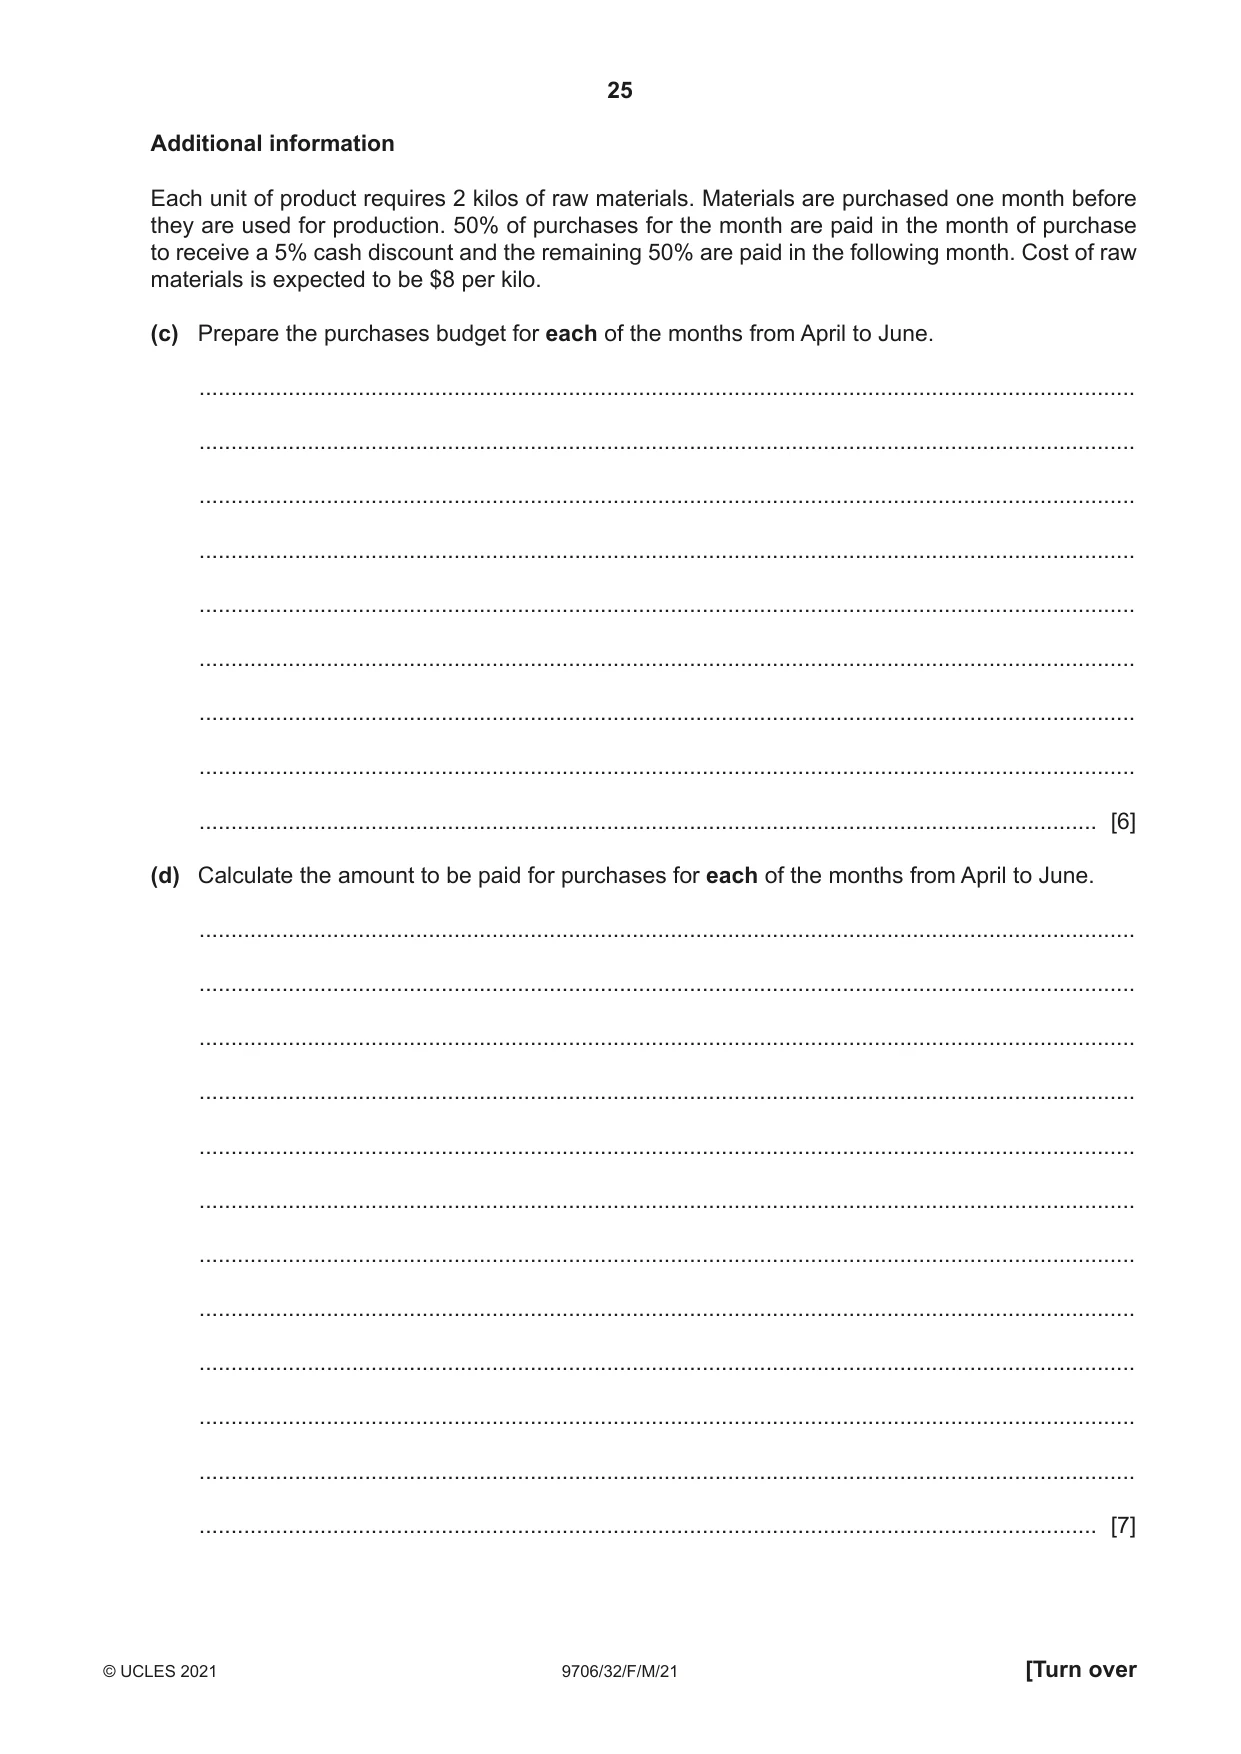
Question paper, page 25
25 9706/32/F/M/21 © UCLES 2021 [Turn over Additional information Each unit of product requires 2 kilos of raw materials. Materials are purchased one month before they are used for production. 50% of purchases for the month are paid in the month of purchase to receive a 5% cash discount and the remaining 50% are paid in the following month. Cost of raw materials is expected to be $8 per kilo. (c) Prepare the purchases budget for each of the months from April to June. … … … … … … … … … [6] (d) Calculate the amount to be paid for purchases for each of the months from April to June. … … … … … … … … … … … … [7]
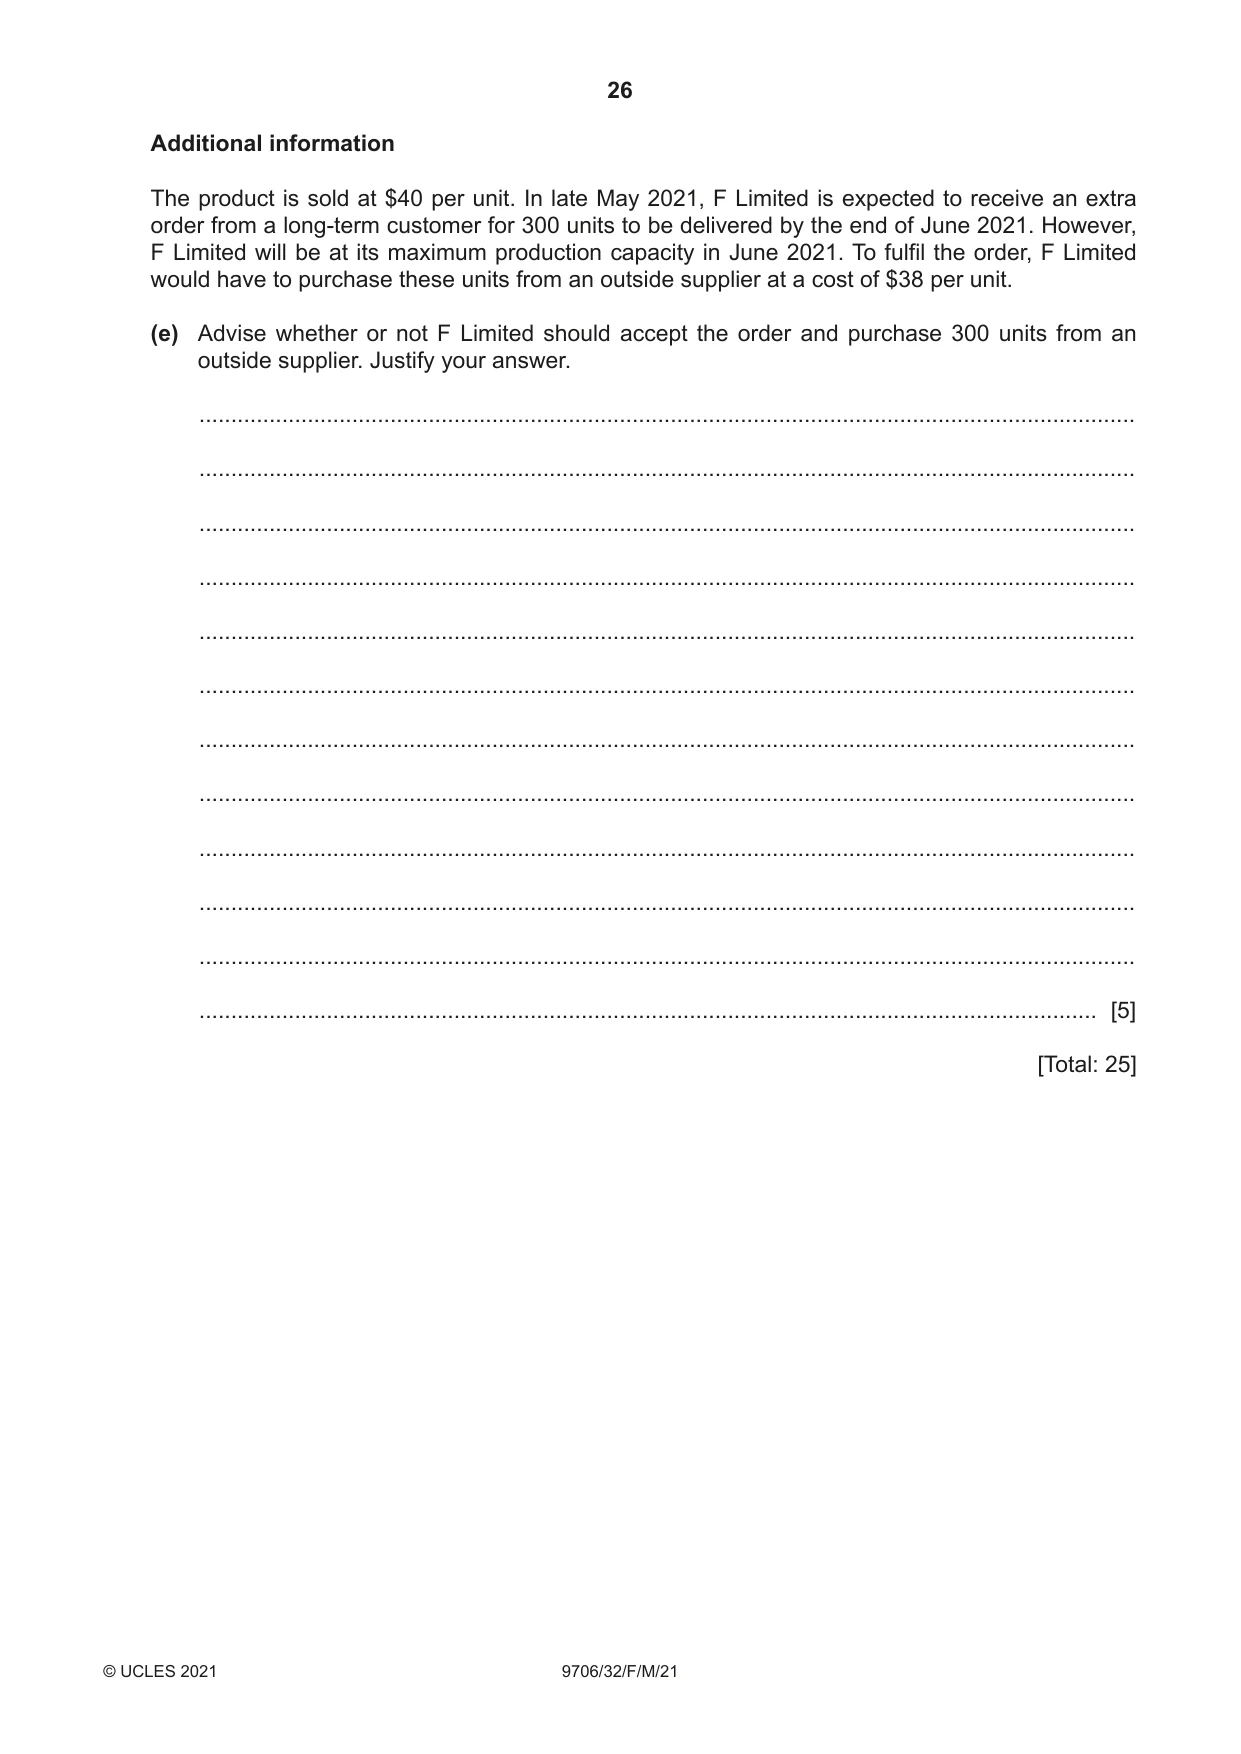
Question paper, page 26
26 9706/32/F/M/21 © UCLES 2021 Additional information The product is sold at $40 per unit. In late May 2021, F Limited is expected to receive an extra order from a long-term customer for 300 units to be delivered by the end of June 2021. However, F Limited will be at its maximum production capacity in June 2021. To fulfil the order, F Limited would have to purchase these units from an outside supplier at a cost of $38 per unit. (e) Advise whether or not F Limited should accept the order and purchase 300 units from an outside supplier. Justify your answer. … … … … … … … … … … … … [5] [Total: 25]
Question paper, page 27
27 9706/32/F/M/21 © UCLES 2021 BLANK PAGE
Question paper, page 28
28 9706/32/F/M/21 © UCLES 2021 BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which itself is a department of the University of Cambridge.
Mark scheme, page 1
This document consists of 19 printed pages. © UCLES 2021 [Turn over Cambridge International AS & A Level ACCOUNTING 9706/32 Paper 3 A Level Structured Questions March 2021 MARK SCHEME Maximum Mark: 150 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the March 2021 series for most Cambridge IGCSE™, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 2 of 19 Generic Marking Principles These general marking principles must be applied by all examiners when marking candidate answers. They should be applied alongside the specific content of the mark scheme or generic level descriptors for a question. Each question paper and mark scheme will also comply with these marking principles. GENERIC MARKING PRINCIPLE 1: Marks must be awarded in line with: • the specific content of the mark scheme or the generic level descriptors for the question • the specific skills defined in the mark scheme or in the generic level descriptors for the question • the standard of response required by a candidate as exemplified by the standardisation scripts. GENERIC MARKING PRINCIPLE 2: Marks awarded are always whole marks (not half marks, or other fractions). GENERIC MARKING PRINCIPLE 3: Marks must be awarded positively: • marks are awarded for correct/valid answers, as defined in the mark scheme. However, credit is given for valid answers which go beyond the scope of the syllabus and mark scheme, referring to your Team Leader as appropriate • marks are awarded when candidates clearly demonstrate what they know and can do • marks are not deducted for errors • marks are not deducted for omissions • answers should only be judged on the quality of spelling, punctuation and grammar when these features are specifically assessed by the question as indicated by the mark scheme. The meaning, however, should be unambiguous. GENERIC MARKING PRINCIPLE 4: Rules must be applied consistently, e.g. in situations where candidates have not followed instructions or in the application of generic level descriptors.
Mark scheme, page 3
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 3 of 19 GENERIC MARKING PRINCIPLE 5: Marks should be awarded using the full range of marks defined in the mark scheme for the question (however; the use of the full mark range may be limited according to the quality of the candidate responses seen). GENERIC MARKING PRINCIPLE 6: Marks awarded are based solely on the requirements as defined in the mark scheme. Marks should not be awarded with grade thresholds or grade descriptors in mind.
Mark scheme, page 4
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 4 of 19 Social Science-Specific Marking Principles (for point-based marking) 1 Components using point-based marking: • Point marking is often used to reward knowledge, understanding and application of skills. We give credit where the candidate’s answer shows relevant knowledge, understanding and application of skills in answering the question. We do not give credit where the answer shows confusion. From this it follows that we: a DO credit answers which are worded differently from the mark scheme if they clearly convey the same meaning (unless the mark scheme requires a specific term) b DO credit alternative answers/examples which are not written in the mark scheme if they are correct c DO credit answers where candidates give more than one correct answer in one prompt/numbered/scaffolded space where extended writing is required rather than list-type answers. For example, questions that require n reasons (e.g. State two reasons …). d DO NOT credit answers simply for using a ‘key term’ unless that is all that is required. (Check for evidence it is understood and not used wrongly.) e DO NOT credit answers which are obviously self-contradicting or trying to cover all possibilities f DO NOT give further credit for what is effectively repetition of a correct point already credited unless the language itself is being tested. This applies equally to ‘mirror statements’ (i.e. polluted/not polluted). g DO NOT require spellings to be correct, unless this is part of the test. However spellings of syllabus terms must allow for clear and unambiguous separation from other syllabus terms with which they may be confused (e.g. Corrasion/Corrosion) 2 Presentation of mark scheme: • Slashes (/) or the word ‘or’ separate alternative ways of making the same point. • Semi colons (;) bullet points (•) or figures in brackets (1) separate different points. • Content in the answer column in brackets is for examiner information/context to clarify the marking but is not required to earn the mark (except Accounting syllabuses where they indicate negative numbers).
Mark scheme, page 5
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 5 of 19 3 Calculation questions: • The mark scheme will show the steps in the most likely correct method(s), the mark for each step, the correct answer(s) and the mark for each answer • If working/explanation is considered essential for full credit, this will be indicated in the question paper and in the mark scheme. In all other instances, the correct answer to a calculation should be given full credit, even if no supporting working is shown. • Where the candidate uses a valid method which is not covered by the mark scheme, award equivalent marks for reaching equivalent stages. • Where an answer makes use of a candidate’s own incorrect figure from previous working, the ‘own figure rule’ applies: full marks will be given if a correct and complete method is used. Further guidance will be included in the mark scheme where necessary and any exceptions to this general principle will be noted. 4 Annotation: • For point marking, ticks can be used to indicate correct answers and crosses can be used to indicate wrong answers. There is no direct relationship between ticks and marks. Ticks have no defined meaning for levels of response marking. • For levels of response marking, the level awarded should be annotated on the script. • Other annotations will be used by examiners as agreed during standardisation, and the meaning will be understood by all examiners who marked that paper.
Mark scheme, page 6
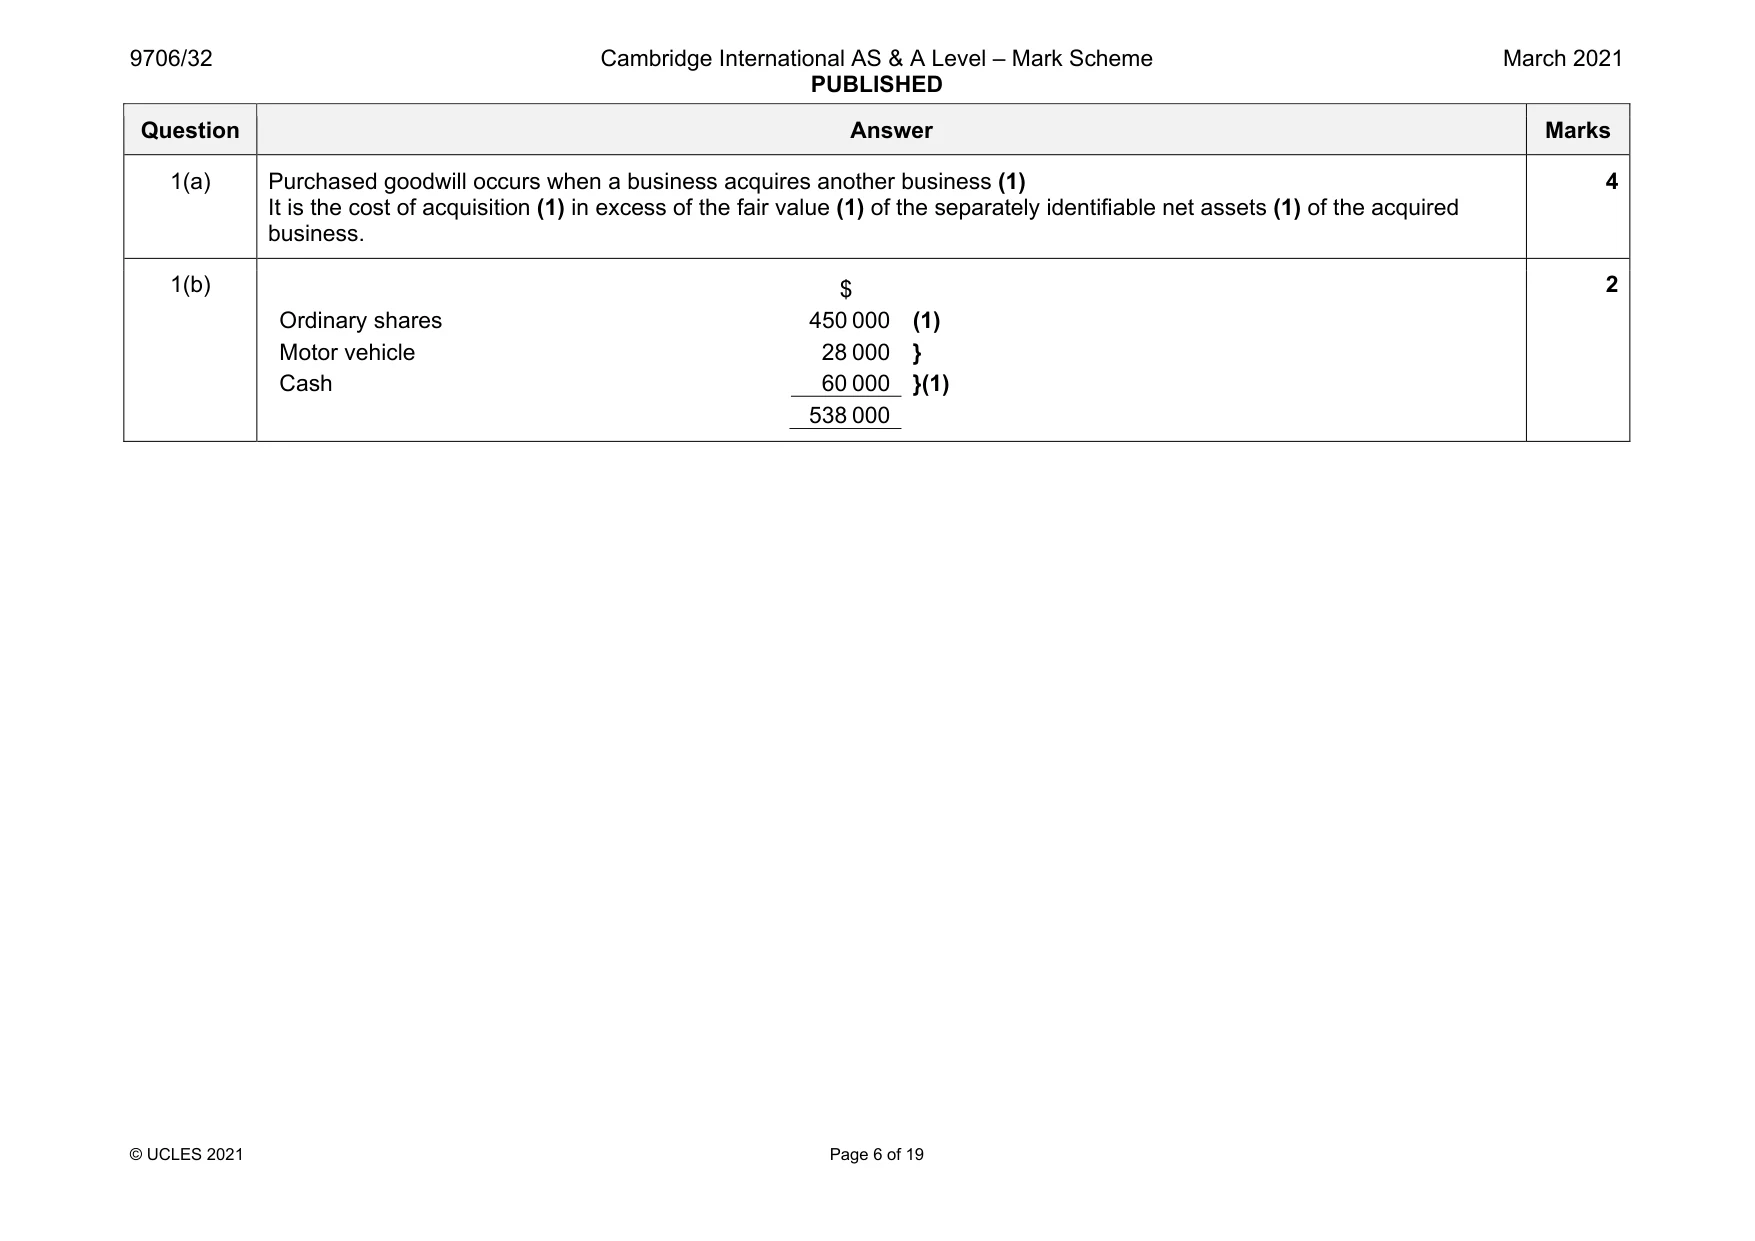
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 6 of 19 Question Answer Marks 1(a) Purchased goodwill occurs when a business acquires another business (1) It is the cost of acquisition (1) in excess of the fair value (1) of the separately identifiable net assets (1) of the acquired business. 4 1(b) $ Ordinary shares 450 000 (1) Motor vehicle 28 000 } Cash 60 000 }(1) 538 000 2
Mark scheme, page 7
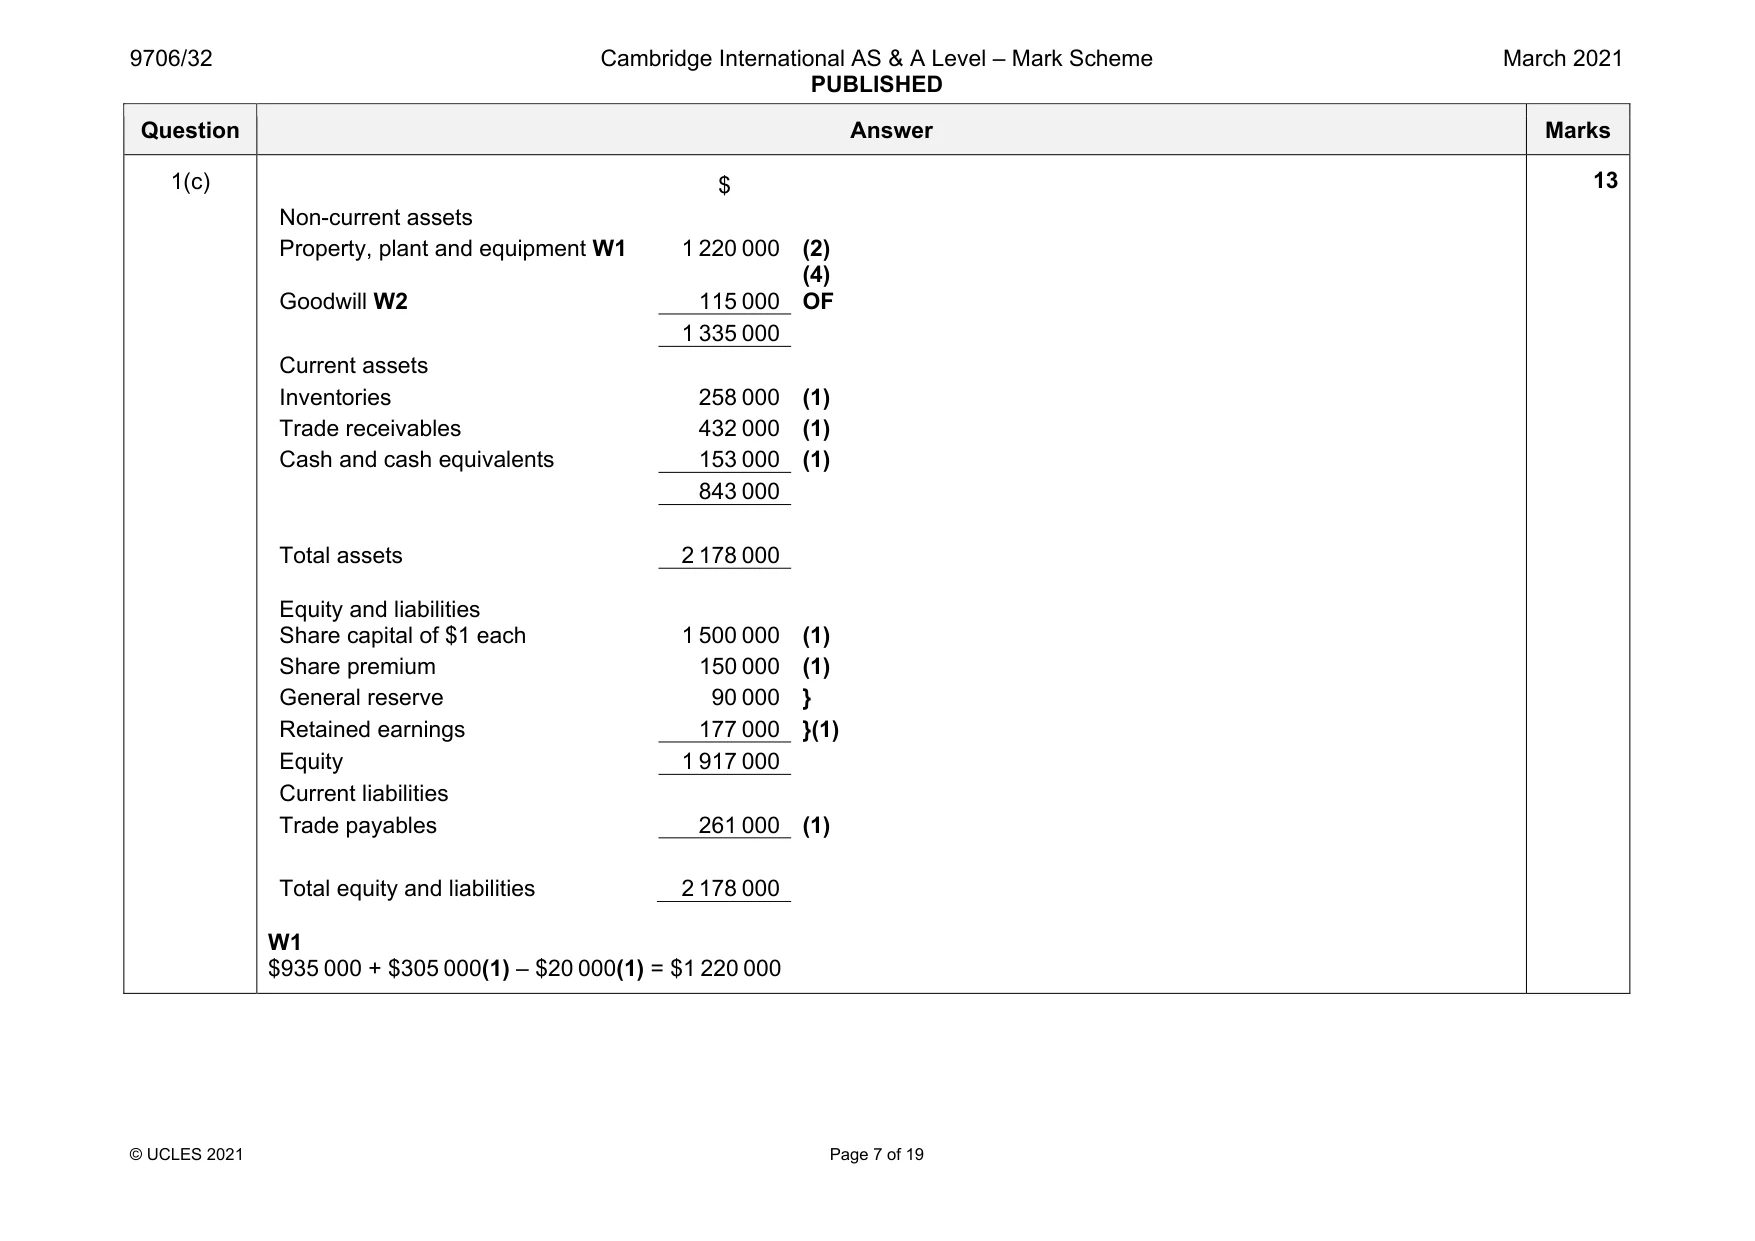
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 7 of 19 Question Answer Marks 1(c) $ Non-current assets Property, plant and equipment W1 1 220 000 (2) Goodwill W2 115 000 (4) OF 1 335 000 Current assets Inventories 258 000 (1) Trade receivables 432 000 (1) Cash and cash equivalents 153 000 (1) 843 000 Total assets 2 178 000 Equity and liabilities Share capital of $1 each 1 500 000 (1) Share premium 150 000 (1) General reserve 90 000 } Retained earnings 177 000 }(1) Equity 1 917 000 Current liabilities Trade payables 261 000 (1) Total equity and liabilities 2 178 000 W1 $935 000 + $305 000(1) – $20 000(1) = $1 220 000 13
Mark scheme, page 8
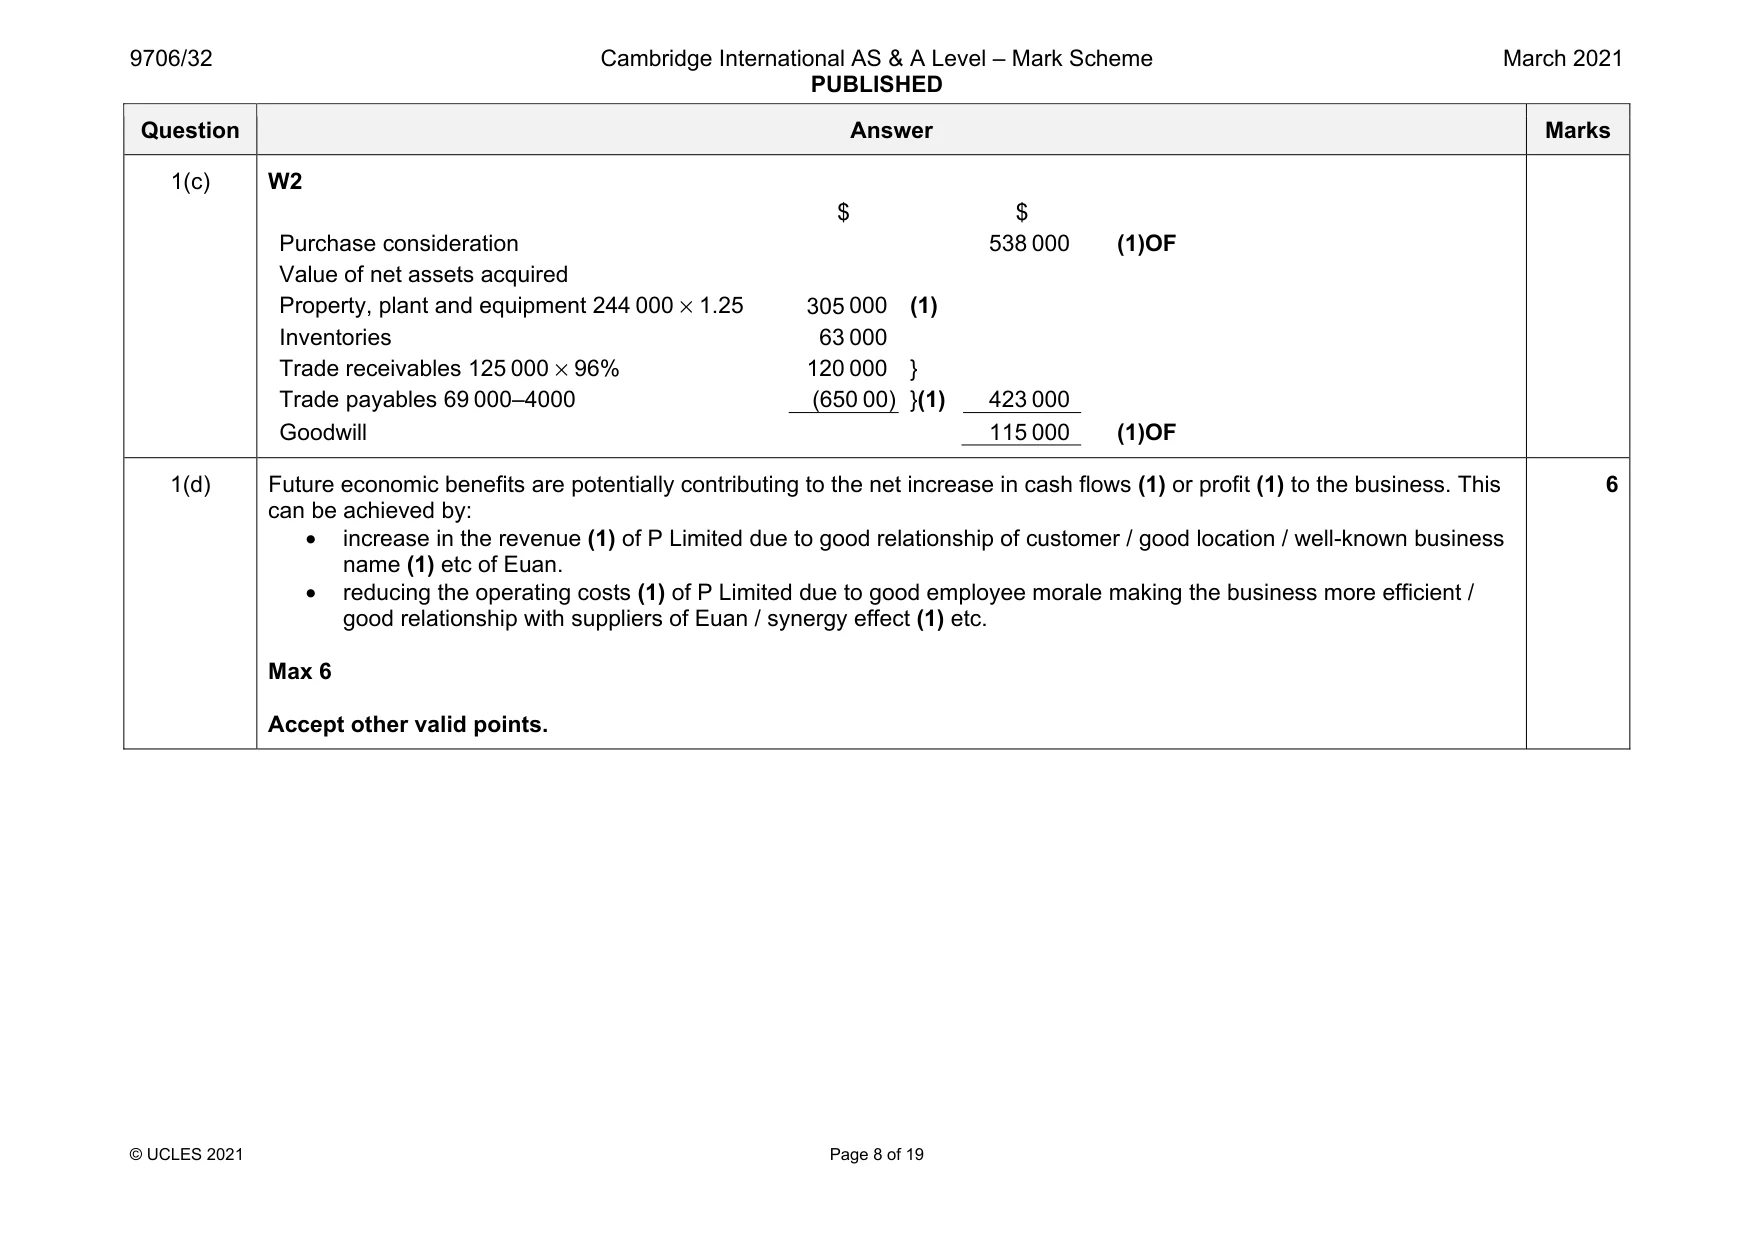
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 8 of 19 Question Answer Marks 1(c) W2 $ $ Purchase consideration 538 000 (1)OF Value of net assets acquired Property, plant and equipment 244 000 × 1.25 305 000 (1) Inventories 63 000 Trade receivables 125 000 × 96% 120 000 } Trade payables 69 000–4000 (650 00) }(1) 423 000 Goodwill 115 000 (1)OF 1(d) Future economic benefits are potentially contributing to the net increase in cash flows (1) or profit (1) to the business. This can be achieved by: • increase in the revenue (1) of P Limited due to good relationship of customer / good location / well-known business name (1) etc of Euan. • reducing the operating costs (1) of P Limited due to good employee morale making the business more efficient / good relationship with suppliers of Euan / synergy effect (1) etc. Max 6 Accept other valid points. 6
Mark scheme, page 9
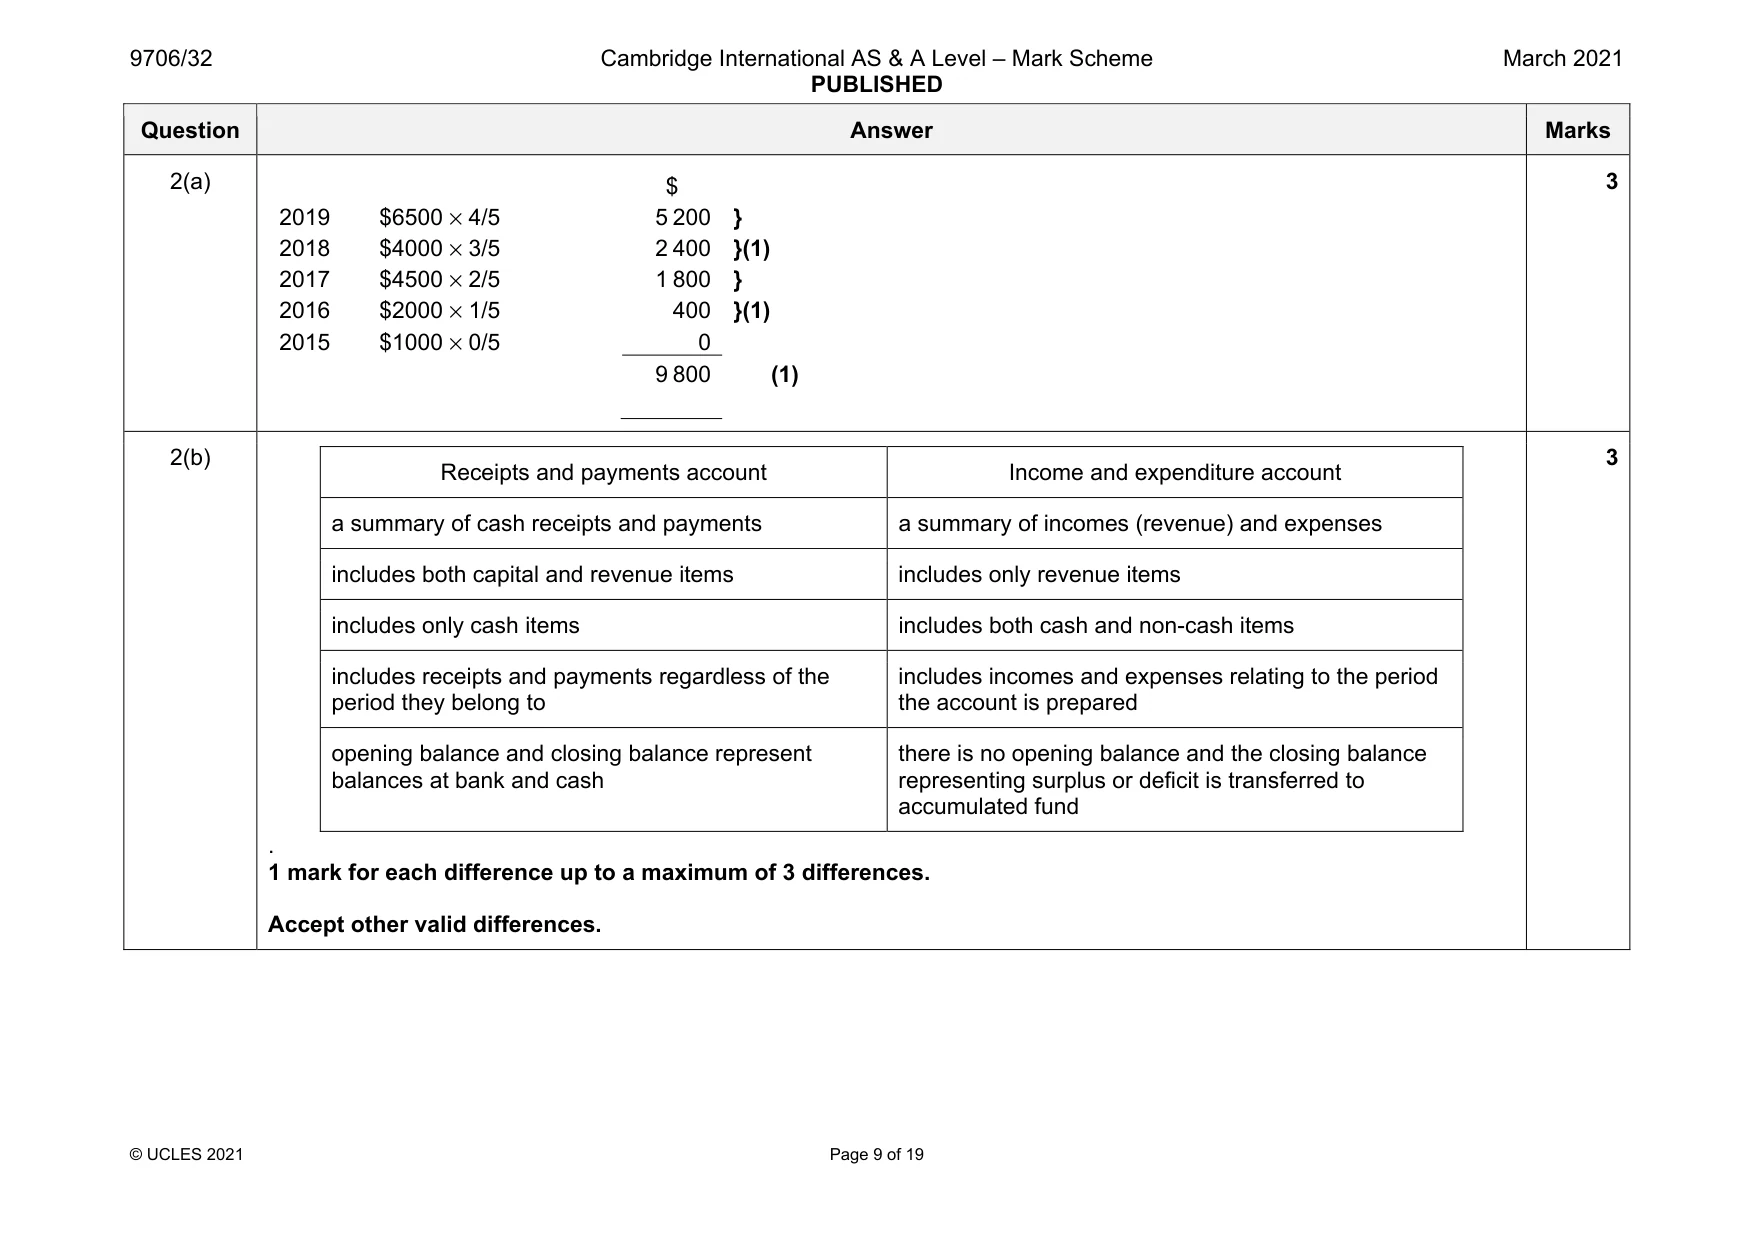
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 9 of 19 Question Answer Marks 2(a) $ 2019 $6500 × 4/5 5 200 } 2018 $4000 × 3/5 2 400 }(1) 2017 $4500 × 2/5 1 800 } 2016 $2000 × 1/5 400 }(1) 2015 $1000 × 0/5 0 9 800 (1) 3 2(b) Receipts and payments account Income and expenditure account a summary of cash receipts and payments a summary of incomes (revenue) and expenses includes both capital and revenue items includes only revenue items includes only cash items includes both cash and non-cash items includes receipts and payments regardless of the period they belong to includes incomes and expenses relating to the period the account is prepared opening balance and closing balance represent balances at bank and cash there is no opening balance and the closing balance representing surplus or deficit is transferred to accumulated fund . 1 mark for each difference up to a maximum of 3 differences. Accept other valid differences. 3
Mark scheme, page 10
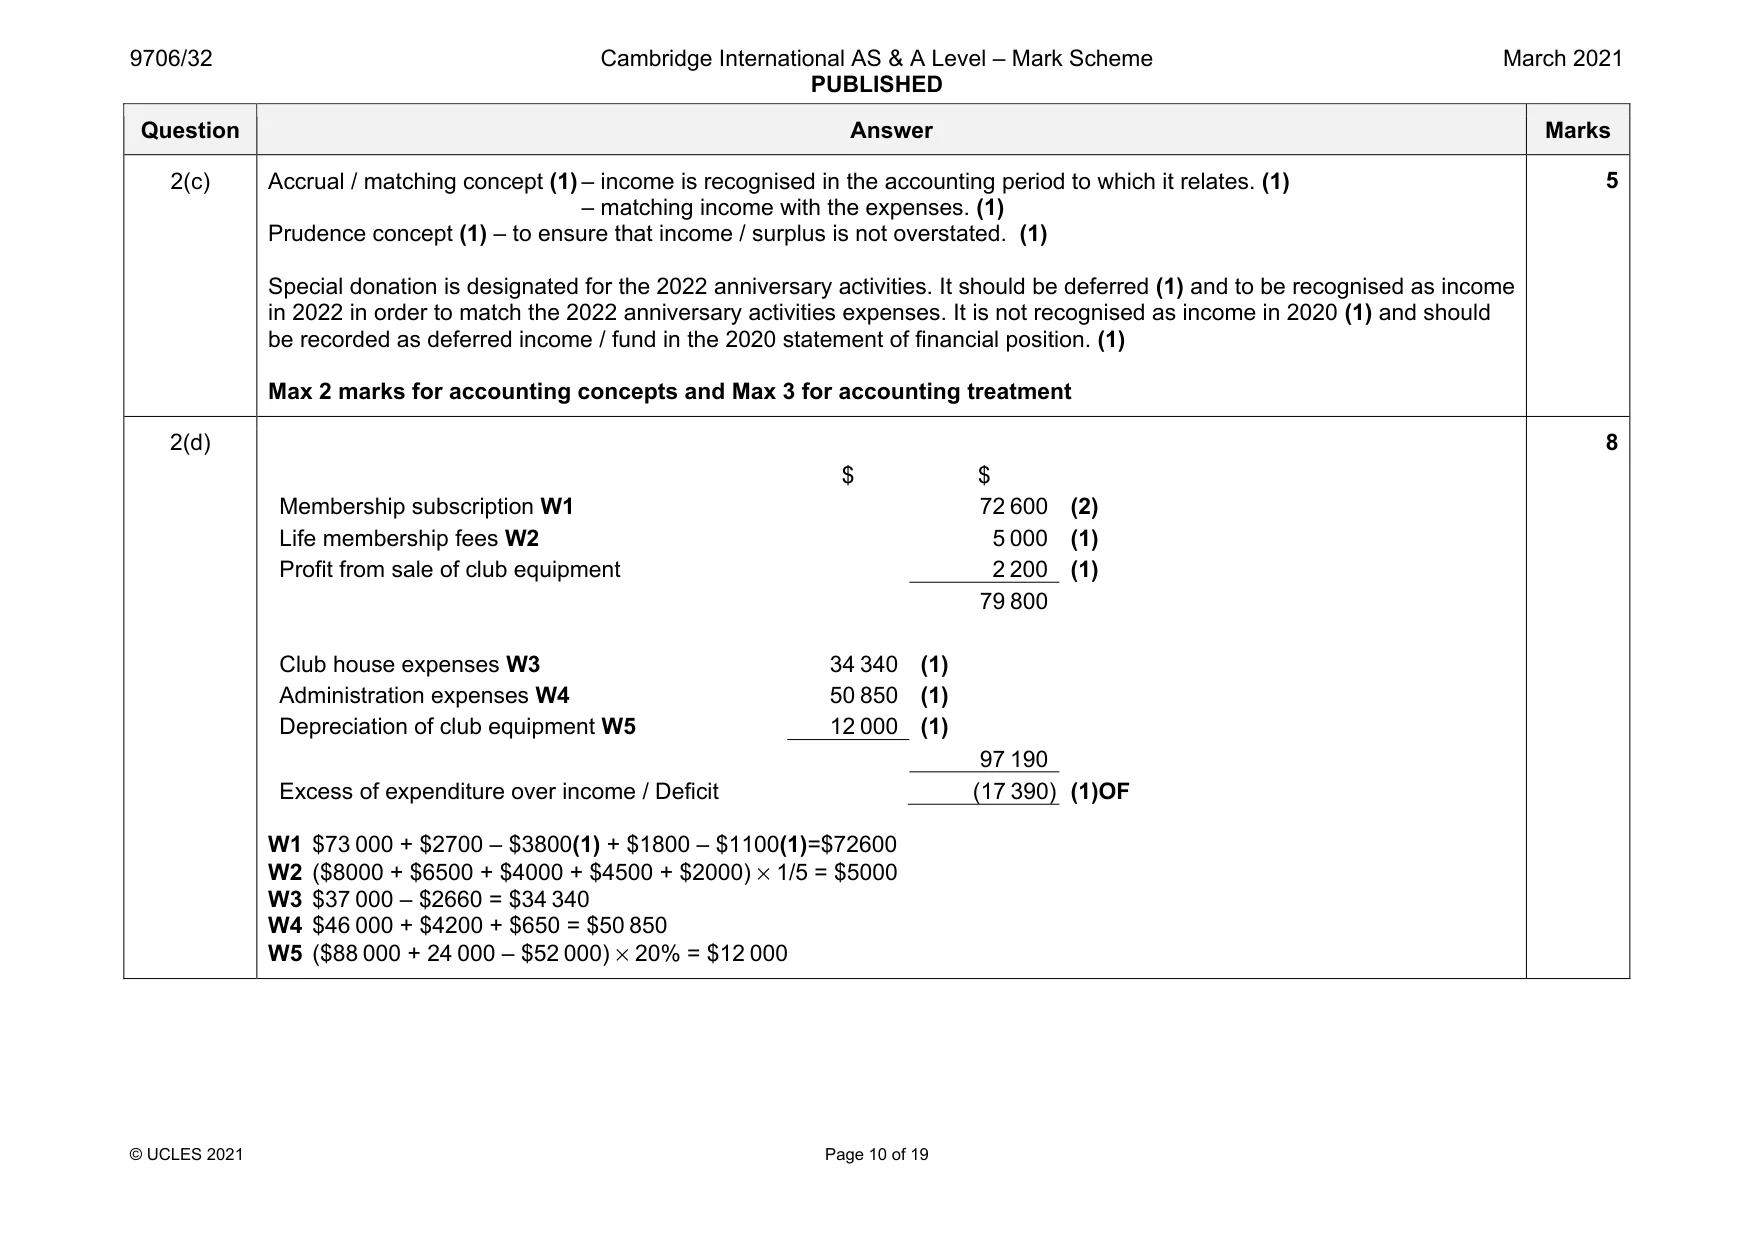
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 10 of 19 Question Answer Marks 2(c) Accrual / matching concept (1) – income is recognised in the accounting period to which it relates. (1) – matching income with the expenses. (1) Prudence concept (1) – to ensure that income / surplus is not overstated. (1) Special donation is designated for the 2022 anniversary activities. It should be deferred (1) and to be recognised as income in 2022 in order to match the 2022 anniversary activities expenses. It is not recognised as income in 2020 (1) and should be recorded as deferred income / fund in the 2020 statement of financial position. (1) Max 2 marks for accounting concepts and Max 3 for accounting treatment 5 2(d) $ $ Membership subscription W1 72 600 (2) Life membership fees W2 5 000 (1) Profit from sale of club equipment 2 200 (1) 79 800 Club house expenses W3 34 340 (1) Administration expenses W4 50 850 (1) Depreciation of club equipment W5 12 000 (1) 97 190 Excess of expenditure over income / Deficit (17 390) (1)OF W1 $73 000 + $2700 – $3800(1) + $1800 – $1100(1)=$72600 W2 ($8000 + $6500 + $4000 + $4500 + $2000) × 1/5 = $5000 W3 $37 000 – $2660 = $34 340 W4 $46 000 + $4200 + $650 = $50 850 W5 ($88 000 + 24 000 – $52 000) × 20% = $12 000 8
Mark scheme, page 11
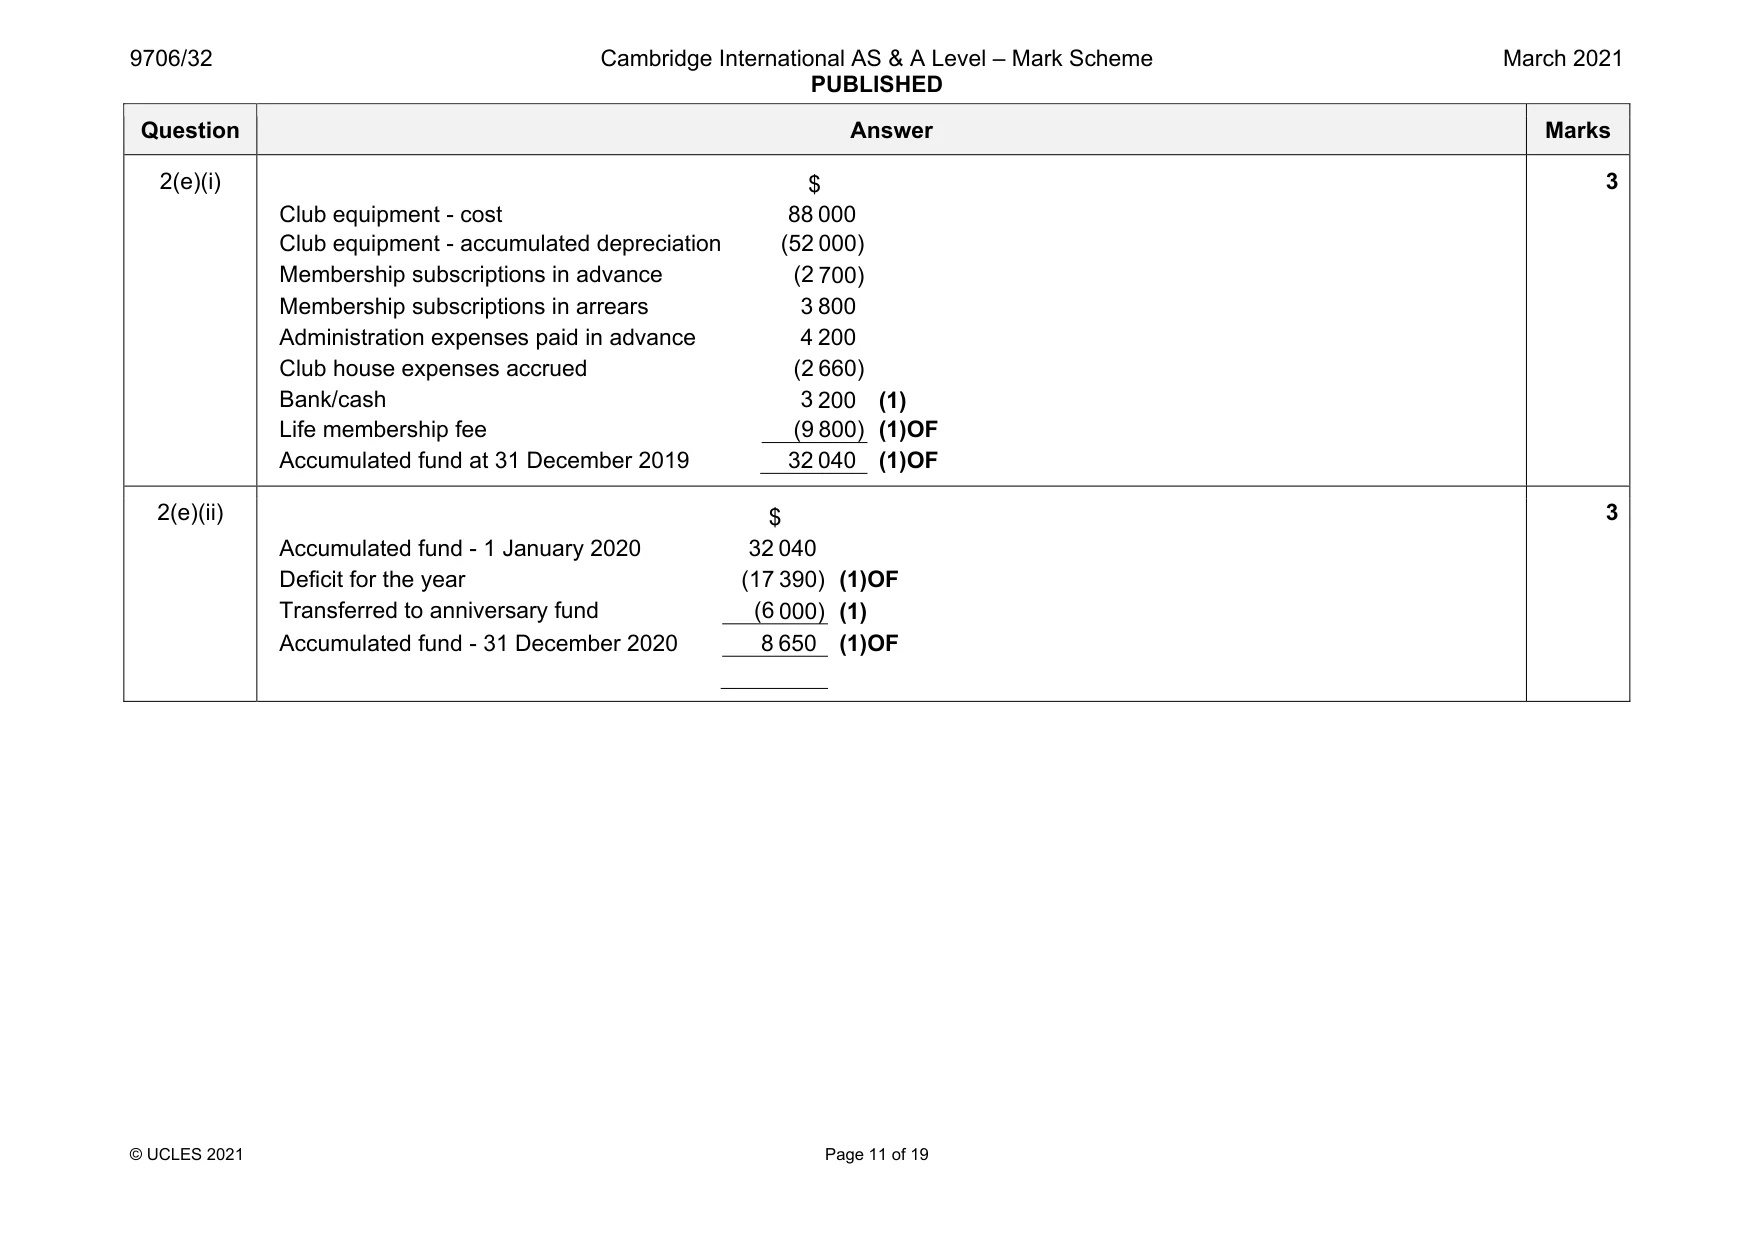
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 11 of 19 Question Answer Marks 2(e)(i) $ Club equipment - cost 88 000 Club equipment - accumulated depreciation (52 000) Membership subscriptions in advance (2 700) Membership subscriptions in arrears 3 800 Administration expenses paid in advance 4 200 Club house expenses accrued (2 660) Bank/cash 3 200 (1) Life membership fee (9 800) (1)OF Accumulated fund at 31 December 2019 32 040 (1)OF 3 2(e)(ii) $ Accumulated fund - 1 January 2020 32 040 Deficit for the year (17 390) (1)OF Transferred to anniversary fund (6 000) (1) Accumulated fund - 31 December 2020 8 650 (1)OF 3
Mark scheme, page 12
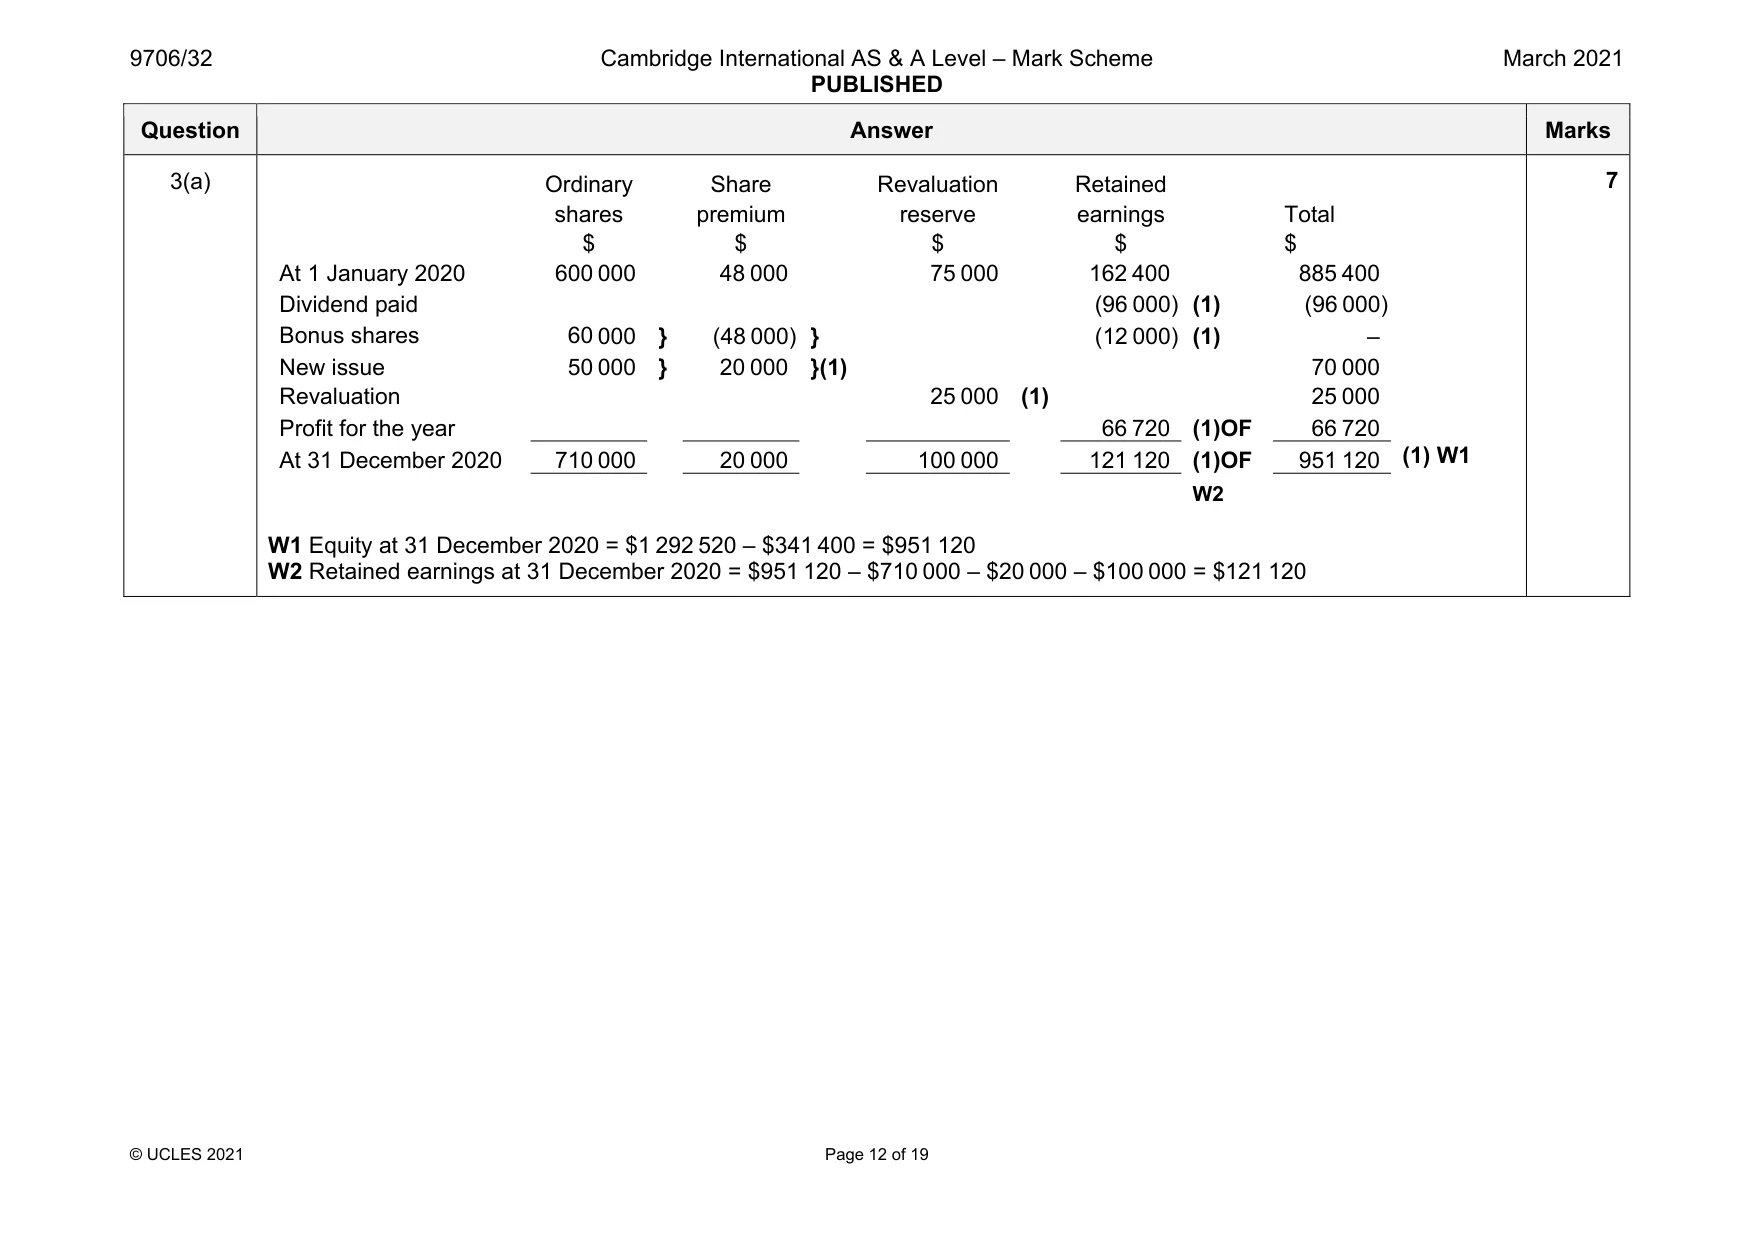
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 12 of 19 Question Answer Marks 3(a) Ordinary Share Revaluation Retained shares premium reserve earnings Total $ $ $ $ $ At 1 January 2020 600 000 48 000 75 000 162 400 885 400 Dividend paid (96 000) (1) (96 000) Bonus shares 60 000 } (48 000) } (12 000) (1) – New issue 50 000 } 20 000 }(1) 70 000 Revaluation 25 000 (1) 25 000 Profit for the year 66 720 (1)OF 66 720 At 31 December 2020 710 000 20 000 100 000 121 120 (1)OF 951 120 (1) W1 W2 W1 Equity at 31 December 2020 = $1 292 520 – $341 400 = $951 120 W2 Retained earnings at 31 December 2020 = $951 120 – $710 000 – $20 000 – $100 000 = $121 120 7
Mark scheme, page 13
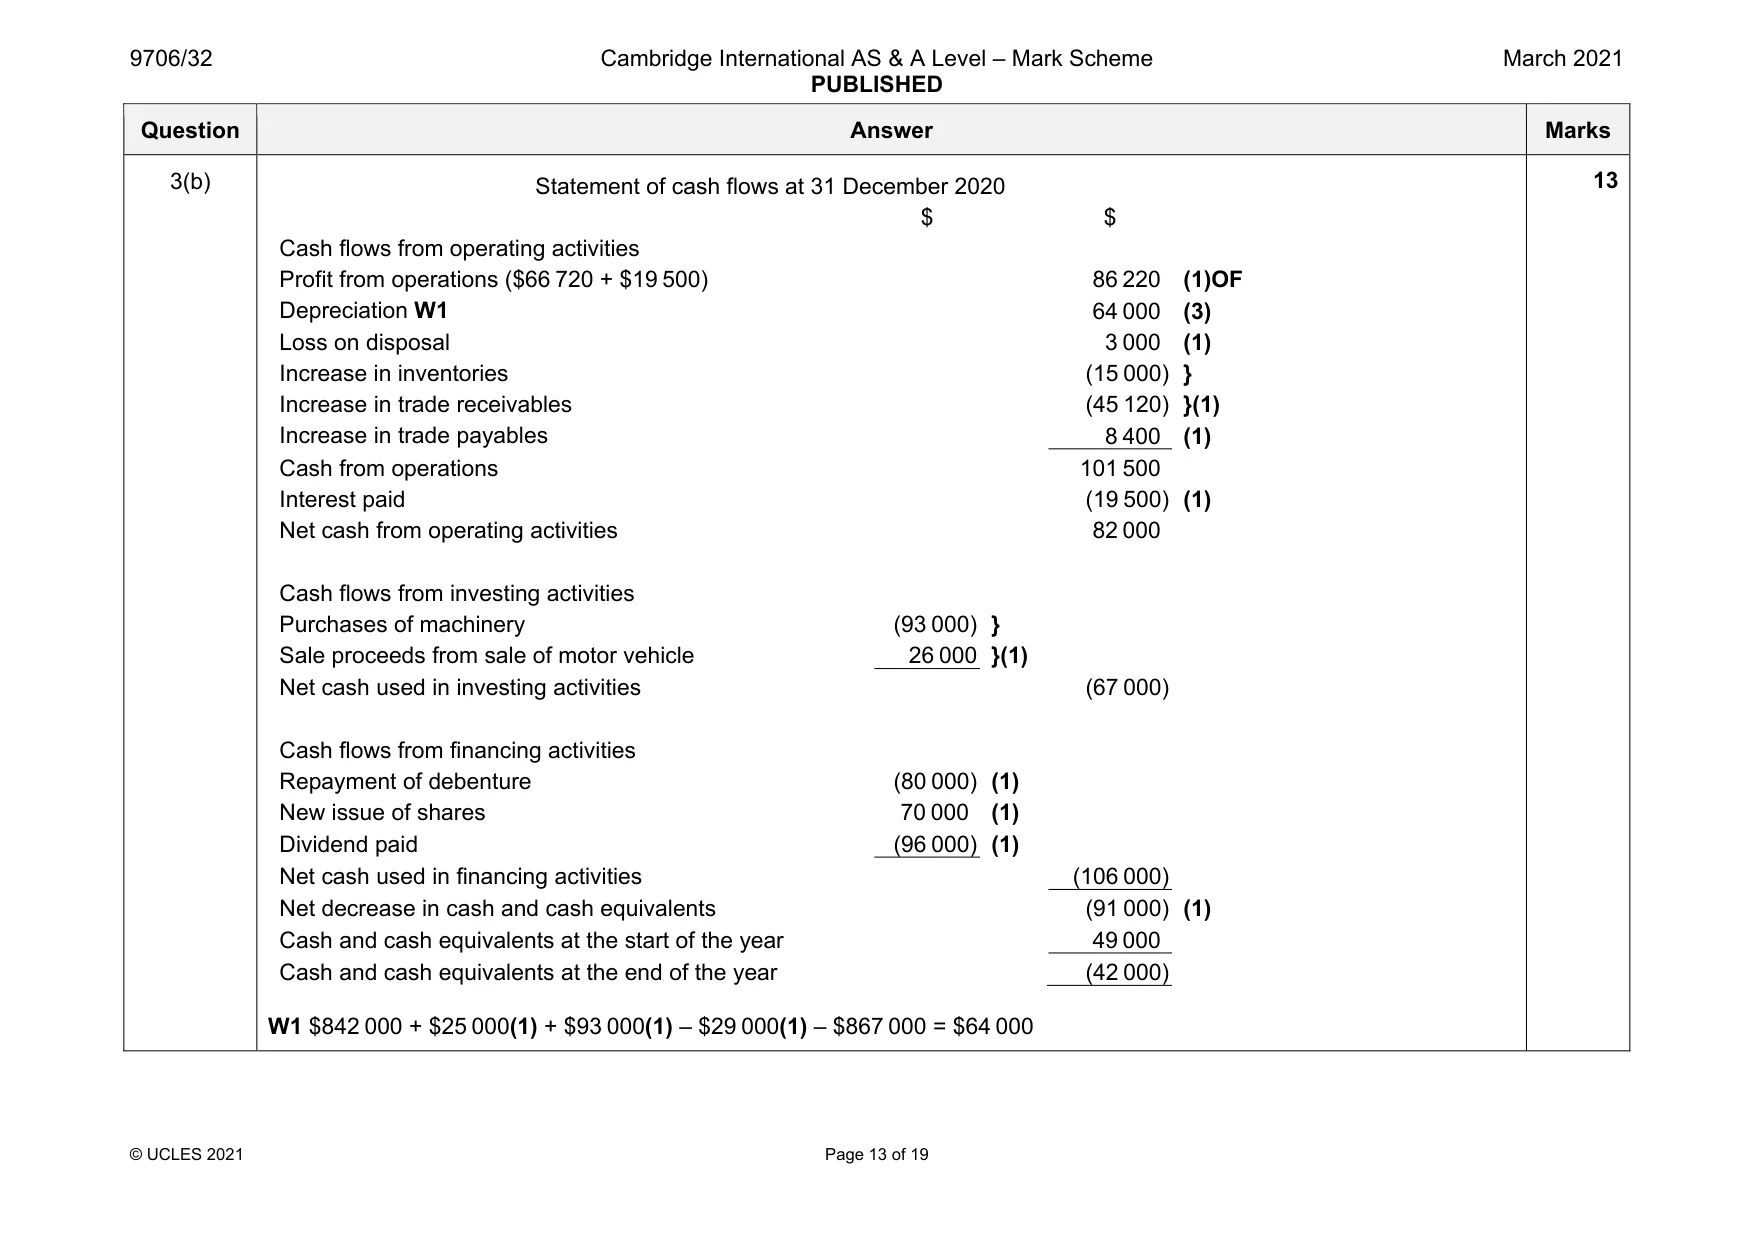
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 13 of 19 Question Answer Marks 3(b) Statement of cash flows at 31 December 2020 $ $ Cash flows from operating activities Profit from operations ($66 720 + $19 500) 86 220 (1)OF Depreciation W1 64 000 (3) Loss on disposal 3 000 (1) Increase in inventories (15 000) } Increase in trade receivables (45 120) }(1) Increase in trade payables 8 400 (1) Cash from operations 101 500 Interest paid (19 500) (1) Net cash from operating activities 82 000 Cash flows from investing activities Purchases of machinery (93 000) } Sale proceeds from sale of motor vehicle 26 000 }(1) Net cash used in investing activities (67 000) Cash flows from financing activities Repayment of debenture (80 000) (1) New issue of shares 70 000 (1) Dividend paid (96 000) (1) Net cash used in financing activities (106 000) Net decrease in cash and cash equivalents (91 000) (1) Cash and cash equivalents at the start of the year 49 000 Cash and cash equivalents at the end of the year (42 000) W1 $842 000 + $25 000(1) + $93 000(1) – $29 000(1) – $867 000 = $64 000 13
Mark scheme, page 14
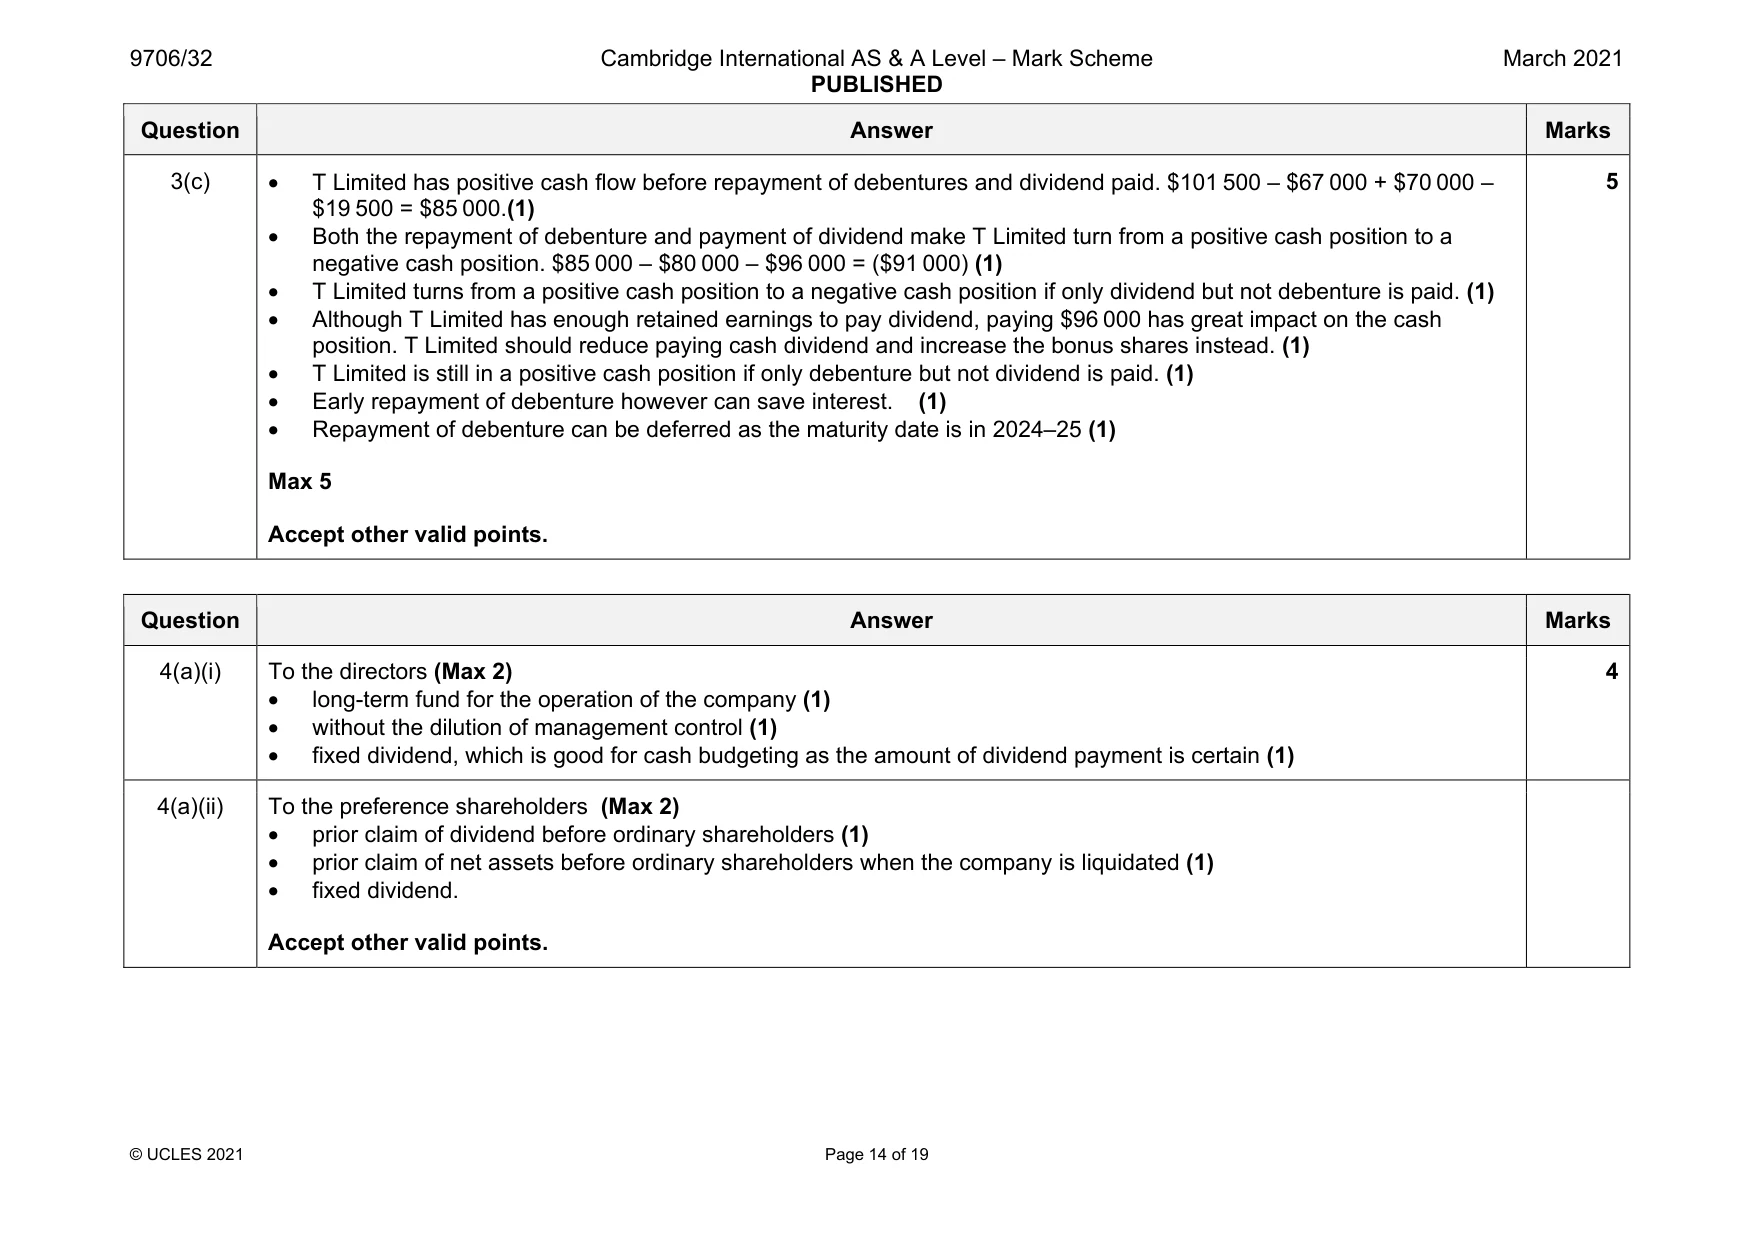
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 14 of 19 Question Answer Marks 3(c) • T Limited has positive cash flow before repayment of debentures and dividend paid. $101 500 – $67 000 + $70 000 – $19 500 = $85 000.(1) • Both the repayment of debenture and payment of dividend make T Limited turn from a positive cash position to a negative cash position. $85 000 – $80 000 – $96 000 = ($91 000) (1) • T Limited turns from a positive cash position to a negative cash position if only dividend but not debenture is paid. (1) • Although T Limited has enough retained earnings to pay dividend, paying $96 000 has great impact on the cash position. T Limited should reduce paying cash dividend and increase the bonus shares instead. (1) • T Limited is still in a positive cash position if only debenture but not dividend is paid. (1) • Early repayment of debenture however can save interest. (1) • Repayment of debenture can be deferred as the maturity date is in 2024–25 (1) Max 5 Accept other valid points. 5 Question Answer Marks 4(a)(i) To the directors (Max 2) • long-term fund for the operation of the company (1) • without the dilution of management control (1) • fixed dividend, which is good for cash budgeting as the amount of dividend payment is certain (1) 4 4(a)(ii) To the preference shareholders (Max 2) • prior claim of dividend before ordinary shareholders (1) • prior claim of net assets before ordinary shareholders when the company is liquidated (1) • fixed dividend. Accept other valid points.
Mark scheme, page 15
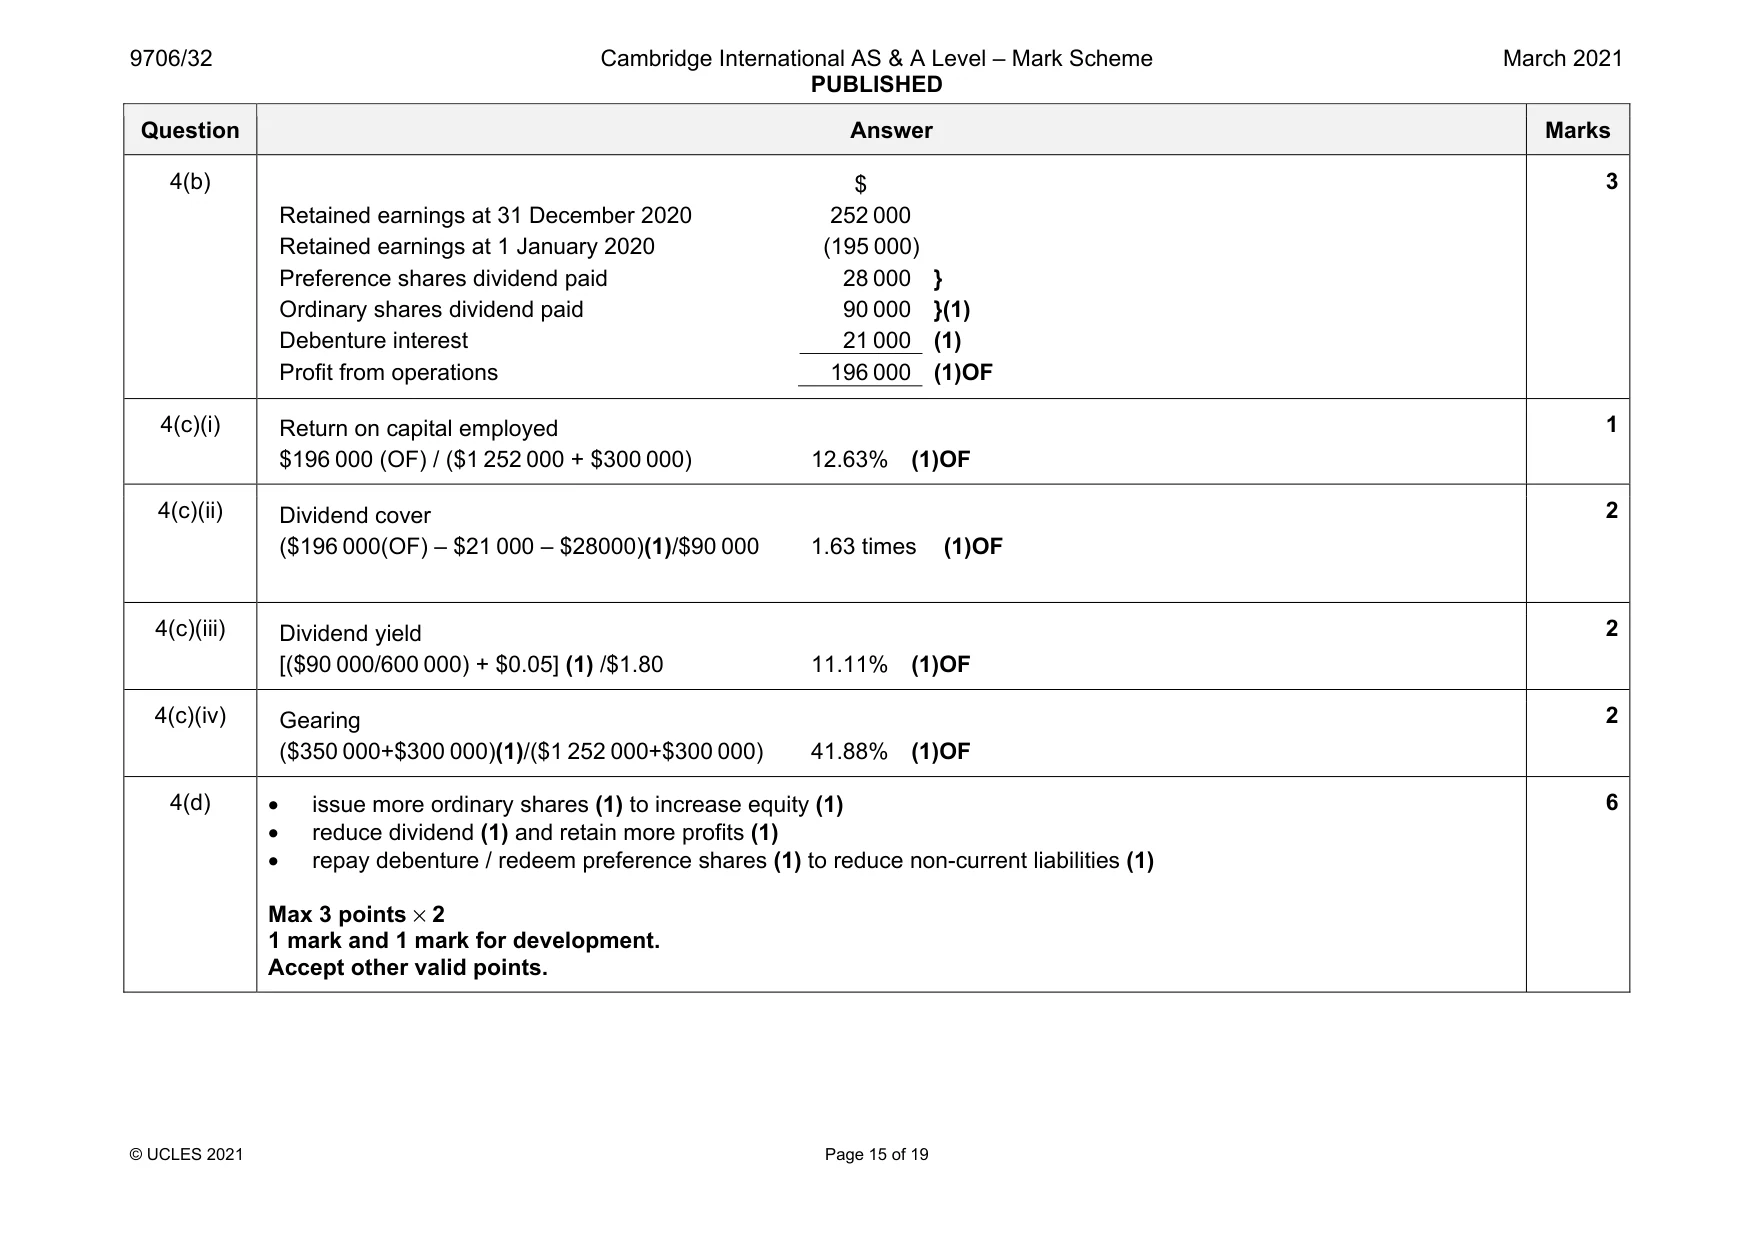
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 15 of 19 Question Answer Marks 4(b) $ Retained earnings at 31 December 2020 252 000 Retained earnings at 1 January 2020 (195 000) Preference shares dividend paid 28 000 } Ordinary shares dividend paid 90 000 }(1) Debenture interest 21 000 (1) Profit from operations 196 000 (1)OF 3 4(c)(i) Return on capital employed $196 000 (OF) / ($1 252 000 + $300 000) 12.63% (1)OF 1 4(c)(ii) Dividend cover ($196 000(OF) – $21 000 – $28000)(1)/$90 000 1.63 times (1)OF 2 4(c)(iii) Dividend yield [($90 000/600 000) + $0.05] (1) /$1.80 11.11% (1)OF 2 4(c)(iv) Gearing ($350 000+$300 000)(1)/($1 252 000+$300 000) 41.88% (1)OF 2 4(d) • issue more ordinary shares (1) to increase equity (1) • reduce dividend (1) and retain more profits (1) • repay debenture / redeem preference shares (1) to reduce non-current liabilities (1) Max 3 points × 2 1 mark and 1 mark for development. Accept other valid points. 6
Mark scheme, page 16
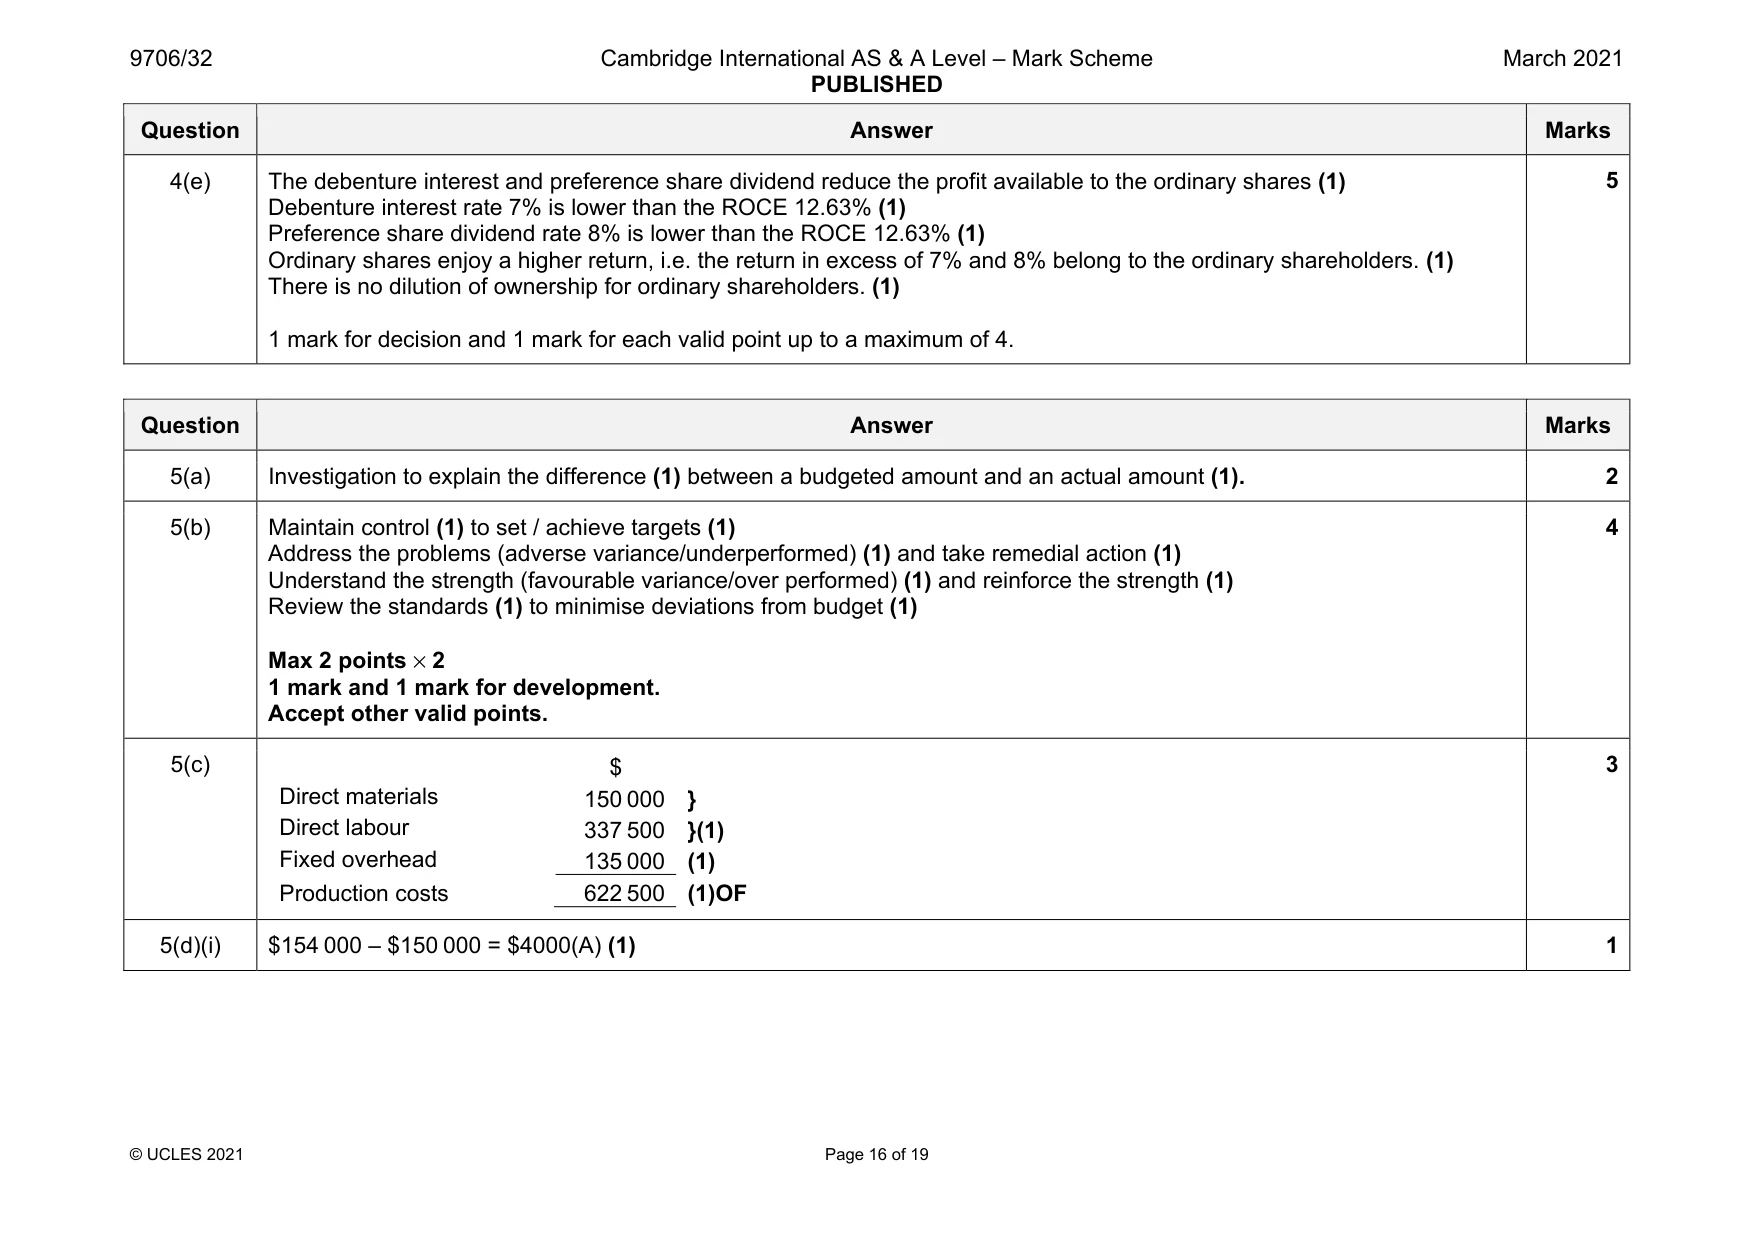
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 16 of 19 Question Answer Marks 4(e) The debenture interest and preference share dividend reduce the profit available to the ordinary shares (1) Debenture interest rate 7% is lower than the ROCE 12.63% (1) Preference share dividend rate 8% is lower than the ROCE 12.63% (1) Ordinary shares enjoy a higher return, i.e. the return in excess of 7% and 8% belong to the ordinary shareholders. (1) There is no dilution of ownership for ordinary shareholders. (1) 1 mark for decision and 1 mark for each valid point up to a maximum of 4. 5 Question Answer Marks 5(a) Investigation to explain the difference (1) between a budgeted amount and an actual amount (1). 2 5(b) Maintain control (1) to set / achieve targets (1) Address the problems (adverse variance/underperformed) (1) and take remedial action (1) Understand the strength (favourable variance/over performed) (1) and reinforce the strength (1) Review the standards (1) to minimise deviations from budget (1) Max 2 points × 2 1 mark and 1 mark for development. Accept other valid points. 4 5(c) $ Direct materials 150 000 } Direct labour 337 500 }(1) Fixed overhead 135 000 (1) Production costs 622 500 (1)OF 3 5(d)(i) $154 000 – $150 000 = $4000(A) (1) 1
Mark scheme, page 17
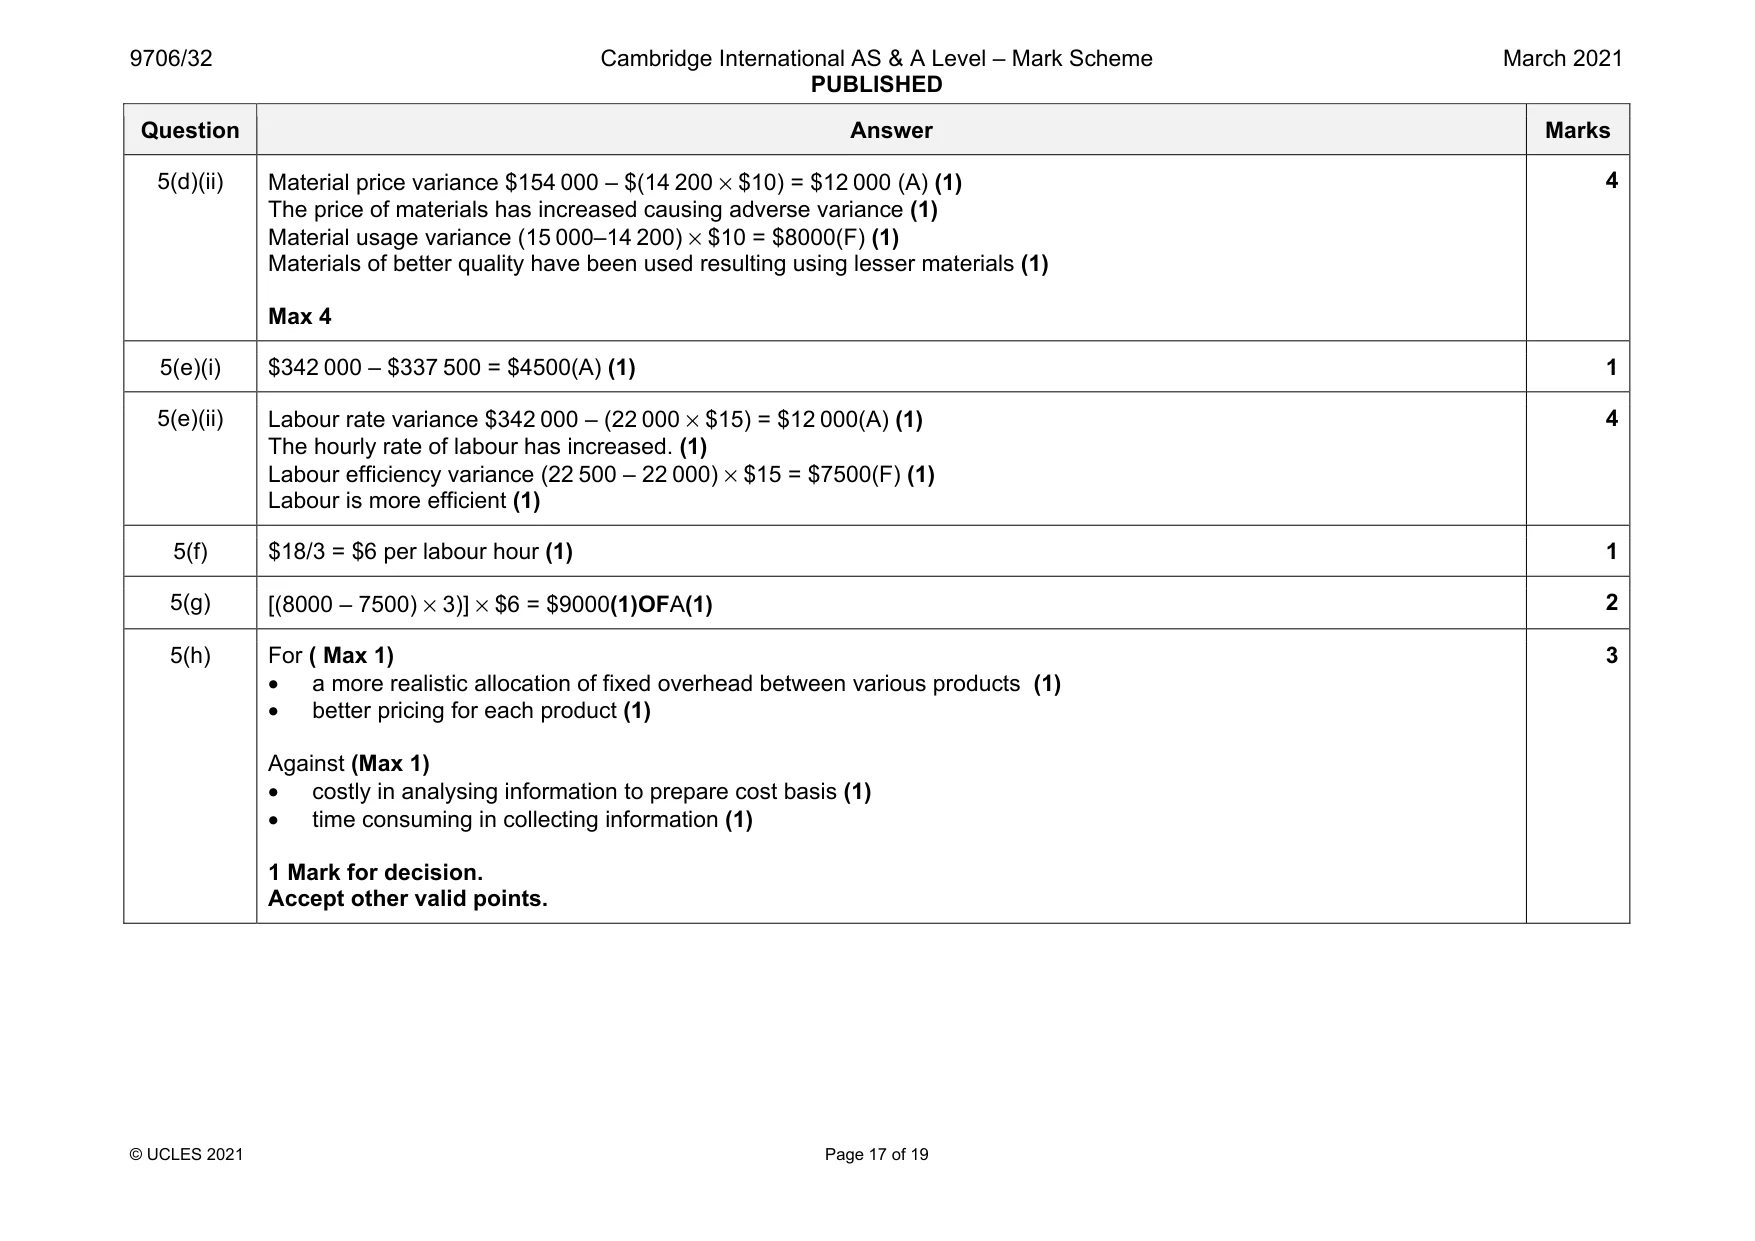
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 17 of 19 Question Answer Marks 5(d)(ii) Material price variance $154 000 – $(14 200 × $10) = $12 000 (A) (1) The price of materials has increased causing adverse variance (1) Material usage variance (15 000–14 200) × $10 = $8000(F) (1) Materials of better quality have been used resulting using lesser materials (1) Max 4 4 5(e)(i) $342 000 – $337 500 = $4500(A) (1) 1 5(e)(ii) Labour rate variance $342 000 – (22 000 × $15) = $12 000(A) (1) The hourly rate of labour has increased. (1) Labour efficiency variance (22 500 – 22 000) × $15 = $7500(F) (1) Labour is more efficient (1) 4 5(f) $18/3 = $6 per labour hour (1) 1 5(g) [(8000 – 7500) × 3)] × $6 = $9000(1)OFA(1) 2 5(h) For ( Max 1) • a more realistic allocation of fixed overhead between various products (1) • better pricing for each product (1) Against (Max 1) • costly in analysing information to prepare cost basis (1) • time consuming in collecting information (1) 1 Mark for decision. Accept other valid points. 3
Mark scheme, page 18
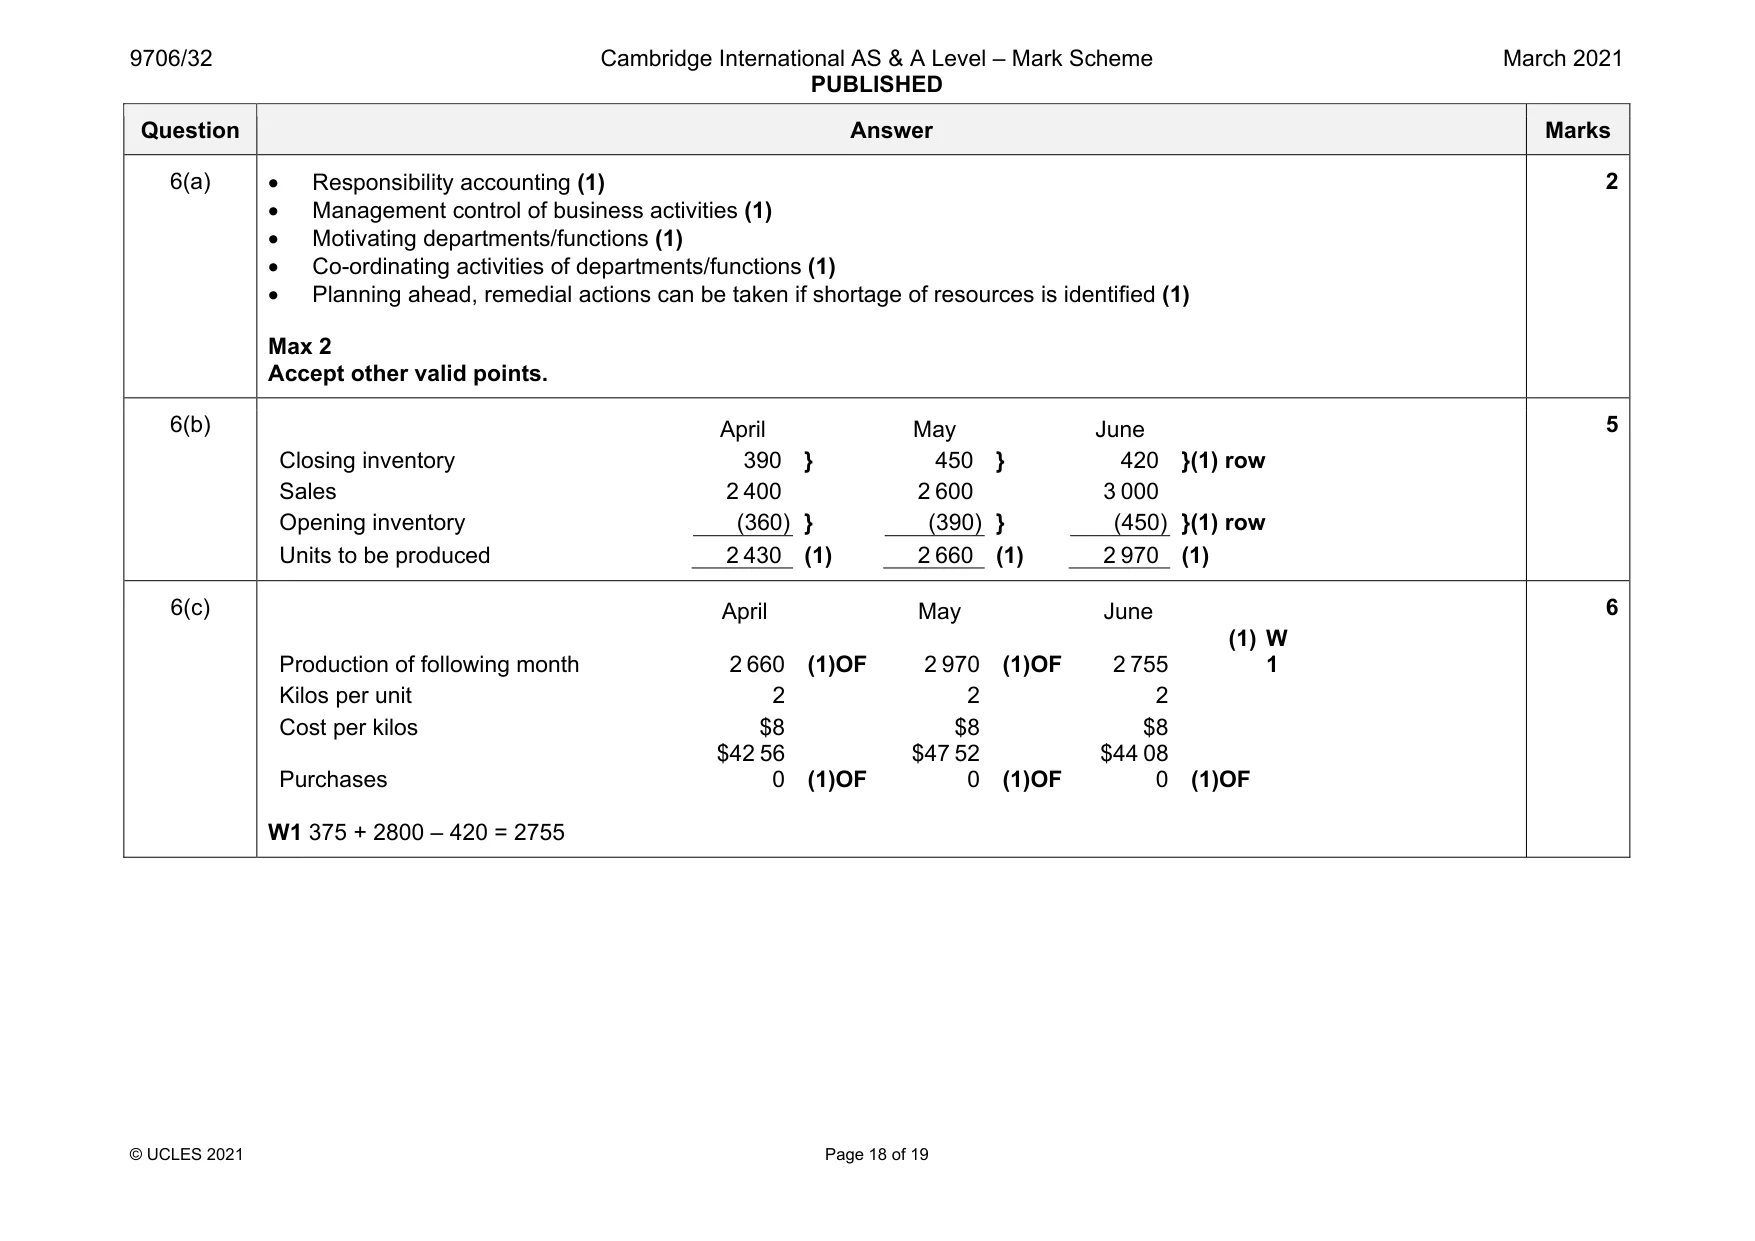
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 18 of 19 Question Answer Marks 6(a) • Responsibility accounting (1) • Management control of business activities (1) • Motivating departments/functions (1) • Co-ordinating activities of departments/functions (1) • Planning ahead, remedial actions can be taken if shortage of resources is identified (1) Max 2 Accept other valid points. 2 6(b) April May June Closing inventory 390 } 450 } 420 }(1) row Sales 2 400 2 600 3 000 Opening inventory (360) } (390) } (450) }(1) row Units to be produced 2 430 (1) 2 660 (1) 2 970 (1) 5 6(c) April May June Production of following month 2 660 (1)OF 2 970 (1)OF 2 755 (1) W 1 Kilos per unit 2 2 2 Cost per kilos $8 $8 $8 Purchases $42 56 0 (1)OF $47 52 0 (1)OF $44 08 0 (1)OF W1 375 + 2800 – 420 = 2755 6
Mark scheme, page 19
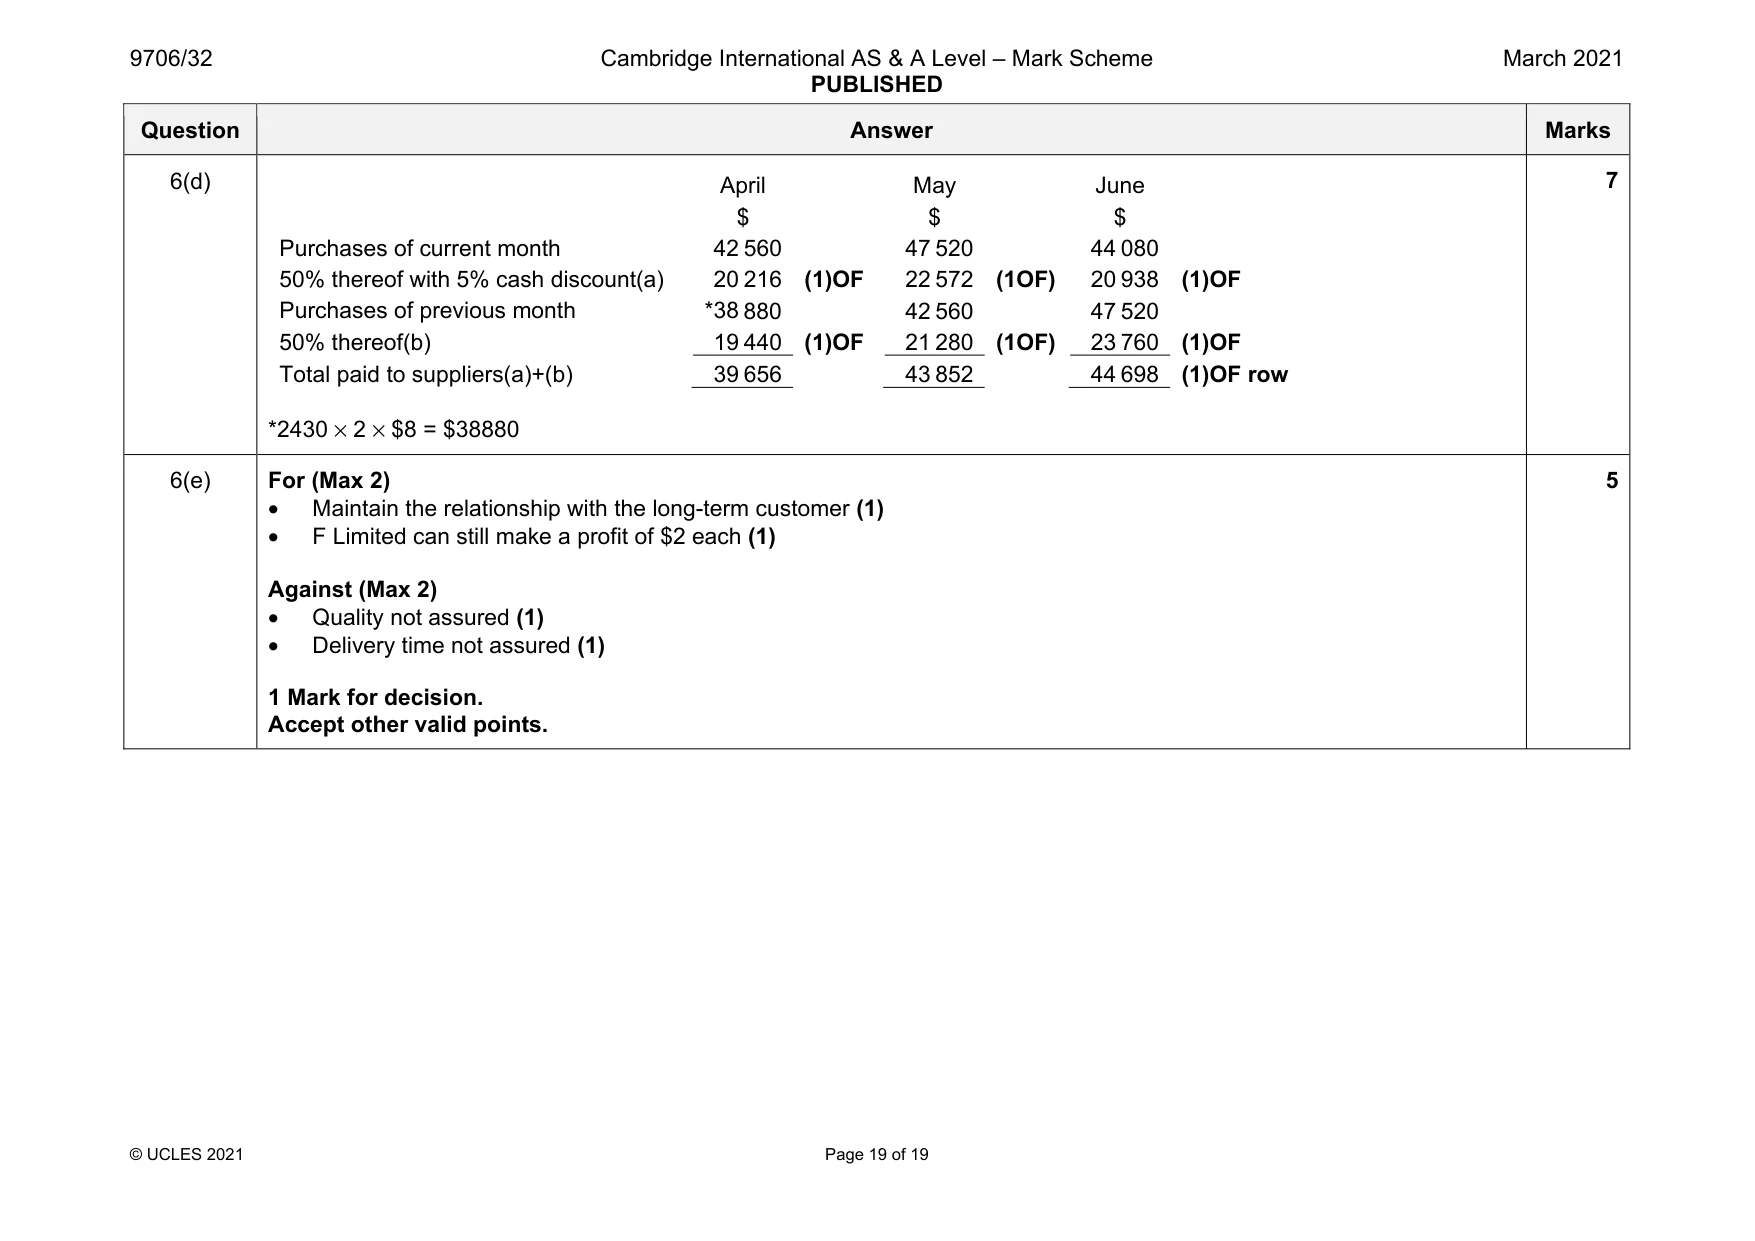
9706/32 Cambridge International AS & A Level – Mark Scheme PUBLISHED March 2021 © UCLES 2021 Page 19 of 19 Question Answer Marks 6(d) April May June $ $ $ Purchases of current month 42 560 47 520 44 080 50% thereof with 5% cash discount(a) 20 216 (1)OF 22 572 (1OF) 20 938 (1)OF Purchases of previous month *38 880 42 560 47 520 50% thereof(b) 19 440 (1)OF 21 280 (1OF) 23 760 (1)OF Total paid to suppliers(a)+(b) 39 656 43 852 44 698 (1)OF row *2430 × 2 × $8 = $38880 7 6(e) For (Max 2) • Maintain the relationship with the long-term customer (1) • F Limited can still make a profit of $2 each (1) Against (Max 2) • Quality not assured (1) • Delivery time not assured (1) 1 Mark for decision. Accept other valid points. 5
What you needed in this session
Cambridge’s own grade thresholds for 2021 Feb/March, Paper 3 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.